William Lyon Homes — Q4 2003 Earnings Presentation
22 slides from William Lyon Homes's earnings presentation, Feb 24, 2004
Slide 1: Fourth Quarter and Year End 2003 Earnings Conference Call
Fourth Quarter and Year End 2003 Earnings Conference Call February 20, 2004
Slide 2: Disclosure Statement
Disclosure Statement • Certain statements contained in this release and conference call that are not historical information contain forward-looking statements. The forward-looking statements involve risk and uncertainties and actual results may differ materially from those projected or implied. Furt
Slide 3: 2003 Highlights & Accomplishments
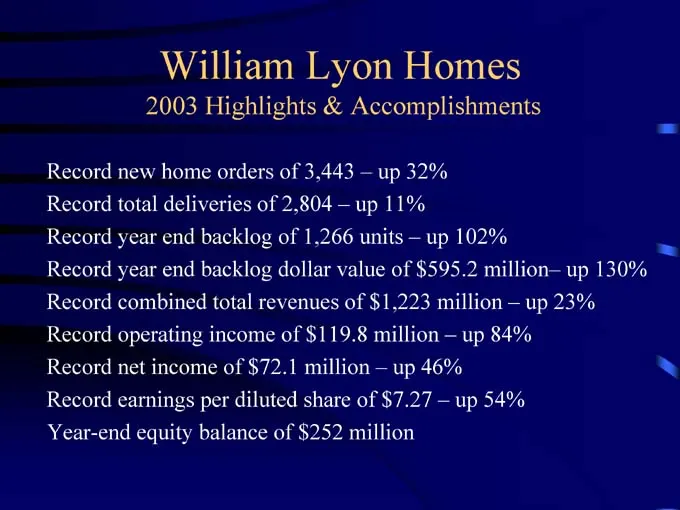
2003 Highlights & Accomplishments Record new home orders of 3,443 – up 32% Record total deliveries of 2,804 – up 11% Record year end backlog of 1,266 units – up 102% Record year end backlog dollar value of $595.2 million– up 130% Record combined total revenues of $1,223 million – up 23% Record opera
Slide 4: 4th Quarter 2003—Summary Results
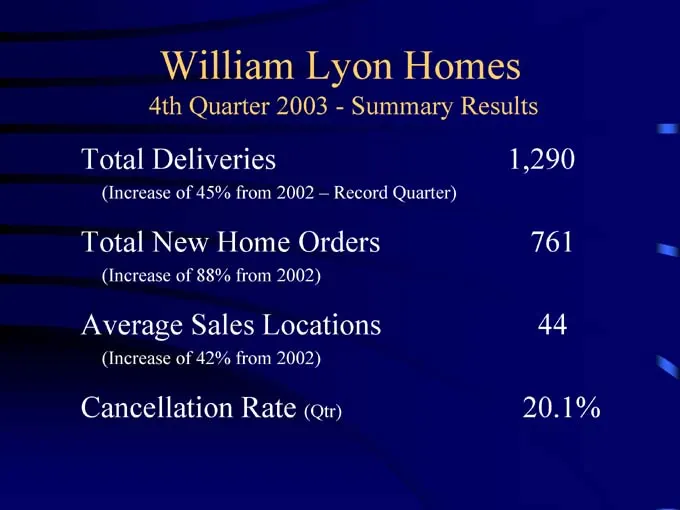
4th Quarter 2003—Summary Results Total Deliveries 1,290 (Increase of 45% from 2002 – Record Quarter) Total New Home Orders 761 (Increase of 88% from 2002) Average Sales Locations 44 (Increase of 42% from 2002) Cancellation Rate (Qtr) 20.1%
Slide 5: 4th Quarter 2003—Summary Results (Wholly-Owned)
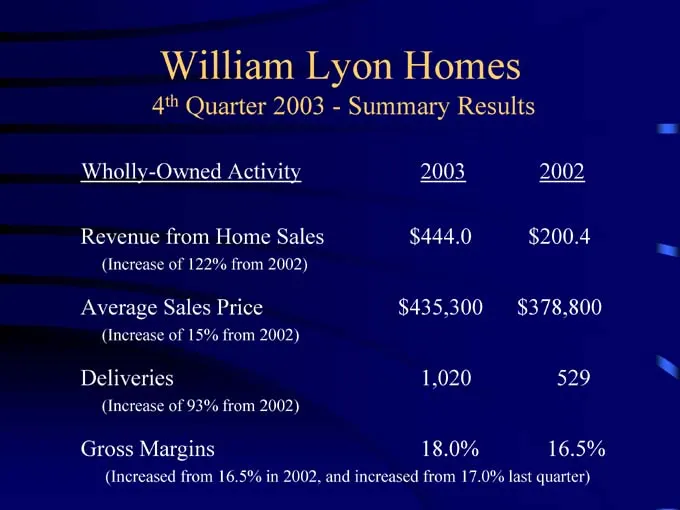
ss 4th Quarter 2003—Summary Results Wholly-Owned Activity 2003 2002 Revenue from Home Sales $444.0 $200.4 (Increase of 122% from 2002) Average Sales Price $435,300 $378,800 (Increase of 15% from 2002) Deliveries 1,020 529 (Increase of 93% from 2002) Gross Margins 18.0% 16.5% (Increased from 16.5% in
Slide 6: 4th Quarter 2003—Summary Results (Joint Venture)
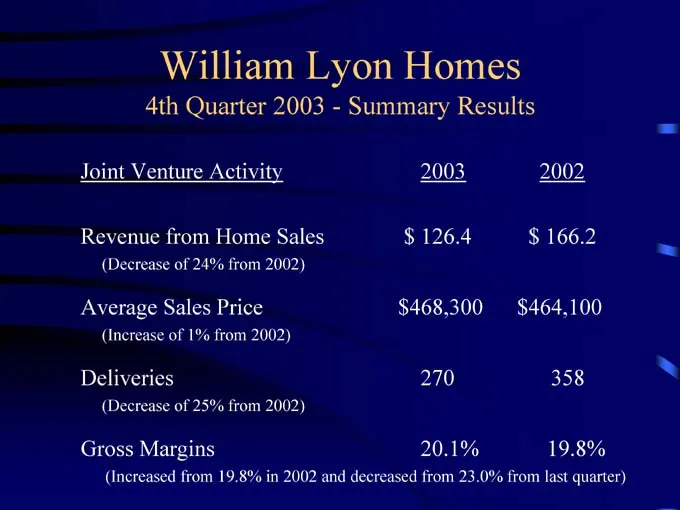
4th Quarter 2003—Summary Results Joint Venture Activity 2003 2002 Revenue from Home Sales $ 126.4 $ 166.2 (Decrease of 24% from 2002) Average Sales Price $468,300 $464,100 (Increase of 1% from 2002) Deliveries 270 358 (Decrease of 25% from 2002) Gross Margins 20.1% 19.8% (Increased from 19.8% in 200
Slide 7: 4th Quarter 2003—Summary Results (Combined)
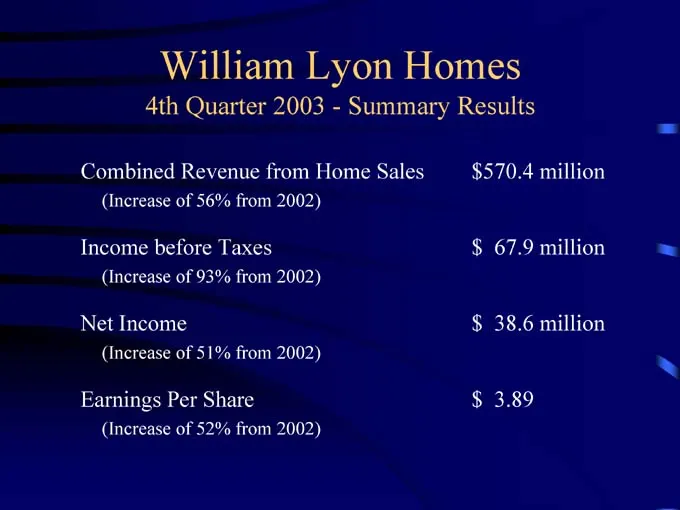
4th Quarter 2003—Summary Results Combined Revenue from Home Sales $570.4 million (Increase of 56% from 2002) Income before Taxes $ 67.9 million (Increase of 93% from 2002) Net Income $ 38.6 million (Increase of 51% from 2002) Earnings Per Share $ 3.89 (Increase of 52% from 2002)
Slide 8: For the year ended December 31, 2003—Summary Results
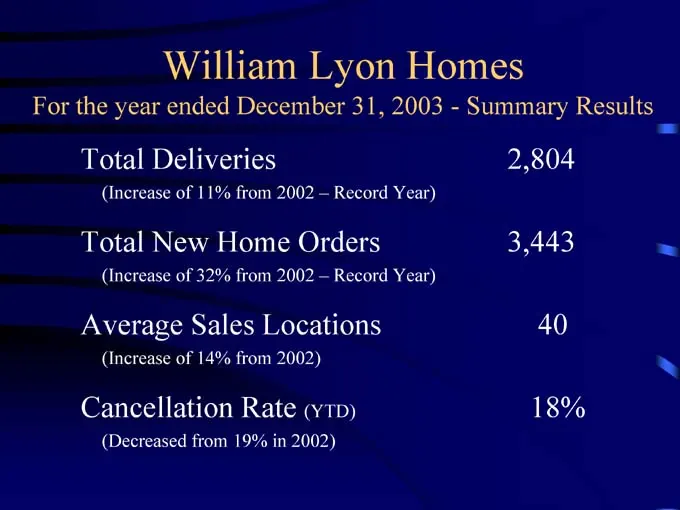
For the year ended December 31, 2003—Summary Results Total Deliveries 2,804 (Increase of 11% from 2002 – Record Year) Total New Home Orders 3,443 (Increase of 32% from 2002 – Record Year) Average Sales Locations 40 (Increase of 14% from 2002) Cancellation Rate (YTD) 18% (Decreased from 19% in 2002)
Slide 9: Sales Locations
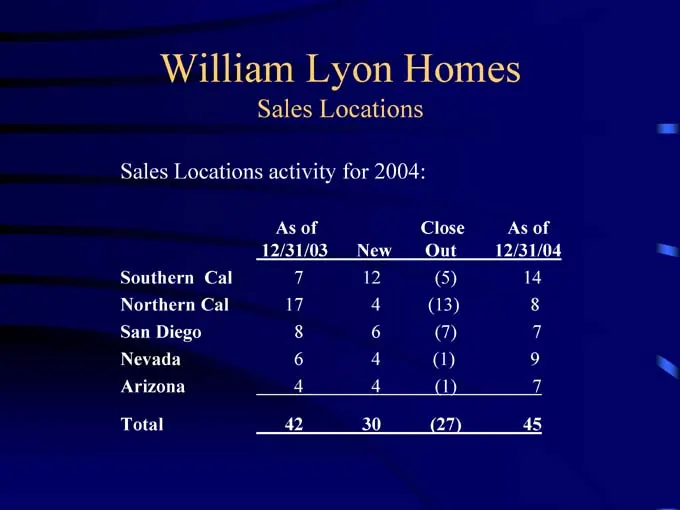
Sales Locations Sales Locations activity for 2004: As of Close As of 12/31/03 New Out 12/31/04 Southern Cal 7 12 (5) 14 Northern Cal 17 4 (13) 8 San Diego 8 6 (7) 7 Nevada 6 4 (1) 9 Arizona 4 4 (1) 7 Total 42 30 (27) 45
Slide 10: Backlog Summary
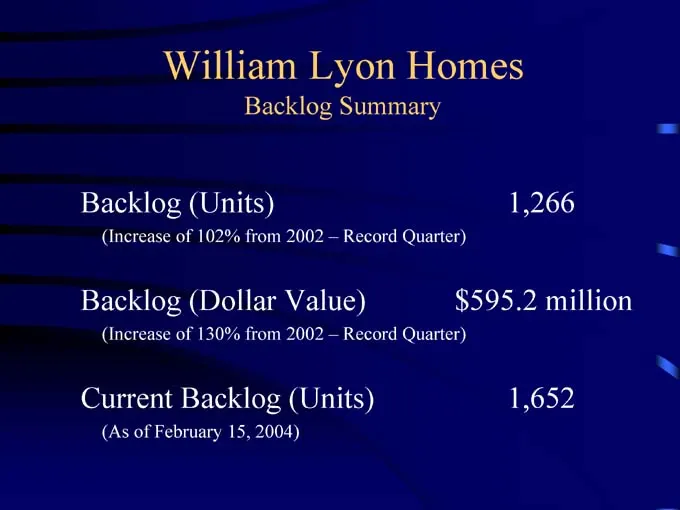
Backlog Summary Backlog (Units) 1,266 (Increase of 102% from 2002 – Record Quarter) Backlog (Dollar Value) $595.2 million (Increase of 130% from 2002 – Record Quarter) Current Backlog (Units) 1,652 (As of February 15, 2004)
Slide 11: For the year ended December 31, 2003—Summary Results (Wholly-Owned)
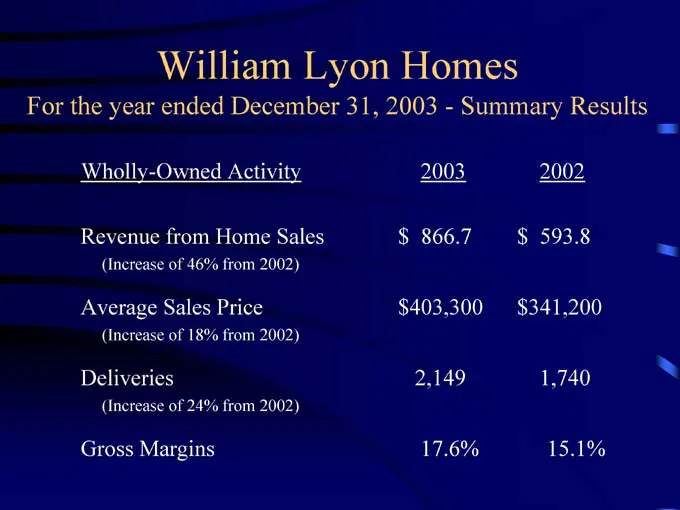
For the year ended December 31, 2003—Summary Results Wholly-Owned Activity 2003 2002 Revenue from Home Sales $ 866.7 $ 593.8 (Increase of 46% from 2002) Average Sales Price $403,300 $341,200 (Increase of 18% from 2002) Deliveries 2,149 1,740 (Increase of 24% from 2002) Gross Margins 17.6% 15.1%
Slide 12: For the year ended December 31, 2003—Summary (Joint Venture)
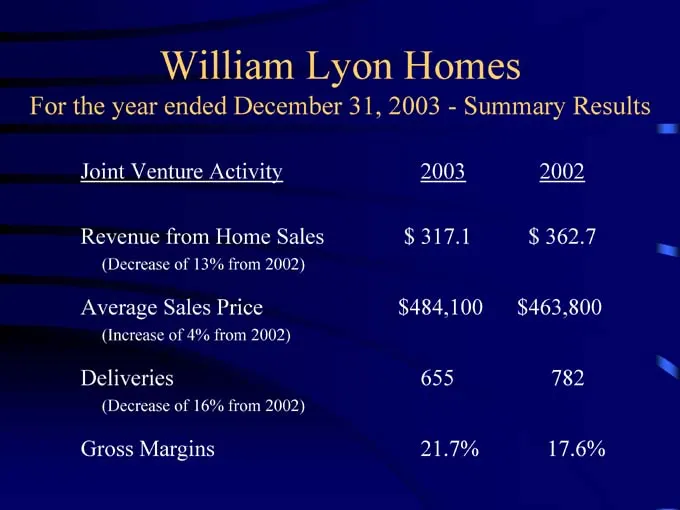
For the year ended December 31, 2003—Summary Joint Venture Activity 2003 2002 Revenue from Home Sales $ 317.1 $ 362.7 (Decrease of 13% from 2002) Average Sales Price $484,100 $463,800 (Increase of 4% from 2002) Deliveries 655 782 (Decrease of 16% from 2002) Gross Margins 21.7% 17.6%
Slide 13: For the year ended December 31, 2003—Summary Results (Combined)
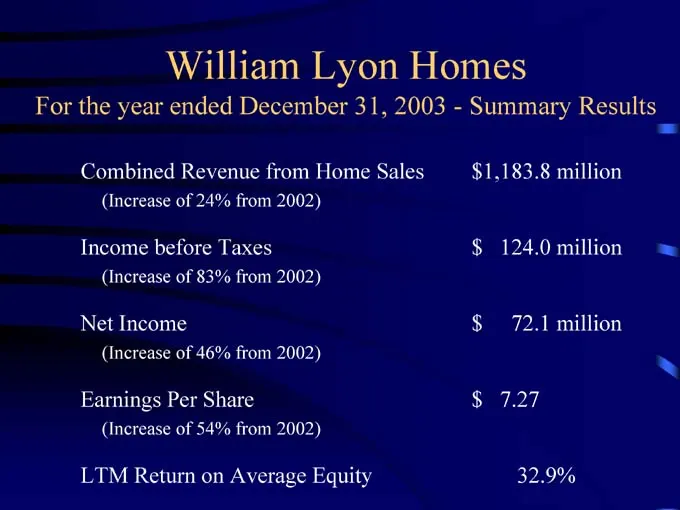
For the year ended December 31, 2003—Summary Results Combined Revenue from Home Sales $1,183.8 million (Increase of 24% from 2002) Income before Taxes $ 124.0 million (Increase of 83% from 2002) Net Income $ 72.1 million (Increase of 46% from 2002) Earnings Per Share $ 7.27 (Increase of 54% from 200
Slide 14: Unconsolidated Joint Ventures Summary Results
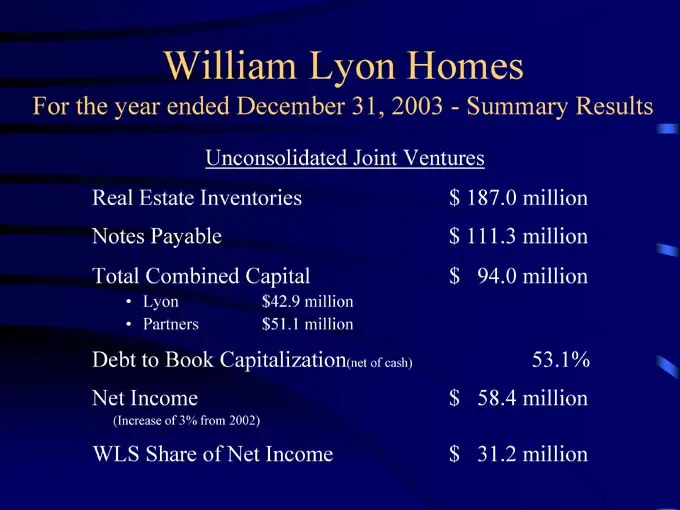
For the year ended December 31, 2003—Summary Results Unconsolidated Joint Ventures Real Estate Inventories $ 187.0 million Notes Payable $ 111.3 million Total Combined Capital $ 94.0 million • Lyon $42.9 million • Partners $51.1 million Debt to Book Capitalization(net of cash) 53.1% Net Income $ 58.
Slide 15: December 31, 2003—Summary Results
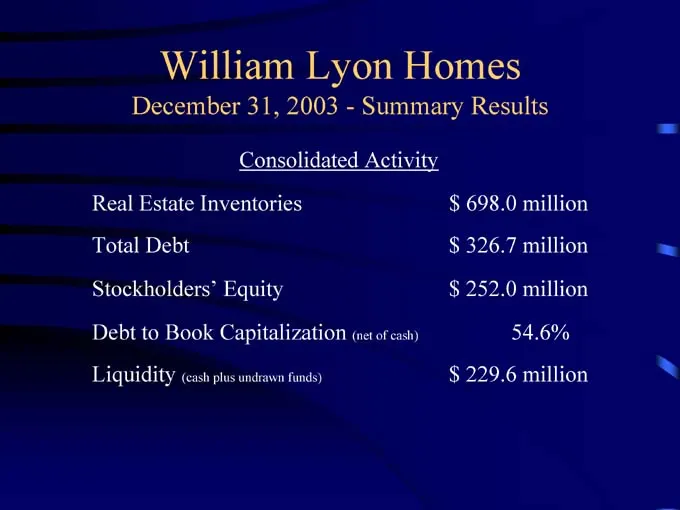
December 31, 2003—Summary Results Consolidated Activity Real Estate Inventories $ 698.0 million Total Debt $ 326.7 million Stockholders’ Equity $ 252.0 million Debt to Book Capitalization (net of cash) 54.6% Liquidity (cash plus undrawn funds) $ 229.6 million
Slide 16: EBITDA
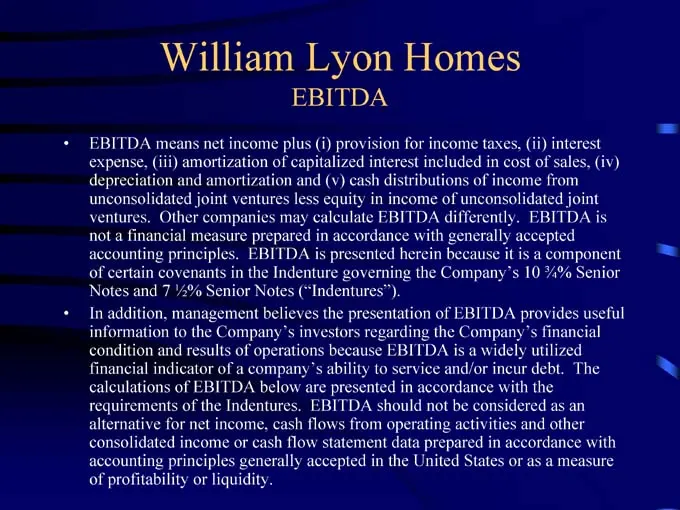
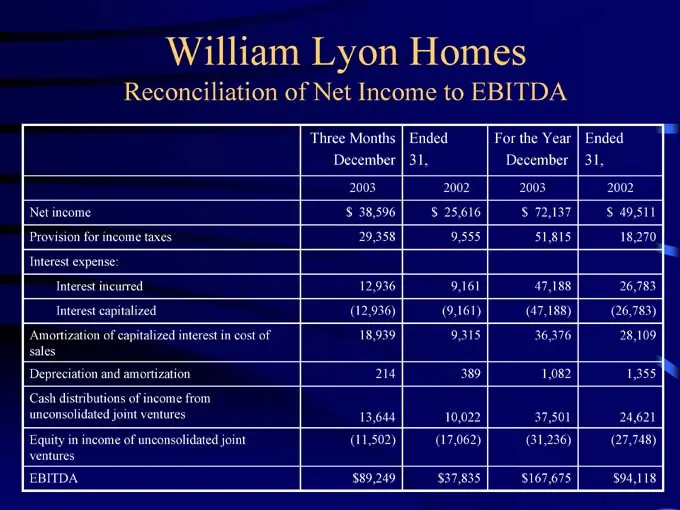
EBITDA • EBITDA means net income plus (i) provision for income taxes, (ii) interest expense, (iii) amortization of capitalized interest included in cost of sales, (iv) depreciation and amortization and (v) cash distributions of income from unconsolidated joint ventures less equity in income of uncon
Slide 17: Reconciliation of Net Income to EBITDA
Reconciliation of Net Income to EBITDA Three Months Ended For the Year Ended December 31, December 31, 2003 2002 2003 2002 Net income $ 38,596 $ 25,616 $ 72,137 $ 49,511 Provision for income taxes 29,358 9,555 51,815 18,270 Interest expense: Interest incurred 12,936 9,161 47,188 26,783 Interest capi
Slide 18: Reconciliation of Net Cash Used in Operating Activities to EBITDA
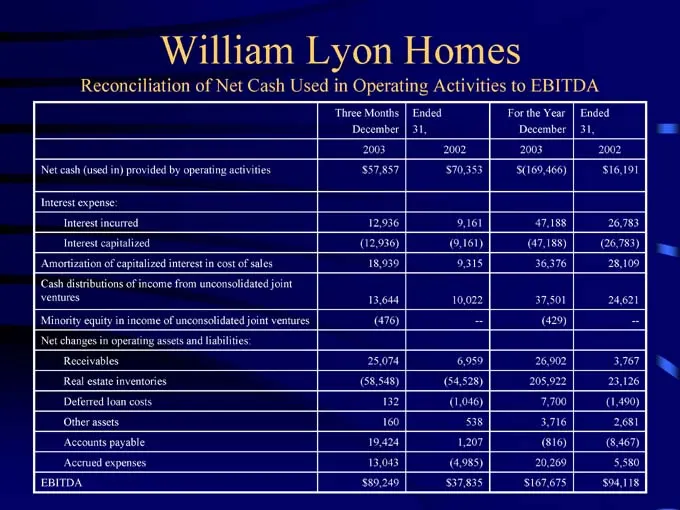
Reconciliation of Net Cash Used in Operating Activities to EBITDA Three Months Ended For the Year Ended December 31, December 31, 2003 2002 2003 2002 Net cash (used in) provided by operating activities $ 57,857 $ 70,353 $ (169,466) $ 16,191 Interest expense: Interest incurred 12,936 9,161 47,188 26,
Slide 19: 4th Quarter 2003 – Summary Financial Data
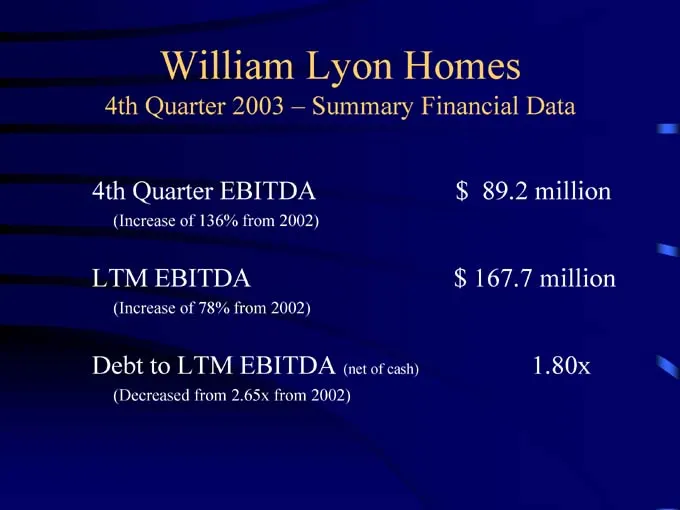
4th Quarter 2003 – Summary Financial Data 4th Quarter EBITDA $ 89.2 million (Increase of 136% from 2002) LTM EBITDA $ 167.7 million (Increase of 78% from 2002) Debt to LTM EBITDA (net of cash) 1.80x (Decreased from 2.65x from 2002)
Slide 20: Lots Owned and Controlled as of December 31, 2003
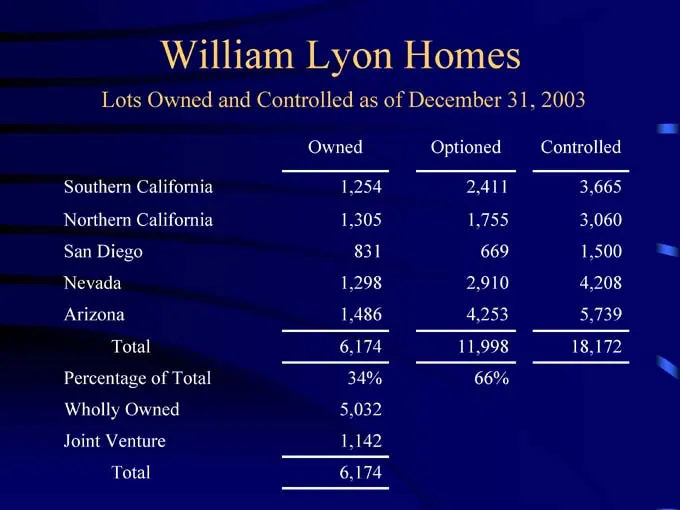
Lots Owned and Controlled as of December 31, 2003 Owned Optioned Controlled Southern California 1,254 2,411 3,665 Northern California 1,305 1,755 3,060 San Diego 831 669 1,500 Nevada 1,298 2,910 4,208 Arizona 1,486 4,253 5,739 Total 6,174 11,998 18,172 Percentage of Total 34% 66% Wholly Owned 5,032
Slide 21: Updated Guidance—2004
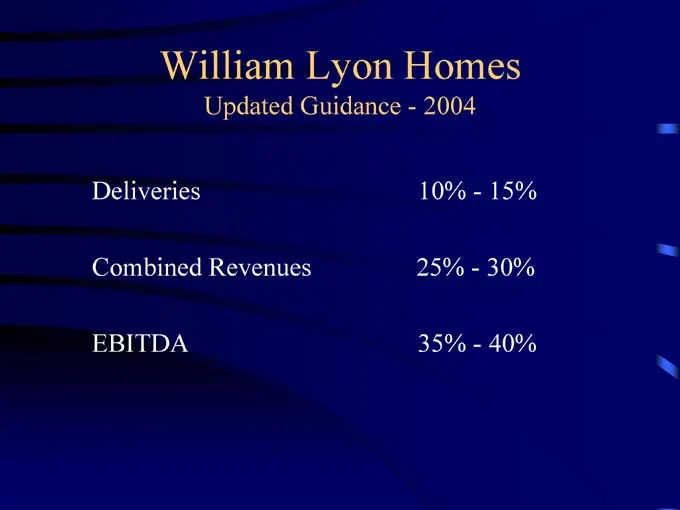
Updated Guidance—2004 Deliveries 10%—15% Combined Revenues 25%—30% EBITDA 35%—40%
Slide 22: Fourth Quarter and Year End 2003 Earnings Conference Call
Fourth Quarter and Year End 2003 Earnings Conference Call February 20, 2004
Source: SEC EDGAR · 8-K filed Feb 24, 2004
More decks from William Lyon Homes
 Merger or Acquisition (November 2019)18 slides · Nov 6, 2019
 Q2 2019 Earnings Presentation15 slides · Aug 1, 2019
 Q1 2019 Earnings Presentation14 slides · May 2, 2019
 Q4 2018 Earnings Presentation18 slides · Feb 14, 2019
 Q3 2018 Earnings Presentation17 slides · Oct 30, 2018
 2018 Zelman Housing Summit31 slides · Sep 27, 2018