Corium International — 17th Annual Needham Healthcare Conference 2018
26 slides from Corium International's conference presentation, Mar 27, 2018
Slide 1: Corium Investor Update: 17th Annual Needham Healthcare Conference
Corium Investor Update 17th Annual Needham Healthcare Conference Nasdaq: CORI March 2018 Corium
Slide 2: Forward-looking Statements
Forward-looking Statements This presentation and the accompanying oral presentation contain “forward-looking” statements that are based on our management’s beliefs and assumptions and on information currently available to management. Forward-looking statements include all statements other than state
Slide 3: Transdermal solutions that transform care
Transdermal solutions that transform care Leading Transdermal Product Innovation Vision Building a robust pipeline of novel CNS products Streamlined path for donepezil Alzheimer’s program Approach Lead Product 15+ years of development & manufacturing expertise Core Strengths 3 corium
Slide 4: Proven Leadership Team
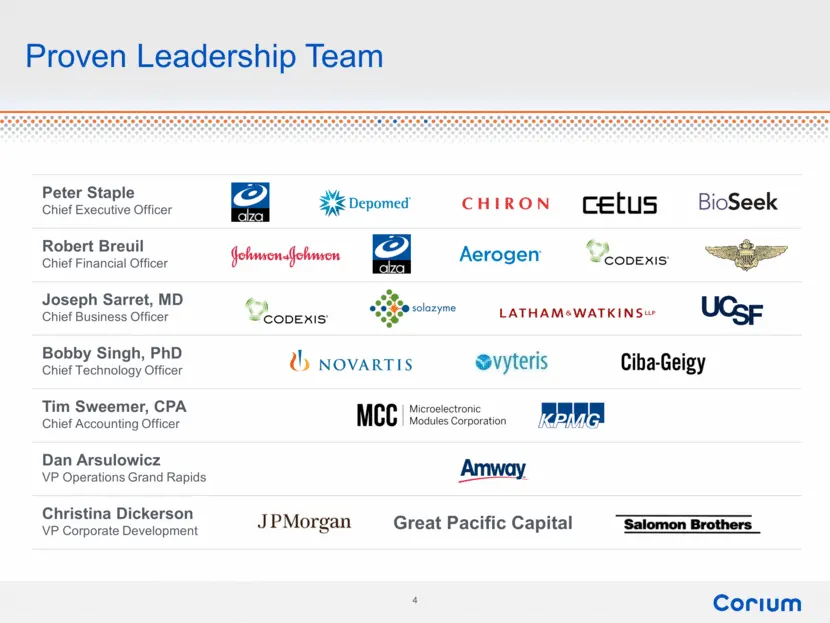
Proven Leadership Team Peter Staple Chief Executive Officer Robert Breuil Chief Financial Officer Joseph Sarret, MD Chief Business Officer Bobby Singh, PhD Chief Technology Officer Tim Sweemer, CPA Chief Accounting Officer Dan Arsulowicz VP Operations Grand Rapids Christina Dickerson VP Corporate De
Slide 5: Strong Track Record in Transdermal Products
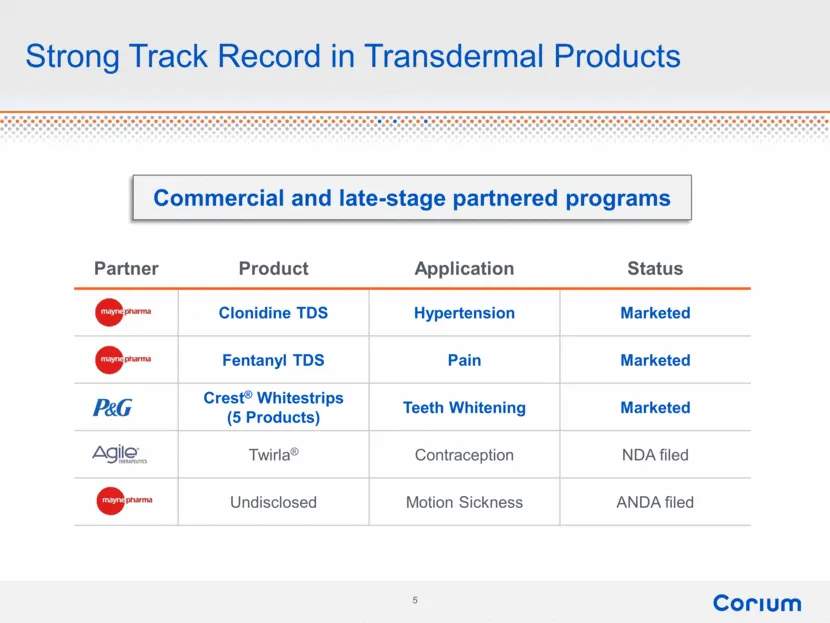
Partner Product Application Status Clonidine TDS Hypertension Marketed Fentanyl TDS Pain Marketed Crest® Whitestrips (5 Products) Teeth Whitening Marketed Twirla® Contraception NDA filed Undisclosed Motion Sickness ANDA filed Strong Track Record in Transdermal Products Commercial and late-stage part
Slide 6: Enabling Sustained Delivery: Corplex Technology
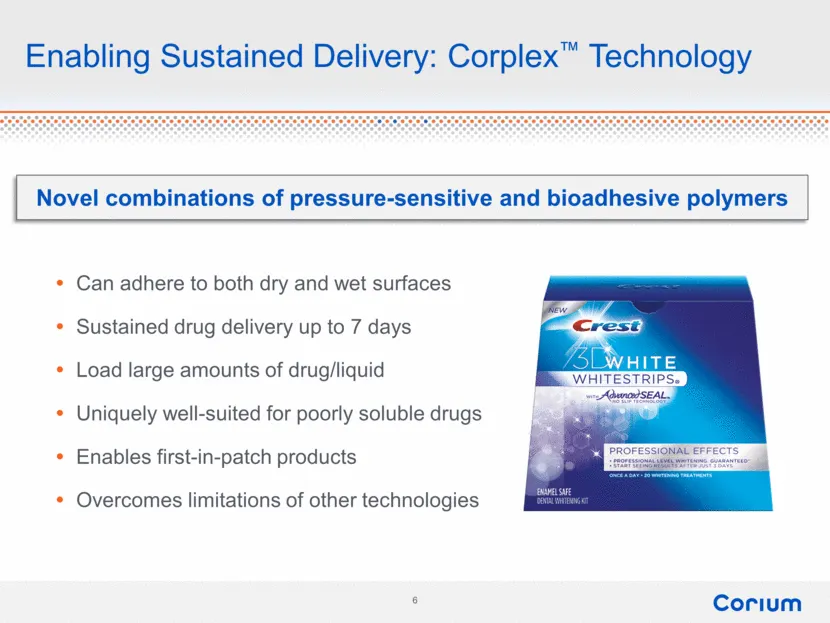
Enabling Sustained Delivery: Corplex™ Technology Can adhere to both dry and wet surfaces Sustained drug delivery up to 7 days Load large amounts of drug/liquid Uniquely well-suited for poorly soluble drugs Enables first-in-patch products Overcomes limitations of other technologies Novel combinations
Slide 7: Alzheimer's: Transformational Market Opportunity
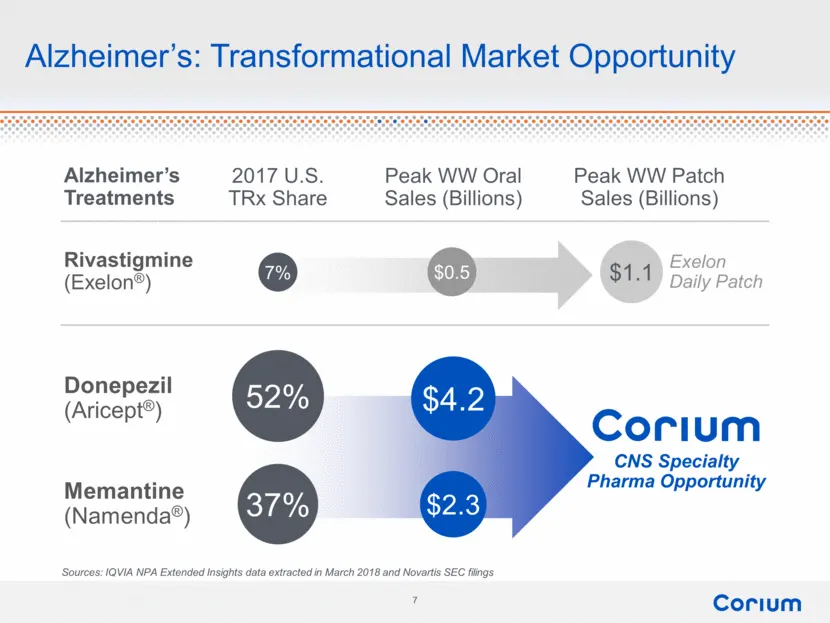
Exelon Daily Patch Alzheimer’s: Transformational Market Opportunity 7% 52% 37% $0.5 $4.2 $2.3 $1.1 Rivastigmine (Exelon®) Donepezil (Aricept®) Memantine (Namenda®) 2017 U.S. TRx Share Peak WW Oral Sales (Billions) Peak WW Patch Sales (Billions) CNS Specialty Pharma Opportunity Alzheimer’s Treatments
Slide 8: Physician Intent to Prescribe is High
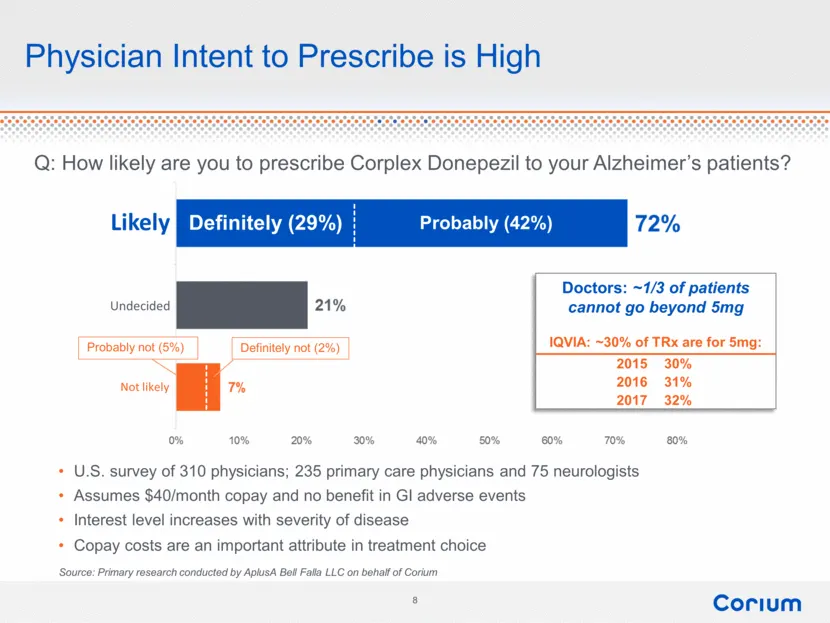
Physician Intent to Prescribe is High Q: How likely are you to prescribe Corplex Donepezil to your Alzheimer’s patients? Probably (42%) Definitely (29%) Undecided Probably not (5%) Definitely not (2%) Likely Not likely U.S. survey of 310 physicians; 235 primary care physicians and 75 neurologists As
Slide 9: Caregiver Interest and Intent to Fill is High
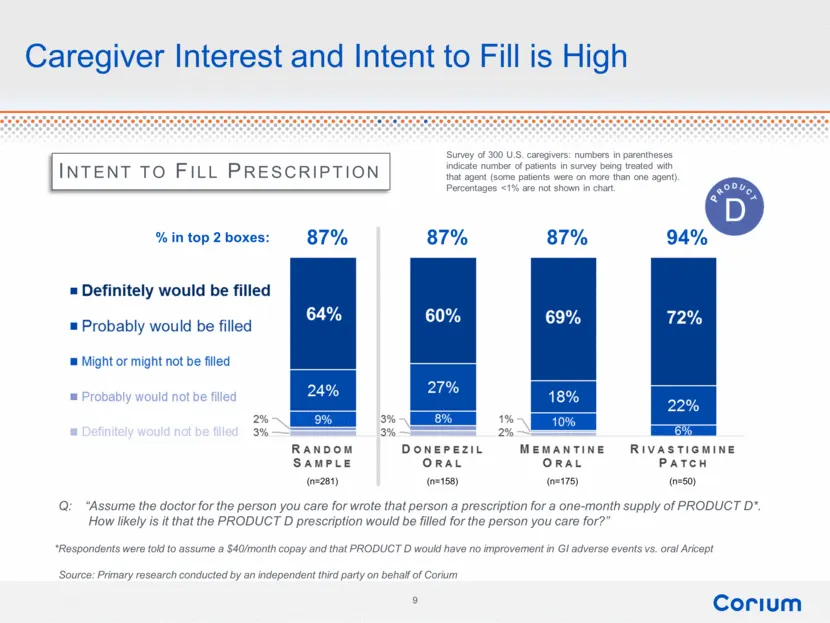
Intent to Fill Prescription Q: “Assume the doctor for the person you care for wrote that person a prescription for a one-month supply of PRODUCT D*. How likely is it that the PRODUCT D prescription would be filled for the person you care for?” 87% 87% 87% 94% (n=281) (n=158) (n=175) (n=50) Survey of
Slide 10: Payer Approach: Consistent with Exelon Patch
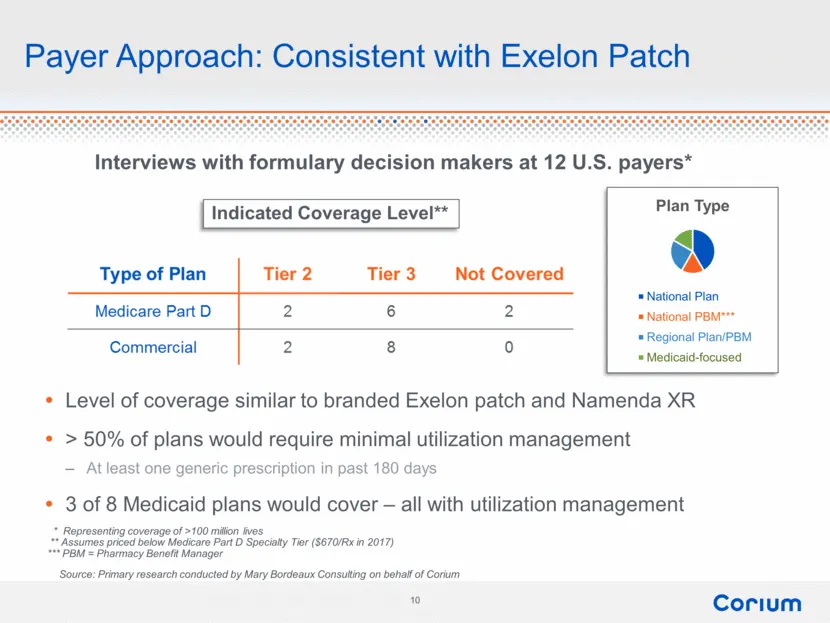
Payer Approach: Consistent with Exelon Patch Interviews with formulary decision makers at 12 U.S. payers* Level of coverage similar to branded Exelon patch and Namenda XR > 50% of plans would require minimal utilization management At least one generic prescription in past 180 days 3 of 8 Medicaid pl
Slide 11: Validated Pricing for Branded Transdermal Products
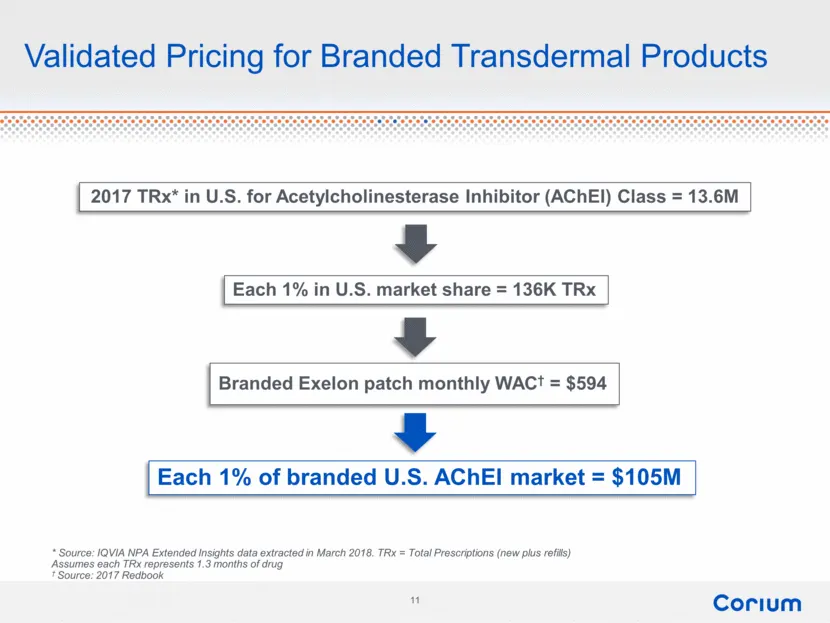
Validated Pricing for Branded Transdermal Products 2017 TRx* in U.S. for Acetylcholinesterase Inhibitor (AChEI) Class = 13.6M Each 1% in U.S. market share = 136K TRx Each 1% of branded U.S. AChEI market = $105M * Source: IQVIA NPA Extended Insights data extracted in March 2018. TRx = Total Prescript
Slide 12: Projected PK Profile Out to Steady State
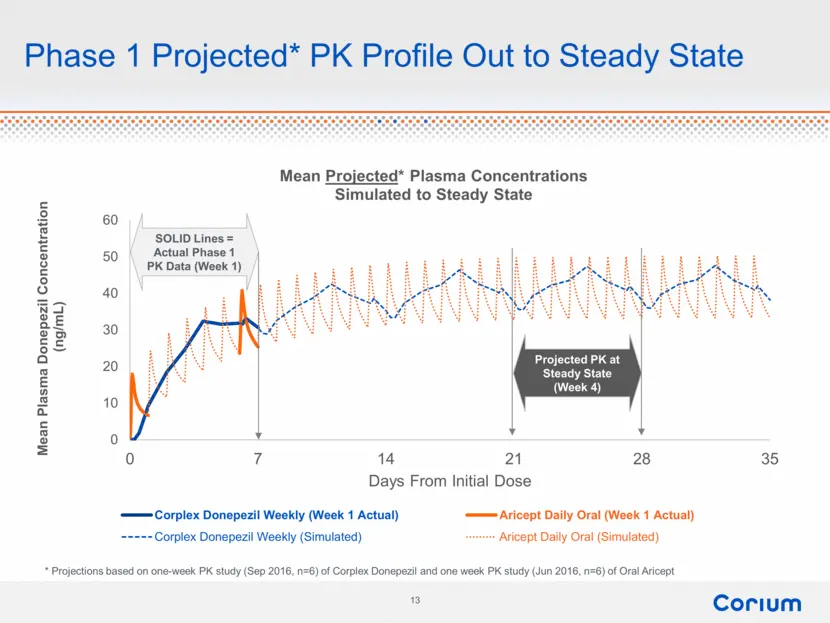
Phase 1 Projected* PK Profile Out to Steady State Mean Plasma Donepezil Concentration (ng/mL) SOLID Lines = Actual Phase 1 PK Data (Week 1) Projected PK at Steady State (Week 4) 0 10 20 30 40 50 60 0 7 14 21 28 35 Corplex Donepezil Weekly (week 1 actual) Corplex Donepezil Weekly (Simulated) Aricept
Slide 13: Projected PK Profile Out to Steady State
Phase 1 Projected* PK Profile Out to Steady State SOLID Lines = Actual Phase 1 PK Data (Week 1) Projected PK at Steady State (Week 4) * Projections based on one-week PK study (Sep 2016, n=6) of Corplex Donepezil and one week PK study (Jun 2016, n=6) of Oral Aricept
Slide 14: Donepezil Pilot Study Design
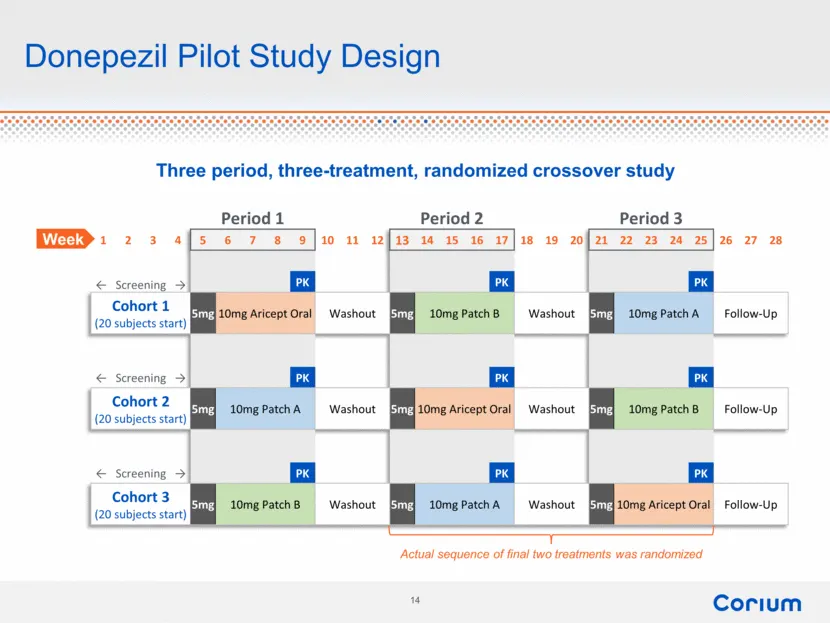
Donepezil Pilot Study Design Three period, three-treatment, randomized crossover study Period 1 Period 2 Period 3 1 2 3 4 5 6 7 8 9 10 11 12 13 14 15 16 17 18 19 20 21 22 23 24 25 26 27 28 ← Screening → PK PK PK Cohort 1 (20 subjects start) 5mg 10mg Aricept Oral Washout 5mg 10mg Patch B Washout 5mg
Slide 15: Pilot Study: Observed PK Profiles at Steady State
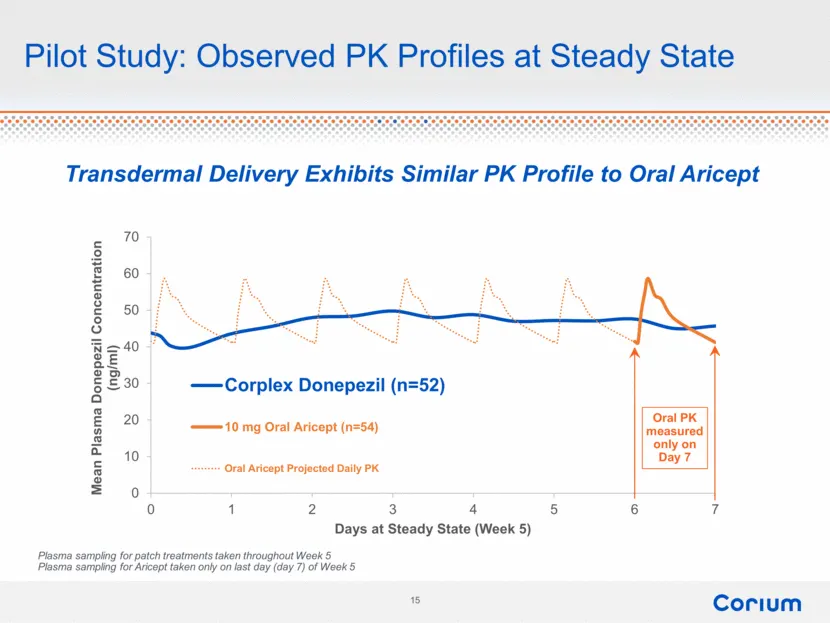
Pilot Study: Observed PK Profiles at Steady State Oral PK measured only on Day 7 Plasma sampling for patch treatments taken throughout Week 5 Plasma sampling for Aricept taken only on last day (day 7) of Week 5 Transdermal Delivery Exhibits Similar PK Profile to Oral Aricept 0 10 20 30 40 50 60 70 0
Slide 16: Bioequivalence Achieved
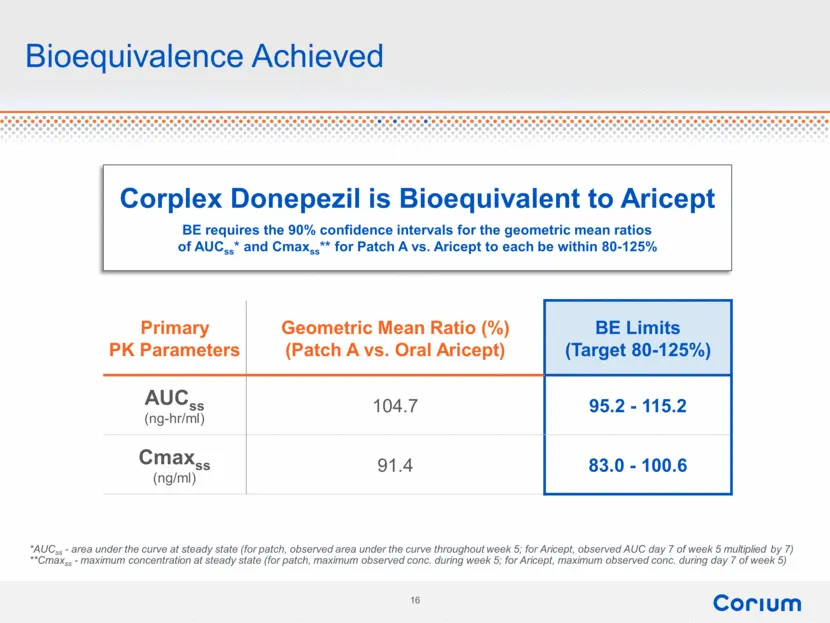
Bioequivalence Achieved Primary PK Parameters Geometric Mean Ratio (%) (Patch A vs. Oral Aricept) BE Limits (Target 80-125%) AUCss (ng-hr/ml) 104.7 95.2 - 115.2 Cmaxss (ng/ml) 91.4 83.0 - 100.6 *AUCss - area under the curve at steady state (for patch, observed area under the curve throughout week 5;
Slide 17: Bioequivalence: Primary and Supportive PK Statistics
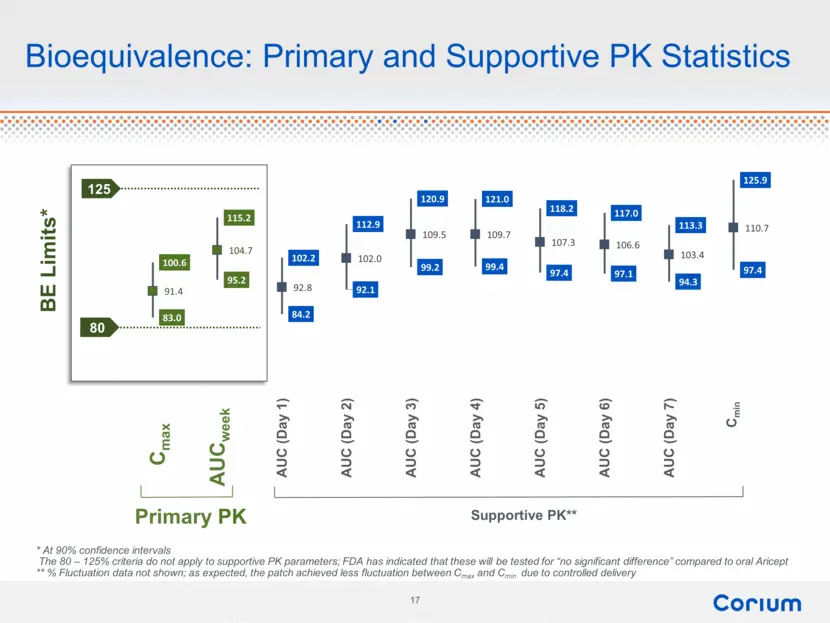
Bioequivalence: Primary and Supportive PK Statistics Primary PK Supportive PK** 125 80 Cmax AUCweek * At 90% confidence intervals The 80 – 125% criteria do not apply to supportive PK parameters; FDA has indicated that these will be tested for “no significant difference” compared to oral Aricept ** %
Slide 18: Most Common GI Side Effects (Pilot Study)
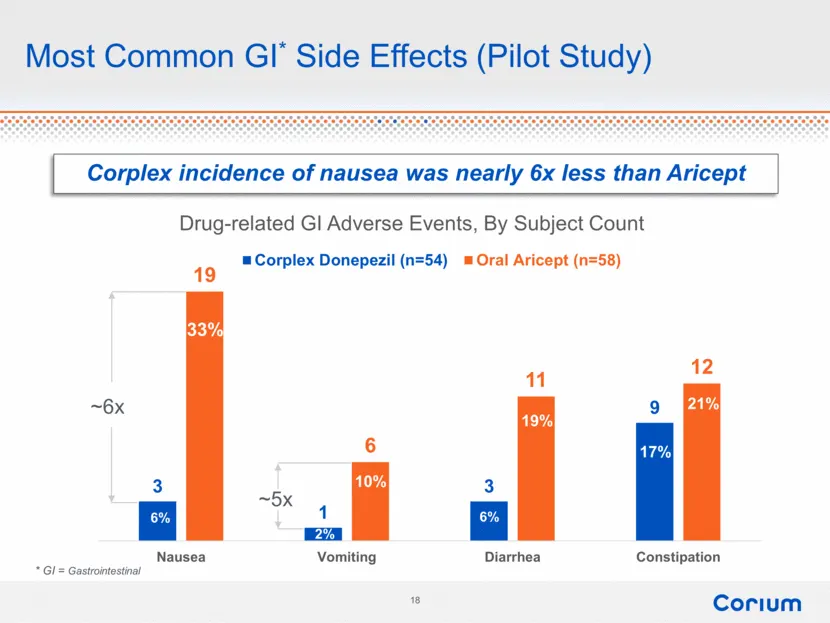
Most Common GI* Side Effects (Pilot Study) * GI = Gastrointestinal Corplex incidence of nausea was nearly 6x less than Aricept 29% 7% 4% 7% 19% 20% 9% 33% 6% 2% 6% 17% 21% 10% 19% ~6x ~5x 3 1 3 9 19 6 11 12 Nausea Vomiting Diarrhea Constipation Drug - related GI Adverse Events, By Subject Count Corp
Slide 19: Favorable Skin Tolerability (Pilot Study)
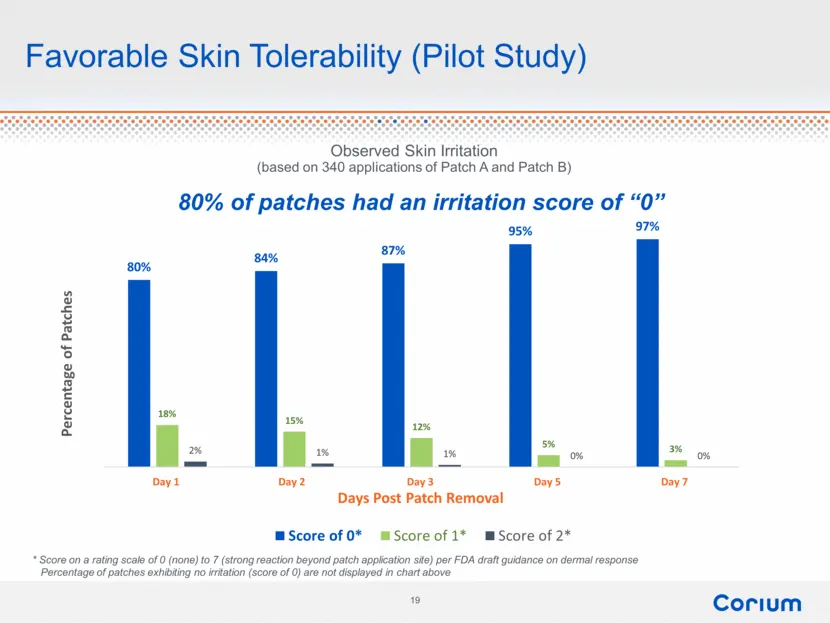
Favorable Skin Tolerability (Pilot Study) * Score on a rating scale of 0 (none) to 7 (strong reaction beyond patch application site) per FDA draft guidance on dermal response Percentage of patches exhibiting no irritation (score of 0) are not displayed in chart above Observed Skin Irritation (based
Slide 20: Recent FDA Feedback (February 2018)
Recent FDA Feedback (February 2018) Based on its preliminary review, FDA advised that the results of the pilot study may, on their face, suffice as the sole basis for demonstrating bioequivalence between the Corplex Donepezil Transdermal System and Aricept. Corium 20
Slide 21: NDA Submission Strategy
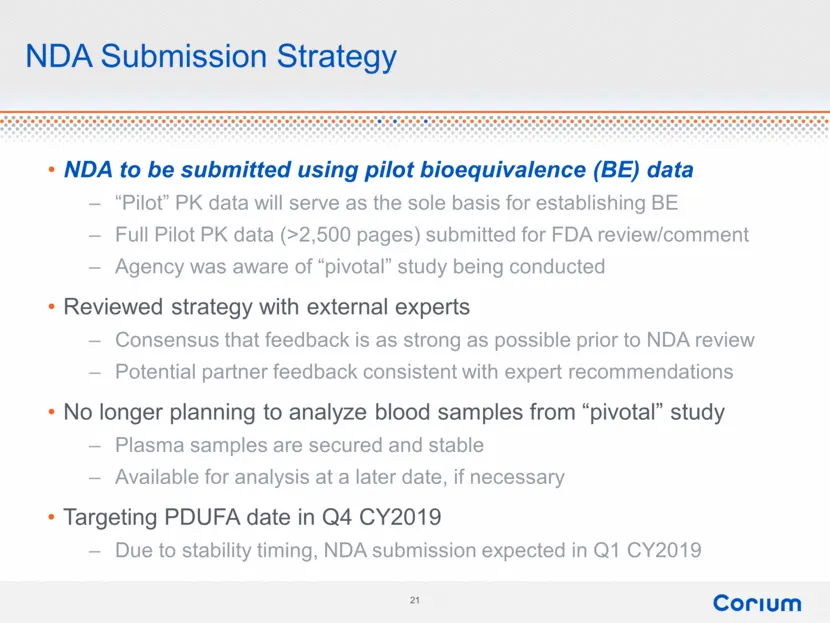
NDA Submission Strategy NDA to be submitted using pilot bioequivalence (BE) data “Pilot” PK data will serve as the sole basis for establishing BE Full Pilot PK data (>2,500 pages) submitted for FDA review/comment Agency was aware of “pivotal” study being conducted Reviewed strategy with external exp
Slide 22: Donepezil: Clear Pathway to Commercialization
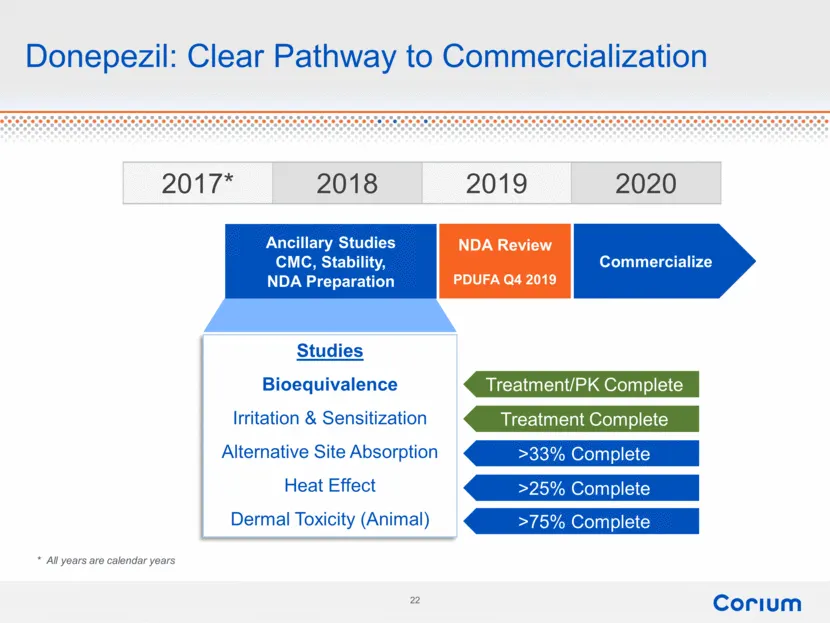
Donepezil: Clear Pathway to Commercialization 2017* 2018 2019 2020 Ancillary Studies CMC, Stability, NDA Preparation NDA Review PDUFA Q4 2019 Commercialize * All years are calendar years Studies Bioequivalence Irritation & Sensitization Alternative Site Absorption Heat Effect Dermal Toxicity (Animal
Slide 23: Financial Highlights at December 31, 2017
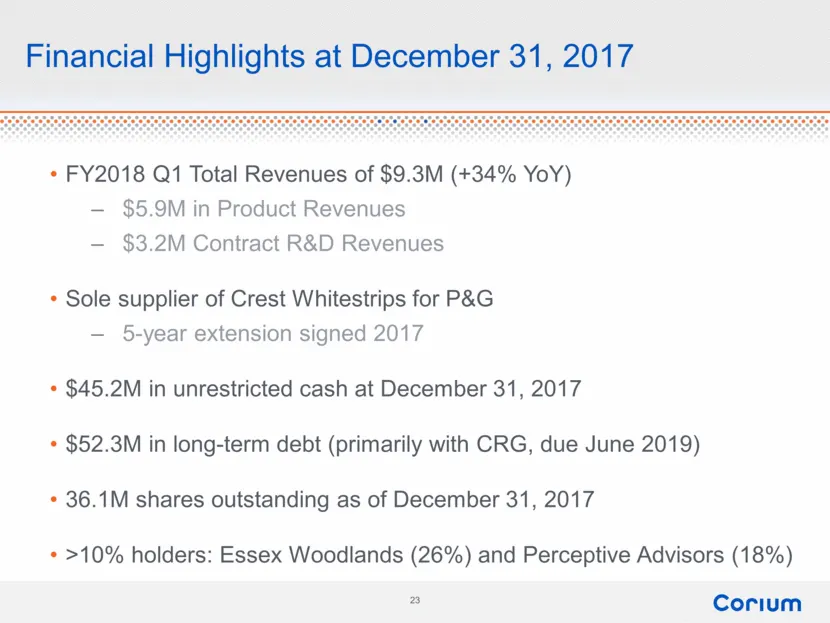
FY2018 Q1 Total Revenues of $9.3M (+34% YoY) $5.9M in Product Revenues $3.2M Contract R&D Revenues Sole supplier of Crest Whitestrips for P&G 5-year extension signed 2017 $45.2M in unrestricted cash at December 31, 2017 $52.3M in long-term debt (primarily with CRG, due June 2019) 36.1M shares outsta
Slide 24: Convertible Notes Offering (March 1, 2018)
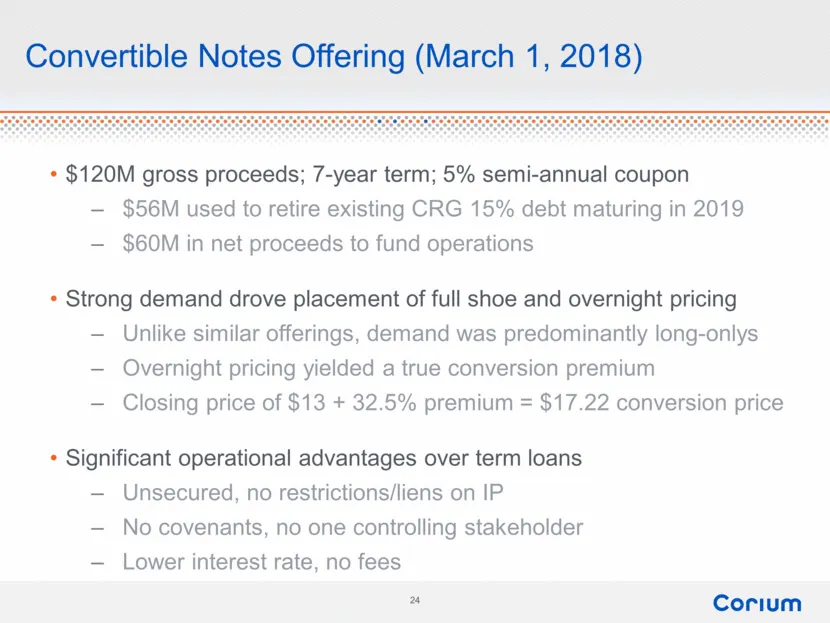
$120M gross proceeds; 7-year term; 5% semi-annual coupon $56M used to retire existing CRG 15% debt maturing in 2019 $60M in net proceeds to fund operations Strong demand drove placement of full shoe and overnight pricing Unlike similar offerings, demand was predominantly long-onlys Overnight pricing
Slide 25: Corium: Growth and Momentum in 2018
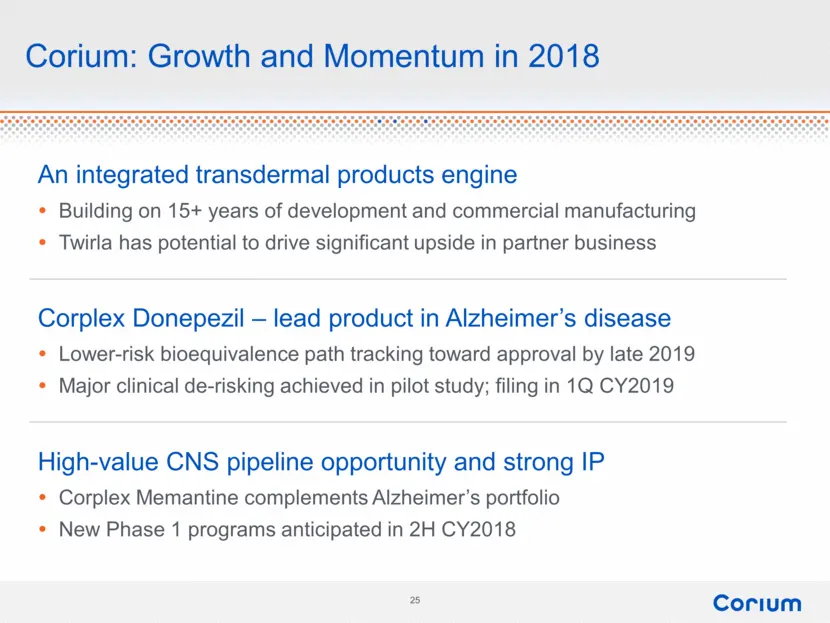
High-value CNS pipeline opportunity and strong IP Corplex Memantine complements Alzheimer’s portfolio New Phase 1 programs anticipated in 2H CY2018 Corium: Growth and Momentum in 2018 Building on 15+ years of development and commercial manufacturing Twirla has potential to drive significant upside i
Slide 26: Thank You
Thank You Corium Nasdaq: CORI
Source: SEC EDGAR · 8-K filed Mar 27, 2018
More decks from Corium International Inc
 Investor Presentation (February 2018)20 slides · Feb 28, 2018
 Technical Presentation (May 2017)21 slides · May 11, 2017
 Investor Presentation (January 2017)33 slides · Jan 9, 2017
 Technical Presentation (February 2016)12 slides · Feb 22, 2016
 Corporate Update (February 2016)10 slides · Feb 3, 2016
 Technical Presentation (July 2015)15 slides · Jul 28, 2015