Blackhawk Network Holdings Inc
Blackhawk Network — Non-Deal Roadshow (April 2014)
28 slides from Blackhawk Network's roadshow presentation, Apr 1, 2014
Slide 1: Roadshow Presentation April 2014
Roadshow Presentation April 2014 Roadshow Presentation April 2014 Exhibit 99.1
Slide 2: Forward Looking Statements
Forward Looking Statements This presentation may contain certain forward-looking statements within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934. Forward-looking statements are indicated by words or phrases such as "guidance," "believ
Slide 3: Blackhawk Overview
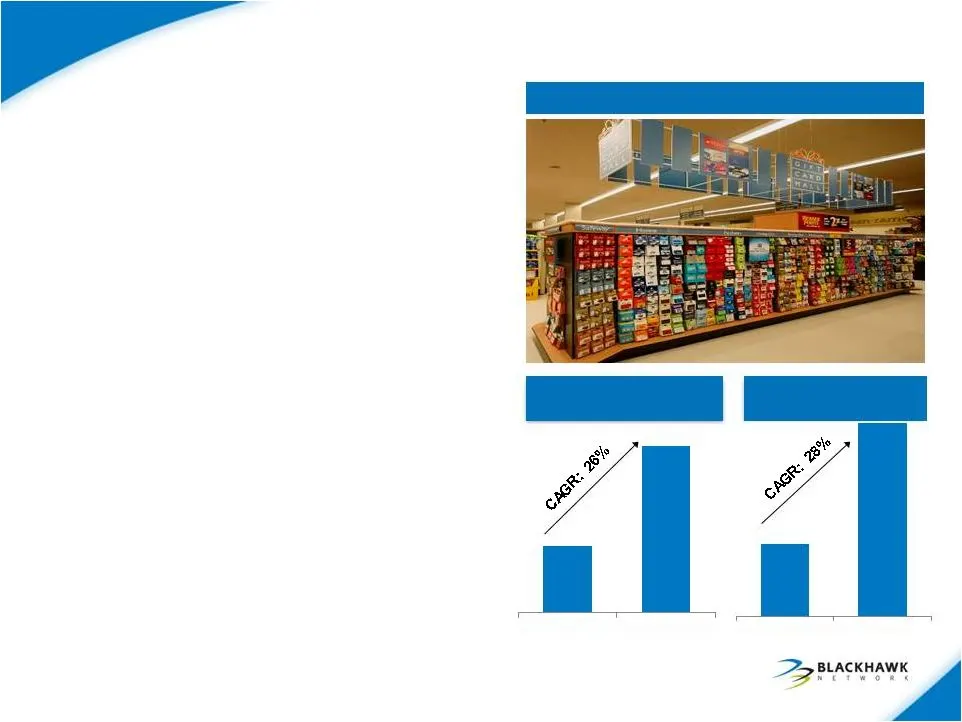
The Gift Card Mall Adjusted Operating Revenue¹ Adjusted EBITDA¹ $216 $541 $43 $114 Blackhawk Overview • Full range of prepaid products • Broadest gift card selection • Distribution in countries -- distribution partners • Proprietary platform for activation, processing and settlement • API-based solu
Slide 4: Blackhawk Overview – Network Benefits
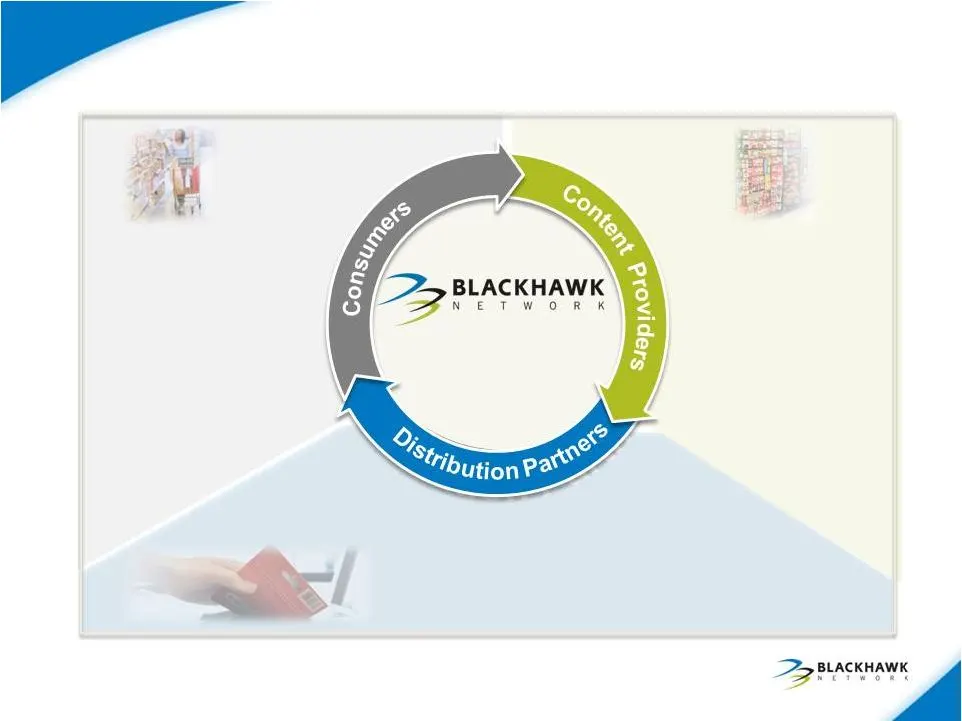
Blackhawk Overview – Network Benefits Consumers Estimated 300 million visits per week Broad selection in convenient, one-stop location Multi-channel: in-store, online and mobile Distribution Partners Over 180,000 active retail distribution locations Highly productive, growing product category “Store
Slide 5: Blackhawk Investment Highlights
Expanding Market Opportunities History Of Innovation Diversified Revenue Base, Good Visibility Growth Track Record A Leading Prepaid Payment Network Blackhawk Investment Highlights
Slide 6: Substantial Opportunity for Growth
Incentives & Rewards Third-Party Gift Cards General Purpose Reloadable Prepaid Telecom Total Addressable Prepaid Market ($B) Powerful Trends Substantial Opportunity for Growth $88 $56 $40 $37 • Channel shift to third-party gift cards with creation of “destination card malls” • “Self-use” of gift car
Slide 7: Pro-forma FY 2013 Financial Performance
Adjusted Operating Revenue Growth YoY Adjusted EBITDA Growth YoY Adjusted Net Income Growth YoY Adjusted EBITDA Margin Pro-forma FY 2013 Financial Performance Since IPO Key Milestones As Reported Strong IPO Year • Worldwide load value growth 17% - Productivity improvements: 8% growth - New Content a
Slide 8: Spin-off Transaction Overview
Shares in 000s (as of March 22, 2014) # Shares % Outstanding Spin-off Transaction Overview • On March 24, 2014 Safeway announced they anticipate completing the distribution of remaining Blackhawk shares to Safeway Inc. stockholders on April 14, 2014 Note 1: Total outstanding includes 12,419 (3.0% vo
Slide 9: Spin-off Transaction Benefits
Expands Distribution Opportunities Strengthens Strategic Positioning Independent Capital Structure Increases Float Retention of Key Personnel Tax Benefit to Blackhawk Spin-off Transaction Benefits Significantly increases from <25% to ~95% Eliminates competitive concerns with certain retail partners;
Slide 10: Potential Tax Benefit
Overview Approximate Financial Impact ($M except per share)(1) Potential Tax Benefit • If Safeway – Albertsons merger consummated, Safeway to bear the cost on taxable distribution of Blackhawk stock • Blackhawk retains the benefit of the tax basis step-up • Subject to terms of Tax Sharing Agreement
Slide 11: Growth Opportunities
1 2 3 4 5 6 Growth Opportunities Enhance Productivity at Retail Expand Content, Products and Services Expand Domestic Distribution Grow International Business Address New Payment Markets Strategic Acquisitions
Slide 12: Enhance Productivity at Retail
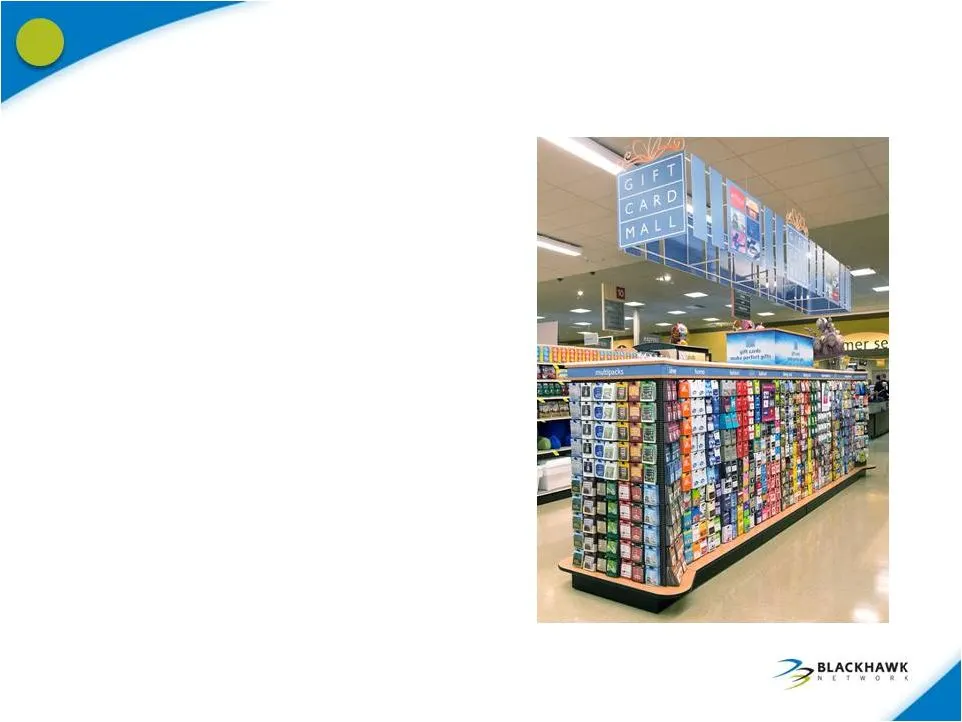
1 Enhance Productivity at Retail • Continue migrating U.S. grocery stores into Best Practices • One additional top 10 distribution partner with fuel loyalty • Continue to expand open loop gift including variable load • Add local/regional content and more discount deals • New planogramming and data a
Slide 13: Expand Products and Services
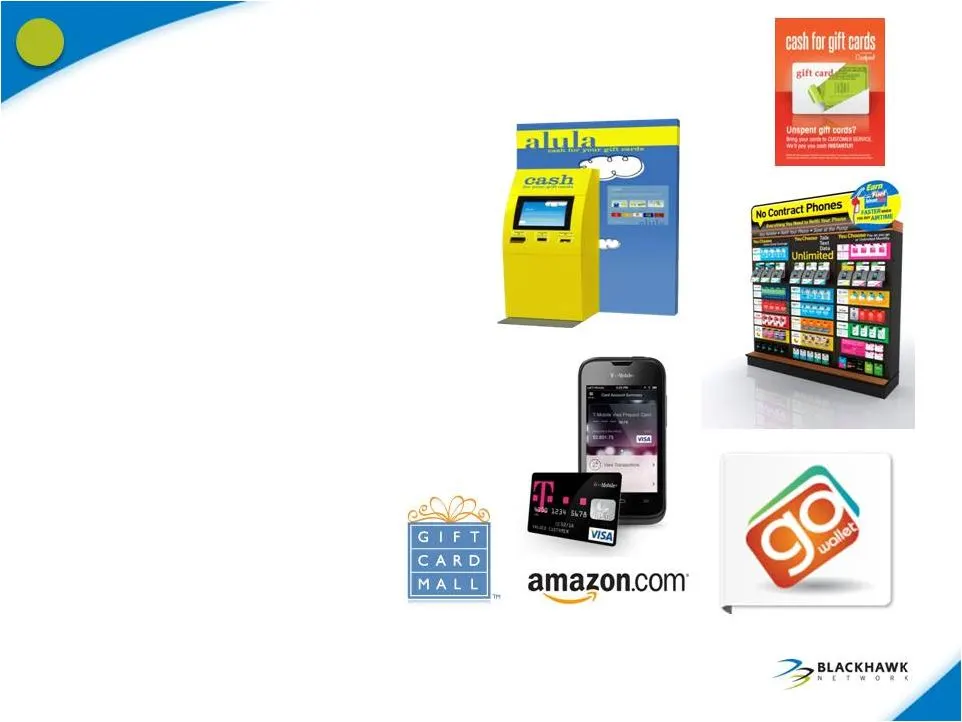
2 Expand Products and Services • Cardpool target revenue growth of 45% • Telecom Online Top-Up and SIM Cards • T-Mobile Mobile Money • Continue development of partners and technology to win in digital and mobile channels
Slide 14: Expand Distribution
3 2014 Prospects New Opportunities Other Q4 2013 Expand Distribution Continuing to sign well recognized, top brands Many opportunities to continue expansion with top names in pipeline Independence from Safeway provides access to new prospects New digital channels beginning to contribute to growth
Slide 15: Grow International Business
4 Grow International Business • Expanding distribution: Japan, Korea, Brazil, South Africa and Singapore • Retailo acquisition provided sizable market share in Germany - 2014 forecast Adjusted Operating Revenue $19M • Recruiting major retailers, banks and telco’s as digital partners • Google Play la
Slide 16: Addressing New Payment Markets: Incentives & Rewards
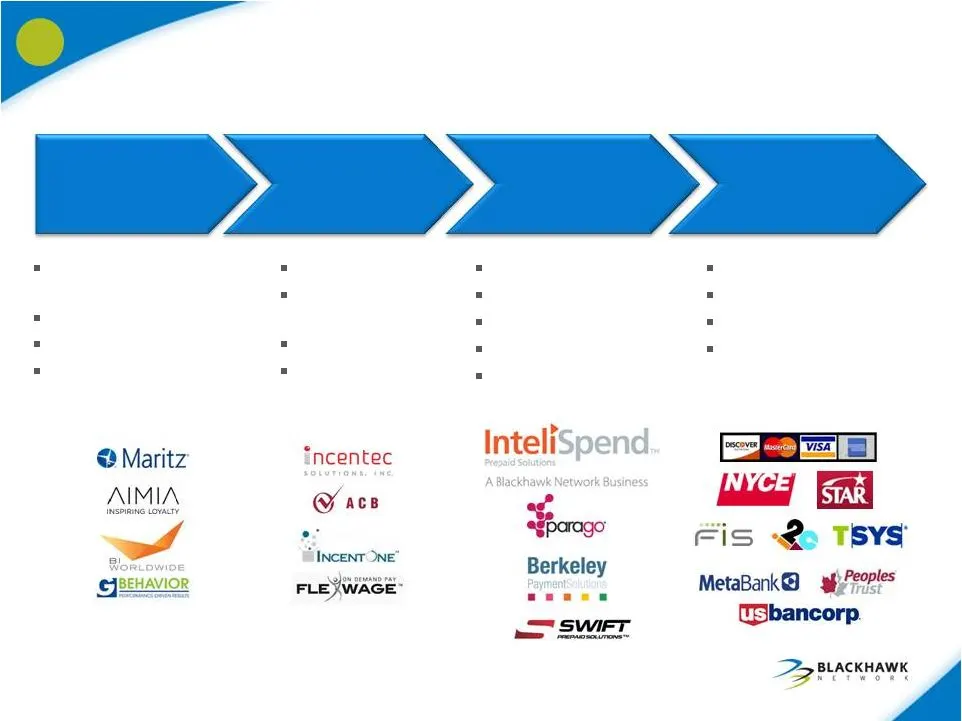
5 Solution Providers Technology Platforms Program Managers Payment Networks Addressing New Payment Markets: Incentives & Rewards Payments Market Incentives & Rewards Solutions Loyalty Solutions Wellness Solutions Program Management Peer-to-Peer Sales Tracking Rebates Loyalty Solution Bundling Produc
Slide 17: 2014 Outlook
5 2014 Outlook $ in millions Addressing New Payment Markets: • Integrate BHN and InteliSpend product offerings • Closed loop, physical and digital cards • Launch new capabilities • Solution Sales - Incentec technology platform • International open loop offering • Improve fulfillment efficiencies inc
Slide 18: Strategic Acquisitions
6 Criteria for Acquisitions Recent Acquisitions Well Positioned to Execute Strategic Acquisitions Independent capital structure and free cash flow make Blackhawk well positioned to evaluate strategic acquisitions • Strategic fit • Earnings accretion • Positive free cash flow • Synergies – revenue an
Slide 19: Financial Review and 2014 Guidance
FINANCIAL REVIEW AND 2014 GUIDANCE
Slide 20: 2014 Growth Targets
2014 Growth Targets • Adjusted Operating Revenue target mid-point +26% – InteliSpend contributes +7% • Adjusted EBITDA target mid-point +22% – Impacted by T-Mobile launch, deferred revenue accounting on InteliSpend and higher distribution program development expenses • Adjusted Net Income target mid
Slide 21: 2014 Annual Financial Guidance
2014 2013 % increase 2014 Annual Financial Guidance Adjusted Operating Revenue $ 670M - $ 690M $ 541M 24% - 28% Adjusted EBITDA $ 137M - $ 142M $ 114M 20% - 24% Adjusted Net Income $ 64M - $ 67M $ 58M 11% - 16% Adjusted Net Income per Share $ 1.19 - $ 1.24 $ 1.09 9% - 14% • Tax rate on “Adjusted Pre
Slide 22: Quarterly Guidance
$ in millions except per share amounts Q1 2014 Preliminary Q1 2013 Actual % Increase Quarterly Guidance Q1’14: Reminder – small $ earnings base in Q1-Q3 can result in large % swings on minor variances Q2’14: YOY impacted by lumpy Visa gift breakage revenue in Asia-Pac in 2013 ($3.5M) Q2’14-Q3’14: Im
Slide 23: Mid- to Long-Term Financial Targets
Adjusted Operating Revenue Growth Adjusted EBITDA Margin¹ Adjusted EPS Growth Mid- to Long-Term Financial Targets 20%+ Low 20s 20%+ 1. Calculated as Adjusted EBITDA divided by Adjusted Operating Revenue.
Slide 24: Credit Facility Overview
Credit Facility Overview • $225M Term Loan, $175M initial draw – $50M delayed draw available through September 2014 – Amortization: 5% year 1; 10% year 2; 15% year 3 • $200M revolving line of credit – Short-term working capital needs – $100M sublimit for trade credit (L/Cs) – Additional $100M with L
Slide 25: Appendix
APPENDIX
Slide 26: Adjusted Operating Revenues Reconciliation
(amounts in millions) 2013 2009 Adjusted Operating Revenues Reconciliation (including Pro forma) Total Operating Revenues $ 1,138 $ 504 Less: Distribution Partner Commissions (597) (266) Less: Issuing bank contract amendment fee adj. (12) Adjusted Operating Revenues $ 541 $ 226 Adjust for Safeway co
Slide 27: Adjusted EBITDA Reconciliation
(amounts in millions) 2013 2009 Adjusted EBITDA Reconciliation (including Pro forma) Net income before allocation to NCI $ 54 Interest income and other income, net - (2) Interest expense - - Income tax expense Depreciation and amortization EBITDA $ 57 Adjustments to EBITDA: Employee stock-based comp
Slide 28: Thank You
Thank You
Source: SEC EDGAR · 8-K filed Apr 1, 2014