Terremark Worldwide — Investor Day (February 2010)
50 slides from Terremark Worldwide's investor day presentation, Feb 26, 2010
Slide 1: Welcome to Analyst Day
Welcome to Analyst Day
Slide 2: Safe Harbor Clause
The following statement is made pursuant to the Safe Harbor for forward-looking statements described in the Private Securities Litigation Reform Act of 1995. In these communications, we may make certain statements that are forward-looking, such as statements regarding Terremark's future results and
Slide 3: Welcome - Manuel D. Medina, Chairman and CEO
Welcome MANUEL D. MEDINA - CHAIRMAN AND CHIEF EXECUTIVE OFFICER
Slide 4: Today's Speakers
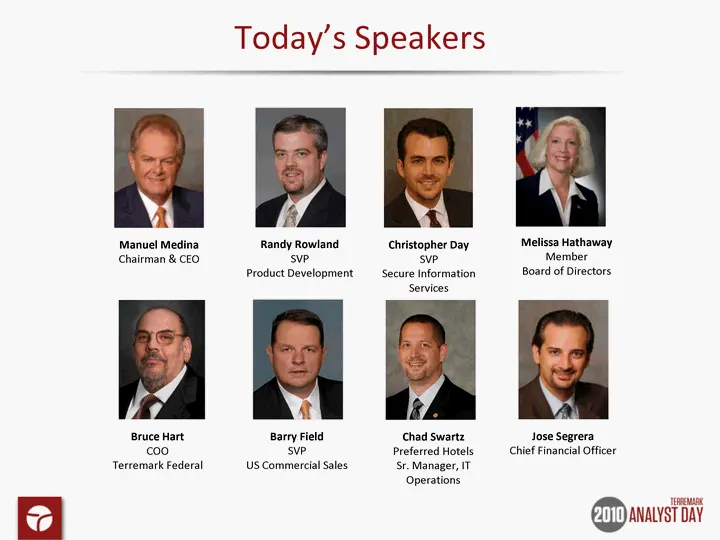
Today's Speakers Manuel Medina Chairman & CEO Jose Segrera Chief Financial Officer Christopher Day SVP Secure Information Services Randy Rowland SVP Product Development Barry Field SVP US Commercial Sales Bruce Hart COO Terremark Federal Melissa Hathaway Member Board of Directors Chad Swartz Preferr
Slide 5: Additional Leadership Here Today
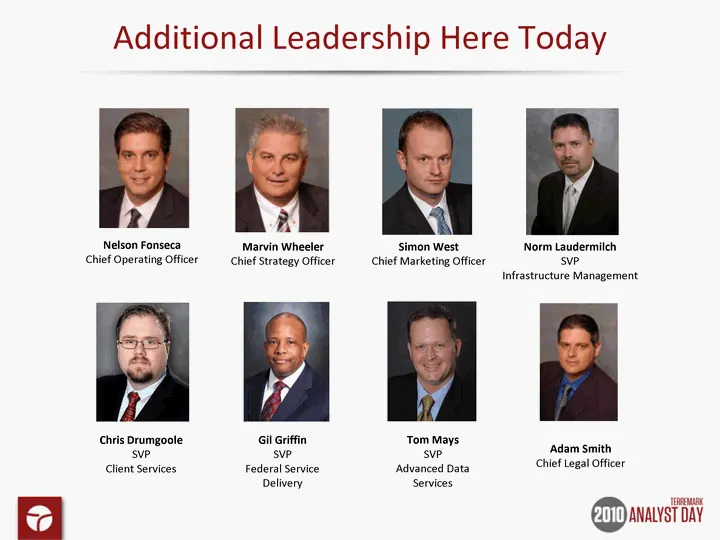
Additional Leadership Here Today Marvin Wheeler Chief Strategy Officer Tom Mays SVP Advanced Data Services Simon West Chief Marketing Officer Norm Laudermilch SVP Infrastructure Management Gil Griffin SVP Federal Service Delivery Chris Drumgoole SVP Client Services Nelson Fonseca Chief Operating Off
Slide 6: Members Of The Board Here Today
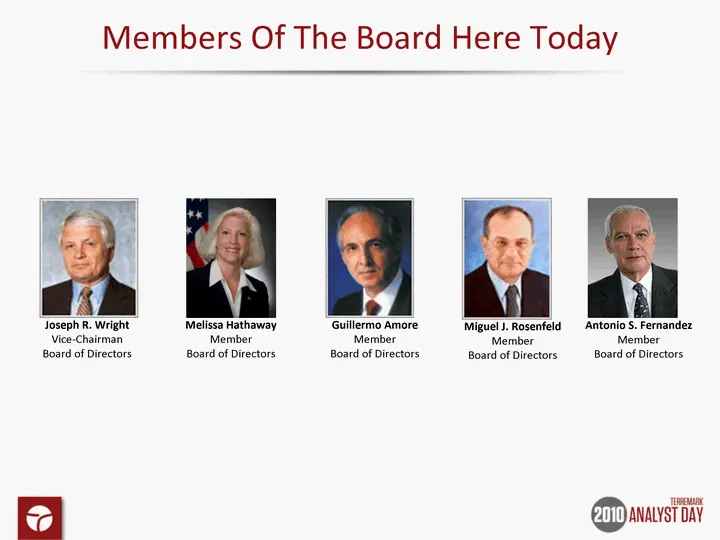
Members Of The Board Here Today Melissa Hathaway Member Board of Directors Joseph R. Wright Vice-Chairman Board of Directors Guillermo Amore Member Board of Directors Miguel J. Rosenfeld Member Board of Directors Antonio S. Fernandez Member Board of Directors
Slide 7: CIO Priorities
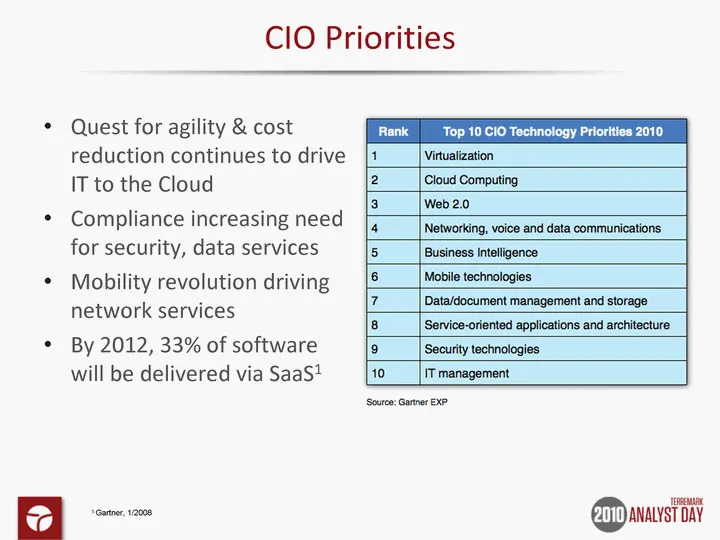
CIO Priorities Quest for agility & cost reduction continues to drive IT to the Cloud Compliance increasing need for security, data services Mobility revolution driving network services By 2012, 33% of software will be delivered via SaaS1 1 Gartner, 1/2008
Slide 8: Utility Computing Platform
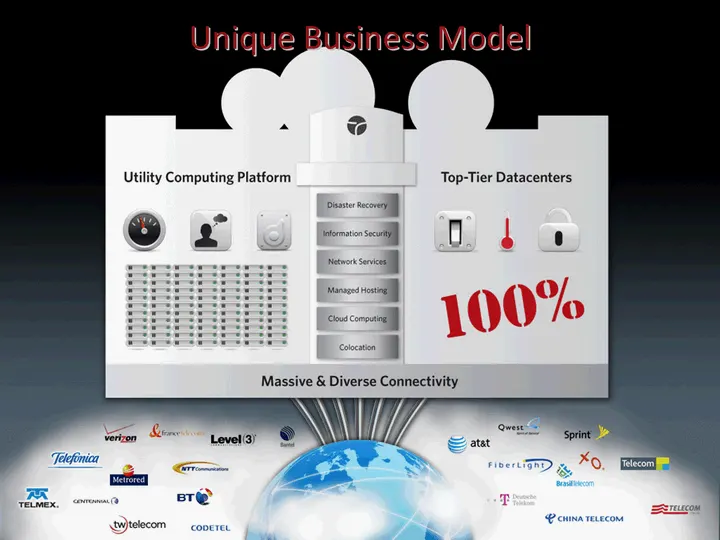
Utility Computing Platform
Slide 9: Strategic Expansion
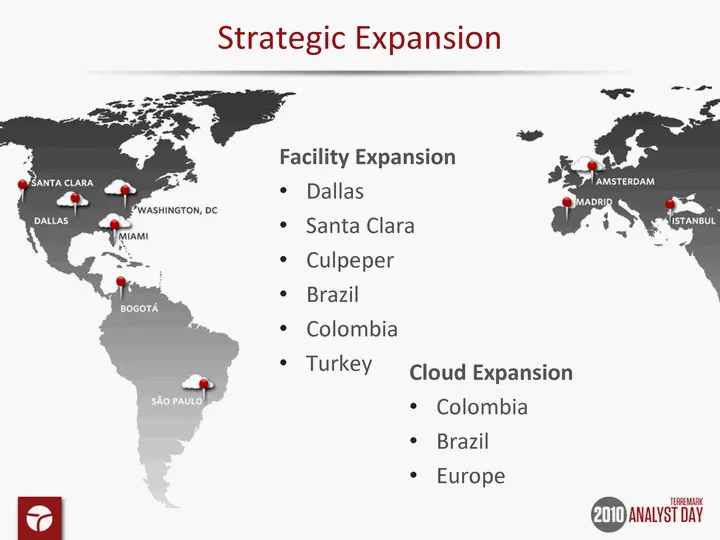
Strategic Expansion Cloud Expansion Colombia Brazil Europe Facility Expansion Dallas Santa Clara Culpeper Brazil Colombia Turkey
Slide 10: The Enterprise Cloud
The Enterprise Cloud RANDY ROWLAND - SVP PRODUCT DEVELOPMENT
Slide 11: Definitions
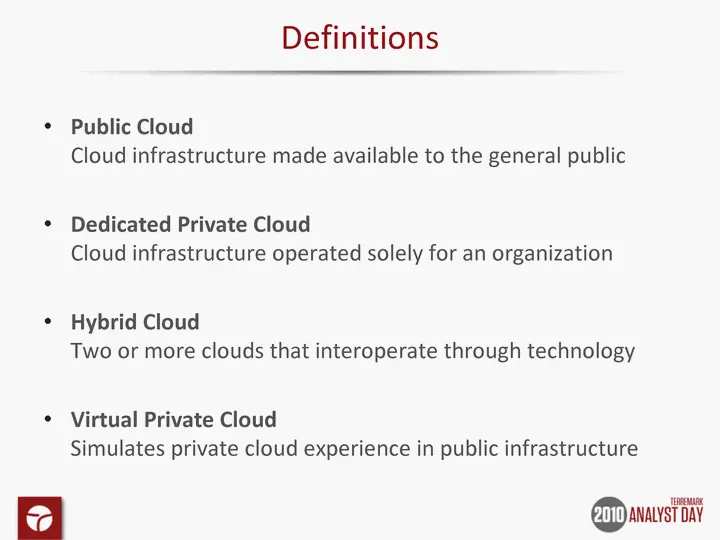
Definitions Public Cloud Cloud infrastructure made available to the general public Dedicated Private Cloud Cloud infrastructure operated solely for an organization Hybrid Cloud Two or more clouds that interoperate through technology Virtual Private Cloud Simulates private cloud experience in public
Slide 12: Built For The Enterprise
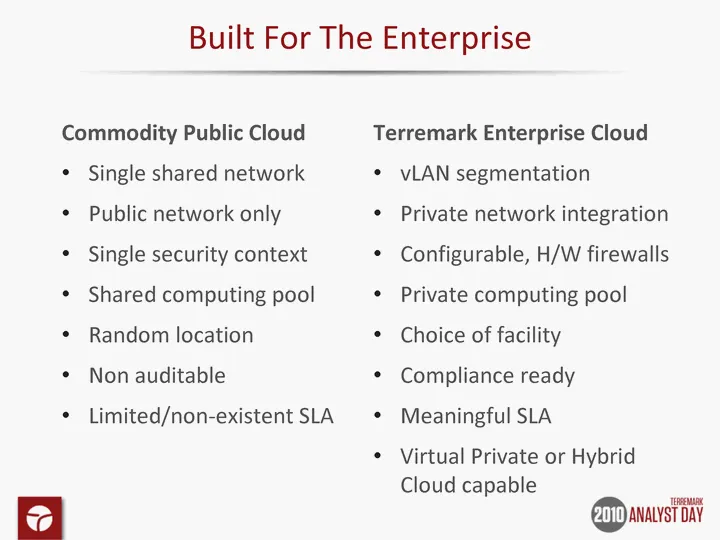
Built For The Enterprise Commodity Public Cloud Single shared network Public network only Single security context Shared computing pool Random location Non auditable Limited/non-existent SLA Terremark Enterprise Cloud vLAN segmentation Private network integration Configurable, H/W firewalls Private
Slide 13: Enterprise-Class Infrastructure
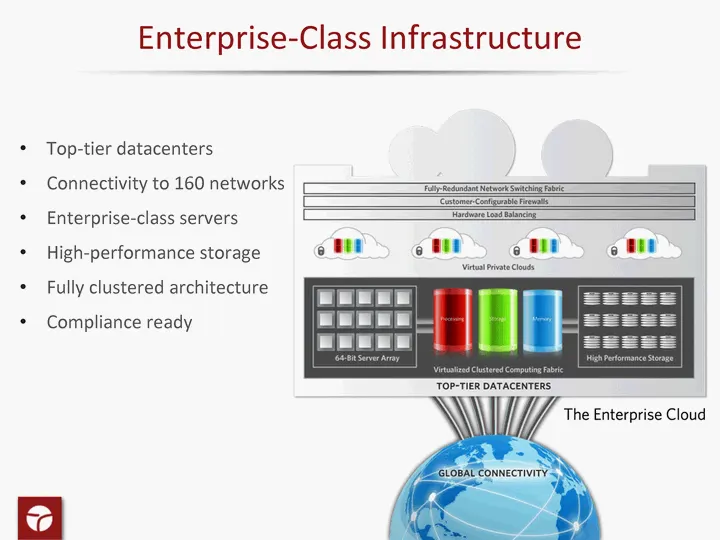
Enterprise-Class Infrastructure Top-tier datacenters Connectivity to 160 networks Enterprise-class servers High-performance storage Fully clustered architecture Compliance ready
Slide 14: Clustered Architecture
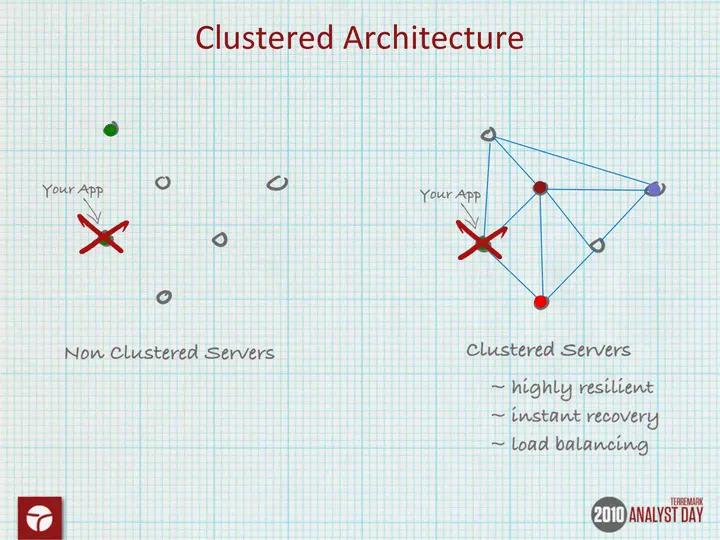
Clustered Architecture
Slide 15: Built For Interoperability
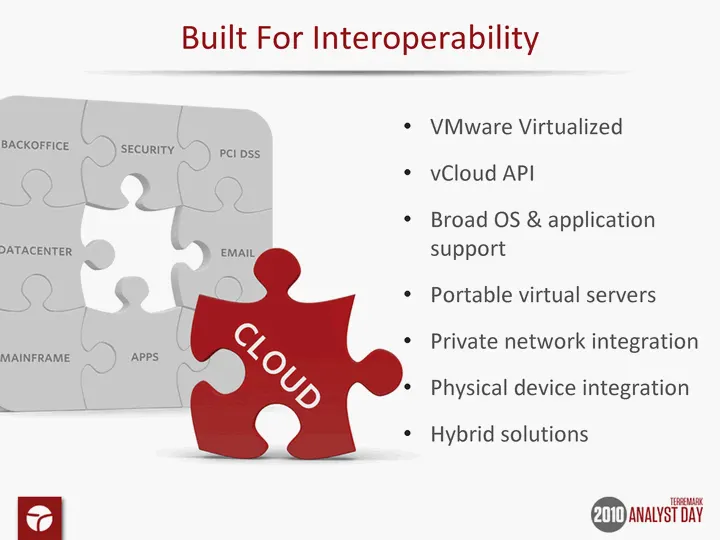
Built For Interoperability VMware Virtualized vCloud API Broad OS & application support Portable virtual servers Private network integration Physical device integration Hybrid solutions
Slide 16: Integrated Security Features
Integrated Security Features Hardware firewalls vLAN segmentation VPN management access Multi-factor authentication Full suite of security services Compliance services
Slide 17: Cloud + Services
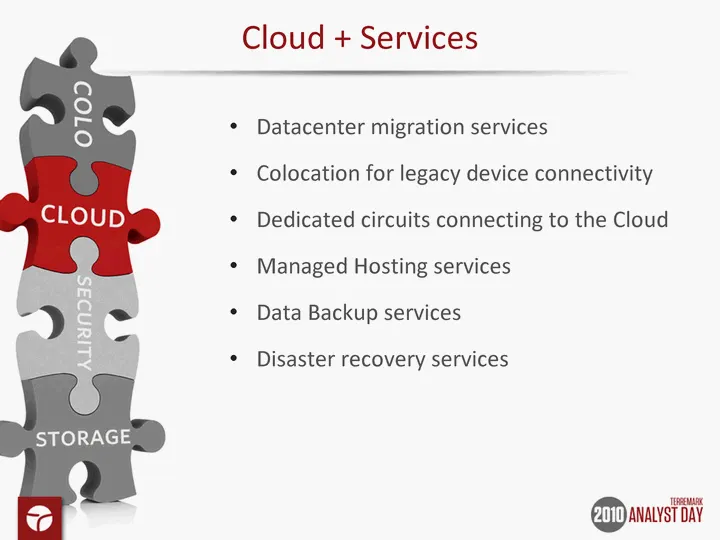
Cloud + Services Datacenter migration services Colocation for legacy device connectivity Dedicated circuits connecting to the Cloud Managed Hosting services Data Backup services Disaster recovery services
Slide 18: Secure Information Systems
Secure Information Systems CHRIS DAY - CHIEF SECURITY ARCHITECT
Slide 19: Google Hacked
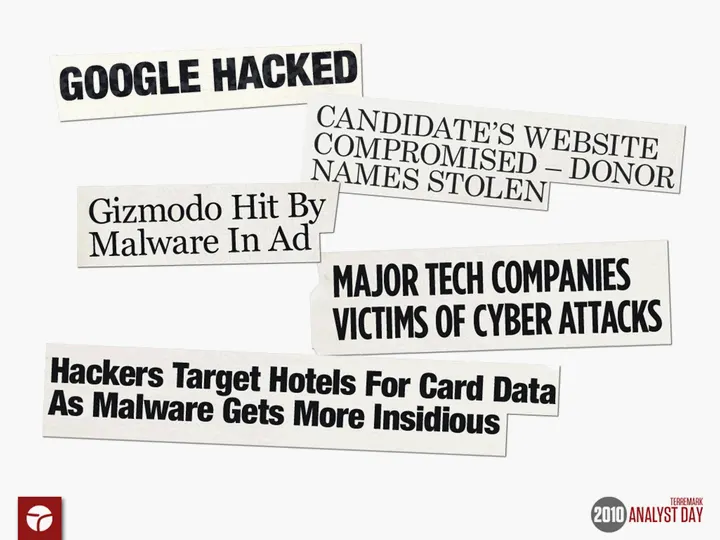
GOOGLE HACKED ~ CANDIDATE: COMPROMISeY EBSITE._| N. ED — | Gizmodo Hit By = STOLEN)» NOR Malware In Ad | MAJOR TECH COMPANIES VICTIMS OF CYBER ATTACKS Hackers Target Hotels Fo As Malware Gets More insidious QD anastctt
Slide 20: Effective Information Security Services
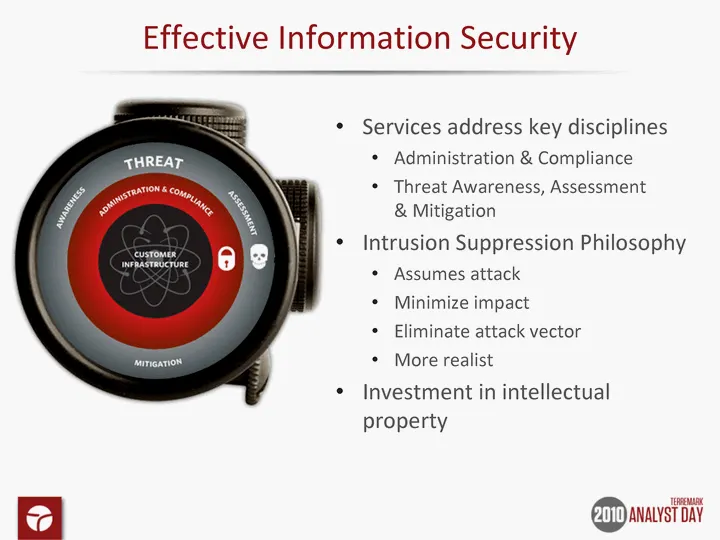
Effective Information Security Services address key disciplines Administration & Compliance Threat Awareness, Assessment & Mitigation Intrusion Suppression Philosophy Assumes attack Minimize impact Eliminate attack vector More realist Investment in intellectual property
Slide 21: Service Portfolio
Service Portfolio Managed Services Managed firewalls Intrusion Detection/Prevention Log Correlation Network Monitoring/Analysis Network Forensics Data Leak Detection/Prevention "SOC-In-A-Box" Engagement Services Incident Response Digital Forensics Vulnerability Assessments Penetration Testing Compli
Slide 22: Securing the Cloud
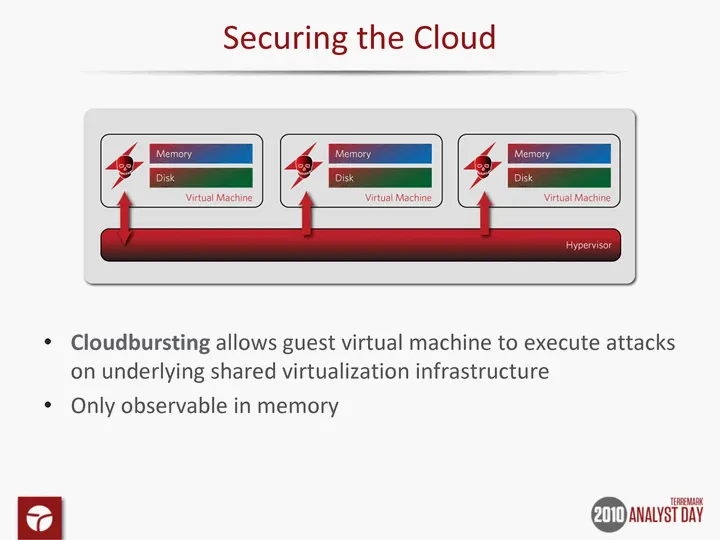
Securing the Cloud Cloudbursting allows guest virtual machine to execute attacks on underlying shared virtualization infrastructure Only observable in memory
Slide 23: Memory Analytics and System Integrity Validation
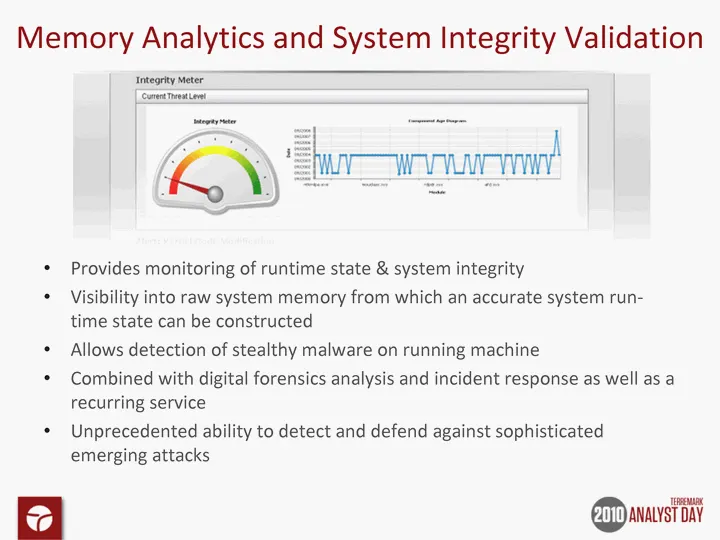
Memory Analytics and System Integrity Validation Provides monitoring of runtime state & system integrity Visibility into raw system memory from which an accurate system run- time state can be constructed Allows detection of stealthy malware on running machine Combined with digital forensics analysis
Slide 24: Enterprise Cloud Demo
2010 ANALYST DAY Enterprise Cloud Demo
Slide 25: Q&A Session
2010 ANALYST DAY Q&A Session
Slide 26: Cybersecurity, A National Imperative
Cybersecurity, A National Imperative MELISSA HATHAWAY - MEMBER, BOARD OF DIRECTORS
Slide 27: Federal Overview
Federal Overview BRUCE HART - COO, TERREMARK FEDERAL
Slide 28: Origins: Classified & Defense
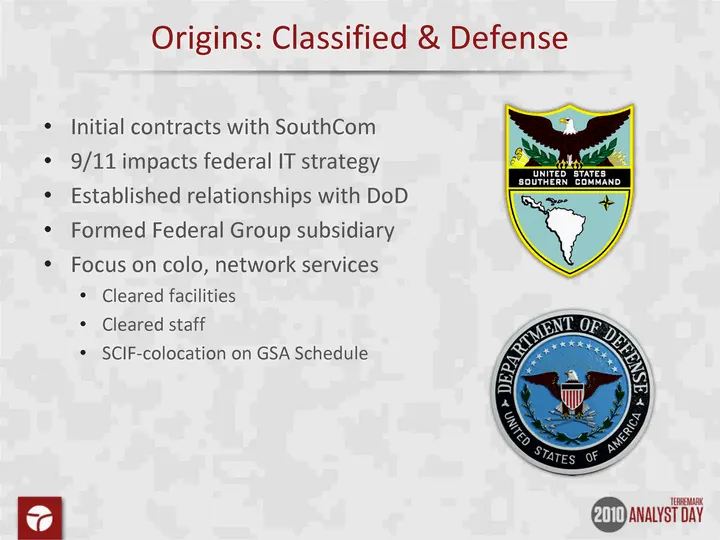
Origins: Classified & Defense Initial contracts with SouthCom 9/11 impacts federal IT strategy Established relationships with DoD Formed Federal Group subsidiary Focus on colo, network services Cleared facilities Cleared staff SCIF-colocation on GSA Schedule
Slide 29: Expansion into Civil Sector
Expansion into Civil Sector Leverage expanded Terremark portfolio Information Security Managed Hosting Early to market with Enterprise Cloud Open Government Initiative Breakthrough Cloud deal with GSA USA.gov - First .gov Cloud application
Slide 30: The Power Of Integration
The Power Of Integration NCR opening provides world-class foundation Fortress + Cloud + Security = unique offering Government Cyber Security Initiative Penetrating national security agencies Integrated Cloud & Security offerings On-premise cloud storage Security services to DHS
Slide 31: Terremark Federal Today
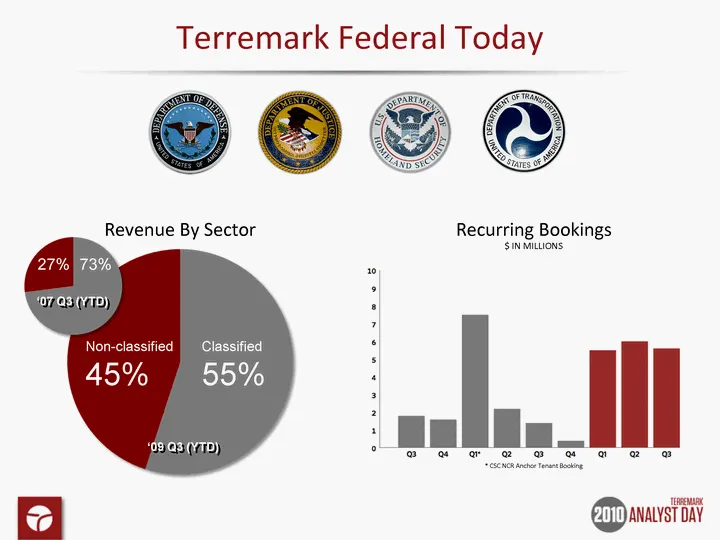
Non-classified 45% '09 Q3 (YTD) Classified 55% Terremark Federal Today '07 Q3 (YTD) 27% 73% * CSC NCR Anchor Tenant Booking Recurring Bookings Revenue By Sector $ IN MILLIONS
Slide 32: The Road Ahead
The Road Ahead Key Initiatives Cyber Security Open Government Key Strategies Direct Sales White Label & Resellers SaaS/PaaS Partners Vertically Integrated Solutions Strategic Partners
Slide 33: Sales Strategy
Sales Strategy BARRY FIELD - SVP COMMERCIAL SALES
Slide 34: Target: Fortune 1,000
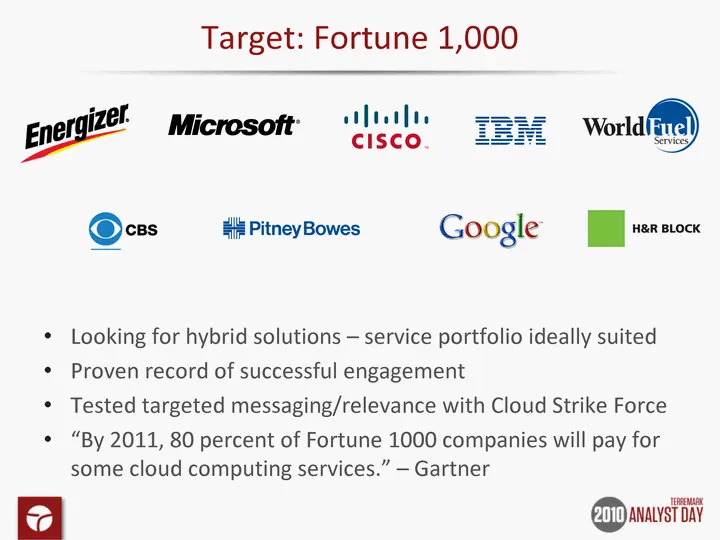
Target: Fortune 1,000 Looking for hybrid solutions - service portfolio ideally suited Proven record of successful engagement Tested targeted messaging/relevance with Cloud Strike Force "By 2011, 80 percent of Fortune 1000 companies will pay for some cloud computing services." - Gartner
Slide 35: Targeted Expansion
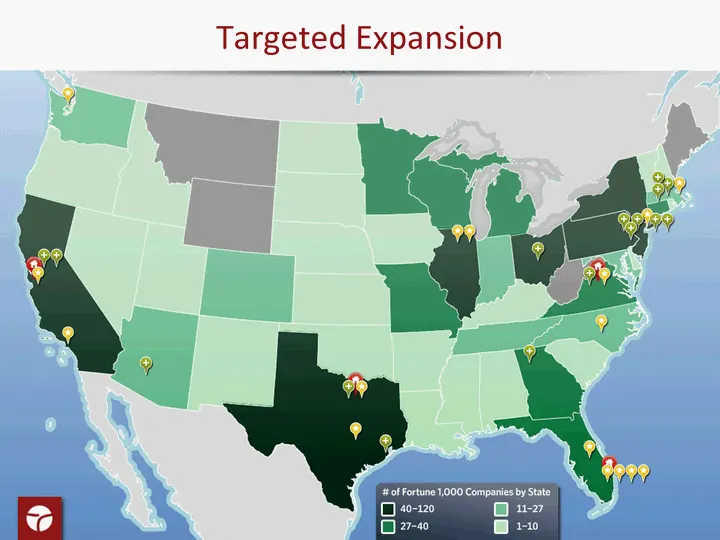
Targeted Expansion
Slide 36: Channel & Strategic Alliances
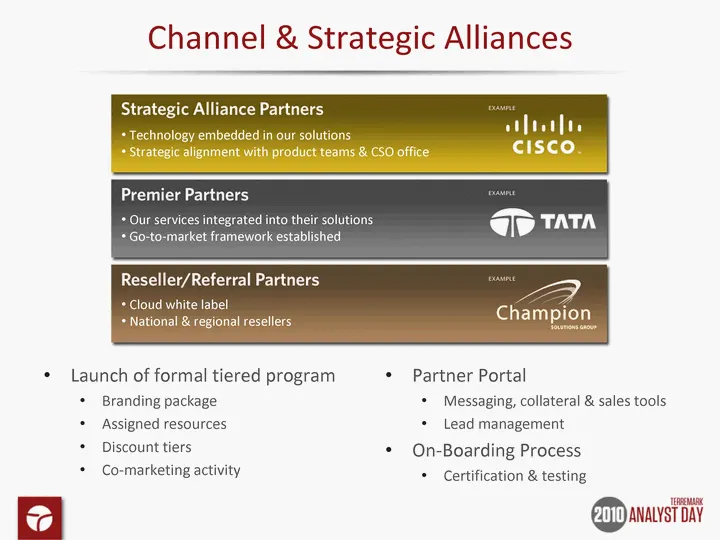
Channel & Strategic Alliances Launch of formal tiered program Branding package Assigned resources Discount tiers Co-marketing activity Partner Portal Messaging, collateral & sales tools Lead management On-Boarding Process Certification & testing Technology embedded in our solutions Strategic alignme
Slide 37: Strategic Account Management
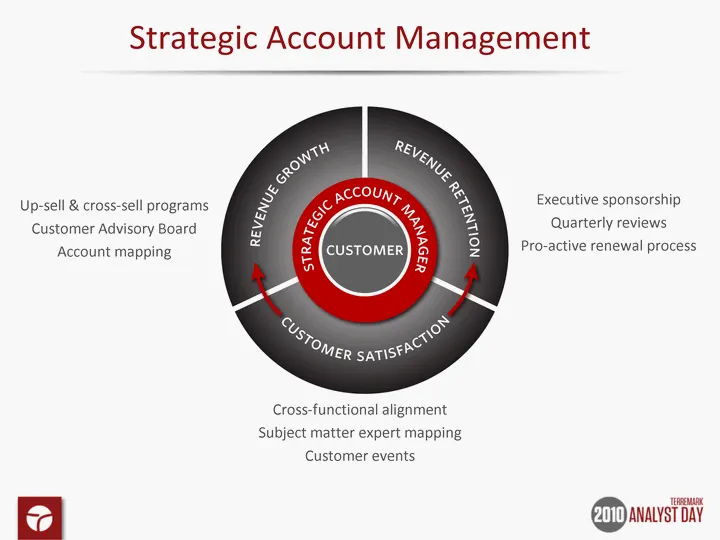
Strategic Account Management Up-sell & cross-sell programs Customer Advisory Board Account mapping Executive sponsorship Quarterly reviews Pro-active renewal process Cross-functional alignment Subject matter expert mapping Customer events
Slide 38: Case Study
Case Study Long-time managed hosting customer Terremark provides services in US, Europe Leveraging the stack Managed services Top-tier facilities Massive connectivity Perfect example of strategic alignment Selected as LEGO Universe hosting provider
Slide 39: Q&A Session
2010 ANALYST DAY Q&A Session
Slide 40: Financial Overview
Financial Overview JOSE SEGRERA - CHIEF FINANCIAL OFFICER
Slide 41: Strong Financial Growth Visibility
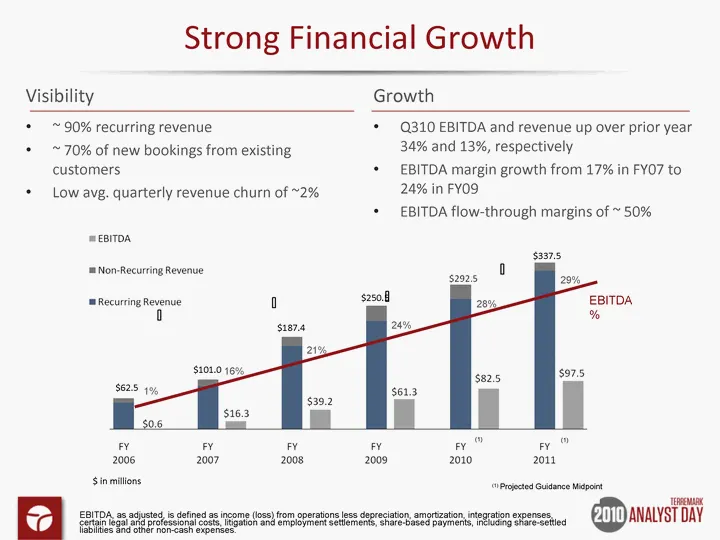
Strong Financial Growth Visibility ~ 90% recurring revenue ~ 70% of new bookings from existing customers Low avg. quarterly revenue churn of ~2% Growth Q310 EBITDA and revenue up over prior year 34% and 13%, respectively EBITDA margin growth from 17% in FY07 to 24% in FY09 EBITDA flow-through margin
Slide 42: Average Quarterly Bookings
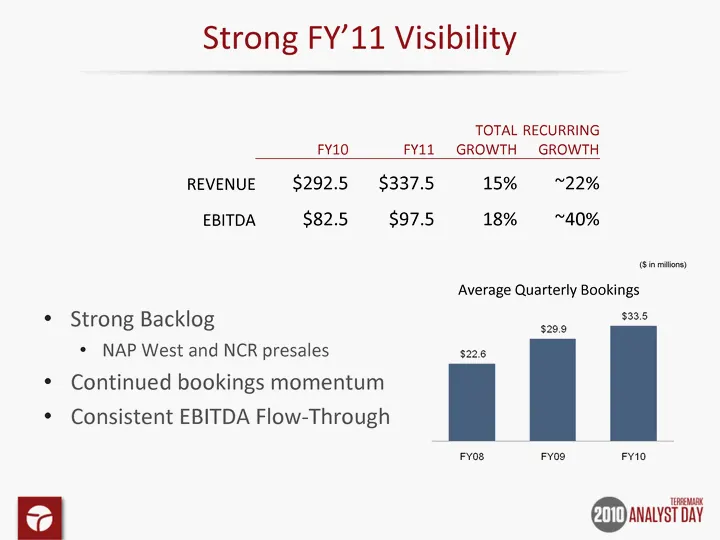
Average Quarterly Bookings FY10 FY11 TOTAL GROWTH RECURRING GROWTH REVENUE $292.5 $337.5 15% ~22% EBITDA $82.5 $97.5 18% ~40% Strong FY'11 Visibility Strong Backlog NAP West and NCR presales Continued bookings momentum Consistent EBITDA Flow-Through ($ in millions)
Slide 43: EBITDA Visibility
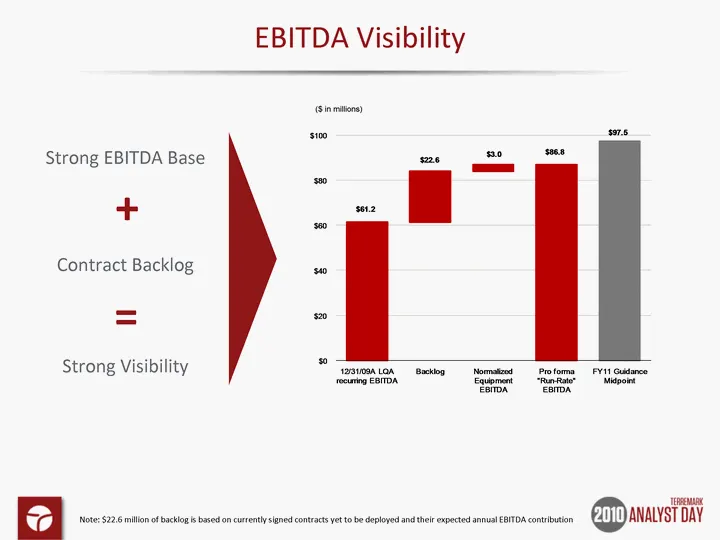
43 EBITDA Visibility ($ in millions) Strong EBITDA Base Contract Backlog Strong Visibility + = Note: $22.6 million of backlog is based on currently signed contracts yet to be deployed and their expected annual EBITDA contribution
Slide 44: Financial Model: Strong Visibility & Highly Predictable Revenue
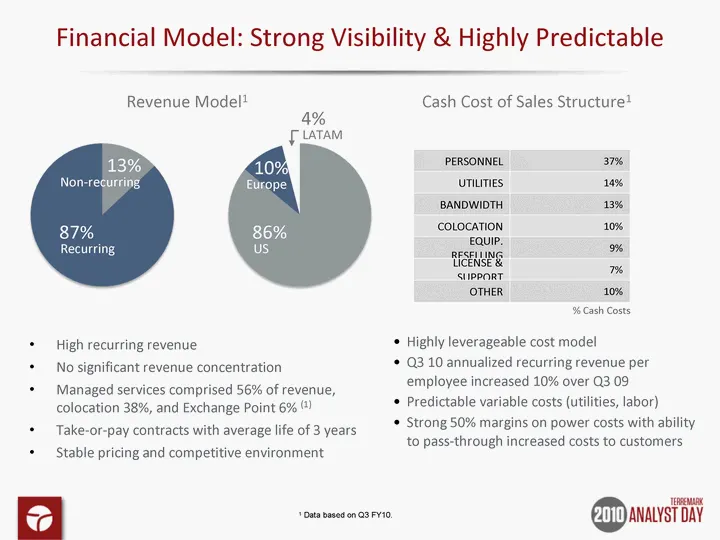
44 44 44 Financial Model: Strong Visibility & Highly Predictable Revenue Model1 Cash Cost of Sales Structure1 Highly leverageable cost model Q3 10 annualized recurring revenue per employee increased 10% over Q3 09 Predictable variable costs (utilities, labor) Strong 50% margins on power costs with a
Slide 45: Capital Expenditure Dynamics
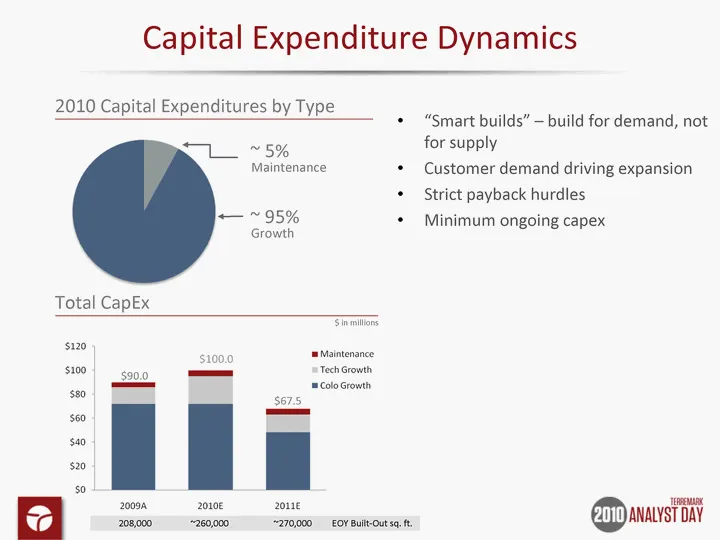
45 45 Capital Expenditure Dynamics "Smart builds" - build for demand, not for supply Customer demand driving expansion Strict payback hurdles Minimum ongoing capex $ in millions 2010 Capital Expenditures by Type ~ 95% Growth ~ 5% Maintenance Total CapEx 208,000 ~260,000 ~270,000 EOY Built-Out sq. ft
Slide 46: Economics of the Business
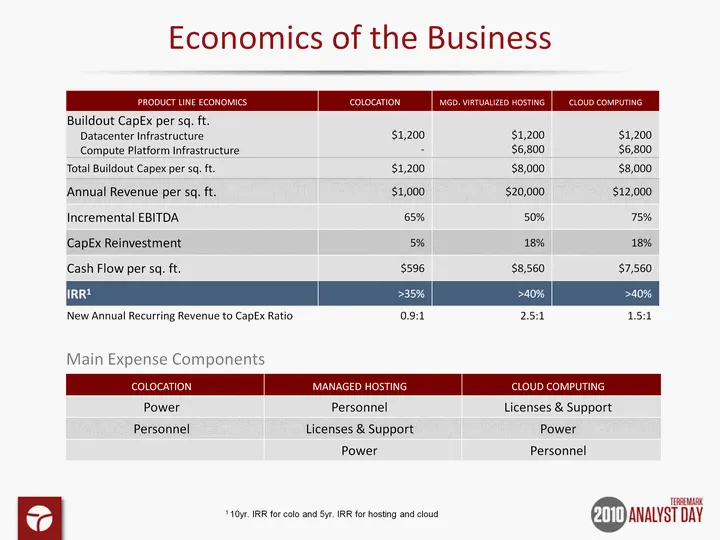
Economics of the Business 1 10yr. IRR for colo and 5yr. IRR for hosting and cloud PRODUCT LINE ECONOMICS COLOCATION MGD. VIRTUALIZED HOSTING CLOUD COMPUTING Buildout CapEx per sq. ft. Datacenter Infrastructure Compute Platform Infrastructure $1,200 - - $1,200 $6,800 $1,200 $6,800 Total Buildout Cape
Slide 47: Growth Potential - Business Plan as Funded Today
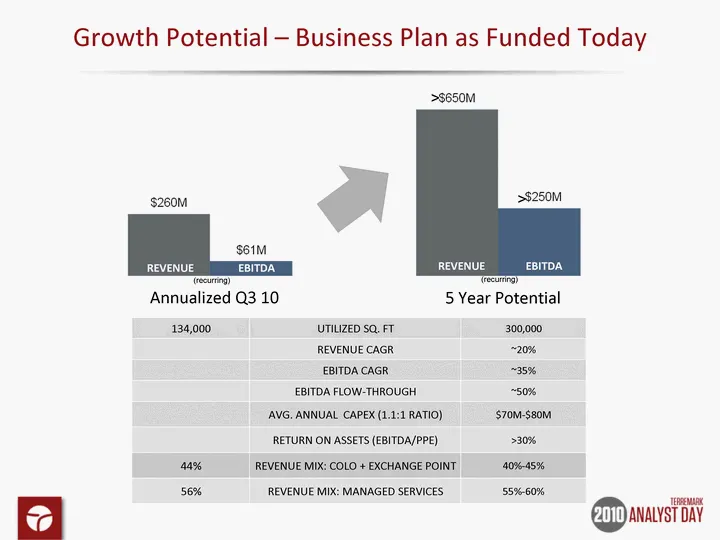
Growth Potential - Business Plan as Funded Today Annualized Q3 10 5 Year Potential > > REVENUE EBITDA REVENUE EBITDA 134,000 UTILIZED SQ. FT 300,000 REVENUE CAGR ~20% EBITDA CAGR ~35% EBITDA FLOW-THROUGH ~50% AVG. ANNUAL CAPEX (1.1:1 RATIO) $70M-$80M RETURN ON ASSETS (EBITDA/PPE) >30% 44% REVENUE MI
Slide 48: Capital Strategy
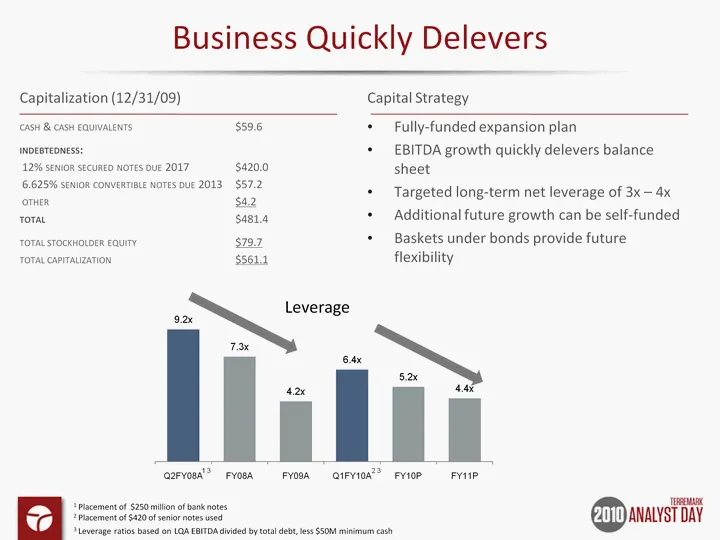
Capital Strategy Fully-funded expansion plan EBITDA growth quickly delevers balance sheet Targeted long-term net leverage of 3x - 4x Additional future growth can be self-funded Baskets under bonds provide future flexibility 1 3 1 Placement of $250 million of bank notes 2 Placement of $420 of senior
Slide 49: Q&A Session
2010 ANALYST DAY Q&A Session
Slide 50: Concluding Remarks
2010 ANALYST DAY Concluding Remarks
Source: SEC EDGAR · 8-K filed Feb 26, 2010
More decks from Terremark Worldwide Inc
 Q2 FY2009 Earnings Presentation16 slides · Nov 5, 2008
 Q4 FY2008 Earnings Presentation19 slides · Jun 3, 2008
 Investor Presentation (May 2008)21 slides · May 28, 2008
 Investor Day (March 2008)66 slides · Mar 3, 2008
 Investor Presentation (July 2007)24 slides · Jul 26, 2007
 Investor Presentation (February 2006)26 slides · Feb 14, 2006