AMAG Pharmaceuticals — J.P. Morgan Healthcare Conference 2017
38 slides from AMAG Pharmaceuticals's conference presentation, Jan 9, 2017
Slide 1: Forward-Looking Statements
Forward-Looking Statements This presentation contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 (PSLRA) and other federal securities laws. Any statements contained herein which do not describe historical facts, including, among others, expe
Slide 2: AMAG Portfolio
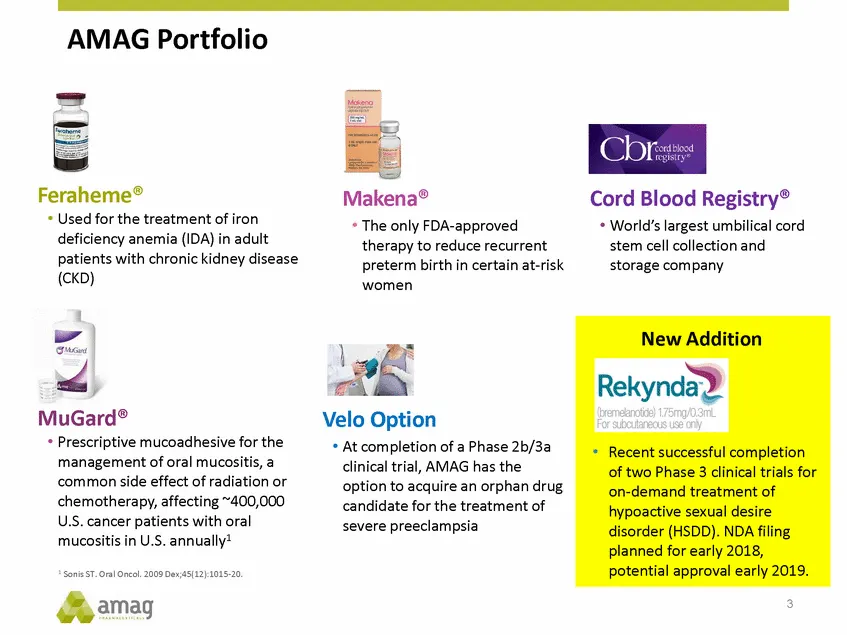
AMAG Portfolio Feraheme® • Used for the treatment of iron deficiency anemia (IDA) in adult patients with chronic kidney disease (CKD) Makena® • The only FDA-approved therapy to reduce recurrent preterm birth in certain at-risk women Cord Blood Registry® • World’s largest umbilical cord stem cell col
Slide 3: 2016 Highlights
2016 Highlights Makena Launched single-dose, preservative free formulation, driving 45% growth over 4Q-2015 Initiated and fully enrolled pharmacokinetic (PK) study –Comparing bioavailability between subcutaneous (SC) and intramuscular (IM) injections Feraheme Completed enrollment in 2,000 patient br
Slide 4: Strong 2016 Financial Results (preliminary and unaudited)
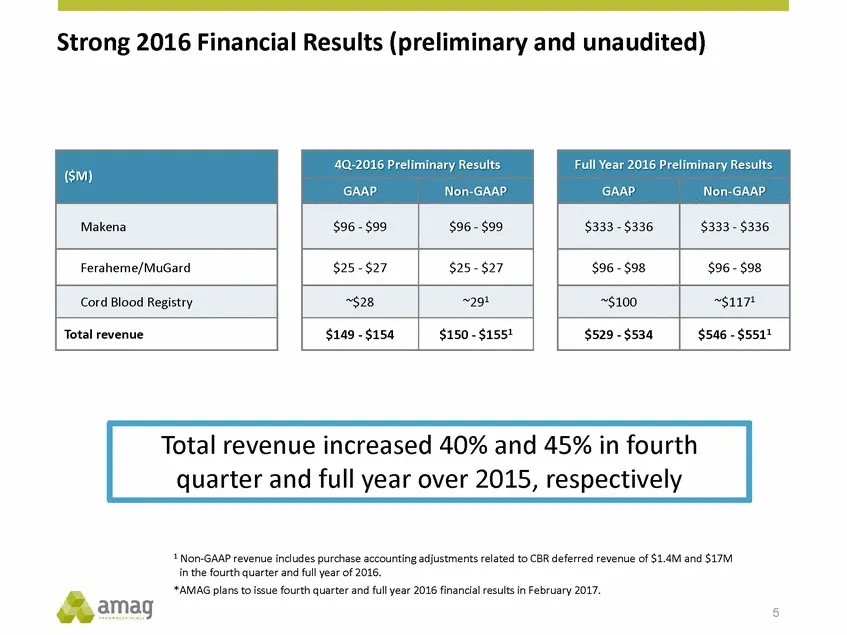
Strong 2016 Financial Results (preliminary and unaudited) 1 Non-GAAP revenue includes purchase accounting adjustments related to CBR deferred revenue of $1.4M and $17M in the fourth quarter and full year of 2016. *AMAG plans to issue fourth quarter and full year 2016 financial results in February 20
Slide 5: A Key Step Forward in Growth Strategy
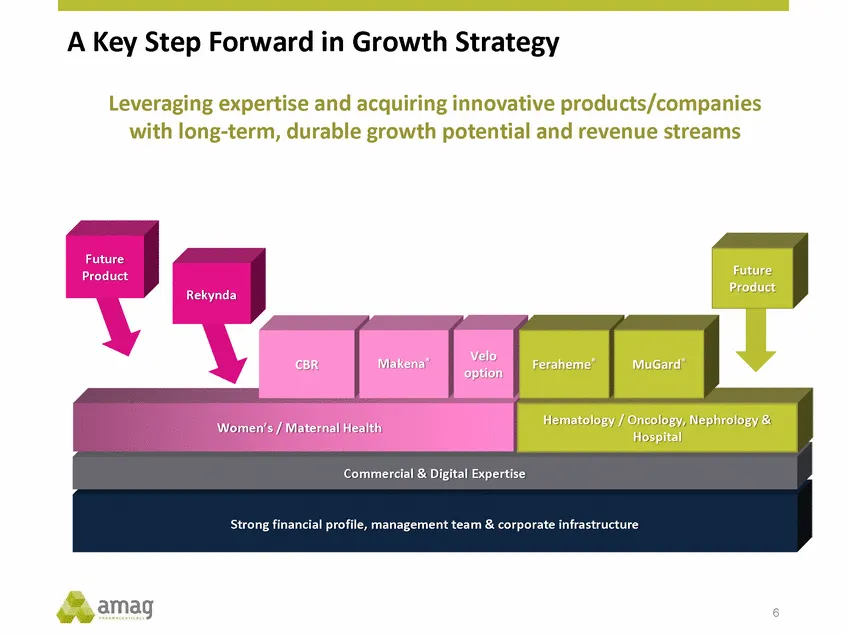
A Key Step Forward in Growth Strategy Leveraging expertise and acquiring innovative products/companies with long-term, durable growth potential and revenue streams Future Product Rekynda Makena® Hematology / Oncology, Nephrology & Hospital Women’s / Maternal Health Commercial & Digital Expertise Str
Slide 6: A Key Step Forward in Growth Strategy
A Key Step Forward in Growth Strategy Leveraging expertise and acquiring innovative products/companies with long-term, durable growth potential and revenue streams Commercial & Digital Expertise Strong financial profile, management team & corporate infrastructure
Slide 7: Rekynda (bremelanotide) Expands AMAG into Women's Health
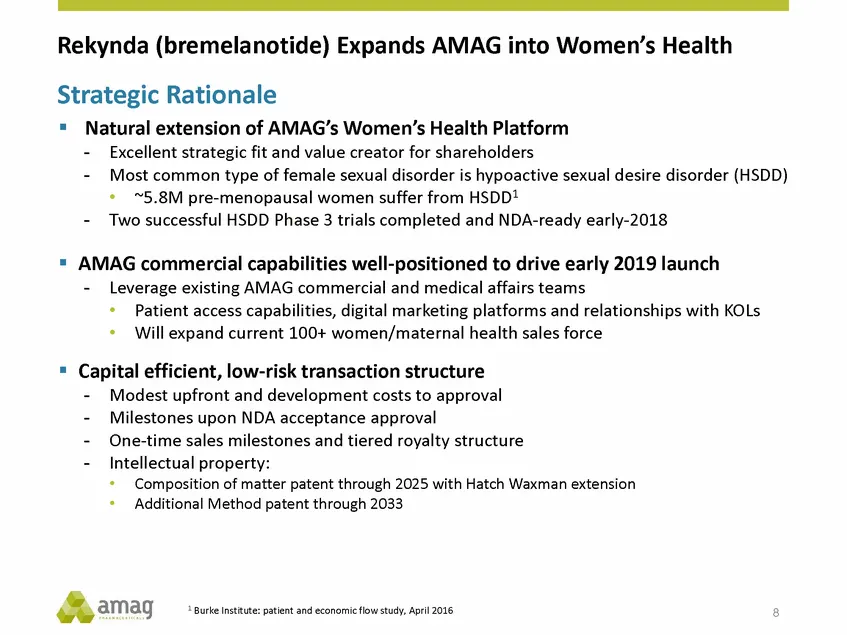
Rekynda (bremelanotide) Expands AMAG into Women’s Health Strategic Rationale Natural extension of AMAG’s Women’s Health Platform - - Excellent strategic fit and value creator for shareholders Most common type of female sexual disorder is hypoactive sexual desire disorder (HSDD) • ~5.8M pre-menopausa
Slide 8: Transaction Designed to Build Long-Term Shareholder Value
Transaction Designed to Build Long-Term Shareholder Value • • • $60M upfront payment; up to $25M funding of development costs to approval Up to $80M upon acceptance and approval of NDA Up to $300M in sales milestones, as well as tiered high-single to low-double-digit royalties – First sales mileston
Slide 9: Significant Market Opportunity with HSDD
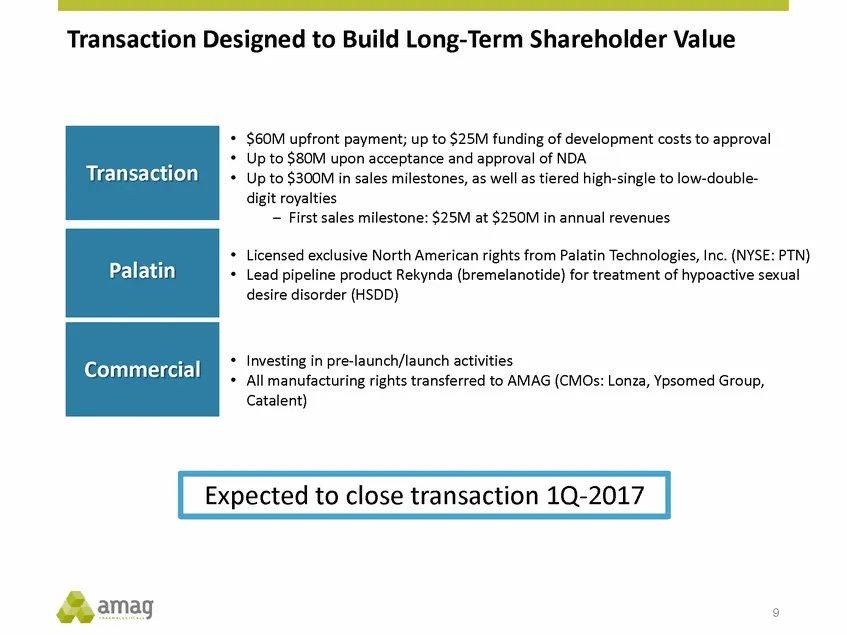
Significant Market Opportunity with HSDD1 ~10M pre-menopausal women in U.S. 5.8M2 women presented to women with 2.8M pre-menopausal symptom) 4.4M3 pre-menopausal women with 15M U.S. women with HSDD1 HSDD (not primary symptom) 4.8M post-menopausal women with HSDD 1 Survey data from Shiren (2008); 201
Slide 10: Rekynda (bremelanotide) Profile & Phase Results
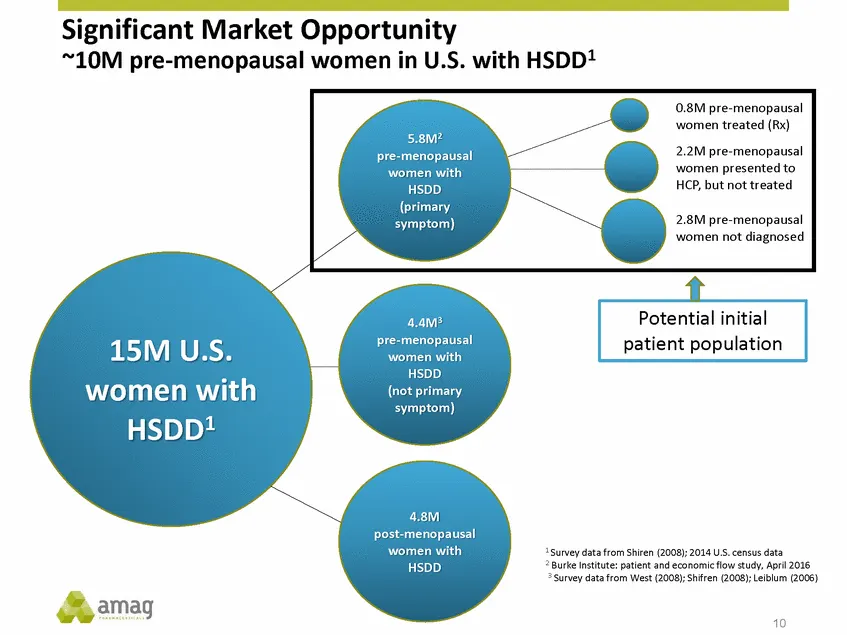
Rekynda (bremelanotide) Profile & Phase 3 Results Taken on-demand with a self-administered auto-injector pen in anticipation of sexual activity Novel mechanism of action: melancortin receptor agonist (MCR4) – Targets pathways involved in sexual desire and arousal response Two successful Phase 3 stud
Slide 11: Rekynda (bremelanotide) Highly Differentiated Target Product Profile
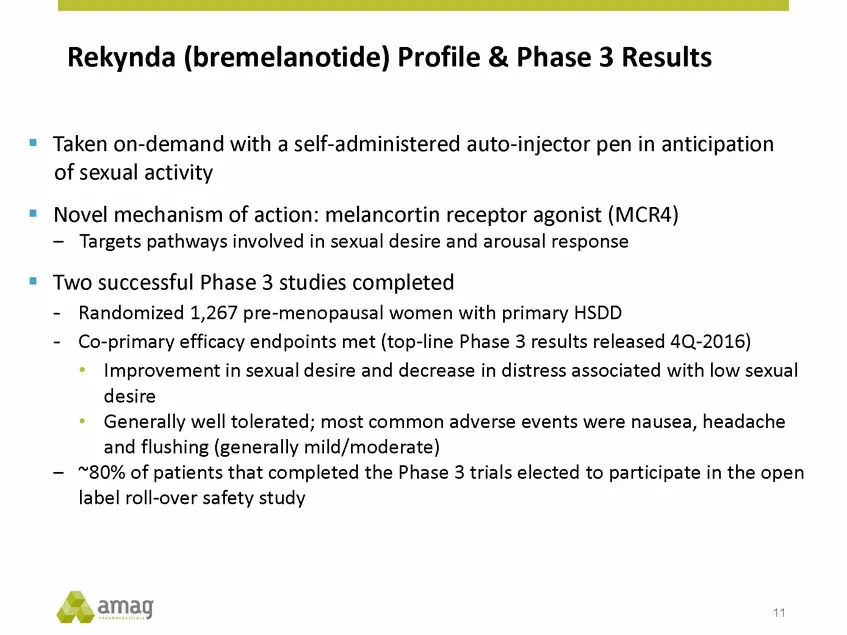
Rekynda (bremelanotide) Highly Differentiated Target Product Profile • Patient administered with subcutaneous auto-injector pen hypoactive sexual desire disorder (HSDD) 12 Rekynda (bremelanotide) Dosing & Administration • Taken on-demand in anticipation of sexual activity • Rapid onset of activity ~
Slide 12: Rekynda (bremelanotide) Timeline
Rekynda (bremelanotide) Timeline Phase 3 trials initiated Completed Phase 3 enrollment Phase 3 studies completed Phase 3 top-line results / Co-primary endpoints met Phase 1 standard safety pharmacology and drug-drug interaction studies NDA submission Expected FDA action 4Q-2014 2H-2015 3Q-2016 4Q-20
Slide 13: Rekynda (bremelanotide) Timeline
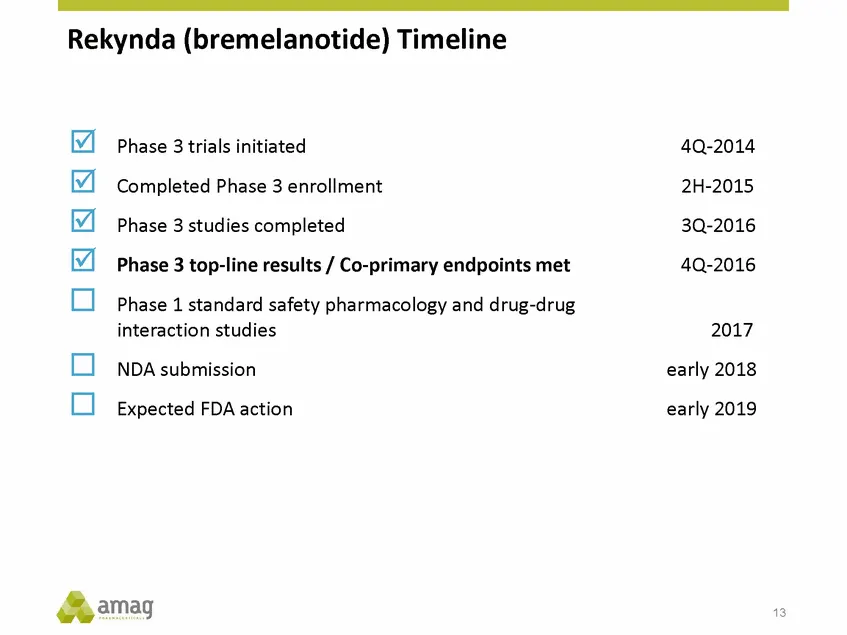
Rekynda (bremelanotide) Timeline Phase 3 trials initiated Completed Phase 3 enrollment Phase 3 studies completed Phase 3 top-line results / Co-primary endpoints met INRRAA Phase 1 standard safety pharmacology and drug-drug interaction studies NDA submission Expected FDA action Qeamag 40-2014 2H-2015
Slide 14: Makena: Strong Execution
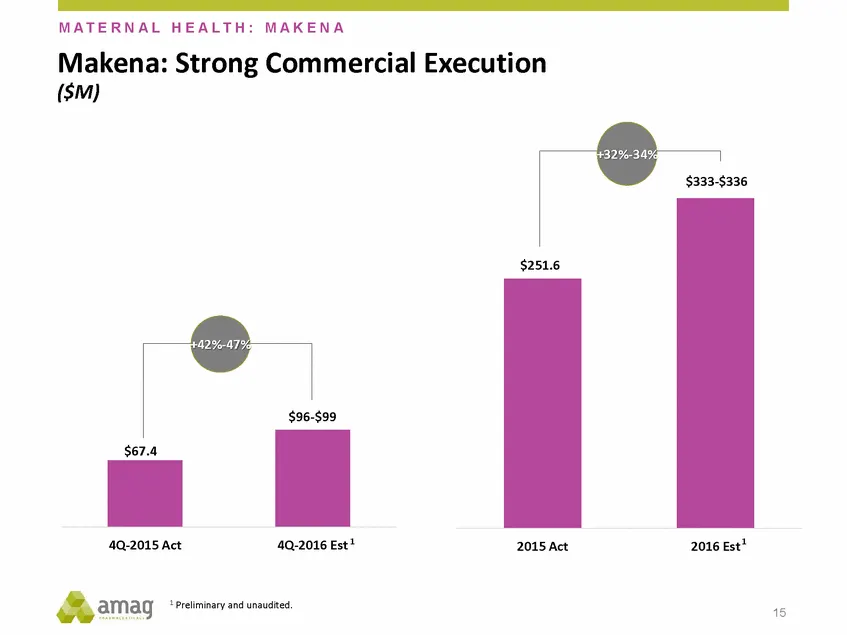
M A T E R N A L H E A L T H : M A K E N A Commercial Makena: ($M) Strong Execution $336 +42%-47% -$99 4Q-2016 Est 1 2016 Est 1 4Q-2015 Act 2015 Act 1 Preliminary and unaudited. 15 $67.4 $96 $251.6 +32%-34% $333-
Slide 15: Makena Gained Percentage Share Points in 2016
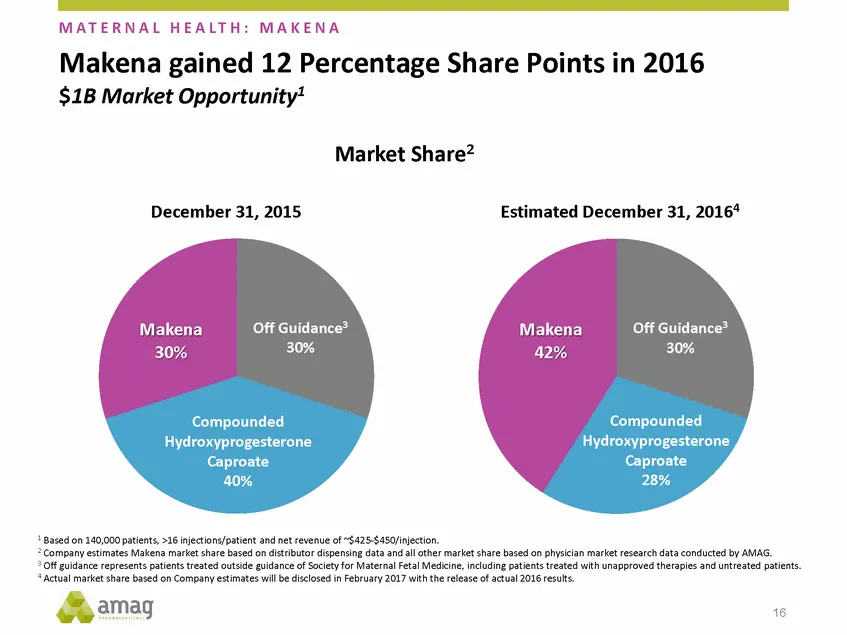
M A T E R N A L H E A L T H : M A K E N A Makena gained 12 Percentage Share Points in 2016 $1B Market Opportunity1 Market Share2 Estimated December 31, 20164 December 31, 2015 Off Guidance3 30% Off Guidance3 30% Makena 30% Makena 42% Compounded Hydroxyprogesterone Caproate 40% Compounded Hydroxyprog
Slide 16: Makena Accomplishments & Growth Drivers
M A T E R N A L H E A L T H :M A K E N A Accomplishments & Growth Drivers 2016 Accomplishments Successfully launched single-dose, preservative free formulation Increased market share by 40% over 2015 Enhanced patient access to Makena Expanded Optum Home Health Services relationship Initiated and ful
Slide 17: Makena Next-Generation Program Update
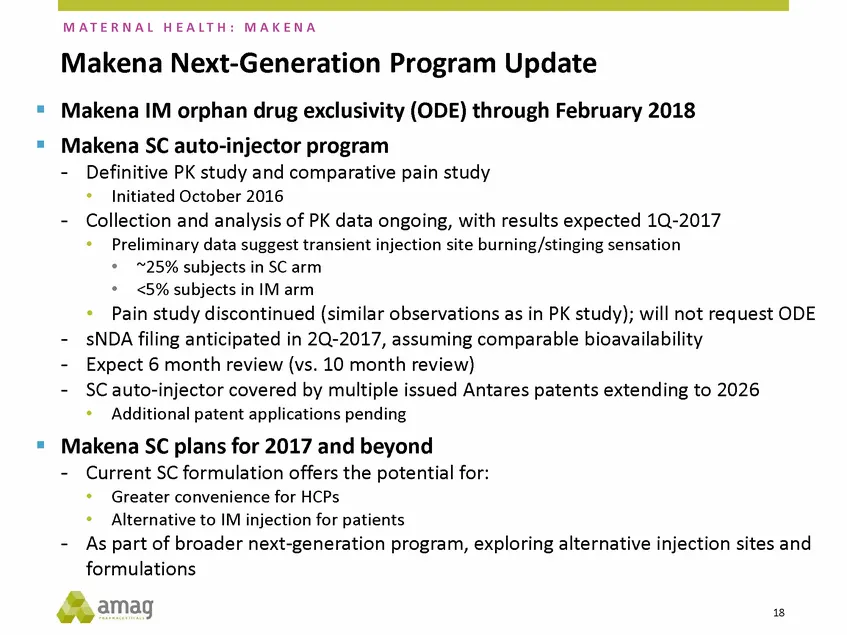
M A T E R N A L H E A L T H : M A K E N A Makena Next-Generation Program Update Makena IM orphan drug exclusivity (ODE) through February 2018 Makena SC auto-injector program - Definitive PK study and comparative pain study • Initiated October 2016 - Collection and analysis of PK data ongoing, with r
Slide 18: Maternal Health: Cord Blood Registry (CBR)
Maternal Health: Cord Blood Registry (CBR)
Slide 19: CBR: Attractive Recurring Revenue Stream
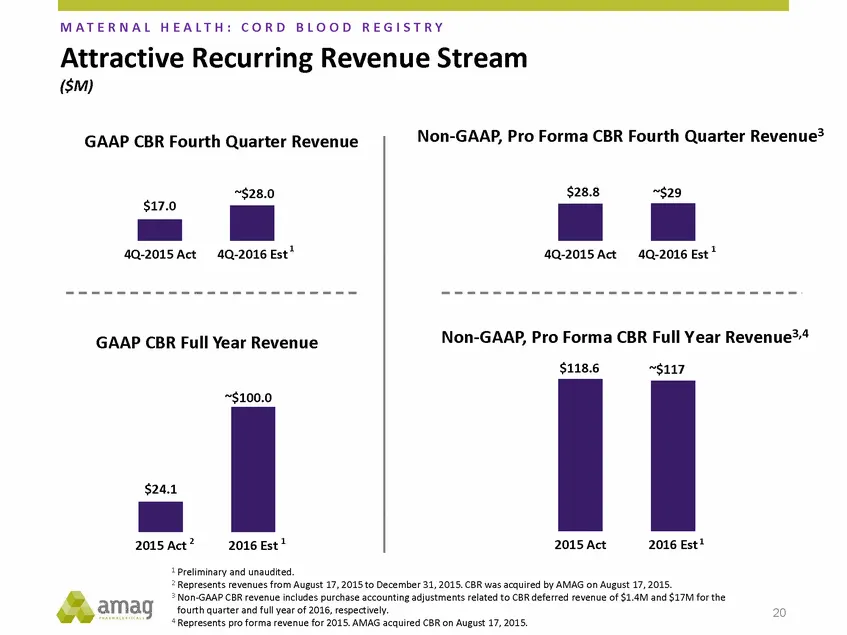
M A T E R N A L H E A L T H : C O R D B L O O D R E G I S T R Y Attractive Recurring Revenue Stream ($M) Non-GAAP, Pro Forma CBR Fourth Quarter Revenue3 GAAP CBR Fourth Quarter Revenue $28.8 ~$28.0 ~$29 $17.0 4Q-2016 Est 1 4Q-2016 Est 1 4Q-2015 Act 4Q-2015 Act Non-GAAP, Pro Forma CBR Full Y ear Reve
Slide 20: CBR Accomplishments & Growth Drivers
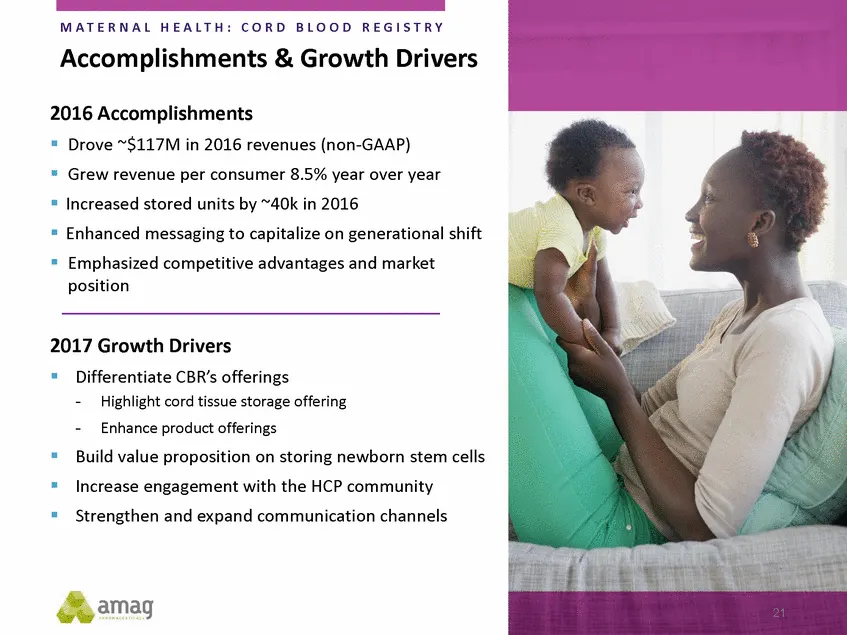
M A T E R N A L H E A L T H : C O R D B L O O D R E G I S T R Y Accomplishments & Growth Drivers 2016 Accomplishments Drove ~$117M in 2016 revenues (non-GAAP) Grew revenue per consumer 8.5% year over year Increased stored units by ~40k in 2016 Enhanced messaging to capitalize on generational shift E
Slide 21: Hematology/Oncology: Feraheme
Hematology/Oncology: Feraheme
Slide 22: Feraheme/MuGard: Differentiated Product, Expect Future Growth
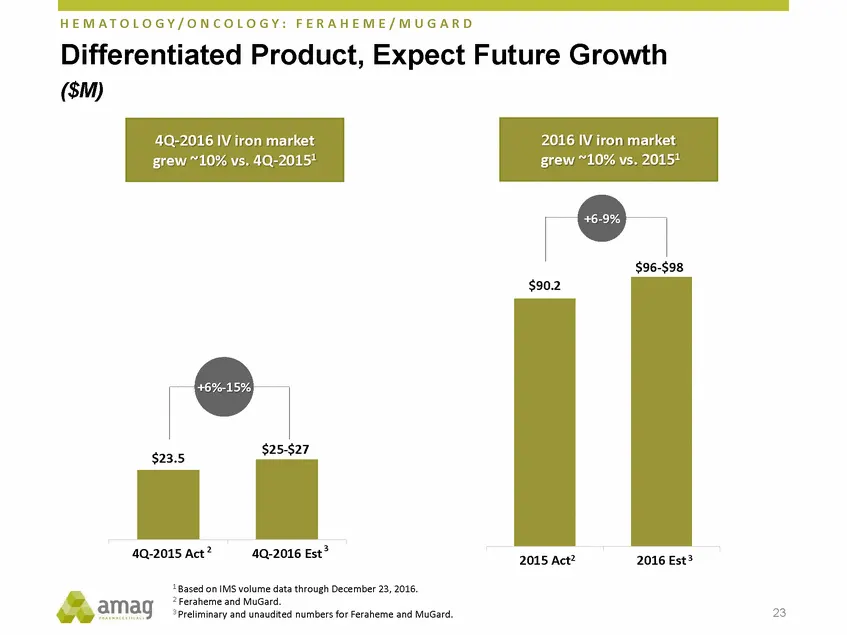
H E M A T O L O G Y / O N C O L O G Y : F E R A H E M E / M U G A R D Differentiated ($M) Product, Expect Future Growth +6-9% $96-$98 +6%-15% $25-$27 $23.5 3 4Q-2015 Act 2 4Q-2016 Est 2015 Act2 2016 Est 3 1 Based on IMS volume data through December 23, 2016. 2 Feraheme and MuGard. 3 Preliminary and
Slide 23: Feraheme Accomplishments & Growth Drivers
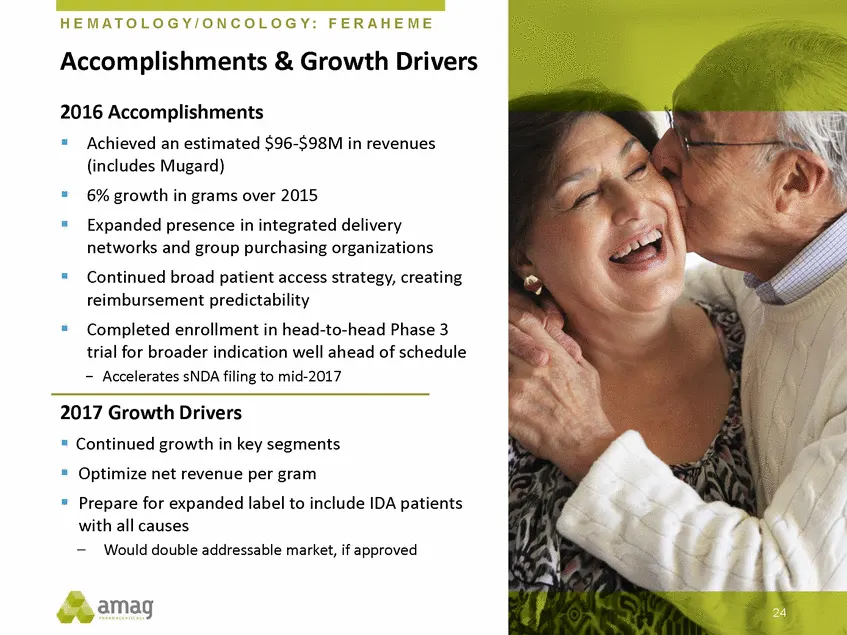
H E M A T O L O G Y / O N C O L O G Y : F E R A H E M E Accomplishments & Growth Drivers 2016 Accomplishments Achieved an estimated $96-$98M in revenues (includes Mugard) 6% growth in grams over 2015 Expanded presence in integrated delivery networks and group purchasing organizations Continued broad
Slide 24: Feraheme Market Opportunity: Broad IDA Label Would Double
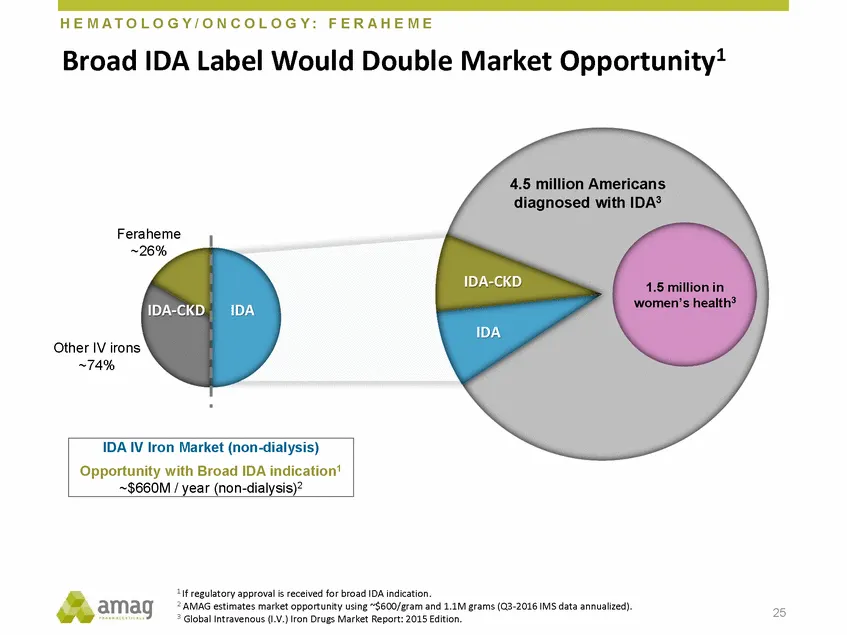
H E M A T O L O G Y / O N C O L O G Y : F E R A H E M E Market Opportunity1 Broad IDA Label Would Double 4.5 million Americans diagnosed with IDA3 Feraheme ~26% IDA-CKD 1.5 million in women’s health3 IDA-CKD IDA IDA Other IV irons ~74% 1 If regulatory approval is received for broad IDA indication. 2
Slide 25: Broad IDA Label Would Double Market Opportunity
HEMATOLOGY/ONCOLOGY: FERAHEME Broad IDA Label Would Double Market Opportunity? Feraheme ~26% IDA-CKD IDA-CKD , IDA Other IV irons ~74% IDA I Iron Market (non-dialysis) Opportunity with Broad IDA indication’ ~$660M / year (non-dialysis)? ®t reglatory approvals ceived for broad IDA indeation. a QIMNAG
Slide 26: Strong GAAP Revenue Growth
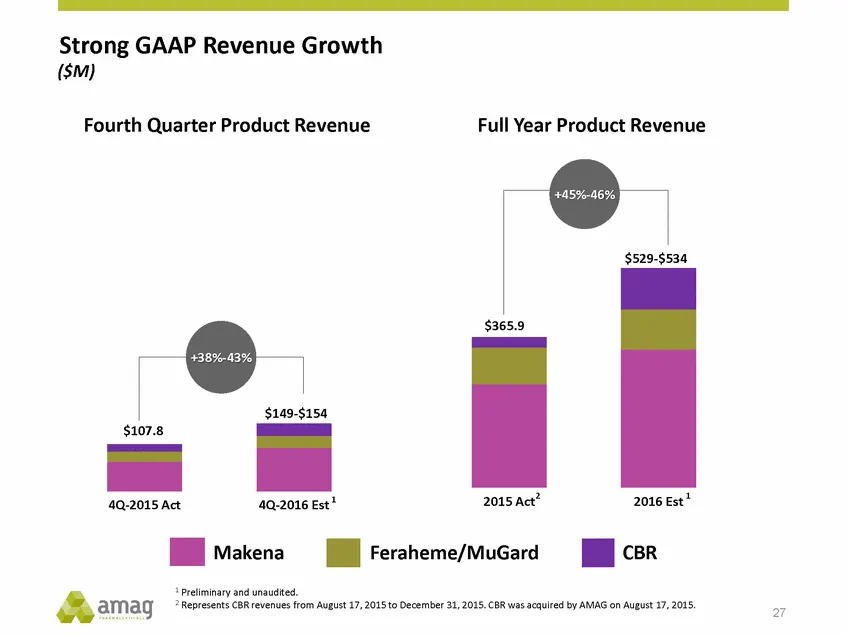
Strong GAAP Revenue Growth ($M) Fourth Quarter Product Revenue Full Year Product Revenue $534 $365.9 +38%-43% $154 $107.8 2 1 4Q-2016 Est 1 2015 Act 2016 Est 4Q-2015 Act Makena Feraheme/MuGard CBR 1 Preliminary and unaudited. 2 Represents CBR revenues from August 17, 2015 to December 31, 2015. CBR w
Slide 27: Strong Non-GAAP Revenue Growth
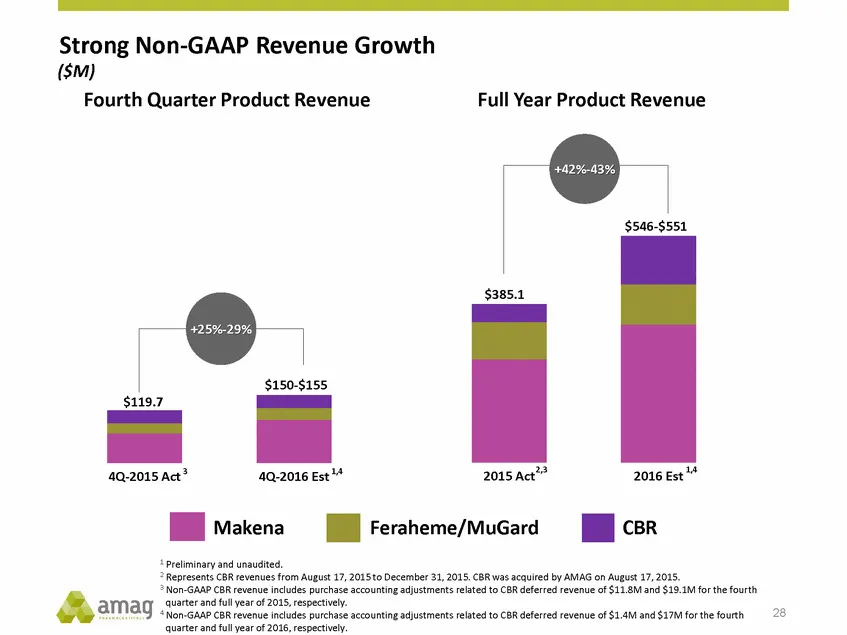
Strong Non-GAAP Revenue Growth ($M) Fourth Quarter Product Revenue Full Year Product Revenue $551 $385.1 +25%-29% $155 $119.7 2015 Act2,3 2016 Est 1,4 4Q-2015 Act 3 4Q-2016 Est 1,4 Makena Feraheme/MuGard CBR 1 Preliminary and unaudited. 2 Represents CBR revenues from August 17, 2015 to December 31,
Slide 28: Strong Cash Flow Generation
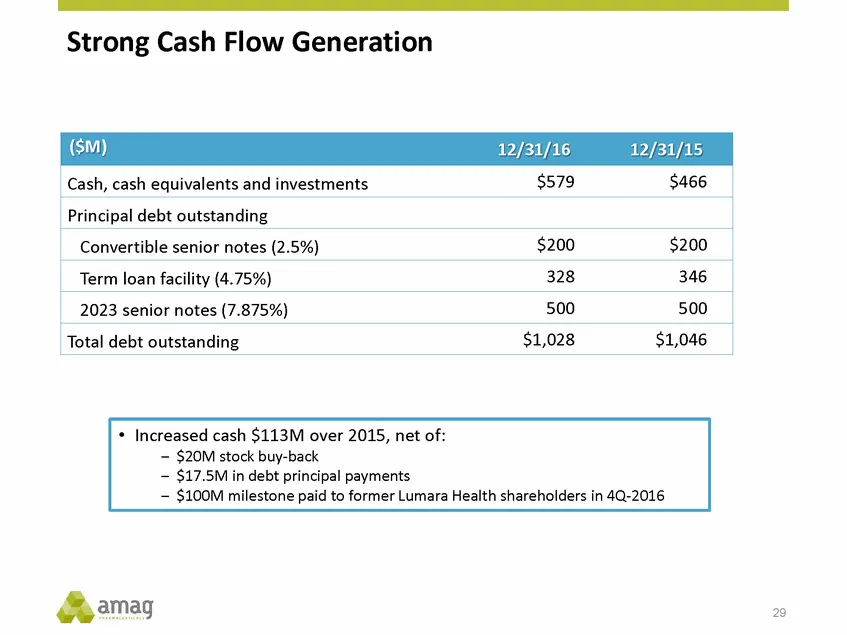
Strong Cash Flow Generation 29 • Increased cash $113M over 2015, net of: – $20M stock buy-back – $17.5M in debt principal payments – $100M milestone paid to former Lumara Health shareholders in 4Q-2016 ($M)12/31/1612/31/15 Cash, cash equivalents and investments$579$466 Principal debt outstanding Con
Slide 29: AMAG: Growth and Diversification
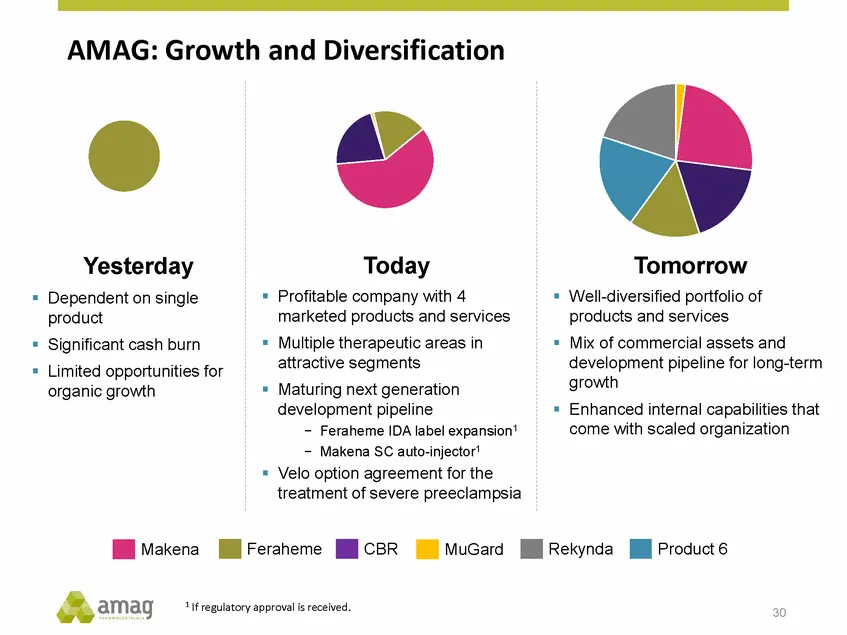
AMAG: Growth and Diversification Today Profitable company with 4 marketed products and services Multiple therapeutic areas in attractive segments Maturing next generation development pipeline - Feraheme IDA label expansion1 - Makena SC auto-injector1 Velo option agreement for the treatment of severe
Slide 30: 2017 Financial Guidance
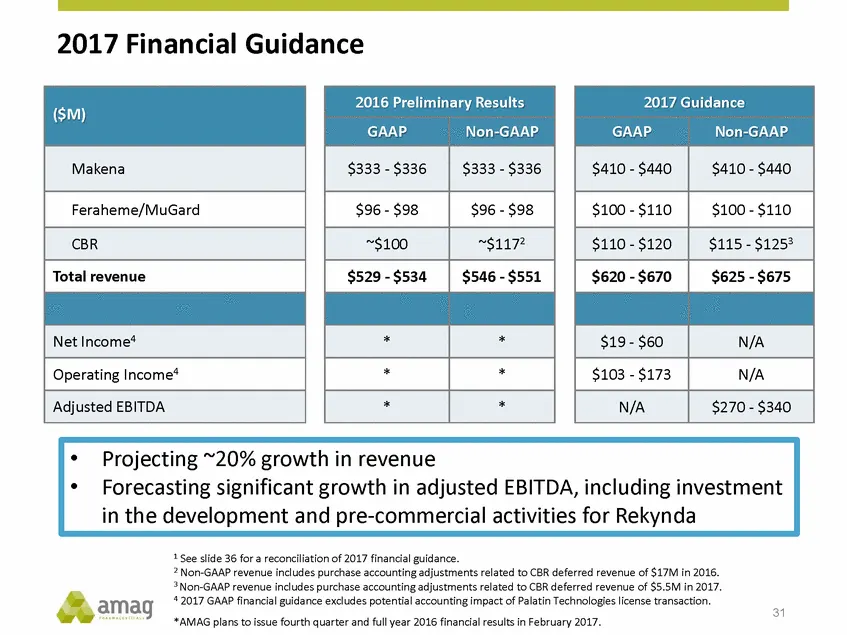
2017 Financial Guidance 1 See slide 36 for a reconciliation of 2017 financial guidance. 2 Non-GAAP revenue includes purchase accounting adjustments related to CBR deferred revenue of $17M in 2016. 3 Non-GAAP revenue includes purchase accounting adjustments related to CBR deferred revenue of $5.5M in
Slide 31: 2017 Financial Guidance
EE ee OO ee OO ee ee 2017 Financial Guidance 2017 Guidance VN Non-GAAP Makena $333-$336 | $333 - $336 $410-$440 | $410- $40 Feraheme/MuGard $96- $98 $96 - $98 $100-$110 | $100-$110 CBR ~$100 “$117? $110-$120 | $115-$125* Total revenue $529-$534 | $546-$551 $620 - $670 $625 - $675 Net Income* * * $19
Slide 32: 2017 Key Priorities
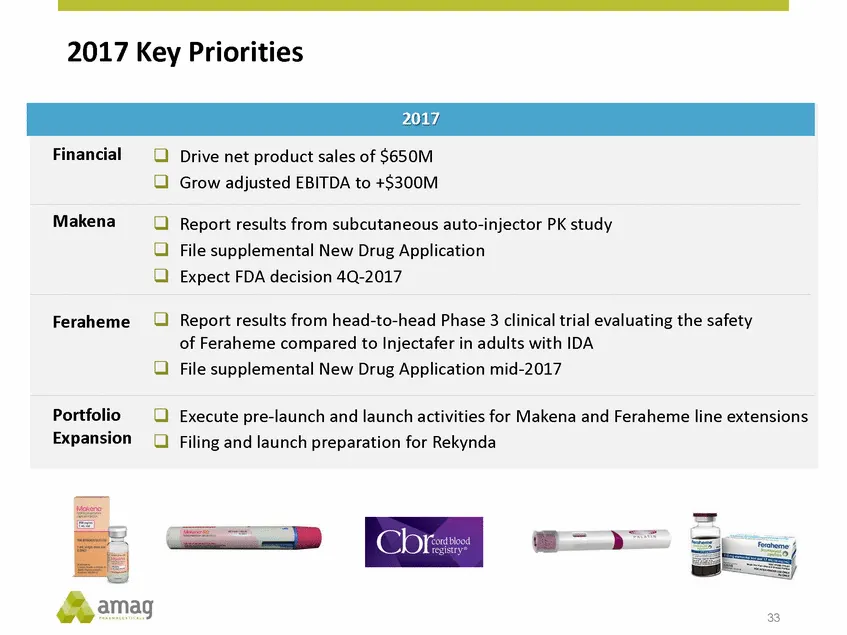
2017 Key Priorities 33 2017 Financial Drive net product sales of $650M Grow adjusted EBITDA to +$300M Makena Report results from subcutaneous auto-injector PK study File supplemental New Drug Application Expect FDA decision 4Q-2017 Feraheme Report results from head-to-head Phase 3 clinical trial eva
Slide 33: AMAG Pharmaceuticals J.P. Morgan Healthcare Conference
AMAG Pharmaceuticals J.P. Morgan Healthcare Conference January 10, 2017
Slide 34: AMAG Pharmaceuticals J.P. Morgan Healthcare Conference
AMAG Pharmaceuticals J.P. Morgan Healthcare Conference January 10, 2017
Slide 35: Reconciliation of 2017 Financial Guidance of Non-GAAP Adjusted EBITDA
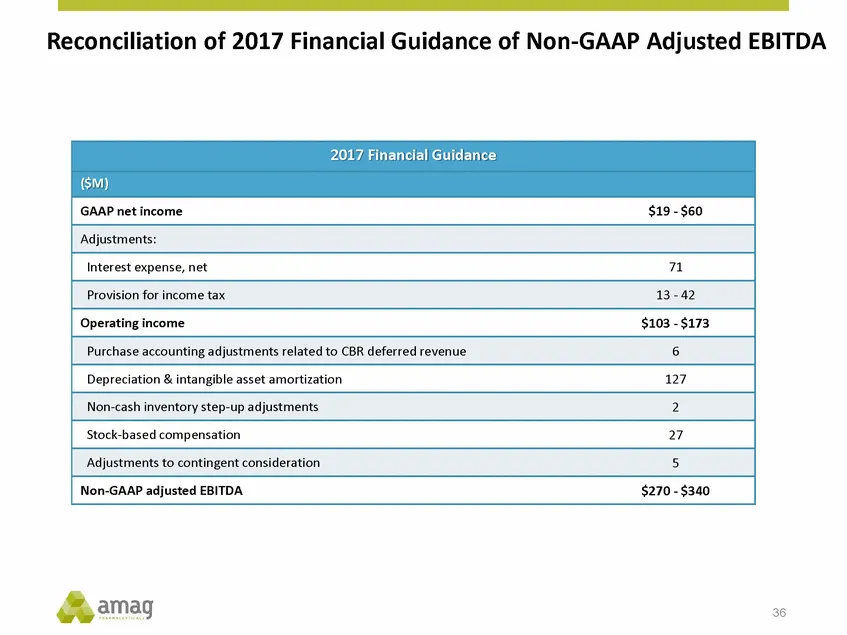
Reconciliation of 2017 Financial Guidance of Non-GAAP Adjusted EBITDA 36 2017 Financial Guidance ($M) GAAP net income$19 - $60 Adjustments: Interest expense, net71 Provision for income tax13 - 42 Operating income$103 - $173 Purchase accounting adjustments related to CBR deferred revenue6 Depreciatio
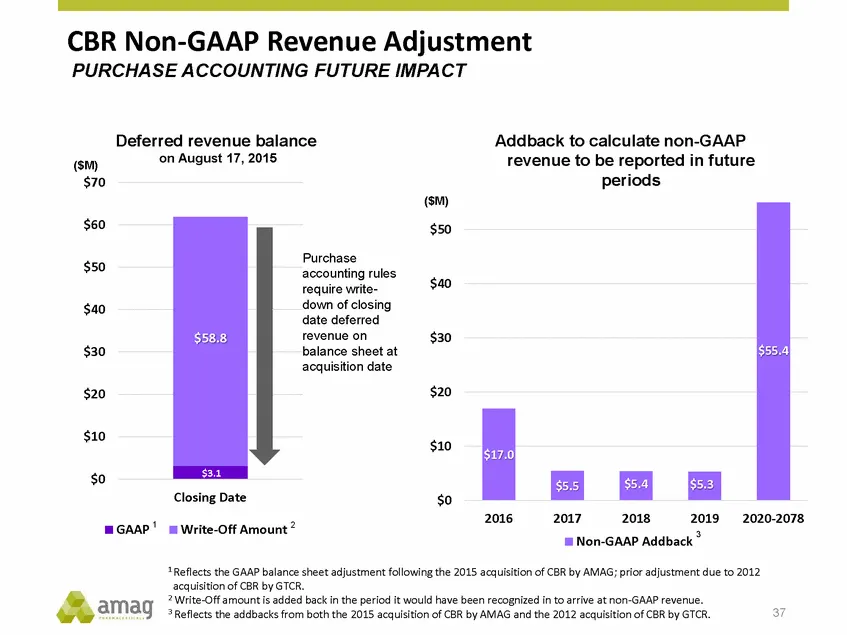
Slide 36: CBR Non-GAAP Revenue Adjustment
CBR Non-GAAP Revenue Adjustment PURCHASE ACCOUNTING FUTURE IMPACT Deferred revenue balance on August 17, 2015 Addback to calculate non-GAAP revenue to be reported in future periods ($M) $70 ($M) $60 $50 Purchase accounting rules $50 $40 require write-down of closing $40 date deferred revenue on bala
Slide 37: AMAG Pharmaceuticals J.P. Morgan Healthcare Conference
AMAG Pharmaceuticals J.P. Morgan Healthcare Conference January 10, 2017
Slide 38: AMAG Pharmaceuticals
AMAG Pharmaceutic
Source: SEC EDGAR · 8-K filed Jan 9, 2017
More decks from AMAG Pharmaceuticals Inc
 Q2 2020 Earnings Presentation16 slides · Aug 6, 2020
 Q1 2020 Earnings Presentation14 slides · May 11, 2020
 JP Morgan 38th Healthcare Conference 202033 slides · Jan 9, 2020
 Q3 2019 Earnings Presentation24 slides · Nov 1, 2019
 Proxy Contest (September 2019)48 slides · Sep 4, 2019
 Q2 2019 Earnings Presentation26 slides · Aug 7, 2019