Comerica — Comerica Inc /New/ — Non-Deal Roadshow (June 2012)
17 slides from Comerica's roadshow presentation, Jun 4, 2012
Slide 1: Comerica Incorporated Investor Roadshow June 5-6, 2012
Comerica IncorporatedInvestor Roadshow June 5-6, 2012 Karen Parkhill Vice Chairman and CFO Darlene Persons Director of Investor Relations Safe Harbor Statement 2 Any statements in this presentation that are not historical facts are forward-looking statements as defined in the Private Securities Liti
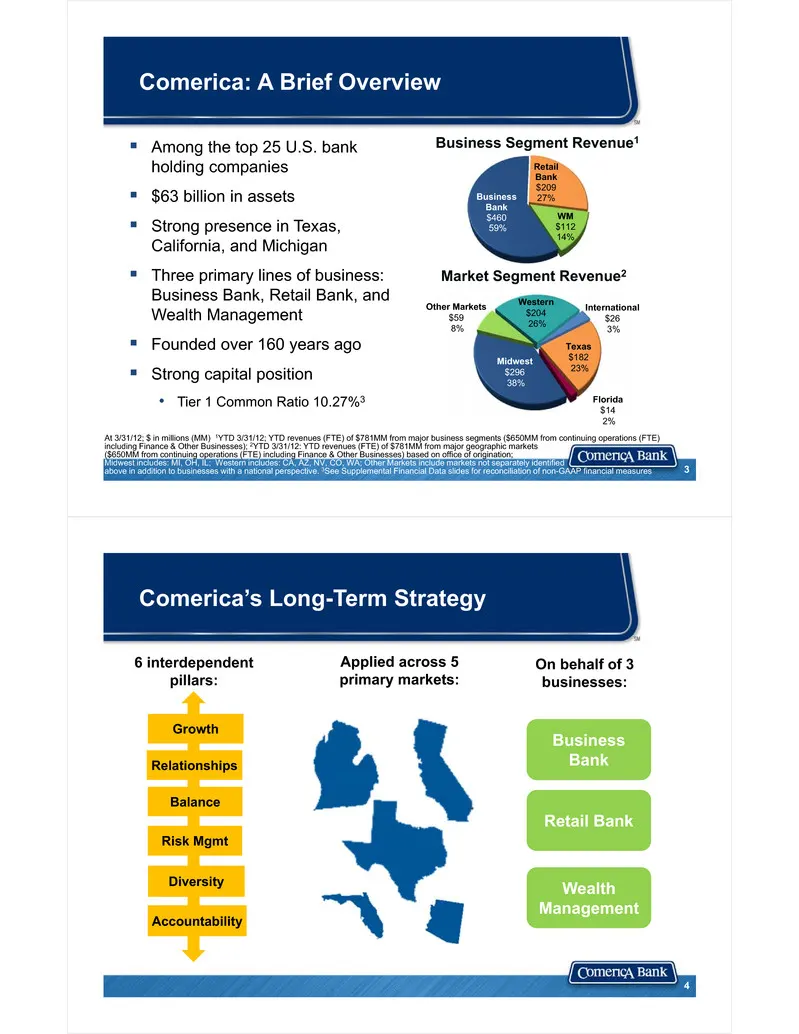
Slide 2: Comerica: A Brief Overview
Comerica: A Brief Overview Among the top 25 U.S. bank holding companies $63 billion in assets Strong presence in Texas, California, and Michigan Three primary lines of business: Business Bank, Retail Bank, and Wealth Management Founded over 160 years ago Strong capital position • Tier 1
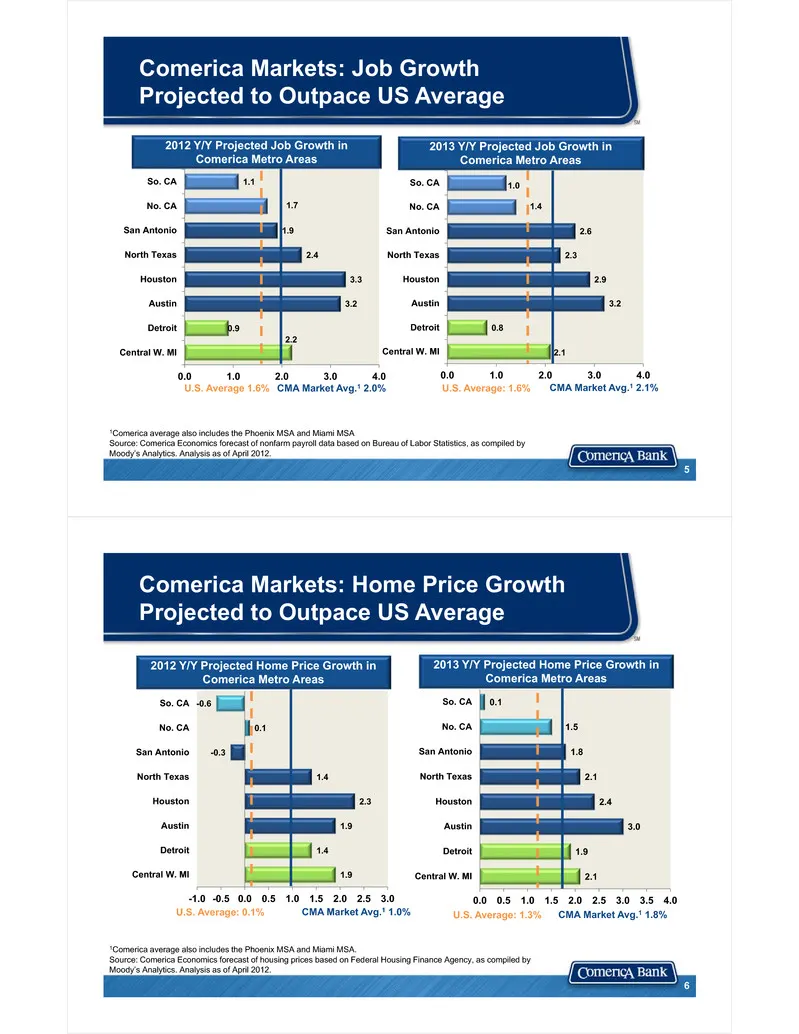
Slide 3: Comerica Markets: Job Growth Projected to Outpace US Average
2.20.9 3.2 3.3 2.4 1.9 1.7 1.1 0.0 1.0 2.0 3.0 4.0 Central W. MI Detroit Austin Houston North Texas San Antonio No. CA So. CA U.S. Average 1.6% CMA Market Avg.1 2.0% 2.1 0.8 3.2 2.9 2.3 2.6 1.4 1.0 0.0 1.0 2.0 3.0 4.0 Central W. MI Detroit Austin Houston North Texas San Antonio No. CA So. CA U.S. Av
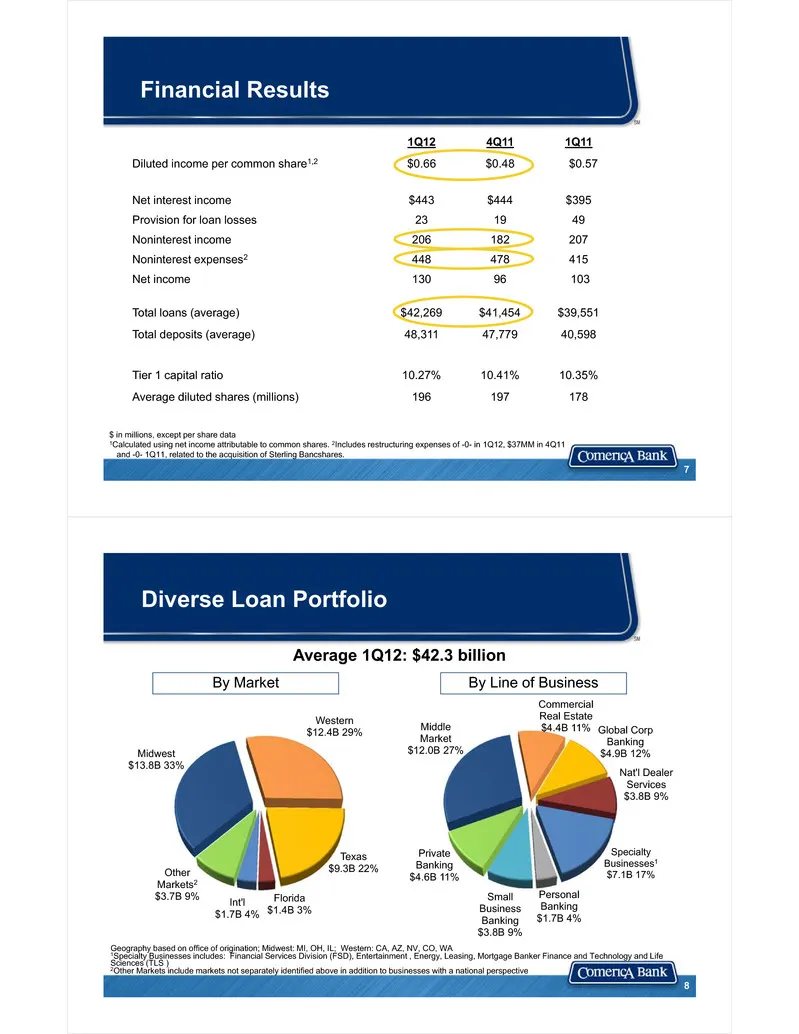
Slide 4: Financial Results
Financial Results $ in millions, except per share data1Calculated using net income attributable to common shares. 2Includes restructuring expenses of -0- in 1Q12, $37MM in 4Q11 and -0- 1Q11, related to the acquisition of Sterling Bancshares. 1Q12 4Q11 1Q11 Diluted income per common share1,2 $0.66 $0
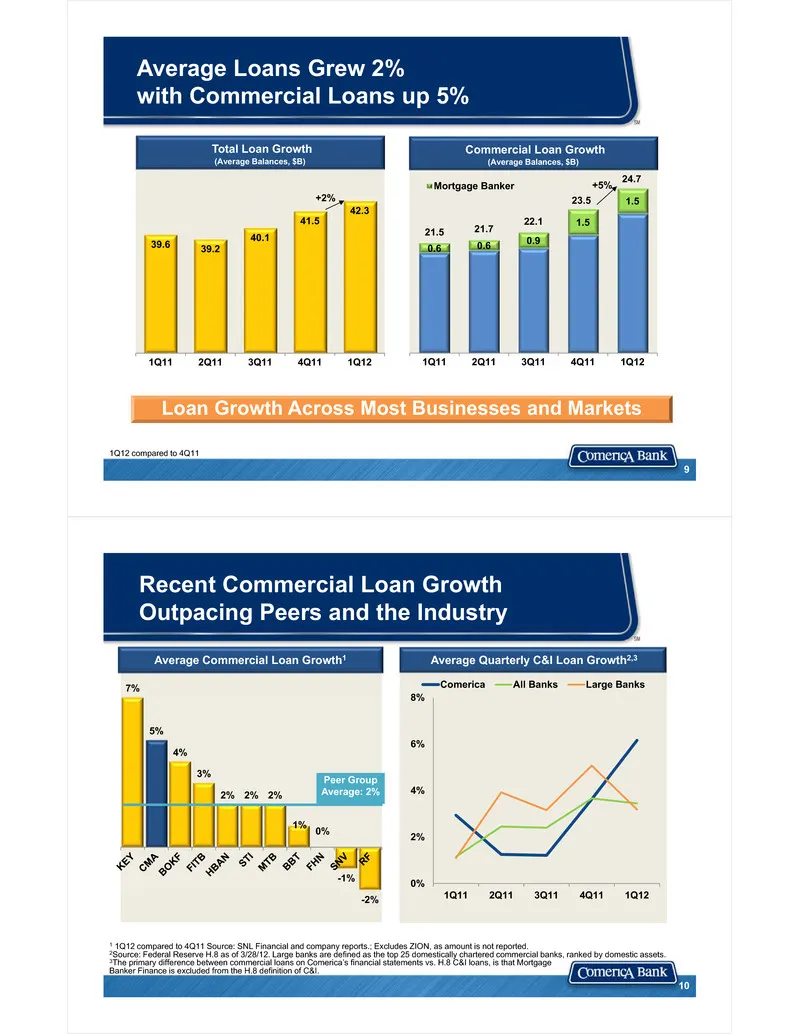
Slide 5: Average Loans Grew 2% with Commercial Loans up 5%
0.6 0.6 0.9 1.5 1.5 21.5 21.7 22.1 23.5 24.7 1Q11 2Q11 3Q11 4Q11 1Q12 Mortgage Banker 39.6 39.2 40.1 41.5 42.3 1Q11 2Q11 3Q11 4Q11 1Q12 +2% Commercial Loan Growth (Average Balances, $B) Average Loans Grew 2% with Commercial Loans up 5% Loan Growth Across Most Businesses and Markets +5% Total Loan Gr
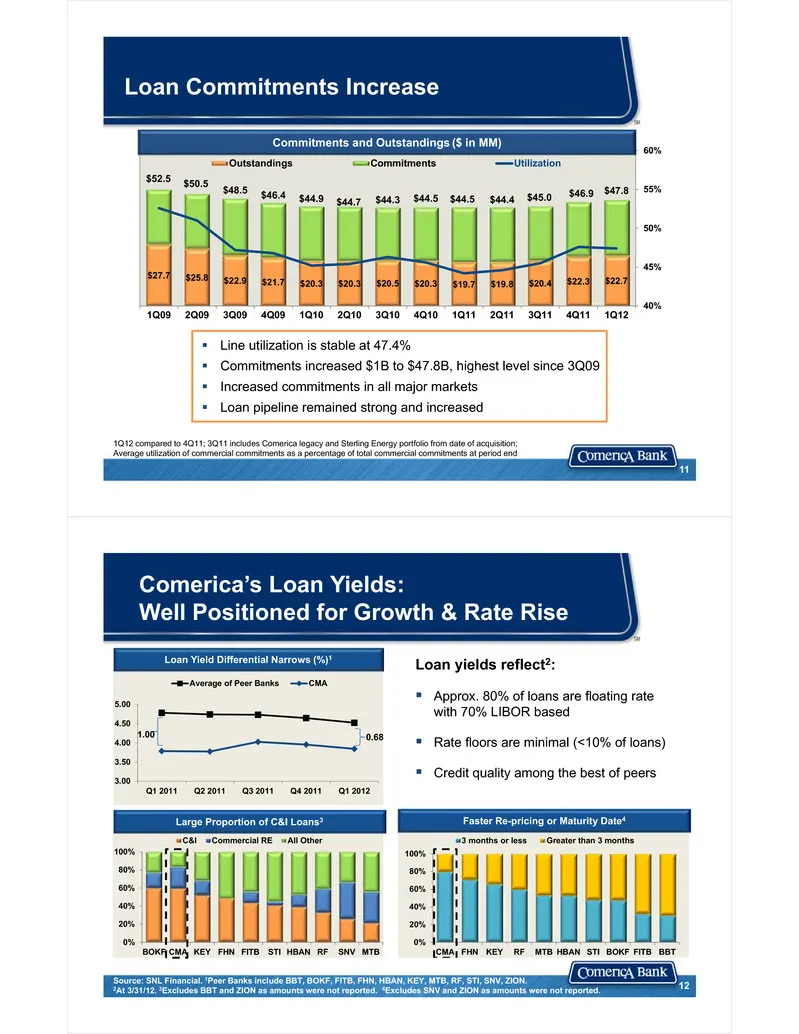
Slide 6: Loan Commitments Increase
Loan Commitments Increase $27.7 $25.8 $22.9 $21.7 $20.3 $20.3 $20.5 $20.3 $19.7 $19.8 $20.4 $22.3 $22.7 $52.5 $50.5 $48.5 $46.4 $44.9 $44.7 $44.3 $44.5 $44.5 $44.4 $45.0 $46.9 $47.8 40% 45% 50% 55% 60% 1Q09 2Q09 3Q09 4Q09 1Q10 2Q10 3Q10 4Q10 1Q11 2Q11 3Q11 4Q11 1Q12 Outstandings Commitments Utilizat
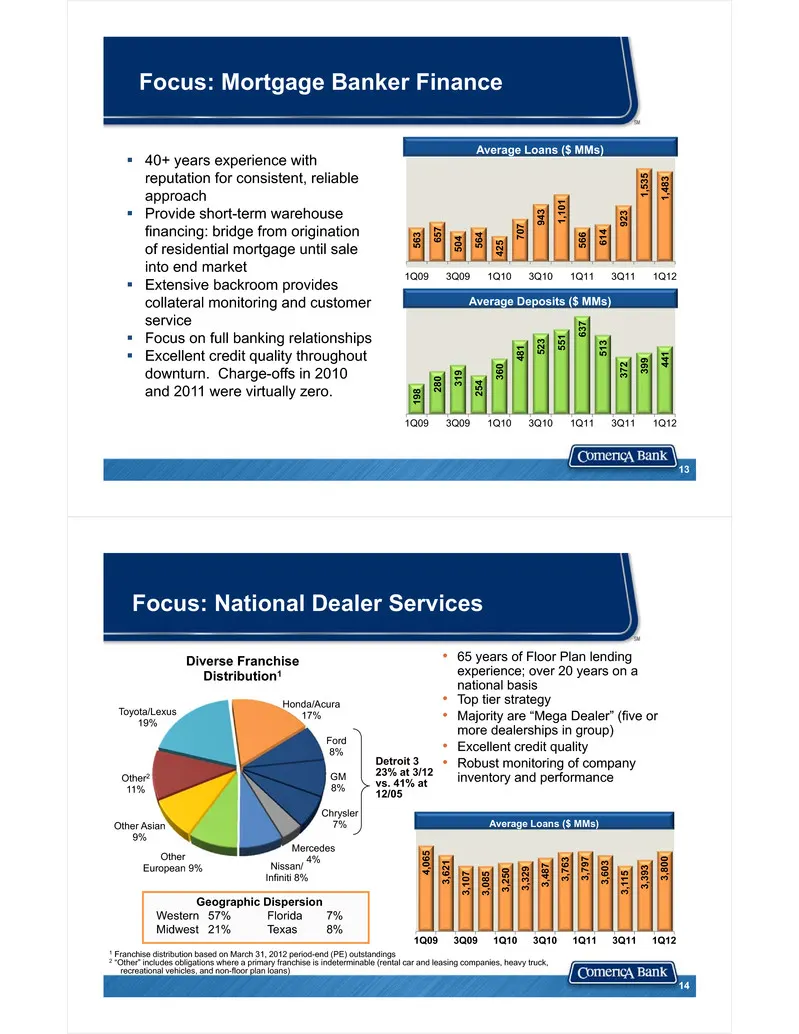
Slide 7: Focus: Mortgage Banker Finance
Focus: Mortgage Banker Finance 13 40+ years experience with reputation for consistent, reliable approach Provide short-term warehouse financing: bridge from origination of residential mortgage until sale into end market Extensive backroom provides collateral monitoring and customer service F
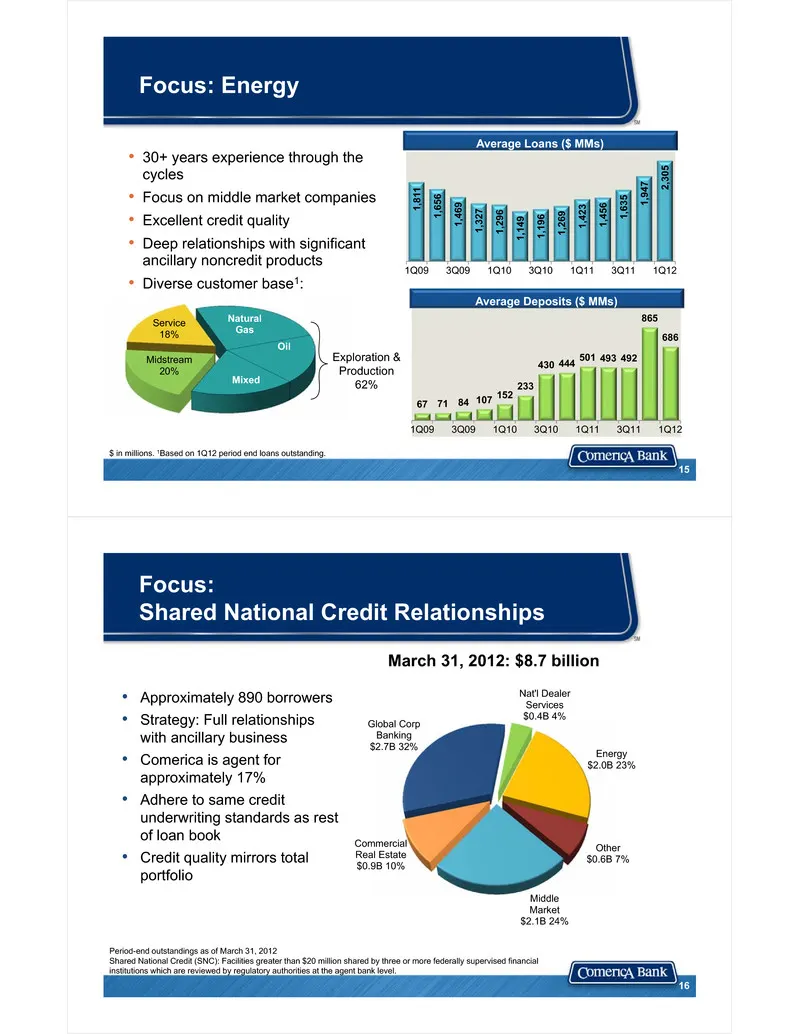
Slide 8: Focus: Energy
Focus: Energy • 30+ years experience through the cycles • Focus on middle market companies• Excellent credit quality• Deep relationships with significant ancillary noncredit products • Diverse customer base1: Natural Gas Oil Mixed Midstream 20% Service 18% Exploration & Production 62% $ in millions.
Slide 9: Focus: Commercial Real Estate
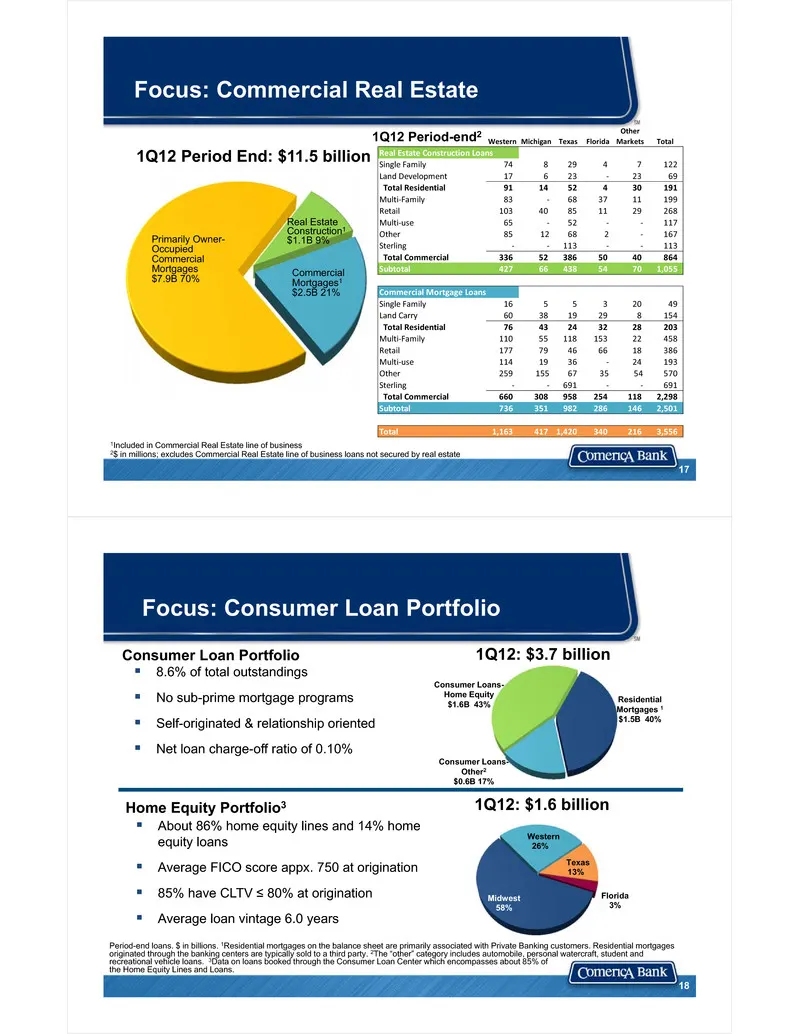
Focus: Commercial Real Estate 1Included in Commercial Real Estate line of business2$ in millions; excludes Commercial Real Estate line of business loans not secured by real estate 1Q12 Period End: $11.5 billion Primarily Owner-Occupied Commercial Mortgages$7.9B 70% Real Estate Construction1 $1.1B 9%
Slide 10: Focus: Government Card Programs
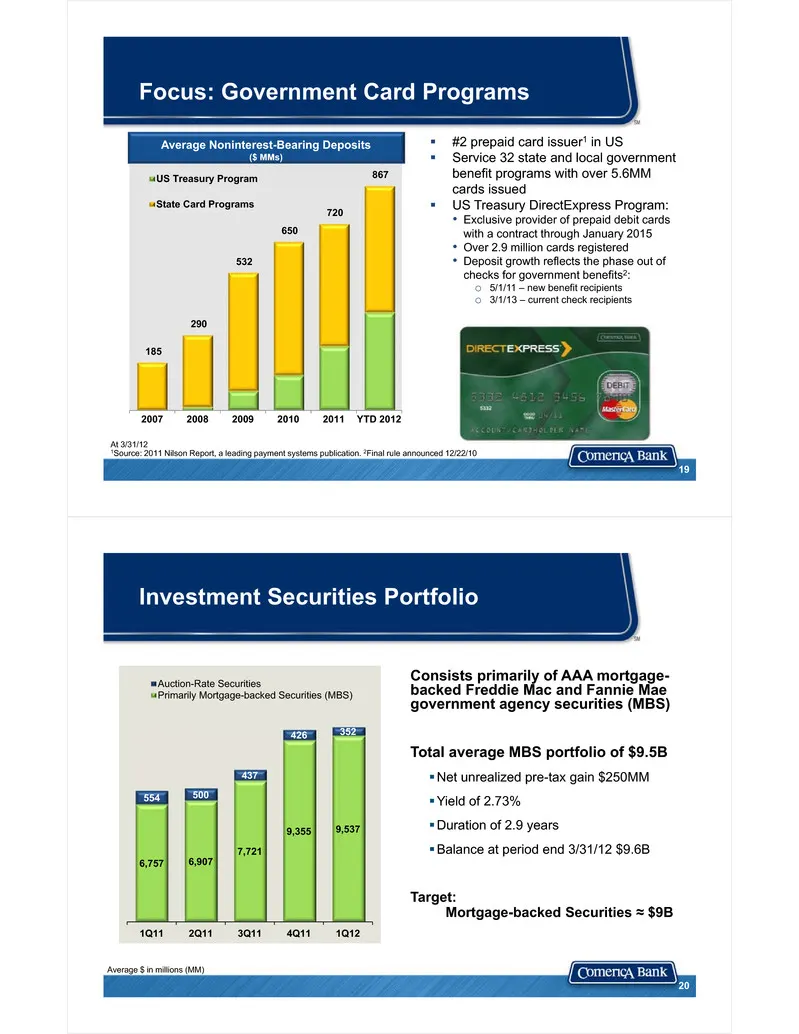
At 3/31/121Source: 2011 Nilson Report, a leading payment systems publication. 2Final rule announced 12/22/10 Focus: Government Card Programs #2 prepaid card issuer1 in US Service 32 state and local government benefit programs with over 5.6MM cards issued US Treasury DirectExpress Program:• Exc
Slide 11: Record Deposit Levels
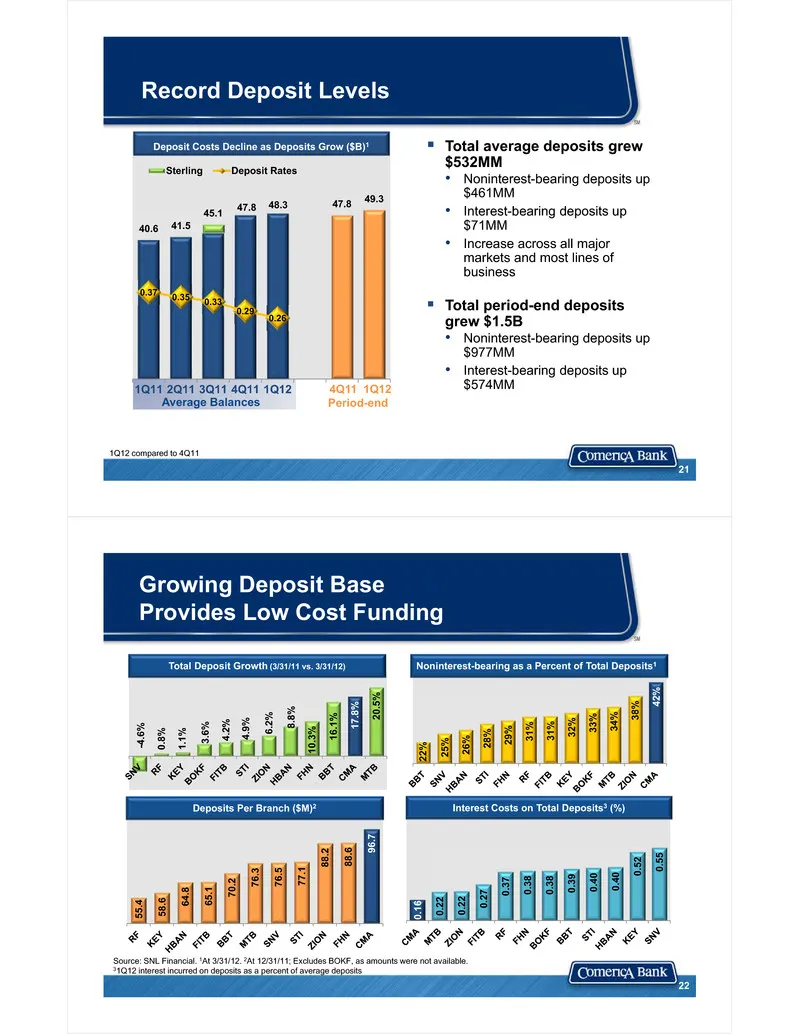
Record Deposit Levels 1Q12 compared to 4Q11 Total average deposits grew $532MM• Noninterest-bearing deposits up $461MM• Interest-bearing deposits up $71MM • Increase across all major markets and most lines of business Total period-end deposits grew $1.5B • Noninterest-bearing deposits up $977MM•
Slide 12: Steady Loan and Declining Deposit Yields
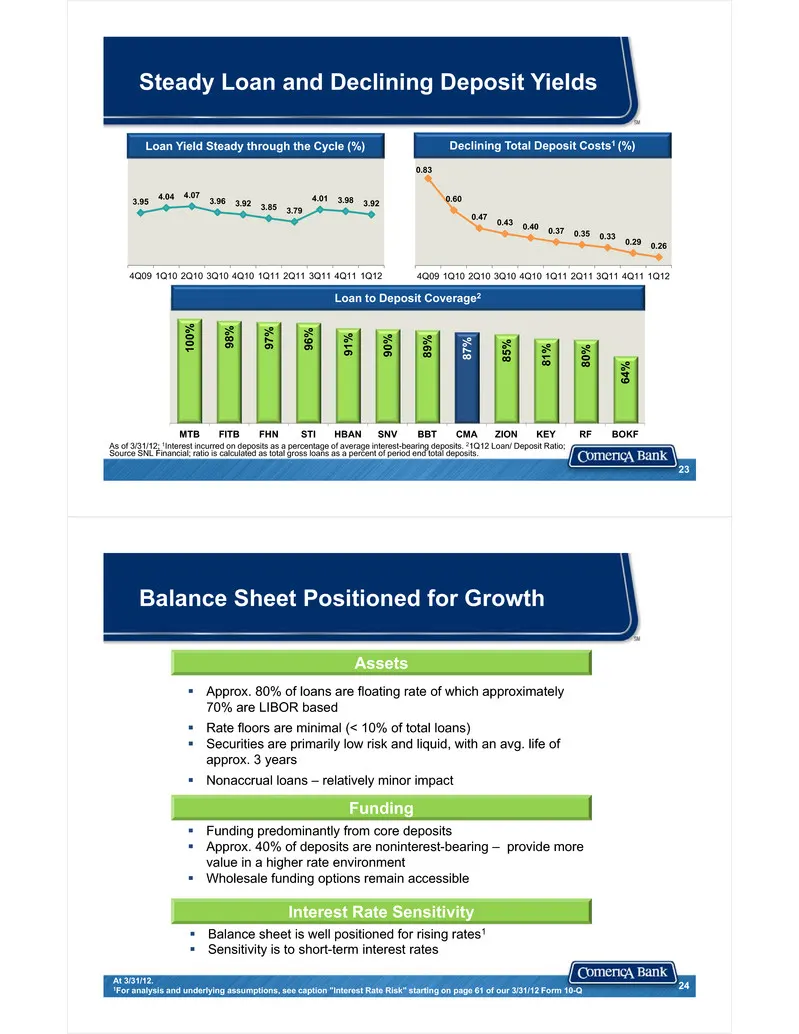
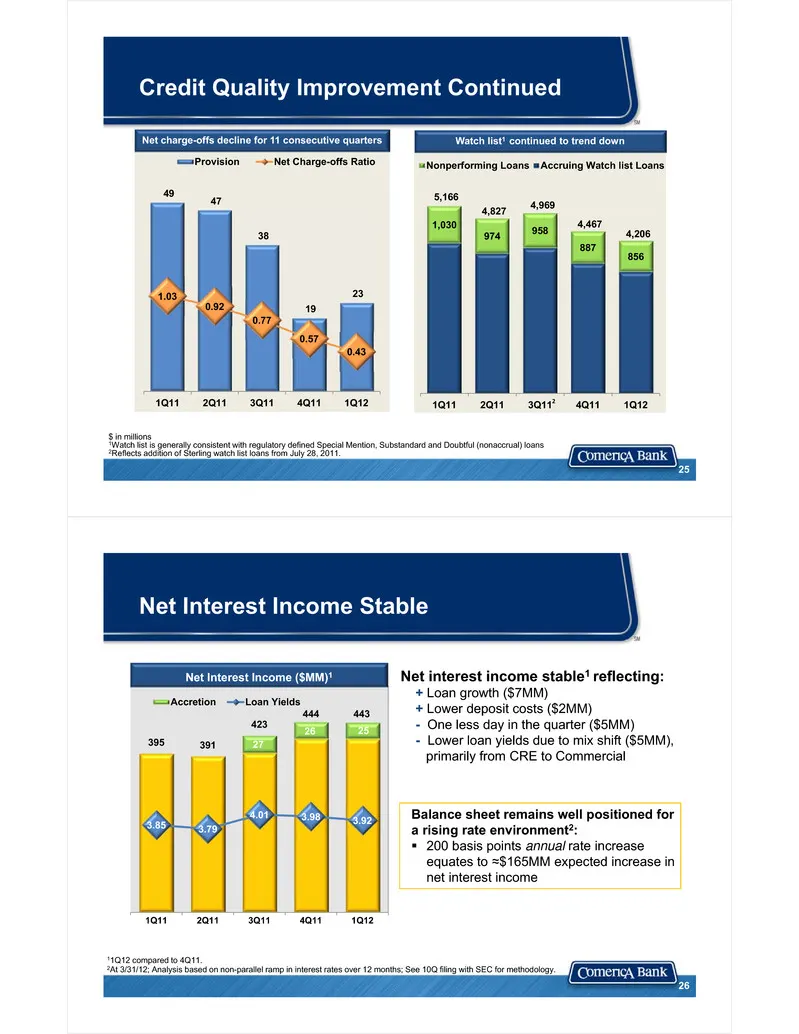
Steady Loan and Declining Deposit Yields 23 3.95 4.04 4.07 3.96 3.92 3.85 3.79 4.01 3.98 3.92 4Q09 1Q10 2Q10 3Q10 4Q10 1Q11 2Q11 3Q11 4Q11 1Q12 0.83 0.60 0.47 0.43 0.40 0.37 0.35 0.33 0.29 0.26 4Q09 1Q10 2Q10 3Q10 4Q10 1Q11 2Q11 3Q11 4Q11 1Q12 Loan Yield Steady through the Cycle (%) Declining Total
Slide 13: Credit Quality Improvement Continued
Credit Quality Improvement Continued $ in millions1Watch list is generally consistent with regulatory defined Special Mention, Substandard and Doubtful (nonaccrual) loans2Reflects addition of Sterling watch list loans from July 28, 2011. 1 25 49 47 38 19 23 1.03 0.92 0.77 0.57 0.43 1Q11 2Q11 3Q11 4Q
Slide 14: Customer Fee Income Growth Offsetting Regulatory Headwinds
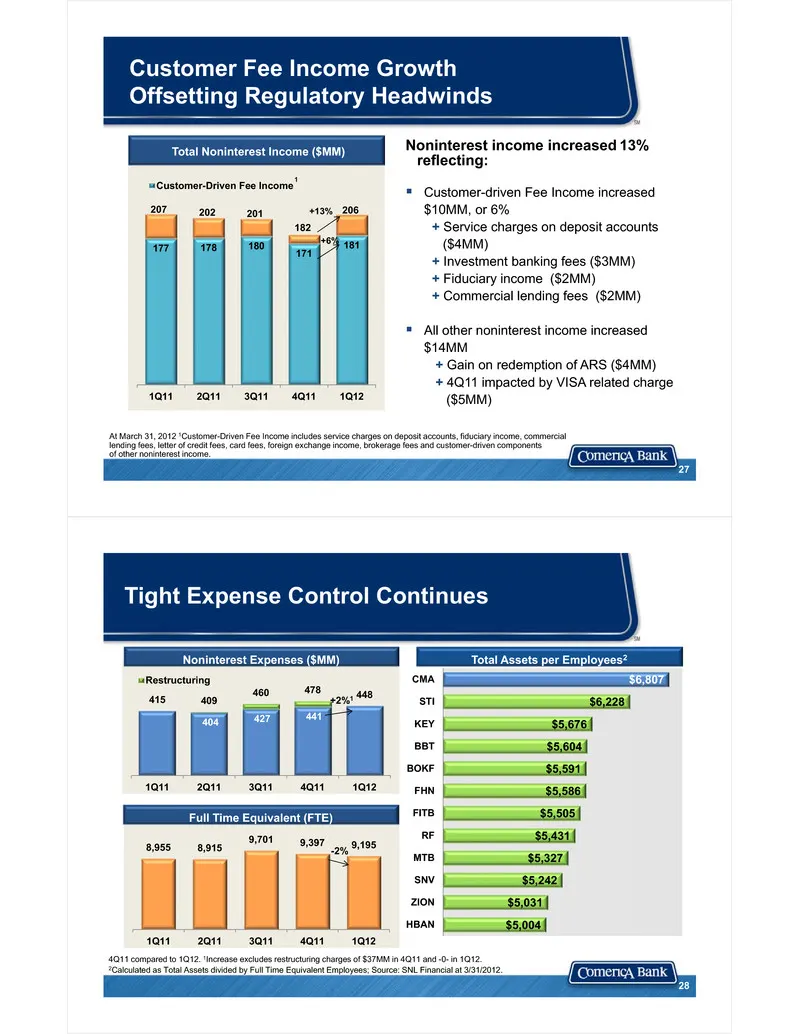
Customer Fee Income GrowthOffsetting Regulatory Headwinds At March 31, 2012 1Customer-Driven Fee Income includes service charges on deposit accounts, fiduciary income, commercial lending fees, letter of credit fees, card fees, foreign exchange income, brokerage fees and customer-driven components of
Slide 15: Active Capital Manager
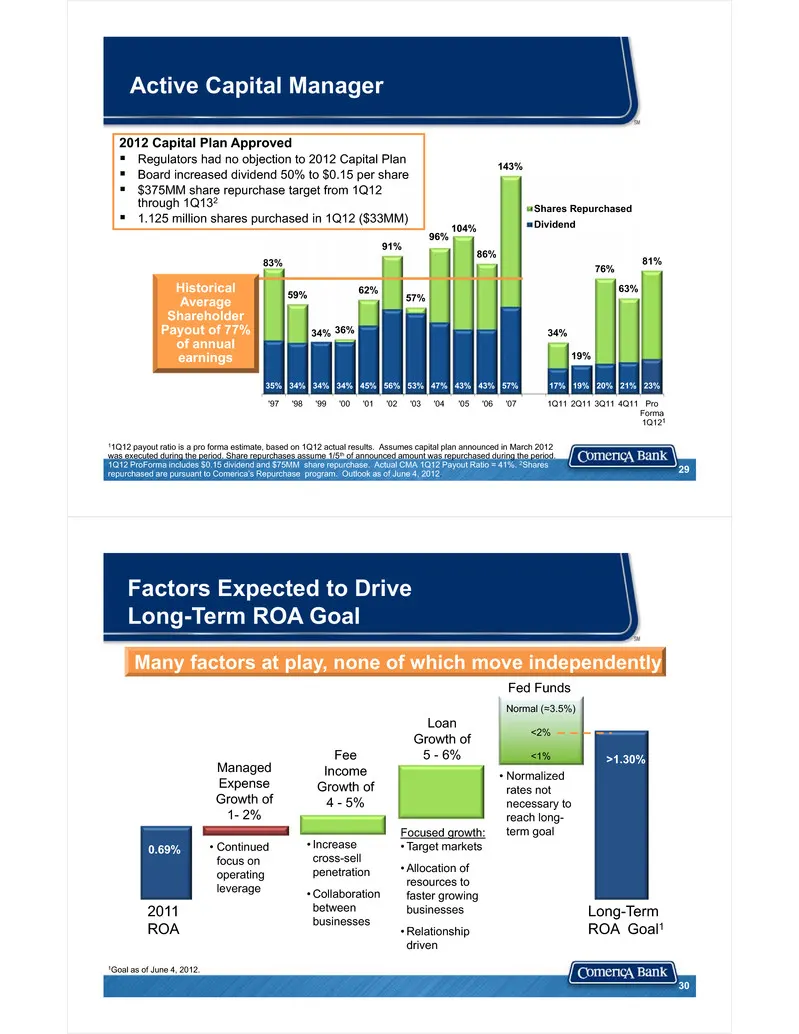
Active Capital Manager 83% 59% 34% 36% 62% 91% 57% 96% 104% 86% 143% 34% 19% 76% 63% 81% 35% 34% 34% 34% 45% 56% 53% 47% 43% 43% 57% 17% 19% 20% 21% 23% '97 '98 '99 '00 '01 '02 '03 '04 '05 '06 '07 1Q11 2Q11 3Q11 4Q11 ProForma1Q12 Shares Repurchased Dividend Historical Average Shareholder Payout of 7
Slide 16: Update on Sterling Acquisition
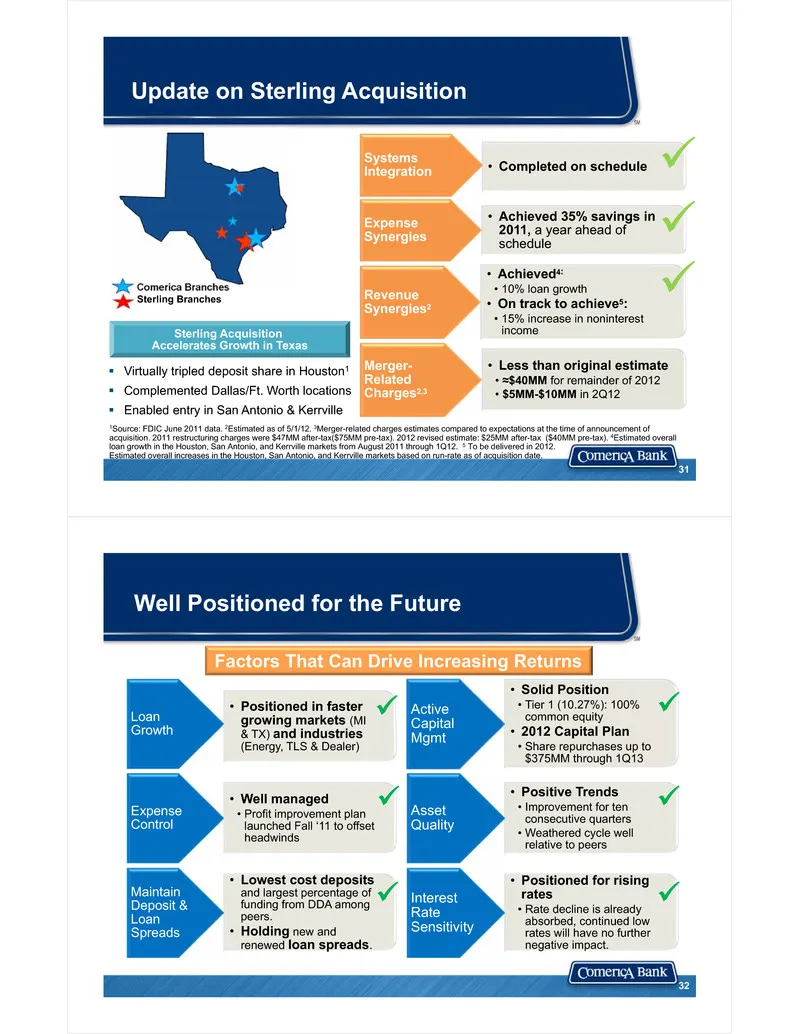
Update on Sterling Acquisition Virtually tripled deposit share in Houston1 Complemented Dallas/Ft. Worth locations Enabled entry in San Antonio & Kerrville 1Source: FDIC June 2011 data. 2Estimated as of 5/1/12. 3Merger-related charges estimates compared to expectations at the time of announcem
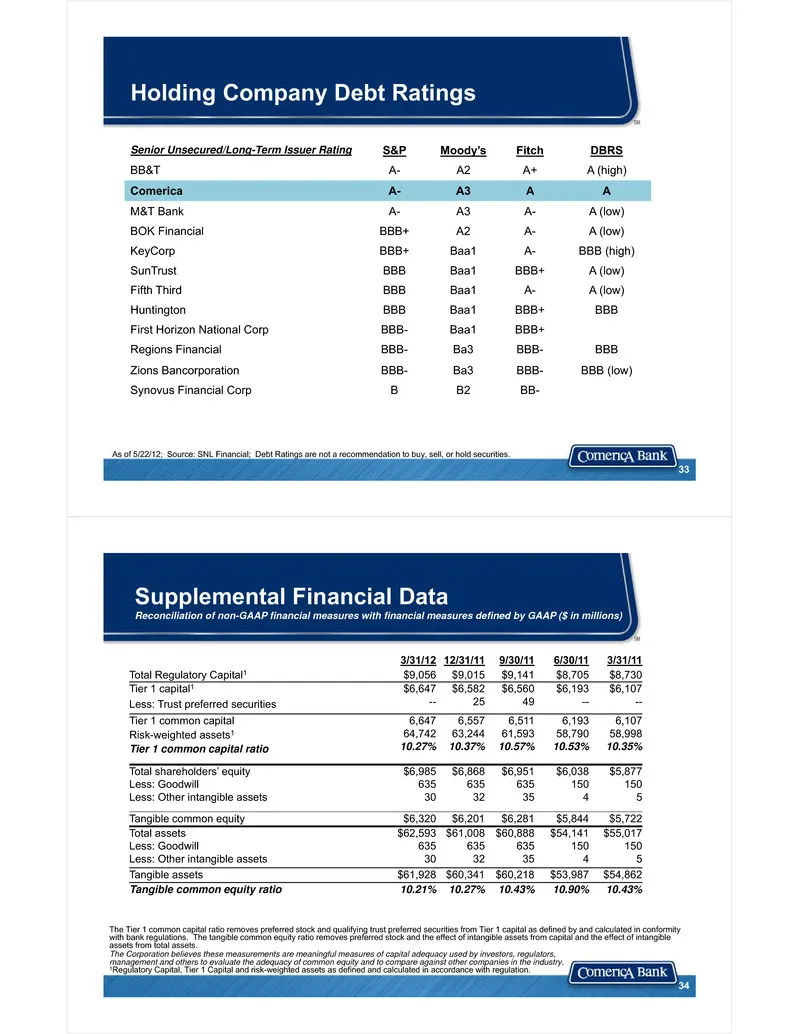
Slide 17: Holding Company Debt Ratings; Supplemental Financial Data
Senior Unsecured/Long-Term Issuer Rating S&P Moody’s Fitch DBRS BB&T A- A2 A+ A (high) Comerica A- A3 A A M&T Bank A- A3 A- A (low) BOK Financial BBB+ A2 A- A (low) KeyCorp BBB+ Baa1 A- BBB (high) SunTrust BBB Baa1 BBB+ A (low) Fifth Third BBB Baa1 A- A (low) Huntington BBB Baa1 BBB+ BBB First Horiz
Source: SEC EDGAR · 8-K filed Jun 4, 2012
More decks from Comerica Incorporated
 Goldman Sachs Financial Services Conference 202520 slides · Dec 11, 2025
 Merger or Acquisition (October 2025)18 slides · Oct 6, 2025
 Barclays Global Financial Services Conference 202524 slides · Sep 8, 2025
 Q2 2025 Earnings Presentation24 slides · Jul 18, 2025
 Q1 2025 Earnings Presentation21 slides · Apr 21, 2025
 Q4 2024 Earnings Presentation24 slides · Jan 22, 2025