Chittenden — Investor Presentation (May 2004)
35 slides from Chittenden's investor presentation, May 21, 2004
Slide 1: As of March 31, 2004
As of March 31, 2004
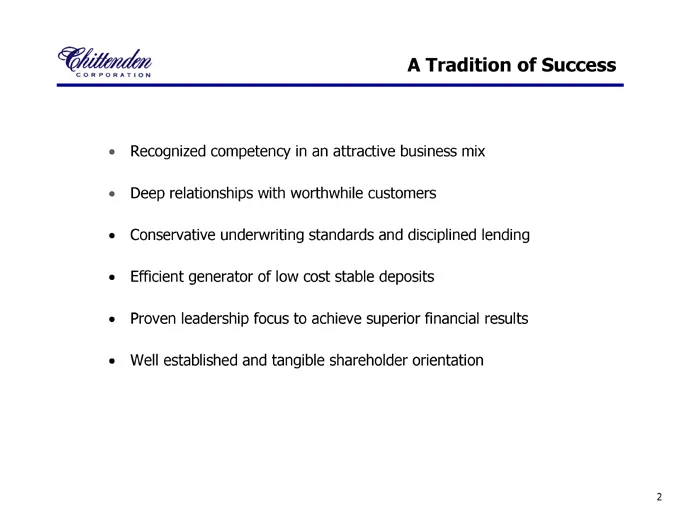
Slide 2: A Tradition of Success
A Tradition of Success Recognized competency in an attractive business mix Deep relationships with worthwhile customers Conservative underwriting standards and disciplined lending Efficient generator of low cost stable deposits Proven leadership focus to achieve superior financial results Well estab
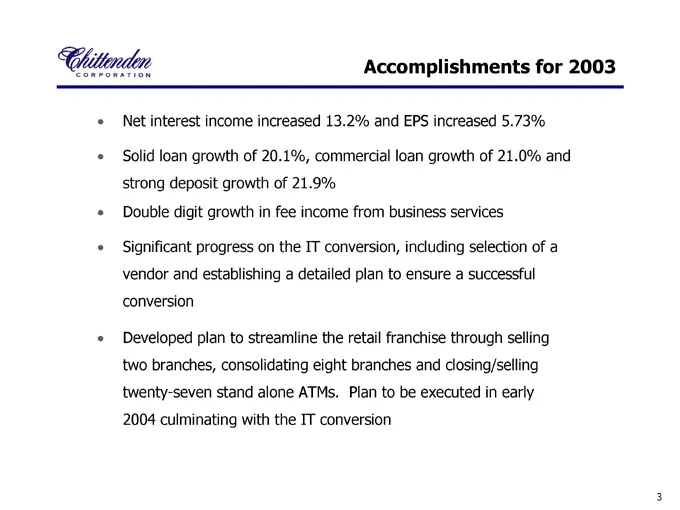
Slide 3: Accomplishments for 2003
Accomplishments for Net interest income increased 13.2% and EPS increased 5.73% Solid loan growth of 20.1%, commercial loan growth of 21.0% and strong deposit growth of 21.9% Double digit growth in fee income from business services Significant progress on the IT conversion, including selection of a
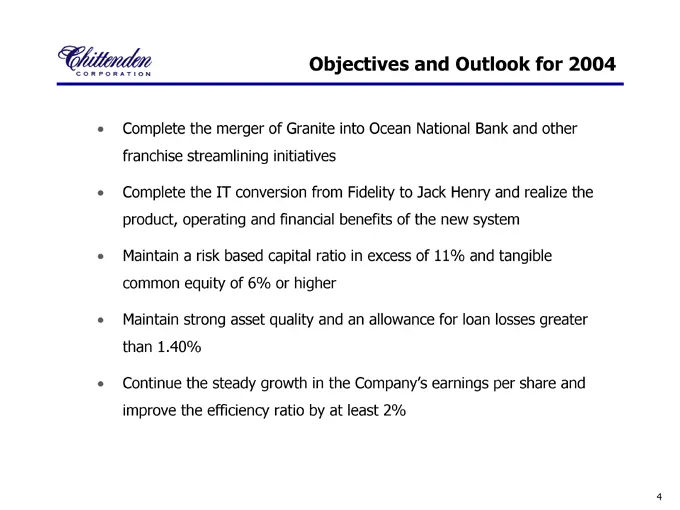
Slide 4: Objectives and Outlook for 2004
Objectives and Outlook for 2004 Complete the merger of Granite into Ocean National Bank and other franchise streamlining initiatives Complete the IT conversion from Fidelity to Jack Henry and realize the product, operating and financial benefits of the new system Maintain a risk based capital ratio
Slide 5: Our Target Markets
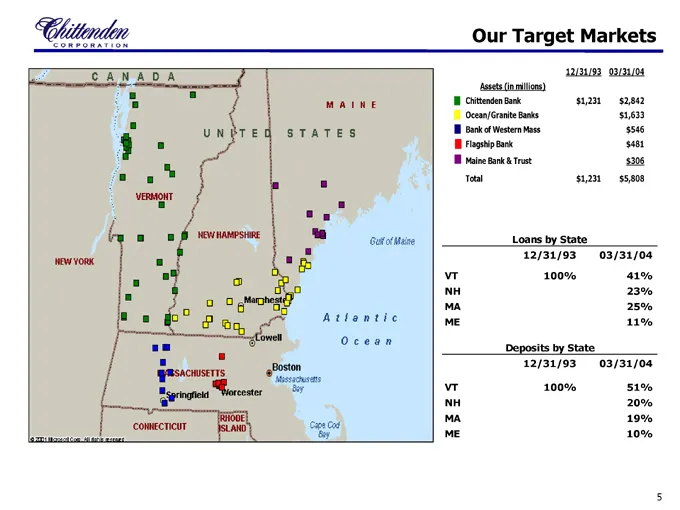
Our Target Markets 12/31/93 03/31/04 Assets (in millions) Chittenden Bank $ 1,231 $ 2,842 Ocean/Granite Banks $ 1,633 Bank of Western Mass $ 546 Flagship Bank $ 481 Maine Bank & Trust $ 306 Total $ 1,231 $ 5,808 Loans by State 12/31/93 03/31/04 VT 100% 41% NH 23% MA 25% ME 11% Deposits by State 12/3
Slide 6: Our Target Markets: Vermont Market
Our Target Markets Vermont Market State population over 600,000 Greater Burlington population over 150,000 11% population growth 1990-2000 Greater Burlington median household income of $48,000 Burlington/Chittenden Co. median age = 34 10,000 new business startups in 2003 23% new job growth 1990-2000
Slide 7: Our Target Markets: Springfield and Worcester
Our Target Markets Greater Springfield Market Population of over 450,000 in Hampden Co. Median household income of $40,000 Median age = 36 Above national/regional employment averages in education, insurance, health services, manufacturing 13 colleges located in Greater Springfield 1993 - 2000 Pionee
Slide 8: Our Target Markets: Southern NH and Portland
Our Target Markets Southern NH/Seacoast Market Total regional population just under 1 million 12% population growth 1990 - Median household income for region of $50,000 Median age for region = 37 Large pool of professionals, 42% of Portsmouth residents hold a bachelor’s degree or > 75% of NH busines
Slide 9: Our Target Customers
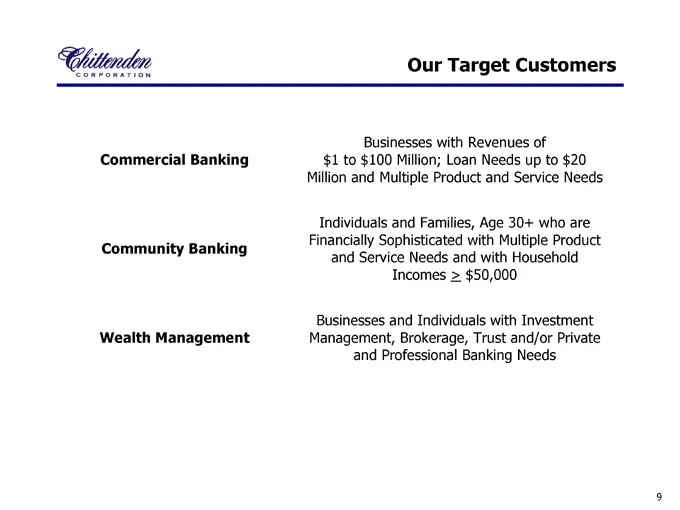
Our Target Customers Commercial Banking Businesses with Revenues of $1 to $100 Million; Loan Needs up to $20 Million and Multiple Product and Service Needs Community Banking Individuals and Families, Age 30+ who are Financially Sophisticated with Multiple Product and Service Needs and with Household
Slide 10: Commercial & Community Banking
Commercial & Community Banking 10
Slide 11: A Diversified Loan Portfolio
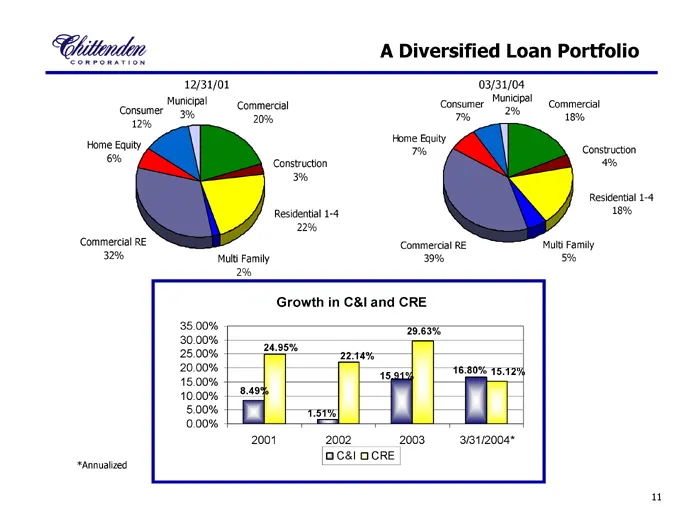
A Diversified Loan Portfolio 12/31/01 Municipal Commercial Consumer 3% 12% 20% Home Equity 6% Construction 3% Residential 1-4 22% Commercial RE 32% Multi Family 2% 03/31/04 Municipal Consumer Commercial 2% 7% 18% Home Equity 7% Construction 4% Residential 1-4 18% Commercial RE Multi Family 39% 5% Gr
Slide 12: Commercial Loan Diversification by Industry
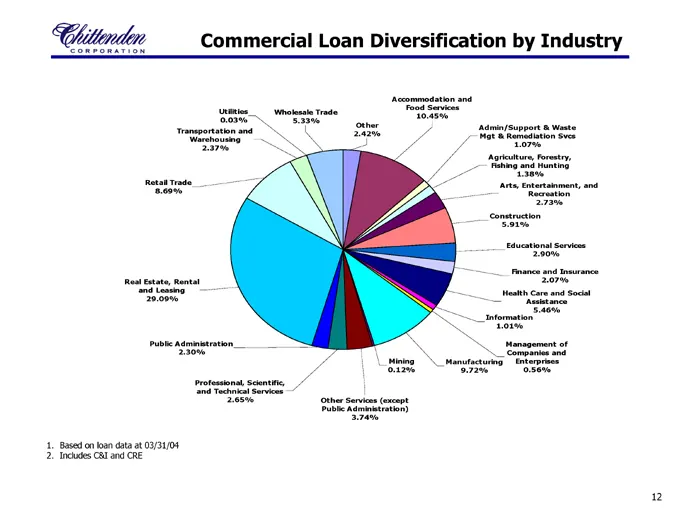
Commercial Loan Diversification by Industry Accommodation and Food Services 10.45% Wholesale Trade 5.33% Utilities 0.03% Other 2.42% Admin/Support & Waste Mgt & Remediation Svcs 1.07% Transportation and Warehousing 2.37% Agriculture, Forestry, Fishing and Hunting 1.38% Retail Trade 8.69% Arts, Enter
Slide 13: Real Estate, Rental and Leasing
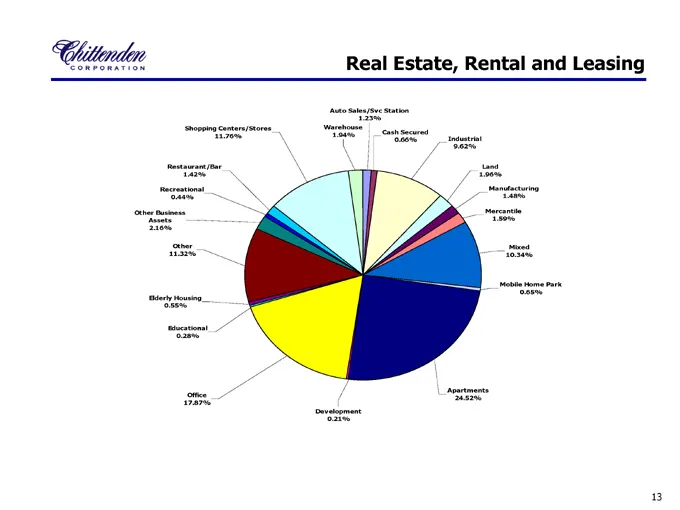
Real Estate, Rental and Leasing Auto Sales/Svc Station 1.23% Shopping Centers/Stores 11.76% Warehouse 1.94% Cash Secured 0.66% Industrial 9.62% Restaurant/Bar 1.42% Land 1.96% Recreational 0.44% Manufacturing 1.48% Other Business Assets 2.16% Mercantile 1.59% Other 11.32% Mixed 10.34% Mobile Home Pa
Slide 14: Continuing Core Deposit Growth
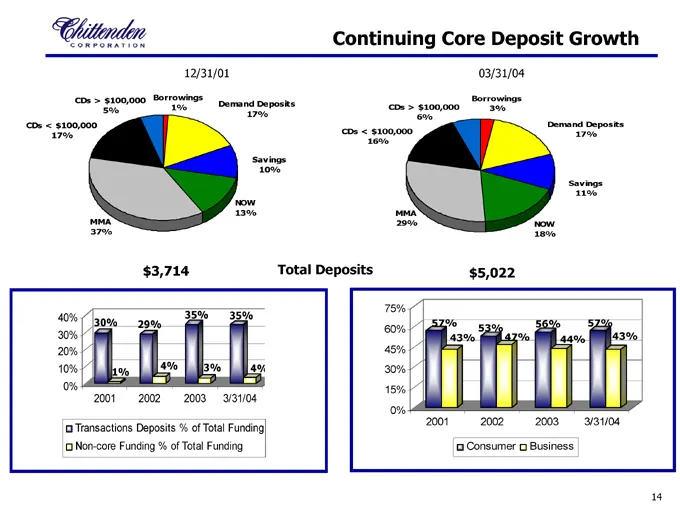
Continuing Core Deposit Growth 12/31/01 CDs > $100,000 5% Borrowings 1% Demand Deposits 17% CDs < $100,000 17% Savings 10% NOW 13% MMA 37% 03/31/04 Borrowings 3% CDs > $100,000 6% Demand Deposits 17% CDs < $100,000 16% Savings 11% MMA 29% NOW 18% $3,714 $5,022 Total Deposits 40% 35% 35% 30% 29% 30%
Slide 15: Business Services
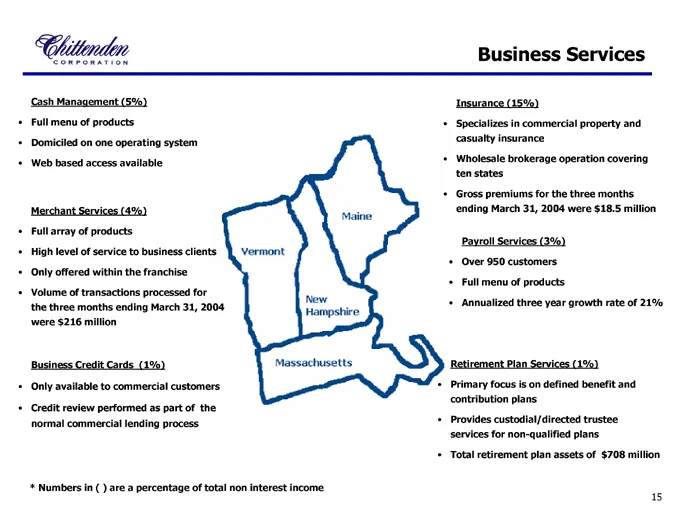
Business Services Cash Management (5%) Full menu of products Domiciled on one operating system Web based access available Merchant Services (4%) Full array of products High level of service to business clients Only offered within the franchise Volume of transactions processed for the three months en
Slide 16: Captive Insurance
Captive Insurance The captive insurance market has grown 10% annually over the last 5 years Vermont is the U.S. domicile of choice for captive insurance companies – 570 Captive Insurers are licensed in VT; 65% bank with Chittenden* Vermont has more captive insurance companies than all other states c
Slide 17: Government Banking
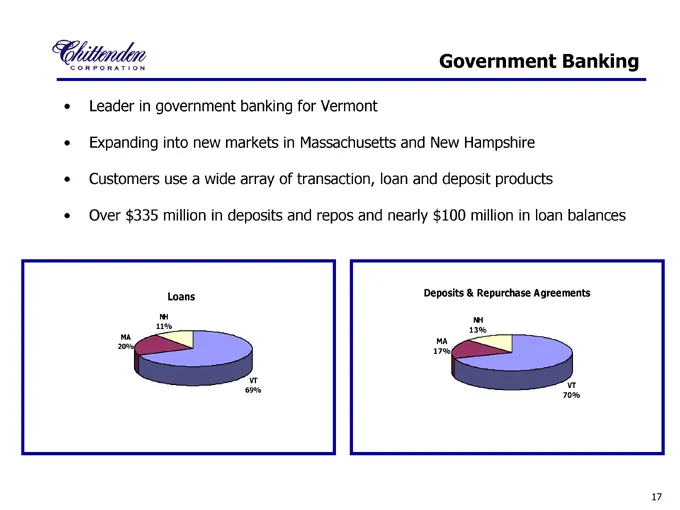
Government Banking Leader in government banking for Vermont Expanding into new markets in Massachusetts and New Hampshire Customers use a wide array of transaction, loan and deposit products Over $335 million in deposits and repos and nearly $100 million in loan balances Loans NH 11% MA 20% VT 69% D
Slide 18: Mortgage Banking
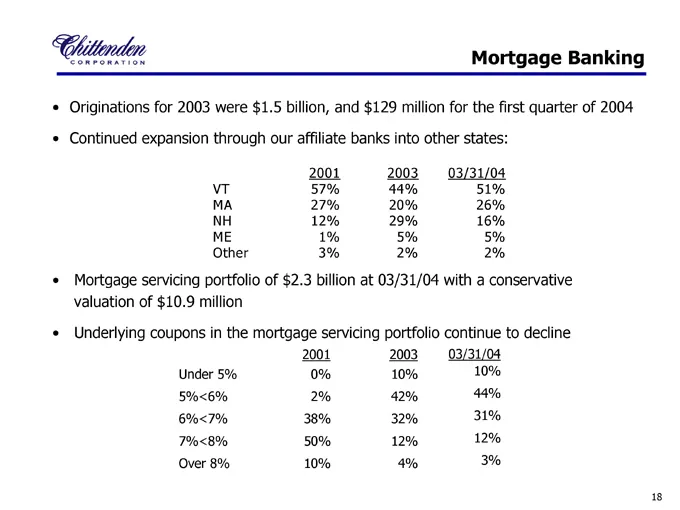
Mortgage Banking Originations for 2003 were $1.5 billion, and $129 million for the first quarter of 2004 Continued expansion through our affiliate banks into other states: 2001 2003 03/31/04 VT 57% 44% 51% MA 27% 20% 26% NH 12% 29% 16% ME 1% 5% 5% Other 3% 2% 2% Mortgage servicing portfolio of $2.3
Slide 19: Wealth Management
Wealth Management 19
Slide 20: Wealth Management
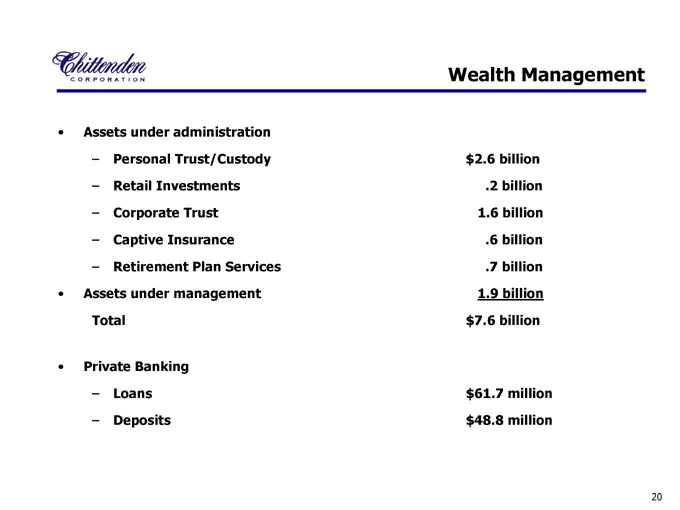
Wealth Management Assets under administration – Personal Trust/Custody $2.6 billion – Retail Investments .2 billion – Corporate Trust 1.6 billion – Captive Insurance .6 billion – Retirement Plan Services .7 billion Assets under management 1.9 billion Total $7.6 billion Private Banking – Loans $61.7
Slide 21: Asset Management
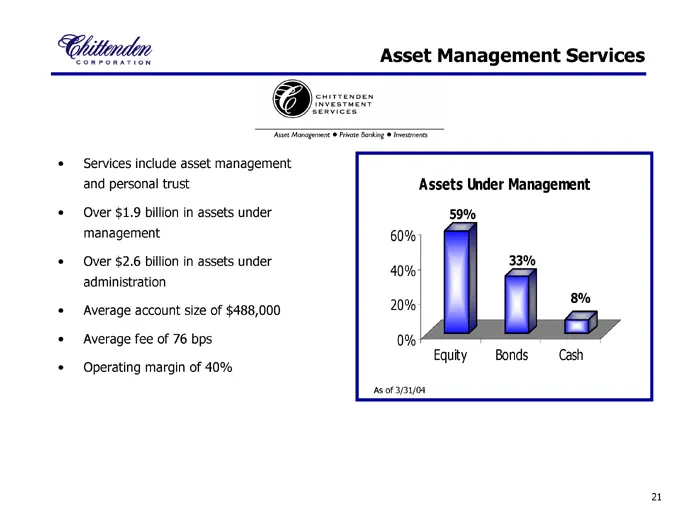
Asset Management Services Services include asset management and personal trust Over $1.9 billion in assets under management Over $2.6 billion in assets under administration Average account size of $488,000 Average fee of 76 bps Operating margin of 40% Assets Under Management 59% 60% 33% 40% 20% 8% 0
Slide 22: Retail Investments—Broker/Dealer
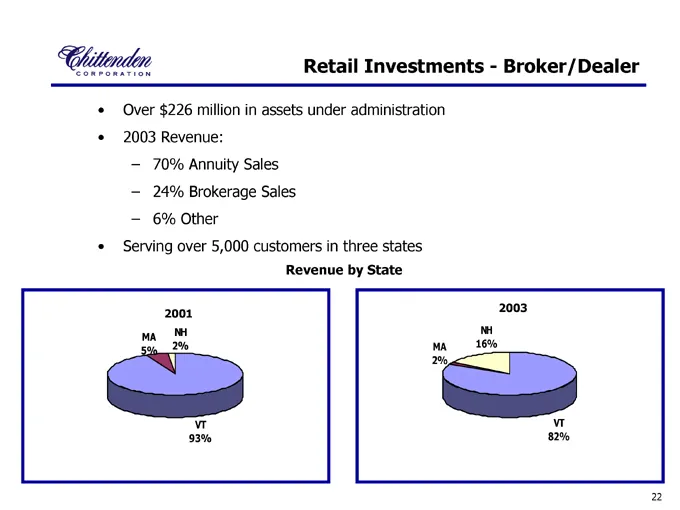
Retail Investments—Broker/Dealer Over $226 million in assets under administration 2003 Revenue: – 70% Annuity Sales – 24% Brokerage Sales – 6% Other Serving over 5,000 customers in three states Revenue by State MA NH 5% 2% VT 93% NH MA 16% 2% VT 82%
Slide 23: Corporate Trust
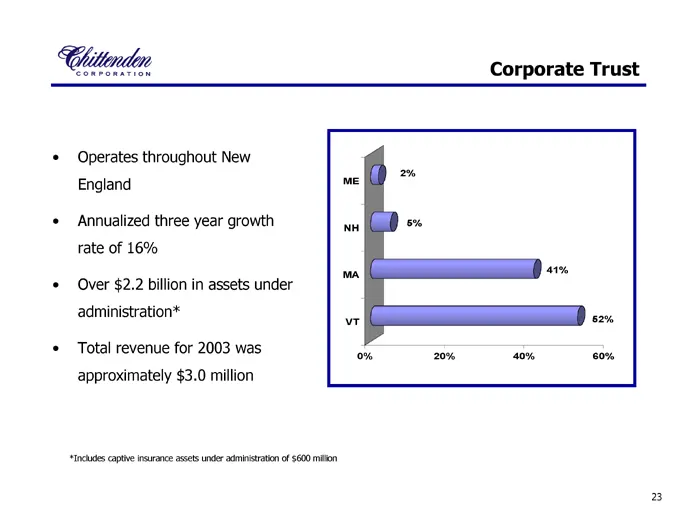
Corporate Trust Operates throughout New England Annualized three year growth rate of 16% Over $2.2 billion in assets under administration* Total revenue for 2003 was approximately $3.0 million 2% ME 5% NH 41% MA VT 52% 0% 20% 40% 60% *Includes captive insurance assets under administration of $600 mi
Slide 24: Financial Performance
Financial Performance ry
Slide 25: Consistent Superior Financial Performance
Consistent Superior Financial Performance Strong net interest margin Low cost stable sources of funding and excellent liquidity position Strong fee based revenues in targeted businesses Conservative reserves and excellent credit quality Strong tier 1 capital base
Slide 26: Financial Summary
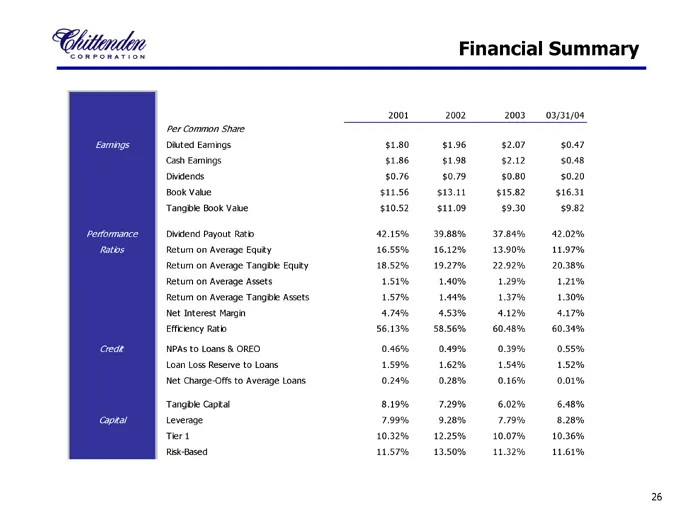
Financial Summary 2001 2002 2003 03/31/04 Per Common Share Earnings Diluted Earnings $ 1.80 $ 1.96 $ 2.07 $0.47 Cash Earnings $ 1.86 $ 1.98 $ 2.12 $0.48 Dividends $ 0.76 $ 0.79 $ 0.80 $0.20 Book Value $ 11.56 $ 13.11 $ 15.82 $ 16.31 Tangible Book Value $ 10.52 $ 11.09 $ 9.30 $9.82 Performance Divide
Slide 27: Book Value, Margin, Returns and Capital Charts
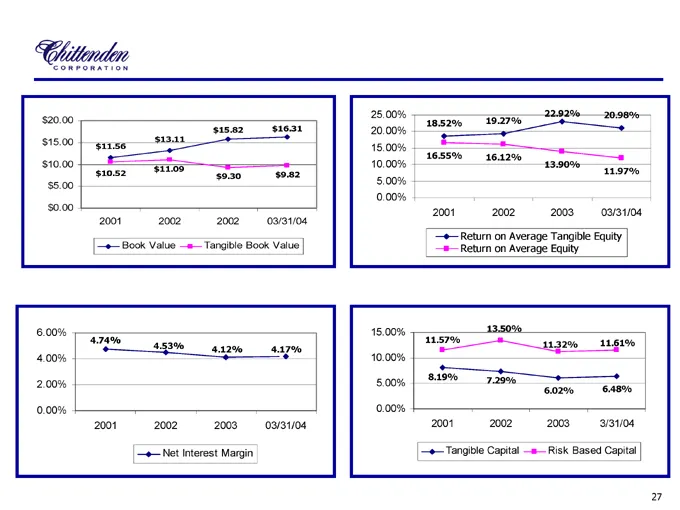
$20.00 $15.82 $16.31 $15.00 $13.11 $11.56 $10.00 $11.09 $10.52 $9.30 $9.82 $5.00 $0.00 2002 2002 03/31/04 Book Value Tangible Book Value 6.00% 4.74% 4.53% 4.12% 4.17% 4.00% 2.00% 0.00% 2001 2002 2003 03/31/04 Net Interest Margin 25.00% 22.92% 20.98% 18.52% 19.27% 20.00% 15.00% 16.55% 16.12% 10.00% 1
Slide 28: Risk Management
Risk Management 28
Slide 29: Credit—Excellent Asset Quality
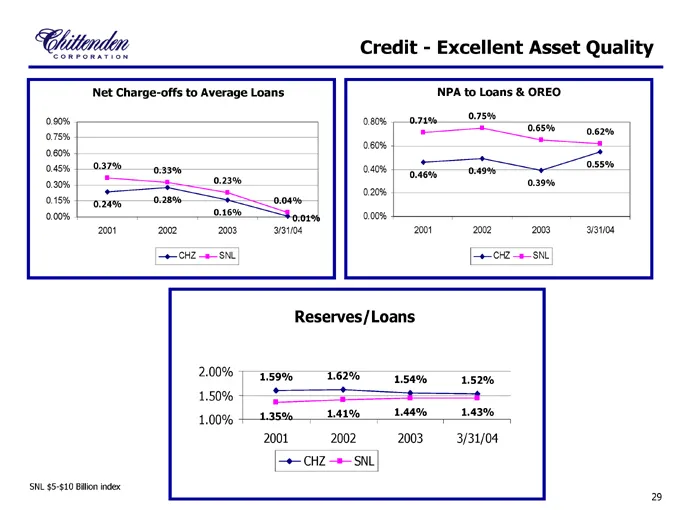
Credit—Excellent Asset Quality Credit—Excellent Asset Quality Net Charge-offs to Average Loans 0.90% 0.75% 0.60% 0.45% 0.37% 0.33% 0.30% 0.23% 0.15% 0.28% 0.04% 0.24% 0.00% 0.16% 0.01% 2001 2002 2003 3/31/04 CHZ SNL NPA to Loans & OREO 0.75% 0.80% 0.71% 0.65% 0.62% 0.60% 0.55% 0.40% 0.49% 0.46% 0.39
Slide 30: Granularity of Non-Accrual Loans
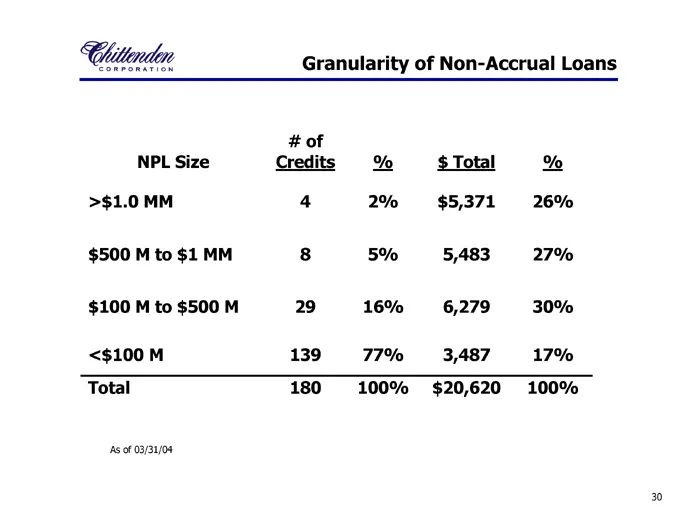
Granularity of Non-Accrual Loans NPL Size # of Credits % $ Total % >$1.0 MM 4 2% $5,371 26% $500 M to $1 MM 8 5% 5,483 27% $100 M to $500 M 29 16% 6,279 30% <$100 M 139 77% 3,487 17% Total 180 100% $20,620 100% As of 03/31/04
Slide 31: Interest Rate Risk
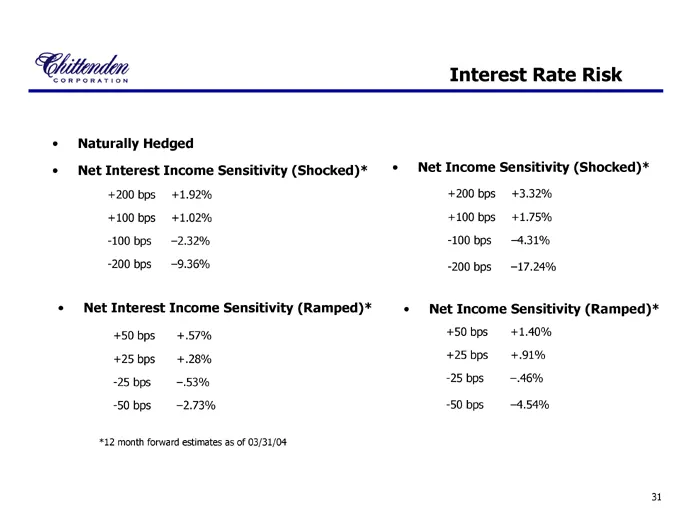
Interest Rate Risk Naturally Hedged Net Interest Income Sensitivity (Shocked)* +200 bps +1.92% +100 bps +1.02% -100 bps –2.32% -200 bps –9.36% Net Interest Income Sensitivity (Ramped)* +50 bps +.57% +25 bps +.28% -25 bps –.53% -50 bps –2.73% Net Income Sensitivity (Shocked)* +200 bps +3.32% +100 bps
Slide 32: Industry Performance Comparison
Industry Performance Comparison
Slide 33: CHZ vs SNL Peer Comparison
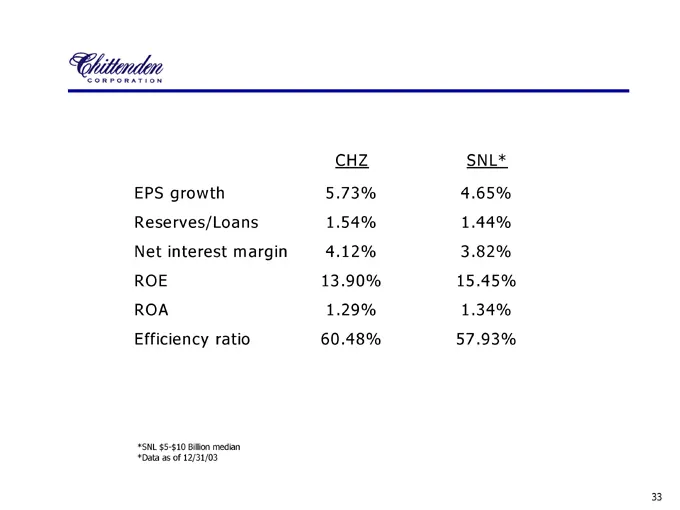
CHZ SNL* EPS growth 5.73% 4.65% Reserves/Loans 1.54% 1.44% Net interest margin 4.12% 3.82% ROE 13.90% 15.45% ROA 1.29% 1.34% Efficiency ratio 60.48% 57.93% *SNL $5-$10 Billion median *Data as of 12/31/03
Slide 34: A Compelling Story
A Compelling Story Strong market share and a proven acquisition acumen Low risk balance sheet with a prudent growth strategy Diversified banking services with a solid balance of revenues Low exposure to volatile sectors with a fortress balance sheet
Slide 35: Visit our website
Visit our website for a wide range of products, latest financial reports and many other interactive services: www.chittendencorp.com This presentation contains “forward-looking statements” which may describe future plans and strategic initiatives. These forward-looking statements are based on curren
Source: SEC EDGAR · 8-K filed May 21, 2004
More decks from Chittenden Corp
 Investor Presentation (September 2007)38 slides · Sep 7, 2007
 Merger or Acquisition (June 2007)27 slides · Jun 27, 2007
 Chittenden — Merger or Acquisition (June 2007)25 slides · Jun 27, 2007
 Merger or Acquisition (June 2007)9 slides · Jun 5, 2007
 Investor Presentation (May 2007)36 slides · May 14, 2007
 Investor Presentation (February 2007)37 slides · Feb 16, 2007