Santander Consumer USA Holdings Inc
Santander Consumer USA — Q1 2020 Earnings Presentation
23 slides from Santander Consumer USA's earnings presentation, Apr 28, 2020
Slide 1: First Quarter 2020
Exhibit 99.2 First Quarter 2020 April 28, 2020
Slide 2: Forward-Looking Statements
Forward-Looking Statements Among the factors that could cause the forward-looking statements in this press release and/or our financial performance to differ materially from that suggested by the forward-looking statements are (a) the adverse impact of COVID-19 on our business, financial condition,
Slide 3: Santander Consumer COVID-19 Relief Efforts
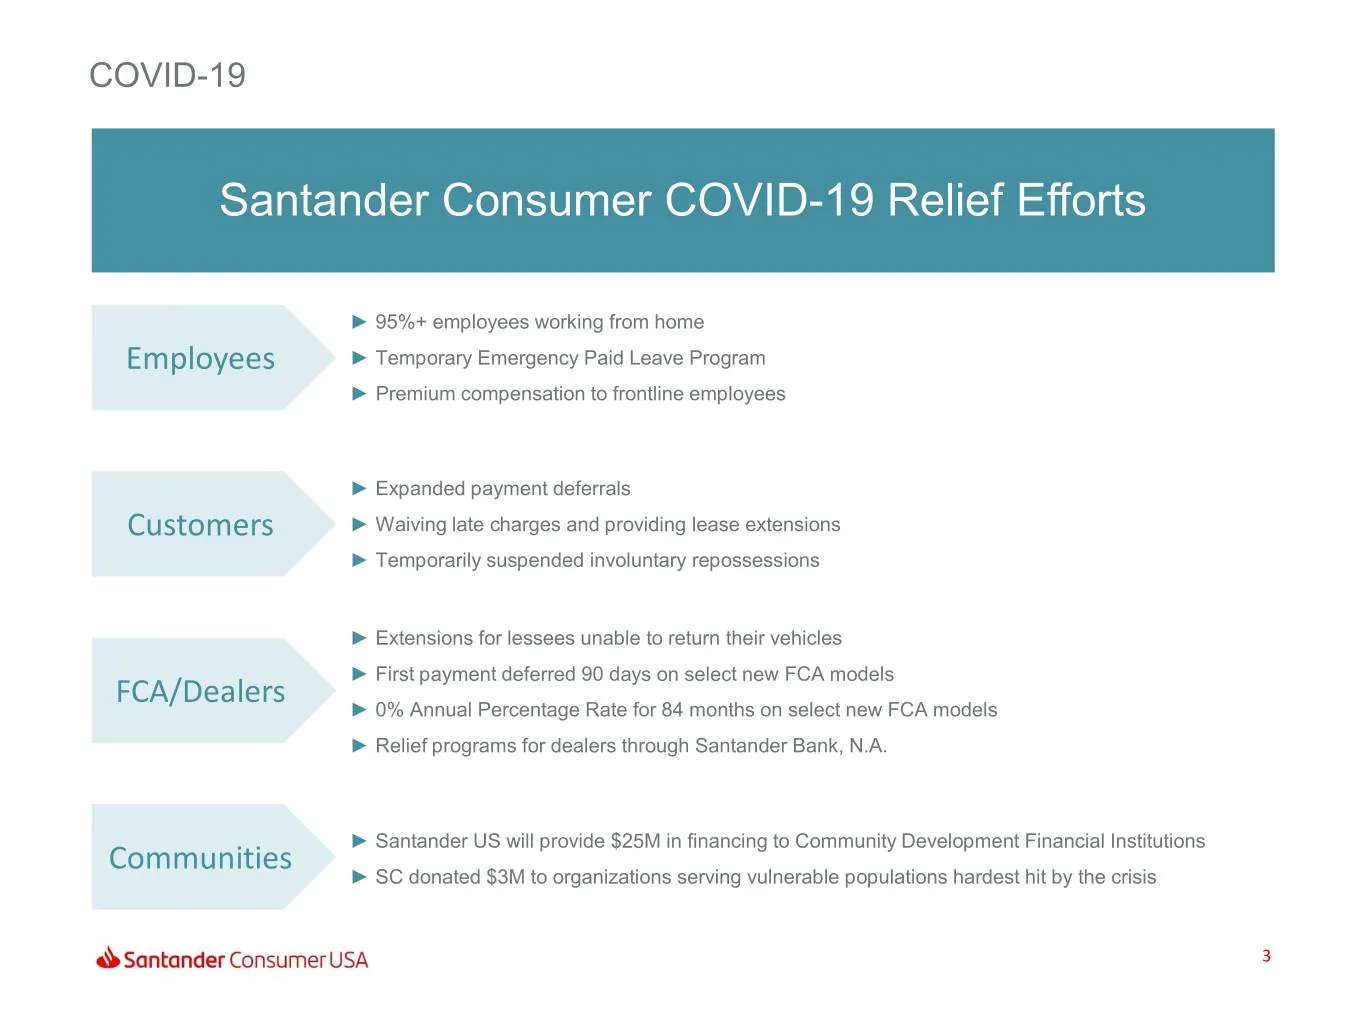
COVID-19 Santander Consumer COVID-19 Relief Efforts ► 95%+ employees working from home Employees ► Temporary Emergency Paid Leave Program ► Premium compensation to frontline employees ► Expanded payment deferrals Customers ► Waiving late charges and providing lease extensions ► Temporarily suspended
Slide 4: Earnings Highlights
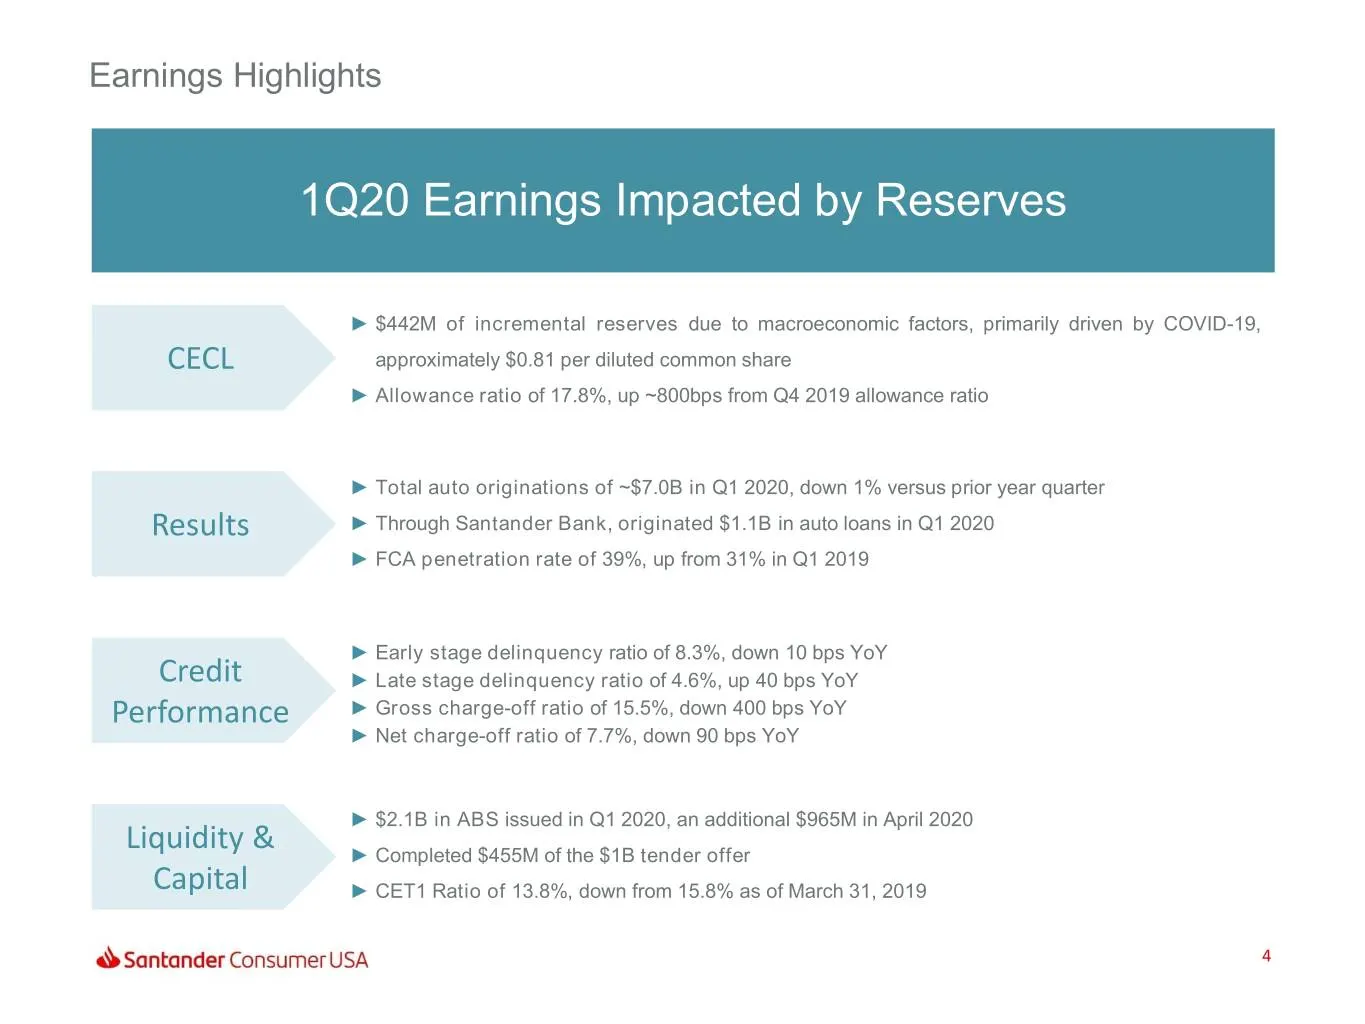
Earnings Highlights 1Q20 Earnings Impacted by Reserves ► $442M of incremental reserves due to macroeconomic factors, primarily driven by COVID-19, CECL approximately $0.81 per diluted common share ► Allowance ratio of 17.8%, up ~800bps from Q4 2019 allowance ratio ► Total auto originations of ~$7.0B
Slide 5: Economic Indicators
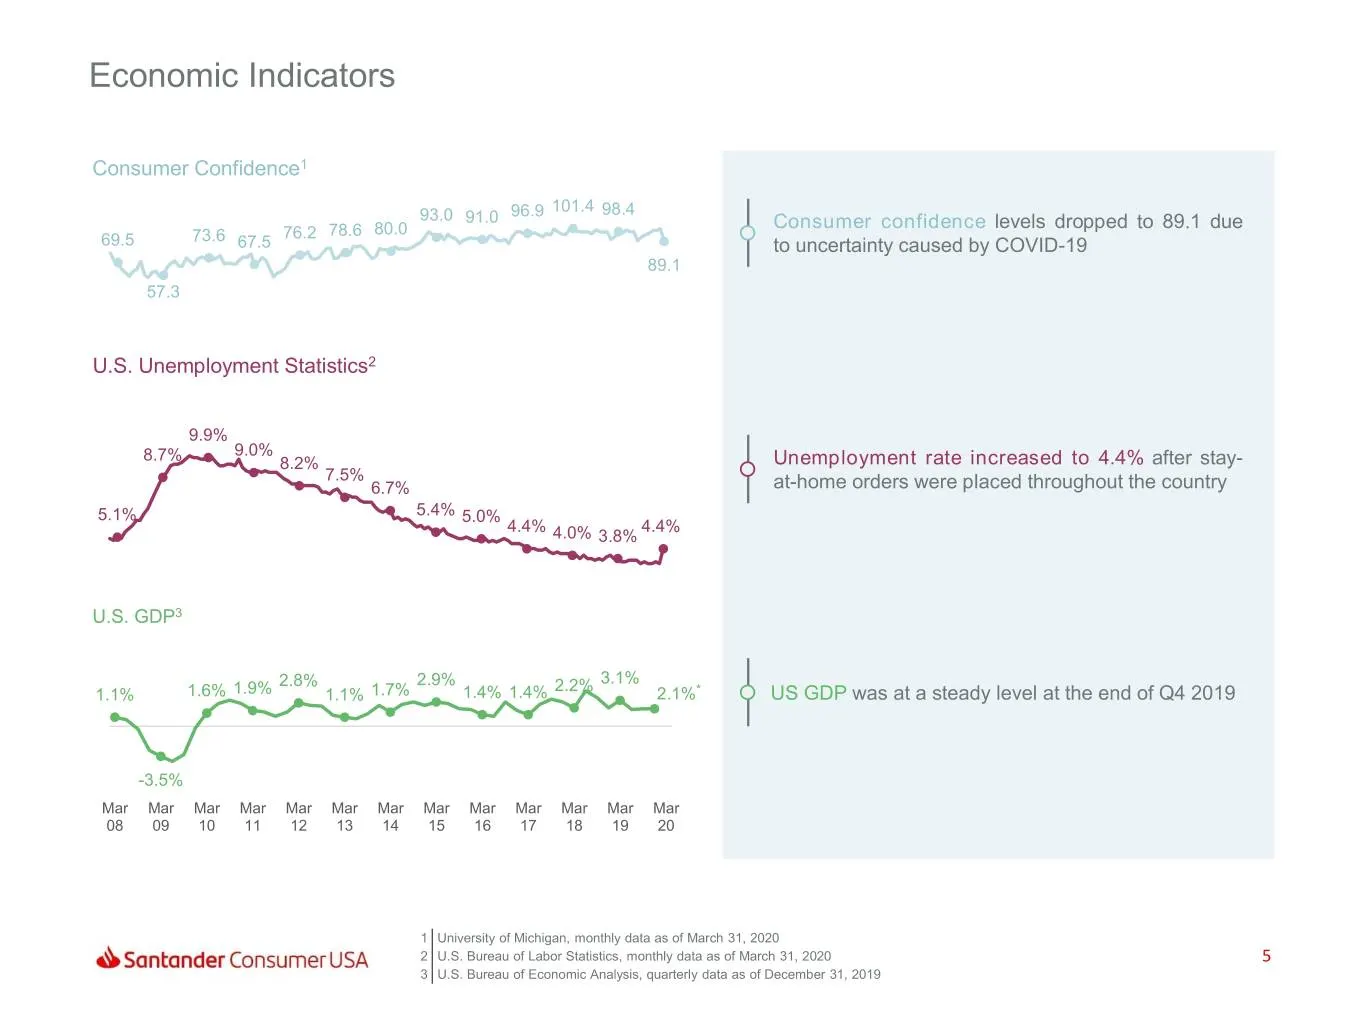
Economic Indicators Consumer Confidence1 96.9 101.4 98.4 93.0 91.0 Consumer confidence levels dropped to 89.1 due 76.2 78.6 80.0 69.5 73.6 67.5 to uncertainty caused by COVID-19 89.1 57.3 U.S. Unemployment Statistics2 9.9% 9.0% 8.7% 8.2% Unemployment rate increased to 4.4% after stay- 7.5% 6.7% at-h
Slide 6: Auto Industry Analysis
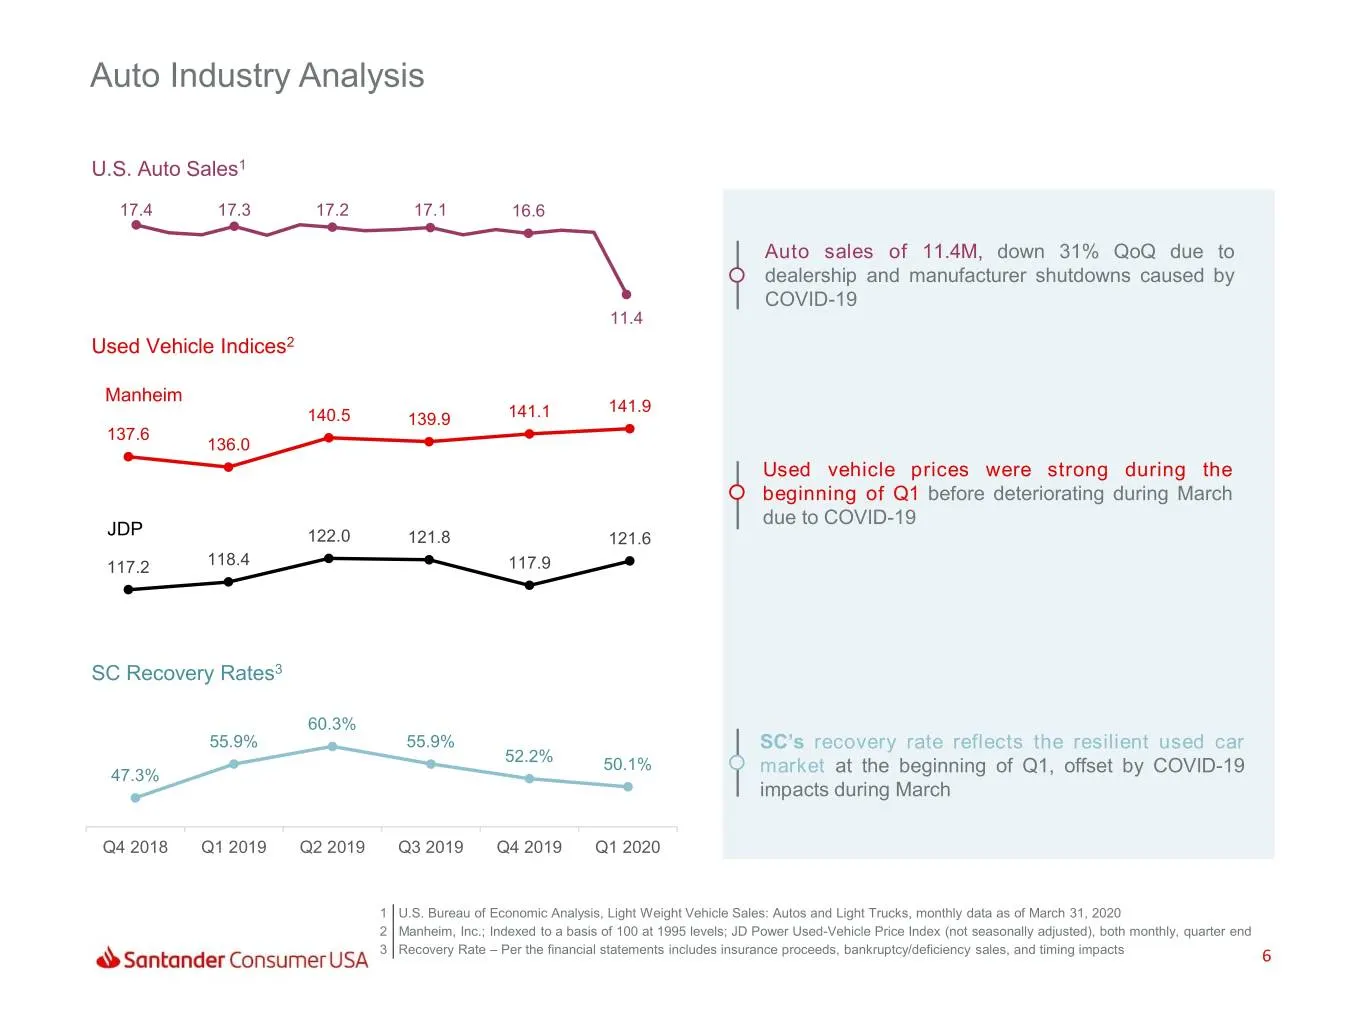
Auto Industry Analysis U.S. Auto Sales1 17.4 17.3 17.2 17.1 16.6 Auto sales of 11.4M, down 31% QoQ due to dealership and manufacturer shutdowns caused by COVID-19 11.4 Used Vehicle Indices2 Manheim 141.9 140.5 139.9 141.1 137.6 136.0 Used vehicle prices were strong during the beginning of Q1 before
Slide 7: Diversified Underwriting Across the Credit Spectrum
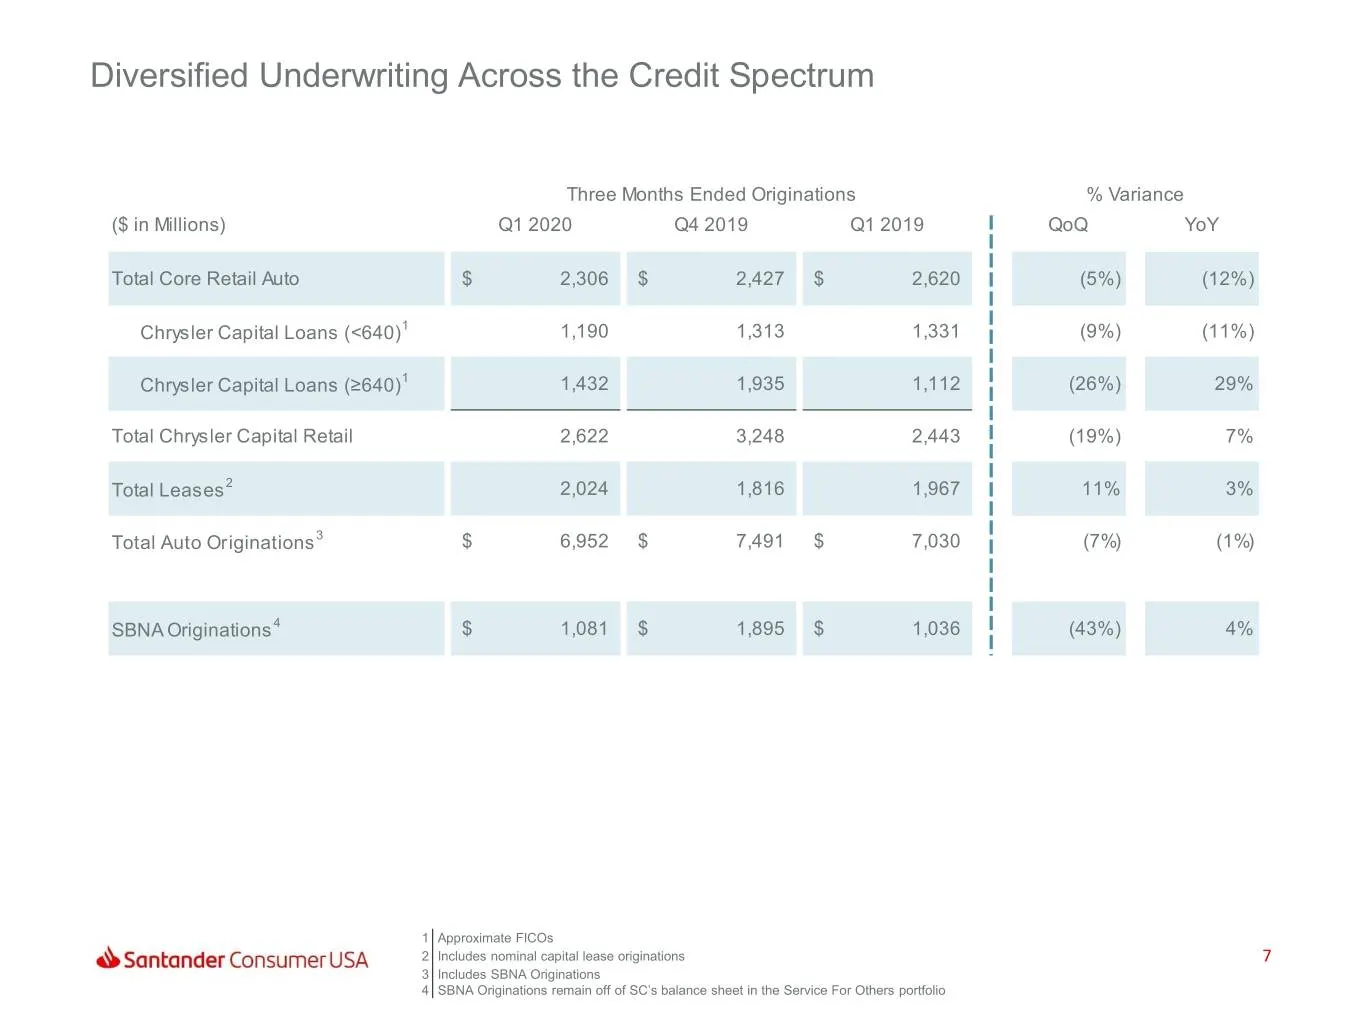
Diversified Underwriting Across the Credit Spectrum Three Months Ended Originations % Variance ($ in Millions) Q1 2020 Q4 2019 Q1 2019 QoQ YoY Total Core Retail Auto $ 2,306 $ 2,427 $ 2,620 (5%) (12%) Chrysler Capital Loans (<640)1 1,190 1,313 1,331 (9%) (11%) Chrysler Capital Loans (≥640)1 1,432 1,
Slide 8: Fiat Chrysler (FCA) Relationship
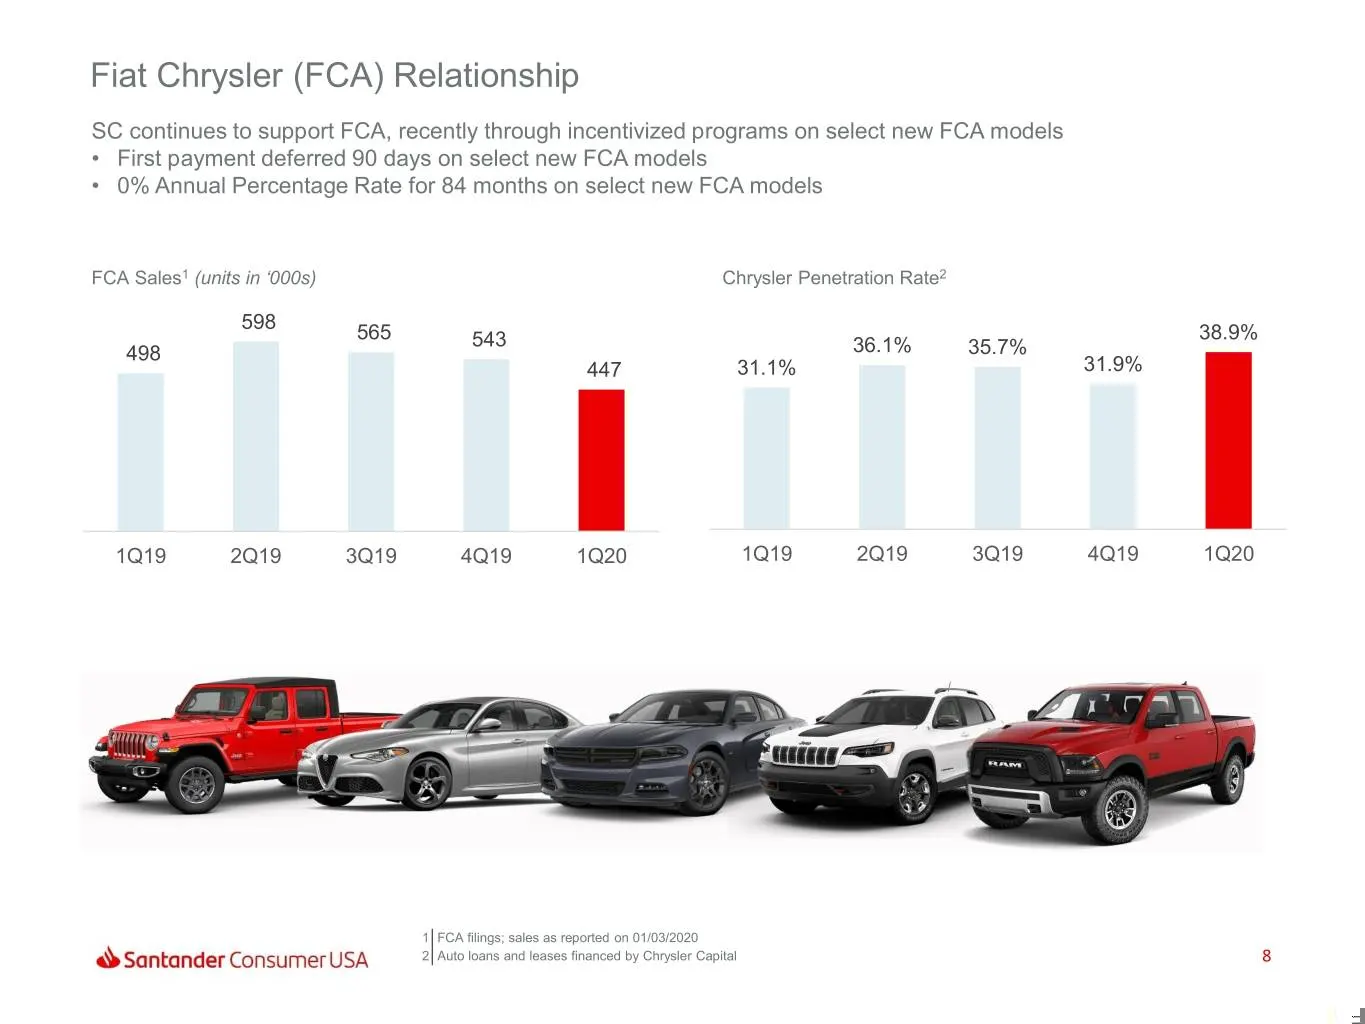
Fiat Chrysler (FCA) Relationship SC continues to support FCA, recently through incentivized programs on select new FCA models • First payment deferred 90 days on select new FCA models • 0% Annual Percentage Rate for 84 months on select new FCA models FCA Sales1 (units in ‘000s) Chrysler Penetration
Slide 9: Serviced for Others (SFO) Platform
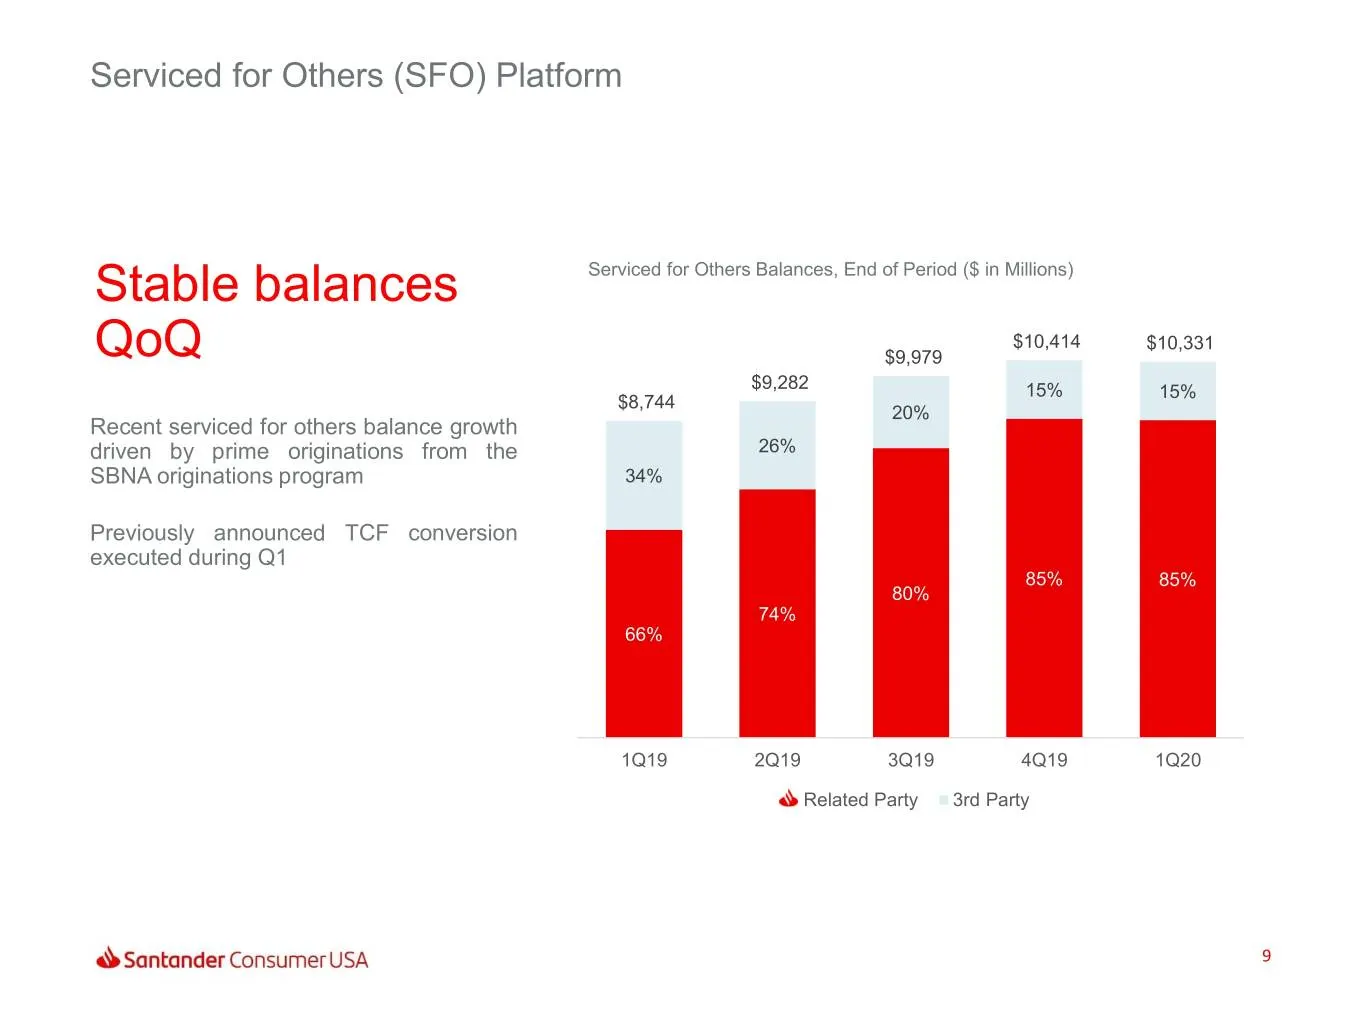
Serviced for Others (SFO) Platform Stable balances Serviced for Others Balances, End of Period ($ in Millions) $10,414 $10,331 QoQ $9,979 $9,282 15% 15% $8,744 20% Recent serviced for others balance growth driven by prime originations from the 26% SBNA originations program 34% Previously announced T
Slide 10: Funding and Liquidity
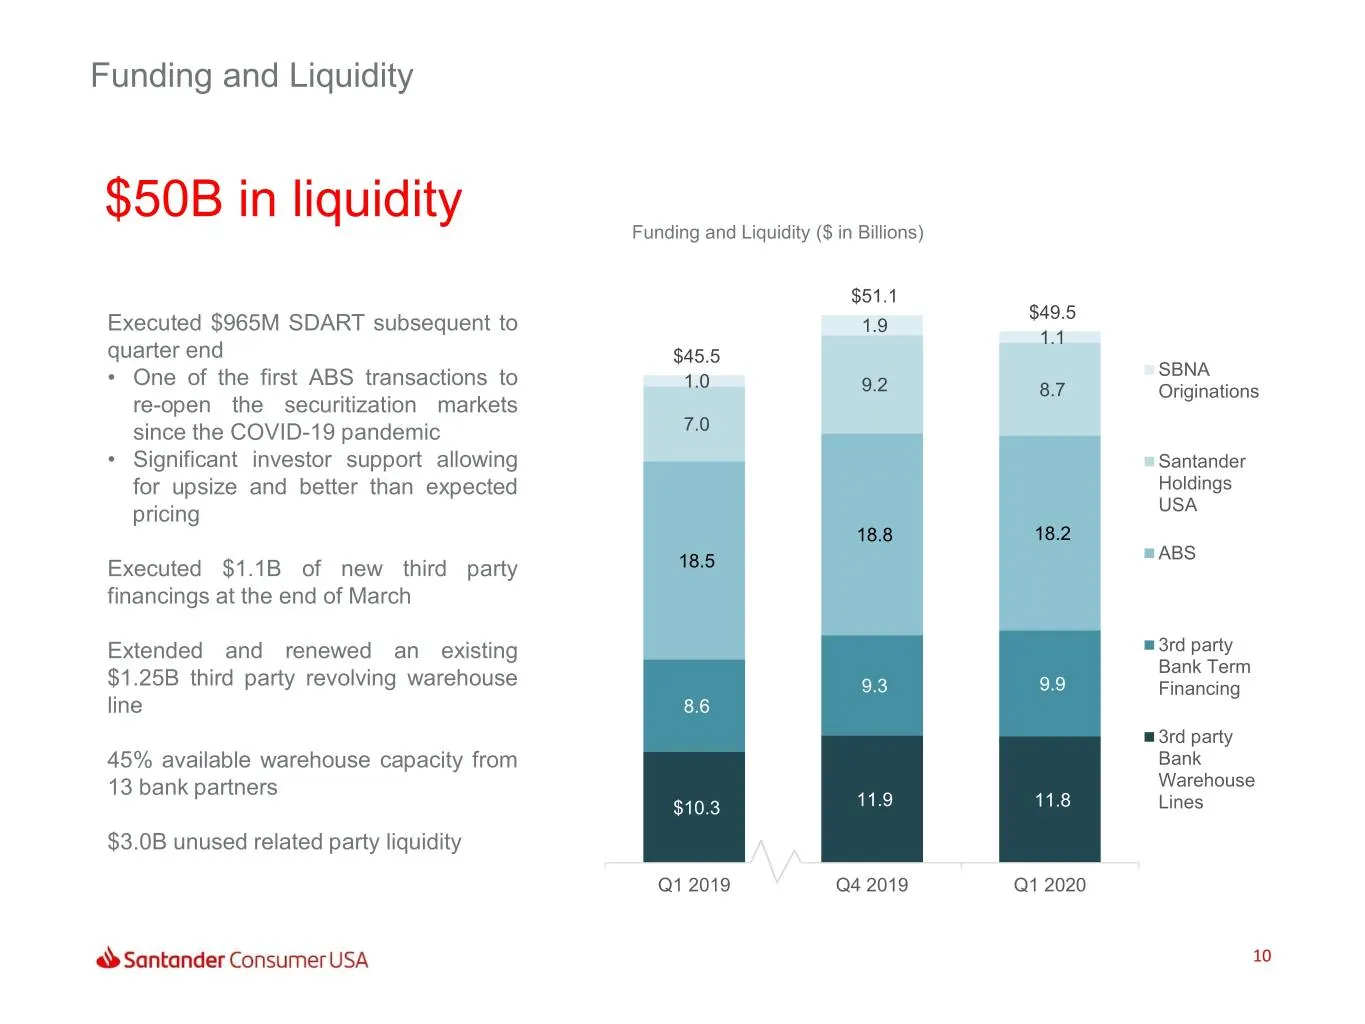
Funding and Liquidity $50B in liquidity Funding and Liquidity ($ in Billions) $51.1 $49.5 Executed $965M SDART subsequent to 1.9 1.1 quarter end $45.5 SBNA • One of the first ABS transactions to 1.0 9.2 8.7 Originations re-open the securitization markets since the COVID-19 pandemic 7.0 • Significant
Slide 11: Q1 2020 Financial Results
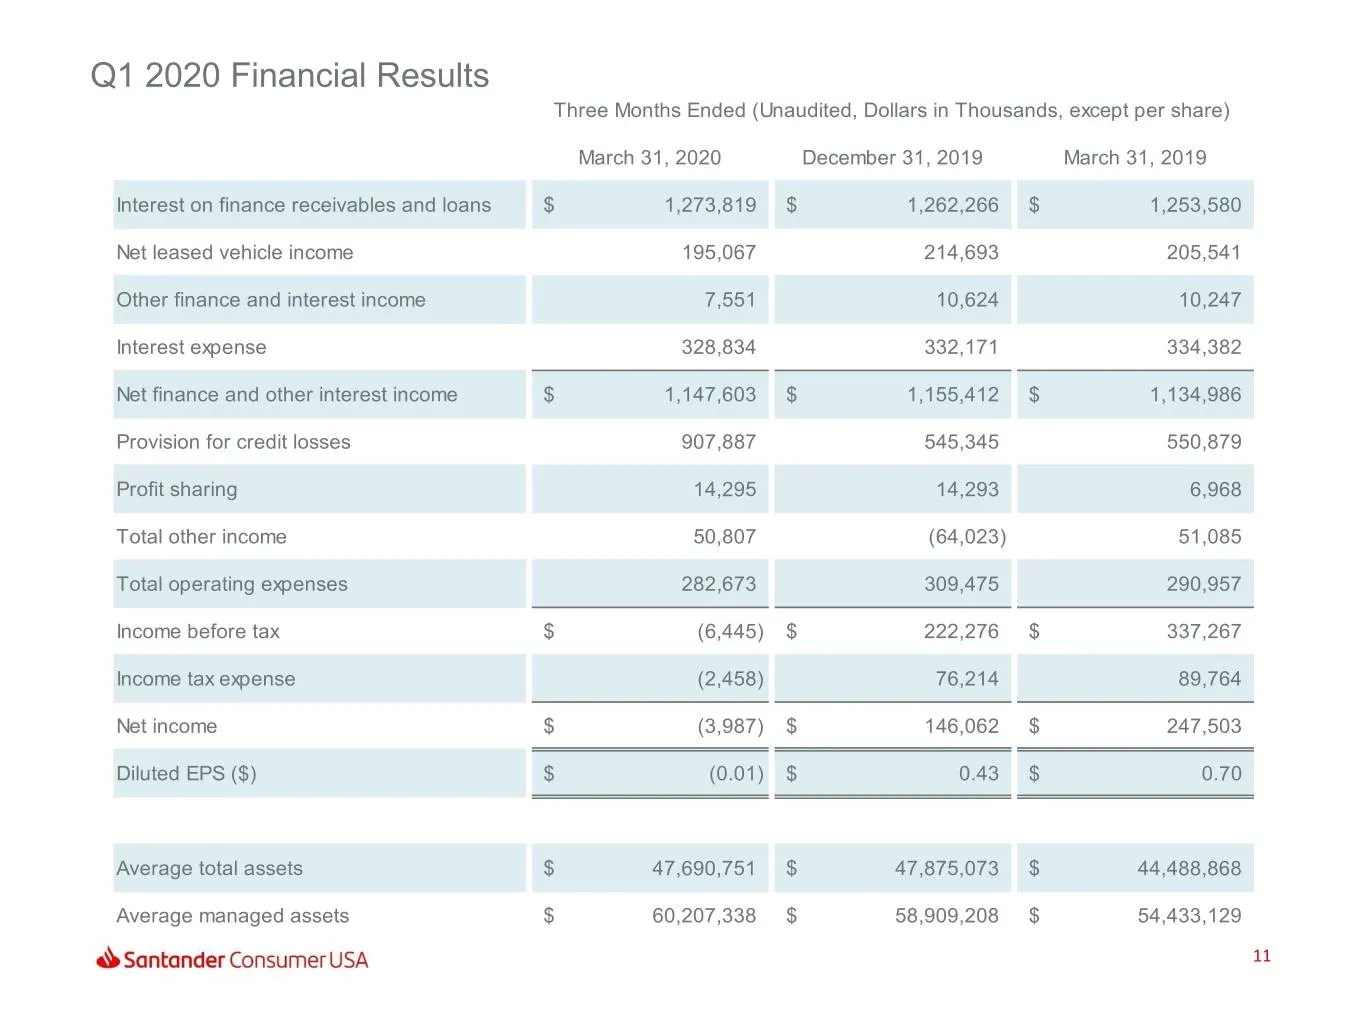
Q1 2020 Financial Results Three Months Ended (Unaudited, Dollars in Thousands, except per share) March 31, 2020 December 31, 2019 March 31, 2019 Interest on finance receivables and loans $ 1,273,819 $ 1,262,266 $ 1,253,580 Net leased vehicle income 195,067 214,693 205,541 Other finance and interest
Slide 12: Delinquency & Loss
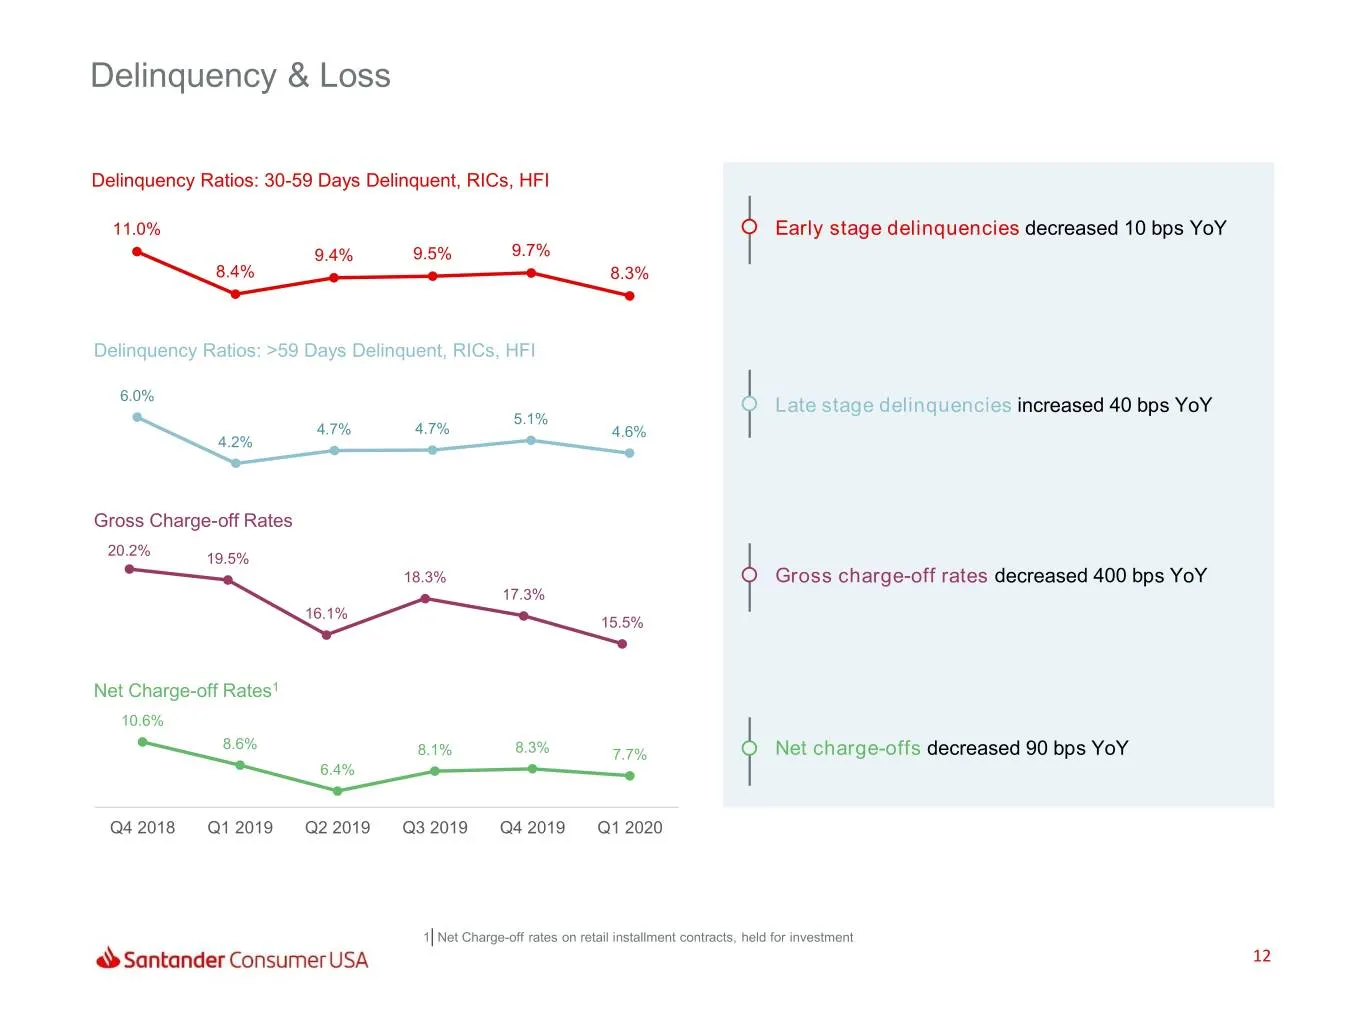
Delinquency & Loss Delinquency Ratios: 30-59 Days Delinquent, RICs, HFI 11.0% Early stage delinquencies decreased 10 bps YoY 9.4% 9.5% 9.7% 8.4% 8.3% Delinquency Ratios: >59 Days Delinquent, RICs, HFI 6.0% Late stage delinquencies increased 40 bps YoY 5.1% 4.7% 4.7% 4.6% 4.2% Gross Charge-off Rates
Slide 13: Loss Detail
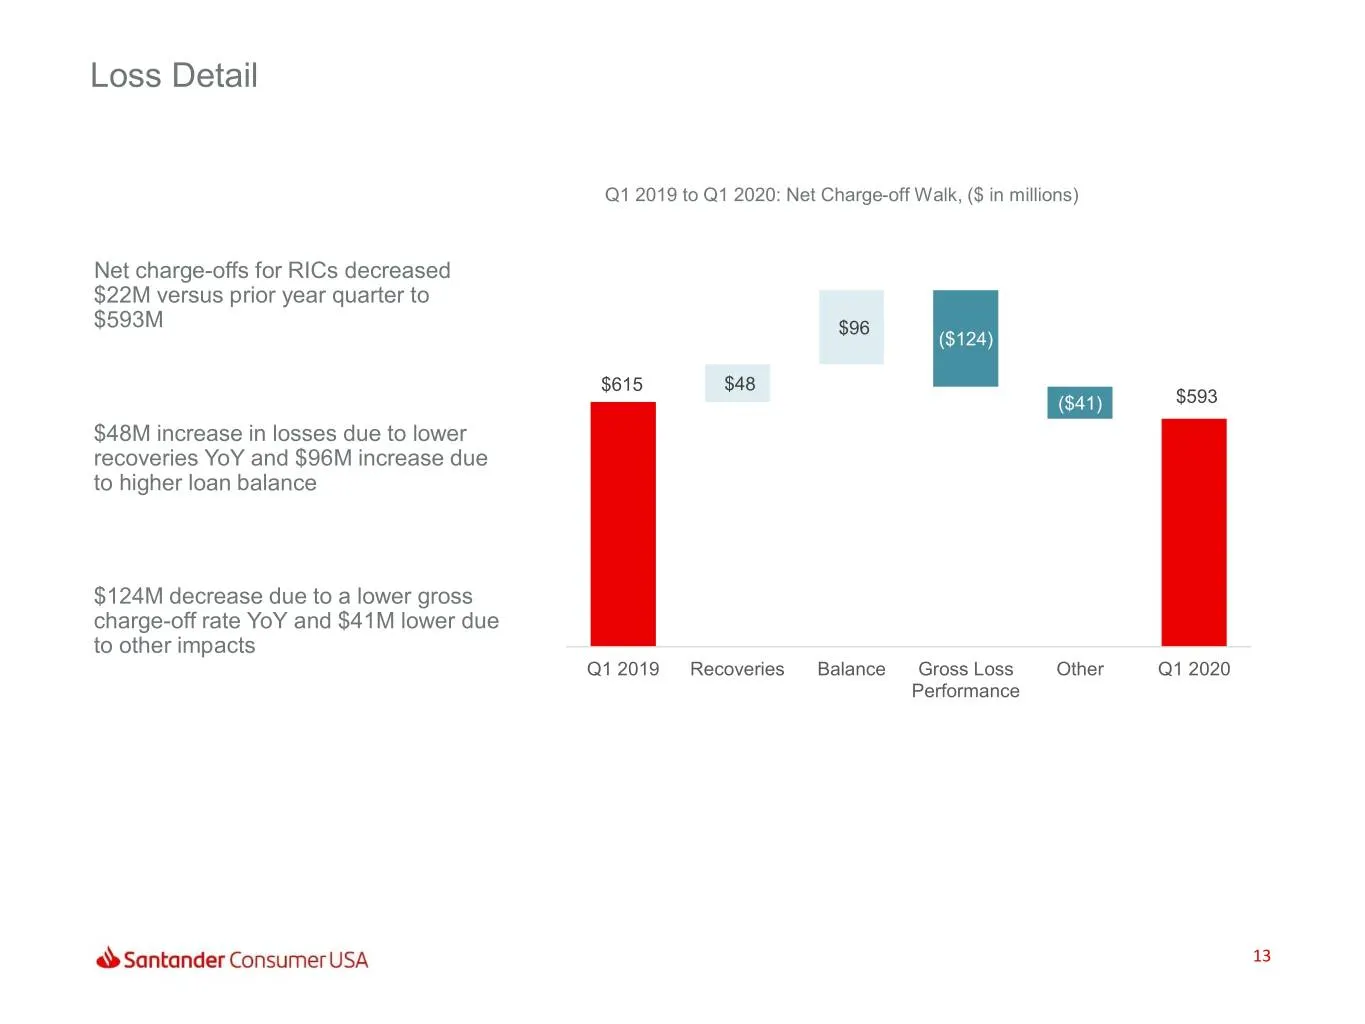
Loss Detail Q1 2019 to Q1 2020: Net Charge-off Walk, ($ in millions) Net charge-offs for RICs decreased $22M versus prior year quarter to $593M $96 ($124) $615 $48 ($41) $593 $48M increase in losses due to lower recoveries YoY and $96M increase due to higher loan balance $124M decrease due to a lowe
Slide 14: Reserves
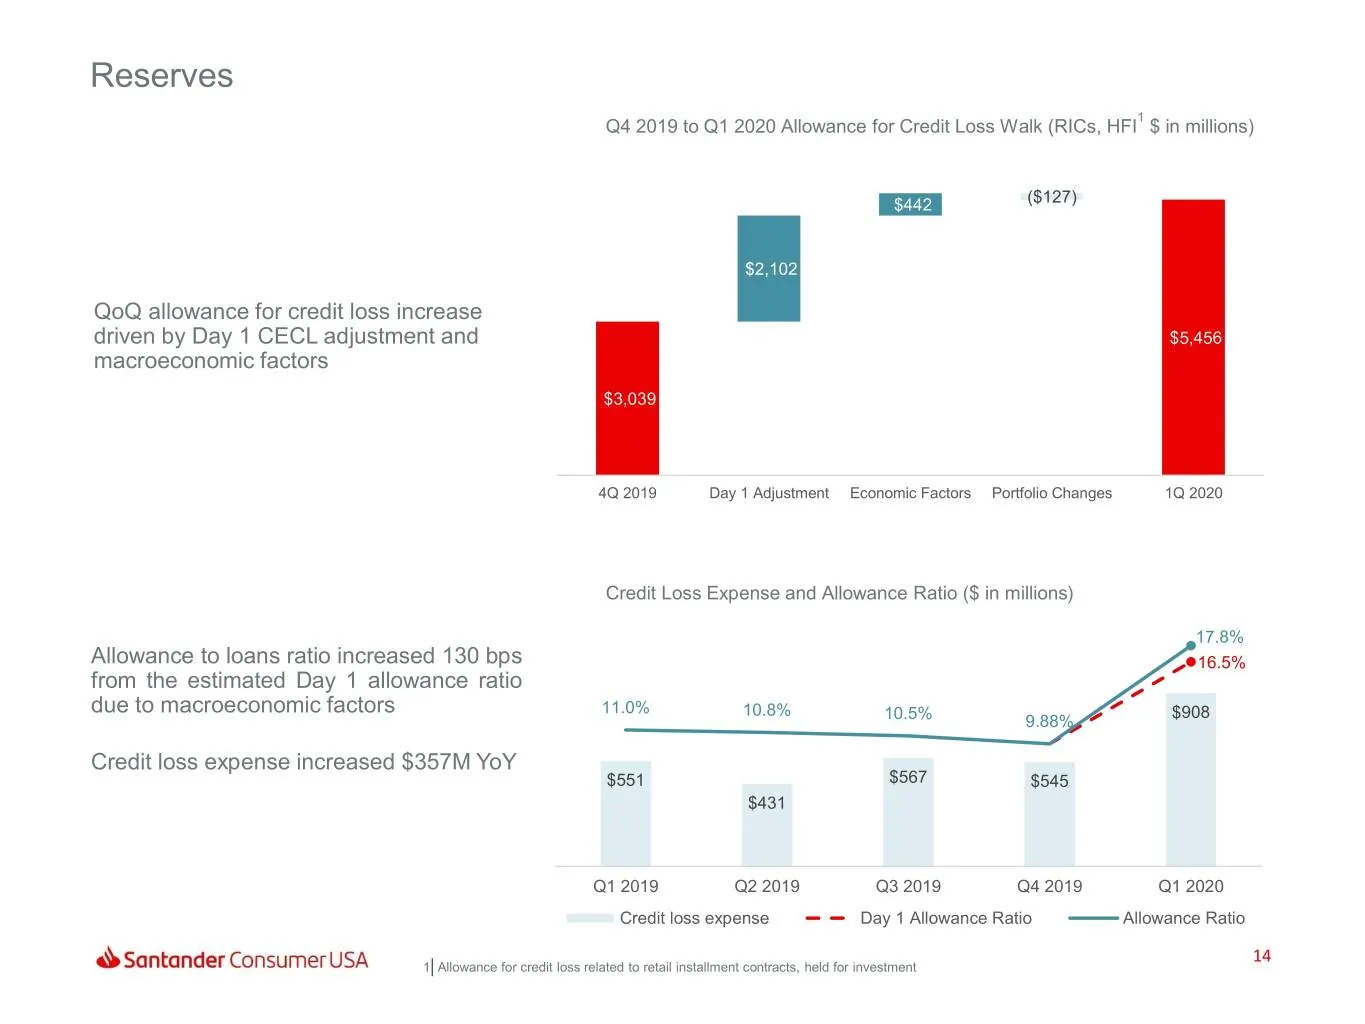
Reserves 1 Q4 2019 to Q1 2020 Allowance for Credit Loss Walk (RICs, HFI $ in millions) $442 ($127) $2,102 QoQ allowance for credit loss increase driven by Day 1 CECL adjustment and $5,141 $5,456 $5,456 macroeconomic factors $3,039 $3,039 4Q 2019 Day 1 Adjustment Economic Factors Portfolio Changes 1Q
Slide 15: Current Expected Credit Losses (CECL)
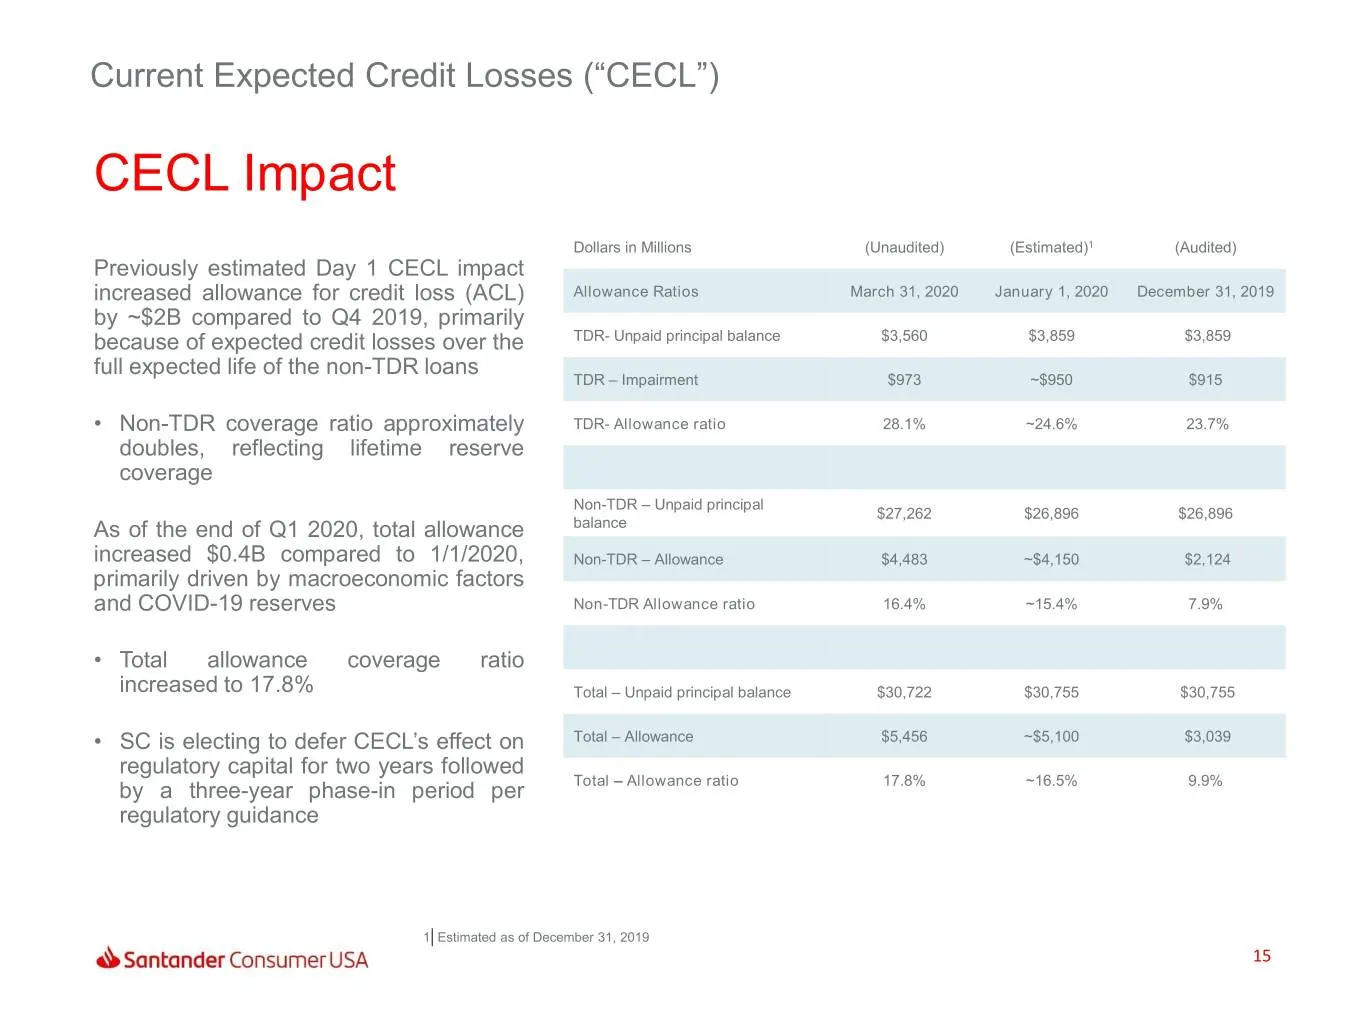
Current Expected Credit Losses (“CECL”) CECL Impact Dollars in Millions (Unaudited) (Estimated)1 (Audited) Previously estimated Day 1 CECL impact increased allowance for credit loss (ACL) Allowance Ratios March 31, 2020 January 1, 2020 December 31, 2019 by ~$2B compared to Q4 2019, primarily because
Slide 16: Expense Management
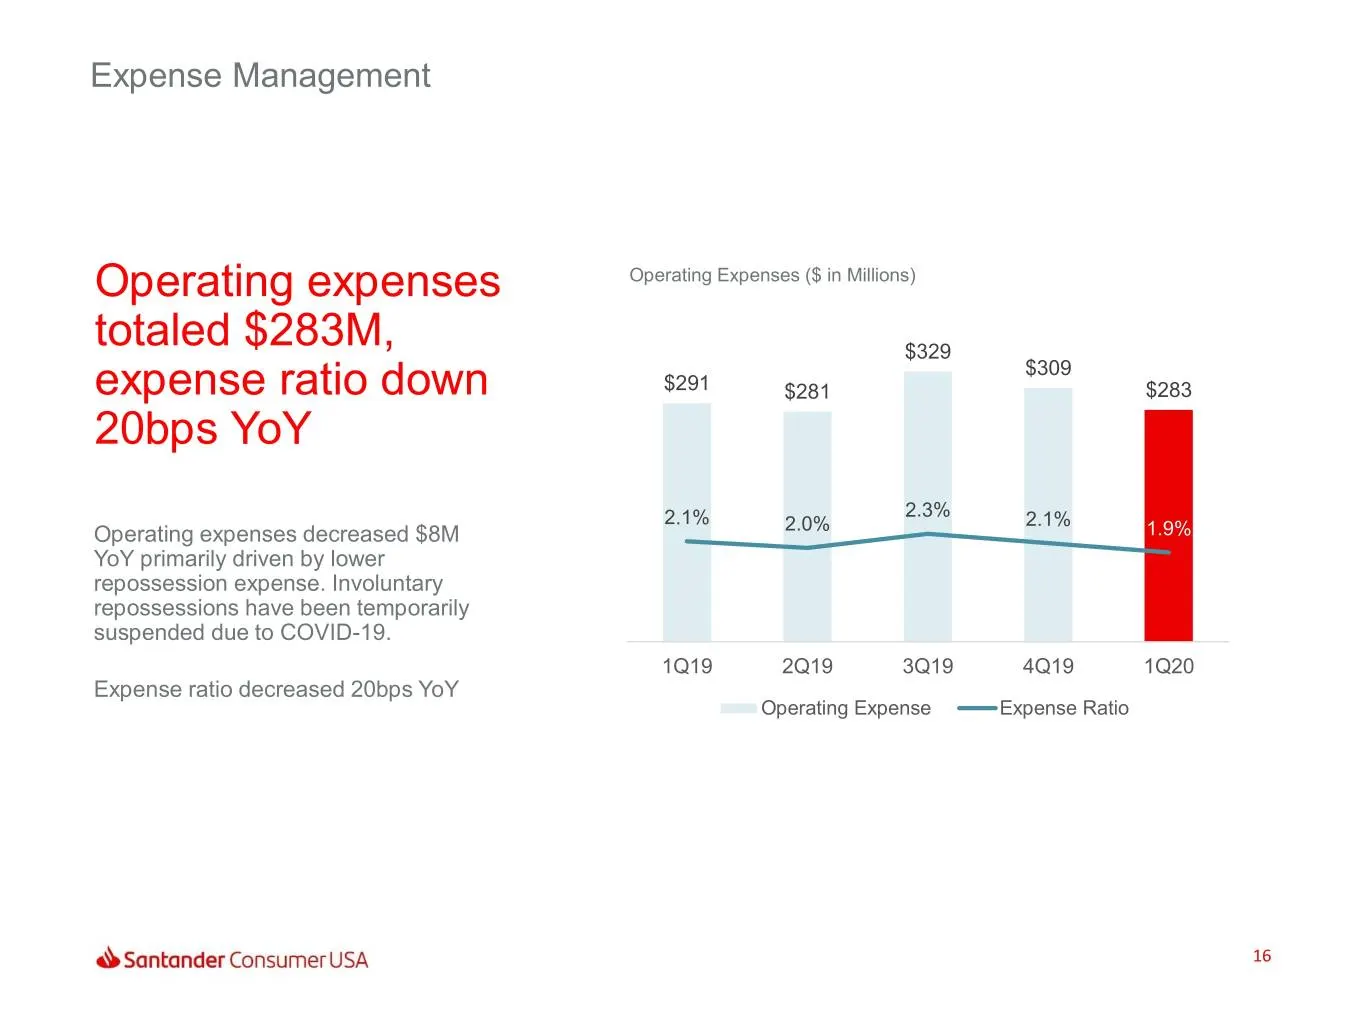
Expense Management Operating expenses Operating Expenses ($ in Millions) totaled $283M, $400 7.0% $350 $329 $309 6.0% $291 expense ratio down $300 $281 $283 5.0% 20bps YoY $250 4.0% $200 2.3% 3.0% $150 2.1% 2.1% Operating expenses decreased $8M 2.0% 1.9% 2.0% YoY primarily driven by lower $100 repos
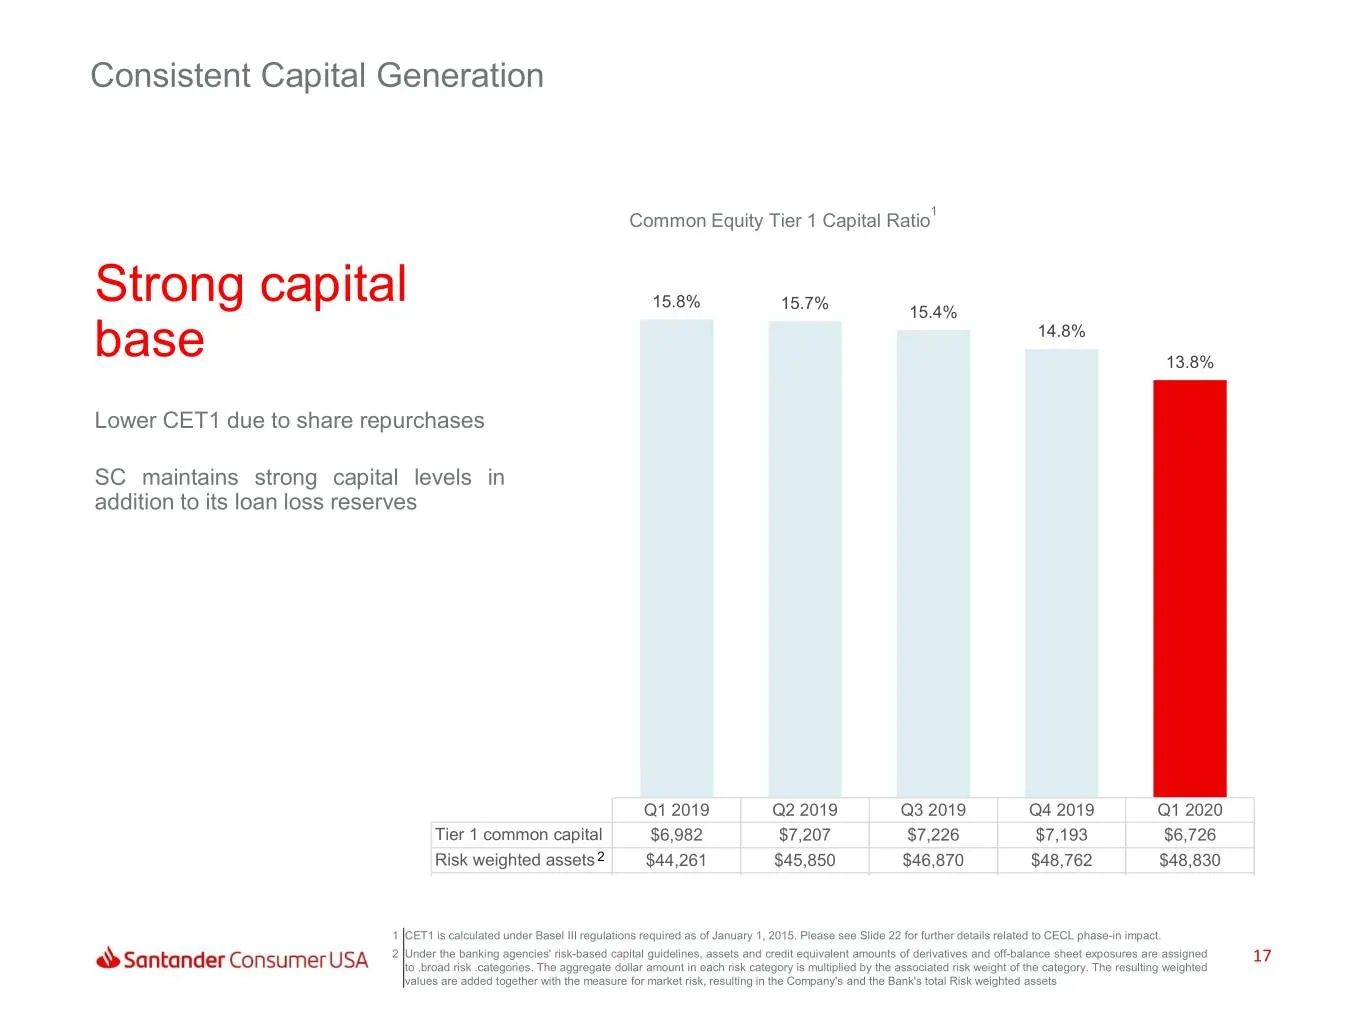
Slide 17: Consistent Capital Generation
Consistent Capital Generation 1 Common Equity Tier 1 Capital Ratio $120,000 18.0% Strong capital 15.8% 15.7% 15.4% 16.0% 14.8% $110,000 base 13.8% 14.0% Lower CET1 due to share repurchases $100,000 12.0% SC maintains strong capital levels in addition to its loan loss reserves 10.0% $90,000 8.0% $80,
Slide 18: Appendix
Appendix
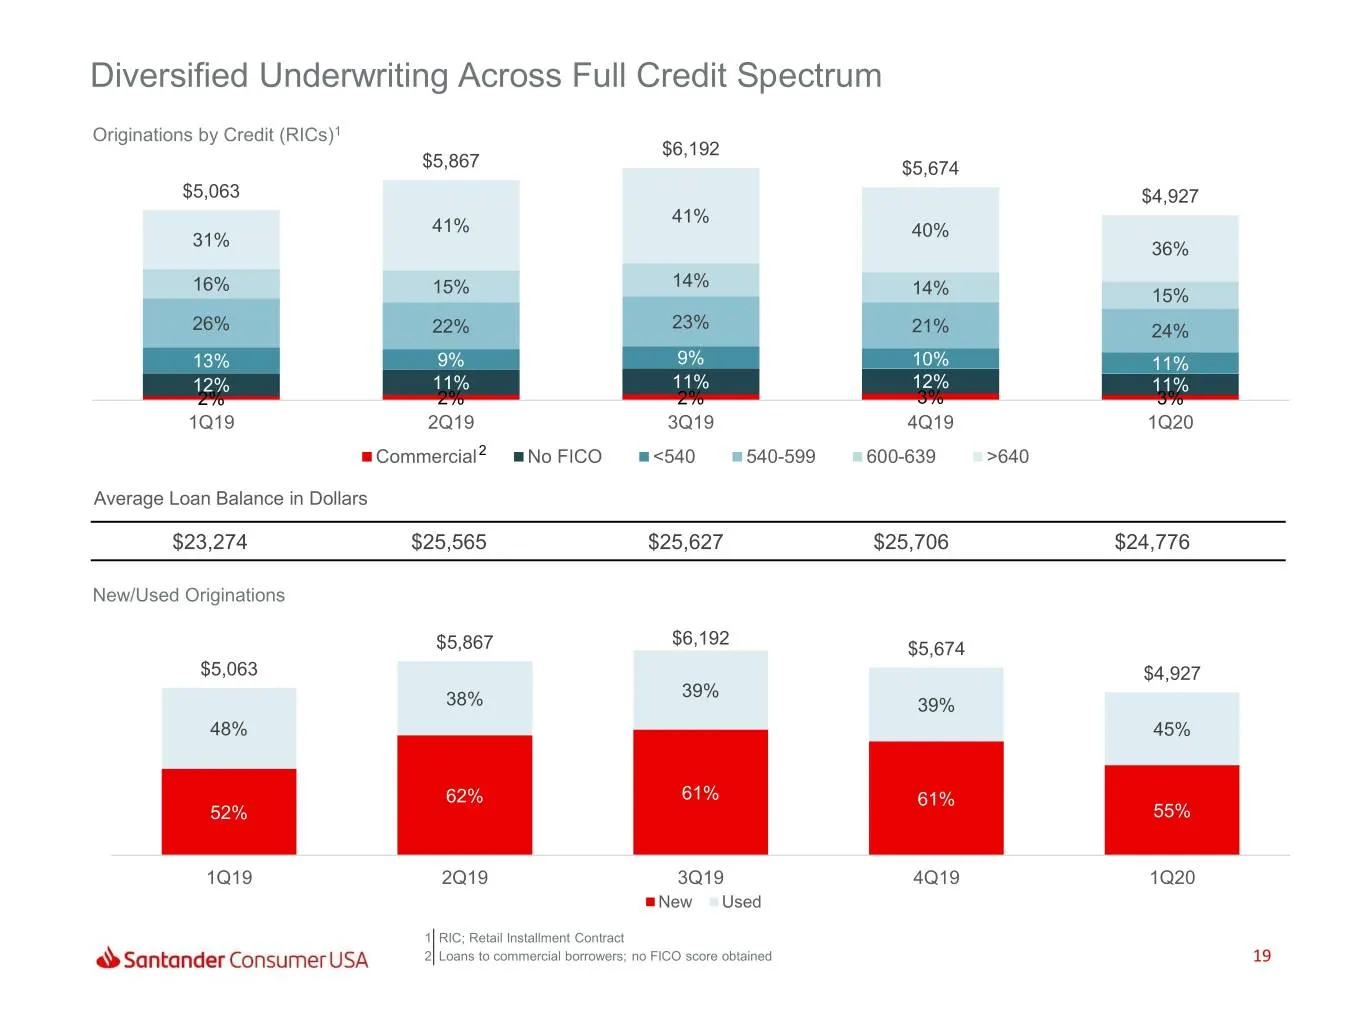
Slide 19: Diversified Underwriting Across Full Credit Spectrum
Diversified Underwriting Across Full Credit Spectrum Originations by Credit (RICs)1 $6,192 $5,867 $5,674 $5,063 $4,927 41% 41% 40% 31% 36% 16% 14% 15% 14% 15% 26% 22% 23% 21% 24% 13% 9% 9% 10% 11% 12% 11% 11% 12% 11% 2% 2% 2% 3% 3% 1Q19 2Q19 3Q19 4Q19 1Q20 Commercial 2 No FICO <540 540-599 600-639 >
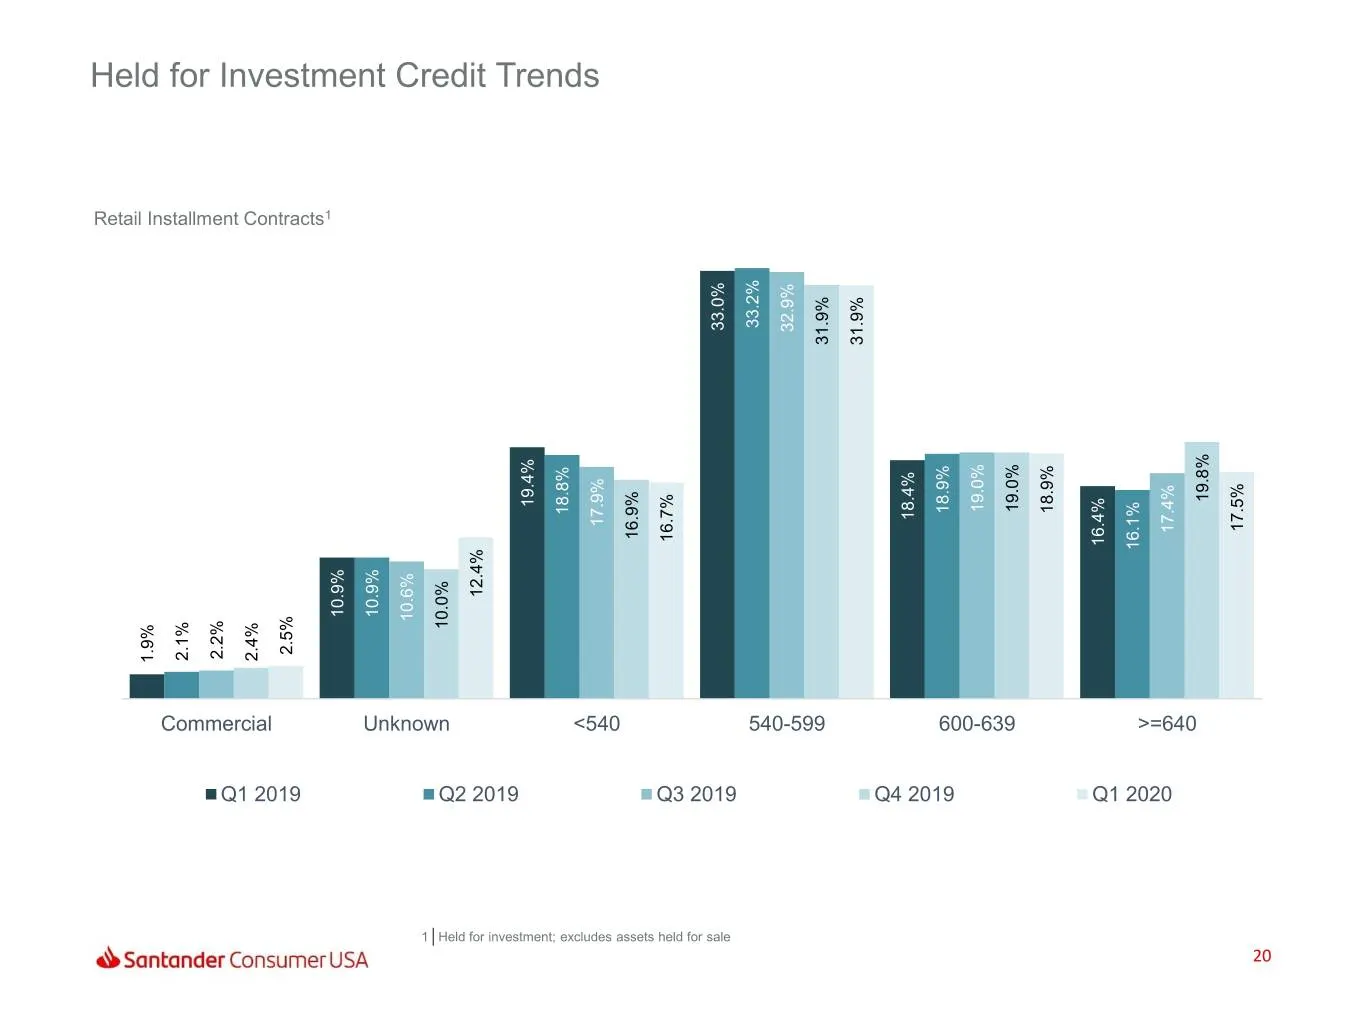
Slide 20: Held for Investment Credit Trends
Heldfor Investment Credit Trends Retail Installment RetailInstallment Contracts 1.9% Commercial 2.1% Q1 2019 2.2% 2.4% 2.5% 1 10.9% Unknown 10.9% 10.6% 1 Held for investment; excludes assets held for sale forheld assets excludes investment; Held for Q2 2019 10.0% 12.4% 19.4% 18.8% <540 17.9% 16.9% Q
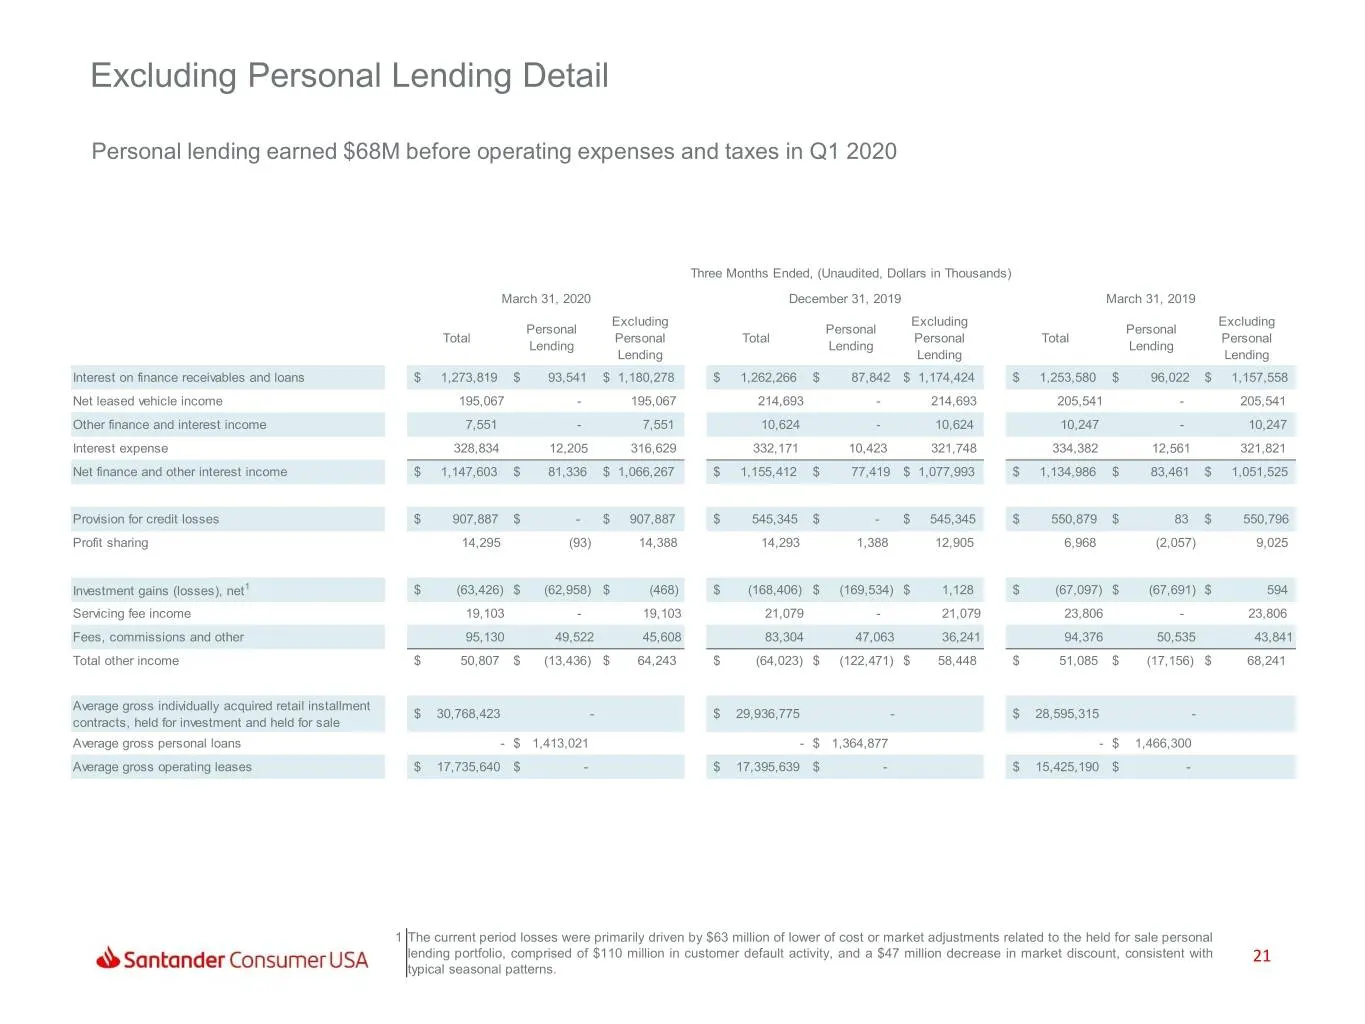
Slide 21: Excluding Personal Lending Detail
Excluding Personal Lending Detail Personal lending earned $68M before operating expenses and taxes in Q1 2020 Three Months Ended, (Unaudited, Dollars in Thousands) March 31, 2020 December 31, 2019 March 31, 2019 Excluding Excluding Excluding Personal Personal Personal Total Personal Total Personal T
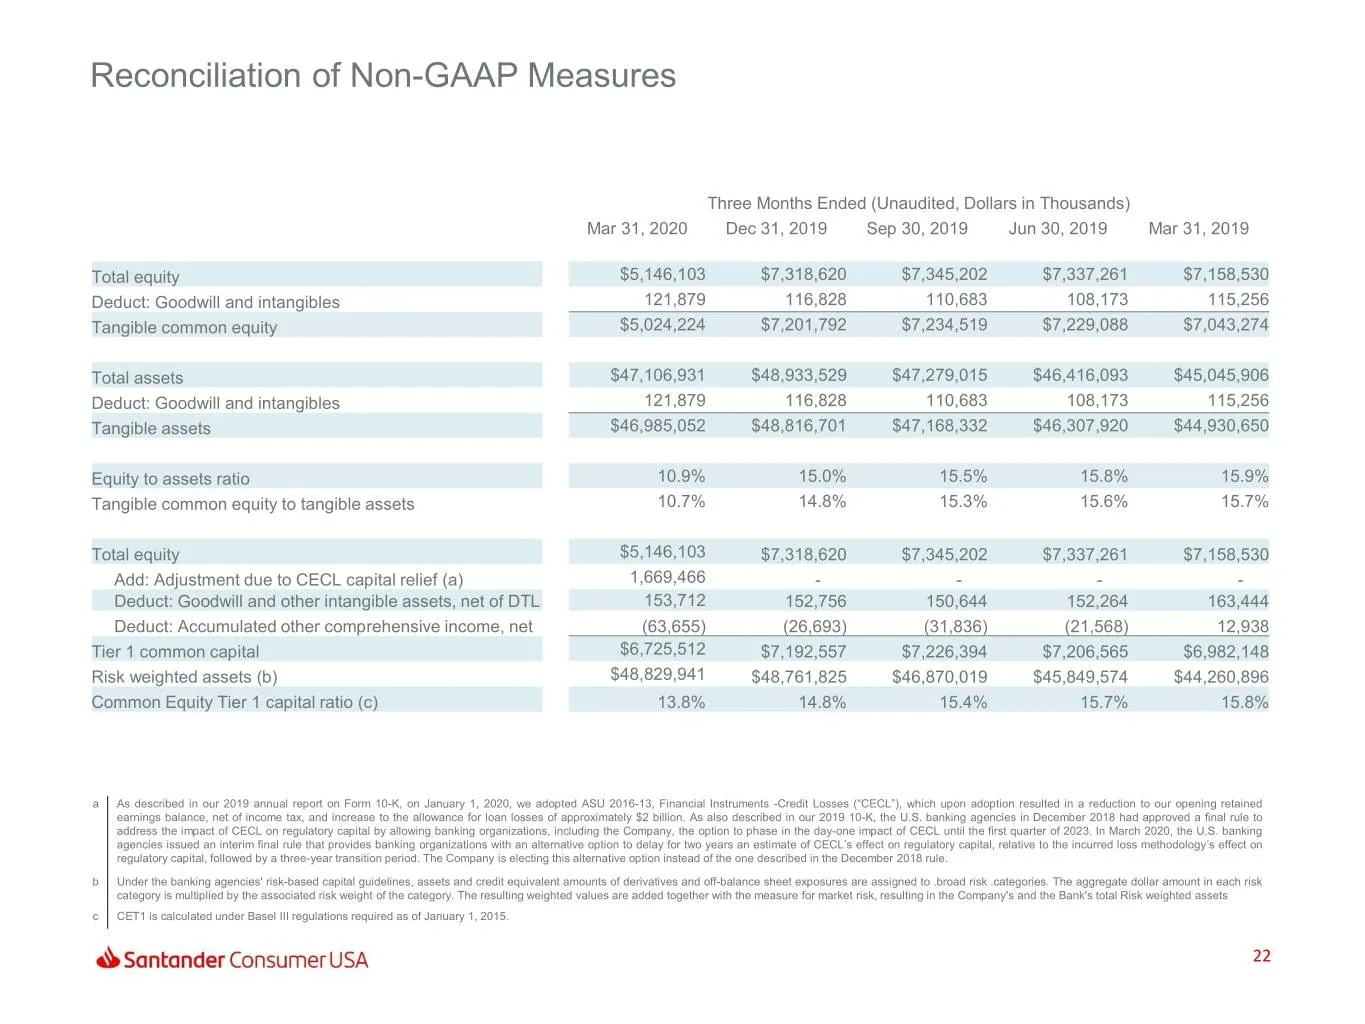
Slide 22: Reconciliation of Non-GAAP Measures
Reconciliation of Non-GAAP Measures Three Months Ended (Unaudited, Dollars in Thousands) Mar 31, 2020 Dec 31, 2019 Sep 30, 2019 Jun 30, 2019 Mar 31, 2019 Total equity $5,146,103 $7,318,620 $7,345,202 $7,337,261 $7,158,530 Deduct: Goodwill and intangibles 121,879 116,828 110,683 108,173 115,256 Tangi
Slide 23: Thank You
Thank You Our purpose is to help people and business prosper. Our culture is based on believing that everything we do should be:
Source: SEC EDGAR · 8-K filed Apr 28, 2020
More decks from Santander Consumer USA Holdings Inc
 Q3 2021 Earnings Presentation24 slides · Oct 27, 2021
 Q2 2021 Earnings Presentation24 slides · Jul 28, 2021
 Q1 2021 Earnings Presentation24 slides · Apr 28, 2021
 FY2020 Earnings Presentation28 slides · Feb 3, 2021
 Q3 2020 Earnings Presentation25 slides · Oct 28, 2020
 Q2 2020 Earnings Presentation26 slides · Jul 29, 2020