United Financial Bancorp — Rockville Financial — FIG Partners Analyst Meeting (February 2013)
39 slides from United Financial Bancorp's conference presentation, Feb 20, 2013
Slide 1: Transition to Success - FIG Partners Analyst Meeting
ExhibitFebruary Transition NASDAQ RCKB 99.1 •Global Values 20, Select • 2013 Success Market FIG Partners Analyst Meeting
Slide 2: Forward-Looking Statements
Forward This management and statements are update forward-looking With 2presented beyond future Presentation regard forward-looking Looking in or can involve our to this and conditional presentations be control nature presentation are contains Statements identified risks subject — we statements and
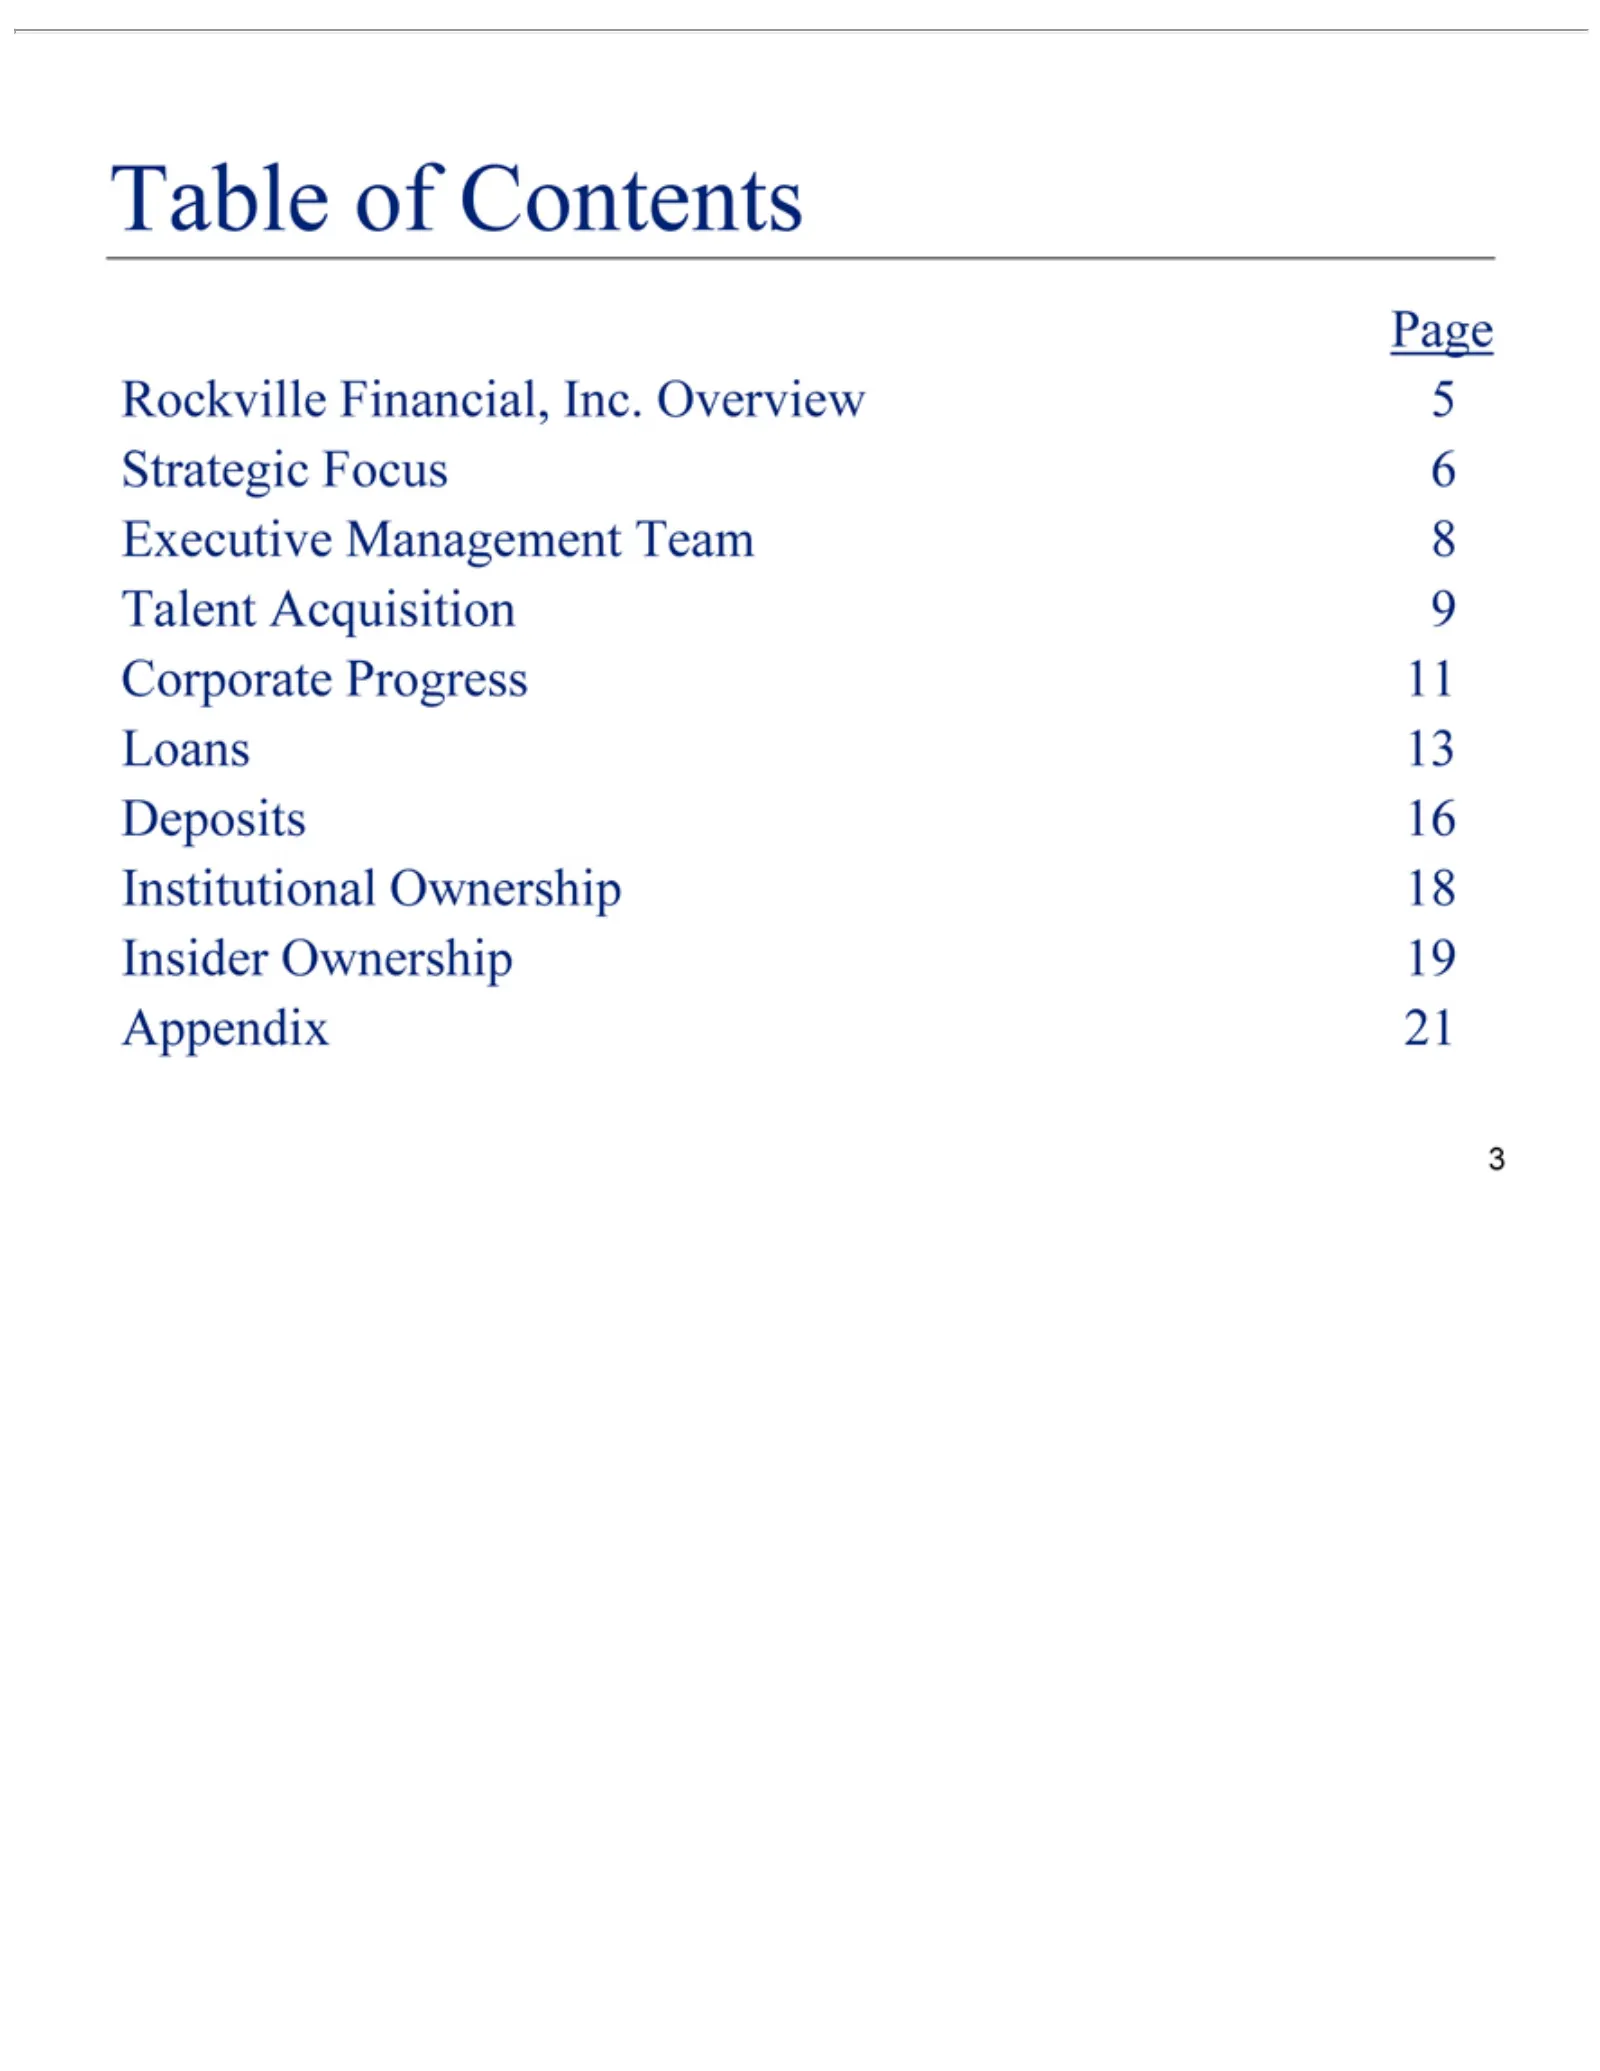
Slide 3: Table of Contents
Table of Rockville Page Strategic Executive Talent Corporate Loans Deposits Institutional Insider 3Appendix Acquisition 13Ownership Contents 16 Focus Financial, 21 Management Progress Ownership 6 919 11Inc.Team 18 Overview 8 5
Slide 4: Corporate Contacts
Corporate William President Scott John Mark Executive Eric Investor Senior 860-291-3622 R. T. C. A.Vice Newell Lund Bechtle H. Information: Kucia &Vice Contacts W. President, Chief or Crawford, President, [email protected] Executive Marliese Director Investor IV Chief Commercial Officer L. Rel
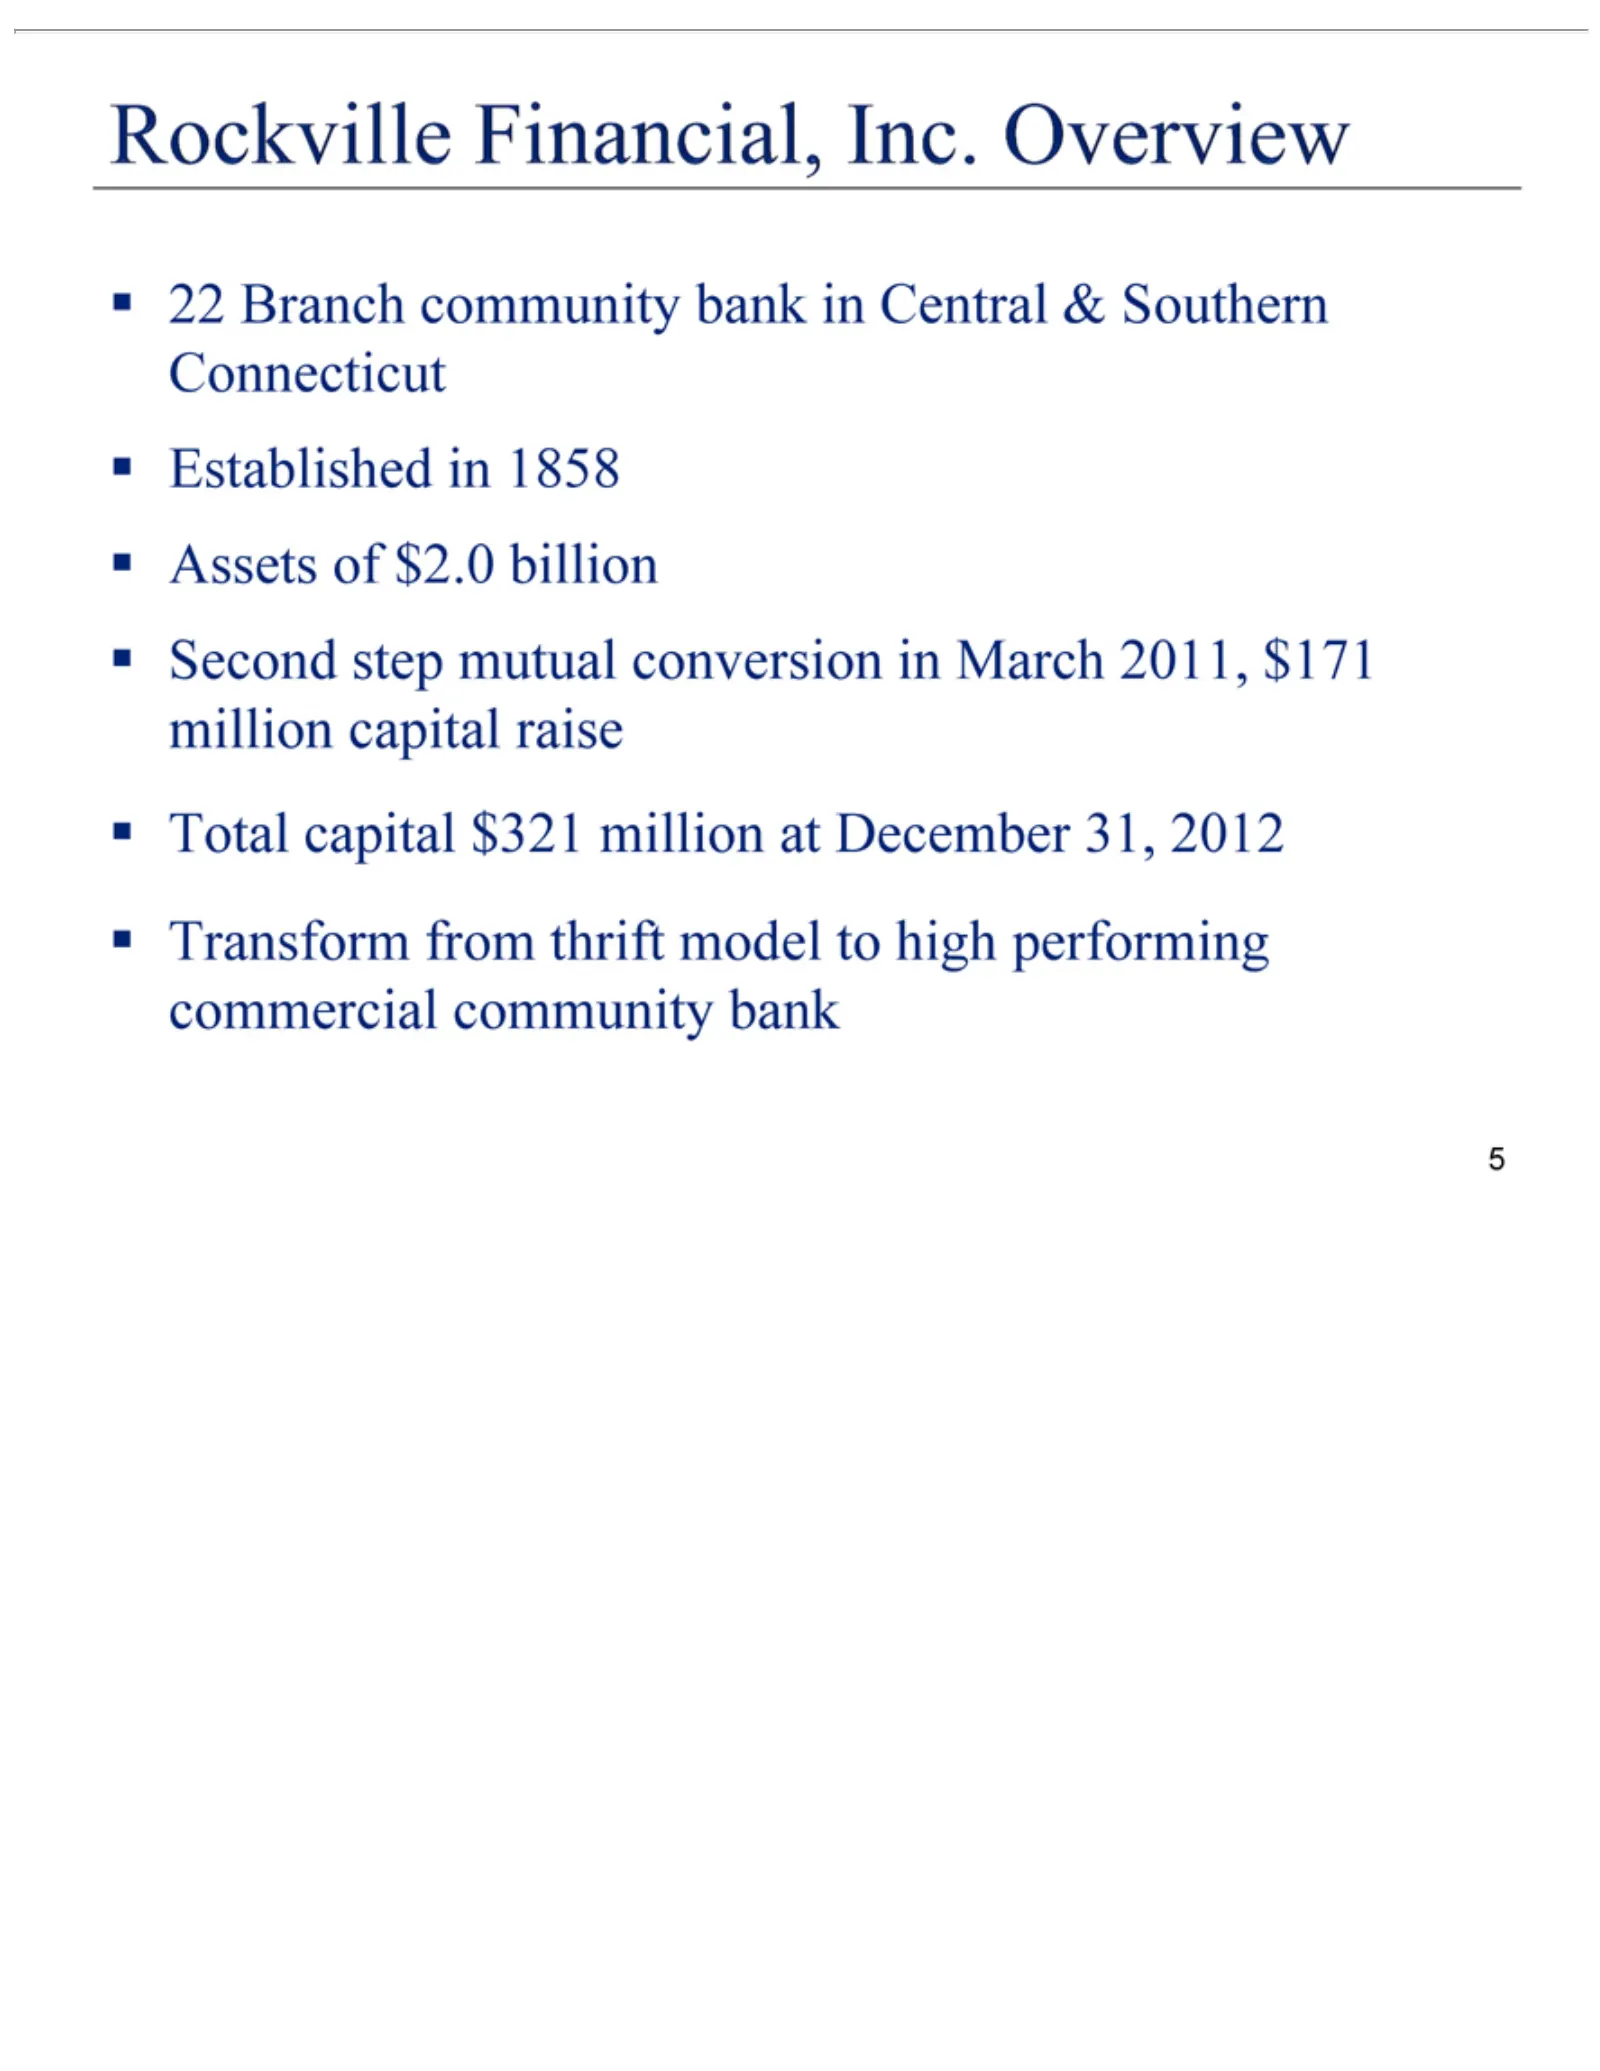
Slide 5: Rockville Financial, Inc. Overview
Rockville 22 5December BranchFinancial, 31, community 2012 Transform Inc. bank Overview in Central from thrift & Southern model toConnecticut high performing Established commercial in 1858 community Assets ofbank $2.0 billion Second step mutual conversion in March 2011, $171 million capital raise To
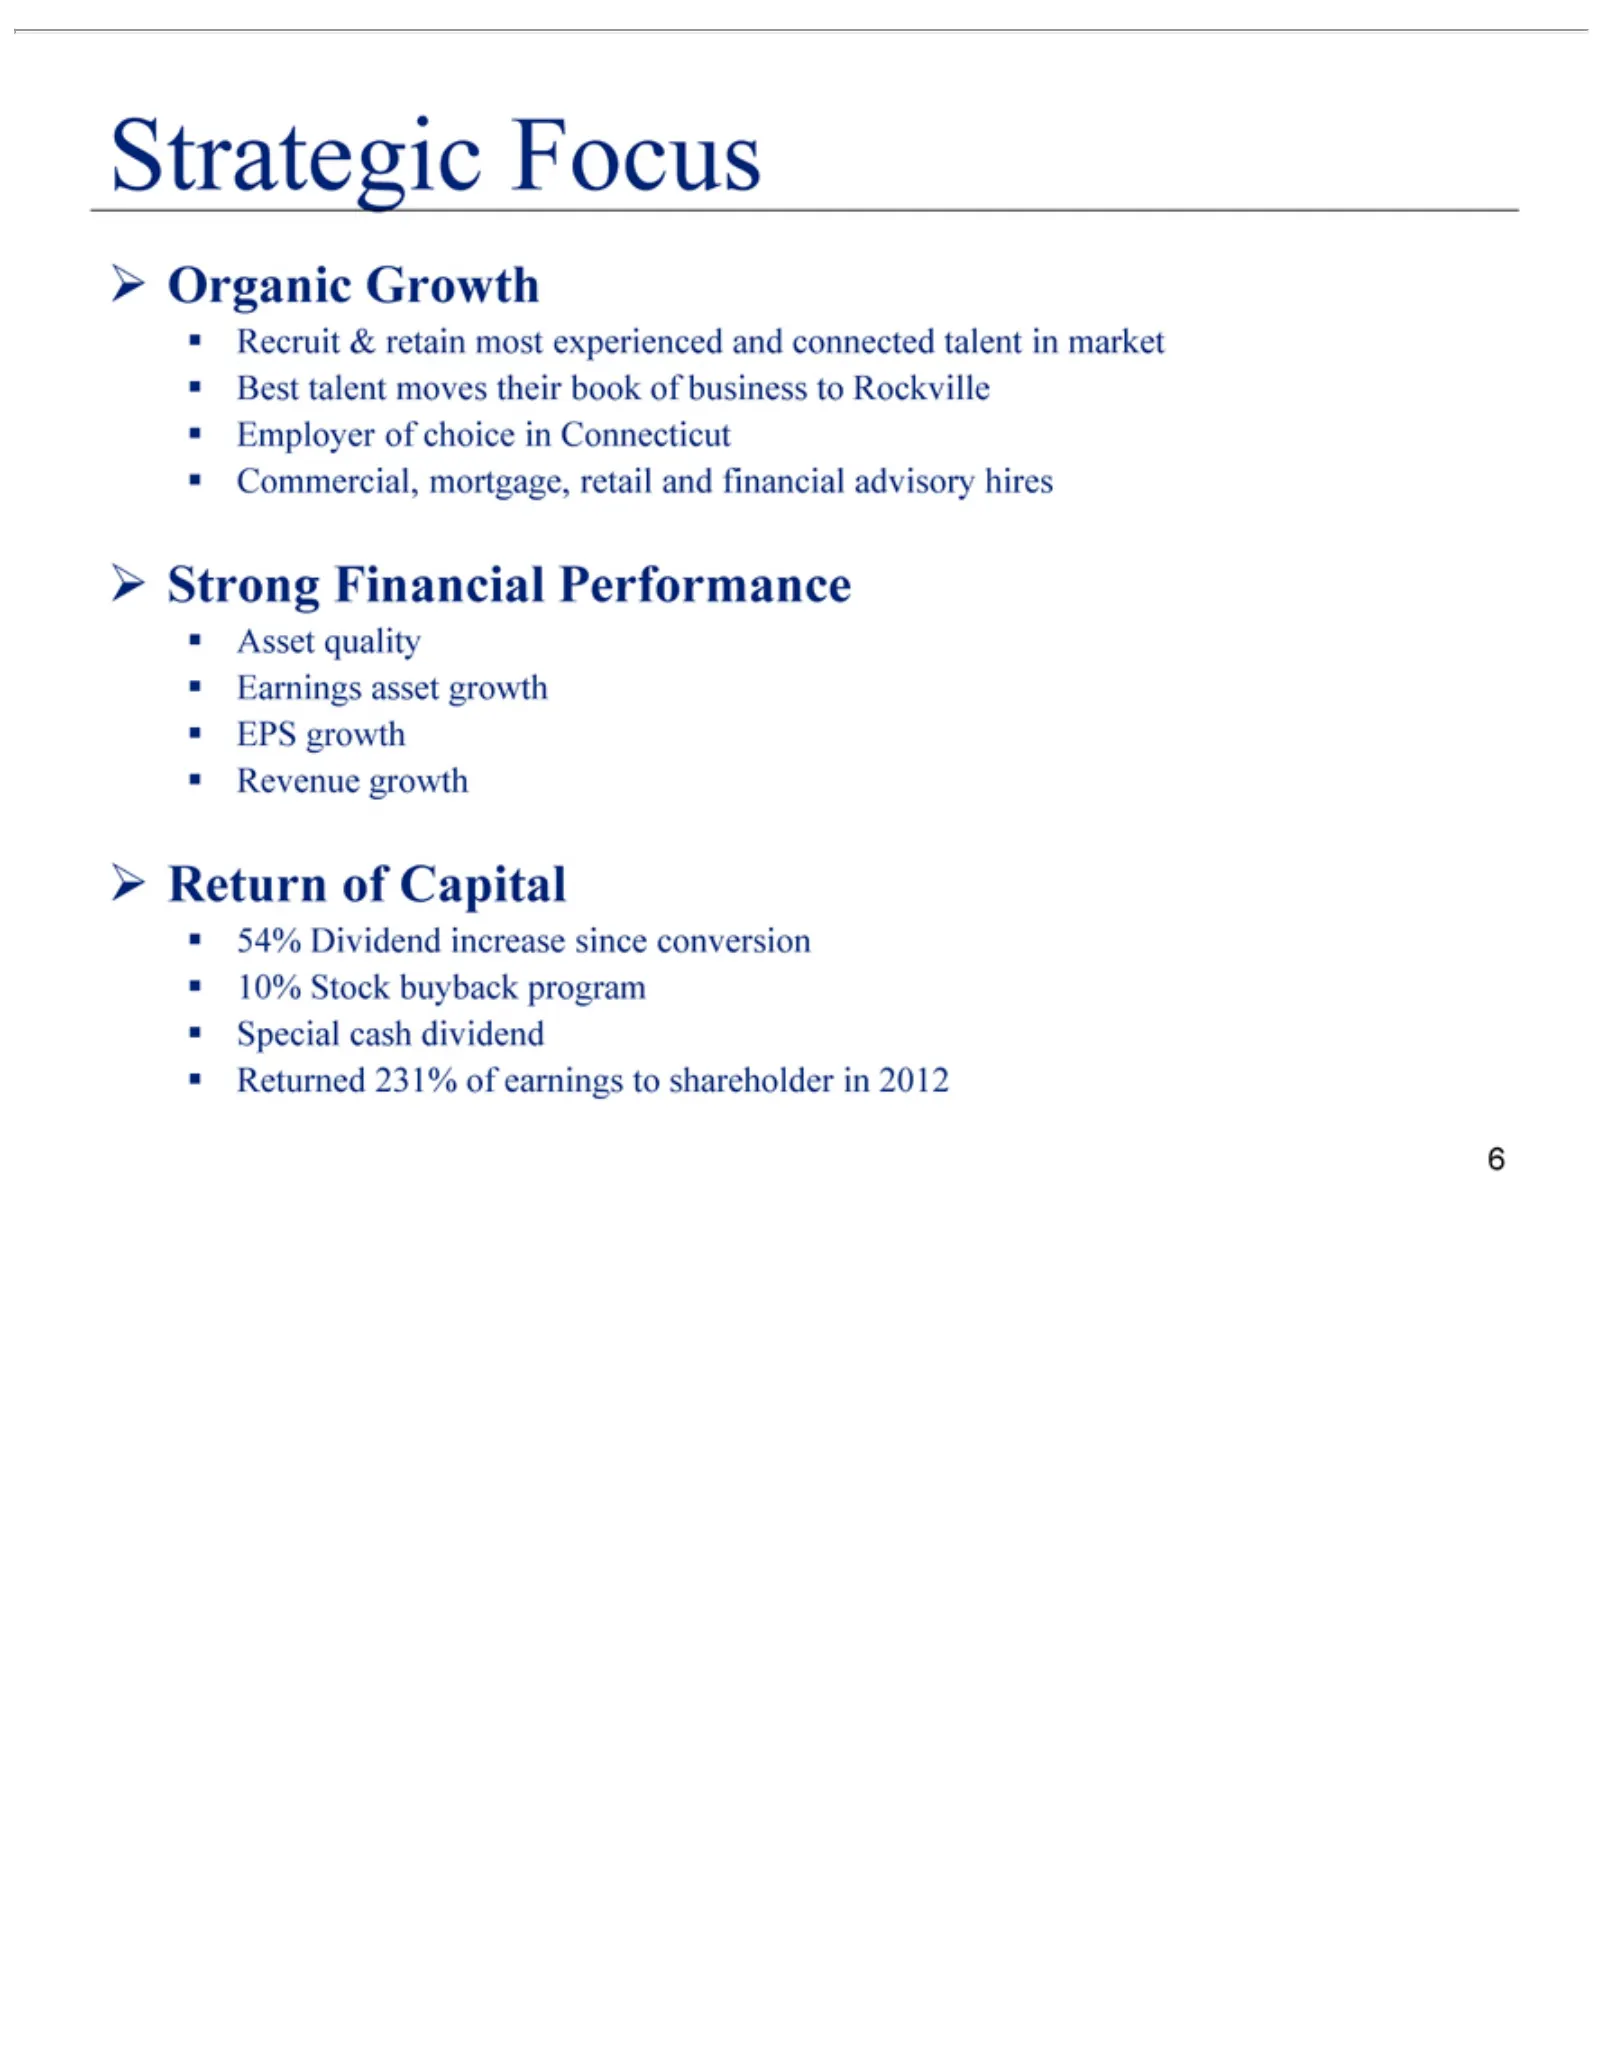
Slide 6: Strategic Progress: Financial Performance
Strategic Organic Recruit Strong Asset Earnings Return 54% 6Returned Dividend quality Financial of &Growth Focus asset 231% Capital retaingrowth increase of most Performance earnings experienced EPS since growth toconversion shareholder and Revenue connected 10% ingrowth 2012 Stock talent buyback in
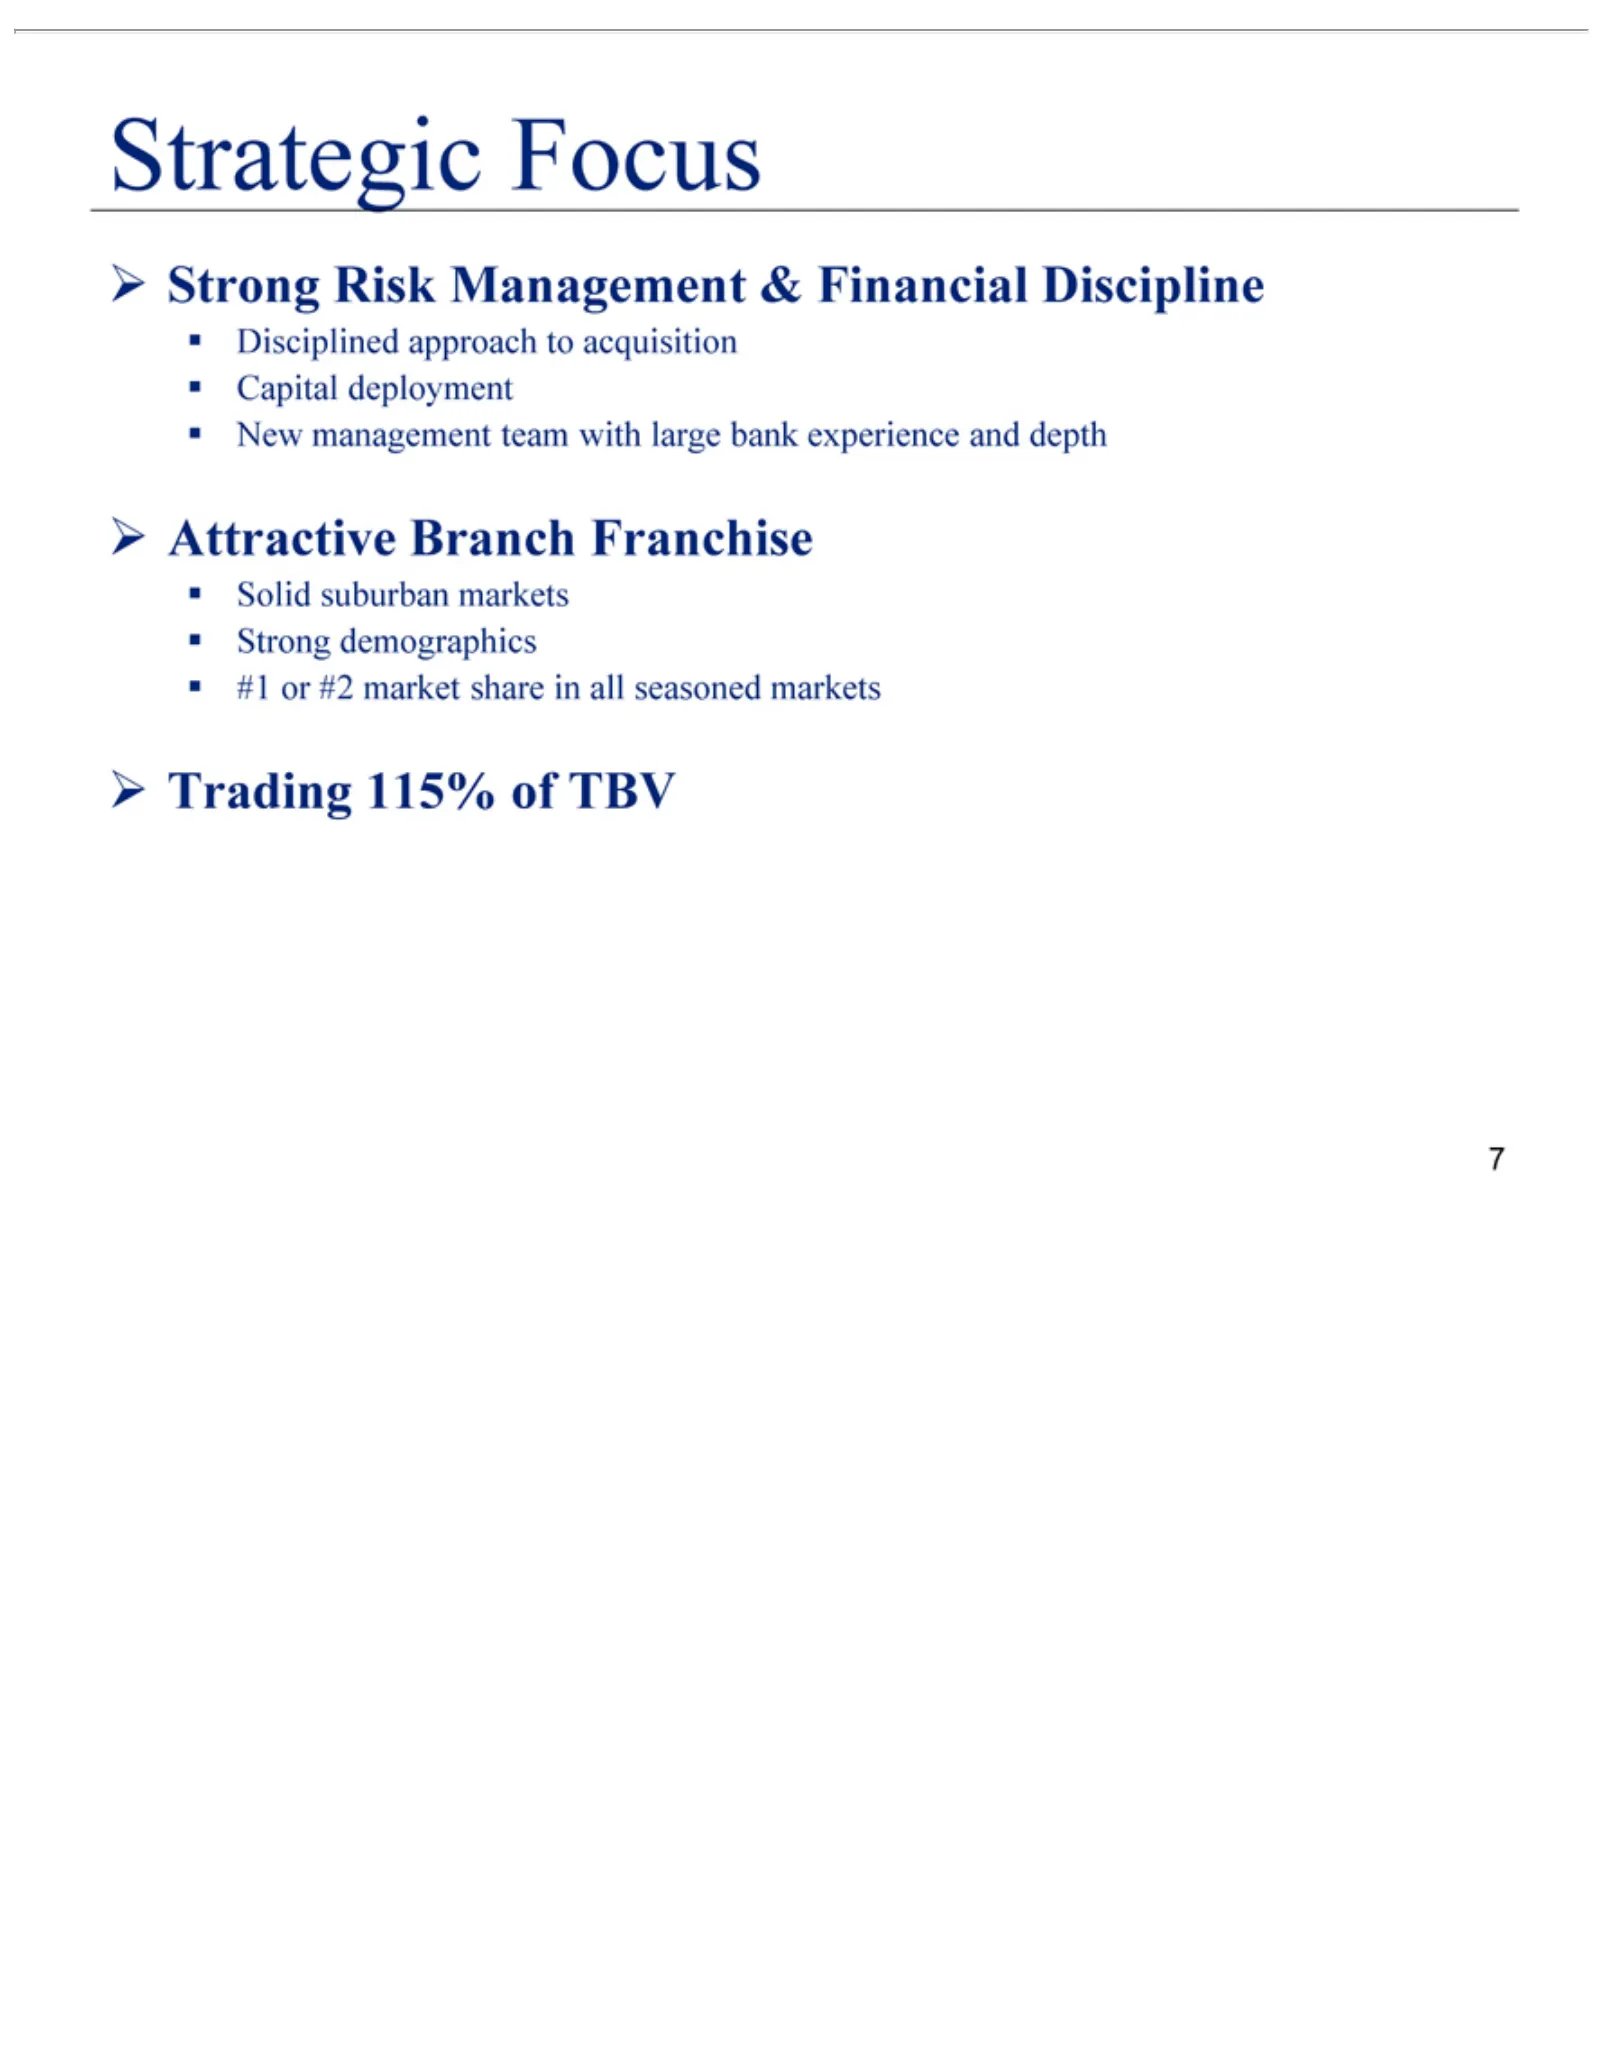
Slide 7: Strategic Focus
Strategic Disciplined Capital New Attractive Solid Strong #1 7Trading or management #2 suburban Risk demographics deployment 115% market Focus Branch approach Management ofmarkets share TBV Franchise teamto inwith acquisition all &seasoned Financial large bank markets Discipline experience and depth
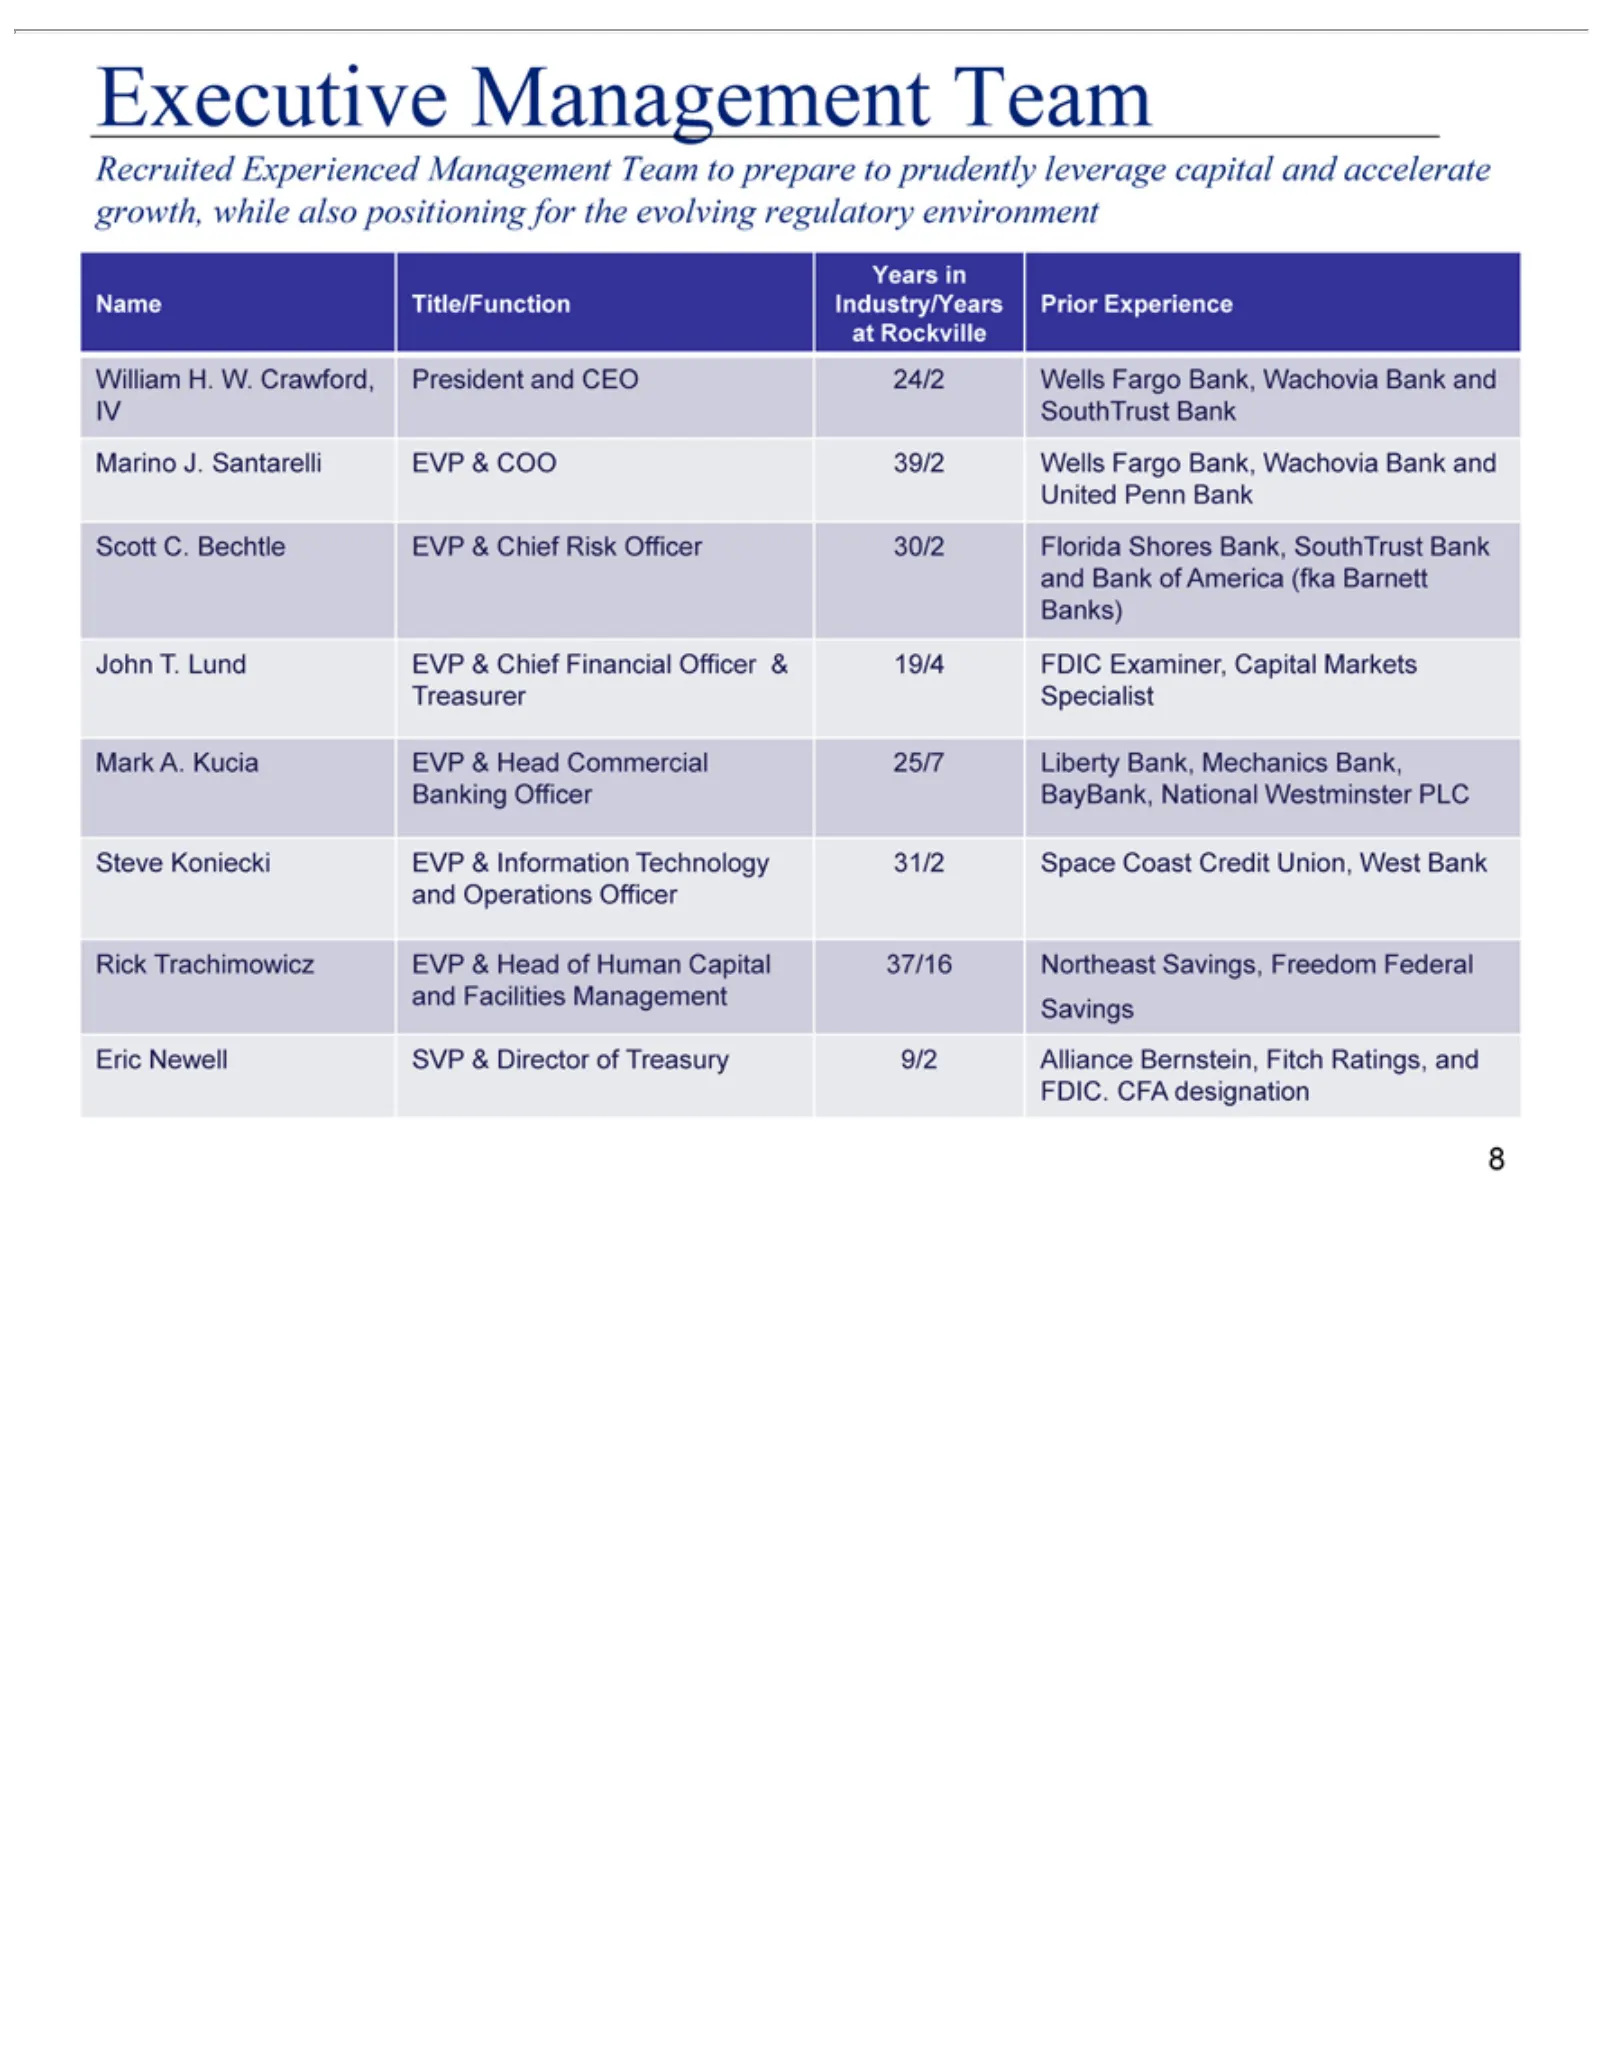
Slide 8: Executive Management Team
Executive Recruited Years Name William IV Marino Scott John Mark Steve Rick and 8Eric SouthTrust Bank Operations Facilities Newell Trachimowicz T. C. A. Koniecki in Title/Function Lund J.Bechtle H. Kucia of Santarelli Experienced Management W.SVP America EVP Management Bank Crawford, EVP Officer EVP
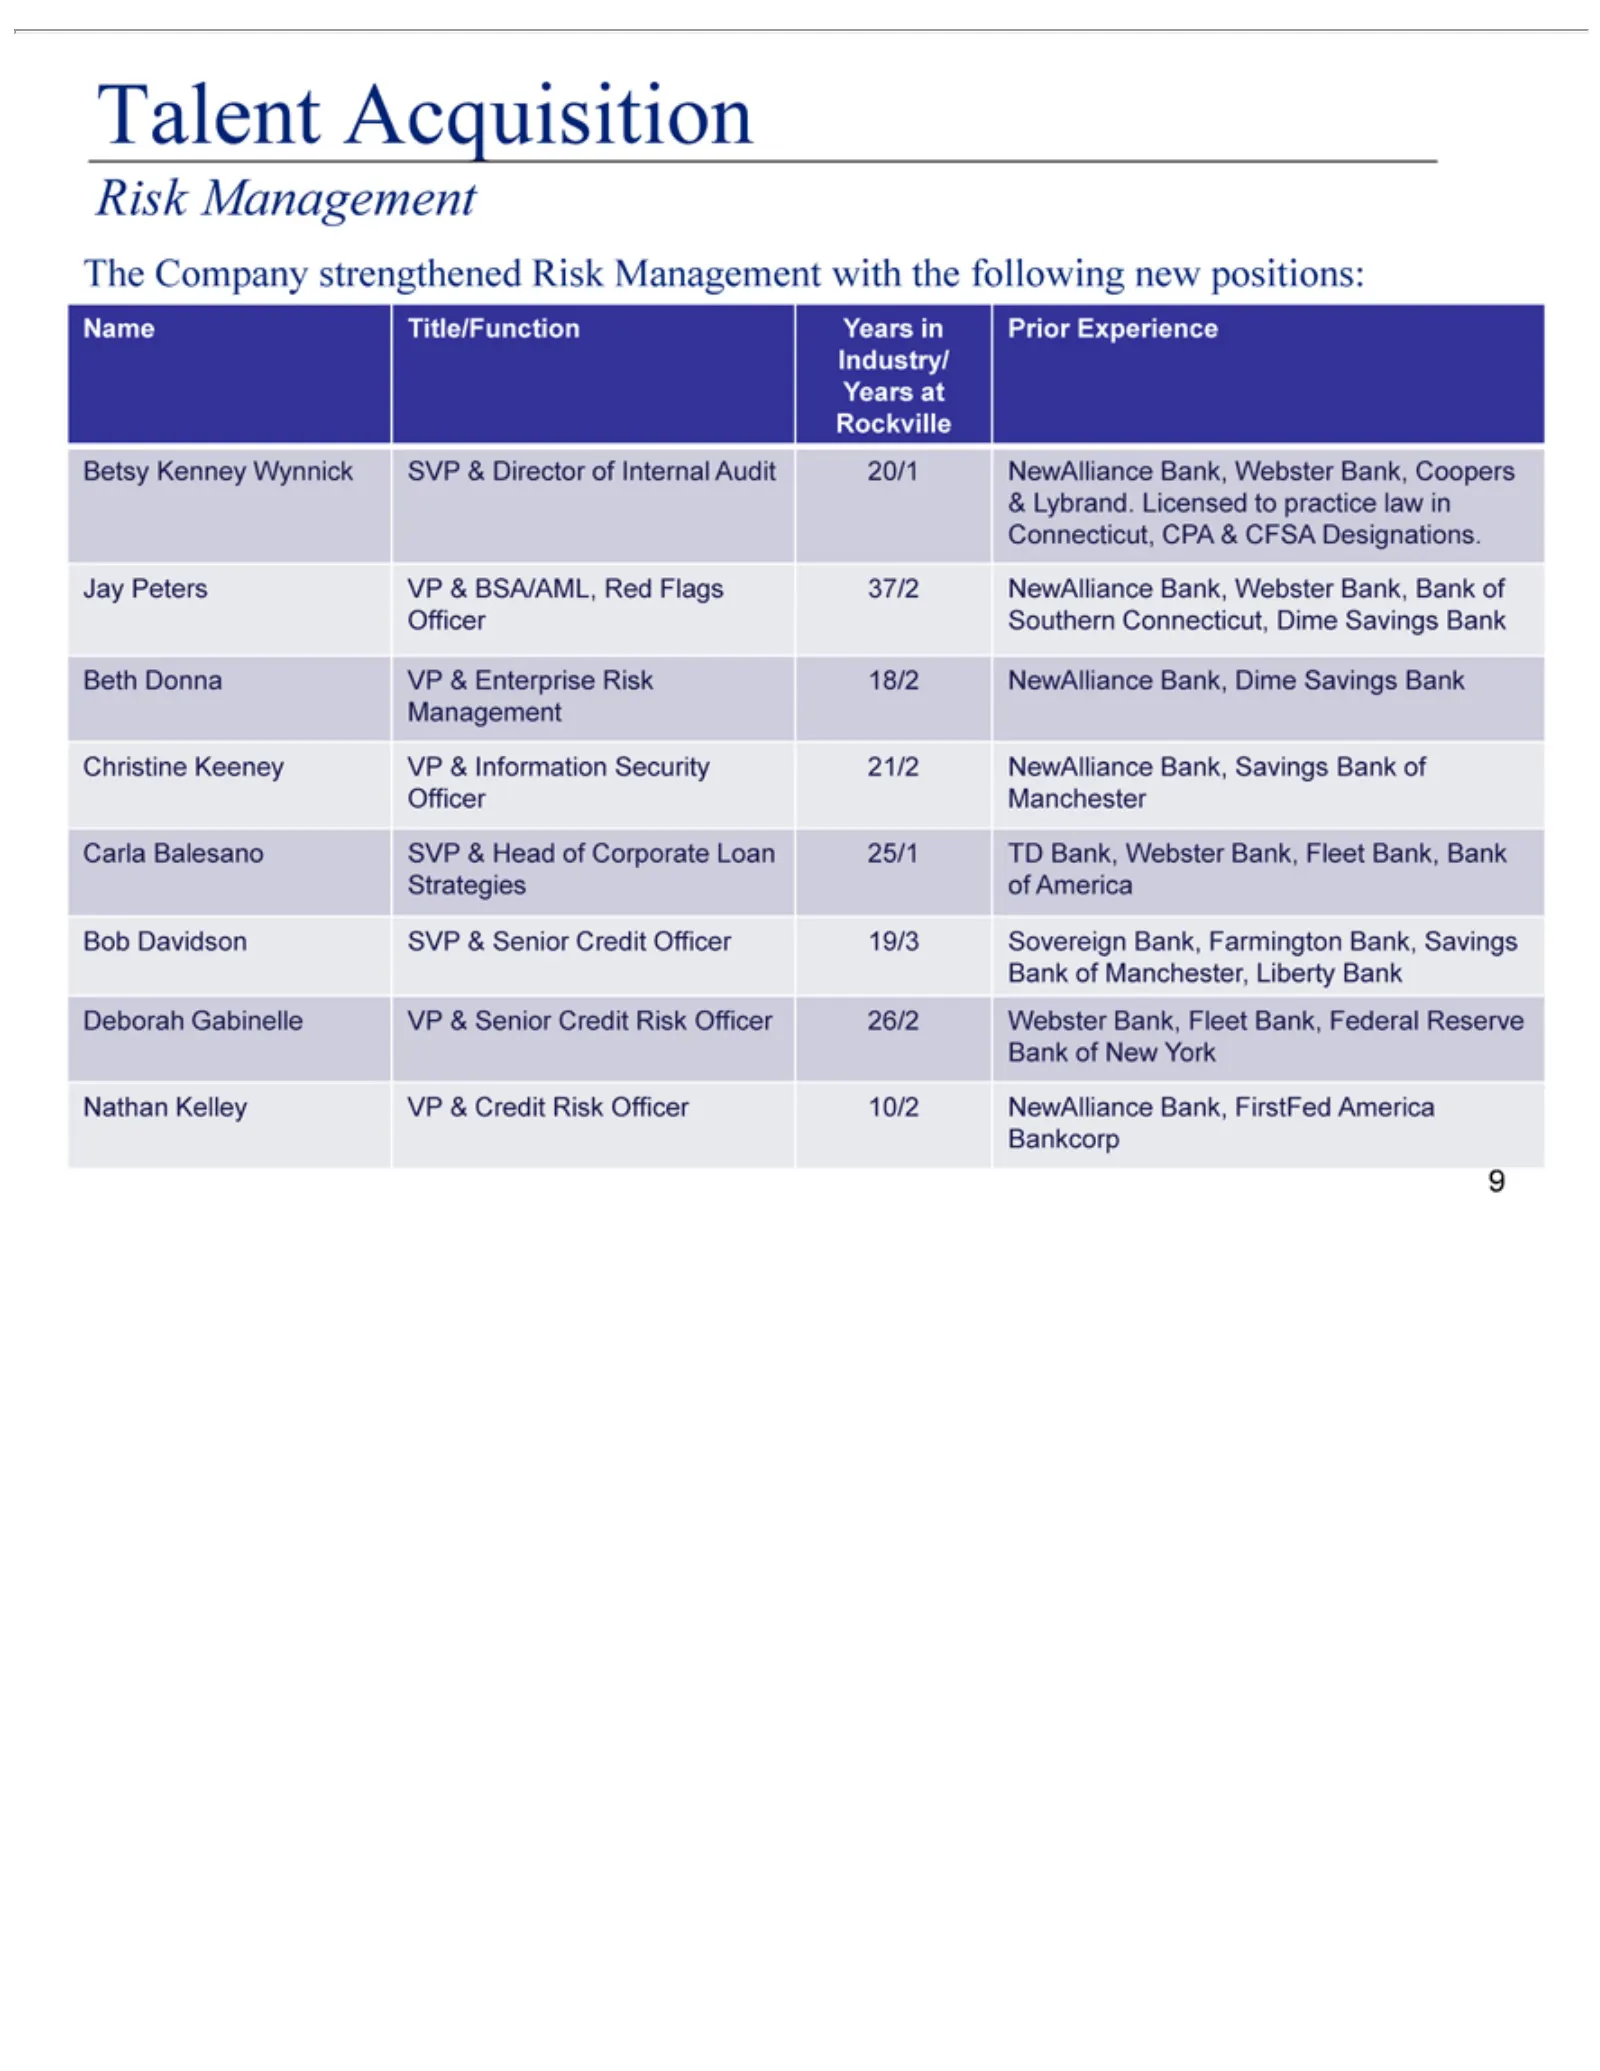
Slide 9: Talent Acquisition: Risk Management Team
Talent Risk The Name Betsy & Jay Officer Beth Christine Carla Strategies Bob Deborah Bank 9Nathan Lybrand. Peters Company Davidson Management Donna of Balesano Kenney Title/Function Acquisition Southern Kelley Manchester, New Gabinelle Keeney of VP Licensed VP America York &Wynnick strengthened SVP
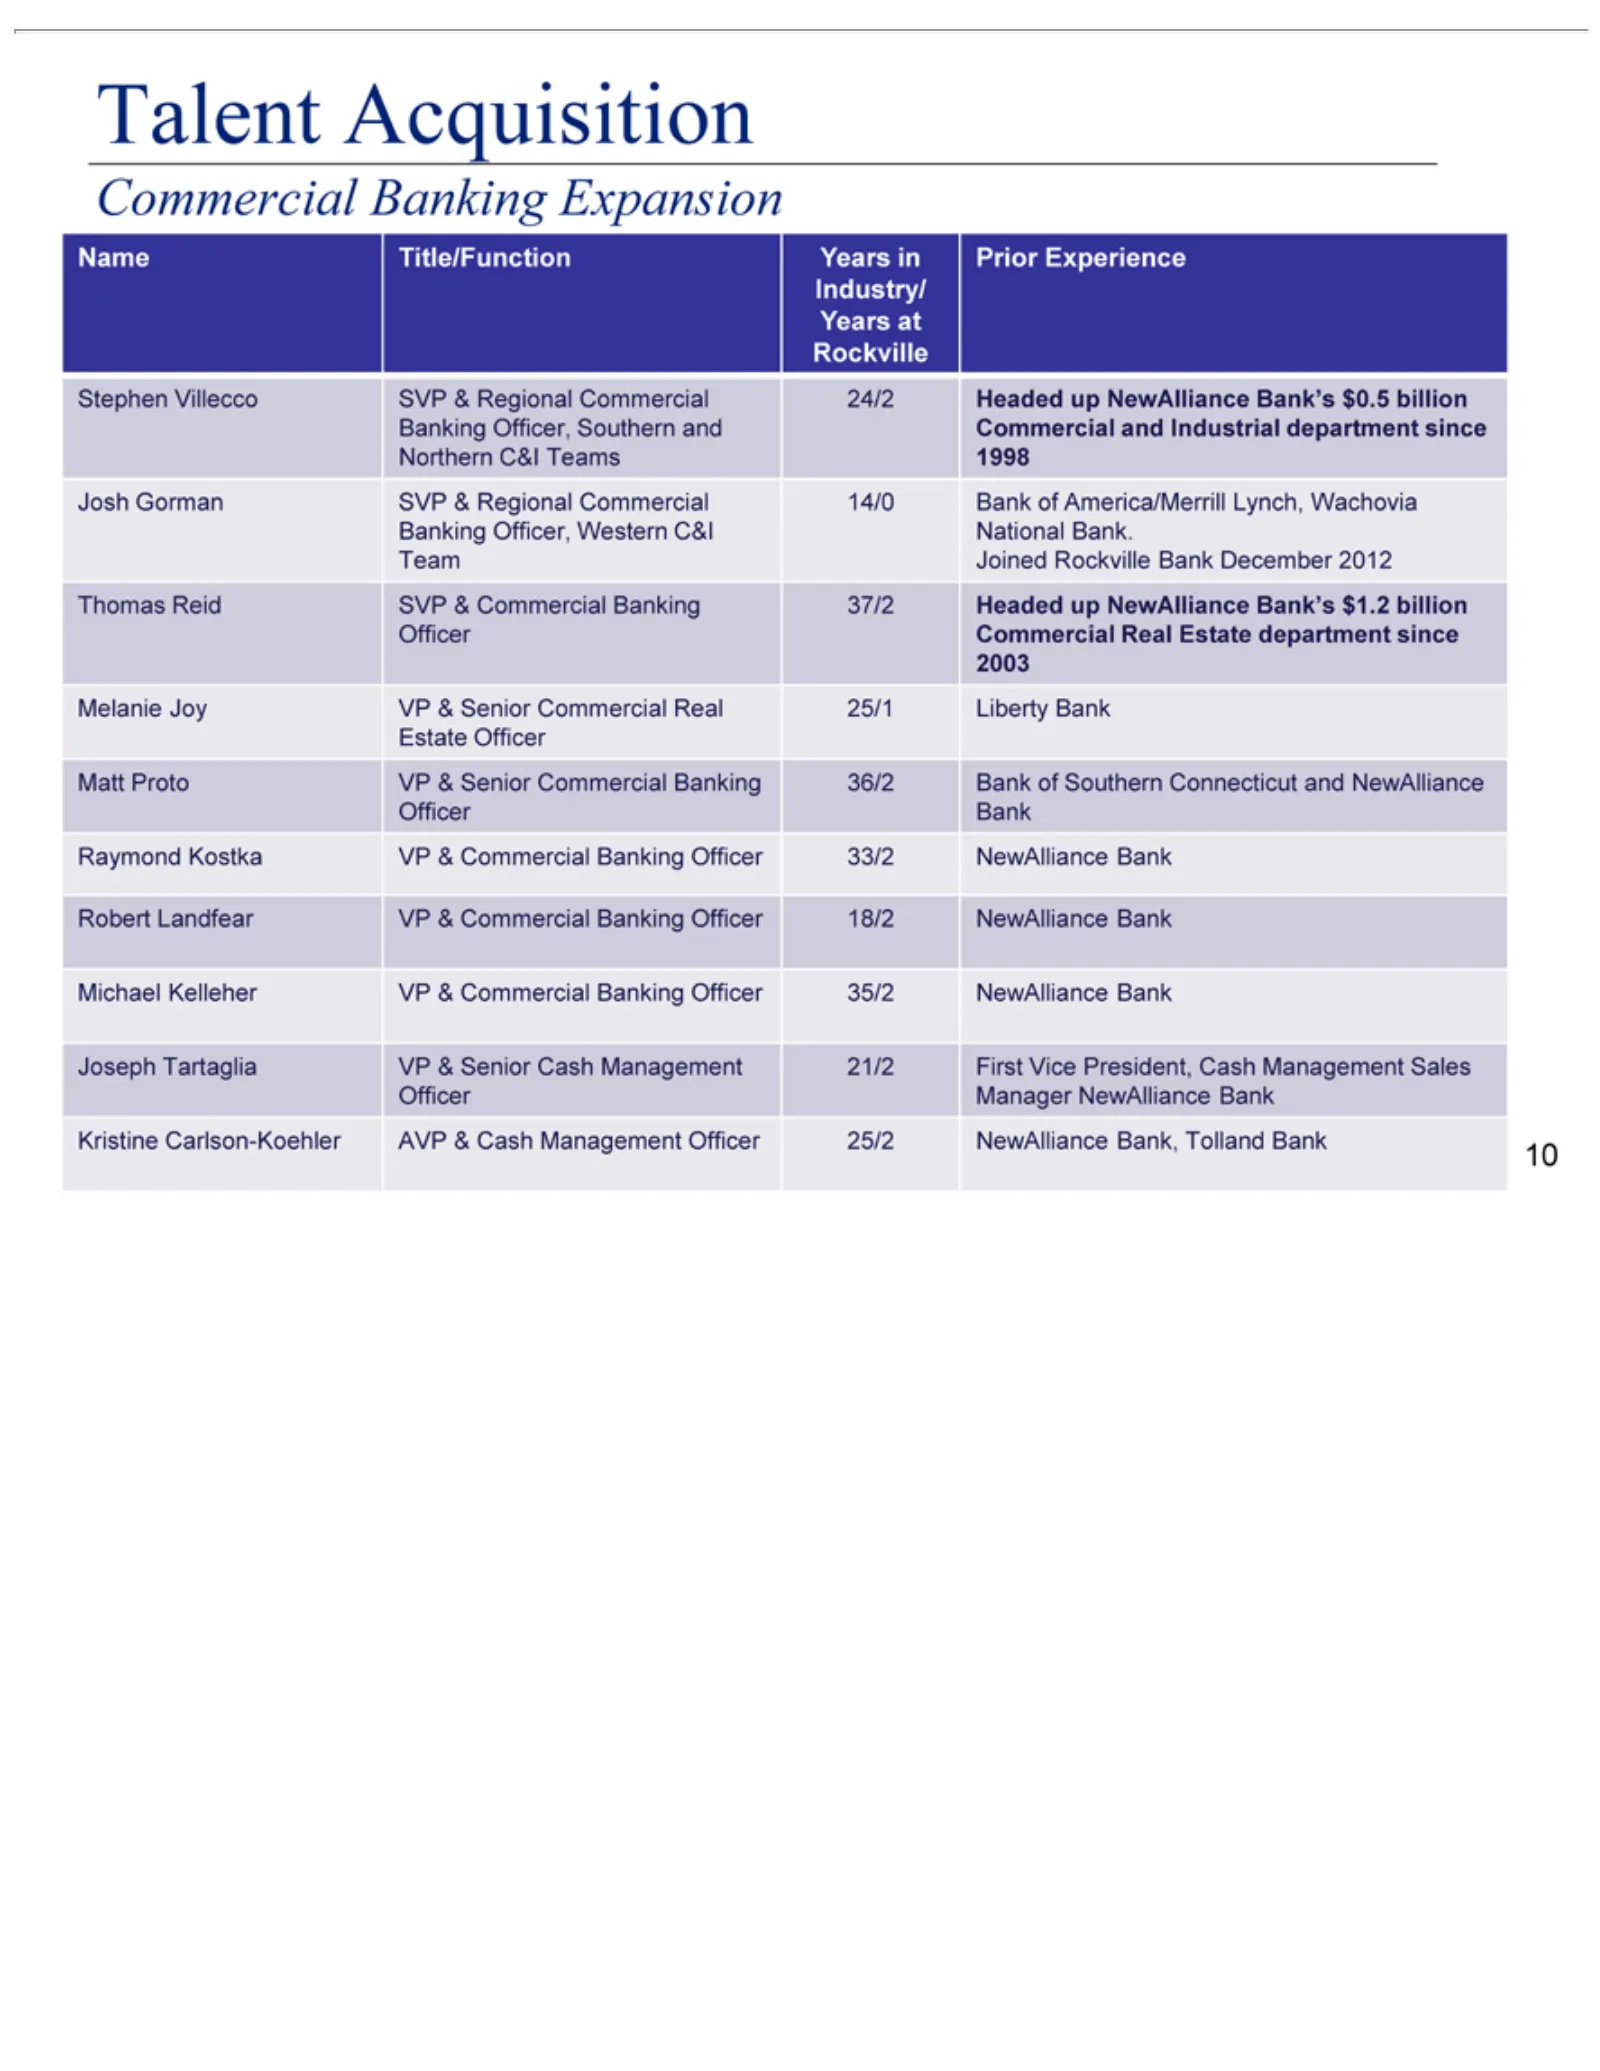
Slide 10: Talent Acquisition: Commercial Banking Teams
TalentGorman Commercial Name Stephen Northern Josh Banking Team Thomas Melanie Matt Raymond Robert Michael Joseph Officer Kristine 10 Proto Joined Title/Function Acquisition Tartaglia Landfear Commercial Bank Manager Villecco Reid Carlson-Koehler Joy Kelleher Officer, C&I Kostka VP VP Banking Rockvi
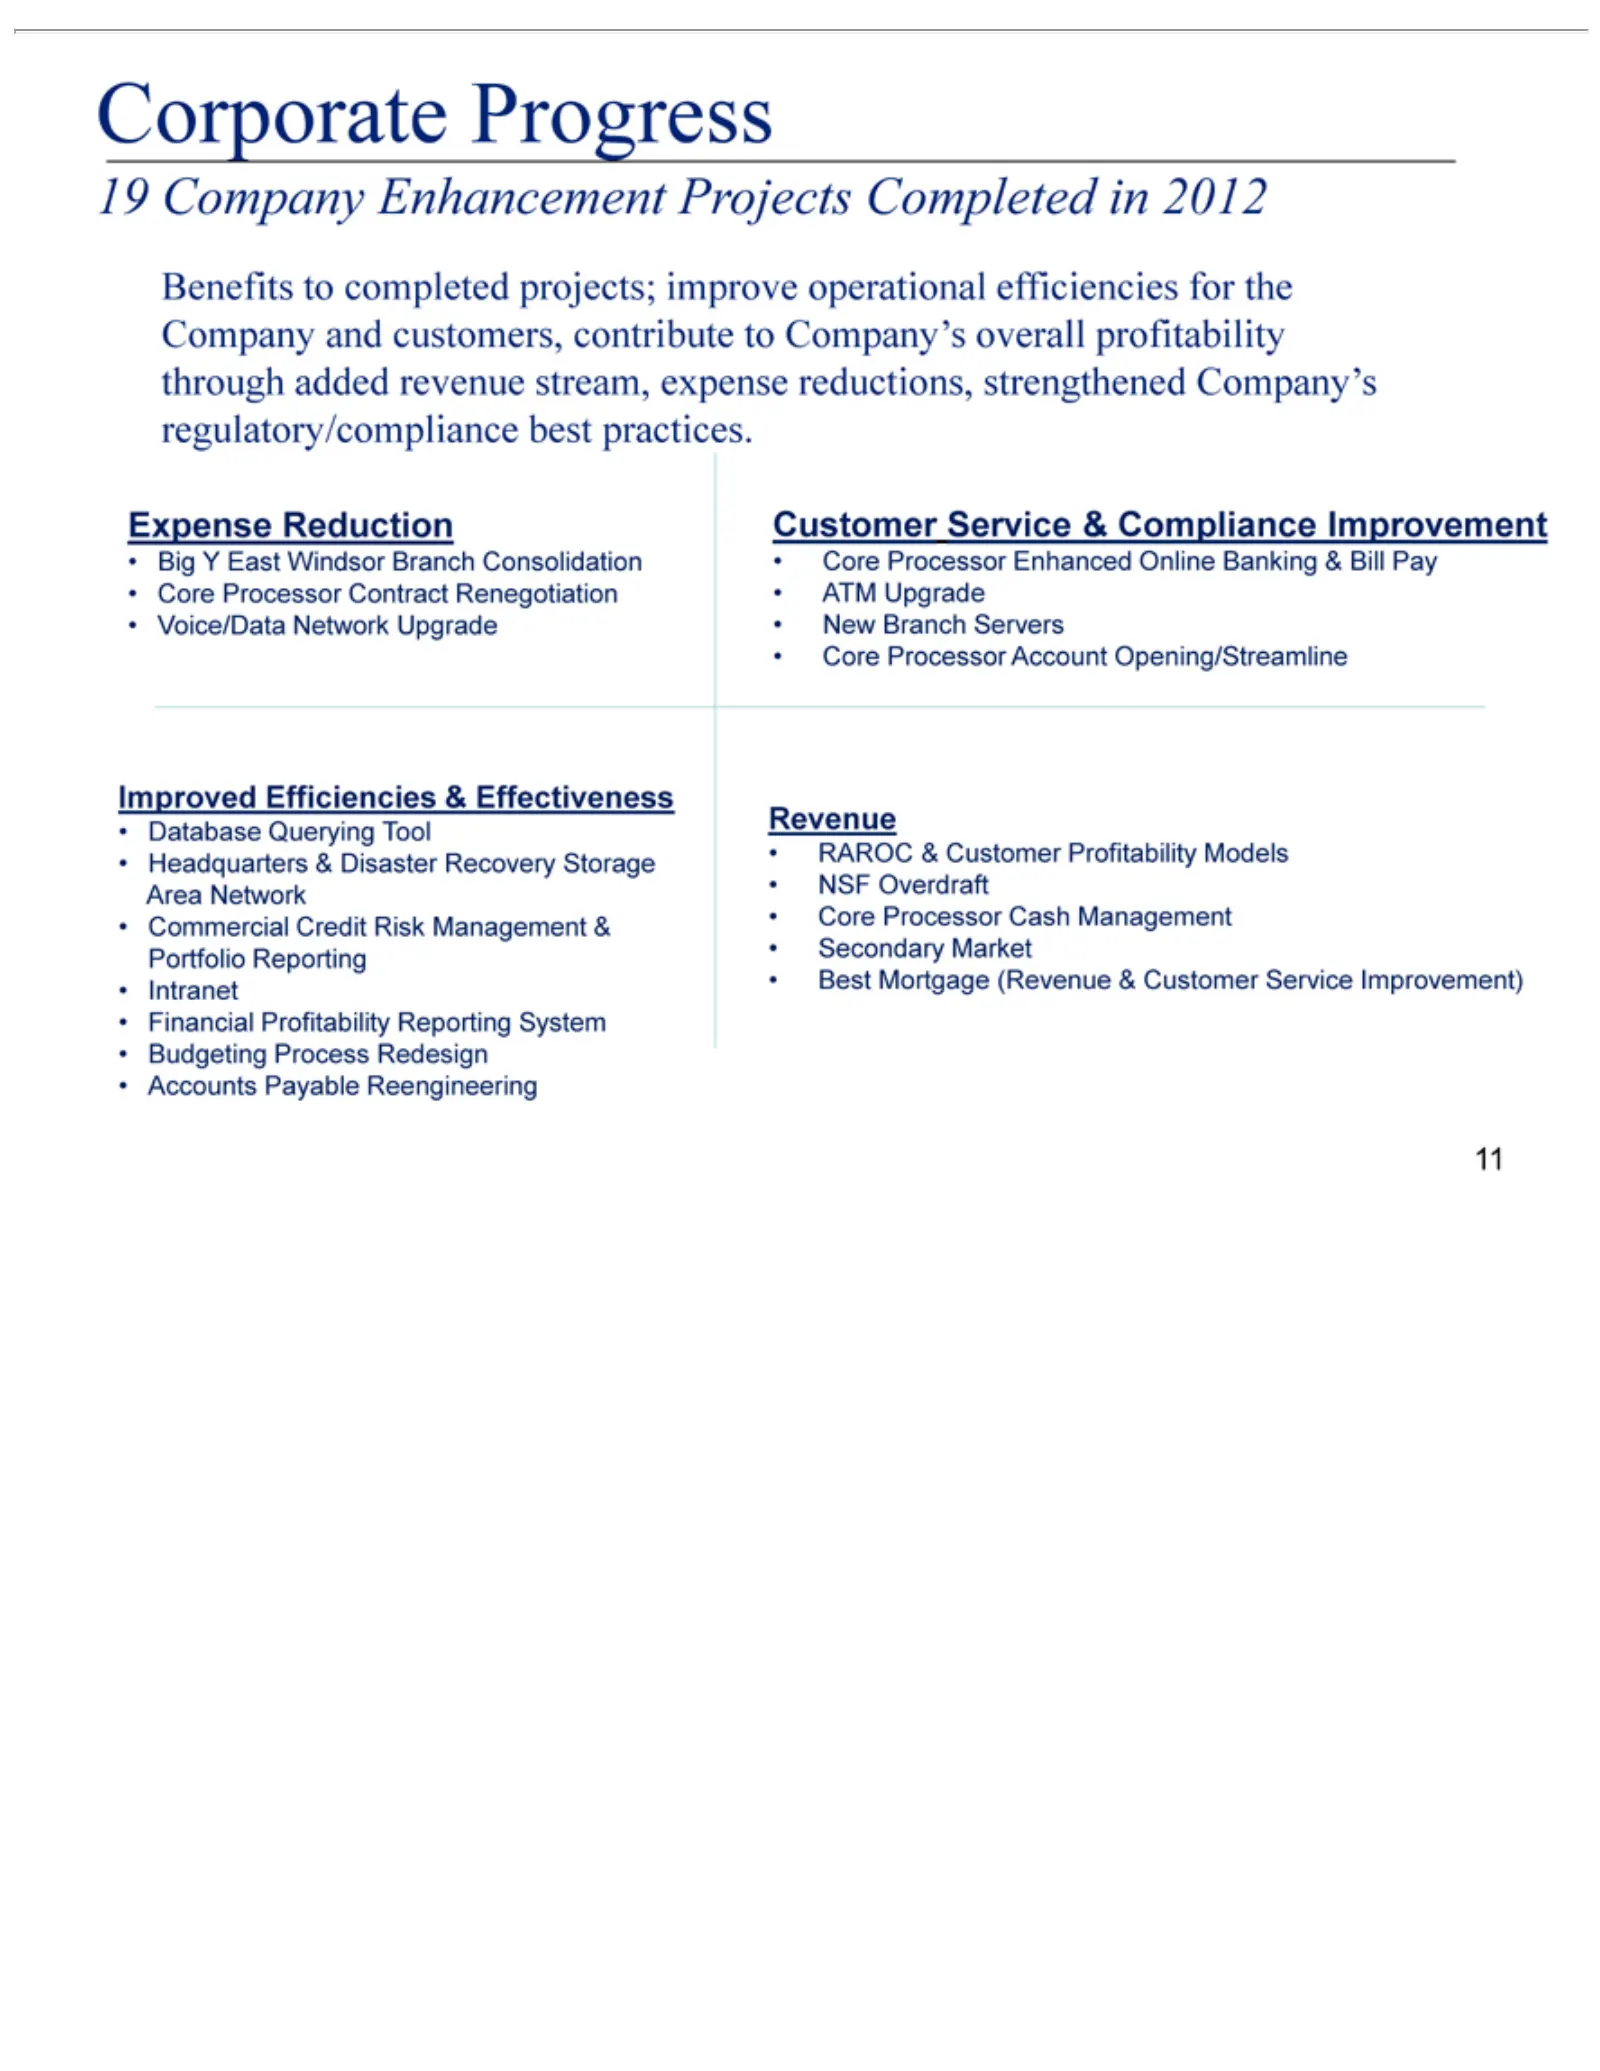
Slide 11: Corporate Progress: Company Benefits
Corporate 19 Benefits Company Expense Big Voice/Data Improved Database Headquarters Commercial Financial Intranet Budgeting Accounts Customer ATM New RAROC Revenue NSF Core Secondary Best 11 Company YMortgage Overdraft Branch Processor Upgrade East to Reduction &Querying Profitability Payable Effici
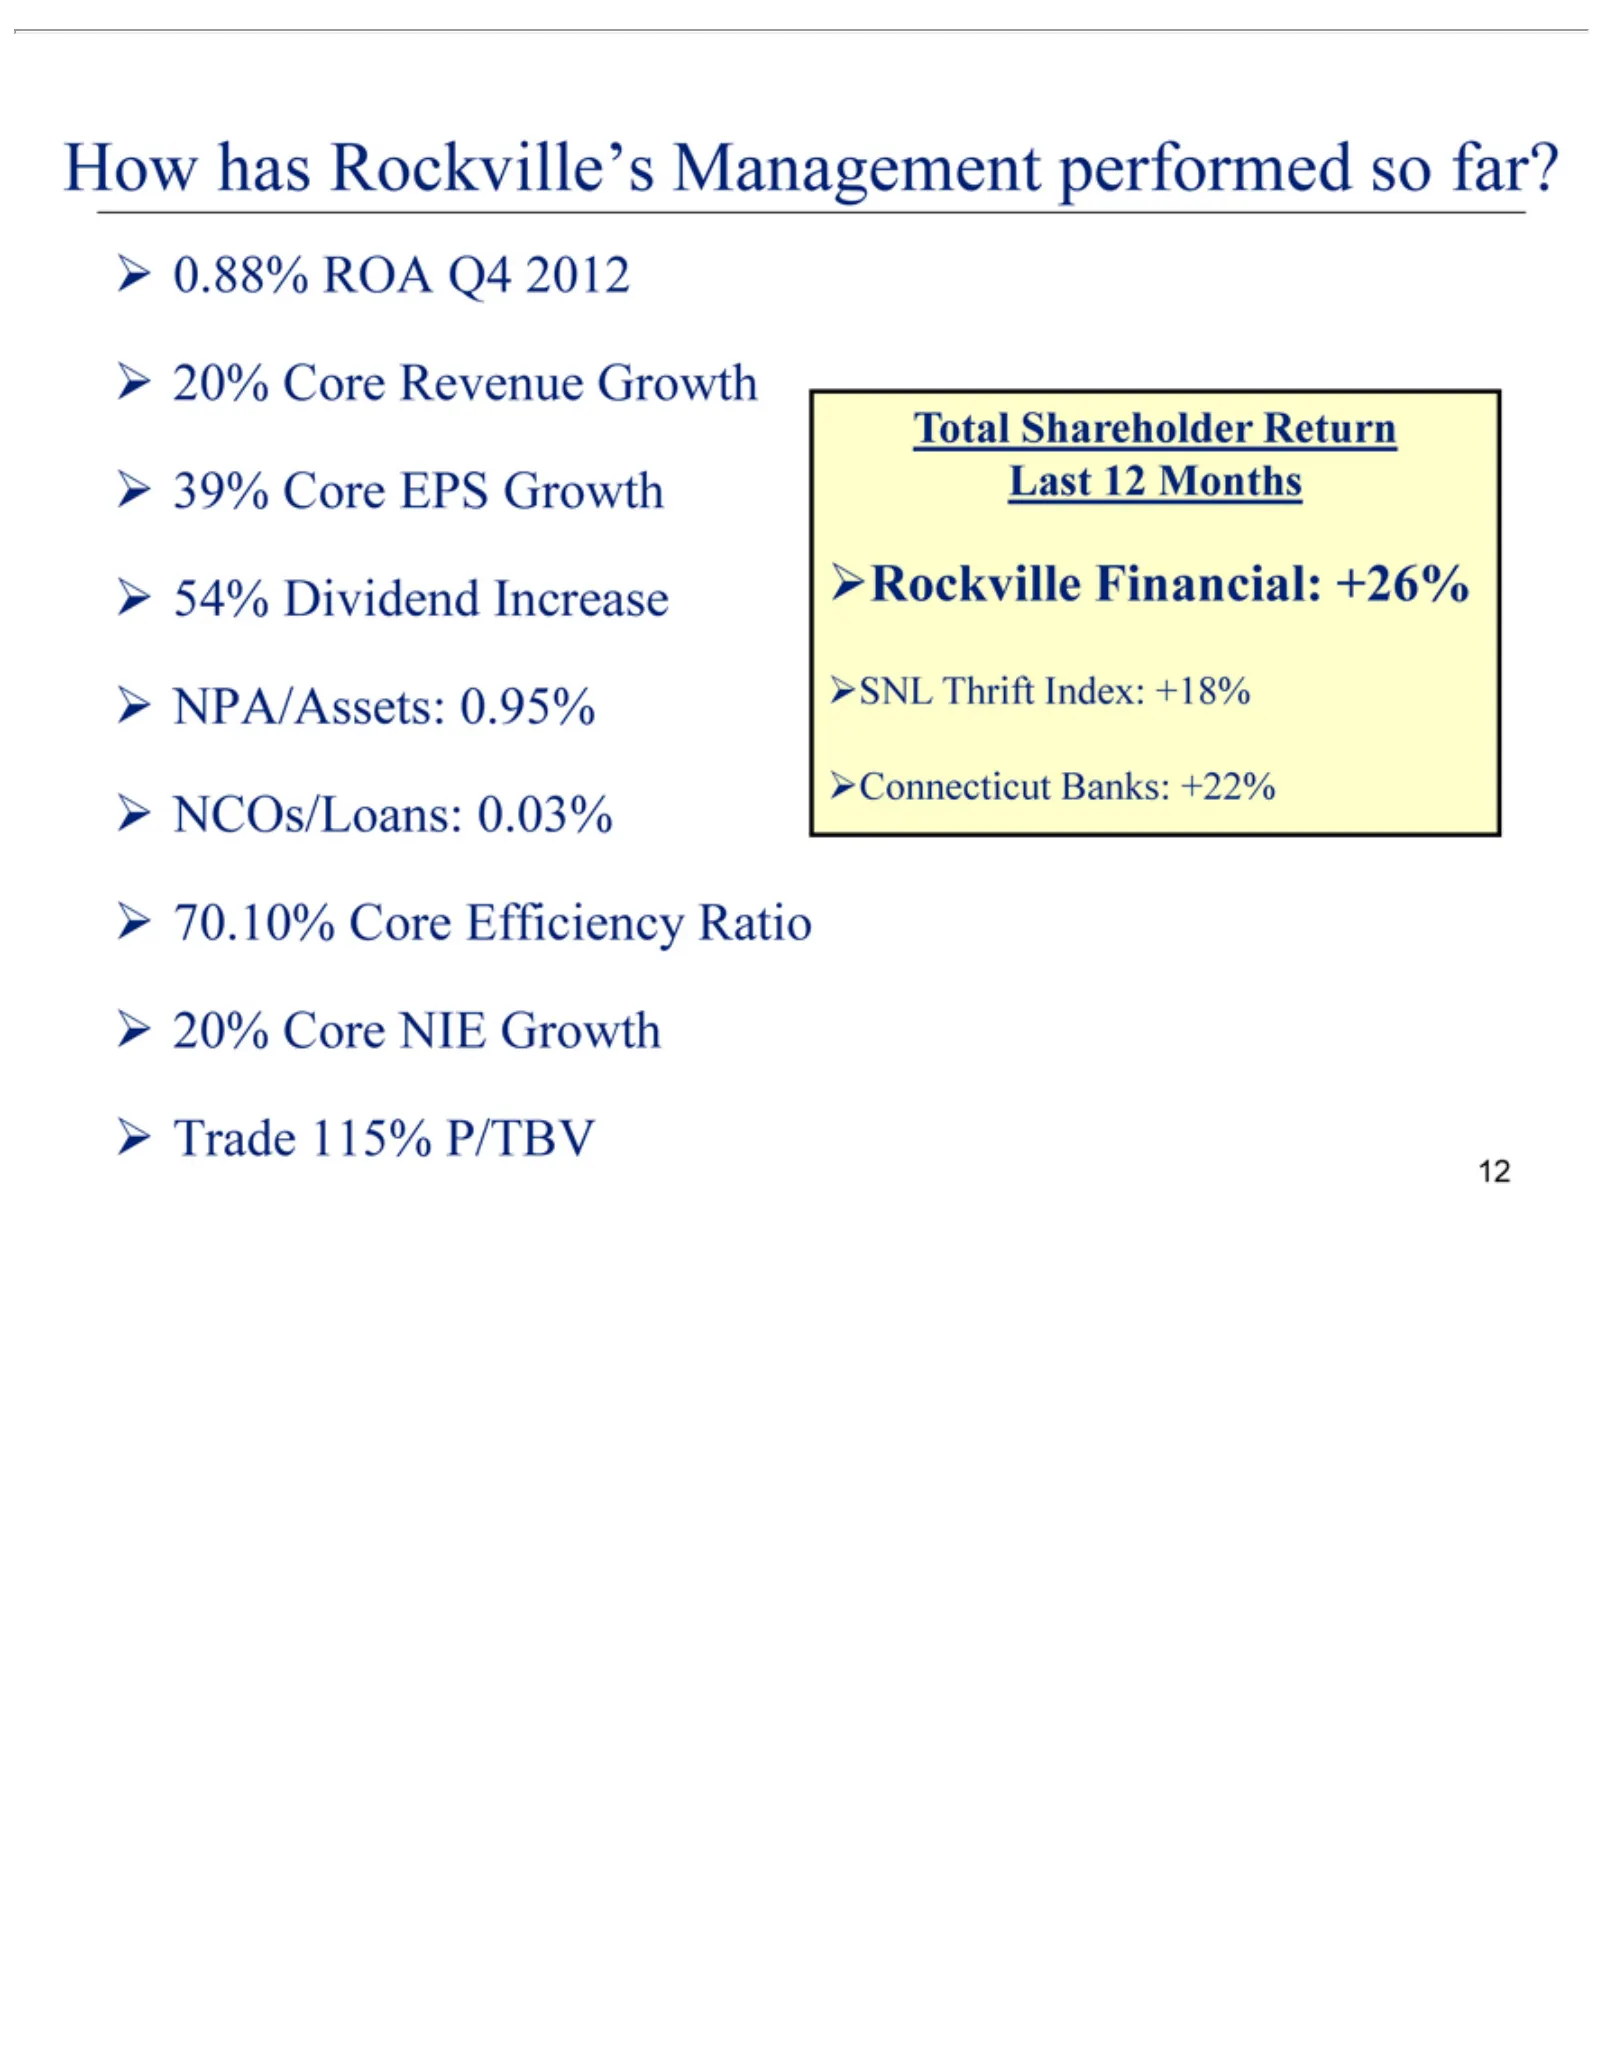
Slide 12: How Has Rockville Performed So Far?
How Core 0.88% 39% 54% NPA/Assets: NCOs/Loans: 70.10% 20% Trade Total Rockville SNL Connecticut 12 Dividend Thrift has Shareholder 115% ROA Core Rockville’s Financial: Revenue EPS NIE Index: Banks: P/TBV Q4 0.95% Efficiency 0.03% Increase Growth 2012 Return +18% Growth +22% +26% Management Ratio Las
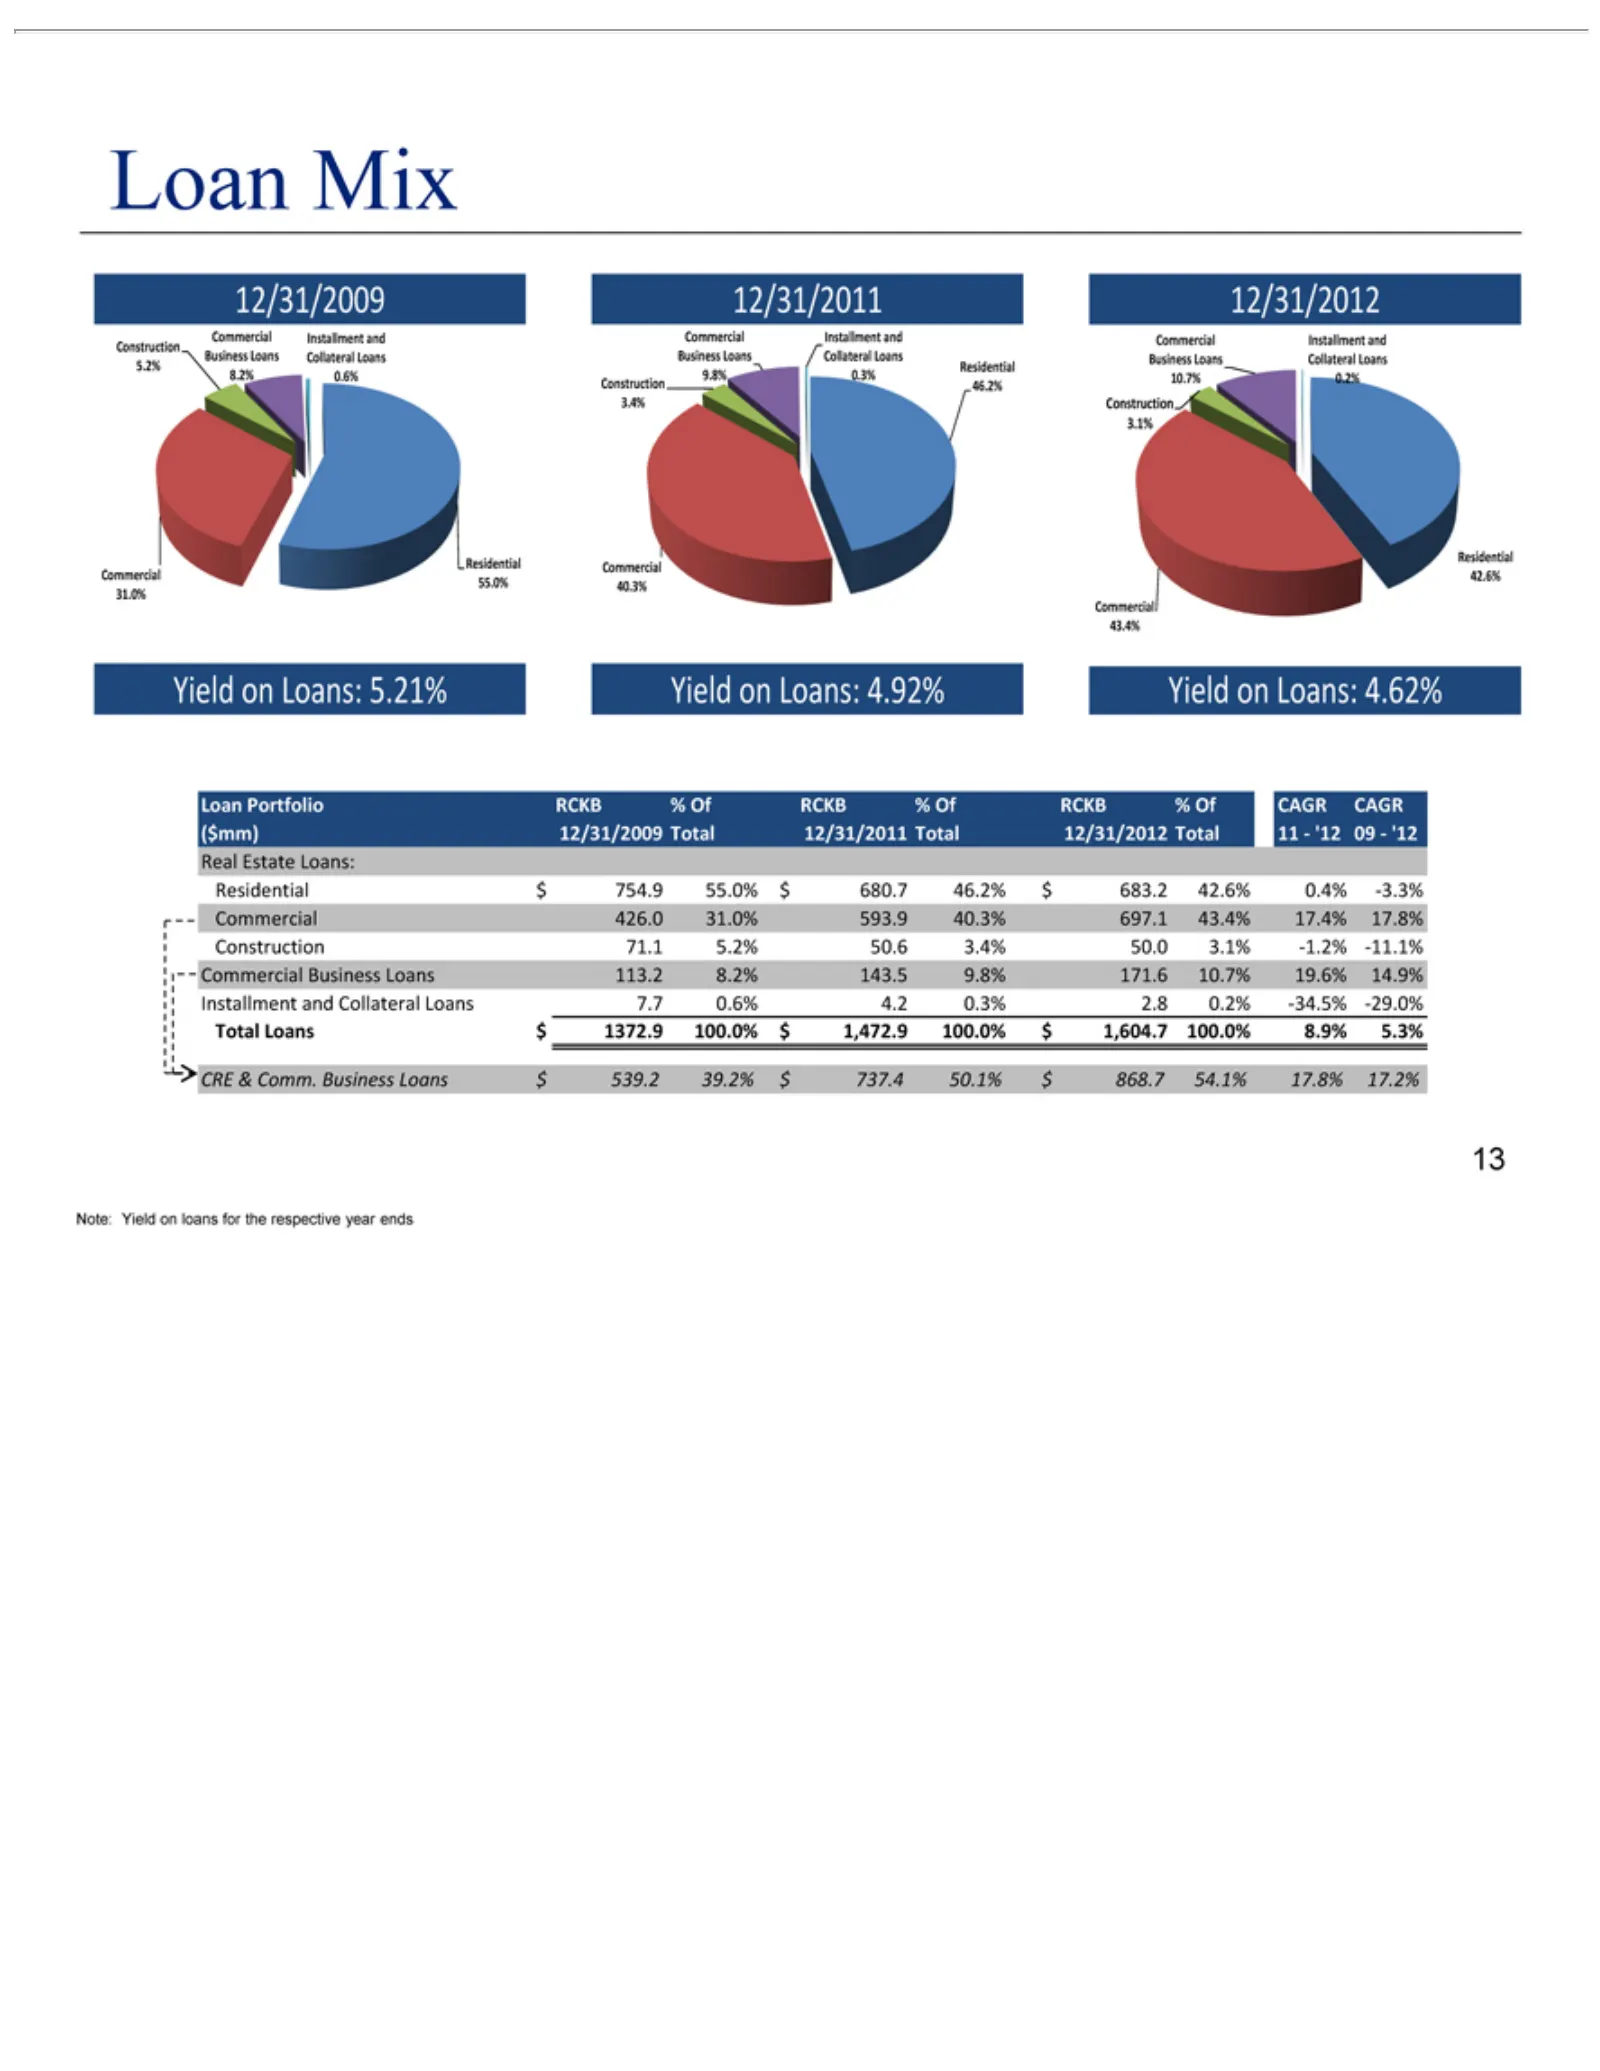
Slide 13: Loan Portfolio Mix and Yield
12/31/2011 12/31/2012 Construction Installment Residential Commercial Yield RCKB 12/31/2009 Loan 426.0 71.1 113.2 $7.7 Note: 13754.9 1372.9 539.2 0.6% 5.2% Mix Portfolio on Yield 8.2% 31.0% %55.0% 39.2% Loans: 100.0% 4.2 Of 50.6 and 55.0% 46.2% 42.6% Total 143.5 on 31.0% 40.3% Business 43.4% 593.9 0
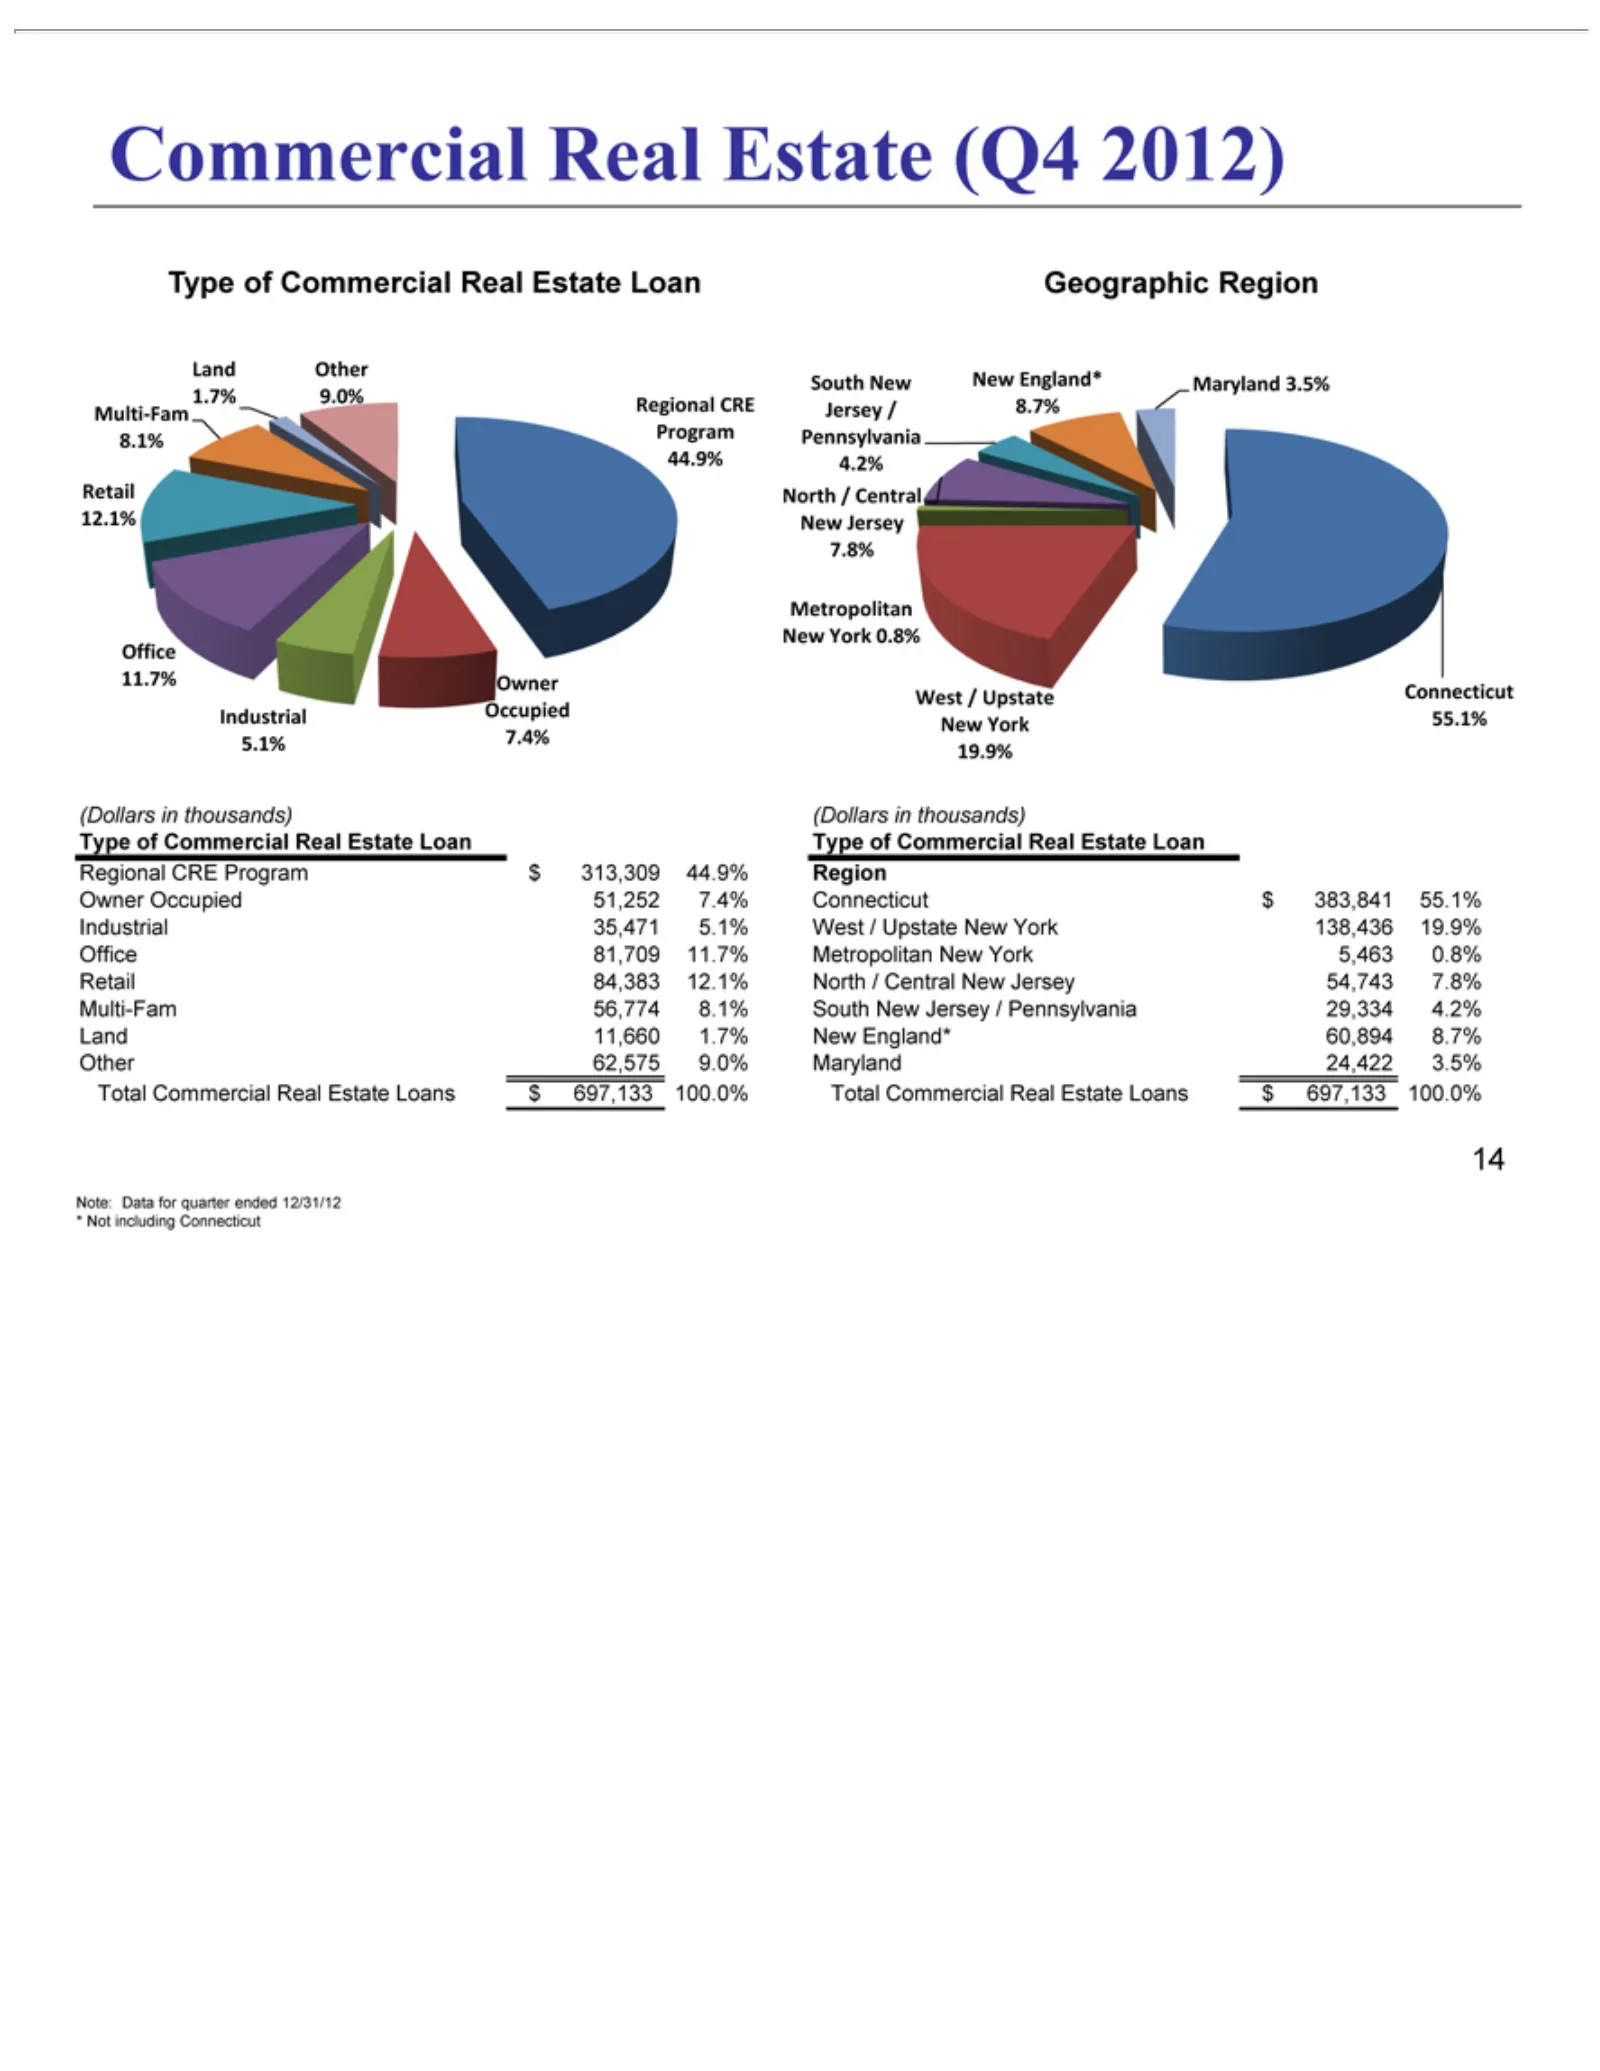
Slide 14: Commercial Real Estate Geographic Breakdown
Commercial Geographic Regional Owner Industrial Office Retail Multi-Fam Land Other (Dollars Type Connecticut Region West Metropolitan North South New Maryland Total *Note: 14NotEngland* /of Commercial 1.7% 11,660 Data including 9.0% 62,575 /New 12.1% 84,383 Upstate 11.7% 81,709 Occupied Central Comm
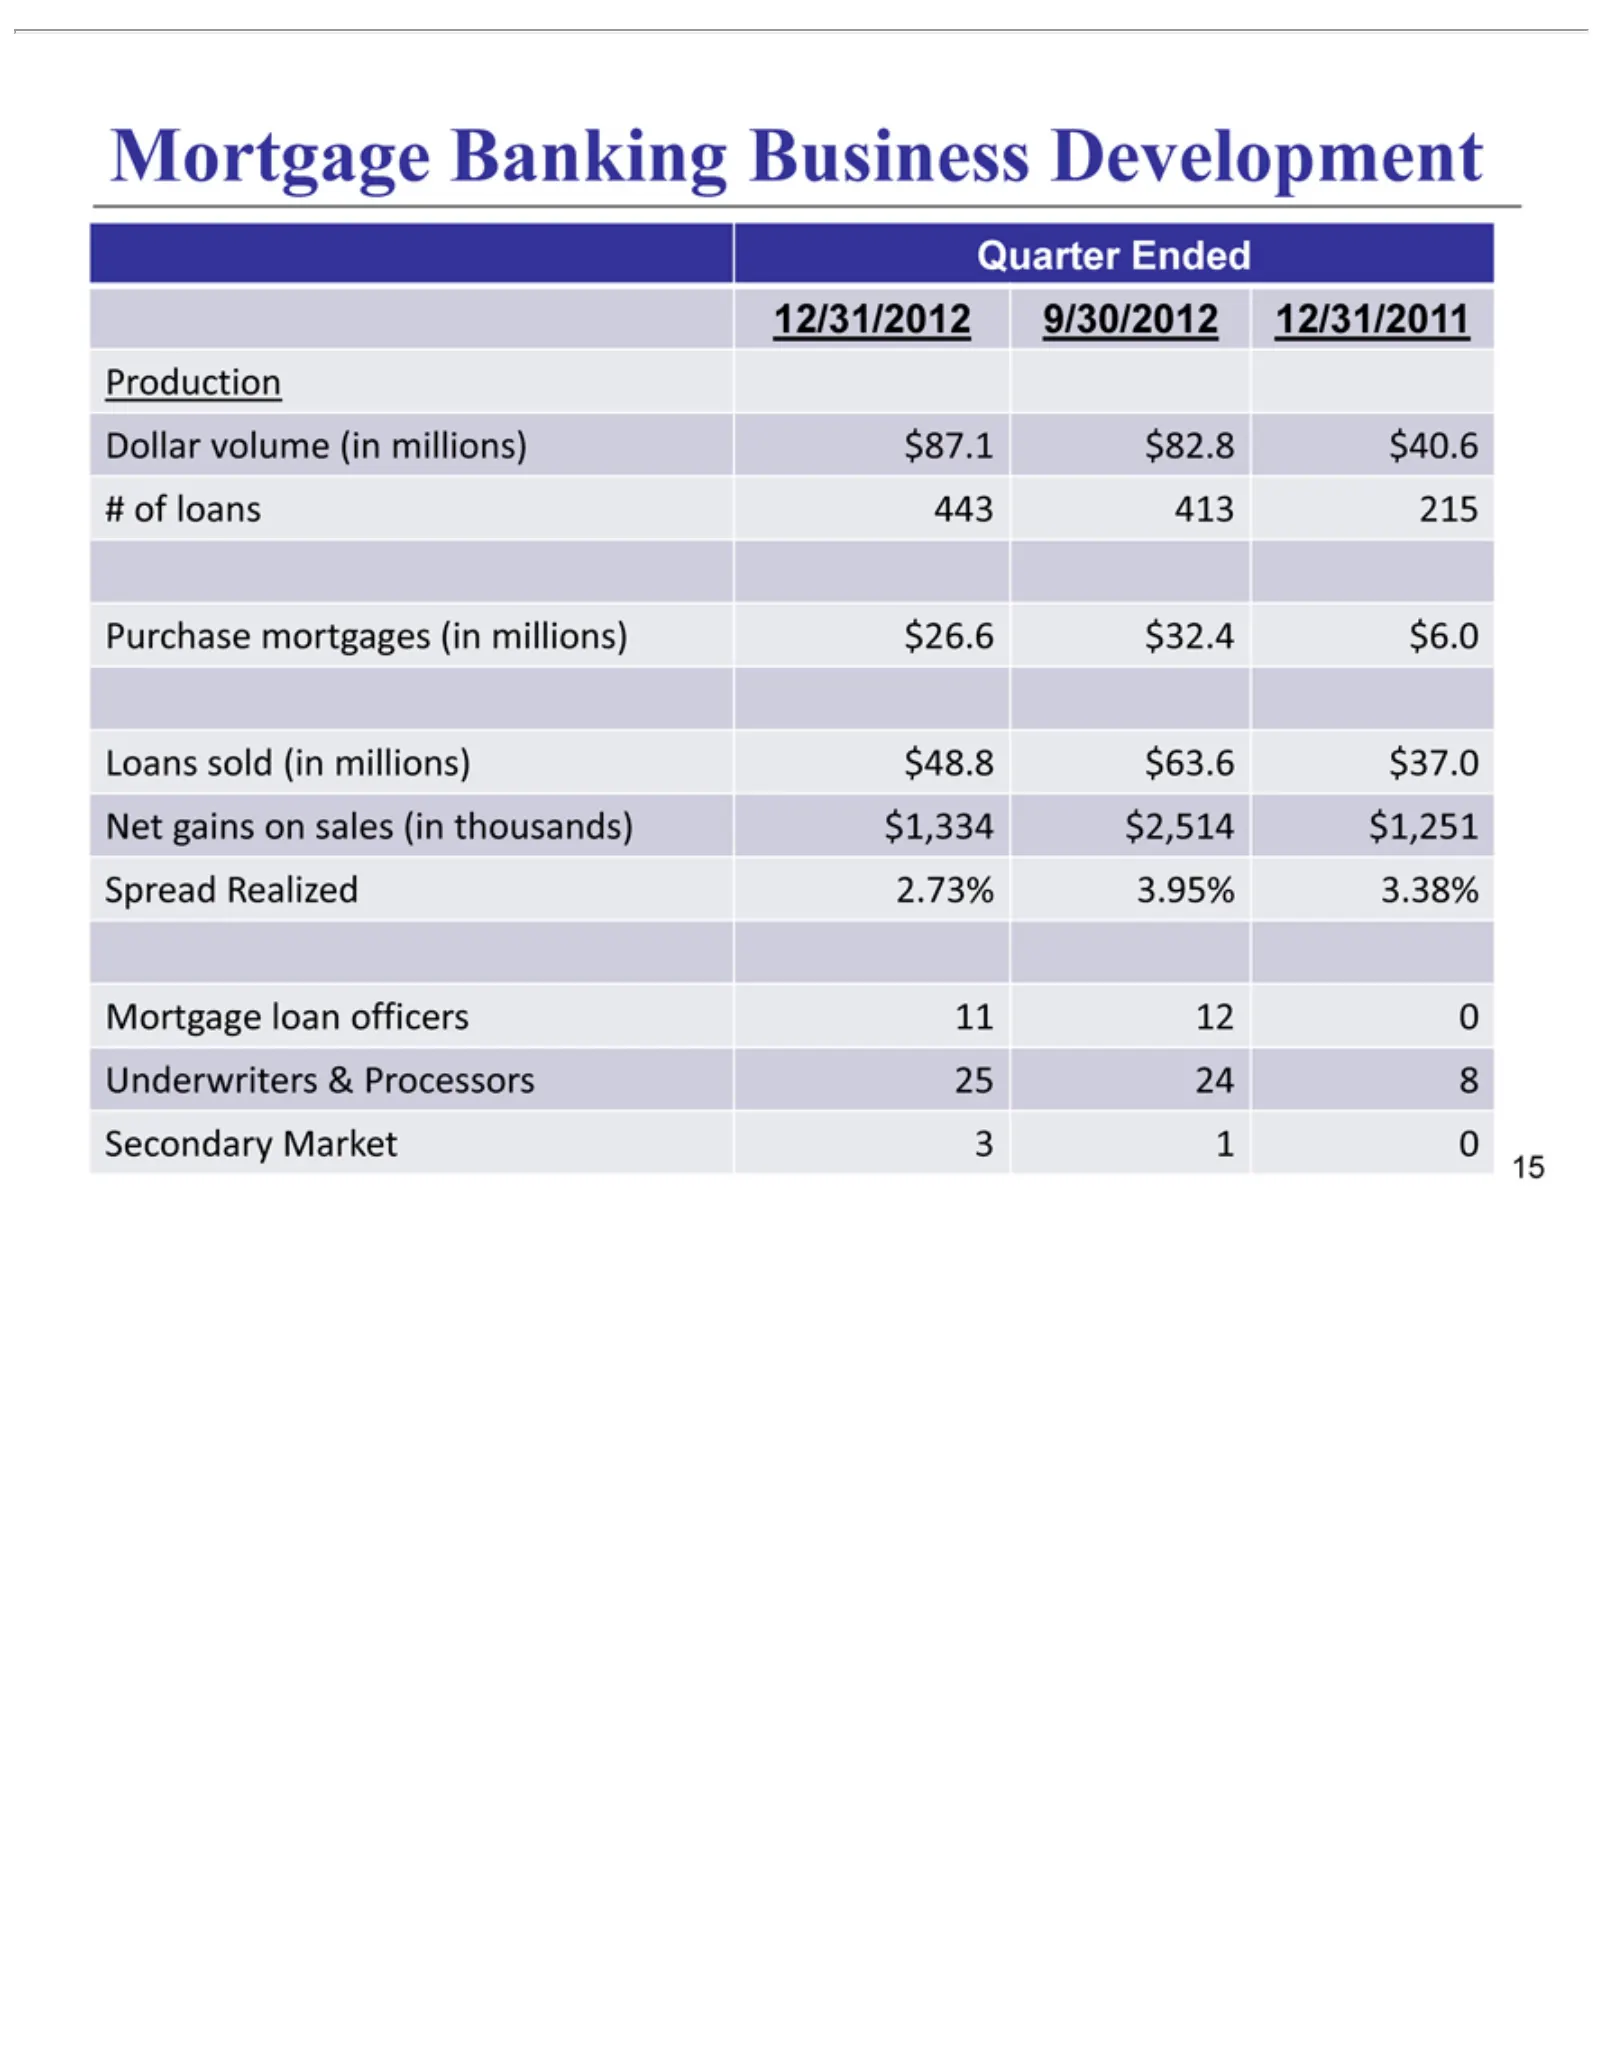
Slide 15: Mortgage Banking Production
Quarter 12/31/2012 Dollar #Production Purchase Loans Net Spread Mortgage Underwriters Secondary 15of gains loans sold volume Realized Ended mortgages on Banking loan 443 Market (in 9/30/2012 sales &413 millions) (in officers Processors 2.73% millions) (in 3215 Business (in 1thousands) 012/31/2011 11
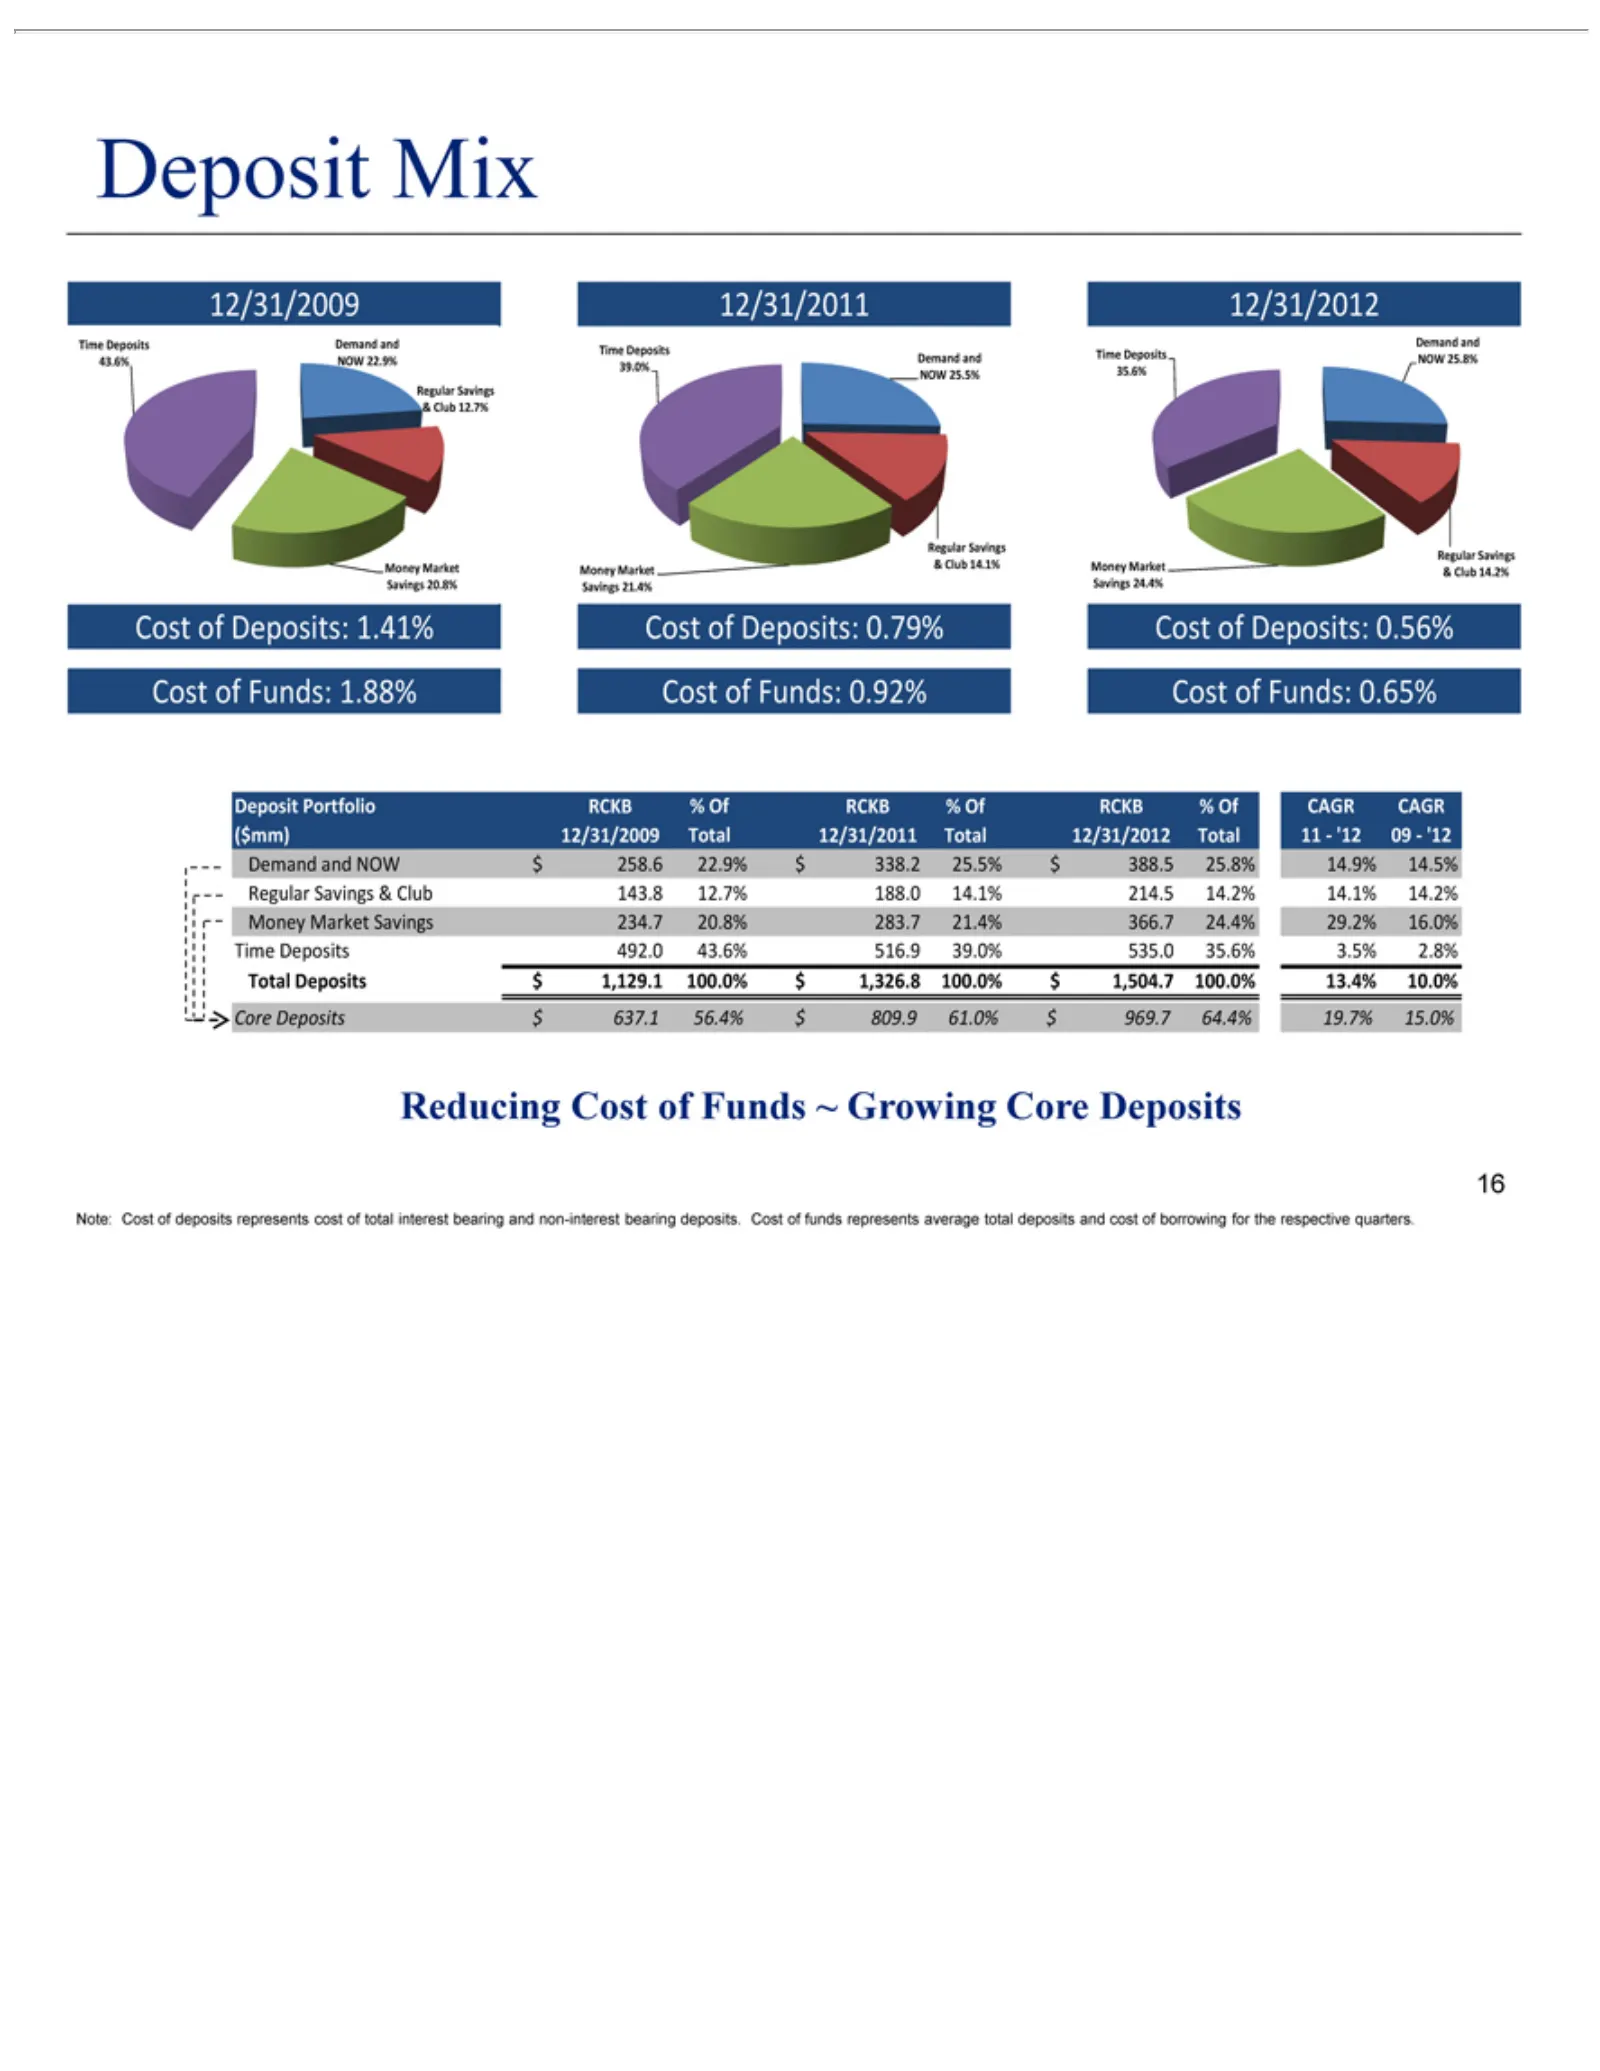
Slide 16: Deposit Portfolio and Cost of Funds
12/31/2009 Savings 12/31/2011 Time 12/31/2012 Money Regular Cost Deposit Demand 143.8 234.7 $492.0 Reducing Note: 16258.6 1,129.1 637.1 of Deposits Cost 12.7% 20.8% 43.6% Market Deposits: Funds: 22.9% 56.4% Mix Portfolio Savings 20.8% and 100.0% Cost ofNOW 188.0 283.7 516.9 deposits 43.6% 39.0% 35.6
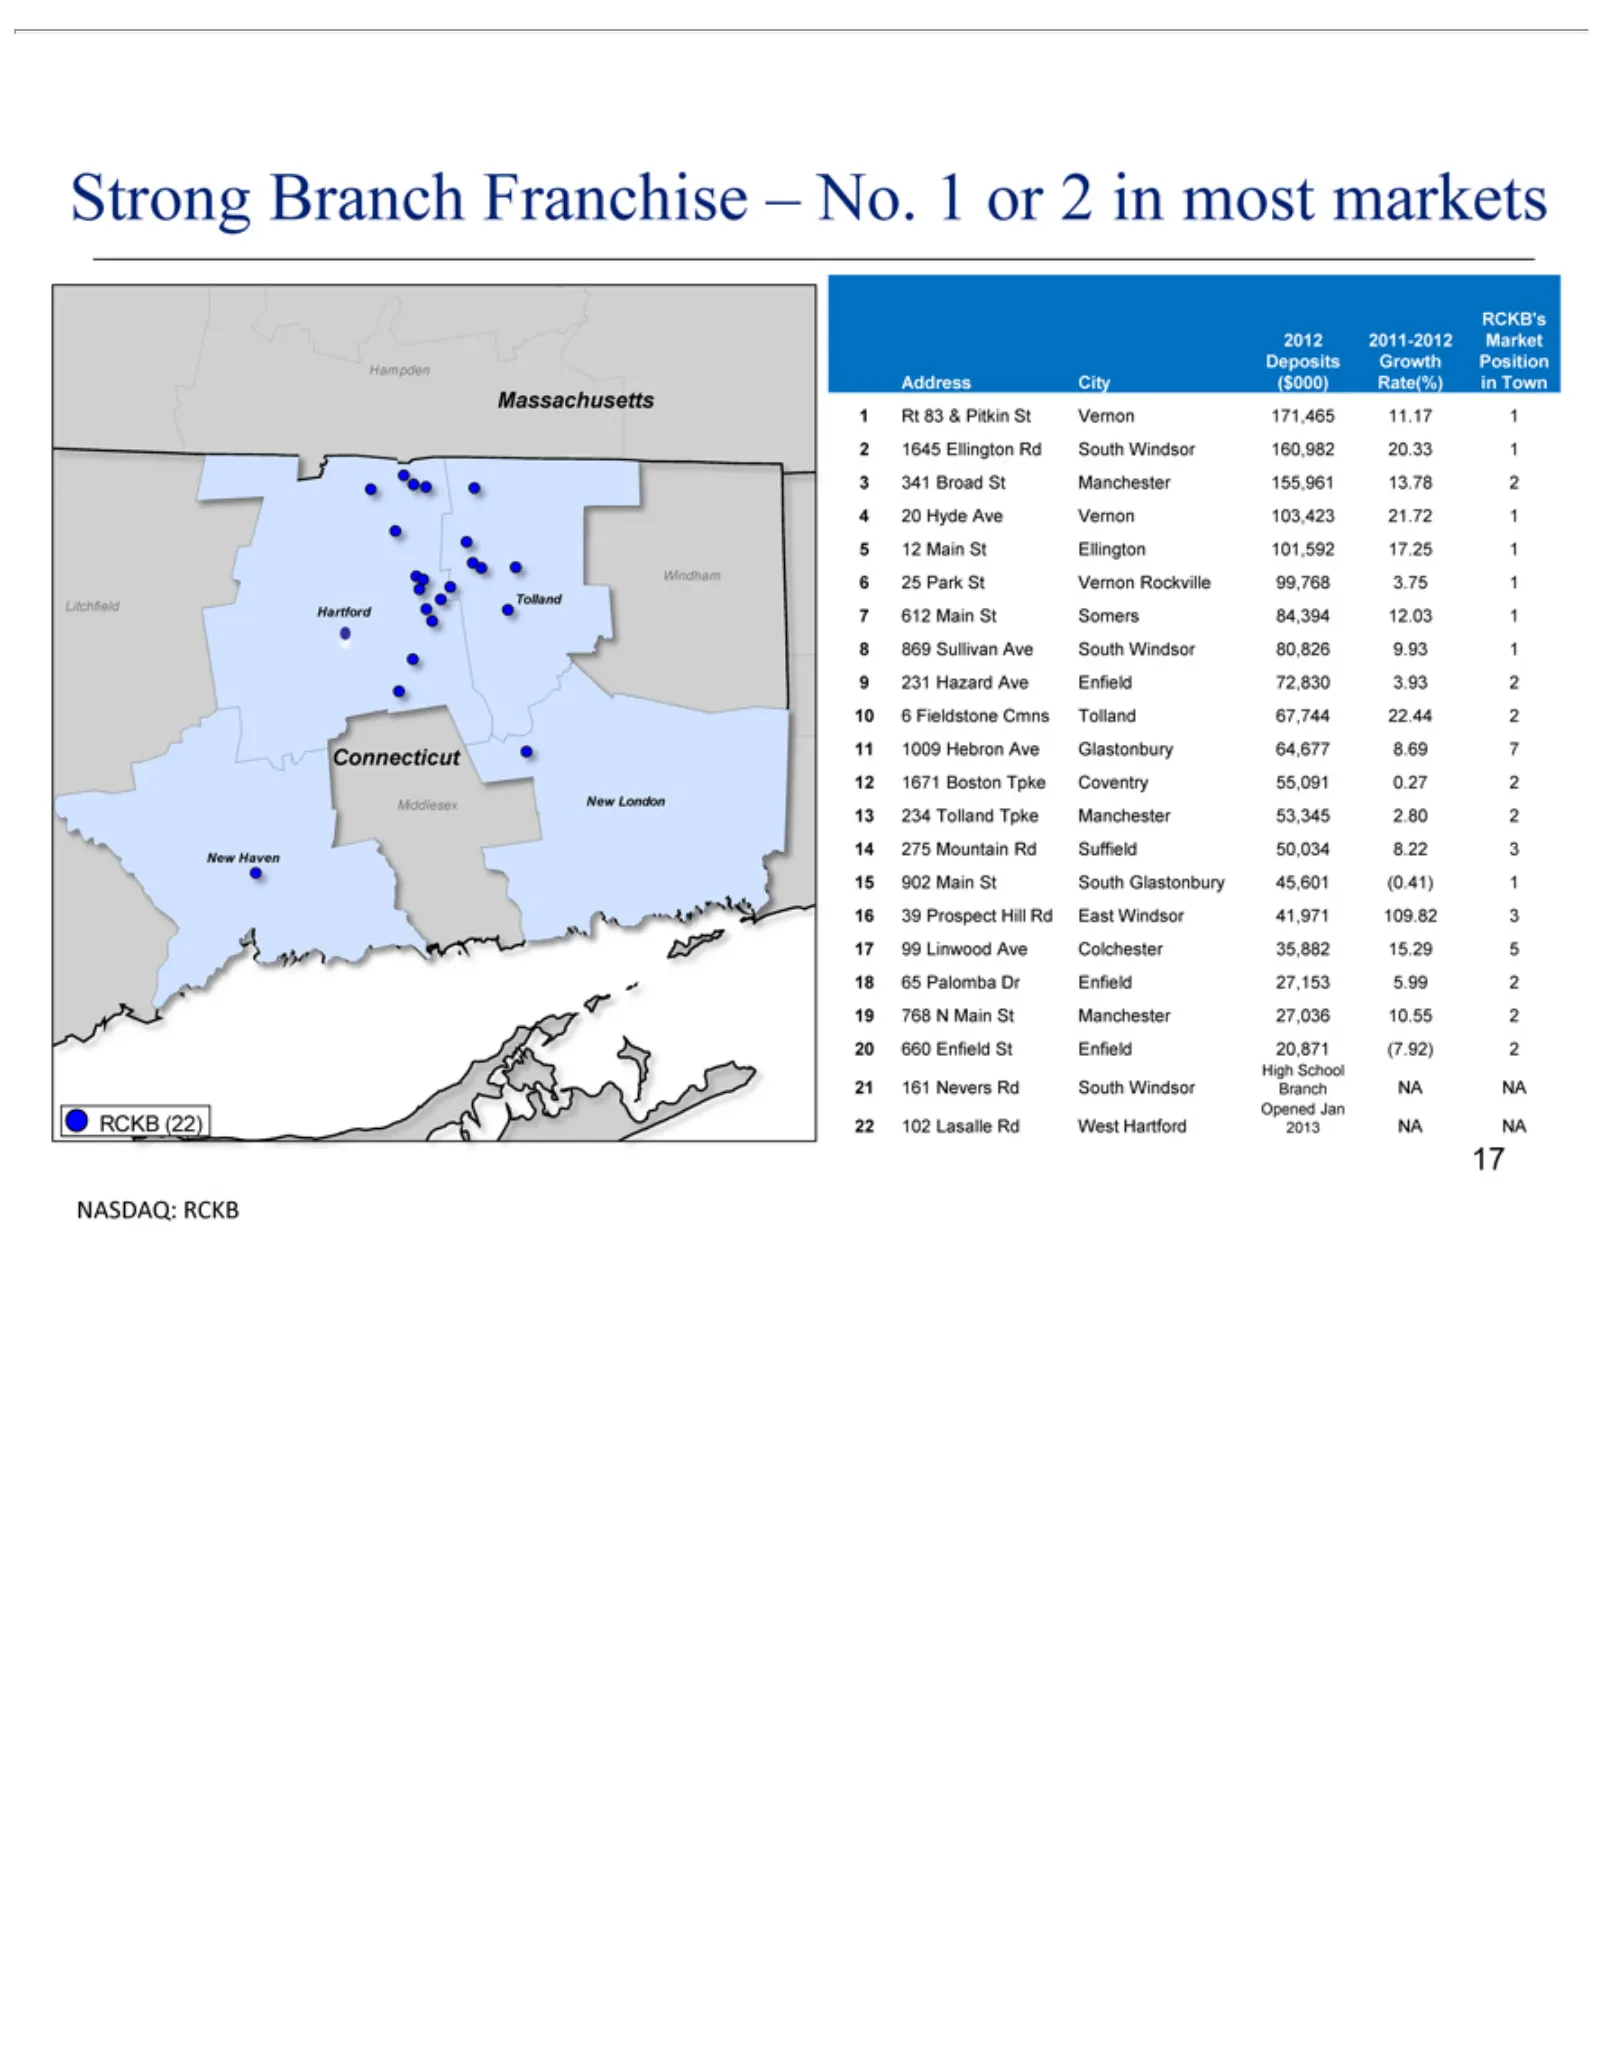
Slide 17: Strong Connecticut Franchise
Strong Hampden Connecticut RCKB 987654321Address 10 11 12 13 14 15 16 18 19 20 21 22 NASDAQ: 17Rt1009 1645 341 20 12 25 612 869 231 6 83 1671 234 275 902 39 99 65 768 660 161 102Hyde Main Park Fieldstone Broad Main Sullivan Hazard Prospect Linwood Palomba Branch (22) Tolland Ellington Mountain Main
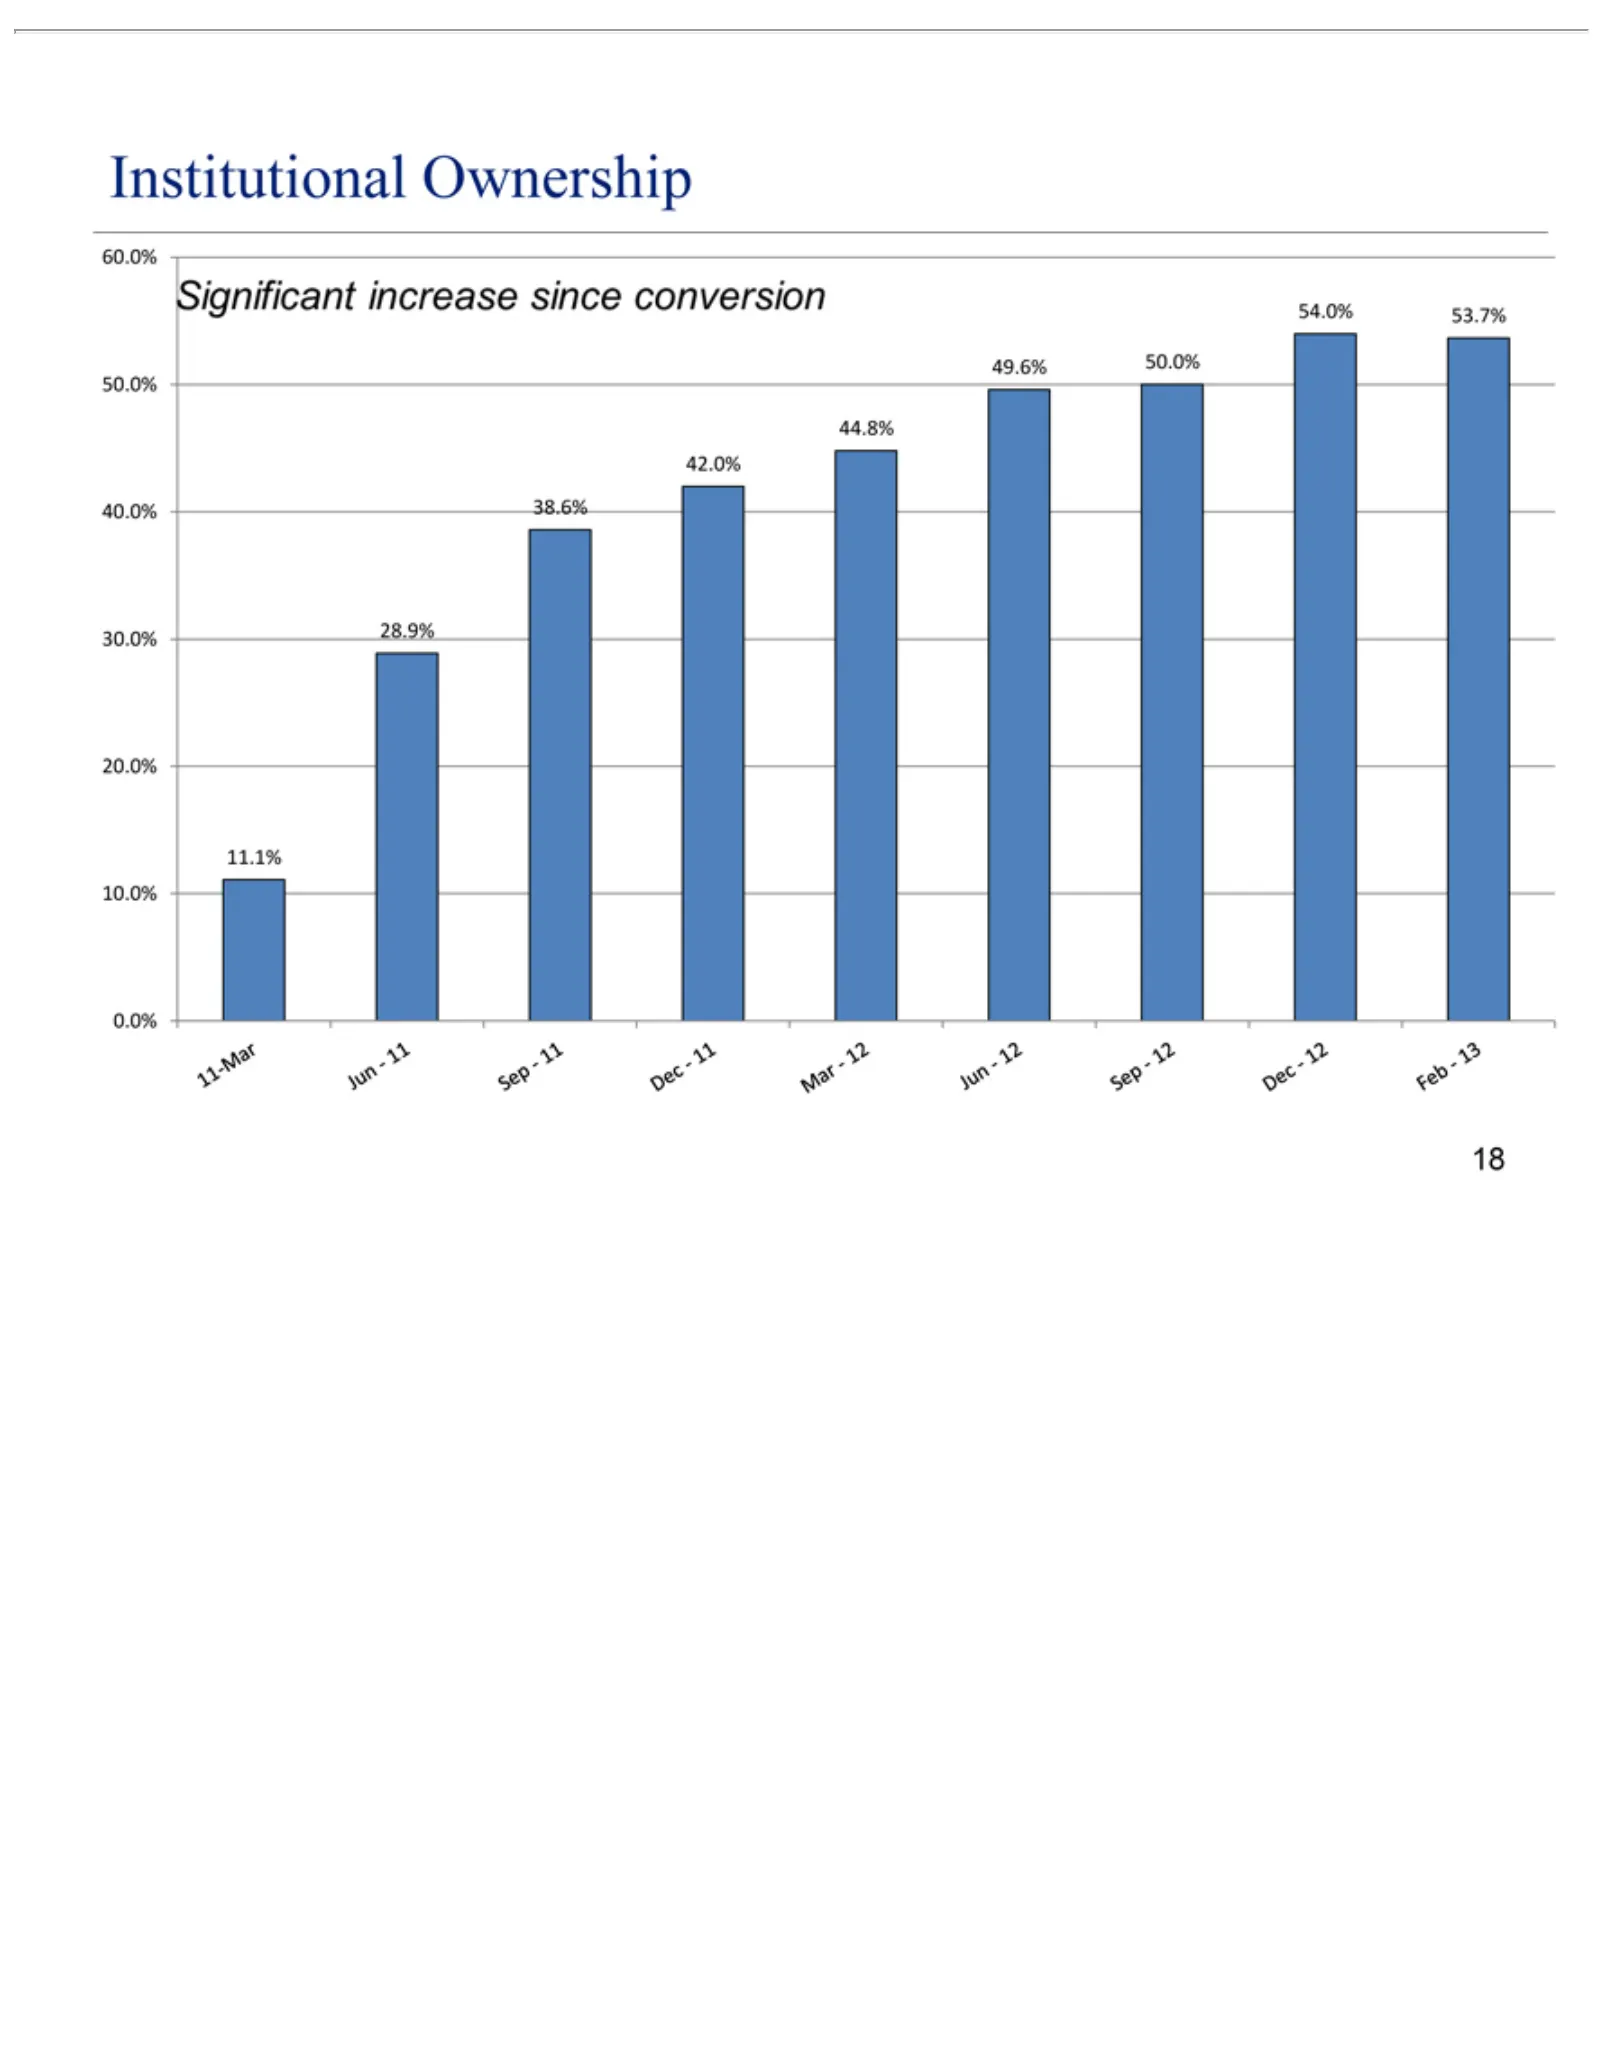
Slide 18: Significant Institutional Ownership
Institutional Significant 60.0% 11.1% 11-Mar 18 28.9% 50.0% Jun increase -Ownership 11 38.6% 40.0% Sepsince -42.0% 30.0% 11 Dec conversion 44.8% 20.0% - 11 Mar 49.6% 10.0% - 1250.0% 0.0% Jun - 54.0% 12 Sep 53.7% - 12 Dec - 12 Feb - 13
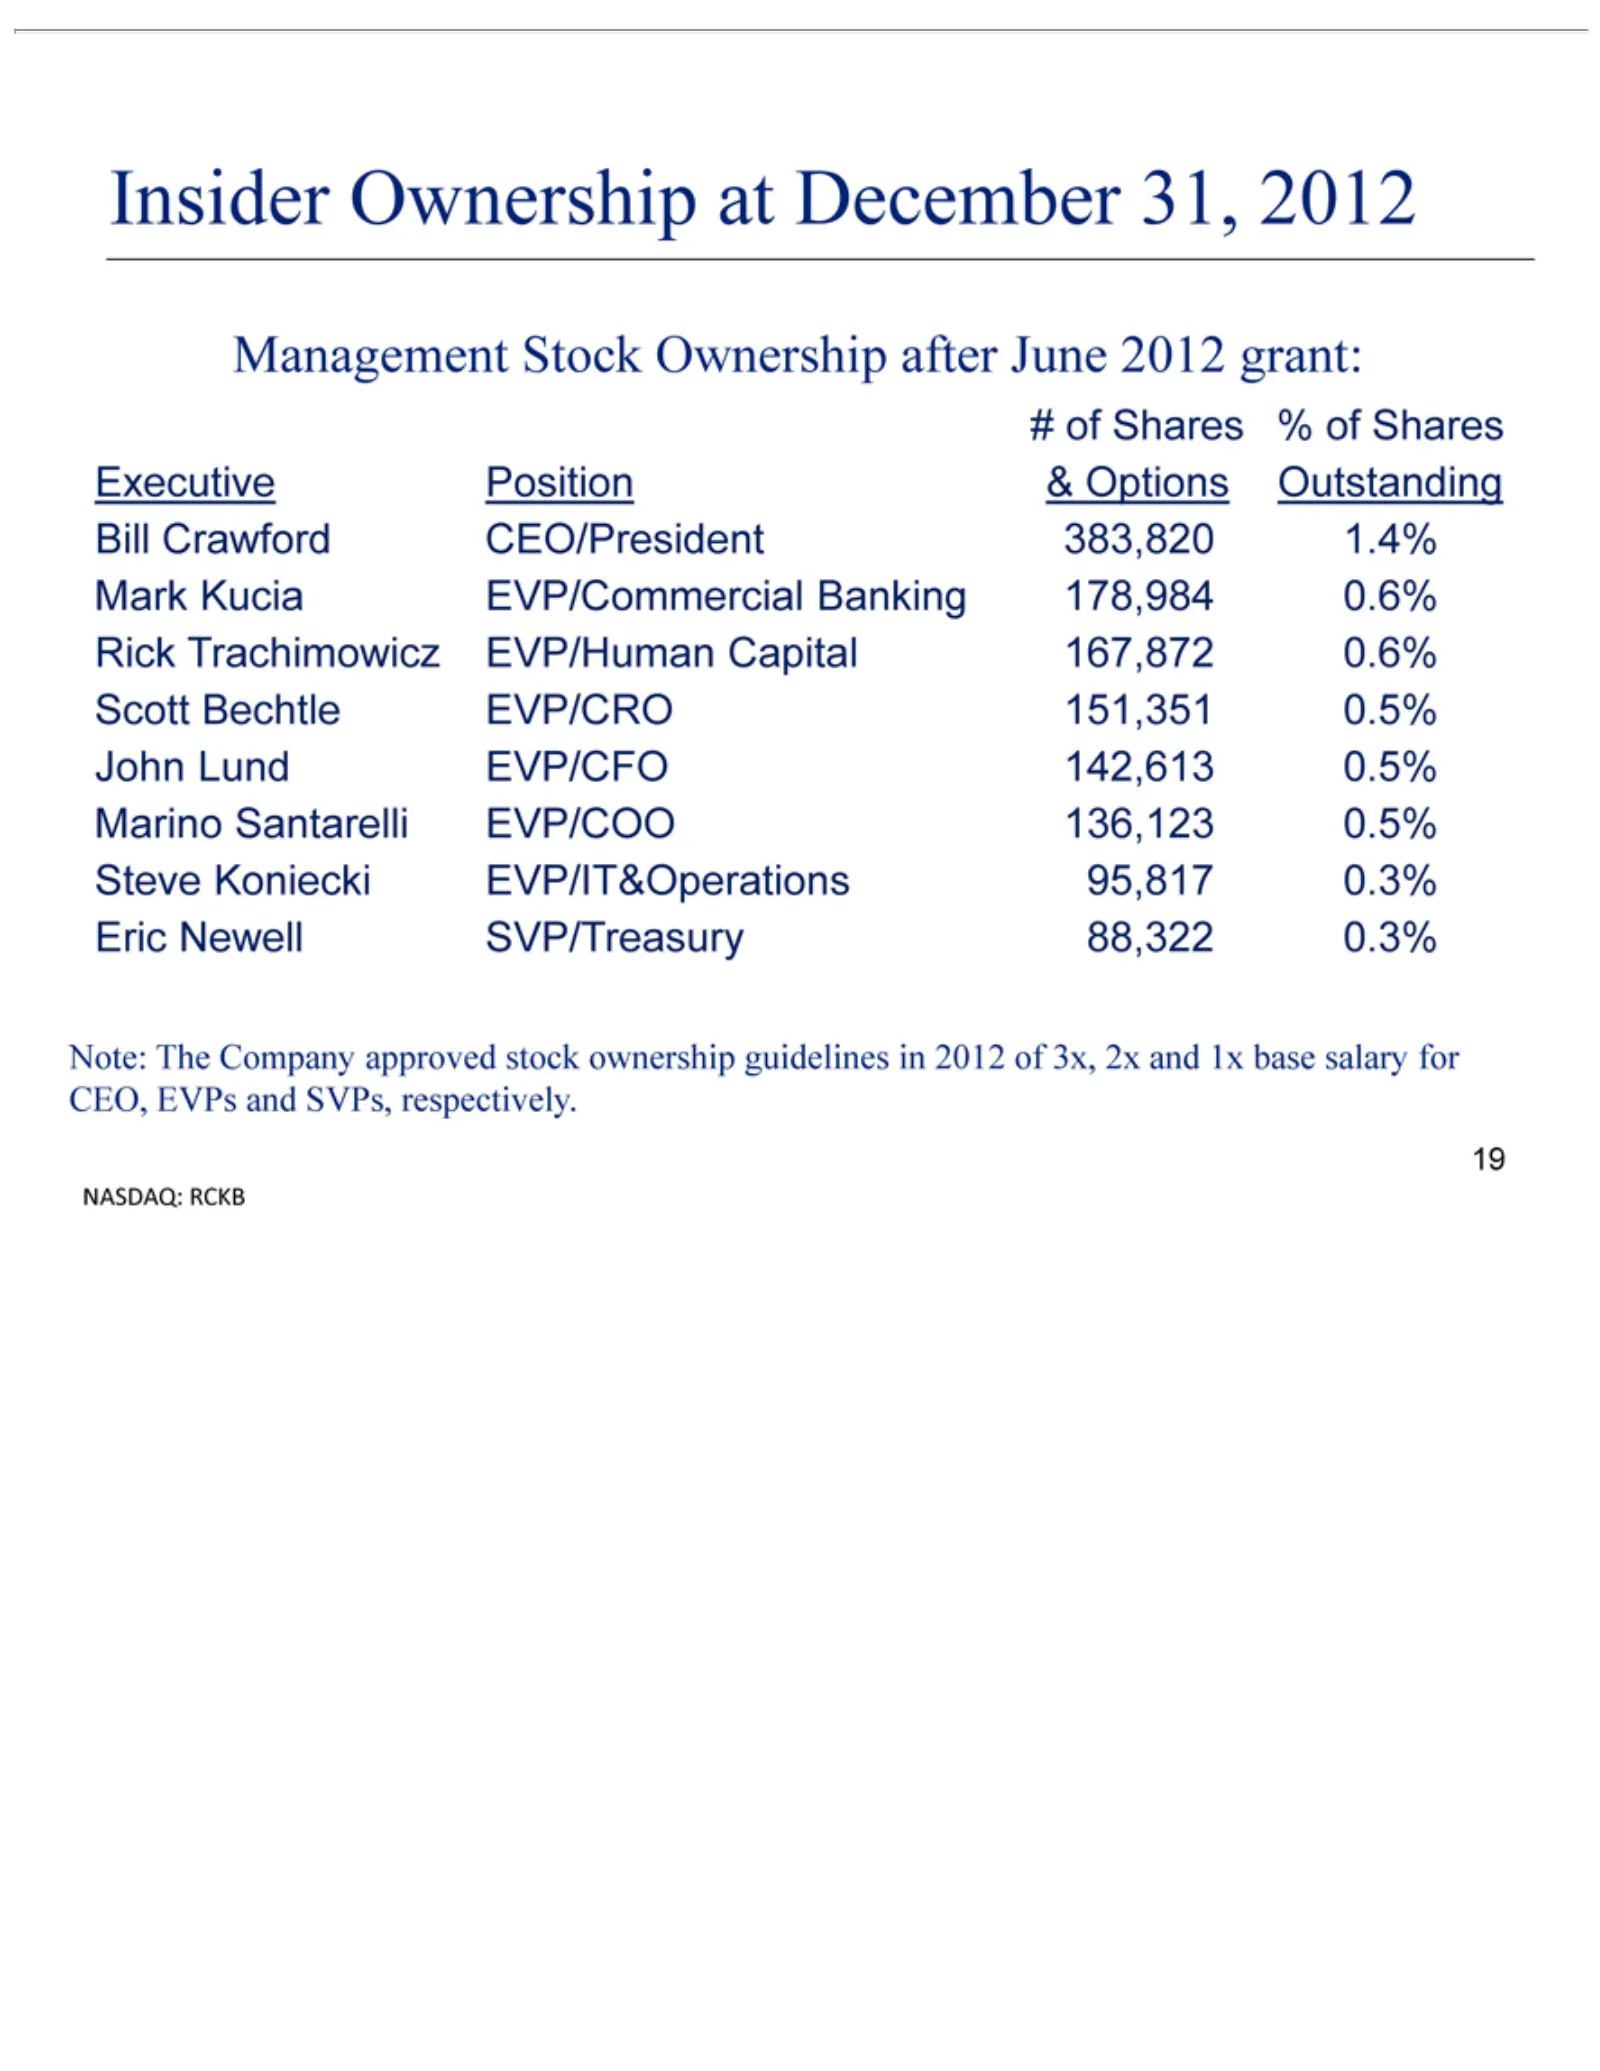
Slide 19: Insider Ownership: Executive Management
Insider Management Executive Bill Mark Rick Scott John Marino Steve Eric Note: NASDAQ: 19 Crawford Newell Trachimowicz Lund Bechtle Kucia The Koniecki Ownership Santarelli Position Company EVP/CFO RCKB SVP/Treasury EVP/Commercial Stock EVP/CRO CEO/President EVP/IT&Operations EVP/COO at #Ownership EV
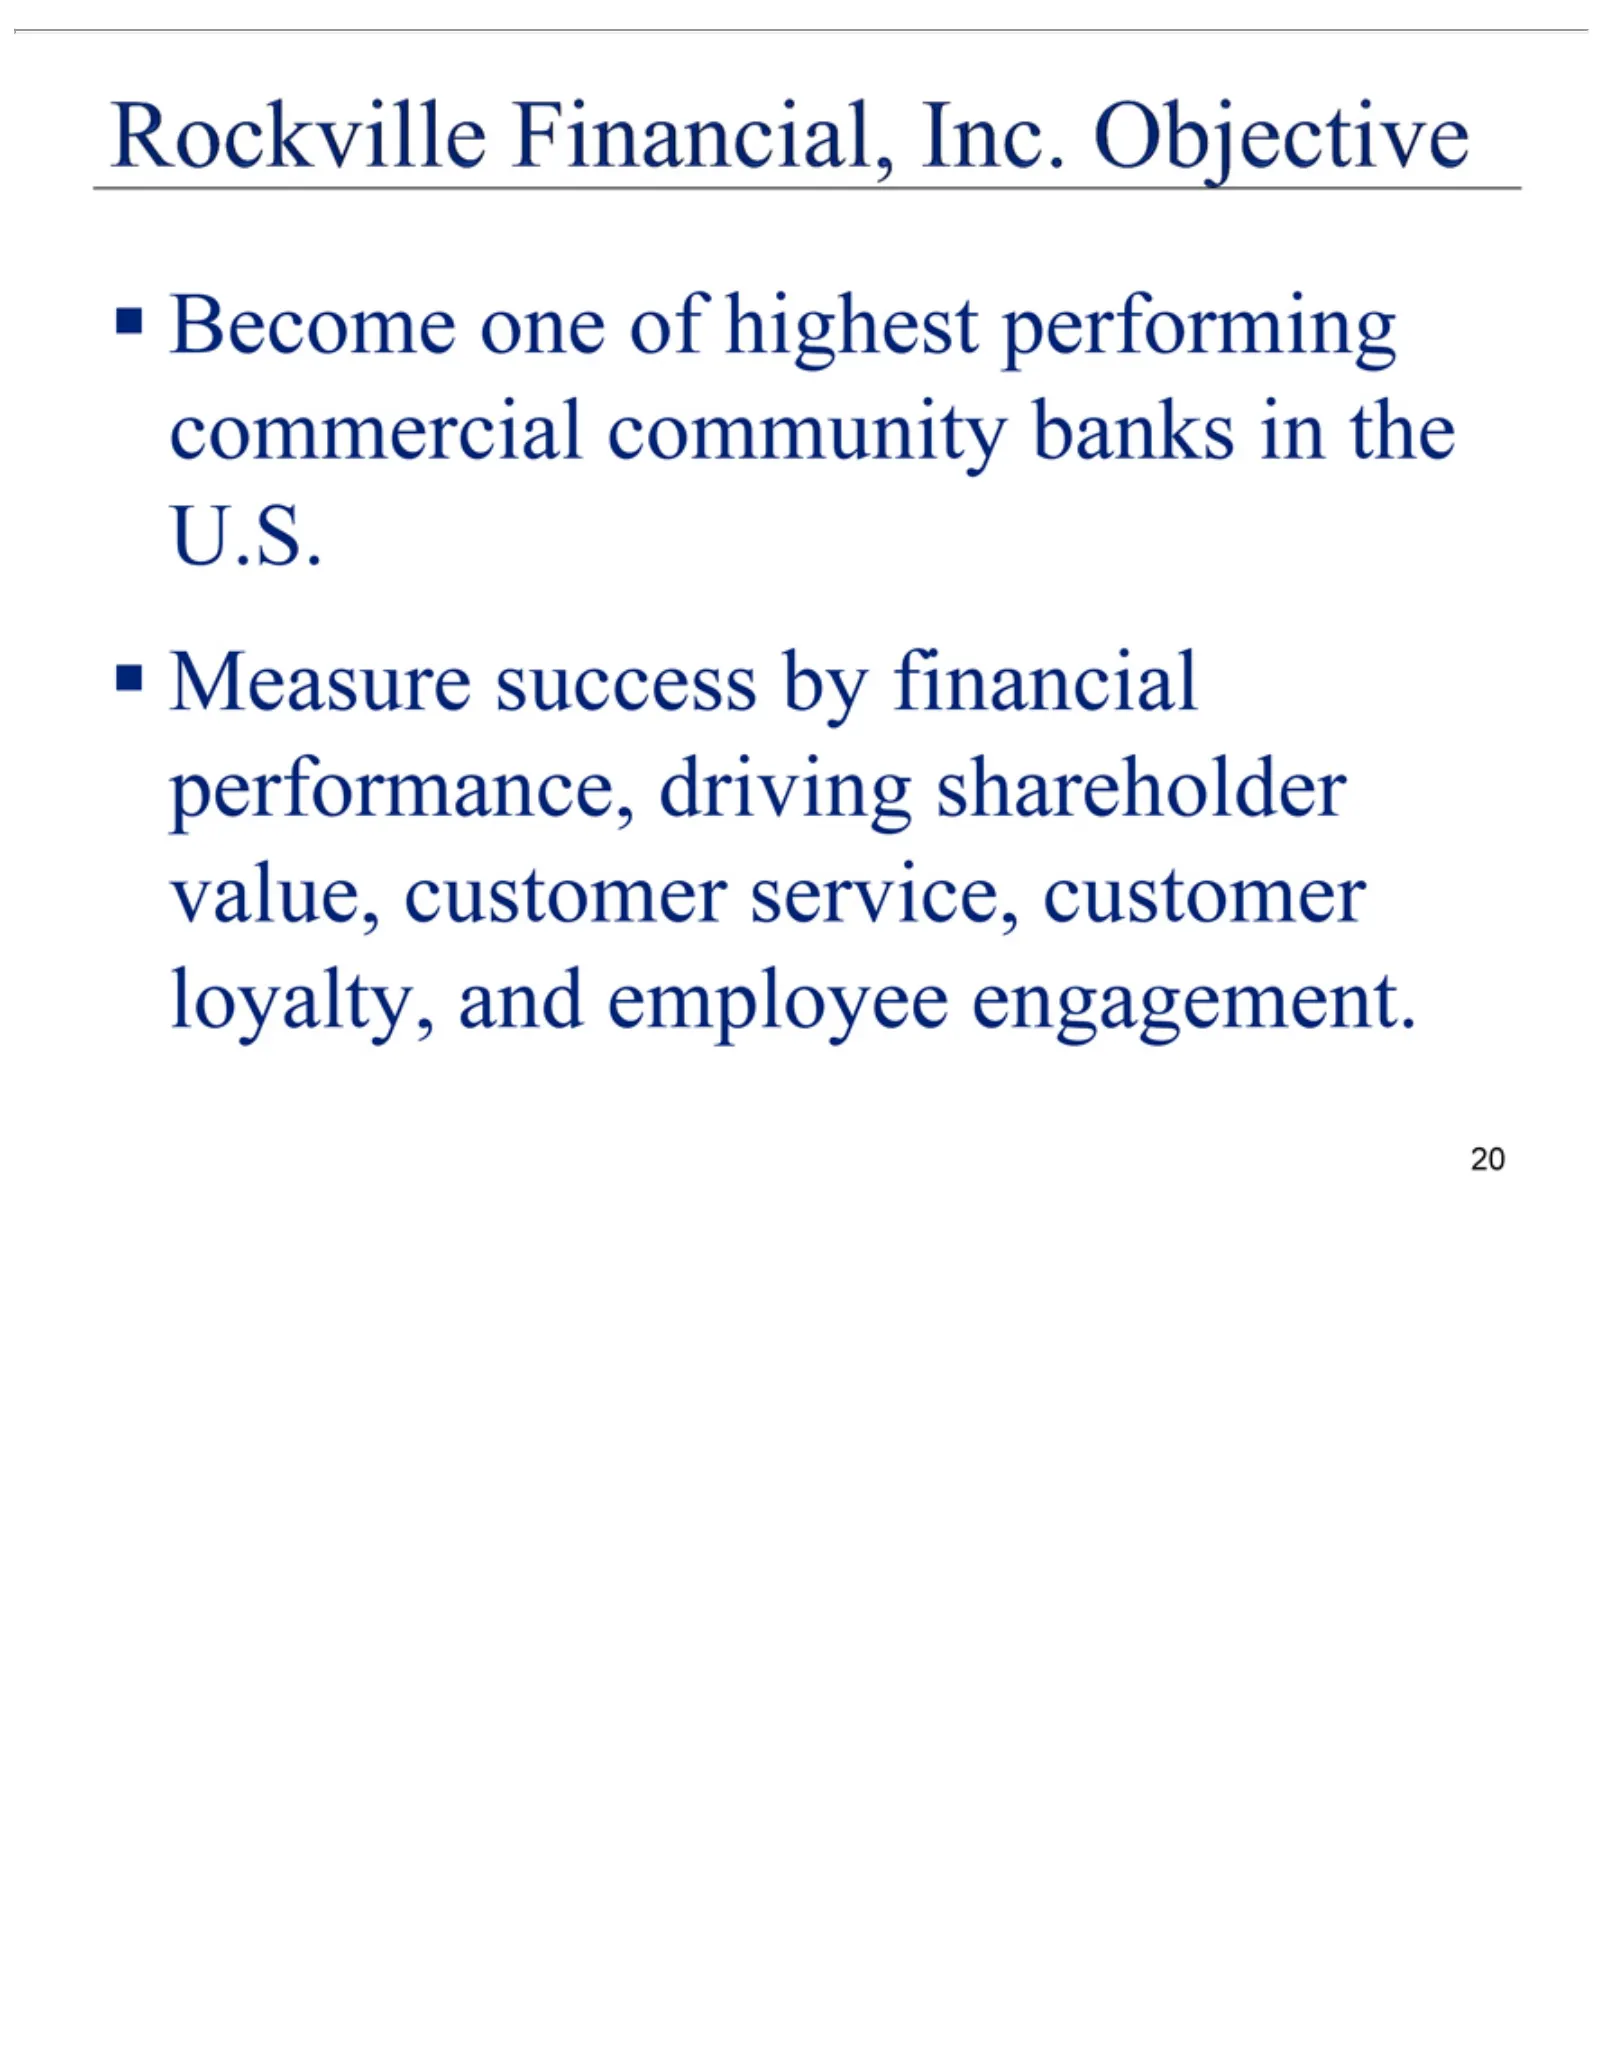
Slide 20: Rockville Financial: Become One of the Highest Performing Banks
Rockvilleone Become Measure 20 success Financial, of highest by financial Inc.performing Objective performance, commercial driving community shareholder banks value, in the customer U.S. service, customer loyalty, and employee engagement.
Slide 21: Appendix
21 APPENDIX
Slide 22: Solid Performance vs. Peers
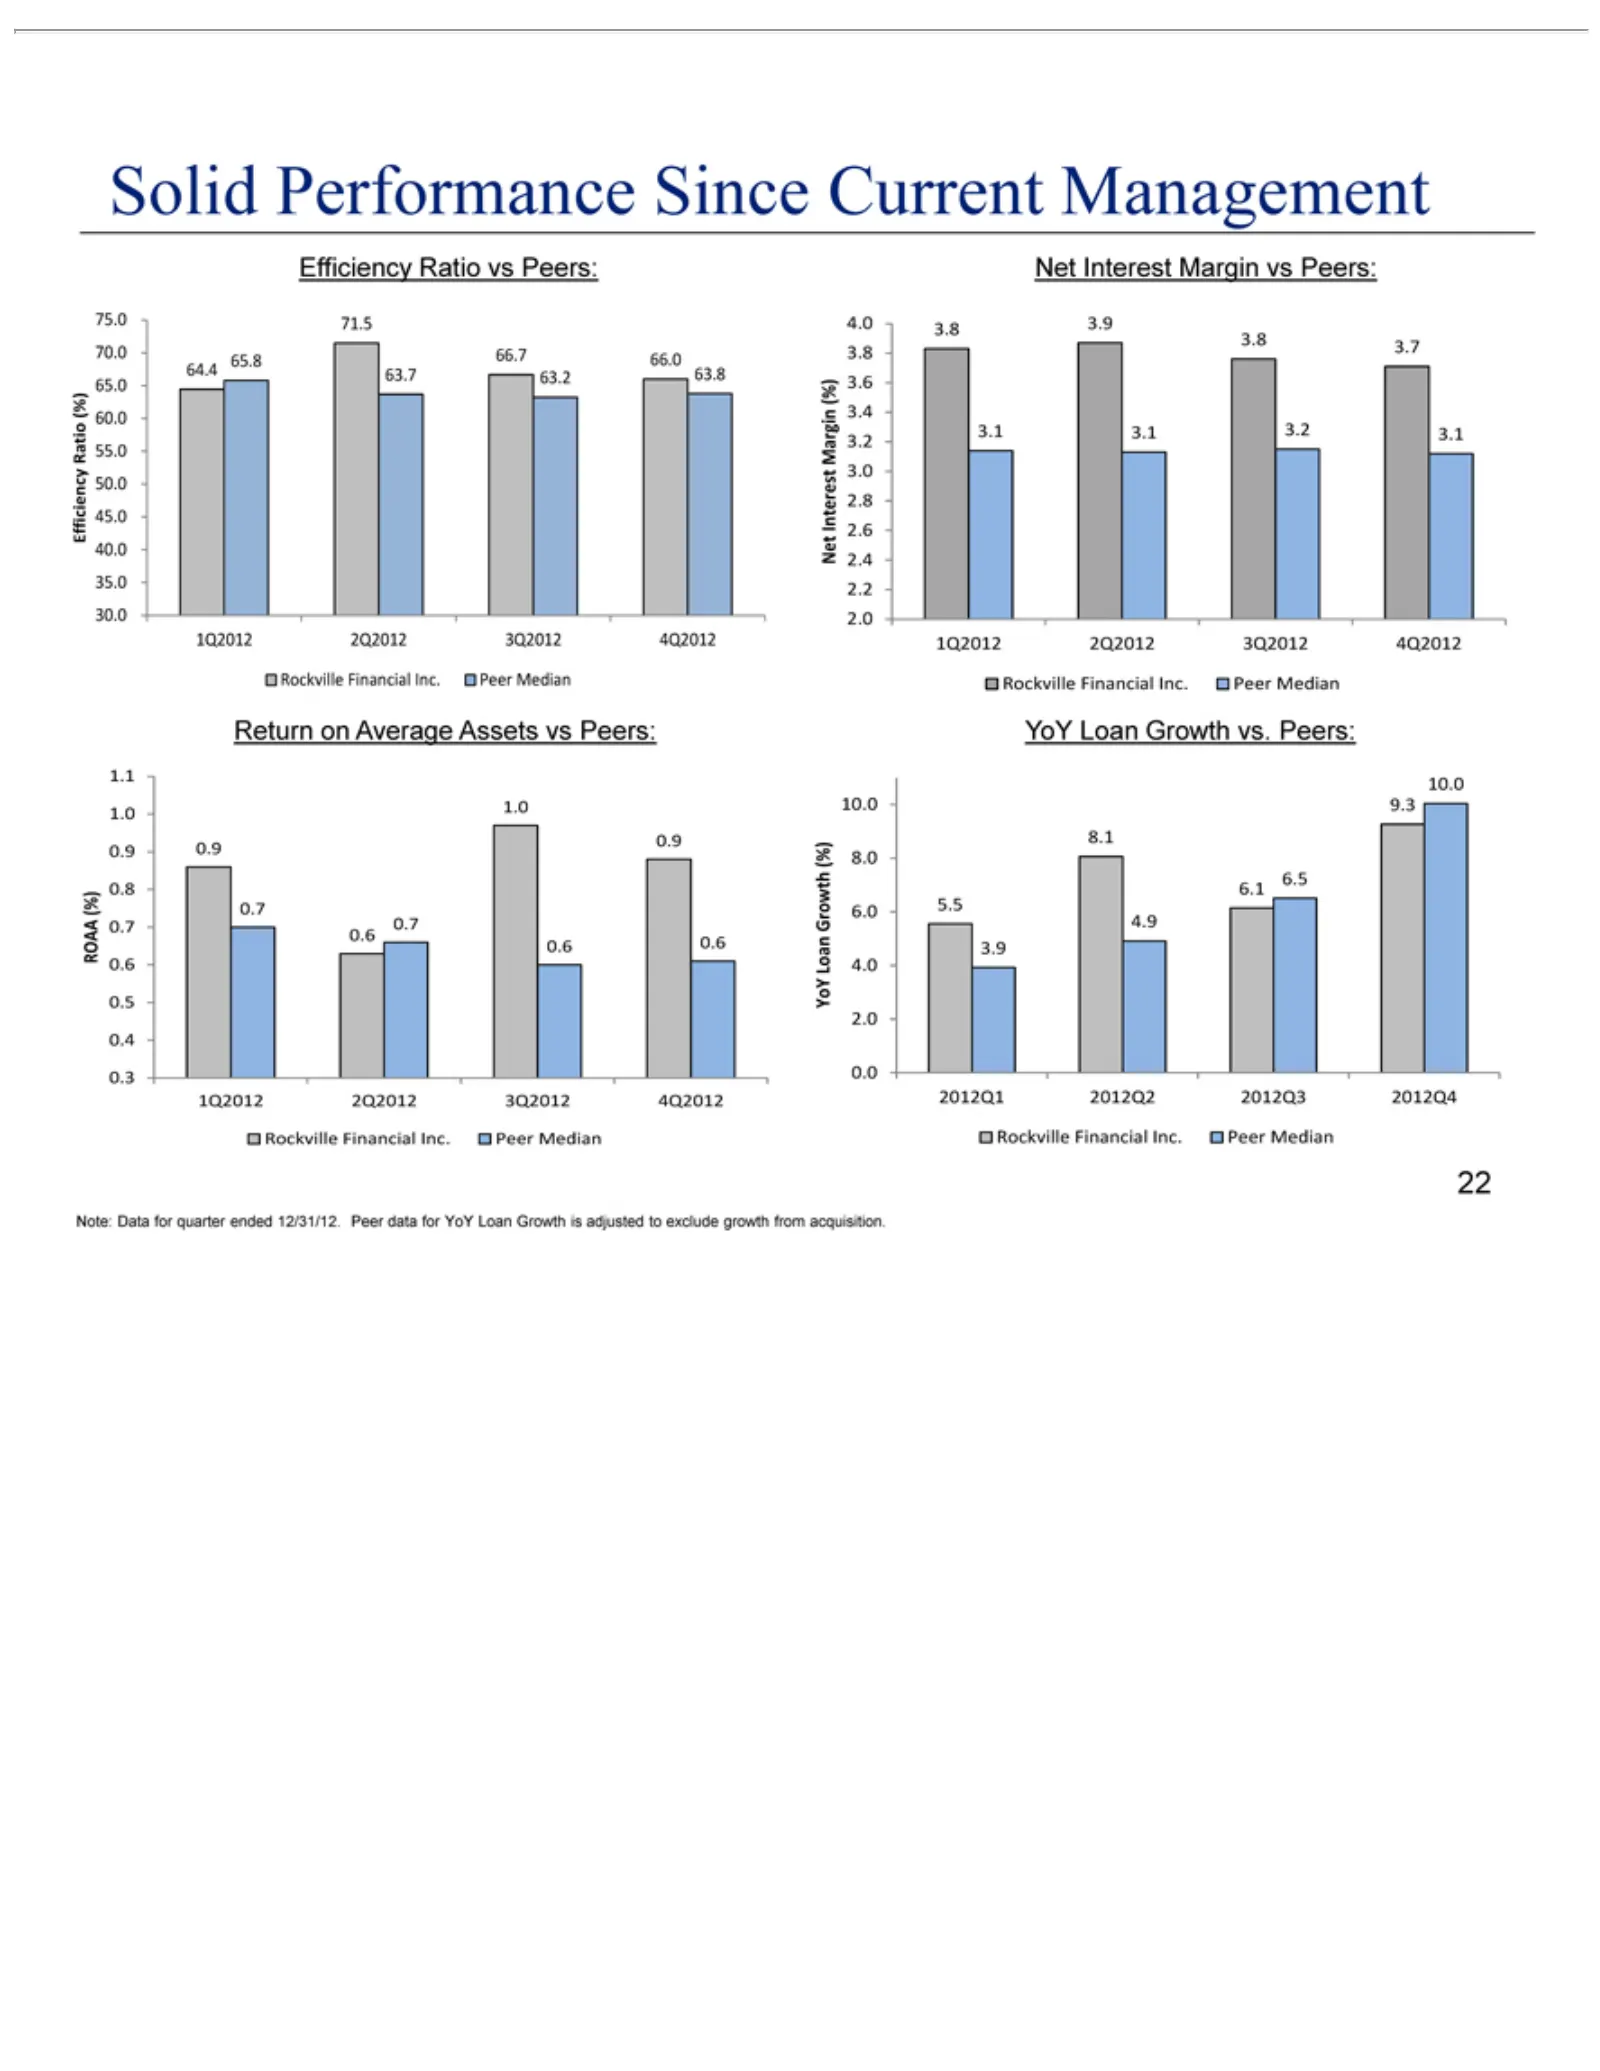
Solid Efficiency 75.0 64.4 Net 4.0 3.8 Return ROAA 1.1 0.9 1Q2012 YoY 10.0 5.5 2012Q1 Rockville Note: 22 3.8 3.1 1.0 0.7 3.9 Interest 70.0 65.8 8.0 Loan Performance Data on 3.6 3.9 0.9 0.6 8.1 (%) 2Q2012 2012Q2 6.0 65.0 71.5 Financial Average Growth Ratio 3.4 3.1 0.8 0.7 4.9 for Margin 4.06.1 60.0 6
Slide 23: Loan Quality Strong
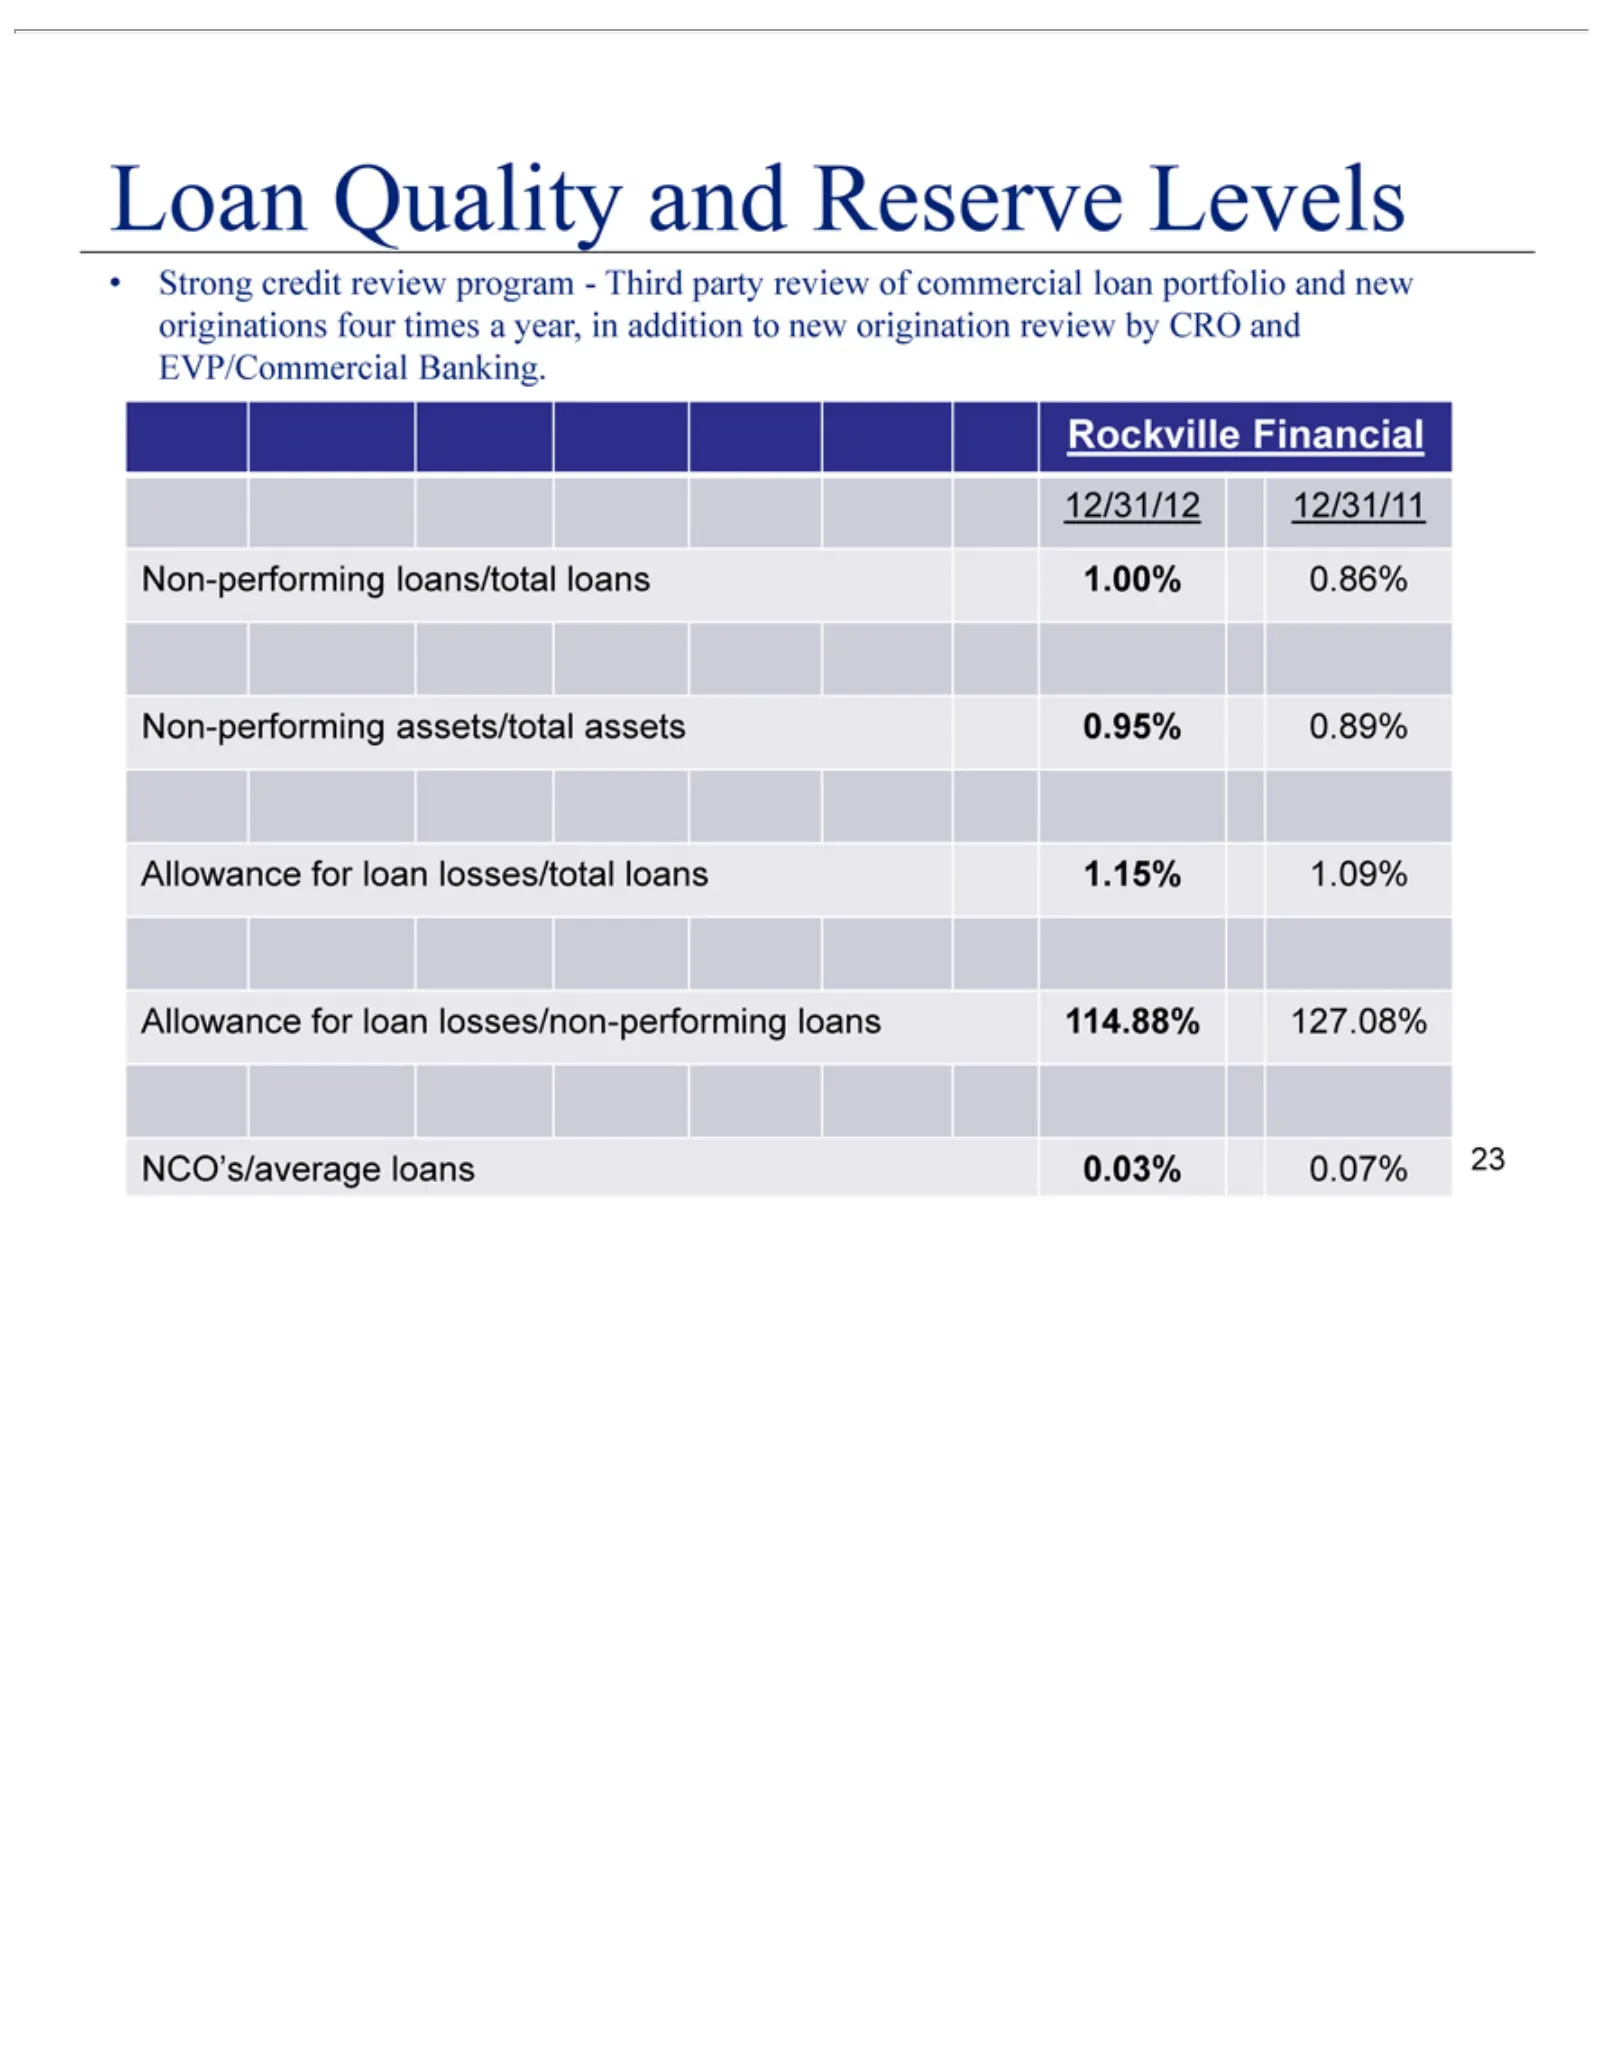
Loan Quality Strong Rockville 12/31/12 Non-performing Allowance NCO’s/average 23 credit 12/31/11 Financial forreview and loan loans loans/total assets/total Reserve losses/total losses/non-performing program 0.03% Levels loans assets 0.07% - Third loans 1.00% 0.95% 1.15% party 0.86% 0.89% loans revi
Slide 24: Solid Loan Quality Compares Favorably
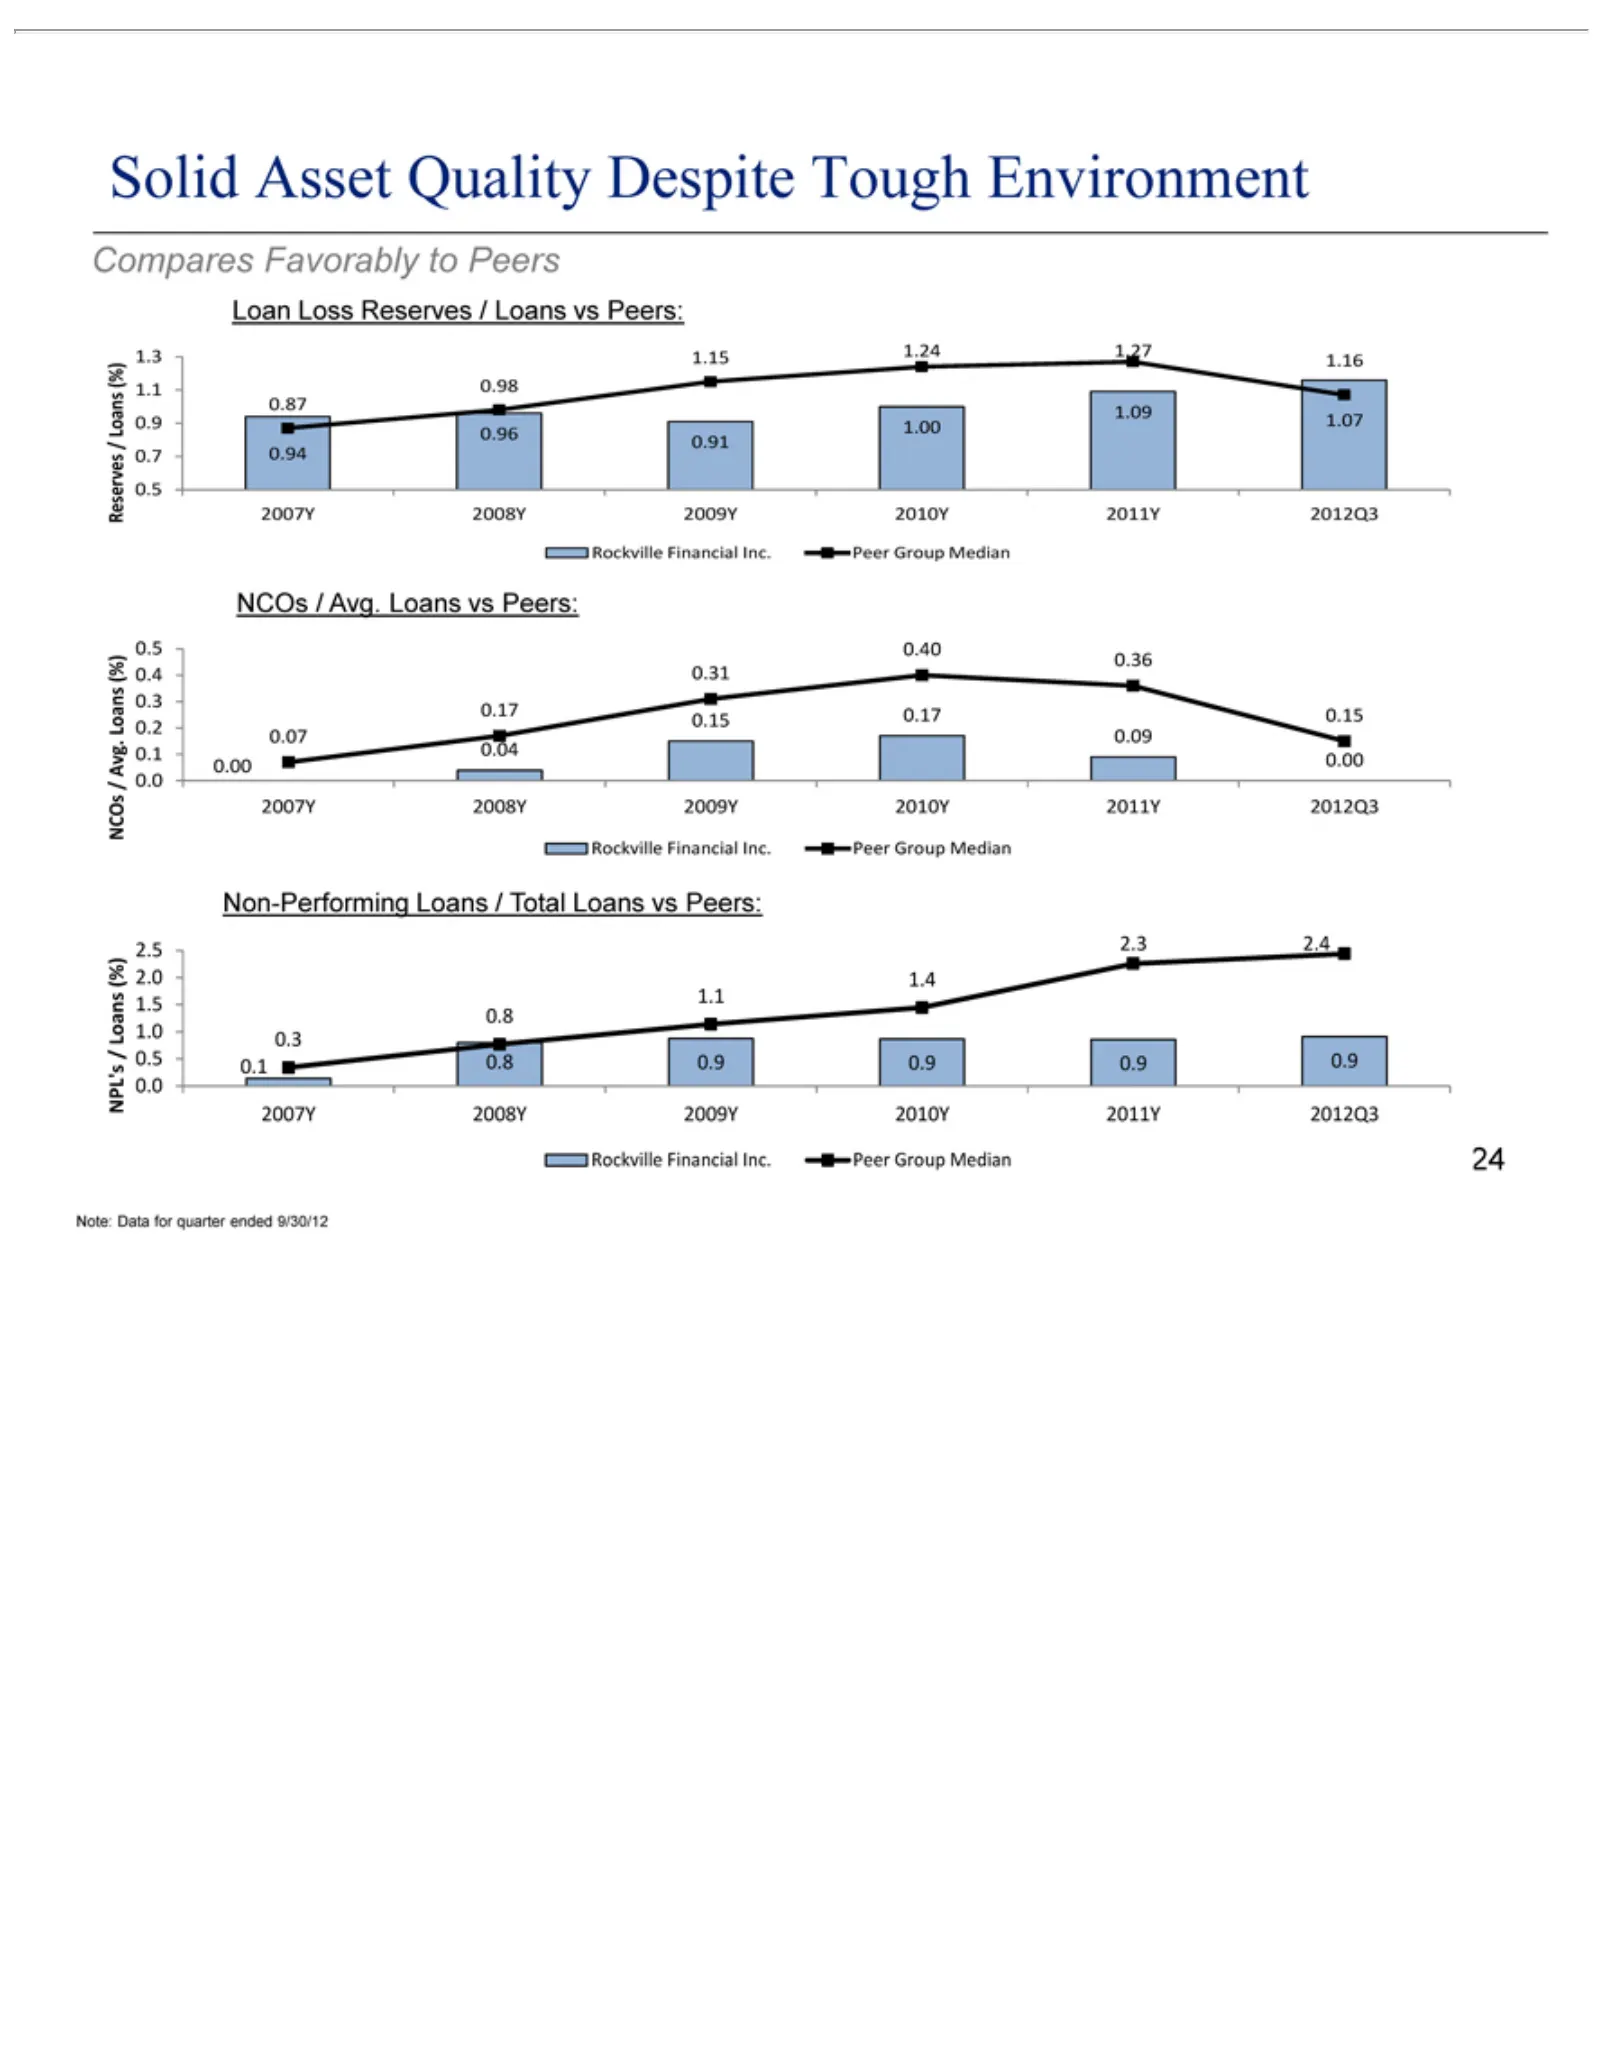
Solid Compares Loan Reserves 1.3 0.87 0.94 NCOs 0.5 Non-Performing NPL’s 2.5 0.8 2007Y Rockville Note: 24 1.1 0.4 2.0 0.9 0.98 0.96 Loss Asset Data /2008Y 0.3 1.5 0.9 Avg. Loans /0.91 1.15 Financial Favorably Loans Reserves 0.7 0.2 1.0 0.9 for Quality Loans 2009Y (%) 1.24 1.00 0.1 0.5 0.9 quarter Lo
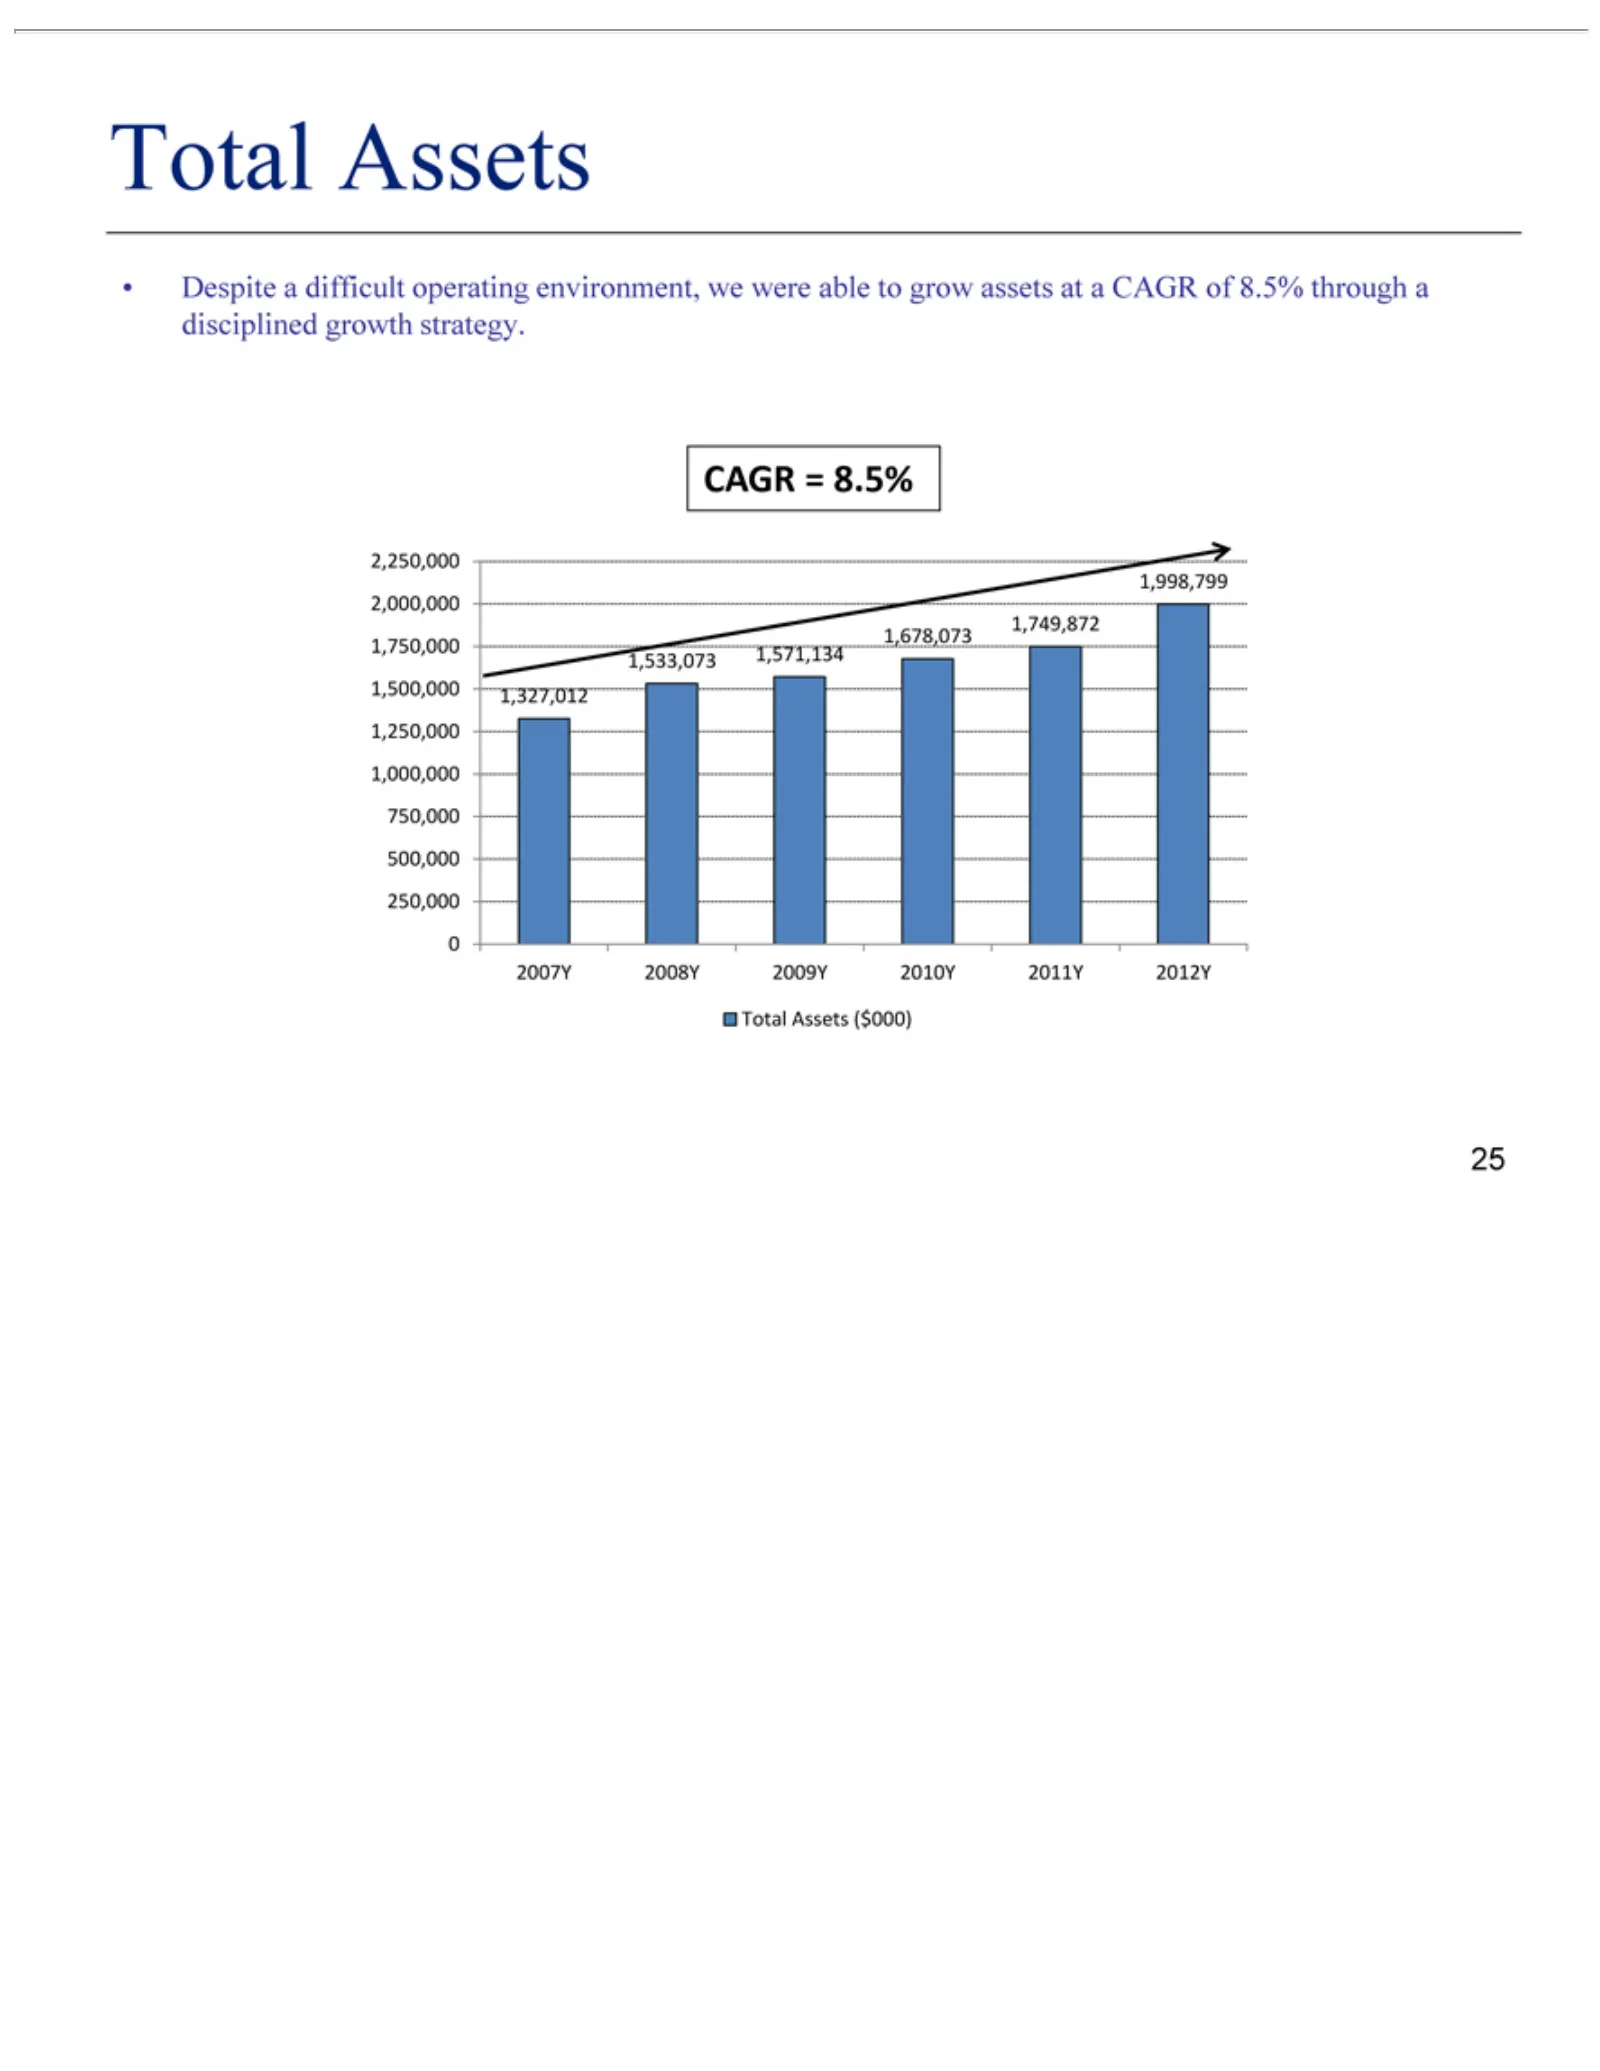
Slide 25: Despite Difficult Environment, Asset Growth
Despite CAGR 2,250,000 1,327,012 2007Y Total 25 Assets 2008Y =a 8.5% difficult 2,000,000 1,533,073 ($000) 2009Yoperating 1,750,000 1,571,134 2010Yenvironment, 2011Y 1,500,000 1,678,073 2012Y1,749,872 1,250,000 we were able 1,000,000 1,998,799 to grow750,000 assets at500,000 a CAGR250,000 of 8.5%0 th
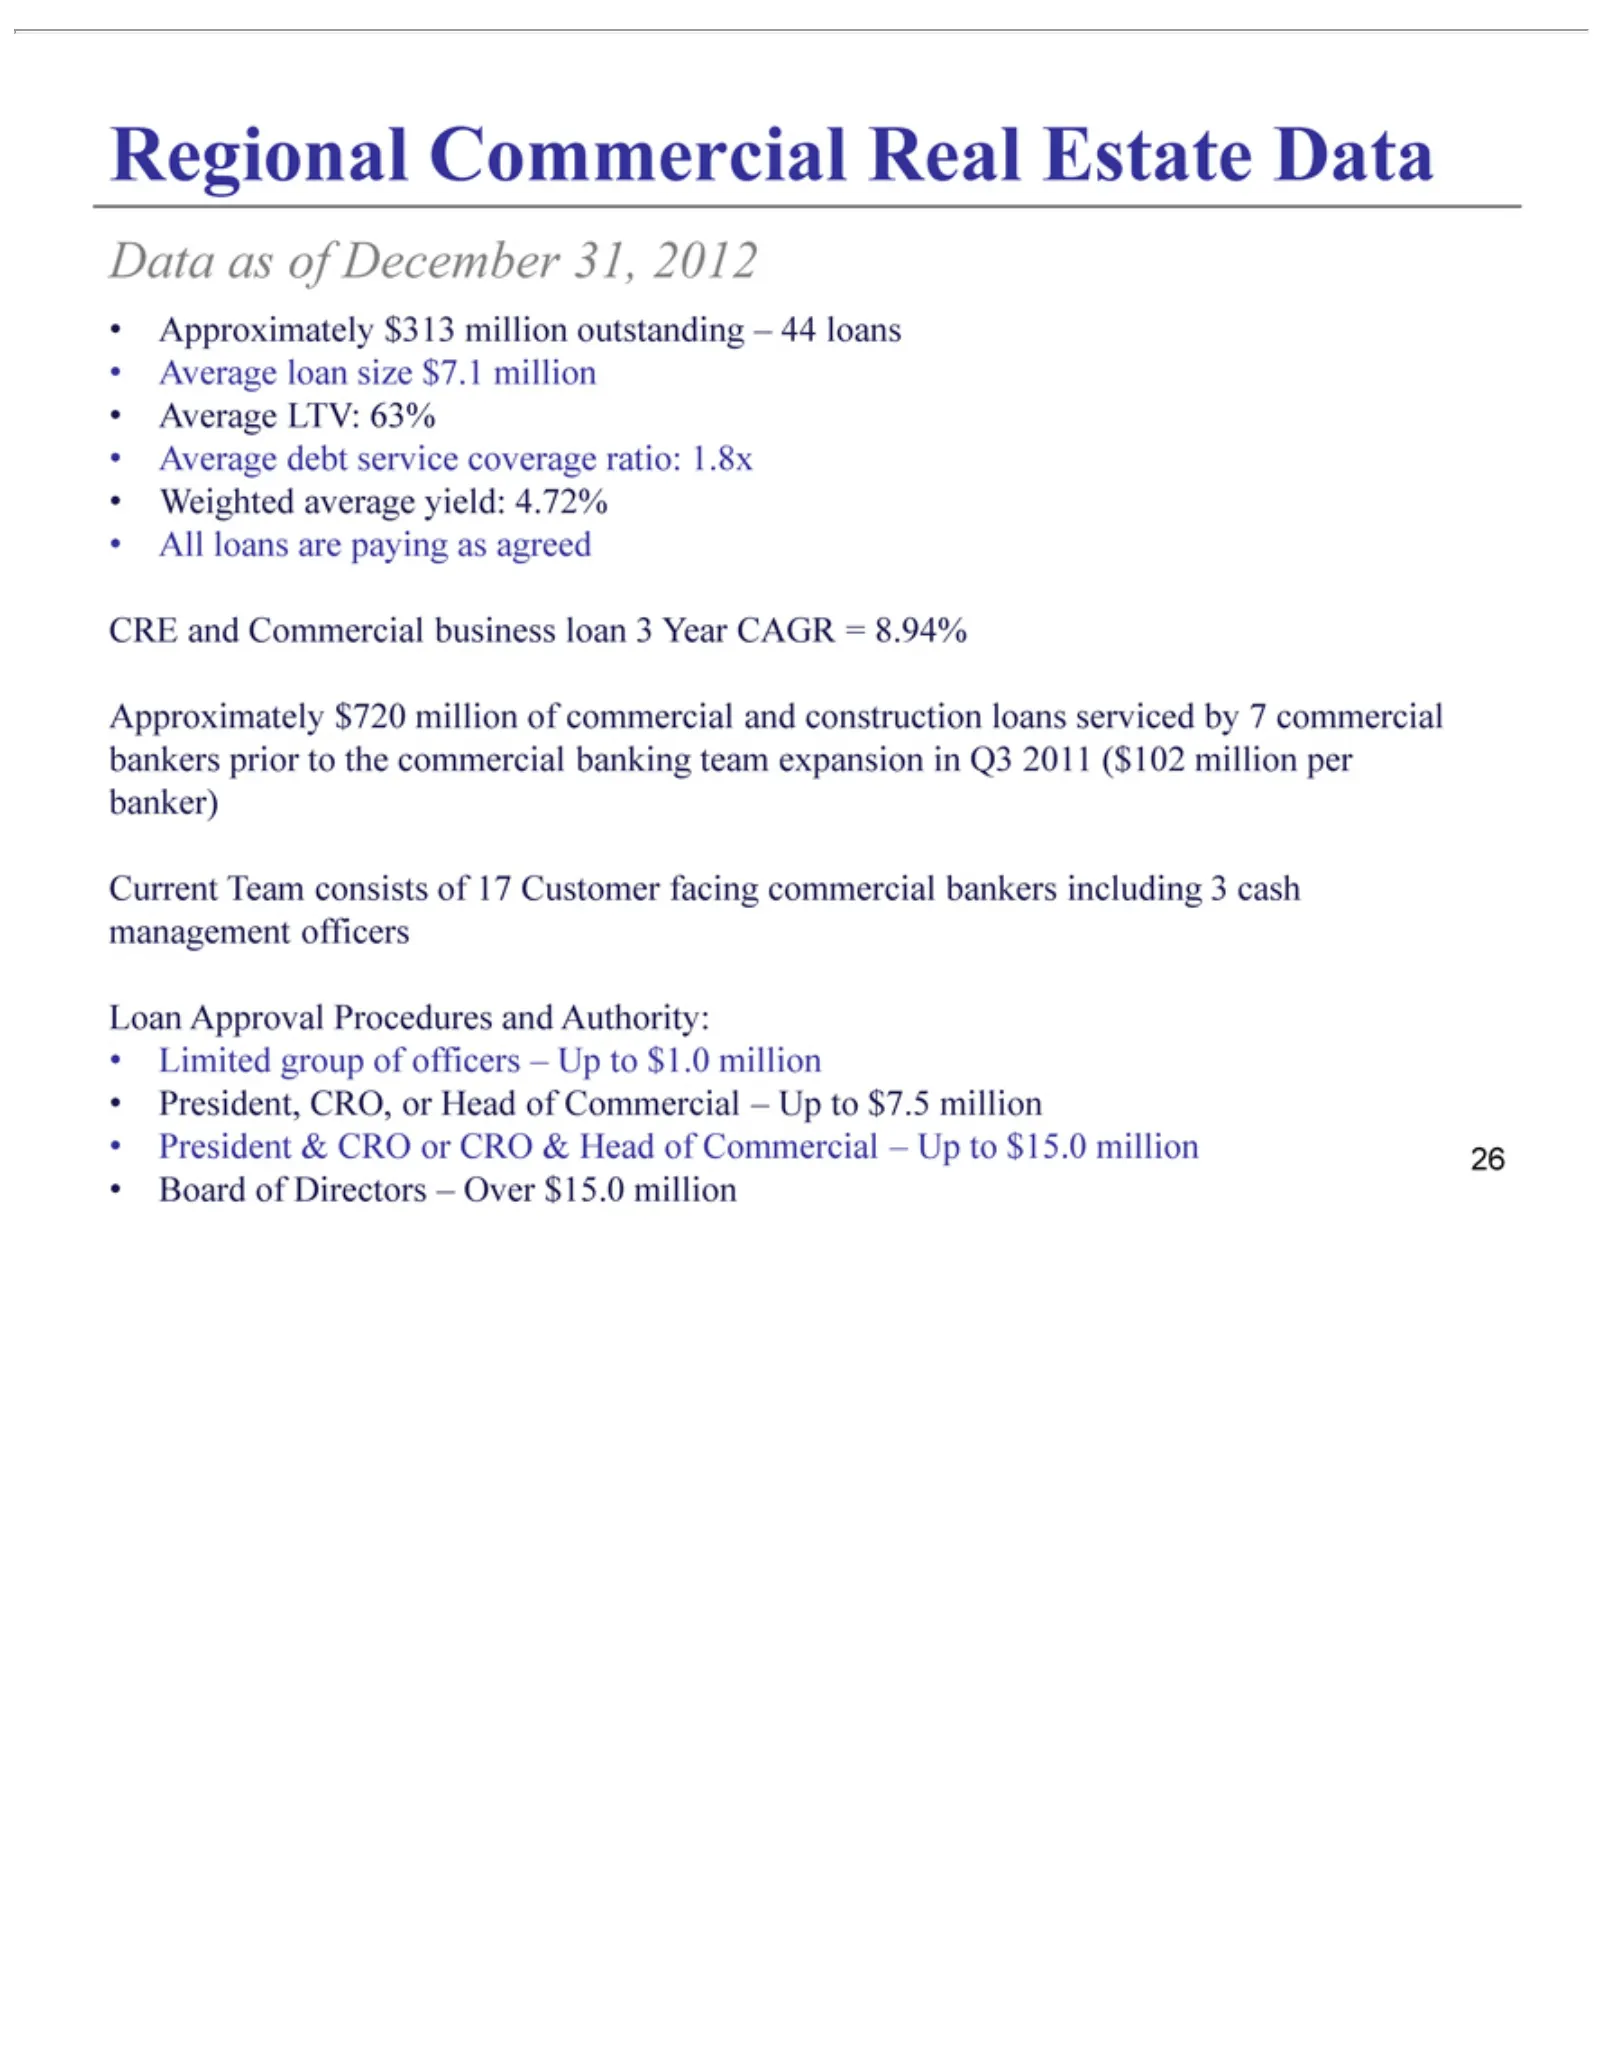
Slide 26: Commercial Real Estate Regional Data
Regional Data CRE Approximately Current Loan Limited President, President 26 as and Approval of Team group Commercial & CRO, December CRO consists of Procedures $313 $720 or officers orHead CRO million 31, Real business of 2012 of 17 –&and Up Estate Commercial Customer outstanding of Head to Authori
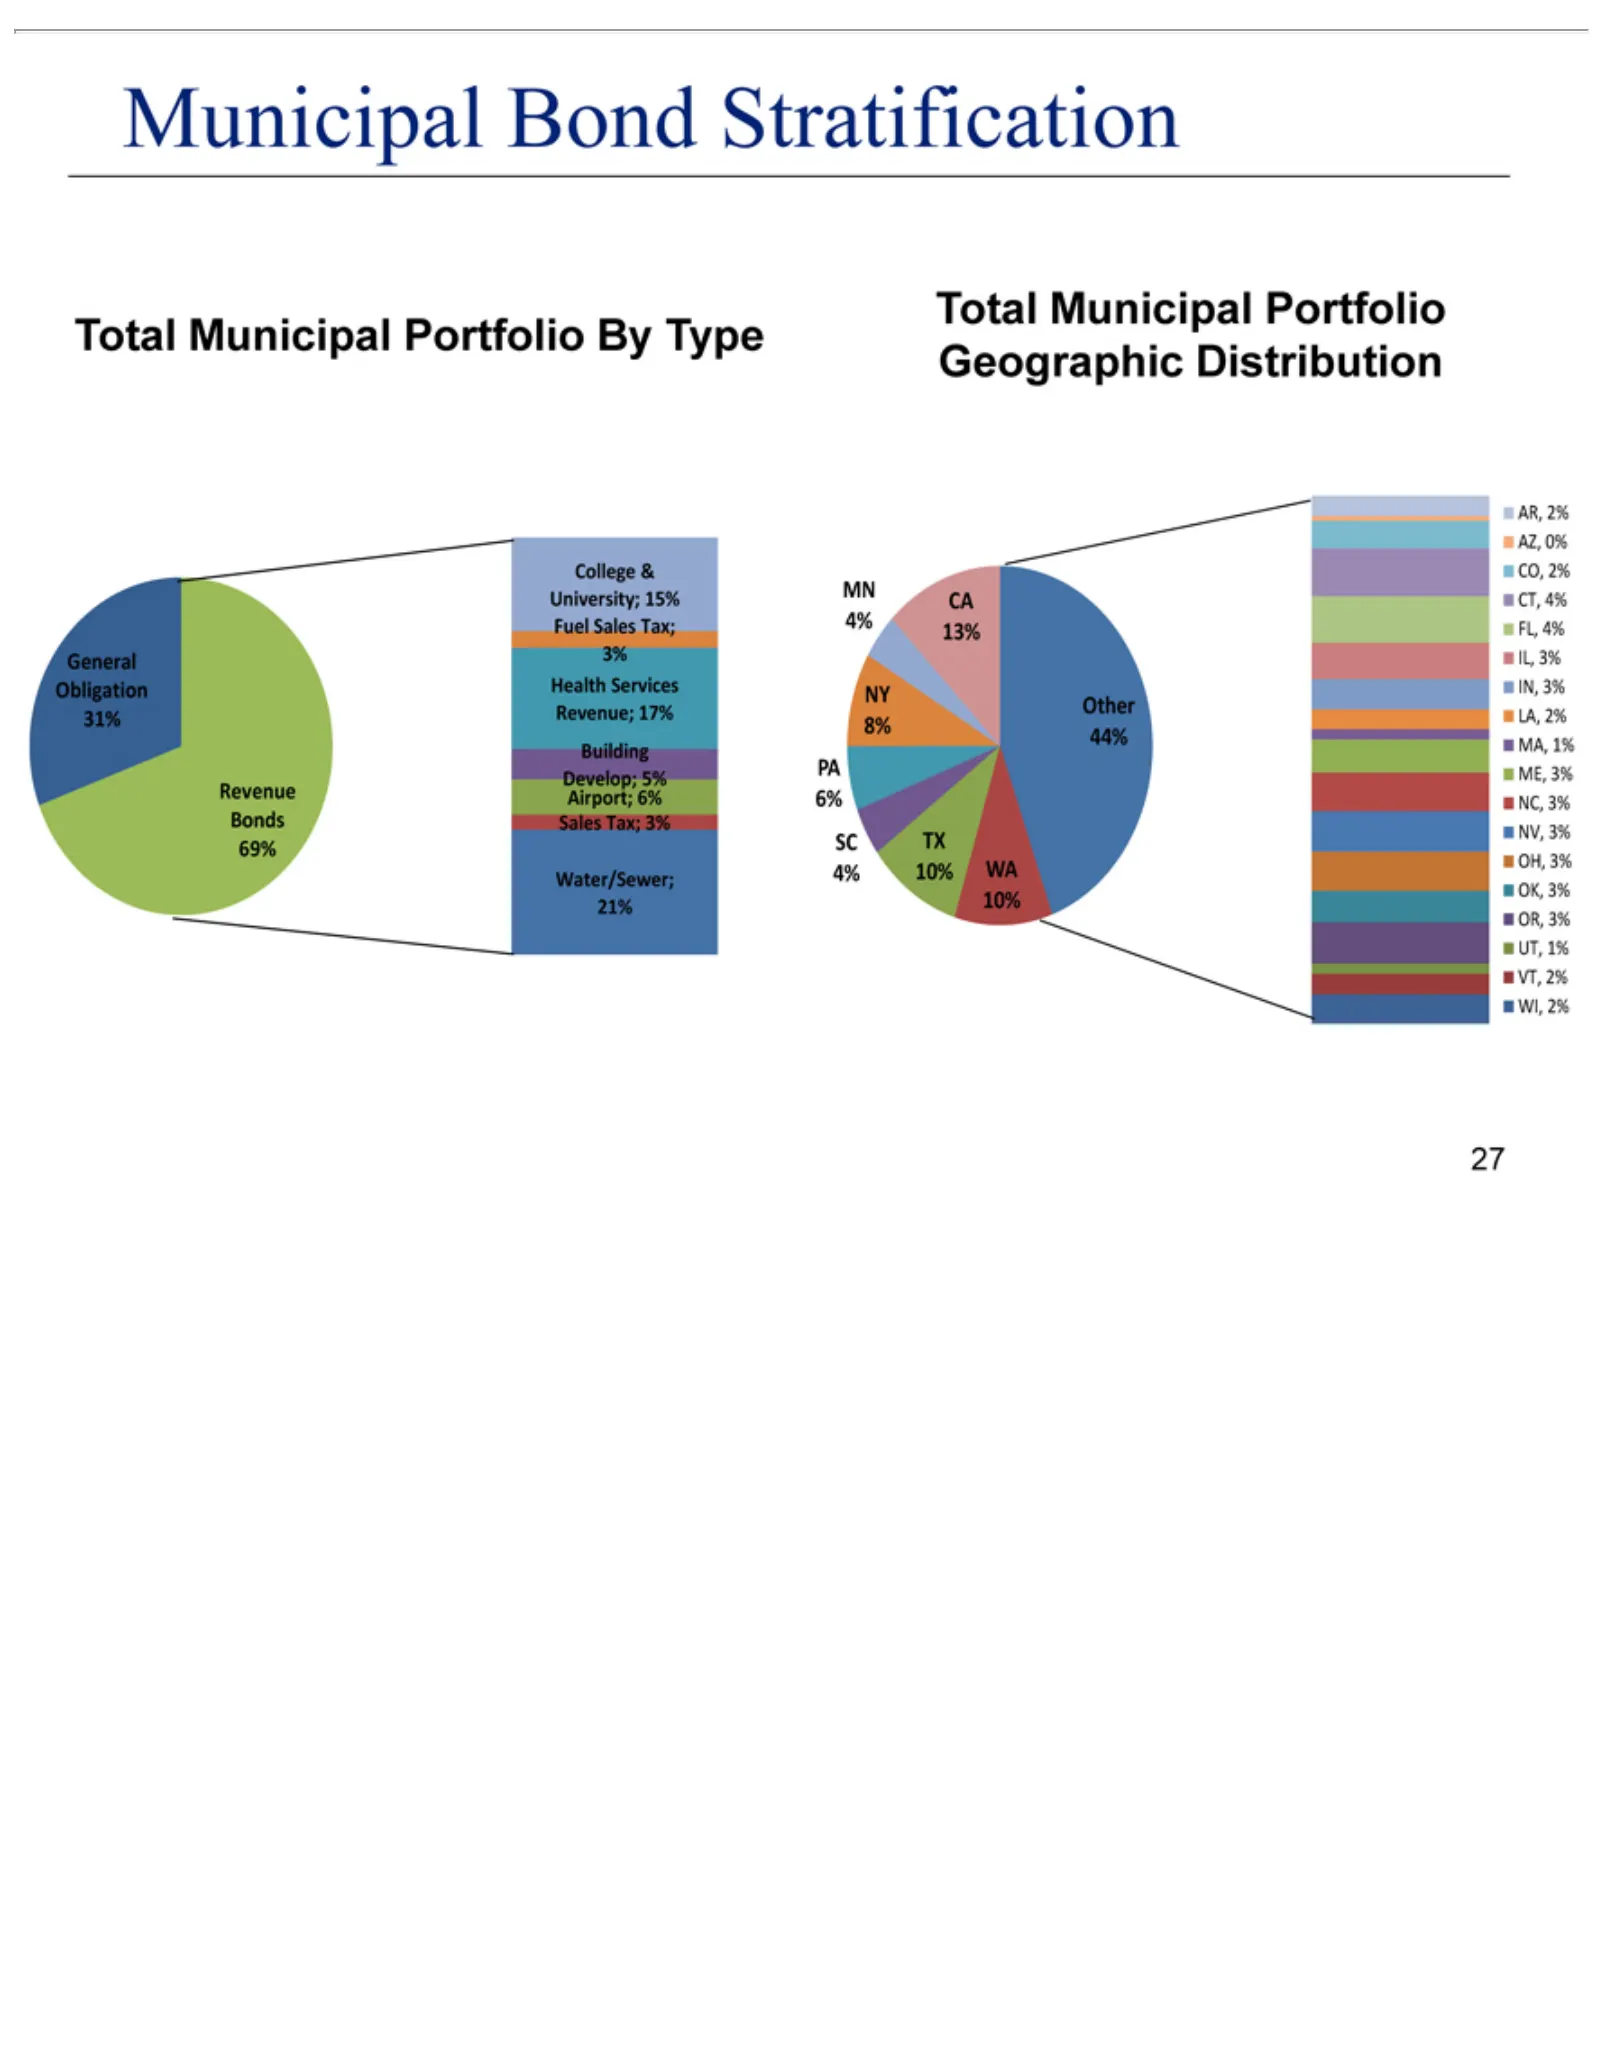
Slide 27: Municipal Bond Portfolio Stratification
Municipal Total General Revenue College Building Water/Sewer; MN CA NY PA SC TX WA Other AR, 27 6% 4% 10% 13% 8% 10% 4% 2% Municipal 44% & Obligation AZ, Bonds Develop; Bond University; 0% 21%69% Portfolio Stratification CO, 5% 31% 2%15% Airport; CT, ByFuel Geographic Type 4% 6% Sales FL, Sales 4% D
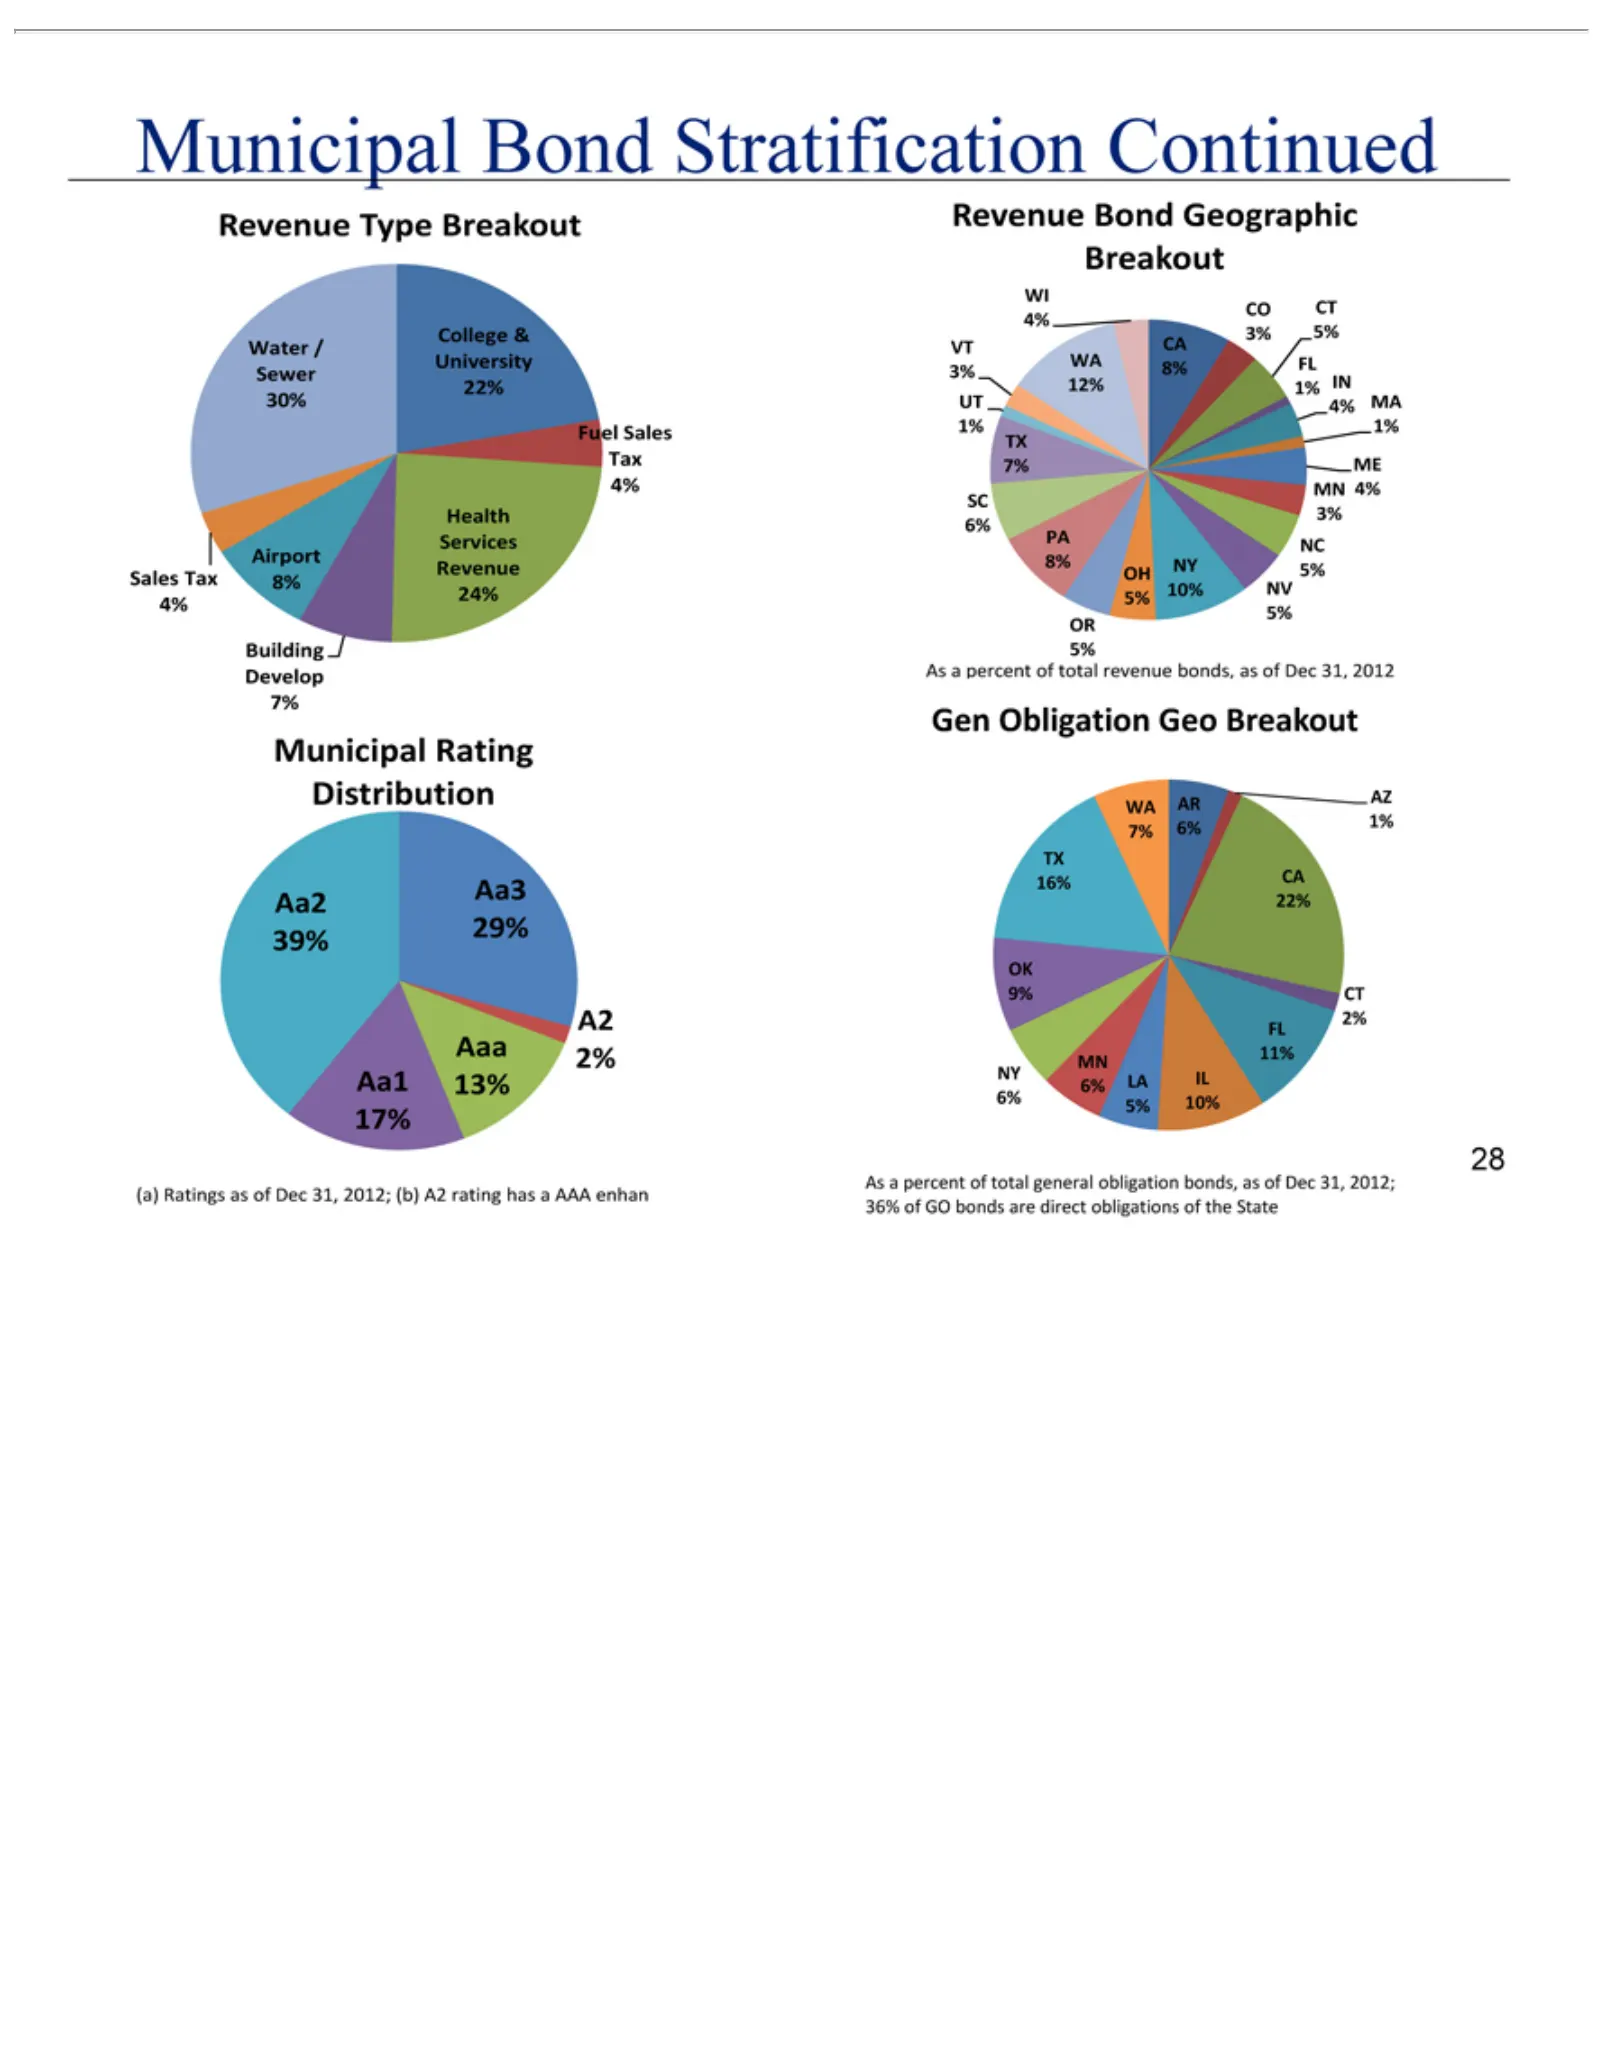
Slide 28: Municipal Bond Portfolio Breakout Continued
Water Sales Airport Building Health College Fuel Municipal Aa2 Aa1 Aaa Aa3 A2 (a) Revenue WI VT UT SC PA OR OH NV CO IN MA ME NC Gen AZ CA CT FL IL LA MN NY OK TX WA AR As 28 10% 4% Ratings a11% 1% 8% 2% 6% 5% 4% 3% 1% 7% 16% 8% 22% 5% 6% 10% 9% 12% 7% 4% 1% 13% 3% 6% 39% 17% 29% Obligation Sales pe
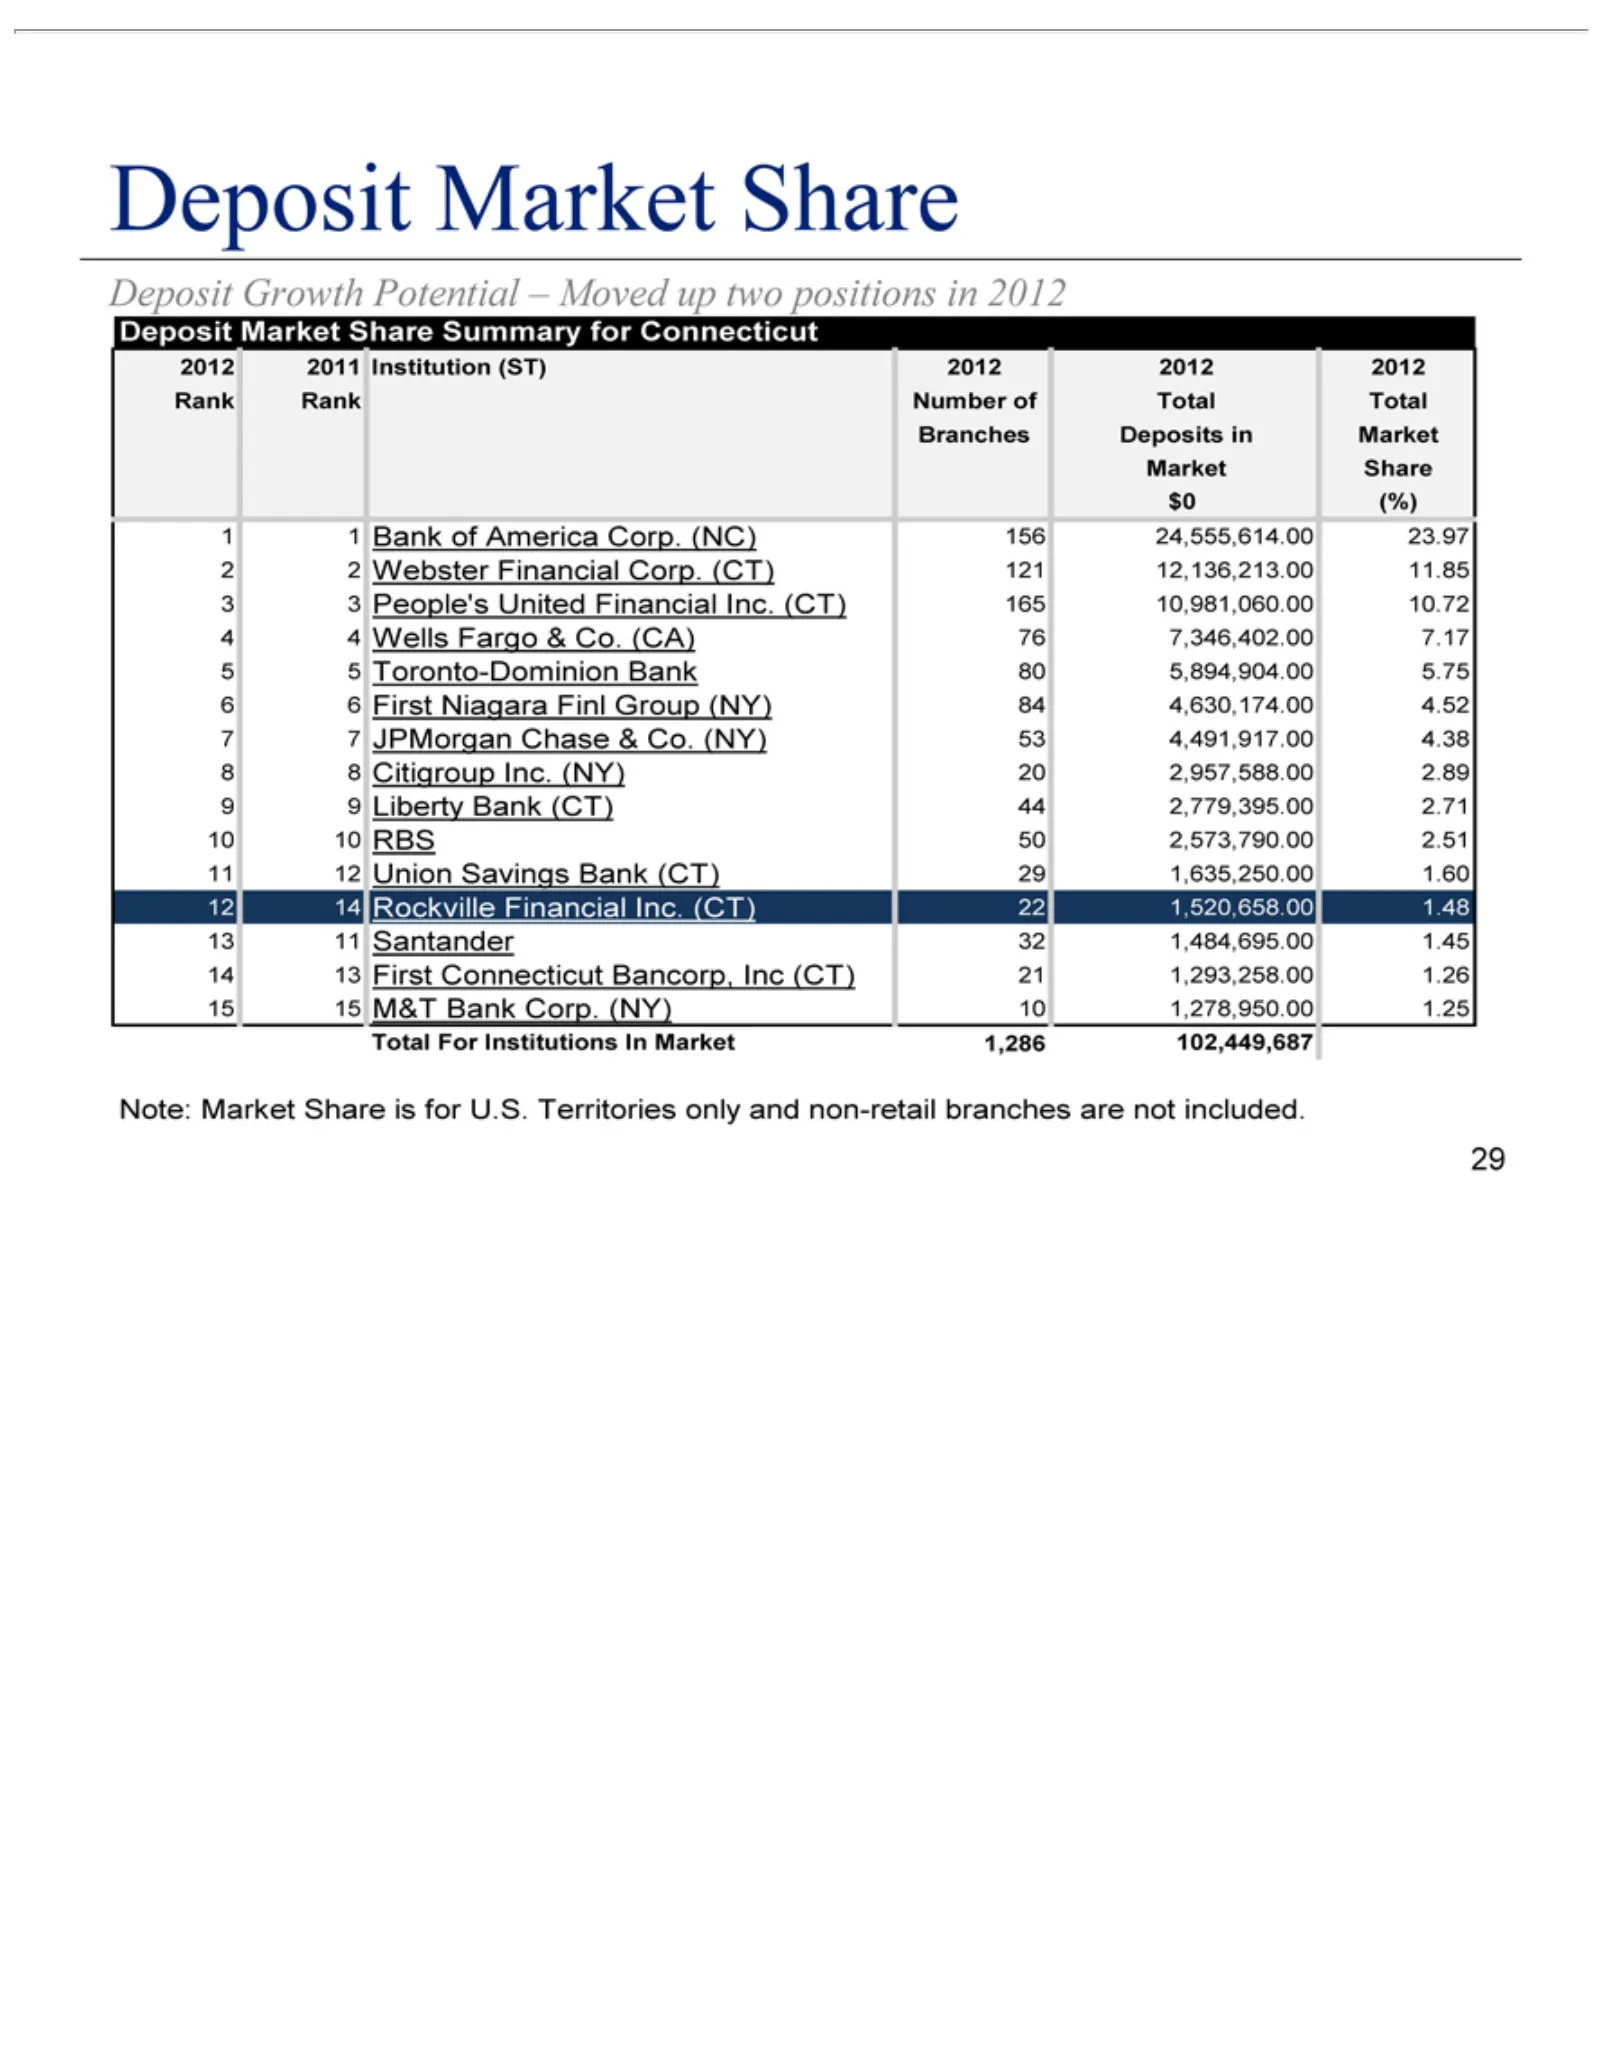
Slide 29: Connecticut Deposit Market Share
Deposit 12011 Institution Bank Citigroup Union First Total 156 1,286 24,555,614.00 2012 102,449,687 Note: 1.25 1.26 1.45 1.48 1.60 2.51 2.71 2.89 4.38 4.52 5.75 7.17 10.72 11.85 23.97 292 3121 Connecticut Rank Total 4For Number of Market Savings 5Market Growth America 165 6Institutions Inc. (ST) 7Ma
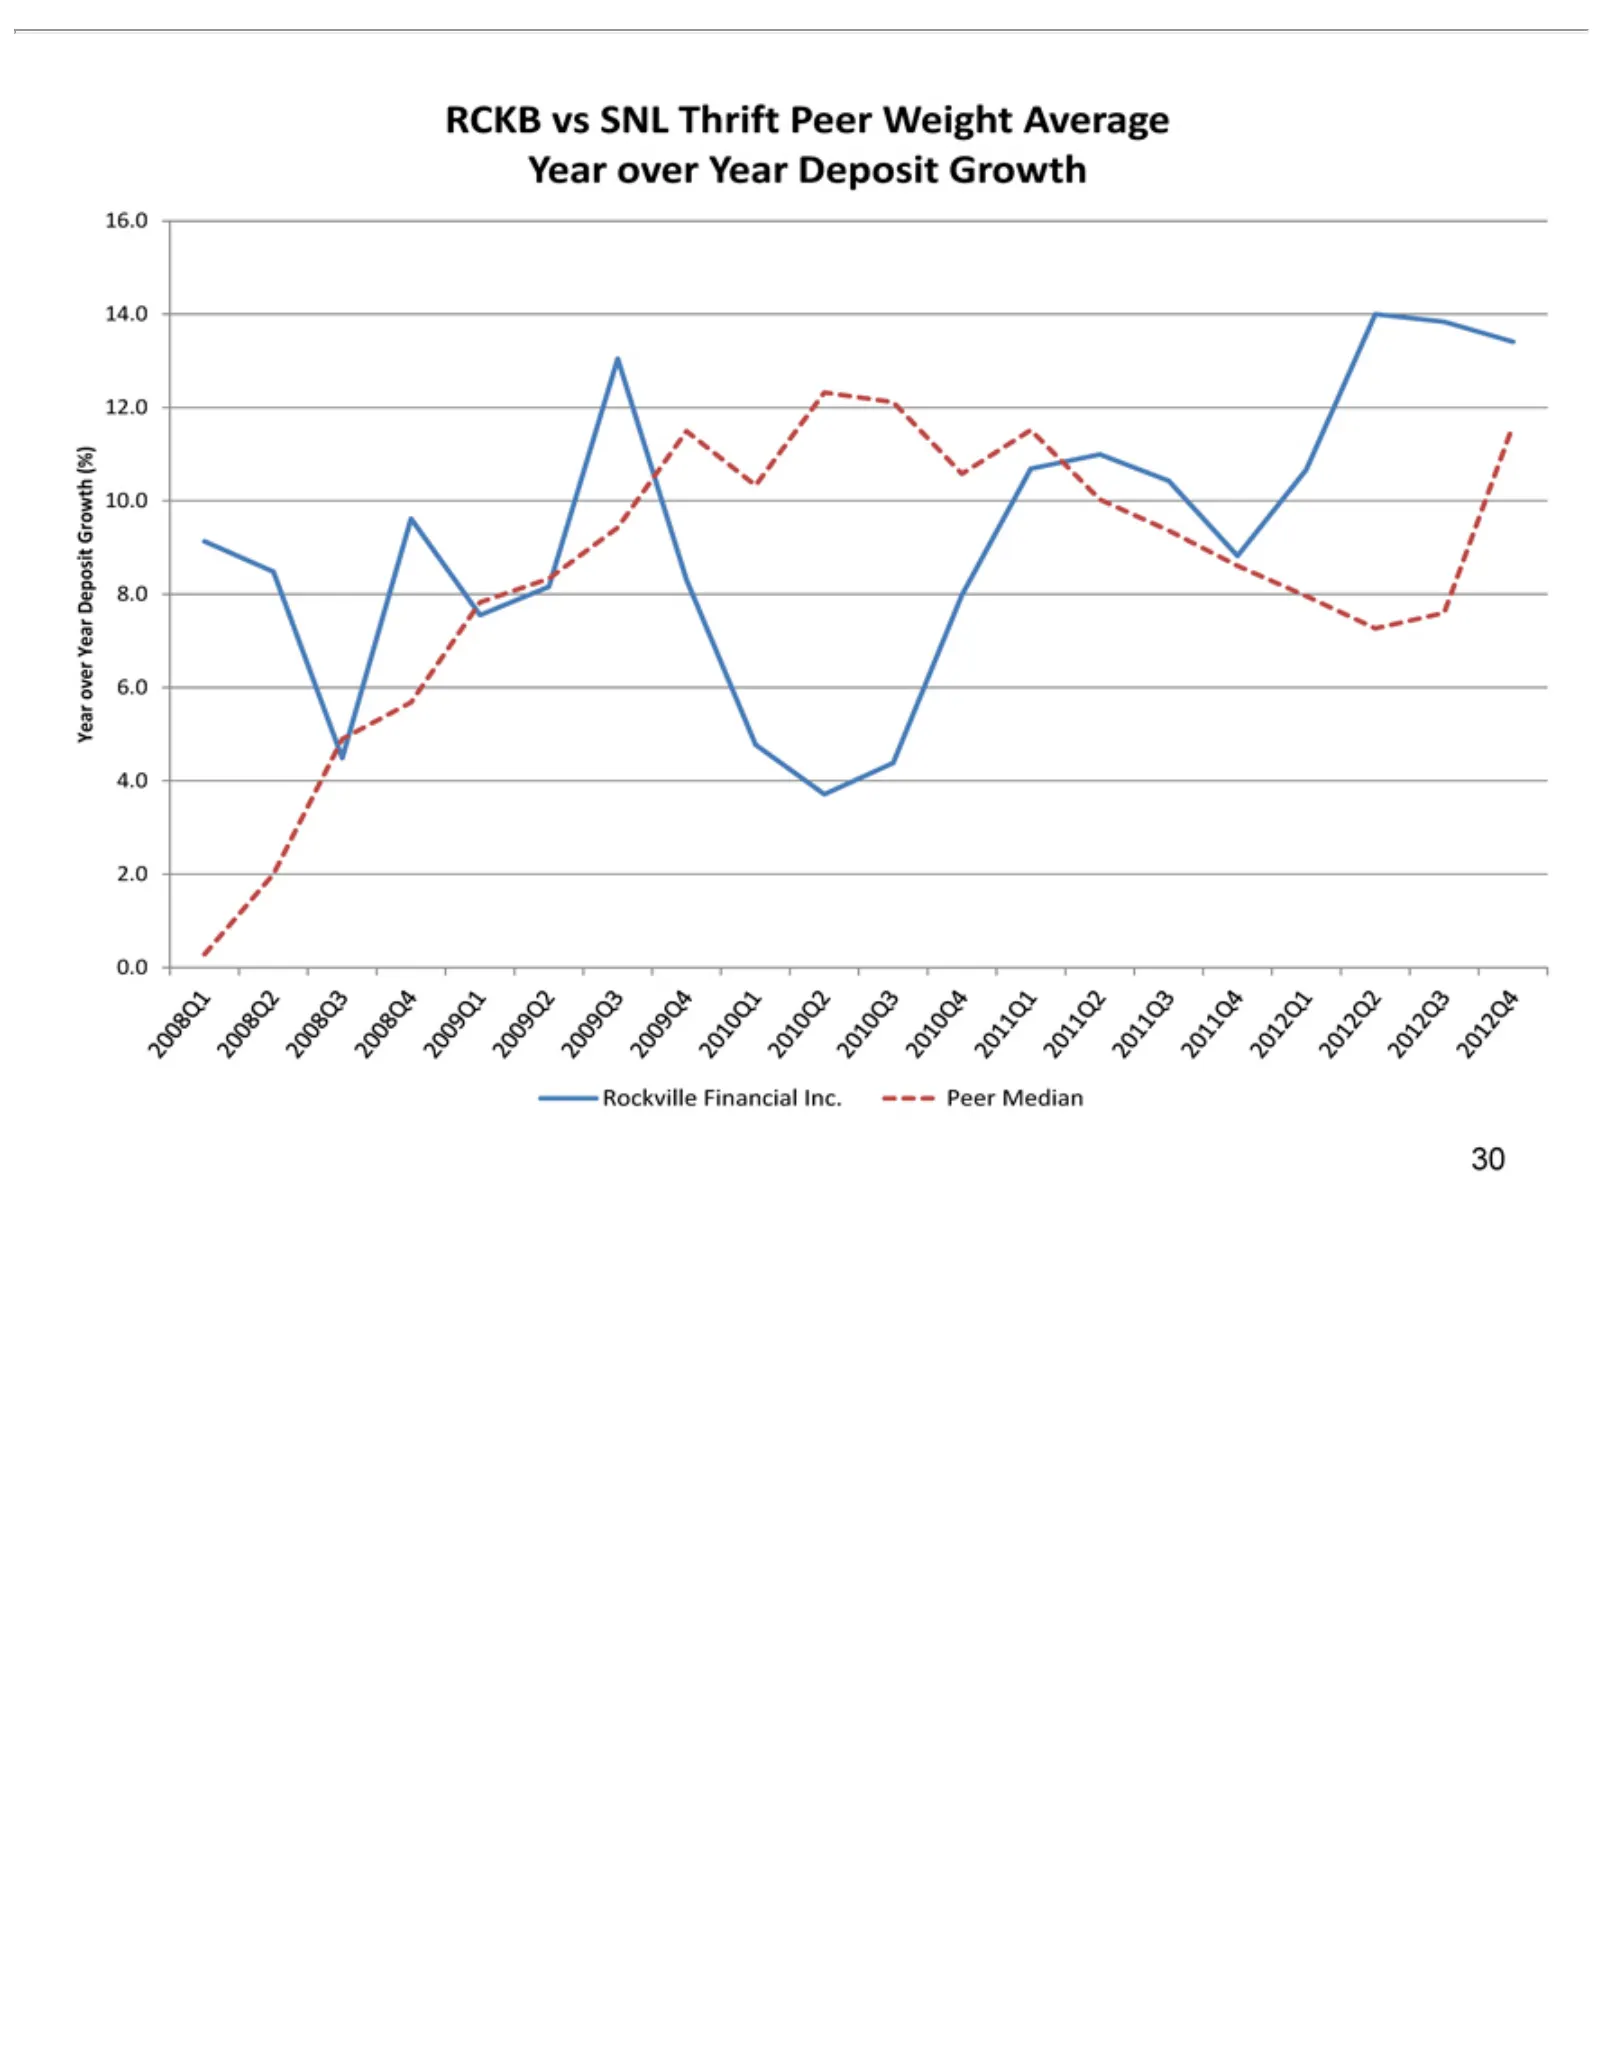
Slide 30: Year over Year Deposit Growth vs. Peers
RCKB Year Rockville 0.0 2.0 4.0 6.0 8.0 10.0 12.0 14.0 16.0 Peer 30 2012Q4 2012Q3 2012Q2 2012Q1 2011Q4 2011Q3 2011Q2 2011Q1 2010Q4 2010Q3 2010Q2 2010Q1 2009Q4 2009Q3 2009Q2 2009Q1 2008Q4 2008Q3 2008Q2 2008Q1 Median over vs Year SNL Financial Deposit ThriftInc. Peer Growth Weight (%)Average Year over
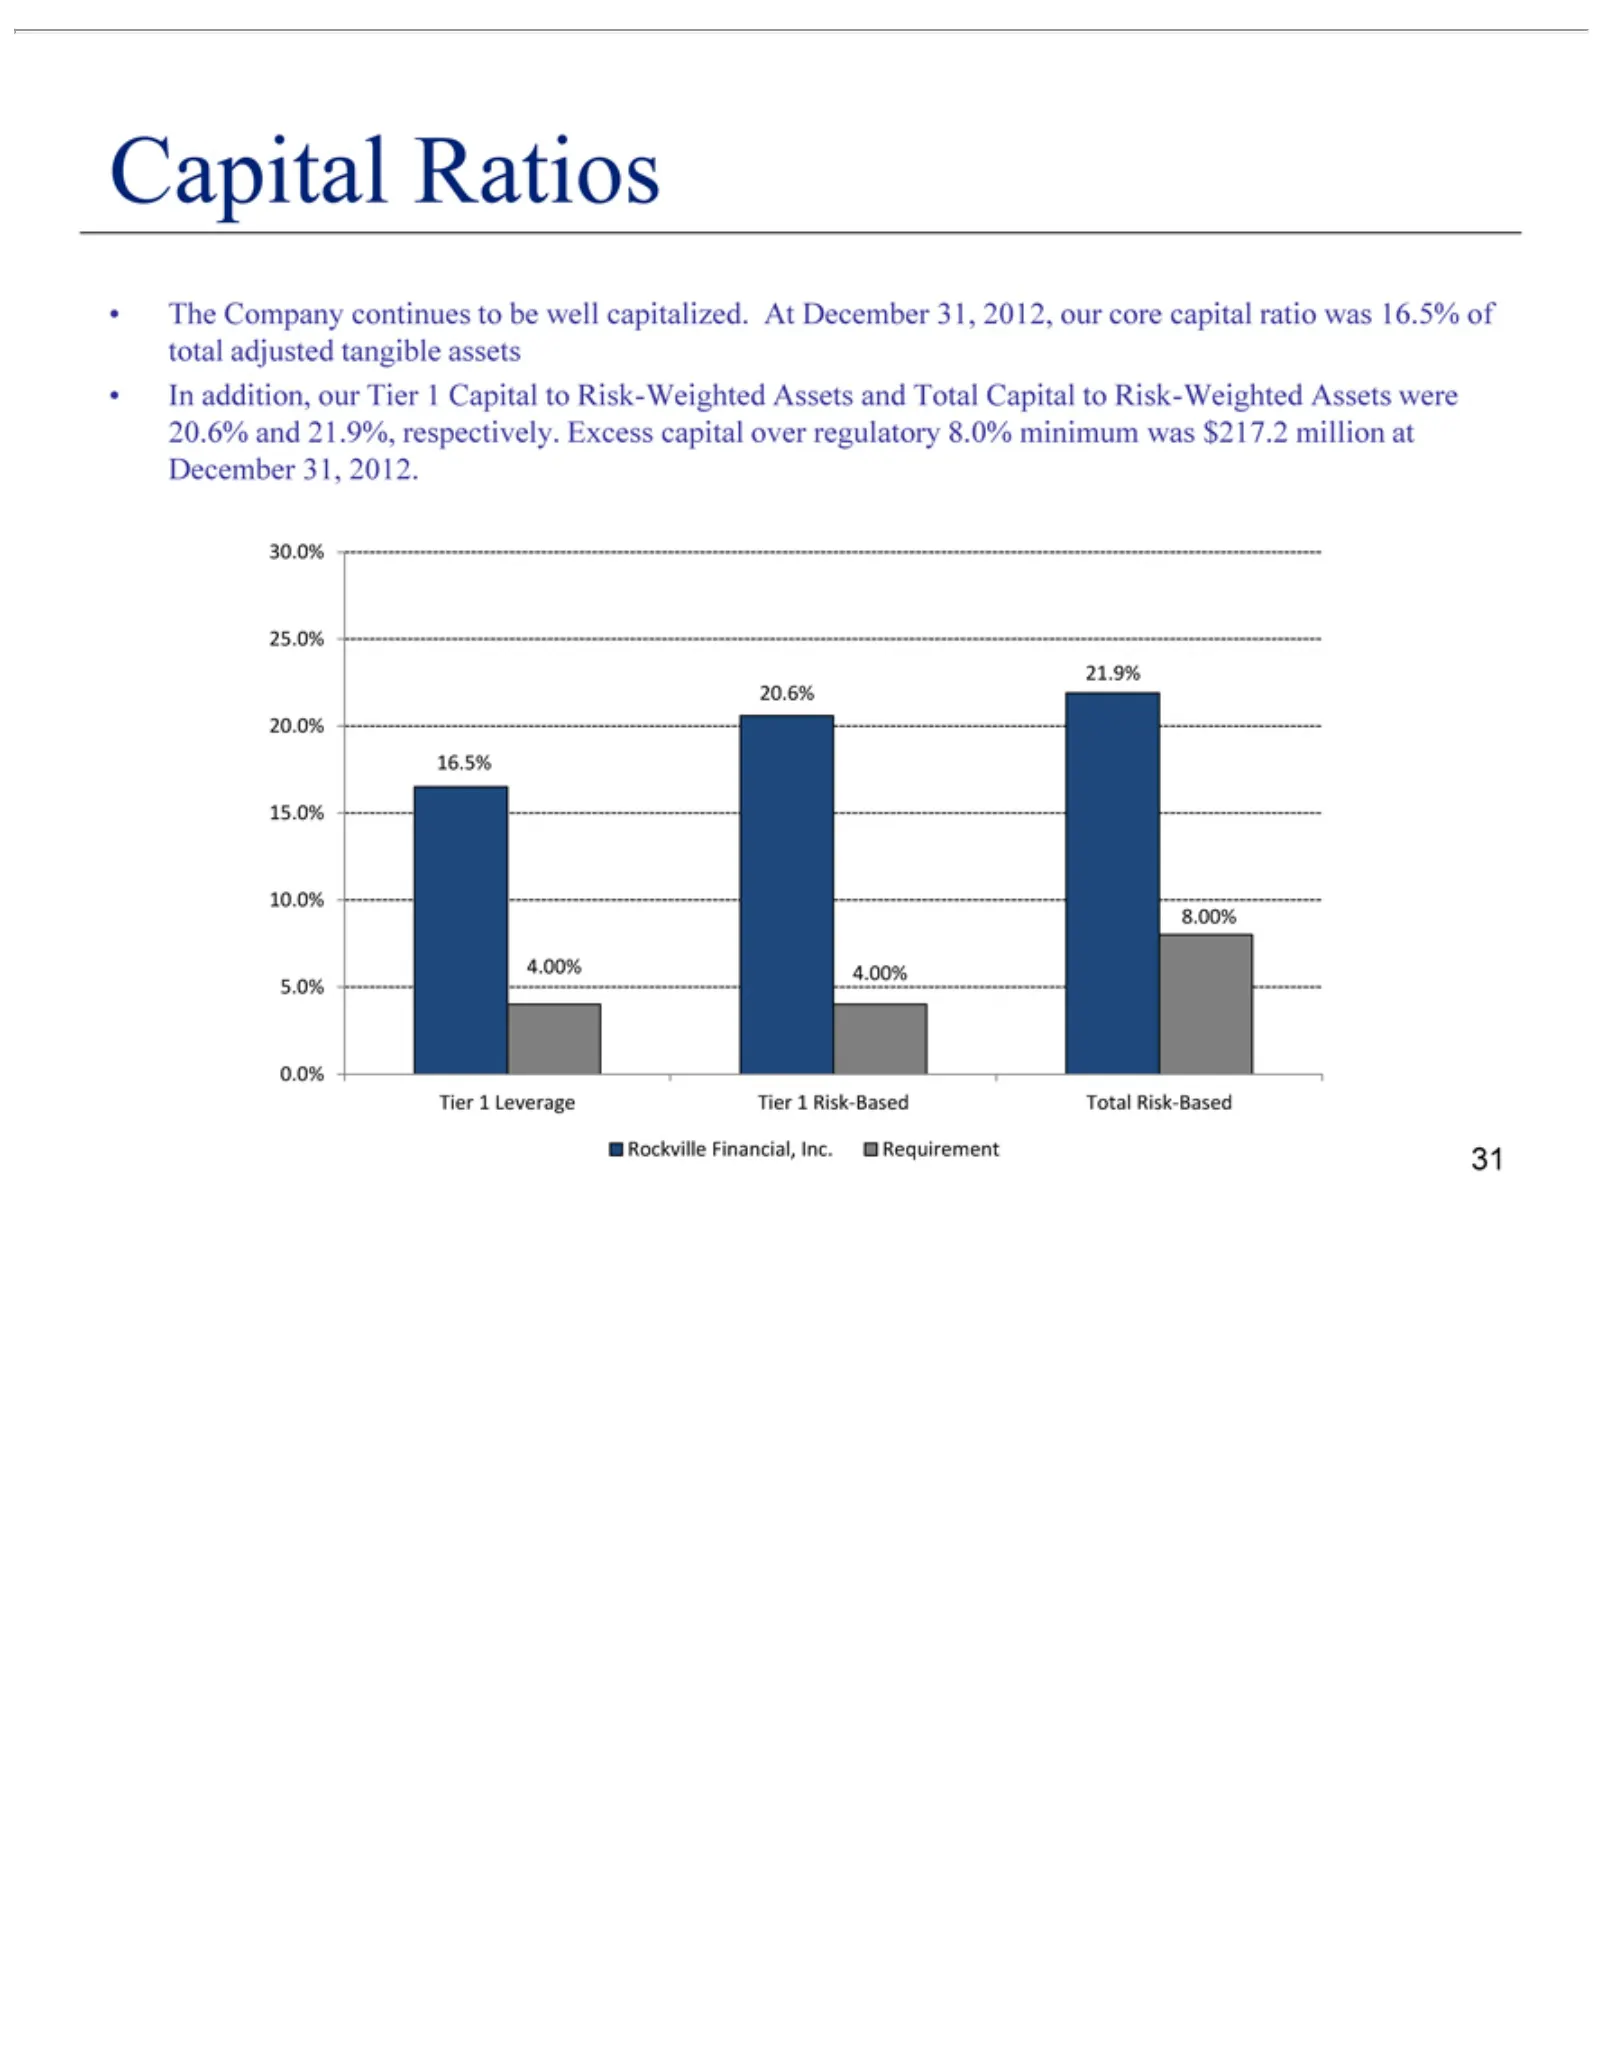
Slide 31: Capital Well Capitalized
Capital The Weighted 10.0% 15.0% 20.0% 25.0% 30.0% 16.5% Tier Rockville 8.00% 21.9% 4.00% 20.6% 31 Requirement Company 1 Risk-Based Leverage and 5.0% Ratios Assets Financial, 21.9%, 0.0% continues were Total respectively. Inc.Risk-Based to be well Excess capitalized. capital over At December regulat
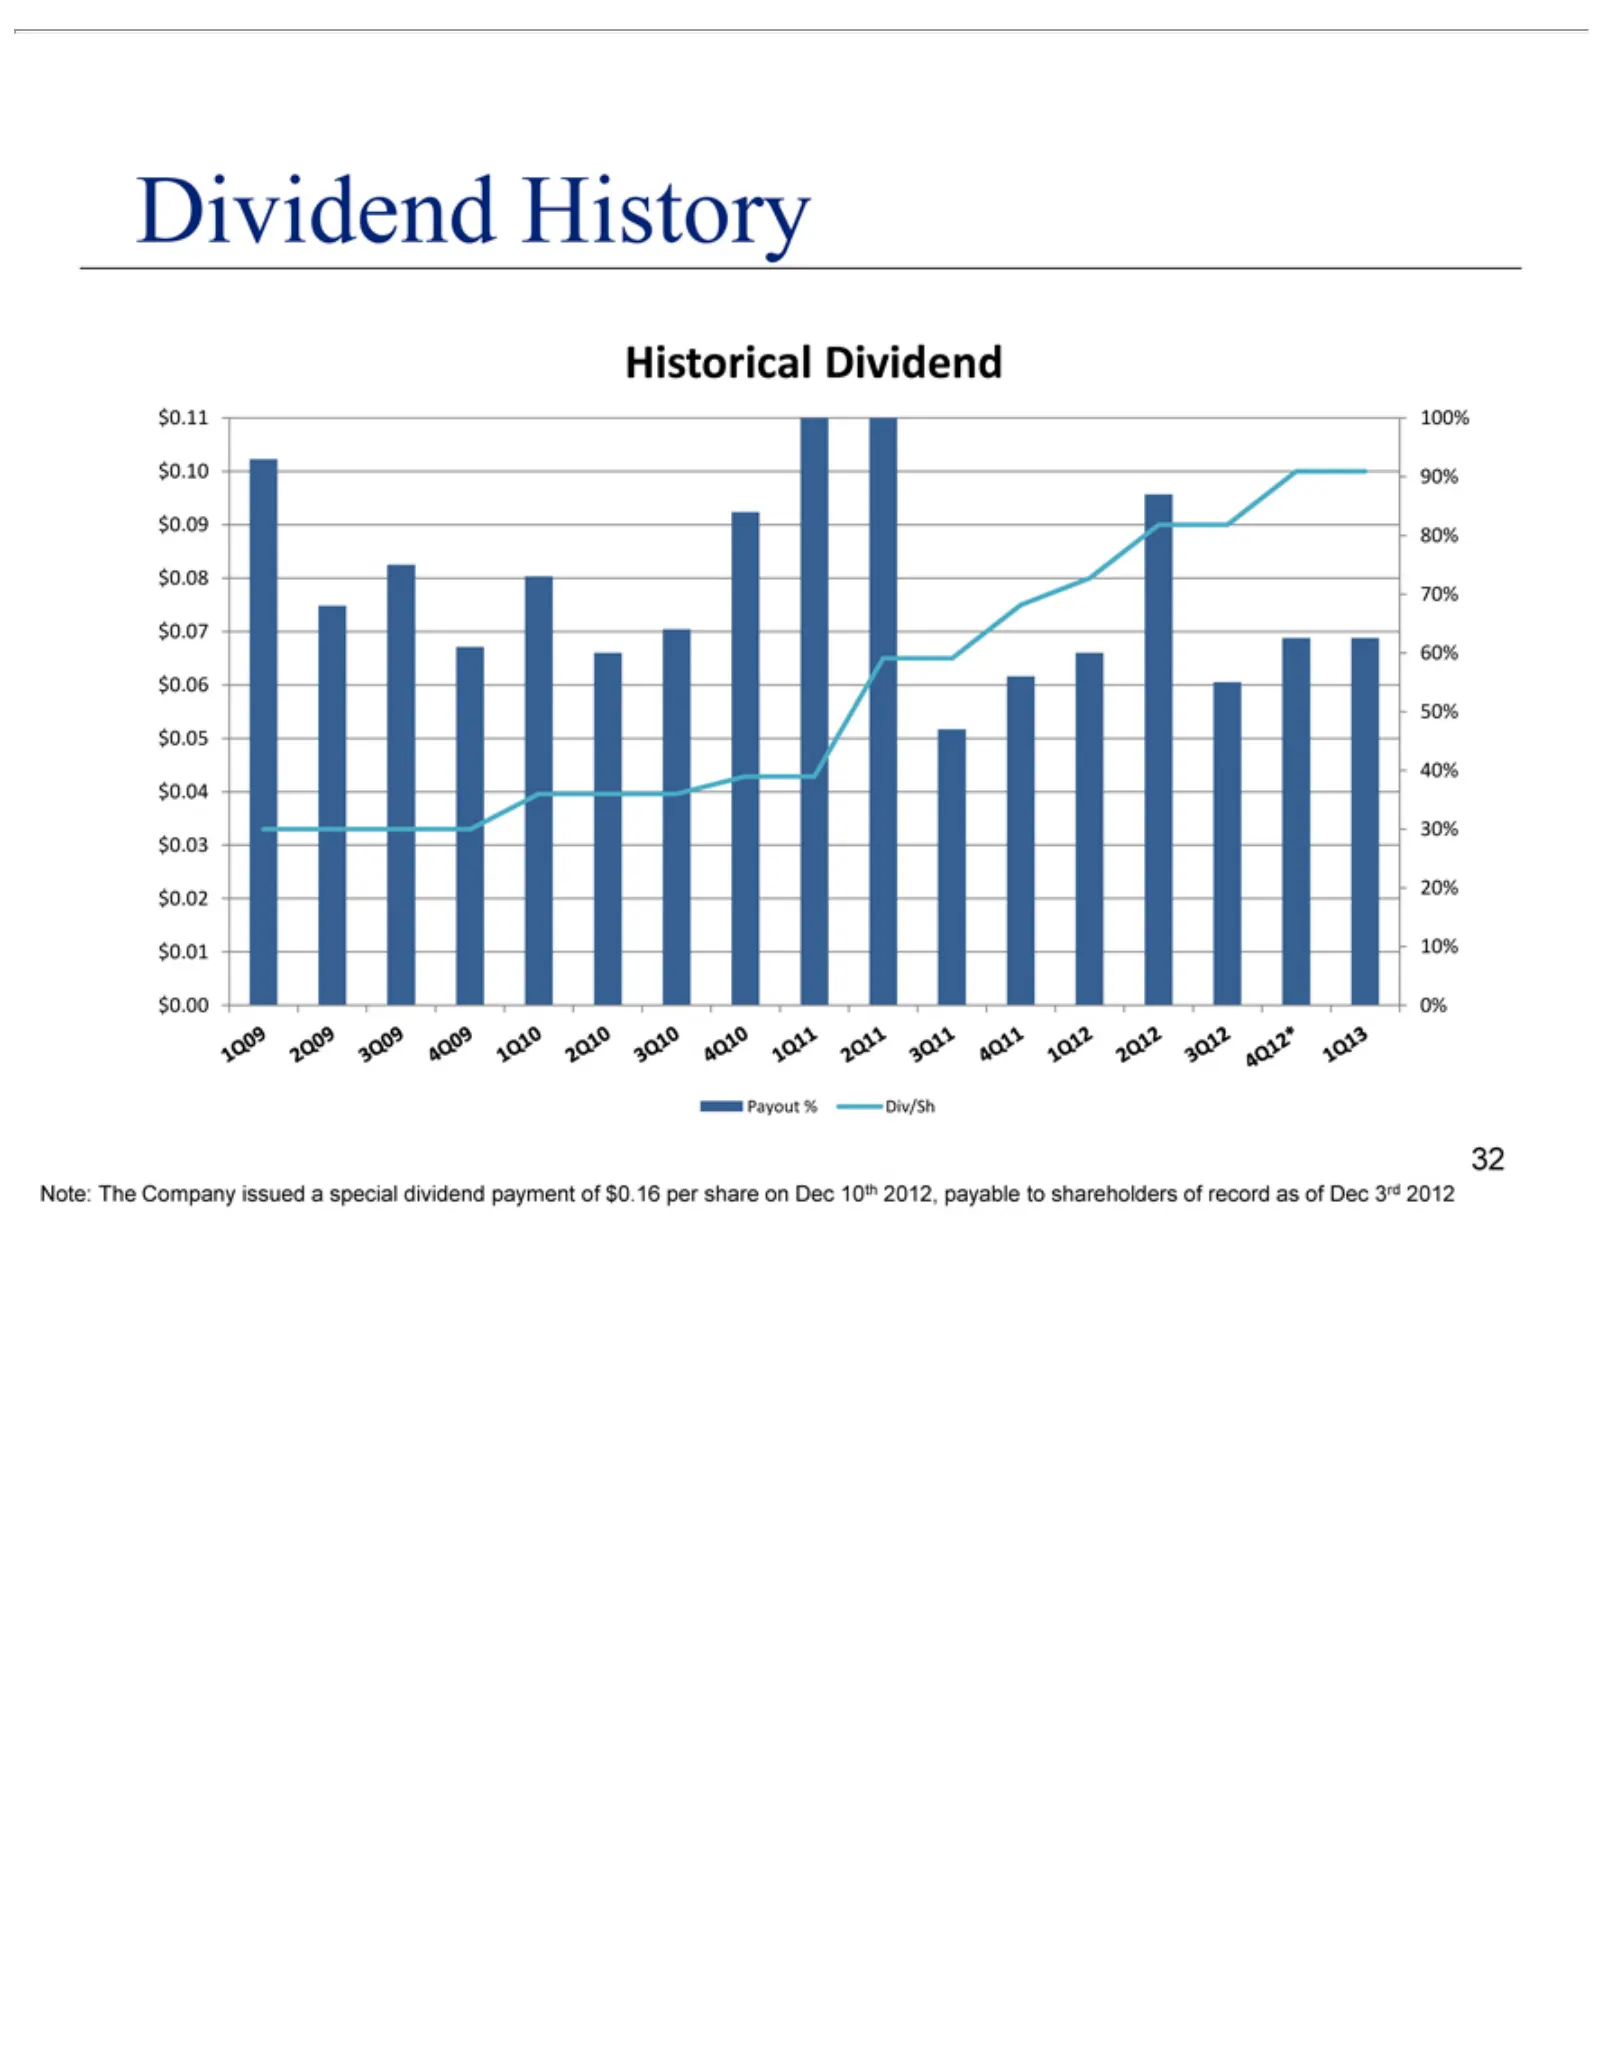
Slide 32: Historical Dividend and Payout
Dividend Historical $0.11 100% Payout 1Q13 4Q12* 3Q12 2Q12 1Q12 4Q11 3Q11 2Q11 1Q11 4Q10 3Q10 2Q10 1Q10 4Q09 3Q09 2Q09 1Q09 Note: Div/Sh 32 The $0.10 90% % History Dividend Company 80% $0.0970% $0.08 issued 60%$0.07 50% a special $0.06 40% dividend $0.05 30% 20% $0.04 payment 10% $0.03 0%of $0.02 $0
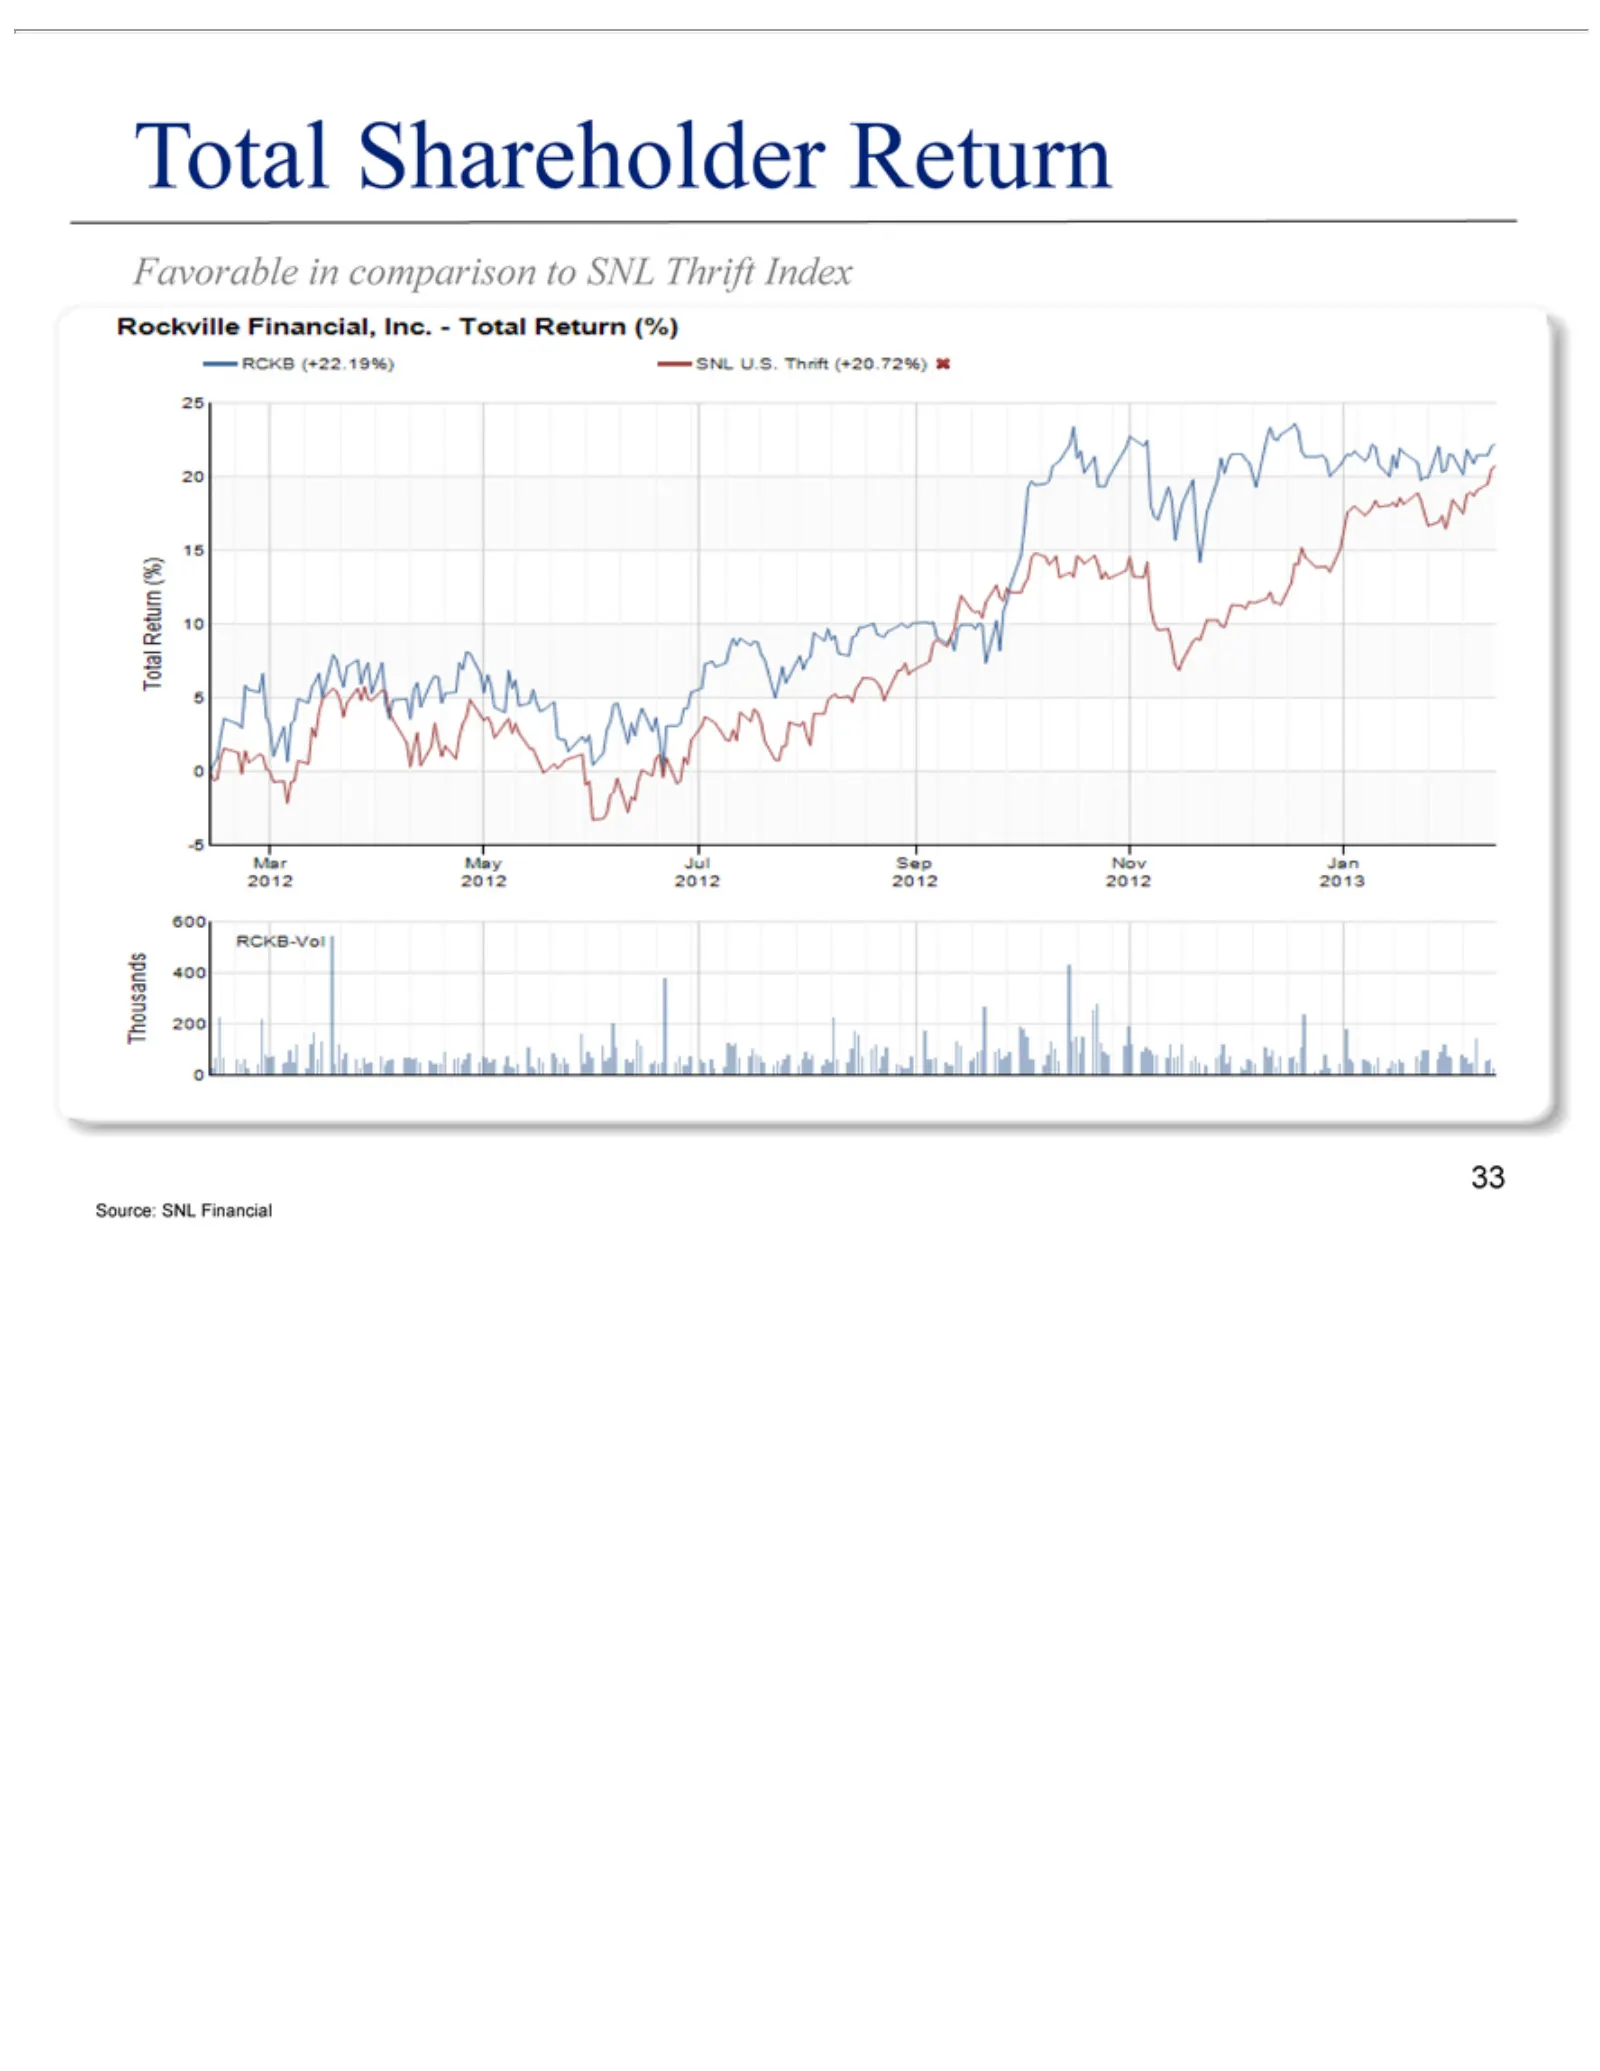
Slide 33: Favorable Total Shareholder Return
Favorable Rockville 5-RCKB 10 15 20 25 0T 200 400 600 Total Mar May Jul Sep Nov Jan Source: RCKB-Vol 33 5housands 2012 2013 2012 2012 2012 Shareholder Return (+22.19%) SNL Financial, in (%) comparison Financial Return SNLInc.U.S. –toTotal SNL Thrift Return Thrift (+20.72%) Index (%) X
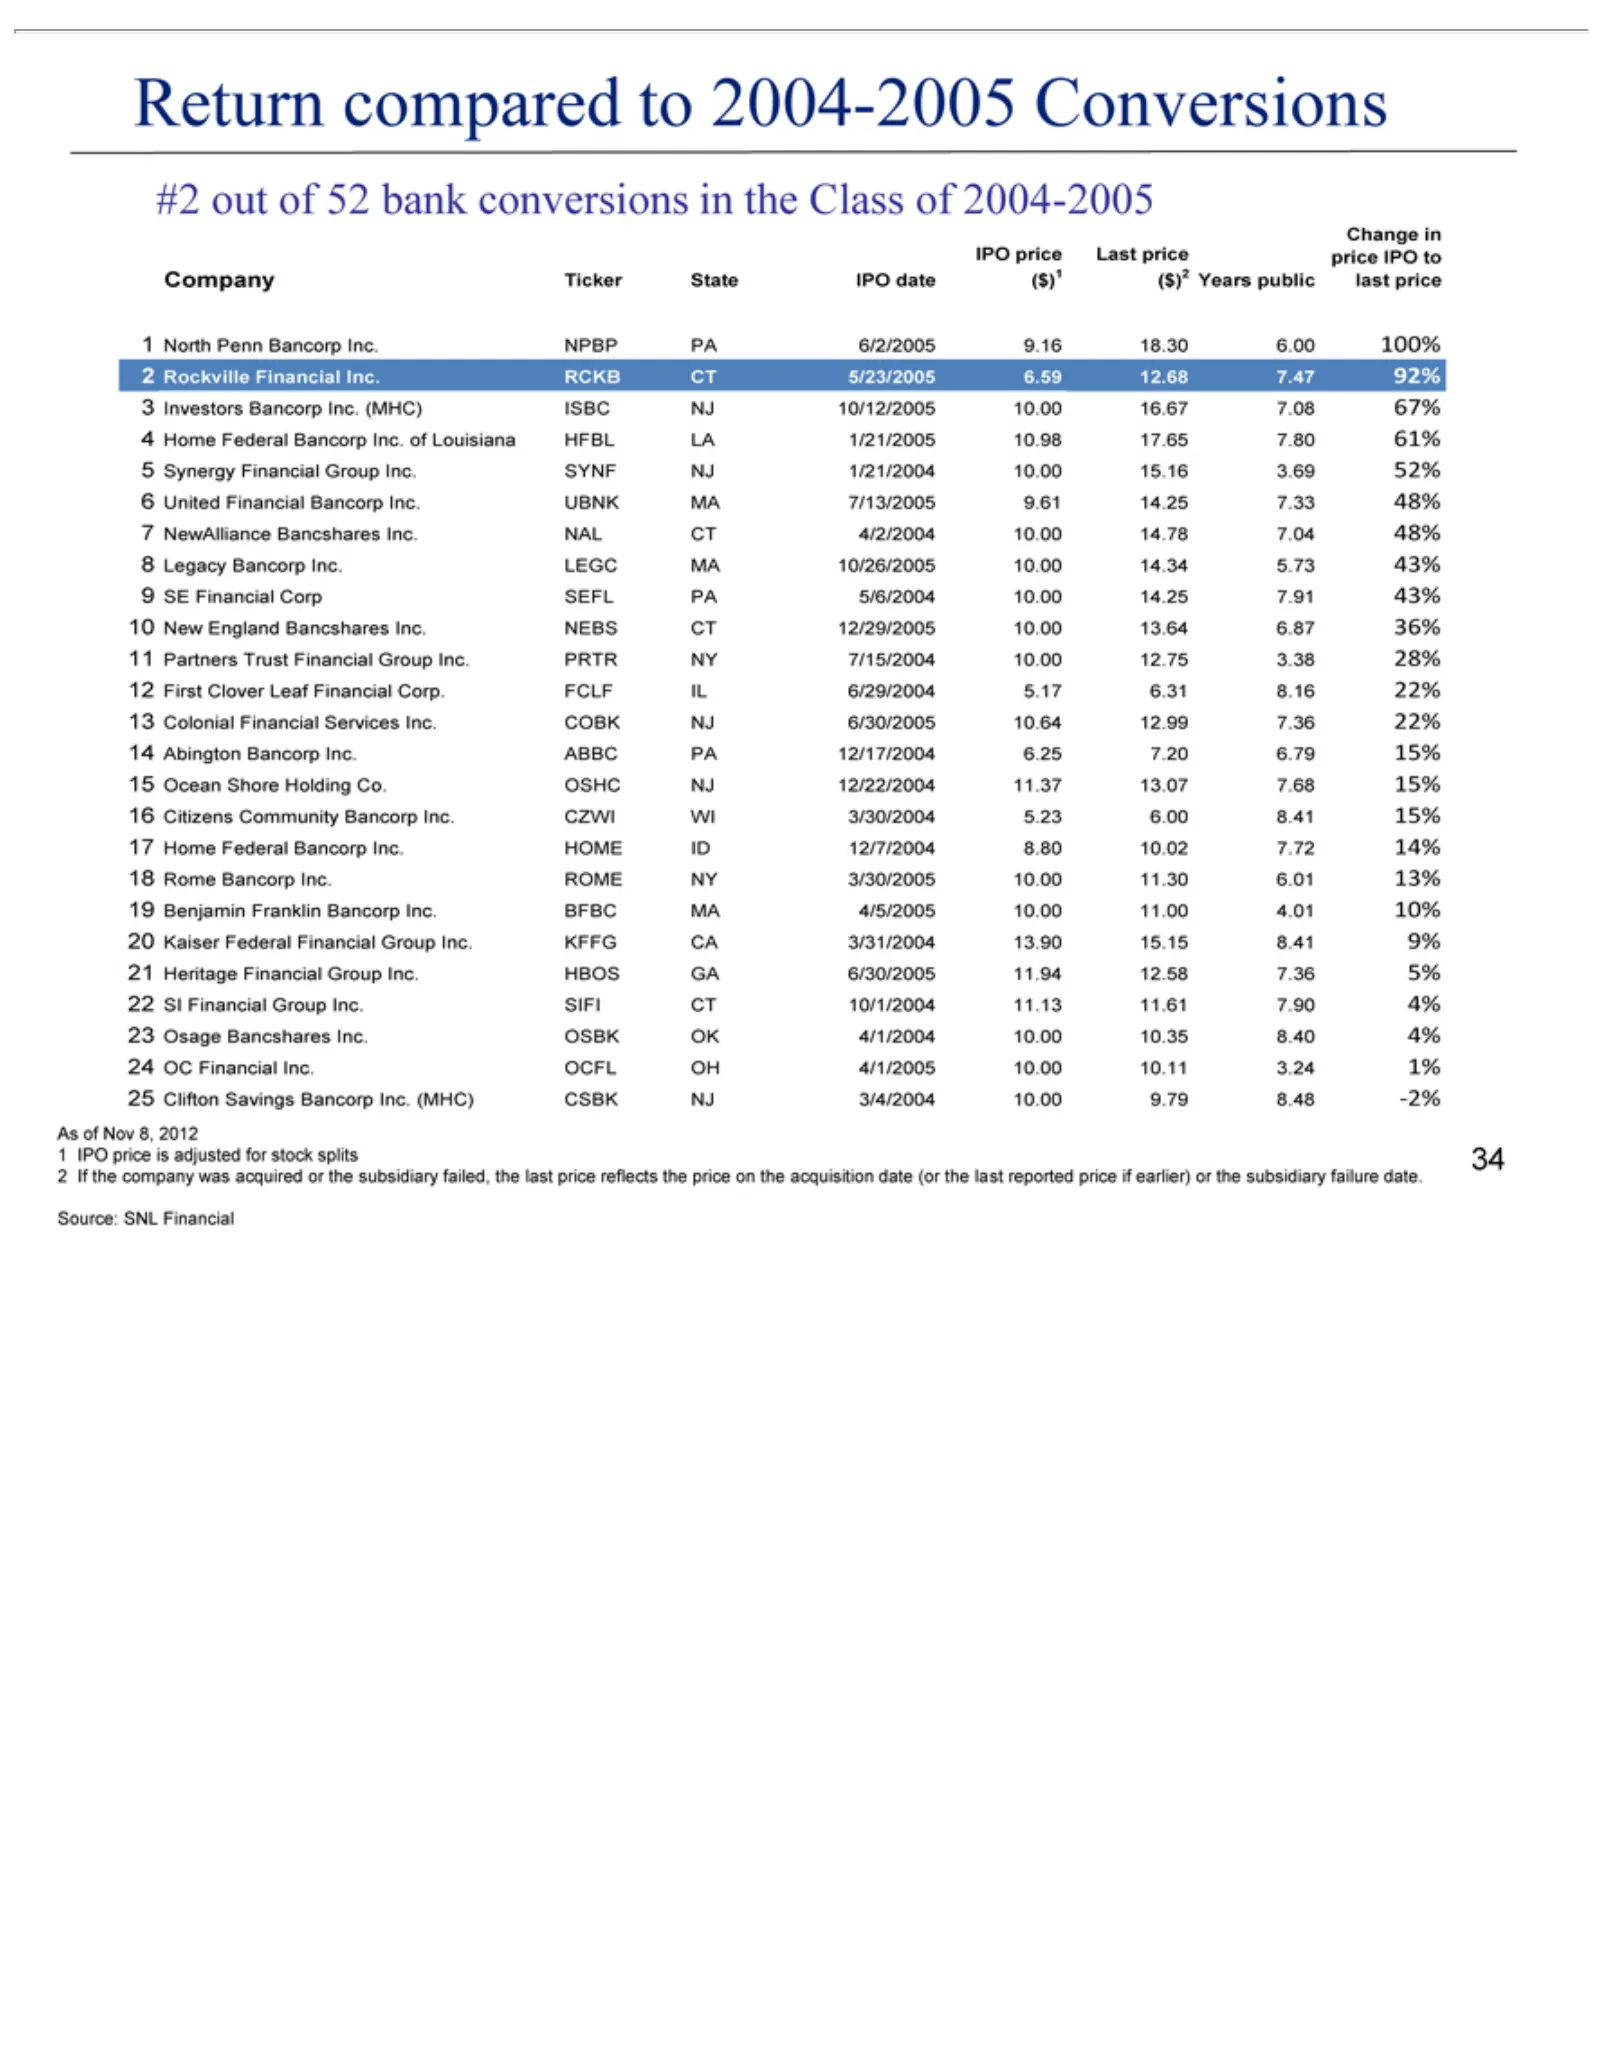
Slide 34: Price Change Since IPO vs. Conversions
Return #2 Change IPO 9876543Company 10 11 12 13 14 15 16 17 18 19 20 21 22 23 24 25 21As Source: 34North Rockville Investors Home Synergy United NewAlliance Legacy SE IPO If Abington Partners out New First Colonial Ocean Citizens Home Rome Benjamin Kaiser Heritage SI Osage OC Clifton of the price Fi
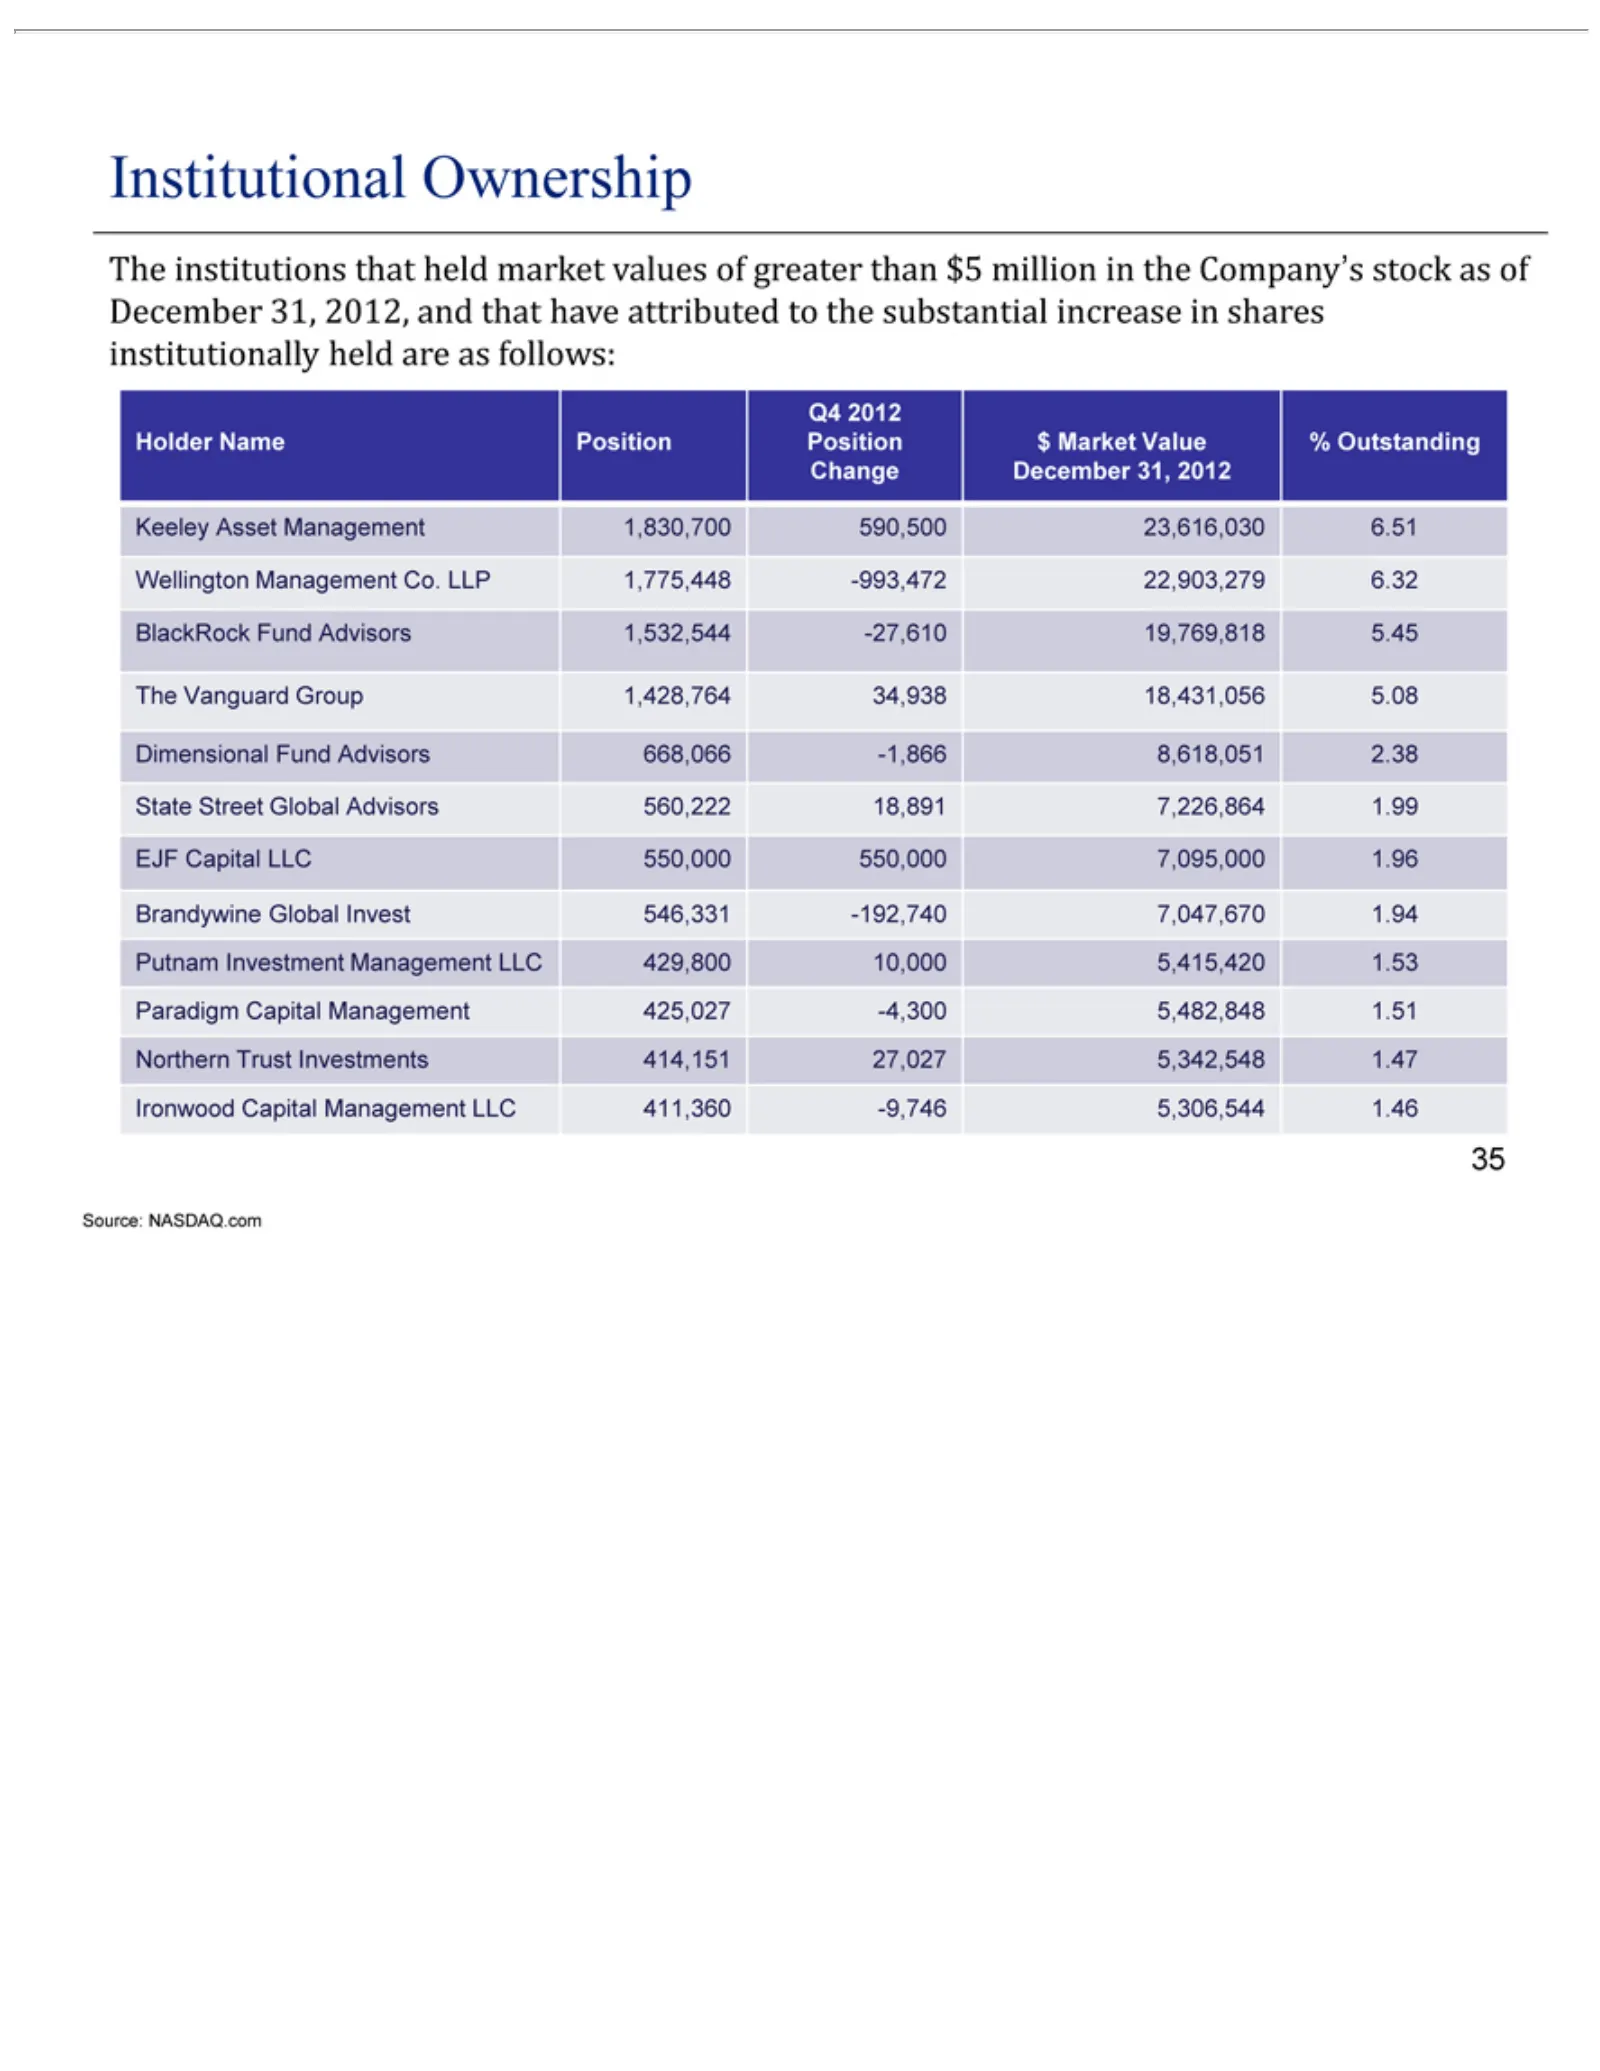
Slide 35: Institutional Holders
Institutional Q4 Holder Change Keeley Wellington BlackRock The Dimensional State EJF Brandywine Putnam Paradigm Northern Ironwood Source: 35 2012 Vanguard institutions Capital Street Asset Name NASDAQ.com December Investment Trust Capital Management Fund Global LLC Ownership Global Fund Management P
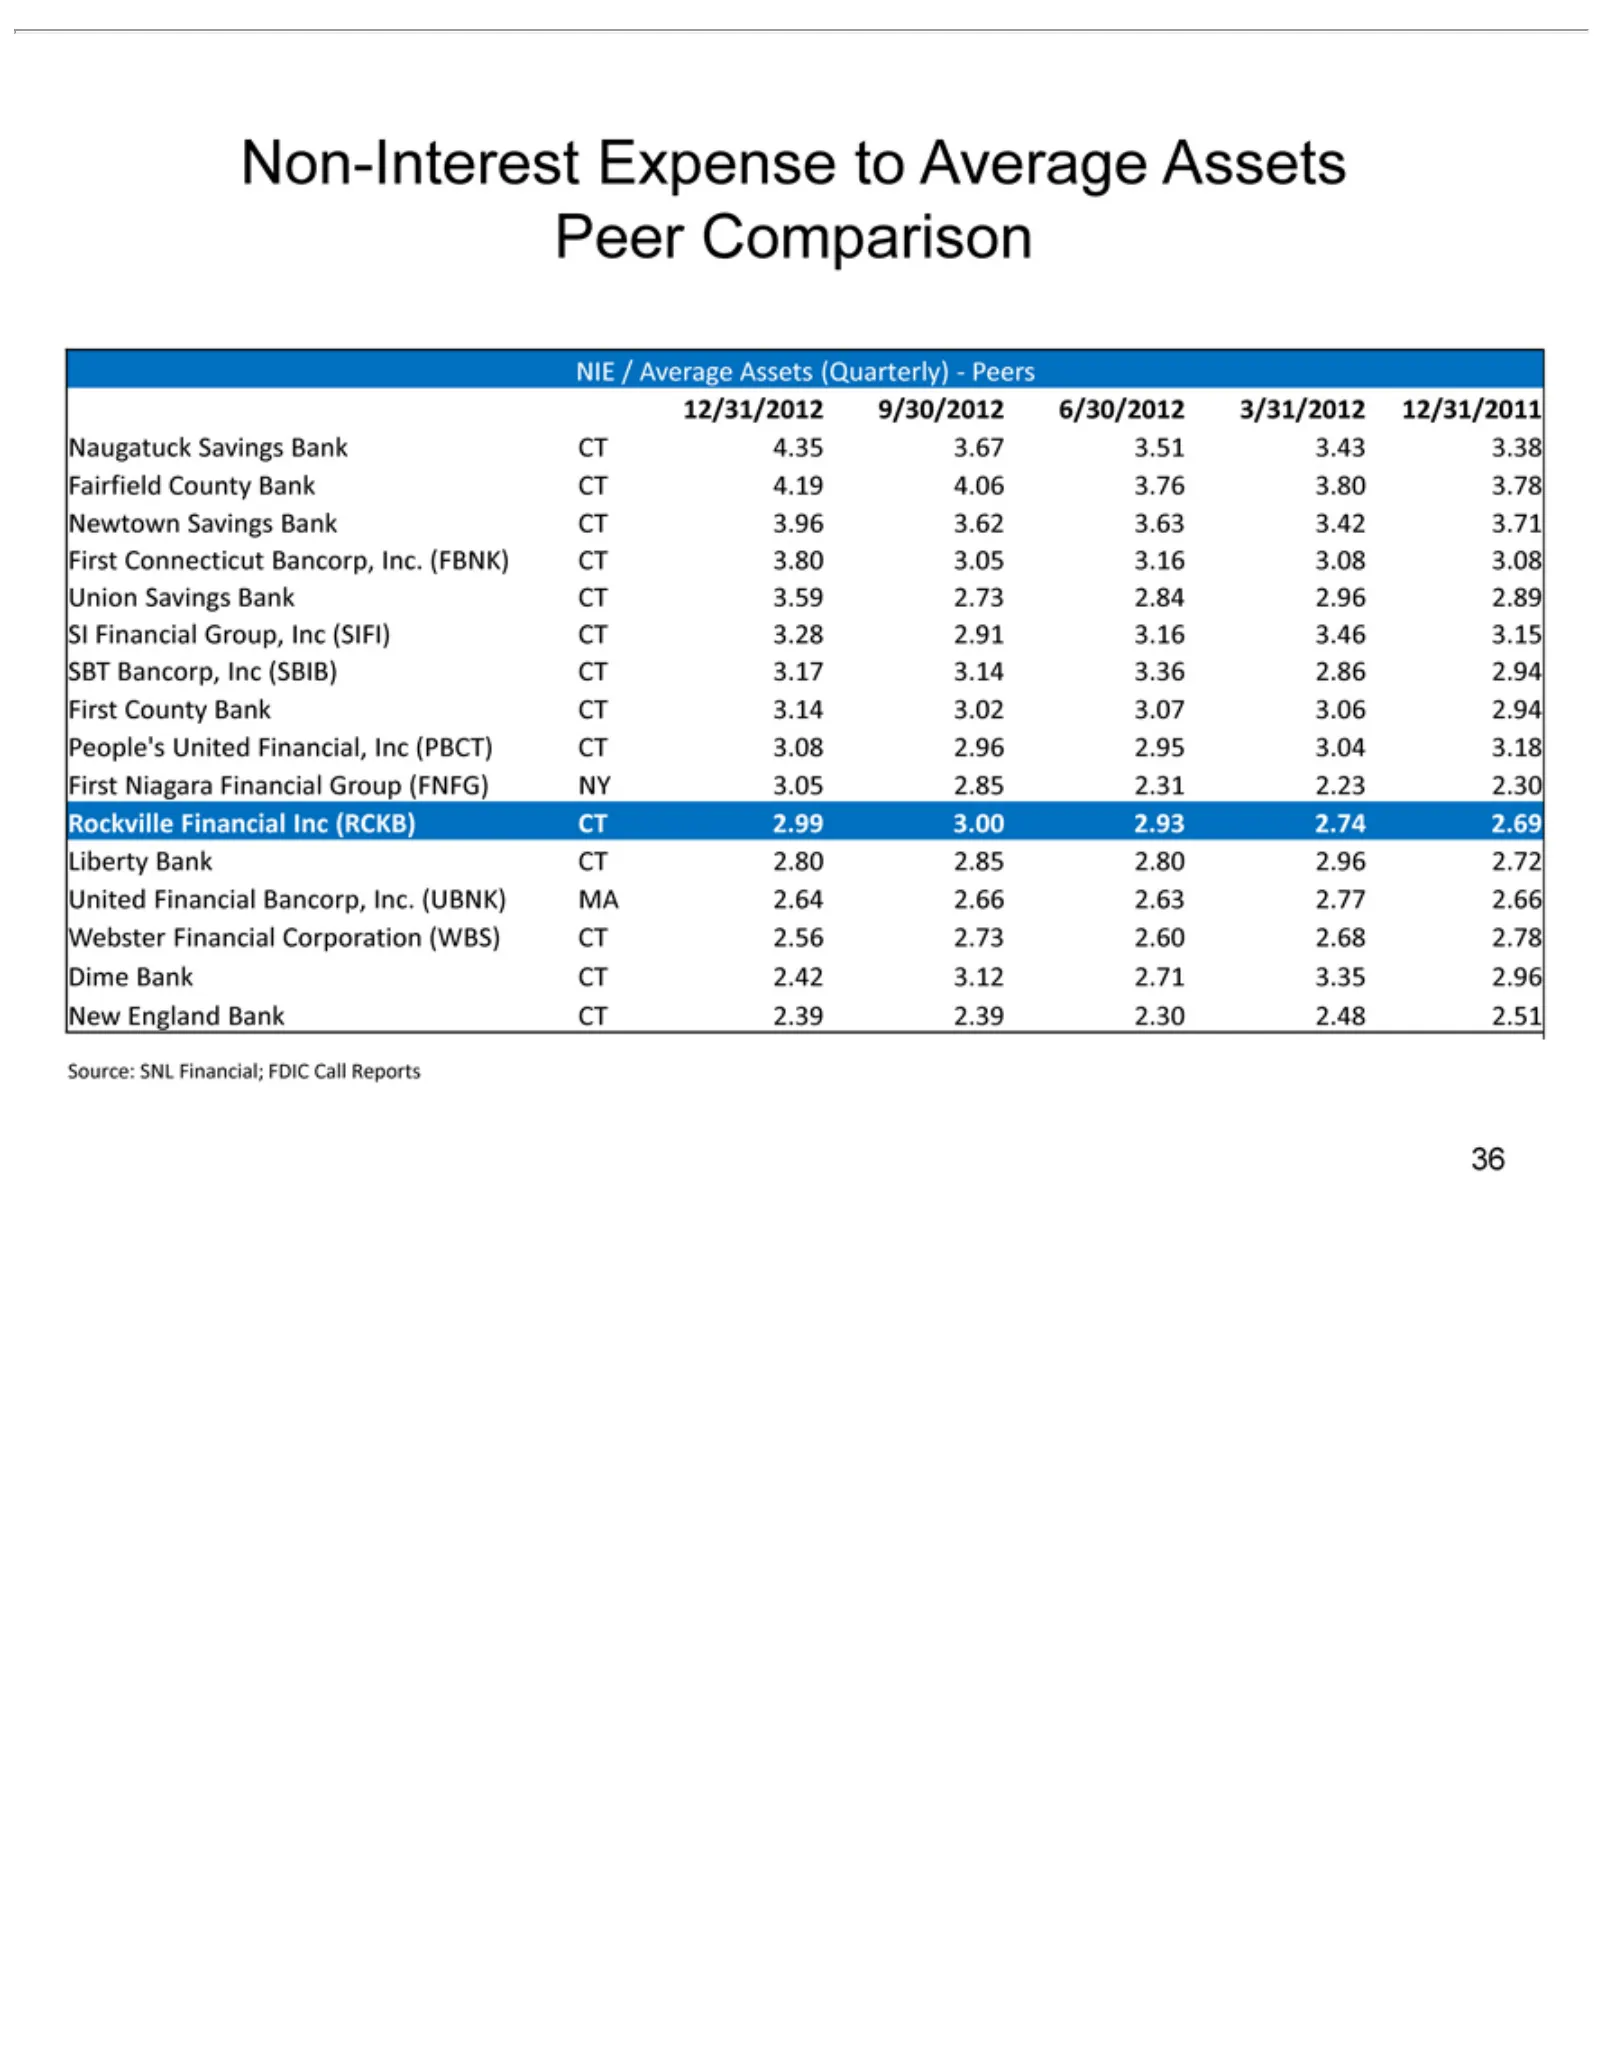
Slide 36: Non-Interest Expense Peer Comparison
Non-Interest NIE 12/31/2012 Naugatuck Fairfield Newtown Union SI SBT People’s First Rockville Liberty United Webster Dime New Source: 36 Financial /Bancorp, Connecticut County Niagara England Average Bank Savings Financial Bank SNL Financial United County Savings Financial Savings 9/30/2012 CT Group
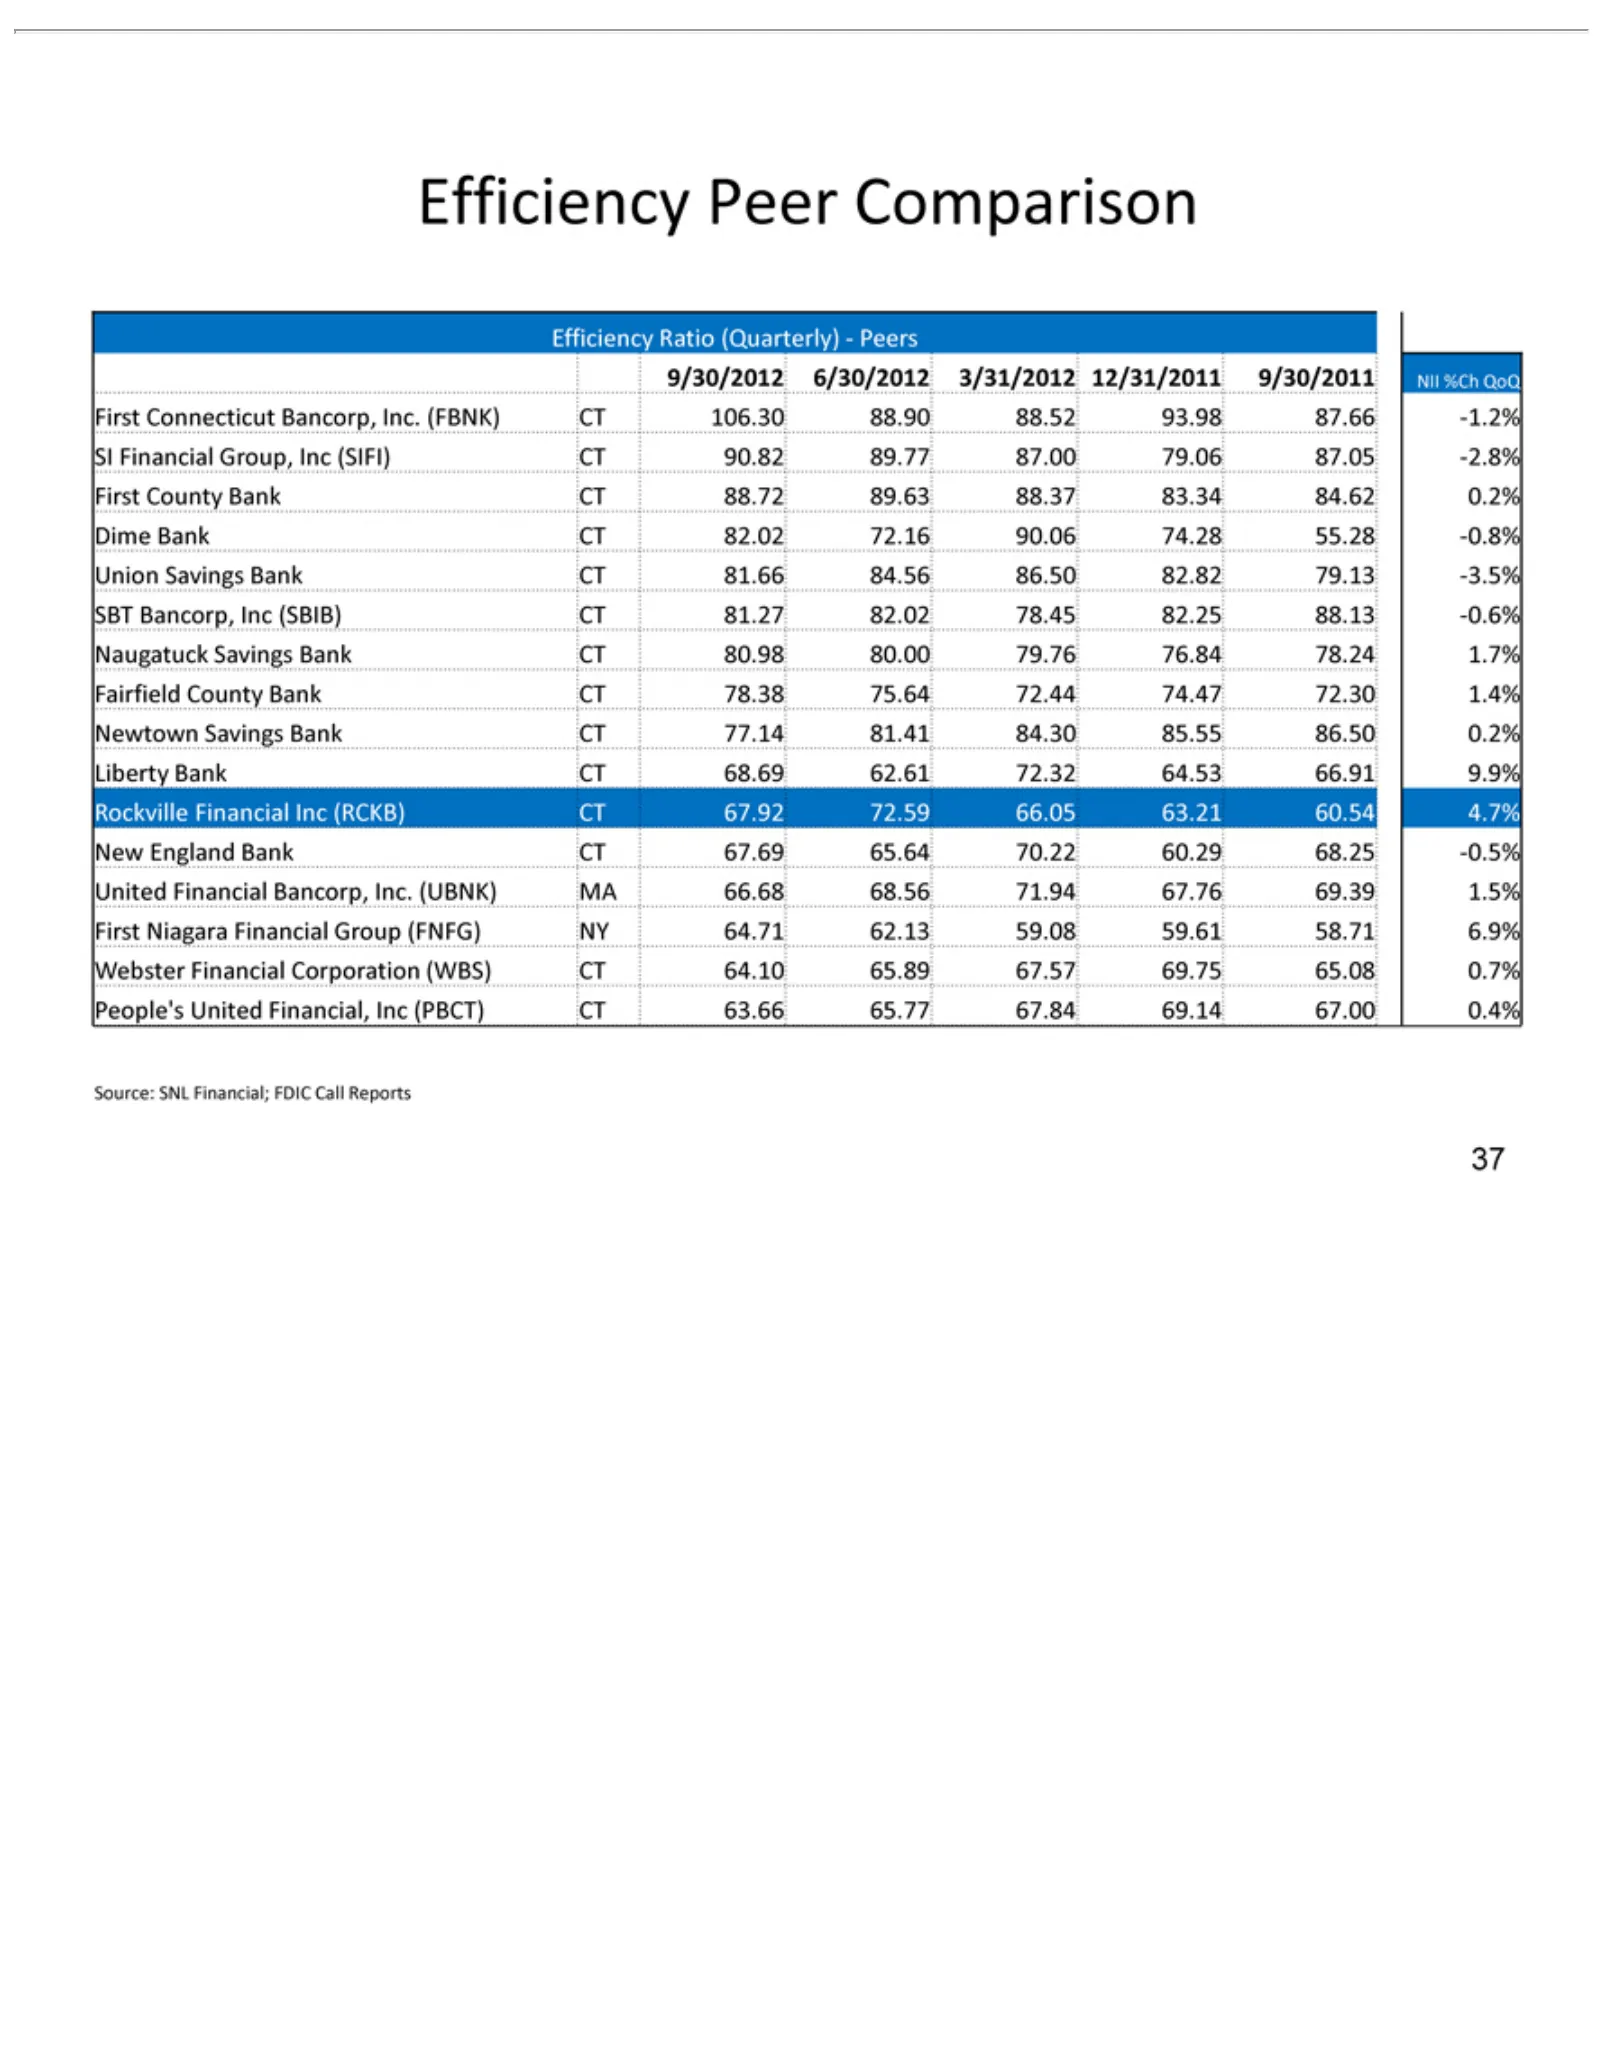
Slide 37: Efficiency Ratio Peer Comparison
Efficiency 9/30/2012 SI Dime Union SBT Naugatuck Fairfield Newtown Liberty Rockville New United First Webster People’s Source: 37 Financial Bancorp, Connecticut County Niagara England Bank Savings Financial Bank SNL Financial United County Savings Financial 6/30/2012 Peer Ratio Savings CT Group, Ban
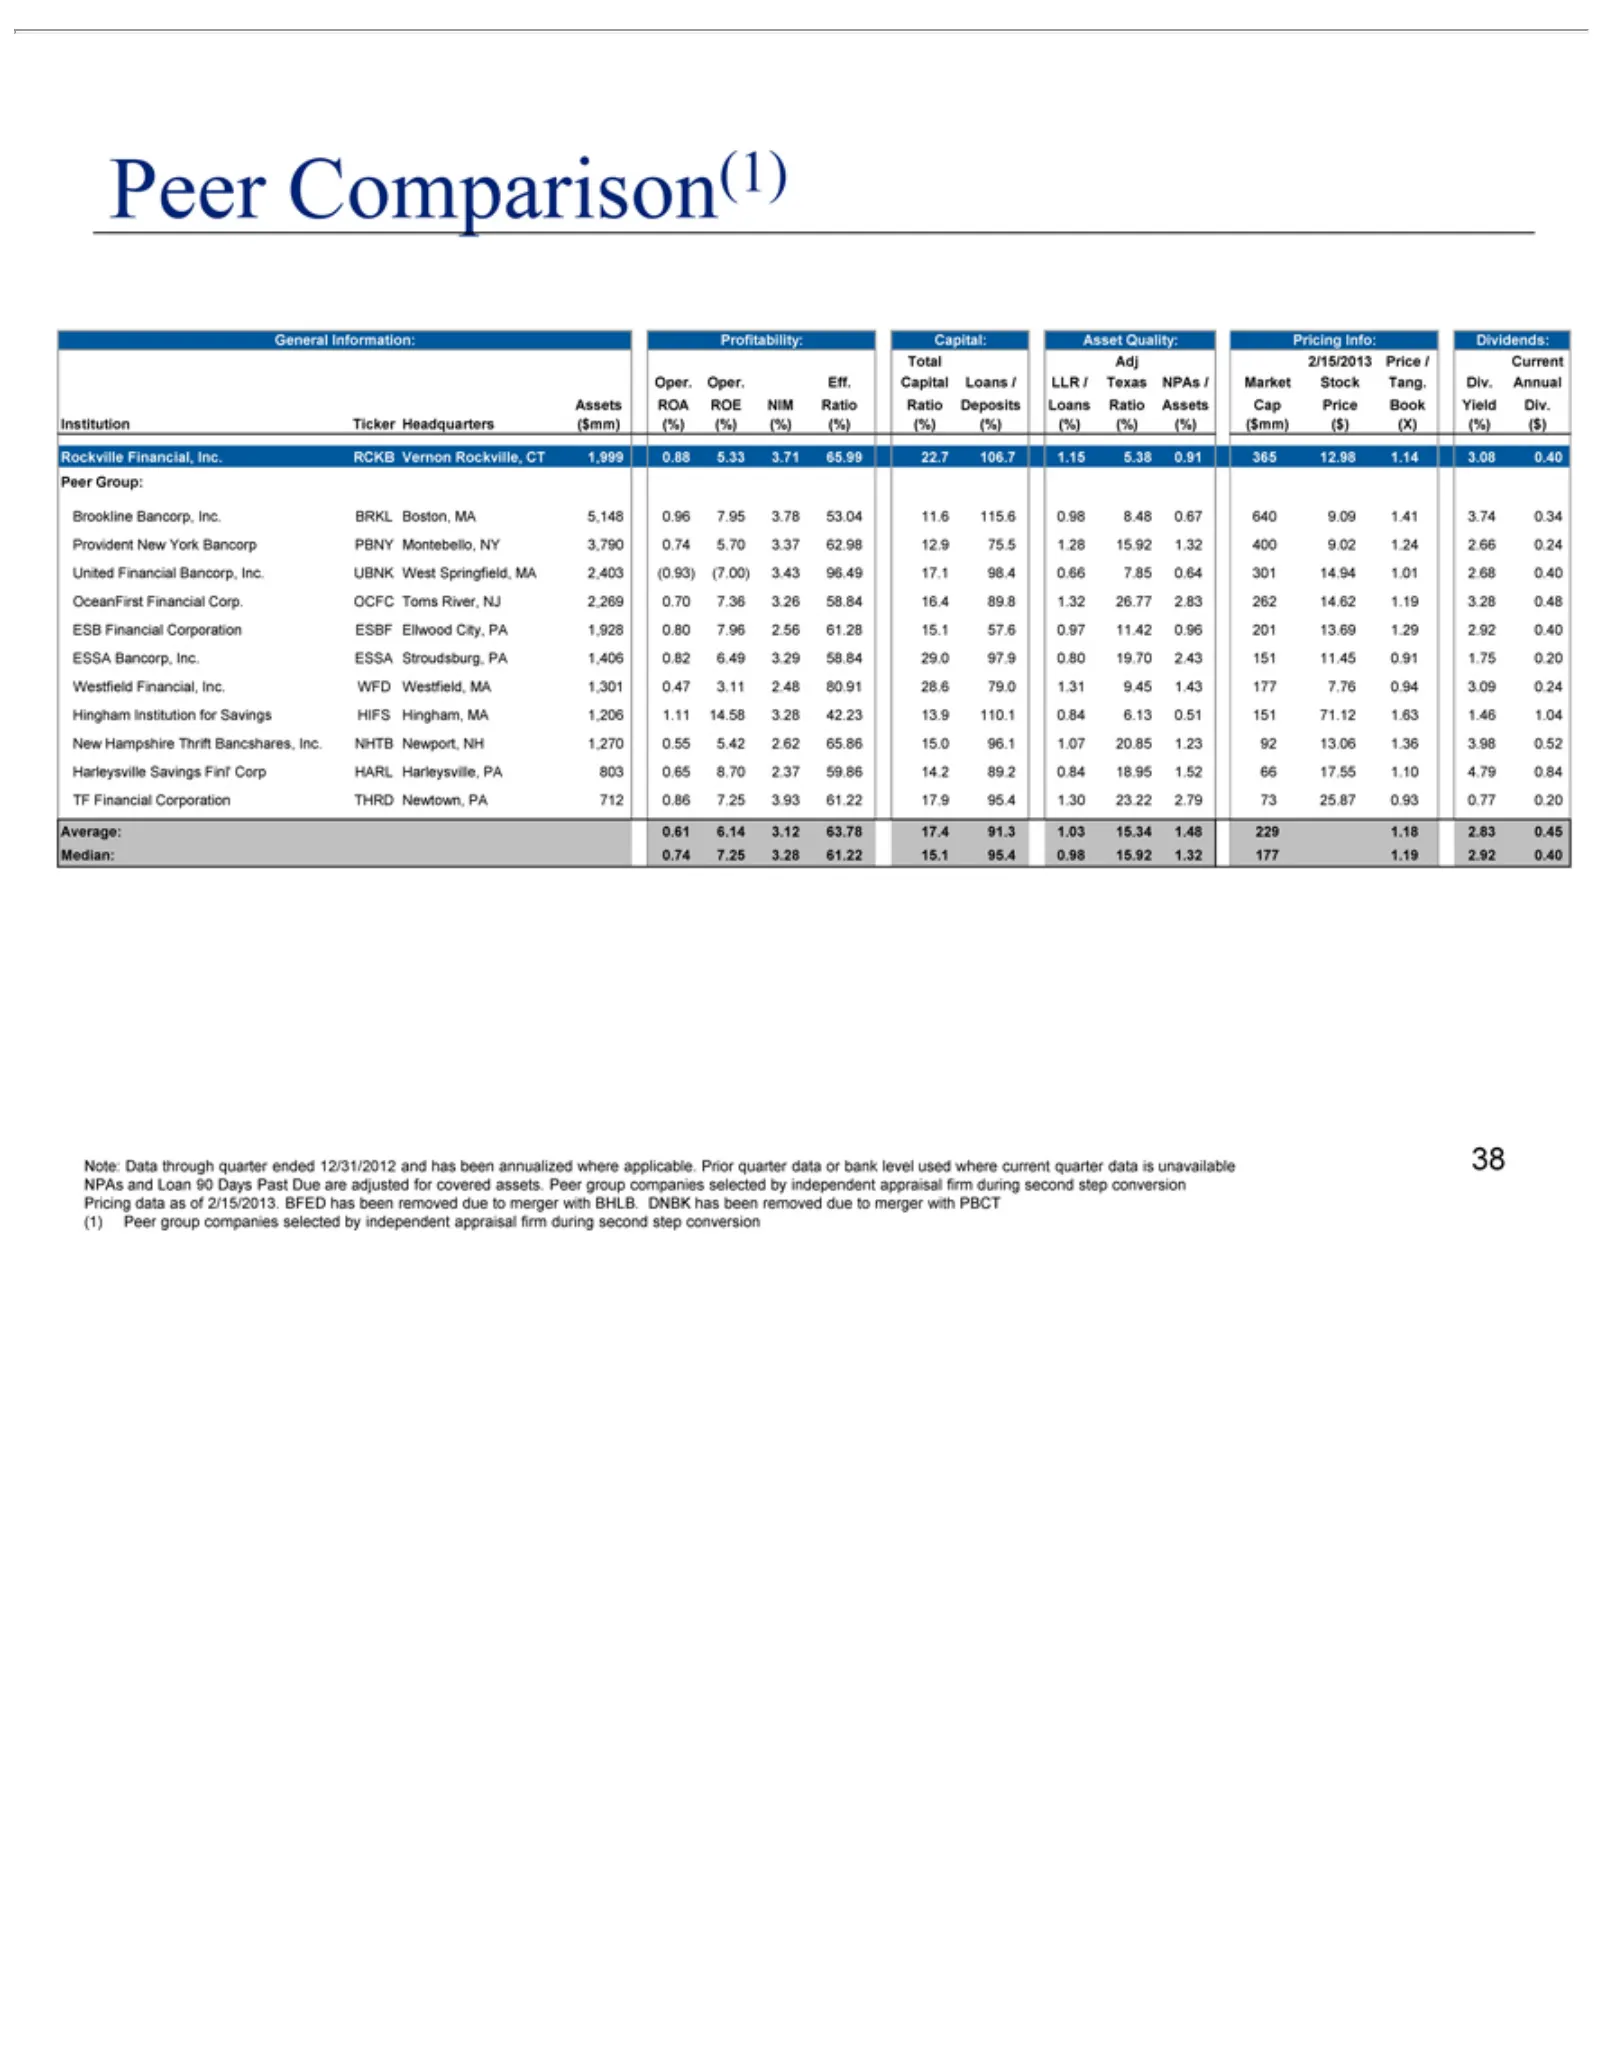
Slide 38: General Financial Information: Peer Group Comparison
General Total Oper. Assets Institution Rockville Peer Brookline Provident United OceanFirst ESB ESSA Westfield Hingham New Harleysville TF Average: Median: Note: for removed (1) 38 covered Peer Financial Comparison(1) Group: Financial Hampshire Adj Oper. Data Bancorp, ROA Financial Information: grou
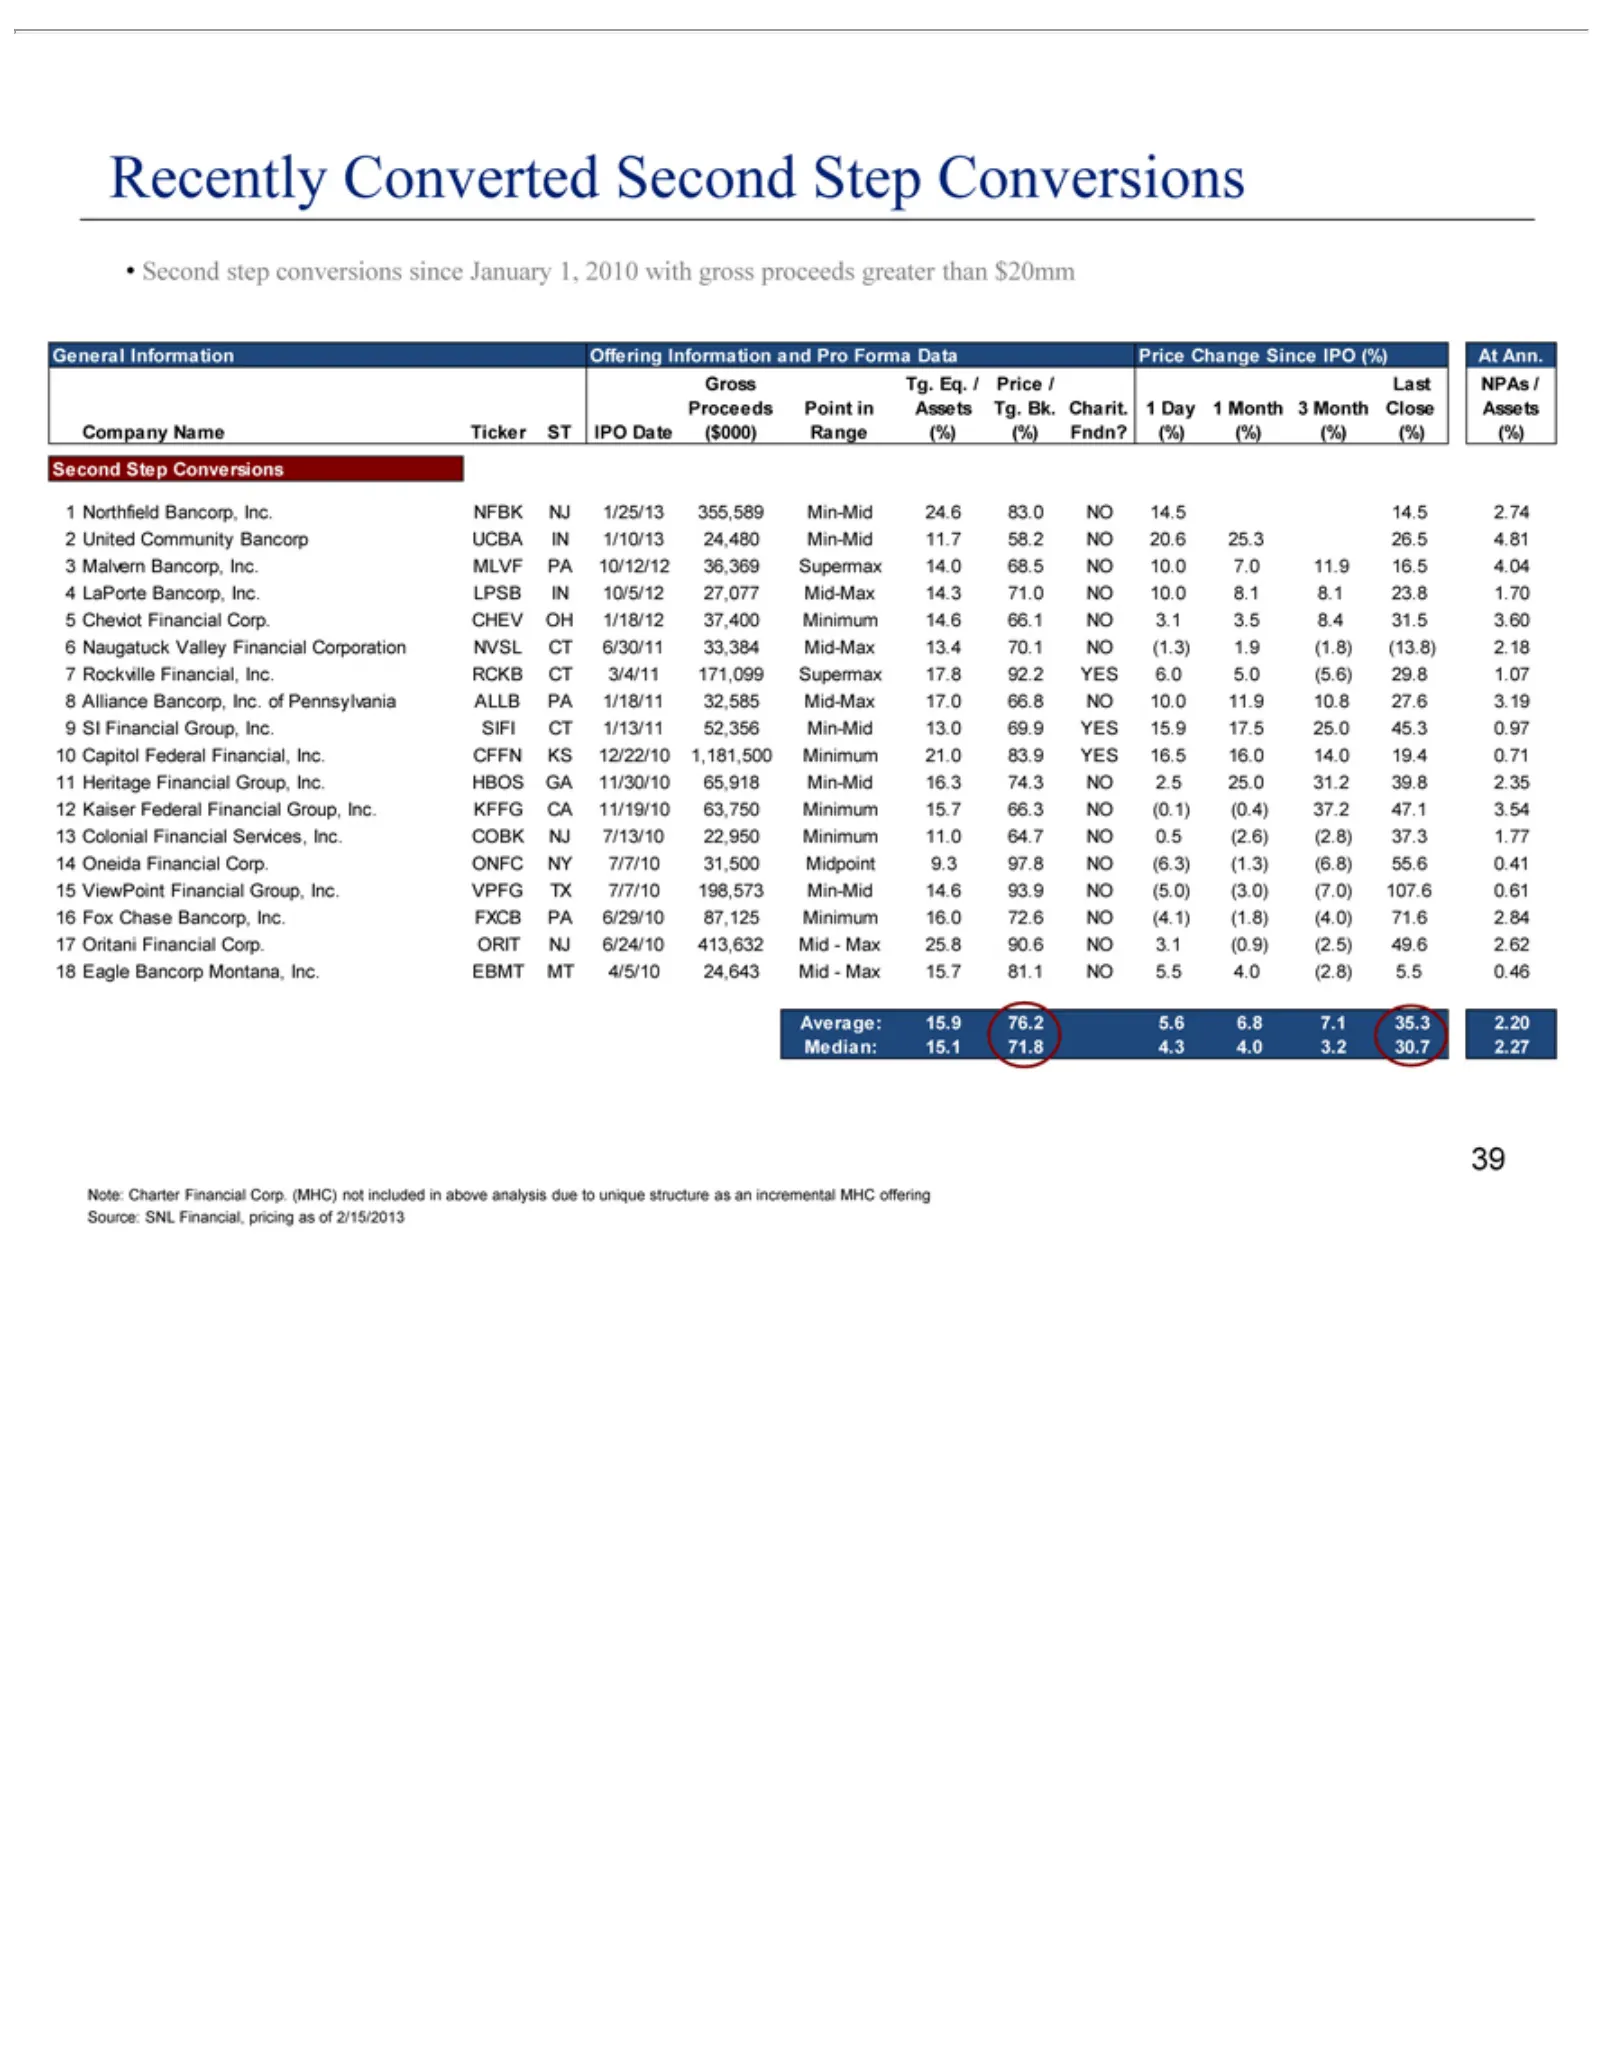
Slide 39: Recently Converted Second Step Conversions
Recently General Gross Proceeds Company 987654321Second 10 11 12 13 14 15 16 17 18 Average: Median: Note: 39 Alliance Northfield United Malvern LaPorte Cheviot Naugatuck Rockville SI Heritage ViewPoint Capitol Kaiser Colonial Oneida Fox Oritani Eagle Financial Charter Tg. Chase step Step Information
Source: SEC EDGAR · 8-K filed Feb 20, 2013
More decks from United Financial Bancorp Inc
 Merger or Acquisition (July 2019)10 slides · Jul 15, 2019
 Shareholder Meeting (May 2019)14 slides · May 13, 2019
 Q1 2019 Earnings Presentation27 slides · Apr 16, 2019
 Q4 2018 Earnings Presentation26 slides · Jan 22, 2019
 Q3 2018 Earnings Presentation25 slides · Oct 16, 2018
 Q2 2018 Earnings Presentation25 slides · Jul 17, 2018