Air Transport Services Group Inc
Air Transport Services — Stephens Fall Investment Conference 2015
16 slides from Air Transport Services's conference presentation, Nov 12, 2015
Slide 1: The global leader in midsize wide-body leasing and operating solutions
The global leader in midsize wide-body leasing and operating solutions Stephens Fall Investment Conference November 11, 2015 Joe Hete President & CEO Quint Turner Chief Financial Officer
Slide 2: Safe Harbor Statement
Safe Harbor Statement Except for historical information contained herein, the matters discussed in this presentation contain forward-looking statements that involve risks and uncertainties. There are a number of important factors that could cause Air Transport Services Group's ("ATSG's") actual resu
Slide 3: Differentiated Business Model
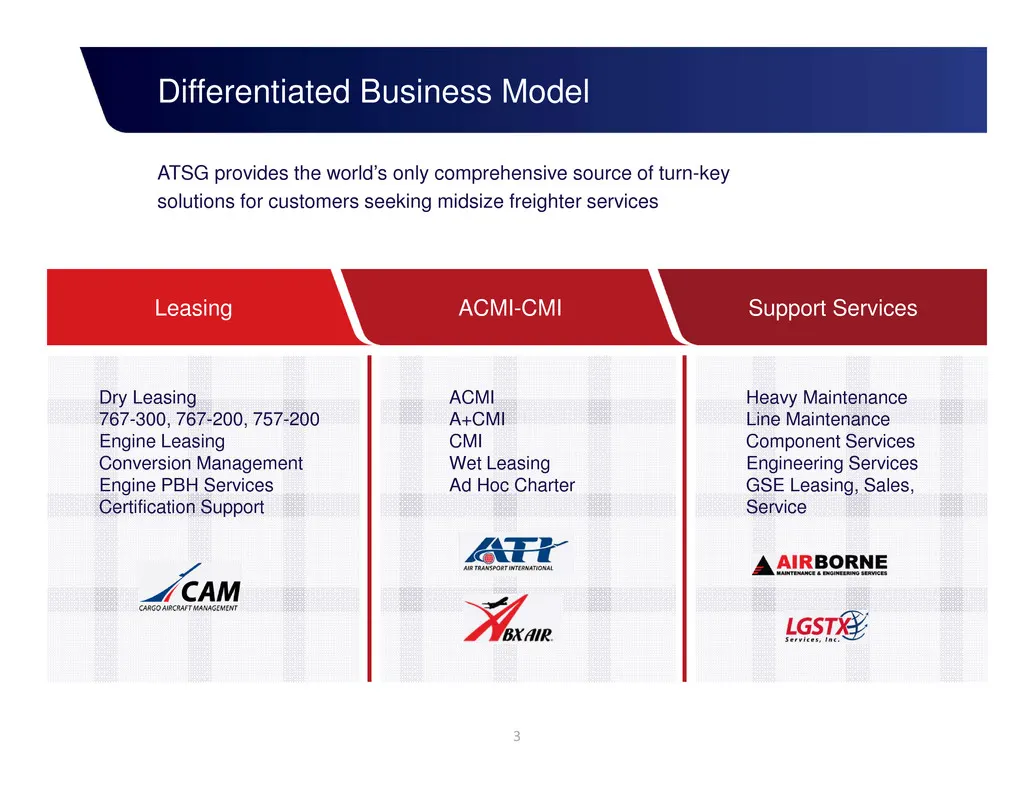
Differentiated Business Model ATSG provides the world’s only comprehensive source of turn-key solutions for customers seeking midsize freighter services Dry Leasing 767-300, 767-200, 757-200 Engine Leasing Conversion Management Engine PBH Services Certification Support Leasing ACMI-CMI Support Servi
Slide 4: Value Creation Begins with Conversions
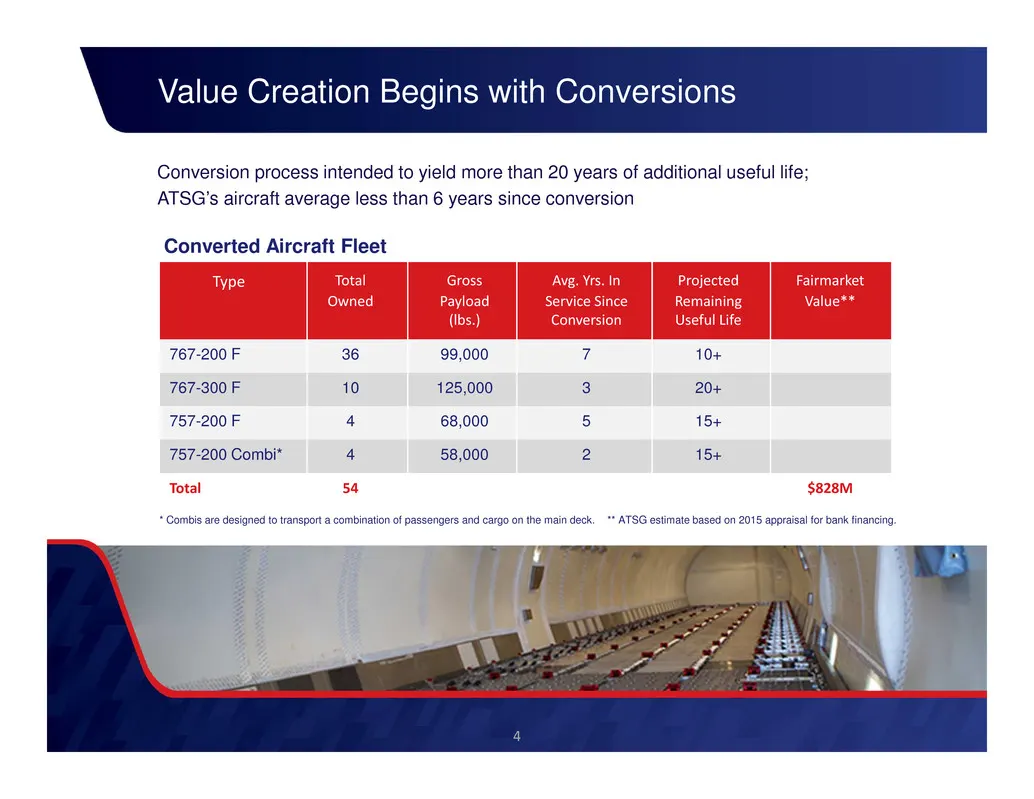
Value Creation Begins with Conversions Conversion process intended to yield more than 20 years of additional useful life; ATSG’s aircraft average less than 6 years since conversion Type Total Owned Gross Payload (lbs.) Avg. Yrs. In Service Since Conversion Projected Remaining Useful Life Fairmarket
Slide 5: Target Growing Network Demand
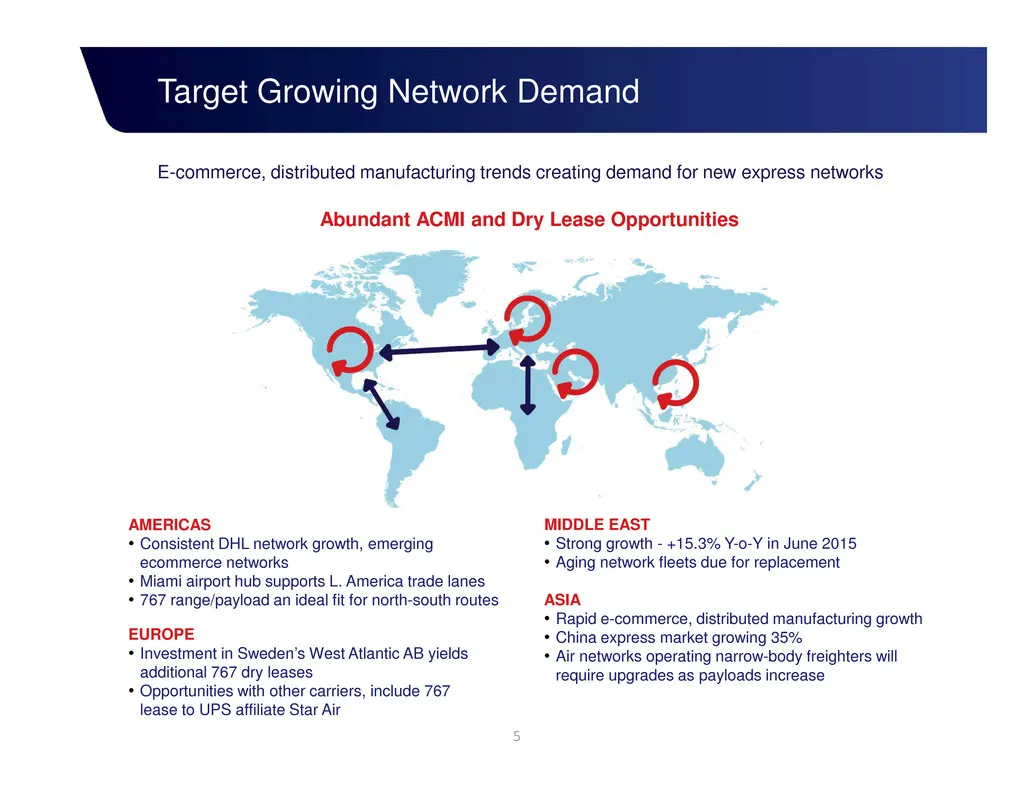
Target Growing Network Demand E-commerce, distributed manufacturing trends creating demand for new express networks Abundant ACMI and Dry Lease Opportunities MIDDLE EAST • Strong growth - +15.3% Y-o-Y in June 2015 • Aging network fleets due for replacement ASIA • Rapid e-commerce, distributed manufa
Slide 6: United Star Express joint venture targeting intra-China express market
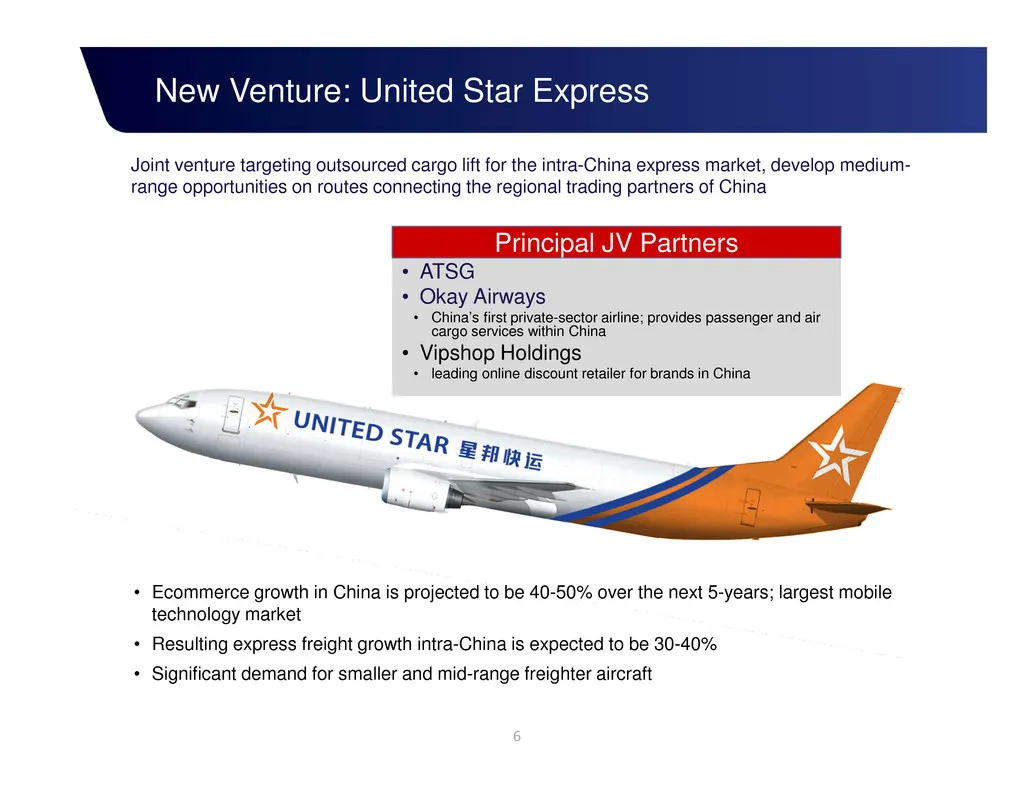
Joint venture targeting outsourced cargo lift for the intra-China express market, develop medium- range opportunities on routes connecting the regional trading partners of China 6 • Ecommerce growth in China is projected to be 40-50% over the next 5-years; largest mobile technology market • Resultin
Slide 7: Favorable Industry Positioning
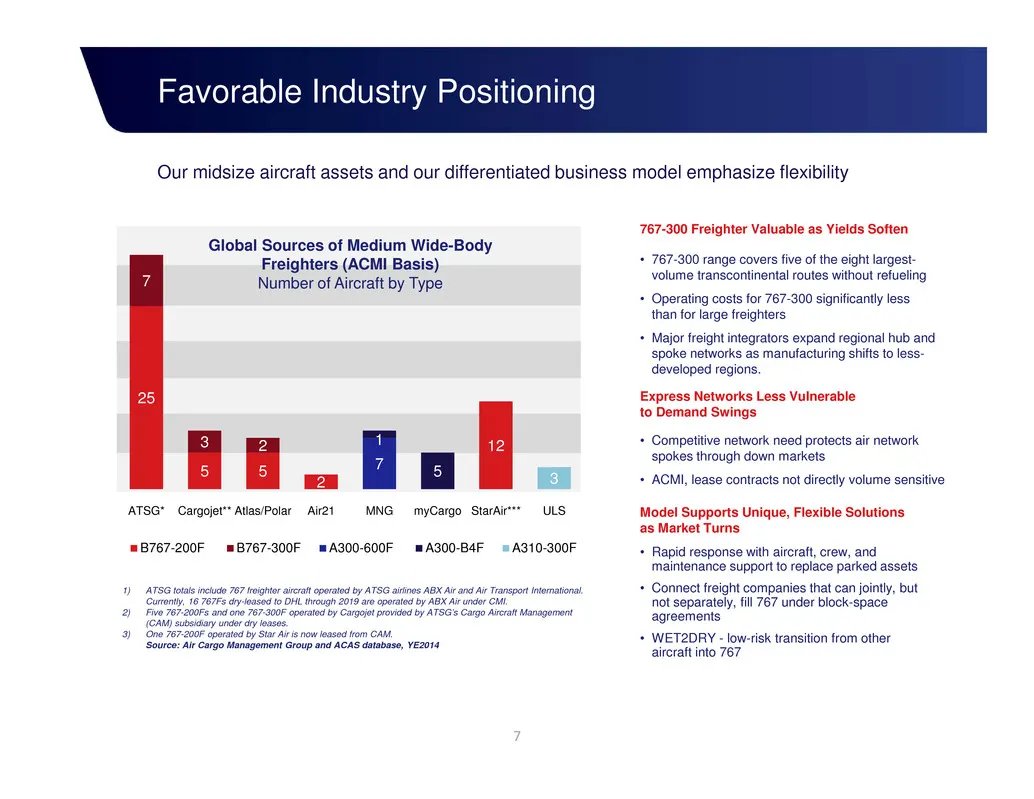
Favorable Industry Positioning Our midsize aircraft assets and our differentiated business model emphasize flexibility 767-300 Freighter Valuable as Yields Soften • 767-300 range covers five of the eight largest- volume transcontinental routes without refueling • Operating costs for 767-300 signific
Slide 8: Lease Demand Drives Growth
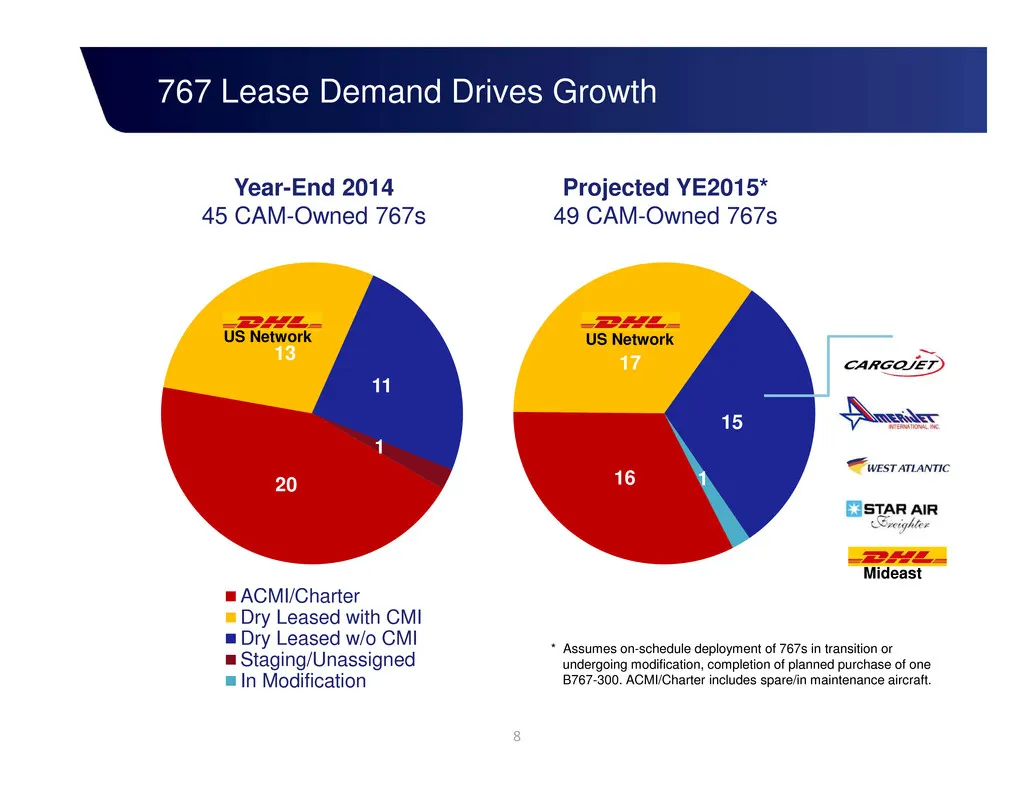
767 Lease Demand Drives Growth Year-End 2014 45 CAM-Owned 767s Projected YE2015* 49 CAM-Owned 767s 20 13 11 1 ACMI/Charter Dry Leased with CMI Dry Leased w/o CMI Staging/Unassigned In Modification 16 17 15 1 8 US NetworkUS Network Mideast * Assumes on-schedule deployment of 767s in transition or und
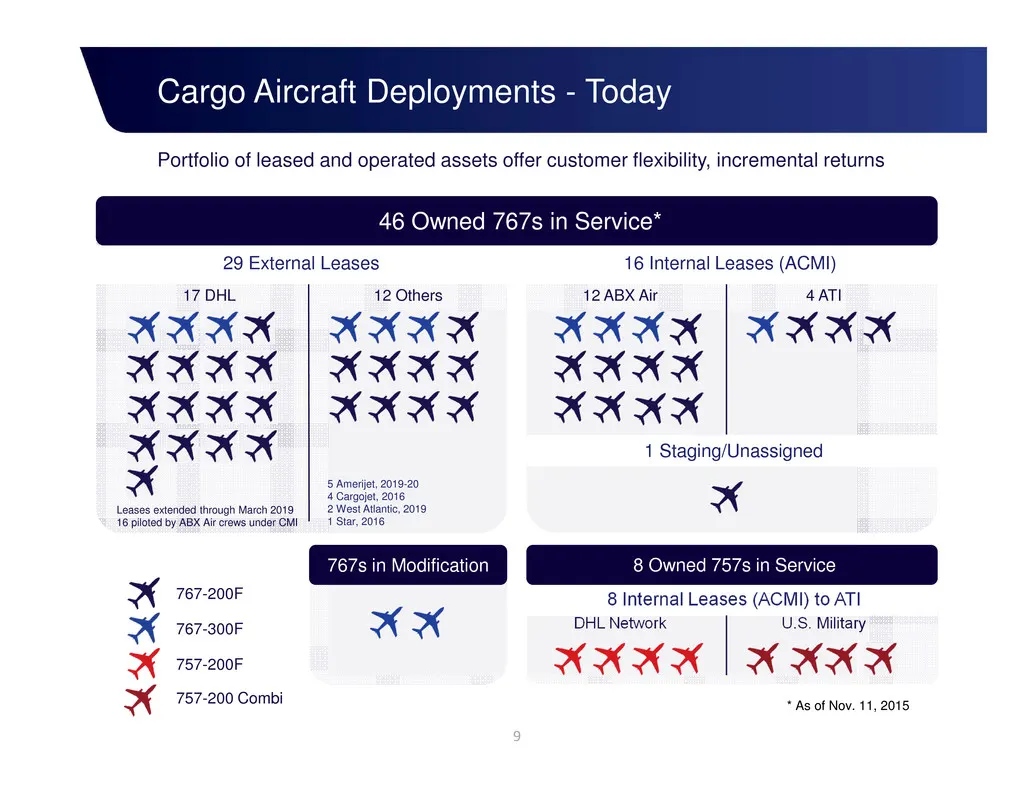
Slide 9: Cargo Aircraft Deployments - Today
Cargo Aircraft Deployments - Today Portfolio of leased and operated assets offer customer flexibility, incremental returns 9 46 Owned 767s in Service* 17 DHL 29 External Leases 16 Internal Leases (ACMI) 12 Others 12 ABX Air 4 ATI 8 Internal Leases (ACMI) to ATI DHL Network U.S. Military 767-200F 767
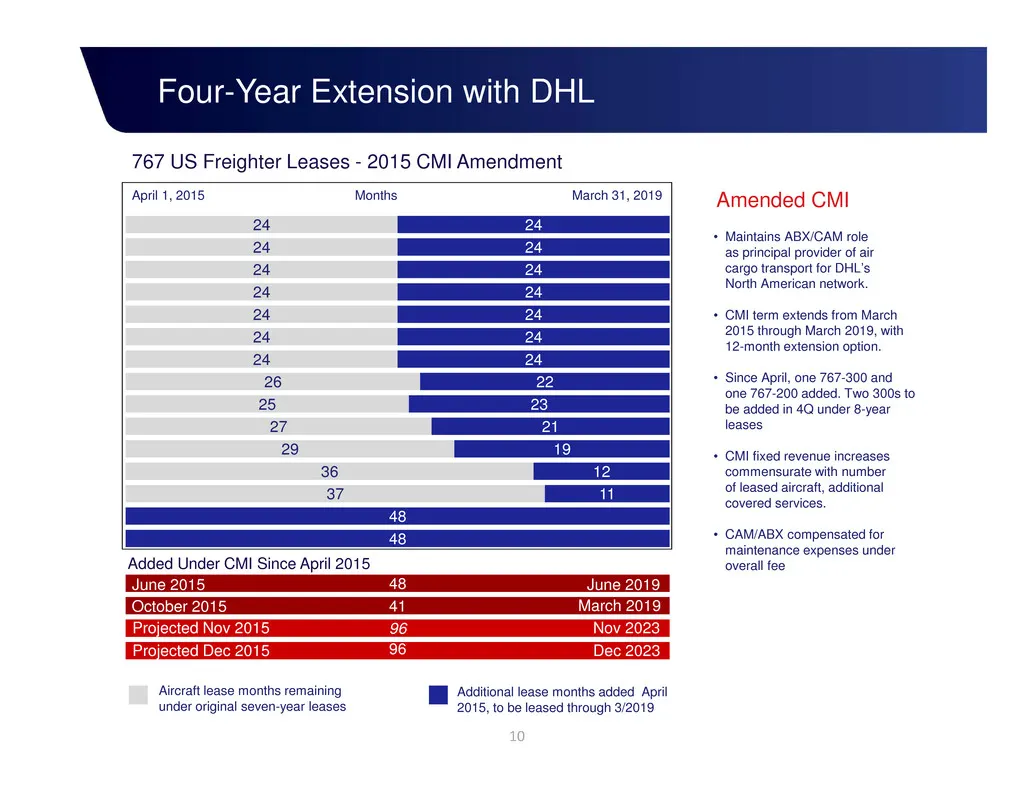
Slide 10: Four-Year Extension with DHL
37 36 29 27 25 26 24 24 24 24 24 24 24 96 96 41 48 48 48 11 12 19 21 23 22 24 24 24 24 24 24 24 Four-Year Extension with DHL April 1, 2015 March 31, 2019 Amended CMI • Maintains ABX/CAM role as principal provider of air cargo transport for DHL’s North American network. • CMI term extends from March
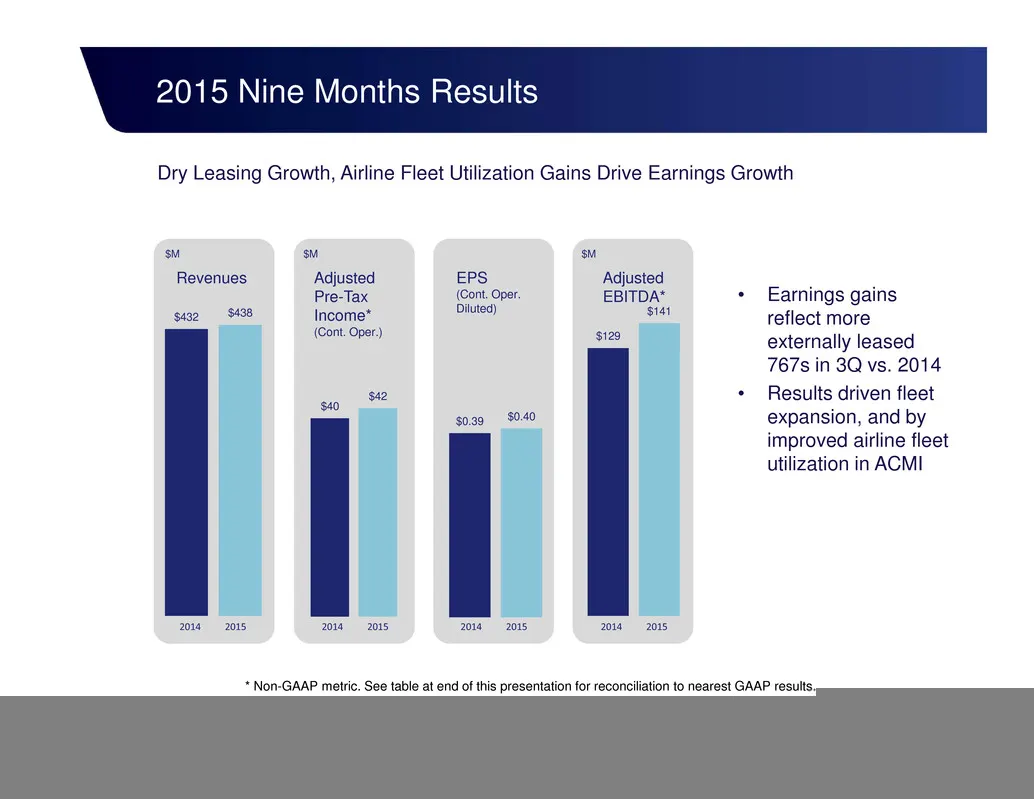
Slide 11: Dry Leasing Growth, Airline Fleet Utilization Gains Drive Earnings Growth
Dry Leasing Growth, Airline Fleet Utilization Gains Drive Earnings Growth 11 • Earnings gains reflect more externally leased 767s in 3Q vs. 2014 • Results driven fleet expansion, and by improved airline fleet utilization in ACMI $432 $438 $40 $42 $0.39 $0.40 $129 $141 2015 Nine Months Results Revenu
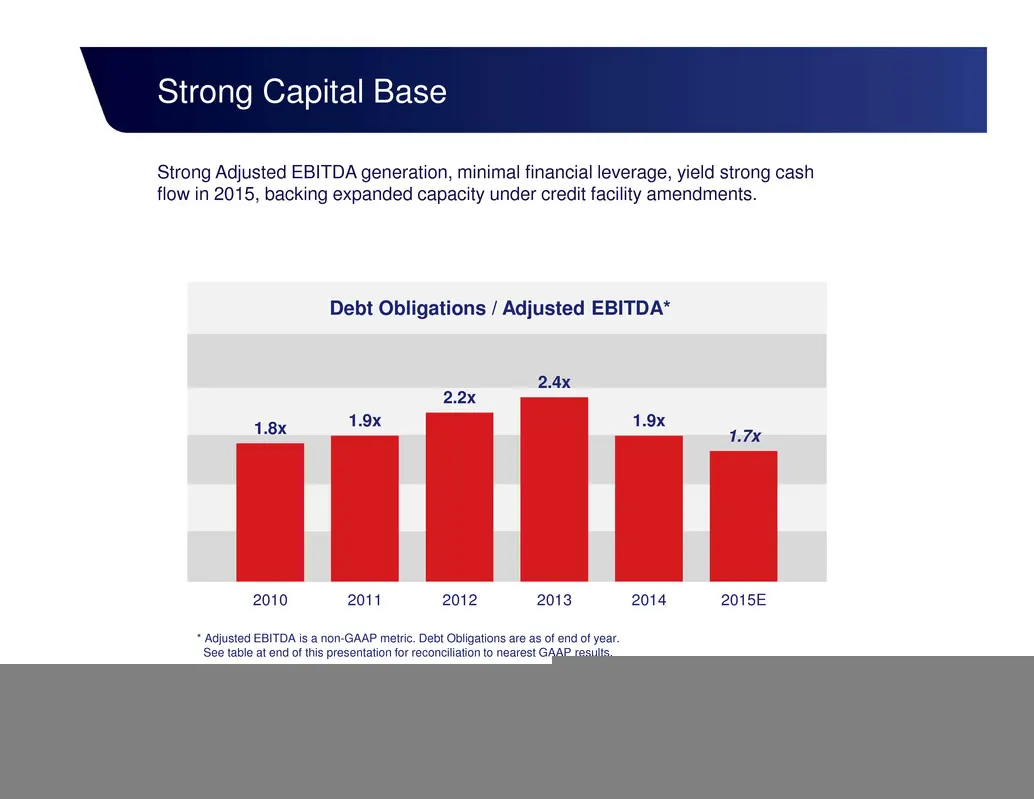
Slide 12: Strong Capital Base
Strong Capital Base Strong Adjusted EBITDA generation, minimal financial leverage, yield strong cash flow in 2015, backing expanded capacity under credit facility amendments. * Adjusted EBITDA is a non-GAAP metric. Debt Obligations are as of end of year. See table at end of this presentation for rec
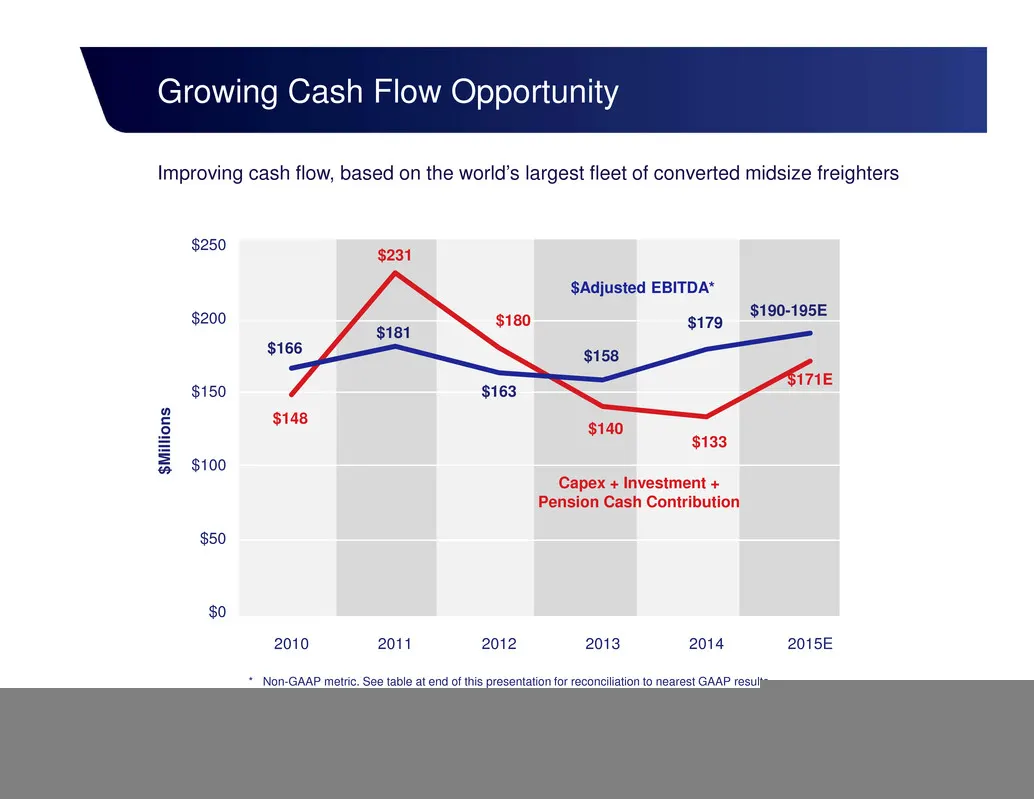
Slide 13: Growing Cash Flow Opportunity
$148 $231 $180 $140 $133 $171E $166 $181 $163 $158 $179 $190-195E $0 $50 $100 $150 $200 $250 2010 2011 2012 2013 2014 2015E Growing Cash Flow Opportunity Improving cash flow, based on the world’s largest fleet of converted midsize freighters $ M i l l i o n s * Non-GAAP metric. See table at end of t
Slide 14: Highlights and Outlook
Highlights and Outlook Unique model augments leasing-driven base return on 100% owned aircraft fleet with complete packaged air cargo solutions Dominant market share in midsize freighter class key to ‘spoke’ transport among global and regional air cargo hubs Reduced cost structure through fleet and
Slide 15: Expanding Free Cash Flow Creates Options
Expanding Free Cash Flow Creates Options Free Cash Flow Options Growth Investments Share Repurchases Debt Reduction ($8.4M YTD) 15
Slide 16: Non-GAAP Reconciliation Statement
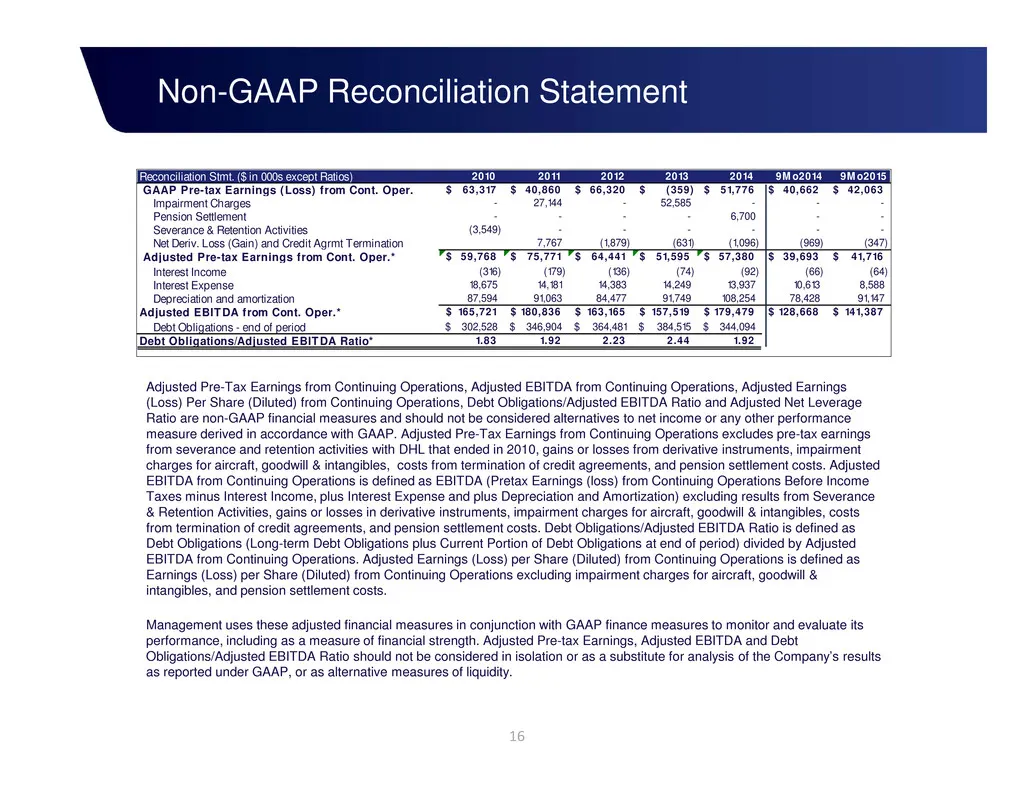
Non-GAAP Reconciliation Statement 2010 2011 2012 2013 2014 9M o2014 9M o2015 63,317$ 40,860$ 66,320$ (359)$ 51,776$ 40,662$ 42,063$ Impairment Charges - 27,144 - 52,585 - - - Pension Settlement - - - - 6,700 - - Severance & Retention Activities (3,549) - - - - - - Net Deriv. Loss (Gain) and Credit A
Source: SEC EDGAR · 8-K filed Nov 12, 2015
More decks from Air Transport Services Group Inc
 Shareholder Meeting (May 2024)26 slides · May 23, 2024
 Stephens Annual Investment Conference 202321 slides · Nov 14, 2023
 Investor Day (September 2023)68 slides · Sep 27, 2023
 Shareholder Meeting (May 2023)25 slides · May 26, 2023
 Stifel conference (February 2023)15 slides · Feb 6, 2023
 Stifel 2020 Transportation & Logistics Conference18 slides · Feb 11, 2020