Southcross Energy Partners L.P
Southcross Energy Partners L.P — Investor Presentation (December 2013)
28 slides from Southcross Energy Partners L.P's investor presentation, Dec 17, 2013
Slide 1: Energy Prospectus Group Investor Presentation December 2013
0 Energy Prospectus Group Investor Presentation December 2013
Slide 2: Cautionary Statements
1 Cautionary Statements This presentation contains forward-looking statements and information. Forward-looking statements include, without limitation, any statement that may project, indicate or imply future results, events, performance or achievements, and may contain the words “expect,” “intend,”
Slide 3: Southcross Overview
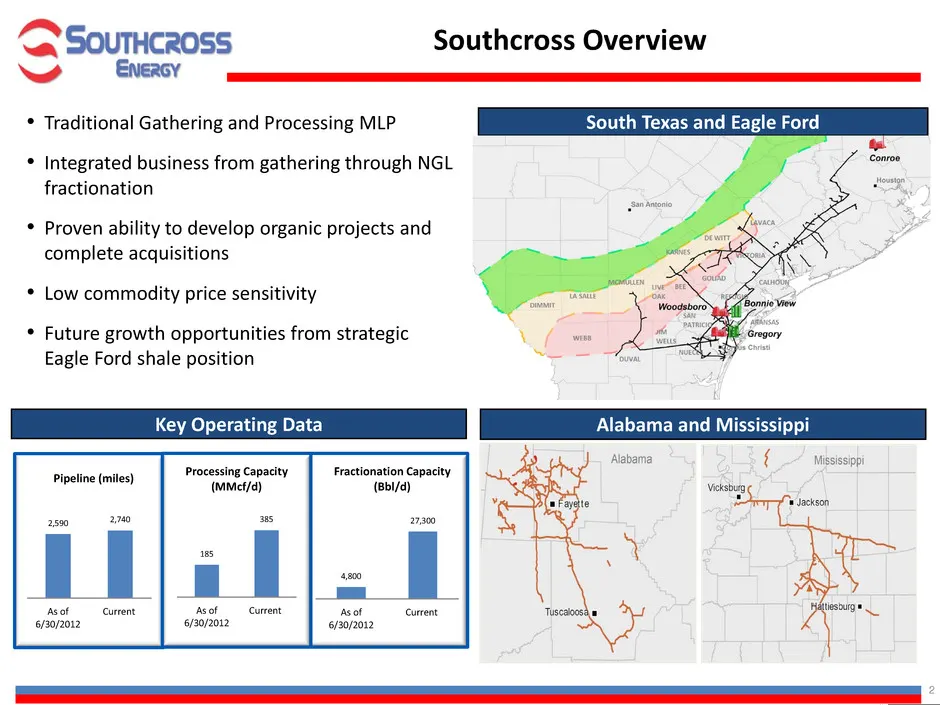
2 Southcross Overview Alabama and Mississippi • Traditional Gathering and Processing MLP • Integrated business from gathering through NGL fractionation • Proven ability to develop organic projects and complete acquisitions • Low commodity price sensitivity • Future growth opportunities from strategi
Slide 4: Southcross History
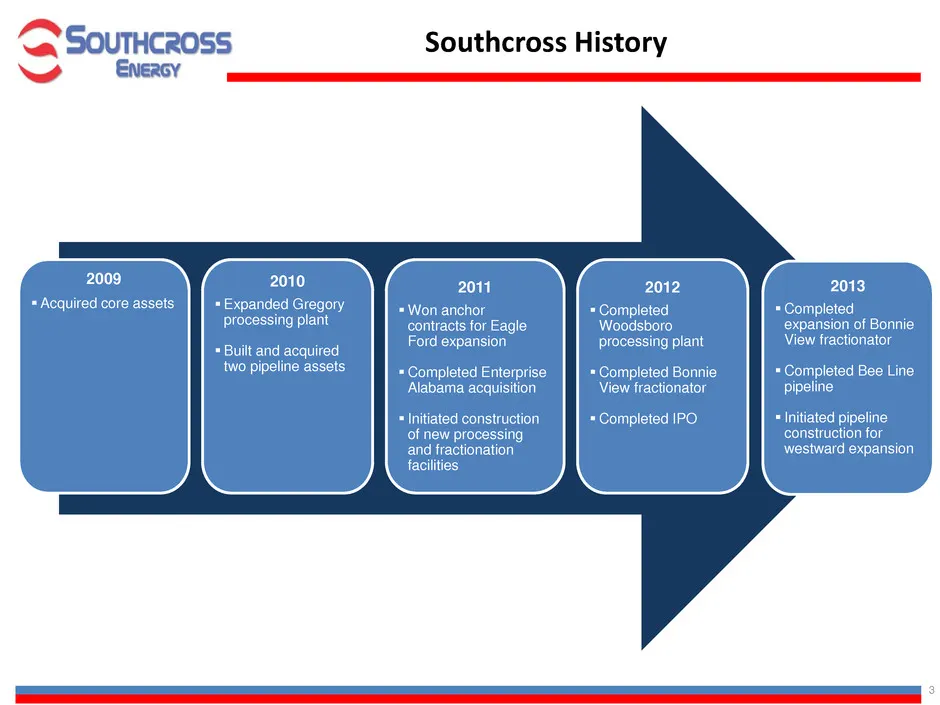
3 Southcross History 2009 Acquired core assets 2010 Expanded Gregory processing plant Built and acquired two pipeline assets 2011 Won anchor contracts for Eagle Ford expansion Completed Enterprise Alabama acquisition Initiated construction of new processing and fractionation facilities 2012
Slide 5: Investment Highlights
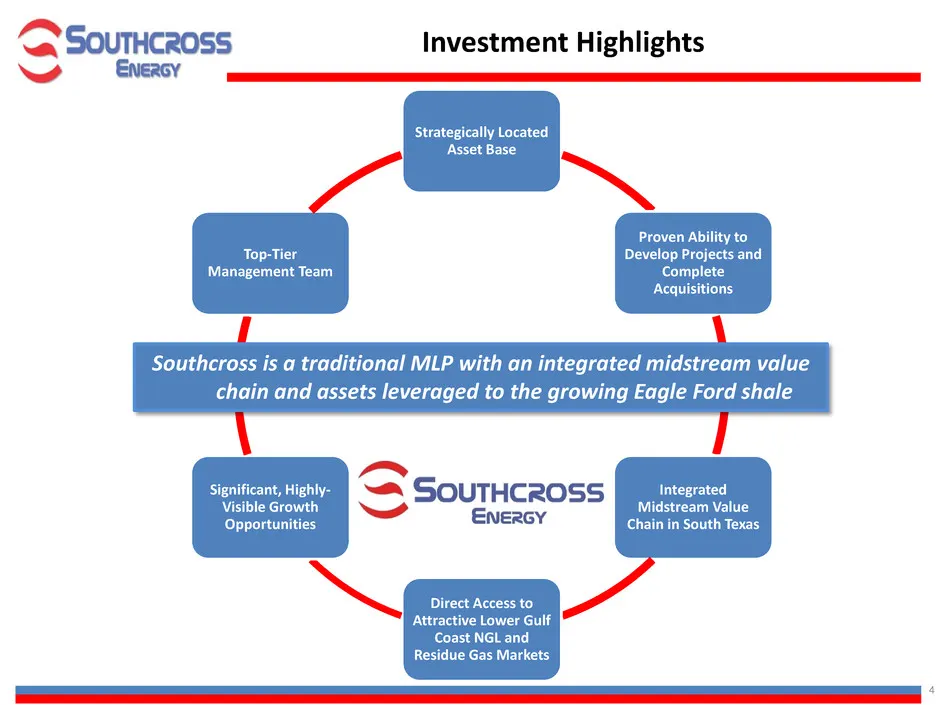
4 Strategically Located Asset Base Proven Ability to Develop Projects and Complete Acquisitions Integrated Midstream Value Chain in South Texas Direct Access to Attractive Lower Gulf Coast NGL and Residue Gas Markets Significant, Highly- Visible Growth Opportunities Top-Tier Management Team Southcro
Slide 6: Senior Management Team
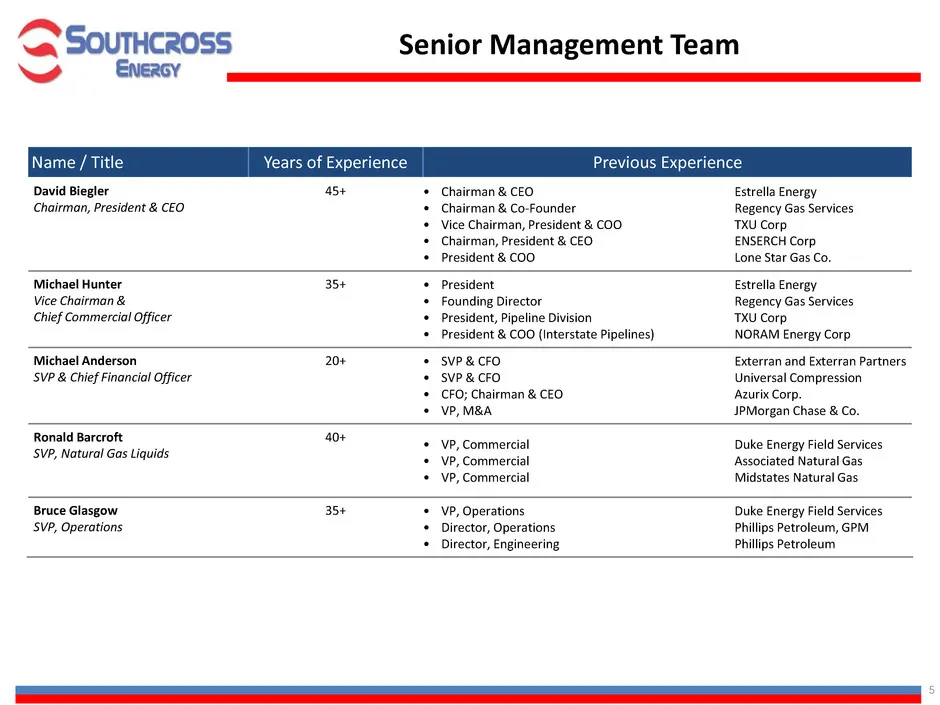
5 Senior Management Team Name / Title Years of Experience Previous Experience David Biegler Chairman, President & CEO 45+ • Chairman & CEO Estrella Energy • Chairman & Co-Founder Regency Gas Services • Vice Chairman, President & COO TXU Corp • Chairman, President & CEO ENSERCH Corp • President & COO
Slide 7: Strategically Located Asset Base
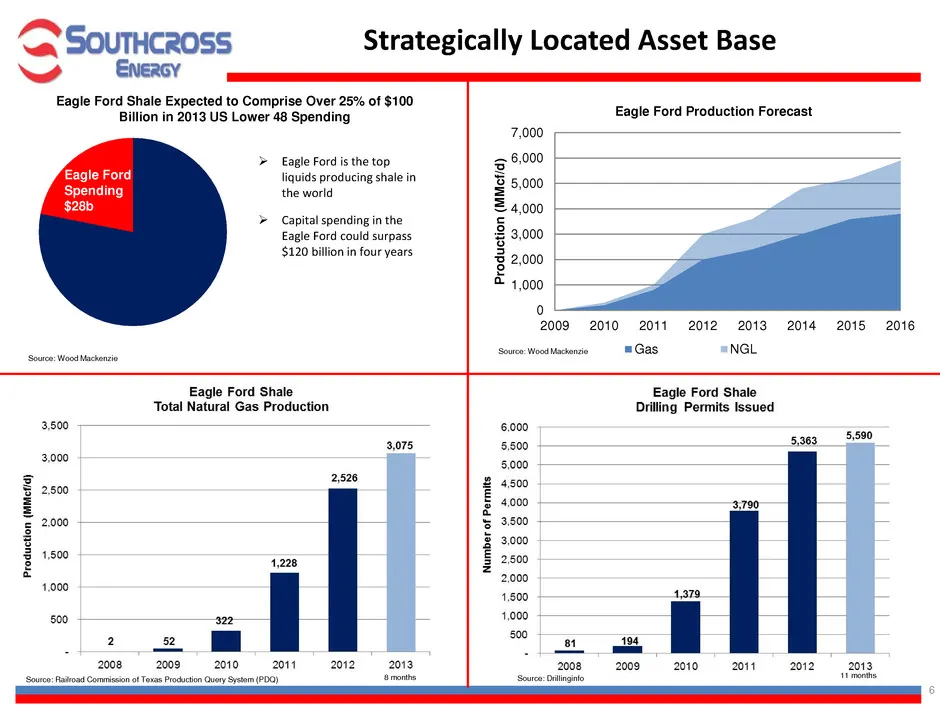
6 Source: Drillinginfo Strategically Located Asset Base Eagle Ford is the top liquids producing shale in the world Capital spending in the Eagle Ford could surpass $120 billion in four years Source: Wood Mackenzie Eagle Ford Shale Expected to Comprise Over 25% of $100 Billion in 2013 US Lower 48
Slide 8: Track Record of Growth
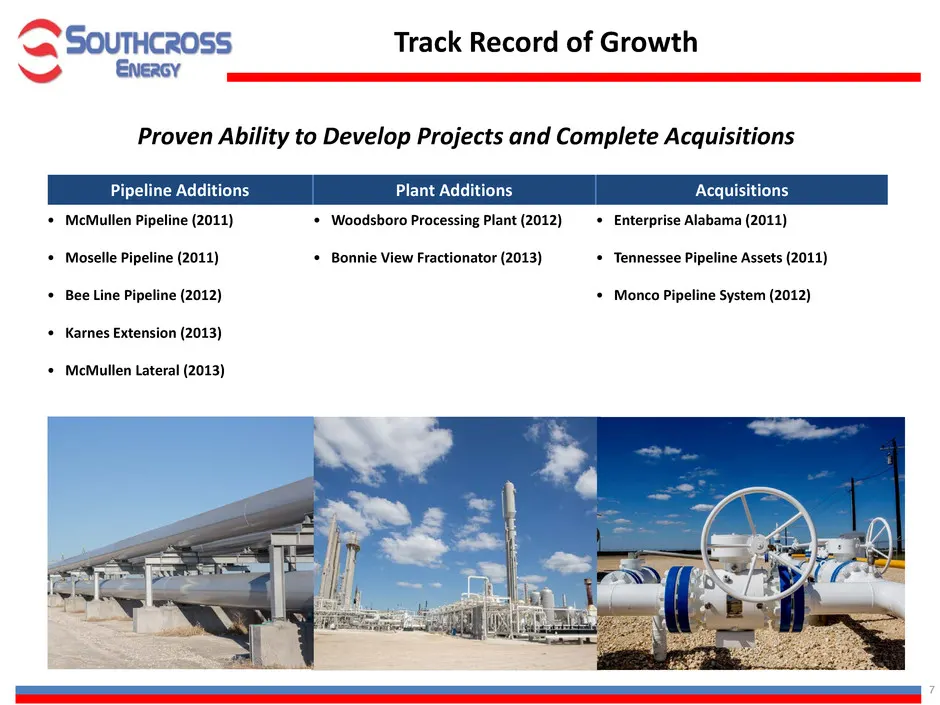
7 Track Record of Growth Pipeline Additions Plant Additions Acquisitions • McMullen Pipeline (2011) • Moselle Pipeline (2011) • Bee Line Pipeline (2012) • Karnes Extension (2013) • McMullen Lateral (2013) • Woodsboro Processing Plant (2012) • Bonnie View Fractionator (2013) • Enterprise Alabama (201
Slide 9: Integrated Midstream Value Chain
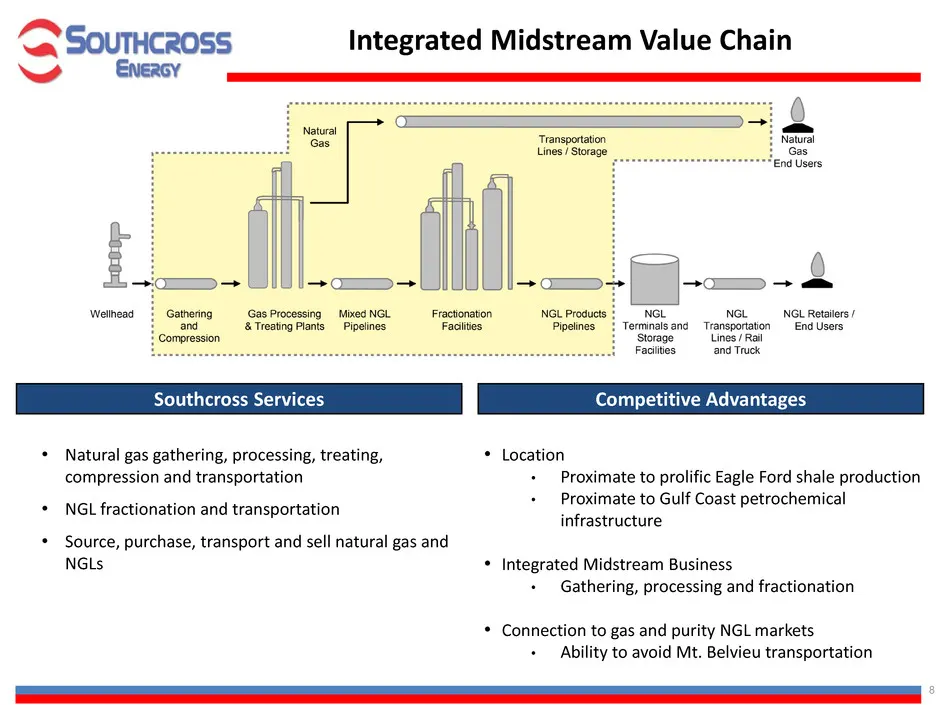
8 Integrated Midstream Value Chain Competitive Advantages Southcross Services • Natural gas gathering, processing, treating, compression and transportation • NGL fractionation and transportation • Source, purchase, transport and sell natural gas and NGLs • Location • Proximate to prolific Eagle Ford
Slide 10: Alabama and Mississippi Assets
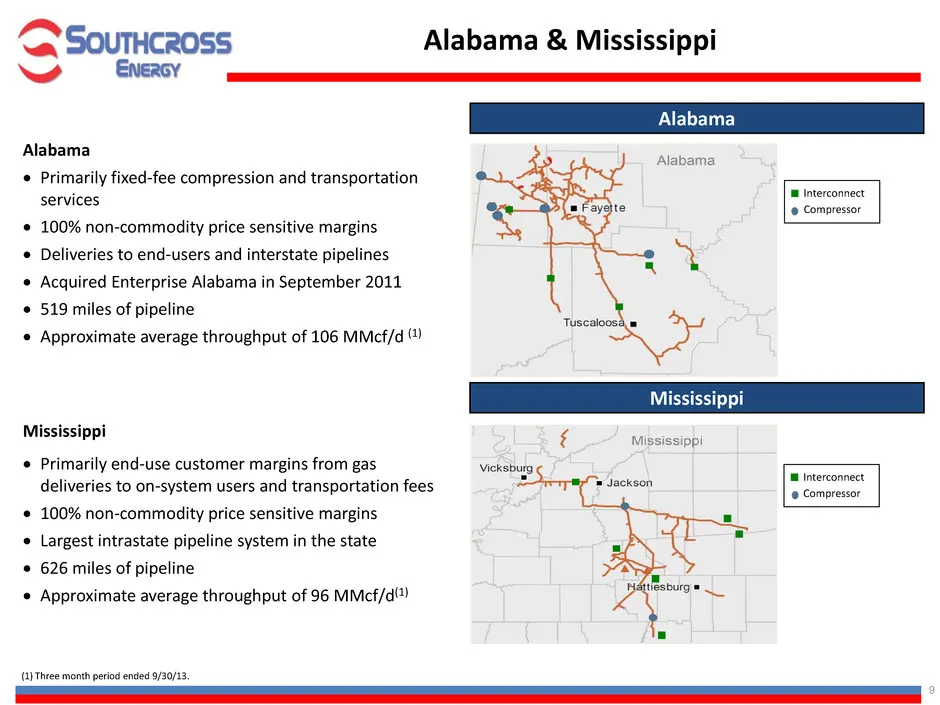
9 Alabama • Primarily fixed-fee compression and transportation services • 100% non-commodity price sensitive margins • Deliveries to end-users and interstate pipelines • Acquired Enterprise Alabama in September 2011 • 519 miles of pipeline • Approximate average throughput of 106 MMcf/d (1) Alabama &
Slide 11: Attractive Contract Structure and Customer Base
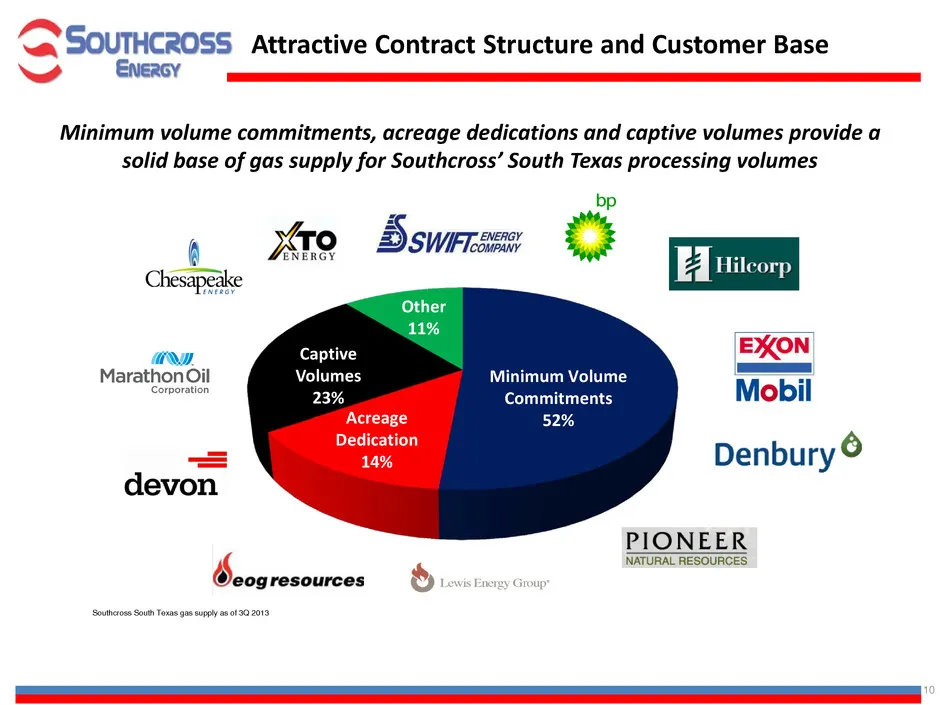
10 Attractive Contract Structure and Customer Base Minimum Volume Commitments 52% Acreage Dedication 14% Captive Volumes 23% Other 11% Minimum volume commitments, acreage dedications and captive volumes provide a solid base of gas supply for Southcross’ South Texas processing volumes Southcross Sout
Slide 12: Commodity Sensitive Typical Southcross Gas Supply Contract
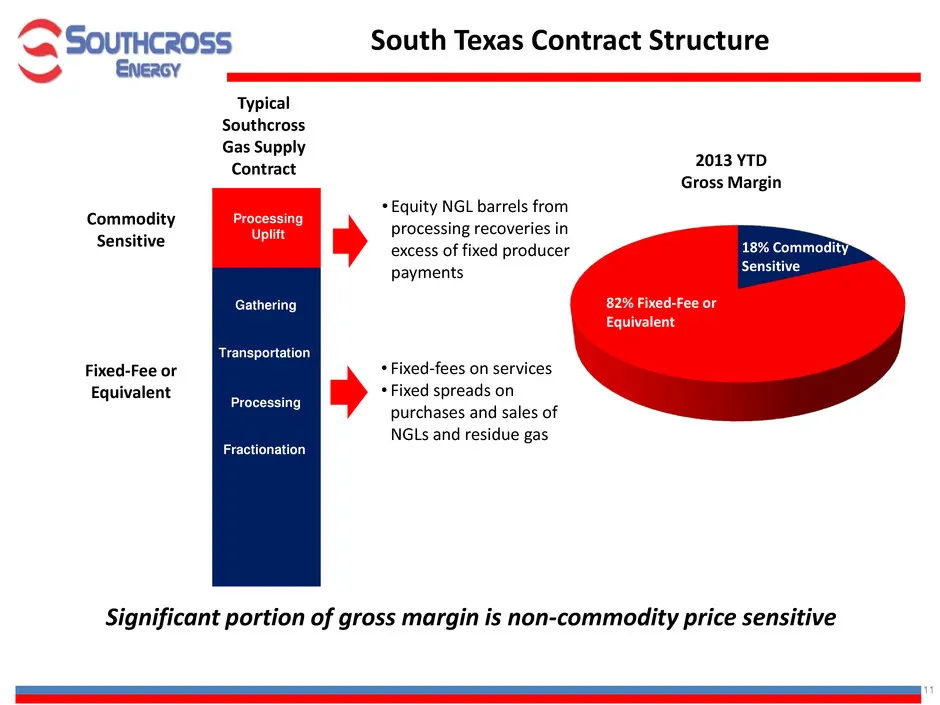
11 Commodity Sensitive Typical Southcross Gas Supply Contract Significant portion of gross margin is non-commodity price sensitive Processing Uplift Gathering Transportation Processing Fractionation Fixed-Fee or Equivalent South Texas Contract Structure 2013 YTD Gross Margin 82% Fixed-Fee or Equival
Slide 13: Attractive Residue and Dry Gas Downstream
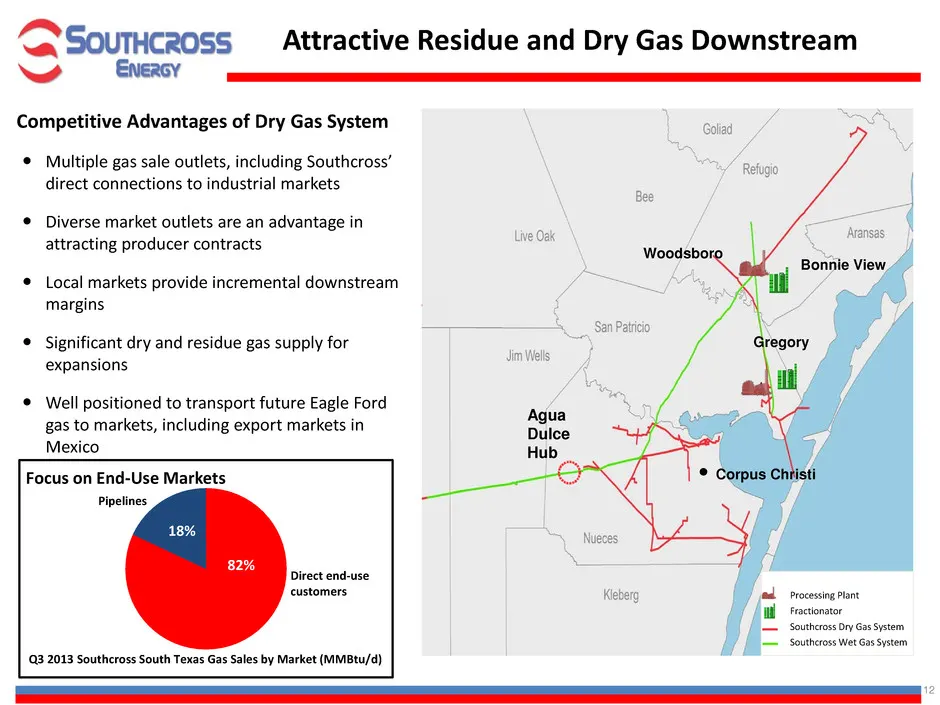
12 Multiple gas sale outlets, including Southcross’ direct connections to industrial markets Diverse market outlets are an advantage in attracting producer contracts Local markets provide incremental downstream margins Significant dry and residue gas supply for expansions Well positioned t
Slide 14: Direct Access to Attractive NGL Markets
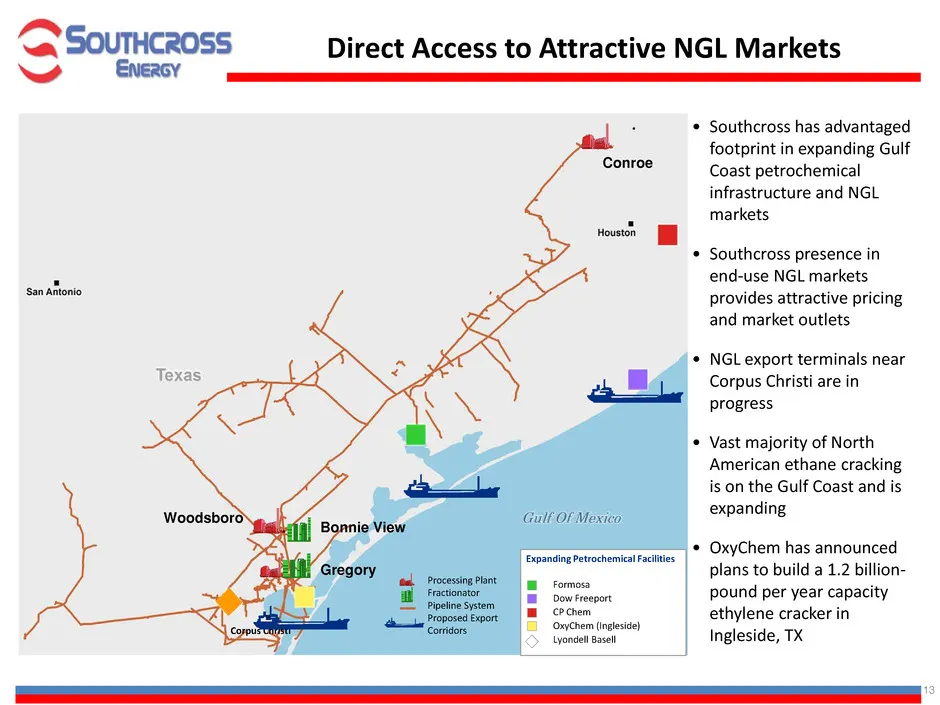
13 • Southcross has advantaged footprint in expanding Gulf Coast petrochemical infrastructure and NGL markets • Southcross presence in end-use NGL markets provides attractive pricing and market outlets • NGL export terminals near Corpus Christi are in progress • Vast majority of North American ethan
Slide 15: Growing NGL Markets in US and for Export
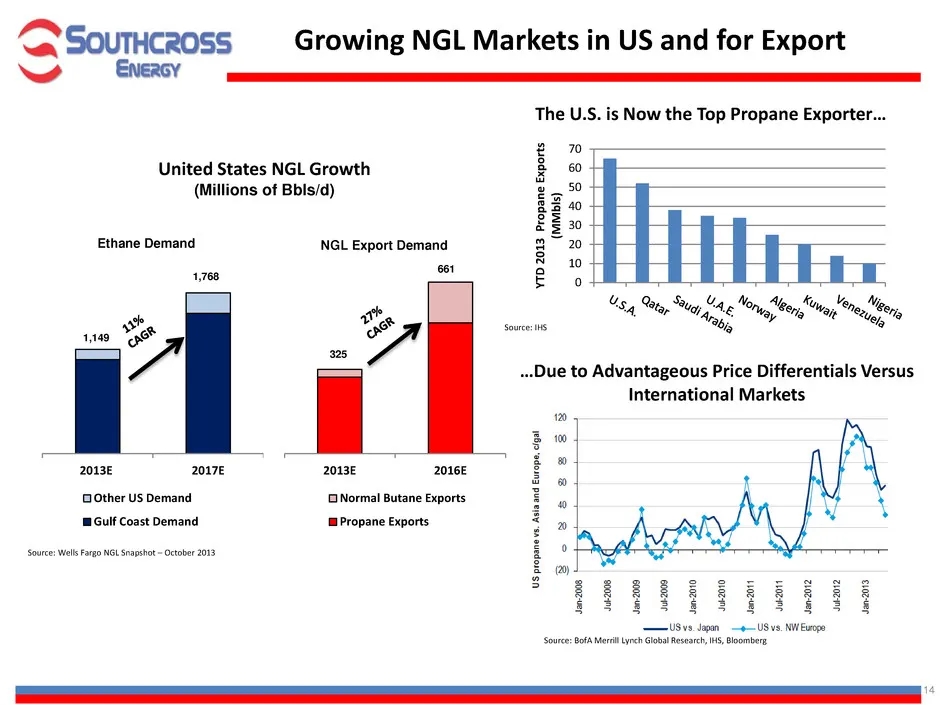
14 2013E 2016E Normal Butane Exports Propane Exports 2013E 2017E Other US Demand Gulf Coast Demand Growing NGL Markets in US and for Export United States NGL Growth (Millions of Bbls/d) Source: Wells Fargo NGL Snapshot – October 2013 The U.S. is Now the Top Propane Exporter… Source: IHS Ethane Deman
Slide 16: Lower Gulf Coast NGL Projects Present Opportunities
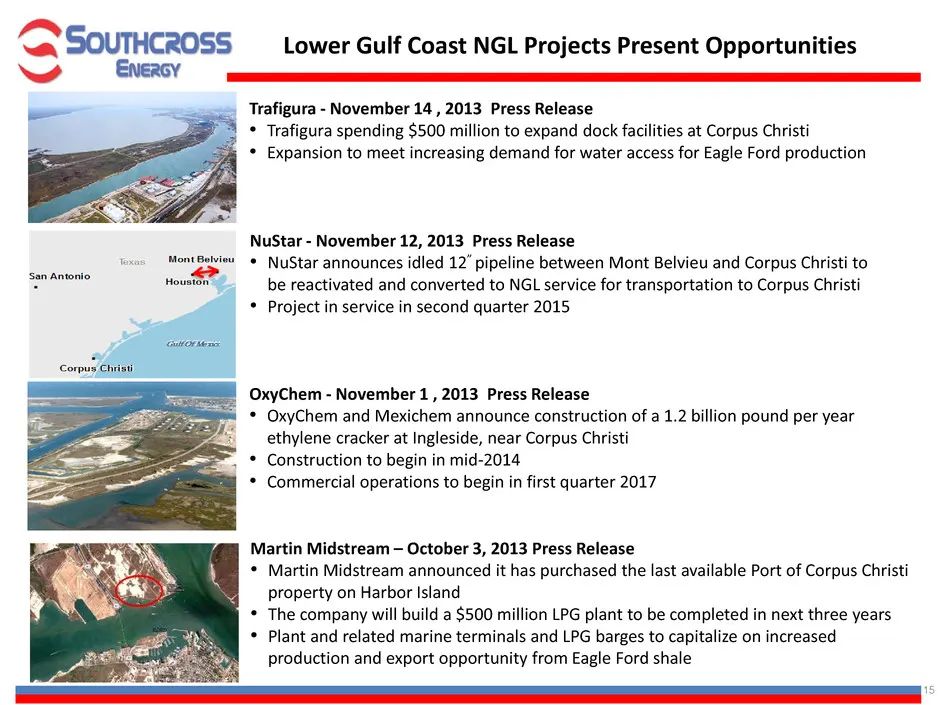
15 Lower Gulf Coast NGL Projects Present Opportunities NuStar - November 12, 2013 Press Release • NuStar announces idled 12” pipeline between Mont Belvieu and Corpus Christi to be reactivated and converted to NGL service for transportation to Corpus Christi • Project in service in second quarter 201
Slide 17: Focused on Growth
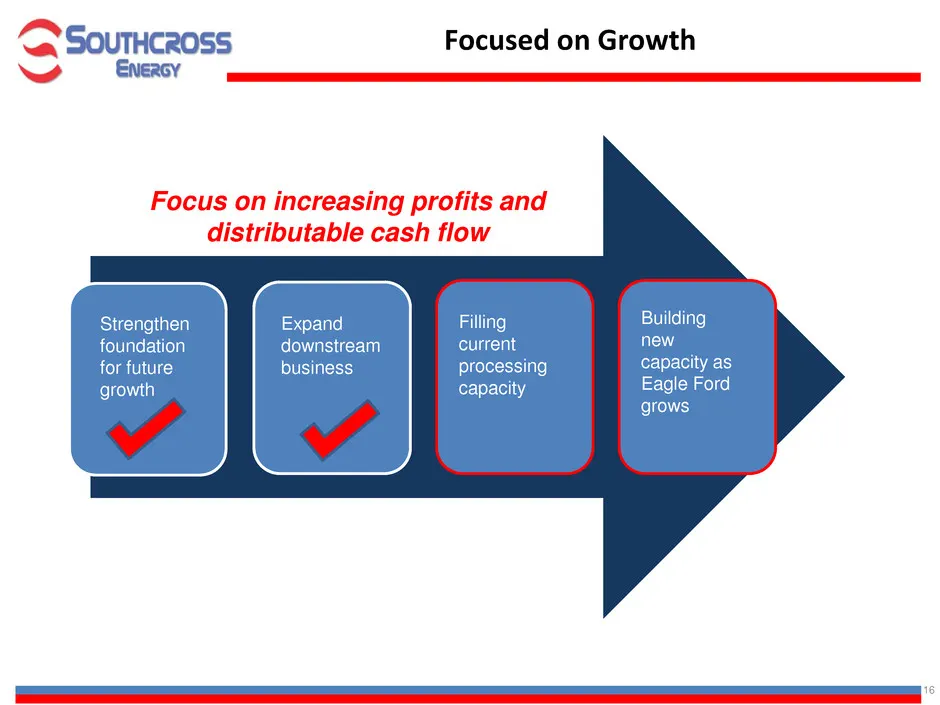
16 Focused on Growth Focus on increasing profits and distributable cash flow Expand downstream business Filling current processing capacity Building new capacity as Eagle Ford grows Strengthen foundation for future growth
Slide 18: Growth Focus
17 Growth Focus • Pipeline laterals to add rich gas supply – Karnes extension – McMullen lateral • Downstream gas market – Adding Corpus Christi markets for residue off-take • Western Eagle Ford Expansion – Initiated construction planning – Pipeline facilitates filling existing processing capacity a
Slide 19: Expansion of Southcross Eagle Ford Footprint
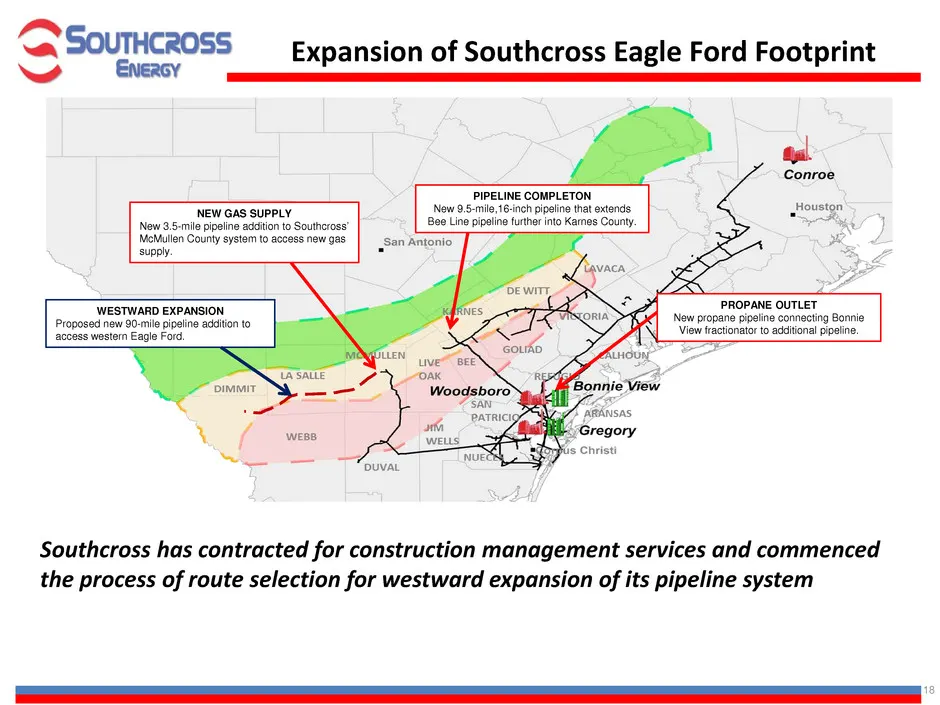
18 Expansion of Southcross Eagle Ford Footprint PROPANE OUTLET New propane pipeline connecting Bonnie View fractionator to additional pipeline. Southcross has contracted for construction management services and commenced the process of route selection for westward expansion of its pipeline system PI
Slide 20: Western Eagle Ford Expansion
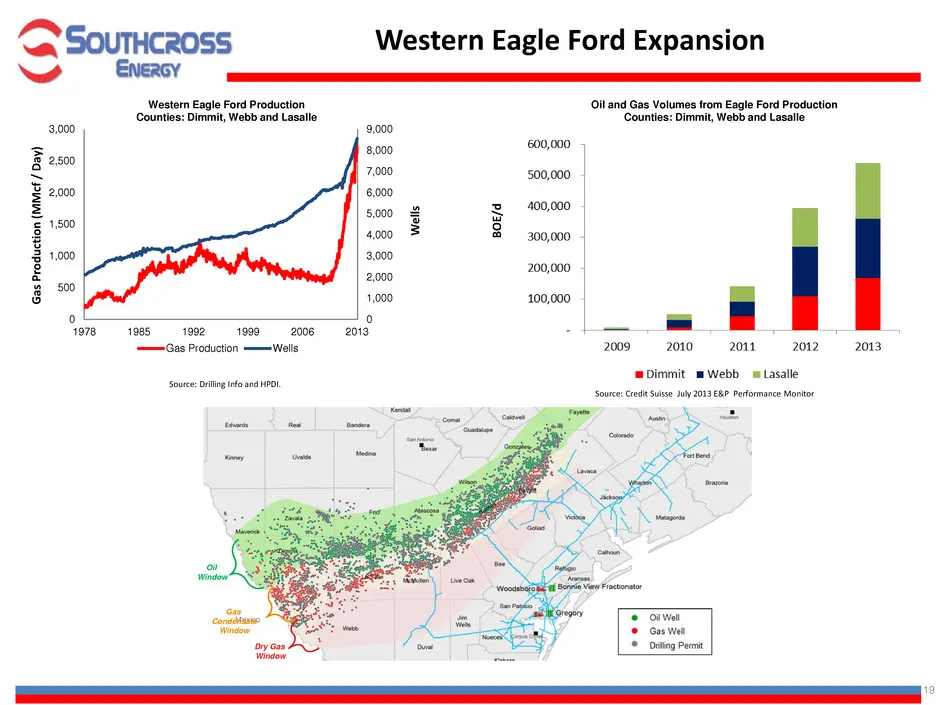
19 0 1,000 2,000 3,000 4,000 5,000 6,000 7,000 8,000 9,000 0 500 1,000 1,500 2,000 2,500 3,000 1978 1985 1992 1999 2006 2013 Gas Production Wells B O E/ d Source: Drilling Info and HPDI. Source: Credit Suisse July 2013 E&P Performance Monitor W el ls G as P ro du ct io n (M M cf / D ay ) Western Eag
Slide 21: Third Quarter Performance
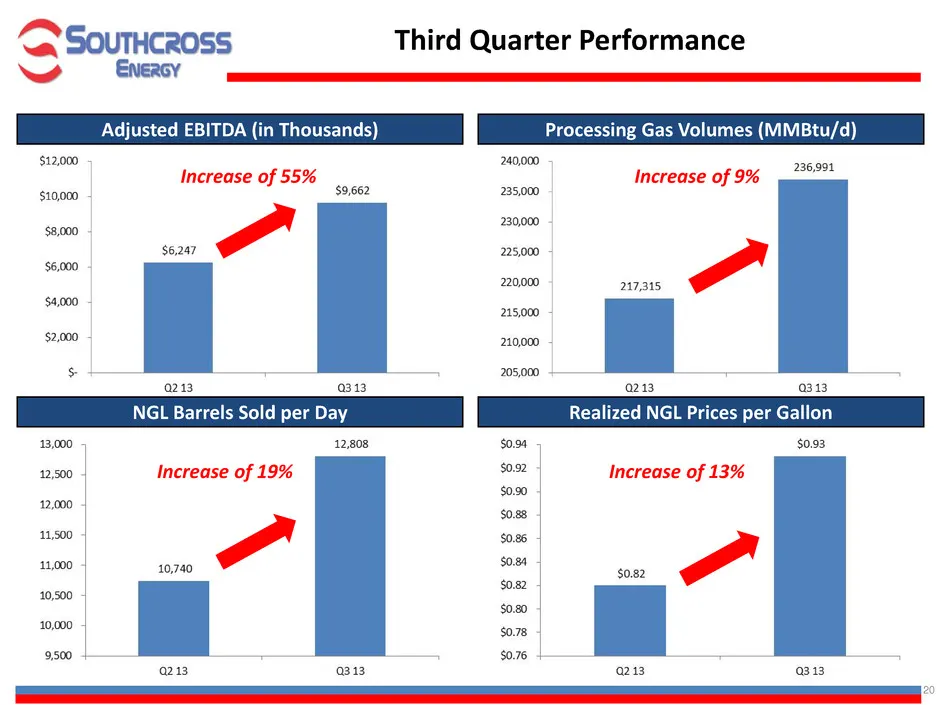
20 Third Quarter Performance Realized NGL Prices per Gallon NGL Barrels Sold per Day Processing Gas Volumes (MMBtu/d) Adjusted EBITDA (in Thousands) Increase of 55% Increase of 9% Increase of 19% Increase of 13%
Slide 22: 2013 Adjusted EBITDA Growth
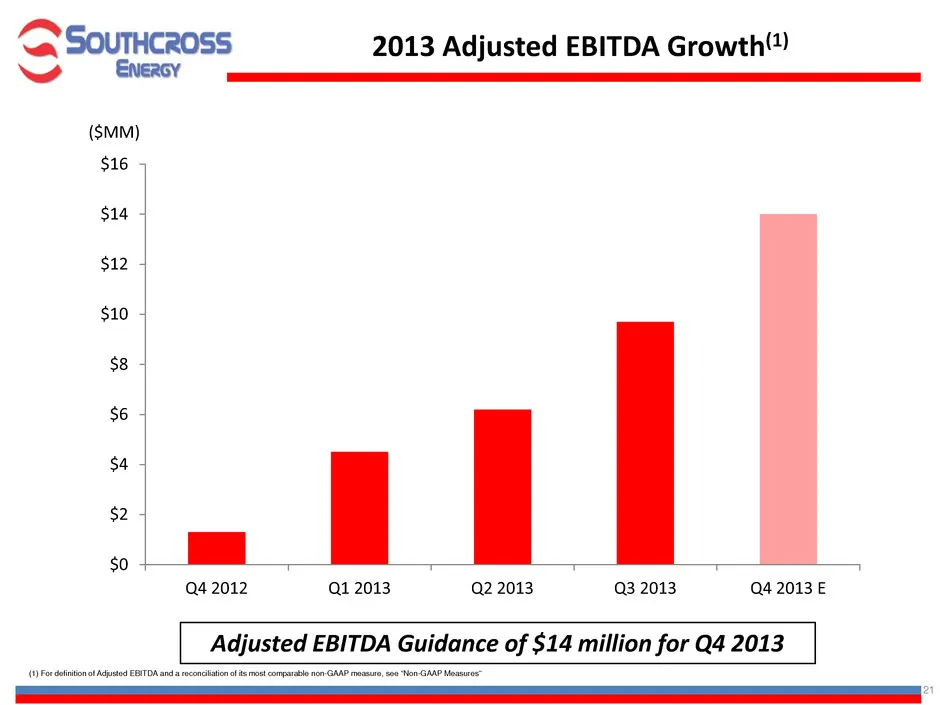
21 2013 Adjusted EBITDA Growth(1) $0 $2 $4 $6 $8 $10 $12 $14 $16 Q4 2012 Q1 2013 Q2 2013 Q3 2013 Q4 2013 E ($MM) Adjusted EBITDA Guidance of $14 million for Q4 2013 (1) For definition of Adjusted EBITDA and a reconciliation of its most comparable non-GAAP measure, see “Non-GAAP Measures”
Slide 23: Comparative Yield
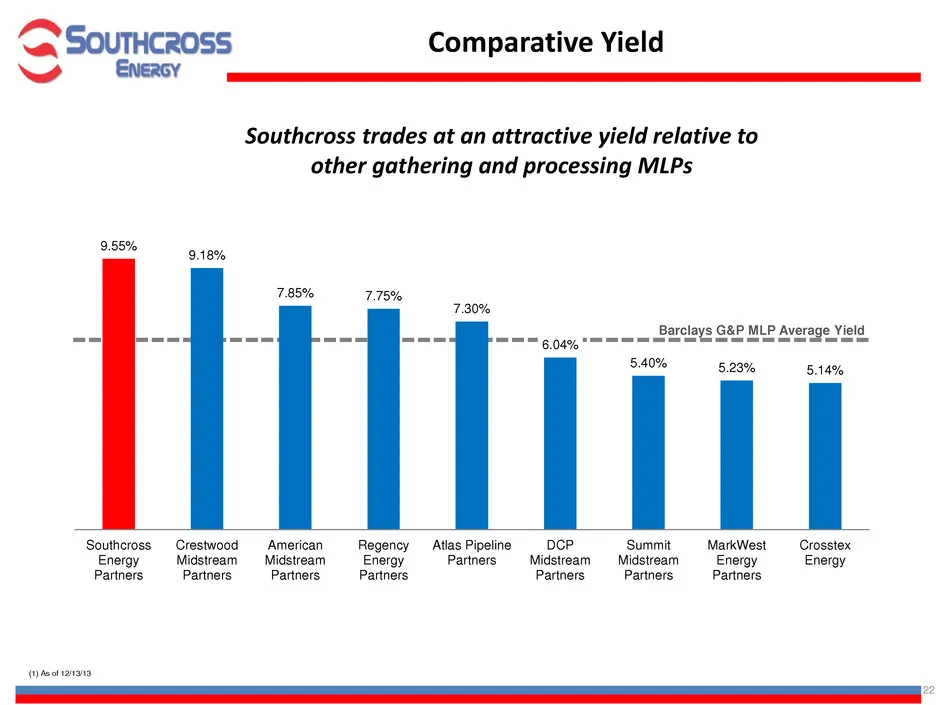
22 Comparative Yield Southcross trades at an attractive yield relative to other gathering and processing MLPs Barclays G&P MLP Average Yield 9.55% 9.18% 7.85% 7.75% 7.30% 6.04% 5.40% 5.23% 5.14% Southcross Energy Partners Crestwood Midstream Partners American Midstream Partners Regency Energy Partne
Slide 24: Southcross Investment Summary
23 Southcross Investment Summary • Strategically located asset base leveraged to Eagle Ford shale growth • Proven ability to develop projects and complete acquisitions • Integrated midstream assets from gathering through NGLs in South Texas • Significant and highly visible growth opportunities in th
Slide 25: Southcross Energy Partners Fact Sheet
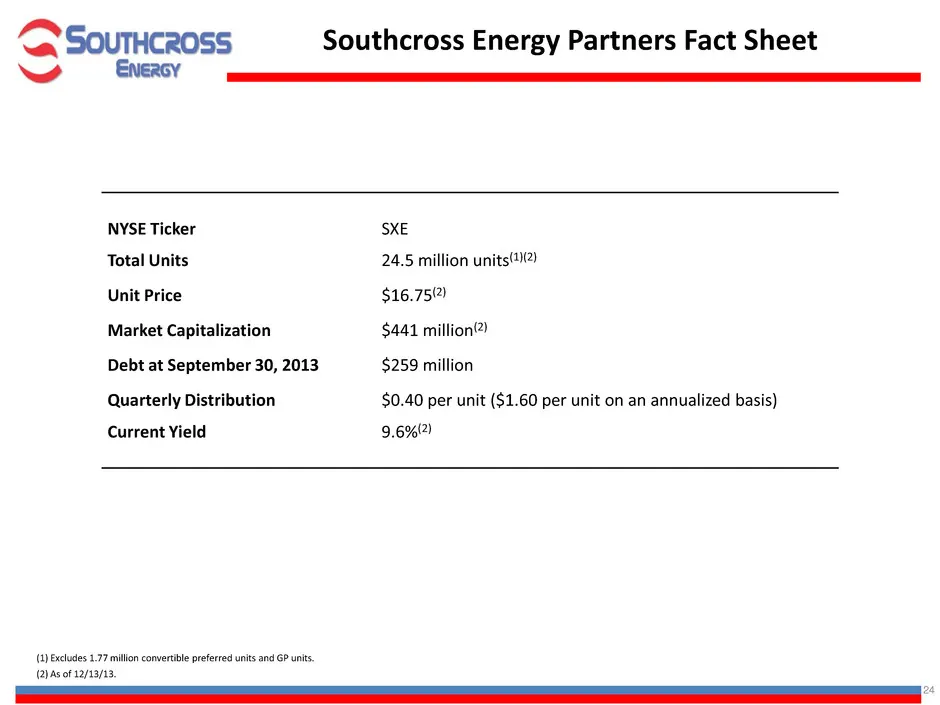
24 Southcross Energy Partners Fact Sheet NYSE Ticker SXE Total Units 24.5 million units(1)(2) Unit Price $16.75(2) Market Capitalization $441 million(2) Debt at September 30, 2013 $259 million Quarterly Distribution $0.40 per unit ($1.60 per unit on an annualized basis) Current Yield 9.6%(2) (2) As
Slide 26: Appendix
> SourHcross ww Enercy Appendix
Slide 27: Non-GAAP Measures
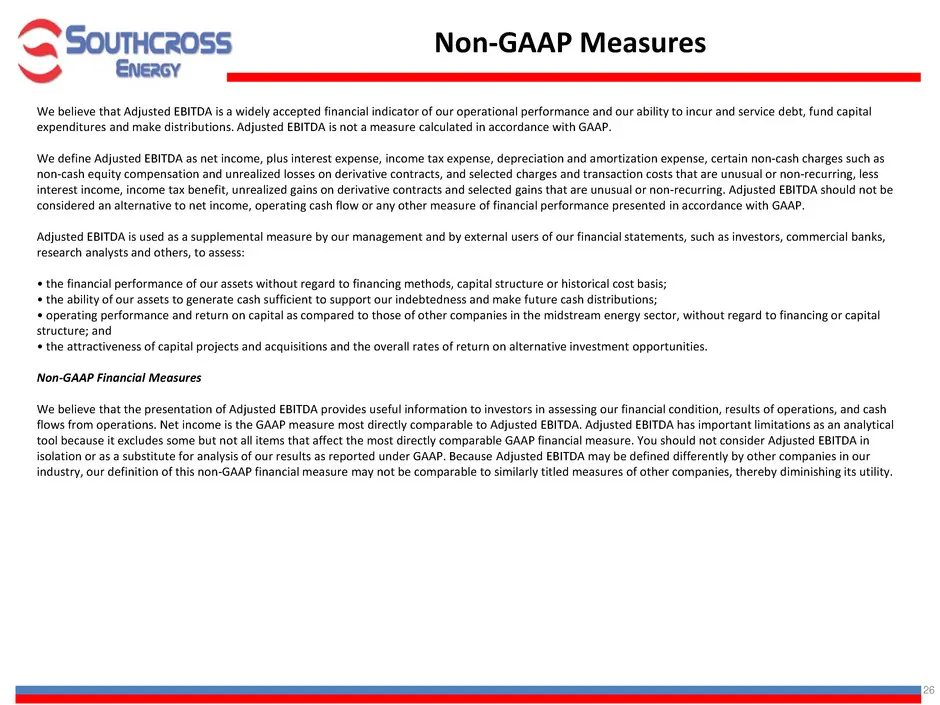
26 Non-GAAP Measures We believe that Adjusted EBITDA is a widely accepted financial indicator of our operational performance and our ability to incur and service debt, fund capital expenditures and make distributions. Adjusted EBITDA is not a measure calculated in accordance with GAAP. We define Adj
Slide 28: Reconciliation to Adjusted EBITDA
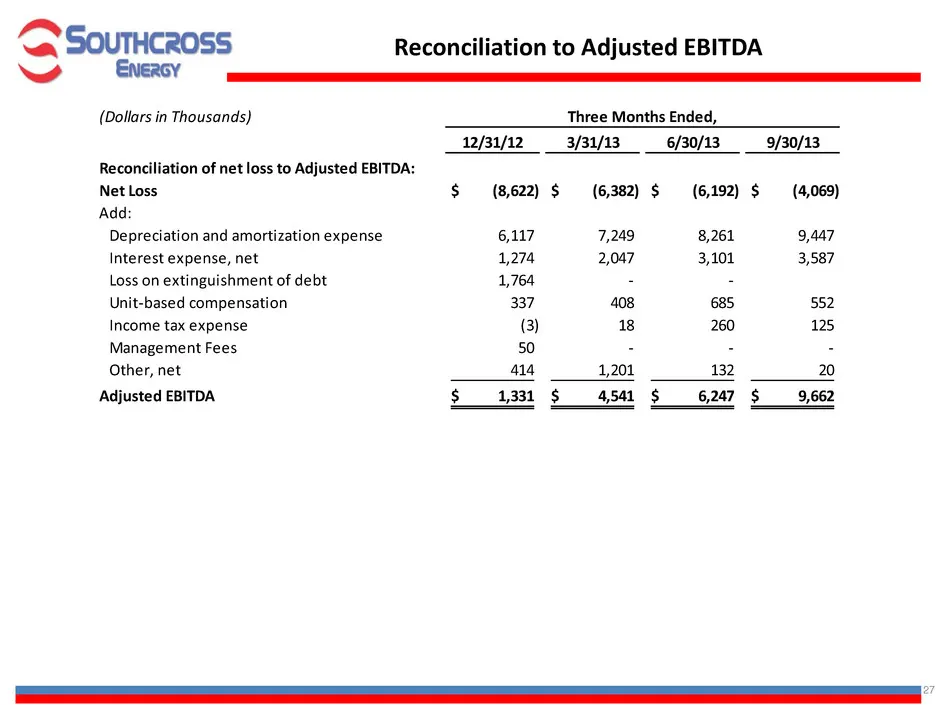
27 Reconciliation to Adjusted EBITDA (Dollars in Thousands) Three Months Ended, 12/31/12 3/31/13 6/30/13 9/30/13 Reconciliation of net loss to Adjusted EBITDA: Net Loss (8,622)$ (6,382)$ (6,192)$ (4,069)$ Add: Depreciation and amortization expense 6,117 7,249 8,261 9,447 Interest expense, net 1,274
Source: SEC EDGAR · 8-K filed Dec 17, 2013
More decks from Southcross Energy Partners L.P
 Merger or Acquisition (February 2018)10 slides · Feb 5, 2018
 Merger or Acquisition (November 2017)17 slides · Nov 2, 2017
 RBC Dallas Investor Meeting July 201526 slides · Jul 16, 2015
 NAPTP 2015 MLP Investor Conference27 slides · May 20, 2015
 Investor Presentation (April 2015)20 slides · Apr 21, 2015
 2014 Wells Fargo Energy Symposium23 slides · Dec 9, 2014