Transocean Partners — 2015 NAPTP MLP Annual Investor Conference
16 slides from Transocean Partners's conference presentation, May 20, 2015
Slide 1: 2015 NAPTP MLP Annual Investor Conference
2015 NAPTP MLP Annual Investor Conference May 2015 Bl transocean PARTNERS LLC
Slide 2: Disclaimer
Disclaimer FORWARD-LOOKING STATEMENTS The statements described in this presentation that are not historical facts are forward-looking statements within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934. These statements contain words such
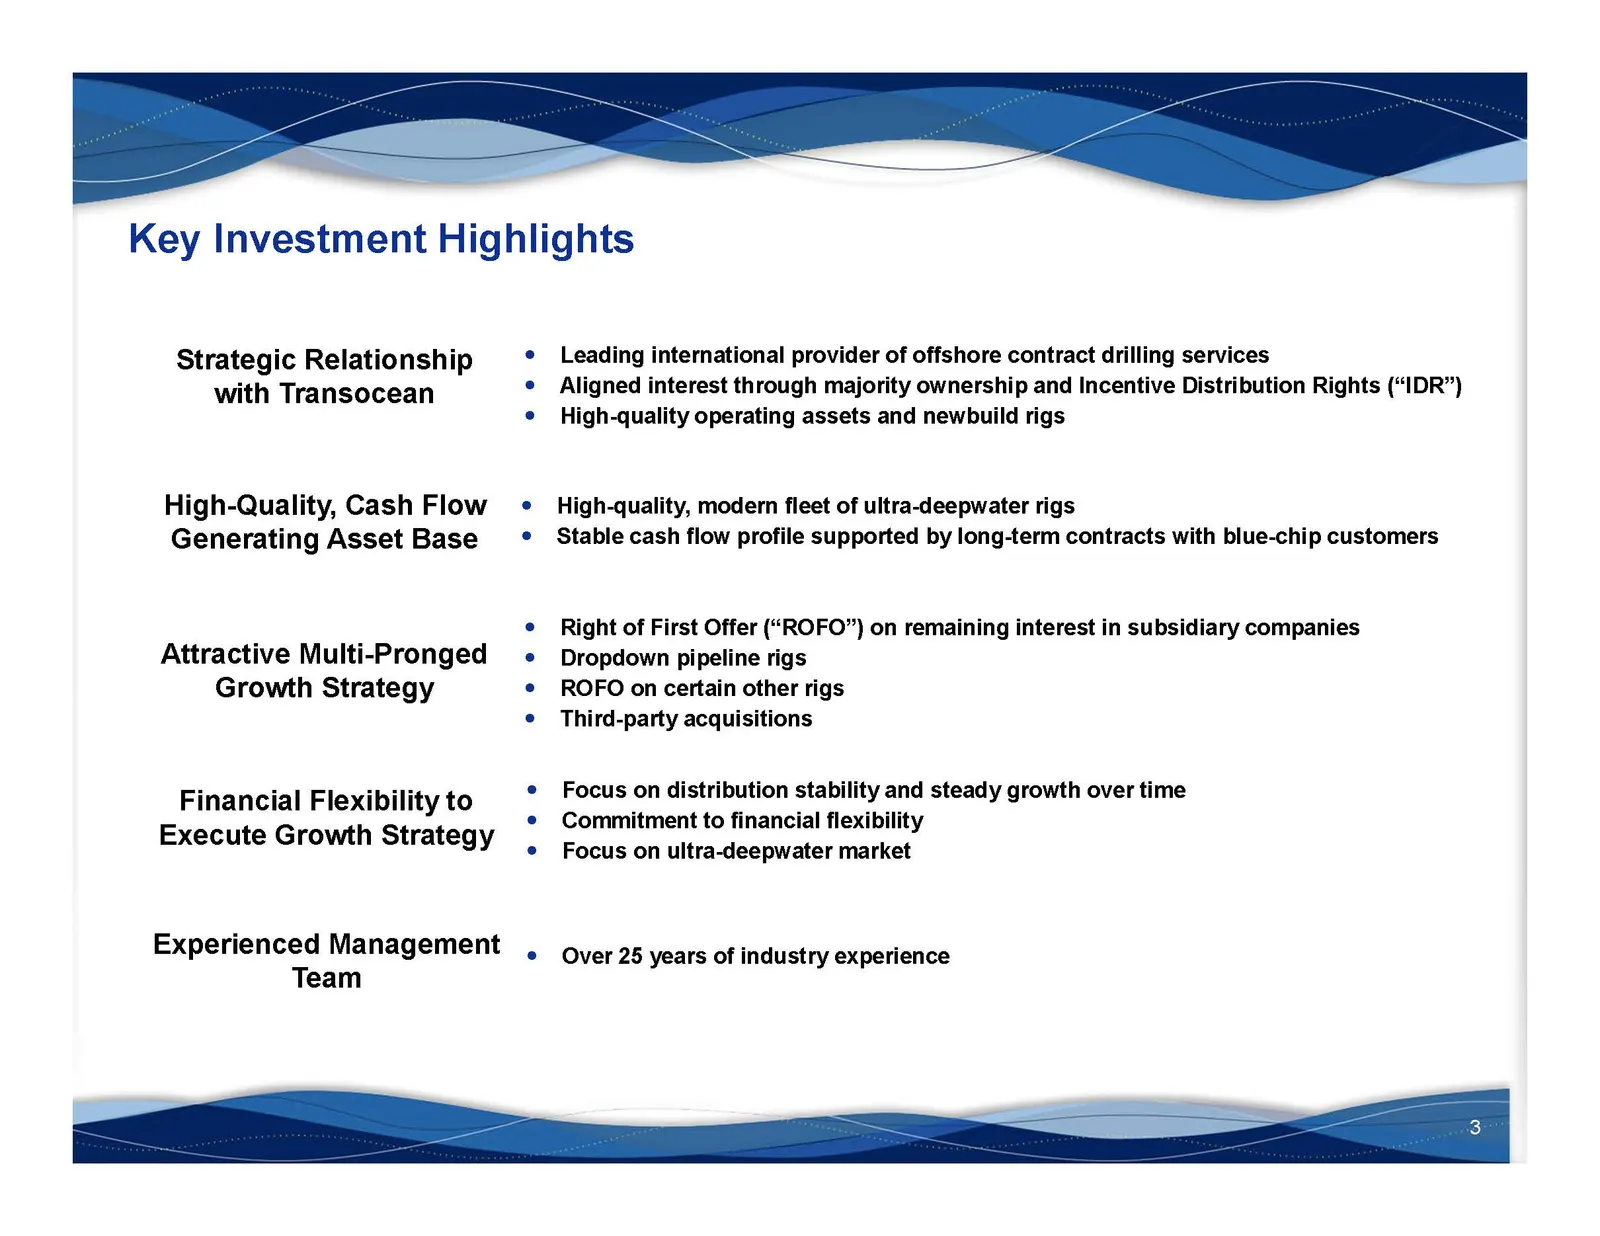
Slide 3: Key Investment Highlights
Key Investment Highlights Strategic Relationship e Leading international provider of offshore contract drilling services with Transocean e Aligned interest through majority ownership and Incentive Distribution Rights (“IDR”) e High-quality operating assets and newbuild rigs High-Quality, Cash Flow ¢
Slide 4: Strategic Relationship with Transocean
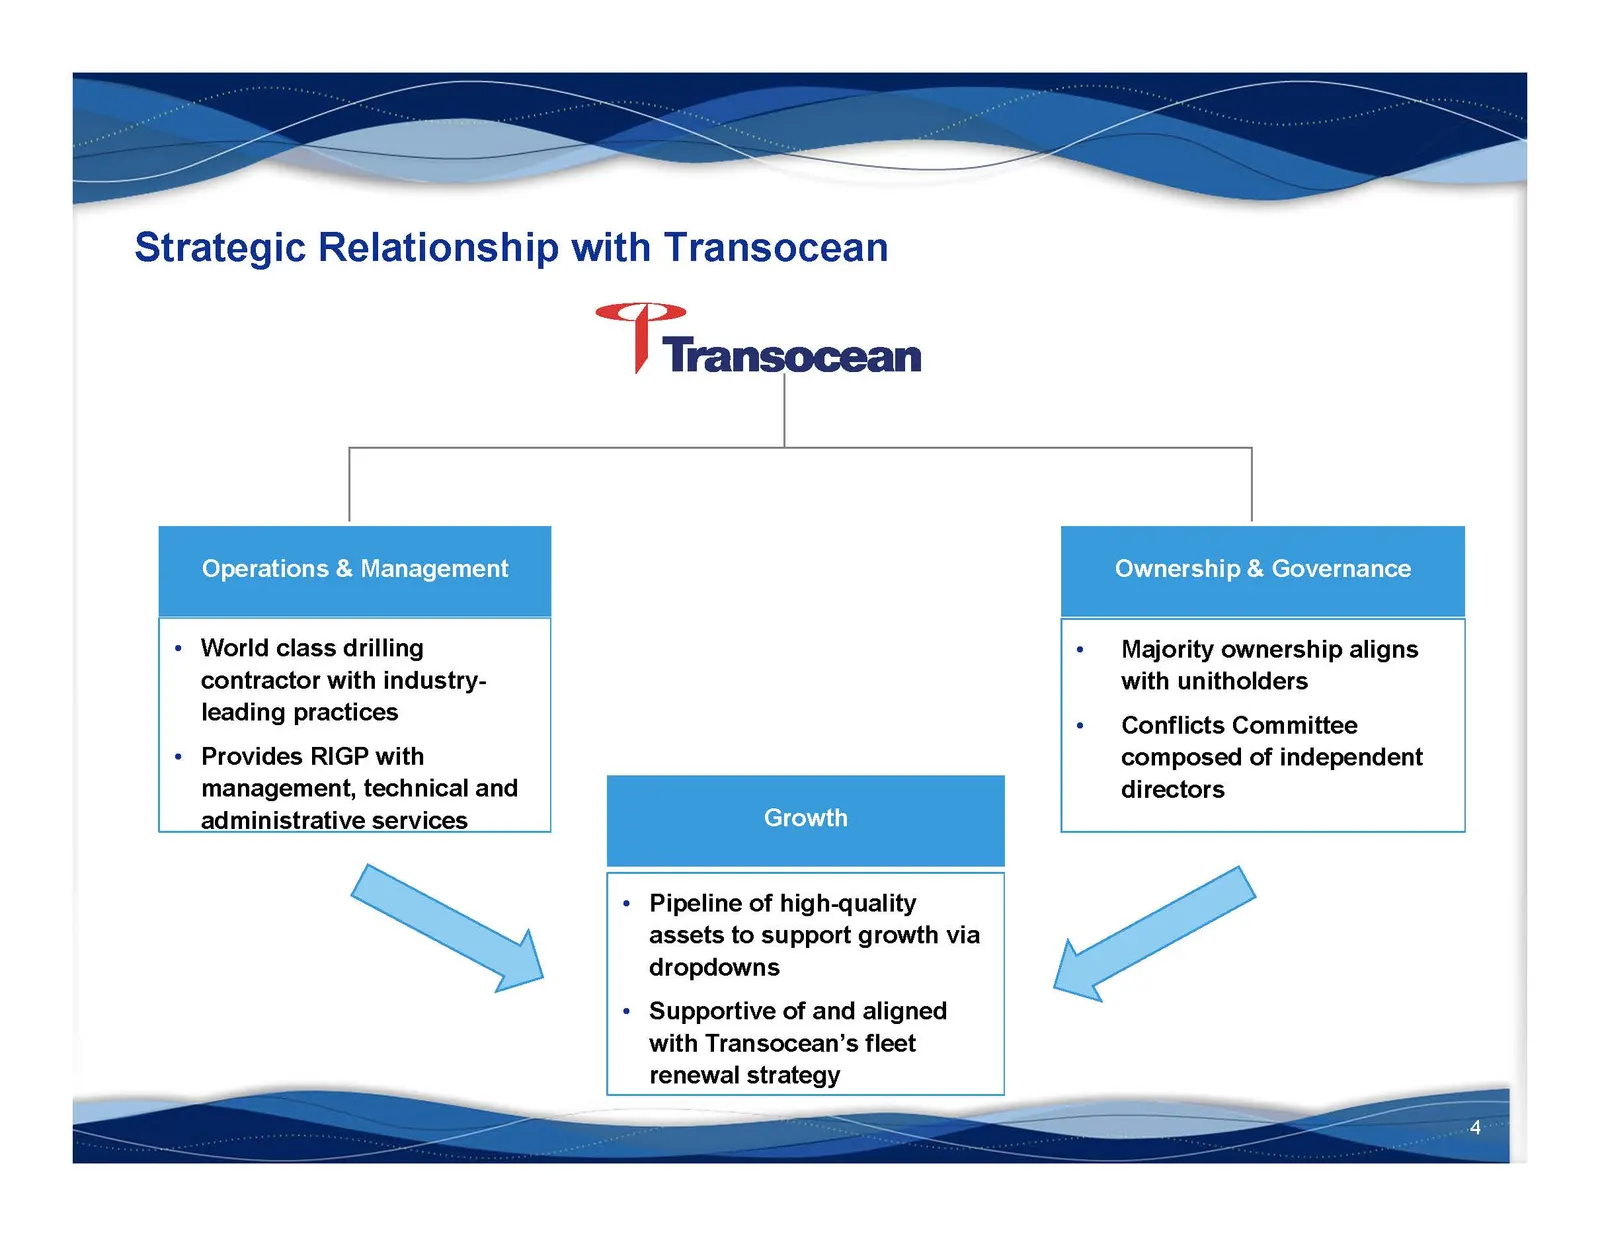
Strategic Relationship with Transocean | =e Operations & Management Ownership & Governance World class drilling ¢ Majority ownership aligns contractor with industry- with unitholders leading practices * Conflicts Committee Provides RIGP with composed of independent management, technical and director
Slide 5: Transocean — A Leading Offshore Driller
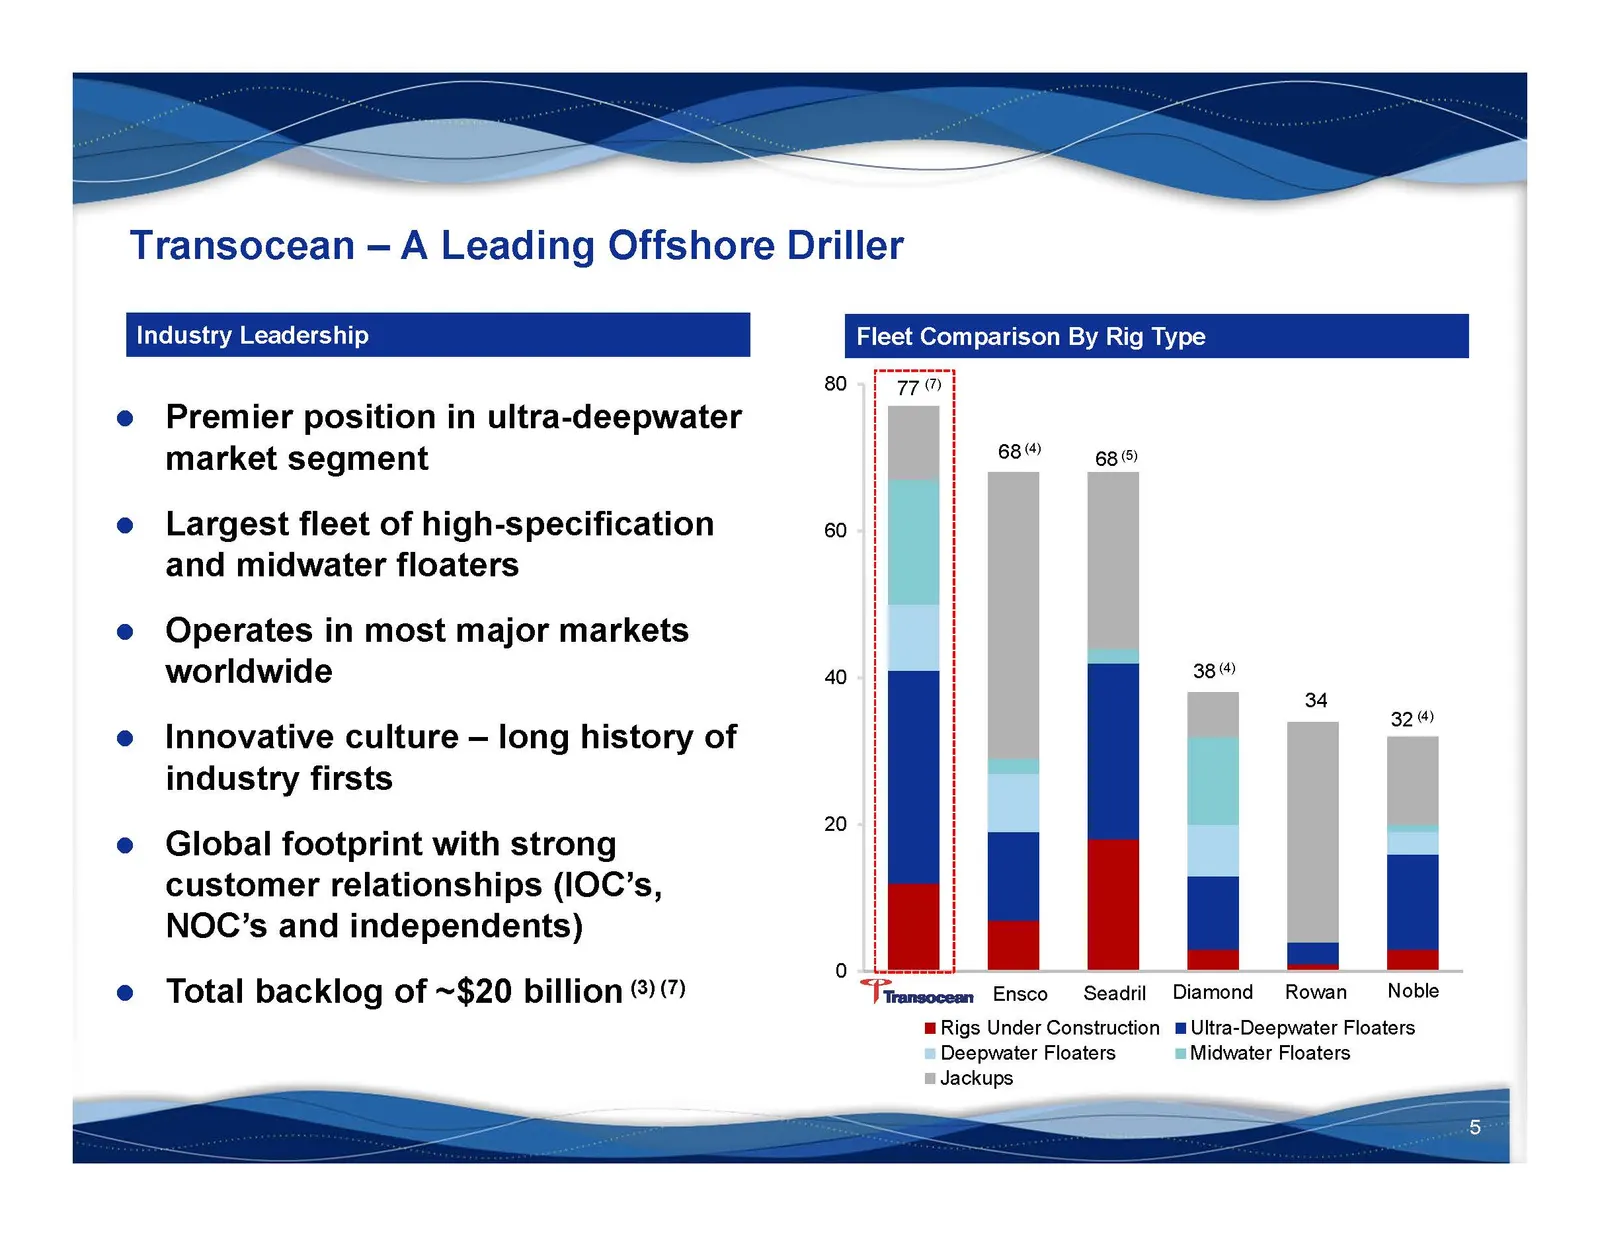
Transocean — A Leading Offshore Driller Industry Leadership Premier position in ultra-deepwater market segment Largest fleet of high-specification and midwater floaters Operates in most major markets worldwide Innovative culture — long history of industry firsts Global footprint with strong customer
Slide 6: RIGP Supports Transocean's Strategic Initiatives
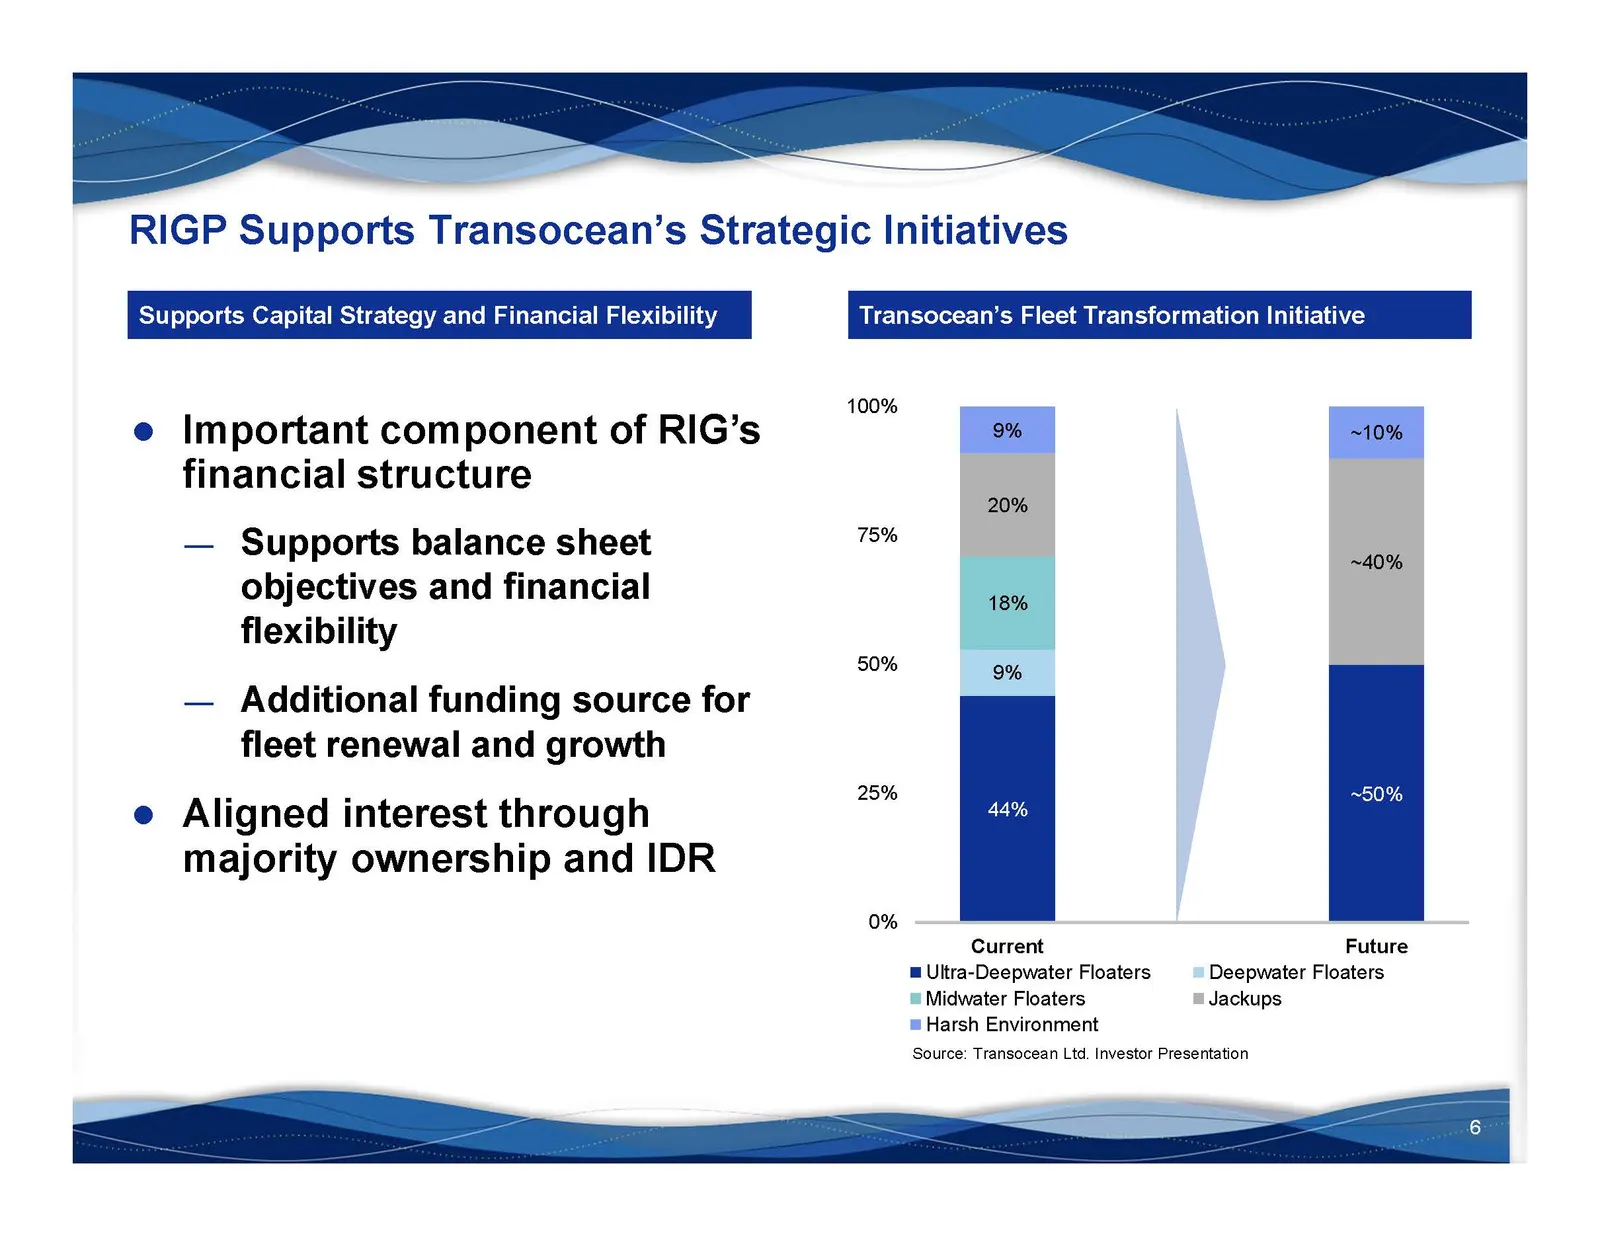
RIGP Supports Transocean’s Strategic Initiatives Supports Capital Strategy and Financial Flexibility Transocean’s Fleet Transformation Initiative e Important component of RIG’s mm financial structure - — Supports balance sheet toes objectives and financial flexibility 50% 9% — Additional funding sou
Slide 7: RIGP's High-Quality Asset Base
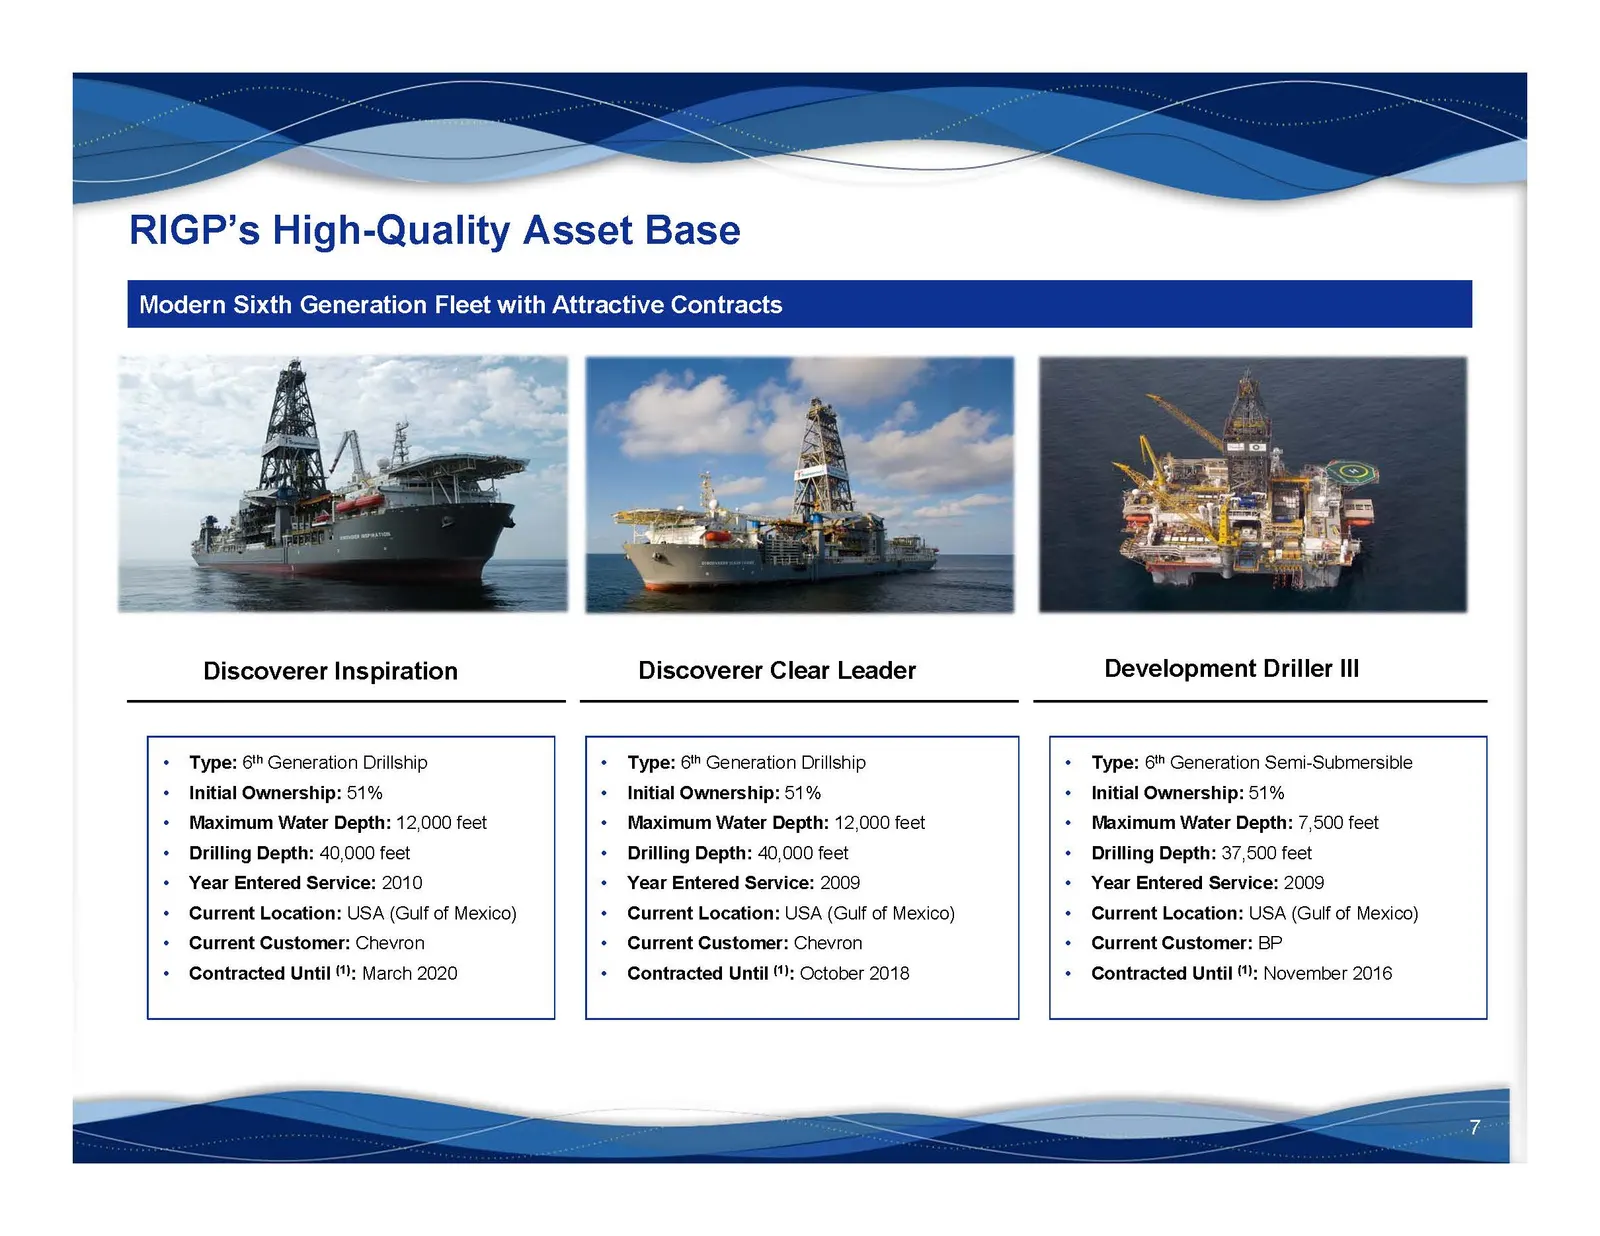
RIGP’s High-Quality Asset Base Modern Sixth Generation Fleet with Attractive Co: Discoverer Inspiration Discoverer Clear Leader Development Driller Ill + Type: 6!" Generation Drillship + Initial Ownership: 51% + Maximum Water Depth: 12,000 feet + Drilling Depth: 40,000 feet + Year Entered Service: 2
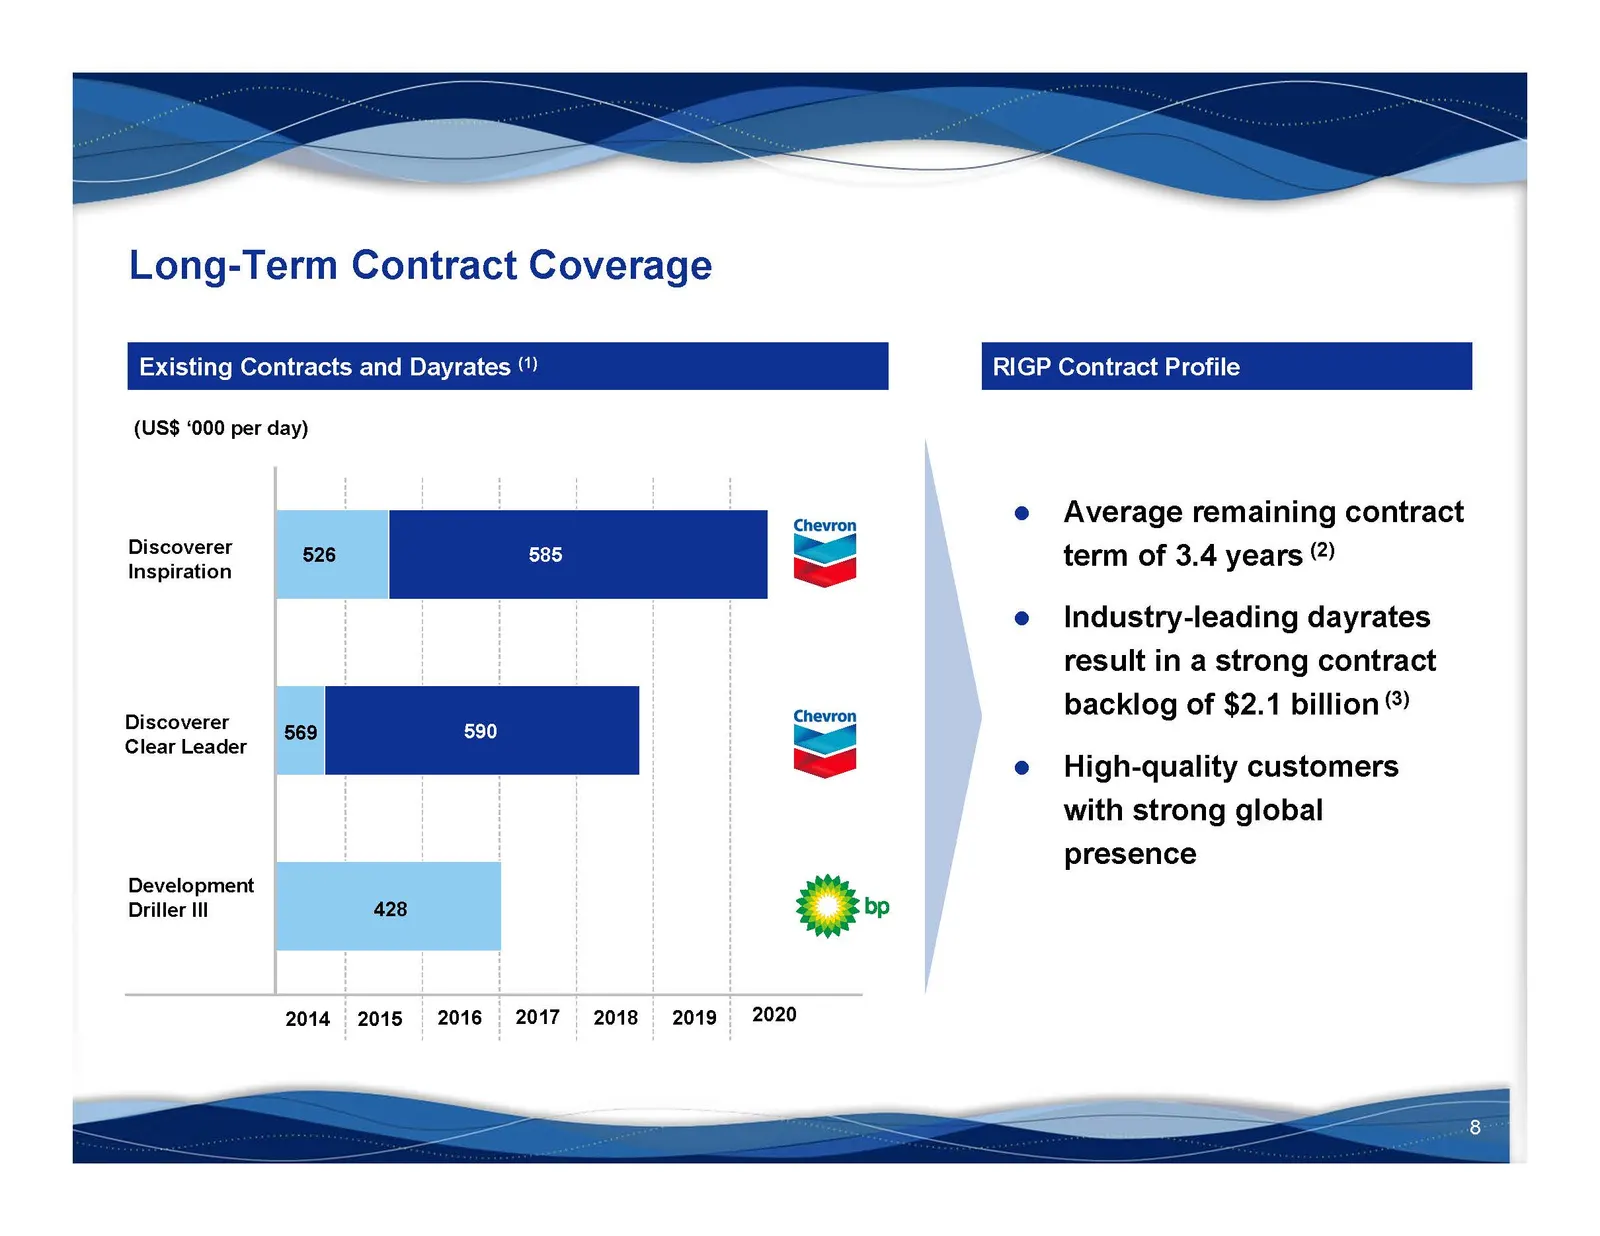
Slide 8: Long-Term Contract Coverage
Long-Term Contract Coverage Existing Contracts and Dayrates “) (US$ ‘000 per day) i Chevron Discoverer 526 <=! Inspiration — lass Discoverer 569 i Chevron Clear Leader H w gi Development 7 H Driller Ill 428 ' i bp 2014 2015 2016 += 2017-2018 +2019 | -2020 RIGP Contract Profile Average remaining cont
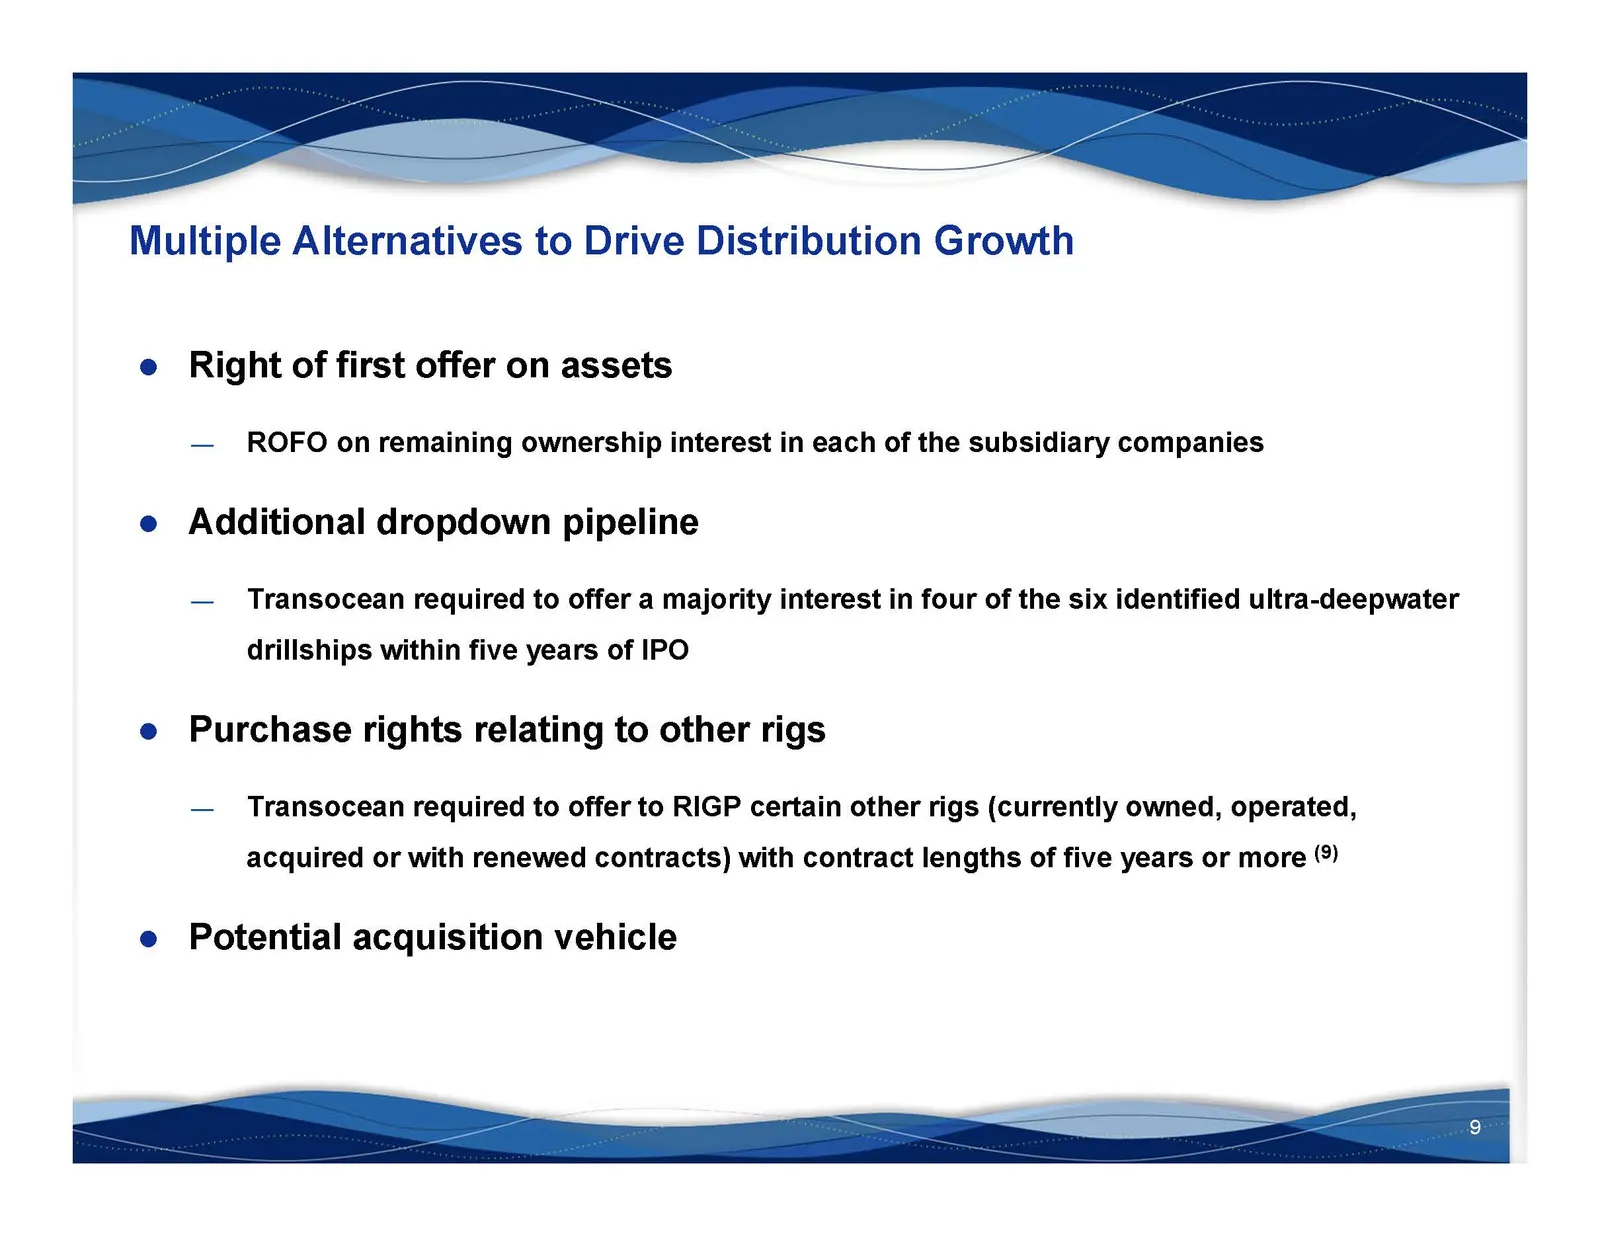
Slide 9: Multiple Alternatives to Drive Distribution Growth
Multiple Alternatives to Drive Distribution Growth Right of first offer on assets — ROFO on remaining ownership interest in each of the subsidiary companies Additional dropdown pipeline — Transocean required to offer a majority interest in four of the six identified ultra-deepwater drillships within
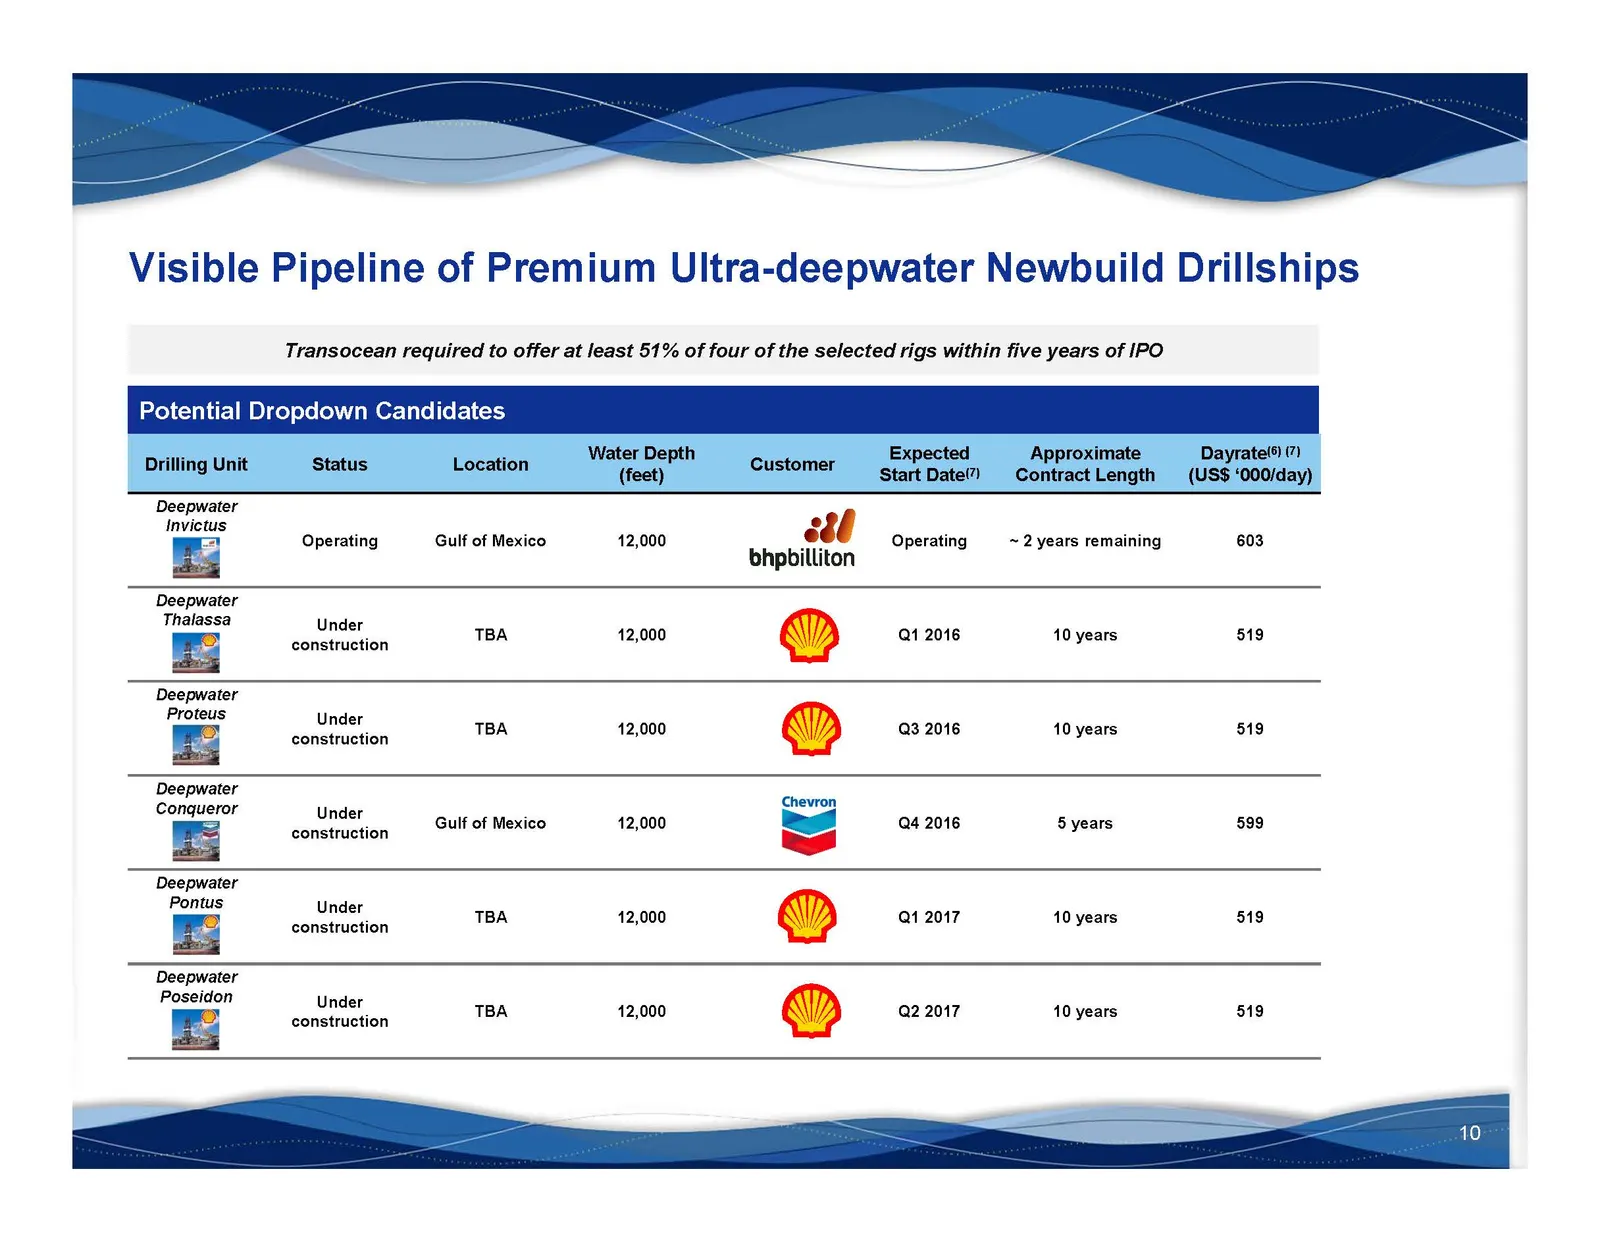
Slide 10: Visible Pipeline of Premium Ultra-deepwater Newbuild Drillships
Visible Pipeline of Premium Ultra-deepwater Newbuild Drillships Transocean required to offer at least 51% of four of the selected rigs within five years of IPO Potential Dropdown Candidates Deepwater Invictus 57 Operating Gulf of Mexico 12,000 et Operating ~2years remaining 603 bhpbilliton Deepwater
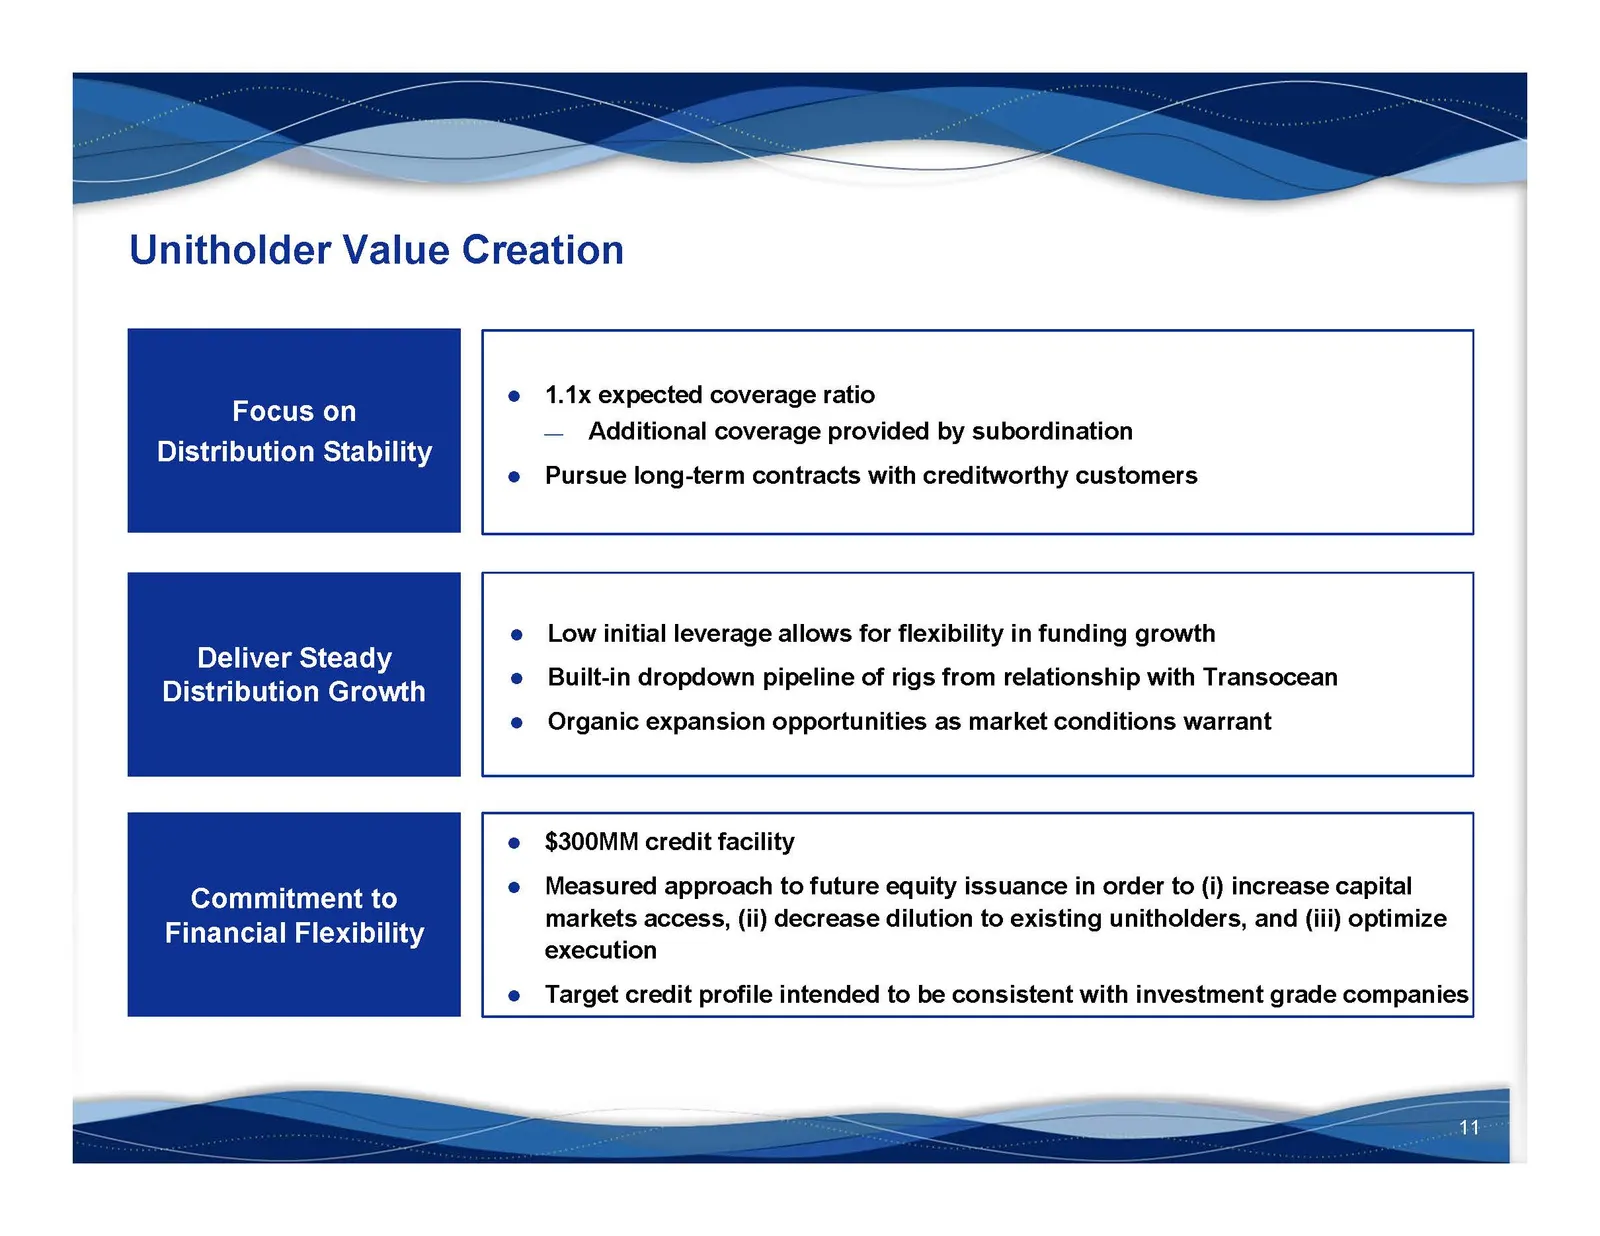
Slide 11: Unitholder Value Creation
Unitholder Value Creation Focus on Distribution Stability Deliver Steady Distribution Growth Commitment to Financial Flexibility 1.1x expected coverage ratio — Additional coverage provided by subordination Pursue long-term contracts with creditworthy customers Low initial leverage allows for flexibi
Slide 12: Current Market is Challenging
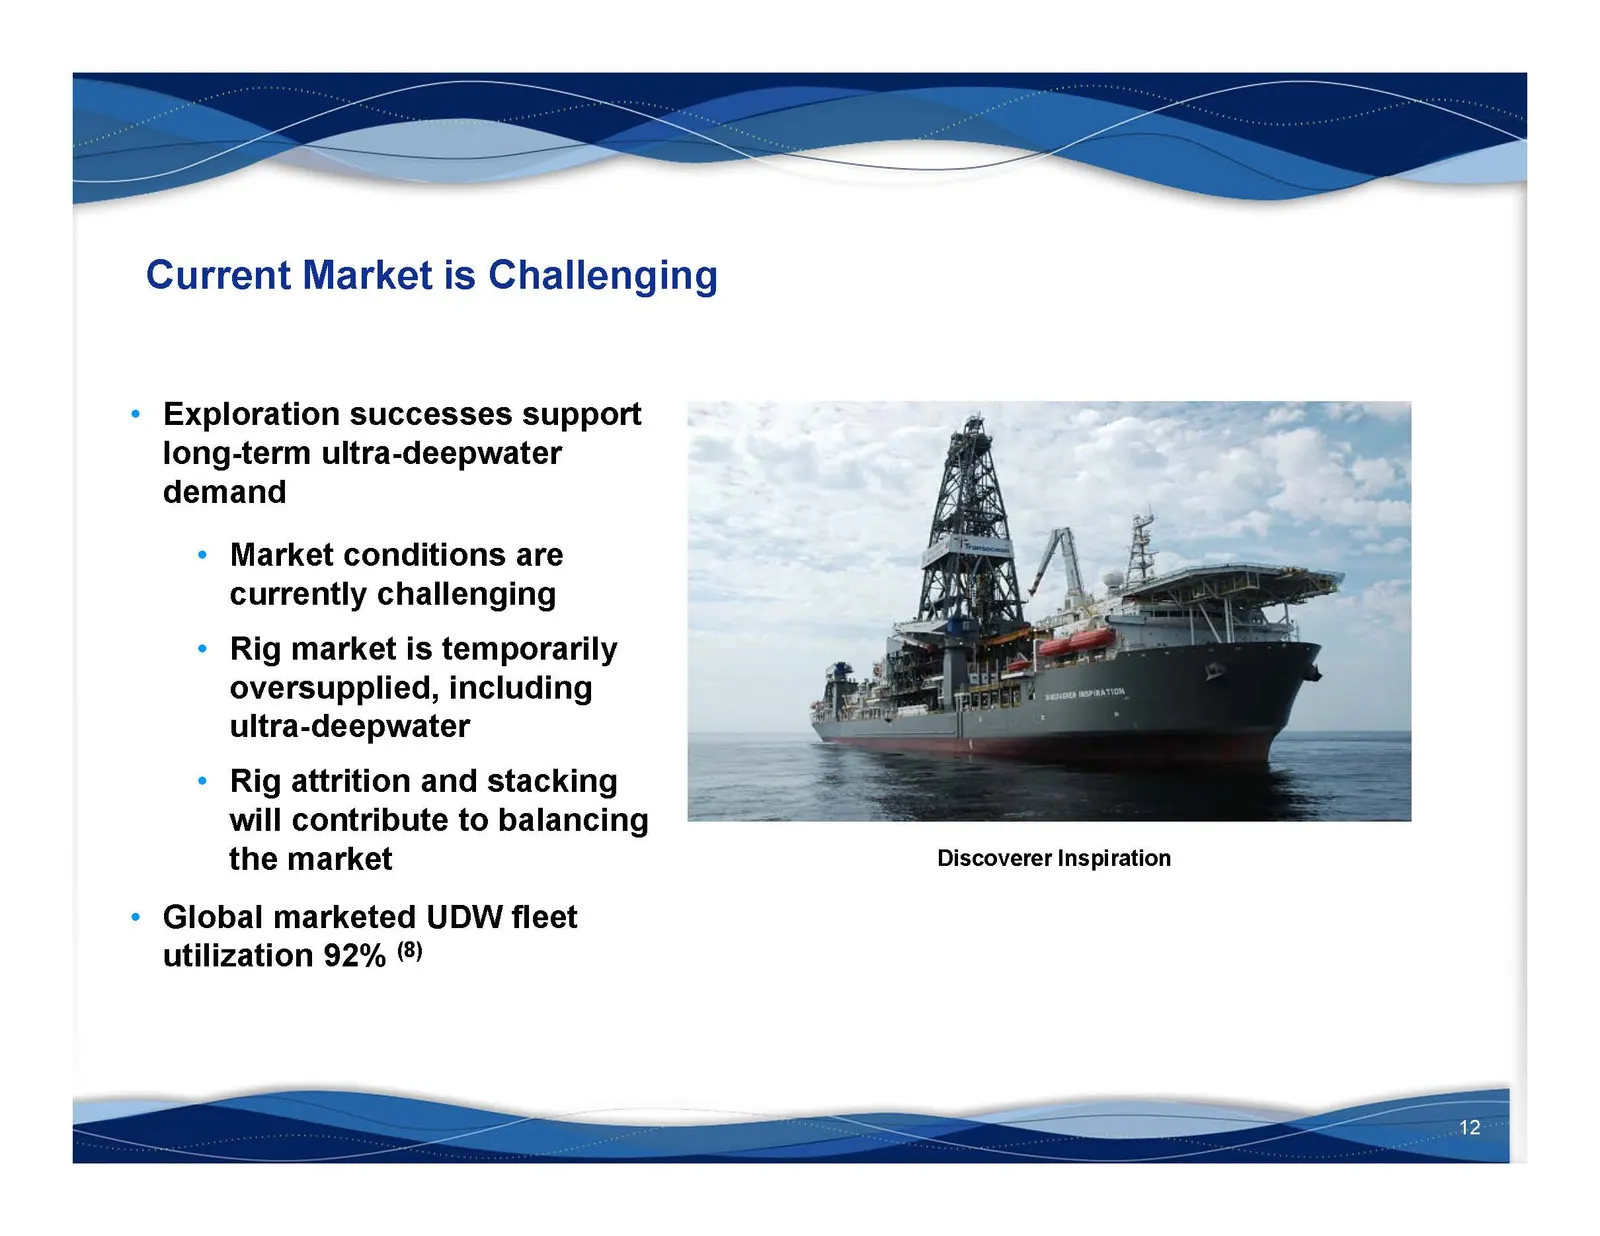
Current Market is Challenging ¢ Exploration successes support P ean st iy 4 long-term ultra-deepwater baal demand ° Market conditions are currently challenging ¢ Rig market is temporarily oversupplied, including ultra-deepwater ° Rig attrition and stacking ———. will contribute to balancing SS the ma
Slide 13: Potential Impact of Rig Attrition
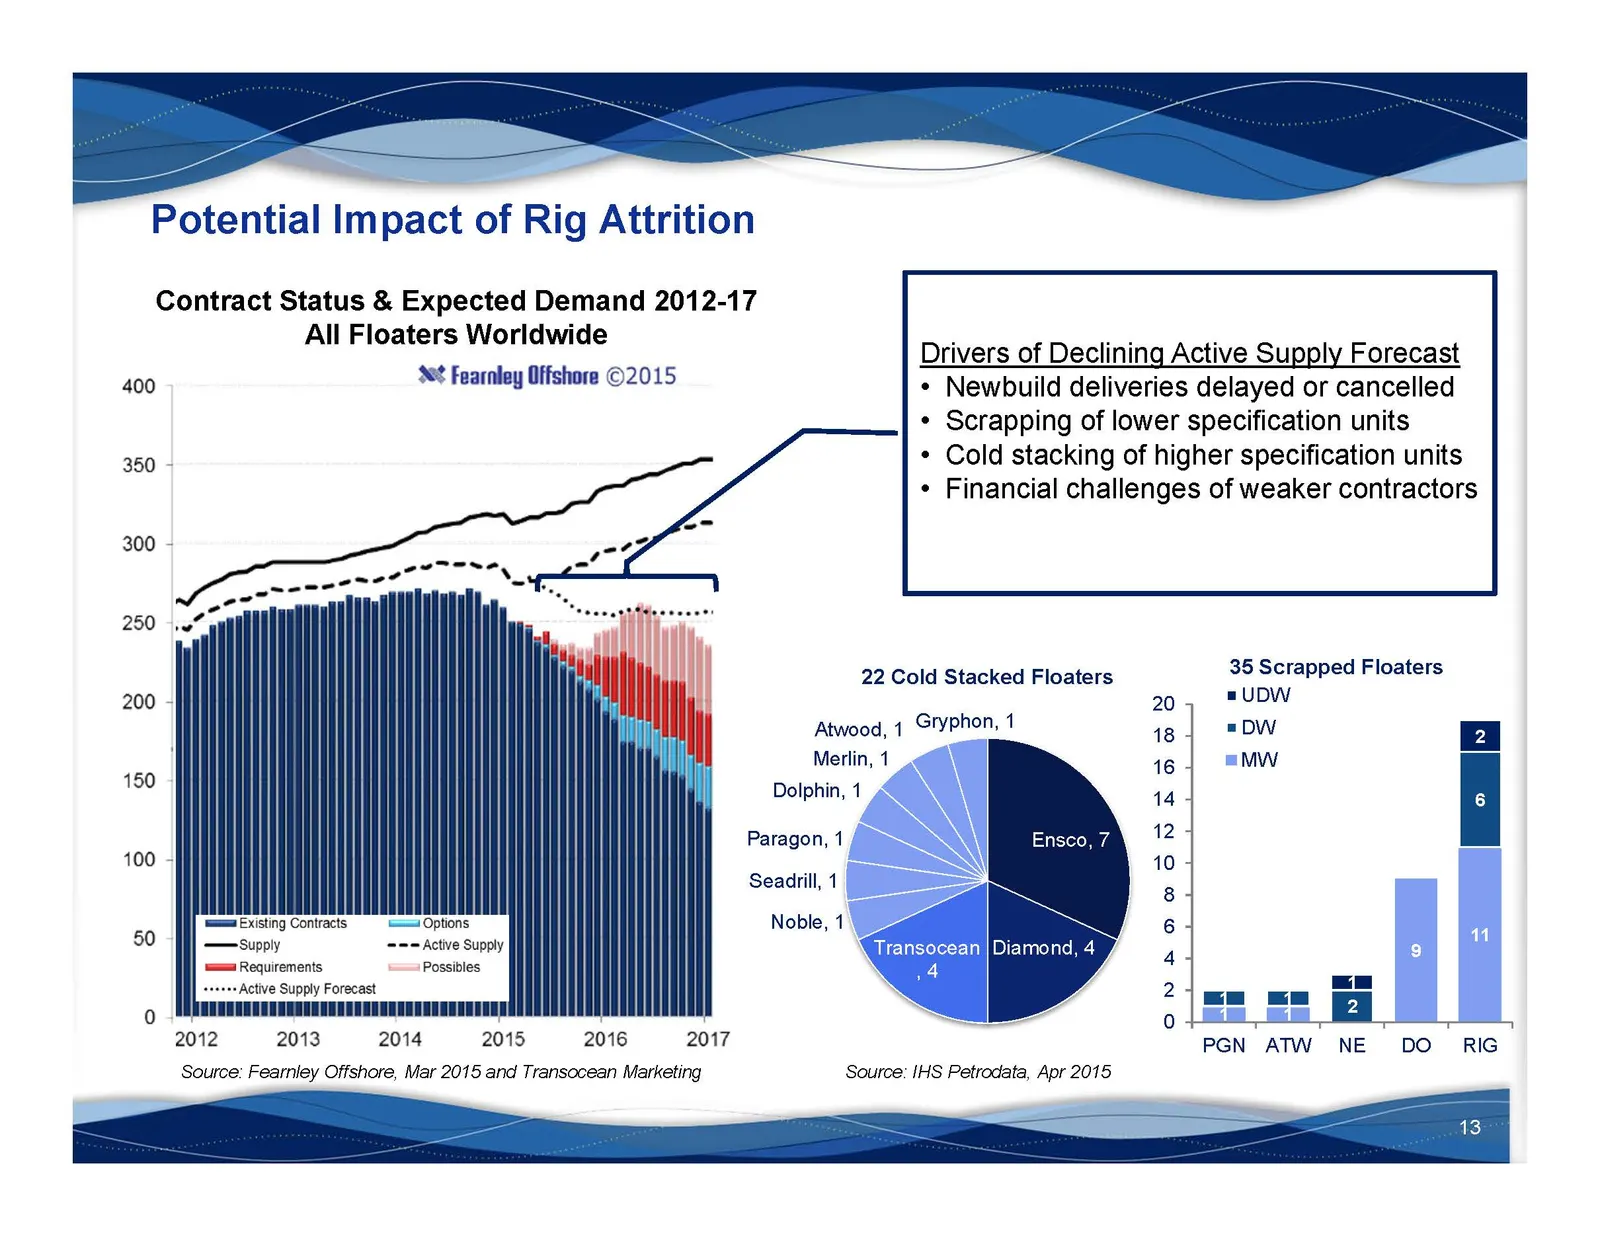
ee Potential Impact of R ig Attrition Contract Status & Expected Demand 2012-17 All Floaters Worldwide 400 S$ Fearnley Offshore ©2015 350 300 250 Drivers of Declining Active Supply Forecast « Newbuild deliveries delayed or cancelled « Scrapping of lower specification units ¢ Cold stacking of higher
Slide 14: Key Investment Highlights
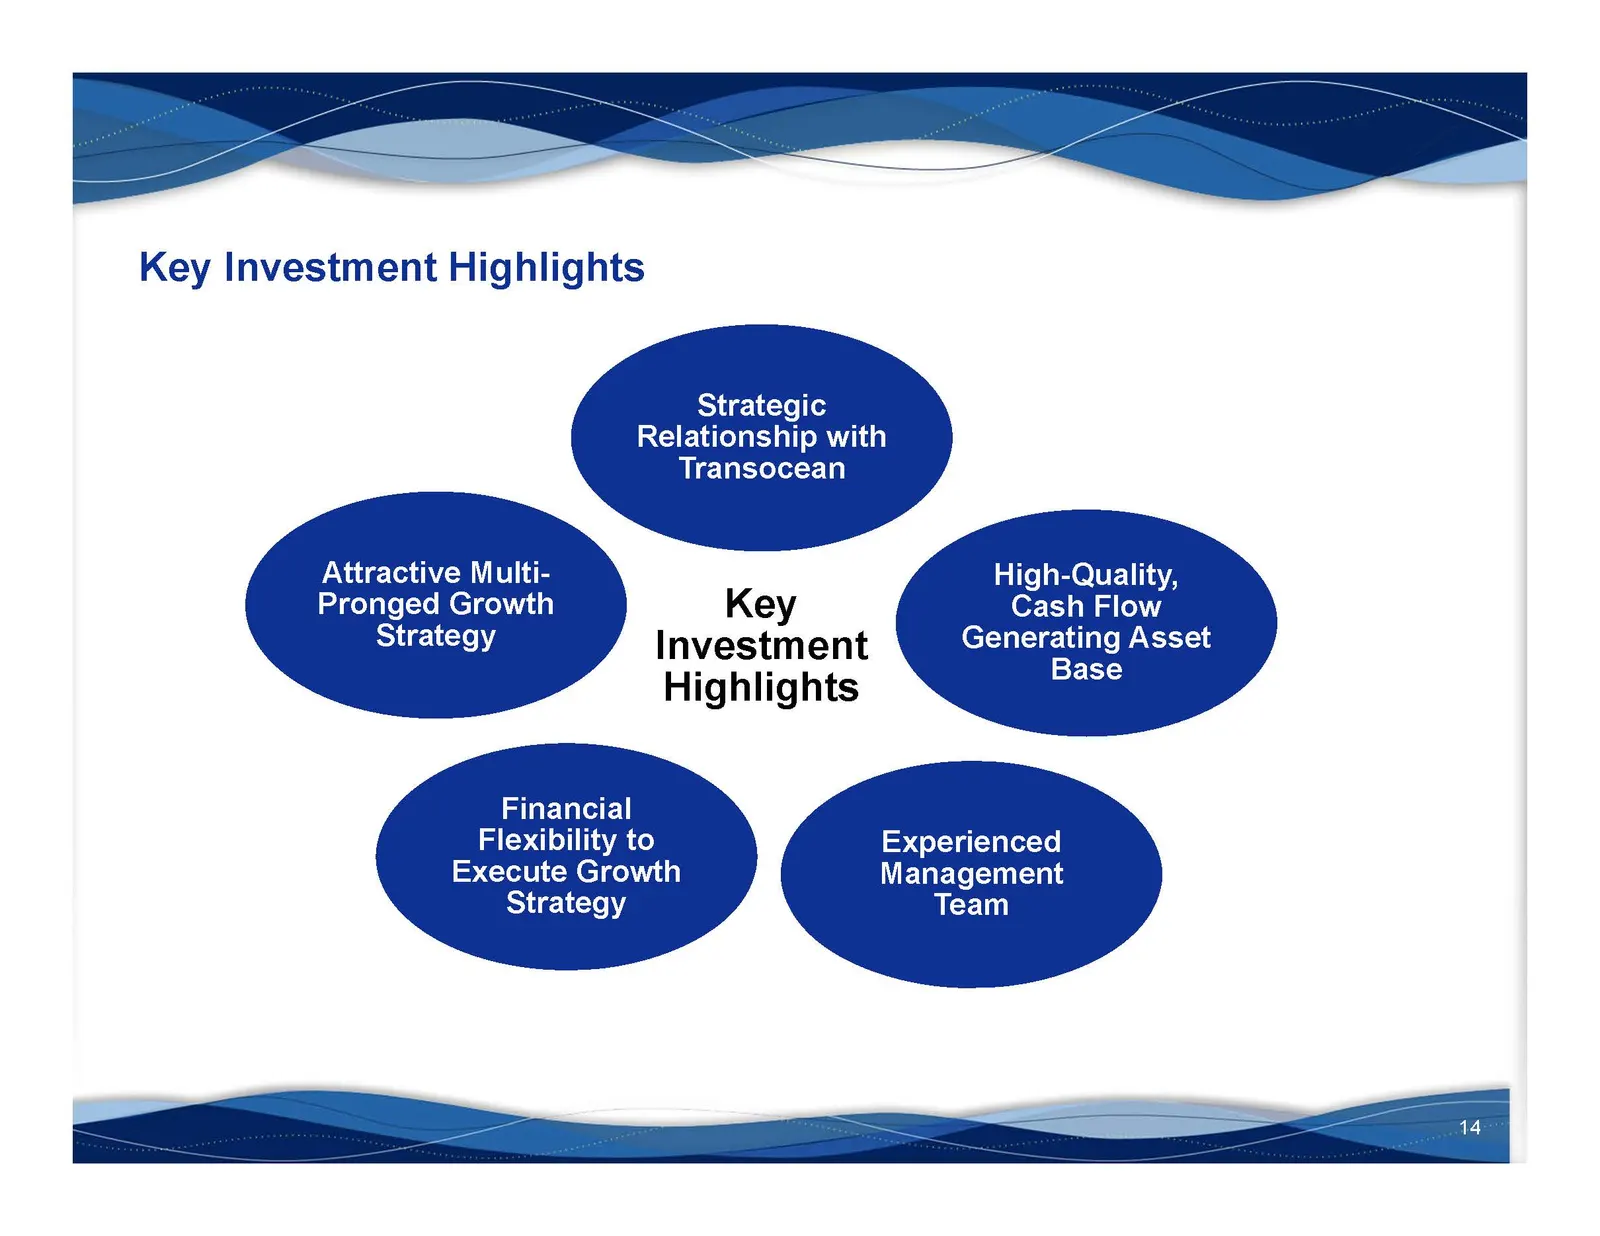
Key Investment Highlights Strategic Relationship with Transocean Attractive Multi- High-Quality, Pronged Growth Key Cash Flow Strategy Investment Generating Asset Highlights a Financial Flexibility to Experienced Execute Growth Management Strategy Team
Slide 15: 2015 NAPTP MLP Annual Investor Conference
2015 NAPTP MLP Annual Investor Conference (1°) May 2015 Bl transocean PARTNERS LLC
Slide 16: Footnotes
Footnotes (1) (2) (3) As of April 16, 2015 Fleet Status Report. As reported in 1Q 2015 Form 10-Q. Calculated by multiplying the contracted operating dayrate by the firm contract period for future periods, as of the Fleet Status Report issued April 16, 2015. Firm commitments are represented by signed
Source: SEC EDGAR · 8-K filed May 20, 2015