Bridge Capital — Carpenter Community BancFund Institutional Investor Conference (April 2010)
32 slides from Bridge Capital's conference presentation, Apr 29, 2010
Slide 1: Investor Update
prince Mi BANK EE iy Investor Update Carpenter Community BancFund Institutional Investor Conference Daniel P. Myers President Chief Executive Officer
Slide 2: Forward Looking Statements
Forward Looking Statements Certain matters discussed herein constitute forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995, and are subject to the safe harbors created by that Act. Forward-looking statements describe future plans, strategies, and exp
Slide 3: Bridge Bank - What We Are
BRIDGE BANK —- What We Are SV Market Management Opportunity Operating Metrics Performance Looking Ahead NASDAQ: BENK a
Slide 4: Bridge Bank
BRIDGE BANK A business banking franchise that is the Professional Business Bank of Choice for small and middle market companies, and emerging technology businesses in the markets we serve = Relationship business banking focus = True business line diversification commercial/industrial - technology -
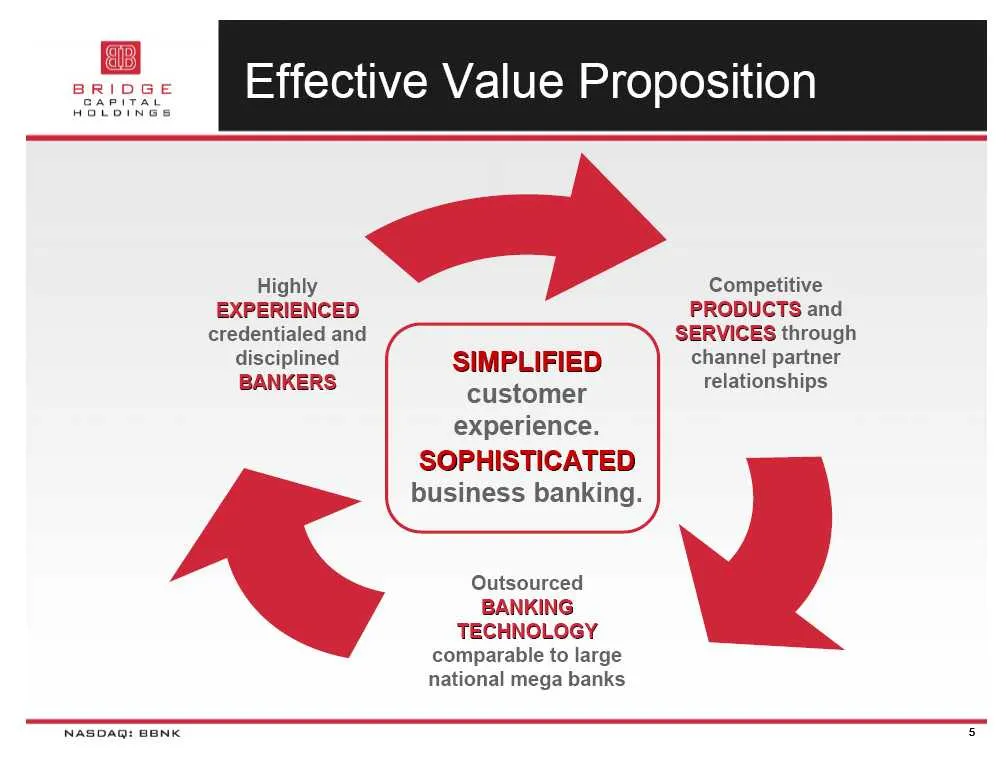
Slide 5: Effective Value Proposition
Effective Value Proposition Highly Competitive EXPERIENCED PRODUCTS and credentialed and SERVICES through disciplined SIMPLIFIED channel partner BANKERS customer relationships experience. SOPHISTICATED business banking. Outsourced BANKING TECHNOLOGY comparable to large national mega banks NASDAQ: BE
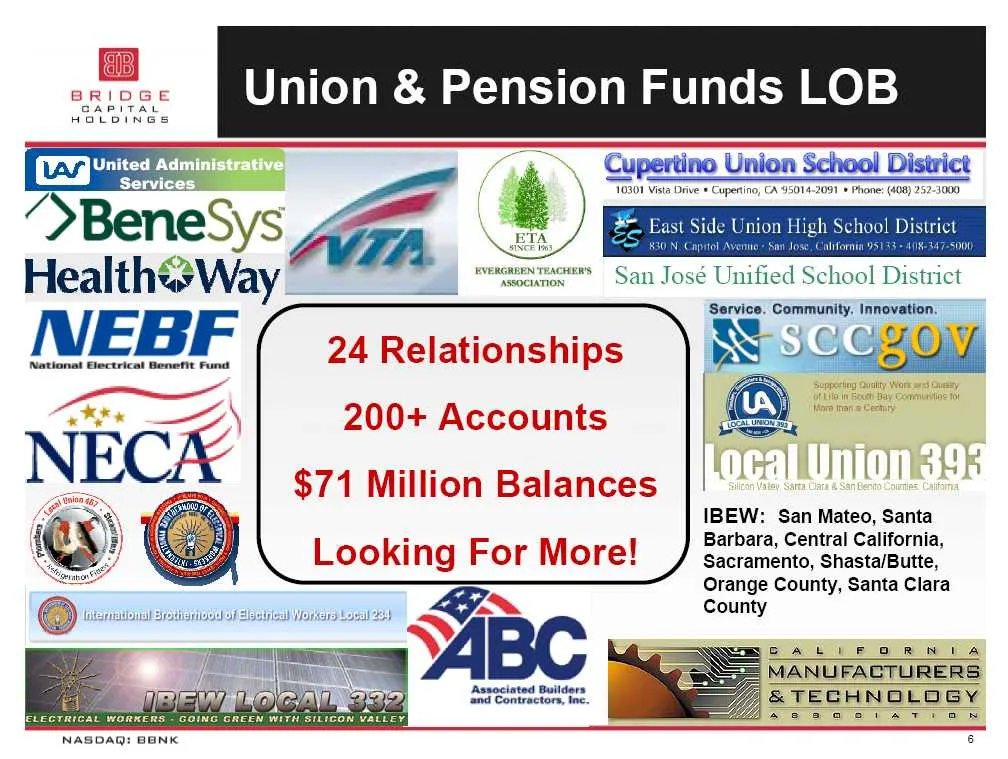
Slide 6: Client and community affiliations
Health: » Way | , | can veactters ~~ San José Unified School District Service. Community, Innovation. NEBF SS 5 SS905 Lb =." : IBEW: San Mateo, Santa Barbara, Central California, Sacramento, Shasta/Butte, Orange County, Santa Clara County ALIFORANULA ANUFACTURERS TECHNOLOGY Associated Builders and C
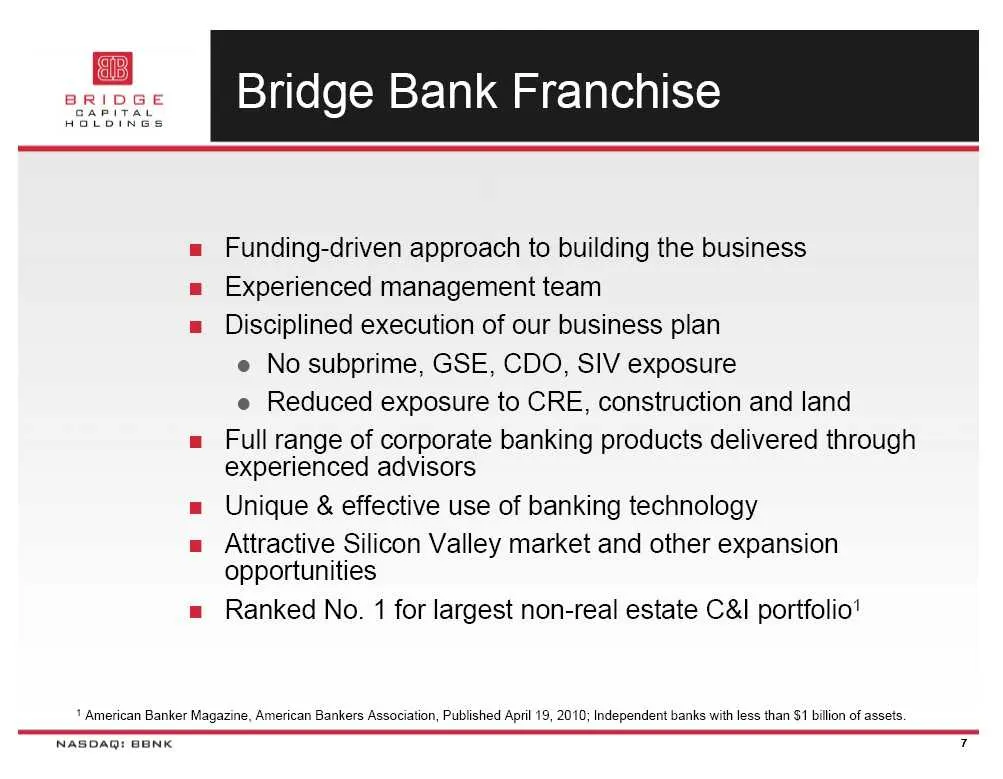
Slide 7: Bridge Bank Franchise
Bridge Bank Franchise Funding-driven approach to building the business Experienced management team Disciplined execution of our business plan e No subprime, GSE, CDO, SIV exposure e Reduced exposure to CRE, construction and land Full range of corporate banking products delivered through experienced
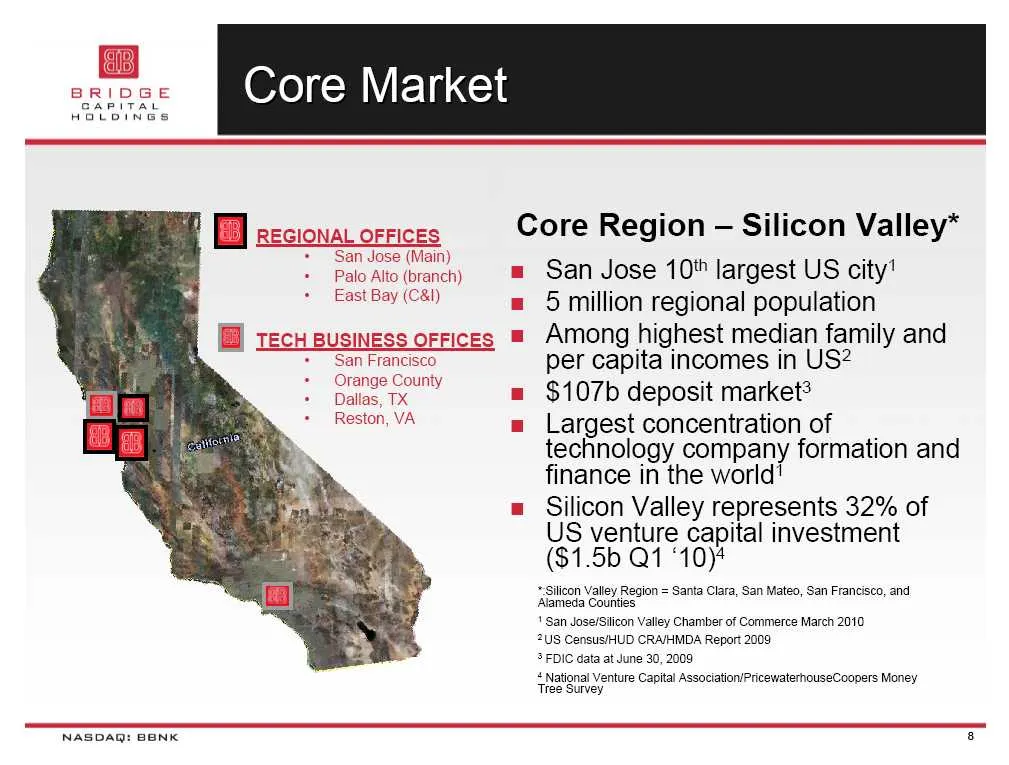
Slide 8: Core Region - Silicon Valley
NASDAQ: BENK Core Region — Silicon Valley* San Jose 10" largest US city! 5 million regional population Among highest median family and per capita incomes in US? $107b deposit market? Largest concentration of technology company formation and finance in the world! 1 Silicon Valley represents 32% of US
Slide 9: Significant Market Opportunity
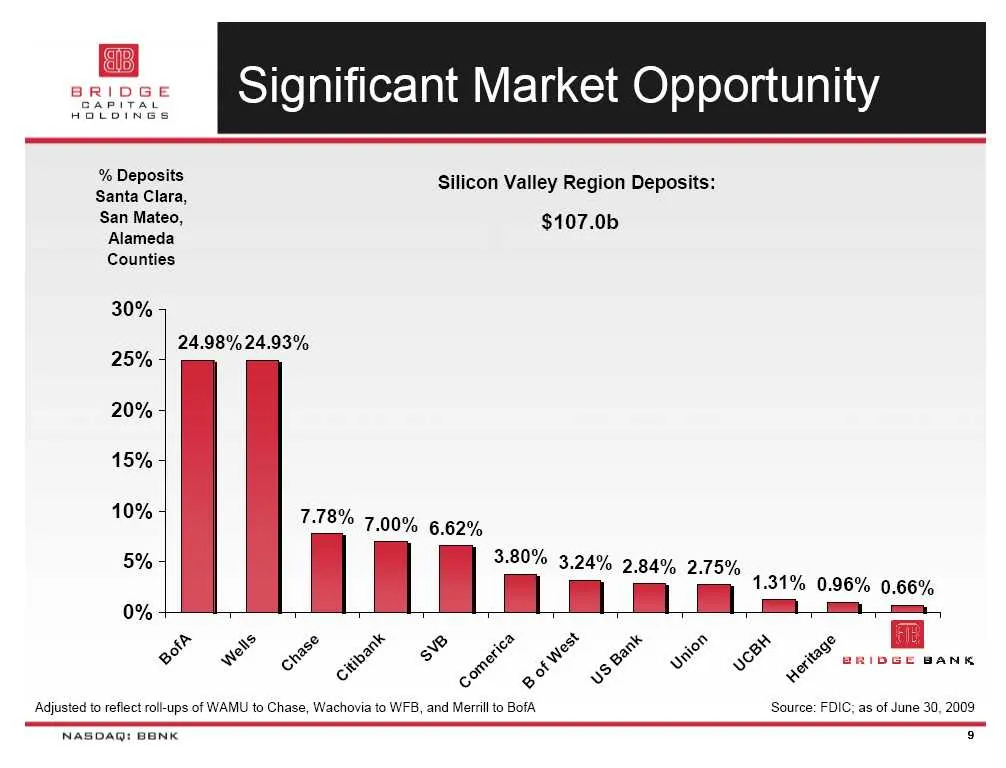
Significant Market Opportunity % Deposits Silicon Valley Region Deposits: Santa Clara, San Mateo, $107.0b Alameda Counties 30% 4 24.98% 24.93% 25% 4 20% 4 15% + o% -| 10% 7.18% 7.90% 6.62% 5% | | i | 3.80% 3.24% 2.84% 2.75% 1.31% 0.96% 0.60% 0% a | a2 = BRIDGE BANK Ng »” e ew * Ra Ee Ra eS es é eo é
Slide 10: Executive Officers & Division Managers
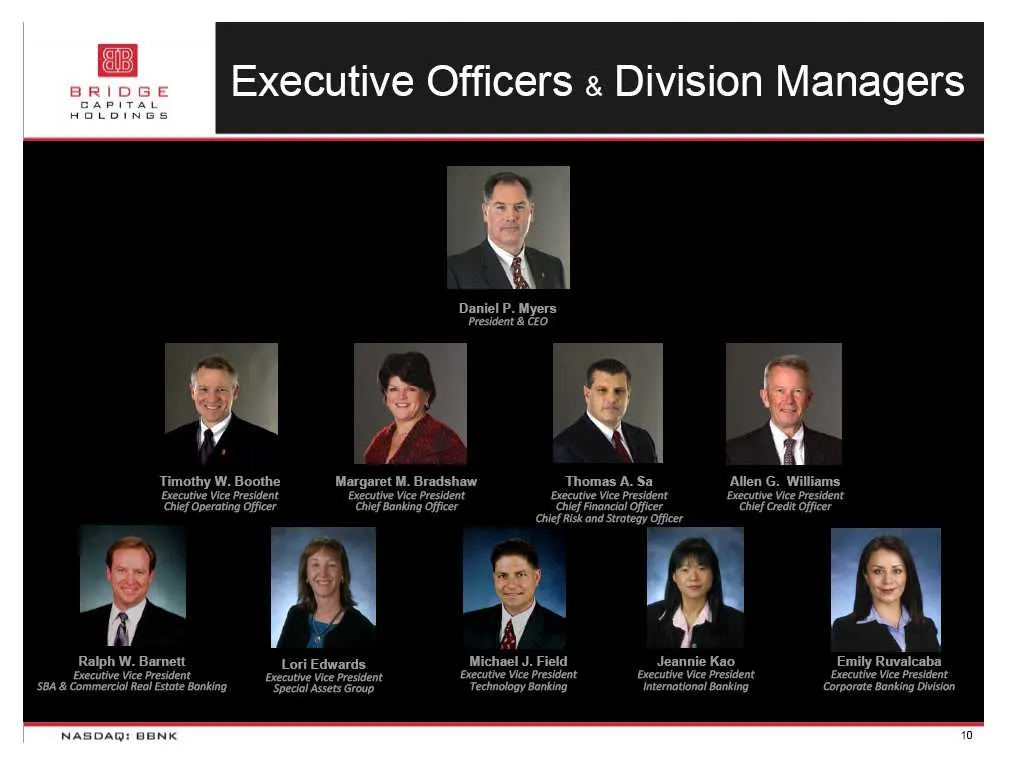
Executive Officers « Division Managers 1 Daniel P. Myers yA Timothy W. Boothe Margaret M. Bradshaw Williams he Be ident Emily Ru Executive Corporate NASDAQ: BENK
Slide 11: Average Total Assets ($M)
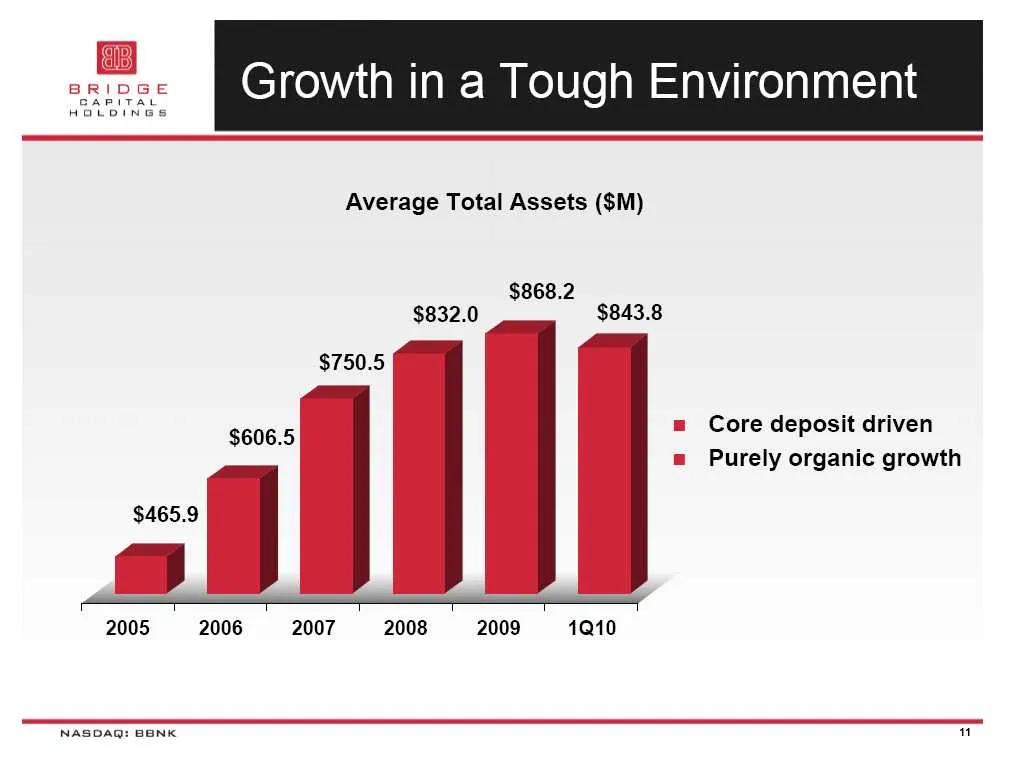
Average Total Assets ($M) $868.2 $832.0 $843.8 = Core deposit driven = Purely organic growth 2005 2006 2007 2008 2009 1Q10 NASDAQ: BENK 1"
Slide 12: Core Deposits
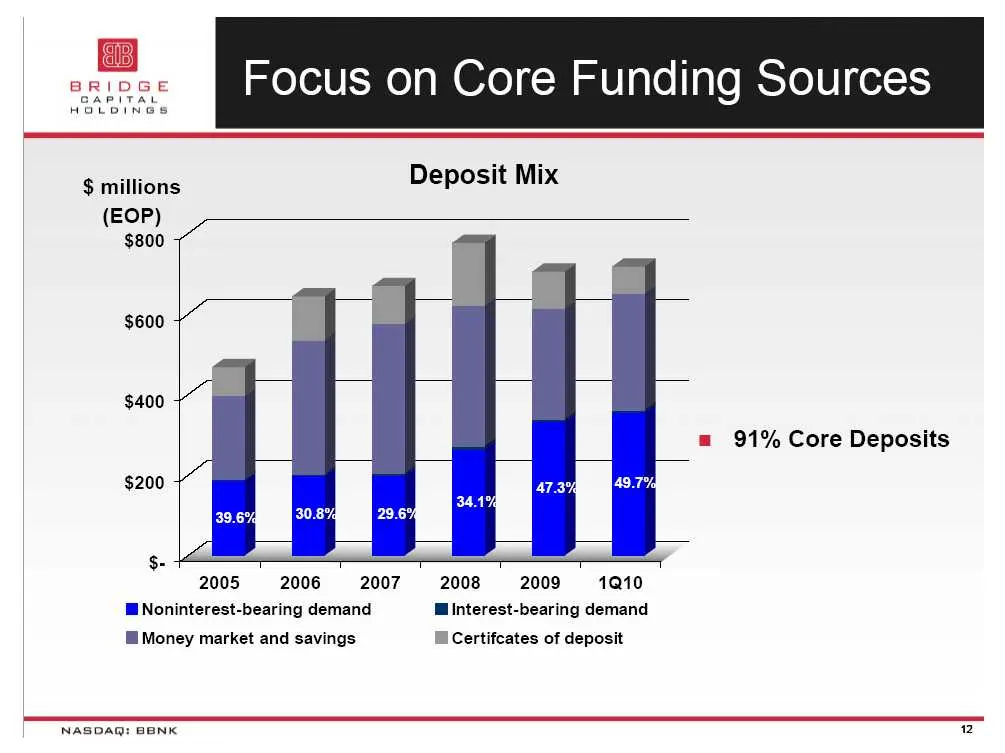
$ millions (EOP) $800 $600 $400 = 91% Core Deposits $- 2005 2006 2007 2008 2009 1Q10 MNoninterest-bearing demand Minterest-bearing demand li Money market and savings Certifcates of deposit NASDAQ: BENK 2
Slide 13: Net interest margin vs peers
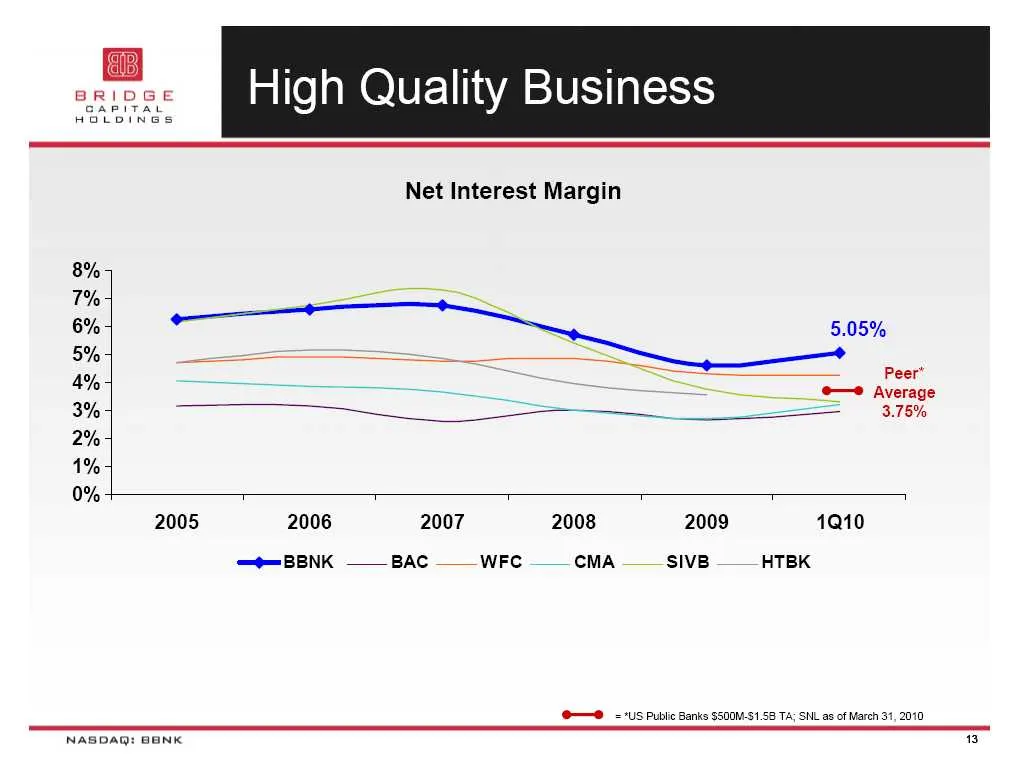
8% T% 6% 5.05% 5% 4% Sa — _ average 3% == - 3.75% 2% 1% 0% + 2005 2006 2007 2008 2009 1Q10 ——BBNK BAC WFC cMA SIVB HTBK @—© = US Public Banks SS00M-S1.58 TA; SNL as of March 31, 2010 NASDAQ: BENK 13
Slide 14: Highly Effective Revenue Generation
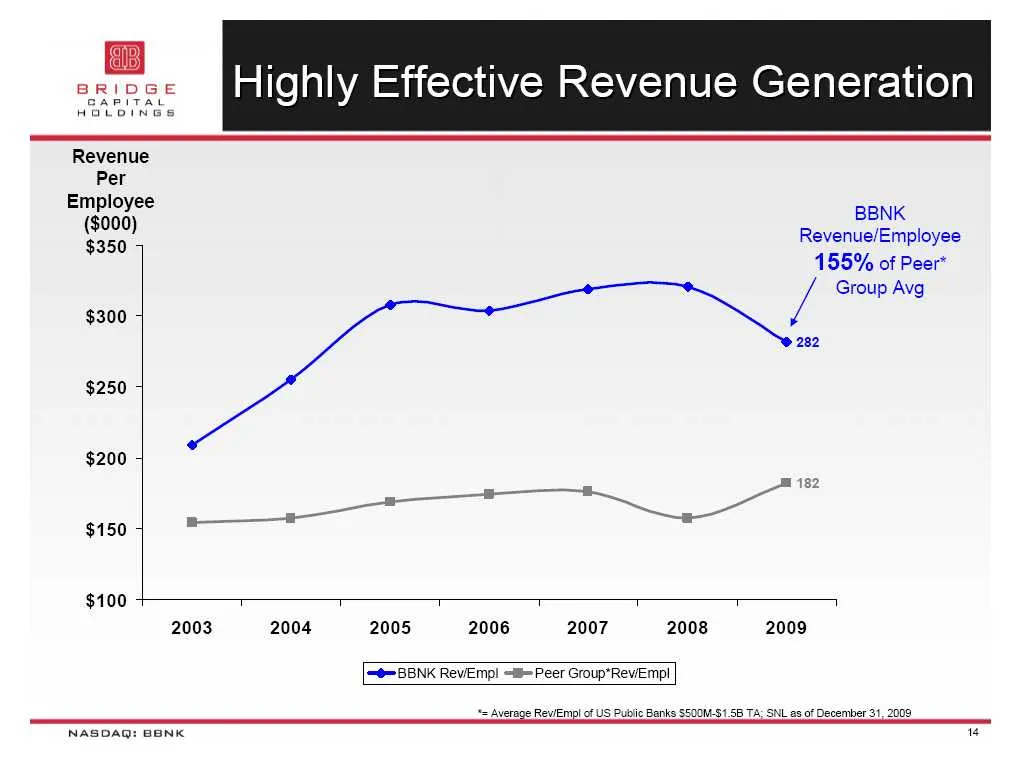
Highly Effective Revenue Generation Revenue Per Employee ($000) $350 4 BBNK Revenue/Employee 155% of Peer* 7 Group Avg $300 4 282 $250 4 $200 4 $150 4 $100 T T T T i T 1 2003 2004 2005 2006 2007 2008 2009 [=0=8BNK ReviEmp! == Peer Group*ReviEmpl *= Average Rev/Empl of US Pubic Banks, of December 31,
Slide 15: Diversification of Lending Activity
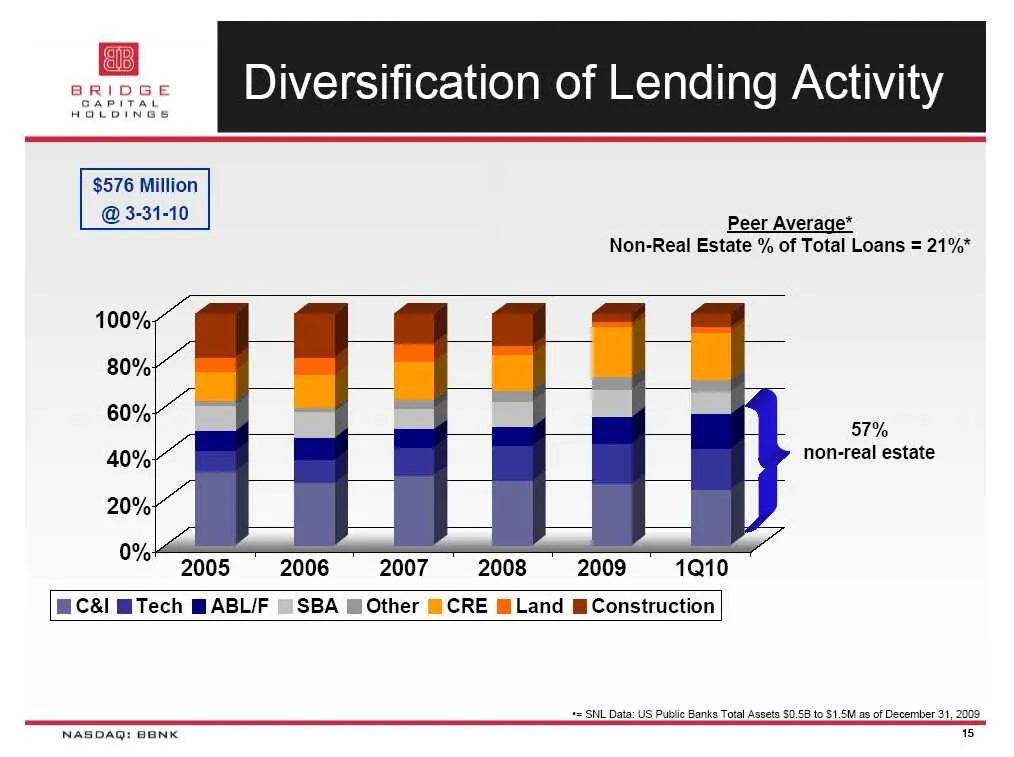
Diversification of Lending Activity $576 Million Gost Peer Average* Non-Real Estate % of Total Loans = 21%* 100% 80% 60Y " 57% 40% non-real estate 20% 0% 2005 2006 2007 2008 2009 1Q10 mC&l mi Tech BABL/F SBA ™ Other ®CRE ®Land @ Construction += SNL Data: US Public Banks T NASDAQ: BENK
Slide 16: Ranked #1 for Largest C&I Portfolio
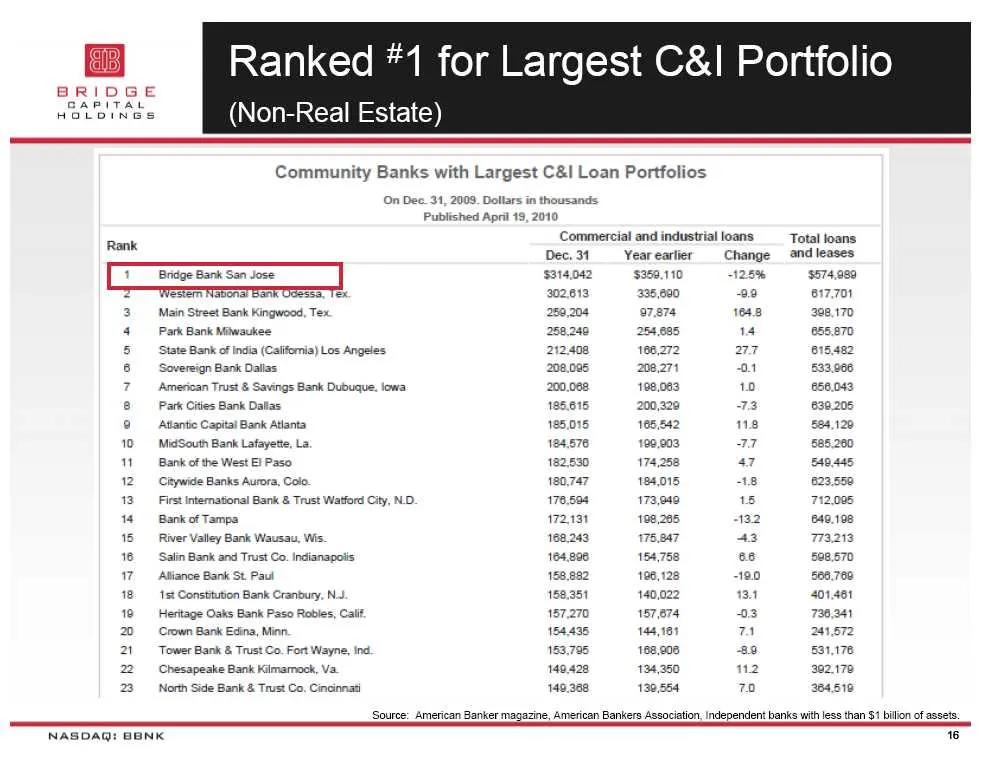
Ranked #1 for Largest C&I Portfolio (Non-Real Estate) Community Banks with Largest C&l Loan Portfolios (On Dec. 31, 2003. Dollars in thousands Published April 19, 2010 Rank Commercial and industrial loans Total loans Dec. 34 Year earlier Change and leases $314,042 $369,110 125% $574,989 Neem Nabonal
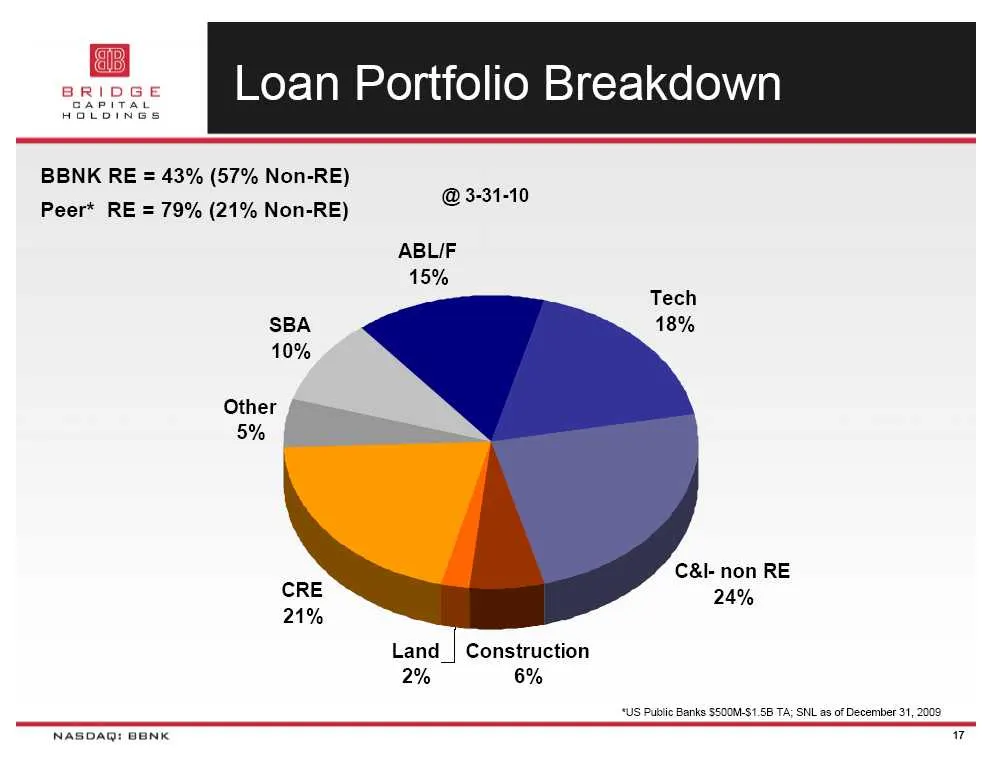
Slide 17: Loan Portfolio Breakdown
fae Loan Portfolio Breakdown BBNK RE = 43% (57% Non-RE) 3-31-10 Peer* RE = 79% (21% Non-RE) @ ABLIF 15% Tech SBA 10% Other 5% C&l- non RE CRE 24% 21% Land_| Construction 2% 6% “US Public Banks OMS SB TA; SNL as of December 31, 2009 NASDAQ: BBNK 7
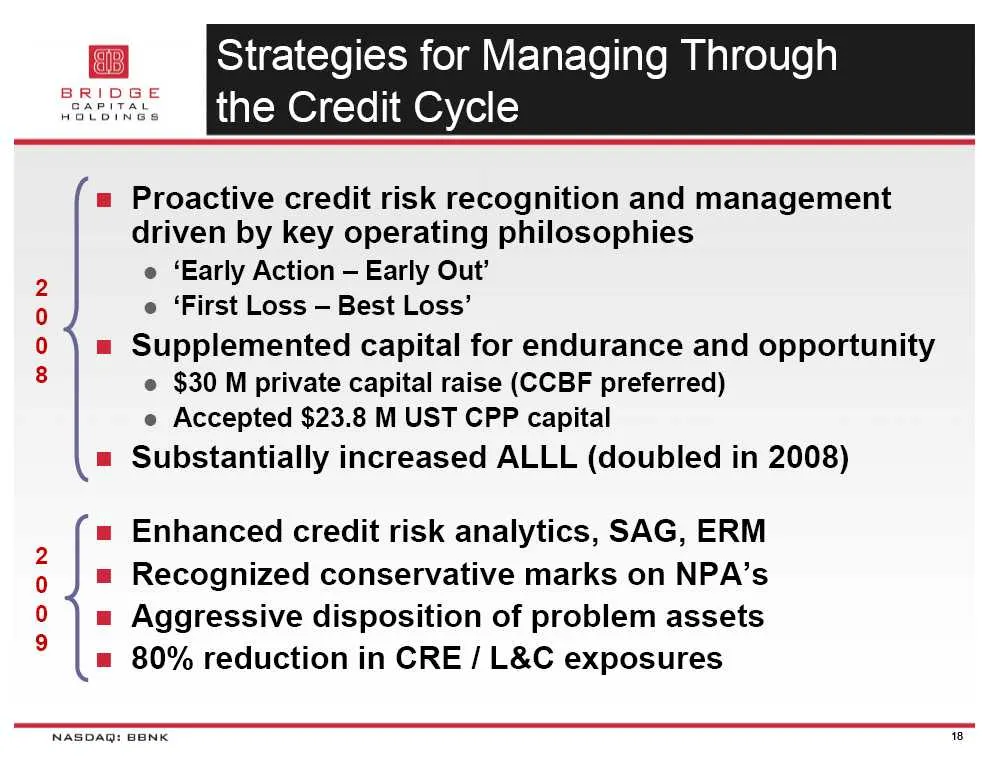
Slide 18: Strategies for Managing Through the Credit Cycle
w~oon o©OOn eB Strategies for Managing Through Saeeee the Credit Cycle Proactive credit risk recognition and management driven by key operating philosophies e ‘Early Action — Early Out’ e ‘First Loss — Best Loss’ Supplemented capital for endurance and opportunity e $30 M private capital raise (CCBF
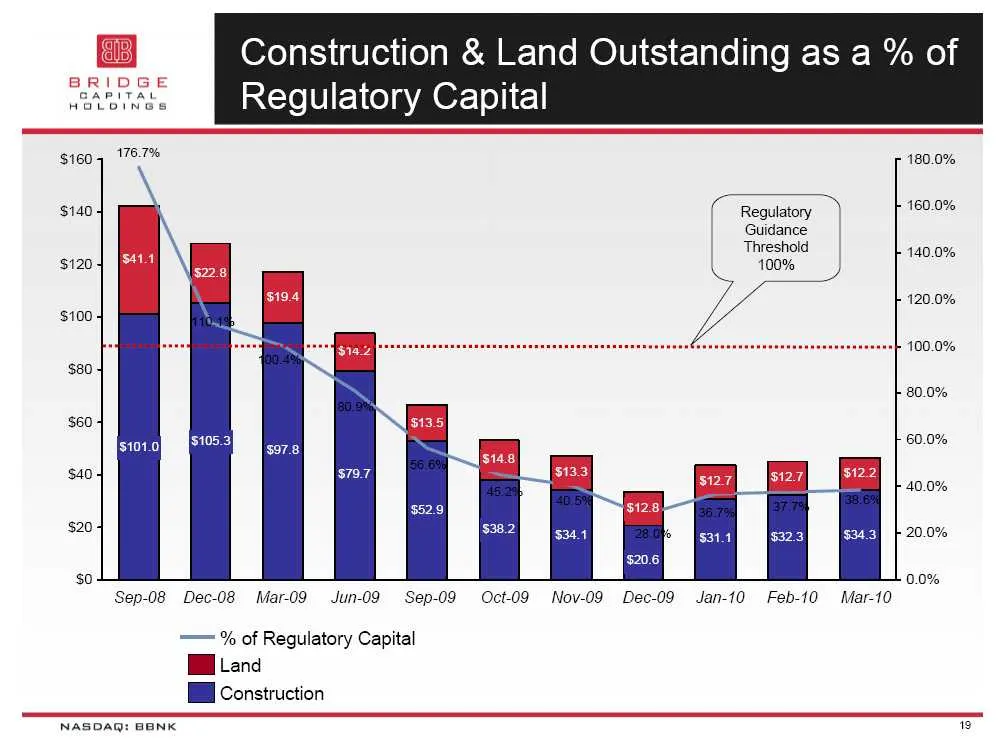
Slide 19: Construction & Land Outstanding as a % of Regulatory Capital
Construction & Land Outstanding as a % of Regulatory Capital si6o4 176.7% 180.0% $140 Regulatory NS Guidance Threshold 140.0% $120 100% 120.0% $100 100.0% ‘$80 80.0% $60 60.0% $40 40.0% 20: 20.0% so 0.0% Sep-08 Dec-08 Mar-09 Jun-09 Sep-09 Oct-09 Nov-09 Dec-09 Jan-10 Feb-10 Mar-10 —— % of Regulatory
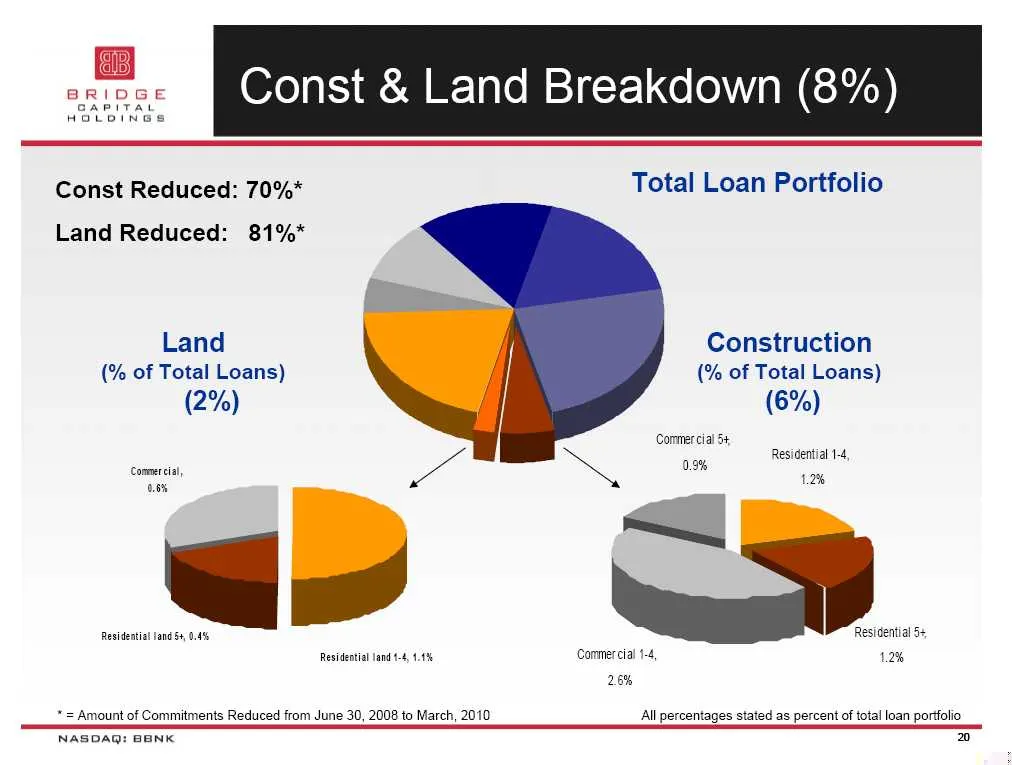
Slide 20: Const & Land Breakdown
Const & Land Breakdown Const Reduced: 70%* Total Loan Portfolio Land Reduced: 81%* Land (% of Total Loans) (2%) Construction (% of Total Loans) (6%) Commer cial 54, 0.9%. Residential 1-4 es 1.2% Residential 5+ Residential Hand 54, 0.4% Residential land 1-4, 1.1% 4 12% * = Amount of Commitments Reduc
Slide 21: Total CRE Outstanding as a % of Regulatory Capital
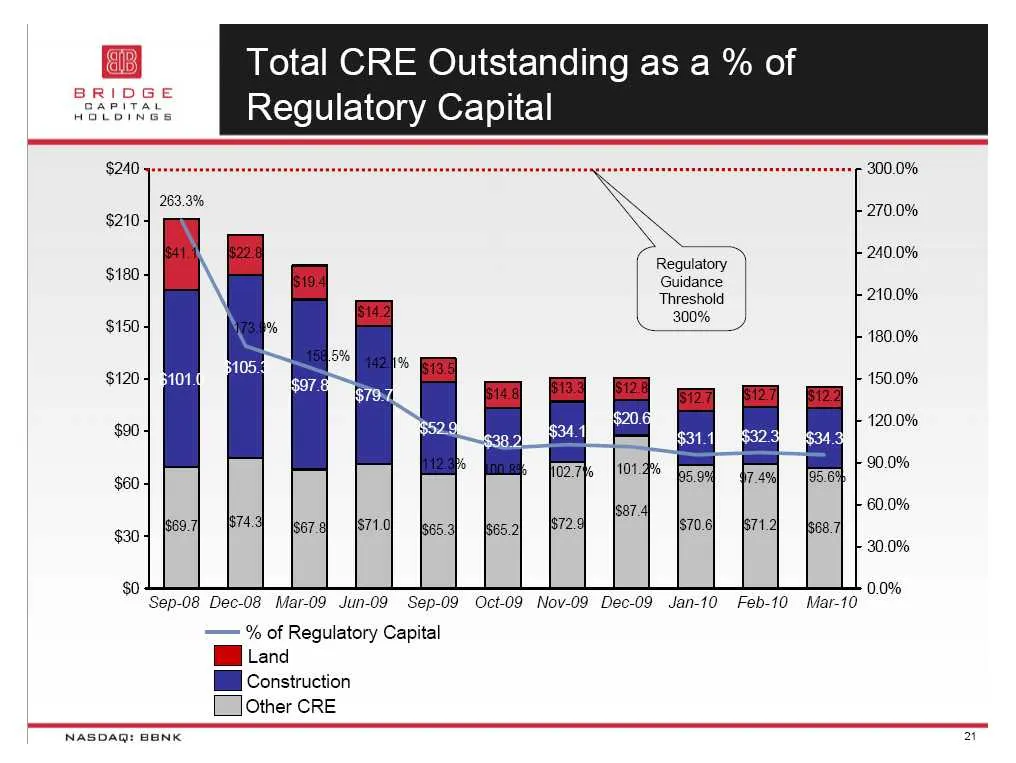
Total CRE Outstanding as a % of Regulatory Capital 300.0% 270.0% =) 240.0% Regulatory ele Guidance Threshold 210.0% ve 180.0% % $120 150.0% $795 $00 29 120.0% 90.0% $60 60.0% B71.) kes} at 20.0% 0.0% 0 Sep-08 Dec-08 Mar-09 Jun-09 Sep-09 Oct-09 Nov-09 Dec-09 Jan-10 Feb-10 Mar-10 —— % of Regulatory Ca
Slide 22: CRE Breakdown
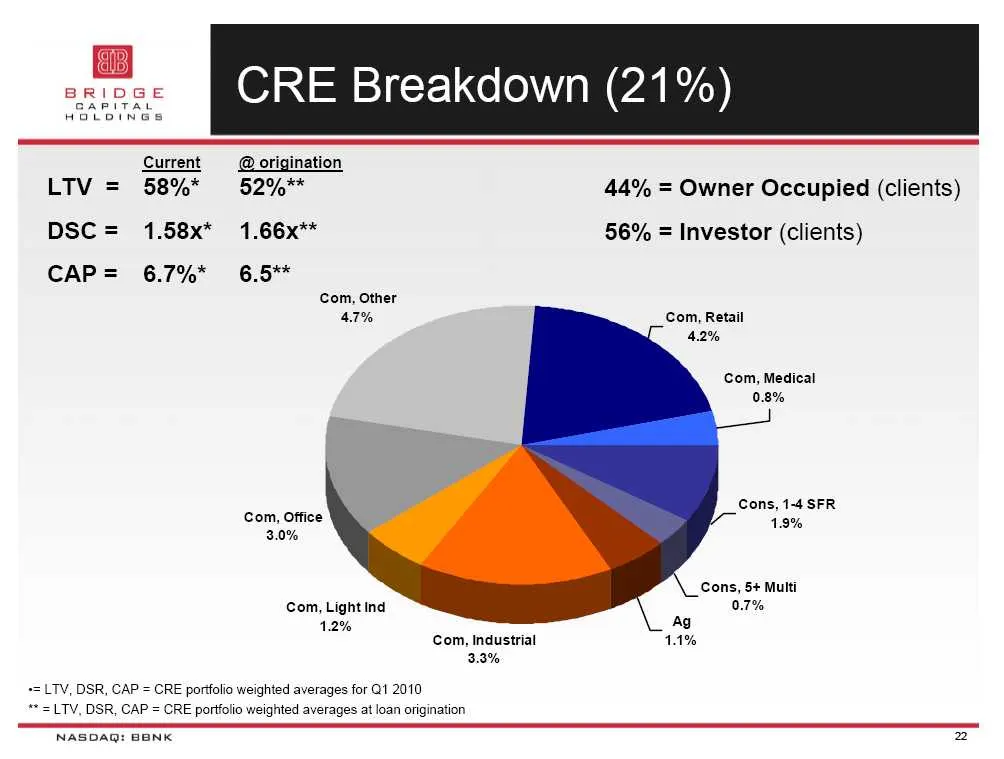
Maw CRE Breakdown (21%) Current @ origination LTV = 58%* 52%** 44% = Owner Occupied (clients) DSC= 1.58x* 1.66x** 56% = Investor (clients) CAP= 6.7%* 6.5** Com, Other 4.7% Com, Retail 42% Com, Medical 0.8% Cons, 1-4 SFR 19% Cons, 5+ Multi Com, Light Ind 0.7% 1.2% Com, Industrial 11% 3.3% += LTV, DSR
Slide 23: Signs of Credit Quality Improvement
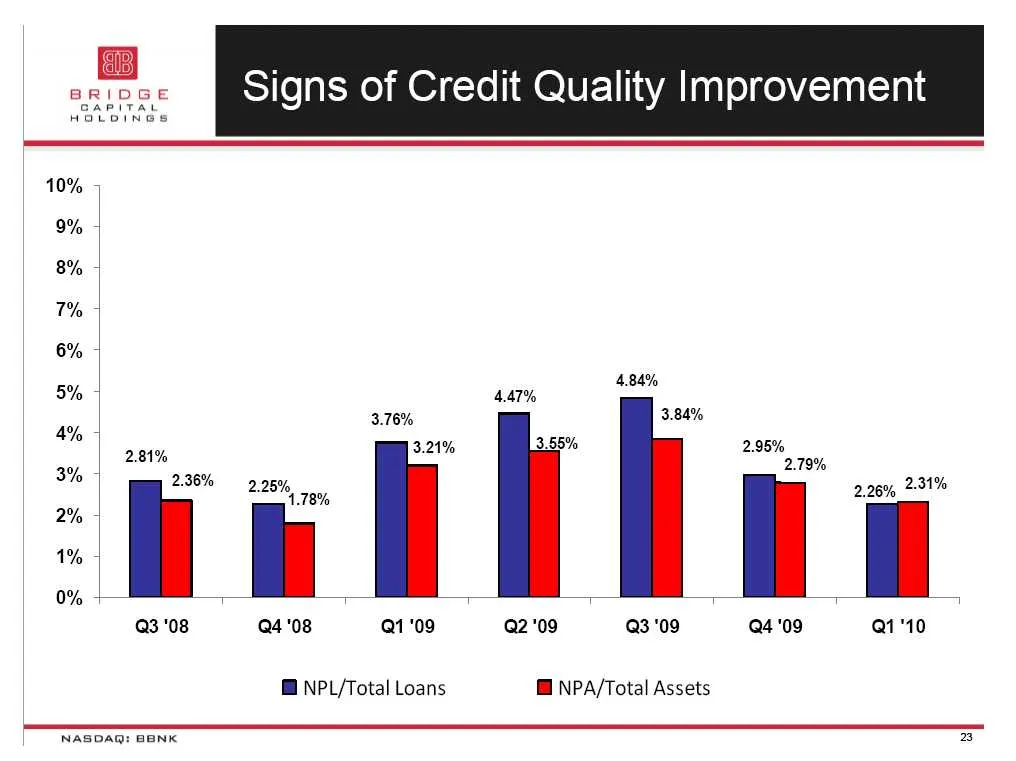
Signs of Credit Quality Improvement 3.76% 281% 3.21% 3% | 2.36% 9.950% "78% Q3 '08 Q4'08 Q1'09 Q2'09 Q3'09 Q4'09 Q110 NPL/Total Loans @ NPA/Total Assets NASDAQ: BENK 2
Slide 24: Reserves Remain High While Credit Losses Trend Lower
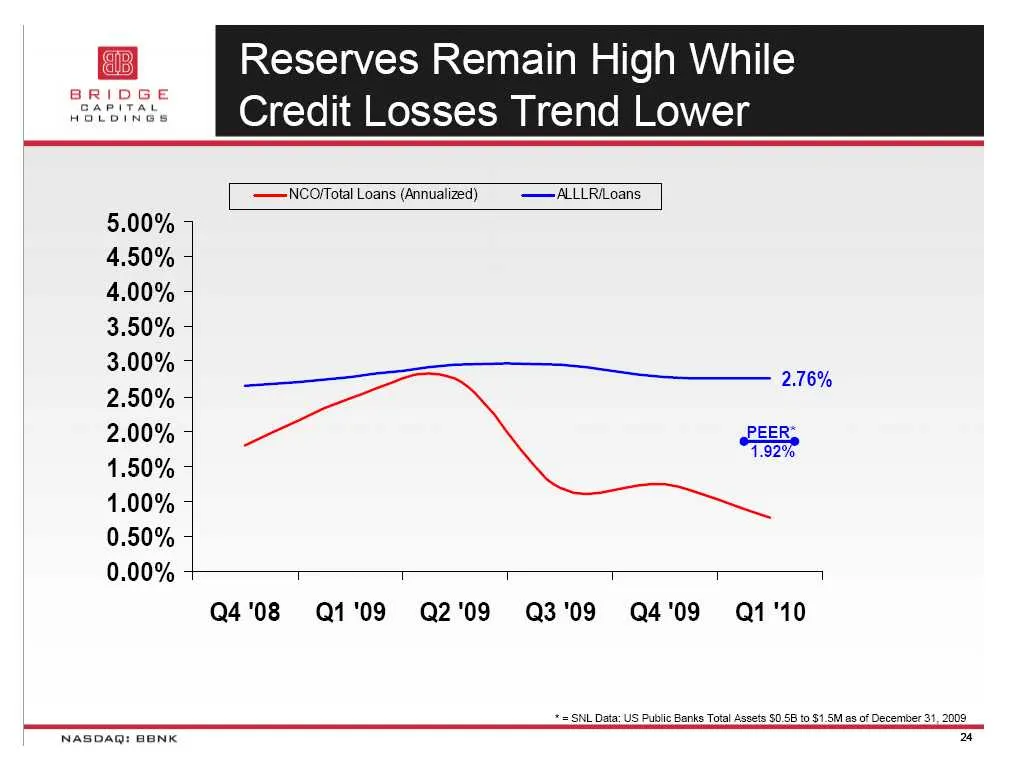
Reserves Remain High While Credit Losses Trend Lower —NCO/Total Loans (Annualized) —ALLLRiLoans 3.00%} "=, 2.00% + SEER, 0.00% T T T T T 1 Q4'08 Q1'09 Q2'09 Q3'09 Q4'09 Q1'10 == SNL Data: US Pubic Banks Total Assets $0.56 to $1 SMas of December 31, 2008 NASDAQ: BENK 4
Slide 25: Capital for Endurance & Opportunity
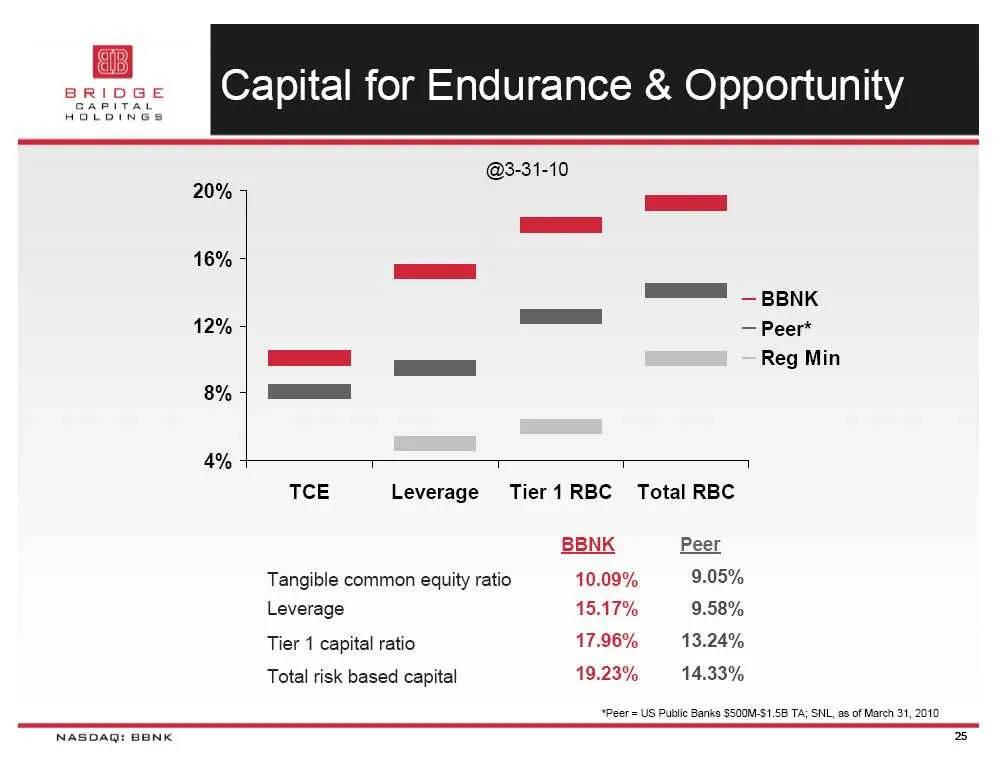
A. Capital for Endurance & Opportunity @3-31-10 9 20% = Es 18% =o EE _ BBNK 12% — peer ===) ] Reg Min 8%) AM + T T T 1 TCE Leverage Tier1 RBC Total RBC BBNK Peer Tangible common equity ratio 10.09% 9.05% Leverage 15.17% 9.58% Tier 1 capital ratio 17.96% 13.24% Total risk based capital 19.23% 14.33%
Slide 26: Q1 2010 Summary
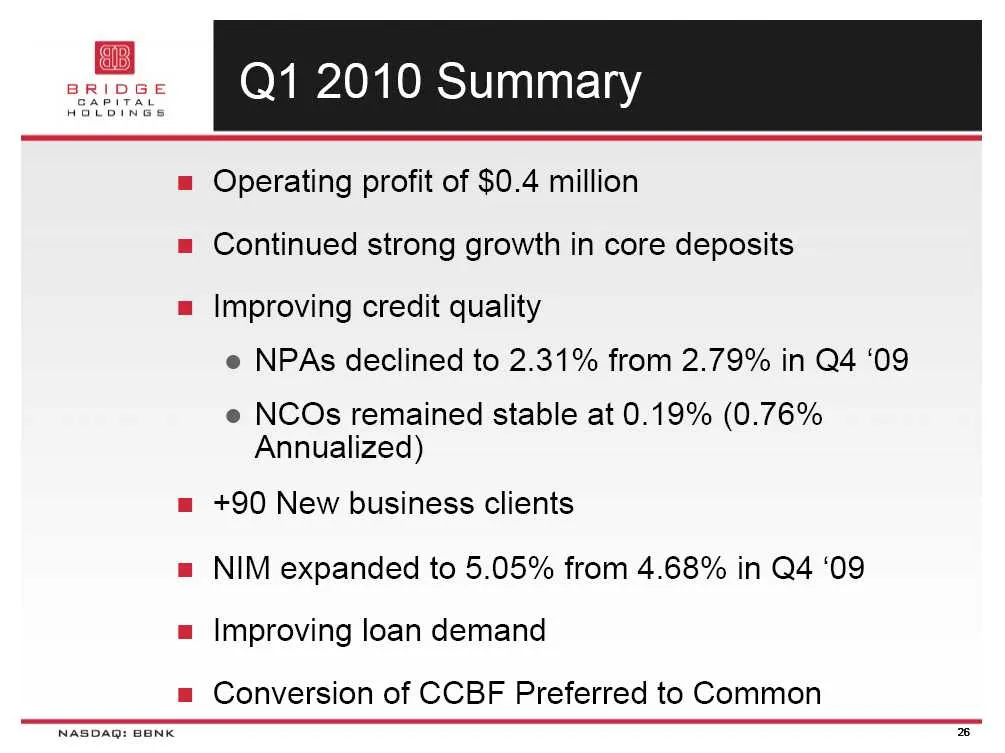
rt me Q1 2010 Summary NASDAQ: BENK Operating profit of $0.4 million Continued strong growth in core deposits Improving credit quality e NPAs declined to 2.31% from 2.79% in Q4 ‘09 e NCOs remained stable at 0.19% (0.76% Annualized) +90 New business clients NIM expanded to 5.05% from 4.68% in Q4 ‘09 I
Slide 27: Earnings trend
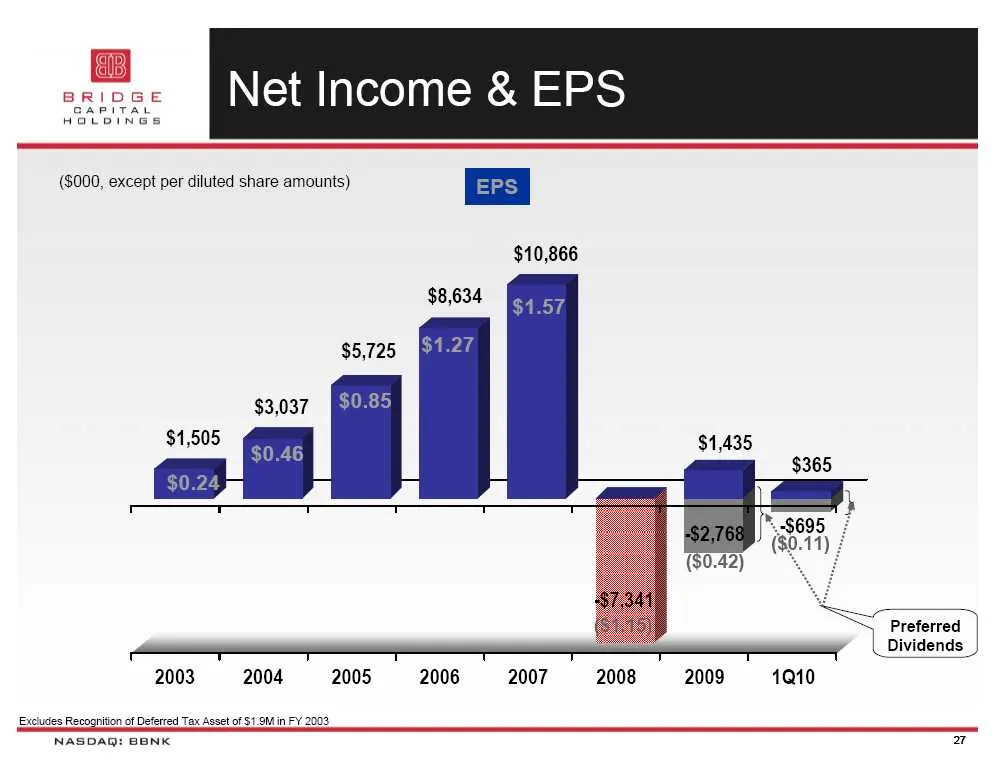
$10,866 2003 2004 2005 2006 2007 2008 2009 1010 Excludes Recognition of Deferred Tax Asset of $1.9M in NASDAQ: BENK Preferred Dividends )
Slide 28: Positioned to Benefit From Potential Tailwinds
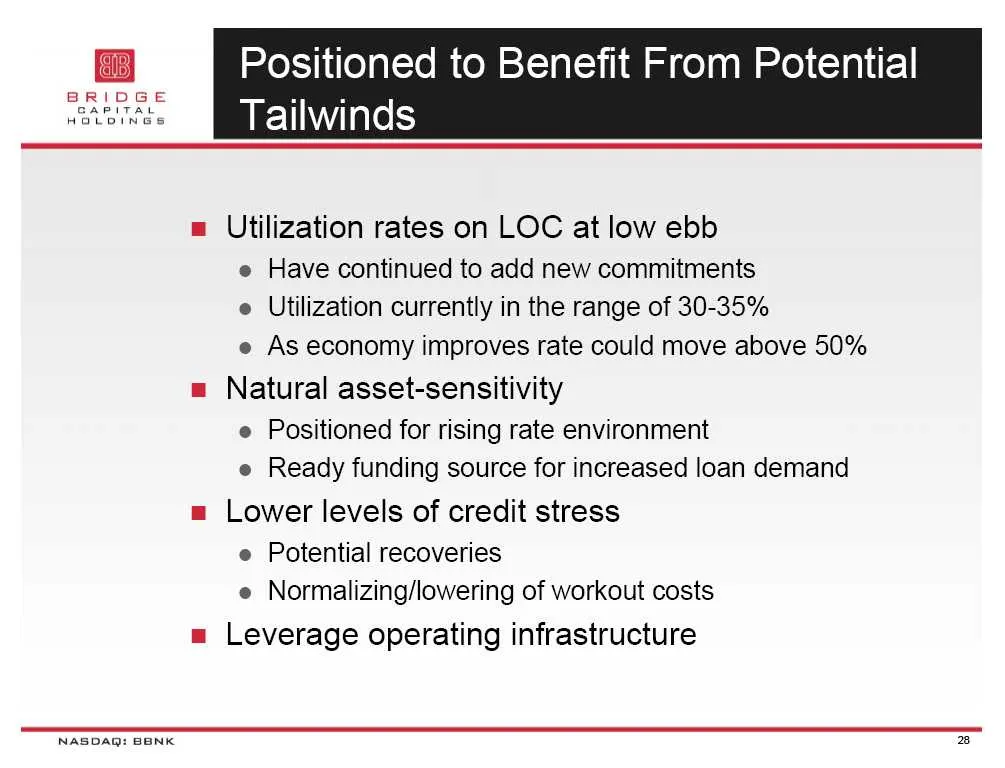
Positioned to Benefit From Potential Tailwinds = Utilization rates on LOC at low ebb e Have continued to add new commitments e Utilization currently in the range of 30-35% e As economy improves rate could move above 50% = Natural asset-sensitivity e Positioned for rising rate environment e Ready fun
Slide 29: Acquire new business relationships
= Acquire new business relationships = Fund primary DDA deposit balances = Issue appropriate new credit commitments NASDAQ: BENK 29
Slide 30: Investment Summary
fa Investment Summary = Improving fundamentals provide strong foundation for increasing profitability e Growing core deposit franchise e Increasing loan demand e Improved operating leverage e Expanding net interest margin = Improving credit quality with minimal exposure to CRE = Strong capital posit
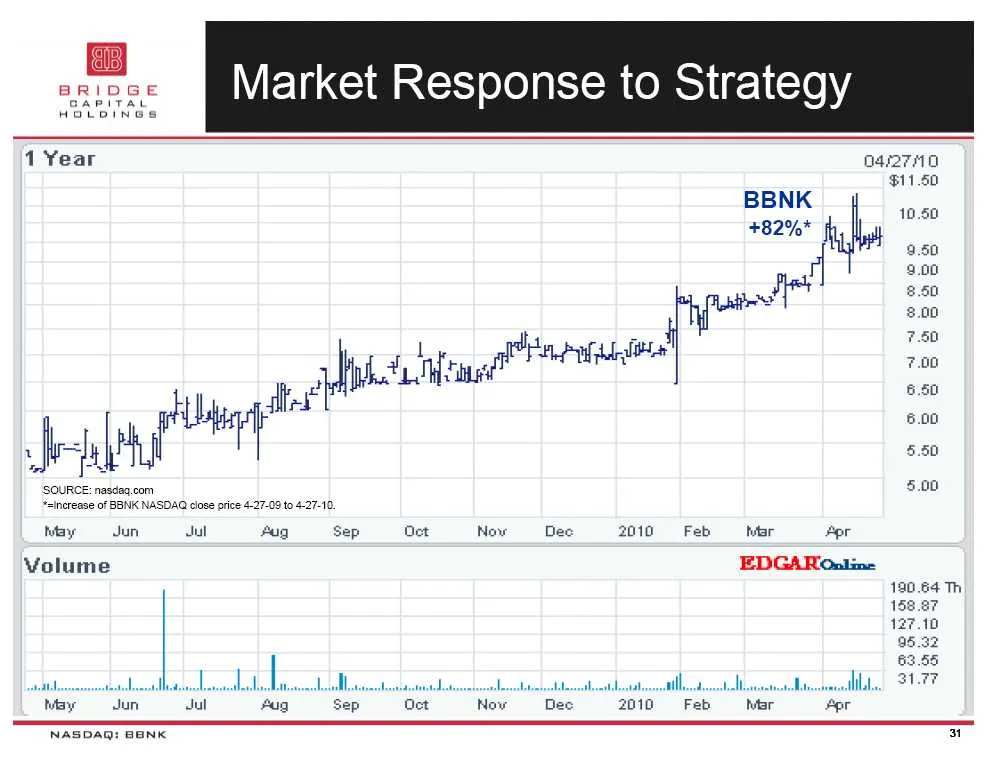
Slide 31: BBNK stock price performance
04270 $11.50 BENK 10.60 +82%* 9.50 9.00 AB 3.00 7.50 7.00 6.60 6.00 5.50 5.00 May = Jun ul Pug Sep Oct Now Dee 2010 Feb Mar fpr Volume EDGAROstine Nay Ju NASDAQ: BENK a
Slide 32: Thank You/Q&A
ra Thank You/Q&A PWelitel Foundation Stimulus} Packages Q im NASDAQ: BENK 32
Source: SEC EDGAR · 8-K filed Apr 29, 2010
More decks from Bridge Capital Holdings
 Merger or Acquisition (March 2015)11 slides · Mar 9, 2015
 Q4 2014 Earnings Presentation22 slides · Feb 4, 2015
 Q2 2014 Earnings Presentation23 slides · Jul 29, 2014
 Shareholder Meeting (May 2014)19 slides · May 28, 2014
 Q1 2014 Earnings Presentation23 slides · May 13, 2014
 Q4 2013 Earnings Presentation24 slides · Feb 5, 2014