Communityone Bancorp — FNB — America's Community Bankers Investor Conference 2005
49 slides from Communityone Bancorp's conference presentation, Nov 9, 2005
Slide 1: America's Community Bankers Investor Conference
America’s Community Bankers Investor Conference New York, NY • November 9-10, 2005 Exhibit 99.1
Slide 2: Forward-Looking Statements
Forward-Looking Statements FNB Corp. has made forward-looking statements in the accompanying presentation materials that are subject to risks and uncertainties. These statements are based on the beliefs and assumptions of the management of FNB Corp., and on the information available to management at
Slide 3: Overview
Overview
Slide 4: FNB Corp. Overview
Overview FNB Corp. Overview • Headquarters Asheboro, NC • Listing NASDAQ NM • Symbol FNBN • Numbers - Assets $930+ Million** - Shares Outstanding 5.626 Million - Insider Ownership 10.7% - Institutional Ownership 6.07% - Market Cap (October 27, 2005) $102 Million • Annual Cash Dividend $0.60 **Not in
Slide 5: Corporate Structure Overview
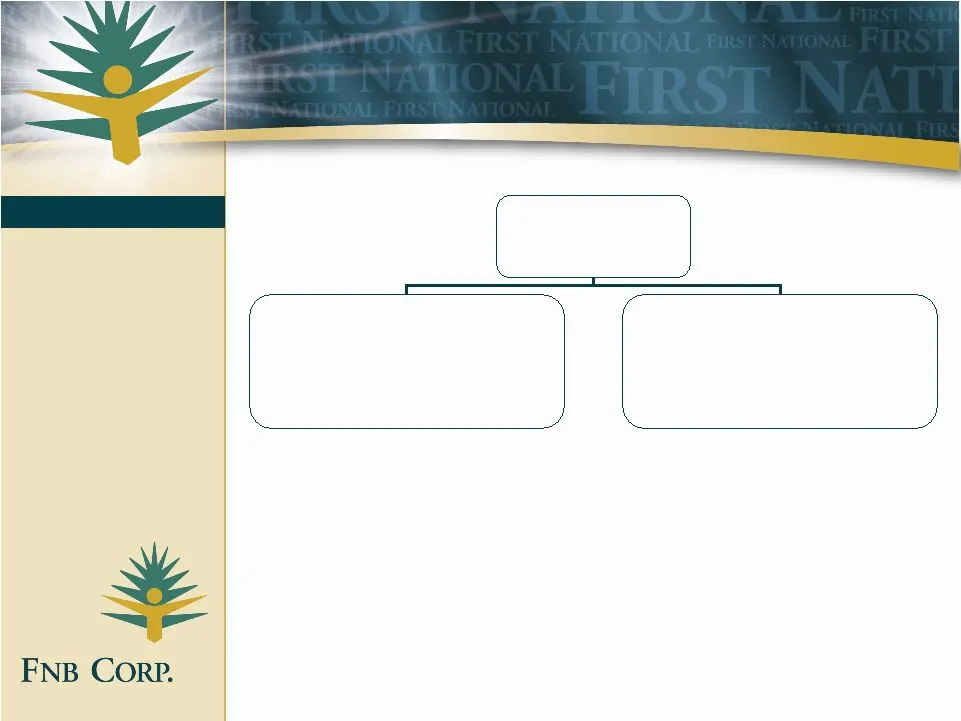
Corporate Structure Overview FNB Corp. (NC) Founded May 1985 First National Bank and Trust Company * Founded December 1907 Dover Mortgage Company Founded May 1986 Acquired by FNB April 2003 *Acquisitions: Richmond Savings Bank – April 2000 Rowan Bank – August 2002
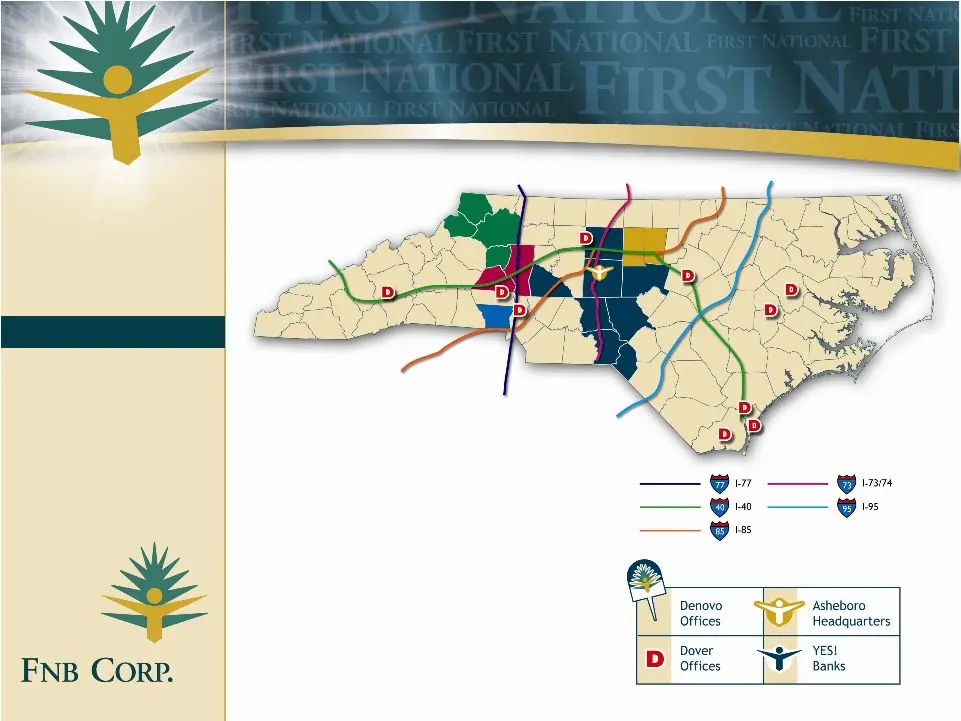
Slide 6: FNB Corp. offices map
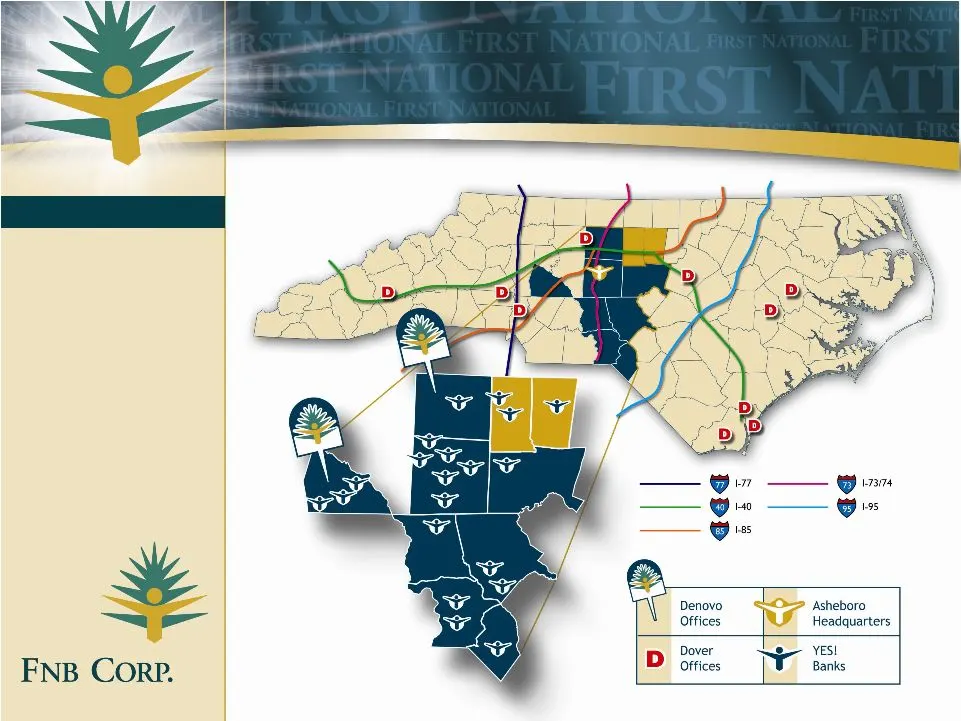
FNB Corp. Denovo Asheboro Offices Headquarters Dover YES! Offices Banks
Slide 7
Slide 8
Slide 9: Latest News Overview
Latest News Overview United Financial Acquisition: 11/4/2005 Assets: $ Million Loans: $ Million Deposits: $ Million FNB Corp. / United Financial Combined Assets: $ 1.080 Billion Loans: $ 790+ Million Deposits: $ 820+ Million
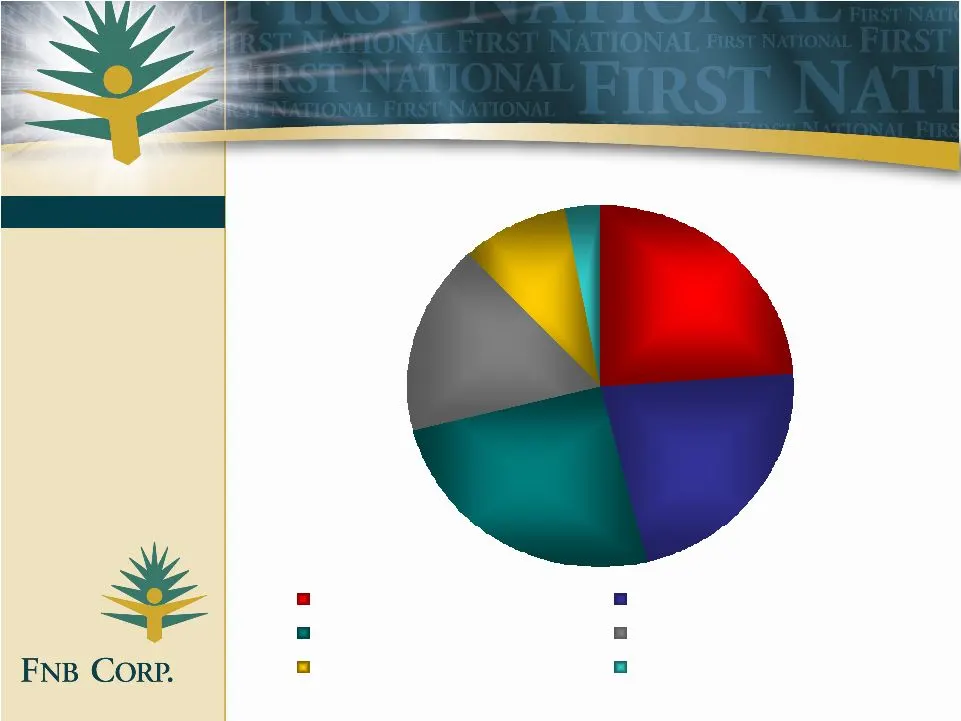
Slide 10: Major Loan Classifications
Major Loan Classifications Overview 24% 22% 25% 17% 9% 3% Commercial/Industrial Residential Real Estate Commercial Real Estate Real Estate Construction Home Equity Line Consumer
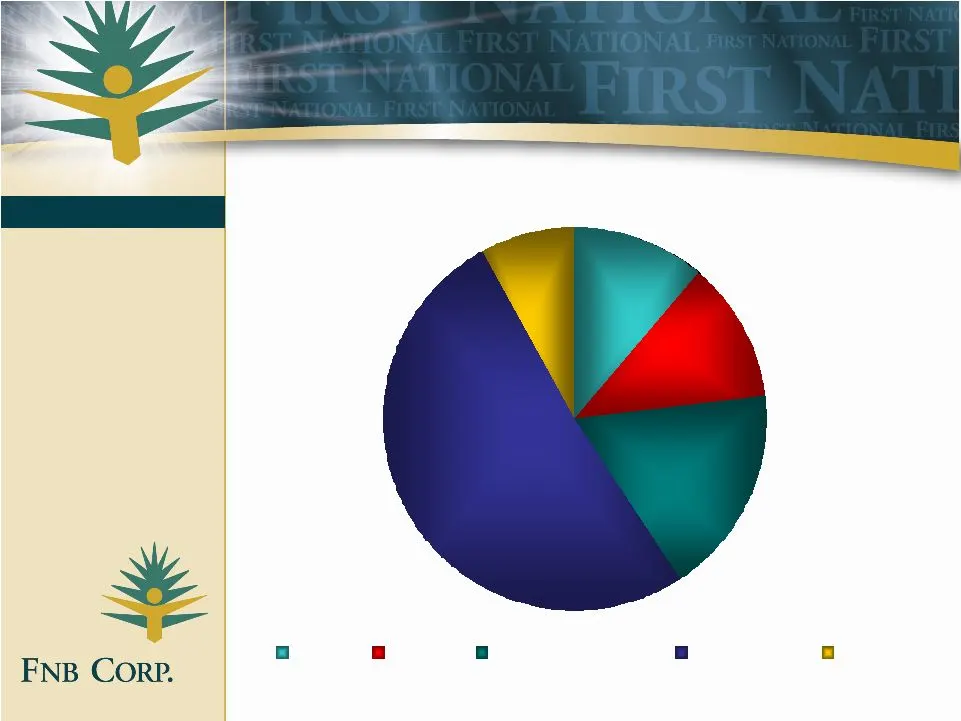
Slide 11: Major Funding Classifications
Major Funding Classifications Overview 8% 51% 12% 18% 11% DDA NOW MM,SAV,Repo CD / IRA FHLB
Slide 12: Competitive Advantages
Competitive Advantages Overview • Only community bank in North Carolina with local, full-service Wealth Management team. • Our business bankers have an average of 25 years of experience each. • We make mortgage loan decisions in less than 24 hours through our “First Reply” program. • Practice, pract
Slide 13: Operating Performance
Operating Performance
Slide 14: Asset Growth
Asset Growth Operating Performance 2001 2002 2003 2004 2005 (Millions) 11.89% 9/30/2005 unaudited
Slide 15: Loan Growth
Loan Growth Operating Performance 2001 2002 2003 2004 2005 15.93% 9/30/2005 unaudited (Millions)
Slide 16: Deposit Growth
Operating Performance Deposit Growth 2001 2002 2003 2004 2005 10.71% (Millions) 9/30/2005 unaudited
Slide 17: Household Growth
Operating Performance 12-01 to 12-04 Household Growth 77% Deposit HH 78% Total HH 46% Core 32% Core 59% Loan HH 37% Core
Slide 18: Net Income
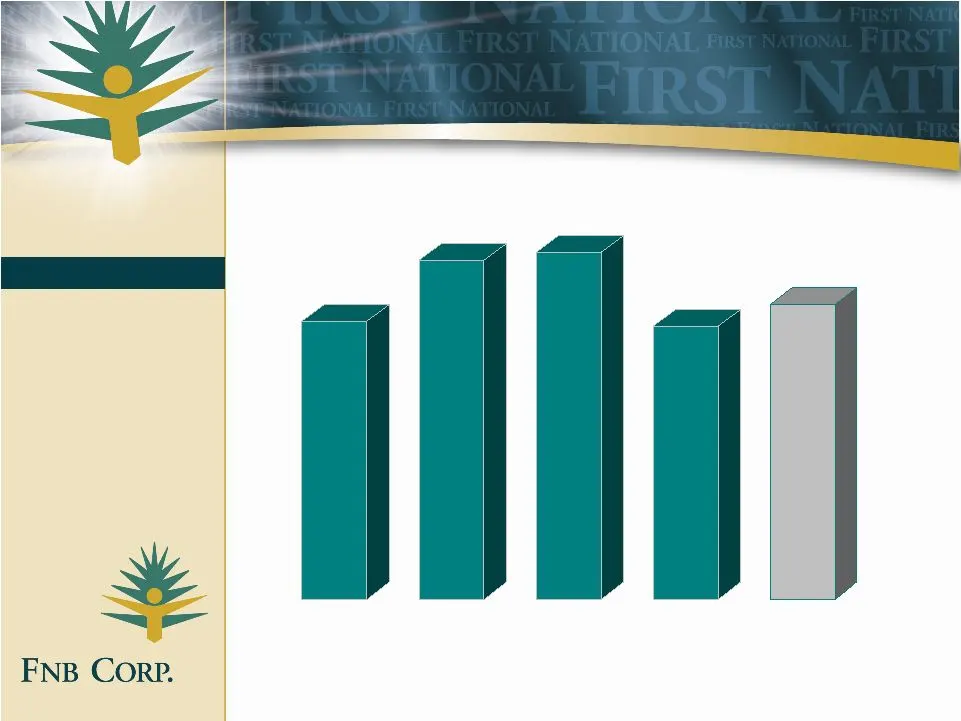
Operating Performance Net Income 6,728 8,200 8,400 6,598 7,137 2001 2002 2003 2004 2005 9/30/2005 unaudited
Slide 19: Earnings Per Share
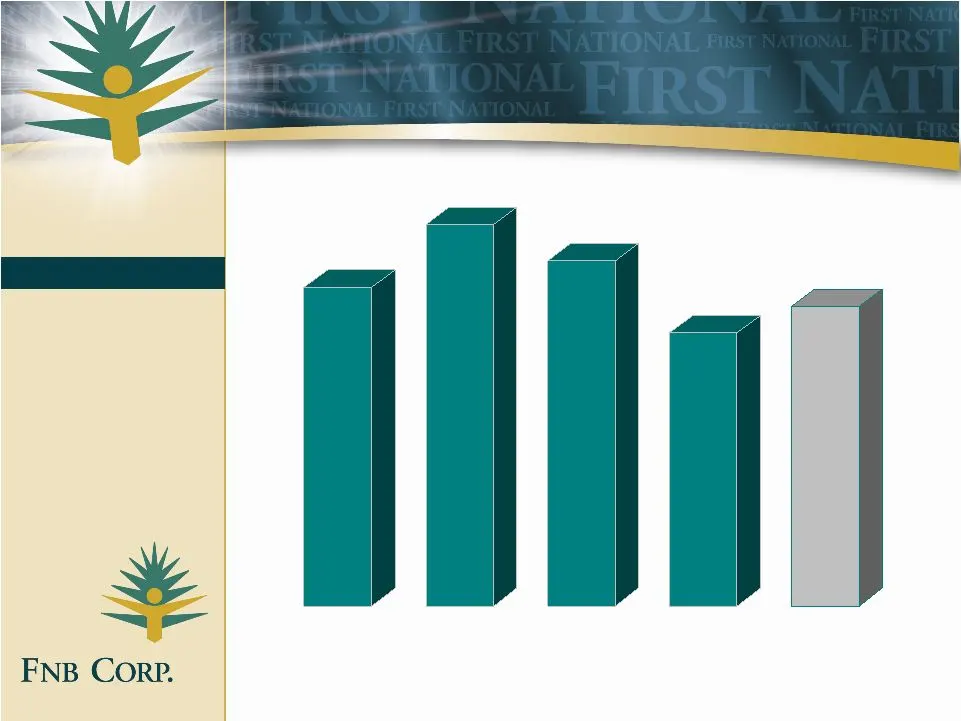
Operating Performance Earnings Per Share 1.32 1.58 1.43 1.13 1.24 2001 2002 2003 2004 2005 9/30/2005 unaudited
Slide 20: Return On Assets
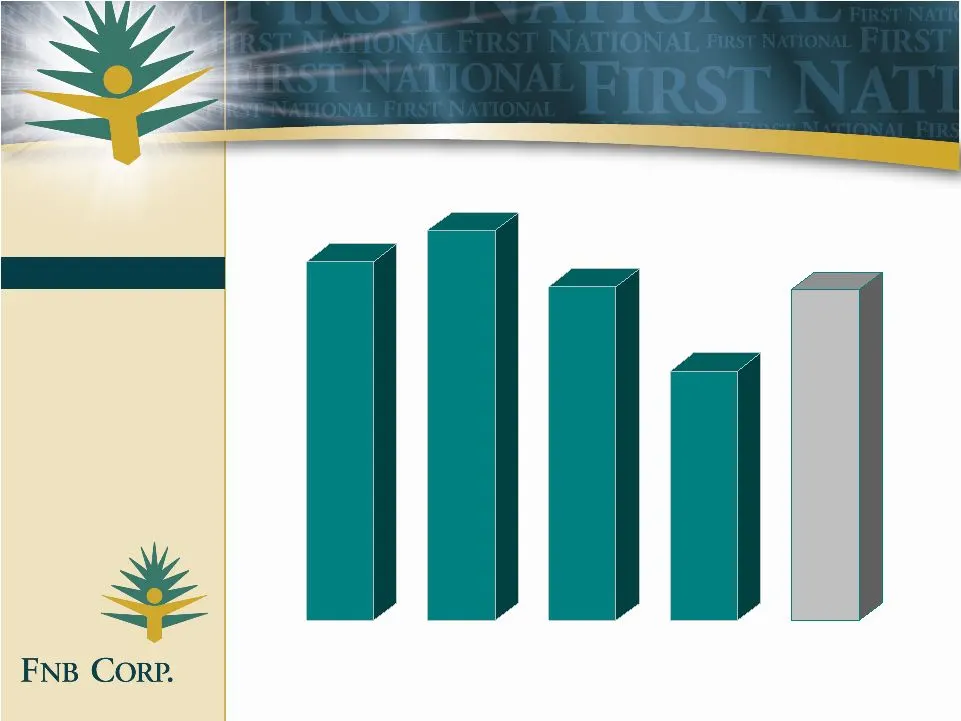
Operating Performance Return On Assets 1.15% 1.25% 1.07% 0.80% 1.06% 2001 2002 2003 2004 2005 9/30/2005 unaudited
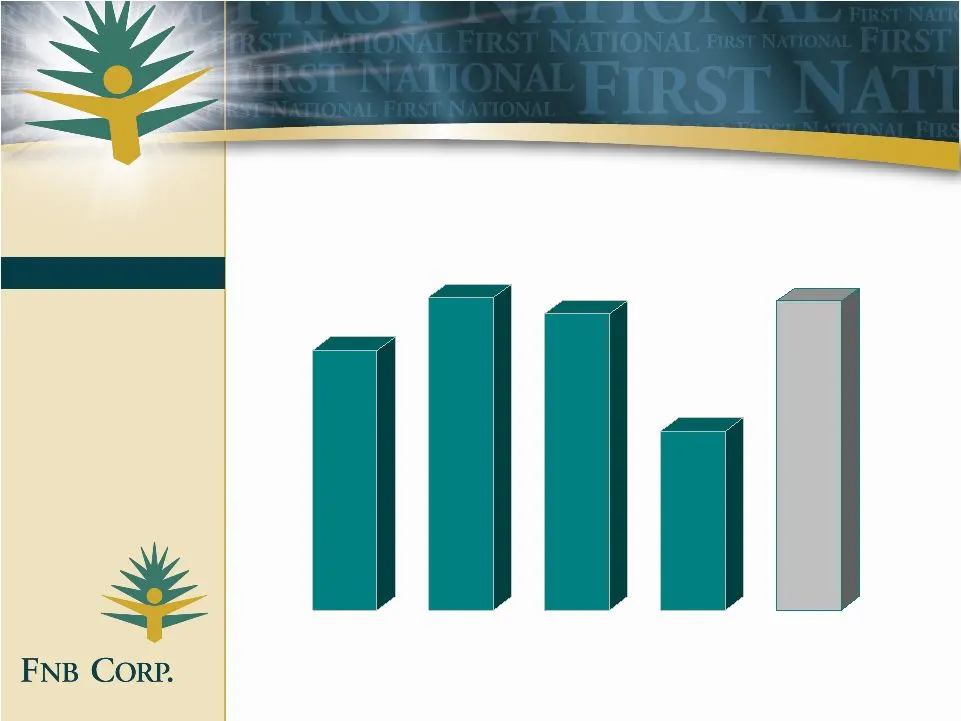
Slide 21: Return On Tangible Equity
Operating Performance Return On Tangible Equity 11.63% 13.99% 13.25% 8.00% 13.82% 2001 2002 2003 2004 2005 9/30/2005 unaudited
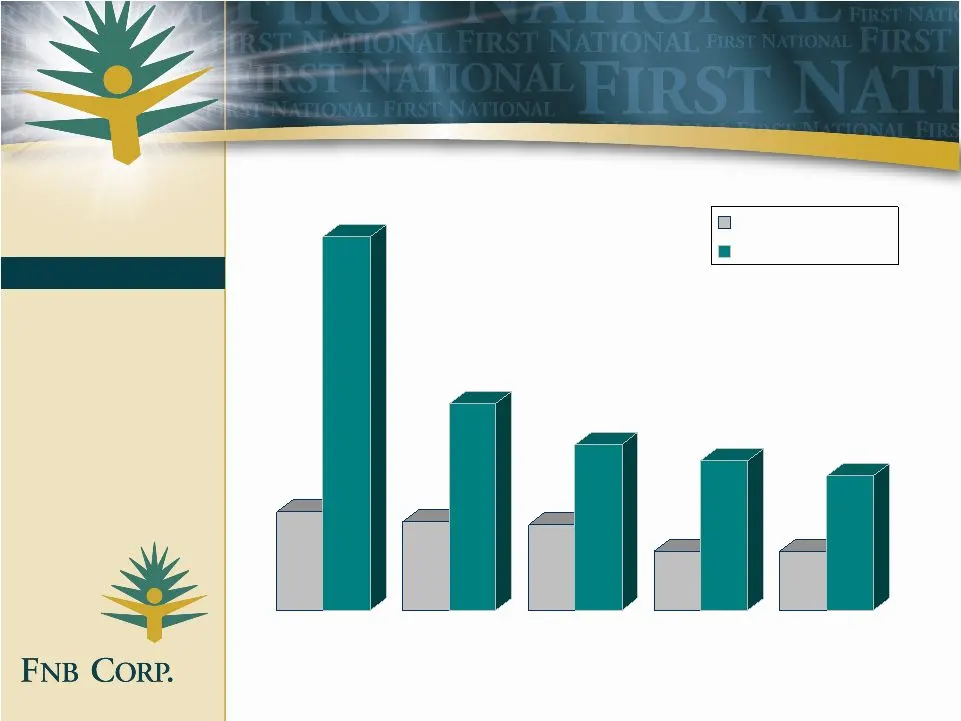
Slide 22: NPA's and Classified Loans
Operating Performance NPA's and Classified Loans 1.49% 5.66% 1.34% 3.14% 1.30% 2.51% 0.90% 2.27% 0.91% 2.05% 2001 2002 2003 2004 2005 NPA Classified Loans *Excludes loans held for sale 9/30/2005 unaudited
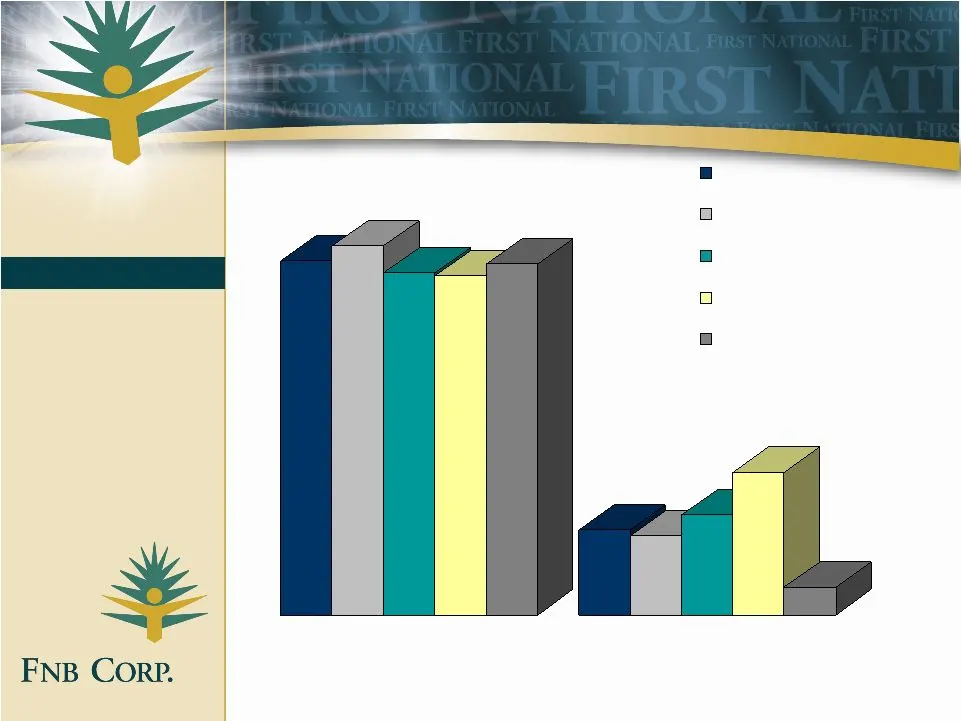
Slide 23: Loan Loss Reserve and Charge-Off Ratios
Operating Performance Loan Loss Reserve and Charge-Off Ratios 1.17% 1.22% 1.13% 1.12% 1.16% 0.28% 0.26% 0.33% 0.47% 0.09% 2001 2002 2003 2004 9/30/2005 unaudited, annualized Reserve*/ Gross Loan Net Charge Offs* *Excludes reserves for, and losses from, overdrafts (effective 2005 ONLY)
Slide 24: Franchise Value
Franchise Value
Slide 25: Franchise Value Strong Points
Franchise Value Strong Points Consistent Financial Performance Long Term Focus Growth Orientation Good Markets / Good State De Novo Offices Productive lines of business Selective Prudent Acquisitions “YES!” Branding Program
Slide 26: Dividend History
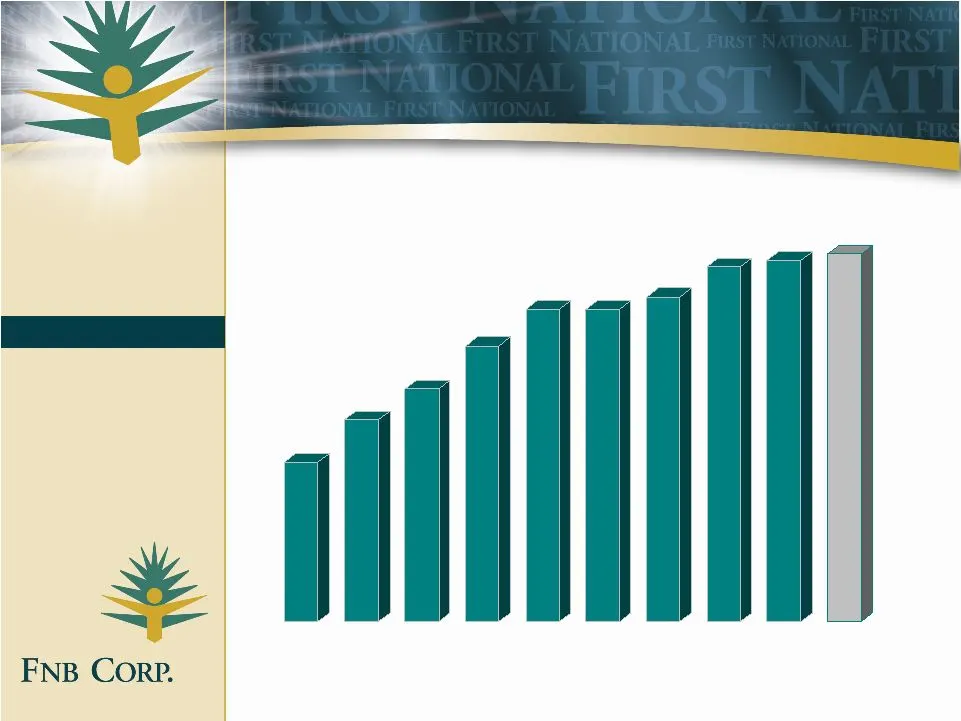
Dividend History Franchise Value 0.26 0.33 0.38 0.45 0.51 0.51 0.53 0.58 0.59 0.60
Slide 27: Growth - United Financial, Inc.
Franchise Growth Franchise Value Growth - United Financial, Inc. • A $150 Million Company headquartered in Graham, NC • Operating subsidiary - Alamance Bank - chartered September 1998. • Three full service banking offices along Interstate 40/85 corridor • Graham • Burlington • Hillsborough
Slide 28: Growth - Integrity Financial, Inc.
Growth Plans Franchise Value Growth - Integrity Financial, Inc. • A $668 Million Company headquartered in Hickory, NC • Operating subsidiaries: – Catawba Valley Bank, Hickory, NC – First Gaston Bank in Gastonia, NC – Integrity Securities, Inc. a full service brokerage office in Hickory, NC
Slide 29: Growth and Expansion
Growth and Expansion Franchise Value
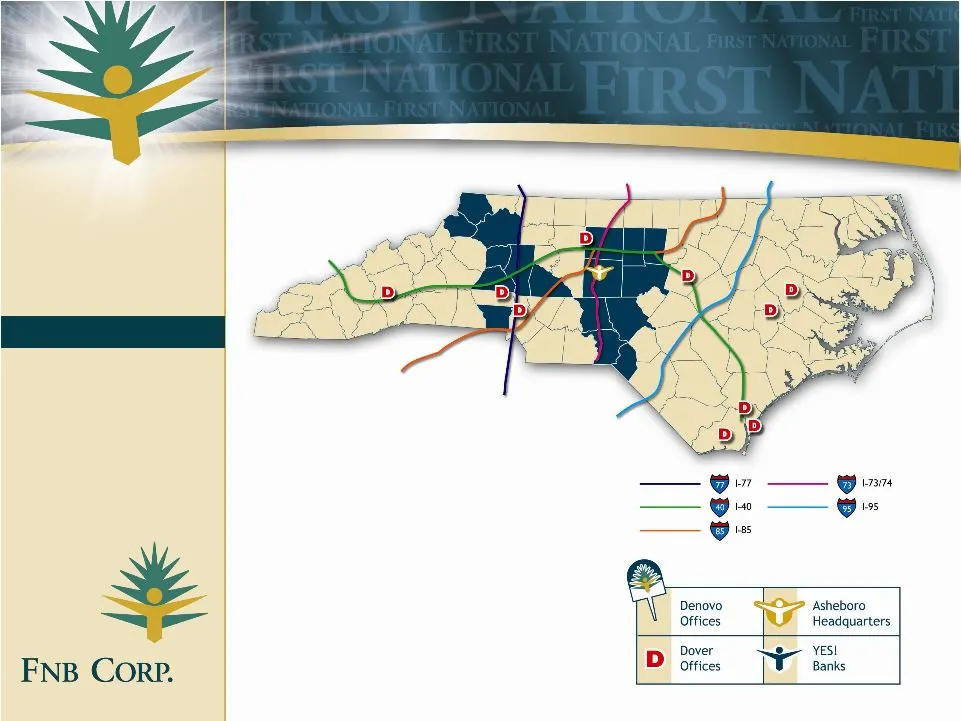
Slide 30: Franchise Growth: Pro-forma Footprint
Franchise Growth Franchise Value • Pro-forma Foot Print - From Central and Southern Piedmont and the Sandhills to the Foothills and Mountains of Western NC • Located in 17 growing counties • 43 banking offices in 31 communities • Strategically located along Interstates corridors of I-85, I-40, I-77,
Slide 31: Pro-forma Combined Company Franchise
Franchise Growth Franchise Value • Asset: $1.8 Billion • Loans: $1.3 Billion • Deposits: $1.3 Billion • Market Cap: $200 Million+ • Top 10 in North Carolina in Assets and Deposits FNB UNITED CORP. Pro-forma Combined Company Franchise
Slide 32: Pro-forma Franchise
Pro-forma Franchise Franchise Value
Slide 33: Franchise Growth
Franchise Growth Franchise Value • Partners bring attractive customer base • Merger adds scale and brings new product and service opportunities in broad, growing markets • Enhances shareholder value through new earnings opportunities
Slide 34: YES! Branding
YES! Branding Franchise Value First National is the YES! Bank. It is plainly stated in our Yes you can ® —Yes we can ® trademarks. It is reflected in the design of our logo and corporate mascot, Jack. And it is repeated in our customer service programs, company spirit campaigns and marketing message
Slide 35: Core Strategies
Core Strategies
Slide 36: Core Strategies
Core Strategies Core Strategies • Credit Quality • Core Deposit Emphasis • Growth Strategy • Increased Penetration of Current Markets • New Markets and Prudent Acquisitions • “Experience” Retail • “Yes” ® Branding – Yes you can® Yes we can® • Continue to Build Performance Culture
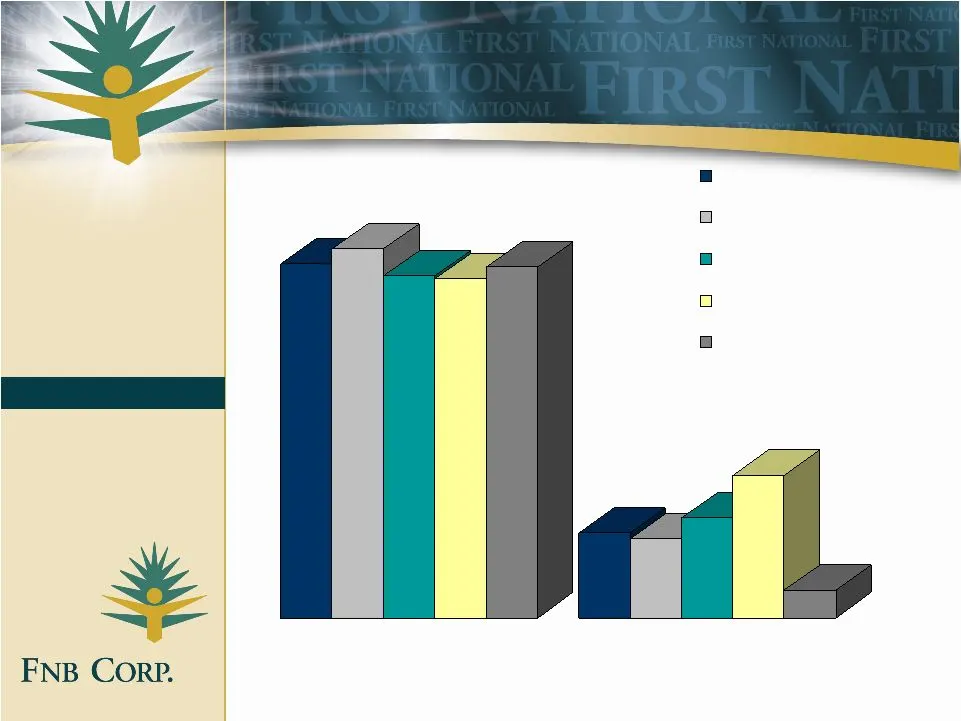
Slide 37: Loan Loss Reserve and Charge-Off Ratios
Loan Loss Reserve and Charge-Off Ratios Core Strategies 1.17% 1.22% 1.13% 1.12% 1.16% 0.28% 0.26% 0.33% 0.47% 0.09% 2001 2002 2003 2004 9/30/2005 unaudited, annualized Reserve*/ Gross Loan Net Charge Offs* *Excludes reserves for, and losses from, overdrafts (effective 2005 ONLY)
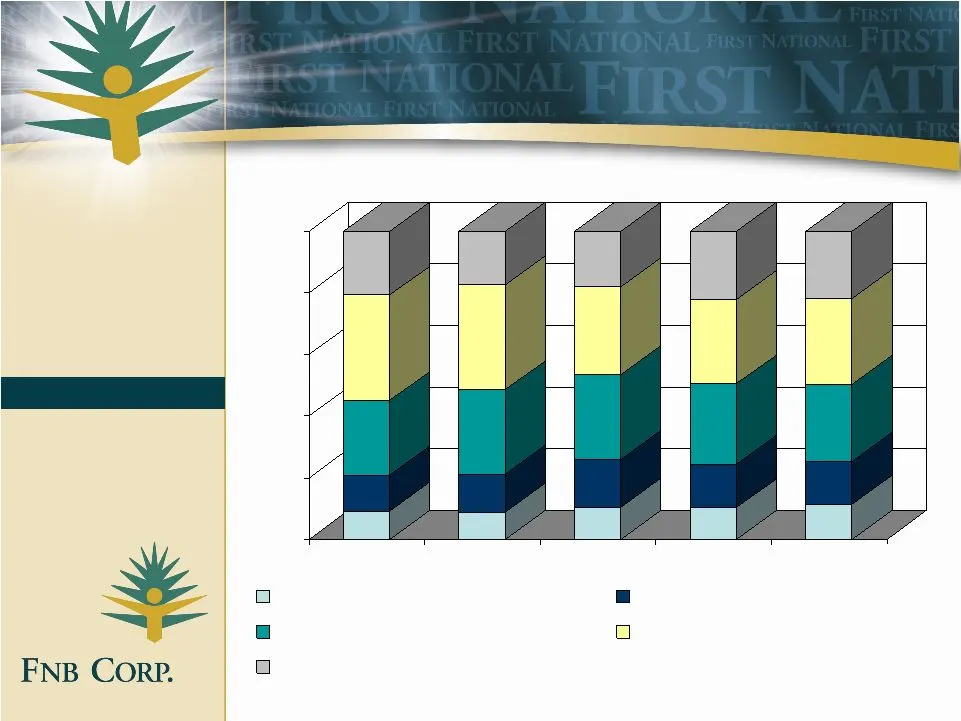
Slide 38: Core Deposit Growth
Core Strategies Core Deposit Growth 0% 20% 40% 60% 80% 100% 2001 2002 2003 2004 Non-interest bearing deposits Transaction accounts MMDA & savings accounts Retail time deposits Jumbo time deposits As of 9/30/2005
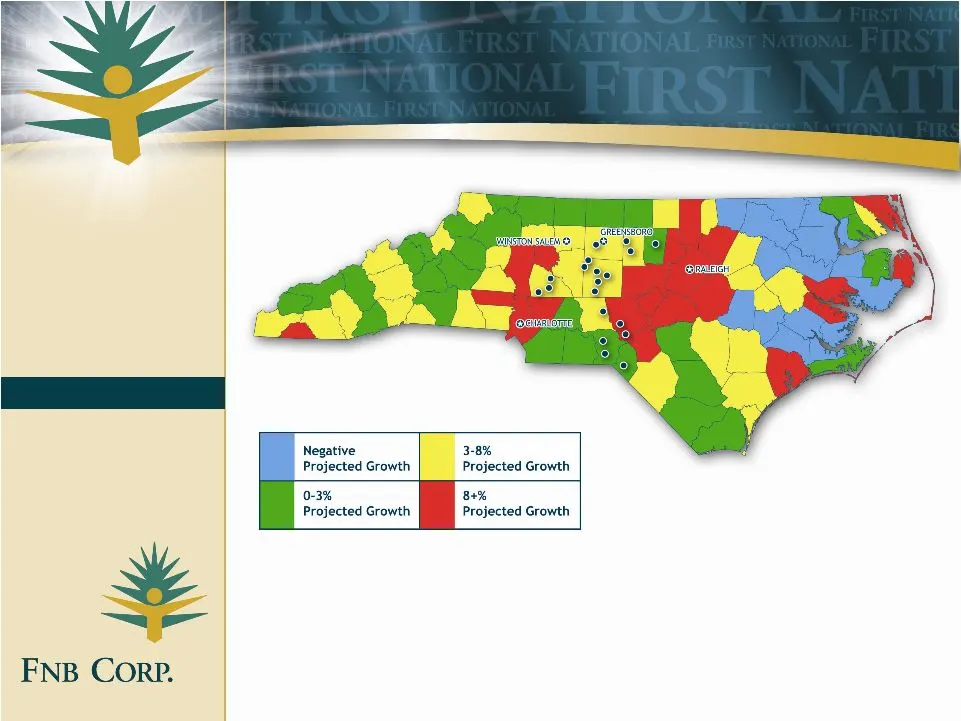
Slide 39: Projected Population Growth
Projected Population Growth Core Strategies
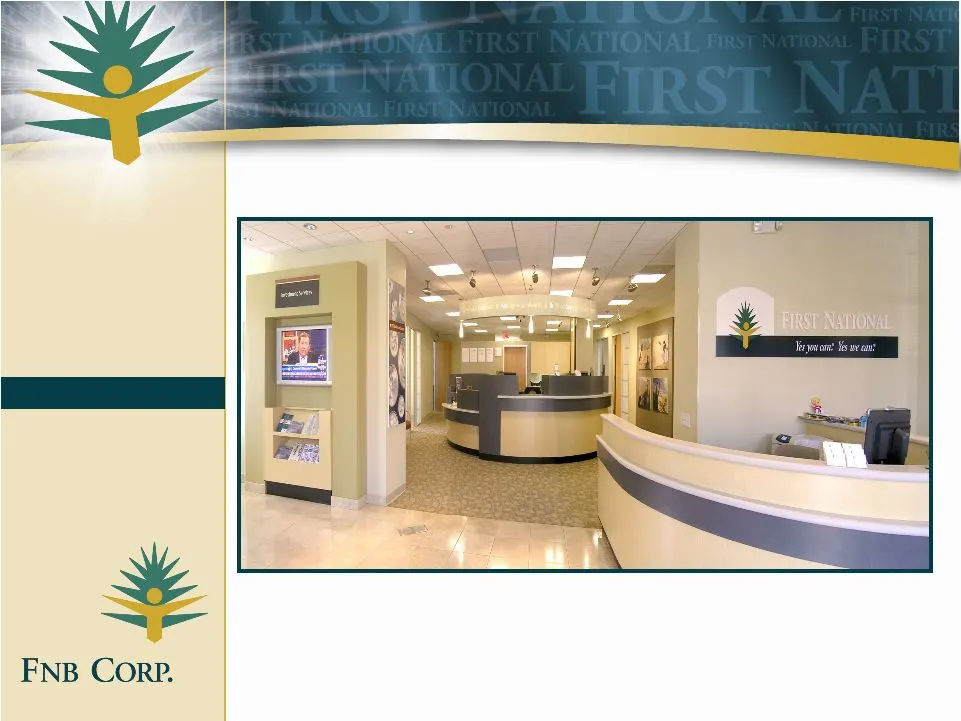
Slide 40: Experience Retail
Experience Retail Core Strategies
Slide 41: Customer Service
Customer Service Core Strategies
Slide 42: Performance Culture
Performance Culture Core Strategies Performance Compensation for STAKEHOLDERS™ • Maximize long-term value of organization • Team orientation - universal participation • Coaching and communication • Educational program
Slide 43: Fun and Friendly Yes! Bank
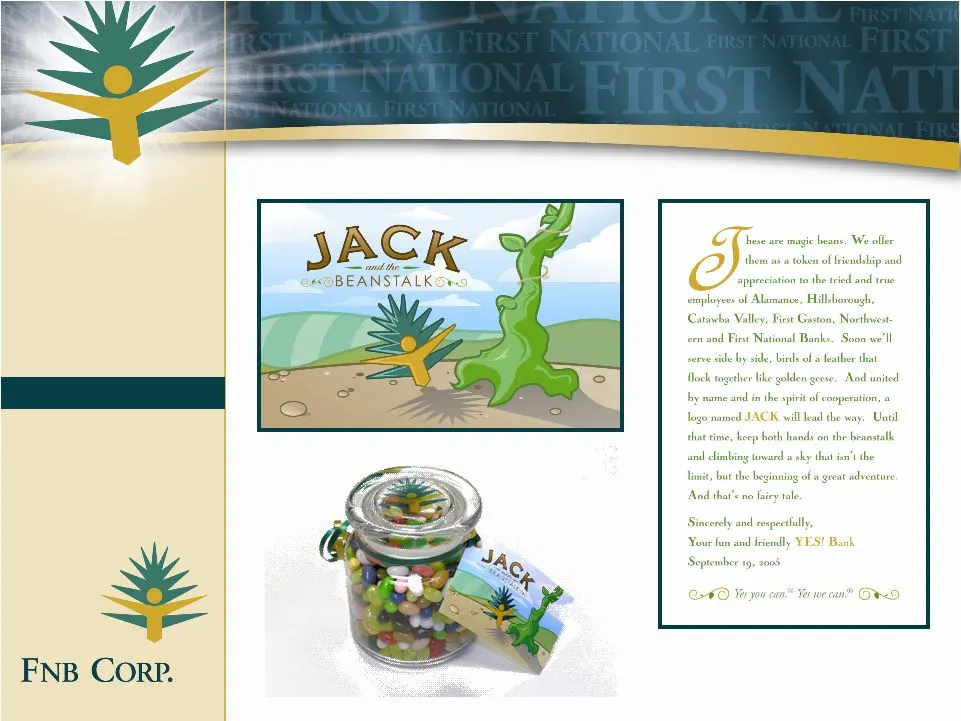
Fun and Friendly Yes! Bank Core Strategies
Slide 44: Performance: Team Focus
Core Strategies Performance: Team Focus
Slide 45: Investor Opportunity
Investor Opportunity
Slide 46: Investor Opportunity
Investor Opportunity Investor Opportunity • Good Markets / Good State • Personnel, Capital, Products and Systems Required for Sustainable, Profitable Growth • Good Franchise Elements • Current Market Valuation
Slide 47: Investor Opportunity: Price / Book vs Peers
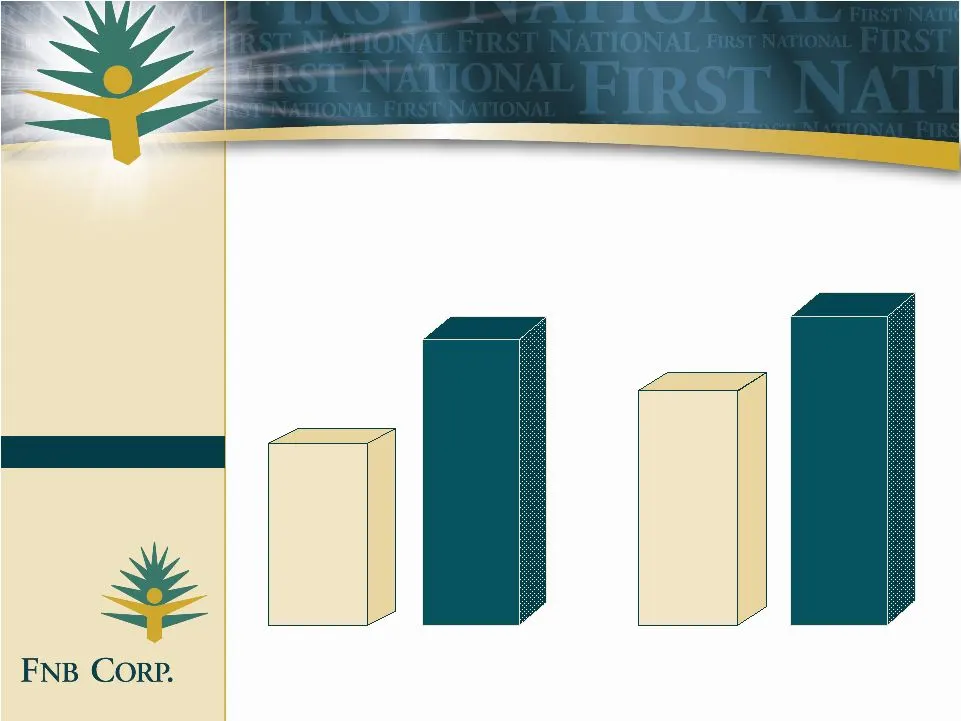
Investor Opportunity Investor Opportunity 146.96 224.50 118.93 189.48 Price / Book (%) Price / Tang.Book (%) FNB Corp . FNB Corp. *SNL Data SE Publicly traded banks between $500 million and $2 billion as of 10/27/2005 Peer Group* Peer Group*
Slide 48: Investor Opportunity: Dividend Yield and P/E vs Peers
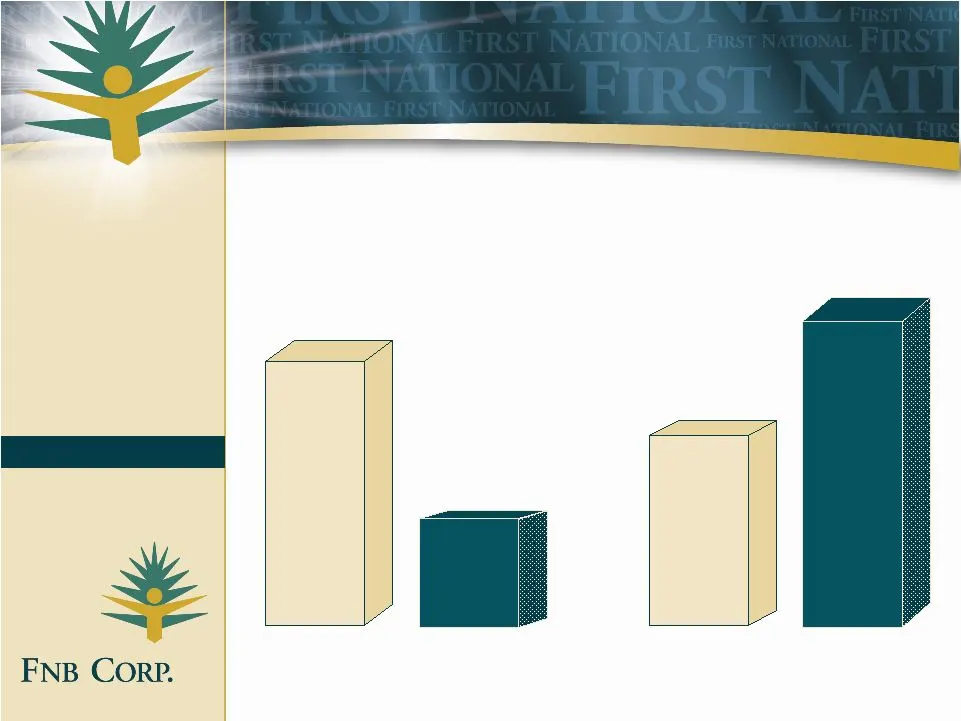
Investor Opportunity Investor Opportunity 11.18 16.90 3.29 1.58 Current Dividend Yield (%) Price / LTM EPS (X) FNB Corp . FNB Corp. *SNL Data SE Publicly traded banks between $500 million and $2 billion as of 10/27/2005 Peer Group* Peer Group*
Slide 49: America's Community Bankers Investor Conference
America’s Community Bankers Investor Conference New York, NY • November 9-10, 2005
Source: SEC EDGAR · 8-K filed Nov 9, 2005
More decks from Communityone Bancorp
 Merger or Acquisition (February 2016)25 slides · Feb 8, 2016
 Q4 2015 Earnings Presentation22 slides · Jan 29, 2016
 Q3 2015 Earnings Presentation17 slides · Oct 30, 2015
 Q2 2015 Earnings Presentation17 slides · Jul 30, 2015
 Q1 2015 Earnings Presentation17 slides · Apr 30, 2015
 Investor Presentation (March 2015)18 slides · Mar 5, 2015