Placer Sierra Bancshares
Placer Sierra Bancshares — Investor Presentation (January 2005)
27 slides from Placer Sierra Bancshares's investor presentation, Jan 28, 2005
Slide 1: Investor Presentation February 2005
Exhibit 99.1 Investor Presentation February 2005
Slide 2: Forward Looking Information
Forward Looking Information This presentation may include forward-looking statements. These forward-looking statements include comments with respect to our objectives and strategies and the results of our operations and our business. However, by their nature, these forward-looking statements involve
Slide 3: Stock Profile
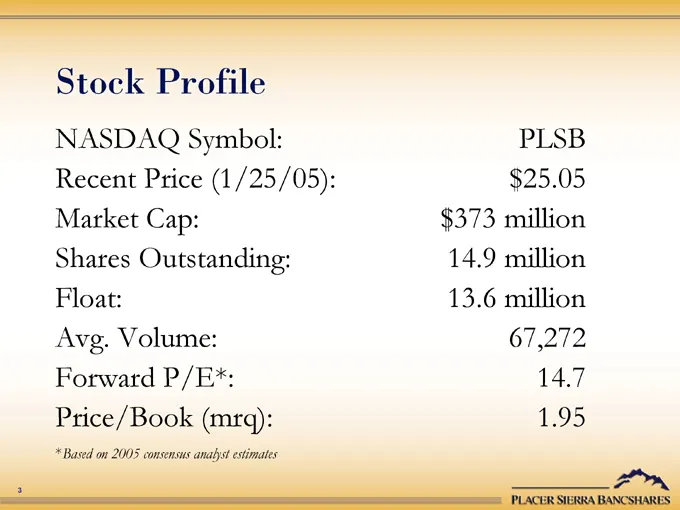
Stock Profile NASDAQ Symbol: PLSB Recent Price (1/25/05): $25.05 Market Cap: $373 million Shares Outstanding: 14.9 million Float: 13.6 million Avg. Volume: 67,272 Forward P/E*: 14.7 Price/Book (mrq): 1.95 *Based on 2005 consensus analyst estimates
Slide 4: Investment Considerations
Investment Considerations Exceptional opportunities in two of California’s high growth markets Experienced management team that has extensive knowledge of both Northern and Southern California banking markets Asset sensitive balance sheet well positioned for a rising interest rate environment Attrac
Slide 5: Company Overview
Fm PLACER SIERRA BANCSHARES Company Overview
Slide 6: Placer Sierra Bancshares
Placer Sierra Bancshares At $1.8 billion, Placer Sierra is the largest community bank headquartered in Central California Placer Sierra operates in the greater Sacramento and Southern California high-growth market areas Experienced M&A and commercial bank management team in both Northern and Souther
Slide 7: Located in High Growth Areas
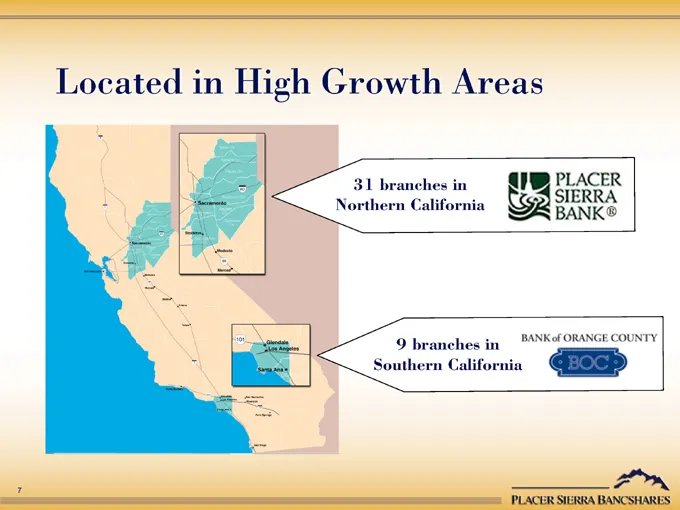
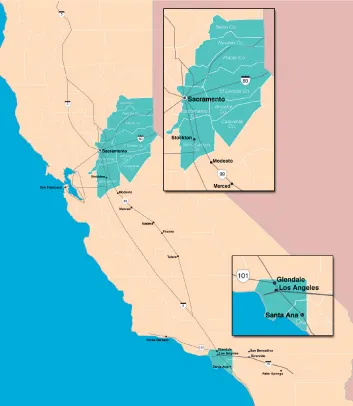
Located in High Growth Areas 31 branches in Northern California 9 branches in Southern California
Slide 8: Strong Trends in Key Metrics
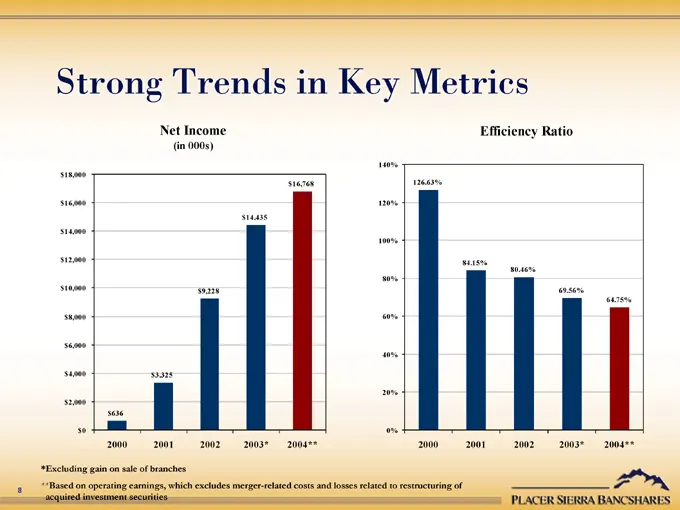
Strong Trends in Key Metrics Net Income (in 000s) $18,000 $16,000 $14,000 $12,000 $10,000 $8,000 $6,000 $4,000 $2,000 $0 $636 $3,325 $9,228 $14,435 $16,768 2000 2001 2002 2003* 2004** Efficiency Ratio 140% 120% 100% 80% 60% 40% 20% 0% 126.63% 84.15% 80.46% 69.56% 64.75% 2001 2002 2003* 2004** *Exclu
Slide 9: Strong Trends in Key Metrics
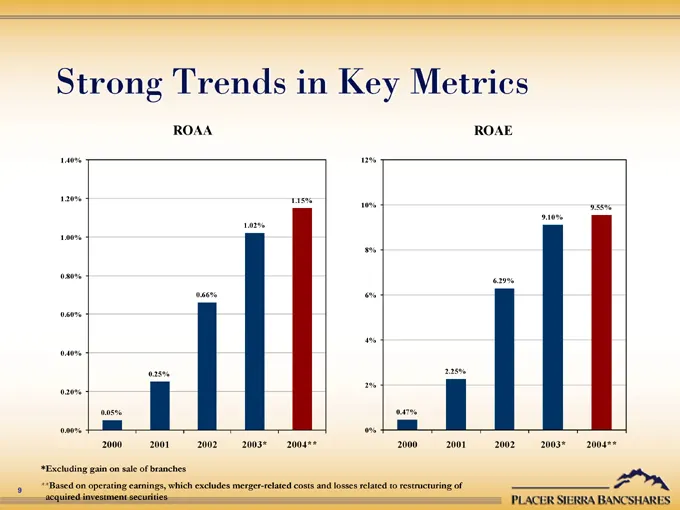
Strong Trends in Key Metrics ROAA 1.40% 1.20% 1.00% 0.80% 0.60% 0.40% 0.20% 0.00% 0.05% 0.25% 0.66% 1.02% 1.15% 2000 2001 2002 2003* 2004** ROAE 12% 10% 8% 6% 4% 2% 0% 0.47% 2.25% 6.29% 9.10% 9.55% 2000 2001 2002 2003* 2004** *Excluding gain on sale of branches **Based on operating earnings, which e
Slide 10: Consistently Strong Growth
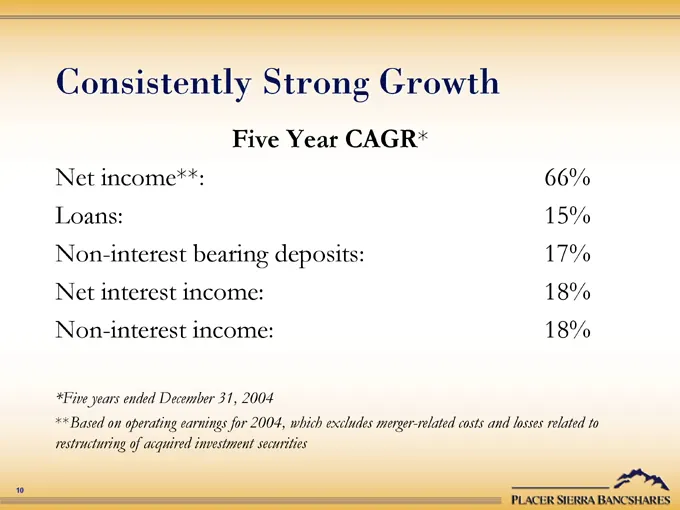
Consistently Strong Growth Five Year CAGR* Net income**: 66% Loans: 15% Non-interest bearing deposits: 17% Net interest income: 18% Non-interest income: 18% *Five years ended December 31, 2004 **Based on operating earnings for 2004, which excludes merger-related costs and losses related to restructu
Slide 11: Attractive Markets: Northern California
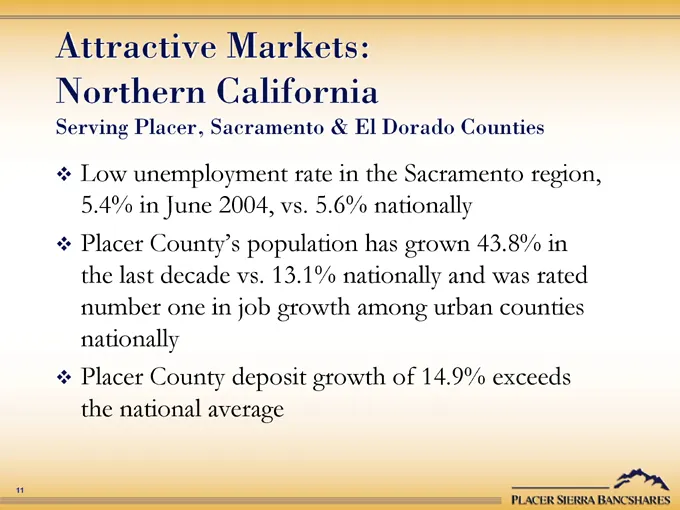
Attractive Markets: Northern California Serving Placer, Sacramento & El Dorado Counties Low unemployment rate in the Sacramento region, 5.4% in June 2004, vs. 5.6% nationally Placer County’s population has grown 43.8% in the last decade vs. 13.1% nationally and was rated number one in job growth amo
Slide 12: Attractive Markets: Southern California
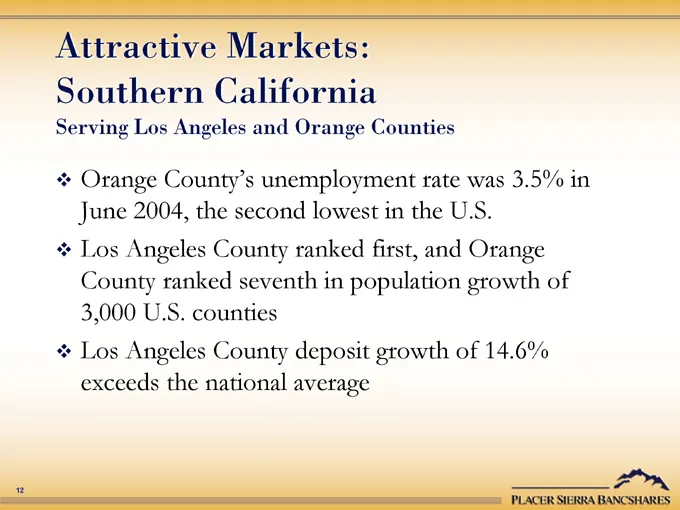
Attractive Markets: Southern California Serving Los Angeles and Orange Counties Orange County’s unemployment rate was 3.5% in June 2004, the second lowest in the U.S. Los Angeles County ranked first, and Orange County ranked seventh in population growth of 3,000 U.S. counties Los Angeles County depo
Slide 13: Operating and Growth Strategies
Operating and Growth Strategies Capitalize on growth opportunities in both our northern and southern California markets Expand through strategically placed new branches in Northern California Acquire one or more retail banking franchises in Southern California to complement Bank of Orange County’s w
Slide 14: Operating and Growth Strategies
Operating and Growth Strategies Use our size to give us a competitive advantage Secured loan lending limit was $58.7 million as of Dec. 31, 2004 Unsecured loan lending limit was $35.2 million as of Dec. 31, 2004 Continue to leverage our integrated, customer-centered sales and service culture Big ban
Slide 15: Financial Performance
Fm PLACER SIERRA BANCSHARES Financial Performance
Slide 16: 2004 Financial Highlights
2004 Financial Highlights Temporary excess liquidity negatively impacted EPS in second half of 2004 by approximately $0.06 per share Operating EPS increased 8.4% Organic loan growth of 14.0% Organic deposit growth of 13.5% Operating ROAA increased to 1.15% from 1.02% Operating ROAE increased to 9.55
Slide 17: Q4 2004 Financial Highlights
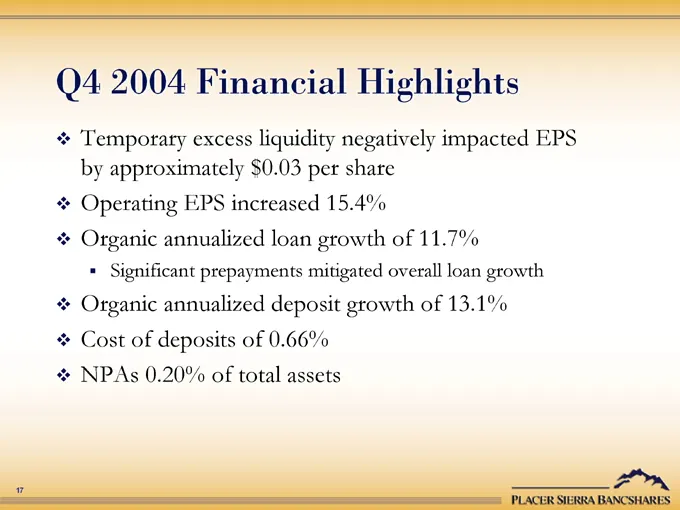
Q4 2004 Financial Highlights Temporary excess liquidity negatively impacted EPS by approximately $0.03 per share Operating EPS increased 15.4% Organic annualized loan growth of 11.7% Significant prepayments mitigated overall loan growth Organic annualized deposit growth of 13.1% Cost of deposits of
Slide 18: Loan Portfolio Composition
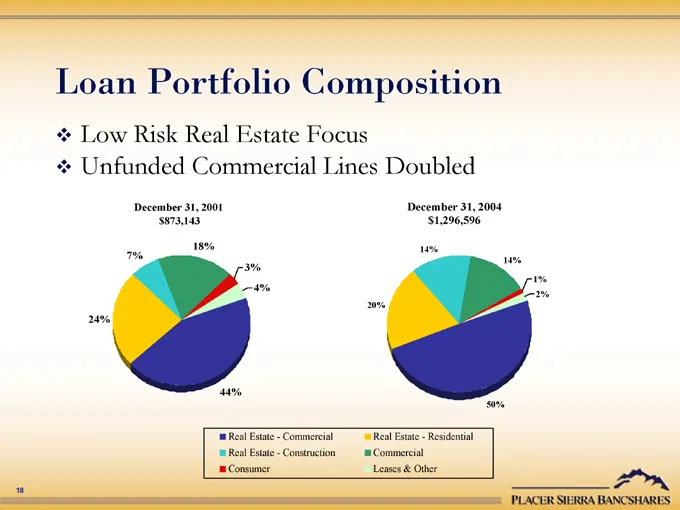
Loan Portfolio Composition Low Risk Real Estate Focus Unfunded Commercial Lines Doubled December 31, 2001 $873,143 24% 7% 18% 3% 4% 44% December 31, 2004 $1,296,596 20% 14% 14% 1% 2% 50% Real Estate—Commercial Real Estate—Construction Consumer Real Estate—Residential Commercial Leases & Other
Slide 19: Deposit Composition
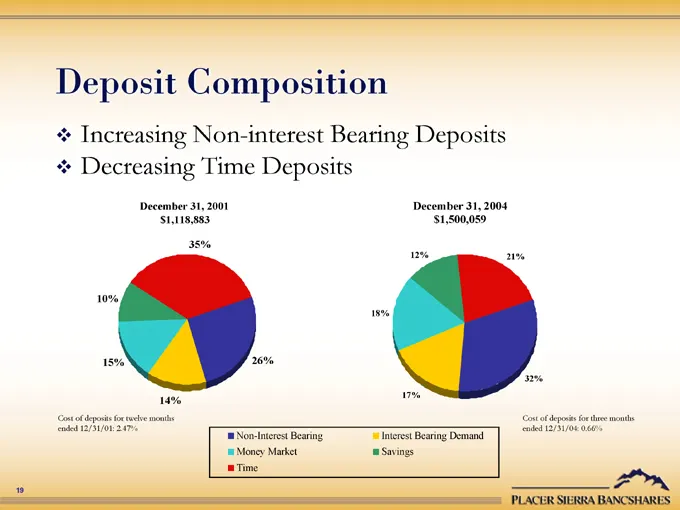
Deposit Composition Increasing Non-interest Bearing Deposits Decreasing Time Deposits December 31, 2001 $1,118,883 35% 10% 15% 14% 26% Cost of deposits for twelve months ended 12/31/01: 2.47% December 31, 2004 $1,500,059 12% 18% 17% 32% 21% Cost of deposits for three months ended 12/31/04: 0.66% Non
Slide 20: Core Deposit Growth
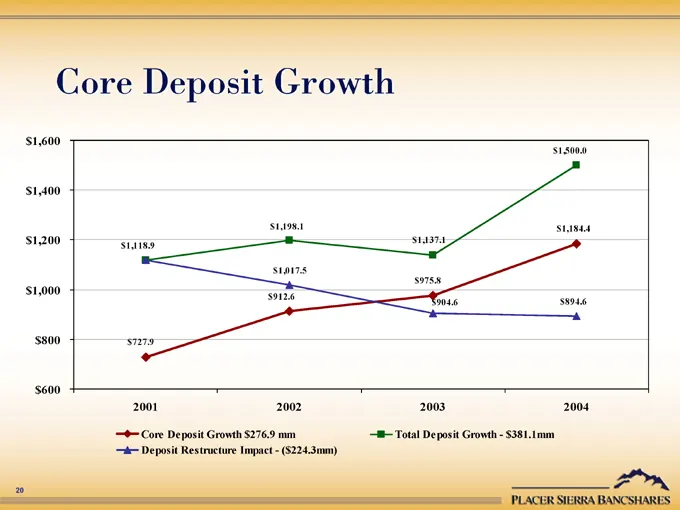
Core Deposit Growth $1,600 $1,400 $1,200 $1,000 $800 $600 $1,118.9 $1,198.1 $1,137.1 $1,500.0 $727.9 $1,017.5 $912.6 $975.8 $904.6 $1,184.4 $894.6 2001 2002 2003 2004 Core Deposit Growth $276.9 mm Deposit Restructure Impact—($224.3mm) Total Deposit Growth—$381.1mm
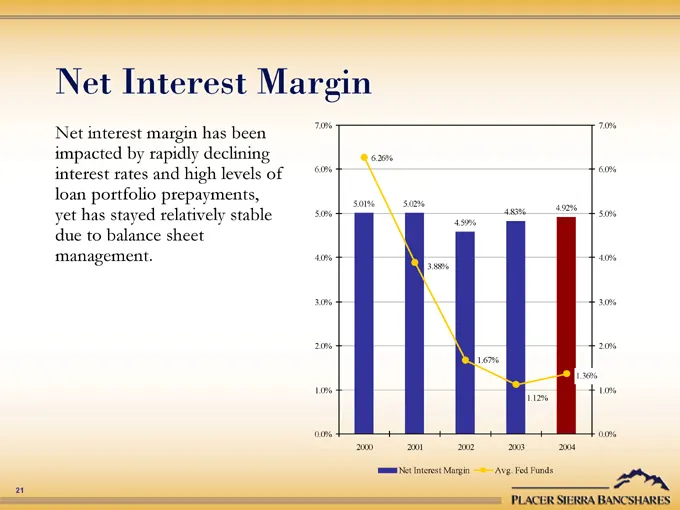
Slide 21: Net Interest Margin
Net Interest Margin Net interest margin has been impacted by rapidly declining interest rates and high levels of loan portfolio prepayments, yet has stayed relatively stable due to balance sheet management. 7.0% 6.0% 5.0% 4.0% 3.0% 2.0% 1.0% 0.0% 5.01% 6.26% 5.02% 3.88% 4.59% 1.67% 4.83% 1.12% 4.92%
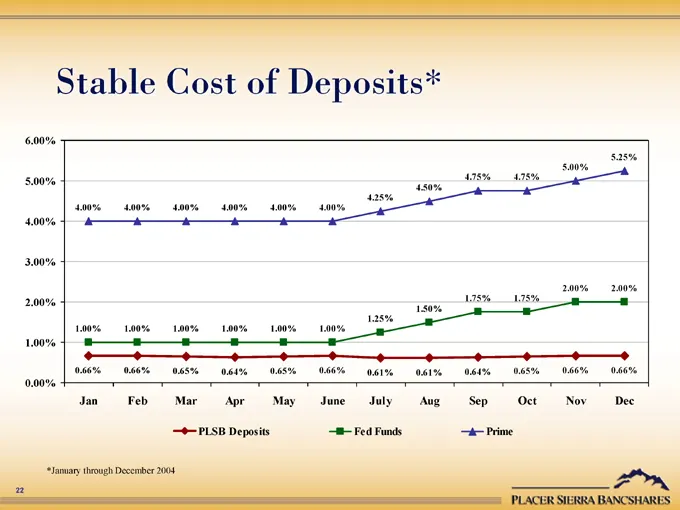
Slide 22: Stable Cost of Deposits
Stable Cost of Deposits* 6.00% 5.00% 4.00% 3.00% 2.00% 1.00% 0.00% 4.00% 4.00% 4.00% 4.00% 4.00% 4.00% 4.25% 4.50% 4.75% 4.75% 5.00% 5.25% 1.00% 1.00% 1.00% 1.00% 1.00% 1.00% 1.25% 1.50% 1.75% 1.75% 2.00% 2.00% 0.66% 0.66% 0.65% 0.64% 0.65% 0.66% 0.61% 0.61% 0.64% 0.65% 0.66% 0.66% Jan Feb Mar Apr M
Slide 23: Catalysts for Strong Future Performance
Catalysts for Strong Future Performance Attractive markets driving balance sheet growth High performance sales culture being adopted at Bank of Orange County and Bank of Lodi Combination of revenue growth and reduction in redundant overhead at Bank of Orange County and Bank of Lodi will drive effici
Slide 24: 2005 Expectations
2005 Expectations Q1 EPS of $0.35 - $0.37 Funded full year loan growth of 11%-12% Loan production expected to be significantly higher CRE loan production being sold to generate near-term income to support expansion in Fresno and Southern California Full year deposit growth of 14%-15% Continued high
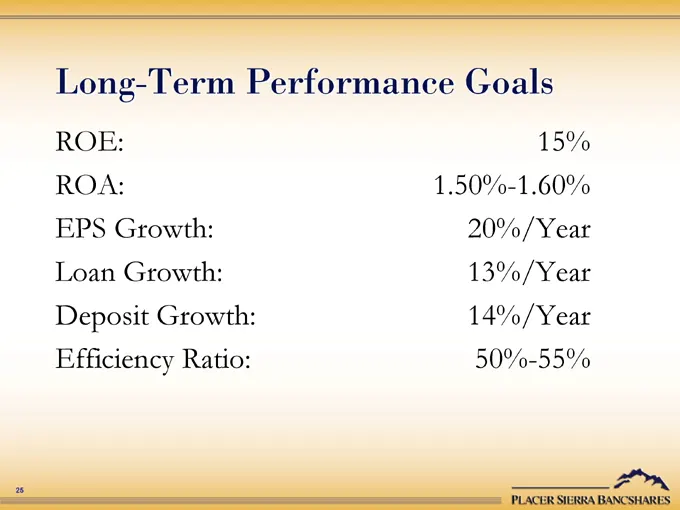
Slide 25: Long-Term Performance Goals
Long-Term Performance Goals ROE: 15% ROA: 1.50%-1.60% EPS Growth: 20%/Year Loan Growth: 13%/Year Deposit Growth: 14%/Year Efficiency Ratio: 50%-55%
Slide 26: Investment Profile February 2005
Investor Presentation February 2005 INVESTMENT PROFILE FEBRUARY 2005
Slide 27: Placer Sierra Bancshares serves small and medium sized businesses
Placer Sierra Bancshares serves small and medium sized businesses, as well as the consumer market. By offering its customers the resources of a large financial institution, with the resourcefulness and superior customer service of a community bank, Placer Sierra has built a successful niche in relat
Source: SEC EDGAR · 8-K filed Jan 28, 2005
More decks from Placer Sierra Bancshares
 Investor Presentation (November 2006)23 slides · Nov 6, 2006
 Shareholder Meeting (May 2006)10 slides · May 31, 2006
 Southwest Community Bancorp — Merger or Acquisition (May 2006)10 slides · May 31, 2006
 Southwest Community Bancorp — Merger or Acquisition (February 2006)13 slides · Feb 16, 2006
 Investor Presentation (July 2005)20 slides · Jul 25, 2005
 Investor Presentation (May 2005)29 slides · May 19, 2005