AMAG Pharmaceuticals — J.P. Morgan Healthcare Conference 2012
25 slides from AMAG Pharmaceuticals's conference presentation, Jan 9, 2012
Slide 1: AMAG Pharmaceuticals J.P. Morgan Healthcare Conference January 2012
AMAG Pharmaceuticals 1 J.P. Morgan Healthcare Conference January 2012
Slide 2: Forward Looking Statements
Forward Looking Statements This presentation contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 and other federal securities laws. Any statements contained herein which do not describe historical facts, including but not limited to, stateme
Slide 3: AMAG Overview
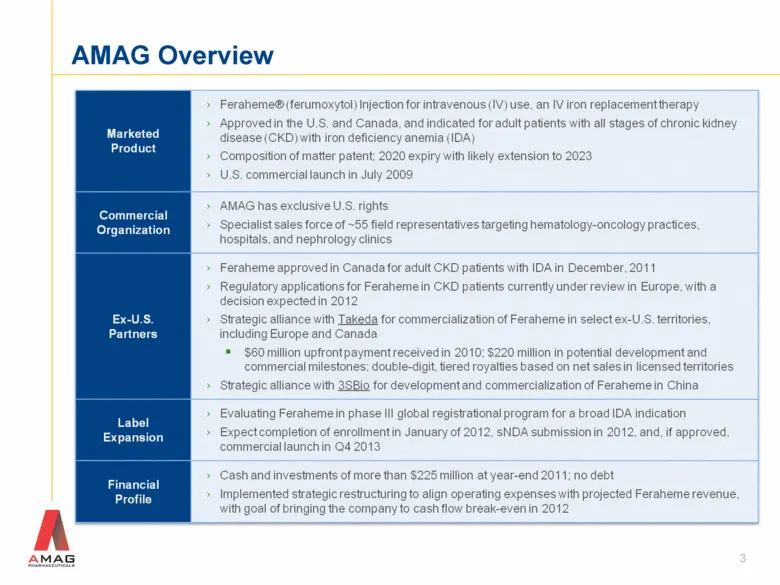
AMAG Overview Marketed Product›Feraheme® (ferumoxytol) Injection for intravenous (IV) use, an IV iron replacement therapy Approved in the U.S. and Canada, and indicated for adult patients with all stages of chronic kidney disease (CKD) with iron deficiency anemia (IDA) Composition of matter patent;
Slide 4: Strong Business Fundamentals
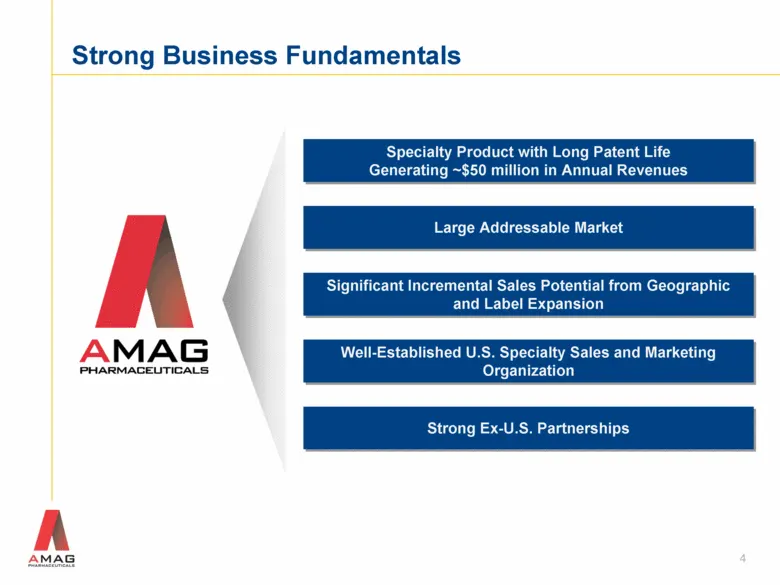
Strong Business Fundamentals 4 Specialty Product with Long Patent Life Generating ~$50 million in Annual Revenues Significant Incremental Sales Potential from Geographic and Label Expansion Large Addressable Market Strong Ex-U.S. Partnerships Well-Established U.S. Specialty Sales and Marketing Organ
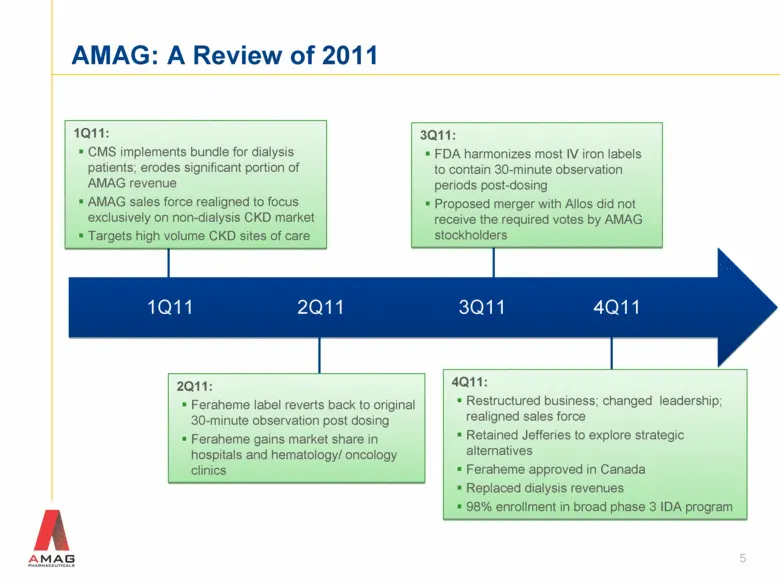
Slide 5: AMAG: A Review of 2011
3Q11: FDA harmonizes most IV iron labels to contain 30-minute observation periods post-dosing Proposed merger with Allos did not receive the required votes by AMAG stockholders 1Q11: CMS implements bundle for dialysis patients; erodes significant portion of AMAG revenue AMAG sales force realigned to
Slide 6: Market Opportunity & Commercial Progress
Market Opportunity & Commercial Progress 6
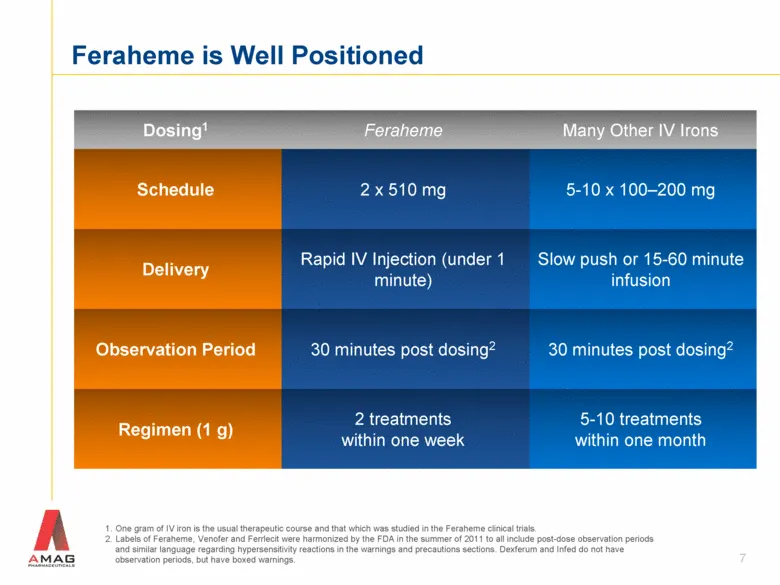
Slide 7: Feraheme is Well Positioned
Dosing1 Feraheme Many Other IV Irons Schedule 2 x 510 mg 5-10 x 100–200 mg Delivery Rapid IV Injection (under 1 minute) Slow push or 15-60 minute infusion Observation Period 30 minutes post dosing2 30 minutes post dosing2 Regimen (1 g) 2 treatments within one week 5-10 treatments within one month On
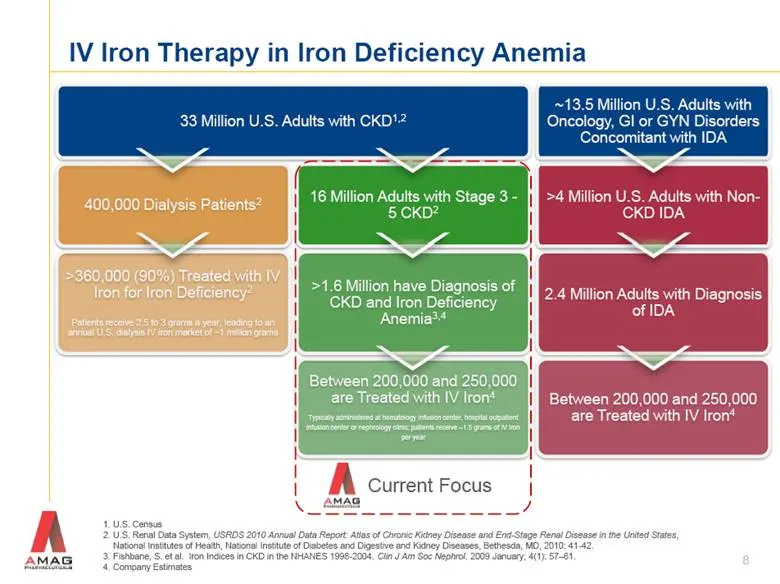
Slide 8: 2.4 Million Adults with Diagnosis of IDA
2.4 Million Adults with Diagnosis of IDA Between 200,000 and 250,000 are Treated with IV Iron4 U.S. Census U.S. Renal Data System, USRDS 2010 Annual Data Report: Atlas of Chronic Kidney Disease and End-Stage Renal Disease in the United States, National Institutes of Health, National Institute of Dia
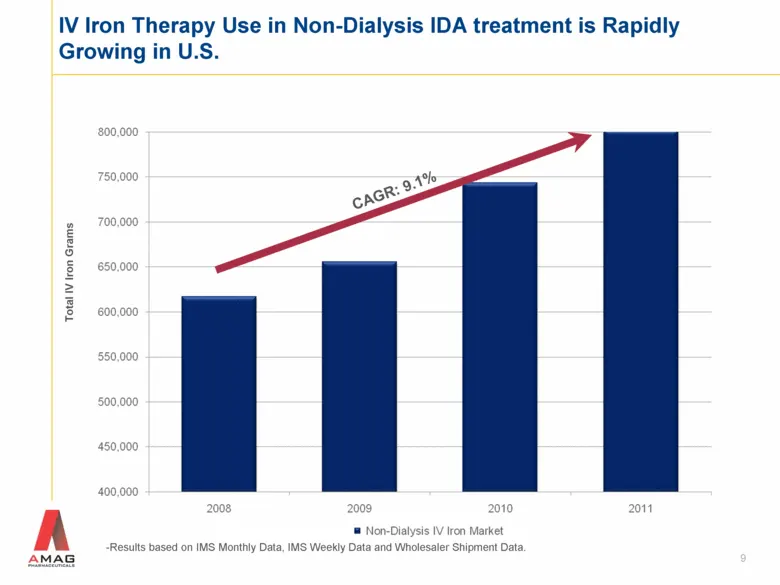
Slide 9: IV Iron Therapy Use in Non-Dialysis Rapidly Growing in U.S.
9 IV Iron Therapy Use in Non-Dialysis IDA treatment is Rapidly Growing in U.S. -Results based on IMS Monthly Data, IMS Weekly Data and Wholesaler Shipment Data. Total IV Iron Grams CAGR: 9.1%
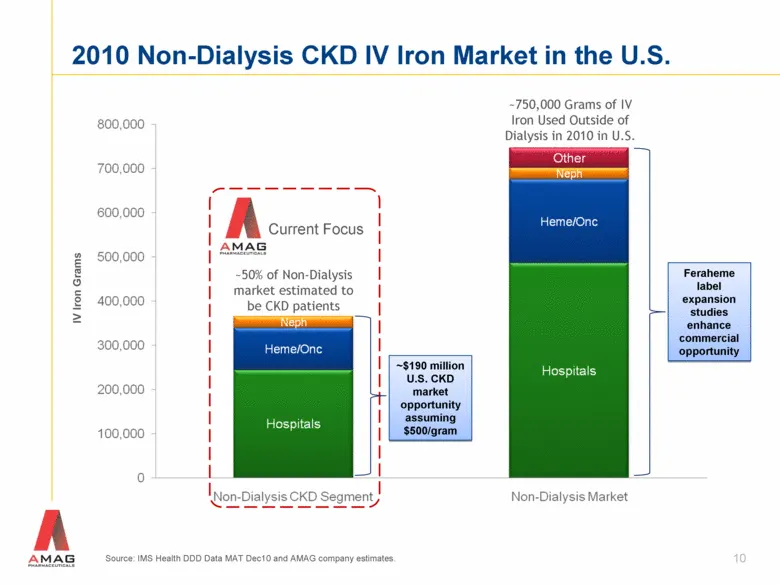
Slide 10: 2010 Non-Dialysis CKD IV Iron Market in the U.S.
Source: IMS Health DDD Data MAT Dec10 and AMAG company estimates. ~750,000 Grams of IV Iron Used Outside of Dialysis in 2010 in U.S. IV Iron Grams ~50% of Non-Dialysis market estimated to be CKD patients 2010 Non-Dialysis CKD IV Iron Market in the U.S. Current Focus 10 ~$190 million U.S. CKD market
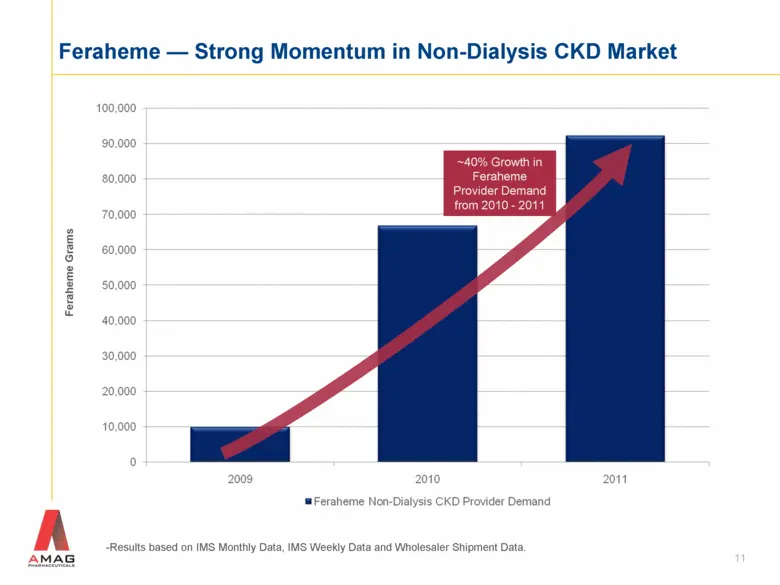
Slide 11: Feraheme — Strong Momentum in Non-Dialysis CKD Market
11 Feraheme — Strong Momentum in Non-Dialysis CKD Market -Results based on IMS Monthly Data, IMS Weekly Data and Wholesaler Shipment Data. Feraheme Grams ~40% Growth in Feraheme Provider Demand from 2010 - 2011
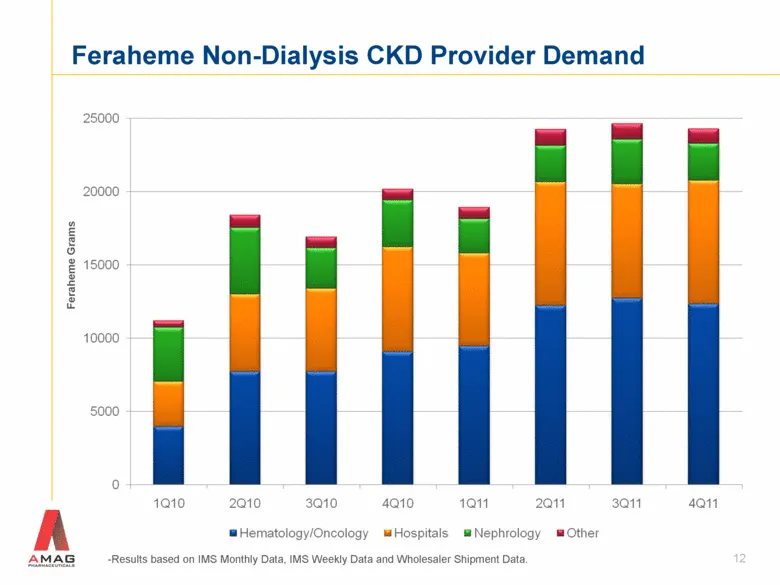
Slide 12: Feraheme Non-Dialysis CKD Provider Demand
Feraheme Non-Dialysis CKD Provider Demand 12 Feraheme Grams -Results based on IMS Monthly Data, IMS Weekly Data and Wholesaler Shipment Data.
Slide 13: 2012 Key Commercial Imperatives
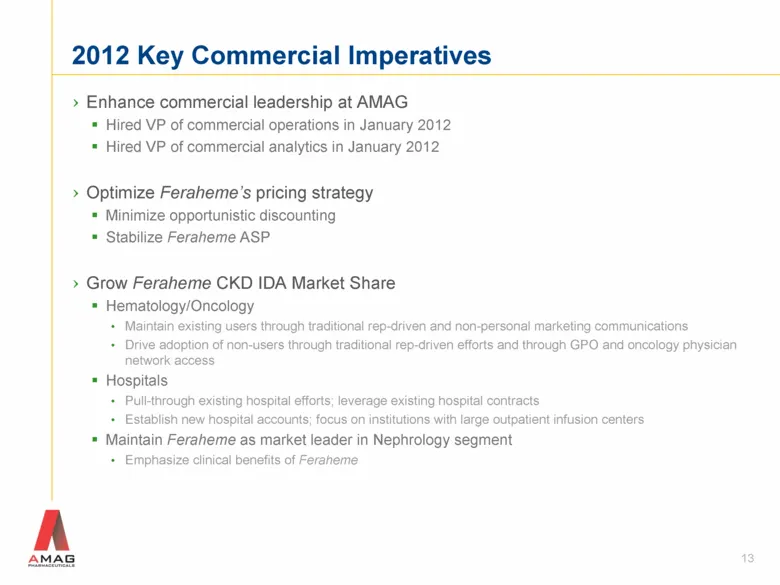
Enhance commercial leadership at AMAG Hired VP of commercial operations in January 2012 Hired VP of commercial analytics in January 2012 Optimize Feraheme’s pricing strategy Minimize opportunistic discounting Stabilize Feraheme ASP Grow Feraheme CKD IDA Market Share Hematology/Oncology Maintain exis
Slide 14: Growth Opportunities
Growth Opportunities 14
Slide 15: Strong Partnerships
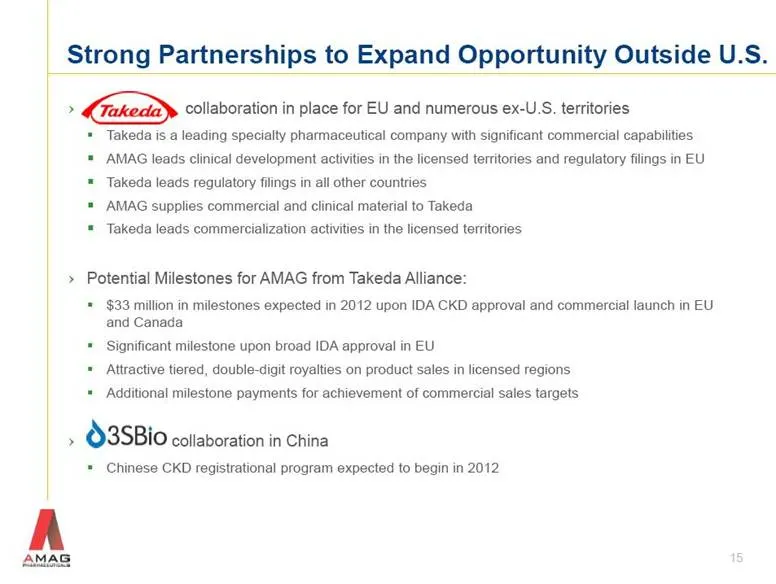
collaboration in place for EU and numerous ex-U.S. territories Takeda is a leading specialty pharmaceutical company with significant commercial capabilities AMAG leads clinical development activities in the licensed territories and regulatory filings in EU Takeda leads regulatory filings in all othe
Slide 16: Ex-US CKD IDA Expansion of Feraheme
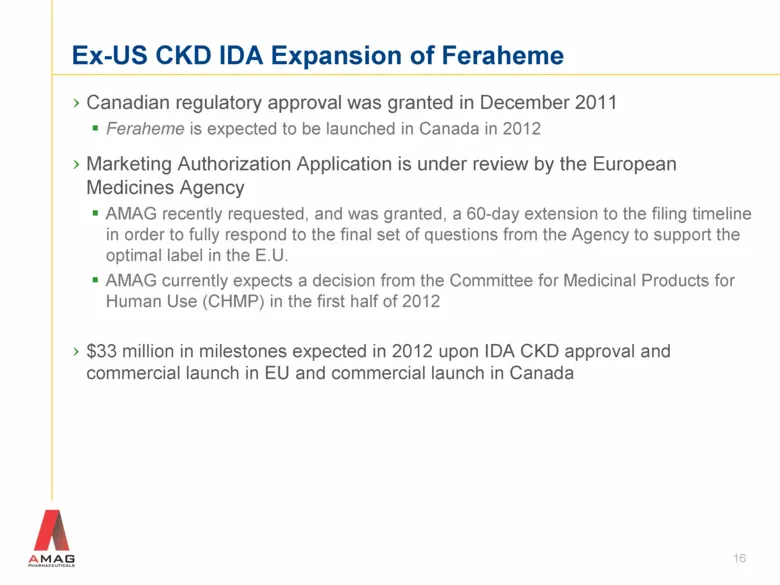
Canadian regulatory approval was granted in December 2011 Feraheme is expected to be launched in Canada in 2012 Marketing Authorization Application is under review by the European Medicines Agency AMAG recently requested, and was granted, a 60-day extension to the filing timeline in order to fully r
Slide 17: Pursuing Broad IDA Label
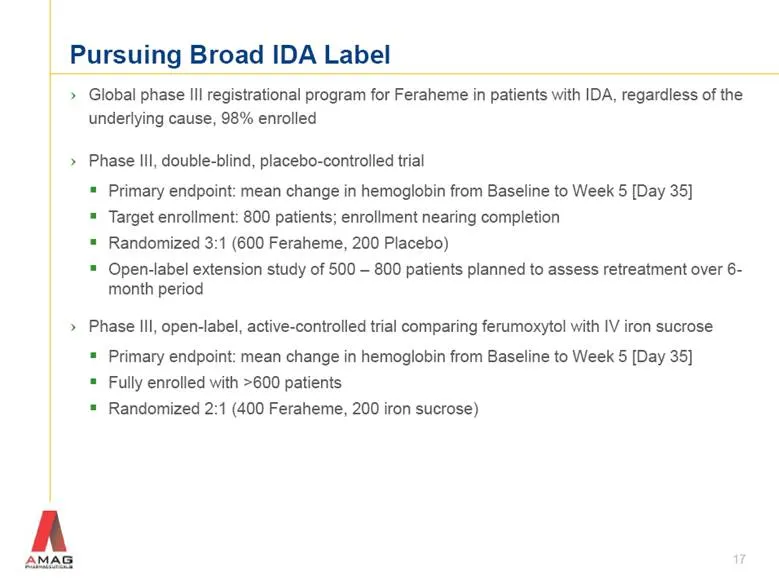
Global phase III registrational program for Feraheme in patients with IDA, regardless of the underlying cause, 98% enrolled Phase III, double-blind, placebo-controlled trial Primary endpoint: mean change in hemoglobin from Baseline to Week 5 [Day 35] Target enrollment: 800 patients; enrollment neari
Slide 18: Non-CKD IDA Represents a Large Underserved Market
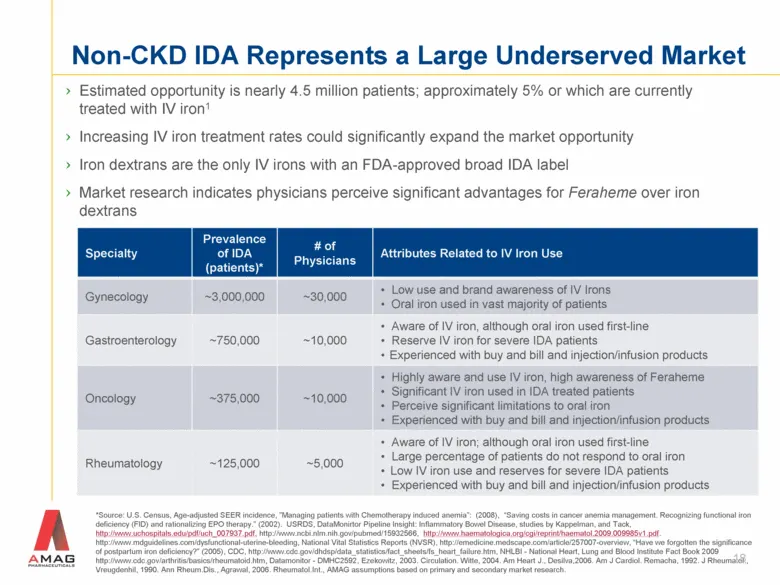
Non-CKD IDA Represents a Large Underserved Market Estimated opportunity is nearly 4.5 million patients; approximately 5% or which are currently treated with IV iron1 Increasing IV iron treatment rates could significantly expand the market opportunity Iron dextrans are the only IV irons with an FDA-a
Slide 19: Expanded Market Opportunity from Broad IDA Label
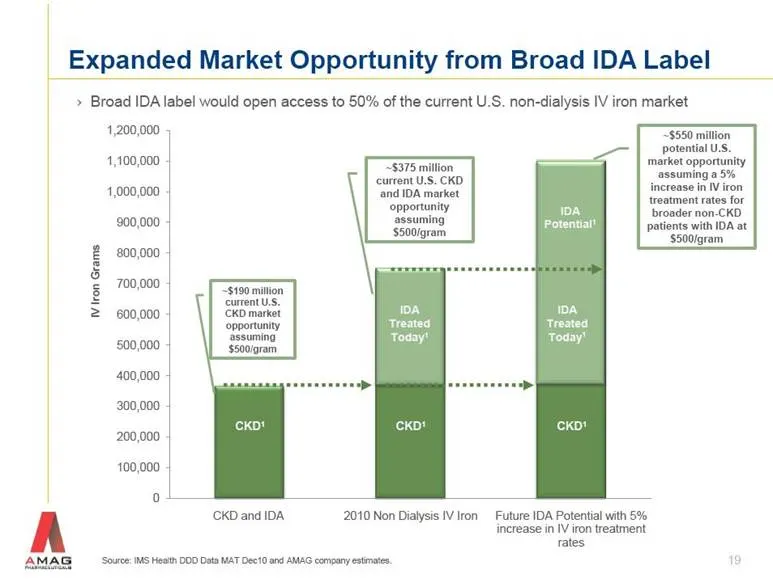
Source: IMS Health DDD Data MAT Dec10 and AMAG company estimates. IV Iron Grams ~$190 million current U.S. CKD market opportunity assuming $500/gram ~$375 million current U.S. CKD and IDA market opportunity assuming $500/gram CKD1 CKD1 IDA Treated Today1 CKD1 IDA Potential1 ~$550 million potential U
Slide 20: Broad IDA Program — Next Steps
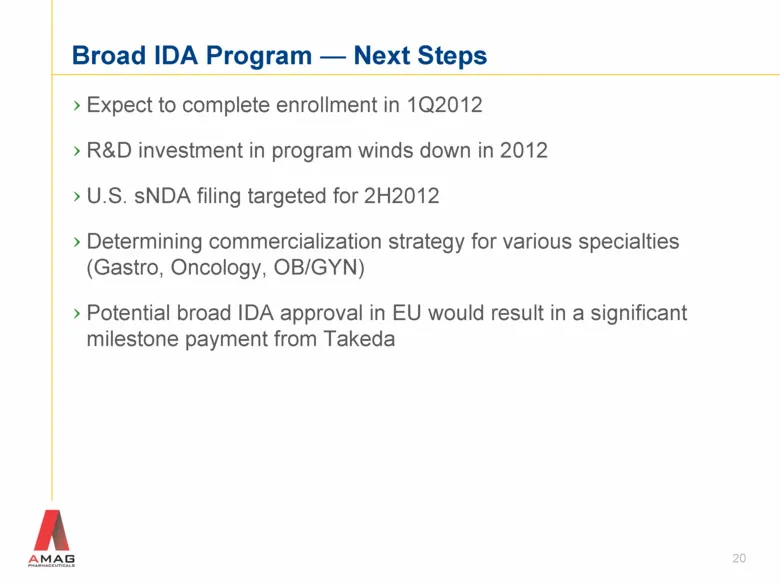
Expect to complete enrollment in 1Q2012 R&D investment in program winds down in 2012 U.S. sNDA filing targeted for 2H2012 Determining commercialization strategy for various specialties (Gastro, Oncology, OB/GYN) Potential broad IDA approval in EU would result in a significant milestone payment from
Slide 21: Financial Overview
Financial Overview 21
Slide 22: 4Q2011 Expected Results
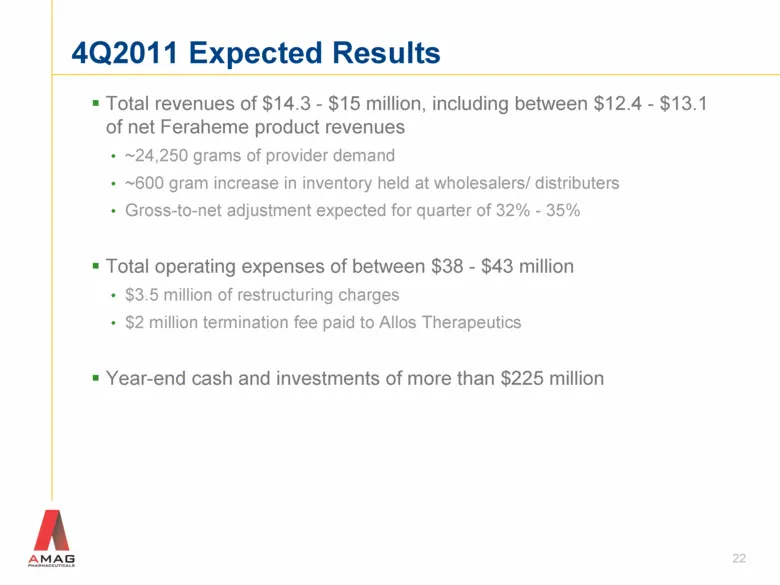
Total revenues of $14.3 - $15 million, including between $12.4 - $13.1 of net Feraheme product revenues ~24,250 grams of provider demand ~600 gram increase in inventory held at wholesalers/ distributers Gross-to-net adjustment expected for quarter of 32% - 35% Total operating expenses of between $38
Slide 23: 2012 Milestones and Financial Outlook
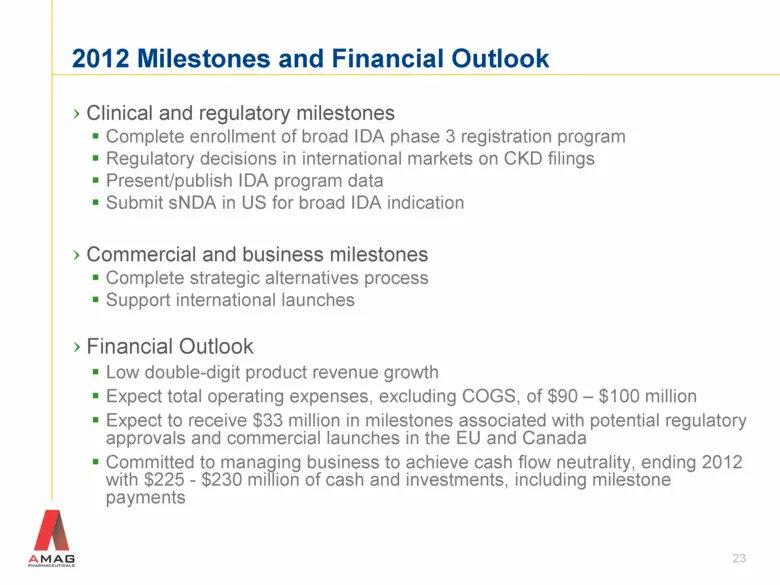
2012 Milestones and Financial Outlook Clinical and regulatory milestones Complete enrollment of broad IDA phase 3 registration program Regulatory decisions in international markets on CKD filings Present/publish IDA program data Submit sNDA in US for broad IDA indication Commercial and business mile
Slide 24: Leveraging Core Assets to Create Long-term Stockholder Value
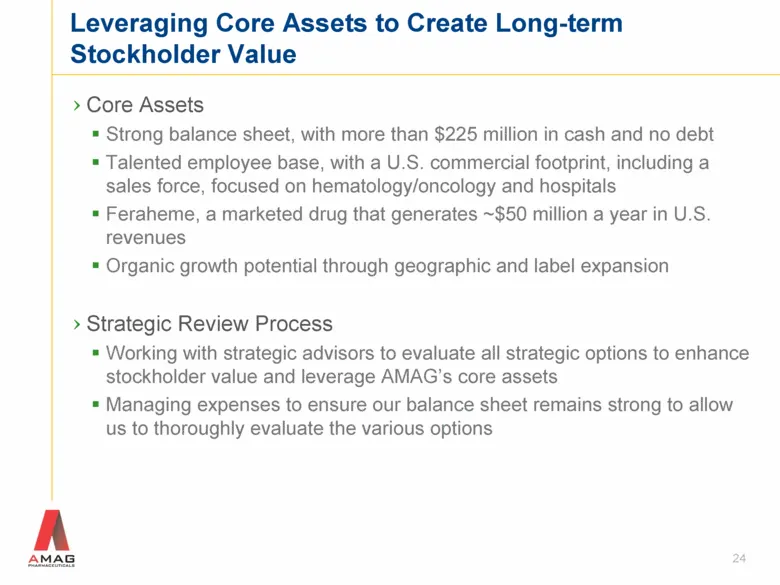
Leveraging Core Assets to Create Long-term Stockholder Value Core Assets Strong balance sheet, with more than $225 million in cash and no debt Talented employee base, with a U.S. commercial footprint, including a sales force, focused on hematology/oncology and hospitals Feraheme, a marketed drug tha
Slide 25: AMAG Pharmaceuticals Investor Relations Contact
AMAG Pharmaceuticals 25 INVESTOR RELATIONS CONTACT: 617-498-3303
Source: SEC EDGAR · 8-K filed Jan 9, 2012
More decks from AMAG Pharmaceuticals Inc
 Q2 2020 Earnings Presentation16 slides · Aug 6, 2020
 Q1 2020 Earnings Presentation14 slides · May 11, 2020
 JP Morgan 38th Healthcare Conference 202033 slides · Jan 9, 2020
 Q3 2019 Earnings Presentation24 slides · Nov 1, 2019
 Proxy Contest (September 2019)48 slides · Sep 4, 2019
 Q2 2019 Earnings Presentation26 slides · Aug 7, 2019