CYS Investments — Barclays 2012 Global Financial Services Conference
22 slides from CYS Investments's conference presentation, Sep 11, 2012
Slide 1: Investment Outlook September 2012
0 D&O Discussion April, 2011 Investment Outlook September 2012 Barclays 2012 Global Financial Services Conference September 11, 2012
Slide 2: Forward Looking Statements
1 Forward Looking Statements This presentation contains forward-looking statements, within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended, that are based on management’s beliefs and assumptions, current expecta
Slide 3: CYS: Overview
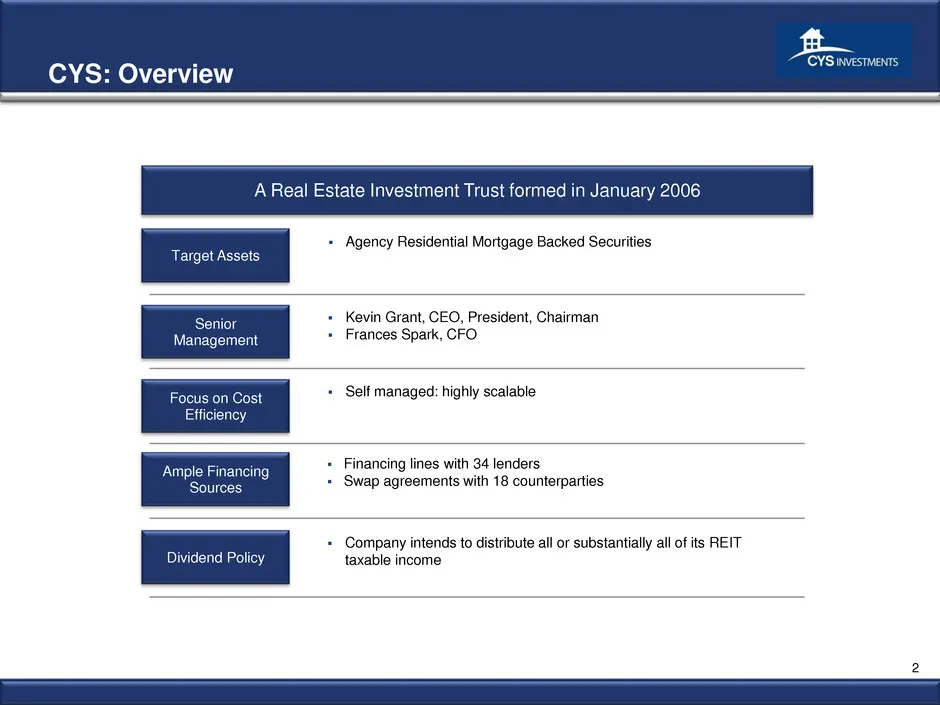
2 CYS: Overview Focus on Cost Efficiency Target Assets Agency Residential Mortgage Backed Securities A Real Estate Investment Trust formed in January 2006 Ample Financing Sources Financing lines with 34 lenders Swap agreements with 18 counterparties Dividend Policy Self managed: highly scala
Slide 4: Spread Environment Becoming More Challenging, However, Hedging Rates Remain Historically Low
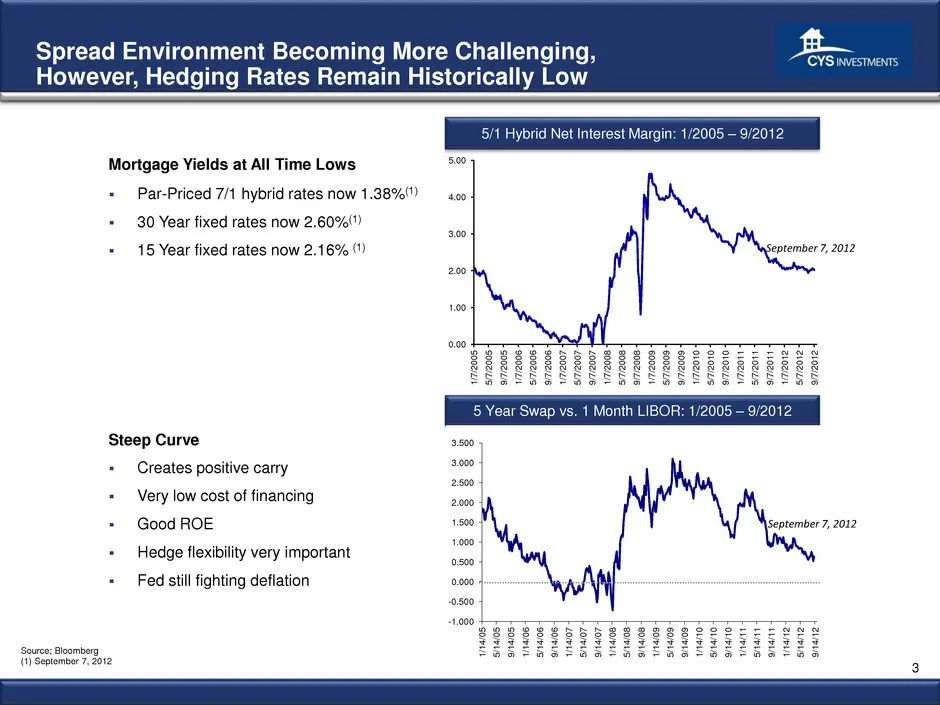
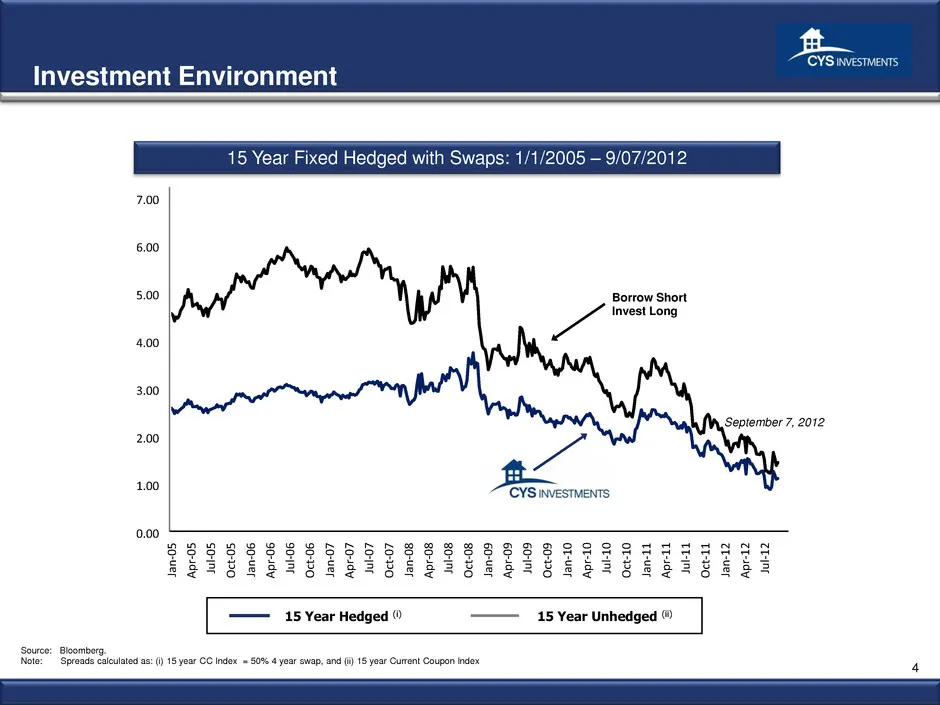
3 Spread Environment Becoming More Challenging, However, Hedging Rates Remain Historically Low Steep Curve Creates positive carry Very low cost of financing Good ROE Hedge flexibility very important Fed still fighting deflation Mortgage Yields at All Time Lows Par-Priced 7/1 hybrid rates
Slide 5: Investment Environment: 15 Year Fixed Hedged with Swaps
4 0.00 1.00 2.00 3.00 4.00 5.00 6.00 7.00 Ja n -0 5 A p r- 0 5 Ju l- 0 5 Oc t- 0 5 Ja n -0 6 A p r- 0 6 Ju l- 0 6 Oc t- 0 6 Ja n -0 7 A p r- 0 7 Ju l- 0 7 Oc t- 0 7 Ja n -0 8 A p r- 0 8 Ju l- 0 8 Oc t- 0 8 Ja n -0 9 A p r- 0 9 Ju l- 0 9 Oc t- 0 9 Ja n -1 0 A p r- 1 0 Ju l- 1 0 Oc t- 1 0 Ja n -1 1 A
Slide 6: Fed Voters More Dovish
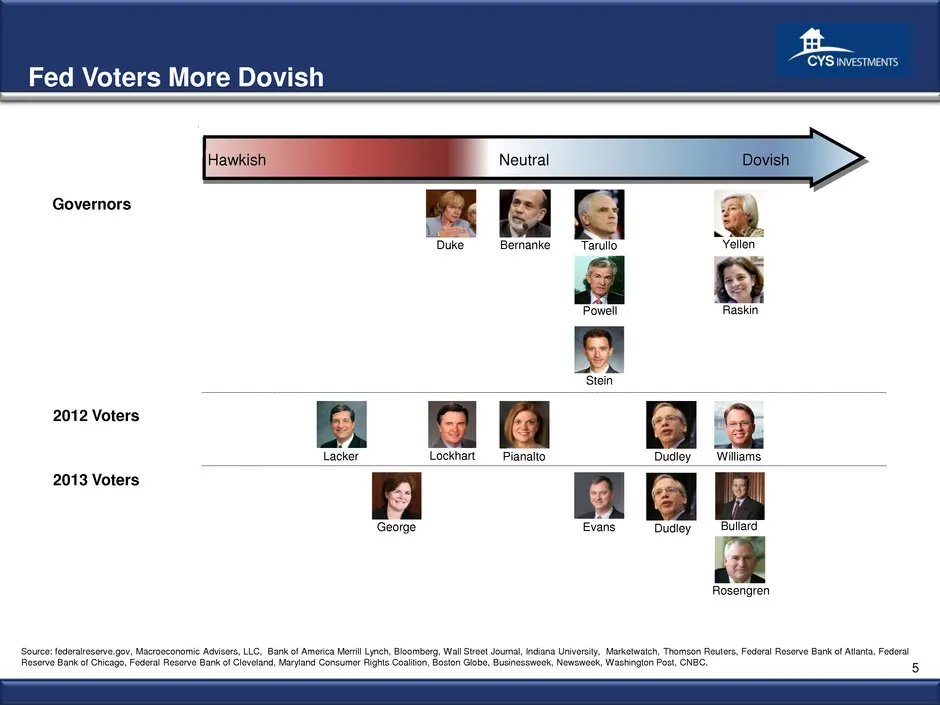
5 Hawkish Dovish Neutral Lacker Duke Tarullo Lockhart Pianalto Yellen Raskin Bernanke Governors 2012 Voters Fed Voters More Dovish Williams 2013 Voters Dudley Evans Rosengren Bullard Powell Stein Dudley George Source: federalreserve.gov, Macroeconomic Advisers, LLC, Bank of America Merrill Lynch, Bl
Slide 7: Fed Ownership Shares of Nominal Notes and Bonds
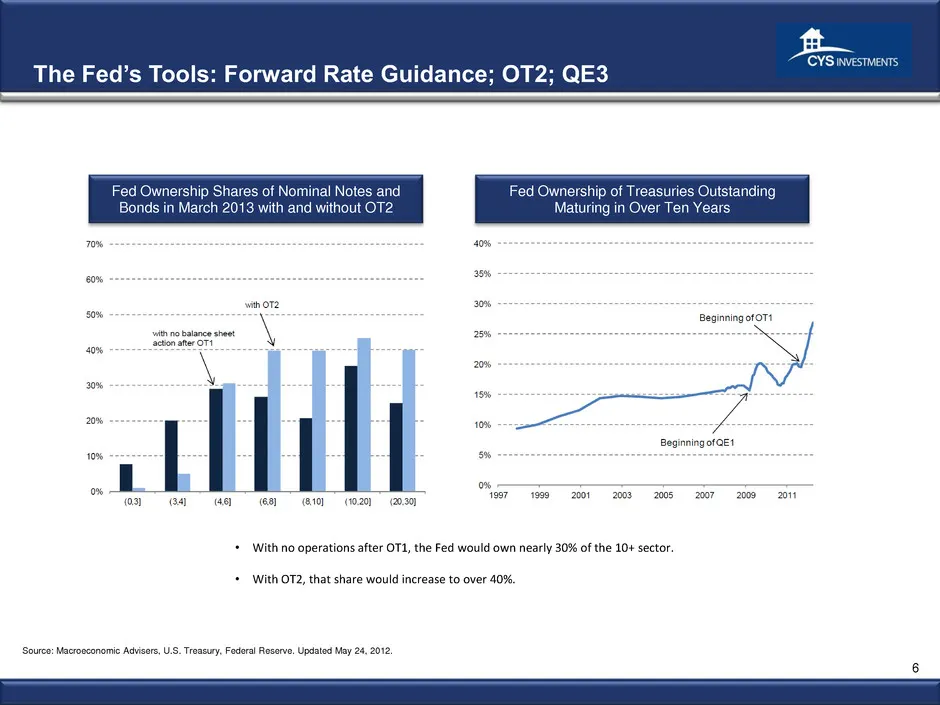
6 Fed Ownership Shares of Nominal Notes and Bonds in March 2013 with and without OT2 • With no operations after OT1, the Fed would own nearly 30% of the 10+ sector. • With OT2, that share would increase to over 40%. Fed Ownership of Treasuries Outstanding Maturing in Over Ten Years The Fed’s Tools:
Slide 8: Will the Fed Rationalize High Unemployment?
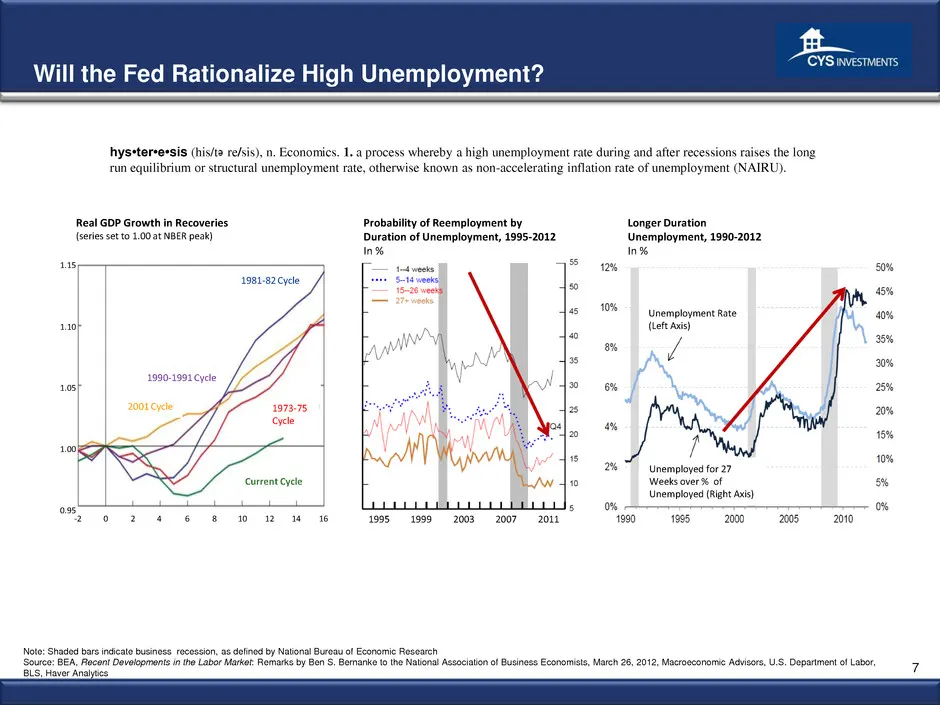
7 Will the Fed Rationalize High Unemployment? hys•ter•e•sis (his/t re/sis), n. Economics. 1. a process whereby a high unemployment rate during and after recessions raises the long run equilibrium or structural unemployment rate, otherwise known as non-accelerating inflation rate of unemployment (NAI
Slide 9: Central Banks Globally Decidedly More Accommodative
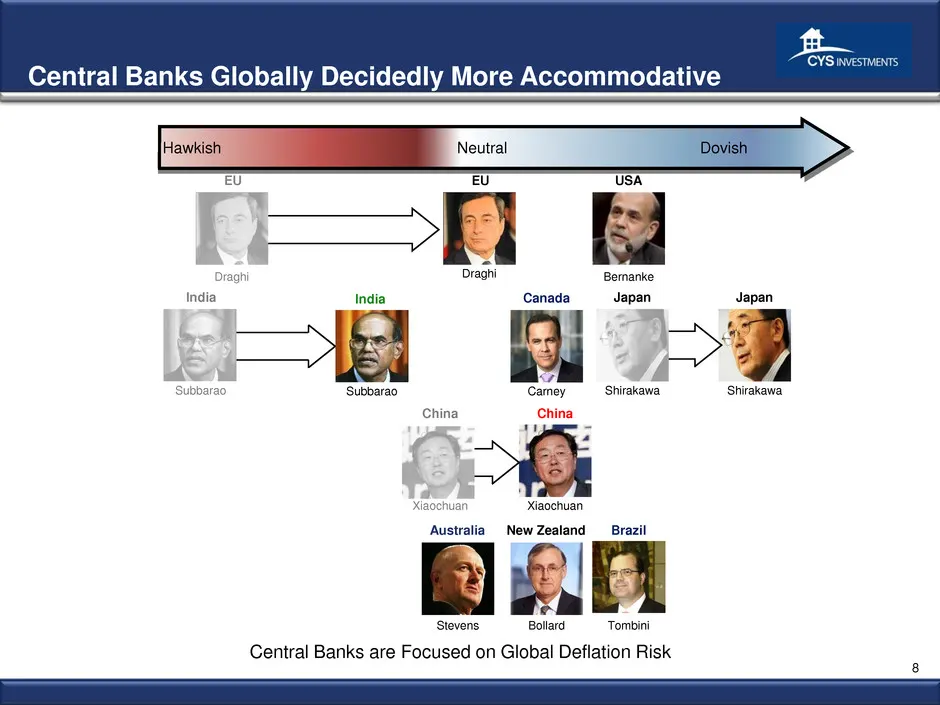
8 Central Banks Globally Decidedly More Accommodative Xiaochuan China Bernanke USA Shirakawa Japan Canada Carney Australia Stevens New Zealand Bollard Draghi EU Tombini Brazil Subbarao India Central Banks are Focused on Global Deflation Risk Hawkish Dovish Neutral Draghi EU Shirakawa Japan Subbarao
Slide 10: Long Term Budget Outlook vs. The Fiscal Cliff
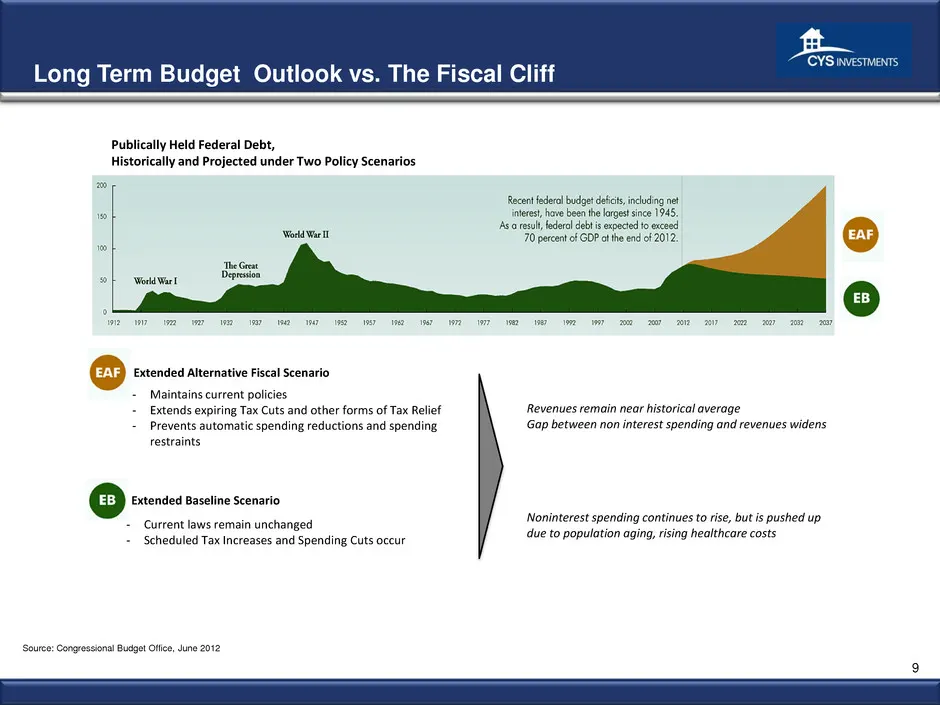
9 Publically Held Federal Debt, Historically and Projected under Two Policy Scenarios Extended Alternative Fiscal Scenario Extended Baseline Scenario - Maintains current policies - Extends expiring Tax Cuts and other forms of Tax Relief - Prevents automatic spending reductions and spending restraint
Slide 11: Economic Recovery Below Normal Pace
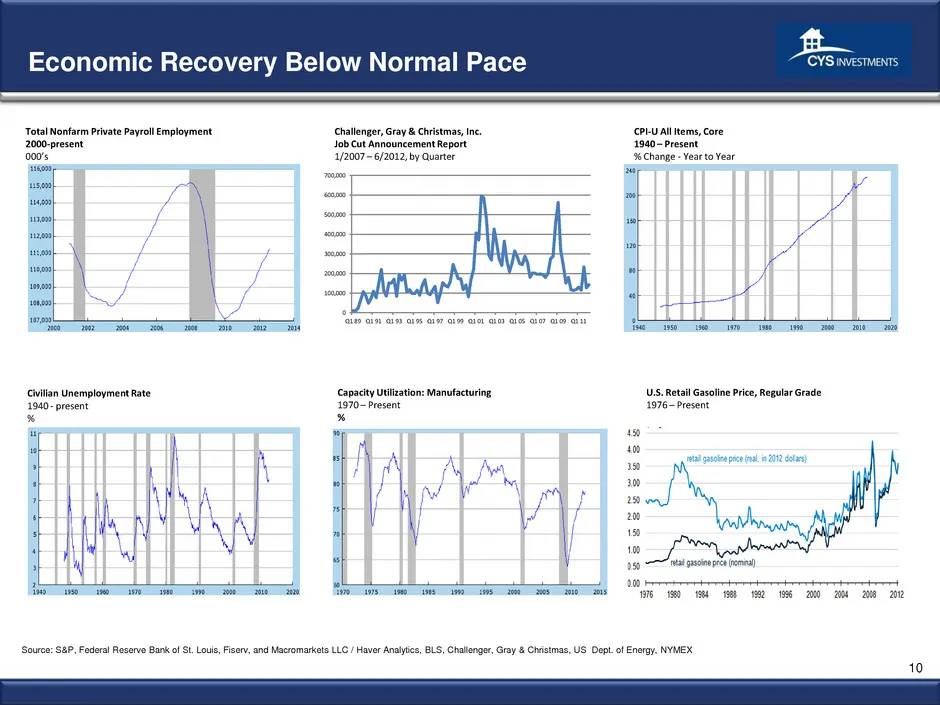
10 U.S. Retail Gasoline Price, Regular Grade 1976 – Present Capacity Utilization: Manufacturing 1970 – Present % Civilian Unemployment Rate 1940 - present % Economic Recovery Below Normal Pace CPI-U All Items, Core 1940 – Present % Change - Year to Year Total Nonfarm Private Payroll Employment 2000-
Slide 12: Mortgage Market Shrinkage Likely to Continue
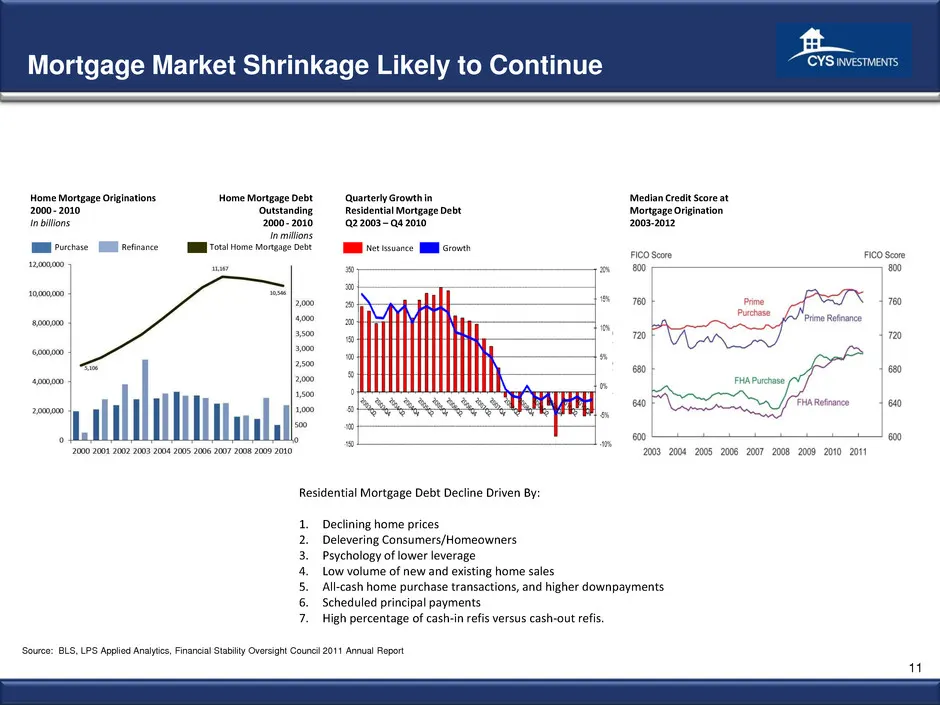
11 Mortgage Market Shrinkage Likely to Continue Residential Mortgage Debt Decline Driven By: 1. Declining home prices 2. Delevering Consumers/Homeowners 3. Psychology of lower leverage 4. Low volume of new and existing home sales 5. All-cash home purchase transactions, and higher downpayments 6. Sch
Slide 13: Iowa Electronic Futures Market: Obama re-elected and a Republican Congress
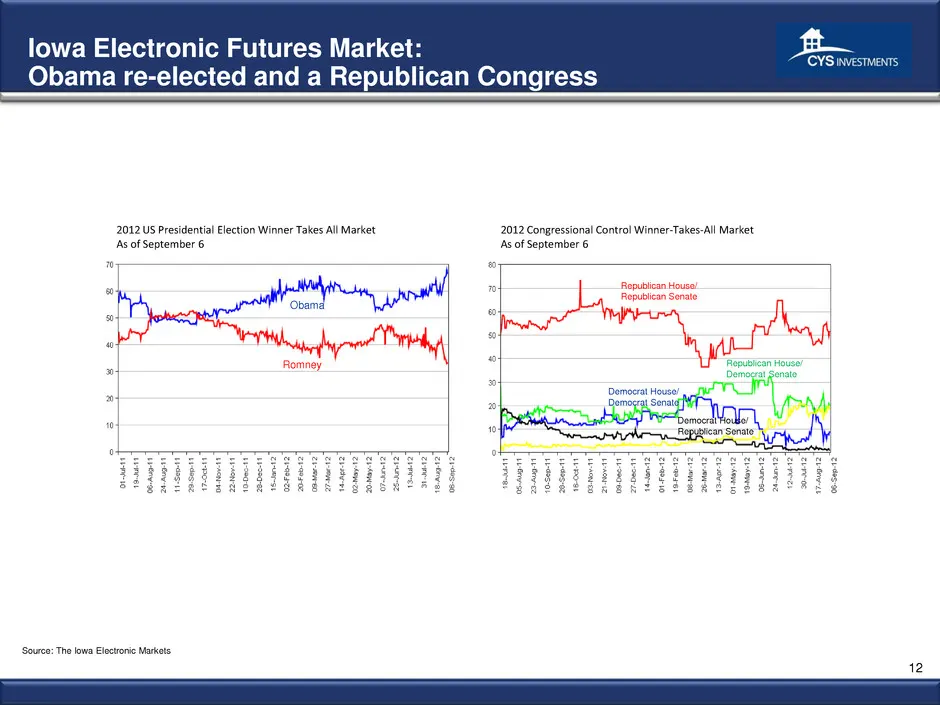
12 Iowa Electronic Futures Market: Obama re-elected and a Republican Congress Source: The Iowa Electronic Markets Romney Obama Republican House/ Democrat Senate Democrat House/ Democrat Senate Democrat House/ Republican Senate Republican House/ Republican Senate 2012 US Presidential Election Winner
Slide 14: Intrade: Obama re-elected and a Republican Congress
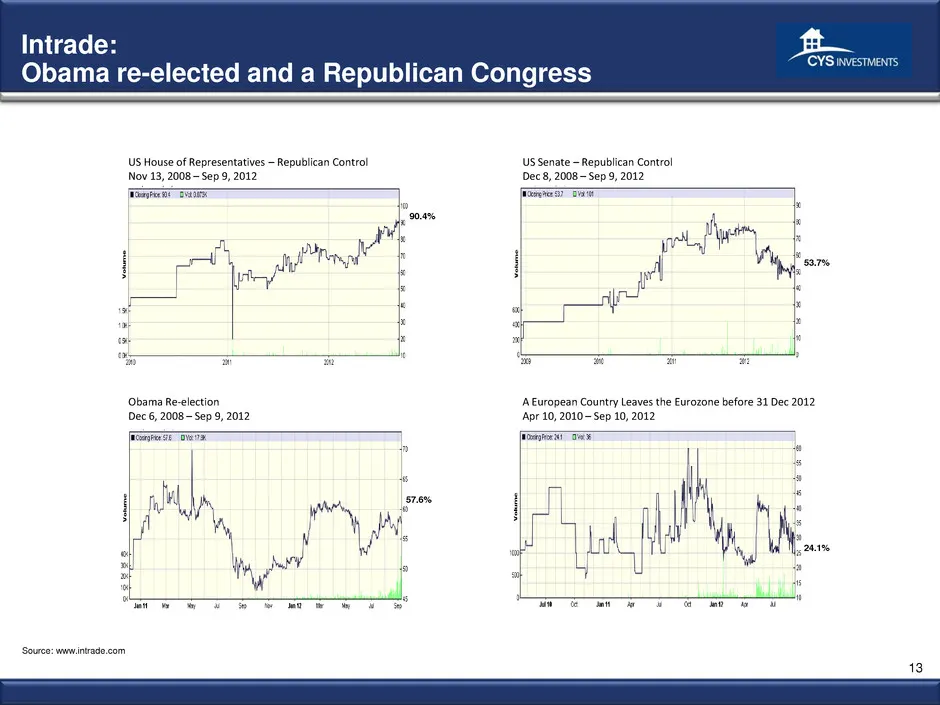
13 US House of Representatives – Republican Control Nov 13, 2008 – Sep 9, 2012 Source: www.intrade.com Democrat US Senate – Republican Control Dec 8, 2008 – Sep 9, 2012 Obama Re-election Dec 6, 2008 – Sep 9, 2012 A European Country Leaves the Eurozone before 31 Dec 2012 Apr 10, 2010 – Sep 10, 2012 I
Slide 15: Electoral Mapping
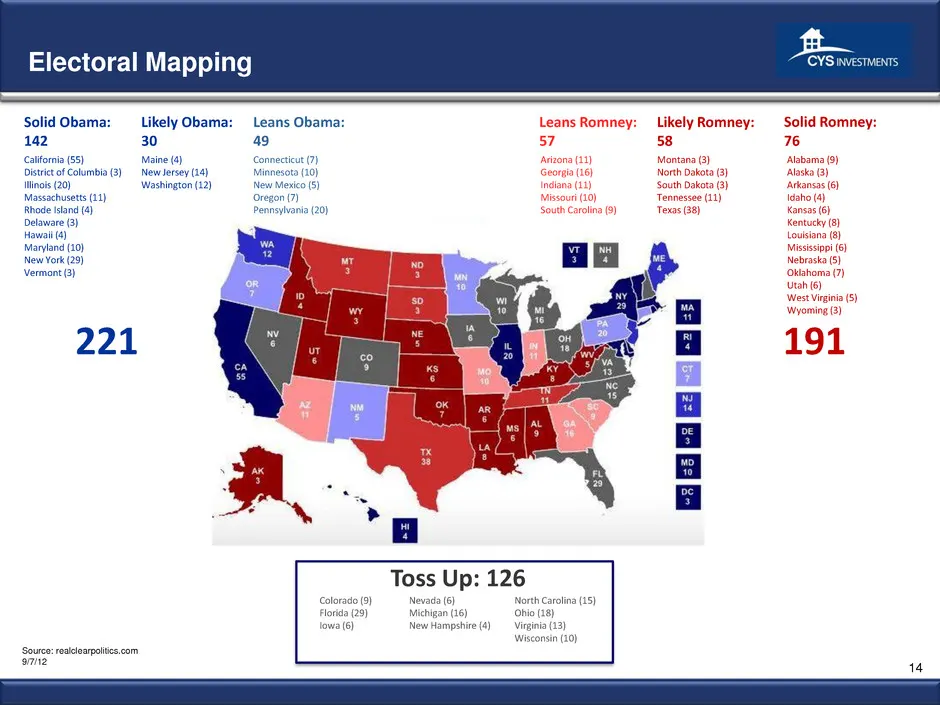
14 Electoral Mapping Connecticut (7) Minnesota (10) New Mexico (5) Oregon (7) Pennsylvania (20) Leans Obama: 49 Arizona (11) Georgia (16) Indiana (11) Missouri (10) South Carolina (9) Leans Romney: 57 Colorado (9) Florida (29) Iowa (6) Nevada (6) Michigan (16) New Hampshire (4) North Carolina (15) O
Slide 16: Economics of Forward Purchase
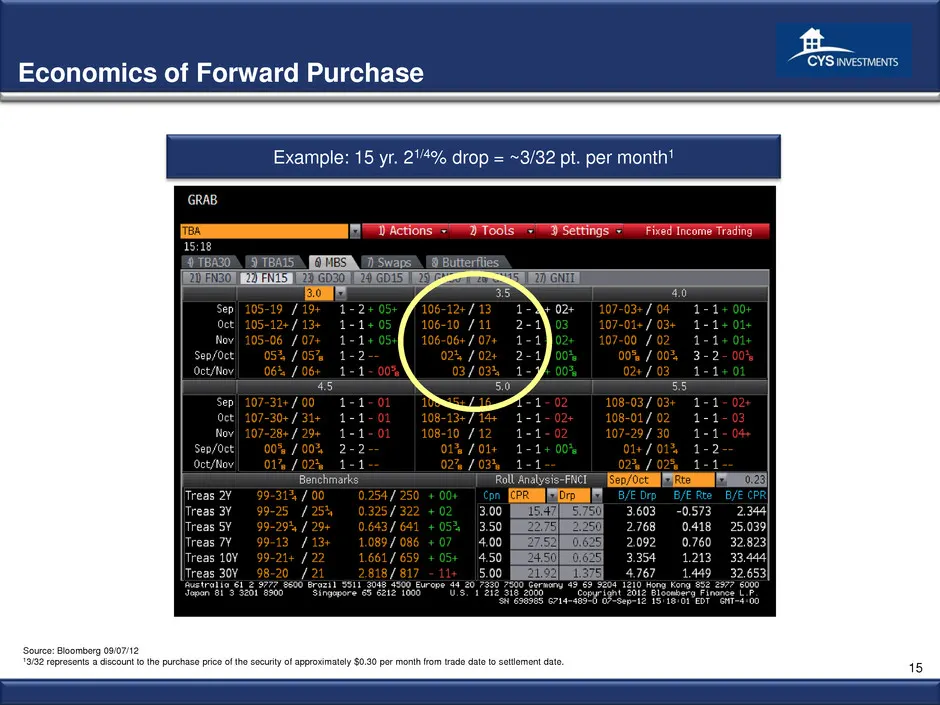
15 Economics of Forward Purchase Example: 15 yr. 21/4% drop = ~3/32 pt. per month1 Source: Bloomberg 09/07/12 13/32 represents a discount to the purchase price of the security of approximately $0.30 per month from trade date to settlement date.
Slide 17: Portfolio Composition and Results
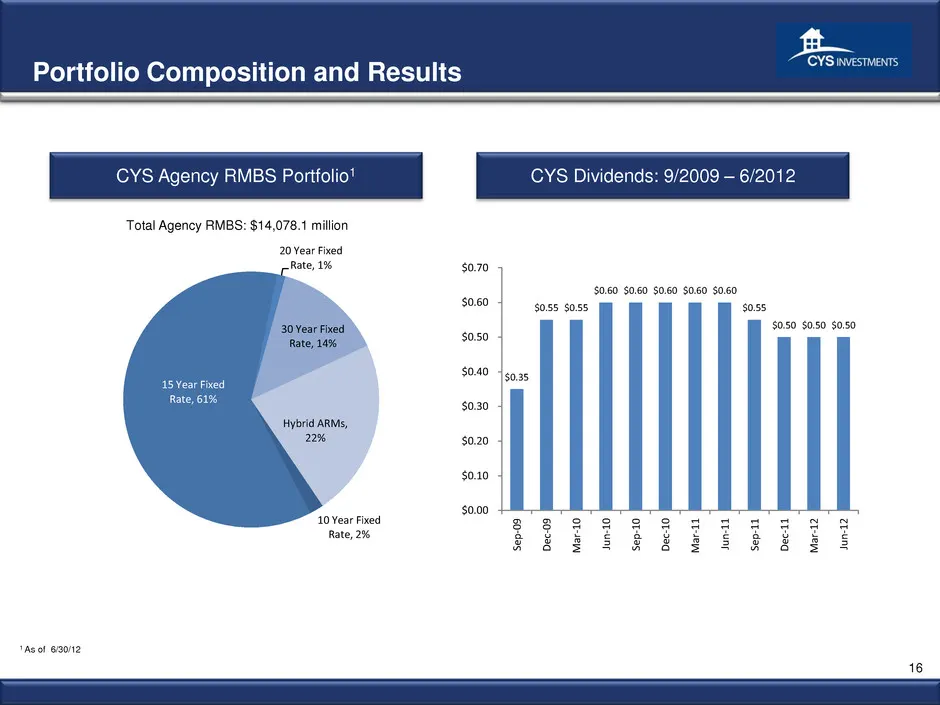
16 34.5% Portfolio Composition and Results CYS Agency RMBS Portfolio1 1 As of 6/30/12 15 Year Fixed Rate: 53.5% Hybrid ARMs: 34.5% Total Agency RMBS: $14,078.1 million CYS Dividends: 9/2009 – 6/2012 $0.35 $0.55 $0.55 $0.60 $0.60 $0.60 $0.60 $0.60 $0.55 $0.50 $0.50 $0.50 $0.00 $0.10 $0.20 $0.30 $0.40
Slide 18: Portfolio Characteristics
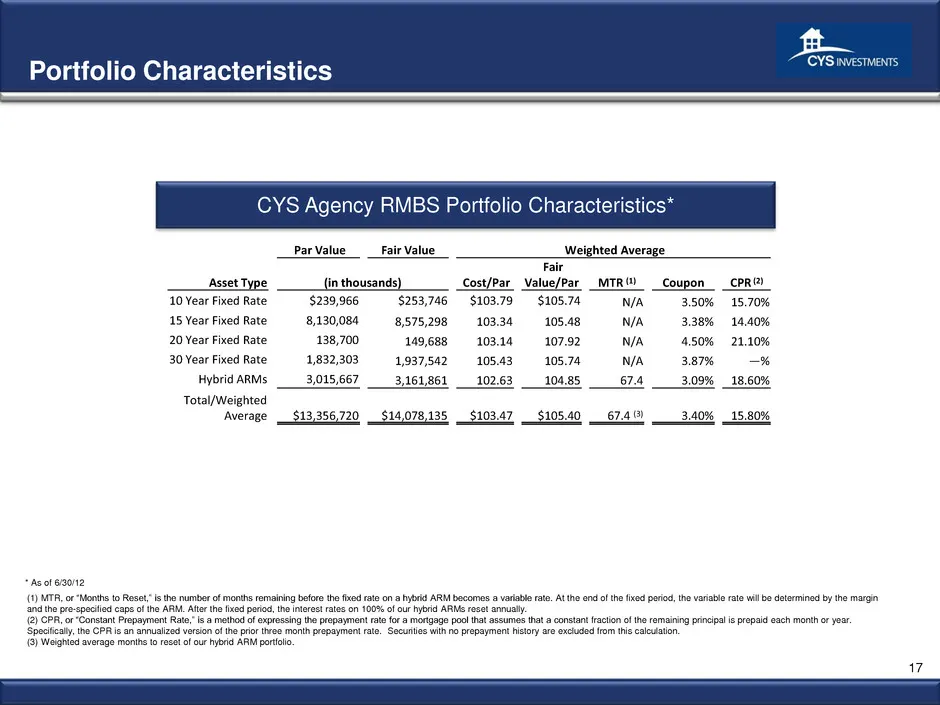
17 Portfolio Characteristics CYS Agency RMBS Portfolio Characteristics* * As of 6/30/12 (1) MTR, or “Months to Reset,” is the number of months remaining before the fixed rate on a hybrid ARM becomes a variable rate. At the end of the fixed period, the variable rate will be determined by the margin a
Slide 19: History of Transparent and Consistent Financial Reporting
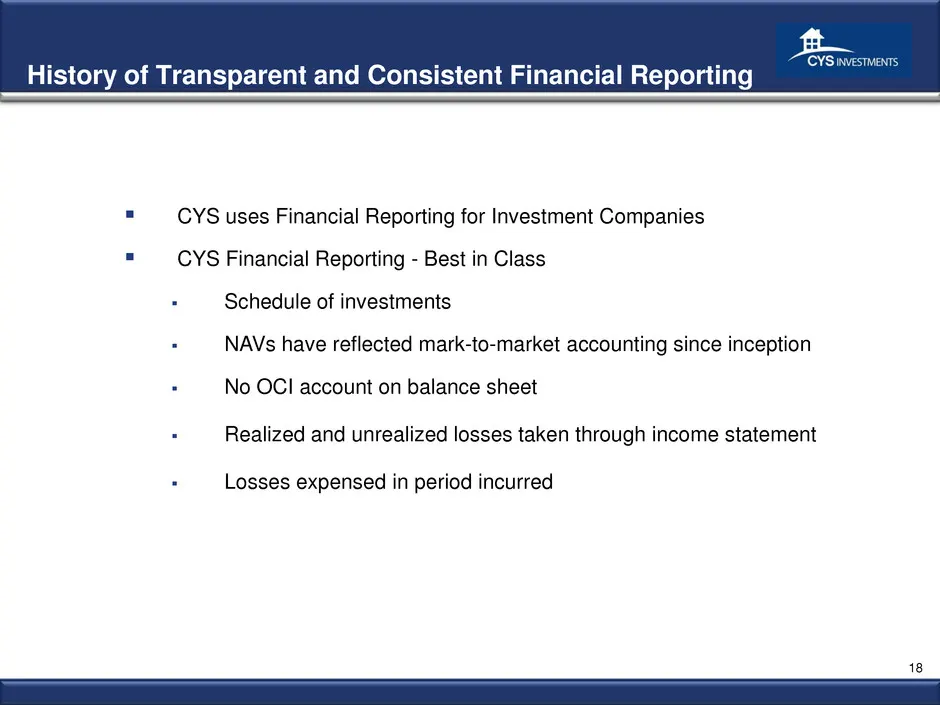
18 History of Transparent and Consistent Financial Reporting CYS uses Financial Reporting for Investment Companies CYS Financial Reporting - Best in Class Schedule of investments NAVs have reflected mark-to-market accounting since inception No OCI account on balance sheet Realized and un
Slide 20: Historical Financials
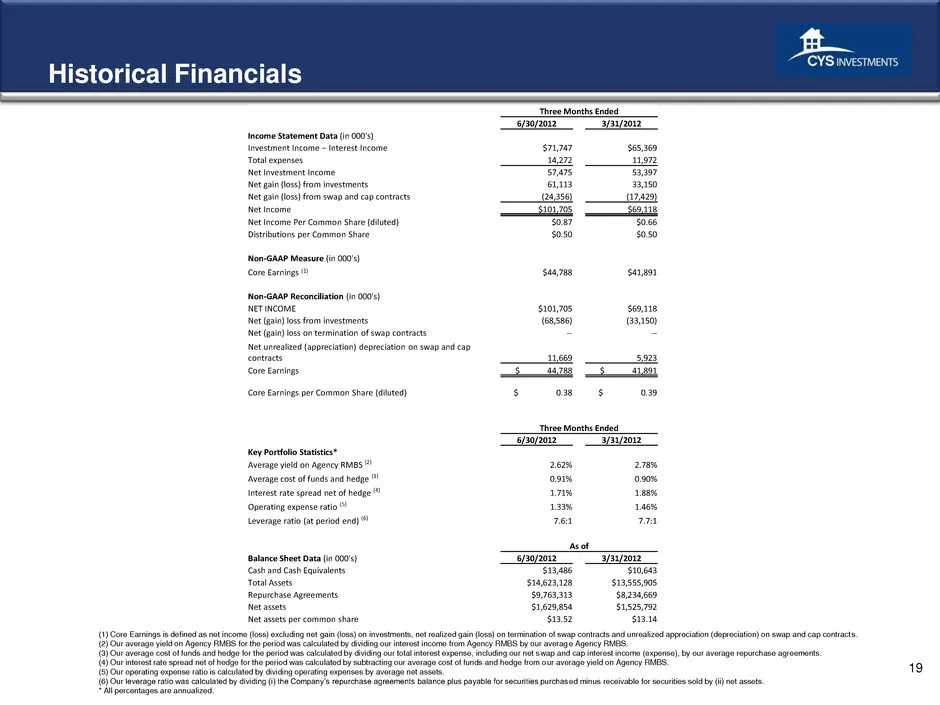
19 Historical Financials (1) Core Earnings is defined as net income (loss) excluding net gain (loss) on investments, net realized gain (loss) on termination of swap contracts and unrealized appreciation (depreciation) on swap and cap contracts. (2) Our average yield on Agency RMBS for the period was
Slide 21: Financial Highlights
20 Financial Highlights Steep yield curve and attractive spreads in target assets Tailwinds likely to continue Fed Transparency very helpful Investment Company accounting provides transparency
Slide 22: Investment Outlook September 2012
21 D&O Discussion April, 2011 Investment Outlook September 2012 Barclays 2012 Global Financial Services Conference September 11, 2012
Source: SEC EDGAR · 8-K filed Sep 11, 2012
More decks from CYS Investments Inc
 Merger or Acquisition (April 2018)12 slides · Apr 26, 2018
 Barclays Global Financial Services Conference 201724 slides · Sep 11, 2017
 JMP Securities Financial Services and Real Estate Conference 201624 slides · Sep 27, 2016
 Barclays Global Financial Services Conference 201624 slides · Sep 12, 2016
 Proxy Contest (May 2016)8 slides · May 4, 2016
 JMP Securities Financial Services and Real Estate Conference 201522 slides · Sep 21, 2015