Ditech — Walter Investment Management — Debt Investor Presentation (May 2011)
59 slides from Ditech's debt investor presentation, May 18, 2011
Slide 1: Presentation to Lenders
Presentation to Lenders $500 million First Lien Term Loan $265 million Second Lien Term Loan May 19, 2011
Slide 2: Forward looking statements
Forward looking statements Safe Harbor Statement Certain statements in this release and in any of Walter Investment Management Corp.'s public documents referred to herein, contain or incorporate by reference "forward-looking" statements as defined in Section 27A of the Securities Act of 1933, as ame
Slide 3: Introducing the Management Team
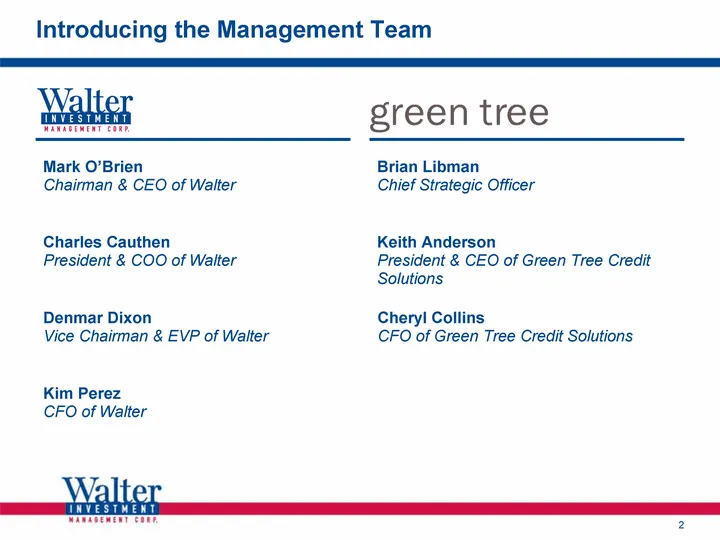
Introducing the Management Team Brian Libman Chief Strategic Officer Charles Cauthen President & COO of Walter Kim Perez CFO of Walter Denmar Dixon Vice Chairman & EVP of Walter Keith Anderson President & CEO of Green Tree Credit Solutions Cheryl Collins CFO of Green Tree Credit Solutions Mark O'Bri
Slide 4: Agenda
Agenda 1. Transaction overview 2. Executive summary 3. Industry overview 4. Walter overview 5. Green Tree overview 6. Financial overview 7. Conclusion Questions & Answers 8. Summary terms and timetable
Slide 5: 1. Transaction overview
MANAGEMENT CORP. 1. Transaction overview Se
Slide 6: Transaction overview
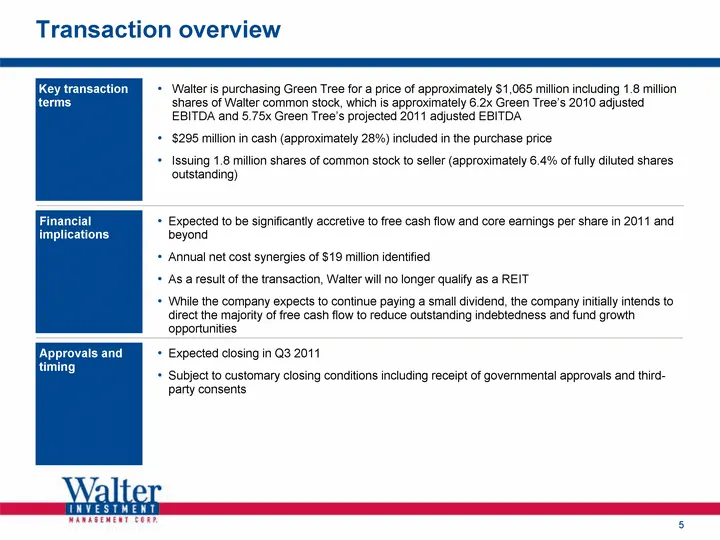
Transaction overview Key transaction terms Financial implications Approvals and timing Walter is purchasing Green Tree for a price of approximately $1,065 million including 1.8 million shares of Walter common stock, which is approximately 6.2x Green Tree's 2010 adjusted EBITDA and 5.75x Green Tree's
Slide 7: Sources and uses
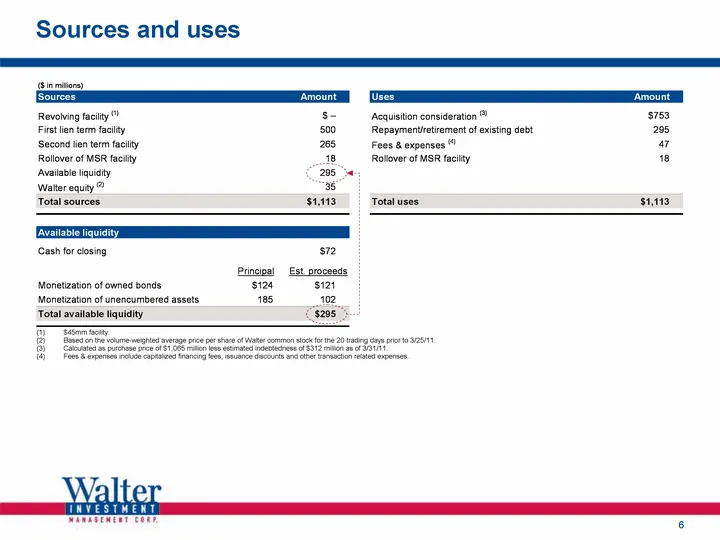
Sources and uses (1) $45mm facility. (2) Based on the volume-weighted average price per share of Walter common stock for the 20 trading days prior to 3/25/11. (3) Calculated as purchase price of $1,065 million less estimated indebtedness of $312 million as of 3/31/11. (4) Fees & expenses include cap
Slide 8: Pro forma capitalization
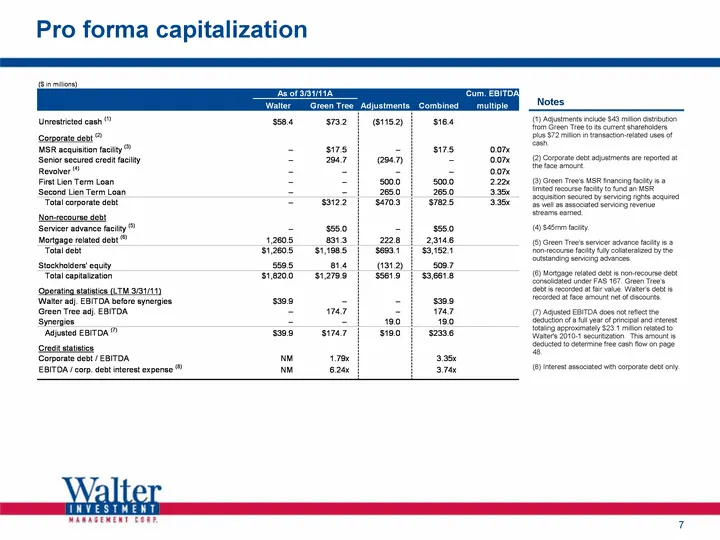
Pro forma capitalization (1) Adjustments include $43 million distribution from Green Tree to its current shareholders plus $72 million in transaction-related uses of cash. (2) Corporate debt adjustments are reported at the face amount. (3) Green Tree's MSR financing facility is a limited recourse fa
Slide 9: Summary organizational chart
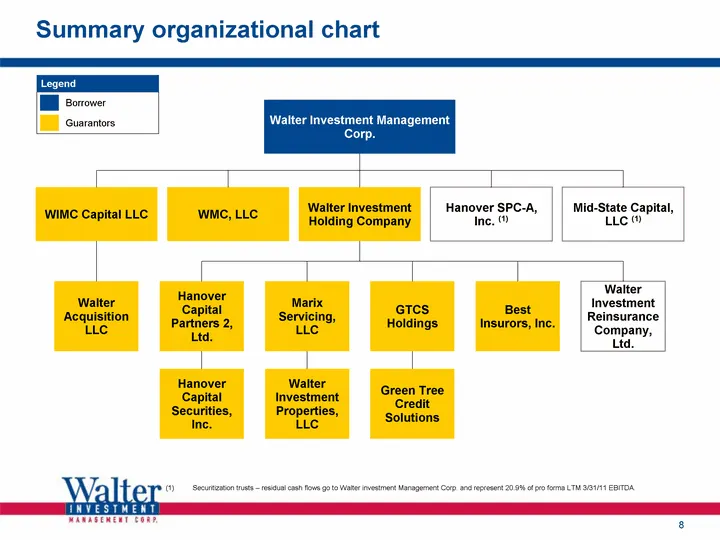
Summary organizational chart Walter Investment Management Corp. WIMC Capital LLC WMC, LLC Mid-State Capital, LLC (1) Walter Investment Holding Company Hanover SPC-A, Inc. (1) Walter Acquisition LLC Hanover Capital Partners 2, Ltd. Best Insurors, Inc. Walter Investment Reinsurance Company, Ltd. Marix
Slide 10: 2. Executive summary
MANAGEMENT CORP. 2. Executive summary PS
Slide 11: Walter company overview
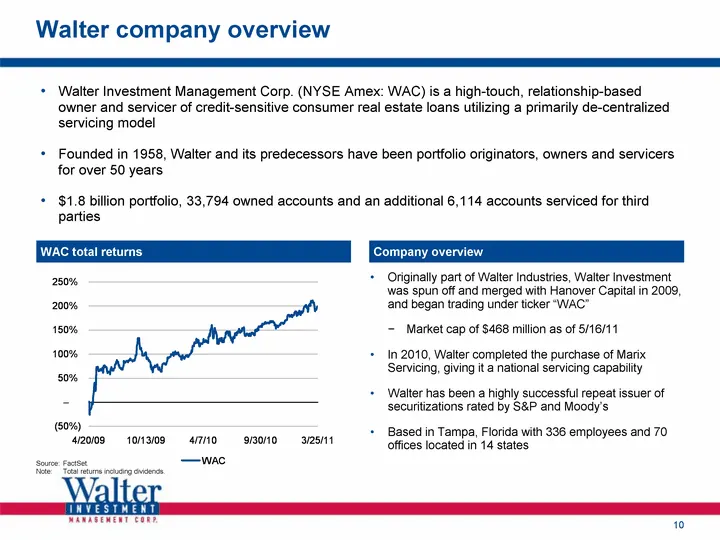
Walter company overview Walter Investment Management Corp. (NYSE Amex: WAC) is a high-touch, relationship-based owner and servicer of credit-sensitive consumer real estate loans utilizing a primarily de-centralized servicing model Founded in 1958, Walter and its predecessors have been portfolio orig
Slide 12: Strategic rationale
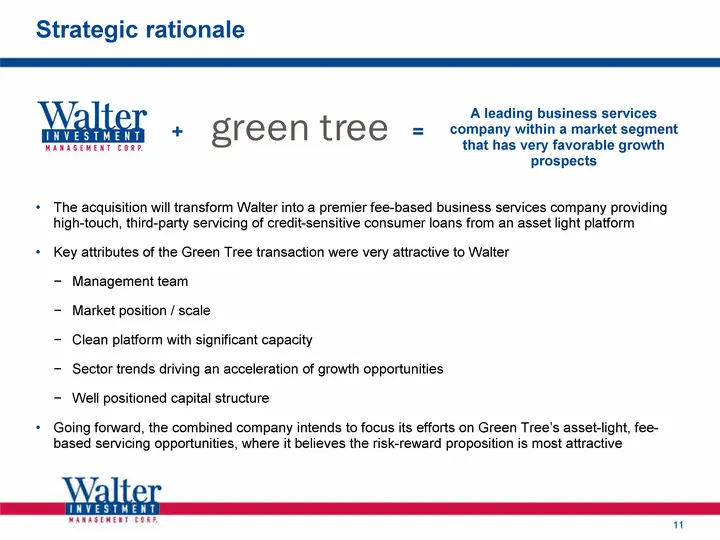
Strategic rationale The acquisition will transform Walter into a premier fee-based business services company providing high-touch, third-party servicing of credit-sensitive consumer loans from an asset light platform Key attributes of the Green Tree transaction were very attractive to Walter Managem
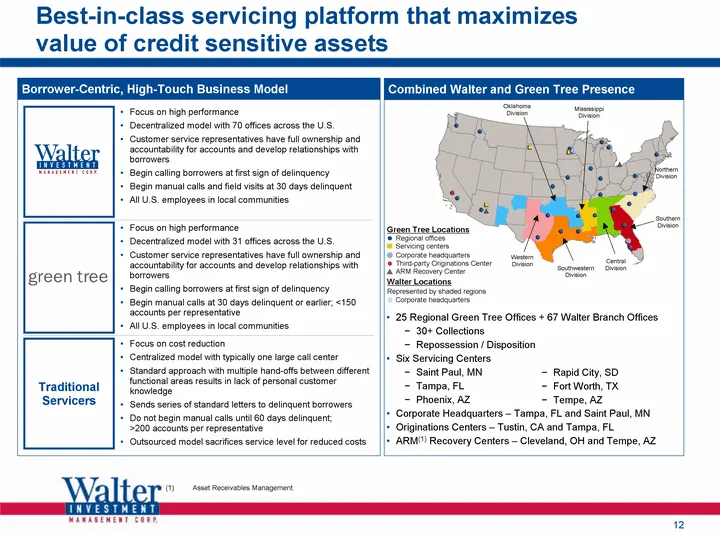
Slide 13: Best-in-class servicing platform that maximizes value of credit sensitive assets
Best-in-class servicing platform that maximizes value of credit sensitive assets Borrower-Centric, High-Touch Business Model Combined Walter and Green Tree Presence Traditional Servicers Focus on high performance Decentralized model with 31 offices across the U.S. Customer service representatives ha
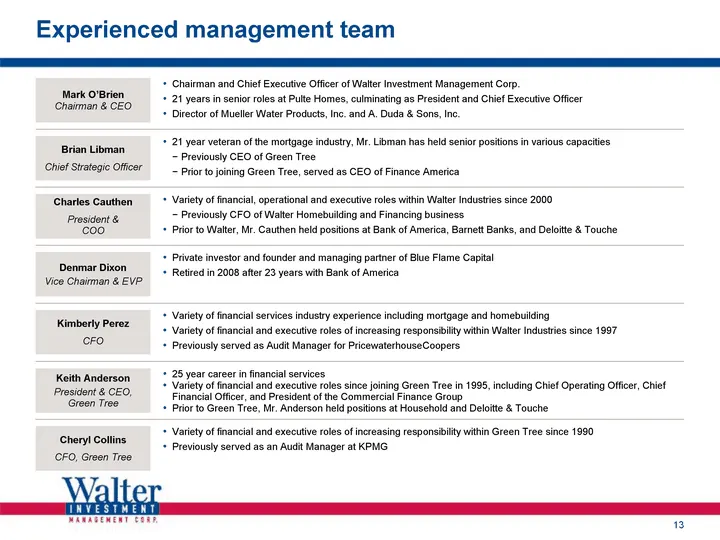
Slide 14: Experienced management team
Experienced management team Variety of financial, operational and executive roles within Walter Industries since 2000 Previously CFO of Walter Homebuilding and Financing business Prior to Walter, Mr. Cauthen held positions at Bank of America, Barnett Banks, and Deloitte & Touche Mark O'Brien Chairma
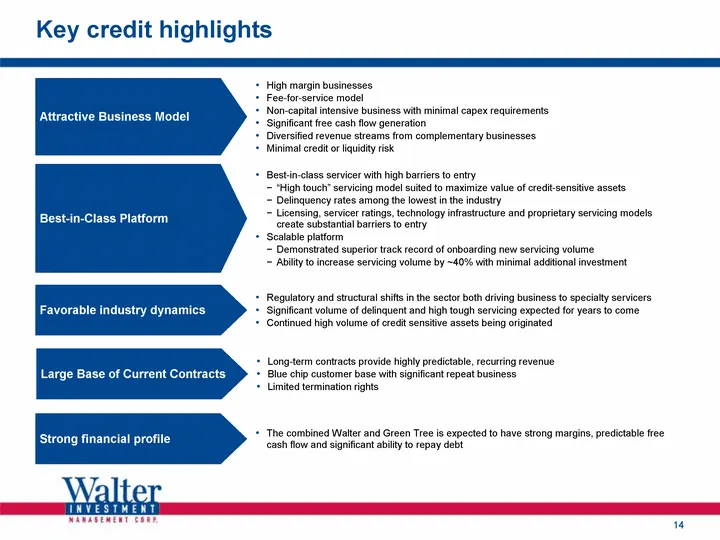
Slide 15: Key credit highlights
Key credit highlights High margin businesses Fee-for-service model Non-capital intensive business with minimal capex requirements Significant free cash flow generation Diversified revenue streams from complementary businesses Minimal credit or liquidity risk Attractive Business Model Best-in-class s
Slide 16: 3. Industry overview
3. MANAGEMENT CORP. Industry overview
Slide 17: Mortgage servicing overview
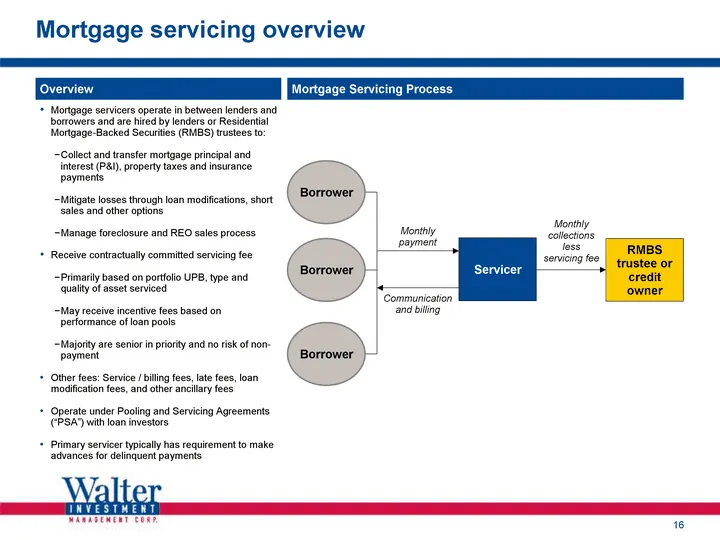
Mortgage servicing overview Overview Mortgage Servicing Process Mortgage servicers operate in between lenders and borrowers and are hired by lenders or Residential Mortgage-Backed Securities (RMBS) trustees to: Collect and transfer mortgage principal and interest (P&I), property taxes and insurance
Slide 18: Transition toward a borrower-centric, high-touch business model
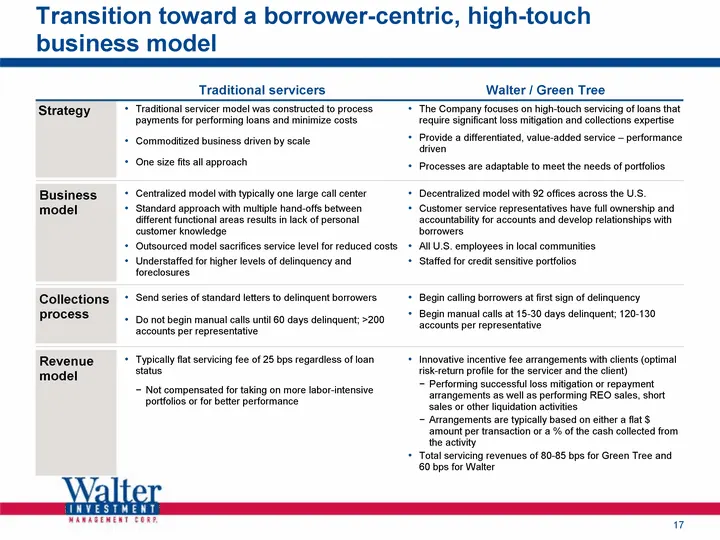
Transition toward a borrower-centric, high-touch business model Strategy Business model Revenue model Traditional servicer model was constructed to process payments for performing loans and minimize costs Commoditized business driven by scale One size fits all approach The Company focuses on high-to
Slide 19: The $10.5 trillion U.S. mortgage market provides specialty servicers with significant opportunity
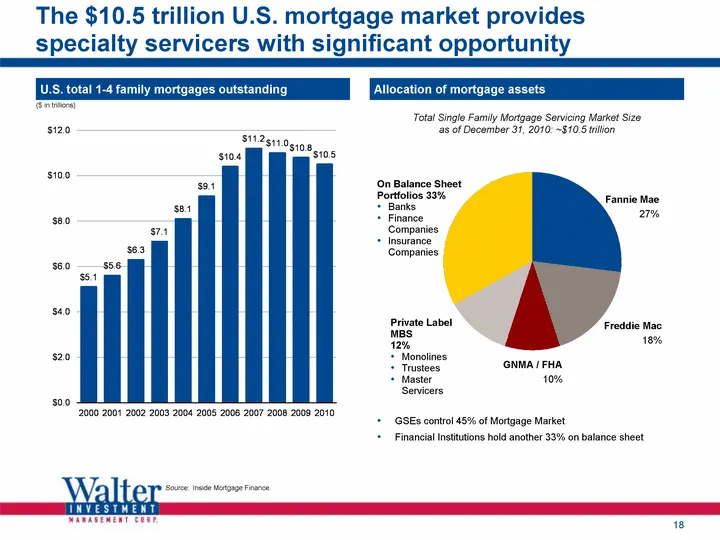
The $10.5 trillion U.S. mortgage market provides specialty servicers with significant opportunity Source: Inside Mortgage Finance. U.S. total 1-4 family mortgages outstanding Allocation of mortgage assets ($ in trillions) GSEs control 45% of Mortgage Market Financial Institutions hold another 33% on
Slide 20: High volume of existing and future delinquent loans
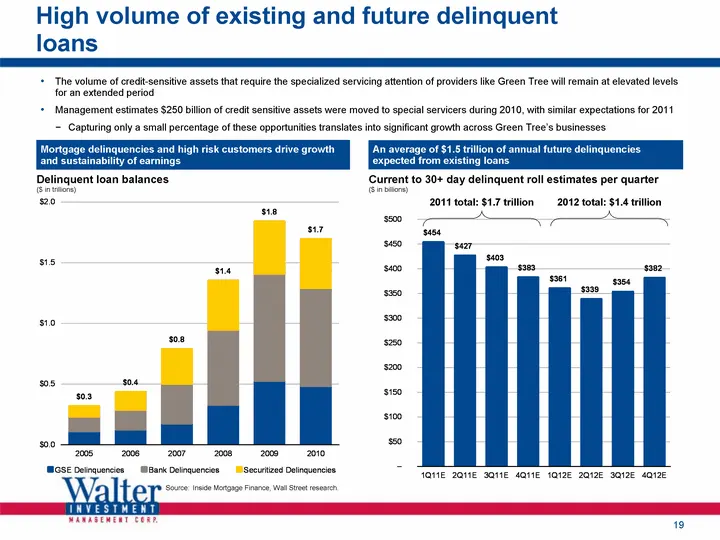
High volume of existing and future delinquent loans Source: Inside Mortgage Finance, Wall Street research. The volume of credit-sensitive assets that require the specialized servicing attention of providers like Green Tree will remain at elevated levels for an extended period Management estimates $2
Slide 21: High risk loans: the market opportunity will continue to be significant
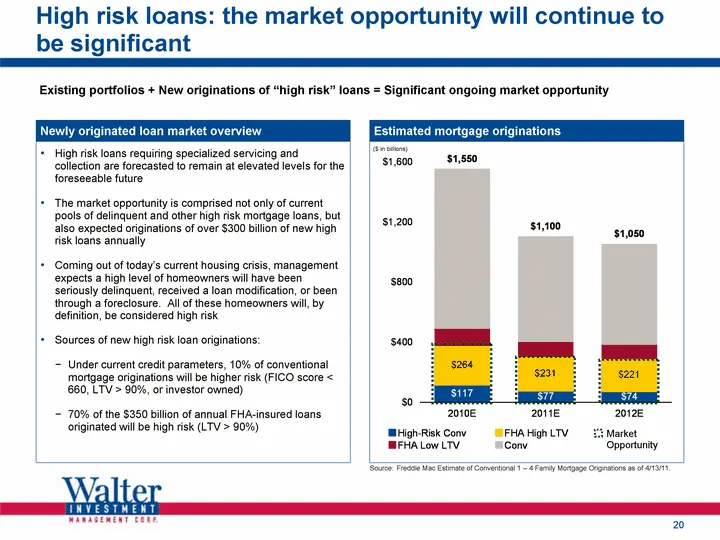
High risk loans: the market opportunity will continue to be significant Newly originated loan market overview High risk loans requiring specialized servicing and collection are forecasted to remain at elevated levels for the foreseeable future The market opportunity is comprised not only of current
Slide 22: Combined company is well positioned to capitalize on sector trends
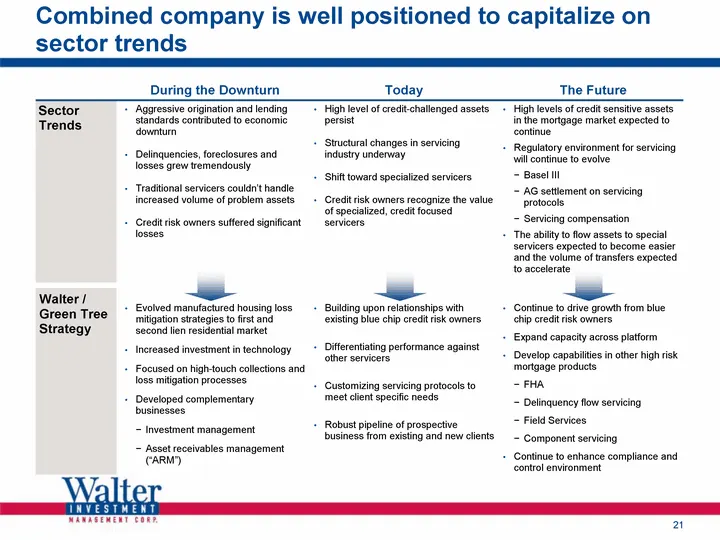
Combined company is well positioned to capitalize on sector trends Sector Trends Walter / Green Tree Strategy Aggressive origination and lending standards contributed to economic downturn Delinquencies, foreclosures and losses grew tremendously Traditional servicers couldn't handle increased volume
Slide 23: 4. Walter overview
4. MANAGEMENT CORP. Walter overview
Slide 24: Walter drivers of profitability
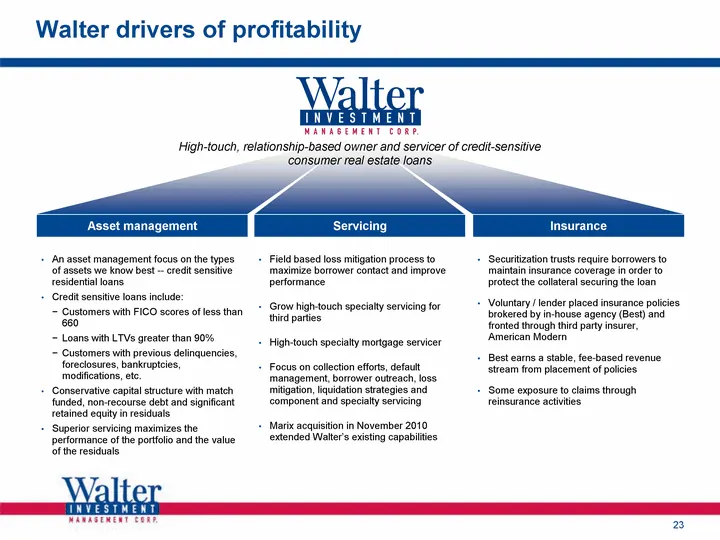
Walter drivers of profitability An asset management focus on the types of assets we know best -- credit sensitive residential loans Credit sensitive loans include: Customers with FICO scores of less than 660 Loans with LTVs greater than 90% Customers with previous delinquencies, foreclosures, bankru
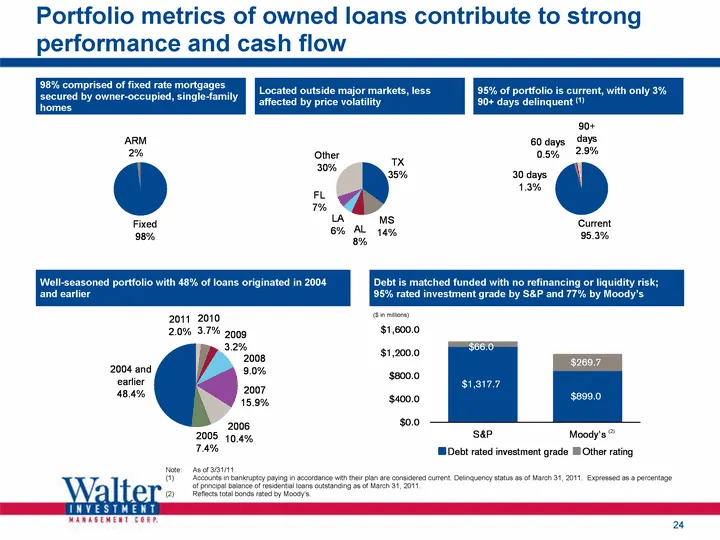
Slide 25: Portfolio metrics of owned loans contribute to strong performance and cash flow
Portfolio metrics of owned loans contribute to strong performance and cash flow 98% comprised of fixed rate mortgages secured by owner-occupied, single-family homes Well-seasoned portfolio with 48% of loans originated in 2004 and earlier Debt is matched funded with no refinancing or liquidity risk;
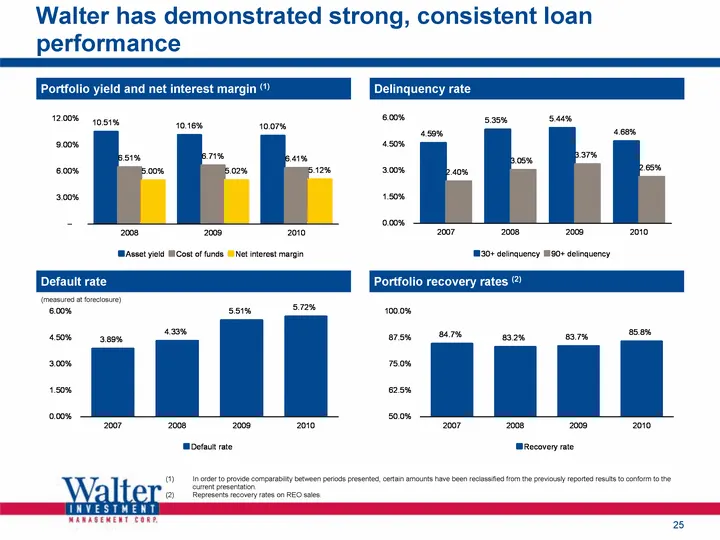
Slide 26: Walter has demonstrated strong, consistent loan performance
Walter has demonstrated strong, consistent loan performance Delinquency rate Portfolio yield and net interest margin (1) Portfolio recovery rates (2) Default rate (measured at foreclosure) (1) In order to provide comparability between periods presented, certain amounts have been reclassified from th
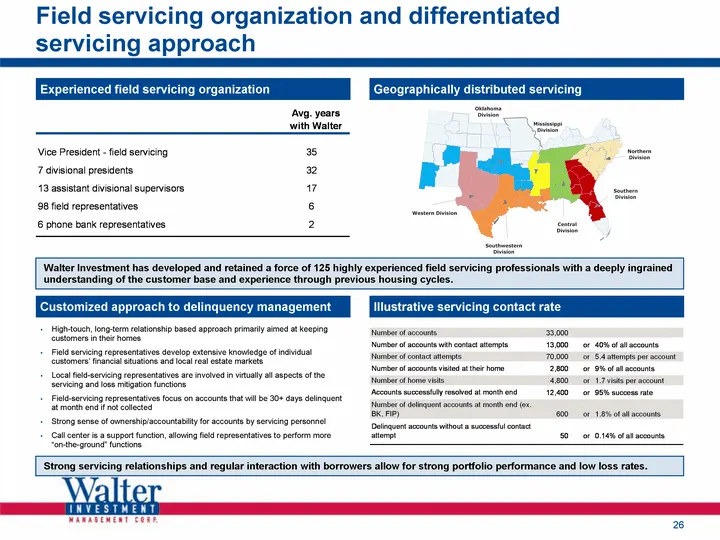
Slide 27: Field servicing organization and differentiated servicing approach
Field servicing organization and differentiated servicing approach Experienced field servicing organization Geographically distributed servicing Customized approach to delinquency management Illustrative servicing contact rate Walter Investment has developed and retained a force of 125 highly experi
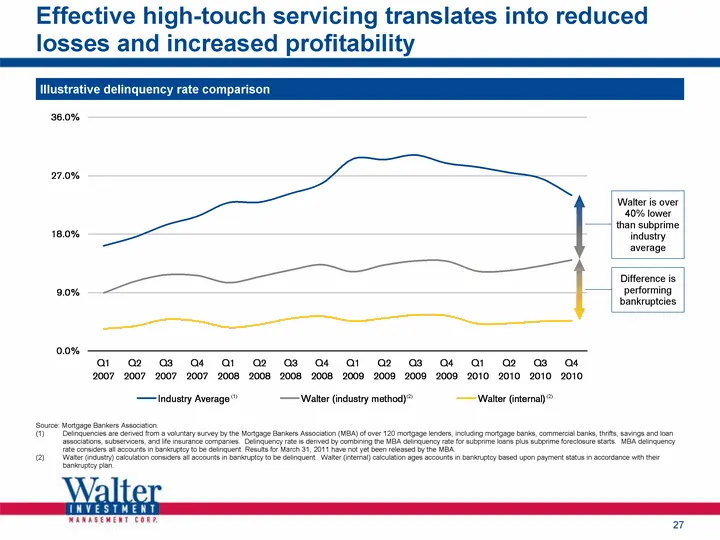
Slide 28: Effective high-touch servicing translates into reduced losses and increased profitability
Effective high-touch servicing translates into reduced losses and increased profitability Illustrative delinquency rate comparison Source: Mortgage Bankers Association. (1) Delinquencies are derived from a voluntary survey by the Mortgage Bankers Association (MBA) of over 120 mortgage lenders, inclu
Slide 29: 5. Green Tree overview
MANAGEMENT CORP. 5. Green Tree overview FS
Slide 30: Green Tree overview
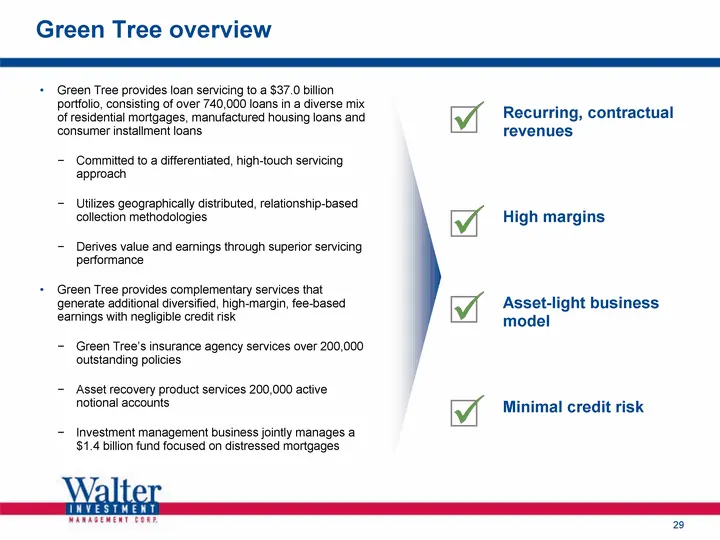
Green Tree overview Green Tree provides loan servicing to a $37.0 billion portfolio, consisting of over 740,000 loans in a diverse mix of residential mortgages, manufactured housing loans and consumer installment loans Committed to a differentiated, high-touch servicing approach Utilizes geographica
Slide 31: Complementary business lines
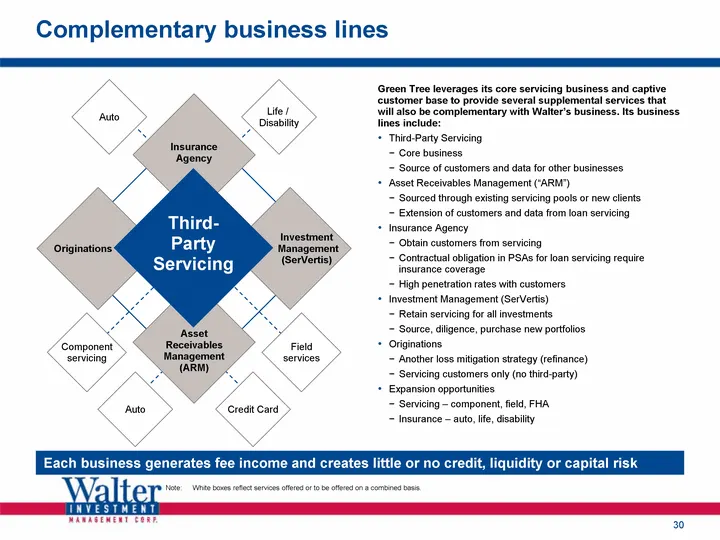
Complementary business lines Each business generates fee income and creates little or no credit, liquidity or capital risk Investment Management (SerVertis) Insurance Agency Asset Receivables Management (ARM) Life / Disability Auto Auto Credit Card Component servicing Field services Originations Thi
Slide 32: Complementary business lines (cont'd)
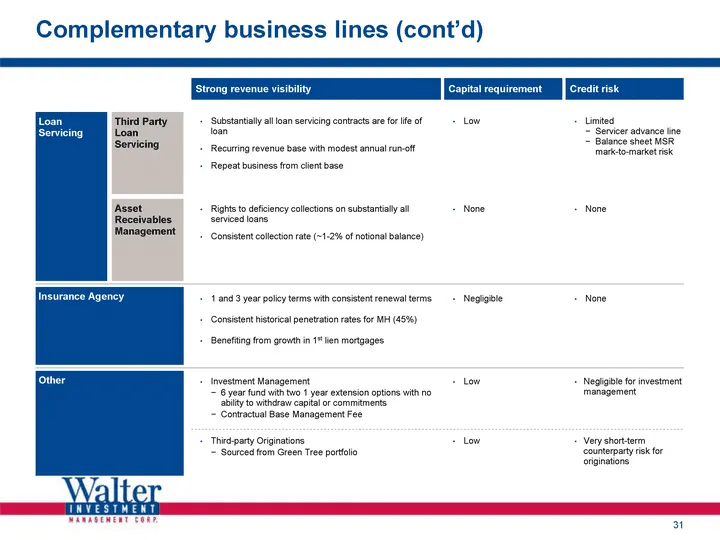
Complementary business lines (cont'd) Third Party Loan Servicing Substantially all loan servicing contracts are for life of loan Recurring revenue base with modest annual run-off Repeat business from client base Strong revenue visibility Low Capital requirement Limited Servicer advance line Balance
Slide 33: Servicing business overview
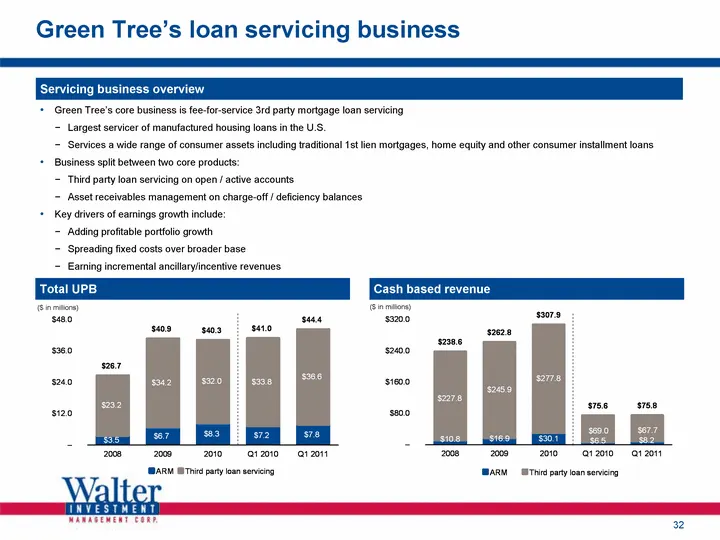
Servicing business overview Green Tree's core business is fee-for-service 3rd party mortgage loan servicing Largest servicer of manufactured housing loans in the U.S. Services a wide range of consumer assets including traditional 1st lien mortgages, home equity and other consumer installment loans B
Slide 34: Third party loan servicing
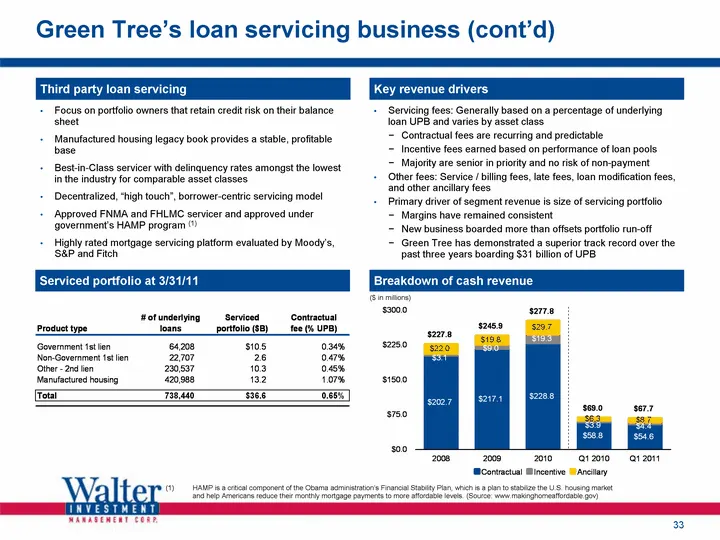
Third party loan servicing Focus on portfolio owners that retain credit risk on their balance sheet Manufactured housing legacy book provides a stable, profitable base Best-in-Class servicer with delinquency rates amongst the lowest in the industry for comparable asset classes Decentralized, "high t
Slide 35: Green Tree's diversified portfolio
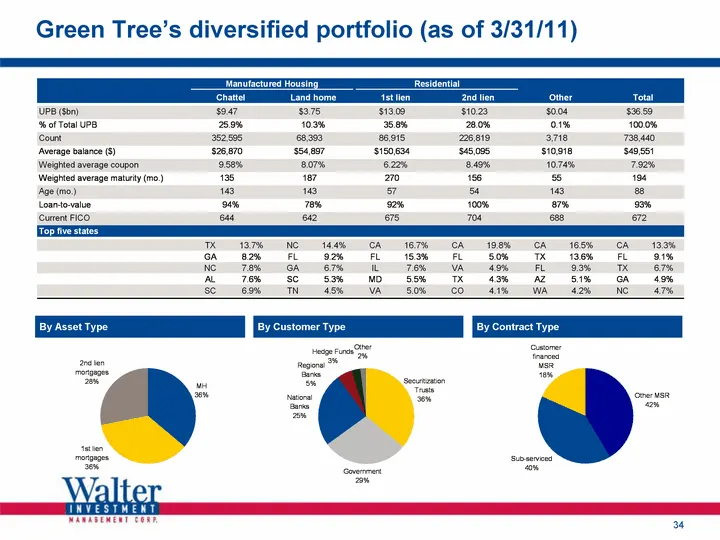
Green Tree's diversified portfolio (as of 3/31/11) By Customer Type By Asset Type By Contract Type
Slide 36: Portfolio performance drives client decision to award business
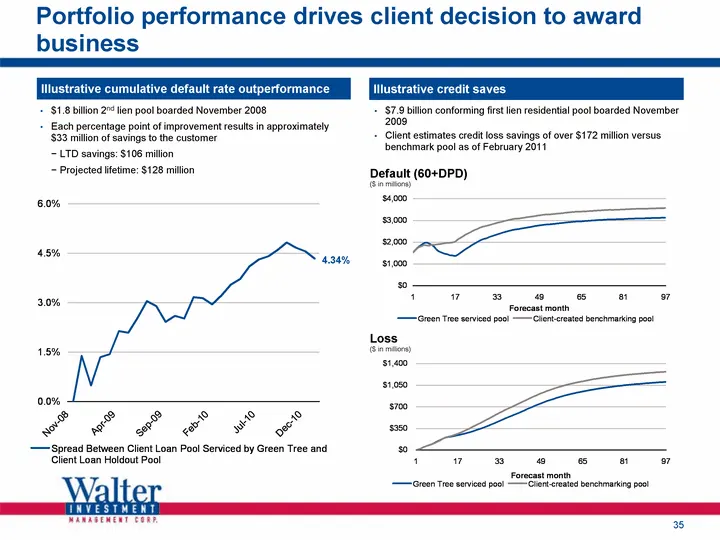
$1.8 billion 2nd lien pool boarded November 2008 Each percentage point of improvement results in approximately $33 million of savings to the customer LTD savings: $106 million Projected lifetime: $128 million 4.34% Illustrative cumulative default rate outperformance Portfolio performance drives clie
Slide 37: Recurring revenue
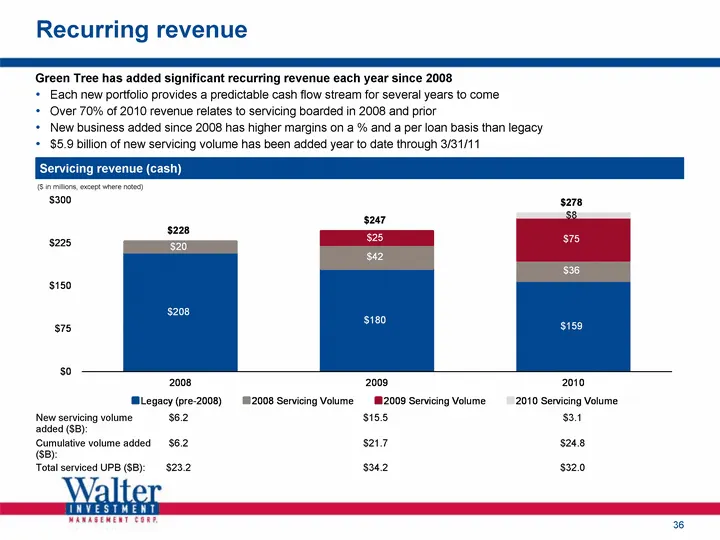
Recurring revenue Servicing revenue (cash) ($ in millions, except where noted) Green Tree has added significant recurring revenue each year since 2008 Each new portfolio provides a predictable cash flow stream for several years to come Over 70% of 2010 revenue relates to servicing boarded in 2008 an
Slide 38: Green Tree has a proven track record of adding new business
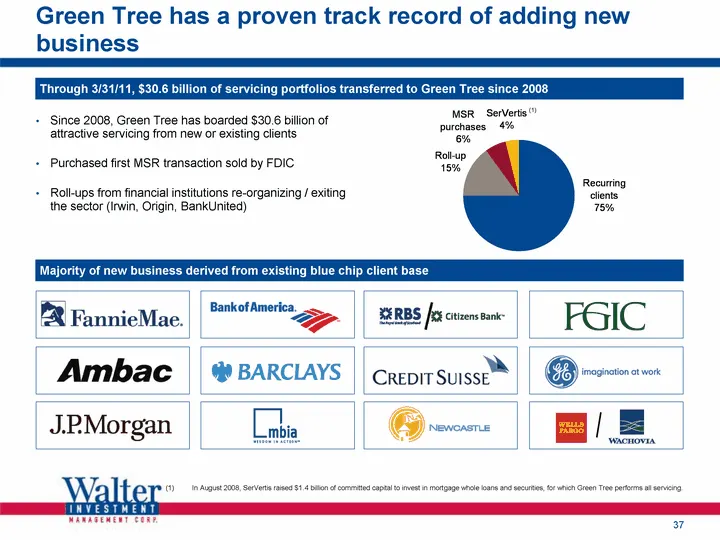
Green Tree has a proven track record of adding new business Since 2008, Green Tree has boarded $30.6 billion of attractive servicing from new or existing clients Purchased first MSR transaction sold by FDIC Roll-ups from financial institutions re-organizing / exiting the sector (Irwin, Origin, BankU
Slide 39: Asset receivables management product overview
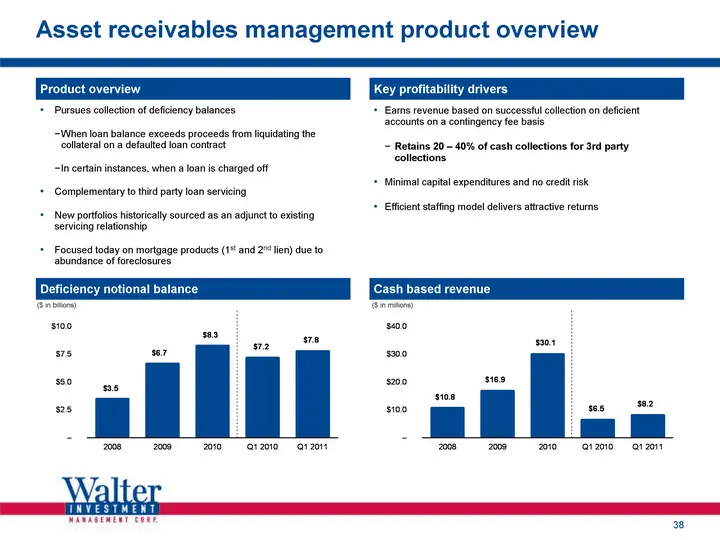
Asset receivables management product overview Product overview Pursues collection of deficiency balances When loan balance exceeds proceeds from liquidating the collateral on a defaulted loan contract In certain instances, when a loan is charged off Complementary to third party loan servicing New po
Slide 40: Green Tree has a robust new business pipeline
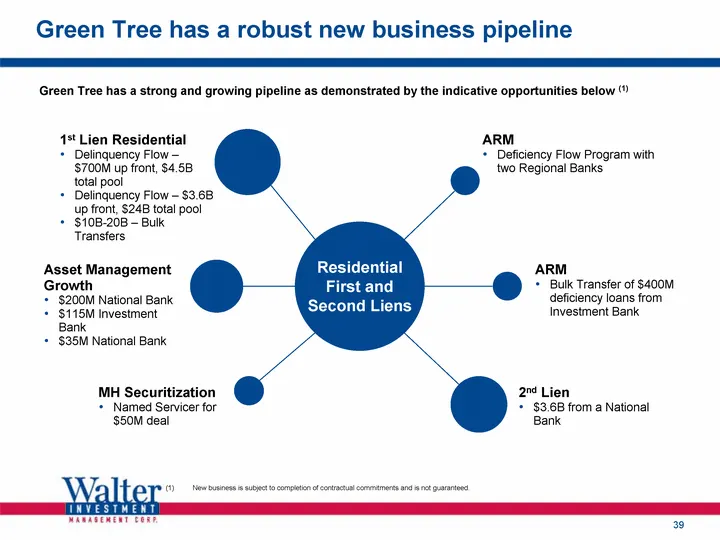
2nd Lien $3.6B from a National Bank ARM Bulk Transfer of $400M deficiency loans from Investment Bank ARM Deficiency Flow Program with two Regional Banks MH Securitization Named Servicer for $50M deal Residential First and Second Liens Asset Management Growth $200M National Bank $115M Investment Bank
Slide 41: Insurance agency business overview
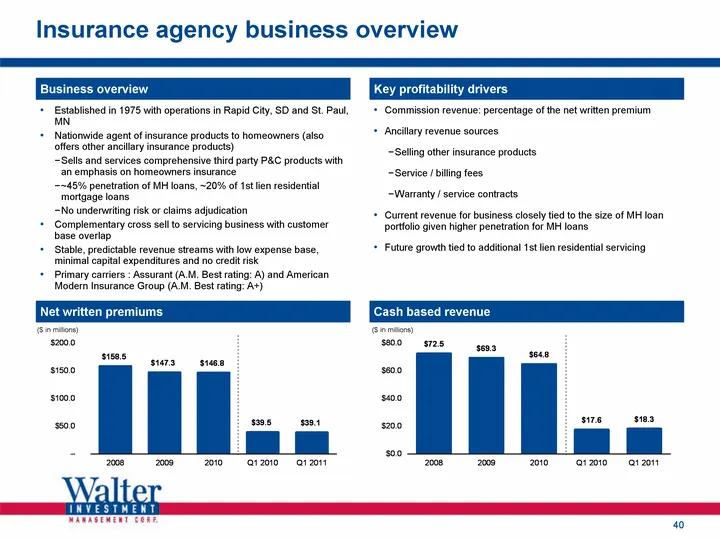
Insurance agency business overview Business overview Established in 1975 with operations in Rapid City, SD and St. Paul, MN Nationwide agent of insurance products to homeowners (also offers other ancillary insurance products) Sells and services comprehensive third party P&C products with an emphasis
Slide 42: Insurance agency key statistics
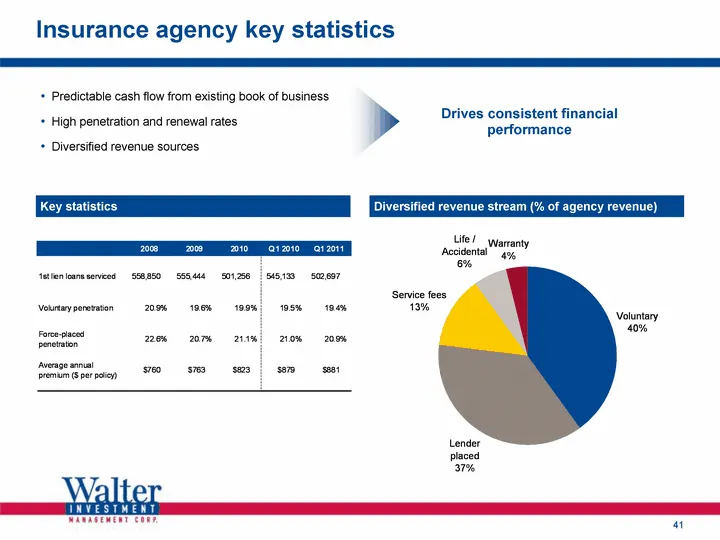
Insurance agency key statistics Predictable cash flow from existing book of business High penetration and renewal rates Diversified revenue sources Key statistics Diversified revenue stream (% of agency revenue) Drives consistent financial performance
Slide 43: Investment management overview
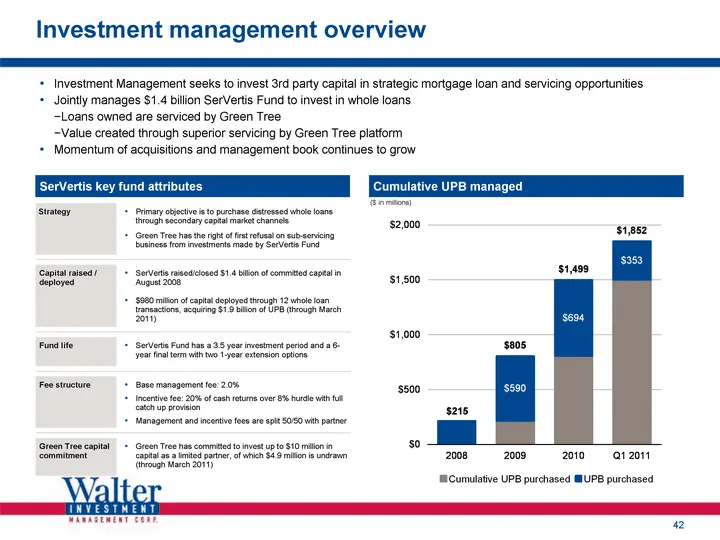
Investment management overview Investment Management seeks to invest 3rd party capital in strategic mortgage loan and servicing opportunities Jointly manages $1.4 billion SerVertis Fund to invest in whole loans Loans owned are serviced by Green Tree Value created through superior servicing by Green
Slide 44: 6. Financial overview
MANAGEMENT CORP. 6. Financial overview See e
Slide 45: Green Tree financial overview
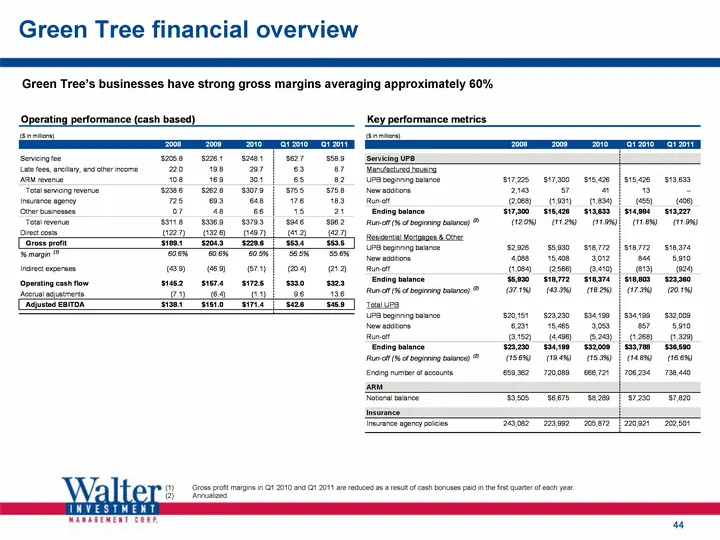
Green Tree financial overview (1) Gross profit margins in Q1 2010 and Q1 2011 are reduced as a result of cash bonuses paid in the first quarter of each year. (2) Annualized. Green Tree's businesses have strong gross margins averaging approximately 60%
Slide 46: Walter financial overview
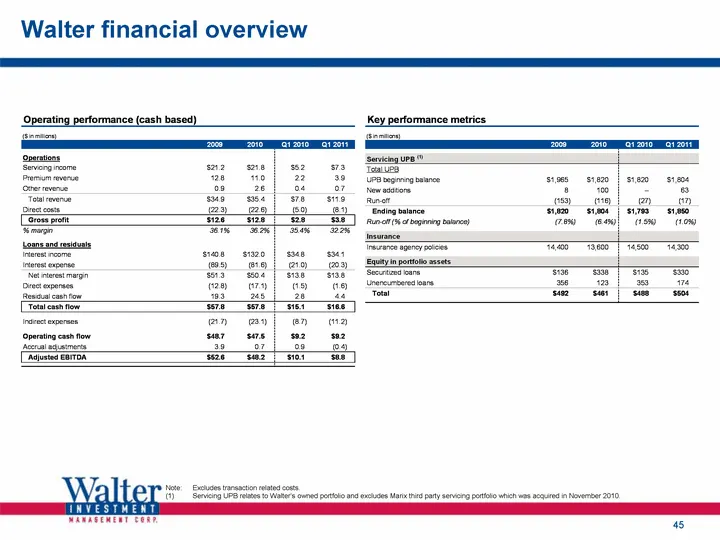
Walter financial overview Note: Excludes transaction related costs. (1) Servicing UPB relates to Walter's owned portfolio and excludes Marix third party servicing portfolio which was acquired in November 2010.
Slide 47: Combined operating performance
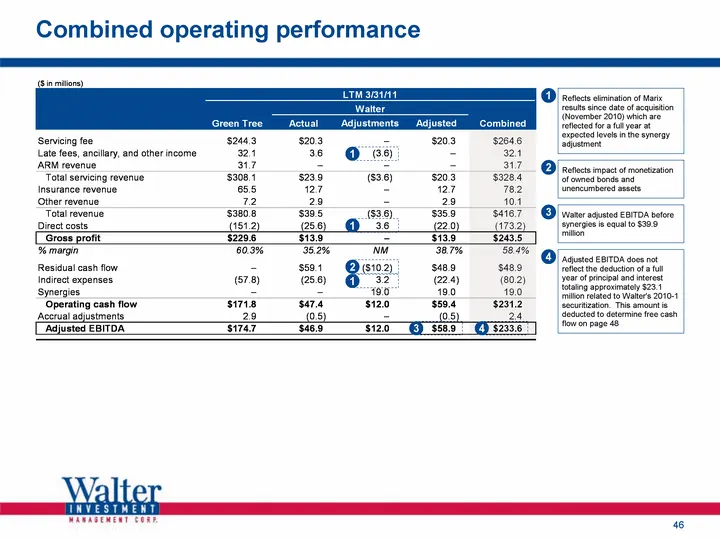
Combined operating performance Walter adjusted EBITDA before synergies is equal to $39.9 million Reflects impact of monetization of owned bonds and unencumbered assets Reflects elimination of Marix results since date of acquisition (November 2010) which are reflected for a full year at expected leve
Slide 48: Combined 2010 EBITDA contribution
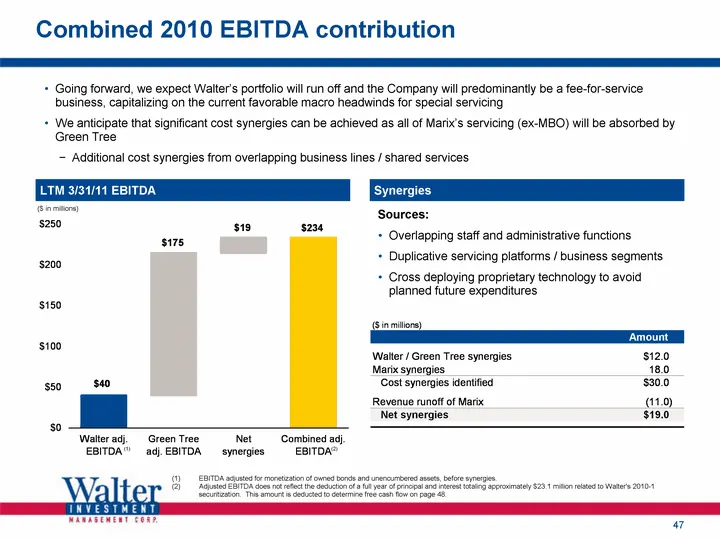
Combined 2010 EBITDA contribution (1) EBITDA adjusted for monetization of owned bonds and unencumbered assets, before synergies. (2) Adjusted EBITDA does not reflect the deduction of a full year of principal and interest totaling approximately $23.1 million related to Walter's 2010-1 securitization.
Slide 49: Significant free cash flow generation
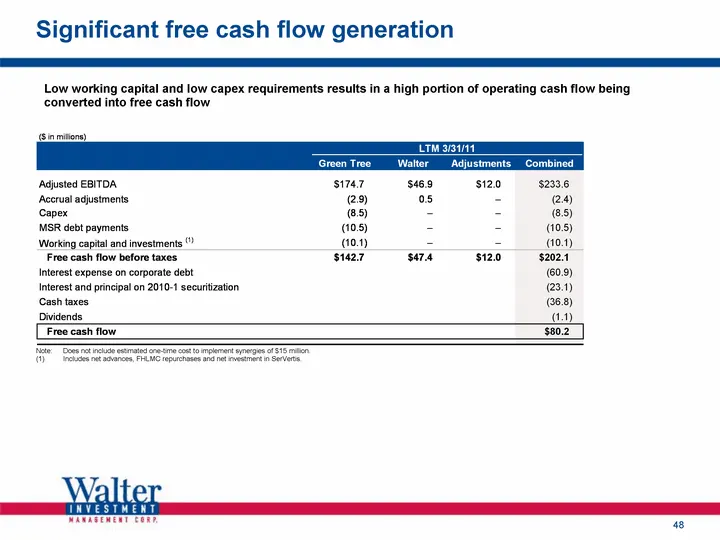
Significant free cash flow generation Low working capital and low capex requirements results in a high portion of operating cash flow being converted into free cash flow Note: Does not include estimated one-time cost to implement synergies of $15 million. (1) Includes net advances, FHLMC repurchases
Slide 50: 7. Conclusion
MANAGEMENT CORP. 7. Conclusion SS
Slide 51: Walter / Green Tree is well positioned to address industry challenges
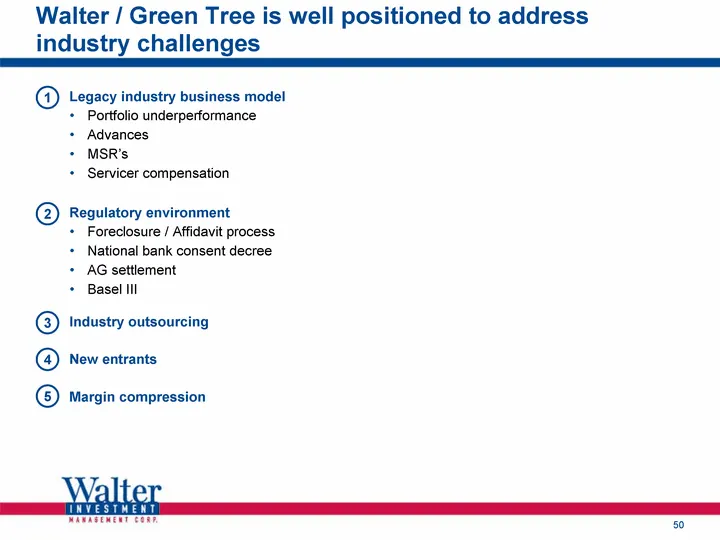
Legacy industry business model Portfolio underperformance Advances MSR's Servicer compensation Walter / Green Tree is well positioned to address industry challenges Industry outsourcing New entrants Margin compression 1 2 3 4 5 Regulatory environment Foreclosure / Affidavit process National bank con
Slide 52: Key credit highlights
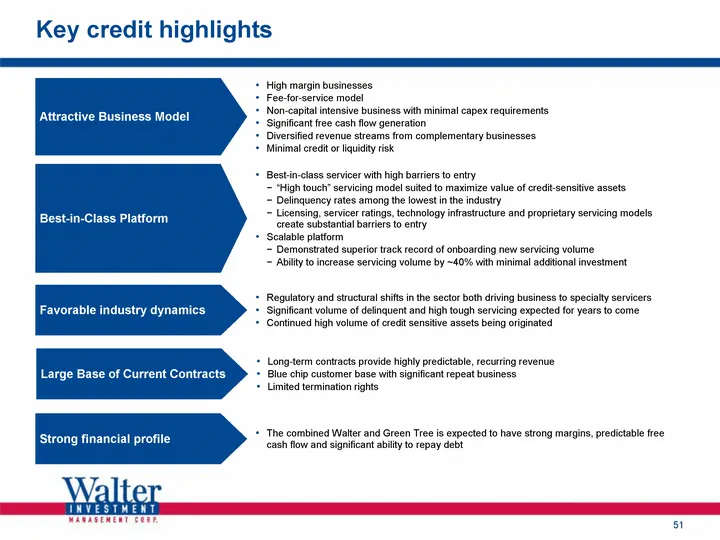
Key credit highlights High margin businesses Fee-for-service model Non-capital intensive business with minimal capex requirements Significant free cash flow generation Diversified revenue streams from complementary businesses Minimal credit or liquidity risk Attractive Business Model Best-in-class s
Slide 53: 8. Summary terms and timetable
8. Summary terms and timetable
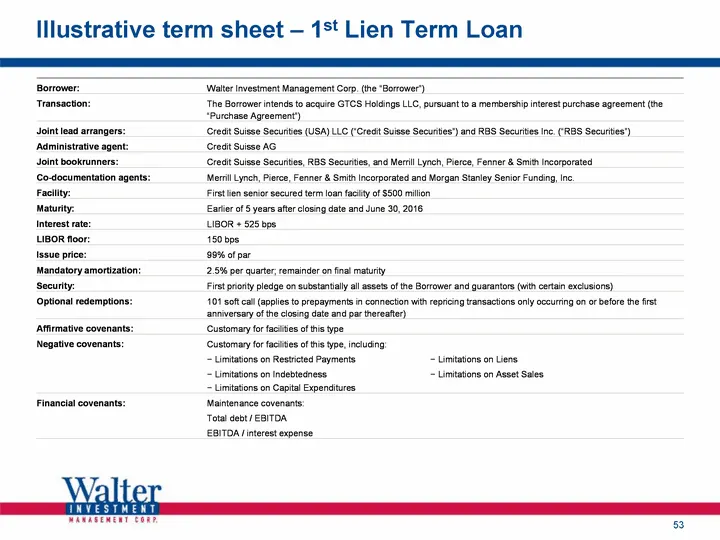
Slide 54: Illustrative term sheet - 1st Lien Term Loan
Illustrative term sheet - 1st Lien Term Loan
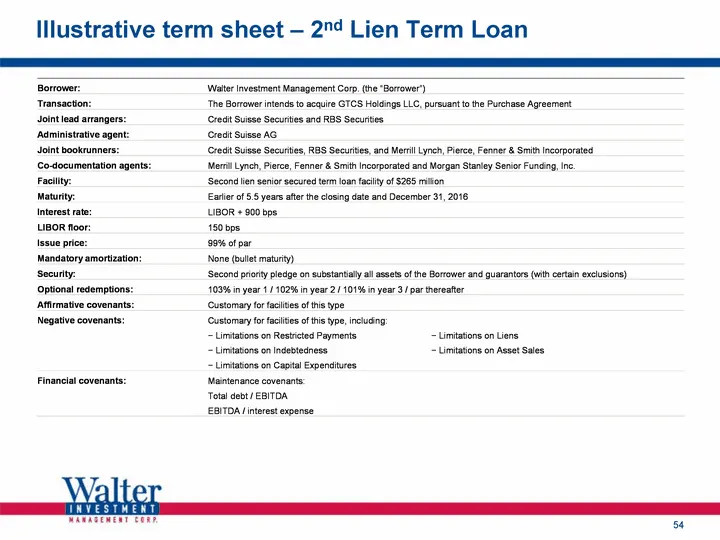
Slide 55: Illustrative term sheet - 2nd Lien Term Loan
Illustrative term sheet - 2nd Lien Term Loan
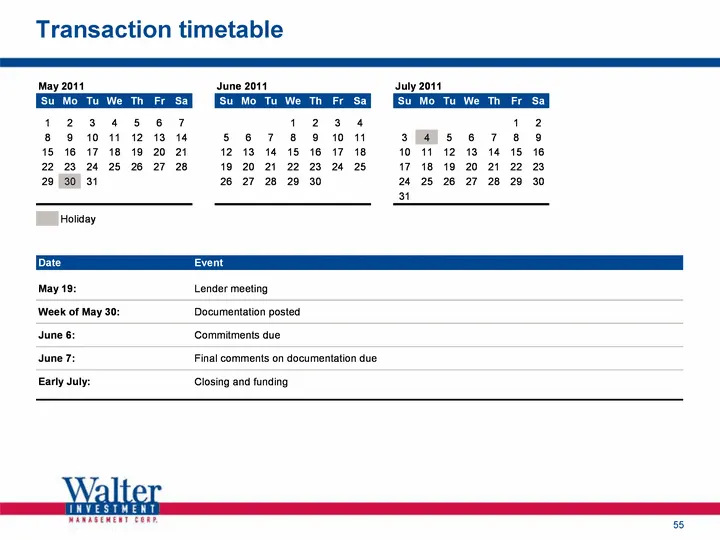
Slide 56: Transaction timetable
Transaction timetable May 2011 June 2014 suiy2011 12346507 1234 12 Linnea soreewn sMsarae Pree er ered Seana ea) Rouse ne won wee 7 wie wa 2 2 ist Bn mm 30 Mo mf 3 HH retsey May 19: Lender meeting ‘Week of May 30: Documentation posted ne 6: Commitments due ‘tune 7: Final comments on documentation ue
Slide 57: Appendix
MANAGEMENT CORP. Appendix
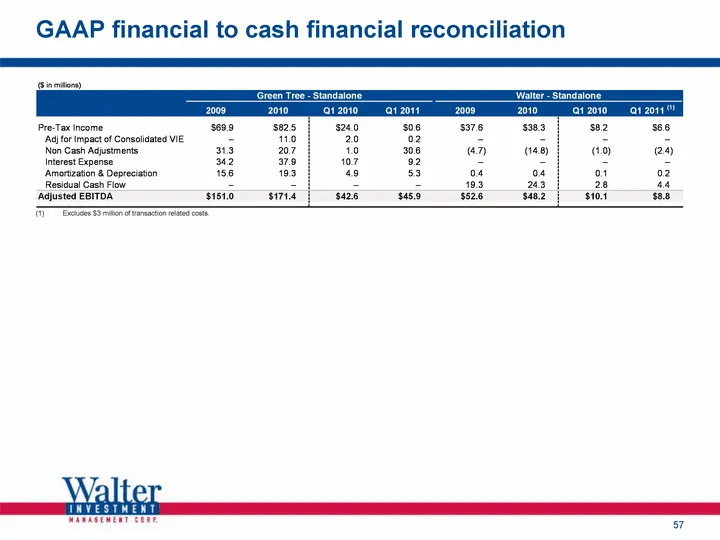
Slide 58: GAAP financial to cash financial reconciliation
GAAP financial to cash financial reconciliation (1) Excludes $3 million of transaction related costs.
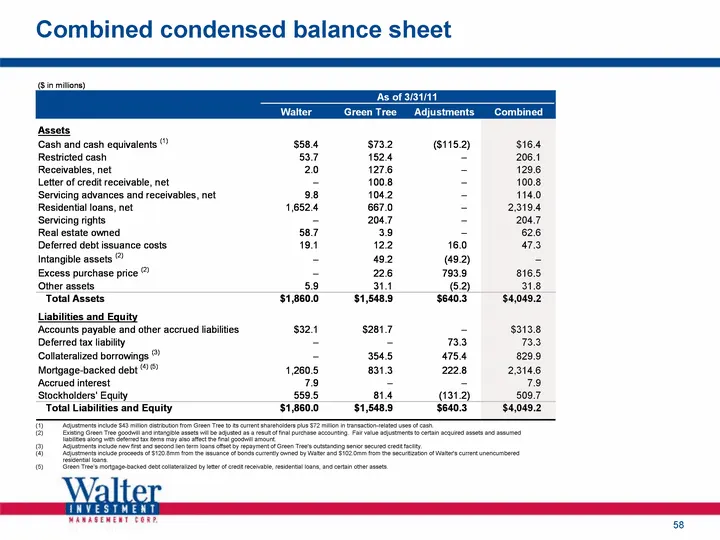
Slide 59: Combined condensed balance sheet
Combined condensed balance sheet (1) Adjustments include $43 million distribution from Green Tree to its current shareholders plus $72 million in transaction-related uses of cash. (2) Existing Green Tree goodwill and intangible assets will be adjusted as a result of final purchase accounting. Fair v
Source: SEC EDGAR · 8-K filed May 18, 2011
More decks from Ditech Holding Corporation
 Presentation (December 2018)27 slides · Dec 14, 2018
 Q2 2018 Earnings Presentation21 slides · Aug 9, 2018
 Q1 2018 Earnings Presentation27 slides · Jun 6, 2018
 Walter Investment Management — Debt Investor Presentation (October 2017)15 slides · Oct 23, 2017
 Walter Investment Management — Debt Investor Presentation (August 2017)35 slides · Aug 1, 2017
 Walter Investment Management — Debt Investor Presentation (August 2017)5 slides · Aug 1, 2017