ASB Bancorp — KBW 2016 Community Bank Investor Conference
42 slides from ASB Bancorp's conference presentation, Jul 29, 2016
Slide 1: KBW 2016 Community Bank Investor Conference
KBW 2016 Community Bank Investor Conference New York, New York August 2 - 3, 2016 Exhibit 99.2
Slide 2: Forward-Looking Statements
2 This presentation, as well as other written communications made from time to time by the Company and its subsidiaries and oral communications made from time to time by authorized officers of the Company, may contain statements relating to the future results of the Company (including certain projec
Slide 3: Investment Highlights
3 » Solid Franchise in Attractive Market Area » Significant Improvement in Key Performance Metrics » Key Performance Indicator Targets Summarize Expectation of Continued Improvement » Significant Additional Cost Reductions Planned » Implementing Long - Term Strategic Plan to Achieve Sustainable Supe
Slide 4: Solid Franchise in Attractive Market Area
Solid Franchise in Attractive Market Area
Slide 5: ASBB Profile
5 » Headquartered in Asheville, North Carolina » Community bank founded in 1936 with total assets of $806 million » 13 offices in 5 Western North Carolina counties » 158 full - time equivalent employees » Converted from the mutual form of ownership on October 11, 2011 ASBB Profile
Slide 6: Executive Management
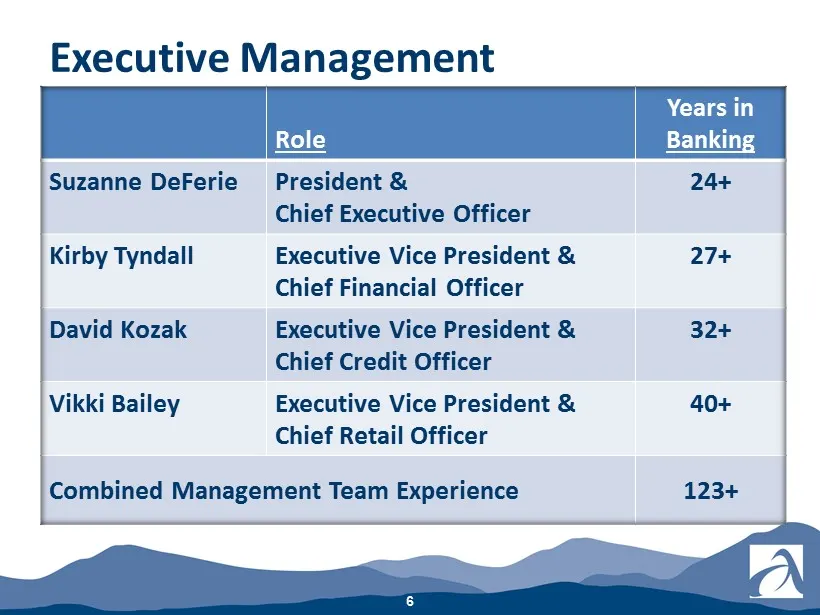
6 Executive Management Role Years in Banking Suzanne DeFerie President & Chief Executive Officer 24+ Kirby Tyndall Executive Vice President & Chief Financial Officer 27+ David Kozak Executive Vice President & Chief Credit Officer 32+ Vikki Bailey Executive Vice President & Chief Retail Officer 40+ C
Slide 7: Attractive Market Area
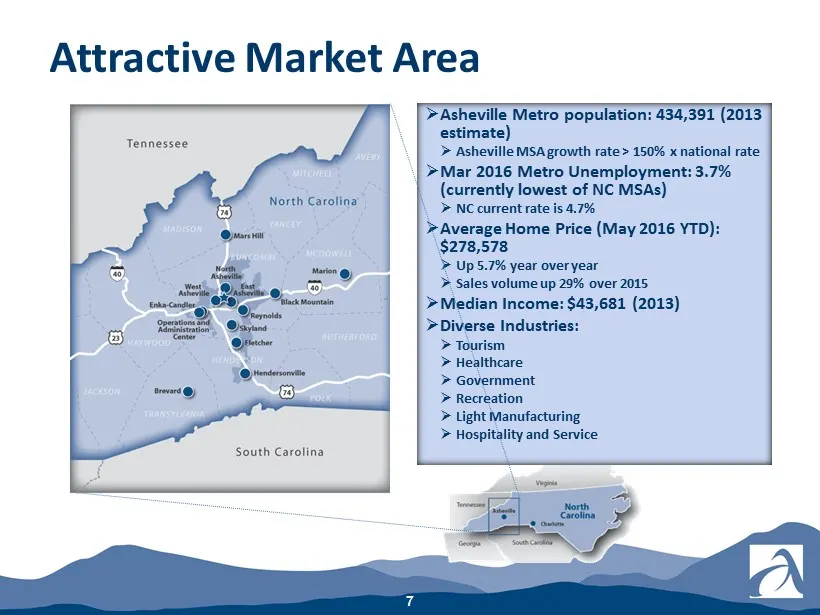
7 Attractive Market Area » Asheville Metro population: 434,391 (2013 estimate) » Asheville MSA growth rate > 150% x national rate » Mar 2016 Metro Unemployment: 3.7% (currently lowest of NC MSAs) » NC current rate is 4.7% » Average Home Price (May 2016 YTD): $278,578 » Up 5.7% year over year » Sales
Slide 8: Local Market - Economic Drivers
8 Local Market Recovery 2013 - present » Increasing loan demand; current low loan delinquencies » Construction returns – with gusto » Current unemployment rate at 3.7% – lowest MSA in NC » Real estate valuations, especially residential, are recovering » Transylvania County (location of most signific
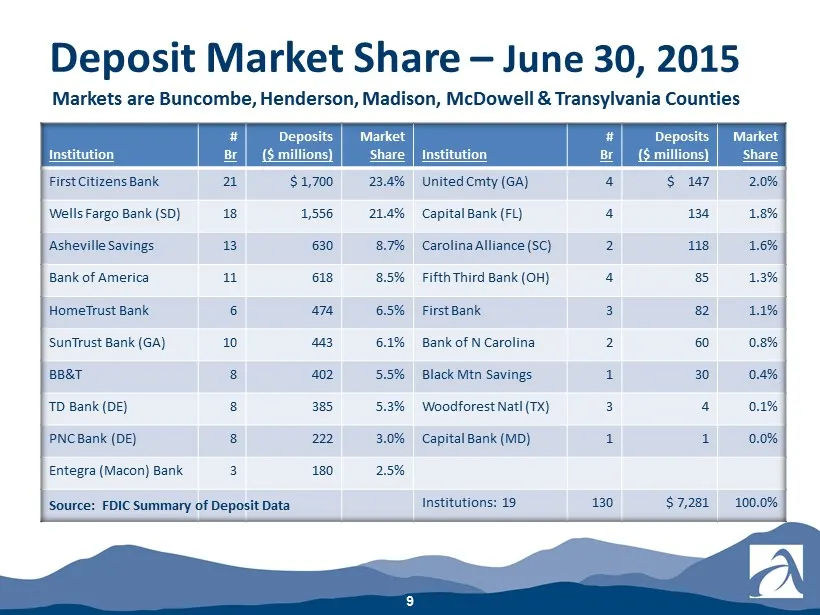
Slide 9: Deposit Market Share – June 30, 2015
9 Deposit Market Share – June 30, 2015 Institution # Br Deposits ($ millions) Market Share Institution # Br Deposits ($ millions) Market Share First Citizens Bank 21 $ 1,700 23.4% United Cmty (GA) 4 $ 147 2.0% Wells Fargo Bank (SD) 18 1,556 21.4% Capital Bank (FL) 4 134 1.8% Asheville Savings 13 630
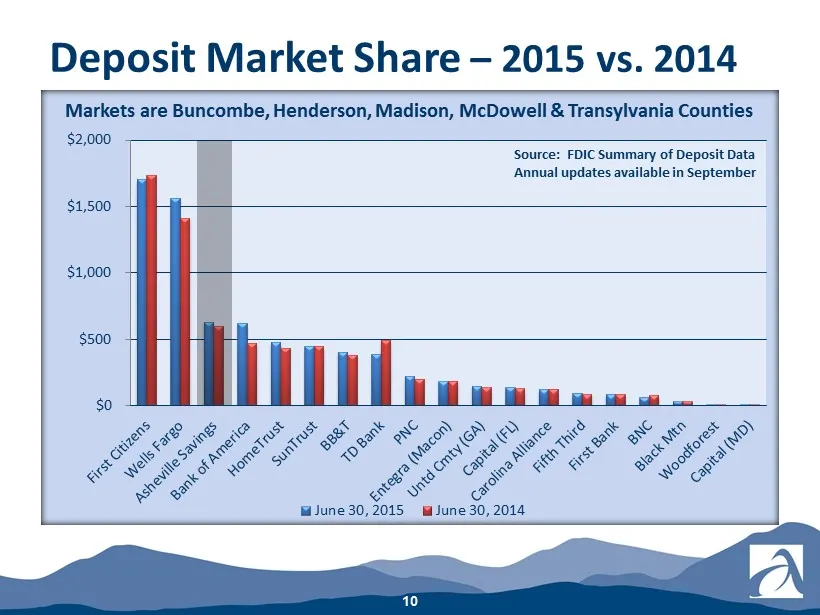
Slide 10: Deposit Market Share – 2015 vs. 2014
10 Markets are Buncombe, Henderson, Madison, McDowell & Transylvania Counties June 30 ($ millions) Deposit Market Share – 2015 vs. 2014 Source: FDIC Deposit Market Share Data $0 $500 $1,000 $1,500 $2,000 June 30, 2015 June 30, 2014 Column1 Source: FDIC Summary of Deposit Data Annual updates availabl
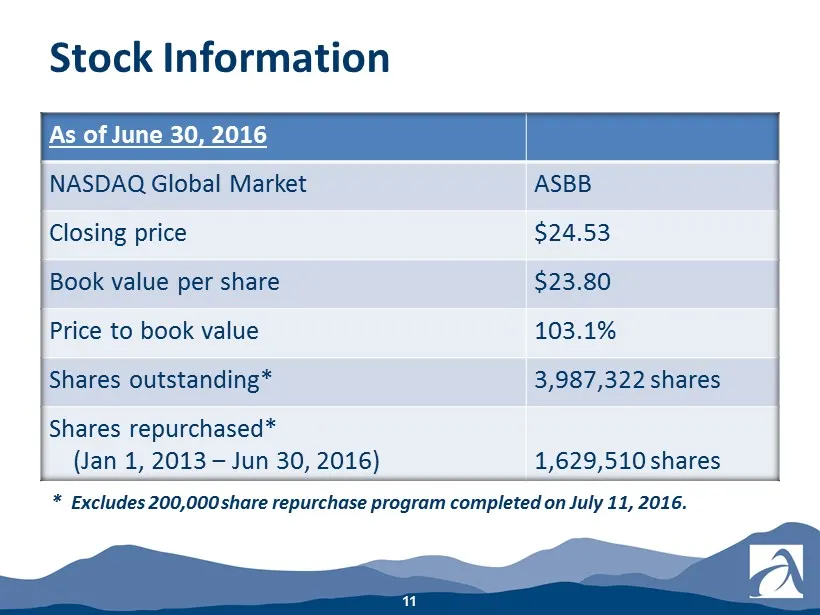
Slide 11: Stock Information
11 As of June 30, 2016 NASDAQ Global Market ASBB Closing price $24.53 Book value per share $23.80 Price to book value 103.1% Shares outstanding* 3,987,322 shares Shares repurchased* (Jan 1, 2013 ‒ Jun 30, 2016) 1,629,510 shares Stock Information * Excludes 200,000 share repurchase program completed
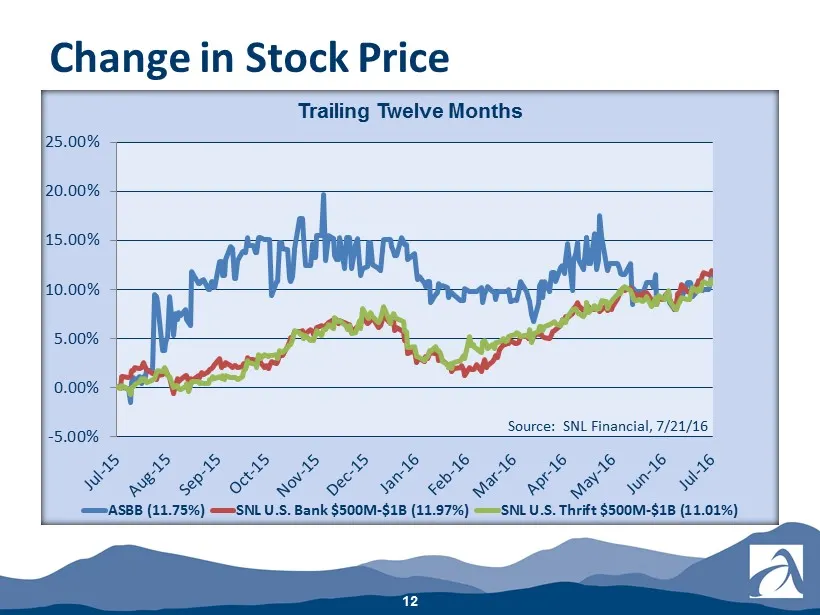
Slide 12: Change in Stock Price
12 Change in Stock Price -5.00% 0.00% 5.00% 10.00% 15.00% 20.00% 25.00% Trailing Twelve Months ASBB (11.75%) SNL U.S. Bank $500M-$1B (11.97%) SNL U.S. Thrift $500M-$1B (11.01%) Source: SNL Financial, 7/21/16
Slide 13: Significant Improvements in Key Performance Metrics
Significant Improvements in Key Performance Metrics
Slide 14: Balance Sheet — Loans Grew
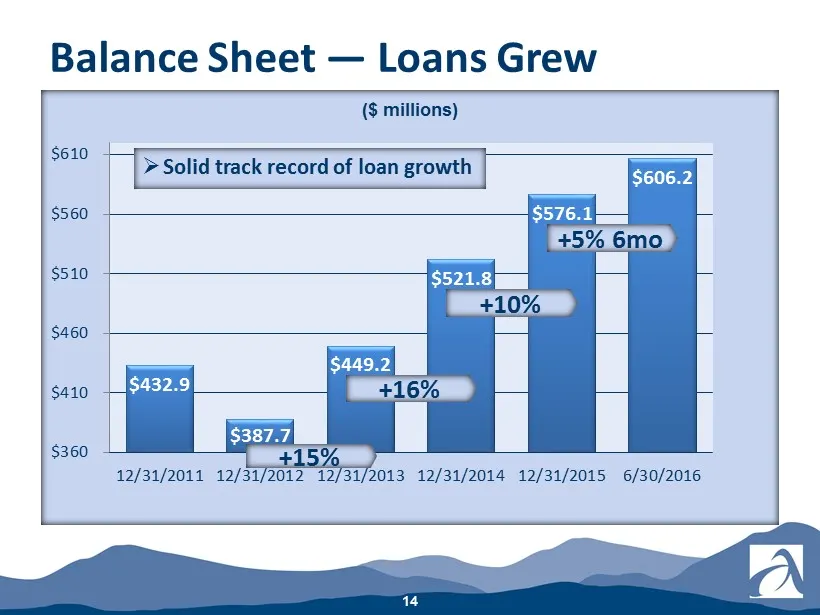
Balance Sheet — Loans Grew 14 $432.9 $387.7 $449.2 $521.8 $576.1 $606.2 $360 $410 $460 $510 $560 $610 12/31/2011 12/31/2012 12/31/2013 12/31/2014 12/31/2015 6/30/2016 ($ millions) +10% +16% » Solid track record of loan growth +15% +5% 6mo
Slide 15: Balance Sheet — Improved Asset Quality
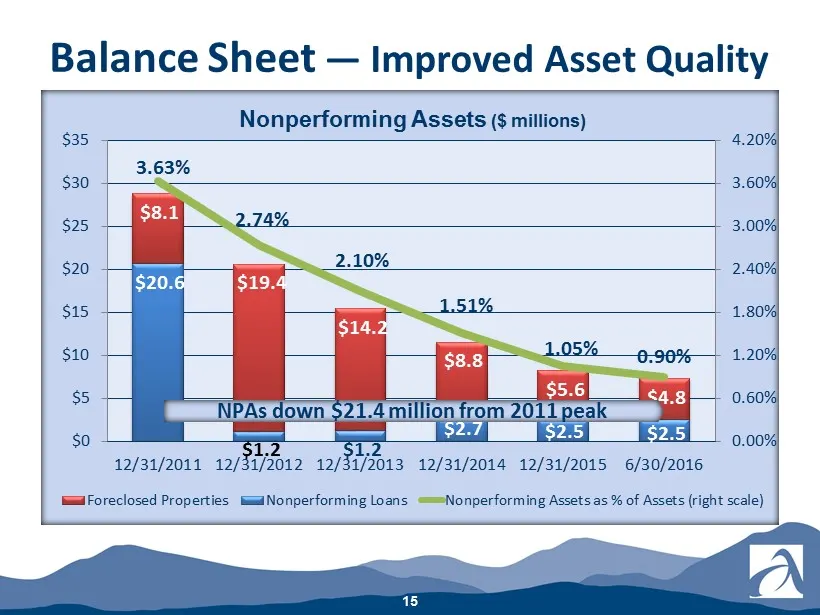
Balance Sheet — Improved Asset Quality 15 $20.6 $1.2 $1.2 $2.7 $2.5 $2.5 $8.1 $19.4 $14.2 $8.8 $5.6 $4.8 3.63% 2.74% 2.10% 1.51% 1.05% 0.90% 0.00% 0.60% 1.20% 1.80% 2.40% 3.00% 3.60% 4.20% $0 $5 $10 $15 $20 $25 $30 $35 12/31/2011 12/31/2012 12/31/2013 12/31/2014 12/31/2015 6/30/2016 Nonperforming As
Slide 16: Balance Sheet — Low Loan Delinquencies
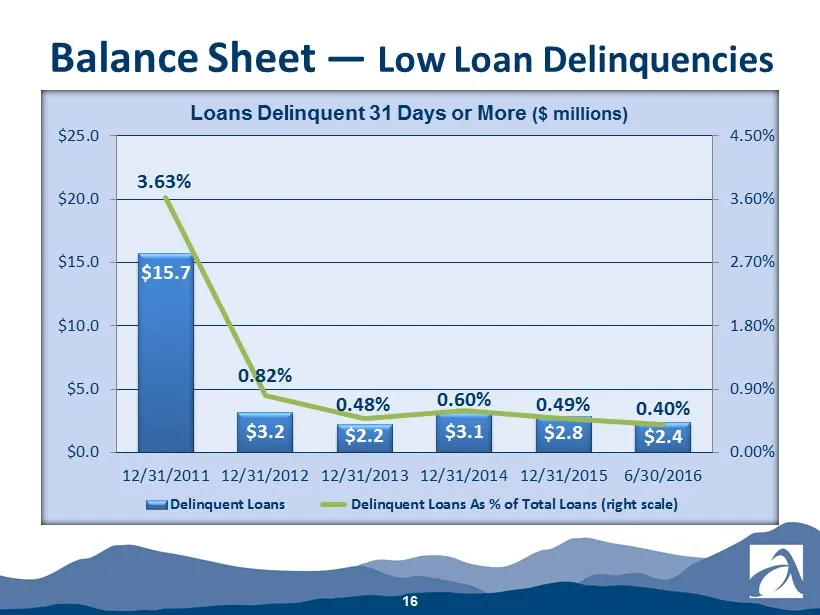
Balance Sheet — Low Loan Delinquencies 16 $15.7 $3.2 $2.2 $3.1 $2.8 $2.4 3.63% 0.82% 0.48% 0.60% 0.49% 0.40% 0.00% 0.90% 1.80% 2.70% 3.60% 4.50% $0.0 $5.0 $10.0 $15.0 $20.0 $25.0 12/31/2011 12/31/2012 12/31/2013 12/31/2014 12/31/2015 6/30/2016 Delinquent Loans Delinquent Loans As % of Total Loans (r
Slide 17: Balance Sheet — Core Deposits
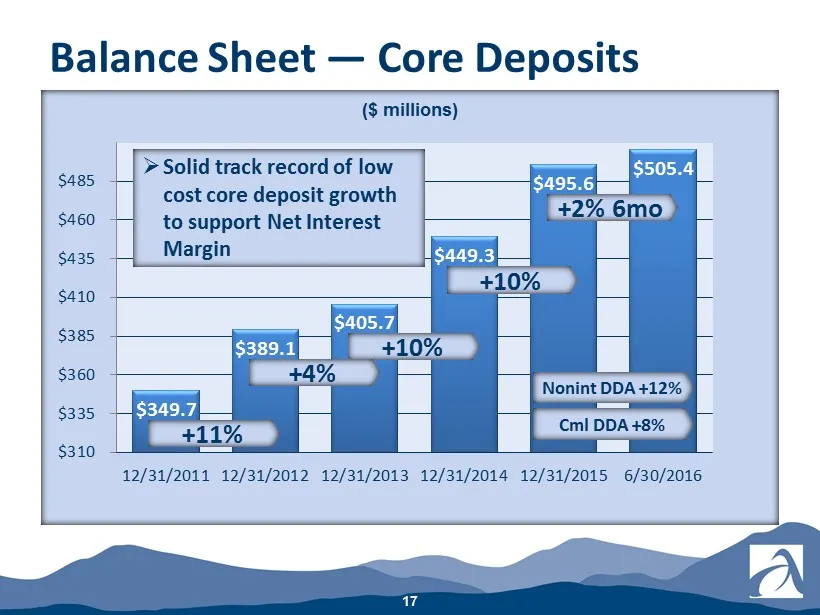
Balance Sheet — Core Deposits 17 $349.7 $389.1 $405.7 $449.3 $495.6 $505.4 $310 $335 $360 $385 $410 $435 $460 $485 12/31/2011 12/31/2012 12/31/2013 12/31/2014 12/31/2015 6/30/2016 ($ millions) » Solid track record of low cost core deposit growth to support Net Interest Margin +10% +10% +4% +11% Cml
Slide 18: Balance Sheet — Commercial Core Deposits
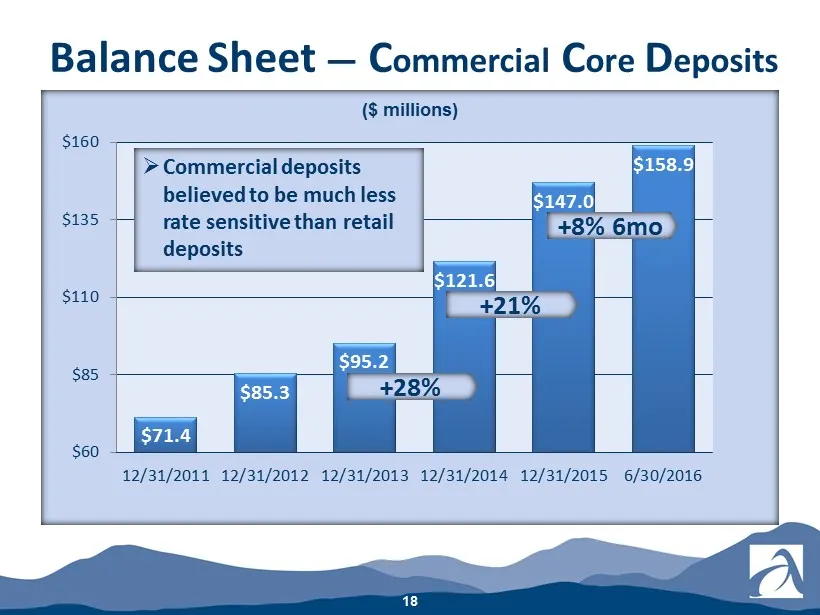
18 Balance Sheet — C ommercial C ore D eposits $71.4 $85.3 $95.2 $121.6 $147.0 $158.9 $60 $85 $110 $135 $160 12/31/2011 12/31/2012 12/31/2013 12/31/2014 12/31/2015 6/30/2016 ($ millions) » Commercial deposits believed to be much less rate sensitive than retail deposits +28% +21% +8% 6mo
Slide 19: Improvement in Operating Results
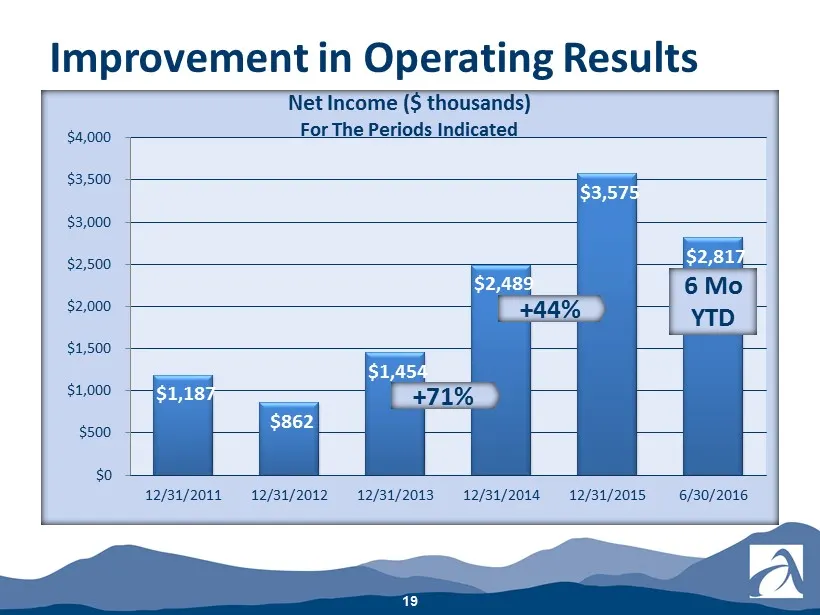
Improvement in Operating Results 19 $1,187 $862 $1,454 $2,489 $3,575 $2,817 $0 $500 $1,000 $1,500 $2,000 $2,500 $3,000 $3,500 $4,000 12/31/2011 12/31/2012 12/31/2013 12/31/2014 12/31/2015 6/30/2016 Net Income ($ thousands) For The Periods Indicated +44% +71% 6 Mo YTD
Slide 20: Improvement in Operating Results
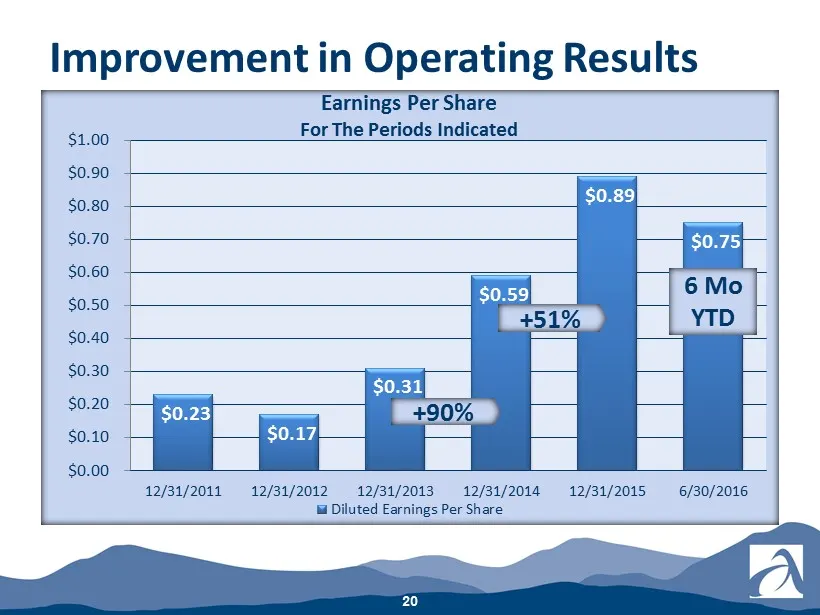
Improvement in Operating Results 20 $0.23 $0.17 $0.31 $0.59 $0.89 $0.75 $0.00 $0.10 $0.20 $0.30 $0.40 $0.50 $0.60 $0.70 $0.80 $0.90 $1.00 12/31/2011 12/31/2012 12/31/2013 12/31/2014 12/31/2015 6/30/2016 Diluted Earnings Per Share Earnings Per Share For The Periods Indicated +51% +90% 6 Mo YTD
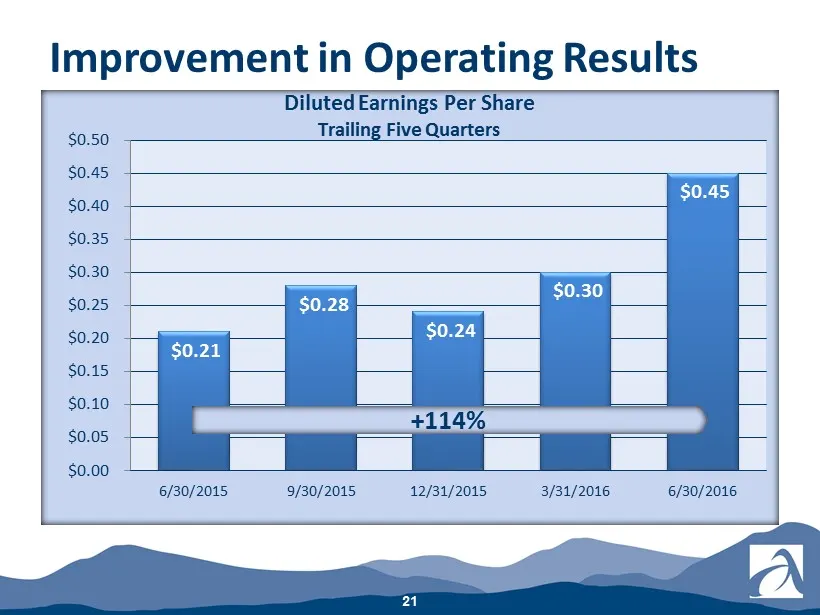
Slide 21: Improvement in Operating Results
Improvement in Operating Results 21 $0.21 $0.28 $0.24 $0.30 $0.45 $0.00 $0.05 $0.10 $0.15 $0.20 $0.25 $0.30 $0.35 $0.40 $0.45 $0.50 6/30/2015 9/30/2015 12/31/2015 3/31/2016 6/30/2016 Diluted Earnings Per Share Trailing Five Quarters +114%
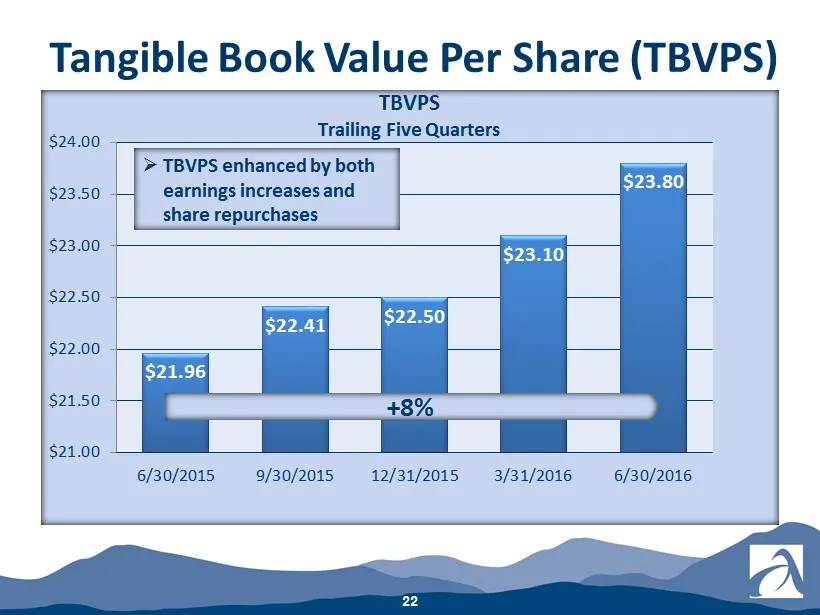
Slide 22: Tangible Book Value Per Share (TBVPS)
Tangible Book Value Per Share (TBVPS) 22 $21.96 $22.41 $22.50 $23.10 $23.80 $21.00 $21.50 $22.00 $22.50 $23.00 $23.50 $24.00 6/30/2015 9/30/2015 12/31/2015 3/31/2016 6/30/2016 » TBVPS enhanced by both earnings increases and share repurchases +8% TBVPS Trailing Five Quarters
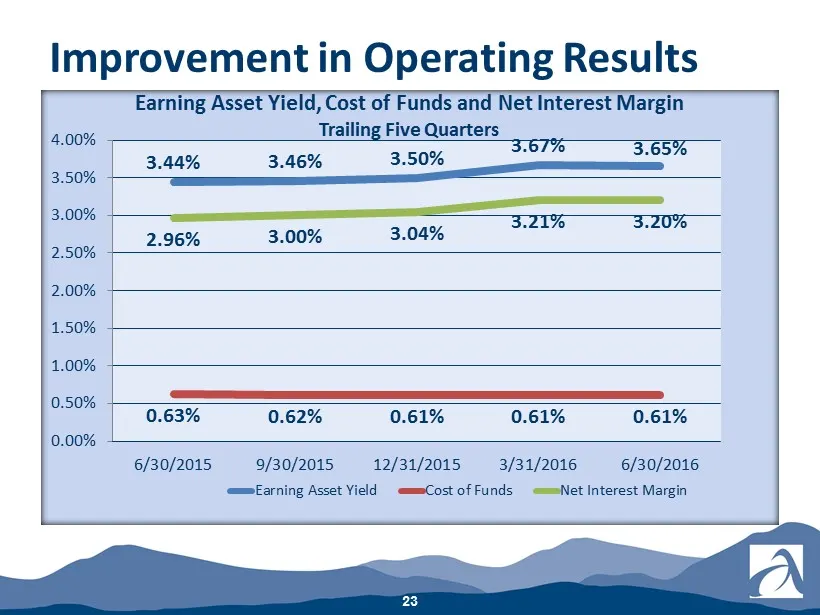
Slide 23: Earning Asset Yield, Cost of Funds and Net Interest Margin
3.44% 3.46% 3.50% 3.67% 3.65% 0.63% 0.62% 0.61% 0.61% 0.61% 2.96% 3.00% 3.04% 3.21% 3.20% 0.00% 0.50% 1.00% 1.50% 2.00% 2.50% 3.00% 3.50% 4.00% 6/30/2015 9/30/2015 12/31/2015 3/31/2016 6/30/2016 Earning Asset Yield Cost of Funds Net Interest Margin Earning Asset Yield, Cost of Funds and Net Interest
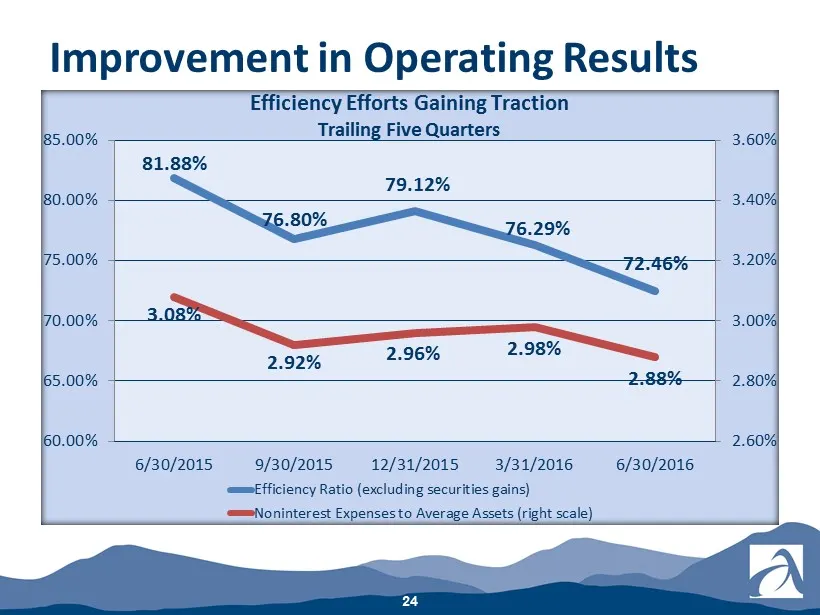
Slide 24: Efficiency Ratio and Noninterest Expenses to Average Assets
24 81.88% 76.80% 79.12% 76.29% 72.46% 3.08% 2.92% 2.96% 2.98% 2.88% 2.60% 2.80% 3.00% 3.20% 3.40% 3.60% 60.00% 65.00% 70.00% 75.00% 80.00% 85.00% 6/30/2015 9/30/2015 12/31/2015 3/31/2016 6/30/2016 Efficiency Ratio (excluding securities gains) Noninterest Expenses to Average Assets (right scale) Effi
Slide 25: Key Performance Indicator Targets Summarize Expectation of Continued Improvement
Key Performance Indicator Targets Summarize Expectation of Continued Improvement
Slide 26: Long-Term Key Performance Targets
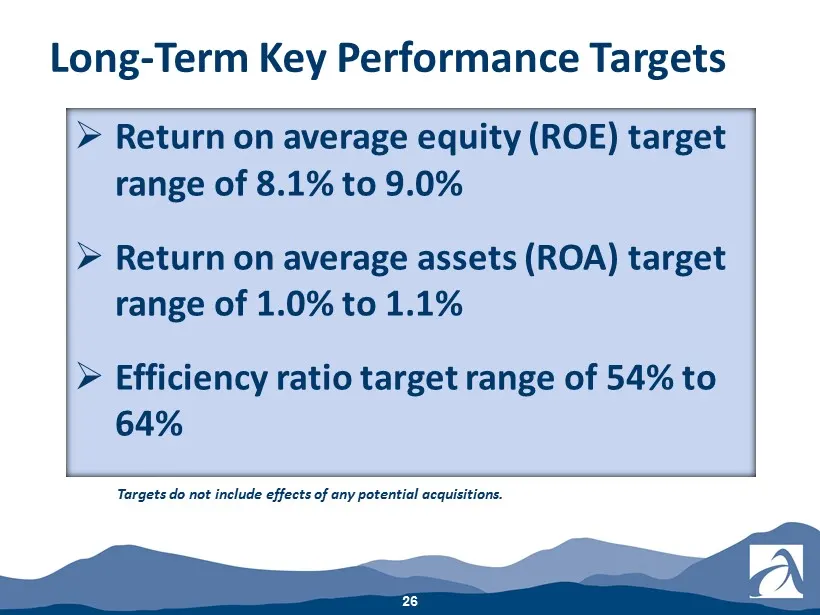
26 » Return on average equity (ROE) target range of 8.1% to 9.0% » Return on average assets (ROA) target range of 1.0% to 1.1% » Efficiency ratio target range of 54% to 64% Targets do not include effects of any potential acquisitions. Long - Term Key Performance Targets
Slide 27: Significant Additional Cost Reductions Planned
Significant Additional Cost Reductions Planned
Slide 28: Significant Additional Cost Reductions Planned
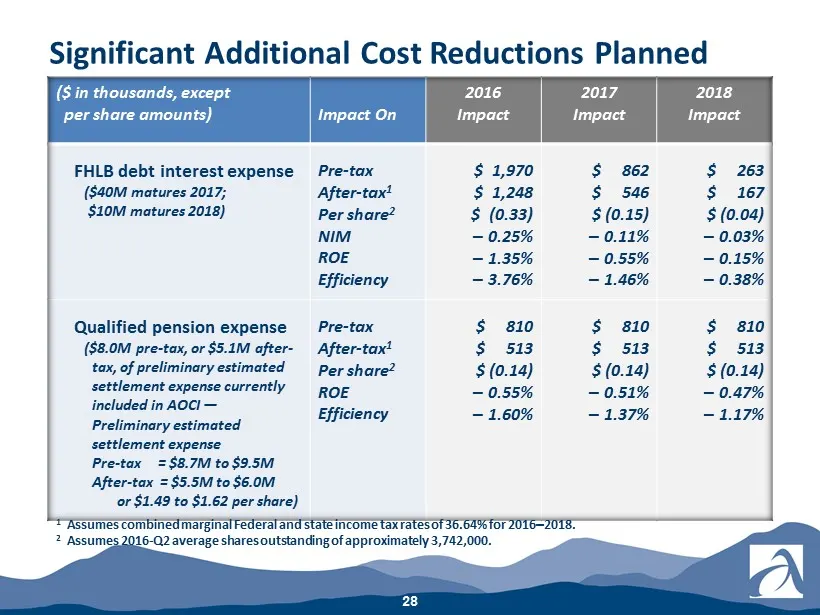
28 Significant Additional Cost Reductions Planned ($ in thousands, except per share amounts) Impact On 2016 Impact 2017 Impact 2018 Impact FHLB debt interest expense ($40M matures 2017; $10M matures 2018) Pre - tax After - tax 1 Per share 2 NIM ROE Efficiency $ 1,970 $ 1,248 $ (0.33) ‒ 0.25% ‒ 1.35%
Slide 29: Implementing Long-Term Strategic Plan to Achieve Sustainable Superior Performance
Implementing Long - Term Strategic Plan to Achieve Sustainable Superior Performance
Slide 30: Strategic Vision: 3 Primary Focus Areas
Strategic Vision: (3 Primary Focus Areas) » Focus: Commercial and Small Business Relationships (Loans & Deposits) for improved NIM » Focus: Mortgage Banking for improved Fee Income and NIM » Focus: Increased Efficiencies and Productivity, for improved expense and efficiency ratio s Implementing Long
Slide 31: Investment Highlights
» Solid Franchise in Attractive Market Area » Significant Improvement in Key Performance Metrics » Key Performance Indicator Targets Summarize Expectation of Continued Improvement » Significant Additional Cost Reductions Planned » Implementing Long - Term Strategic Plan to Achieve Sustainable Superi
Slide 32: Appendix
Appendix EE —E———
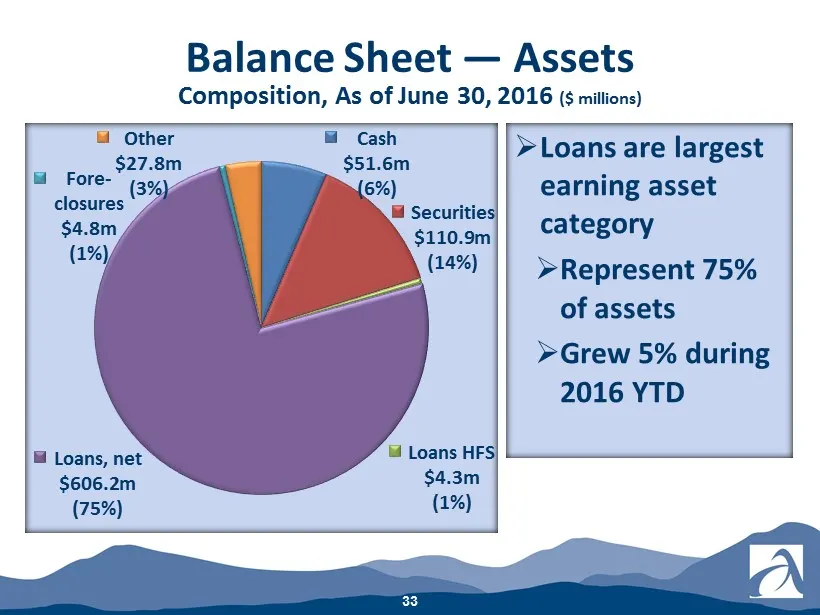
Slide 33: Balance Sheet — Assets Composition
33 Cash $51.6m (6%) Securities $110.9m (14%) Loans HFS $4.3m (1%) Loans, net $606.2m (75%) Fore - closures $4.8m (1%) Other $27.8m (3%) » Loans are largest earning asset category » Represent 75% of assets » Grew 5% during 2016 YTD Balance Sheet — Assets Composition, As of June 30, 2016 ($ millions)
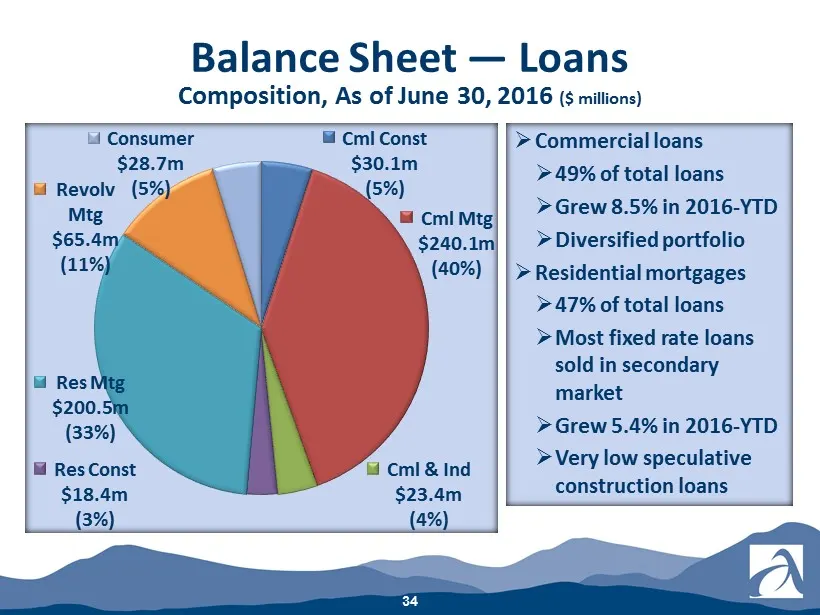
Slide 34: Balance Sheet — Loans Composition
Balance Sheet — Loans Composition, As of June 30, 2016 ($ millions) 34 Cml Const $30.1m (5%) Cml Mtg $240.1m (40%) Cml & Ind $23.4m (4%) Res Const $18.4m (3%) Res Mtg $200.5m (33%) Revolv Mtg $65.4m (11%) Consumer $28.7m (5%) » Commercial loans » 49% of total loans » Grew 8.5% in 2016 - YTD » Divers
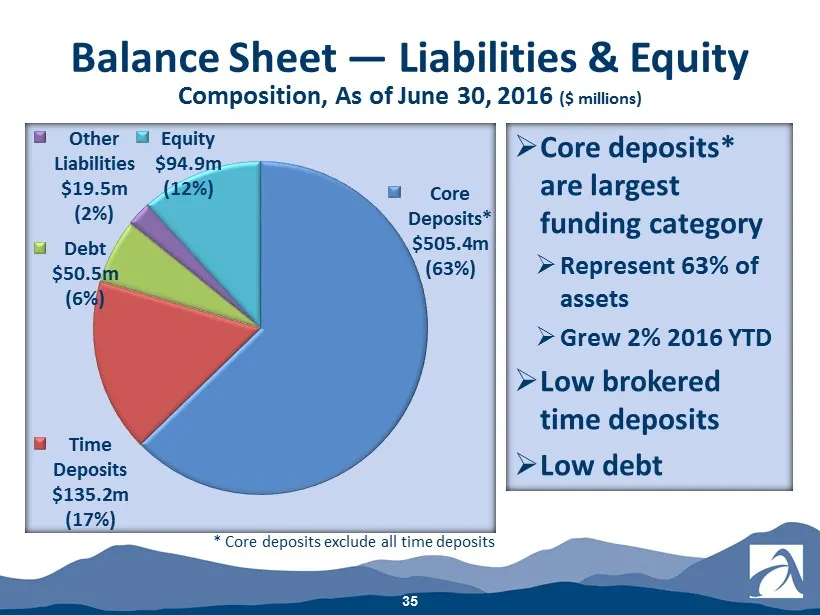
Slide 35: Balance Sheet — Liabilities & Equity Composition
35 Balance Sheet — Liabilities & Equity Composition, As of June 30, 2016 ($ millions) Core Deposits* $505.4m (63%) Time Deposits $135.2m (17%) Debt $50.5m (6%) Other Liabilities $19.5m (2%) Equity $94.9m (12%) » Core deposits* are largest funding category » Represent 63% of assets » Grew 2% 2016 YTD
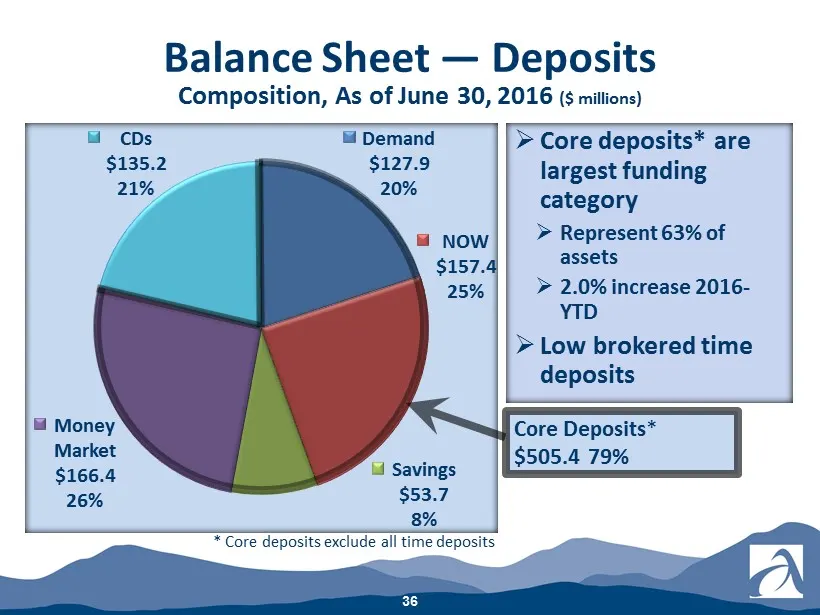
Slide 36: Balance Sheet — Deposits Composition
Balance Sheet — Deposits Composition, As of June 30, 2016 ($ millions) 36 Demand $127.9 20% NOW $157.4 25% Savings $53.7 8% Money Market $166.4 26% CDs $135.2 21% » Core deposits* are largest funding category » Represent 63% of assets » 2.0% increase 2016 - YTD » Low brokered time deposits Core Depo
Slide 37: Improvement in Operating Results
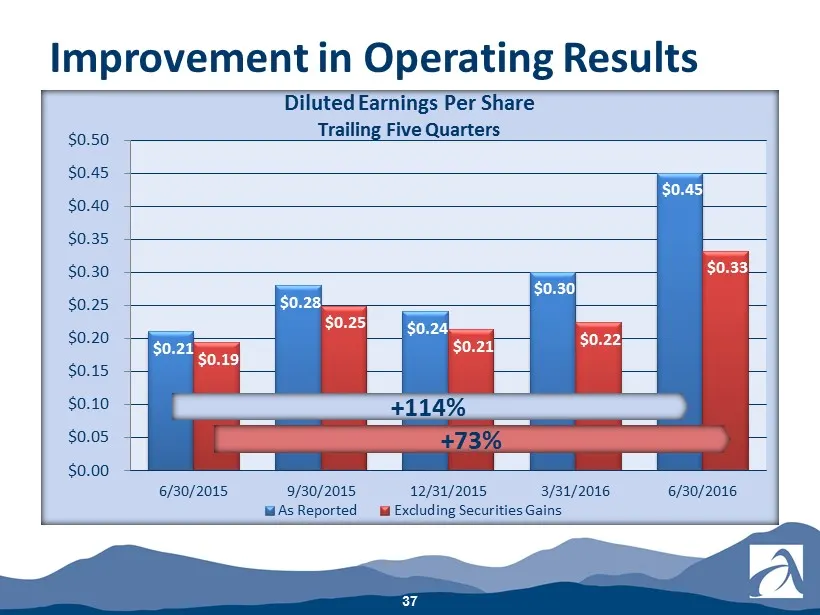
Improvement in Operating Results 37 $0.21 $0.28 $0.24 $0.30 $0.45 $0.19 $0.25 $0.21 $0.22 $0.33 $0.00 $0.05 $0.10 $0.15 $0.20 $0.25 $0.30 $0.35 $0.40 $0.45 $0.50 6/30/2015 9/30/2015 12/31/2015 3/31/2016 6/30/2016 As Reported Excluding Securities Gains Diluted Earnings Per Share Trailing Five Quarter
Slide 38: Noninterest Income Trailing Five Quarters
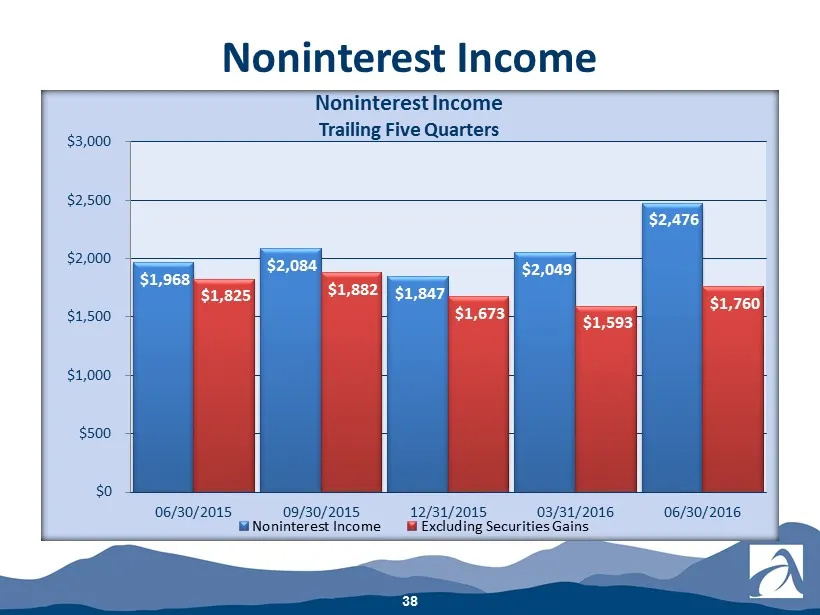
Noninterest Income 38 Diluted Earnings Per Share Trailing Five Quarters $1,968 $2,084 $1,847 $2,049 $2,476 $1,825 $1,882 $1,673 $1,593 $1,760 $0 $500 $1,000 $1,500 $2,000 $2,500 $3,000 06/30/2015 09/30/2015 12/31/2015 03/31/2016 06/30/2016 Noninterest Income Excluding Securities Gains Noninterest In
Slide 39: Noninterest Expenses Trailing Five Quarters
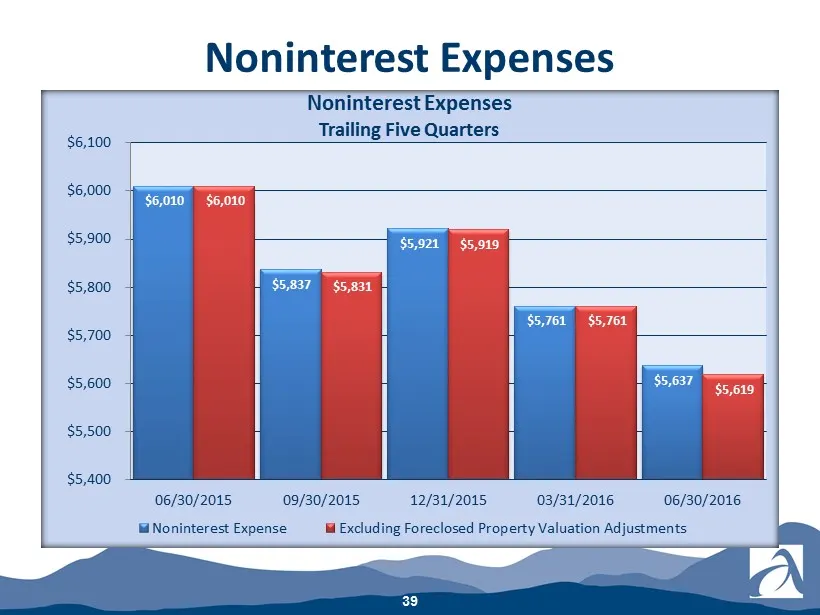
Noninterest Expenses 39 $6,010 $5,837 $5,921 $5,761 $5,637 $6,010 $5,831 $5,919 $5,761 $5,619 $5,400 $5,500 $5,600 $5,700 $5,800 $5,900 $6,000 $6,100 06/30/2015 09/30/2015 12/31/2015 03/31/2016 06/30/2016 Noninterest Expense Excluding Foreclosed Property Valuation Adjustments Noninterest Expenses Tr
Slide 40: Reconciliation of Non-GAAP to GAAP Items
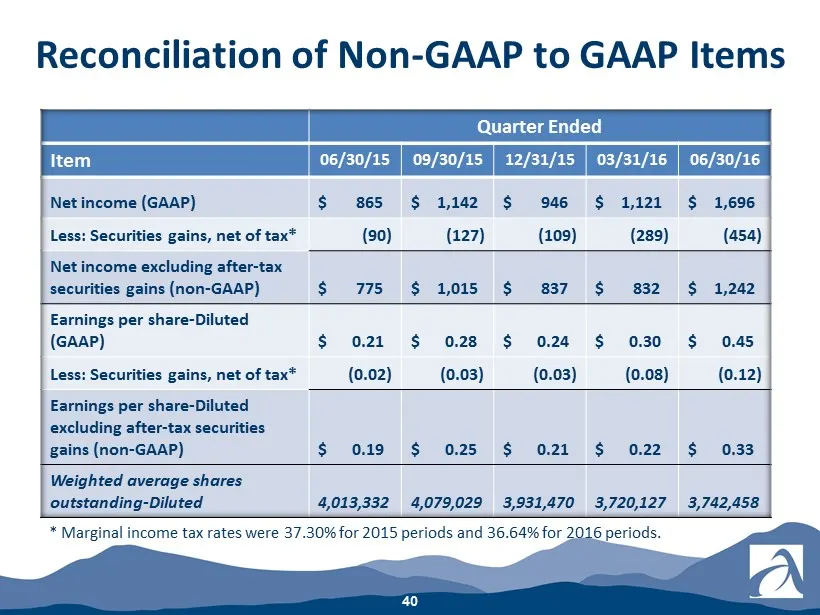
40 Quarter Ended Item 06/30/15 09/30/15 12/31/15 03/31/16 06/30/16 Net income (GAAP) $ 865 $ 1,142 $ 946 $ 1,121 $ 1,696 Less: Securities gains, net of tax* (90) (127) (109) (289) (454) Net income excluding after - tax securities gains (non - GAAP) $ 775 $ 1,015 $ 837 $ 832 $ 1,242 Earnings per shar
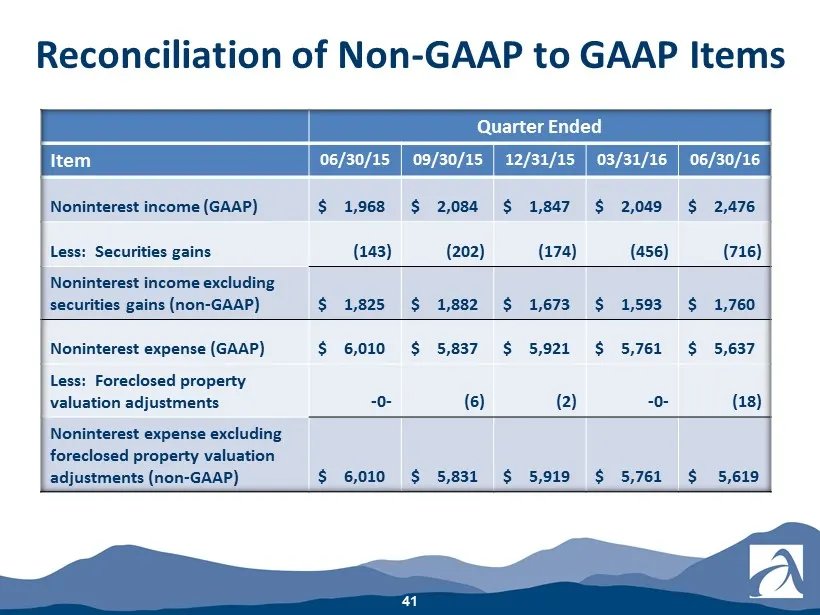
Slide 41: Reconciliation of Non-GAAP to GAAP Items
41 Quarter Ended Item 06/30/15 09/30/15 12/31/15 03/31/16 06/30/16 Noninterest income (GAAP) $ 1,968 $ 2,084 $ 1,847 $ 2,049 $ 2,476 Less: Securities gains (143) (202) (174) (456) (716) Noninterest income excluding securities gains (non - GAAP) $ 1,825 $ 1,882 $ 1,673 $ 1,593 $ 1,760 Noninterest exp
Slide 42: Inquiries may be directed to
Inquiries may be directed to : Suzanne DeFerie, President & Chief Executive Officer Kirby Tyndall, Executive Vice President & Chief Financial Officer
Source: SEC EDGAR · 8-K filed Jul 29, 2016
More decks from ASB Bancorp Inc
 Shareholder Meeting (May 2017)34 slides · May 19, 2017
 Merger or Acquisition (May 2017)15 slides · May 1, 2017
 Shareholder Meeting (May 2016)34 slides · May 20, 2016
 Investor Presentation (August 2015)44 slides · Aug 25, 2015
 Shareholder Meeting (May 2015)37 slides · May 22, 2015
 2015 Sterne Agee Financial Institutions Investor Conference29 slides · Feb 11, 2015