Approach Resources — EnerCom's The Oil & Services Conference IX (February 2011)
31 slides from Approach Resources's conference presentation, Feb 22, 2011
Slide 1: Approach Resources Inc. EnerCom's The Oil & Services Conference IX
Approach Resources Inc. EnerCom’s The Oil & Services Conference IX February 22, 2011
Slide 2: Forward-looking statements
Slide 2 Forward-looking statements This presentation contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934. All statements, other than statements of historical facts, included in this presentation th
Slide 3: Company overview
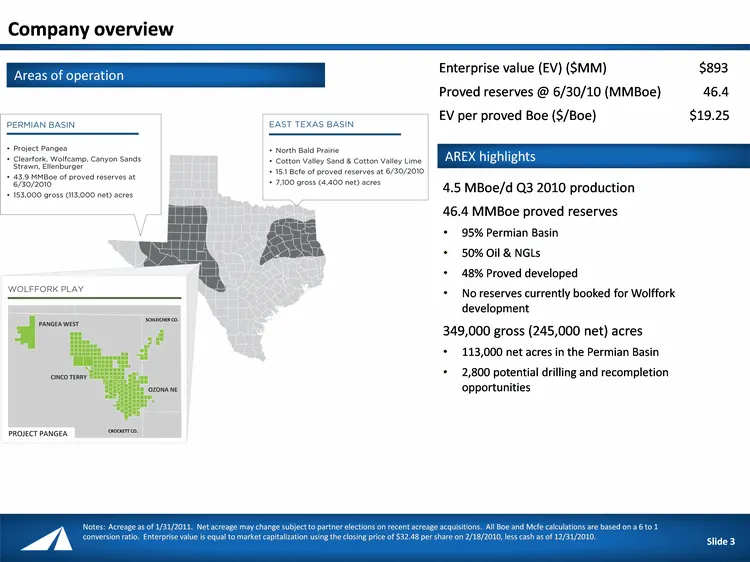
Company overview Notes: Acreage as of 1/31/2011. Net acreage may change subject to partner elections on recent acreage acquisitions. All Boe and Mcfe calculations are based on a 6 to 1 conversion ratio. Enterprise value is equal to market capitalization using the closing price of $32.48 per share on
Slide 4: Key investor highlights
Key investor highlights Concentrated geographic footprint focused on West Texas Permian Basin oil/liquids rich plays 113,000+ net, primarily contiguous acres, 100% operated More than 400 wells drilled by Approach since 2004, with a 93%+ success rate Established basin infrastructure Strong growth tra
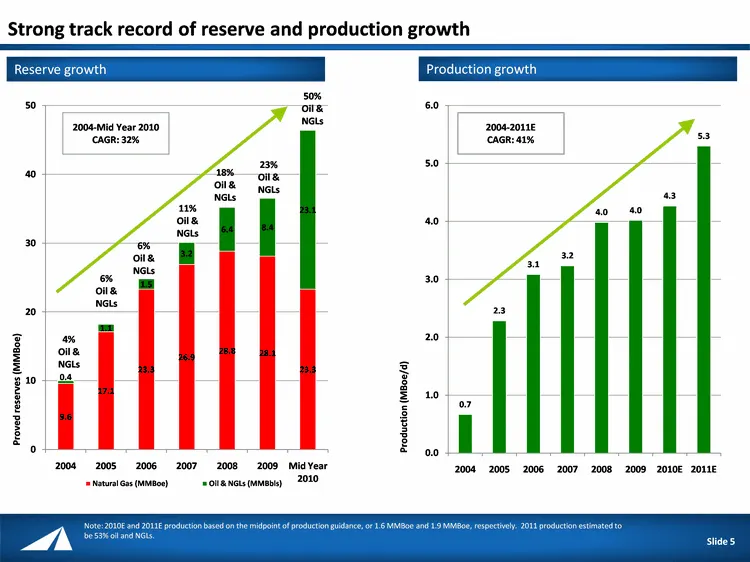
Slide 5: Strong track record of reserve and production growth
(CHART) (CHART) Strong track record of reserve and production growth October 12, 2010 Slide 5 Note: 2010E and 2011E production based on the midpoint of production guidance, or 1.6 MMBoe and 1.9 MMBoe, respectively. 2011 production estimated to be 53% oil and NGLs. 4% Oil & NGLs 6% Oil & NGLs 6% Oil
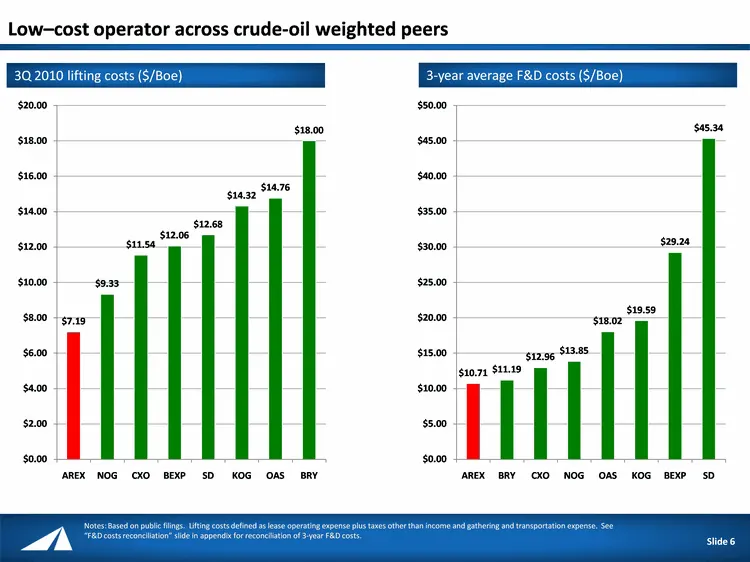
Slide 6: Low-cost operator across crude-oil weighted peers
Low-cost operator across crude-oil weighted peers October 12, 2010 Slide 6 Notes: Based on public filings. Lifting costs defined as lease operating expense plus taxes other than income and gathering and transportation expense. See "F&D costs reconciliation" slide in appendix for reconciliation of 3-
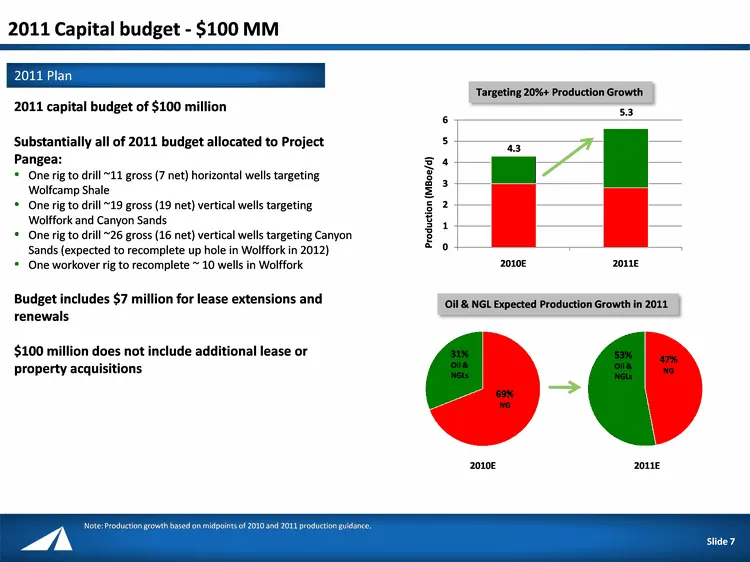
Slide 7: 2011 Capital budget - $100 MM
2011 Capital budget - $100 MM October 12, 2010 Slide 7 2011 Plan 2011 capital budget of $100 million Substantially all of 2011 budget allocated to Project Pangea: One rig to drill ~11 gross (7 net) horizontal wells targeting Wolfcamp Shale One rig to drill ~19 gross (19 net) vertical wells targeting
Slide 8: 2011 Plan - What are our objectives?
2011 Plan - What are our objectives? October 12, 2010 Slide 8 2011 Objectives Delineate Wolffork oil shale play across Project Pangea with a combination of vertical, horizontal and recompletion projects Improve initial production rates by refining our perforation and fracture stimulation strategy Ad
Slide 9: Overview of AREX's Permian Basin assets
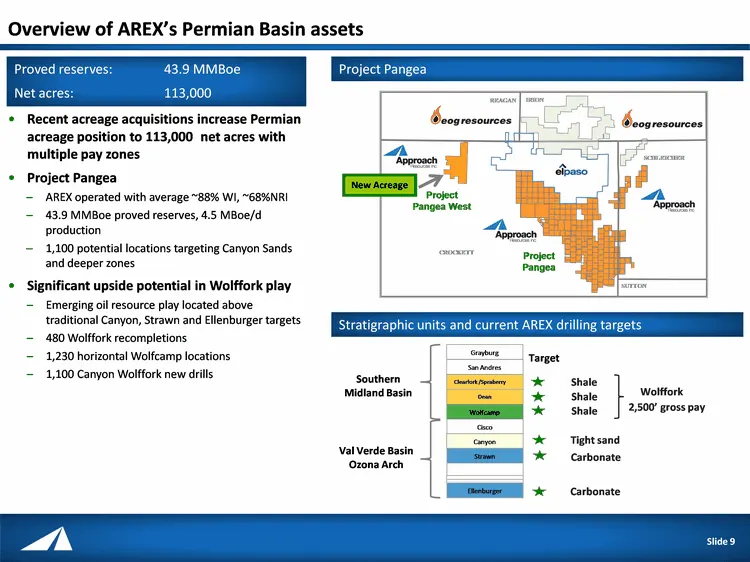
Overview of AREX's Permian Basin assets Recent acreage acquisitions increase Permian acreage position to 113,000 net acres with multiple pay zones Project Pangea AREX operated with average ~88% WI, ~68%NRI 43.9 MMBoe proved reserves, 4.5 MBoe/d production 1,100 potential locations targeting Canyon S
Slide 10: AREX acreage is favorably located in Southern Midland Basin
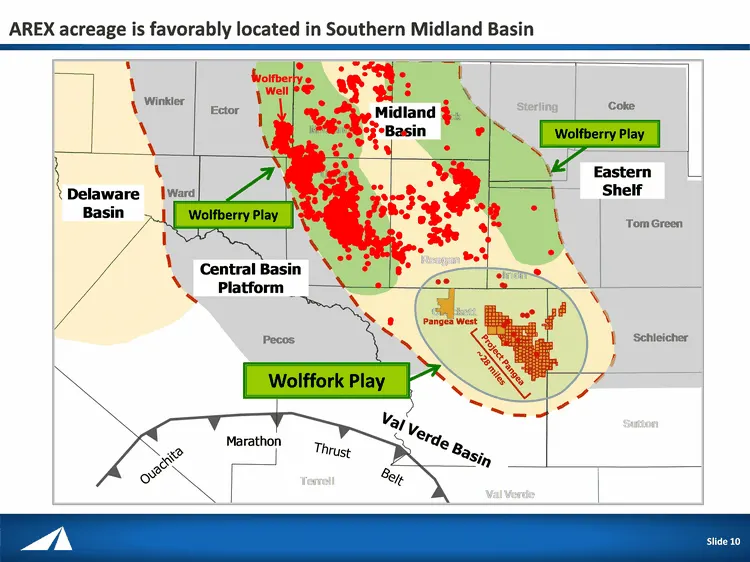
Slide 10 AREX acreage is favorably located in Southern Midland Basin Slide 10 Wolfberry Well ~28 miles Pangea West Wolffork Play Wolfberry Play Wolfberry Play Project Pangea
Slide 11: Industry activity in Southern Midland Basin
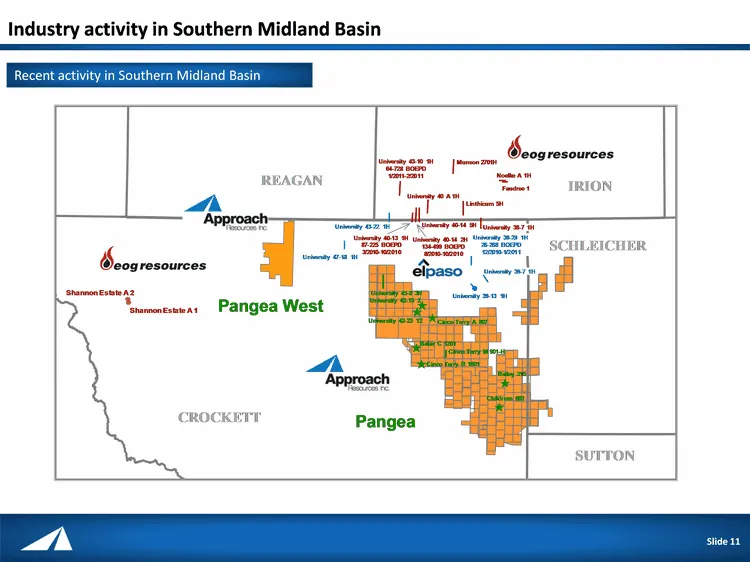
Industry activity in Southern Midland Basin Slide 11 Recent activity in Southern Midland Basin Slide 11
Slide 12: Wolffork play recognition
Wolffork play recognition Slide 12 Crockett County has been viewed as a gassy area - when oil and gas price ratio ranges from 16 to 20, operators are pursuing oily plays Almost all published, regional maps of the Permian Basin indicate that Northern Crockett County is located on top of the Ozona Arc
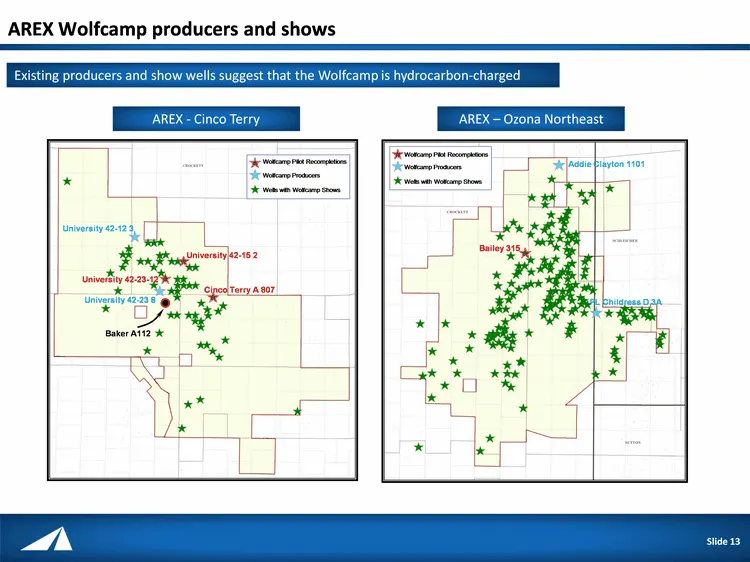
Slide 13: AREX Wolfcamp producers and shows
AREX Wolfcamp producers and shows Slide 13 University 42-23-12 University 42-23 8 Cinco Terry A 807 University 42-15 2 University 42-12 3 Addie Clayton 1101 PL Childress D 3A Bailey 315 Existing producers and show wells suggest that the Wolfcamp is hydrocarbon-charged AREX - Cinco Terry AREX - Ozona
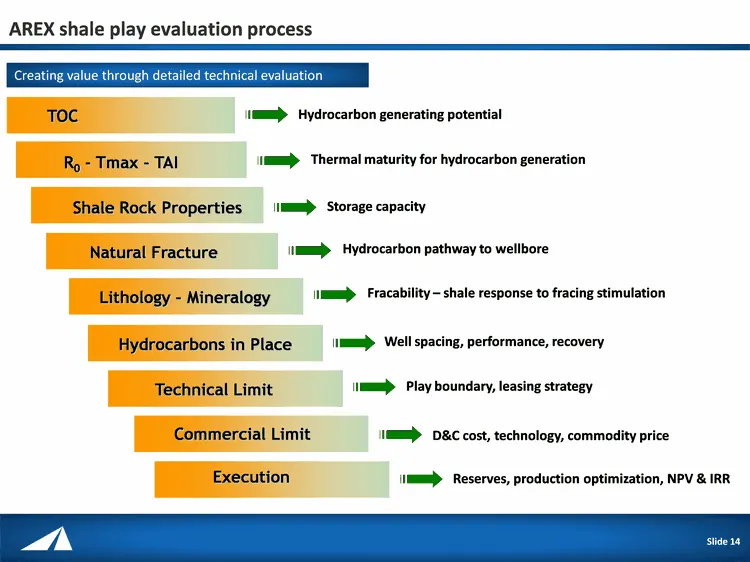
Slide 14: AREX shale play evaluation process
AREX shale play evaluation process Slide 14 Hydrocarbon generating potential TOC R0 - Tmax - TAI Shale Rock Properties Lithology - Mineralogy Hydrocarbons in Place Technical Limit Commercial Limit Thermal maturity for hydrocarbon generation Storage capacity Fracability - shale response to fracing st
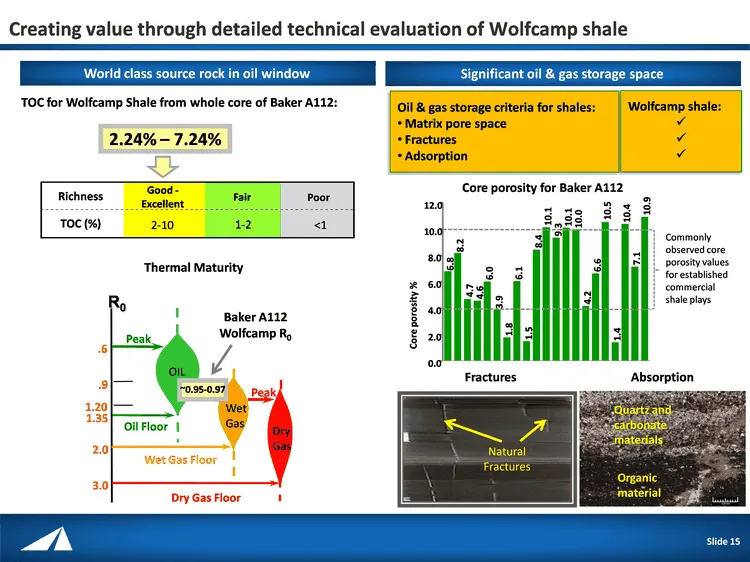
Slide 15: Creating value through detailed technical evaluation of Wolfcamp shale
Creating value through detailed technical evaluation of Wolfcamp shale Slide 15 TOC for Wolfcamp Shale from whole core of Baker A112: World class source rock in oil window Thermal Maturity OIL ..6 ..9 1.20 1.35 2.0 3.0 Peak Wet Gas Dry Gas Peak Oil Floor Wet Gas Floor Dry Gas Floor R0 Baker A112 Wol
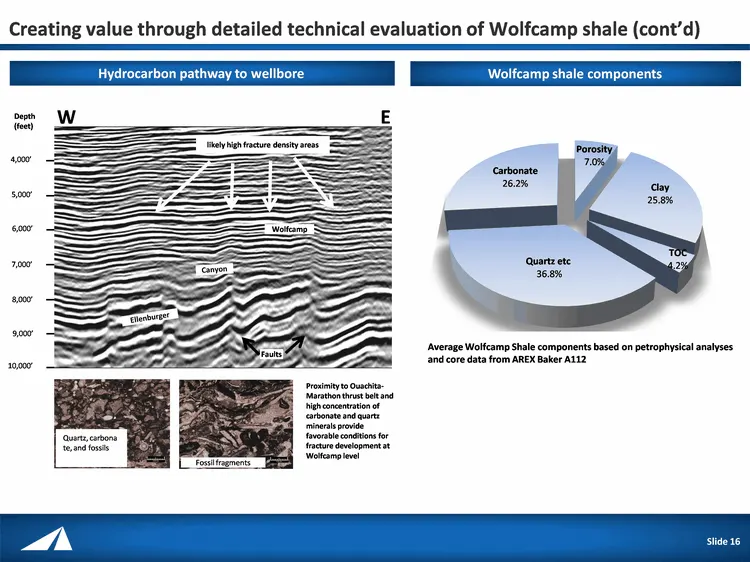
Slide 16: Creating value through detailed technical evaluation of Wolfcamp shale (cont'd)
Creating value through detailed technical evaluation of Wolfcamp shale (cont'd) Slide 16 Hydrocarbon pathway to wellbore Wolfcamp shale components W E Ellenburger Canyon Wolfcamp Proximity to Ouachita- Marathon thrust belt and high concentration of carbonate and quartz minerals provide favorable con
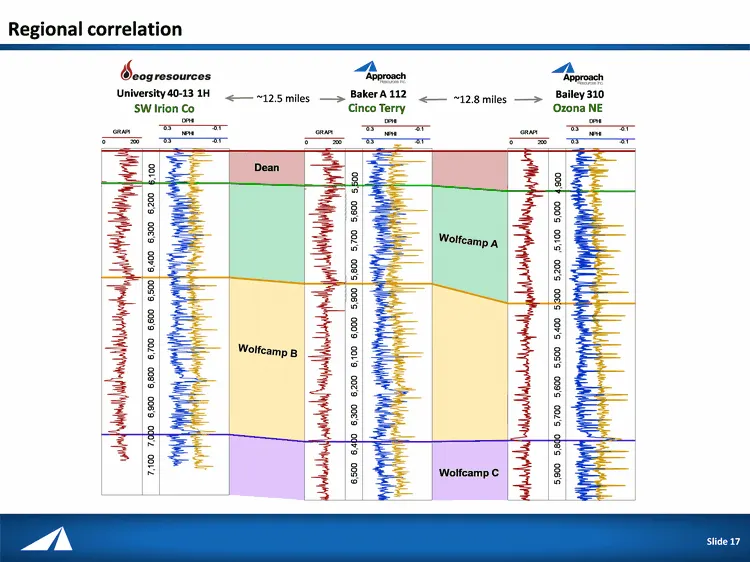
Slide 17: Regional correlation
Regional correlation Slide 17 University 40-13 1H Baker A 112 Bailey 310 ~12.5 miles ~12.8 miles SW Irion Co Cinco Terry Ozona NE Dean 6,100 6,200 6,300 6,400 6,500 6,600 6,700 6,800 6,900 7,000 7,100 5,500 5,600 5,700 5,800 5,900 6,000 6,100 6,200 6,300 6,400 6,500 4,900 5,000 ,5,100 5,200 5,300 5,
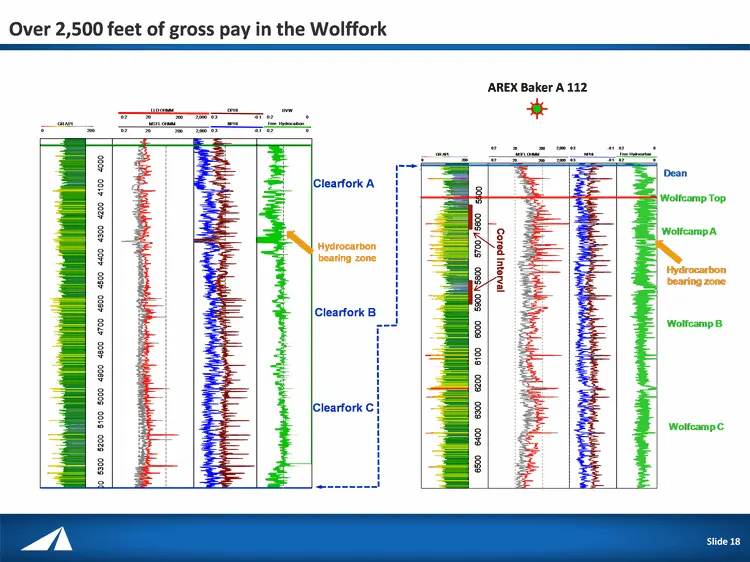
Slide 18: Over 2,500 feet of gross pay in the Wolffork
Over 2,500 feet of gross pay in the Wolffork Slide 18 AREX Baker A 112 Clearfork A Clearfork B Clearfork C Hydrocarbon bearing zone Slide 18
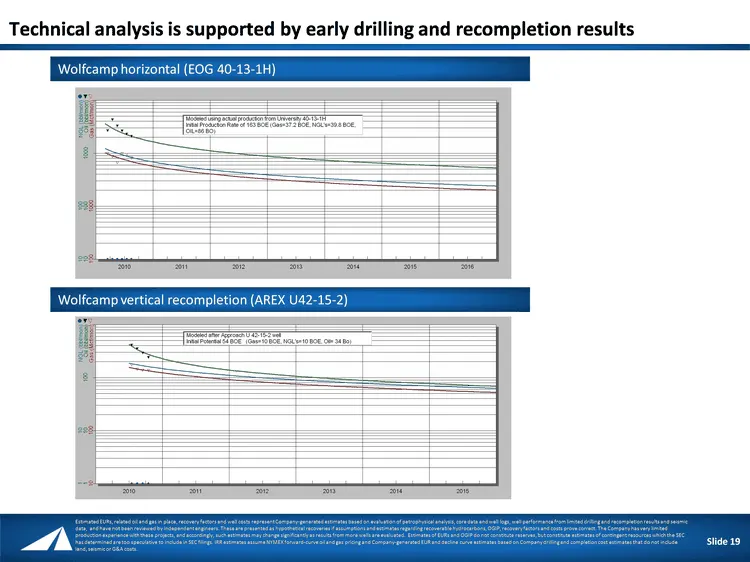
Slide 19: Technical analysis supported by early drilling and recompletion results
Wolfcamp horizontal (EOG 40-13-1H) Technical analysis is supported by early drilling and recompletion results Wolfcamp vertical recompletion (AREX U42-15-2) Estimated EURs, related oil and gas in place, recovery factors and well costs represent Company-generated estimates based on evaluation of petr
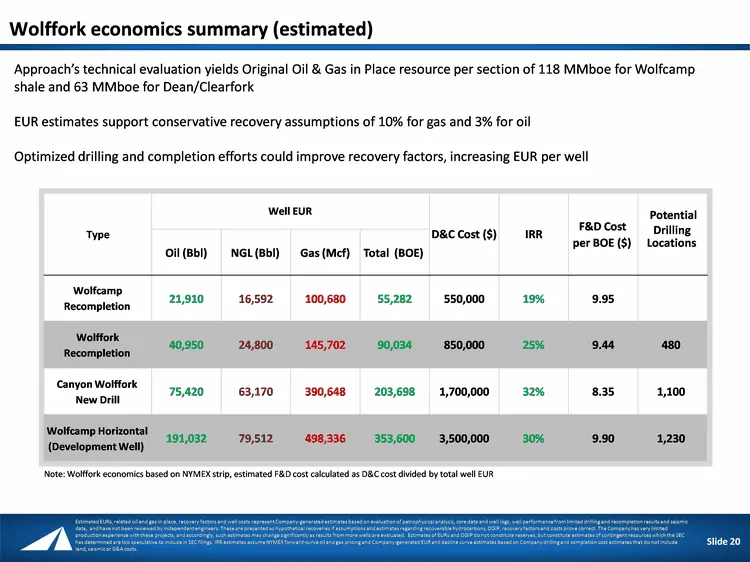
Slide 20: Wolffork economics summary (estimated)
Note: Wolffork economics based on NYMEX strip, estimated F&D cost calculated as D&C cost divided by total well EUR Wolffork economics summary (estimated) Approach's technical evaluation yields Original Oil & Gas in Place resource per section of 118 MMboe for Wolfcamp shale and 63 MMboe for Dean/Clea
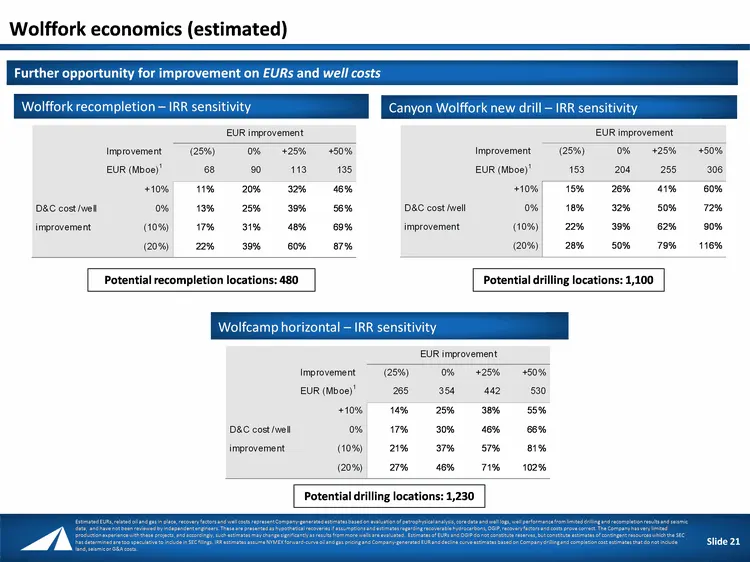
Slide 21: Wolffork economics (estimated) - IRR sensitivity
Wolffork recompletion - IRR sensitivity Canyon Wolffork new drill - IRR sensitivity Wolfcamp horizontal - IRR sensitivity Further opportunity for improvement on EURs and well costs Wolffork economics (estimated) Potential drilling locations: 1,230 Potential recompletion locations: 480 Potential dril
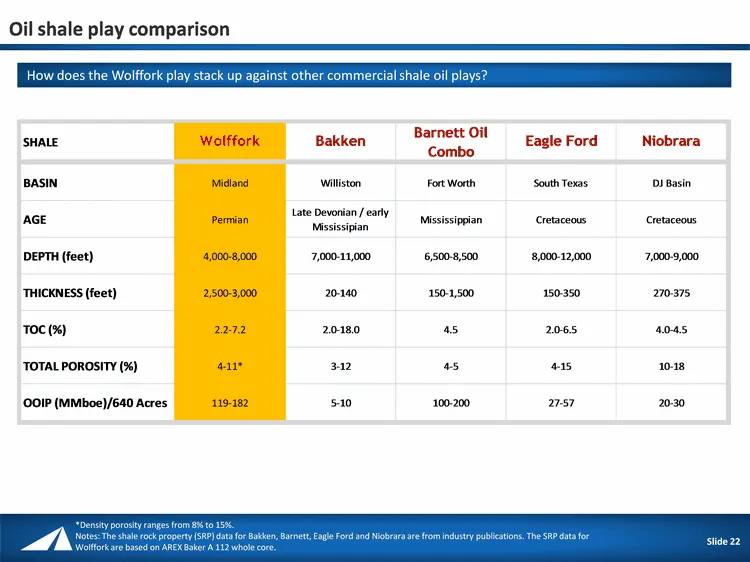
Slide 22: Oil shale play comparison
Oil shale play comparison Slide 22 How does the Wolffork play stack up against other commercial shale oil plays? *Density porosity ranges from 8% to 15%. Notes: The shale rock property (SRP) data for Bakken, Barnett, Eagle Ford and Niobrara are from industry publications. The SRP data for Wolffork a
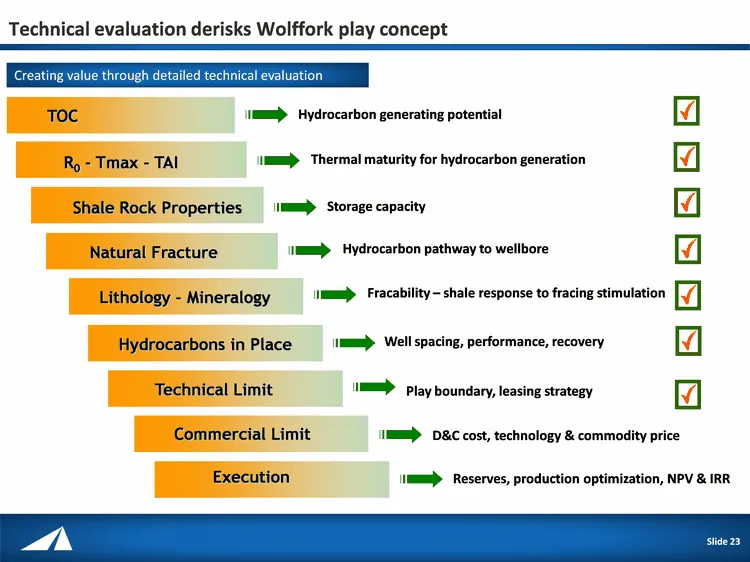
Slide 23: Technical evaluation derisks Wolffork play concept
Technical evaluation derisks Wolffork play concept Slide 23 Hydrocarbon generating potential TOC R0 - Tmax - TAI Shale Rock Properties Lithology - Mineralogy Hydrocarbons in Place Technical Limit Commercial Limit Thermal maturity for hydrocarbon generation Storage capacity Fracability - shale respon
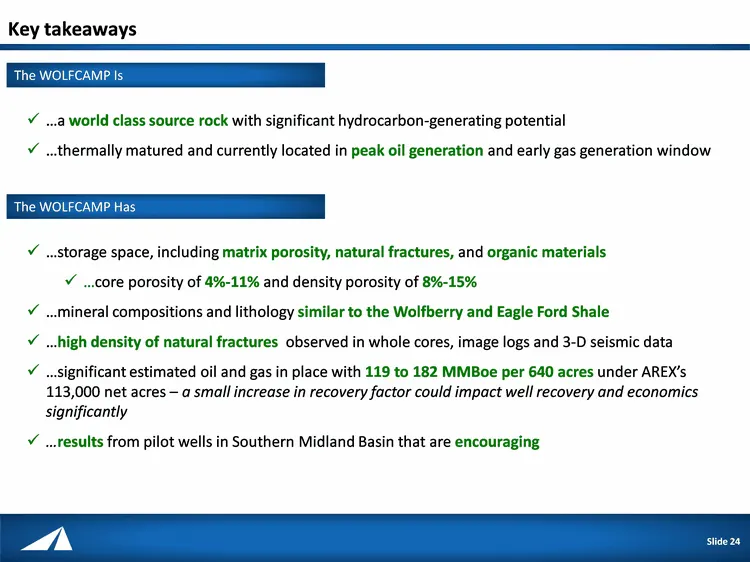
Slide 24: Key takeaways
Key takeaways ....a world class source rock with significant hydrocarbon-generating potential ....thermally matured and currently located in peak oil generation and early gas generation window The WOLFCAMP Is ....storage space, including matrix porosity, natural fractures, and organic materials ....
Slide 25: Fesox088
Fesox088 1
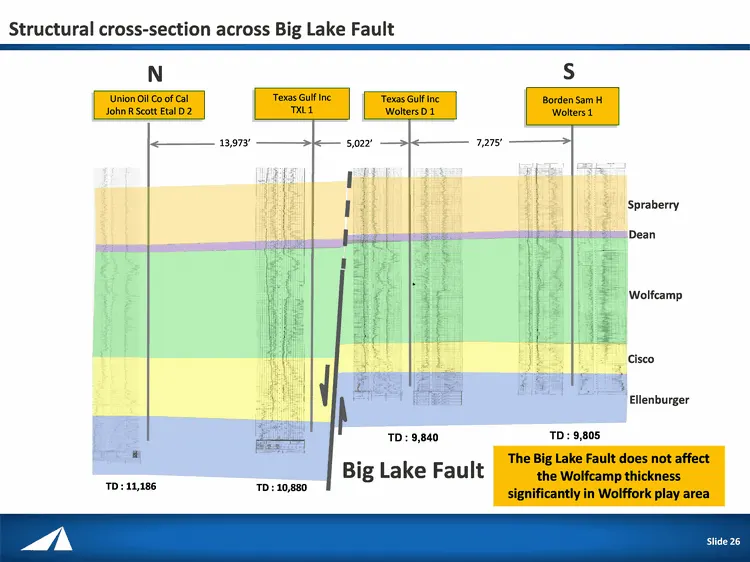
Slide 26: Structural cross-section across Big Lake Fault
Structural cross-section across Big Lake Fault Slide 26 The Big Lake Fault does not affect the Wolfcamp thickness significantly in Wolffork play area Union Oil Co of Cal John R Scott Etal D 2 Texas Gulf Inc TXL 1 Texas Gulf Inc Wolters D 1 Borden Sam H Wolters 1 13,973' 5,022' 7,275' TD : 11,186 TD
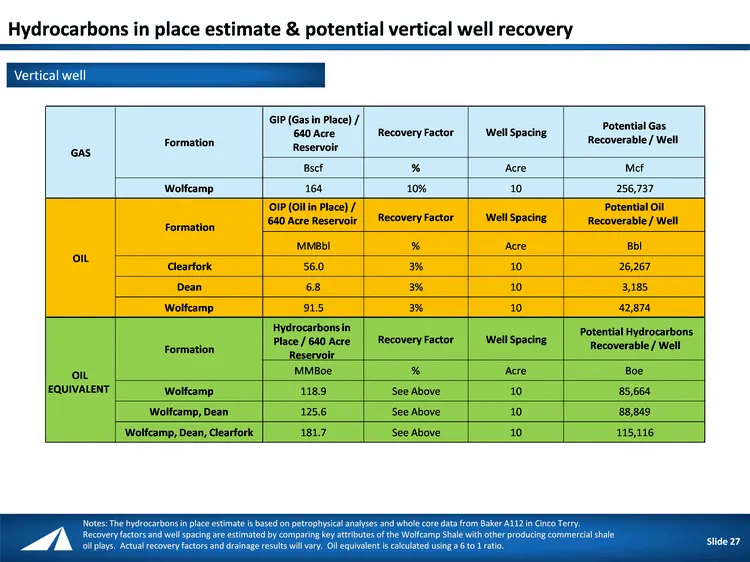
Slide 27: Hydrocarbons in place estimate & potential vertical well recovery
27 Hydrocarbons in place estimate & potential vertical well recovery Slide 27 GIP (Gas in Place) / 640 Acre Reservoir Recovery Factor Well Spacing Potential Gas Recoverable / Well B scf % Acre Mcf Wolfcamp 164 10% 10 256,737 Recovery Factor Well Spacing MM Bbl % Acre Bbl Clearfork 56.0 3% 10 26,267
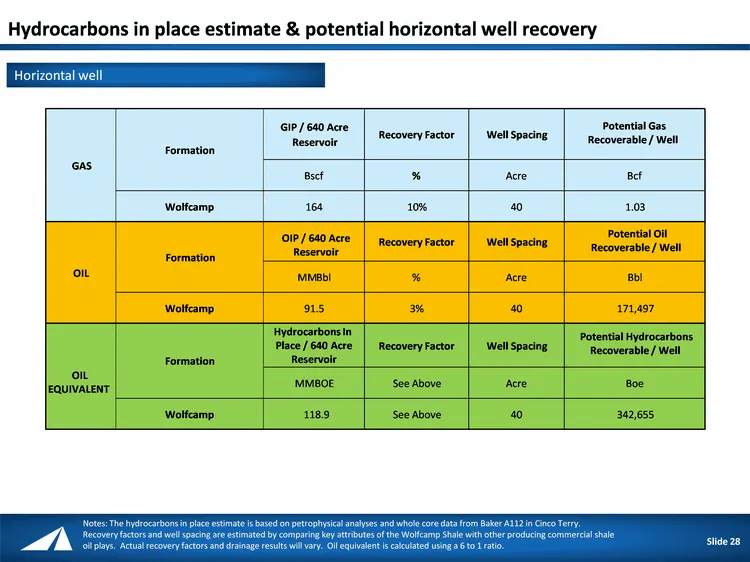
Slide 28: Hydrocarbons in place estimate & potential horizontal well recovery
28 Slide 28 Horizontal well GIP / 640 Acre Reservoir Recovery Factor Well Spacing B scf % Acre Bcf Wolfcamp 164 10% 40 1.03 OIP / 640 Acre Reservoir Recovery Factor Well Spacing MM Bbl % Acre Bbl Wolfcamp 91.5 3% 40 171,497 Hydrocarbons In Place / 640 Acre Reservoir Recovery Factor Well Spacing MMBO
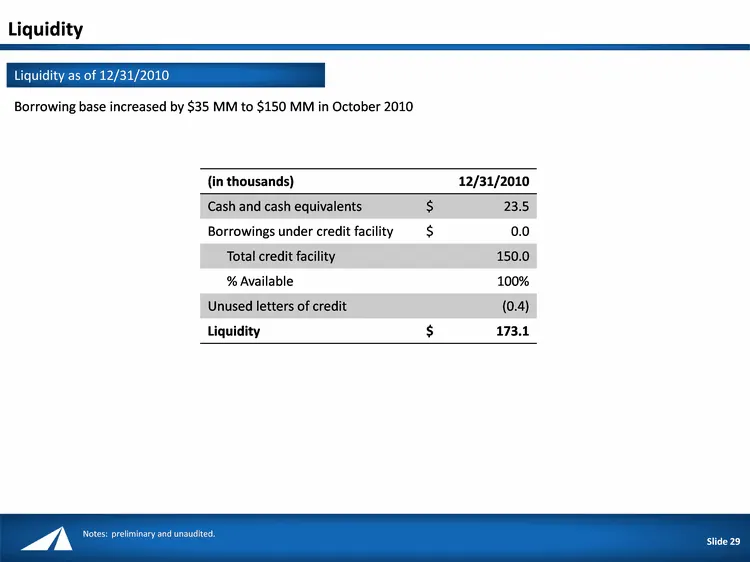
Slide 29: Liquidity as of 12/31/2010
Liquidity (in thousands) 12/31/2010 12/31/2010 Cash and cash equivalents $ 23.5 Borrowings under credit facility $ 0.0 Total credit facility 150.0 % Available 100% Unused letters of credit (0.4) Liquidity $ 173.1 Liquidity as of 12/31/2010 Borrowing base increased by $35 MM to $150 MM in October 201
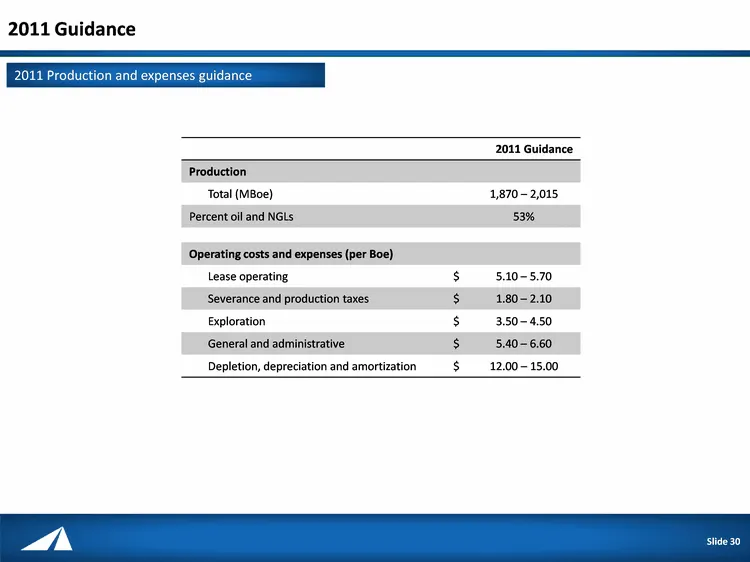
Slide 30: 2011 Guidance
2011 Guidance 2011 Production and expenses guidance Slide 30 2011 Guidance 2011 Guidance Production Total (MBoe) 1,870 - 2,015 Percent oil and NGLs 53% Operating costs and expenses (per Boe) Lease operating $ 5.10 - 5.70 Severance and production taxes $ 1.80 - 2.10 Exploration $ 3.50 - 4.50 General
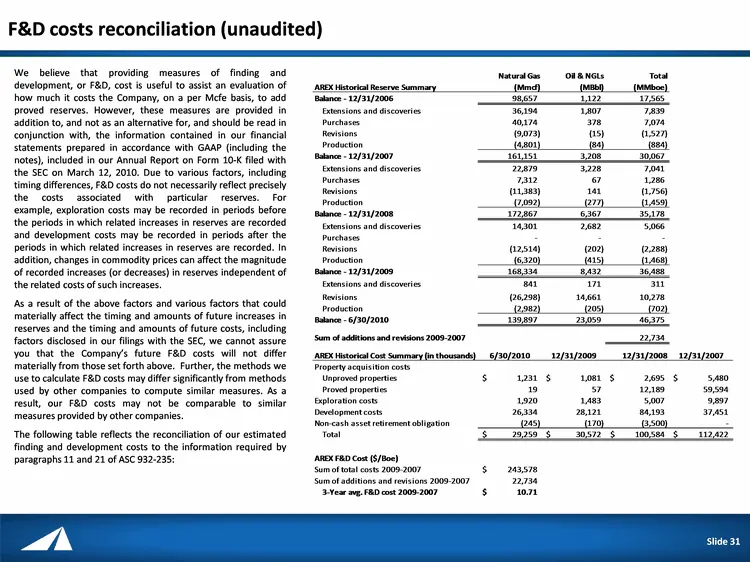
Slide 31: F&D costs reconciliation (unaudited)
F&D costs reconciliation (unaudited) We believe that providing measures of finding and development, or F&D, cost is useful to assist an evaluation of how much it costs the Company, on a per Mcfe basis, to add proved reserves. However, these measures are provided in addition to, and not as an alterna
Source: SEC EDGAR · 8-K filed Feb 22, 2011
More decks from Approach Resources Inc
 Investor Presentation (January 2017)46 slides · Jan 9, 2017
 Proxy Contest (January 2017)47 slides · Jan 5, 2017
 Investor Presentation (December 2016)45 slides · Dec 20, 2016
 Q3 2016 Earnings Presentation33 slides · Nov 3, 2016
 Q3 2015 Earnings Presentation19 slides · Nov 5, 2015
 Q2 2015 Earnings Presentation21 slides · Aug 6, 2015