Village Bank and Trust Financial
Village Bank and Trust Financial — Q4 2019 Earnings Presentation
24 slides from Village Bank and Trust Financial's earnings presentation, Jan 28, 2020
Slide 1: You're a Neighbor, Not a Number Q4 2019 Investor Presentation
You're a Neighbor, Not a Number Q4 201 9 Investor Presentation Exhibit 99.1
Slide 2: Cautionary Statement Regarding Forward-Looking Statements
Cautionary Statement Regarding Forward - Looking Statements This presentation contains forward - looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These forward - looking statements include, but are not limited to, statements about (i) the Company’s plans
Slide 3: Non-GAAP Financial Measures
Non - GAAP Financial Measures The accounting and reporting polices of the Company conform to generally accepted accounting principles (“GAAP”) in the United States and prevailing practices in the banking industry. However, management uses certain non - GAAP measures to supplement the evaluation of t
Slide 4: Why Village
Why Village Vision, Discipline, Execution – We think and behave like long term investors Market – Strong market position in a very attractive market Opportunity – Excellent opportunity to take m arket share Differentiated – A strong community bank with a successful mortgage company Transparency and
Slide 5: Company Overview
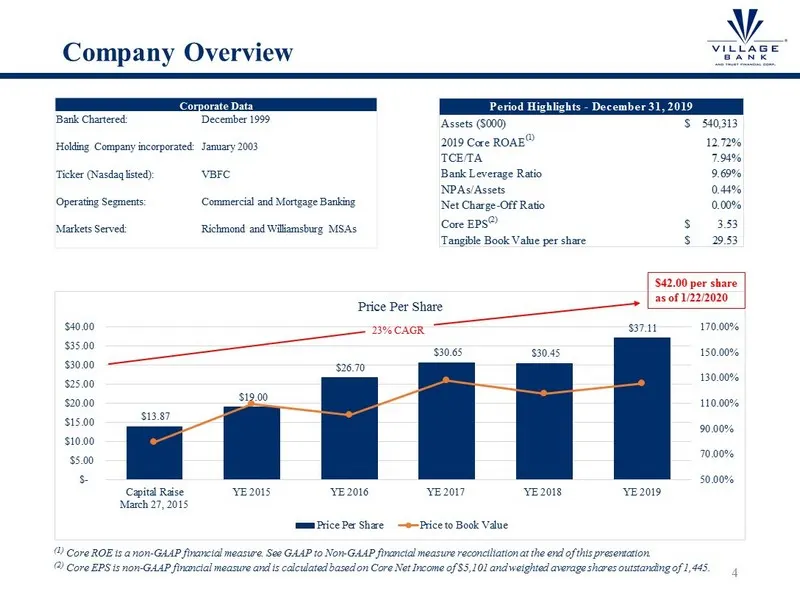
Company Overview 4 Corporate Data Bank Chartered: December 1999 Holding Company incorporated: January 2003 Ticker (Nasdaq listed): VBFC Operating Segments: Commercial and Mortgage Banking Markets Served: Richmond and Williamsburg MSAs (1) Core ROE is a non - GAAP financial measure. See GAAP to Non -
Slide 6: Richmond MSA
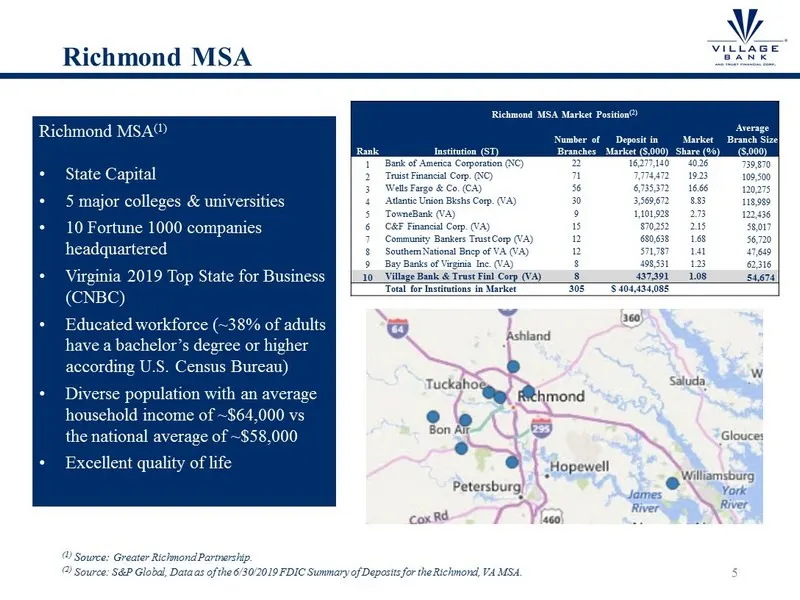
Richmond MSA 5 (1) Source: Greater Richmond Partnership. (2) Source : S&P Global, Data as of the 6/30/2019 FDIC Summary of Deposits for the Richmond, VA MSA . Richmond MSA Market Position (2) Rank Institution (ST) Number of Branches Deposit in Market ($,000) Market Share (%) Average Branch Size ($,0
Slide 7: Management Team
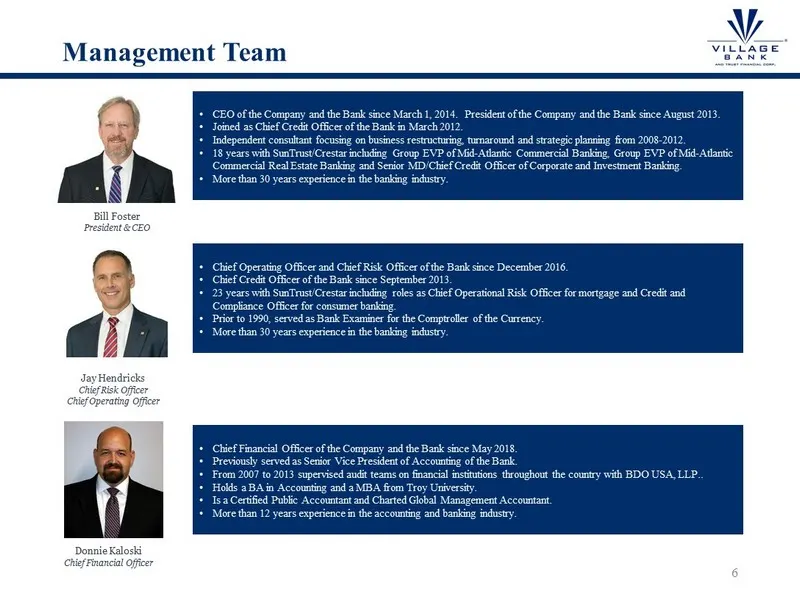
Management Team 6 Bill Foster President & CEO Jay Hendricks Chief Risk Officer Chief Operating Officer Donnie Kaloski Chief Financial Officer • CEO of the Company and the Bank since March 1, 2014. President of the Company and the Bank since August 2013. • Joined as Chief Credit Officer of the Bank i
Slide 8: Management Team
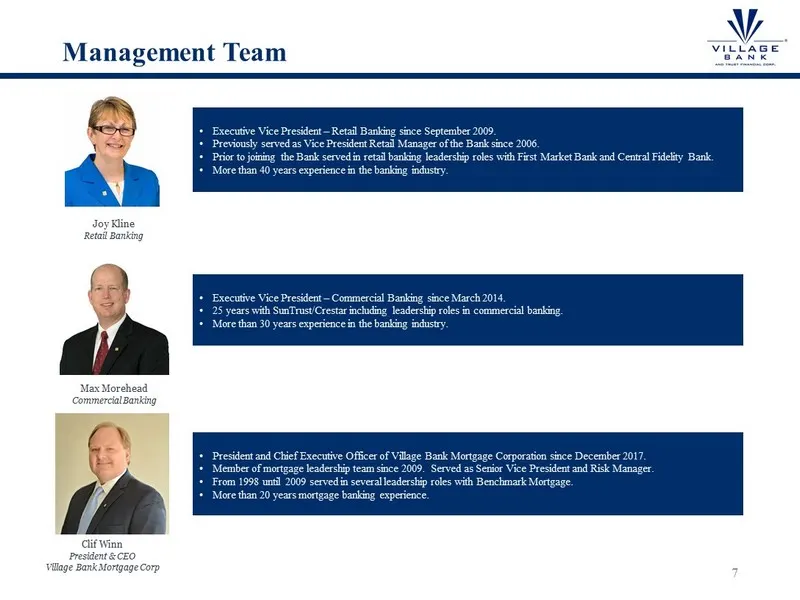
Management Team 7 • Executive Vice President – Retail Banking since September 2009. • Previously served as Vice President Retail Manager of the Bank since 2006. • Prior to joining the Bank served in retail banking leadership roles with First Market Bank and Central Fidelity Bank. • More than 40 year
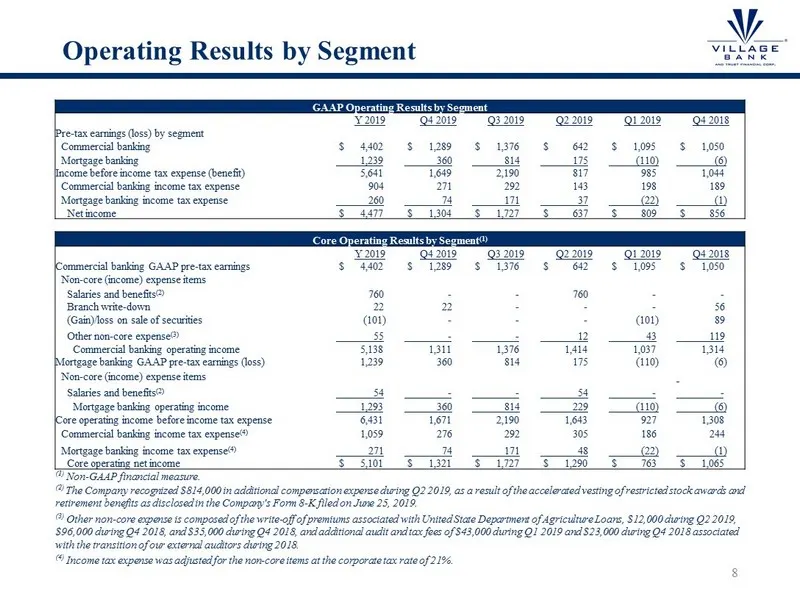
Slide 9: Operating Results by Segment
Operating Results by Segment 8 GAAP Operating Results by Segment Y 2019 Q4 2019 Q3 2019 Q2 2019 Q1 2019 Q4 2018 Pre - tax earnings (loss) by segment Commercial banking $ 4,402 $ 1,289 $ 1,376 $ 642 $ 1,095 $ 1,050 Mortgage banking 1,239 360 814 175 (110) (6) Income before income tax expense (benefit
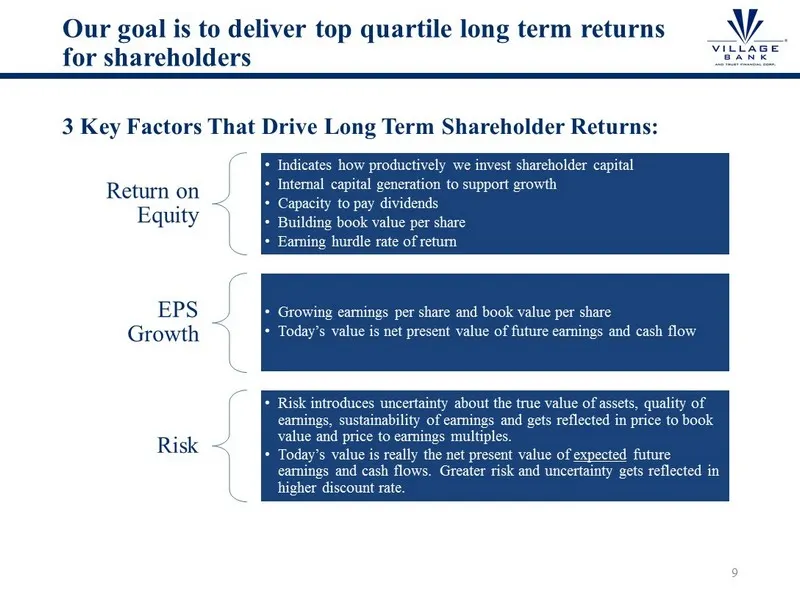
Slide 10: Our goal is to deliver top quartile long term returns for shareholders
Our goal is to deliver top quartile l ong t erm returns for shareholders Return on Equity • Indicates how productively we invest shareholder capital • Internal capital generation to support growth • Capacity to pay dividends • Building book value per share • Earning hurdle rate of return EPS Growth
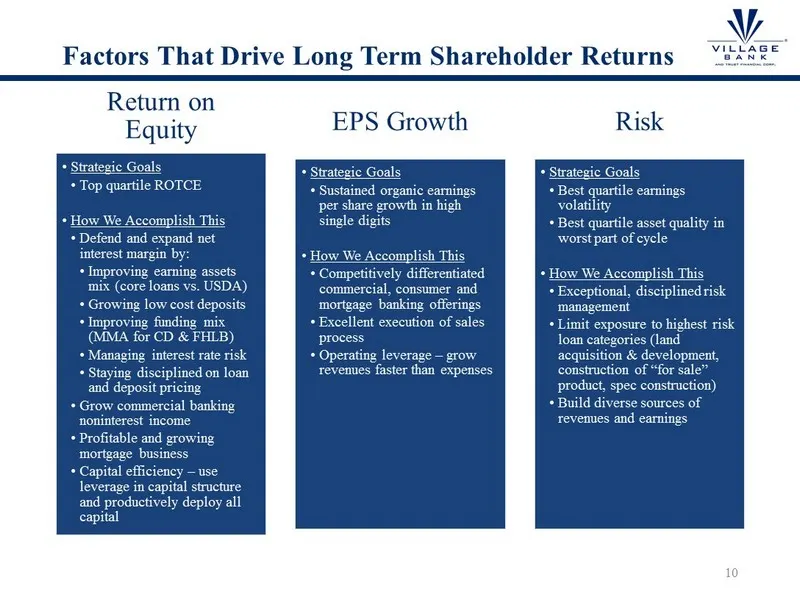
Slide 11: Factors That Drive Long Term Shareholder Returns
Factors That Drive Long Term Shareholder Returns Return on Equity • Strategic Goals • Top quartile ROTCE • How We Accomplish This • Defend and expand net interest margin by: • Improving earning assets mix (core loans vs. USDA) • Growing low cost deposits • Improving funding mix (MMA for CD & FHLB) •
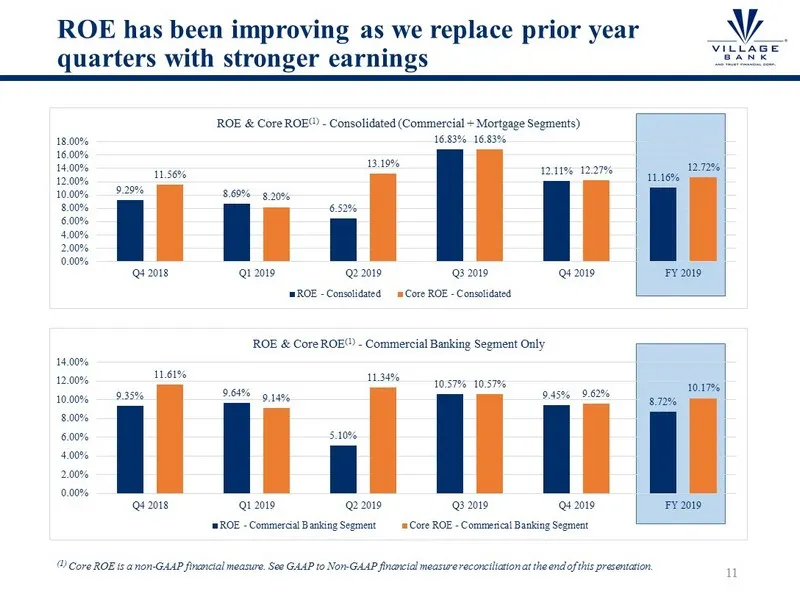
Slide 12: ROE has been improving as we replace prior year quarters with stronger earnings
ROE has been improving as we replace prior year quarters with stronger earnings (1) Core ROE is a non - GAAP financial measure. See GAAP to Non - GAAP financial measure reconciliation at the end of this presentation. 11 9.29% 8.69% 6.52% 16.83% 12.11% 11.16% 11.56% 8.20% 13.19% 16.83% 12.27% 12.72%
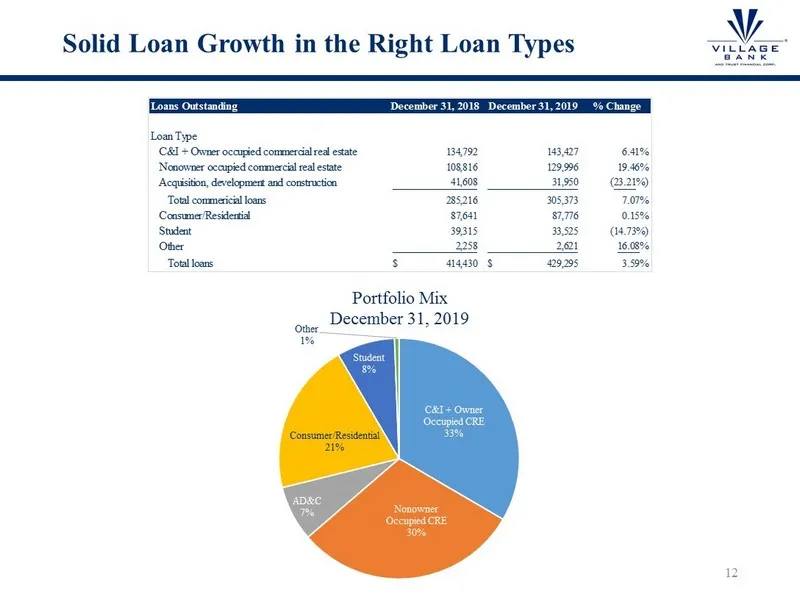
Slide 13: Solid Loan Growth in the Right Loan Types
Solid Loan Growth in the Right Loan Types 12 Loans Outstanding December 31, 2018 December 31, 2019 % Change Loan Type C&I + Owner occupied commercial real estate 134,792 143,427 6.41% Nonowner occupied commercial real estate 108,816 129,996 19.46% Acquisition, development and construction 41,608 31,
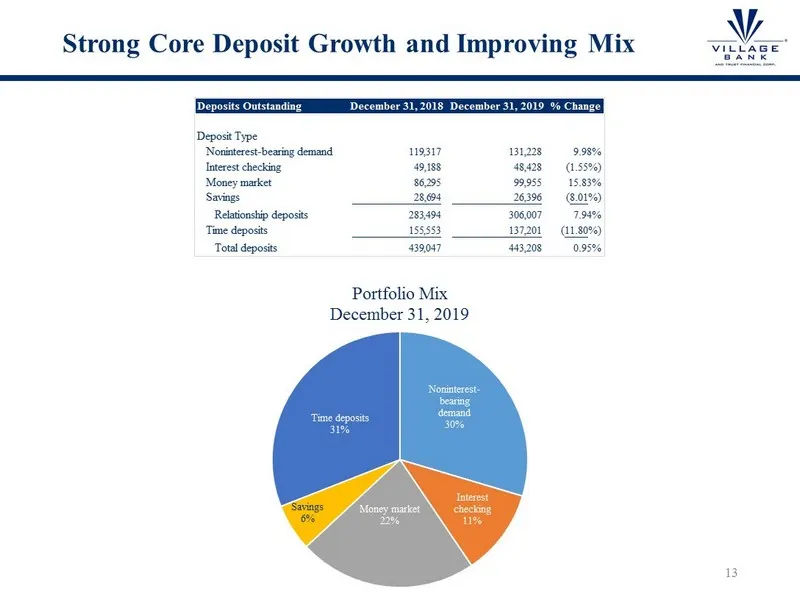
Slide 14: Strong Core Deposit Growth and Improving Mix
Strong Core Deposit Growth and Improving Mix 13 Deposits Outstanding December 31, 2018 December 31, 2019 % Change Deposit Type Noninterest-bearing demand 119,317 131,228 9.98% Interest checking 49,188 48,428 (1.55%) Money market 86,295 99,955 15.83% Savings 28,694 26,396 (8.01%) Relationship deposit
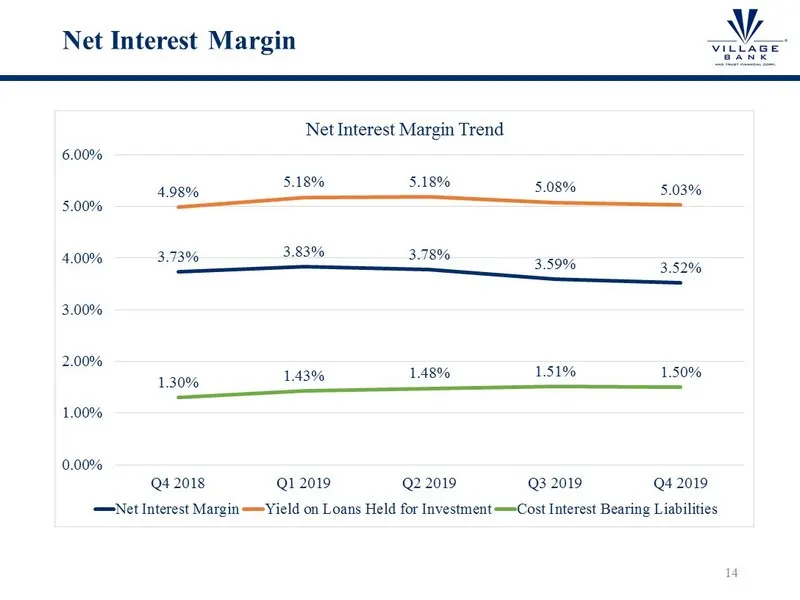
Slide 15: Net Interest Margin
Net Interest Margin 14 3.73% 3.83% 3.78% 3.59% 3.52% 4.98% 5.18% 5.18% 5.08% 5.03% 1.30% 1.43% 1.48% 1.51% 1.50% 0.00% 1.00% 2.00% 3.00% 4.00% 5.00% 6.00% Q4 2018 Q1 2019 Q2 2019 Q3 2019 Q4 2019 Net Interest Margin Trend Net Interest Margin Yield on Loans Held for Investment Cost Interest Bearing Li
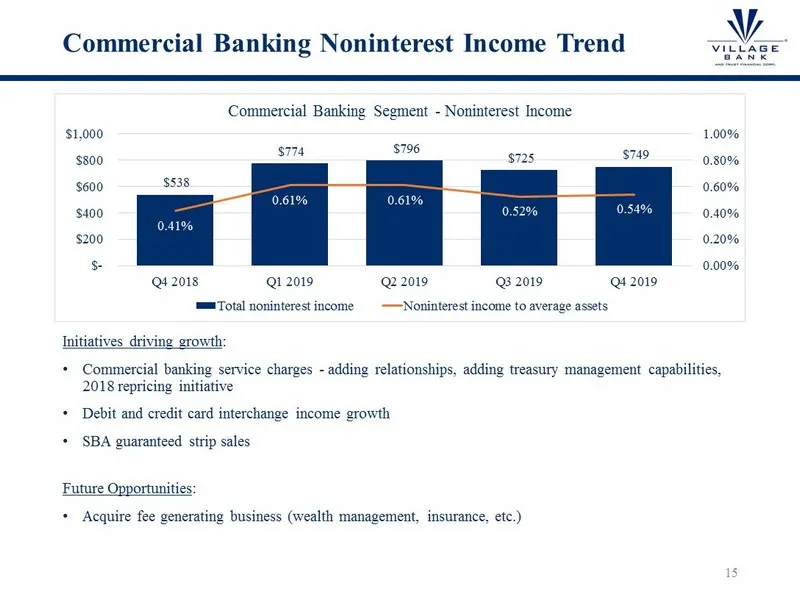
Slide 16: Commercial Banking Noninterest Income Trend
Commercial Banking Noninterest Income Trend Initiatives driving growth : • Commercial banking service charges - adding relationships, adding treasury management capabilities, 2018 repricing initiative • Debit and credit card interchange income growth • SBA guaranteed strip sales Future Opportunities
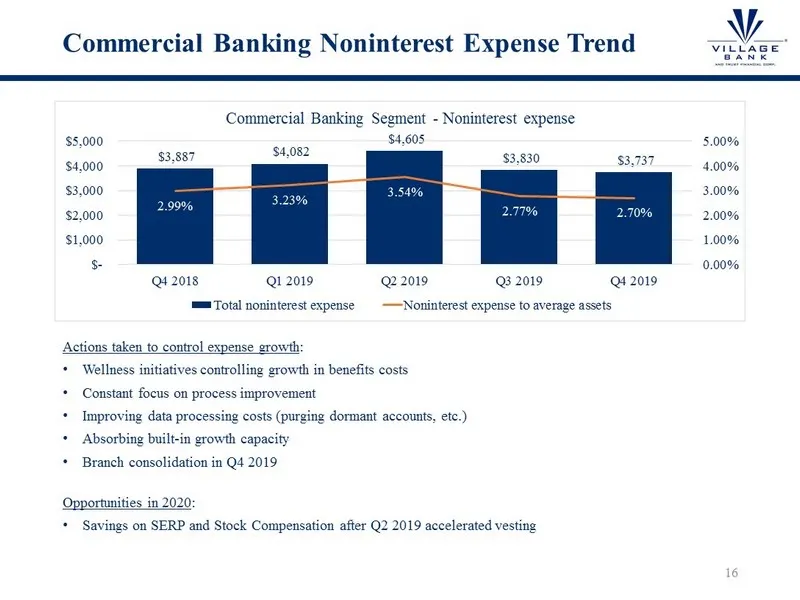
Slide 17: Commercial Banking Noninterest Expense Trend
Commercial Banking Noninterest Expense Trend Actions taken to control expense growth : • Wellness initiatives controlling growth in benefits costs • Constant focus on process improvement • Improving data processing costs (purging dormant accounts, etc.) • Absorbing built - in growth capacity • Branc
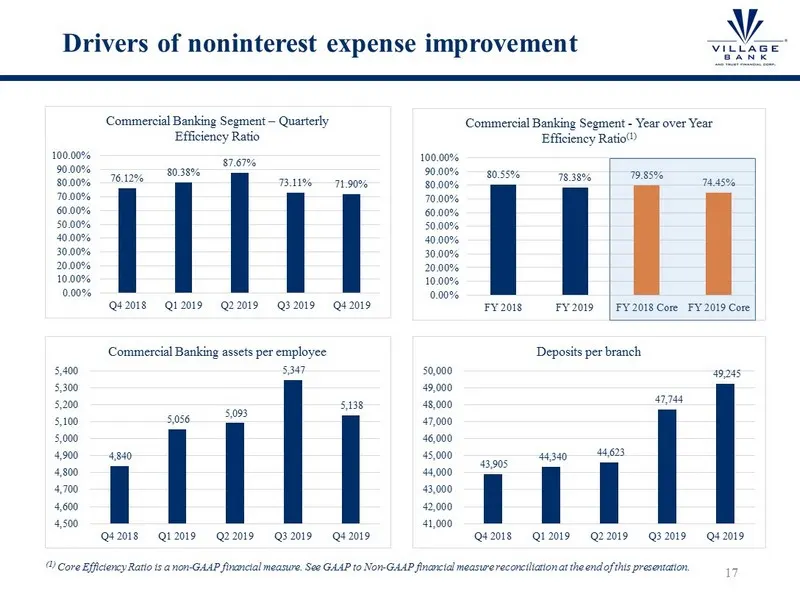
Slide 18: Drivers of noninterest expense improvement
Drivers of noninterest expense improvement (1) Core Efficiency Ratio is a non - GAAP financial measure. See GAAP to Non - GAAP financial measure reconciliation at the end of this presentation. 17 76.12% 80.38% 87.67% 73.11% 71.90% 0.00% 10.00% 20.00% 30.00% 40.00% 50.00% 60.00% 70.00% 80.00% 90.00%
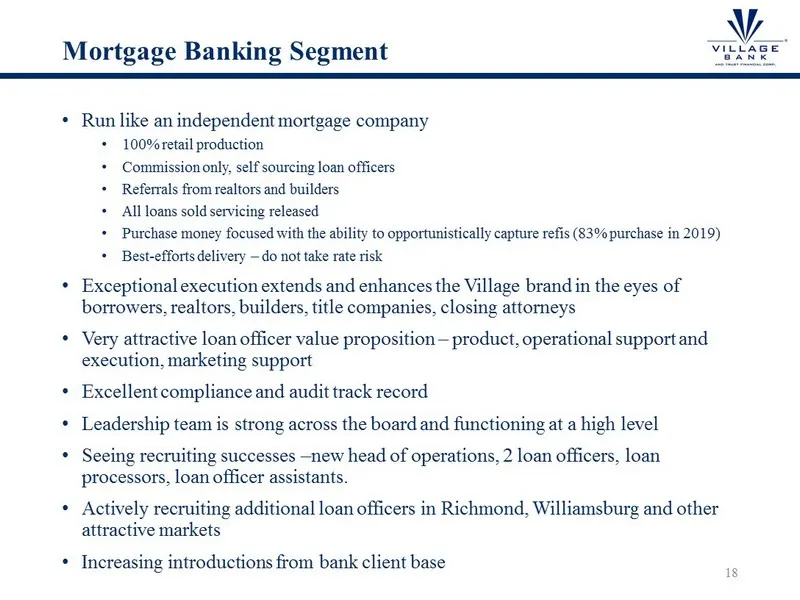
Slide 19: Mortgage Banking Segment
Mortgage Banking Segment • Run like an independent mortgage company • 100% retail production • Commission only, self sourcing loan officers • Referrals from realtors and builders • A ll loans sold servicing released • Purchase money focused with the ability to opportunistically capture refis (83% pu
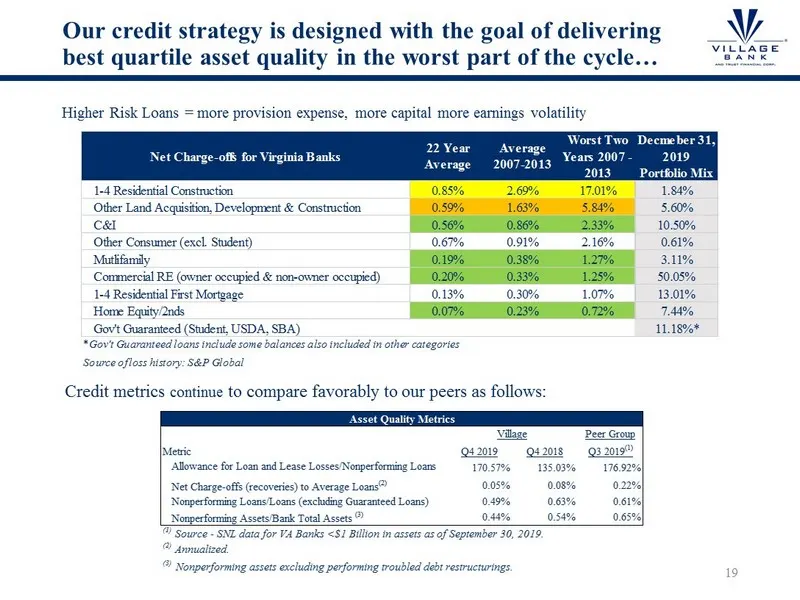
Slide 20: Our credit strategy is designed to deliver best quartile asset quality
Our credit strategy is designed with the goal of delivering best quartile asset quality in the worst part of the cycle… Higher Risk Loans = more provision expense, more capital more earnings volatility Credit metrics continue to compare favorably to our peers as follows: 19 Net Charge-offs for Virgi
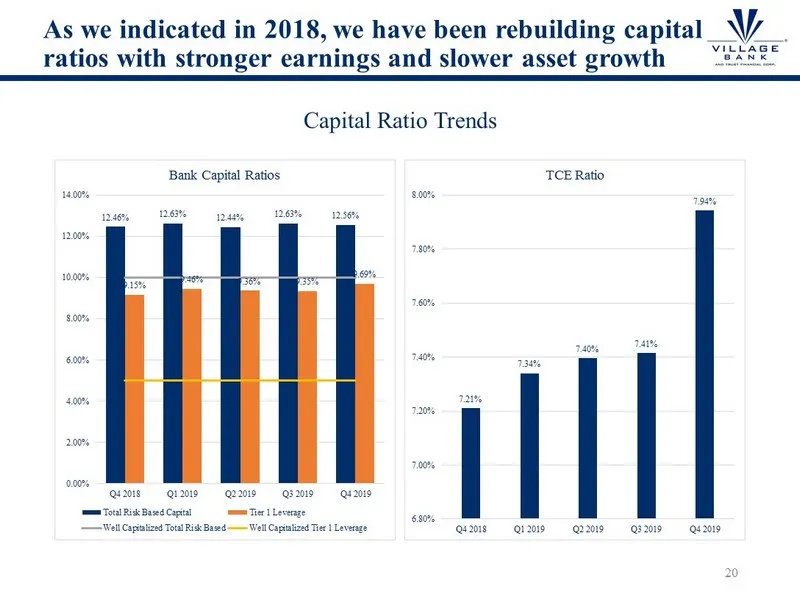
Slide 21: Rebuilding capital ratios with stronger earnings
As we indicated in 2018, we have been rebuilding capital ratios with stronger earnings and slower asset growth Capital Ratio Trends 20 12.46% 12.63% 12.44% 12.63% 12.56% 9.15% 9.46% 9.36% 9.35% 9.69% 0.00% 2.00% 4.00% 6.00% 8.00% 10.00% 12.00% 14.00% Q4 2018 Q1 2019 Q2 2019 Q3 2019 Q4 2019 Bank Capi
Slide 22: 2020 Opportunities and Challenges
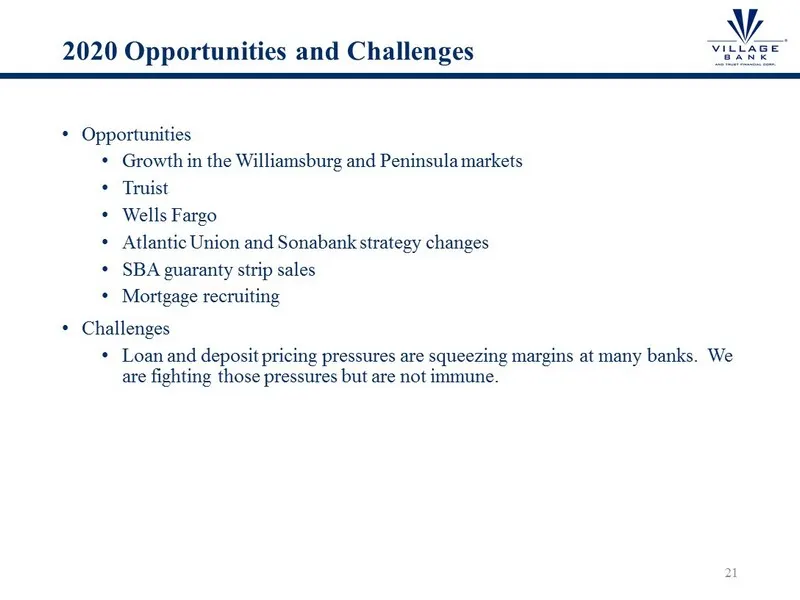
2020 Opportunities and Challenges • Opportunities • Growth in the Williamsburg and Peninsula markets • Truist • Wells Fargo • Atlantic Union and Sonabank strategy changes • SBA guaranty strip sales • Mortgage recruiting • Challenges • Loan and deposit pricing pressures are squeezing margins at many
Slide 23: Why Village
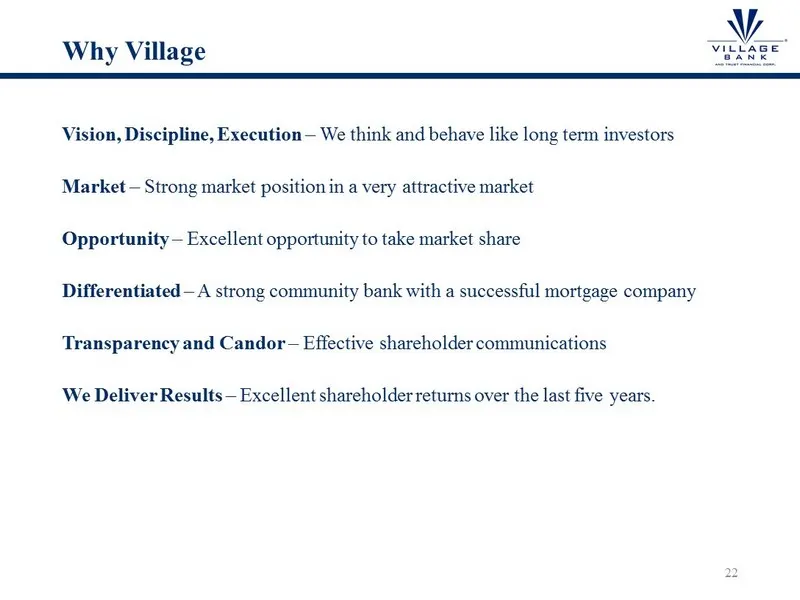
Why Village Vision, Discipline, Execution – We think and behave like long term investors Market – Strong market position in a very attractive market Opportunity – Excellent opportunity to take m arket share Differentiated – A strong community bank with a successful mortgage company Transparency and
Slide 24: Reconciliation of Non-GAAP Financial Measures
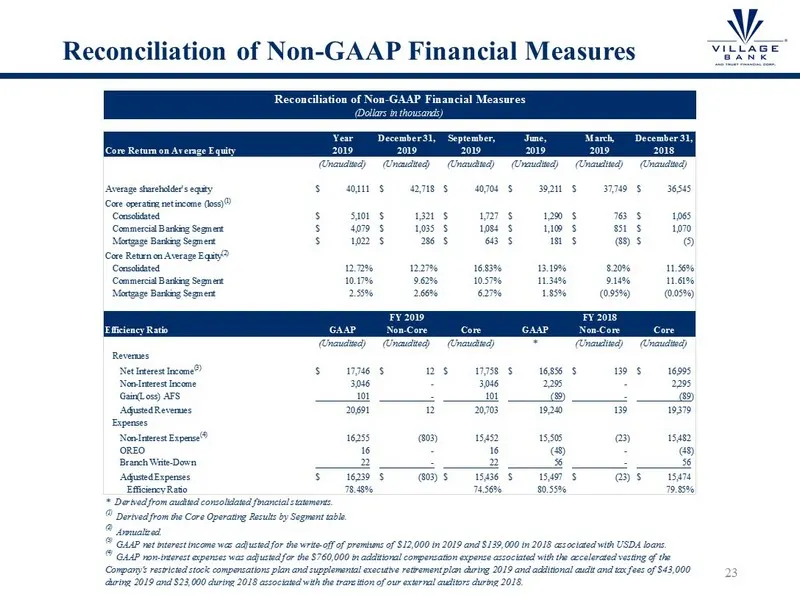
Reconciliation of Non - GAAP Financial Measures 23 Year December 31, September, June, March, December 31, Core Return on Average Equity 2019 2019 2019 2019 2019 2018 (Unaudited) (Unaudited) (Unaudited) (Unaudited) (Unaudited) (Unaudited) Average shareholder's equity 40,111$ 42,718$ 40,704$ 39,211$ 3
Source: SEC EDGAR · 8-K filed Jan 28, 2020
More decks from Village Bank and Trust Financial
 Shareholder Meeting (May 2024)23 slides · May 21, 2024
 Investor Presentation (January 2024)27 slides · Jan 26, 2024
 Shareholder Meeting (May 2023)25 slides · May 23, 2023
 Investor Presentation (September 2022)27 slides · Sep 19, 2022
 Shareholder Meeting (May 2022)19 slides · May 24, 2022
 Investor Presentation (January 2022)26 slides · Jan 28, 2022