Medco Health Solutions — Thomas Weisel Partners Healthcare Conference 2009
22 slides from Medco Health Solutions's conference presentation, Sep 11, 2009
Slide 1: Advancing Pharmacy - Reforming Healthcare
Advancing Pharmacy - Reforming Healthcare Thomas Weisel Partners Healthcare Conference 2009 September 11, 2009 Brian T. Griffin Group President, Health Plans Richard J. Rubino SVP, Finance and CFO
Slide 2: Forward-Looking Statements
Forward-Looking Statements This presentation contains "forward-looking statements" as that term is defined in the Private Securities Litigation Reform Act of 1995. These statements involve risks and uncertainties that may cause results to differ materially from those set forth in the statements. No
Slide 3: Who is Medco
Who is Medco Ranked #45 on the Fortune 100* List $51.3 Billion in Revenues for 2008 $29.8 Billion YTD June 2009 60+ Million Members Largest Independent PBM Measured by Drug Spend Largest Specialty Pharmacy Largest Mail-Order Pharmacies in the World Leader in Clinical Innovation *2008 Rankings
Slide 4: What is Driving Our Growth
What is Driving Our Growth Strong Sales & Client Retention Mail-Order Prescriptions Generic Dispensing Specialty Pharmacy Medicare Business Clinical Leadership - Improving Health Outcomes at Lower Total Healthcare Cost
Slide 5: New-Named & Net-New Sales Performance
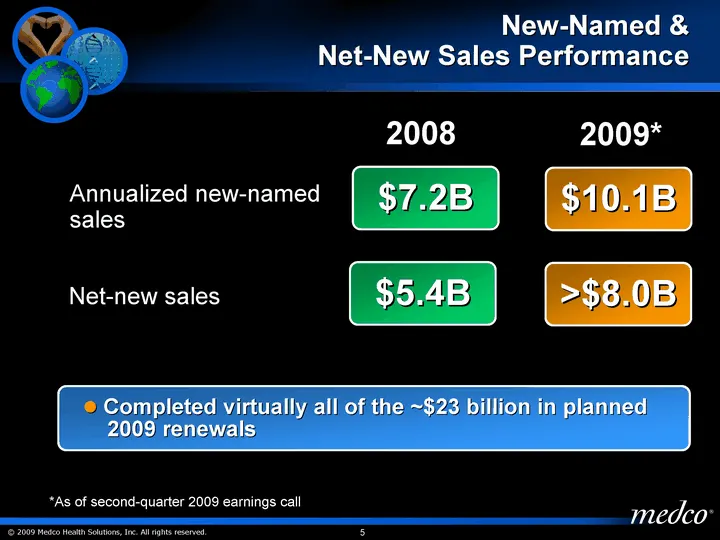
New-Named & Net-New Sales Performance *As of second-quarter 2009 earnings call $7.2B Annualized new-named sales Net-new sales $10.1B $5.4B >$8.0B 2008 2009* Completed virtually all of the ~$23 billion in planned 2009 renewals
Slide 6: Early View of 2010 Sales Performance
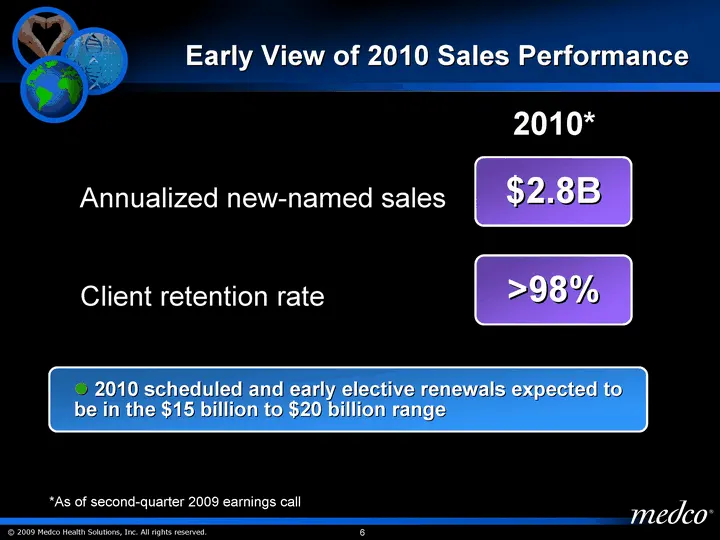
Early View of 2010 Sales Performance *As of second-quarter 2009 earnings call Annualized new-named sales $2.8B 2010* 2010 scheduled and early elective renewals expected to be in the $15 billion to $20 billion range Client retention rate >98%
Slide 7: Mail-Order Script Volume and Growth Opportunity
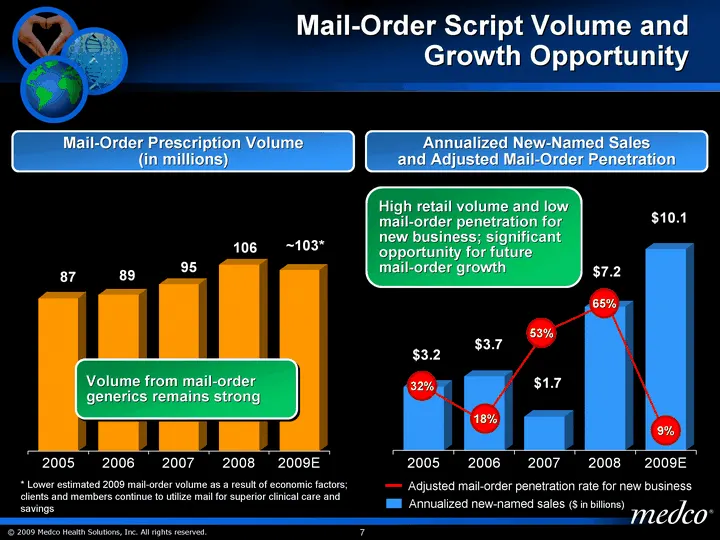
Mail-Order Script Volume and Growth Opportunity Annualized new-named sales ($ in billions) 2005 2006 2007 2008 2009E New Business 4 4.7 2.9 Mail-Order Volume 87 89 95 106 103 Mail-Order Prescription Volume (in millions) Annualized New-Named Sales and Adjusted Mail-Order Penetration 2005 2006 2007 20
Slide 8: Generics Growth Opportunity
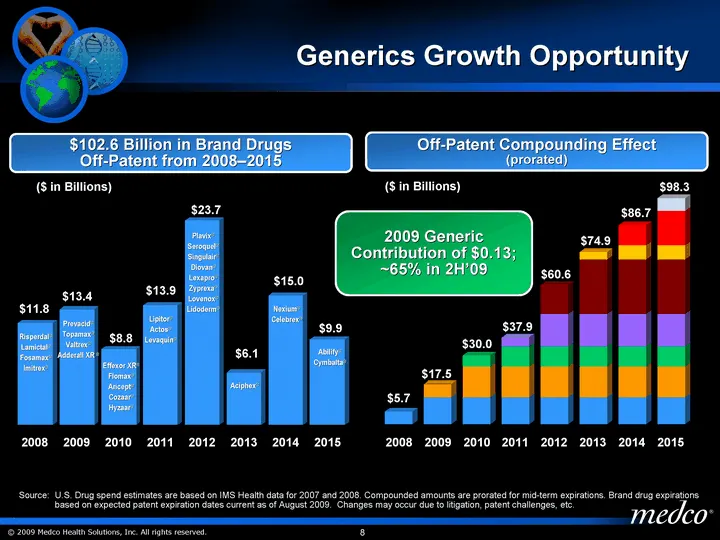
2008 2009 2010 2011 2012 2013 2014 2015 Acute Chronic/Complex 11.8 13.4 8.8 13.9 23.7 6.1 15 9.9 Generics Growth Opportunity Risperdal(r) Lamictal(r) Fosamax(r) Imitrex(r) Prevacid(r) Topamax(r) Valtrex(r) Adderall XR (r) Effexor XR(r) Flomax(r) Aricept(r) Cozaar(r) Hyzaar(r) Lipitor(r) Actos(r) Lev
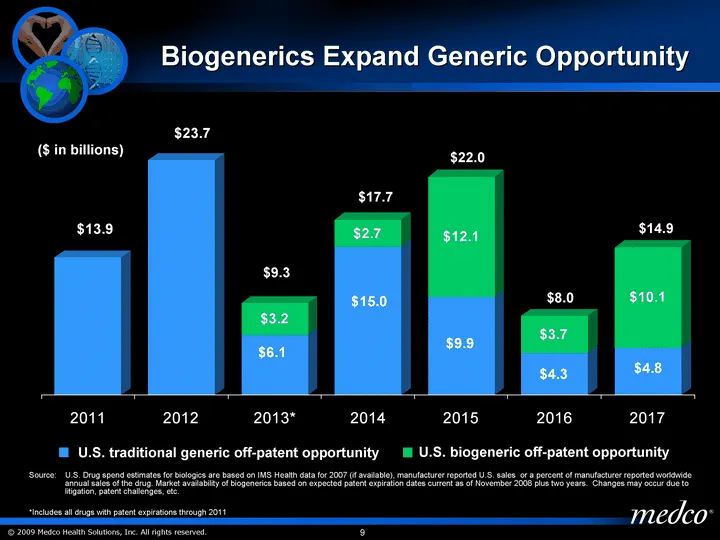
Slide 9: Biogenerics Expand Generic Opportunity
2011 2012 2013* 2014 2015 2016 2017 Acute Chronic/Complex 13.9 23.7 6.1 15 9.9 4.3 4.8 3.2 2.7 12.1 3.7 10.1 Biogenerics Expand Generic Opportunity ($ in billions) U.S. traditional generic off-patent opportunity $9.3 $17.7 $22.0 U.S. biogeneric off-patent opportunity $8.0 $14.9 Source: U.S. Drug spe
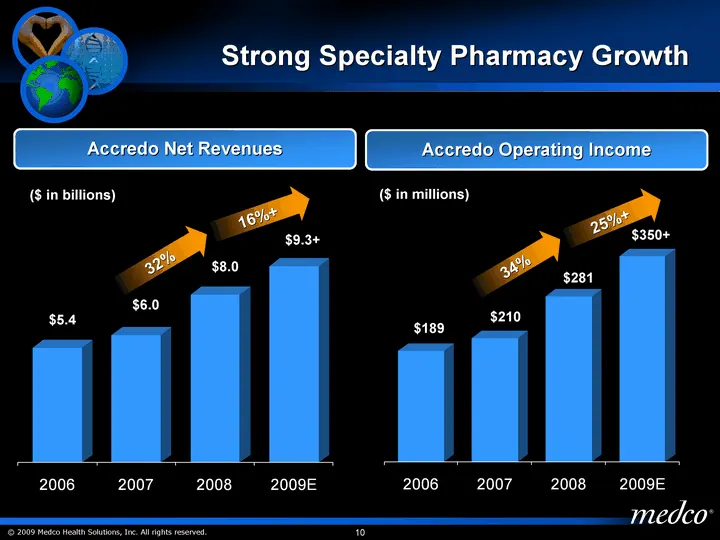
Slide 10: Strong Specialty Pharmacy Growth
2006 2007 2008 2009E Acute Chronic/Complex 5437 6043 7974 9300 Strong Specialty Pharmacy Growth Accredo Net Revenues $5.4 $9.3+ $8.0 $6.0 Accredo Operating Income 2006 2007 2008 2009E 189 210 281 350 $189 $281 $350+ $210 32% 34% ($ in billions) ($ in millions) 16%+ 25%+
Slide 11: Retiree Solutions - Casting a Broad Net
Retiree Solutions - Casting a Broad Net 2Q09 Medicare PDP revenues up 72.8% from 2Q08 to a record $282.6 million Over 300% growth in total retiree lives for 2009; majority are no risk, ASO contracts Expanding health plan Medicare ASO footprint increases retiree recapture capability and access to new
Slide 12: Clinical Innovations - Medco Therapeutic Resource Centers
Clinical Innovations - Medco Therapeutic Resource Centers(r) Medco Therapeutic Resource Centers(r) (TRCs) Full-service platform, housing specialized pharmacists to deliver superior clinical and financial outcomes for clients and members Focuses on chronic and complex conditions accounting for 96 per
Slide 13: Clinical Innovations - Personalized Medicine
Clinical Innovations - Personalized Medicine Pharmacogenomics ("Personalized Medicine") Leveraging the TRC platform, Medco launched two pilots using genetic tests to personalize with precision drug selection/delivery/dosing Collaboration with The Mayo Clinic for Coumadin Collaboration with LabCorp f
Slide 14: International Initiatives
International Initiatives Acquired a majority stake in Netherlands-based Europa Apotheek Venlo, a mail-order pharmacy serving Germany Germany market had 2008 drug spend of $31 billion (Rx) and $6 billion (OTC) Opportunity leverages Medco's core competencies Partnered with Apoteket to create the firs
Slide 15: Strong Balance Sheet and Cash Flows
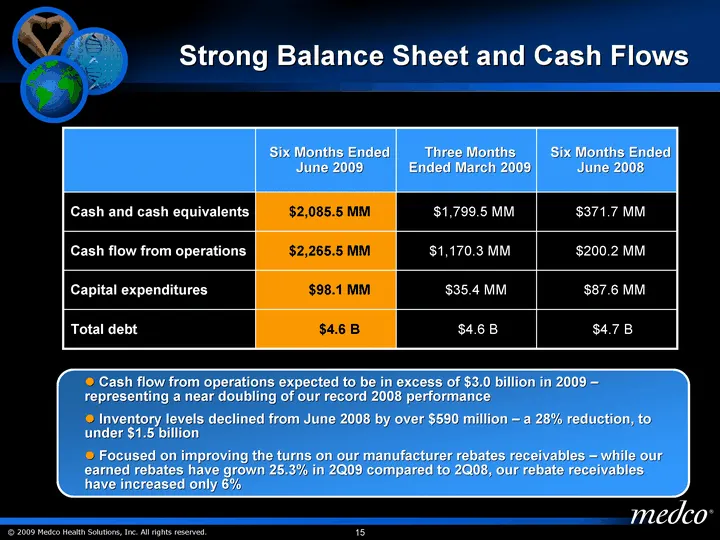
Strong Balance Sheet and Cash Flows Six Months Ended June 2009 Three Months Ended March 2009 Six Months Ended June 2008 Cash and cash equivalents $2,085.5 MM $1,799.5 MM $371.7 MM Cash flow from operations $2,265.5 MM $1,170.3 MM $200.2 MM Capital expenditures $98.1 MM $35.4 MM $87.6 MM Total debt $
Slide 16: Continued Financial Strength in a Weak Economy
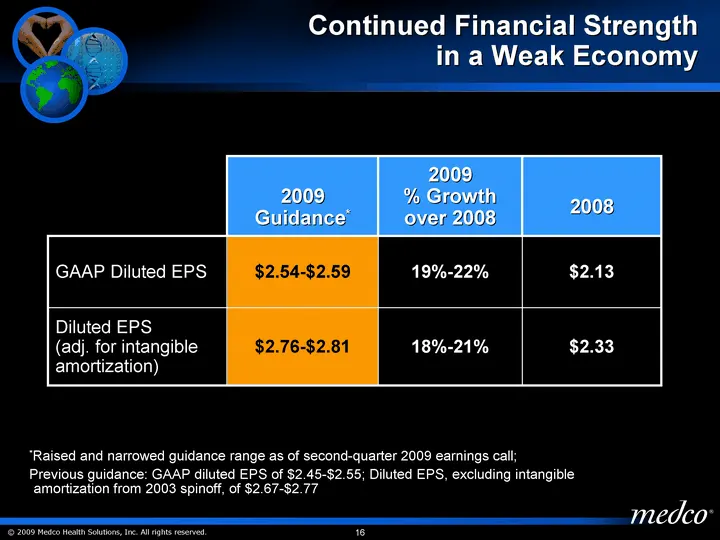
Continued Financial Strength in a Weak Economy 2009 Guidance* 2009 % Growth over 2008 2008 GAAP Diluted EPS $2.54-$2.59 19%-22% $2.13 Diluted EPS (adj. for intangible amortization) $2.76-$2.81 18%-21% $2.33 *Raised and narrowed guidance range as of second-quarter 2009 earnings call; Previous guidanc
Slide 17: Medco
medco’
Slide 18: Medco's Role in Healthcare Reform
Medco's Role in Healthcare Reform Facts: When you manage drugs better, you manage the whole healthcare system better For prescription drugs, healthcare is wired today Chronic and complex diseases are responsible for 96% of drug costs and 75% of medical expenses in the U.S. For 88% of chronic and com
Slide 19: National Healthcare Reform Agenda
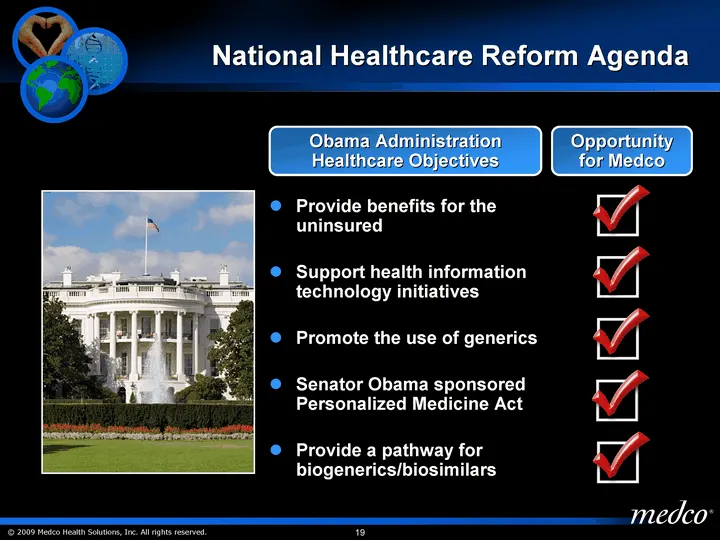
National Healthcare Reform Agenda Provide benefits for the uninsured Support health information technology initiatives Promote the use of generics Senator Obama sponsored Personalized Medicine Act Provide a pathway for biogenerics/biosimilars Opportunity for Medco Obama Administration Healthcare Obj
Slide 20: Brand and Generic Trend
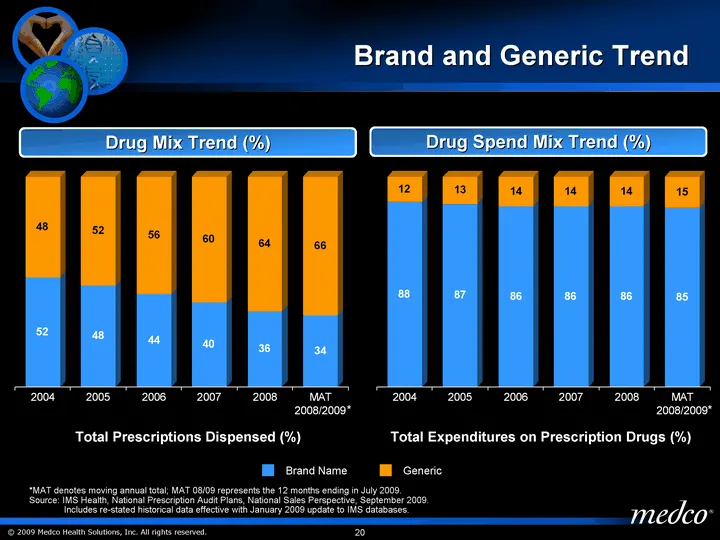
Brand and Generic Trend *MAT denotes moving annual total; MAT 08/09 represents the 12 months ending in July 2009. Source: IMS Health, National Prescription Audit Plans, National Sales Perspective, September 2009. Includes re-stated historical data effective with January 2009 update to IMS databases.
Slide 21: Reconciliation Tables
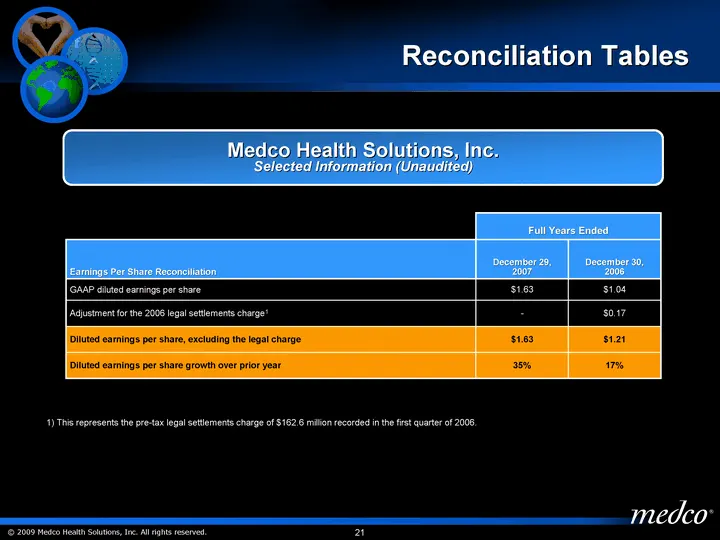
Reconciliation Tables Medco Health Solutions, Inc. Selected Information (Unaudited) Full Years Ended Full Years Ended Earnings Per Share Reconciliation December 29, 2007 December 30, 2006 GAAP diluted earnings per share $1.63 $1.04 Adjustment for the 2006 legal settlements charge1 - $0.17 Diluted ea
Slide 22: Reconciliation Tables
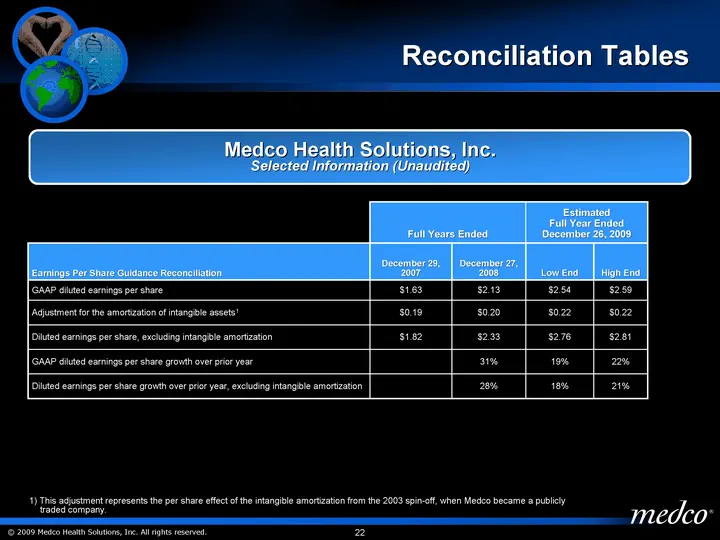
Reconciliation Tables Medco Health Solutions, Inc. Selected Information (Unaudited) Full Years Ended Full Years Ended Estimated Full Year Ended December 26, 2009 Estimated Full Year Ended December 26, 2009 Earnings Per Share Guidance Reconciliation December 29, 2007 December 27, 2008 Low End High En
Source: SEC EDGAR · 8-K filed Sep 11, 2009
More decks from Medco Health Solutions Inc
 Merger or Acquisition (July 2011)20 slides · Jul 22, 2011
 Sanford C. Bernstein 27th Annual Strategic Decisions Conference 201125 slides · Jun 1, 2011
 Deutsche Bank 36th Annual Health Care Conference 201130 slides · May 3, 2011
 Investor Presentation (March 2011)36 slides · Mar 24, 2011
 Barclays Capital 2011 Global Health Care Conference36 slides · Mar 17, 2011
 Citi 2011 Global Health Care Conference37 slides · Mar 1, 2011