Great Plains Energy Incorporated
Great Plains Energy — Merrill Lynch Power and Gas Conference 2008
20 slides from Great Plains Energy's conference presentation, Sep 23, 2008
Slide 1: Great Plains Energy Merrill Lynch Power and Gas Conference
Great Plains Energy Merrill Lynch Power and Gas Conference September 23-24, 2008 Exhibit 99.1 Terry Bassham, CFO Executive Vice President Finance & Strategic Development
Slide 2: Forward-looking statements
Statements made in this presentation that are not based on historical facts are forward-looking, may involve risks and uncertainties, and are intended to be as of the date when made. Forward-looking statements include, but are not limited to, the outcome of regulatory proceedings, cost estimates of
Slide 3: Great Plains Energy Business Overview
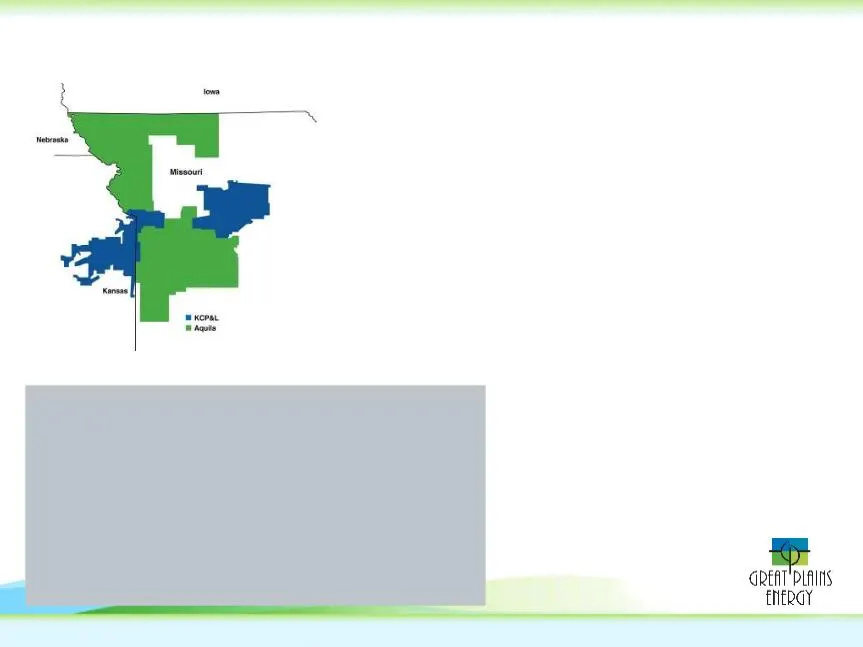
Regulated vertically integrated electric utility operations: • $7.7 billion in assets* • $1.9 billion in revenues* • $2.7 billion market cap - NYSE:GXP • Approx. 800,000 customers in KS and MO • Low retail utility rates • Total generation capacity of over 5,700 MWs Solid Midwest electric utility - K
Slide 4: Three Key Initiatives
• Rate base growth through KCP&L’s Comprehensive Energy Plan and plant investments by KCP&L GMO (Aquila) • Aquila integration and synergy target attainment • Rate case filings to include investments in rate base and to share synergies with customers Three Key Initiatives
Slide 5: Experienced Management Team Aligned to Succeed
Mike Chesser - CEO years experience Terry Bassham - CFO years experience Bill Downey - COO years experience John Marshall - EVP Utility Operations years experience • Accounting • Finance and IR • Risk Management • Strategic Planning • Internal Audit • Construction • Regulatory • Public Affairs • Bus
Slide 6: Comprehensive Energy Plan & KCP&L GMO Plant Investments
Comprehensive Energy Plan & KCP&L GMO Plant Investments
Slide 7: Comprehensive Energy Plan
Spearville Wind Energy Facility ü 100MW completed on schedule and under budget LaCygne ü Phase 1: Unit 1 SCR - Completed on schedule, under budget, and performing per specification • Phase 2: Unit 1 - bag house and scrubber environmental upgrades: >Project Definition Report completed in Q3 2007 >Eva
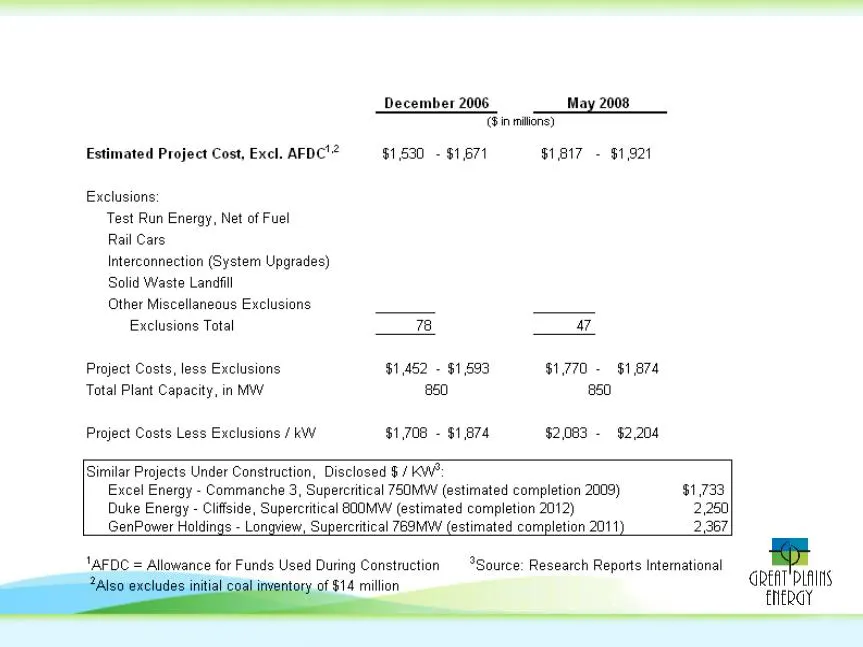
Slide 8: Iatan 2 Estimated Project Cost Comparison
December 2006 May 2008 Gin mitionsy Estimated Project Cost, Excl. AFDC’? = $1,530 - $1,671 $1817 - $1,921 Exclusions: Test Run Energy, Net of Fuel Rail Cars Interconnection (System Upgrades) Solid Waste Landfill Other Miscellaneous Exclusions Exclusions Total 47 Project Costs, less Exclusions $1452
Slide 9: Integration of the Aquila Transaction & Synergy Attainment
Combined Company Integration of the Aquila Transaction & Synergy Attainment
Slide 10: Integration Scope of the Effort
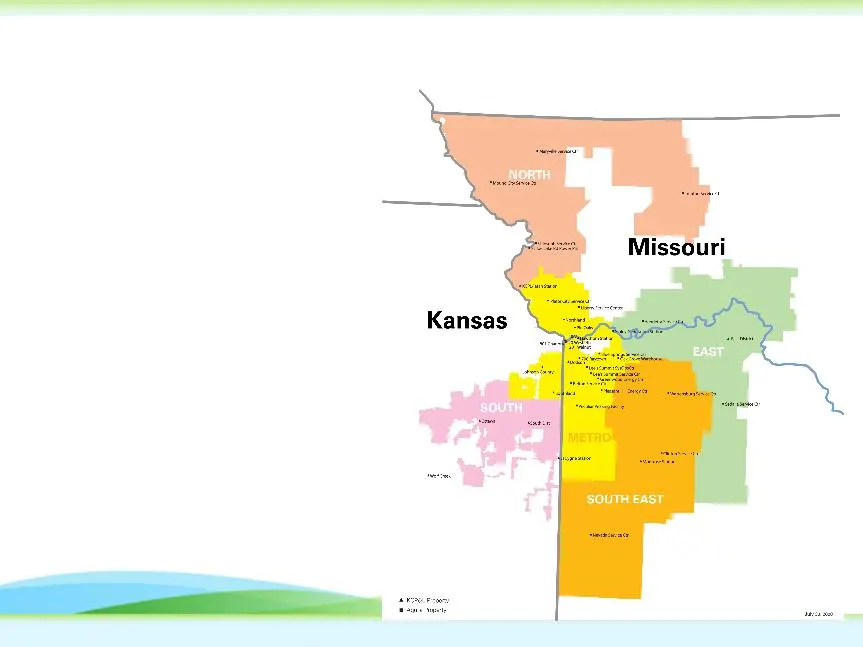
Integration Coordination Scope of the effort • 805,100 customers across counties in MO and KS covering 17,934 sq. miles • 3,170 employees - - including new hires • 30 office/service center locations • 9 generation plant sites and peaking facilities • 3,309 miles transmission, 24,466 miles distributi
Slide 11: Early Integration Successes
Early Integration Successes Infrastructure • Combined several key systems (billing, accounting, HR) as well as telecom and network platforms into a single KCP&L version for each Operations • Two Aquila unions consolidated into the three existing KCP&L unions • Training initiated to align work rules,
Slide 12: Significant Synergies Expected
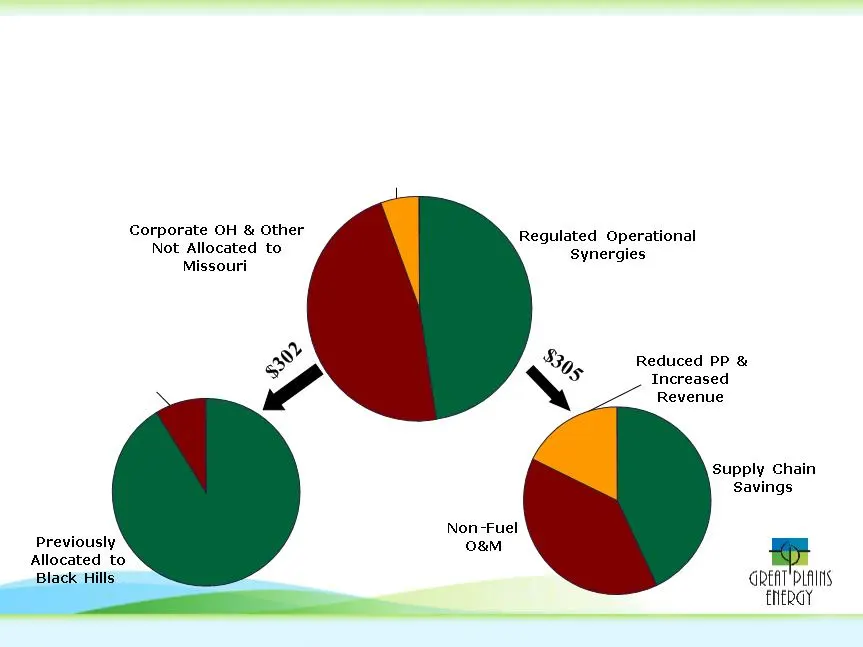
$302 $305 $68 $120 $131 $54 $27 $275 Great Plains expects to realize $675 million of total savings and synergies over five years Interest Savings Corporate Retained & Merchant Savings Significant Synergies Expected
Slide 13: Path to Synergy Sharing
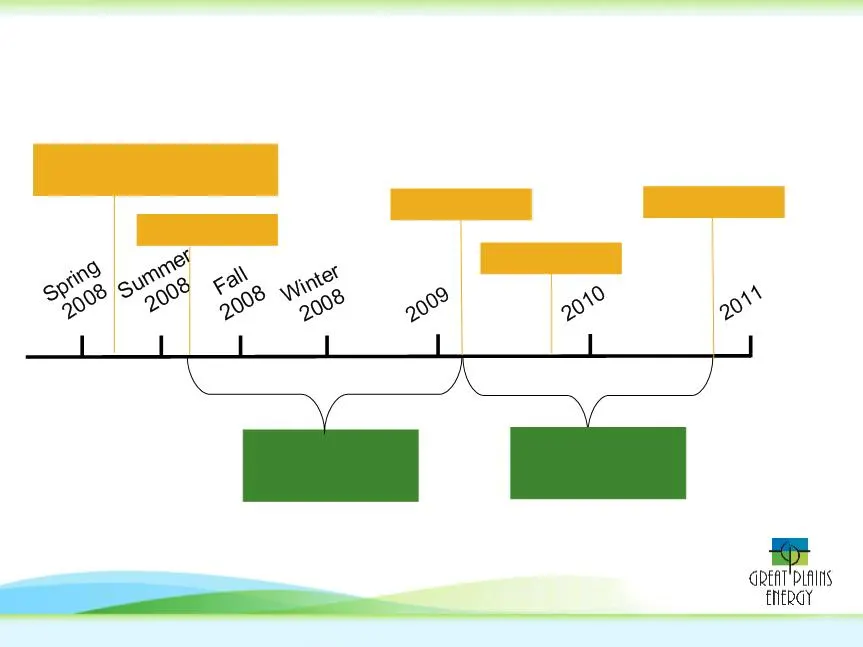
Shareholders receive benefits of synergies Shareholders receive benefits of new synergies Missouri Hearings, Approval and Close File Rate Case File Rate Case Rates Effective Rates Effective Path to Synergy Sharing
Slide 14: Recent Rate Case Filings for Recovery of Investments & Sharing of Synergies
Recent Rate Case Filings for Recovery of Investments & Sharing of Synergies
Slide 15: Missouri and Kansas Rates Below National Average
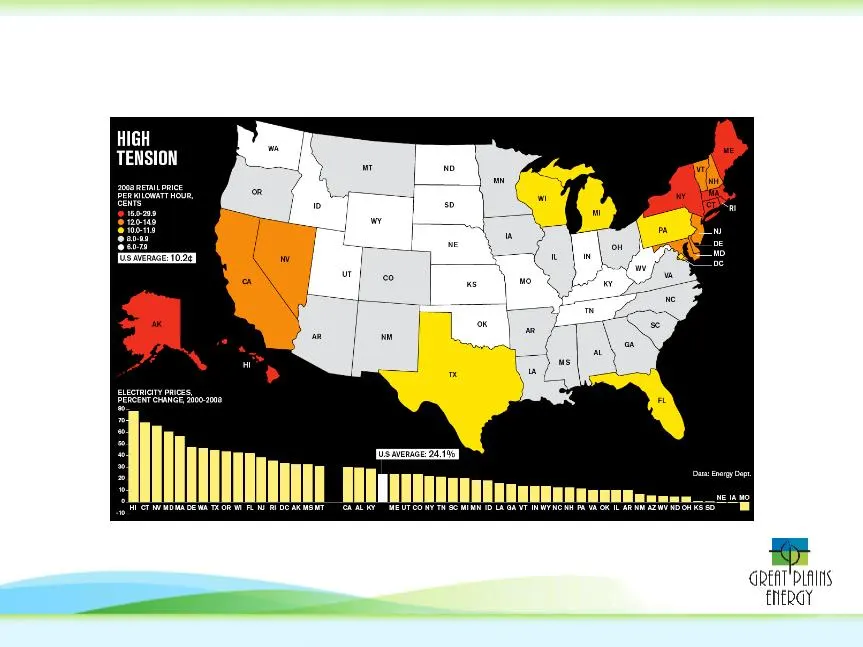
Business Week July 24, 2008 Missouri and Kansas Rates Below National Average
Slide 16: Summary of Rate Cases
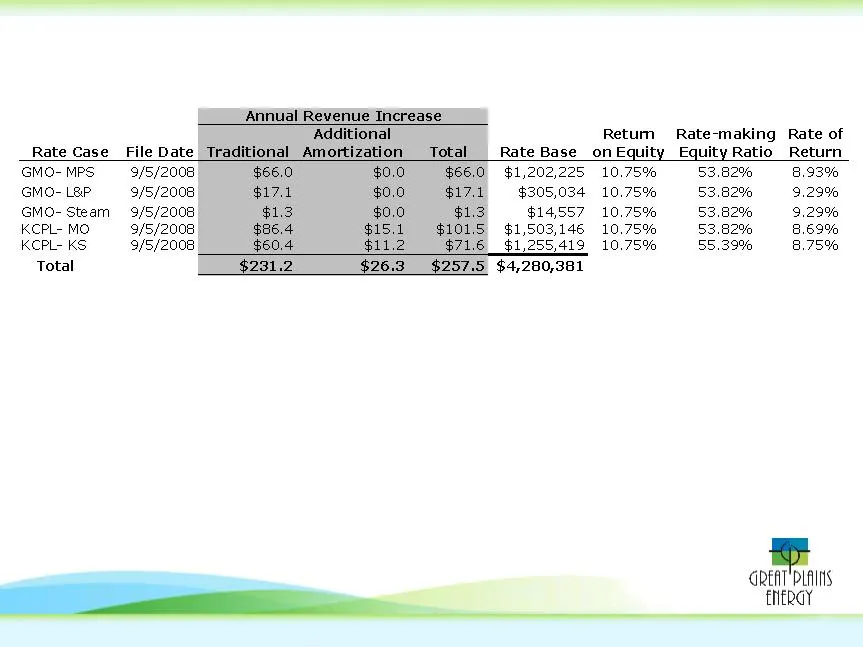
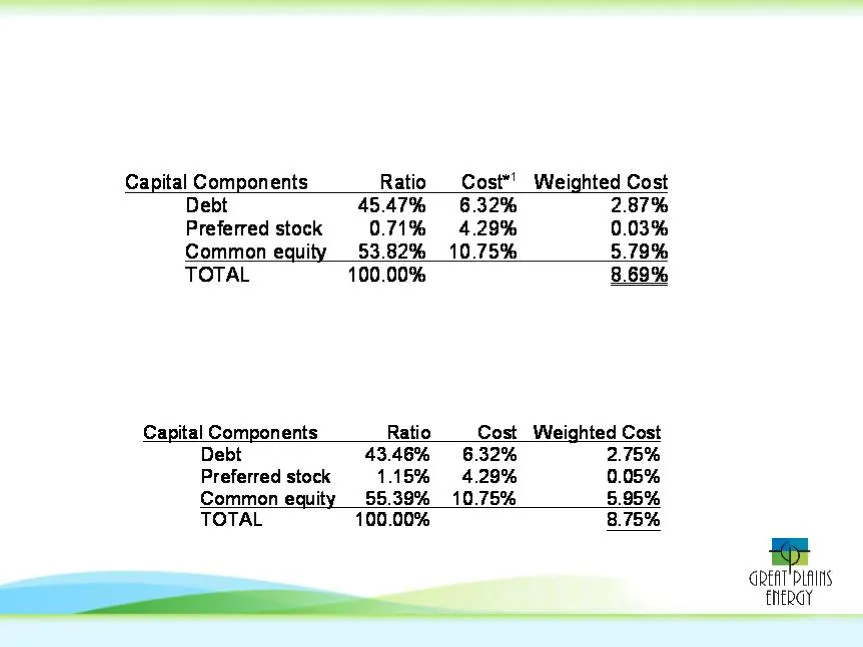
• Requested ROE reasonable based on extensive cost of capital analysis • Capital structure based on Great Plains Energy consolidated capital structure >Excludes short-term debt >Per the Aquila transaction approval, Kansas filing excludes Aquila cap structure impact and synergies Summary of Rate Case
Slide 17: Requested Capital Structure
Requested Capital Structure - Missouri Requested Capital Structure - Kansas Note *1: Cost of debt varies by case as follows: KCPL MO- 6.32%, GMO MPS- 6.851%, GMO L&P (electric and steam)- 7.634% Requested Capital Structure
Slide 18: Rate Base Growth
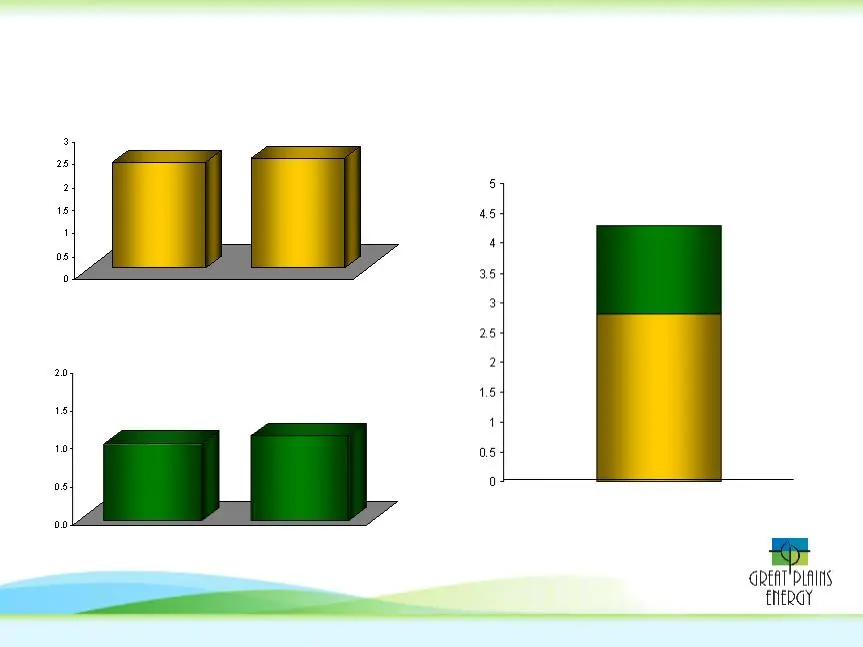
$1.5 KCP&L GMO $2.8 KCP&L $1.0 $4.3 $2.4 $1.1 $2.3 Rate Cases Filed 8/5/2008 KCP&L Historical Rate Base Aquila (KCP&L GMO) Historical Rate Base Rates Effective 1/1/2007 Rates Effective 1/1/2008 Rates Effective 5/31/2007 Rates Effective 3/1/2006 Projected Combined Rate Base March 31, 2009 (in billion
Slide 19: Projected Missouri Regulatory Timeline
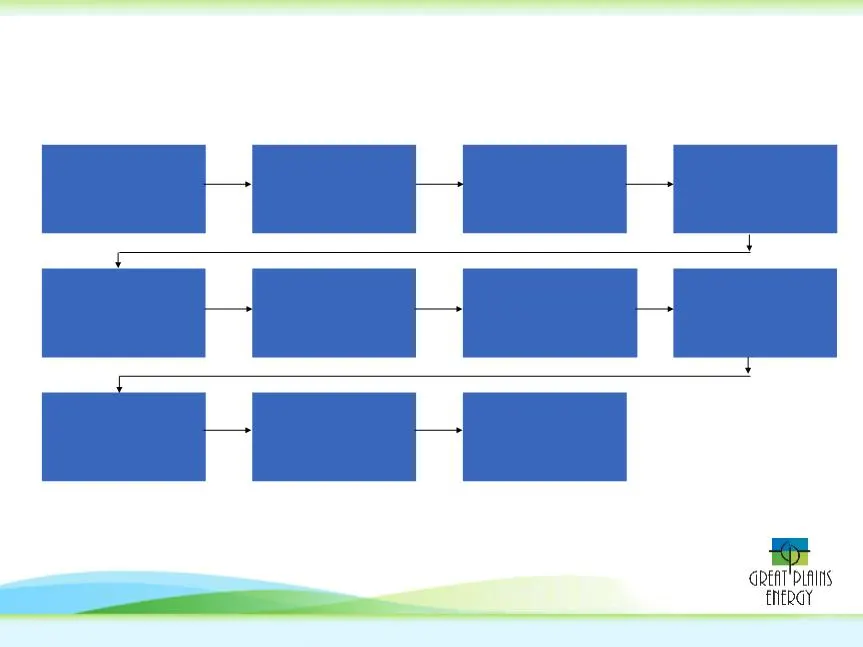
Applications filed with MPSC Sept. 5, 2008 Staff conducts audit of entire operations Now - - March 2009 Update of revenue requirement model based on Oct. 31, 2008. Submitted approx. Jan. 1, 2009 Staff and interveners file March 2009 Rebuttal testimony March 2009 Pre-hearing conference April 2009 Tru
Slide 20: A Path to Growth: Extend the Platform
and beyond: Extend the platform • Complete and include Iatan 1 AQCS and Sibley environmental work in rates effective in 2009 • Include Crossroads plant in rates effective 2009 • Integrate Aquila and deliver synergies • Evaluate 400 MW of additional wind • Complete and include Iatan 2 in rates effect
Source: SEC EDGAR · 8-K filed Sep 23, 2008
More decks from Great Plains Energy Incorporated
 Merger or Acquisition (January 2018)27 slides · Jan 10, 2018
 2017 Edison Electric Institute Financial Conference25 slides · Nov 3, 2017
 Merger or Acquisition (October 2017)14 slides · Oct 31, 2017
 Merger or Acquisition (October 2017)9 slides · Oct 31, 2017
 Merger or Acquisition (August 2017)18 slides · Aug 8, 2017
 Merger or Acquisition (August 2017)9 slides · Aug 8, 2017