Diversicare Healthcare Services Inc
Diversicare Healthcare Services — Shareholder Meeting (June 2014)
25 slides from Diversicare Healthcare Services's shareholder meeting presentation, Jun 5, 2014
Slide 1: Annual Meeting of Shareholders June 5, 2014
Annual Meeting of Shareholders June 5, 2014
Slide 2: Forward-Looking Statements
Forward-Looking Statements Forward-looking statements made in this presentation involve a number of risks and uncertainties, but not limited to, our ability to successfully operate the new nursing centers in Alabama, Kansas, Kentucky, Ohio, and Indiana, our ability to increase patients served at our
Slide 3: Senior Leadership
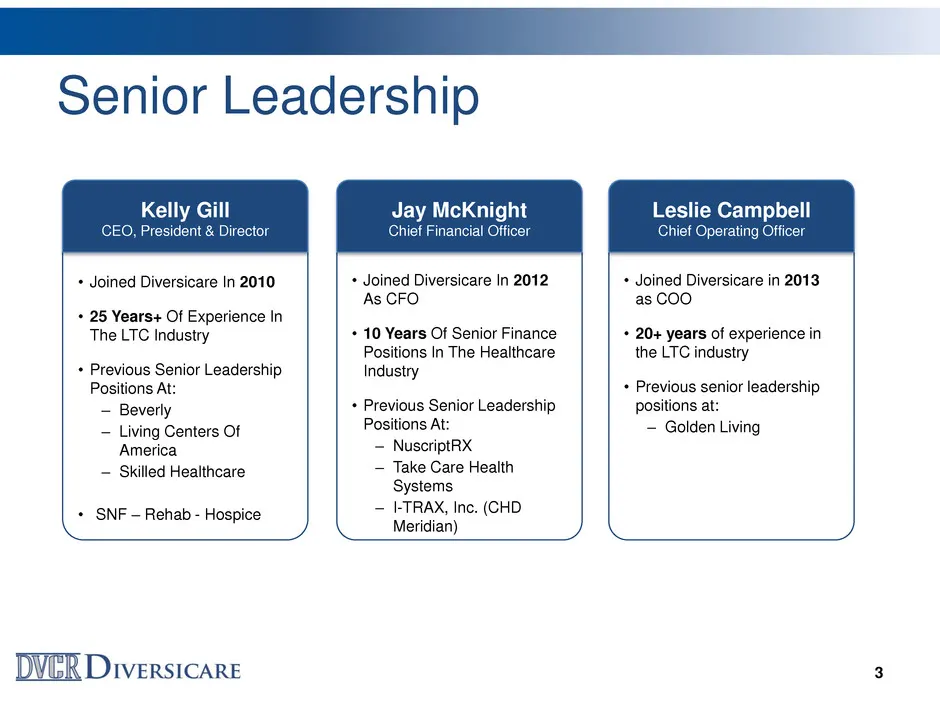
• Joined Diversicare in 2013 as COO • 20+ years of experience in the LTC industry • Previous senior leadership positions at: ‒ Golden Living Senior Leadership 3 • Joined Diversicare In 2012 As CFO • 10 Years Of Senior Finance Positions In The Healthcare Industry • Previous Senior Leadership Position
Slide 4: Board of Directors
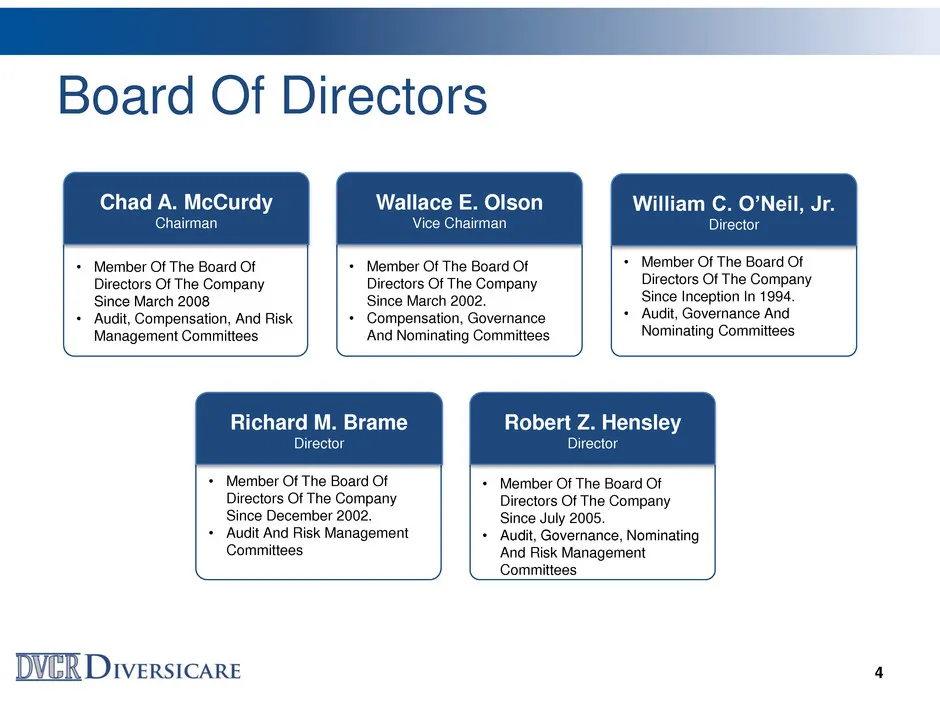
• Member Of The Board Of Directors Of The Company Since Inception In 1994. • Audit, Governance And Nominating Committees Board Of Directors 4 • Member Of The Board Of Directors Of The Company Since March 2002. • Compensation, Governance And Nominating Committees • Member Of The Board Of Directors Of
Slide 5: Investment Highlights
Investment Highlights Leading Skilled Nursing Provider Compelling Demographic Trends Management’s Strategic Vision Yielding Results Improving Patient Quality Measures, Census And Skilled Mix Demonstrated Ability To Grow And Enhance Portfolio Positively Trending Financial Results 5
Slide 6: Diversicare At A Glance
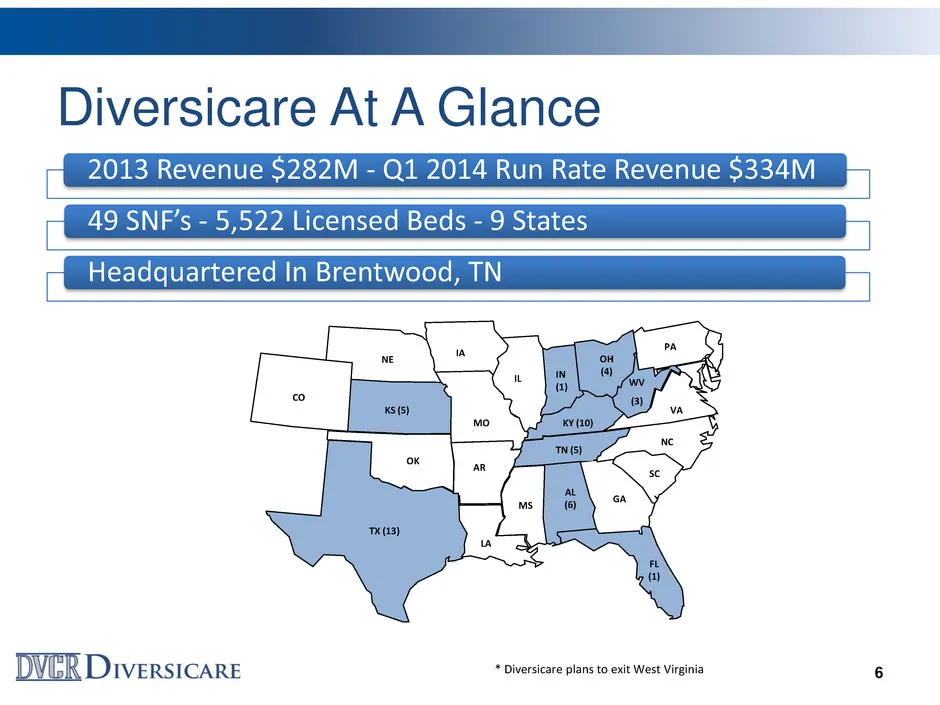
Diversicare At A Glance 2013 Revenue $282M - Q1 2014 Run Rate Revenue $334M 49 SNF’s - 5,522 Licensed Beds - 9 States Headquartered In Brentwood, TN 6 NE CO OK LA FL (1) IA IL KS (5) OH (4) IN (1) MO AR KY (10) TN (5) PA MS AL (6) SC NC GA VA WV (3) * Diversicare plans to exit West Virginia TX (13)
Slide 7: Compelling Industry Demographics
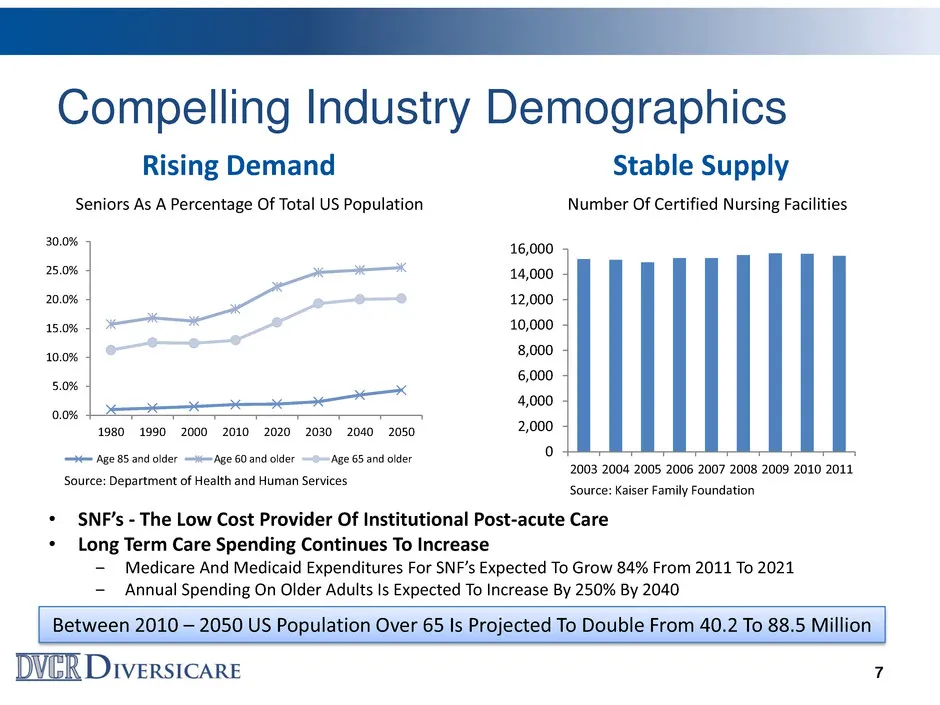
Compelling Industry Demographics 7 • SNF’s - The Low Cost Provider Of Institutional Post-acute Care • Long Term Care Spending Continues To Increase ‒ Medicare And Medicaid Expenditures For SNF’s Expected To Grow 84% From 2011 To 2021 ‒ Annual Spending On Older Adults Is Expected To Increase By 250%
Slide 8: Core Foundation Activities
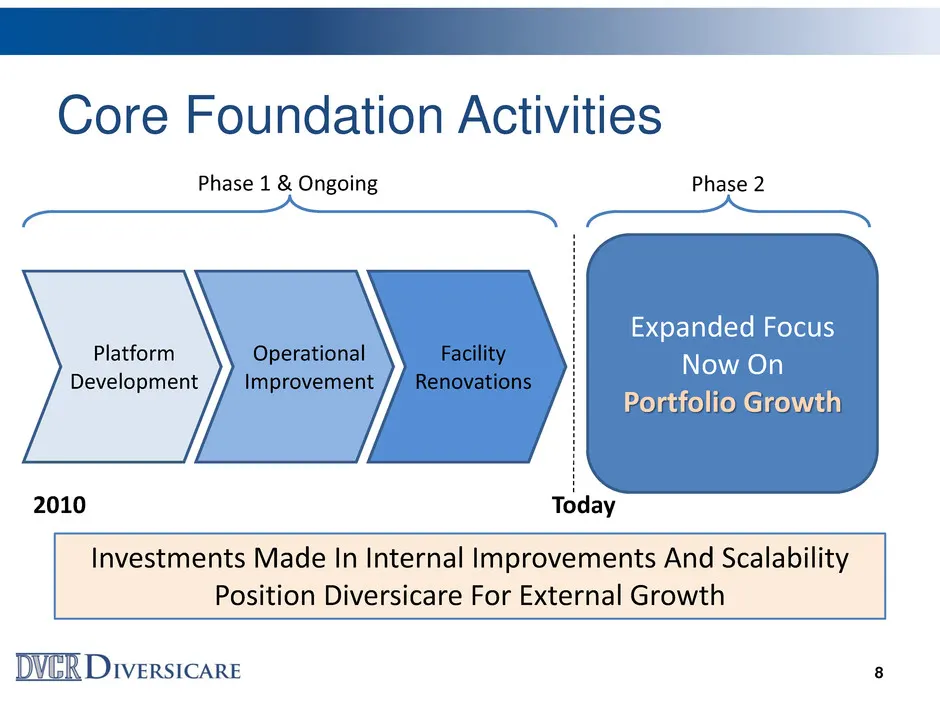
Core Foundation Activities Investments Made In Internal Improvements And Scalability Position Diversicare For External Growth 8 2010 Today Expanded Focus Now On Portfolio Growth Phase 1 & Ongoing Phase 2 Platform Development Operational Improvement Facility Renovations
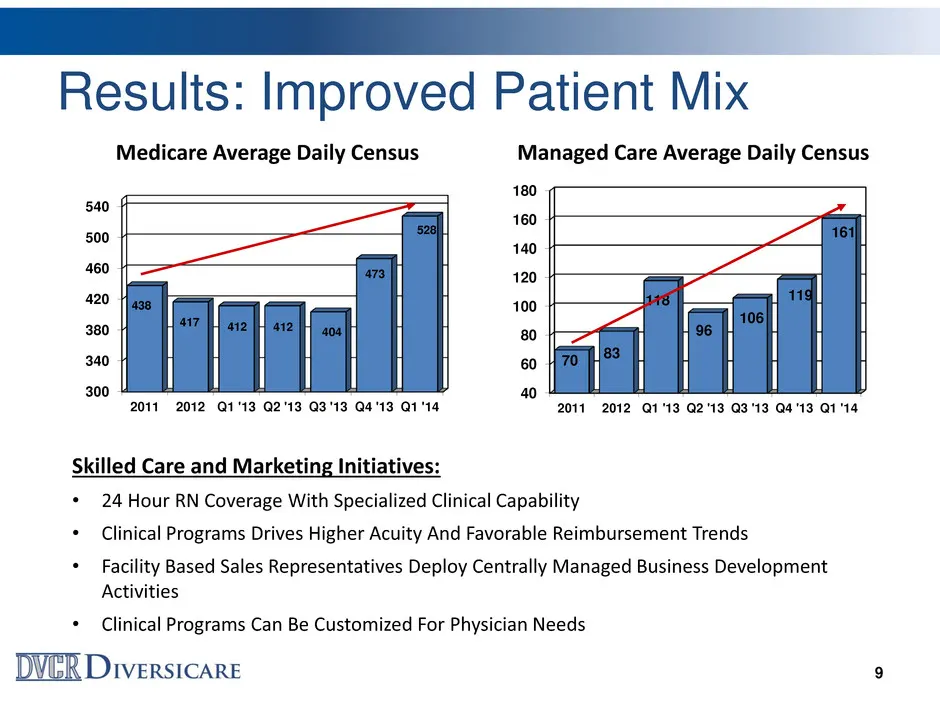
Slide 9: Results: Improved Patient Mix
Results: Improved Patient Mix Medicare Average Daily Census Managed Care Average Daily Census 9 300 340 380 420 460 500 540 2011 2012 Q1 '13 Q2 '13 Q3 '13 Q4 '13 Q1 '14 438 417 412 412 404 473 528 40 60 80 100 120 140 160 180 2011 2012 Q1 '13 Q2 '13 Q3 '13 Q4 '13 Q1 '14 70 83 118 96 106 119 161 Skil
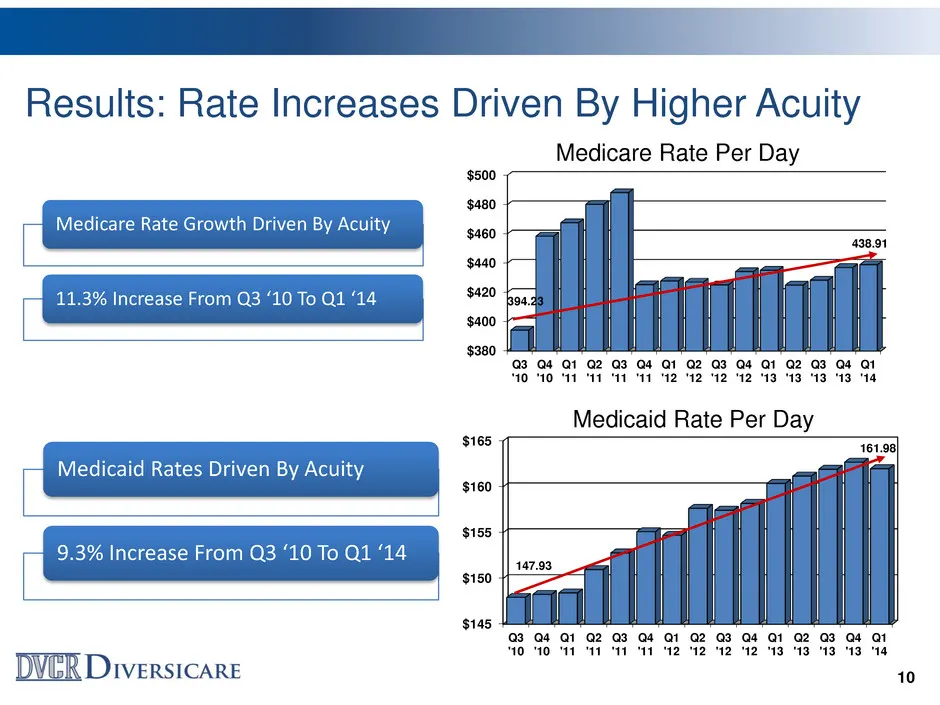
Slide 10: Results: Rate Increases Driven By Higher Acuity
$145 $150 $155 $160 $165 Q3 '10 Q4 '10 Q1 '11 Q2 '11 Q3 '11 Q4 '11 Q1 '12 Q2 '12 Q3 '12 Q4 '12 Q1 '13 Q2 '13 Q3 '13 Q4 '13 Q1 '14 147.93 161.98 $380 $400 $420 $440 $460 $480 $500 Q3 '10 Q4 '10 Q1 '11 Q2 '11 Q3 '11 Q4 '11 Q1 '12 Q2 '12 Q3 '12 Q4 '12 Q1 '13 Q2 '13 Q3 '13 Q4 '13 Q1 '14 394.23 438.91 Re
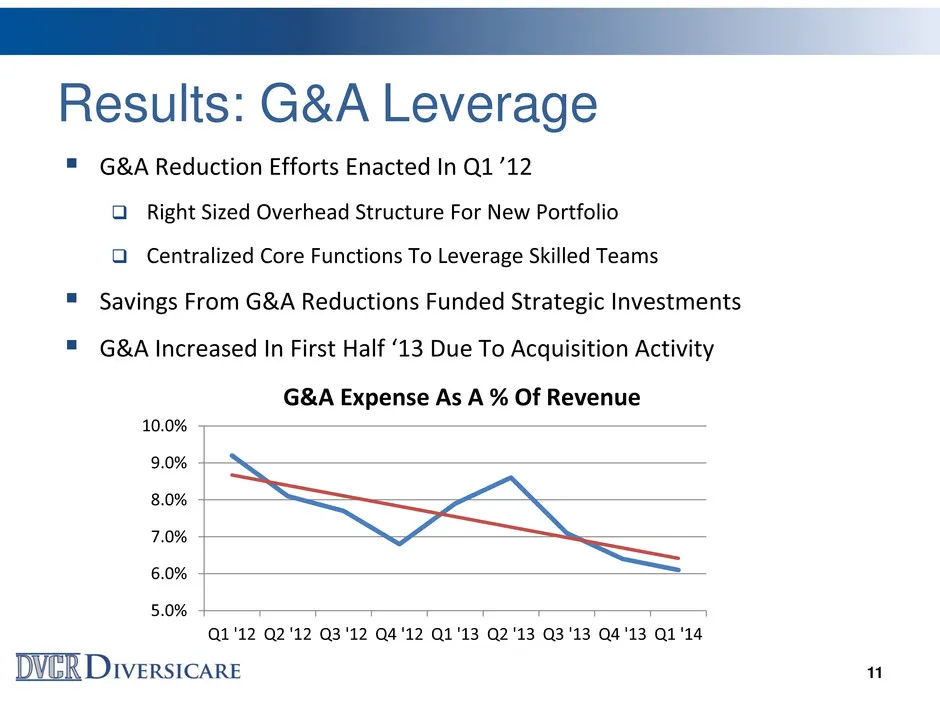
Slide 11: Results: G&A Leverage
Results: G&A Leverage 11 5.0% 6.0% 7.0% 8.0% 9.0% 10.0% Q1 '12 Q2 '12 Q3 '12 Q4 '12 Q1 '13 Q2 '13 Q3 '13 Q4 '13 Q1 '14 G&A Expense As A % Of Revenue G&A Reduction Efforts Enacted In Q1 ’12 Right Sized Overhead Structure For New Portfolio Centralized Core Functions To Leverage Skilled Teams S
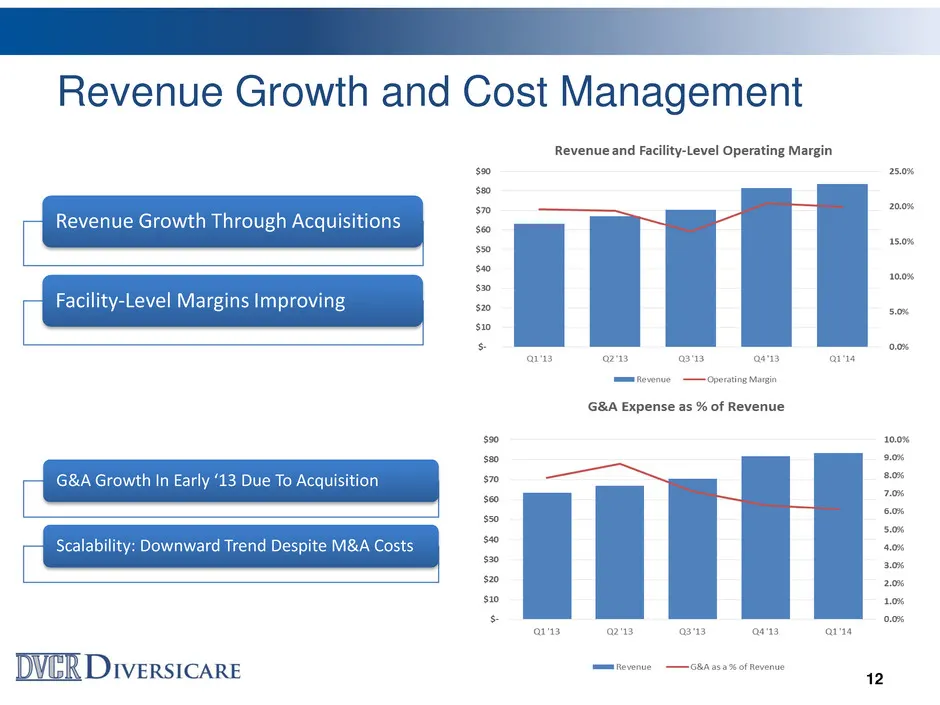
Slide 12: Revenue Growth and Cost Management
Revenue Growth and Cost Management Revenue Growth Through Acquisitions Facility-Level Margins Improving G&A Growth In Early ‘13 Due To Acquisition Scalability: Downward Trend Despite M&A Costs 12
Slide 13: Results: Improved Quality Measures
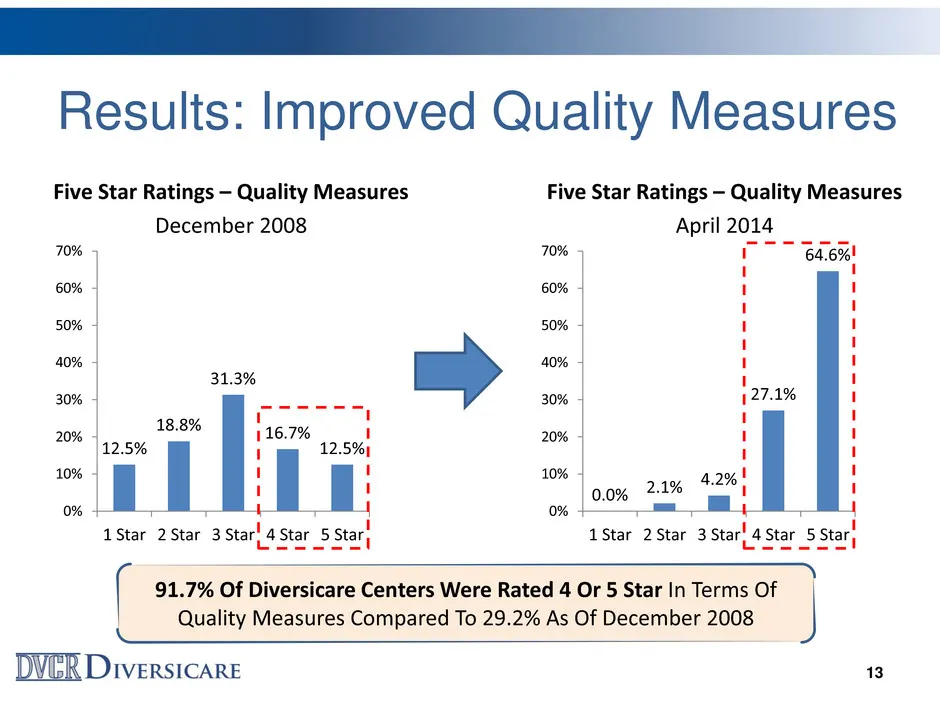
Results: Improved Quality Measures 13 12.5% 18.8% 31.3% 16.7% 12.5% 0% 10% 20% 30% 40% 50% 60% 70% 1 Star 2 Star 3 Star 4 Star 5 Star Five Star Ratings – Quality Measures December 2008 0.0% 2.1% 4.2% 27.1% 64.6% 0% 10% 20% 30% 40% 50% 60% 70% 1 Star 2 Star 3 Star 4 Star 5 Star Five Star Ratings – Qu
Slide 14: Results: Platform Upgrades
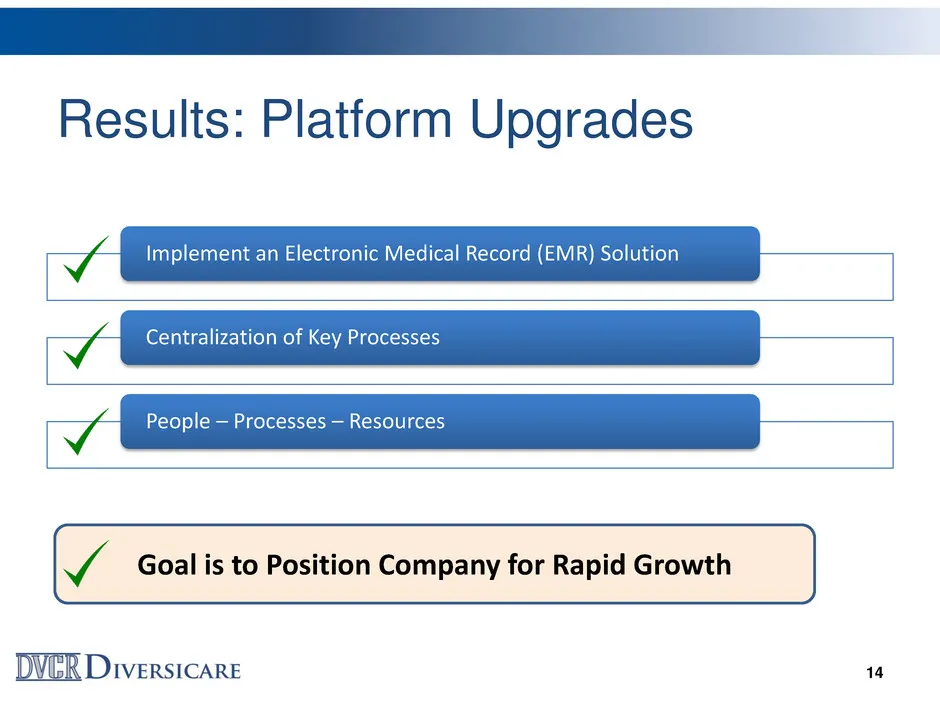
Results: Platform Upgrades Implement an Electronic Medical Record (EMR) Solution Centralization of Key Processes People – Processes – Resources 14 Goal is to Position Company for Rapid Growth
Slide 15: Results: Facility Renovations Initiative
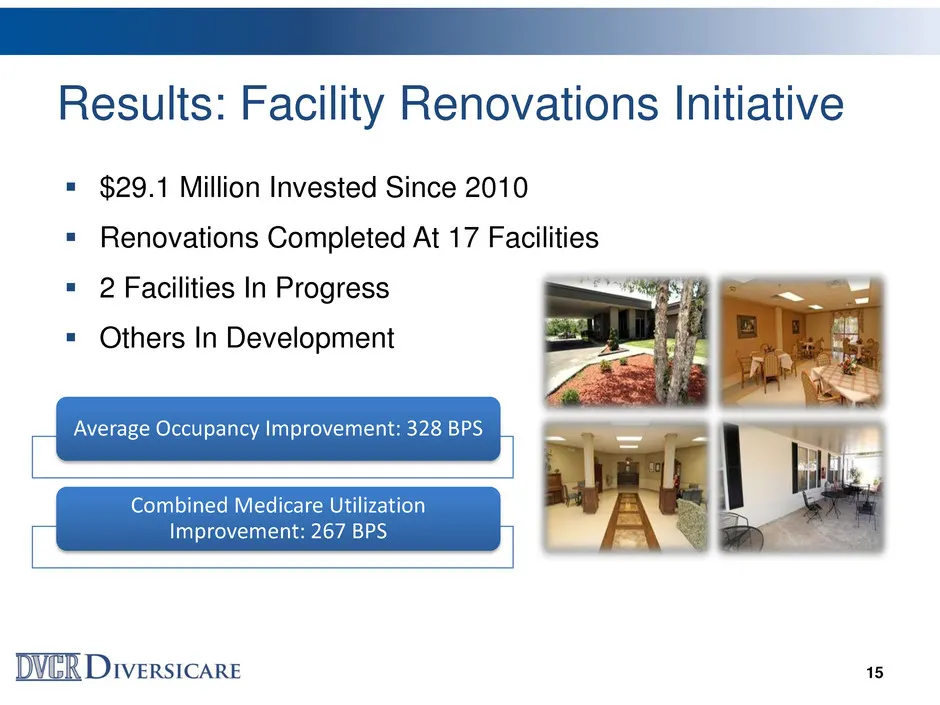
Results: Facility Renovations Initiative $29.1 Million Invested Since 2010 Renovations Completed At 17 Facilities 2 Facilities In Progress Others In Development Average Occupancy Improvement: 328 BPS Combined Medicare Utilization Improvement: 267 BPS 15
Slide 16: Continue To Enhance Existing Portfolio
Continue To Enhance Existing Portfolio 16 Continual Improvement Of Quality Measures Continue to Drive Volume Of Patients Served Improve Skilled Mix / Provide High-Acuity Services Ongoing Renovation Of Facilities
Slide 17: Portfolio Growth Is Now Added Focus
Portfolio Growth Is Now Added Focus Active Pipeline And Buyer-Friendly Market Target 5-10 New Facilities Per Year Expanded Operating Infrastructure = Scalability Flexibility On Structure = Several Sources Of Financial Capacity 17
Slide 18: Results: Quarterly Revenue Trends
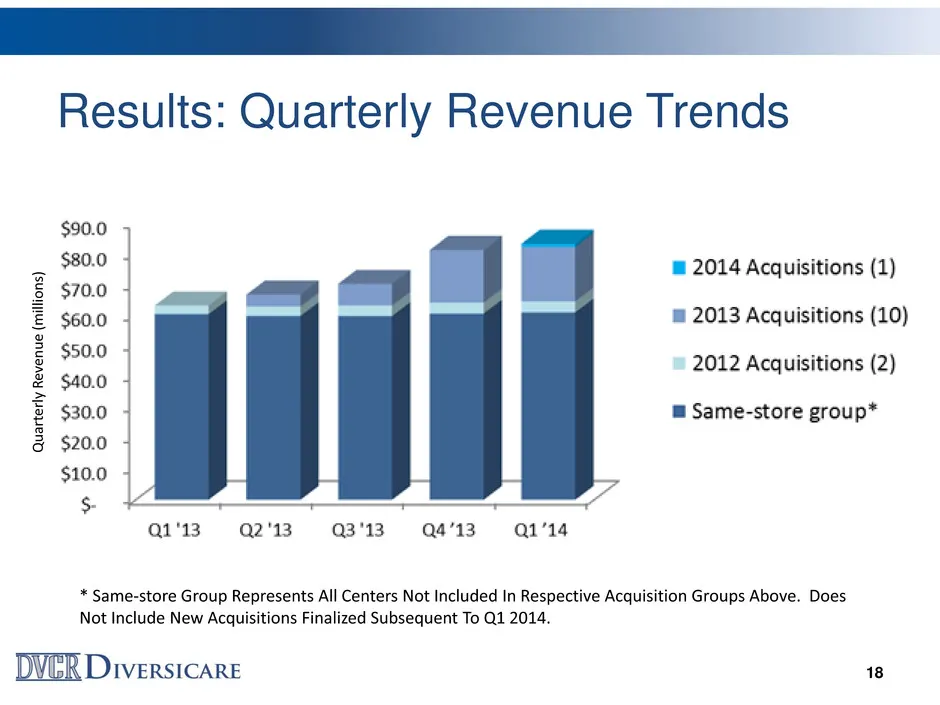
Results: Quarterly Revenue Trends 18 * Same-store Group Represents All Centers Not Included In Respective Acquisition Groups Above. Does Not Include New Acquisitions Finalized Subsequent To Q1 2014. Qu ar terly R ev en u e (milli o n s)
Slide 19: Results: New Centers And Same-Store
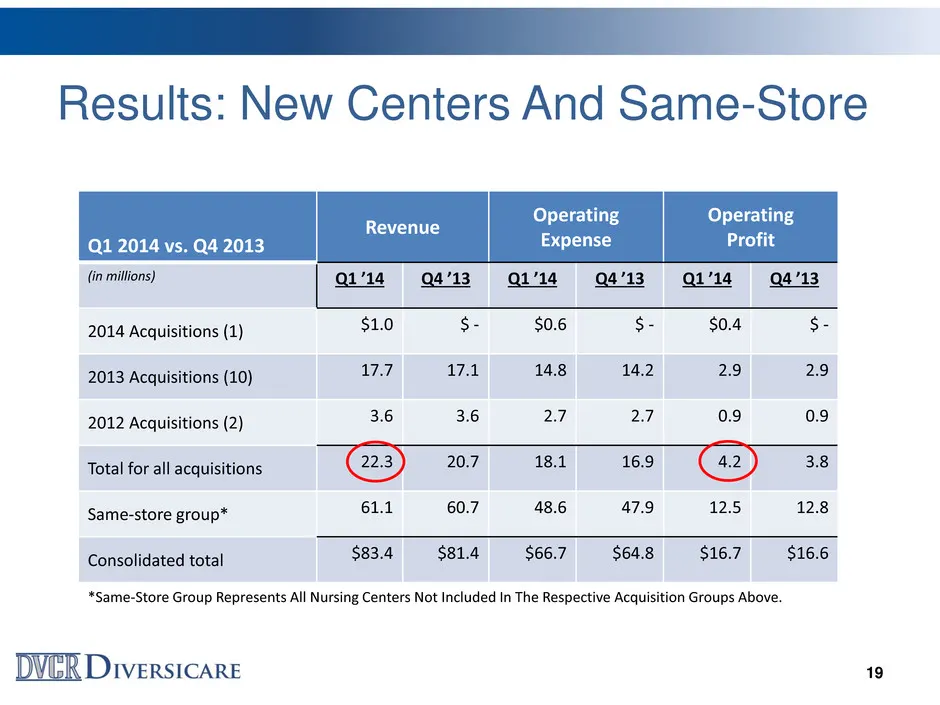
Results: New Centers And Same-Store 19 Q1 2014 vs. Q4 2013 Revenue Operating Expense Operating Profit (in millions) Q1 ’14 Q4 ’13 Q1 ’14 Q4 ’13 Q1 ’14 Q4 ’13 2014 Acquisitions (1) $1.0 $ - $0.6 $ - $0.4 $ - 2013 Acquisitions (10) 17.7 17.1 14.8 14.2 2.9 2.9 2012 Acquisitions (2) 3.6 3.6 2.7 2.7 0.9
Slide 20: Results: Impact Of New Centers
Results: Impact Of New Centers 20 Most Acquisitions Are Accretive To Earnings Within A Quarter Of Acquisitions Date – The Exceptions Being Development Opportunities Like Rose Terrace & Clinton, KY Demonstrated Platform Scalability By Increasing Revenues With A Resulting Reduction in G&A Expense As P
Slide 21: Deepen and Expand Existing Footprint
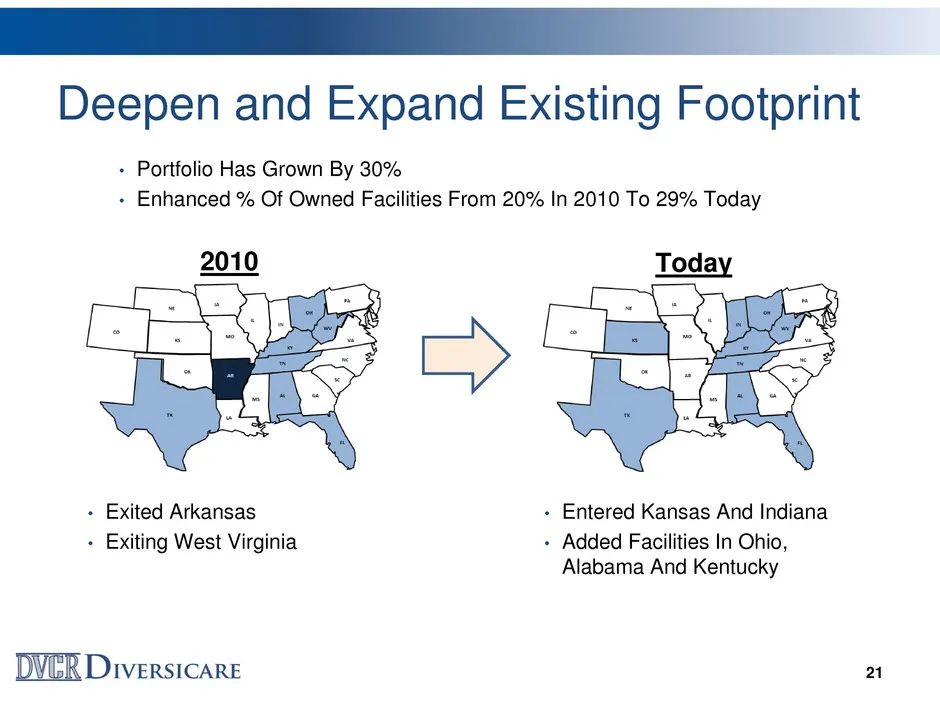
Deepen and Expand Existing Footprint 21 Today 2010 • Portfolio Has Grown By 30% • Enhanced % Of Owned Facilities From 20% In 2010 To 29% Today • Exited Arkansas • Exiting West Virginia • Entered Kansas And Indiana • Added Facilities In Ohio, Alabama And Kentucky
Slide 22: Flexible Acquisition Structures Broaden Pipeline
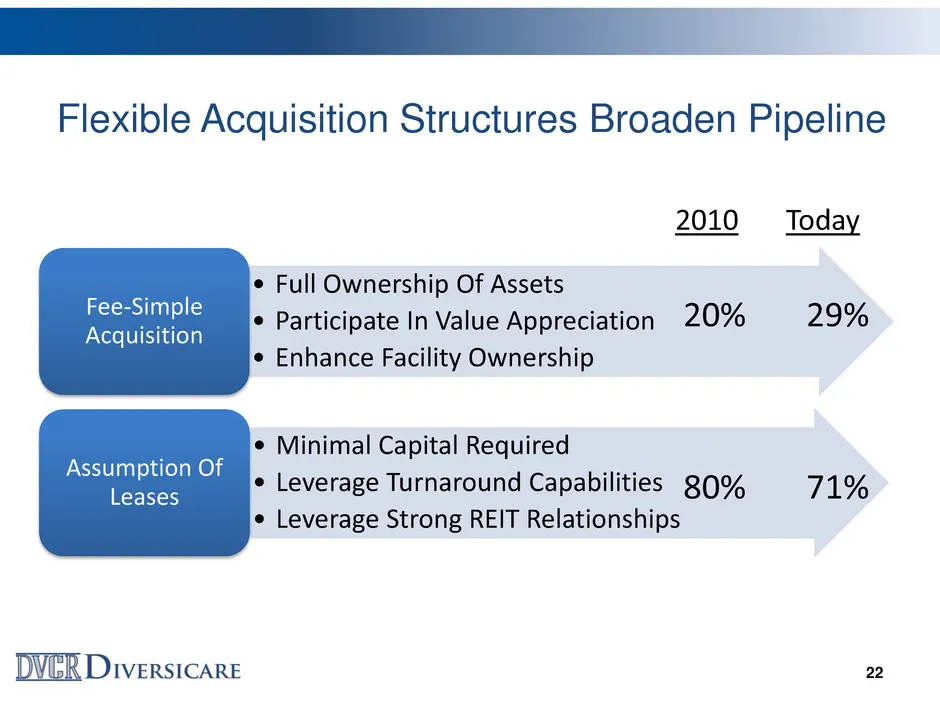
Flexible Acquisition Structures Broaden Pipeline • Full Ownership Of Assets • Participate In Value Appreciation • Enhance Facility Ownership Fee-Simple Acquisition • Minimal Capital Required • Leverage Turnaround Capabilities • Leverage Strong REIT Relationships Assumption Of Leases 22 2010 Today 20
Slide 23: Key Financial and Operating Statistics
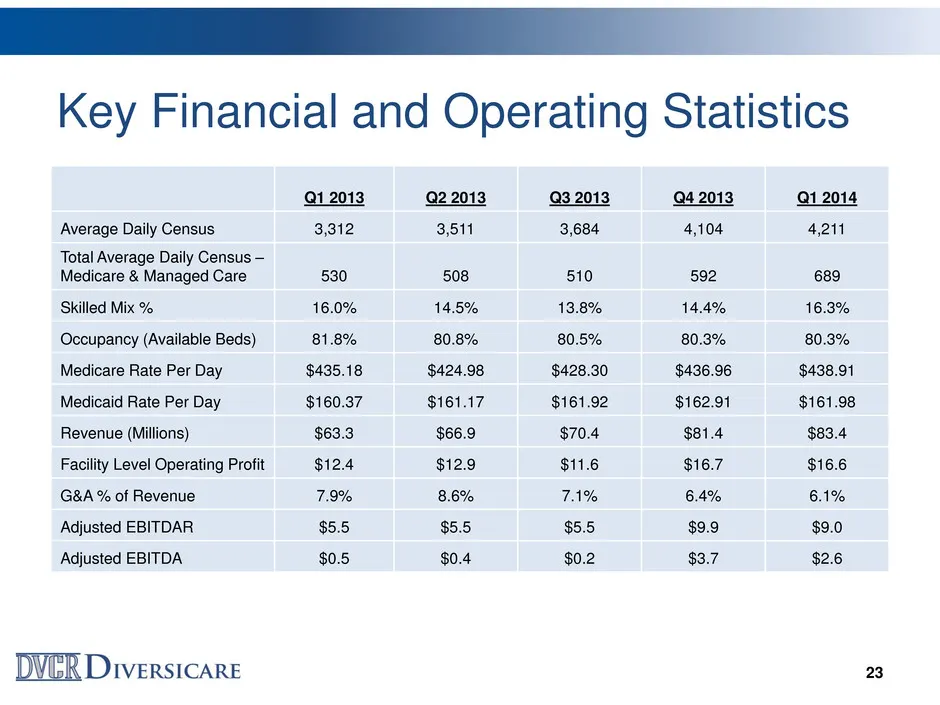
Key Financial and Operating Statistics Q1 2013 Q2 2013 Q3 2013 Q4 2013 Q1 2014 Average Daily Census 3,312 3,511 3,684 4,104 4,211 Total Average Daily Census – Medicare & Managed Care 530 508 510 592 689 Skilled Mix % 16.0% 14.5% 13.8% 14.4% 16.3% Occupancy (Available Beds) 81.8% 80.8% 80.5% 80.3% 80
Slide 24: Investment Highlights
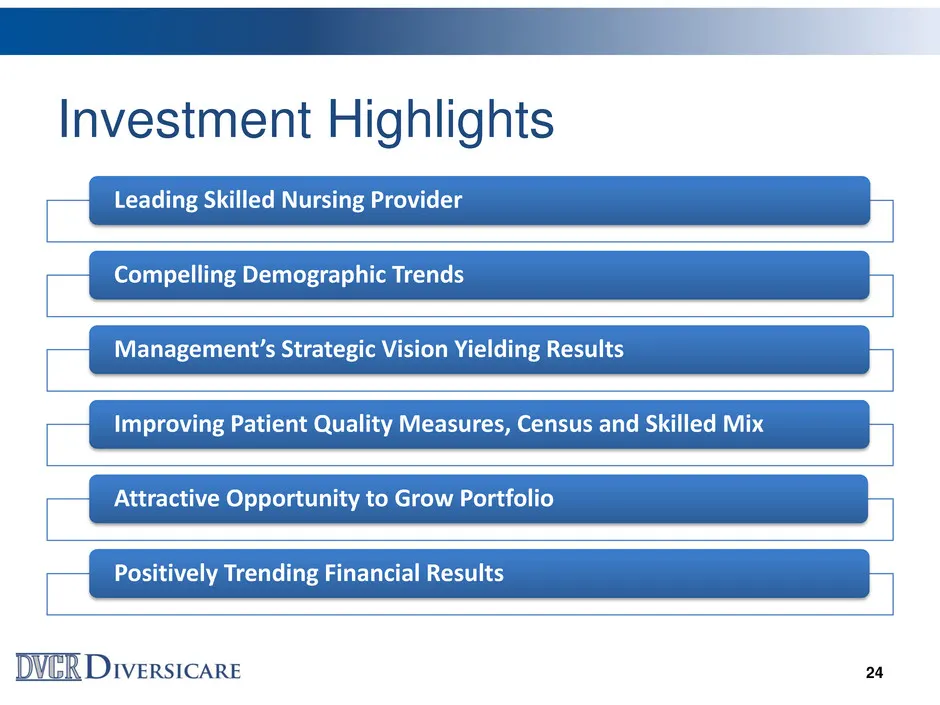
Investment Highlights Leading Skilled Nursing Provider Compelling Demographic Trends Management’s Strategic Vision Yielding Results Improving Patient Quality Measures, Census and Skilled Mix Attractive Opportunity to Grow Portfolio Positively Trending Financial Results 24
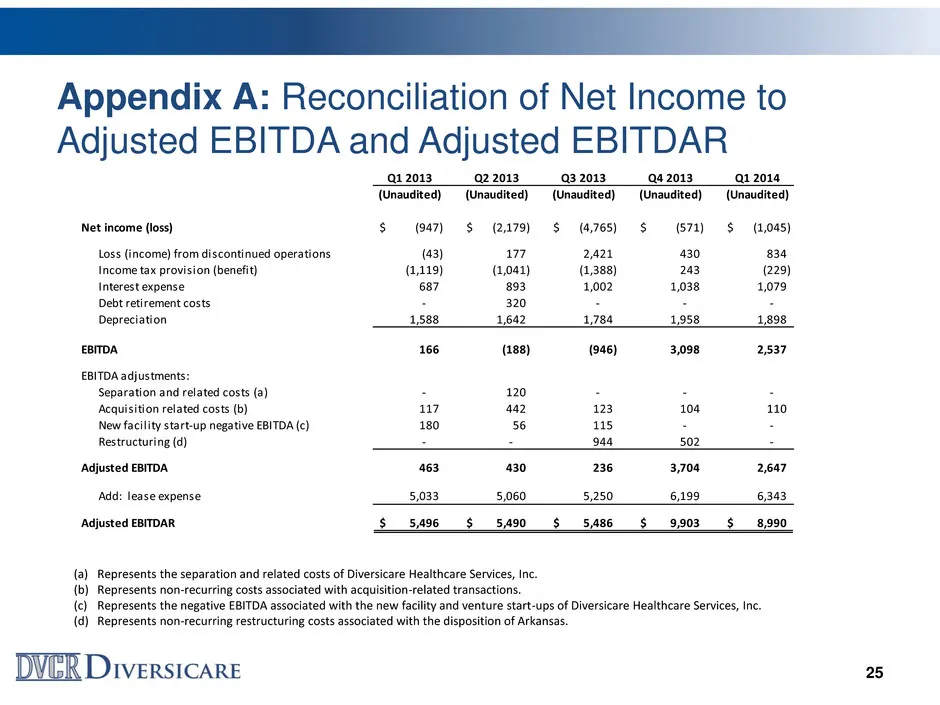
Slide 25: Appendix A: Reconciliation of Net Income to Adjusted EBITDA and EBITDAR
Appendix A: Reconciliation of Net Income to Adjusted EBITDA and Adjusted EBITDAR 25 (a) Represents the separation and related costs of Diversicare Healthcare Services, Inc. (b) Represents non-recurring costs associated with acquisition-related transactions. (c) Represents the negative EBITDA associa
Source: SEC EDGAR · 8-K filed Jun 5, 2014
More decks from Diversicare Healthcare Services Inc
 Q2 2021 Earnings Presentation31 slides · Aug 10, 2021
 Q1 2021 Earnings Presentation31 slides · May 11, 2021
 Q4 2020 Earnings Presentation31 slides · Mar 11, 2021
 Q3 2019 Earnings Presentation5 slides · Oct 31, 2019
 Q2 2018 Earnings Presentation35 slides · Aug 2, 2018
 Q1 2018 Earnings Presentation35 slides · May 3, 2018