The Empire District Electric Company
The Empire District Electric — Empire District Electric — Q2 2014 Earnings Presentation
43 slides from The Empire District Electric's earnings presentation, Sep 3, 2014
Slide 1: Second Quarter 2014 Analyst Presentation
Second Quarter 2014 Analyst Presentation 9/3/14 The Empire District Electric Company
Slide 2: [LOGO]
[LOGO]
Slide 3: Forward Looking Statements
Forward Looking Statements This presentation discusses various matters that are “forward-looking statements” intended to qualify for the safe harbor from liability established by the Private Securities Litigation Reform Act of 1995. Such statements address or may address future plans, objectives, ex
Slide 4: [LOGO]
[LOGO]
Slide 5: Investor Relations Team
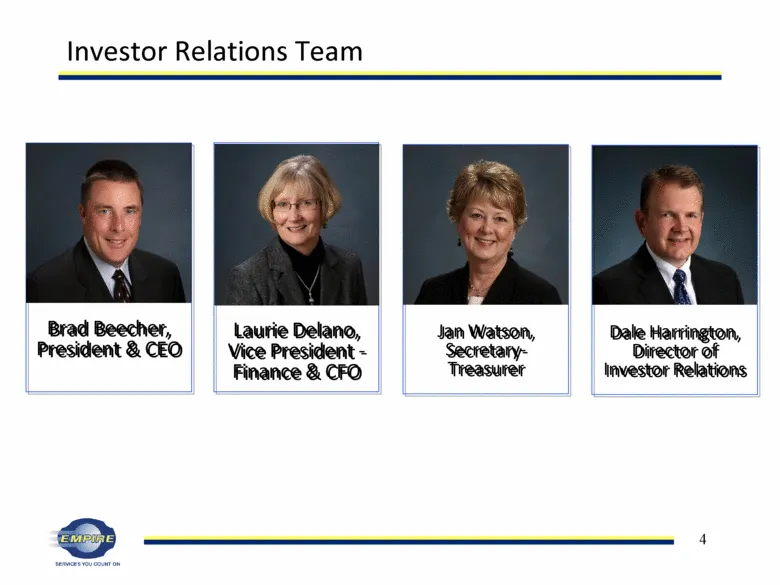
Brad Beecher, President & CEO Laurie Delano, Vice President - Finance & CFO Investor Relations Team Jan Watson, Secretary-Treasurer Dale Harrington, Director of Investor Relations
Slide 6: [LOGO]
[LOGO]
Slide 7: Company Overview and Most Recent Quarter
Company Overview and Most Recent Quarter
Slide 8: Company Overview
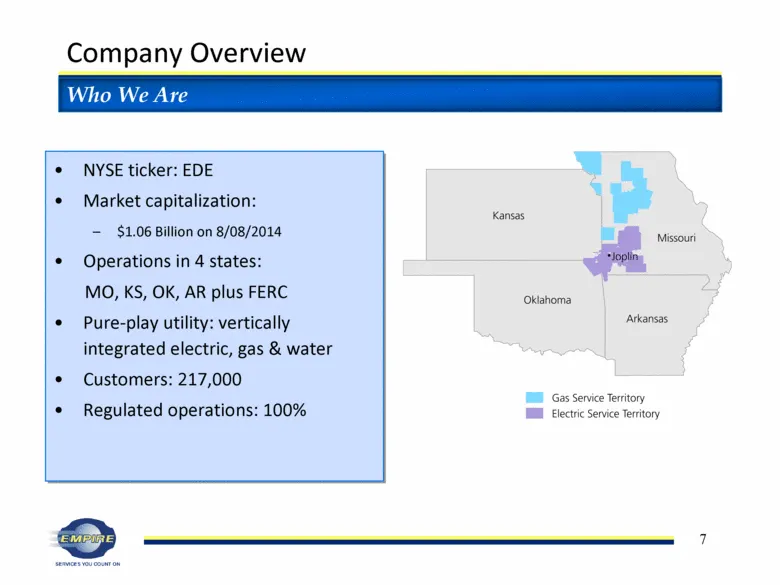
Company Overview NYSE ticker: EDE Market capitalization: $1.06 Billion on 8/08/2014 Operations in 4 states: MO, KS, OK, AR plus FERC Pure-play utility: vertically integrated electric, gas & water Customers: 217,000 Regulated operations: 100% Who We Are
Slide 9: Second Quarter, Year to Date, and Twelve Month Ended Highlights
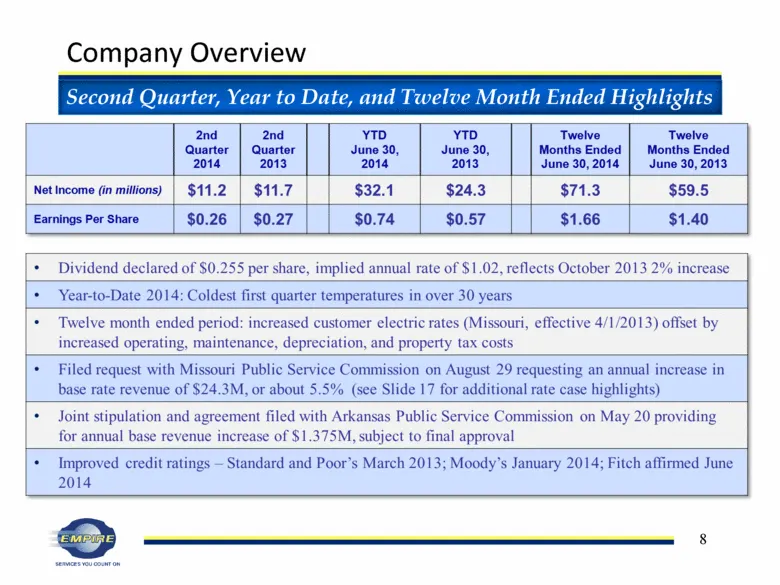
Company Overview Second Quarter, Year to Date, and Twelve Month Ended Highlights 2nd Quarter 2014 2nd Quarter 2013 YTD June 30, 2014 YTD June 30, 2013 Twelve Months Ended June 30, 2014 Twelve Months Ended June 30, 2013 Net Income (in millions) $11.2 $11.7 $32.1 $24.3 $71.3 $59.5 Earnings Per Share $
Slide 10: Second Quarter, Year to Date, and Twelve Month Ended Highlights Continued
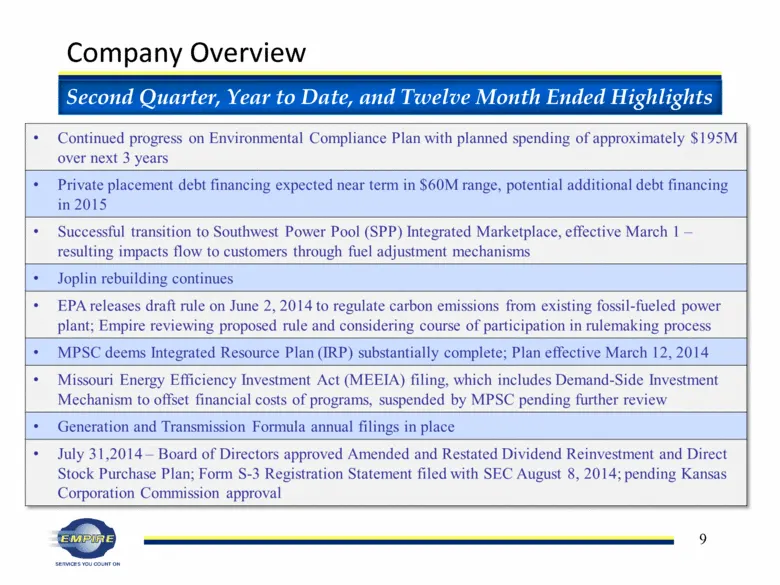
Company Overview Second Quarter, Year to Date, and Twelve Month Ended Highlights Continued progress on Environmental Compliance Plan with planned spending of approximately $195M over next 3 years Private placement debt financing expected near term in $60M range, potential additional debt financing
Slide 11: Consolidated EPS After Tax Increase (Decrease)
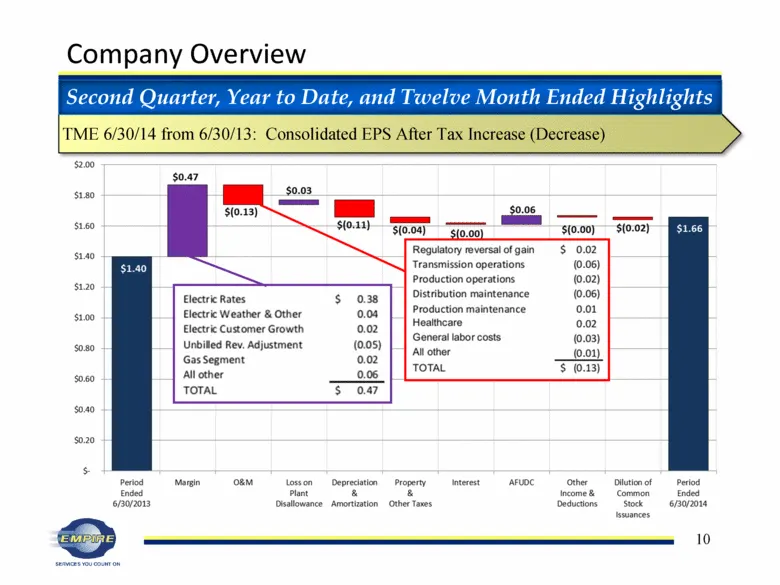
Company Overview TME 6/30/14 from 6/30/13: Consolidated EPS After Tax Increase (Decrease) Second Quarter, Year to Date, and Twelve Month Ended Highlights
Slide 12: Compelling Investment Platform / Empire Strategy
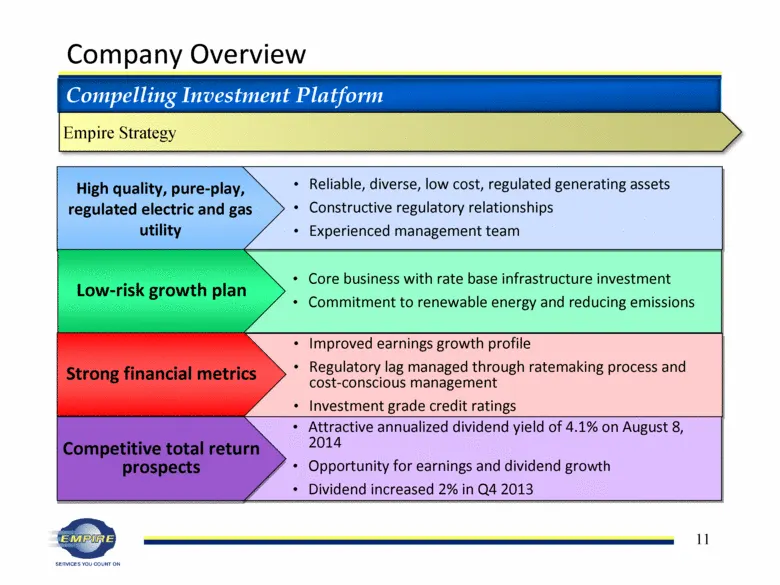
Core business with rate base infrastructure investment Commitment to renewable energy and reducing emissions Company Overview Reliable, diverse, low cost, regulated generating assets Constructive regulatory relationships Experienced management team High quality, pure-play, regulated electric and gas
Slide 13: Pure-Play Regulated Electric and Gas Utility
Pure-Play Regulated Electric and Gas Utility
Slide 14: Favorable Energy Supply Portfolio
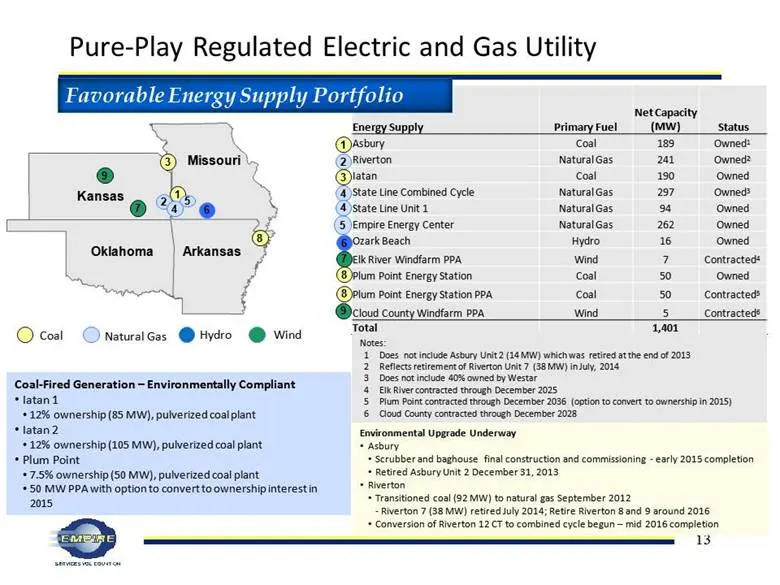
Energy Supply Primary Fuel Net Capacity (MW) Status Asbury Coal 189 Owned1 Riverton Natural Gas 241 Owned2 Iatan Coal 190 Owned State Line Combined Cycle Natural Gas 297 Owned3 State Line Unit 1 Natural Gas 94 Owned Empire Energy Center Natural Gas 262 Owned Ozark Beach Hydro 16 Owned Elk River Wind
Slide 15: Favorable Energy Supply Portfolio - Environmental Compliance
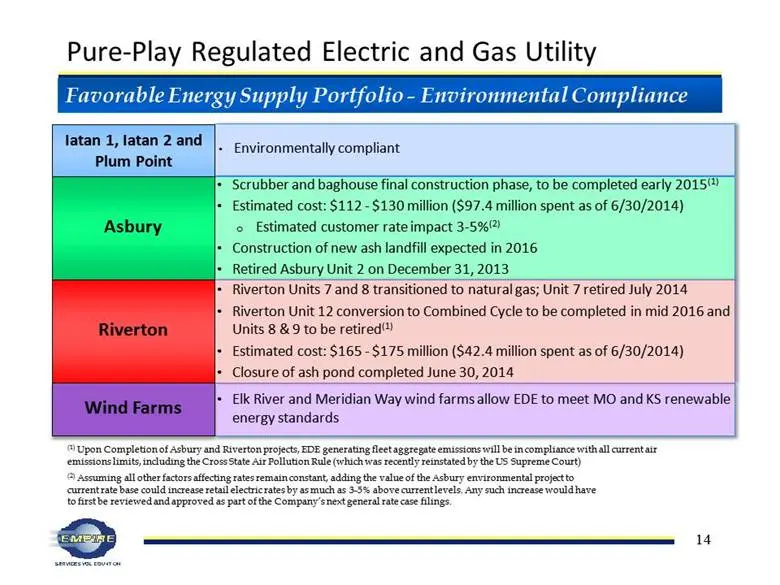
Environmentally compliant Elk River and Meridian Way wind farms allow EDE to meet MO and KS renewable energy standards Scrubber and baghouse final construction phase, to be completed early 2015(1) Estimated cost: $112 - $130 million ($97.4 million spent as of 6/30/2014) Estimated customer rate impac
Slide 16: Pure-Play Regulated Electric and Gas Utility
Pure-Play Regulated Electric and Gas Utility
Slide 17: Constructive Regulatory Relationships
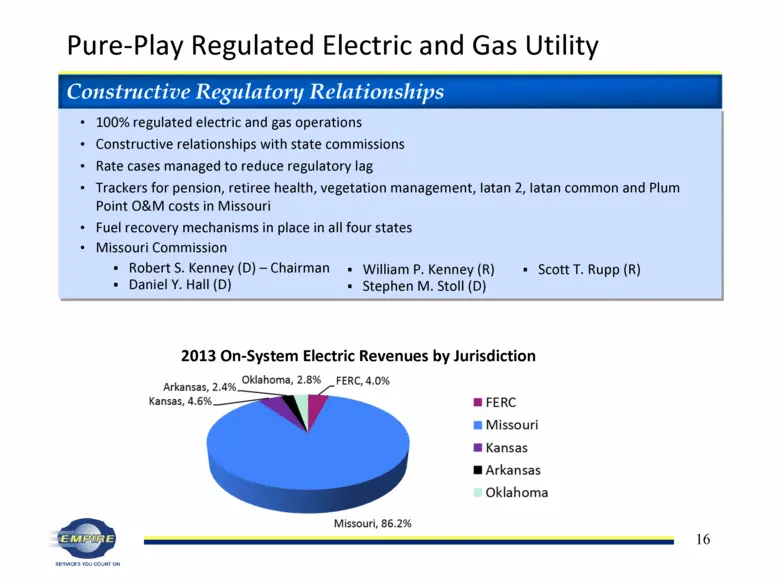
Pure-Play Regulated Electric and Gas Utility Constructive Regulatory Relationships 100% regulated electric and gas operations Constructive relationships with state commissions Rate cases managed to reduce regulatory lag Trackers for pension, retiree health, vegetation management, Iatan 2, Iatan comm
Slide 18: Missouri Rate Case Highlights
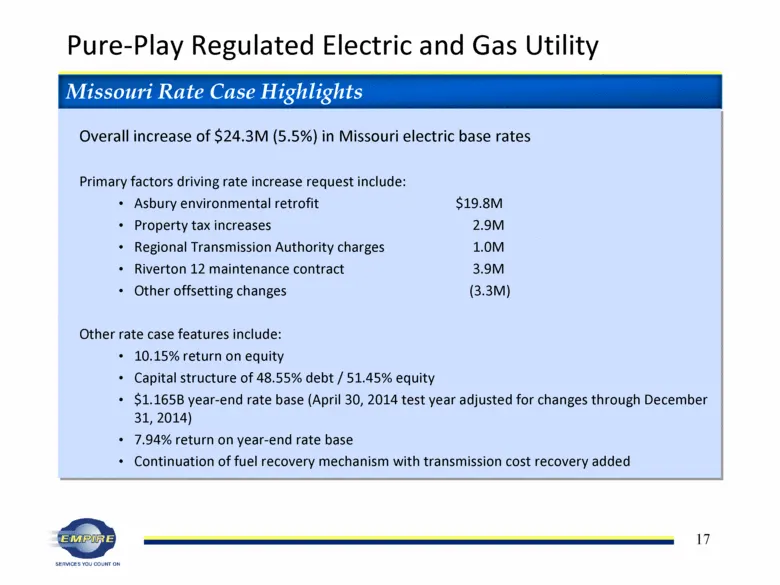
Pure-Play Regulated Electric and Gas Utility Missouri Rate Case Highlights Overall increase of $24.3M (5.5%) in Missouri electric base rates Primary factors driving rate increase request include: Asbury environmental retrofit $19.8M Property tax increases 2.9M Regional Transmission Authority charges
Slide 19: Low-Risk Growth Plan
Low-Risk Growth Plan ©
Slide 20: Build Core Business with Rate Base Infrastructure
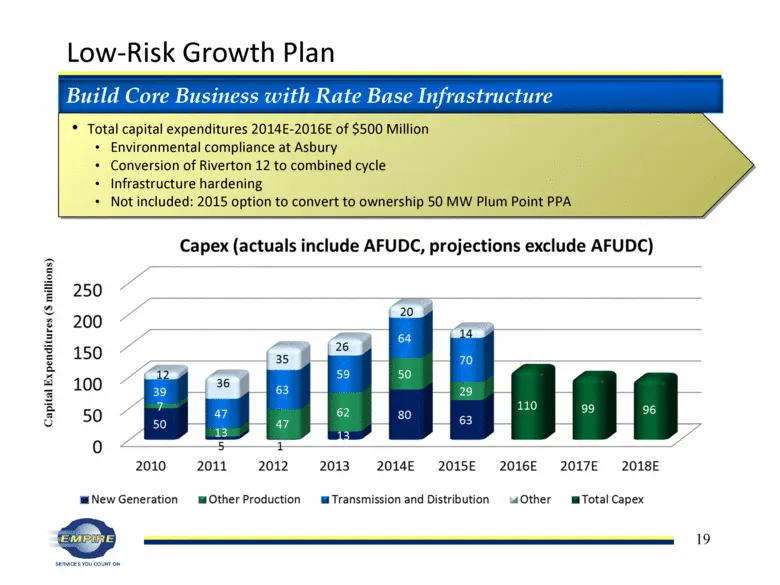
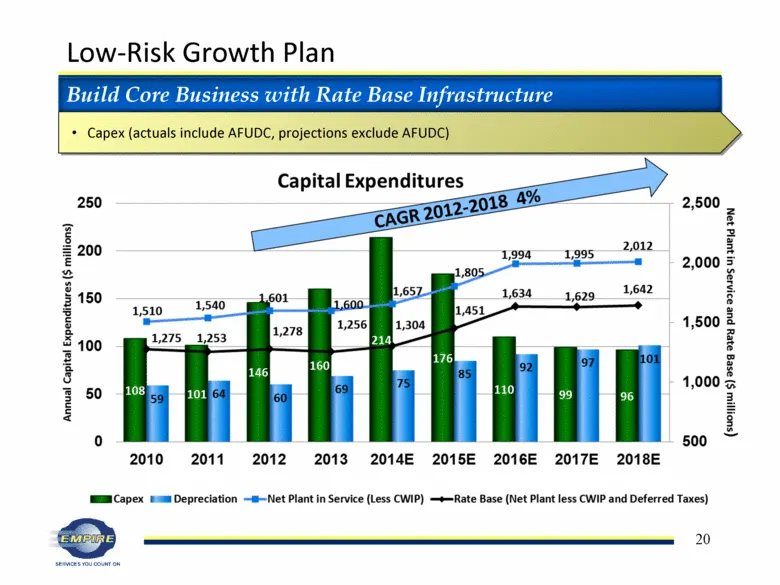
Low-Risk Growth Plan Build Core Business with Rate Base Infrastructure Total capital expenditures 2014E-2016E of $500 Million Environmental compliance at Asbury Conversion of Riverton 12 to combined cycle Infrastructure hardening Not included: 2015 option to convert to ownership 50 MW Plum Point PPA
Slide 21: Capex Actuals and Projections
Low-Risk Growth Plan Build Core Business with Rate Base Infrastructure Capex (actuals include AFUDC, projections exclude AFUDC)
Slide 22: [LOGO]
[LOGO]
Slide 23: Strong Financial Metrics
Strong Financial Metrics 22
Slide 24: Improved Earnings Growth Profile
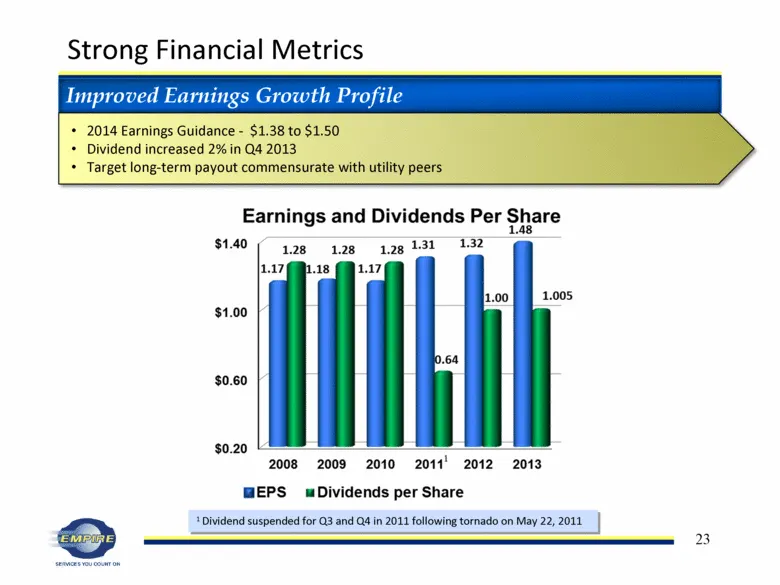
Strong Financial Metrics 1 Dividend suspended for Q3 and Q4 in 2011 following tornado on May 22, 2011 Improved Earnings Growth Profile 2014 Earnings Guidance - $1.38 to $1.50 Dividend increased 2% in Q4 2013 Target long-term payout commensurate with utility peers
Slide 25: Historical Financial Performance
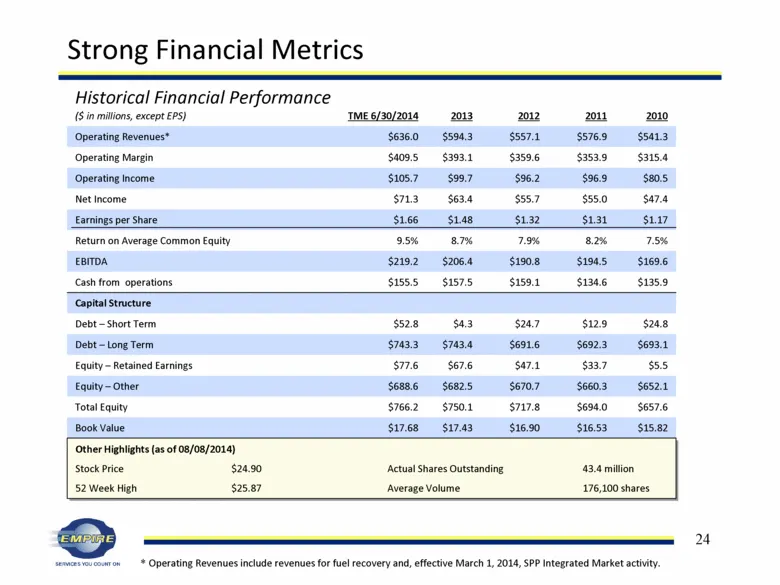
Historical Financial Performance * Operating Revenues include revenues for fuel recovery and, effective March 1, 2014, SPP Integrated Market activity. ($ in millions, except EPS) TME 6/30/2014 2013 2012 2011 2010 Operating Revenues* $636.0 $594.3 $557.1 $576.9 $541.3 Operating Margin $409.5 $393.1 $
Slide 26: Commitment to Credit Quality
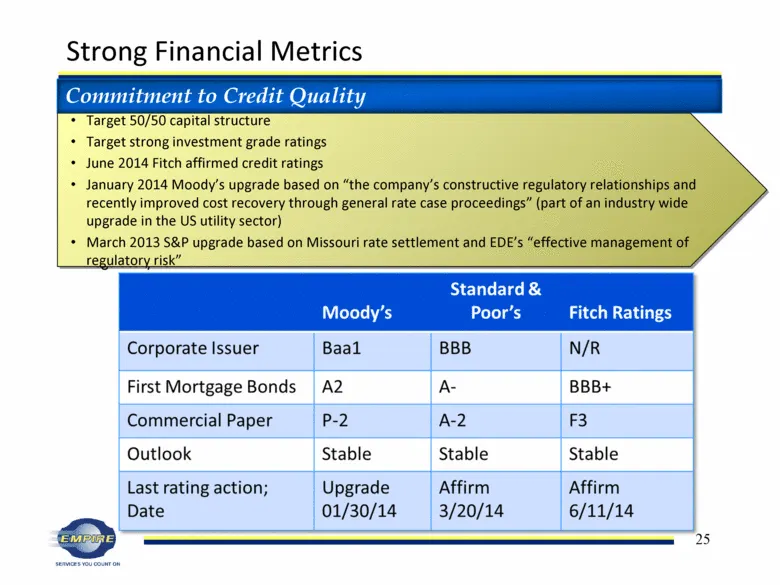
Commitment to Credit Quality Strong Financial Metrics Commitment to Credit Quality Target 50/50 capital structure Target strong investment grade ratings June 2014 Fitch affirmed credit ratings January 2014 Moody’s upgrade based on “the company’s constructive regulatory relationships and recently imp
Slide 27: Financing Outlook and Debt Maturities
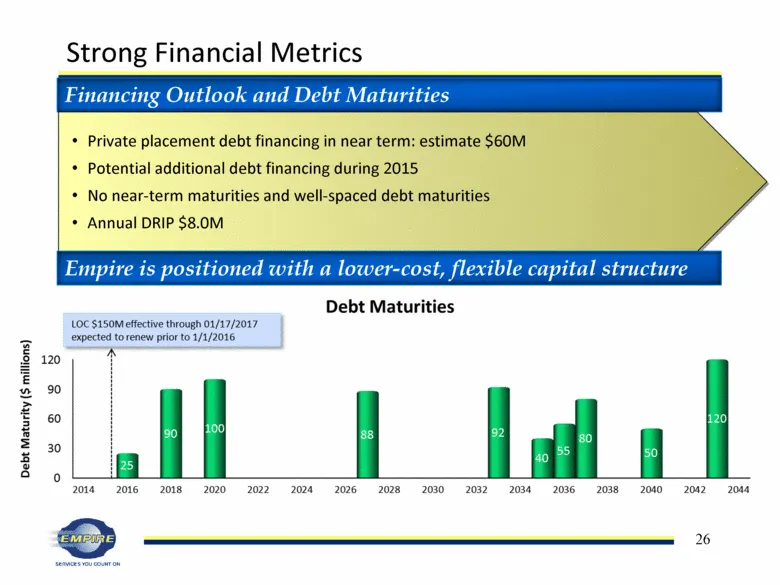
Strong Financial Metrics Financing Outlook and Debt Maturities Private placement debt financing in near term: estimate $60M Potential additional debt financing during 2015 No near-term maturities and well-spaced debt maturities Annual DRIP $8.0M Empire is positioned with a lower-cost, flexible capit
Slide 28: [LOGO]
[LOGO]
Slide 29: Competitive Total Return Prospects
Competitive Total Return Prospects
Slide 30: Key Earnings Drivers, Attractive Dividend, Competitive Total Return
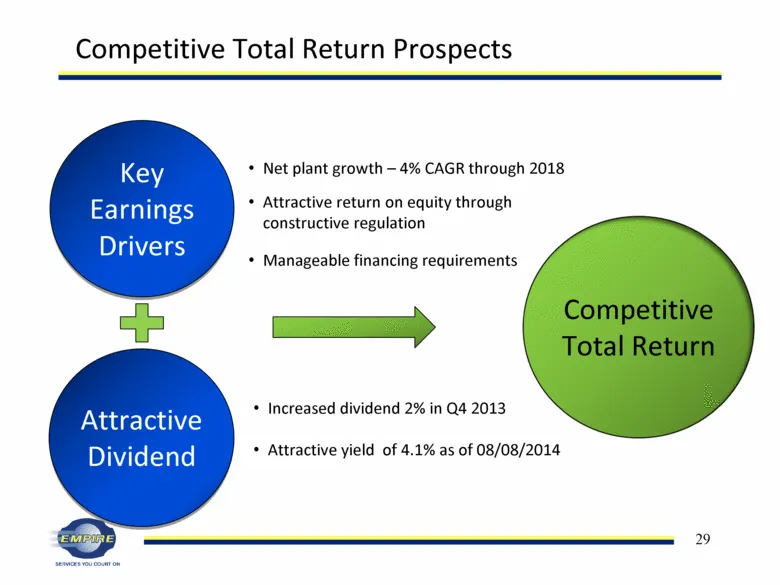
Competitive Total Return Prospects Key Earnings Drivers Attractive Dividend Competitive Total Return Net plant growth – 4% CAGR through 2018 Attractive return on equity through constructive regulation Manageable financing requirements Increased dividend 2% in Q4 2013 Attractive yield of 4.1% as of 0
Slide 31: Competitive Total Return Prospects
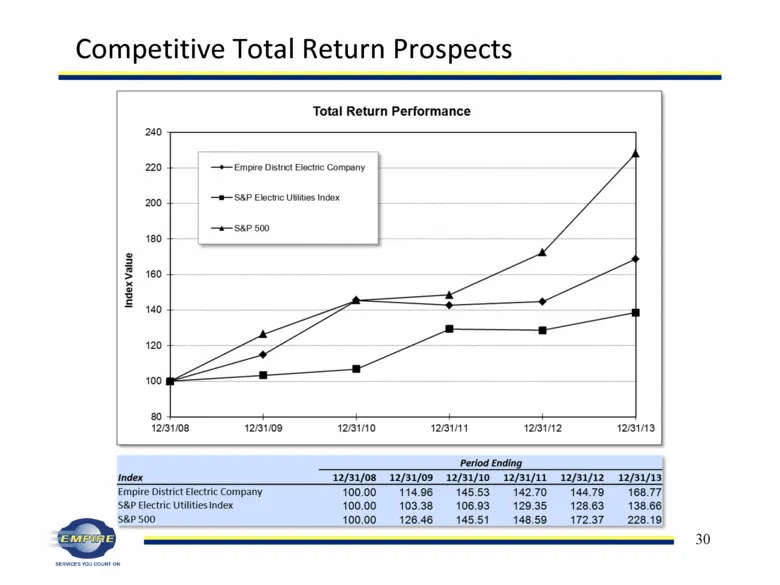
Competitive Total Return Prospects Period Ending Index 12/31/08 12/31/09 12/31/10 12/31/11 12/31/12 12/31/13 Empire District Electric Company 100.00 114.96 145.53 142.70 144.79 168.77 S&P Electric Utilities Index 100.00 103.38 106.93 129.35 128.63 138.66 S&P 500 100.00 126.46 145.51 148.59 172.37 22
Slide 32: Summary: Compelling Investment Platform
Summary: Compelling Investment Platform Pure-play regulated utility Low risk growth plan Strong financial metrics Attractive dividend yield and total return prospects
Slide 33: Regulated Electric and Gas Utility Supplemental Materials
Regulated Electric and Gas Utility Data Generation Mix Electric Customer Growth Residential Rates State Commission Profiles Management and Organization Management Biographies Contact Information Supplemental Materials
Slide 34: Net Plant in Service and Revenue Sources
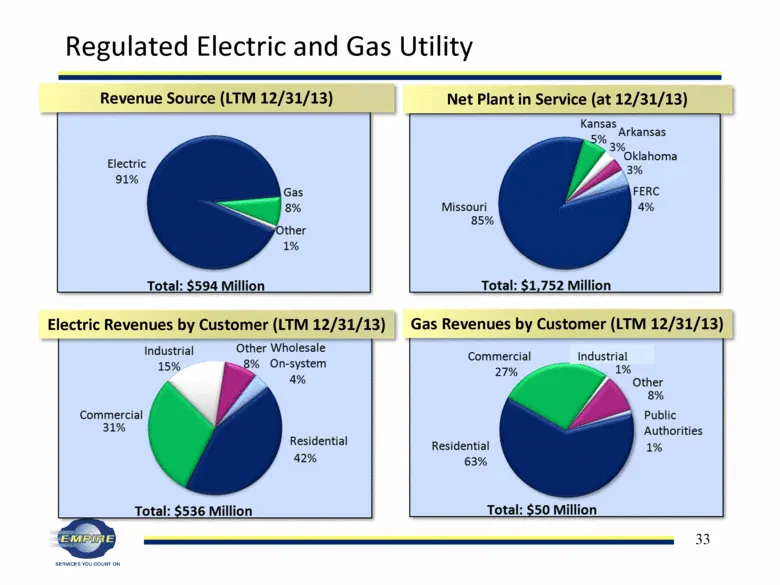
Regulated Electric and Gas Utility Net Plant in Service (at 12/31/13) Oklahoma Revenue Source (LTM 12/31/13) Electric Revenues by Customer (LTM 12/31/13) Gas Revenues by Customer (LTM 12/31/13)
Slide 35: Diverse Generation/Balanced Mix of Resources
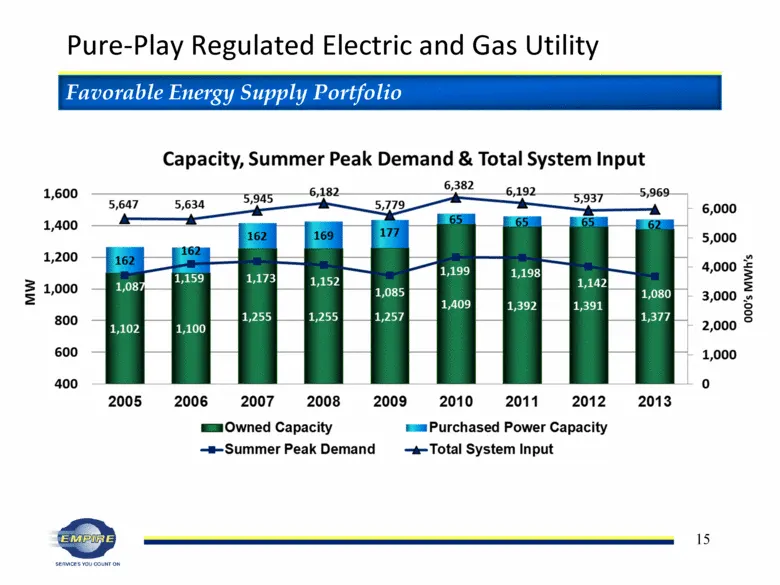
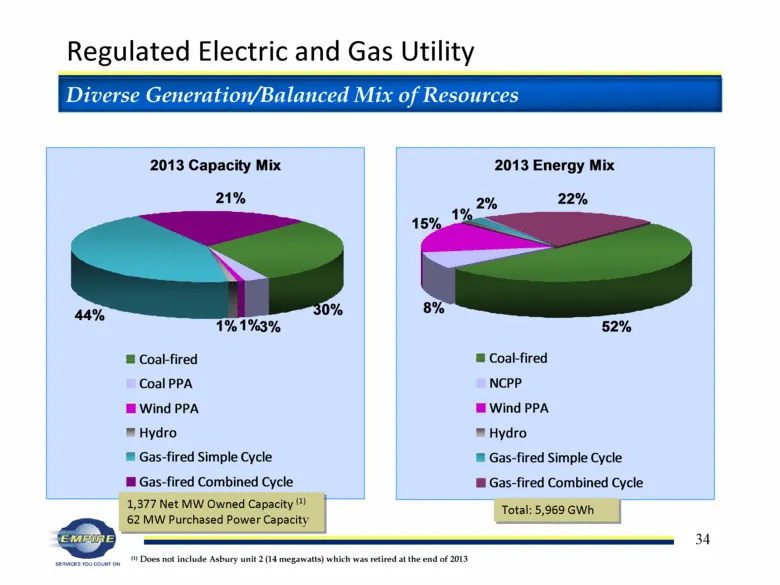
Regulated Electric and Gas Utility Diverse Generation/Balanced Mix of Resources 1,377 Net MW Owned Capacity (1) 62 MW Purchased Power Capacity Total: 5,969 GWh (1) Does not include Asbury unit 2 (14 megawatts) which was retired at the end of 2013 2013 Capacity Mix 21% 44% 1% 3% 30% 1% Coal-fired Coa
Slide 36: Customer Growth
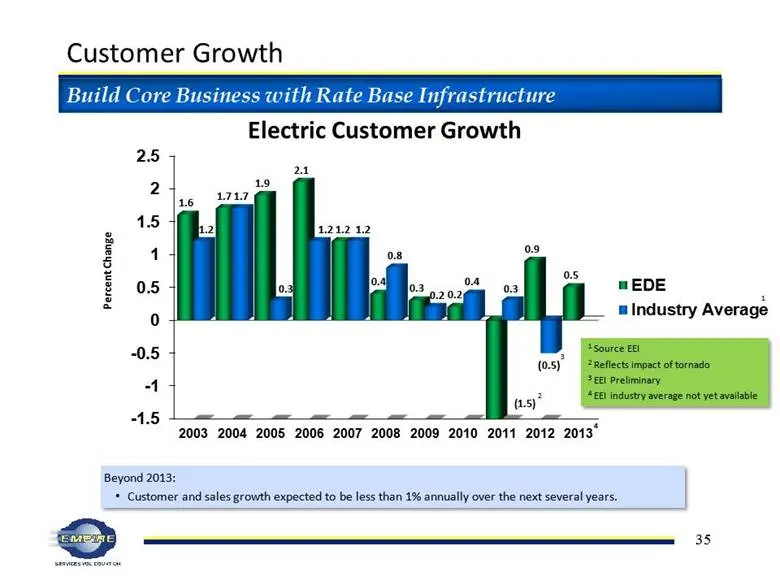
Customer Growth Electric Customer Growth Beyond 2013: Customer and sales growth expected to be less than 1% annually over the next several years. Build Core Business with Rate Base Infrastructure 4
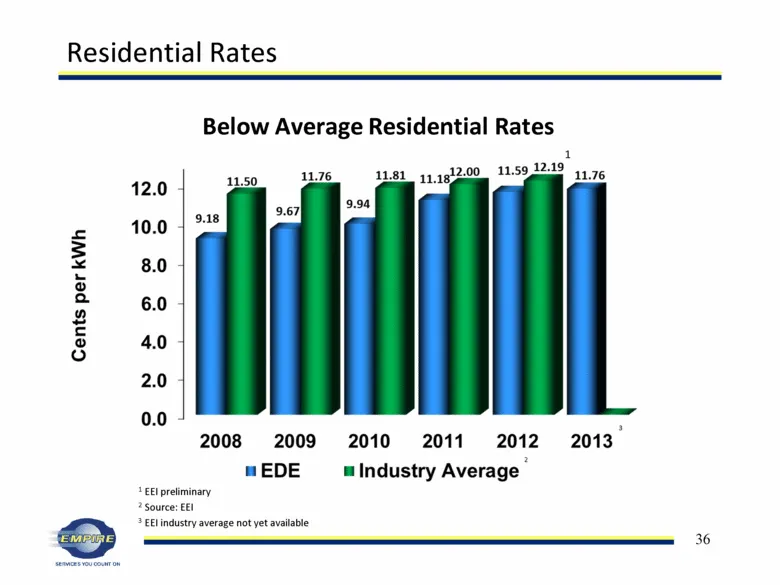
Slide 37: Below Average Residential Rates
Below Average Residential Rates Residential Rates 1 EEI preliminary 2 Source: EEI 3 EEI industry average not yet available 2 1 3
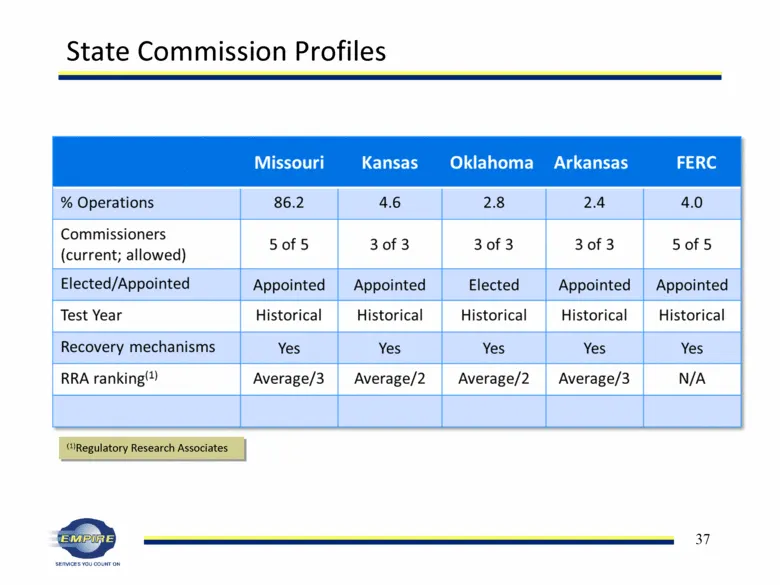
Slide 38: State Commission Profiles
State Commission Profiles (1)Regulatory Research Associates Missouri Kansas Oklahoma Arkansas FERC % Operations 86.2 4.6 2.8 2.4 4.0 Commissioners (current; allowed) 5 of 5 3 of 3 3 of 3 3 of 3 5 of 5 Elected/Appointed Appointed Appointed Elected Appointed Appointed TestYear Historical Historical Hi
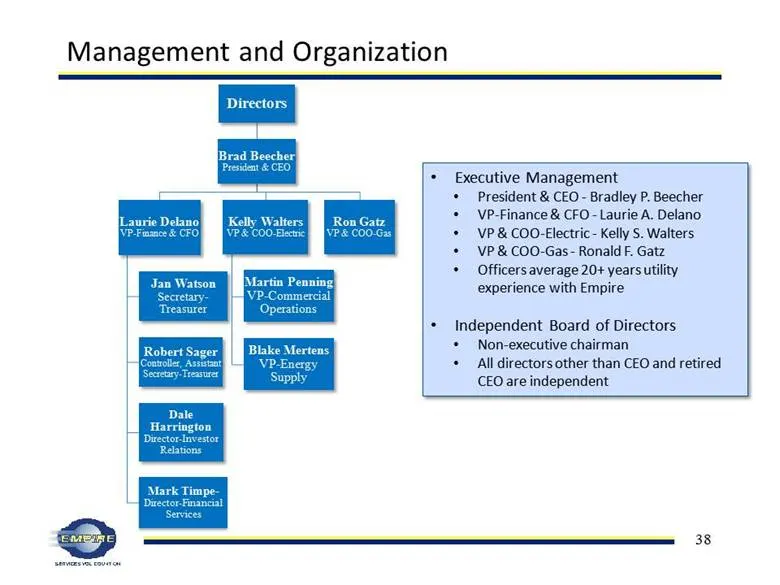
Slide 39: Executive Management
Executive Management President & CEO - Bradley P. Beecher VP-Finance & CFO - Laurie A. Delano VP & COO-Electric - Kelly S. Walters VP & COO-Gas - Ronald F. Gatz Officers average 20+ years utility experience with Empire Independent Board of Directors Non-executive chairman All directors other than CE
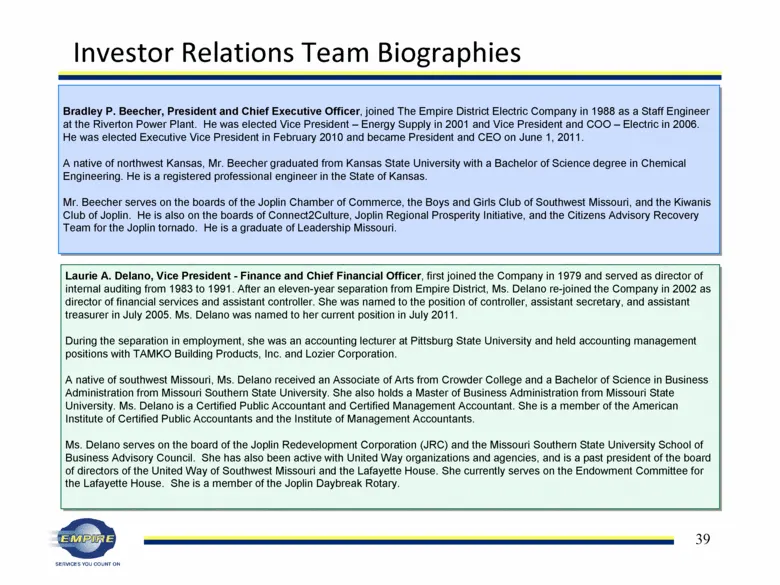
Slide 40: Investor Relations Team Biographies
Investor Relations Team Biographies Bradley P. Beecher, President and Chief Executive Officer, joined The Empire District Electric Company in 1988 as a Staff Engineer at the Riverton Power Plant. He was elected Vice President – Energy Supply in 2001 and Vice President and COO – Electric in 2006. He
Slide 41: Investor Relations Team Biographies
Investor Relations Team Biographies Janet S. Watson, Secretary-Treasurer, joined The Empire District Electric Company in 1994 as Accounting Staff Specialist and was elected to her present position in 1995. Prior to joining Empire, Ms. Watson was Accounting Superintendent with Missouri-American Water
Slide 42: Contact Us
Empire District Electric Company 602 S. Joplin Avenue Joplin, MO 64801 www.empiredistrict.com Jan Watson Office: 417-625-5108 Cell: 417-850-7903 [email protected] Dale Harrington Office: 417-625-4222 Cell: 417-825-8281 [email protected] Laurie Delano Office: 417-625-5127 Cell:
Slide 43: Making lives better every day with reliable energy and service
Making lives better every day with reliable energy and service
Source: SEC EDGAR · 8-K filed Sep 3, 2014
More decks from The Empire District Electric Company
 Q3 2016 Earnings Presentation32 slides · Nov 7, 2016
 Investor Presentation (September 2016)33 slides · Sep 19, 2016
 Merger or Acquisition (May 2016)35 slides · May 18, 2016
 Q1 2016 Earnings Presentation32 slides · May 6, 2016
 Merger or Acquisition (April 2016)8 slides · Apr 12, 2016
 Merger or Acquisition (March 2016)28 slides · Mar 29, 2016