Texas Industries — Southwest Securities Investor Conference 2009
48 slides from Texas Industries's conference presentation, Feb 17, 2009
Slide 1: Southwest Securities Investor Conference 2009
SOUTHWEST SECURITIES INVESTOR CONFERENCE 2009 DALLAS, TEXAS FEBRUARY 12, 2009
Slide 2: Forward-Looking Statement
SS FORWARD-LOOKING STATEMENT Certain statements contained in this presentation are “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. Such statements are subject to risks, uncertainties and other factors, which could cause actual results to diffe
Slide 3: A Building Materials Company
a A BUILDING MATERIALS COMPANY « Cement, Aggregate and Concrete + Used in all types of construction « Cement accounts for approximately 75% of earnings
Slide 4: Primary Earnings Drivers
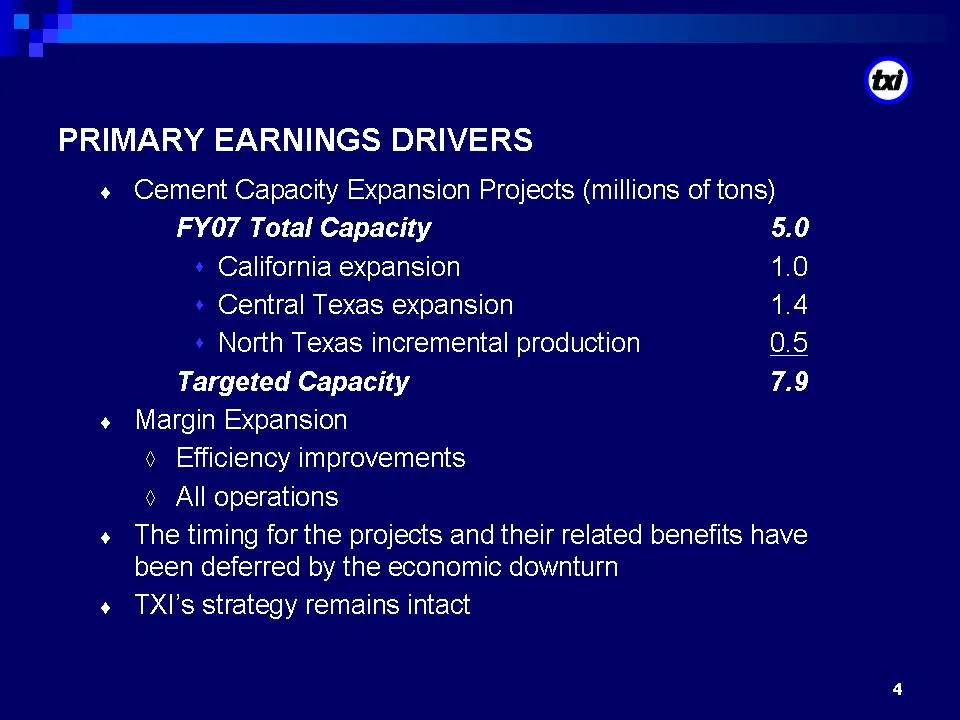
SS PRIMARY EARNINGS DRIVERS ¢« Cement Capacity Expansion Projects (millions of tons) FY07 Total Capacity 5.0 » California expansion 1.0 » Central Texas expansion 1.4 » North Texas incremental production 05 Targeted Capacity 7.9 « Margin Expansion > Efficiency improvements > All operations ¢ The timi
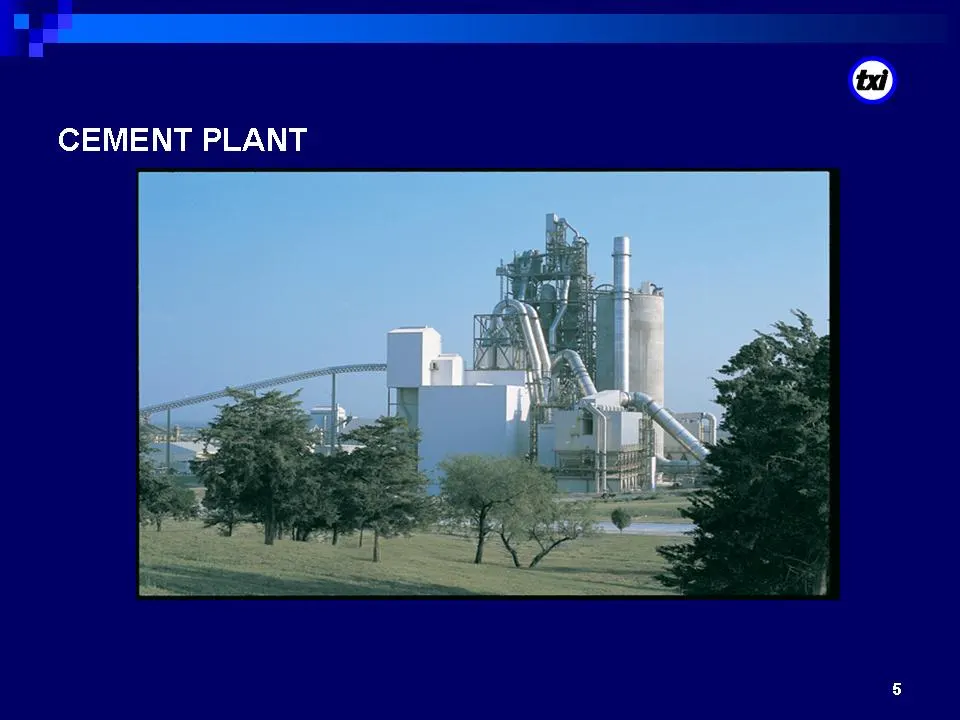
Slide 5: Cement Plant
a CEMENT PLANT tea)
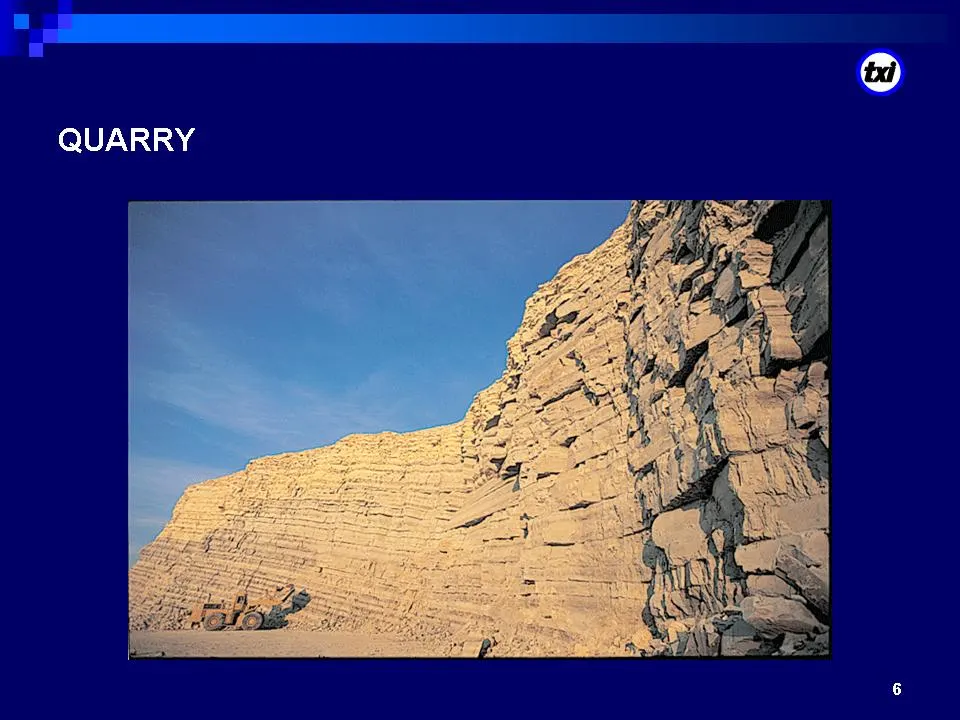
Slide 6: Quarry
QUARRY
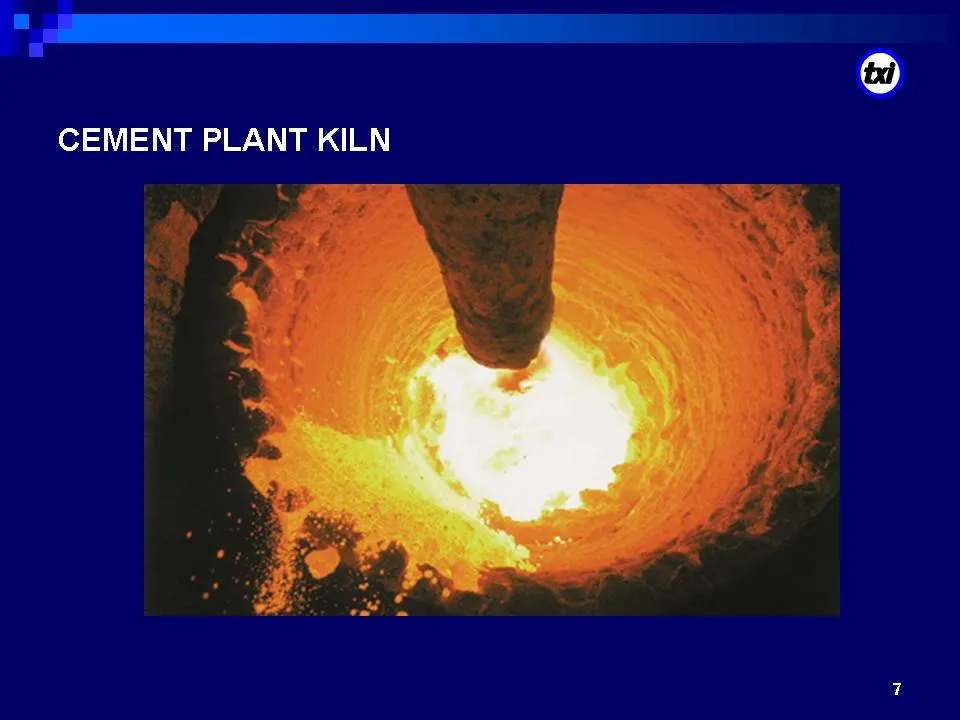
Slide 7: Cement Plant Kiln
CEMENT PLANT KILN
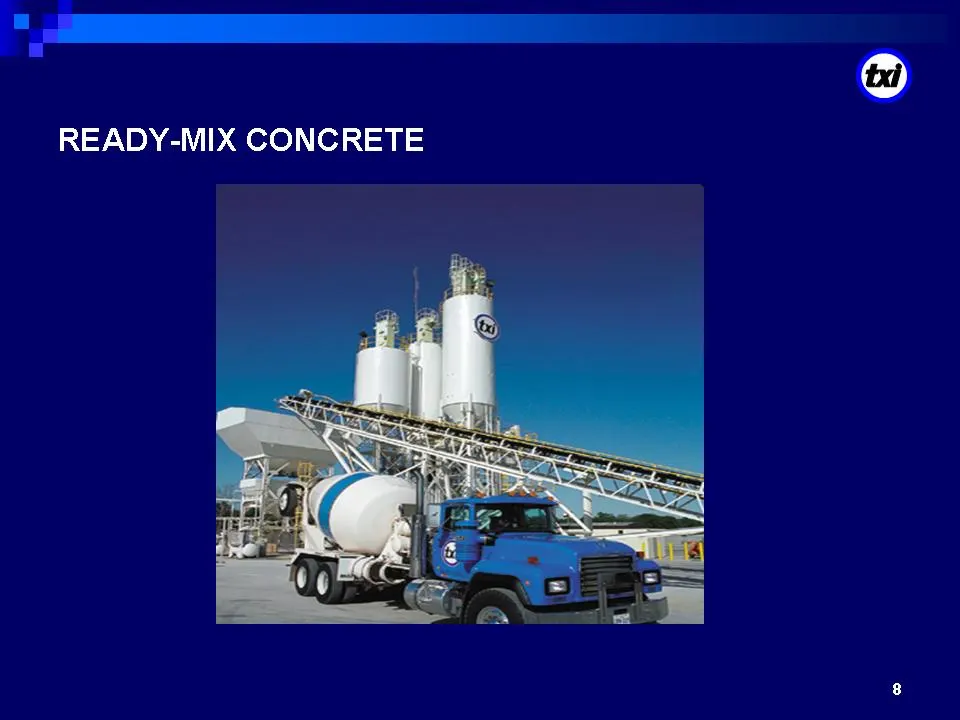
Slide 8: Ready-Mix Concrete
READY-MIX CONCRETE @
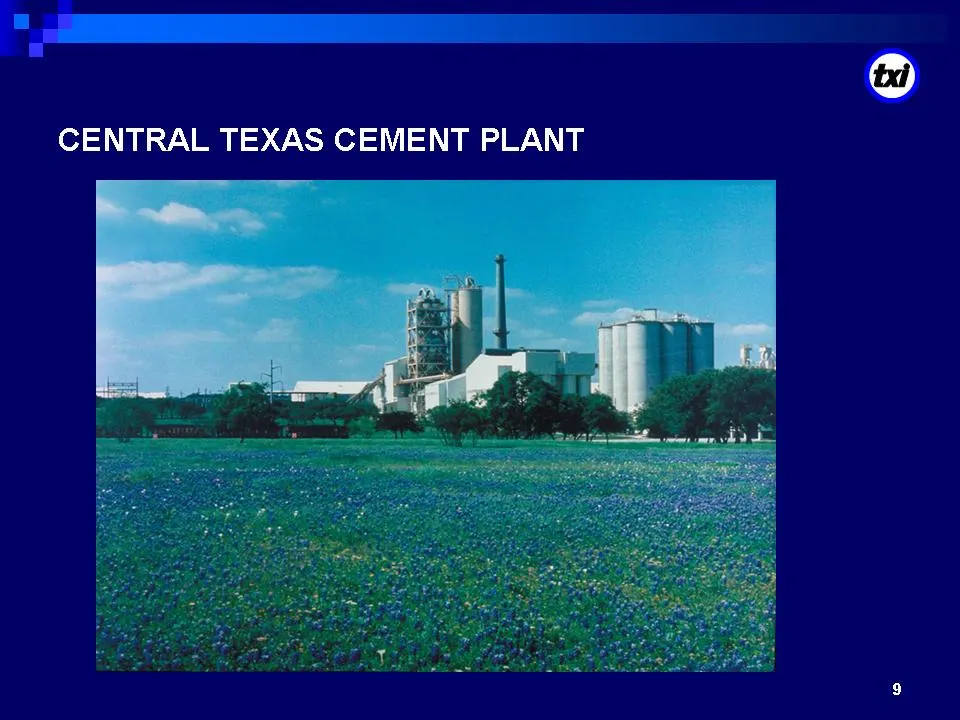
Slide 9: Central Texas Cement Plant
SS CENTRAL TEXAS CEMENT PLANT
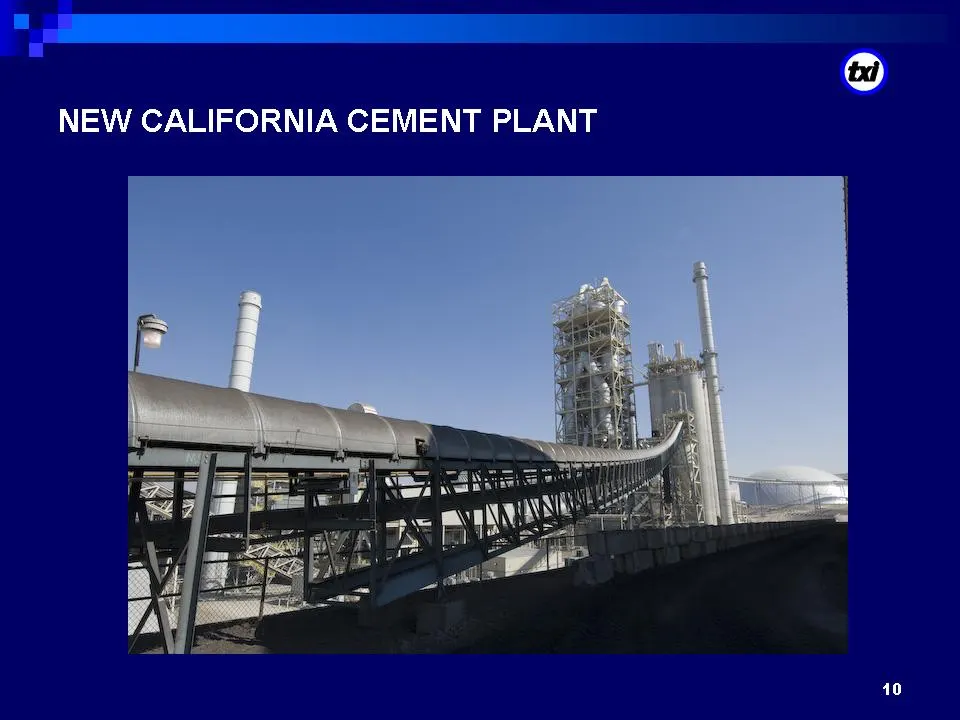
Slide 10: New California Cement Plant
NEW CALIFORNIA CEMENT PLANT 40
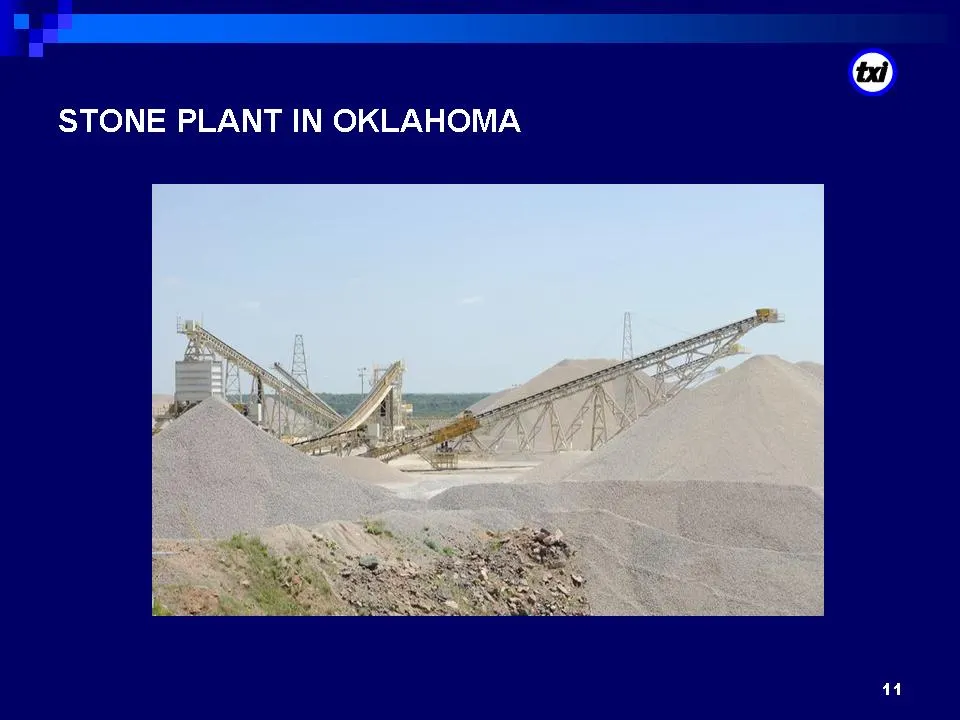
Slide 11: Stone Plant in Oklahoma
a STONE PLANT IN OKLAHOMA 41
Slide 12: Drivers of Cement Demand
DRIVERS OF CEMENT DEMAND 42
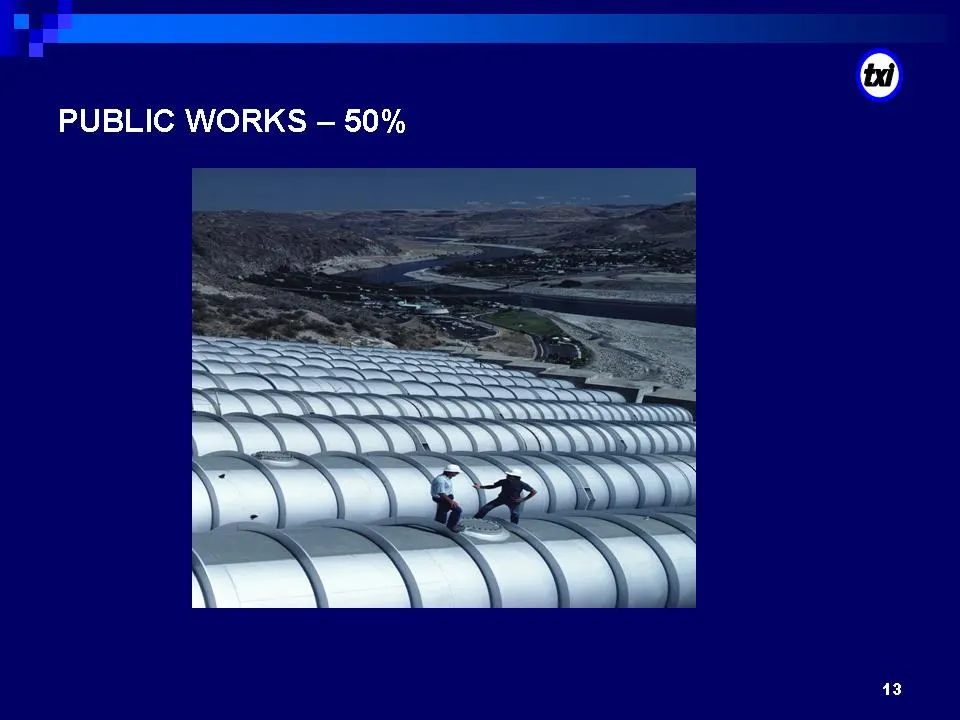
Slide 13: Public Works - 50%
a PUBLIC WORKS - 50% 43
Slide 14: Residential - 25%
— RESIDENTIAL — 25% 14
Slide 15: Non-Residential - 25%
NON-RESIDENTIAL — 25% 45
Slide 16: Favorable Industry Structure
FAVORABLE INDUSTRY STRUCTURE 416
Slide 17: Favorable Industry Structure
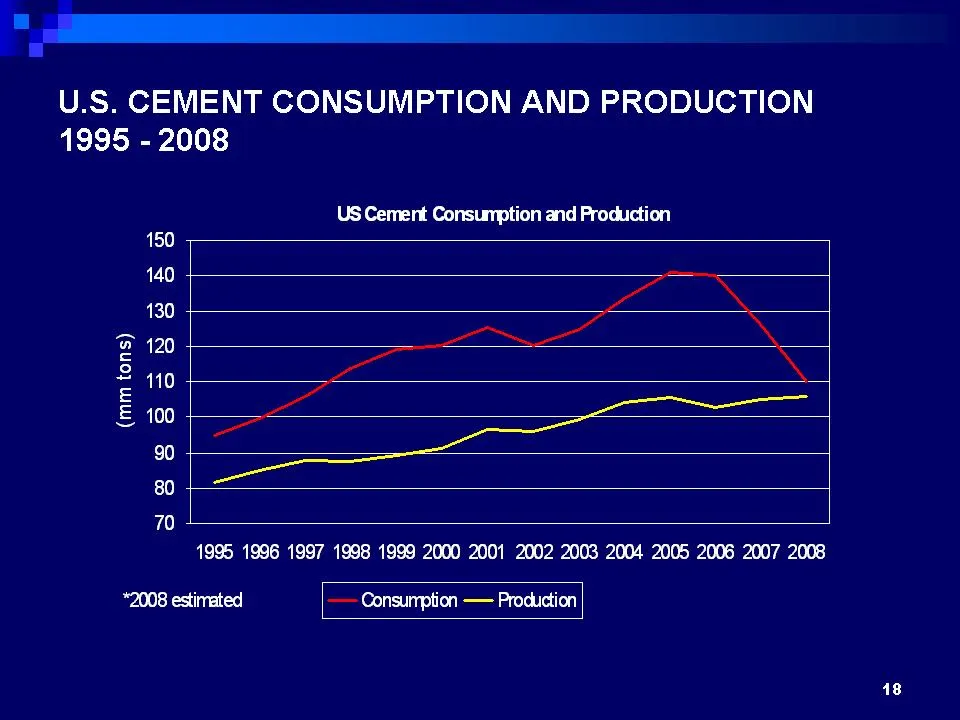
a FAVORABLE INDUSTRY STRUCTURE © #U. S. cement consumption has historically exceeded domestic production capacity 47
Slide 18: U.S. Cement Consumption and Production
a U.S. CEMENT CONSUMPTION AND PRODUCTION 1995 - 2008 US Cement Consumption and Production (mm tons) 3 1995 1996 1997 1998 1999 2000 2001 2002 2003 2004 2005 2006 2007 2008 *2008 estimated —— Consumption — Production
Slide 19: Favorable Industry Structure
a FAVORABLE INDUSTRY STRUCTURE © #U. S. cement consumption has historically exceeded domestic production capacity U.S. cement capacity and import terminals are largely owned or controlled by international producers Significant barriers to entry exist for new cement capacity Significant transportatio
Slide 20: Texas and California
TEXAS AND CALIFORNIA ATTRACTIVE LONG-TERM MARKETS 20
Slide 21: Texas and California: Attractive Long-Term Markets
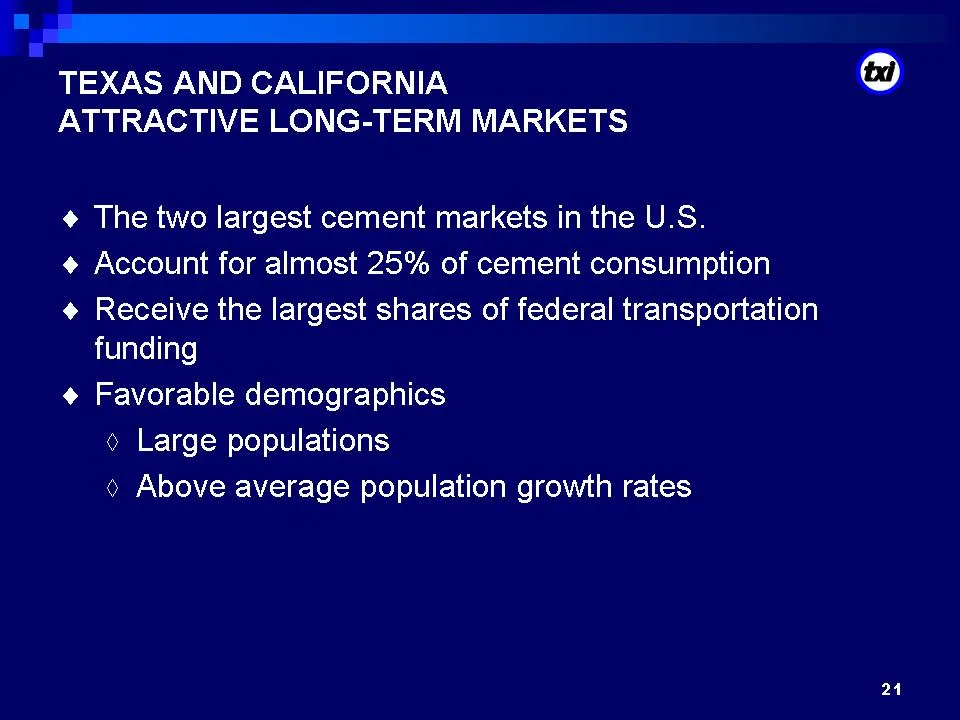
SS TEXAS AND CALIFORNIA {e) ATTRACTIVE LONG-TERM MARKETS ¢ The two largest cement markets in the U.S. ¢ Account for almost 25% of cement consumption ¢ Receive the largest shares of federal transportation funding ¢ Favorable demographics © Large populations © Above average population growth rates 24
Slide 22: Texas Cement Consumption and Production
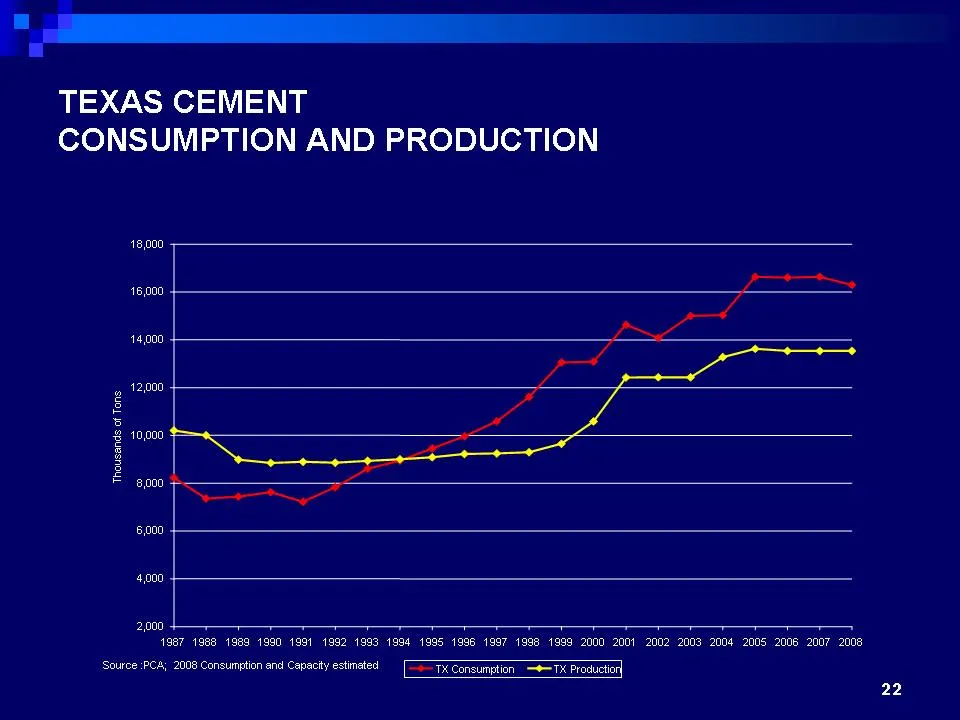
SS TEXAS CEMENT CONSUMPTION AND PRODUCTION 48900 48900 44000 al 42900 Z 10,000 Thousands of Tans 8,000 6,000 4,00 2,00 1987 1968 1989 1990 1991 1992 1993 1994 1935 1996 1997 1995 1993 2000 2001 2002 2003 2004 2005 2006 2007 2008 Source :PCA; 2008 Consumption and Capacty estimated — [Tx Consumption =
Slide 23: Texas Construction
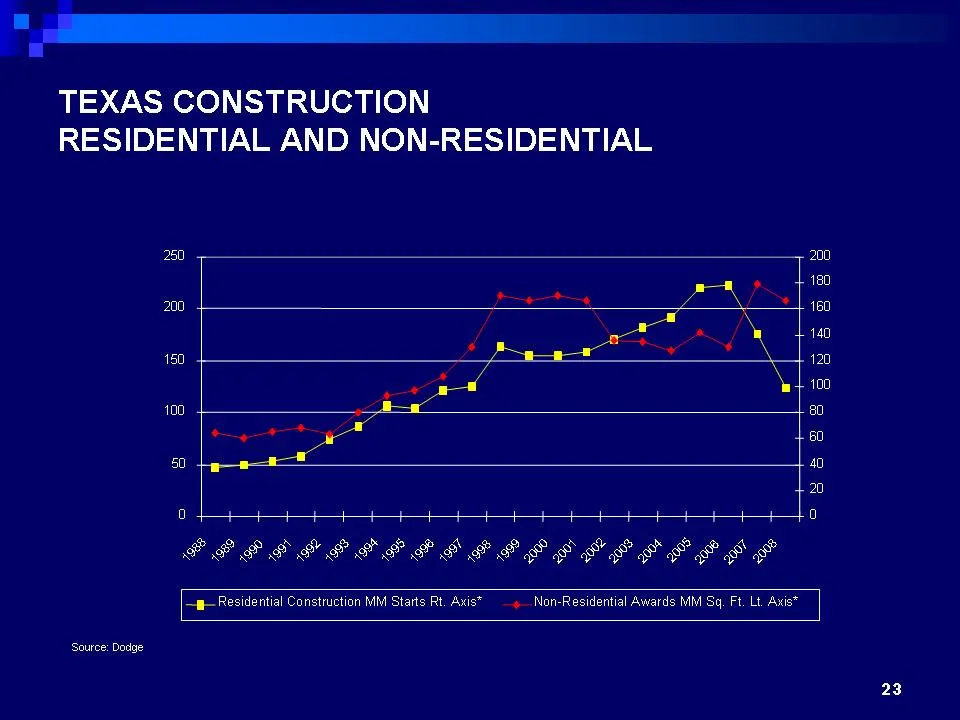
a TEXAS CONSTRUCTION RESIDENTIAL AND NON-RESIDENTIAL , 200 pararteet PORES 160 150 120 Ni 100 100 60 60 50 40 20 a a FEE LEE PE EEE ESEEEE ESS S —g- Residential Construction MM Starts Rt. Axis* 5 Non-Residential Awards MM Sq. Ft. Lt. Axis™ Source: Dodge 23
Slide 24: Texas Construction: Non-Building and Highway Awards
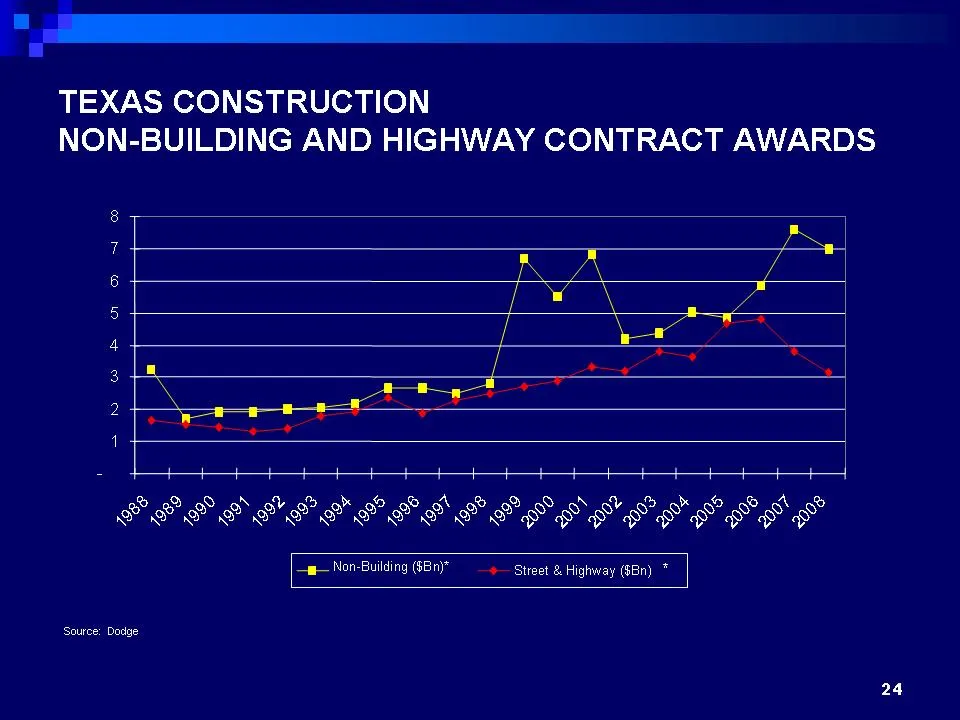
SS TEXAS CONSTRUCTION NON-BUILDING AND HIGHWAY CONTRACT AWARDS KA ~ Ce se ee} | DO aN kV GP GI GD GO GU GD ONY 9 Pe we PPP PPE PF PE EF SF s ~ S ~ ss ~~ ~ es SS —a- Non-Building ($6n)* 6 Street & Highway ($Bn) * Source: Dodge 24
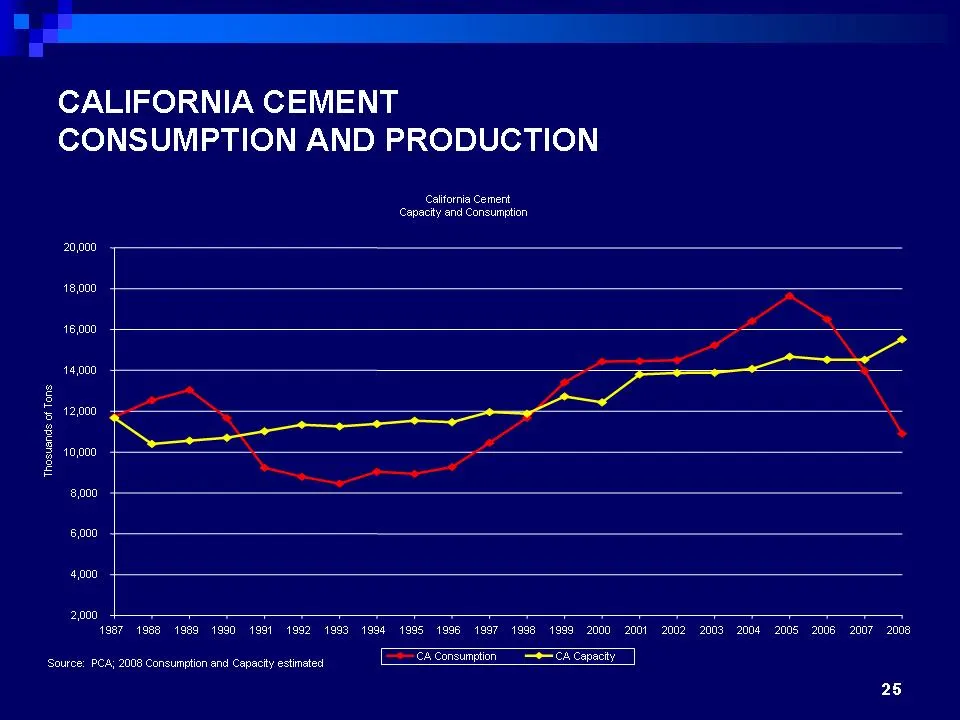
Slide 25: California Cement Consumption and Production
SS CALIFORNIA CEMENT CONSUMPTION AND PRODUCTION California Cement Capacity and Consumption 20,000 4000 4000 ee 14,000 ae Ay ‘o,000 ———=— 8000 Thasuands of Tans 6,000 4,00 2,00 1987 1956 1989 1930 1991 1992 1993 1994 1995 1998 1997 1998 1939 2000 2001 2002 2003 2004 2005 2006 2007 2008 Source: PCA; 2
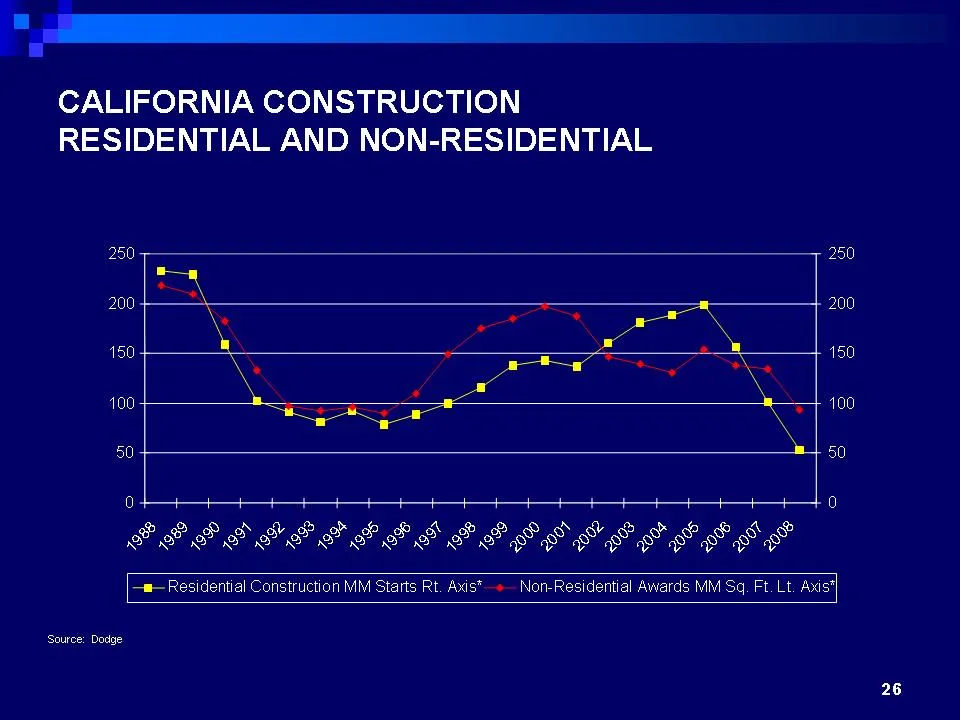
Slide 26: California Construction
a CALIFORNIA CONSTRUCTION RESIDENTIAL AND NON-RESIDENTIAL 250 250 200 200 150 150 + 100 —+ 100 50 50 0 0 2 ~~ rt) sel S hb ca SFP PE SOS PEF acon FF es ws PCPS s —a— Residential Construction MM Starts Rt. Axis* » Non-Residential Awards MM Sq. Ft. Lt. Axis*) Source: Dodge 26
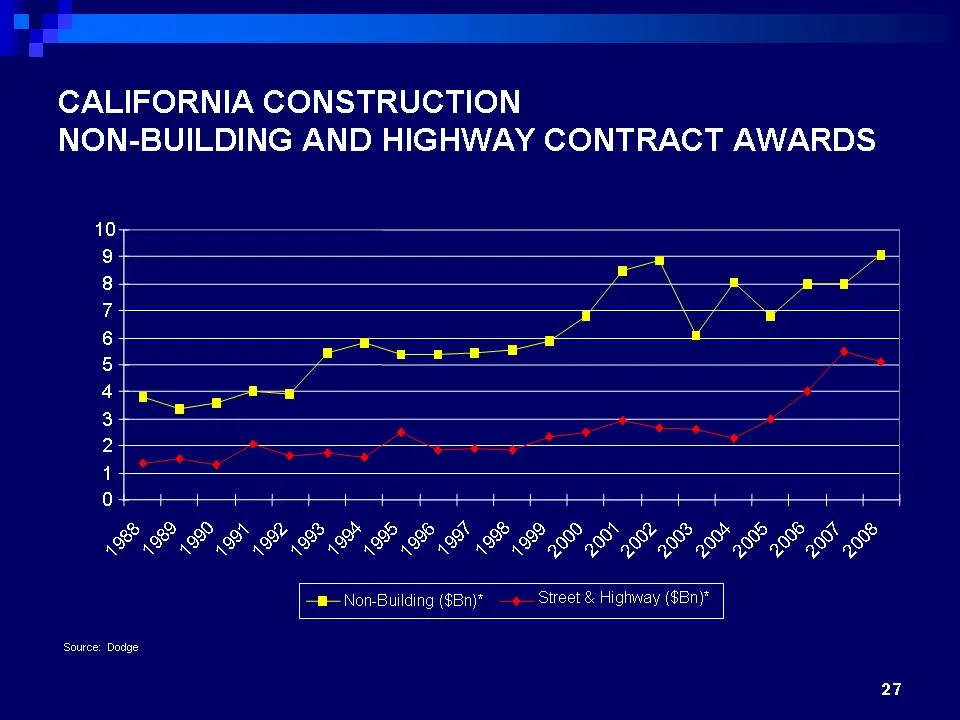
Slide 27: California Construction: Non-Building and Highway Awards
LL CALIFORNIA CONSTRUCTION NON-BUILDING AND HIGHWAY CONTRACT AWARDS 10 9 ram we 8 TX Wa zi VY w : sa 5 —- 4 rs x 3 ; 7 oe ; =S=s =e ——> ot4 o M D > A 2D Od 2 <a] A EEEPOPEPEPSES SPM PF CPSs —a—Non-Building ($Bn)* _»— Street & Highway ($Bn)* ree: Dadge 2H:
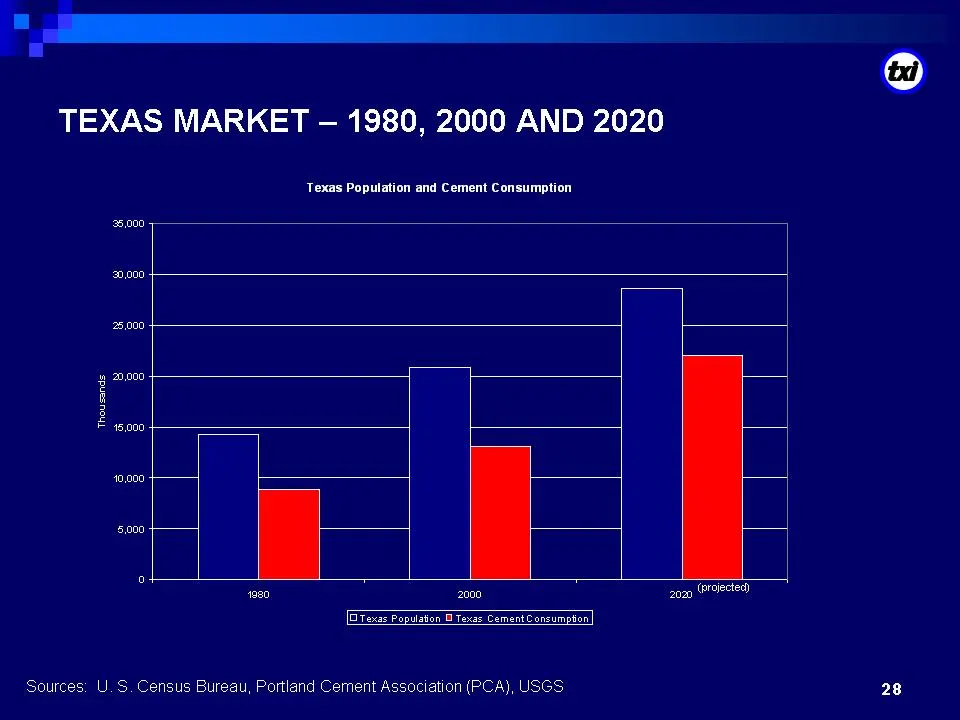
Slide 28: Texas Market - 1980, 2000 and 2020
SS TEXAS MARKET — 1980, 2000 AND 2020 Texas Population and Cement Consumption 36,000 sn,000 25,000 8 Thousands 16,000 40,000 5,000 1920 2000 [BiTexaz Population O Texar Cement Consumption Sources: U.S. Census Bureau, Portland Cement Association (PCA), USGS. 200 (projected) 28
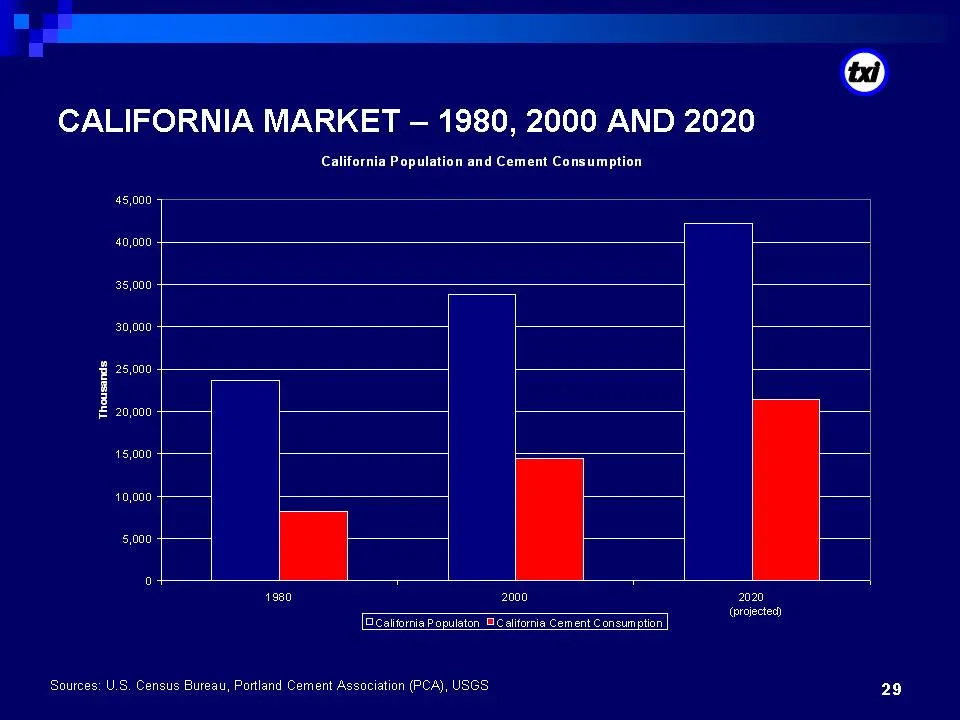
Slide 29: California Market - 1980, 2000 and 2020
a CALIFORNIA MARKET — 1980, 2000 AND 2020 California Population and Cement Consumption ie] - [| 0 1980 2000 2020 (projected) ([EiCatiorria Populston OC alifernia Cement Consumption Sources: U.S. Census Bureau, Portland Cement Association (PCA), USGS 29
Slide 30: Strong Competitive Position
STRONG COMPETITIVE POSITION 30
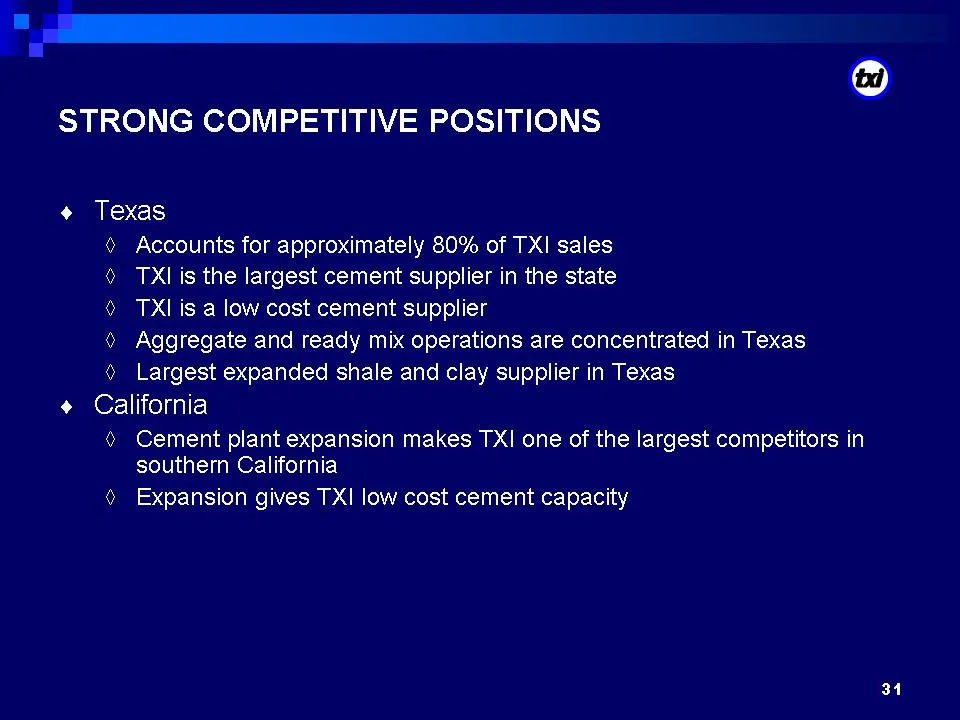
Slide 31: Strong Competitive Positions
a STRONG COMPETITIVE POSITIONS + Texas Accounts for approximately 80% of TXI sales ® TXl is the largest cement supplier in the state ® TXl is a low cost cement supplier ® Aggregate and ready mix operations are concentrated in Texas Largest expanded shale and clay supplier in Texas ¢ California & Cem
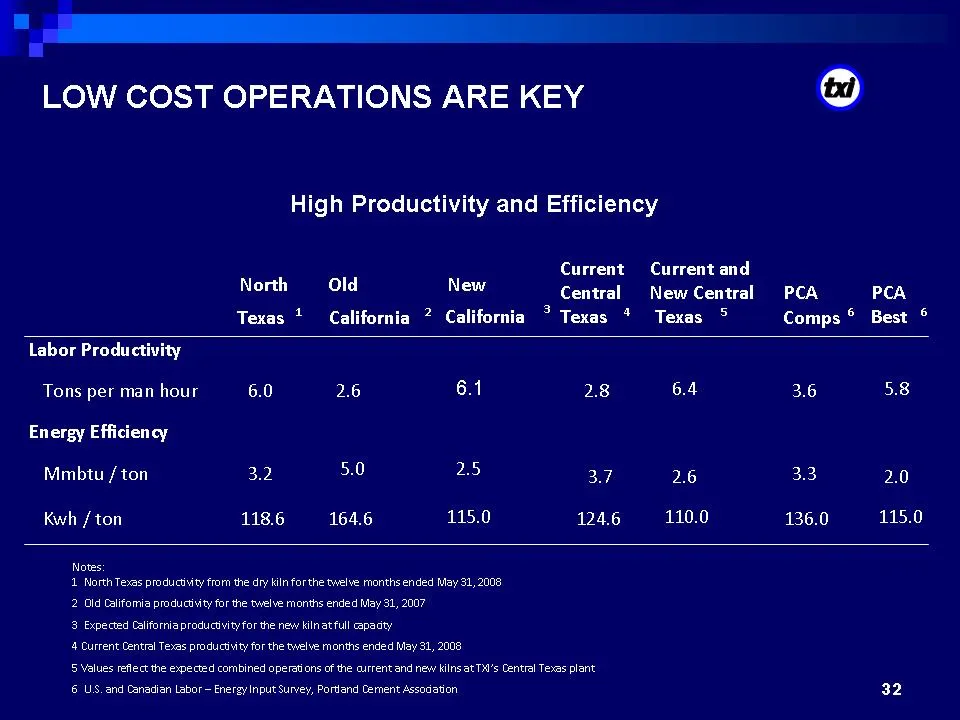
Slide 32: Low Cost Operations Are Key
a LOW COST OPERATIONS ARE KEY {e) High Productivity and Efficiency Current Current and Noah Old New Central New Central PCA PCA Texas + California ? California ° Texas * Texas ° Comps © Best © Labor Productivity Tons per man hour 6.0 2.6 6.1 2.8 6.4 3.6 58 Energy Efficiency Mmbtu / ton 3.2 5.0 2.5 3
Slide 33: Cement Plant Expansions
CEMENT PLANT EXPANSIONS 33
Slide 34: California Cement Plant: Modernization and Expansion
SS CALIFORNIA CEMENT PLANT ® MODERNIZATION AND EXPANSION or + + Commissioned May 2008 Added 2.3 million tons of state-of-the-art annual cement capacity Replaced 1.3 million tons of 50 year old production capacity Combined benefit of more capacity and significantly increased production efficiencies ©
Slide 35: Central Texas Cement Plant Expansion
SS CENTRAL TEXAS CEMENT PLANT EXPANSION @ Enhances TXI’s market-leading position in Texas Adds 1.4 million tons of state-of-the-art cement capacity Existing .9 million ton cement facility will remain in operation Required permits and permissions are in place Completion of the project has been delaye
Slide 36: North Texas Cement Plant: Incremental Production
SS NORTH TEXAS CEMENT PLANT INCREMENTAL PRODUCTION © ¢ The plant’s current annual production capacity is 2.8 million tons ¢ We plan to increase capacity by .5 million tons annually ¢ The increased production will come from a series of projects to improve the kiln that was added in 2001 ¢ Significant
Slide 37: Current Market Conditions
CURRENT MARKET CONDITIONS 37
Slide 38: Current Economic Conditions
SS CURRENT ECONOMIC CONDITIONS @ ¢ The U.S. economy continues to contract « After showing marked resilience through the summer, Texas economic activity declined significantly during the last months of 2008 ¢« The Texas economy continues to be one of the better economies in the nation ¢ California ec
Slide 39: Summary of Construction Activity
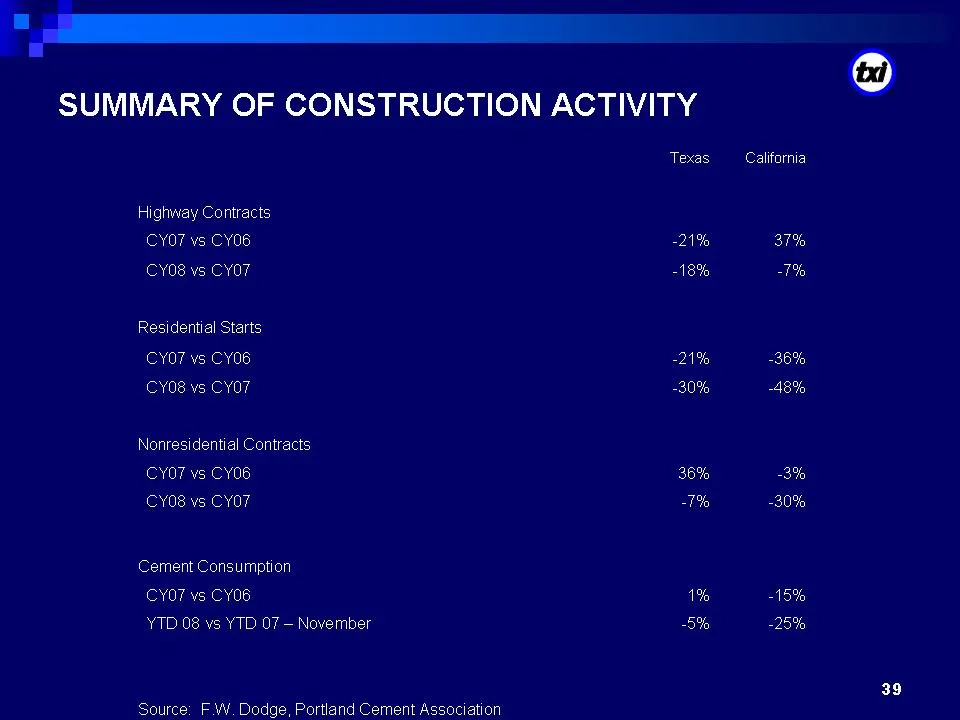
a SUMMARY OF CONSTRUCTION ACTIVITY Texas Highway Contracts CYO07 vs CYO8 -21% CY08 vs CYO7 -18% Residential Starts CYO07 vs CYOS “21% CY08 vs CYO7 -30% Nonresidential Contracts CYO07 vs CYO8 36% CY08 vs CYO7 -T% Cement Consumption CYO07 vs CYO8 1% YTD 08 vs YTD 07 — November -5% Source: F.\W. Dodge,
Slide 40: Federal Stimulus Program
SS FEDERAL STIMULUS PROGRAM @ ¢ The current program calls for approximately $27 - 30 billion to be invested in highways and bridges ¢ Total recent annual U.S. investment (all sources) in highways and bridges has approximated $75 billion ¢ Roadbuilding: © Creates jobs © Creates a foundation for furth
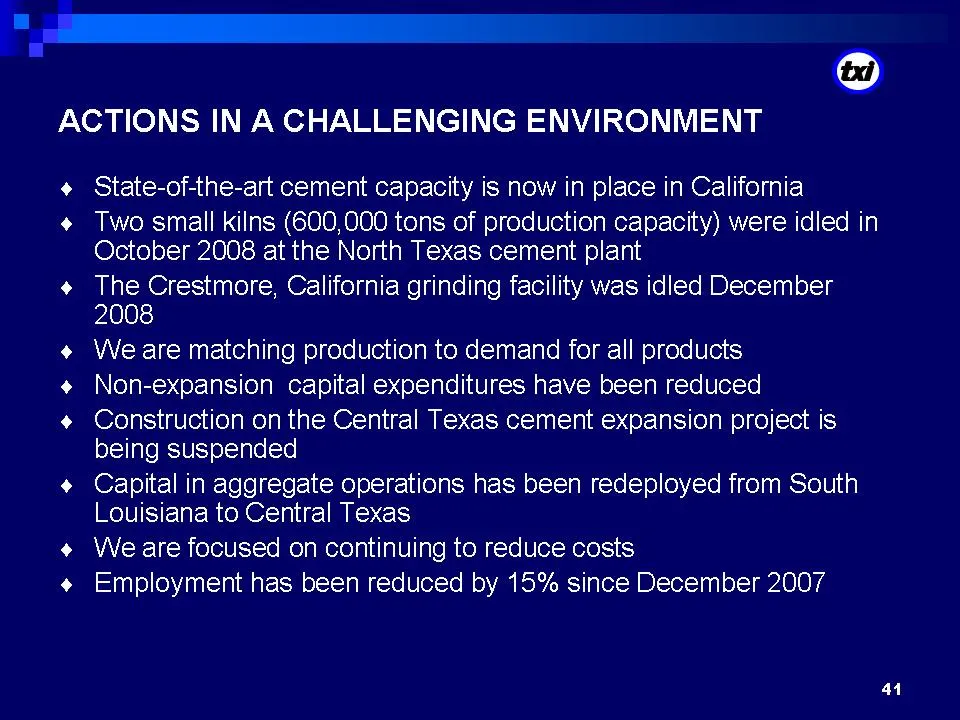
Slide 41: Actions in a Challenging Environment
SS tex) ACTIONS IN A CHALLENGING ENVIRONMENT ¢ State-of-the-art cement capacity is now in place in California ¢# Two small kilns (600,000 tons of production capacity) were idled in October 2008 at the North Texas cement plant ¢« The Crestmore, California grinding facility was idled December 2008 ¢ W
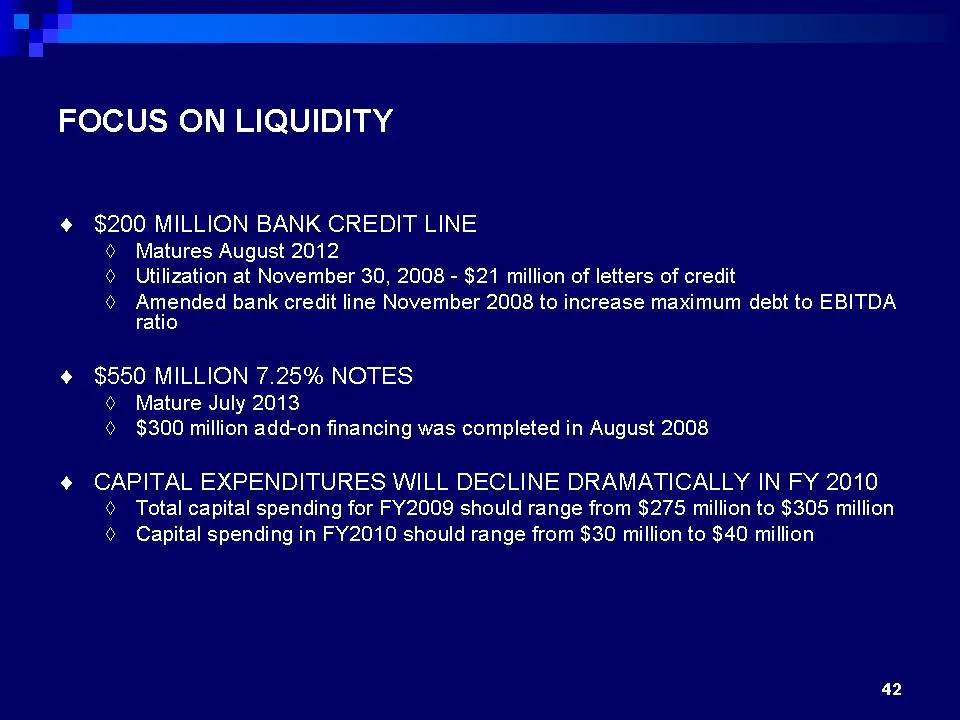
Slide 42: Focus on Liquidity
a FOCUS ON LIQUIDITY ¢# $200 MILLION BANK CREDIT LINE ® Matures August 2012 © Utilization at November 30, 2008 - $21 million of letters of credit ® Amended bank credit line November 2008 to increase maximum debt to EBITDA ratio + $550 MILLION 7.25% NOTES ® Mature July 2013 © $300 million add-on fina
Slide 43: Earnings Potential and Strategy
EARNINGS POTENTIAL AND STRATEGY 43
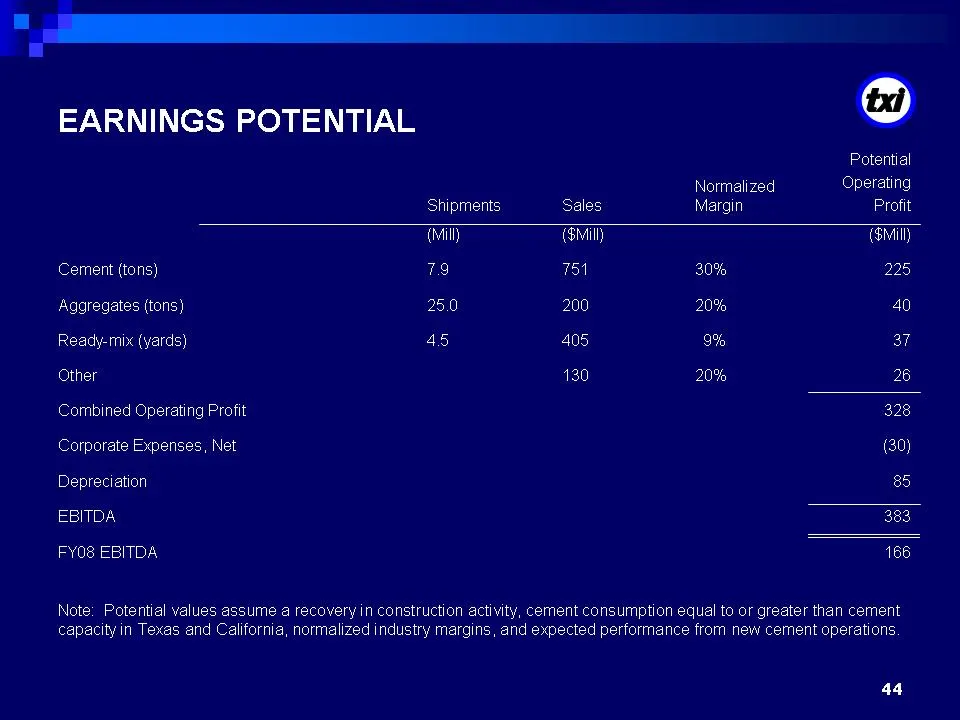
Slide 44: Earnings Potential
a EARNINGS POTENTIAL © Potential Normalized Operating Shipments Sales Margin Profit (mail) Mil) Mil) Cement (tons) 79 751 30% 225 Aggregates (tons) 25.0 200 20% 40 Ready-mix (yards) 45 405 2% 37 Other 130 20% 26 Combined Operating Profit 328 Corporate Expenses, Net (30) Depreciation 85 EBITDA 383 FY
Slide 45: TXI's Strategy Remains Intact
a TXI’S STRATEGY REMAINS INTACT « Expand TXl’s most important business line - Cement — by 60% © All projects are at existing sites + They utilize infrastructure already in place + The underlying permits are already in place + Growth is organic rather than through acquisitions © All projects are in a
Slide 46: Addendum - Reconciliation
ADDENDUM - RECONCILIATION EBITDA TO NET INCOME 46
Slide 47: Reconciliation of EBITDA to Net Income
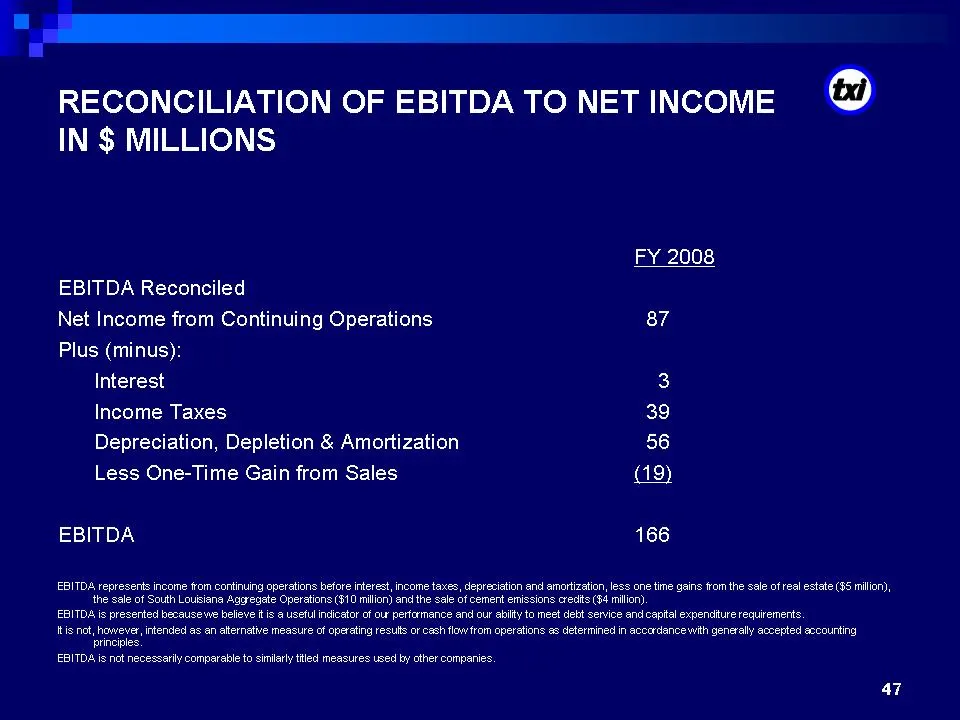
a RECONCILIATION OF EBITDA TO NET INCOME @ IN $ MILLIONS FY 2008 EBITDA Reconciled Net Income from Continuing Operations 87 Plus (minus): Interest 3 Income Taxes 39 Depreciation, Depletion & Amortization 56 Less One-Time Gain from Sales (19) EBITDA 166 EBITDA represents income ftom continuing operat
Slide 48: Southwest Securities Investor Conference
SOUTHWEST SECURITIES INVESTOR CONFERENCE DALLAS, TEXAS February 12, 2009 48
Source: SEC EDGAR · 8-K filed Feb 17, 2009
More decks from Texas Industries Inc
 BB&T 8th Annual Commercial & Industrial Investor Conference (March 2014)26 slides · Mar 26, 2014
 Merger or Acquisition (January 2014)16 slides · Jan 28, 2014
 Stephens Conference 201337 slides · Nov 12, 2013
 Investor Presentation (March 2013)39 slides · Mar 5, 2013
 Investor Presentation (September 2012)33 slides · Sep 11, 2012
 Bank of America Merrill Lynch Leveraged Finance Conference 201133 slides · Dec 1, 2011