Memry — Westergaard Conference November 2007
31 slides from Memry's conference presentation, Nov 13, 2007
Slide 1: Westergaard Conference November 2007
MIEMRY Westergaard Conference November 2007
Slide 2: Forward-looking statements
This presentation contains certain forward-looking statements which involve known and unknown risks, uncertainties or other factors not under the Company’s control which may cause actual results, performance or achievements of the Company to be materially different from the results, performance, or
Slide 3: Compelling Value Proposition
Compelling Value Proposition Innovative, Strategic Technology Solutions Large and Growing Medical Device Market Strong Growing Pipeline Strong Balance Sheet Strong Cash Generator Building Momentum Trading Near Book Value
Slide 4: Enabling minimally invasive and targeted therapies for the medical industry
“Enabling minimally invasive and targeted therapies for the medical industry”
Slide 5: Materials & Processes Enabling Properties
Materials & Processes Enabling Properties Superelastic & Shape Kink resistance Memory Nitinol Alloys Crush resistance Ability to recover large Wire & Tube Drawing deformation ; Thermal Recovery Laser Cutting Confined Access & Delivery Stent Manufacturing Wire Forming Surface Finishing Grinding & Coa
Slide 6: Materials & Processes Enabling Properties
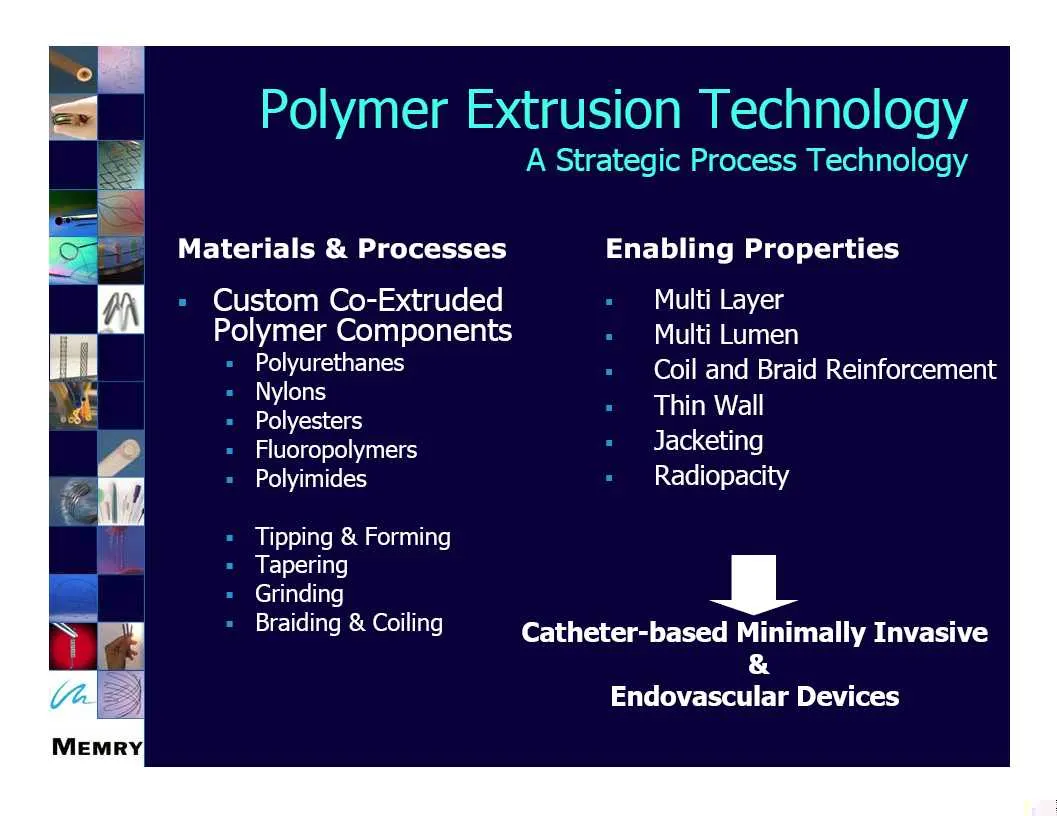
Materials & Processes Enabling Properties Custom Co-Extruded Multi Layer Polymer Components Multi Lumen pepeetenes Coil and Braid Reinforcement lenis Thin Wall Polyesters : Fluoropolymers Jacketing Polyimides Radiopacity Tipping & Forming Tapering Grinding Braiding & Coiling Catheter-based Minimally
Slide 7: 2005 Surgical Devices & Instruments
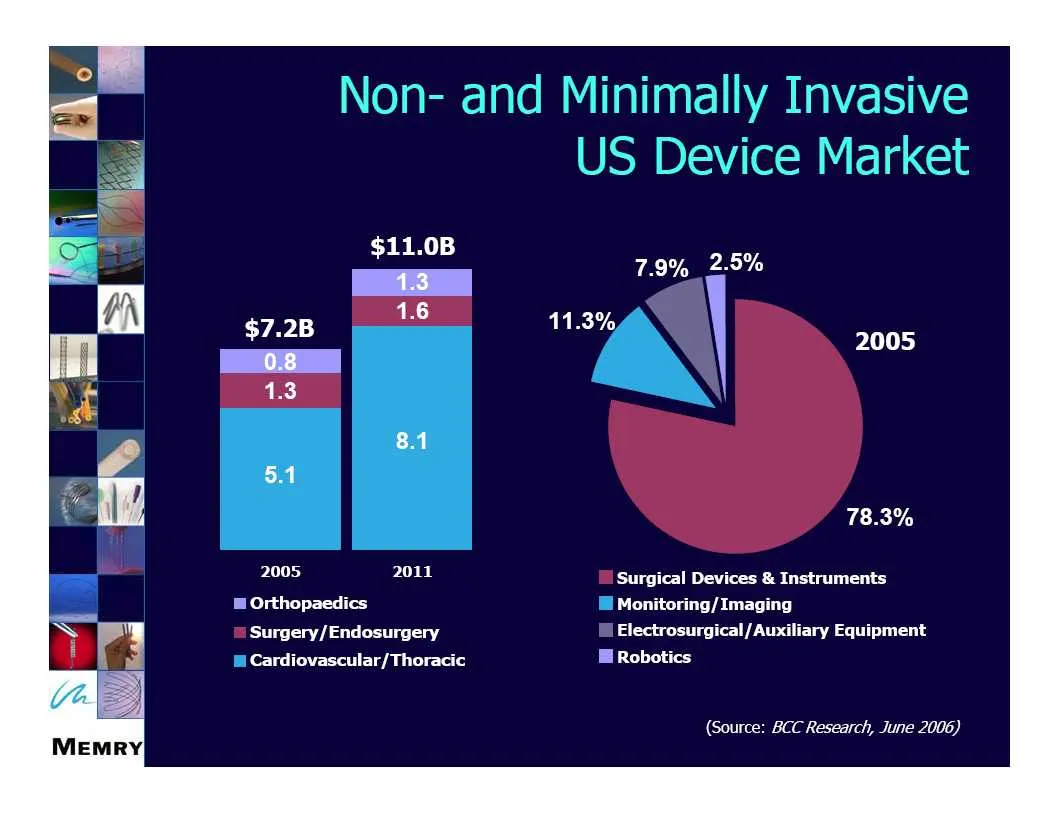
78.3% 2005 @ Surgical Devices & Instruments ™ Orthopaedics Monitoring/Imagin; =m Surgery/Endosurgery i Electrosurgical /Auxiliary Equipment Cardiovascular/Thoracic Robotics (Source: BCC Research, June 2006)
Slide 8: Improving Quality of Healthcare
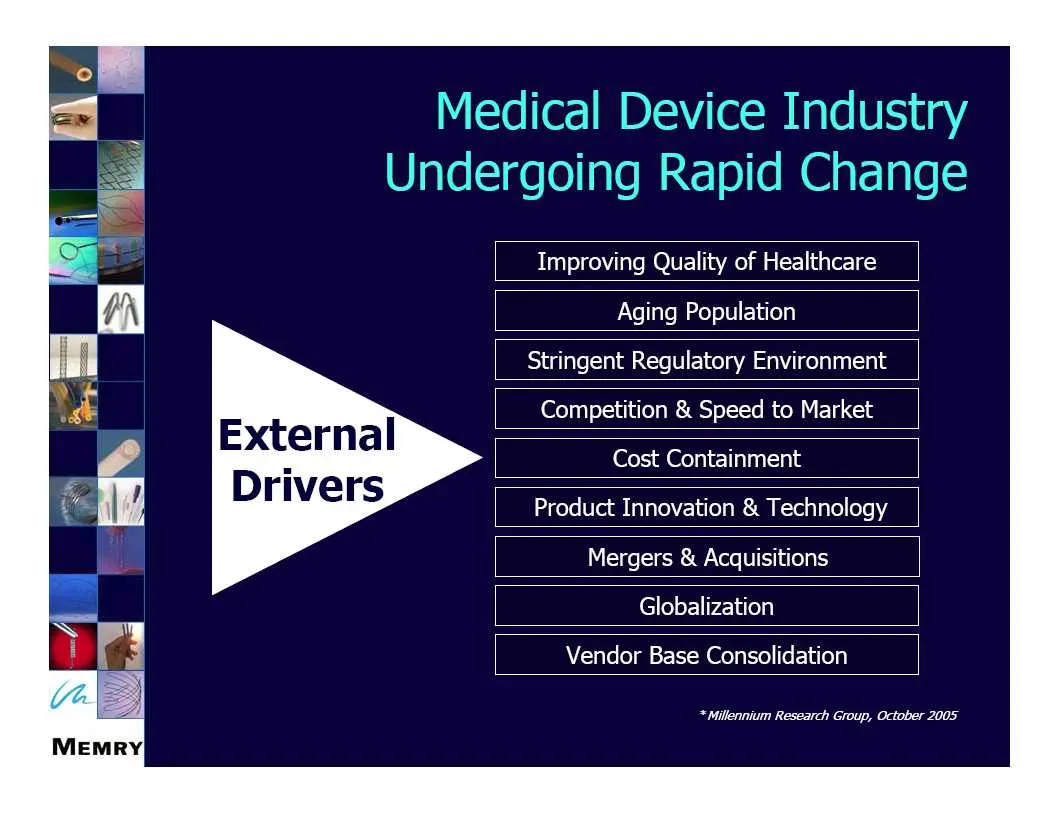
Improving Quality of Healthcare Aging Population Stringent Regulatory Environment Competition & Speed to Market External Drivers Cost Containment Product Innovation & Technology Mergers & Acquisitions Globalization Vendor Base Consolidation * millennium Research Group, October 2005
Slide 9: Device OEMs want to focus on R&D, Technology, Sales & Marketing
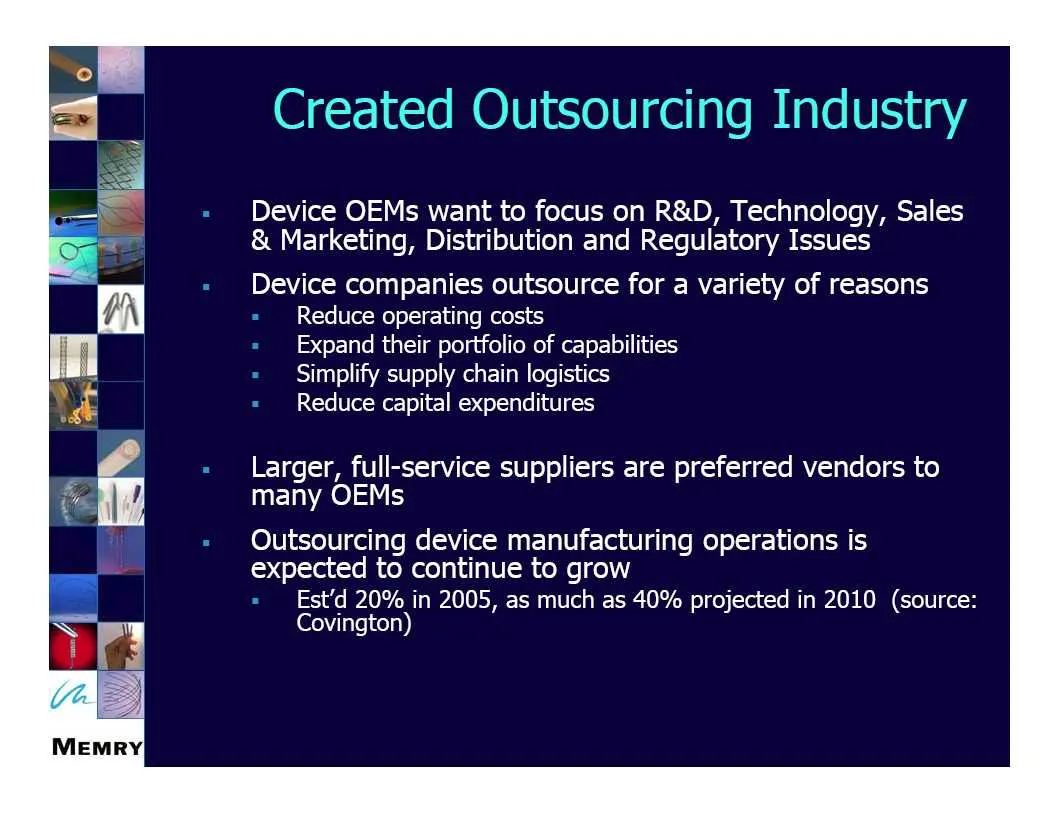
Device OEMs want to focus on R&D, Technology, Sales & Marketing, Distribution and Regulatory Issues Device companies outsource for a variety of reasons Reduce operating costs Expand their portfolio of capabilities Simplify supply chain logistics Reduce capital expenditures Larger, full-service suppl
Slide 10: Full Suite of Capabilities
Full Suite of Capabilities Supply Chain Management Technology Leadership Rapid Turnaround Quality & Competitive Pricing Device Application Knowledge Globalization
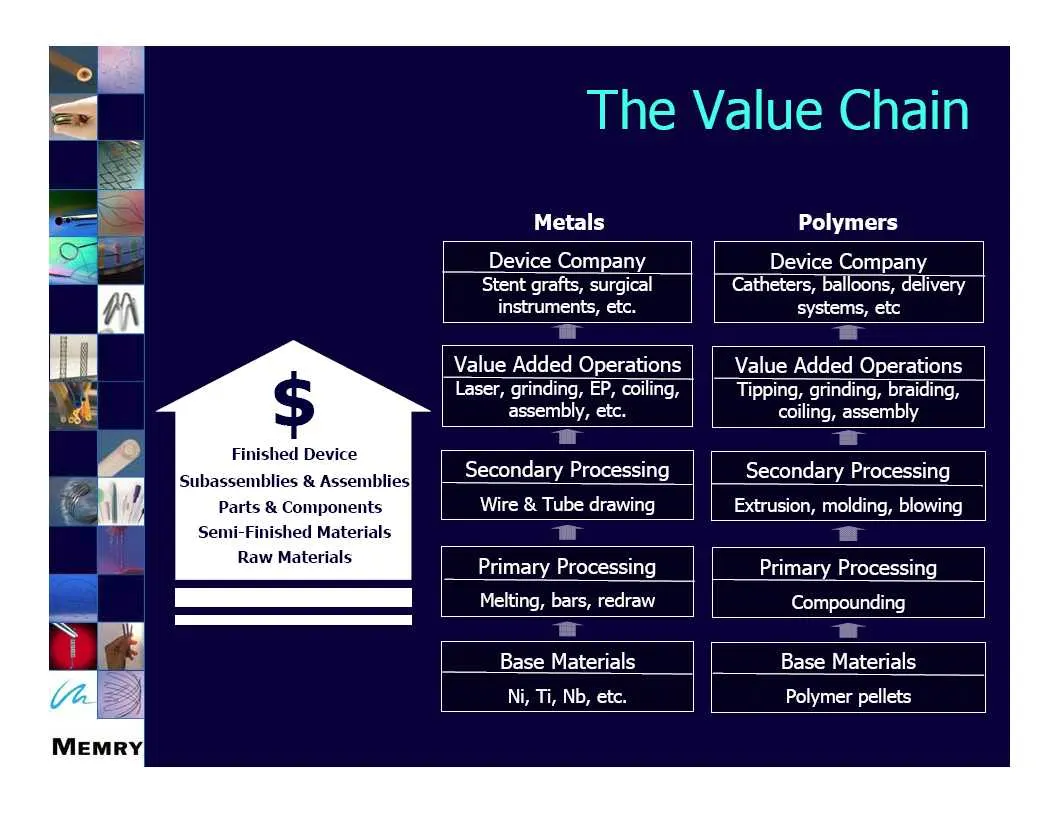
Slide 11: Value chain: from raw materials to finished device
Finished Device Subassemblies & Assemblies| Parts & Components Semi-Finished Materials Raw Materials Metals Polymers Device Company Device Company Stent grafts, surgical instruments, etc. Catheters, balloons, delivery systems, etc J Value Added Operations Value Added Operations Laser, grinding, EP,
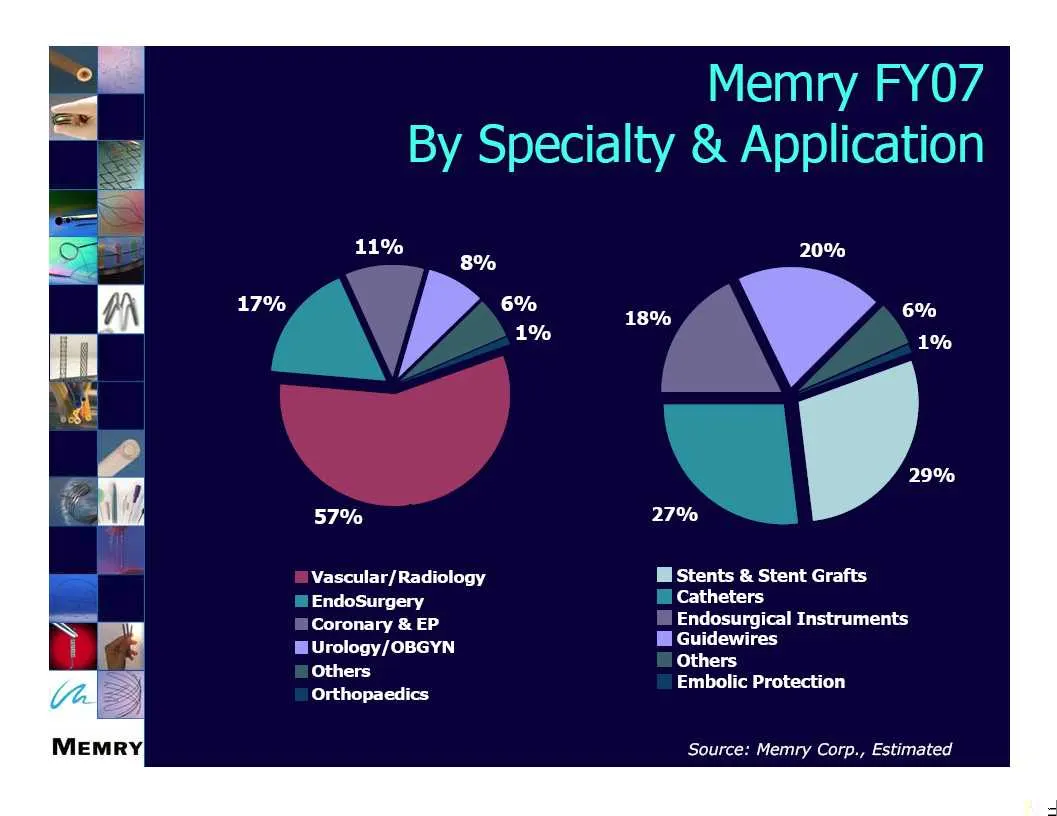
Slide 12: Vascular/Radiology market and product breakdown
57% l™Vascular/Radiology EndoSurgery 5 Coronary & EP i Urology/OBGYN Others Orthopaedics 27% M@ Stents & Stent Grafts Catheters Endosurgical Instruments li Guidewires Others Embolic Protection Source: Memry Corp., Estimated
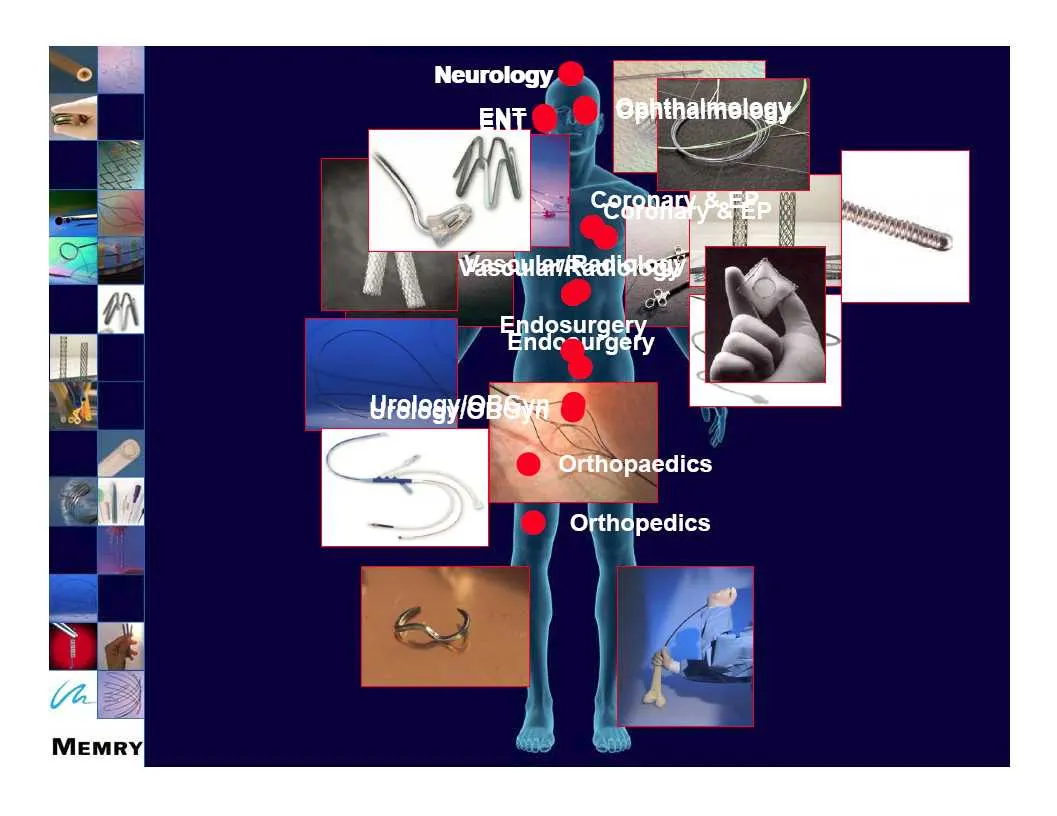
Slide 13: Pritt
Pritt / y Ni ) | paedics O} - le
Slide 14: Laser capability upgrade
Laser capability upgrade Introduction of V2 ultra small diameter nitinol tubing Addition of plasma welding capability Launch of new product line, Putnam Plastics Plus Enhanced capability of guidewire finishing and coating
Slide 15: ISO 13485:2003 Certification for all plants (completed)
ISO 13485:2003 Certification for all plants (completed) Electropolishing capability and facility upgrade Addition of insert molding line for catheter manufacturing Addition of high volume hydrophilic coating line for guidewires Implementation fast turnaround tubing line
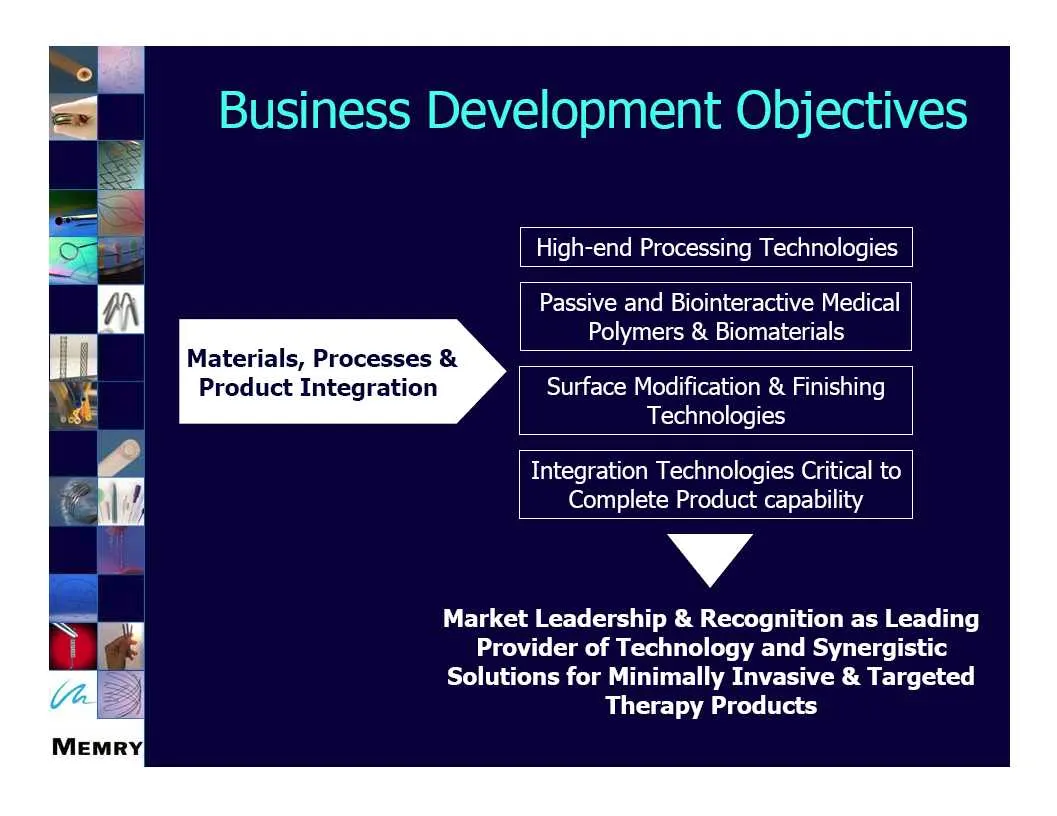
Slide 16: High-end Processing Technologies
High-end Processing Technologies Passive and Biointeractive Medical Polymers & Biomaterials Materials, Processes & Product Integration Surface Modification & Finishing Technologies Integration Technologies Critical to Complete Product capability 4 Market Leadership & Recognition as Leading Provider
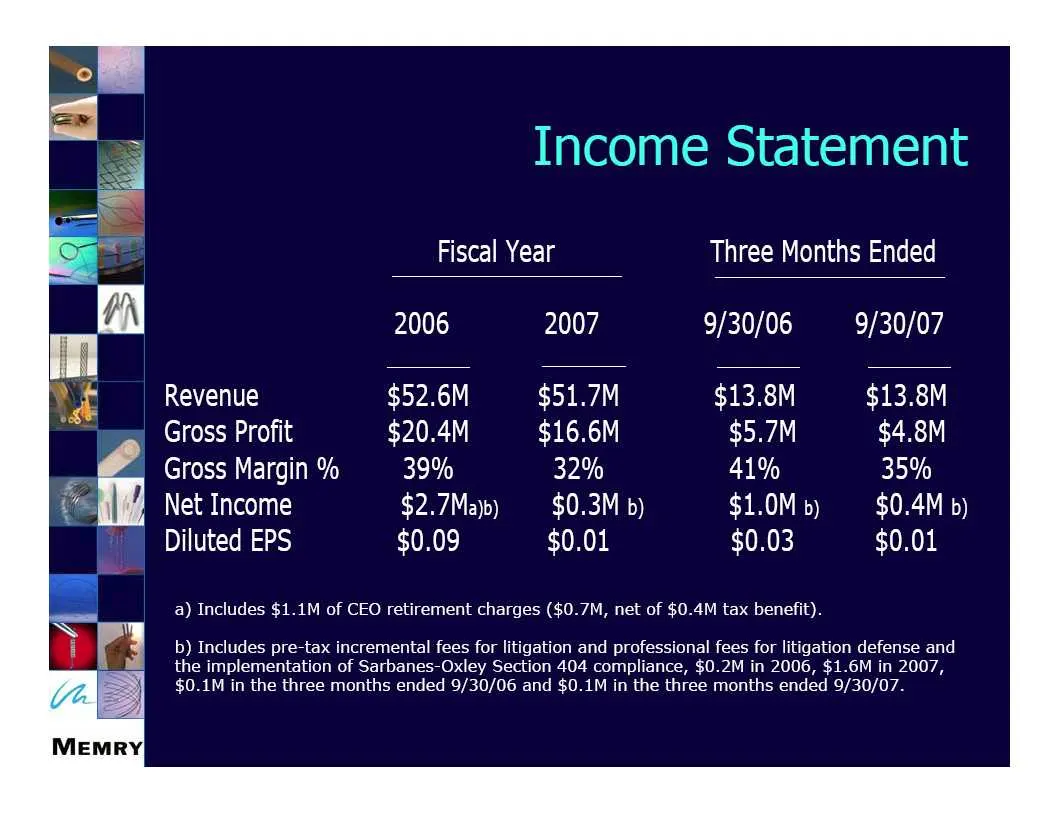
Slide 17: Fiscal Year and Three Months Ended results
Fiscal Year Three Months Ended 2006 2007 9/30/06 9/30/07 Revenue $52.6M $51.7M $13.8M $13.8M Gross Profit $20.4M $16.6M $5.7M $4.8M Gross Margin % 39% 32% 41% 35% Net Income $2.7Ma)b) $0.3M b) $1.0M b) $0.4M b) Diluted EPS $0.09 $0.01 $0.03 $0.01 a) Includes $1.1M of CEO retirement charges ($0.7M, n
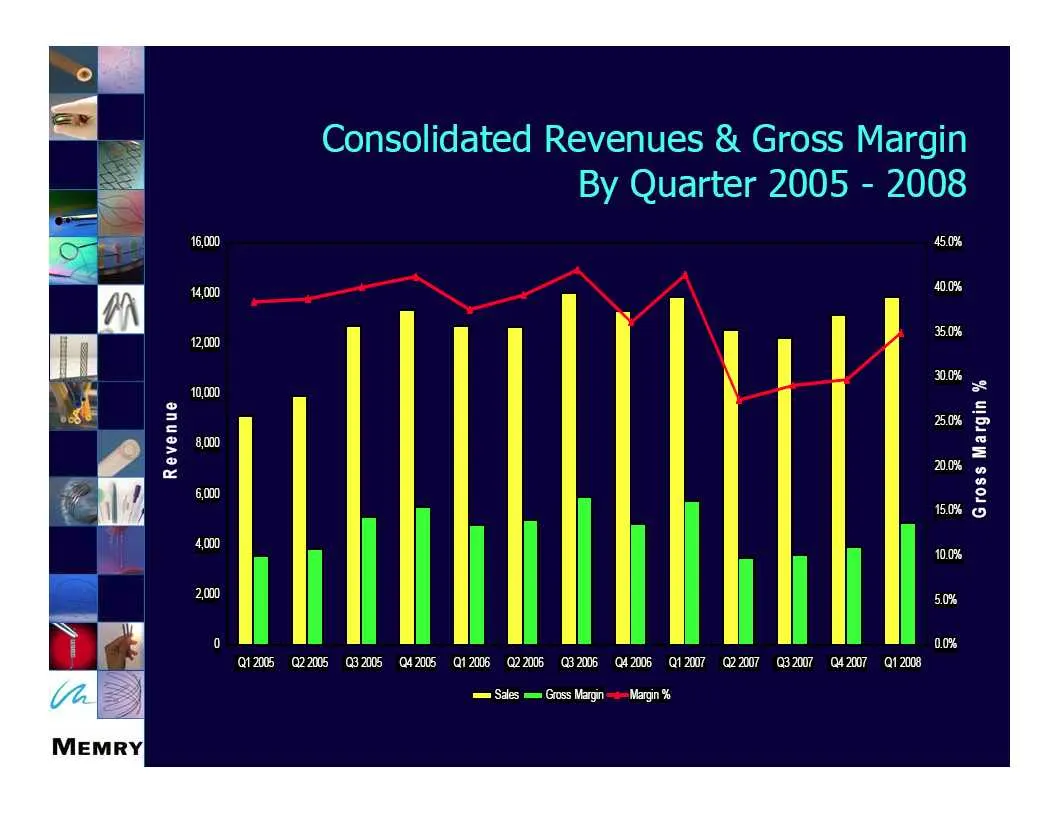
Slide 18: Consolidated Revenues & Gross Margin
Consolidated Revenues & Gross Margin By Quarter 2005 - 2008 45.0% 40.0% s ® RB Ed ° Ss = ° S ° 4 8 2 Gross Margin % g 12005 CRS BANG HAN AIAG 2206 325 CHING I GRA C3207 CAI A128 sm Sales mm Gross Margin —e-=Margin %
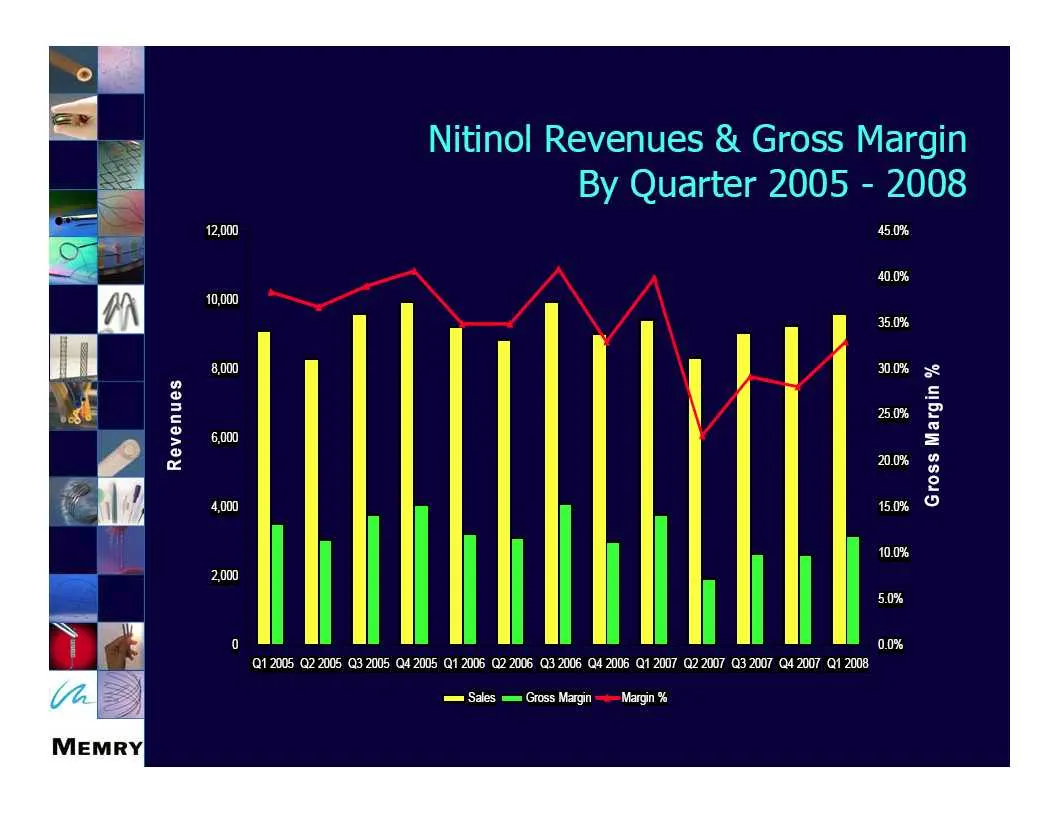
Slide 19: Nitinol Revenues & Gross Margin
Nitinol Revenues & Gross Margin By Quarter 2005 - 2008 45.0% 40.0% 36.0% 30.0% 25.0% 20.0% o o 3 5 o > a “4 Gross Margin % 15.0% 10.0% 5.0% 00% 1.2005 22005 03.2005 G4 2005 Q1 2006 G2 2006 032006 G4 2006 Q1 2007 G2 2007 a3 2007 G4 2007 a1 2008 Sales =x Gross Margin Margin %
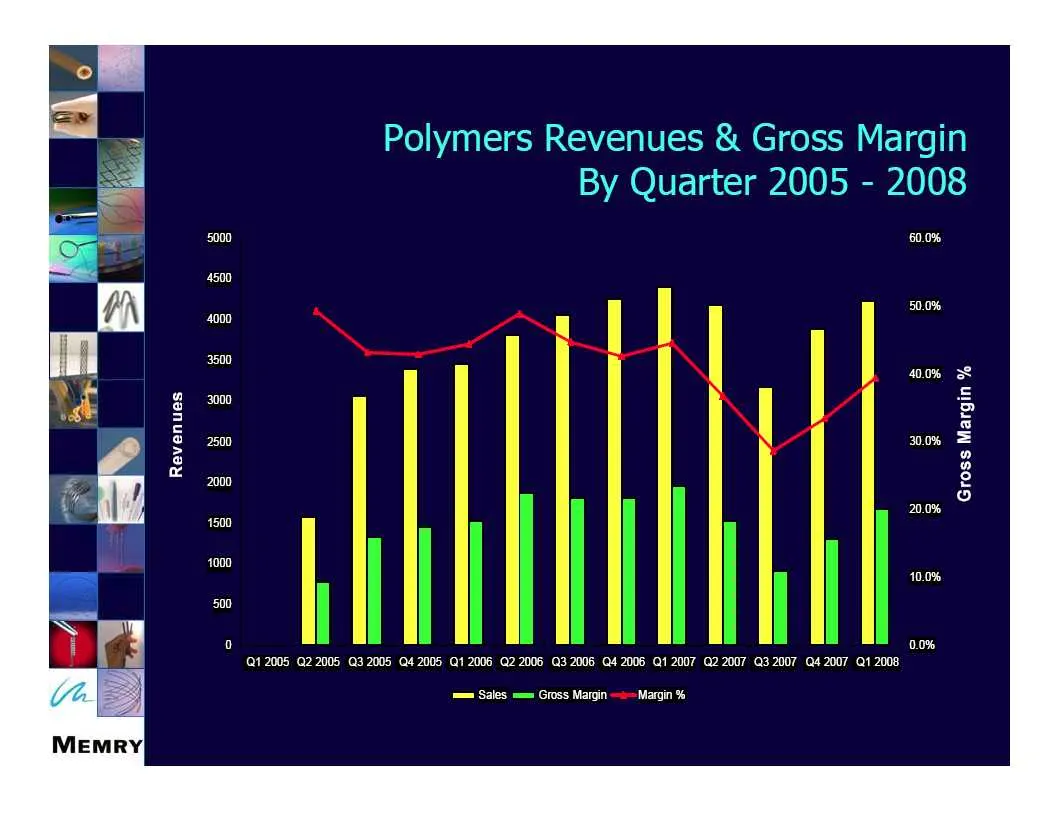
Slide 20: Polymers Revenues & Gross Margin
Polymers Revenues & Gross Margin By Quarter 2005 - 2008 60.0% x 4 £ g 2 5 = s = ry 3 « 8 ° L L - 0.0% Q1 2005 2.2005 3 2005 G4 2005 Q1 2006 G2 2006 Q3 2006 G4 2006 Q1 2007 G2 2007 G3 2007 Q4 2007 Qt 2008 m Sales mem Gross Margin —e=Margin %
Slide 21: Invest in areas to generate revenue growth
Invest in areas to generate revenue growth Development Projects New Technologies Sales & Marketing Look for cost improvement opportunities Operations Supply Chain Management Administrative Overhead Achieve process efficiencies
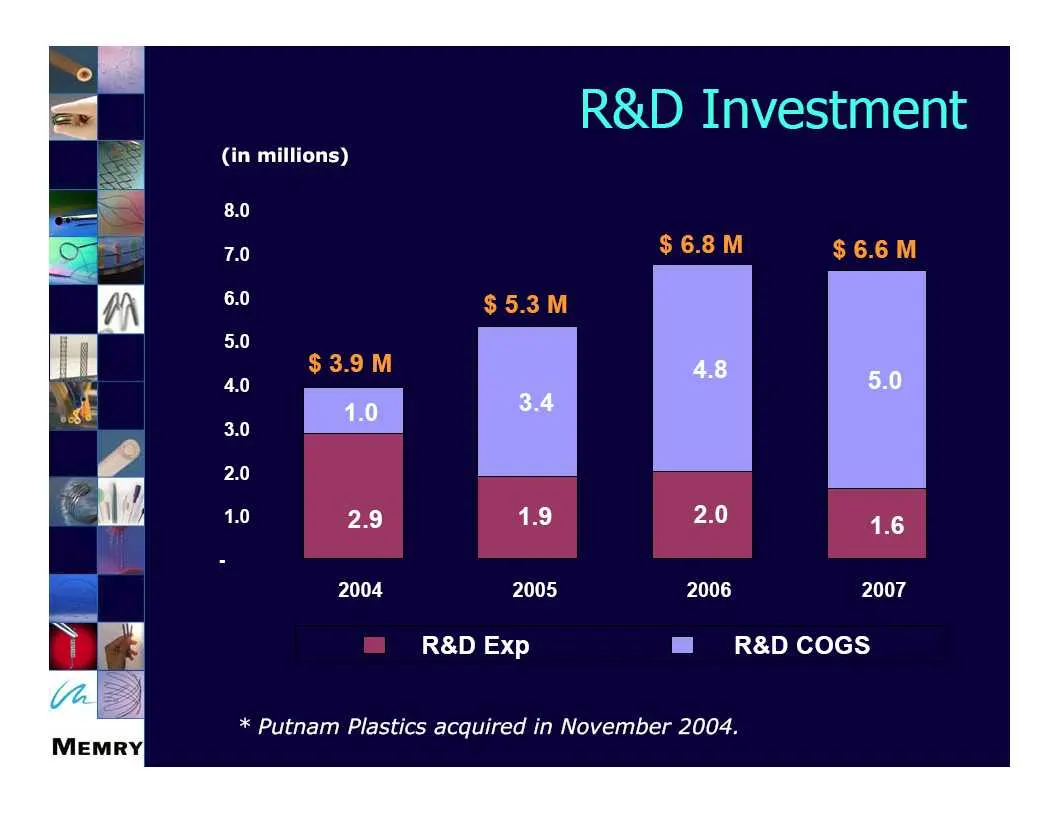
Slide 22: R&D Investment
R&D Investment (in millions) 8.0 7.0 6.0 5.0 4.0 3.0 2.0 1.0 2007 R&D COGS * Putnam Plastics acquired in November 2004.
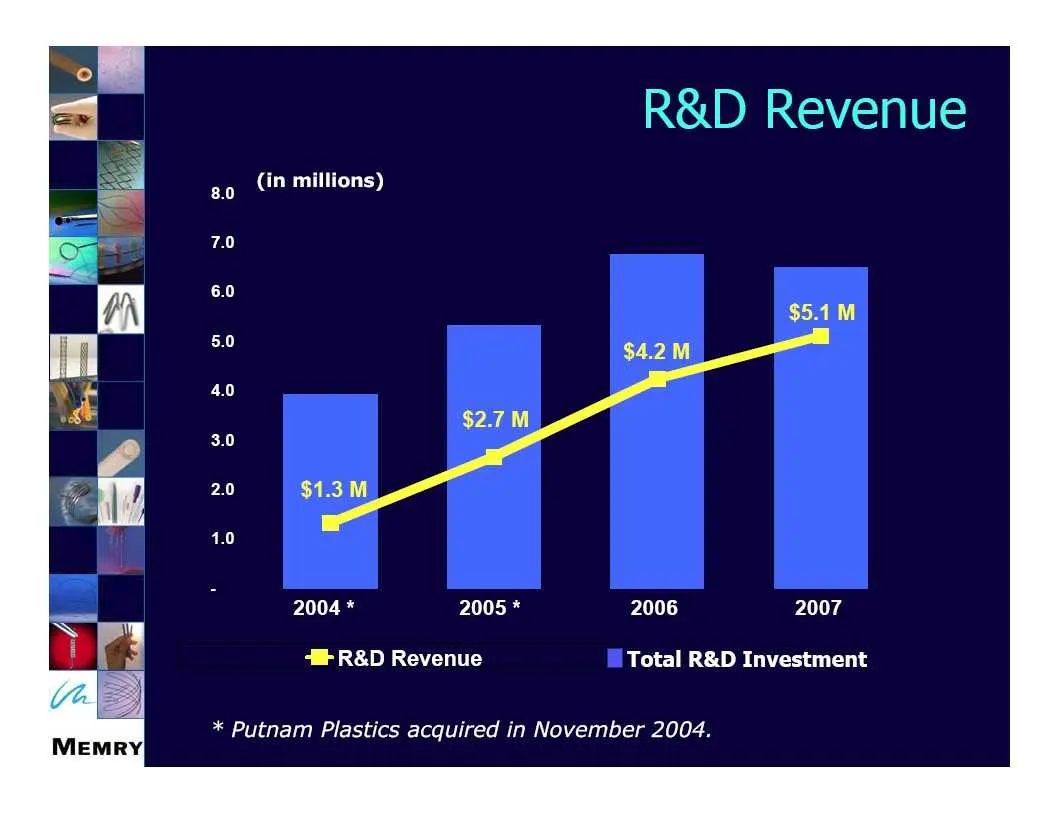
Slide 23: R&D Revenue
R&D Revenue AD (in millions) 7.0 6.0 5.0 4.0 3.0 2.0 2004 * 2005 * 2006 2007 4H R&D Revenue Total R&D Investment * Putnam Plastics acquired in November 2004.
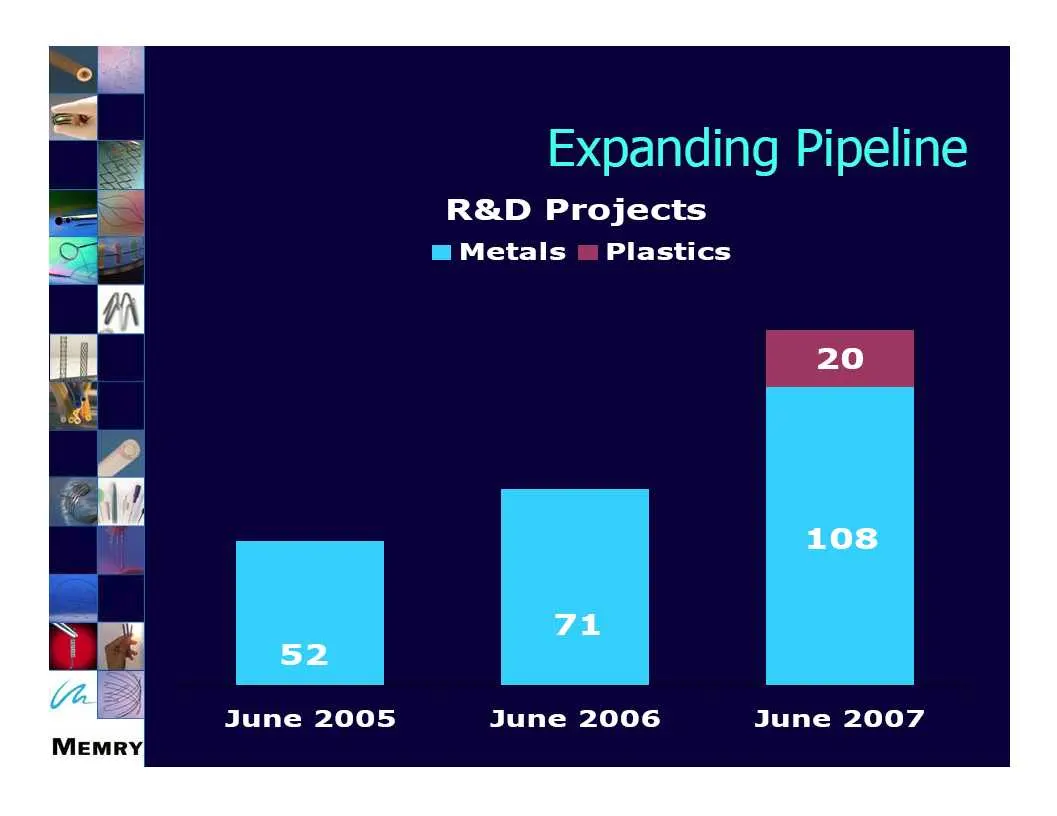
Slide 24: R&D Projects
R&D Projects Metals © Plastics 71 52 June 2005 June 2006 June 2007
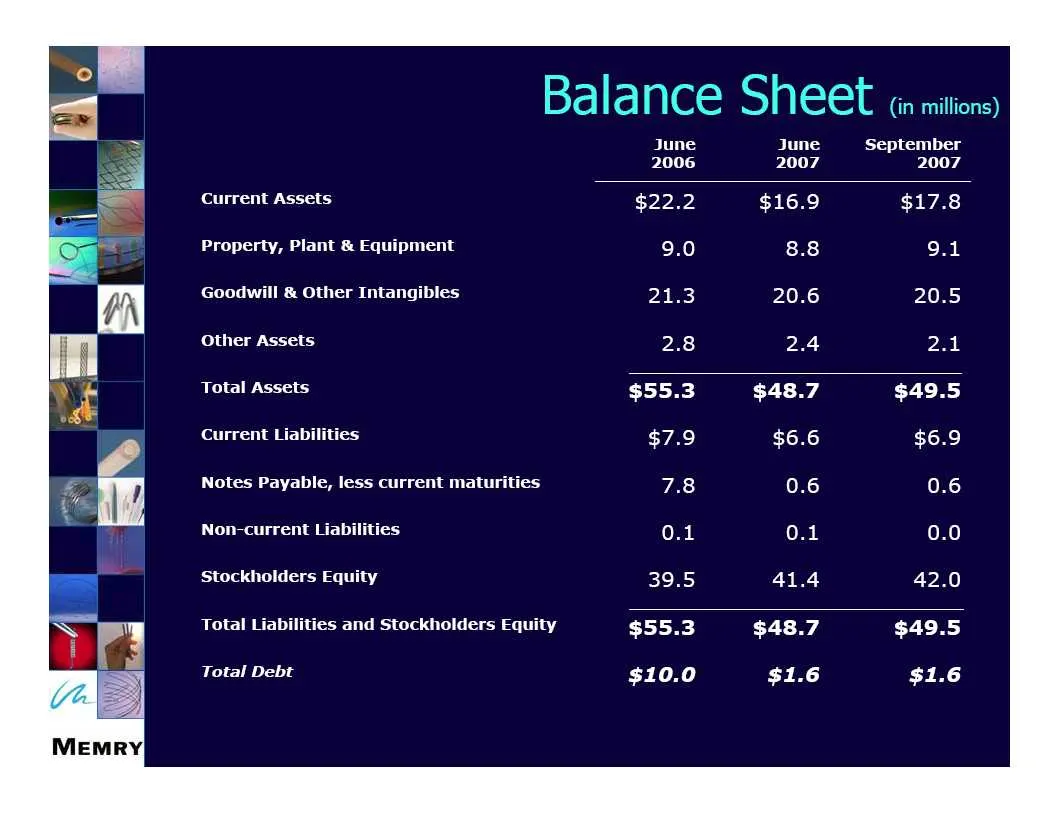
Slide 25: Current Assets
Current Assets Property, Plant & Equipment Goodwill & Other Intangibles Other Assets Total Assets Current Liabilities Notes Payable, less current maturities Non-current Liabilities Stockholders Equity Total Liabilities and Stockholders Equity Total Debt September 2007 $17.8 9.1 20.5 Pars
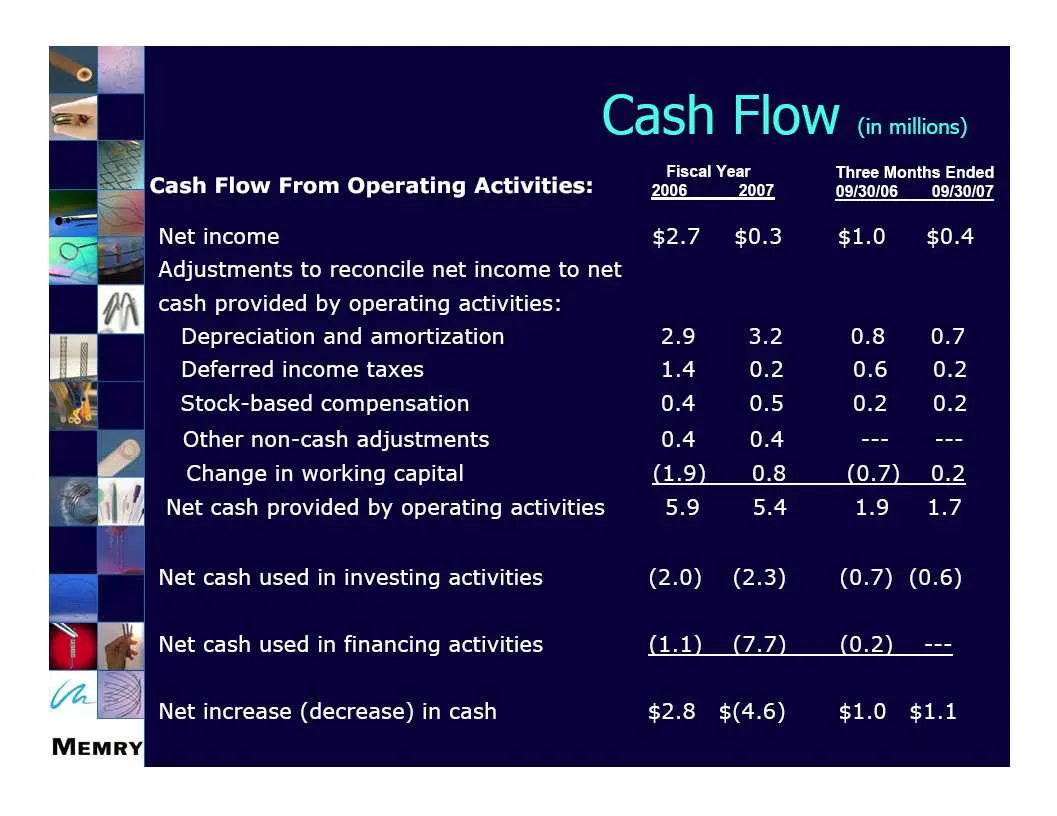
Slide 26: Cash Flow From Operating Activities
= | Cash Flow From Operating Activities: _ _ Net income ral Adjustments to reconcile net income to net cash provided by operating activities: Depreciation and amortization Deferred income taxes Stock-based compensation Other non-cash adjustments Change in working capital Net cash provided by operati
Slide 27: EBITDA and Adjusted EBITDA definitions
In this presentation, the Company refers to EBITDA and Adjusted EBITDA, financial measures that are not recognized under accounting principles generally accepted in the United States of America (“GAAP”). The Company defines EBITDA as earnings before income taxes, interest income (expense), net, depr
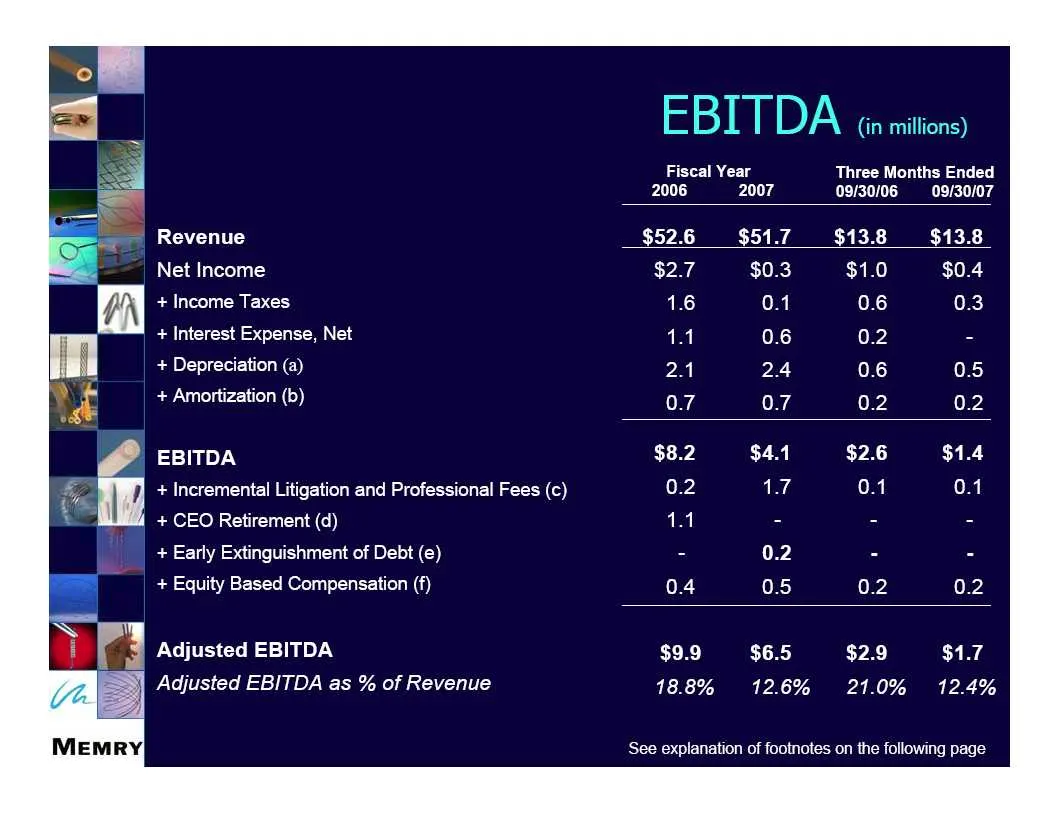
Slide 28: Fiscal Year Three Months Ended EBITDA reconciliation
Fiscal Year Three Months Ended 2006 2007 09/30/06 09/30/07 — _ Revenue $52.6 $51.7 $13.8 $13.8 Net Income $2.7 $0.3 $1.0 $0.4 + Income Taxes 1.6 0.1 0.6 0.3 + Interest Expense, Net 11 0.6 0.2 = + Depreciation (a) 24 24 0.6 0.5 + Amortization (b) 07 07 0.2 0.2 EBITDA $4.1 $2.6 $1.4 + Incremental Liti
Slide 29: EBITDA footnotes
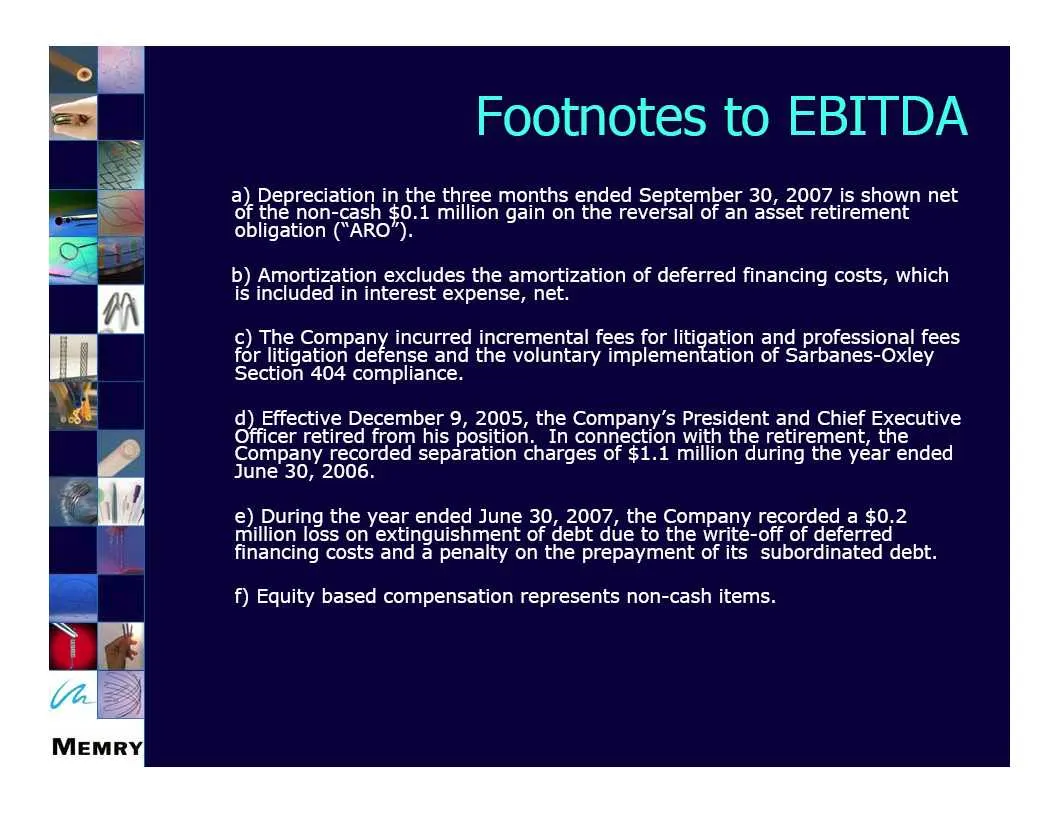
2 Depreciation in the three months ended September 30, 2007 is shown net of the non-cash $0.1 million gain on the reversal of an asset retirement obligation (“ARO”). b) Amortization excludes the amortization of deferred financing costs, which is included in interest expense, net. c) The Company incu
Slide 30: Compelling Value Proposition
Compelling Value Proposition Innovative, Strategic Technology Solutions Large and Growing Medical Device Market Strong Growing Pipeline Strong Balance Sheet Strong Cash Generator Building Momentum Trading Near Book Value
Slide 31: Memry Capability / PPC Capability
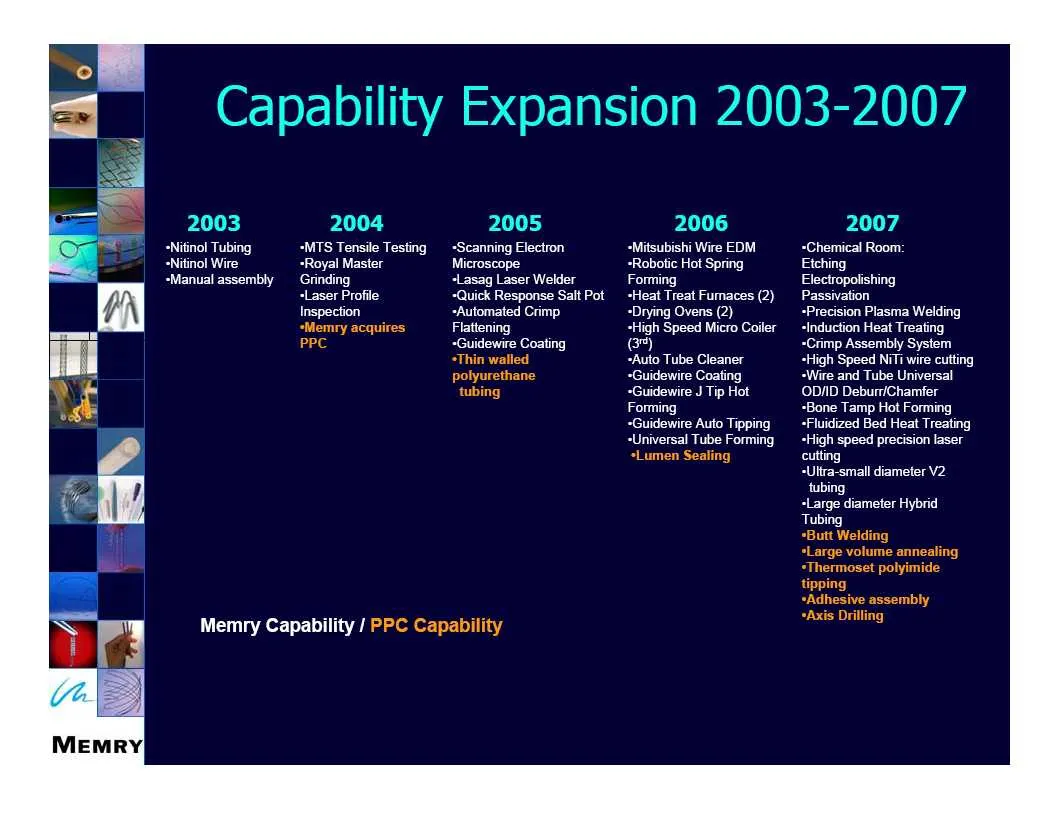
-Nifinol Tubing -MTS Tensile Testing *Nifinol Wire -Royal Master -Manual assembly Grinding -Laser Profile Inspection *Memry acquires PPC -Scanning Electron Microscope -Lasag Laser Welder -Quick Response Salt Pot Automated Crimp Flattening -Guidewire Coating “Thin walled polyurethane tubing Memry Cap
Source: SEC EDGAR · 8-K filed Nov 13, 2007