Southwest Bancorp — Stifel Nicolaus Conference 2007
25 slides from Southwest Bancorp's conference presentation, Dec 4, 2007
Slide 1: Investor Presentation December 6, 2007
Investor Presentation December 6, 2007 NASDAQ Global Select - OKSB
Slide 2: Forward Looking Statements
1 Forward Looking Statements This presentation includes forward-looking statements such as: statements of Southwest's goals, intentions, and expectations; estimates of risks and of future costs and benefits; expectations regarding future financial performance of Southwest and its operating segments;
Slide 3: Corporate Profile
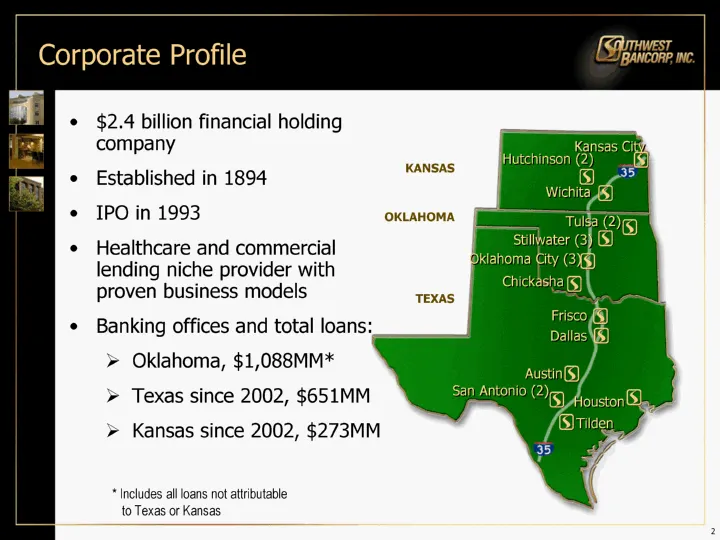
3 Corporate Profile $2.4 billion financial holding company Established in 1894 IPO in 1993 Healthcare and commercial lending niche provider with proven business models Banking offices and total loans: Oklahoma, $1,088MM* Texas since 2002, $651MM Kansas since 2002, $273MM KANSAS OKLAHOMA TEXAS Kansas
Slide 4: Successful Growth Strategy Results
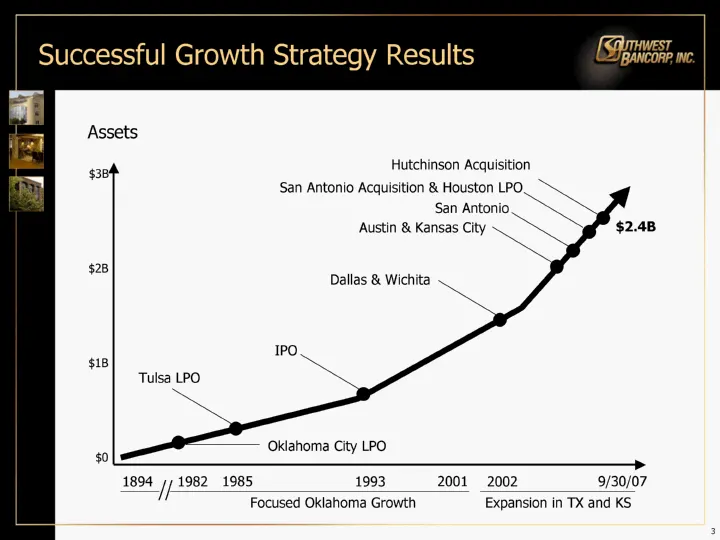
5 Successful Growth Strategy Results Assets $3B 1894 1982 1993 Focused Oklahoma Growth Expansion in TX and KS $0 $1B $2.4B San Antonio Acquisition & Houston LPO San Antonio Austin & Kansas City Dallas & Wichita IPO Oklahoma City LPO Tulsa LPO 2002 1985 9/30/07 2001 $2B Hutchinson Acquisition
Slide 5: Impressive Performance Record
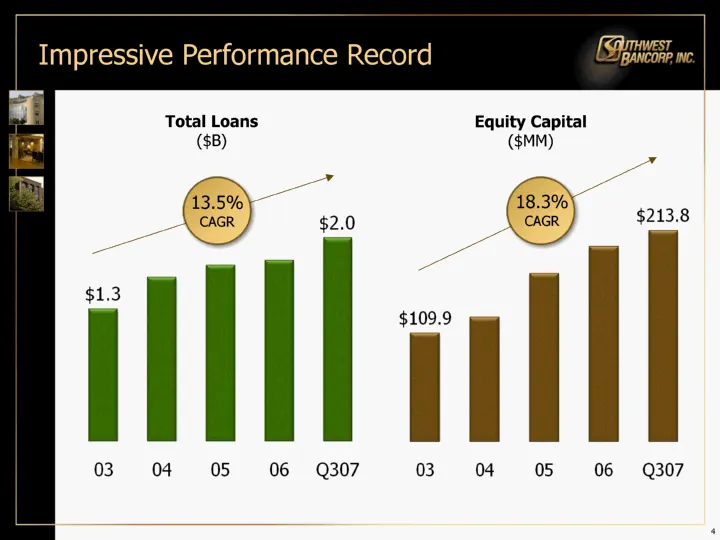
7 Impressive Performance Record 13.5% CAGR Total Loans ($B) Equity Capital ($MM) 18.3% CAGR
Slide 6: Risk Trends
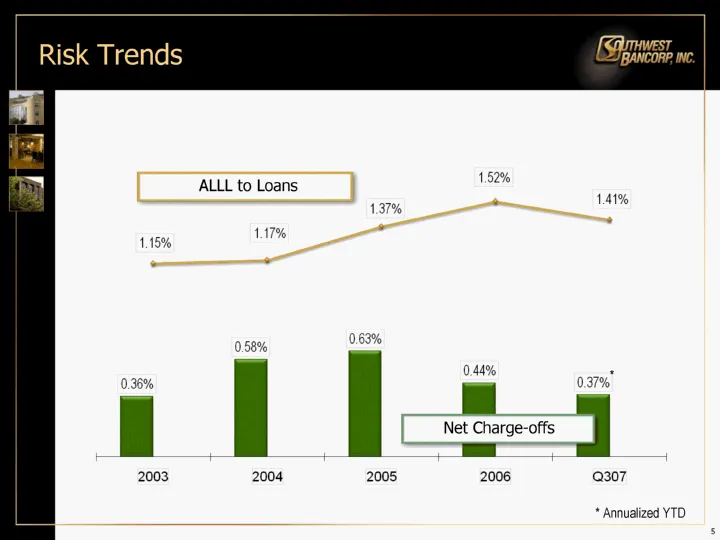
9 Risk Trends Net Charge-offs ALLL to Loans * * Annualized YTD
Slide 7: How Do We Grow?
11 How Do We Grow? Niche Banking* Community Banking** Secondary Market and other lending initiatives * Top Line Revenue Initiative ** Deposit / Efficient Funds Gathering
Slide 8: Niche Banking Model Generates Loans
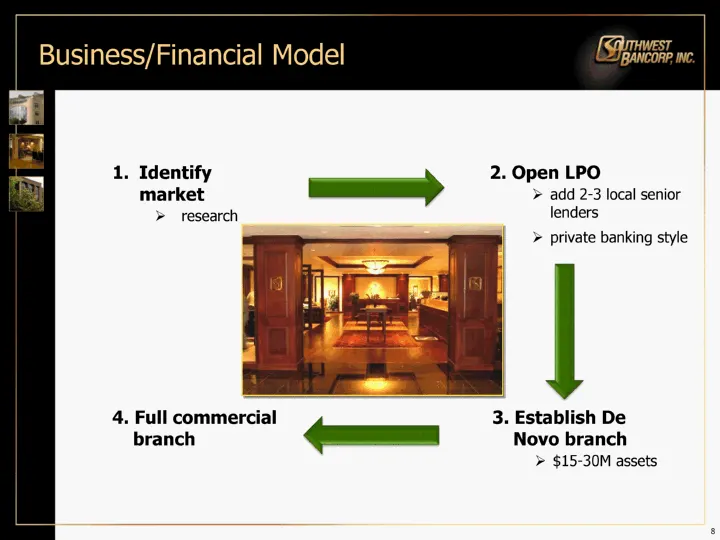
13 Niche Banking Model Generates Loans Primary lending targets: Healthcare Commercial Commercial Real Estate Select desirable markets Identify & recruit key, experienced senior lenders Implement model & grow
Slide 9: Business/Financial Model
15 Business/Financial Model 2. Open LPO add 2-3 local senior lenders private banking style 3. Establish De Novo branch $15-30M assets 4. Full commercial branch Identify market research
Slide 10: Branch Model at Work Frisco: A Closer Look
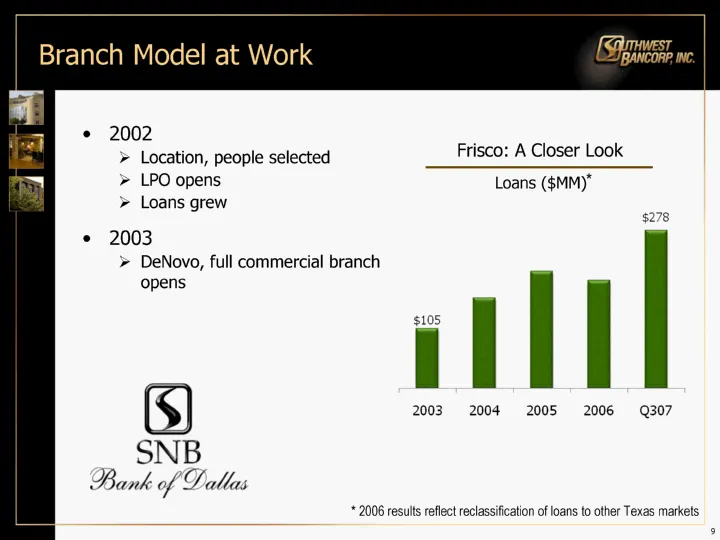
2002 Location, people selected LPO opens Loans grew 2003 DeNovo, full commercial branch opens 17 Branch Model at Work Frisco: A Closer Look Loans ($MM) * 2006 results reflect reclassification of loans to other Texas markets *
Slide 11: Implemented in Texas: Branch Model at Work
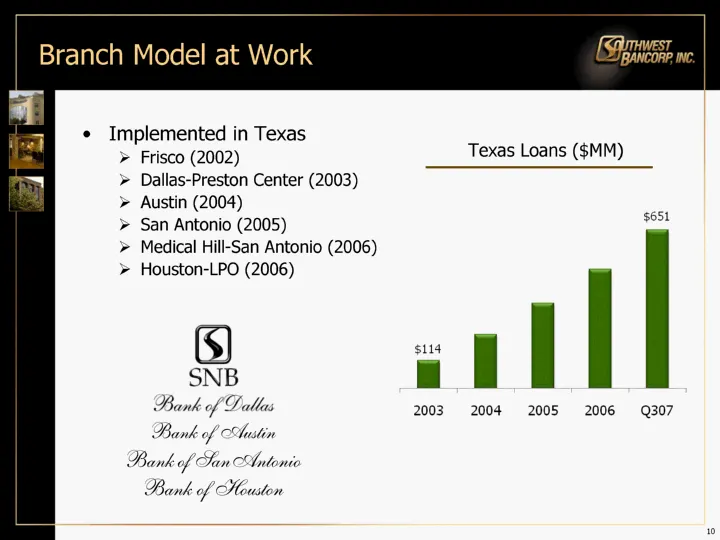
Implemented in Texas Frisco (2002) Dallas-Preston Center (2003) Austin (2004) San Antonio (2005) Medical Hill-San Antonio (2006) Houston-LPO (2006) 19 Branch Model at Work Texas Loans ($MM)
Slide 12: Effective Community Banking
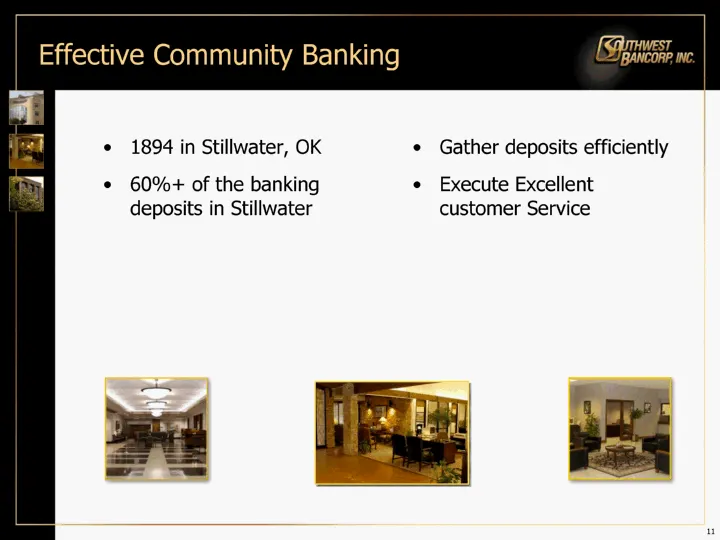
21 Effective Community Banking Gather deposits efficiently Execute Excellent customer Service 1894 in Stillwater, OK 60%+ of the banking deposits in Stillwater
Slide 13: Efficient Funding
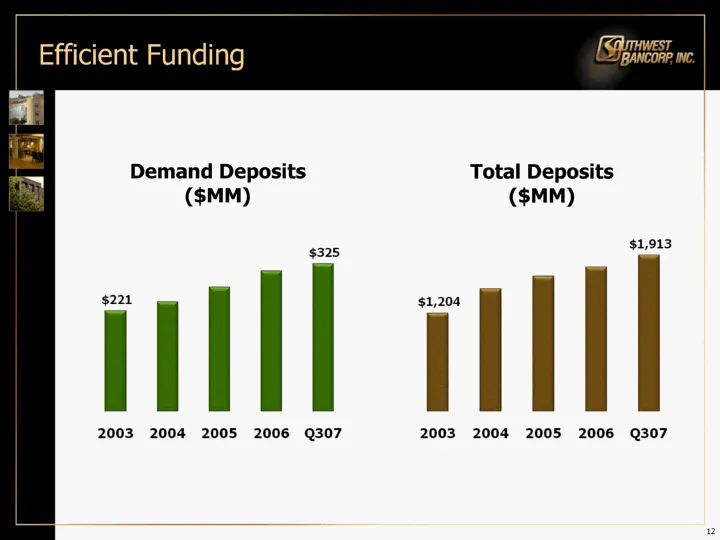
23 Efficient Funding Demand Deposits ($MM) Total Deposits ($MM)
Slide 14: Key Initiatives in Capital Utilization
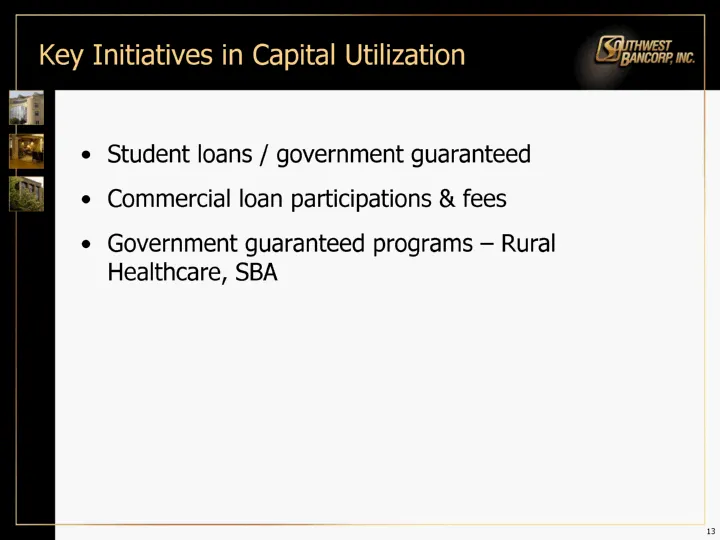
25 Key Initiatives in Capital Utilization Student loans / government guaranteed Commercial loan participations & fees Government guaranteed programs - Rural Healthcare, SBA
Slide 15: Growth Strategy Summarized
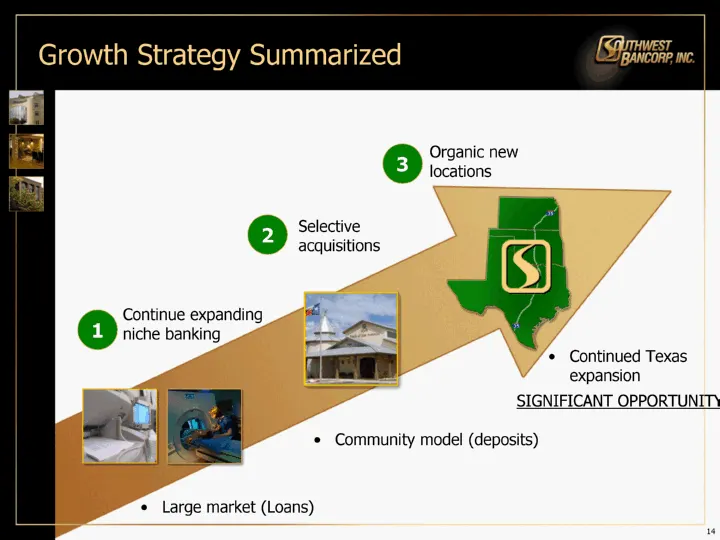
27 Growth Strategy Summarized Continue expanding niche banking Large market (Loans) 1 Selective acquisitions Community model (deposits) 2 Organic new locations Continued Texas expansion 3 SIGNIFICANT OPPORTUNITY
Slide 16: Strategic Success of Portfolio Growth
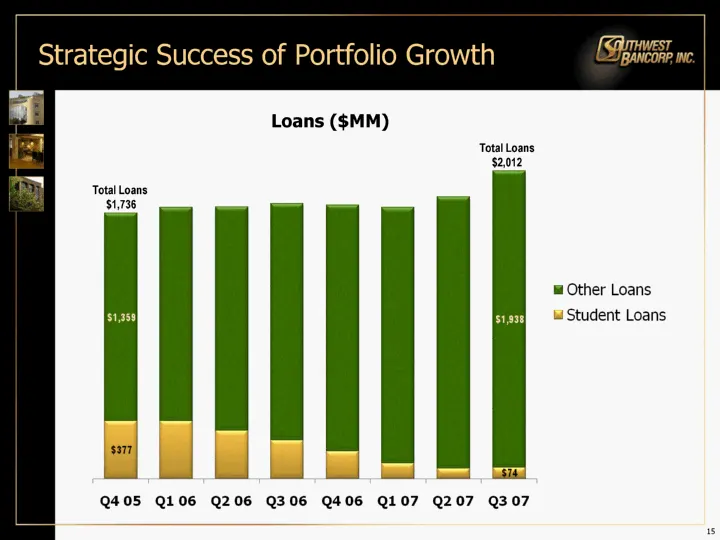
29 Strategic Success of Portfolio Growth Total Loans $1,736 Total Loans $2,012 Loans ($MM)
Slide 17: Loan Portfolio Composition
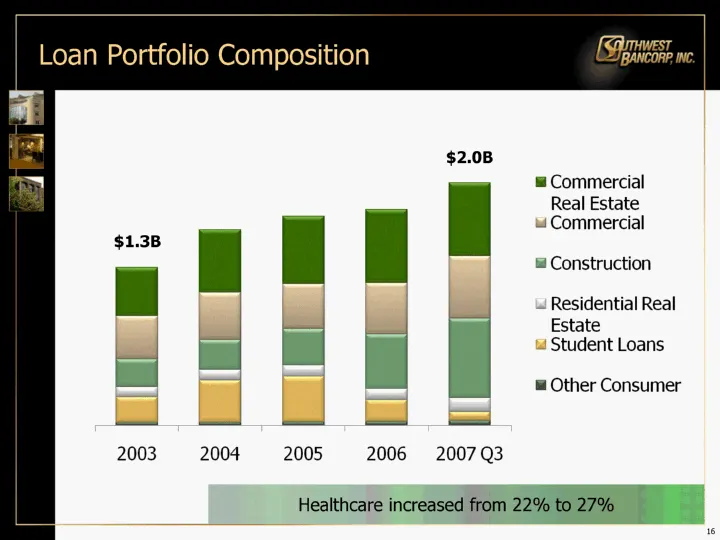
31 Loan Portfolio Composition $2.0B $1.3B Healthcare increased from 22% to 27%
Slide 18: Reserve for Unfunded Commitments ($000)
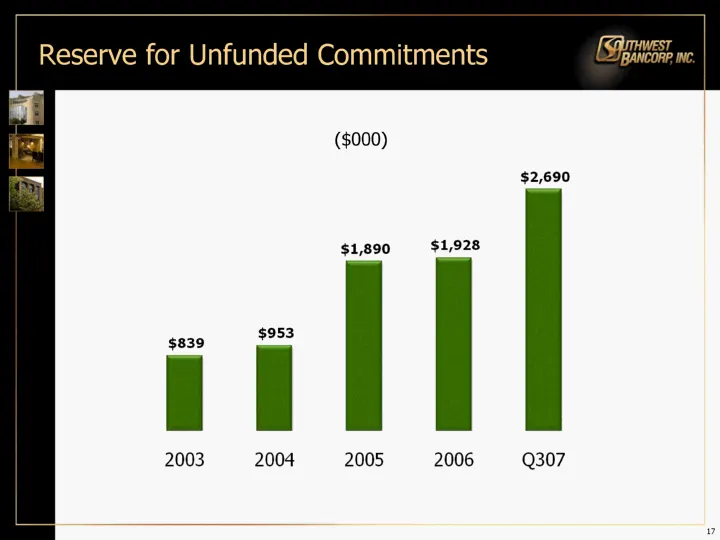
33 Reserve for Unfunded Commitments ($000)
Slide 19: Proven Ability to Resolve Credits
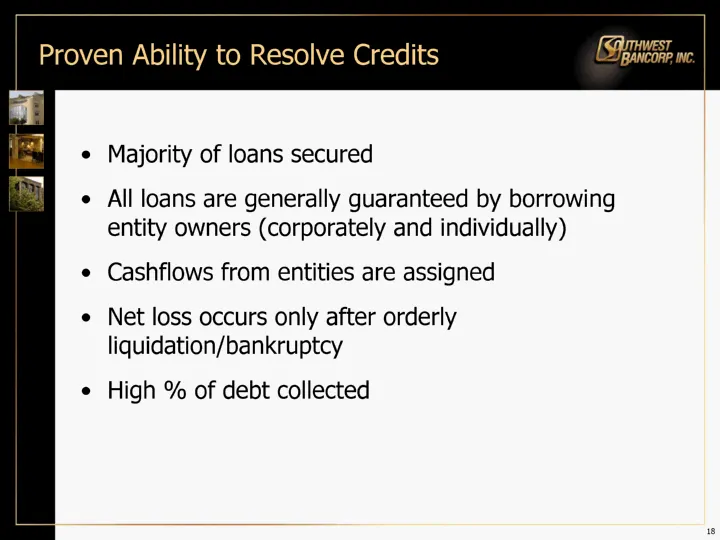
35 Proven Ability to Resolve Credits Majority of loans secured All loans are generally guaranteed by borrowing entity owners (corporately and individually) Cashflows from entities are assigned Net loss occurs only after orderly liquidation/bankruptcy High % of debt collected
Slide 20: Credit Approval Process
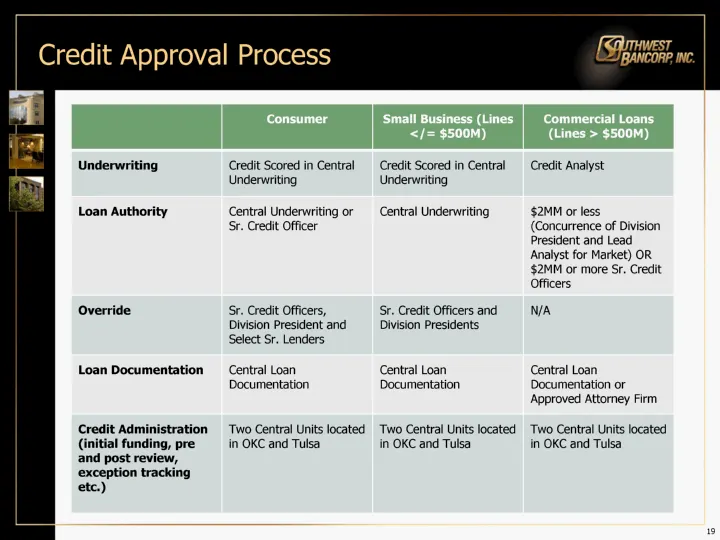
37 Credit Approval Process Consumer Small Business (Lines </= $500M) Commercial Loans (Lines > $500M) Underwriting Credit Scored in Central Underwriting Credit Scored in Central Underwriting Credit Analyst Loan Authority Central Underwriting or Sr. Credit Officer Central Underwriting $2MM or less (C
Slide 21: Differentiator = Experienced Underwriting
39 Differentiator = Experienced Underwriting All Senior Credit Officers have a minimum of twenty years experience in credit-related fields Credit team experience includes: National Bank Examining Bank Management Problem Loan Workout Credit Underwriting Risk Management
Slide 22: Semi Annual Economic Review
41 Semi Annual Economic Review* Panel of top executives CEO, CLO Senior credit officers Board members Extensive review of business models in all markets Real estate trends/economy/politics Healthcare trends/economy/politics Analysis of risk trends, credit limits Short-term actions * Loan Portfolio A
Slide 23: Strategic Success of Portfolio Growth
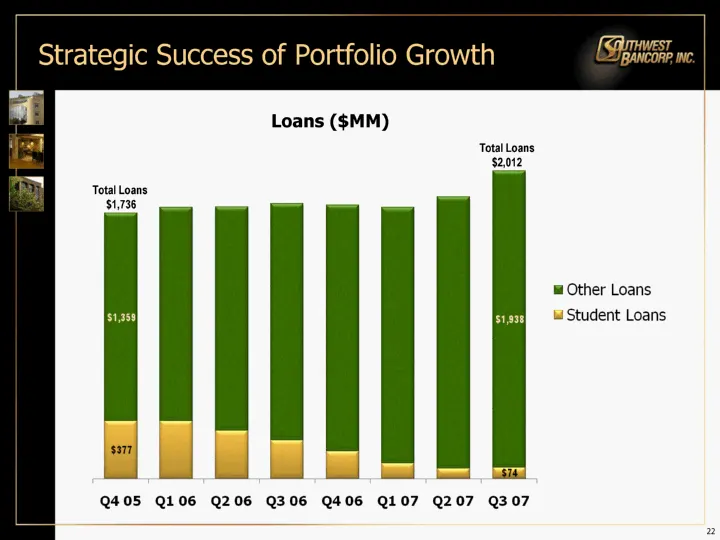
43 Strategic Success of Portfolio Growth Total Loans $1,736 Total Loans $2,012 Loans ($MM)
Slide 24: Summary of Performance Results
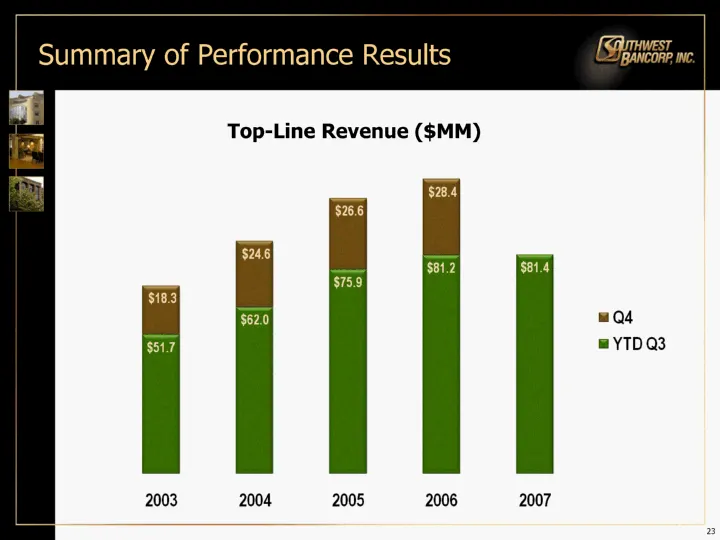
45 Summary of Performance Results Top-Line Revenue ($MM)
Slide 25: (DEES me
(DEES me Dis = ap December 6, 2007
Source: SEC EDGAR · 8-K filed Dec 4, 2007
More decks from Southwest Bancorp Inc
 Merger or Acquisition (September 2017)41 slides · Sep 5, 2017
 Q2 2017 Earnings Presentation31 slides · Jul 25, 2017
 Merger or Acquisition (May 2017)43 slides · May 15, 2017
 Q1 2017 Earnings Presentation31 slides · Apr 25, 2017
 Merger or Acquisition (February 2017)45 slides · Feb 8, 2017
 Q4 2016 Earnings Presentation32 slides · Jan 24, 2017