Goodrich — Lehman Brothers Industrial Select Conference 2006
21 slides from Goodrich's conference presentation, Feb 14, 2006
Slide 1: Lehman Brothers Industrial Select Conference
Lehman Brothers Industrial Select Conference February 15, 2006 Marshall Larsen Chairman, President and CEO
Slide 2: Forward Looking Statements
Certain statements made in this presentation are forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 regarding the Company's future plans, objectives and expected performance. The Company cautions readers that any such forward- looking statements are
Slide 3: Goodrich Value Proposition and Key Performance Drivers
Goodrich Value Proposition and Key Performance Drivers
Slide 4: The Value Proposition for Goodrich 2006 - 2010 Expectations
Great market positions Good top line growth Substantial margin improvement opportunity Significant cash flow improvement expected in 2007 Sustainable income growth beyond the OE cycle The Value Proposition for Goodrich 2006 - 2010 Expectations
Slide 5: Goodrich - Key Market Leadership Positions
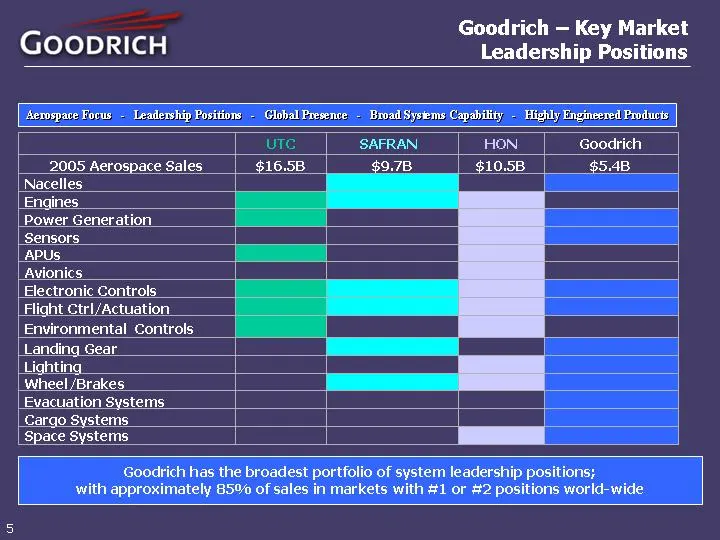
Goodrich - Key Market Leadership Positions $5.4B $10.5B $9.7B $16.5B 2005 Aerospace Sales Sensors Cargo Systems APUs Wheel/Brakes Evacuation Systems Lighting Space Systems Landing Gear Environmental Controls Flight Ctrl/Actuation Electronic Controls Avionics Power Generation Engines Nacelles Goodric
Slide 6: Full Year 2005 Sales by Market Channel
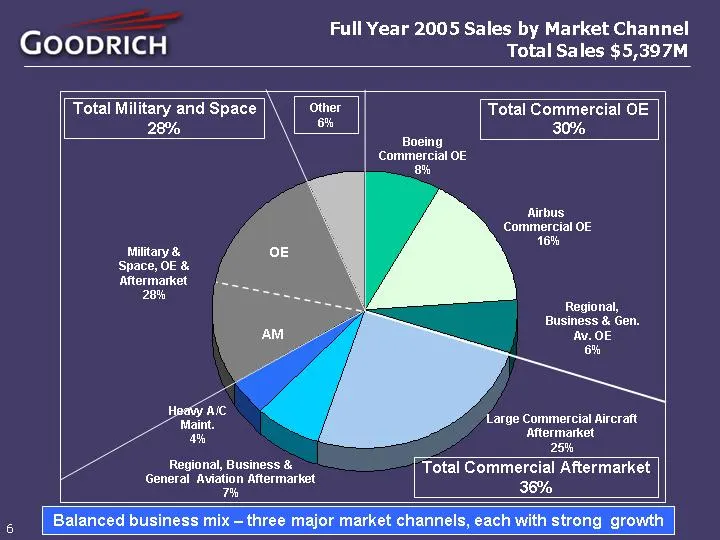
Boeing Airbus Regional, Business, GA OE Commercial A/C Aftermarket Regional, Business & GA Aftmkt Heavy Maintenance Military Other East 8 16 6 25 7 4 28 6 Full Year 2005 Sales by Market Channel Total Sales $5,397M Large Commercial Aircraft Aftermarket 25% Regional, Business & General Aviation Afterm
Slide 7: Top Line Growth - Large Commercial OE Market
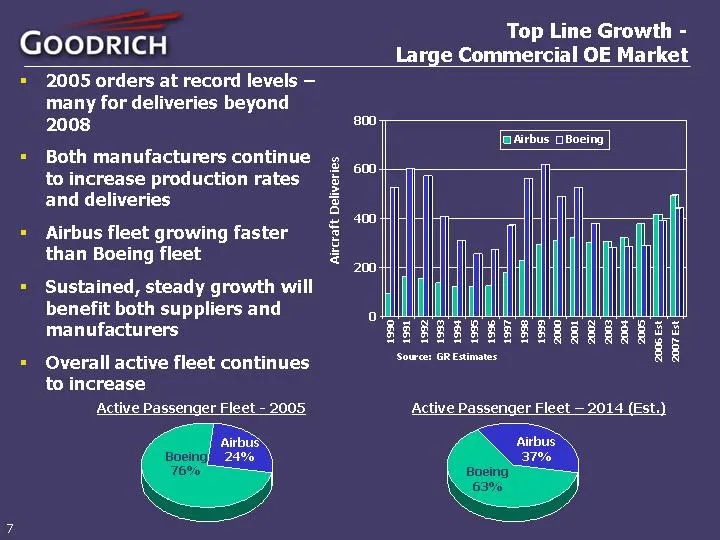
Top Line Growth - Large Commercial OE Market 2005 orders at record levels - many for deliveries beyond 2008 Both manufacturers continue to increase production rates and deliveries Airbus fleet growing faster than Boeing fleet Sustained, steady growth will benefit both suppliers and manufacturers Ove
Slide 8: Top Line Growth - Regional Jet Market
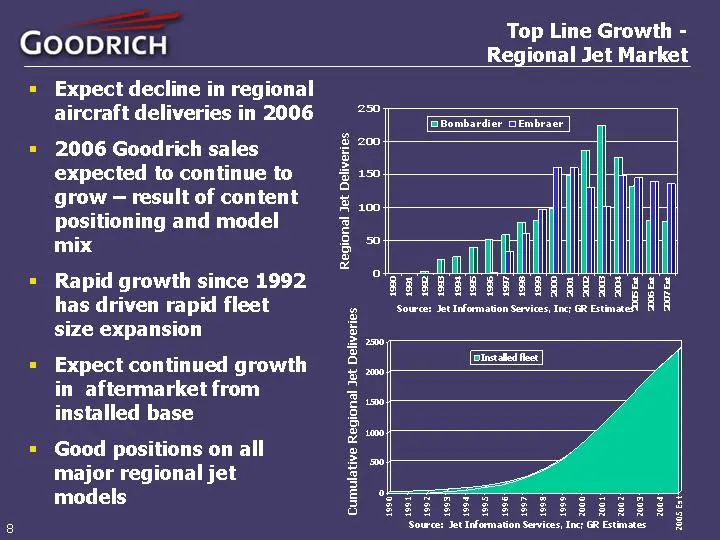
Top Line Growth - Regional Jet Market Expect decline in regional aircraft deliveries in 2006 2006 Goodrich sales expected to continue to grow - result of content positioning and model mix Rapid growth since 1992 has driven rapid fleet size expansion Expect continued growth in aftermarket from instal
Slide 9: Top Line Growth - Aftermarket Products and Services
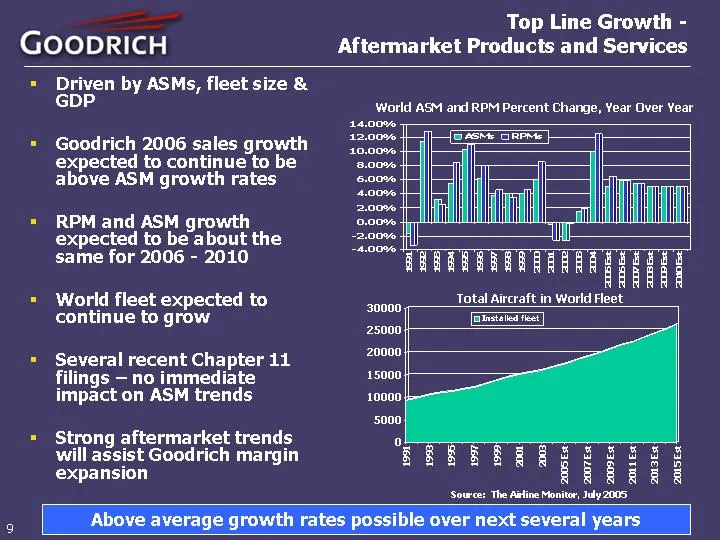
1991 1992 1993 1994 1995 1996 1997 1998 1999 2000 2001 2002 2003 2004 2005 Est 2006 Est 2007 Est 2008 Est 2009 Est 2010 Est 2011 Est 2012 Est 2013 Est 2014 Est 2015 Est Installed fleet 9326 9992 10514 10991 11377 11805 12332 12969 13713 14612 15115 15580 16132 16816 17480 18319 19130 19928 20773 216
Slide 10: Top Line Growth - Military Market
Top Line Growth - Military Market Goodrich product focus Surveillance and reconnaissance High usage platforms - helicopters, transport aircraft, fighters New platforms US in transition to "network-centric warfare" More focus on Surveillance and Reconnaissance to provide Intelligence Fewer new platfo
Slide 11: 2006 Sales Expectations By Market Channel
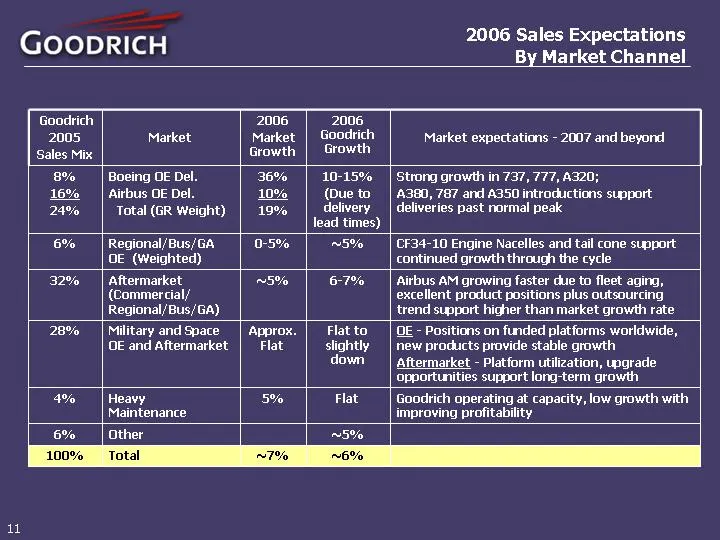
2006 Sales Expectations By Market Channel Goodrich 2005 Sales Mix Market 2006 Market Growth 2006 Goodrich Growth Market expectations - 2007 and beyond 8% 16% 24% Boeing OE Del. Airbus OE Del. Total (GR Weight) 36% 10% 19% 10-15% (Due to delivery lead times) Strong growth in 737, 777, A320; A380, 787
Slide 12: Sustainable Growth Sales from Key New Programs
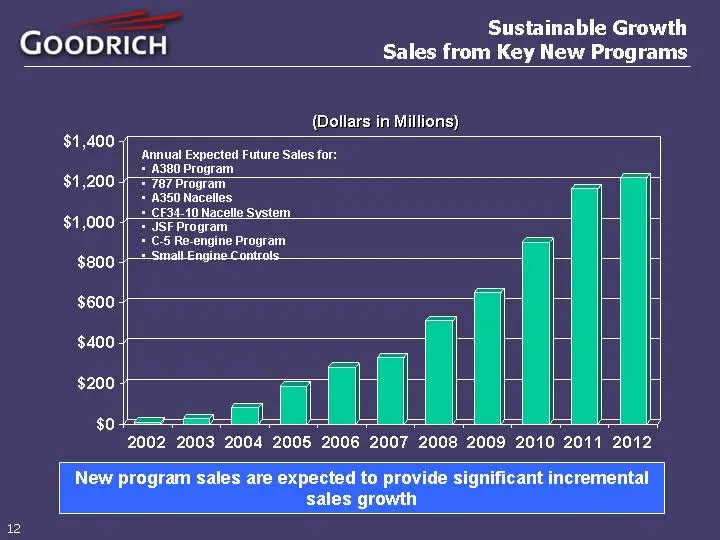
Sustainable Growth Sales from Key New Programs New program sales are expected to provide significant incremental sales growth (Dollars in Millions) Annual Expected Future Sales for: A380 Program 787 Program A350 Nacelles CF34-10 Nacelle System JSF Program C-5 Re-engine Program Small Engine Controls
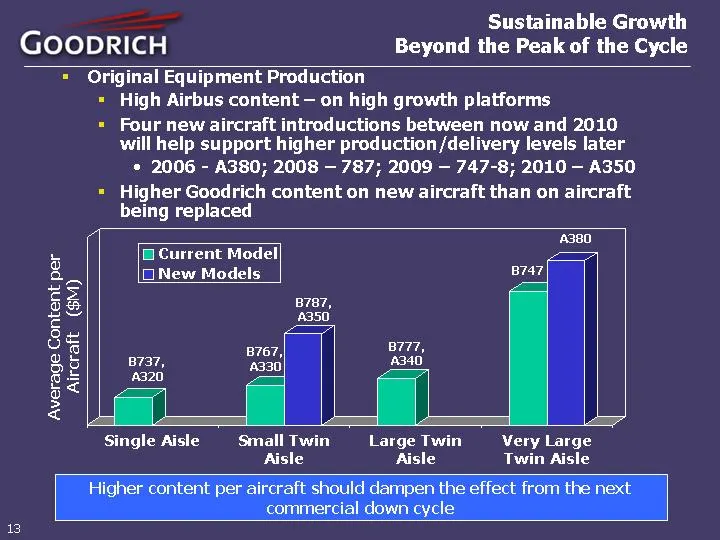
Slide 13: Sustainable Growth Beyond the Peak of the Cycle - OE Production
Sustainable Growth Beyond the Peak of the Cycle Original Equipment Production High Airbus content - on high growth platforms Four new aircraft introductions between now and 2010 will help support higher production/delivery levels later 2006 - A380; 2008 - 787; 2009 - 747-8; 2010 - A350 Higher Goodri
Slide 14: Sustainable Growth Beyond the Peak of the Cycle - Commercial Aftermarket
Sustainable Growth Beyond the Peak of the Cycle Commercial Aftermarket Significantly larger fleet should fuel aftermarket strength Excellent balance between Boeing and Airbus Airbus and regional jet fleet is getting older, more mature - increased aftermarket support More long-term agreements More op
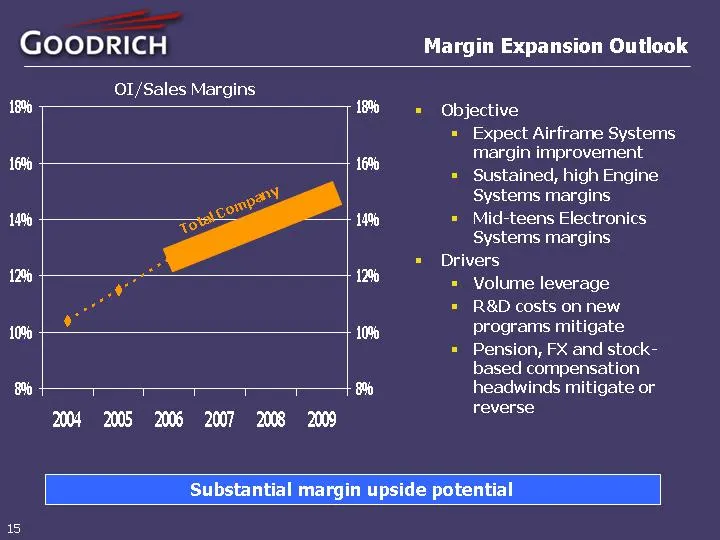
Slide 15: Margin Expansion Outlook
Margin Expansion Outlook 2004 2005 2006 2007 2008 2009 Airframe Electronics Engines Co 0.104 0.115 0.126 OI/Sales Margins Total Company Objective Expect Airframe Systems margin improvement Sustained, high Engine Systems margins Mid-teens Electronics Systems margins Drivers Volume leverage R&D costs
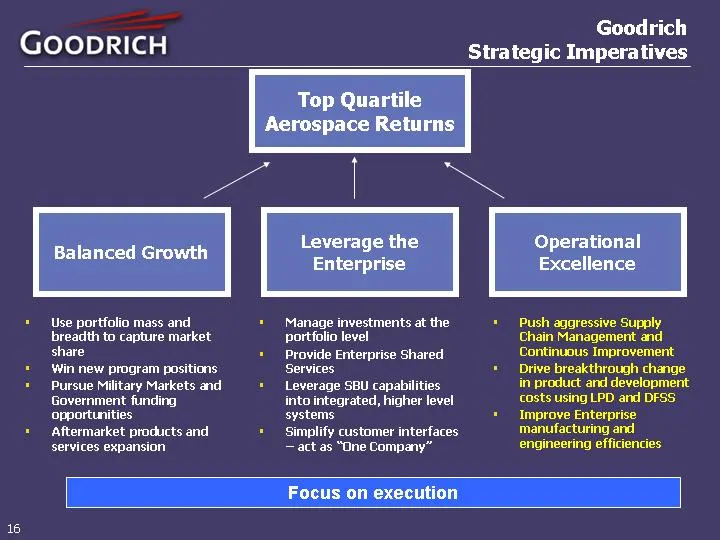
Slide 16: Conclusion: Goodrich Strategic Imperatives
Conclusion Top Quartile Aerospace Returns Operational Excellence Leverage the Enterprise Balanced Growth Push aggressive Supply Chain Management and Continuous Improvement Drive breakthrough change in product and development costs using LPD and DFSS Improve Enterprise manufacturing and engineering e
Slide 17: Full Year 2005 Financial Summary and 2006 Outlook
Full Year 2005 Financial Summary and 2006 Outlook
Slide 18: 2006 Outlook P&L Summary
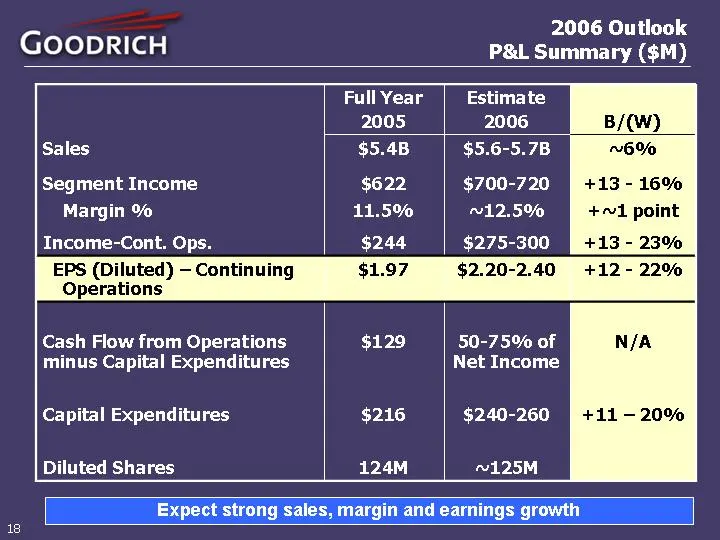
2006 Outlook P&L Summary ($M) Full Year 2005 Estimate 2006 B/(W) Sales $5.4B $5.6-5.7B ~6% Segment Income $622 $700-720 +13 - 16% Margin % 11.5% ~12.5% +~1 point Income-Cont. Ops. $244 $275-300 +13 - 23% EPS (Diluted) - Continuing Operations $1.97 $2.20-2.40 +12 - 22% Cash Flow from Operations minus
Slide 19: 2006 Outlook
2006 Outlook Continued robust growth in most market channels Margin expansion continues ~+100 basis points to ~12.5% On track to achieve mid-teens segment margin by 2009-2010 EPS growth constrained by headwinds in pension, FX and stock-based compensation of ~$0.31
Slide 20: 2006 Outlook Summary
2006 Outlook Summary Approximately 6% sales growth ~100 basis point segment margin expansion Operational excellence and volume leverage 12% to 22% growth in EPS from continuing operations Cash flow from operations minus capital expenditures of 50-75% of net income reflects new program success New pr
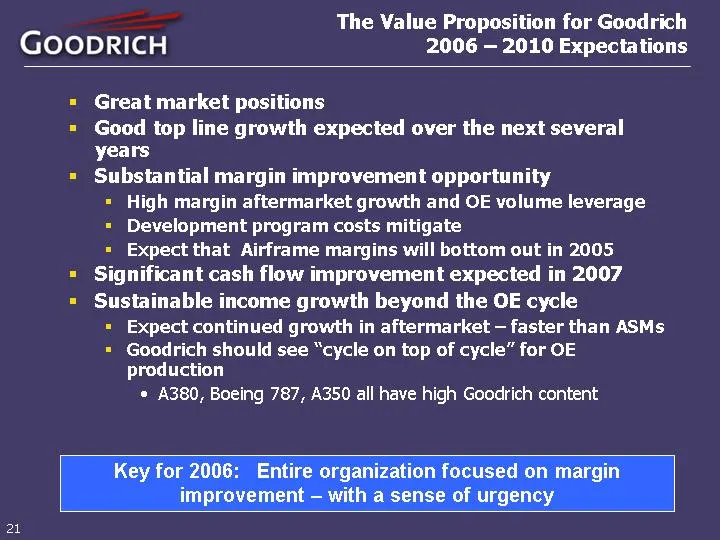
Slide 21: The Value Proposition for Goodrich 2006 - 2010 Expectations
The Value Proposition for Goodrich 2006 - 2010 Expectations Great market positions Good top line growth expected over the next several years Substantial margin improvement opportunity High margin aftermarket growth and OE volume leverage Development program costs mitigate Expect that Airframe margin
Source: SEC EDGAR · 8-K filed Feb 14, 2006
More decks from Goodrich Corp
 Q4 2009 Earnings Presentation23 slides · Jan 28, 2010
 Q3 2009 Earnings Presentation21 slides · Oct 22, 2009
 Q2 2009 Earnings Presentation21 slides · Jul 23, 2009
 Macquarie Capital Aerospace & Defense Conference 200920 slides · May 14, 2009
 Q1 2009 Earnings Presentation21 slides · Apr 23, 2009
 FY2008 Earnings Presentation28 slides · Feb 4, 2009