Axiall — Goldman Sachs Houston Chemical Intensity Day March 2014
23 slides from Axiall's conference presentation, Mar 25, 2014
Slide 1: Goldman Sachs Houston Chemical Intensity Day March 2014
Goldman Sachs Houston Chemical Intensity Day March 2014
Slide 2: Forward-Looking Statements
Forward-Looking Statements This presentation contains certain statements relating to future events and our intentions, beliefs, expectations, and predictions for the future. Any such statements other than statements of historical fact are forward-looking statements within the meaning of the Securiti
Slide 3: Agenda
Agenda Axiall Overview Global Chlor-alkali and Vinyls Summary
Slide 4: Axiall Overview
- xo Axiall Overview
Slide 5: Axiall Value Drivers
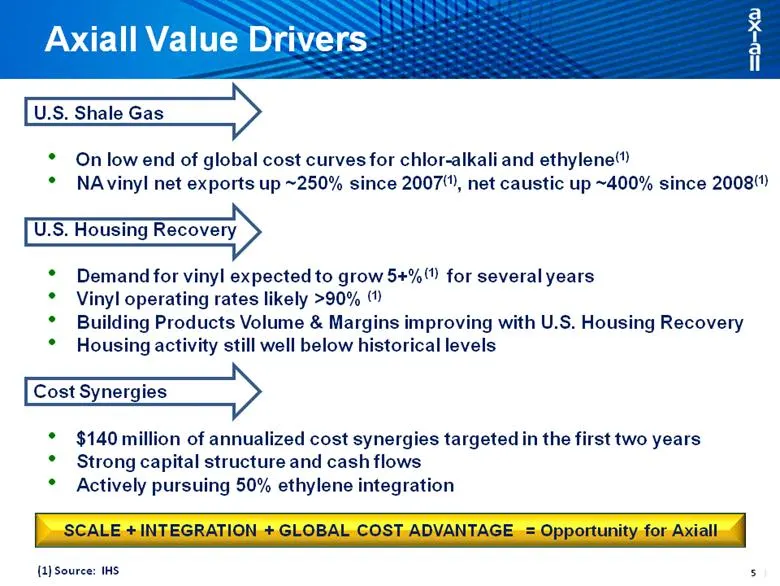
Axiall Value Drivers U.S. Shale Gas On low end of global cost curves for chlor-alkali and ethylene(1) NA vinyl net exports up ~250% since 2007(1), net caustic up ~400% since 2008(1) U.S. Housing Recovery Demand for vinyl expected to grow 5+%(1) for several years Vinyl operating rates likely >90% (1)
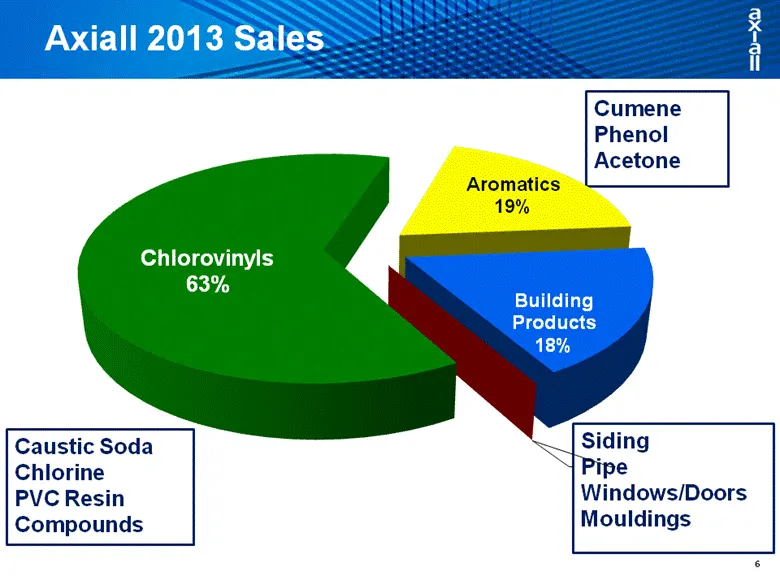
Slide 6: Axiall product chain: chlorovinyls, aromatics and building products
Cumene Phenol Acetone Chlorovinyls 63% Caustic Soda ~_| Siding Chlorine ‘Pipe PVC Resin Windows/Doors Compounds Mouldings
Slide 7: Building Products Sales Mix & Drivers
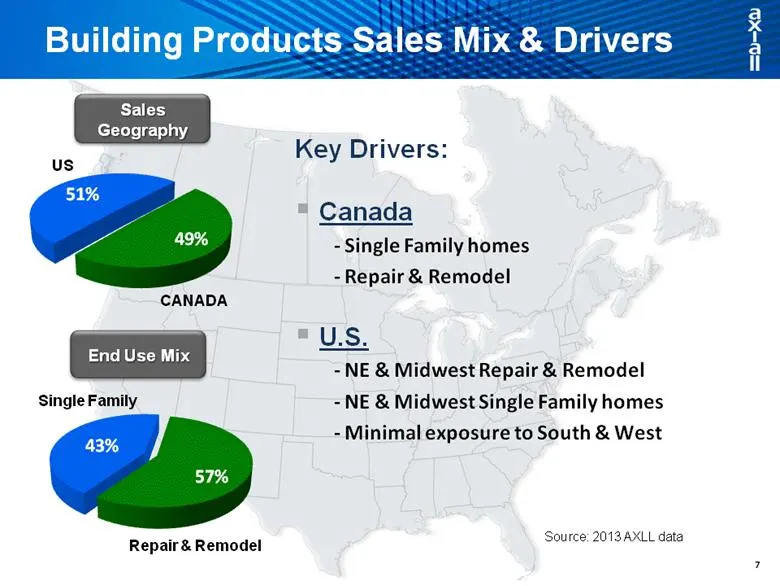
Building Products Sales Mix & Drivers Key Drivers: Canada - Single Family homes - Repair & Remodel U.S. - NE & Midwest Repair & Remodel - NE & Midwest Single Family homes - Minimal exposure to South & West End Use Mix Sales Geography Source: 2013 AXLL data
Slide 8: Building Products Portfolio
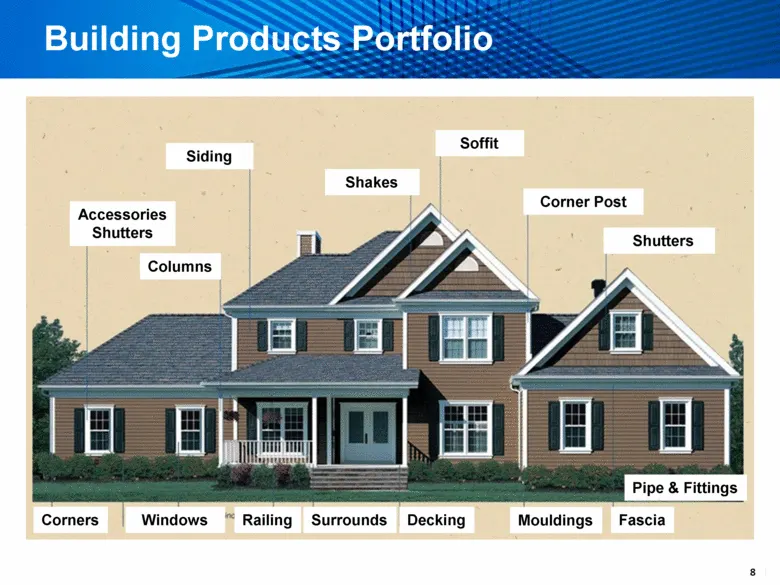
Accessories Shutters Columns Siding Shakes Soffit Corner Post Shutters Corners Windows Railing Surrounds Decking Mouldings Fascia Building Products Portfolio Pipe & Fittings
Slide 9: Chlorovinyls – Building Products Integration
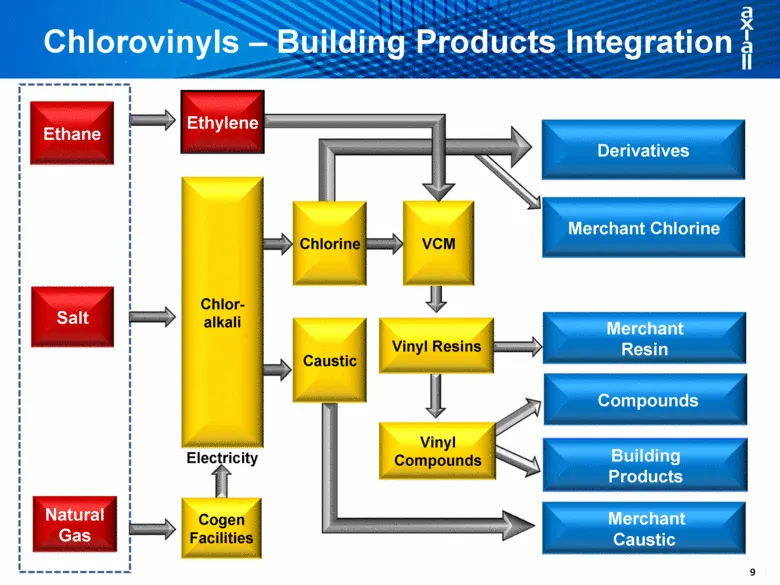
Chlorine Merchant Resin VCM Electricity Building Products Chlorovinyls – Building Products Integration Merchant Chlorine Merchant Caustic Salt Natural Gas Ethane Derivatives Compounds Caustic Chlor-alkali Ethylene Vinyl Resins Vinyl Compounds Cogen Facilities
Slide 10: Diverse Product Portfolio Creates Optionality
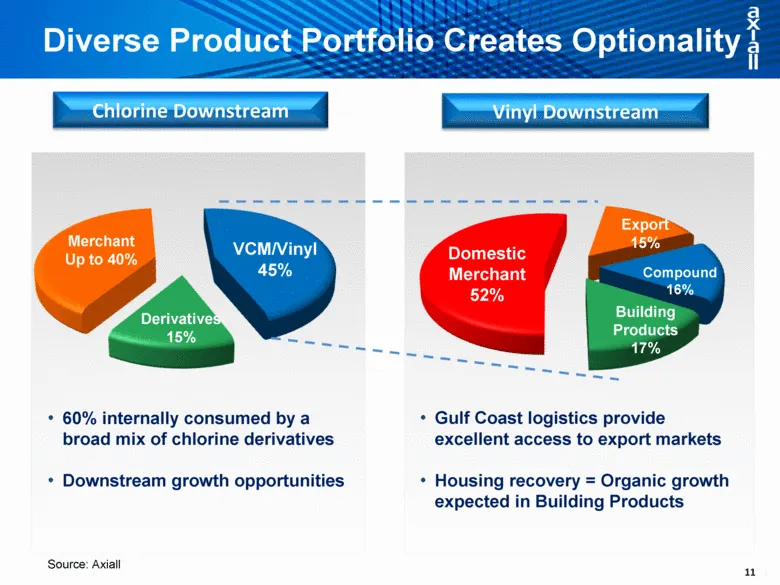
Diverse Product Portfolio Creates Optionality Chlorine Downstream Vinyl Downstream 60% internally consumed by a broad mix of chlorine derivatives Downstream growth opportunities Gulf Coast logistics provide excellent access to export markets Housing recovery = Organic growth expected in Building Pro
Slide 11: New External Synergy Target: $140 MM
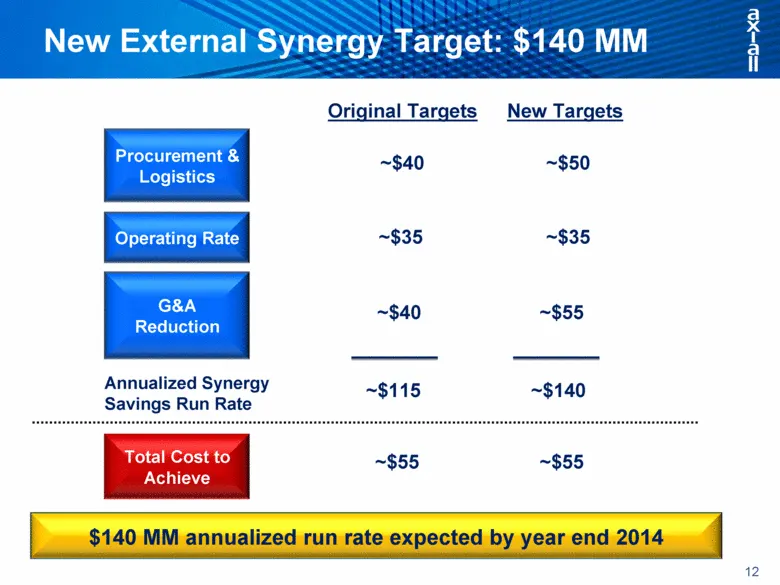
New External Synergy Target: $140 MM Original Targets ~$40 ~$35 ~$115 Procurement & Logistics Operating Rate G&A Reduction ~$40 Total Cost to Achieve ~$55 Annualized Synergy Savings Run Rate $140 MM annualized run rate expected by year end 2014 New Targets ~$50 ~$35 ~$140 ~$55 ~$55 12
Slide 12: Combined Mid-Cycle EBITDA to $850mm+
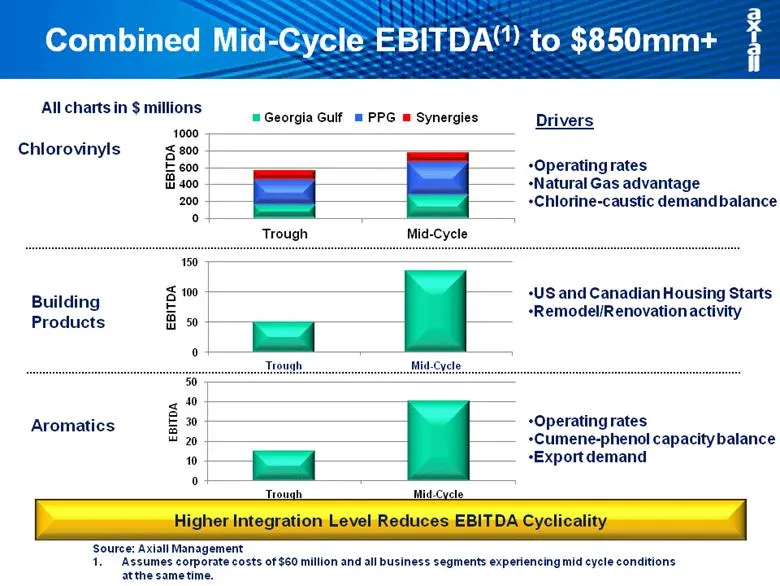
Combined Mid-Cycle EBITDA(1) to $850mm+ Higher Integration Level Reduces EBITDA Cyclicality Source: Axiall Management Assumes corporate costs of $60 million and all business segments experiencing mid cycle conditions at the same time. Chlorovinyls Building Products Aromatics Operating rates Natural
Slide 13: Global Chlor-alkali and Vinyls
Global Chlor-alkali and Vinyls
Slide 14: Global Chlor-alkali Capacity Growth
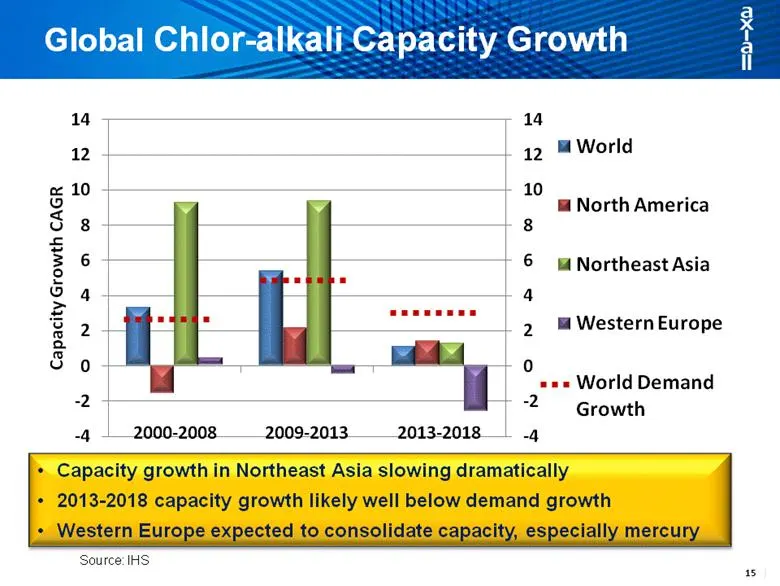
Global Chlor-alkali Capacity Growth Capacity growth in Northeast Asia slowing dramatically 2013-2018 capacity growth likely well below demand growth Western Europe expected to consolidate capacity, especially mercury Source: IHS
Slide 15: Global PVC Capacity Growth
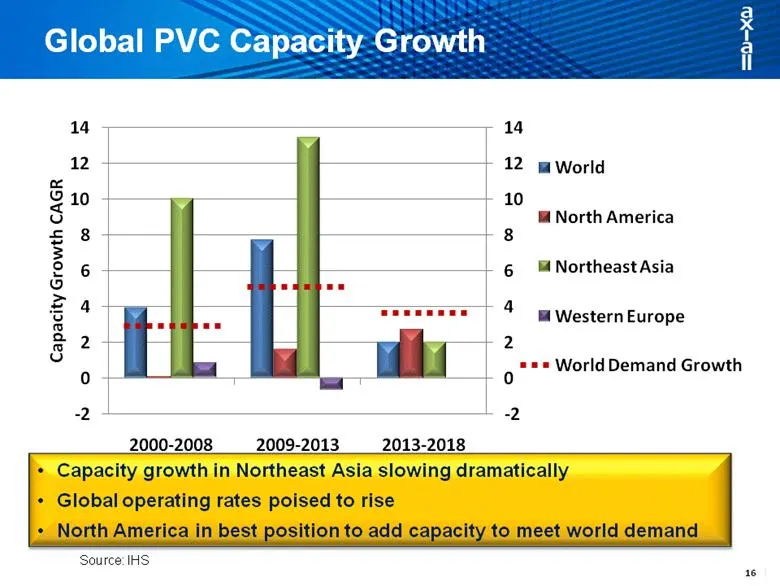
Global PVC Capacity Growth Capacity growth in Northeast Asia slowing dramatically Global operating rates poised to rise North America in best position to add capacity to meet world demand Source: IHS
Slide 16: PVC consumption per capita - 2013
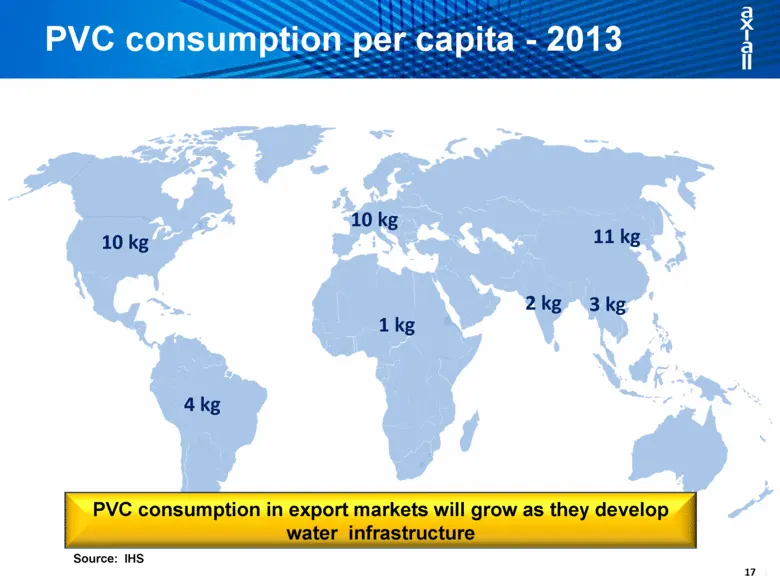
PVC consumption per capita - 2013 10 kg 10 kg 4 kg 1 kg 2 kg 11 kg Source: IHS 3 kg PVC consumption in export markets will grow as they develop water infrastructure
Slide 17: Global Chlor-Alkali Manufacturing Costs
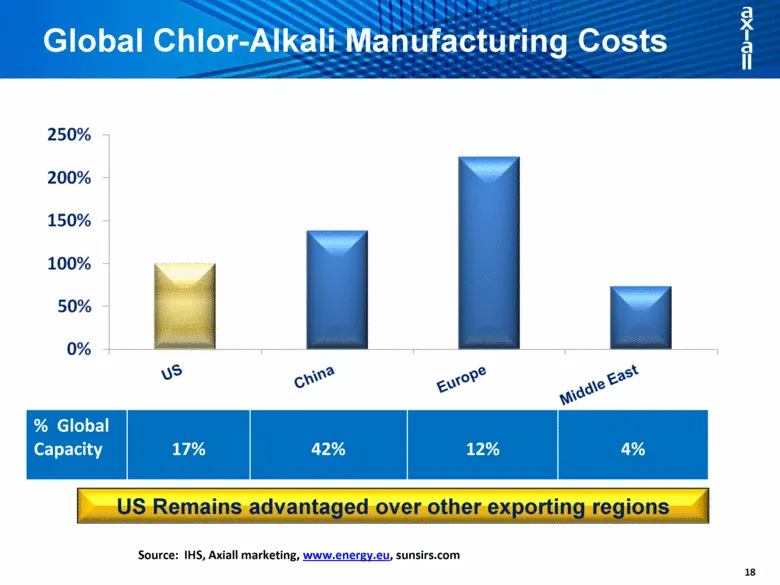
Global Chlor-Alkali Manufacturing Costs Source: IHS, Axiall marketing, www.energy.eu, sunsirs.com % Global Capacity 17% 42% 12% 4% US Remains advantaged over other exporting regions
Slide 18: North American Net ECU Capacity Additions
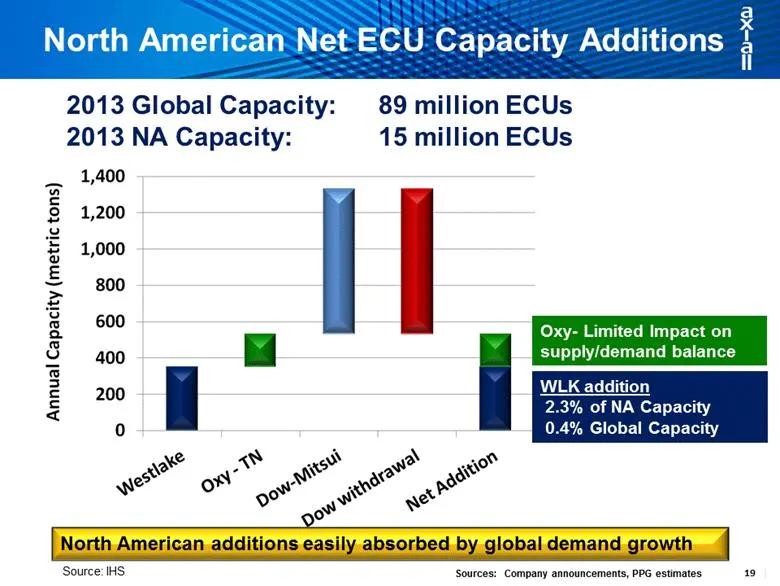
North American Net ECU Capacity Additions Sources: Company announcements, PPG estimates 2013 Global Capacity: 89 million ECUs 2013 NA Capacity: 15 million ECUs WLK addition 2.3% of NA Capacity 0.4% Global Capacity Oxy- Limited Impact on supply/demand balance North American additions easily absorbed
Slide 19: North American Chlorine Demand
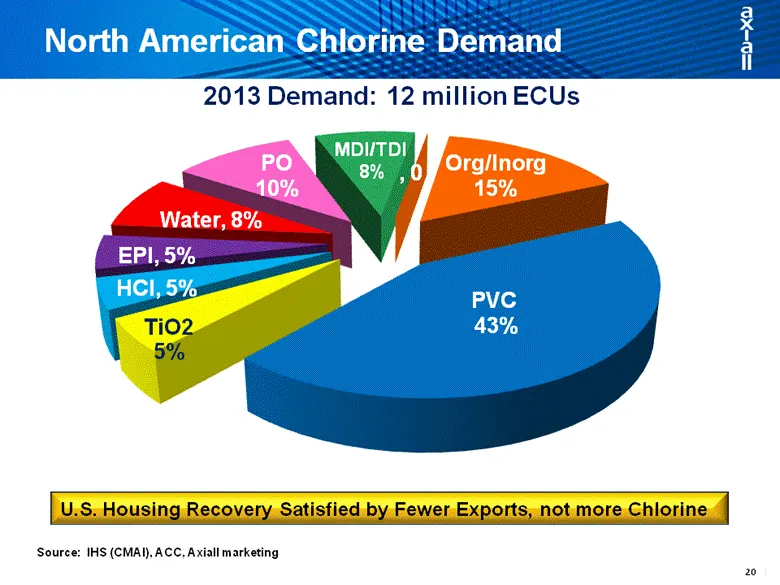
North American Chlorine Demand 2012 Demand: 12 million ECUs U.S. Housing Recovery Satisfied by Fewer Exports, not more Chlorine Source: IHS (CMAI), ACC, Axiall marketing
Slide 20: U.S. Operating Rates
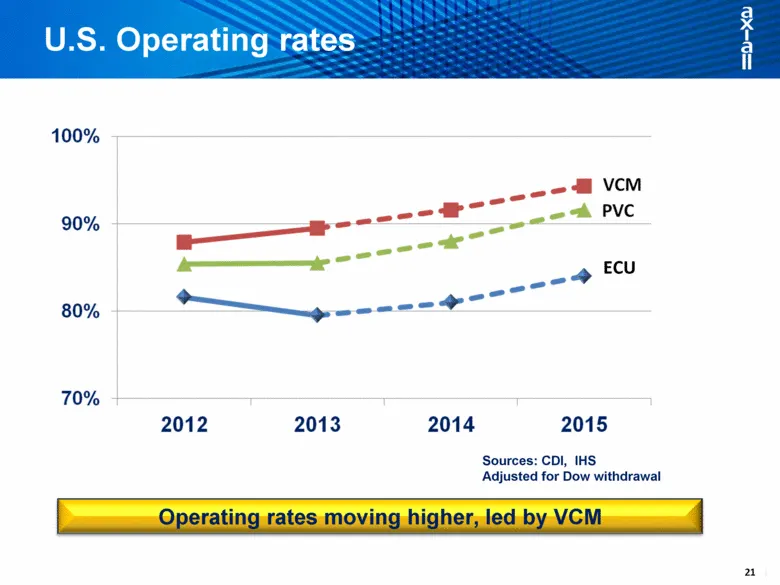
U.S. Operating rates Sources: CDI, IHS Adjusted for Dow withdrawal Operating rates moving higher, led by VCM ECU
Slide 21: Summary
x-0= Summary
Slide 22: Axiall Value Drivers
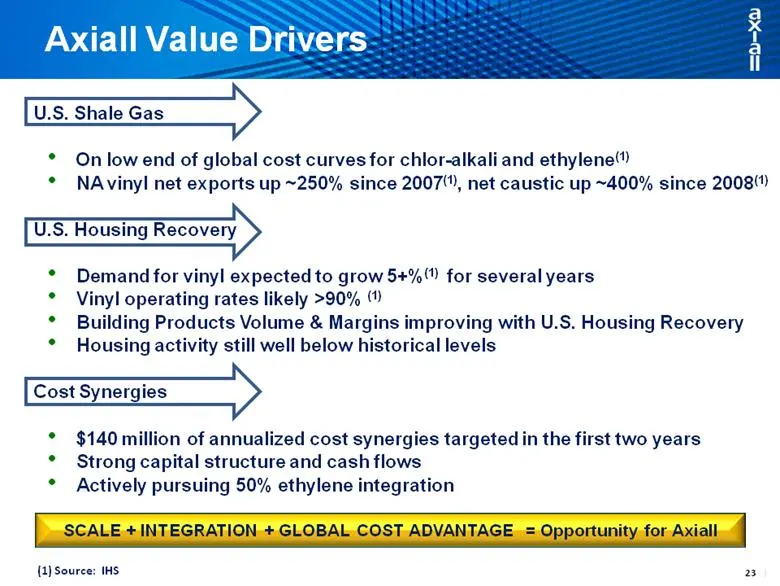
Axiall Value Drivers U.S. Shale Gas On low end of global cost curves for chlor-alkali and ethylene(1) NA vinyl net exports up ~250% since 2007(1), net caustic up ~400% since 2008(1) U.S. Housing Recovery Demand for vinyl expected to grow 5+%(1) for several years Vinyl operating rates likely >90% (1)
Slide 23: Q&A
ox-0= Q&A
Source: SEC EDGAR · 8-K filed Mar 25, 2014