Communityone Bancorp — FNB United — Community Bank Investor Conference 2007
48 slides from Communityone Bancorp's conference presentation, Nov 1, 2007
Slide 1: FNB United Corp. Community Bank Investor Conference
F NB U NITED C ORP . America’s Community Banks Community Bank Investor Conference New York City, NY Yes You Can ® Yes We Can ® November 1-2, 2007 Exhibit 99.1
Slide 2: Forward-Looking Statements
Forward-Looking Statements FNB United Corp. has made forward-looking statements in the accompanying presentation materials that are subject to risks and uncertainties. These statements are based on the beliefs and assumptions of the management of FNB United Corp., and on the information available to
Slide 3: Presentation Contents
F NB U NITED – Presentation Contents • Why F NB U NITED Metrics Markets Management • Financial Highlights • Business Strategy – Earnings and Growth Opportunities • Questions
Slide 4: Why FNB United
Why FNB UNITED • Metrics – Investor Opportunity • Markets – Where We Are, Where We Plan to Grow • Management – Who We Are, What We Do
Slide 5: Metrics: Investor Opportunity
Yes You Can ® Yes We Can ® Metrics: Investor Opportunity Yes You Can ® Yes We Can ®
Slide 6: Why FNB United
Why FNB UNITED FNBN NASDAQ Symbol: 1907, as First National Bank of Asheboro Founded: 43 Banking Offices 35 Communities 17 Counties Locations: $1.52 Billion Deposits: $1.45 Billion Loans: $1.89 Billion Assets: th Largest Financial Service Company HQ’d in North Carolina
Slide 7: Why FNB - Investor Opportunity
Why FNB - Investor Opportunity An Attractive Value • Strong Dividend Yield • Trade at Discount to Peers • Historical Strong Operating Performance
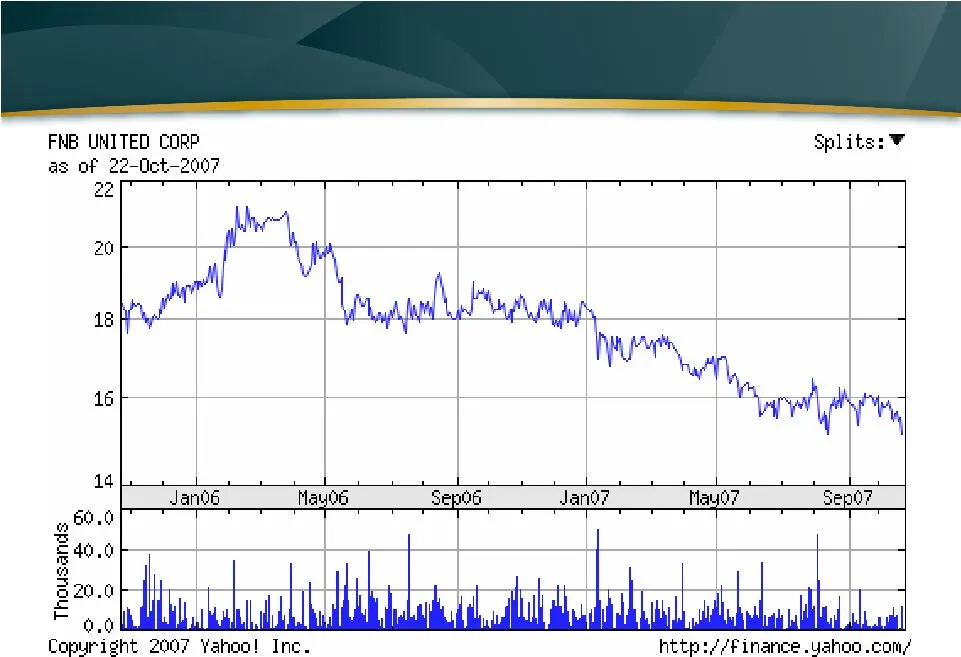
Slide 8: FNBN 2-Yr Trading History
FNBN 2-Yr Trading History October 2005 – October 2007
Slide 9: Dividend History
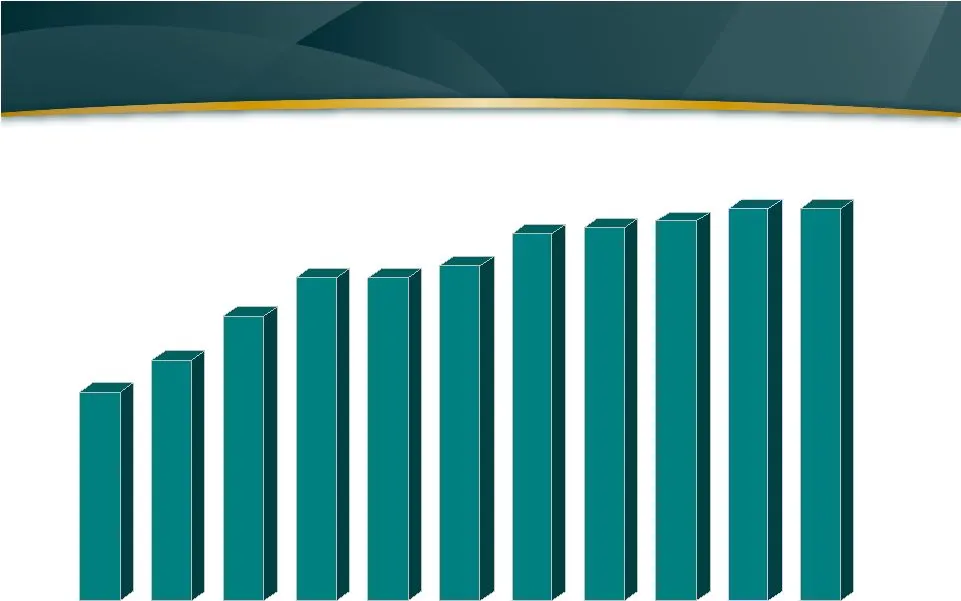
Dividend History $0.33 $0.38 $0.45 $0.51 $0.51 $0.53 $0.58 $0.59 $0.60 $0.62 $0.62 1996 1997 1998 1999 2000 2001 2002 2003 2004 2005 2006
Slide 10: Investor Opportunity
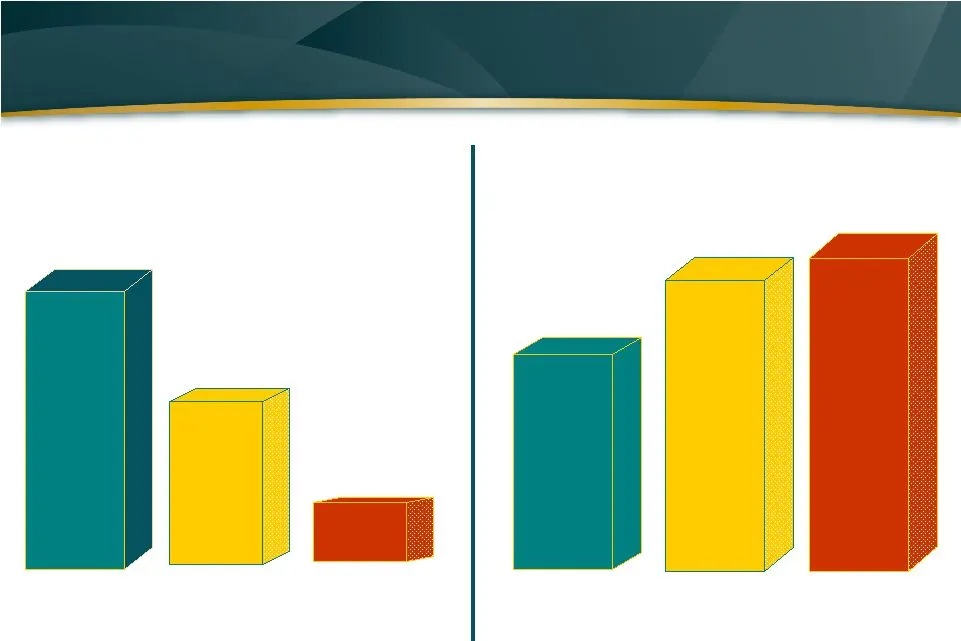
Investor Opportunity Dividend Yield (%) 3.95 FNB United Corp . 2.67 SNL Banks Peer Group* Price / LTM EPS (X) 12.2 FNB United Corp. 14.9 SNL Banks Peer Group* 0.68 NC Banks** 15.25 NC Banks** *SNL Data – Banks between $1 - $5 billion as of 10/25/07 **SNL Data – NC State Public Bank Median as of 10/2
Slide 11: Investor Opportunity
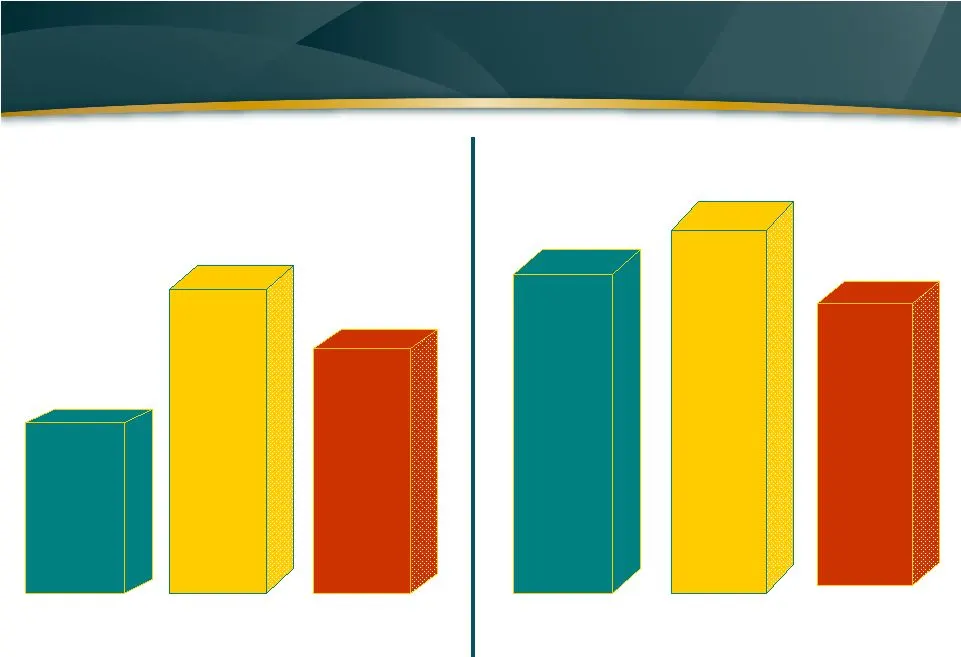
Investor Opportunity Price / Book (%) Price / Tangible Book (%) *SNL Data – Banks between $1 - $5 billion as of 10/25/07 **SNL Data – NC State Public Bank Median as of 10/25/07 80.5 FNB United Corp . 165.9 SNL Banks Peer Group* 177.2 FNB United Corp. 224.0 SNL Banks Peer Group* 129.2 NC Banks** 142.
Slide 12: Markets: Where We Are, Where We Plan to Grow
Yes You Can ® Yes We Can ® Markets: Where We Are, Where We Plan to Grow Yes You Can ® Yes We Can ®
Slide 13: FNB United Acquisitions
FNB United Acquisitions $1,091 MM TOTAL OTHER $25MM Dover Mortgage Company April 2003 Offices Assets BANKS $680 MM $151 MM $134 MM $126 MM Integrity Financial Inc. (Catawba Valley/First Gaston/Northwestern Banks) United Financial Inc. (Alamance/Hillsborough Banks) Rowan Bancorp. (Rowan Savings Bank)
Slide 14: The Yes! Bank Franchise
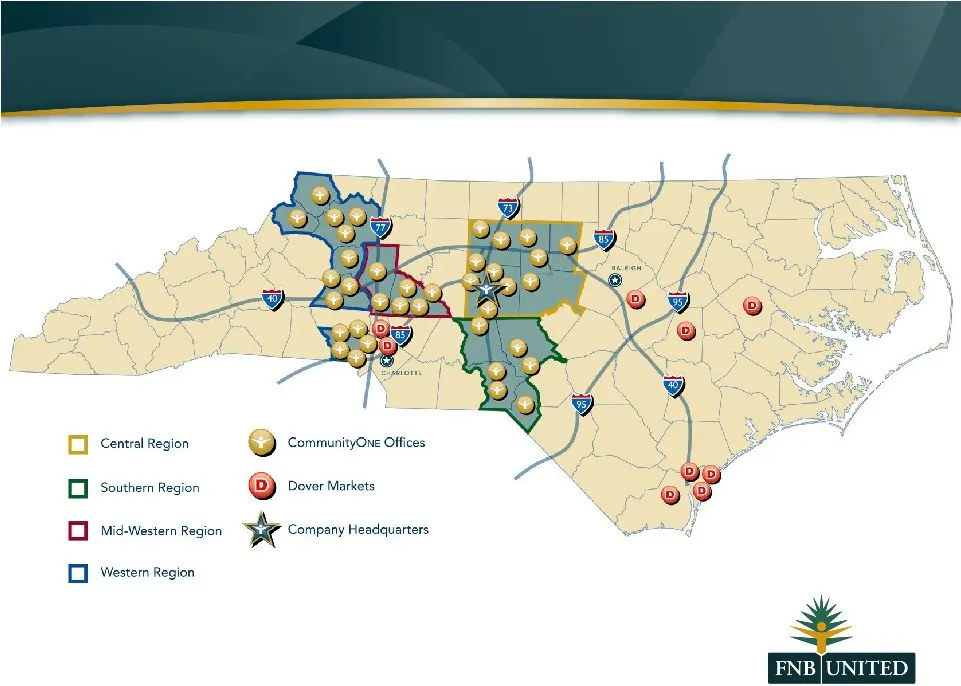
Yes You Can ® Yes We Can ® The Yes! Bank Franchise
Slide 15: Brand Unification
Brand Unification and its divisions
Slide 16: Growth Strategy
Growth Strategy • Increase Penetration of Current Markets Attractive New Markets & Customer Base • De Novo Offices Two Offices opened in 2006 (Greensboro - Salisbury) Two Offices underway to open in 2008 (Greensboro-Cornelius) • Integrated Wealth Management/Mortgage Services
Slide 17: Market Growth Potential
Market Growth Potential *Source: SNL Financial *Top 5 in 8 of 17 Counties Rank Institution Branch Count Total Deposits in Market ($000) Total (%) of Market Share Wachovia 5,770,318 21.27% BB&T 4,633,702 17.08% Sun Trust 2,285,674 8.43% Bank of America 2,251,509 8.30% FNB United Corp. (NC) 1,448,532
Slide 18: Market Growth Potential
Market Growth Potential $51,658 $52,663 $54,979 $49,483 $53,182 $49,596 $48,368 Median Household Income 9.19% 14.47% 5.82% 2.73% 13.64% 5.54% 6.90% Projected Population Change (2007-2012) 16.34% 16. 39% 17.61% 15.33% 16.00% 13.56% 15.74% Projected HH Income Change (2007-2012) 458,085 $49,194 Third o
Slide 19: Market Growth Potential: Contiguous Counties
Market Growth Potential Contiguous Counties / Future Markets Under Consideration $64,184 $65,741 $49,819 $58,493 $45,881 $46,080 $54,157 Median Household Income 31.78% 15.27% 9.63% 13.88% 2.59% 4.95% 2.94% Projected Population Change (2007-2012) 19.01% 19.52% 11.84% 15.31% 13.89% 13.15% 17.90% Proje
Slide 20: Management & Culture
Yes You Can ® Yes We Can ® Management & Culture Yes You Can ® Yes We Can ®
Slide 21: Experienced Management Team
Experienced Management Team Journalism, SVP, Chief Human Res. Deborah B. Auman Planters NB, Bank of Candor SVP, Chief Credit Officer William S. Bruton Camco, FCNB Corp. Union Planters KPMG < 1 EVP, Chief Financial Officer Mark A. Severson Wachovia EVP, Chief Banking Officer R. Mark Hensley President
Slide 22: Experienced Management Team
Experienced Management Team FNB/SE, RMIC, Southern National < 1 SVP, Chief Accounting Ofc Dwight Willoughby Western Savings, Zions Bancorporation SVP, Chief Risk Officer Dean S. Tingey Fidelity Federal B & T, Resource Management Assoc < 1 SVP, Chief Information Officer David E. Miller Wachovia SVP,
Slide 23: Our Culture
Our Culture • Performance and Team Oriented • Participative and Positive • Service • Education / Training • Leadership Team Sets the Tone
Slide 24: Performance and Team Oriented
Performance and Team Oriented • Maximize Long-term Value Of Organization • Team Orientation - Universal Participation • Coaching And Communication • Educational Program Performance Compensation for STAKEHOLDERS™
Slide 25: Participative and Positive
Participative and Positive YES! Branding CommunityO NE is the YES! Bank. It is plainly stated in our Yes you can ® —Yes we can ® trademarks. It is reflected in the design of our logo and corporate mascot, Jack. And it is repeated in our customer service programs, company spirit campaigns and marketi
Slide 26: YESPY Awards
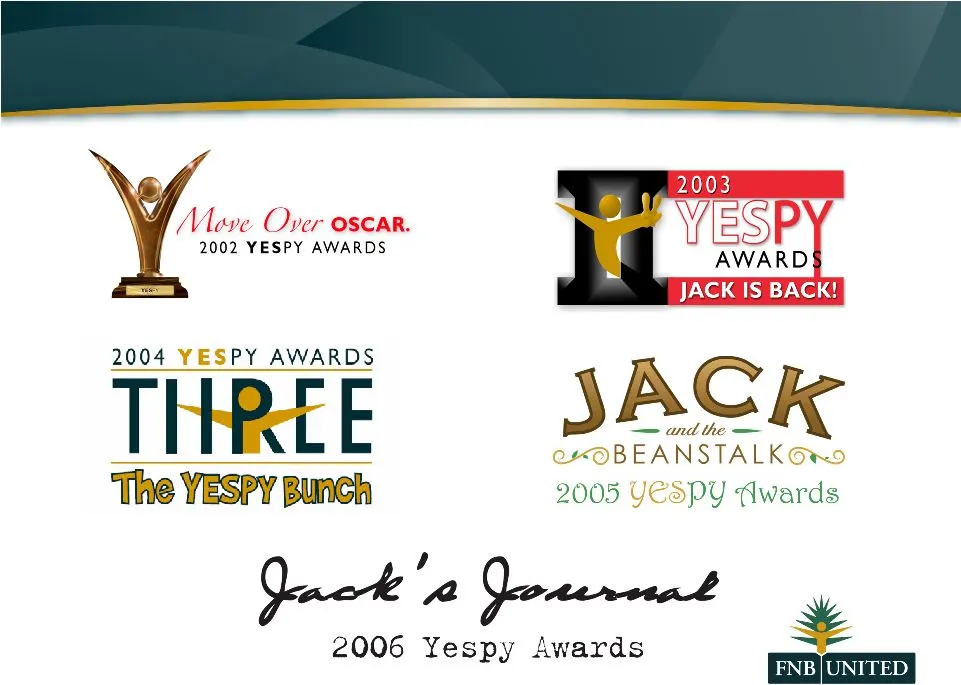
2002 YESPY AWARDS . AWARD$ JACK IS BACK! 2004 PY AWARDS THREE Ck AL . SAG The YESPY BuNCh 2003 YESPY Awards d Qaak va Qrotereent 2006 Yespy Awards R27 UNITED 4
Slide 27: Financial Highlights
Yes You Can ® Yes We Can ® Financial Highlights Yes You Can ® Yes We Can ®
Slide 28: Asset Composition
Yes You Can ® Yes We Can ® Asset Composition • No Sub-Prime • No Alt-A • No Non-Agency MBS/CMOs • No CDOs Yes You Can ® Yes We Can ®
Slide 29: Loan and Deposit Growth
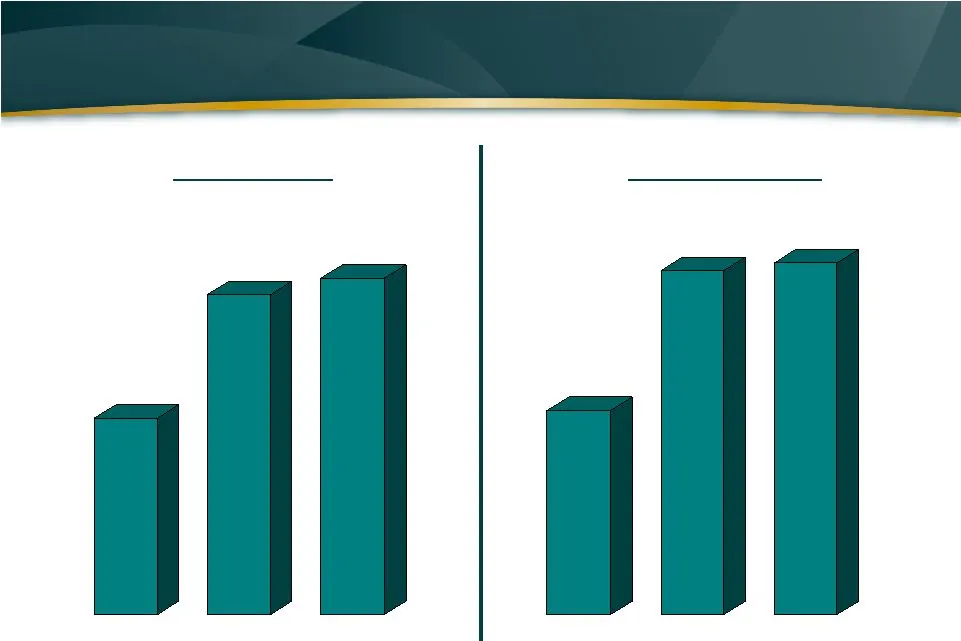
Loan and Deposit Growth $813 $1,323 $1,388 $842 $1,421 $1,452 2005 2006 YTD 9-07 2005 2006 YTD 9-07 (In Millions) Loan Growth Deposit Growth
Slide 30: Loan Portfolio Mix
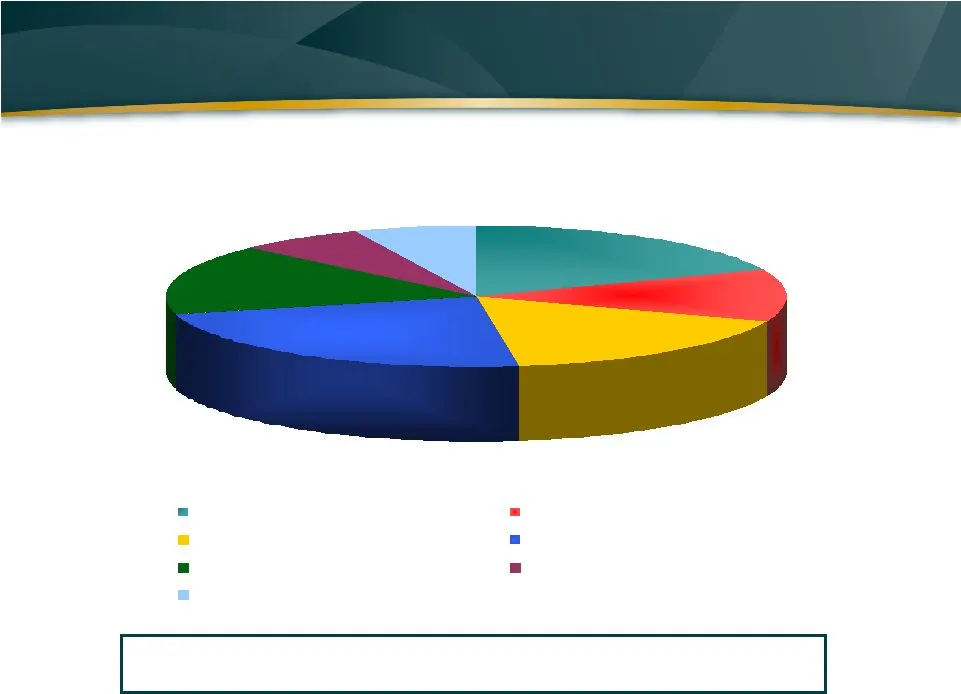
Loan Portfolio Mix 16.1% 6.6% 6.4% 23.1% 12.0% 17.1% 18.7% Commercial/Industrial Commercial RE-Income Commercial RE-Owner Occupied RE Construction & Development 1-4 Residential 1st Mortgage Home Equity Lines of Credit Consumer/Other Approximately 75.0% secured by real estate Variable rate loans acco
Slide 31: Funding Mix
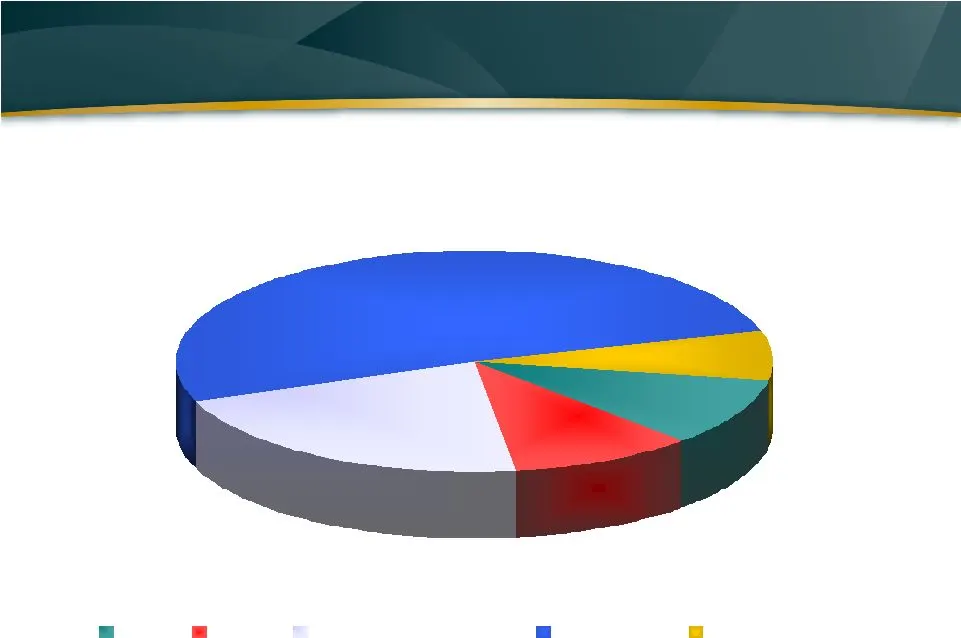
Funding Mix 7.2% 51.5% 10.1% 21.2% 10.0% DDA NOW IMM/SAV/Repo CD / IRA FHLB/FFP Funding Portfolio September 30, 2007
Slide 32: Profitability
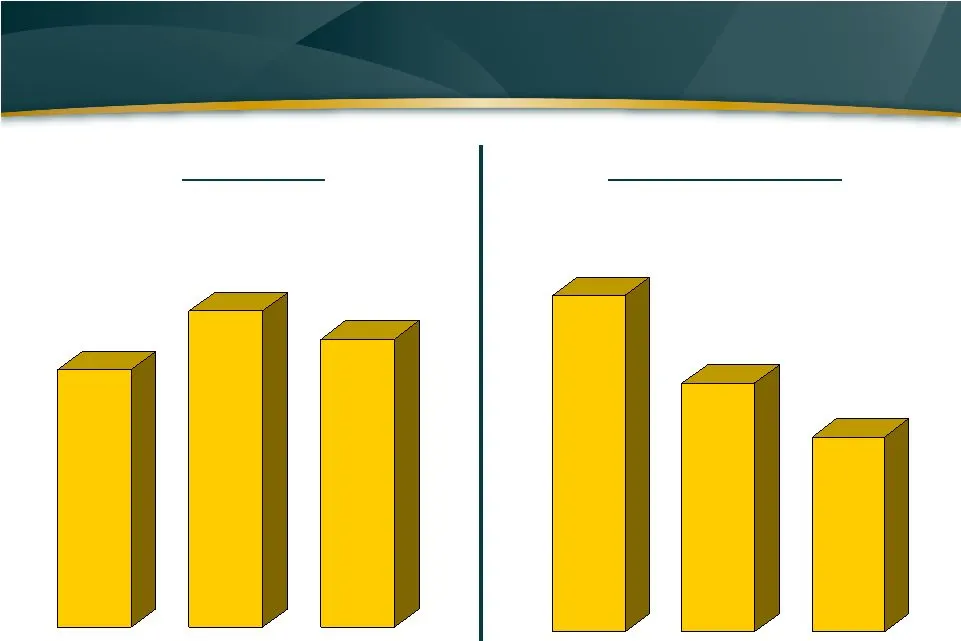
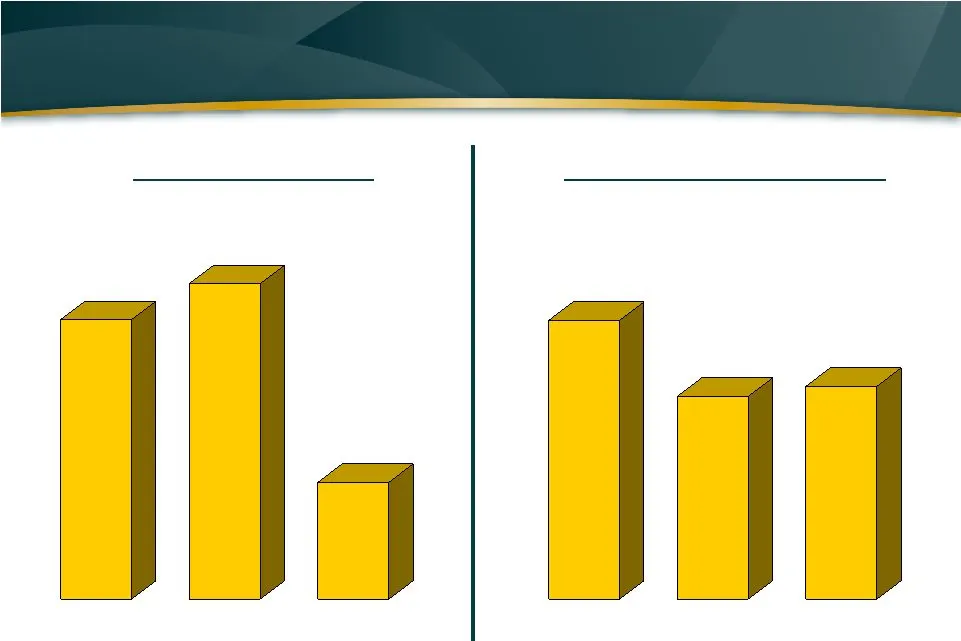
Profitability $9,937 $12,187 $11,109 2005 2006 YTD 9-07 $1.69 $1.25 $0.98 2005 2006 YTD 9-07 Net Income Earnings Per Share (In Thousands)
Slide 33: Profitability
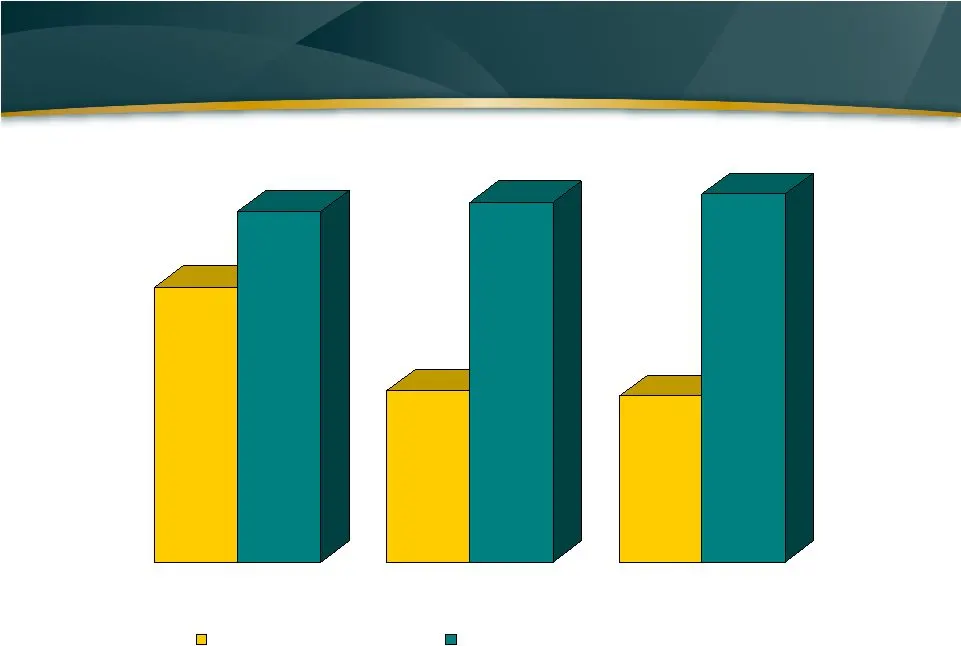
Profitability 4.16% 4.20% 3.98% 2005 2006 YTD 9-07 Net Interest Margin Return On Average Assets 1.06% 0.77% 0.81% 2005 2006 YTD 9-07
Slide 34: Return On Equity
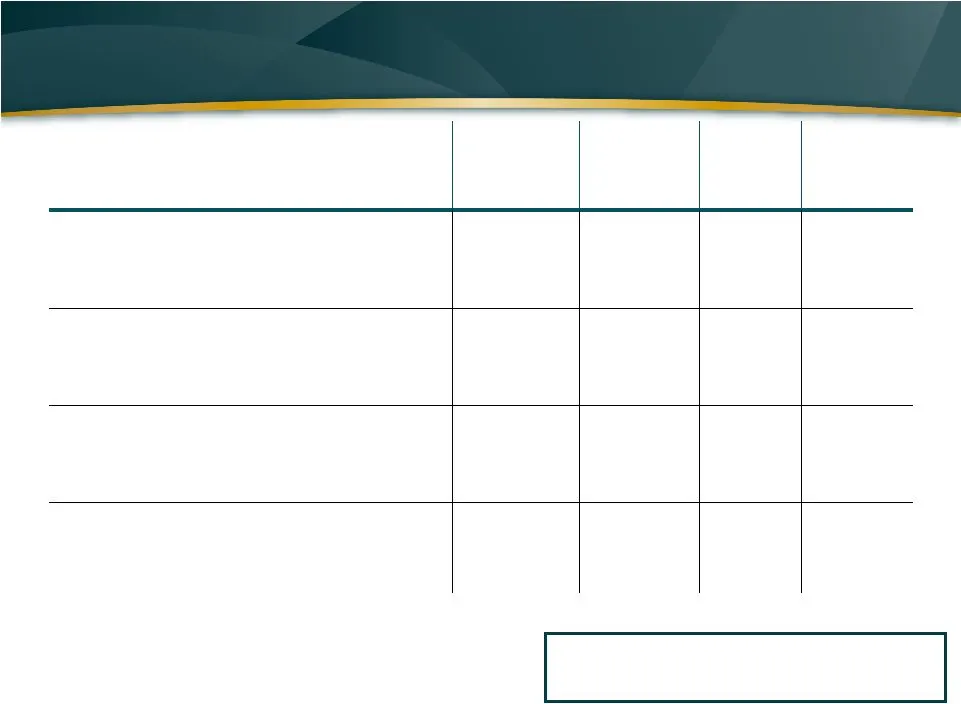
Return On Equity 11.25% 14.36% 7.00% 14.73% 6.79% 15.05% 2005 2006 YTD 9-07 Return on Ave. Equity Return on Ave. Tangible Equity
Slide 35: Asset Quality
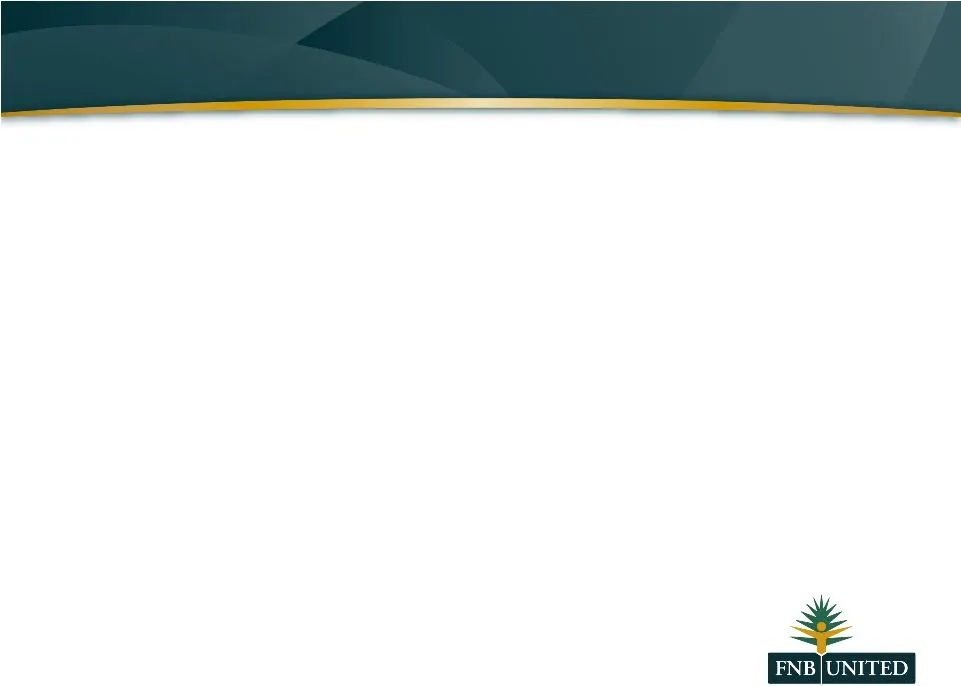
Asset Quality 0.47% 139.53% 1.12% 0.80% 2004 0.22% 164.49% 1.25% 0.76% 2005 0.16% 149.27% 1.28% 0.86%** 2006 0.167% (annualized) Net Charge Offs Average Loans 134.96%* (139.28%) Loan Loss Reserve Nonperforming Loans 1.16%* (1.20%) Loan Loss Reserve Total Loans Held for Investment 0.86% Nonperforming
Slide 36: Business Strategy – Earnings and Growth Opportunities
Yes You Can ® Yes We Can ® Business Strategy – Earnings and Growth Opportunities Yes You Can ® Yes We Can ®
Slide 37: Core Strategies
Core Strategies • Improve Asset Quality • Complete Integration of Acquisitions – Resume Pre- Merger Financial Performance • Grow Fee Income – Wealth Management, Mortgage Banking and Electronic Transactions • Franchise Growth Increase Penetration of Current Markets DeNovo Offices “ Yes ” ® Branding –
Slide 38: Improving Financial Performance
Improving Financial Performance Sales Initiatives: • Core Deposit Focus New CheckingO NE Deposit (NOW) Account Increase Fee Income • Enhance Corporate Cash Management Increase Merchant Service Relationship Promote Remote Capture • Community Office Sales Coaches • New CEO Dover Mortgage Company
Slide 39: Improving Financial Performance
Improving Financial Performance Integration and Cost Savings Initiatives: • Sold Credit Card Portfolio Net, One-Time Gain Improve Product Offering, Increase Fee Income, Reduce Risk Reduce Overhead (five providers) • Consolidate ATM Switch and Debit Card Processing Increase Fee Income Reduce Expenses
Slide 40: Improving Financial Performance
Improving Financial Performance Integration and Cost Savings Initiatives: • Consolidated Item Processing/Promote E-Stmts • Completed Teller Platform Conversion • Refinance/Payoff of Acquired TPS in 2008 • Dover Mortgage – Reorganize to Bank Subsidiary & Consolidate Offices/Processing
Slide 41: Improving Financial Performance
Improving Financial Performance Goals over the next three years include: • Annual earnings per share growth: 7.5 - 10% • Annual loan growth: 8 - 10 % • Non - interest income: 25%+ of revenues • Efficiency ratio: 60 - 63% Position ourselves as a Preeminent Community Bank in Southeastern U. S.
Slide 42: Summary
Yes You Can ® Yes We Can ® Summary Yes You Can ® Yes We Can ®
Slide 43: Summary – Why FNB United!
Summary – Why F NB U NITED ! • Growing Company in Good Markets • Experienced Management Team • Proven Integrator • Focused on Performance Improvement … equals … Compelling Investment Opportunity
Slide 44: Questions?
Summary – Why FNB UNITED ! Questions ?
Slide 45: Contact Information
Contact Information Michael C. Miller Chairman, President & CEO [email protected] Mark A. Severson Chief Financial Officer [email protected] FNB United Corp. CommunityONE Bank, N.A. 150 S. Fayetteville Street PO Box 1328 Asheboro, NC 27204 336.626.8300 Yes You Can ® Yes We Can ®
Slide 46: Appendix
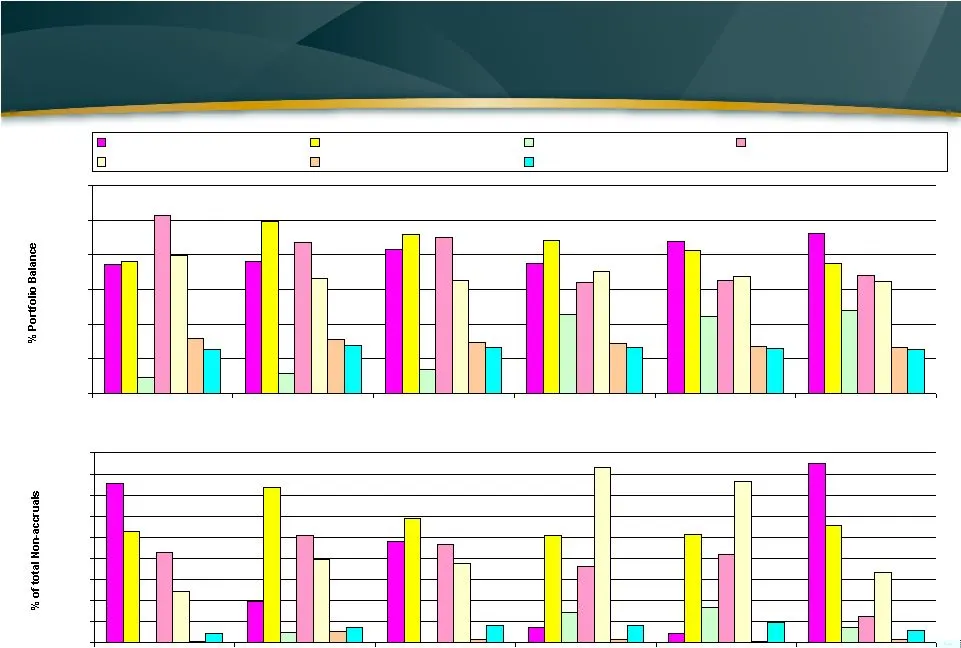
Appendix 0.0% 5.0% 10.0% 15.0% 20.0% 25.0% 30.0% Jun-06 Sep-06 Dec-06 Mar-07 Jun-07 Sep-07 C&D - combined Commercial & Industrial Commercial Income RE Commercial Owner-Occupied 1-4 Residential 1st Mortgage Home Equity Line of Credit Other 0.0% 5.0% 10.0% 15.0% 20.0% 25.0% 30.0% 35.0% 40.0% 45.0% Jun
Slide 47: Concentrations and Quality Migration thru Merger
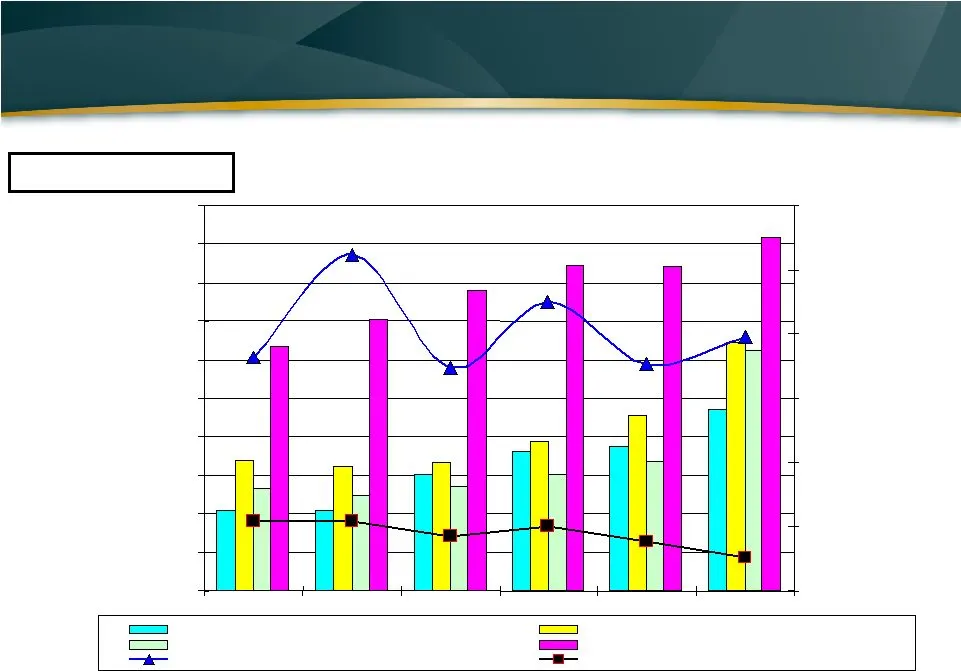
Appendix Concentrations and Quality Migration thru Merger 0.0% 5.0% 10.0% 15.0% 20.0% 25.0% 30.0% 35.0% 40.0% 45.0% 50.0% 2006ii 2006iii 2006iv 2007i 2007ii 2007iii % of Capital (bars) 0.000% 0.200% 0.400% 0.600% 0.800% 1.000% 1.200% *capital adjusted for post-merger comparability % of Portfolio (li
Slide 48: Historical Asset Quality Measurements
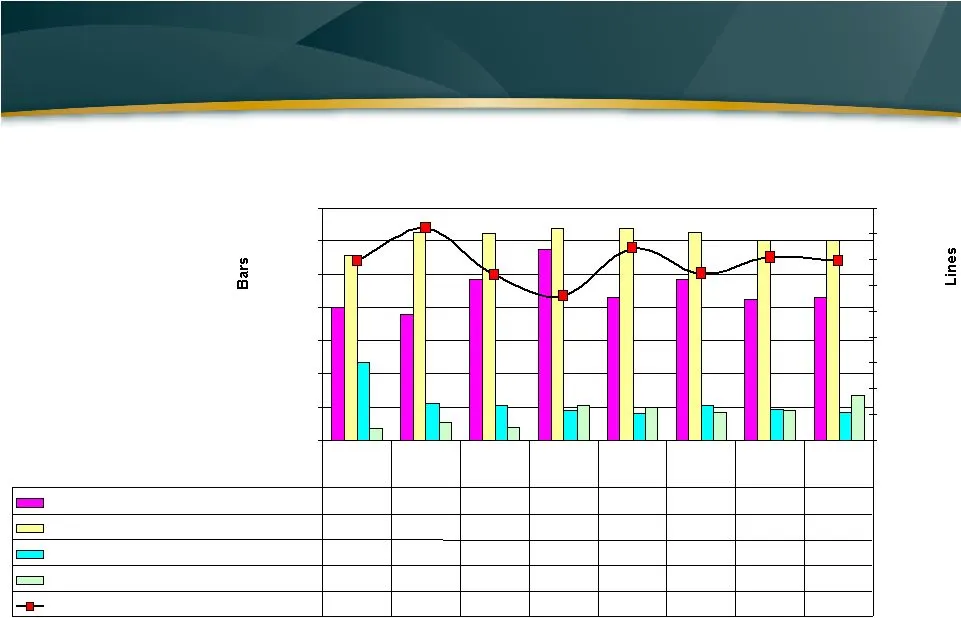
Appendix Historical Asset Quality Measurements 0.00% 0.20% 0.40% 0.60% 0.80% 1.00% 1.20% 1.40% Annually, and Quarterly Through Merger 0.00% 20.00% 40.00% 60.00% 80.00% 100.00% 120.00% 140.00% 160.00% 180.00% Nonperforming Loans / Total Loans HFI 0.80% 0.76% 0.97% 1.15% 0.86% 0.97% 0.85% 0.86% Reserv
Source: SEC EDGAR · 8-K filed Nov 1, 2007
More decks from Communityone Bancorp
 Merger or Acquisition (February 2016)25 slides · Feb 8, 2016
 Q4 2015 Earnings Presentation22 slides · Jan 29, 2016
 Q3 2015 Earnings Presentation17 slides · Oct 30, 2015
 Q2 2015 Earnings Presentation17 slides · Jul 30, 2015
 Q1 2015 Earnings Presentation17 slides · Apr 30, 2015
 Investor Presentation (March 2015)18 slides · Mar 5, 2015