Hanger — Hanger Orthopedic Group — Investor Presentation (February 2012)
29 slides from Hanger's investor presentation, Feb 28, 2012
Slide 1: Investor Presentation February 2012: Advancing the Vision
Investor Presentation February 2012 ADVANCING THE VISION
Slide 2: Safe Harbor
Except for the historical information contained herein, the matters discussed in this presentation constitute forward-looking statements that involve risks and uncertainties that could cause actual results to differ materially from those projected. These include the rate at which Hanger grows same-c
Slide 3: Vision
Be the partner of choice for products and services that enhance human physical capability. VISION 2
Slide 4: Overview
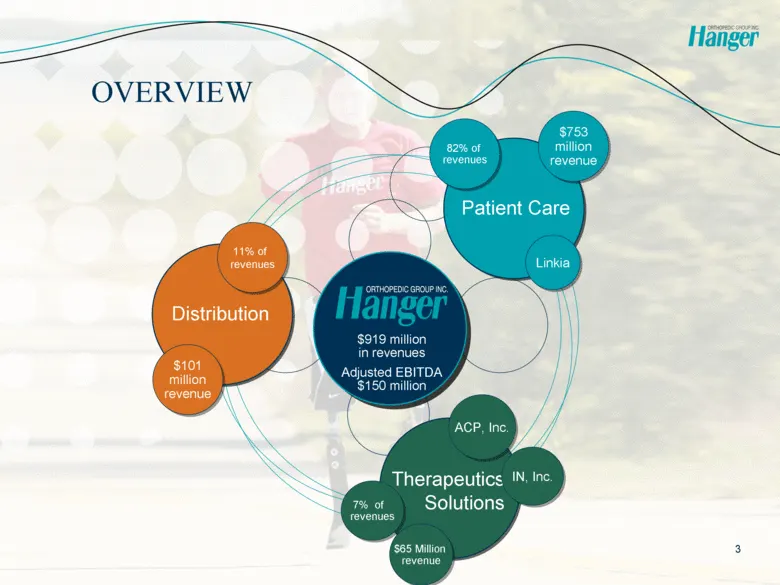
OVERVIEW Distribution Patient Care Therapeutics Solutions 11% of revenues $101 million revenue 82% of revenues Linkia 7% of revenues ACP, Inc. IN, Inc. $753 million revenue $919 million in revenues Adjusted EBITDA $150 million 3 $65 Million revenue
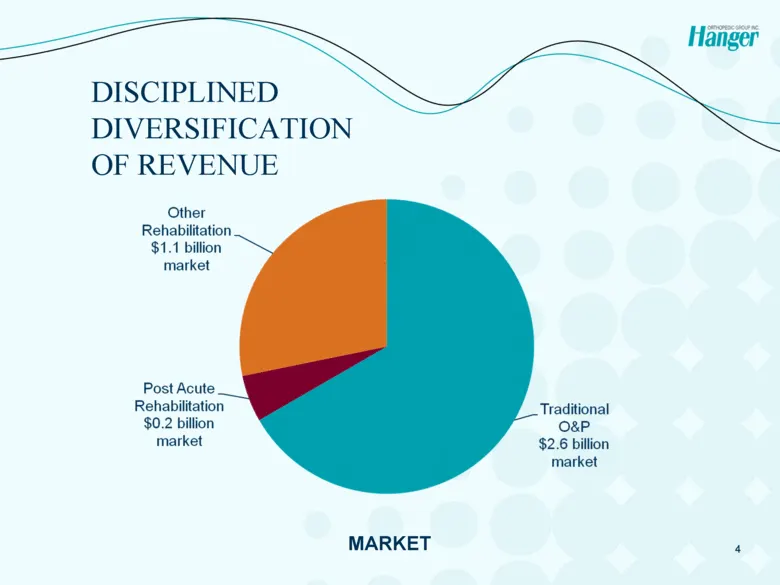
Slide 5: Disciplined Diversification of Revenue: Market
DISCIPLINED DIVERSIFICATION OF REVENUE MARKET 4
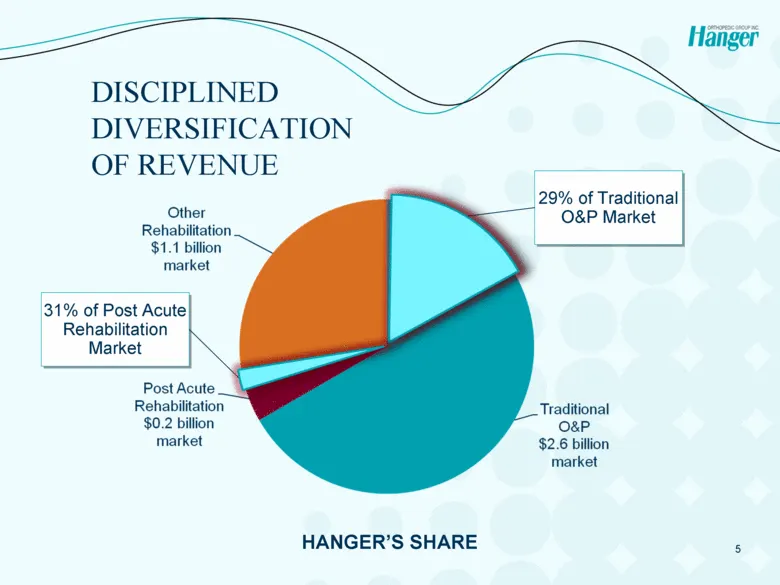
Slide 6: Disciplined Diversification of Revenue: Hanger's Share
DISCIPLINED DIVERSIFICATION OF REVENUE 5 HANGER’S SHARE 29% of Traditional O&P Market 31% of Post Acute Rehabilitation Market
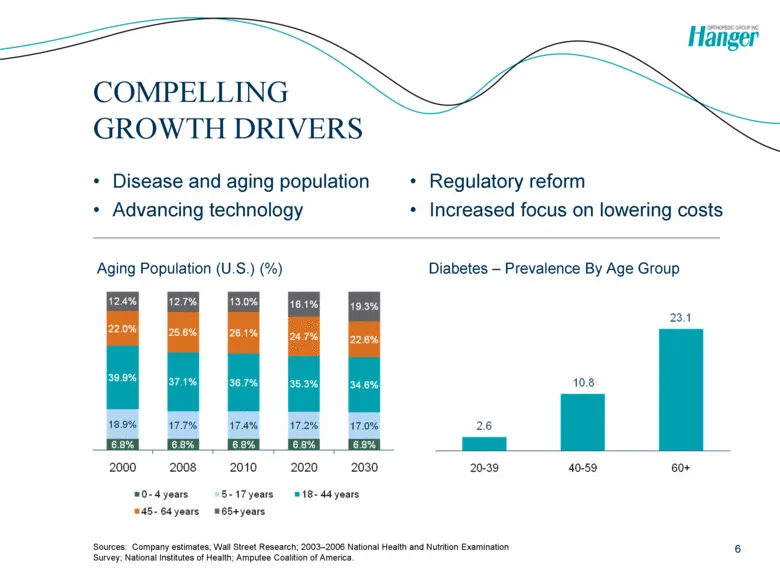
Slide 7: Compelling Growth Drivers
COMPELLING GROWTH DRIVERS Sources: Company estimates; Wall Street Research; 2003–2006 National Health and Nutrition Examination Survey; National Institutes of Health; Amputee Coalition of America. Aging Population (U.S.) (%) Diabetes – Prevalence By Age Group Disease and aging population Advancing t
Slide 8: Patient Care
Hanger PATIENT CARE
Slide 9: Patient Care Profile
One or more certified practitioners Technical personnel Office administrators Line of site incentives to grow revenues and collect receivables CAGR of 6.7% (2008 - 2011) PATIENT CARE PROFILE BUSINESS OVERVIEW CENTER OVERVIEW Over 700 O&P patient-care centers Over 1,100 O&P certified and licensed pra
Slide 10: Patient Care Market Position
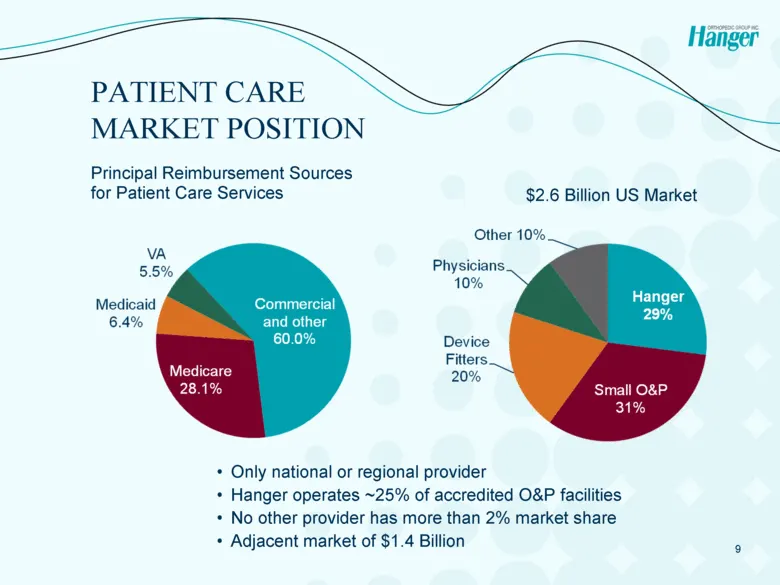
PATIENT CARE MARKET POSITION Only national or regional provider Hanger operates ~25% of accredited O&P facilities No other provider has more than 2% market share Adjacent market of $1.4 Billion Principal Reimbursement Sources for Patient Care Services $2.6 Billion US Market 9
Slide 11: Patient Care Growth Opportunities
First to market with new technologies and products Linkia Network Management Diversification into new adjacent businesses CARES Dosteon Solutions Small O&P acquisitions Sales synergies with ACP PATIENT CARE GROWTH OPPORTUNITIES 10
Slide 12: Linkia Network Management
First and only O&P network management company Insurers’ exclusive or preferred provider of their network Hanger network of approximately 1,030 O&P centers 52 contracts; 1-3 years; auto renew Value proposition to large name companies through expanded services 28% CAGR of contracted revenues (2008 - 2
Slide 13: Distribution
7 ea DISTRIBUTION
Slide 14: Distribution Profile
Largest dedicated distributor of O&P devices and components Over 29,000 O&P related items 6 strategically located distribution facilities Comprehensive Customer Service Manufacture and distribute therapeutic footwear Net sales $101 million and CAGR of 7.6% (2008 - 2011) Inter-company sales $190 mill
Slide 15: Distribution Opportunities
Increase depth and breadth of product line Increase penetration of existing customer base Expand customer base Expand market presence geographically Apply core competencies to adjacent businesses Expand O&P fabrication operation to Independent O&P Providers DISTRIBUTION OPPORTUNITIES 14
Slide 16: Therapeutic Solutions
~ 900<Caa THERAPEUTIC SOLUTIONS
Slide 17: Therapeutic Solutions – Diversification of Revenue
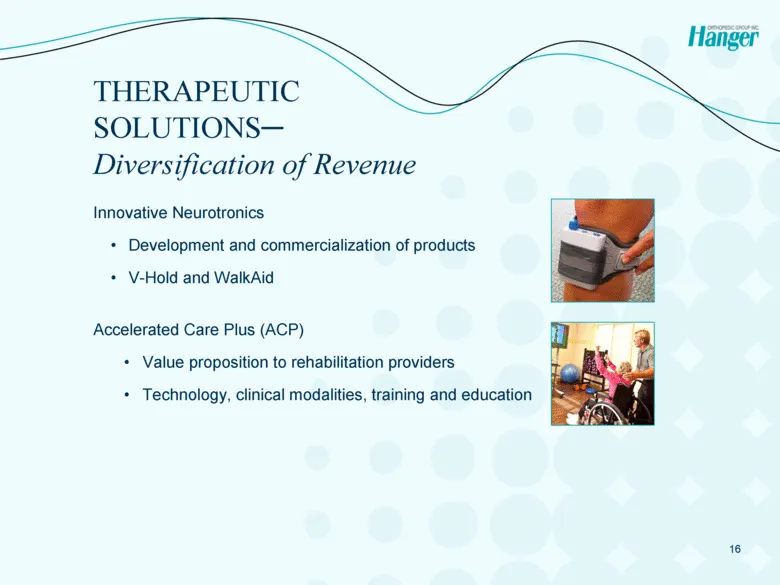
Innovative Neurotronics Development and commercialization of products V-Hold and WalkAid Accelerated Care Plus (ACP) Value proposition to rehabilitation providers Technology, clinical modalities, training and education THERAPEUTIC SOLUTIONS– Diversification of Revenue 16
Slide 18: ACP Overview
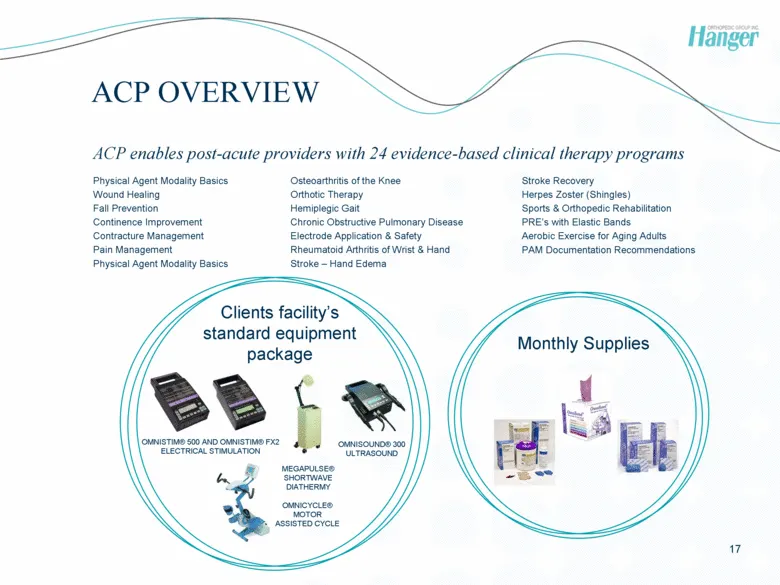
17 ACP OVERVIEW ACP enables post-acute providers with 24 evidence-based clinical therapy programs Physical Agent Modality Basics Wound Healing Fall Prevention Continence Improvement Contracture Management Pain Management Physical Agent Modality Basics Osteoarthritis of the Knee Orthotic Therapy Hemi
Slide 19: ACP Market Opportunities
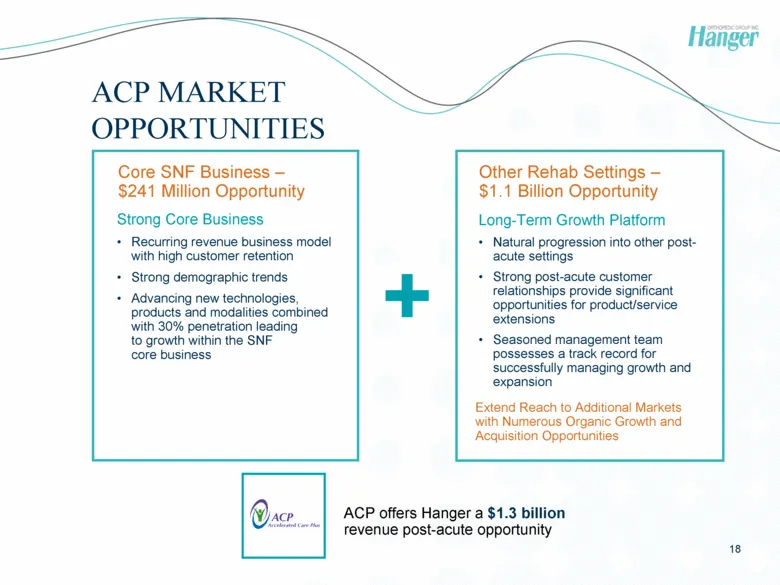
18 ACP MARKET OPPORTUNITIES ACP offers Hanger a $1.3 billion revenue post-acute opportunity Core SNF Business – $241 Million Opportunity Strong Core Business Recurring revenue business model with high customer retention Strong demographic trends Advancing new technologies, products and modalities co
Slide 20: Financial Overview
FINANCIAL OVERVIEW
Slide 21: Solid Financial Position
Earnings and margin growth Substantial cash flow generation Strong balance sheet management Moderate leverage post ACP acquisition Consistent Reduction of Leverage SOLID FINANCIAL POSITION 20
Slide 22: 2011 in Review
Same Store Sales 2.6% YTD and 2.2% for 4th Quarter 22.8% growth in Adjusted EBITDA Improved Operating Margins Repriced Debt (March 2011) 15.5% increase in adjusted earnings per share 2011 IN REVIEW 21
Slide 23: Revenue Growth
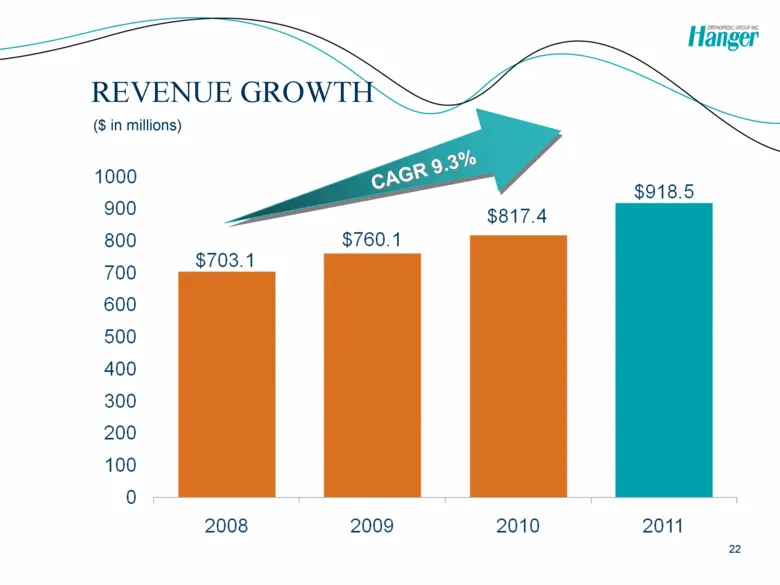
22 REVENUE GROWTH CAGR 9.3% ($ in millions) 1000 900 800 700 600 500 400 300 200 100 0 2008 2009 2010 2011 $703.1 $760.1 $817.4 $918.5
Slide 24: Adjusted EBITDA Growth and Margins
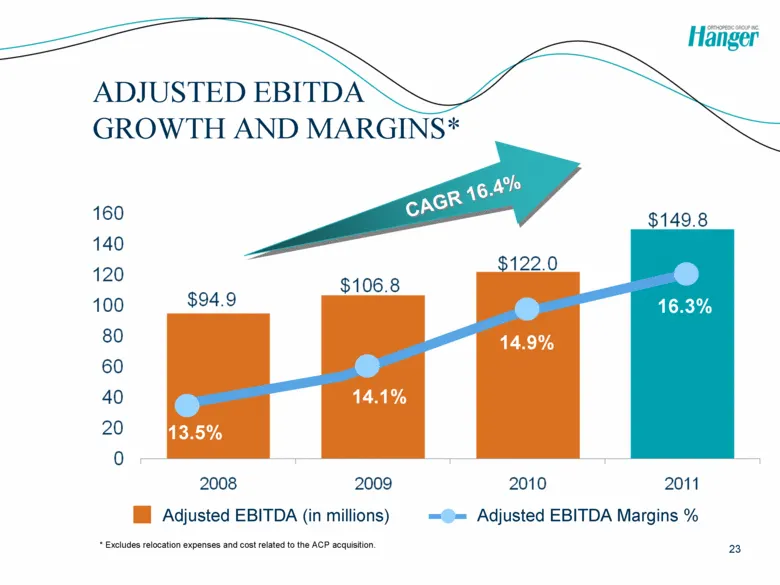
23 ADJUSTED EBITDA GROWTH AND MARGINS* CAGR 16.4% * Excludes relocation expenses and cost related to the ACP acquisition. 13.5% 14.1% 14.9% Adjusted EBITDA (in millions) Adjusted EBITDA Margins % 16.3% 160 140 120 100 80 60 40 20 0 2008 2009 2010 2011 $94.9 $106.8 $122.0 $149.8
Slide 25: Growth in Adjusted EPS
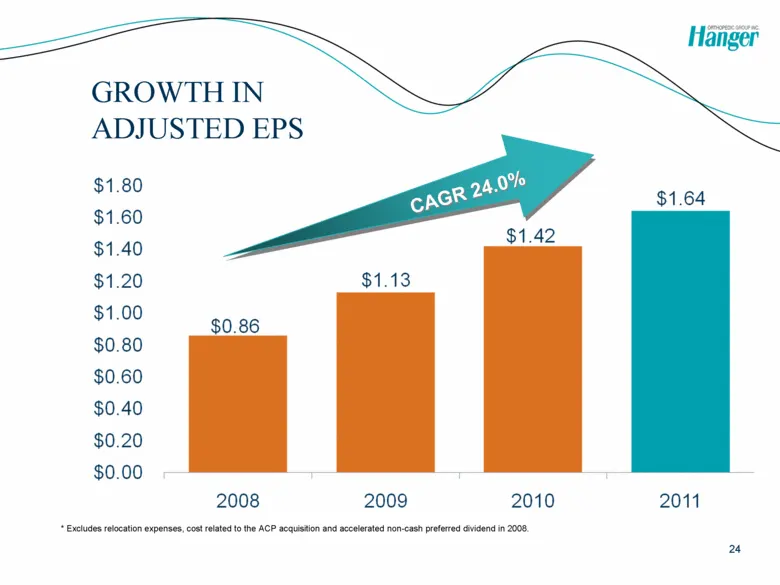
24 GROWTH IN ADJUSTED EPS * Excludes relocation expenses, cost related to the ACP acquisition and accelerated non-cash preferred dividend in 2008. CAGR 24.0% $0.86 $1.13 $1.42 $1.64 2008 2009 2010 2011
Slide 26: Steady Comparable Quarter Growth
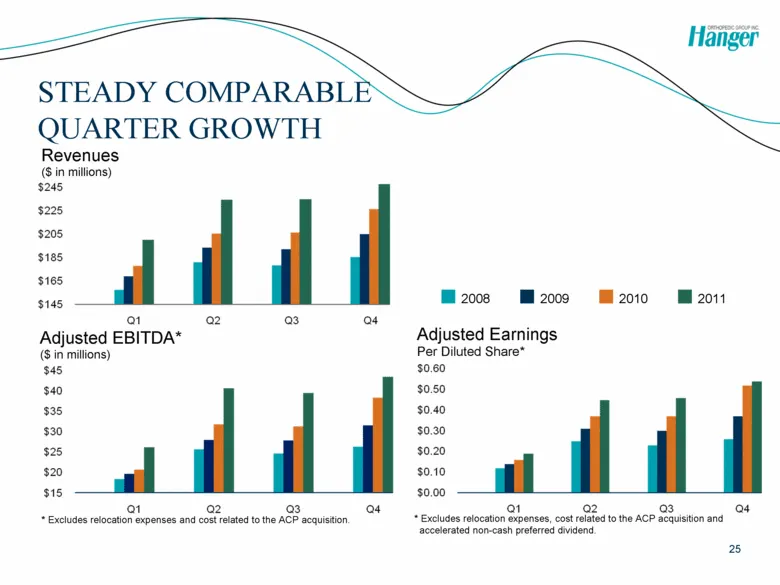
STEADY COMPARABLE QUARTER GROWTH 2008 2009 2010 2011 Adjusted EBITDA* ($ in millions) * Excludes relocation expenses and cost related to the ACP acquisition. Revenues ($ in millions) Adjusted Earnings Per Diluted Share* * Excludes relocation expenses, cost related to the ACP acquisition and accelera
Slide 27: Improved Leverage & Liquidity
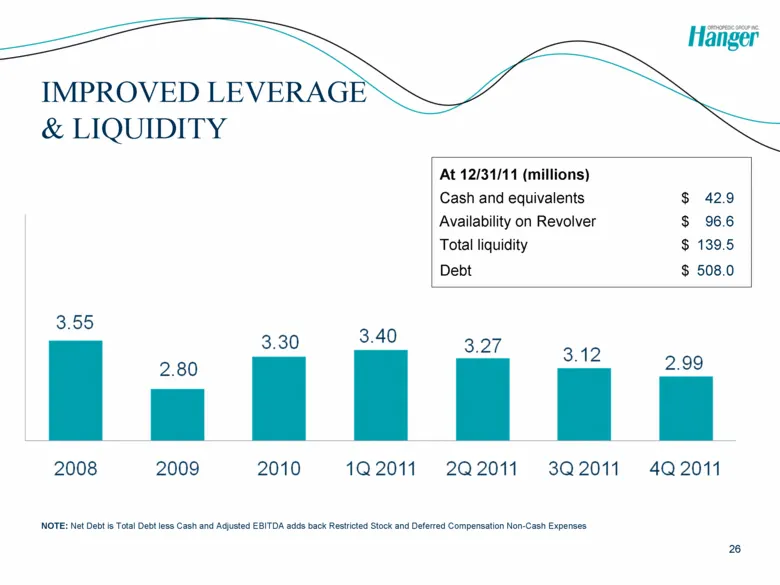
IMPROVED LEVERAGE & LIQUIDITY 26 NOTE: Net Debt is Total Debt less Cash and Adjusted EBITDA adds back Restricted Stock and Deferred Compensation Non-Cash Expenses At 12/31/11 (millions) Cash and equivalents $ 42.9 Availability on Revolver $ 96.6 Total liquidity $ 139.5 Debt $ 508.0
Slide 28: Key Investment Points
Compelling industry growth drivers Dominant market position Attractive organic growth opportunities Adjacent continuum of care opportunities Proven acquisition capabilities Solid financial position KEY INVESTMENT POINTS 27
Slide 29: Hanger Orthopedic Group Inc.
ORTHOPEDIC GROUP INC. anger Hager (NYSE: HGR) = SPS LINKIA Experience Our Commitment 0) ACP Sureitr CCleS Ovex: tetigual fy DOSTECN NEUROTRONICS
Source: SEC EDGAR · 8-K filed Feb 28, 2012
More decks from Hanger Inc
 Investor Presentation (May 2020)38 slides · May 18, 2020
 Investor Presentation (December 2018)30 slides · Dec 4, 2018
 Investor Presentation (August 2018)39 slides · Aug 22, 2018
 Investor Presentation (November 2013)24 slides · Nov 12, 2013
 Investor Presentation (August 2013)24 slides · Aug 21, 2013
 Investor Presentation (February 2013)29 slides · Feb 25, 2013