Newalliance Bancshares — Barclays Capital Global Financial Services Conference 2009
41 slides from Newalliance Bancshares's conference presentation, Sep 16, 2009
Slide 1: NewAlliance Bancshares
NewAlliance Bancshares Barclays Capital Global Financial Services Conference September 16, 2009
Slide 2: Disclaimer & Forward-Looking Statements
Disclaimer & Forward-Looking Statements Statements in this document and presented orally at the conference, if any, concerning future results, performance, expectations or intentions are forward-looking statements. Actual results, performance or developments may differ materially from forward-lookin
Slide 3: Discussion Topics
Discussion Topics Company Profile and Business Focus Key 2009 Business Priorities Highlights of Second Quarter 2009 Credit Quality Organizational Strengths Investor Presentation - September 2009 3
Slide 4: NewAlliance Bank Executive Management Team
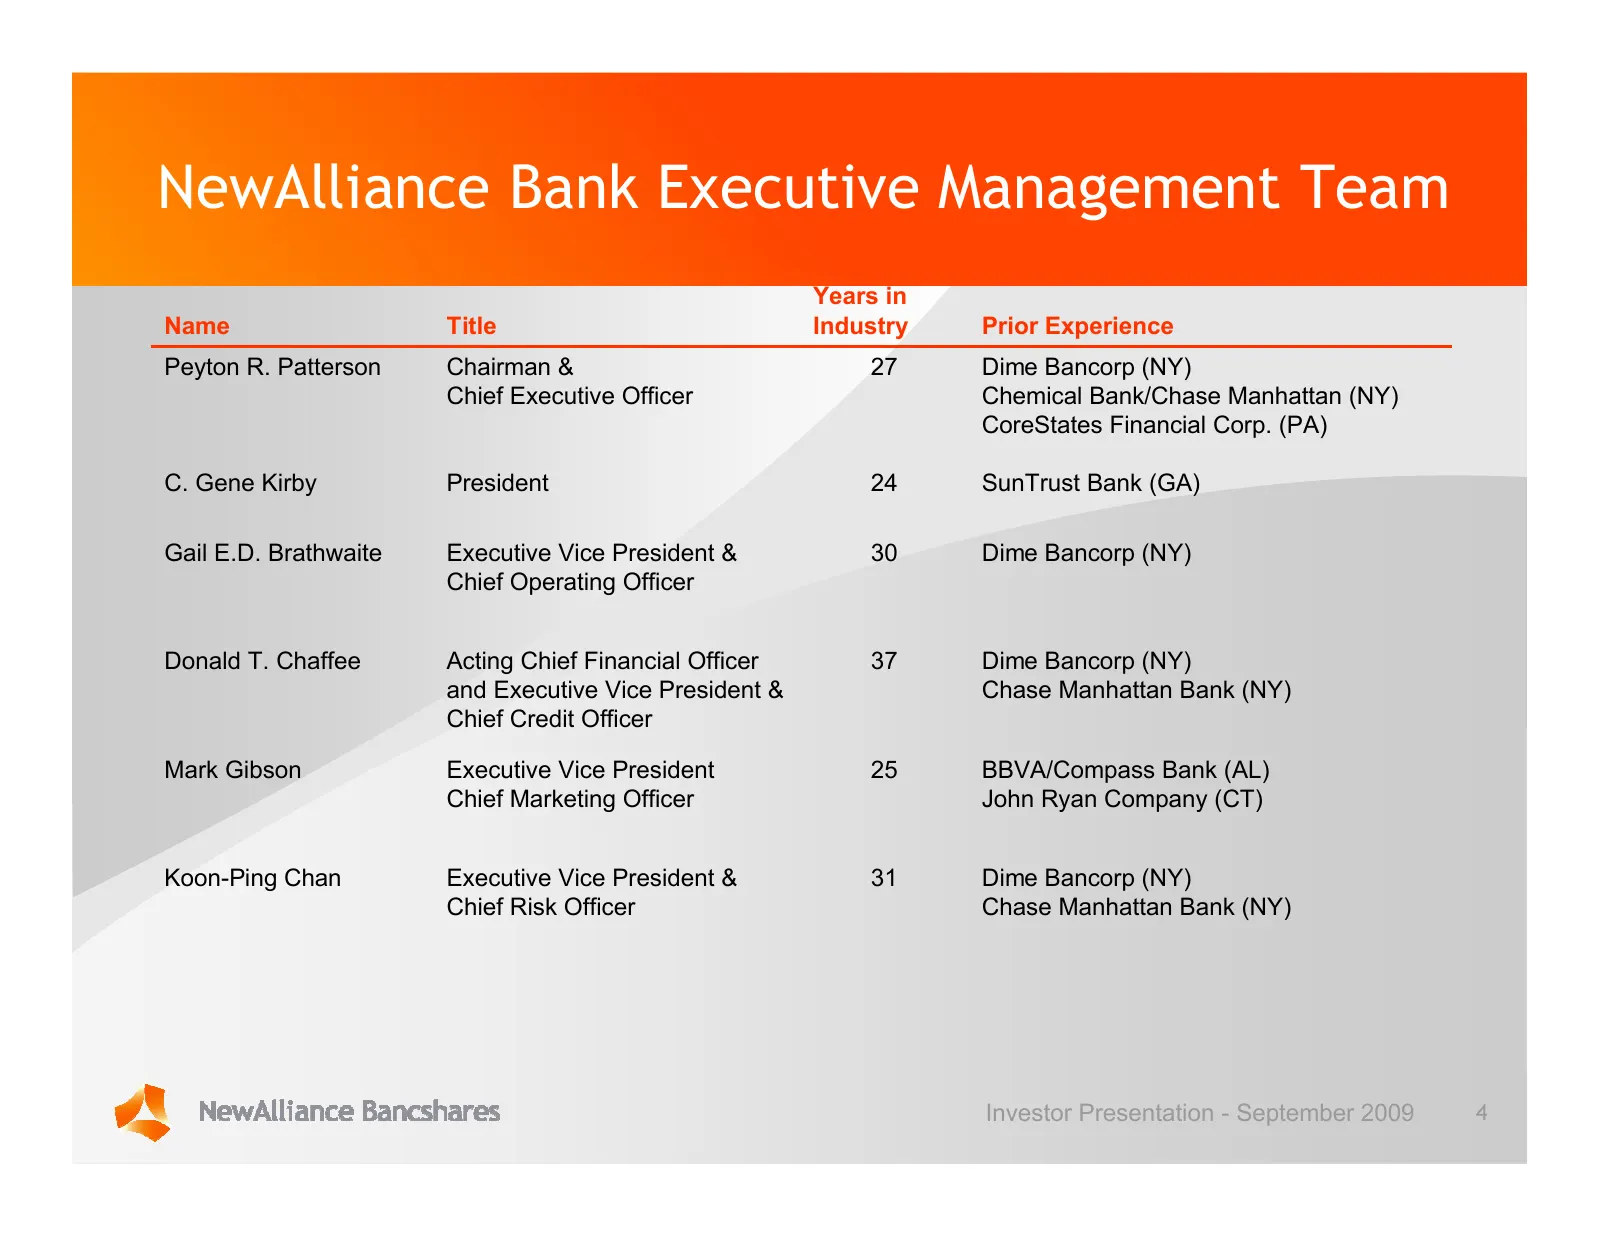
NewAlliance Bank Executive Management Team Years in Name Title Industry Prior Experience Peyton R. Patterson Chairman & 27 Dime Bancorp (NY) Chief Executive Officer Chemical Bank/Chase Manhattan (NY) CoreStates Financial Corp. (PA) C. Gene Kirby President 24 SunTrust Bank (GA) Gail E.D. Brathwaite E
Slide 5: Company Profile & Organizational Strengths
Company Profile & Organizational Strengths NewAlliance is a regional community bank with a significant southern New England presence. Top New England community bank 87 branches in Connecticut and Massachusetts #4 bank headquartered in New England with $8.6bn in assets Strong credit quality driven by
Slide 6: Company Profile & Organizational Strengths (continued)
Company Profile & Organizational Strengths (continued) Strong balance sheet growth driven by sales culture and acquisitions 14.4% asset growth CAGR since April 1, 2004 7.0% deposit growth CAGR since April 1, 2004 Successful acquisition history Strong financial performance with levers to enhance earn
Slide 7: The NewAlliance Franchise
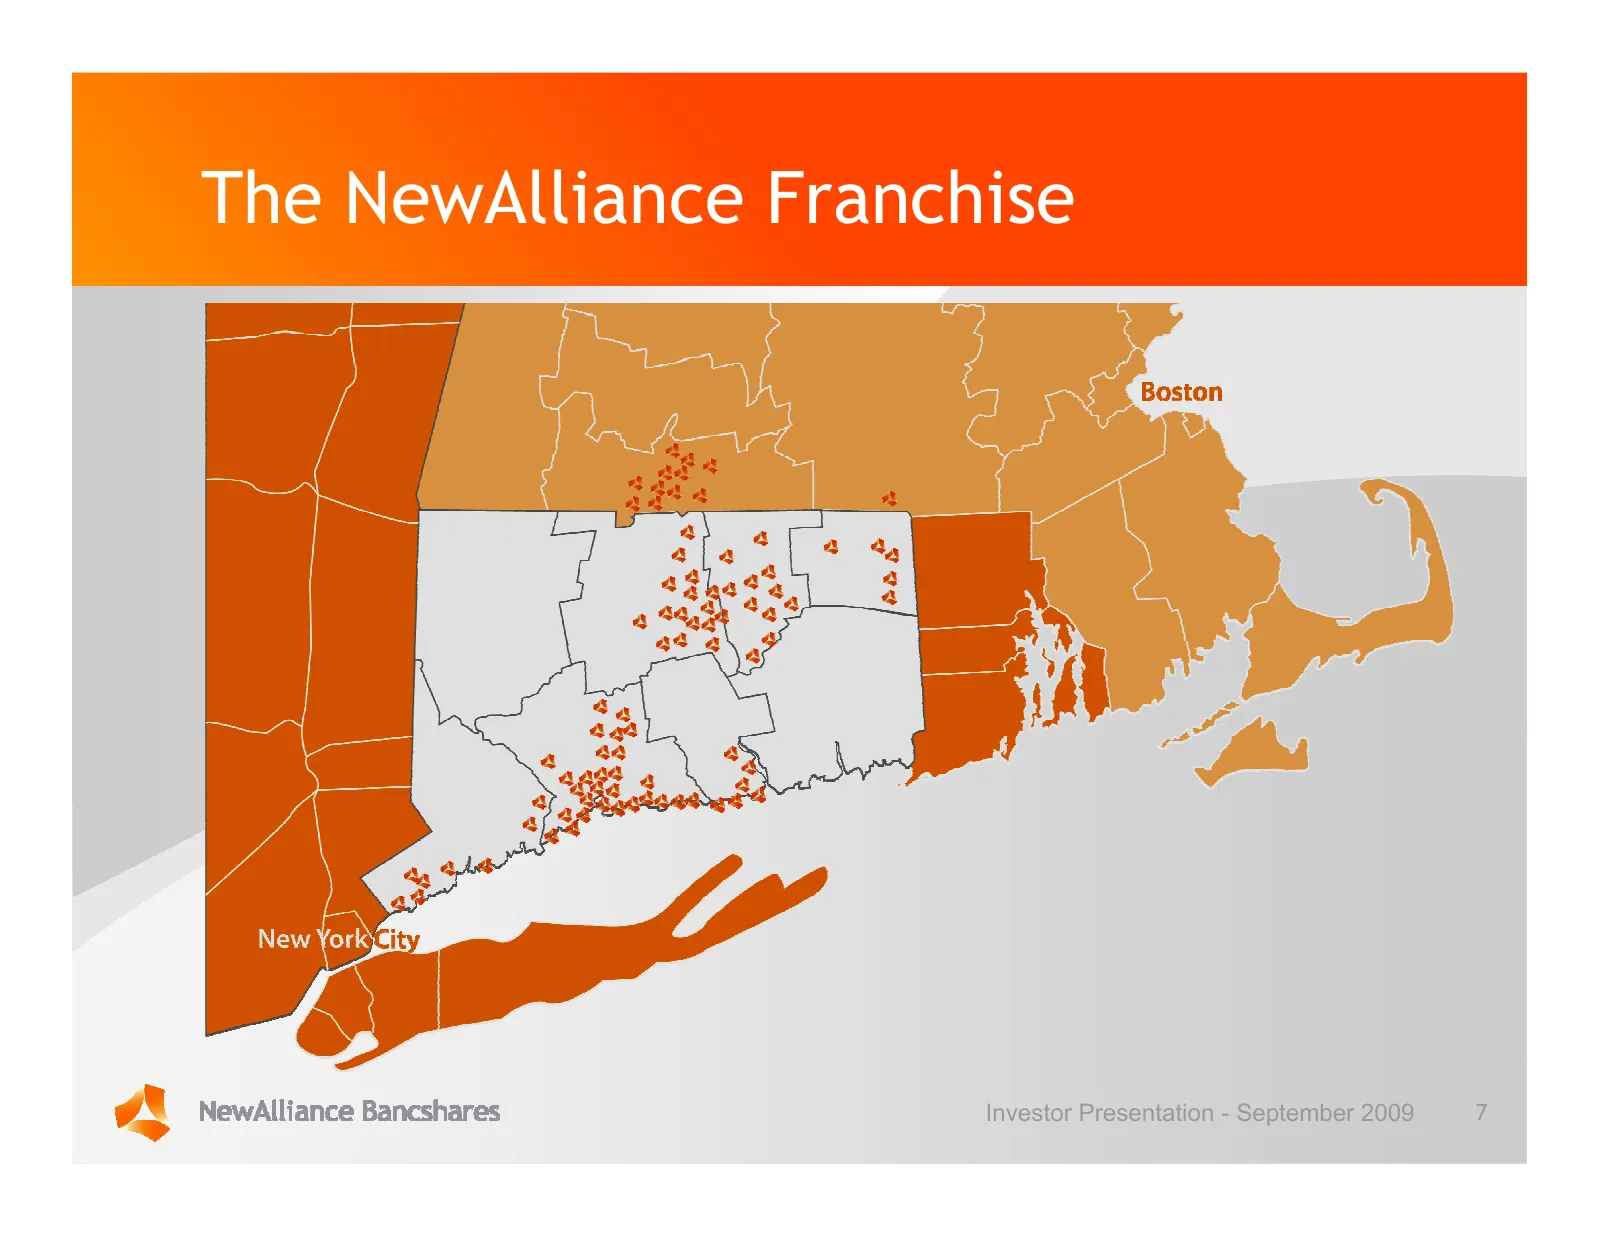
The NewAlliance Franchise Investor Presentation - September 2009 7
Slide 8: Credit Quality Trends — NAL vs. Peers
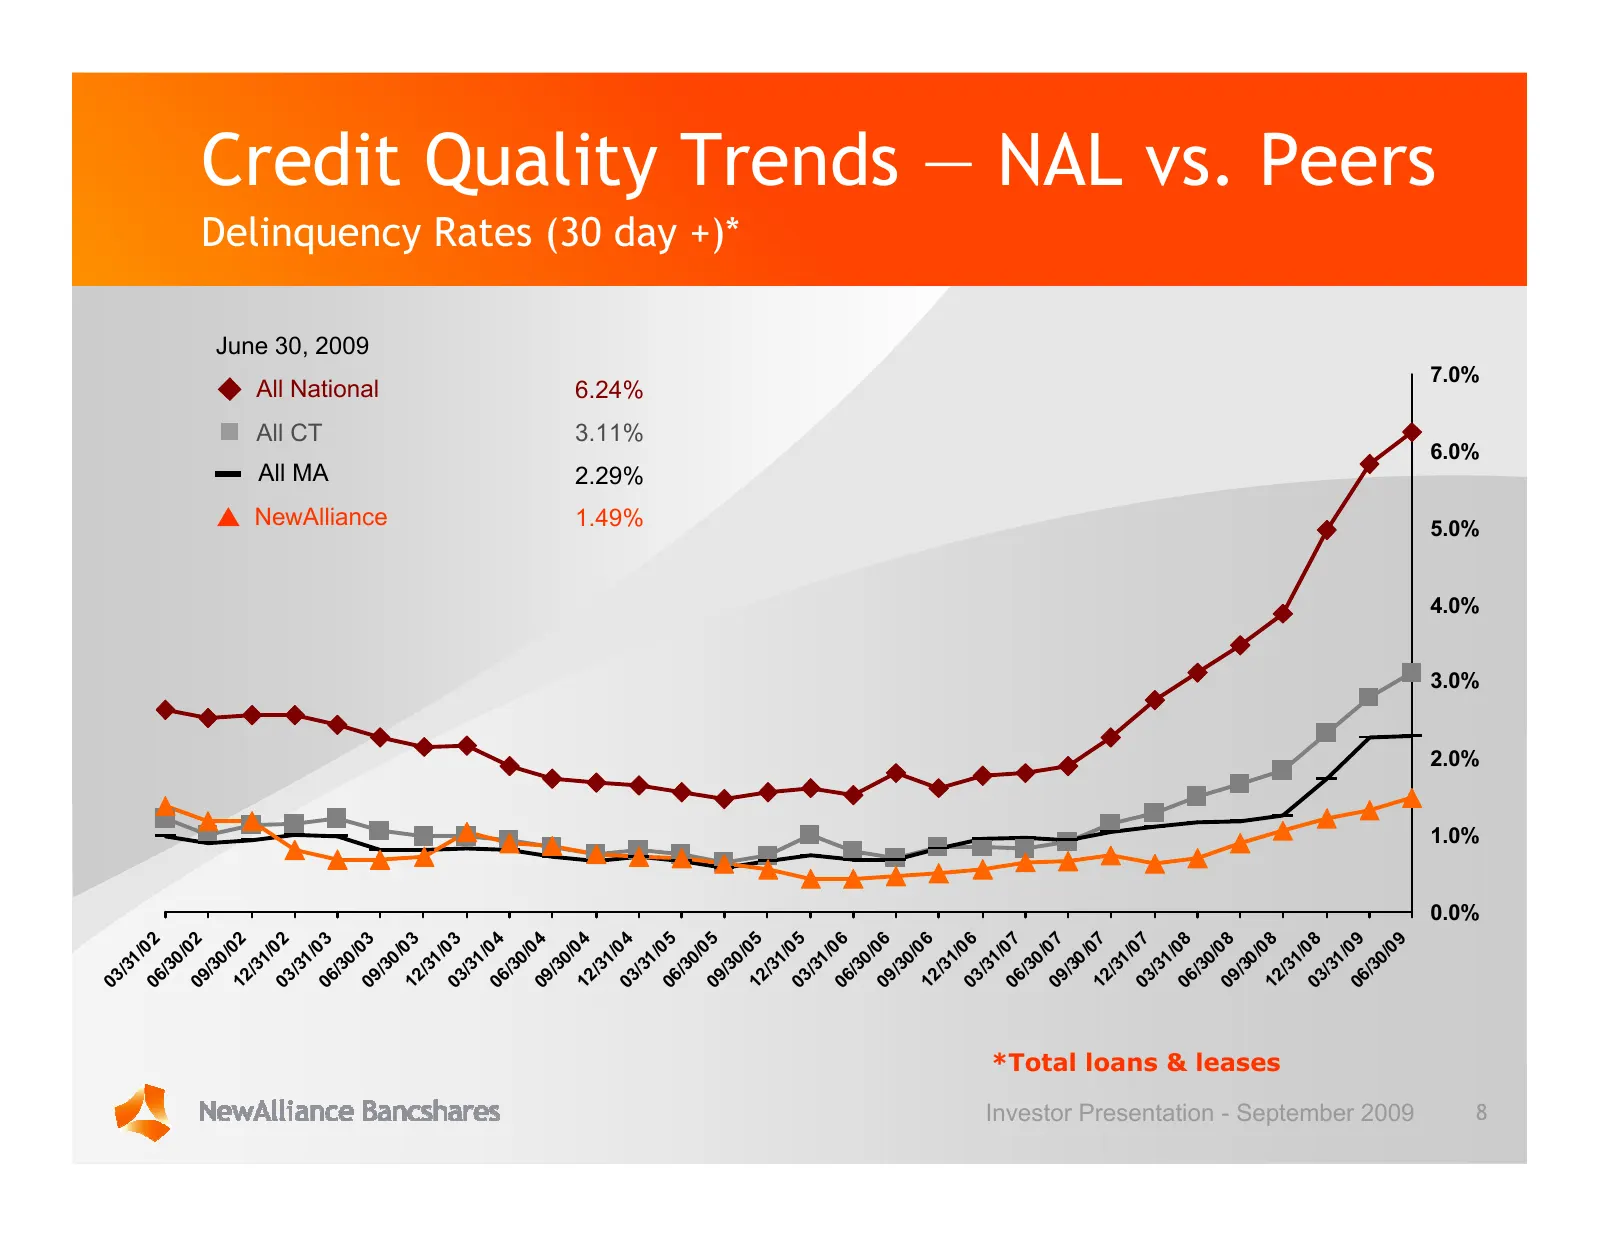
03 /3 1/ 06 0 2 /3 0/ 02 09 /3 0/ 12 0 2 /3 1/ 03 0 2 /3 1/ All CT All MA 06 0 3 /3 0/ June 30, 2009 All National 09 0 3 NewAlliance /3 0/ 12 0 3 /3 1/ 03 0 3 /3 1/ 06 0 4 /3 0/ 04 09 /3 0/ 12 0 4 /3 1/ 03 0 4 1.49% 2.29% 3.11% 6.24% /3 1/ 06 0 5 /3 0/ 05 09 /3 Delinquency Rates (30 day +)* 0/ 12 0
Slide 9: NewAlliance History
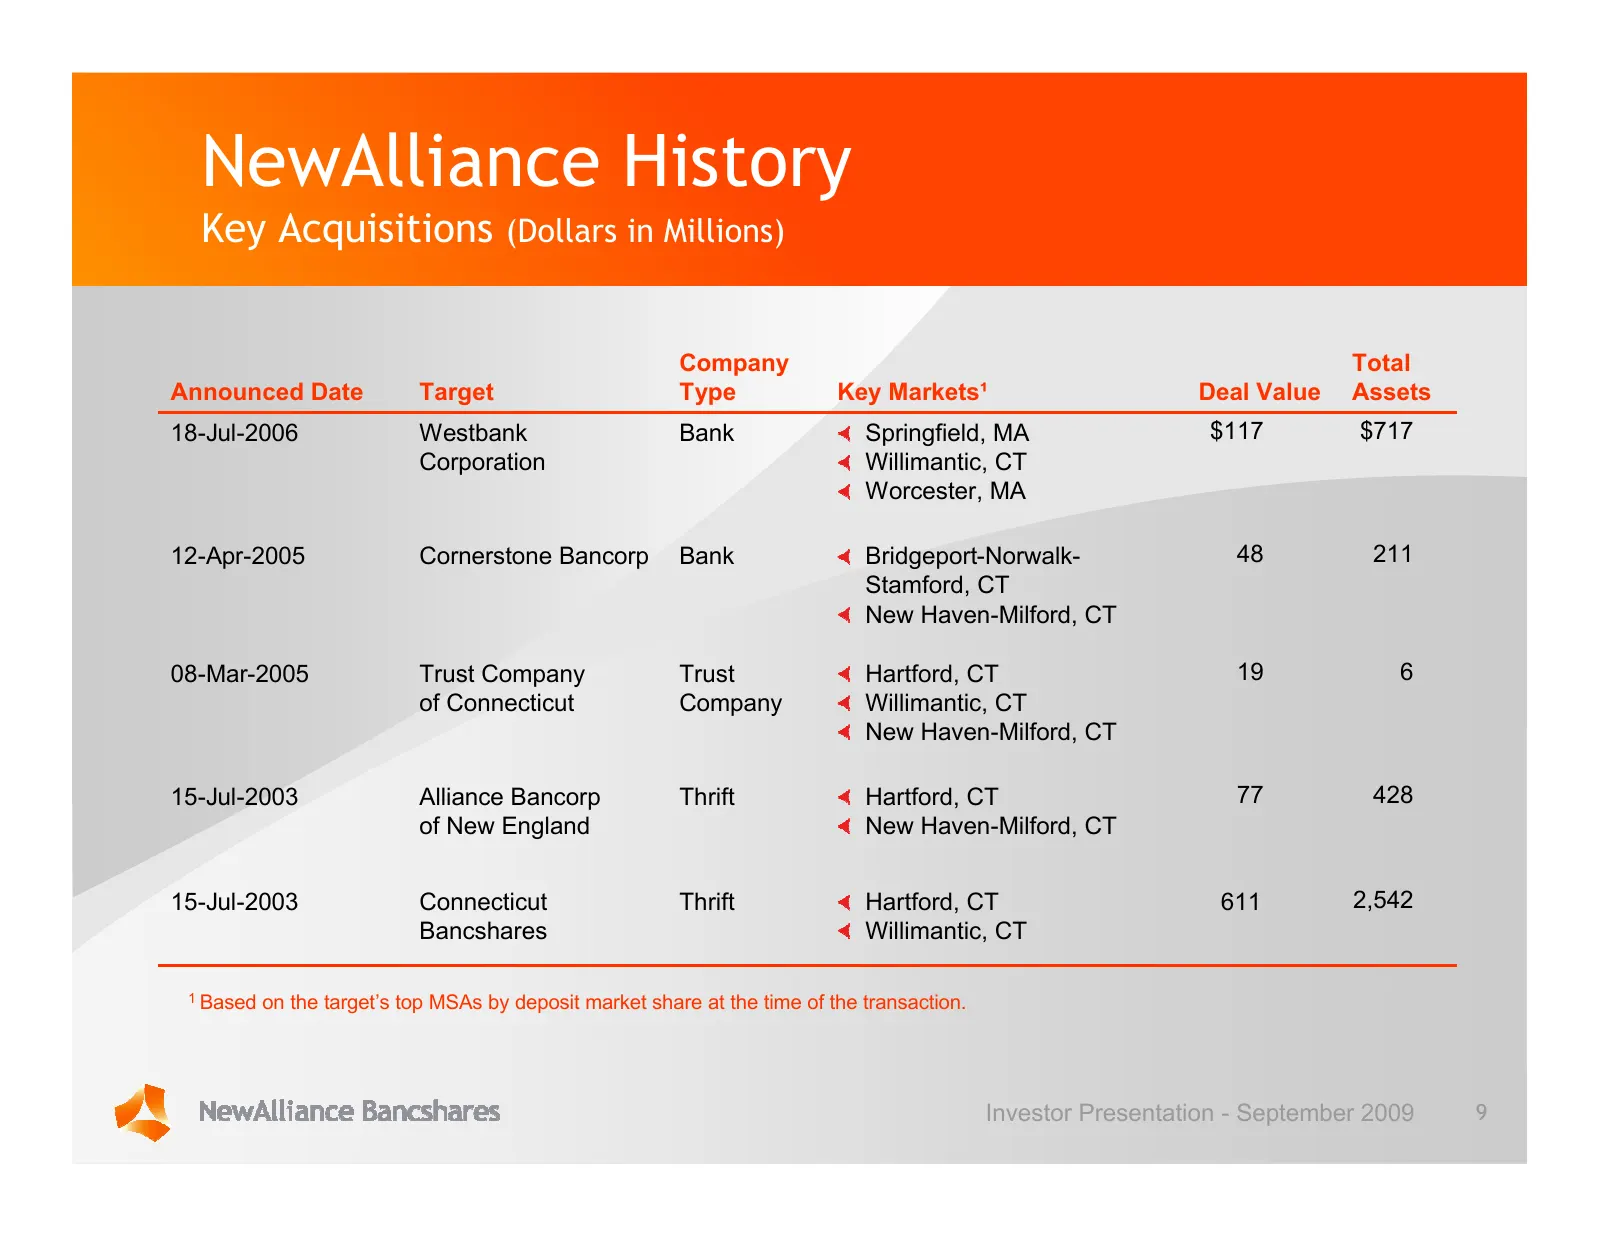
NewAlliance History Key Acquisitions (Dollars in Millions) Company Total Announced Date Target Type Key Markets¹ Deal Value Assets 18-Jul-2006 Westbank Bank Springfield, MA $117 $717 Corporation Willimantic, CT Worcester, MA 12-Apr-2005 Cornerstone Bancorp Bank Bridgeport-Norwalk- 48 211 Stamford, C
Slide 10: Key 2009 Business Priorities
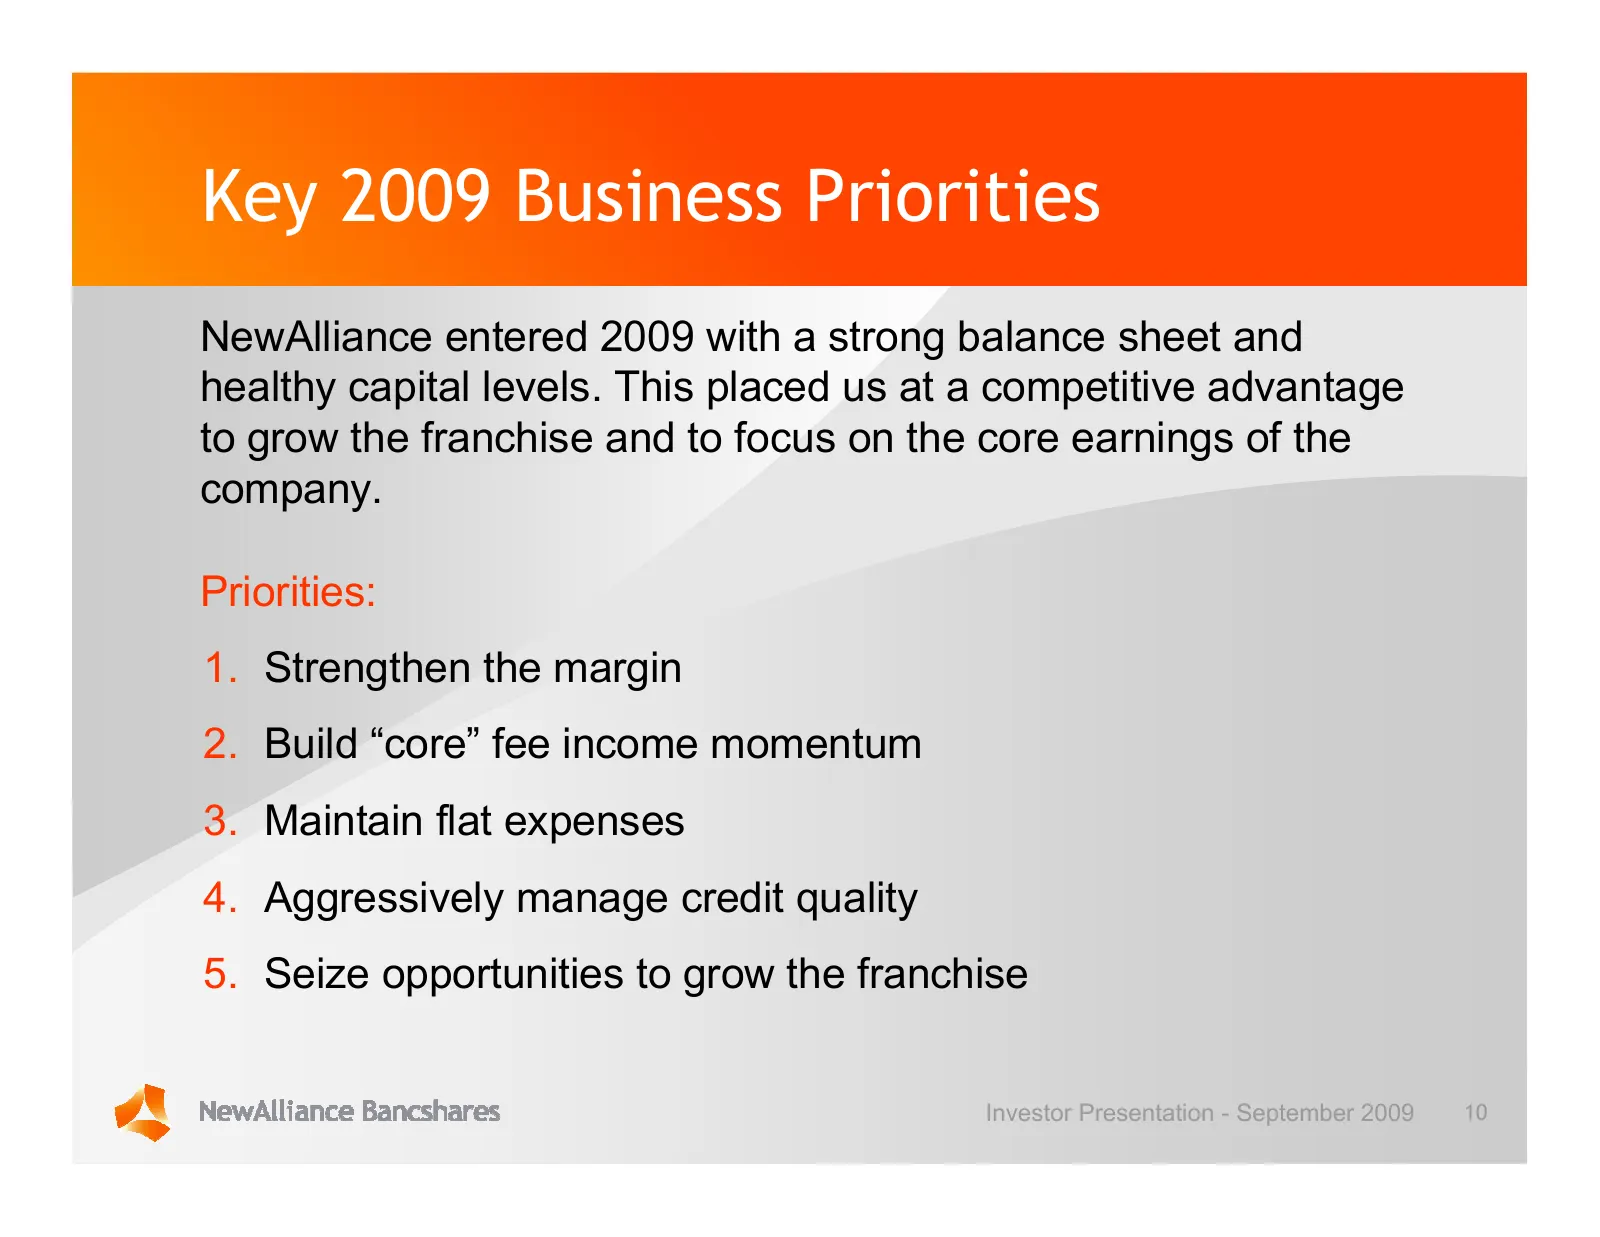
Key 2009 Business Priorities NewAlliance entered 2009 with a strong balance sheet and healthy capital levels. This placed us at a competitive advantage to grow the franchise and to focus on the core earnings of the company. Priorities: 1. Strengthen the margin 2. Build “core” fee income momentum 3.
Slide 11: Consolidated Statements of Income
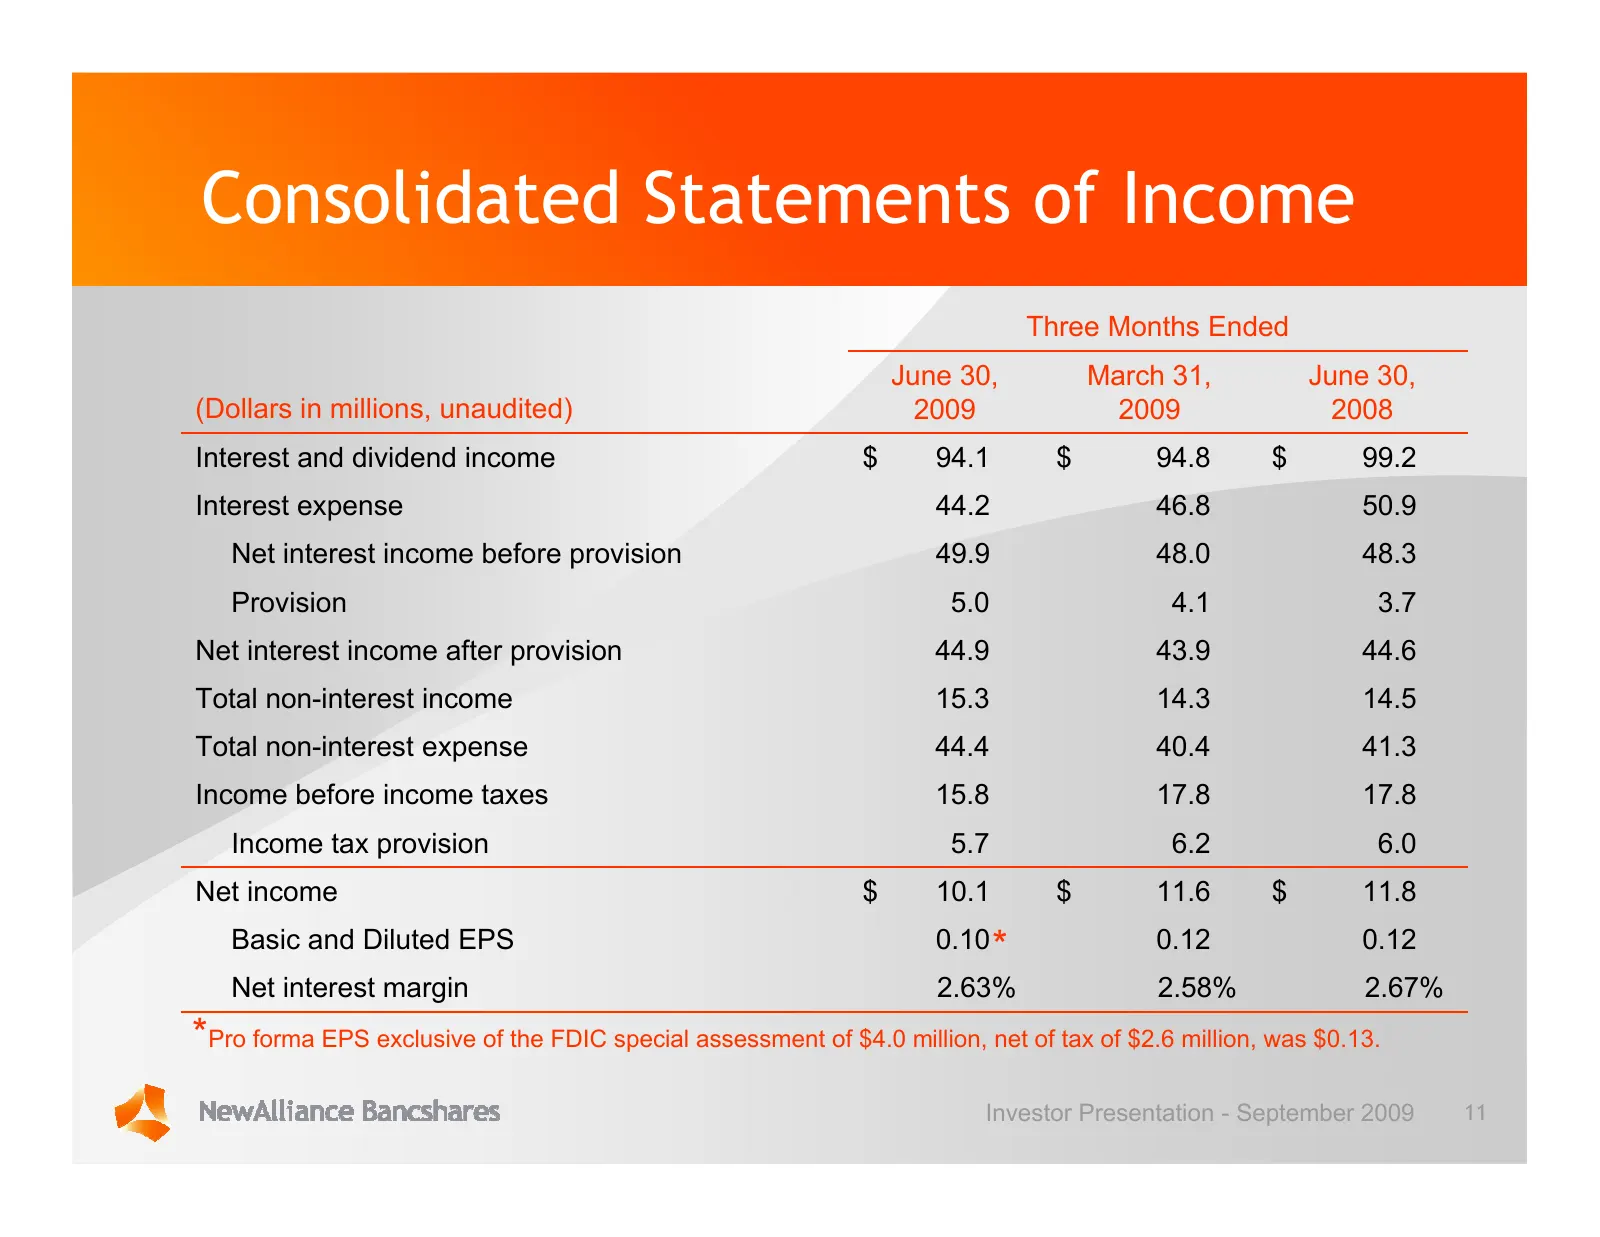
Consolidated Statements of Income Three Months Ended June 30, March 31, June 30, (Dollars in millions, unaudited) 2009 2009 2008 Interest and dividend income $ 94.1 $ 94.8 $ 99.2 Interest expense 44.2 46.8 50.9 Net interest income before provision 49.9 48.0 48.3 Provision 5.0 4.1 3.7 Net interest in
Slide 12: Highlights of Second Quarter 2009: Strengthen the Margin
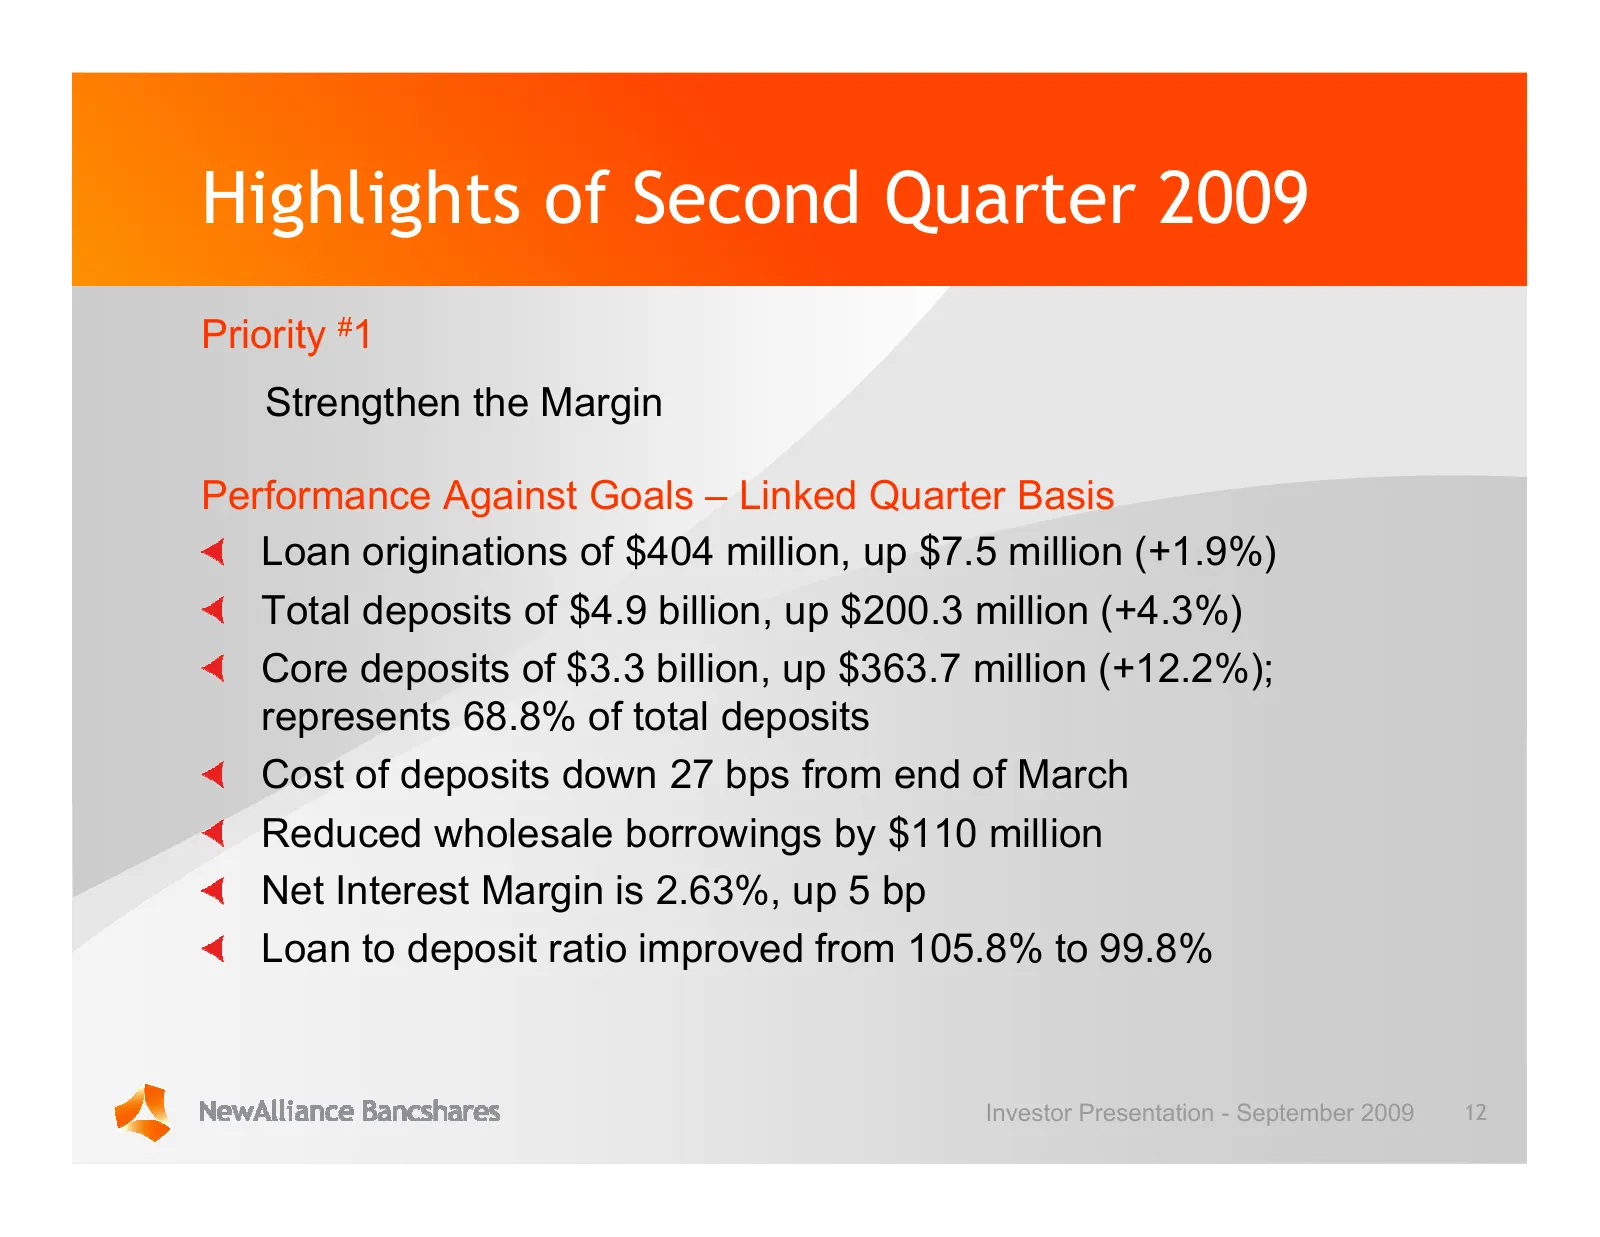
Highlights of Second Quarter 2009 Priority #1 Strengthen the Margin Performance Against Goals – Linked Quarter Basis Loan originations of $404 million, up $7.5 million (+1.9%) Total deposits of $4.9 billion, up $200.3 million (+4.3%) Core deposits of $3.3 billion, up $363.7 million (+12.2%); represe
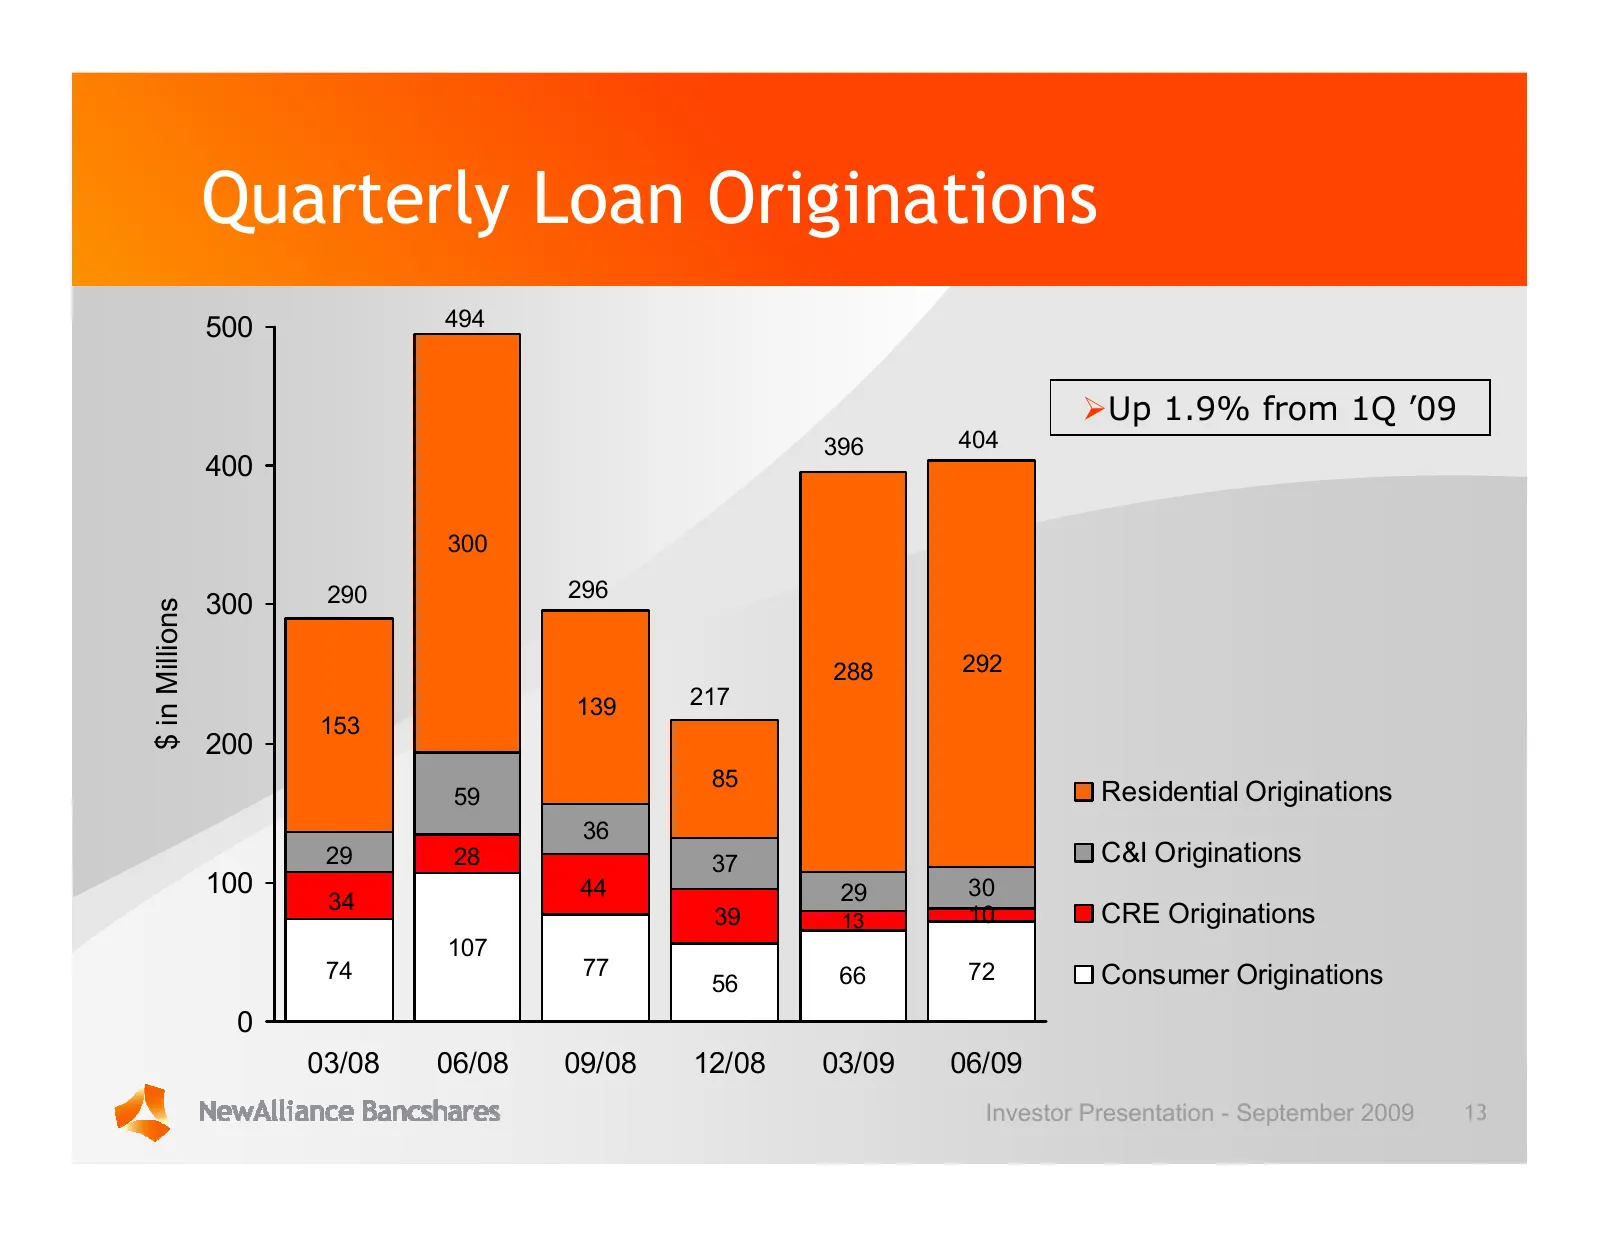
Slide 13: Quarterly Loan Originations
Quarterly Loan Originations 500 494 ØUp 1.9% from 1Q ’09 396 404 400 300 290 296 300 $ in Millions 288 292 139 217 153 200 85 59 Residential Originations 36 29 28 37 C&I Originations 100 44 29 30 34 39 13 10 CRE Originations 107 74 77 66 72 Consumer Originations 56 0 03/08 06/08 09/08 12/08 03/09 06
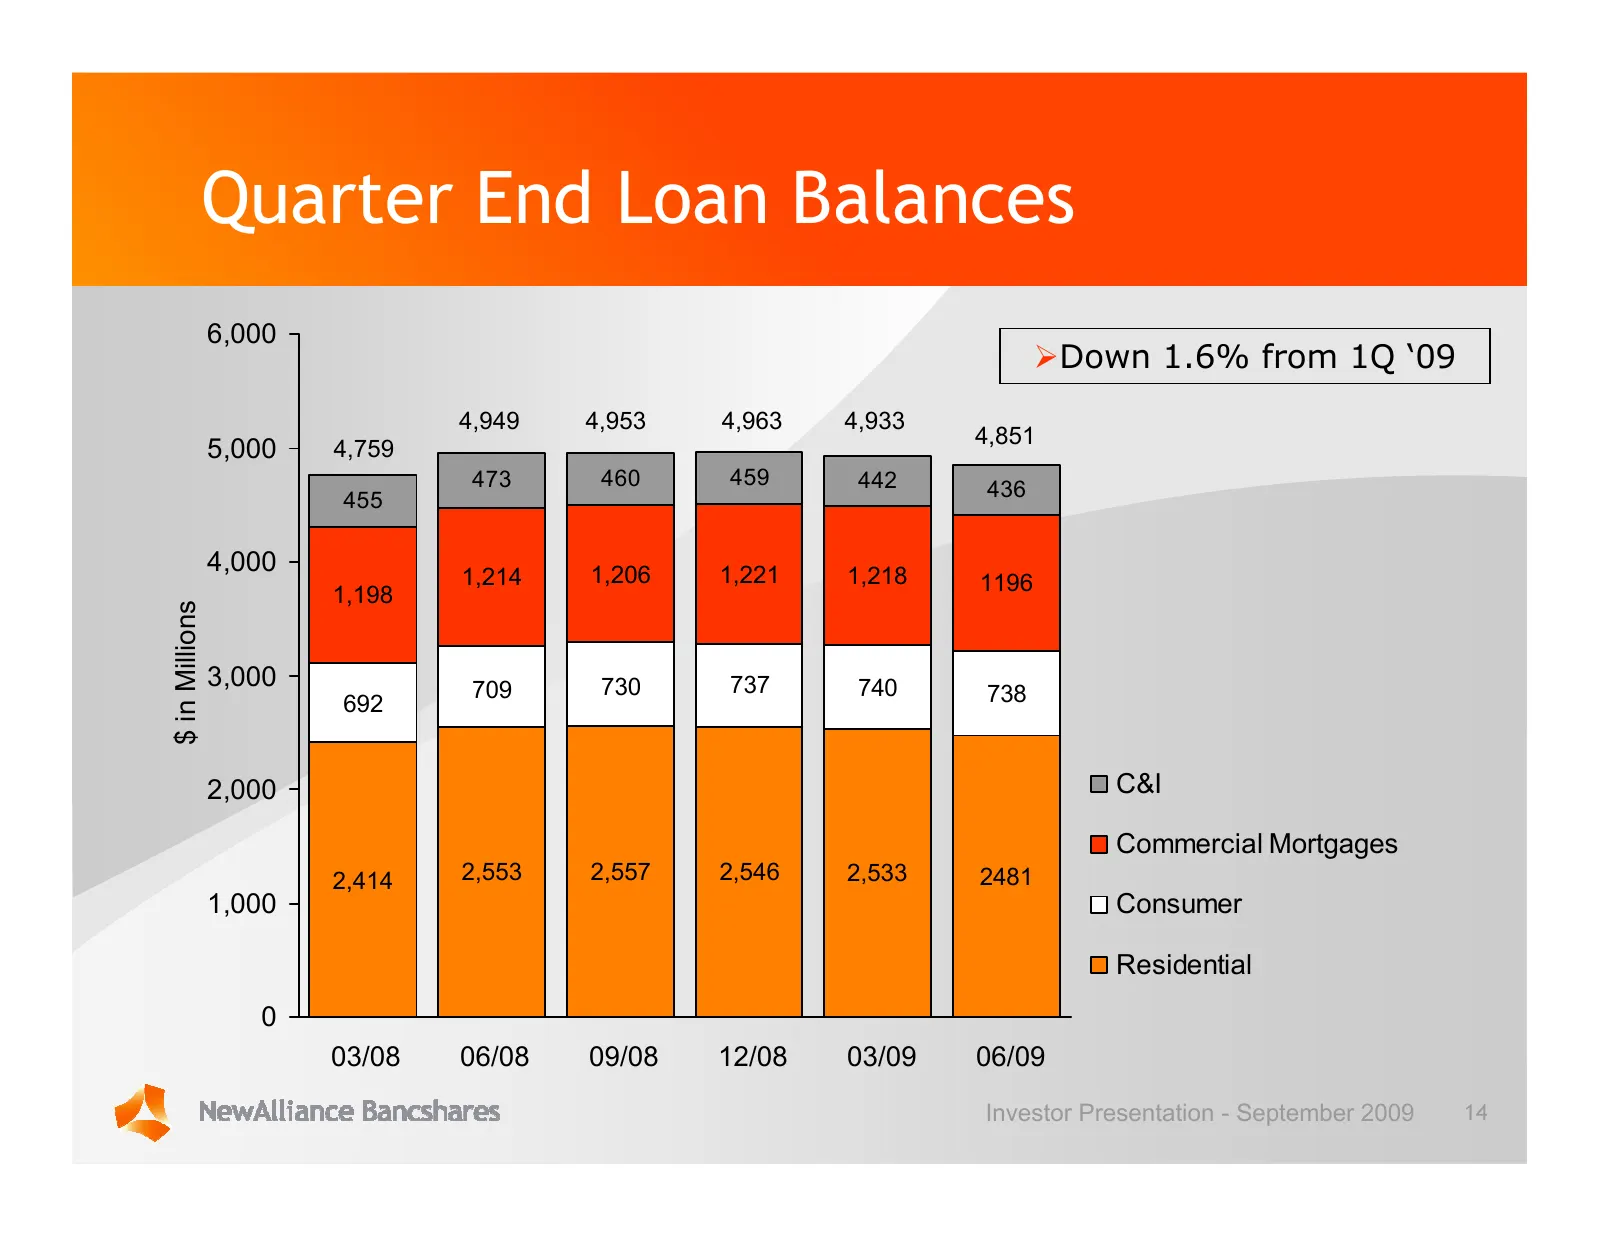
Slide 14: Quarter End Loan Balances
Quarter End Loan Balances 6,000 ØDown 1.6% from 1Q ‘09 4,949 4,953 4,963 4,933 4,851 5,000 4,759 473 460 459 442 455 436 4,000 1,206 1,221 1,218 1,214 1196 1,198 $ in Millions 3,000 709 730 737 740 692 738 2,000 C&I Commercial Mortgages 2,414 2,553 2,557 2,546 2,533 2481 1,000 Consumer Residential 0
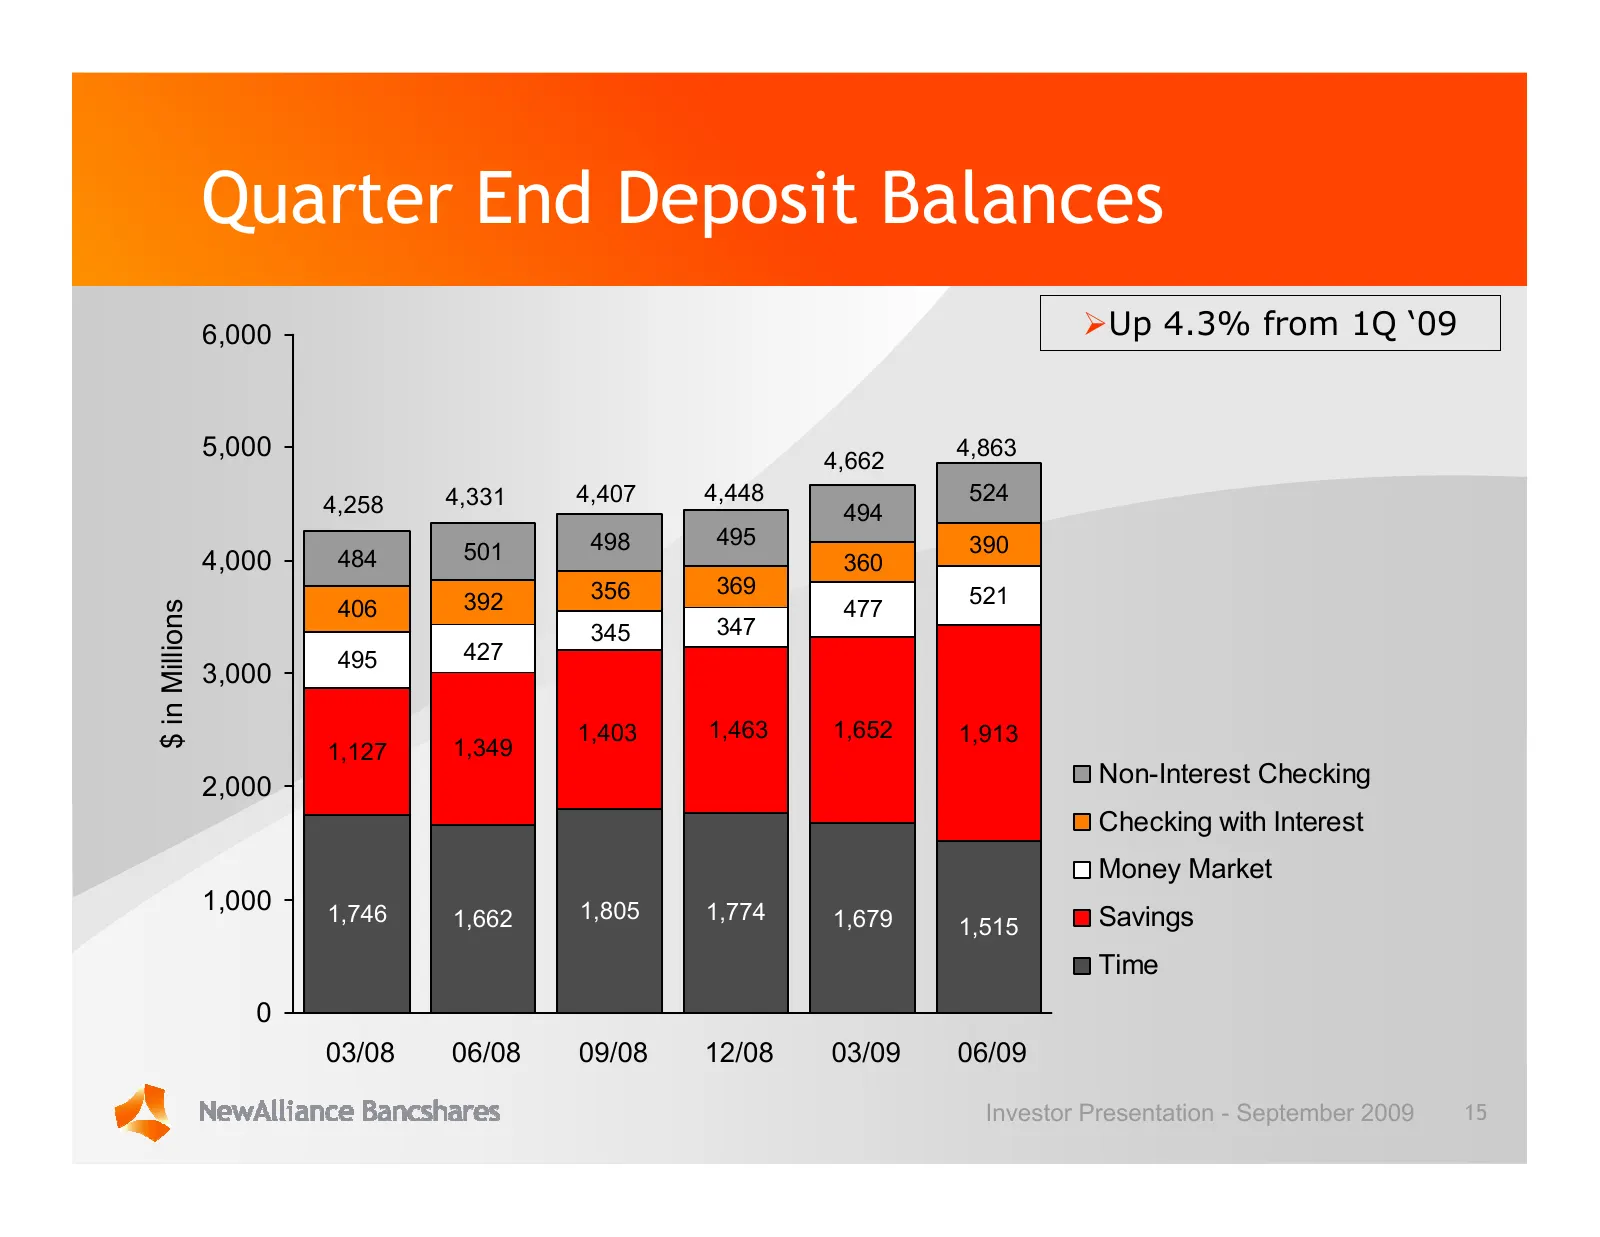
Slide 15: Quarter End Deposit Balances
Quarter End Deposit Balances 6,000 ØUp 4.3% from 1Q ‘09 5,000 4,662 4,863 4,331 4,407 4,448 524 4,258 494 498 495 390 4,000 484 501 360 356 369 521 406 392 477 $ in Millions 345 347 495 427 3,000 1,403 1,463 1,652 1,913 1,127 1,349 2,000 Non-Interest Checking Checking with Interest Money Market 1,00
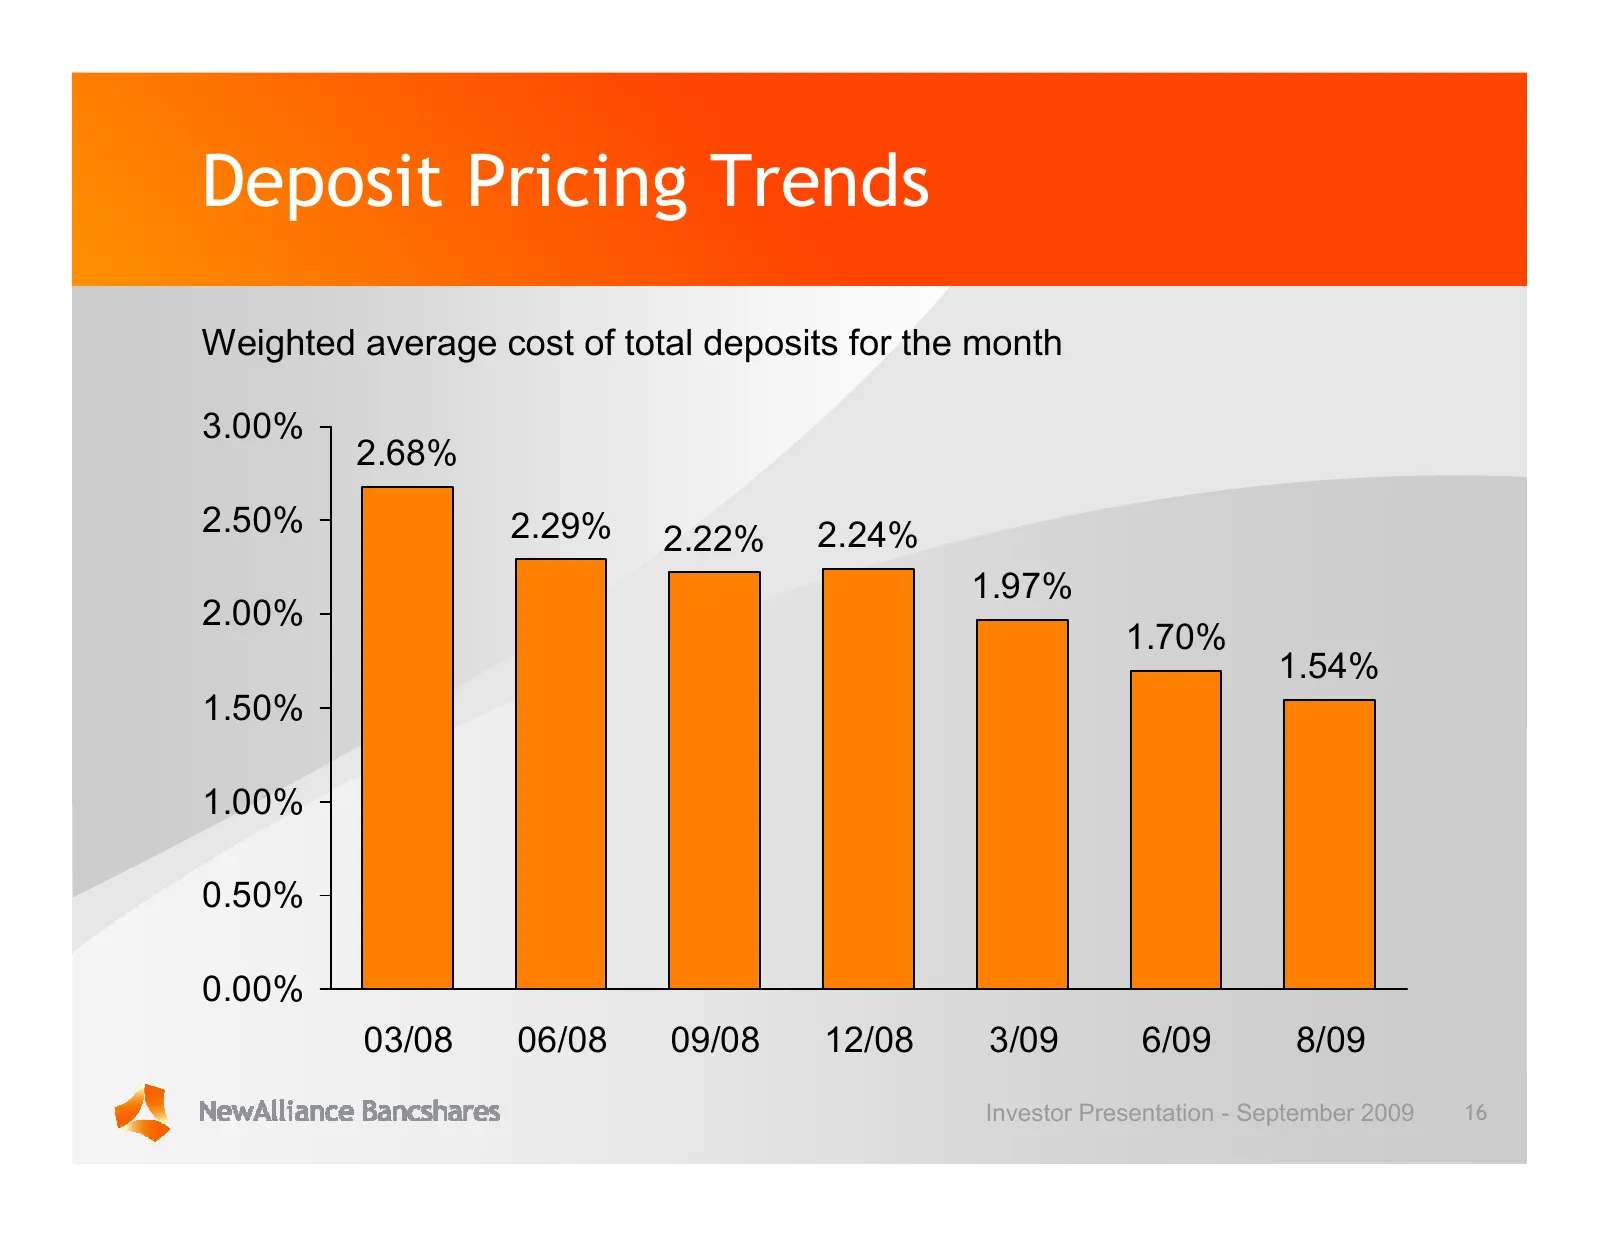
Slide 16: Deposit Pricing Trends
Deposit Pricing Trends Weighted average cost of total deposits for the month 3.00% 2.68% 2.50% 2.29% 2.24% 2.22% 1.97% 2.00% 1.70% 1.54% 1.50% 1.00% 0.50% 0.00% 03/08 06/08 09/08 12/08 3/09 6/09 8/09 Investor Presentation - September 2009 16
Slide 17: Highlights of Second Quarter 2009: Build Core Fee Income
Highlights of Second Quarter 2009 Priority #2 Build “Core” Fee Income Performance Against Goals – Linked Quarter Basis Overall non-interest income was up $1.0 million (+7.2%) Depositor service charges up $1.0 million (+16.8) Originating fixed rate mortgage loans for sale generated $1.5 million vs. $
Slide 18: Highlights of Second Quarter 2009: Manage Credit Quality
Highlights of Second Quarter 2009 Priority #3 Aggressively Manage Credit Quality Performance Against Goals Total delinquencies – 1.51%; down from May NPL’s -- 1.13%; rate of increase declined from 31% to 9% Net charge-offs -- 34 bp Loan loss provision of $5.0 million; reserve of $51.5 million Reserv
Slide 19: Highlights of Second Quarter 2009: Maintain Flat Expenses
Highlights of Second Quarter 2009 Priority #4 Maintain Flat Expenses Performance Against Goals Total non-interest expense, excluding the FDIC special assessment of $4.0 million, was flat from 1Q’09 and was $1.0 million lower than 2Q’08 Continue to execute on process improvements Remain committed to
Slide 20: Highlights of Second Quarter 2009: Grow the Franchise
Highlights of Second Quarter 2009 Priority #5 Seize Opportunities to Grow the Franchise Performance Against Goals Core deposits grew by $678 million, up 25% since June ‘08 Total Assets increased to $8.6 billion Capital remains strong 10.49% tangible common equity ratio 19.43% Tier 1 risk based ratio
Slide 21: Highlights of Second Quarter 2009: Grow the Franchise (continued)
Highlights of Second Quarter 2009 Priority #5 (continued) Seize Opportunities to Grow the Franchise Performance Against Goals M & A strategy will focus on: FDIC assisted transactions “Healthy bank” transactions Branch divestitures Investor Presentation - September 2009 21
Slide 22: Last Twelve Months Stock Price Performance
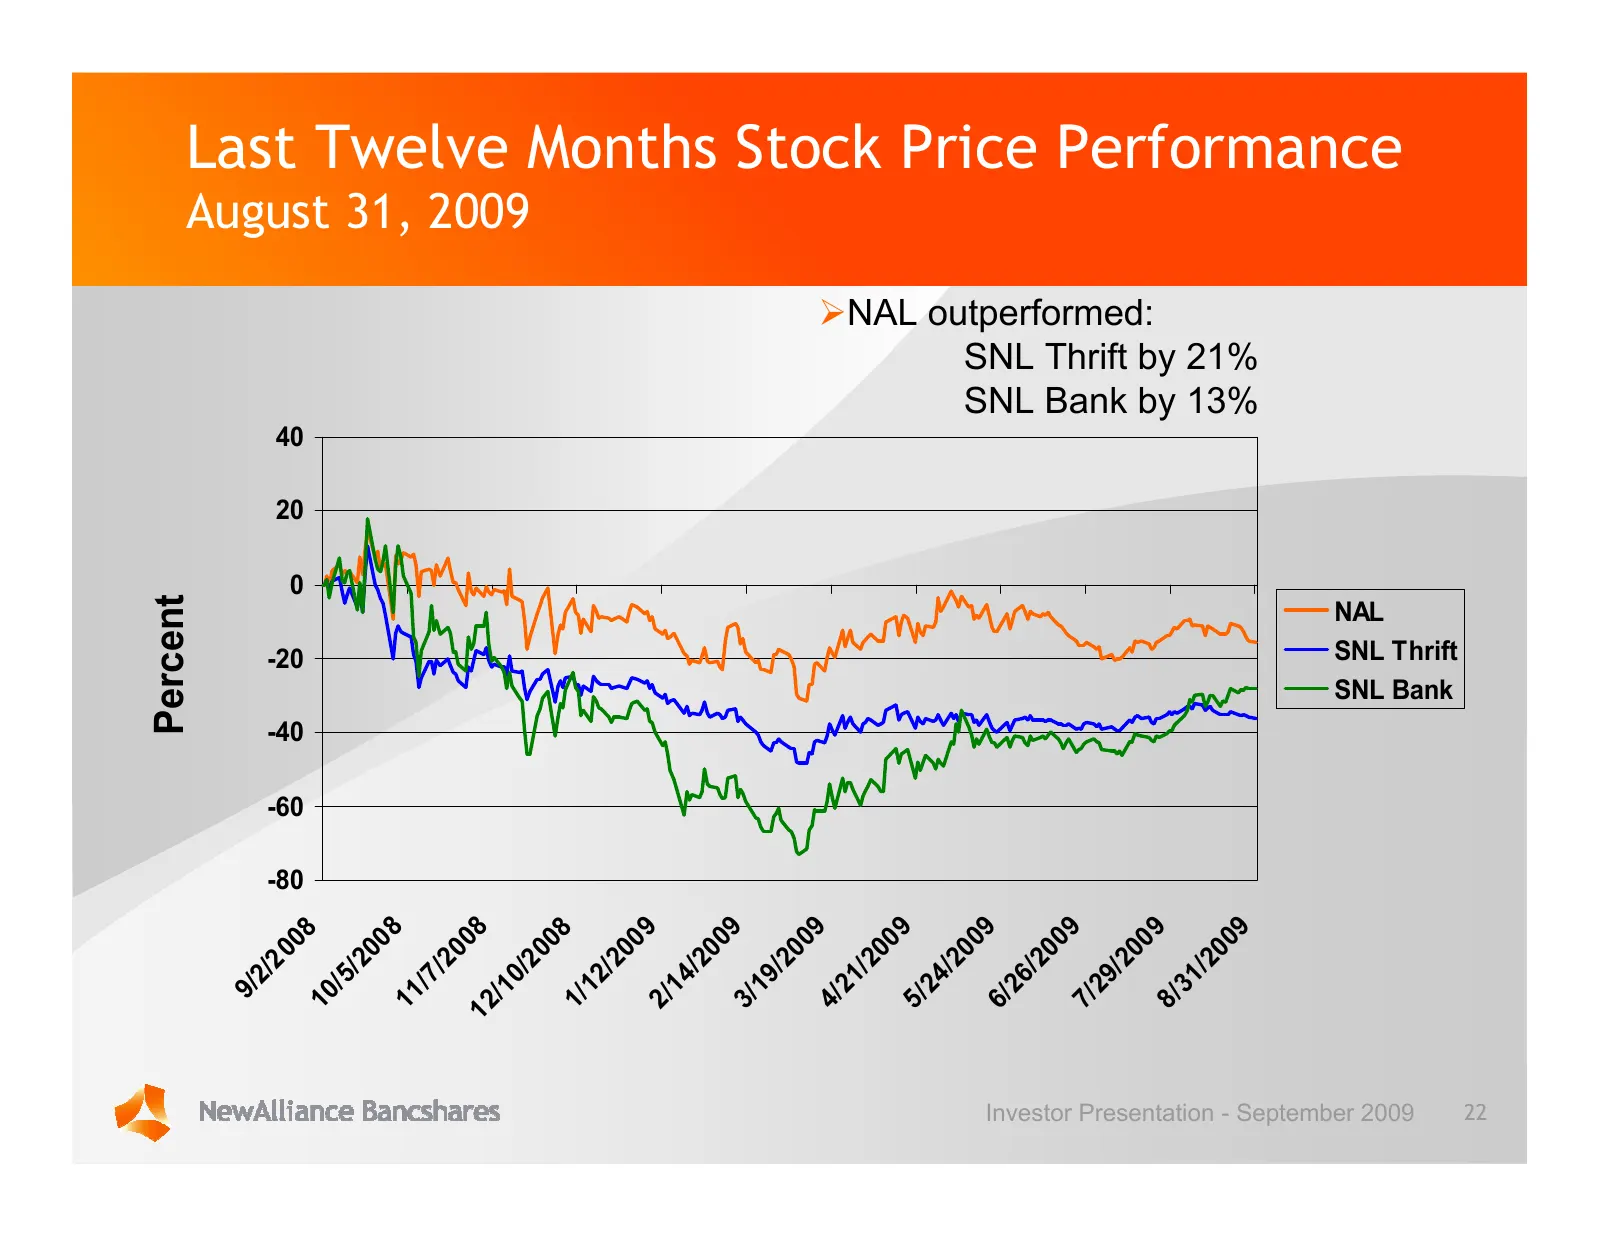
Last Twelve Months Stock Price Performance August 31, 2009 ØNAL outperformed: SNL Thrift by 21% SNL Bank by 13% 40 20 0 Percent NAL -20 SNL Thrift SNL Bank -40 -60 -80 9 9 8 9 9 9 9 9 9 8 08 08 00 00 00 00 00 00 00 00 00 00 20 20 /2 /2 /2 /2 /2 /2 /2 /2 /2 /2 0/ 2/ 19 26 14 24 31 /5 /7 12 21 29 /1 9
Slide 23: Balance Sheet and Credit Quality
Balance Sheet and Credit Quality
Slide 24: Balance Sheet
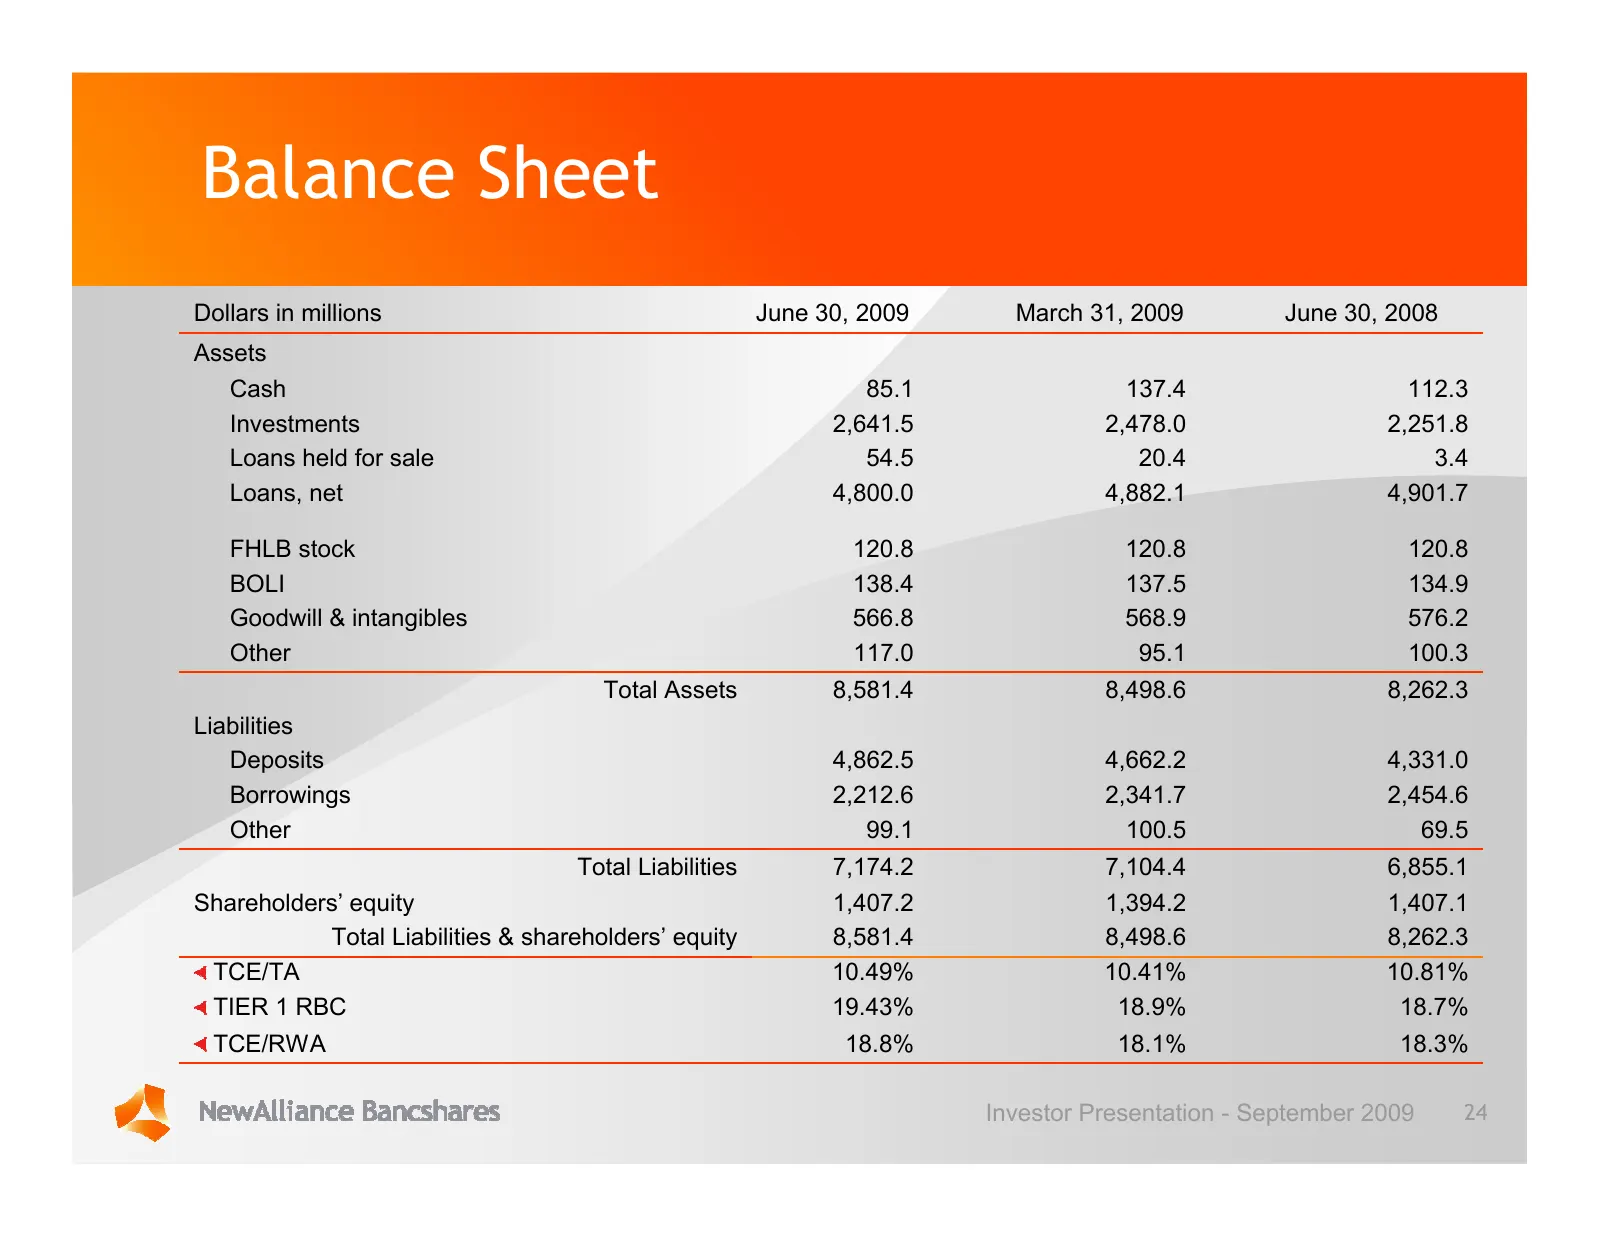
Balance Sheet Dollars in millions June 30, 2009 March 31, 2009 June 30, 2008 Assets Cash 85.1 137.4 112.3 Investments 2,641.5 2,478.0 2,251.8 Loans held for sale 54.5 20.4 3.4 Loans, net 4,800.0 4,882.1 4,901.7 FHLB stock 120.8 120.8 120.8 BOLI 138.4 137.5 134.9 Goodwill & intangibles 566.8 568.9 57
Slide 25: Residential Portfolio Snapshot
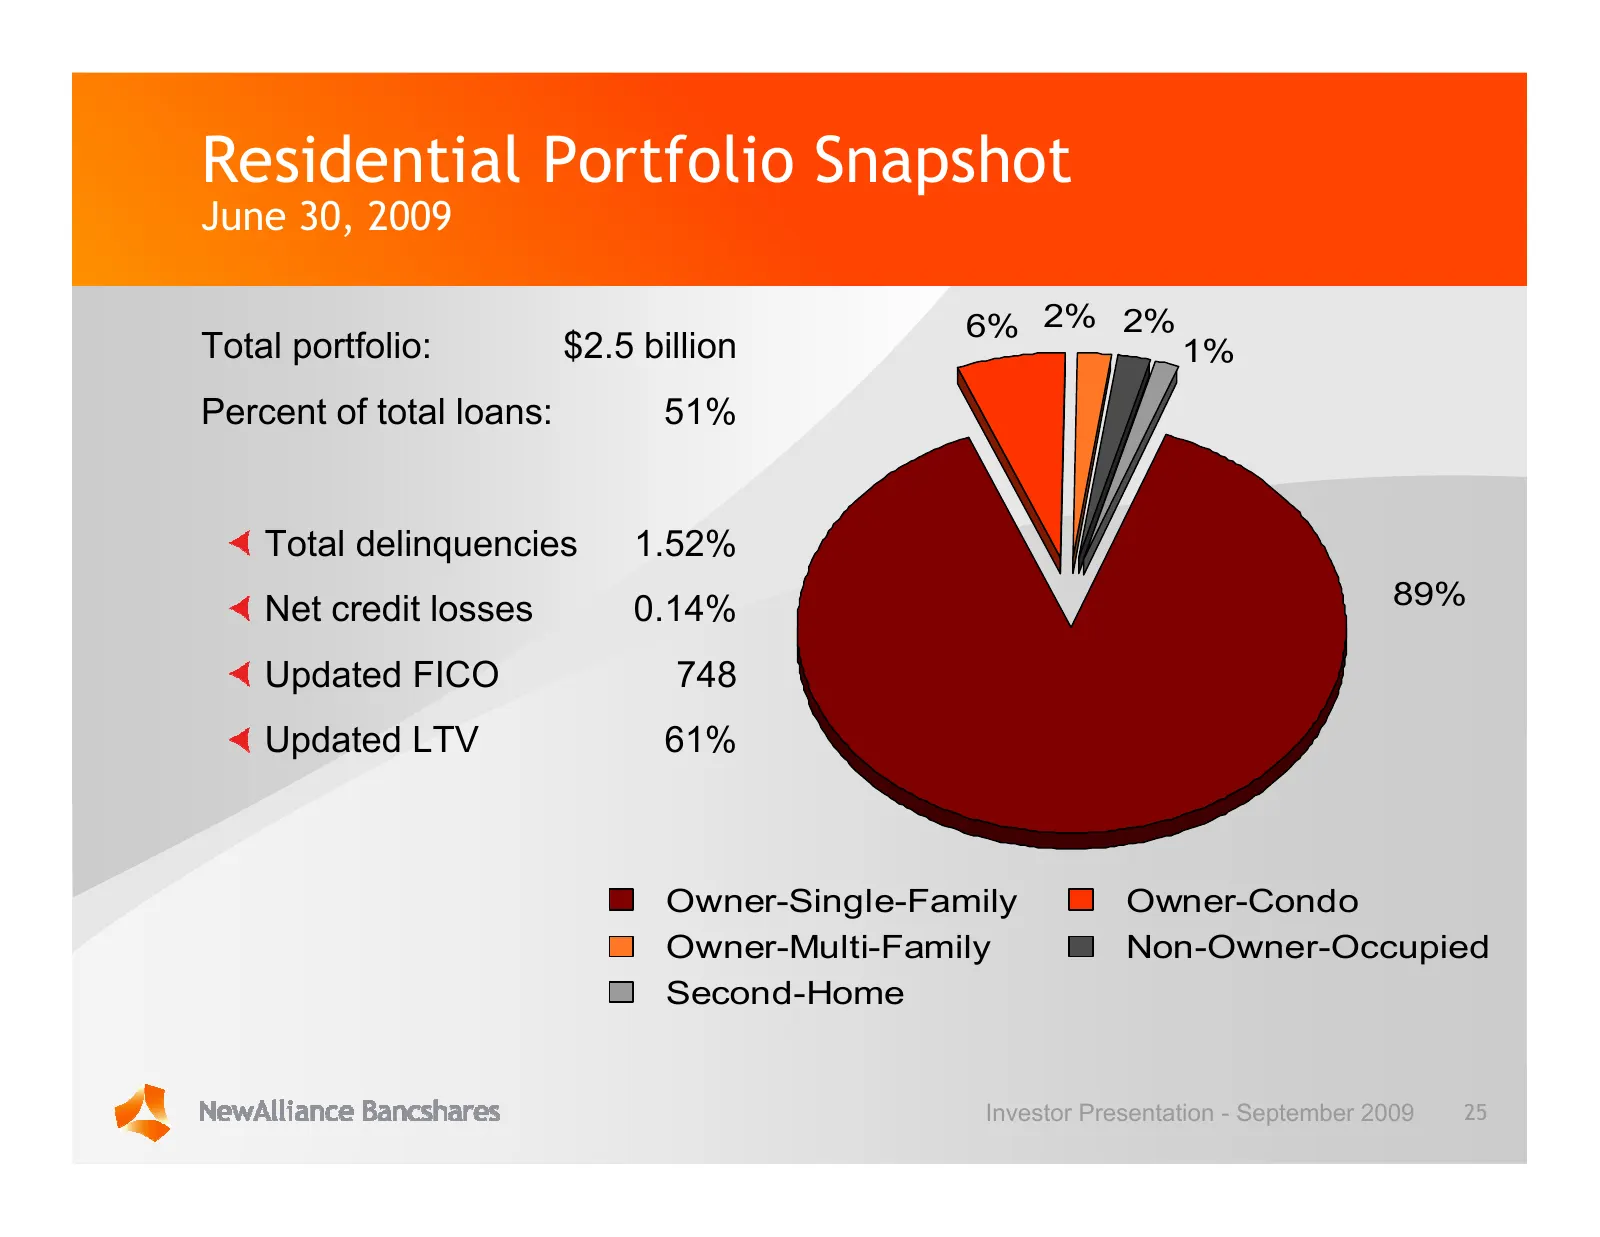
Residential Portfolio Snapshot June 30, 2009 6% 2% 2% Total portfolio: $2.5 billion 1% Percent of total loans: 51% Total delinquencies 1.52% Net credit losses 0.14% 89% Updated FICO 748 Updated LTV 61% Owner-Single-Family Owner-Condo Owner-Multi-Family Non-Owner-Occupied Second-Home Investor Present
Slide 26: Residential Portfolio FICO Score Distribution
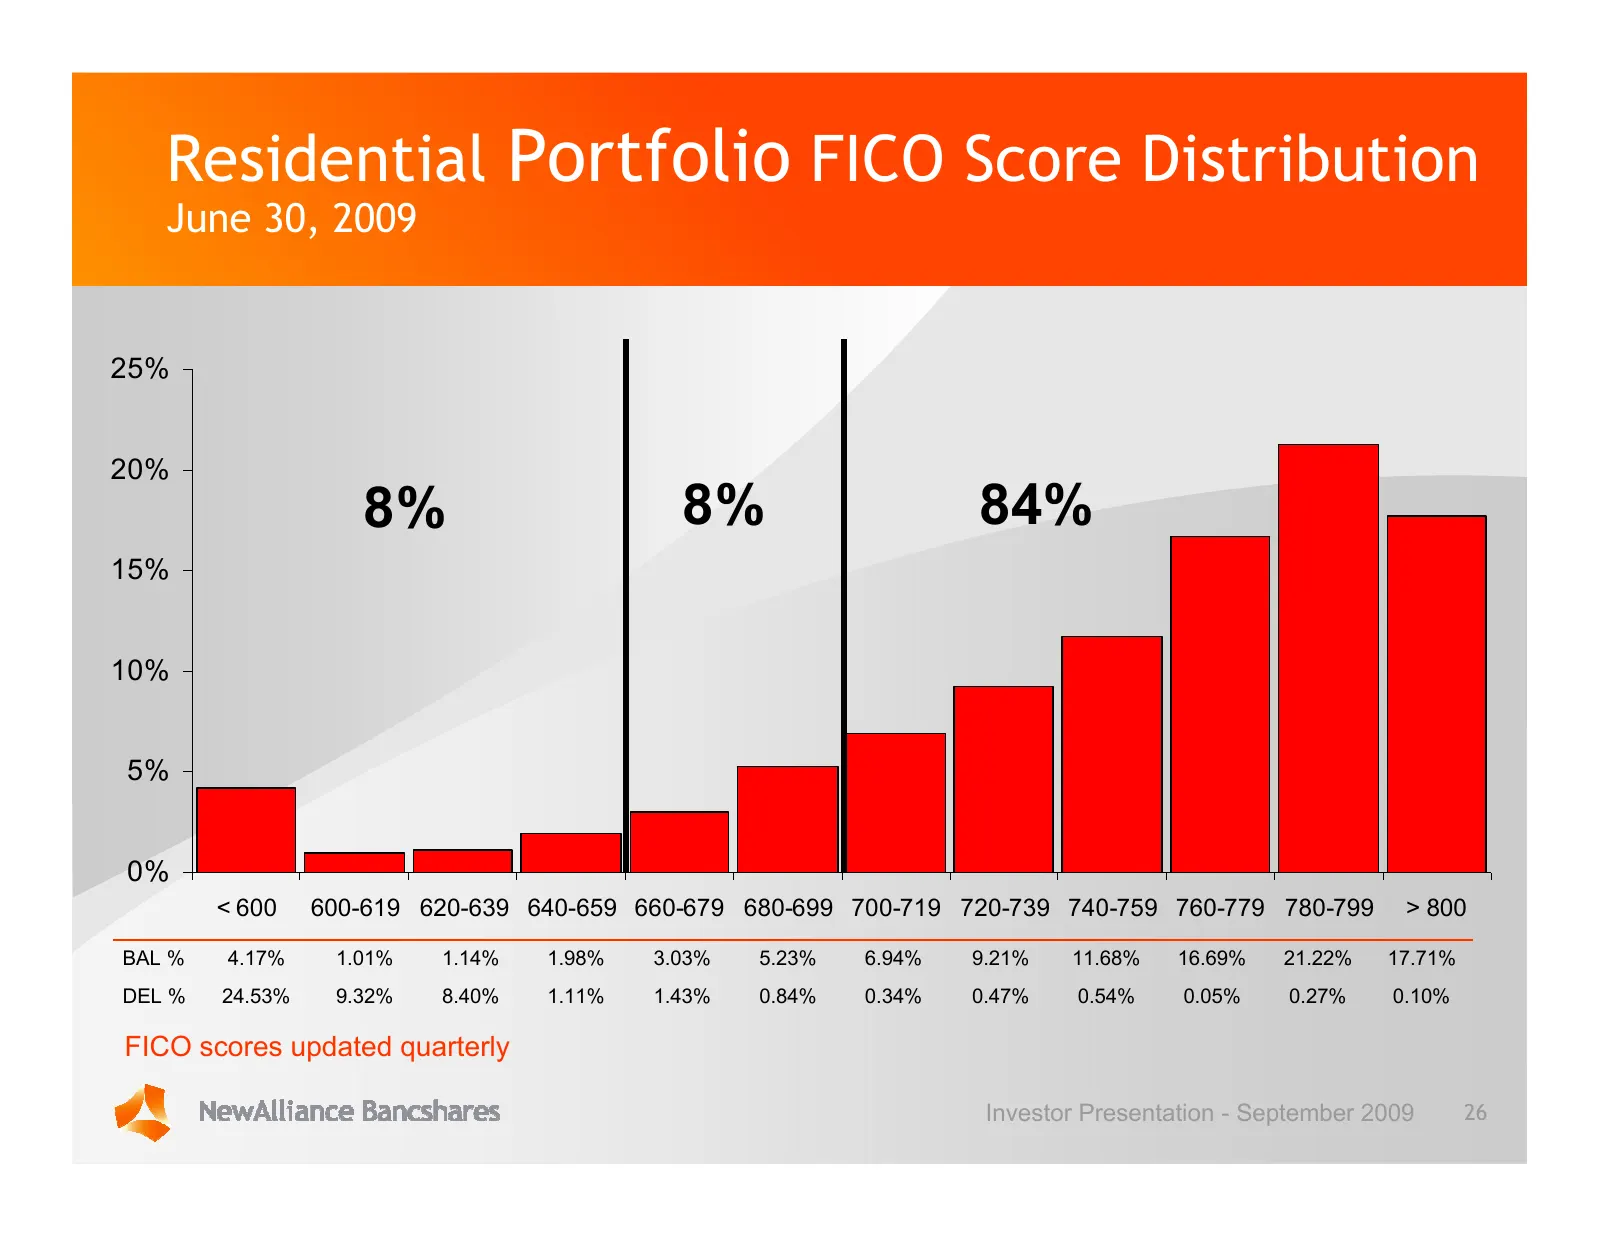
Residential Portfolio FICO Score Distribution June 30, 2009 25% 20% 8% 8% 84% 15% 10% 5% 0% < 600 600-619 620-639 640-659 660-679 680-699 700-719 720-739 740-759 760-779 780-799 > 800 BAL % 4.17% 1.01% 1.14% 1.98% 3.03% 5.23% 6.94% 9.21% 11.68% 16.69% 21.22% 17.71% DEL % 24.53% 9.32% 8.40% 1.11% 1.4
Slide 27: Residential Mortgage FICO/LTV/Volume Matrix
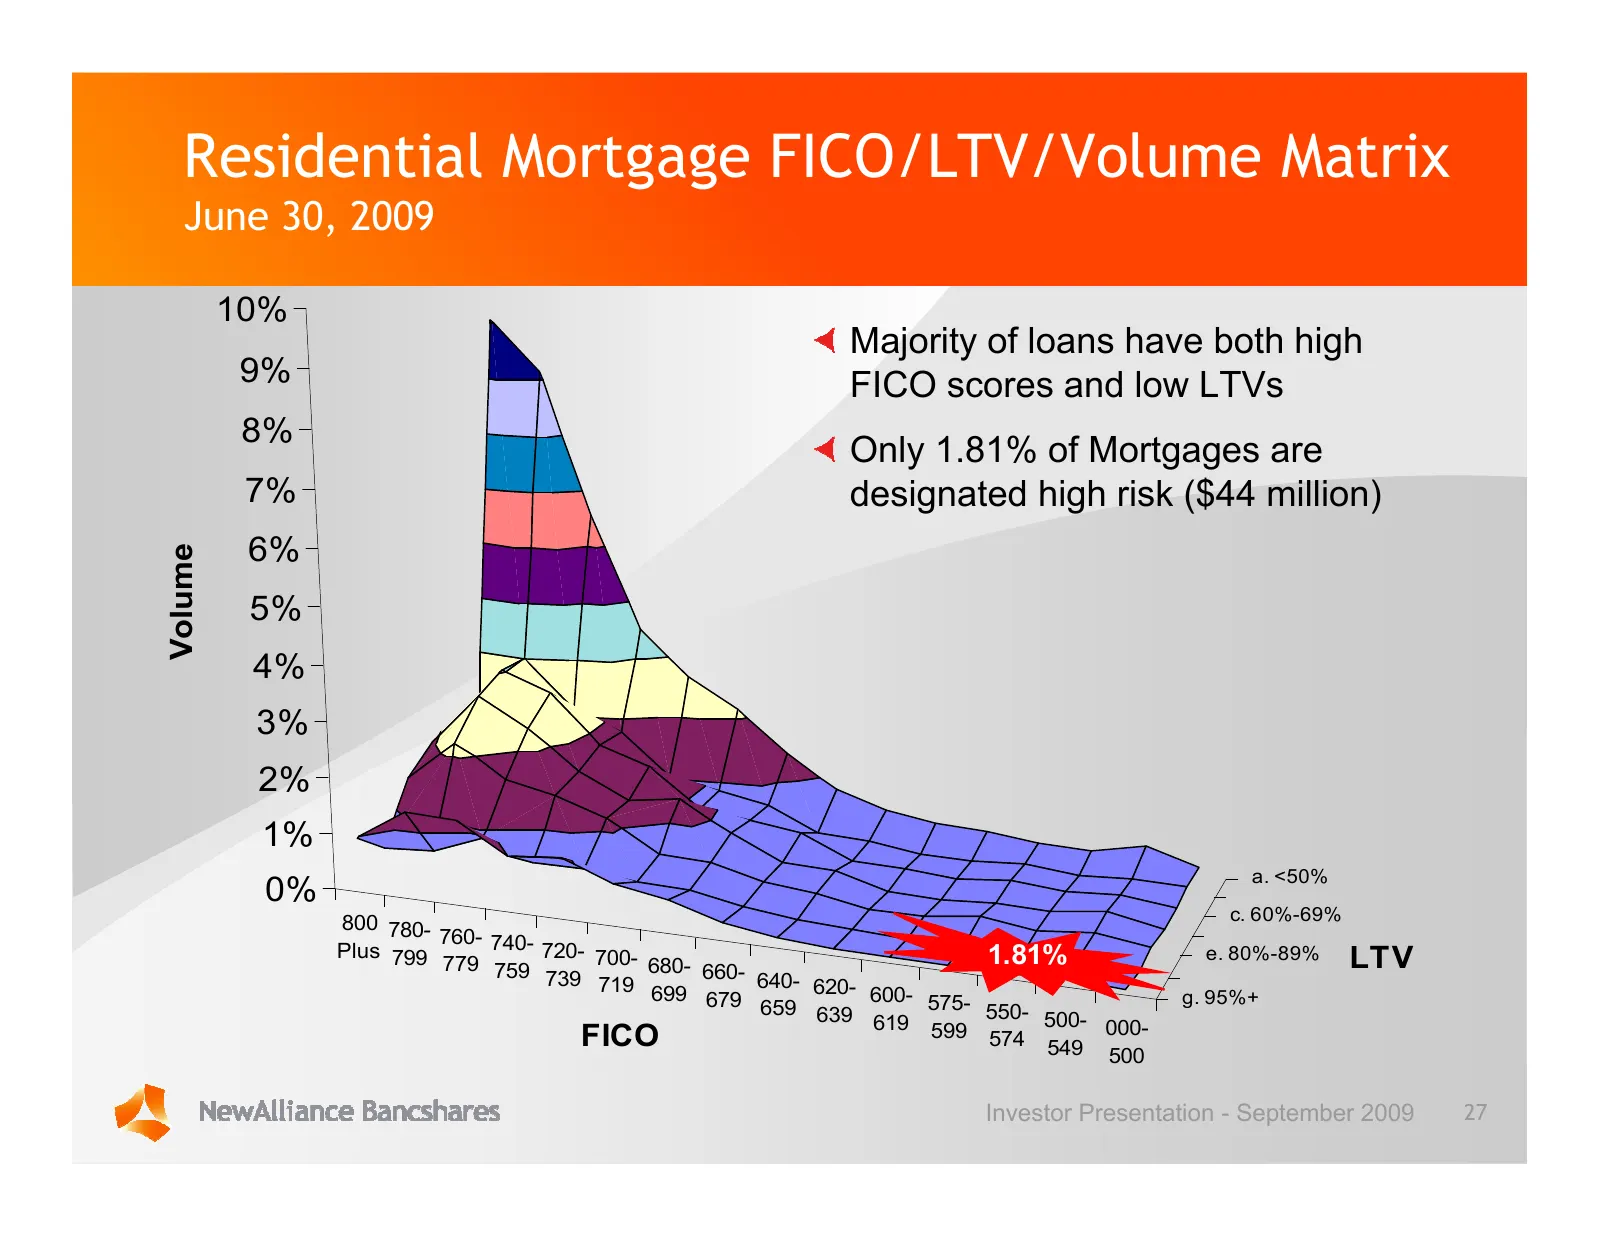
Residential Mortgage FICO/LTV/Volume Matrix June 30, 2009 10% Majority of loans have both high 9% FICO scores and low LTVs 8% Only 1.81% of Mortgages are 7% designated high risk ($44 million) 6% Volume 5% 4% 3% 2% 1% a. <50% 0% 800 780- c. 60%-69% 760- 740- Plus 799 720- 700- 1.81% e. 80%-89% LTV 77
Slide 28: Home Equity Portfolio Snapshot
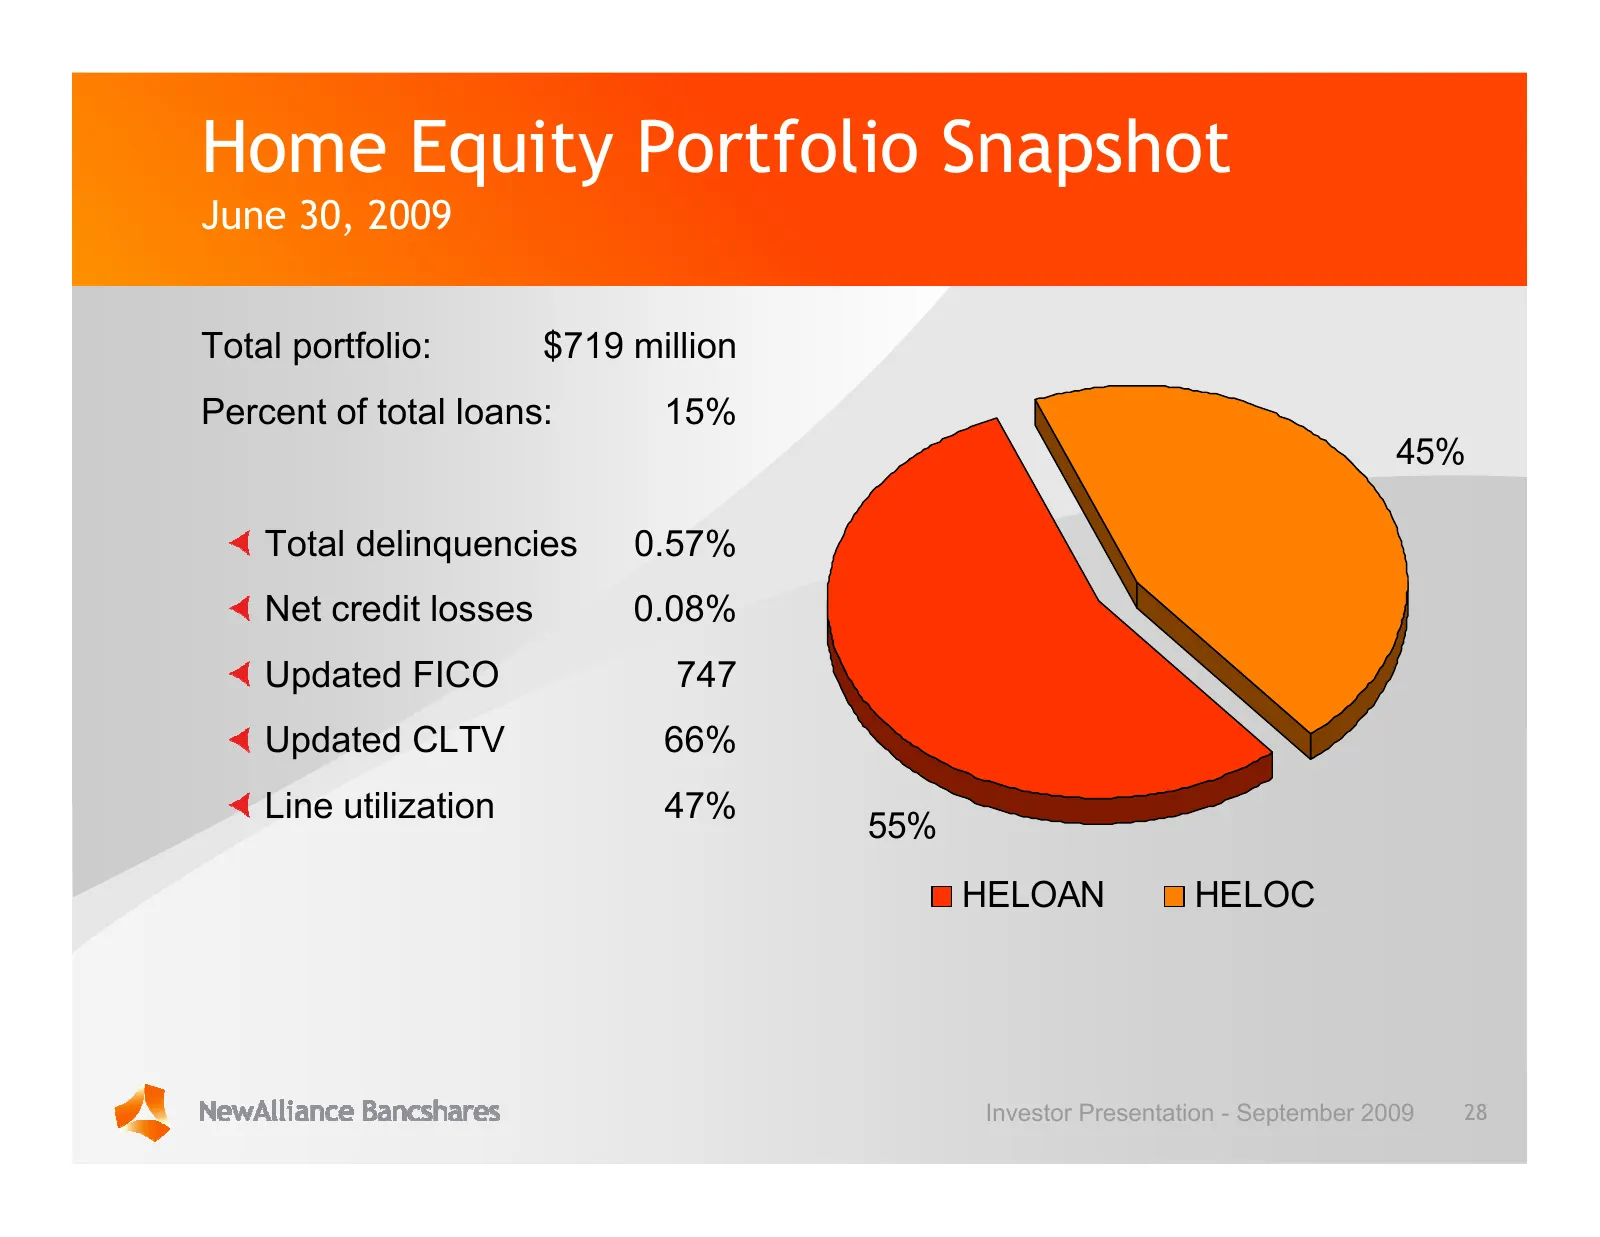
Home Equity Portfolio Snapshot June 30, 2009 Total portfolio: $719 million Percent of total loans: 15% 45% Total delinquencies 0.57% Net credit losses 0.08% Updated FICO 747 Updated CLTV 66% Line utilization 47% 55% HELOAN HELOC Investor Presentation - September 2009 28
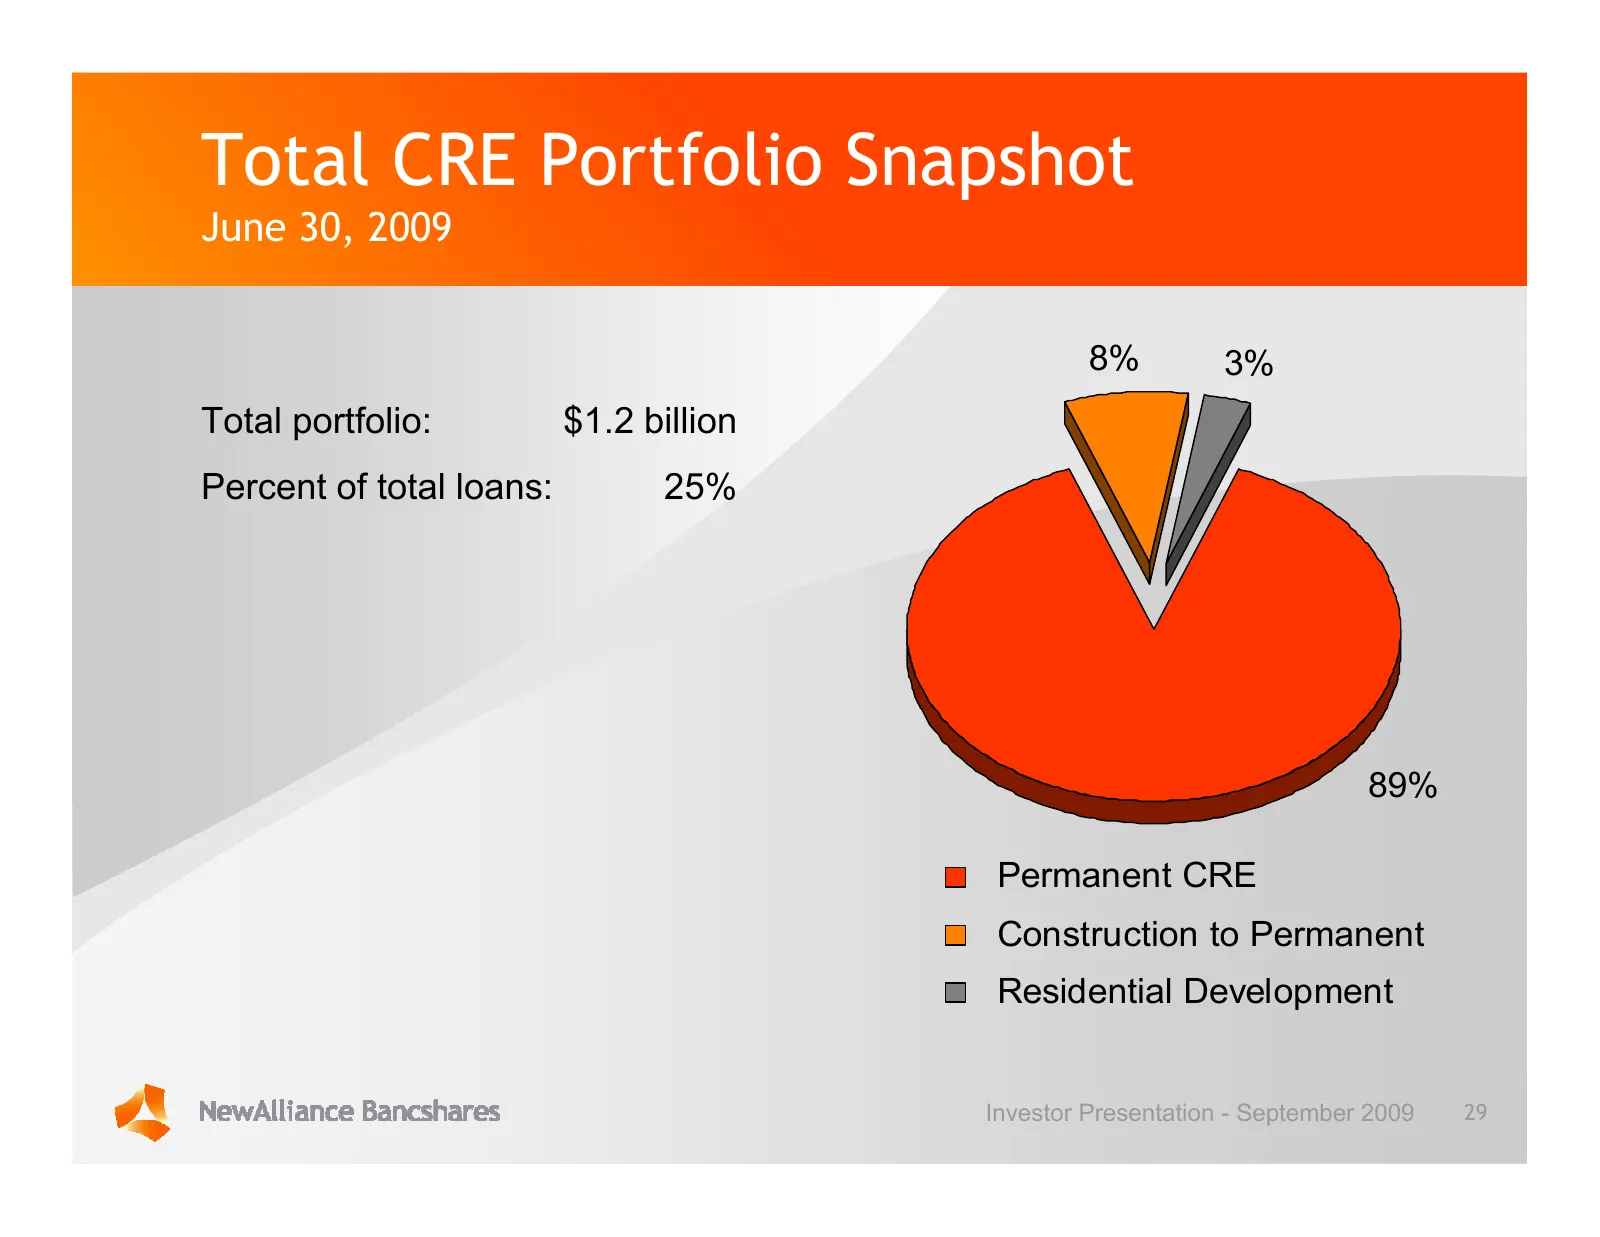
Slide 29: Total CRE Portfolio Snapshot
Total CRE Portfolio Snapshot June 30, 2009 8% 3% Total portfolio: $1.2 billion Percent of total loans: 25% 89% Permanent CRE Construction to Permanent Residential Development Investor Presentation - September 2009 29
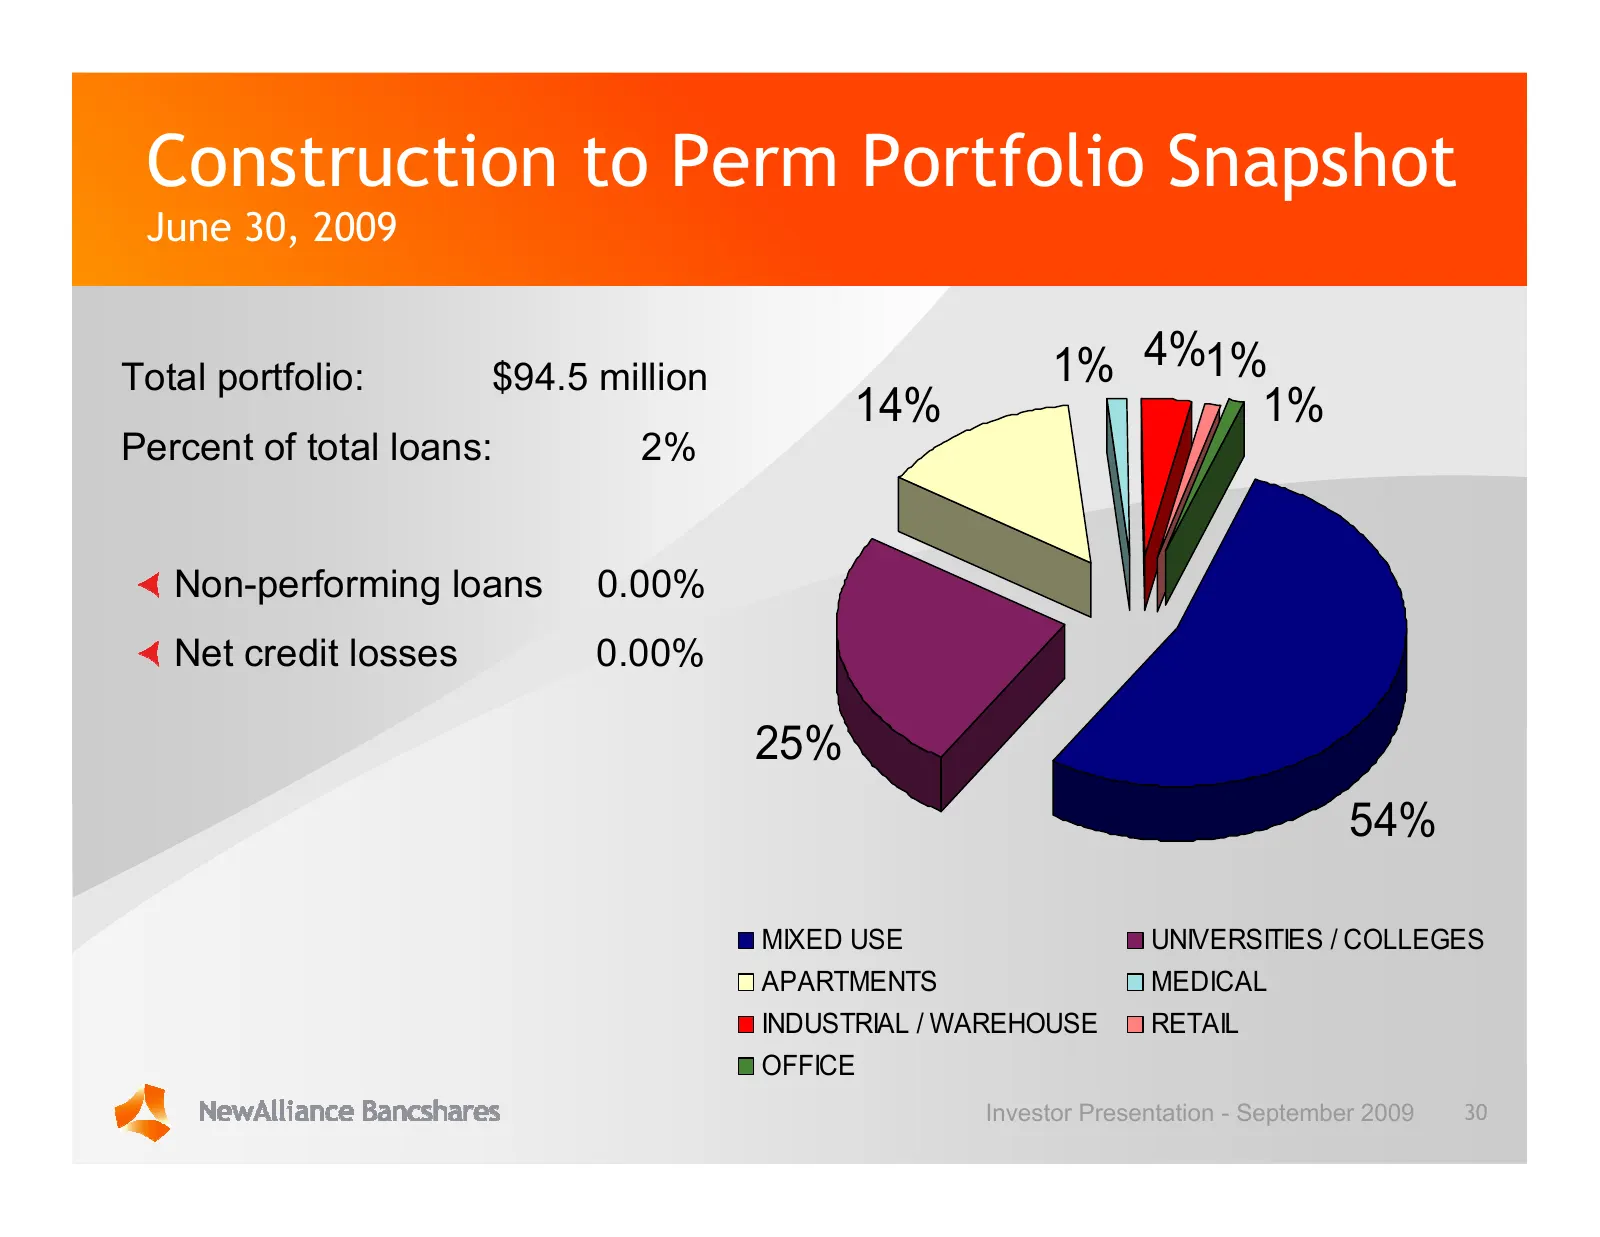
Slide 30: Construction to Perm Portfolio Snapshot
Construction to Perm Portfolio Snapshot June 30, 2009 Total portfolio: $94.5 million 1% 4%1% 14% 1% Percent of total loans: 2% Non-performing loans 0.00% Net credit losses 0.00% 25% 54% MIXED USE UNIVERSITIES / COLLEGES APARTMENTS MEDICAL INDUSTRIAL / WAREHOUSE RETAIL OFFICE Investor Presentation -
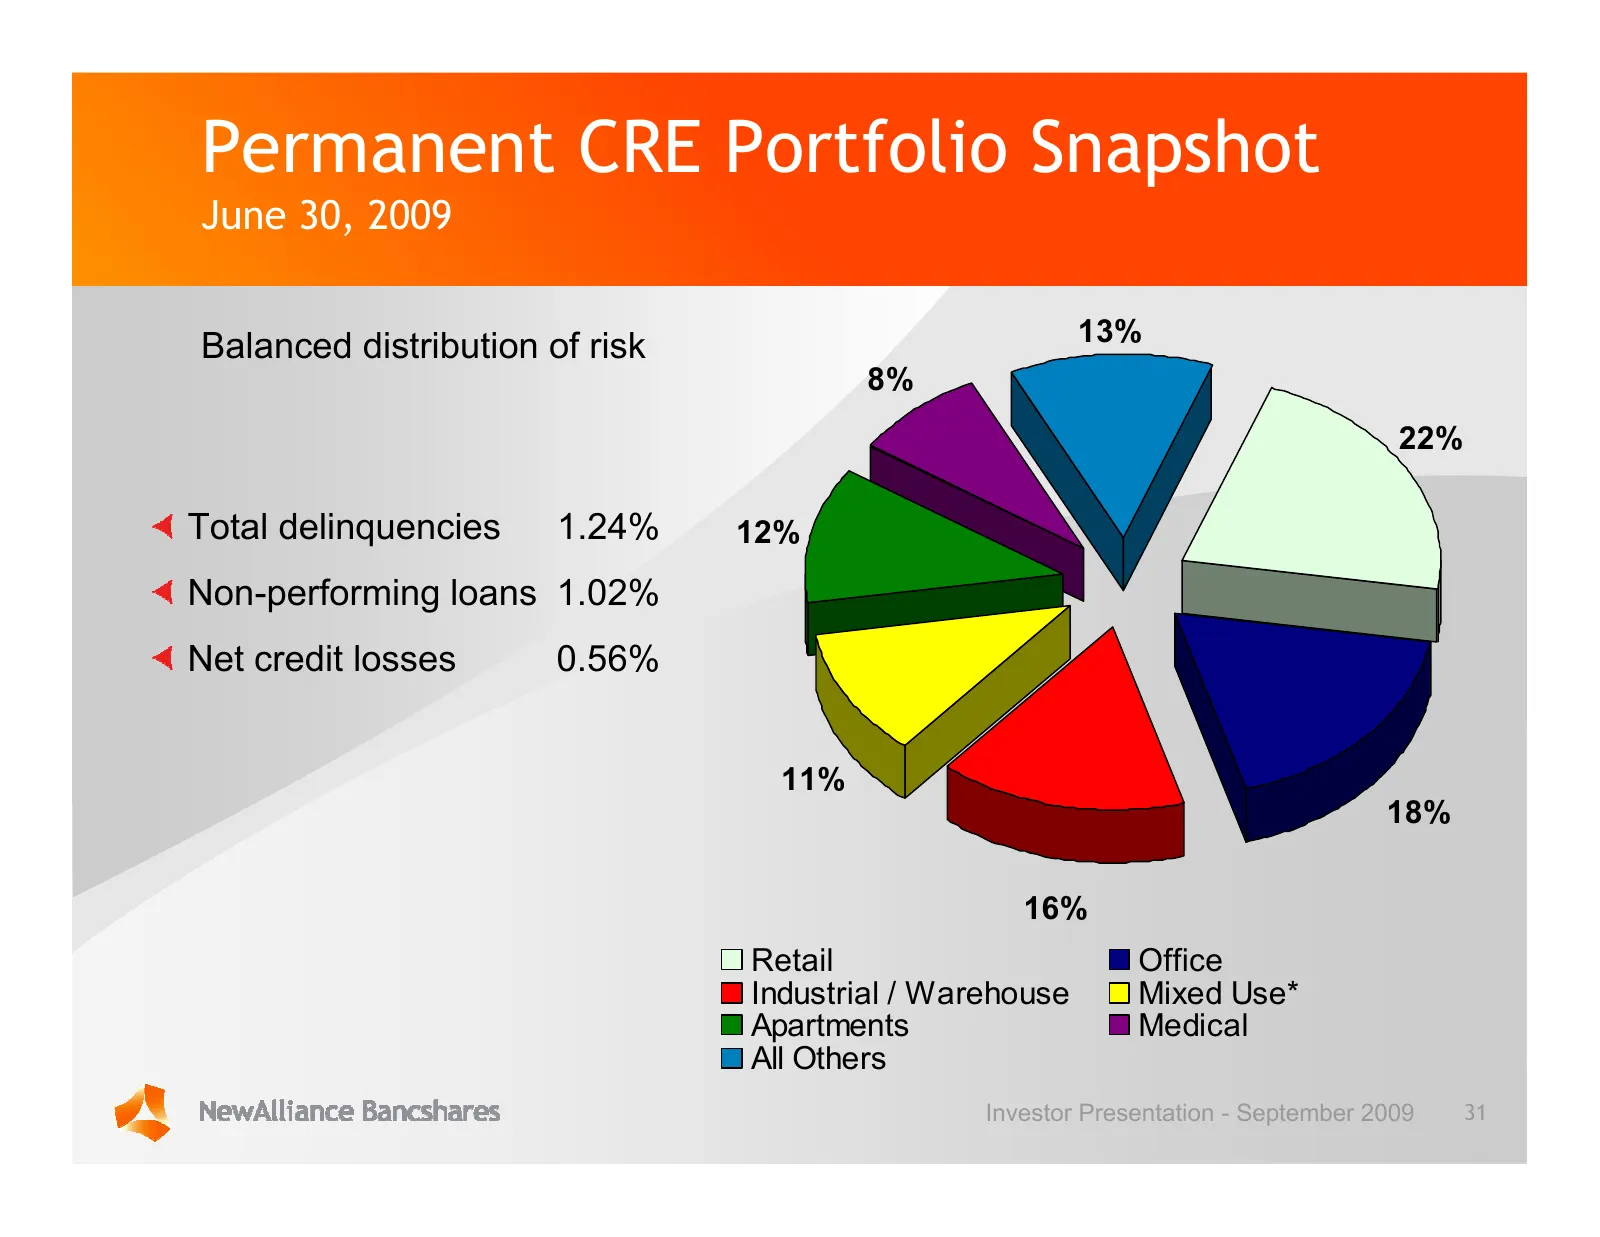
Slide 31: Permanent CRE Portfolio Snapshot
Permanent CRE Portfolio Snapshot June 30, 2009 13% Balanced distribution of risk 8% 22% Total delinquencies 1.24% 12% Non-performing loans 1.02% Net credit losses 0.56% 11% 18% 16% Retail Office Industrial / Warehouse Mixed Use* Apartments Medical All Others Investor Presentation - September 2009 31
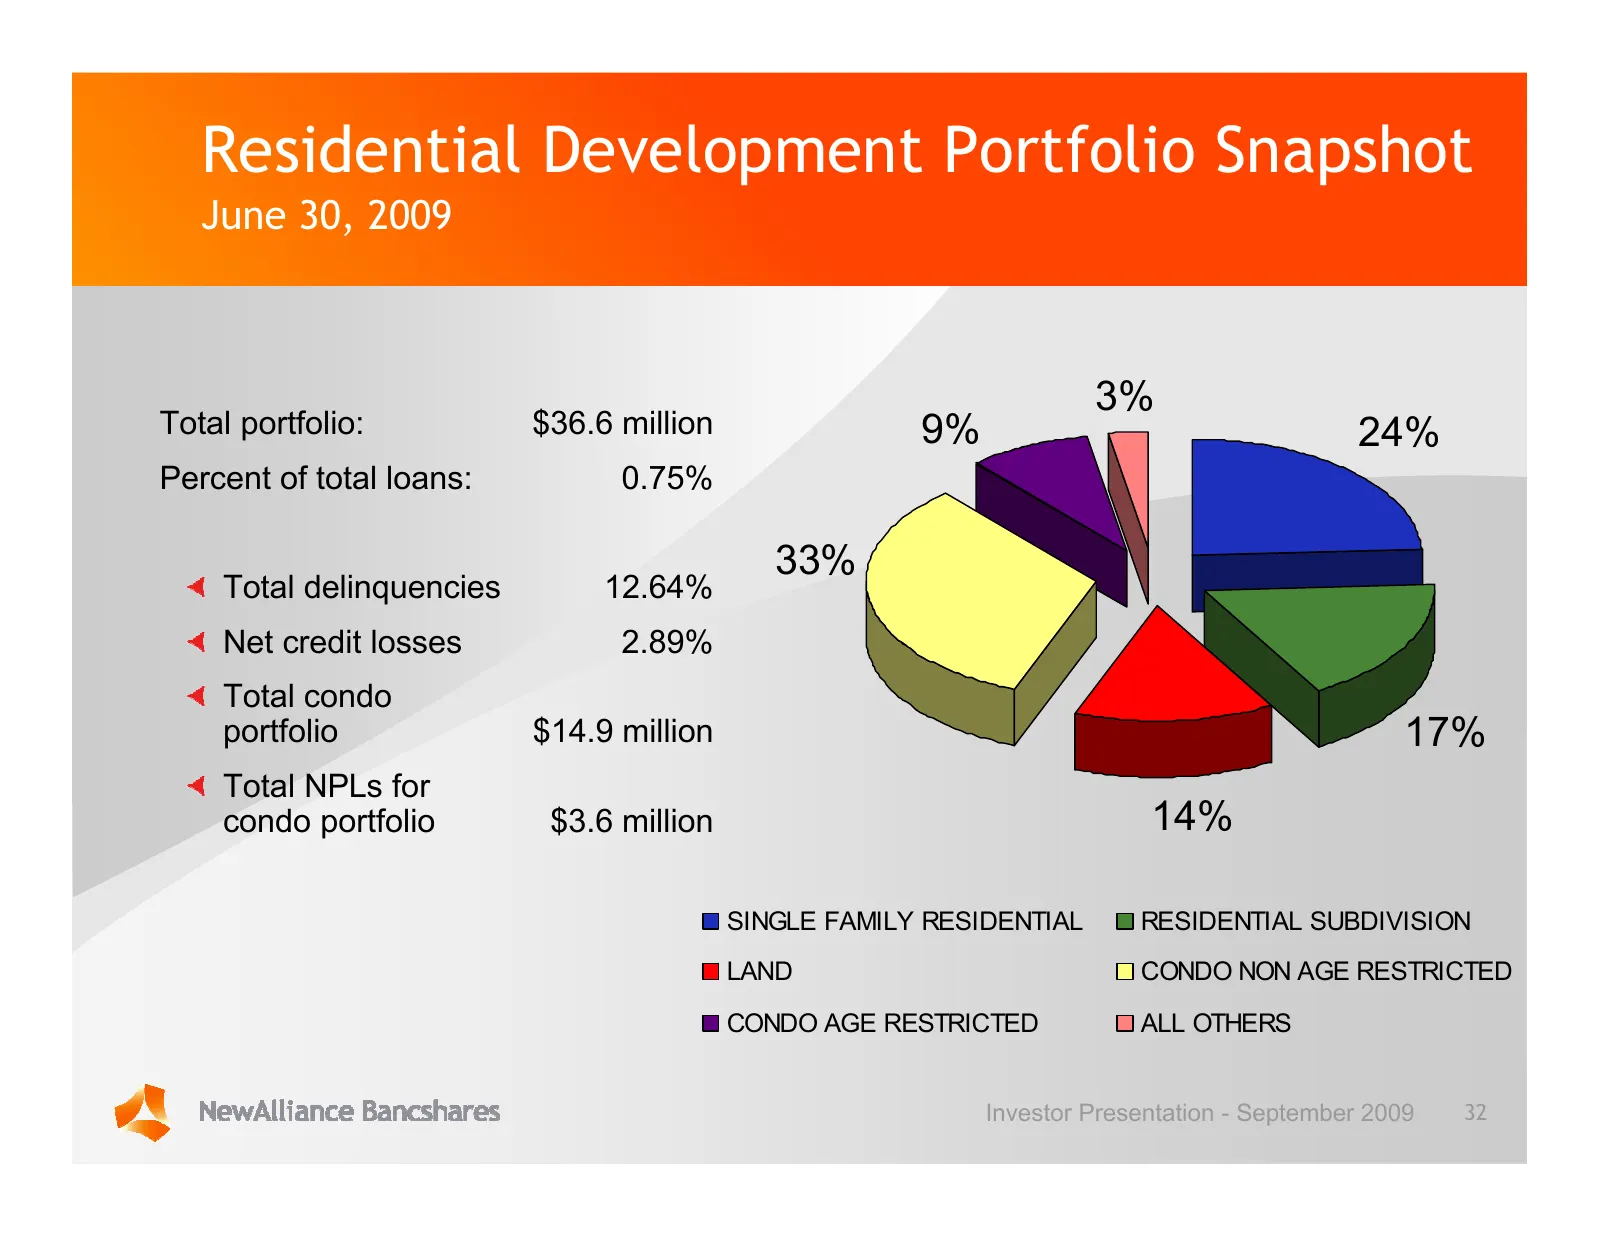
Slide 32: Residential Development Portfolio Snapshot
Residential Development Portfolio Snapshot June 30, 2009 3% Total portfolio: $36.6 million 9% 24% Percent of total loans: 0.75% 33% Total delinquencies 12.64% Net credit losses 2.89% Total condo portfolio $14.9 million 17% Total NPLs for condo portfolio $3.6 million 14% SINGLE FAMILY RESIDENTIAL RES
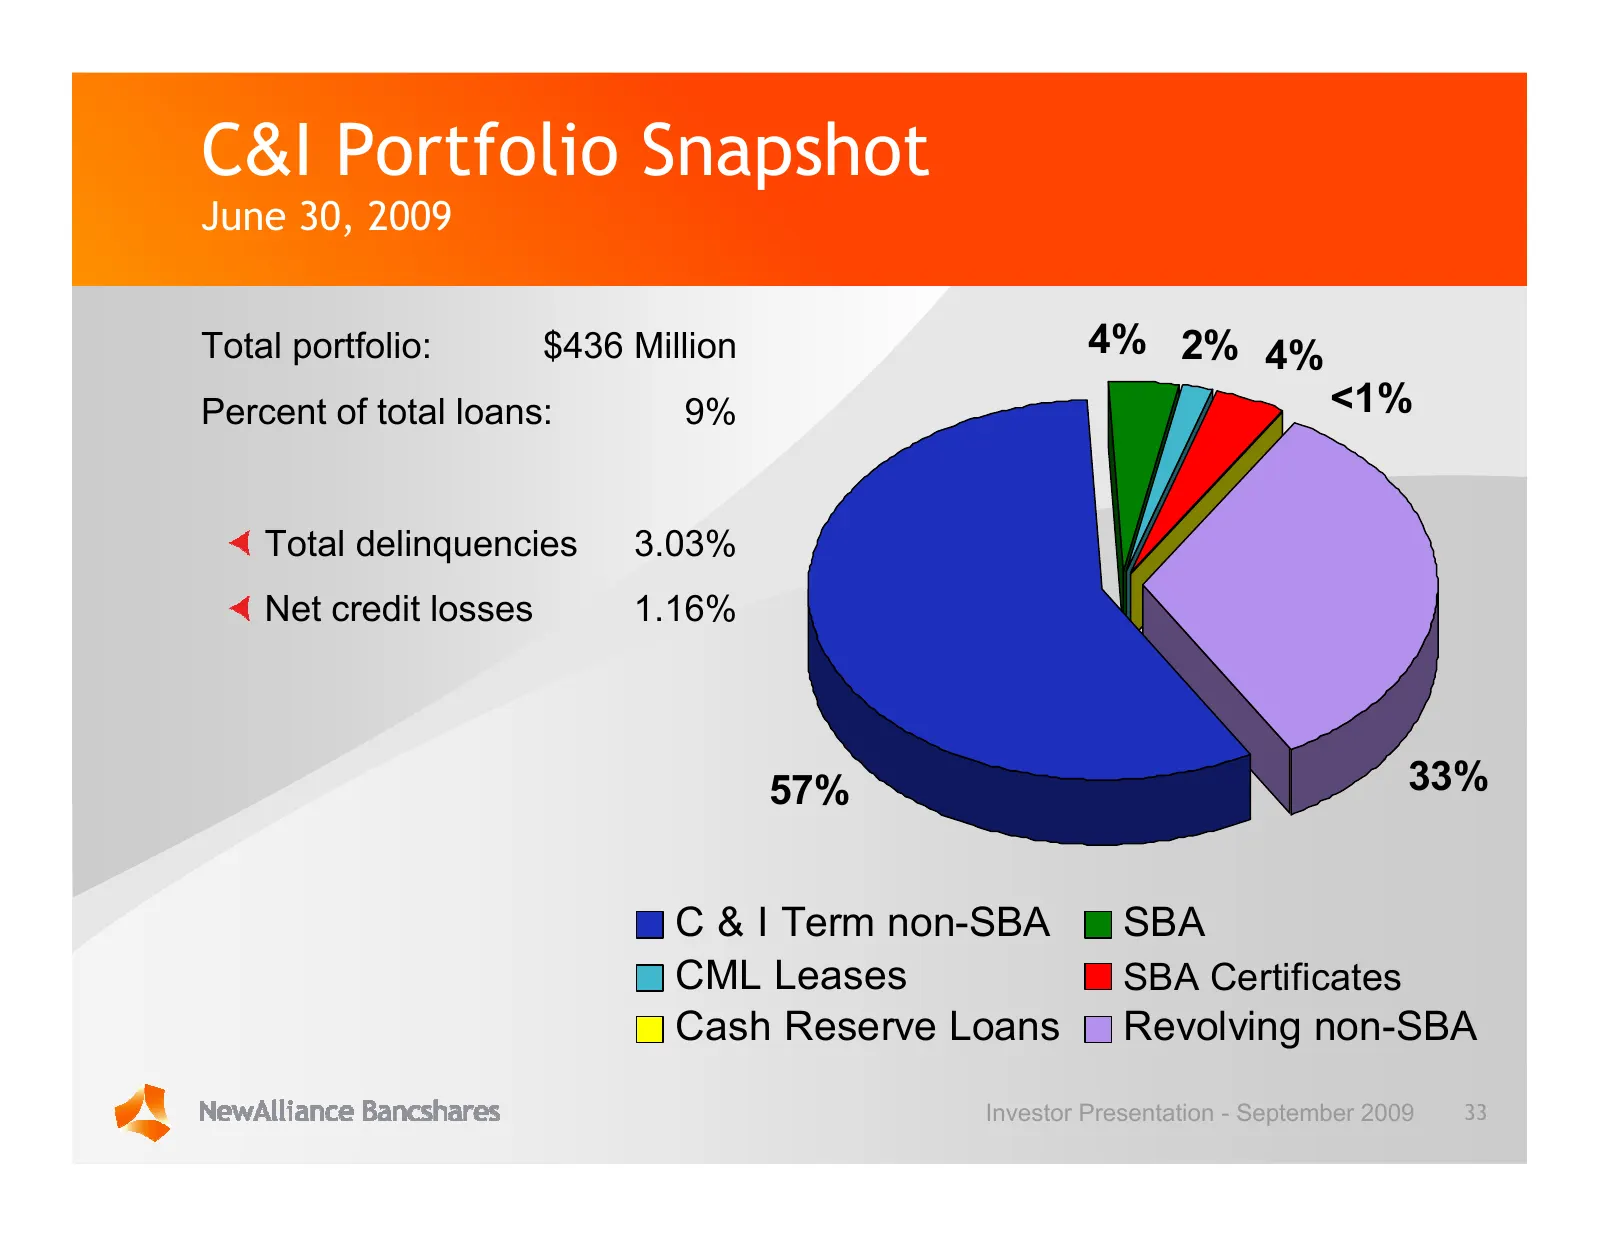
Slide 33: C&I Portfolio Snapshot
C&I Portfolio Snapshot June 30, 2009 Total portfolio: $436 Million 4% 2% 4% Percent of total loans: 9% <1% Total delinquencies 3.03% Net credit losses 1.16% 57% 33% C & I Term non-SBA SBA CML Leases SBA Certificates Cash Reserve Loans Revolving non-SBA Investor Presentation - September 2009 33
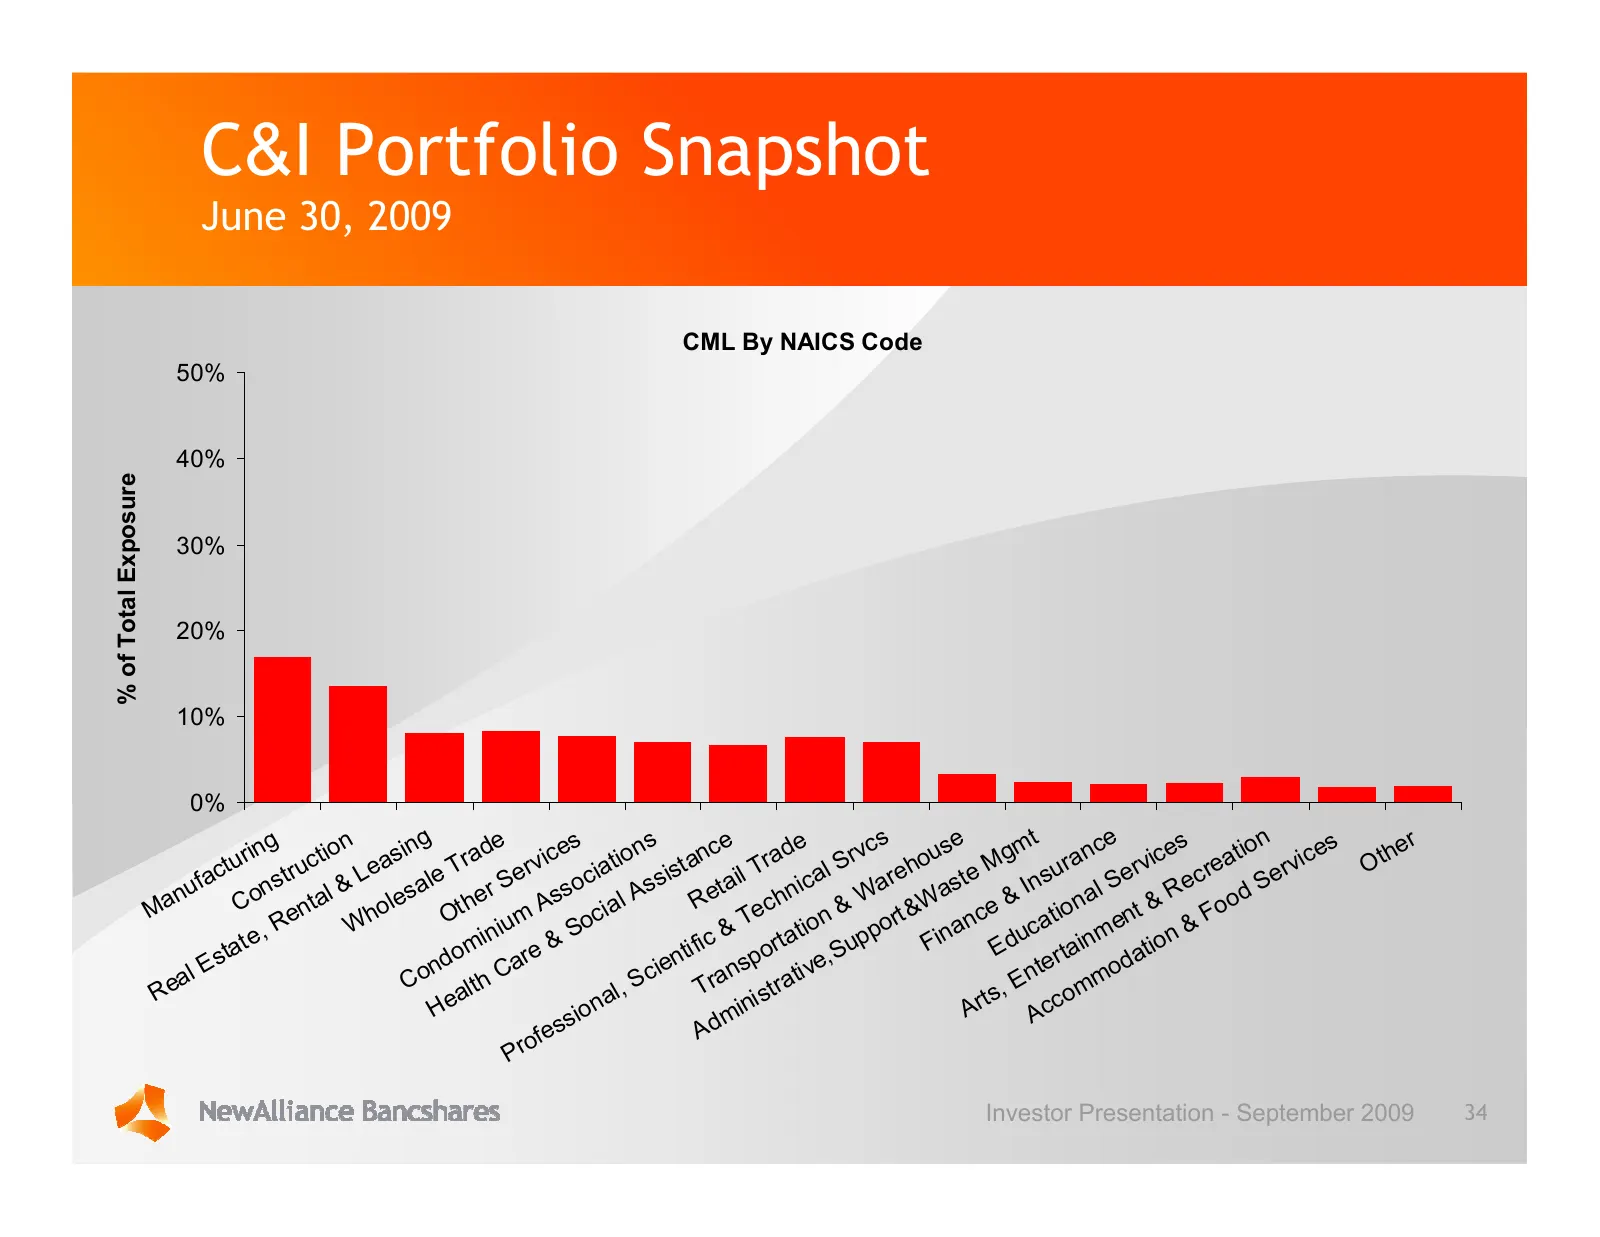
Slide 34: C&I Portfolio Snapshot: CML by NAICS Code
C&I Portfolio Snapshot June 30, 2009 CML By NAICS Code 50% 40% % of Total Exposure 30% 20% 10% 0% ring ction asing rade vices tions ance rade Srvc s u se g m t ance ices ation ices he r tu u e T er cia ssis t il T ical o reh ste M su r erv ecre Serv Ot u fac nstr l & L a le S o t a a I n l S n Co en
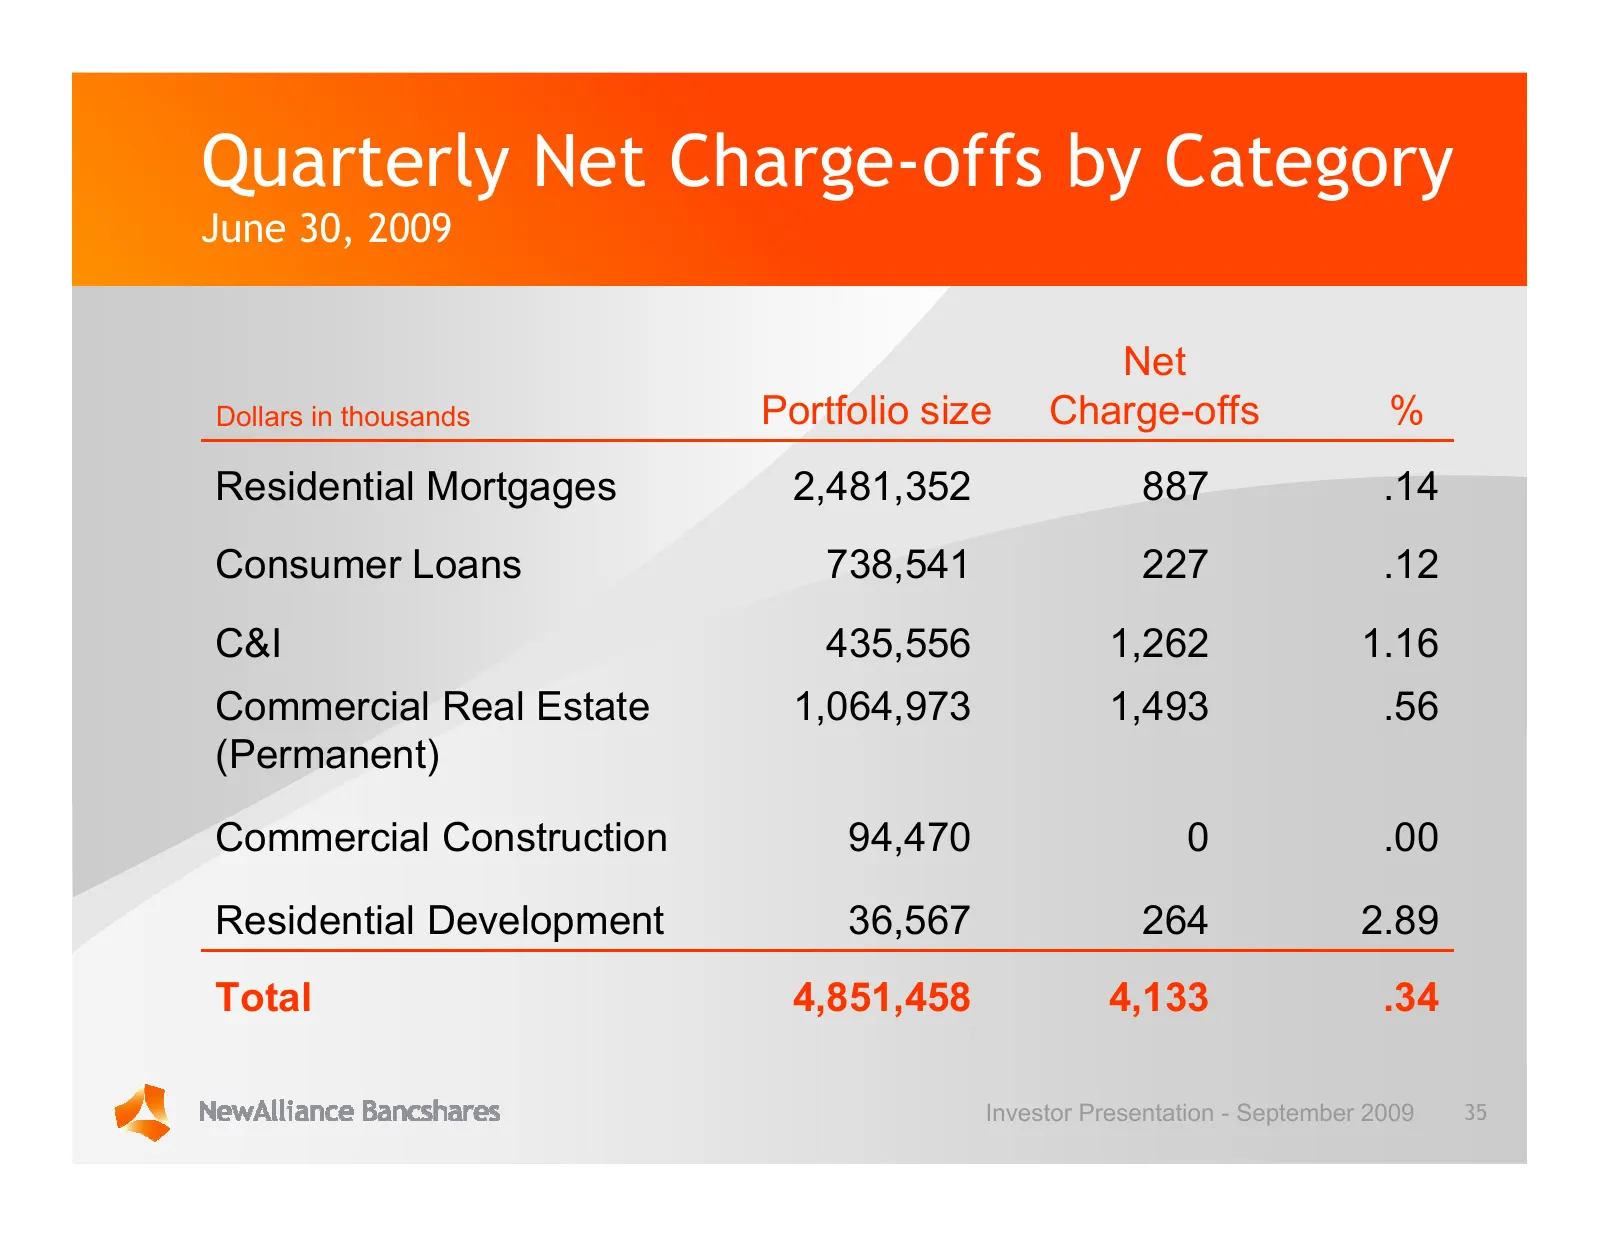
Slide 35: Quarterly Net Charge-offs by Category
Quarterly Net Charge-offs by Category June 30, 2009 Net Dollars in thousands Portfolio size Charge-offs % Residential Mortgages 2,481,352 887 .14 Consumer Loans 738,541 227 .12 C&I 435,556 1,262 1.16 Commercial Real Estate 1,064,973 1,493 .56 (Permanent) Commercial Construction 94,470 0 .00 Resident
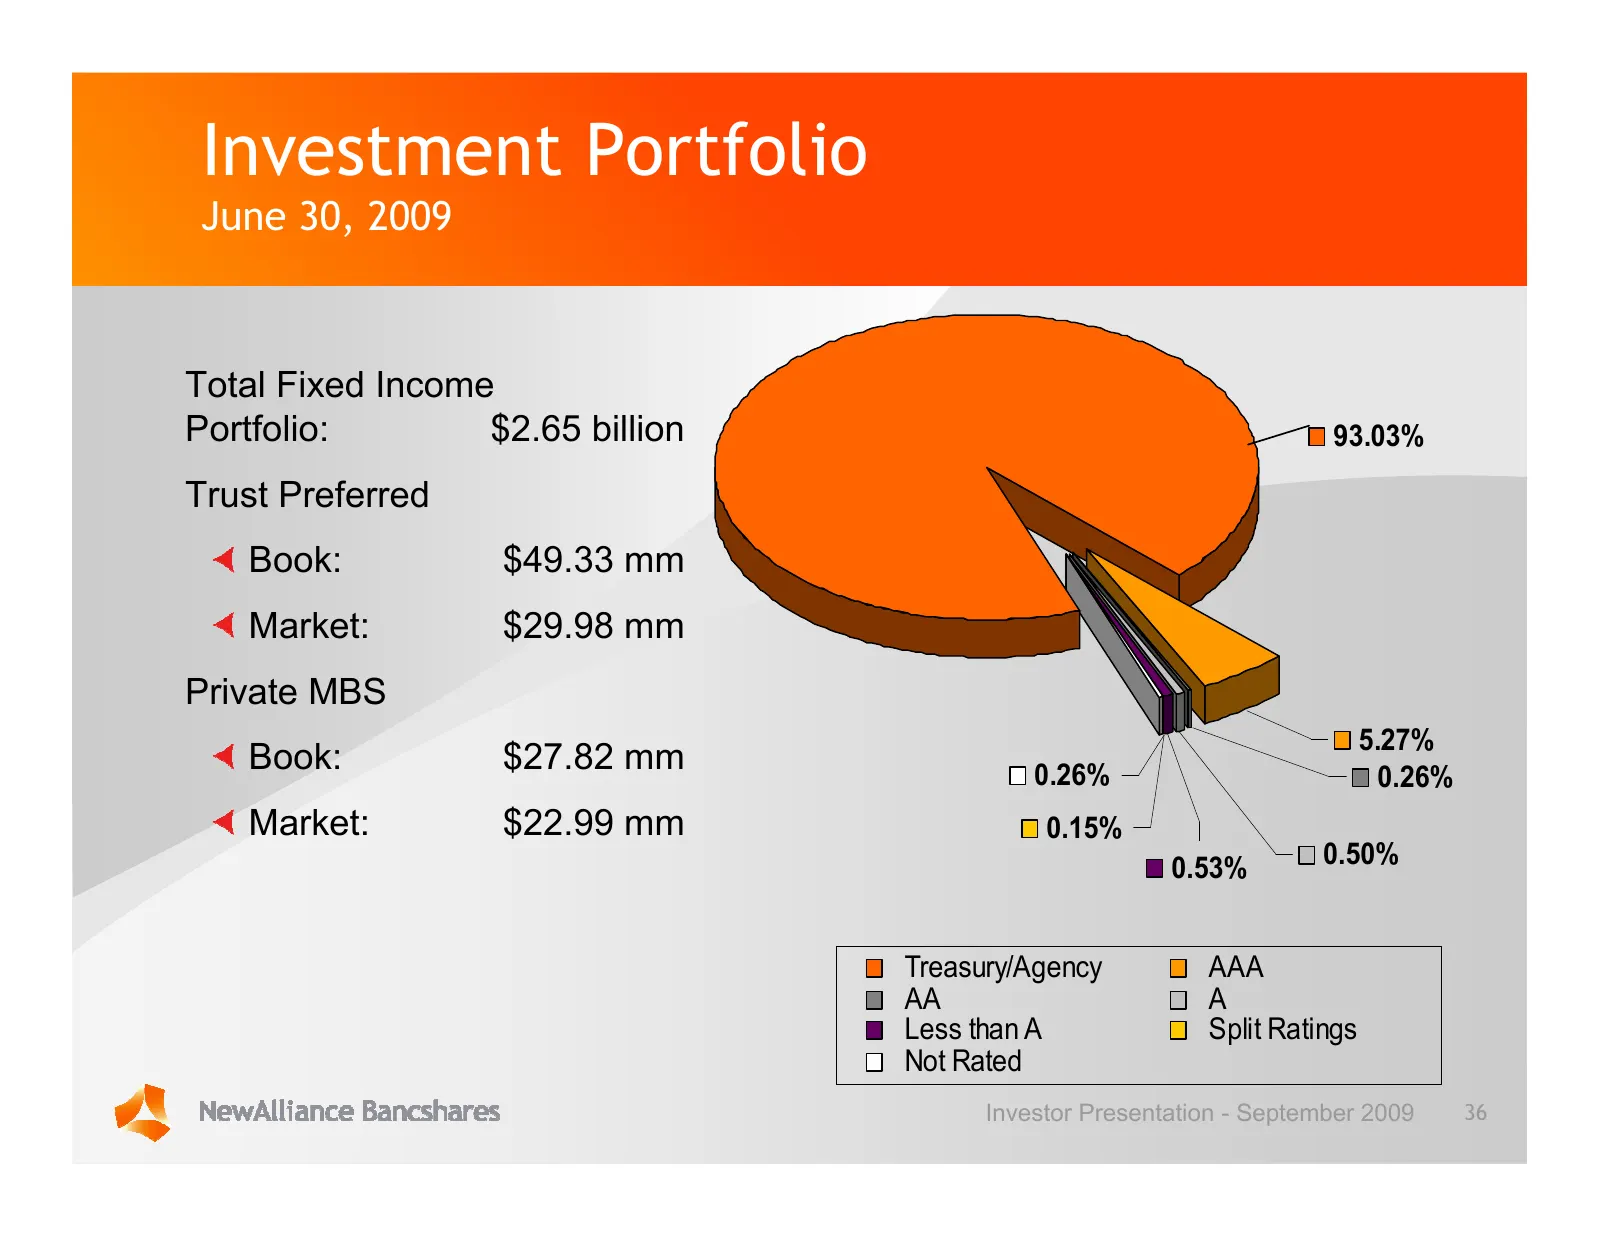
Slide 36: Investment Portfolio
Investment Portfolio June 30, 2009 Total Fixed Income Portfolio: $2.65 billion 93.03% Trust Preferred Book: $49.33 mm Market: $29.98 mm Private MBS 5.27% Book: $27.82 mm 0.26% 0.26% Market: $22.99 mm 0.15% 0.53% 0.50% Treasury/Agency AAA AA A Less than A Split Ratings Not Rated Investor Presentation
Slide 37: Gap Report
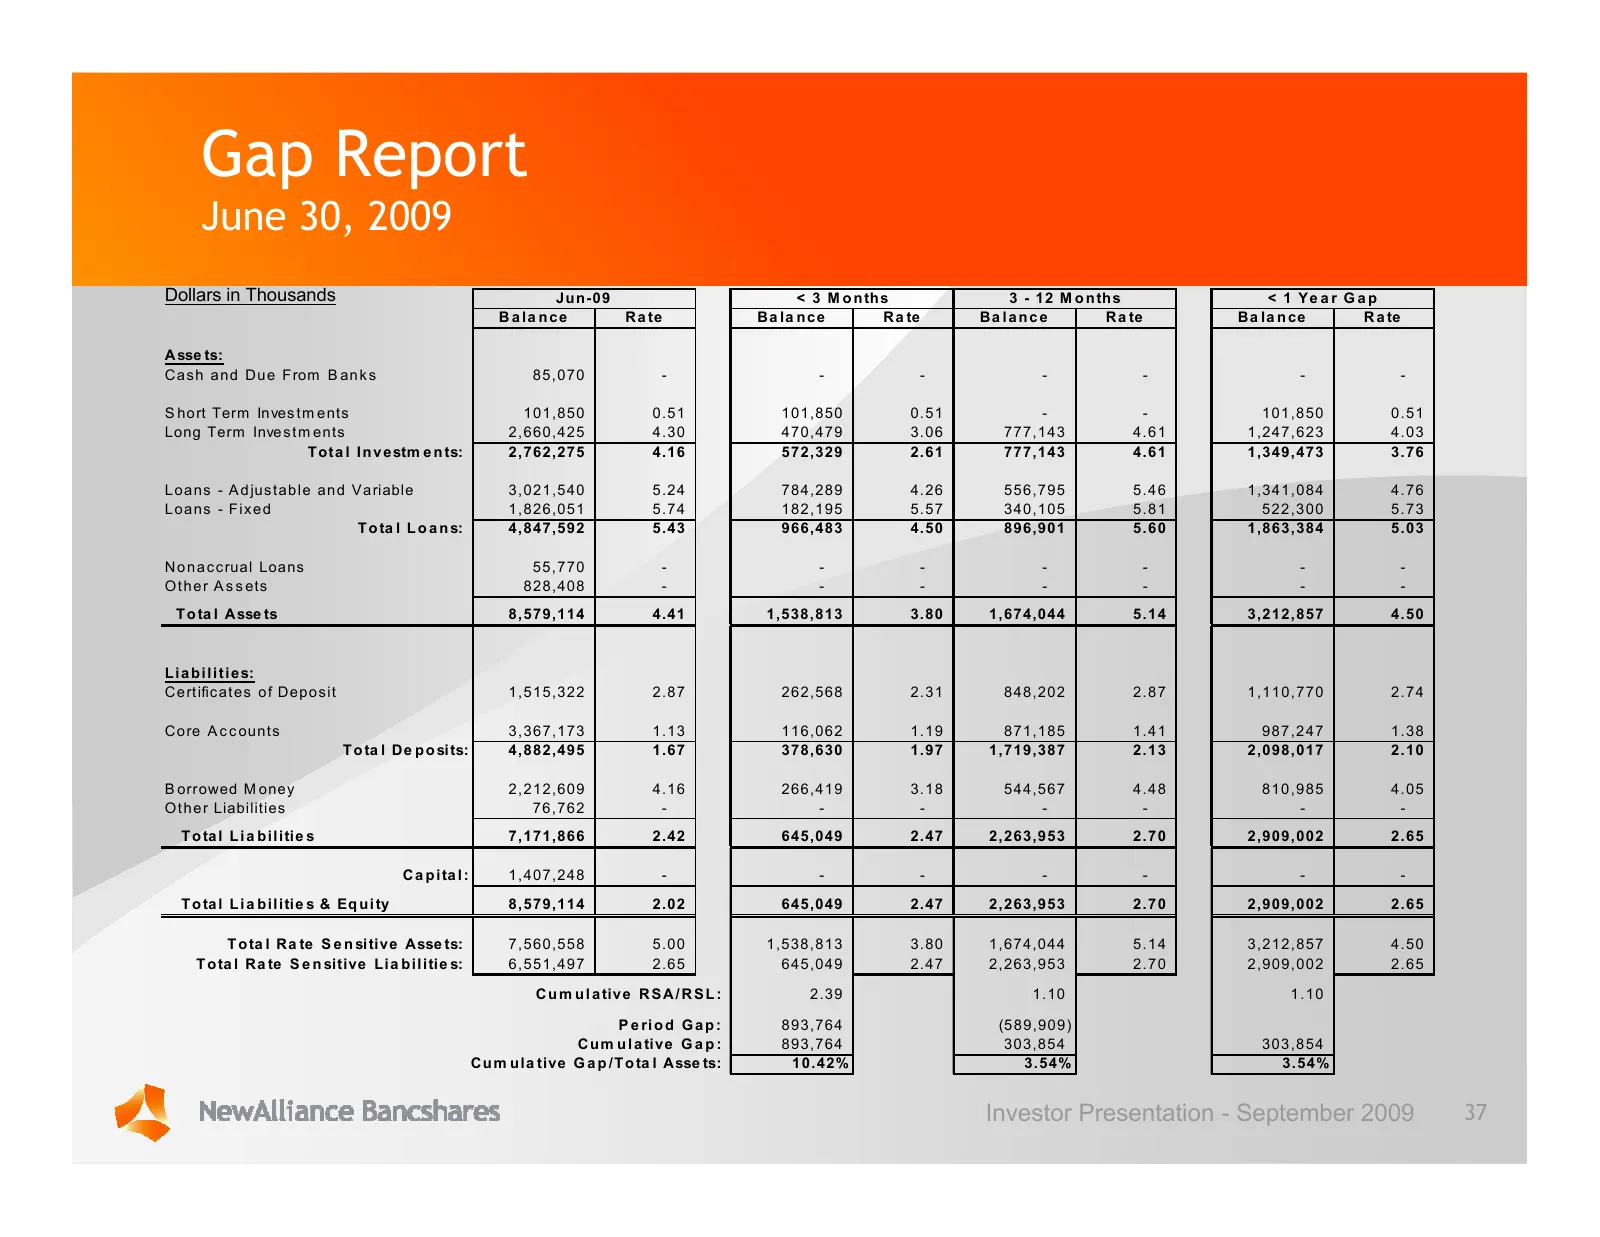
Gap Report June 30, 2009 Dollars in Thousands Jun-09 < 3 M o n th s 3 - 12 M o n th s < 1 Ye a r G a p B a la n c e R a te B a la n c e R a te Ba lance R a te B a la n ce R a te A sse ts: C a s h a n d D u e F rom B an k s 85,070 - - - - - - - S ho rt Term In ves tm e nts 101,850 0.51 101,850 0.51 -
Slide 38: Outlook for 2009
. q Outlook for 2009
Slide 39: Key 2009 Business Priorities
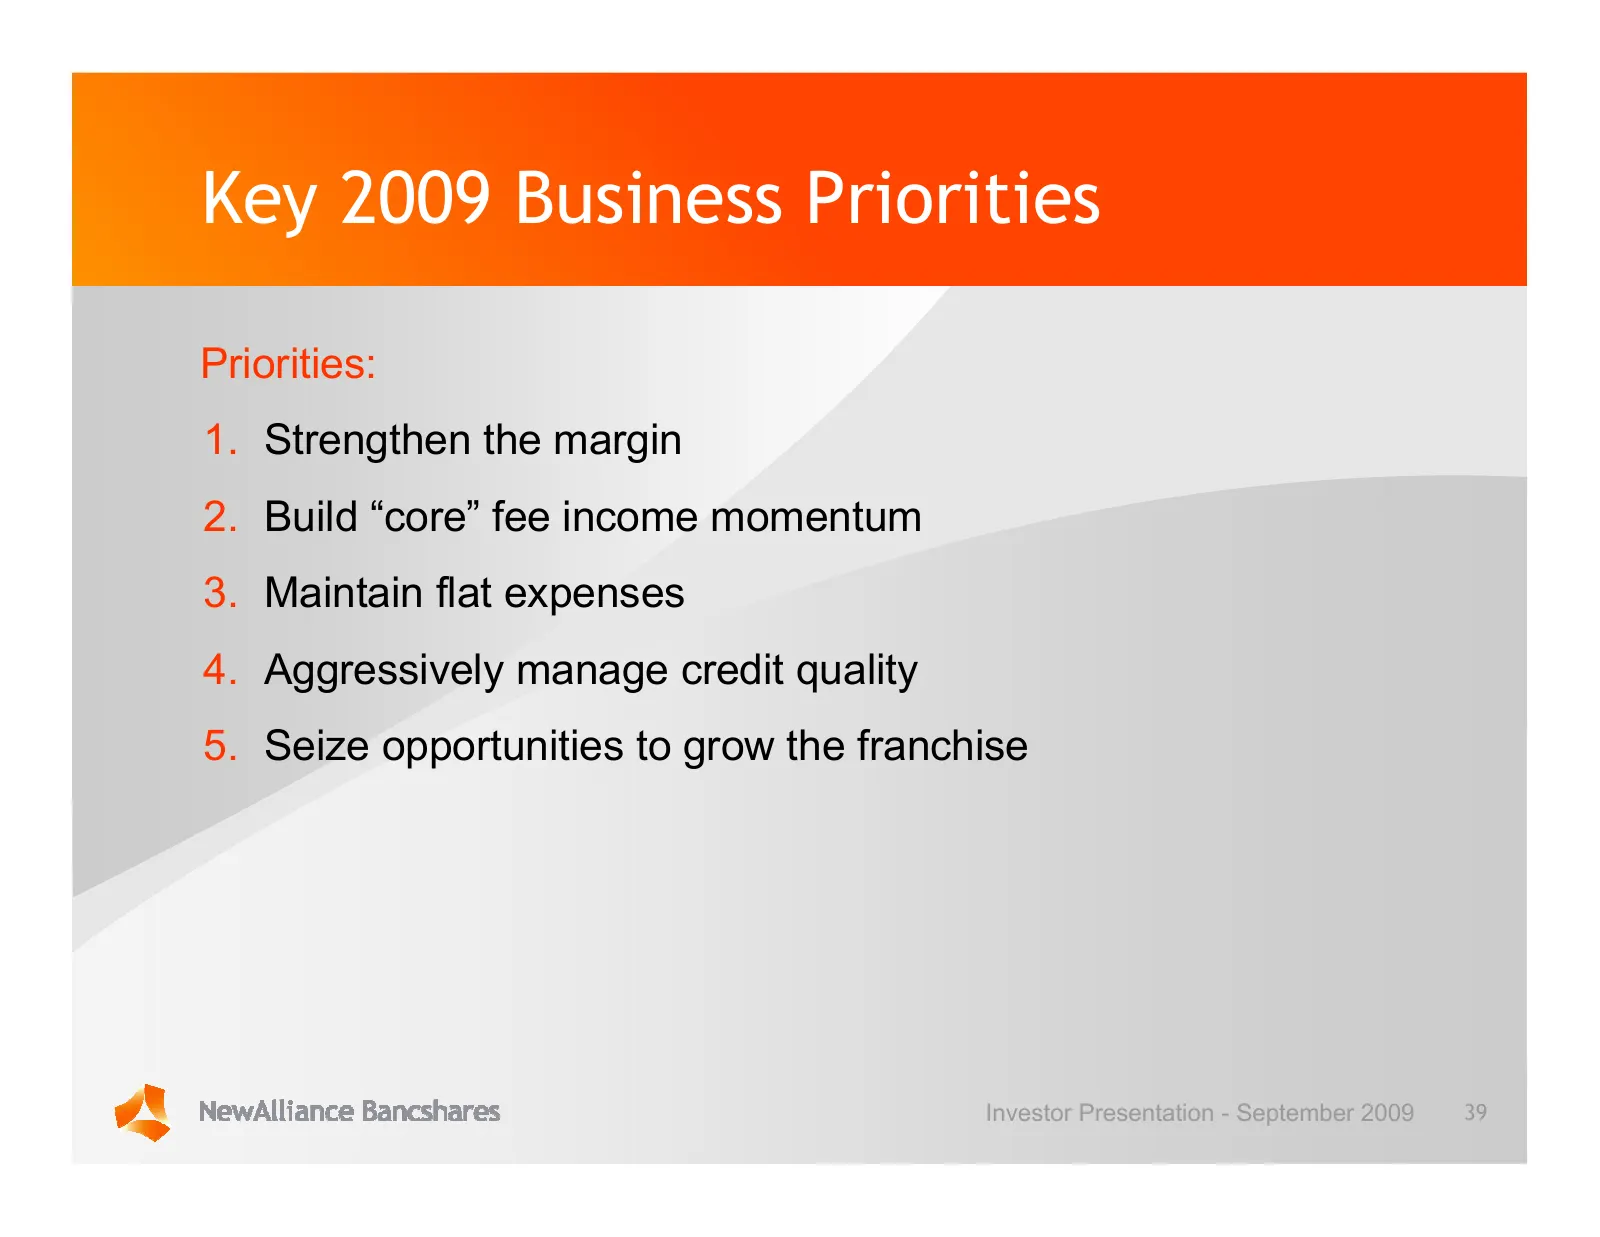
Key 2009 Business Priorities Priorities: 1. Strengthen the margin 2. Build “core” fee income momentum 3. Maintain flat expenses 4. Aggressively manage credit quality 5. Seize opportunities to grow the franchise Investor Presentation - September 2009 39
Slide 40: Organizational Strengths
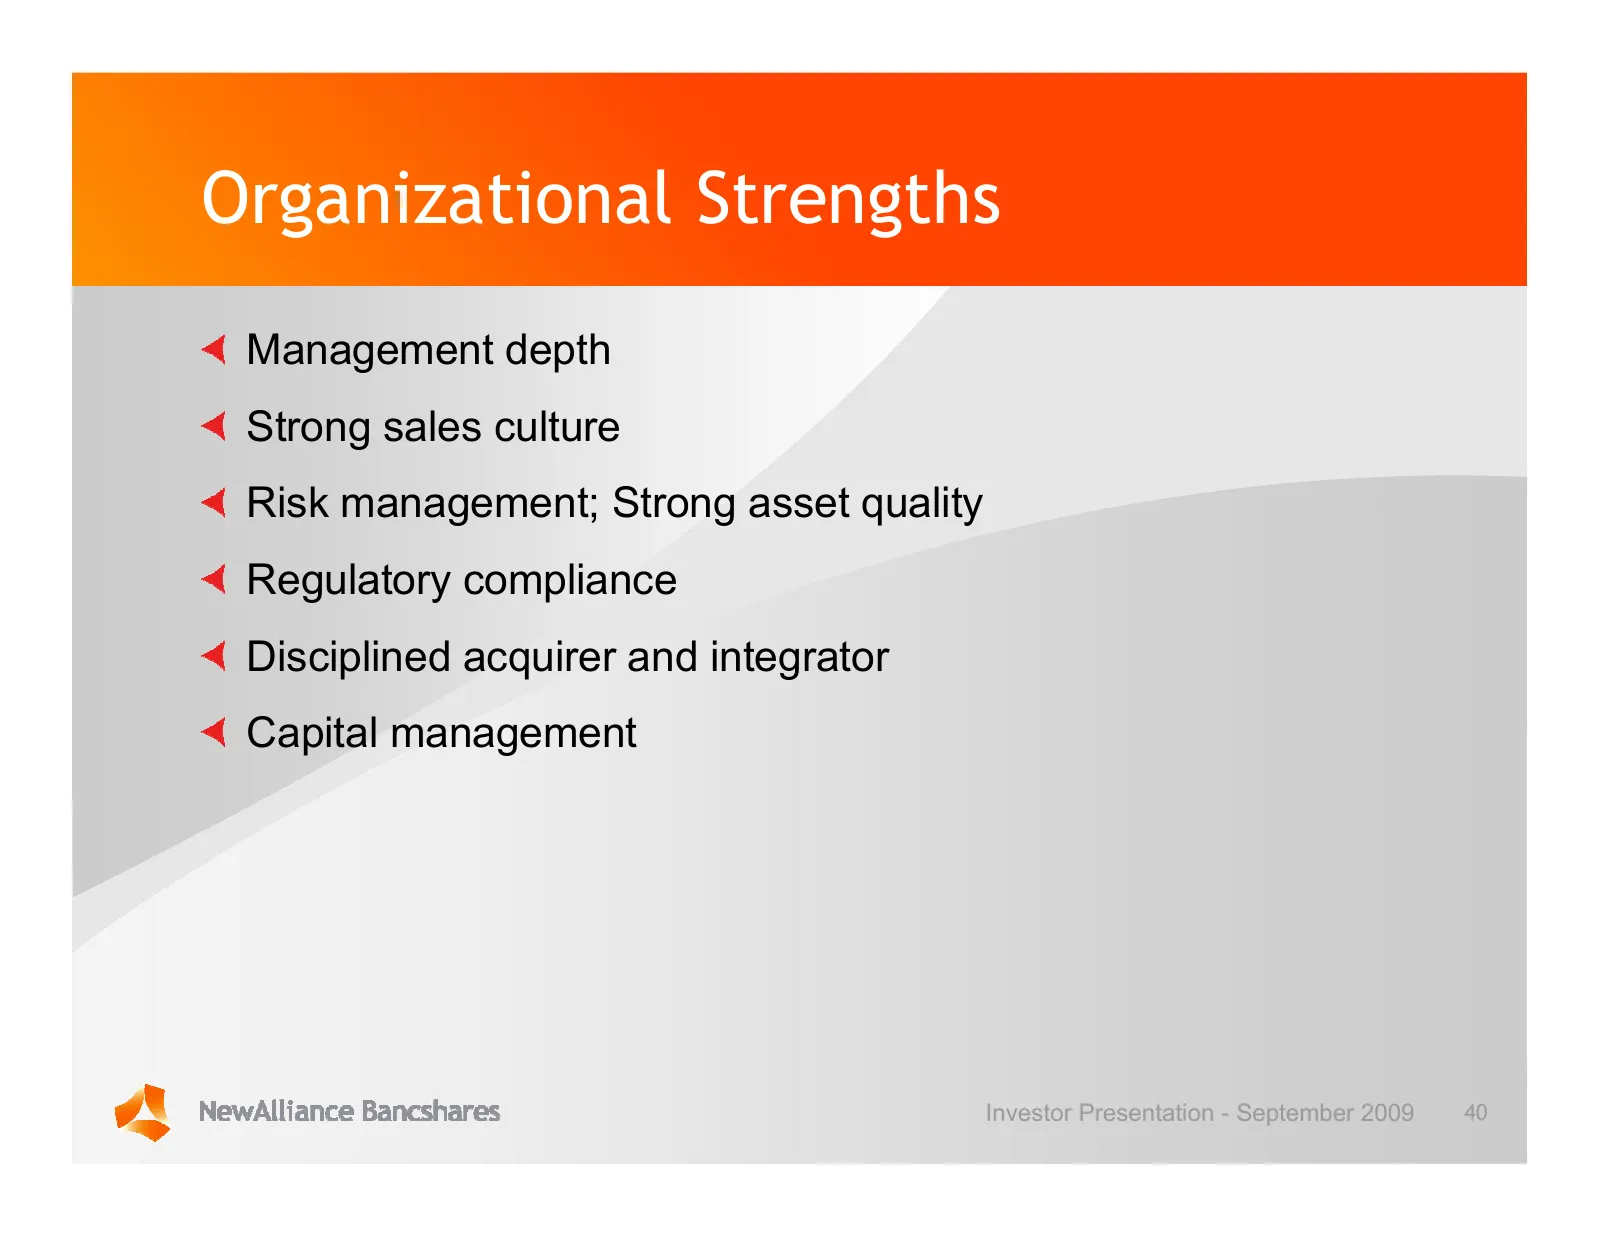
Organizational Strengths Management depth Strong sales culture Risk management; Strong asset quality Regulatory compliance Disciplined acquirer and integrator Capital management Investor Presentation - September 2009 40
Slide 41: NewAlliance Bancshares
! q NewaAlliance Bancsharé
Source: SEC EDGAR · 8-K filed Sep 16, 2009
More decks from Newalliance Bancshares Inc
 Merger or Acquisition (November 2010)45 slides · Nov 18, 2010
 Stifel, Nicolaus & Company, Inc. Bank and Thrift Conference 201037 slides · Nov 3, 2010
 Merger or Acquisition (August 2010)25 slides · Aug 25, 2010
 Merger or Acquisition (August 2010)24 slides · Aug 19, 2010
 Merger or Acquisition (August 2010)23 slides · Aug 19, 2010
 Q2 2010 Earnings Presentation31 slides · Jul 28, 2010