CYS Investments — 2013 Banking and Financial Services Conference
23 slides from CYS Investments's conference presentation, Nov 12, 2013
Slide 1: Investment Outlook - November 2013
Exhibit 99.1 Investment Kevin 2013 November Banking E. Grant, 12, Outlook and 2013 CFAFinancial - Chief November Executive Services 2013Conference Officer
Slide 2: Forward-Looking Statements
Forward-Looking Act expectations government information Company’s equity, the uncertainties, or implied otherwise. Federal of 1934, availability by Reserve, or future under backed for as 2you this the amended, distributions, forward-looking should Statements Federal performance the and bonds, and fe
Slide 3: CYS Overview
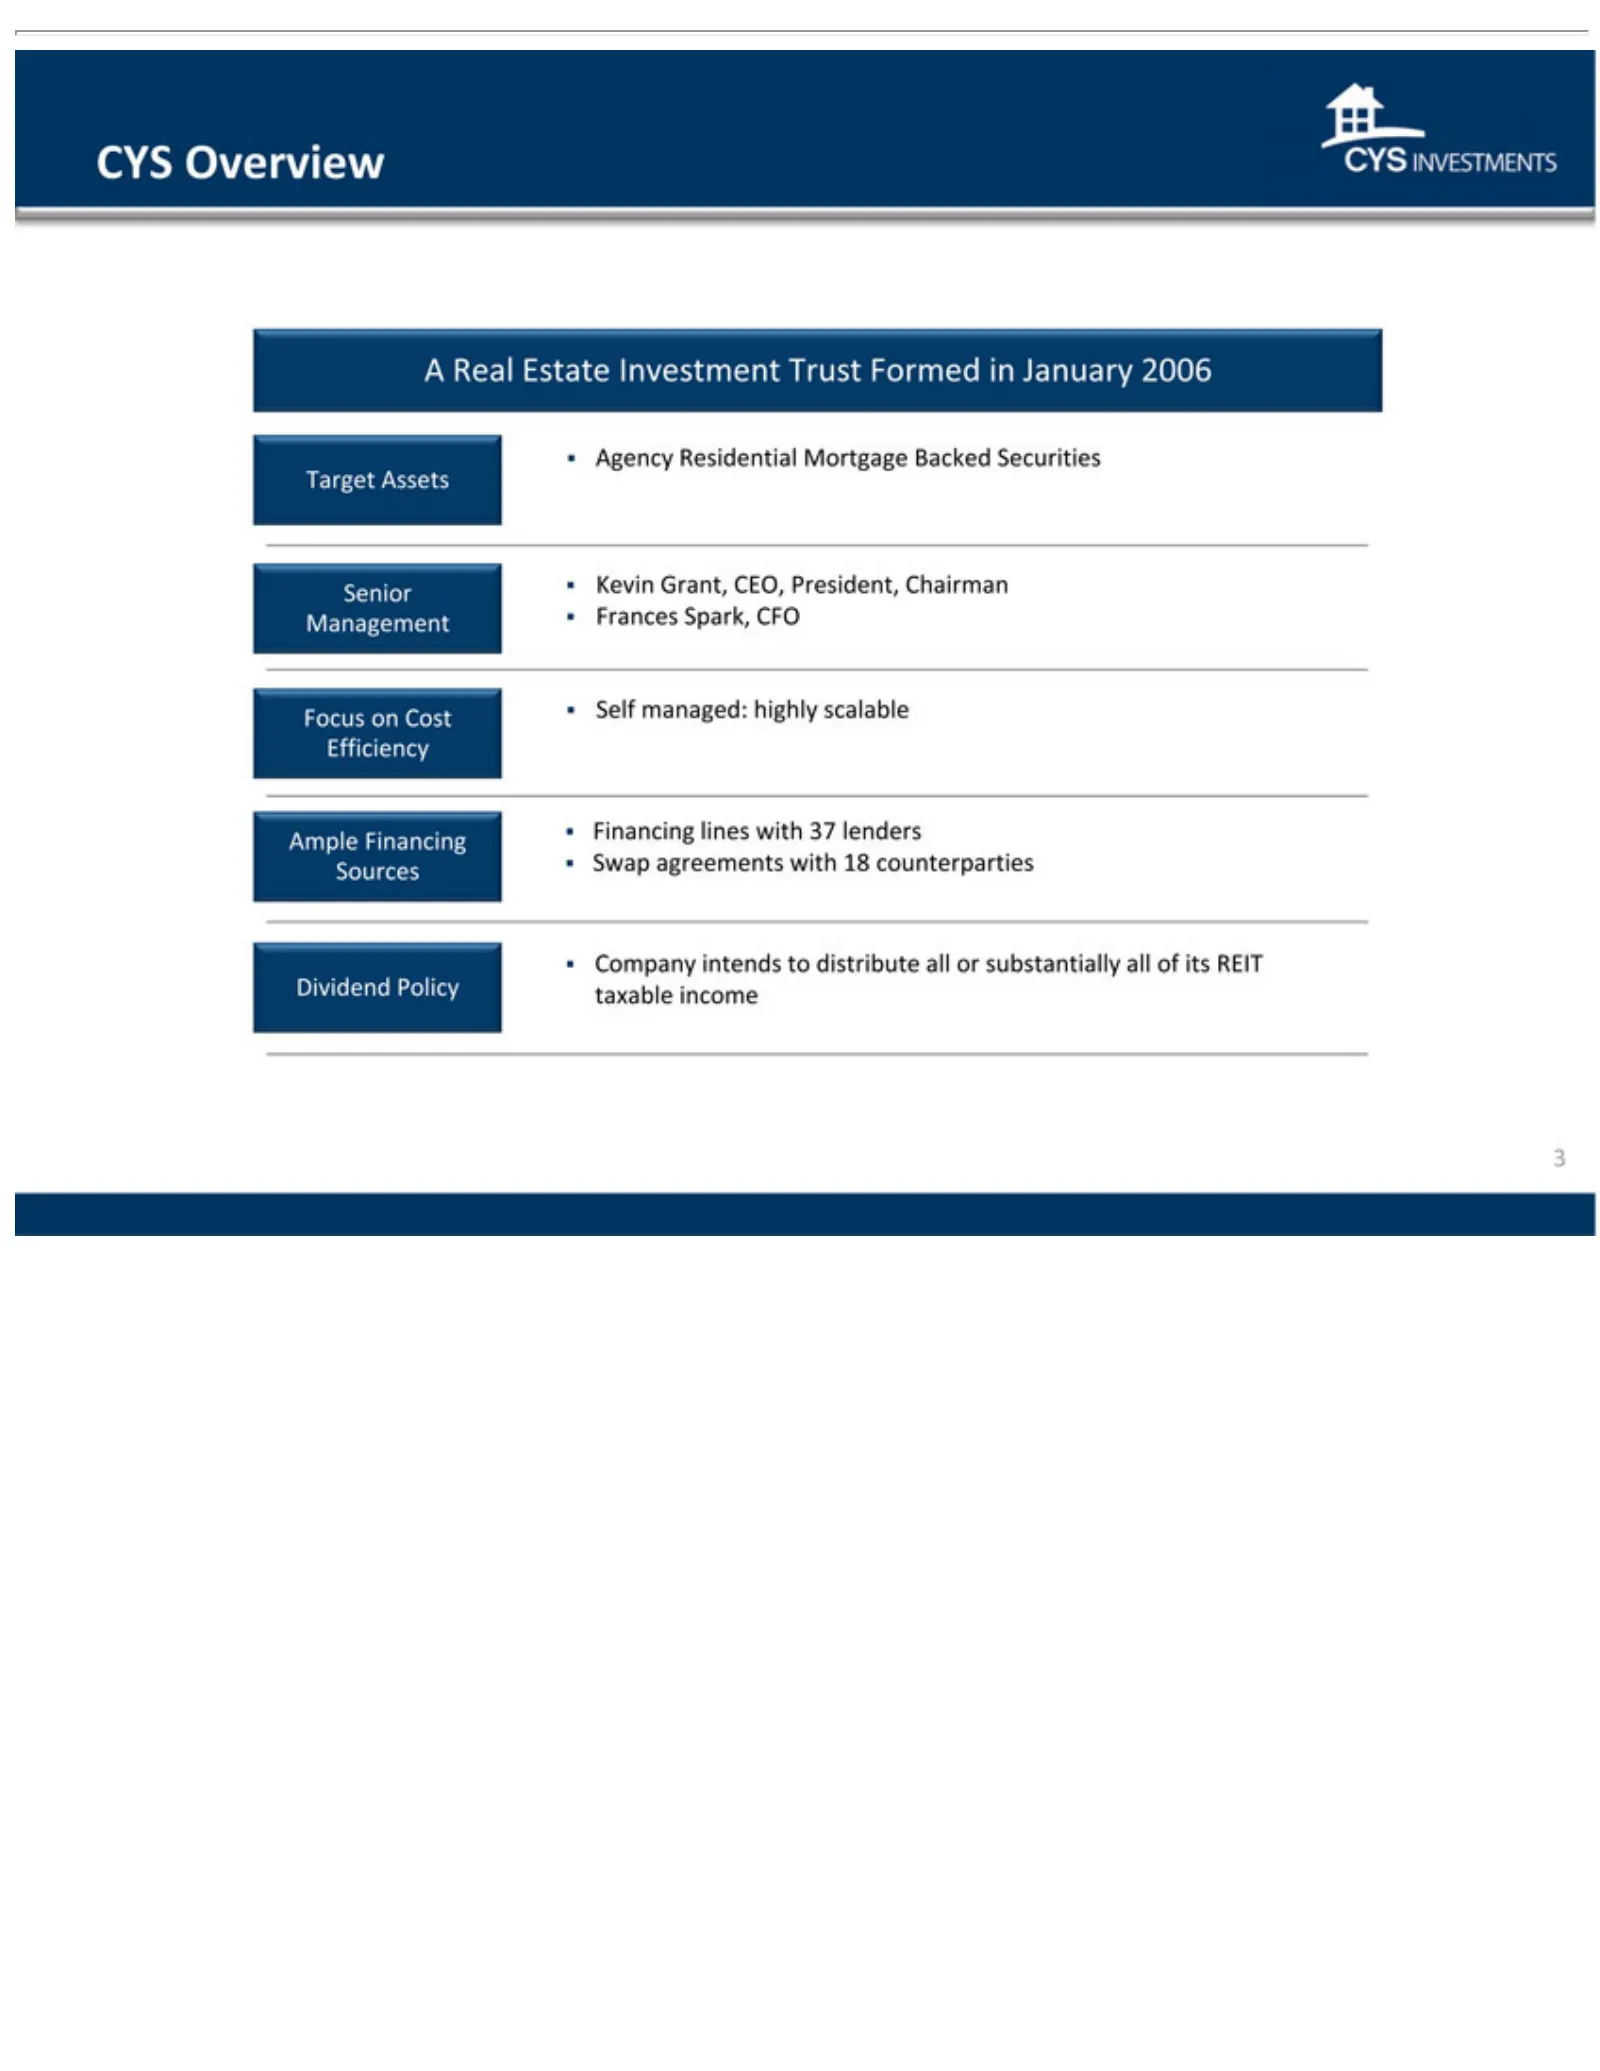
CYS Overview Frances Company Spark, intends CFO A Real to distribute Focus Estate onInvestment Cost all orSelf substantially managed: Trust Formed all highly of its inscalable January REIT Dividend Efficiency 2006 Agency Policy Financing Residential taxablelines income Mortgage with337 lenders Backe
Slide 4: Cheapening of Agency MBS Market: Hedged vs. Unhedged
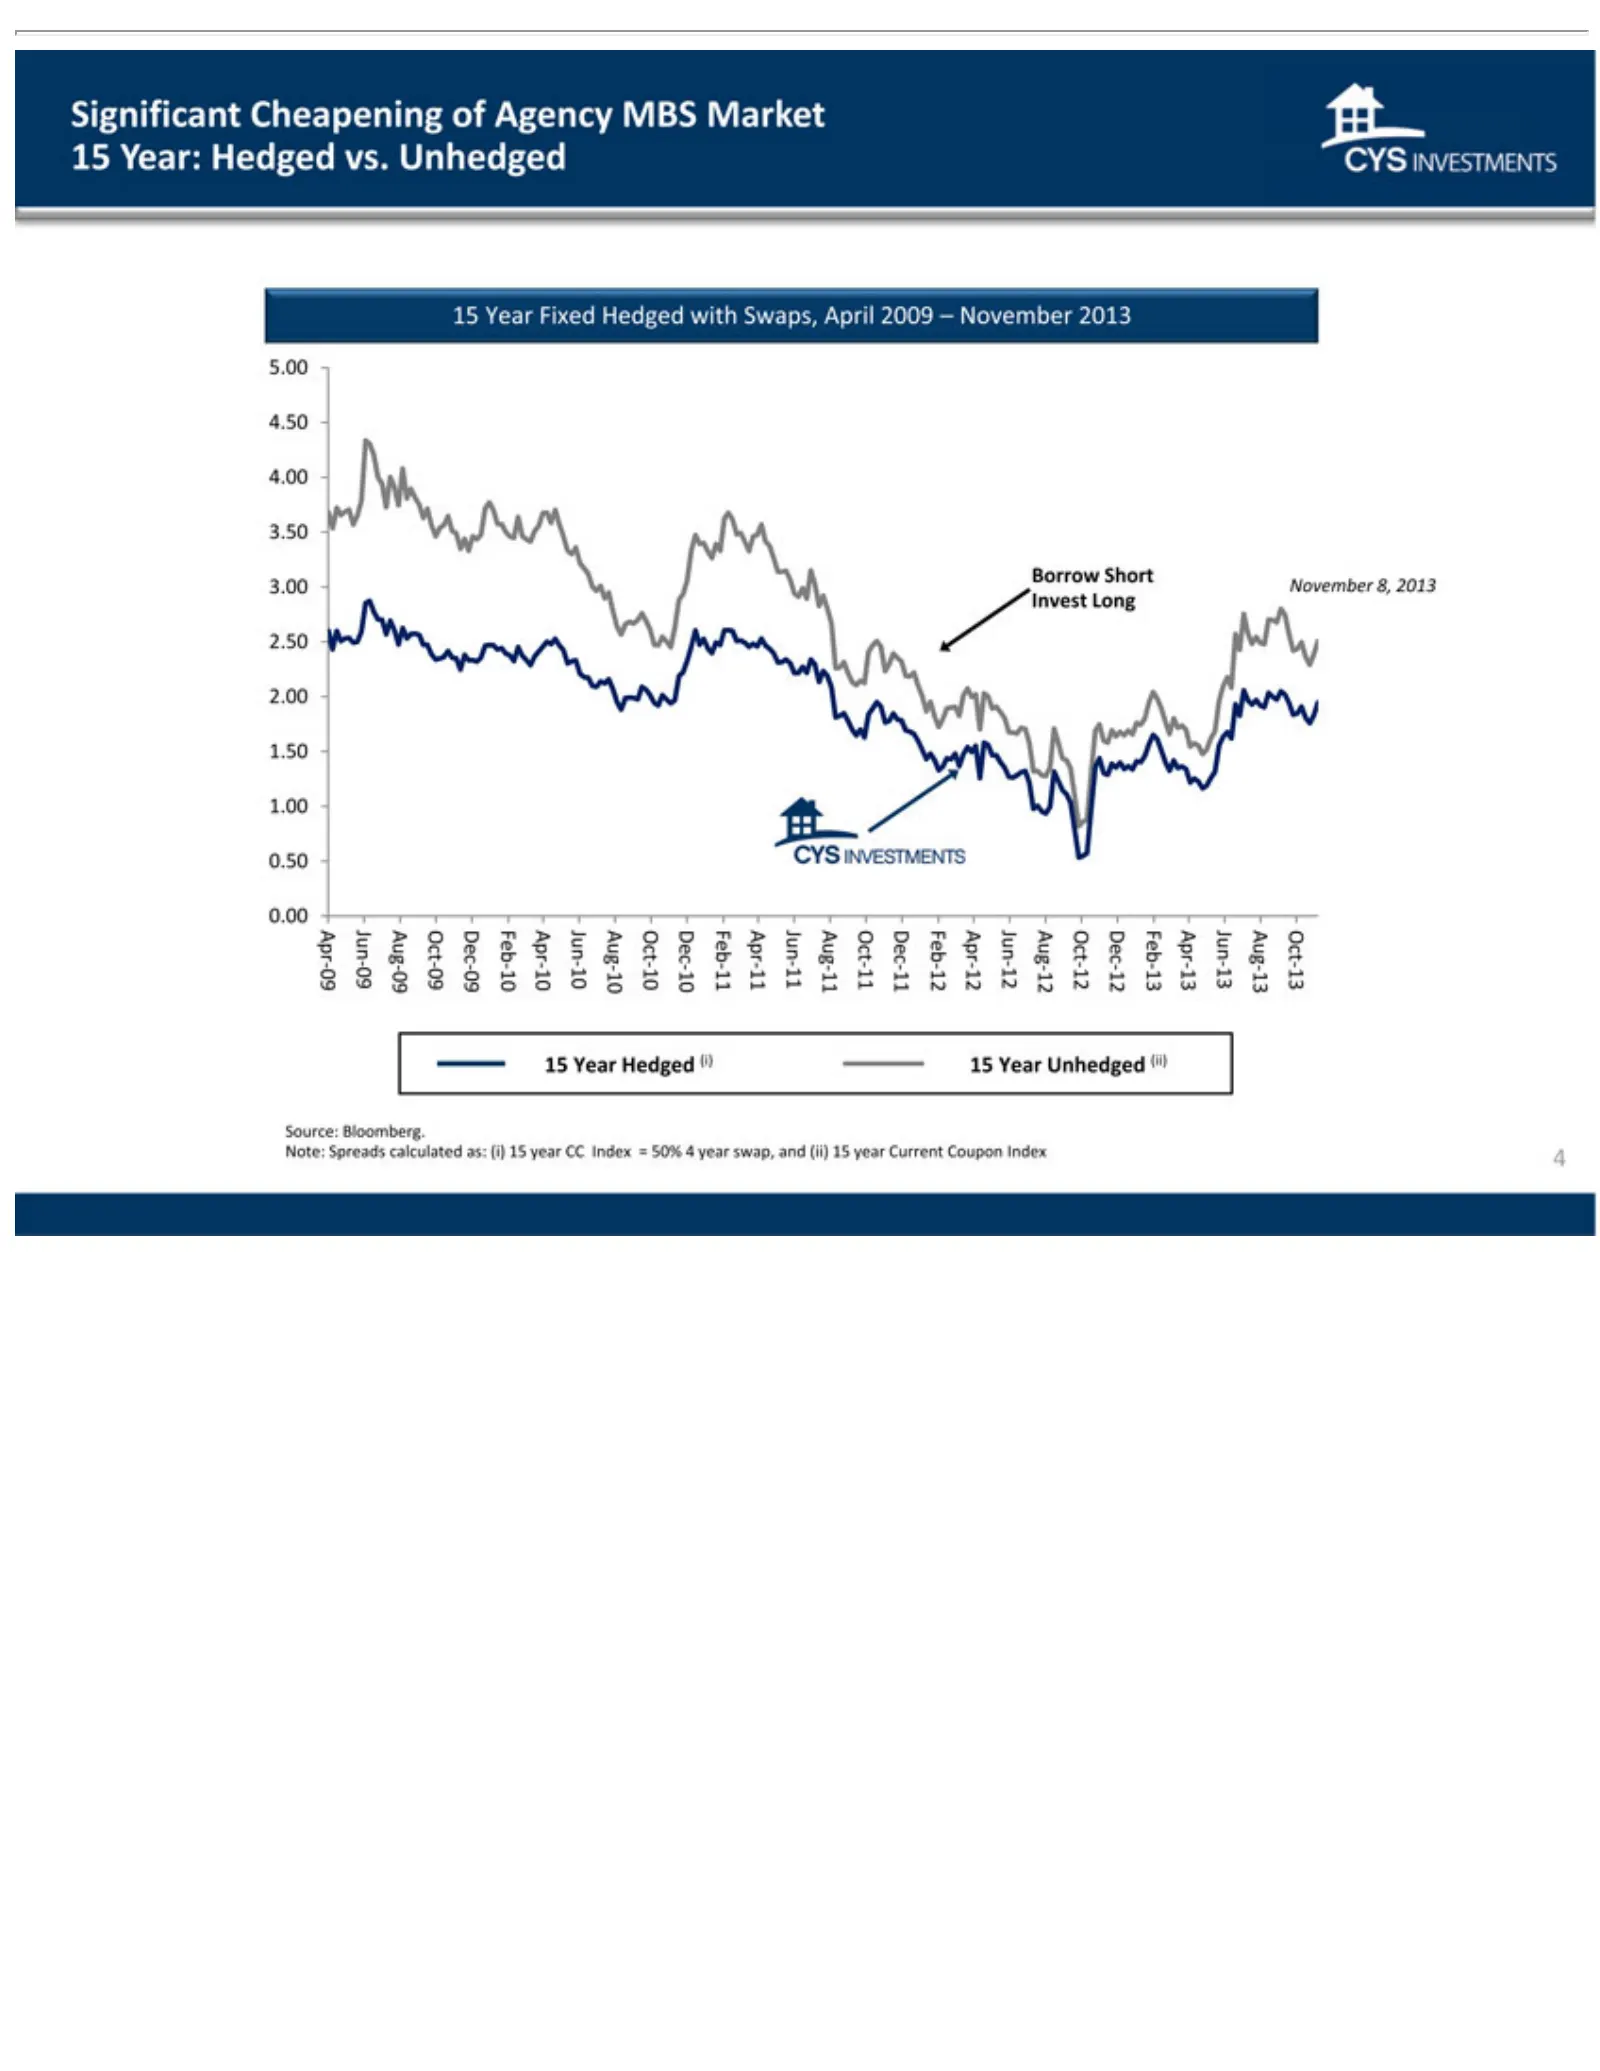
Significant Feb-13 5Apr-09 4 4 3 3Short 002 .2Cheapening 50 1Dec-12 1. .000 0 Source: 50 Long .of00Agency Oct-12 .Bloomberg. 50 . . MBS Borrow 00 50 Market Note: . 00 Invest . 50 Spreads 15Aug-12 . .Year: 00 calculated Hedged Jun-12 Apr-12 vs. as: Unhedged (i) 15 Feb-12 year15 Dec-11 CCYear Index Fi
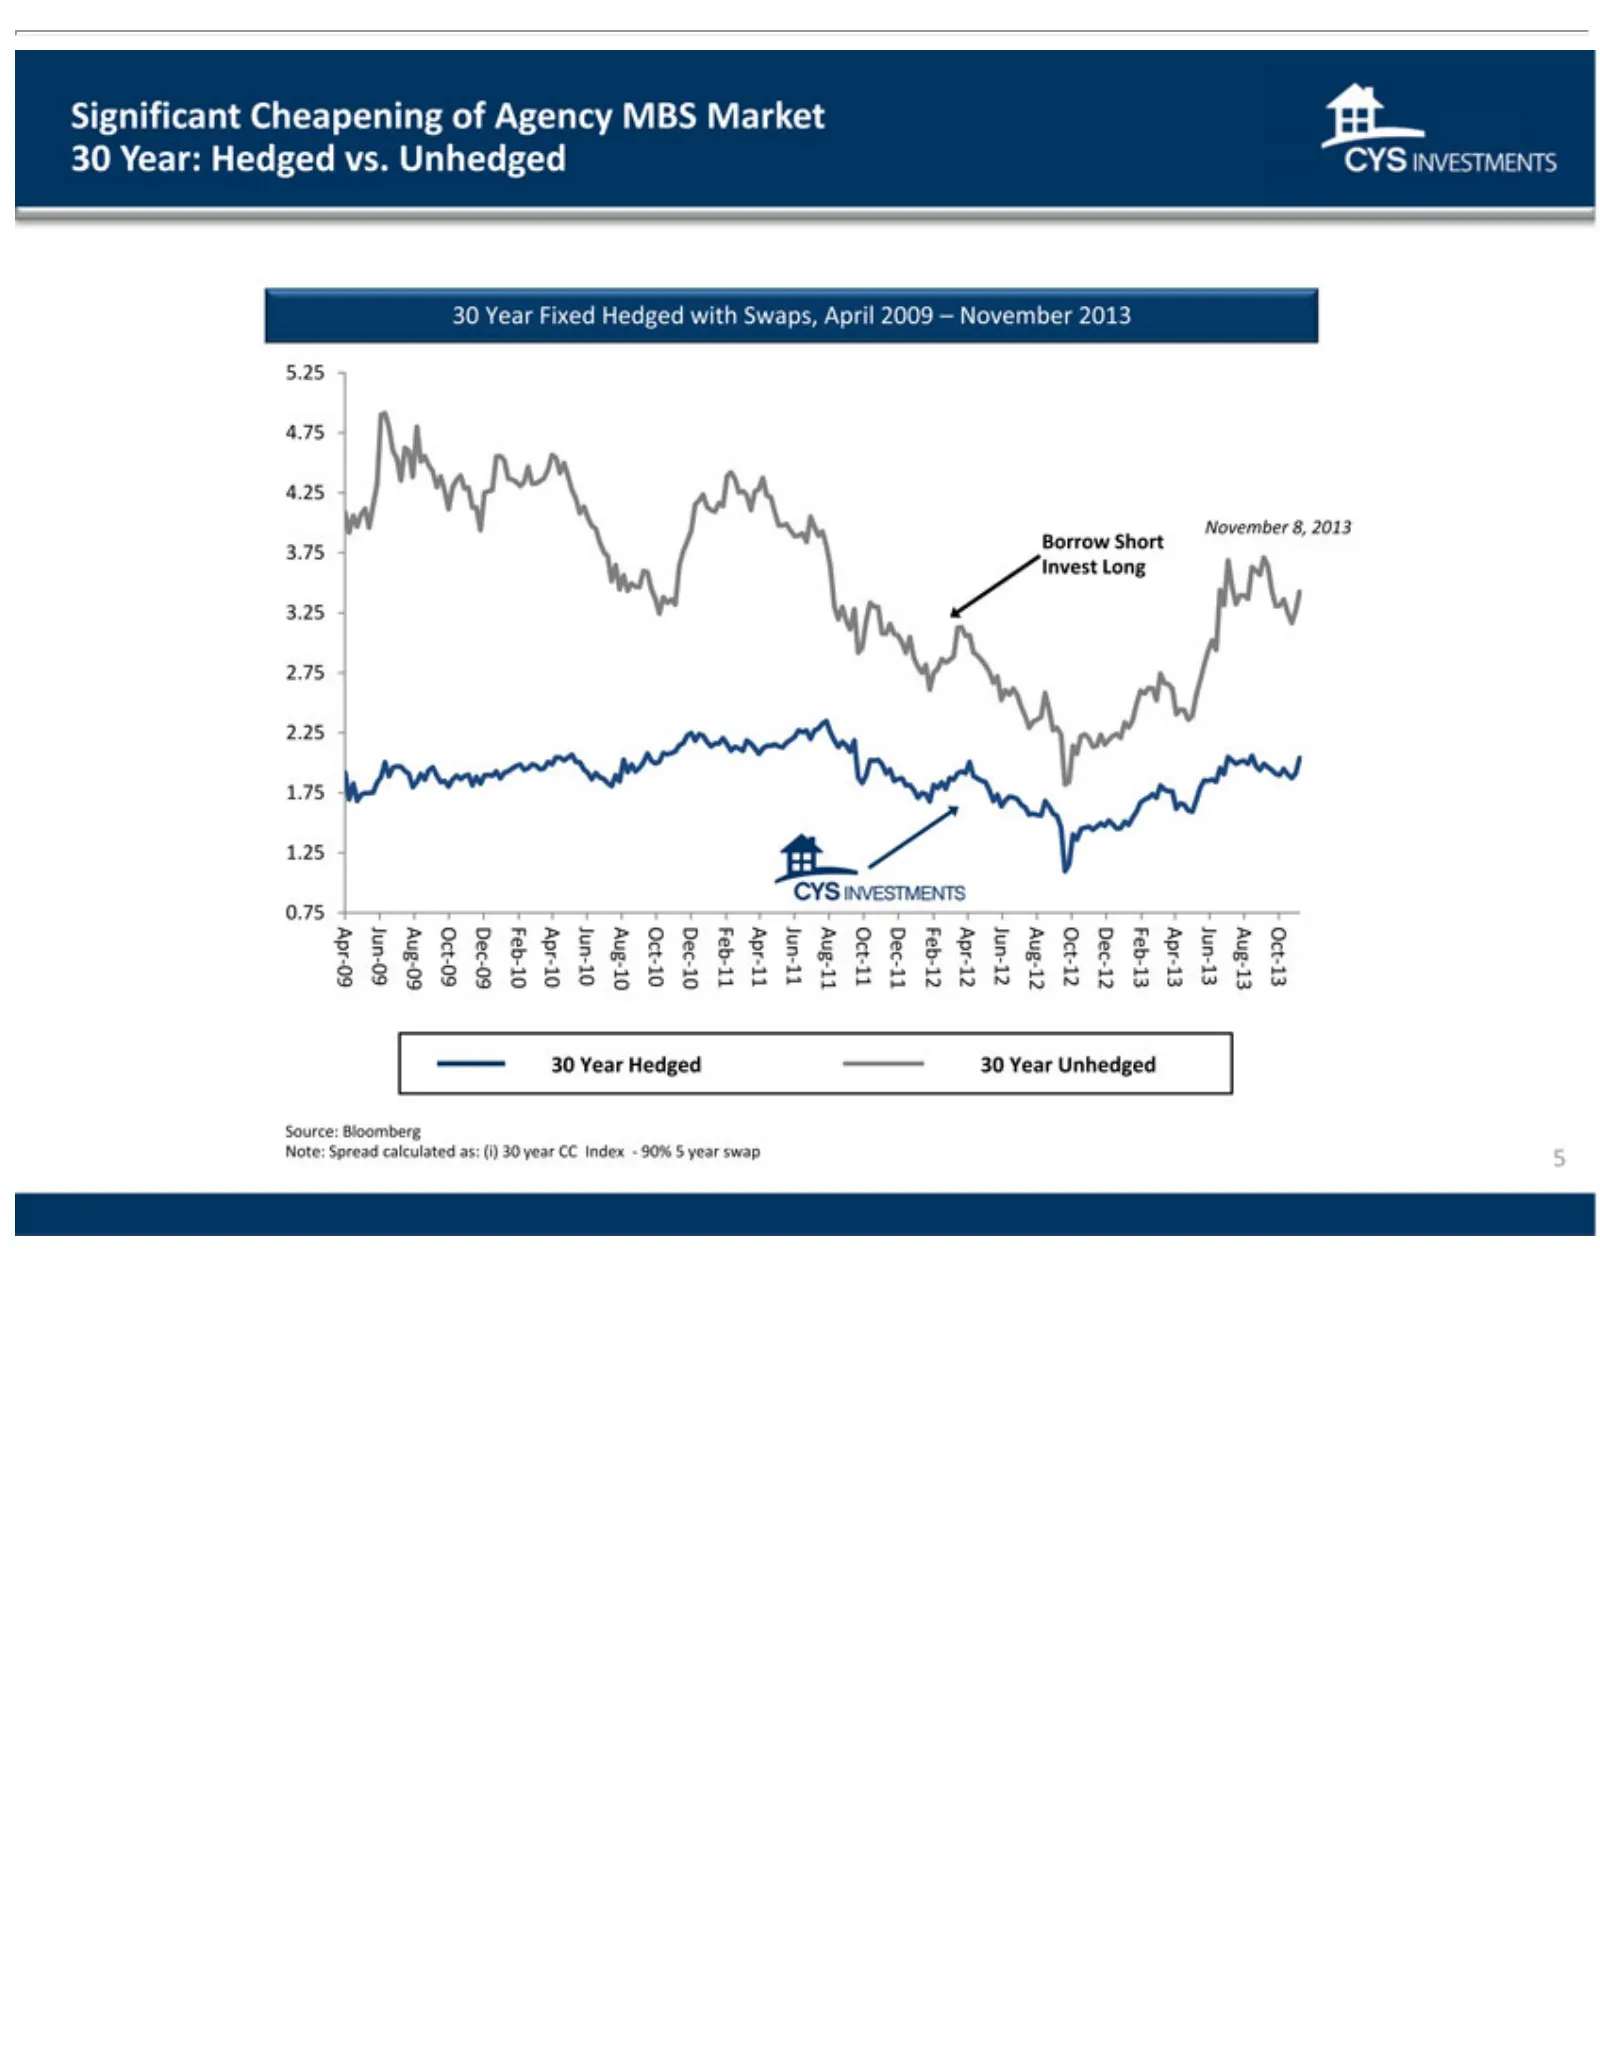
Slide 5: Cheapening of Agency MBS Market: 30 Year Hedged vs. Unhedged
Significant Short Apr-09Feb-13 25 .Cheapening 75Long . 25 Dec-12 . 75 .of25Agency Borrow . . 75 25 MBS Invest . 75 Market . Oct-12 . 25 7530 Aug-12 . 5Year: 4 4 3Hedged Jun-12 3 2 2 1Apr-12 vs. 1 0Unhedged 30 Year Feb-12 Hedged 30 Dec-11 Year 30Fixed Oct-11 Year Hedged Unhedged Aug-11with Jun-11 Sou
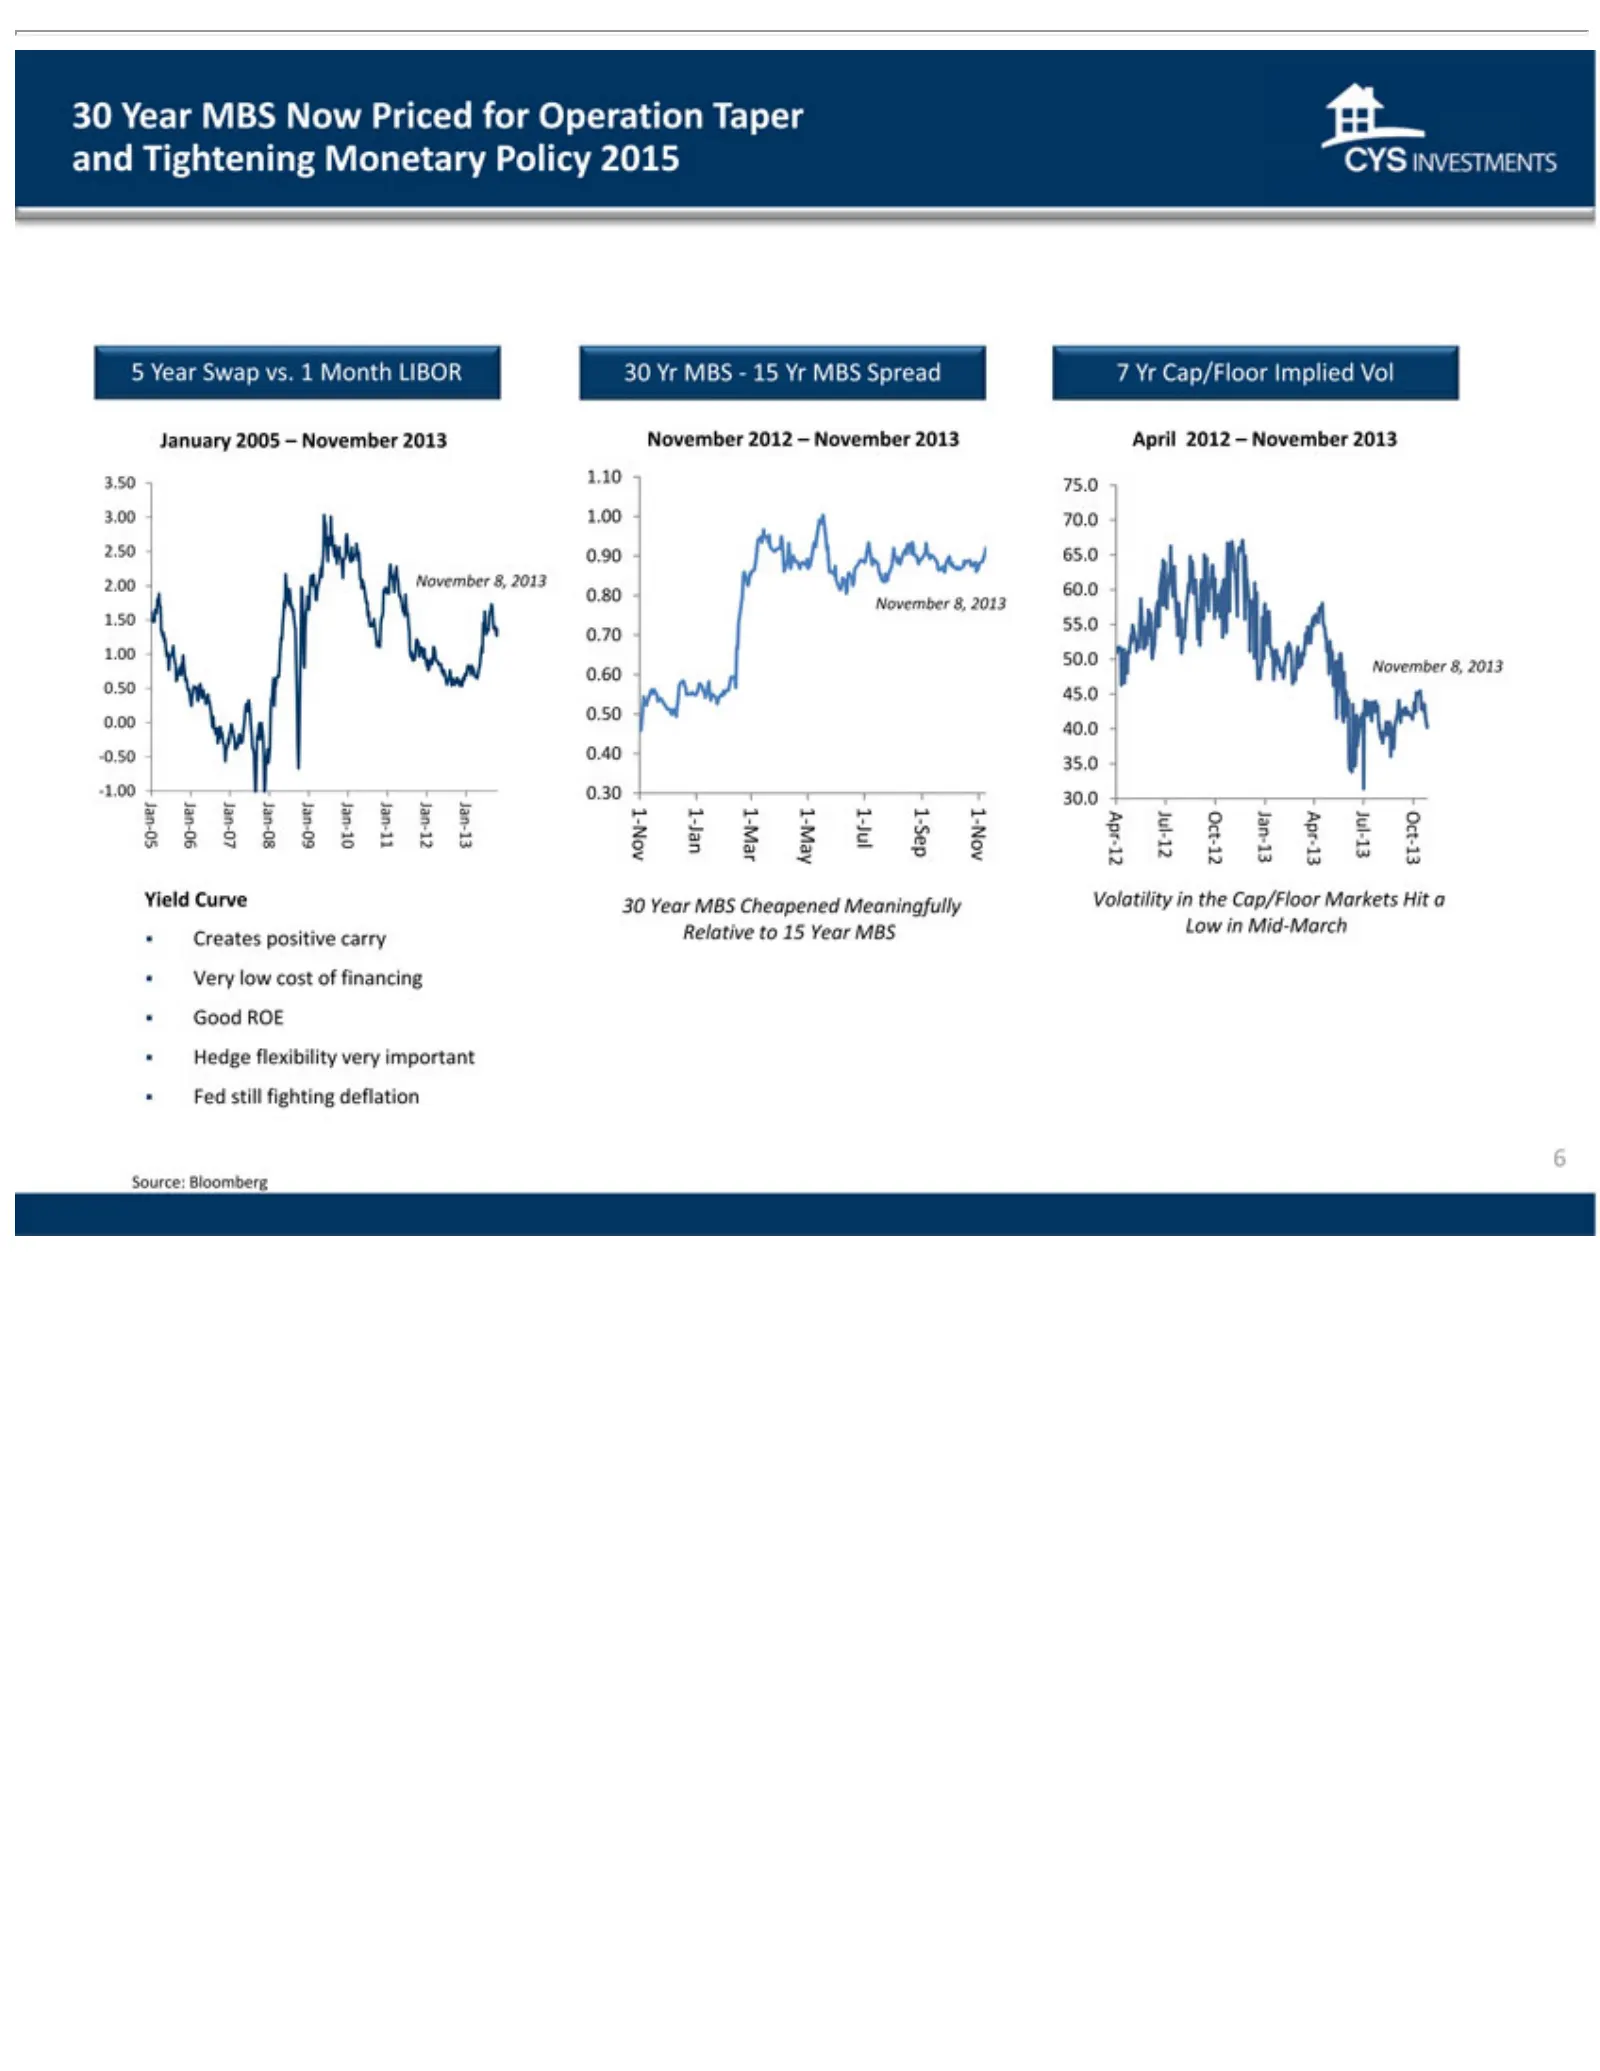
Slide 6: 30 Year MBS Cheapened Meaningfully Since May 2013
30 Year November Mar Creates Jul positive MBS Sep8, 2013 Nov 2013 Nowcarry November - 12 0.50 Priced -Very 13 0.60 for May low 2012 45.0 Operation 12 cost –0.50 12 November of13 0.00 financing Taper 13 40.0 132013 and Jan-14 -0.50 Good Tightening April 1-Jan 0.40 ROE 2012 35.0 Jan-14 Hedge Monetary
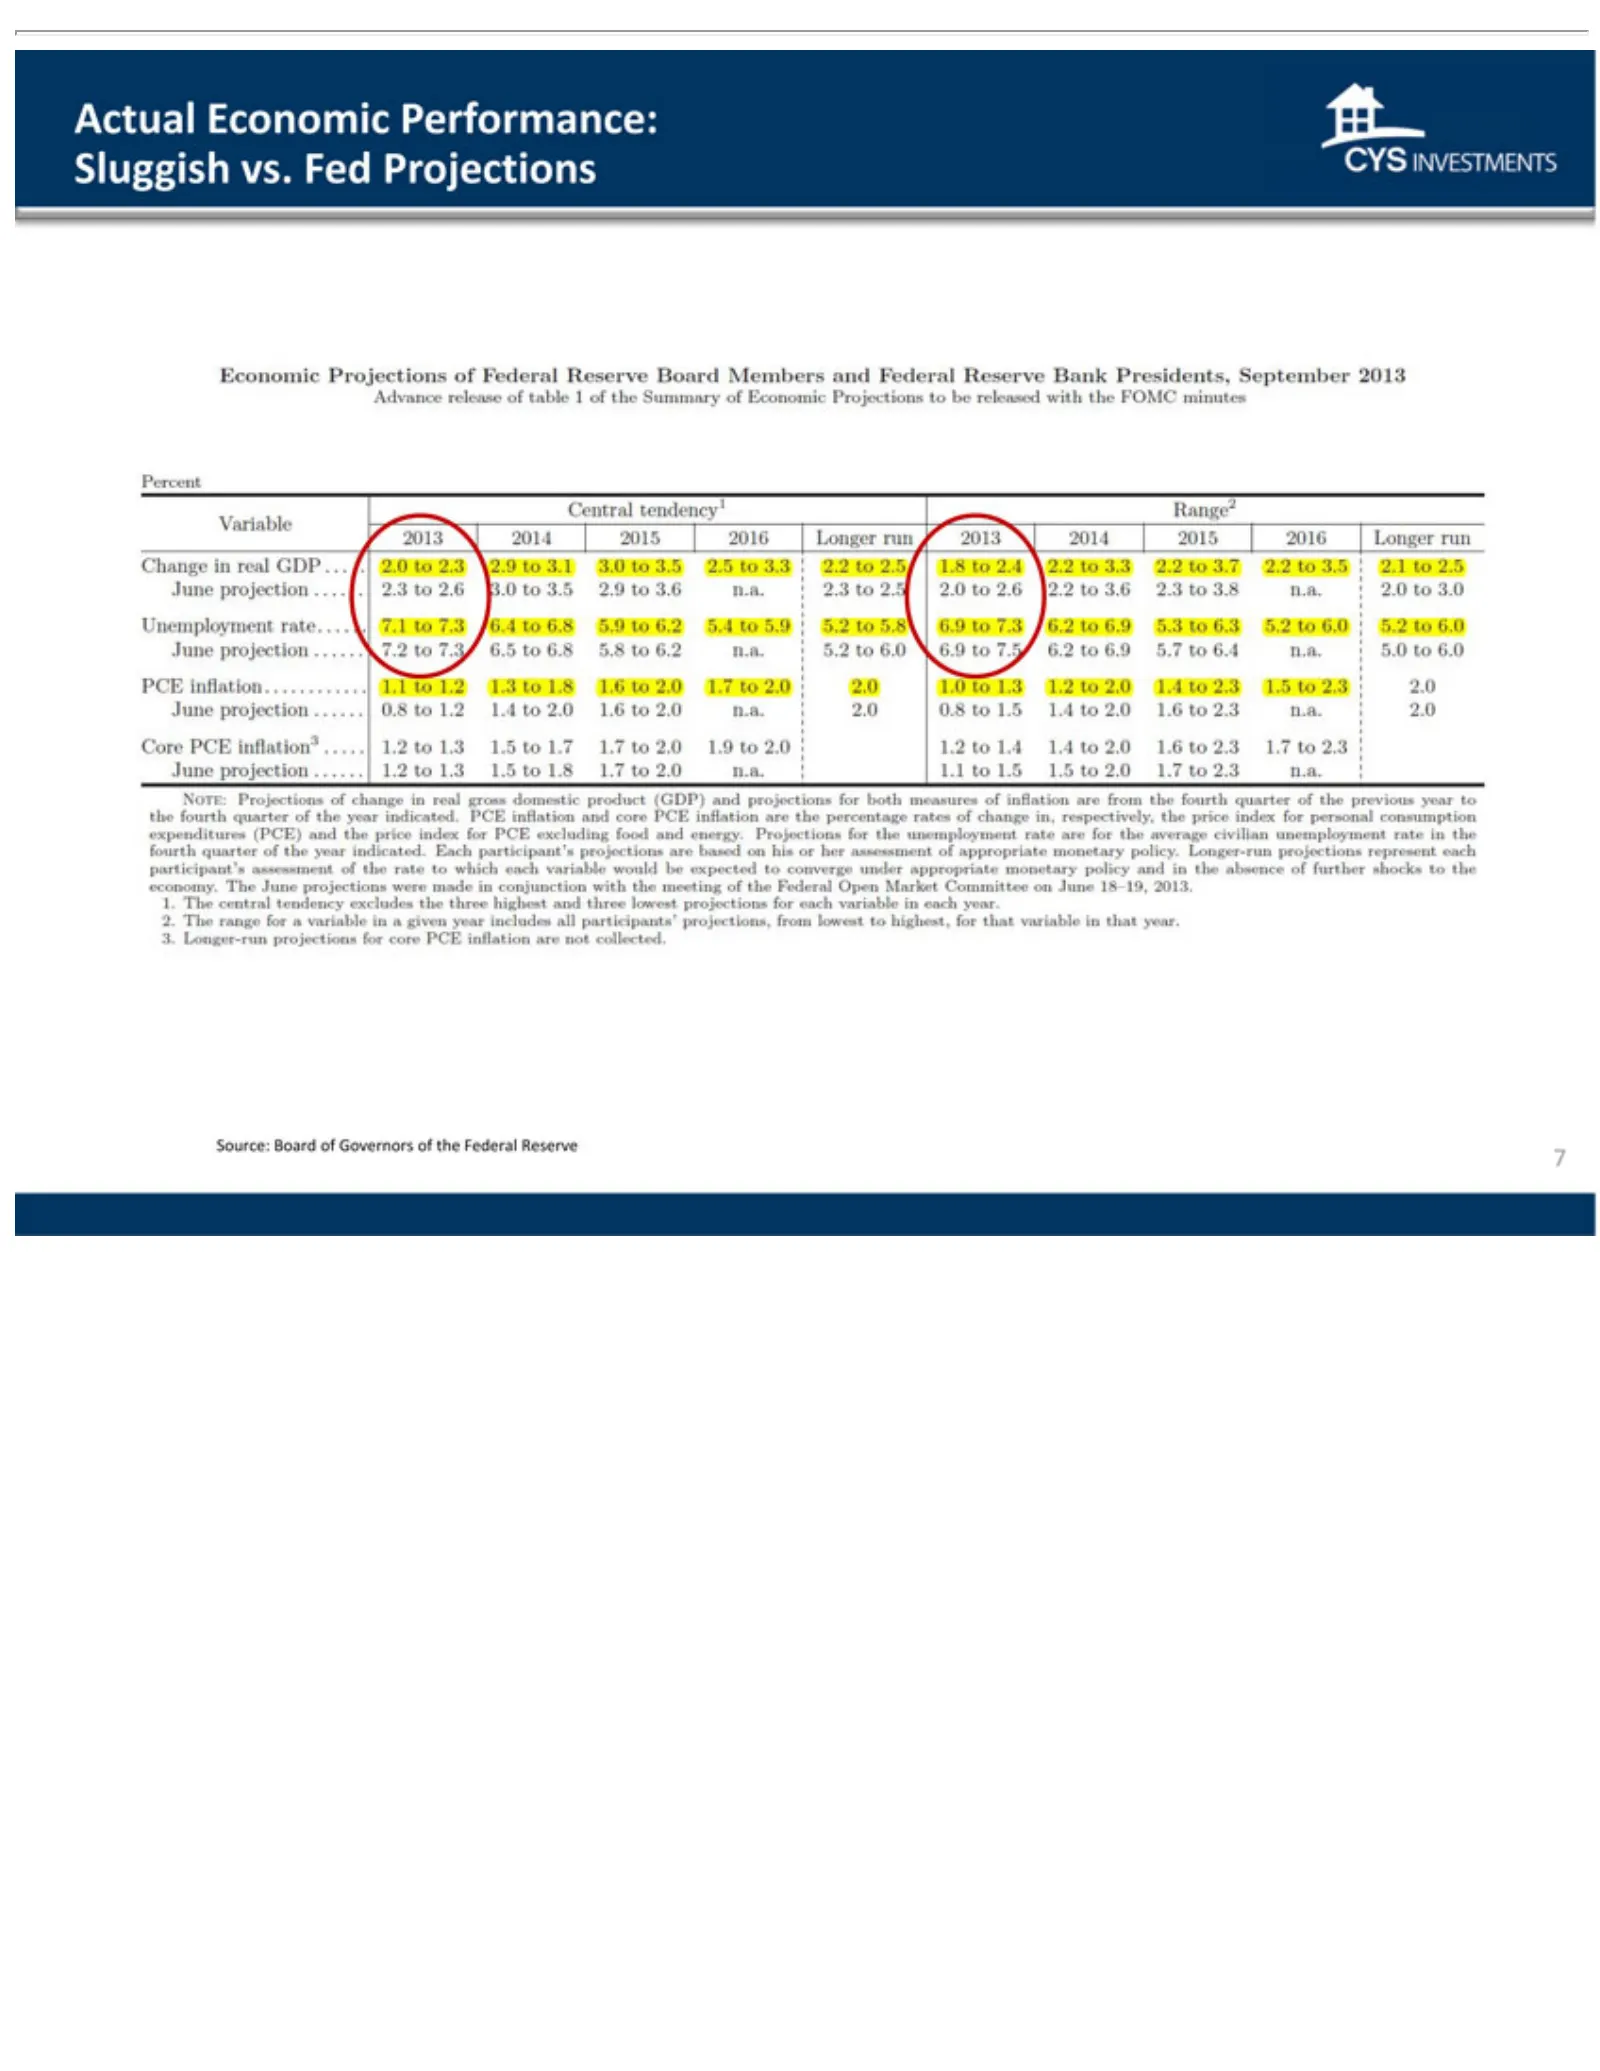
Slide 7: Actual Economic Performance: Sluggish vs. Fed Projections
Actual Economic Performance: Sluggish vs. Fed Projections Source: Board of Governors of the Federal Reserve 7
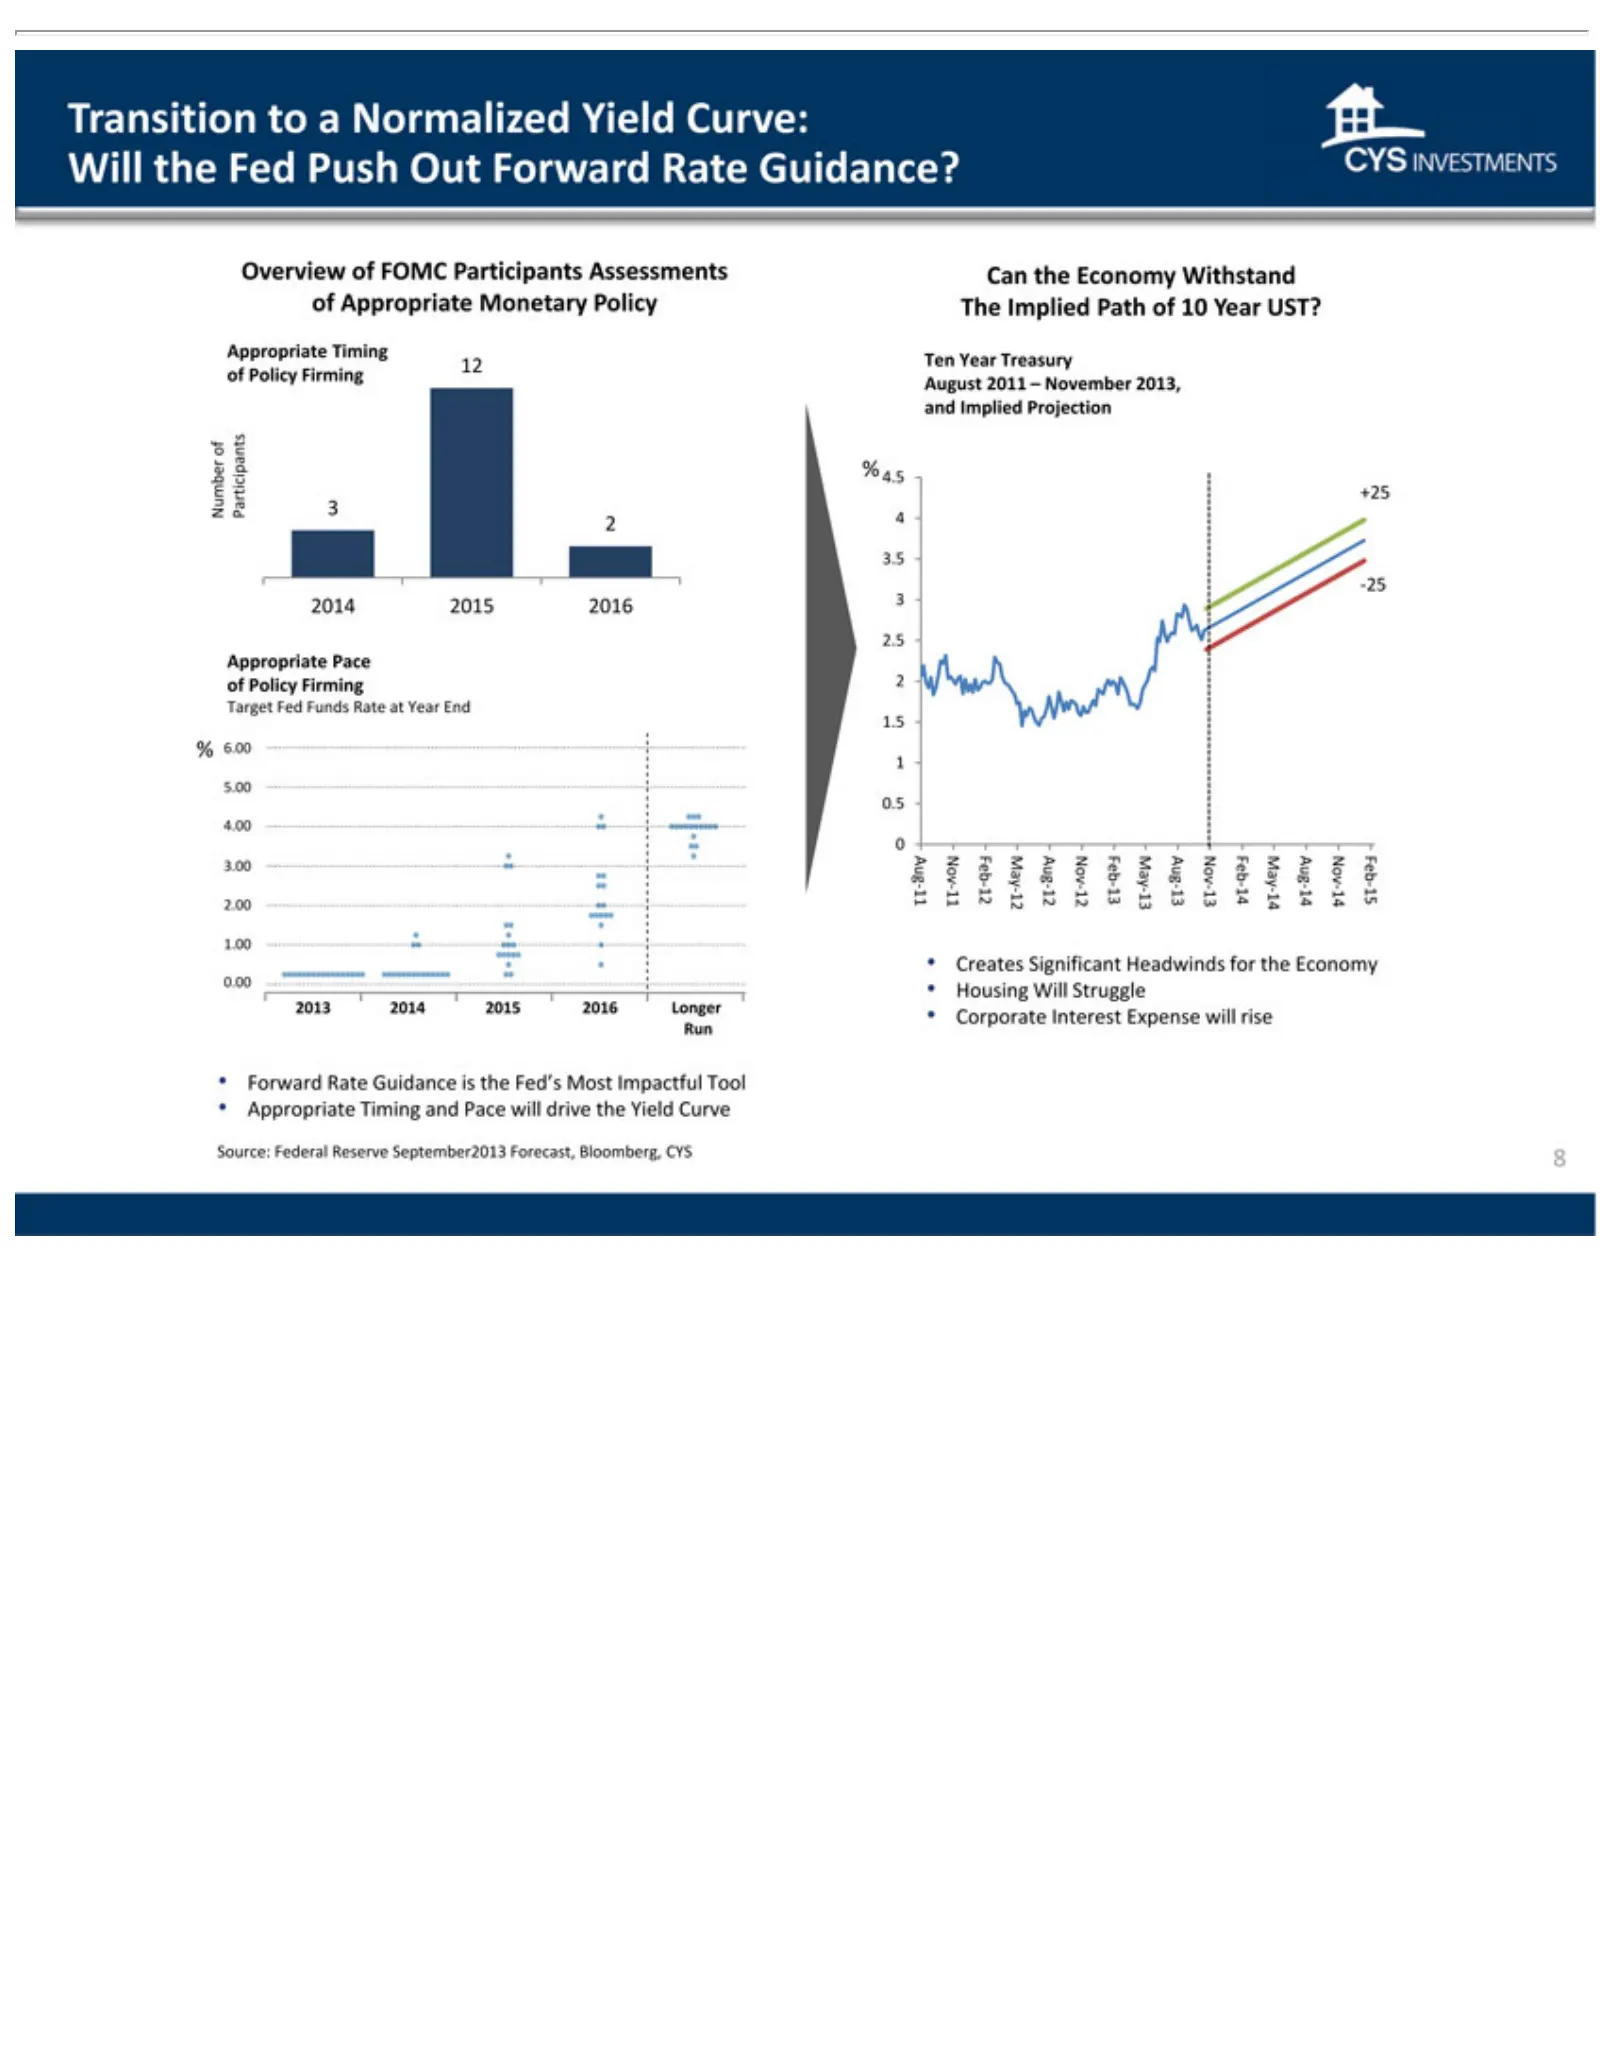
Slide 8: Transition of Forward Guidance
Transition of Forward Can Nov Corporate Policy the - Feb Economy Rate Firming Interest May to aGuidance Normalized Aug of Withstand Expense Nov Number isFeb the Yield will The Participants -Fed’s May rise Curve: Implied Most 8AugWill Nov Path Impactful 3 2 the 2014 -of Feb Fed 102015 11 Tool Year Pu
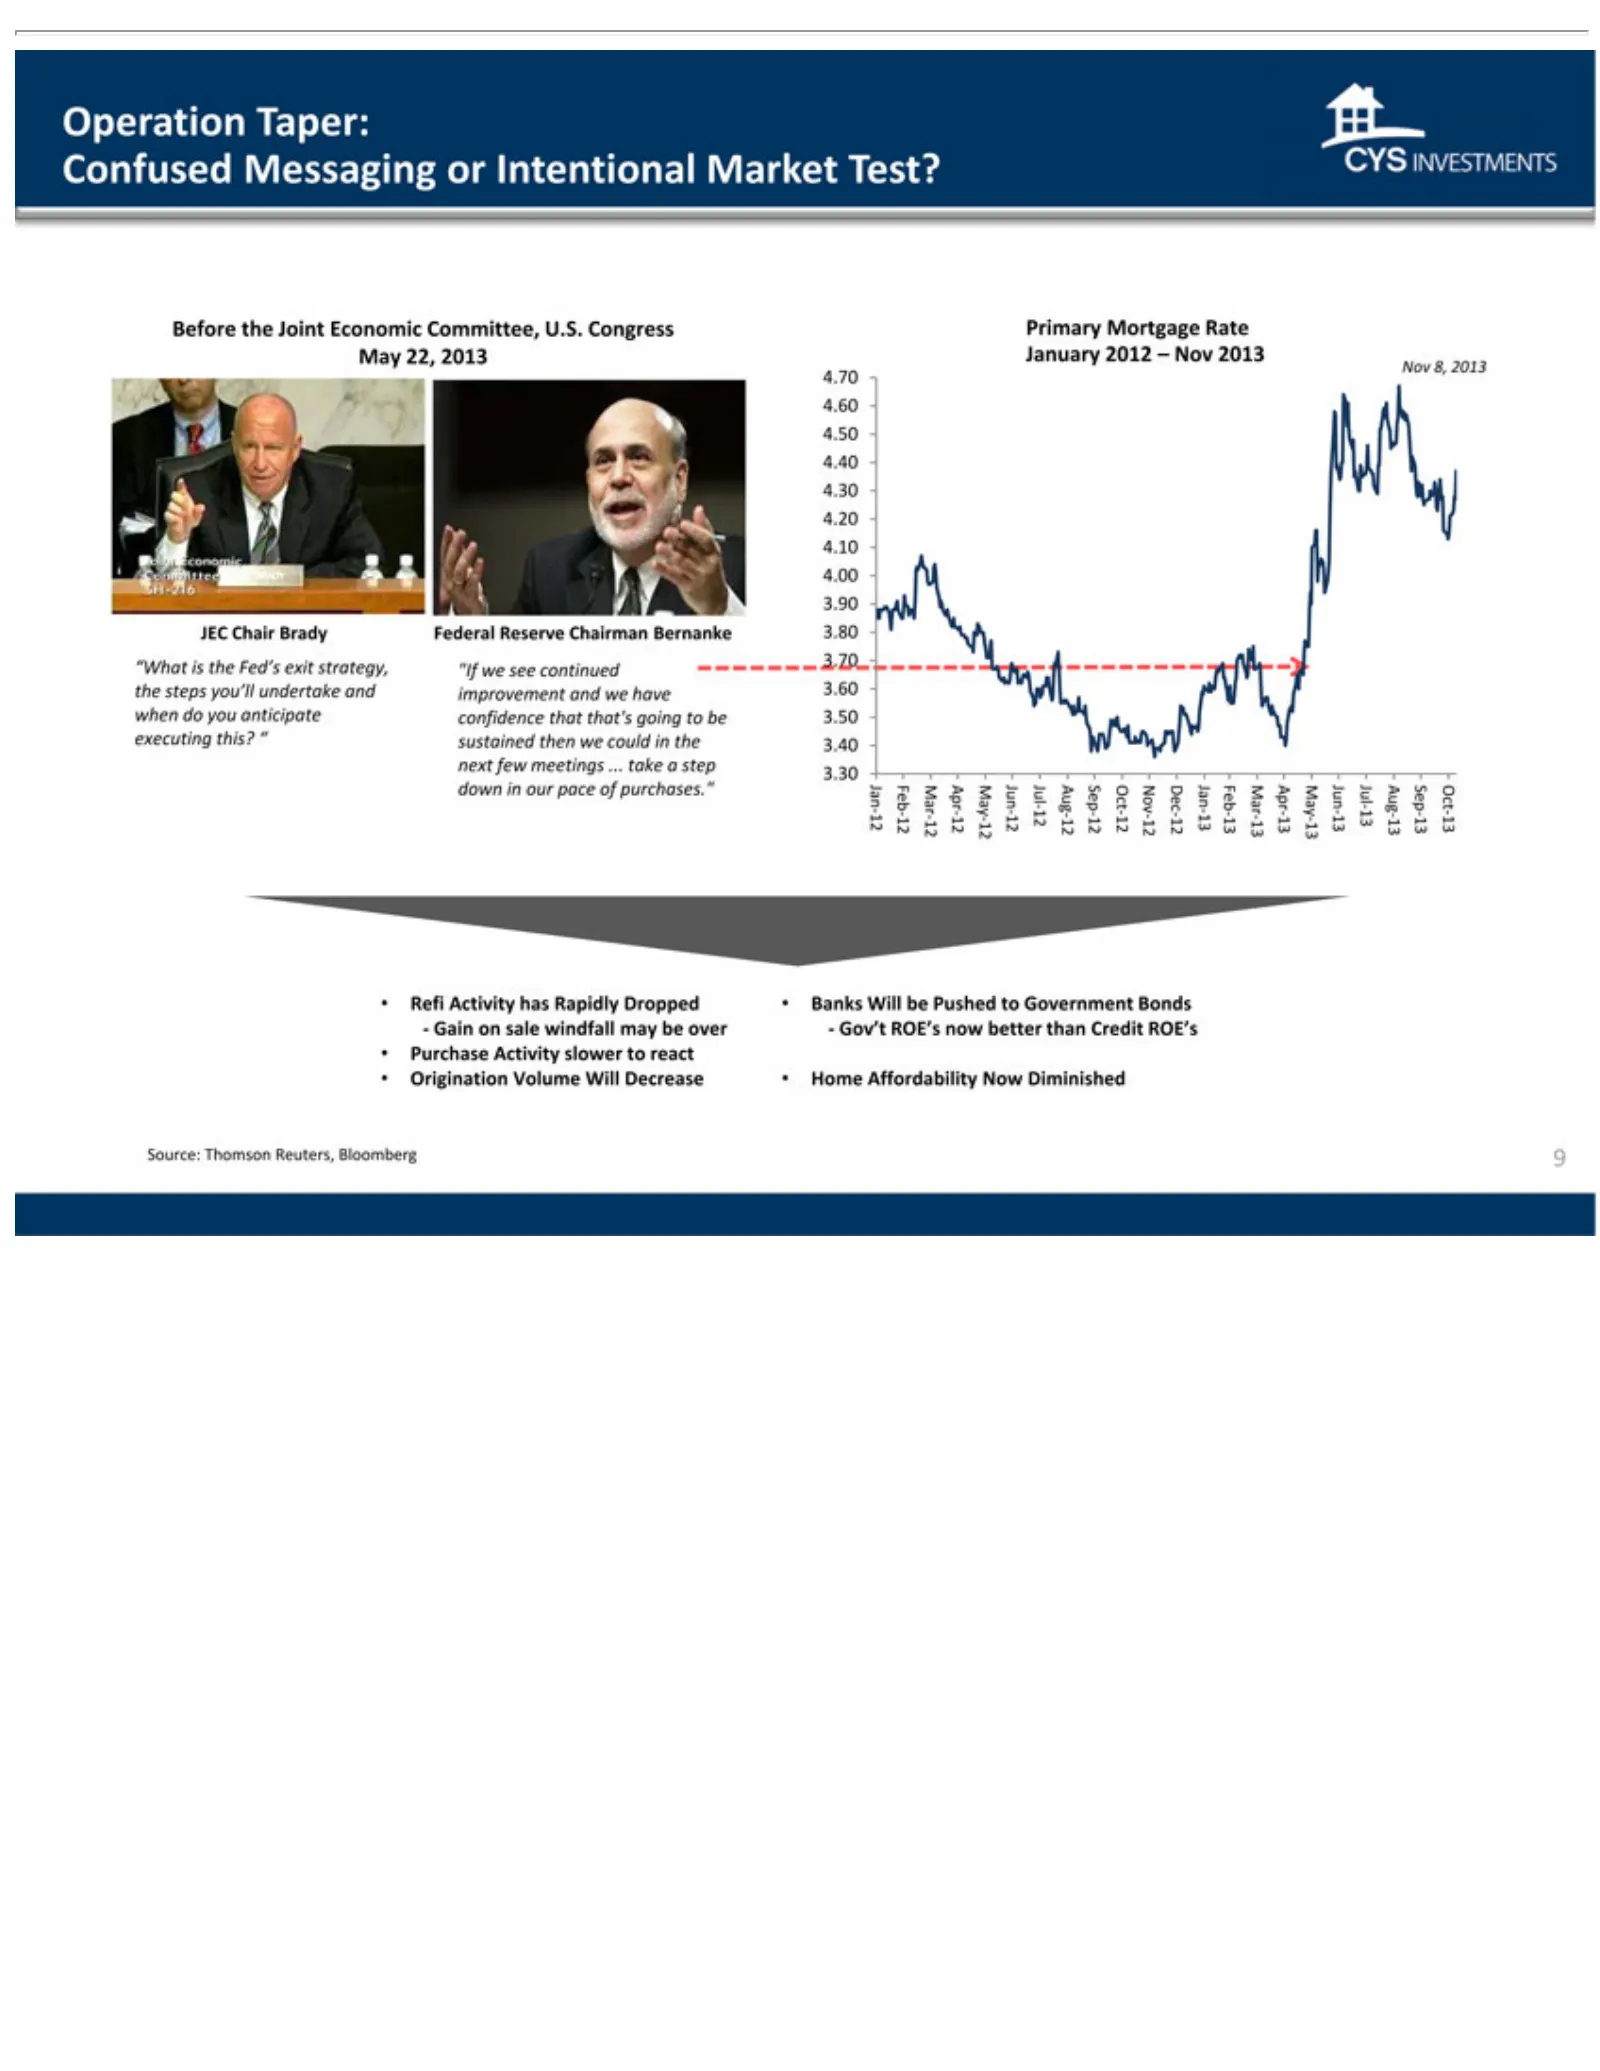
Slide 9: Operation Taper: Confused Fed Messaging
Operation “What sustained 412 Gov’t 4–3Nov-12 3ROE’s is 3 3the then Taper: 3 Fed’s 3Mortgage now we 3 Refi Confused could better exitActivity strategy, 2012 in than the Messaging Oct-12 Credit has next “IfRapidly few we ROE’s Sep-12 or see meetings Intentional Dropped continued Home Aug-12 ...Afford
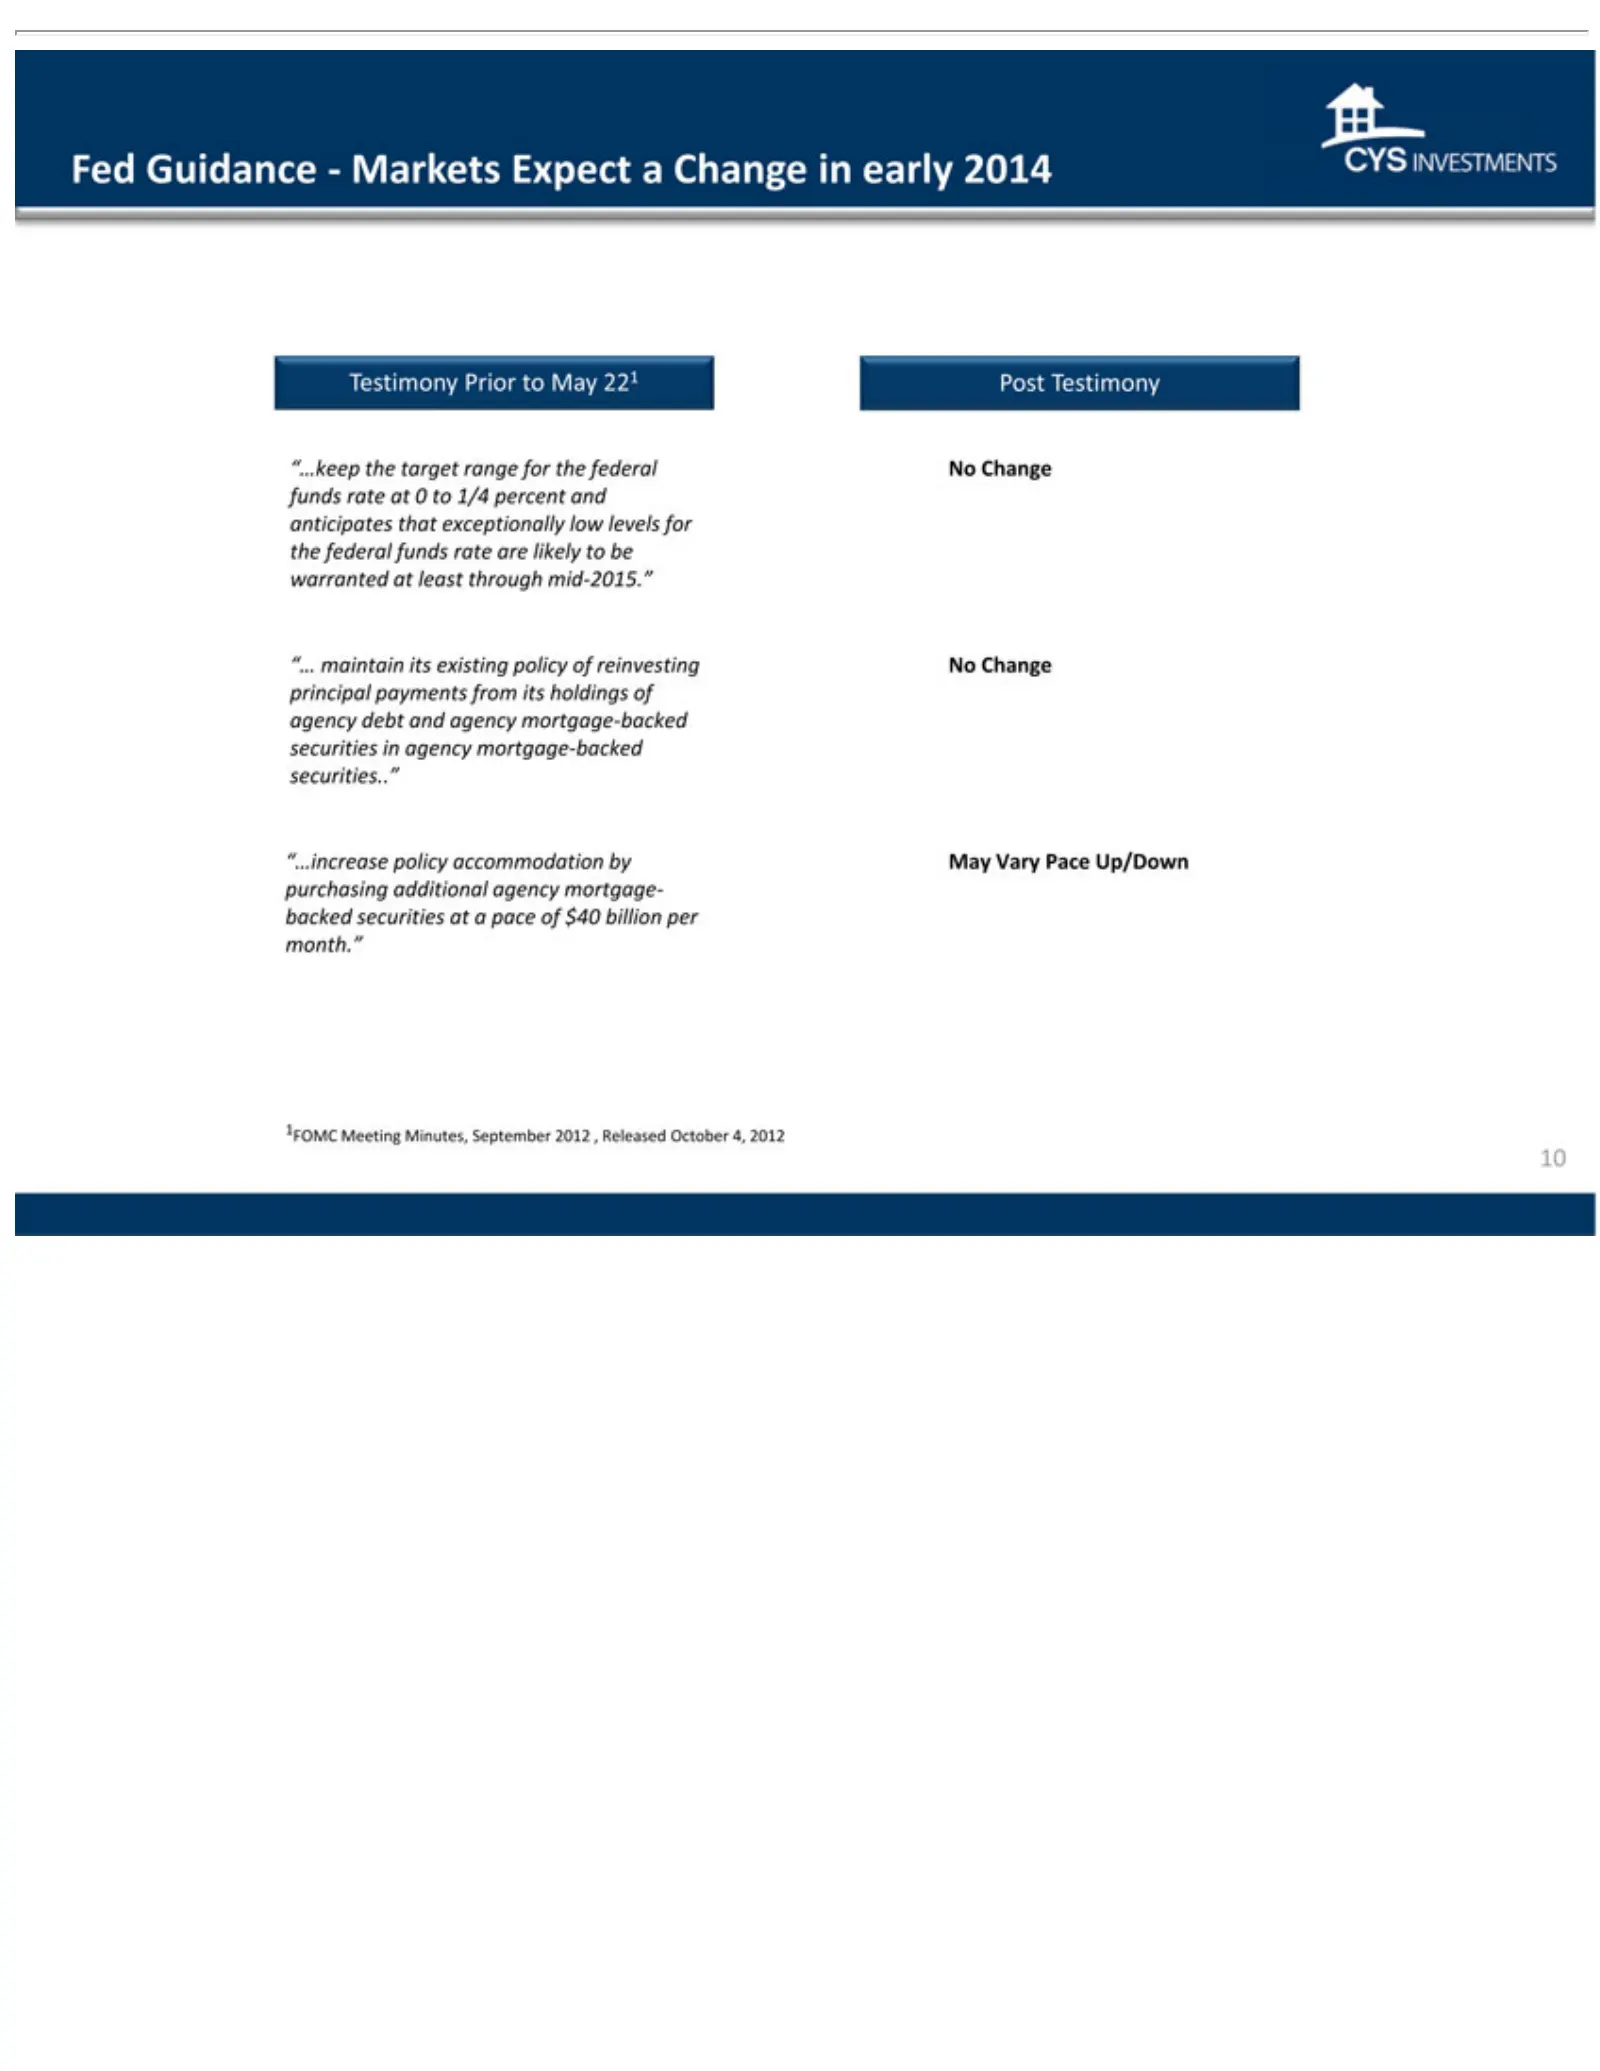
Slide 10: Fed Guidance
Fed Guidance funds principal purchasing ratepayments atadditional 0 -Markets to 1/4from percent agency Expect its holdings and mortgage-backed a anticipates Change of agency in early thatdebt securities exceptionally 2014 andTestimony agency at a pace low mortgage-backed Prior of levels $40 tofor bi
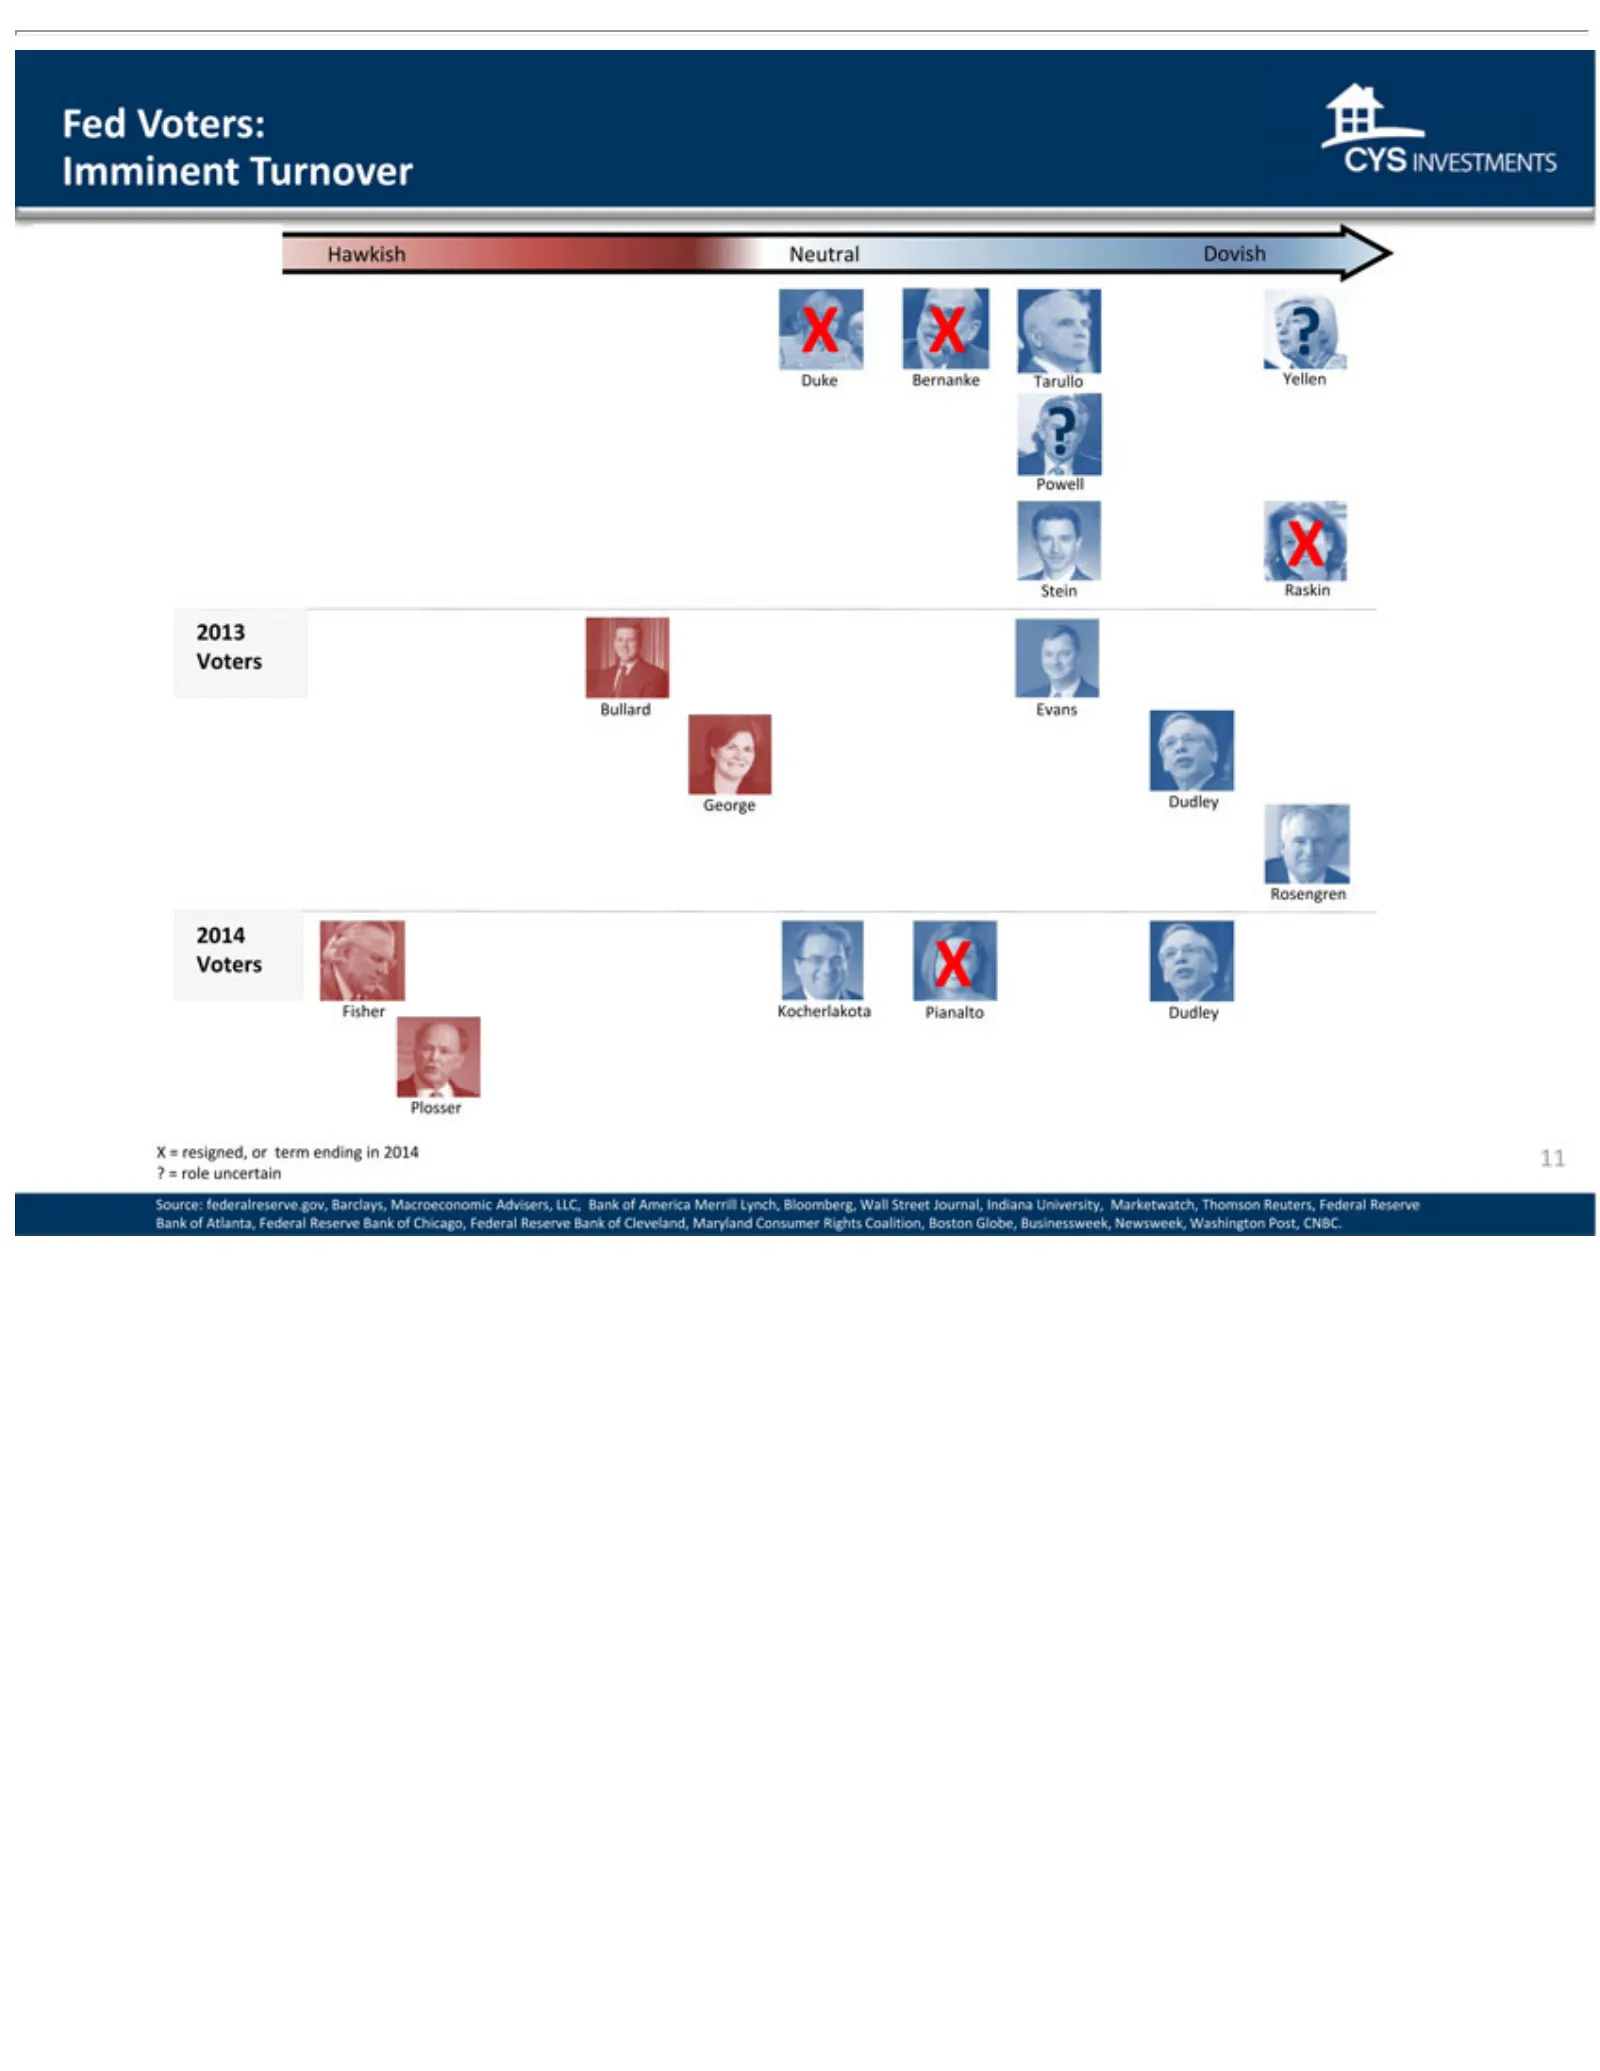
Slide 11: Fed Voters: Imminent Turnover
Fed Voters: Pianalto Journal, Rights Coalition, Indiana Dudley Imminent University, Plosser ostonTurnover Globe, X =Marketwatch, resigned, Businesswee Hawkishor term Neutral Thomson k, ending Newsweek, Dovish Reuters, in 2014 XX Washington Federal Duke ? = role Bernanke Reserve uncertain Post, CNBC.
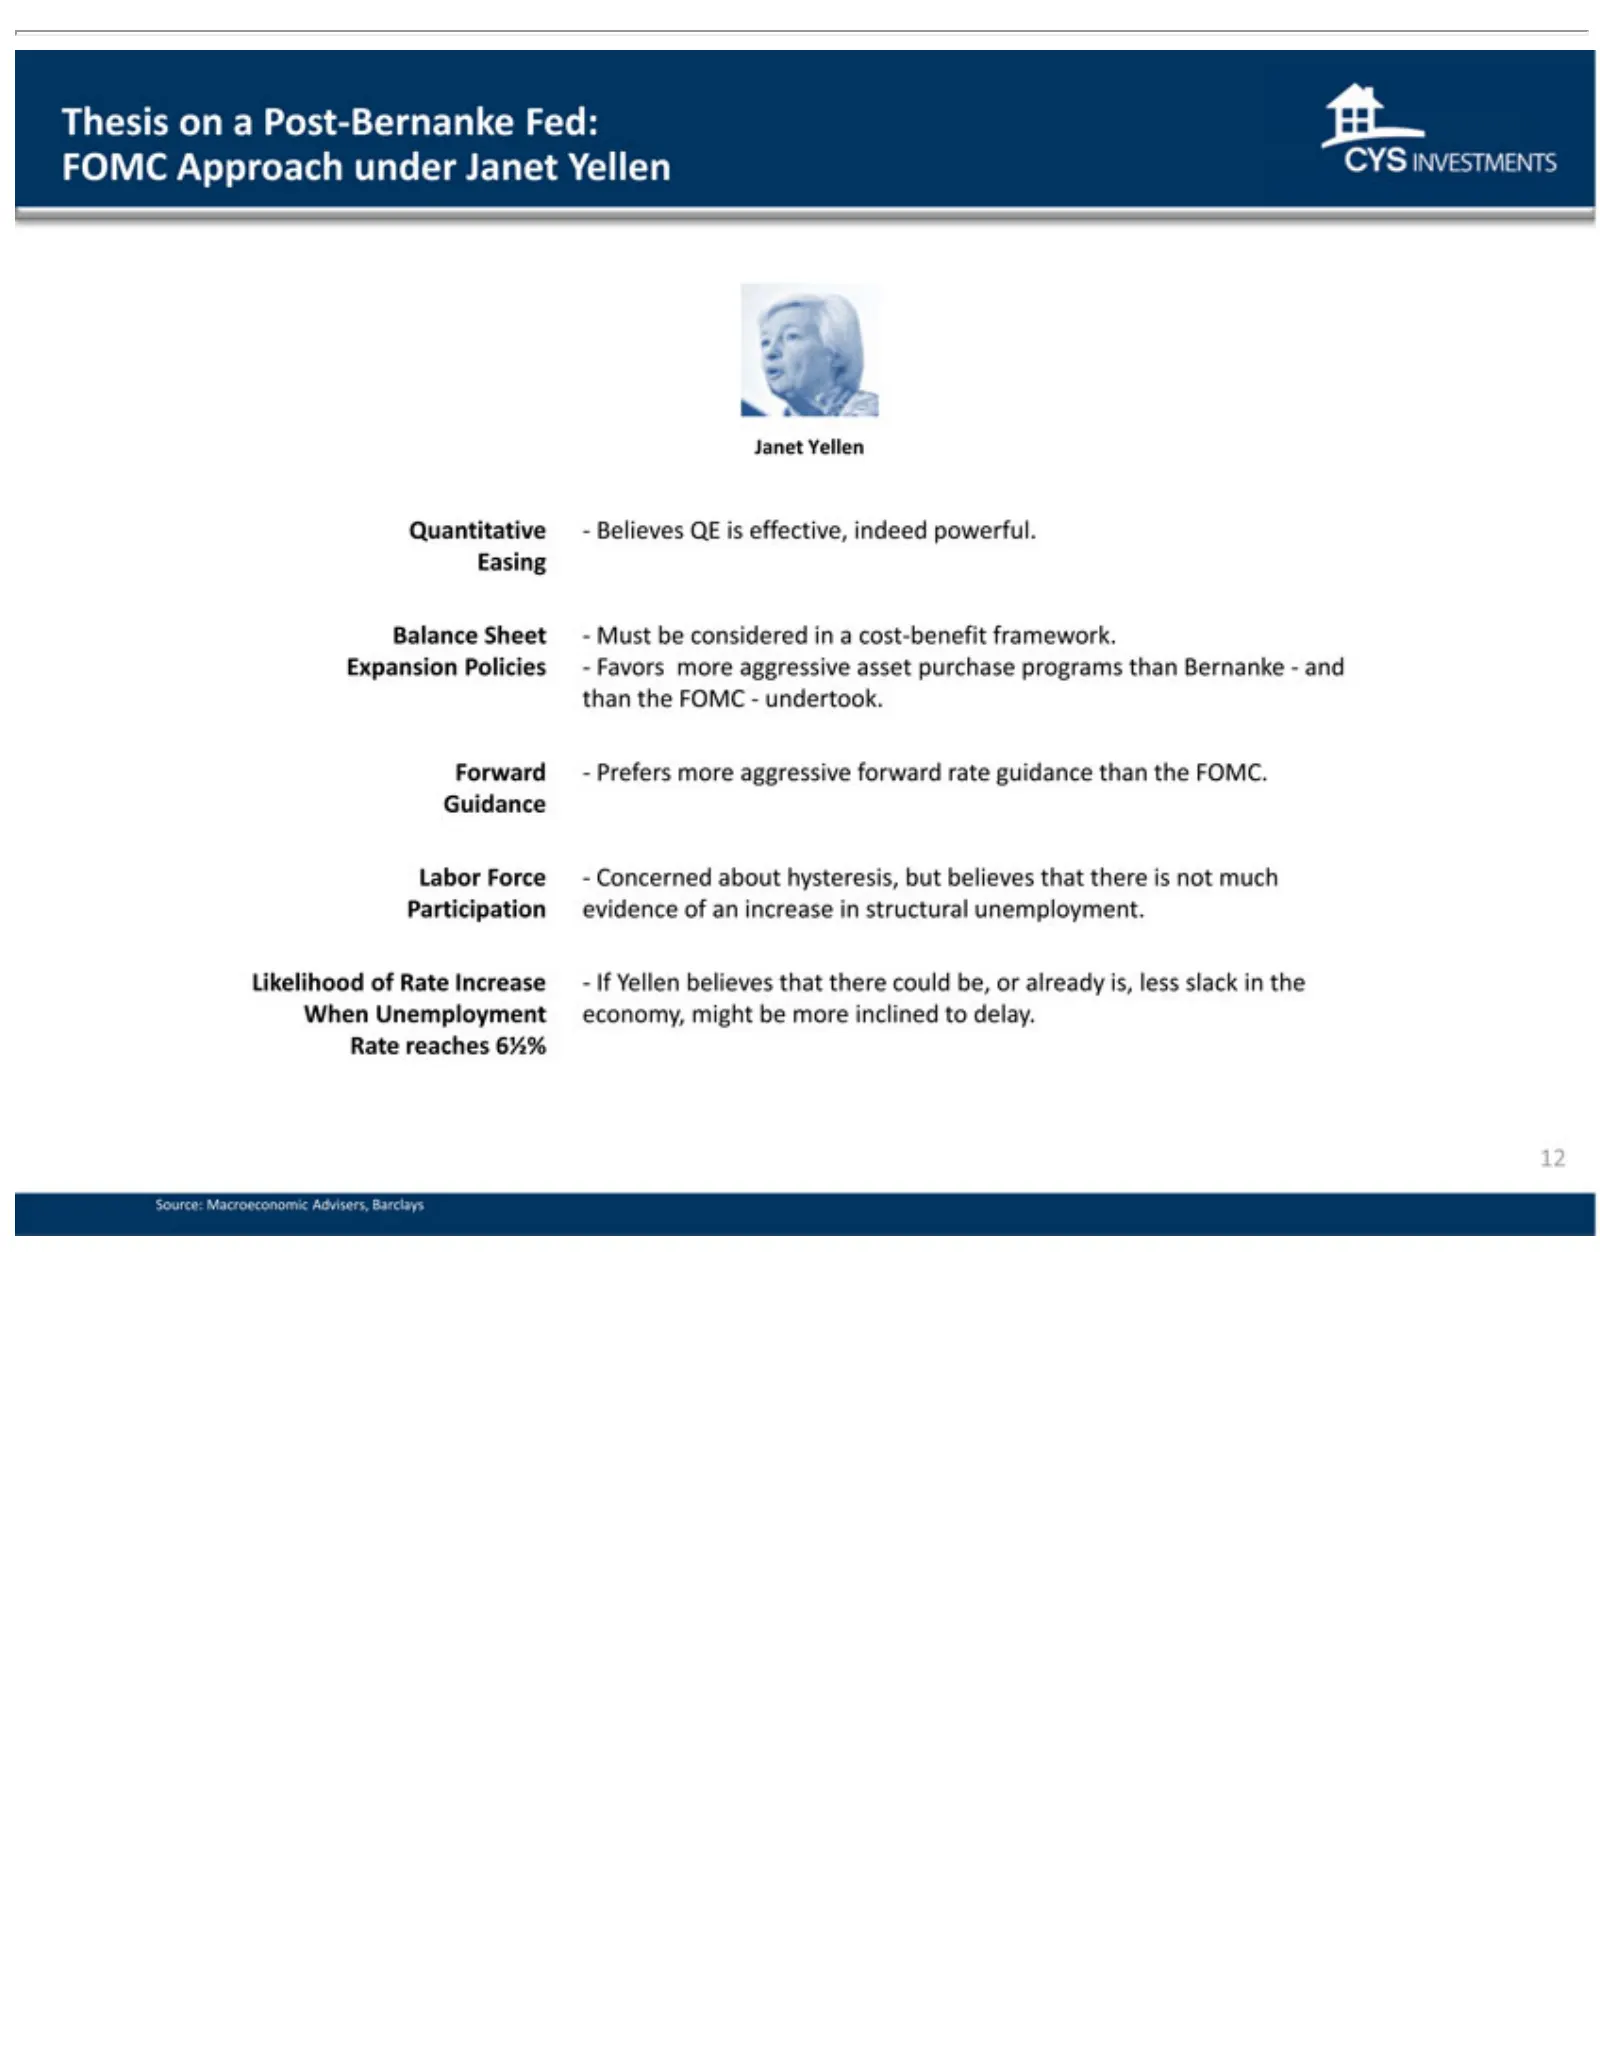
Slide 12: Post-Bernanke Fed: Janet Yellen
Thesis on benefit Prefers evidence economy,framework. more of might a Post-Bernanke anaggressive increase be more Expansion in forward inclined structural Fed:Policies FOMC rate to unemployment. delay. guidance -Favors Approach Ratethan more reaches under the Likelihood aggressive FOMC. 6% Janet Sou
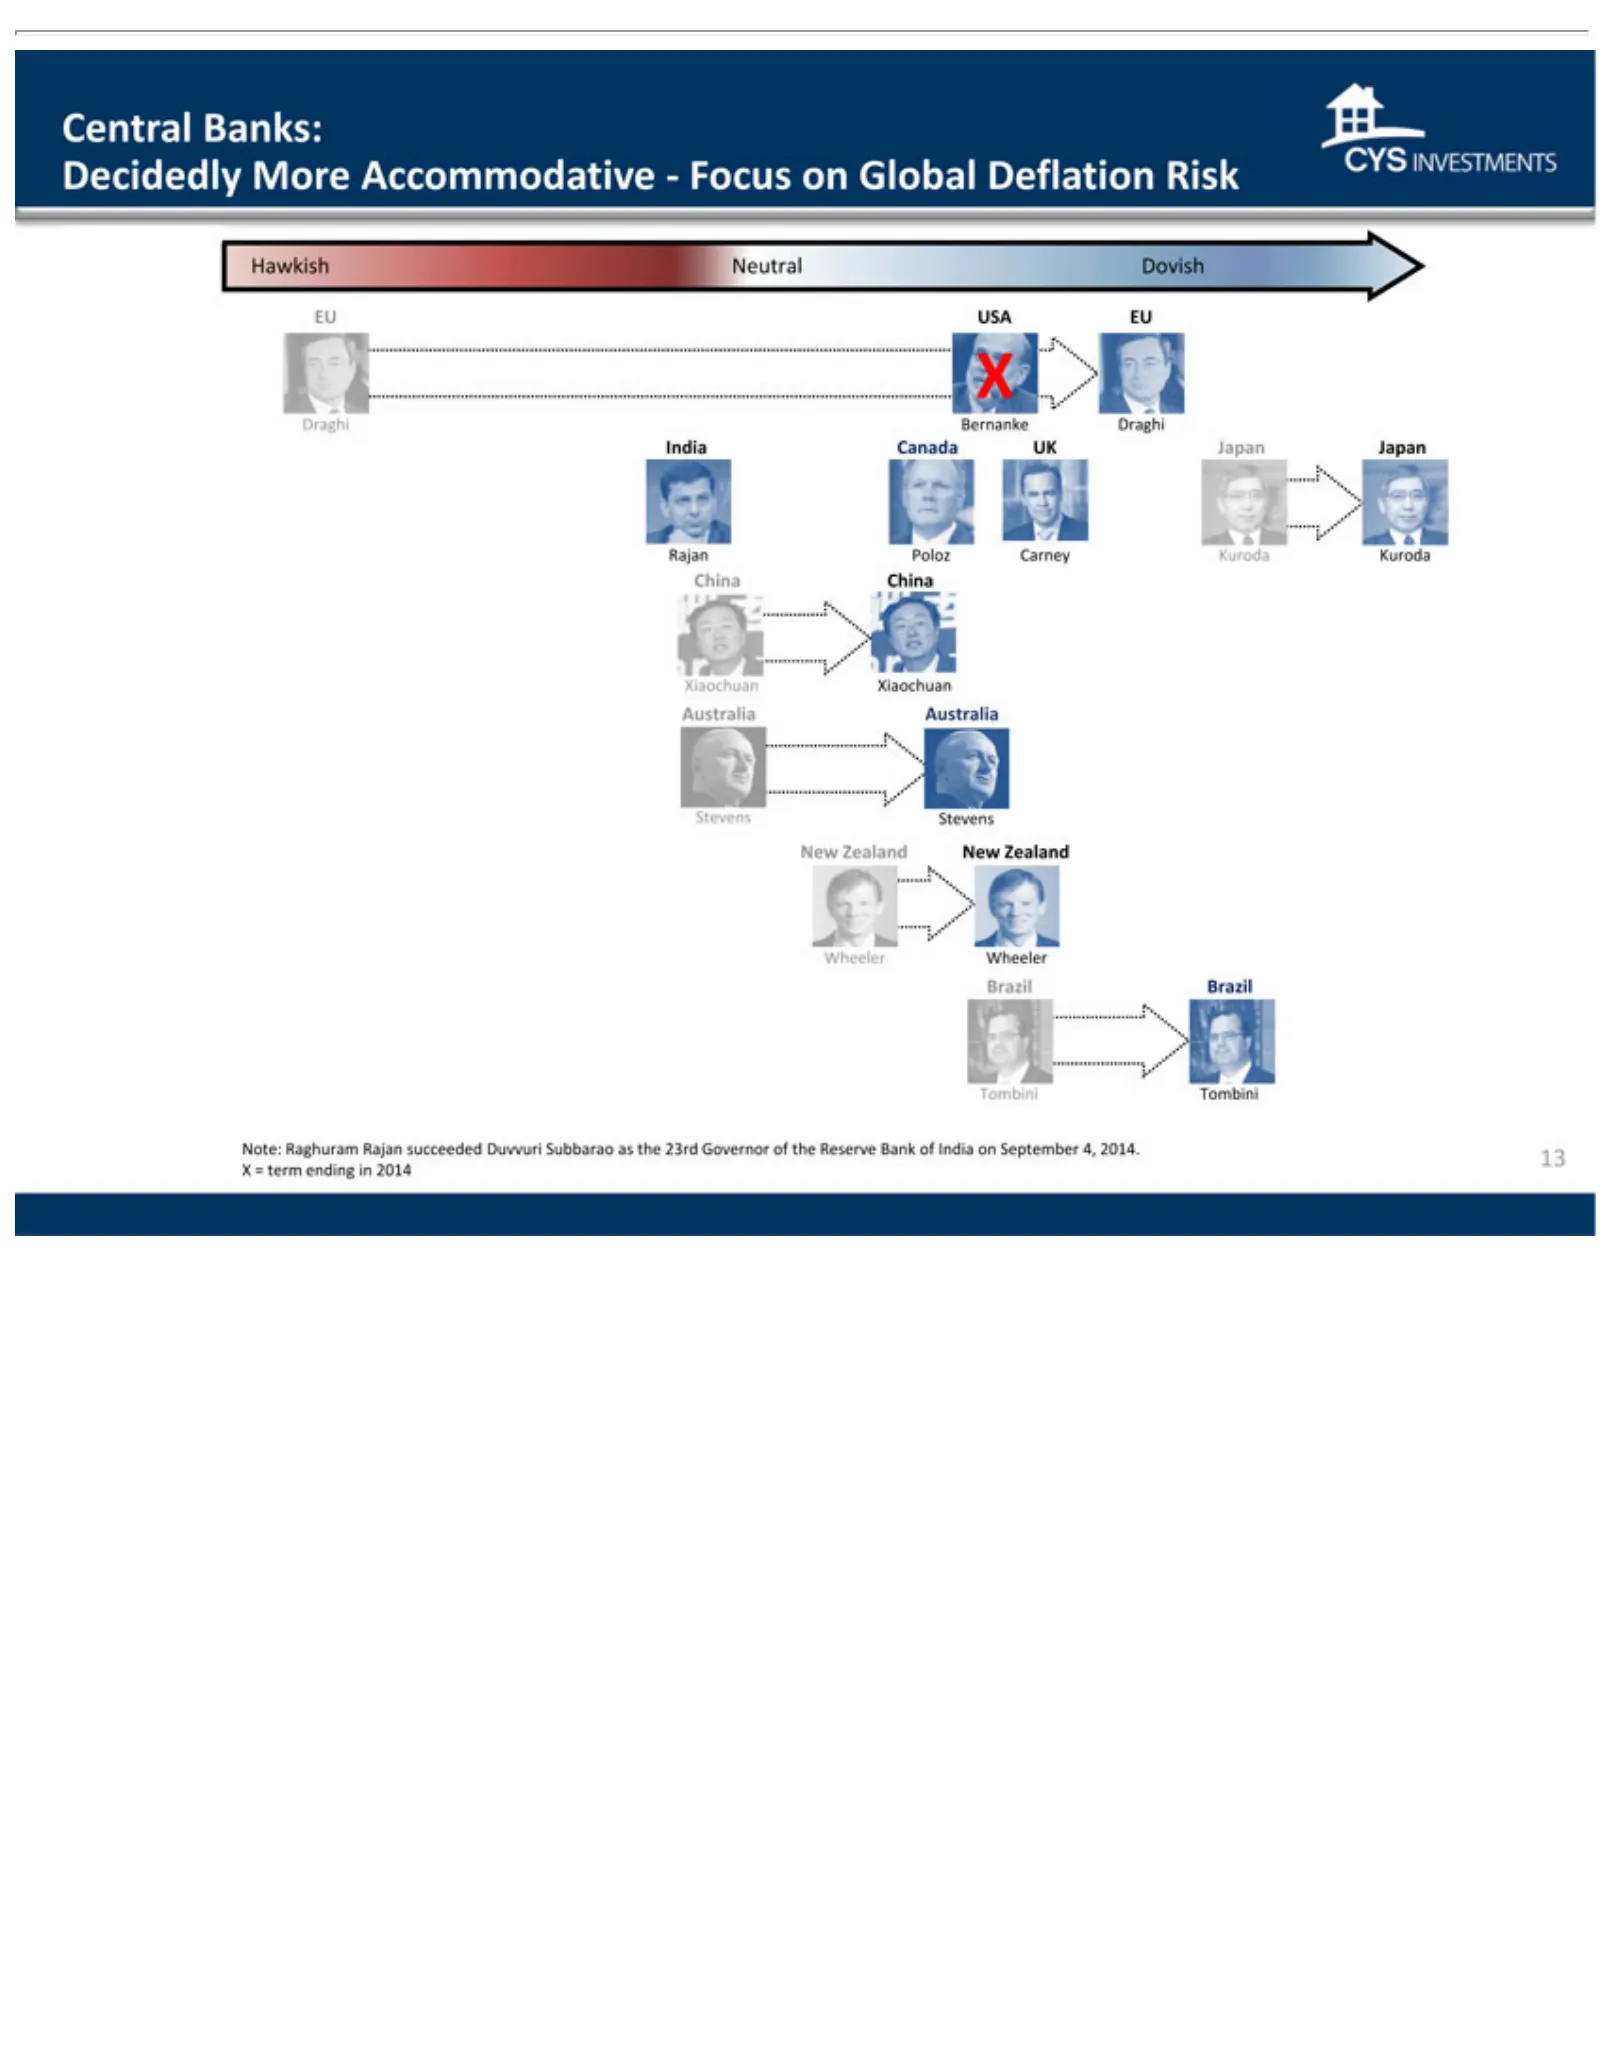
Slide 13: Central Banks
Central Banks: Kuroda succeeded Kuroda Duvvuri Decidedly China Subbarao China More Xiaochuan as Accommodative the 23rdXiaochuan Governor -Focus of Australia theon Reserve Global Australia Bank Deflation Stevens of India Risk Stevens onHawkish September NewNeutral Zealand 4, 2014. Dovish New X =Zeala
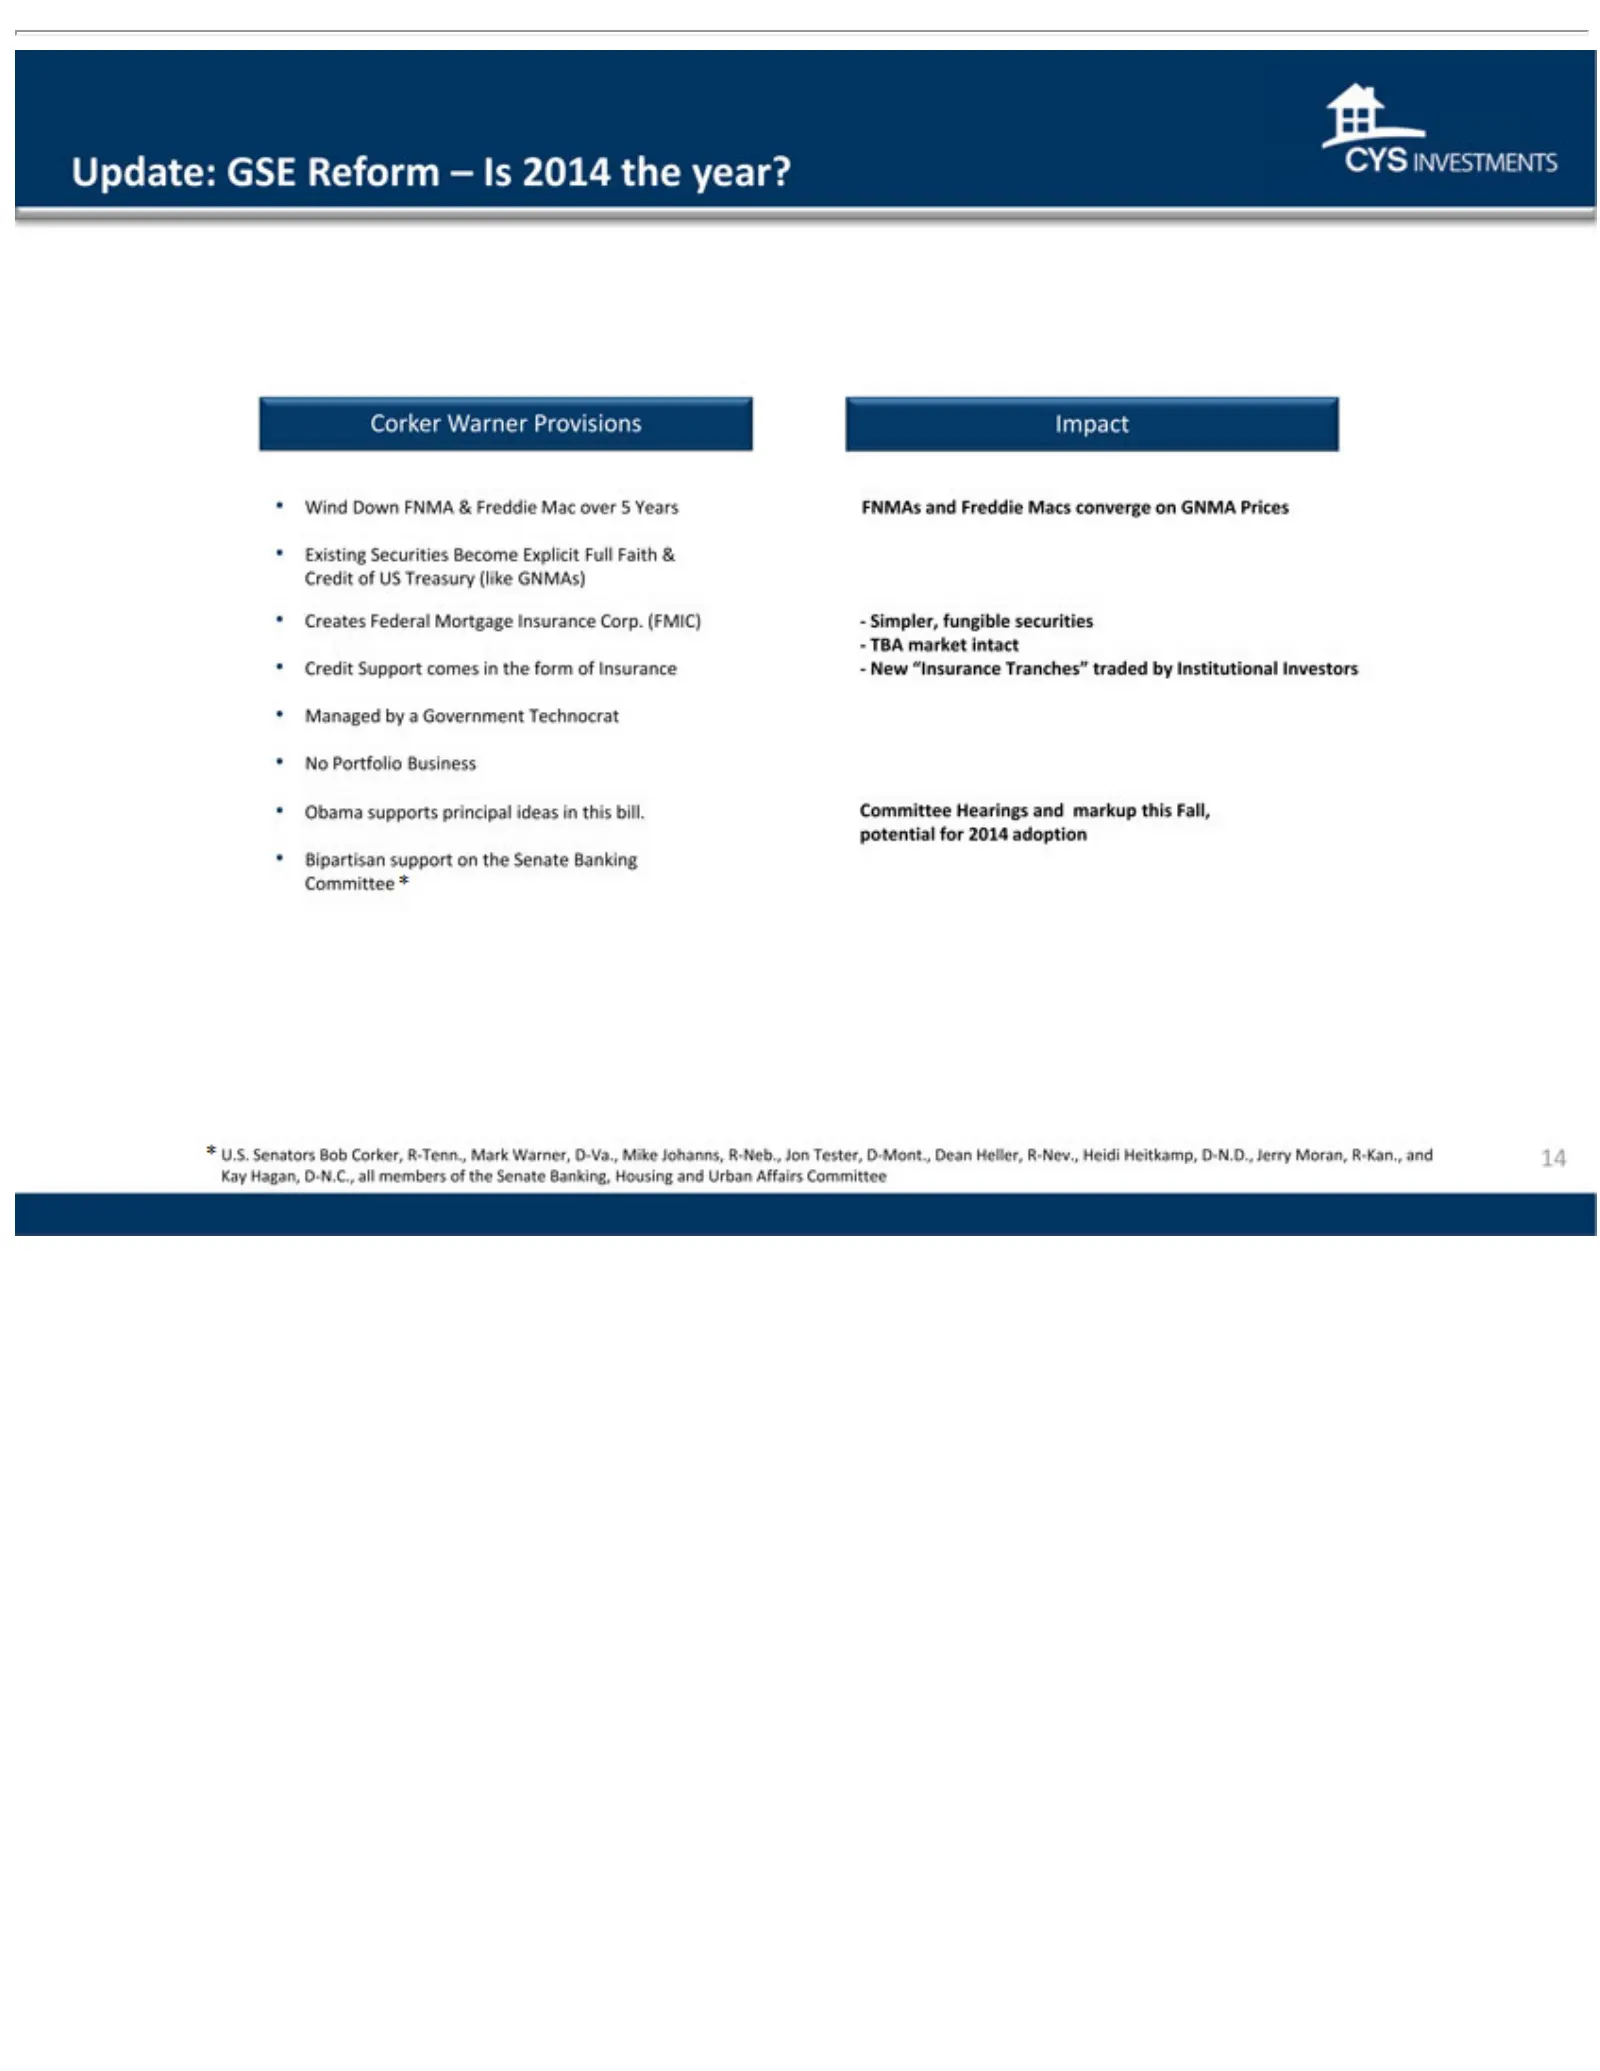
Slide 14: Update: Existing Credit Support / GSE Reform
Update: Existing Credit Obama Tenn., N.C., all Mark Support supports GSE Securities members Warner, Reform comes principal of Become D-Va., the –inIsthe Senate ideas 2014 Explicit Mike formthe in Banking, of Johanns, this year Full Insurance bill. Corker Faith Housing Committee R-Neb., -New &Warner
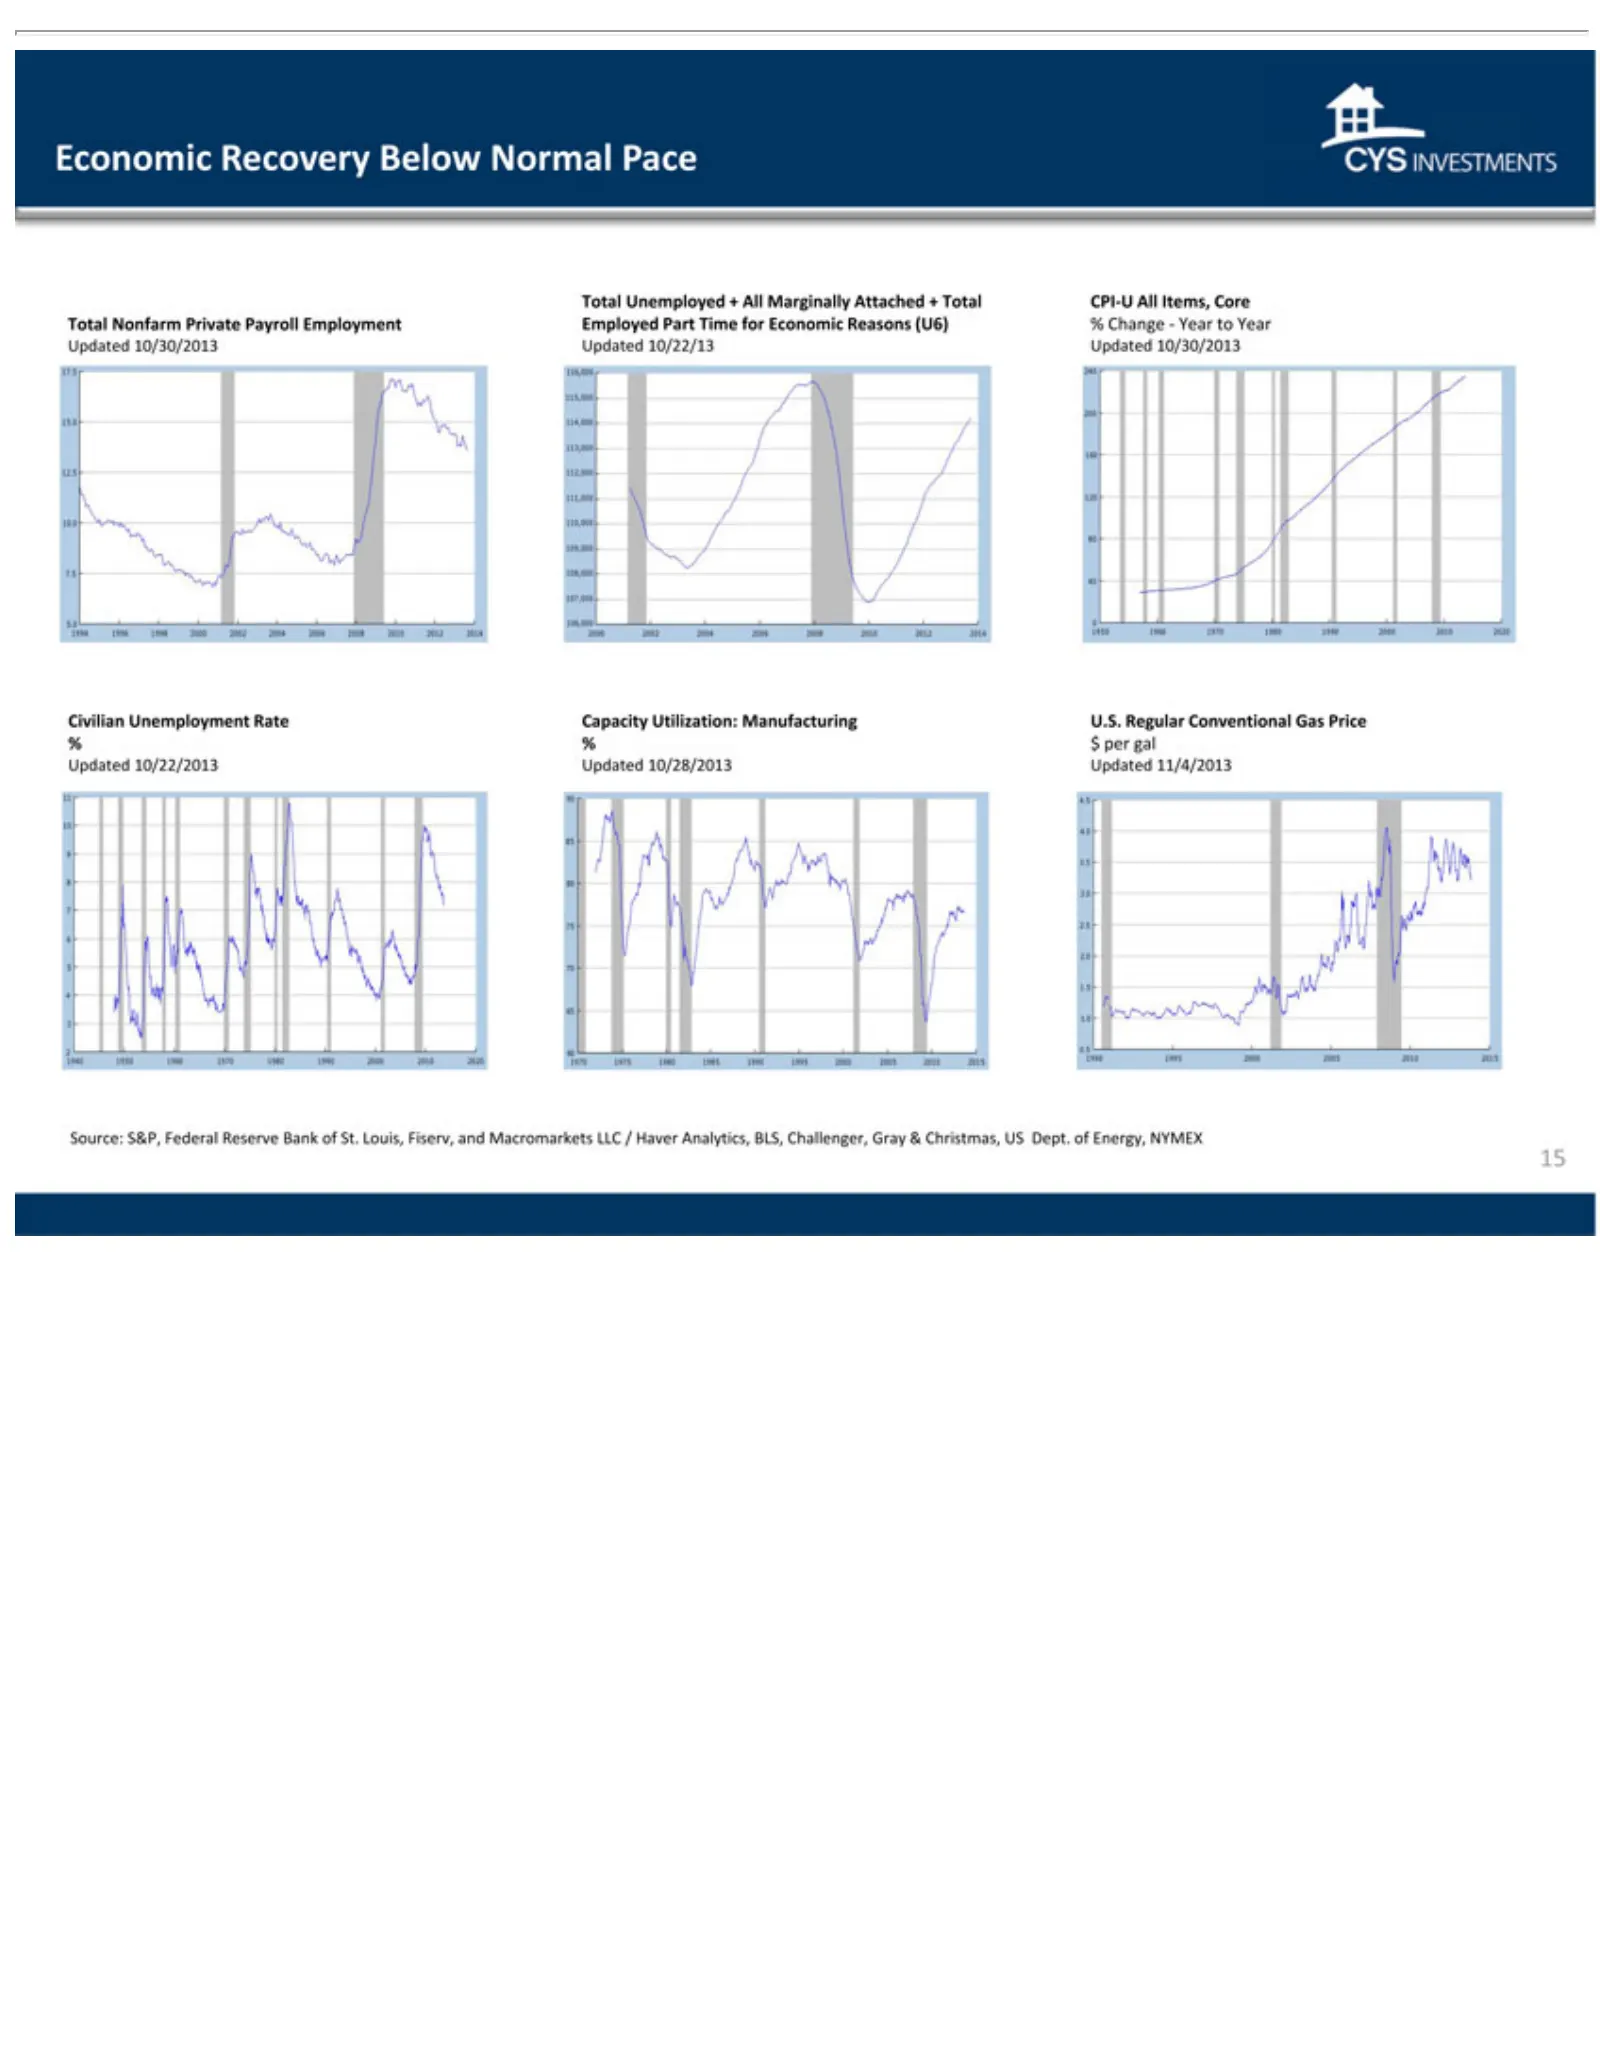
Slide 15: Economic Recovery Below Normal Pace
Economic Total Civilian Source: Nonfarm S&P, Unemployment Recovery Federal Private Below Reserve Payroll Rate Normal Capacity Bank Employment Pace of St. Utilization: Total Louis, Employed Unemployed Fiserv, Manufacturing Part andTime +Macromarkets Allfor Marginally U.S. Economic Regular LLC Attache
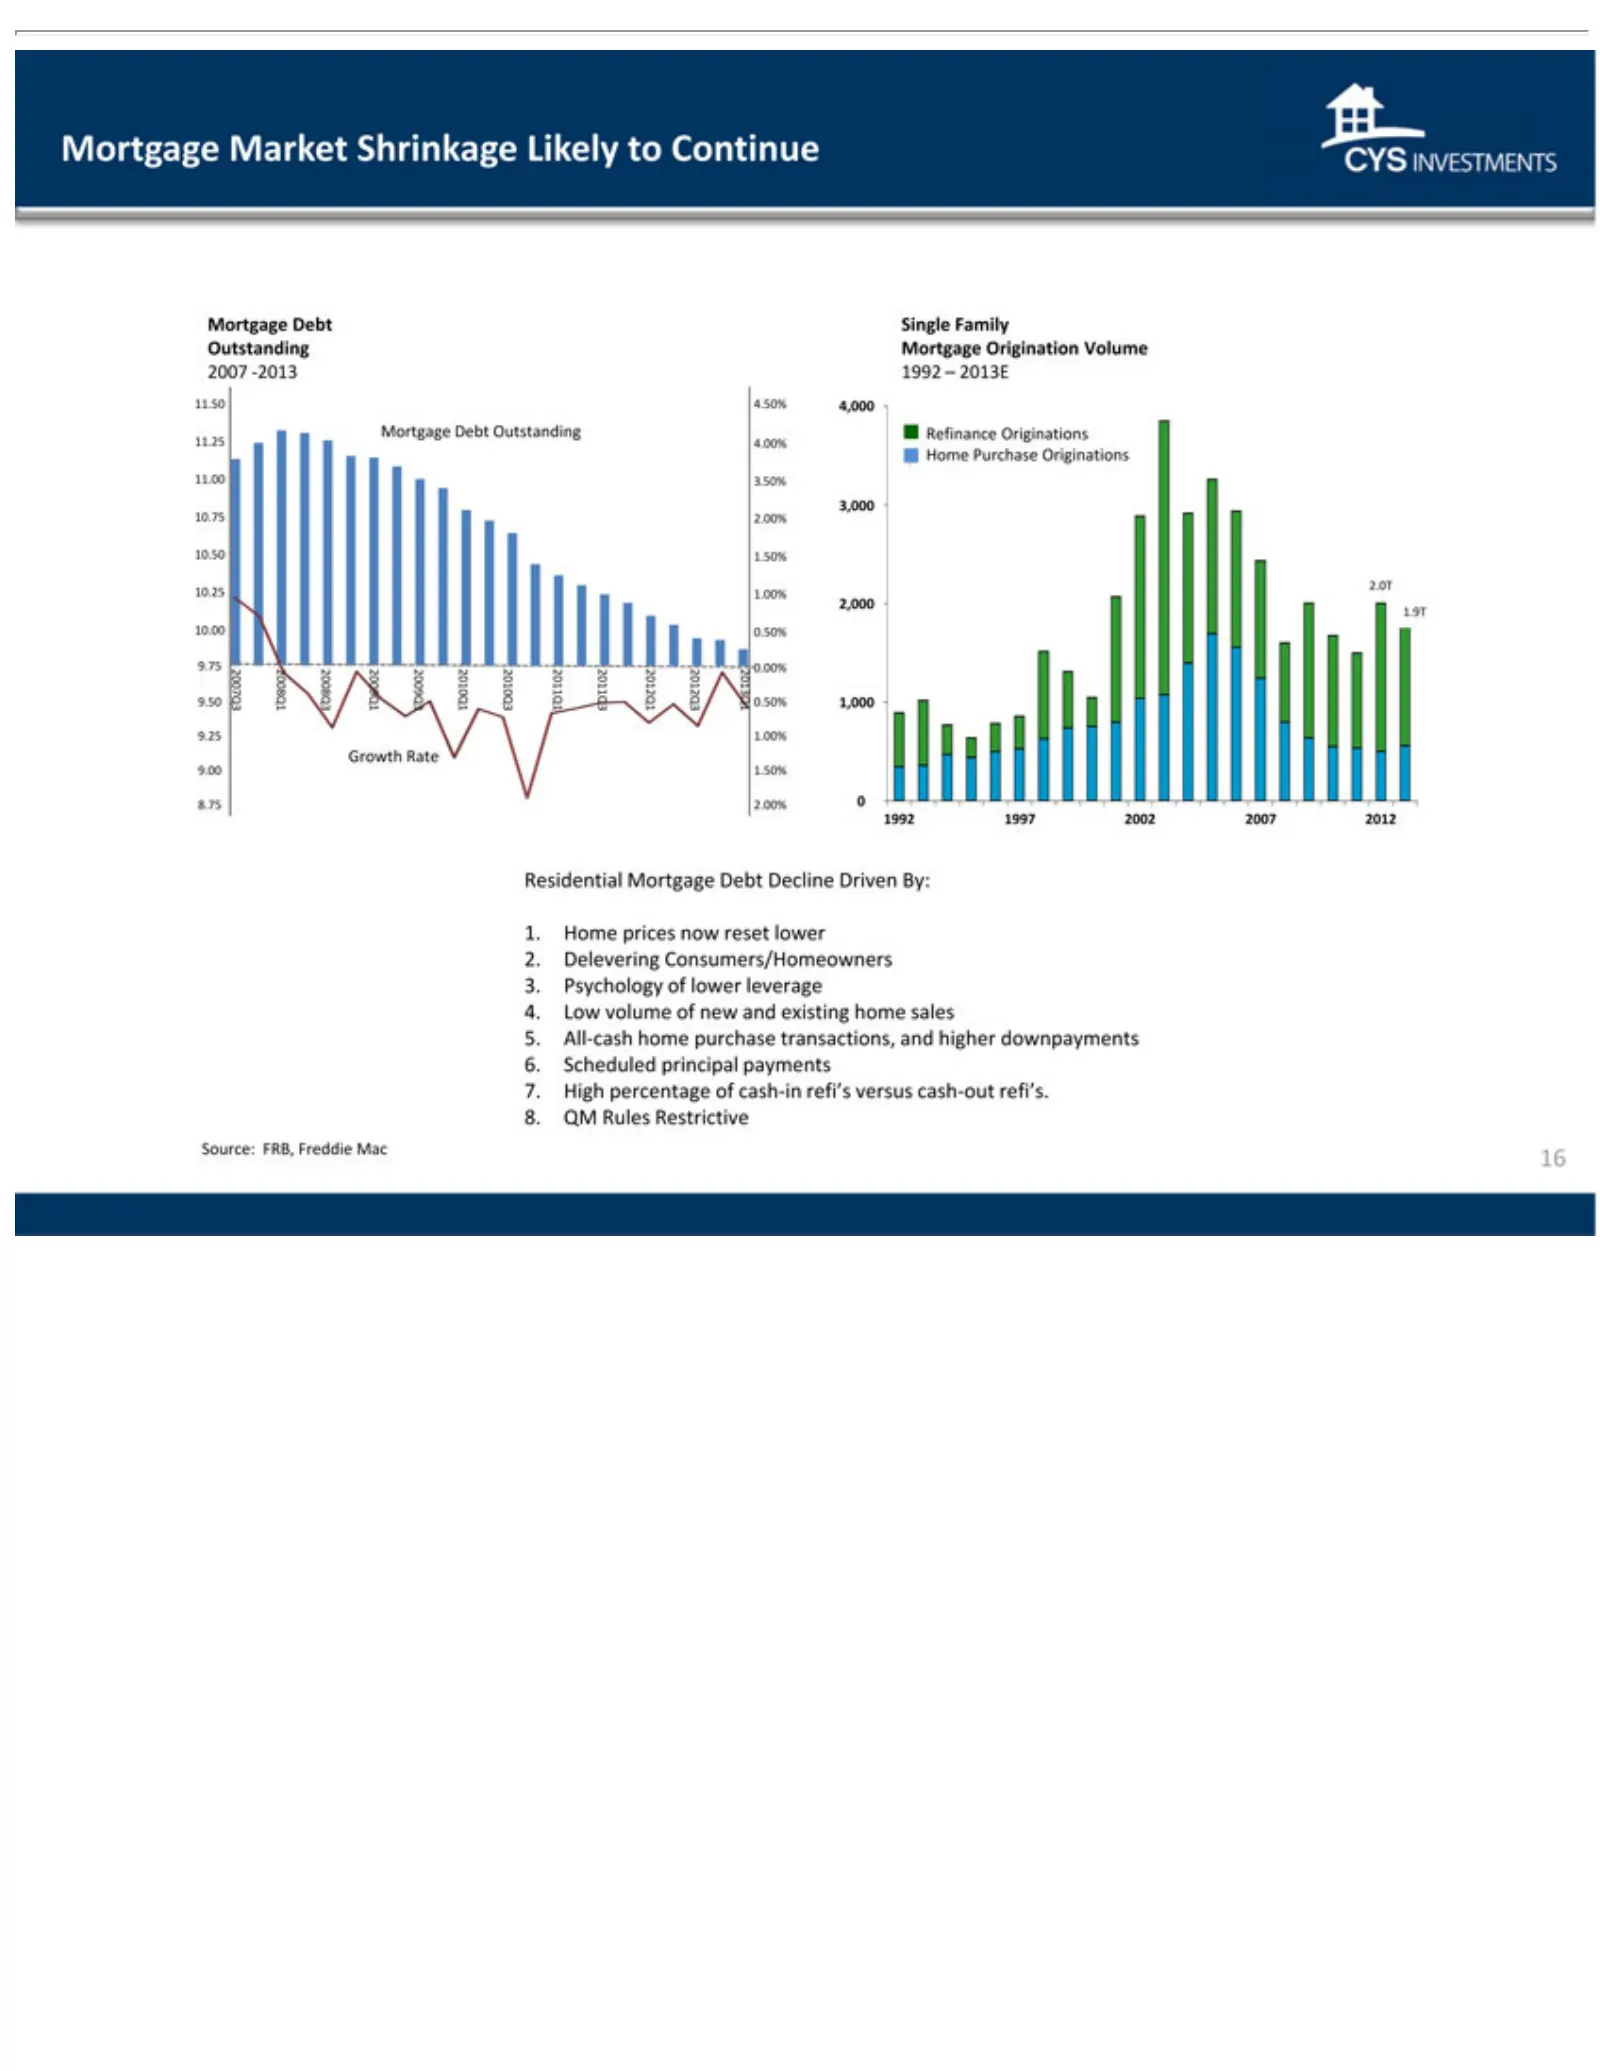
Slide 16: Mortgage Market Shrinkage Likely to Continue
Mortgage 4.00% 2009Q3 1. cash Home home Refinance 2010Q1 prices Market purchase now 2010Q3 Originations Shrinkage transactions, reset 2011Q1 lower Likely Home 2.and 2011Q3 Delevering toPurchase higher Continue 2012Q1 downpayments Consumers/Homeowners Originations Mortgage 2012Q3Debt 11.00 2013Q1 6.
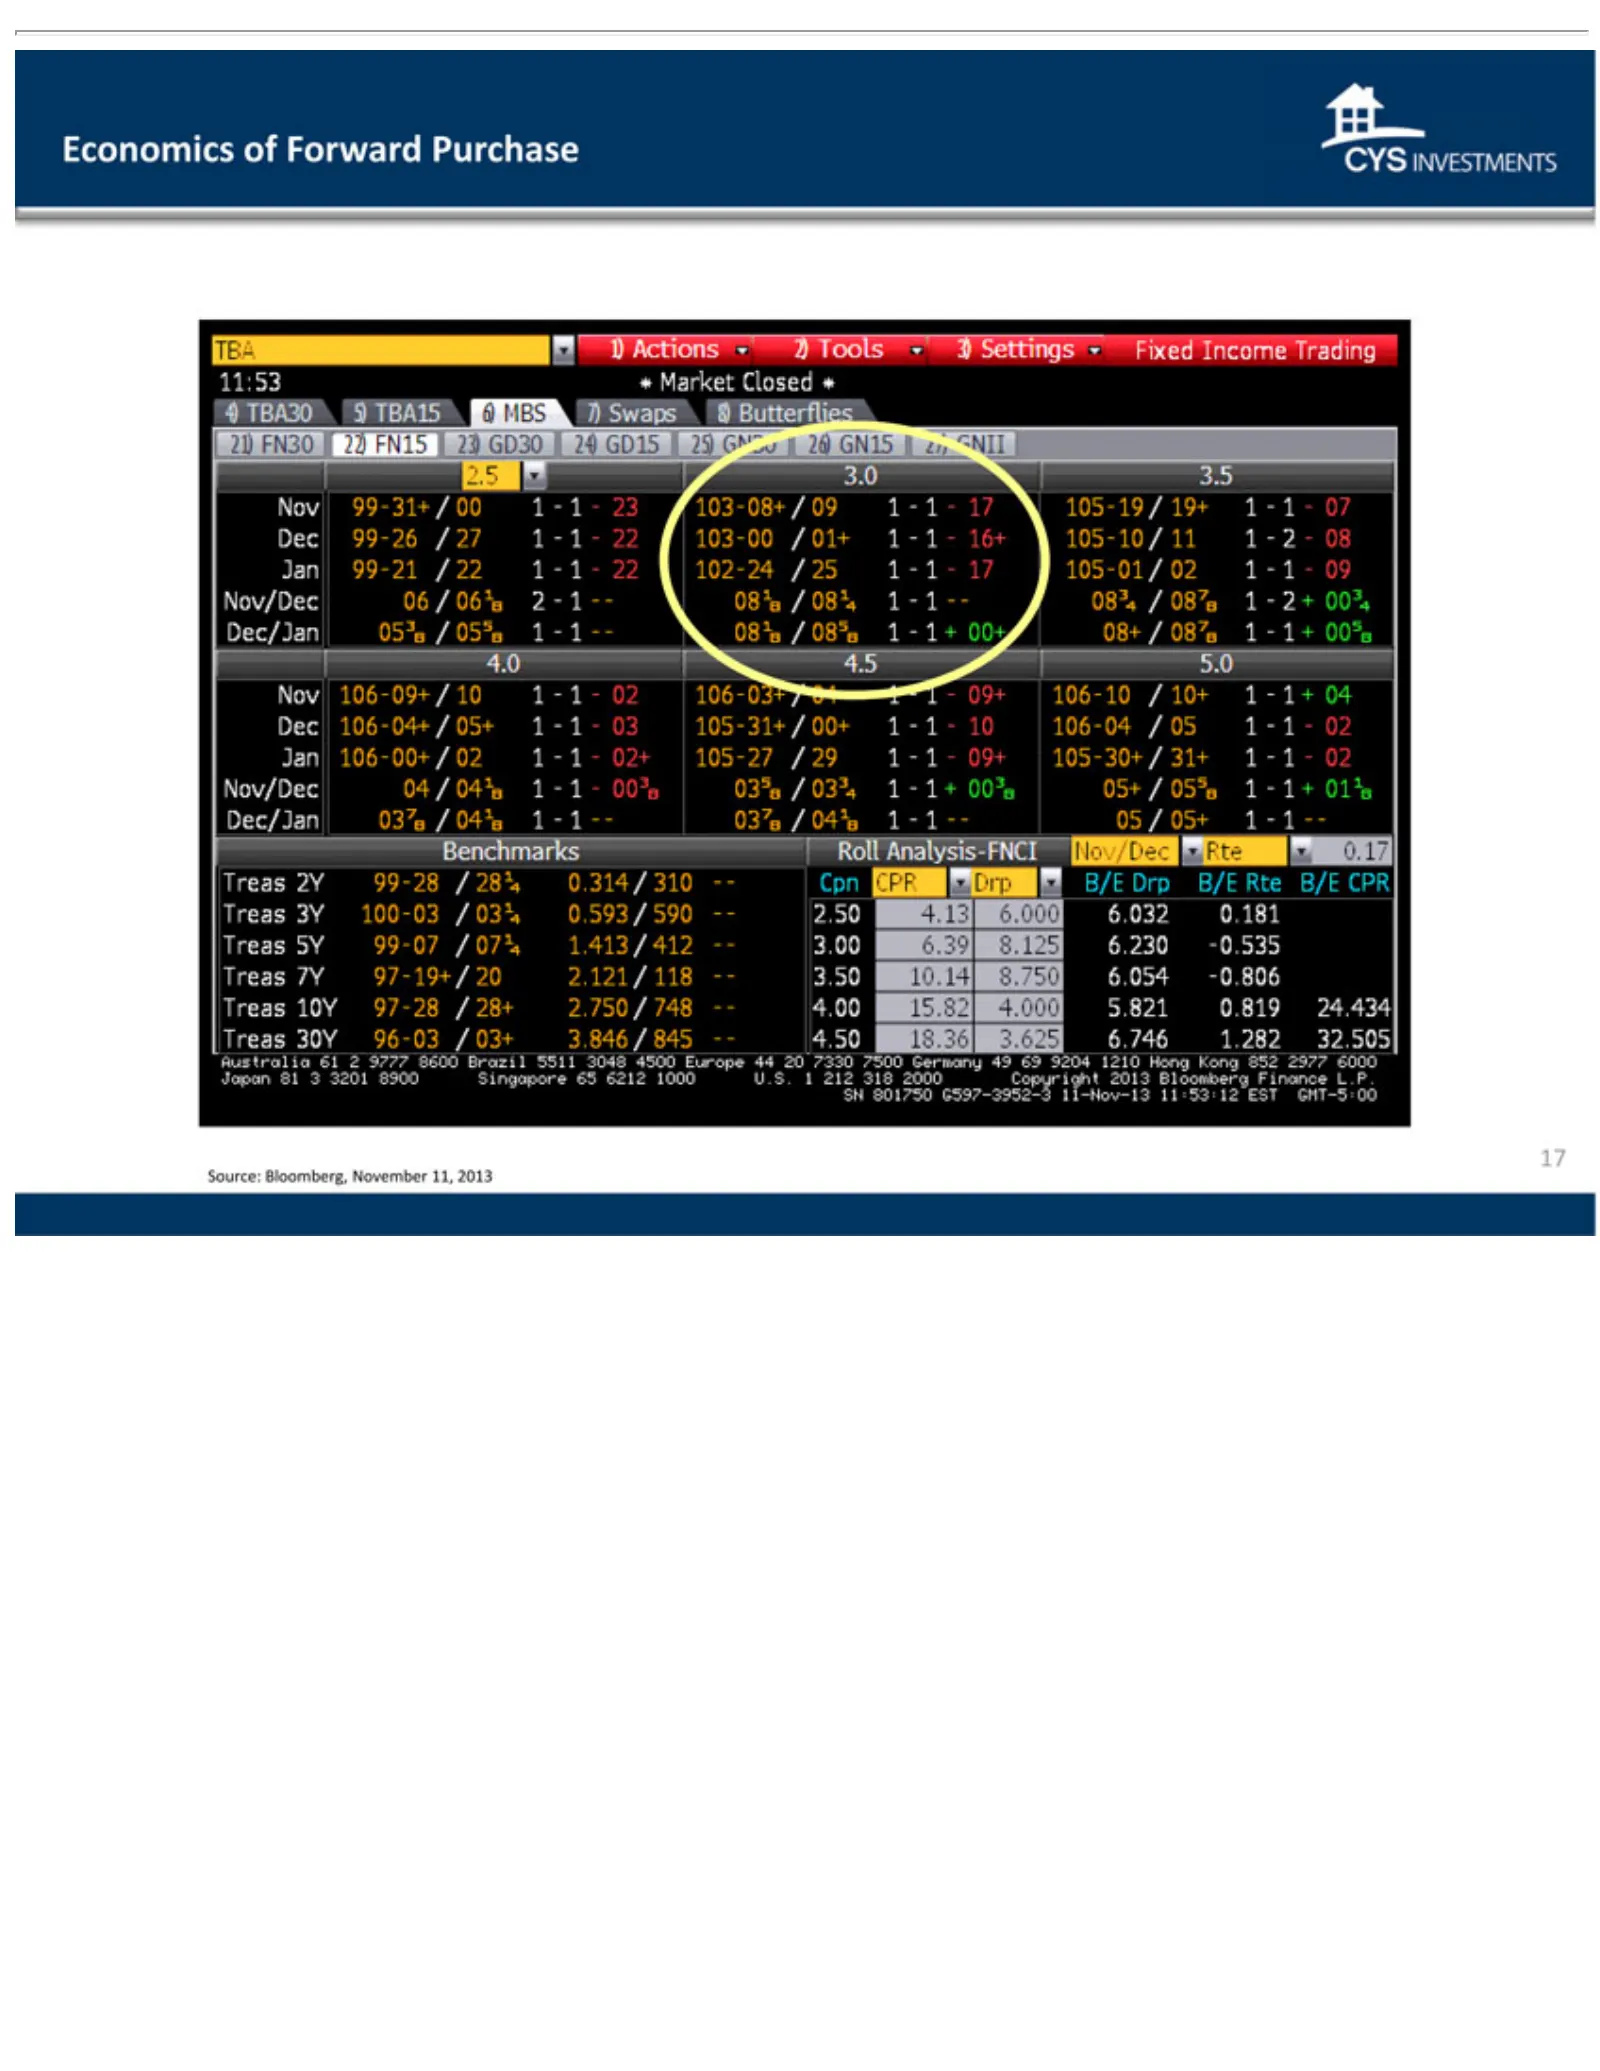
Slide 17: Economics of Forward Purchase
Economics of Forward Purchase 17 Source: Bloomberg, November 11, 2013 17
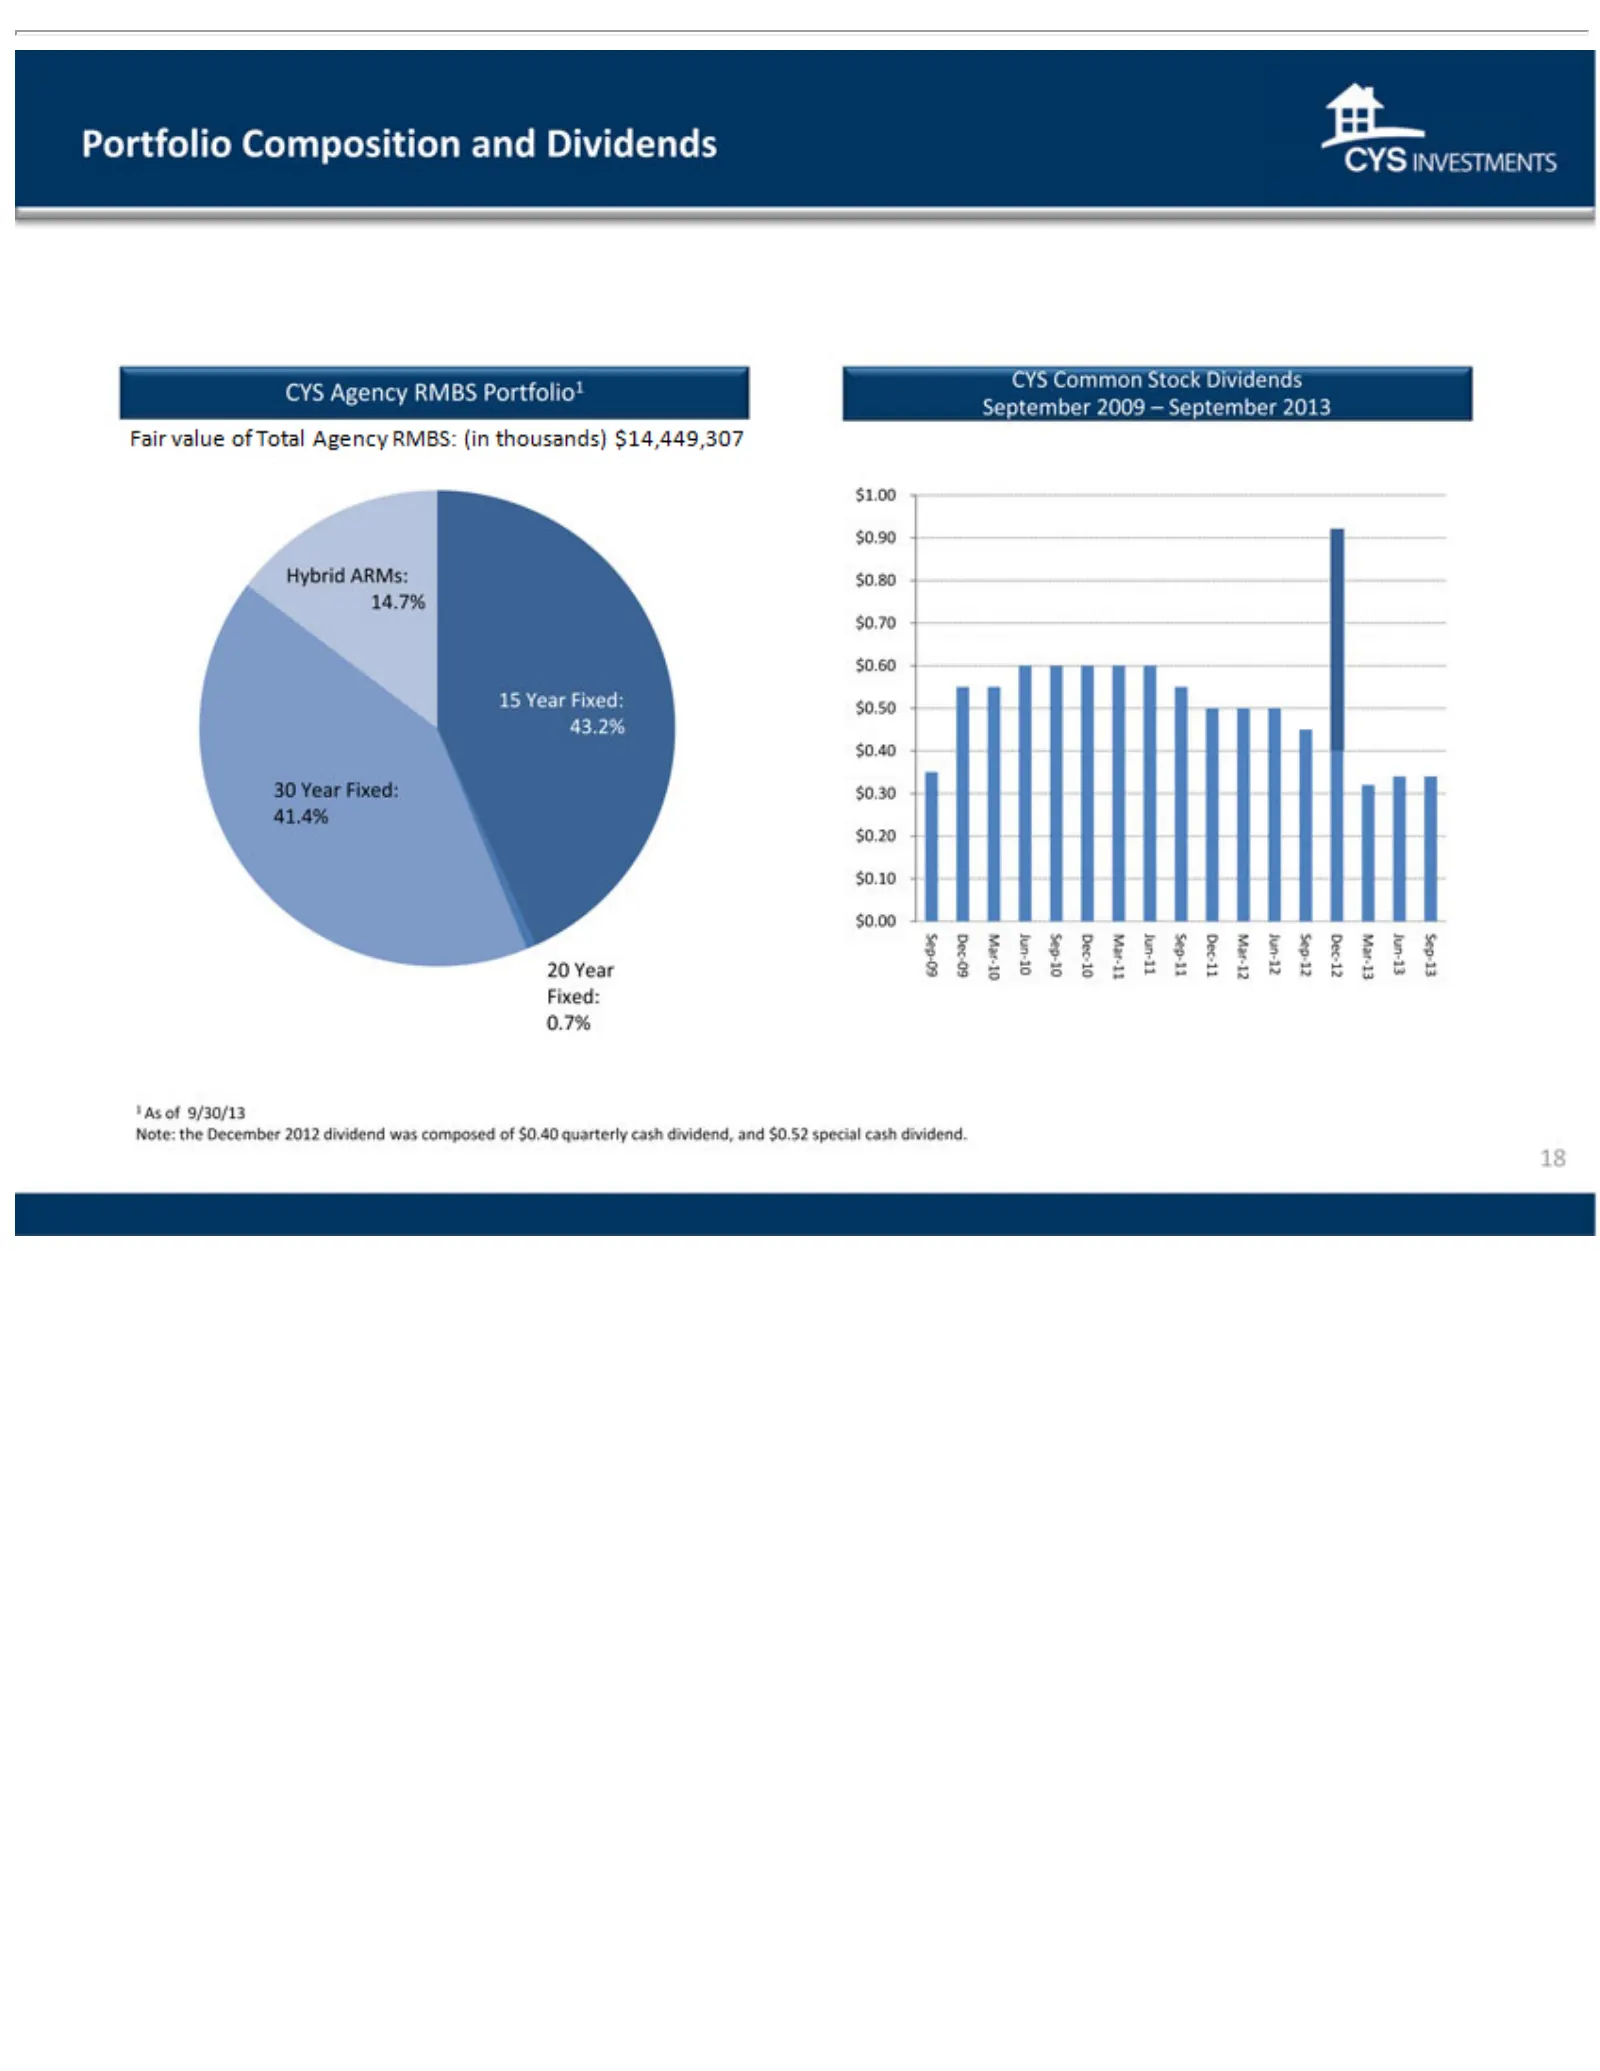
Slide 18: Portfolio Composition
Portfolio $1.00 20 Note: Year the $0.90 09 Composition December - Hybrid 10 10 - ARMs: 11 2012 and 11 dividend -Dividends $0.80 12 12 14.7% - was 13113 CYS composed $0.70 09 10 Common $0.60 10 of 11$0.40 15 11 Stock Year 12quarterly 12Dividends Fixed: 13 Fixed: $0.50 cash CYS 0.7% dividend, 43.2% Ag
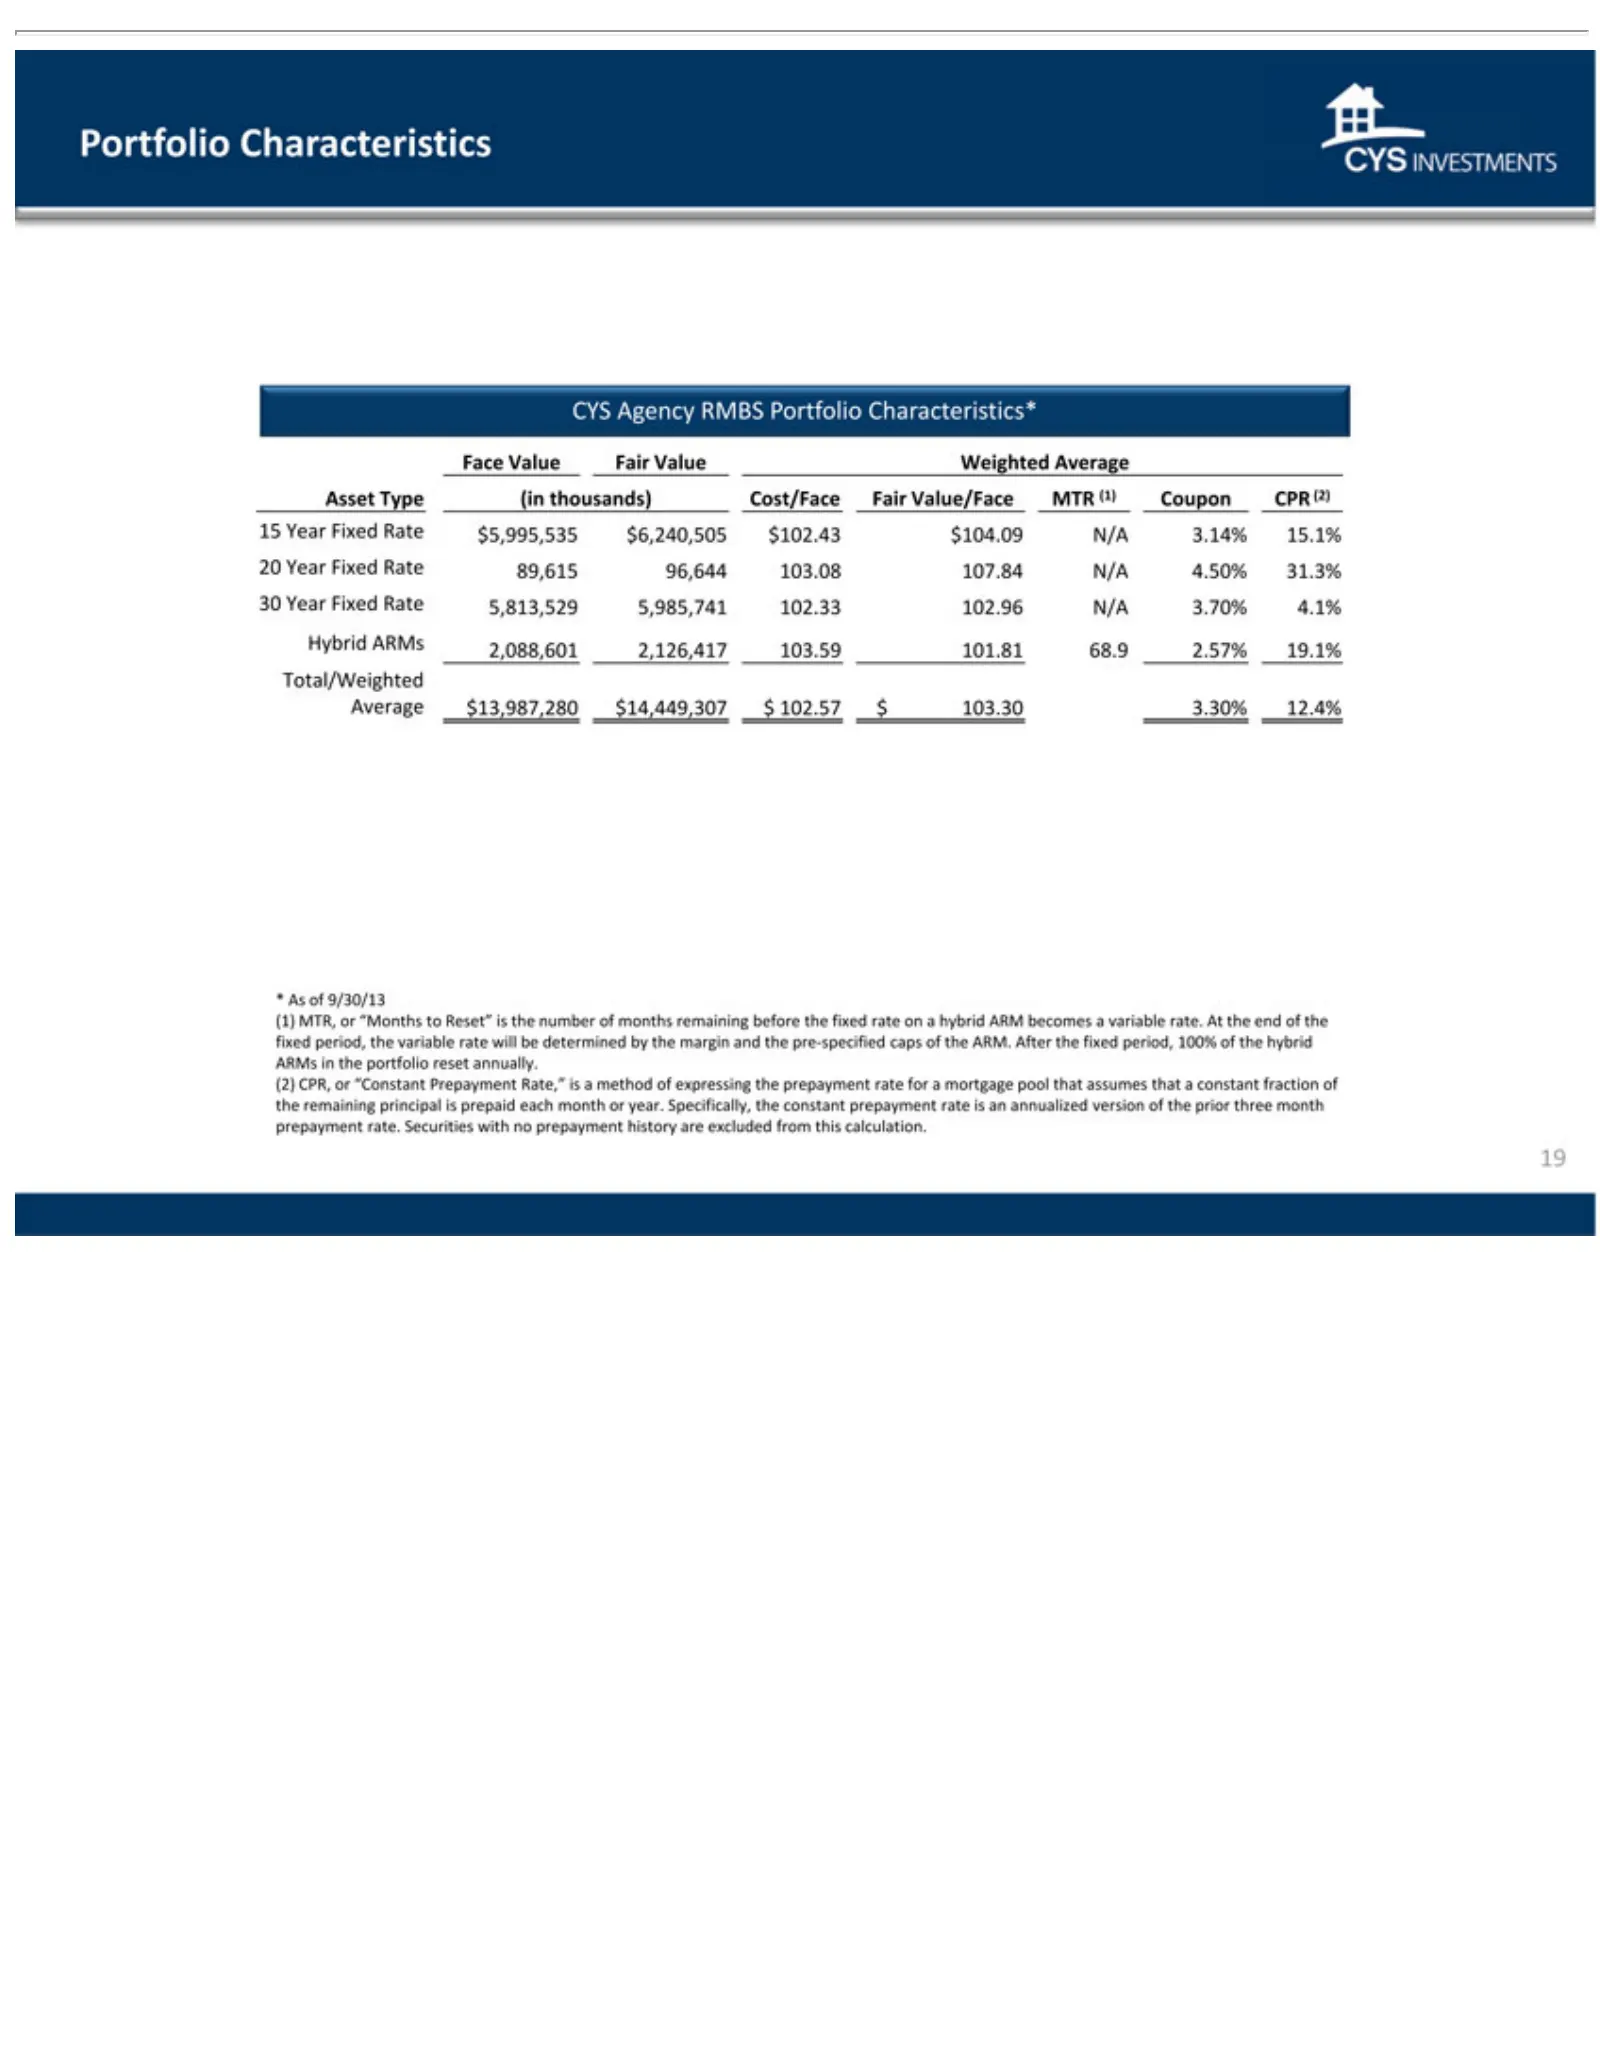
Slide 19: Portfolio Characteristics
Portfolio 15 102.33 (1) At (2) constant the Year the MTR, CPR, prior end 102.96 Fixed fraction three Characteristics or or ofConstant “Months the Rate month N/Aof fixed $5,995,535 3.70% the Prepayment prepayment toperiod, remaining Reset” CYS 4.1%Agency the $6,240,505 isHybrid rate. Rate,” the princ
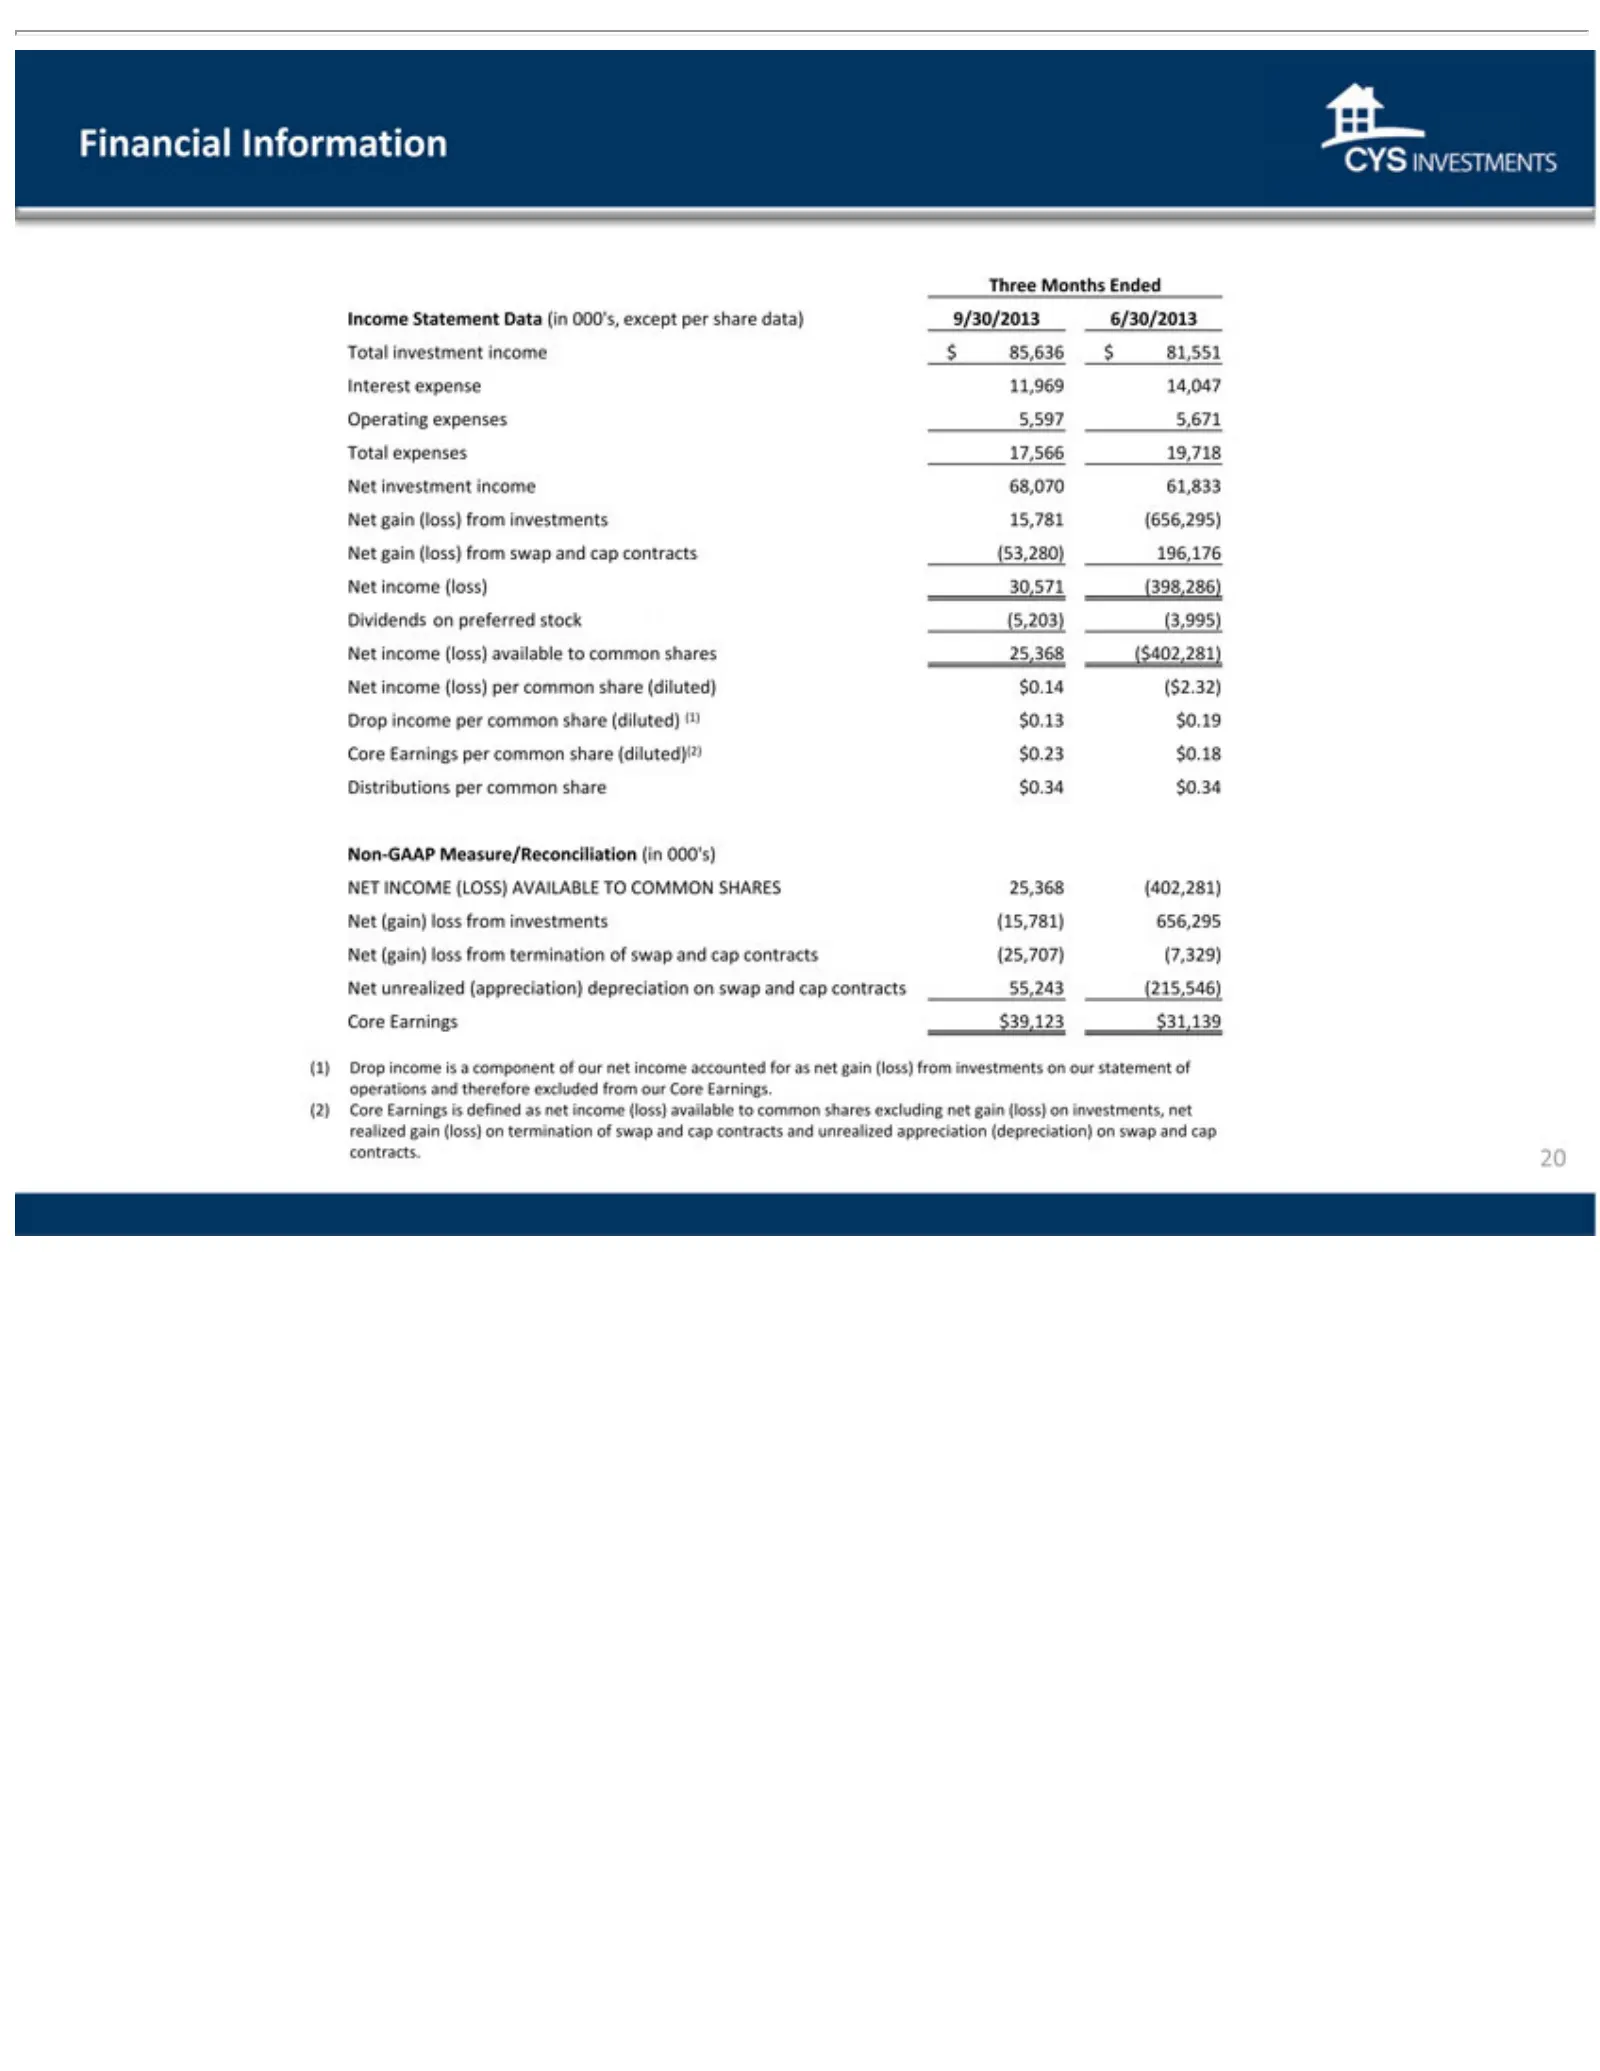
Slide 20: Financial Information: Core Earnings Reconciliation
Financial 11,969 25,368 $0.23 Net 55,243 operations (loss) gain (gain) on $0.18 14,047 ($402,281) (215,546) (loss) termination Information loss and Distributions Operating therefore from Core Net swap investments ofThree income Earnings swap excluded expenses per and Months and common cap (loss) $39
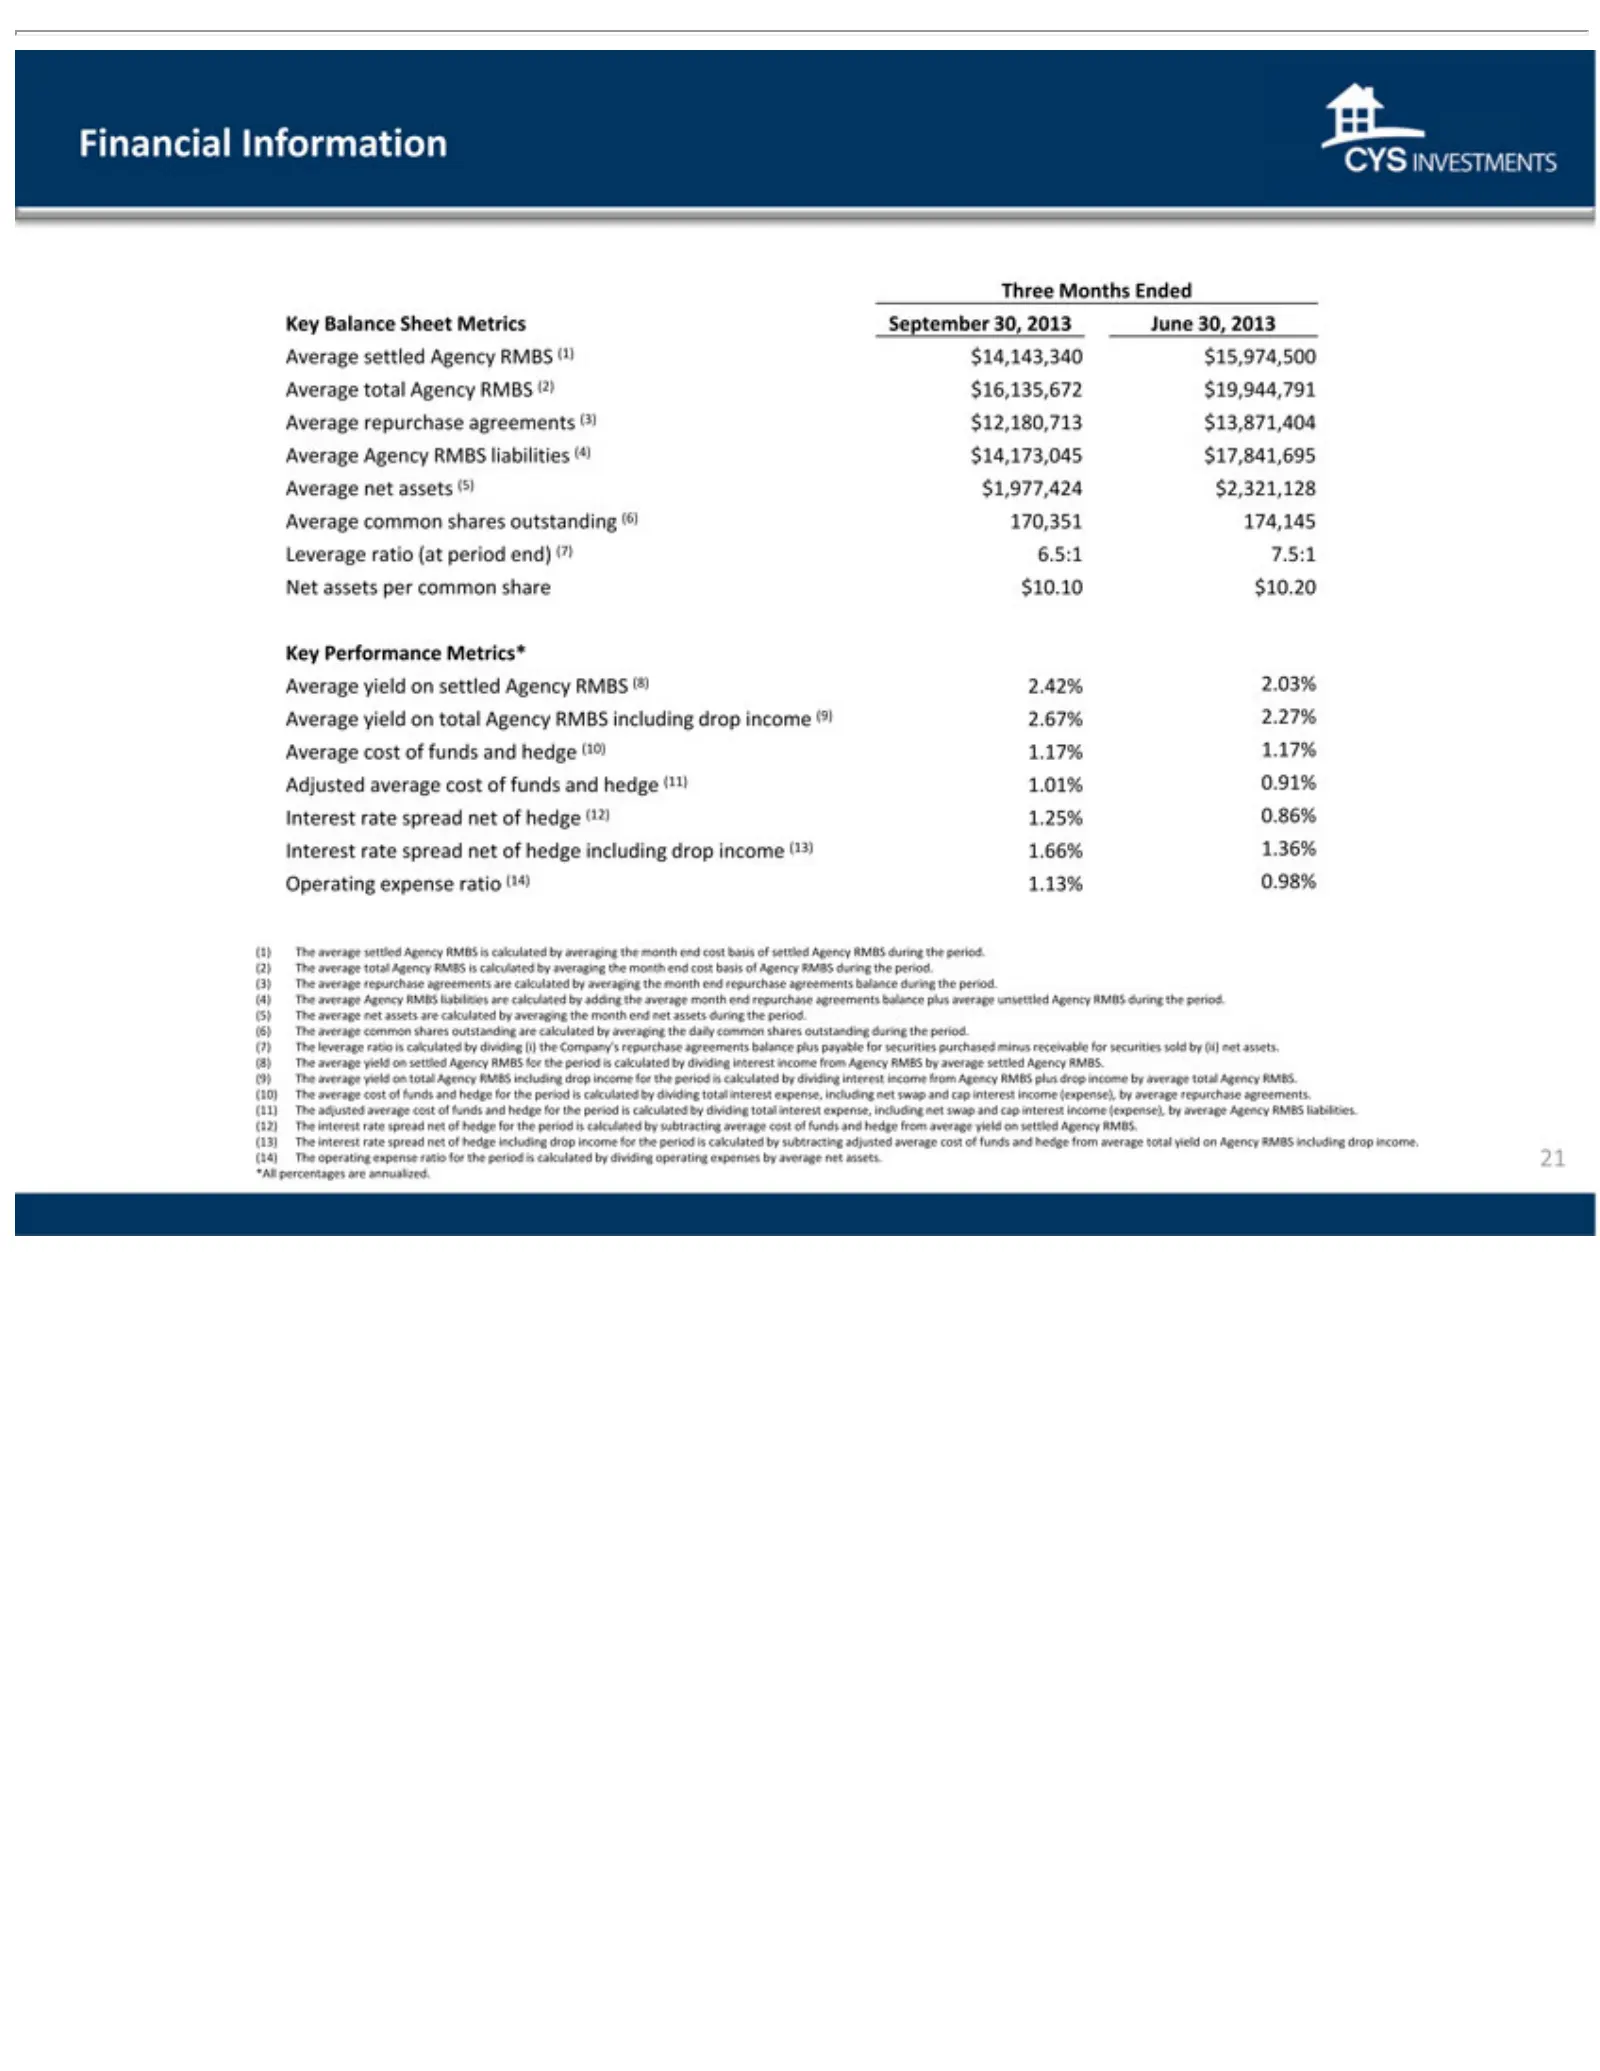
Slide 21: Financial Information: Key Balance Sheet Metrics
Financial Three Key $12,180,713 174,145 Average Interest hedge The leverage average adjusted interest operating Balance Months including rate Leverage settled yield Information spread rate Agency settled total repurchase net common yield cost $13,871,404 Sheet average ratio on expense Ended Agency a
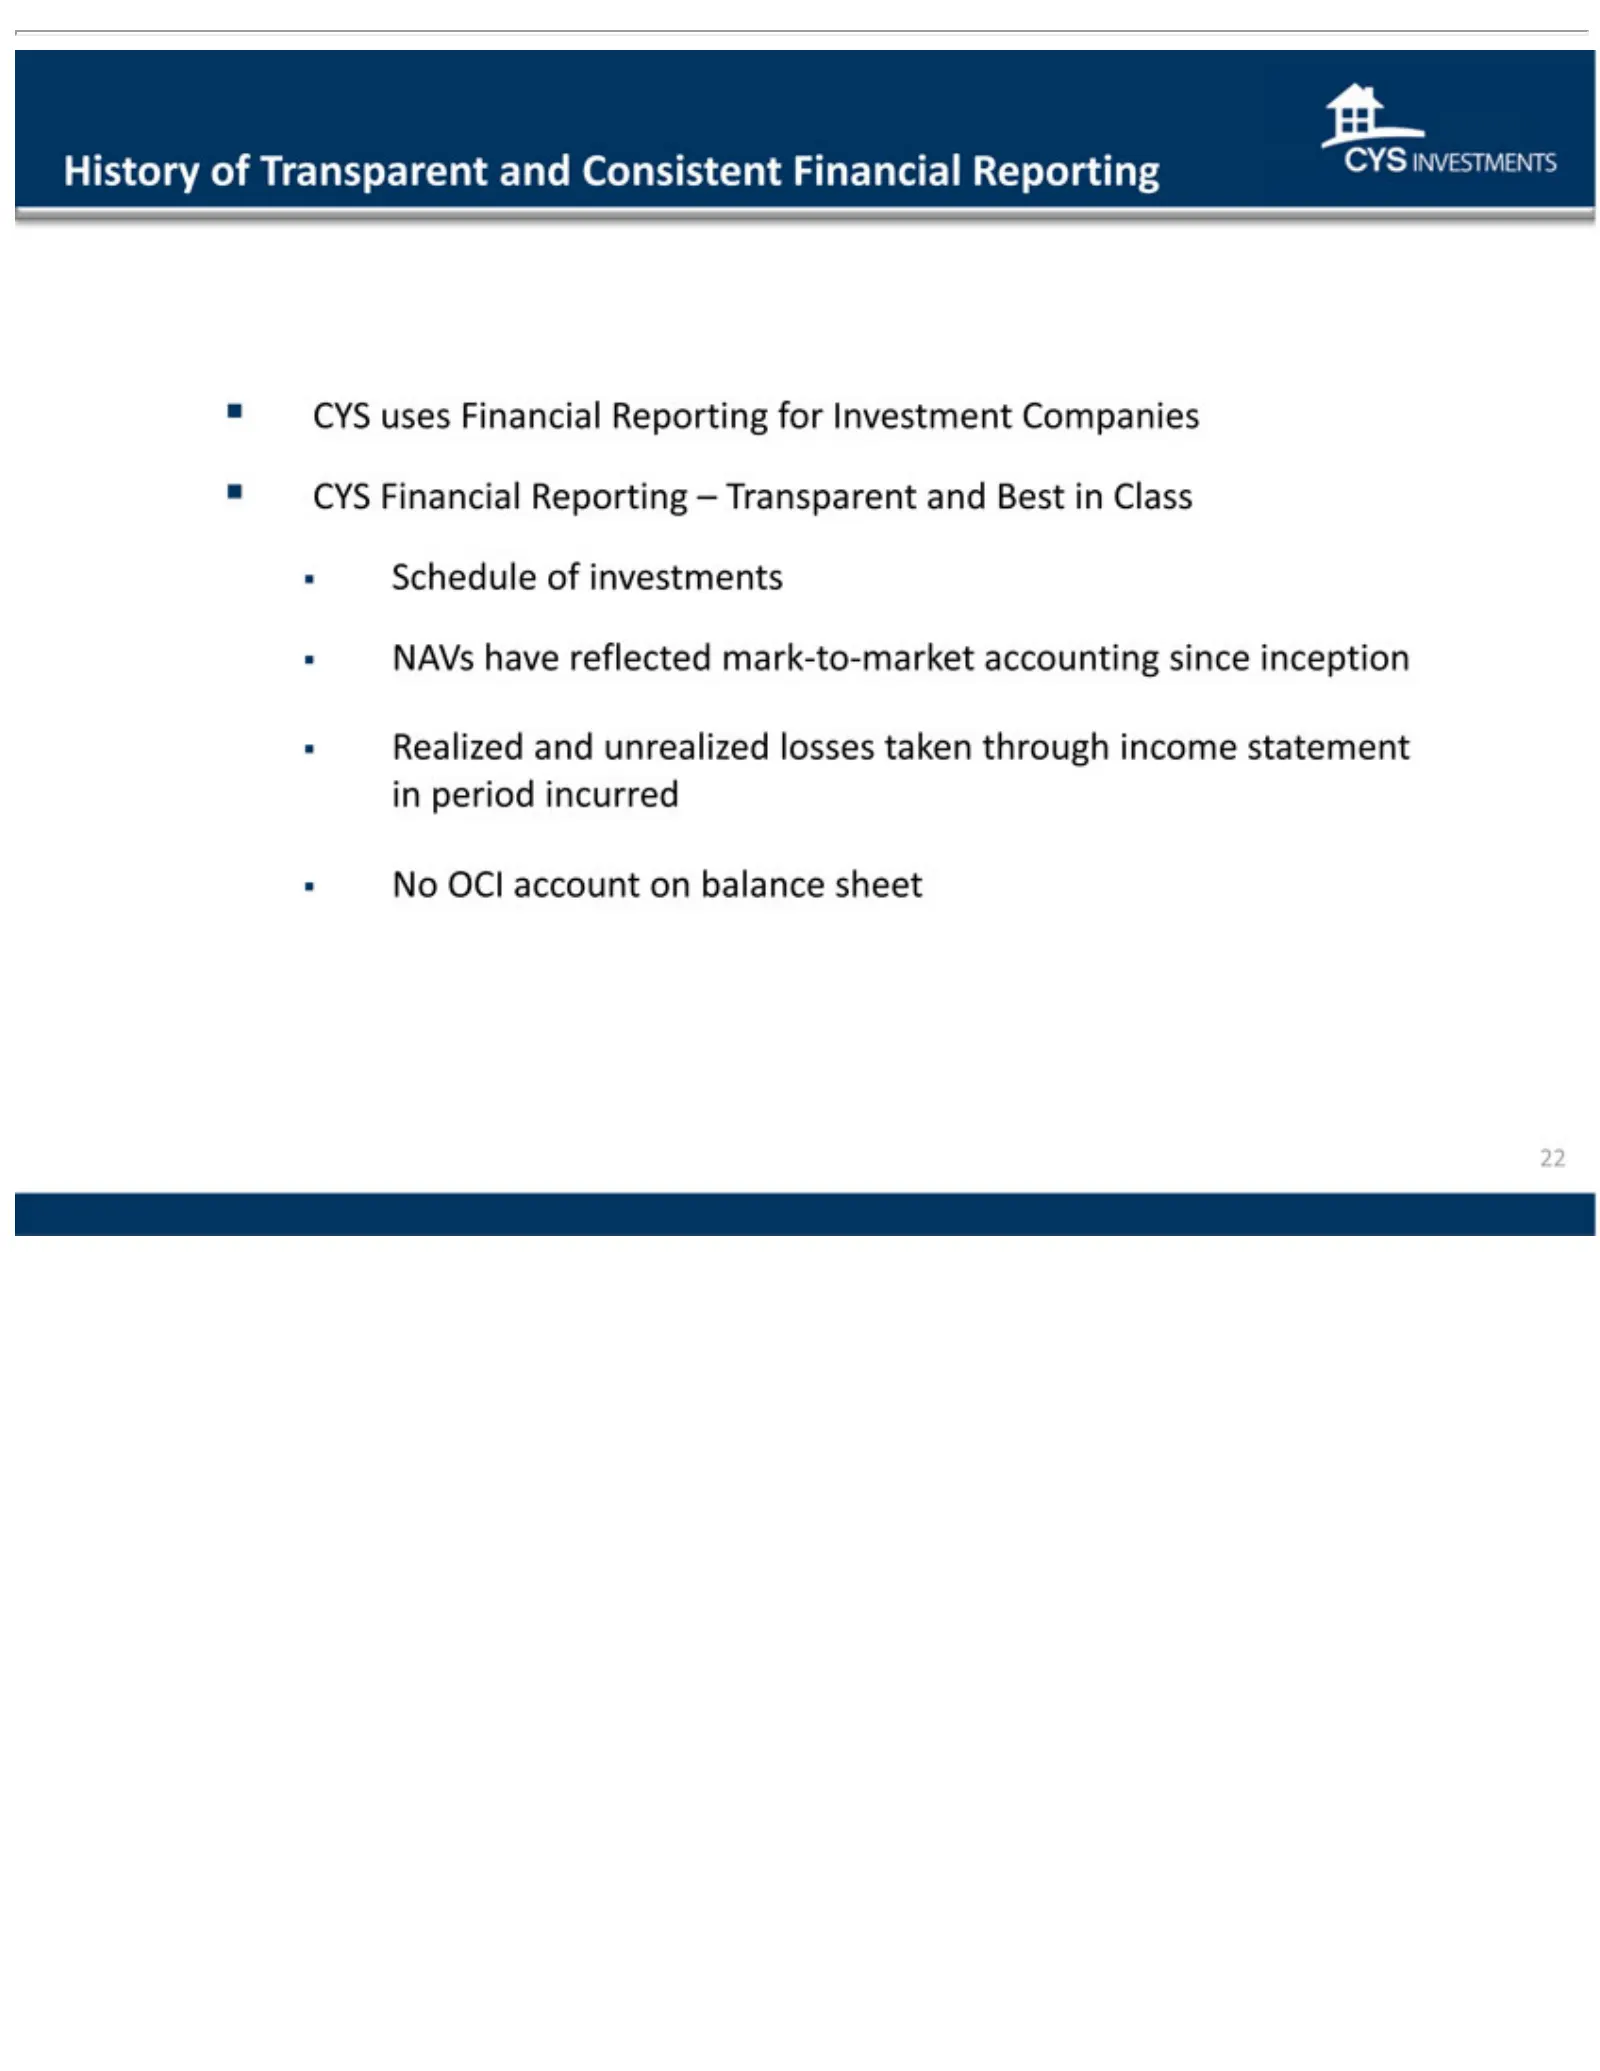
Slide 22: Transparent and Consistent Financial Reporting
Historyhave NAVs of Transparent reflected mark-to-market and Consistentaccounting Financial Reporting since inception CYS uses Realized Financial and unrealized Reportinglosses for Investment taken through Companies incomeCYS statement Financial in period Reporting incurred – Transparent No OCI acco
Slide 23: Investment Outlook - November 2013
Investment Outlook -November 2013 Kevin E. Grant, CFA Chief Executive Officer 2013 Banking and Financial Services Conference November 12, 2013 23
Source: SEC EDGAR · 8-K filed Nov 12, 2013
More decks from CYS Investments Inc
 Merger or Acquisition (April 2018)12 slides · Apr 26, 2018
 Barclays Global Financial Services Conference 201724 slides · Sep 11, 2017
 JMP Securities Financial Services and Real Estate Conference 201624 slides · Sep 27, 2016
 Barclays Global Financial Services Conference 201624 slides · Sep 12, 2016
 Proxy Contest (May 2016)8 slides · May 4, 2016
 JMP Securities Financial Services and Real Estate Conference 201522 slides · Sep 21, 2015