Curo — William Blair Growth Stock Conference 2021
40 slides from Curo's conference presentation, Jun 3, 2021
Slide 1: William Blair Growth Stock Conference
June 3, 2021 William Blair Growth Stock Conference
Slide 2: Disclaimer
Disclaimer 2 IMPORTANT: You must read the following information before continuing to the rest of the presentation, which is being provided to you for informational purposes only. Financial information contained in this presentation is unaudited. Forward-Looking Statements This presentation contains
Slide 3: Company Introduction
3 Company Introduction
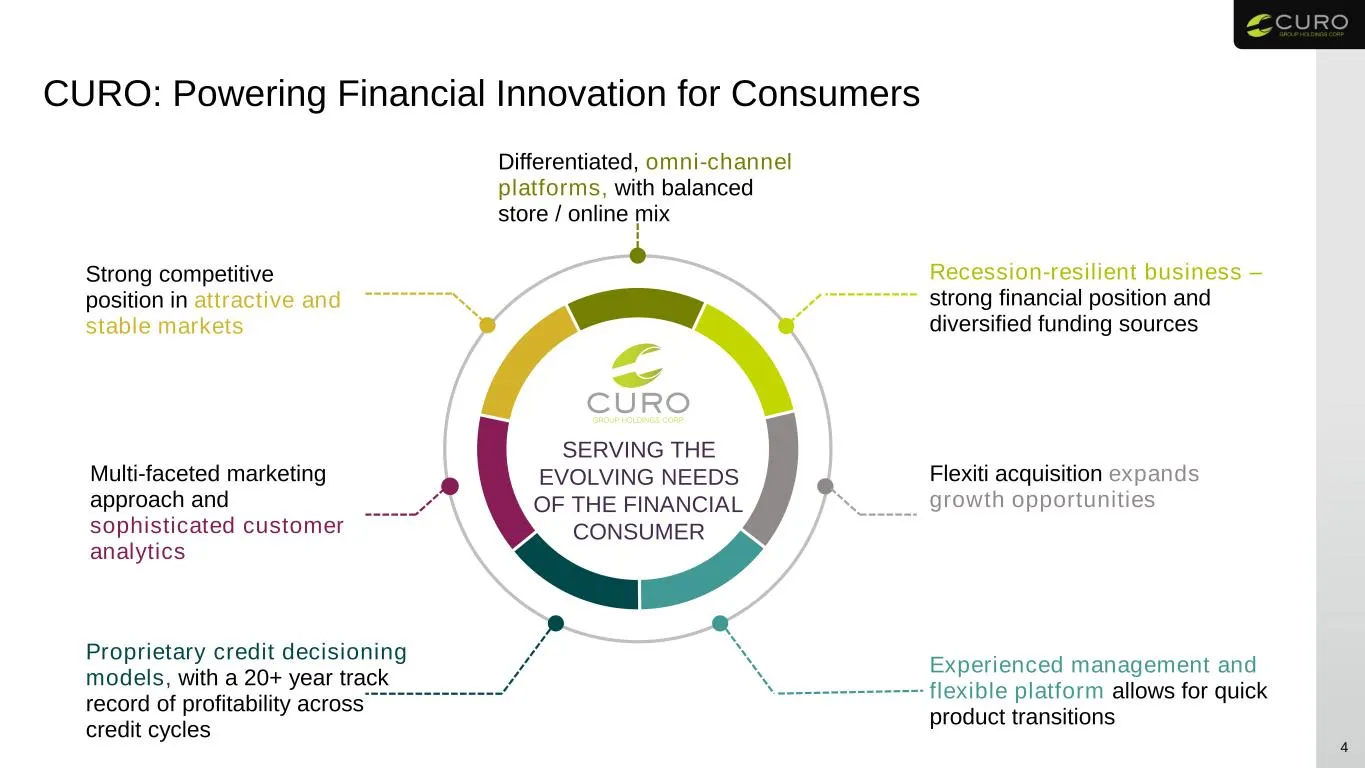
Slide 4: CURO: Powering Financial Innovation for Consumers
CURO: Powering Financial Innovation for Consumers 4 SERVING THE EVOLVING NEEDS OF THE FINANCIAL CONSUMER Differentiated, omni-channel platforms, with balanced store / online mix Recession-resilient business – strong financial position and diversified funding sources Flexiti acquisition expands growt
Slide 5: CURO at a Glance
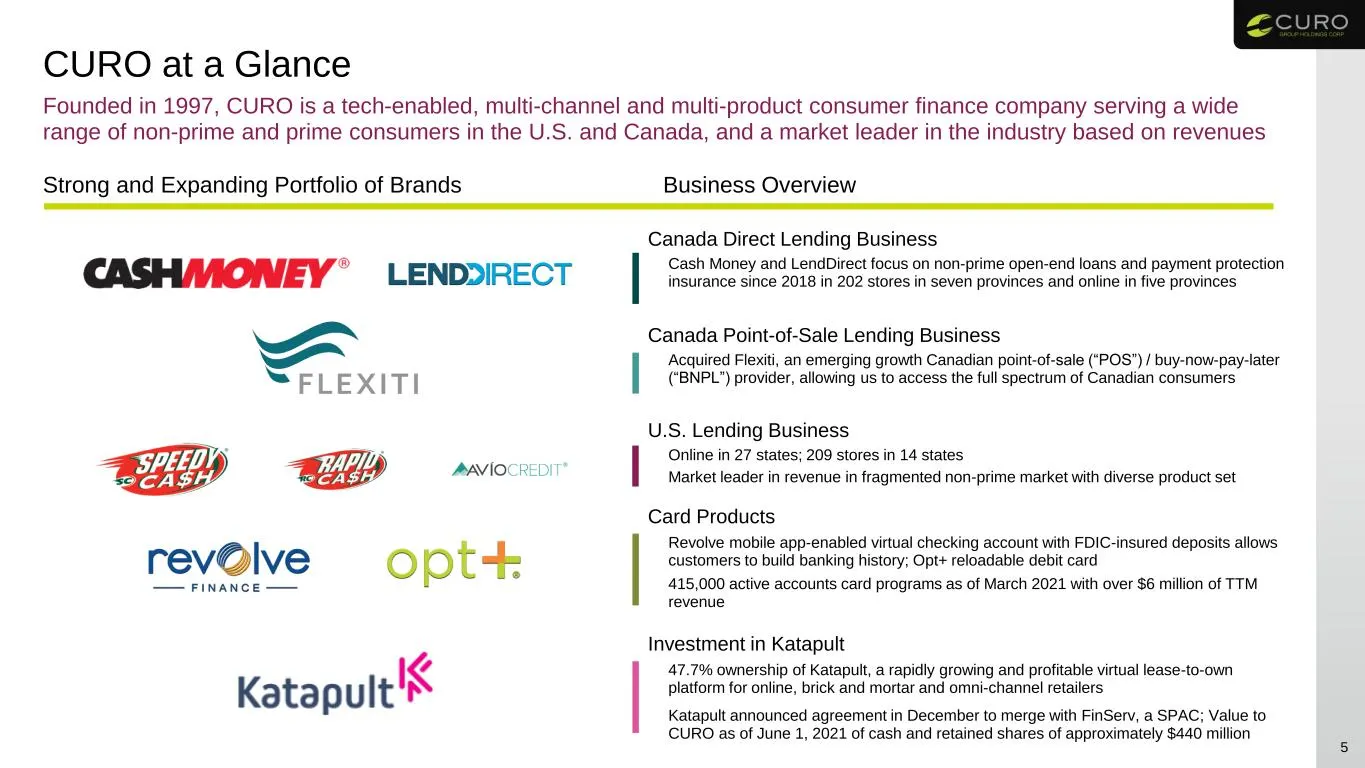
CURO at a Glance 5 Canada Point-of-Sale Lending Business Acquired Flexiti, an emerging growth Canadian point-of-sale (“POS”) / buy-now-pay-later (“BNPL”) provider, allowing us to access the full spectrum of Canadian consumers U.S. Lending Business Online in 27 states; 209 stores in 14 states Market
Slide 6: CURO covers all bases for how consumers access credit in the U.S. and Canada
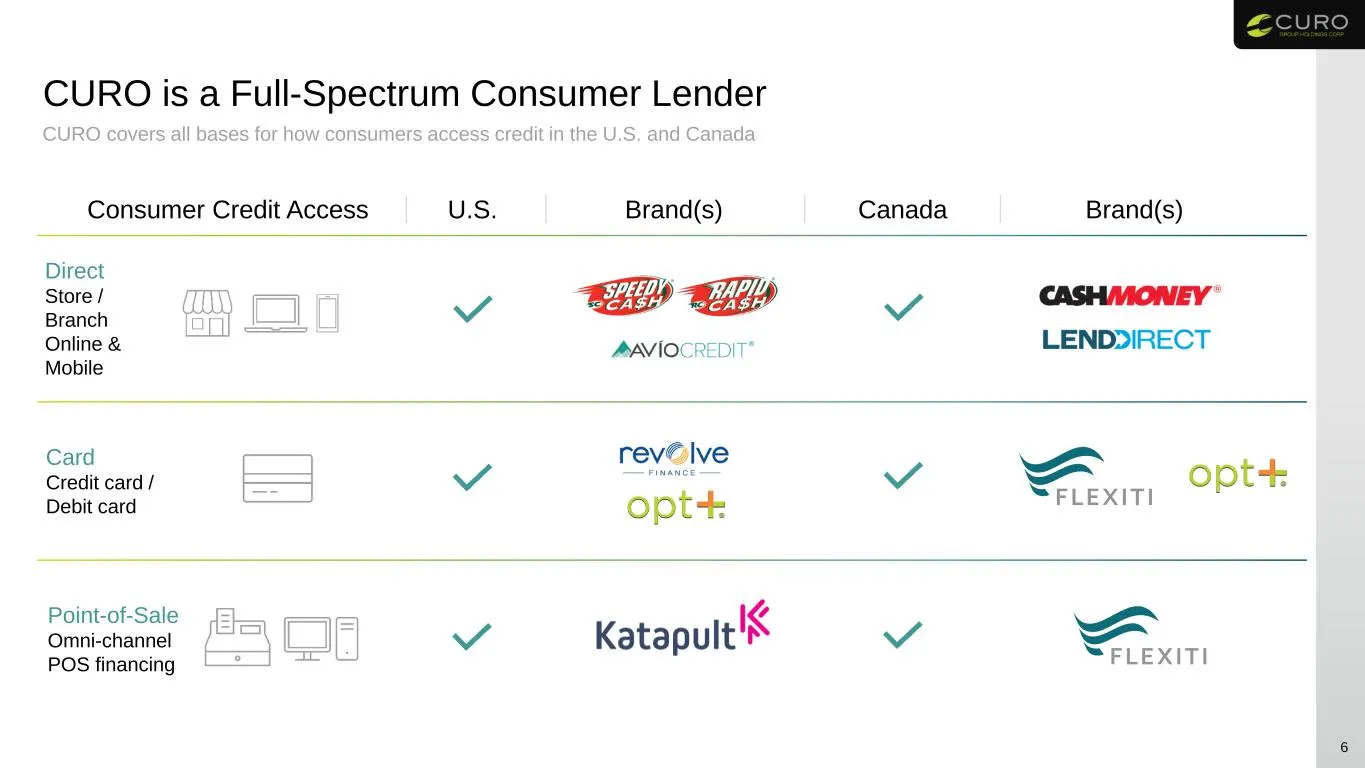
CURO covers all bases for how consumers access credit in the U.S. and Canada CURO is a Full-Spectrum Consumer Lender 6 21% 15% Direct Store / Branch Online & Mobile Card Credit card / Debit card Point-of-Sale Omni-channel POS financing Consumer Credit Access U.S. Brand(s) Canada Brand(s) 6%
Slide 7: CURO's Place in the Alternative Financial Product Market
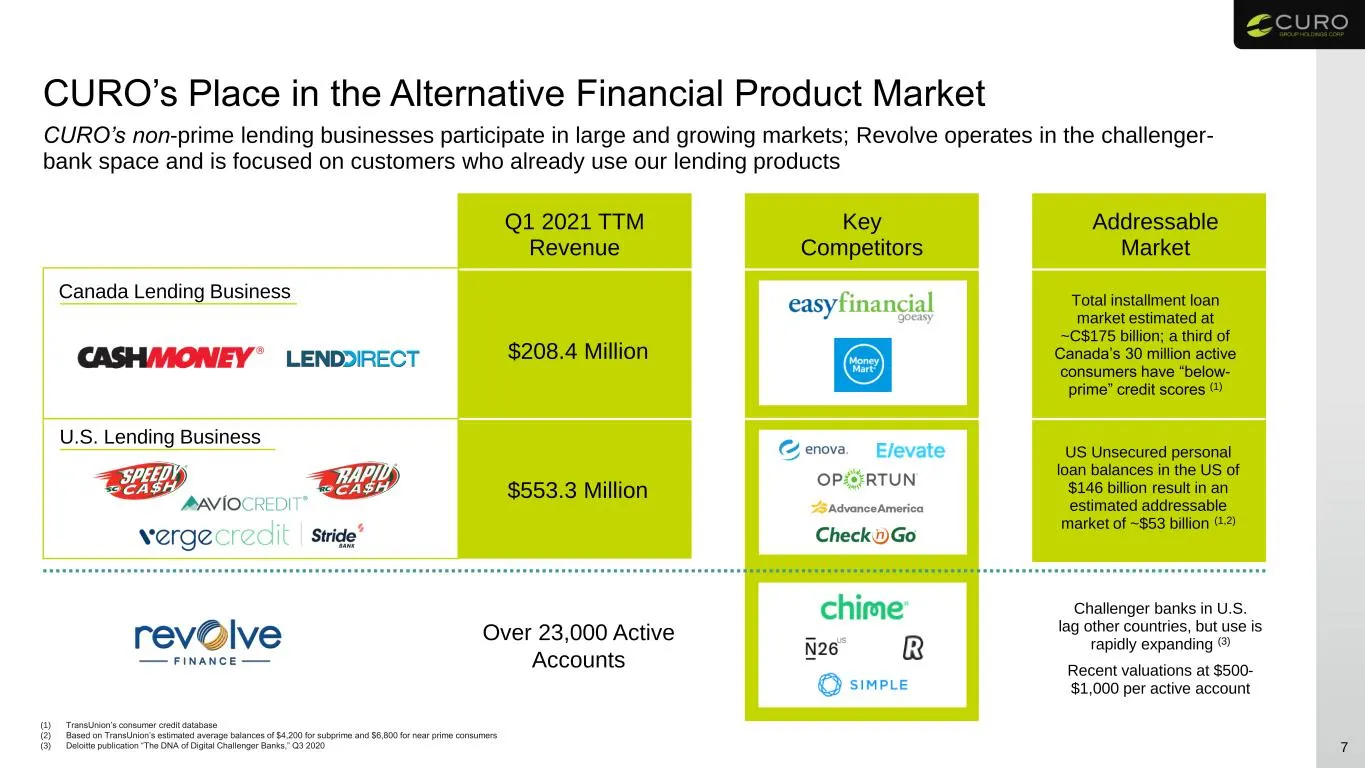
CURO’s Place in the Alternative Financial Product Market 7 (1) TransUnion’s consumer credit database (2) Based on TransUnion’s estimated average balances of $4,200 for subprime and $6,800 for near prime consumers (3) Deloitte publication “The DNA of Digital Challenger Banks,” Q3 2020 CURO’s non-prim
Slide 8: Drive Channel, Product and Geographic Diversification
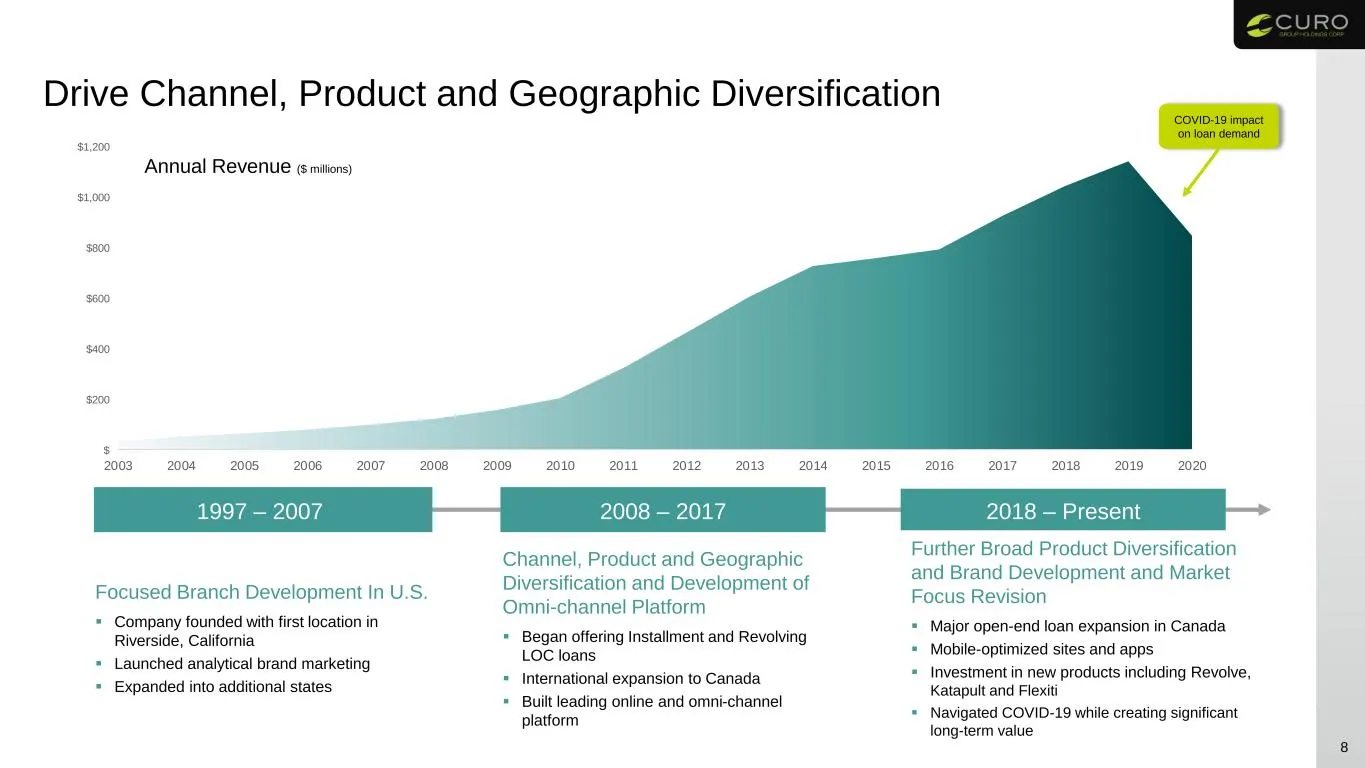
Drive Channel, Product and Geographic Diversification 8 Annual Revenue ($ millions) Focused Branch Development In U.S. Company founded with first location in Riverside, California Launched analytical brand marketing Expanded into additional states Channel, Product and Geographic Diversificatio
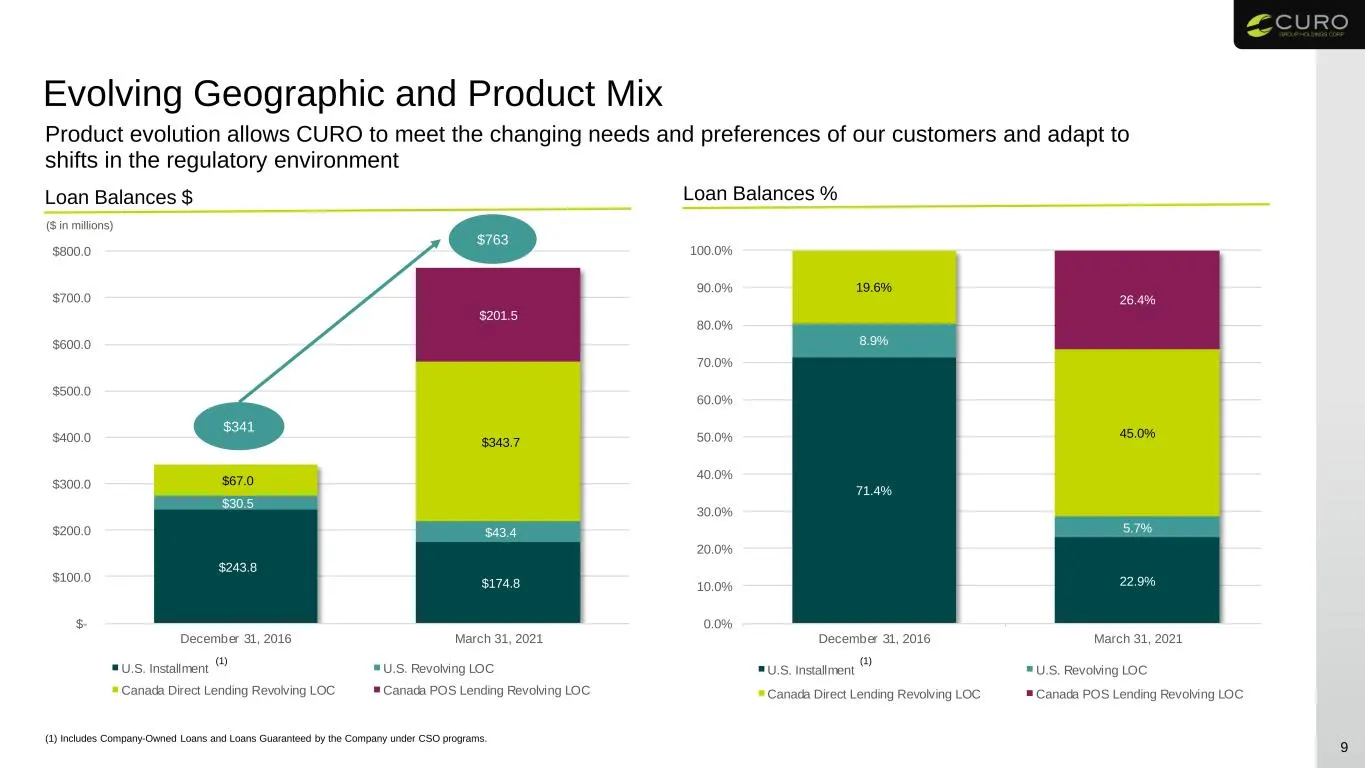
Slide 9: Evolving Geographic and Product Mix: Loan Balances
71.4% 22.9% 8.9% 5.7% 19.6% 45.0% 26.4% 0.0% 10.0% 20.0% 30.0% 40.0% 50.0% 60.0% 70.0% 80.0% 90.0% 100.0% December 31, 2016 March 31, 2021 U.S. Installment U.S. Revolving LOC Canada Direct Lending Revolving LOC Canada POS Lending Revolving LOC $243.8 $174.8 $30.5 $43.4 $67.0 $343.7 $201.5 $- $100.0
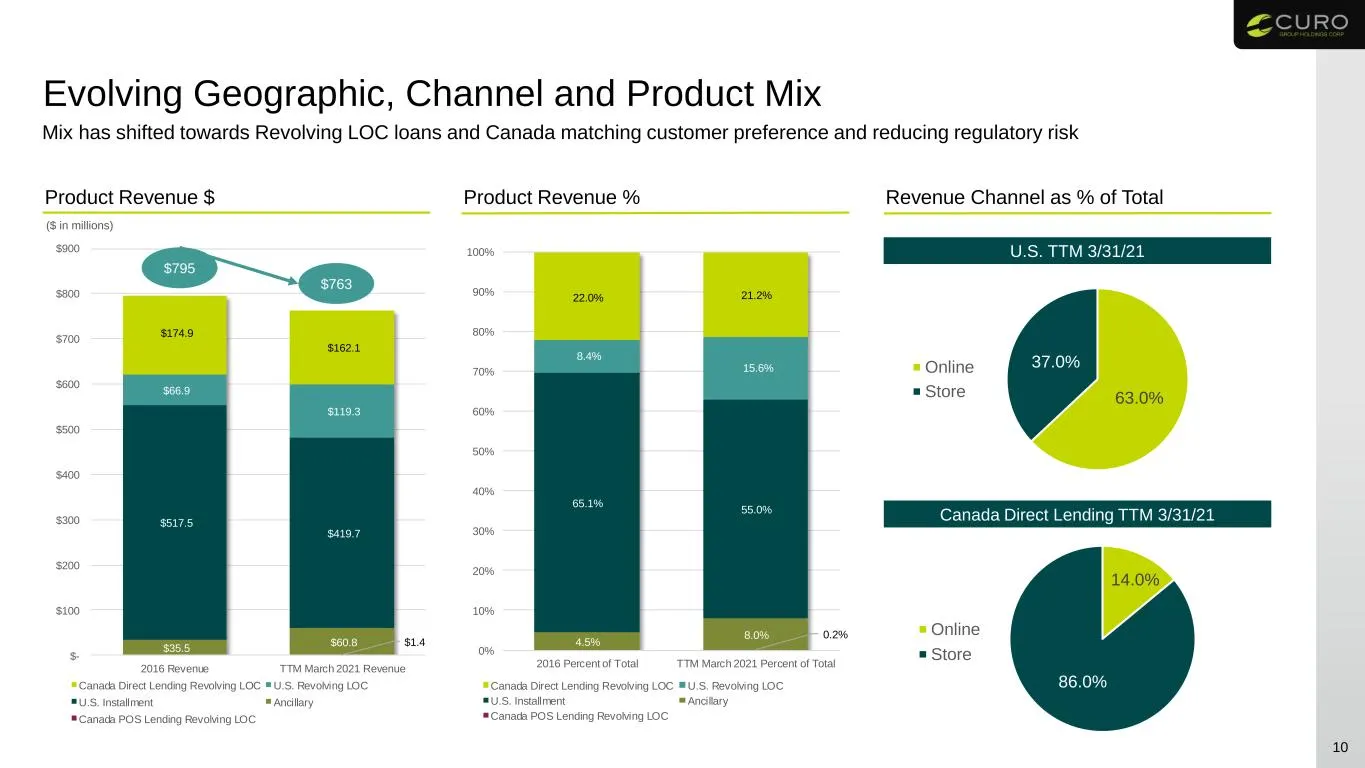
Slide 10: Evolving Geographic, Channel and Product Mix: Revenue
$35.5 $60.8 $517.5 $419.7 $66.9 $119.3 $174.9 $162.1 $1.4 $- $100 $200 $300 $400 $500 $600 $700 $800 $900 2016 Revenue TTM March 2021 Revenue Canada Direct Lending Revolving LOC U.S. Revolving LOC U.S. Installment Ancillary Canada POS Lending Revolving LOC Evolving Geographic, Channel and Product Mi
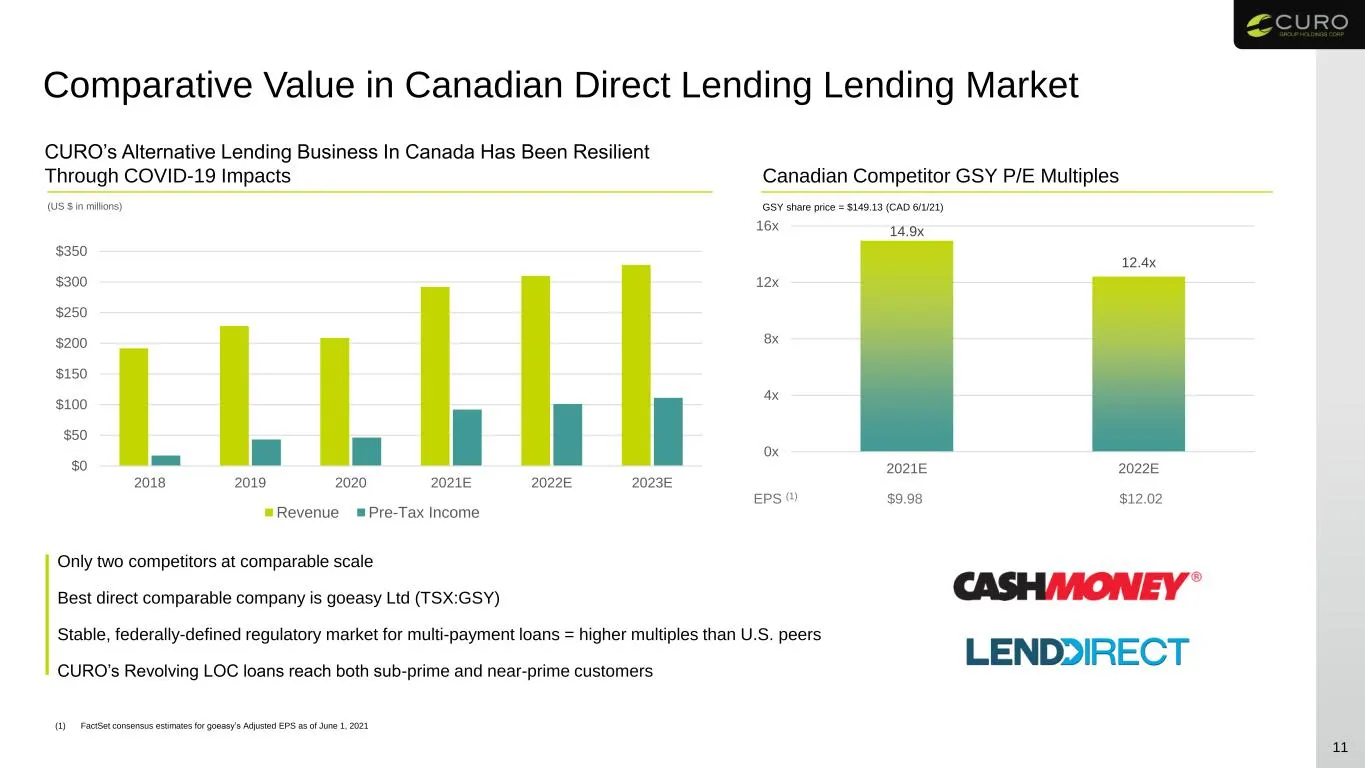
Slide 11: Comparative Value in Canadian Direct Lending
Comparative Value in Canadian Direct Lending Lending Market 11 CURO’s Alternative Lending Business In Canada Has Been Resilient Through COVID-19 Impacts (US $ in millions) Only two competitors at comparable scale Best direct comparable company is goeasy Ltd (TSX:GSY) Stable, federally-defined regula
Slide 12: Market Overview
12 Market Overview
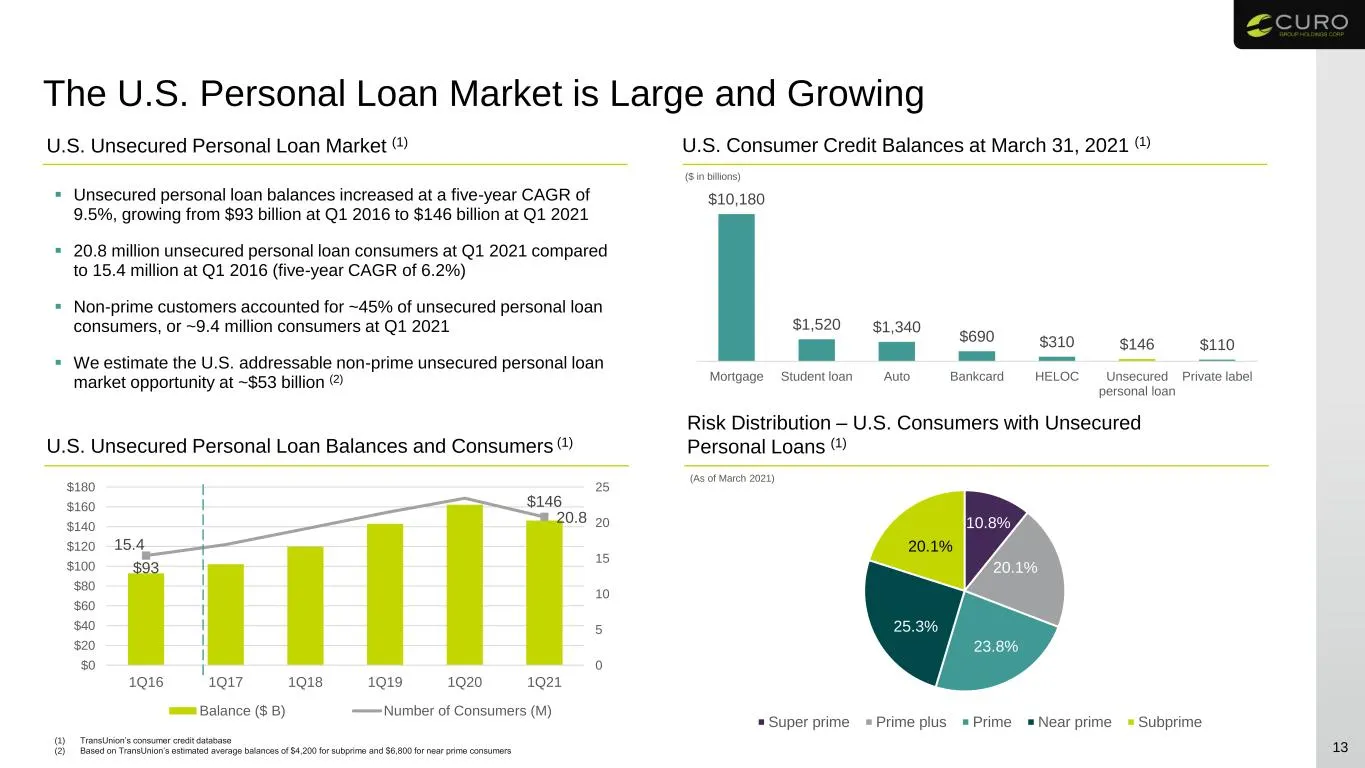
Slide 13: The U.S. Personal Loan Market is Large and Growing
The U.S. Personal Loan Market is Large and Growing (1) TransUnion’s consumer credit database (2) Based on TransUnion’s estimated average balances of $4,200 for subprime and $6,800 for near prime consumers U.S. Consumer Credit Balances at March 31, 2021 (1) U.S. Unsecured Personal Loan Balances and C
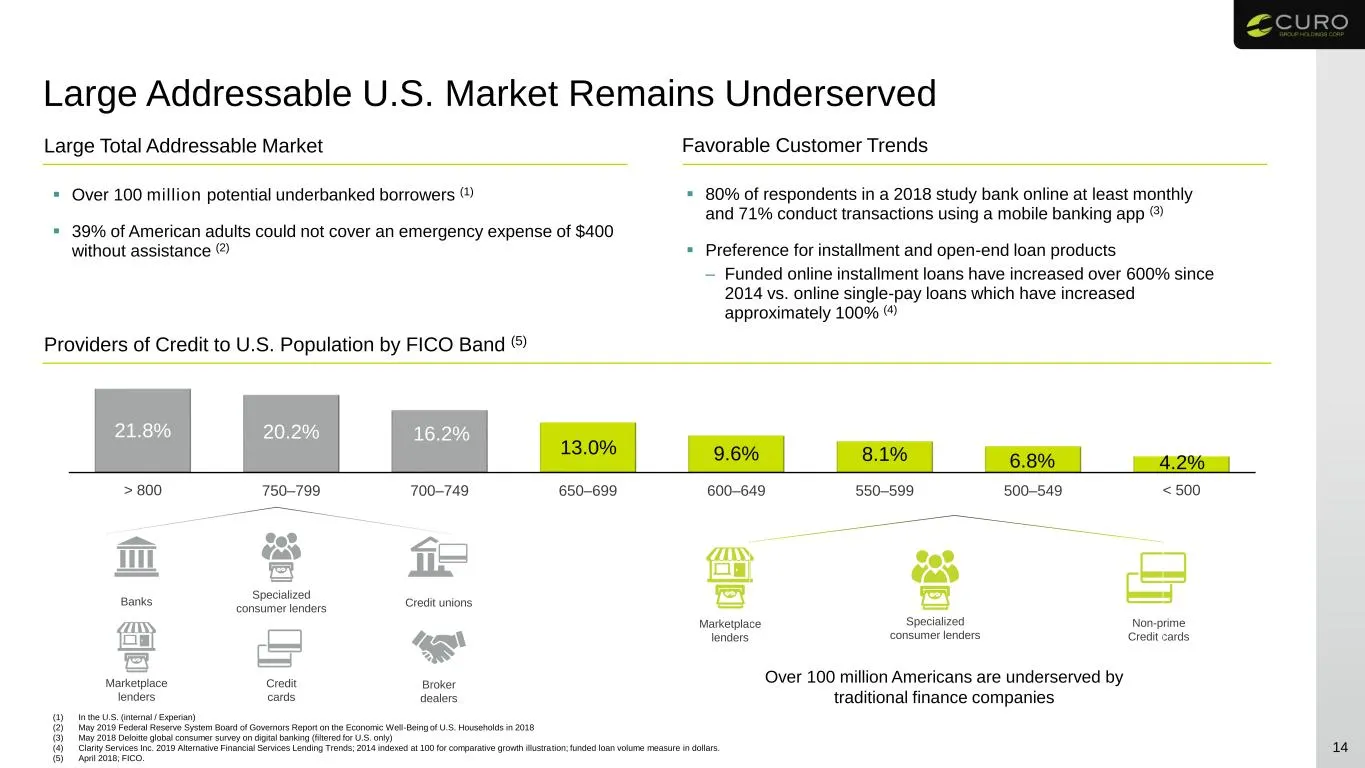
Slide 14: Large Addressable U.S. Market Remains Underserved
Large Addressable U.S. Market Remains Underserved 14 (1) In the U.S. (internal / Experian) (2) May 2019 Federal Reserve System Board of Governors Report on the Economic Well-Being of U.S. Households in 2018 (3) May 2018 Deloitte global consumer survey on digital banking (filtered for U.S. only) (4)
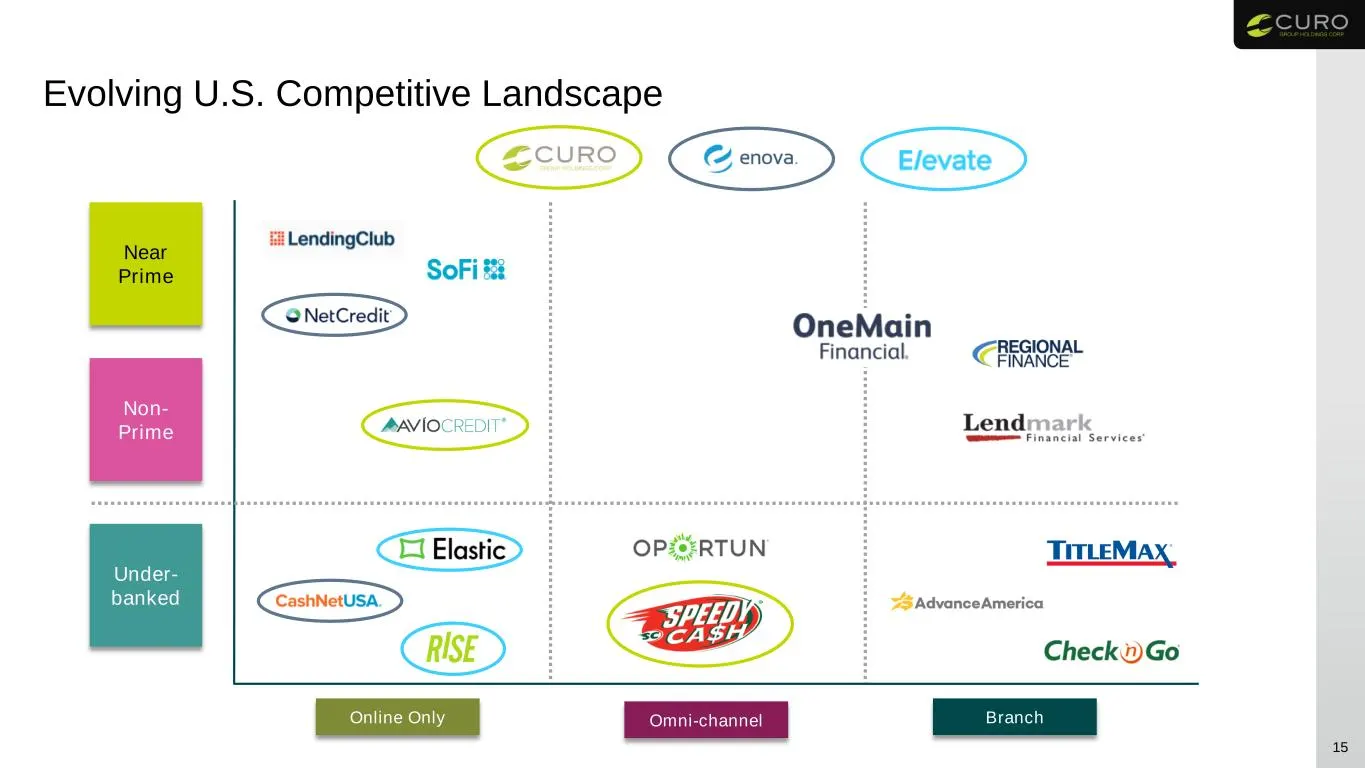
Slide 15: Evolving U.S. Competitive Landscape
Evolving U.S. Competitive Landscape 15 Online Only Omni-channel Near Prime Non- Prime Under- banked Branch
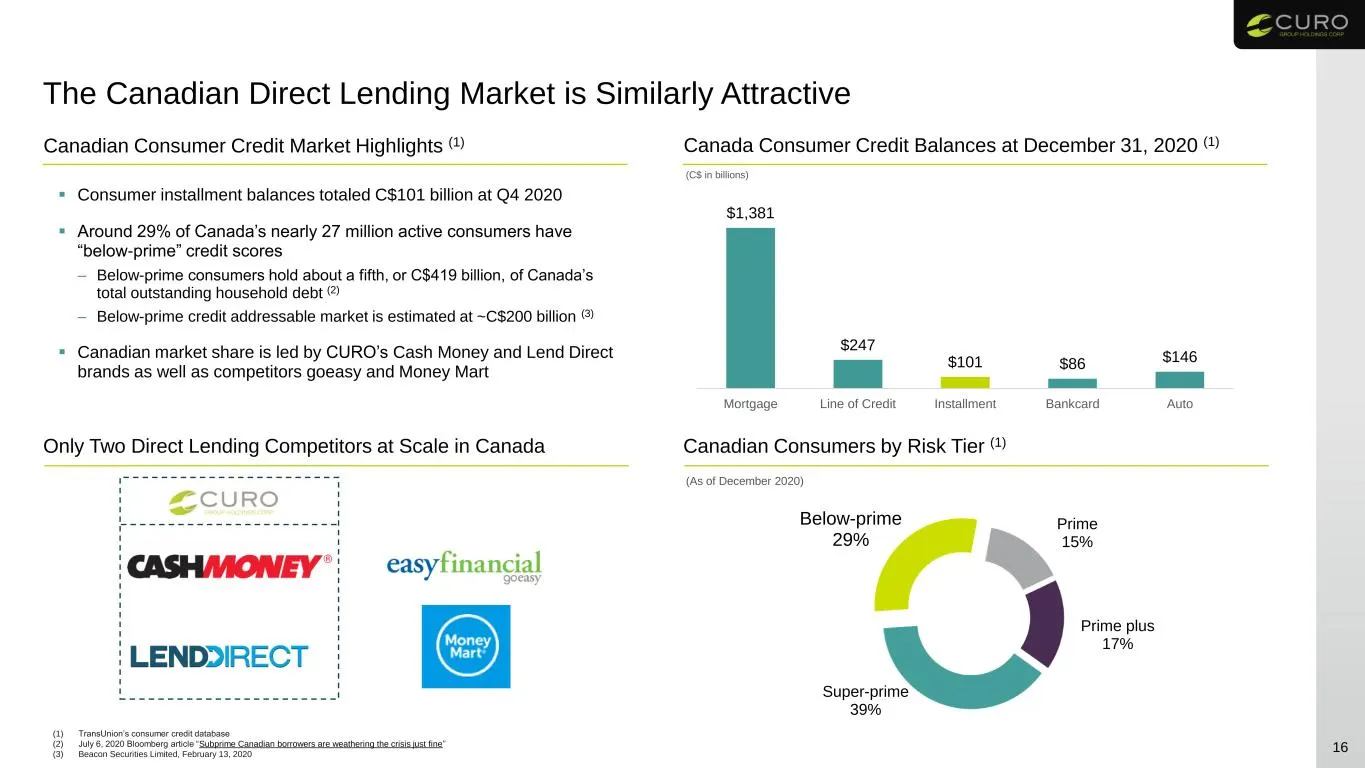
Slide 16: Only Two Direct Lending Competitors at Scale in Canada
Only Two Direct Lending Competitors at Scale in Canada $1,381 $247 $101 $86 $146 Mortgage Line of Credit Installment Bankcard Auto The Canadian Direct Lending Market is Similarly Attractive 16 (1) TransUnion’s consumer credit database (2) July 6, 2020 Bloomberg article “Subprime Canadian borrowers a
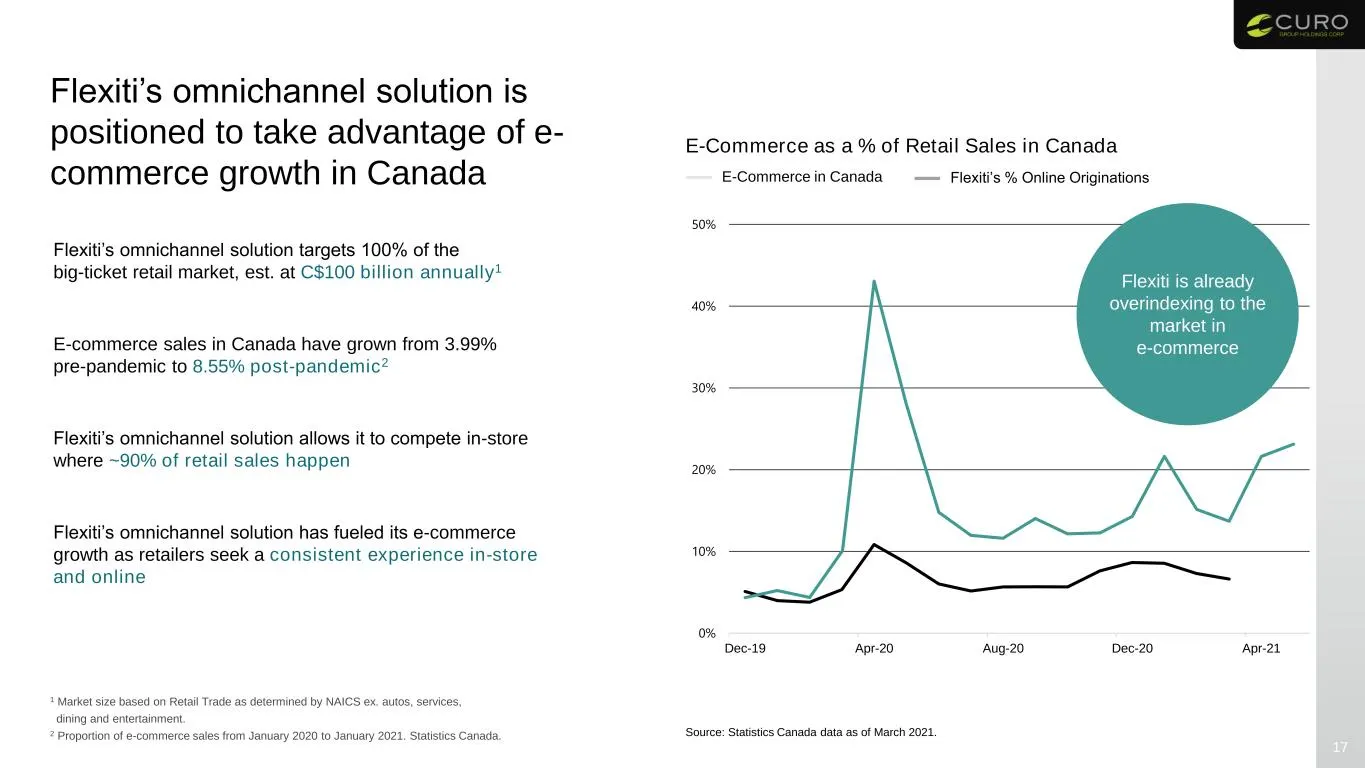
Slide 17: E-Commerce in Canada
0% 10% 20% 30% 40% 50% Dec-19 Apr-20 Aug-20 Dec-20 Apr-21 17 1 Market size based on Retail Trade as determined by NAICS ex. autos, services, dining and entertainment. 2 Proportion of e-commerce sales from January 2020 to January 2021. Statistics Canada. E-Commerce as a % of Retail Sales in Canada Fl
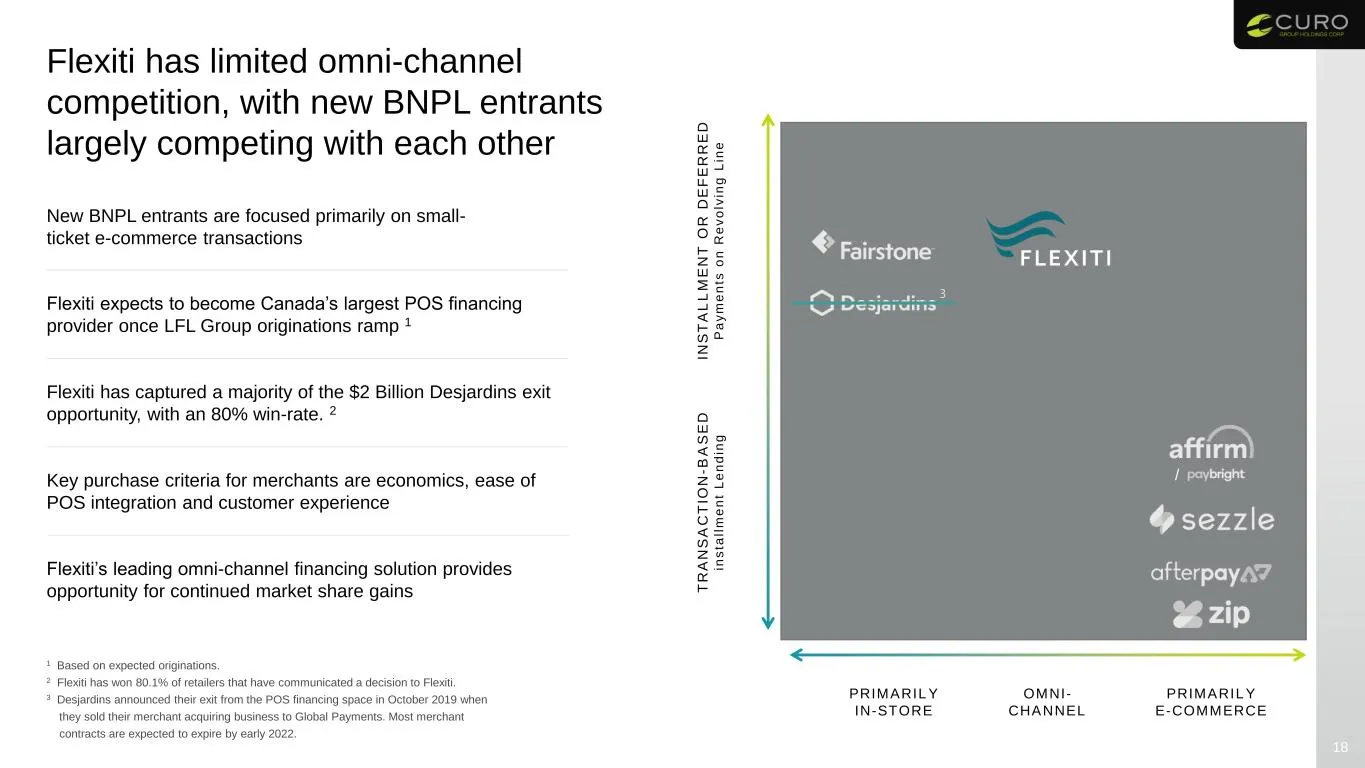
Slide 18: Flexiti has limited omni-channel competition
Flexiti has limited omni-channel competition, with new BNPL entrants largely competing with each other 18 Flexiti expects to become Canada’s largest POS financing provider once LFL Group originations ramp 1 Flexiti has captured a majority of the $2 Billion Desjardins exit opportunity, with an 80% wi
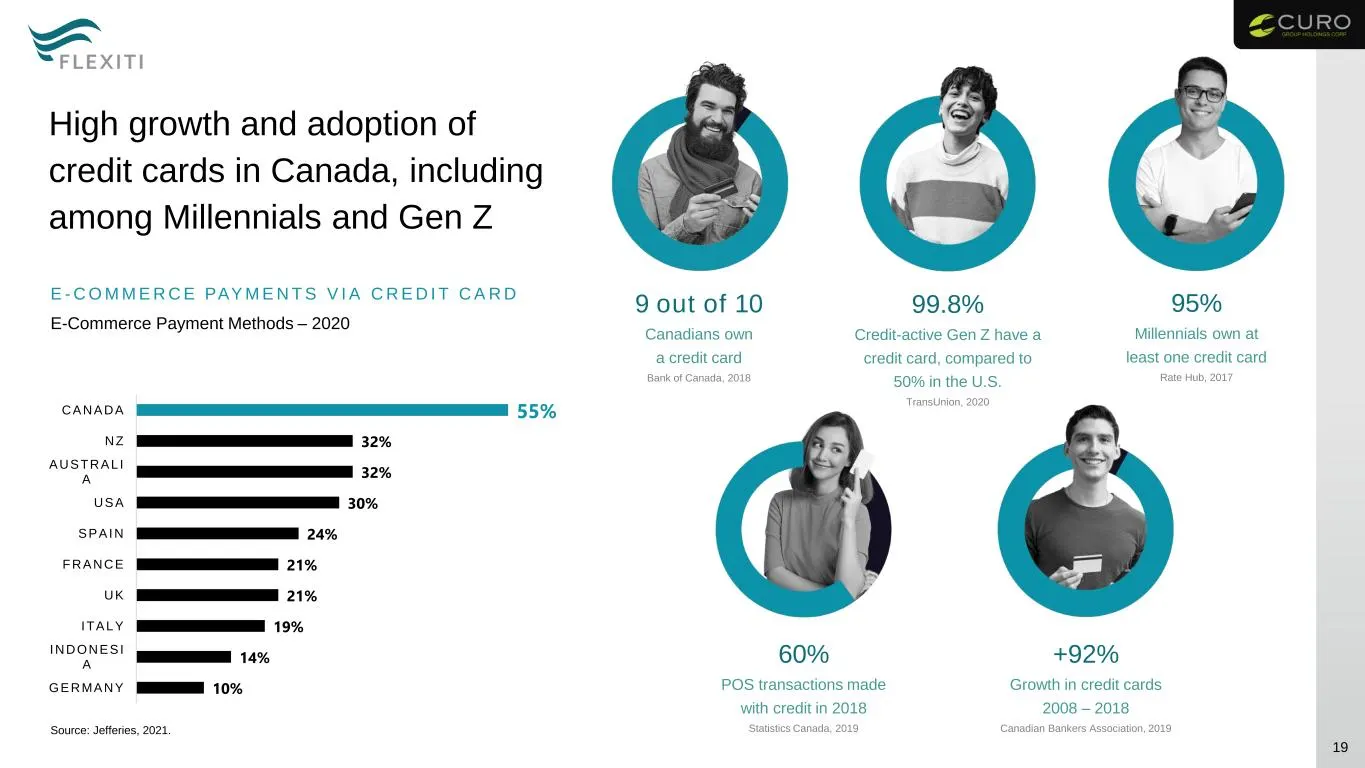
Slide 19: High growth and adoption of credit cards in Canada
19 10% 14% 19% 21% 21% 24% 30% 32% 32% 55% GERMANY INDONESI A ITALY UK FRANCE SPAIN USA AUSTRAL I A NZ CANADA High growth and adoption of credit cards in Canada, including among Millennials and Gen Z E - C O M M E R C E PAY M E N T S V I A C R E D I T C AR D E-Commerce Payment Methods – 2020 Source:
Slide 20: Strategic Growth Opportunities
20 Strategic Growth Opportunities
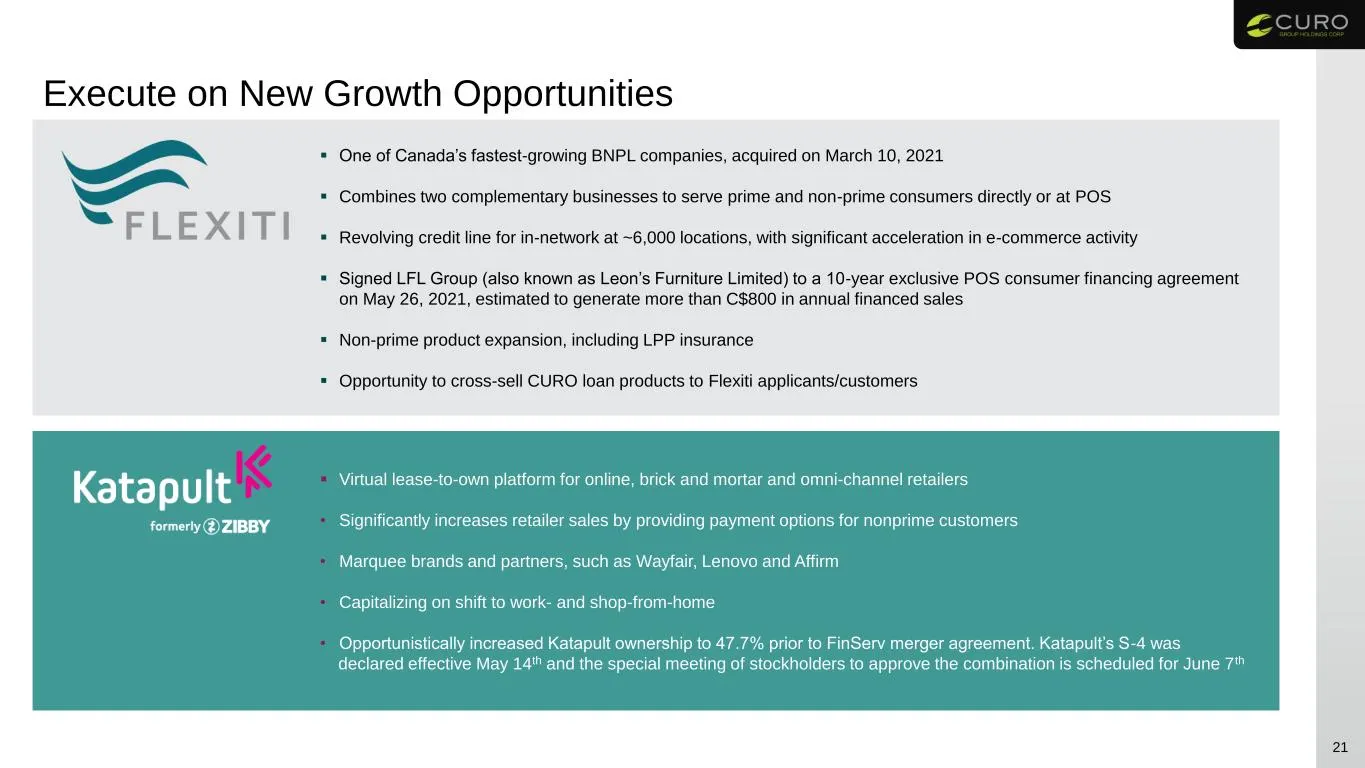
Slide 21: Execute on New Growth Opportunities
Execute on New Growth Opportunities Virtual lease-to-own platform for online, brick and mortar and omni-channel retailers • Significantly increases retailer sales by providing payment options for nonprime customers • Marquee brands and partners, such as Wayfair, Lenovo and Affirm • Capitalizing on
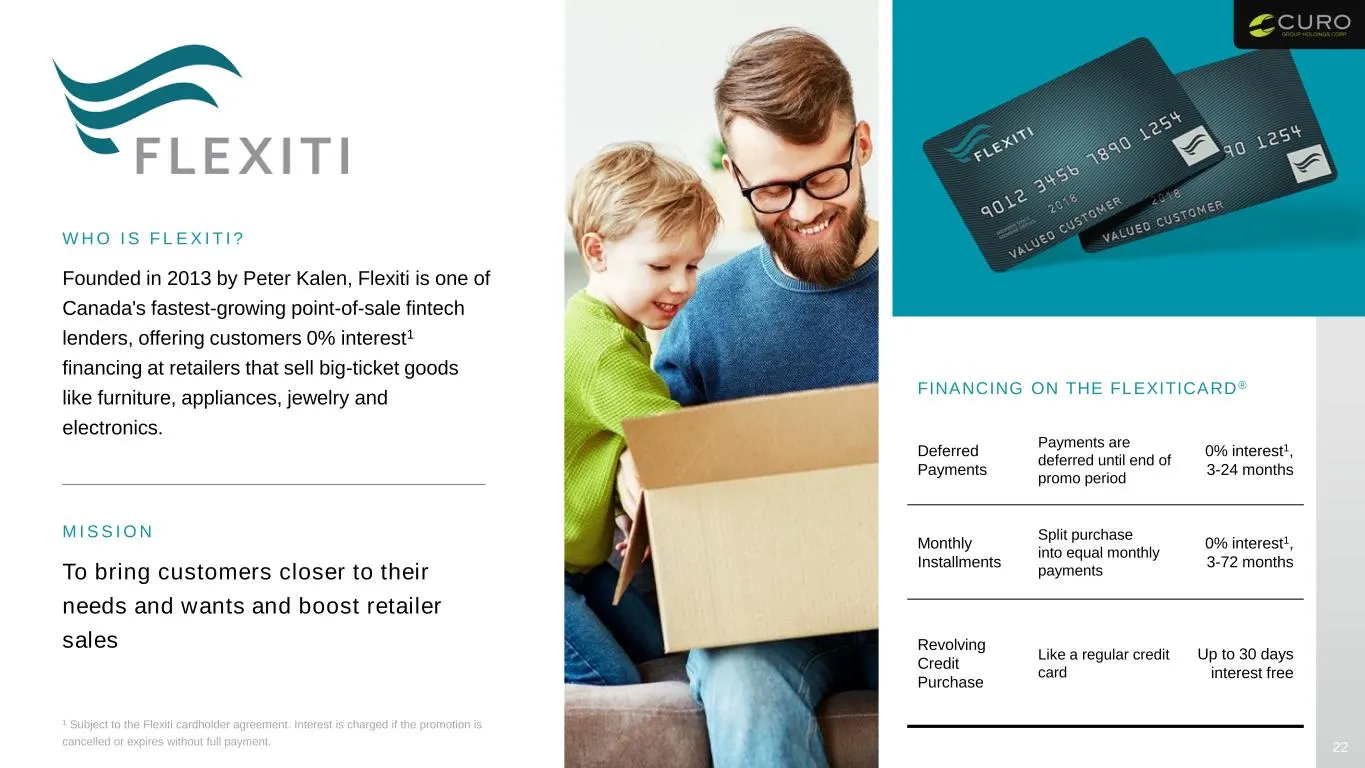
Slide 22: Financing on the Flexiticard
22 FINANCING ON THE FLEXITICARD® Deferred Payments Payments are deferred until end of promo period 0% interest1, 3-24 months Monthly Installments Split purchase into equal monthly payments 0% interest1, 3-72 months Revolving Credit Purchase Like a regular credit card Up to 30 days interest free M I
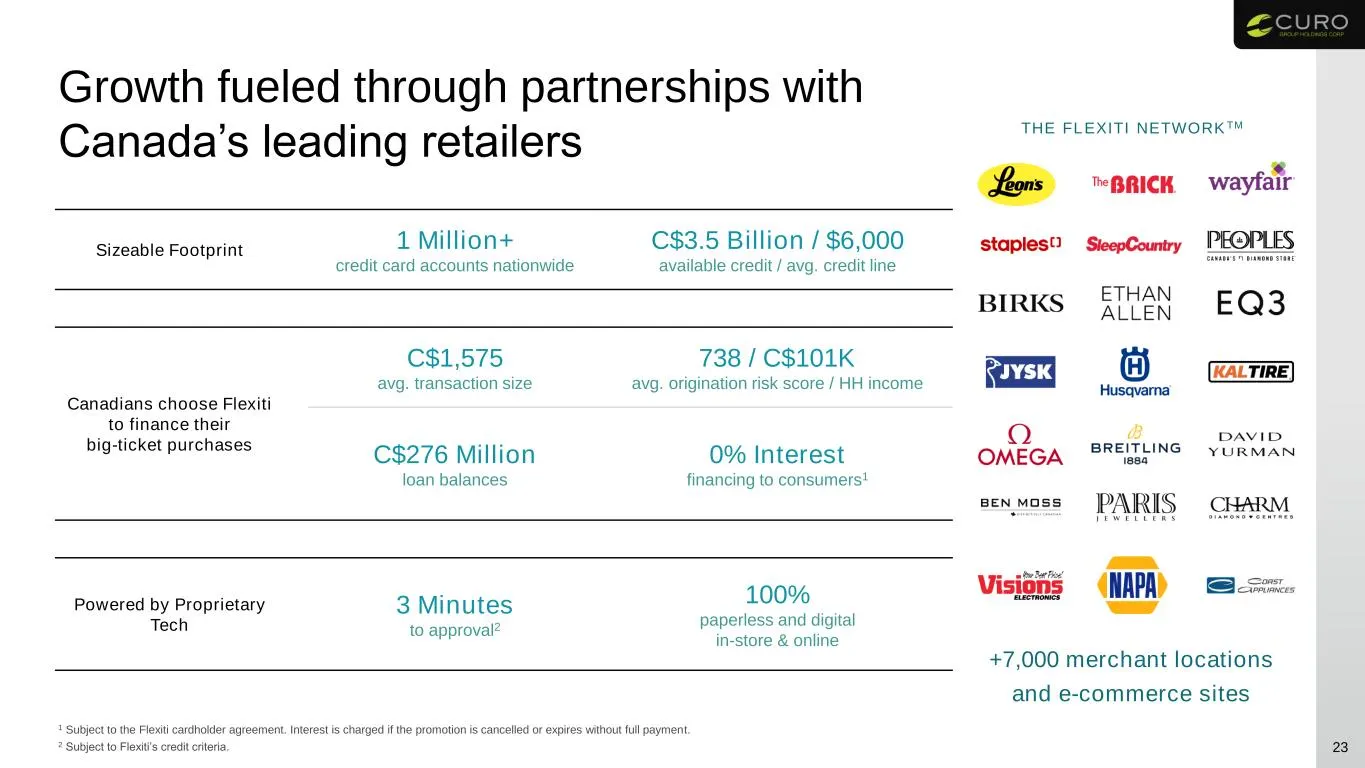
Slide 23: Growth fueled through partnerships with Canada's leading retailers
23 Growth fueled through partnerships with Canada’s leading retailers Sizeable Footprint 1 Million+ credit card accounts nationwide C$3.5 Billion / $6,000 available credit / avg. credit line Canadians choose Flexiti to finance their big-ticket purchases C$1,575 avg. transaction size 738 / C$101K avg
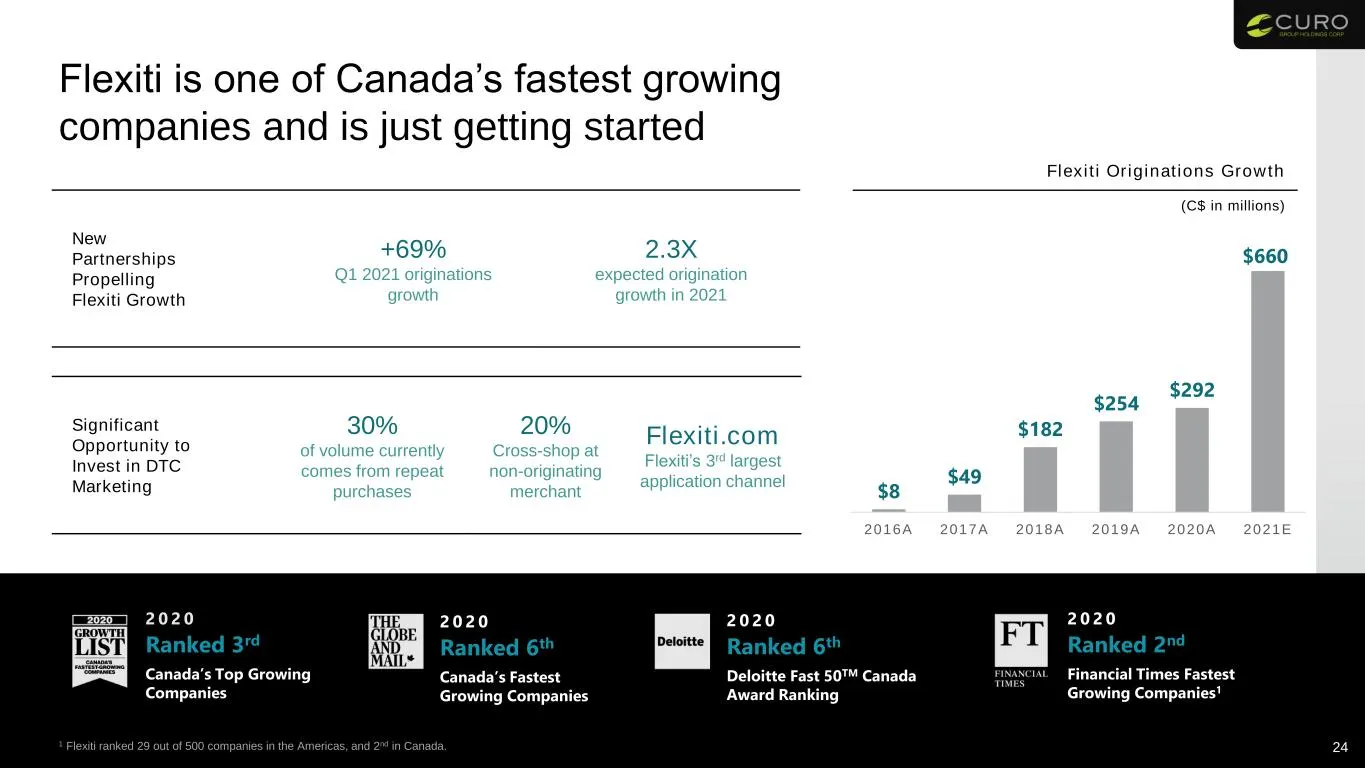
Slide 24: Flexiti is one of Canada's fastest growing companies
24 Flexiti is one of Canada’s fastest growing companies and is just getting started New Partnerships Propelling Flexiti Growth +69% Q1 2021 originations growth 2.3X expected origination growth in 2021 Significant Opportunity to Invest in DTC Marketing 30% of volume currently comes from repeat purcha
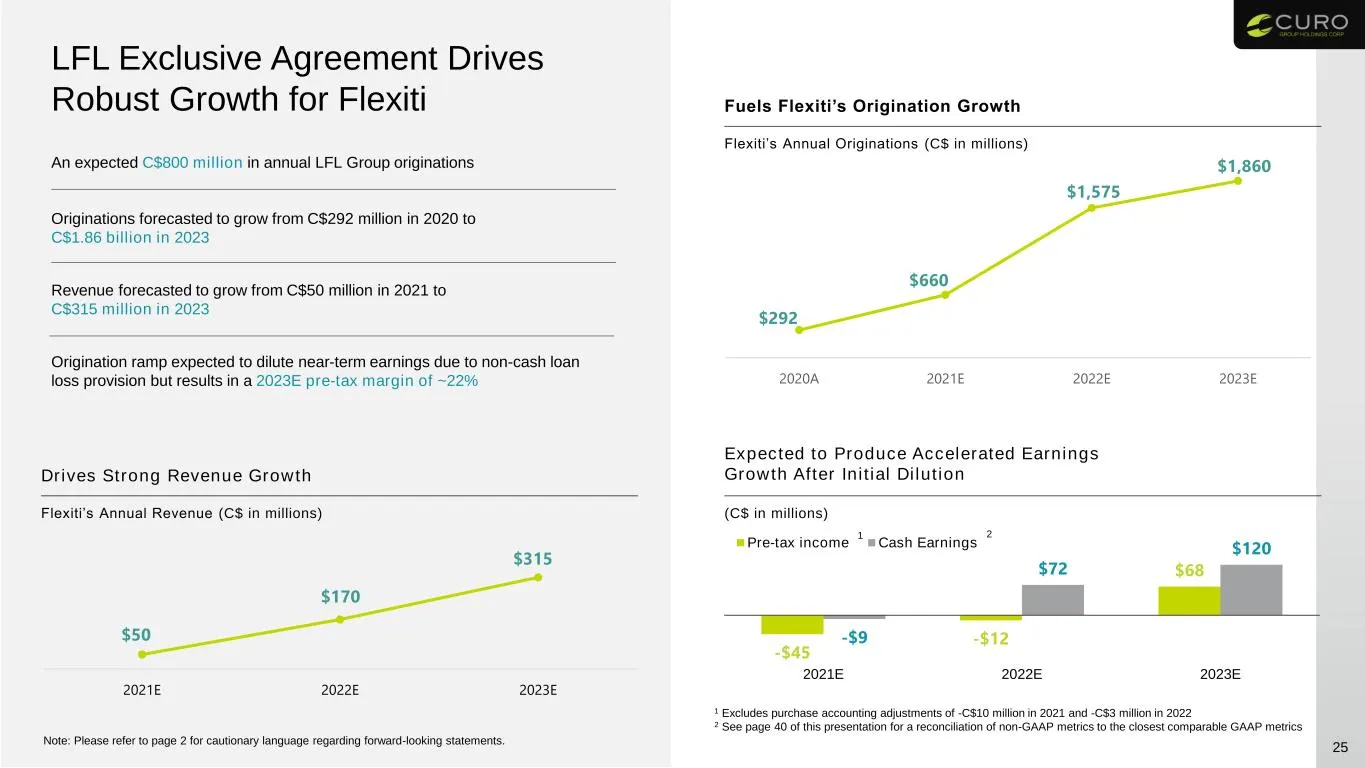
Slide 25: LFL Exclusive Agreement Drives Robust Growth for Flexiti
25 LFL Exclusive Agreement Drives Robust Growth for Flexiti An expected C$800 million in annual LFL Group originations Originations forecasted to grow from C$292 million in 2020 to C$1.86 billion in 2023 Revenue forecasted to grow from C$50 million in 2021 to C$315 million in 2023 Origination ramp e
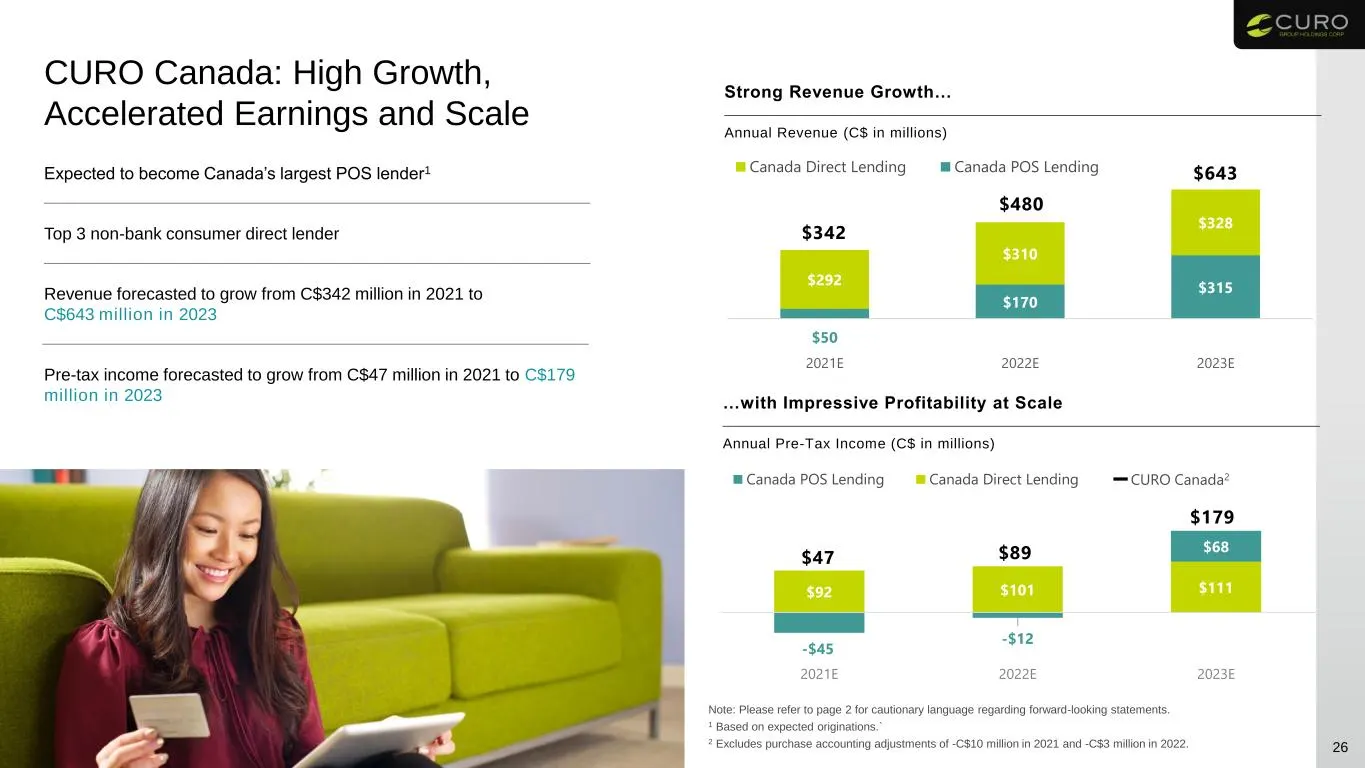
Slide 26: CURO Canada: High Growth, Accelerated Earnings and Scale
CURO Canada: High Growth, Accelerated Earnings and Scale 26 Expected to become Canada’s largest POS lender1 Top 3 non-bank consumer direct lender Revenue forecasted to grow from C$342 million in 2021 to C$643 million in 2023 Pre-tax income forecasted to grow from C$47 million in 2021 to C$179 millio
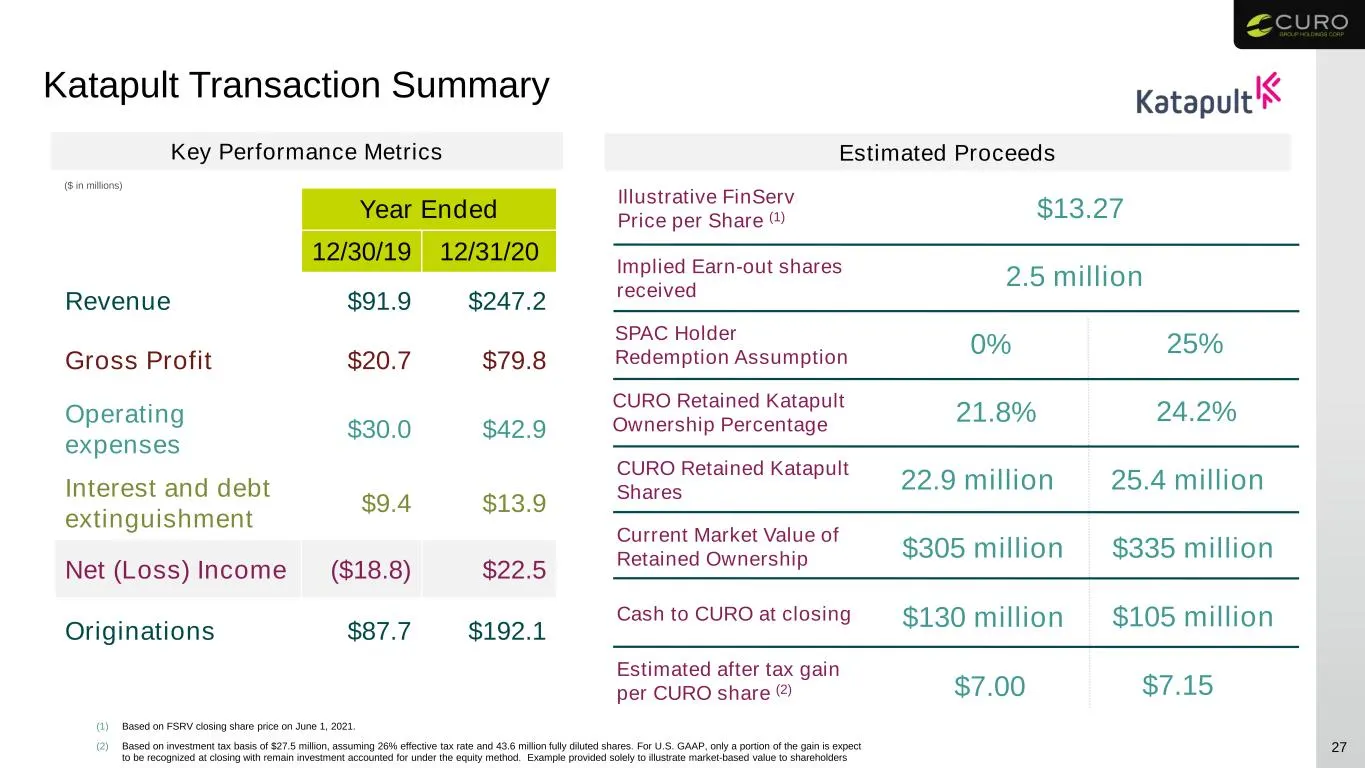
Slide 27: Katapult Transaction Summary
27 Katapult Transaction Summary Key Performance Metrics Illustrative FinServ Price per Share (1) $13.27 0% Estimated Proceeds SPAC Holder Redemption Assumption 25% Cash to CURO at closing $130 million $105 million CURO Retained Katapult Ownership Percentage 2.5 million Implied Earn-out shares receiv
Slide 28: Company Performance During COVID-19
28 Company Performance During COVID-19
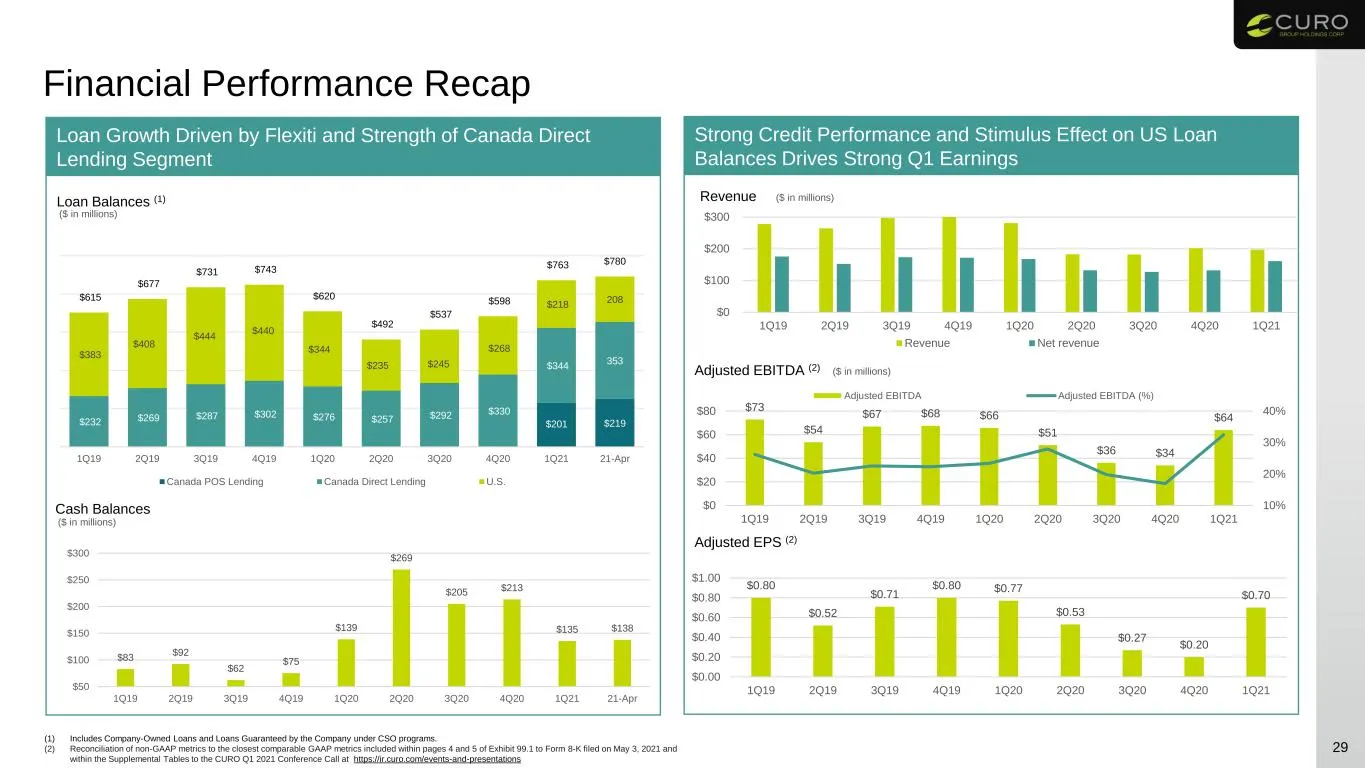
Slide 29: Strong Credit Performance and Stimulus Effect on US Loan Balances
Strong Credit Performance and Stimulus Effect on US Loan Balances Drives Strong Q1 Earnings 29 Revenue $0 $100 $200 $300 1Q19 2Q19 3Q19 4Q19 1Q20 2Q20 3Q20 4Q20 1Q21 Revenue Net revenue ($ in millions) Adjusted EBITDA (2) ($ in millions) $73 $54 $67 $68 $66 $51 $36 $34 $64 10% 20% 30% 40% $0 $20 $40
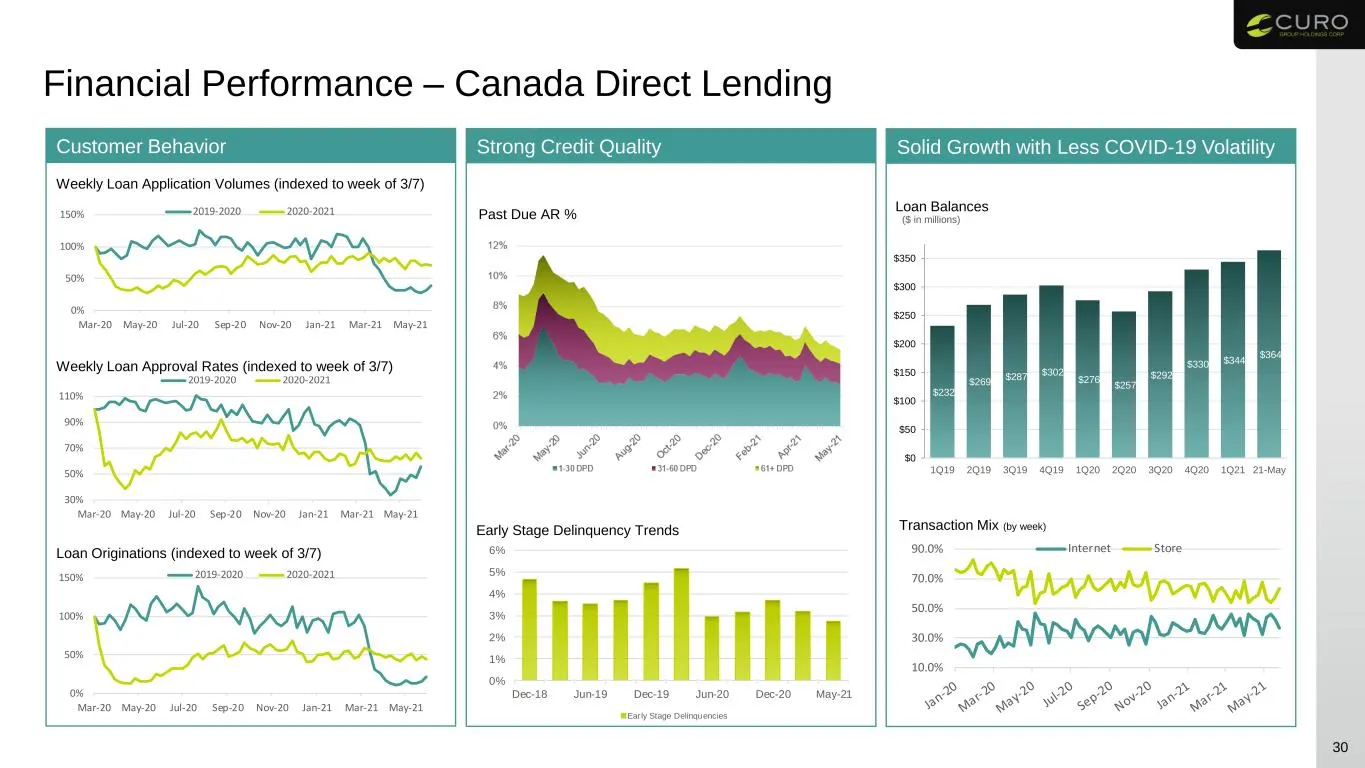
Slide 30: Financial Performance – Canada Direct Lending
Financial Performance – Canada Direct Lending 30 Transaction Mix (by week) $232 $269 $287 $302 $276 $257 $292 $330 $344 $364 $0 $50 $100 $150 $200 $250 $300 $350 1Q19 2Q19 3Q19 4Q19 1Q20 2Q20 3Q20 4Q20 1Q21 21-May Loan Balances ($ in millions) Early Stage Delinquency Trends Past Due AR % Customer Be
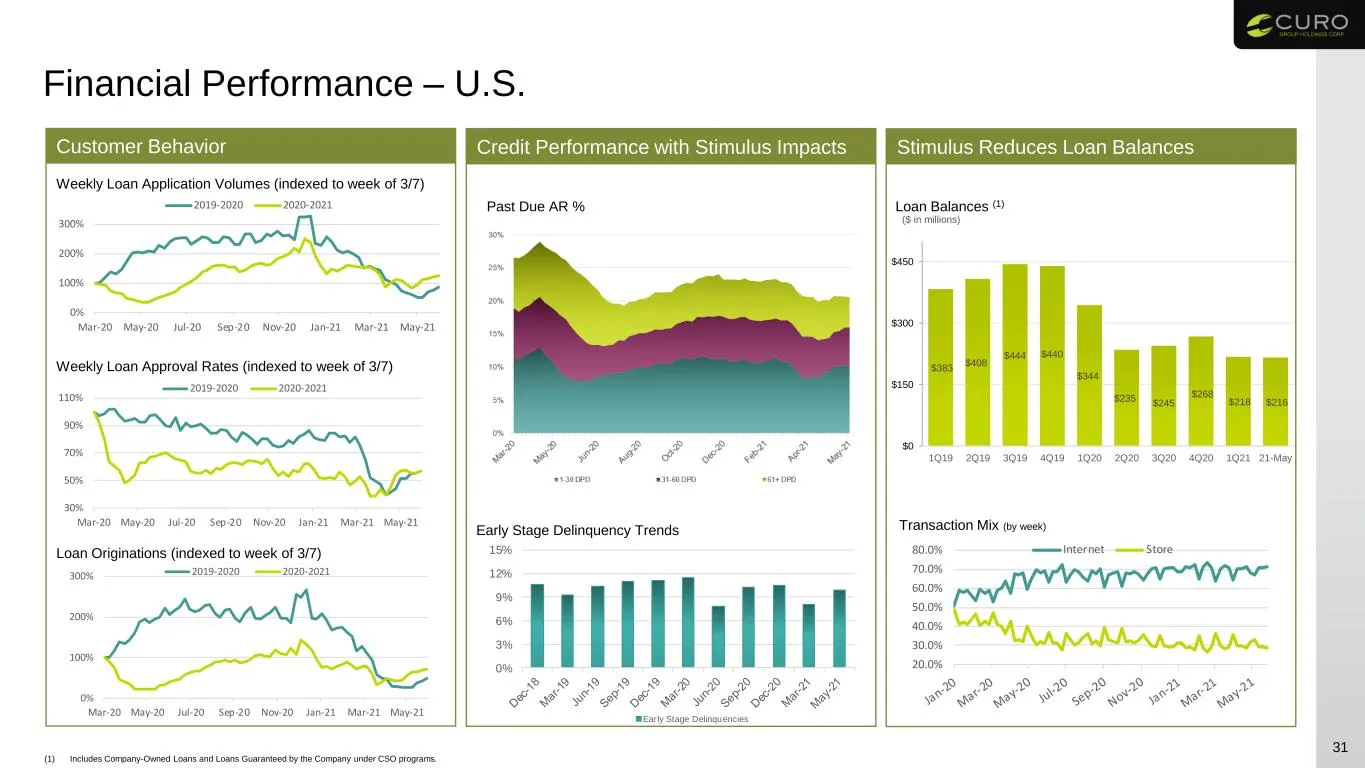
Slide 31: Financial Performance – U.S.
Financial Performance – U.S. 31 Transaction Mix (by week) Loan Balances (1) ($ in millions) Early Stage Delinquency Trends Past Due AR % Customer Behavior Weekly Loan Application Volumes (indexed to week of 3/7) Weekly Loan Approval Rates (indexed to week of 3/7) Loan Originations (indexed to week o
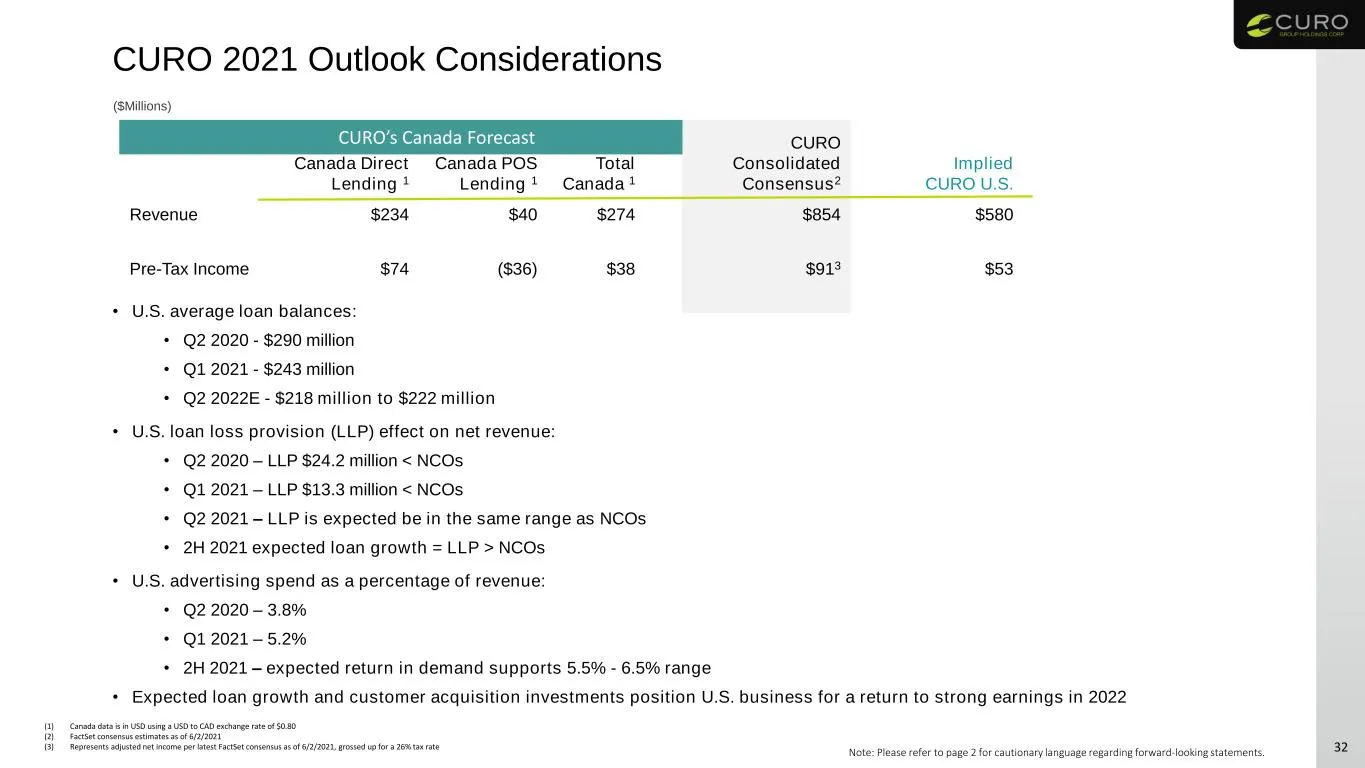
Slide 32: CURO 2021 Outlook Considerations
• U.S. average loan balances: • Q2 2020 - $290 million • Q1 2021 - $243 million • Q2 2022E - $218 million to $222 million • U.S. loan loss provision (LLP) effect on net revenue: • Q2 2020 – LLP $24.2 million < NCOs • Q1 2021 – LLP $13.3 million < NCOs • Q2 2021 – LLP is expected be in the same range
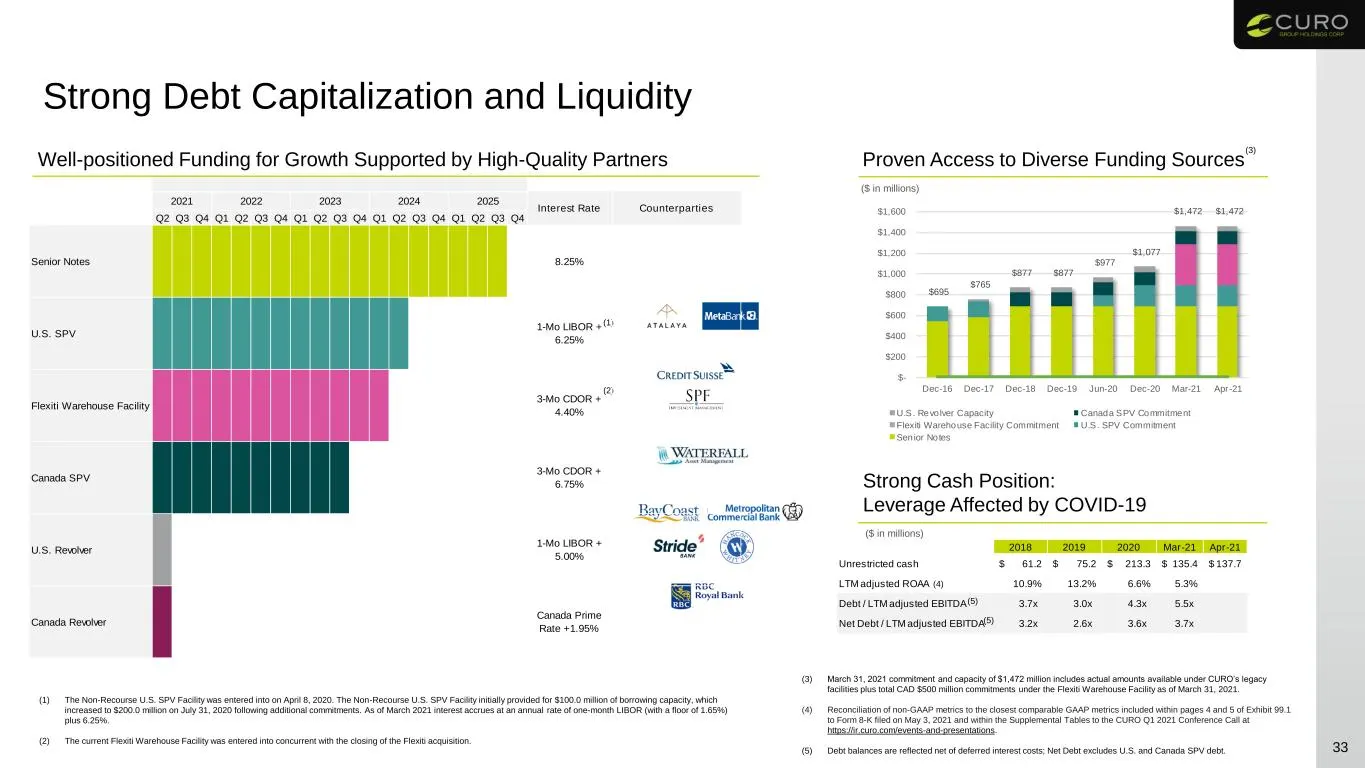
Slide 33: Strong Debt Capitalization and Liquidity
2018 2019 2020 Mar-21 Apr-21 Unrestricted cash 61.2$ 75.2$ 213.3$ 135.4$ 137.7$ LTM adjusted ROAA 10.9% 13.2% 6.6% 5.3% Debt / LTM adjusted EBITDA 3.7x 3.0x 4.3x 5.5x Net Debt / LTM adjusted EBITDA 3.2x 2.6x 3.6x 3.7x Strong Debt Capitalization and Liquidity 33 (3) March 31, 2021 commitment and capa
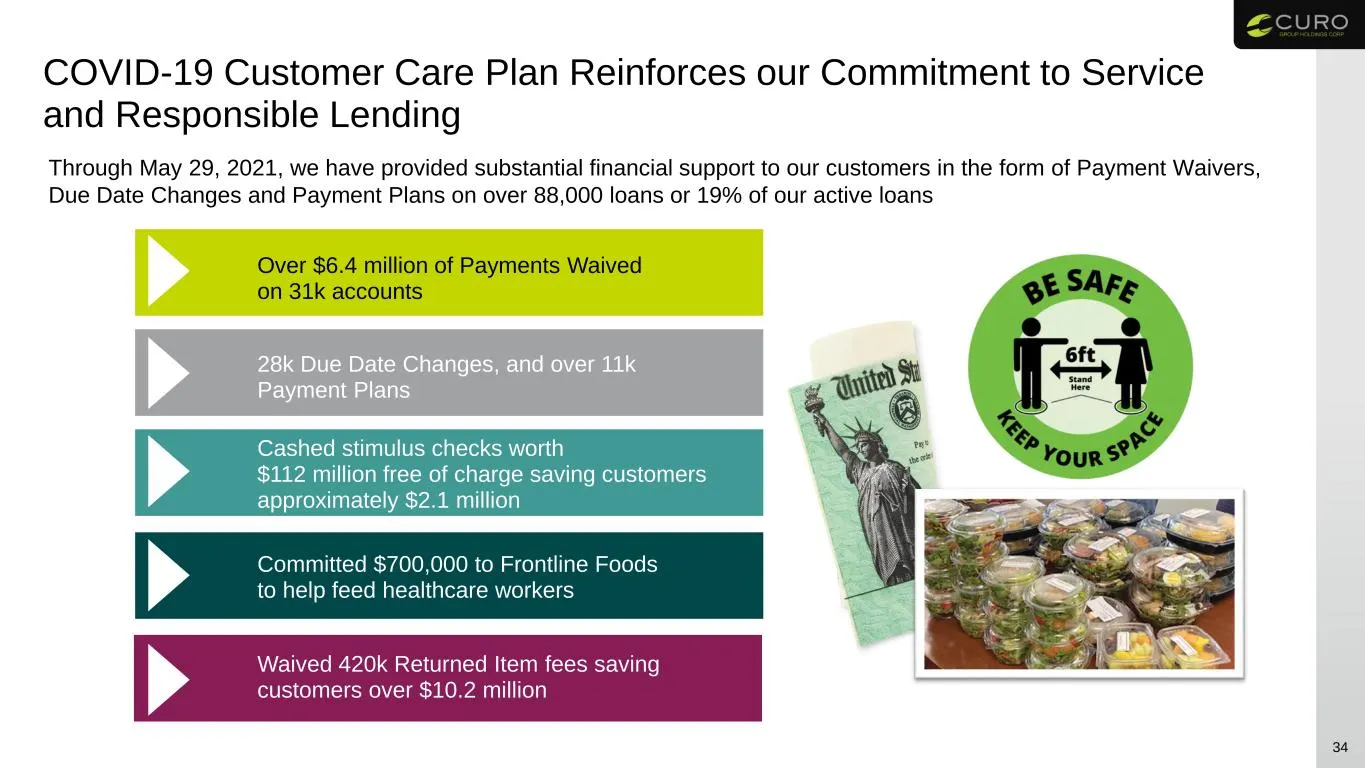
Slide 34: COVID-19 Customer Care Plan Reinforces our Commitment to Service
COVID-19 Customer Care Plan Reinforces our Commitment to Service and Responsible Lending 34 Through May 29, 2021, we have provided substantial financial support to our customers in the form of Payment Waivers, Due Date Changes and Payment Plans on over 88,000 loans or 19% of our active loans Over $6
Slide 35: Appendix
35 Appendix
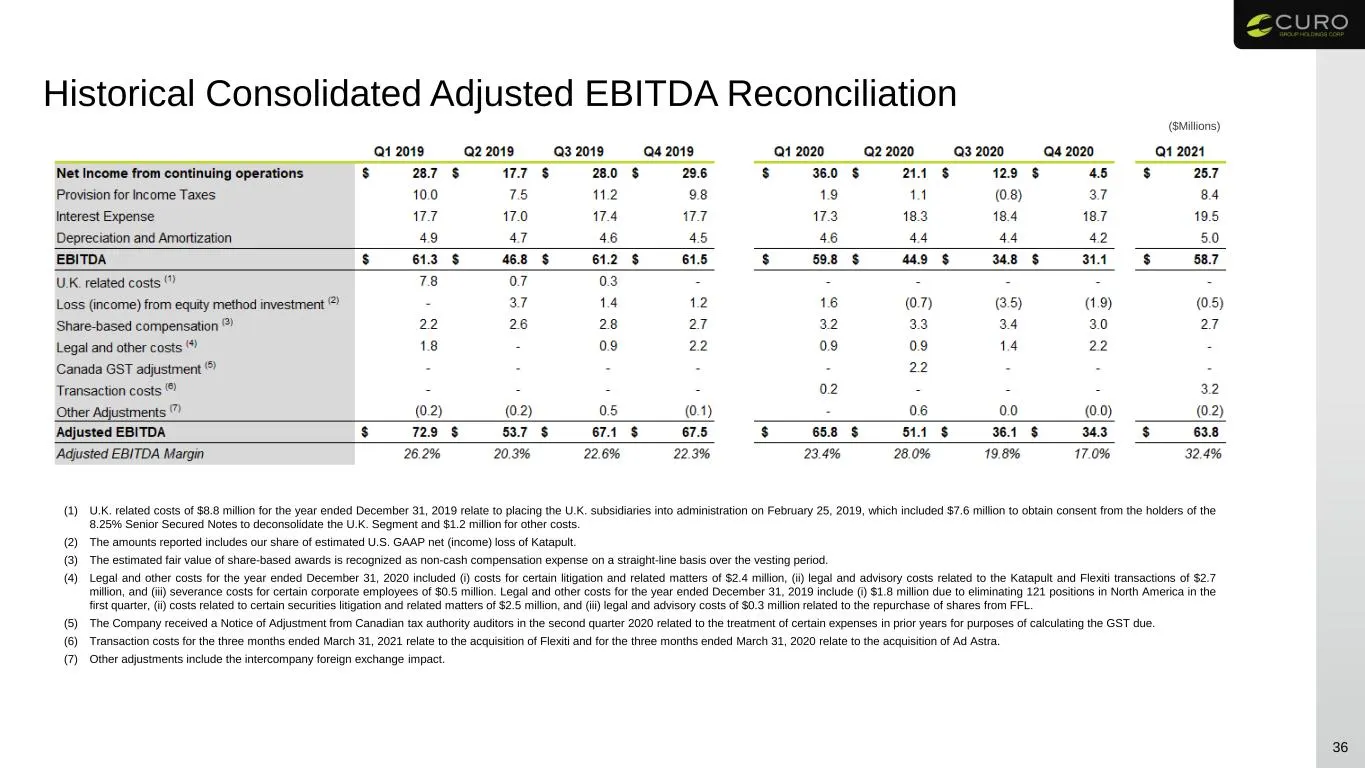
Slide 36: Historical Consolidated Adjusted EBITDA Reconciliation
Historical Consolidated Adjusted EBITDA Reconciliation 36 ($Millions) (1) U.K. related costs of $8.8 million for the year ended December 31, 2019 relate to placing the U.K. subsidiaries into administration on February 25, 2019, which included $7.6 million to obtain consent from the holders of the 8.
Slide 37: Historical Consolidated Adjusted Net Income Reconciliation
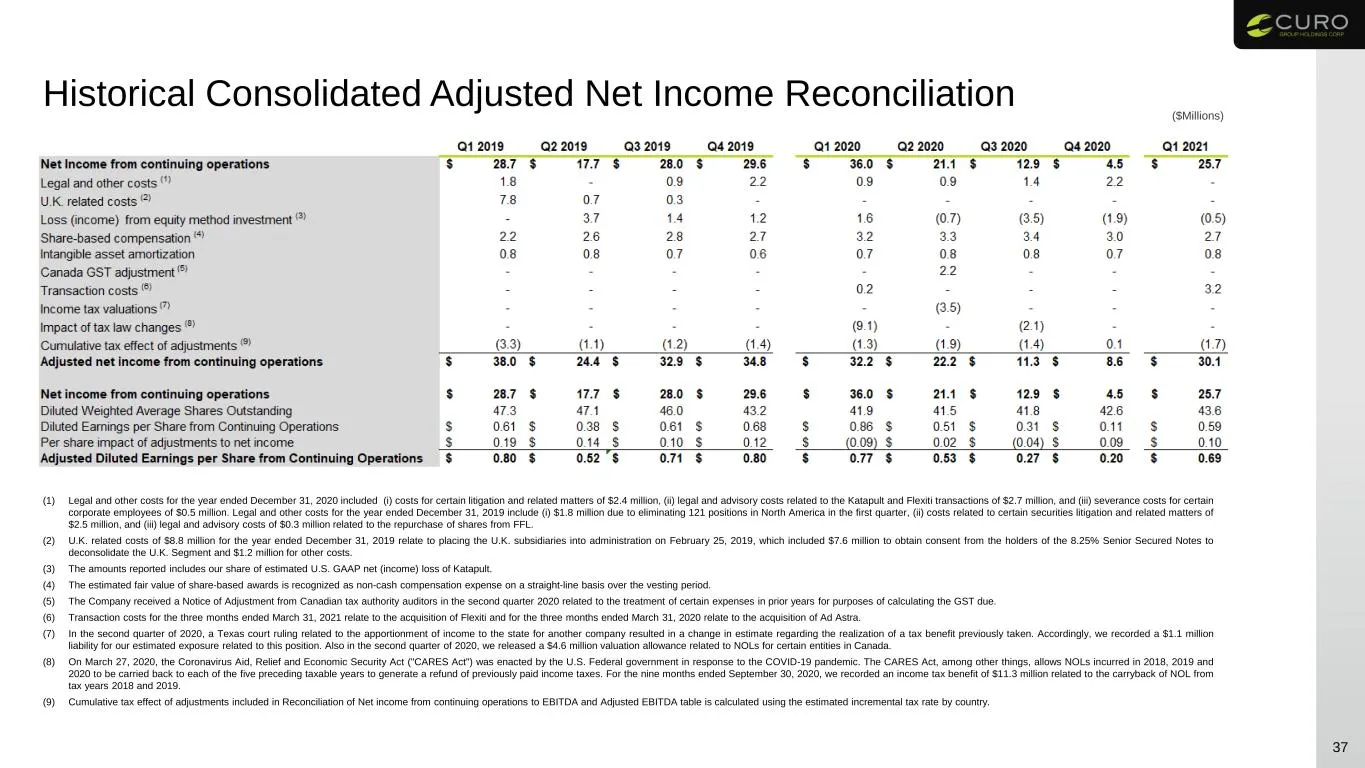
Historical Consolidated Adjusted Net Income Reconciliation 37 ($Millions) (1) Legal and other costs for the year ended December 31, 2020 included (i) costs for certain litigation and related matters of $2.4 million, (ii) legal and advisory costs related to the Katapult and Flexiti transactions of $2
Slide 38: Historical Gross Combined Loan Receivables and Adjusted ROAA Reconciliations
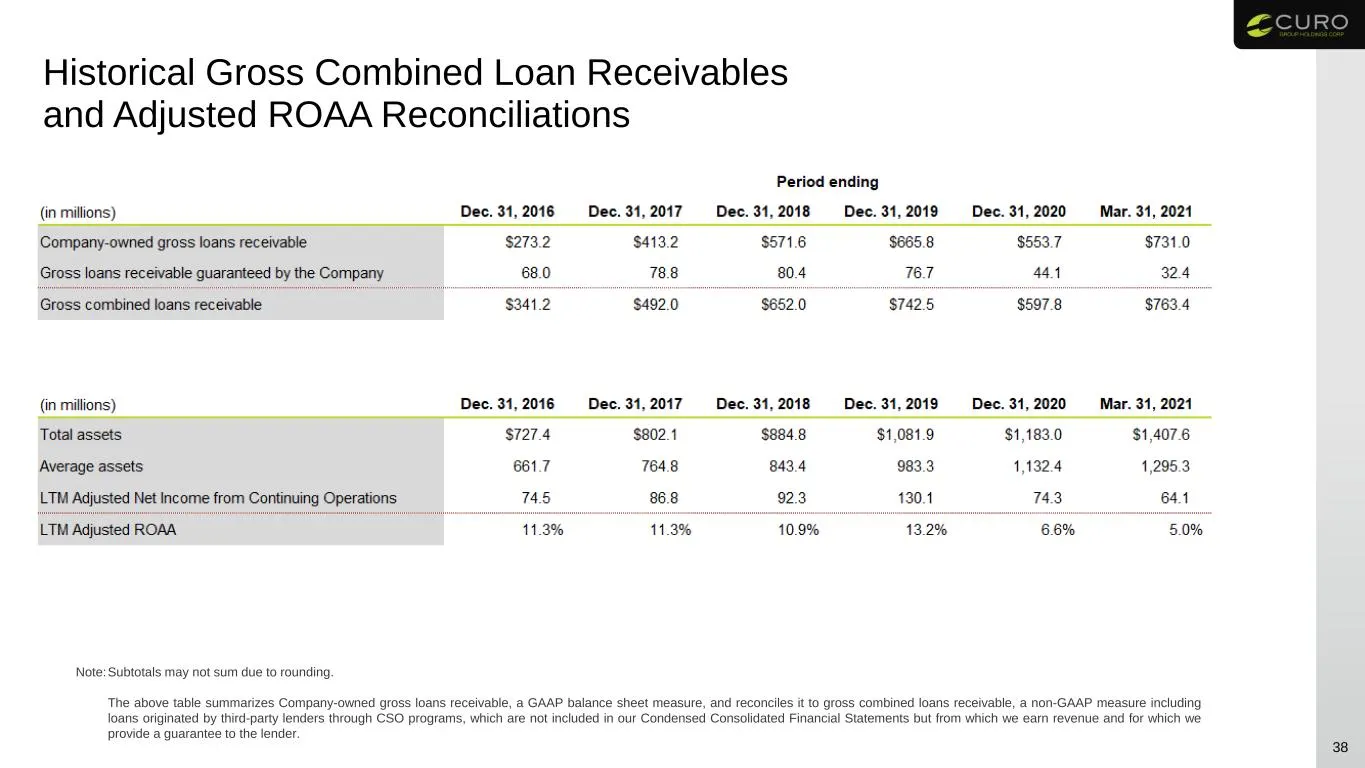
Historical Gross Combined Loan Receivables and Adjusted ROAA Reconciliations 38 Note:Subtotals may not sum due to rounding. The above table summarizes Company-owned gross loans receivable, a GAAP balance sheet measure, and reconciles it to gross combined loans receivable, a non-GAAP measure includin
Slide 39: Core Operating Expense Reconciliation
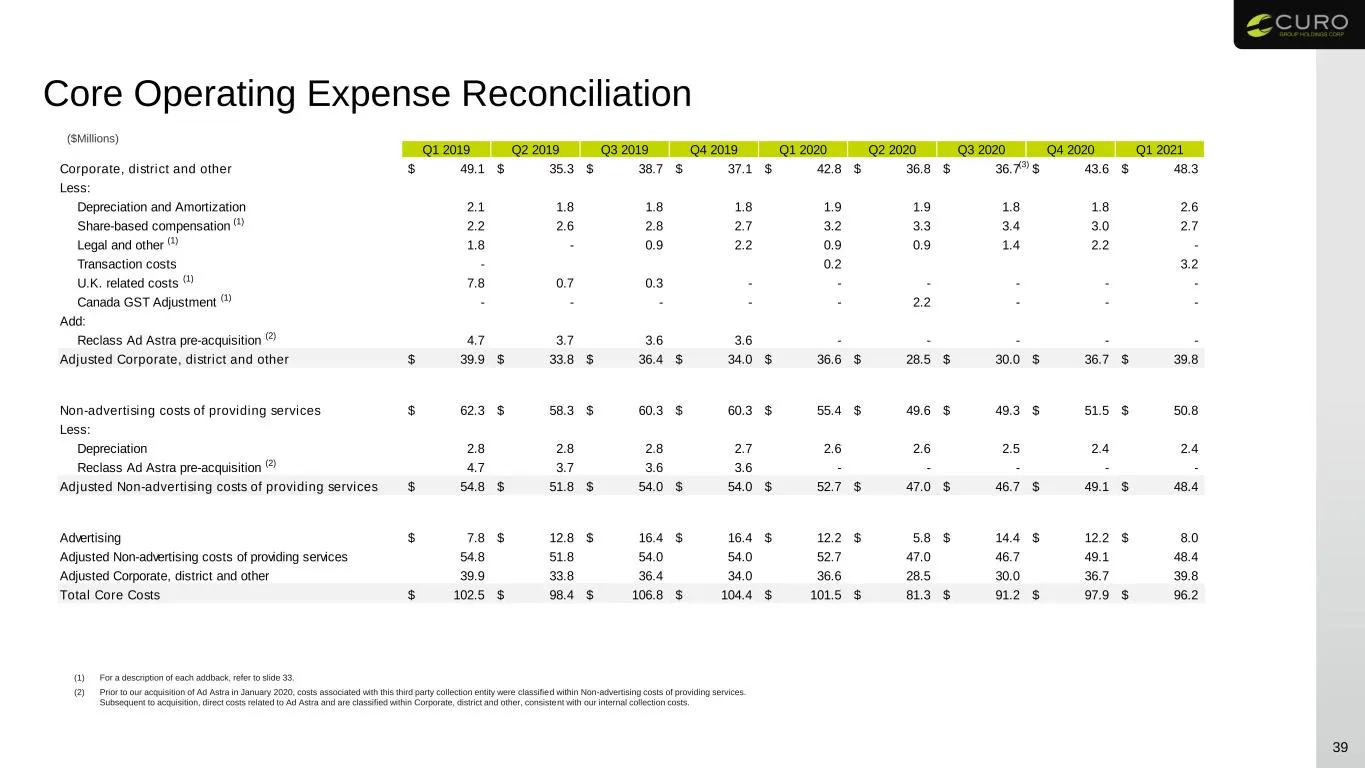
Core Operating Expense Reconciliation 39 (1) For a description of each addback, refer to slide 33. (2) Prior to our acquisition of Ad Astra in January 2020, costs associated with this third party collection entity were classified within Non-advertising costs of providing services. Subsequent to acqu
Slide 40: Canada POS Cash Earnings Reconciliation
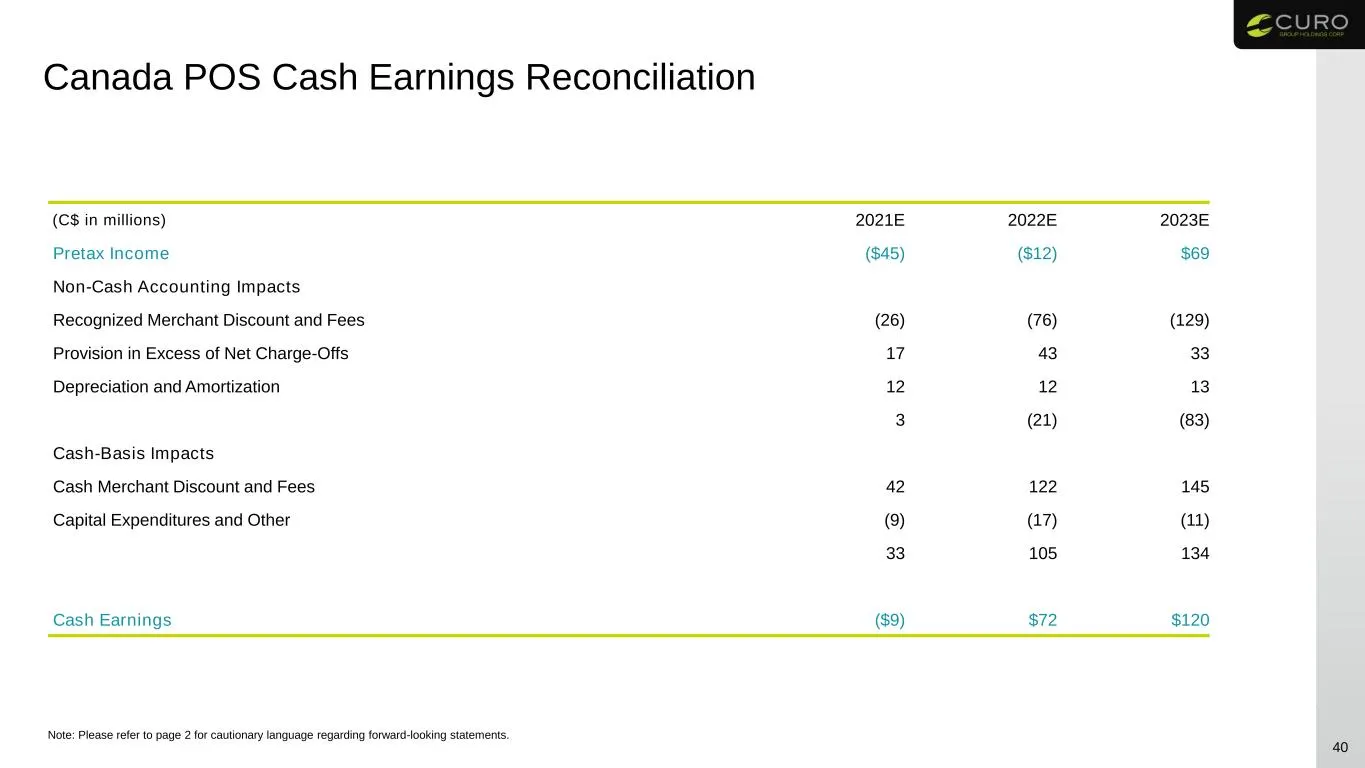
40 (C$ in millions) 2021E 2022E 2023E Pretax Income ($45) ($12) $69 Non-Cash Accounting Impacts Recognized Merchant Discount and Fees (26) (76) (129) Provision in Excess of Net Charge-Offs 17 43 33 Depreciation and Amortization 12 12 13 3 (21) (83) Cash-Basis Impacts Cash Merchant Discount and Fees
Source: SEC EDGAR · 8-K filed Jun 3, 2021
More decks from Curo Group Holdings Corp
 Q4 2023 Earnings Presentation21 slides · Feb 12, 2024
 Investor Presentation (November 2023)15 slides · Nov 13, 2023
 Q3 2023 Earnings Presentation20 slides · Nov 2, 2023
 Debt Investor Presentation (October 2023)21 slides · Oct 23, 2023
 Investor Presentation (September 2023)15 slides · Sep 25, 2023
 Q2 2023 Earnings Presentation21 slides · Aug 3, 2023