TC PipeLines LP — The Master Limited Partnership Investor Conference 2004
19 slides from TC PipeLines LP's conference presentation, Mar 2, 2004
Slide 1: The Master Limited Partnership Investor Conference
The Master Limited Partnership Investor Conference March 2, 2004 Ron Turner, President & CEO (@) TC PipeLines, LP
Slide 2: Forward Looking Information
Forward Looking Information This presentation includes forward-looking statements regarding future events and the future financial performance of TC PipeLines, LP. Words such as “believes”, “expects”, “intends”, “forecasts”, “projects”, and similar expressions, identify forward-looking statements wi
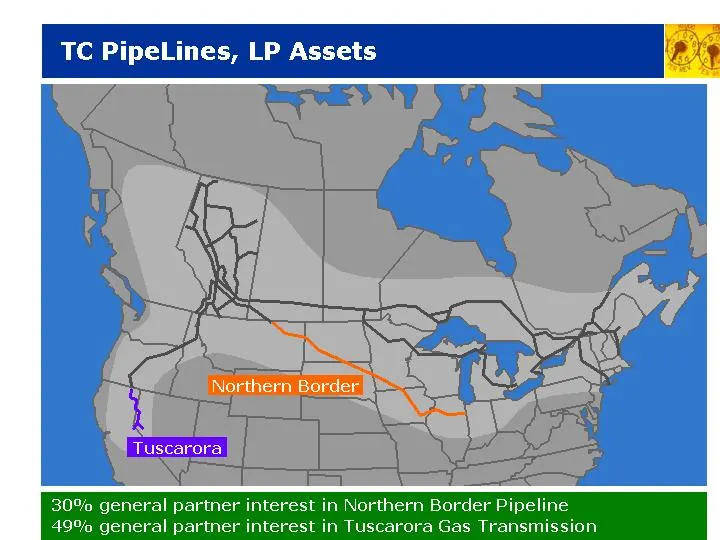
Slide 3: Tuscarora
Tuscarora = MY TC PipeLines,
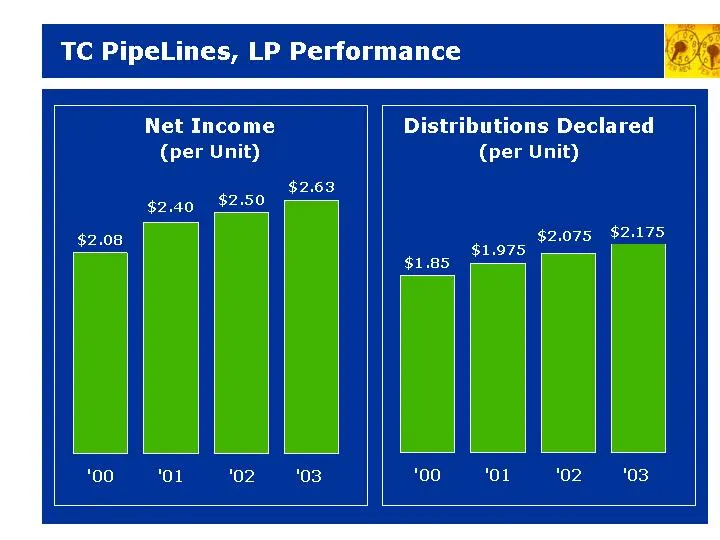
Slide 4: Performance
TC PipeLines, LP Performance Net Income Distributions Declared (per Unit) (per Unit) $2,075 $2.175 1,975 / j ; ; ‘00. ‘Ol ‘02 ‘03
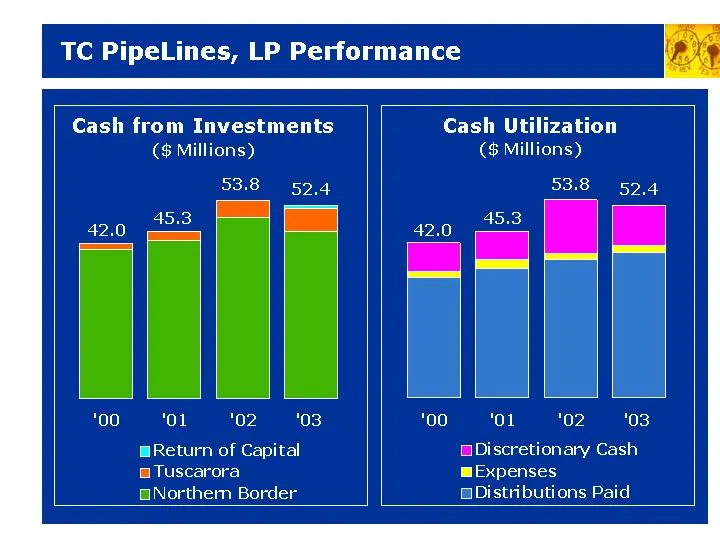
Slide 5: Performance
TC PipeLines, LP Performance Cash from Investments Cash Utilization ($ Millions) ($ Millions) 53.8 52.4 ‘00 ‘Ol ‘02 mReturn of Capital Discretionary Cash Tuscarora Expenses BNorthem Border Distributions Paid
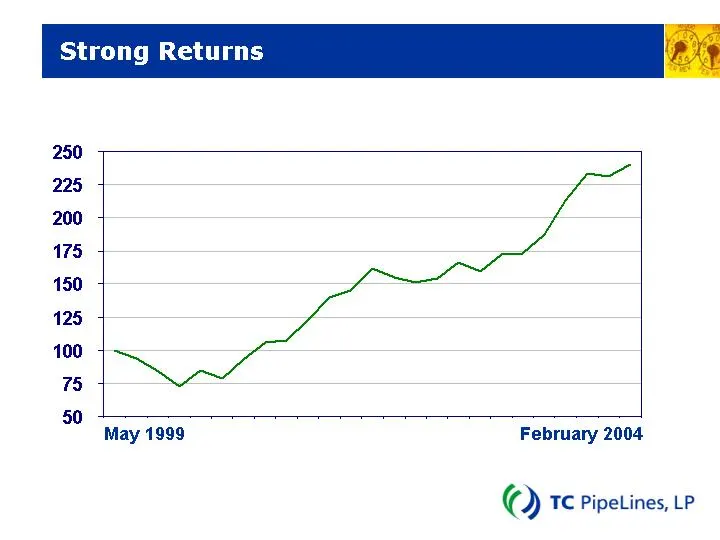
Slide 6: Strong Returns
Strong Returns 250 225 200 175 150 125 100 75 50 May 1999 February 2004 (2) TC Pipelines, LP
Slide 7: Yield Comparison
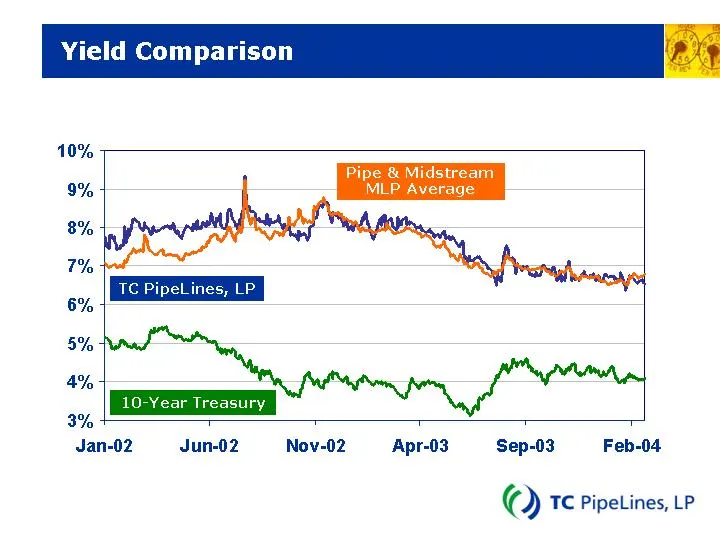
Yield Comparison la 10% 9% 8% 7% ‘ 6% 5% 4% 10-Year Treasury 3% Jan-02 Jun-02 Nov-02 Apr-03 Sep-03 Feb-04 (@) TC PipeLines, LP
Slide 8: Focus on natural gas transmission assets
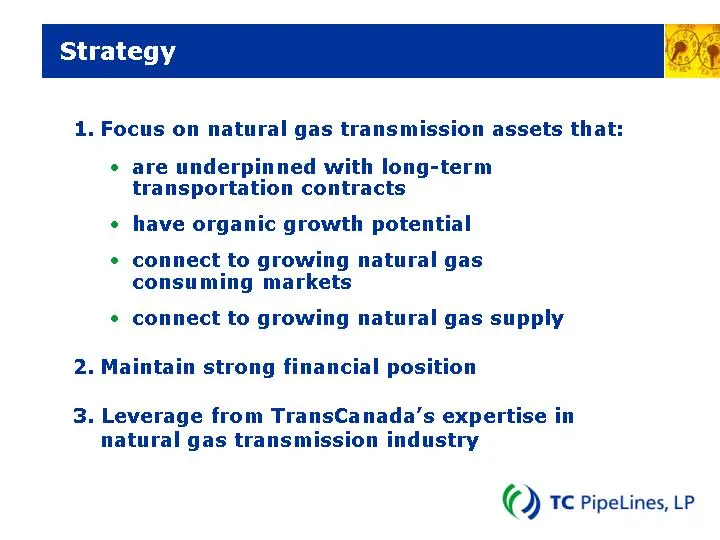
1. Focus on natural gas transmission assets that: ¢ are underpinned with long-term transportation contracts ¢ have organic growth potential ¢ connect to growing natural gas consuming markets ¢ connect to growing natural gas supply 2. Maintain strong financial position 3. Leverage from TransCanada’s
Slide 9: Northern Border, Great Lakes, Iroquois and other pipelines
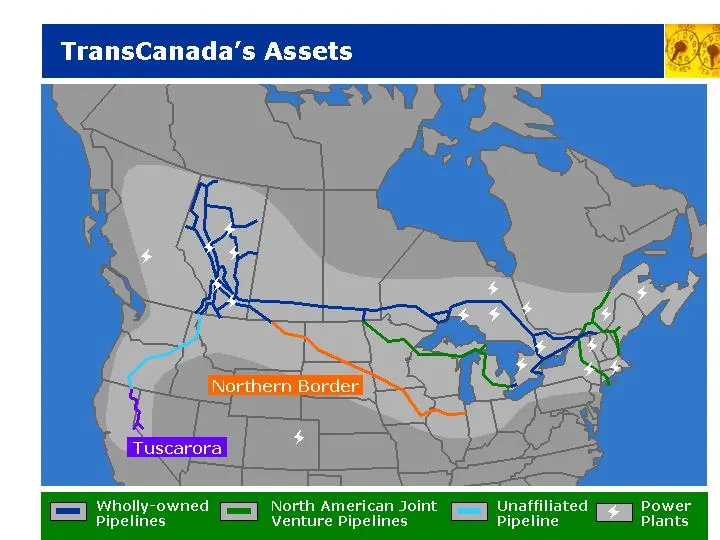
Ne i Northern Border North American J Venture Pipelines Plants
Slide 10: Gas Demand (Bcf/d)
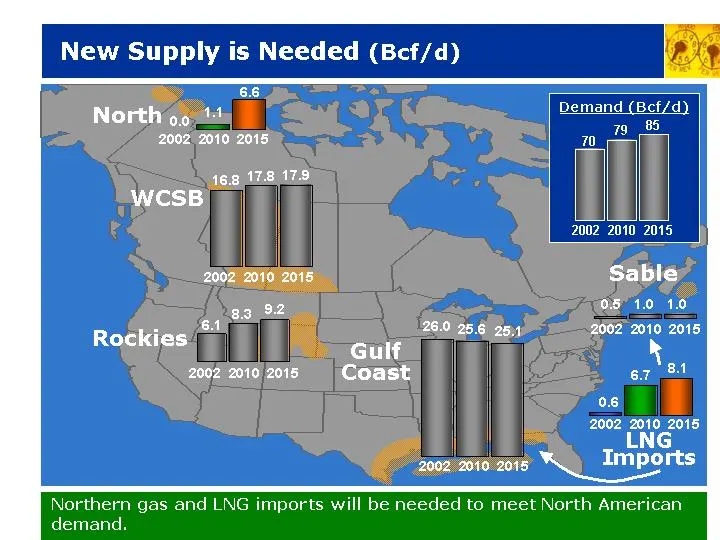
Slide 11: New Supply is Needed (Bcf/d)
New Supply is Needed (Bcf/d)
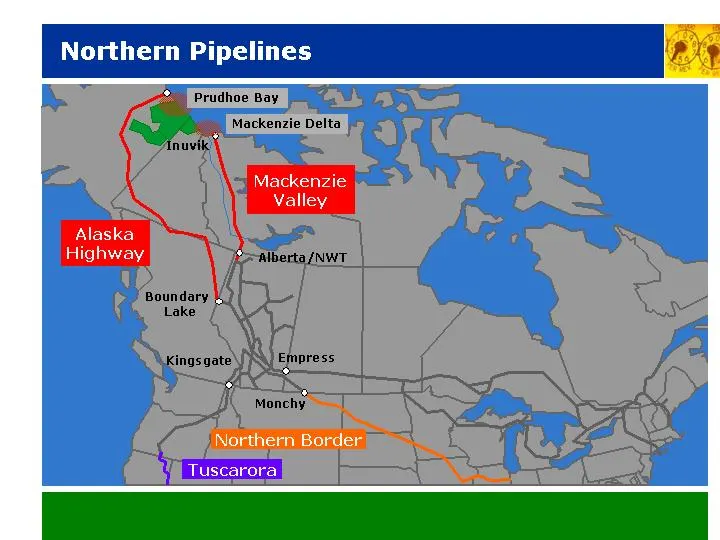
Slide 12: Northern Pipelines
Northern Pipelines ‘Prudhoe Bay (= ‘Mackenzie Delta Tuscarora
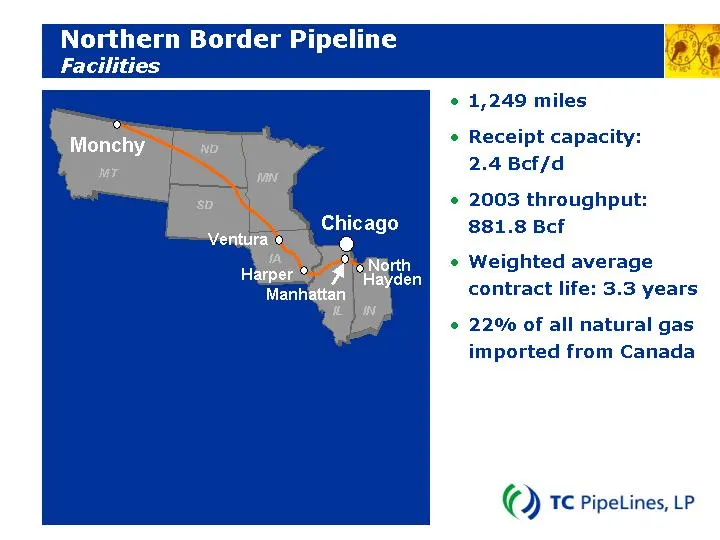
Slide 13: Northern Border Pipeline
Northern Border Pipel Facilities Chicago 1,249 miles Receipt capacity: 2.4 Bcf/d 2003 throughput: 881.8 Bcf Weighted average contract life: 3.3 years 22% of all natural gas imported from Canada (@) TC PipeLines, LP
Slide 14: Re-contracting, Recapitalization, PUHCA
e Re-contracting e Recapitalization « PUHCA (2) TC Pipelines, LP
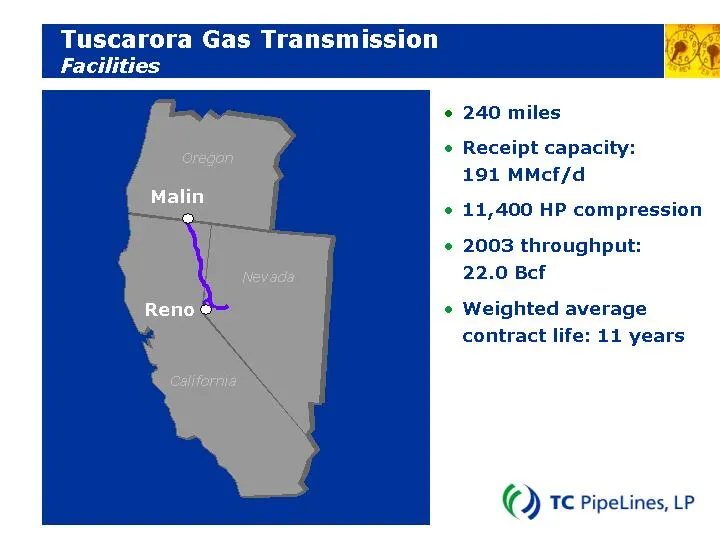
Slide 15: Tuscarora Gas Transmission
Tuscar Gas Transmission Facilities ¢ 240 miles « Receipt capacity: 191 MMcf/d e¢ 11,400 HP compression e¢ 2003 throughput: 22.0 Bcf e¢ Weighted average contract life: 11 years (@) TC PipeLines, LP
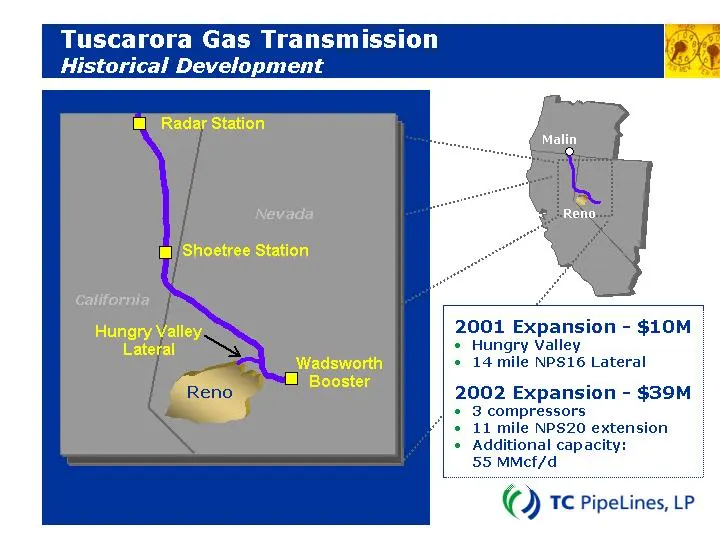
Slide 16: Tuscarora Gas Transmission Historical Development
Tusc Gas Transm Historical Development 2001 Expansion - $10M * Hungry Valley * 14 mile NPS16 Lateral 2002 Expansion - $39M * 3 compressors 11 mile NPS20 extension * Additional capacity: 55 MMcf/d (@) TC Pipelines, ip:
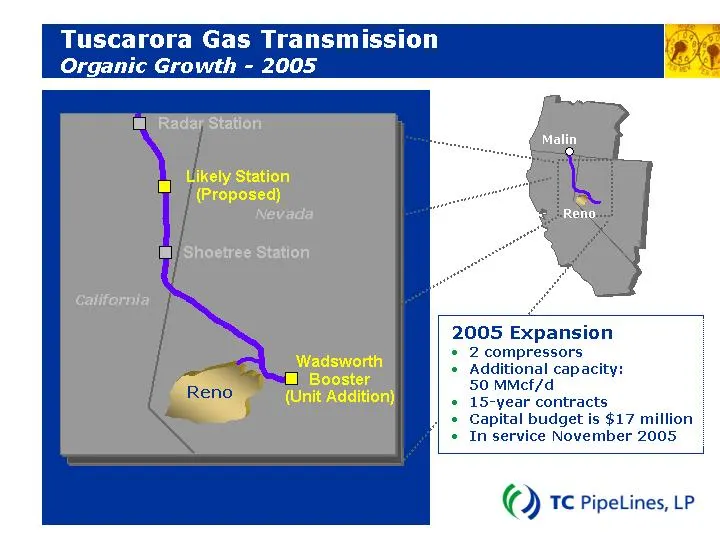
Slide 17: Tuscarora Organic Growth - 2005
Tusc Gas Transm Organic Growth - 2005 ——— 2005 Expansion * 2 compressors * Additional capacity: 50 MMcf/d * 15-year contracts || © Capital budget is $17 million * Inservice November 2005 (@) TC Pipelines, LP
Slide 18: Well positioned assets
¢ Well positioned assets ¢ Solid cash flow coverages e Attractive yield ¢ General partner is recognized for expertise in natural gas transmission industry ¢ Disciplined growth strategy (2) TC Pipelines, LP
Slide 19: Searchable text section of graphics
Searchable text section of graphics shown above The Master Limited Partnership Investor Conference March 2, 2004 Ron Turner, President & CEO [LOGO] [ GRA PHIC] Forward Looking Information This presentation includes forward-looking statements regarding future events and the future financial performan
Source: SEC EDGAR · 8-K filed Mar 2, 2004