Mead Johnson Nutrition — Barclays Capital Back-to-School Consumer Conference 2012
39 slides from Mead Johnson Nutrition's conference presentation, Sep 5, 2012
Slide 1: Barclays Capital Back-to-School Consumer Conference
Barclays Capital Back-to-School Consumer Conference September 6, 2012 Boston Pete Leemputte Executive Vice President and CFO Steve Golsby President and Chief Executive Officer
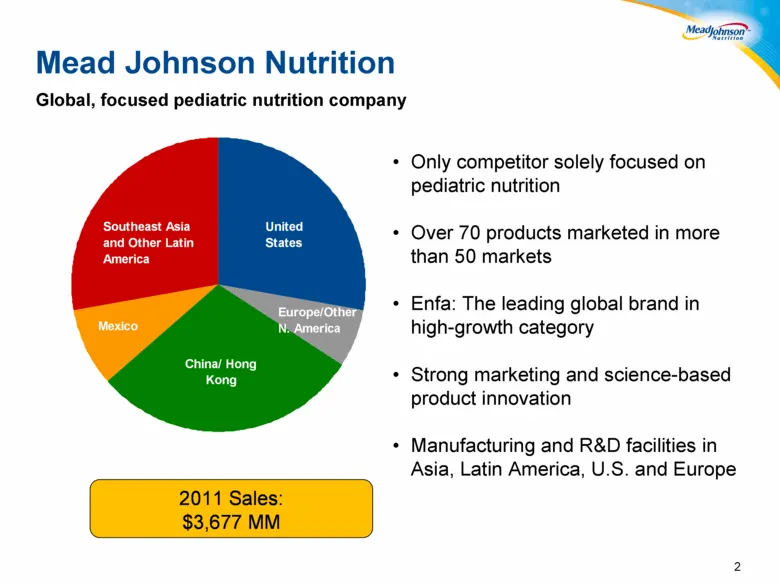
Slide 2: Global, focused pediatric nutrition company
2 2 Only competitor solely focused on pediatric nutrition Over 70 products marketed in more than 50 markets Enfa: The leading global brand in high-growth category Strong marketing and science-based product innovation Manufacturing and R&D facilities in Asia, Latin America, U.S. and Europe Mead Johns
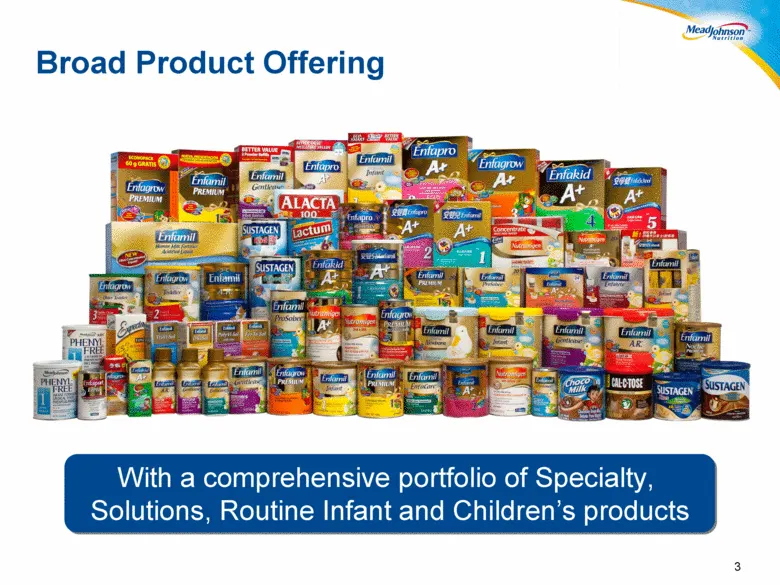
Slide 3: Broad Product Offering
3 With a comprehensive portfolio of Specialty, Solutions, Routine Infant and Children’s products Broad Product Offering
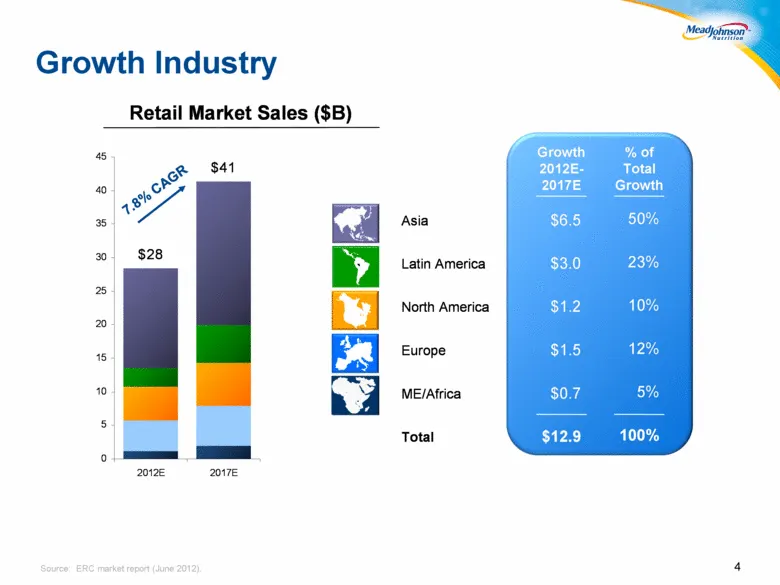
Slide 4: Growth Industry
4 Source: ERC market report (June 2012). Growth Industry $28 $41 0 5 10 15 20 25 30 35 40 45 2012 E 2017 E Asia Latin America North America Europe ME/Africa Total $6.5 $3.0 $1.2 $1.5 $0.7 $12.9 Growth 2012E - 2017E ` ` ` 50% 23% 10% 12% 5% 100% % of Total Growth Retail Market Sales ($B) Retail Marke
Slide 5: Key Drivers of Long Term Growth
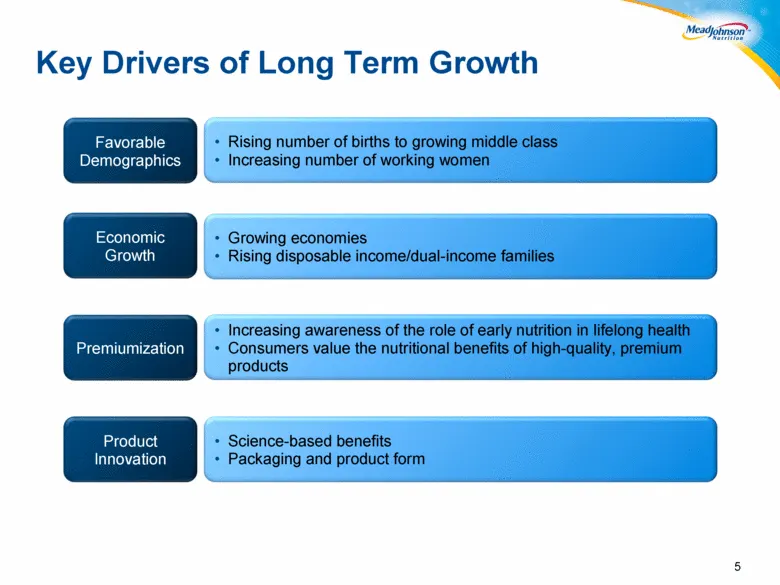
5 5 Premiumization Product Innovation Economic Growth Favorable Demographics Growing economies Rising disposable income/dual-income families Increasing awareness of the role of early nutrition in lifelong health Consumers value the nutritional benefits of high-quality, premium products Science-based
Slide 6: Key Growth Driving Trends
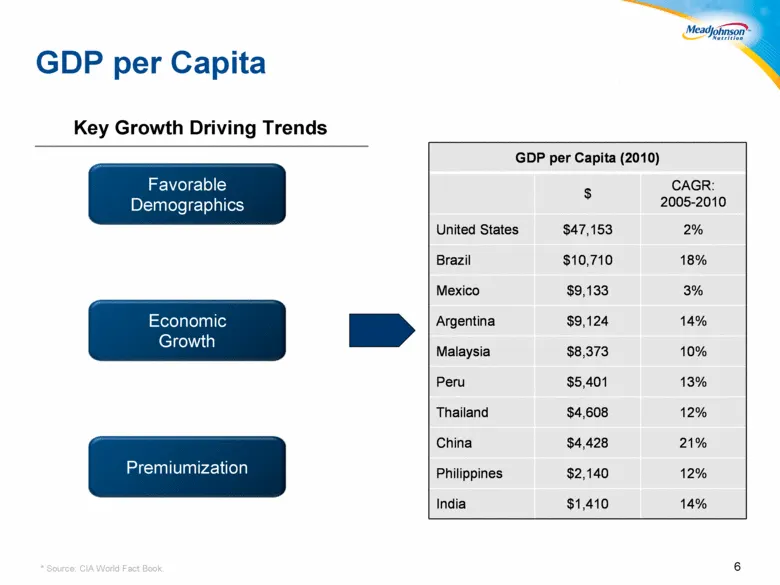
6 6 * Source: CIA World Fact Book. Favorable Demographics Premiumization Economic Growth Key Growth Driving Trends GDP per Capita GDP per Capita (2010) $ CAGR: 2005 - 2010 United States $47,153 2% Brazil $10,710 18% Mexico $9,133 3% Argentina $9,124 14% Malaysia $8,373 10% Peru $5,401 13% Thailand $
Slide 7: Focus on Premium Segment
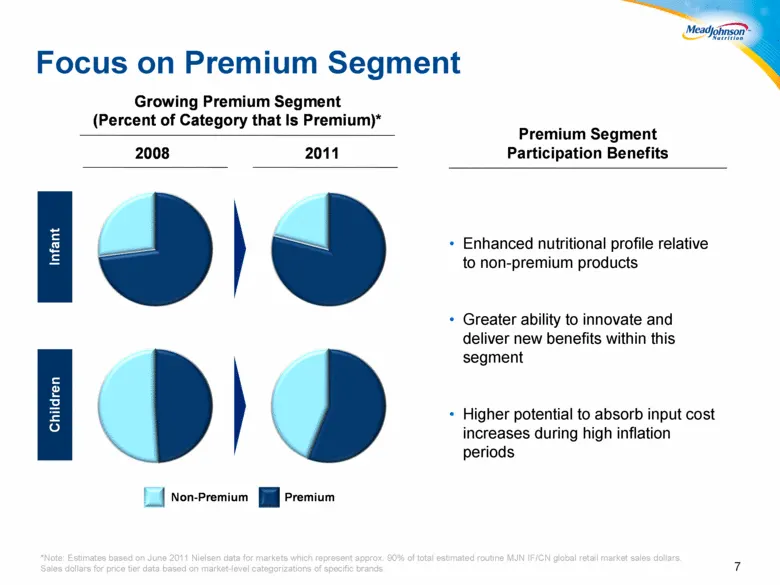
7 Enhanced nutritional profile relative to non-premium products Greater ability to innovate and deliver new benefits within this segment Higher potential to absorb input cost increases during high inflation periods Premium Segment Participation Benefits *Note: Estimates based on June 2011 Nielsen da
Slide 8: Births and Industry Consumption
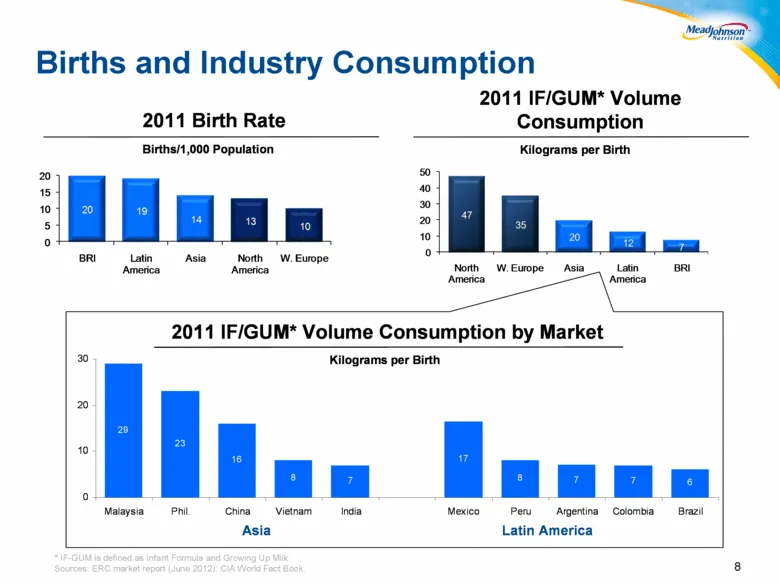
8 8 Births and Industry Consumption * IF-GUM is defined as Infant Formula and Growing Up Milk Sources: ERC market report (June 2012); CIA World Fact Book. 2011 IF/GUM* Volume Consumption Kilograms per Birth 47 35 20 12 7 0 10 20 30 40 50 North America W. Europe Asia Latin America BRI 2011 Birth Rate
Slide 9: Scientific Research Drives Innovation
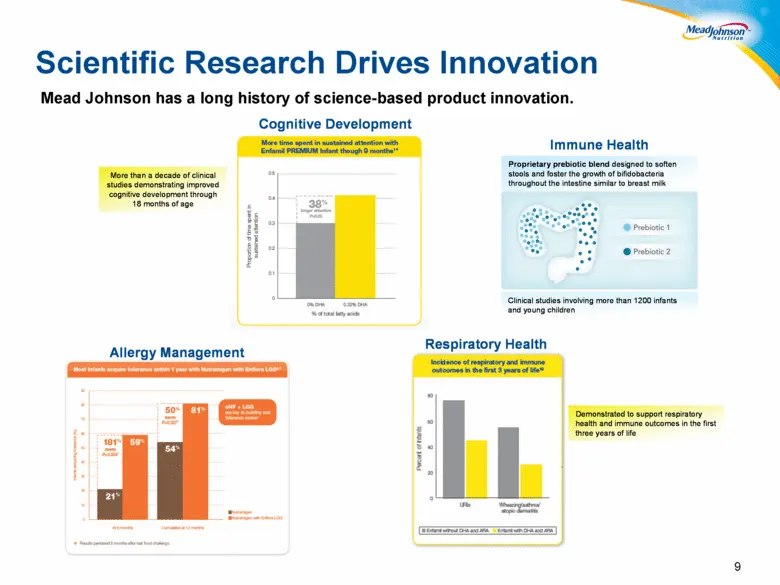
Scientific Research Drives Innovation Mead Johnson has a long history of science-based product innovation. 9 Respiratory Health Immune Health Allergy Management Cognitive Development More than a decade of clinical studies demonstrating improved cognitive development through 18 months of age Propriet
Slide 10: Absolute Commitment to Quality
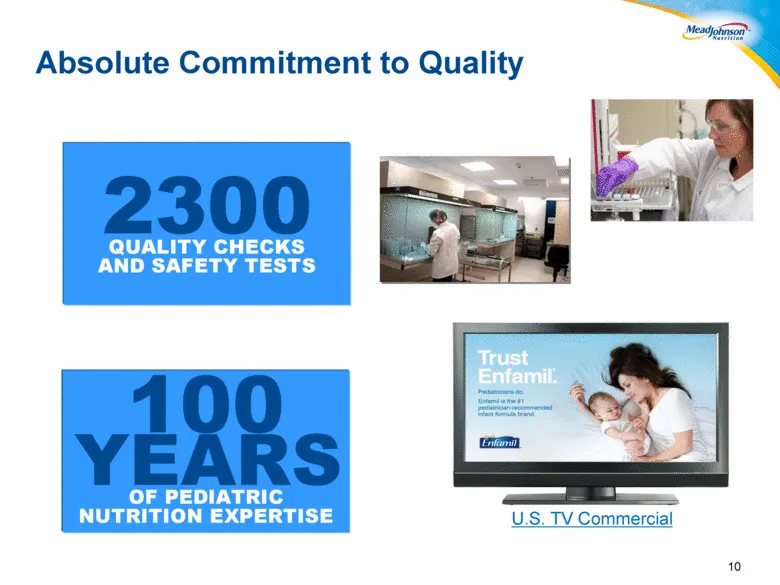
Absolute Commitment to Quality U.S. TV Commercial QUALITY CHECKS AND SAFETY TESTS 2300 OF PEDIATRIC NUTRITION EXPERTISE 100 YEARS 10
Slide 11: Strong Pipeline of Innovation
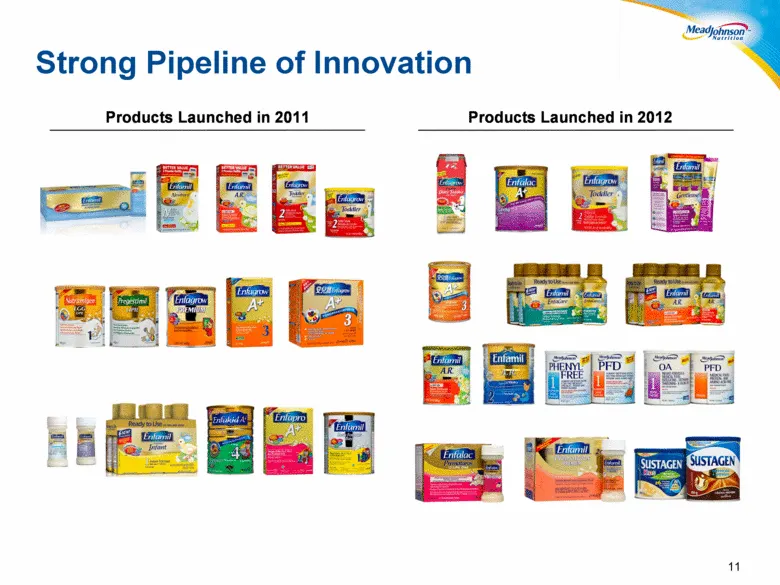
11 Strong Pipeline of Innovation Products Launched in 2011 Products Launched in 2012
Slide 12: Proven Demand Generation Model
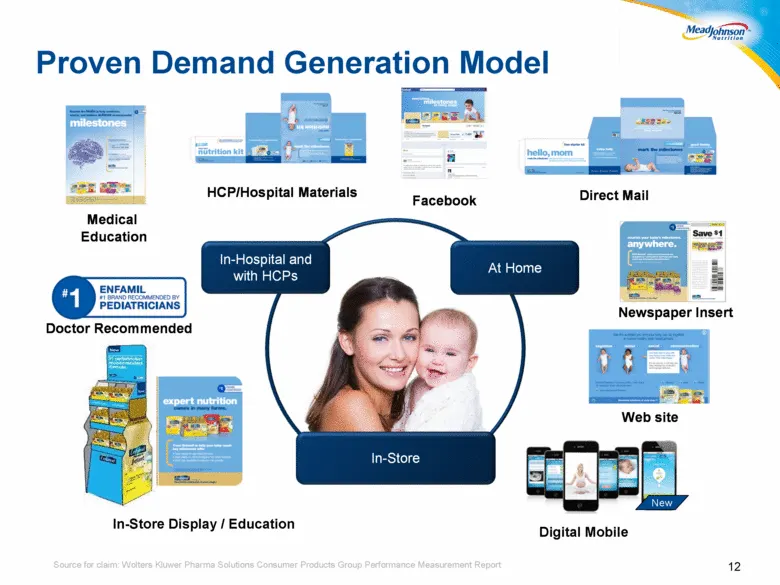
12 12 Source for claim: Wolters Kluwer Pharma Solutions Consumer Products Group Performance Measurement Report Proven Demand Generation Model In-Store Display / Education Digital Mobile In - Store In - Store In - Hospital and with HCPs In - Hospital and with HCPs At Home At Home New Facebook HCP/Hos
Slide 13: Strong Financial Performance
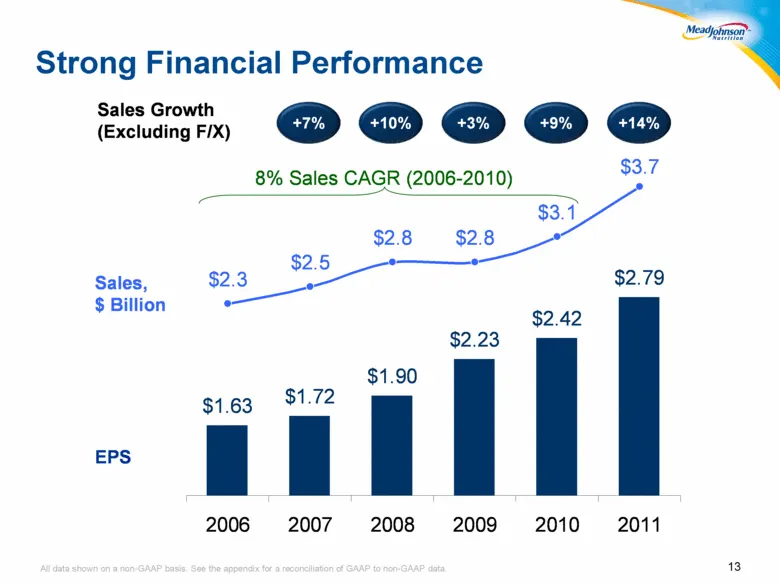
13 All data shown on a non-GAAP basis. See the appendix for a reconciliation of GAAP to non-GAAP data. Strong Financial Performance Sales, $ Billion EPS +9% +9% +3% +3% +10% +10% Sales Growth (Excluding F/X) +14% +14% +7% +7% $1.63 $1.72 $1.90 $2.23 $2.42 $2.79 $2.3 $2.5 $2.8 $2.8 $3.1 $3.7 2006 200
Slide 14: The China Opportunity
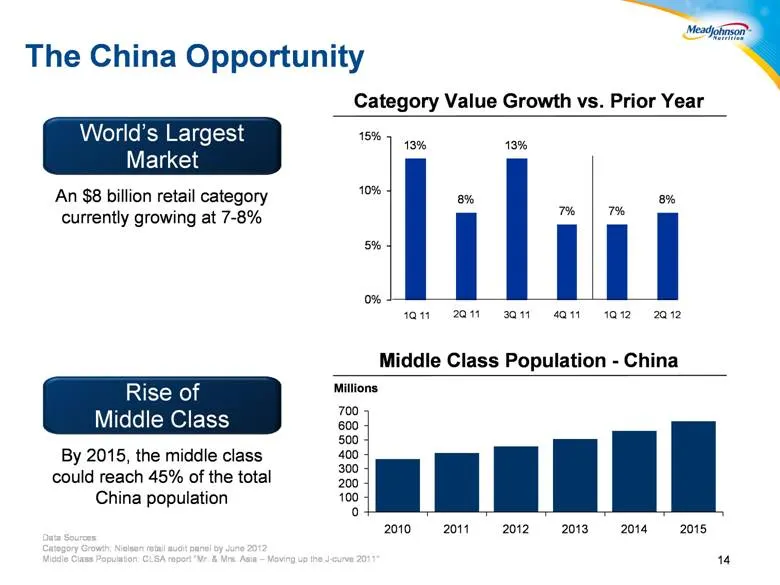
14 The China Opportunity Data Sources: Category Growth: Nielsen retail audit panel by June 2012 13% 8% 13% 7% 7% 8% 0% 5% 10% 15% 1Q 11 1Q 12 3Q 11 2Q 12 2Q 11 4Q 11 World ’ s Largest Market An $8 billion retail category currently growing at 7 - 8% World ’ s Largest Market World ’ s Largest Market A
Slide 15: China market share
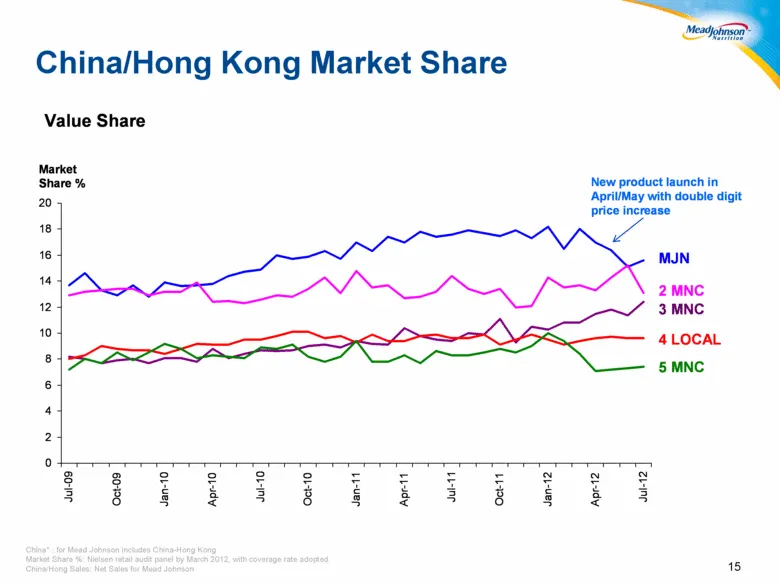
15 15 China* : for Mead Johnson includes China-Hong Kong Market Share %: Nielsen retail audit panel by March 2012, with coverage rate adopted. China/Hong Sales: Net Sales for Mead Johnson China/Hong Kong Market Share 0 2 4 6 8 10 12 14 16 18 20 Jul-09 Oct-09 Jan-10 Apr-10 Jul-10 Oct-10 Jan-11 Apr-11
Slide 16: 2012 "Smarties" Product Innovation
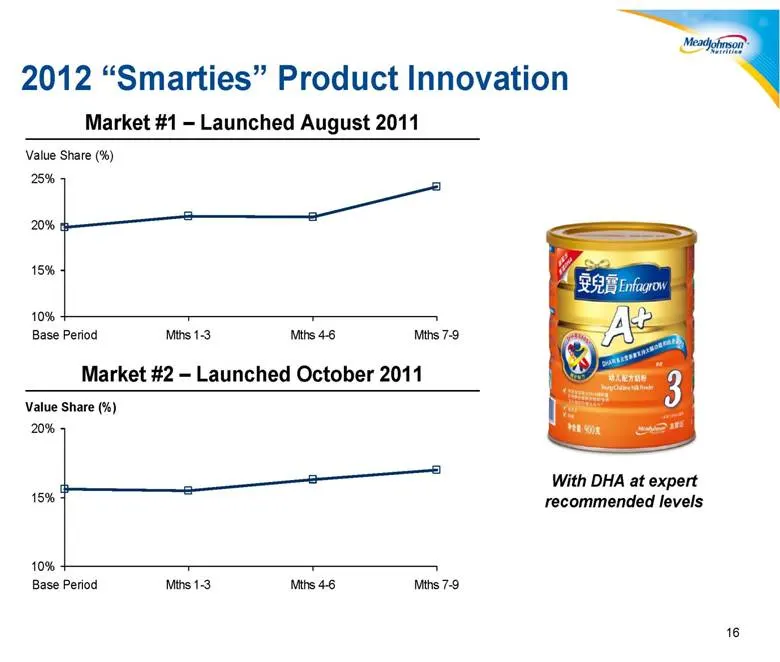
16 2012 “Smarties” Product Innovation Value Share (%) Market #1 – Launched August 2011 Market #1 – Launched August 2011 10% 15% 20% 25% Base Period Mths 1-3 Mths 4-6 Mths 7-9 Value Share (%) Market #2 – Launched October 2011 Market #2 – Launched October 2011 10% 15% 20% Base Period Mths 1-3 Mths 4-6
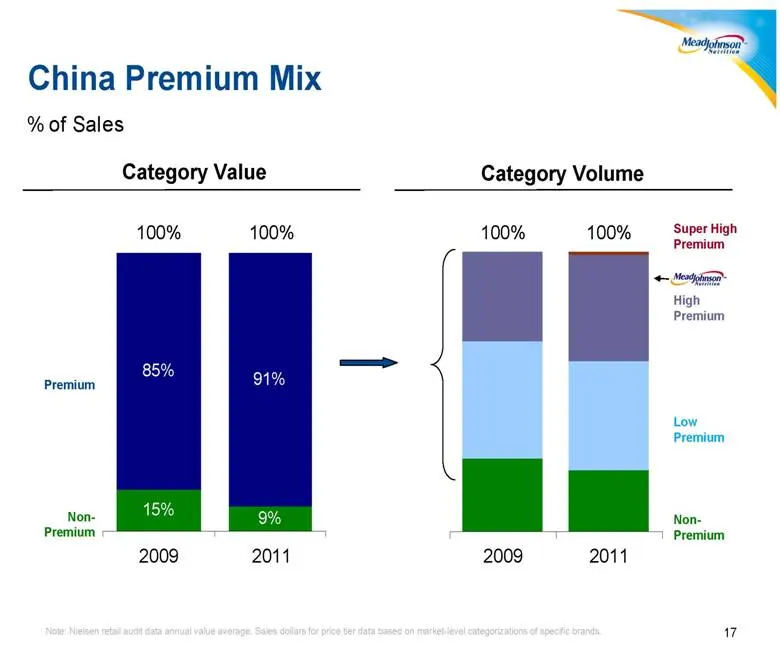
Slide 17: China Premium Mix
17 Note: Nielsen retail audit data annual value average. Sales dollars for price tier data based on market-level categorizations of specific brands. China Premium Mix 85% 91% 100% 100% 9% 15% 0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100% 2009 2011 100% 100% 0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100%
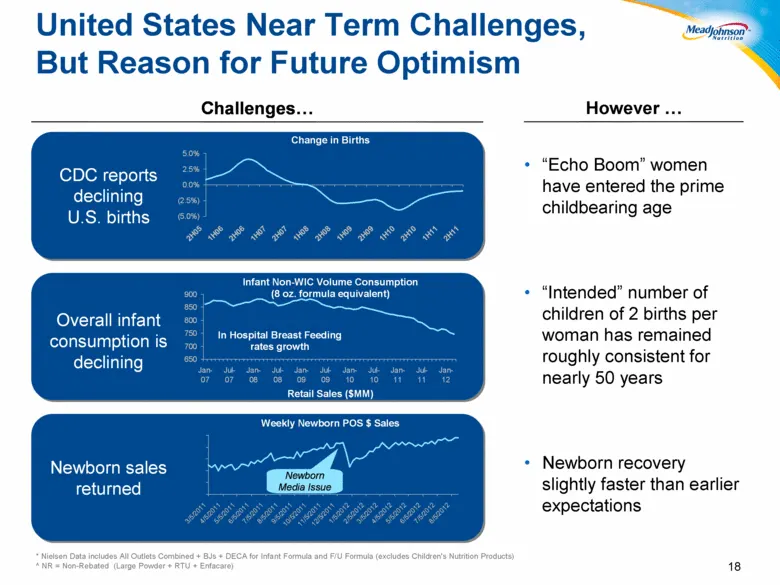
Slide 18: United States: Near Term Challenges, Future Optimism
18 “Echo Boom” women have entered the prime childbearing age “Intended” number of children of 2 births per woman has remained roughly consistent for nearly 50 years Newborn recovery slightly faster than earlier expectations However * Nielsen Data includes All Outlets Combined + BJs + DECA for Infant
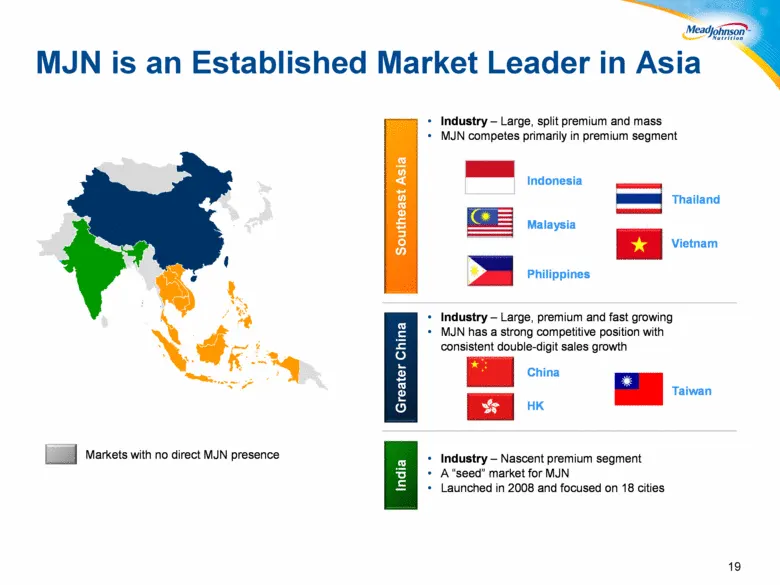
Slide 19: MJN is an Established Market Leader in Asia
19 MJN is an Established Market Leader in Asia Greater China Greater China Markets with no direct MJN presence Southeast Asia Southeast Asia • Industry – Large, premium and fast growing • MJN has a strong competitive position with consistent double - digit sales growth • Industry – Large, split prem
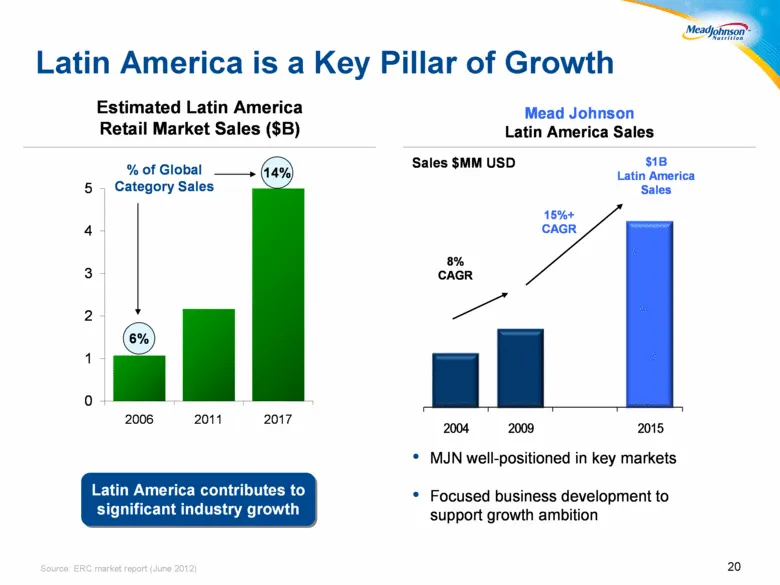
Slide 20: Latin America is a Key Pillar of Growth
20 Source: ERC market report (June 2012) Latin America is a Key Pillar of Growth 2004 2009 2015 Sales $MM USD $1B Latin America Sales Mead Johnson Latin America Sales 8% CAGR 15%+ CAGR • MJN well - positioned in key markets • Focused business development to support growth ambition 0 1 2 3 4 5 2006 2
Slide 21: Growth Opportunities in Latin America
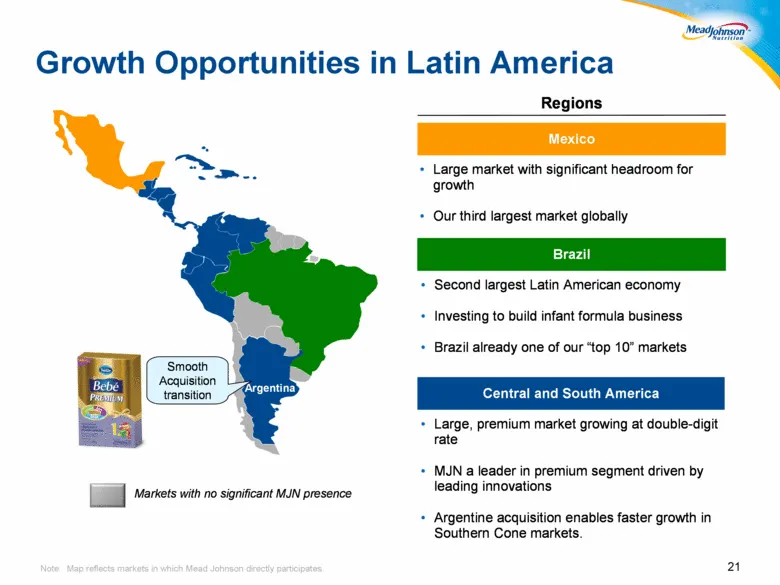
21 Note: Map reflects markets in which Mead Johnson directly participates. Growth Opportunities in Latin America Mexico • Large market with significant headroom for growth • Our third largest market globally Central and South America • Large, premium market growing at double - digit rate • MJN a lea
Slide 22: Global, focused pediatric nutrition company
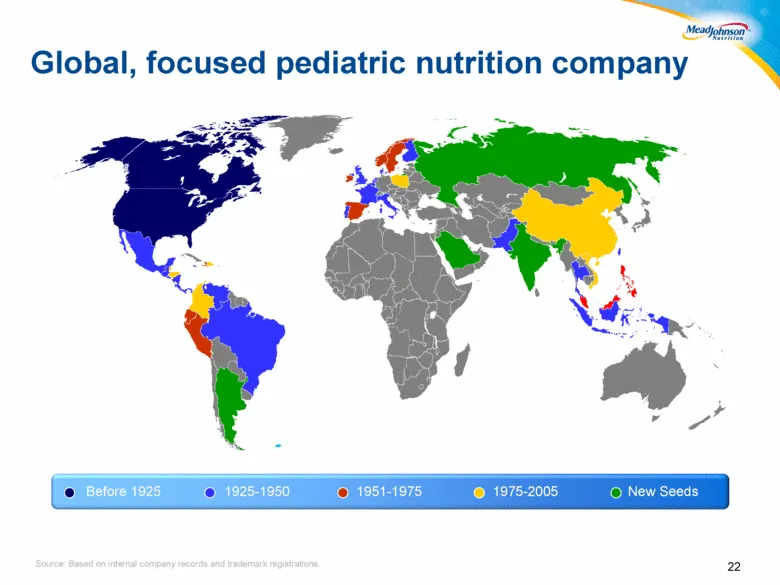
22 Source: Based on internal company records and trademark registrations. Global, focused pediatric nutrition company Before 1925 1925 - 1950 1951 - 1975 1975 - 2005 New Seeds Before 1925 1925 - 1950 1951 - 1975 1975 - 2005 New Seeds
Slide 23: Financial Overview
23 Financial Overview
Slide 24: Strong Financial Performance
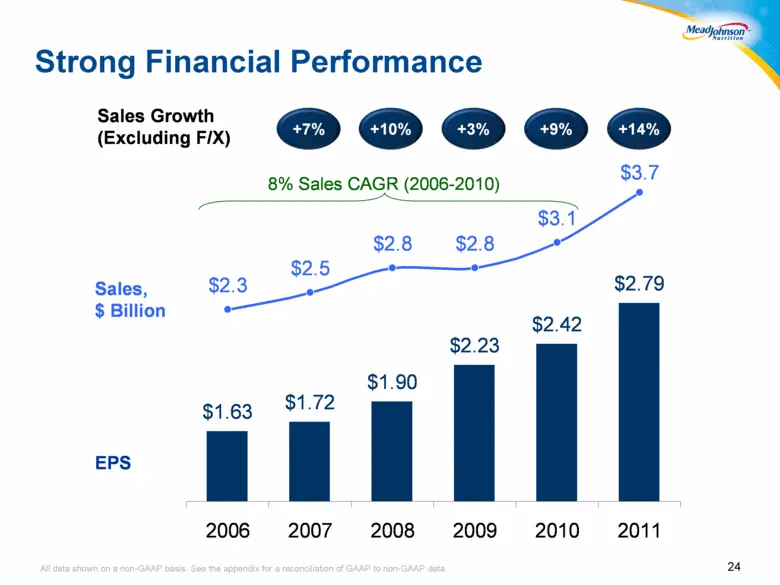
24 Strong Financial Performance All data shown on a non-GAAP basis. See the appendix for a reconciliation of GAAP to non-GAAP data. Sales, $ Billion EPS +9% +9% +3% +3% +10% +10% Sales Growth (Excluding F/X) +14% +14% +7% +7% $1.63 $1.72 $1.90 $2.23 $2.42 $2.79 $2.3 $2.5 $2.8 $2.8 $3.1 $3.7 2006 200
Slide 25: Strong and Diverse Emerging Market Growth
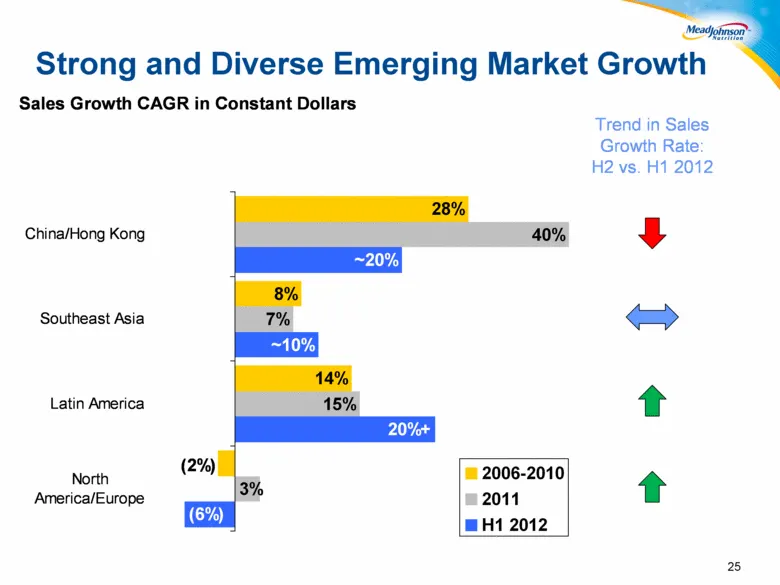
25 Strong and Diverse Emerging Market Growth Trend in Sales Growth Rate: H2 vs. H1 2012 Sales Growth CAGR in Constant Dollars (6%) 3% 15% 7% 40% 14% 8% 28% 20%+ ~10% ~20% (2%) North America/Europe Latin America Southeast Asia China/Hong Kong 2006-2010 2011 H1 2012
Slide 26: Inflationary Pressures in 2012
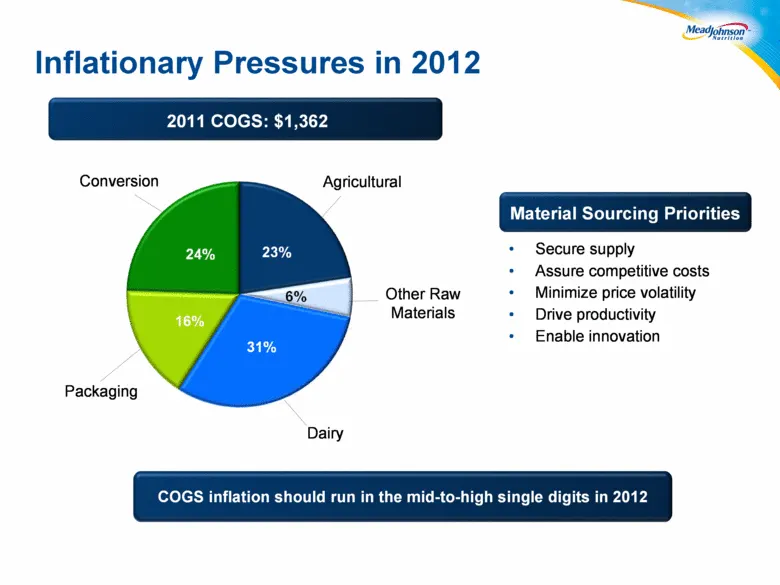
Inflationary Pressures in 2012 Material Sourcing Priorities • Secure supply • Assure competitive costs • Minimize price volatility • Drive productivity • Enable innovation 2011 COGS: $1,362 Other Raw Materials Agricultural Packaging Conversion Dairy COGS inflation should run in the mid - to - high s
Slide 27: Dairy Spot Prices
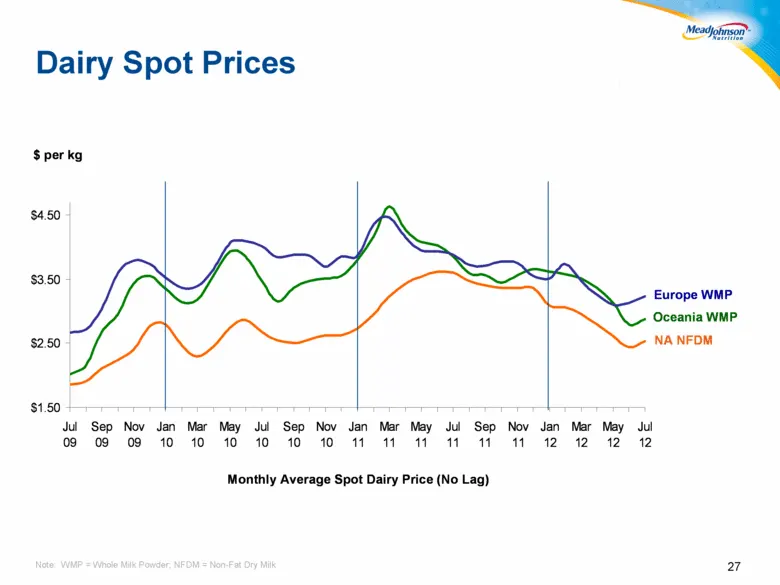
27 27 Dairy Spot Prices Note: WMP = Whole Milk Powder; NFDM = Non-Fat Dry Milk $1.50 $2.50 $3.50 $4.50 Jul 09 Sep 09 Nov 09 Jan 10 Mar 10 May 10 Jul 10 Sep 10 Nov 10 Jan 11 Mar 11 May 11 Jul 11 Sep 11 Nov 11 Jan 12 Mar 12 May 12 Jul 12 $ per kg Monthly Average Spot Dairy Price (No Lag) Europe WMP NA
Slide 28: Importance of Productivity to Gross Margins
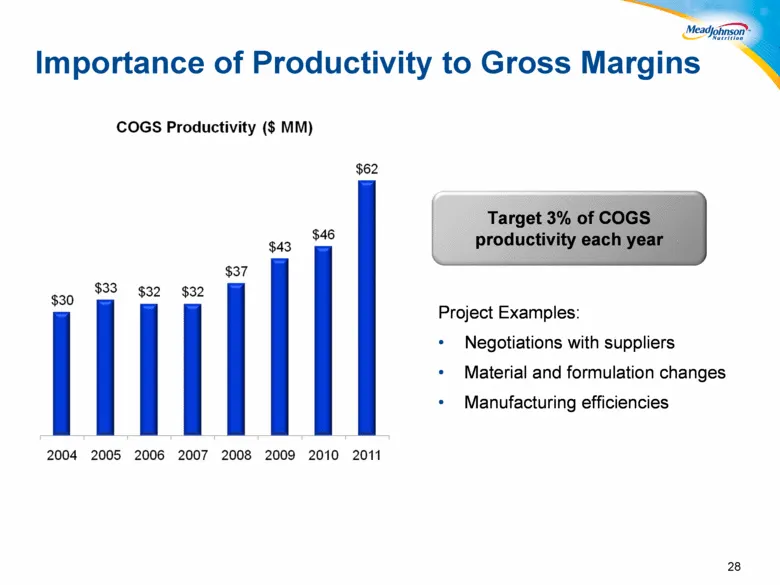
28 Importance of Productivity to Gross Margins Target 3% of COGS productivity each year Target 3% of COGS productivity each year Project Examples: • Negotiations with suppliers • Material and formulation changes • Manufacturing efficiencies
Slide 29: Operating Expenses (% of Sales)
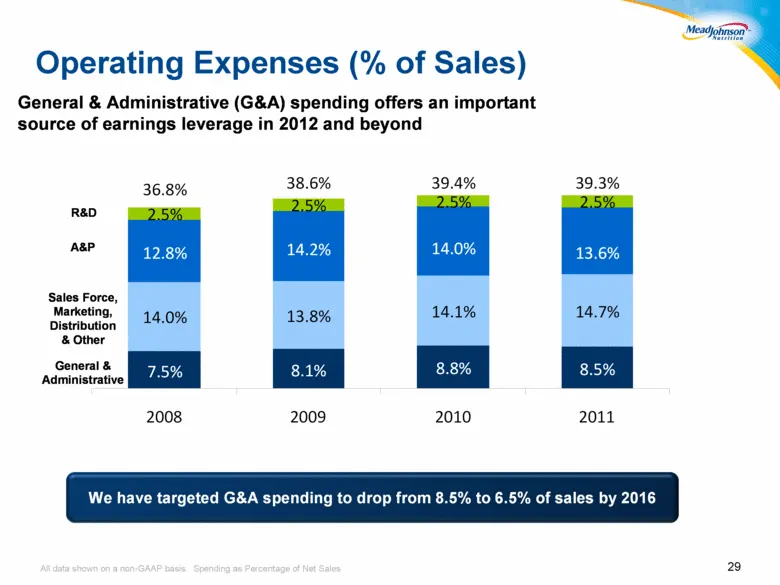
29 Operating Expenses (% of Sales) All data shown on a non-GAAP basis. Spending as Percentage of Net Sales 14.0% 13.8% 14.1% 2.5% 2.5% 2.5% 2.5% 36.8% 38.6% 39.4% 39.3% 7.5% 8.1% 8.8% 8.5% 14.7% 12.8% 14.2% 14.0% 13.6% 2008 2009 2010 2011 General & Administrative (G&A) spending offers an important s
Slide 30: Effective Tax Rate: Another source of earnings leverage
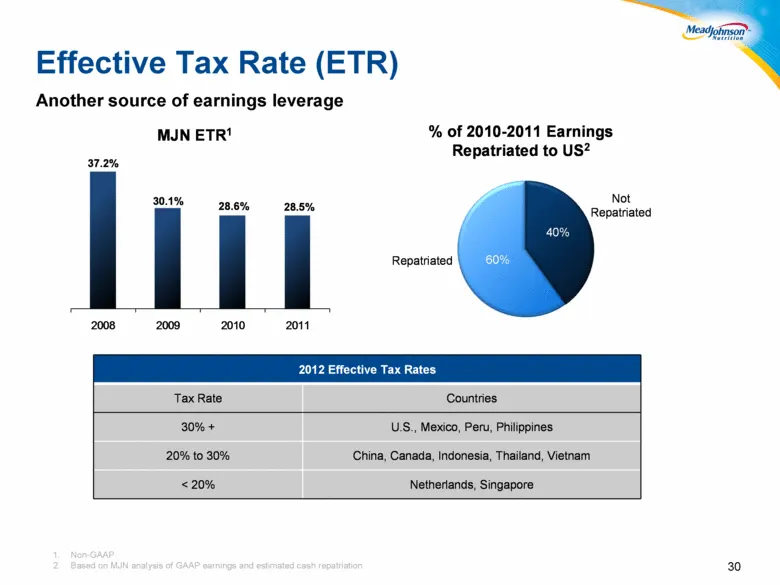
Non-GAAP Based on MJN analysis of GAAP earnings and estimated cash repatriation 30 Effective Tax Rate (ETR) Another source of earnings leverage 2008 2009 2010 2011 37.2% 28.6% 30.1% MJN ETR 1 % of 2010 - 2011 Earnings Repatriated to US 2 60% 40% Repatriated Not Repatriated % of 2010 - 2011 Earnings
Slide 31: Optimizing Asia Supply Chain
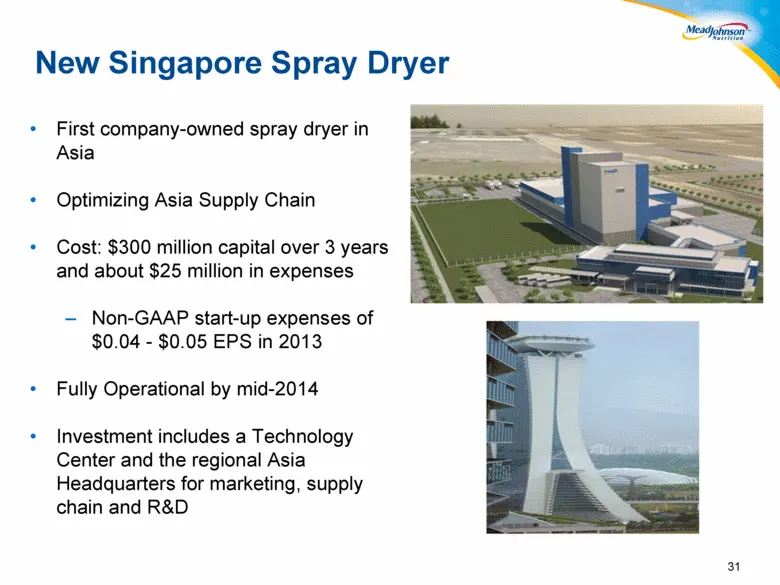
31 New Singapore Spray Dryer First company-owned spray dryer in Asia Optimizing Asia Supply Chain Cost: $300 million capital over 3 years and about $25 million in expenses Non-GAAP start-up expenses of $0.04 - $0.05 EPS in 2013 Fully Operational by mid-2014 Investment includes a Technology Center an
Slide 32: Strong and Stable Free Cash Flow
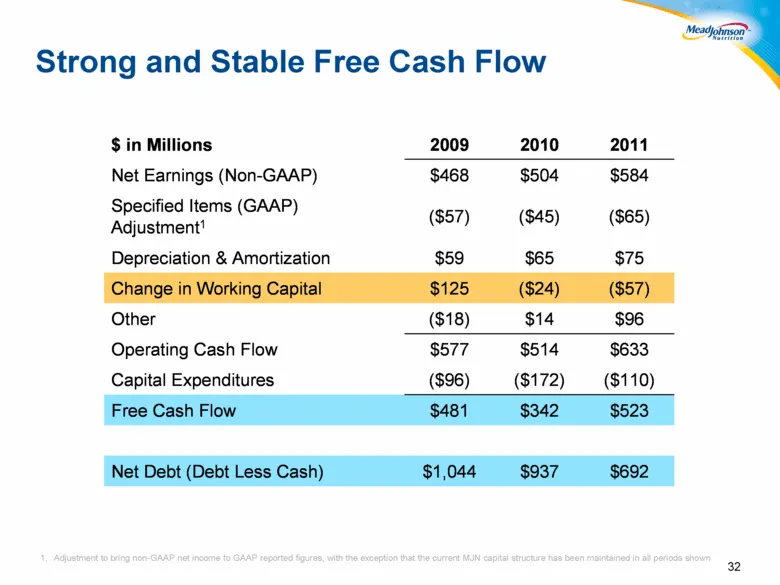
32 Strong and Stable Free Cash Flow Adjustment to bring non-GAAP net income to GAAP reported figures, with the exception that the current MJN capital structure has been maintained in all periods shown 2009 2010 Full Year $ in Millions 2009 2010 2011 Net Earnings (Non - GAAP) $468 $504 $584 Specified
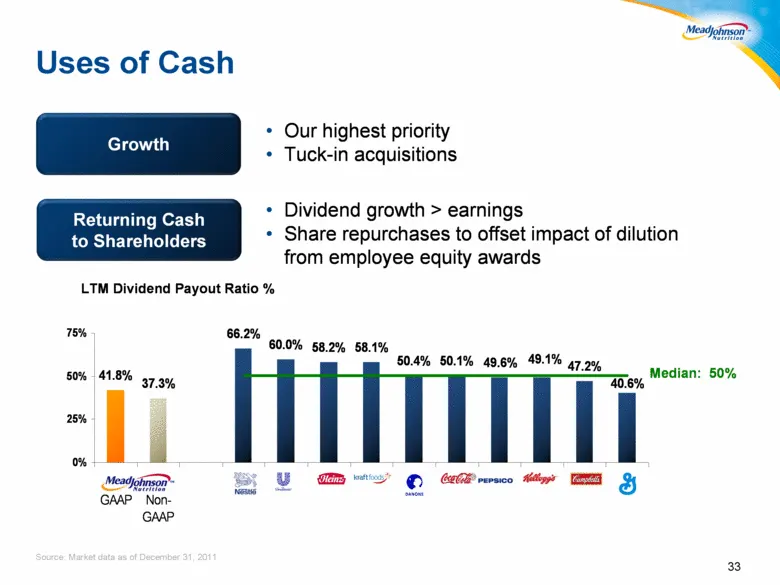
Slide 33: Uses of Cash
33 Uses of Cash Source: Market data as of December 31, 2011 • Our highest priority • Tuck - in acquisitions Growth Growth Returning Cash to Shareholders Returning Cash to Shareholders • Dividend growth > earnings • Share repurchases to offset impact of dilution from employee equity awards LTM Divide
Slide 34: Mead Johnson Strengths
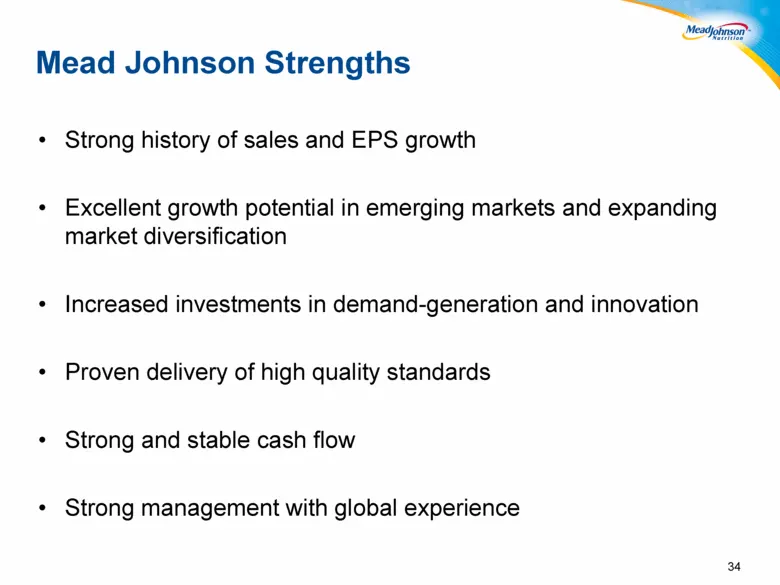
34 Mead Johnson Strengths Strong history of sales and EPS growth Excellent growth potential in emerging markets and expanding market diversification Increased investments in demand-generation and innovation Proven delivery of high quality standards Strong and stable cash flow Strong management with
Slide 35: Mead Johnson Nutrition
Meadjohnson” Nutrition
Slide 36: Appendix
36 Appendix
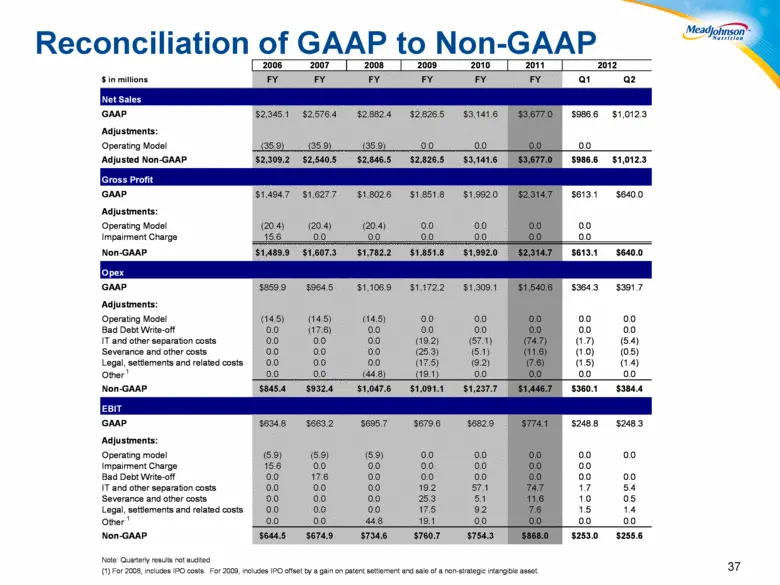
Slide 37: Reconciliation of GAAP to Non-GAAP
37 Reconciliation of GAAP to Non-GAAP $ in millions FY FY FY FY FY FY Q1 Q2 Net Sales GAAP $2,345.1 $2,576.4 $2,882.4 $2,826.5 $3,141.6 $3,677.0 $986.6 $1,012.3 Adjustments: Operating Model (35.9) (35.9) (35.9) 0.0 0.0 0.0 0.0 Adjusted Non-GAAP $2,309.2 $2,540.5 $2,846.5 $2,826.5 $3,141.6 $3,677.0 $
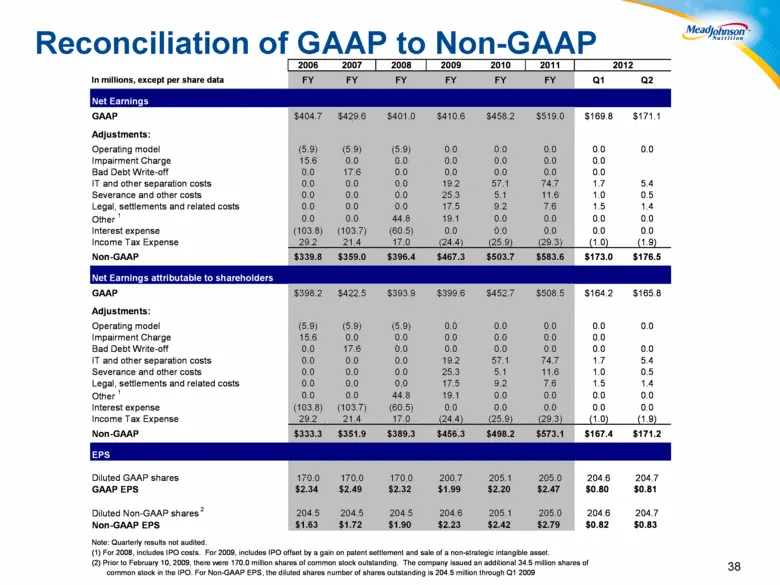
Slide 38: Reconciliation of GAAP to Non-GAAP
38 Reconciliation of GAAP to Non-GAAP In millions, except per share data FY FY FY FY FY FY Q1 Q2 Net Earnings GAAP $404.7 $429.6 $401.0 $410.6 $458.2 $519.0 $169.8 $171.1 Adjustments: Operating model (5.9) (5.9) (5.9) 0.0 0.0 0.0 0.0 0.0 Impairment Charge 15.6 0.0 0.0 0.0 0.0 0.0 0.0 Bad Debt Write-
Slide 39: Mead Johnson Nutrition
Meadjohnson” Nutrition
Source: SEC EDGAR · 8-K filed Sep 5, 2012
More decks from Mead Johnson Nutrition CO
 Morgan Stanley Global Consumer & Retail Conference 201616 slides · Nov 15, 2016
 Barclays Global Consumer Staples Conference 201618 slides · Sep 7, 2016
 Q1 2016 Earnings Presentation20 slides · Apr 28, 2016
 FY2015 Earnings Presentation23 slides · Jan 28, 2016
 Q3 2015 Earnings Presentation26 slides · Oct 22, 2015
 Investor Day (October 2015)15 slides · Oct 22, 2015