State Bancorp — Shareholder Meeting (April 2008)
21 slides from State Bancorp's shareholder meeting presentation, Apr 30, 2008
Slide 1: Annual Stockholders' Meeting
@ STATE BANCORP INC. Annual Stockholders’ Meeting
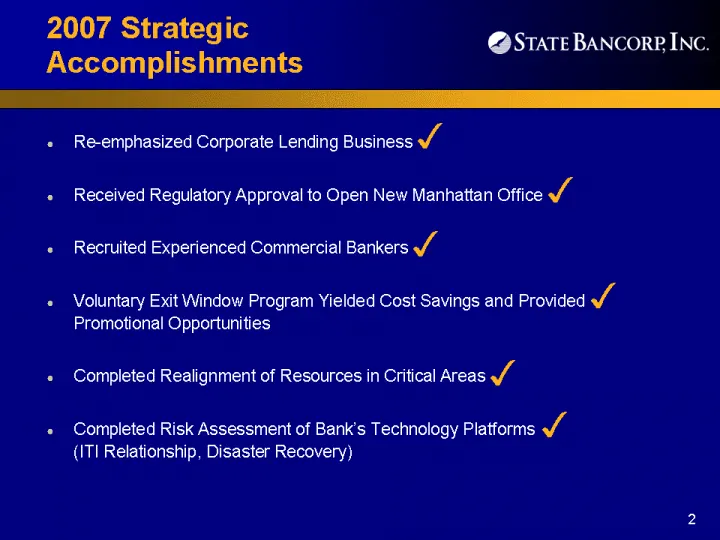
Slide 2: 2007 Strategic Accomplishments
2007 Strategic Accomplishments « Re-emphasized Corporate Lending Business J « Received Regulatory Approval to Open New Manhattan Office Vv « Recruited Experienced Commercial Bankers A « Voluntary Exit Window Program Yielded Cost Savings and Provided Jf Promotional Opportunities « Completed Realignme
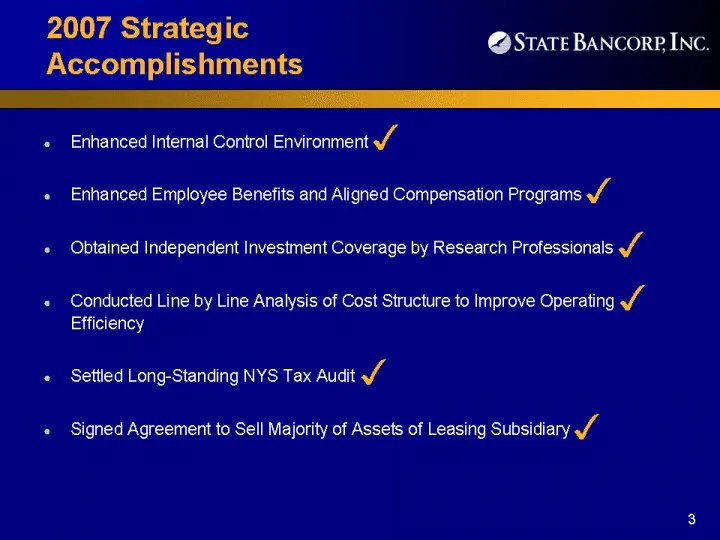
Slide 3: 2007 Strategic Accomplishments
2007 Strategic Accomplishments «Enhanced intemal Control Environment « Enhanced Employee Benefits and Aligned Compensation Programs J + Obtained Independent Investment Coverage by Research Professionals « Conducted Line by Line Analysis of Cost Structure to Improve Operating Of Efficiency + Settled
Slide 4: Financial Review
Financial Review
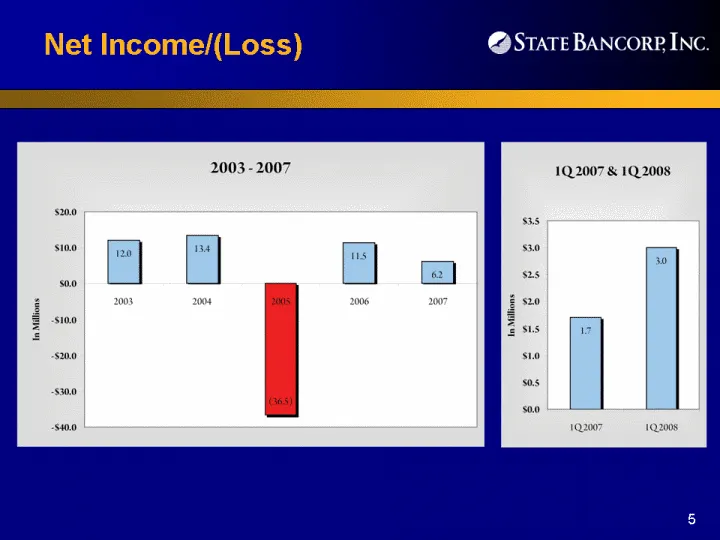
Slide 5: 2003 - 2007, 1Q2007 & 1Q2008
2003 - 2007 1Q2007 & 12008
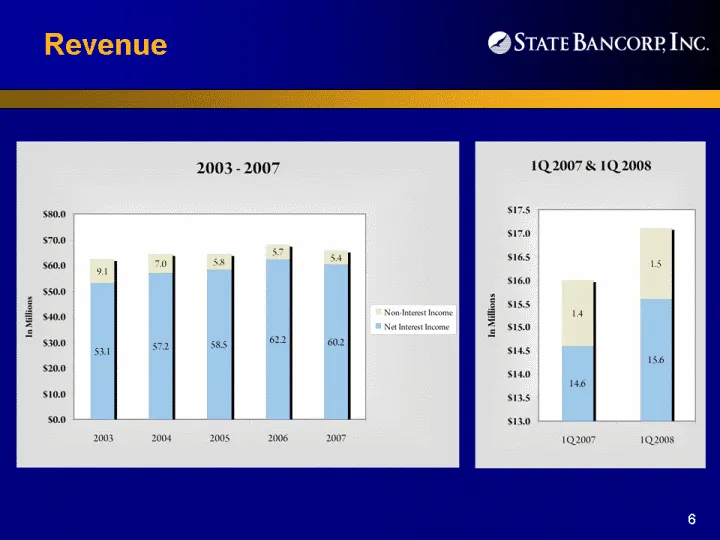
Slide 6: Revenue
Revenue @ STATE BANCORP INC. 2003 1Q.2007 & 1Q 2008 S600 ssoo S200 soo soo
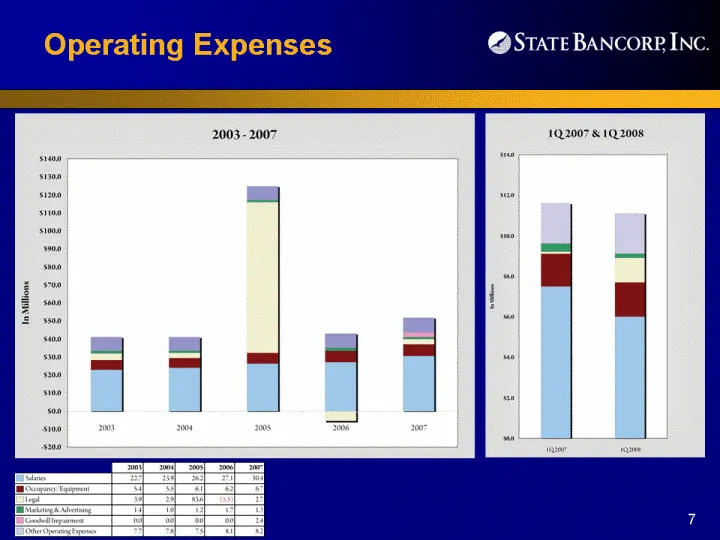
Slide 7: Operating Expenses
Operating Expenses @ STATE BANCORP INC. 2003-2007 1.2007 & 12008
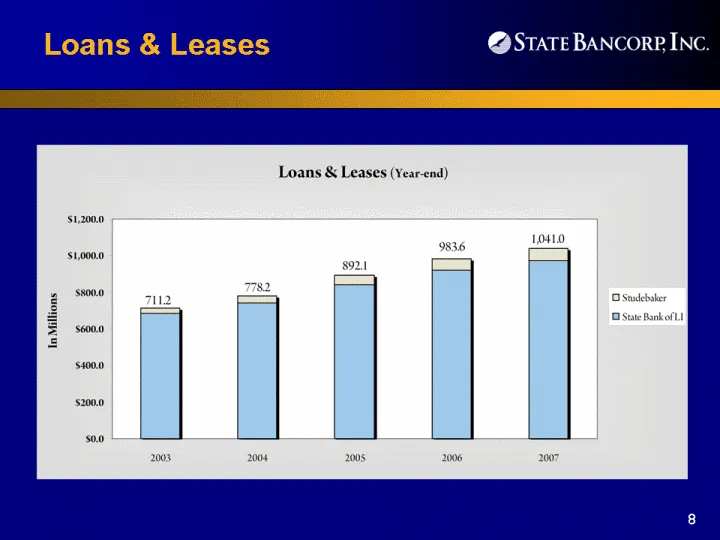
Slide 8: Loans & Leases
Loans & Leases @ STATE BANCORP INC. Loans & Leases (Year-end) si.2000 10410 1,000.0 1000 s200.0
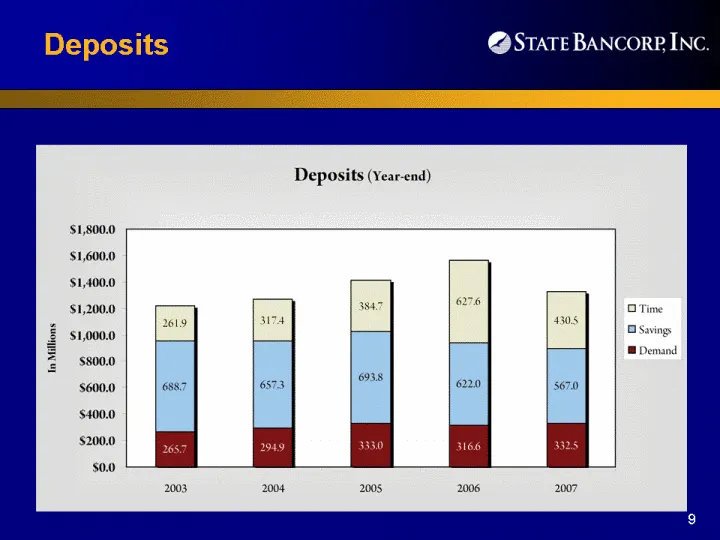
Slide 9: Deposits
Deposits @ STATE BANCORR INC. Deposits (Year-end) $1,800.0 $1,600.0 $1,400.0 $1,200.0 | " Time $1,000.0 Bsavings @ Demand $800.0 $600.0 $400.0 $200.0 $0.0
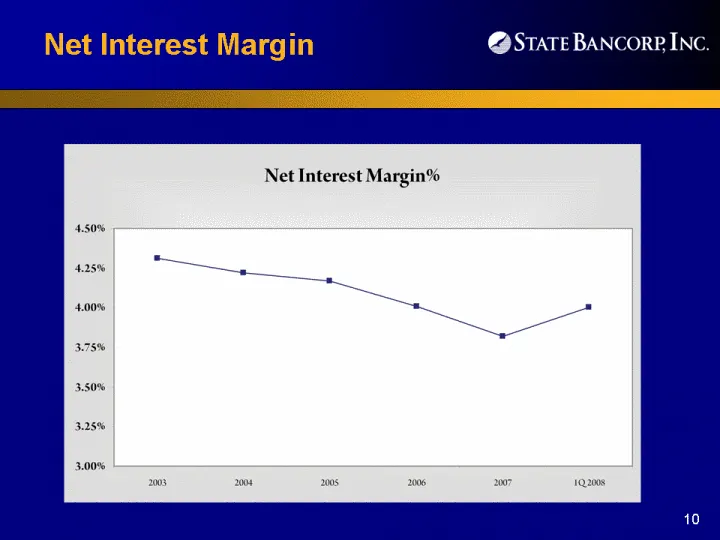
Slide 10: Net Interest Margin
Net Interest Margin @ STATE BANCORP INC. Net Interest Margin®%
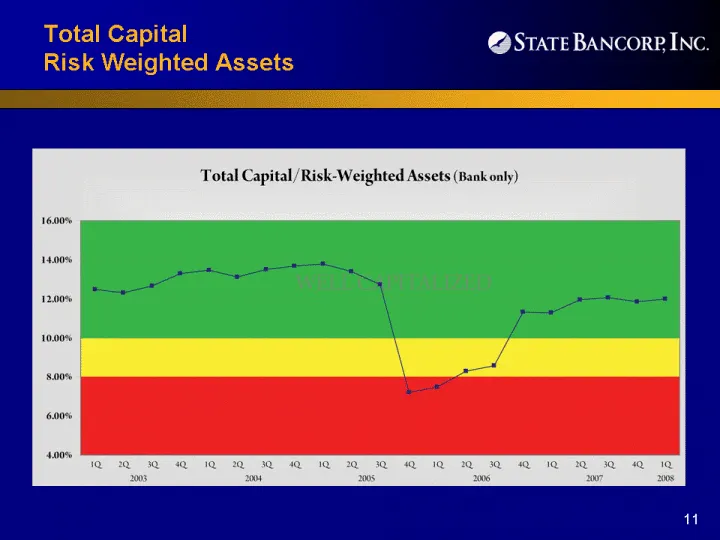
Slide 11: Total Capital
Total Capital Risk Weighted Assets @ STATE BANCORP INC. Total Capital /Risk-Weighted Assets (Bank only)
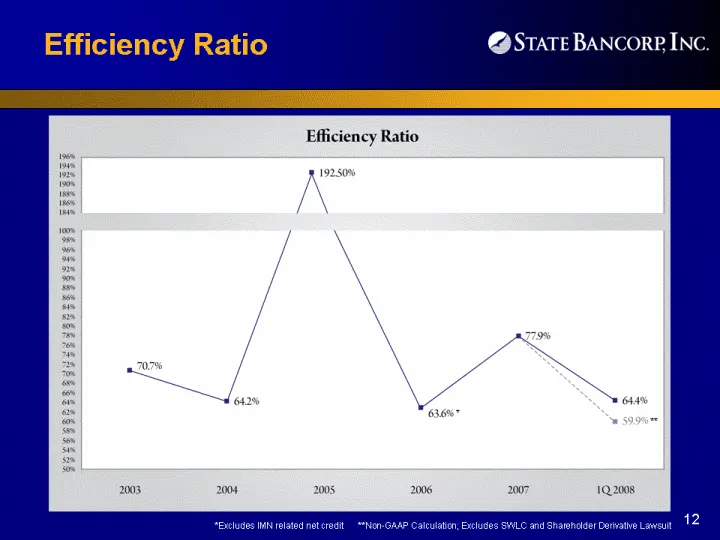
Slide 12: Efficiency Ratio
Efficiency Ratio @ STATE BANCORP INC. Efficiency Ratio 9 19250 1Q.2008 treated euaon, Exclude
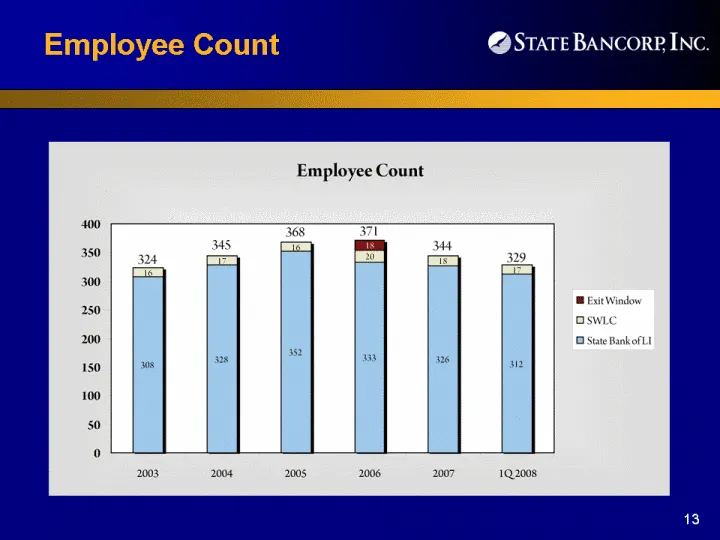
Slide 13: Employee Count
Employee Count @ STATE BANCORP INC. Employee Count 12008
Slide 14: 2008 Strategic Objectives
2008 Strategic Objectives
Slide 15: 2008 Economic Outlook & Market Climate
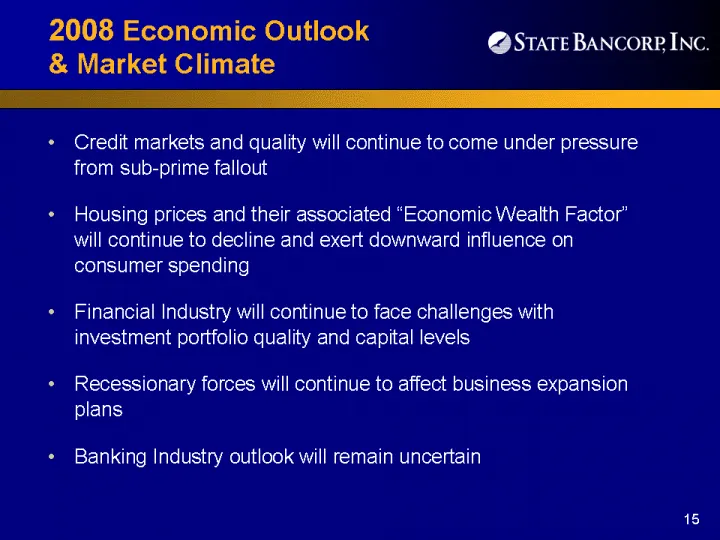
2008 Economic Outlook & Market Climate * Credit markets and quality will continue to come under pressure from sub-prime fallout + Housing prices and their associated “Economic Wealth Factor” will continue to decline and exert downward influence on consumer spending + Financial Industry will continue
Slide 16: 2008 Key Objectives
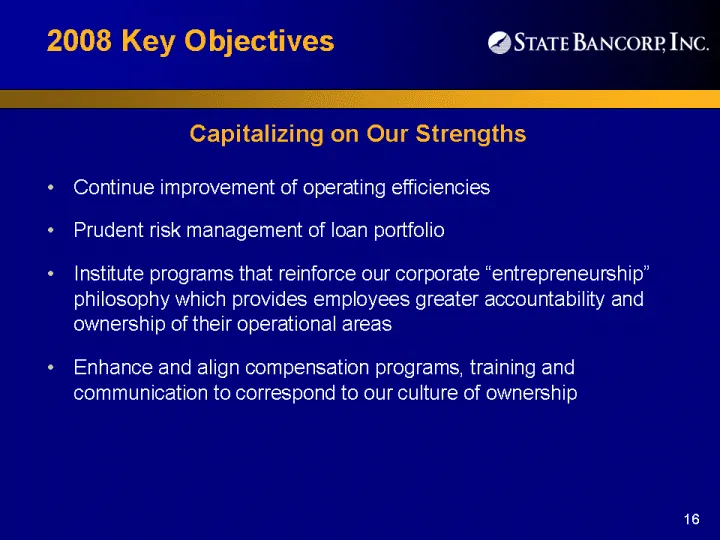
2008 Key Objectives Capitalizing on Our Strengths * Continue improvement of operating efficiencies + Prudent risk management of loan portfolio + Institute programs that reinforce our corporate “entrepreneurship” philosophy which provides employees greater accountability and ownership of their operat
Slide 17: 2008 Key Objectives
2008 Key Objectives Capitalizing on Our Strengths + Enhance our technology infrastructure and implement new back Office and front office systems to improve processing efficiencies and customer service delivery « Refine compliance procedures and systems to adhere to best practices standard to ensure
Slide 18: 2008 Key Objectives
2008 Key Objectives Capitalizing on Our Strengths + Further enhance our product and service experience to achieve unparalleled customer satisfaction by: + Strengthening our sales and service culture + Augmenting and promoting Small Business Product Line + Implementing Targeted Business Marketing Ini
Slide 19: 2008 Key Objectives
2008 Key Objectives Capitalizing on Our Strengths + Partner with employees to develop continued community presence and awareness + Assess and improve branch image, messaging, and merchandising to build State Bank brand and name recognition
Slide 20: Thank You!
Thank You!
Slide 21: Forward-Looking Statements and Risk Factors
Forward-Looking Statements and Risk Factors The foregoing contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Words such as “may,” “could,” “should,” “would,” “believe,” “anticipate,” “estimate,” “expect,” “intend,” “plan,” “project,” “is c
Source: SEC EDGAR · 8-K filed Apr 30, 2008
More decks from State Bancorp Inc.
 Merger or Acquisition (December 2011)14 slides · Dec 5, 2011
 Shareholder Meeting (April 2011)23 slides · Apr 26, 2011
 Sandler O'Neill + Partners East Coast Financial Services Conference (November 2010)18 slides · Nov 10, 2010
 Shareholder Meeting (April 2010)23 slides · Apr 27, 2010
 Investor Presentation (March 2010)17 slides · Mar 11, 2010
 Sandler O'Neill + Partners East Coast Financial Services Conference 20097 slides · Nov 12, 2009