Stillwater Mining — Proxy Contest (April 2013)
39 slides from Stillwater Mining's proxy contest presentation, Apr 8, 2013
Slide 1: Schedule 14A Proxy Statement - Stillwater Mining Company
UNITED STATES SECURITIES AND EXCHANGE COMMISSION Washington, D.C. 20549 SCHEDULE 14A Proxy Statement Pursuant to Section 14(a) of the Securities Exchange Act of 1934 Filed by the Registrant x Filed by a Party other than the Registrant ¨ Check the appropriate box: ¨ Preliminary Proxy Statement ¨ Conf
Slide 2: Investor Presentation April 2013
Investor April 2013 Presentation
Slide 3: Forward-Looking Statements
isclaimer SUNALLA > Forward-Looking Statements *SOME STATEMENTS CONTAINED IN THIS PRESENTATION ARE FORWARD-LOOKING WITHIN THE MEANING OF SECTION 27A OF THE U.S. SECURITIES ACT OF 1933, AS AMENDED, AND SECTION 21E OF THE U.S. SECURITIES EXCHANGE ACT OF 1934, AS AMENDED, AND, THEREFORE, INVOLVE UNCERT
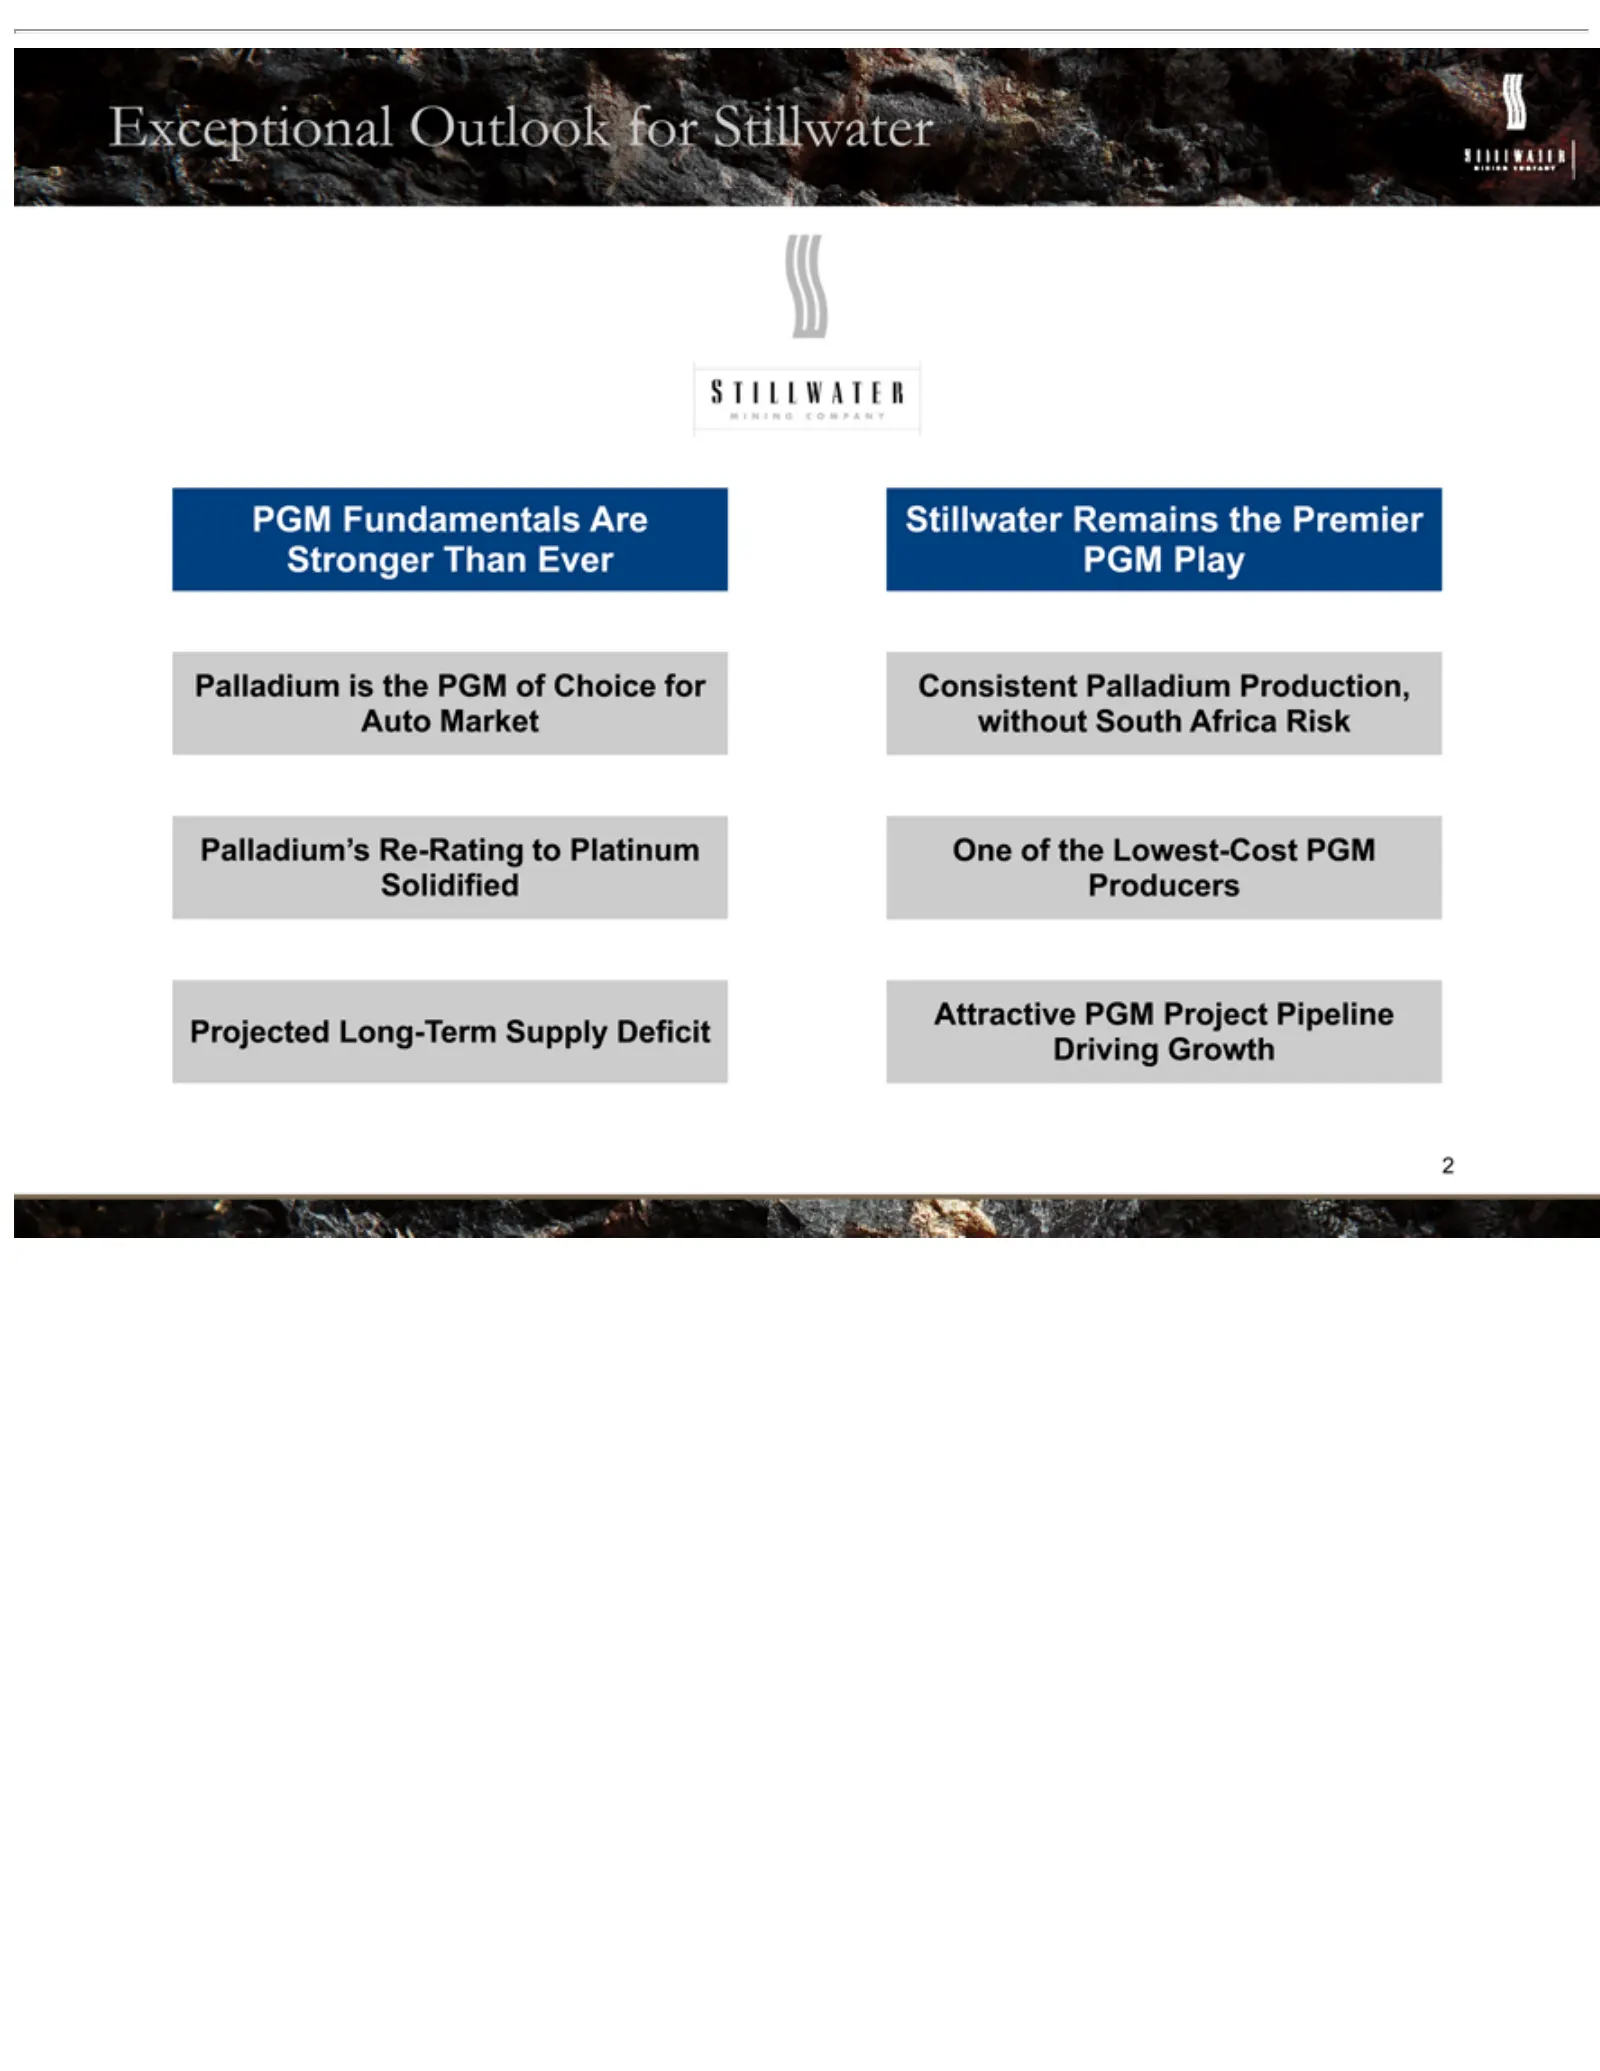
Slide 4: Exceptional Palladium Exposure: Key Investment Points
Exceptional PGM Palladium Palladium’s Projected Solidified Stillwater Consistent One 3Attractive ofFundamentals theLong-Term Remains PGM is Lowest-Cost Palladium Re-Rating Outlook the Project PGMthe Are for Production, Supply of to Premier Pipeline PGM Stillwater Stronger Choice Platinum Deficit Pro
Slide 5: 1. PGM Fundamentals Are Stronger Than Ever
1. PGM Are EverStronger Fundamentals Than
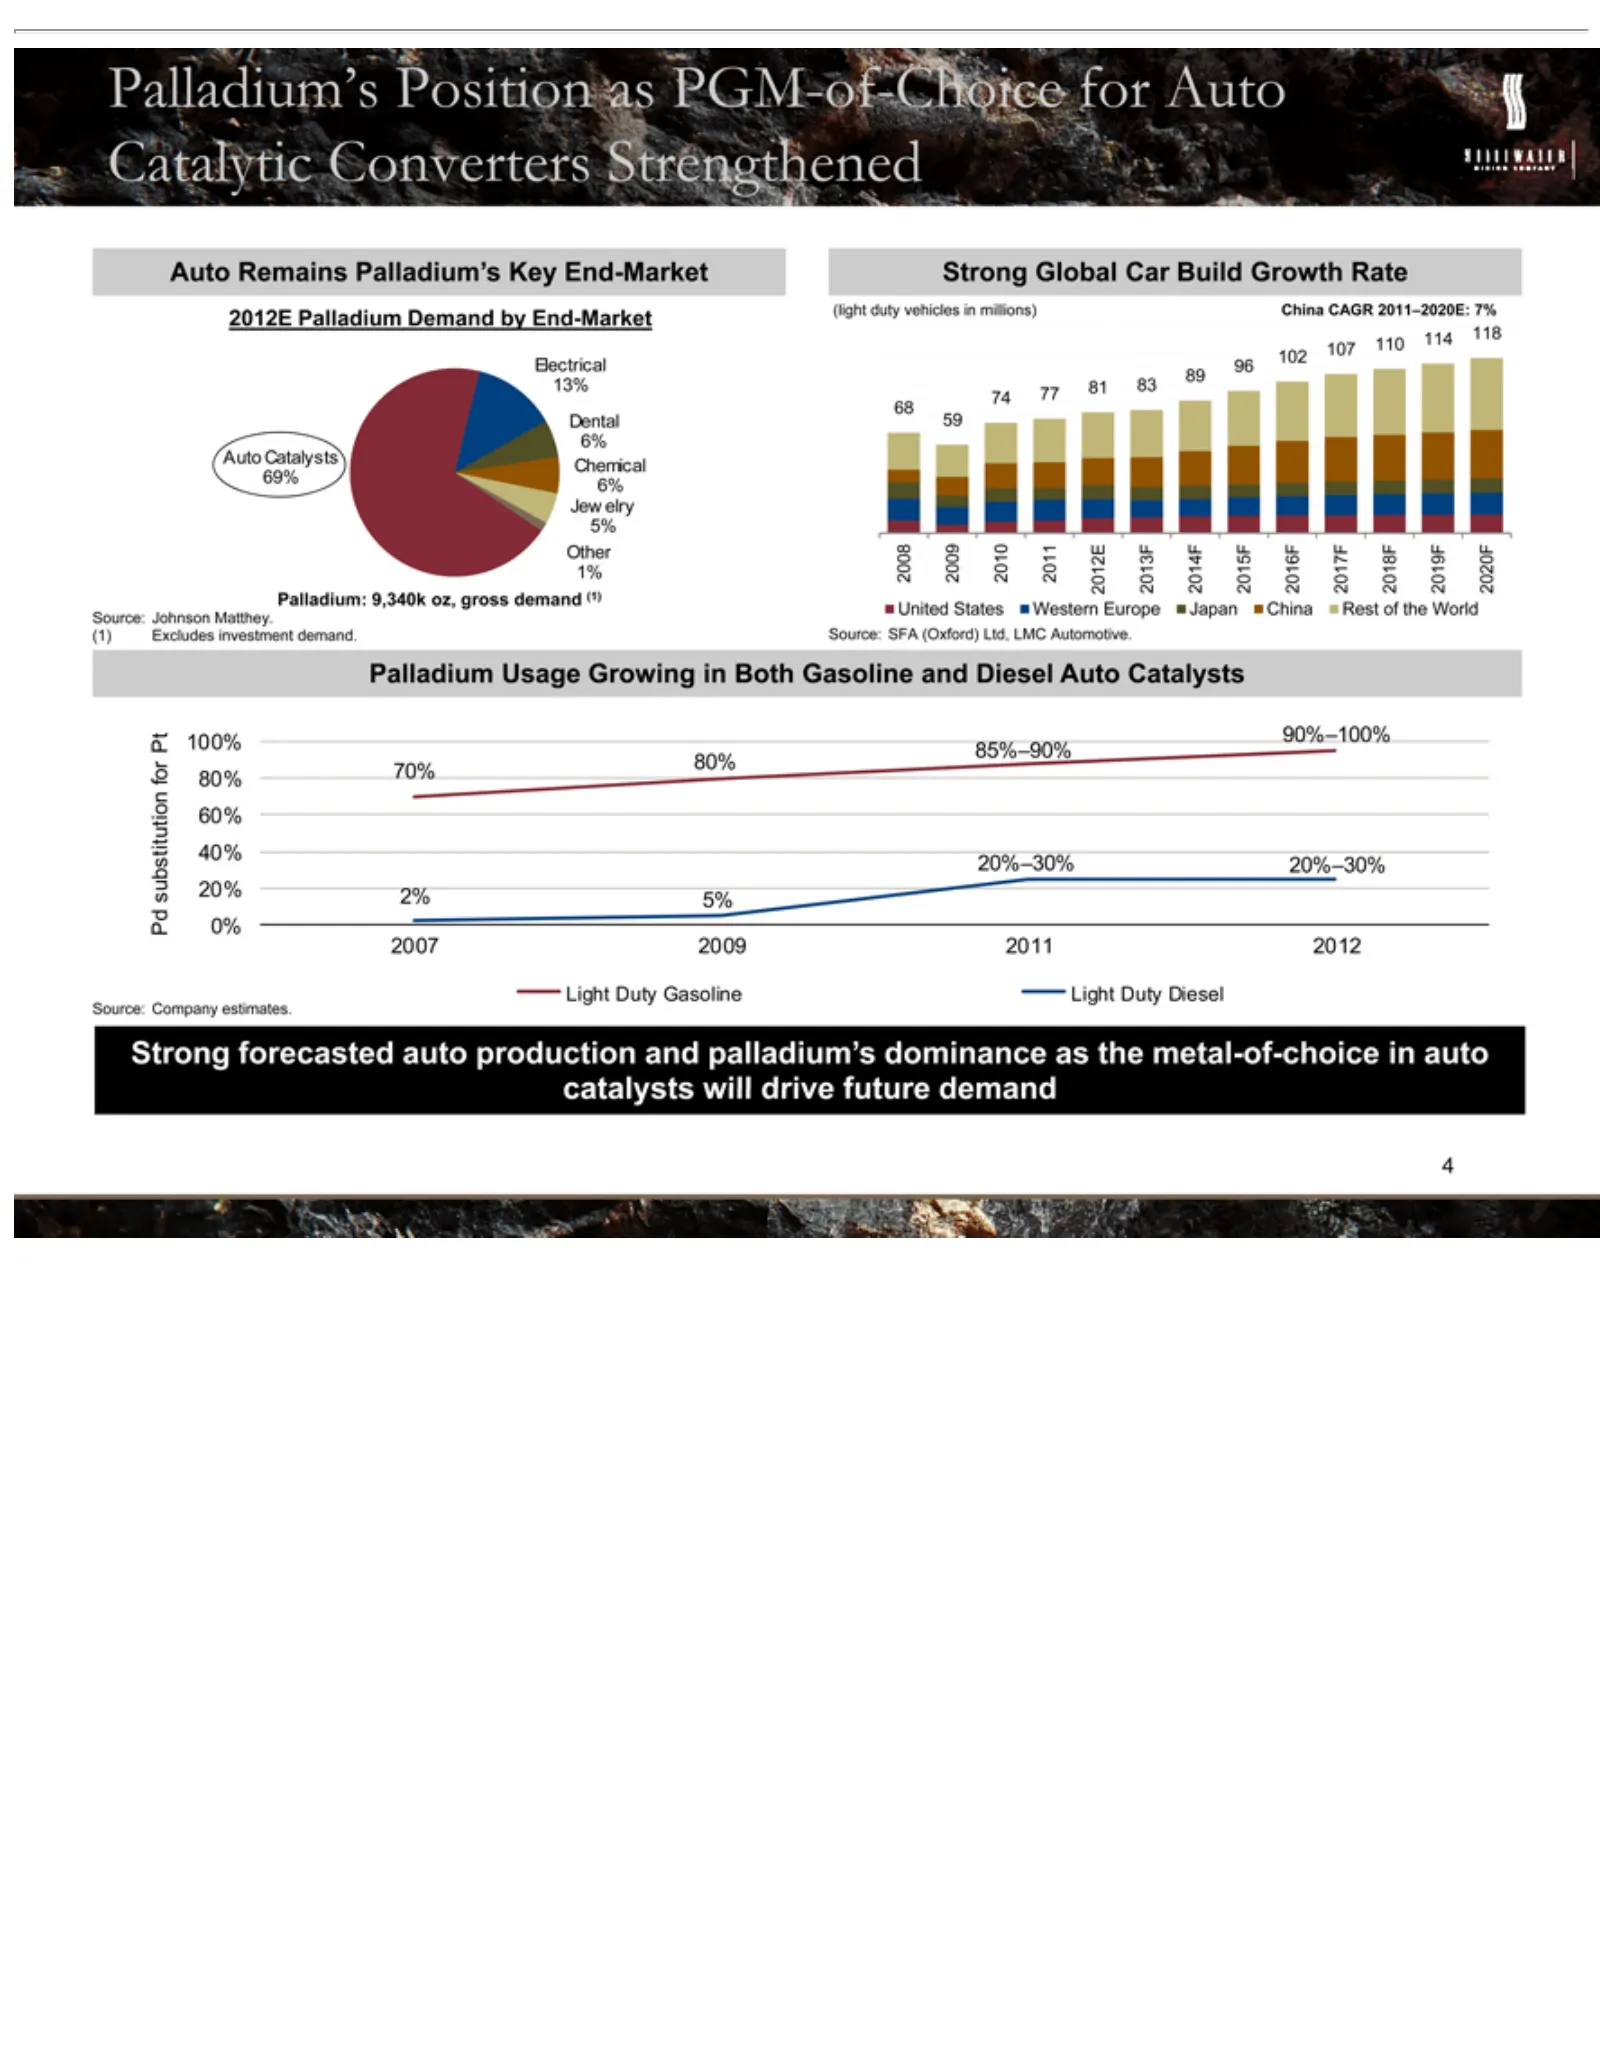
Slide 6: Palladium's Position as PGM-of-Choice for Auto Catalysts Strengthened
Palladium’s Position inas PGM-of-Choice for Auto Catalytic Converters Strengthened 2012E Auto Electrical Dental Palladium: Source: (1) Strong (light Excludes Remains Catalysts duty Palladium 6% Global Johnson 13% vehicles Chemical 9,340k investment Car Palladium’s 69%Matthey. Demand Build oz,6% mill
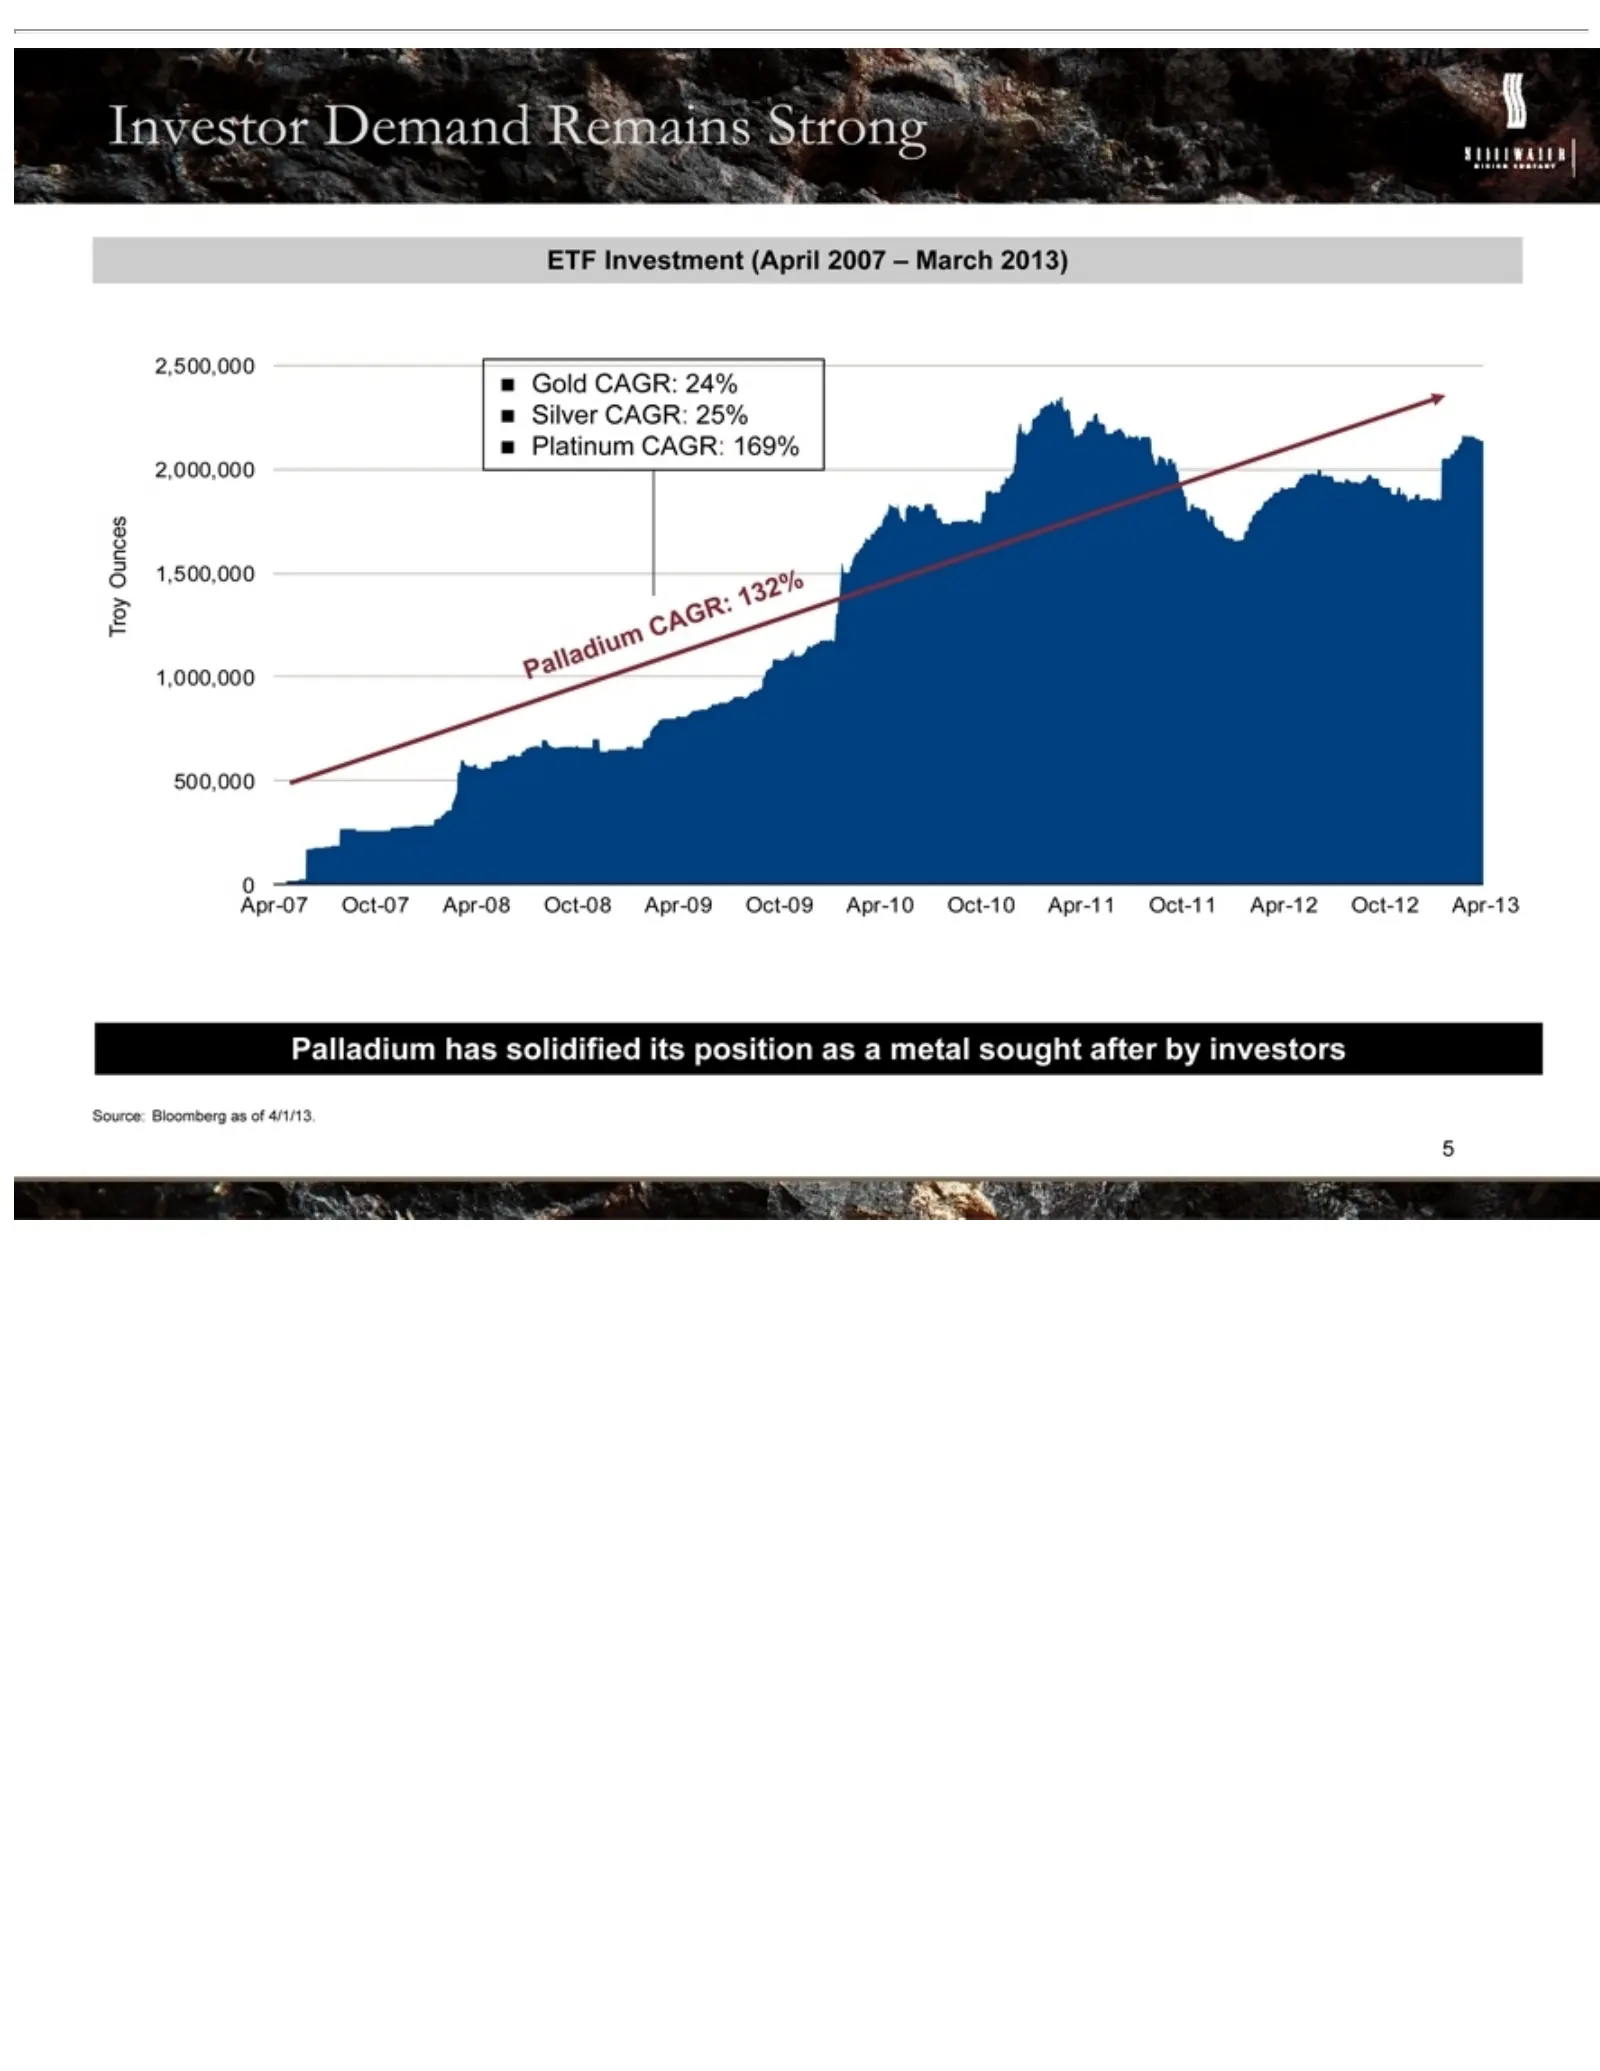
Slide 7: Investor Demand Remains Strong
Investor Demand Remains Strong Gold ETF Ou nces 2,000,000 2,500,000 1,000,000 Apr-07 Apr-08 1,500,000 Investment CAGR: Oct-07 Oct-08 500,000 24% oy Apr-09 (April TrSilver 0as of Oct-09 2007 CAGR:–Apr-10 March 25% as2013) Oct-10 aPlatinum metalApr-11 CAGR: Oct-11 169%Apr-12 Oct-12 Apr-13 Palladium 6S
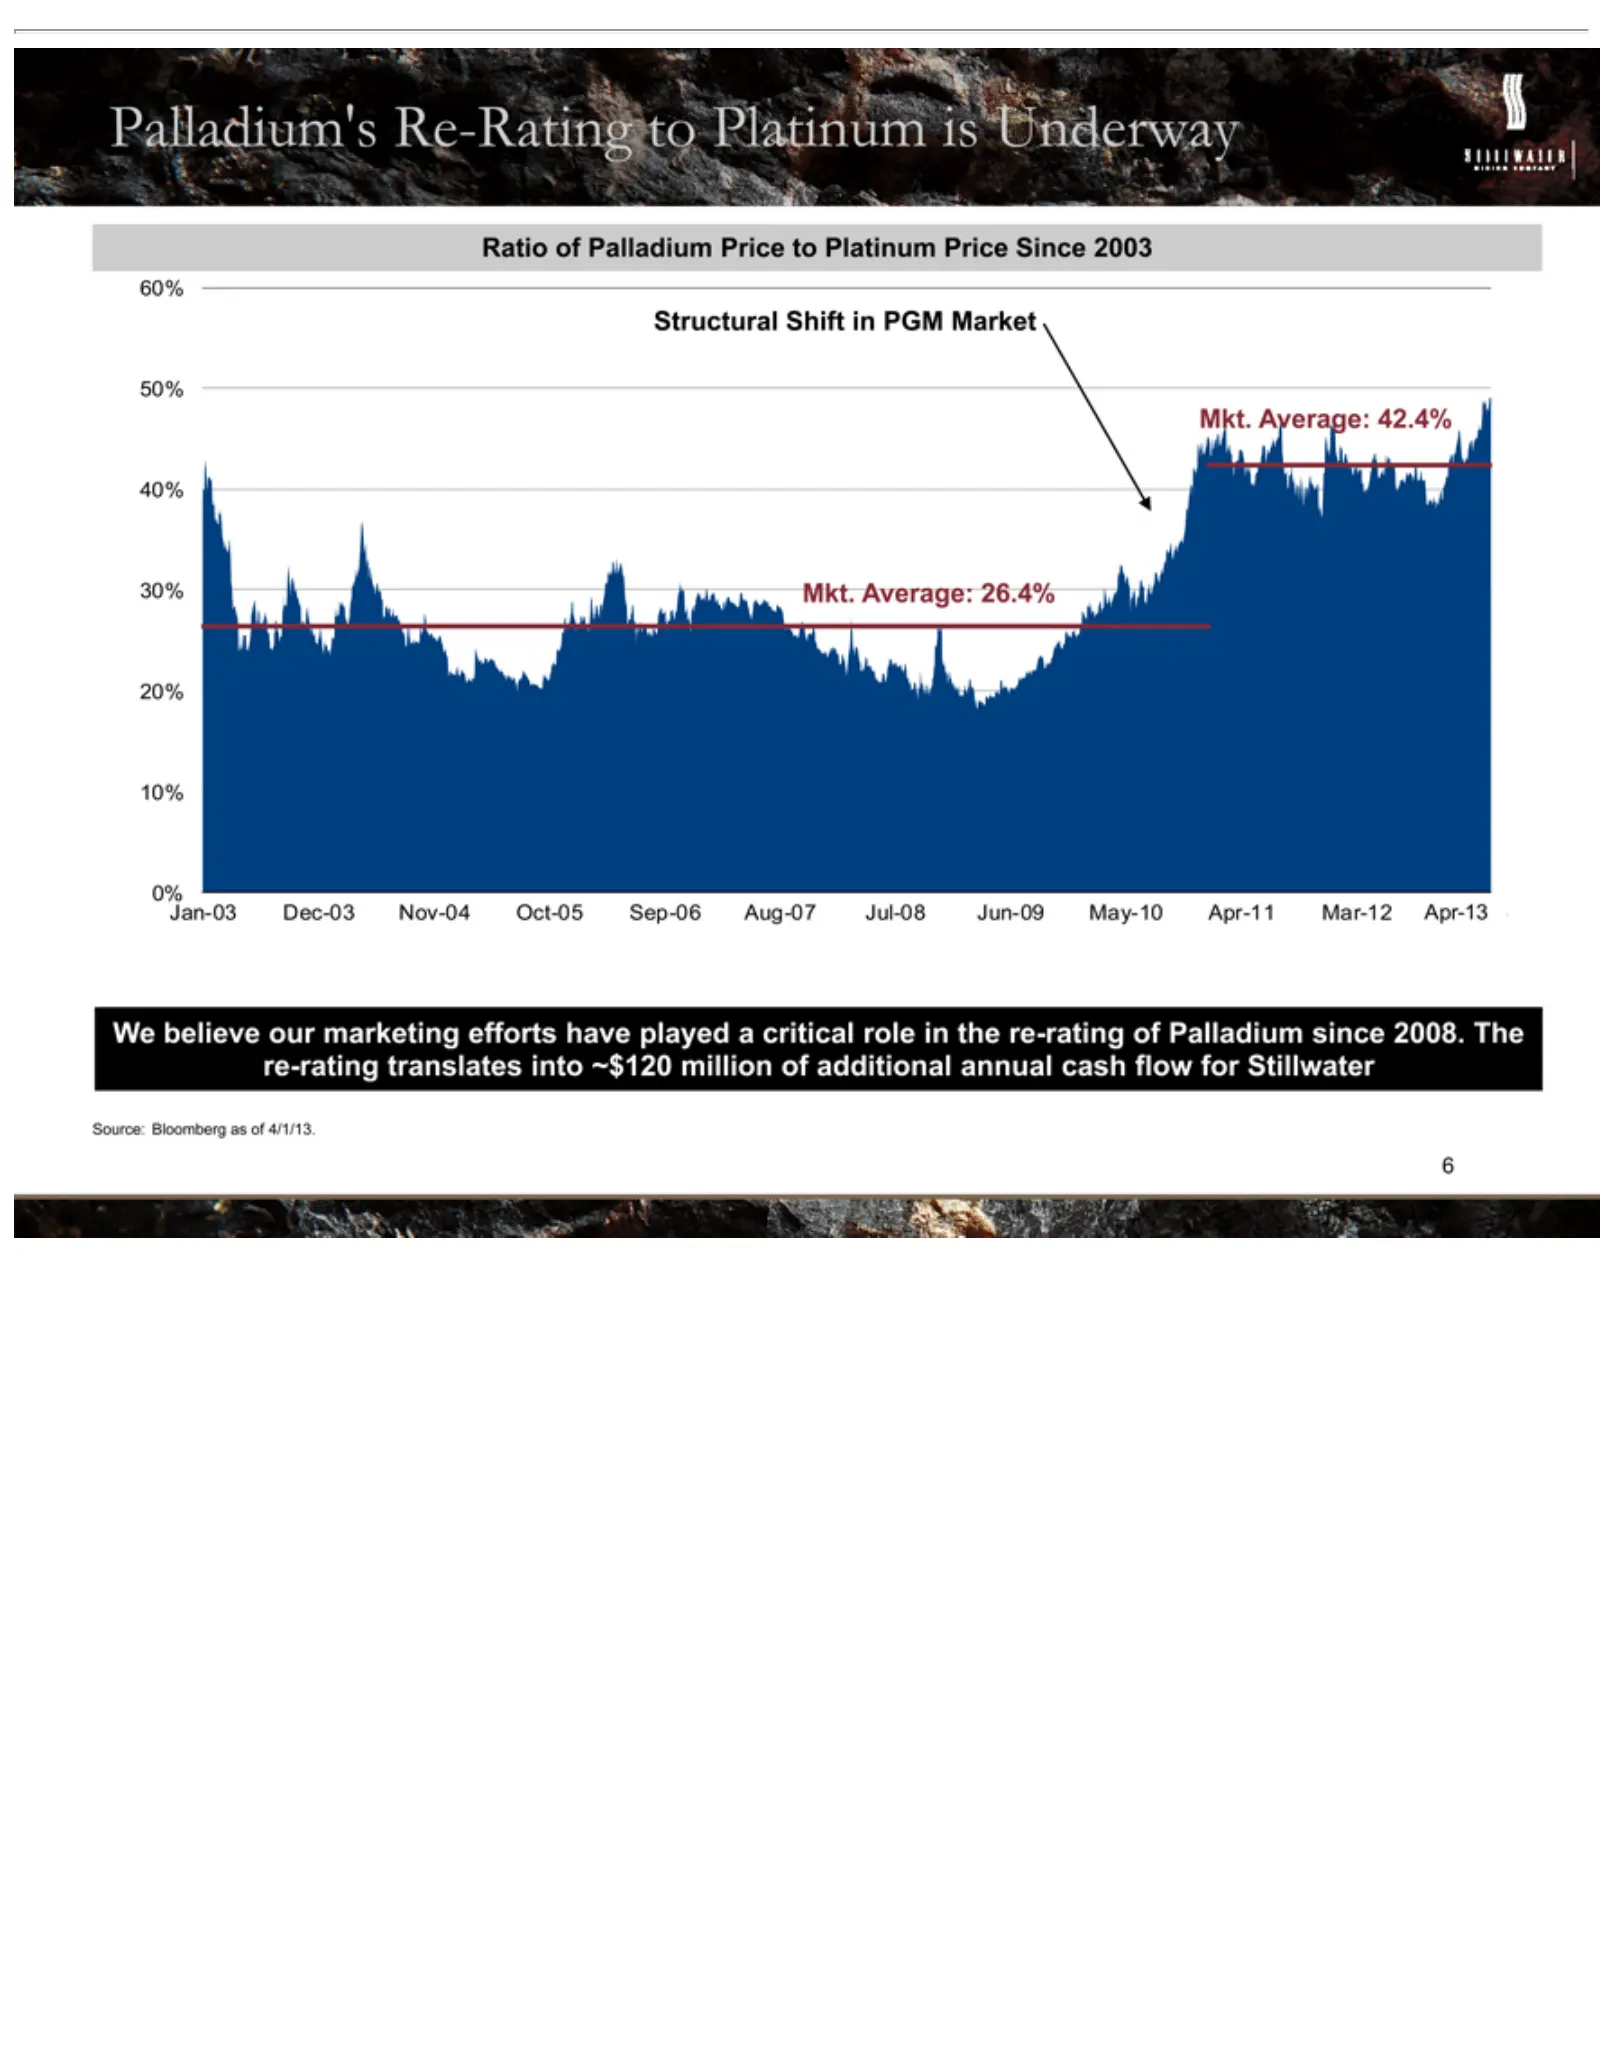
Slide 8: Palladium's Re-Rating Versus Platinum Is Structural
Palladium’s Ratio Structural 0% 10% 20% 30% 40% 50% 60% Mkt. Jan-03 Nov-04 We 7Source: believe Average: ofDec-03 Bloomberg Oct-05 Palladium Shift our Re-Rating 42.4% 26.4% marketing Sep-06 in PGM Price as of to Aug-07 Market to 4/1/13. Platinum efforts Platinum Jul-08 have is Price Underway Jun-09 p
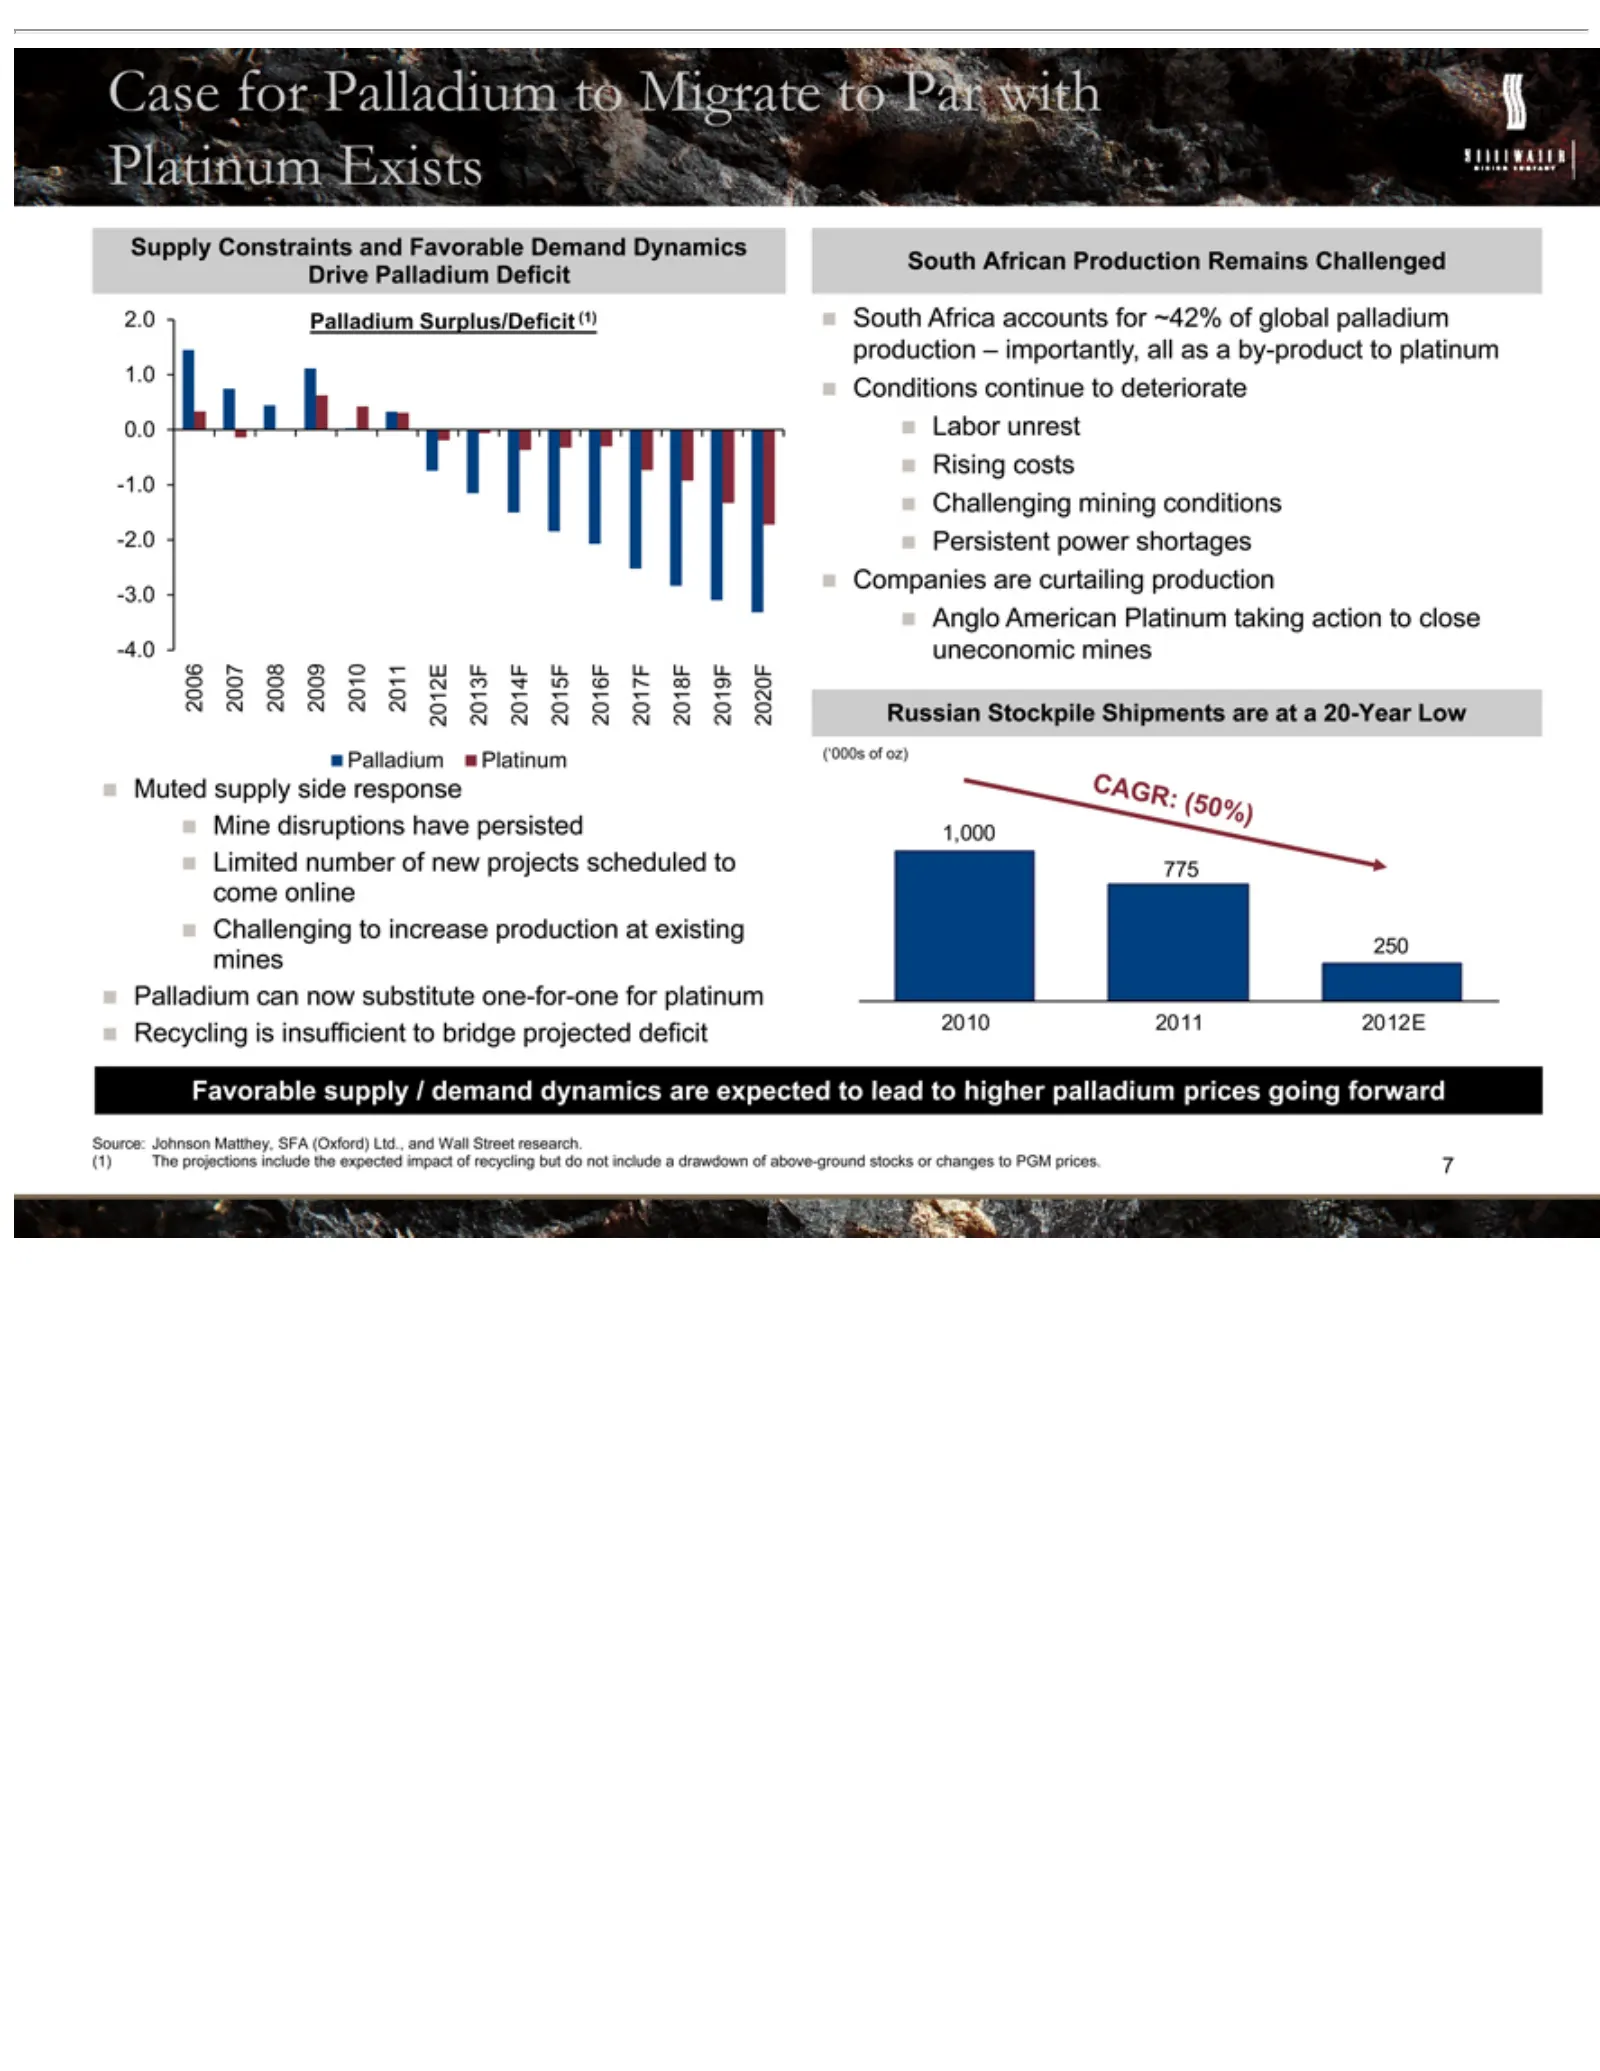
Slide 9: Palladium Supply Deficit and Constrained Supply
(‘000s Case Supply 2.0 2006 2011 2010 4F Palladium 2020F 2019F nMuted deficit South Persistent Russian Mine Limited 2015F 1.0 for 2012E 2007 African Africa of supply 0.0 Constraints disruptions Stockpile Palladium oz) 2016F power number Surplus/Deficit Platinum -1.0 2008 2013F accounts side Producti
Slide 10: 2. Stillwater Remains the Premier PGM Play
2. Stillwater Premier PGMRemains Play the
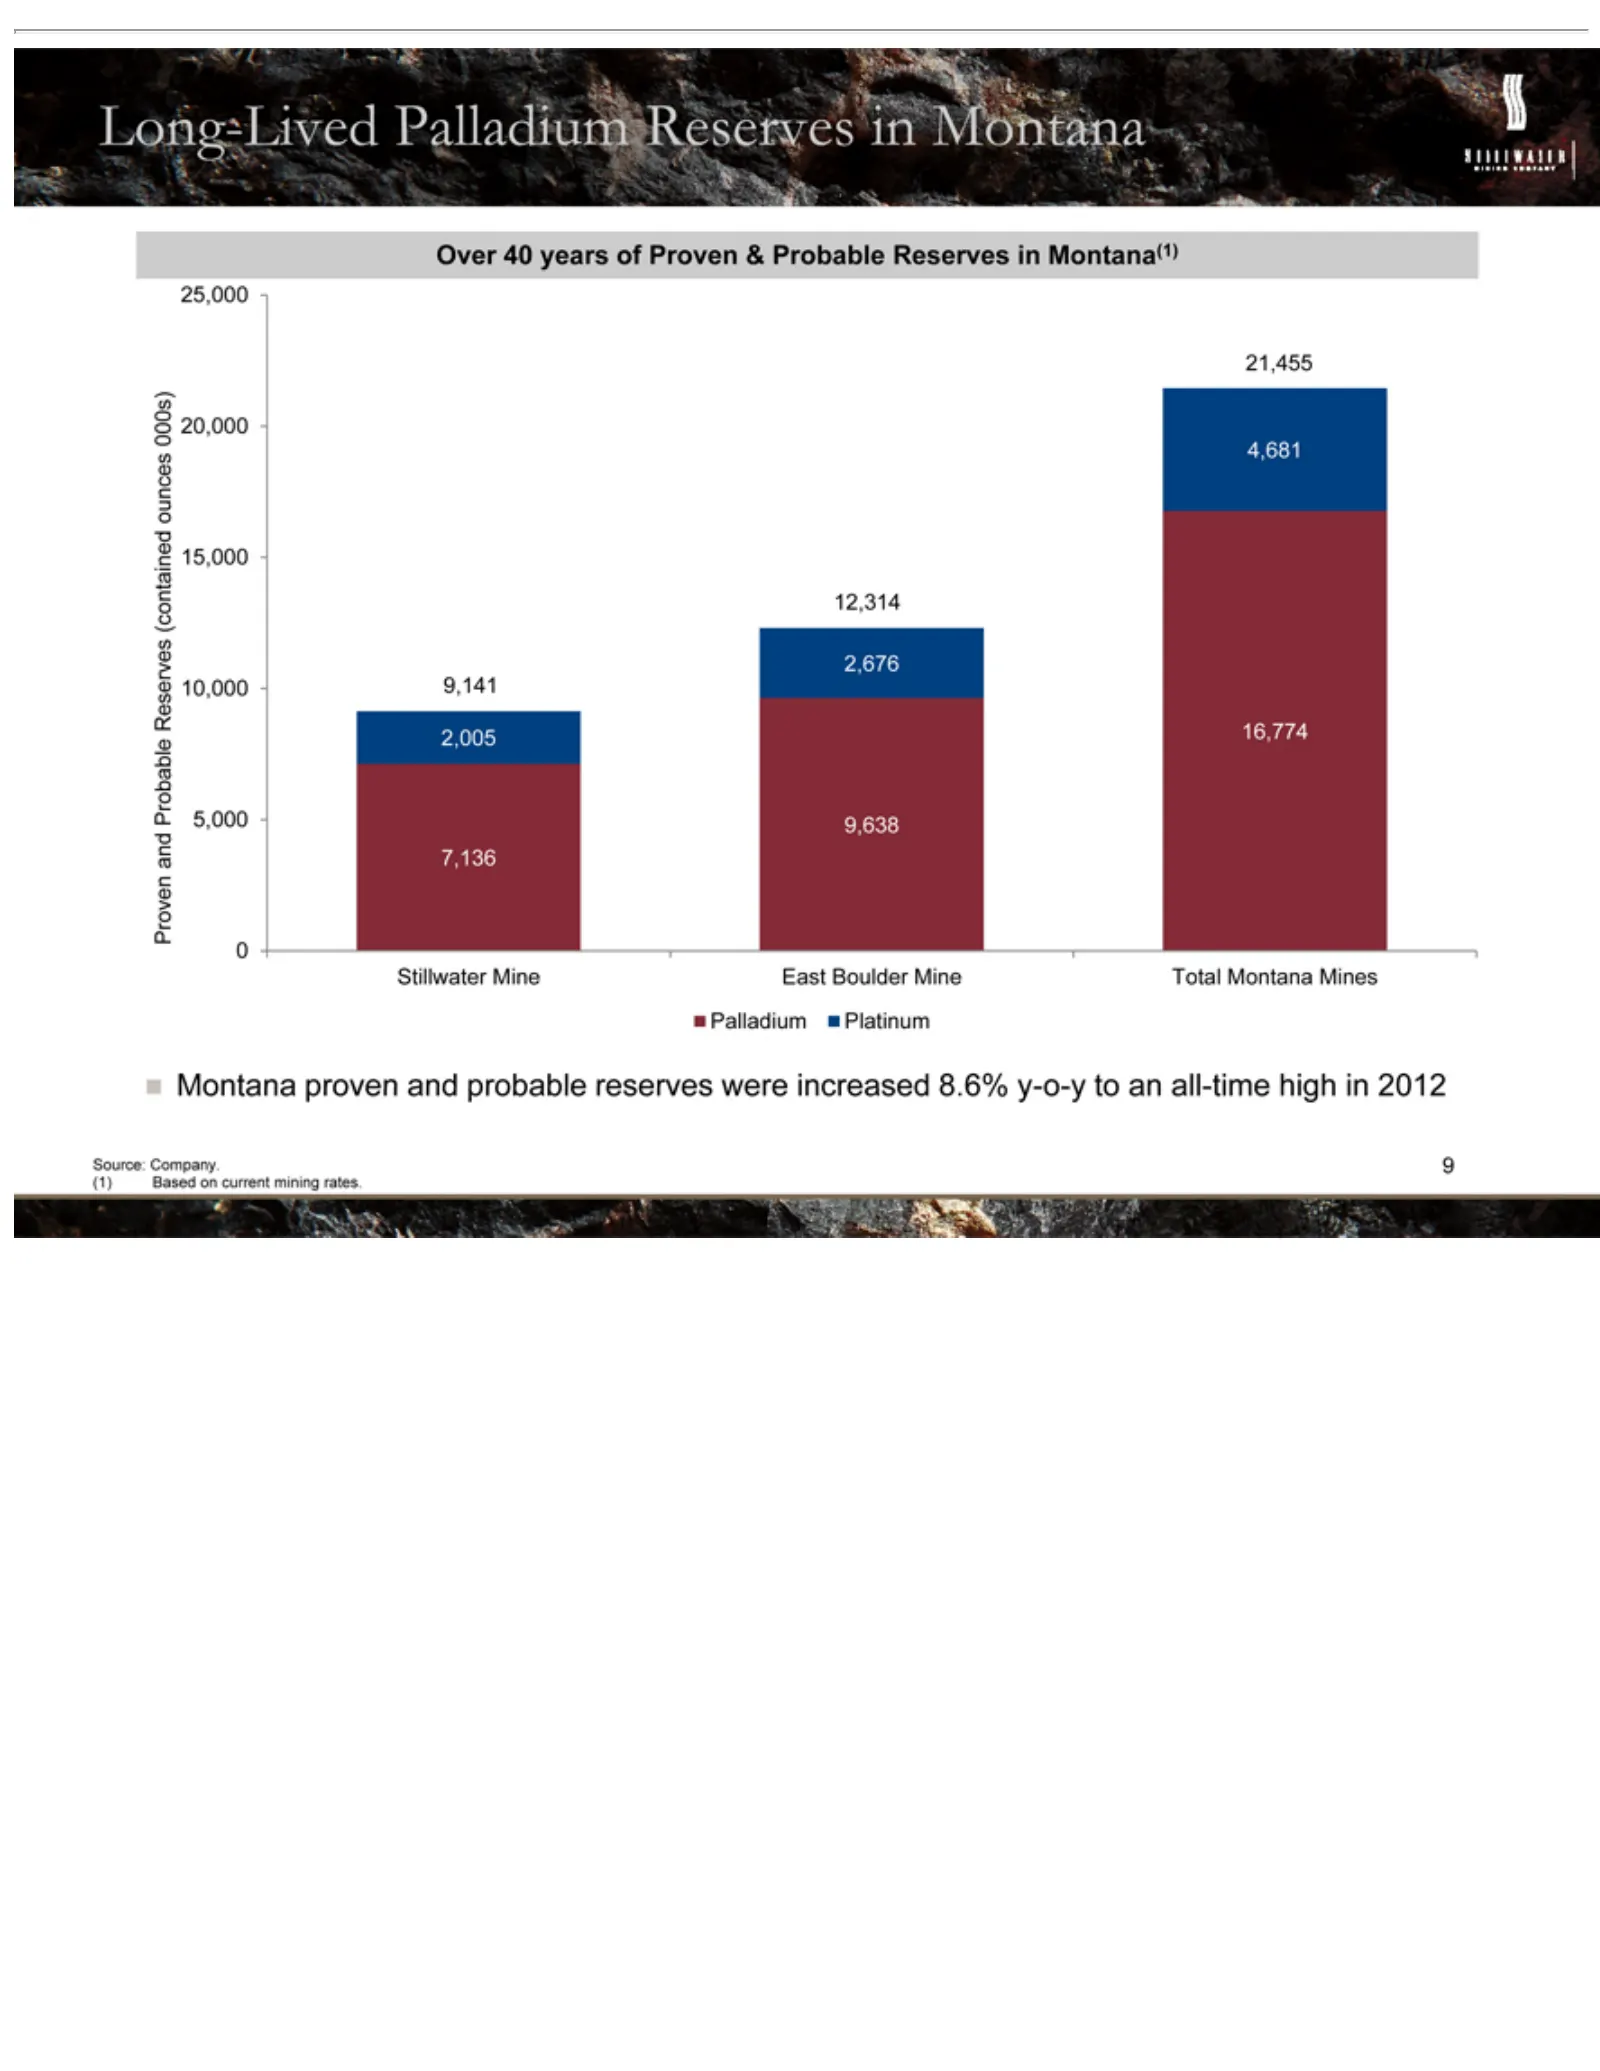
Slide 11: Long-Lived Palladium Reserves in Montana
Long-Lived Palladium Reserves in Montana Over 0Proven Stillwater 16,774 4,681 21,455 9,638 2,676 12,314 7,136 2,005 9,141 Palladium Montana Source: (1) 105,000 Based 40and 10,000 Company. years proven on Mine Platinum Probable current of15,000 East and Proven mining Boulder probable Reserves 20,000
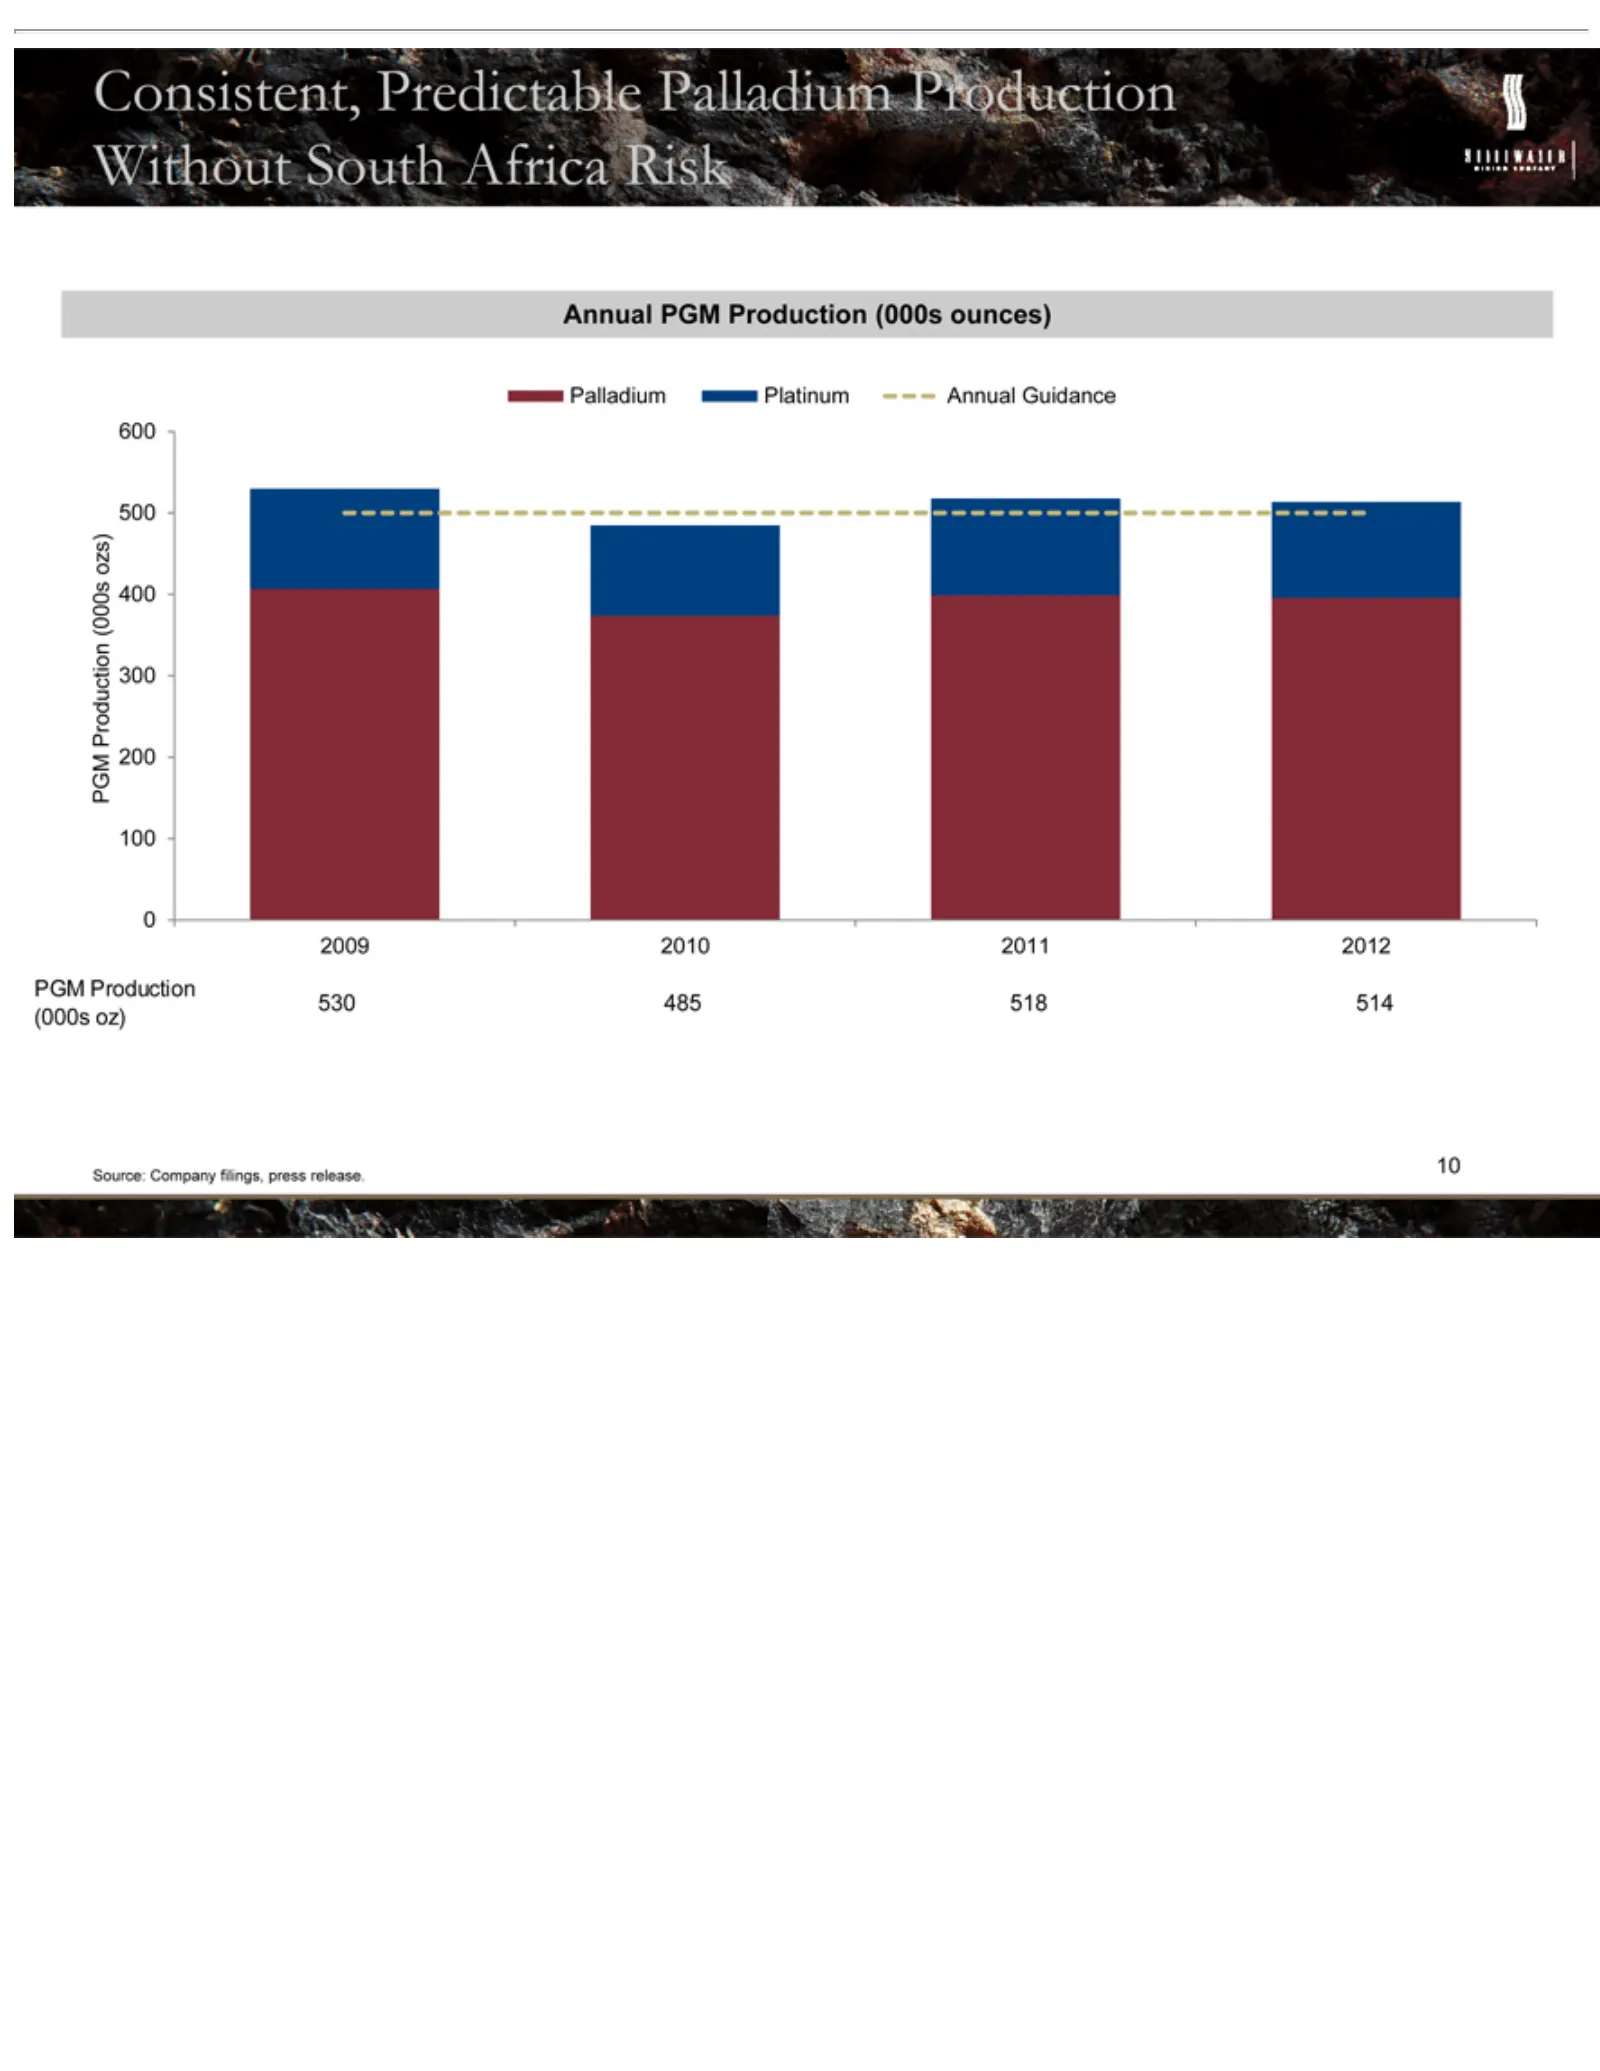
Slide 12: Consistent, Predictable Palladium Production Without South Africa Risk
Consistent, Predictable Palladium Production Without South Africa Risk Annual 0Palladium 2009 PGM Source: 514 518 485 530 111002010 Production 200 PGM Company 300 Platinum 2011 Production 400 2012 (000s filings, 500 Annual 600 ozs) oz)(000s press Guidance ounces) release.
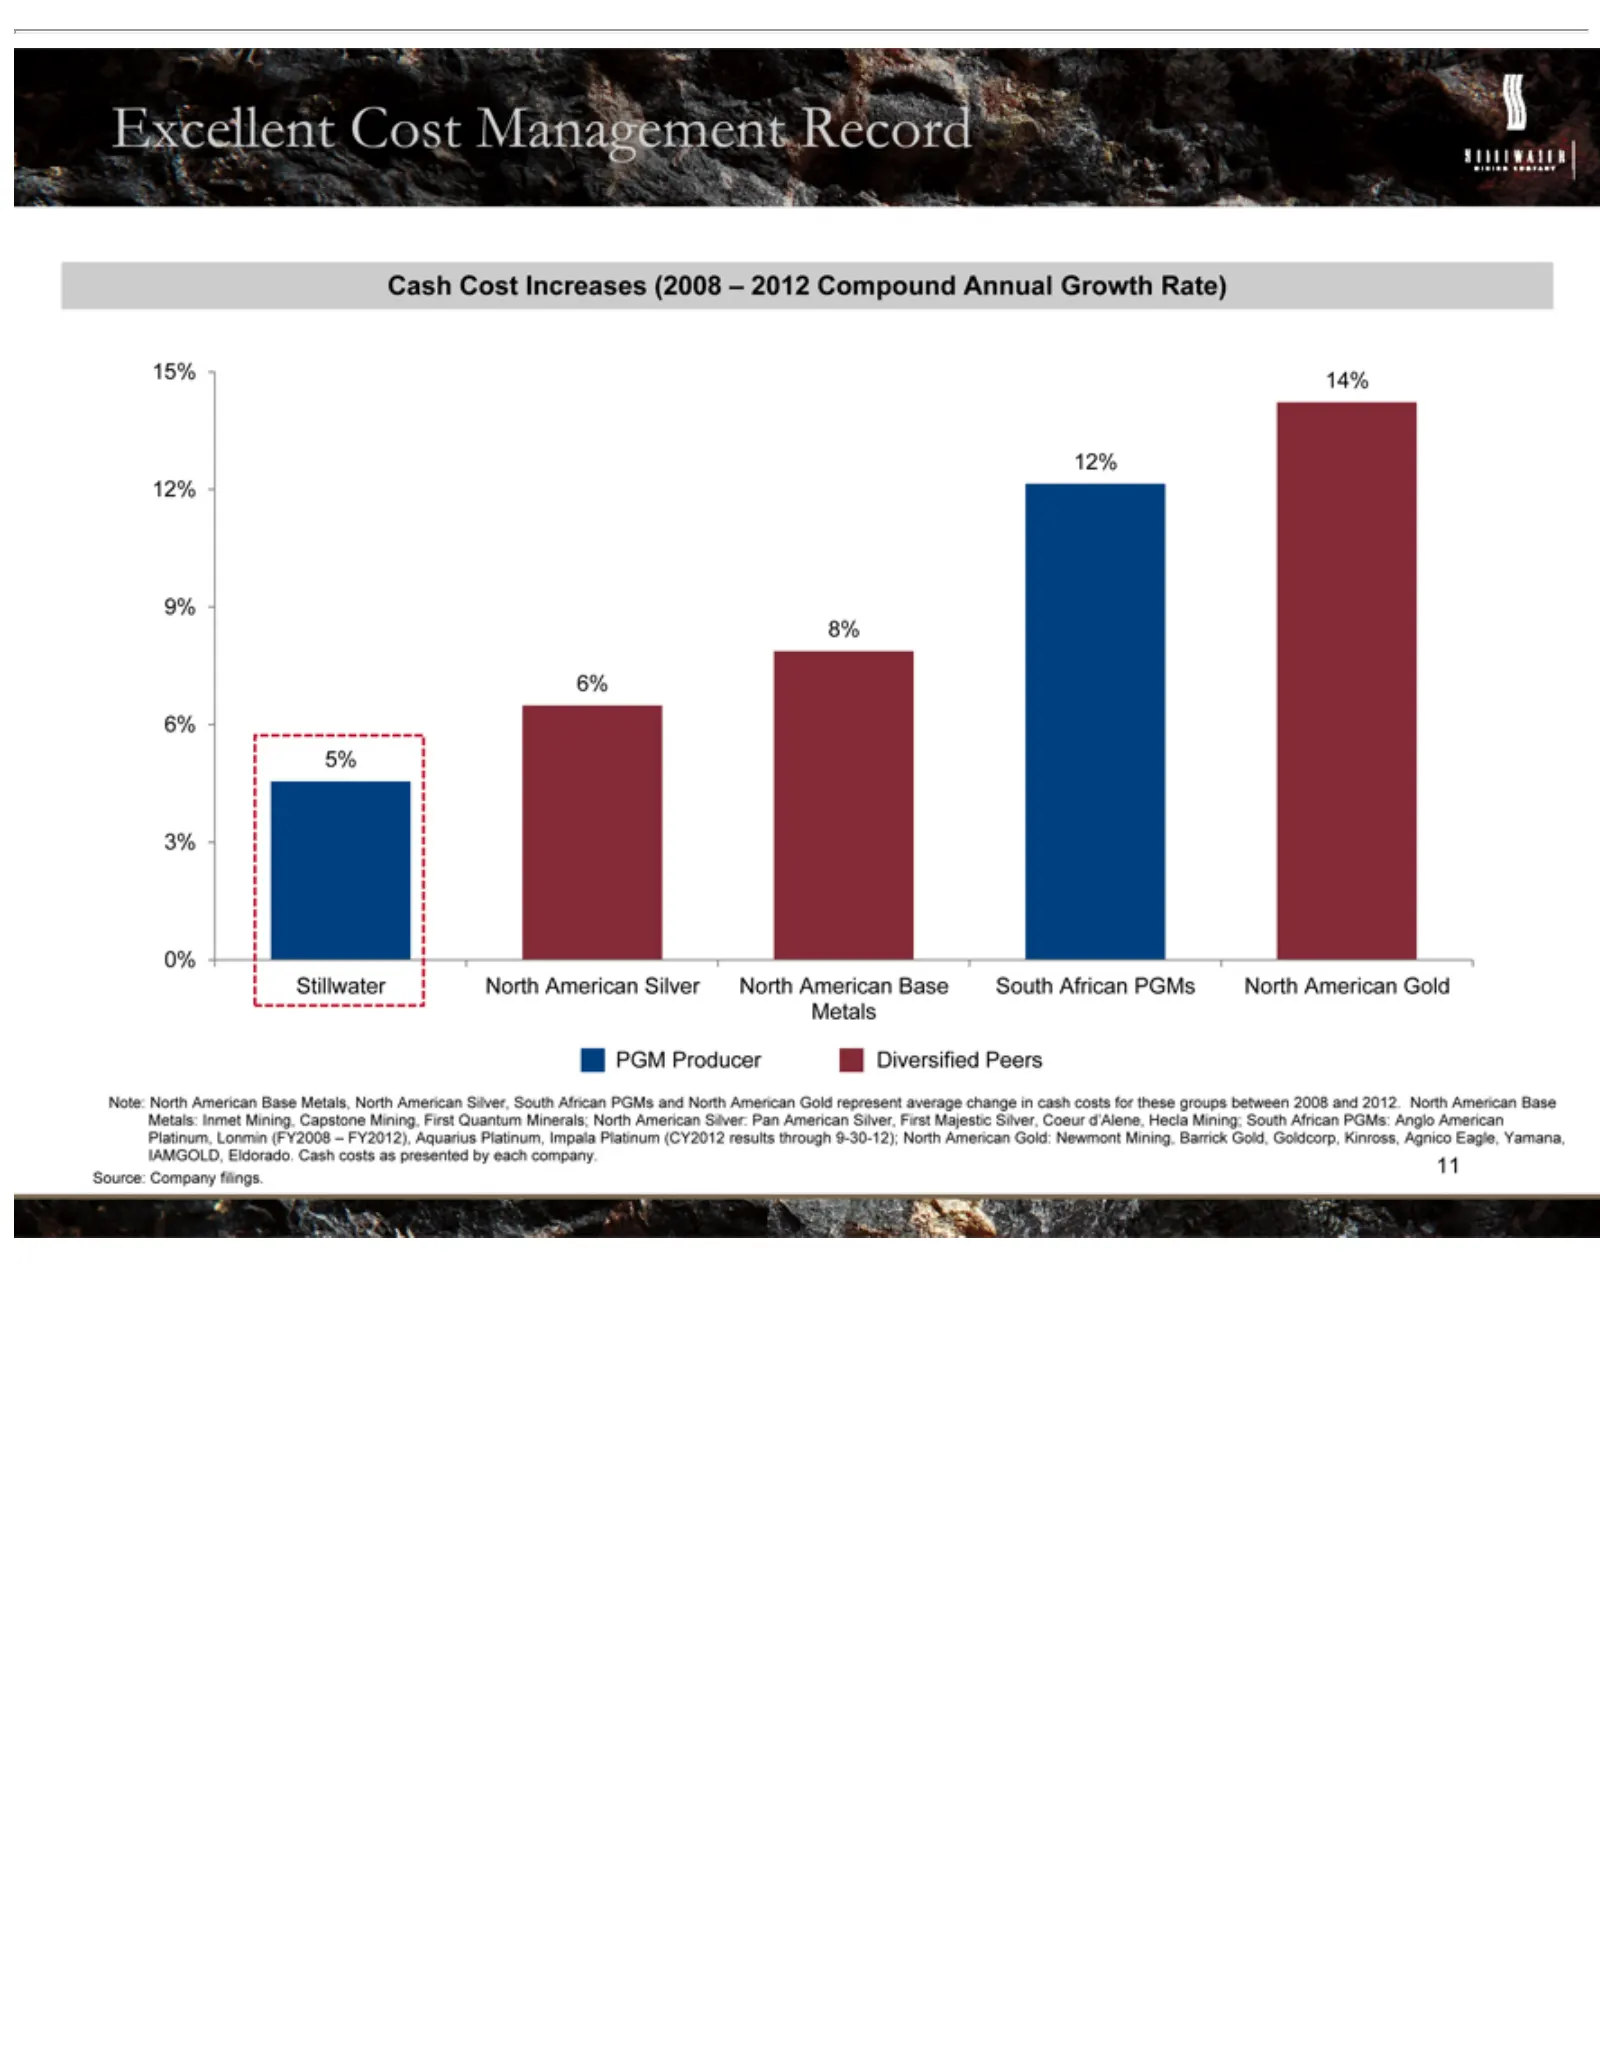
Slide 13: Excellent Cash Cost Management
Excellent Cash 12% 15% Stillwater 14% 12% 8% 6% 5% PGM Metals Note: North Metals: Platinum, IAMGOLD, Source: 12 Cost Cost Producer North American Inmet Company Management Lonmin North 9% Increases American Eldorado. 6% Mining, Diversified American Base 3% filings. (FY2008 (2008 0% Base –Record Capst
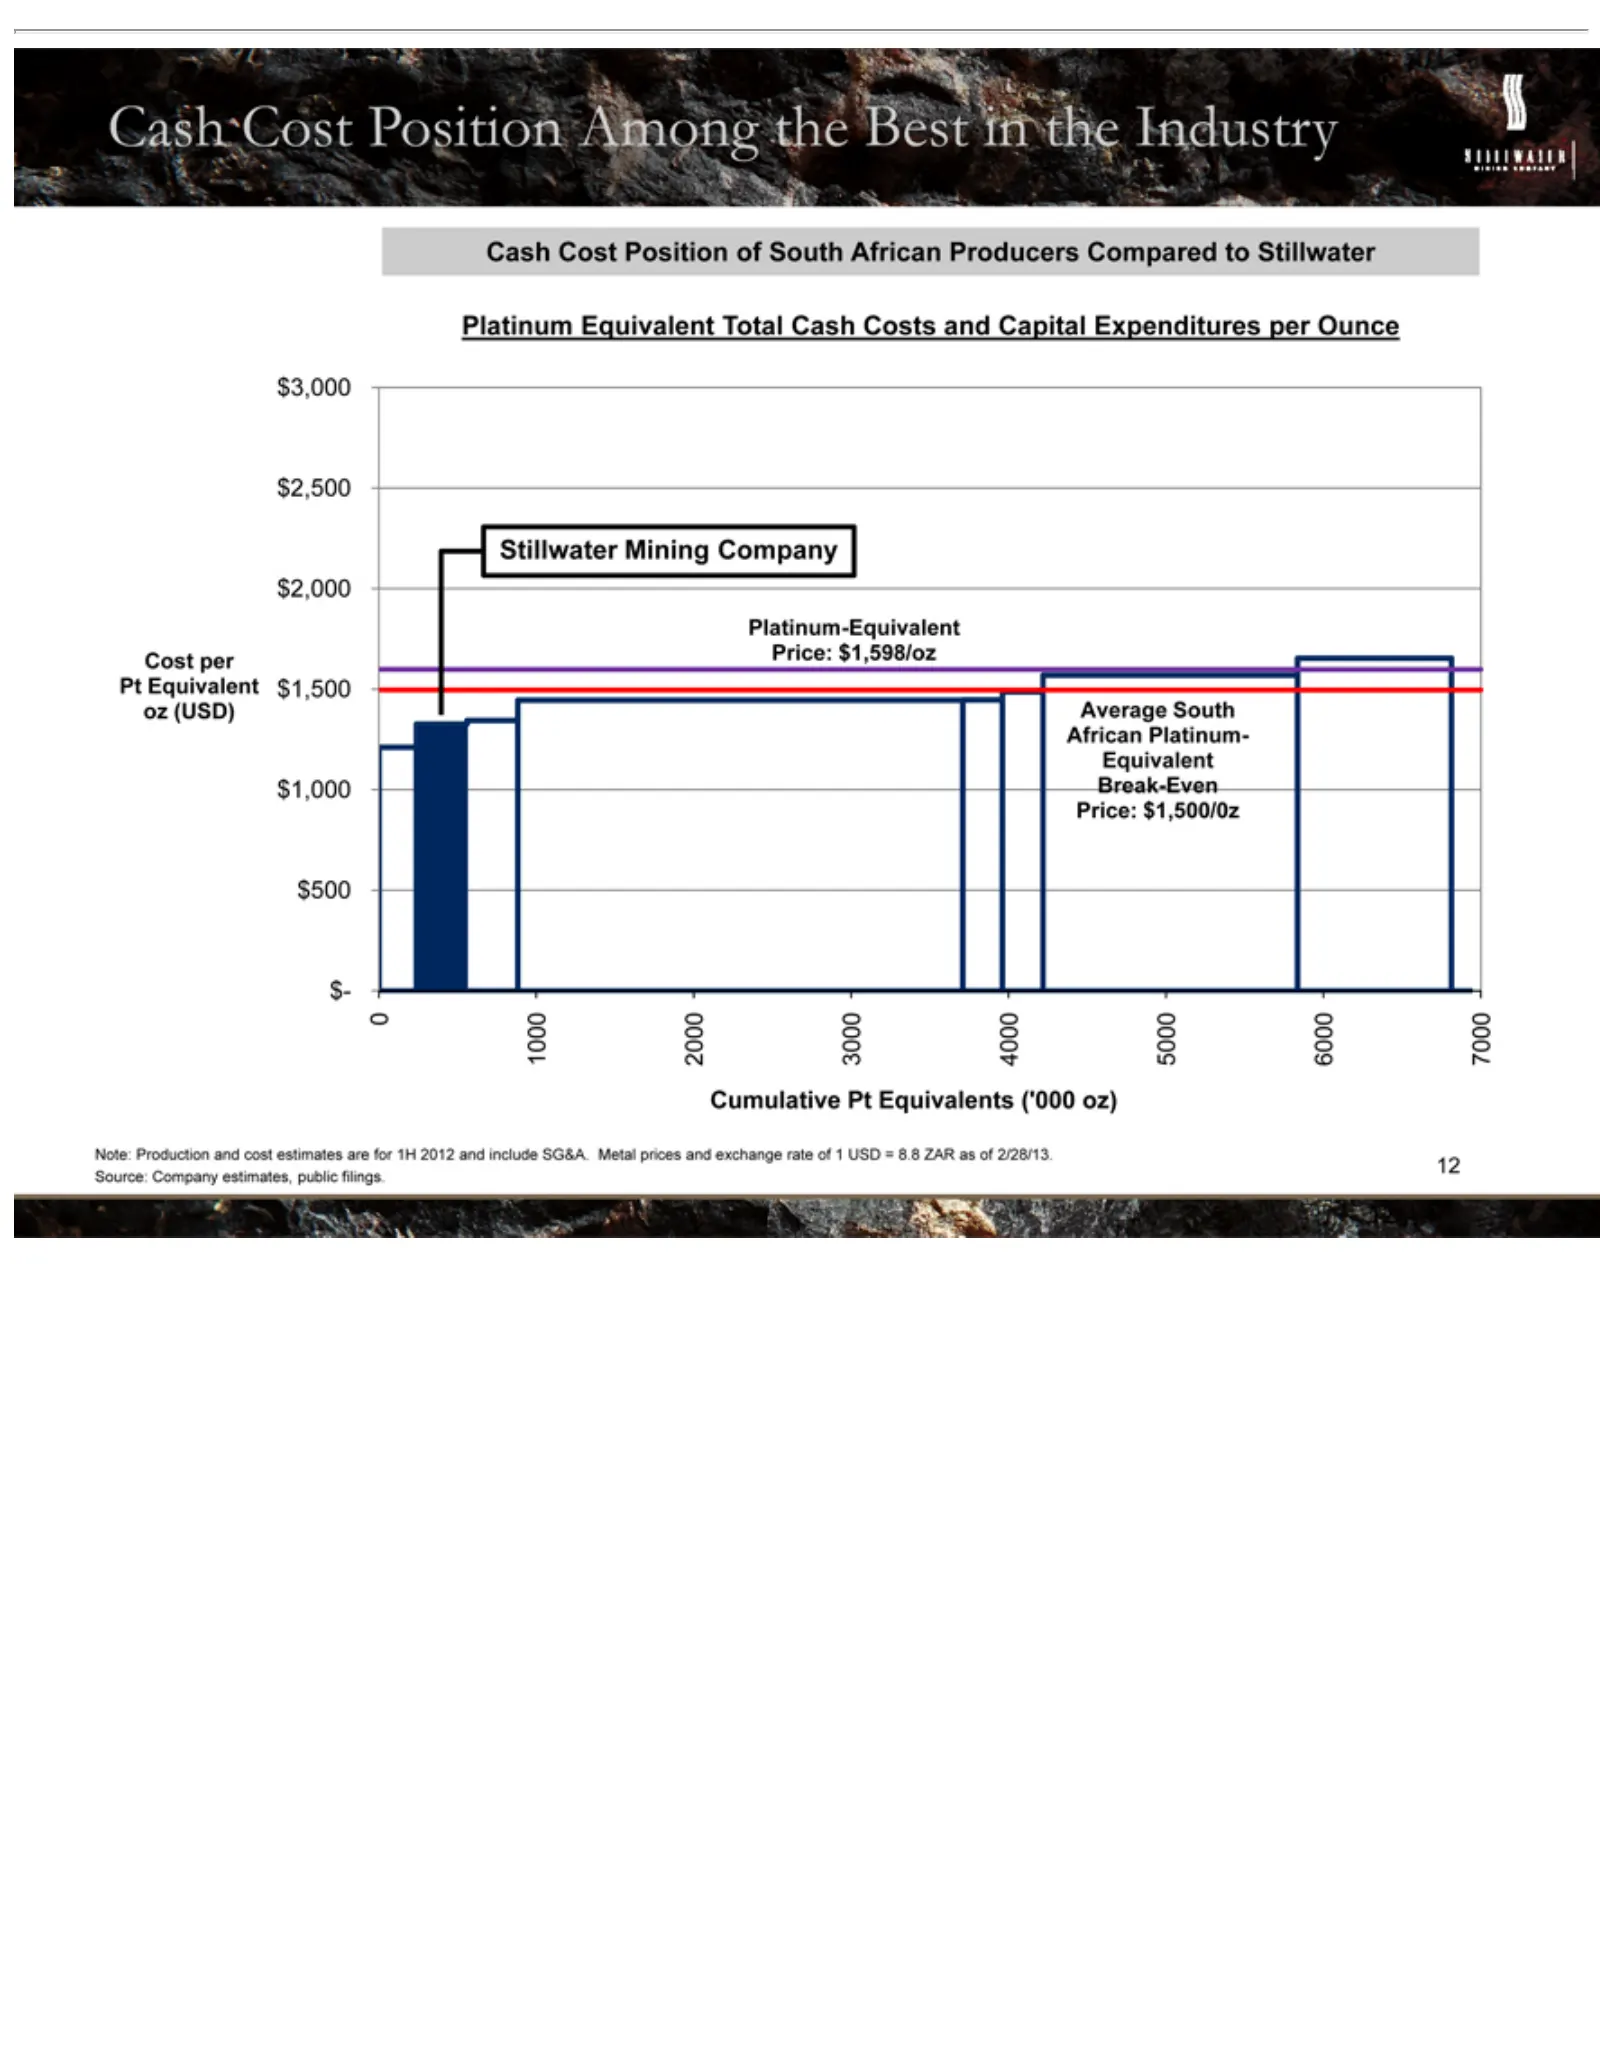
Slide 14: Among the Best in the Industry on Cost Position
Platinum Cash CostEquivalent Position Among ofTotal South Cash the African Best Costsin Producers and the Industry Capital Compared Expenditures to Stillwater per Ounce Cost $3,000 Stillwater Platinum-Equivalent 000 per Average Price: 2000 $2,500 PtMining 01Break-Even 3000 Cumulative Note: 13 4000 E
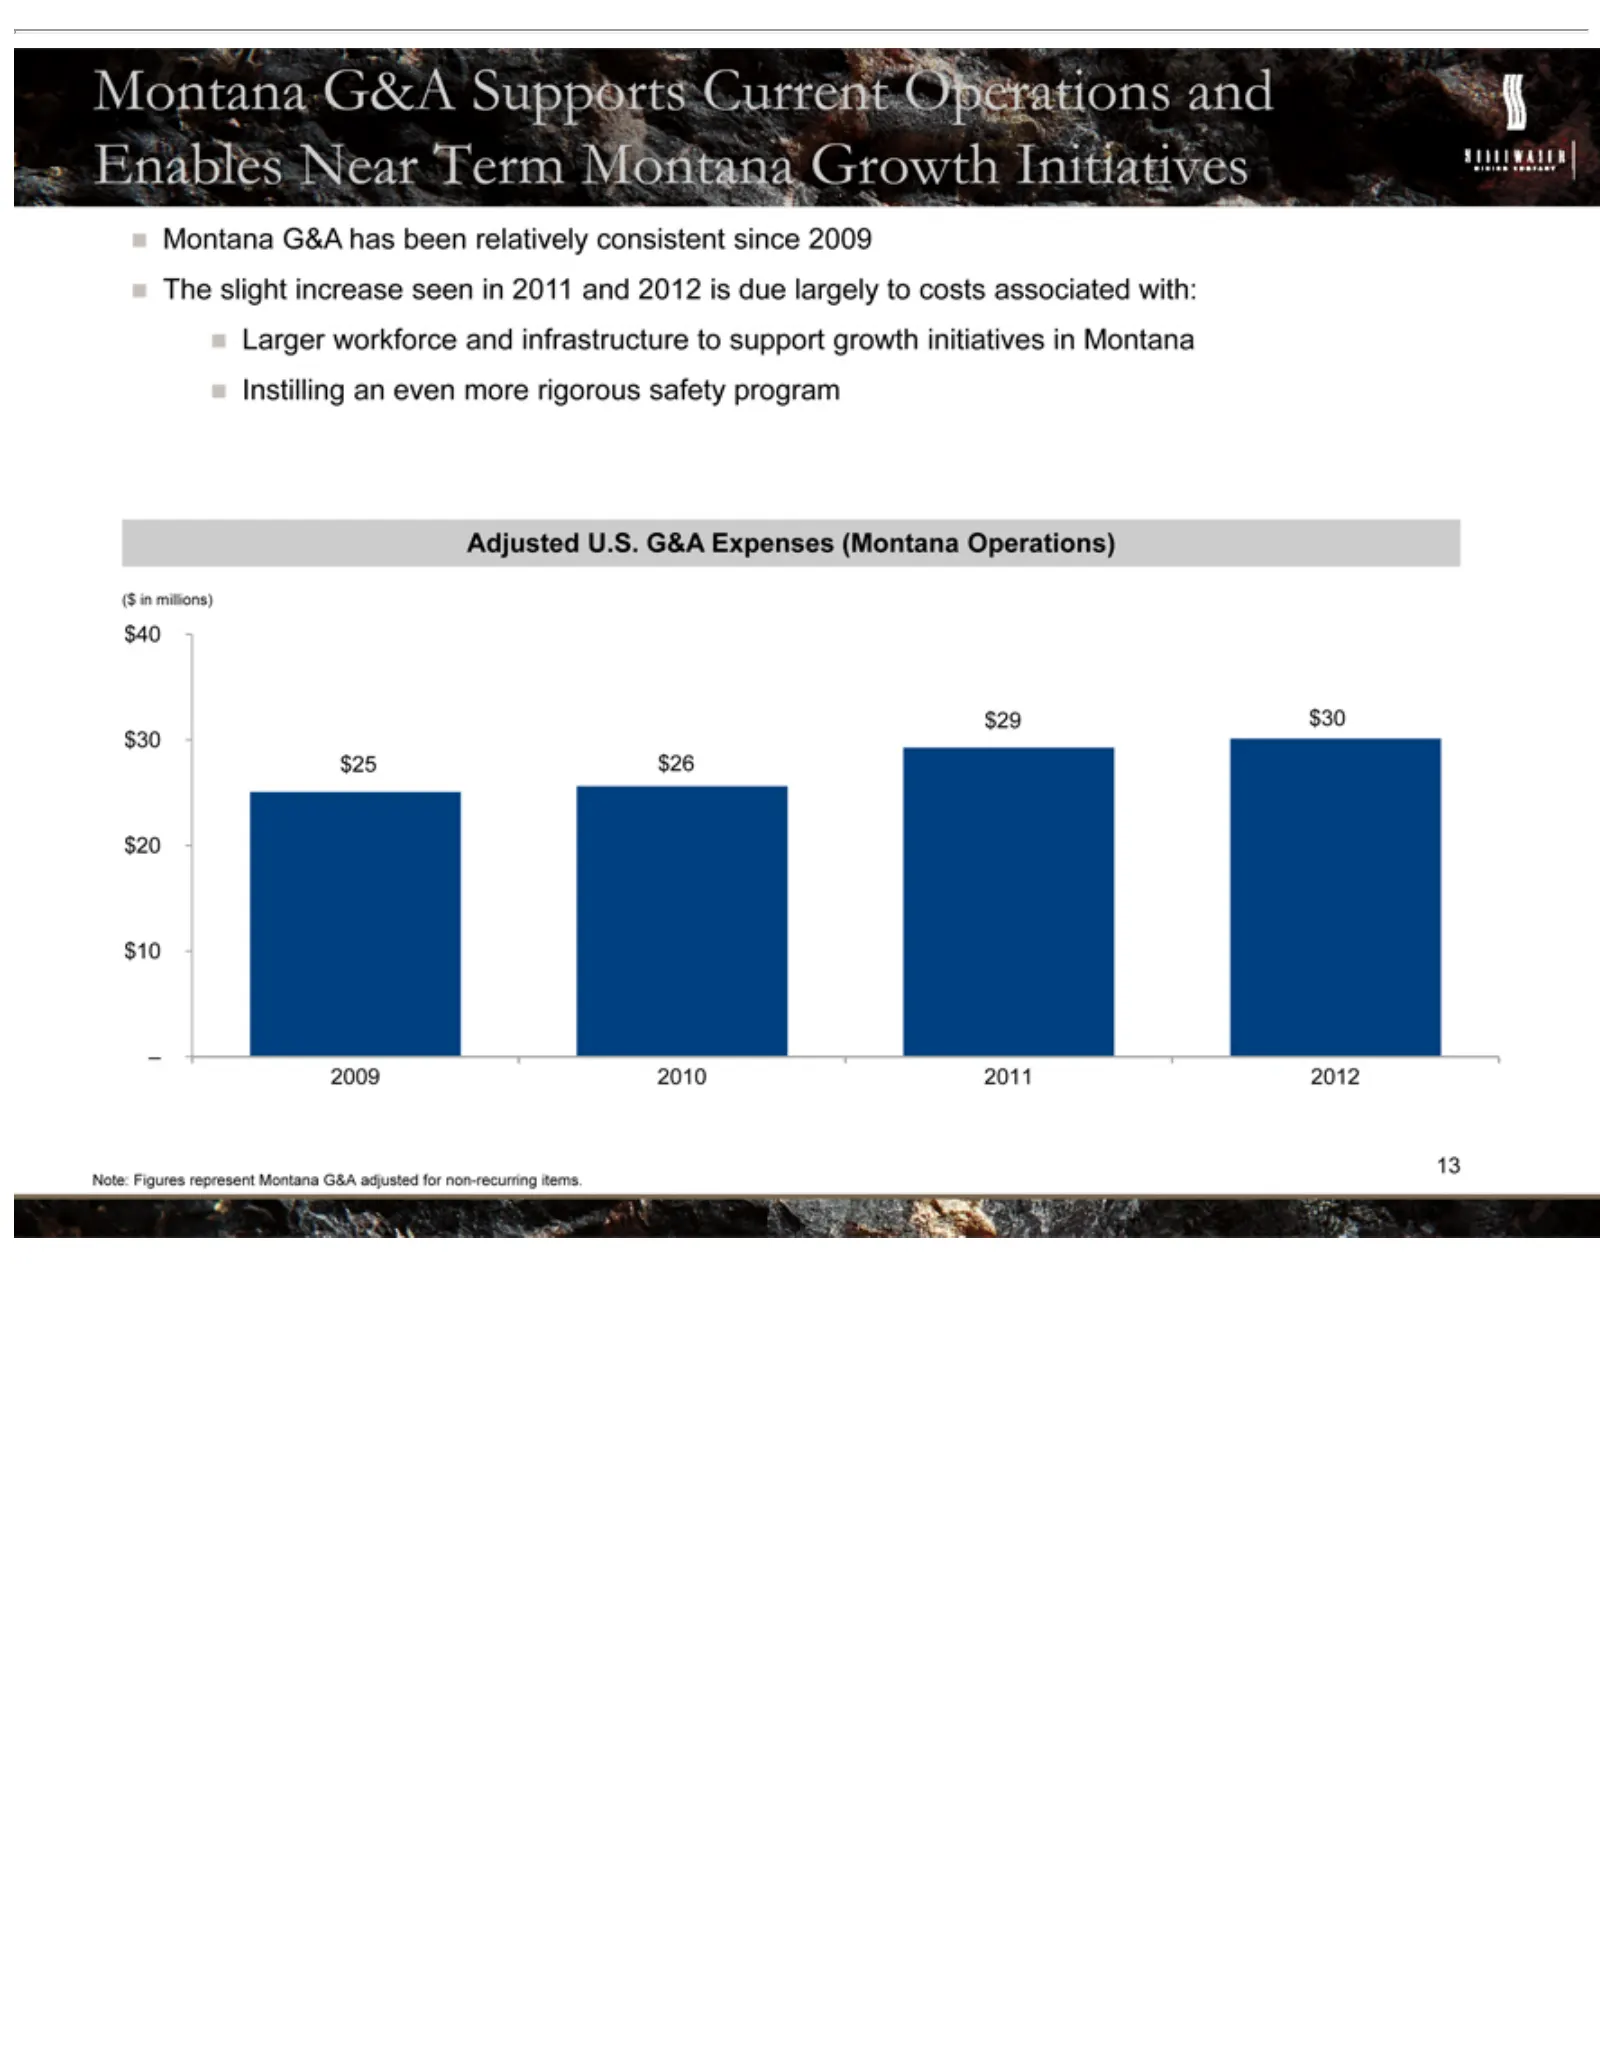
Slide 15: Adjusted G&A Supports Current Operations and Near-Term Growth
Montana The Adjusted ($ –$$40 2009 $30 $29 2011 Note: 14 25in$26 $30 slight millions) 2012 2010 Figures $20 G&A U.S. increase $10 represent G&A Supports has seen been Expenses Montana in relatively Current 2011(Montana and Operations G&A consistent 2012 adjusted Operations) is due and since for larg
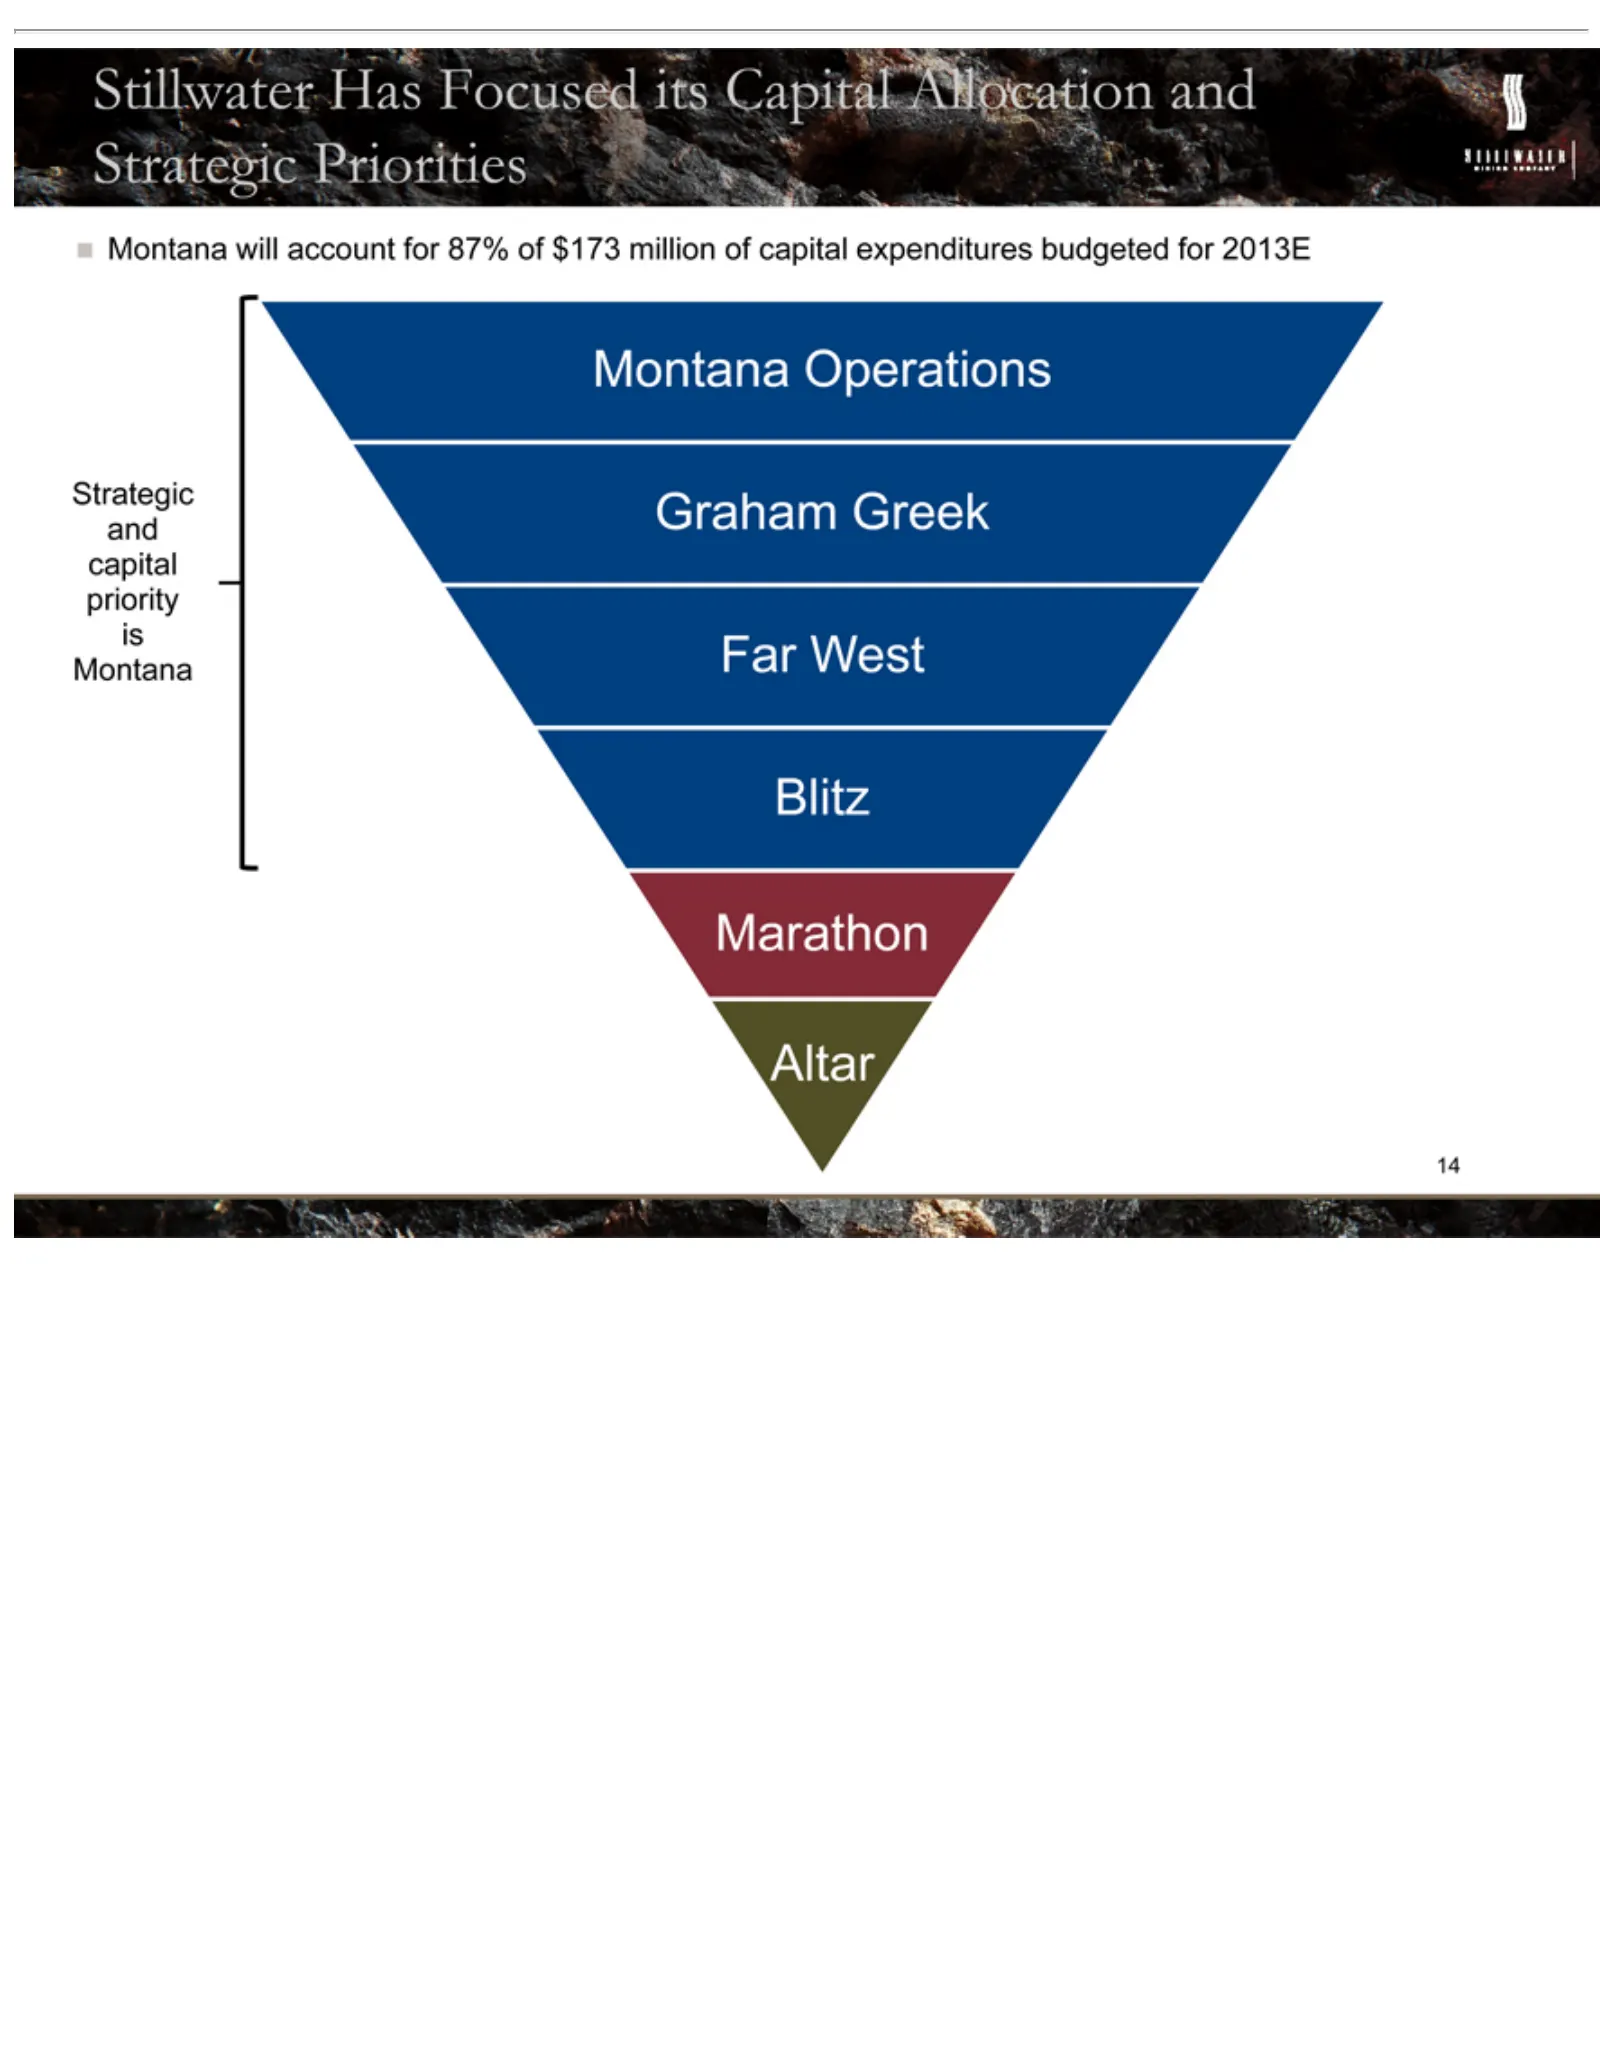
Slide 16: Strategic Priorities: Capital Allocation Focused on Montana
Stillwater Strategic Montana Graham Far 15 Altar Marathon BlitzWestGreek and will Operations Hascapital account Focused priority for its87% Capital is of Montana $173 Allocation millionand of Strategic capital expenditures Priorities budgeted for 2013E
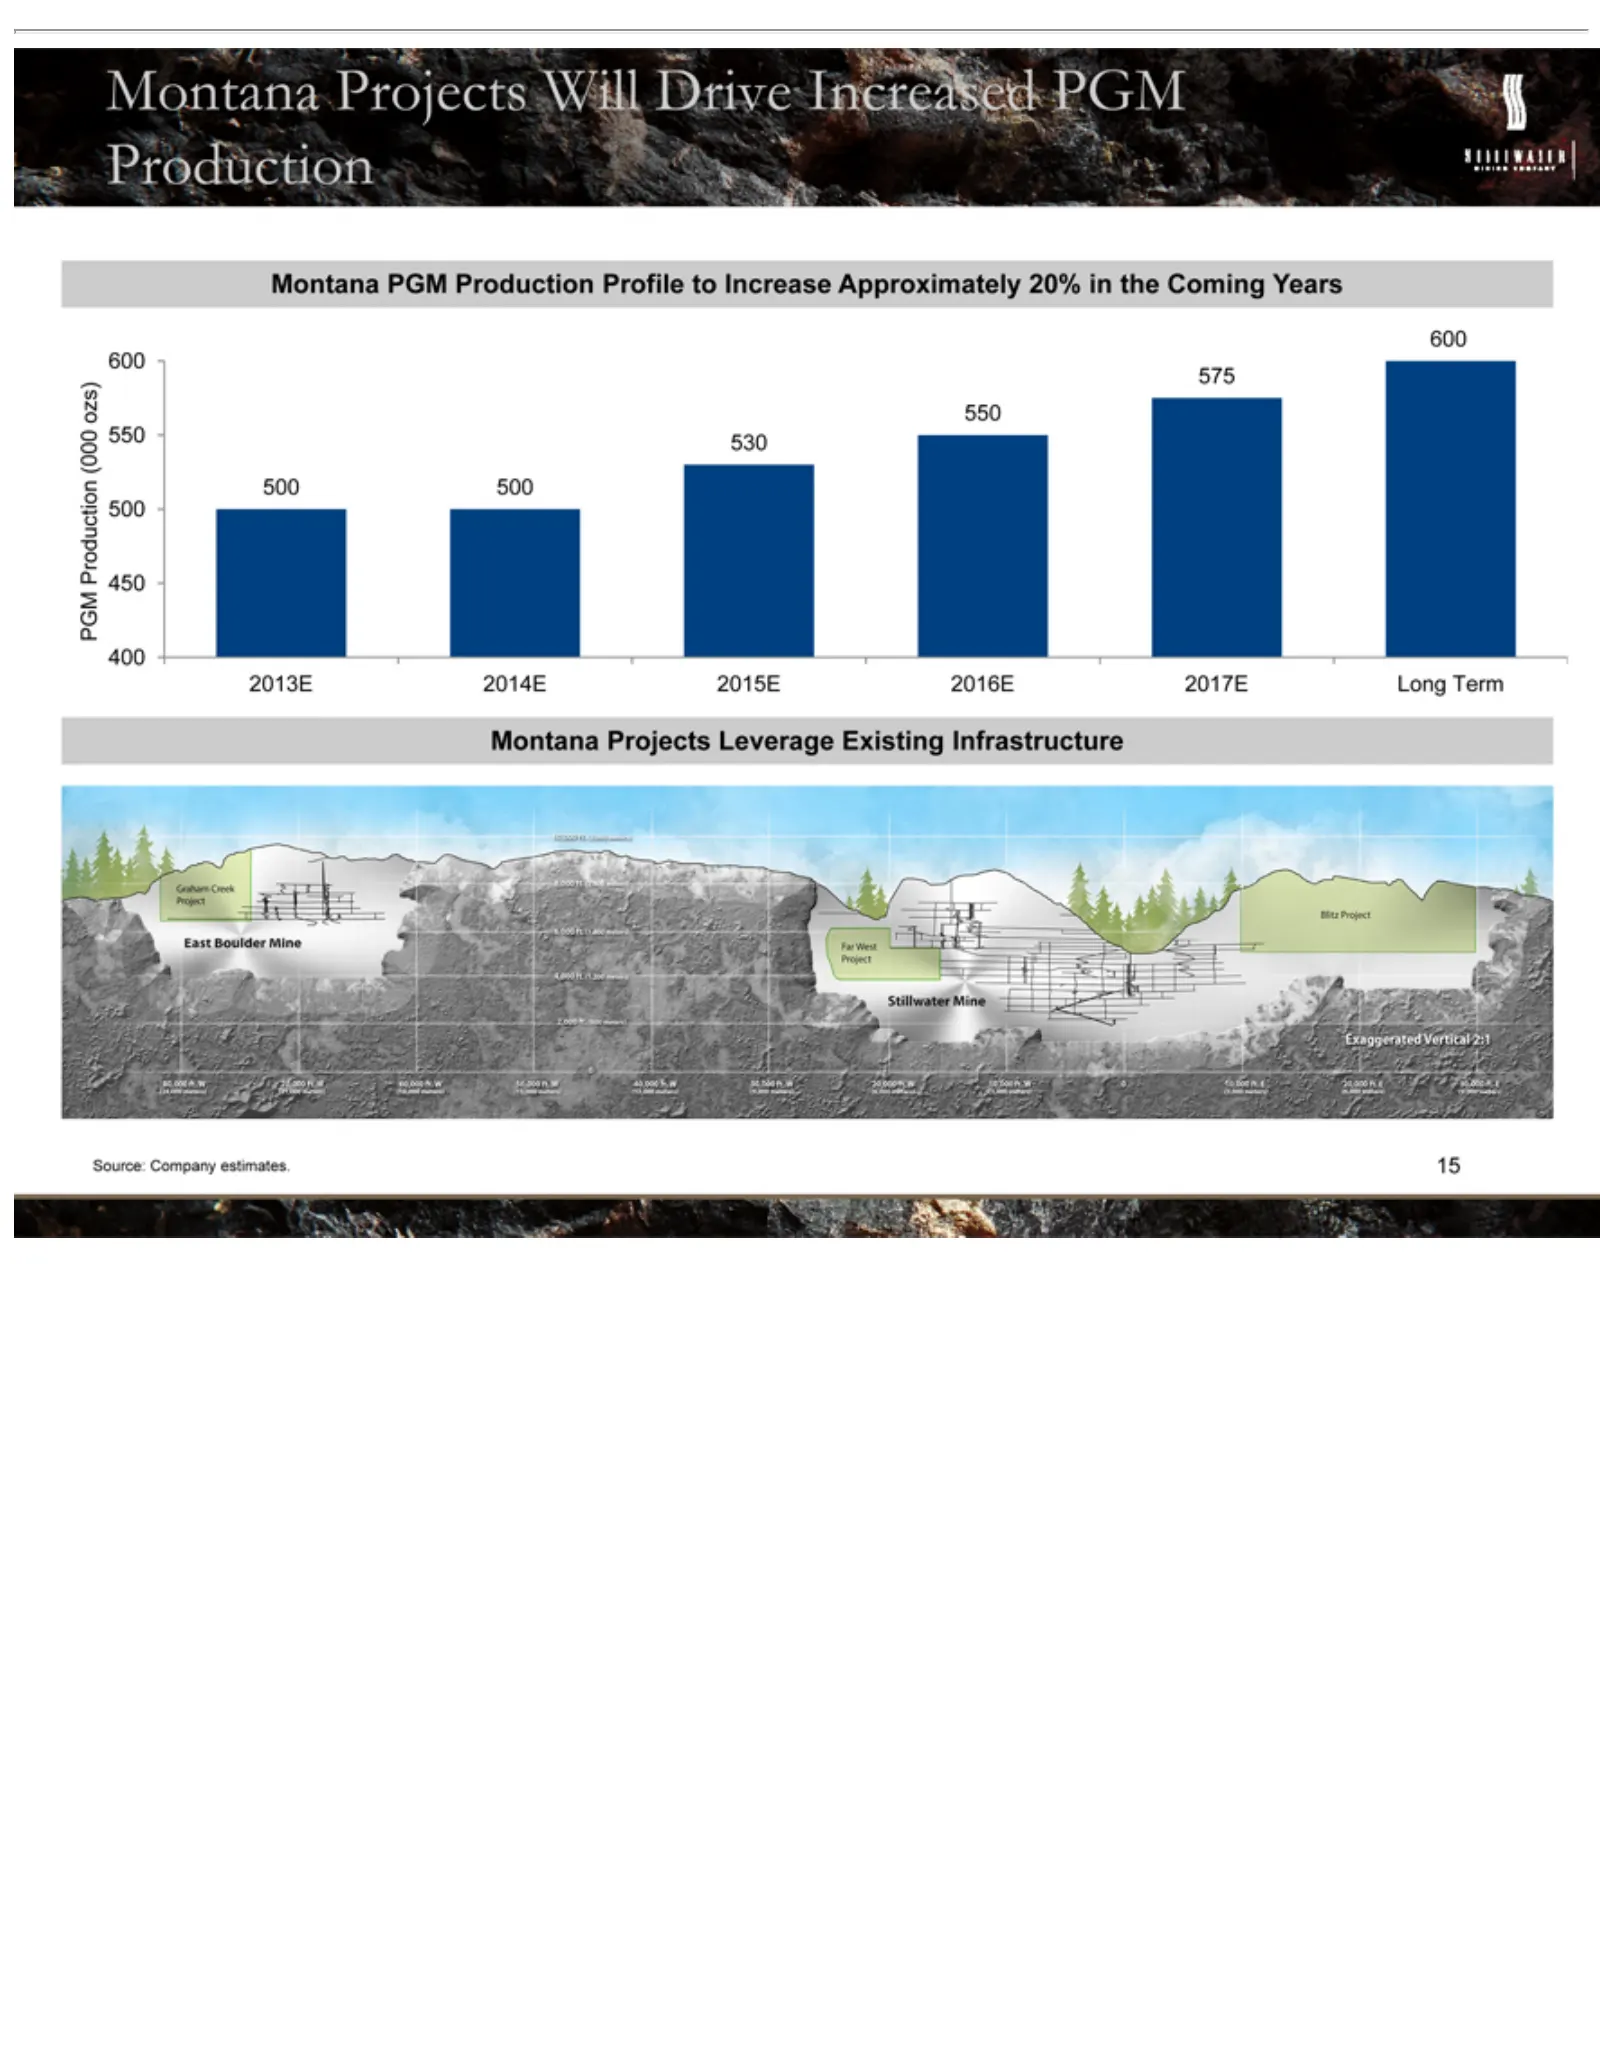
Slide 17: 2013E Montana PGM Production Profile
PGM500 400 500 2013E 600 575 550 530 Montana Source: 16 450 Production 2014E Company 500 PGM Projects 550 2015E Production 600 (000 Will Leverage estimates. 2016E ozs) DriveProfile Existing 2017E Increased toLong Infrastructure Increase PGM TermProduction Approximately 20% in the Coming Years
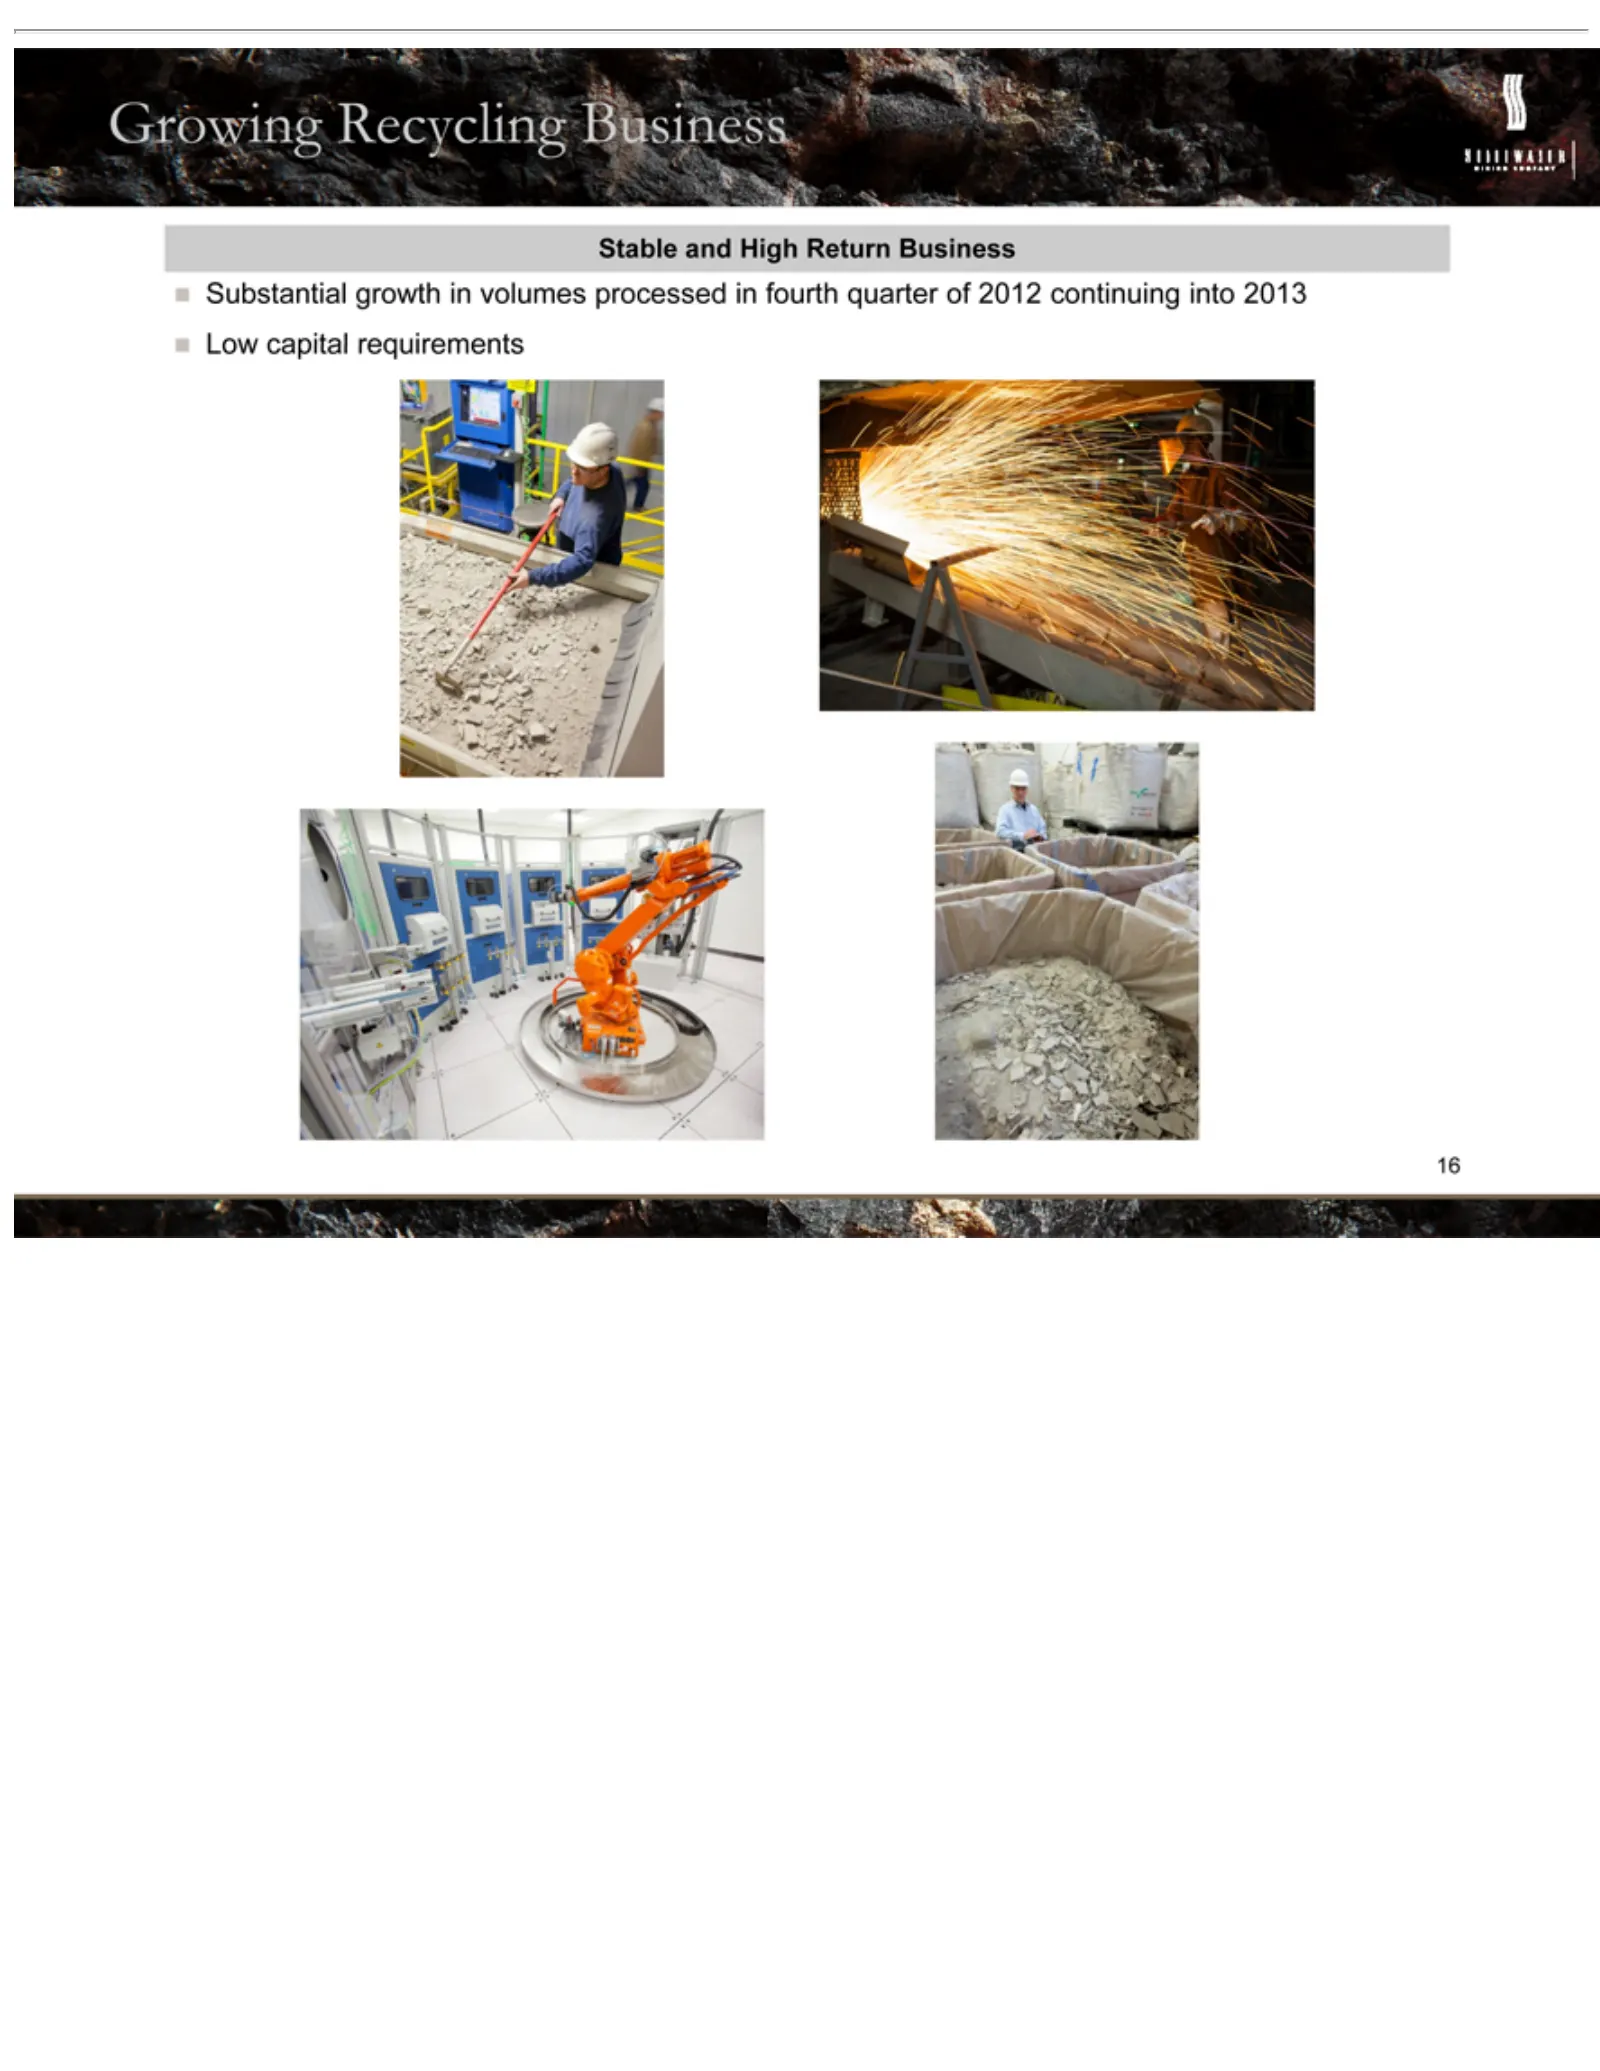
Slide 18: Growing, Stable Recycling Business
Growing Stable Substantial 17 andRecycling High growth Return inBusiness volumes Business processed in fourth quarter of 2012 continuing into 2013 Low capital requirements
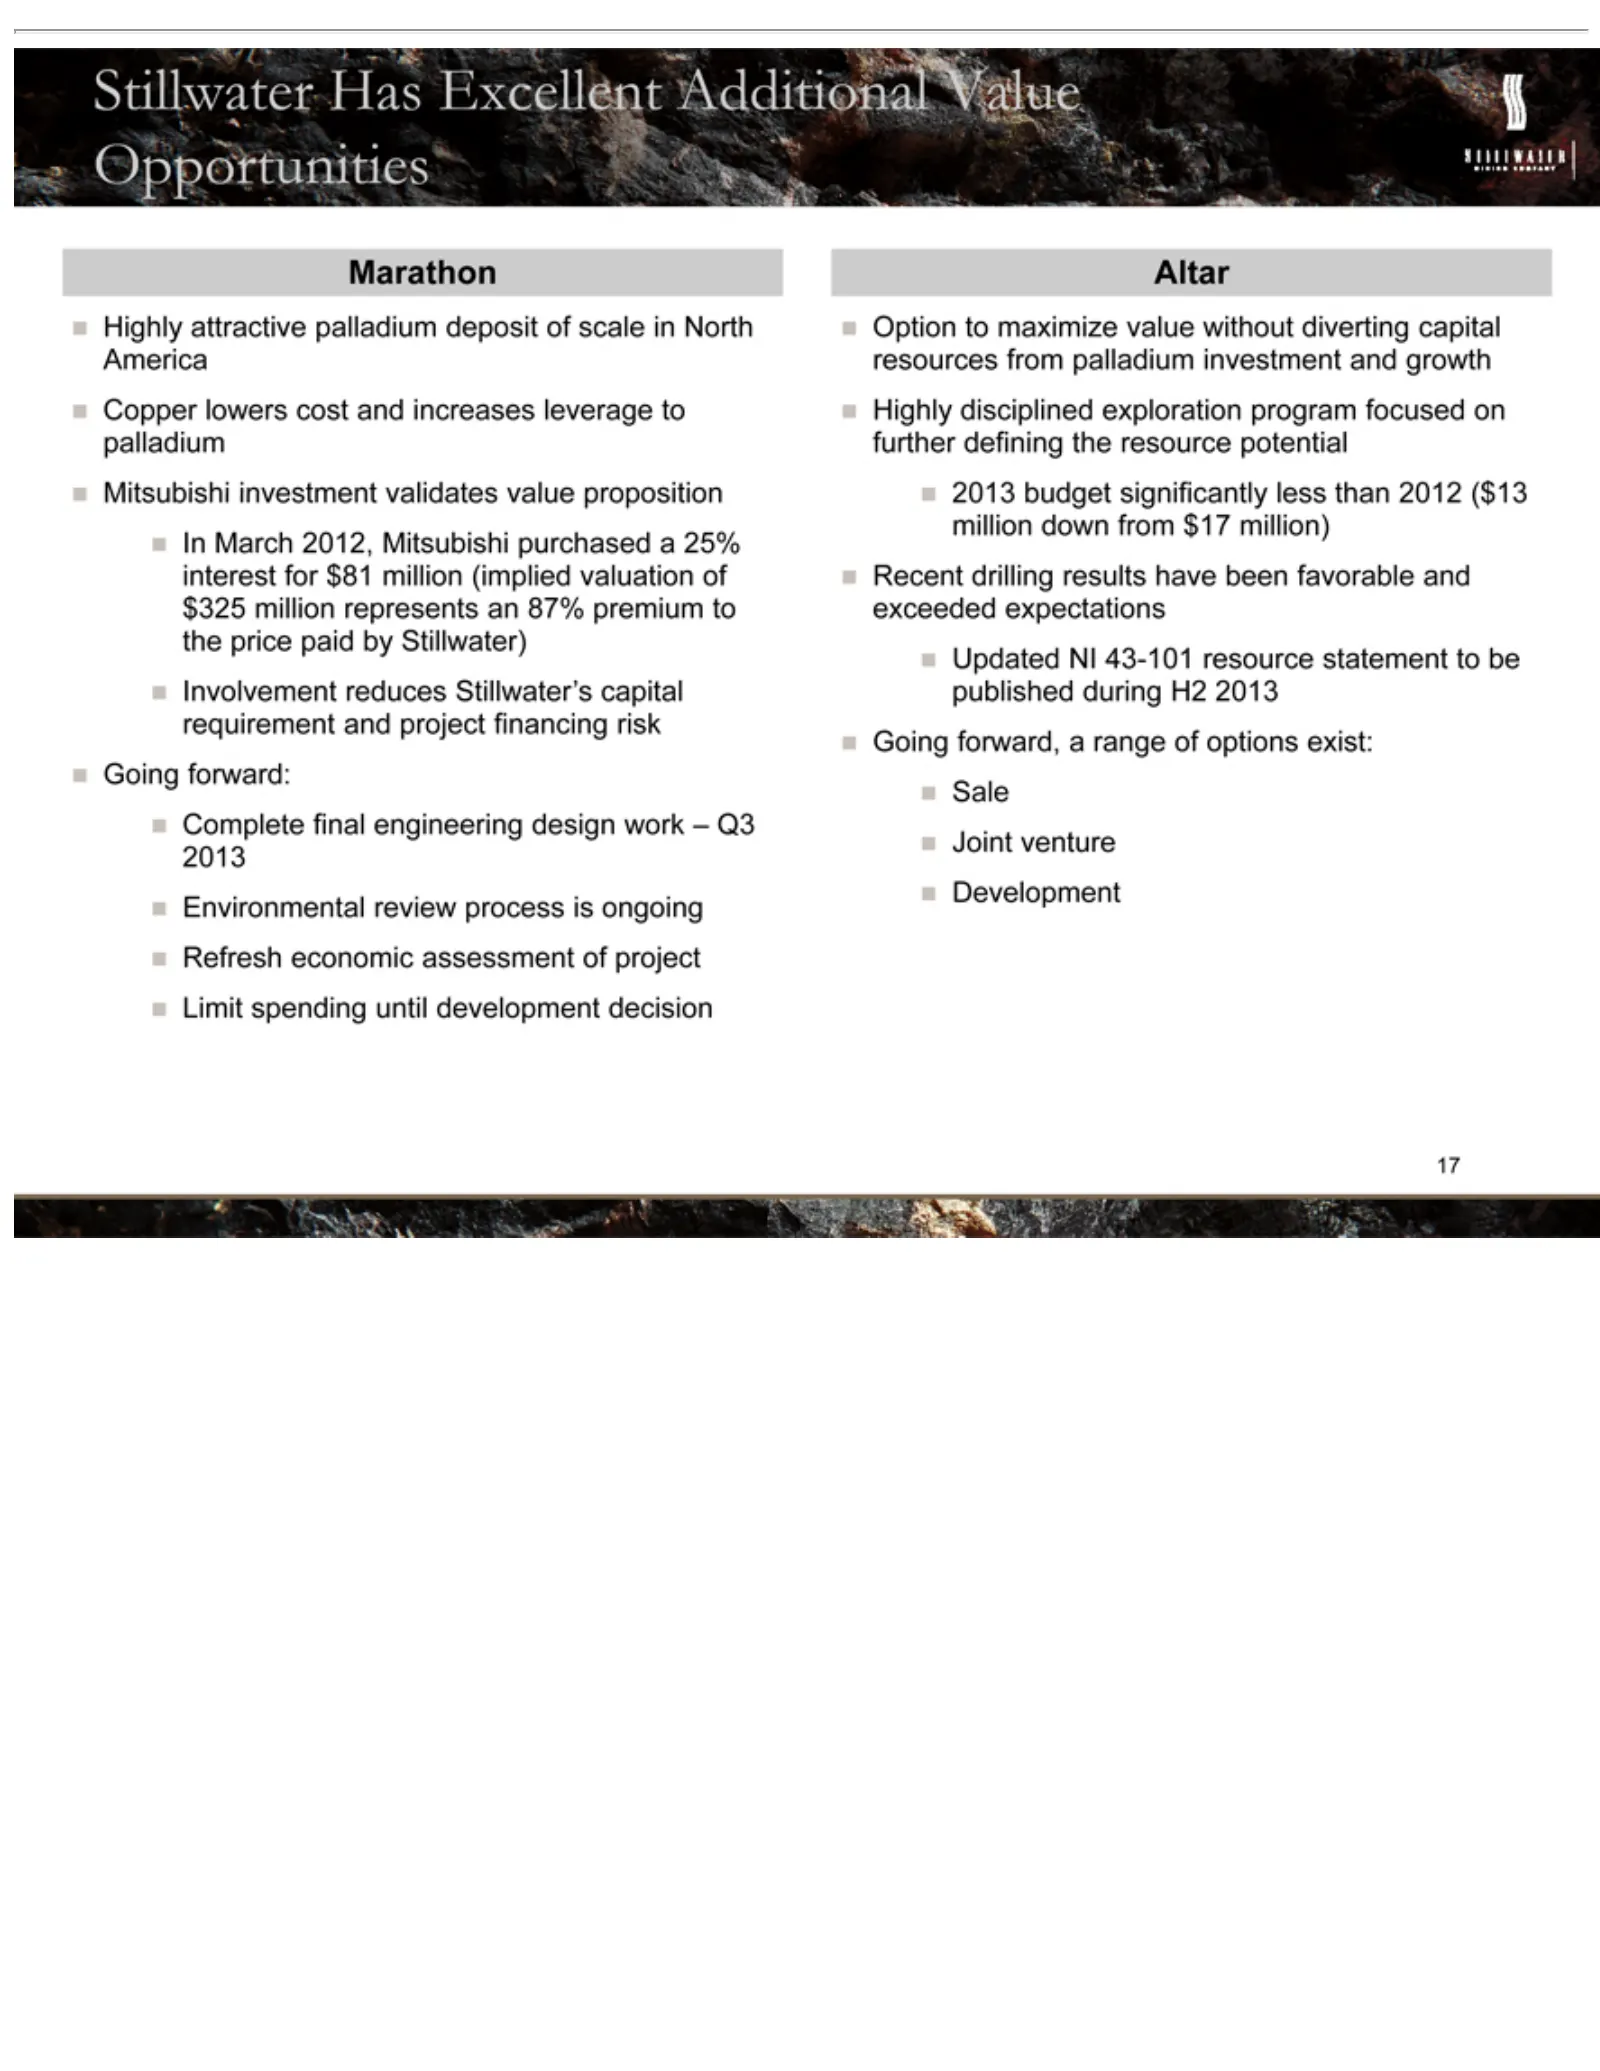
Slide 19: Stillwater Highly Attractive Marathon and Altar Options
Stillwater Highly Marathon interest Complete Option Altar significantly forward, 18 attractive to for amaximize Has final range $81 less Excellent engineering million of palladium than options value 2012 (implied Additional without exist: design ($13 deposit valuation million ndiverting work Sale of
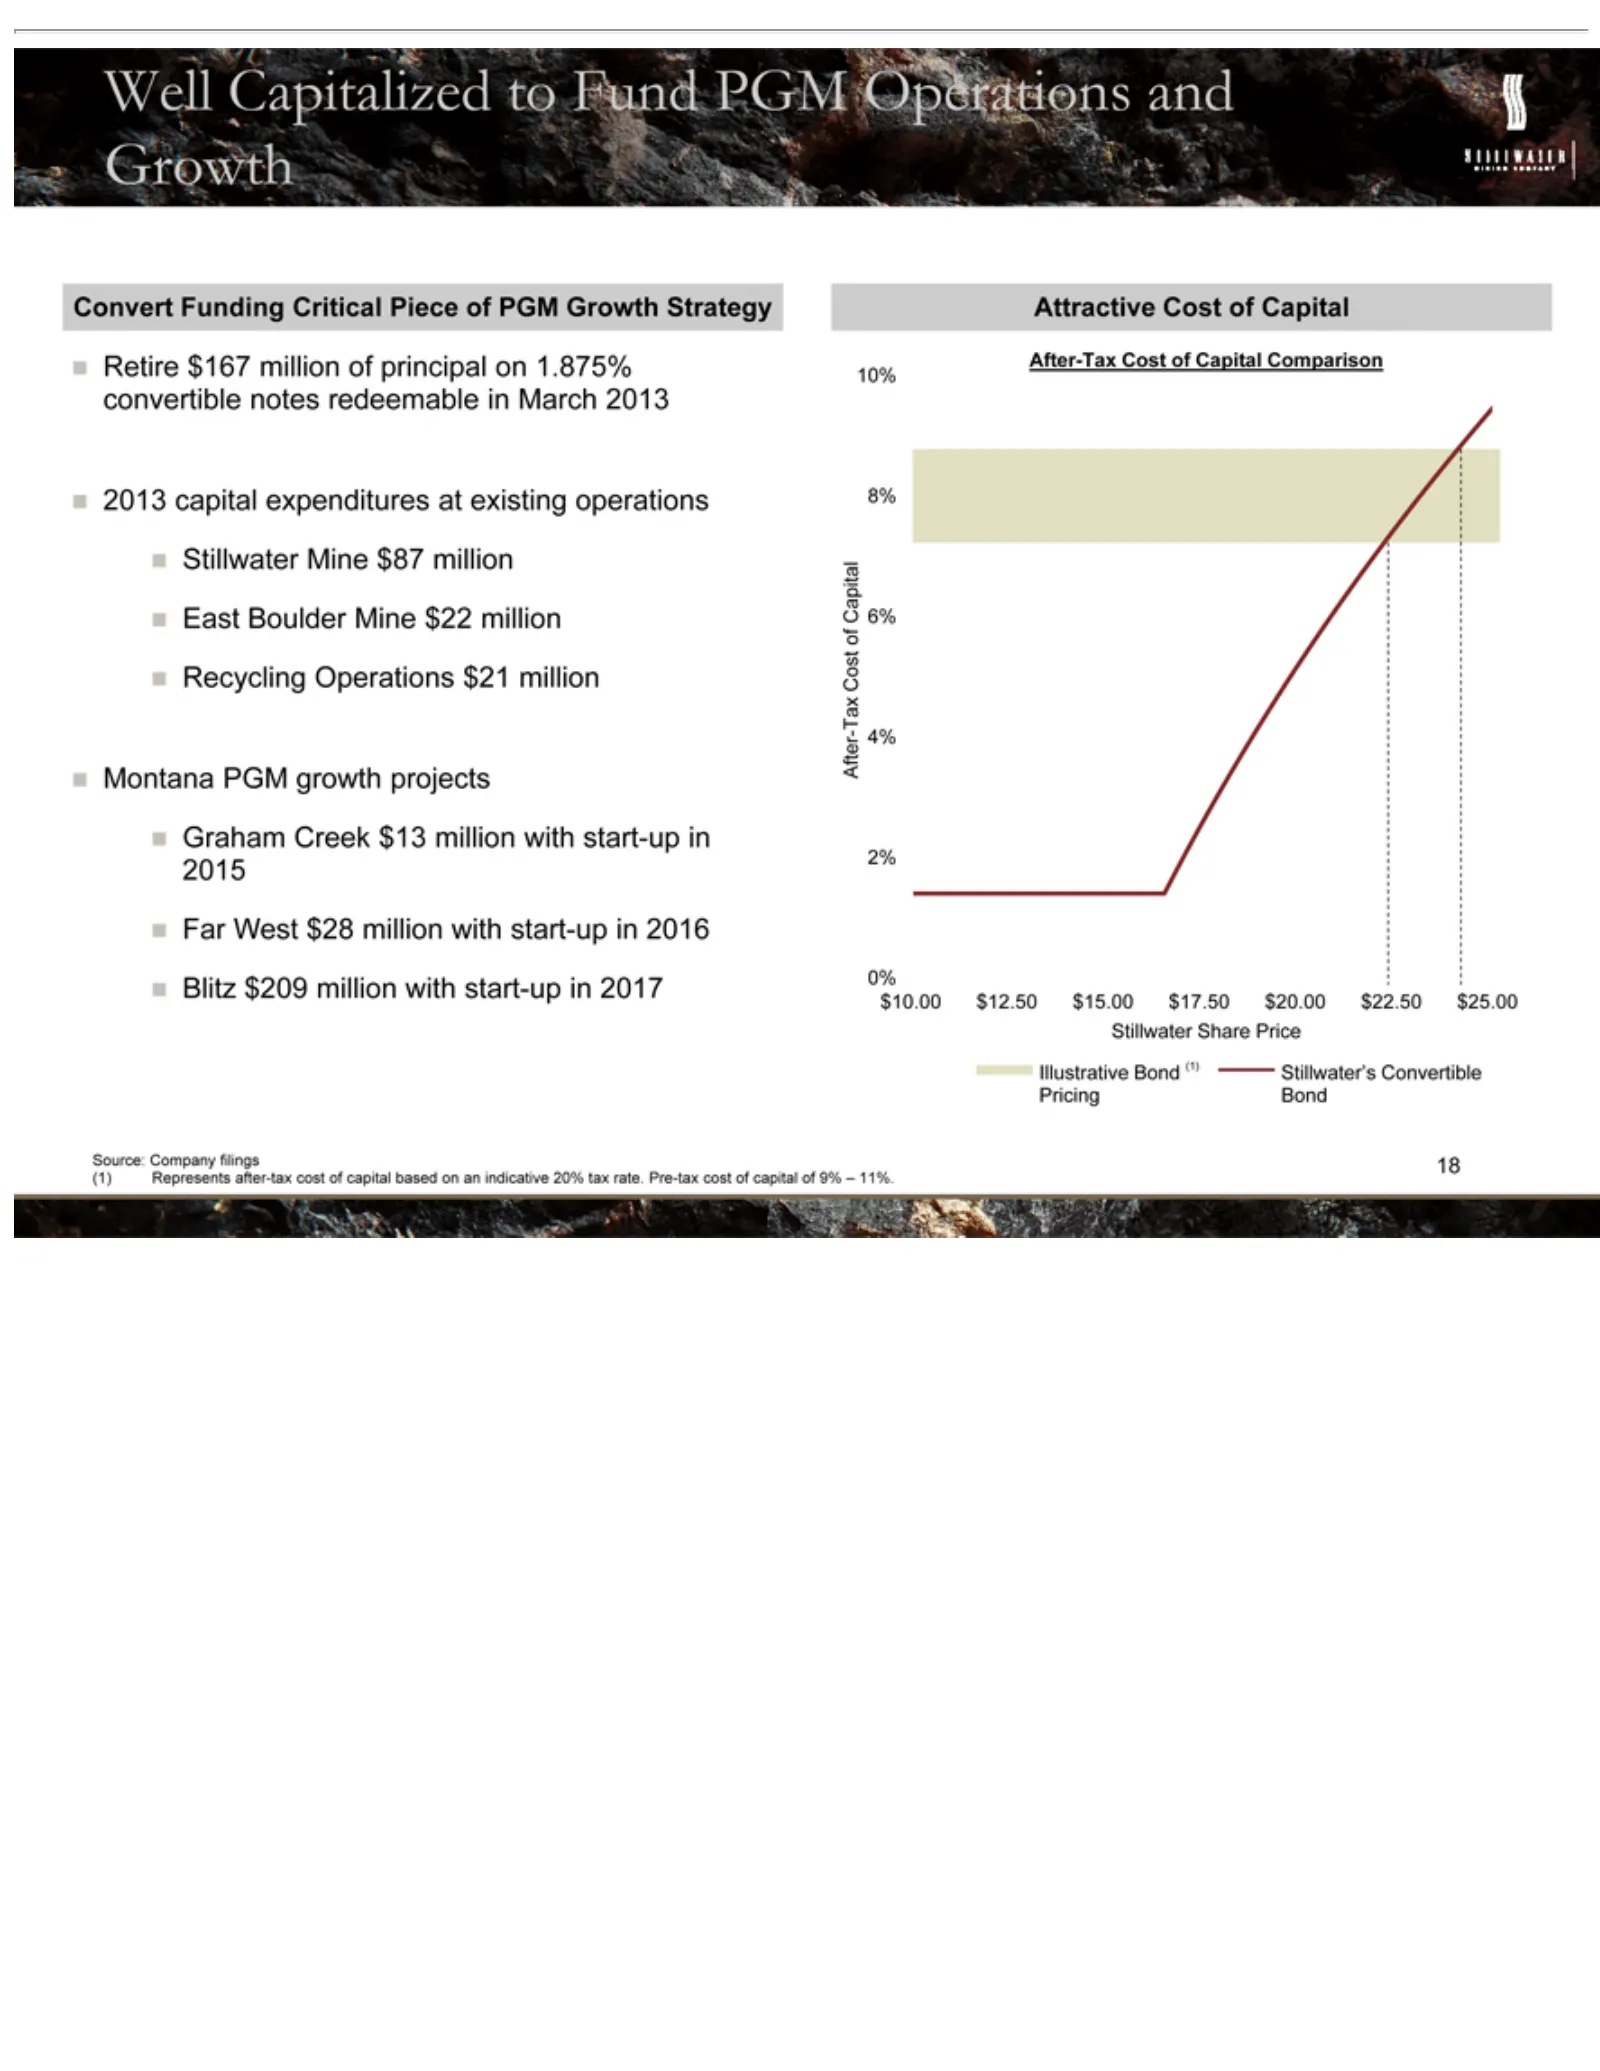
Slide 20: Well-Funded Growth Strategy with Convertible Notes
Well nConvert Attractive After-Tax 2% $10.00 0% Stillwater Illustrative Stillwater’s Source: Bond (1) 19 Retire 2013 Montana Graham Far Blitz Represents 4%Capitalized West $209 capital $12.50 6% Company $167 Funding Share Cost Creek $28 PGM Bond 8% Convertible million million expenditures $15.00 aft
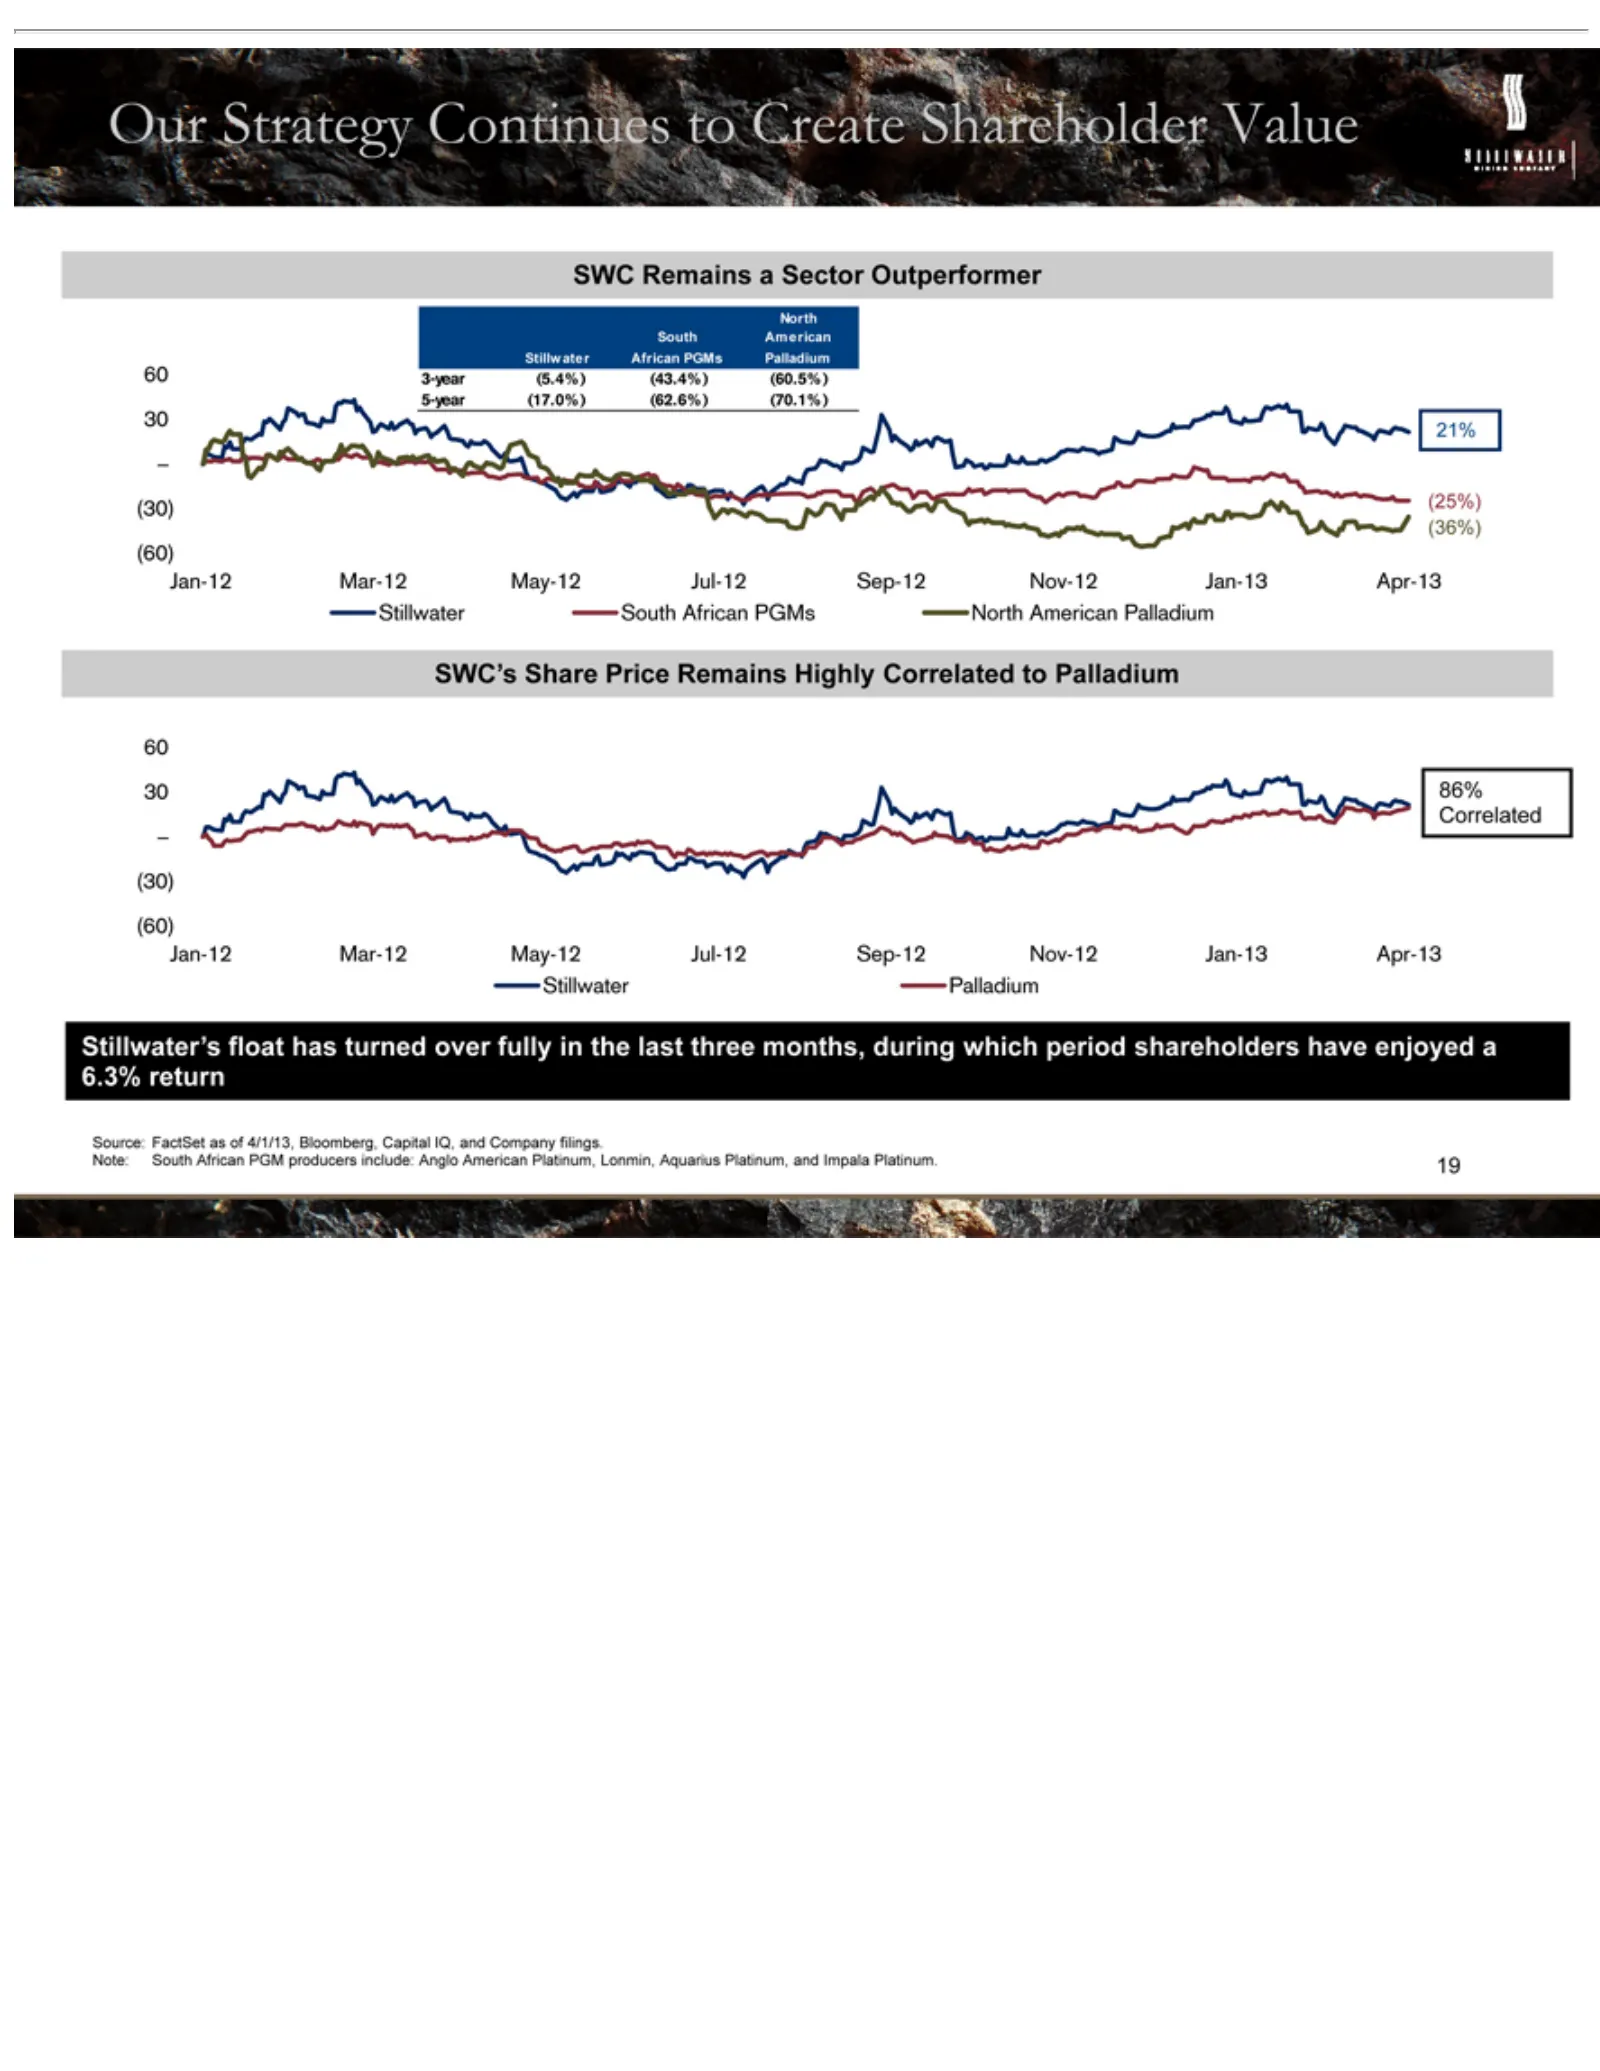
Slide 21: Our Strategy Continues to Create Shareholder Value
Our Strategy Continues to Create Shareholder Value SWC Stillw Mar-12 5-year(17.0%)(62.6%)(70.1%) 3-year(5.4%)(43.4%)(60.5%) South North (25%) 21% –(SWC’s 30 60 Jan-12 (60) Stillwater Stillwater’s Correlated 86% 6.3% Source: Note: 30) return Remains South American African ater (36%) Mar-12 Share May-
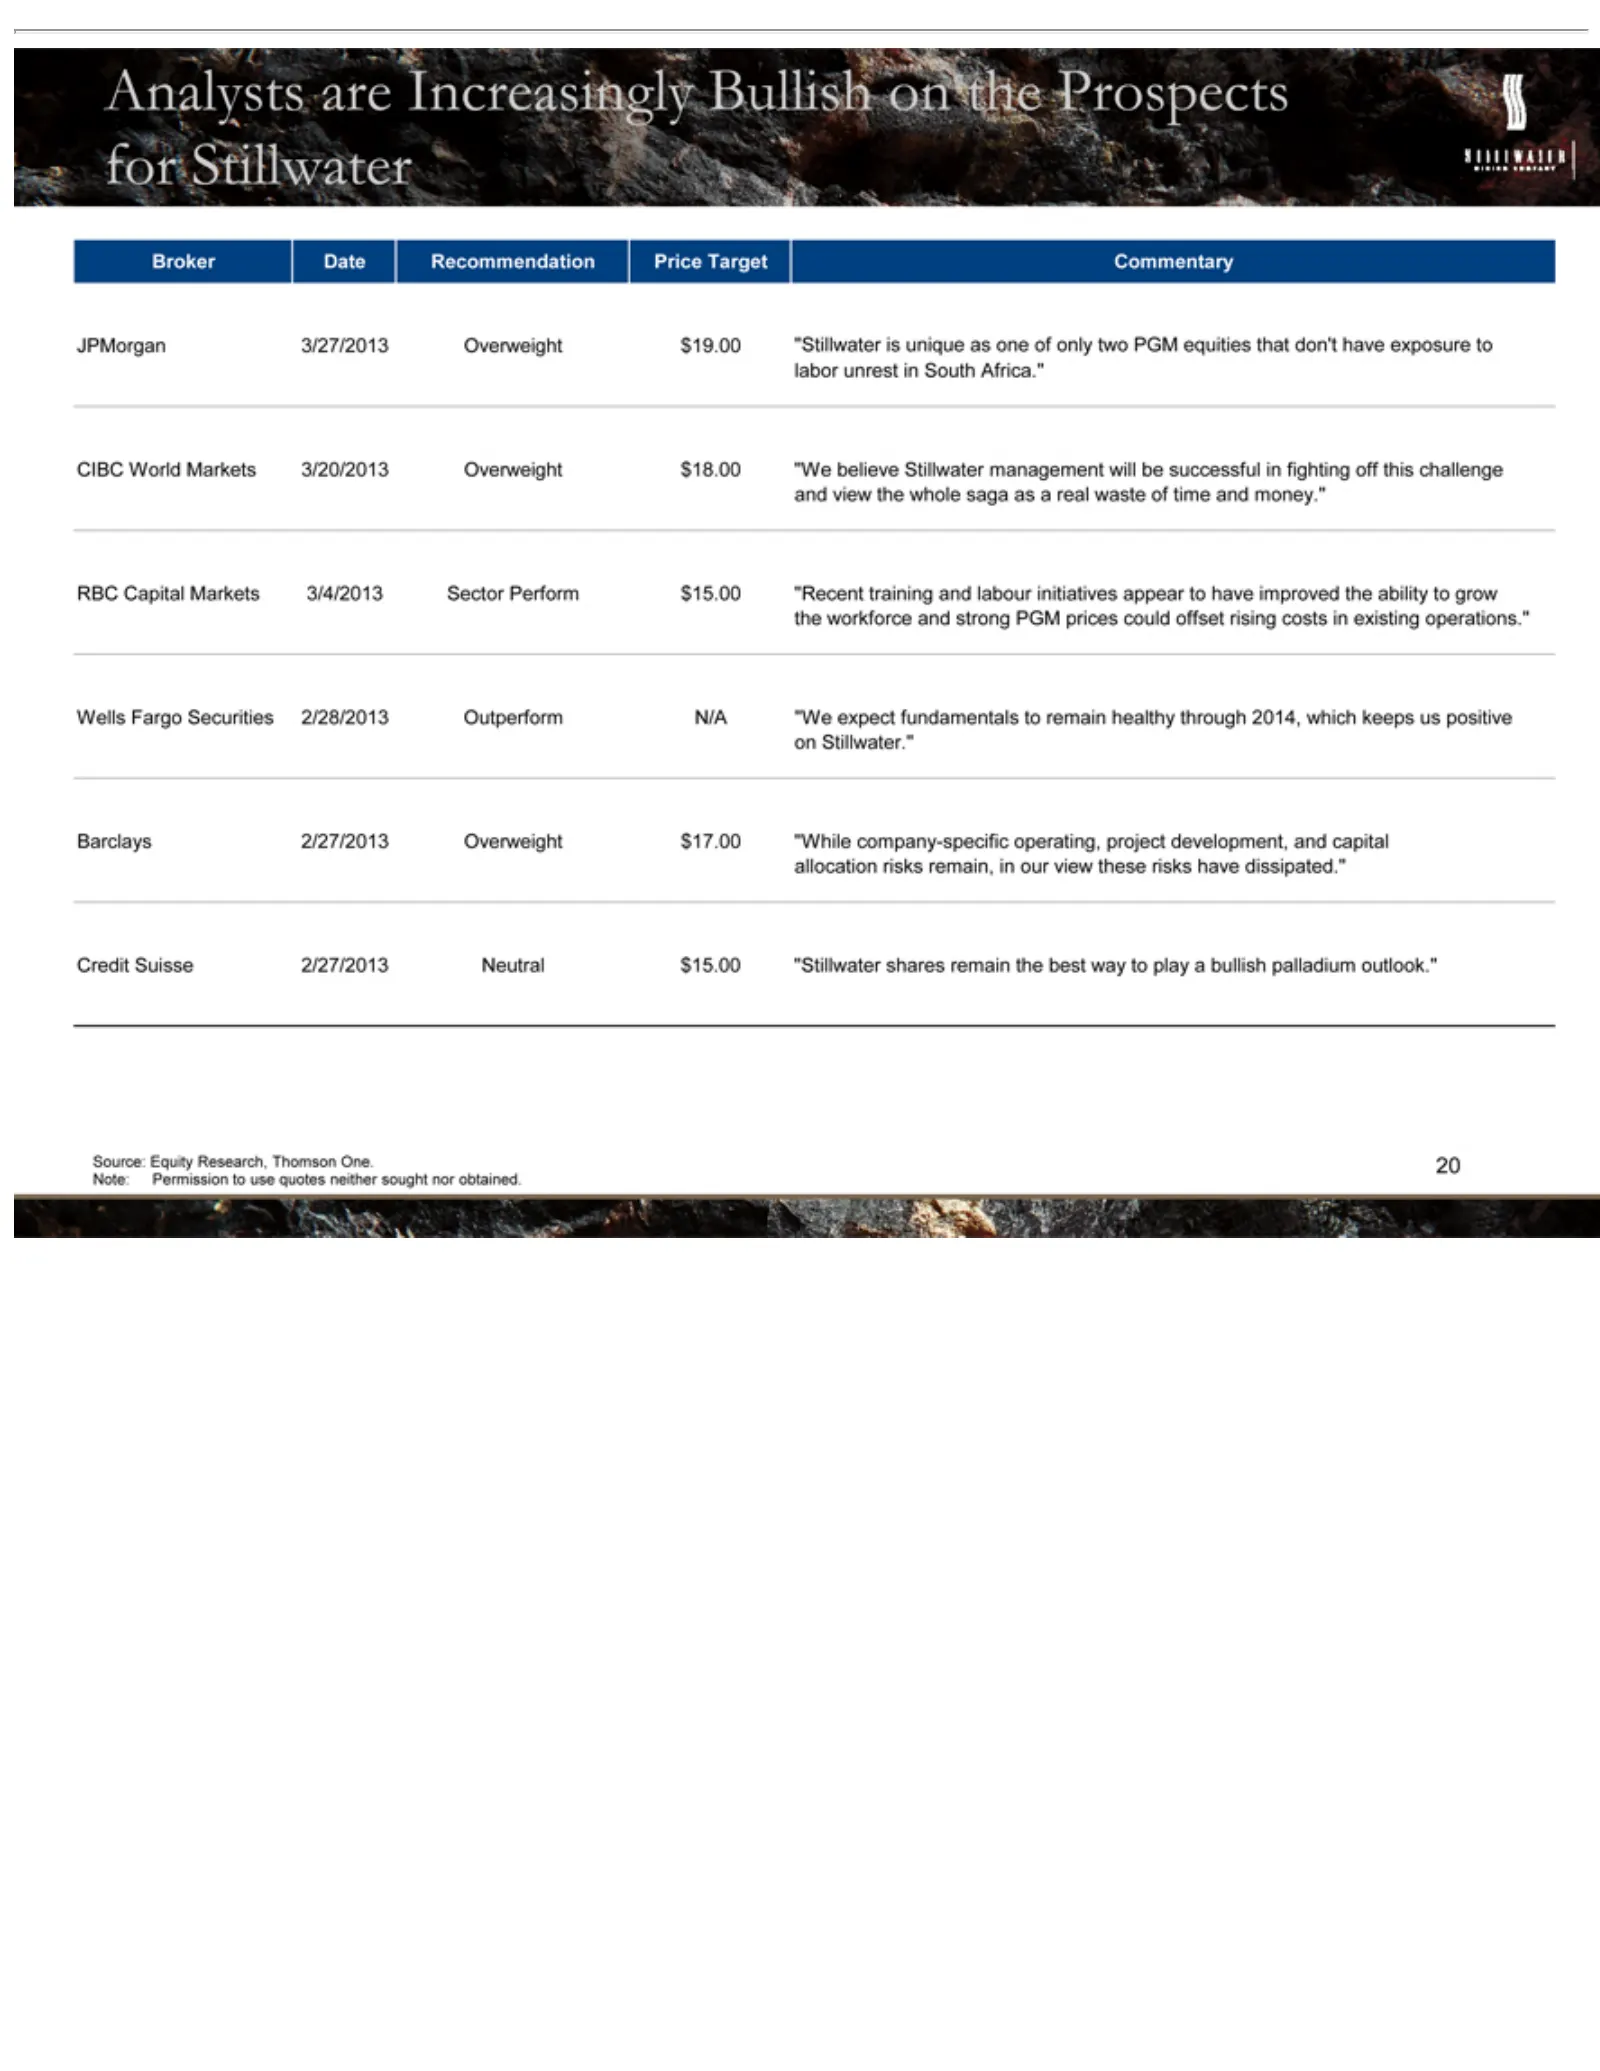
Slide 22: Analyst Commentary on Stillwater
Analysts Broker JPMorgan labor CIBC and RBC the Wells on Barclays allocation Credit Source: Note: 21 Stillwater.” workforce view Capital unrest Permission Fargo World Suisse Date Equity 2/27/2013 are the risks 3/27/2013 in Securities Recommendation Increasingly Markets whole 2/27/2013 and South Rese
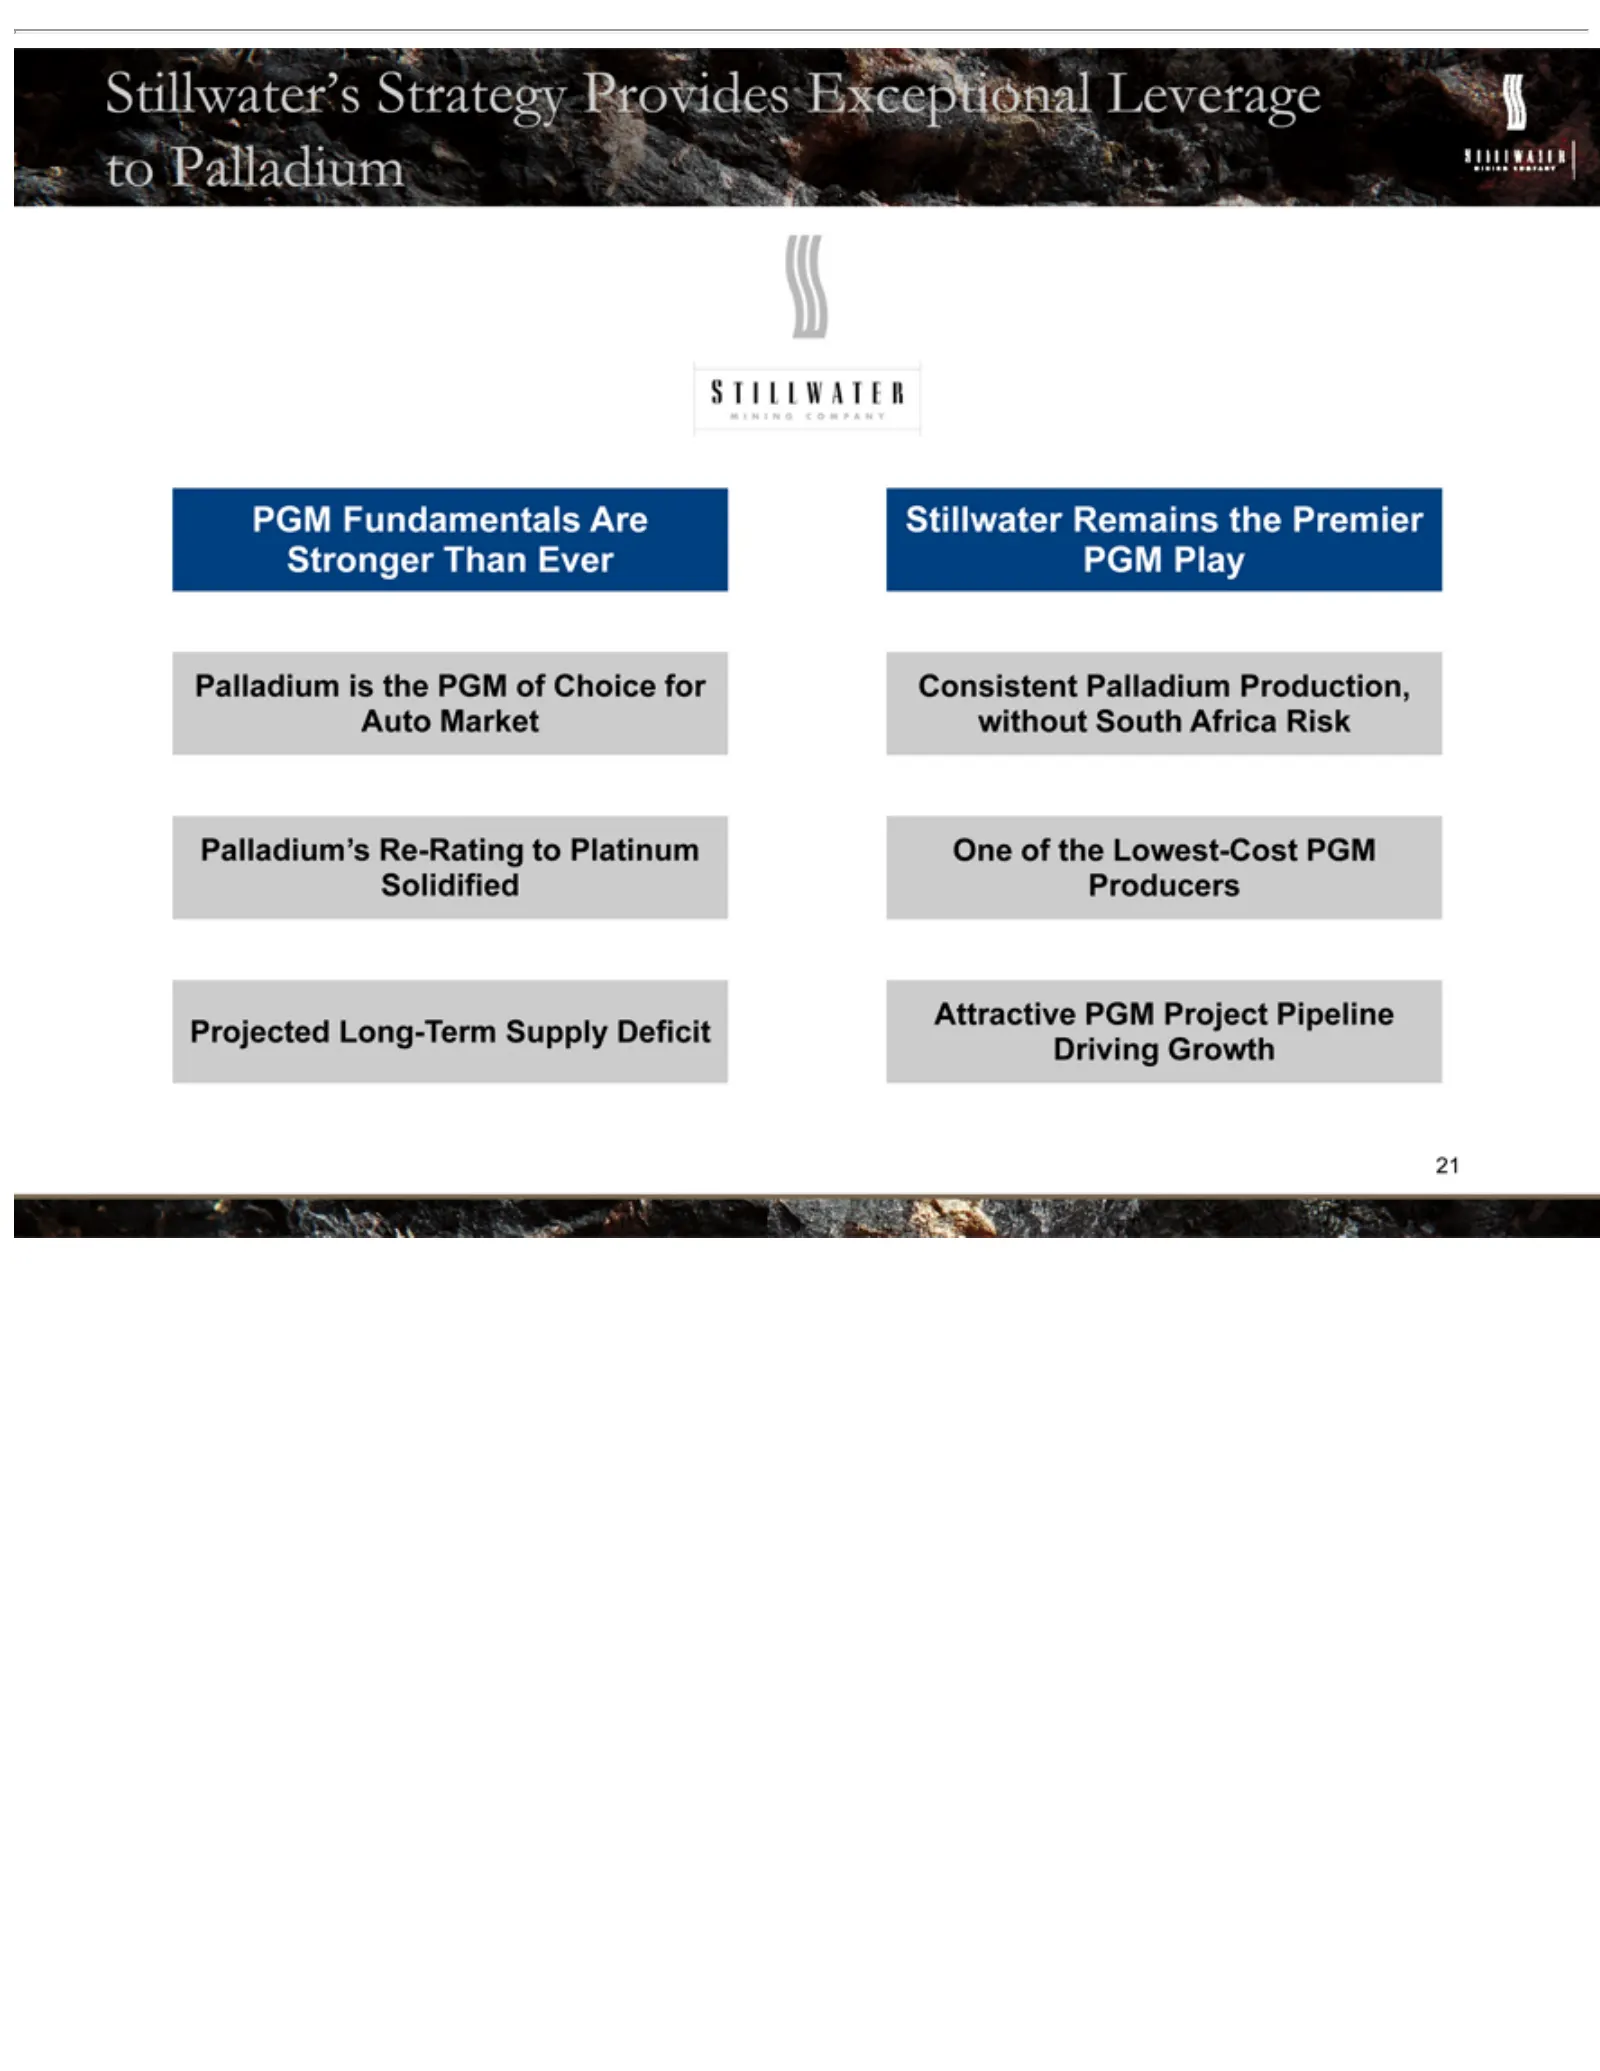
Slide 23: Stillwater's Strategy Provides Exceptional Leverage to Palladium
Stillwater’s PGM Palladium Palladium’s Projected Solidified Stillwater Consistent One Attractive 22 ofFundamentals theLong-Term Remains PGM is Lowest-Cost Palladium Strategy Re-Rating the Project PGMthe Are Provides Production, Supply of to Premier Pipeline PGM Stronger Choice Platinum Deficit Excep
Slide 24: 3. Strong Corporate Governance and Track Record
3. Strong of Governance Corporate Track Record
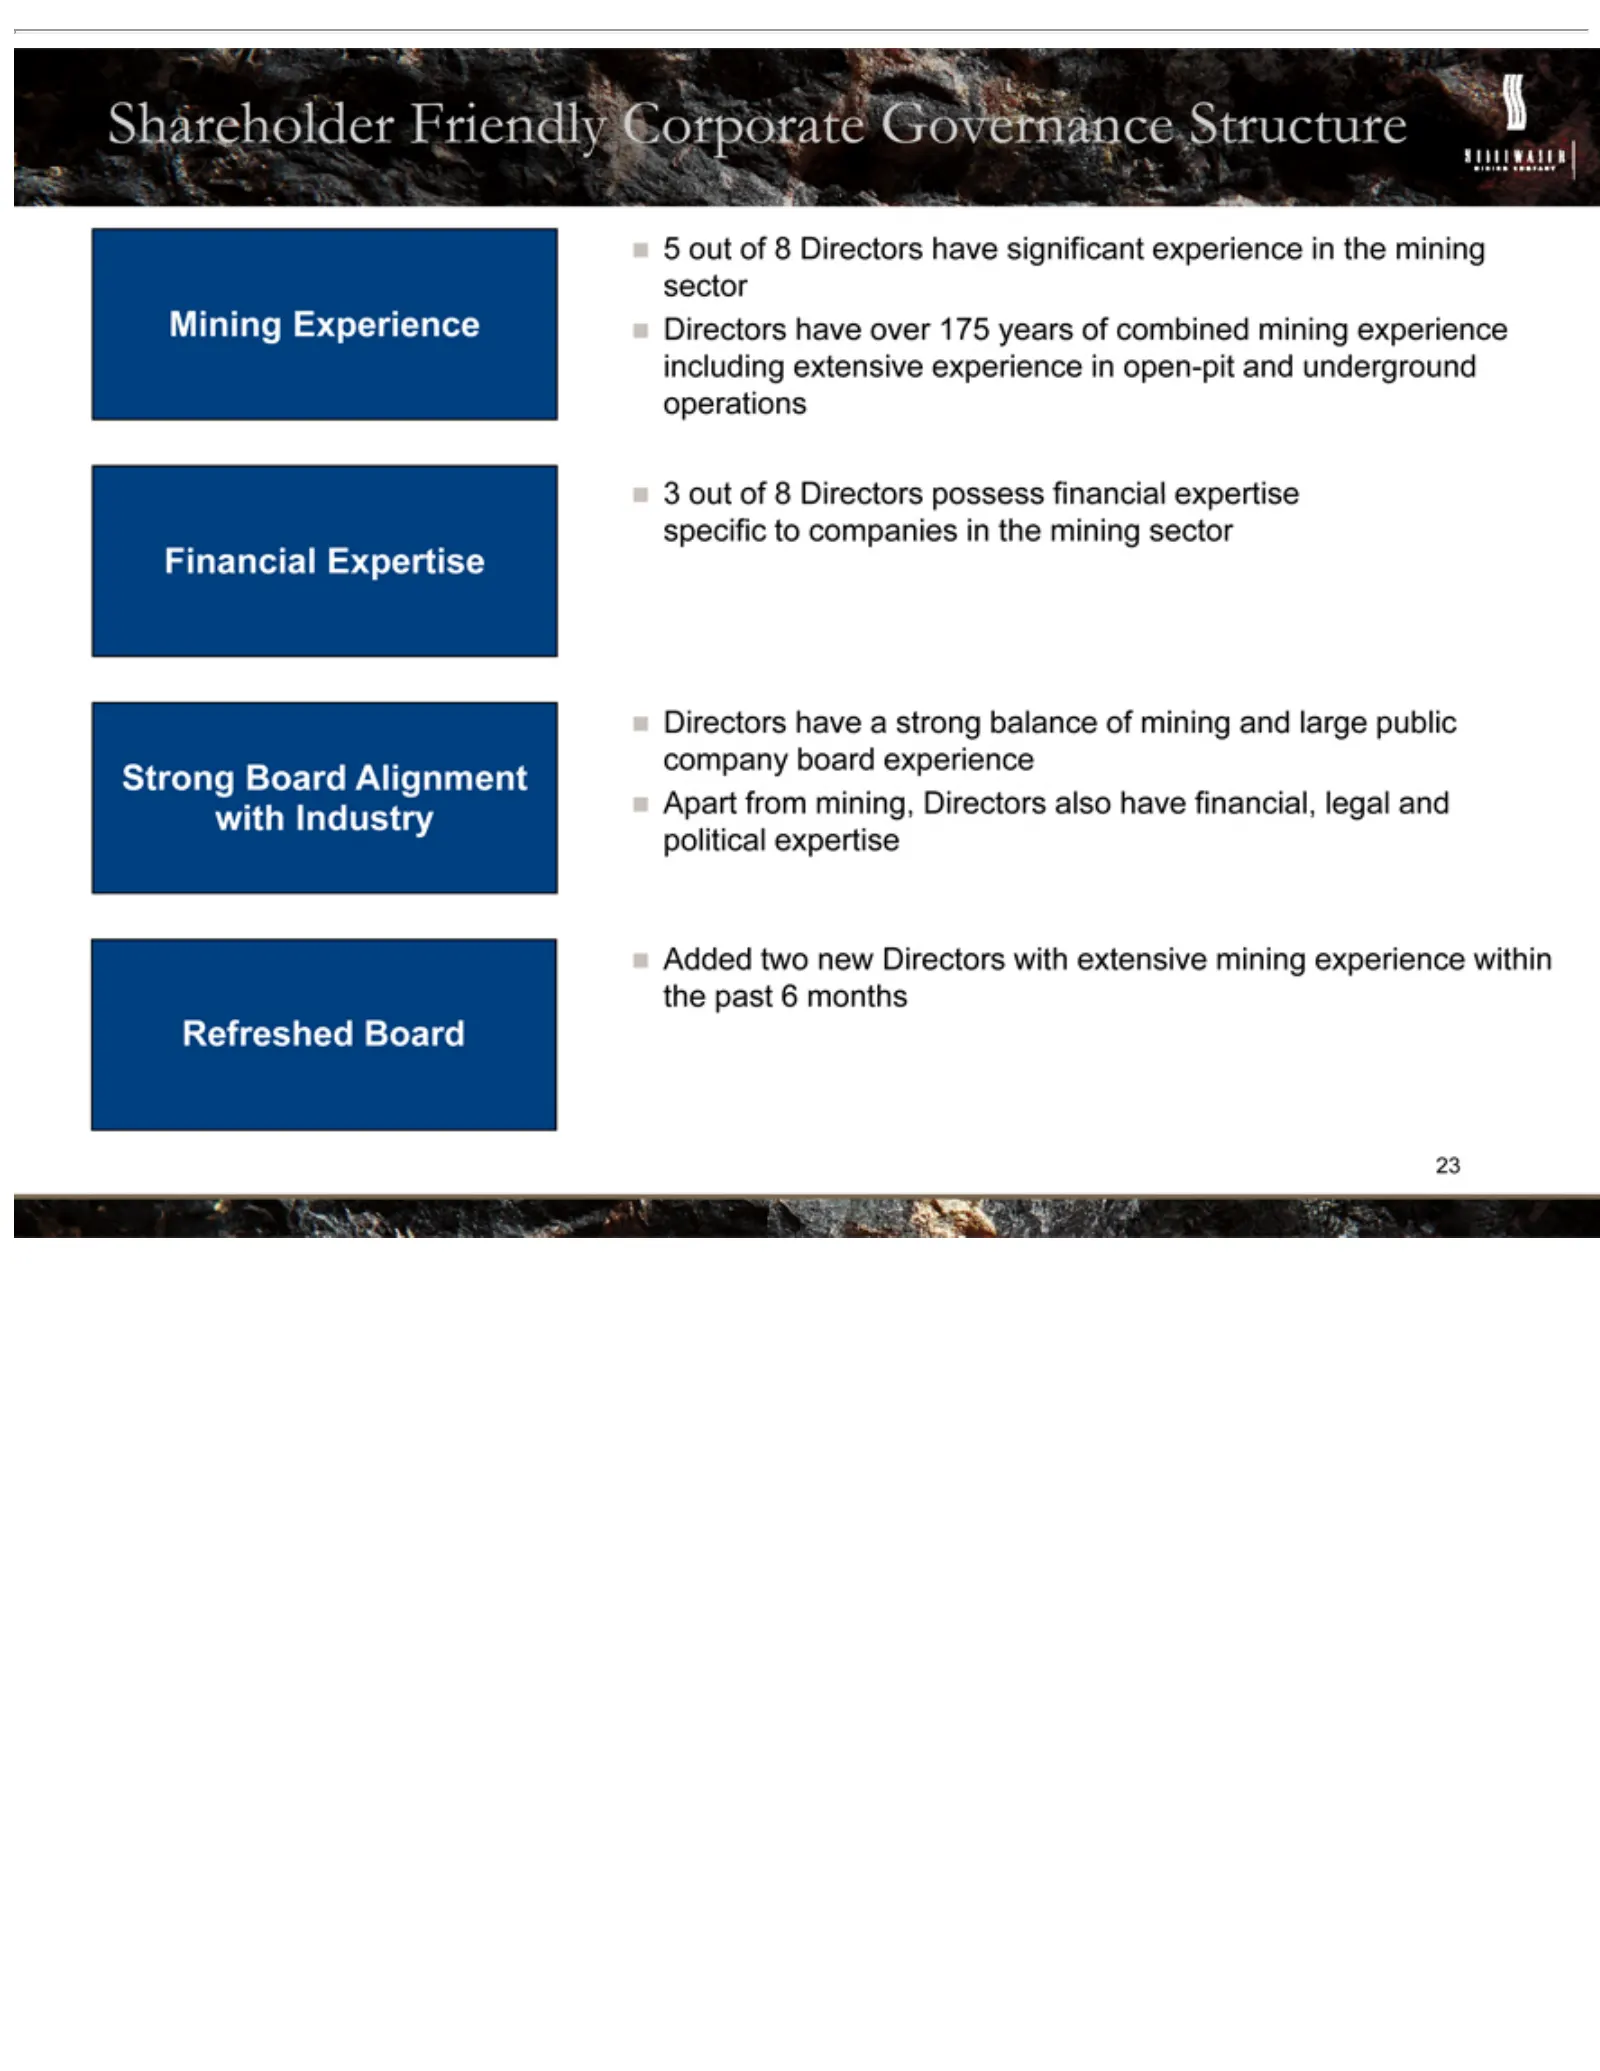
Slide 25: Shareholder-Friendly Board with Mining and Financial Expertise
Shareholder Mining Financial Strong 35Refreshed Directors Added 24out oftwo Board Experience 8 have Expertise Directors Board new Friendly Alignment aDirectors strong have possess Corporate balance with significant with financial Industry extensive of Governance mining experience expertise mining an
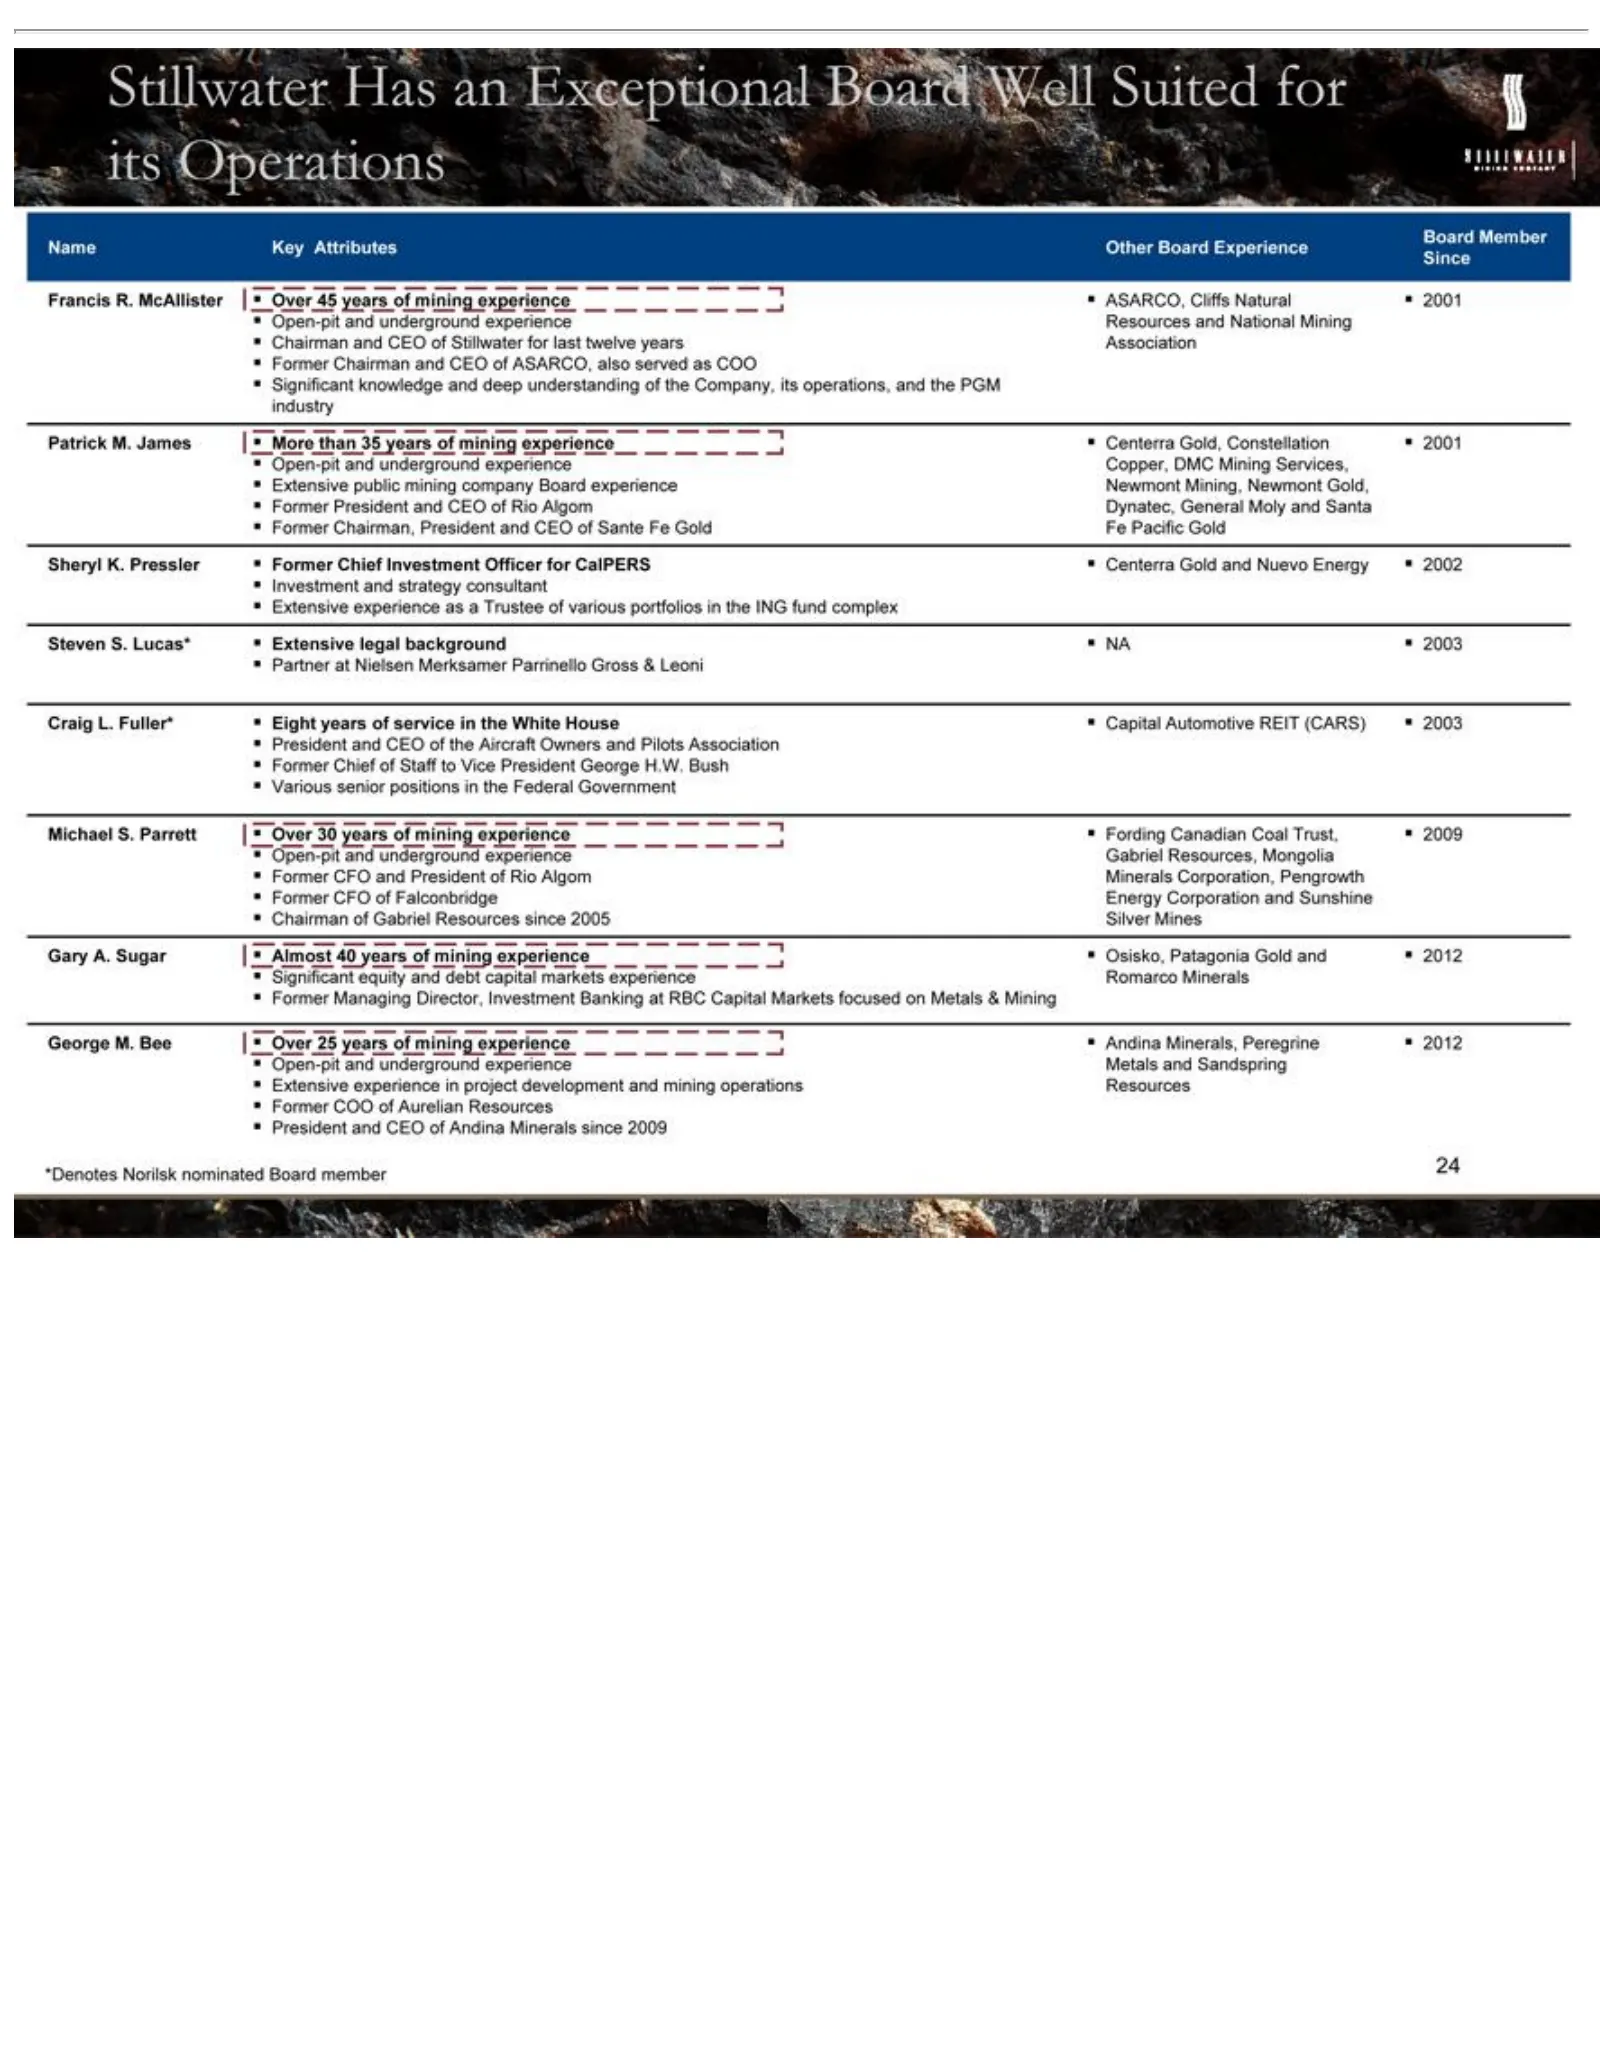
Slide 26: Stillwater Board Nominees
Stillwater Name Francis Since Patrick industry Sheryl Steven Craig Michael Gary nGeorge Various Investment Partner Public Chairman Significant Open-pit Extensive Former President A. L. Key K. S. *Denotes 25 M. R. Sugar Advocate S. Fuller* at Chairman President Chairman, Chief CFO Managing COO Lucas*
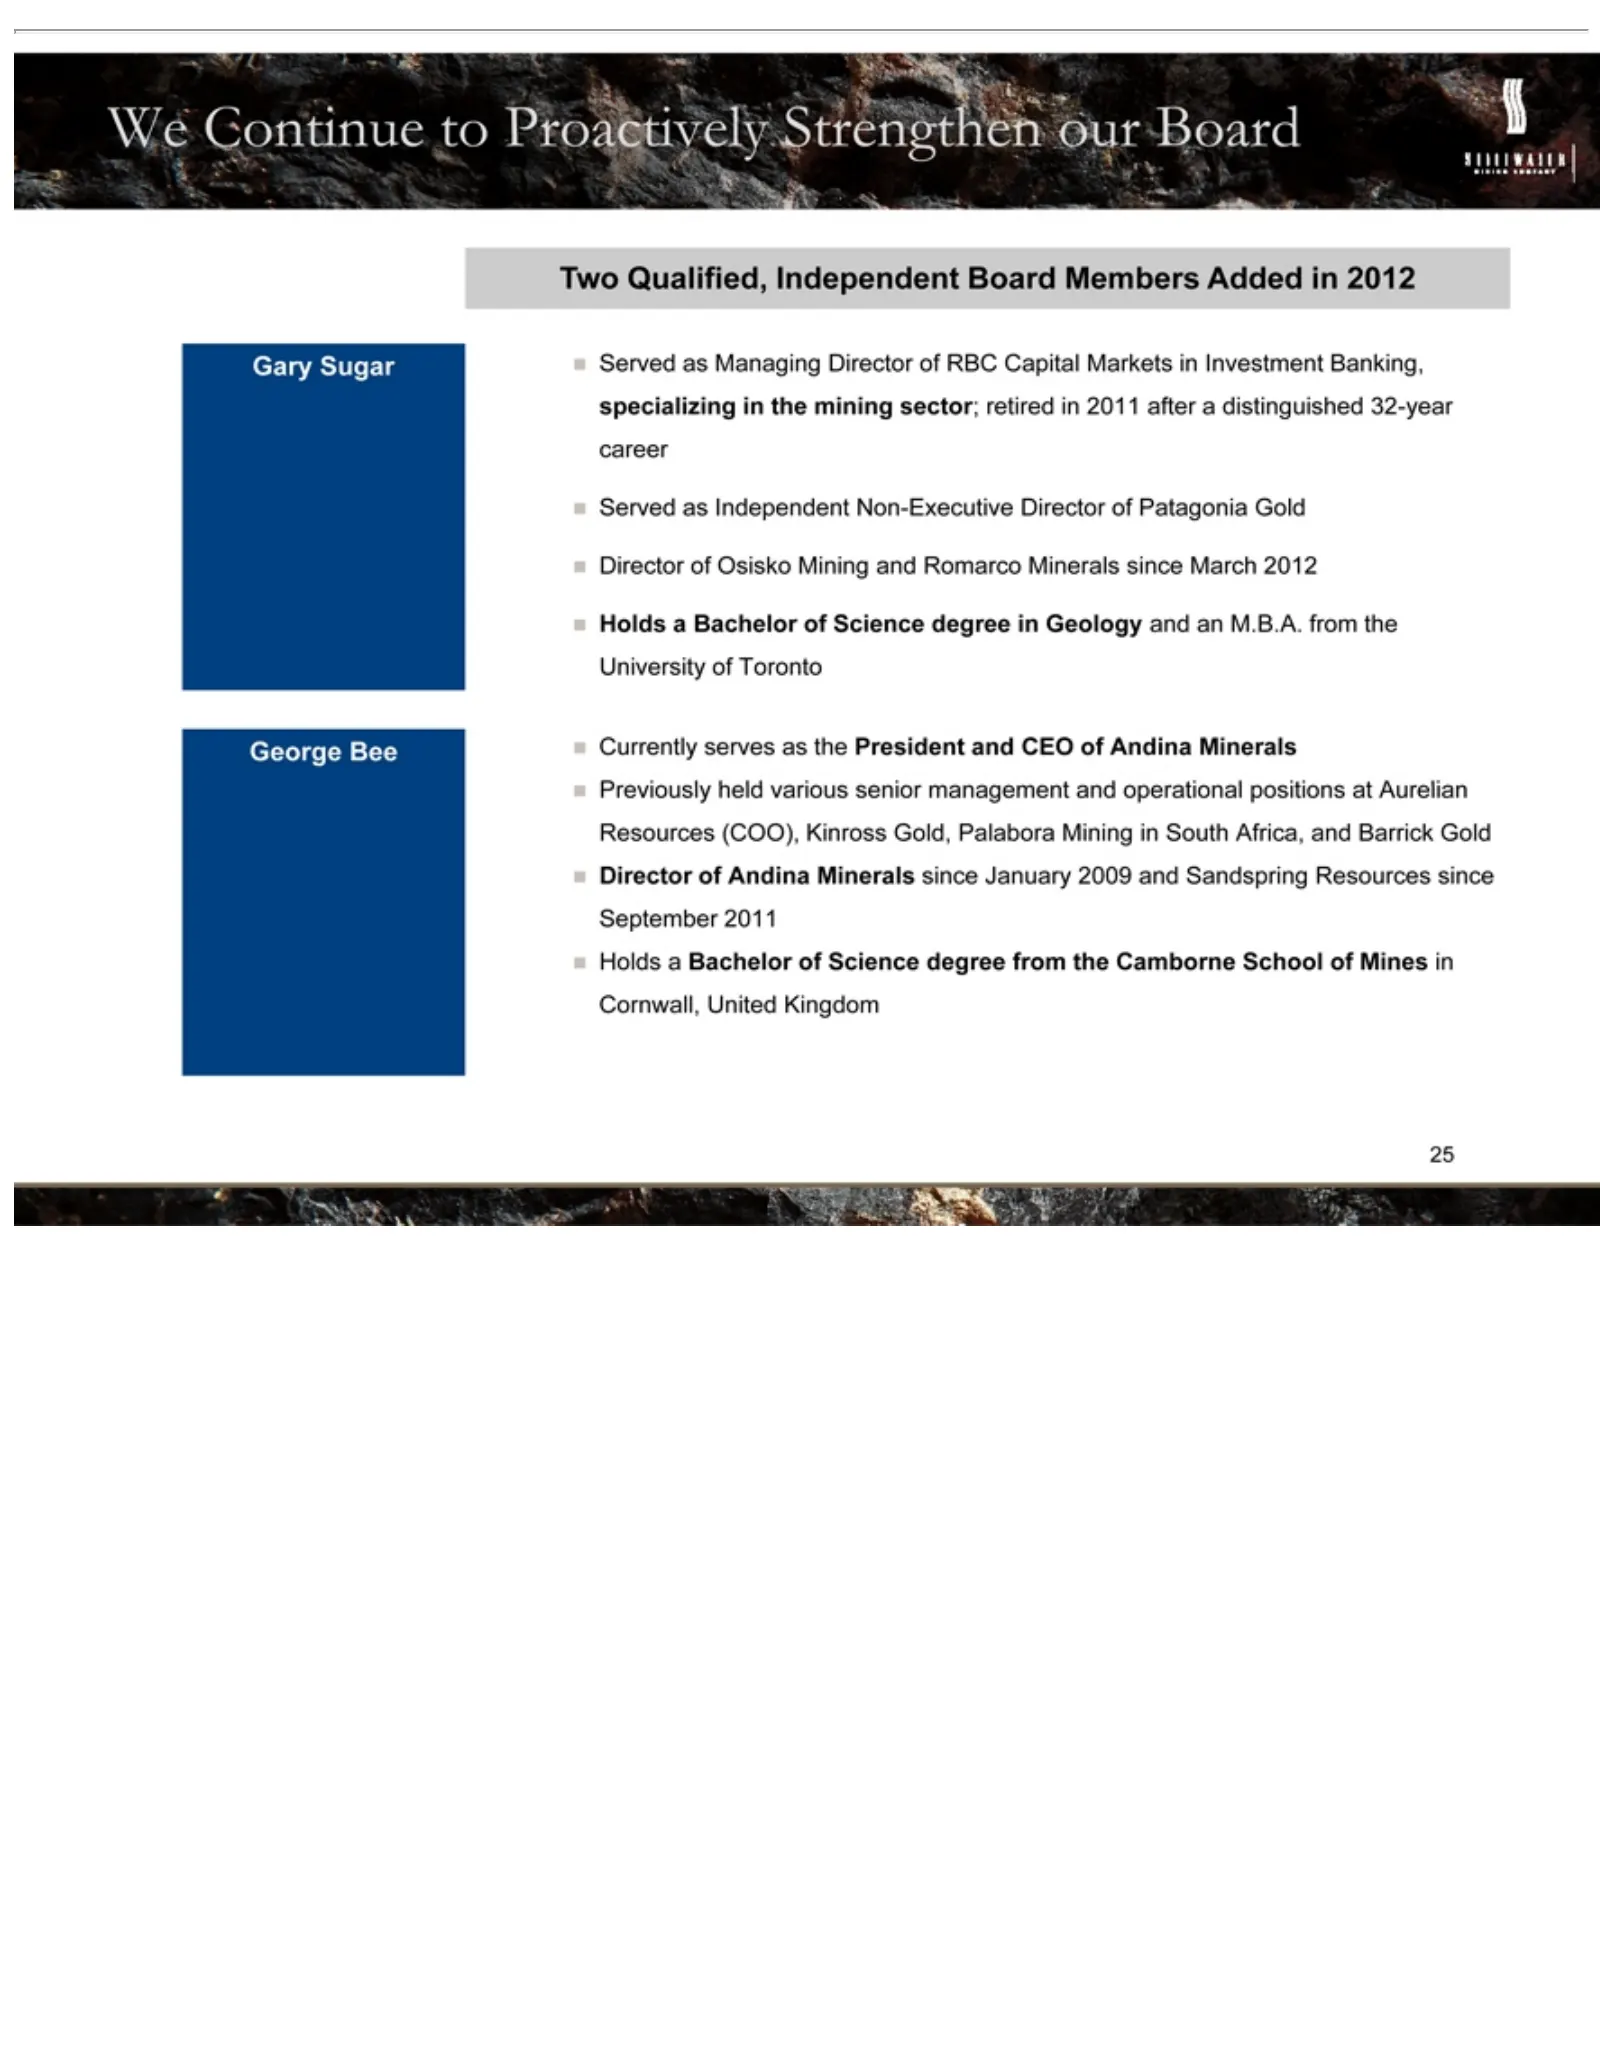
Slide 27: We Continue to Strengthen Our Board
We Continue Two Gary Served Director Independent University George Currently Previously and Holds Cornwall, 26 Sandspring Qualified, Sugar aas Bee Bachelor ofserves Managing United of held Osisko Non-Executive to Toronto Independent Resources various Proactively asof Kingdom Mining the Science Direc
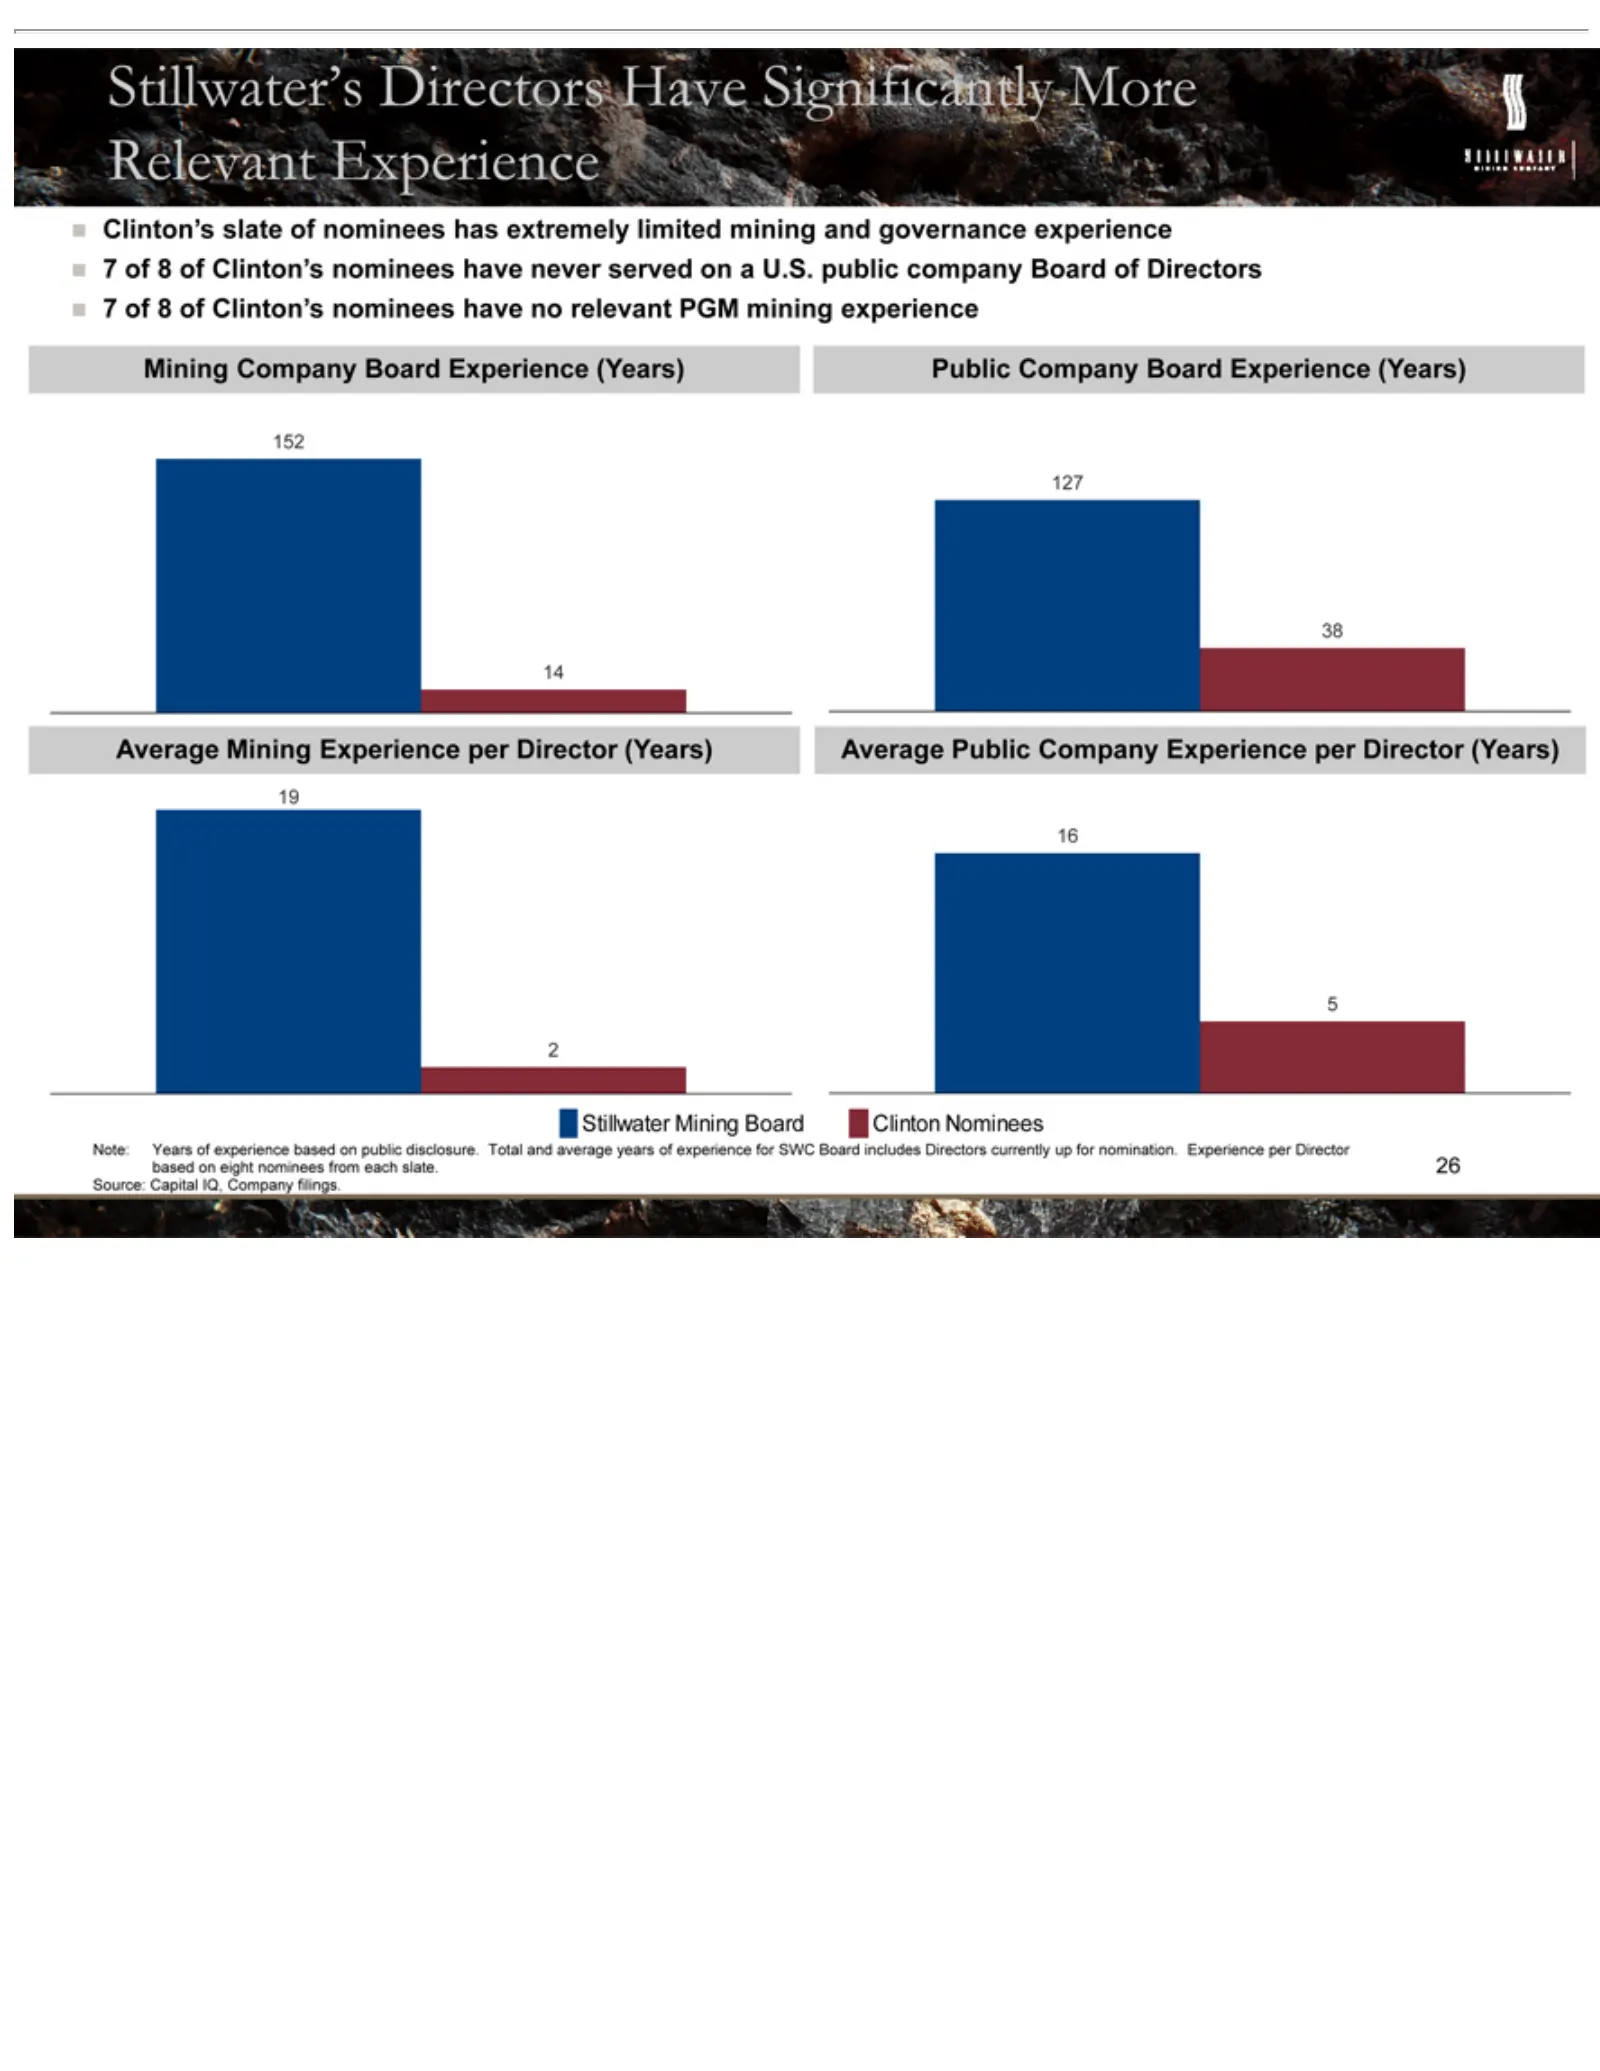
Slide 28: Stillwater's Nominees Have More Relevant Mining Experience
Stillwater’s Relevant 7Clinton’s Mining Average 38 126 143 2A 16 5S 14 Note: 27tillwater verage of 8 Years ofCompany Mining Public Clinton’s Experience slate Mining Directors of experience ofCompany Experience nominees Board nominees Have Clinton Experience Experience based has Significantly per hav
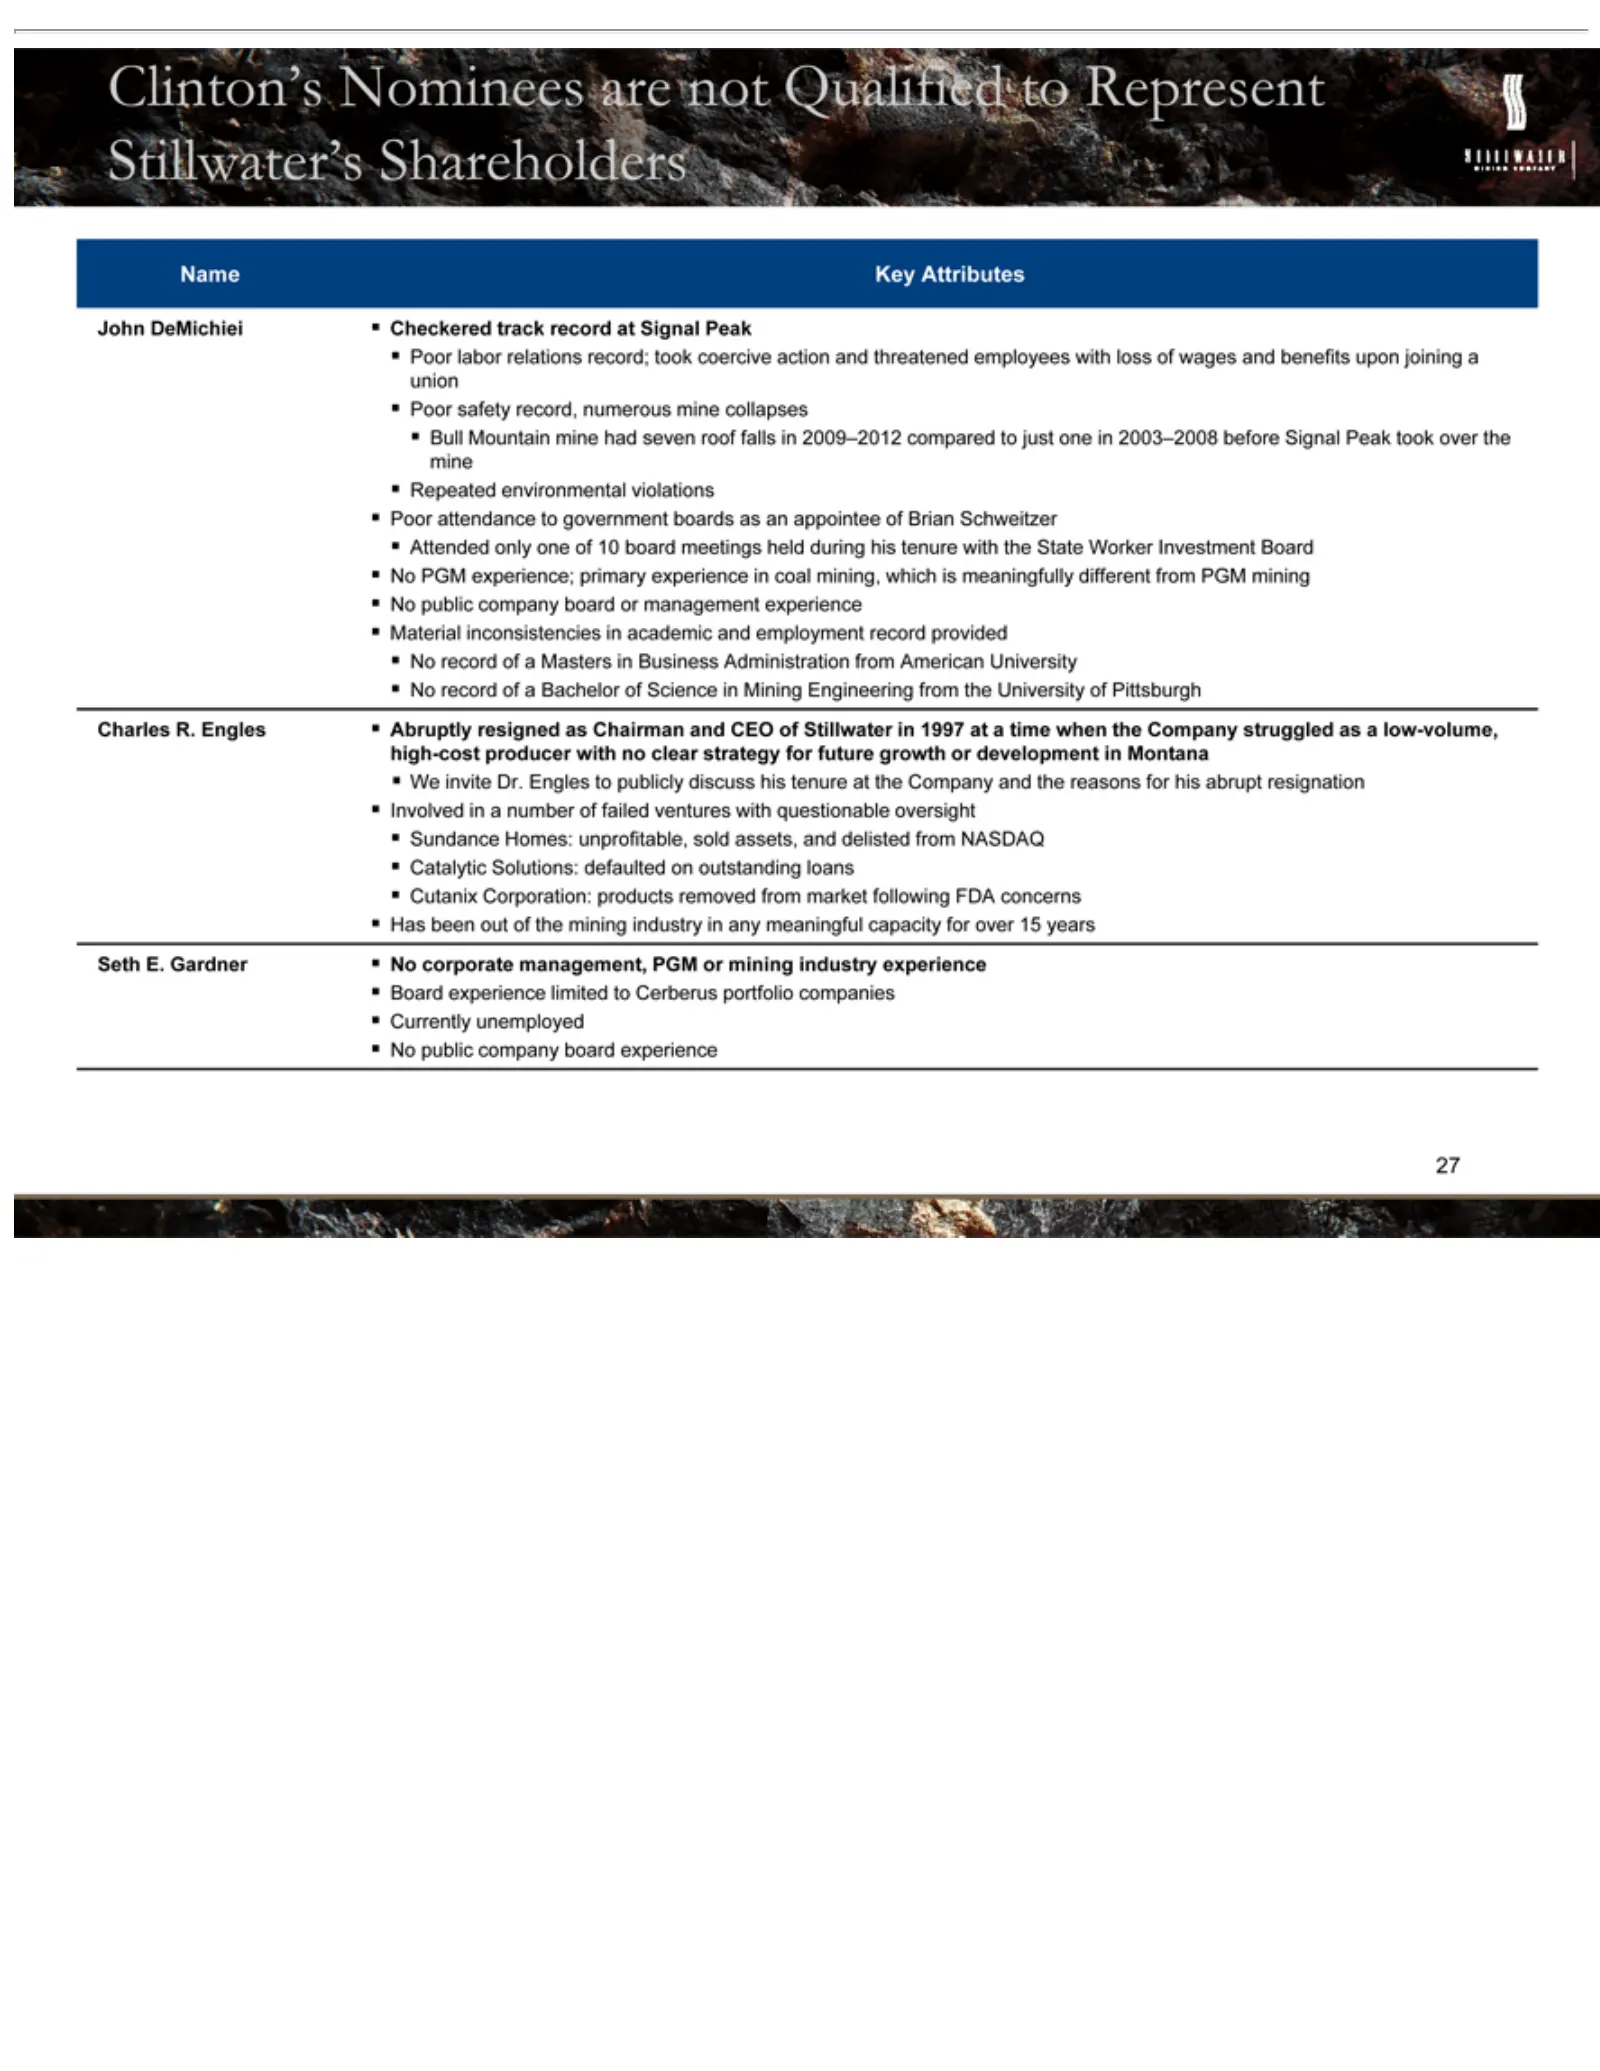
Slide 29: Clinton's Nominees Lack Relevant Experience
Clinton’s Name John union mine Charles high-cost nSeth 28 Attended We BullE. Repeated Poor Material Involved Sundance Catalytic Cutanix Has Board Currently No DeMichiei PGM record public invite been Key Mountain labor safety attendance Gardner R. experience Nominees producer Corporation: inconsisten
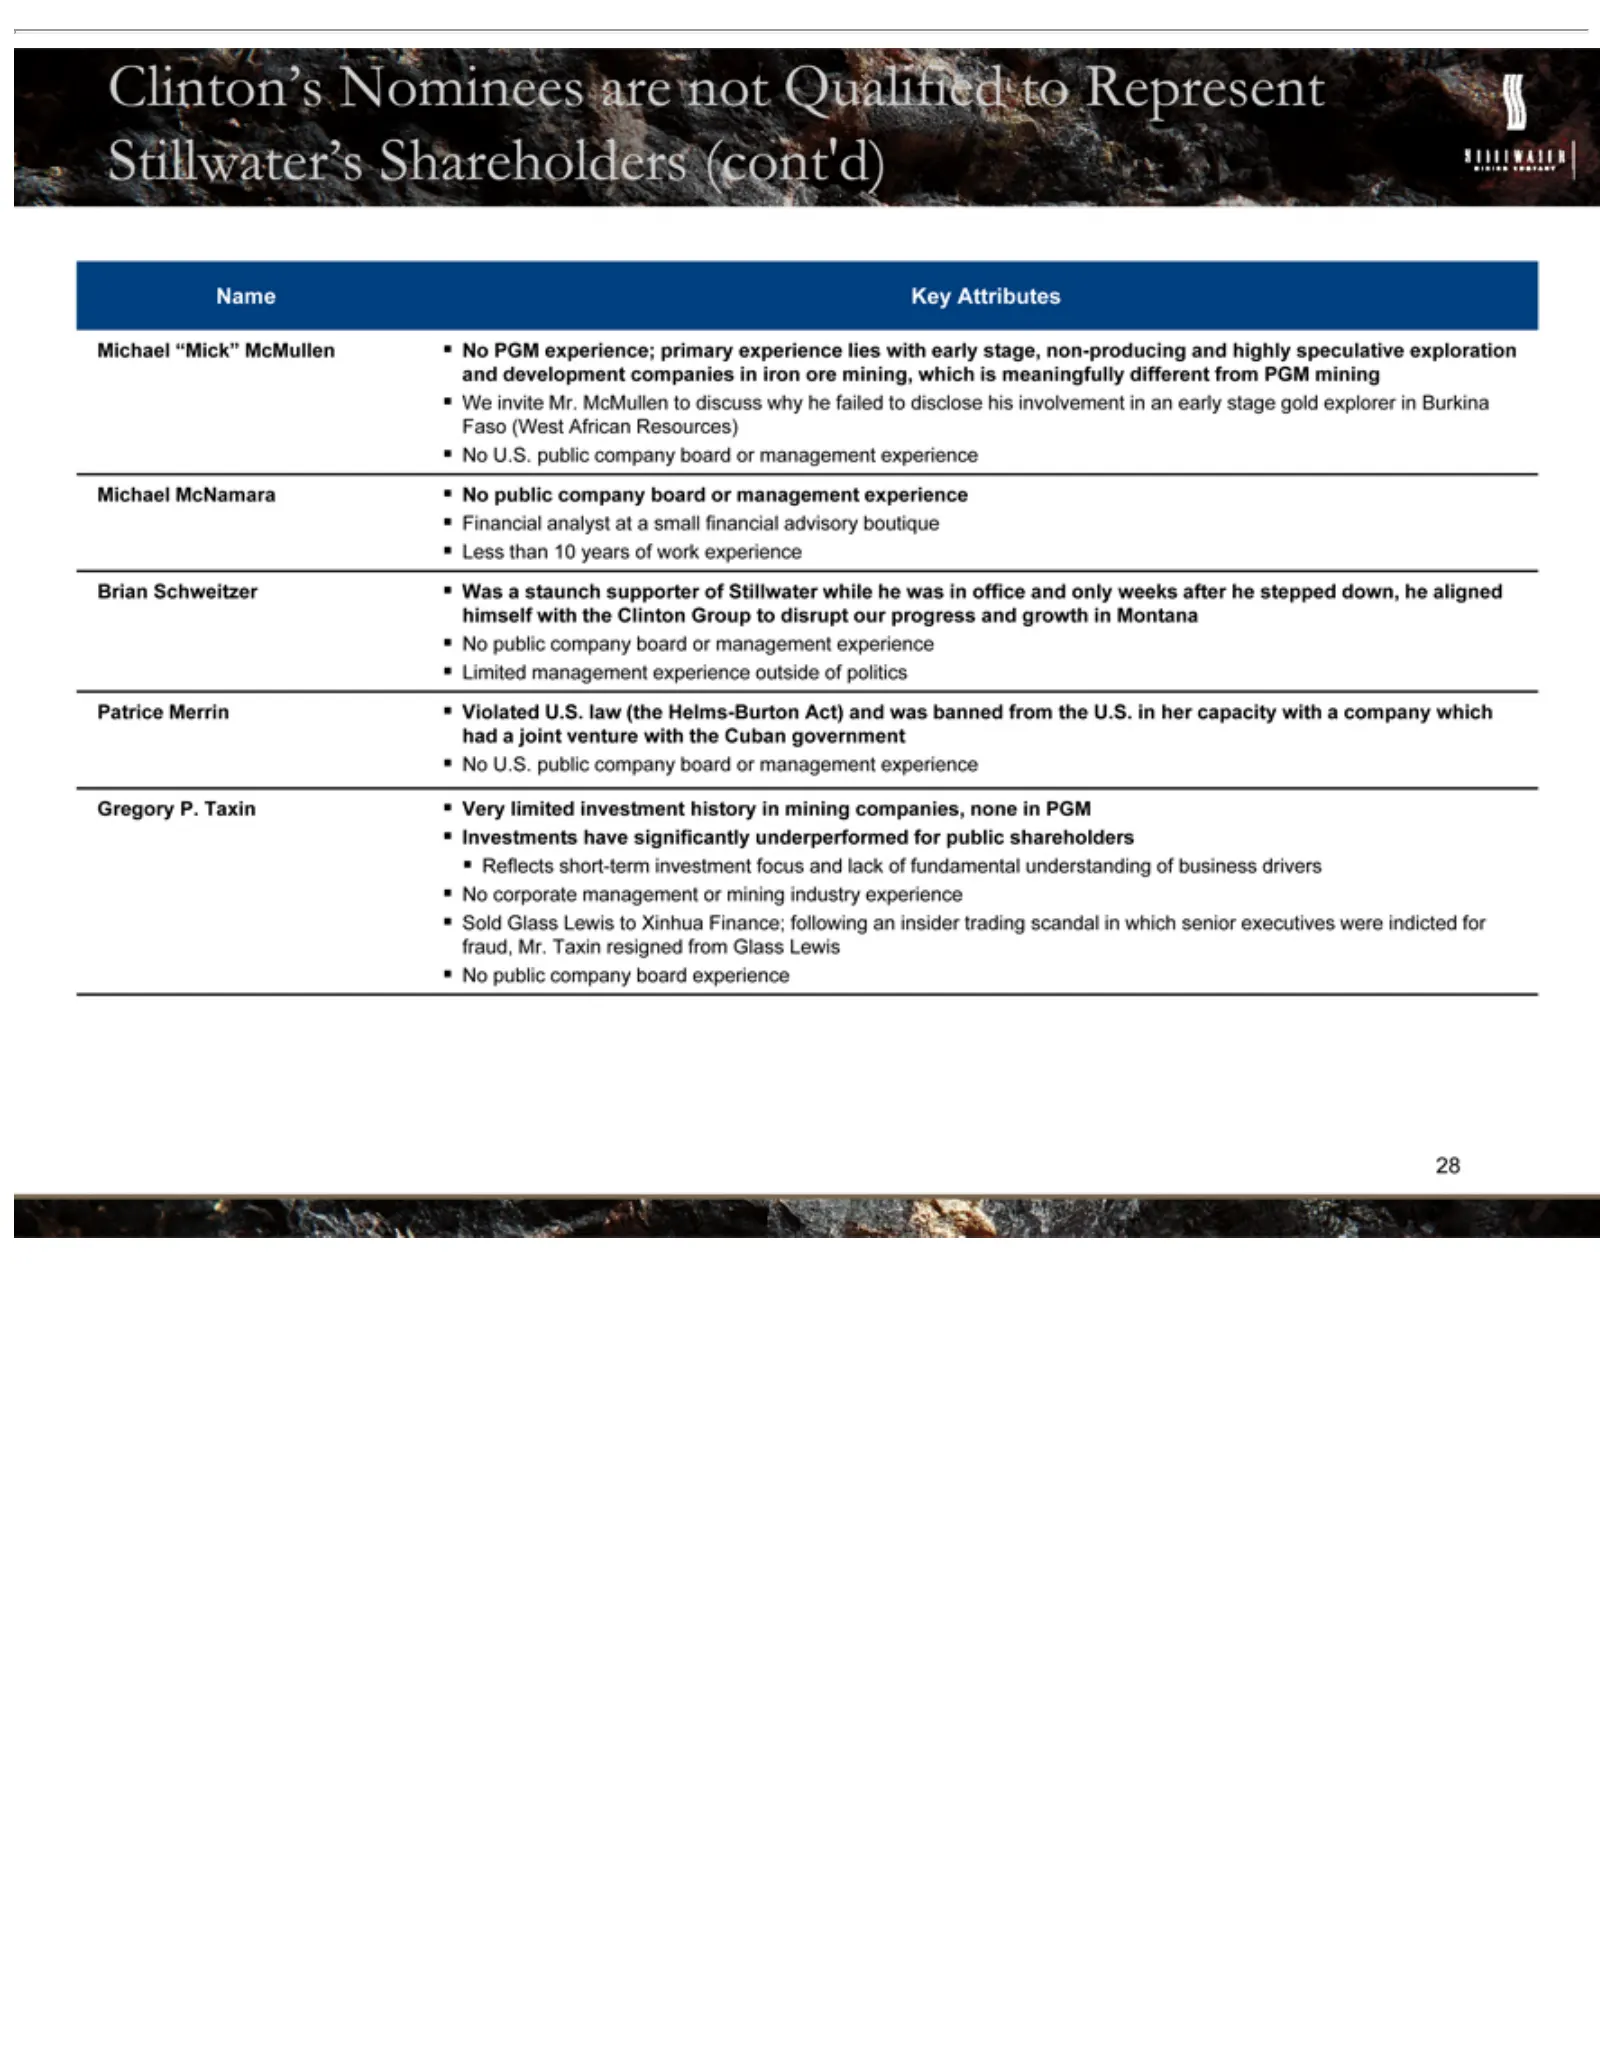
Slide 30: Clinton's Nominees Lack Relevant Experience (continued)
Clinton’s Name and Faso Michael Brian himself Patrice had Gregory nfraud, 29We Financial Less Limited Investments Reflects Sold Noadevelopment (West U.S. corporate public invite joint Schweitzer Mr. Key than Glass Merrin with “Mick” McNamara P.Nominees management public Taxin short-term venture Attr
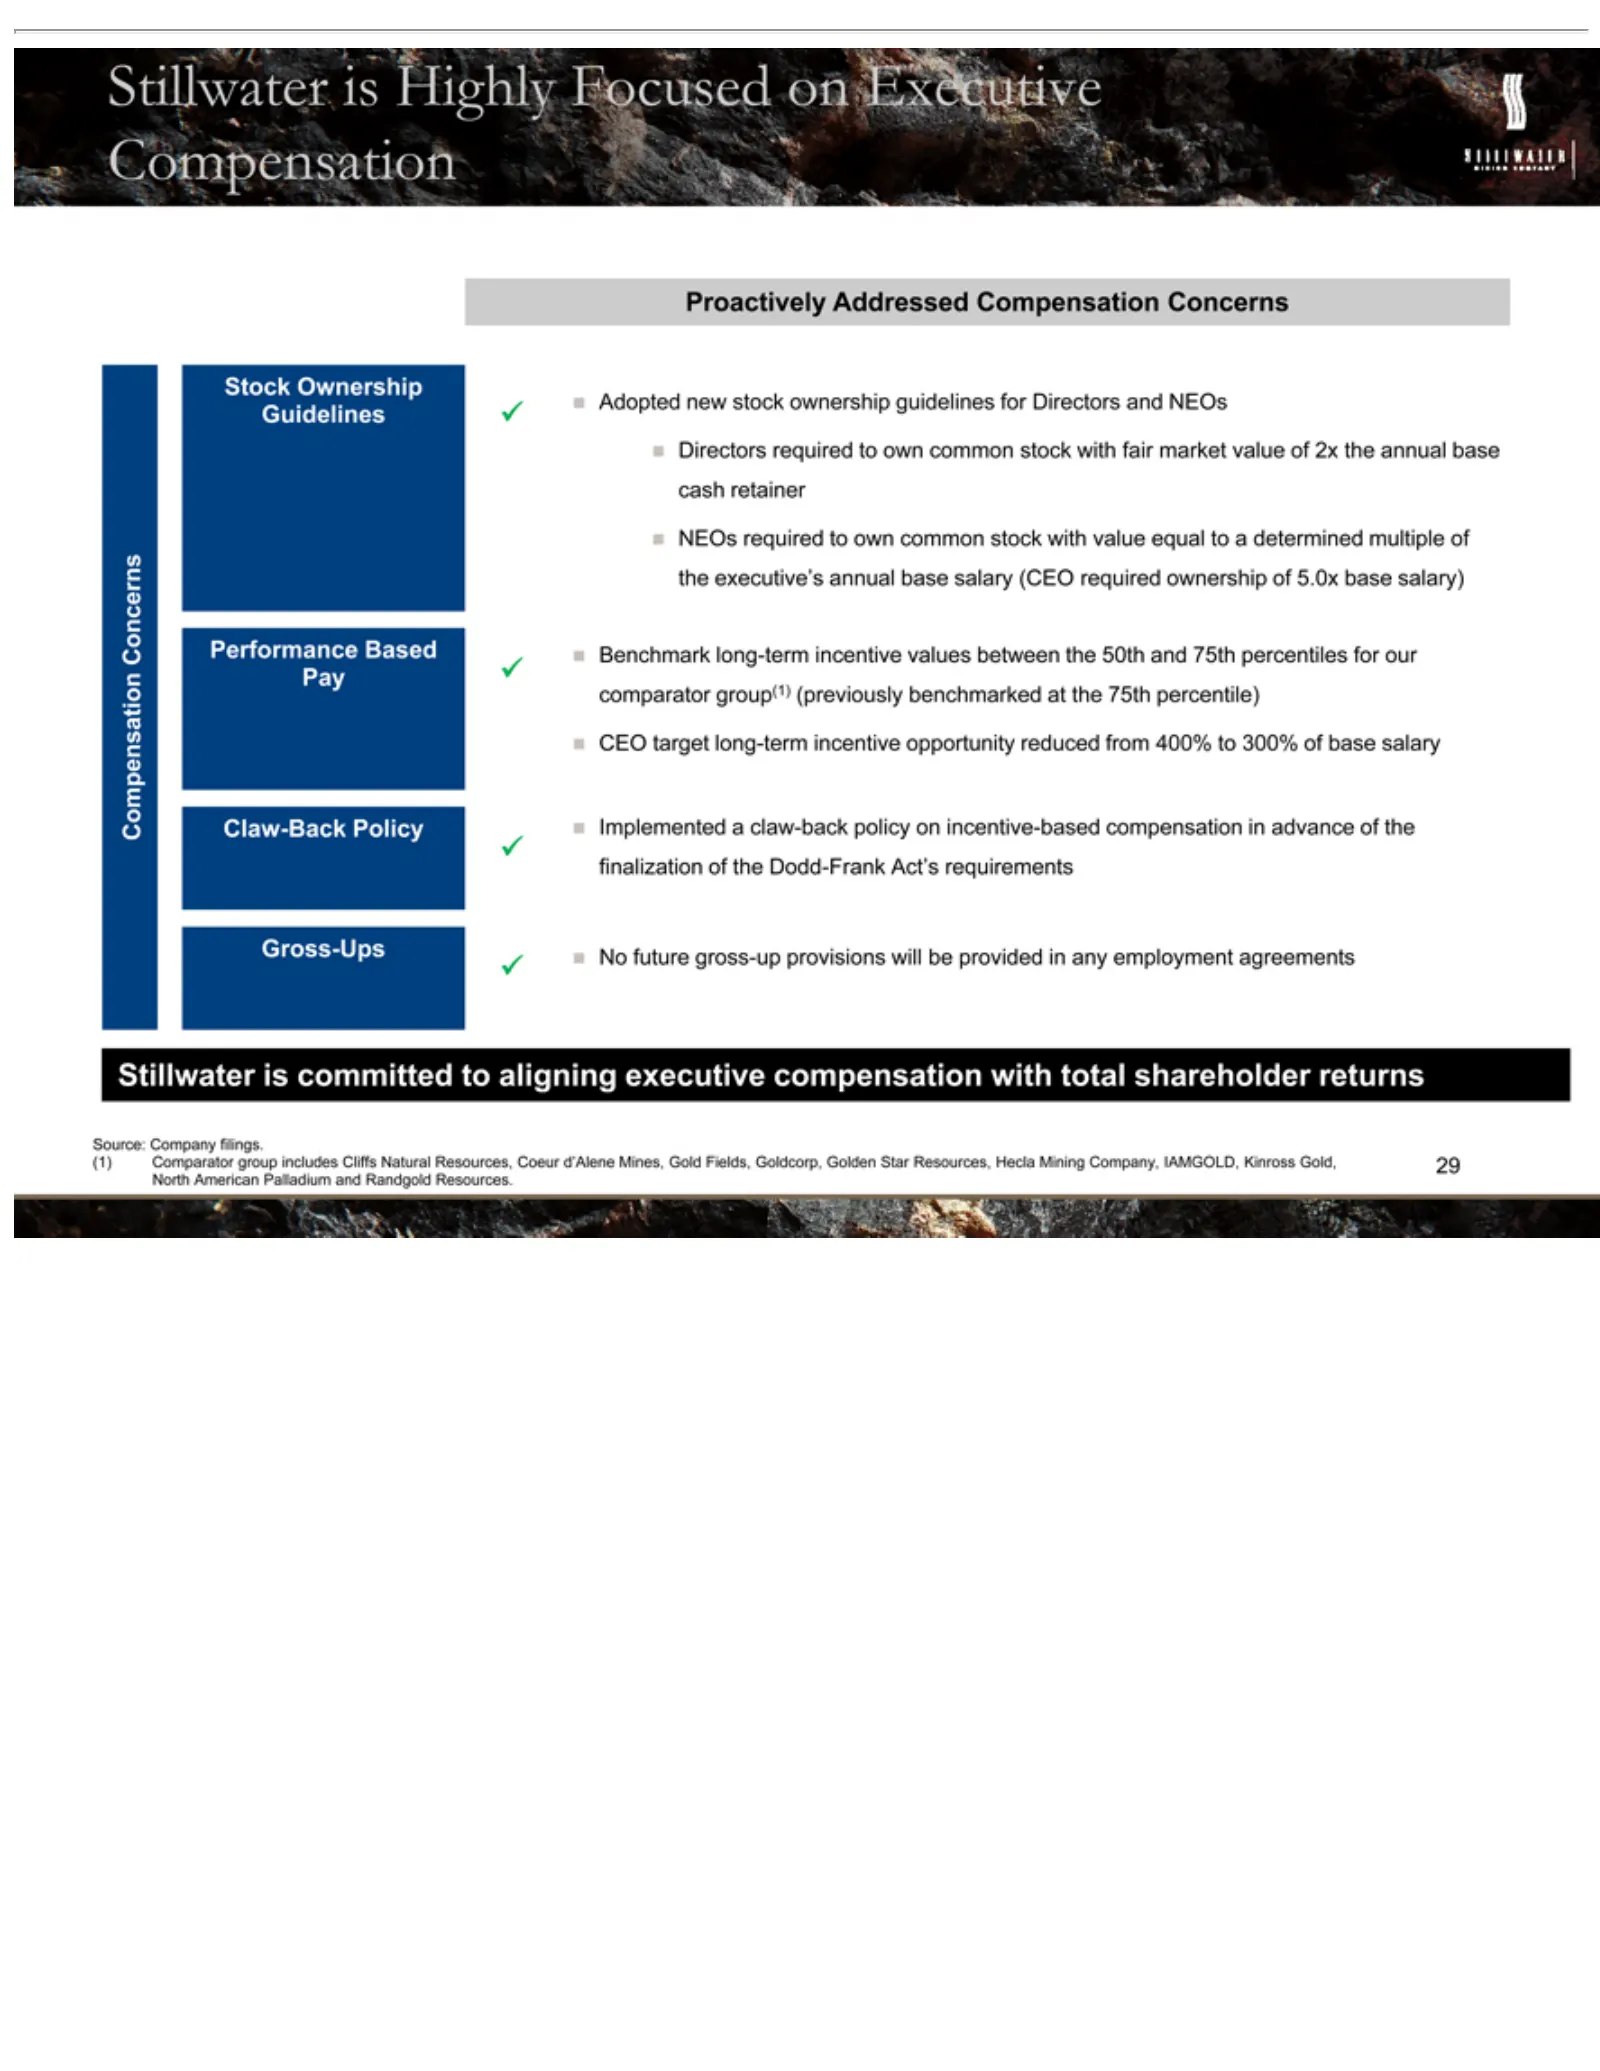
Slide 31: Proactively Addressed Compensation and Governance Concerns
Proactively Compensation ll Stock Marathon Claw-Back Planning Spending Altar Adopted Reviewed D cash nU the Benchmark comparator CEO Unfavorable Potential Implemented finalization Final No relative Stillwater Source: (1) IAMGOLD,producerKinross North 30irectors nfavorable ll ComparPalladiumtor execu
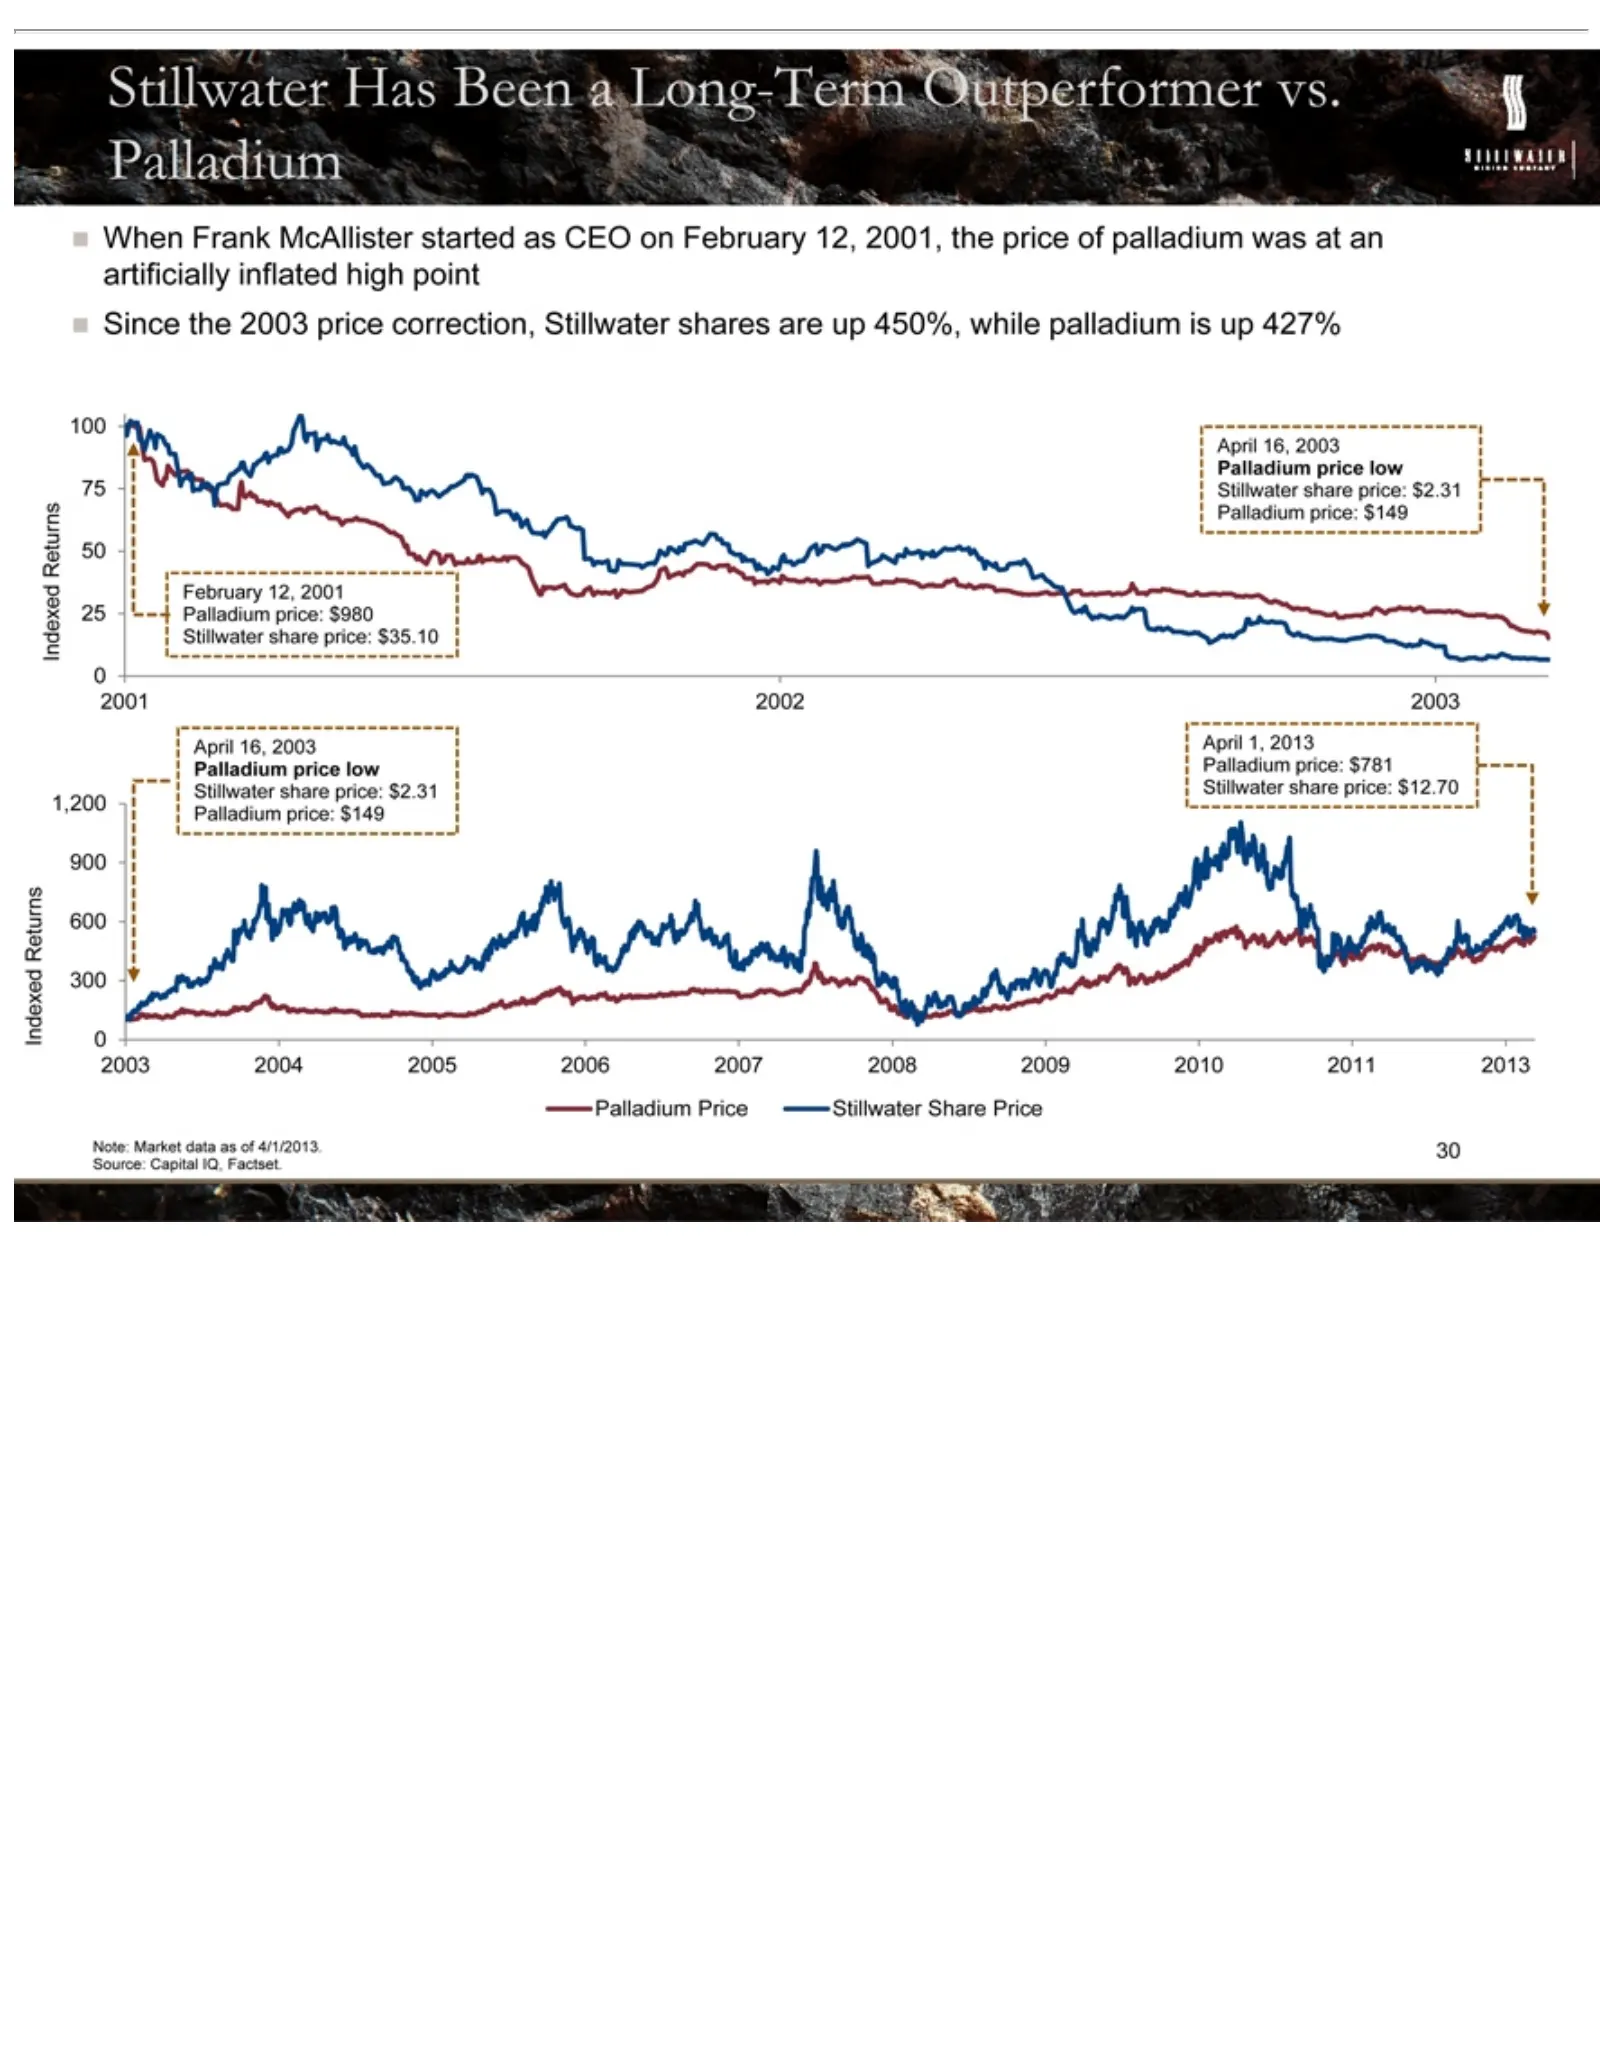
Slide 32: Stillwater Share Price Indexed Versus Palladium
When 75 100 February Indexed 2002 02001 April Stillwater 2003 Palladium Note: 31300 Returns 2004 16, 1, Market 600 Frank 2013 Returns 12, 2003 Has share 900 price price: Price 2005 50McAllister 2001 data Indexed Been 1,200 price: low Stillwater 2006 $781 as Palladium aofLong-Term 2007 $35.10 $2.31 $
Slide 33: 4. Conclusion
4. Conclusion
Slide 34: Clinton's Misguided, Value-Destructive Demands
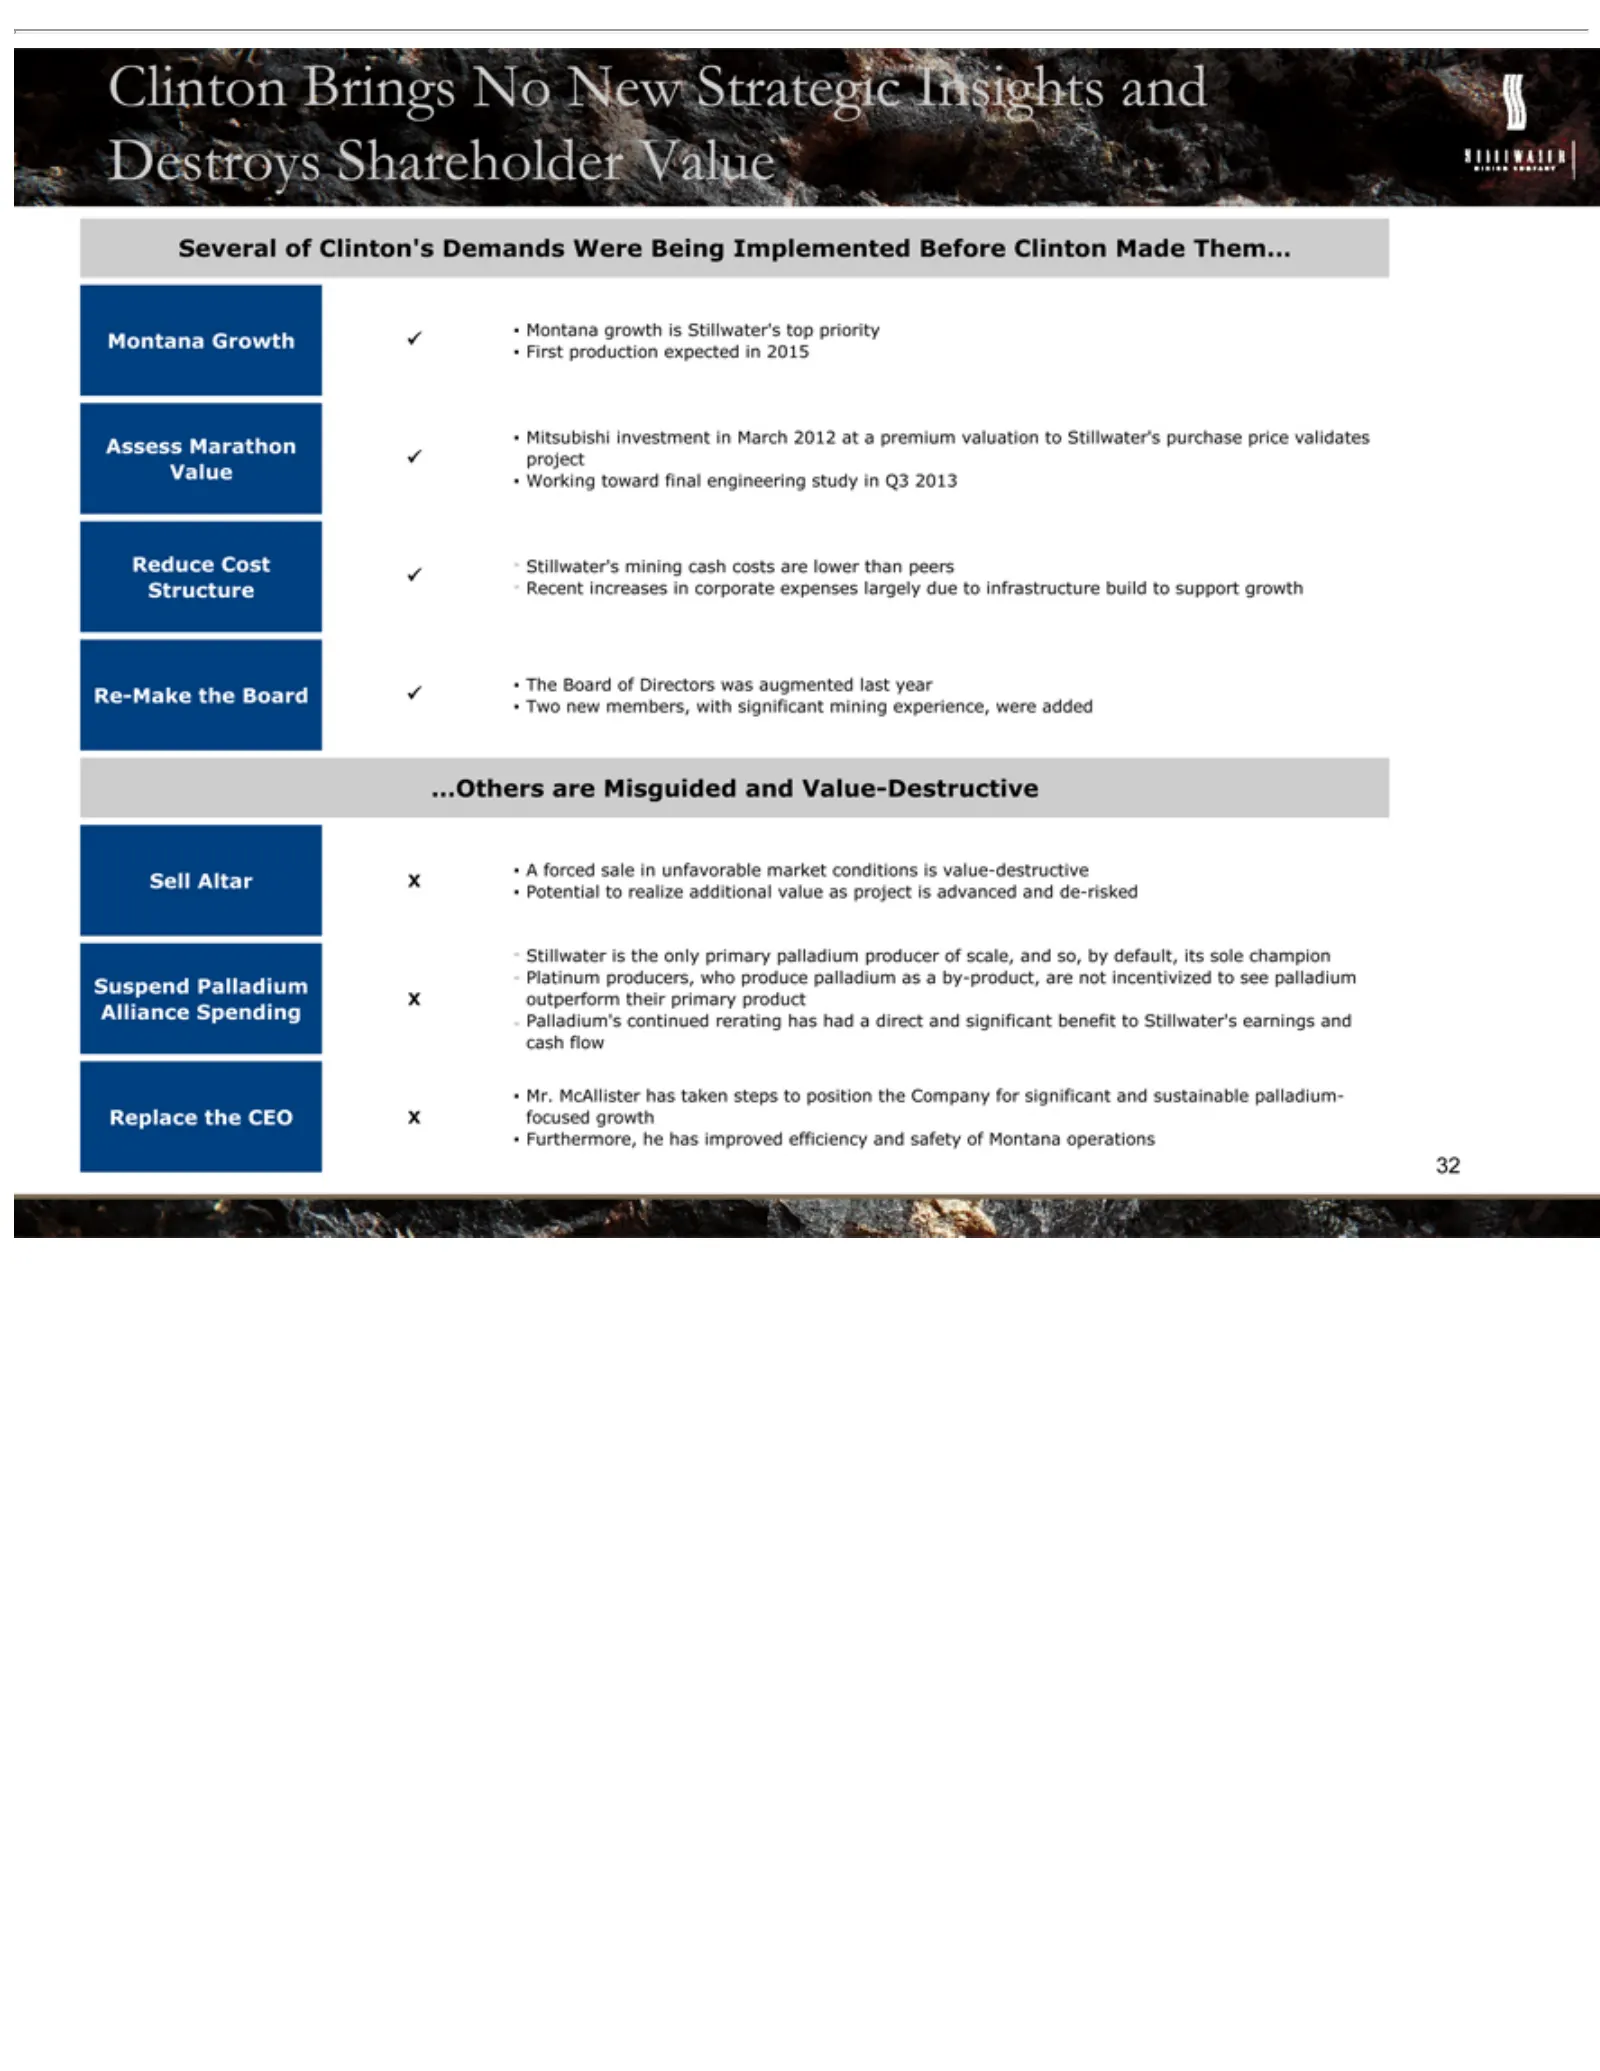
Clinton Several Montana Assess Reduce Re-Make …Others Sell Suspend •Replace 33 A Working The Two Montana First Mitsubishi project Stillwater’s Recent Potential Stillwater Platinum outperform Palladium’s cash Mr. Furthermore, forced Altar McAllister Board new flow production Marathon of Cost Brings t
Slide 35: Clinton Group Track Record of Short-Term Activism
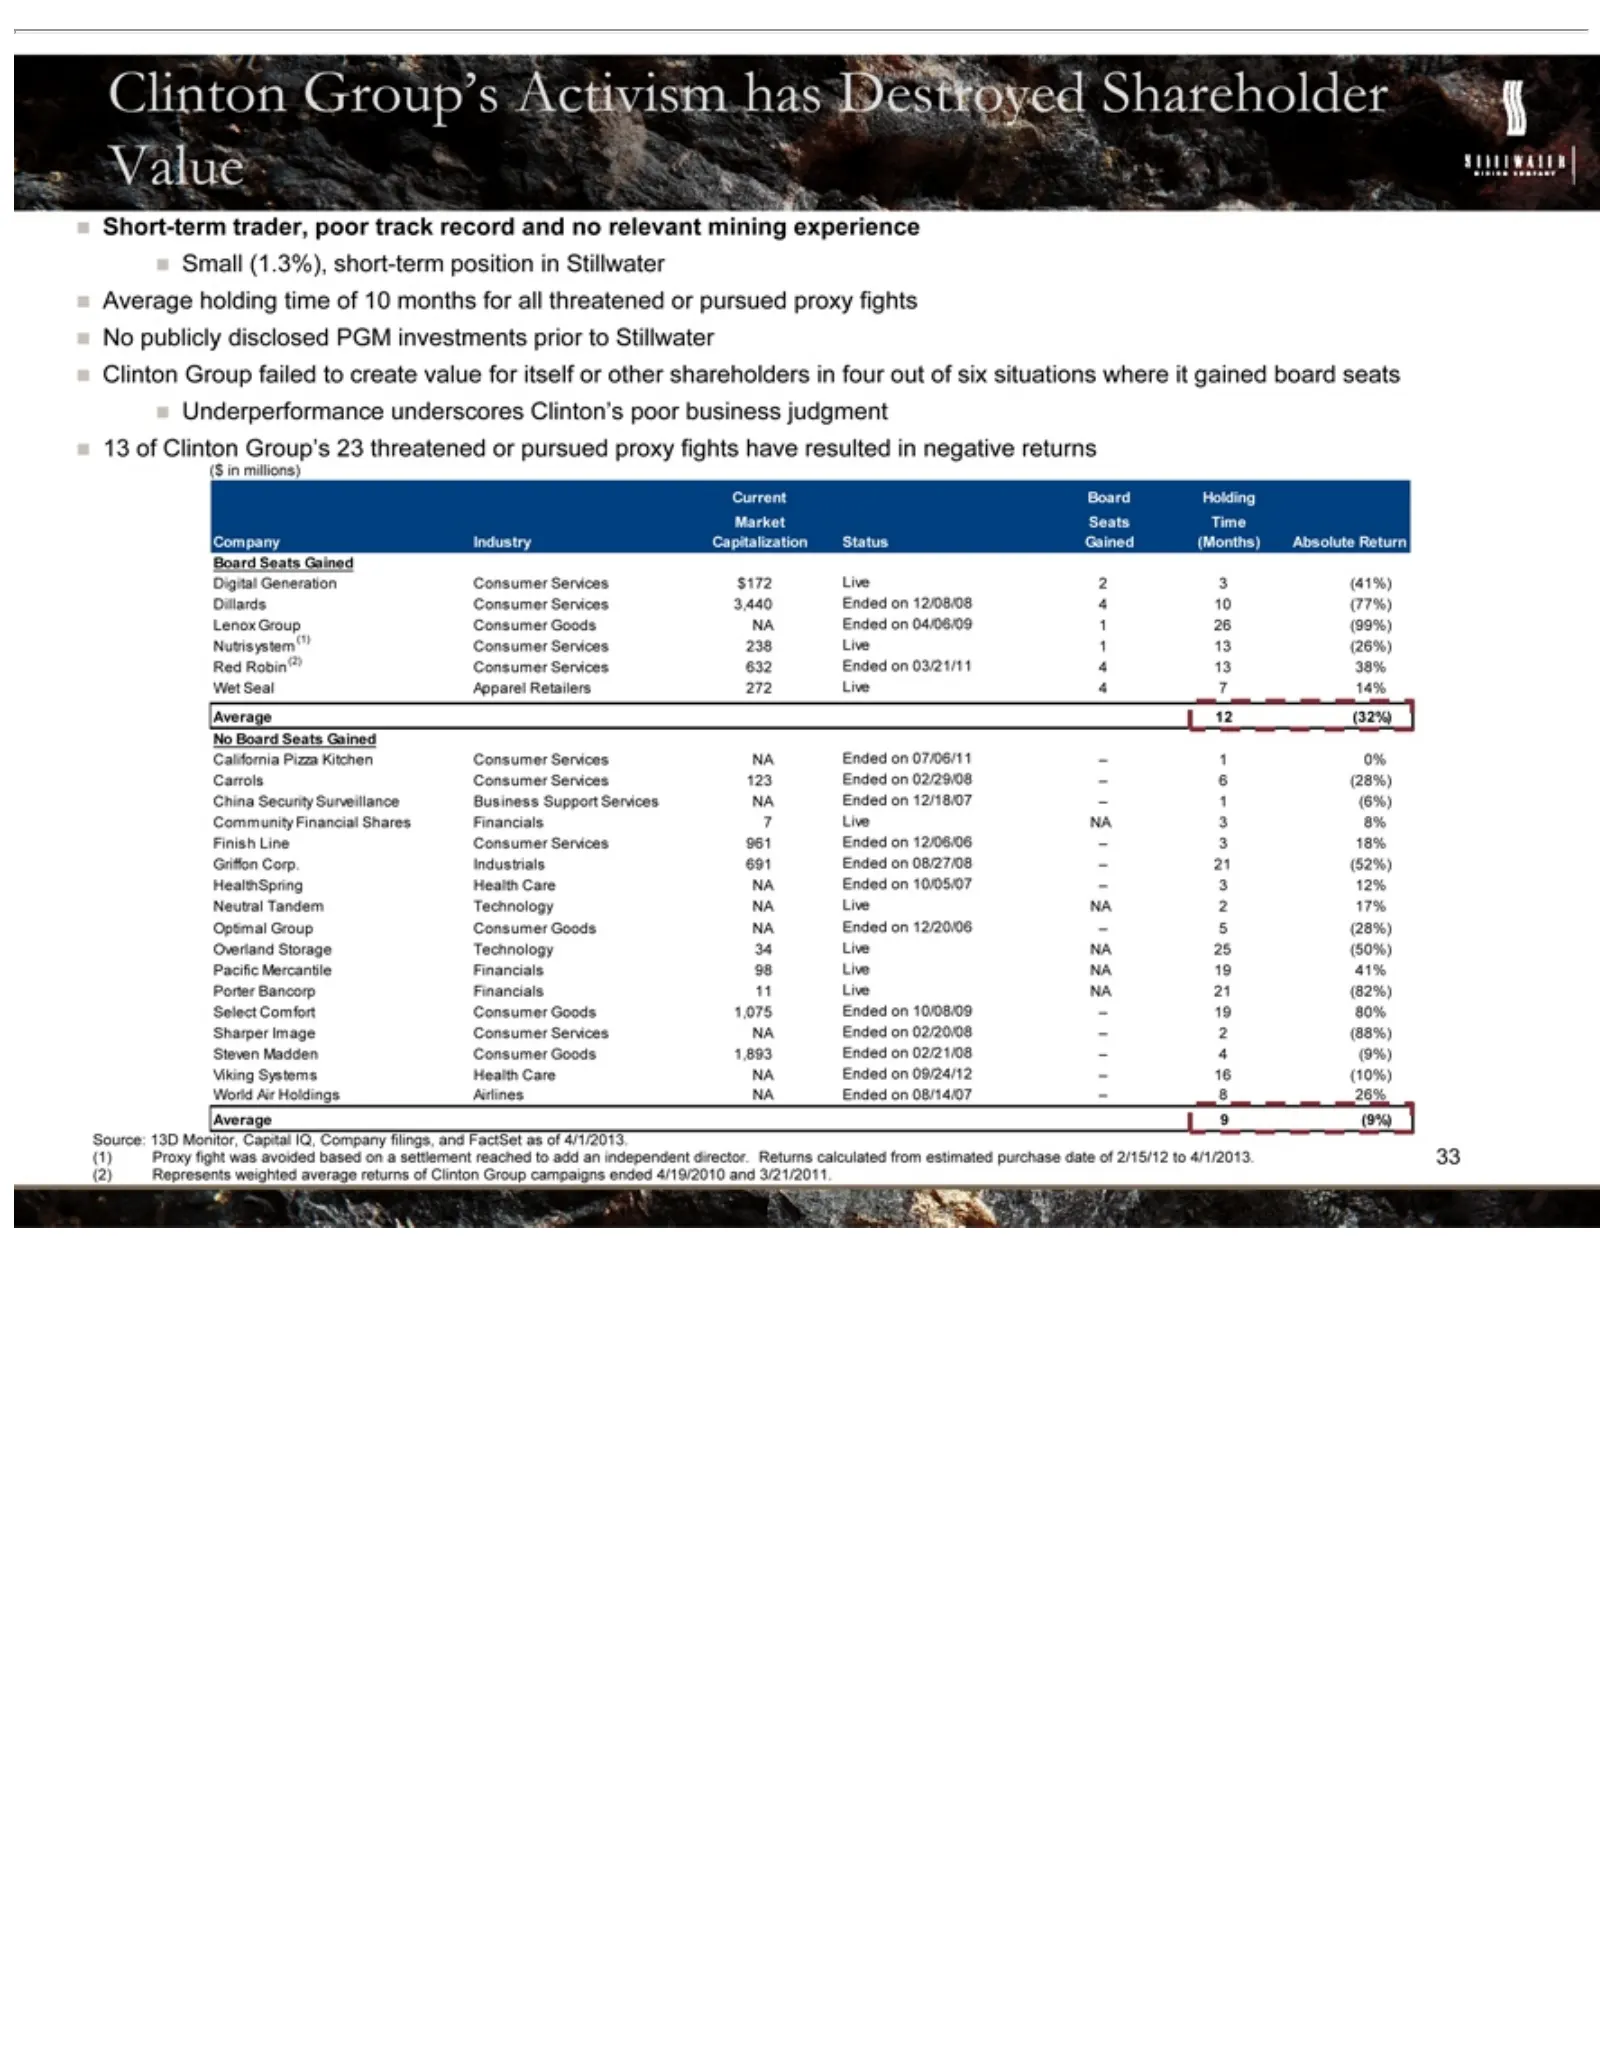
Short-term Value nClinton 13 ($ Current Market Company Board Digital Dillards Lenox Nutrisystem Red Wet No California Carrols China Community Finish Griffon HealthSpring Neutral Optimal Overland Pacific Porter Select Sharper Steven Viking World Average Source: (1) Group 34Small Underperformance in o
Slide 36: Stillwater Conclusion
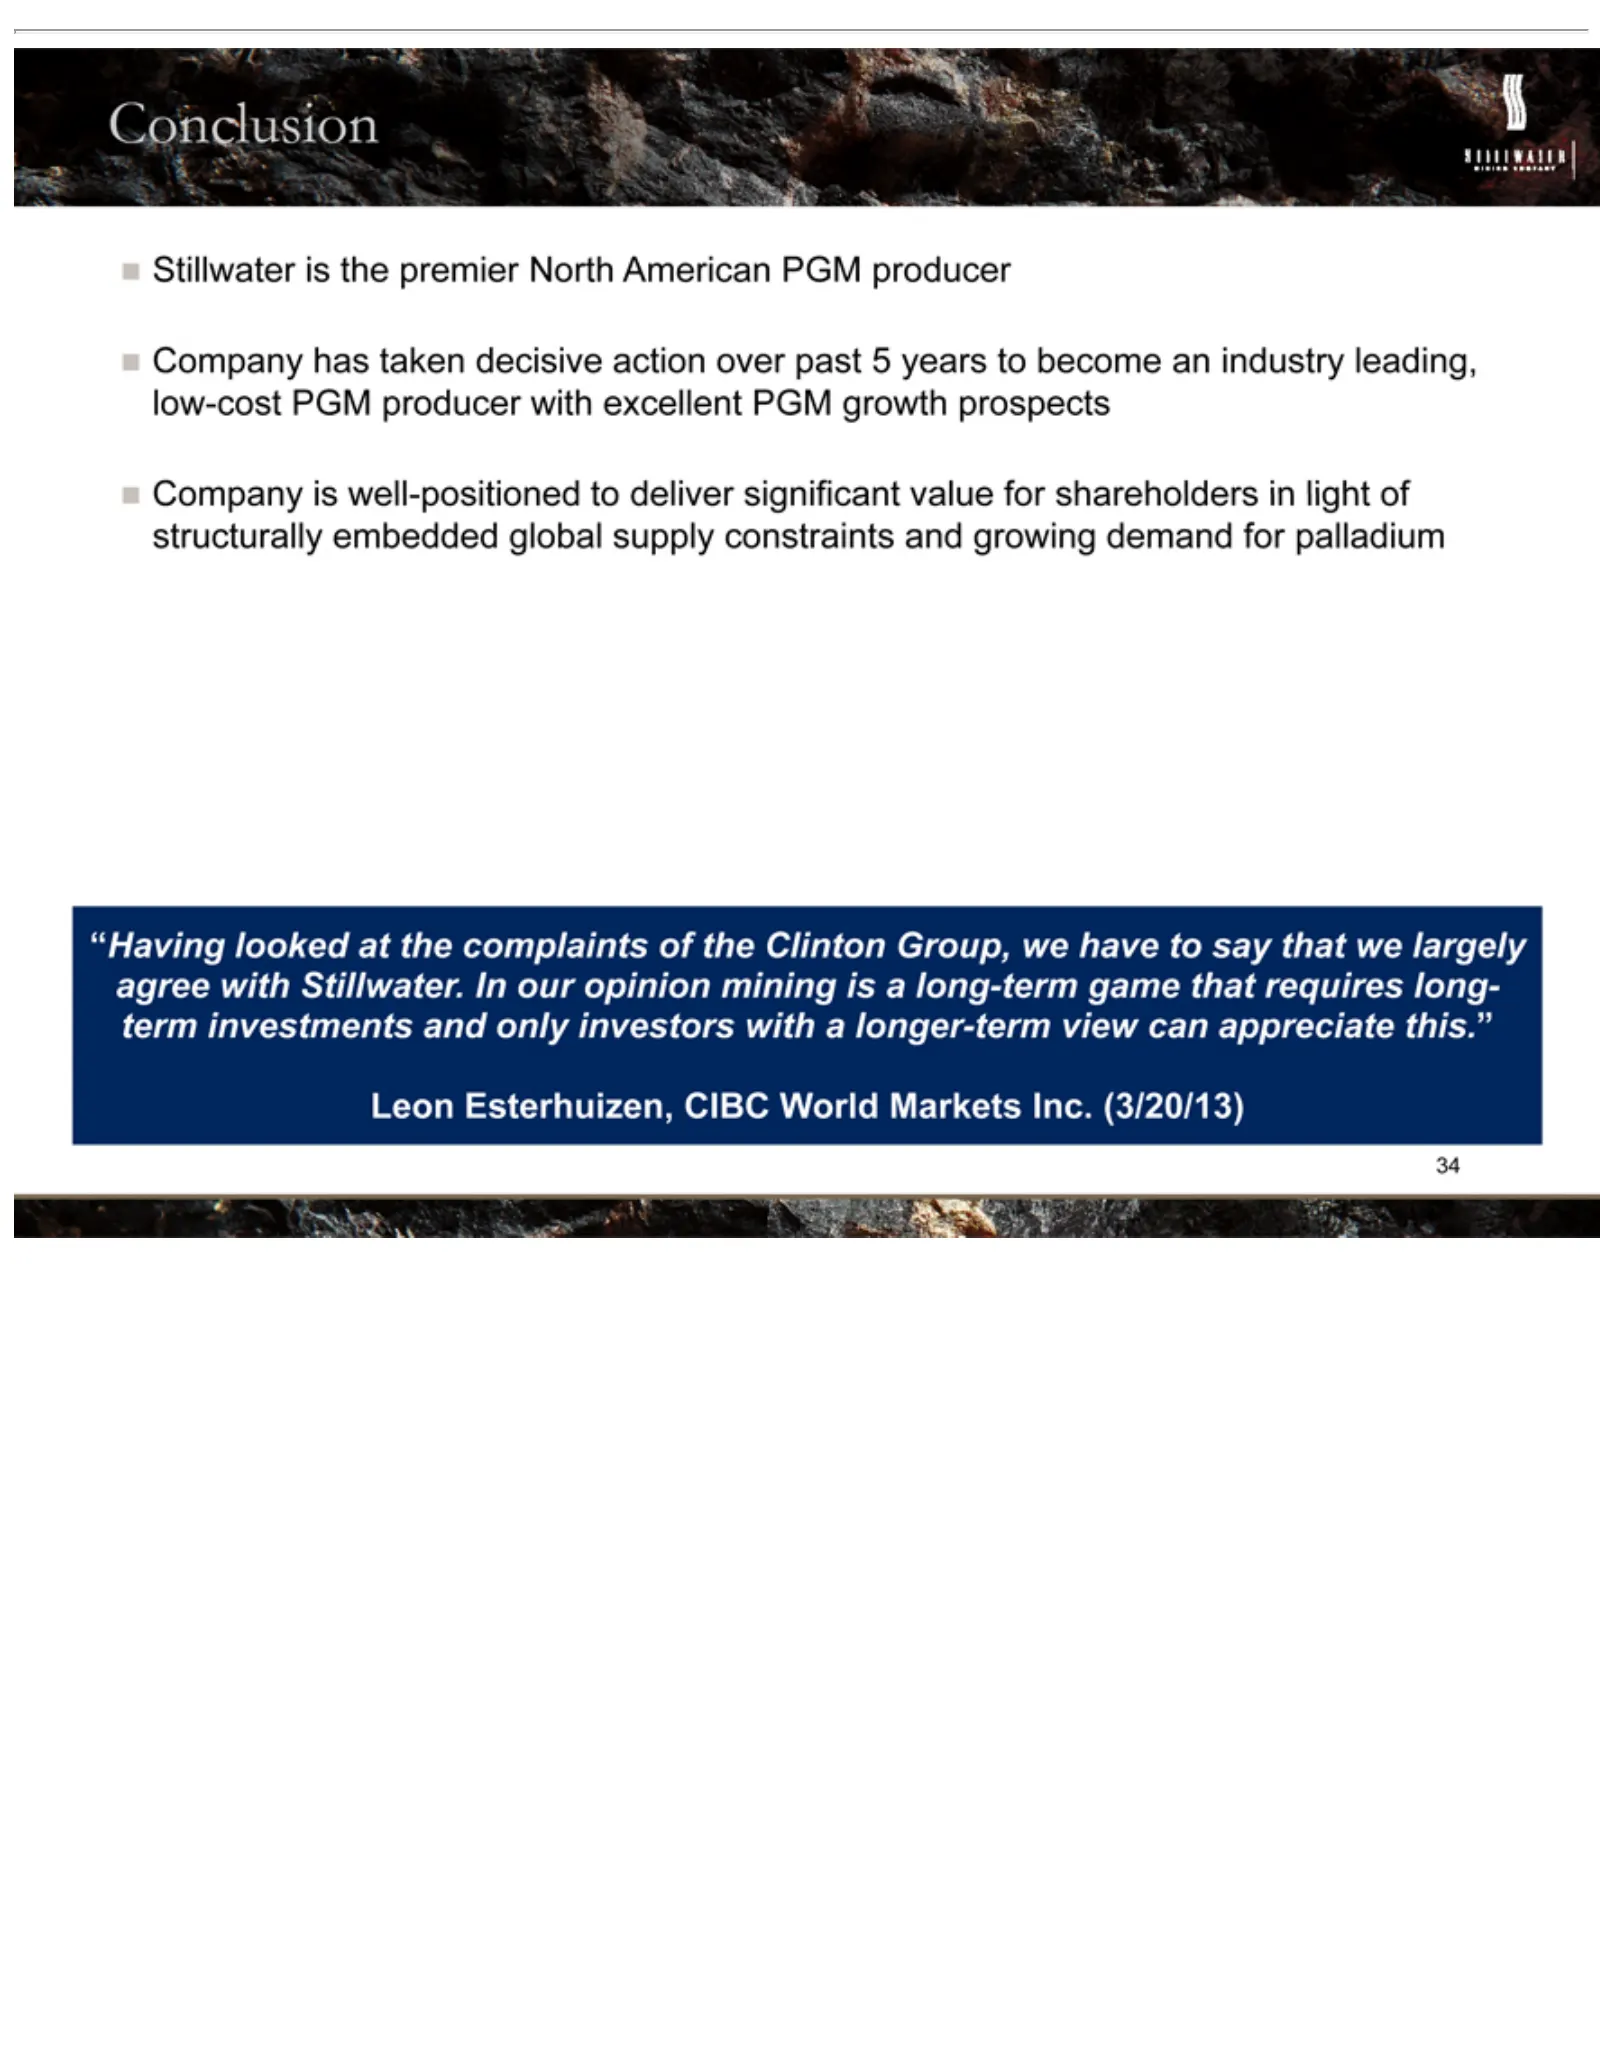
Stillwater Conclusion Company “Having longer-term Leon 35 Esterhuizen, looked is hasview the well-positioned taken premier atcan CIBC the decisive appreciate complaints North World to action American deliver Markets this.” ofover thesignificant Clinton Inc. past PGM (3/20/13) 5 years producer Group,
Slide 37: Appendix
Appendix
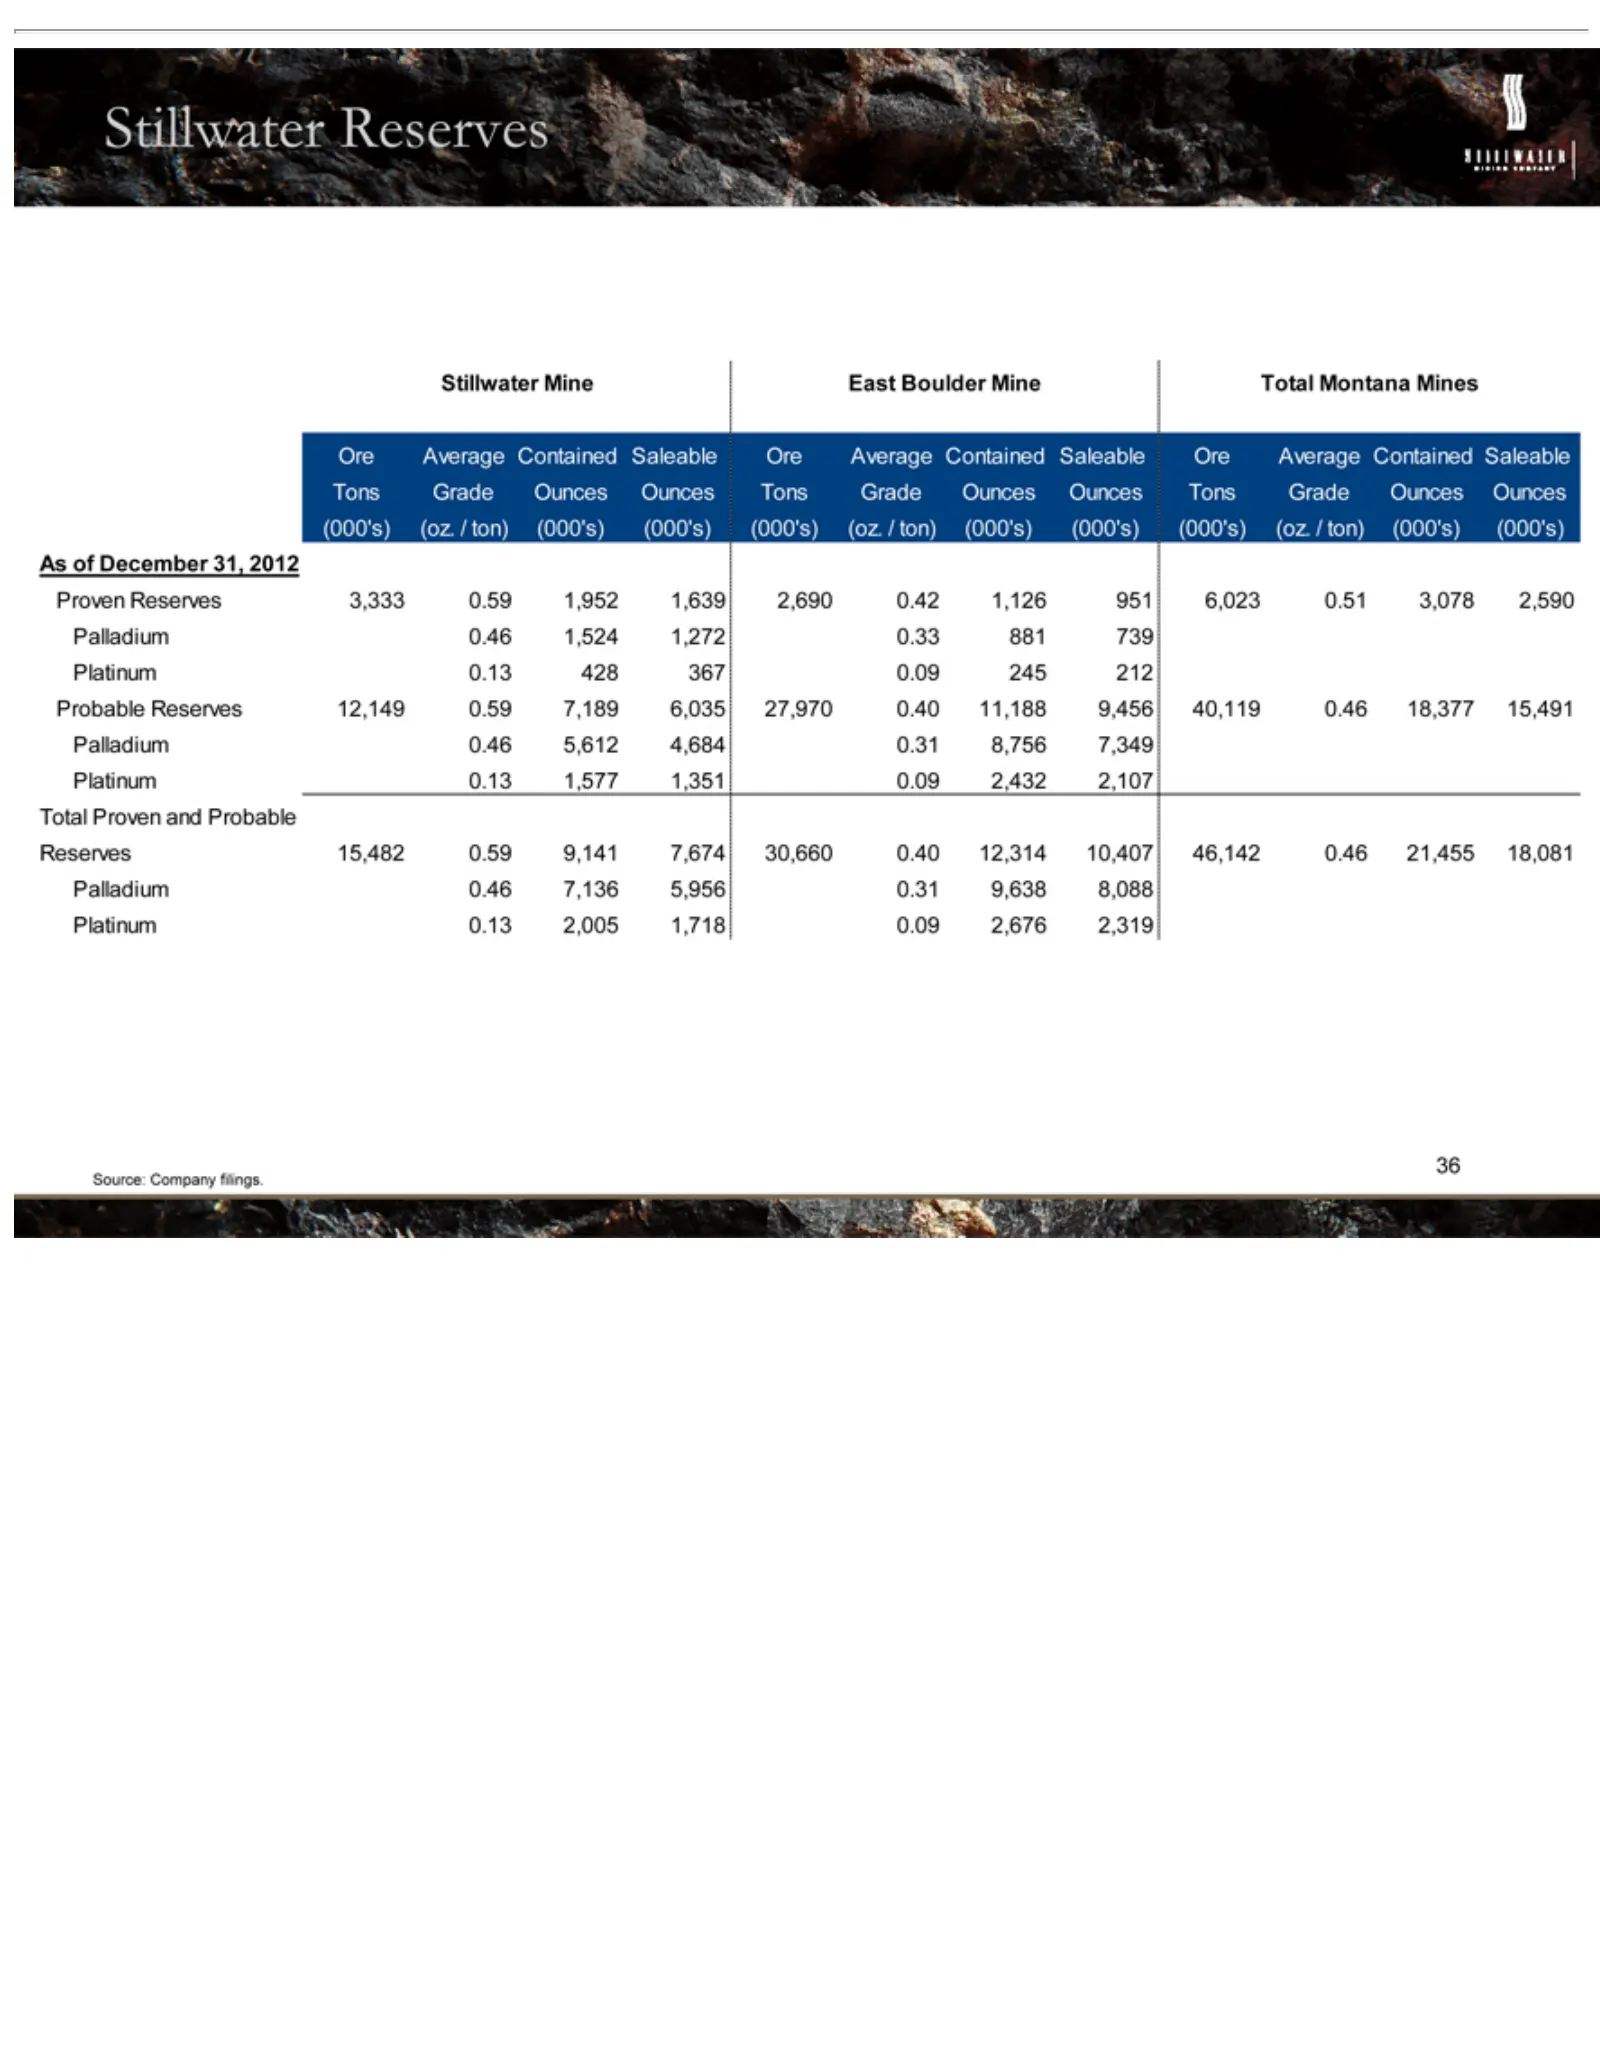
Slide 38: Stillwater Reserves as of December 31, 2012
Stillwater Ore Tons (000’s)(oz. As Proven Probable Total Reserves Palladium Platinum Source: 37 of Average Grade Proven December Reserves Company Reserves 15,482 0.13 Reserves Mine 0.46 /Ounces ton)(000’s)(000’s)(000’s)(oz. Contained and 428 1,577 2,005 1,524 5,612 7,136 East 31, 0.59 3,333 Probable
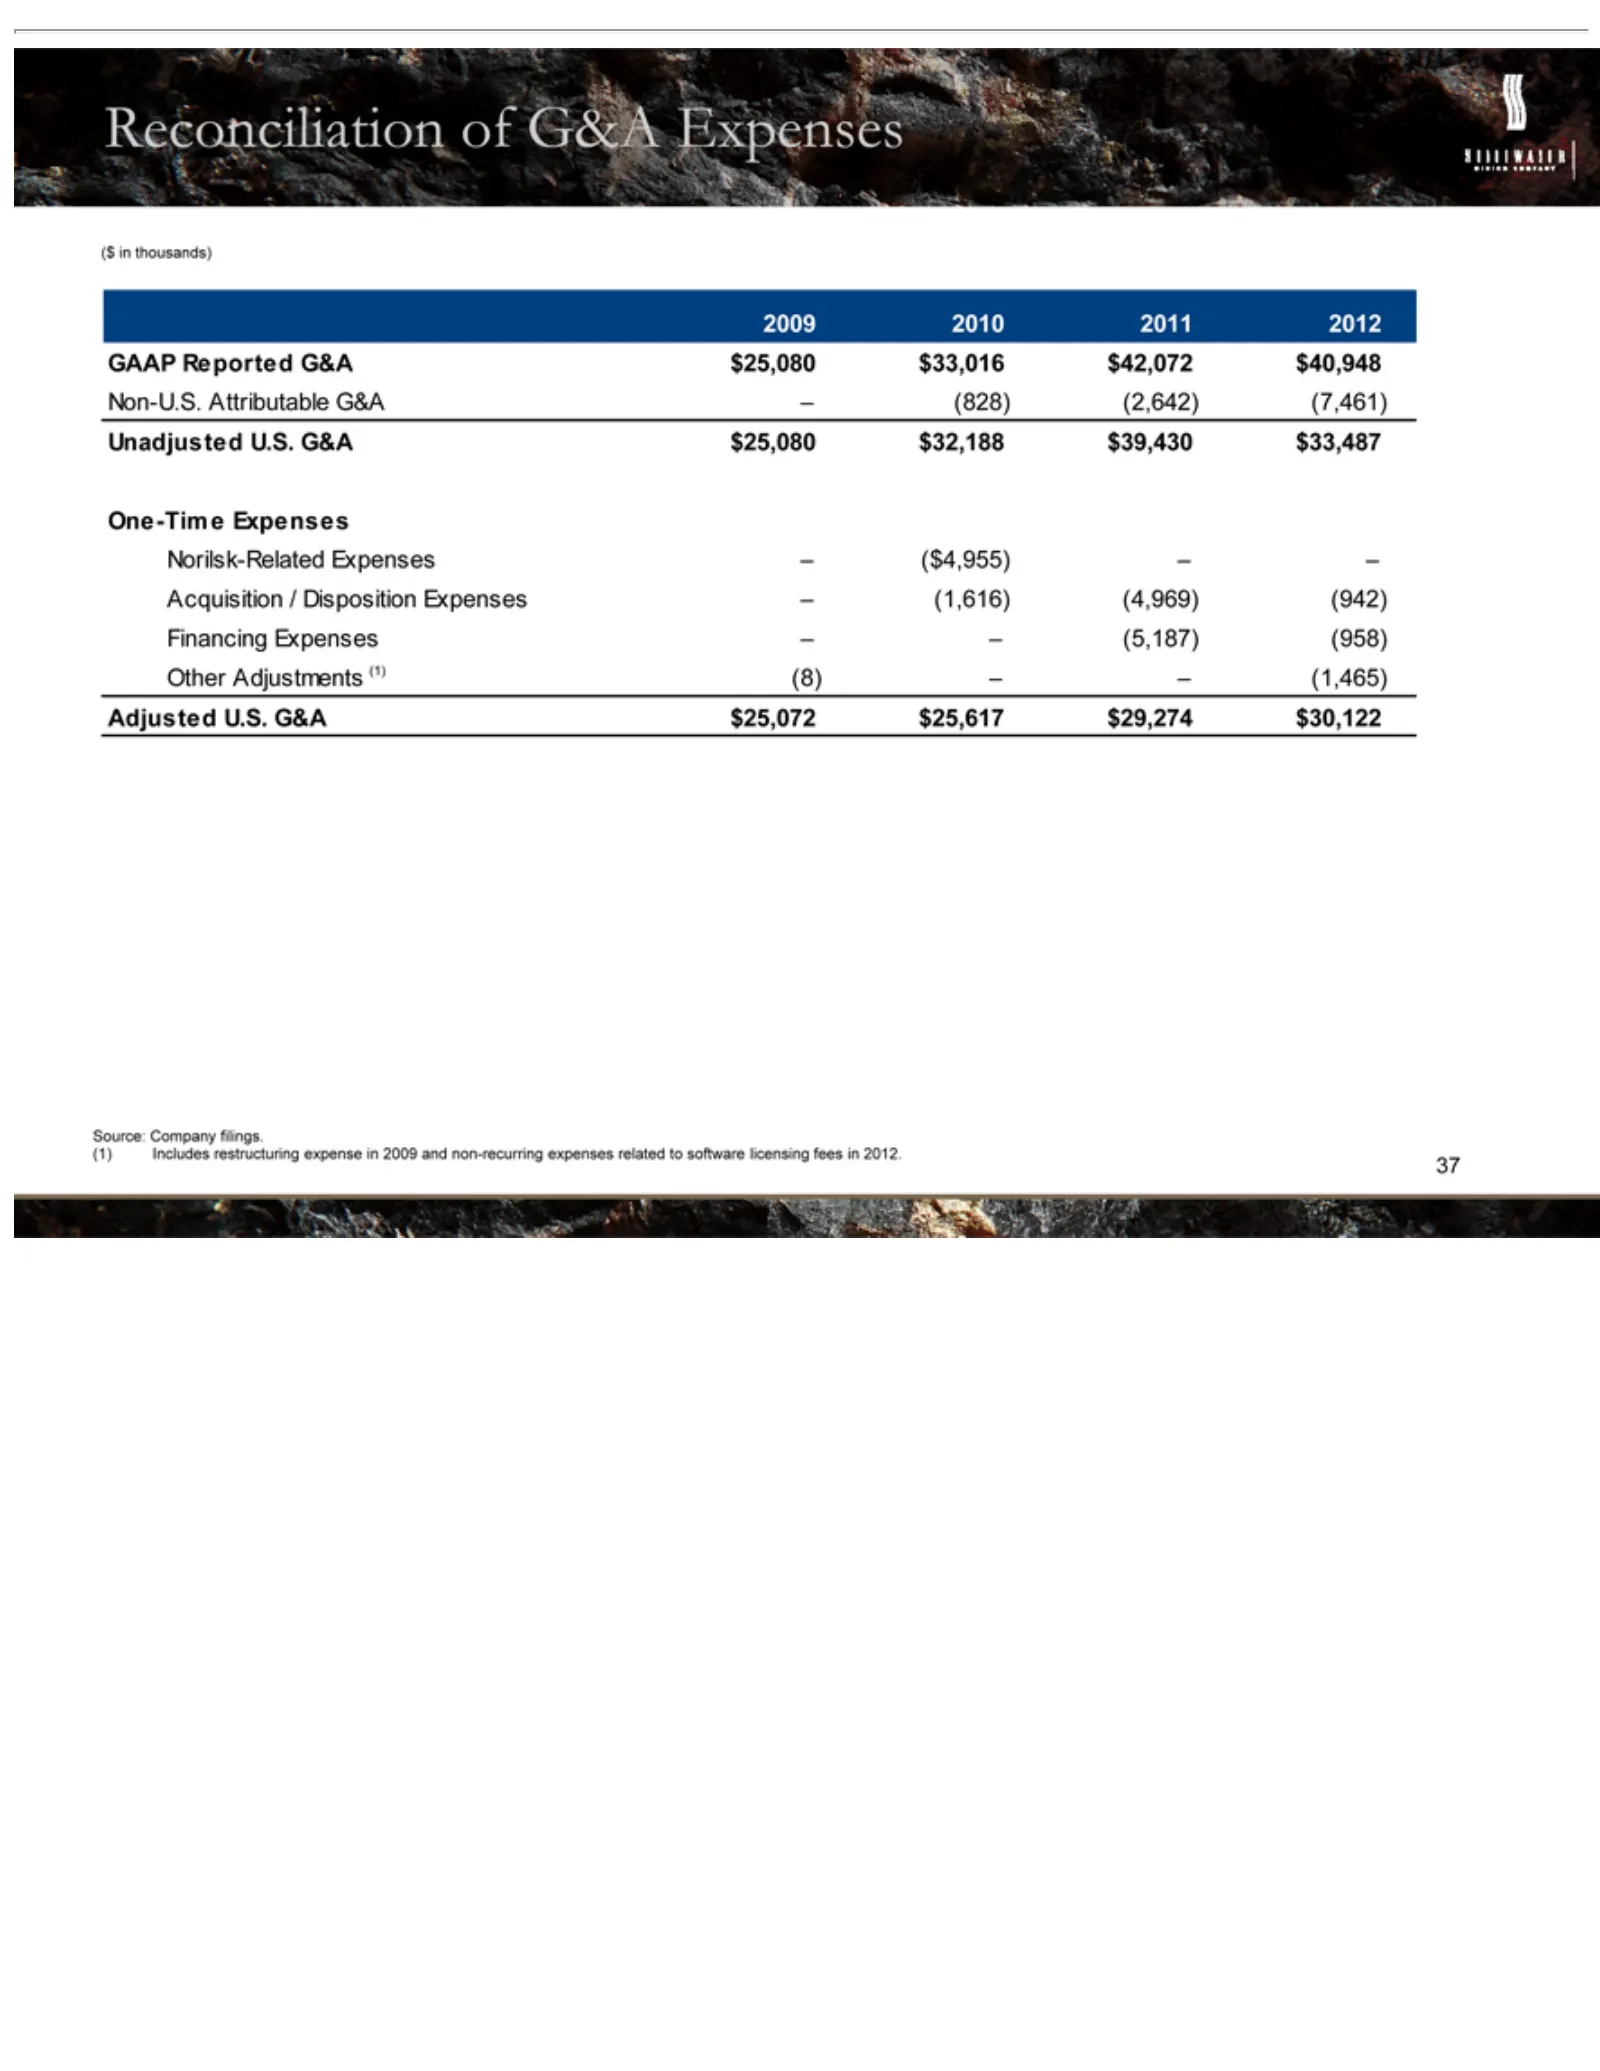
Slide 39: Reconciliation of GAAP to Non-GAAP U.S. G&A Expenses
Reconciliation ($ 2009 GAAP Non-U.S. Unadjusted One Norilsk-Related Acquisition Financing Other Adjusted Source: (1) 38 inIncludes -Time thousands) 2010 Adjustments Reported Company U.S. Attributable Expenses 2011 Expenses U.S. /restructuring Disposition G&A ofExpenses 2012 G&A G&A filings. (1)(8) –
Source: SEC EDGAR · DEFA14A filed Apr 8, 2013
More decks from Stillwater Mining Company
 FY2016 Earnings Presentation34 slides · Feb 23, 2017
 Merger or Acquisition (February 2017)51 slides · Feb 15, 2017
 Merger or Acquisition (February 2017)46 slides · Feb 3, 2017
 Merger or Acquisition (December 2016)35 slides · Dec 13, 2016
 Merger or Acquisition (December 2016)44 slides · Dec 12, 2016
 RBC Global Mining & Materials Conference 201642 slides · Jun 15, 2016