Iconix Brand — Investor Day (November 2016)
68 slides from Iconix Brand's investor day presentation, Nov 15, 2016
Slide 1: November 15, 2016 Investor Day
NOVEMBER 15, 2016 INVESTOR DAY Exhibit 99.1
Slide 2: Overview
OVERVIEW
Slide 3: Roadmap to Value Creation
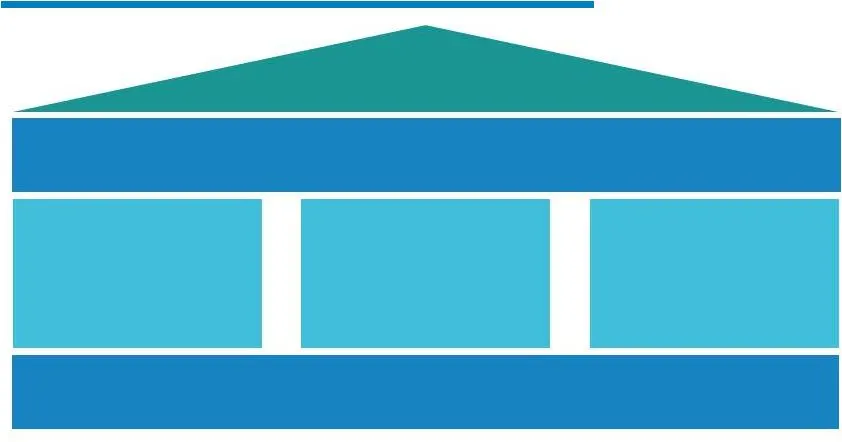
HIGH OPERATING MARGIN, STRONG FREE CASH FLOW, ASSET LIGHT EXPERIENCED LEADERSHIP, WORLD CLASS IP PORTFOLIO, ACTIVE BRAND MANAGEMENT TOP 25% TSR PERFORMANCE PORTFOLIO MANAGEMENT GLOBAL ORGANIC GROWTH PRUDENT CAPITAL MANAGEMENT + + ROADMAP TO VALUE CREATION
Slide 4: Strategic Plan: 2016 Transition, 2017 Evolution, 2018/2019 Growth
2017 EVOLUTION 2018 / 2019 GROWTH 2016 TRANSITION STRATEGIC PLAN • Solve 2018 convertible notes • Leverage ratio < 7.0x • Active brand management & new brand building tools • Prioritize resources • Modest organic growth • Domestic, international & global targets • Maximize available capital • Mid si
Slide 5: Iconix Today
ICONIX TODAY
Slide 6: Iconix – The Premier Global Brand Management Company
ACTIVE BRAND MARKETERS DTRs 60 $13 BILLION RETAIL EQUIVALENT SALES WORLDWIDE 30 BRANDS OWNERS 1,700 LICENSES INNOVATIVE PARTNER TO WORLD’S LEADING RETAILERS 100+ COUNTRIES PREEMINENT GLOBAL BRAND MANAGEMENT COMPANY ICONIX – THE PREMIER GLOBAL BRAND MANAGEMENT COMPANY
Slide 7: Experienced Leadership Team with Deep Industry Knowledge
John Haugh CEO Carolyn D’Angelo Women’s & Home Vincent Nesi Men’s Willy Burkhardt International Roz Nowicki Entertainment Mary Gleason Incubator EXPERIENCED LEADERSHIP TEAM WITH DEEP INDUSTRY KNOWLEDGE Peter Cuneo Chairman (Entertainment) Drew Cohen (Licensing) Sue Gove (CEO/CFO Retail) Jim Marcum (
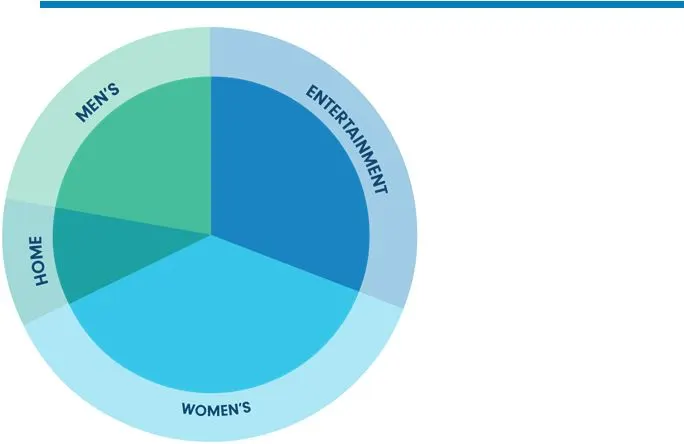
Slide 8: World Class Brand Portfolio
32% 22% 11% 35% WOMEN’S CANDIES BONGO JOE BOXER RAMPAGE MUDD LONDON FOG MOSSIMO OCEAN PACIFIC DANSKIN MATERIAL GIRL HYDRAULIC MEN’S ROCAWEAR STARTER ECKO UNLTD. ZOO YORK MODERN AMUSEMENT ED HARDY NICK GRAHAM UMBRO PONY ARTFUL DODGER LEE COOPER HOME CANNON FIELDCREST CHARISMA ROYAL VELVET SHARPER IMA
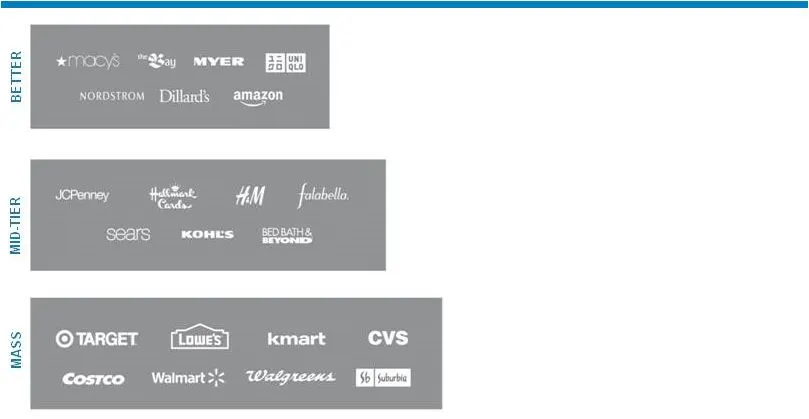
Slide 9: Partnering with Best-in-Class Retailers at All Tiers of Distribution
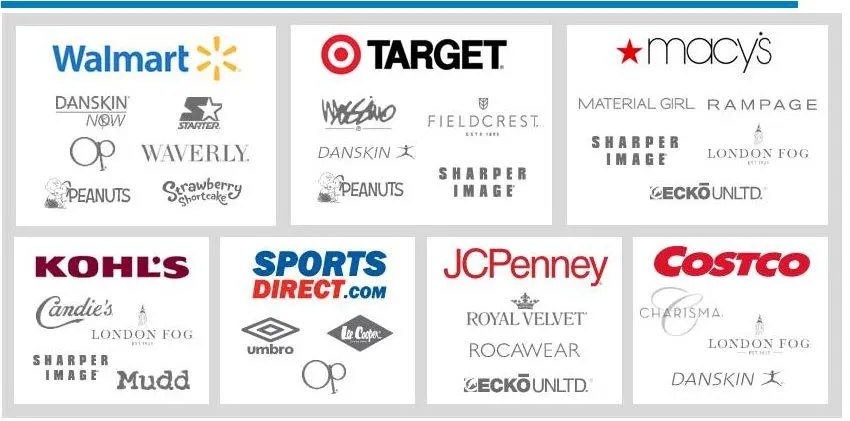
Bongo Candie’s Cannon Charisma Joe Boxer Mudd Peanuts Royal Velvet Sharper Image Waverly Zoo York Danskin Ecko Unltd. Material Girl Peanuts Rocawear Starter London Fog Cannon Charisma Danskin Now Fieldcrest Joe Boxer Waverly Mossimo OP Peanuts Sharper Image Starter PARTNERING WITH BEST-IN-CLASS RETA
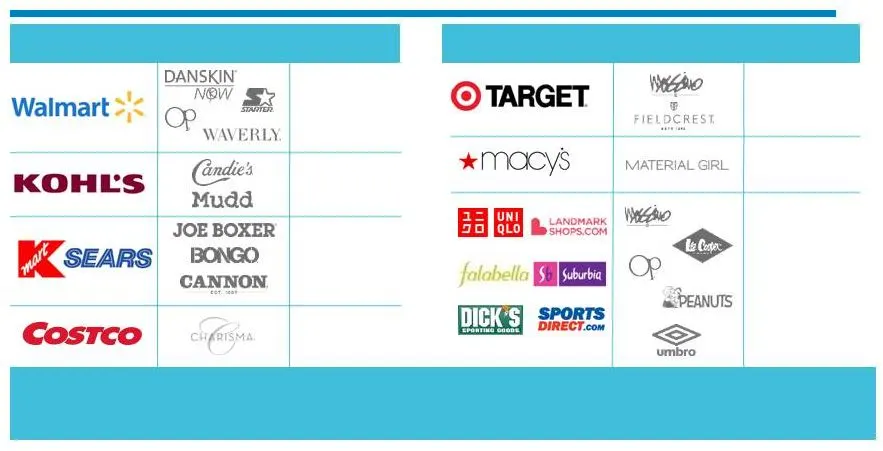
Slide 10: Industry Leading Record of Renewals
37 TOTAL LARGE DTR RENEWALS RETAILER BRAND RENEWALS RETAILER BRAND RENEWALS INDUSTRY LEADING RECORD OF RENEWALS 10x 3x 1x 8x 8x 3x 4x
Slide 11: Business Underpinned by Significant GMRs
AGGREGATE FUTURE GUARANTEED MINIMUMS 2016 GUARANTEED MINIMUMS BUSINESS UNDERPINNED BY SIGNIFICANT GMRs $800M+ OVER OF EXPECTED REVENUE GUARANTEED 60% Note: Aggregate guaranteed minimums as of 10/1/16
Slide 12: Comprehensive Strategic Review
COMPREHENSIVE STRATEGIC REVIEW
Slide 13: Value Creation Assessment
1. Market & Consumer Analysis 2. In-Depth Review of Iconix Business 3. Individual Brand Assessment VALUE CREATION ASSESSMENT • Adopting more data-driven, fact-based, analytical and objective approach
Slide 14: Market & Consumer Analysis
DISTRIBUTION CHANNELS GLOBAL LICENSING INDUSTRY APPAREL HOME ENTERTAINMENT CONSUMER TRENDS • $13+ billion industry • Fragmented market • Apparel, Accessories, Home & Toys lead • $500 billion market • 4% CAGR 2011-2015 • Highest growth categories o Sports Apparel o Footwear o Accessories • $27 billio
Slide 15: In-Depth Review of Iconix Business
BUSINESS MODEL SEGMENTS DISTRIBUTION CHANNELS INTERNATIONAL • Over 50% of International revenue driven by two brands (Umbro, Lee Cooper) • Global break-out potential for additional brands • High concentration of revenue generated by Mass & Mid-Tier retail partners • DTR business dependable with larg
Slide 16: Individual Brand Assessment
RETAILER LANDSCAPE BRAND POSITIONING & STRENGTHS MARKET TRENDS & OPPORTUNITIES LICENSE STRUCTURE • Royalty rate • Advertising fee • Expiration • Categories • Geographies • Brand DNA • Core consumer • Price and product positioning • Competition • Distribution channel volume • Retailer initiatives and
Slide 17: Brand Categorization
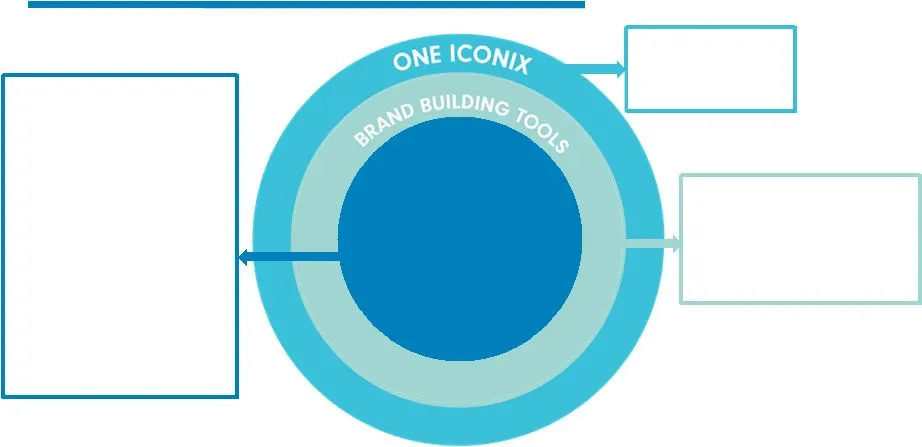
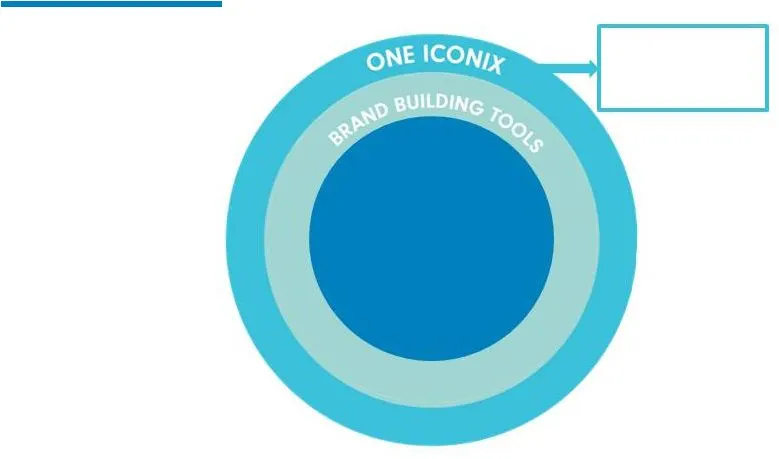
BRAND CATEGORIZATION STRATEGIC REVIEW LED TO… ONE ICONIX • Deeper relationships • Holistic approach BRAND BUILDING TOOLS • Marketing • Trend and merchandising • Design, product development, sourcing DRIVERS Significant growth initiatives across market segments, distribution channels & geographies MA
Slide 18: Iconix Brand Categorization
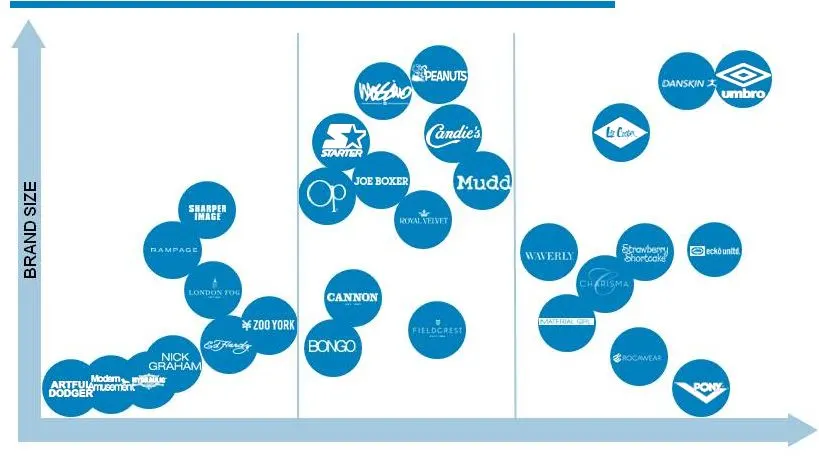
INCUBATE MAINTAIN DRIVERS REVENUE GROWTH POTENTIAL ICONIX BRAND CATEGORIZATION
Slide 19: Roadmap to Value Creation
ROADMAP TO VALUE CREATION
Slide 20: Roadmap to Value Creation
HIGH OPERATING MARGIN, STRONG FREE CASH FLOW, ASSET LIGHT EXPERIENCED LEADERSHIP, WORLD CLASS IP PORTFOLIO, ACTIVE BRAND MANAGEMENT TOP 25% TSR PERFORMANCE PORTFOLIO MANAGEMENT GLOBAL ORGANIC GROWTH PRUDENT CAPITAL MANAGEMENT + + ROADMAP TO VALUE CREATION
Slide 21: Path to Organic Revenue Growth of $50 Million by 2019
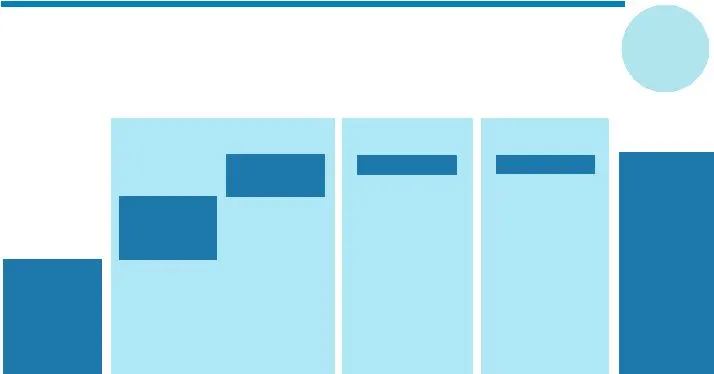
($7M) MAINTAIN INCUBATE +$7M PATH TO ORGANIC REVENUE GROWTH OF $50 MILLION BY 2019 +$20M +$30M DRIVERS International 4% CAGR Domestic
Slide 22: Drivers Brands
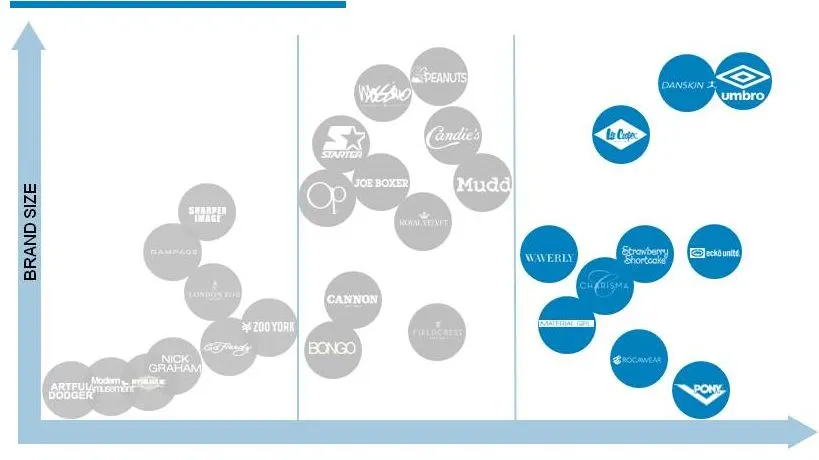
INCUBATE MAINTAIN DRIVERS DRIVERS BRANDS REVENUE GROWTH POTENTIAL
Slide 23: Drivers – Key Opportunities
DRIVERS ACTIVE SEGMENT NEW DISTRIBUTION CHANNELS DIRECT-TO-CONSUMER “DTC” INTERNATIONAL OPPORTUNITY BACKGROUND Danskin, Umbro, Starter, PONY High brand equity Strong growth market Penetrate untapped, large distribution channels Control brand and gain knowledge about consumer Maximize value of brands
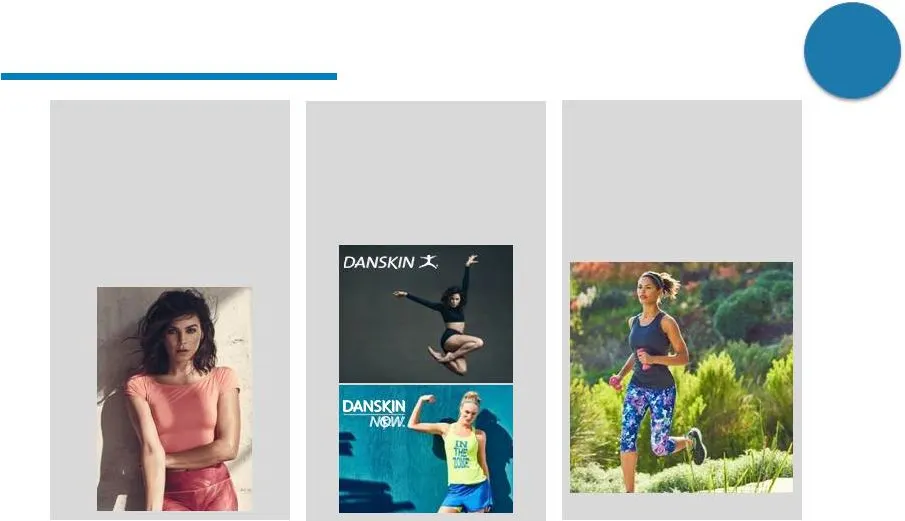
Slide 24: Active – Danskin
DRIVERS • Heritage and brand equity • 100+ years old • 1st women’s only activewear and dancewear brand • Ageless consumer BRAND DNA RETAIL POSITIONING • $1B+ DanskinNow business at Walmart this year • Halo, gymnastics, and dancewear lines ACTIVE - DANSKIN GO FORWARD STRATEGY • Actively maintain core
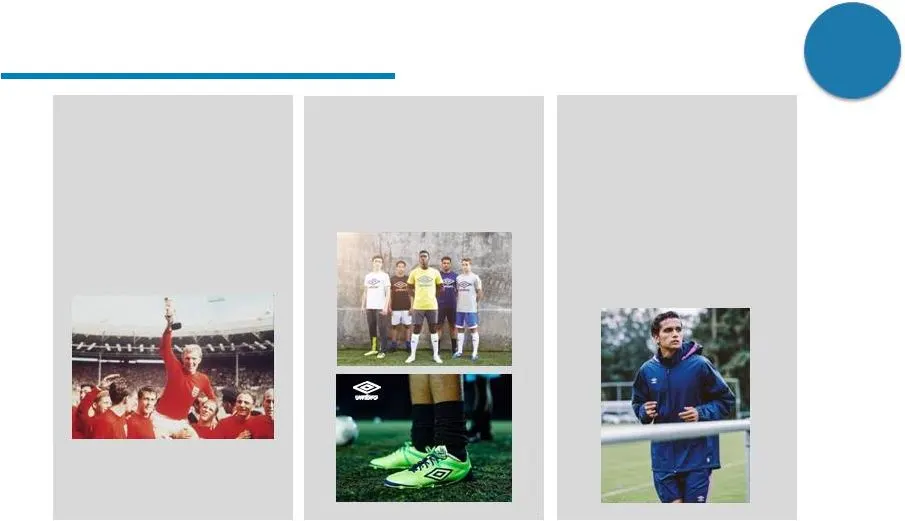
Slide 25: Active – Umbro U.S.
DRIVERS BRAND DNA RETAIL POSITIONING • 90+ year brand history • Rich heritage blends performance with style for players, teams and fans • Ignite Umbro brand in U.S. • Dominate teamwear • Leverage growing soccer popularity in U.S. • 2018 World Cup marketing exposure • DTR license with Dick’s Sporting
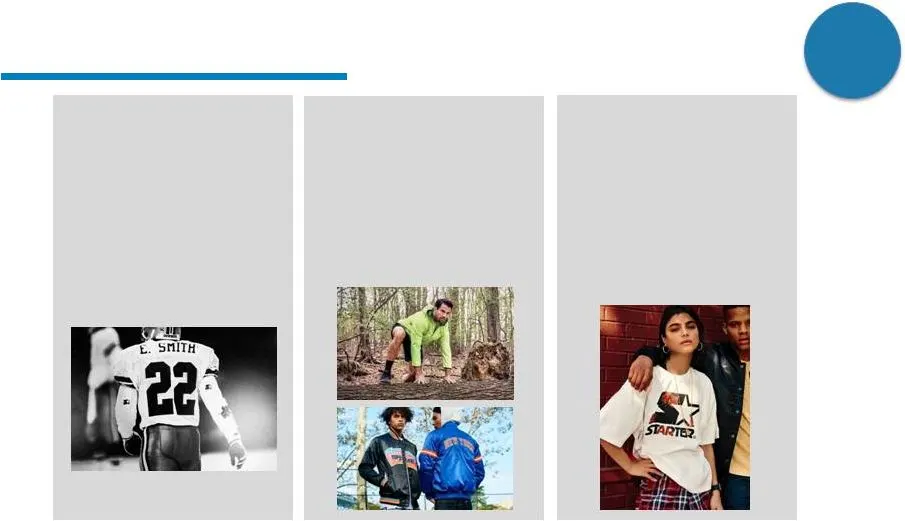
Slide 26: Active – Starter
DRIVERS BRAND DNA RETAIL POSITIONING • Performance everyday athleticwear with quality and style • Founded in 1971, pioneered fusion of sports and culture by partnering with leagues and colleges • Infusion of new design for men and women that leverages everyday athleticwear heritage • Grow curated ha
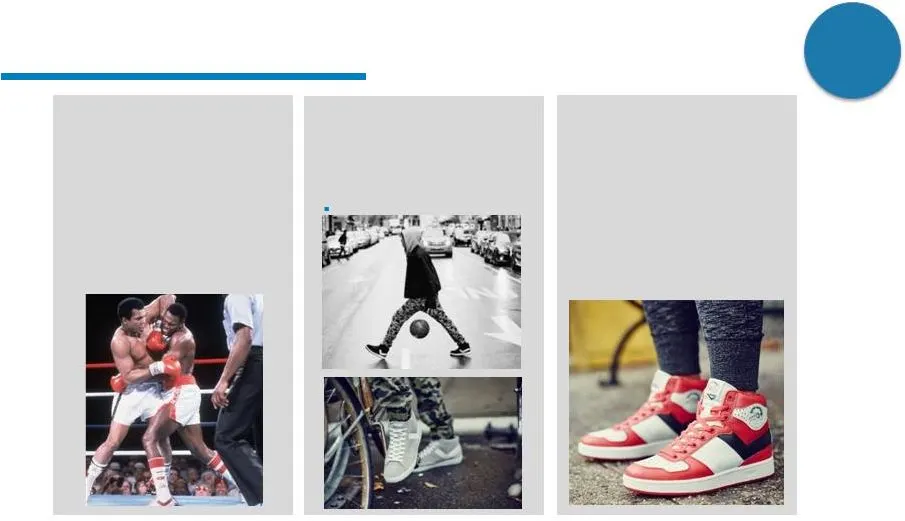
Slide 27: Active – PONY U.S.
DRIVERS BRAND DNA RETAIL POSITIONING • Retro footwear inspired brand for fashionable sports minded consumer • Three tiers – PONY Sport, PONY Classics, Product of New York • Launch core footwear in Spring 2017 with strong marketing activation • Expand product assortment and brand presence with ambass
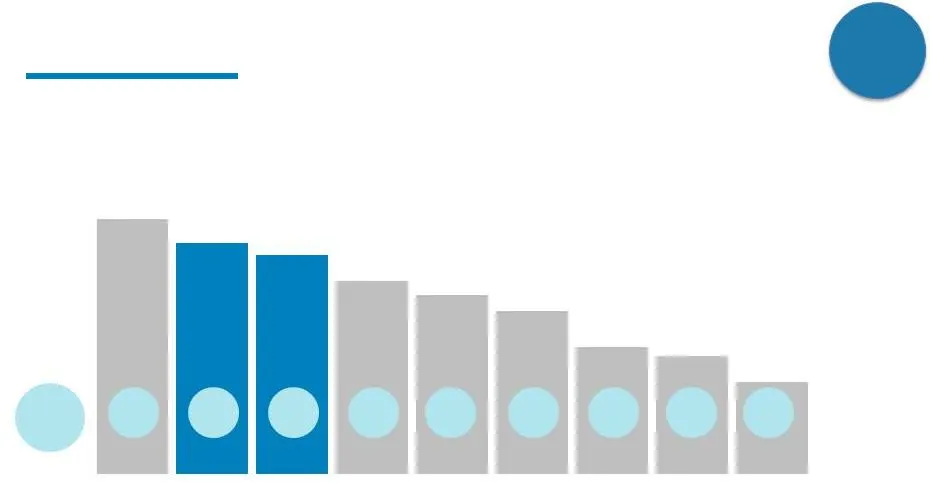
Slide 28: Drivers – Apparel Market by Channel
DRIVERS $90B • Strength in Mass & Mid-Tier; $175B+ addressable market Total Estimated Apparel, Footwear & Accessories Market by Channel 68% $65B 14% $35B 0% $16B 1% $15B 4% $4B 0% $86B 5% $40B 4% 4% MASS MID-TIER DOLLAR CLUB PURE E-COM OFF-PRICE DRUG DEPT STORE SPECIALTY % of ICONIX REV CHANNELS Sou
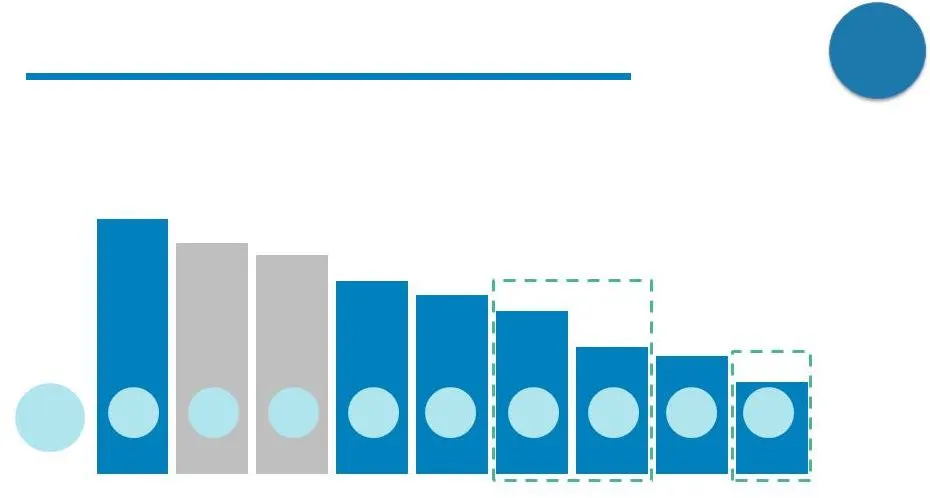
Slide 29: Channels – New Opportunity
DRIVERS CHANNELS - NEW OPPORTUNITY • Penetrate untapped, large distributions channels; addressable market of $280B+ • Momentum for our brands in Drug, Dollar and E-Commerce $90B Total Estimated Apparel, Footwear & Accessories Market by Channel 68% $65B 14% $35B 0% $16B 1% $15B 4% $4B 0% $86B 5% $40B
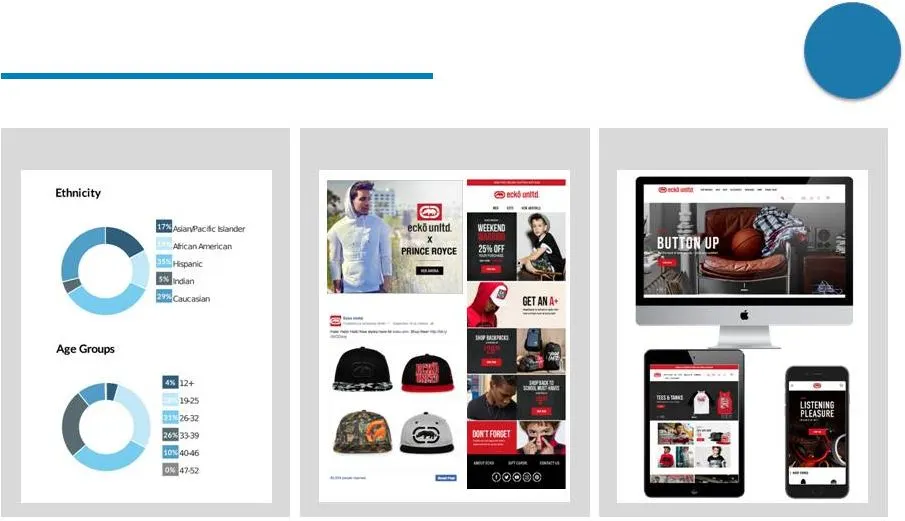
Slide 30: Direct-to-Consumer
DRIVERS DIRECT-TO-CONSUMER CONSUMER INTELLIGENCE/DATA* CONSUMER ENGAGEMENT E-COMMERCE • Control brand and gain knowledge about consumer *For illustrative purposes only
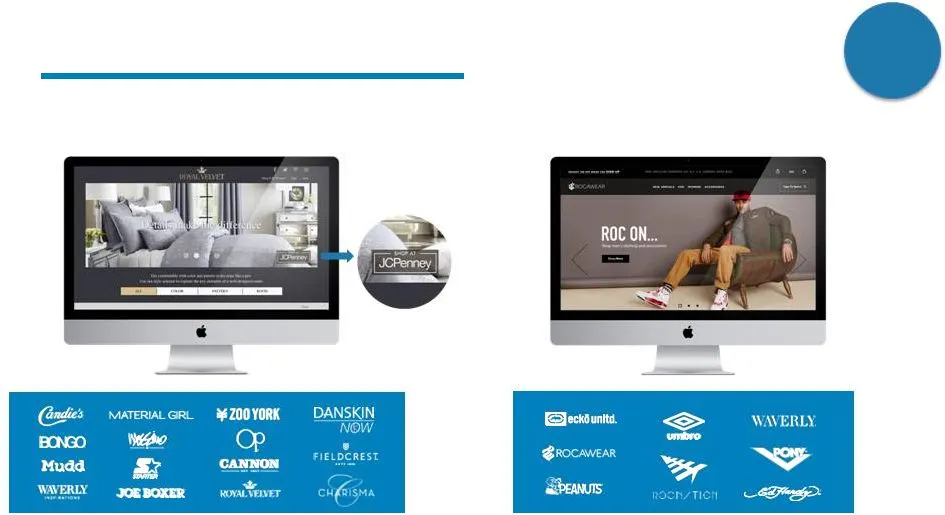
Slide 31: Consumer Engagement & E-Commerce Revenue
DRIVERS CONSUMER ENAGEMENT & E-COMMERCE REVENUE CONSUMER ENGAGEMENT & LINK TO RETAIL PARTNER DIRECT-TO-CONSUMER
Slide 32: Direct-to-Consumer: Asset-Light E-Commerce Model
OPERATING PARTNER ICONIX DRIVERS BRANDING COMMUNICATION ASSORTMENT INVENTORY ORDER MANAGEMENT SYSTEM DISTRIBUTION • E-Commerce asset-light business model DIRECT-TO-CONSUMER
Slide 33: International – Iconix Today
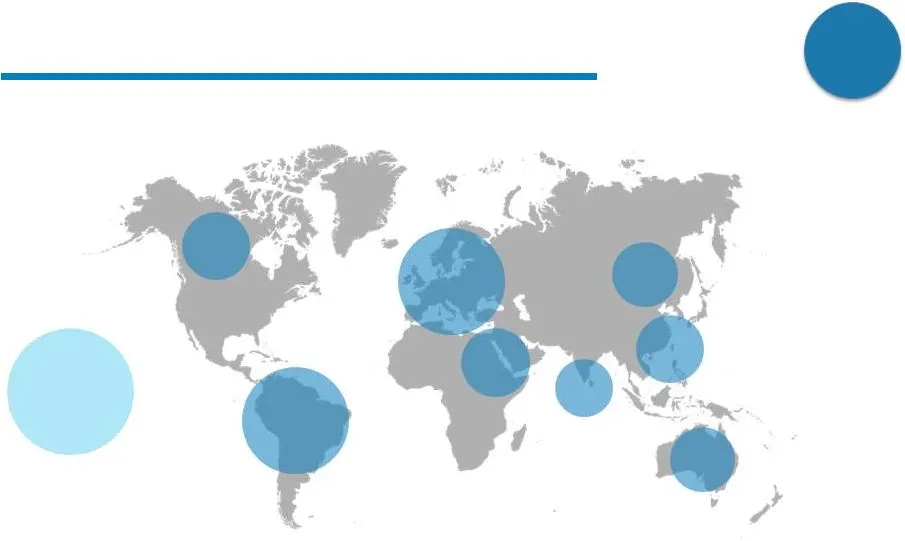
DRIVERS NYC HEADQUARTERS 24% EUROPE LONDON, MANCHESTER OFFICES 24% LATIN AMERICA SANTIAGO, SAO PAULO OFFICES 8% CANADA 11% MEA 6% SOUTHEAST ASIA 4% CHINA HONG KONG, SHANGHAI OFFICES • Expertise on the ground • Growing network in-market 6% AUSTRALIA 5% INDIA INTERNATIONAL - ICONIX TODAY Note: Percent
Slide 34: International – Iconix Growth
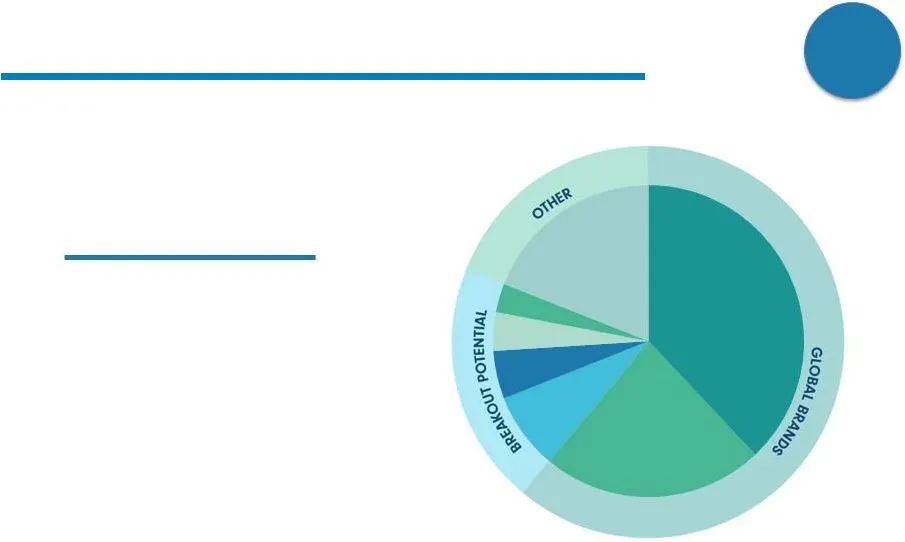
DRIVERS UMBRO 38% LEE COOPER 23% MOSSIMO 8% ECKO 5% DANSKIN 4% STARTER 3% OTHER 19% INTERNATIONAL - ICONIX GROWTH • 6 brands driving over 80% of growth • 4 territories driving over 70% of growth TERRITORY % OF INT’L GROWTH (2016-2019) EUROPE LATIN AMERICA CHINA MEA 24% 23% 16% 10% 2016 estimated Int
Slide 35: International – China
TRADITIONAL LICENSING LICENSING/EQUITY HYBRID EQUITY IN OPERATING COMPANIES IP SALES DRIVERS • LEE COOPER • JOE BOXER • ROCAWEAR • RAMPAGE • UMBRO • DANSKIN • CANDIES • MATERIAL GIRL • ECKO UNLTD • MARC ECKO CUT & SEW • ZOO YORK • ARTFUL DODGER • BADGLEY MISCHKA • LONDON FOG • ED HARDY $8M+ GMRs To
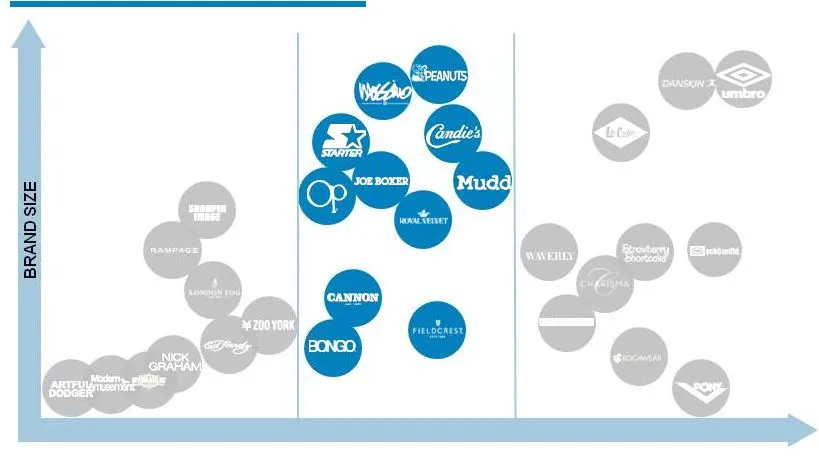
Slide 36: Maintain Brands
MAINTAIN BRANDS INCUBATE MAINTAIN DRIVERS REVENUE GROWTH POTENTIAL
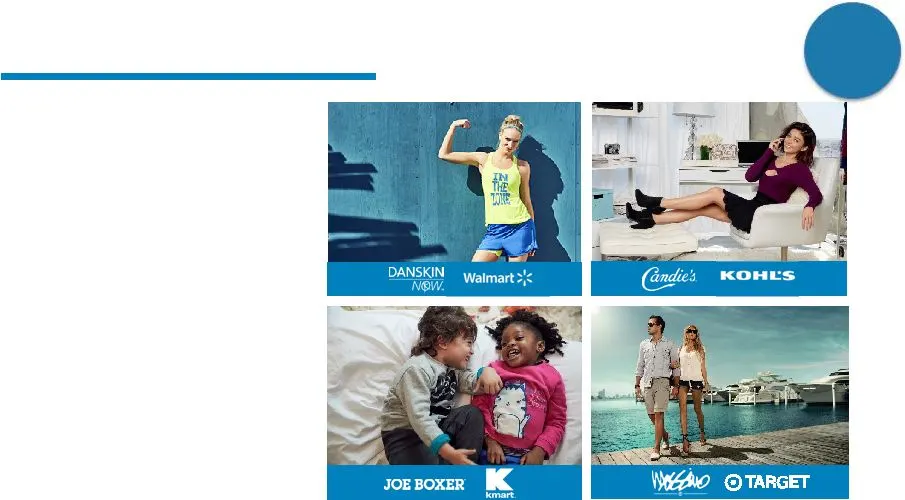
Slide 37: Maintain – Women's Business
MAINTAIN $6B+ RETAIL EQUIVALENT WOMEN’S BUSINESS • Anchored by large and stable direct-to-retail businesses with best-in- class partners • Improving trend and design, social media presence and in-store experience • Maintain high margins
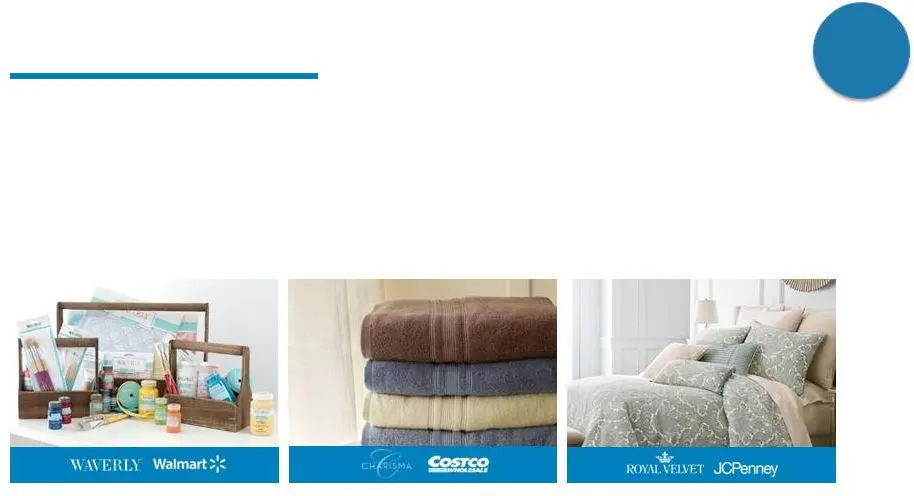
Slide 38: Maintain – Home Business
MAINTAIN • Healthy home business in the U.S. driven by successful DTR strategy with major retailers • Charisma and Waverly largest growth opportunities HOME BUSINESS $1B+ RETAIL EQUIVALENT
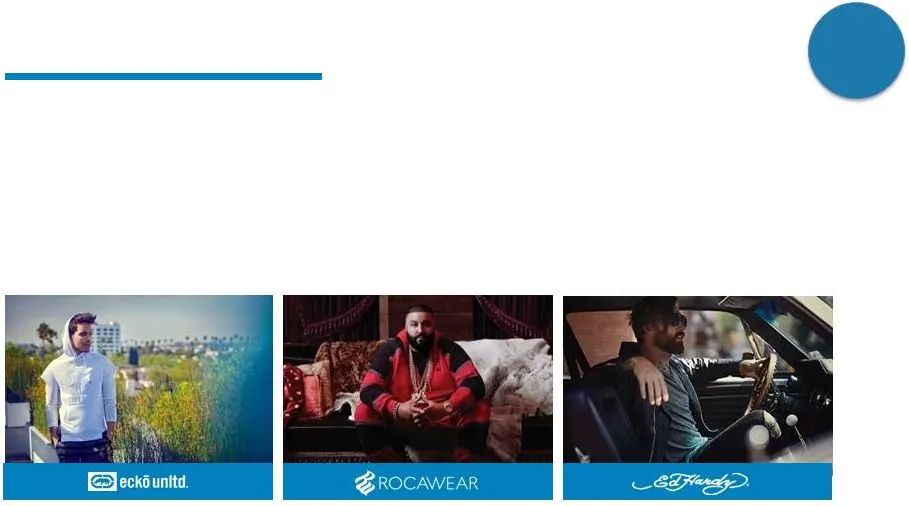
Slide 39: Maintain – Men's Business
MAINTAIN • Stabilizing business • Executing on e-commerce strategy • Mid-Tier distribution opportunity MEN’S BUSINESS $2.5B+ RETAIL EQUIVALENT
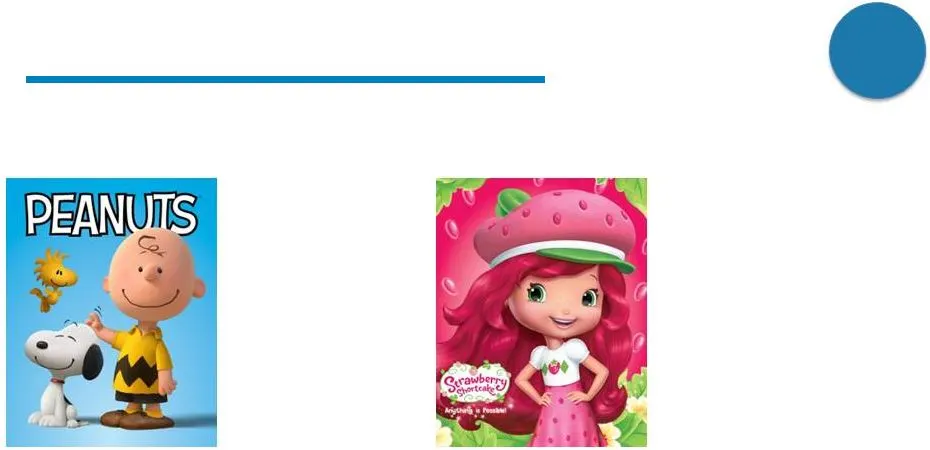
Slide 40: Maintain – Entertainment Business
MAINTAIN • Global brand with 99% consumer awareness • 1,000 licenses globally • Strong movie momentum • Iconic girls property with over 35 years heritage • 350+ licenses globally • Investing in new content PEANUTS STRAWBERRY SHORTCAKE ENTERTAINMENT BUSINESS $2.5B RETAIL EQUIVALENT
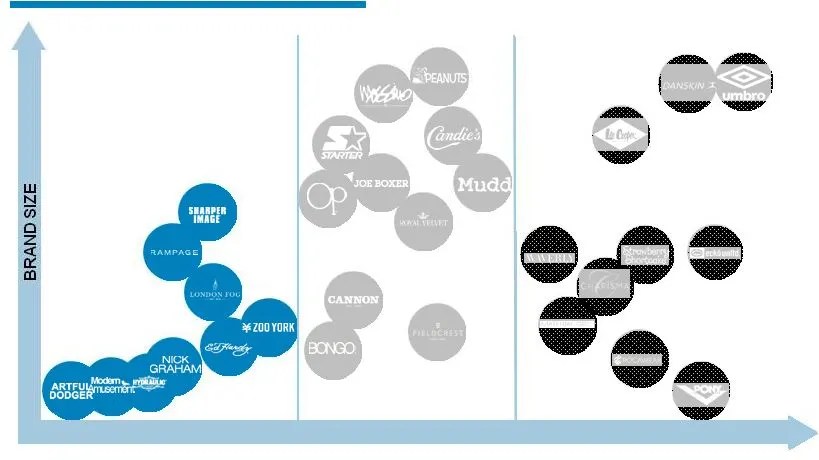
Slide 41: Brand Size
BRAND SIZE Nick GRAHAM}
Slide 42: Incubate Strategy
INCUBATE STRATEGY Brand Size Unclear Fit Market Position BRANDS REVENUE $30M • Allocate separate, dedicated leadership to potentially valuable but challenged brands • Prioritize resources focused on greatest return INCUBATE STRATEGY Note: Revenue refers to 2016 expectations
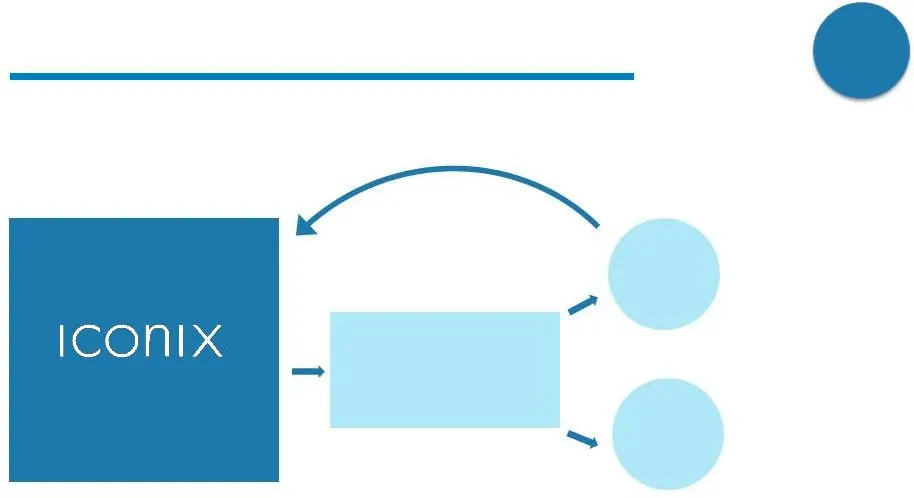
Slide 43: Future Position Within Iconix
CORE BUSINESS INCUBATE Maintain or Drivers Divest BRAND INCUBATOR • Continuous evaluation process for incubate brands FUTURE POSITION WITHIN ICONIX
Slide 44: Brand Building Tools
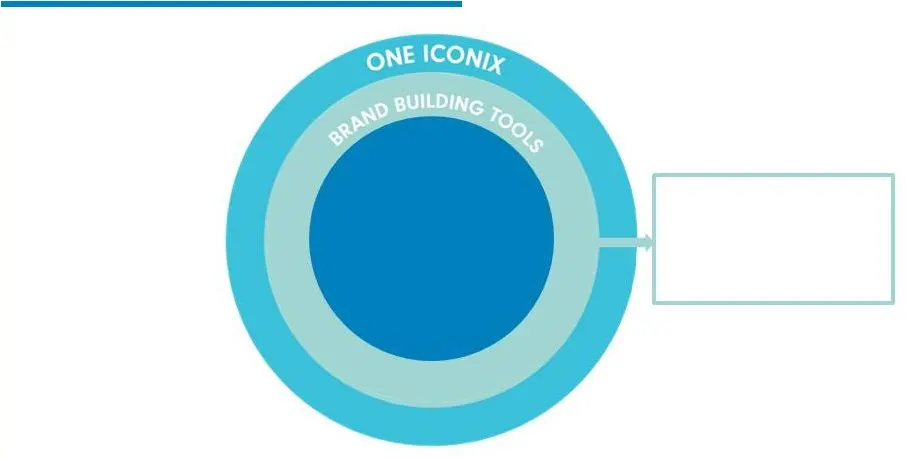
BRAND CATEGORIZATION BRAND BUILDING TOOLS DRIVERS MAINTAIN INCUBATE BRAND BUILDING TOOLS • Marketing • Trend and merchandising • Design, product development, sourcing
Slide 45: Strengthen & Add Tools
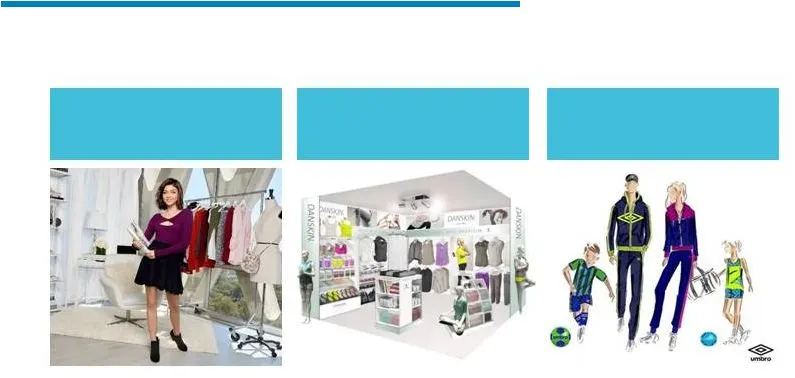
MARKETING TREND & MERCHANDISING DESIGN, PRODUCT DEVELOPMENT & SOURCING • Create long-term opportunities for organic growth Build brands with new 360 Communication Strategy Support partners with enhanced services to maintain and grow market share Provide leadership and expertise to drive product qual
Slide 46: Marketing Evolution: 360 Communication Strategy
IN-STORE EXPERIENCE VISUAL MERCHANDISING DIGITAL BANNERS OUTDOOR PAID SEARCH PR SOCIAL MEDIA EMAILS NATIONAL ADVERTISING BRAND AMBASSADORS MARKETING EVOLUTION 360 COMMUNICATION STRATEGY • Maintain national brand image and awareness • Driving sales to our retail partners: brick & mortar and e-commerc
Slide 47: 360 Communication Strategy
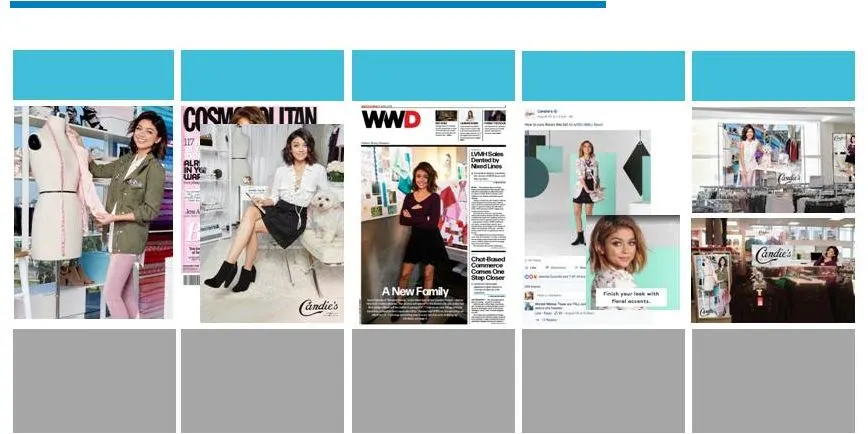
PR • Online/Print Editorial • Fashion, Trade, Lifestyle, and Entertainment Features MEDIA PARTNERSHIPS • Refinery29 • Cosmopolitan • WhoWhatWear.com IN-STORE • Campaign Signage DIGITAL/SOCIAL • Social Media Activations & Takeovers • Website Re-launch PRODUCT • Creative direction for capsule collecti
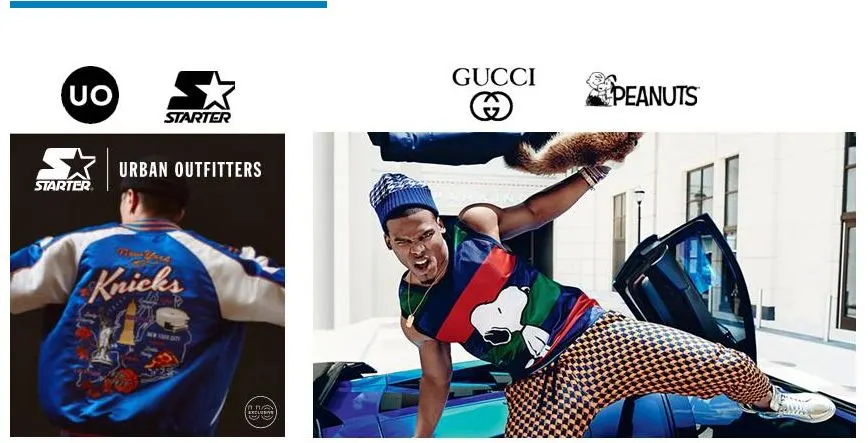
Slide 48: Brand Building: Strategic Collaborations
X • Strategic collaborations and capsule collections to drive brand relevancy X BRAND BUILDING
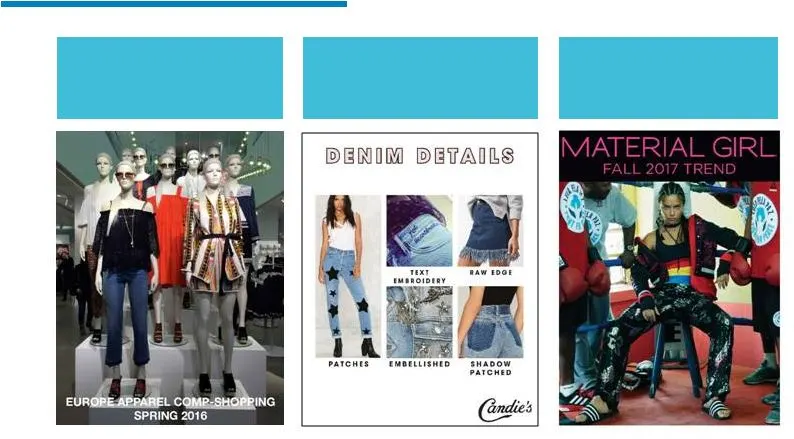
Slide 49: Trend Expertise
SHOP GLOBAL MARKET FOR TRENDS TRANSLATE INTO SPECIFIC APPLICATIONS FOR ICONIX BRANDS PRESENT QUARTERLY STRATEGY TO PARTNERS TREND EXPERTISE
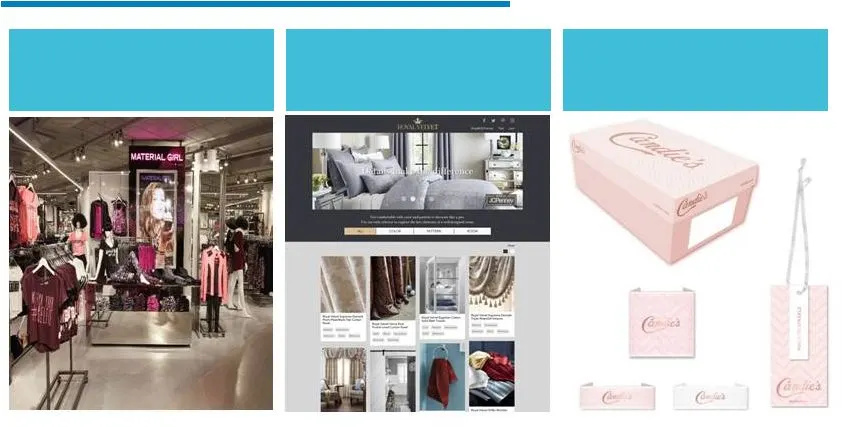
Slide 50: Merchandising Support
CREATE IN-STORE FIXTURE CONCEPTS PROVIDE ONLINE ENVIRONMENTS EVOLVE PACKAGING & LOGOS MERCHANDISING SUPPORT
Slide 51: Design, Product Development & Sourcing
BRAND & PRODUCT SOURCING PRODUCT DEVELOPMENT DESIGN DESIGN, PRODUCT DEVELOPMENT & SOURCING • Creating value for brands and products DESIGN • Clearly defined aesthetic standards across categories • Superior materials and execution SOURCING • Competitive quality • Optimized profitability • Increased s
Slide 52: Diamond ICON
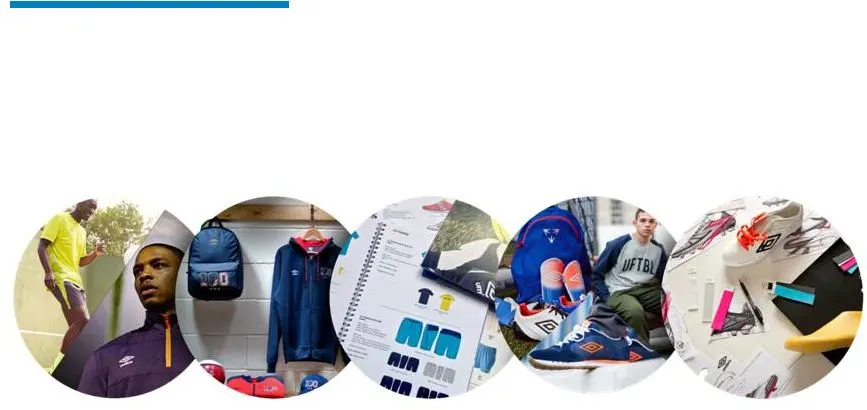
DIAMOND ICON • Leverage existing design, product development and sourcing platform • 30+ person team based in Manchester, UK • Over 5,500 SKUs per year across footwear, apparel, accessories and equipment • Facilitate placement and production of orders for ~$300M retail sales Note: Iconix owns 51% of
Slide 53: One Iconix
BRAND CATEGORIZATION ONE ICONIX ONE ICONIX • Deeper relationships • Holistic approach DRIVERS MAINTAIN INCUBATE
Slide 54: Broader, Deeper Relationships with Retailers
BROADER, DEEPER RELATIONSHIPS WITH RETAILERS
Slide 55: Holistic Approach to Key Categories
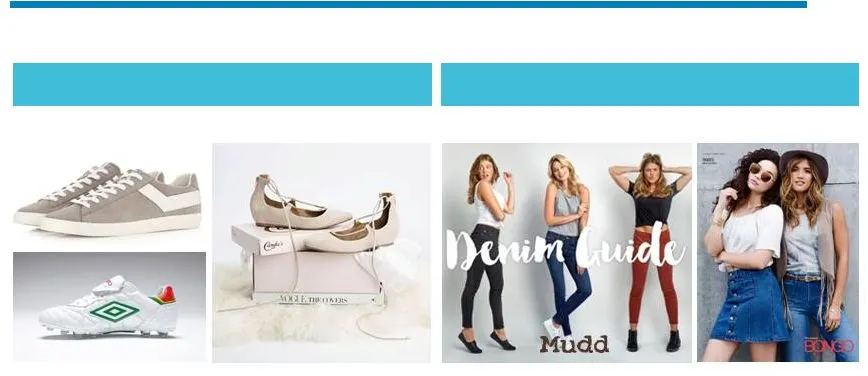
FOOTWEAR DENIM HOLISTIC APPROACH TO KEY CATEGORIES • Leverage knowledge and total category volume across brands $1B+ Retail Equivalent Sales $500M+ Retail Equivalent Sales Candie’s, Bongo, Rampage, London Fog, OP, Danskin, Material Girl, Joe Boxer, Mudd, Mossimo, Starter, Zoo York, Ecko Unltd., Roca
Slide 56: Roadmap to Value Creation
HIGH OPERATING MARGIN, STRONG FREE CASH FLOW, ASSET LIGHT EXPERIENCED LEADERSHIP, WORLD CLASS IP PORTFOLIO, ACTIVE BRAND MANAGEMENT TOP 25% TSR PERFORMANCE PORTFOLIO MANAGEMENT GLOBAL ORGANIC GROWTH PRUDENT CAPITAL MANAGEMENT + + ROADMAP TO VALUE CREATION
Slide 57: Acquisition Goals
INTERNATIONAL GLOBAL DOMESTIC • Additional $25M of annual royalty revenue by year-end • Focus on core categories of Fashion, Active and Home ACQUISITION GOALS • Tuck-in; leverage existing network and expertise • Utilize growing teams on the ground to source, structure and diligence • Transformative
Slide 58: Proposed Iconix Canada & Buffalo IP Transactions
PROPOSED ICONIX CANADA & BUFFALO IP TRANSACTIONS Expected to be net neutral to earnings and positive to cash flow Proceeds to be used to reduce debt or strategic acquisition Expected to close within 60 days Note: There can be no assurance the proposed transactions will be consummated PLAN TO ACQUIRE
Slide 59: Total Projected Revenue Growth
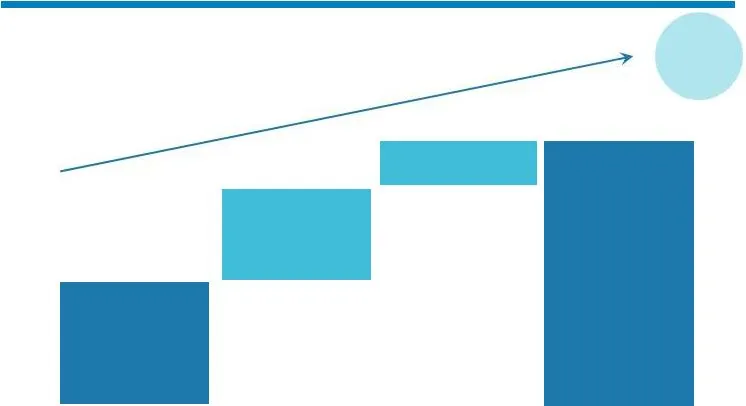
ORGANIC ACQUISITIONS REVENUE REVENUE $350M $425M $50M $25M TOTAL PROJECTED REVENUE GROWTH Note: 2016 Revenue adjusted for Buffalo transaction +7% CAGR
Slide 60: 3 Year Financial Plan
2016 ESTIMATED 2019 PROJECTED $425M 50% • $50M organic • $25M acquisitions • Profitable organic • Accretive acquisitions PATH TO GROWTH $1.25 $1.25 • Revenue growth • Margin expansion REVENUE OPERATING MARGIN $350M 48% EPS: • NON-GAAP • GAAP $1.06 $0.89 3 YEAR FINANCIAL PLAN Note: 2016 Revenue adjus
Slide 61: Roadmap to Value Creation
HIGH OPERATING MARGIN, STRONG FREE CASH FLOW, ASSET LIGHT EXPERIENCED LEADERSHIP, WORLD CLASS IP PORTFOLIO, ACTIVE BRAND MANAGEMENT TOP 25% TSR PERFORMANCE PORTFOLIO MANAGEMENT GLOBAL ORGANIC GROWTH PRUDENT CAPITAL MANAGEMENT + + ROADMAP TO VALUE CREATION
Slide 62: Current Cash Summary
$69M U.S. Unrestricted $110M U.S. Restricted $74M International Unrestricted $250M TOTAL CASH CURRENT CASH SUMMARY • $46M wholly owned • $23M consolidated JVs • $64M available for acquisitions • $46M securitization facility • $74M available for international acquisitions $138M available for acquisit
Slide 63: Current Capital Structure
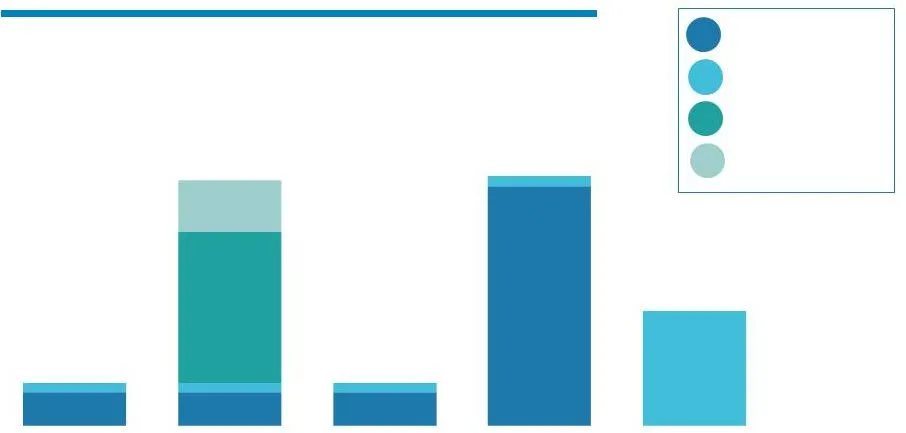
• Plan to extend $100M VFN maturity to January 2020 • Repurchased ~$105M of 2018 convertible notes at a discount • ~$295M convertible notes due March 2018 CURRENT CAPITAL STRUCTURE $471M $484M $228M $76M $76M Securitization Term Loan Convertible Note VFN
Slide 64: 2018 Convertible Notes
2018 CONVERTIBLE NOTES • ~$295M outstanding ~$70M expected to be paid with existing cash and free cash flow ~$225M expected to be refinanced • Top priority • Healthy lending environment • Stabilized business and new management team • SEC accounting review/restatements completed
Slide 65: De-Levering
$1.35B $1.0B ~8.0x ~5.0x DE-LEVERING • Expect to generate over $400M of free cash flow over next 3 years • Natural de-levering via $76M amortization per year • Projecting EBITDA growth • Asset dispositions could accelerate de-levering • Target leverage ~5.0x by 2019 Year-end Year-end TOTAL DEBT
Slide 66: Key Takeaways
KEY TAKEAWAYS • Iconix is the Leader in Large and Highly Profitable Global Brand Management Industry • New Management Team with Deep Industry Experience • Path to Organic Growth Driven By Strategic Choices, Enhanced Toolset • Portfolio Management Approach to M&A and Brand Ownership • Plan for Improv
Slide 67: Q&A
Q&A
Slide 68: November 15, 2016 Investor Day
NOVEMBER 15, 2016 INVESTOR DAY
Source: SEC EDGAR · 8-K filed Nov 15, 2016