Argo Group International Holdings Ltd
Argo Group International — Investor Presentation (November 2018)
22 slides from Argo Group International's investor presentation, Nov 14, 2018
Slide 1: 2018 Q3 Investor Presentation
2018 Investor Presentation Q3 Exhibit 99.1
Slide 2: Forward-looking statements
This presentation may include forward-looking statements, both with respect to Argo Group and its industry, that reflect our current views with respect to future events and financial performance. These statements are made pursuant to the safe harbor provisions of the Private Securities Litigation Re
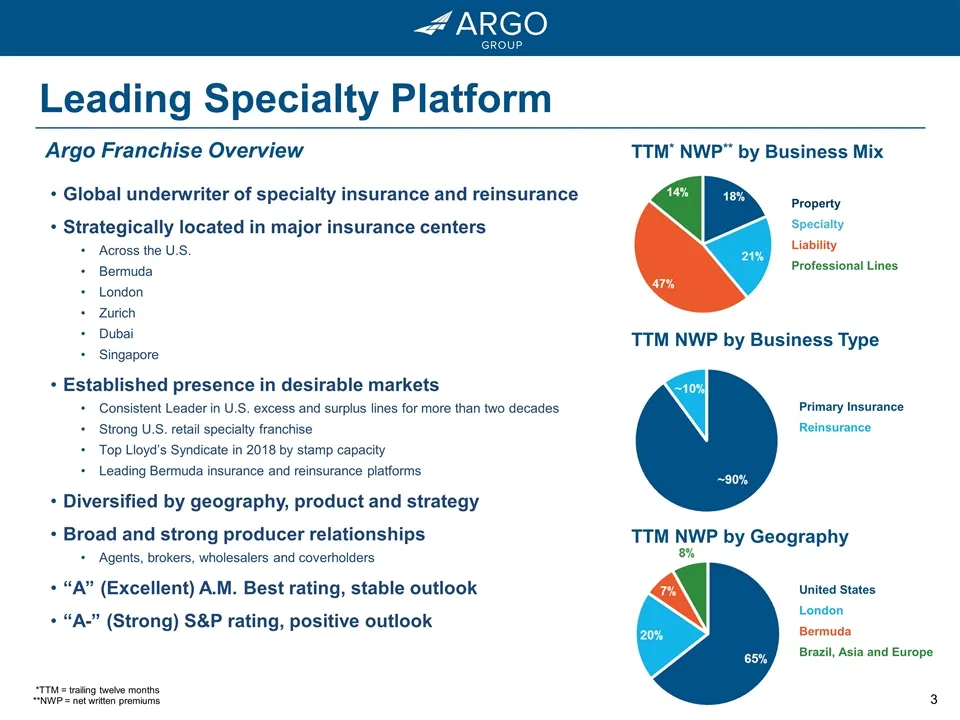
Slide 3: Argo Franchise Overview: Leading Specialty Platform
Global underwriter of specialty insurance and reinsurance Strategically located in major insurance centers Across the U.S. Bermuda London Zurich Dubai Singapore Established presence in desirable markets Consistent Leader in U.S. excess and surplus lines for more than two decades Strong U.S. retail s
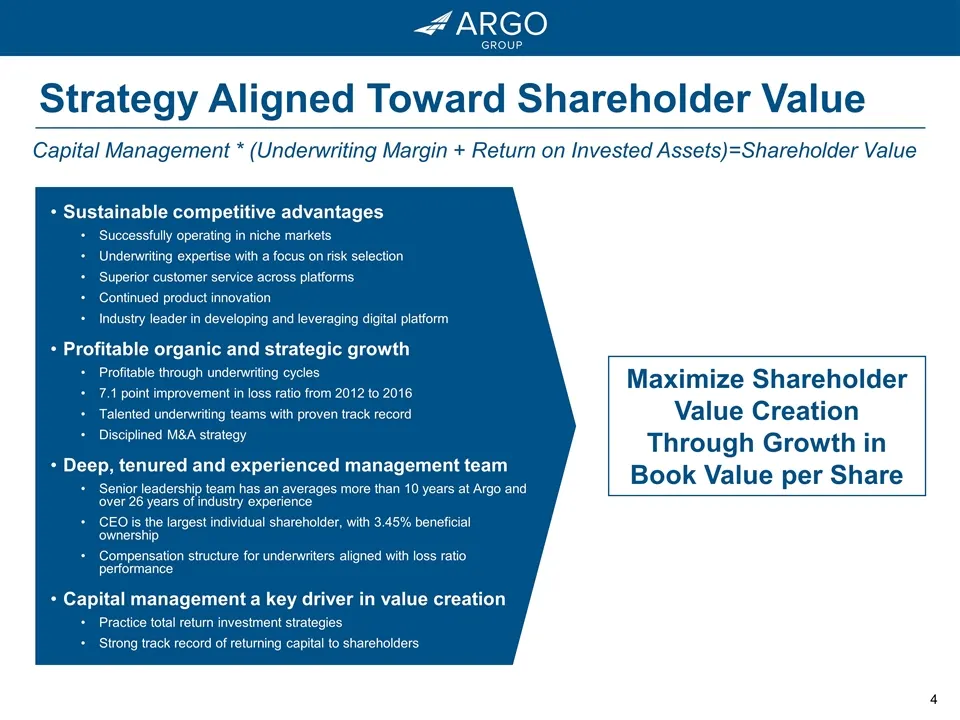
Slide 4: Strategy Aligned Toward Shareholder Value
Capital Management * (Underwriting Margin + Return on Invested Assets)=Shareholder Value Maximize Shareholder Value Creation Through Growth in Book Value per Share Strategy Aligned Toward Shareholder Value Sustainable competitive advantages Successfully operating in niche markets Underwriting expert
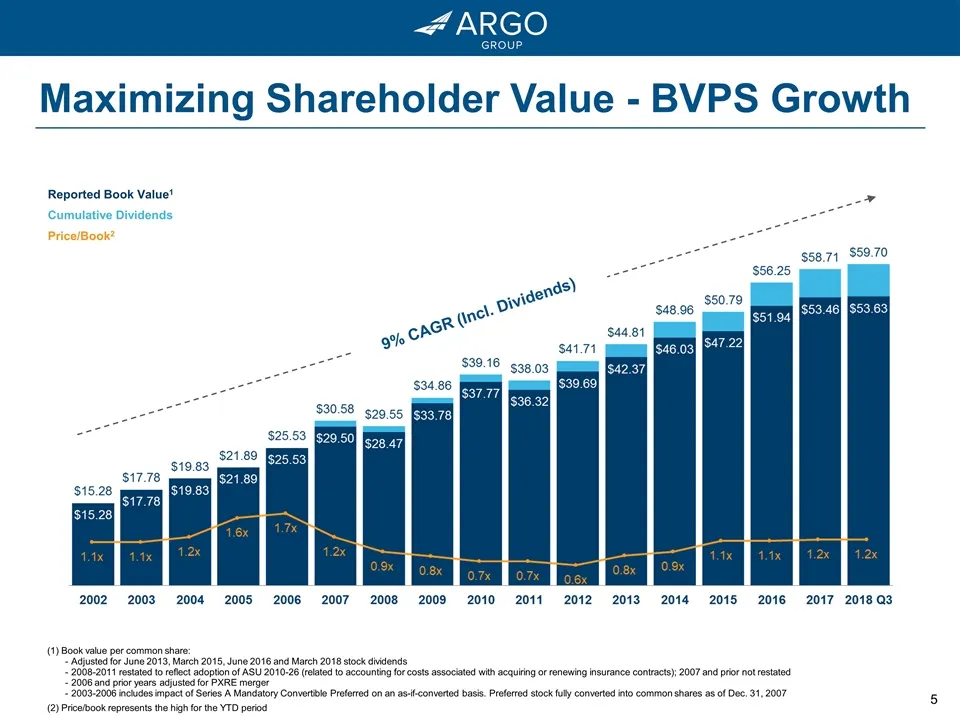
Slide 5: Maximizing Shareholder Value - BVPS Growth
9% CAGR (Incl. Dividends) Reported Book Value1 Cumulative Dividends Price/Book2 (1) Book value per common share: Adjusted for June 2013, March 2015, June 2016 and March 2018 stock dividends 2008-2011 restated to reflect adoption of ASU 2010-26 (related to accounting for costs associated with acquiri
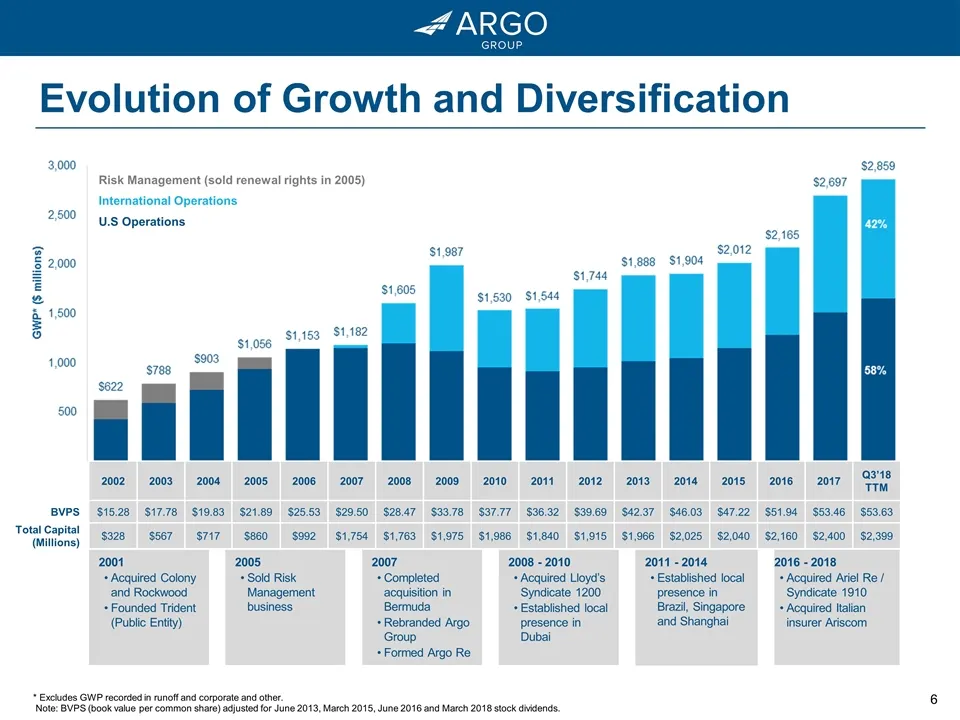
Slide 6: Substantial Growth and Financial Strength: history and BVPS
2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 Q3’18 TTM BVPS $15.28 $17.78 $19.83 $21.89 $25.53 $29.50 $28.47 $33.78 $37.77 $36.32 $39.69 $42.37 $46.03 $47.22 $51.94 $53.46 $53.63 Total Capital (Millions) $328 $567 $717 $860 $992 $1,754 $1,763 $1,975 $1,986 $1,840 $
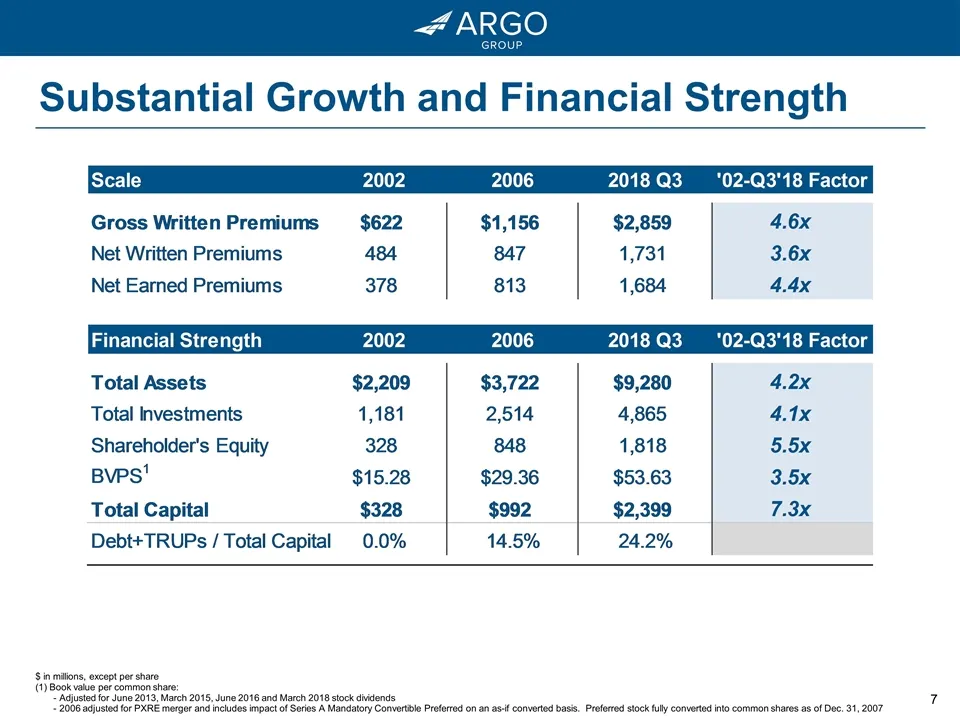
Slide 7: Substantial Growth and Financial Strength
$ in millions, except per share (1) Book value per common share: Adjusted for June 2013, March 2015, June 2016 and March 2018 stock dividends 2006 adjusted for PXRE merger and includes impact of Series A Mandatory Convertible Preferred on an as-if converted basis. Preferred stock fully converted int
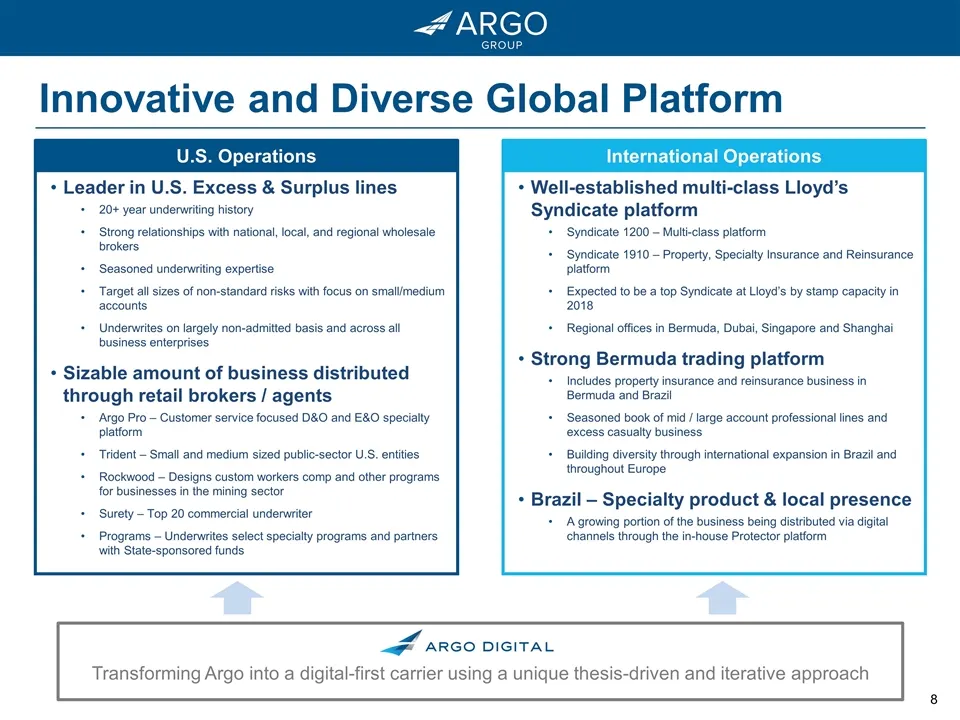
Slide 8: Innovative and Diverse Global Platform
Innovative and Diverse Global Platform Well-established multi-class Lloyd’s Syndicate platform Syndicate 1200 – Multi-class platform Syndicate 1910 – Property, Specialty Insurance and Reinsurance platform Expected to be a top Syndicate at Lloyd’s by stamp capacity in 2018 Regional offices in Bermuda
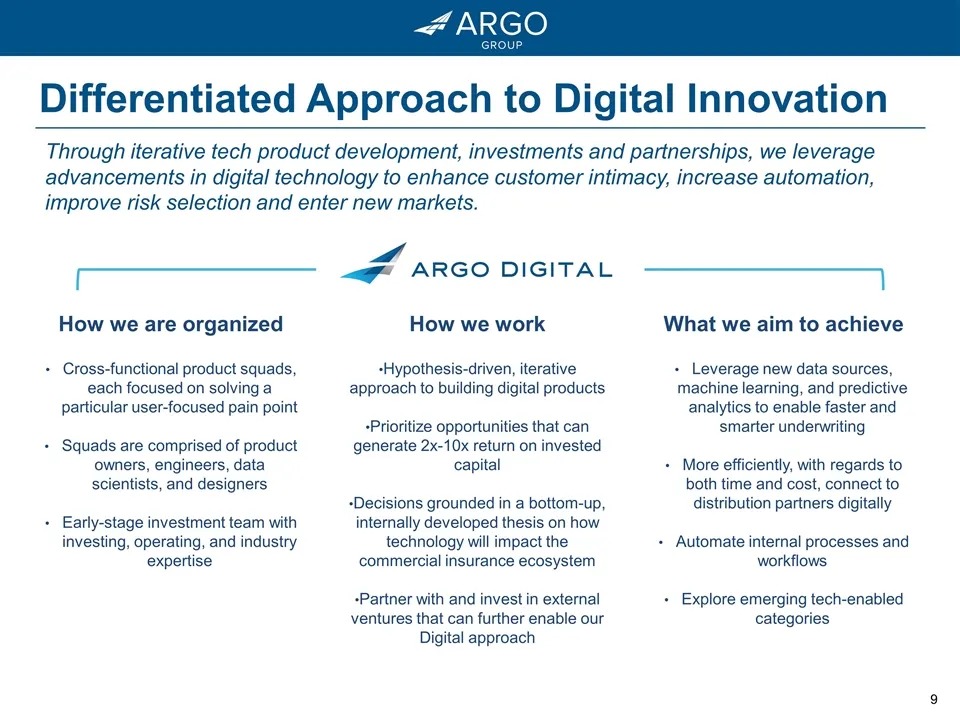
Slide 9: Differentiated Approach to Digital Innovation
Differentiated Approach to Digital Innovation Through iterative tech product development, investments and partnerships, we leverage advancements in digital technology to enhance customer intimacy, increase automation, improve risk selection and enter new markets. How we are organized Cross-functiona
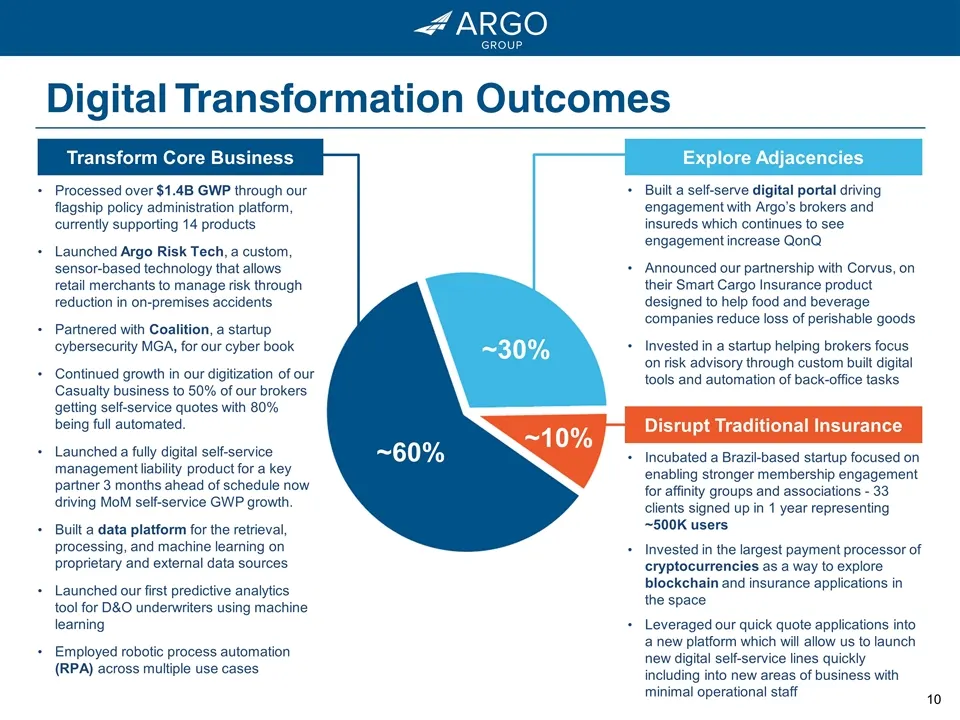
Slide 10: Digital Transformation Outcomes
Digital Transformation Outcomes Processed over $1.4B GWP through our flagship policy administration platform, currently supporting 14 products Launched Argo Risk Tech, a custom, sensor-based technology that allows retail merchants to manage risk through reduction in on-premises accidents Partnered w
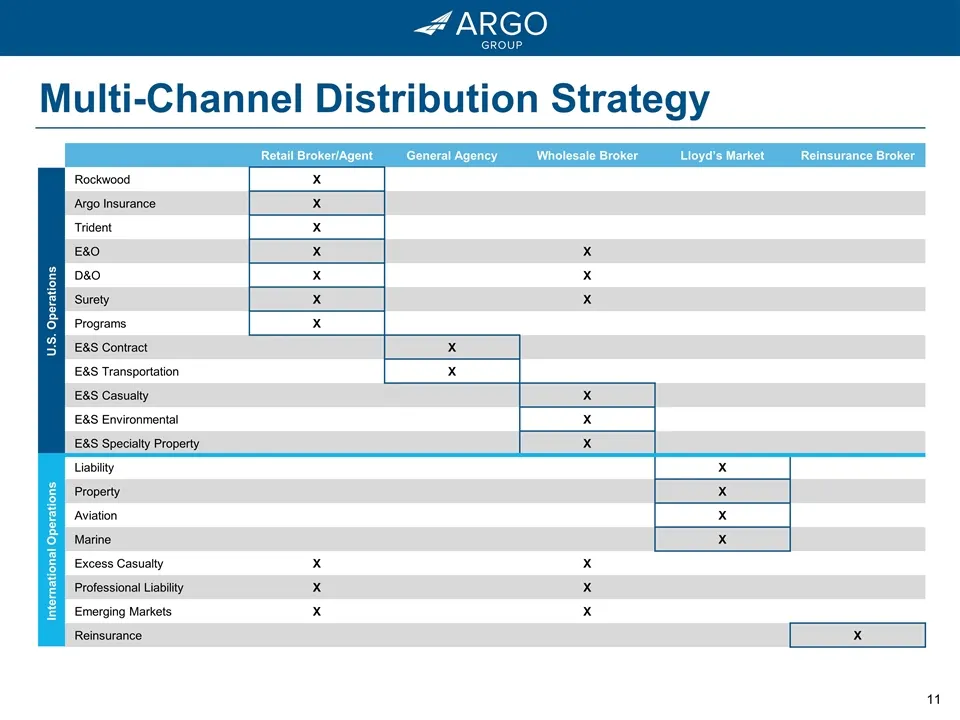
Slide 11: Multi-Channel Distribution Strategy
Multi-Channel Distribution Strategy Retail Broker/Agent General Agency Wholesale Broker Lloyd’s Market Reinsurance Broker U.S. Operations Rockwood X Argo Insurance X Trident X E&O X X D&O X X Surety X X Programs X E&S Contract X E&S Transportation X E&S Casualty X E&S Environmental X E&S Specialty P
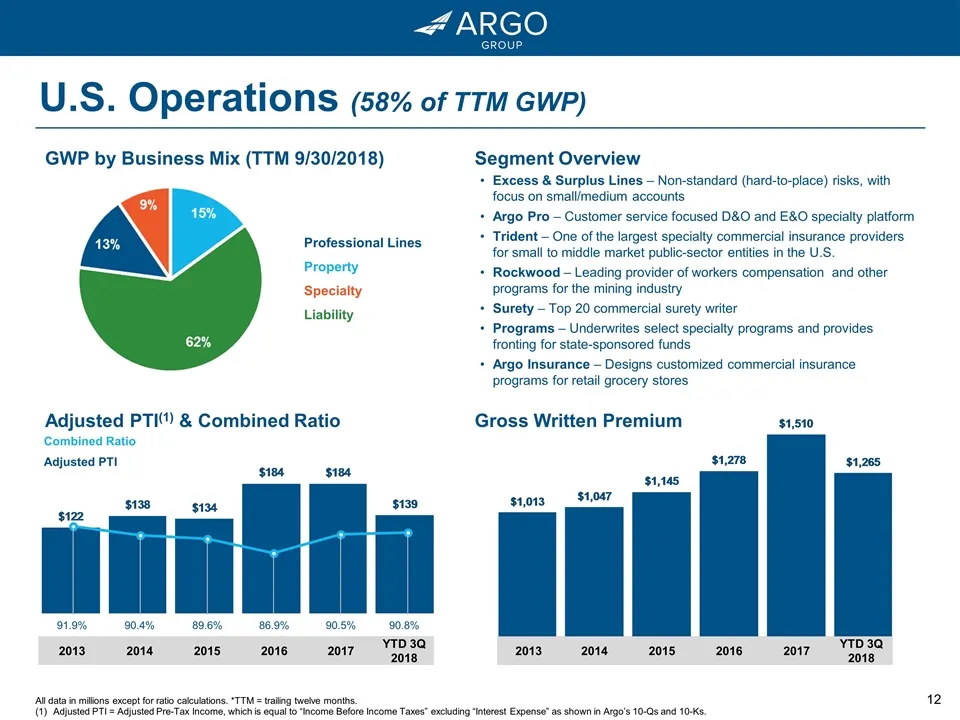
Slide 12: U.S. Operations (58% of TTM GWP)
U.S. Operations (58% of TTM GWP) All data in millions except for ratio calculations. *TTM = trailing twelve months. Adjusted PTI = Adjusted Pre-Tax Income, which is equal to “Income Before Income Taxes” excluding “Interest Expense” as shown in Argo’s 10-Qs and 10-Ks. GWP by Business Mix (TTM 9/30/20
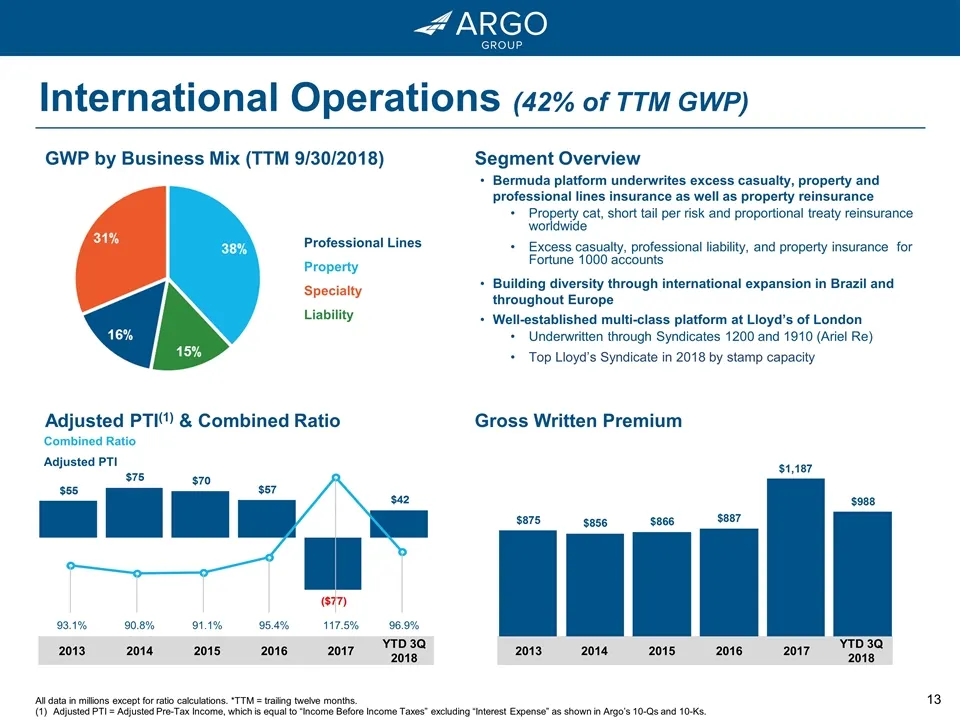
Slide 13: International Operations (42% of TTM GWP)
International Operations (42% of TTM GWP) All data in millions except for ratio calculations. *TTM = trailing twelve months. Adjusted PTI = Adjusted Pre-Tax Income, which is equal to “Income Before Income Taxes” excluding “Interest Expense” as shown in Argo’s 10-Qs and 10-Ks. GWP by Business Mix (TT
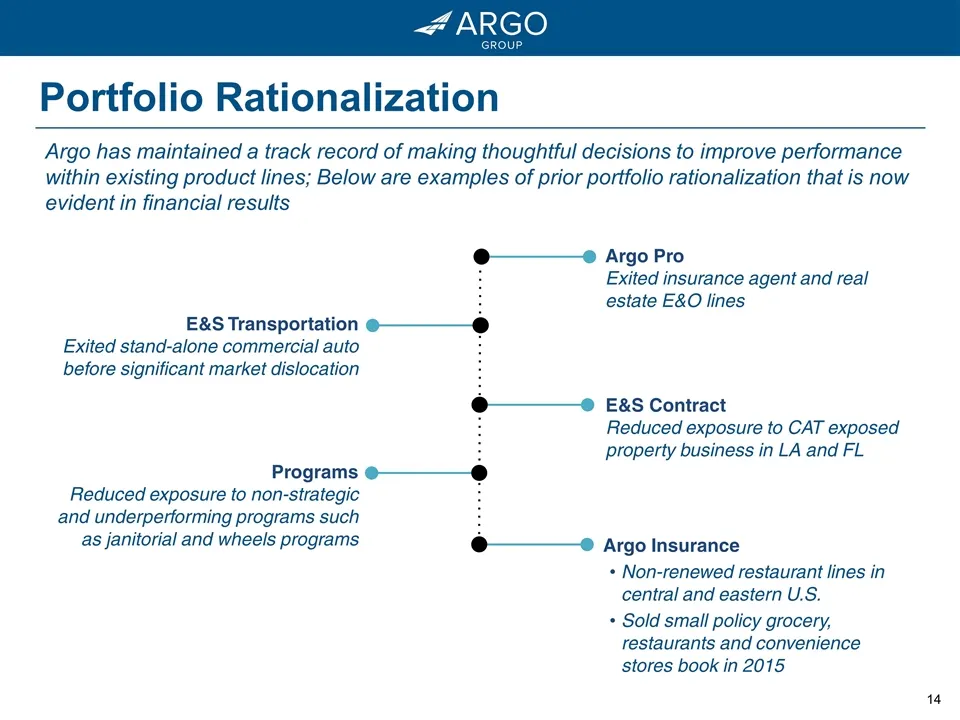
Slide 14: Portfolio Rationalization
Portfolio Rationalization Argo has maintained a track record of making thoughtful decisions to improve performance within existing product lines; Below are examples of prior portfolio rationalization that is now evident in financial results Argo Pro Exited insurance agent and real estate E&O lines E
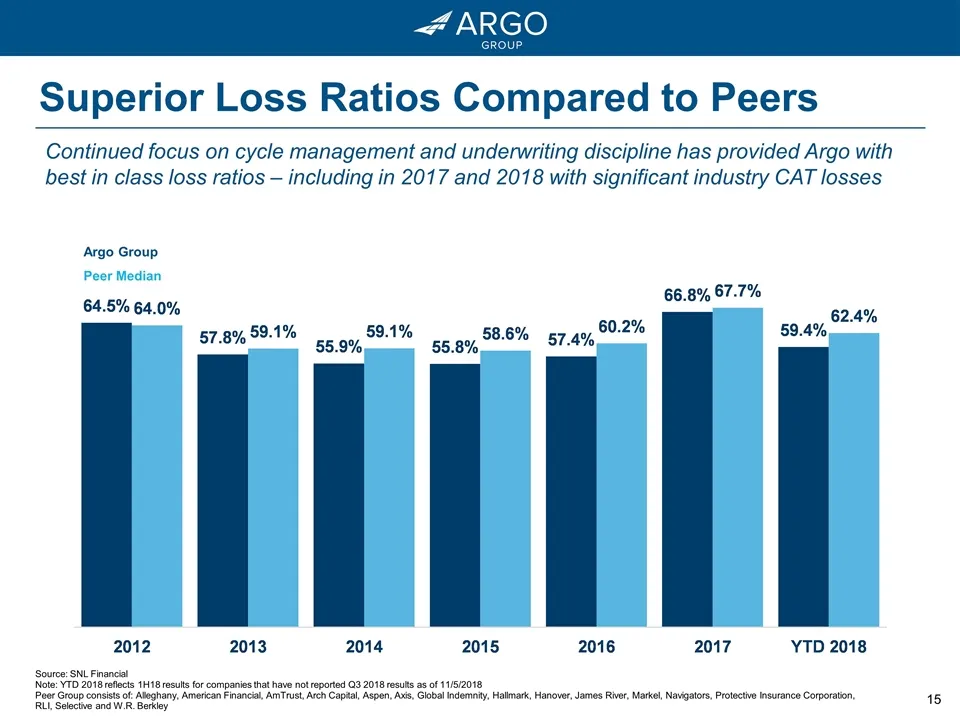
Slide 15: Superior Loss Ratios Compared to Peers
Superior Loss Ratios Compared to Peers Continued focus on cycle management and underwriting discipline has provided Argo with best in class loss ratios – including in 2017 and 2018 with significant industry CAT losses Argo Group Peer Median Source: SNL Financial Note: YTD 2018 reflects 1H18 results
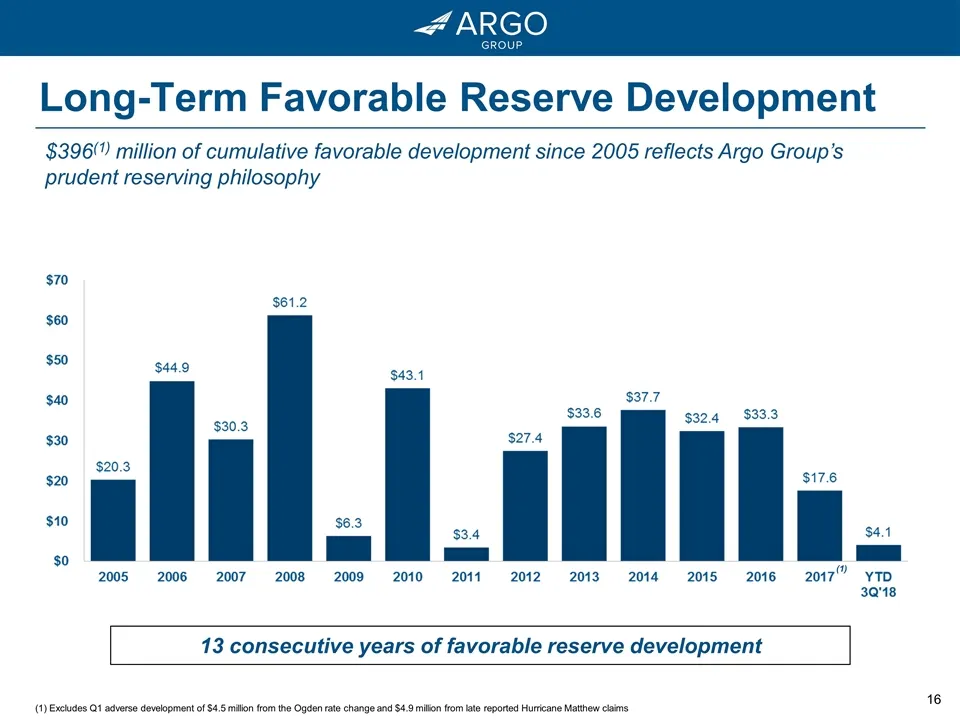
Slide 16: Long-Term Favorable Reserve Development
Long-Term Favorable Reserve Development $396(1) million of cumulative favorable development since 2005 reflects Argo Group’s prudent reserving philosophy (1) (1) Excludes Q1 adverse development of $4.5 million from the Ogden rate change and $4.9 million from late reported Hurricane Matthew claims 13
Slide 17: Balanced Investment Strategy
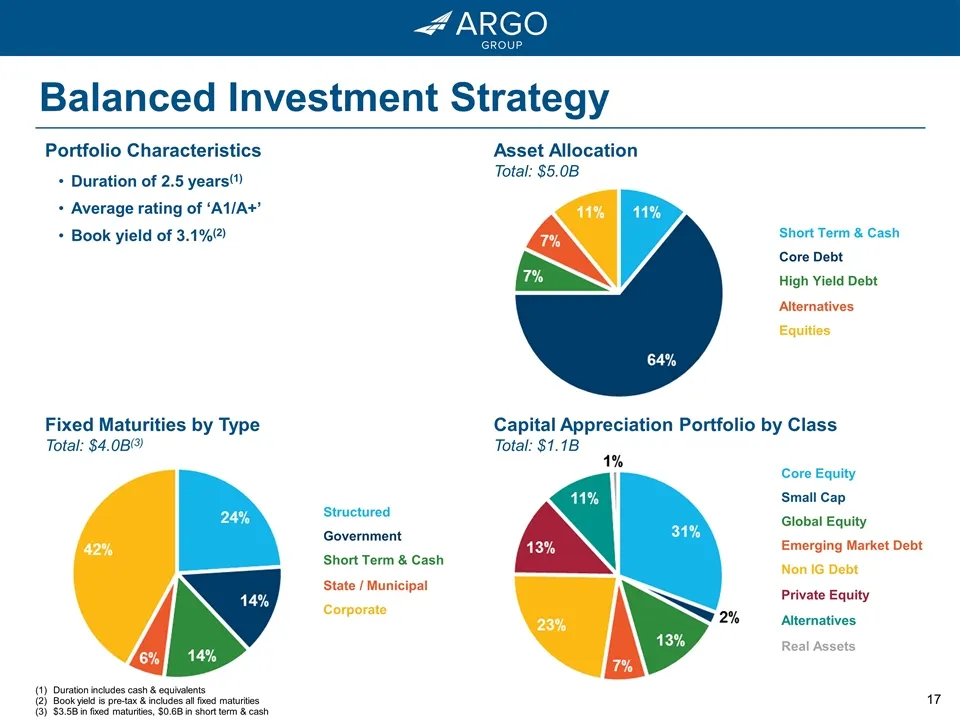
Balanced Investment Strategy Duration includes cash & equivalents Book yield is pre-tax & includes all fixed maturities $3.5B in fixed maturities, $0.6B in short term & cash Portfolio Characteristics Asset Allocation Total: $5.0B Fixed Maturities by Type Total: $4.0B(3) Capital Appreciation Portfoli
Slide 18: 3Q 2018 Operating Results
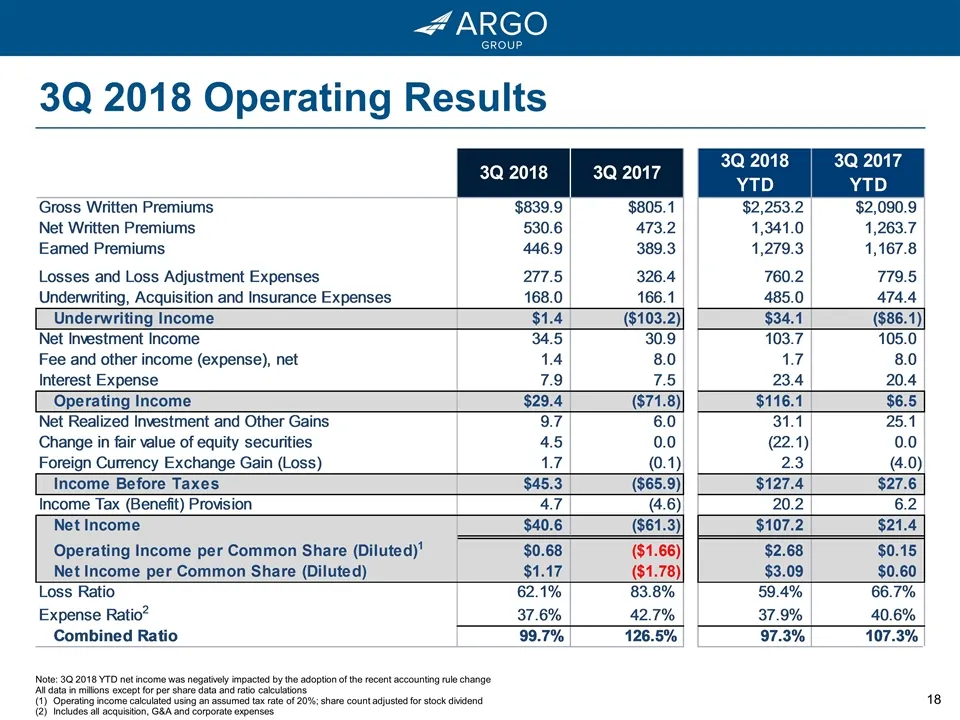
3Q 2018 Operating Results Note: 3Q 2018 YTD net income was negatively impacted by the adoption of the recent accounting rule change All data in millions except for per share data and ratio calculations Operating income calculated using an assumed tax rate of 20%; share count adjusted for stock divid
Slide 19: Active Capital Management
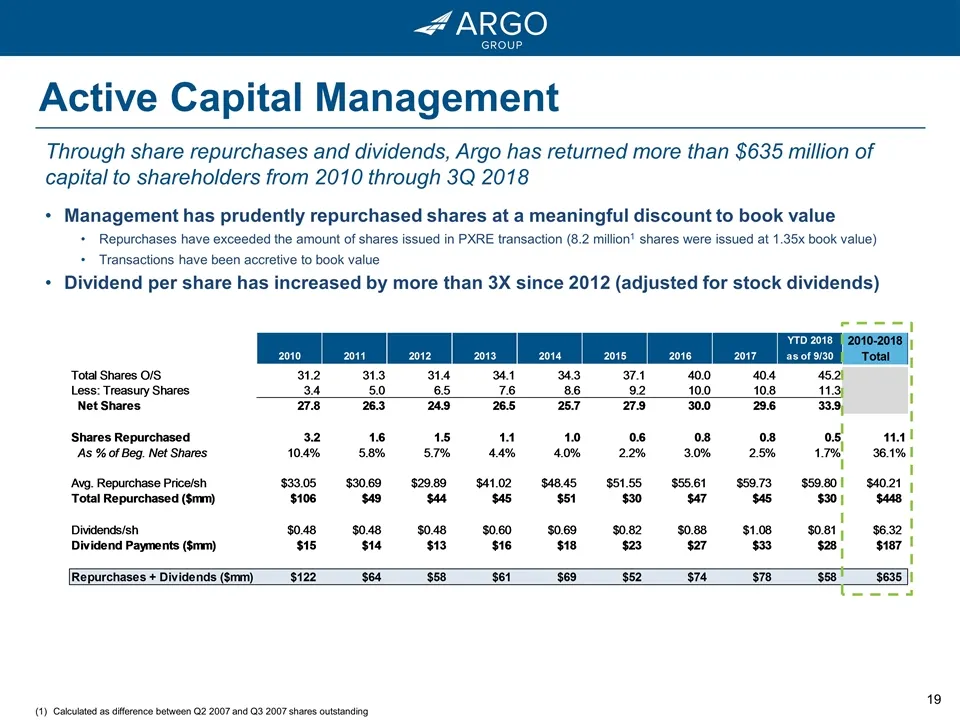
Active Capital Management Through share repurchases and dividends, Argo has returned more than $635 million of capital to shareholders from 2010 through 3Q 2018 Management has prudently repurchased shares at a meaningful discount to book value Repurchases have exceeded the amount of shares issued in
Slide 20: Stock Price Performance
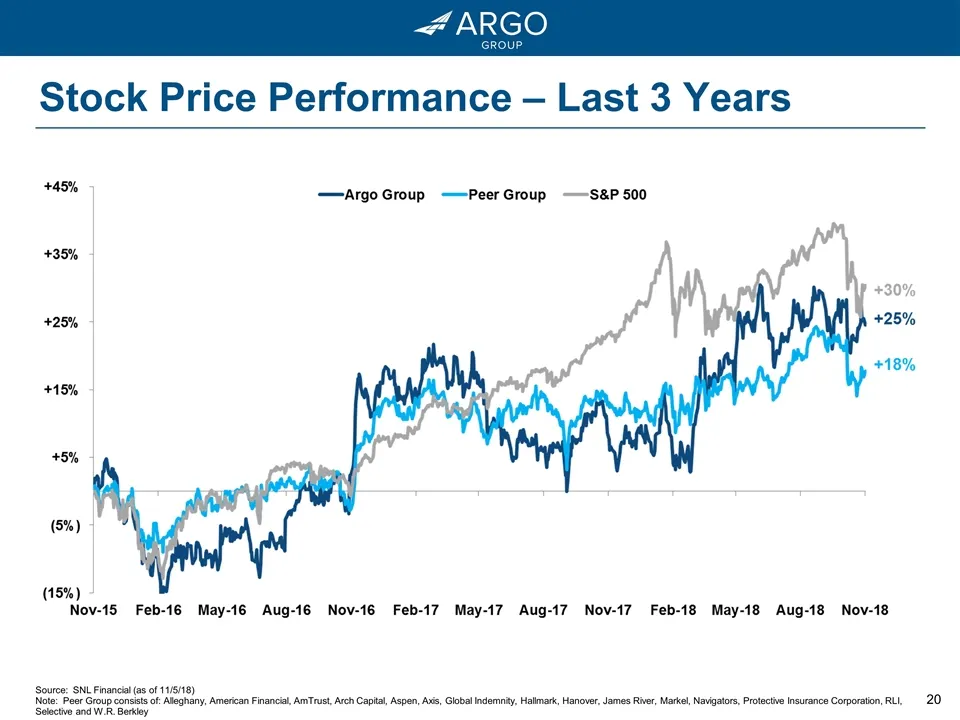
Stock Price Performance – Last 3 Years Source: SNL Financial (as of 11/5/18) Note: Peer Group consists of: Alleghany, American Financial, AmTrust, Arch Capital, Aspen, Axis, Global Indemnity, Hallmark, Hanover, James River, Markel, Navigators, Protective Insurance Corporation, RLI, Selective and W.R
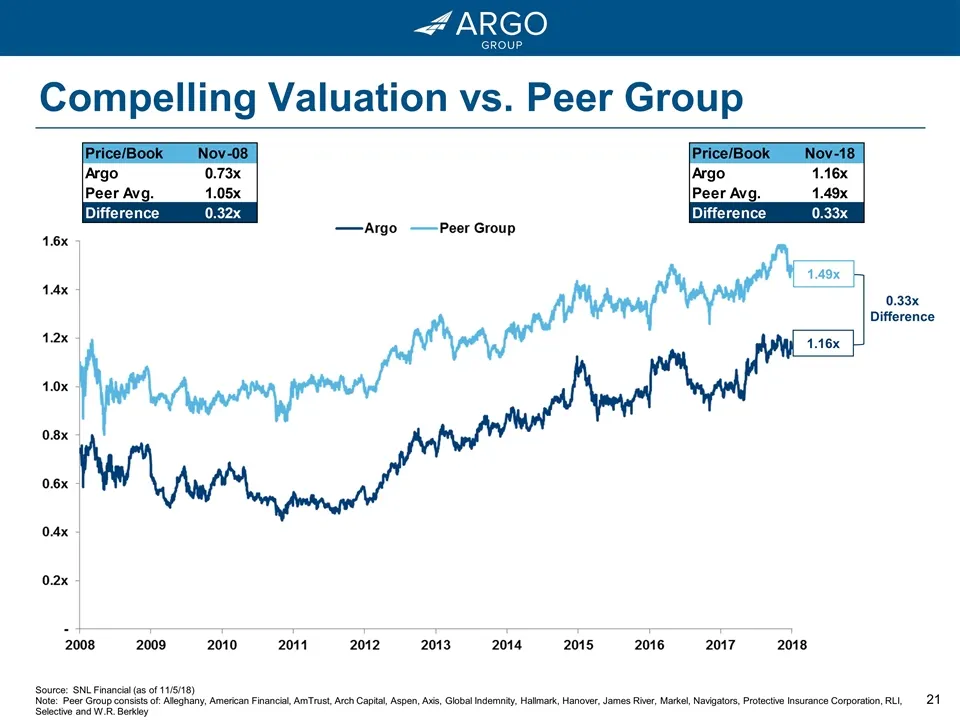
Slide 21: Compelling Valuation vs. Peer Group
Compelling Valuation vs. Peer Group Source: SNL Financial (as of 11/5/18) Note: Peer Group consists of: Alleghany, American Financial, AmTrust, Arch Capital, Aspen, Axis, Global Indemnity, Hallmark, Hanover, James River, Markel, Navigators, Protective Insurance Corporation, RLI, Selective and W.R. B
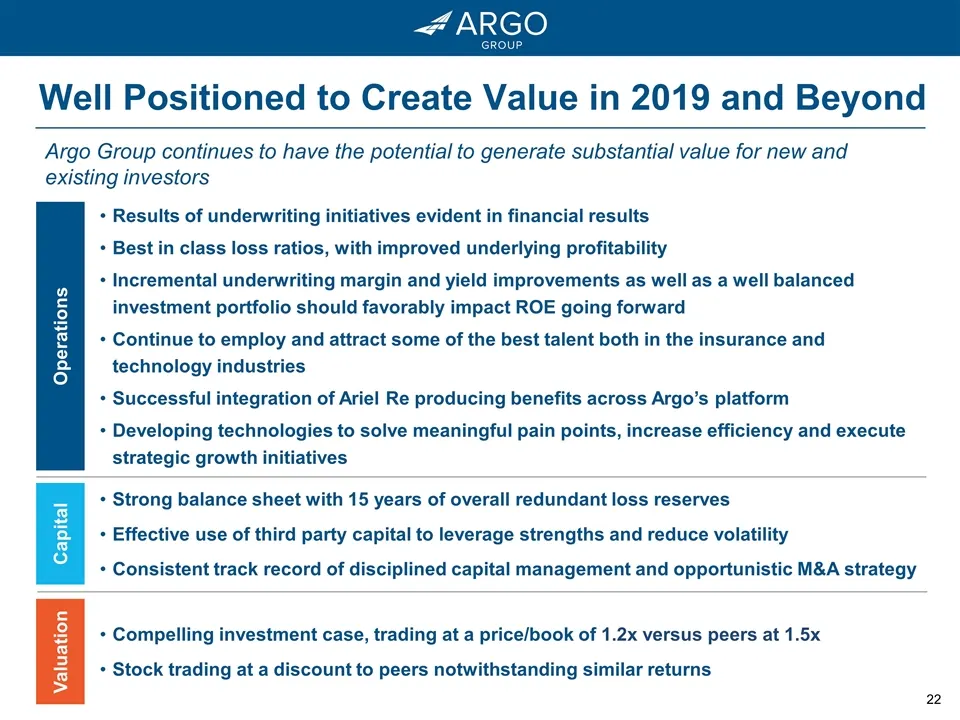
Slide 22: Operations, Capital, Valuation: investment case
Operations Capital Valuation Compelling investment case, trading at a price/book of 1.2x versus peers at 1.5x Stock trading at a discount to peers notwithstanding similar returns Strong balance sheet with 15 years of overall redundant loss reserves Effective use of third party capital to leverage st
Source: SEC EDGAR · 8-K filed Nov 14, 2018
More decks from Argo Group International Holdings Ltd
 Proxy Contest (November 2022)39 slides · Nov 18, 2022
 Corporate Update (September 2022)23 slides · Sep 8, 2022
 Investor Presentation (February 2022)24 slides · Feb 23, 2022
 Q3 2021 Earnings Presentation7 slides · Nov 3, 2021
 Investor Day (March 2021)59 slides · Mar 12, 2021
 Investor Presentation (November 2020)17 slides · Nov 10, 2020