VEREIT — American Realty Capital Properties — Merger or Acquisition (February 2014)
11 slides from VEREIT's merger presentation, Feb 10, 2014
Slide 1: American Realty Capital Properties Completes Acquisition of Cole Companies
American Realty Capital Properties Completes Acquisition of Cole Companies February 10, 2014
Slide 2: Forward-looking statements
2 Information set forth herein (including information included or incorporated by reference herein) contains “forward - looking statements” (as defined in Section 21 E of the Securities Exchange Act of 1934 , as amended), which reflect American Realty Capital Properties, Inc . ’s (“ARCP”) expectatio
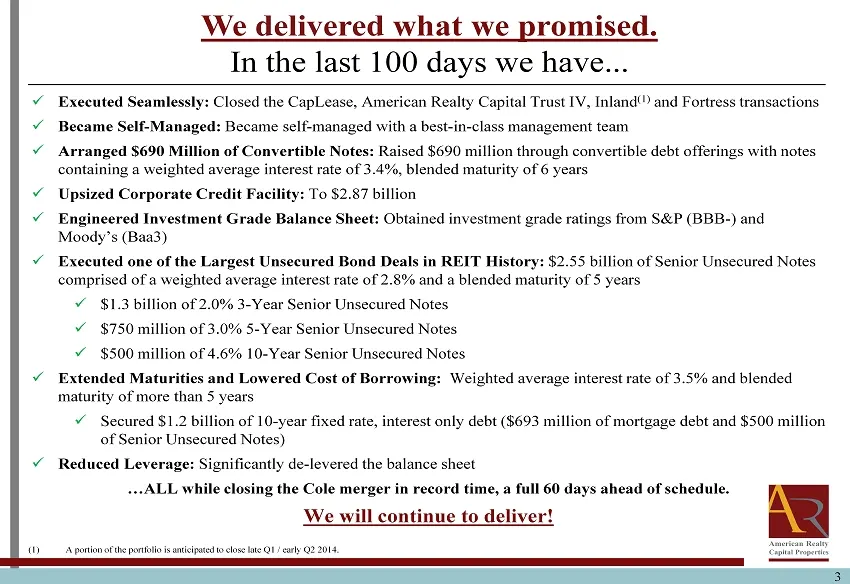
Slide 3: We delivered what we promised
3 We delivered w hat w e promised. In the last 100 days we have... x Executed Seamlessly: Closed the CapLease , American Realty Capital Trust IV, Inland (1) and Fortress transactions x Became Self - Managed: Became self - managed with a best - in - class management team x Arranged $690 Million of Co
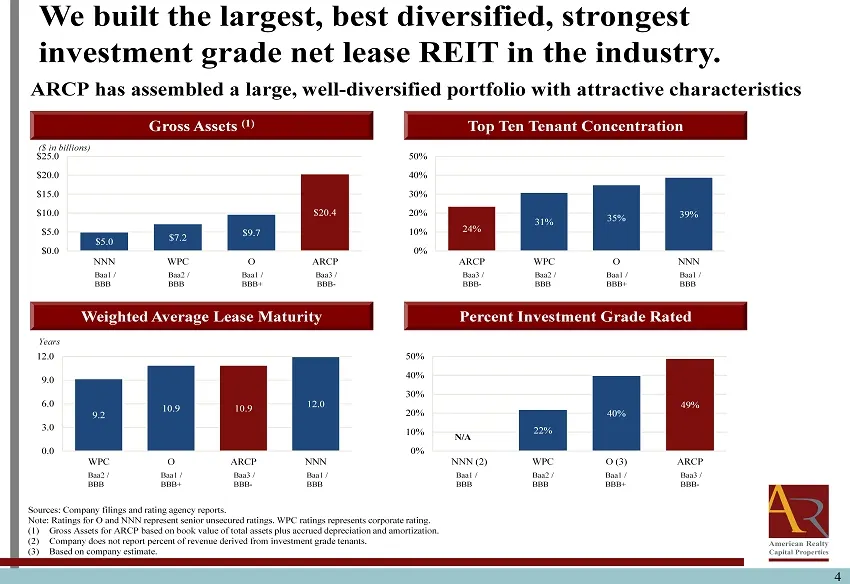
Slide 4: ARCP has assembled a large, well-diversified portfolio with attractive characteristics
4 Gross Assets (1) Weighted Average Lease Maturity ARCP has assembled a large, well - diversified portfolio with attractive characteristics We built the largest, best diversified, strongest investment grade net l ease REIT in the industry. Top Ten Tenant Concentration Percent Investment Grade Rated
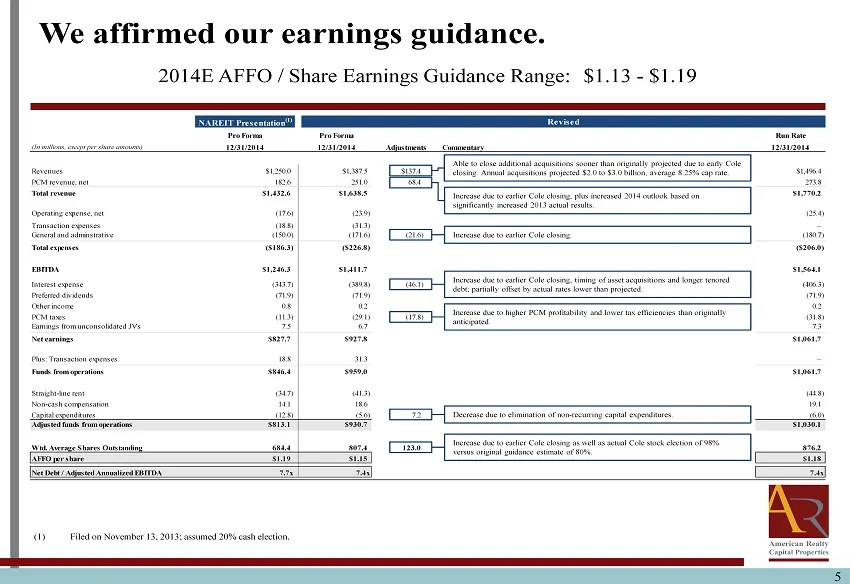
Slide 5: Pro Forma Run Rate (NAREIT presentation)
5 NAREIT Presentation (1) Revised Pro Forma Pro Forma Run Rate (In millions, except per share amounts) 12/31/2014 12/31/2014 Adjustments Commentary 12/31/2014 Revenues $1,250.0 $1,387.5 $137.4 $1,496.4 PCM revenue, net 182.6 251.0 68.4 273.8 Total revenue $1,432.6 $1,638.5 $1,770.2 Operating expense
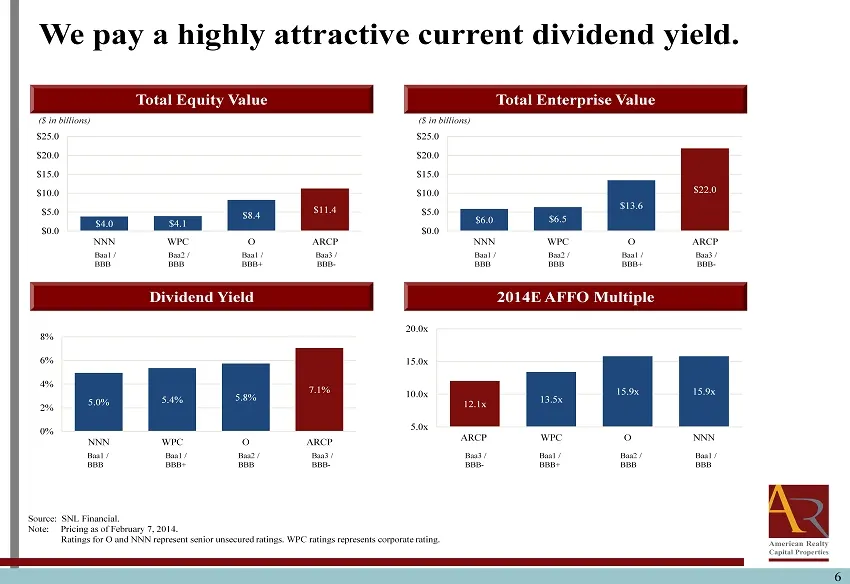
Slide 6: We pay a highly attractive current dividend yield
6 Total Equity Value Dividend Yield Total Enterprise Value 2014E AFFO Multiple $4.0 $4.1 $8.4 $11.4 $0.0 $5.0 $10.0 $15.0 $20.0 $25.0 NNN WPC O ARCP ($ in billions) Baa1 / BBB Baa2 / BBB Baa1 / BBB + Baa3 / BBB - 5.0% 5.4% 5.8% 7.1% 0% 2% 4% 6% 8% NNN WPC O ARCP Baa1 / BBB Baa1 / BBB + Baa2 / BBB Ba
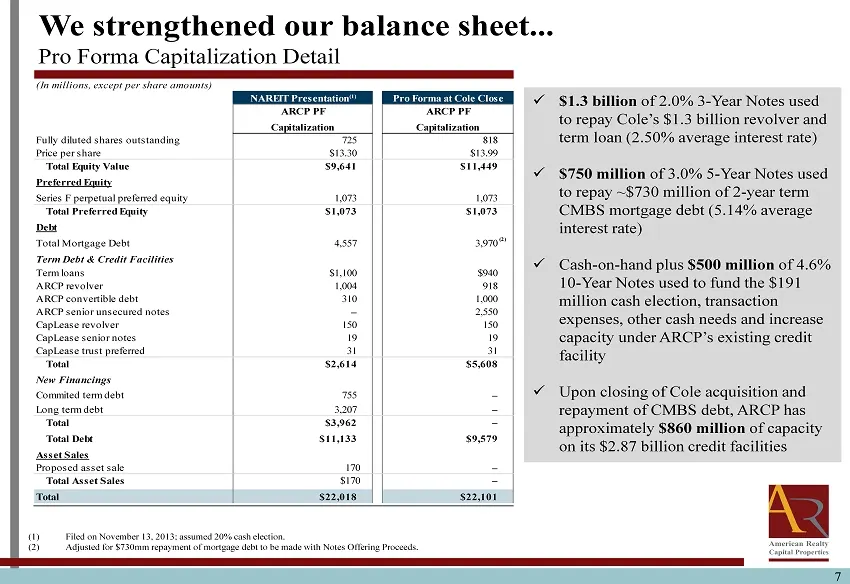
Slide 7: We strengthened our balance sheet
7 We strengthened our balance sheet... Pro Forma Capitalization Detail (1) (2) Filed on November 13, 2013; a ssumed 20% cash election . Adjusted for $730mm repayment of mortgage debt to be made with Notes Offering Proceeds. x $1.3 billion of 2.0% 3 - Year Notes used to repay Cole’s $1.3 billion revo
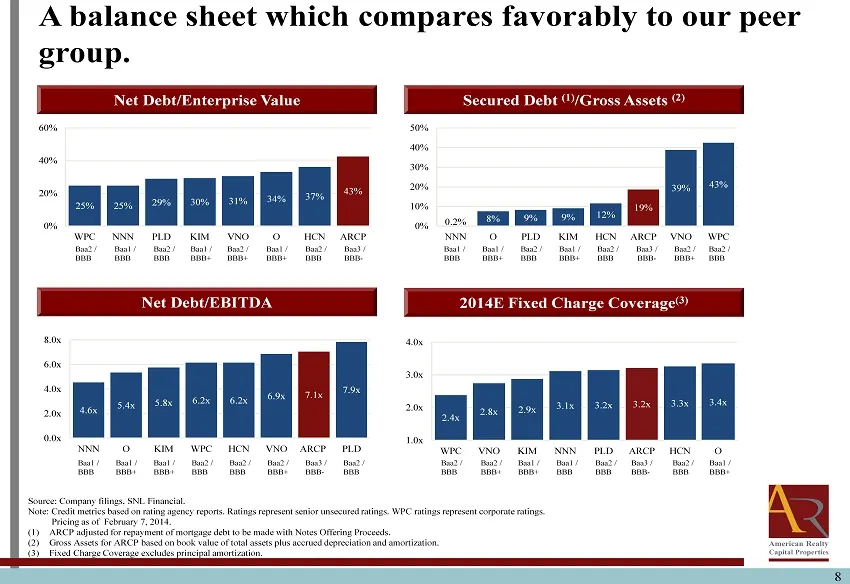
Slide 8: A balance sheet which compares favorably to our peer group
8 A balance sheet which compares favorably to our peer group. Net Debt/EBITDA Secured Debt (1) /Gross Assets (2) 2014E Fixed Charge Coverage (3) Net Debt/Enterprise Value 25% 25% 29% 30% 31% 34% 37% 43% 0% 20% 40% 60% WPC NNN PLD KIM VNO O HCN ARCP Baa3 / BBB - 4.6x 5.4x 5.8x 6.2x 6.2x 6.9x 7.1x 7.9
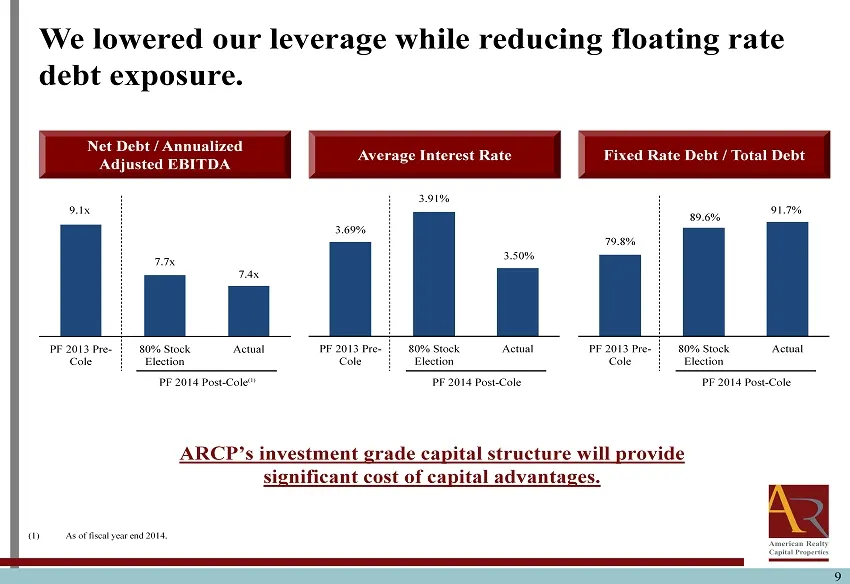
Slide 9: We lowered our leverage while reducing floating rate debt exposure
9 We lowered our leverage while reducing floating rate debt exposure. 9.1x 7.7x 7.4x PF 2013 Pre- Cole 80% Stock Election Actual PF 2014 Post - Cole (1) 3.69% 3.91% 3.50% PF 2013 Pre- Cole 80% Stock Election Actual PF 2014 Post - Cole ARCP’s investment grade capital structure will provide significan
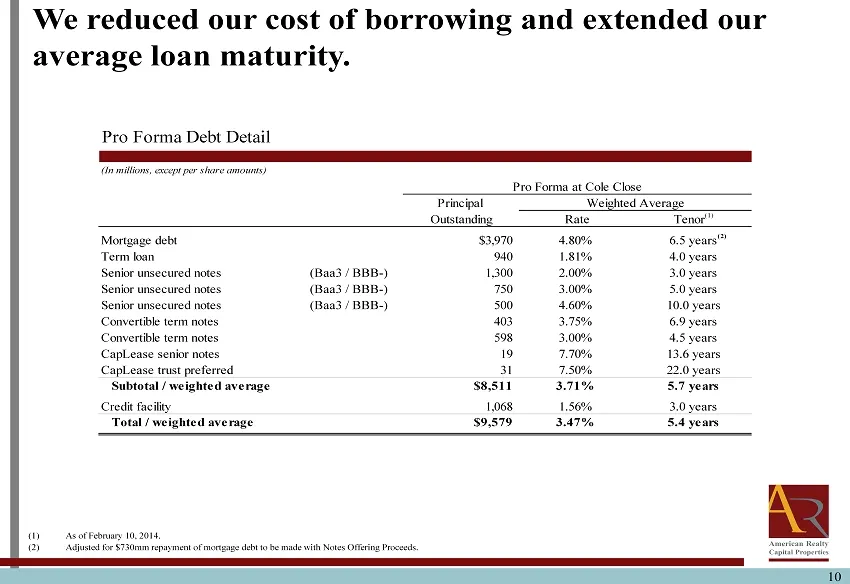
Slide 10: We reduced our cost of borrowing and extended our average loan maturity
10 We reduced our cost of borrowing and extended our average loan maturity. (1) As of February 10, 2014. (2) A djusted for $730mm repayment of mortgage debt to be made with Notes Offering Proceeds. Pro Forma Debt Detail (In millions, except per share amounts) Pro Forma at Cole Close Principal Weight
Slide 11: EBITDA and Adjusted Annualized EBITDA non-GAAP disclosure
11 EBITDA and Adjusted Annualized EBITDA are not calculated in accordance with GAAP . ARCP believes these measures are important supplemental measures of operating performance as they allow comparisons of ARCP’s operating results without regard to financing methods and capital structure . Accordingl
Source: SEC EDGAR · 8-K filed Feb 10, 2014
More decks from VEREIT Inc
 Q3 2021 Earnings Presentation35 slides · Oct 29, 2021
 Q2 2021 Earnings Presentation35 slides · Aug 5, 2021
 Q1 2021 Earnings Presentation35 slides · May 6, 2021
 Merger or Acquisition (April 2021)16 slides · Apr 29, 2021
 Q4 2020 Earnings Presentation44 slides · Feb 24, 2021
 Q1 2021 Earnings Presentation39 slides · 2021