Shyft — Spartan Motors — Investor Day (October 2017)
59 slides from Shyft's investor day presentation, Oct 12, 2017
Slide 1: 2017 Analyst and Investor Day
~ SPAR 2017 ANALYST AND INVESTOR DAY SPARTAN
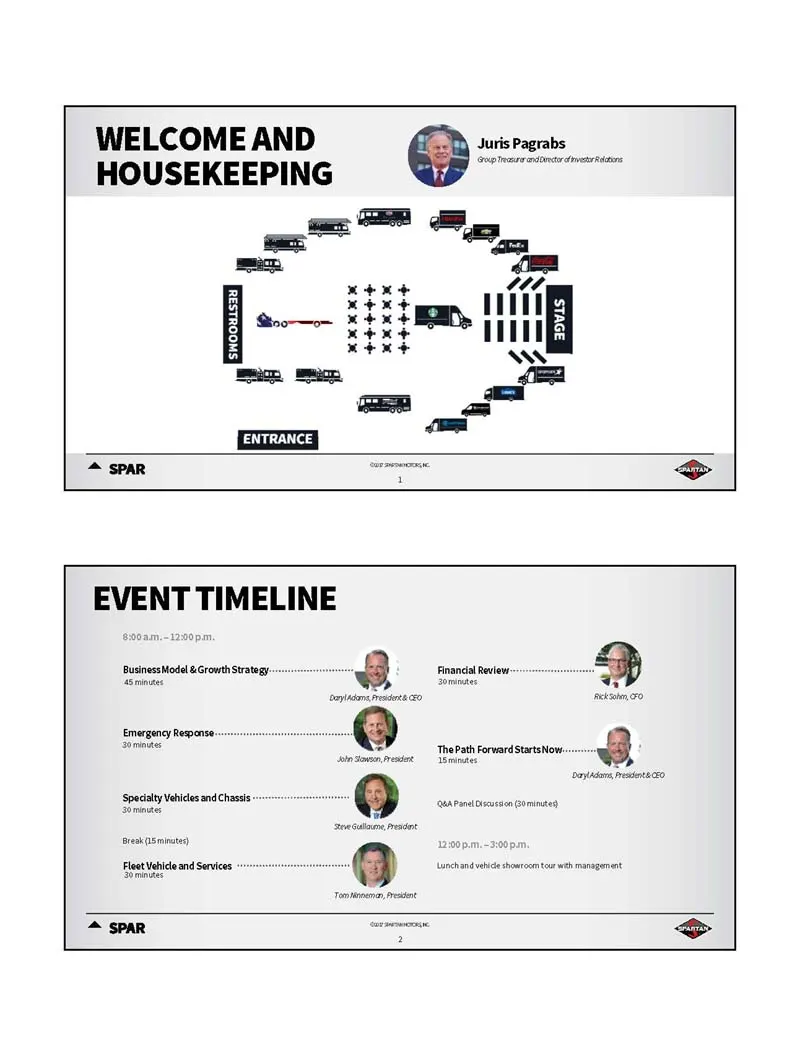
Slide 2: Welcome and Housekeeping
WELCOME AND HOUSEKEEPING & Juris Pagrabs EVENT TIMELINE Business Model & Growth Strategy. Financial Review lads Fredo c20 ksh £0 Emergency Respense i snnesennns S0minites ‘The ath ForwardStartsNow..- Dantas Prescot 60 ‘Specialty Vehicles and Chassis ~ ‘enamel Hscussen Gominte teak (15 minutes Fleet
Slide 3: Forward Looking Statements
FORWARD LOOKING STATEMENTS Compleat tatny as atlecingthe mplemeticn ou plan and ber beh conbned preter cased economies nthe pce nd ‘sot tthe sear recvay-ehtenge army acm cernecon tthe ntptcn ne usnerceror atte segura ste dipsten fee ae Uniueto government conang such cmpenbeodding prcesesquasiaicneem
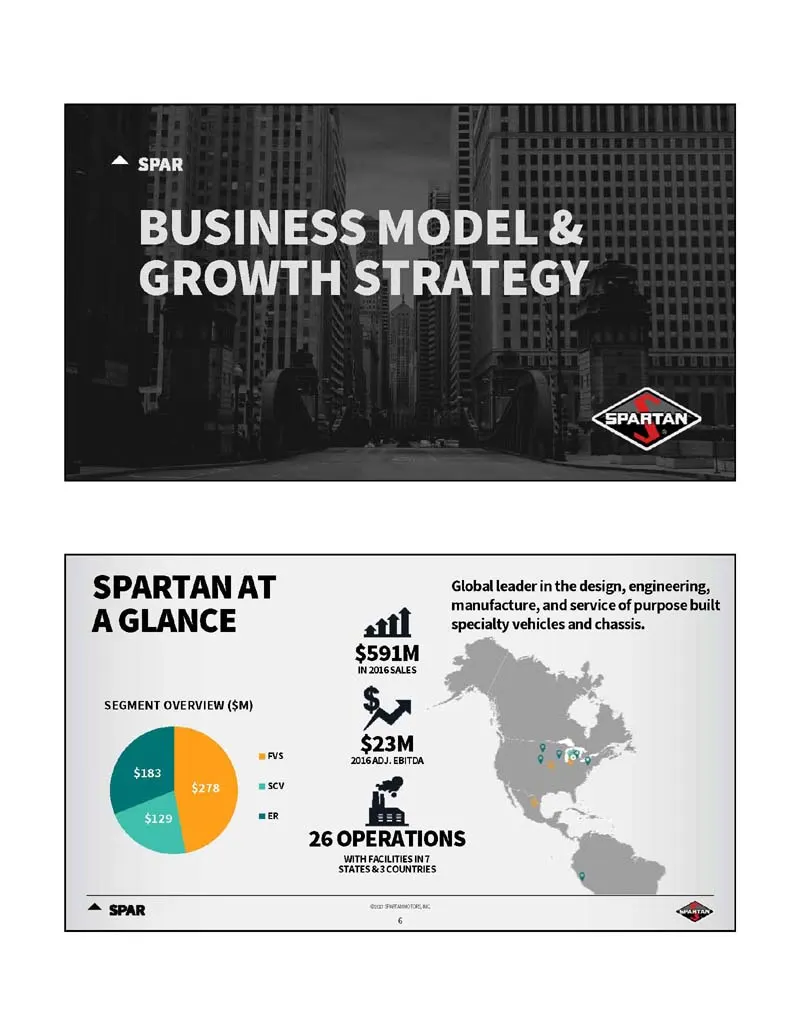
Slide 4: Spartan at a Glance
SPAR BUSINESS MODEL & GROWTH STRATEGY SPARTAN AT AGLANCE ‘SEGMENT OVERVIEW ($M) é aatl $591M TH2016SALES sv 23M 201640). EBITDA rid Global leader in the design, engineering, manufacture, and service of purpose built specialty vehicles and chassis. 26 OPERATIONS ATH FACILITIES 7 STATES&3 COUNTRIES
Slide 5: Company Timeline
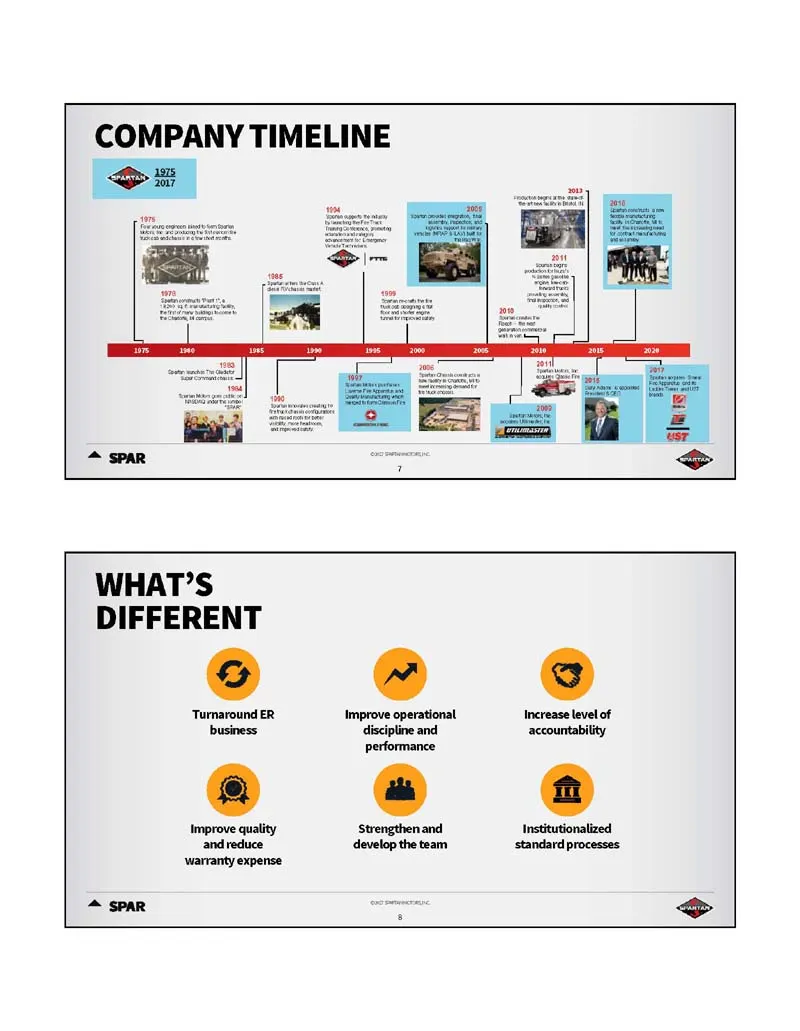
COMPANY TIMELINE WHAT’S DIFFERENT ‘Turnaround ER Improve operational Increase level of business discipline and accountability performance Improve quality Strengthen and Institutionalized and reduce develop the team standard processes warranty expense
Slide 6: Manufacturing Improvements Gaining Traction
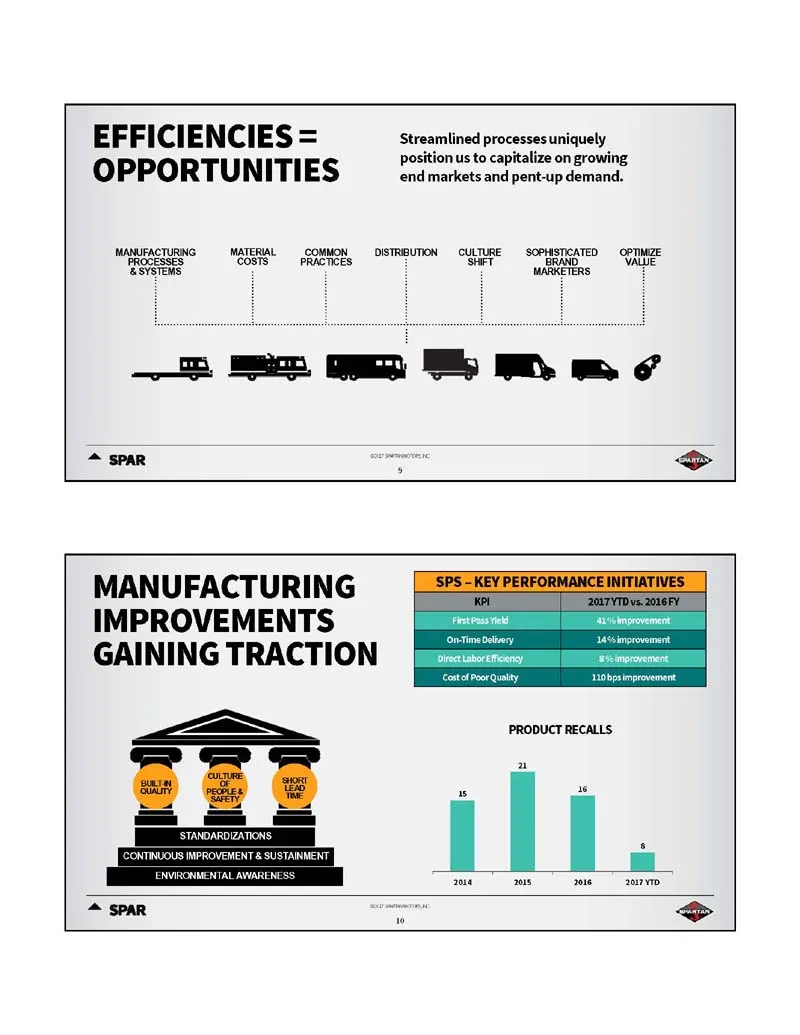
EFFICIENCIES = Streamlined procesesuniauely sition us to capitalize on growin, OPPORTUNITIES —chimarketsandpentup demand. MANUFACTURING MATERIAL COMMON. DISTRIBUTION. CULTURE SOPHISTICATED OP MME. PROCESSES. ‘Costs, PRACTICES ‘SHFT BRAND, VAWE ‘SSYSTEMS MARKETERS : — ao oe i oo? ~~ MANUFACTURING ee
Slide 7: Improved Financial Performance
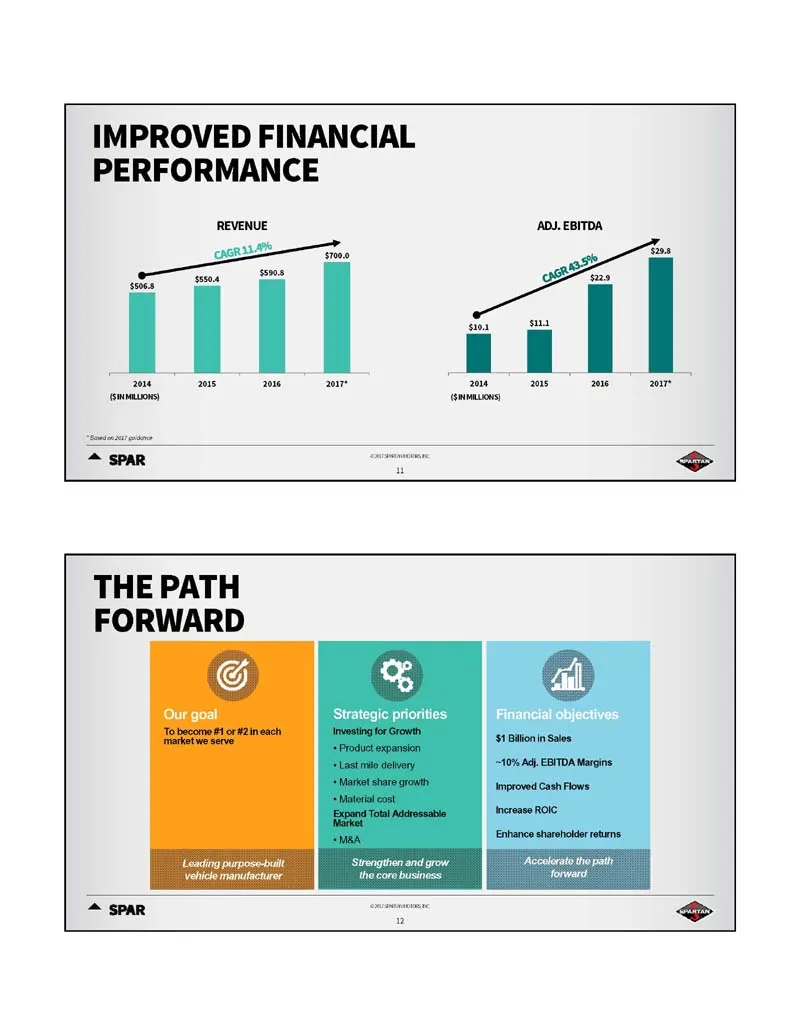
IMPROVED FINANCIAL PERFORMANCE REVENUE ‘ADJ. EBITDA cn Gos is x mr [| gn. l | i | ems 201 aor oo 201s ais ao sma smu THE PATH FORWARD G % Our goal Strategic priorities
Slide 8: Macro Trends Drive Sustainable Growth
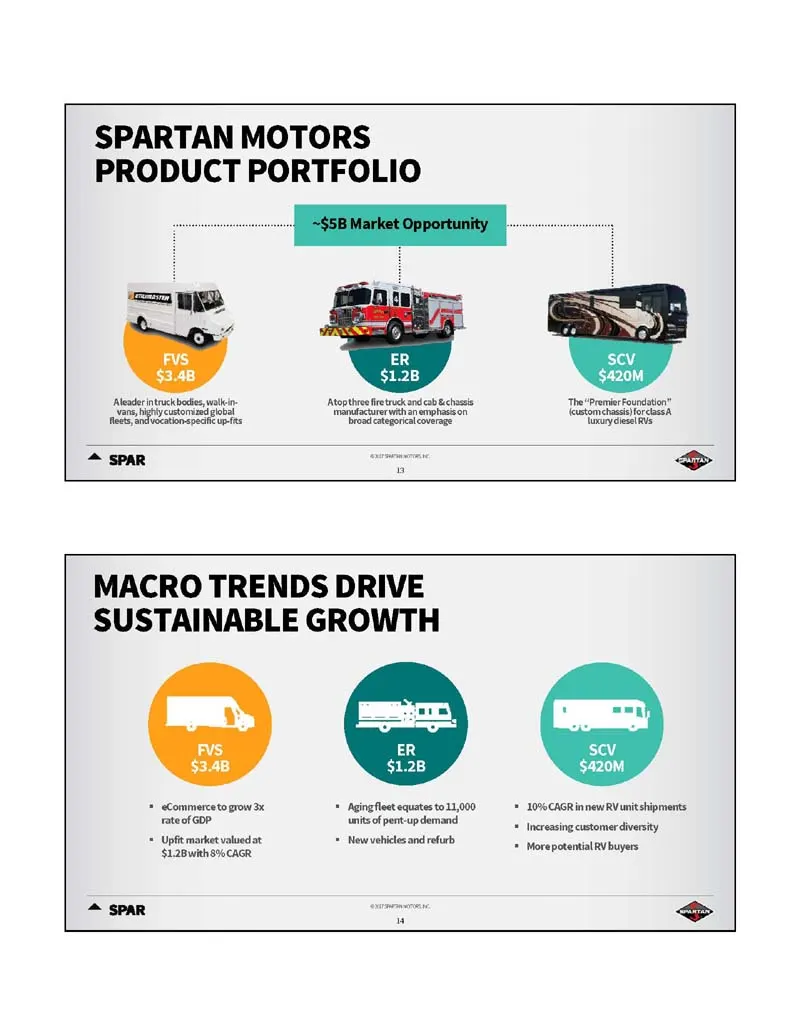
SPARTAN MOTORS PRODUCT PORTFOLIO MACRO TRENDS DRIVE SUSTAINABLE GROWTH -, = ee oe Fvs ER scv $3.4B $1.2B $420M. + Agingfleetequates 13,000 * 10% CAGRnnewRVunitshipments units of pent-up demand + Increasing customer diversity teem vaticies ere rebxt * Morepotential RVbuyers
Slide 9: Influences on Fleet Growth Opportunities
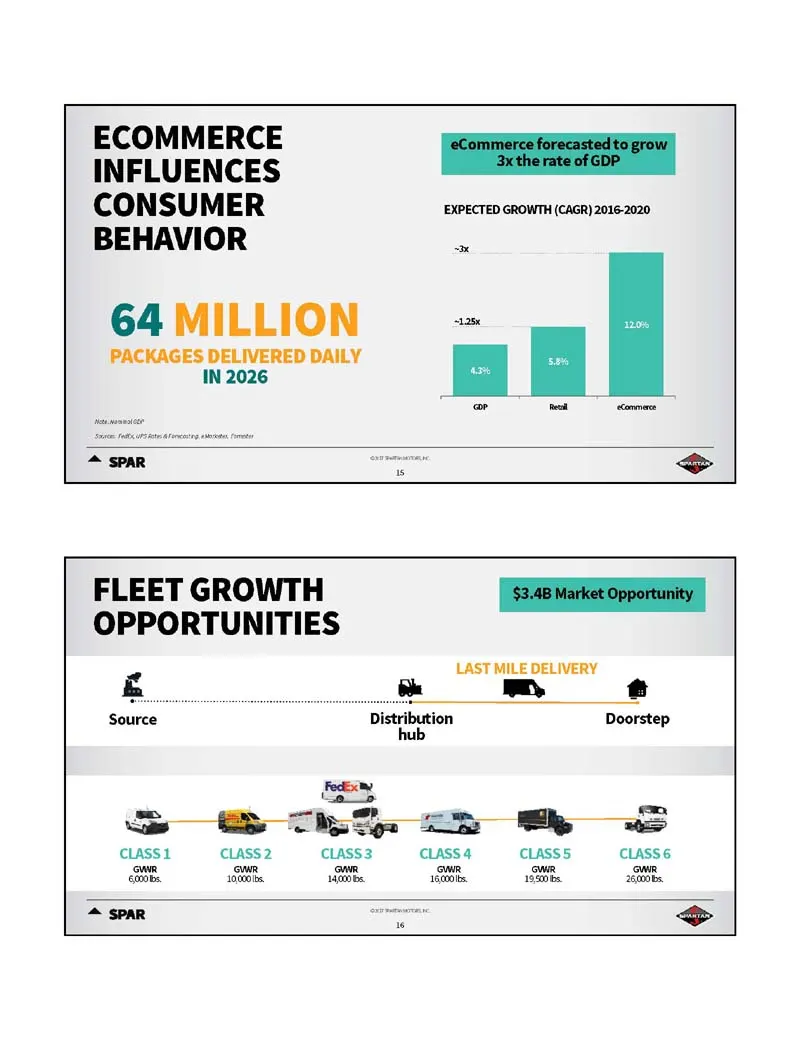
rmences one " INFLUENCES CONSUMER EXPECTED GROWTH cAGR) 20162520 BEHAVIOR 6 64 MILLION 125 PACKAGES DELIVERED DAILY IN 2026 ned or ek FLEET GROWTH "$248 Market Opportunity OPPORTUNITIES LAST MILE DELIVERY Source Distribution Doorstep hub FedExmy = = — oP = Lend CLASS1 CLASS 2 CLASS3 CLASS 4 CLASS5 C
Slide 10: Accelerating Growth
SPAR ACCELERATING GROWTH SOLUTION-BASED FOCUS Starbucks Coca-Cola
Slide 11: Disruptive Innovation
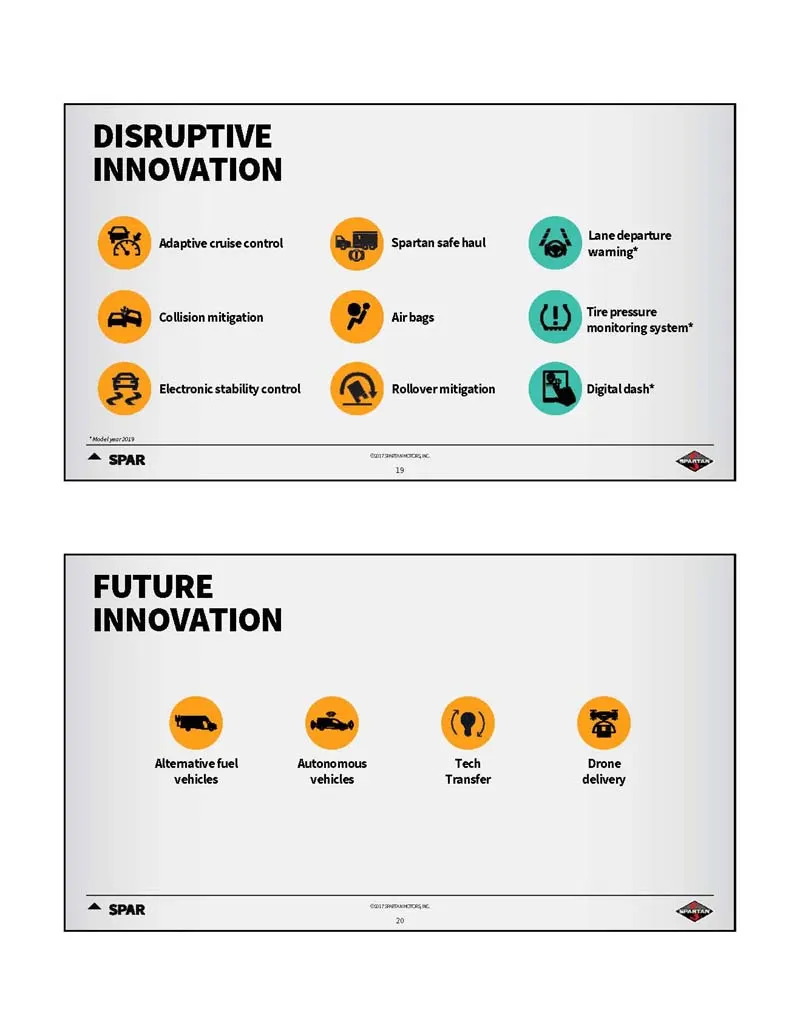
DISRUPTIVE INNOVATION r _ Lanedeparture e ‘Adaptive cruise control - Spartan safe haul cy waming* cI Collision mitigation @ Airbags o bled SPAR FUTURE INNOVATION Altemative fuel Autonomous Tech Drone vehicles vehicles Transfer delivery ~ SPAR
Slide 12: Simplified and Streamlined; M&A Bolsters Market Presence
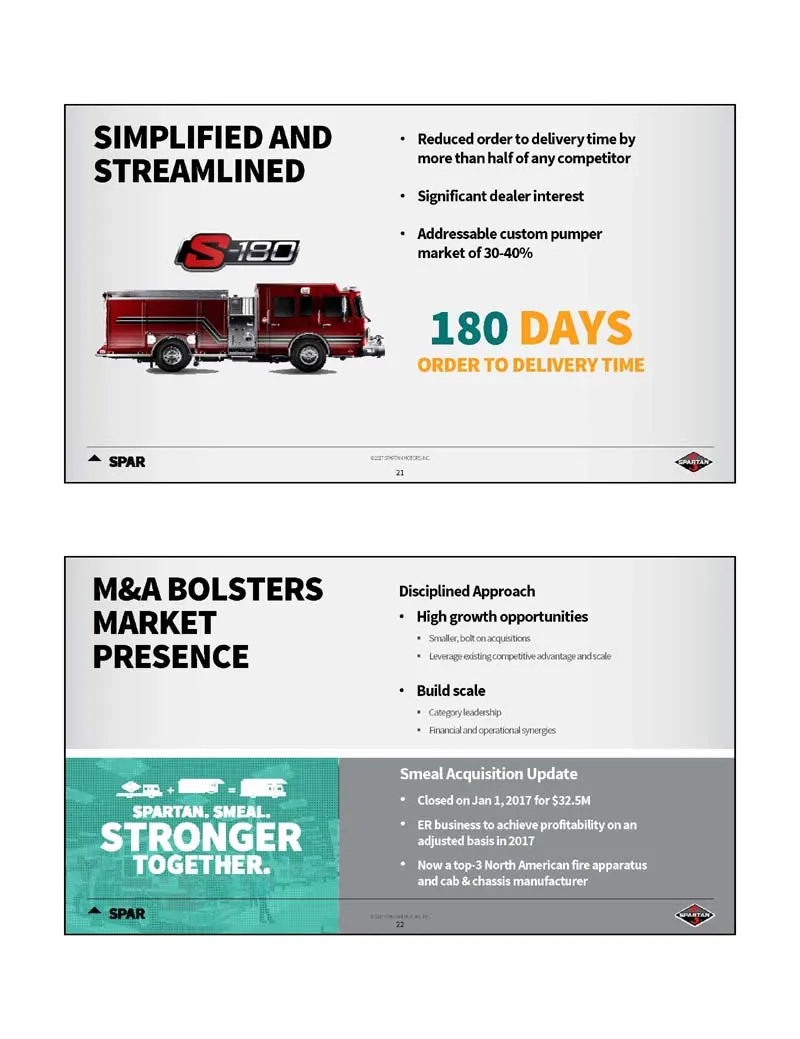
SIMPLIFIED AND > eee aeeati hint STREAMLINED dan + Significant dealer interest + Addressable custom pumper , S78) market of 30-40% ~ 180DAYS ORDER TO DELIVERY TIME @ ~ SPAR = M&A BOLSTERS Disciptined Approach MARKET + High growth opportunities PRESENCE eee * Build scale + Conegeryleestp + Frundoland
Slide 13: Accelerating Growth
ACCELERATING GROWTH Customer-centric Disruptive Solutions focus innovation based Streamlined M&A ‘operations SPAR @ SPAR EMERGENCY RESPONSE
Slide 14: Emergency Response: John Slawson
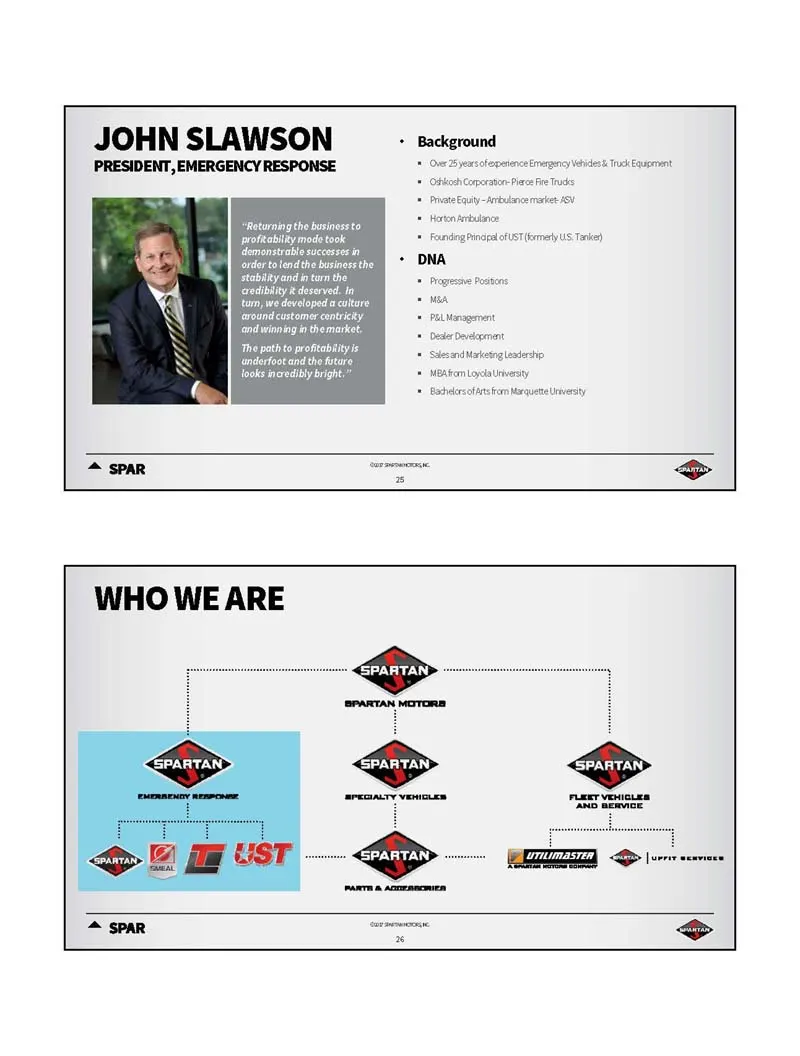
Background fepatence Emergency Vein Truck JOHN SLAWSON PRESIDENT, EMERGENCY RESPONSE © Ove 25yen eporaton- ics Fre Tusks torning the businessto profeaby modetook omonstabe cers ordertolendthe businessthe [Muay ‘Reblky cod torn the Sl regehe mea credibility R deserved. in . tum, we developed a cultur
Slide 15: Emergency Response (ER)
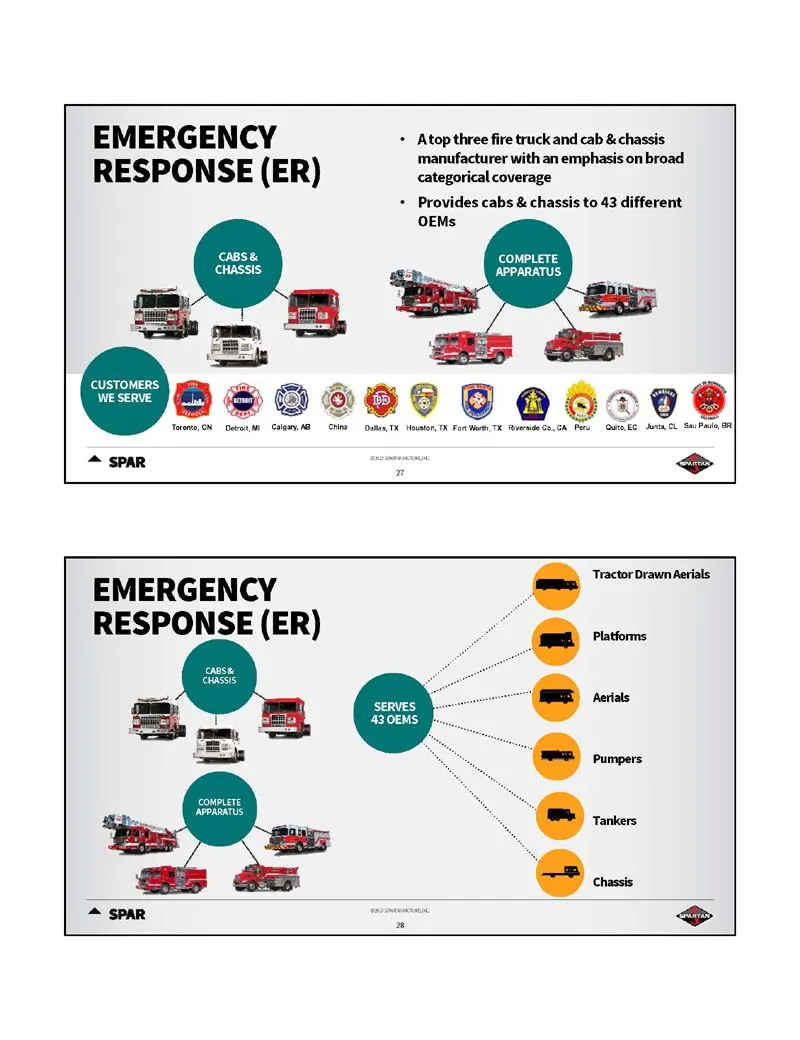
EMERGENCY + Atoptiveeretrucand cab cht RESPONSE (ER) casera cara + Provides cabs & chassis to 43 different OEMs COMPLETE APPARATUS CUSTOMERS WE SERVE @2O660 6 @6208 * soar = s EMERGENCY ow“ RESPONSE (ER) e~-
Slide 16: ER Strategy Summary
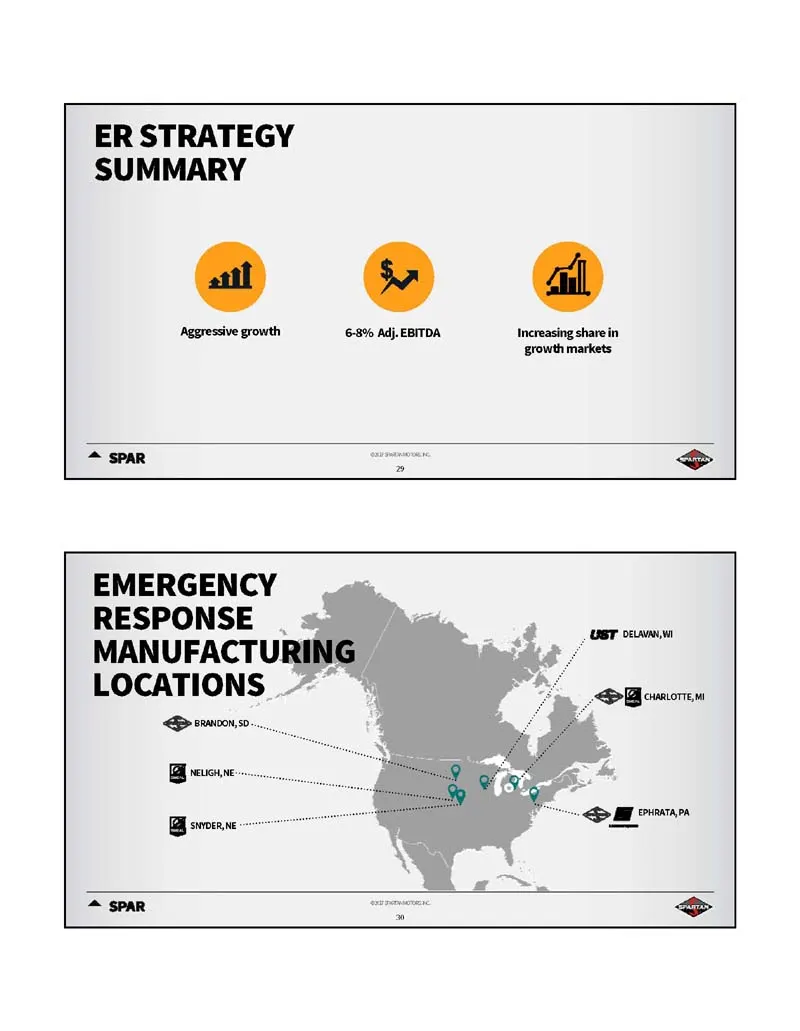
ER STRATEGY SUMMARY Aggressive growth 68% Adj. EBITDA Increasing share in growth markets & SPAR = S} EMERGENCY RESPONSE .. MANUFACTURING LOCATIONS ape
Slide 17: ER Dealers: Sales & Service
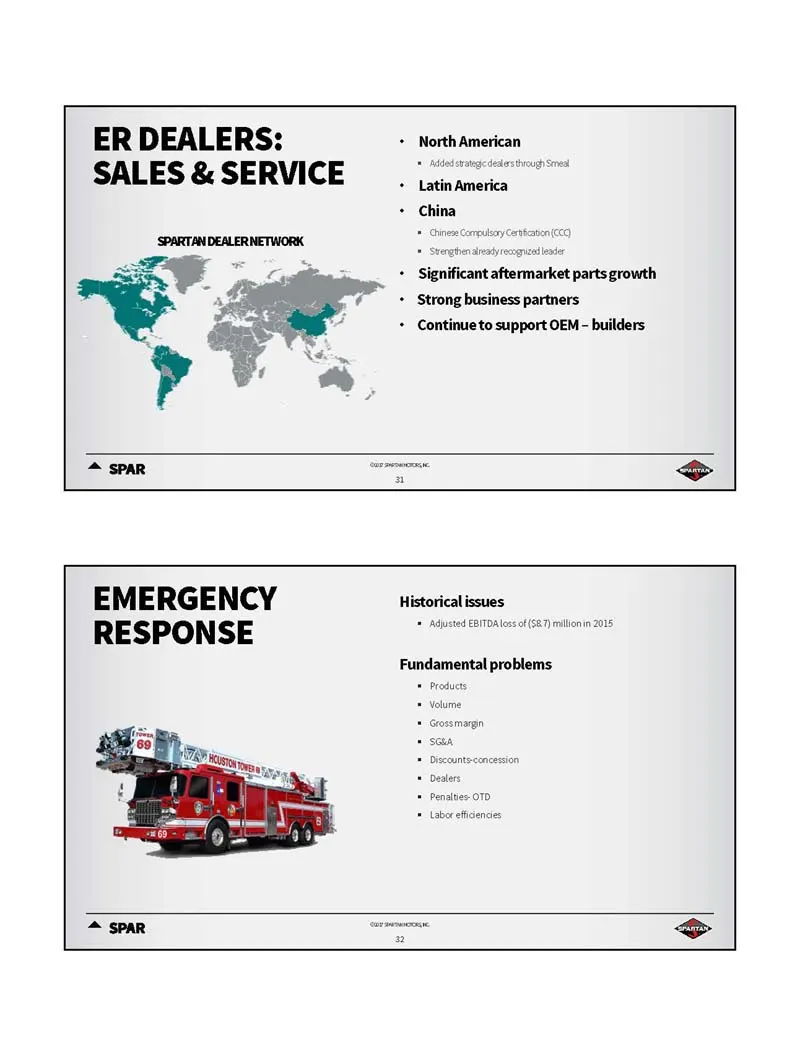
ER DEALERS: SALES & SERVICE + North American + Latin America + China + Significant aftermarket parts growth + Strong business partners + Continueto support OEM - builders ~ SPAR EMERGENCY RESPONSE Historical issues + dusted EBITDA ess of $87 milion 2015 Fundamental problems + radu
Slide 18: What Did We Need to Fix?
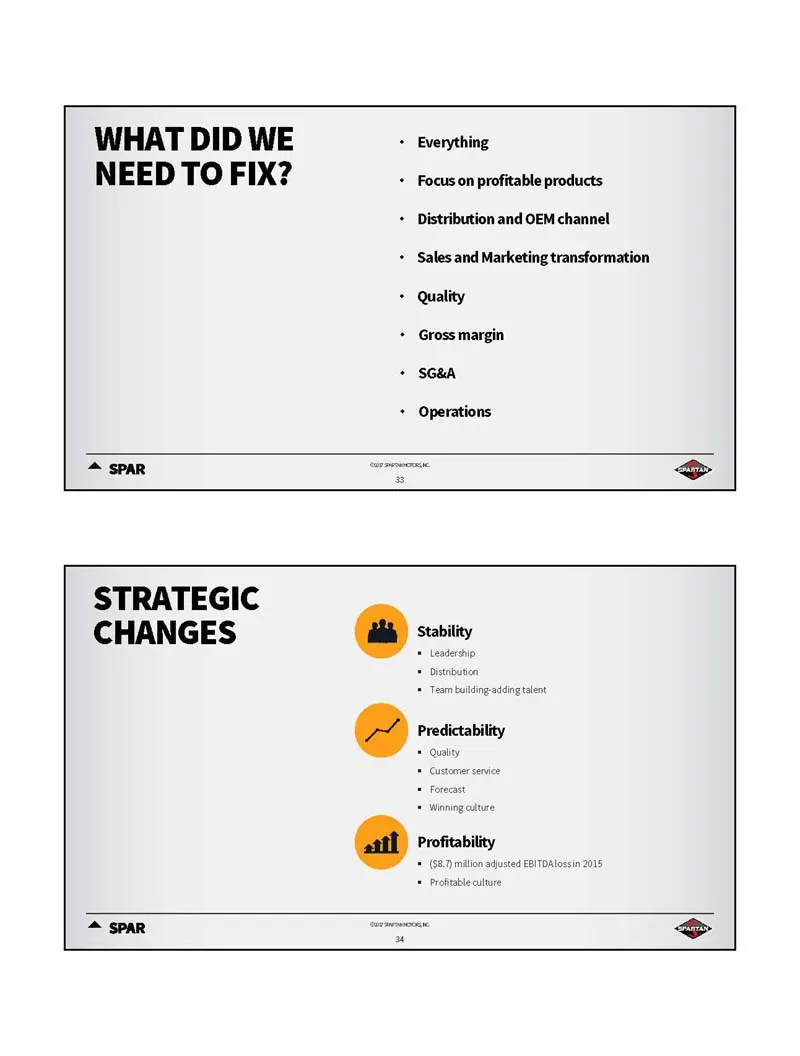
WHAT DID WE NEED TO FIX? + Everything + Focus on profitable products + Distribution and OEM channel + Sales and Marketing transformation + Quality + Gross margin + SG&A + Operations STRATEGIC CHANGES lding adding talent vw Predictability Profitability rion adjusted EBTDAlssin 2015
Slide 19: Improved Financial Performance
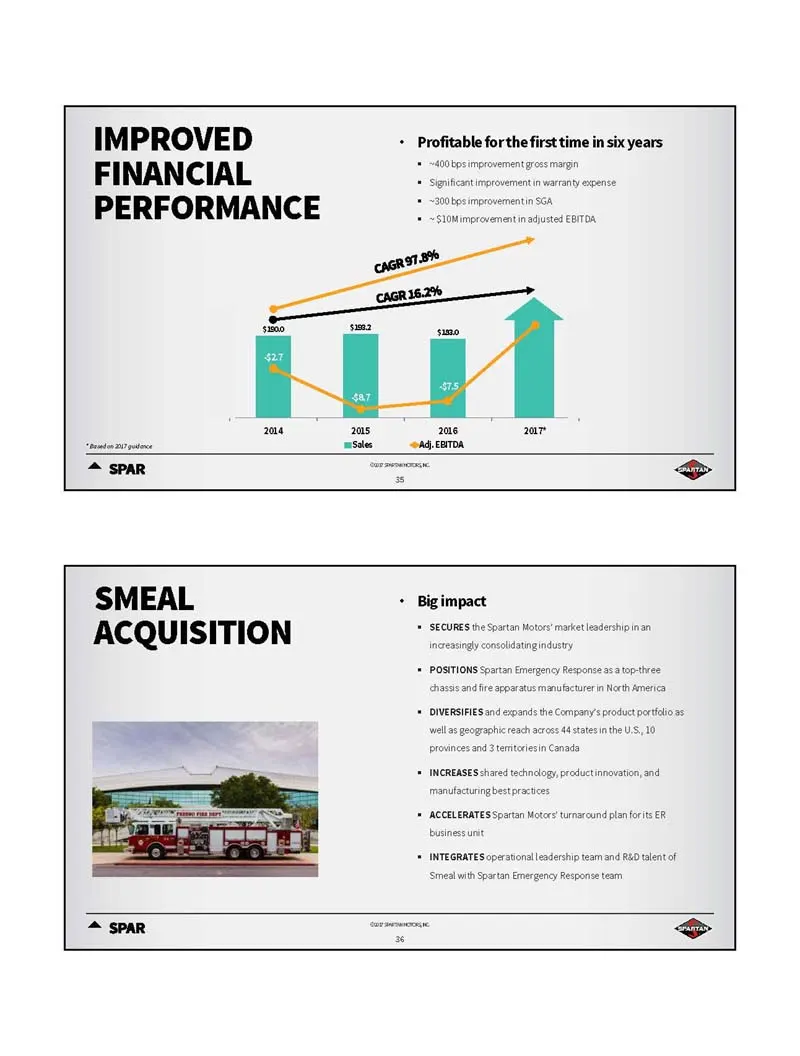
IMPROVED + Profitable for the first time in six years FINANCIAL ; : PERFORMANCE 204 aus ans 207 SMEAL ACQUISITION + INCREASES shared tchnclogy, productinnovation, and ‘manufacuringbest practices 1 ACCELERATES Spartan Motersturnacund plan forts ER business un + INTEGRATES op nand R80 talent of ‘sme w
Slide 20: Smeal Acquisition
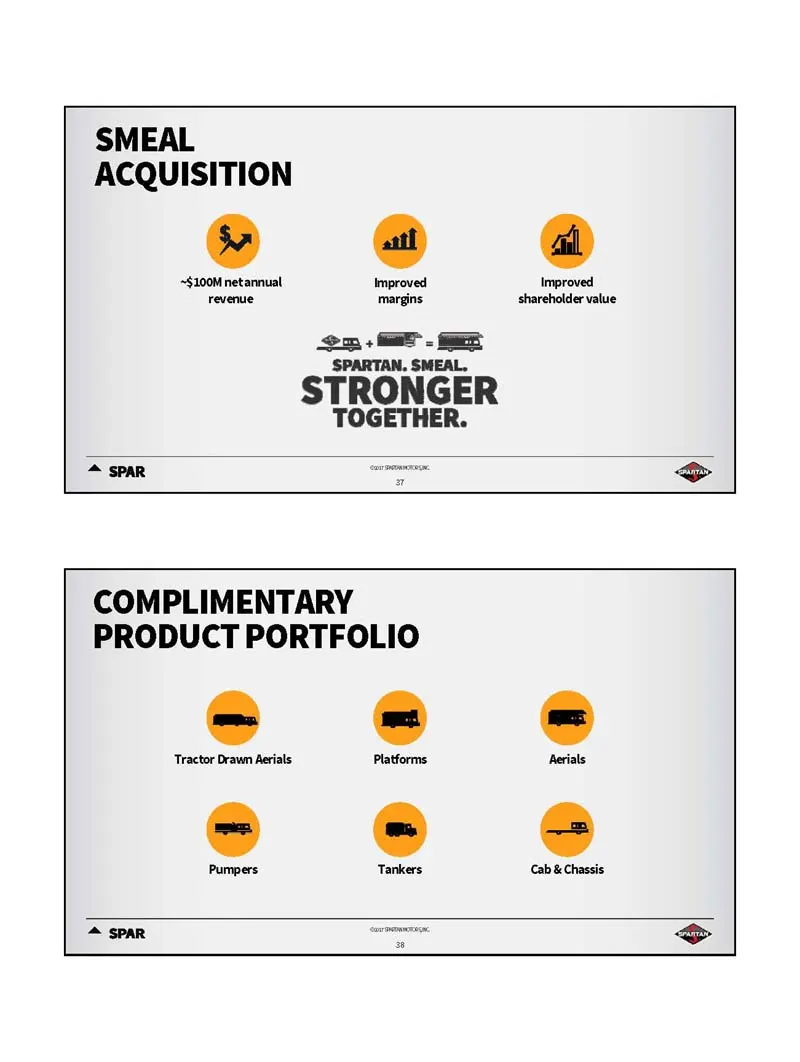
SMEAL ACQUISITION ~$100M netannual Improved improved even margins shareholder value on ae. =e SPARTAN. SMEAL. STRONGER TOGETHER. COMPLIMENTARY PRODUCT PORTFOLIO z g gy Ey H 2 a boa
Slide 21: Territory Coverage
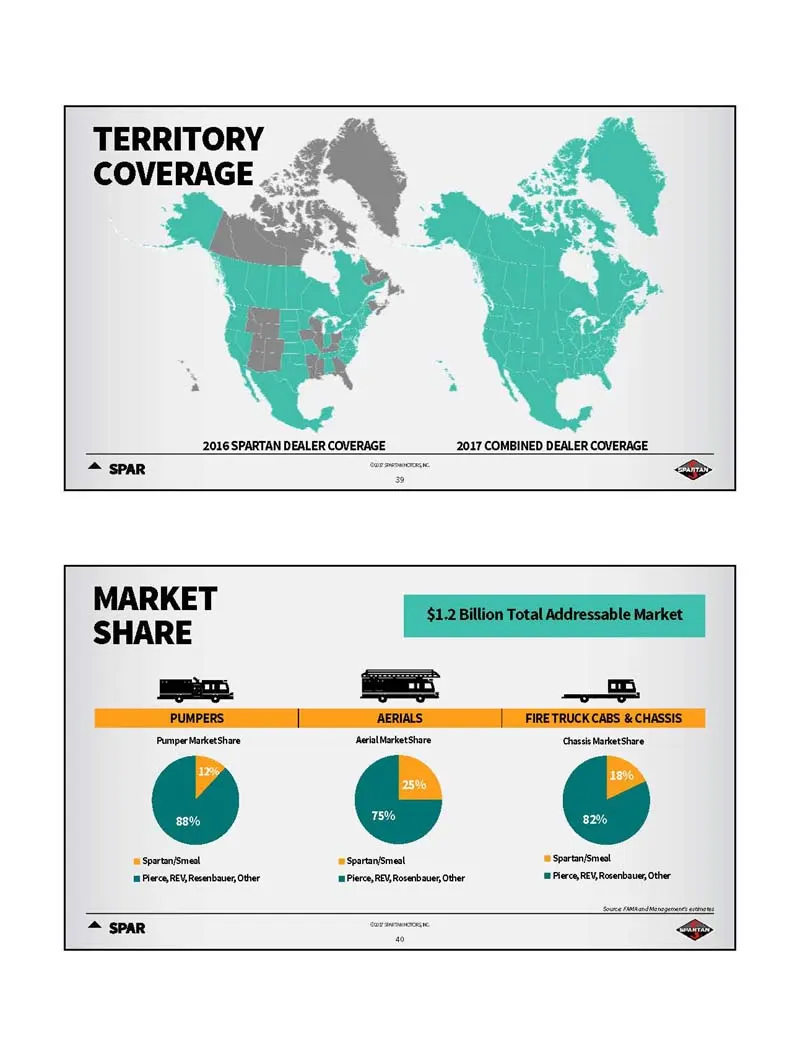
TERRITORY COVERAGE 2016 SPARTAN DEALER COVERAGE 2017 COMBINED DEALER COVERAGE ~ SPAR = SB Pamper Marketshare ‘Aero Marketshare Chasse aret share “s Sparta ‘eSpartysmeal se SpartnfSmel merc REV; Recenbaver Other merce, REV, Rovenbauer Other 15 PlrcaREV,Rorenboue, Other
Slide 22: Customer Centric Model
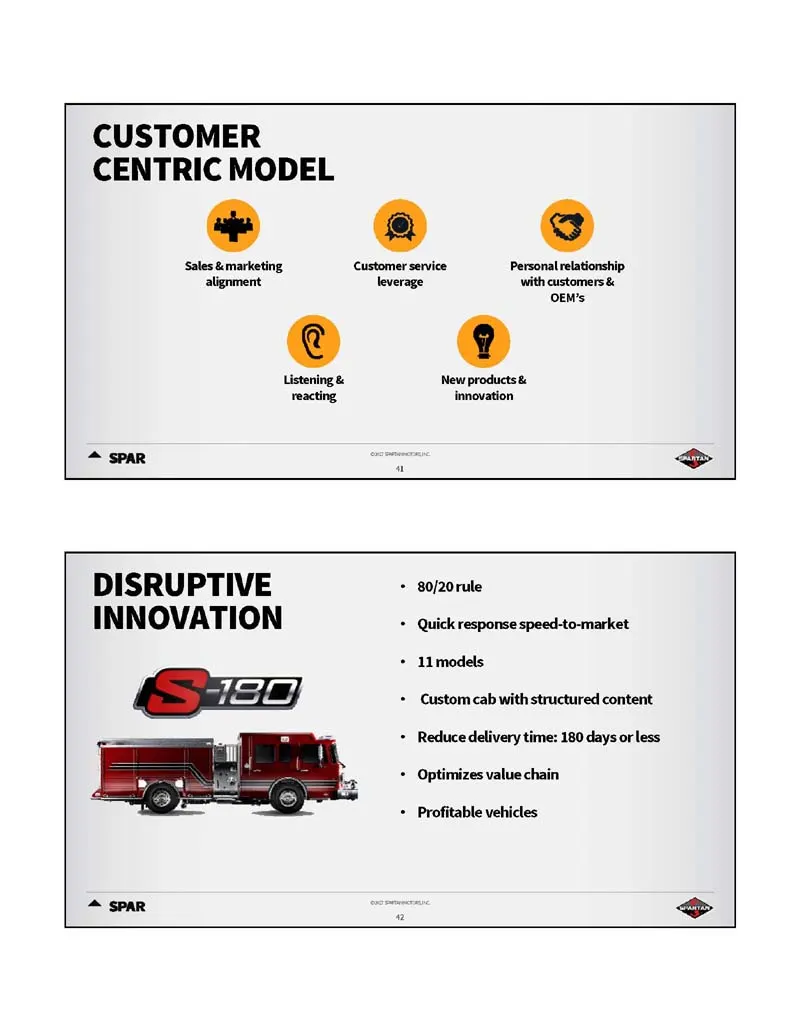
CUSTOMER CENTRIC MODEL Sales & marketing Customer service Personal relationship alignment leverage with customers & OEM's Listening & New products & reacting innovation ~ SPAR DISRUPTIVE + s0/20rule INNOVATION + Quick response speed-to-market + 11models * Custom cab with structured content + Reduce
Slide 23: Tech Transfer and Industry Best; Demographic Drivers
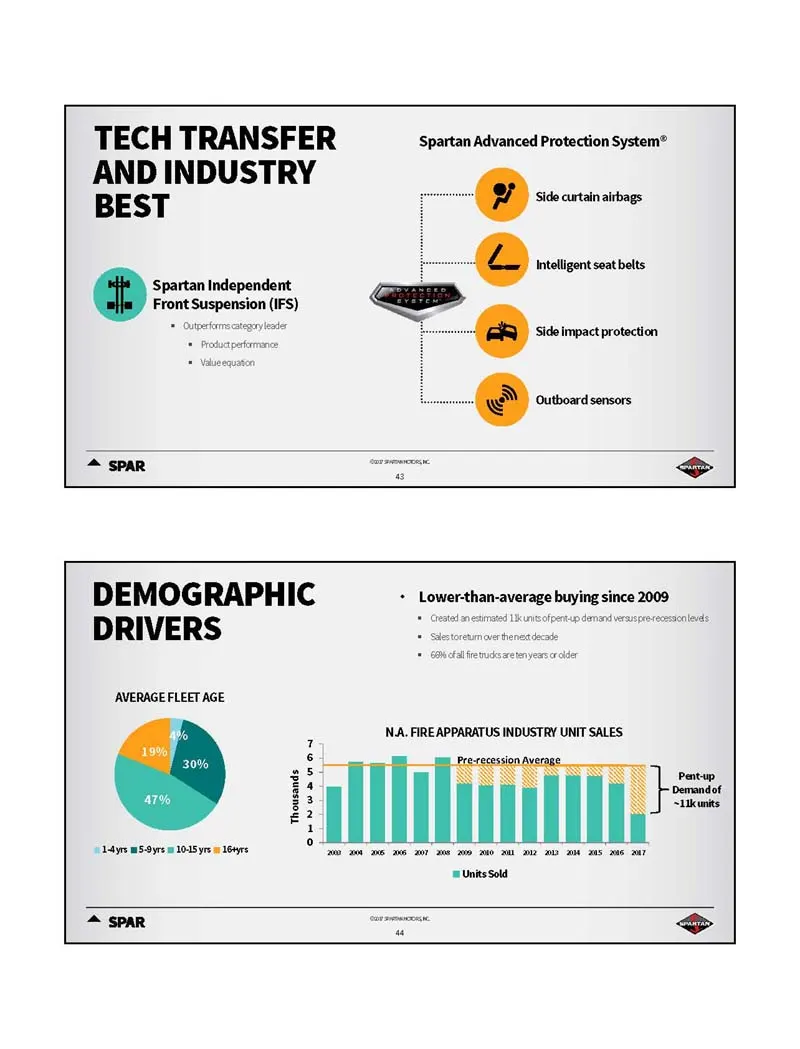
TECH TRANSFER AND INDUSTRY BEST Spartan Independent Front Suspension (IFS) Spartan Advanced Protection System? @--- DEMOGRAPHIC DRIVERS AVERAGE FLEET AGE Lys m5 9yrs 1035 yr 16s
Slide 24: Market Drivers
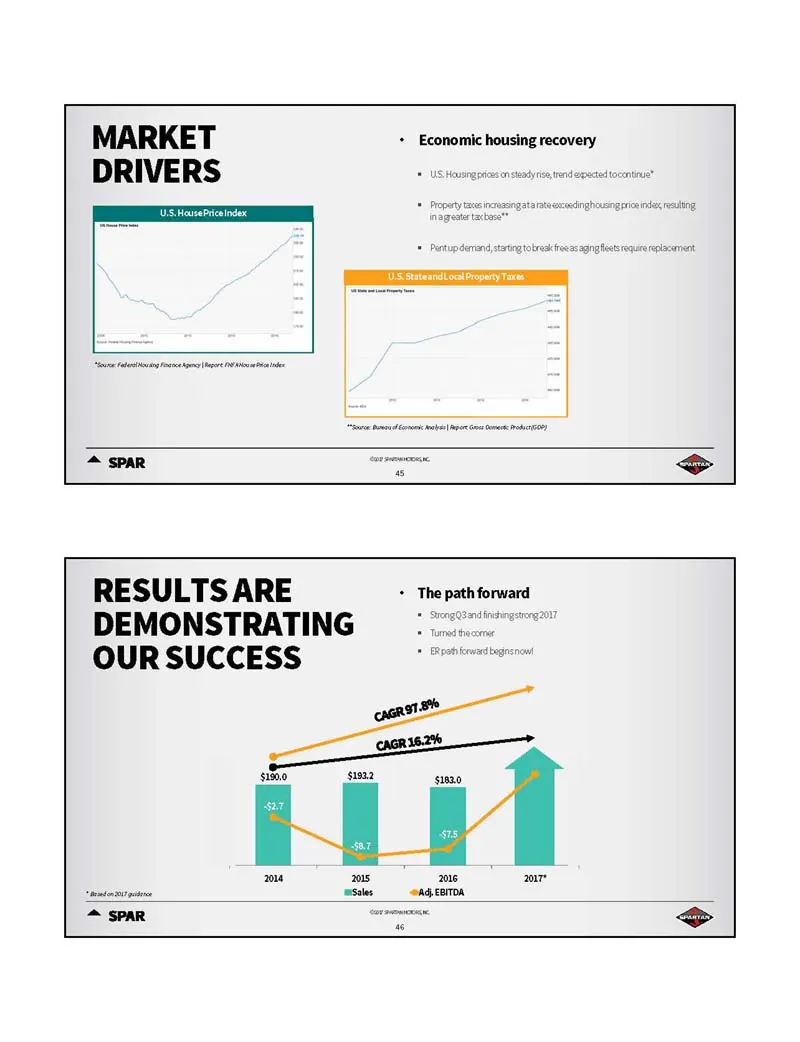
MARKET + Economic housing recovery DRIVERS “ screener RESULTS ARE Teena DEMONSTRATING = 2 OUR SUCCESS ca cAGRI6.2% $10 $1932 Ae ™ bir bs aT penis a
Slide 25: Specialty Vehicles: Steve Guillaume
SPAR SPECIALTY VEHICLES STEVE GUILLAUME | extend PRESIDENT, SPECIALTY VEHICLES
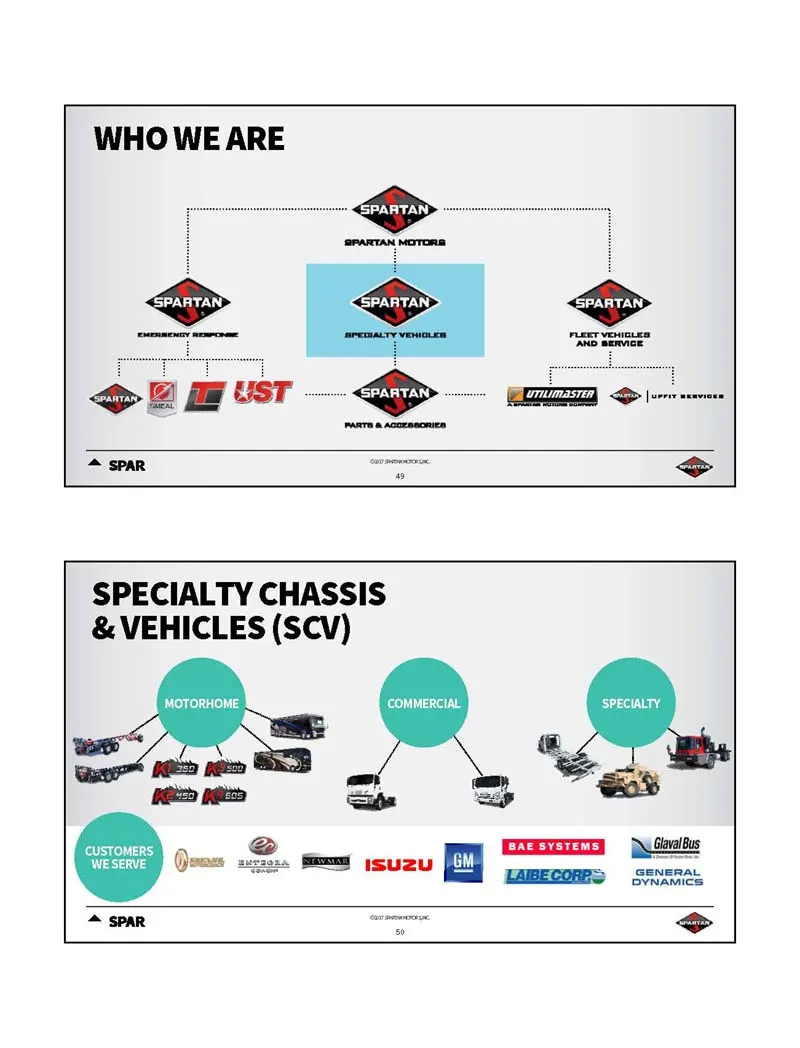
Slide 26: Who We Are: Specialty Chassis & Vehicles
WHO WE ARE "aso Semis "SPARTAN, SPARTAN a UST .- SPARTAN z ee. Se SPECIALTY CHASSIS & VEHICLES (SCV) MOTORHOME ay «& T — & 3 es custonen : Sis @-2---2 = = = Pea = S
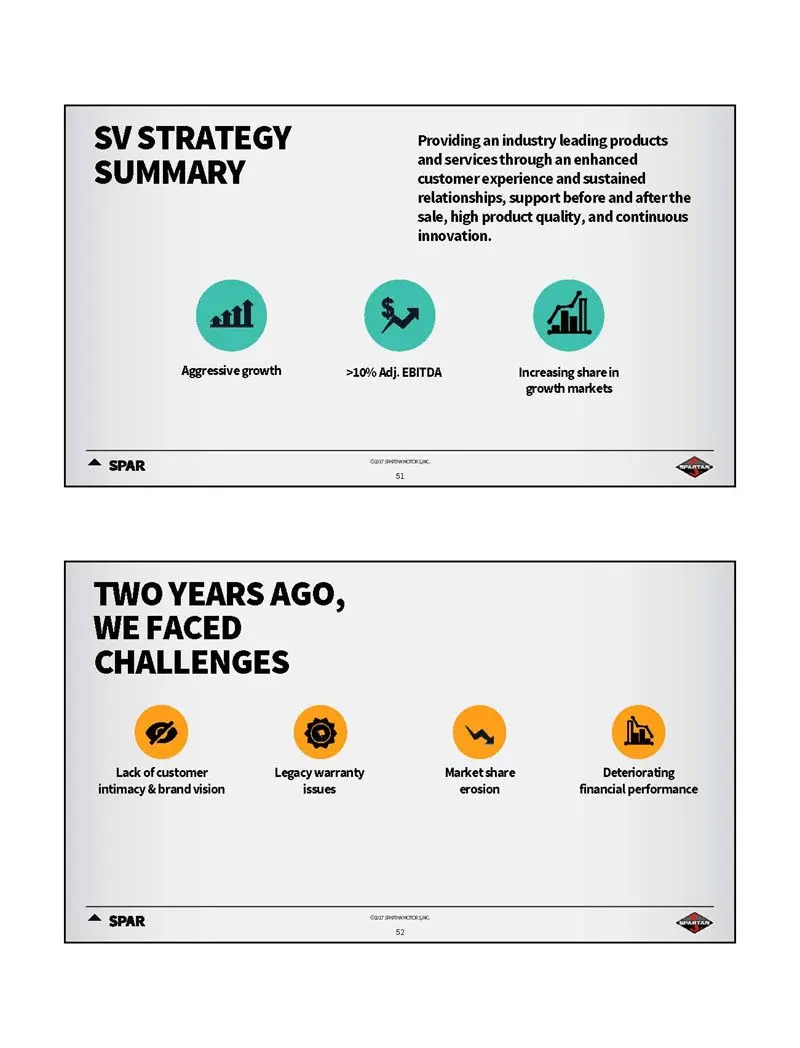
Slide 27: SV Strategy Summary
SV STRATEGY SUMMARY Providing an industry leading products and servicesthrough an enhanced customer experience and sustained relationships, support before and afterthe sale, high product quality, and continuous innovation. Aggressive growth >10% Adj. EBITDA Increasing sharein growth markets TWO YEAR
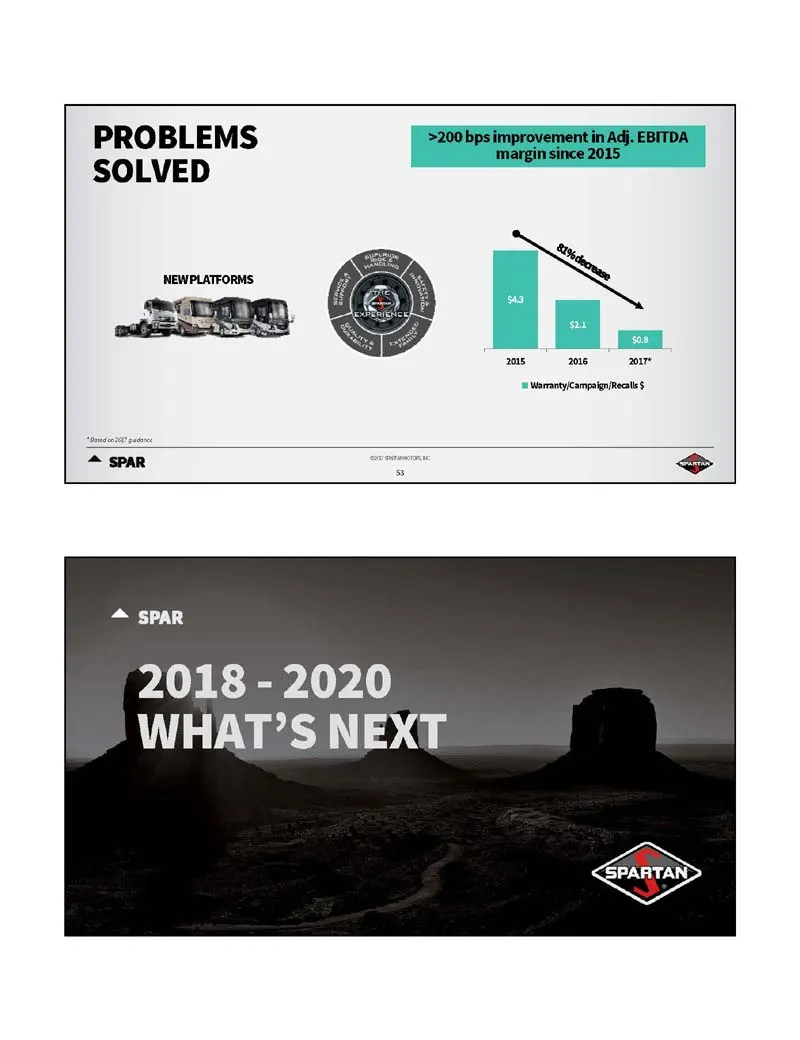
Slide 28: Problems Solved; What's Next
PROBLEMS ONT cleat te EBITDA SOLVED Worantyicampaig/Recls§ SPAR 2018 - 2020 WHAT’S NEXT
Slide 29: Continued Favorable Macro Environment
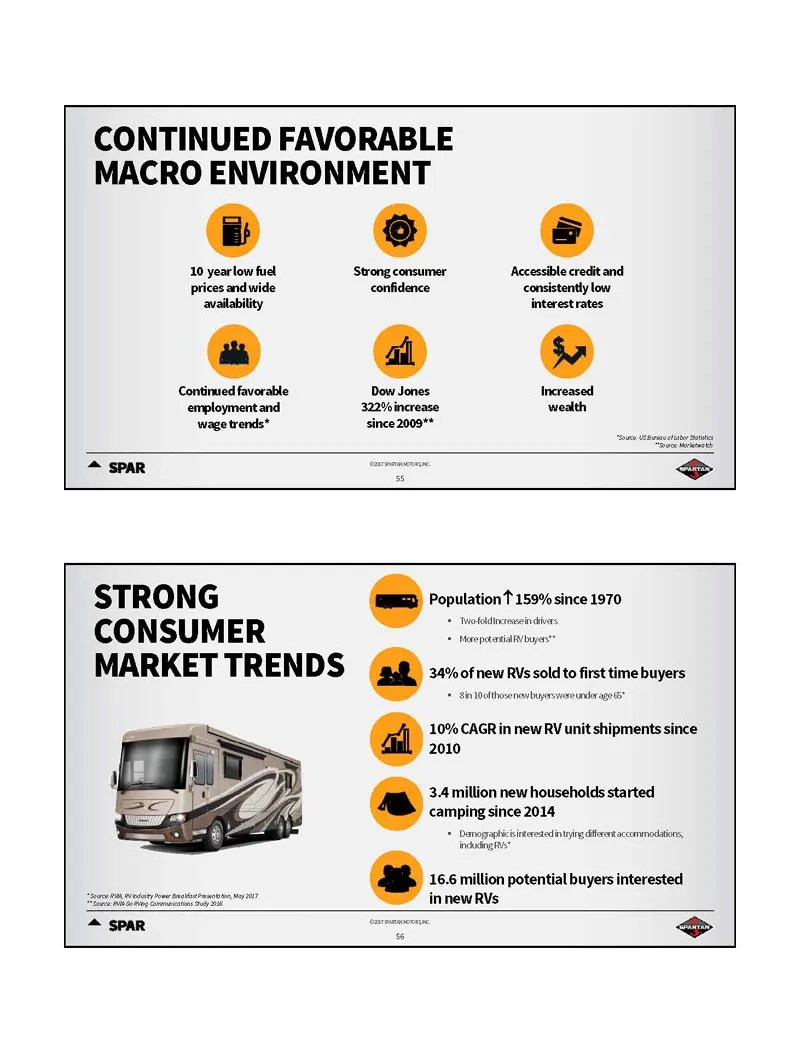
CONTINUED FAVORABLE MACRO ENVIRONMENT 10 yearlow fuel Strong consumer Accessible credit and prices andwide confidence consistently low availability interest rates Continued favorable Dow Jones Increased employmentand 322%increase wealth wage trends* since2009"* STRONG Population T 159% since 1970 CO
Slide 30: Growth: Motorhome and Commercial
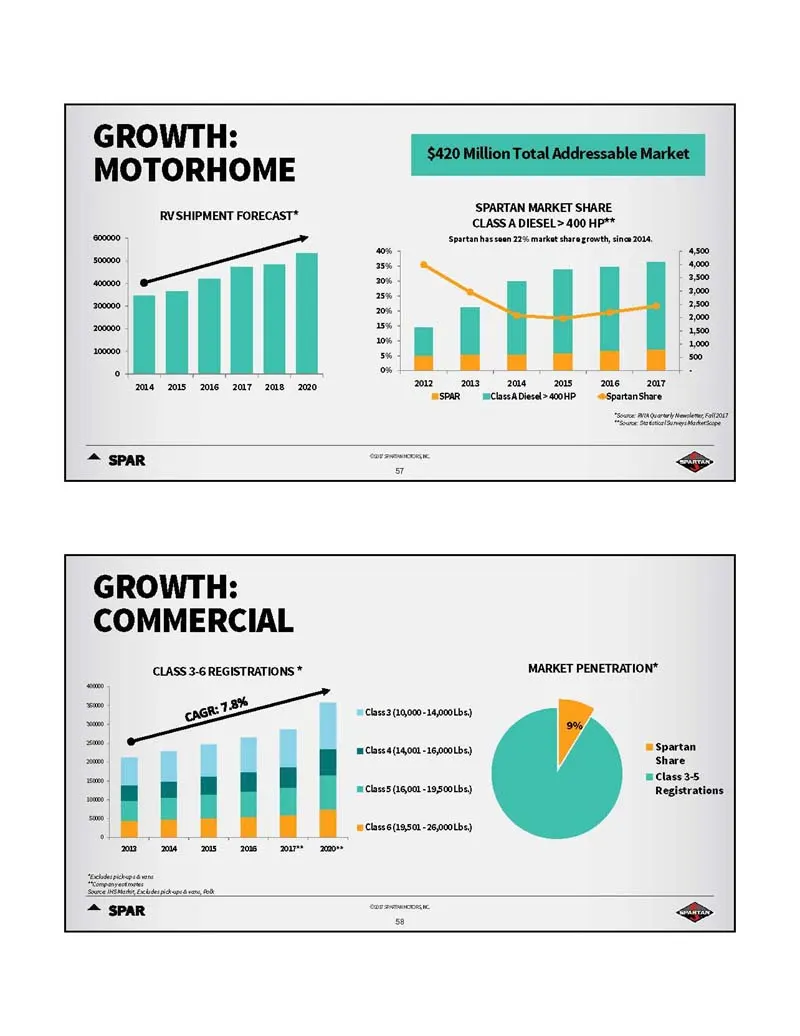
GROWTH: MOTORHOME RVSHIPMENT FORECAST* =|_—sa ‘SPARTAN MARKET SHARE CLASS A DIESEL> 400 HP** Spartan bassean 20% markt share gronth ion 2014 6 400 a6 000 8 2300 25% 3000 2% 2300 2000 : | | ce az m3 | ame ams ame 207 TRSPAR— mclazADietd>a00HP —Spartanshare ~ SPAR GROWTH: COMMERCIAL CLASS 3-6 REGISTRA
Slide 31: Why We're Leaders
SPAR WHY WE’RE LEADERS CROSS FUNCTIONAL CUSTOMER SUPPORT
Slide 32: First to Market Innovation
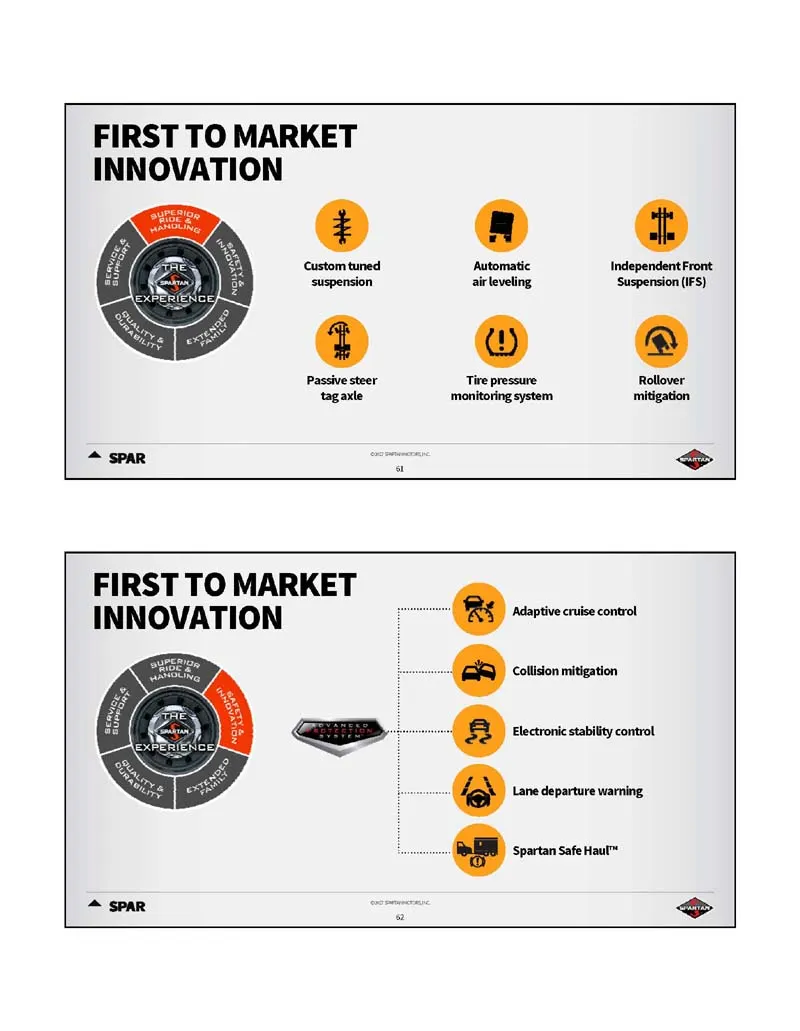
FIRST TO MARKET INNOVATION Tire pressure: Rollover onitoring system mitigation FIRST TO MARKET INNOVATION -_
Slide 33: Future Innovation; Customer Support as Differentiator
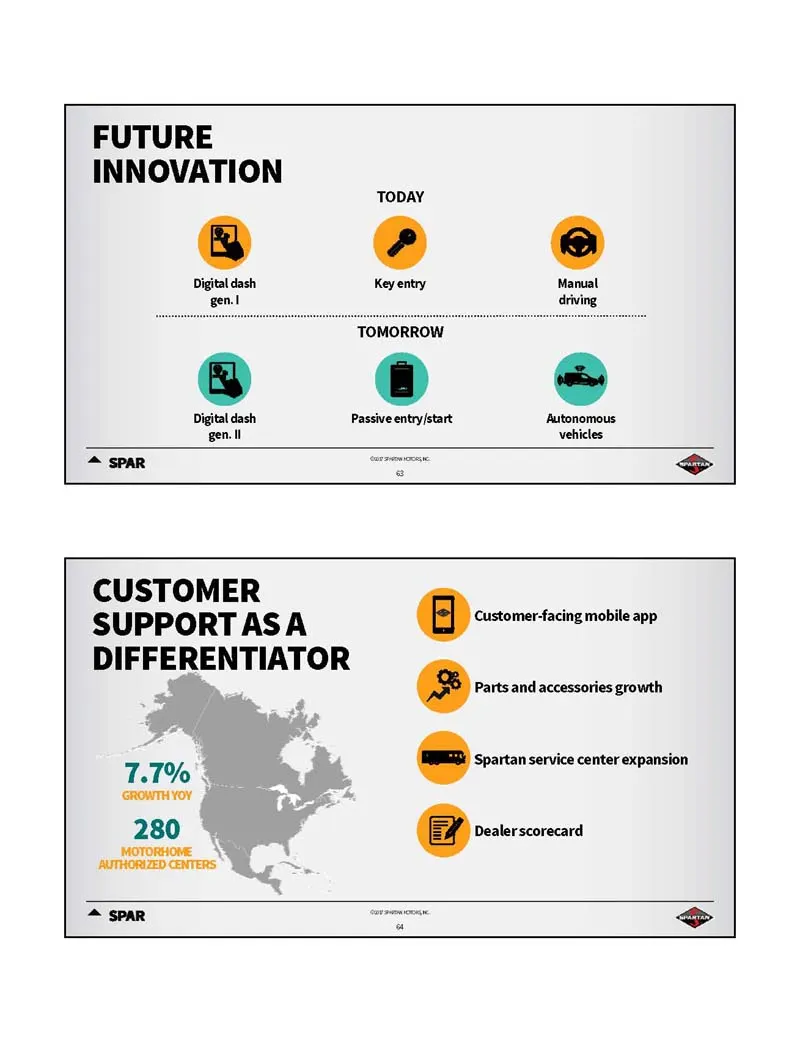
FUTURE INNOVATION TODAY Keyentry Manual iving “TOMORROW — Passive entry/start Autonomous vehicles E S CUSTOMER SUPPORT ASA DIFFERENTIATOR 7.7% ‘GROWTHYOY 280 a Customer-facing mobile app s Parts and accessories growth = Spartan service center expansion ia esteemed ~ SPAR
Slide 34: Results and the Future
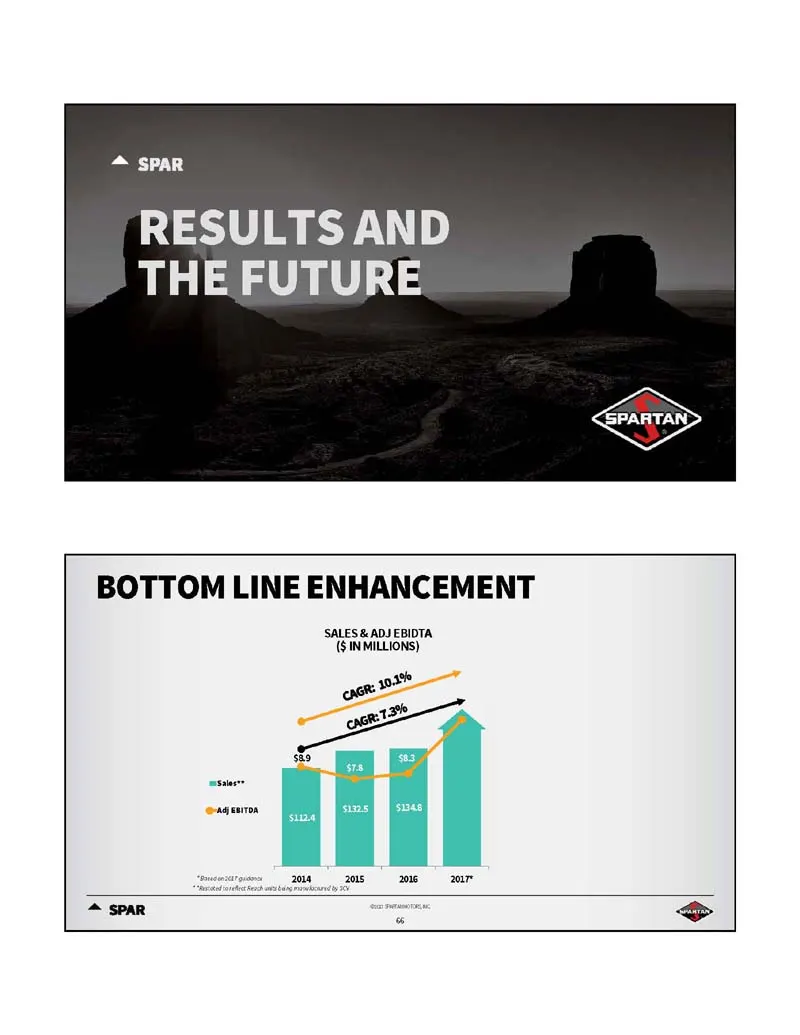
SPAR RESULTS AND THE FUTURE BOTTOM LINE ENHANCEMENT SALES & ADJ EBIDTA (SINMILLIONS)
Slide 35: Tremendous Opportunity Ahead
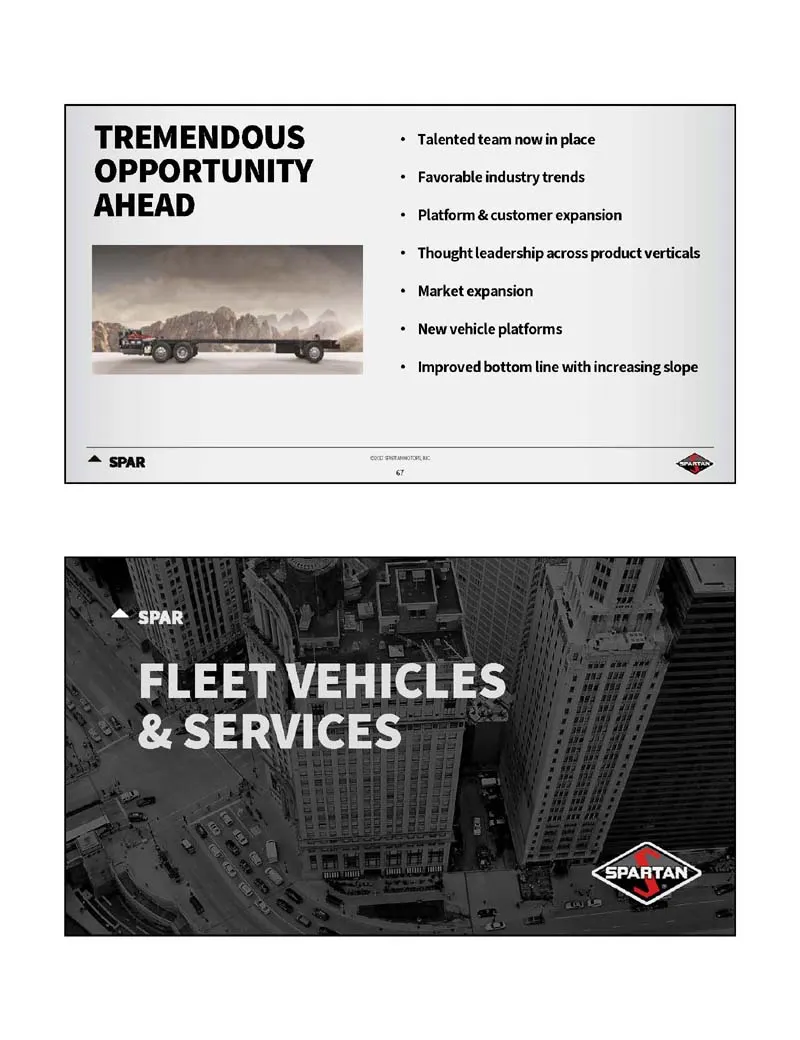
TREMENDOUS + Talented team now in place OPPORTUNITY + Favorable industry trends AHEAD + Platform & customer expansion EE + Thought leadership across product verticals Market expansion a) + New vehicle platforms Improved bottom line with increasing slope Ste < Ss SPAR FLEET VEHICLES & SERVICES
Slide 36: Fleet Vehicles & Services: Tom Ninneman
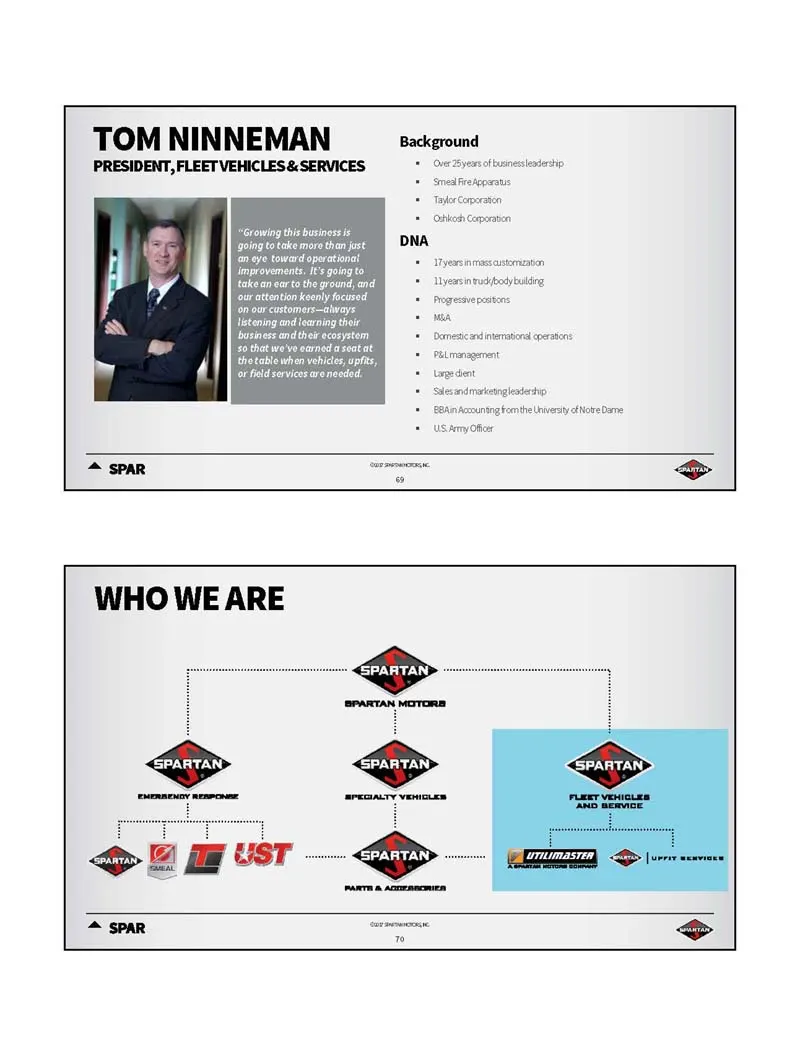
TOM NINNEMAN PRESIDENT, FLEET VEHICLES & SERVICES sessed med rekepactis Tylor Corperaten nhc Cxperaon owing thie bosinoss ‘going totakemorethan jst MUAIaN aye toward operational + Tyecinmasanemuagin Improvements. I's going to EERO 6 Tyersintwitodytulirg cour attention keenly fcused + Progeamepantone
Slide 37: Fleet Vehicles and Services (FVS)
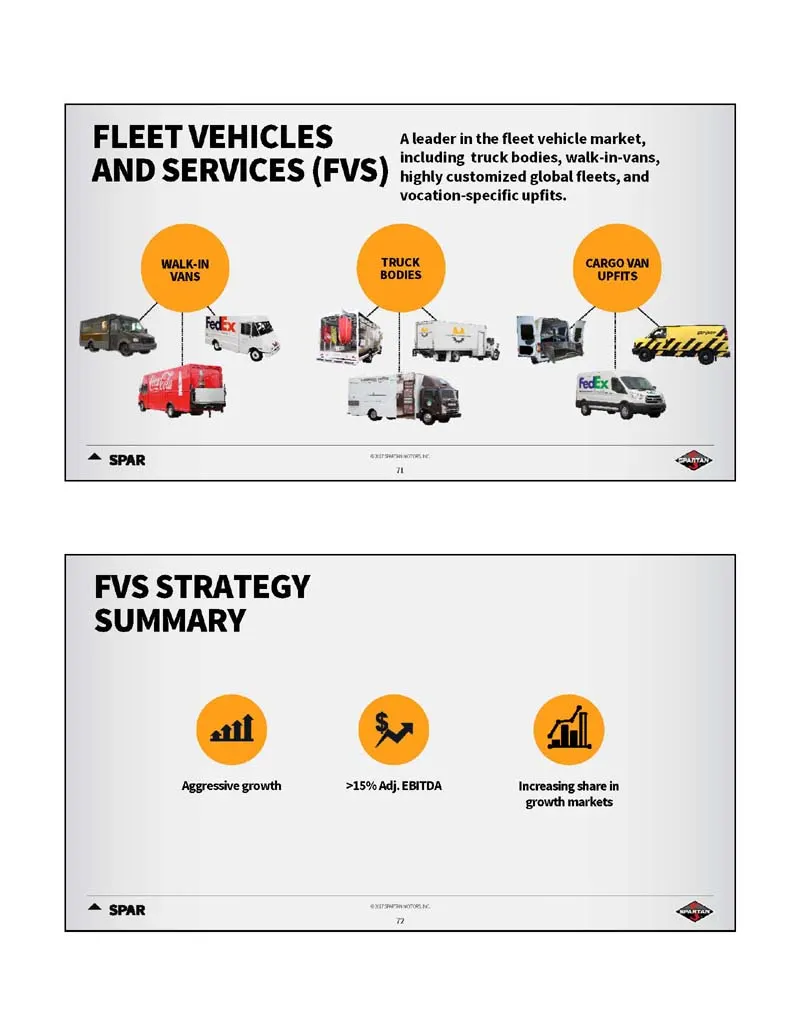
FLEET VEHICLES Aleader inthe feet vehicle market AND SERVICES (FVS) sishiy customized global tects, and vocation-specific upfits. at eT rs ~ SPAR S&S FVS STRATEGY SUMMARY ‘Aggressive growth 1596 Adj. EBITDA ase 7
Slide 38: Go-to-Market Strategy
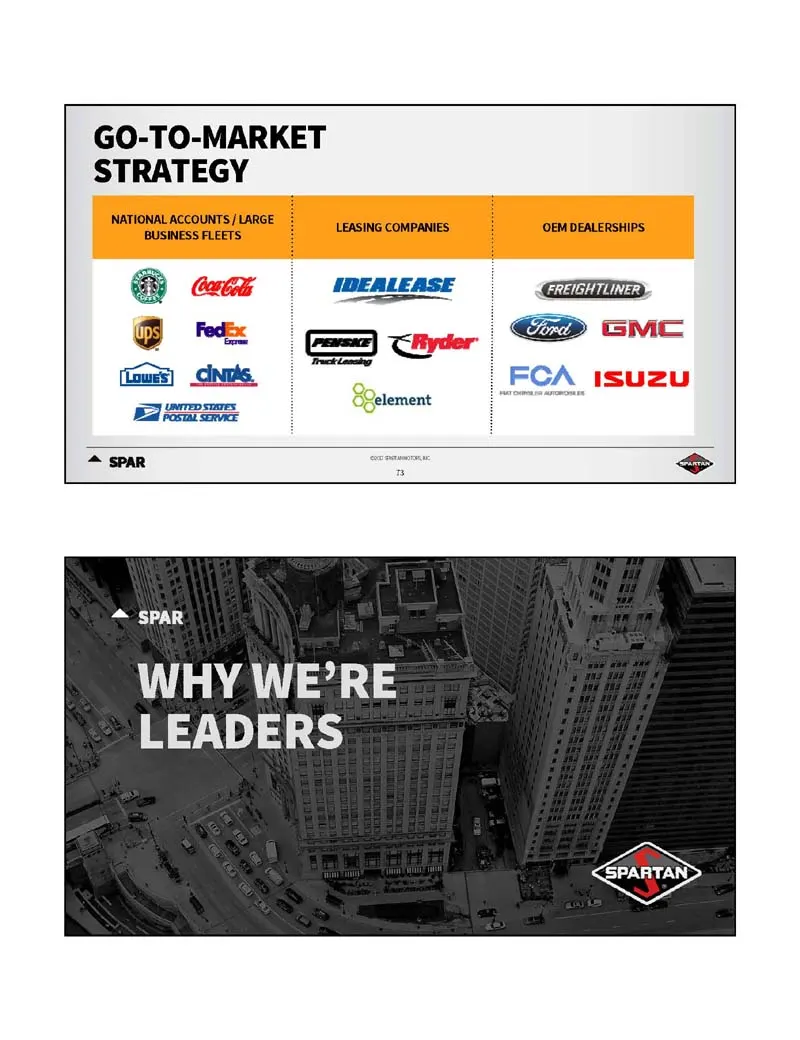
GO-TO-MARKET STRATEGY NATIONAL ACCOUNTS / LARGE NAL ACCOUNTS/LARGE | ASING COMPANIES & IDEALEASE ——~ es Ge (Tewes} _clnutAs. G2element (OEM DEALERSHIPS & FREIGHTLINER omc ECA SPAR SPAR WHY WE’RE LEADERS
Slide 39: Fleet Growth Opportunities; FVS Market Share
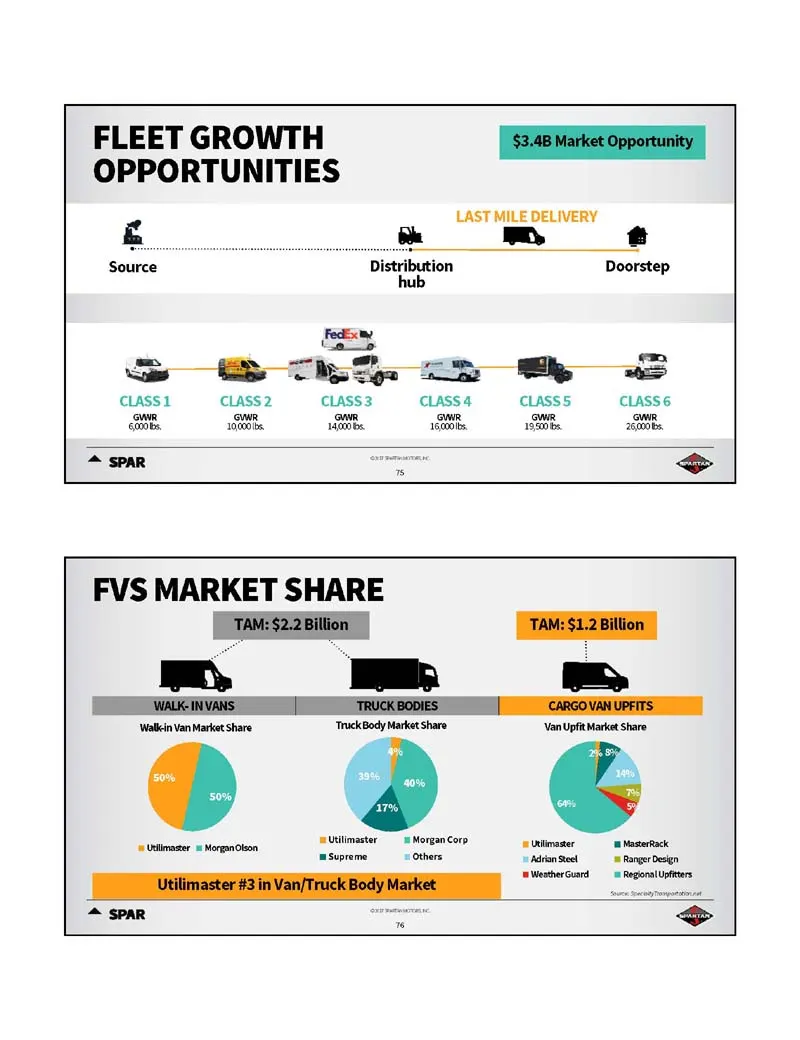
FLEET GROWTH "sea Market oppor OPPORTUNITIES LAST MILE DELIVERY Distribution Doorstep hub cLASS1 CLAss2 cLass3 CLASS 4 CLASS5 classé awe cue owe owe owen ame 6b, 0000 bs, abs 16000, sab 26000, ~ SPAR aa } FVS MARKET SHARE Ea Li p. ae eUulimaster = MorganCorp keer |) immer oo wmSupreme Others AéanSte
Slide 40: FVS Van/Truck Body Market Outlook
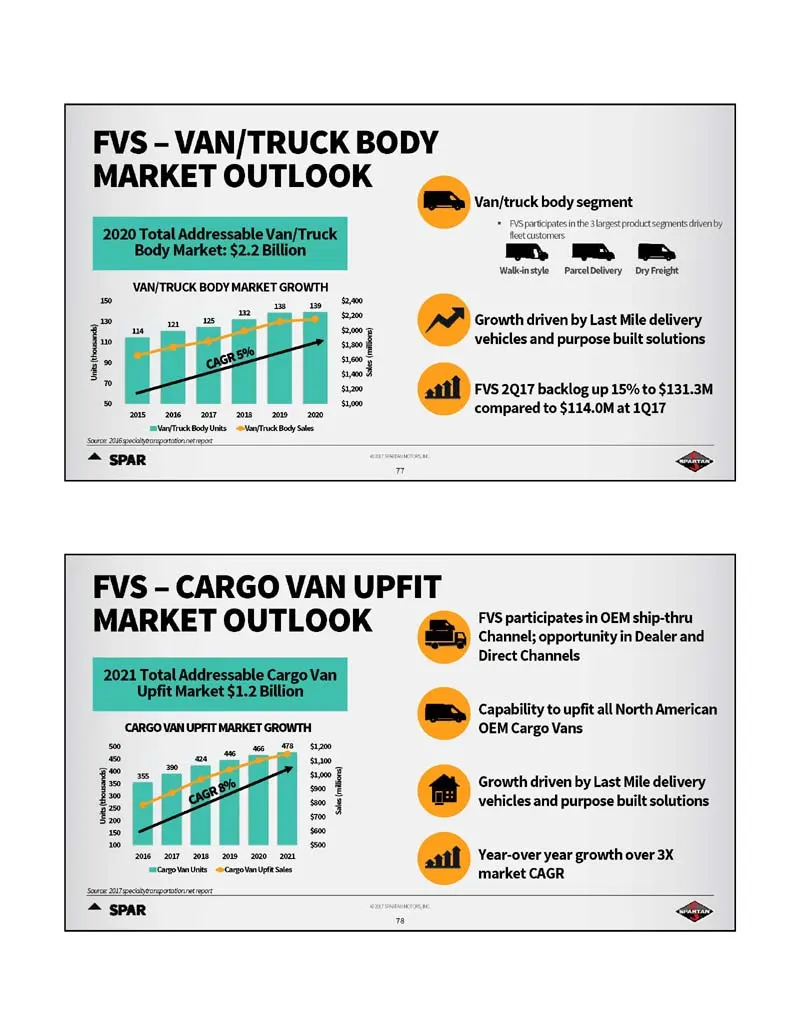
FVS - VAN/TRUCK BODY MARKET OUTLOOK a~ \VAN/TRUCK BODY MARKET GROWTH Vanitruck body segment inthe Slnpetpocitsegrentsienby Walkinsiyle ParelDatvery ry Freight = nw Growth driven by Last Mile delivery j=, vehicles and purpose built solutions eal sae FVS 2917 backlog up 15% to $131.3M a as a compared
Slide 41: Competitive Advantage
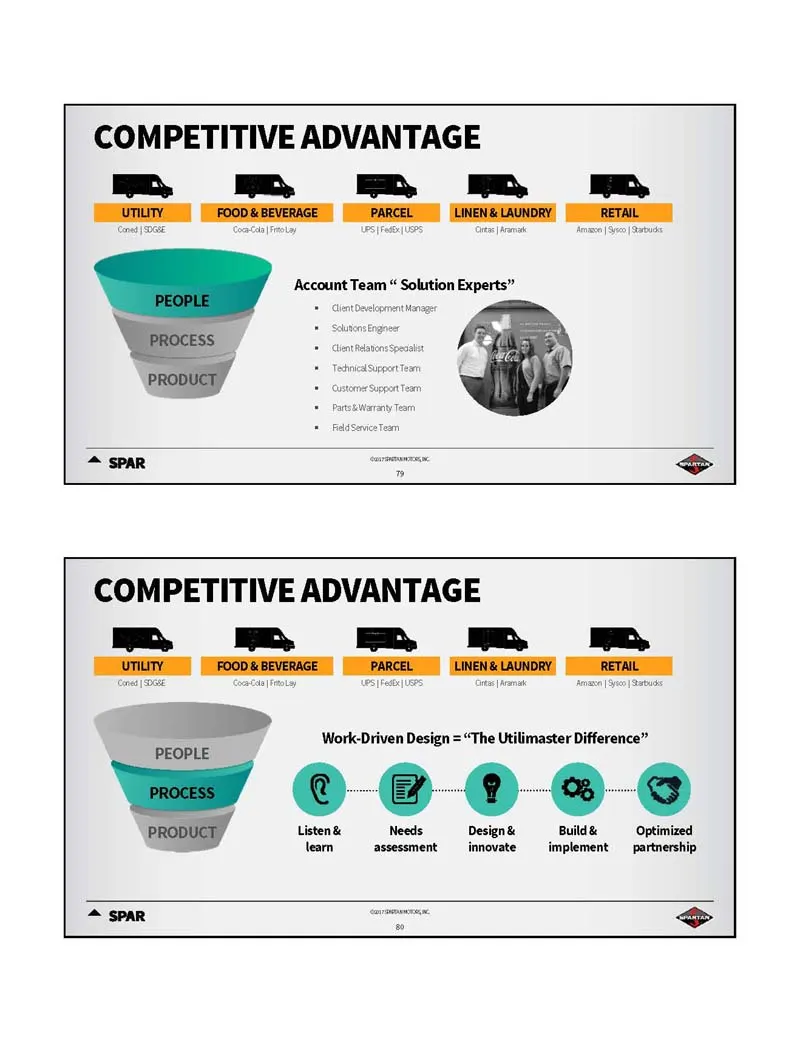
COMPETITIVE ADVANTAGE »> Work-Driven Design = “The Utilimaster Difference” PEOPLE pRopucty Listen & Needs ign & Build& Optimized learn assessment fate implement —_ partnership. Ay ae =>
Slide 42: Competitive Advantage: Product Customization
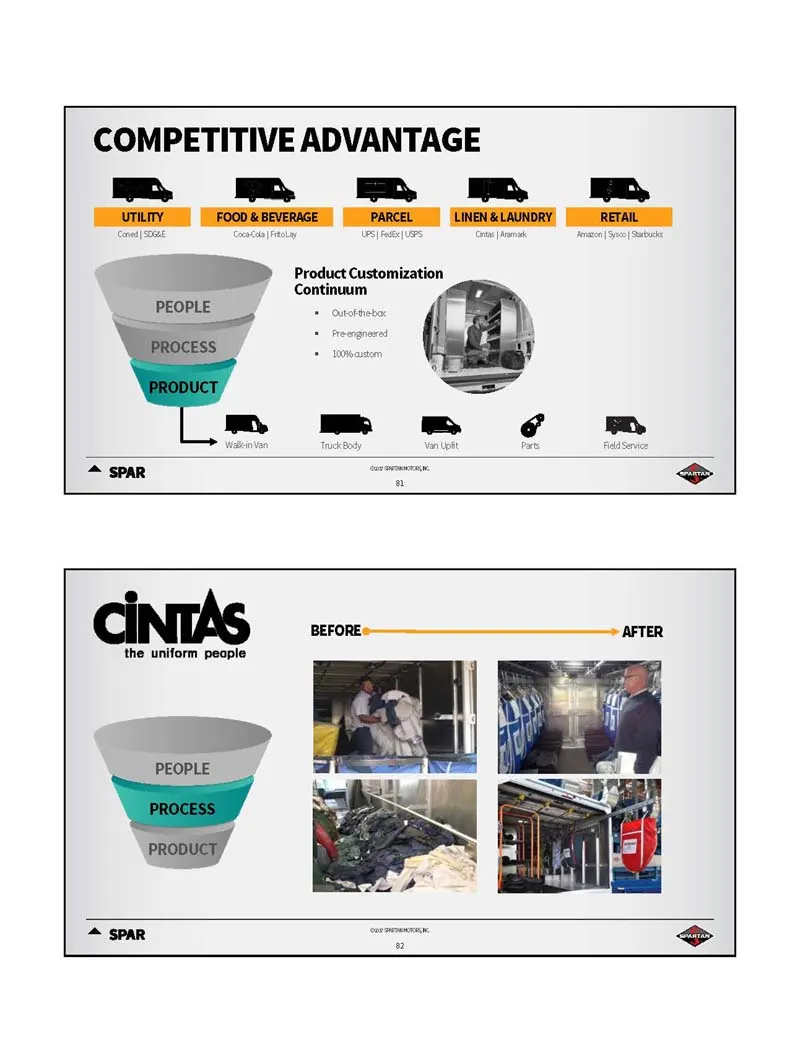
COMPETITIVE ADVANTAGE Product Customization Continuum _ — = == £ =
Slide 43: The Uniform People
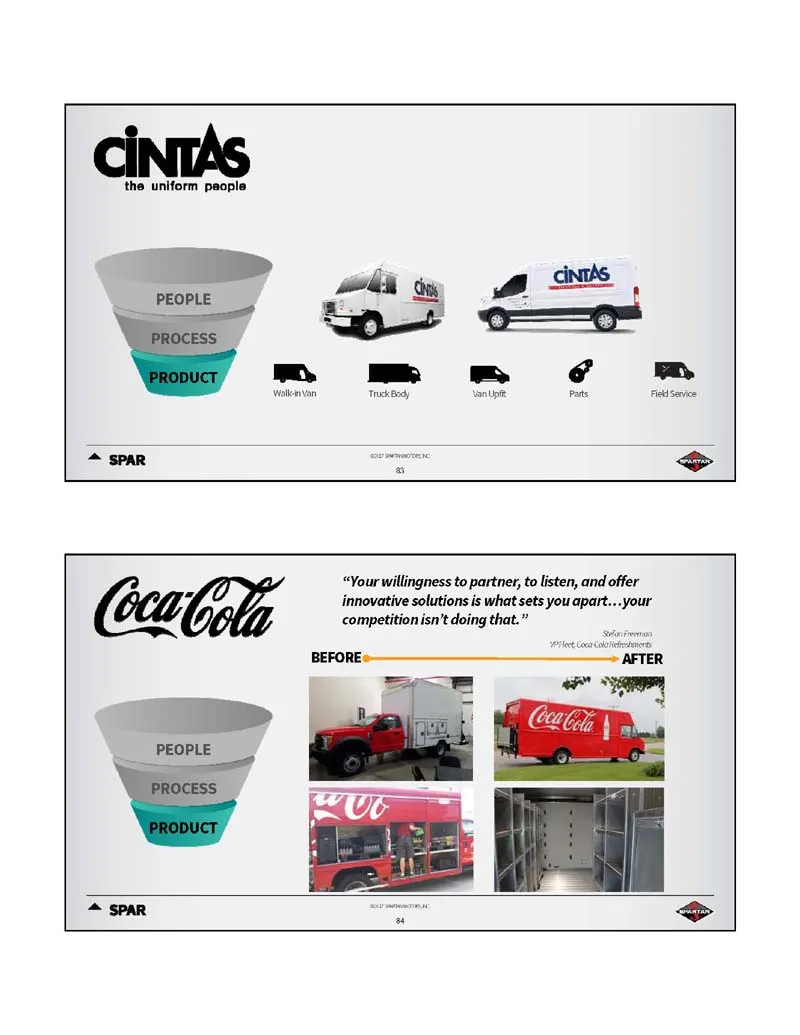
the uniform people Wallan Thuy Van “Your willingness to partner, to listen, and offer Cll innovative solutions is what sets you apart...your competition isn't doing that.”
Slide 44: Leading Toward 2020
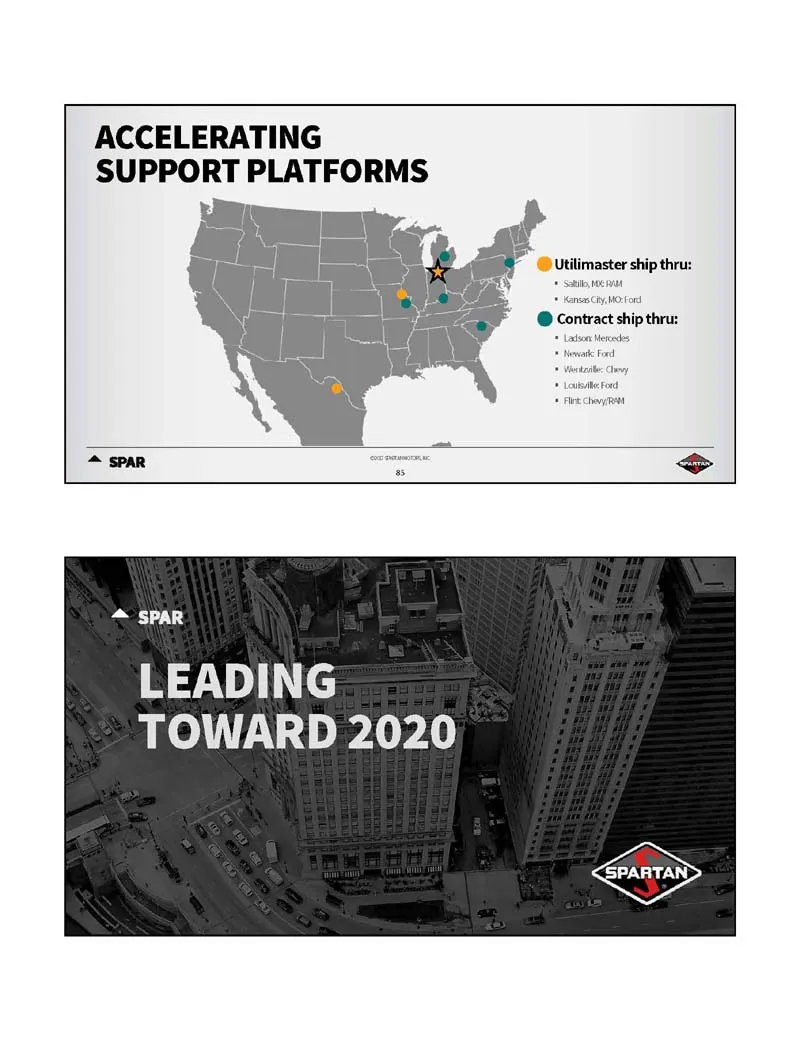
ACCELERATING SUPPORT PLATFORMS SPAR LEADING TOWARD 2020
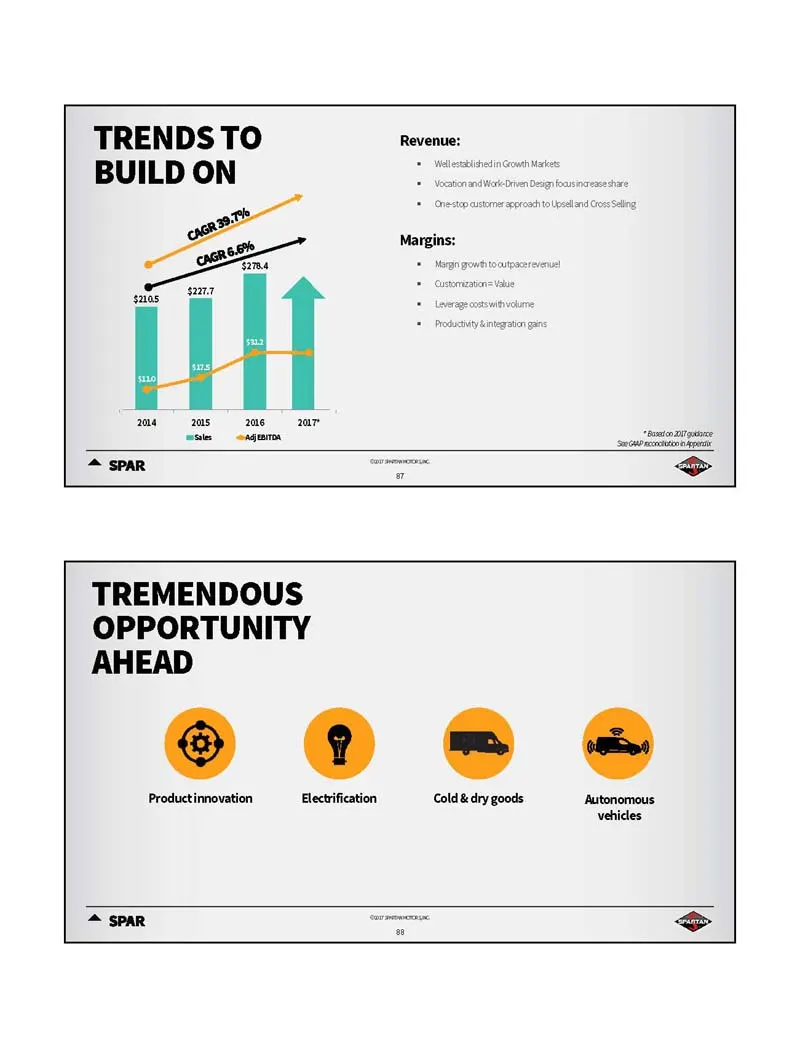
Slide 45: Tremendous Opportunity Ahead
TREMENDOUS OPPORTUNITY AHEAD Productinnovation Electrification Cold & dry goods
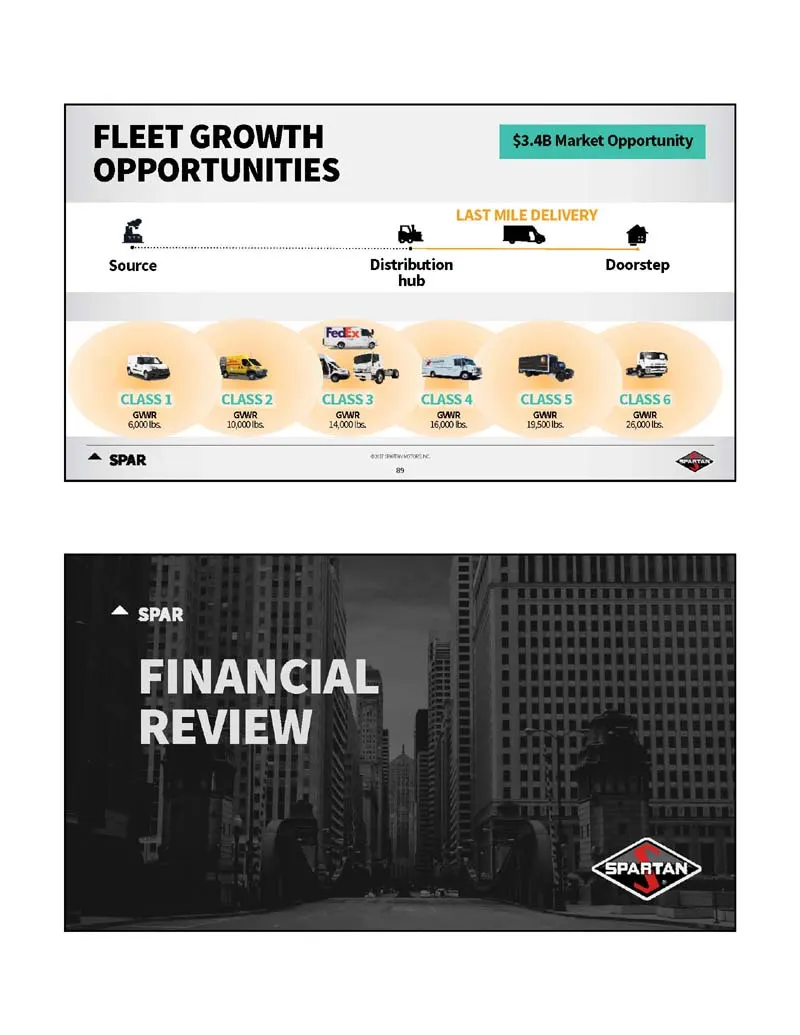
Slide 46: Fleet Growth Opportunities
FLEET GROWTH OPPORTUNITIES & oe Source Distribution hub $3.48 Market Opportunity SPAR FINANCIAL REVIEW
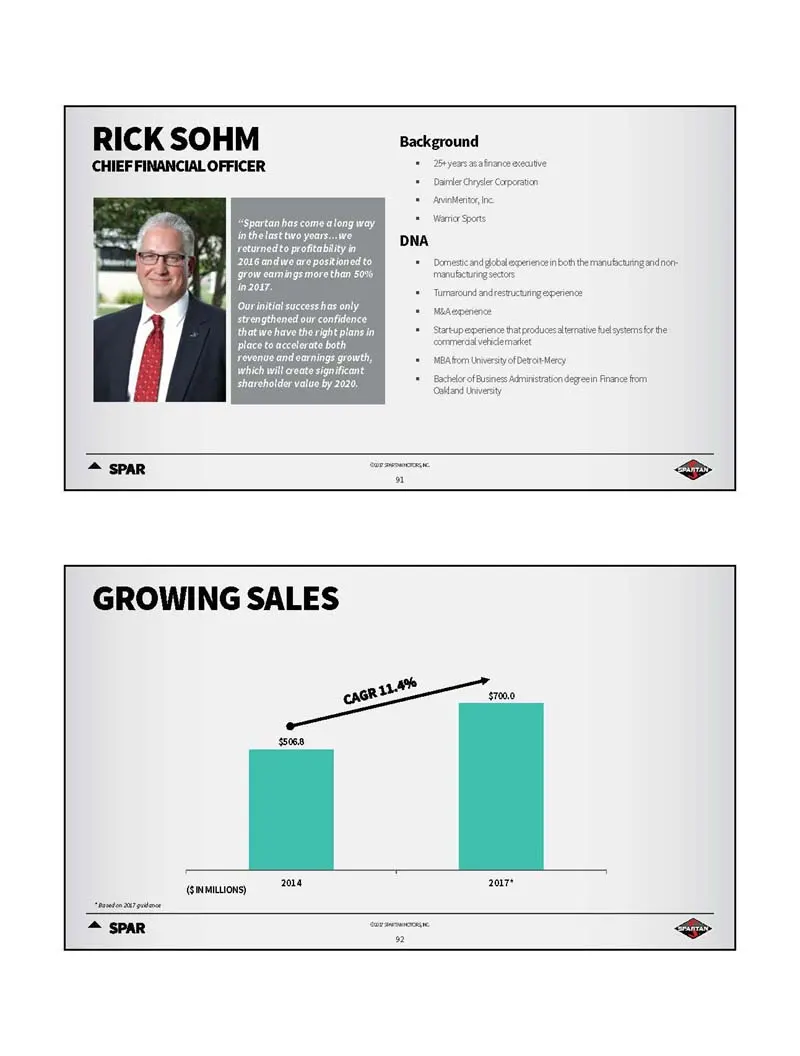
Slide 47: Financial Review: Rick Sohm
RICK SOHM CHIEF FINANCIAL OFFICER “Spartan has come along way Jntholast ovo years..we roturnedto profitability 12016 andwe are poskioned to {row earings more than 50% in2017. ur initial successhas only strengthened our confidence thatwe have the right plans in lace to accelerate both ‘revenue and ea
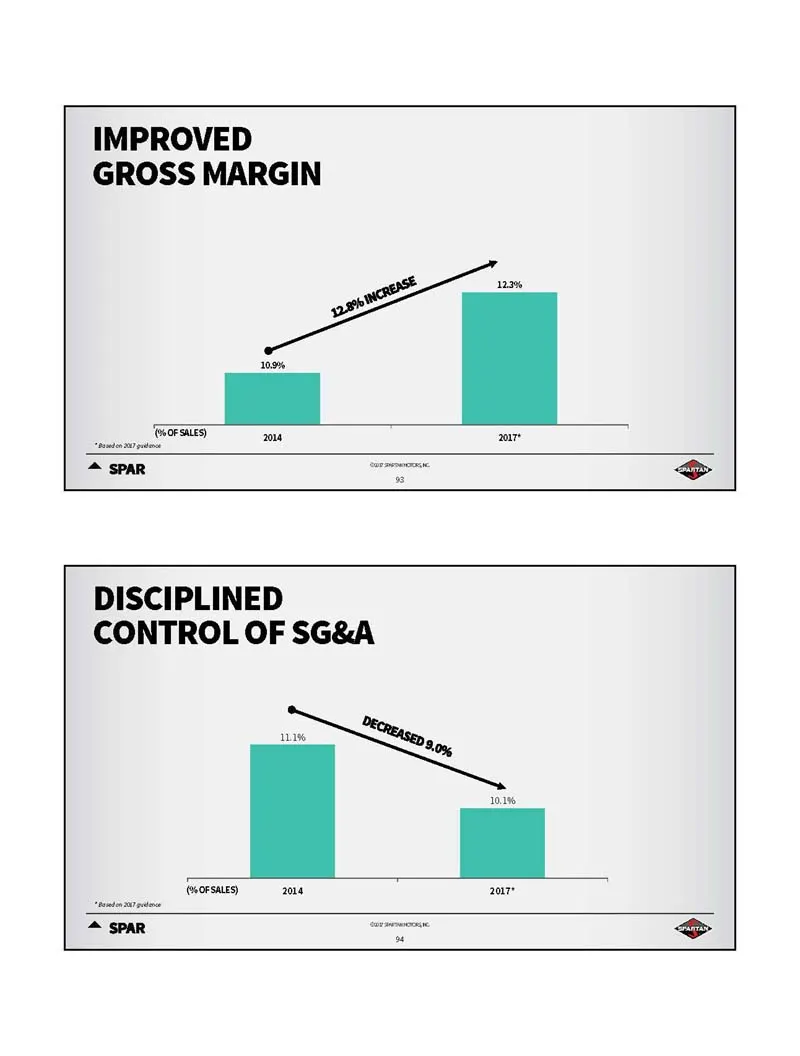
Slide 48: Improved Gross Margin; Disciplined Control of SG&A
IMPROVED GROSS MARGIN ~ SPAR pS DISCIPLINED CONTROL OF SG&A ese
Slide 49: Improved Adjusted EBITDA; Balance Sheet Strength & Liquidity
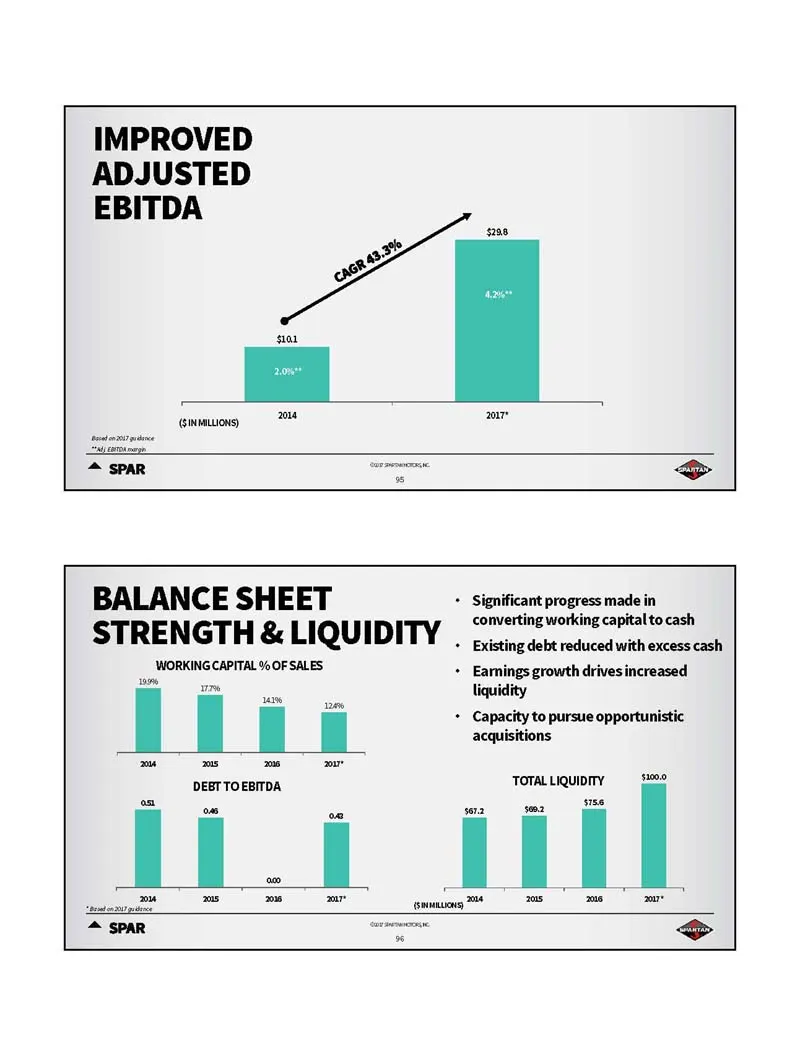
IMPROVED ADJUSTED EBITDA sian sas mmuonsy 7 20" ~ SPAR a BALANCE SHEET STRENGTH & LIQUIDITY . + Significant progress made in converting working capital to cash Existing debt reduced with excess cash Be CATAL ROFSALES + Earnings growth drivesincreased os liquidity = + Capacity to pursue opportunistic
Slide 50: Financial Strength; FY2017 Guidance
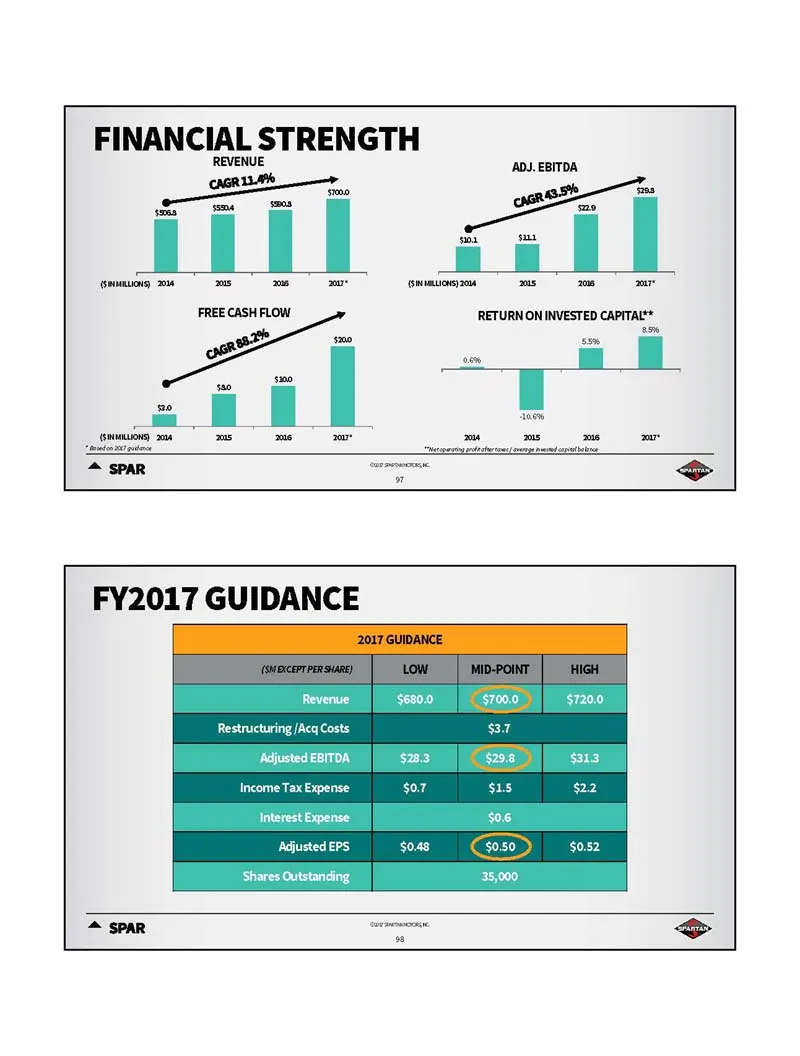
FINANCIAL STRENGTH ‘ADJ. EBITDA © an (onmuons 24 ‘mamuiensj20u mas 2m mr FREE CASH FLOW RETURN ON INVESTED CAPITAL | a gravis 2a es FY2017 GUIDANCE Revenue Restructuring /Acq Costs Adjusted EBITDA Income Tax Expense Interest Expense Adjusted EPS Shares Outstanding
Slide 51: Long-Term Sales Targets
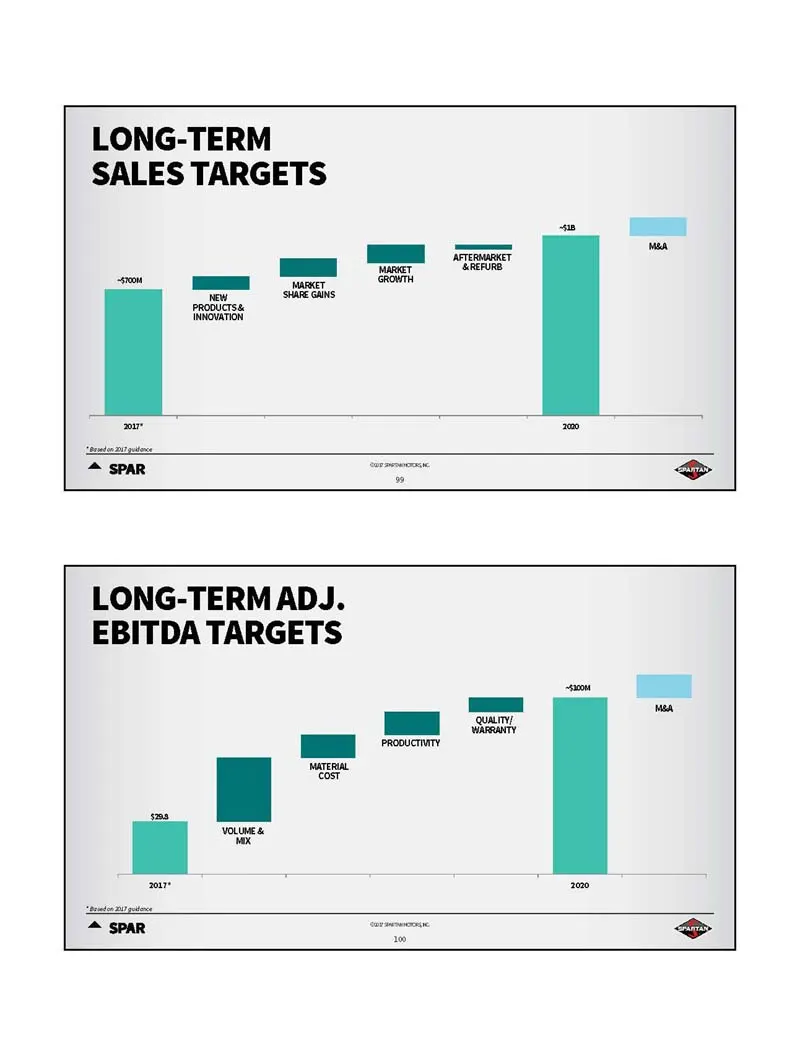
LONG-TERM SALES TARGETS +0 = | oo ome SPAR S LONG-TERMADJ. EBITDA TARGETS a =
Slide 52: Business Units' Long-Term Adj. EBITDA Targets
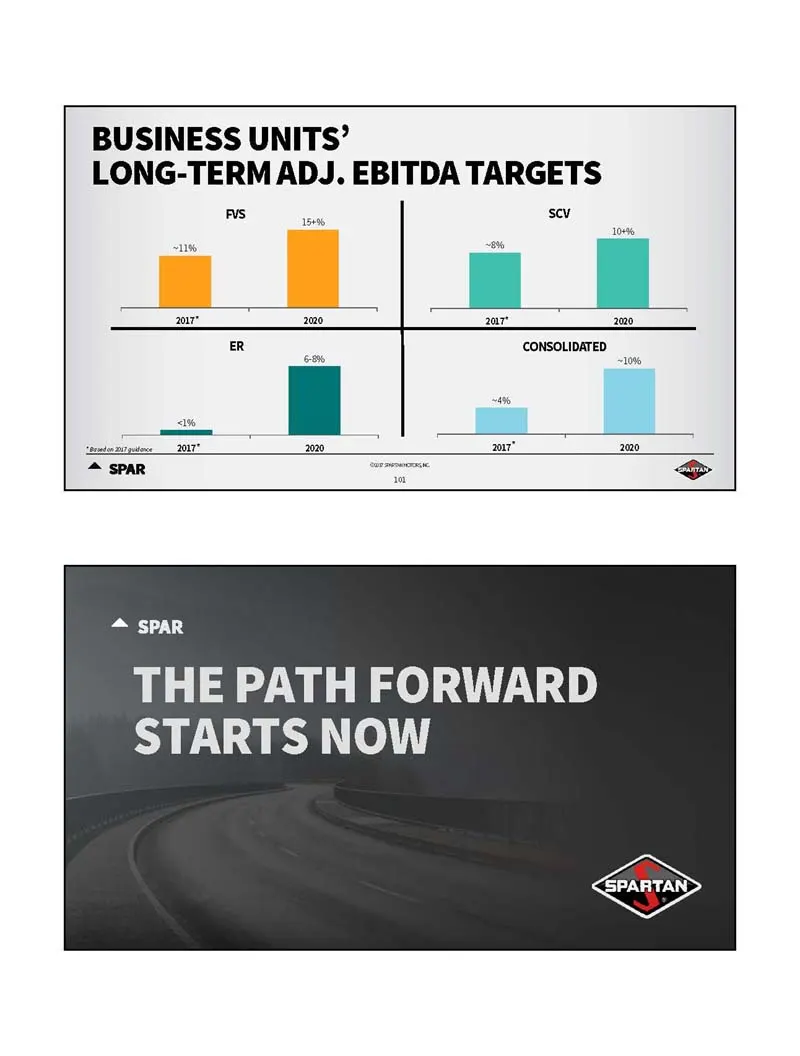
BUSINESS UNITS’ LONG-TERM ADJ. EBITDA TARGETS Fs _ sev 11% ~2% ant" 200 207 200 ER ‘CONSOLIDATED 6 10% SPAR THE PATH FORWARD STARTS NOW
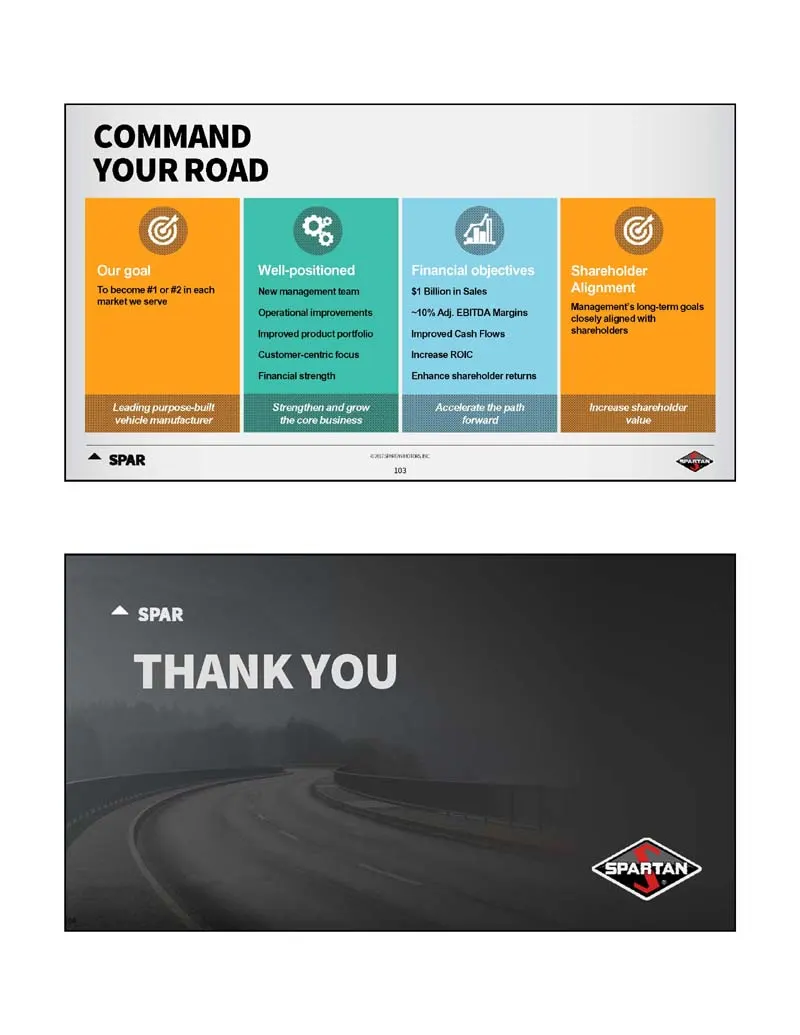
Slide 53: The Path Forward Starts Now
COMMAND YOUR ROAD e | = [al o ‘Tobecen marketwe serve ‘Management’ long-term goals ‘Operationalimprovements _-~10% Ad. EBITDA Margins eee Improved productportioio Improved Cash Flows shareholders CCustomer-centic focus Increase ROIC Financial strength Enhance shareholder turns SPAR THANK YOU
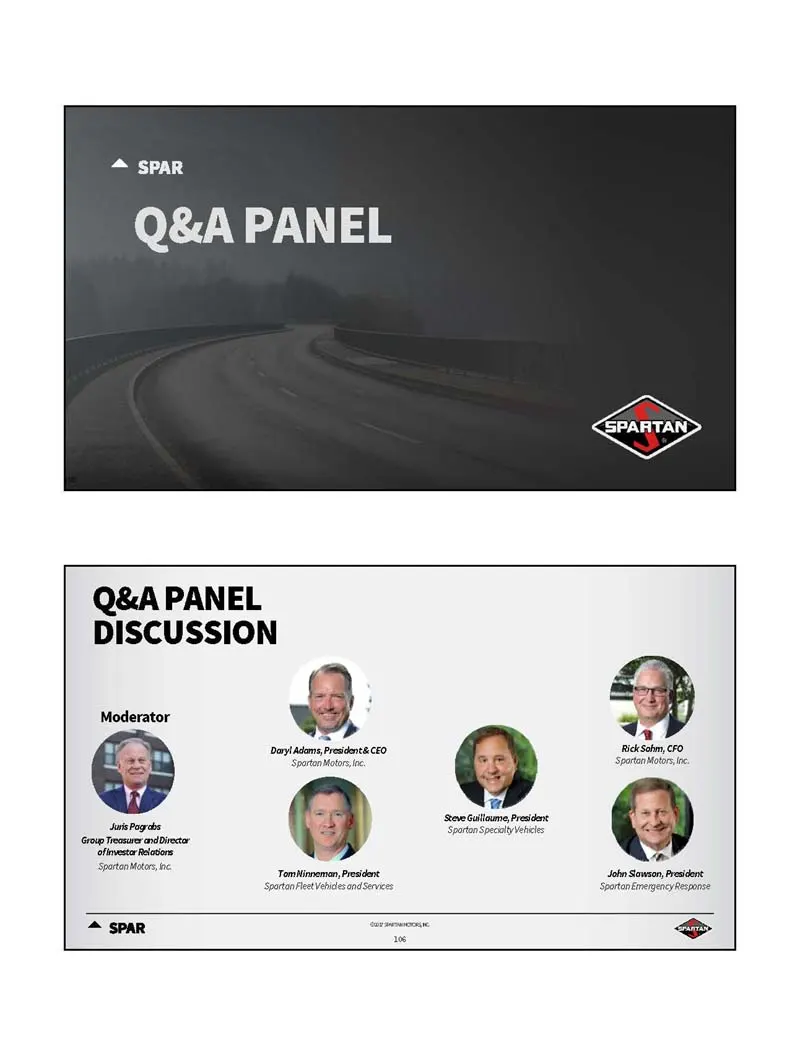
Slide 54: Q&A Panel Discussion
SPAR Q&A PANEL Q&A PANEL DISCUSSION
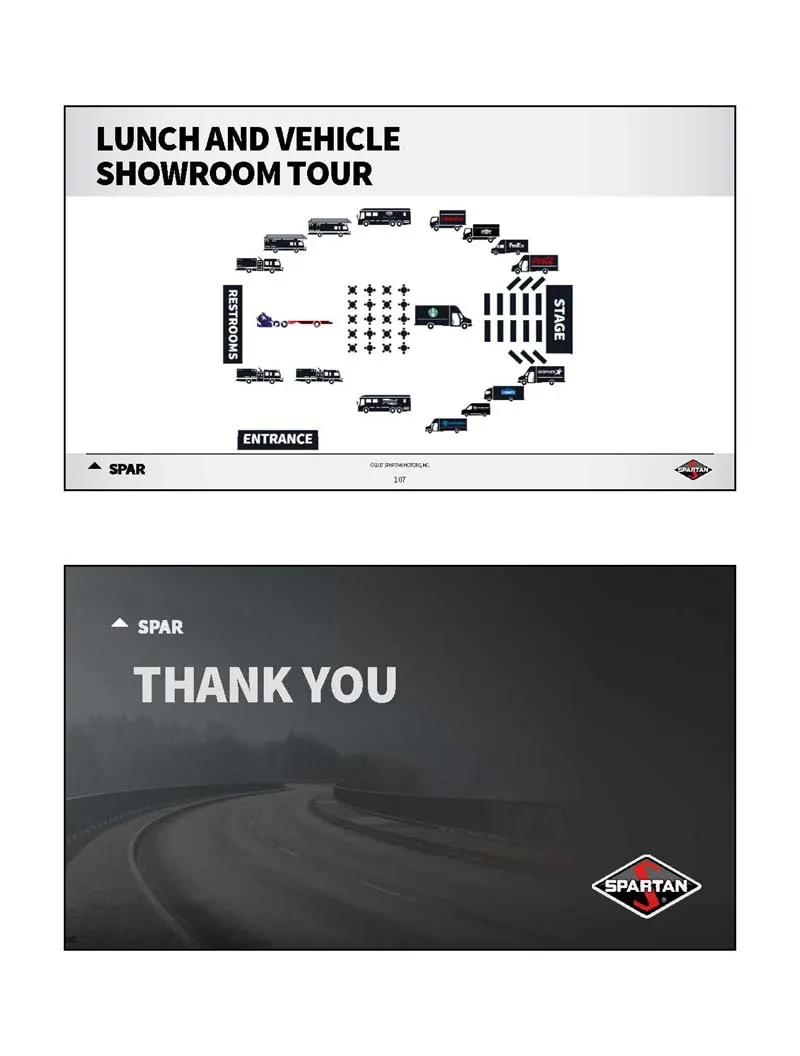
Slide 55: Lunch and Vehicle Showroom Tour
LUNCH AND VEHICLE SHOWROOM TOUR SWOOUISIY = a ps | P| - a = = SPAR THANK YOU
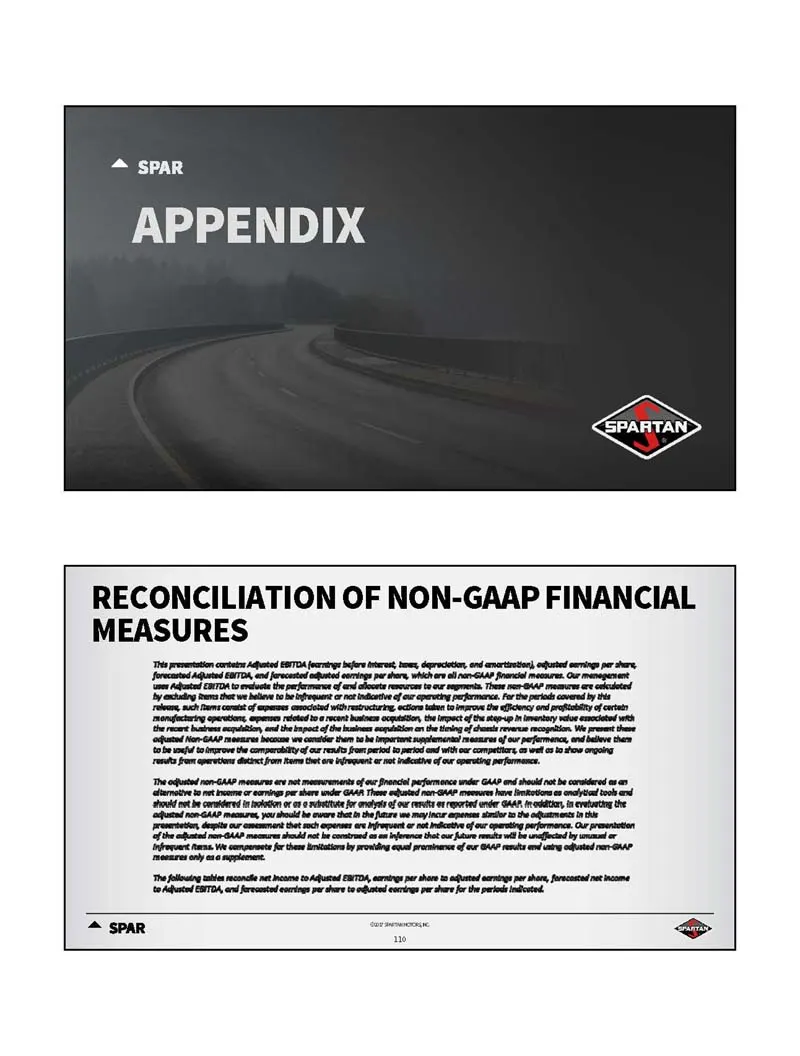
Slide 56: Appendix: Reconciliation of Non-GAAP Financial Measures
SPAR APPENDIX RECONCILIATION OF NON-GAAP FINANCIAL MEASURES freer Atel ETA, od share wich re ‘er Ainted CTA the parker of rd chert eect 0 re By extadry Remade we Me ob rrp’ ort inert rane Pr rds covered ys at fy a inpetof e Sere baer nd te tec of une (he ting of rv We pret tw (fund Nar CUP een the t
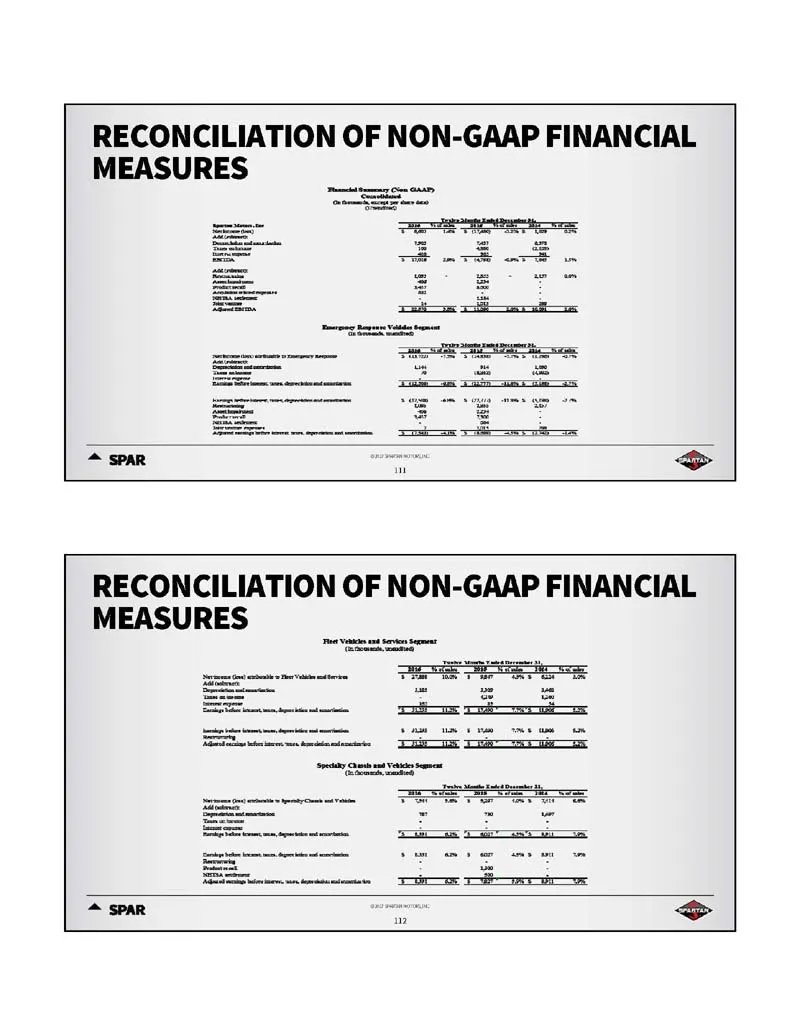
Slide 57: Reconciliation of Non-GAAP Financial Measures
RECONCILIATION OF NON-GAAP FINANCIAL MEASURES RECONCILIATION OF NON-GAAP FINANCIAL MEASURES
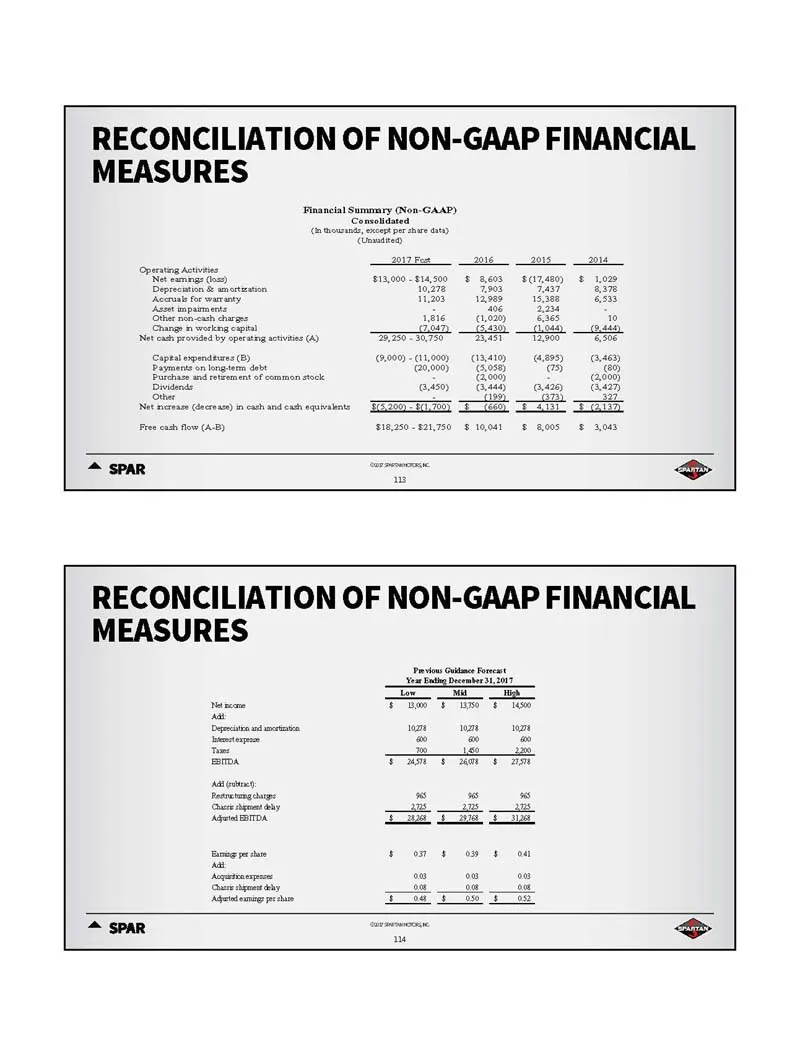
Slide 58: Reconciliation of Non-GAAP Financial Measures
RECONCILIATION OF NON-GAAP FINANCIAL MEASURES RECONCILIATION OF NON-GAAP FINANCIAL MEASURES
Slide 59: Thank You
SPAR THANK YOU
Source: SEC EDGAR · 8-K filed Oct 12, 2017
More decks from Shyft Group Inc
 Merger or Acquisition (April 2025)37 slides · Apr 29, 2025
 Q1 2025 Earnings Presentation18 slides · Apr 24, 2025
 Merger or Acquisition (April 2025)21 slides · Apr 4, 2025
 Q4 2024 Earnings Presentation17 slides · Feb 20, 2025
 Merger or Acquisition (January 2025)50 slides · Jan 13, 2025
 Merger or Acquisition (December 2024)22 slides · Dec 16, 2024