Air Transport Services Group Inc
Air Transport Services — BB&T Capital Markets Transportation Services Conference 2015
16 slides from Air Transport Services's conference presentation, Feb 10, 2015
Slide 1: The Global Leader in Midsize Wide-Body Leasing and Operating Solutions
1 The Global Leader in Midsize Wide-Body Leasing and Operating Solutions BB&T Capital Markets Transportation Services Conference February 11, 2015 Joe Hete President & Chief Executive Officer Quint Turner Chief Financial Officer Rich Corrado Chief Commercial Officer
Slide 2: Safe Harbor Statement
Except for historical information contained herein, the matters discussed in this presentation contain forward- looking statements that involve risks and uncertainties. There are a number of important factors that could cause Air Transport Services Group's ("ATSG's") actual results to differ materia
Slide 3: Differentiated Business Model
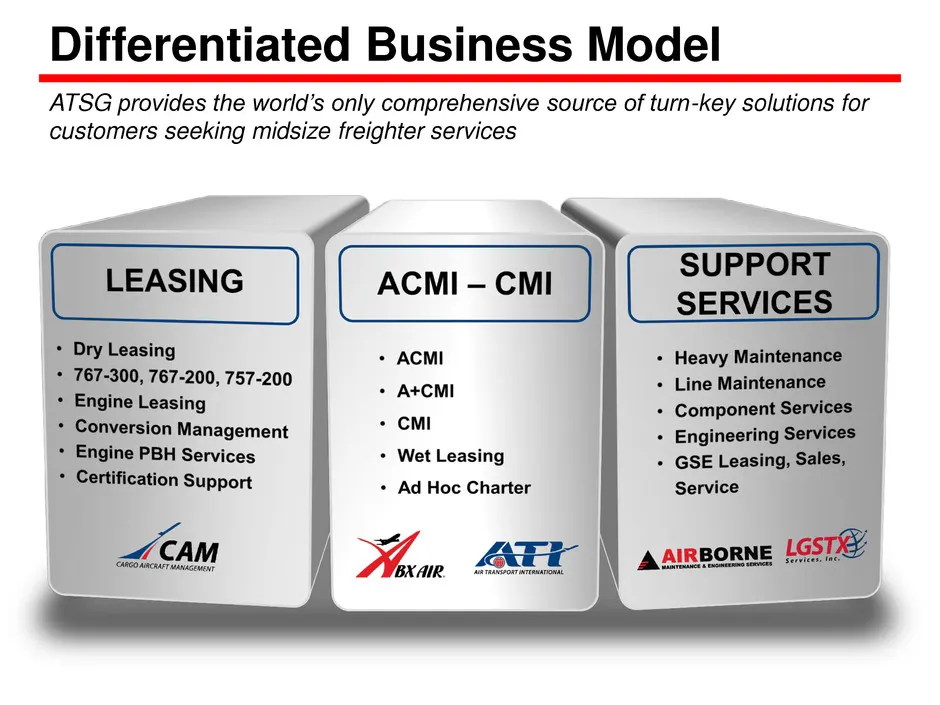
Differentiated Business Model ATSG provides the world’s only comprehensive source of turn-key solutions for customers seeking midsize freighter services
Slide 4: Value Creation Begins with Conversions
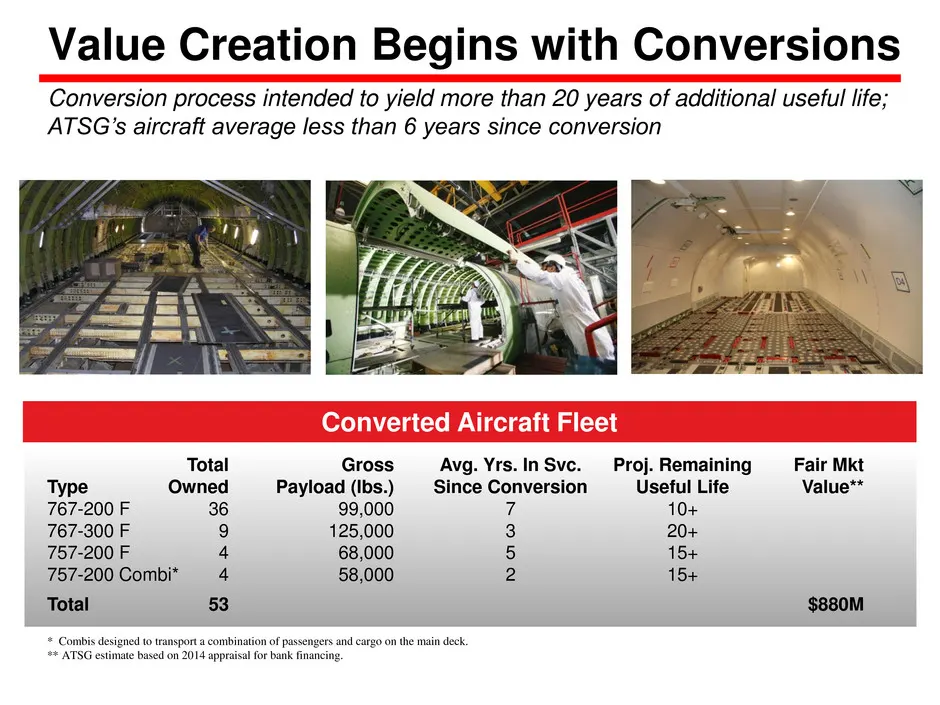
Value Creation Begins with Conversions Converted Aircraft Fleet Conversion process intended to yield more than 20 years of additional useful life; ATSG’s aircraft average less than 6 years since conversion Total Gross Avg. Yrs. In Svc. Proj. Remaining Fair Mkt Type Owned Payload (lbs.) Since Convers
Slide 5: Improved Market Dynamics
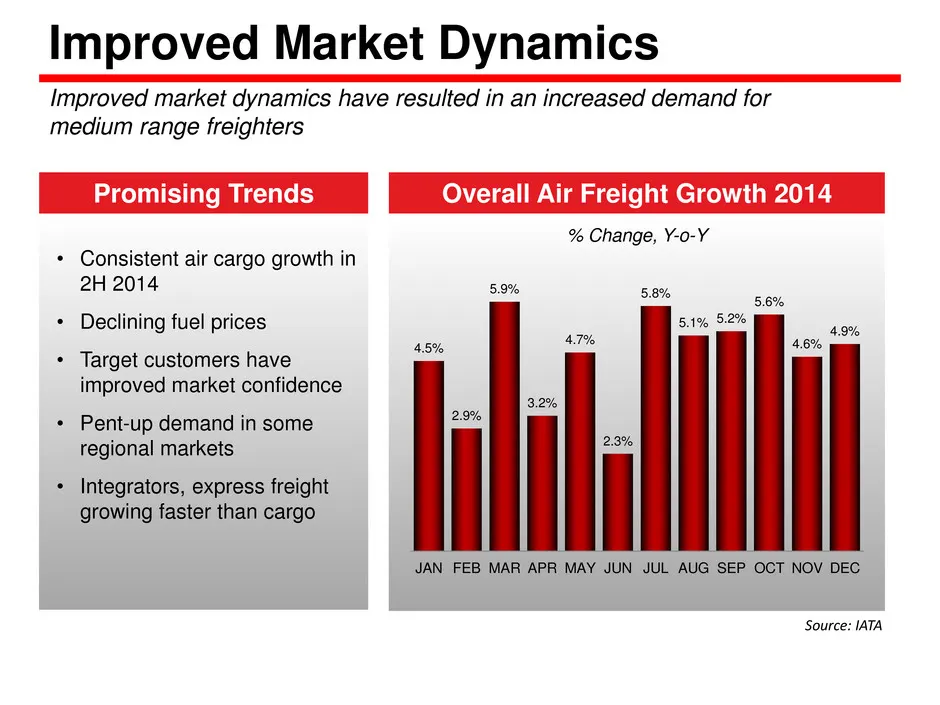
Improved Market Dynamics Source: IATA Overall Air Freight Growth 2014 % Change, Y-o-Y Improved market dynamics have resulted in an increased demand for medium range freighters Promising Trends • Consistent air cargo growth in 2H 2014 • Declining fuel prices • Target customers have improved market co
Slide 6: Wet Lease or ACMI Turn-Key Solution
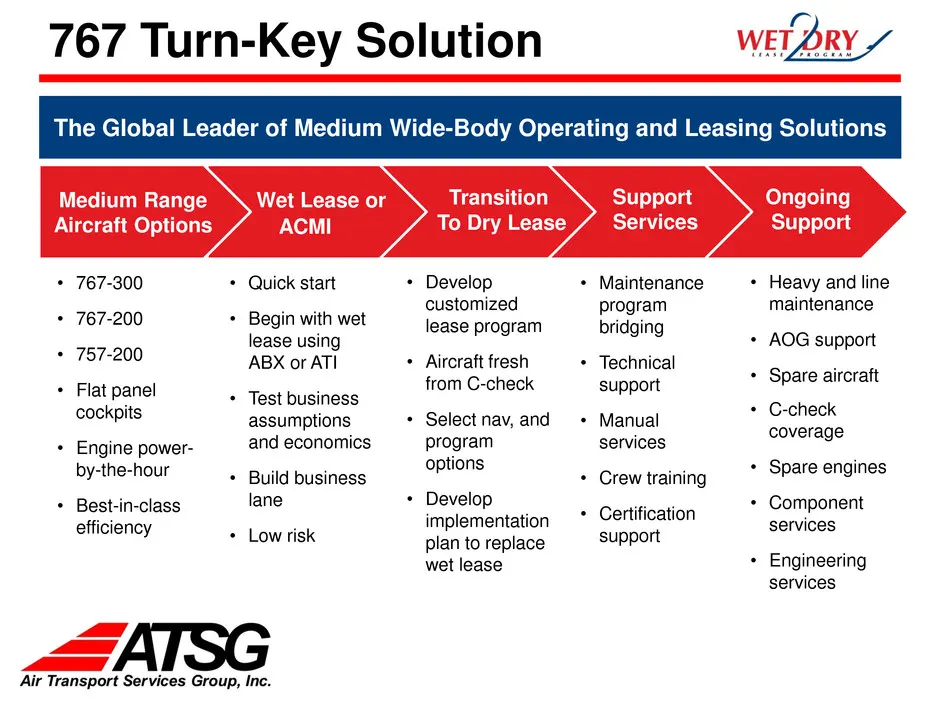
Wet Lease or ACMI 767 Turn-Key Solution • 767-300 • 767-200 • 757-200 • Flat panel cockpits • Engine power- by-the-hour • Best-in-class efficiency The Global Leader of Medium Wide-Body Operating and Leasing Solutions Medium Range Aircraft Options • Quick start • Begin with wet lease using ABX or ATI
Slide 7: Unrivaled Leader in Medium Wide-Body
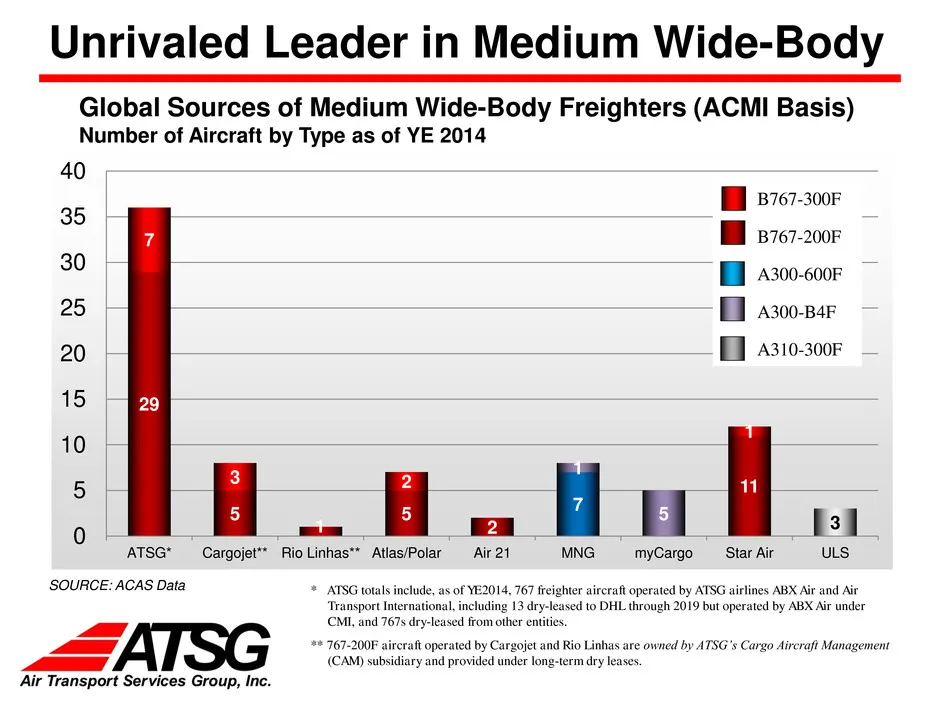
29 5 5 2 11 7 3 2 1 7 1 5 3 0 5 10 15 20 25 30 35 40 ATSG* Cargojet** Rio Linhas** Atlas/Polar Air 21 MNG myCargo Star Air ULS * ATSG totals include, as of YE2014, 767 freighter aircraft operated by ATSG airlines ABX Air and Air Transport International, including 13 dry-leased to DHL through 2019 bu
Slide 8: New Leases with Longtime Customers
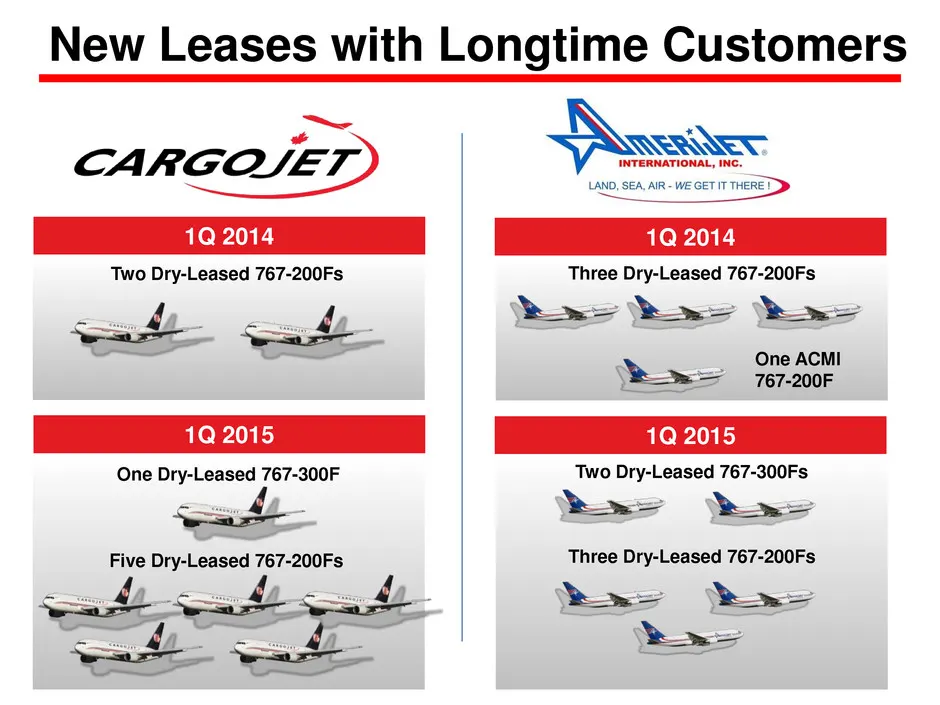
New Leases with Longtime Customers 1Q 2014 1Q 2015 One ACMI 767-200F Three Dry-Leased 767-200Fs Two Dry-Leased 767-300Fs 1Q 2014 1Q 2015 Two Dry-Leased 767-200Fs Three Dry-Leased 767-200Fs Five Dry-Leased 767-200Fs One Dry-Leased 767-300F 1Q 2014
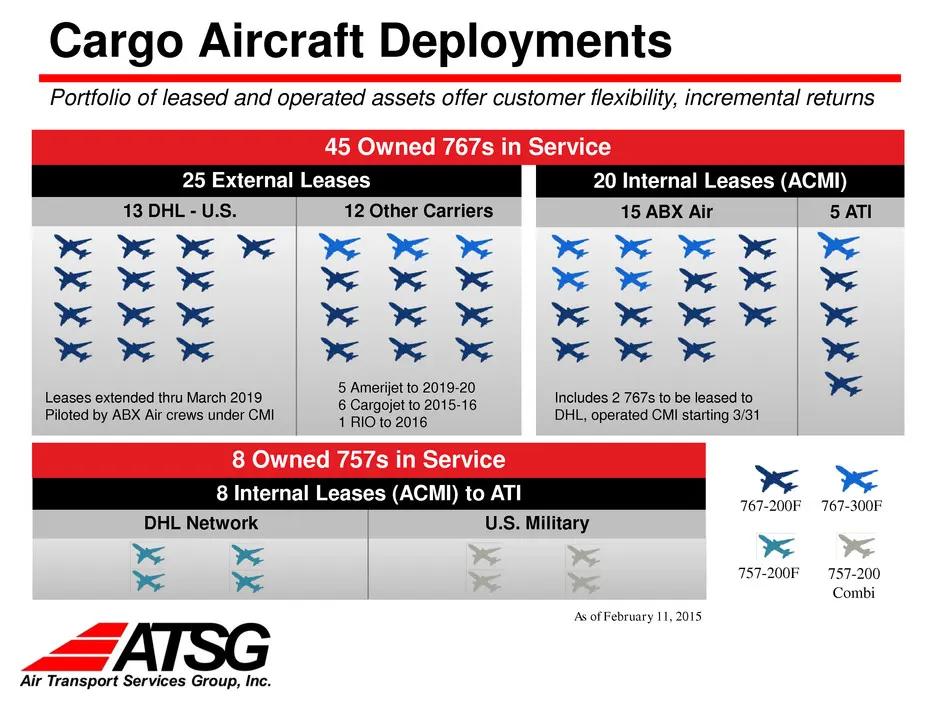
Slide 9: Cargo Aircraft Deployments
DHL Network U.S. Military 13 DHL - U.S. 12 Other Carriers 5 ATI 15 ABX Air 25 External Leases 20 Internal Leases (ACMI) 767-200F 767-300F Leases extended thru March 2019 Piloted by ABX Air crews under CMI 45 Owned 767s in Service 757-200F 757-200 Combi 8 Internal Leases (ACMI) to ATI 8 Owned 757s in
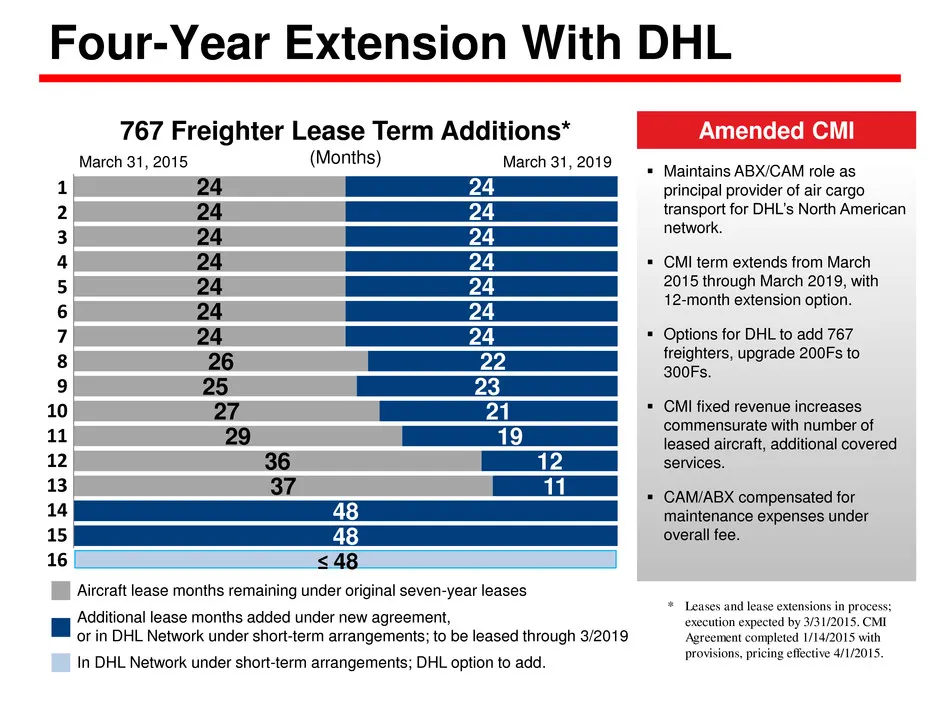
Slide 10: Four-Year Extension With DHL
37 36 29 27 25 26 24 24 24 24 24 24 24 48 48 11 12 19 21 23 22 24 24 24 24 24 24 24 Four-Year Extension With DHL 767 Freighter Lease Term Additions* (Months) March 31, 2015 March 31, 2019 ≤ 48 Maintains ABX/CAM role as principal provider of air cargo transport for DHL’s North American network. C
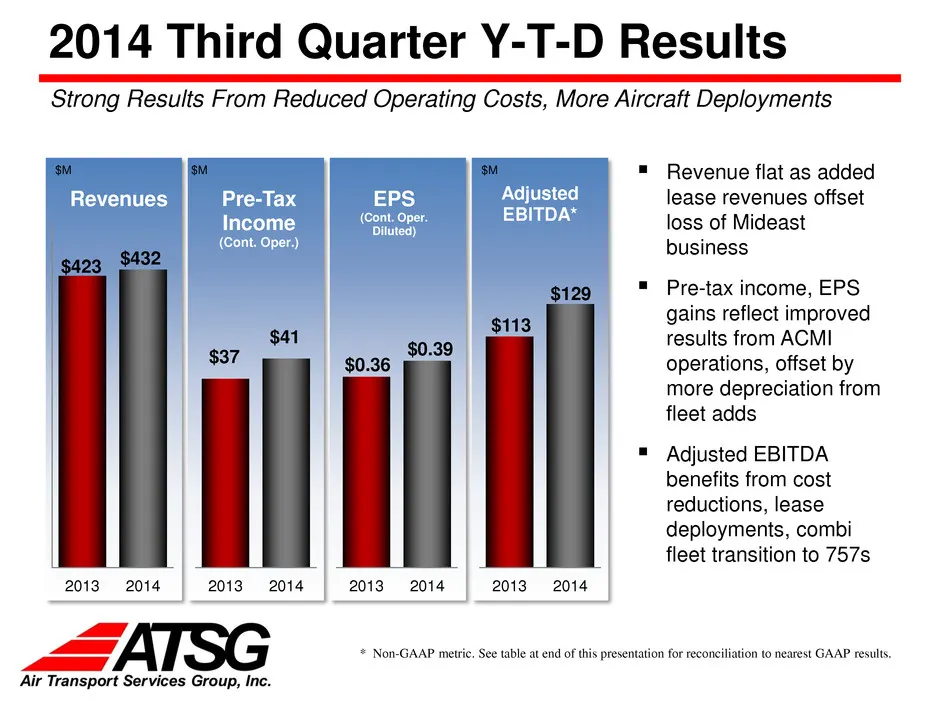
Slide 11: 2014 Third Quarter Y-T-D Results
2014 Third Quarter Y-T-D Results Revenue flat as added lease revenues offset loss of Mideast business Pre-tax income, EPS gains reflect improved results from ACMI operations, offset by more depreciation from fleet adds Adjusted EBITDA benefits from cost reductions, lease deployments, combi fle
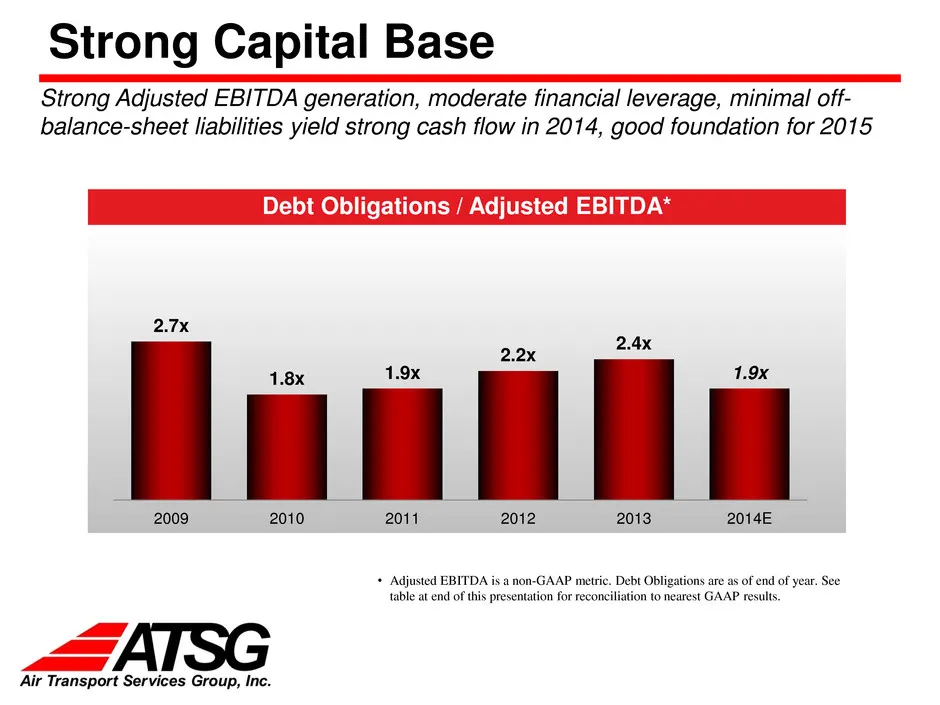
Slide 12: Strong Capital Base
2.7x 1.8x 1.9x 2.2x 2.4x 1.9x 2009 2010 2011 2012 2013 2014E Debt Obligations / Adjusted EBITDA* • Adjusted EBITDA is a non-GAAP metric. Debt Obligations are as of end of year. See table at end of this presentation for reconciliation to nearest GAAP results. Strong Capital Base Strong Adjusted EBITD
Slide 13: Growing Cash Flow Opportunity
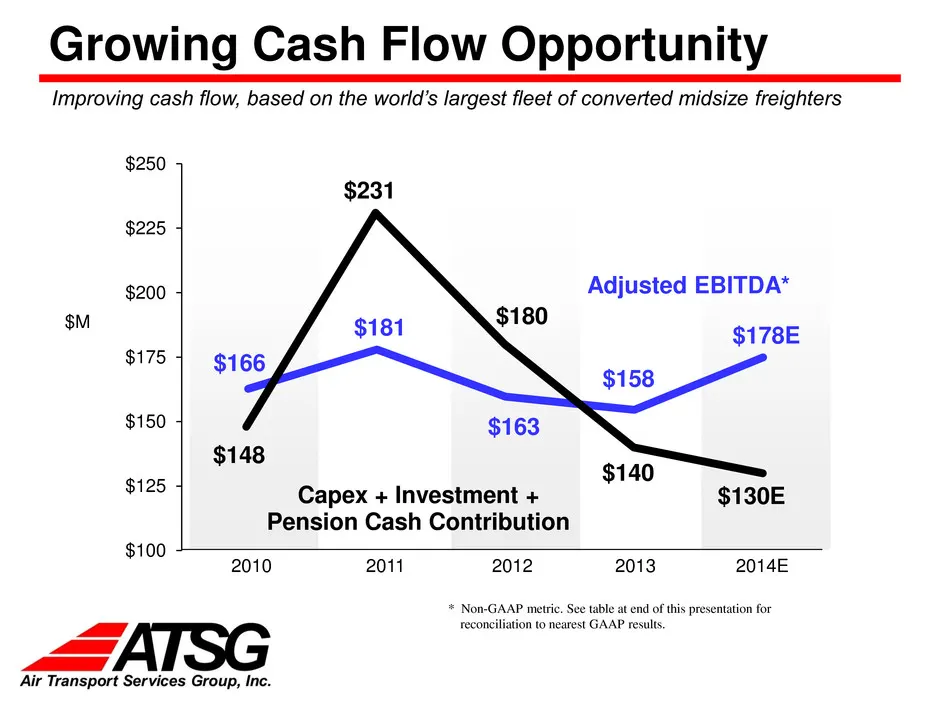
$166 $181 $163 $158 $178E Adjusted EBITDA* Improving cash flow, based on the world’s largest fleet of converted midsize freighters Growing Cash Flow Opportunity 2010 2011 2012 2013 2014E * Non-GAAP metric. See table at end of this presentation for reconciliation to nearest GAAP results. $M $148 $231
Slide 14: Highlights and Outlook
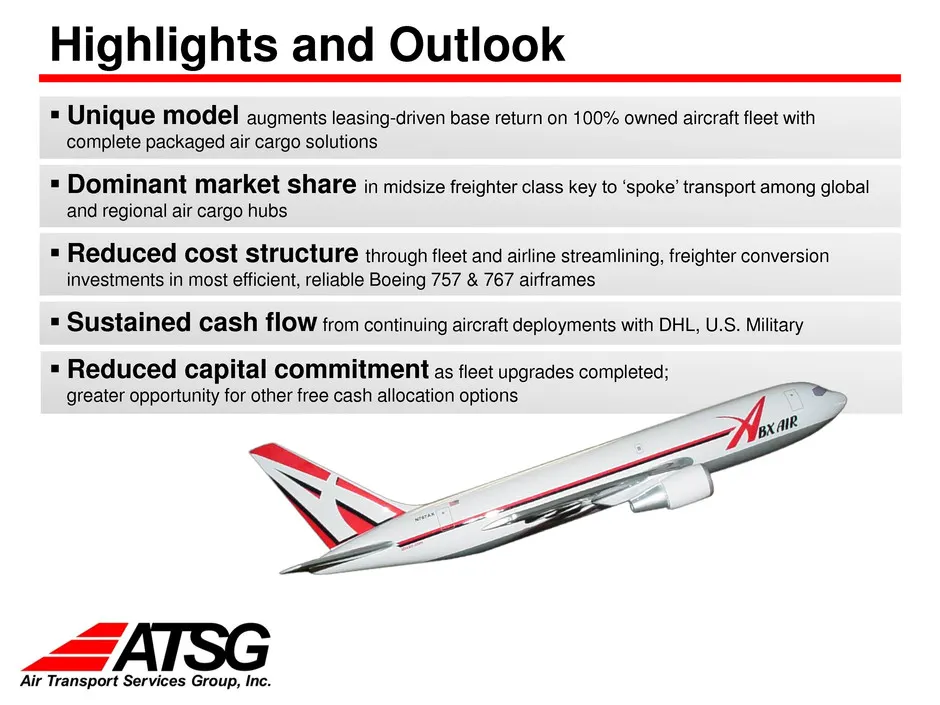
Highlights and Outlook Unique model augments leasing-driven base return on 100% owned aircraft fleet with complete packaged air cargo solutions Dominant market share in midsize freighter class key to ‘spoke’ transport among global and regional air cargo hubs Reduced cost structure through flee
Slide 15: Expanding Free Cash Flow Creates Options
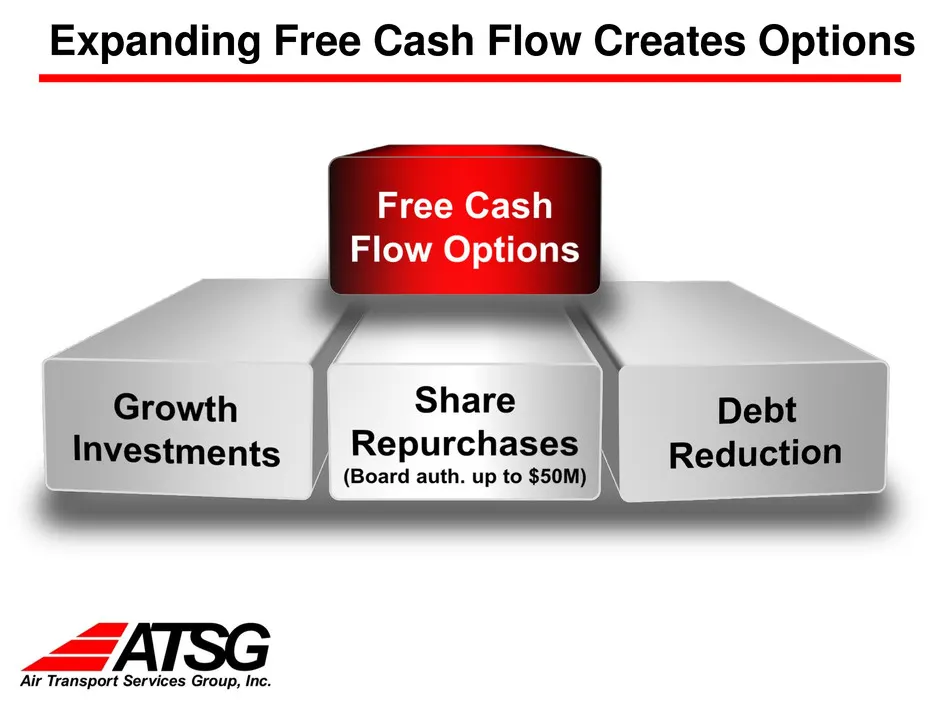
Expanding Free Cash Flow Creates Options
Slide 16: Non-GAAP Reconciliation Statement
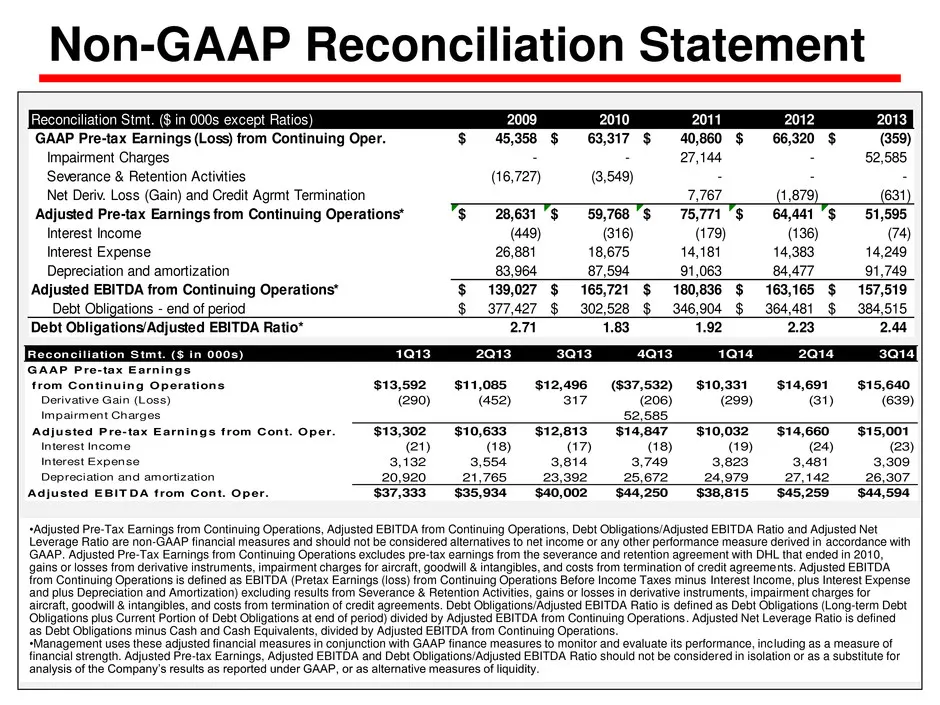
Non-GAAP Reconciliation Statement •Adjusted Pre-Tax Earnings from Continuing Operations, Adjusted EBITDA from Continuing Operations, Debt Obligations/Adjusted EBITDA Ratio and Adjusted Net Leverage Ratio are non-GAAP financial measures and should not be considered alternatives to net income or any o
Source: SEC EDGAR · 8-K filed Feb 10, 2015
More decks from Air Transport Services Group Inc
 Shareholder Meeting (May 2024)26 slides · May 23, 2024
 Stephens Annual Investment Conference 202321 slides · Nov 14, 2023
 Investor Day (September 2023)68 slides · Sep 27, 2023
 Shareholder Meeting (May 2023)25 slides · May 26, 2023
 Stifel conference (February 2023)15 slides · Feb 6, 2023
 Stifel 2020 Transportation & Logistics Conference18 slides · Feb 11, 2020