Home Loan Servicing Solutions Ltd
Home Loan Servicing Solutions — Debt Investor Presentation (January 2013)
31 slides from Home Loan Servicing Solutions's debt investor presentation, Jan 25, 2013
Slide 1: HLSS Servicer Advance Receivables Trust Investor Presentation
Exhibit 99.1 HLSS Servicer Advance Receivables Trust Investor Presentation
Slide 2: Disclaimer
Disclaimer FORWARD-LOOKING STATEMENTS: OUR PRESENTATION MAY CONTAIN CERTAIN FORWARD-LOOKING STATEMENTS THAT ARE MADE PURSUANT TO THE SAFE HARBOR PROVISIONS OF THE FEDERAL SECURITIES LAWS. THESE FORWARD-LOOKING STATEMENTS MAY BE IDENTIFIED BY A REFERENCE TO A FUTURE PERIOD OR BY THE USE OF FORWARD-LO
Slide 3: Table of Contents
Table of Contents Agenda 1. HLSS Overview 2. Ocwen Overview 3. HSART Master Trust Overview 4. Appendices 3
Slide 4: HLSS Overview
HOME LOAN” PEE SERVICING SOLUTIONS HOME LOAN” PEE SERVICING SOLUTIONS HLSS Overview
Slide 5: HLSS Overview
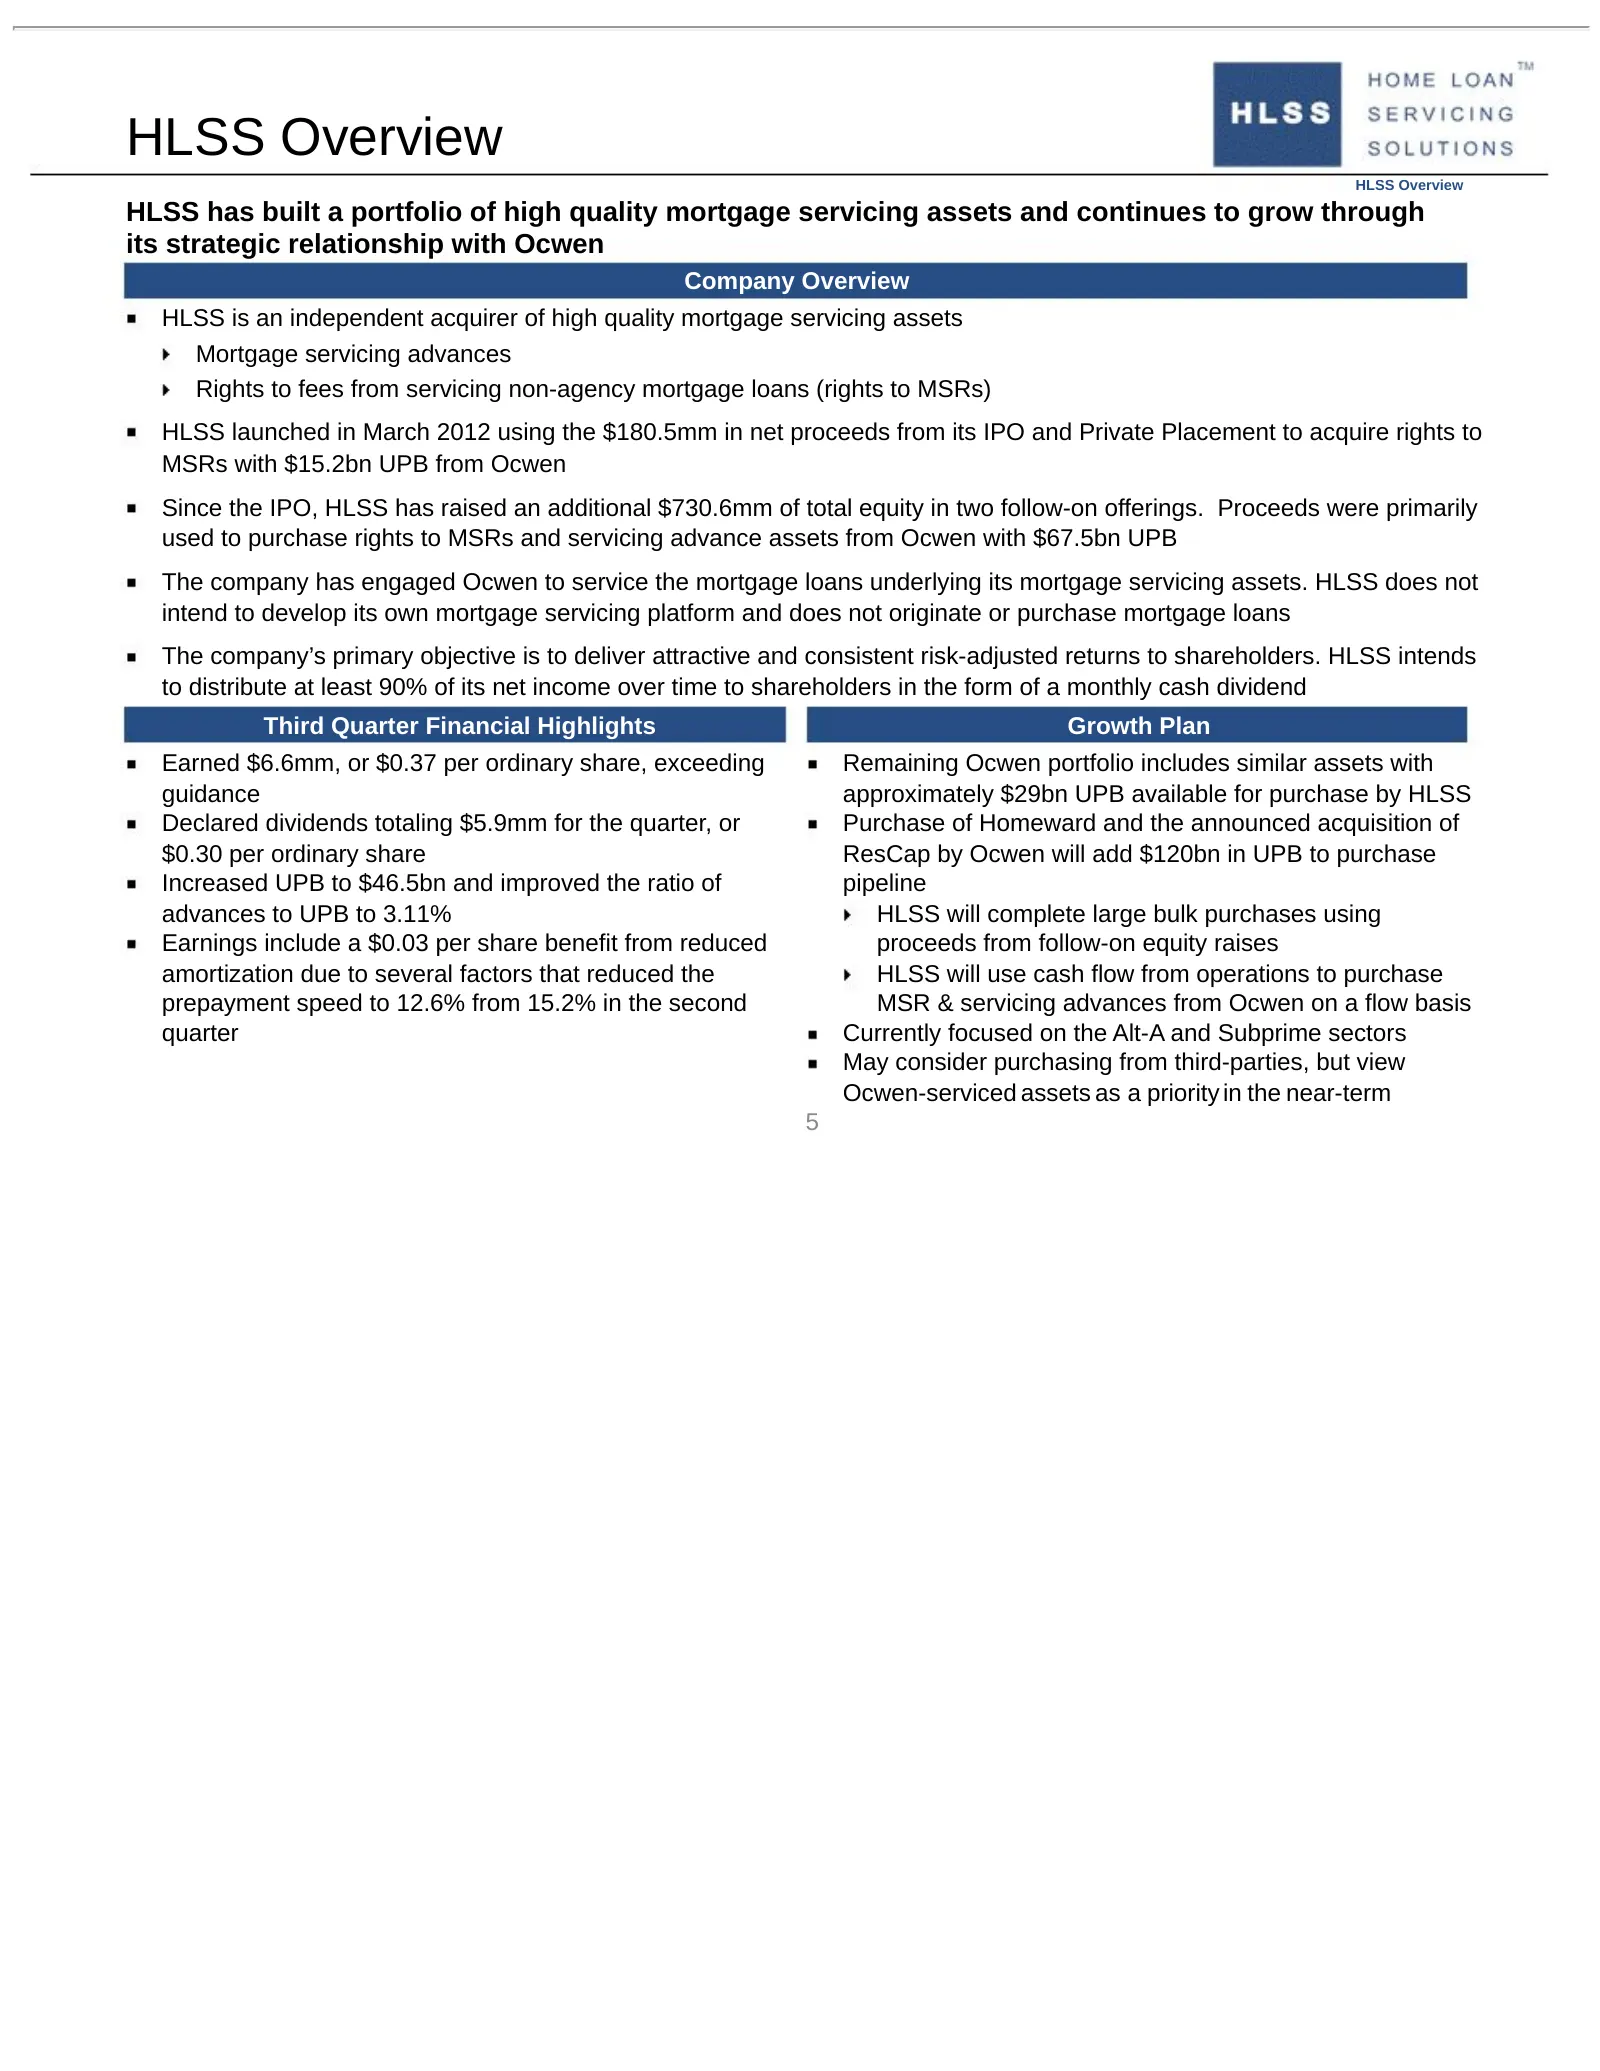
HLSS Overview HLSS Overview HLSS has built a portfolio of high quality mortgage servicing assets and continues to grow through its strategic relationship with Ocwen Company Overview HLSS is an independent acquirer of high quality mortgage servicing assets Mortgage servicing advances Rights to fees f
Slide 6: Portfolio Acquisitions and Milestones
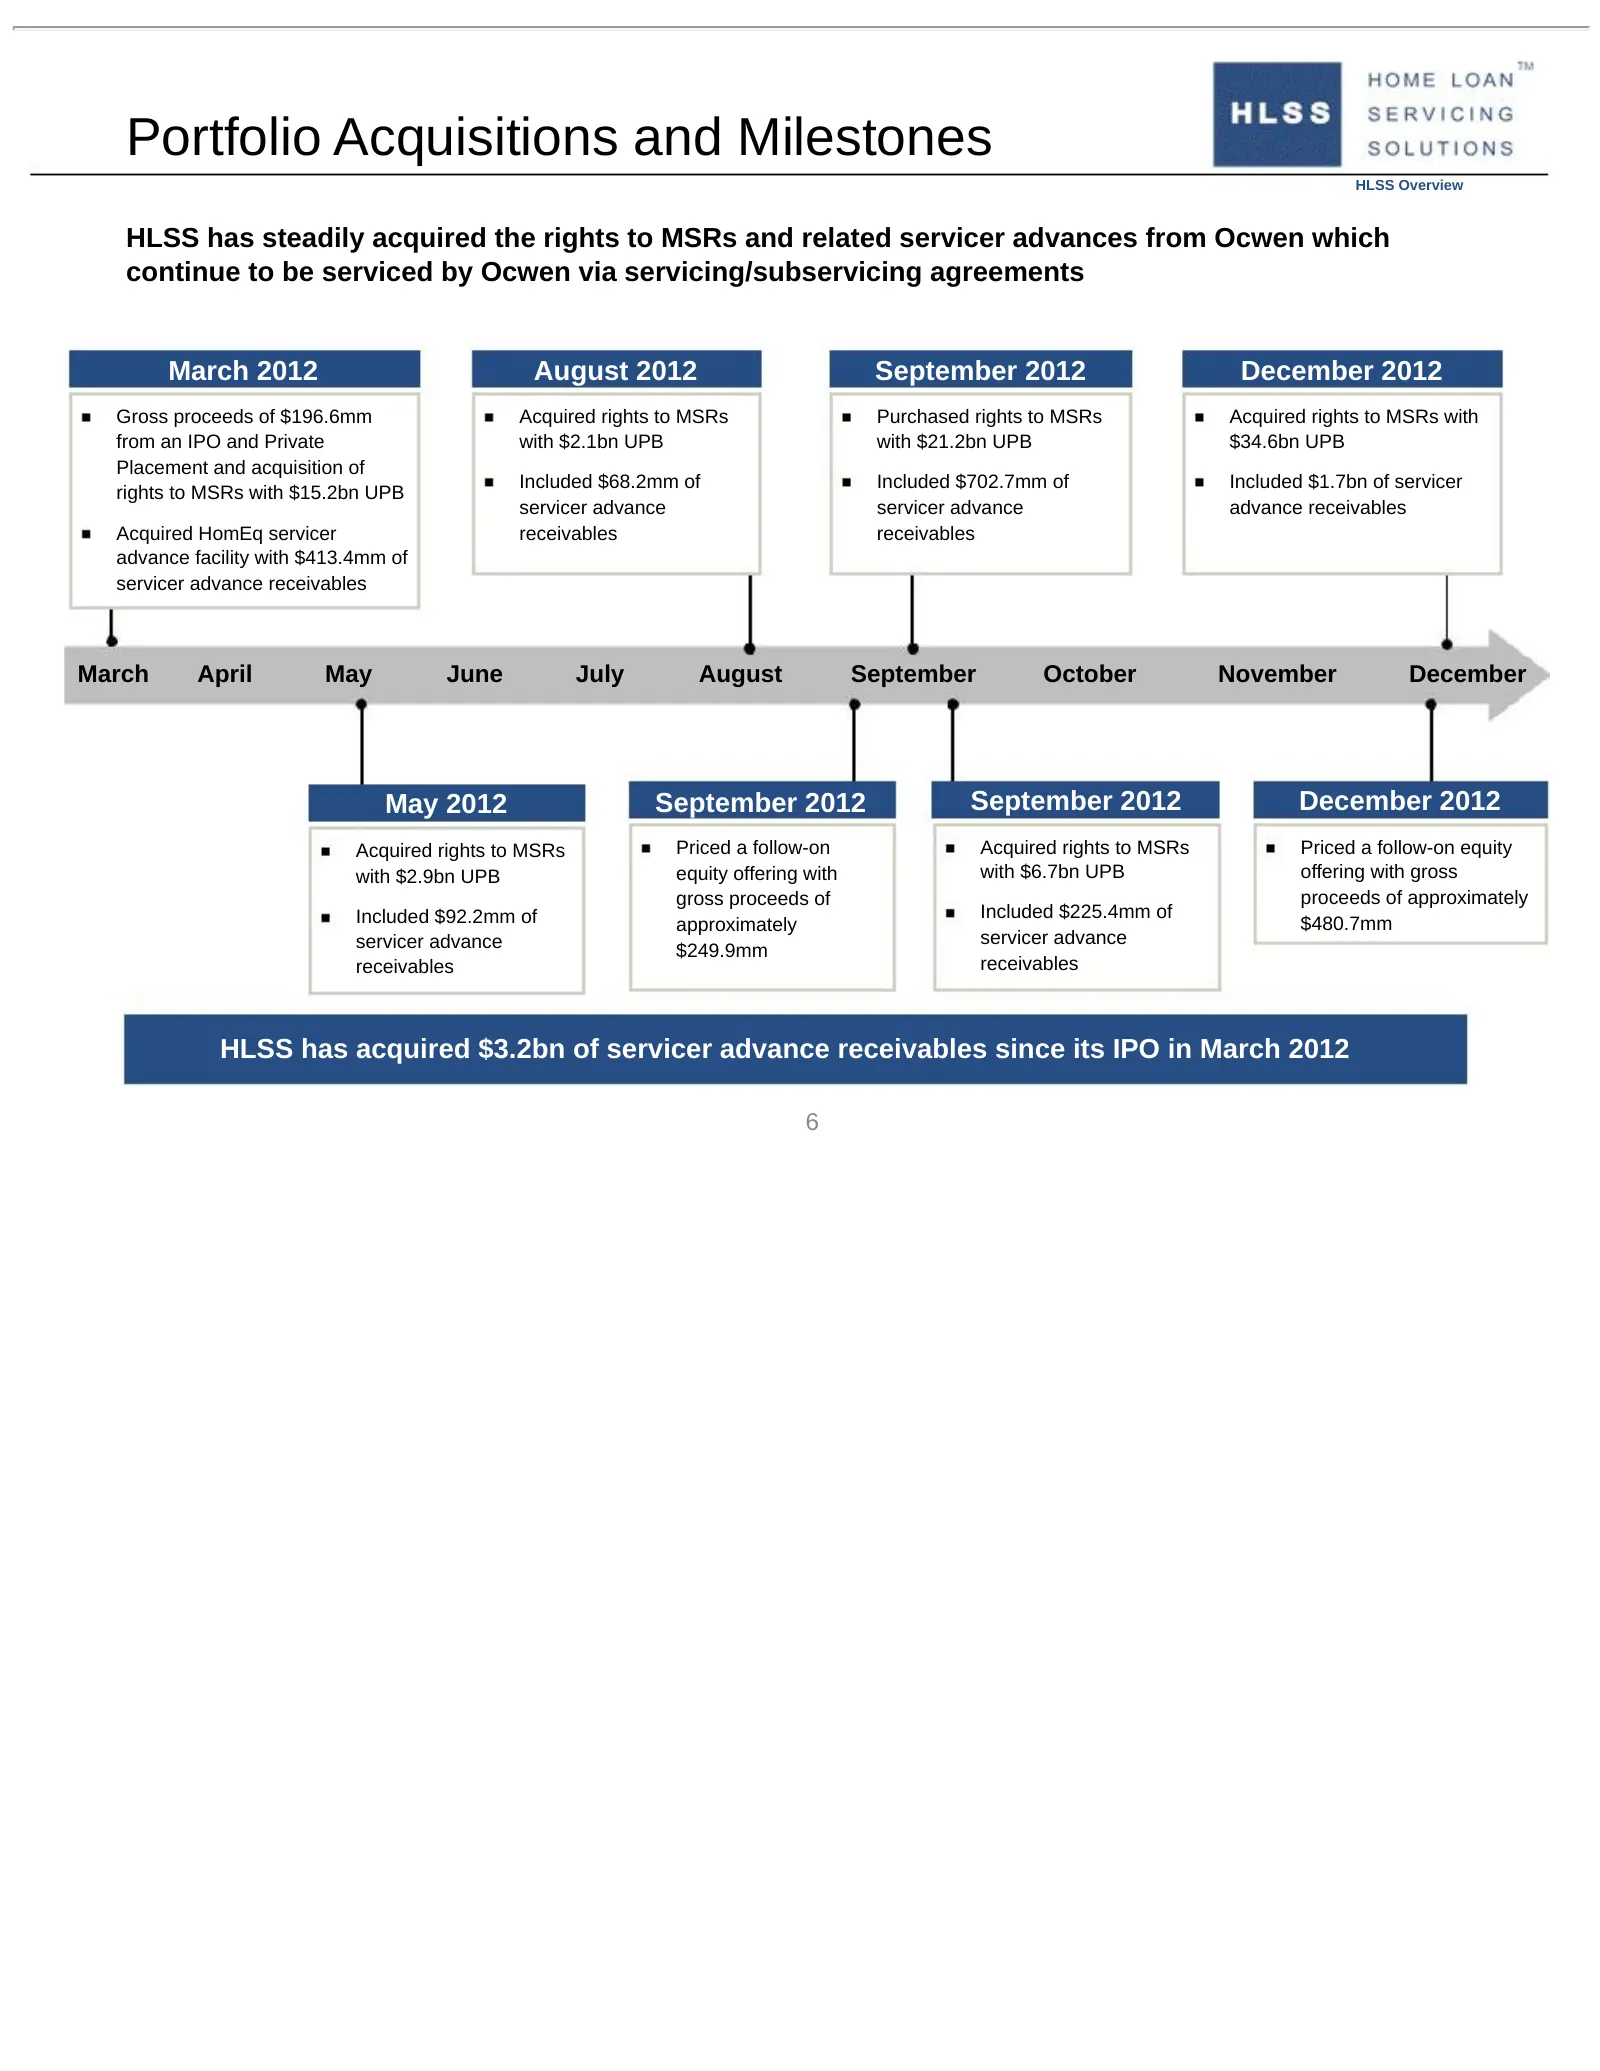
Portfolio Acquisitions and Milestones HLSS Overview HLSS has steadily acquired the rights to MSRs and related servicer advances from Ocwen which continue to be serviced by Ocwen via servicing/subservicing agreements March 2012 August 2012 September 2012 December 2012 Gross proceeds of $196.6mm Acqui
Slide 7: HLSS Leadership Team
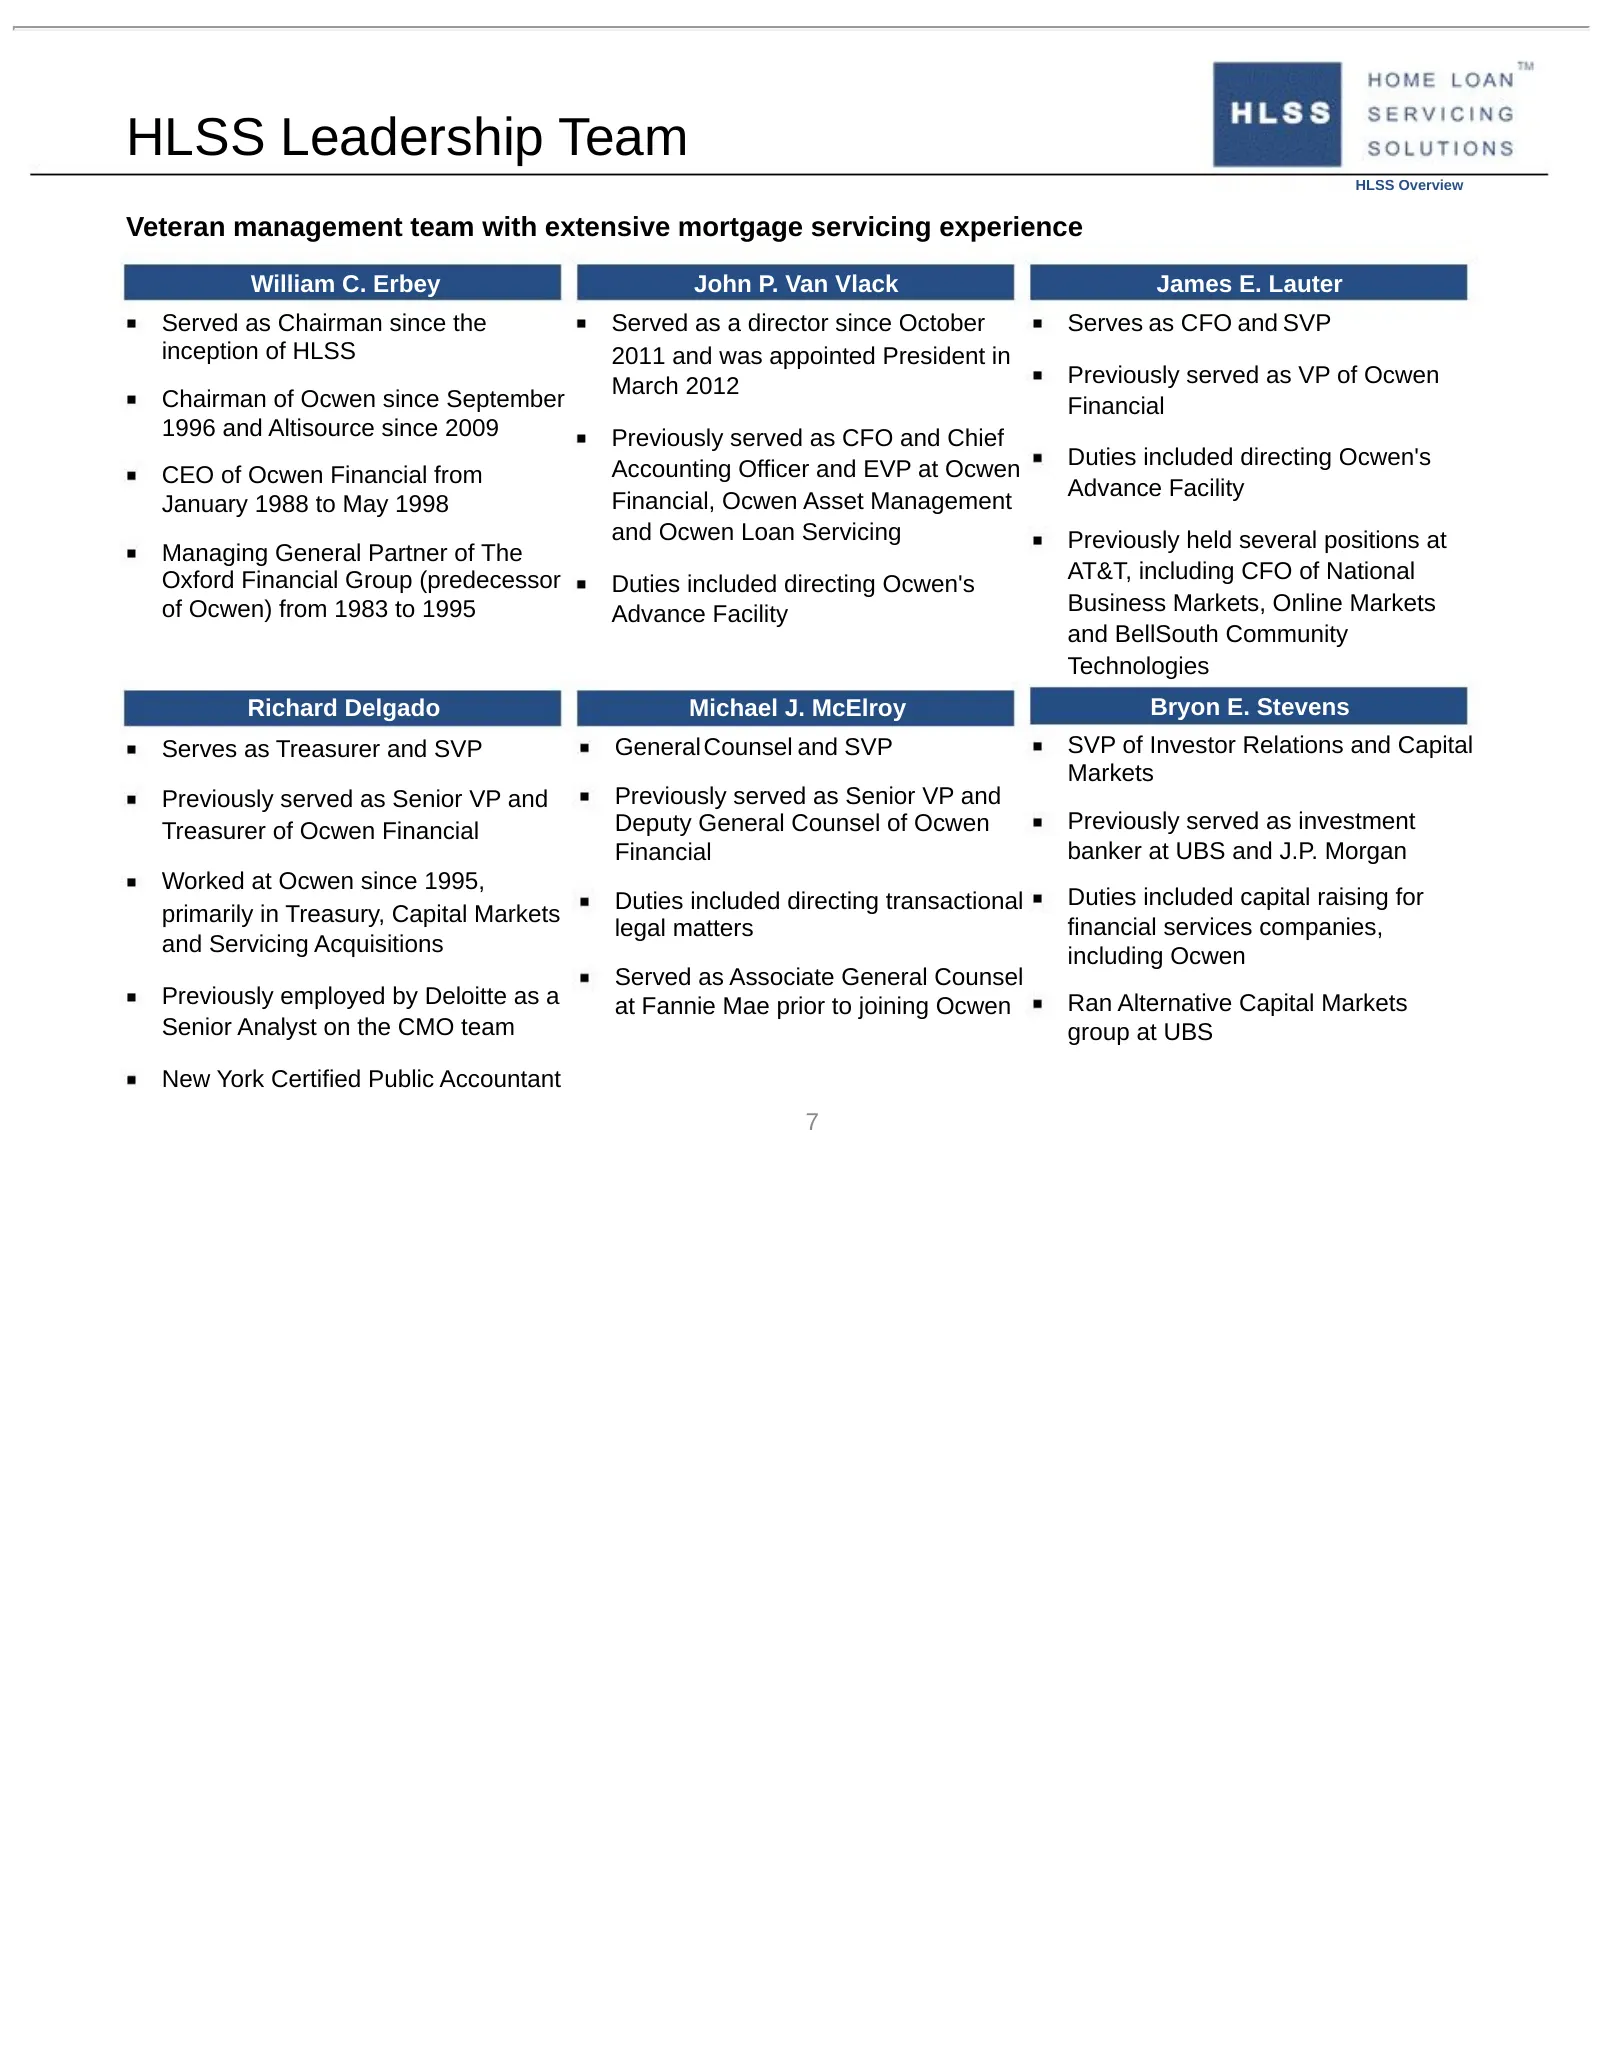
HLSS Leadership Team HLSS Overview Veteran management team with extensive mortgage servicing experience William C. Erbey John P. Van Vlack James E. Lauter Served as Chairman since the Served as a director since October Serves as CFO and SVP inception of HLSS 2011 and was appointed President in March
Slide 8: HLSS has Limited Asset Valuation Risk
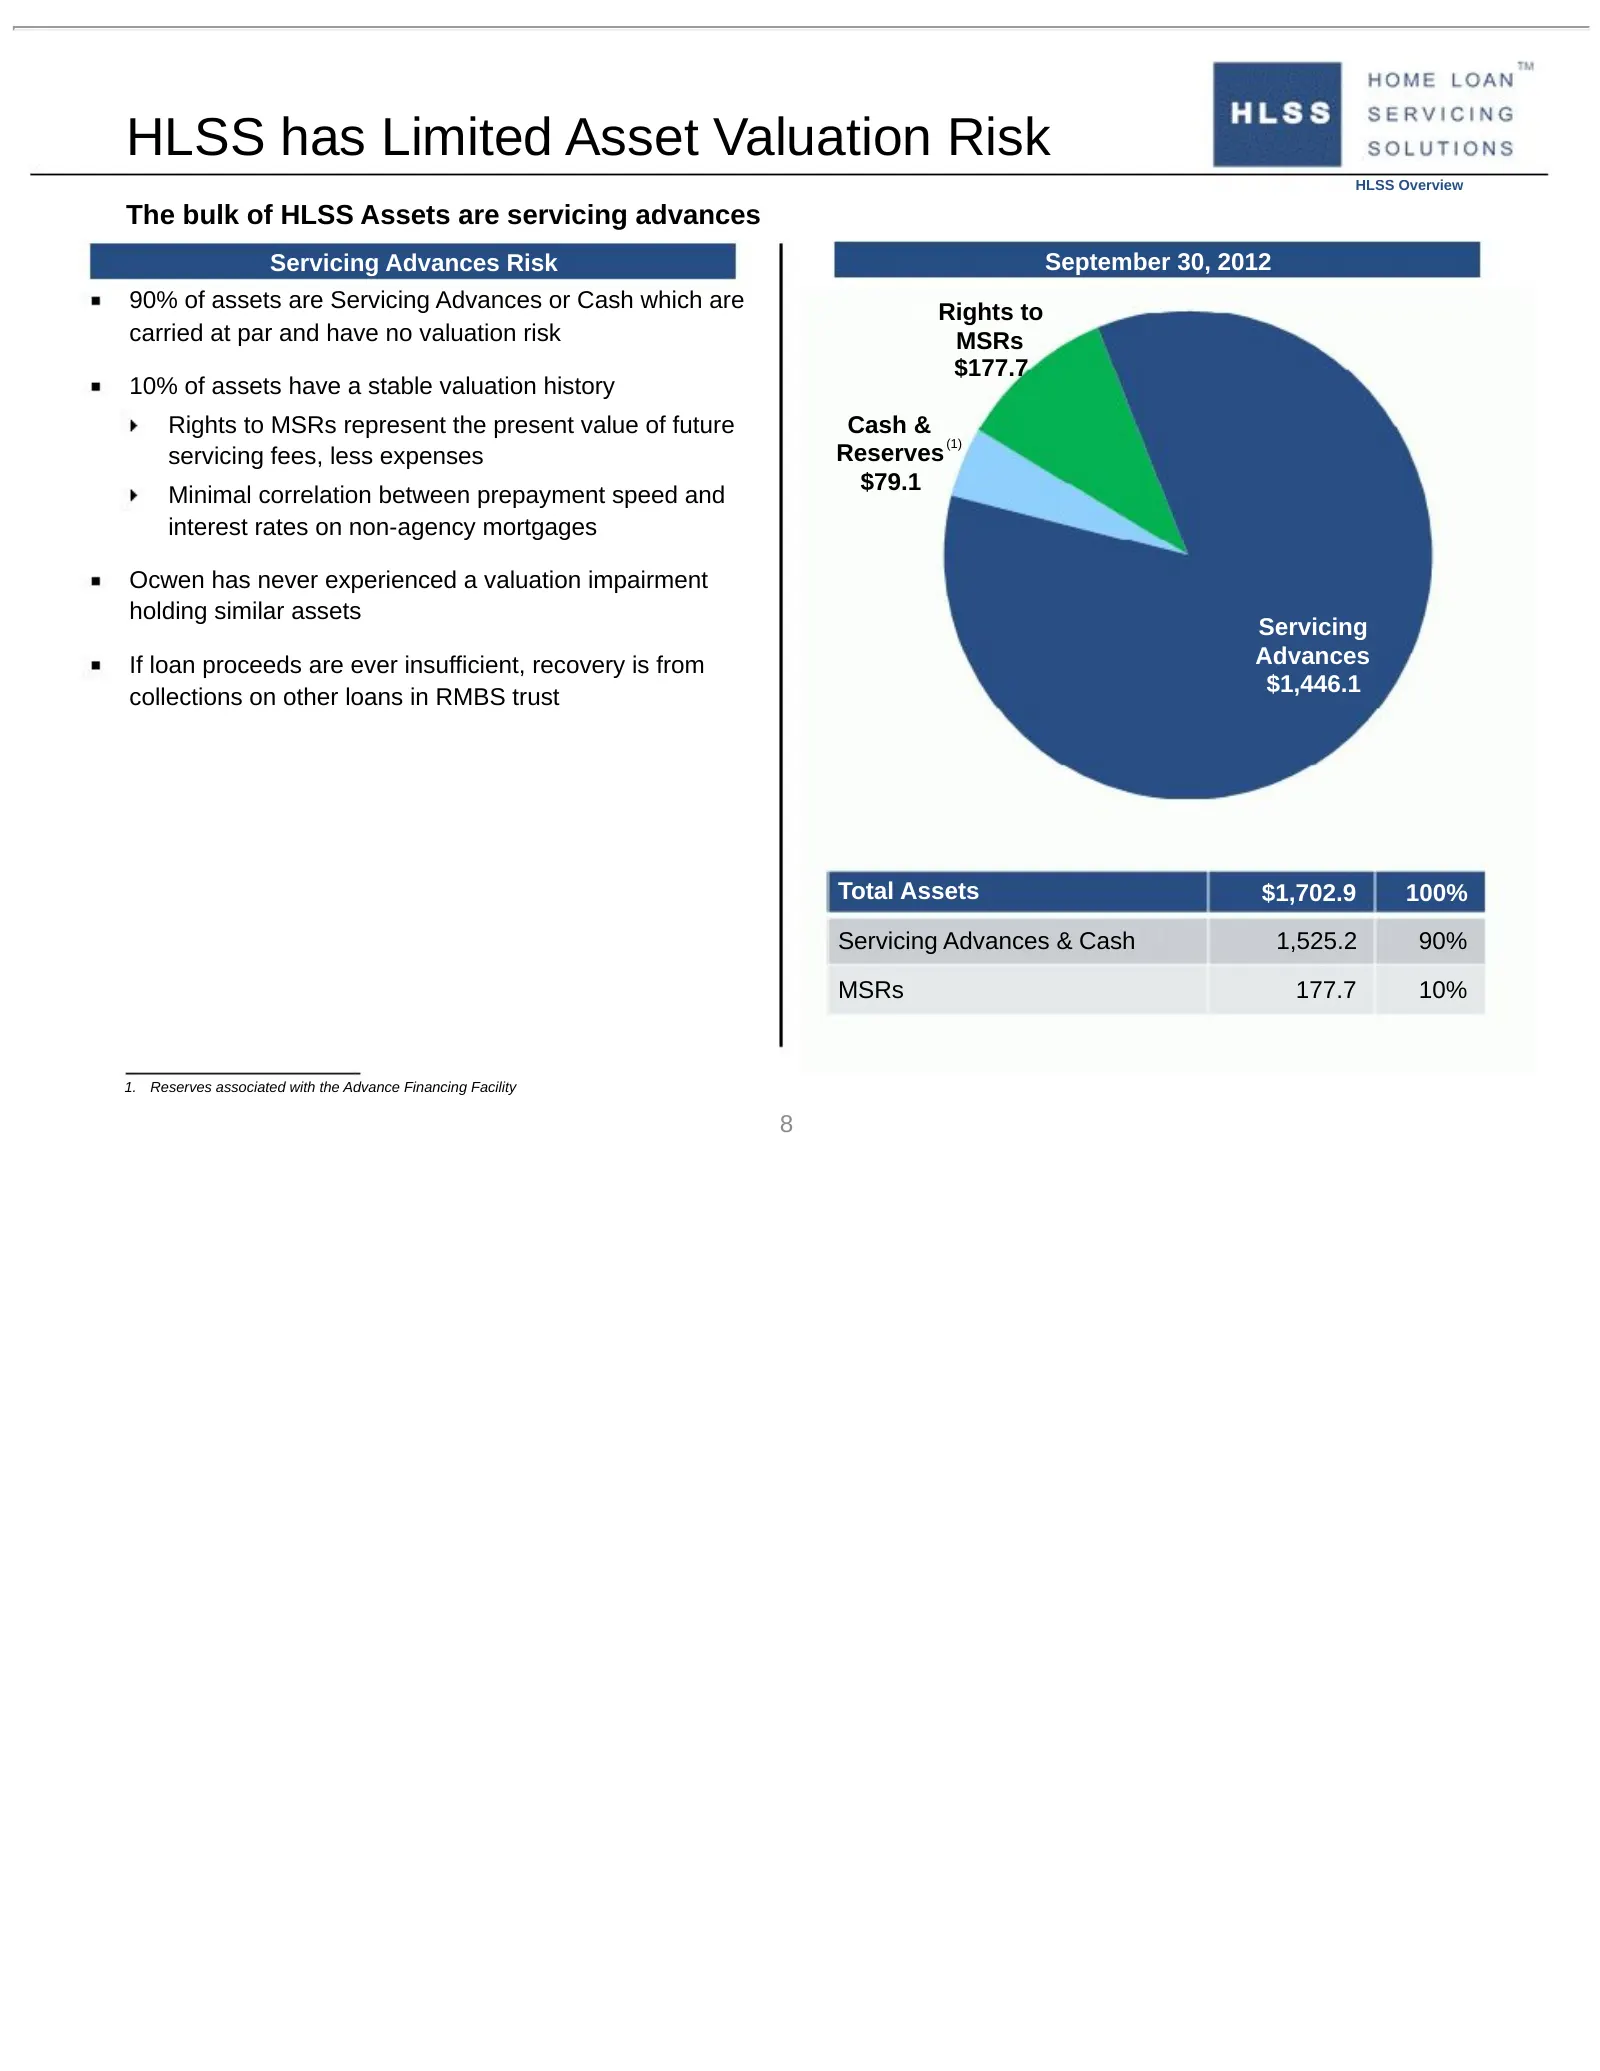
HLSS has Limited Asset Valuation Risk HLSS Overview The bulk of HLSS Assets are servicing advances Servicing Advances Risk September 30, 2012 90% of assets are Servicing Advances or Cash which are Rights ($ in to Millions) carried at par and have no valuation risk MSRs $177.7 10% of assets have a st
Slide 9: Assets are a 4% First-Priority Claim
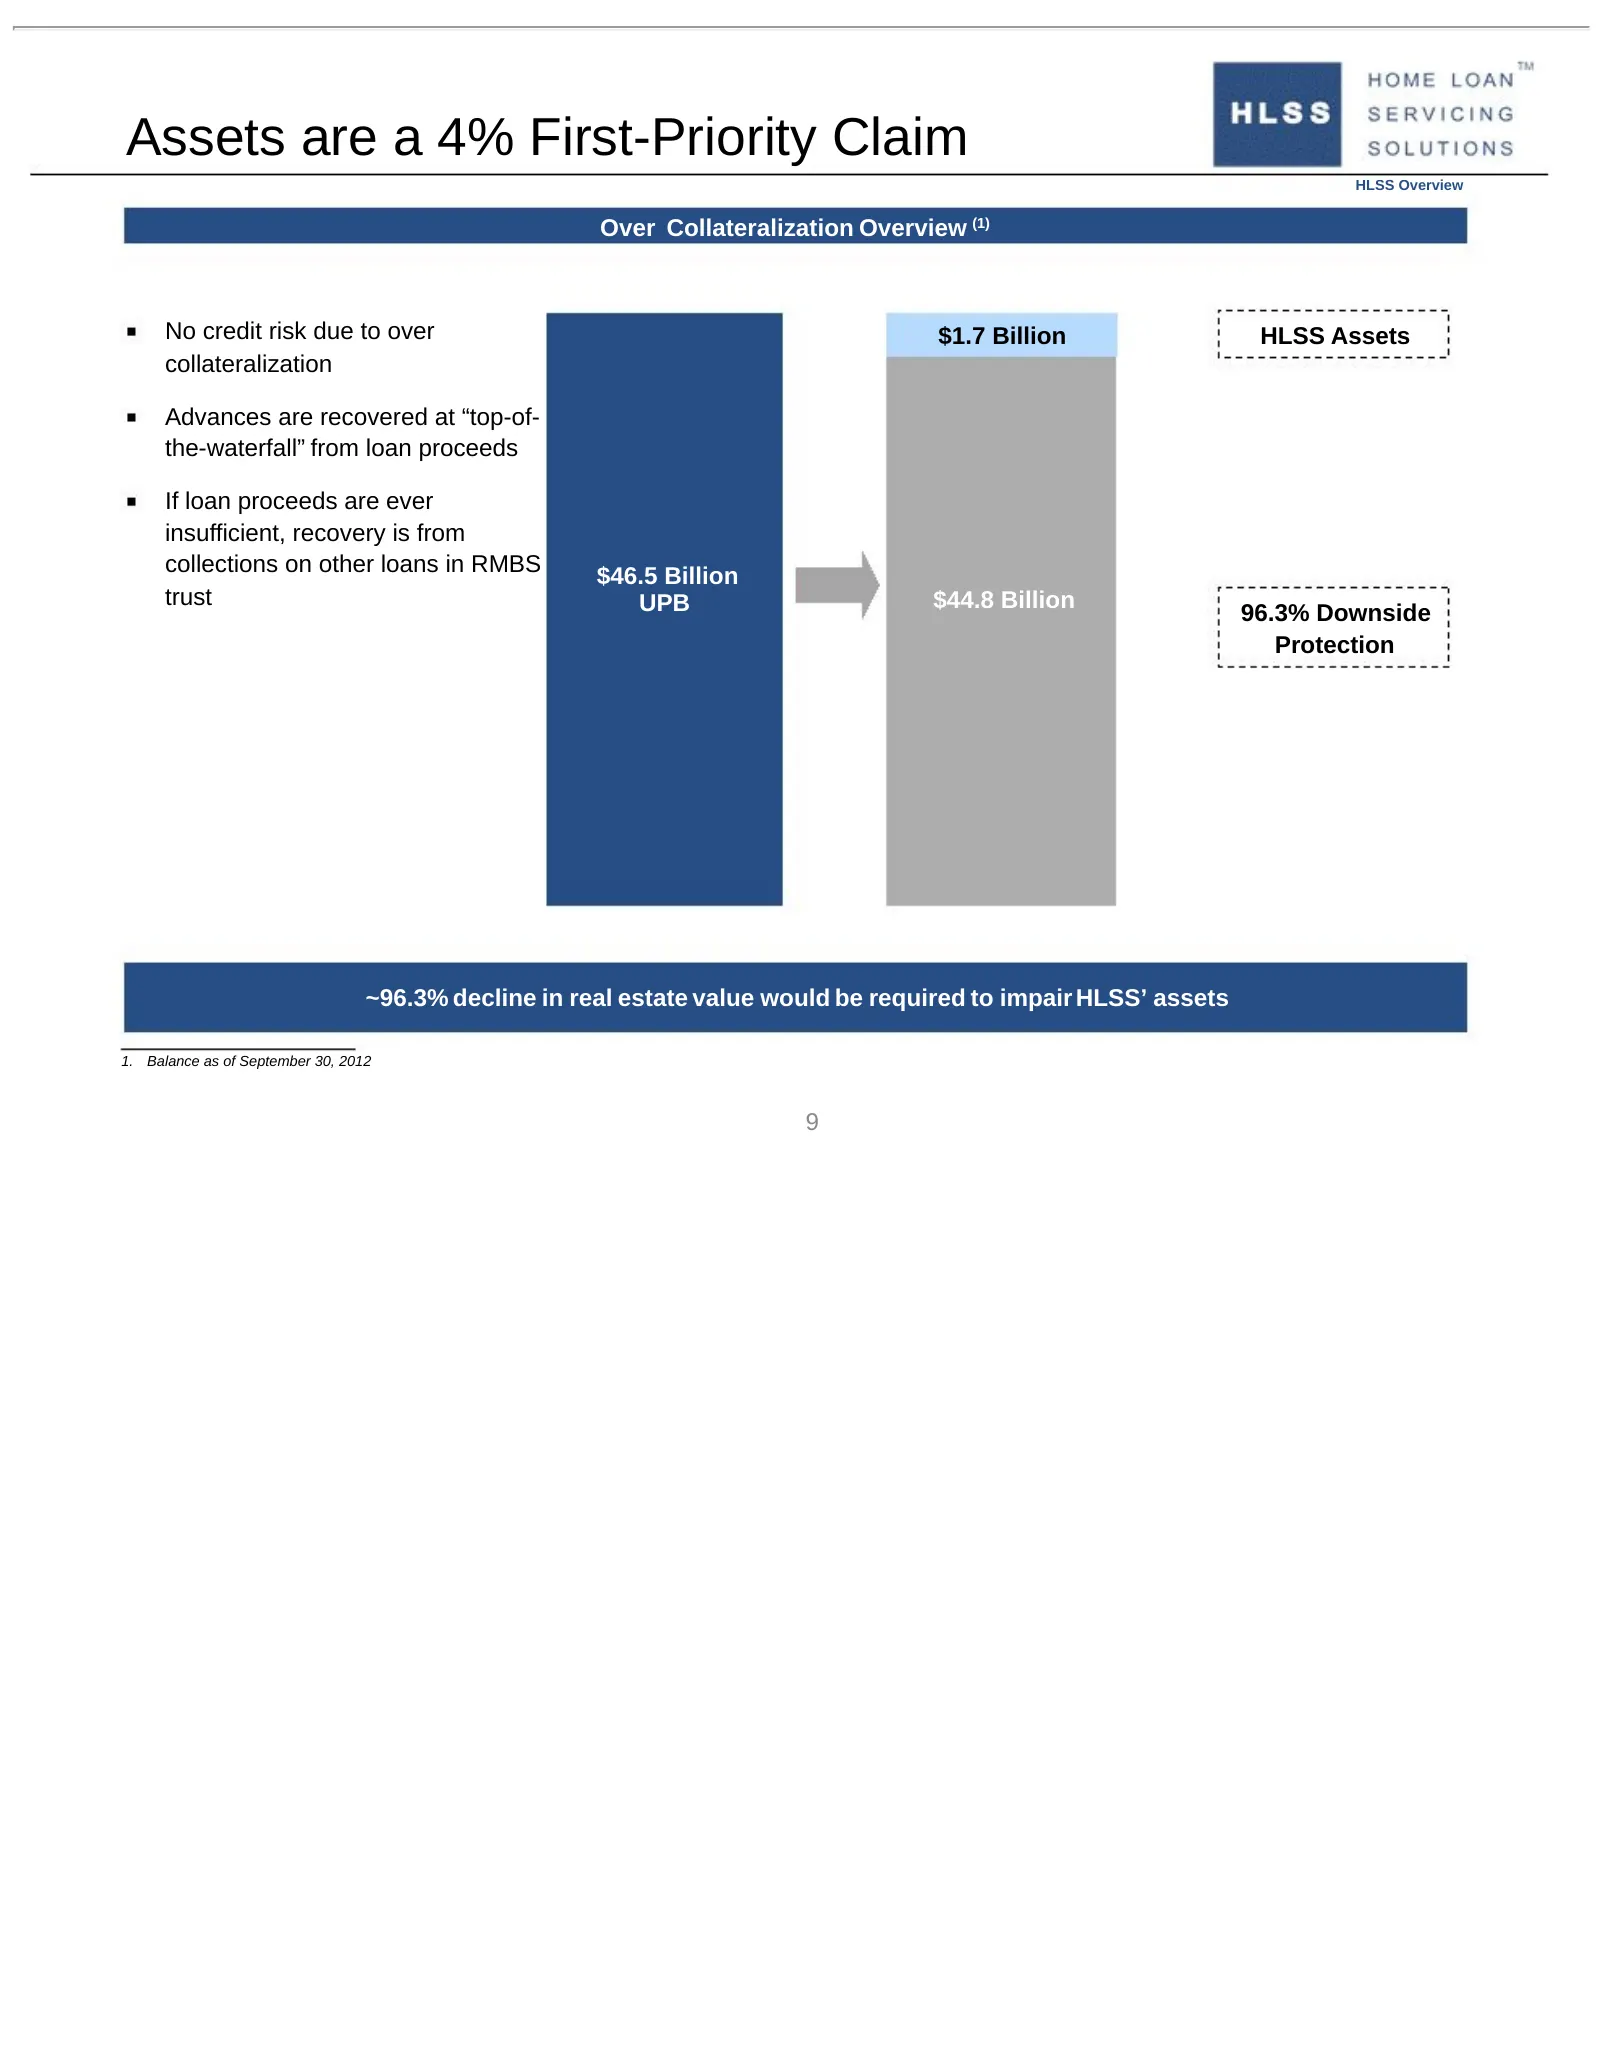
Assets are a 4% First-Priority Claim HLSS Overview Over Collateralization Overview (1) No credit risk due to over $1.7 Billion HLSS Assets collateralization Advances are recovered at “top-of- the-waterfall” from loan proceeds If loan proceeds are ever insufficient, recovery is from collections on ot
Slide 10: HLSS Term Note Issuance Program
HLSS Term Note Issuance Program HLSS Overview HLSS expects to be a regular issuer in the Term ABS markets as it continues to acquire servicing advance assets from Ocwen Ocwen has an existing portfolio of servicing rights of more than $29bn in securitized non-agency UPB available for purchase and con
Slide 11: HLSS Term Note Issuance Program
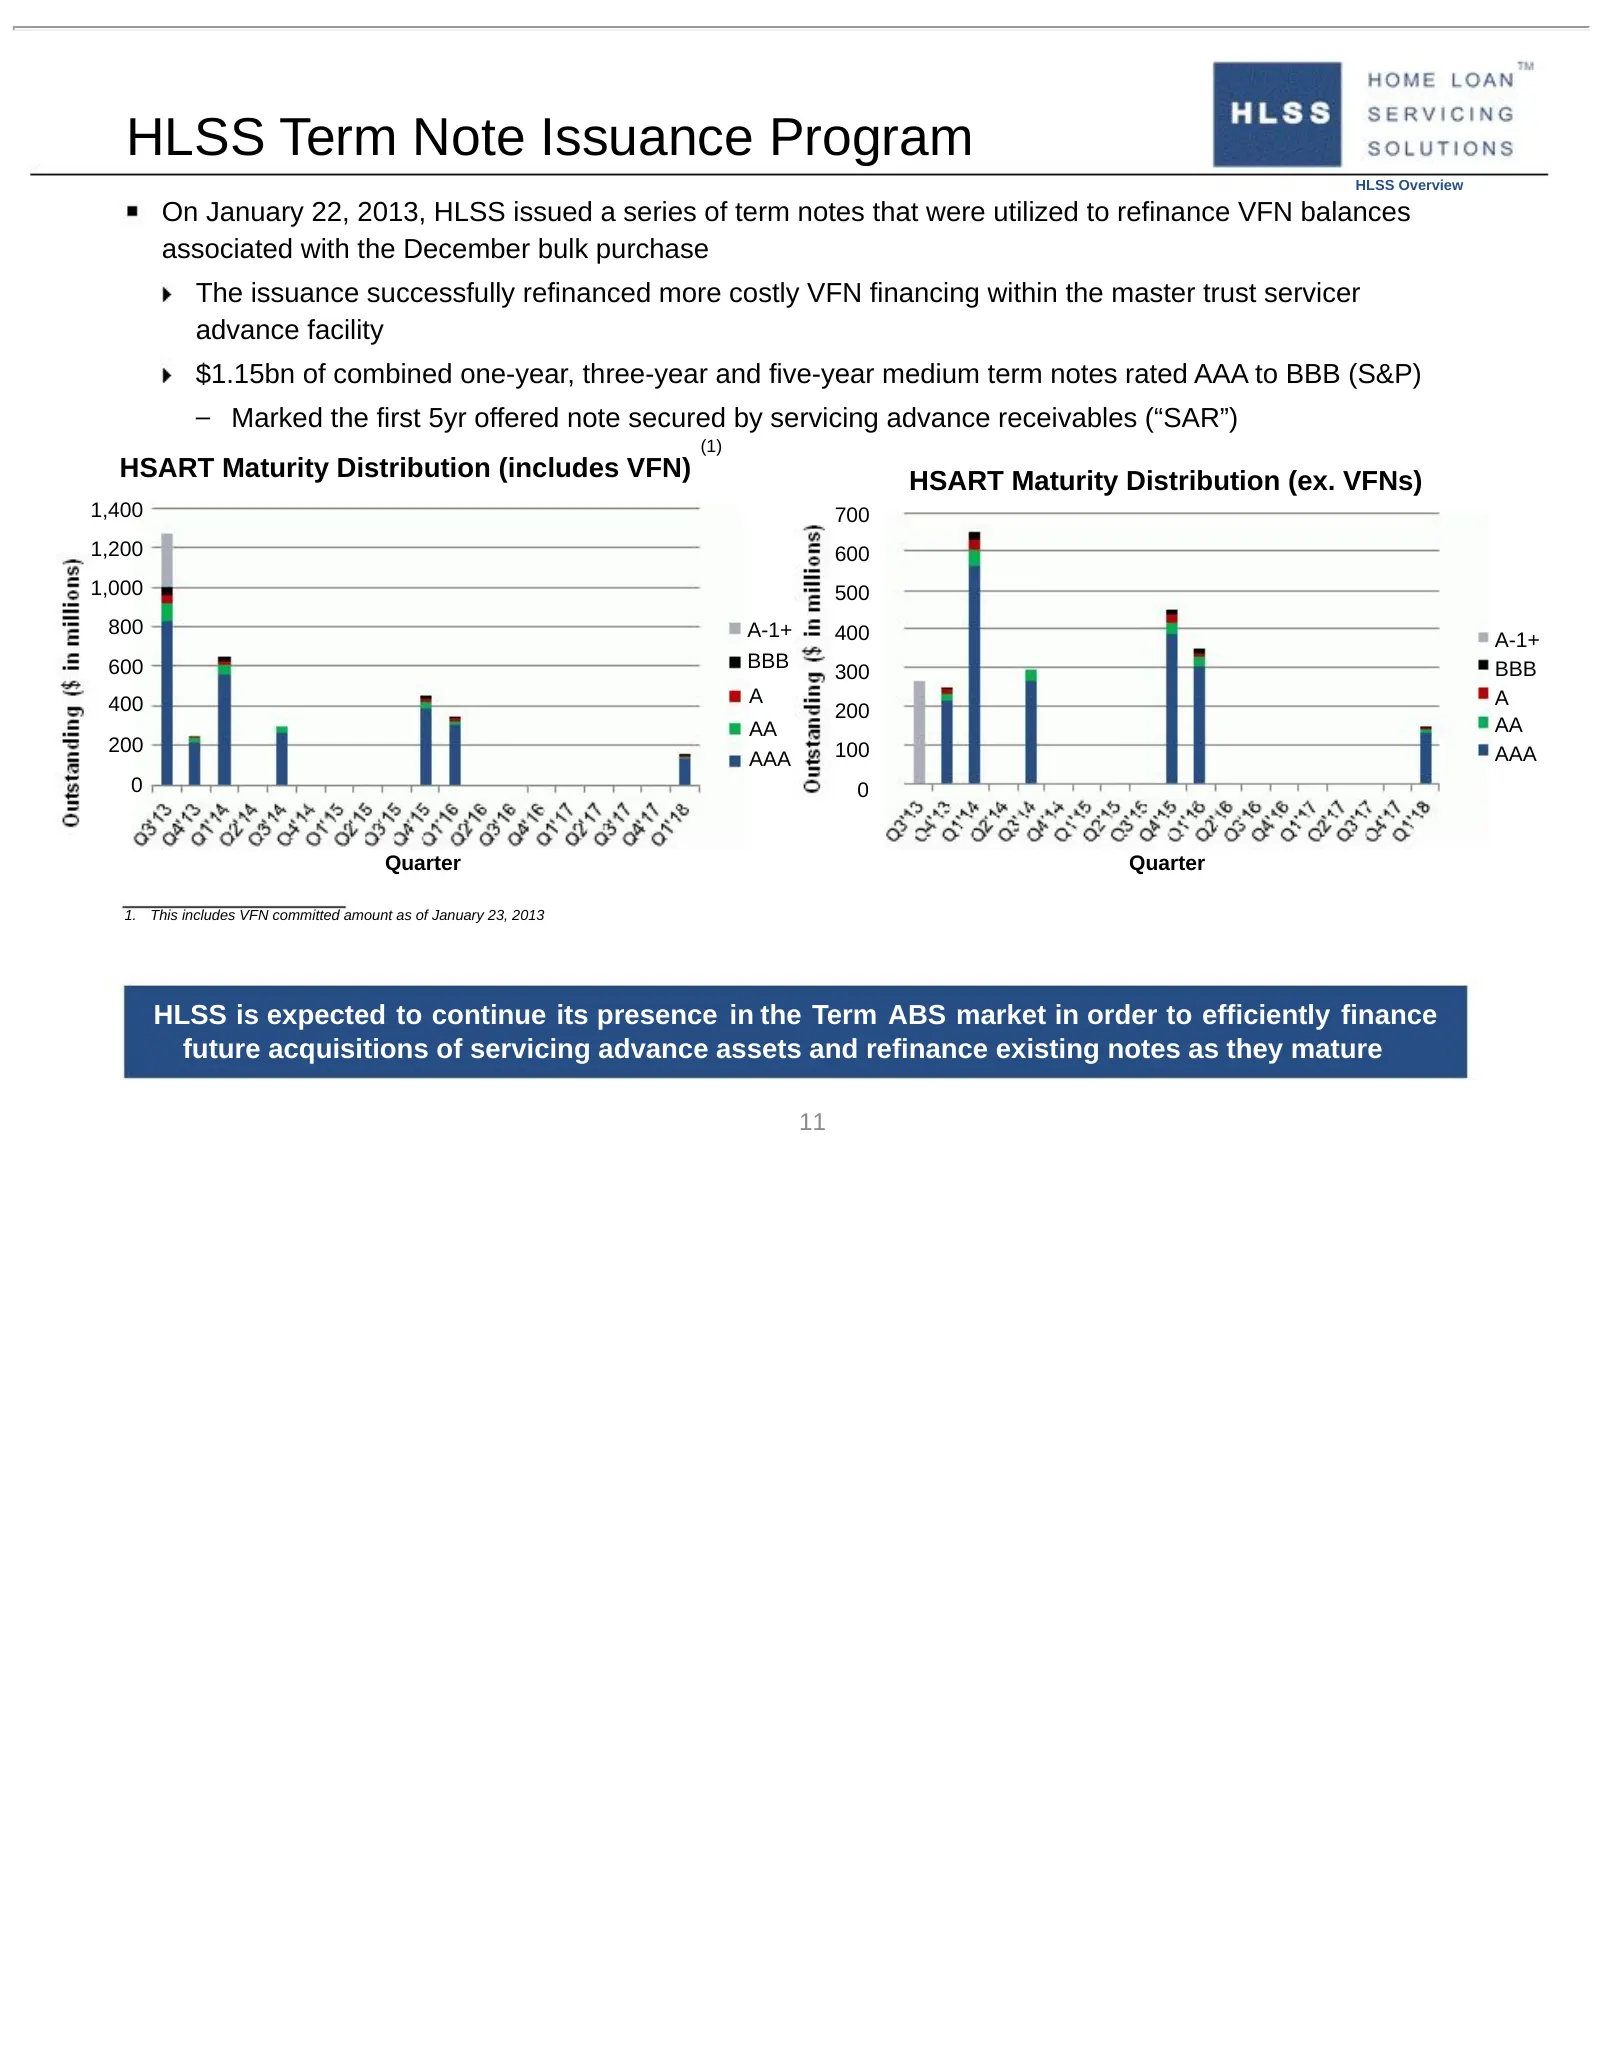
HLSS Term Note Issuance Program HLSS Overview On January 22, 2013, HLSS issued a series of term notes that were utilized to refinance VFN balances associated with the December bulk purchase The issuance successfully refinanced more costly VFN financing within the master trust servicer advance facili
Slide 12: Ocwen Overview
HOME LOAN” PEE SERVICING SOLUTIONS HOME LOAN” PSE SERVICING SOLUTIONS Ocwen Overview 12
Slide 13: HLSS-Ocwen Subservicing Relationship
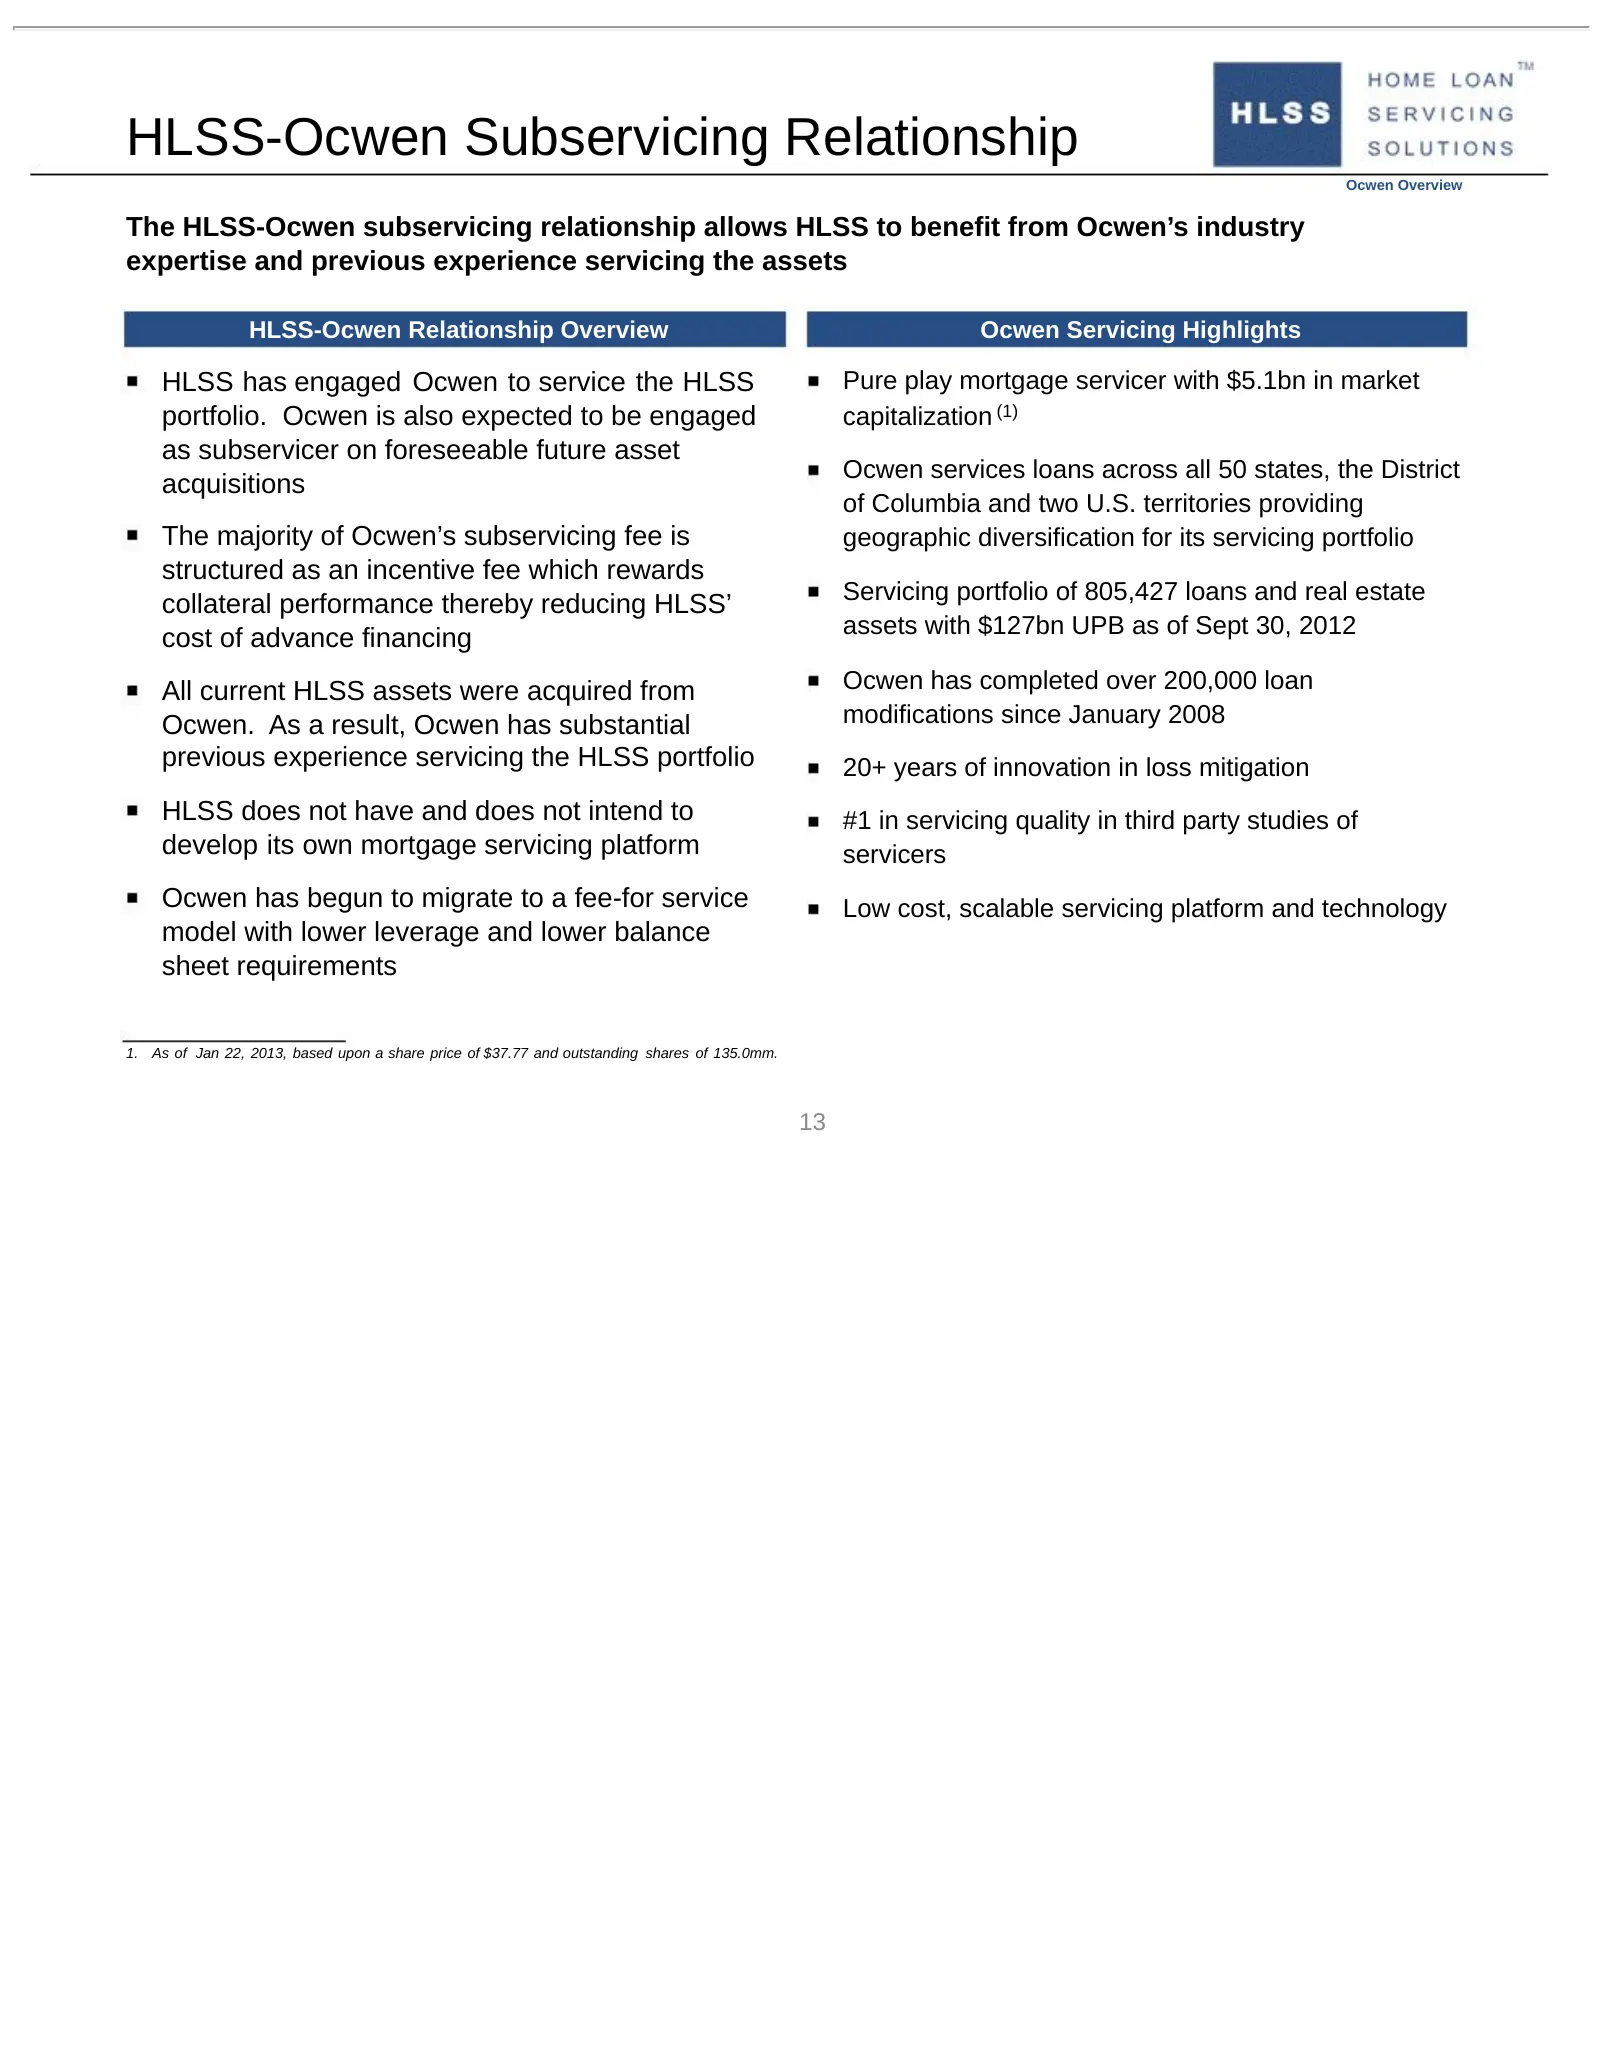
HLSS-Ocwen Subservicing Relationship Ocwen Overview The HLSS-Ocwen subservicing relationship allows HLSS to benefit from Ocwen’s industry expertise and previous experience servicing the assets HLSS-Ocwen Relationship Overview Ocwen Servicing Highlights HLSS has engaged Ocwen to service the HLSS Pure
Slide 14: Subservicing Fee Adjusts to Support Targeted Yield
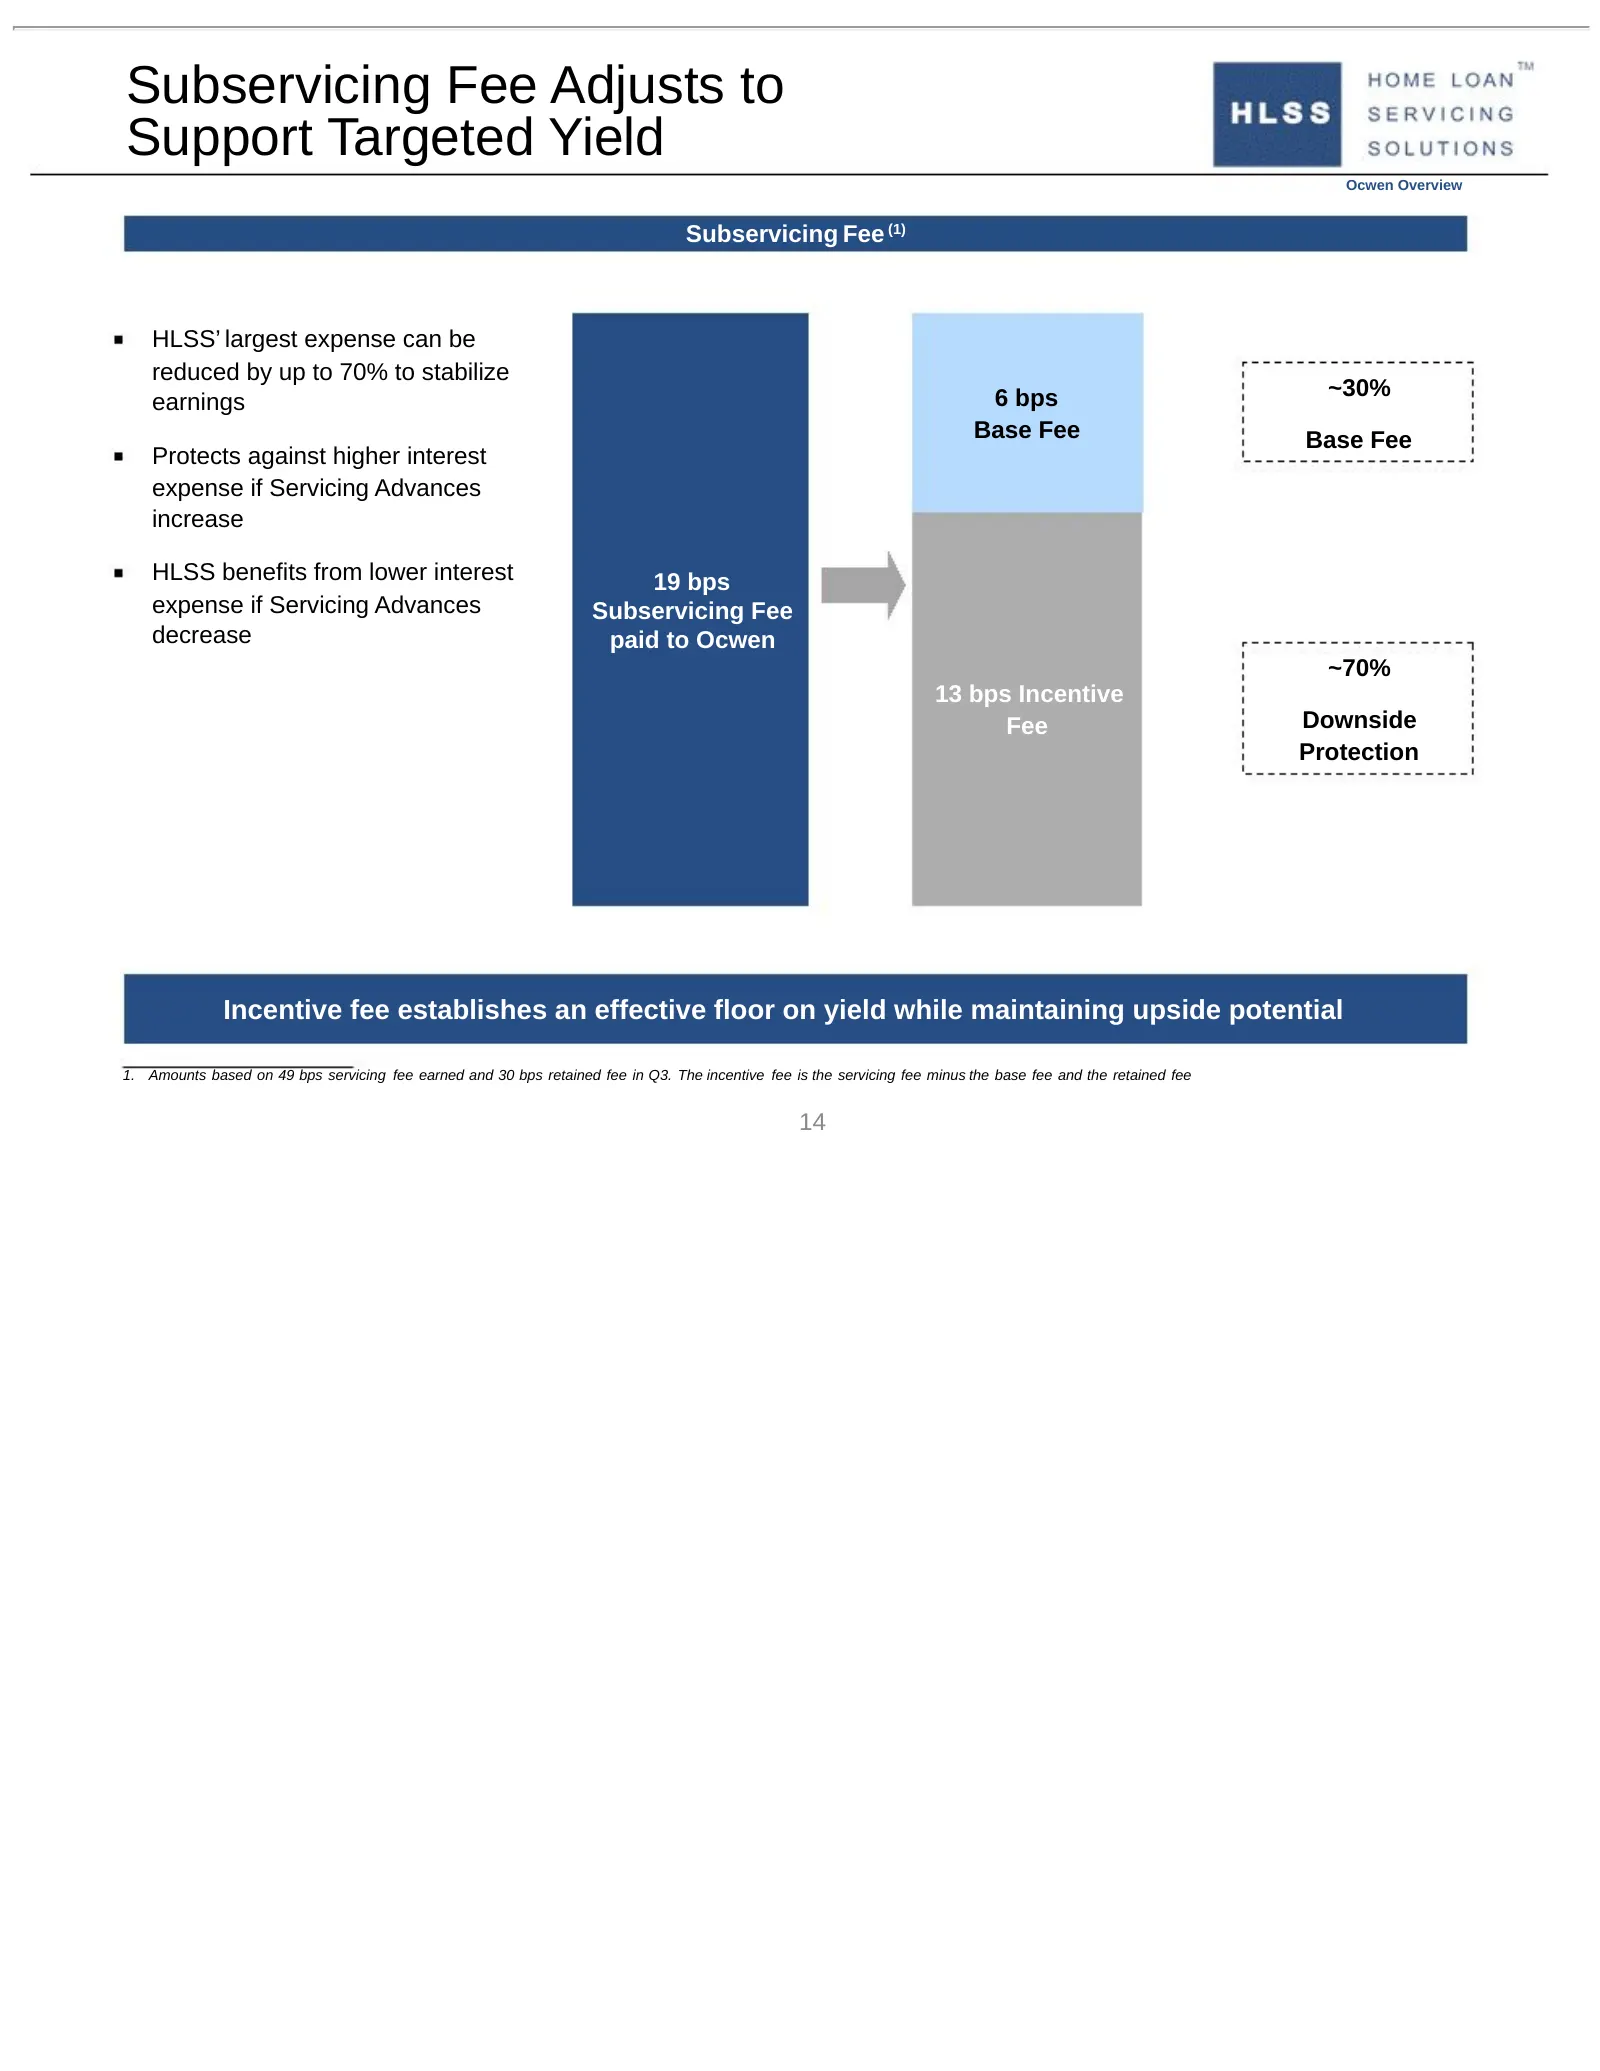
Subservicing Fee Adjusts to Support Targeted Yield Ocwen Overview Subservicing Fee (1) HLSS’ largest expense can be reduced by up to 70% to stabilize 6 bps ~30% earnings Base Fee Base Fee Protects against higher interest expense if Servicing Advances increase HLSS benefits from lower interest 19 bps
Slide 15: Global Servicing Platform
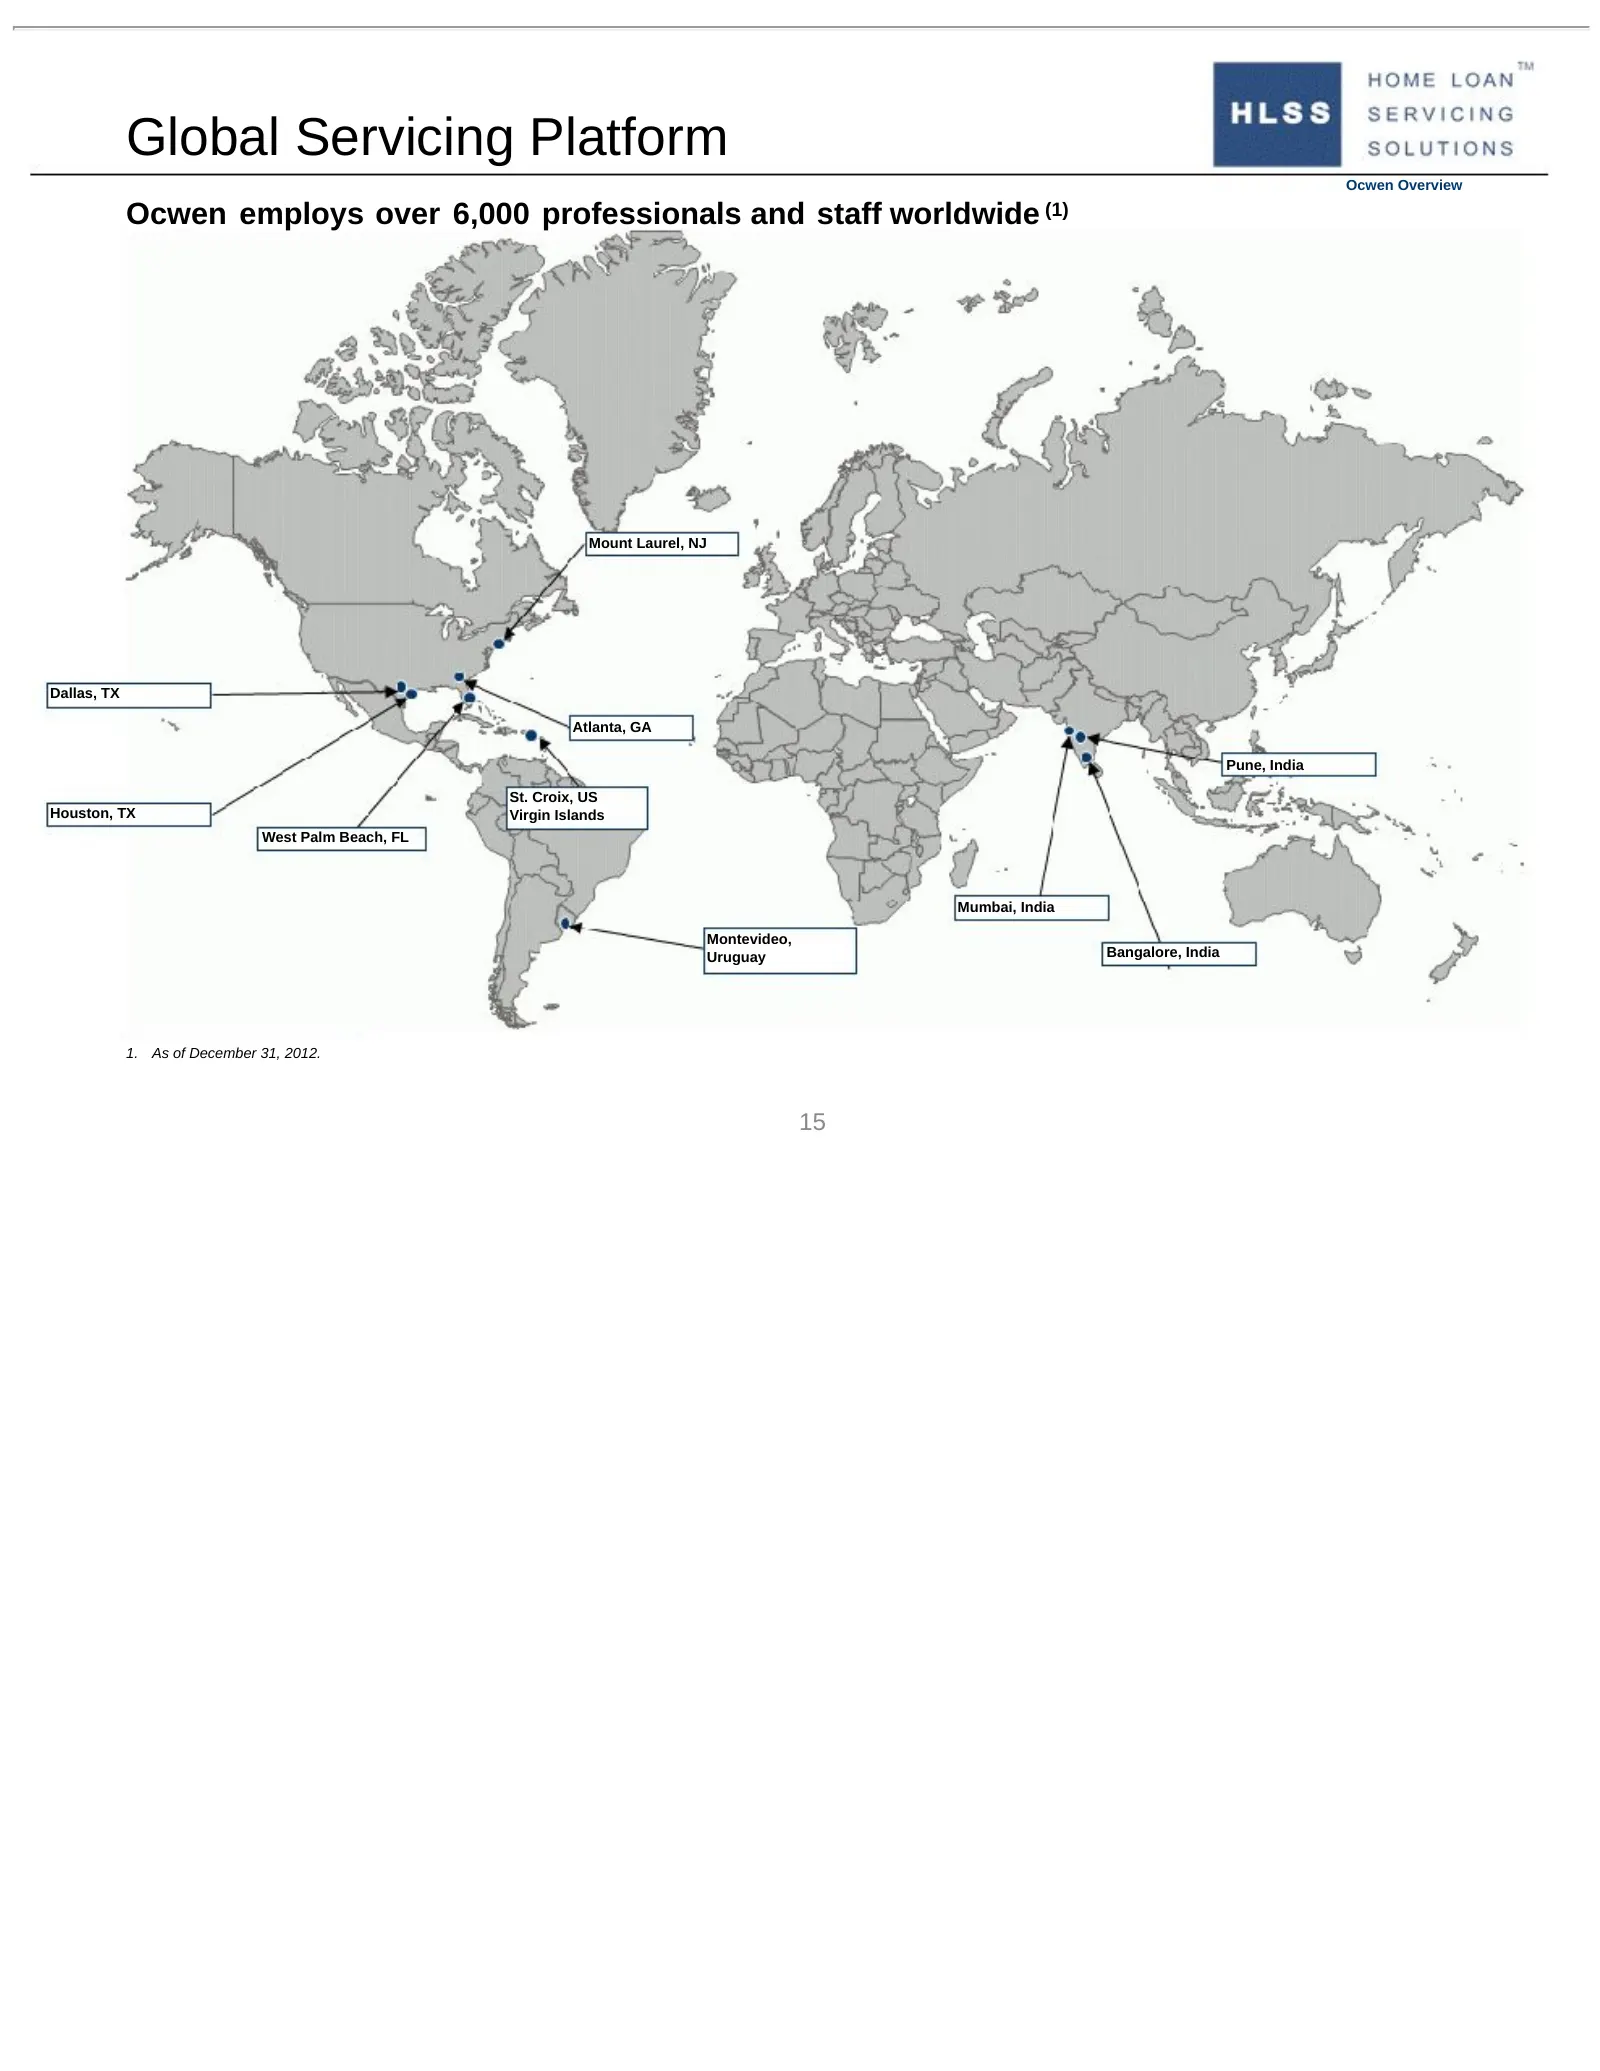
Global Servicing Platform Ocwen Overview Ocwen employs over 6,000 professionals and staff worldwide (1) Mount Laurel, NJ Dallas, TX Atlanta, GA Pune, India St. Croix, US Houston, TX Virgin Islands West Palm Beach, FL Mumbai, India Montevideo, Uruguay Bangalore, India 1. As of December 31, 2012. 15
Slide 16: Ocwen Servicing Portfolio History
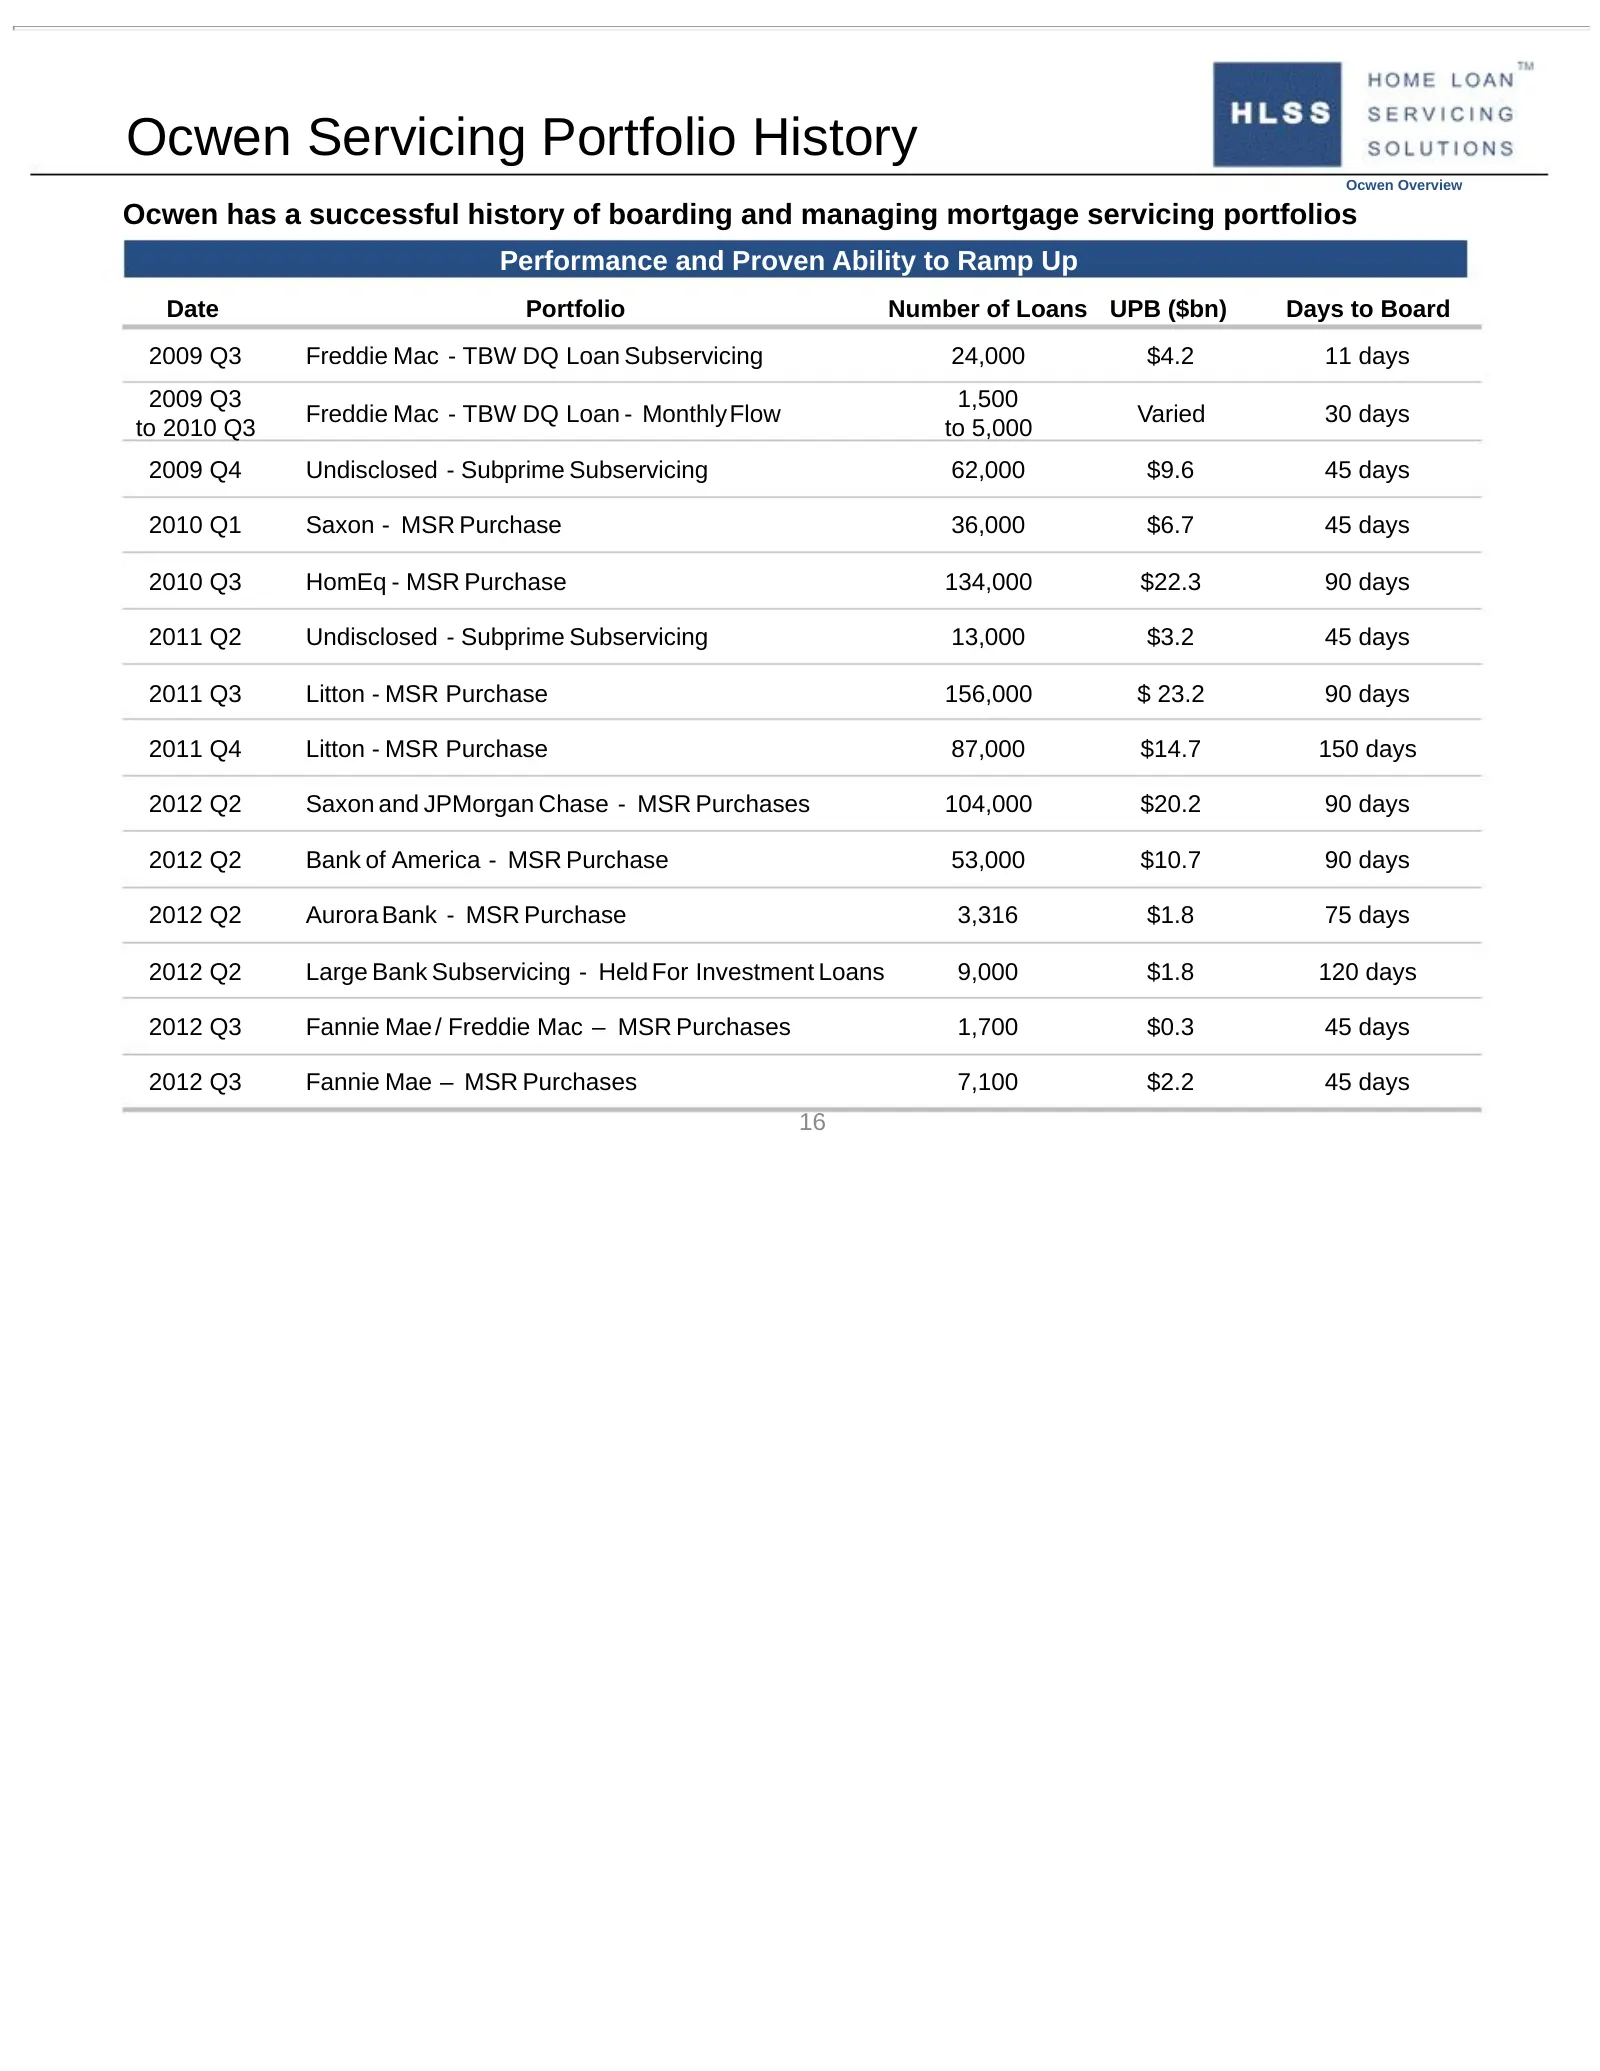
Ocwen Servicing Portfolio History Ocwen Overview Ocwen has a successful history of boarding and managing mortgage servicing portfolios Performance and Proven Ability to Ramp Up Date Portfolio Number of Loans UPB ($bn) Days to Board 2009 Q3 Freddie Mac - TBW DQ Loan Subservicing 24,000 $4.2 11 days 2
Slide 17: Ocwen Servicing Portfolio Update
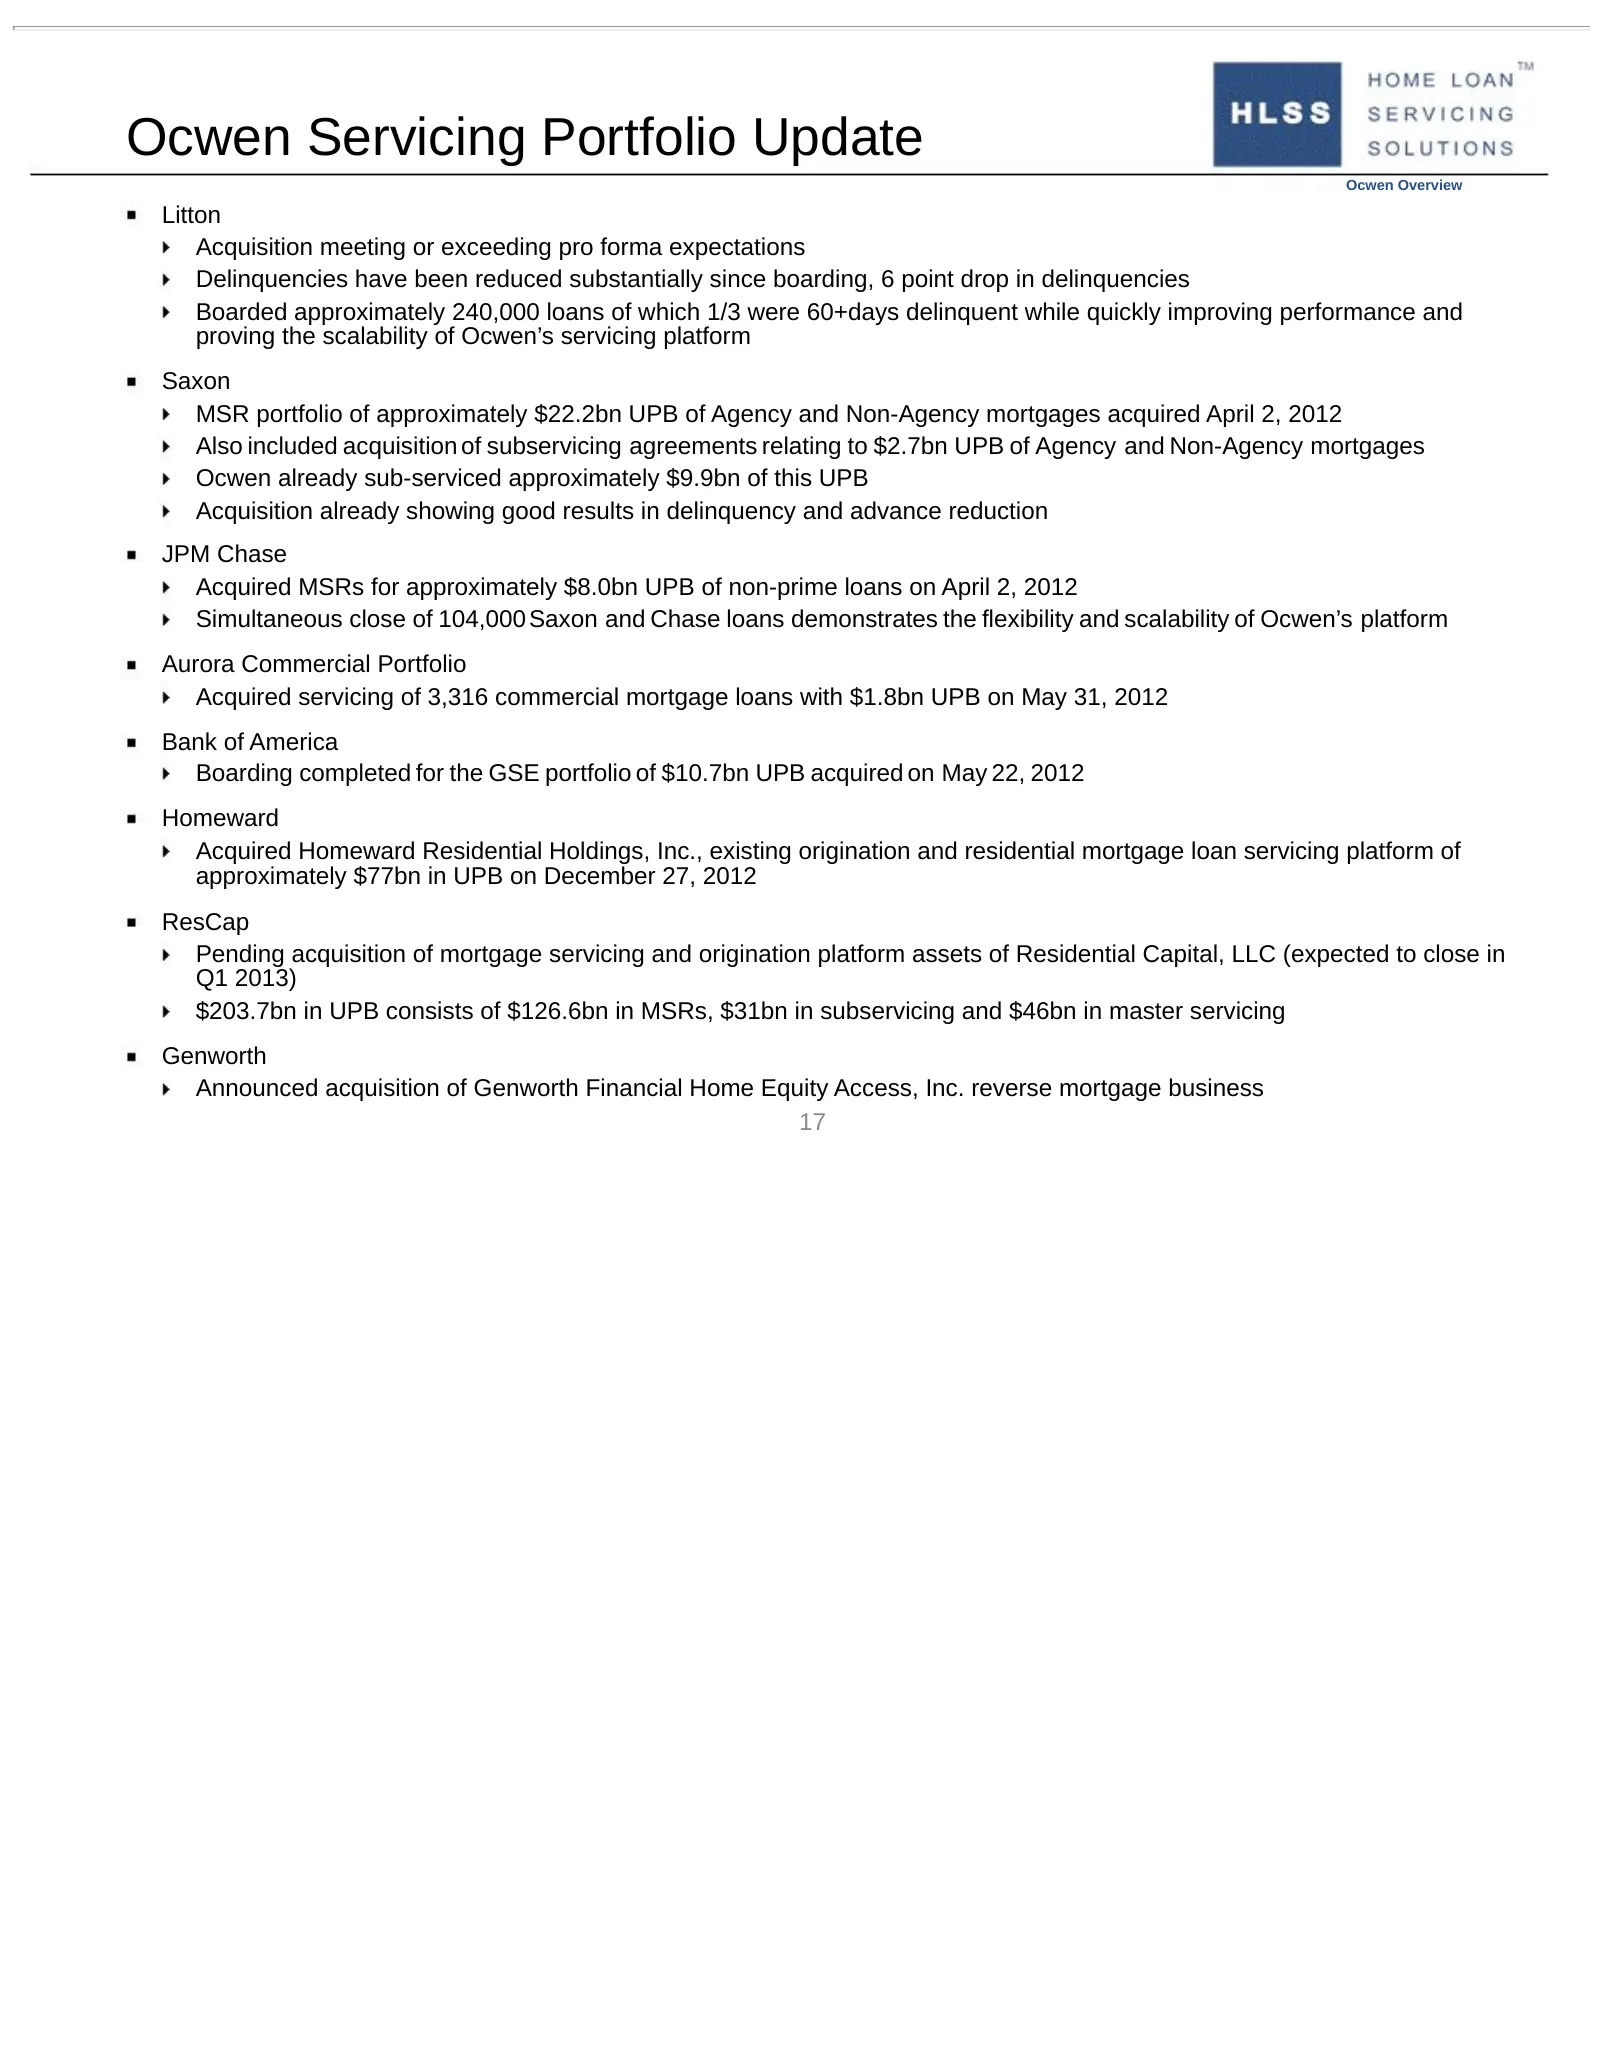
Ocwen Servicing Portfolio Update Ocwen Overview Litton Acquisition meeting or exceeding pro forma expectations Delinquencies have been reduced substantially since boarding, 6 point drop in delinquencies Boarded approximately 240,000 loans of which 1/3 were 60+days delinquent while quickly improving
Slide 18: Ocwen Servicing Effectiveness
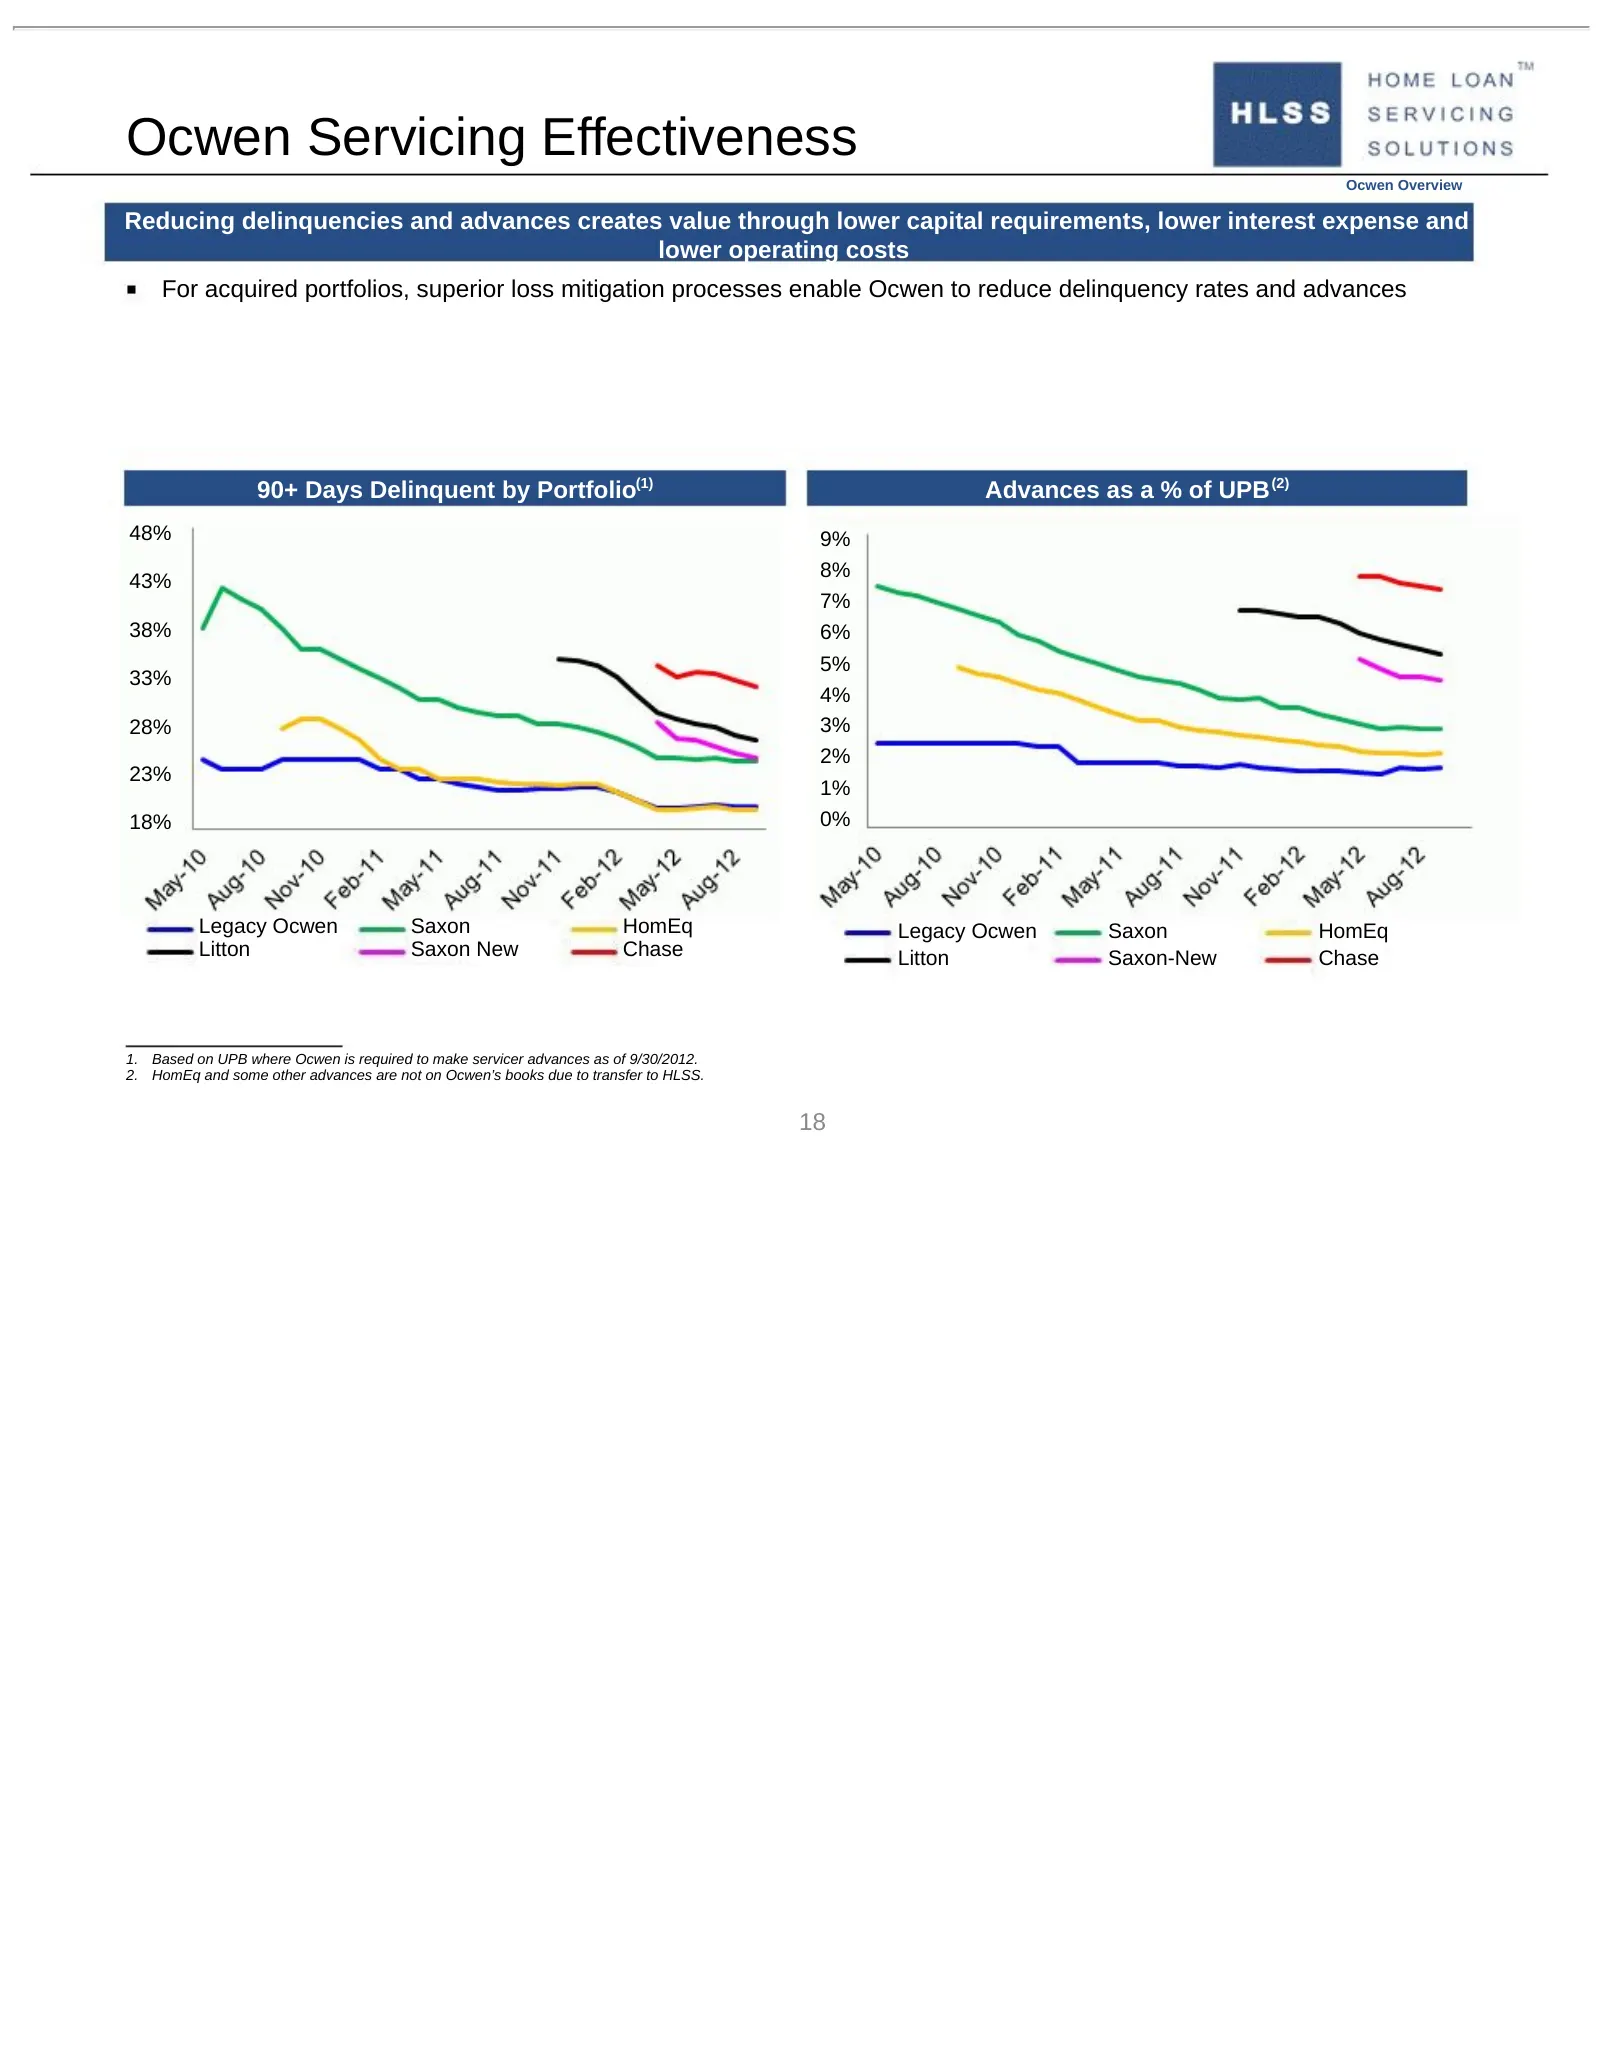
Ocwen Servicing Effectiveness Ocwen Overview Reducing delinquencies and advances creates value through lower capital requirements, lower interest expense and lower operating costs For acquired portfolios, superior loss mitigation processes enable Ocwen to reduce delinquency rates and advances 90+ Da
Slide 19: Ocwen Servicing Portfolio Details
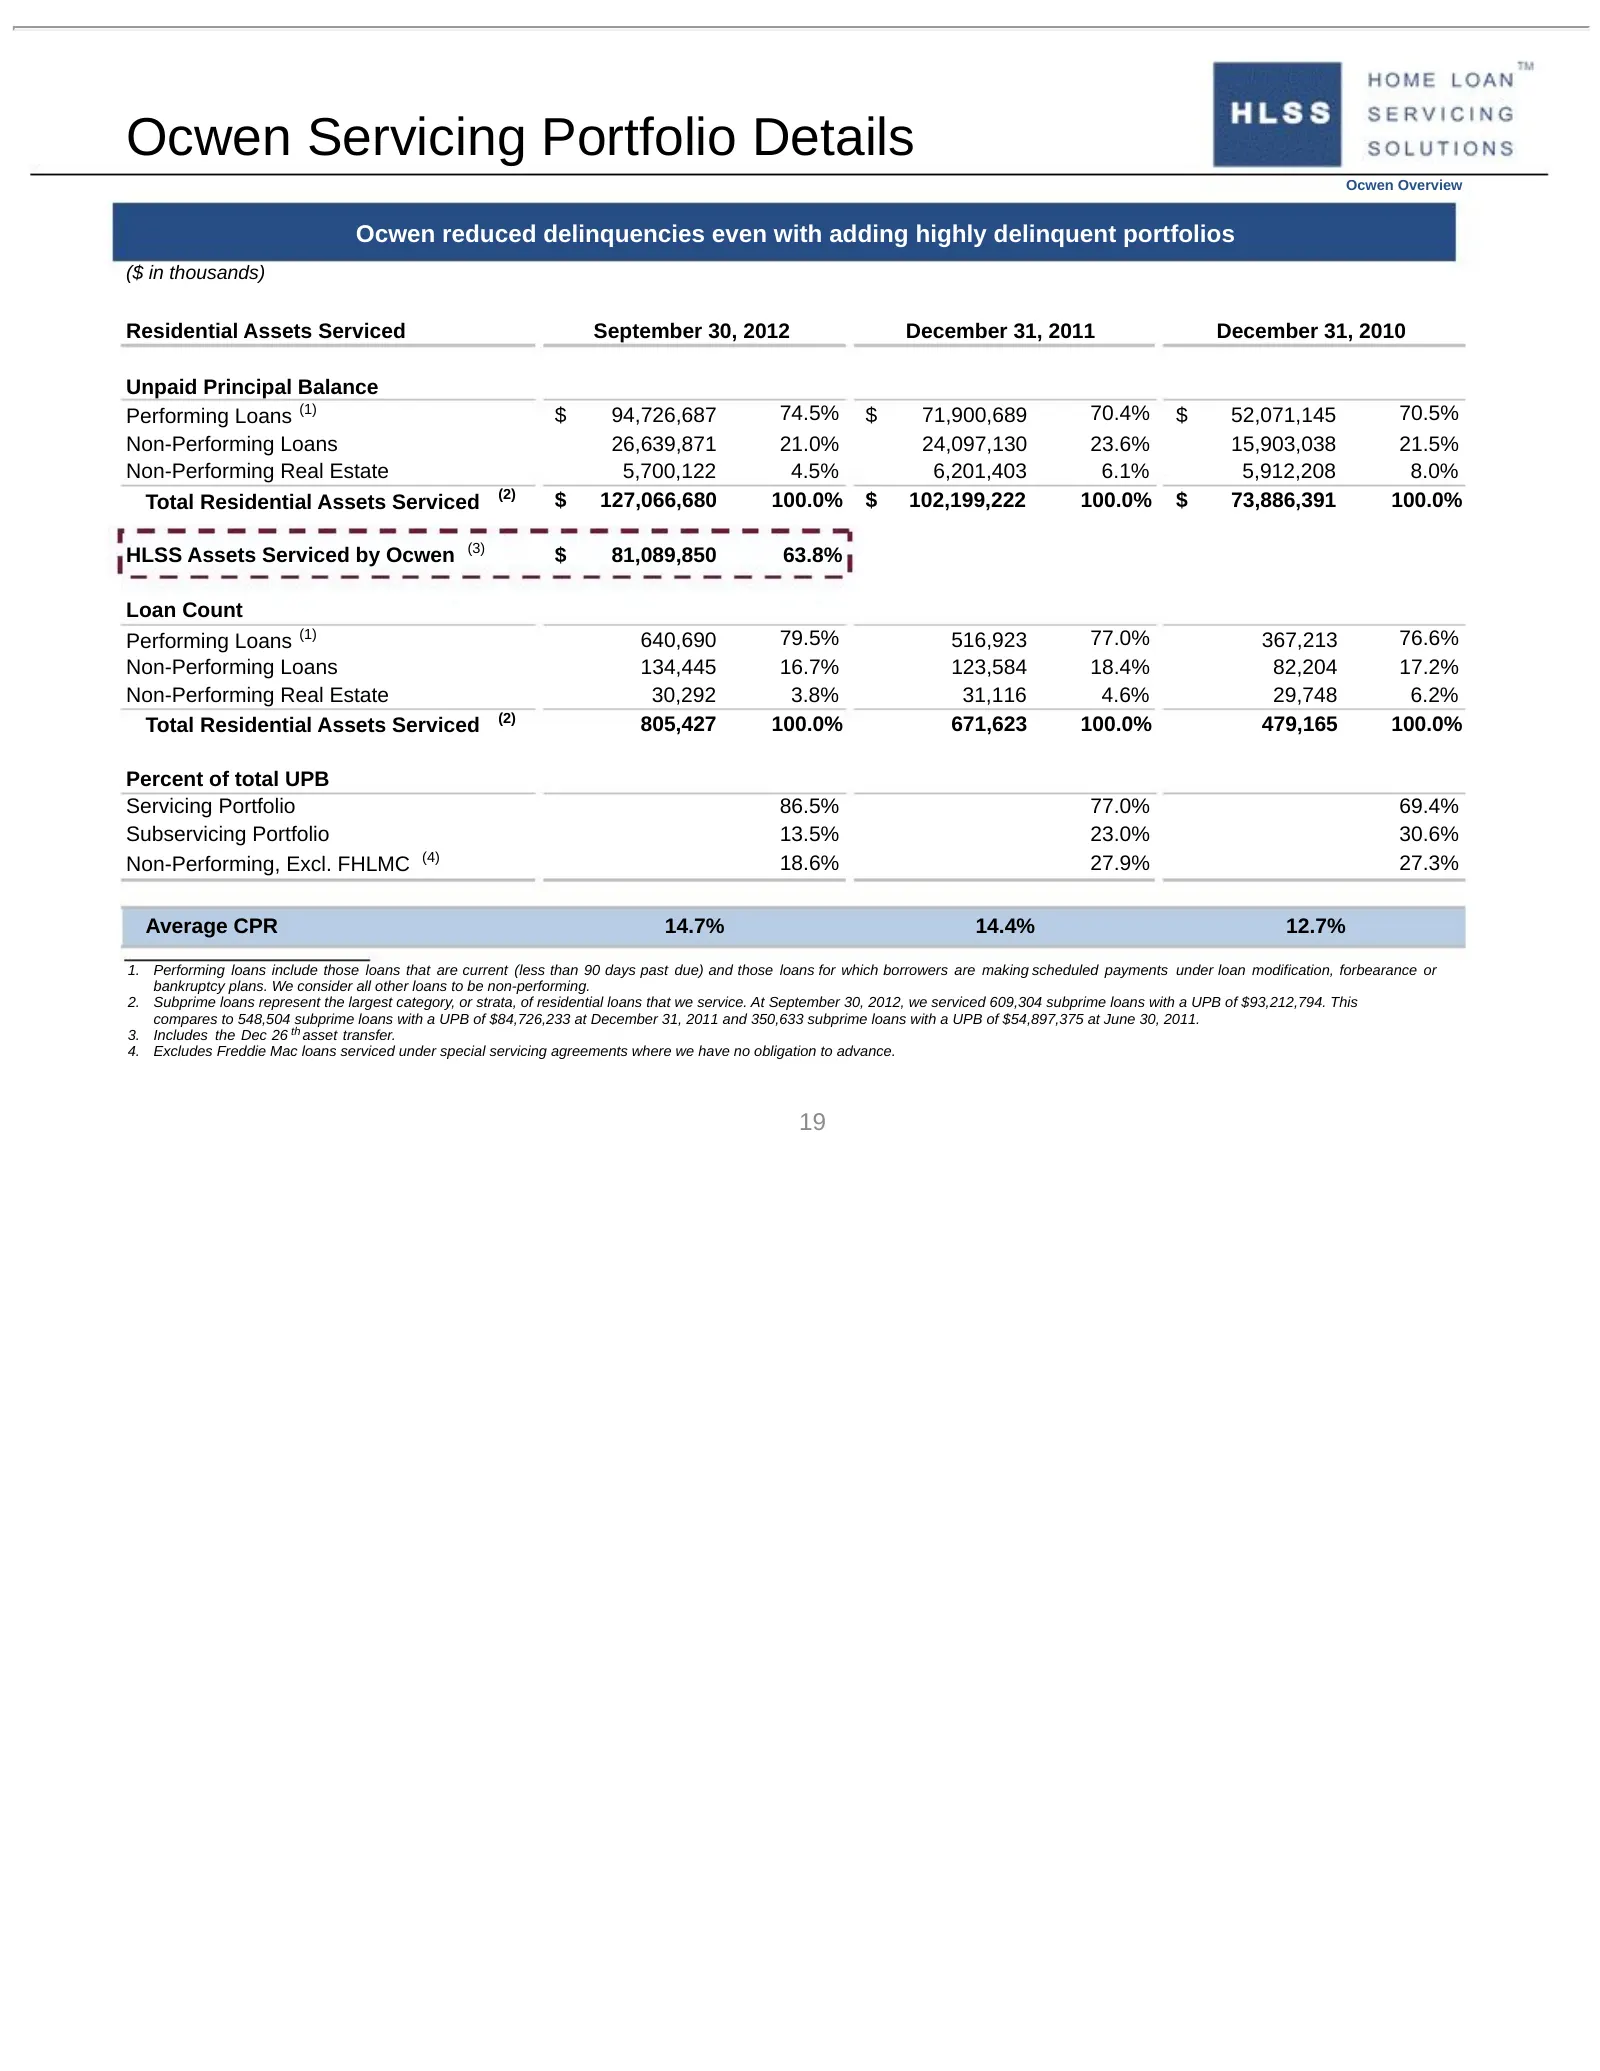
Ocwen Servicing Portfolio Details Ocwen Overview Ocwen reduced delinquencies even with adding highly delinquent portfolios ($ in thousands) Residential Assets Serviced September 30, 2012 December 31, 2011 December 31, 2010 Unpaid Principal Balance Performing Loans (1) $ 94,726,687 74.5% $ 71,900,689
Slide 20: HSART Master Trust Overview
HSART Master Trust Overview 20
Slide 21: HSART Structural Summary
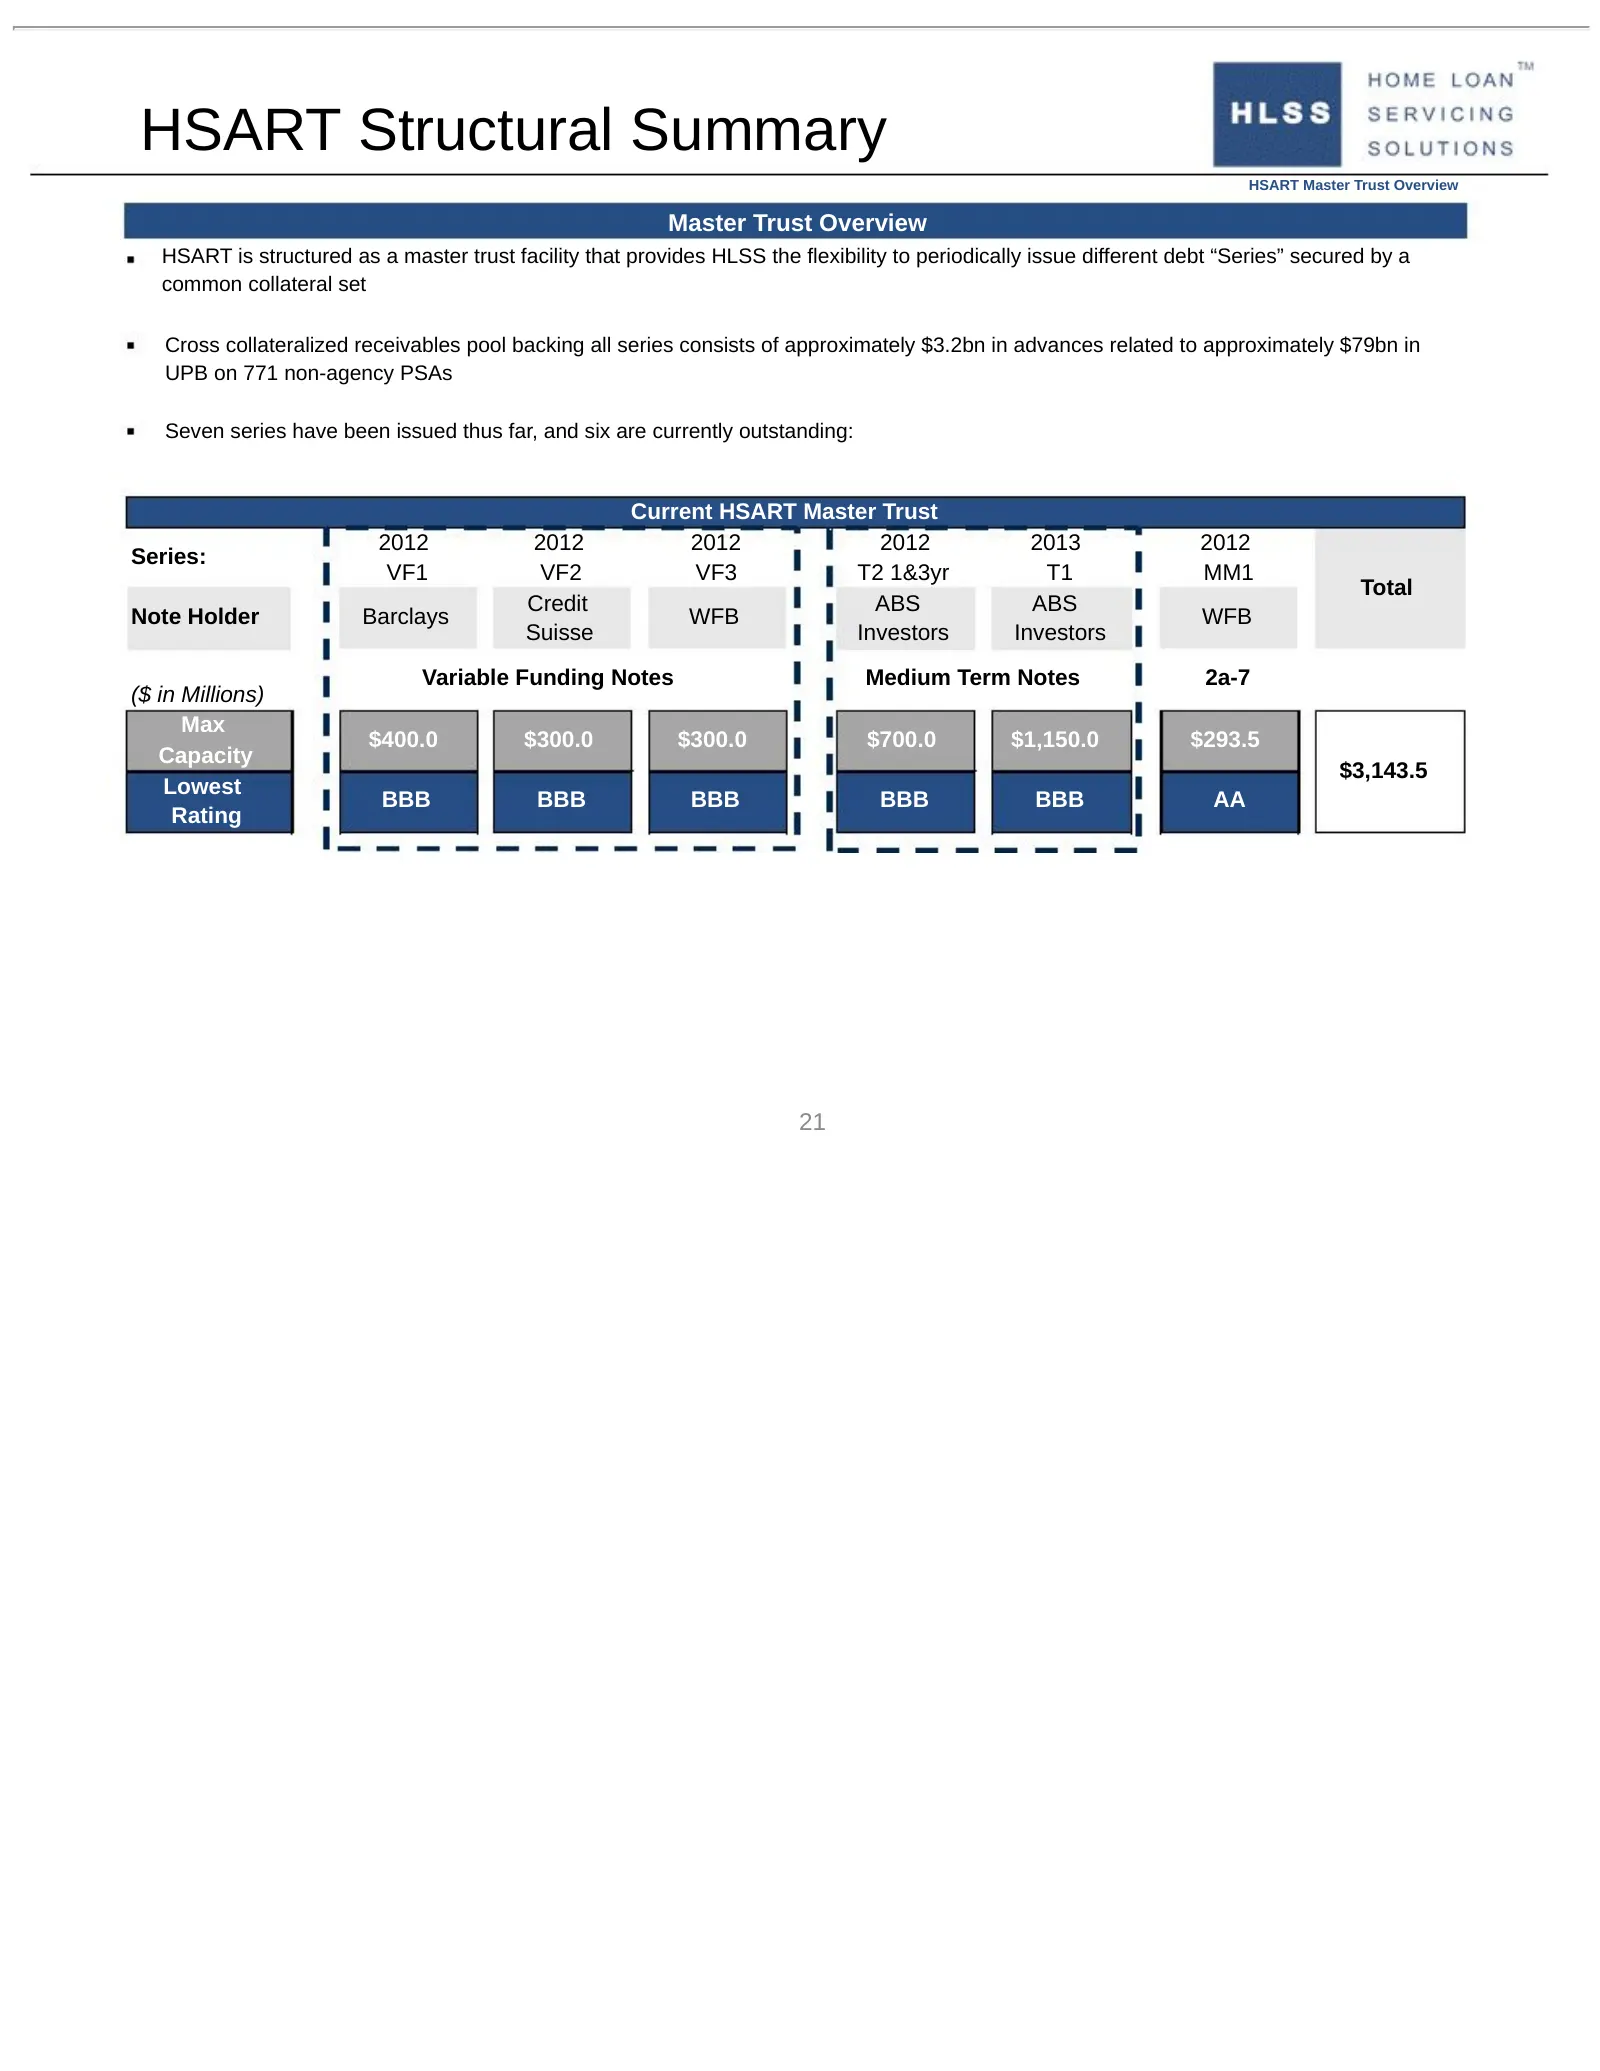
HSART Structural Summary HSART Master Trust Overview Master Trust Overview HSART is structured as a master trust facility that provides HLSS the flexibility to periodically issue different debt “Series” secured by a common collateral set Cross collateralized receivables pool backing all series consi
Slide 22: Master Trust Receivables Distribution
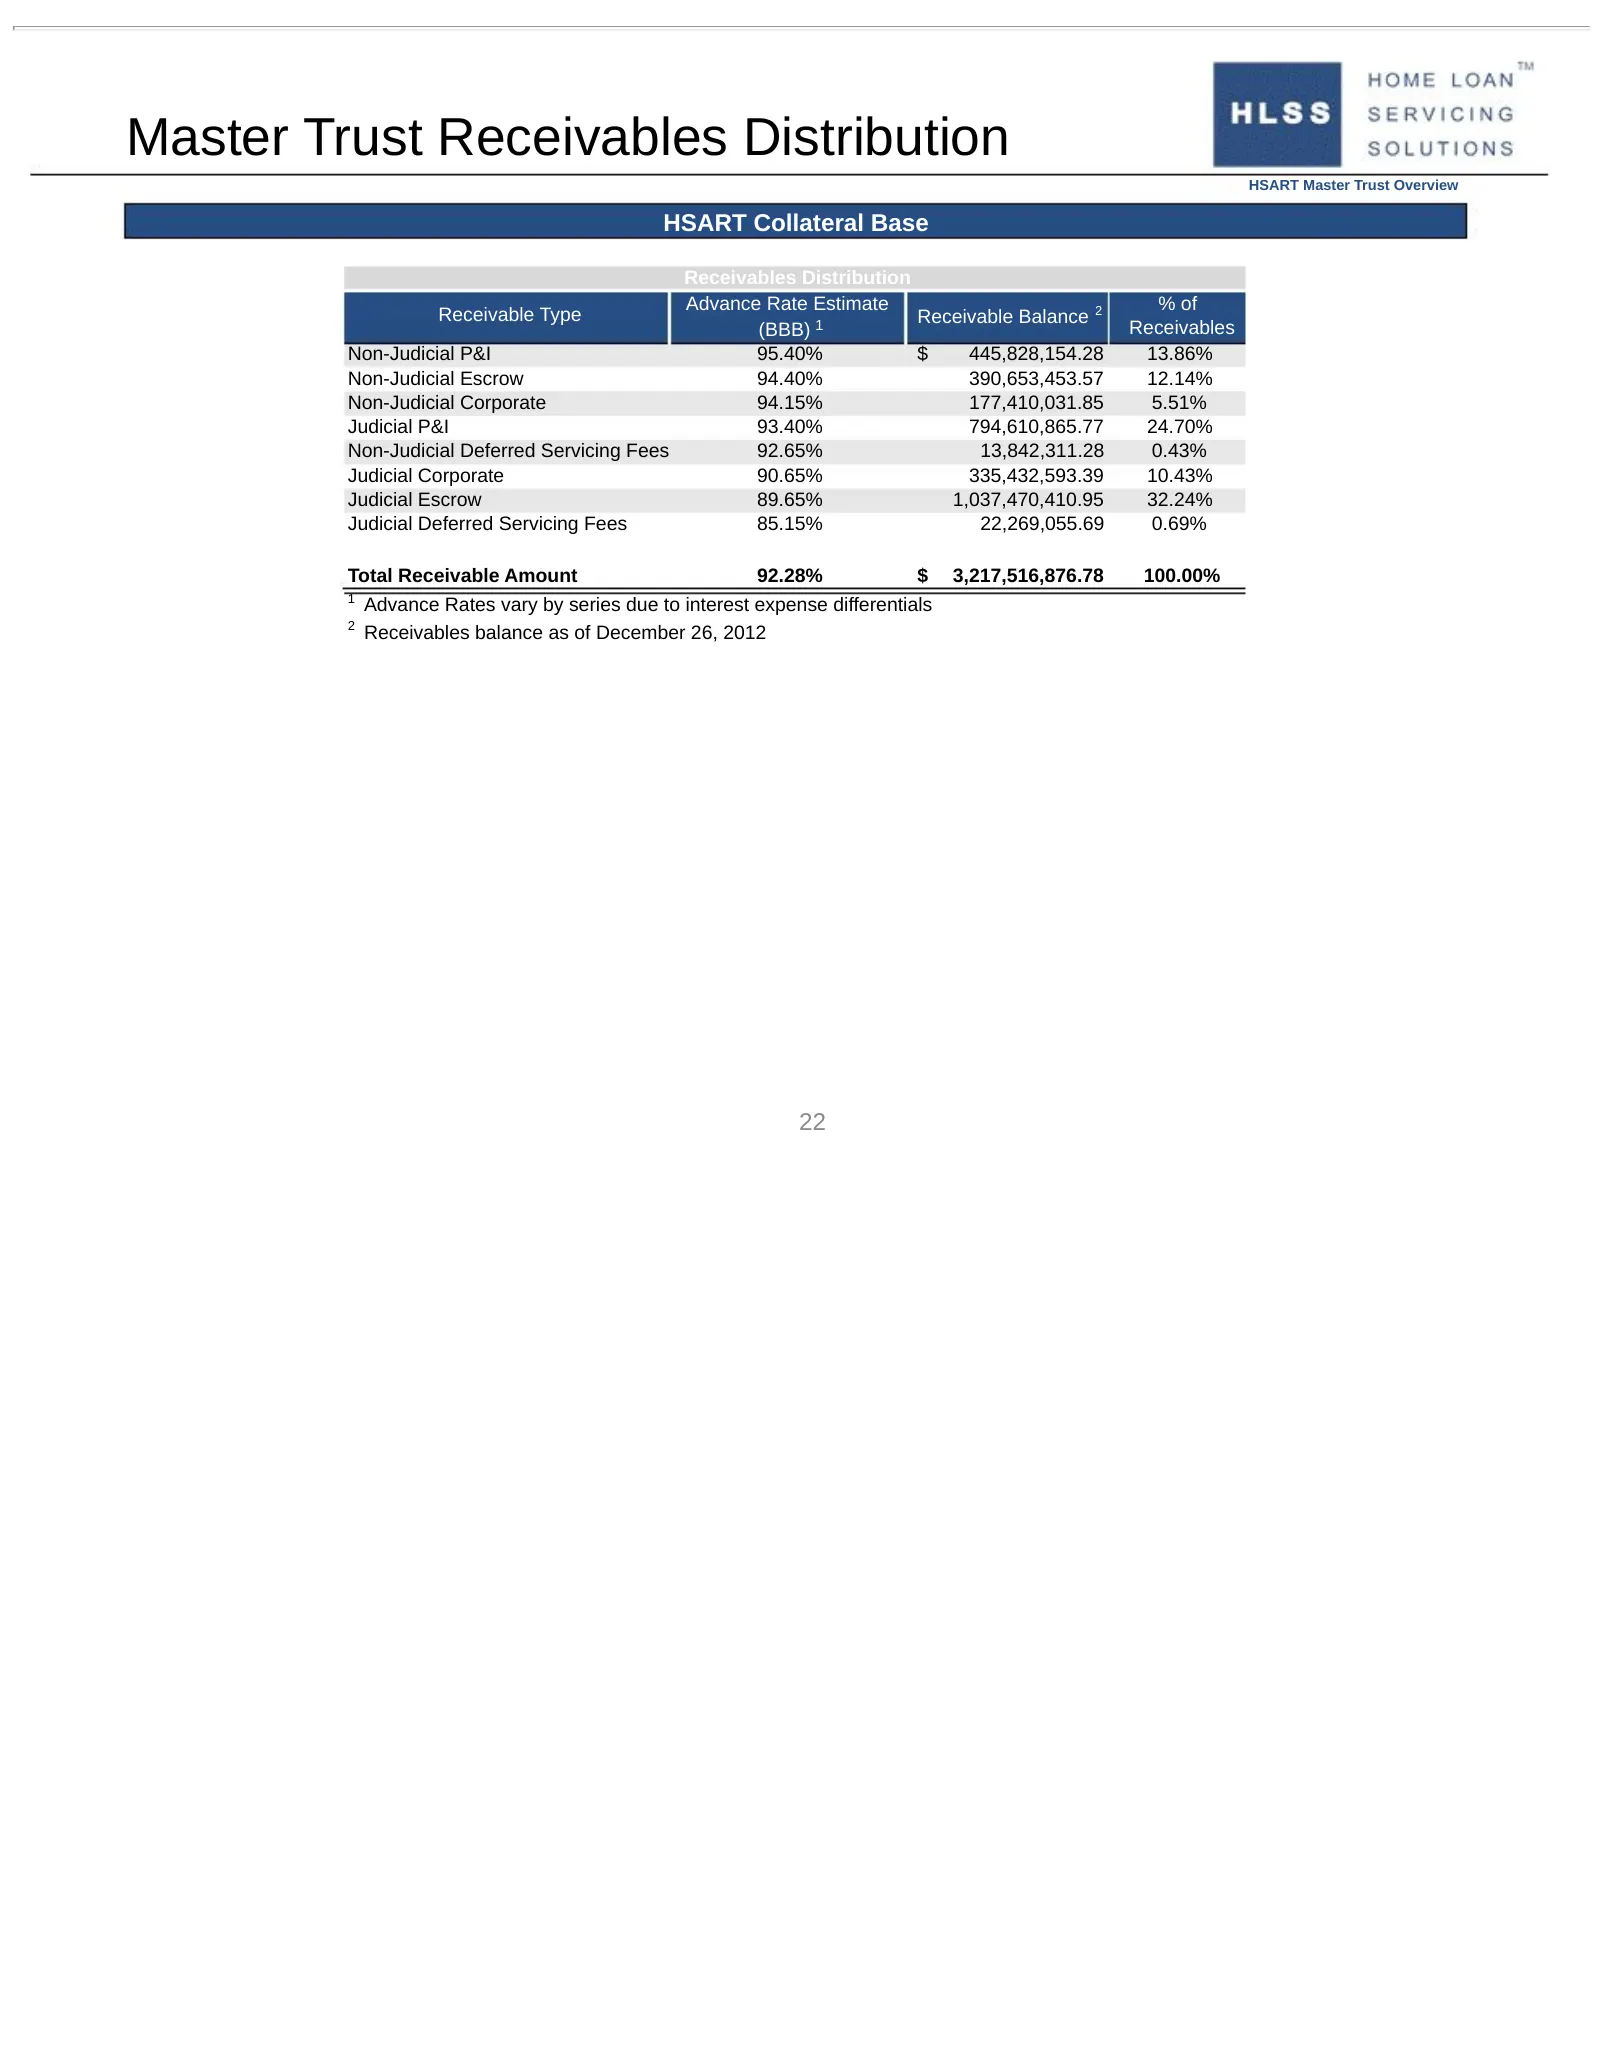
Master Trust Receivables Distribution HSART Master Trust Overview HSART Collateral Base Receivables Distribution Advance Rate Estimate % of Receivable Type Receivable Balance 2 (BBB) 1 Receivables Non-Judicial P&I 95.40% $ 445,828,154.28 13.86% Non-Judicial Escrow 94.40% 390,653,453.57 12.14% Non-Ju
Slide 23: HSART Series 2013 – T1 Marketing Summary
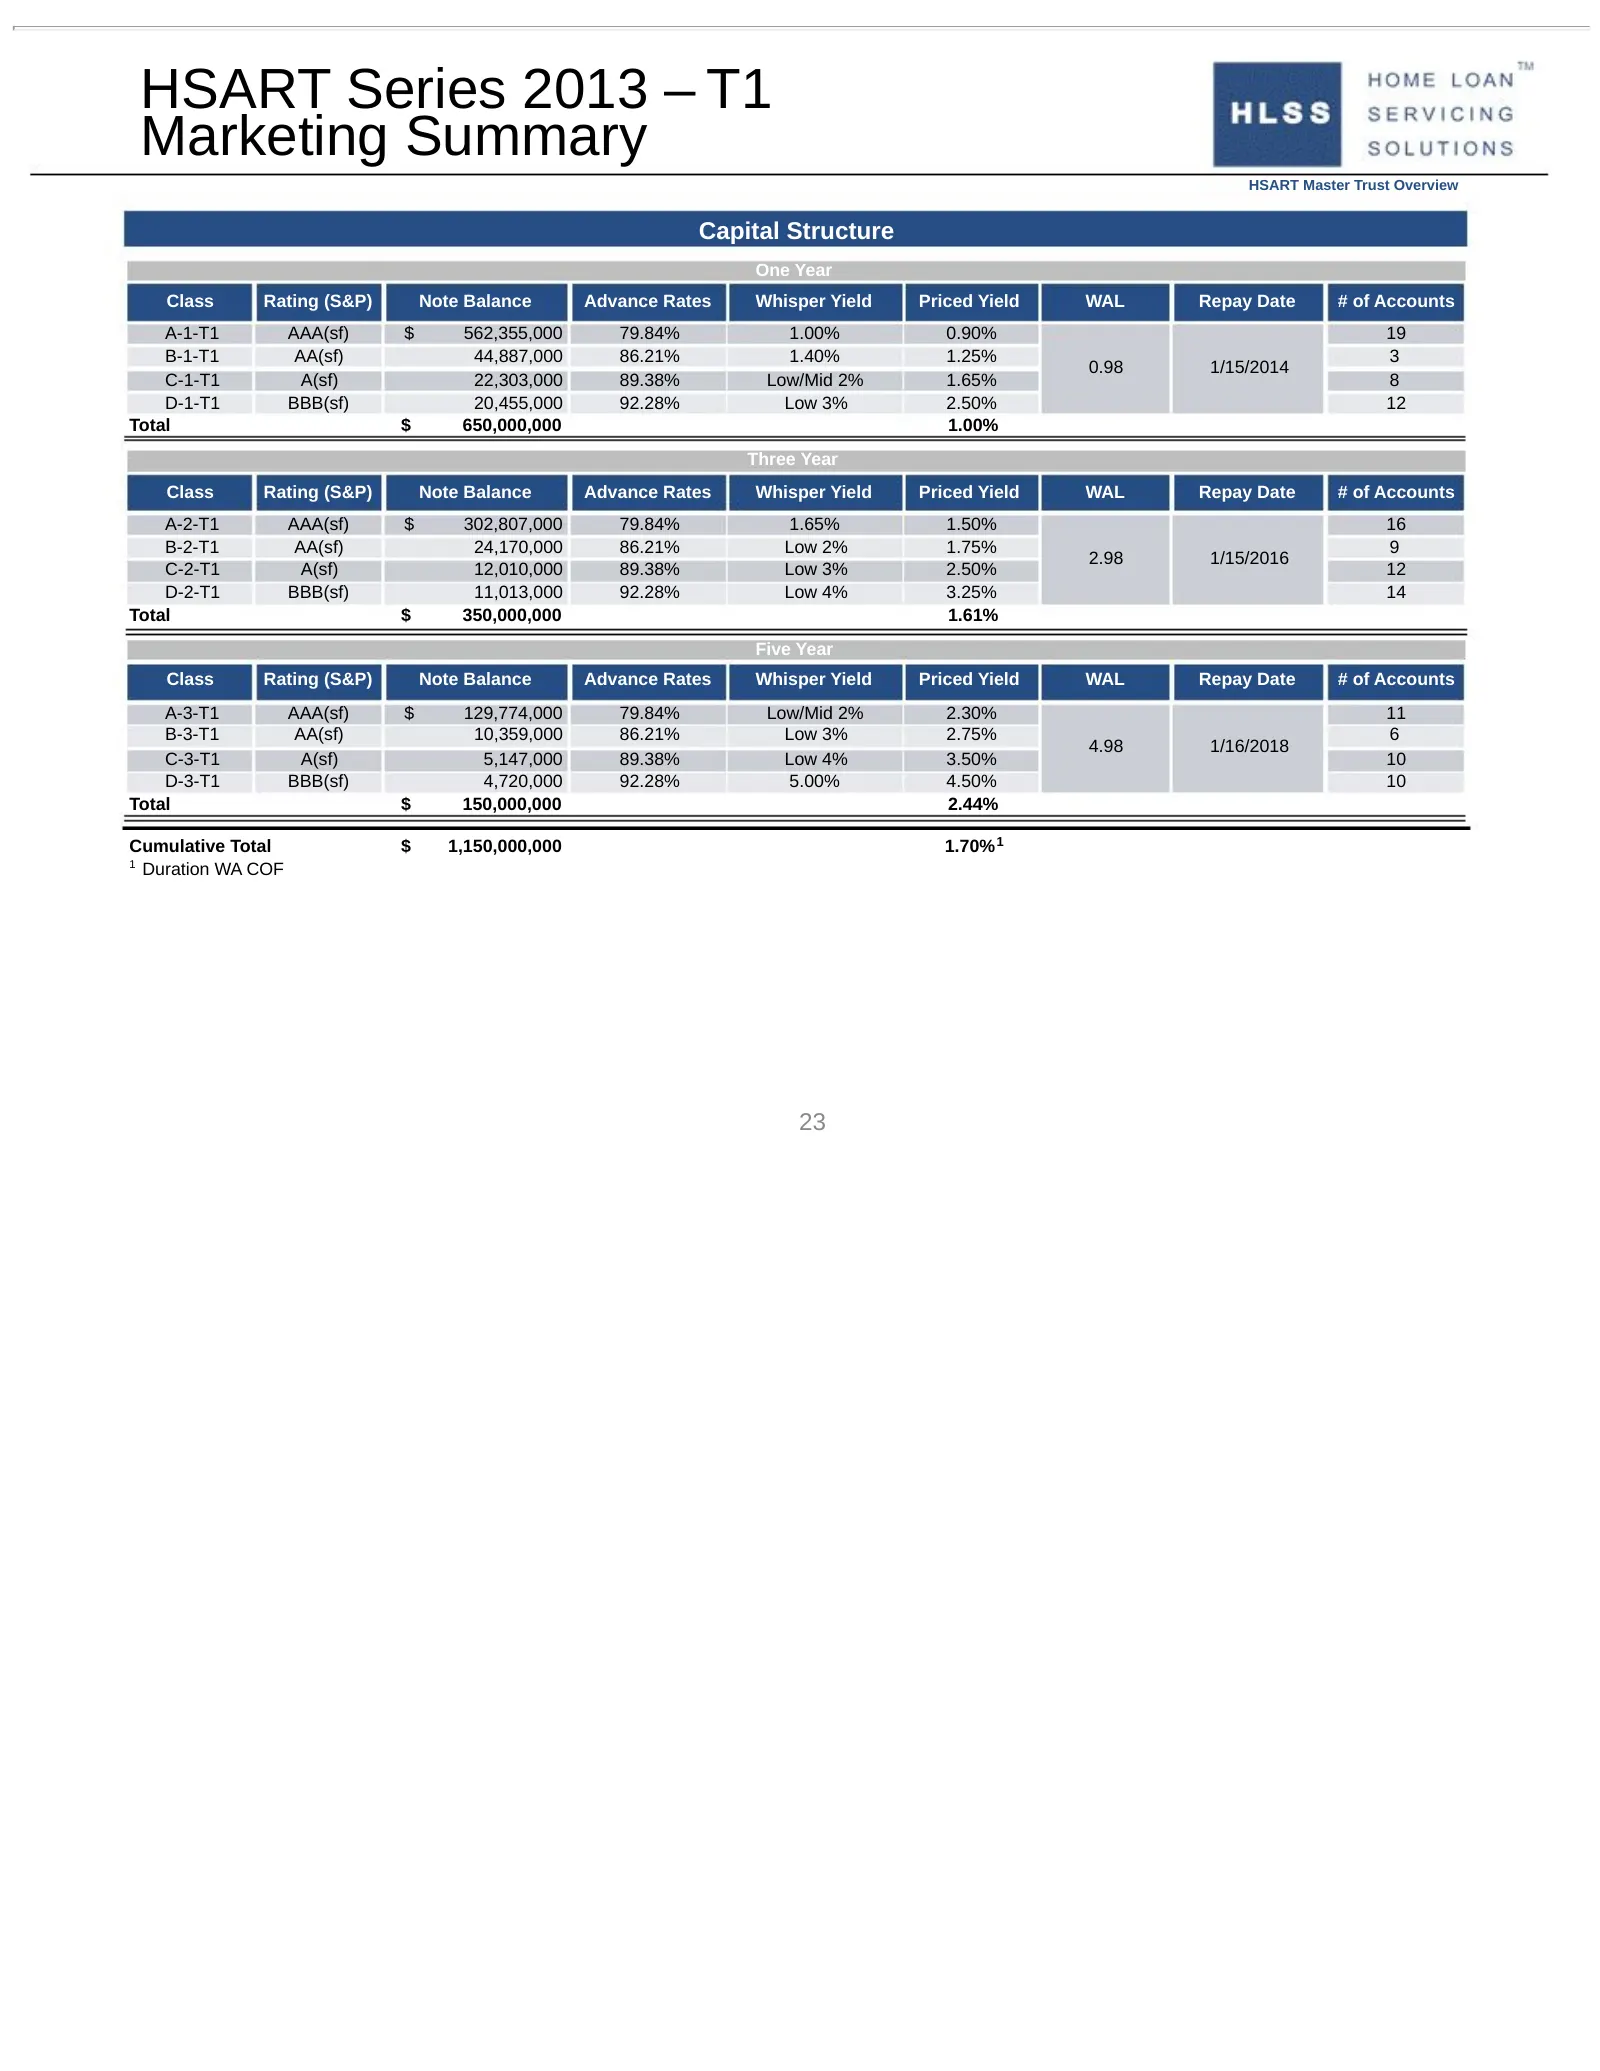
HSART Series 2013 – T1 Marketing Summary HSART Master Trust Overview Capital Structure One Year Class Rating (S&P) Note Balance Advance Rates Whisper Yield Priced Yield WAL Repay Date # of Accounts A-1-T1 AAA(sf) $ 562,355,000 79.84% 1.00% 0.90% 19 B-1-T1 AA(sf) 44,887,000 86.21% 1.40% 1.25% 3 0.98
Slide 24: HSART Series 2013 – T1 Marketing Summary
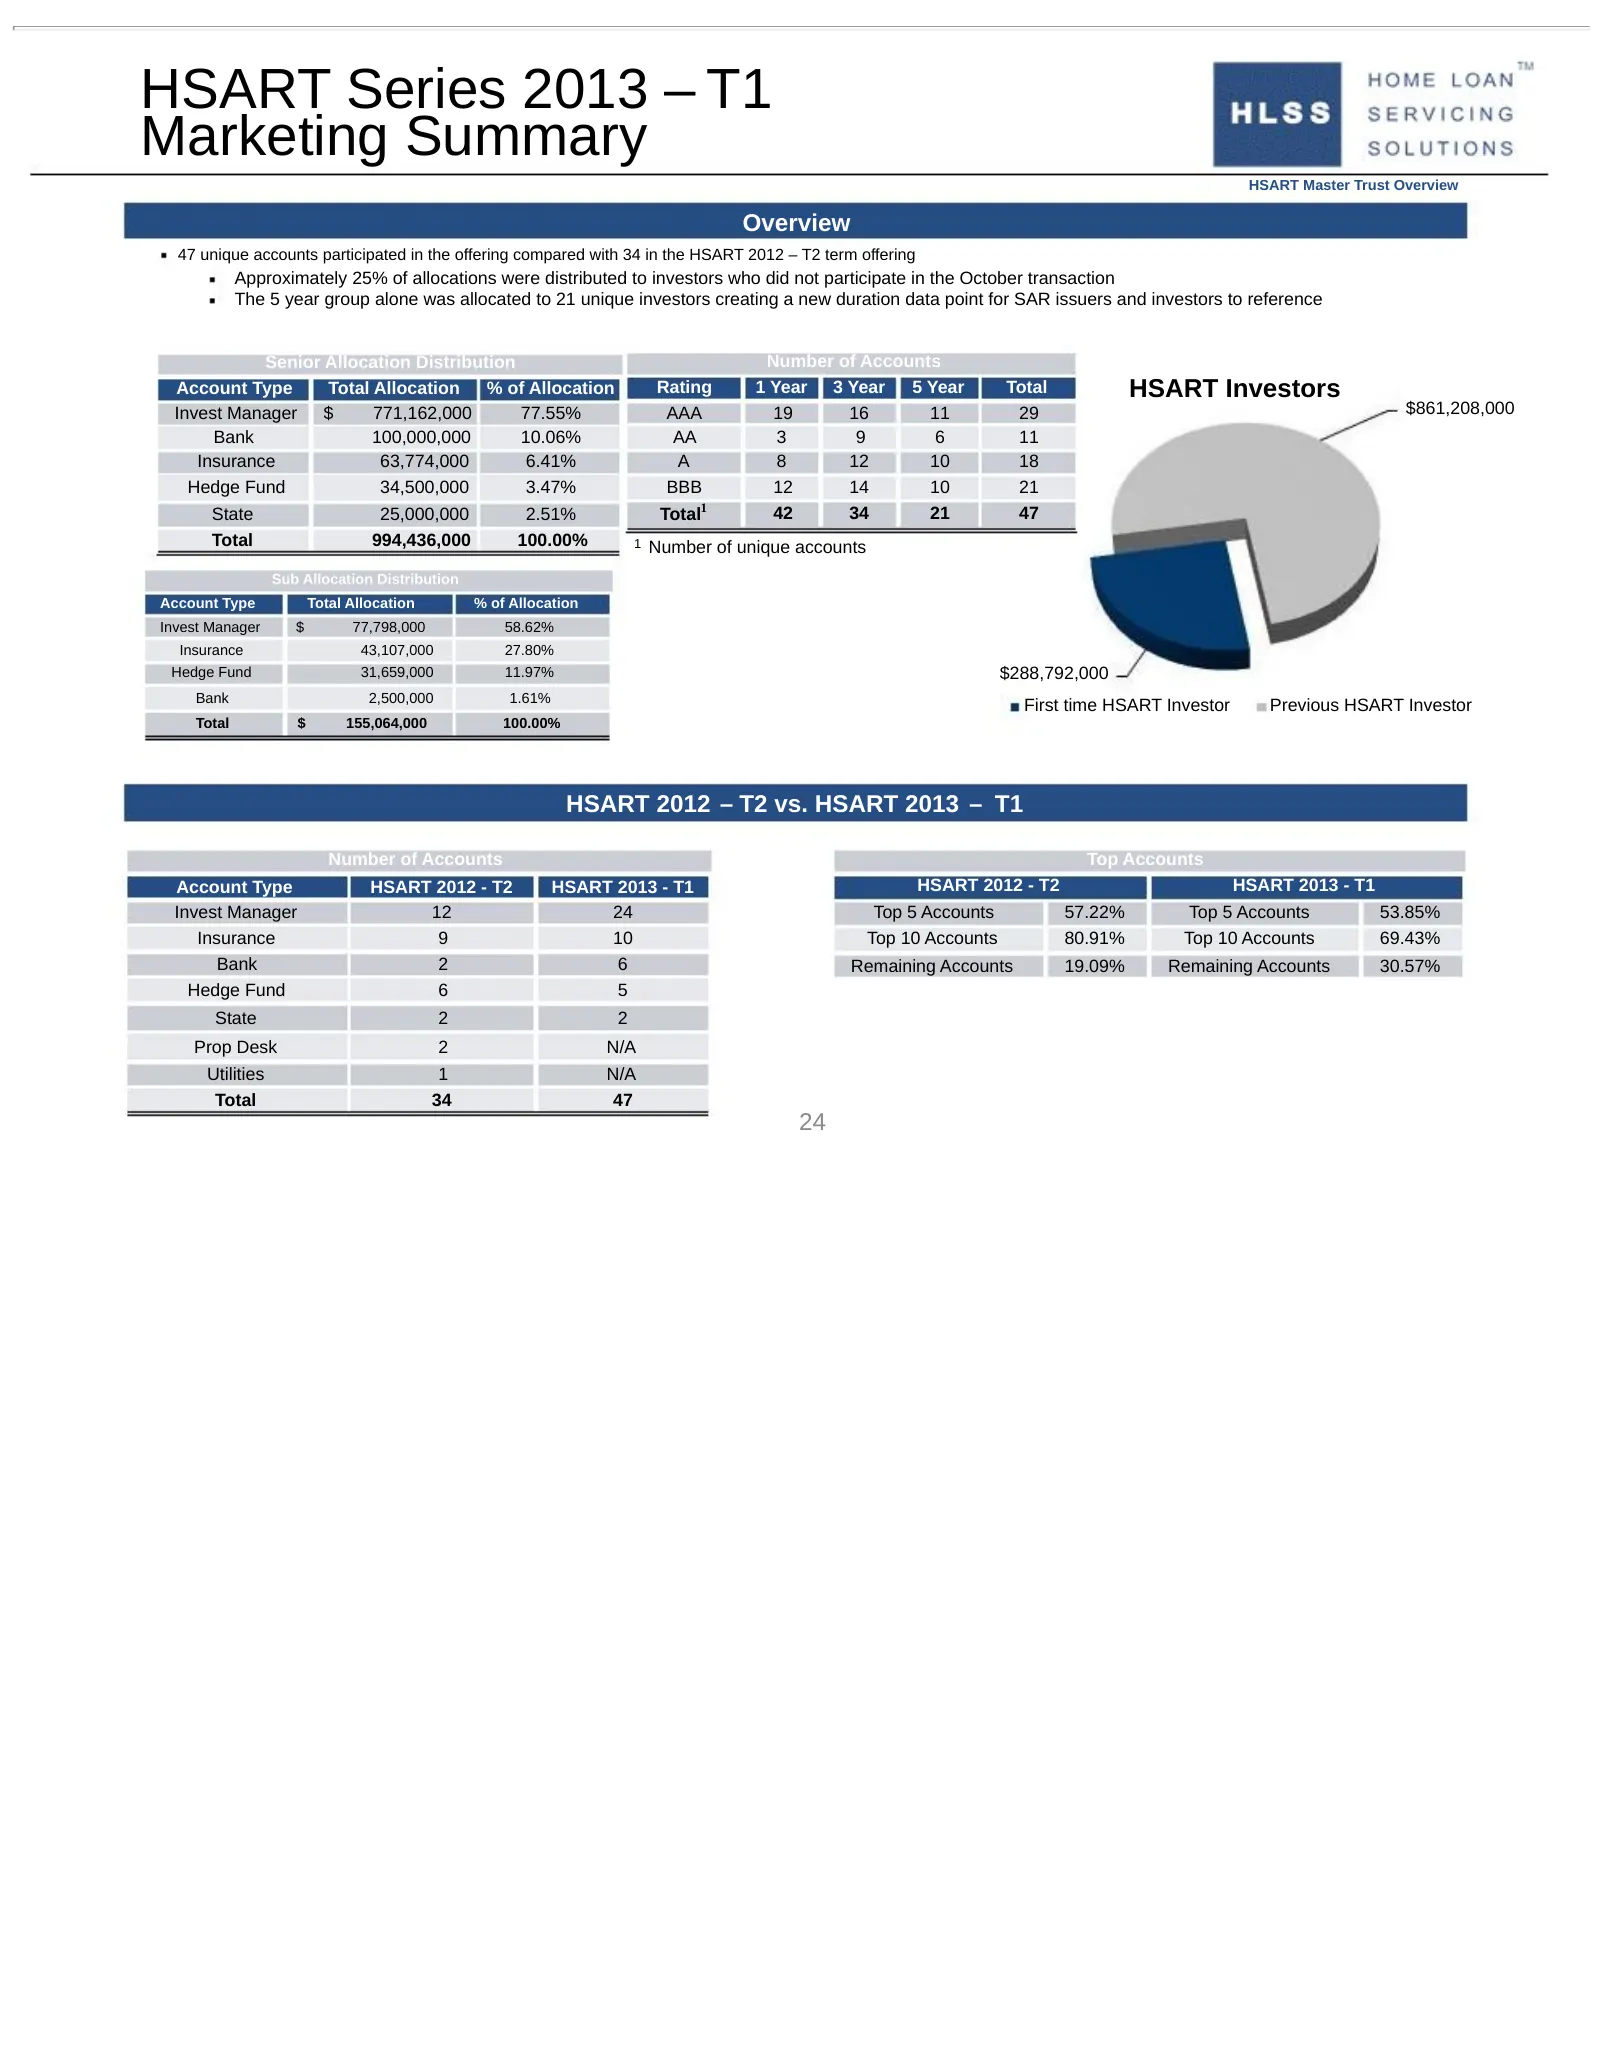
HSART Series 2013 – T1 Marketing Summary HSART Master Trust Overview Overview 47 unique accounts participated in the offering compared with 34 in the HSART 2012 – T2 term offering Approximately 25% of allocations were distributed to investors who did not participate in the October transaction The 5
Slide 25: HSART Investor Protections
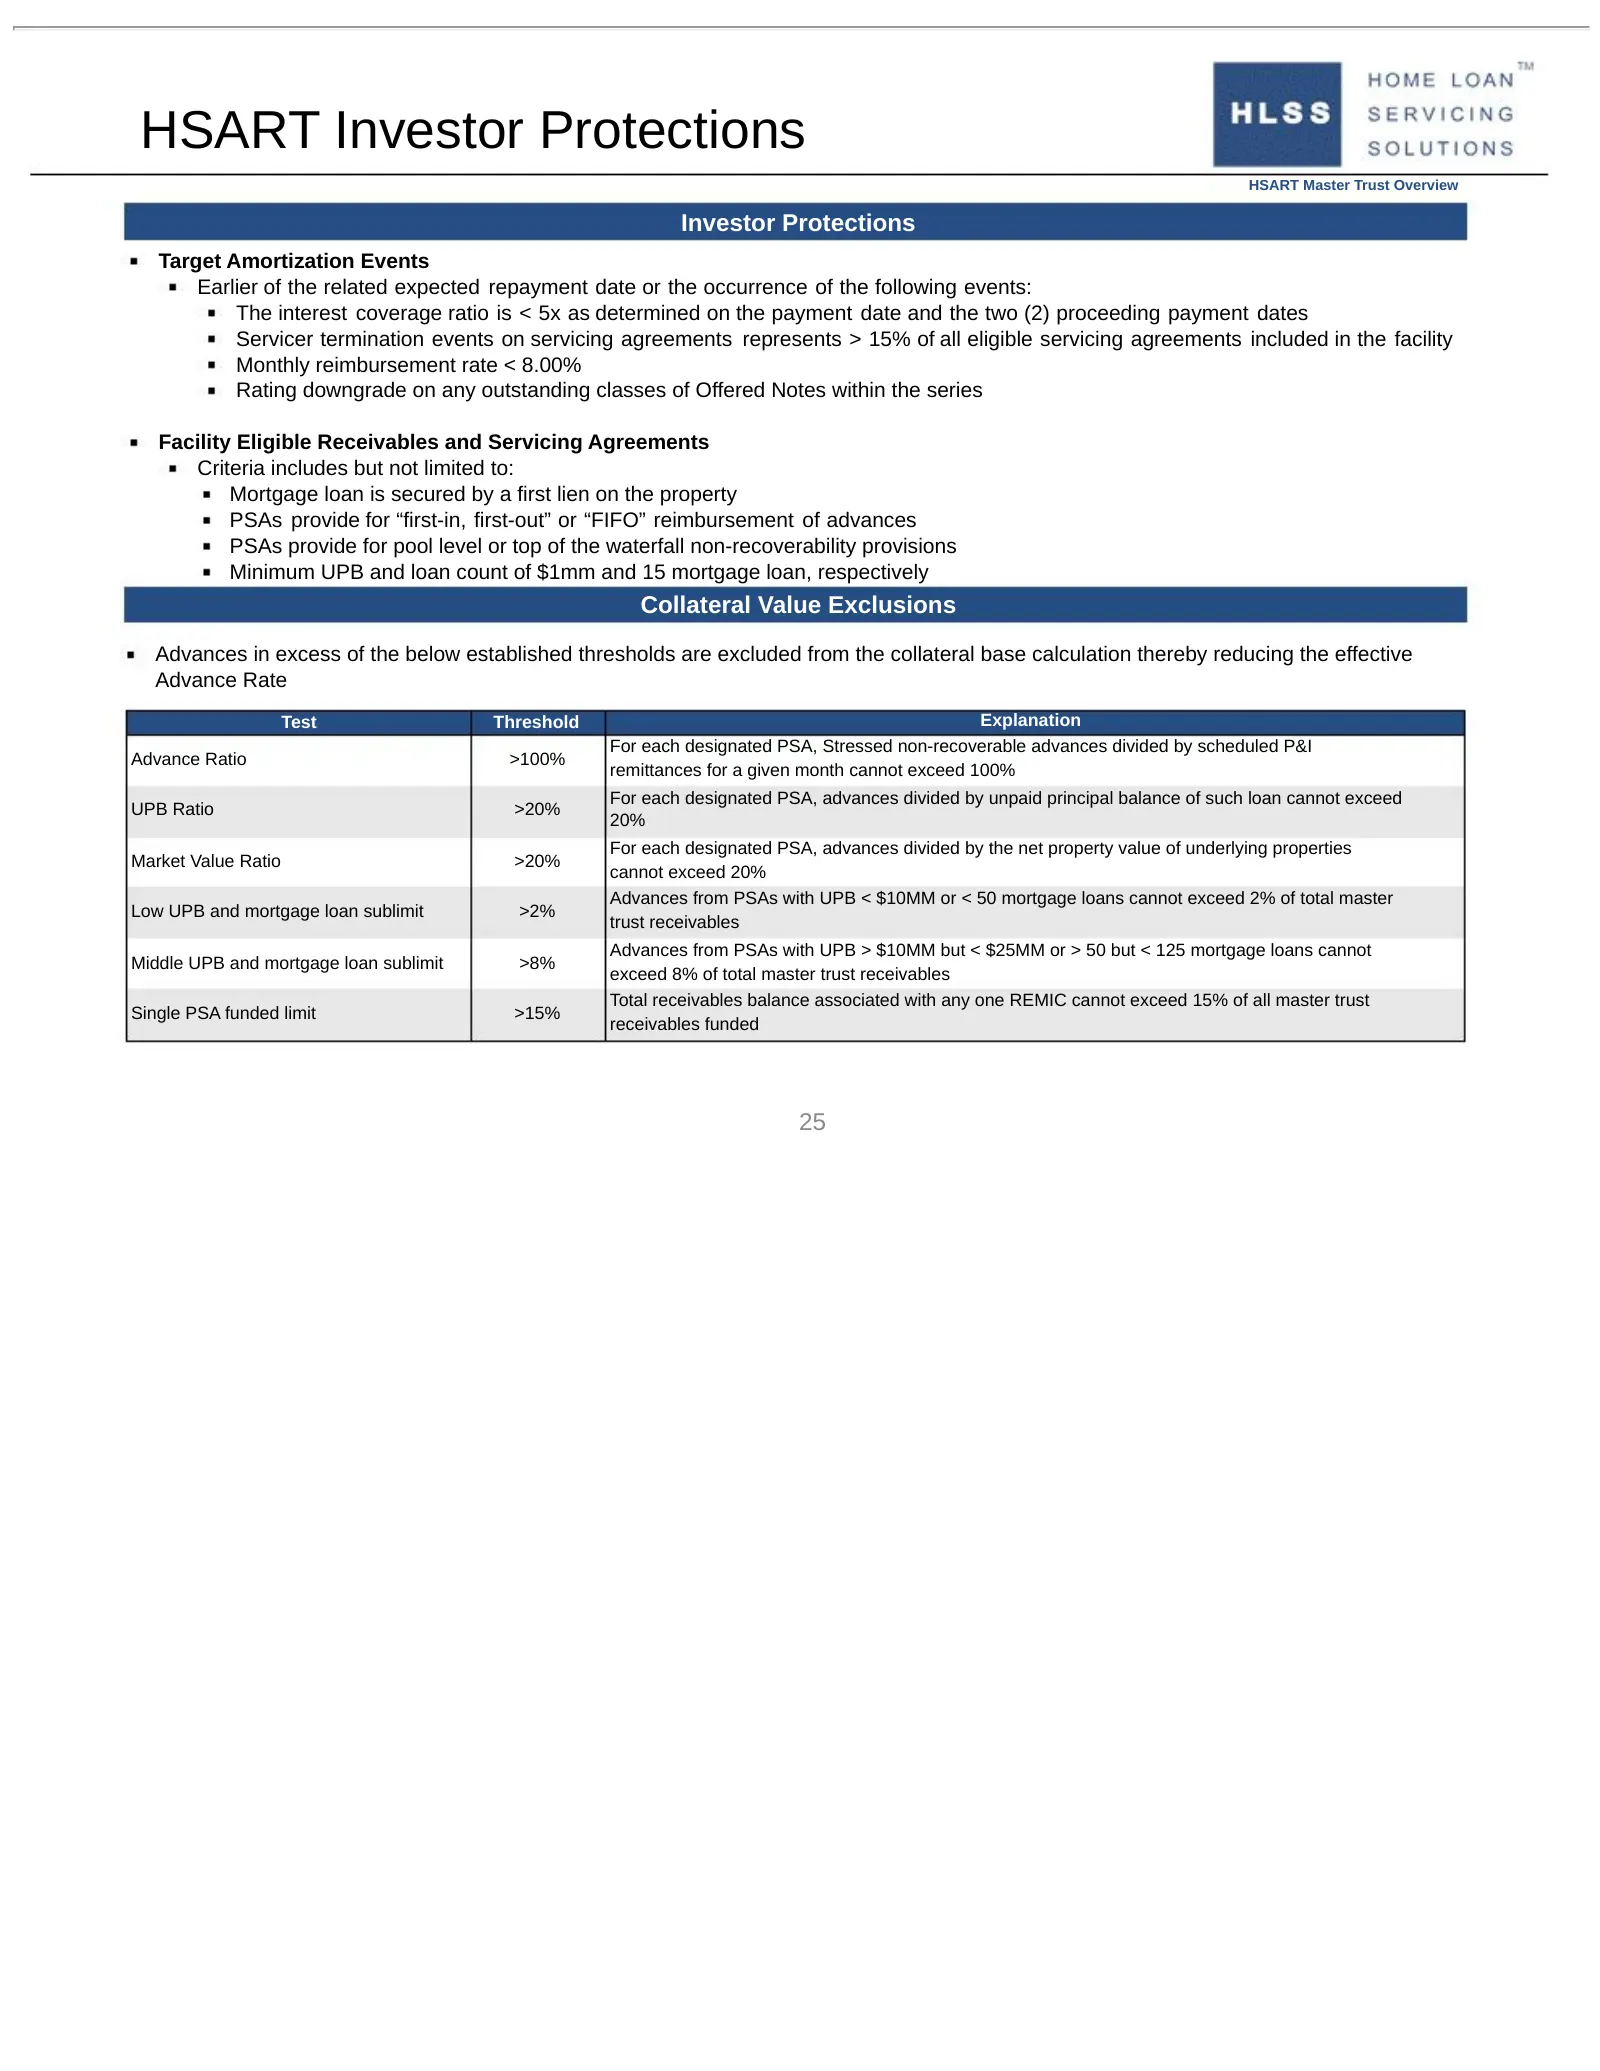
HSART Investor Protections HSART Master Trust Overview Investor Protections Target Amortization Events Earlier of the related expected repayment date or the occurrence of the following events: The interest coverage ratio is < 5x as determined on the payment date and the two (2) proceeding payment da
Slide 26: HSART Transaction Phases
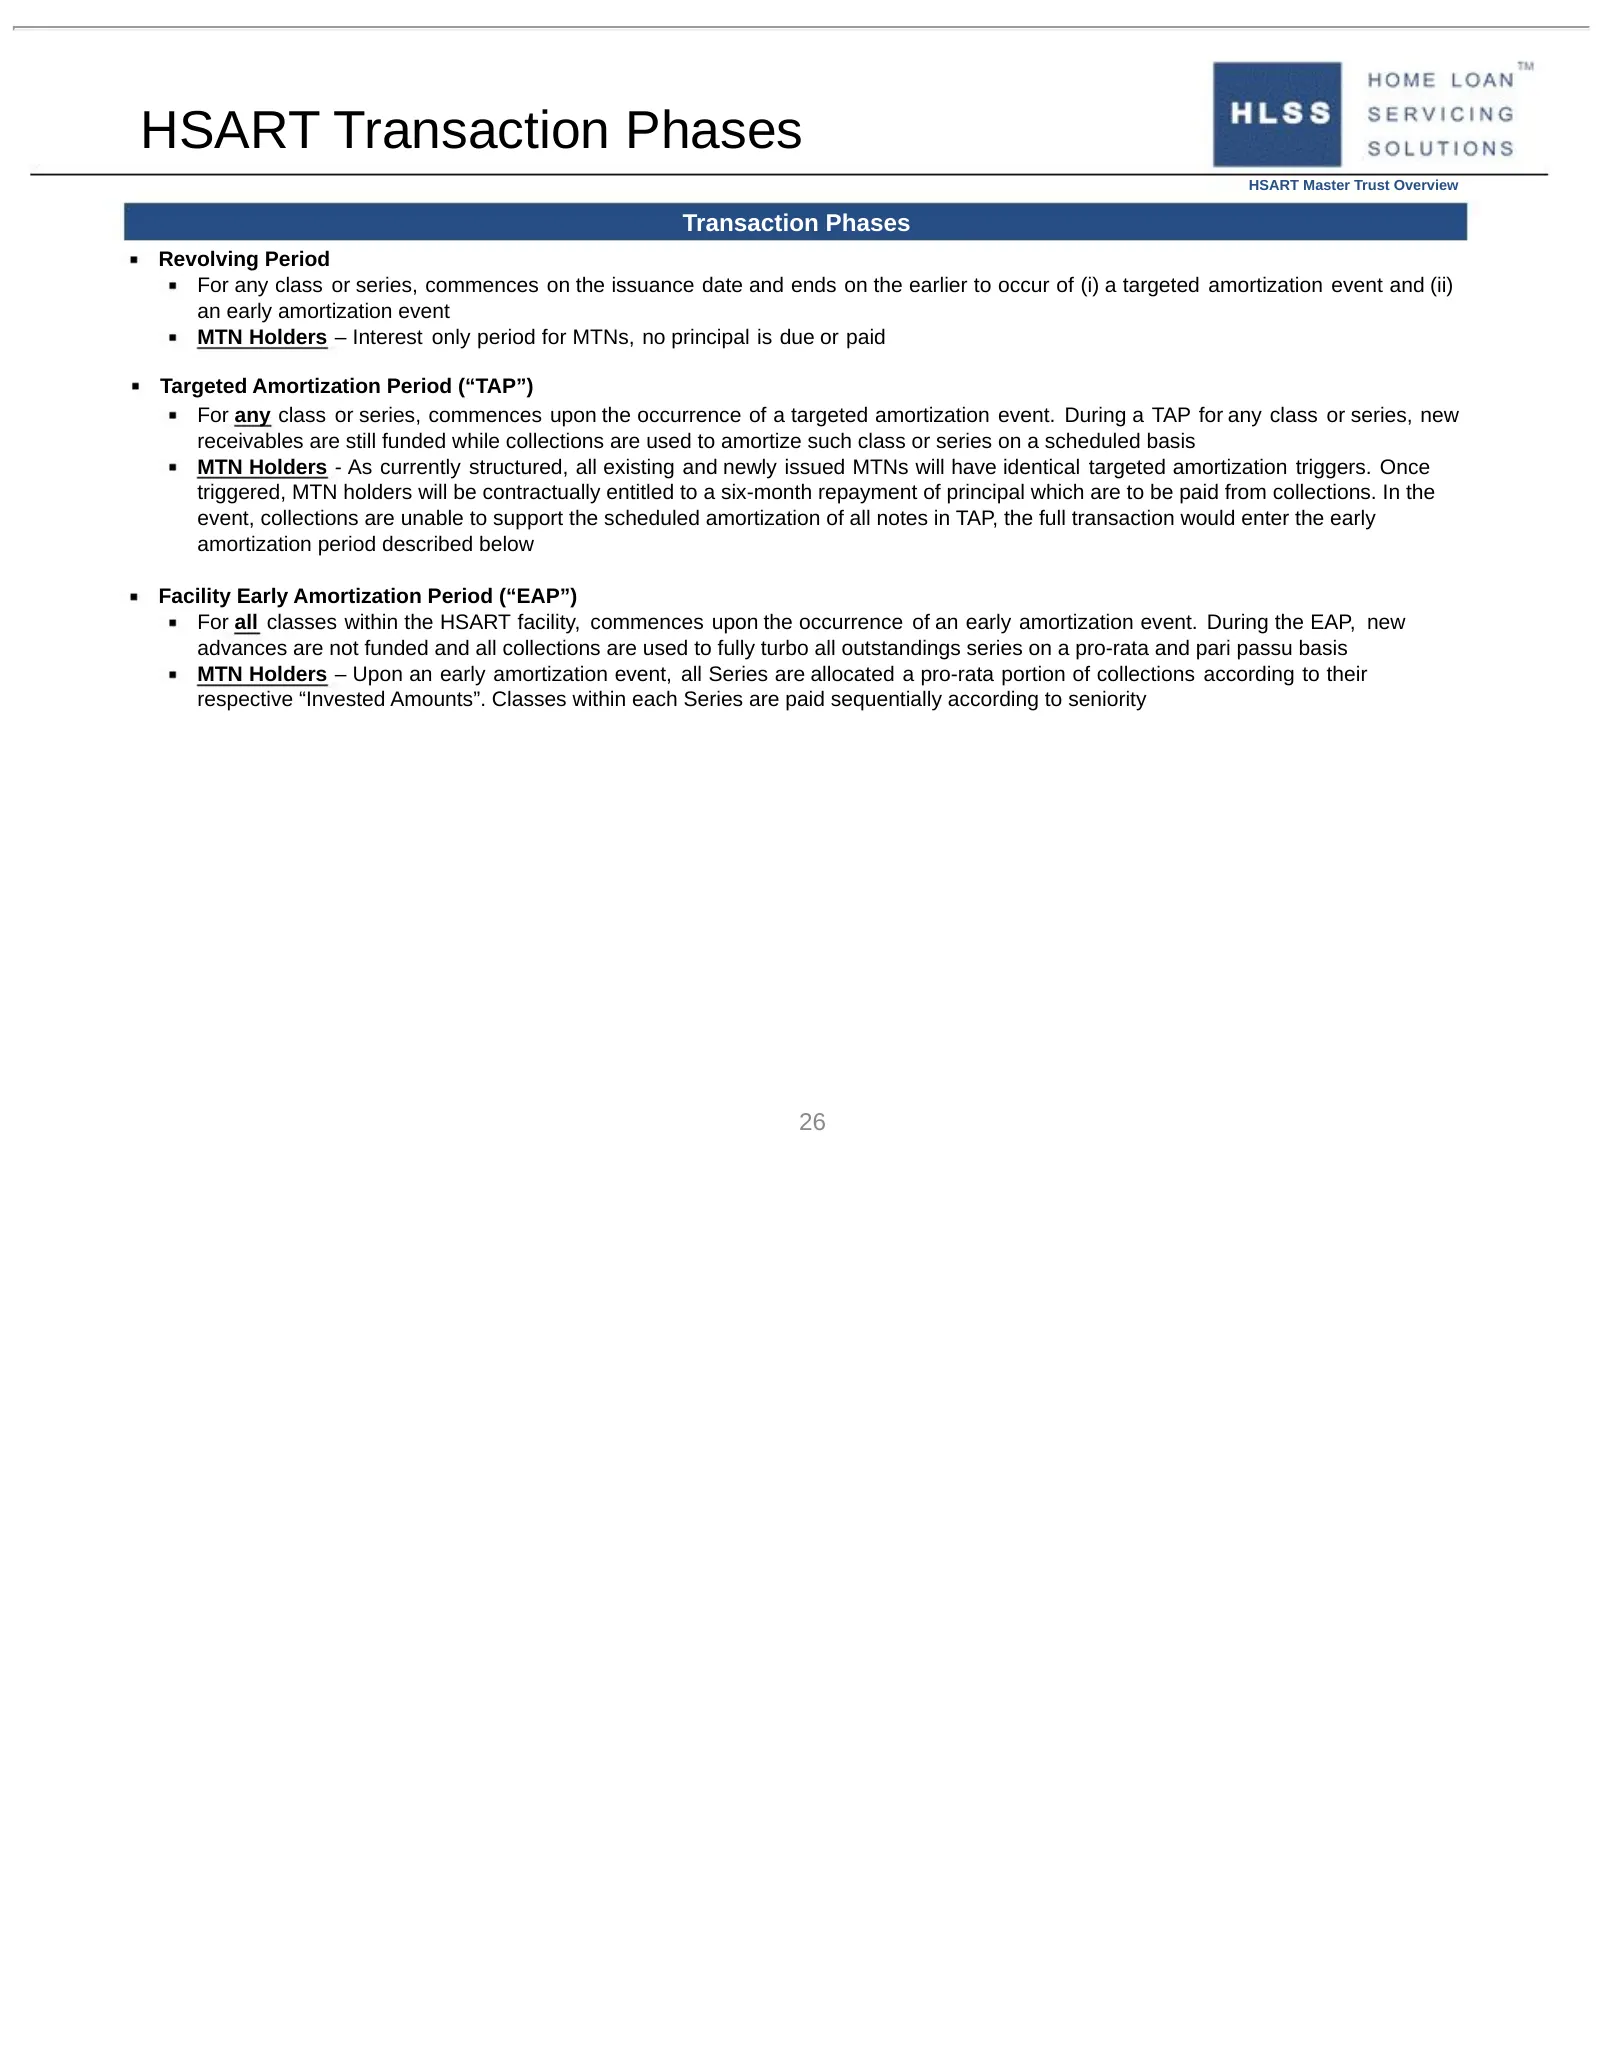
HSART Transaction Phases HSART Master Trust Overview Transaction Phases Revolving Period For any class or series, commences on the issuance date and ends on the earlier to occur of (i) a targeted amortization event and (ii) an early amortization event MTN Holders – Interest only period for MTNs, no
Slide 27: HSART Market Making
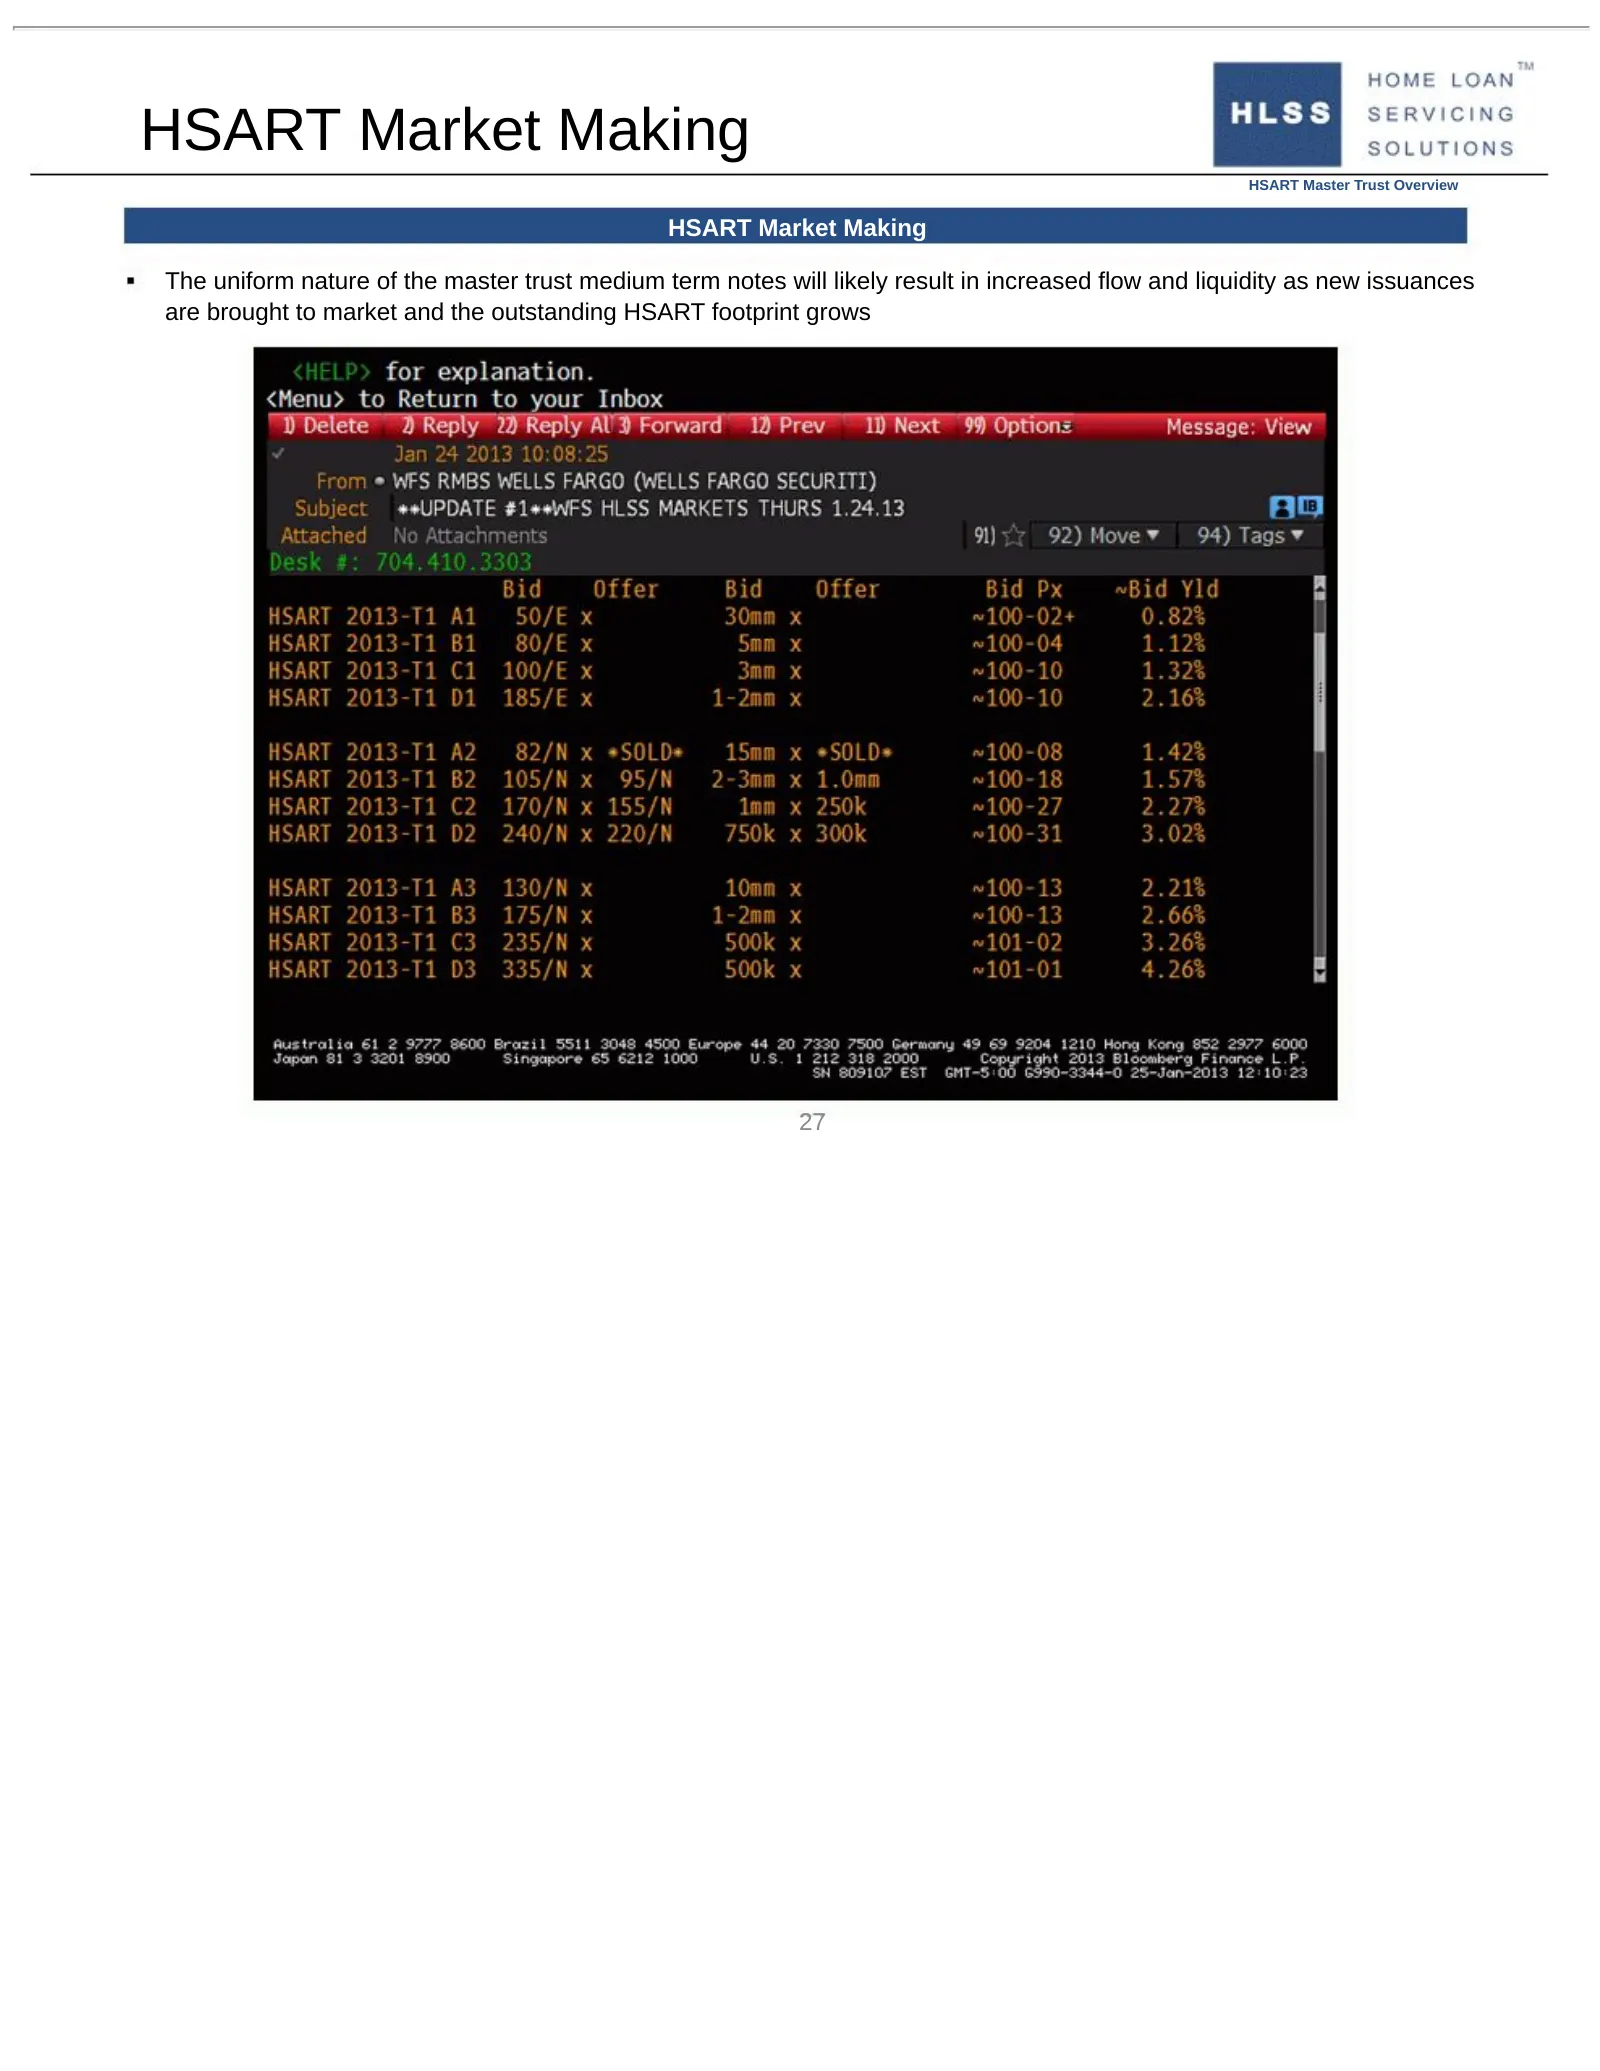
HSART Market Making HSART Master Trust Overview HSART Market Making The uniform nature of the master trust medium term notes will likely result in increased flow and liquidity as new issuances are brought to market and the outstanding HSART footprint grows 27
Slide 28: Appendices
HOME LOAN” Eee SERVICING SOLUTIONS Appendices 28
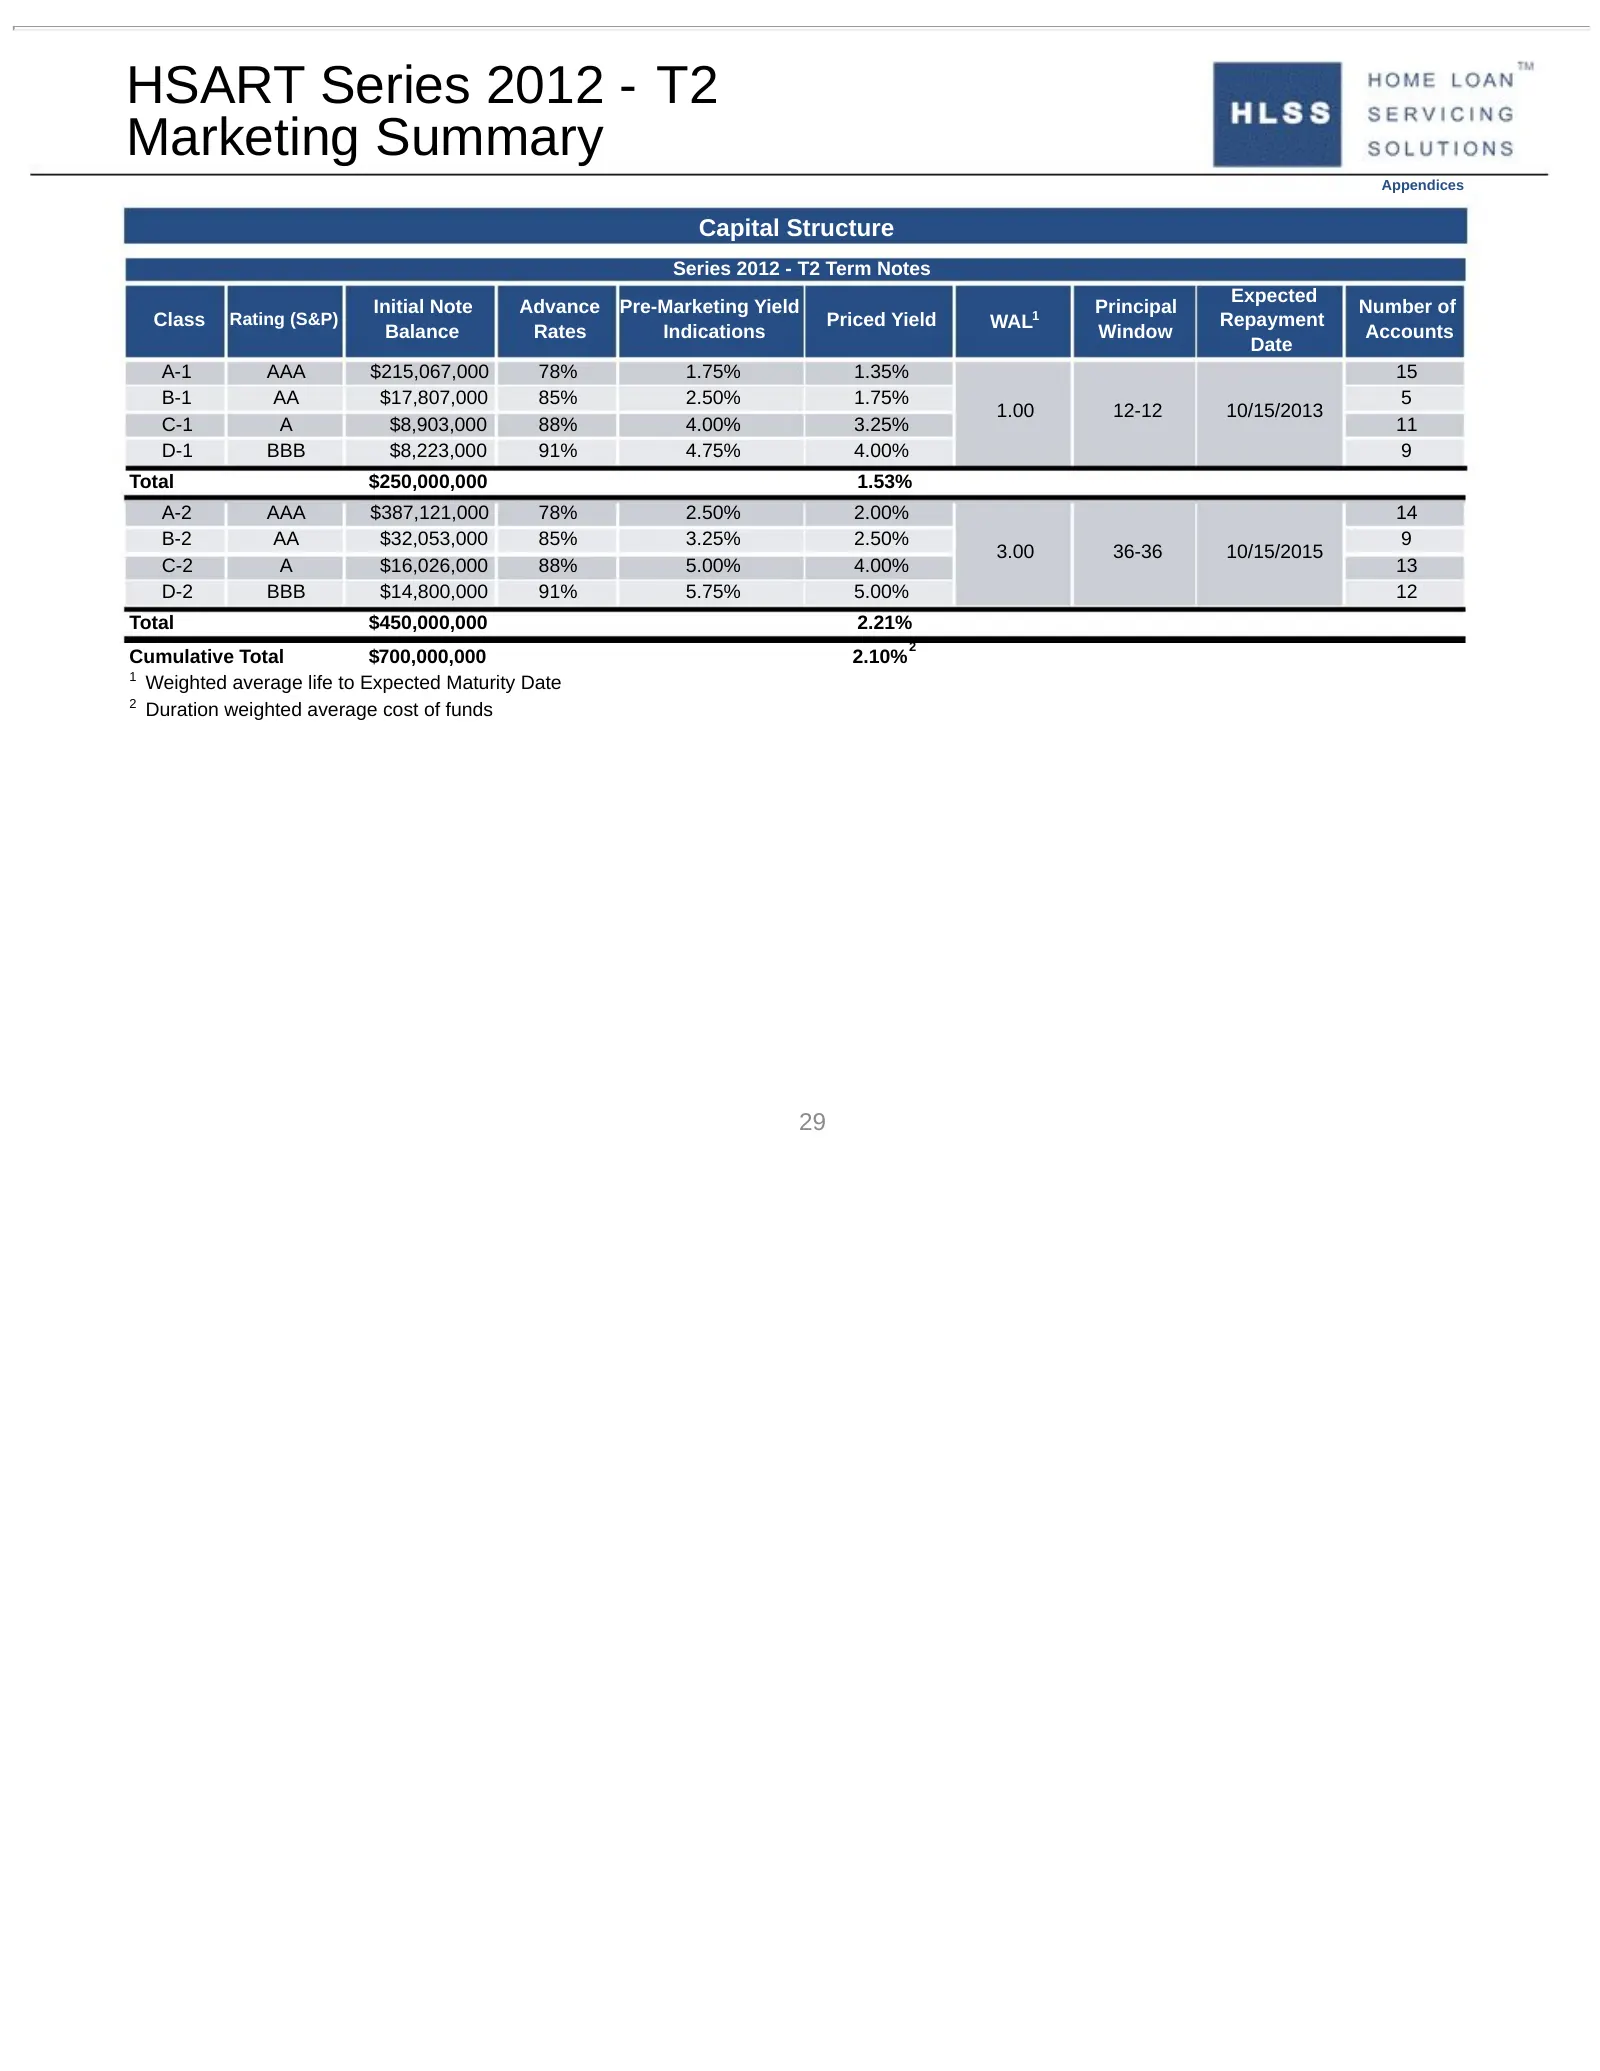
Slide 29: HSART Series 2012 - T2 Marketing Summary
HSART Series 2012 - T2 Marketing Summary Appendices Capital Structure Series 2012 - T2 Term Notes Expected Initial Note Advance Pre-Marketing Yield Principal Number of Class Rating (S&P) Priced Yield WAL1 Repayment Balance Rates Indications Window Accounts Date A-1 AAA $215,067,000 78% 1.75% 1.35% 1
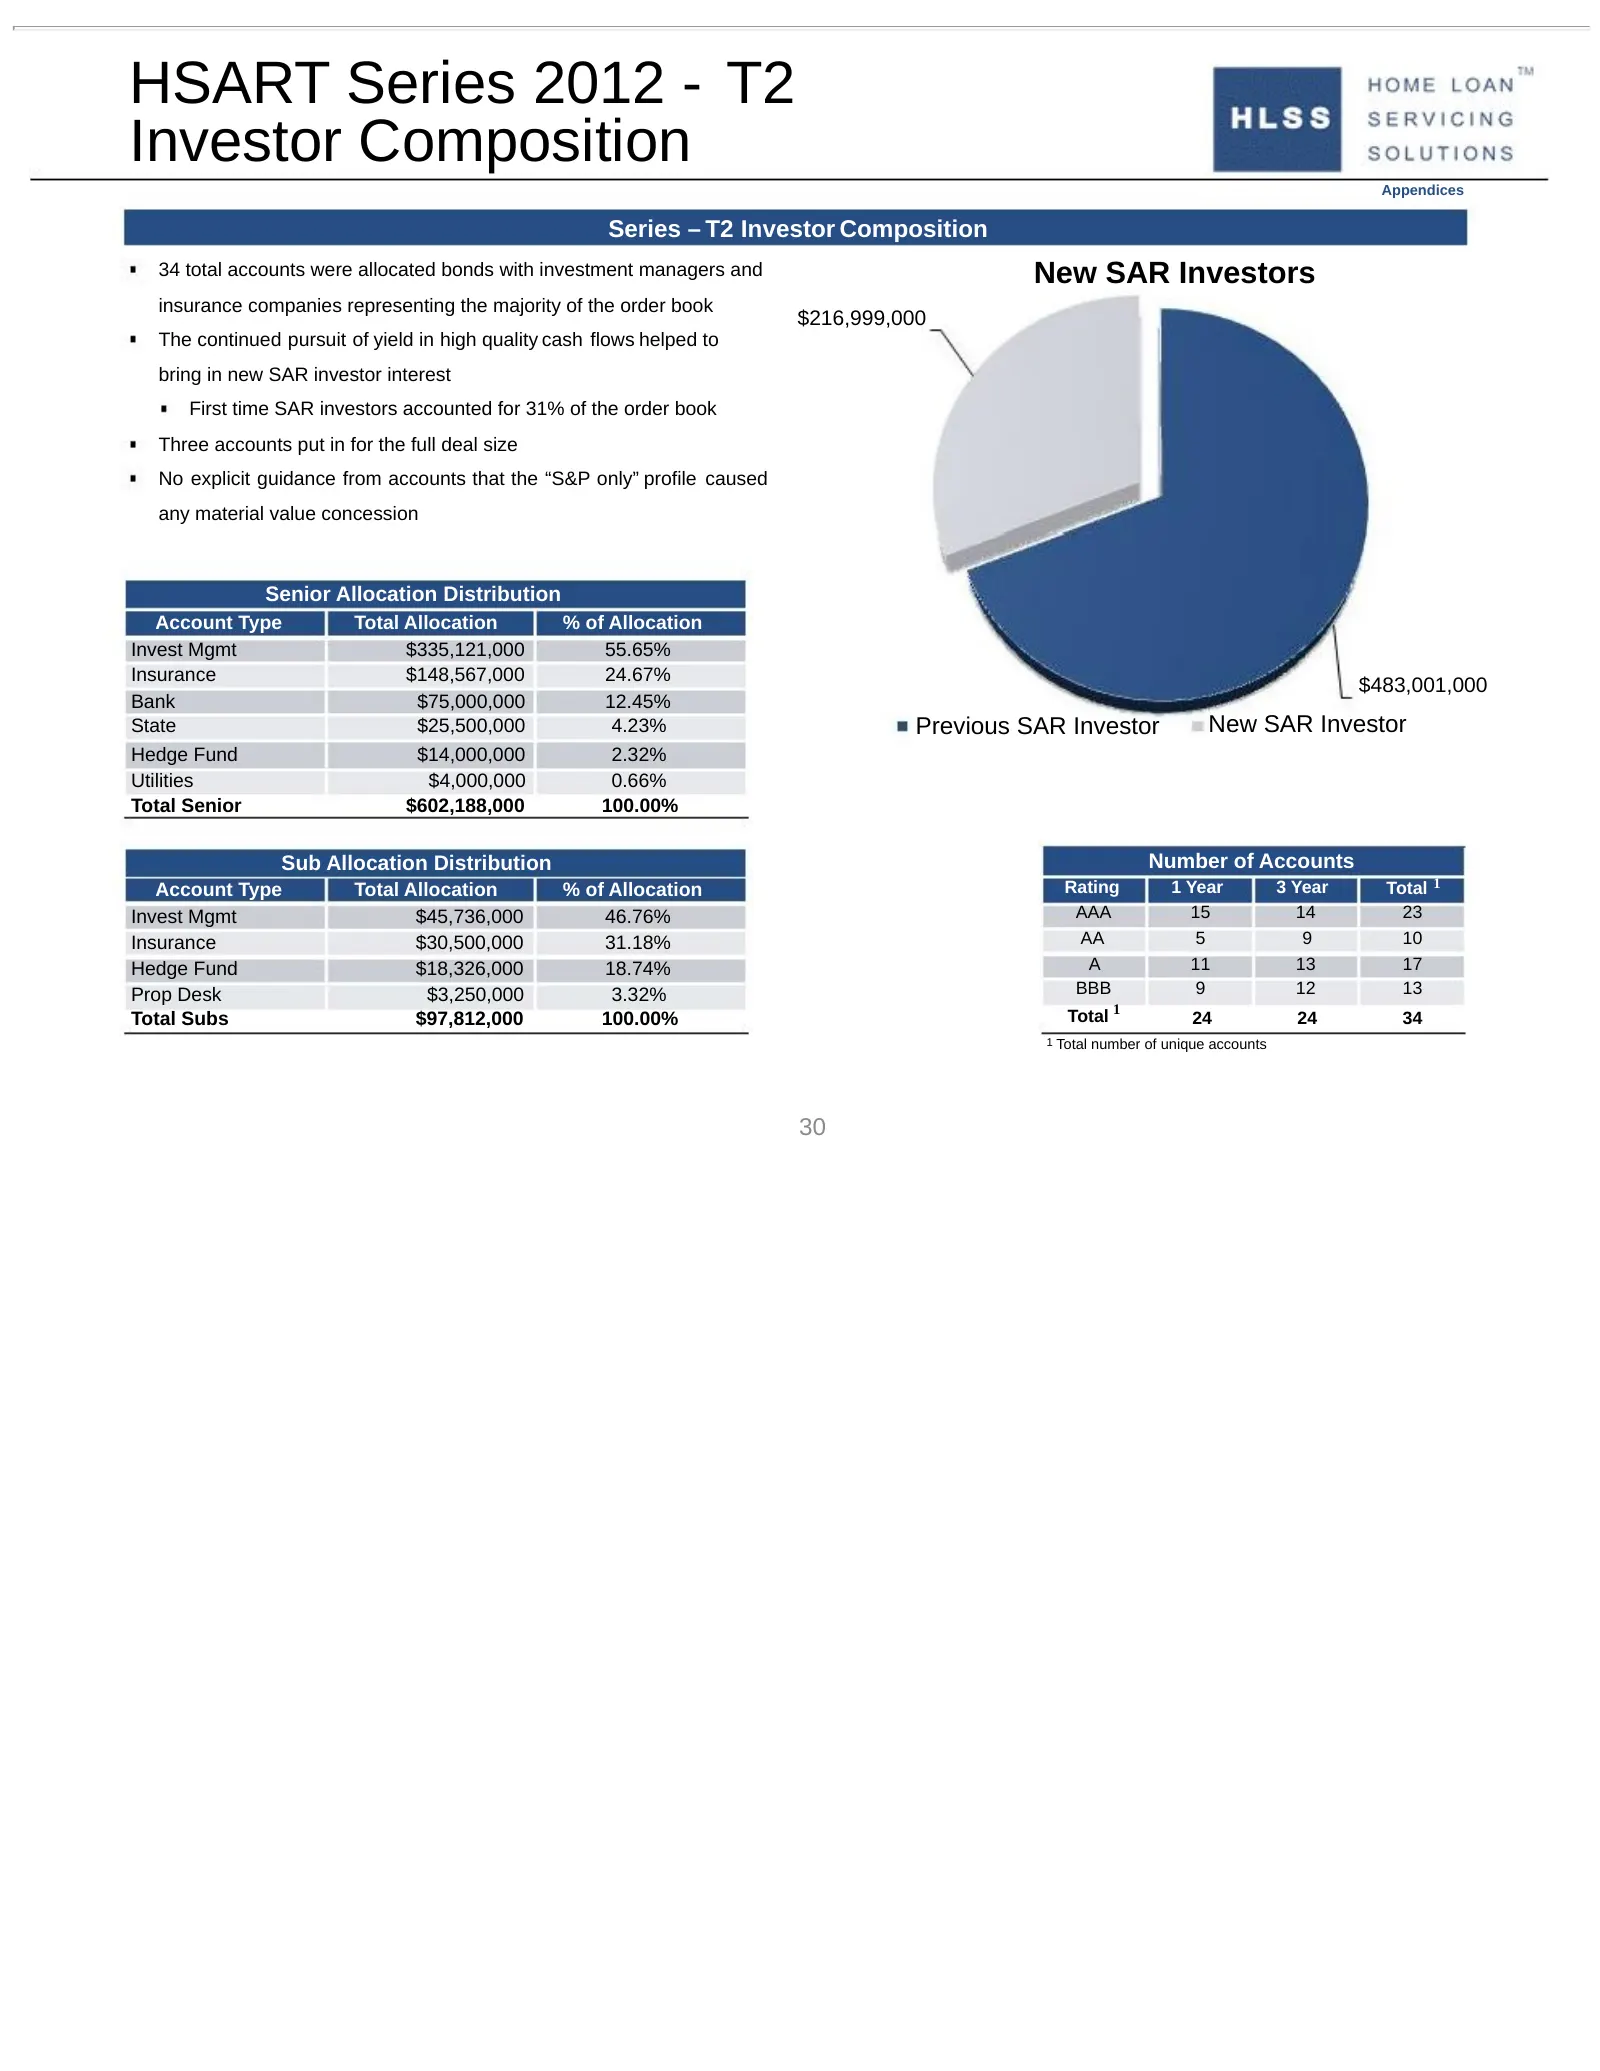
Slide 30: HSART Series 2012 - T2 Investor Composition
HSART Series 2012 - T2 Investor Composition Appendices Series – T2 Investor Composition 34 total accounts were allocated bonds with investment managers and New SAR Investors insurance companies representing the majority of the order book $216,999,000 The continued pursuit of yield in high quality ca
Slide 31: HLSS Servicer Advance Receivables Trust
HLSS Servicer Advance Receivables Trust
Source: SEC EDGAR · 8-K filed Jan 25, 2013
More decks from Home Loan Servicing Solutions Ltd
 Merger or Acquisition (February 2015)6 slides · Feb 23, 2015
 Q3 2014 Earnings Presentation15 slides · Oct 21, 2014
 Debt Investor Presentation (September 2014)40 slides · Sep 22, 2014
 Investor Presentation (September 2014)14 slides · Sep 8, 2014
 Investor Presentation (May 2014)17 slides · May 20, 2014
 Debt Investor Presentation (January 2014)45 slides · Jan 23, 2014