Santander Consumer USA Holdings Inc
Santander Consumer USA — Investor Day (December 2016)
31 slides from Santander Consumer USA's investor day presentation, Dec 8, 2016
Slide 1: 2016 ABS Investor Day
December 8, 2016 SANTANDER CONSUMER USA HOLDINGS INC. 2016 ABS Investor Day Exhibit 99.1
Slide 2: Important Information: Forward-Looking Statements
IMPORTANT INFORMATION Forward-Looking Statements This presentation contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Any statements about our expectations, beliefs, plans, predictions, forecasts, objectives, assumptions, or future events
Slide 3: Agenda
AGENDA CORPORATE OVERVIEW AND STRATEGY ORIGINATIONS, UNDERWRITING AND DEALER MANAGEMENT SERVICING, COLLECTIONS AND REMARKETING
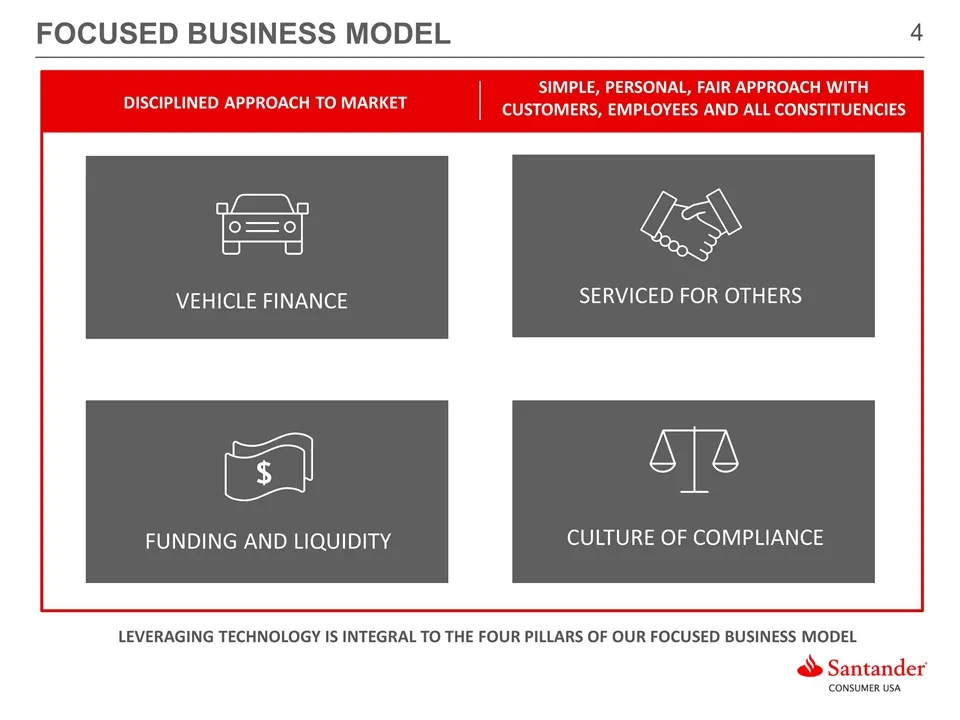
Slide 4: Leveraging Technology Is Integral to the Four Pillars of Our Focused Business Model
VEHICLE FINANCE LEVERAGING TECHNOLOGY IS INTEGRAL TO THE FOUR PILLARS OF OUR FOCUSED BUSINESS MODEL FOCUSED BUSINESS MODEL DISCIPLINED APPROACH TO MARKET SIMPLE, PERSONAL, FAIR APPROACH WITH CUSTOMERS, EMPLOYEES AND ALL CONSTITUENCIES SERVICED FOR OTHERS FUNDING AND LIQUIDITY CULTURE OF COMPLIANCE
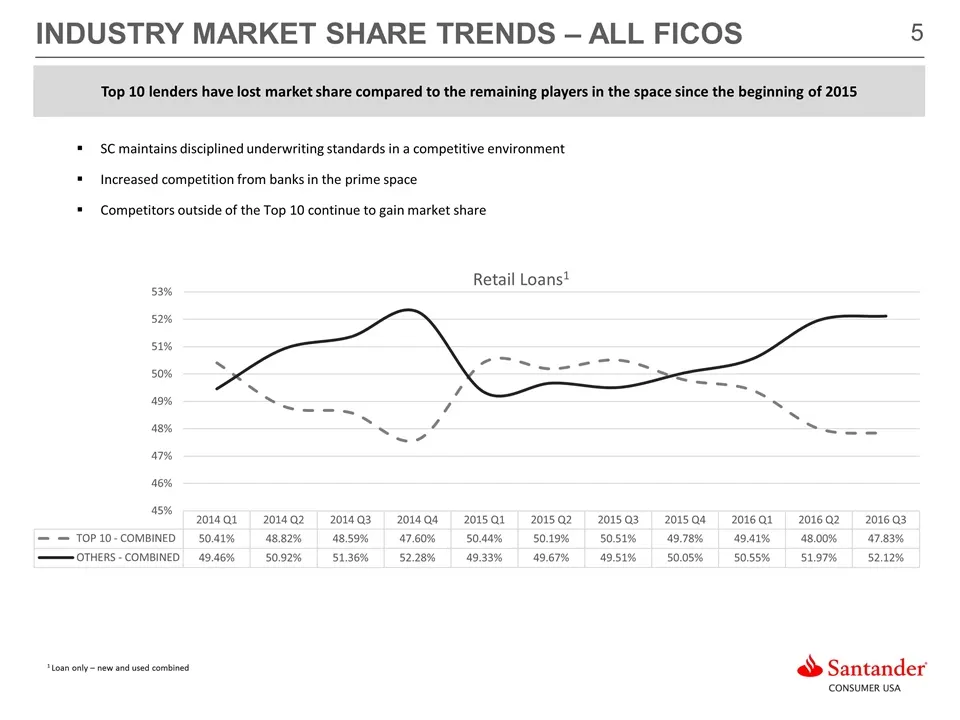
Slide 5: Industry Market Share Trends – All FICOs
INDUSTRY MARKET SHARE TRENDS – ALL FICOs SC maintains disciplined underwriting standards in a competitive environment Increased competition from banks in the prime space Competitors outside of the Top 10 continue to gain market share Top 10 lenders have lost market share compared to the remaining pl
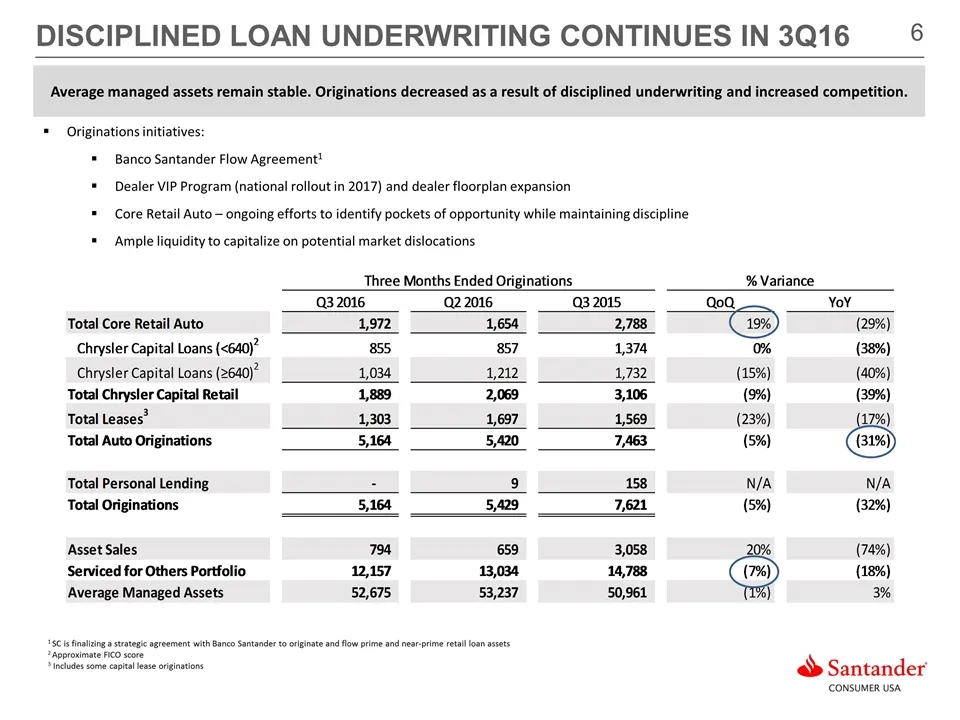
Slide 6: Disciplined Loan Underwriting Continues in 3Q16
DISCIPLINED LOAN UNDERWRITING CONTINUES IN 3Q16 1 SC is finalizing a strategic agreement with Banco Santander to originate and flow prime and near-prime retail loan assets 2 Approximate FICO score 3 Includes some capital lease originations Average managed assets remain stable. Originations decreased
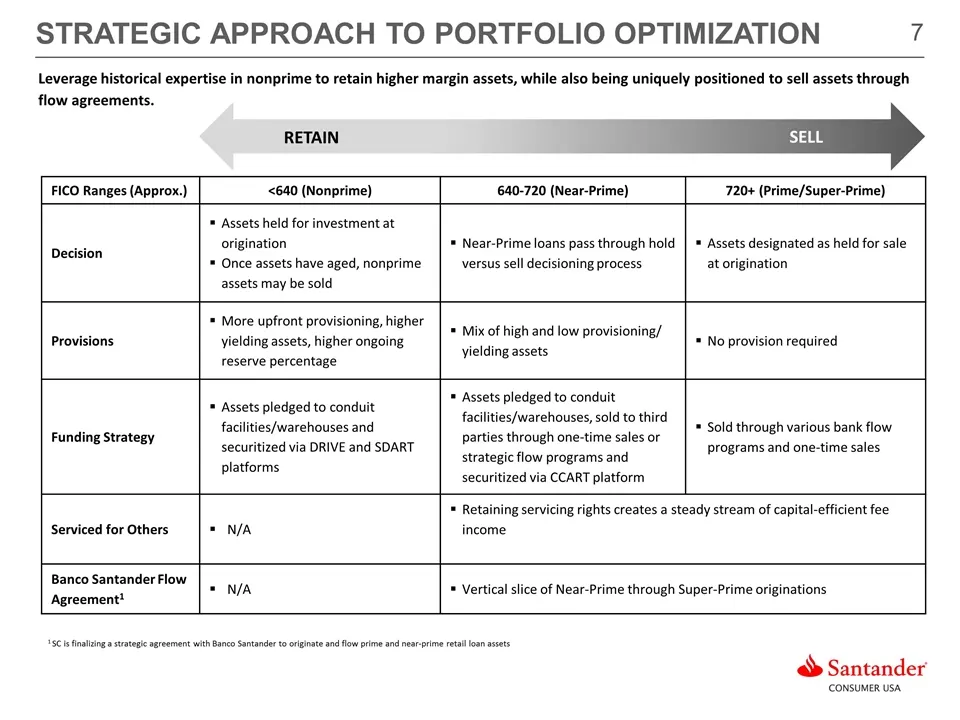
Slide 7: Strategic Approach to Portfolio Optimization
STRATEGIC approach to portfolio optimization SELL FICO Ranges (Approx.) <640 (Nonprime) 640-720 (Near-Prime) 720+ (Prime/Super-Prime) Decision Assets held for investment at origination Once assets have aged, nonprime assets may be sold Near-Prime loans pass through hold versus sell decisioning proce
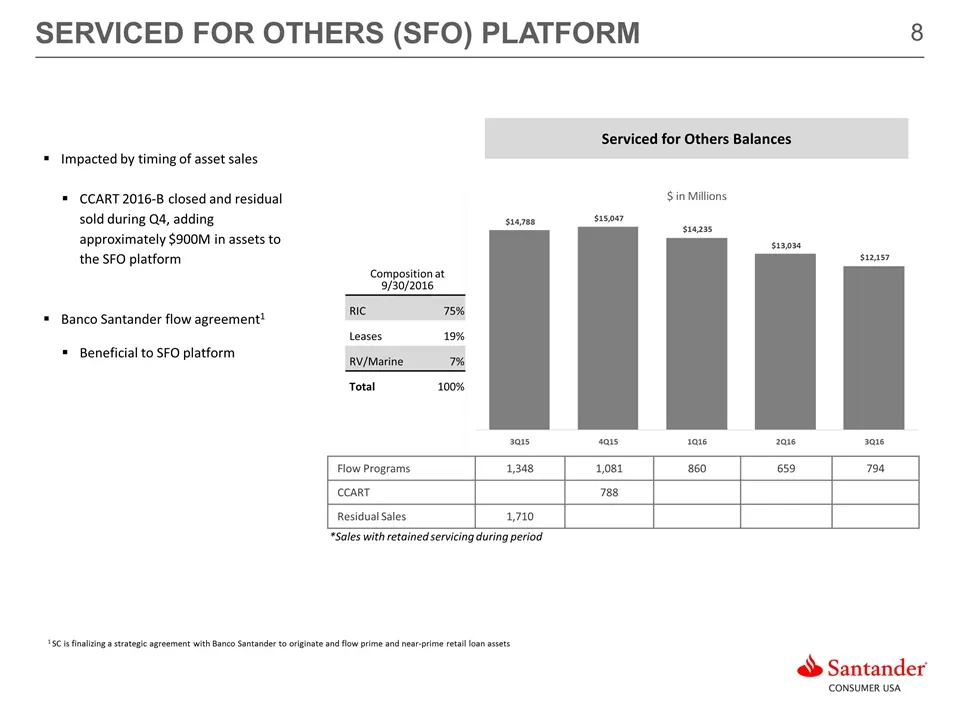
Slide 8: Serviced for Others (SFO) Platform
Flow Programs 1,348 1,081 860 659 794 CCART 788 Residual Sales 1,710 Impacted by timing of asset sales CCART 2016-B closed and residual sold during Q4, adding approximately $900M in assets to the SFO platform Banco Santander flow agreement1 Beneficial to SFO platform SERVICED FOR OTHERS (SFO) PLATFO
Slide 9: Q4 2016 Funding and Liquidity Update
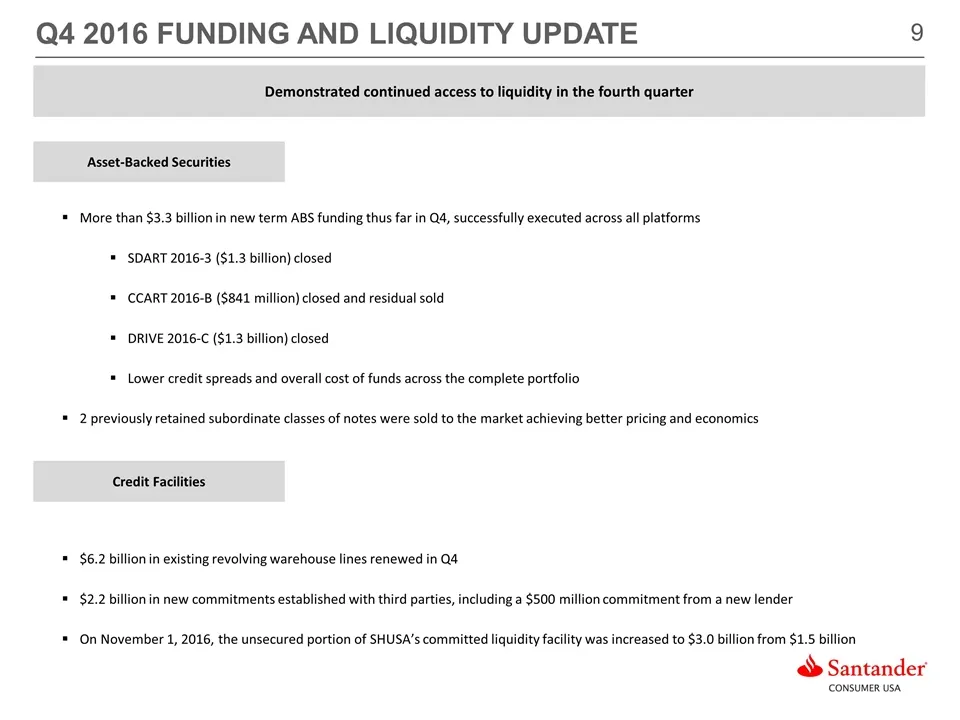
Q4 2016 FUNDING AND LIQUIDITY UPDATE More than $3.3 billion in new term ABS funding thus far in Q4, successfully executed across all platforms SDART 2016-3 ($1.3 billion) closed CCART 2016-B ($841 million) closed and residual sold DRIVE 2016-C ($1.3 billion) closed Lower credit spreads and overall c
Slide 10: Consistent Capital Generation
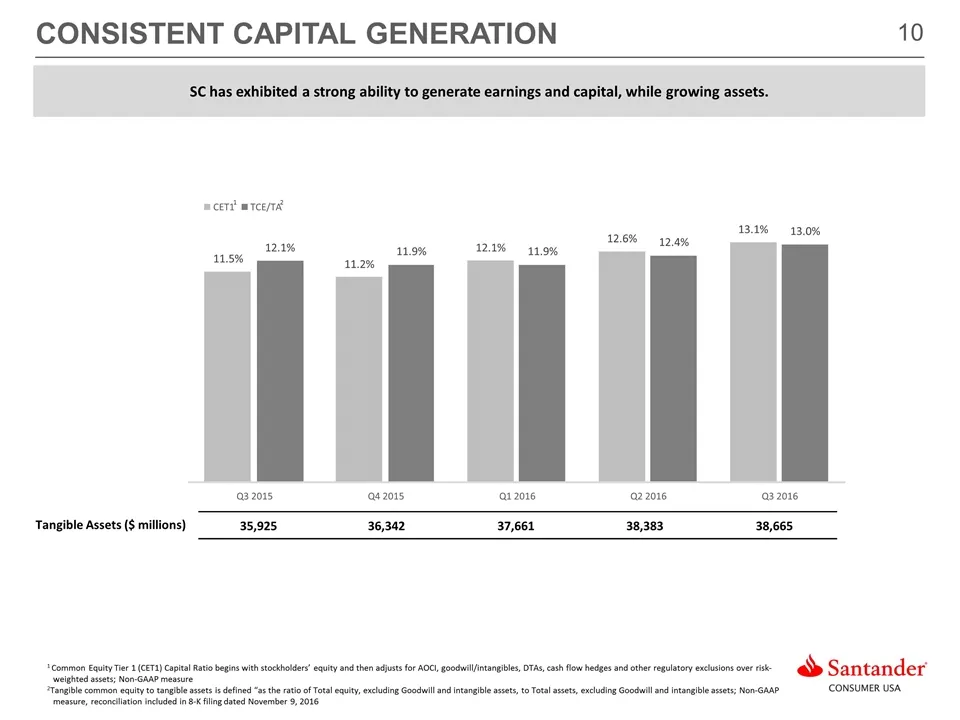
CONSISTENT CAPITAL GENERATION 1 Common Equity Tier 1 (CET1) Capital Ratio begins with stockholders’ equity and then adjusts for AOCI, goodwill/intangibles, DTAs, cash flow hedges and other regulatory exclusions over risk-weighted assets; Non-GAAP measure 2Tangible common equity to tangible assets is
Slide 11: Credit Quality: Net Loss Curves
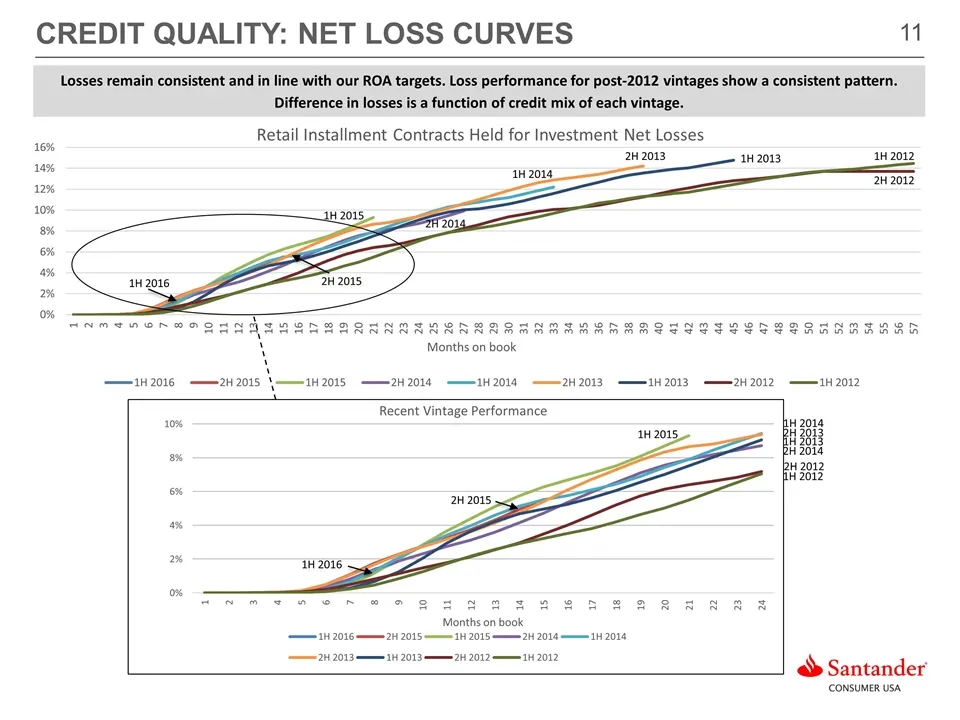
CREDIT QUALITY: NET LOSS CURVES Losses remain consistent and in line with our ROA targets. Loss performance for post-2012 vintages show a consistent pattern. Difference in losses is a function of credit mix of each vintage. 1H 2012 1H 2012 2H 2012 2H 2012 1H 2013 2H 2013 1H 2014 1H 2013 2H 2013 1H 2
Slide 12: Agenda
AGENDA CORPORATE OVERVIEW AND STRATEGY ORIGINATIONS, UNDERWRITING AND DEALER MANAGEMENT SERVICING, COLLECTIONS AND REMARKETING
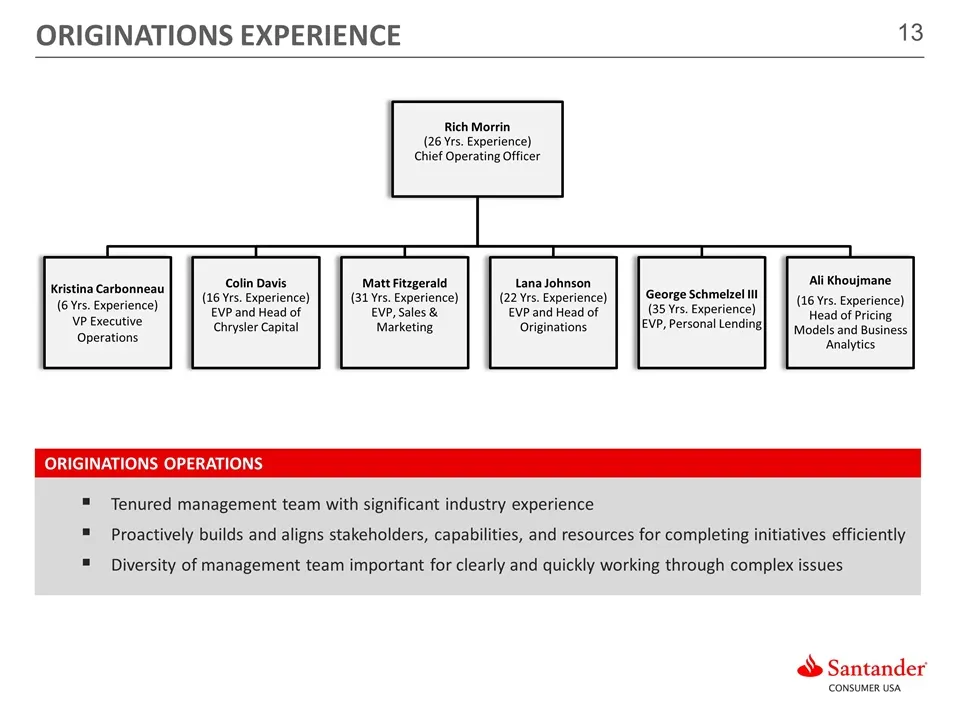
Slide 13: Tenured management team with significant industry experience (Originations)
Tenured management team with significant industry experience Proactively builds and aligns stakeholders, capabilities, and resources for completing initiatives efficiently Diversity of management team important for clearly and quickly working through complex issues ORIGINATIONS OPERATIONS ORIGINATIO
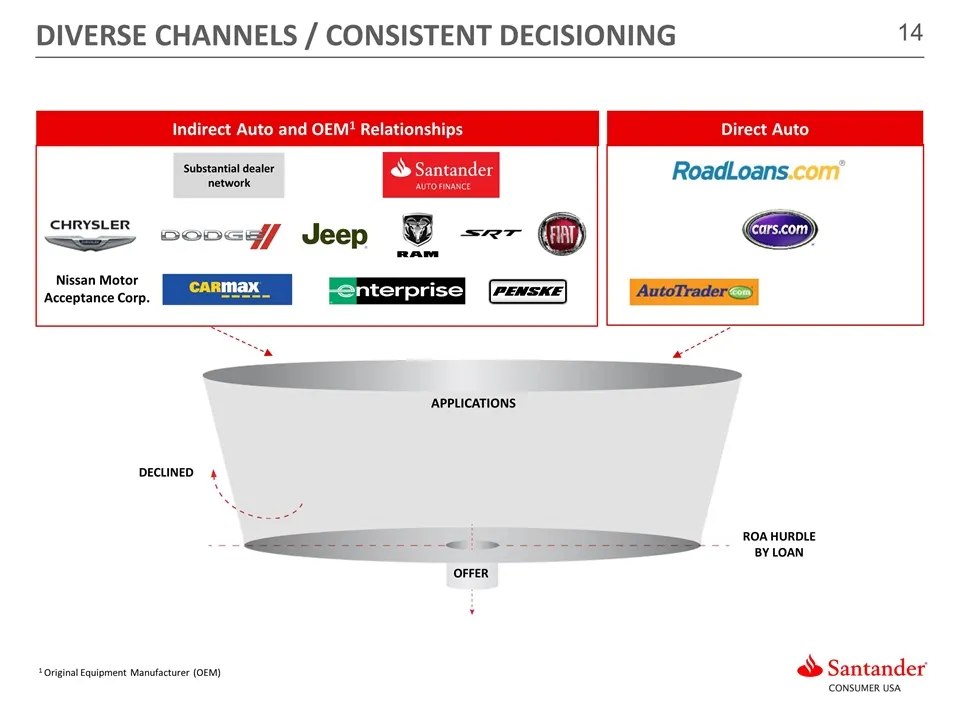
Slide 14: Diverse Channels / Consistent Decisioning
DIVERSE CHANNELS / CONSISTENT DECISIONING ROA HURDLE BY LOAN DECLINED OFFER Substantial dealer network 1 Original Equipment Manufacturer (OEM) Direct Auto Indirect Auto and OEM1 Relationships Nissan Motor Acceptance Corp. APPLICATIONs
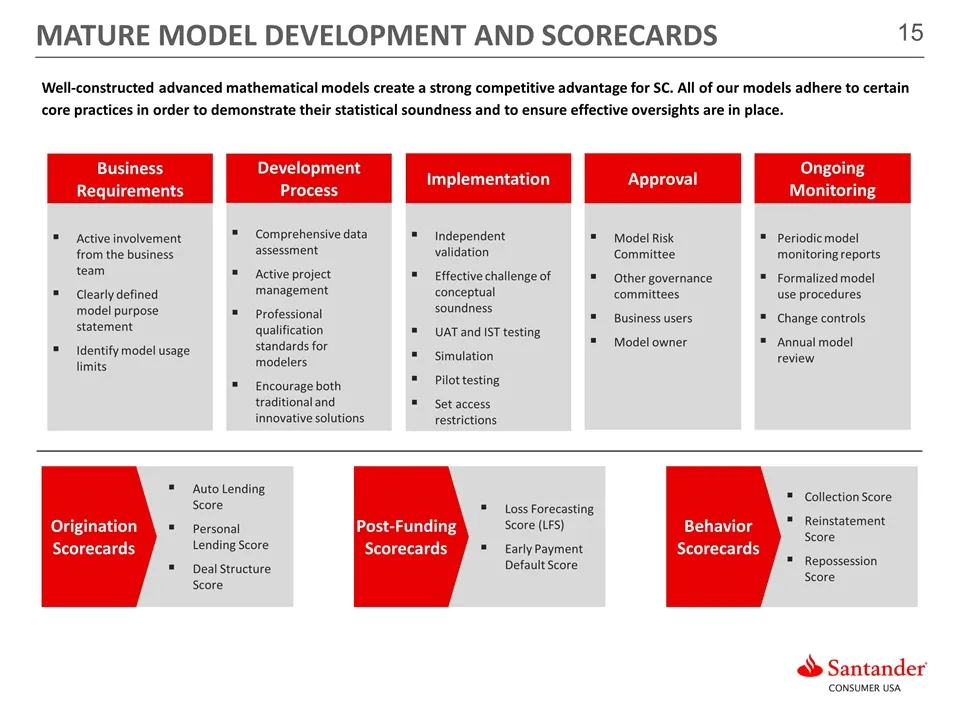
Slide 15: Advanced mathematical models create a strong competitive advantage
Well‐constructed advanced mathematical models create a strong competitive advantage for SC. All of our models adhere to certain core practices in order to demonstrate their statistical soundness and to ensure effective oversights are in place. Active involvement from the business team Clearly define
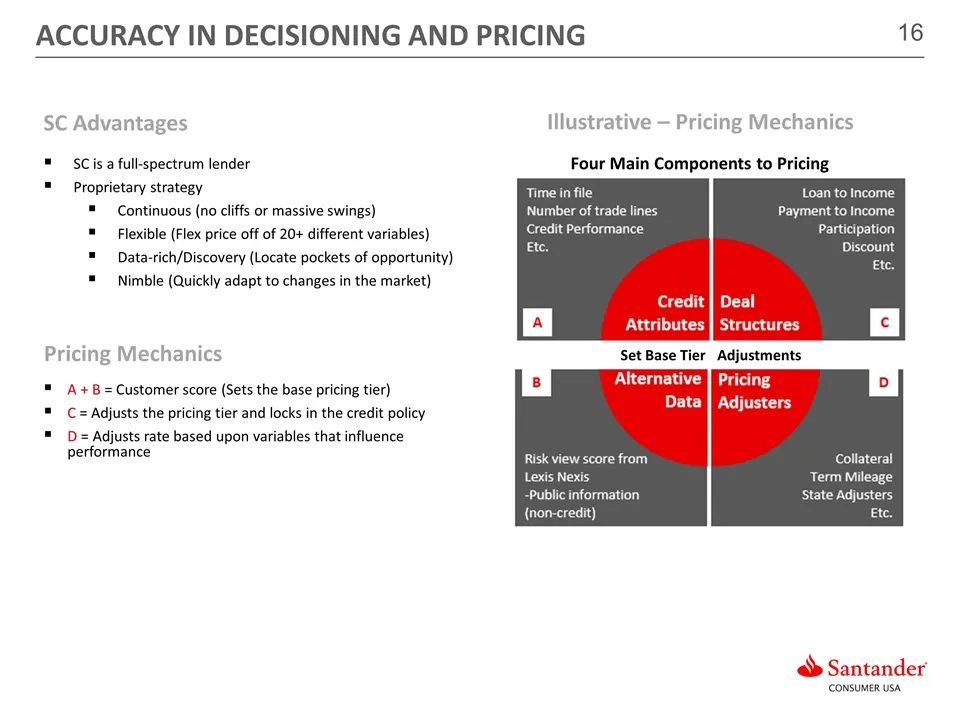
Slide 16: SC Advantages: Accuracy in Decisioning and Pricing
SC Advantages SC is a full-spectrum lender Proprietary strategy Continuous (no cliffs or massive swings) Flexible (Flex price off of 20+ different variables) Data-rich/Discovery (Locate pockets of opportunity) Nimble (Quickly adapt to changes in the market) Illustrative – Pricing Mechanics A + B = C
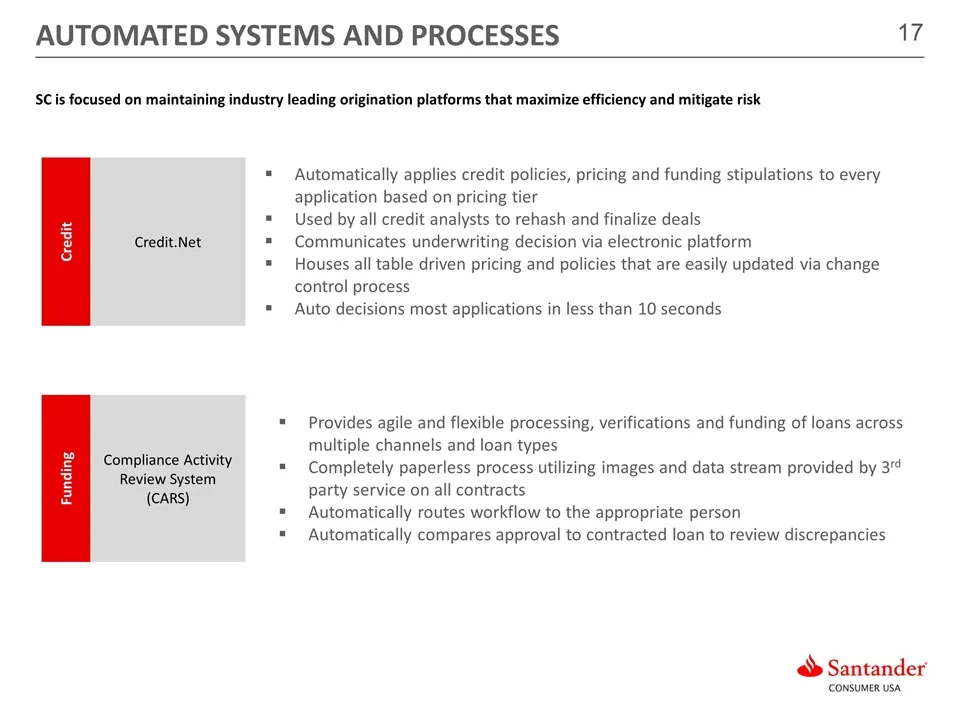
Slide 17: Agile and flexible loan processing, verification and funding
Provides agile and flexible processing, verifications and funding of loans across multiple channels and loan types Completely paperless process utilizing images and data stream provided by 3rd party service on all contracts Automatically routes workflow to the appropriate person Automatically compar
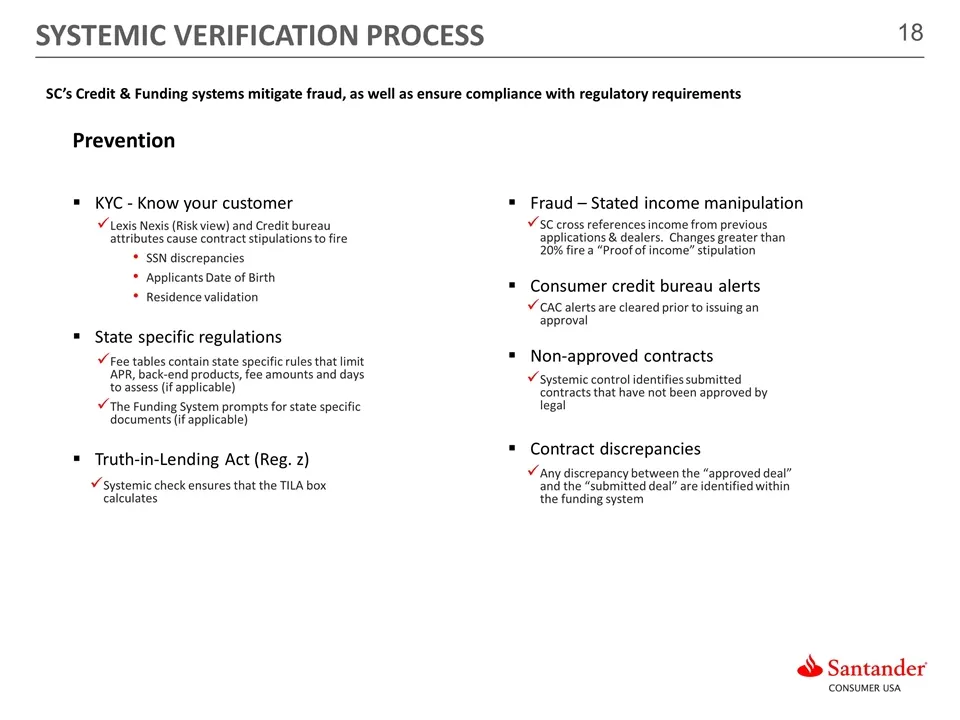
Slide 18: Fraud prevention and regulatory compliance controls
Lexis Nexis (Risk view) and Credit bureau attributes cause contract stipulations to fire SSN discrepancies Applicants Date of Birth Residence validation SC’s Credit & Funding systems mitigate fraud, as well as ensure compliance with regulatory requirements Prevention KYC - Know your customer State s
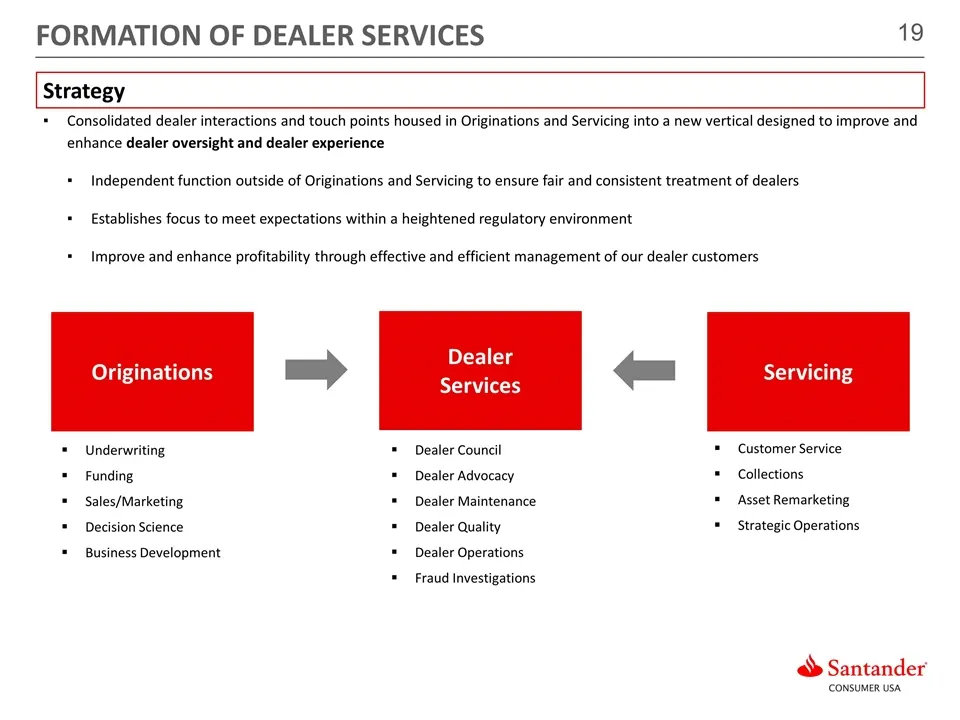
Slide 19: Originations Strategy: Dealer Services
Originations Strategy Dealer Services Servicing Consolidated dealer interactions and touch points housed in Originations and Servicing into a new vertical designed to improve and enhance dealer oversight and dealer experience Independent function outside of Originations and Servicing to ensure fair
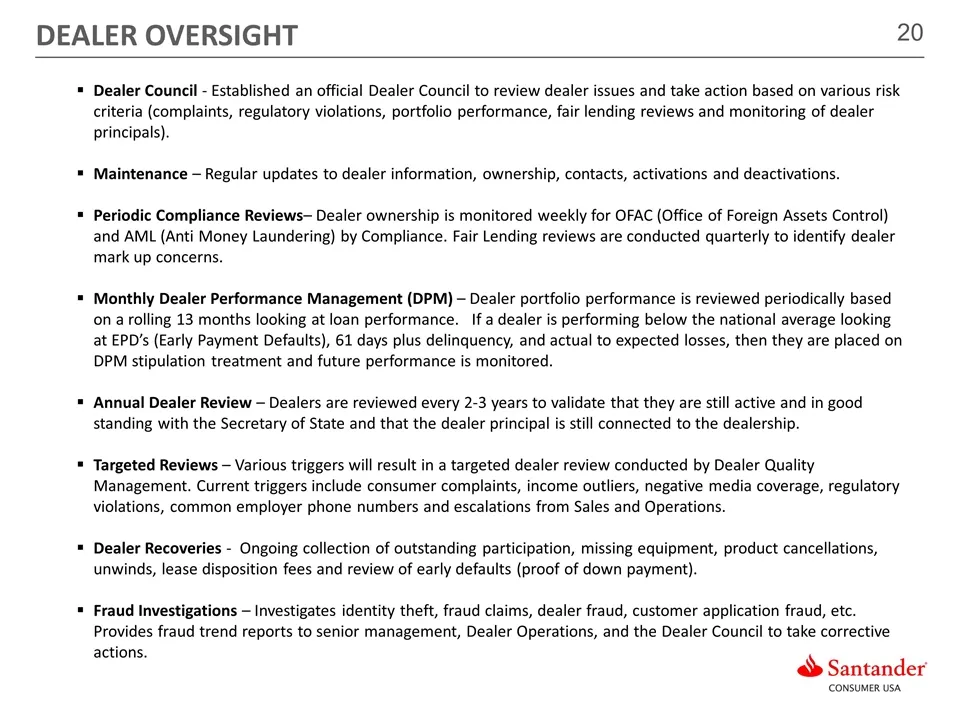
Slide 20: Dealer Oversight
Dealer oversight Dealer Council - Established an official Dealer Council to review dealer issues and take action based on various risk criteria (complaints, regulatory violations, portfolio performance, fair lending reviews and monitoring of dealer principals). Maintenance – Regular updates to deale
Slide 21: Agenda
AGENDA CORPORATE OVERVIEW AND STRATEGY ORIGINATIONS, UNDERWRITING AND DEALER MANAGEMENT SERVICING, COLLECTIONS AND REMARKETING
Slide 22: Tenured management team with significant industry experience (Servicing)
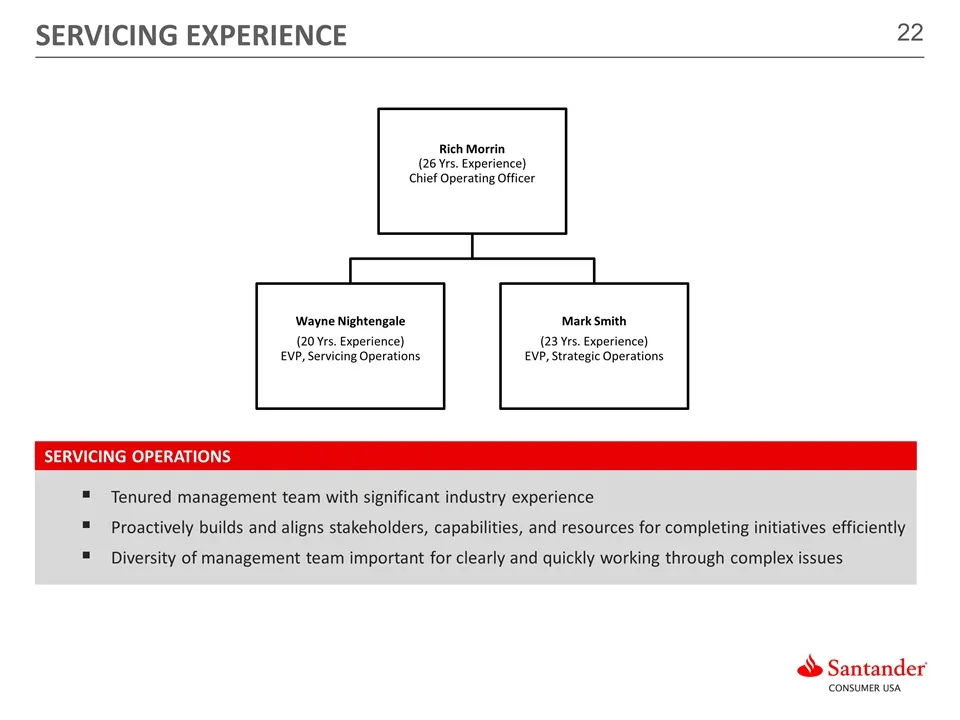
Tenured management team with significant industry experience Proactively builds and aligns stakeholders, capabilities, and resources for completing initiatives efficiently Diversity of management team important for clearly and quickly working through complex issues SERVICING OPERATIONS SERVICING EXP
Slide 23: Servicing Overview
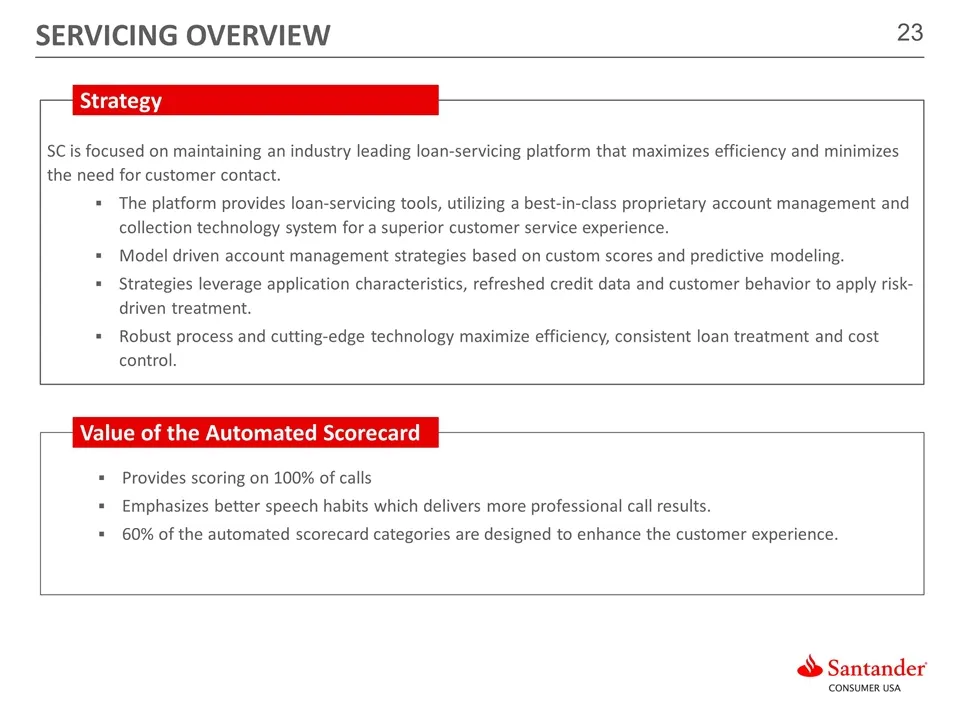
SERVICING OVERVIEW SC is focused on maintaining an industry leading loan-servicing platform that maximizes efficiency and minimizes the need for customer contact. The platform provides loan-servicing tools, utilizing a best-in-class proprietary account management and collection technology system for
Slide 24: Geographic & Timezone Diversification
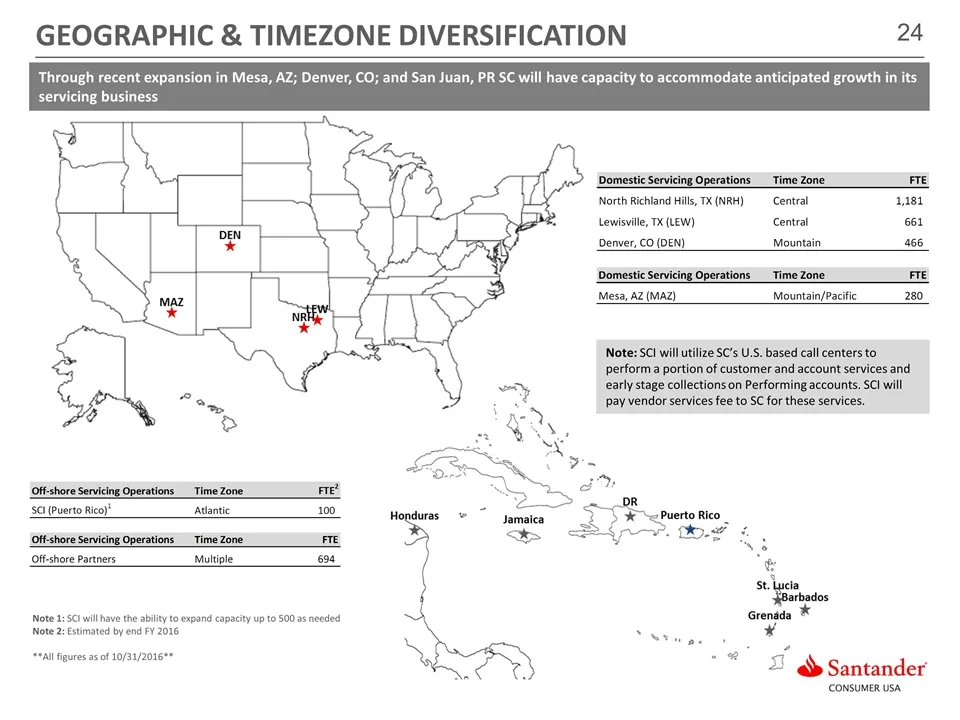
GEOGRAPHIC & TIMEZONE DIVERSIFICATION Note: SCI will utilize SC’s U.S. based call centers to perform a portion of customer and account services and early stage collections on Performing accounts. SCI will pay vendor services fee to SC for these services. Through recent expansion in Mesa, AZ; Denver,
Slide 25: Welcome – New Customers
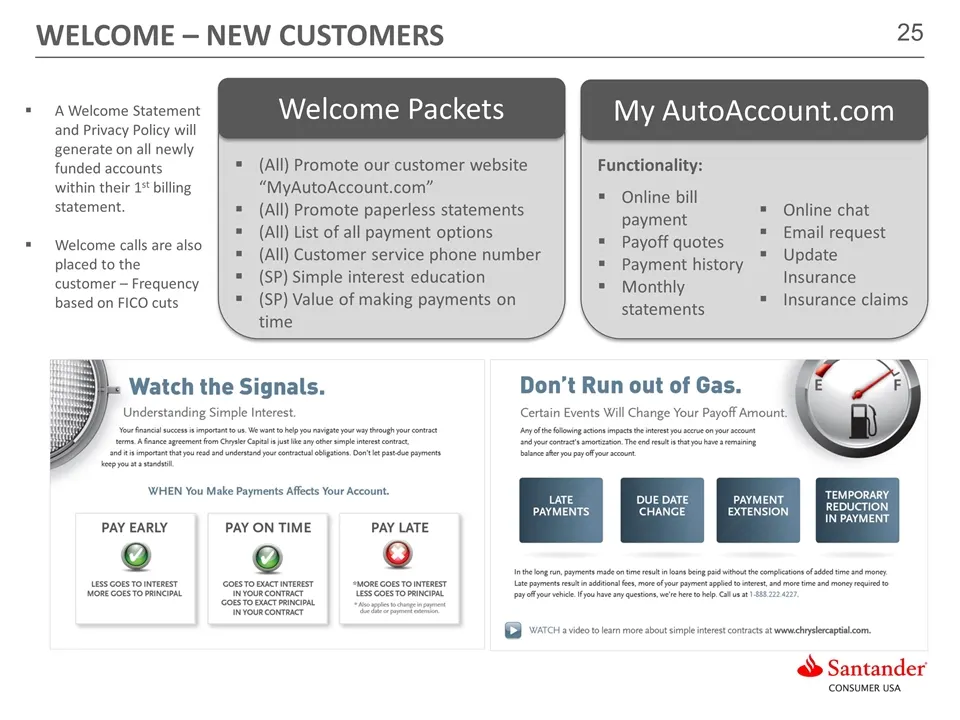
A Welcome Statement and Privacy Policy will generate on all newly funded accounts within their 1st billing statement. Welcome calls are also placed to the customer – Frequency based on FICO cuts (All) – Promote (All) Promote our customer website “MyAutoAccount.com” (All) Promote paperless statements
Slide 26: Speech analytics for quality assurance
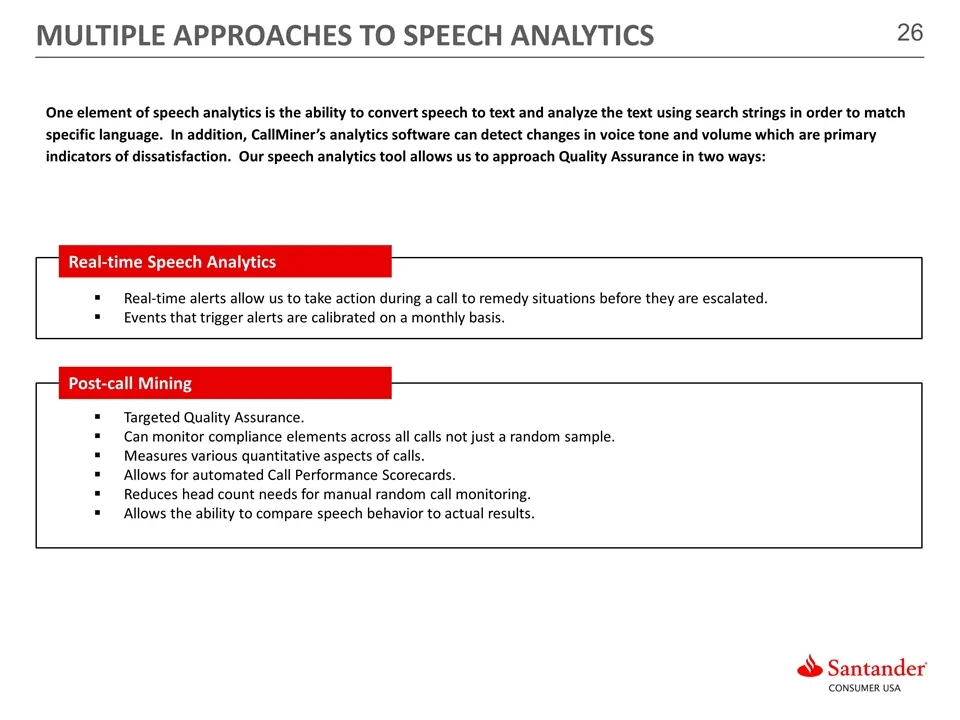
One element of speech analytics is the ability to convert speech to text and analyze the text using search strings in order to match specific language. In addition, CallMiner’s analytics software can detect changes in voice tone and volume which are primary indicators of dissatisfaction. Our speech
Slide 27: CallMiner – Real-Time Speech Analytics Software
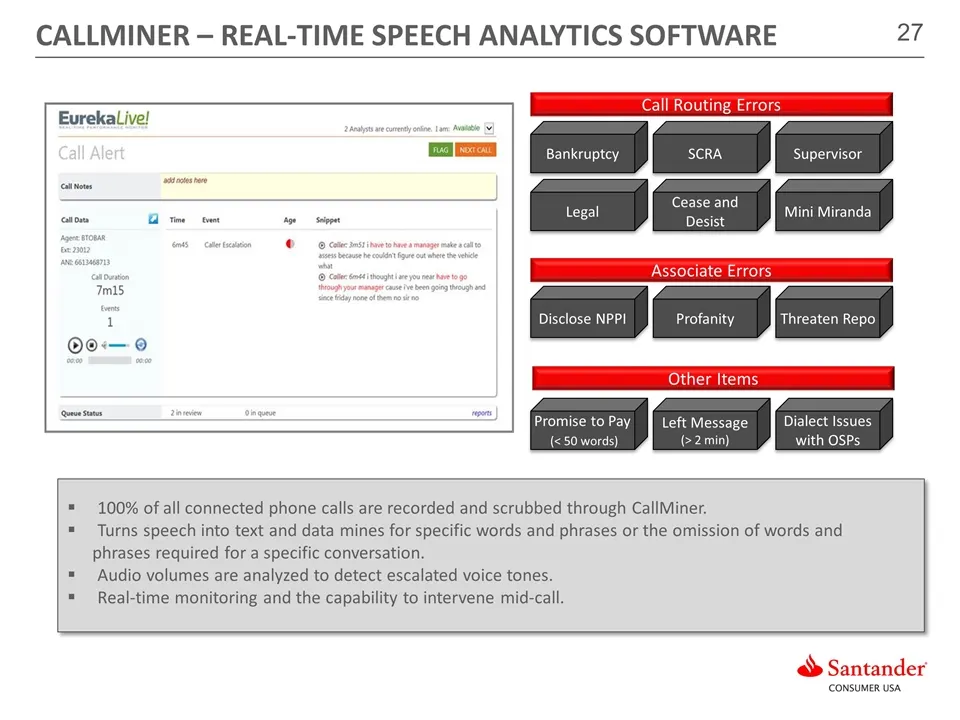
Bankruptcy SCRA Supervisor Cease and Desist Mini Miranda Legal Call Routing Errors Profanity Threaten Repo Disclose NPPI Promise to Pay (< 50 words) Left Message (> 2 min) Dialect Issues with OSPs Associate Errors Other Items 100% of all connected phone calls are recorded and scrubbed through CallMi
Slide 28: Collections scoring: behavior, deferment, repossession, recovery
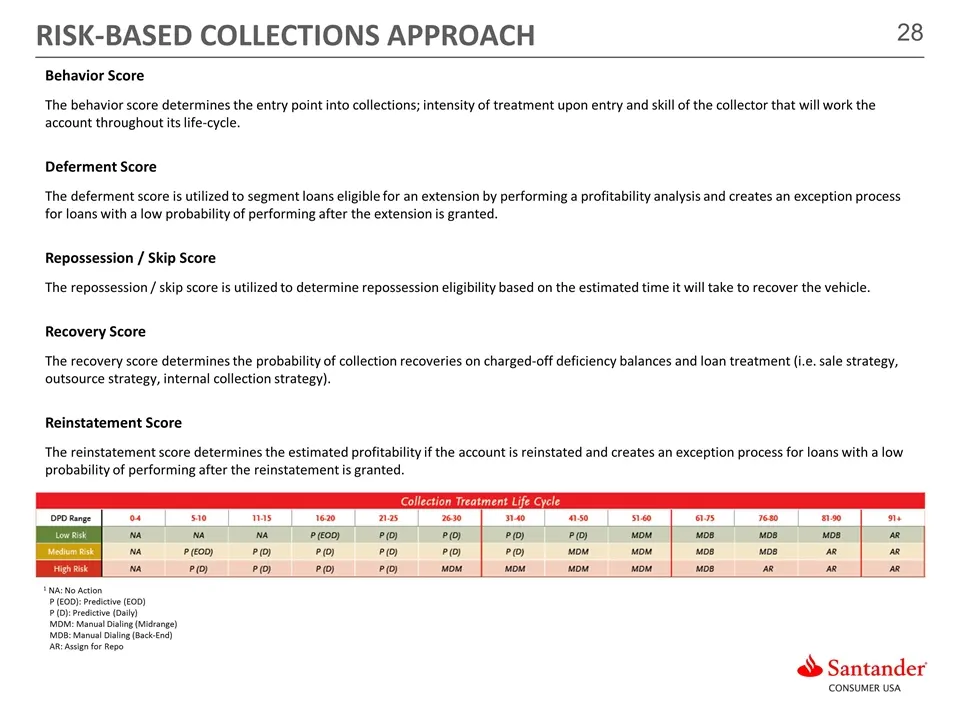
Behavior Score The behavior score determines the entry point into collections; intensity of treatment upon entry and skill of the collector that will work the account throughout its life-cycle. Deferment Score The deferment score is utilized to segment loans eligible for an extension by performing a
Slide 29: Right to cure and repossession process
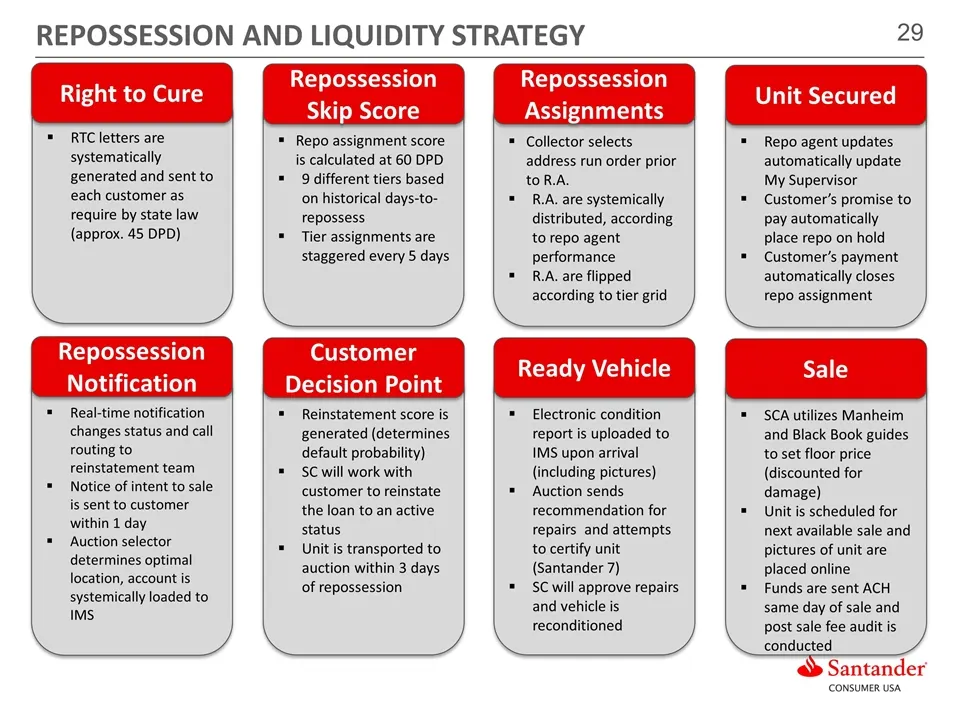
RTC letters are systematically generated and sent to each customer as require by state law (approx. 45 DPD) Right to Cure (All) – Promote Repo assignment score is calculated at 60 DPD 9 different tiers based on historical days-to-repossess Tier assignments are staggered every 5 days Repossession Ski
Slide 30: Competitive Strength – Proprietary Servicing System
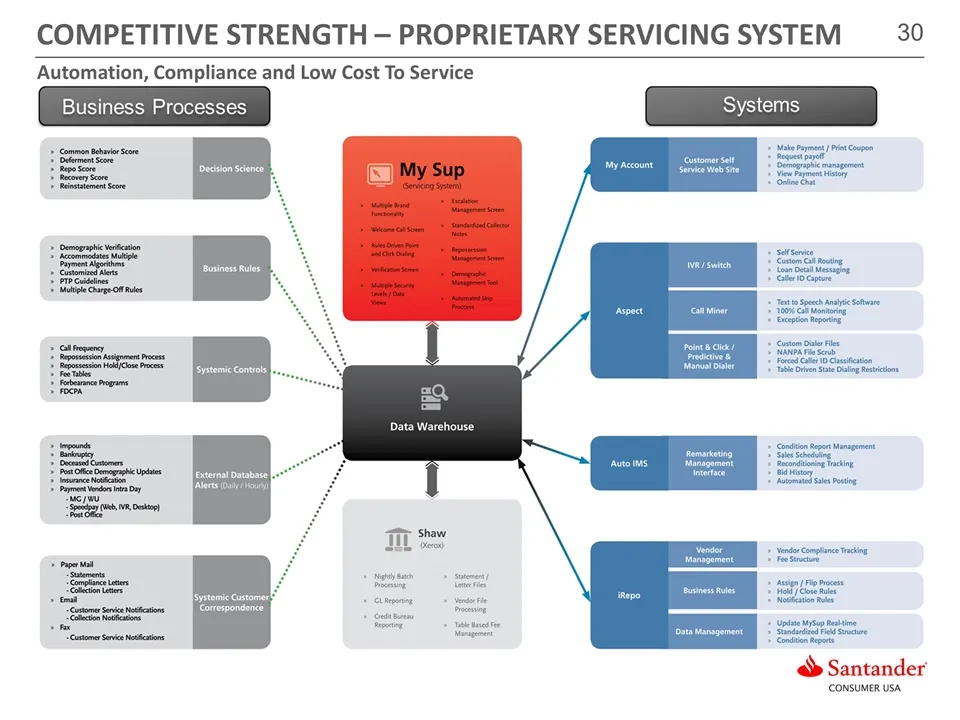
Automation, Compliance and Low Cost To Service COMPETITIVE STRENGTH – PROPRIETARY SERVICING SYSTEM
Slide 31: Santander Consumer USA
® Santander CONSUMER USA
Source: SEC EDGAR · 8-K filed Dec 8, 2016
More decks from Santander Consumer USA Holdings Inc
 Q3 2021 Earnings Presentation24 slides · Oct 27, 2021
 Q2 2021 Earnings Presentation24 slides · Jul 28, 2021
 Q1 2021 Earnings Presentation24 slides · Apr 28, 2021
 FY2020 Earnings Presentation28 slides · Feb 3, 2021
 Q3 2020 Earnings Presentation25 slides · Oct 28, 2020
 Q2 2020 Earnings Presentation26 slides · Jul 29, 2020