Curo — Credit Suisse Annual Financial Services Forum 2020
31 slides from Curo's conference presentation, Feb 26, 2020
Slide 1: February 2020 Credit Suisse Annual Financial Services Forum
February 2020 Credit Suisse Annual Financial Services Forum
Slide 2: Disclaimer
Disclaimer IMPORTANT: You must read the following information before continuing to the rest of the presentation, which is being provided to you for informational purposes only. Forward-Looking Statements This presentation contains forward-looking statements. These forward-looking statements include
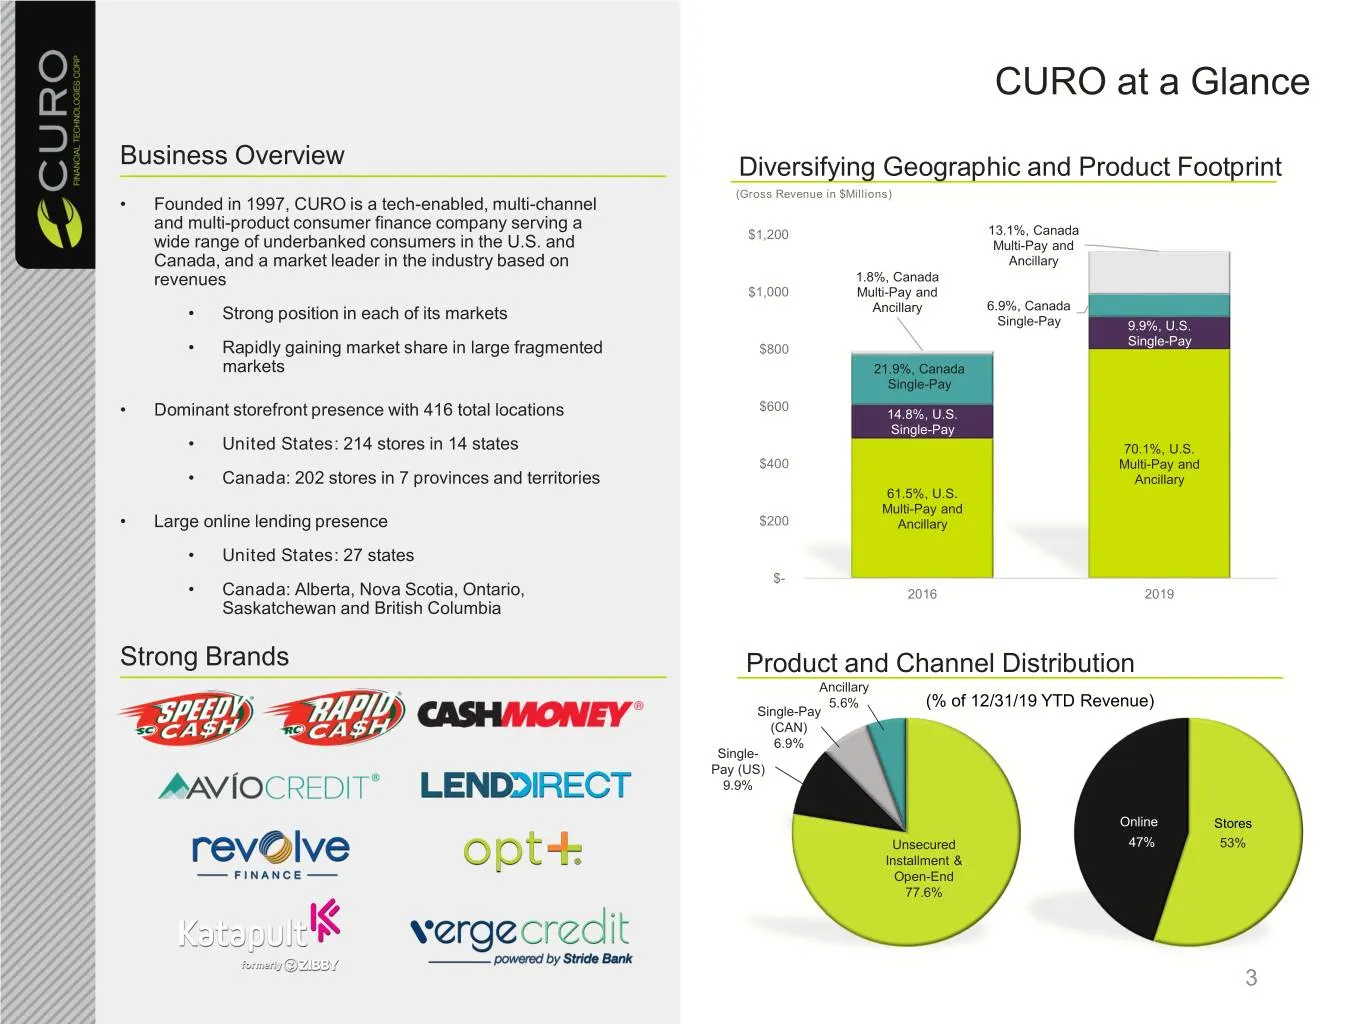
Slide 3: CURO at a Glance
CURO at a Glance Business Overview Diversifying Geographic and Product Footprint (Gross Revenue in $Millions) • Founded in 1997, CURO is a tech-enabled, multi-channel and multi-product consumer finance company serving a $1,200 13.1%, Canada wide range of underbanked consumers in the U.S. and Multi-P
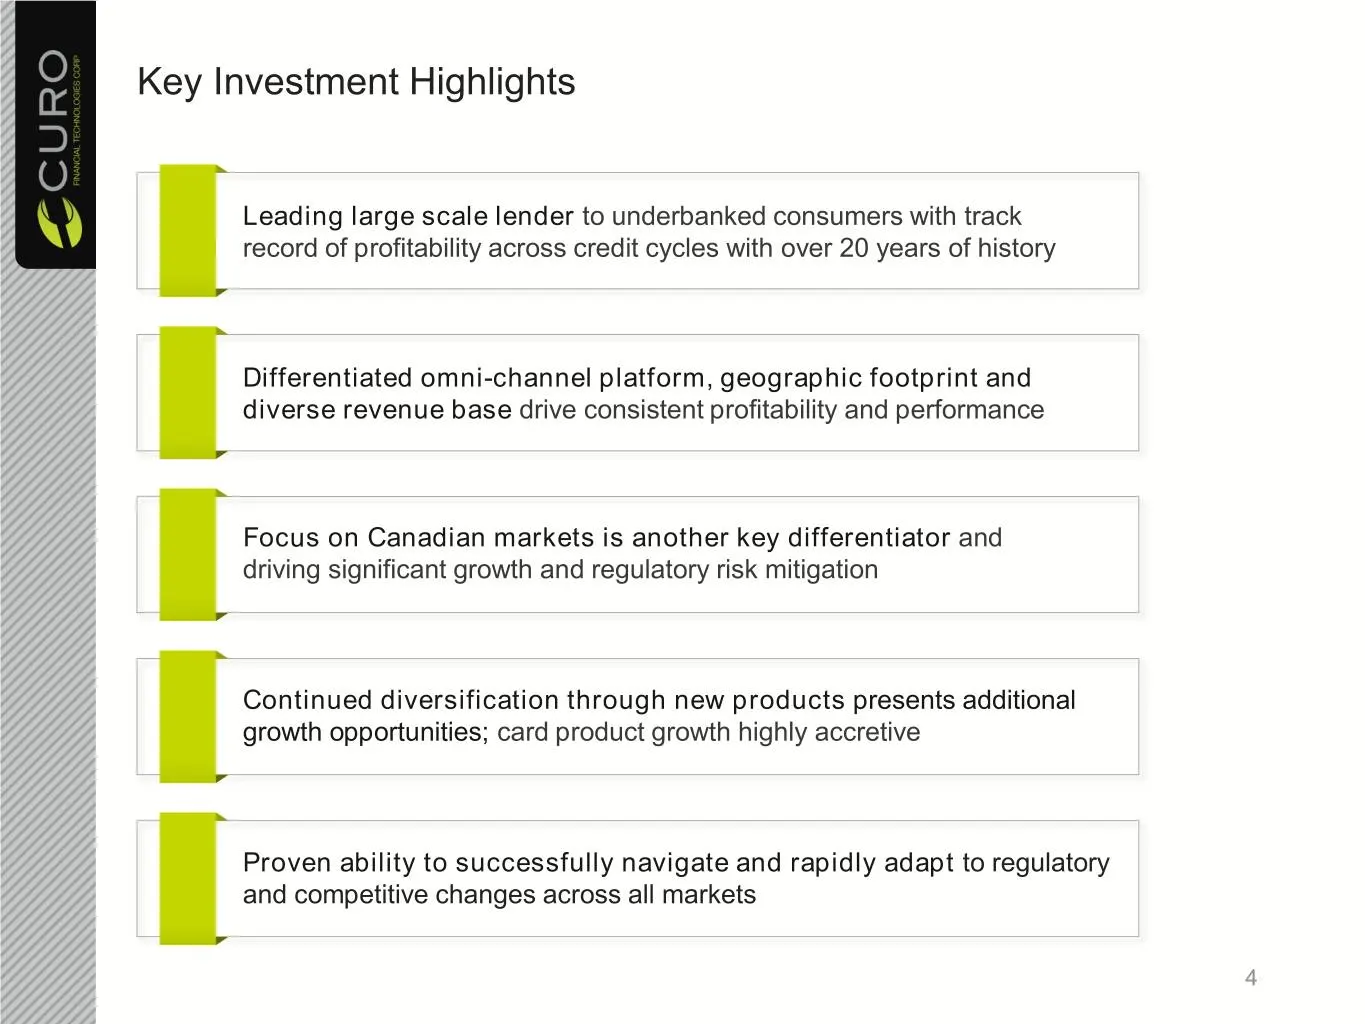
Slide 4: Key Investment Highlights
Key Investment Highlights Leading large scale lender to underbanked consumers with track record of profitability across credit cycles with over 20 years of history Differentiated omni-channel platform, geographic footprint and diverse revenue base drive consistent profitability and performance Focus
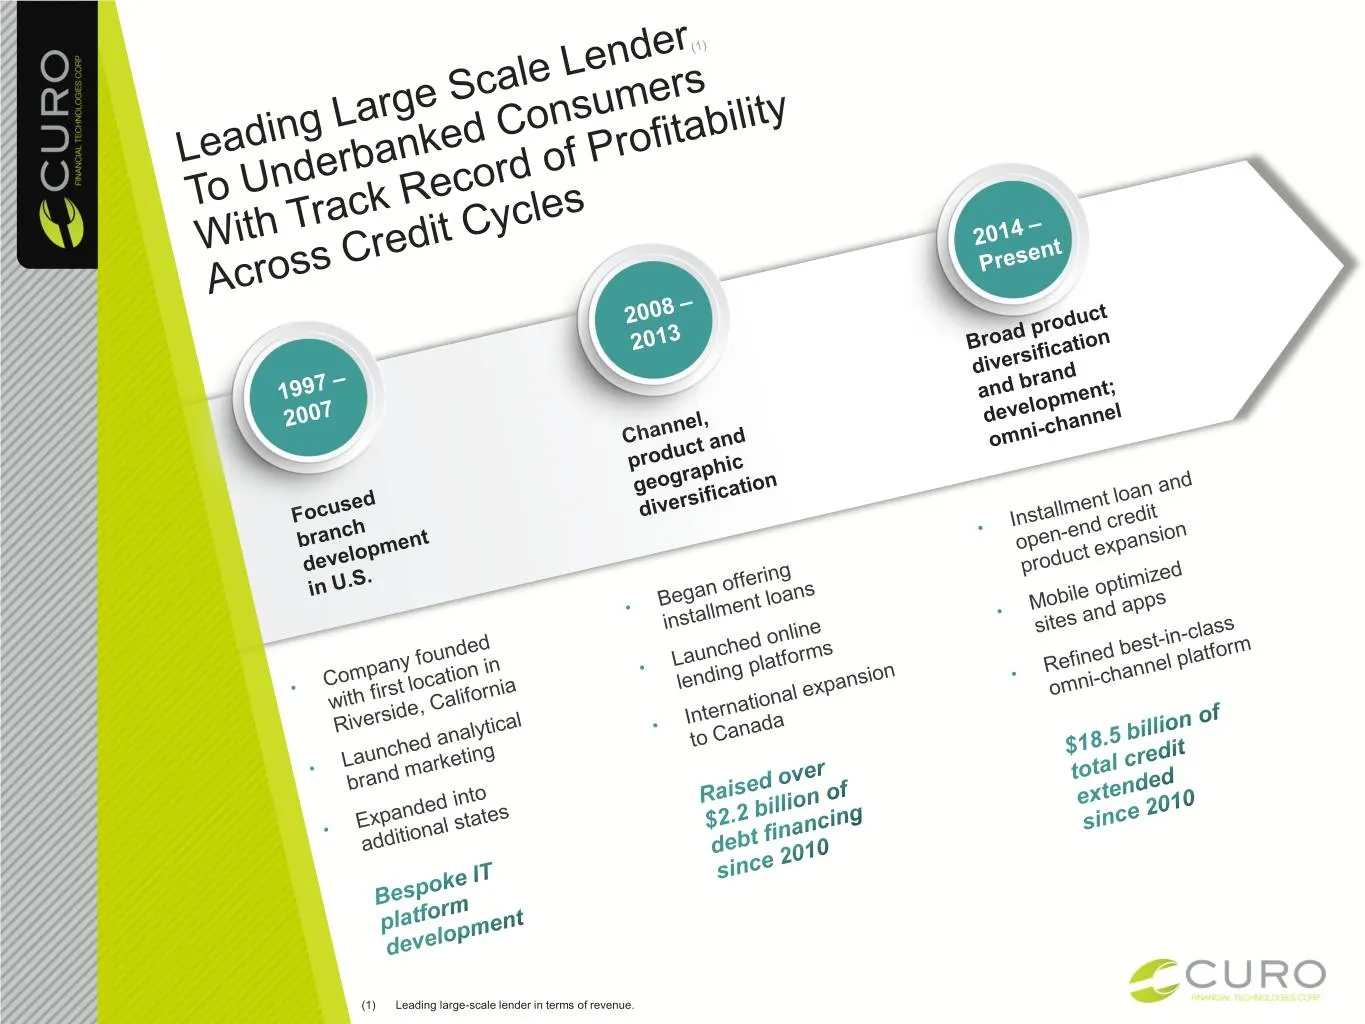
Slide 5: Leading large-scale lender in terms of revenue
(1) Leading large-scale lender in terms of revenue.
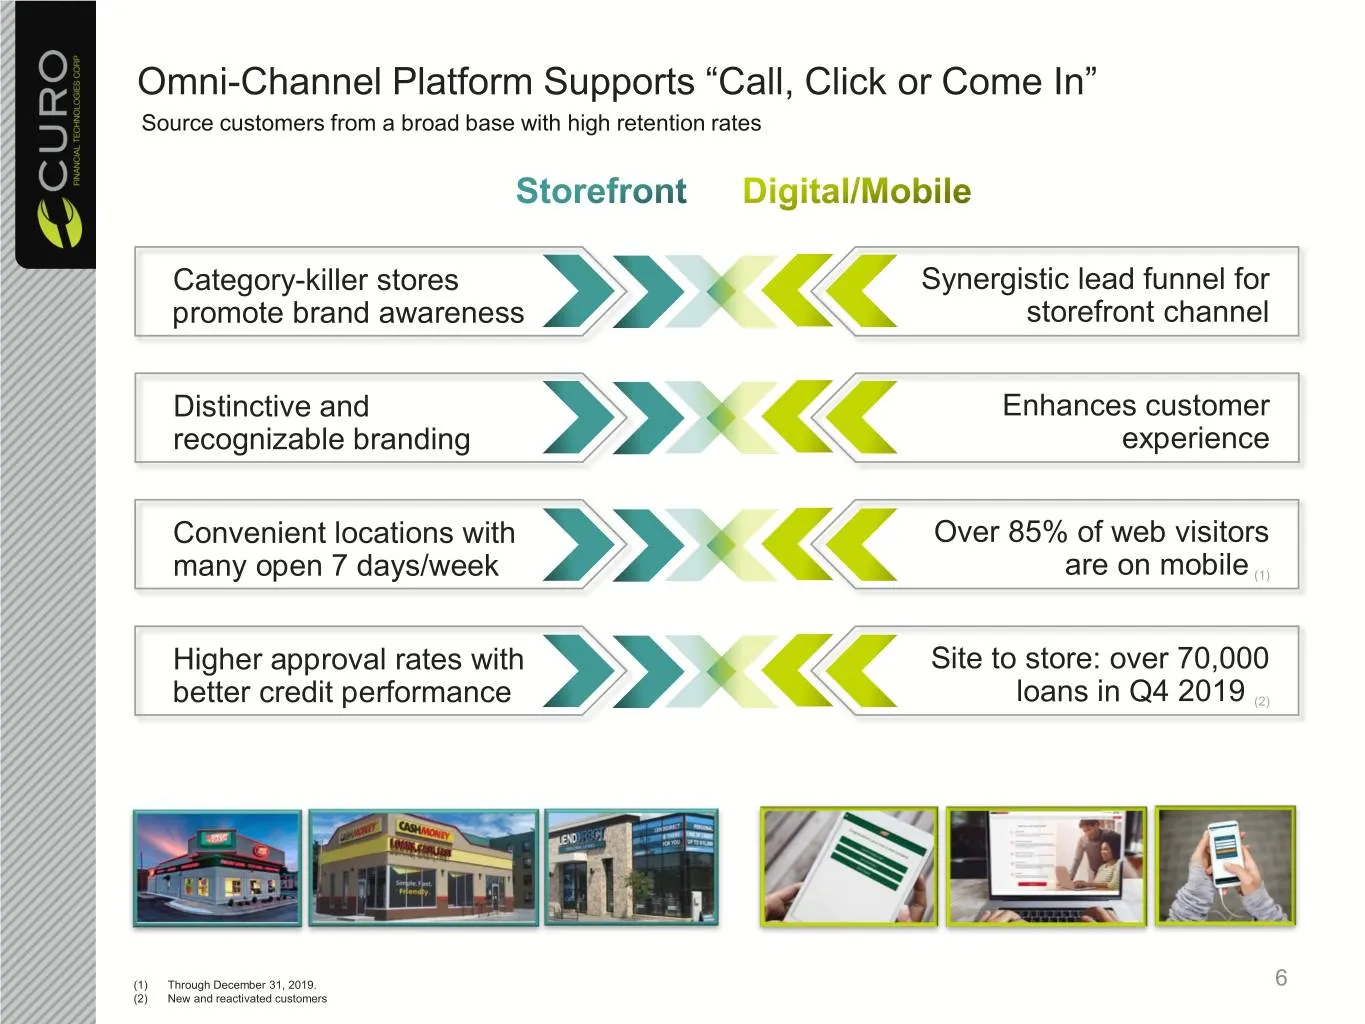
Slide 6: Omni-Channel Platform Supports "Call, Click or Come In"
Omni-Channel Platform Supports “Call, Click or Come In” Source customers from a broad base with high retention rates Category-killer stores Synergistic lead funnel for promote brand awareness storefront channel Distinctive and Enhances customer recognizable branding experience Convenient locations w
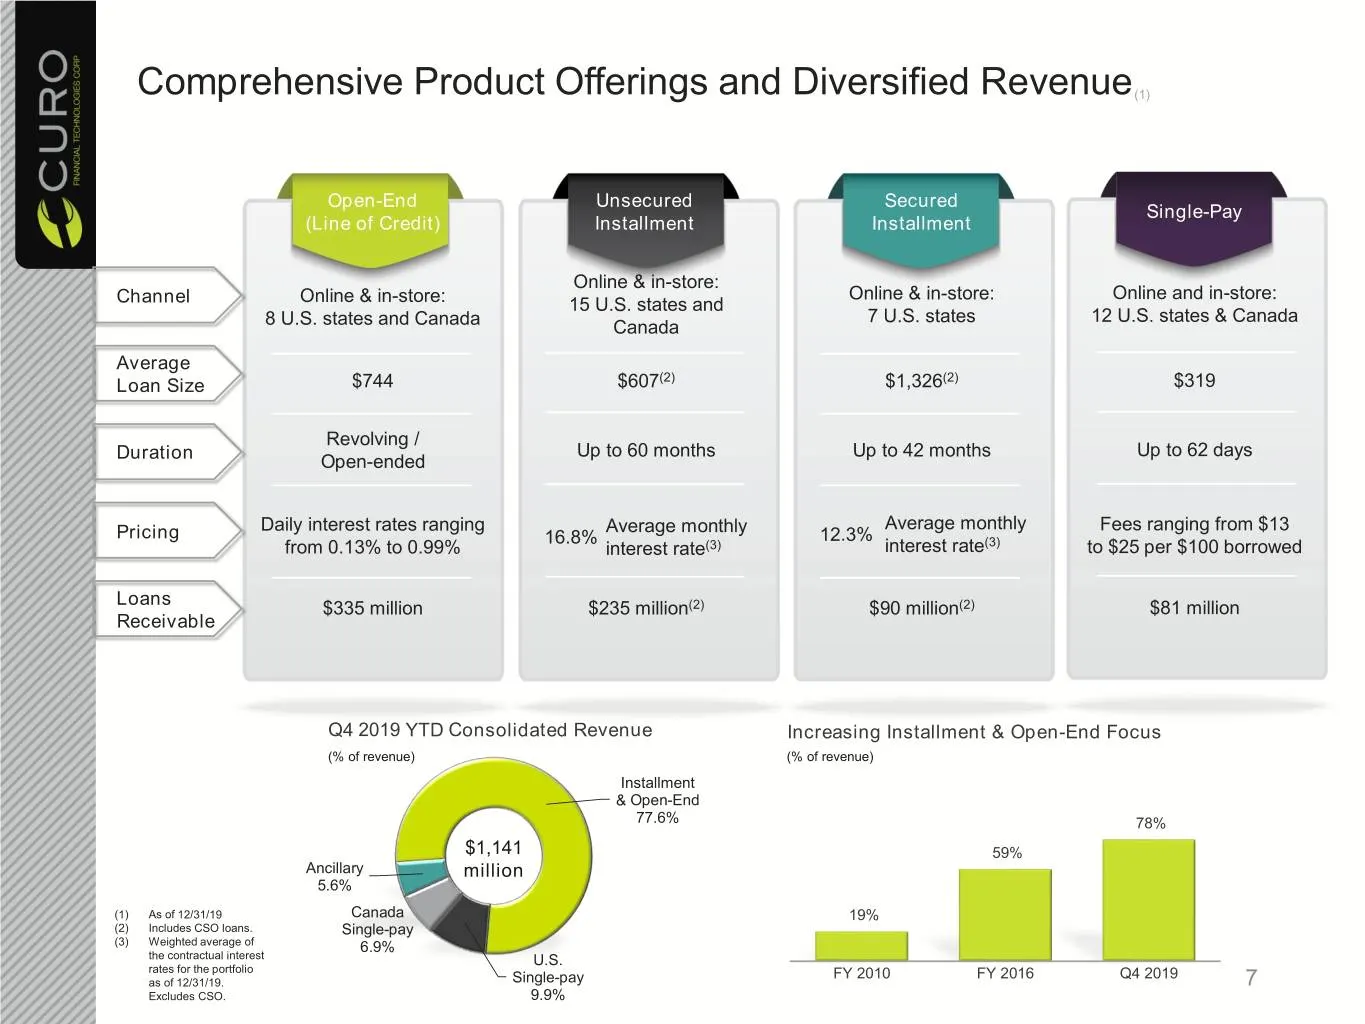
Slide 7: Comprehensive Product Offerings and Diversified Revenue
Comprehensive Product Offerings and Diversified Revenue (1) Open-End Unsecured Secured Single-Pay (Line of Credit) Installment Installment Online & in-store: Online & in-store: Online and in-store: Channel Online & in-store: 15 U.S. states and 7 U.S. states 12 U.S. states & Canada 8 U.S. states and
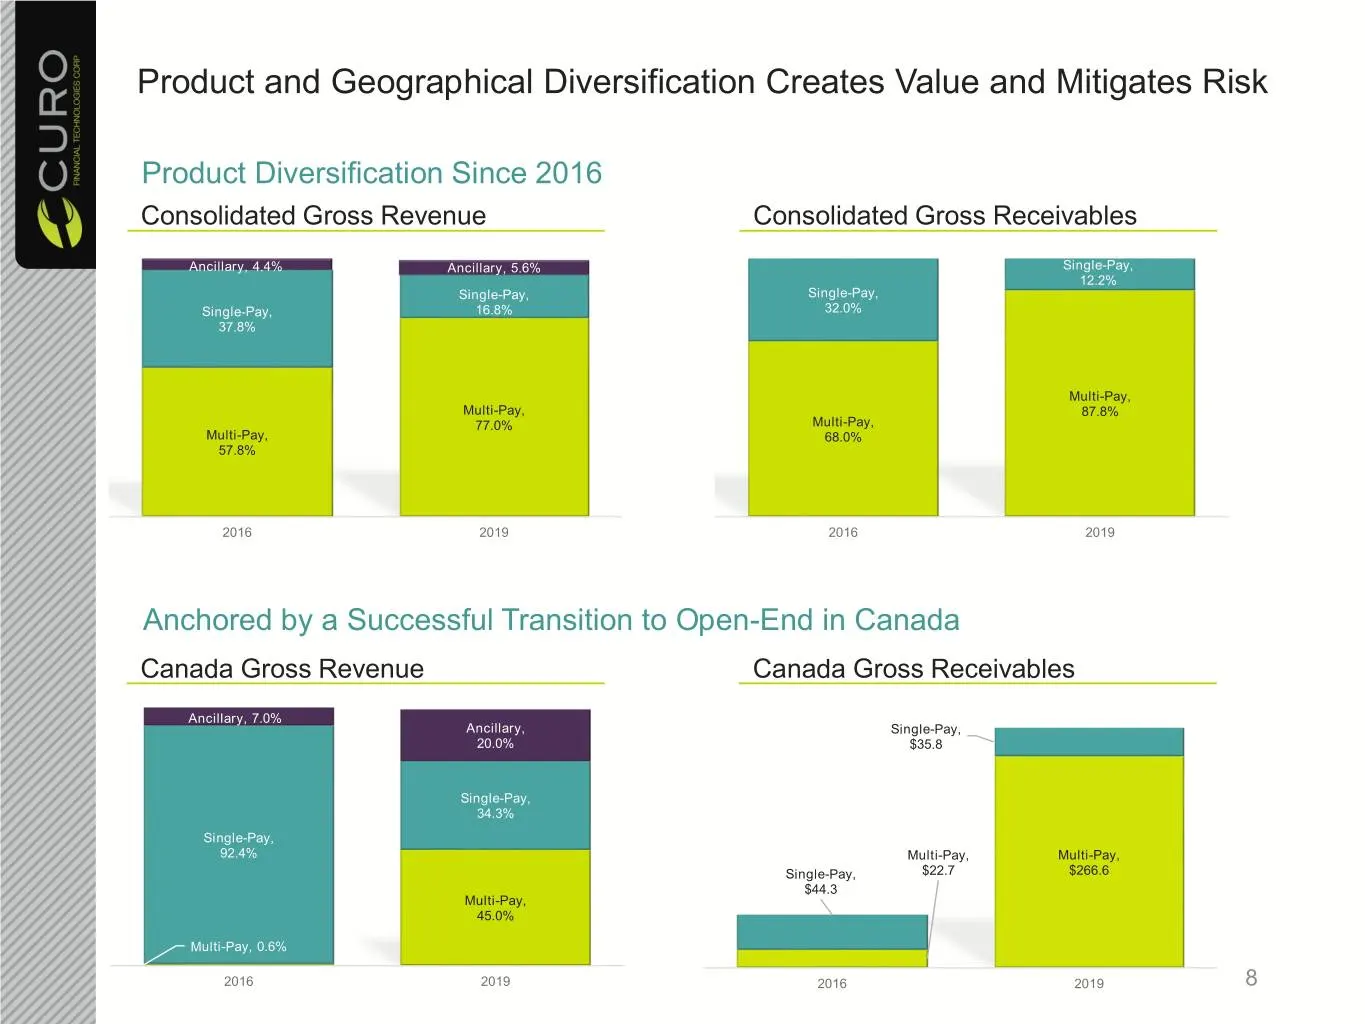
Slide 8: Product and Geographical Diversification Creates Value and Mitigates Risk
Product and Geographical Diversification Creates Value and Mitigates Risk Product Diversification Since 2016 Consolidated Gross Revenue Consolidated Gross Receivables Ancillary, 4.4% Ancillary, 5.6% Single-Pay, 12.2% Single-Pay, Single-Pay, Single-Pay, 16.8% 32.0% 37.8% Multi-Pay, Multi-Pay, 87.8% 7
Slide 9: Large Addressable Market in US is Underserved
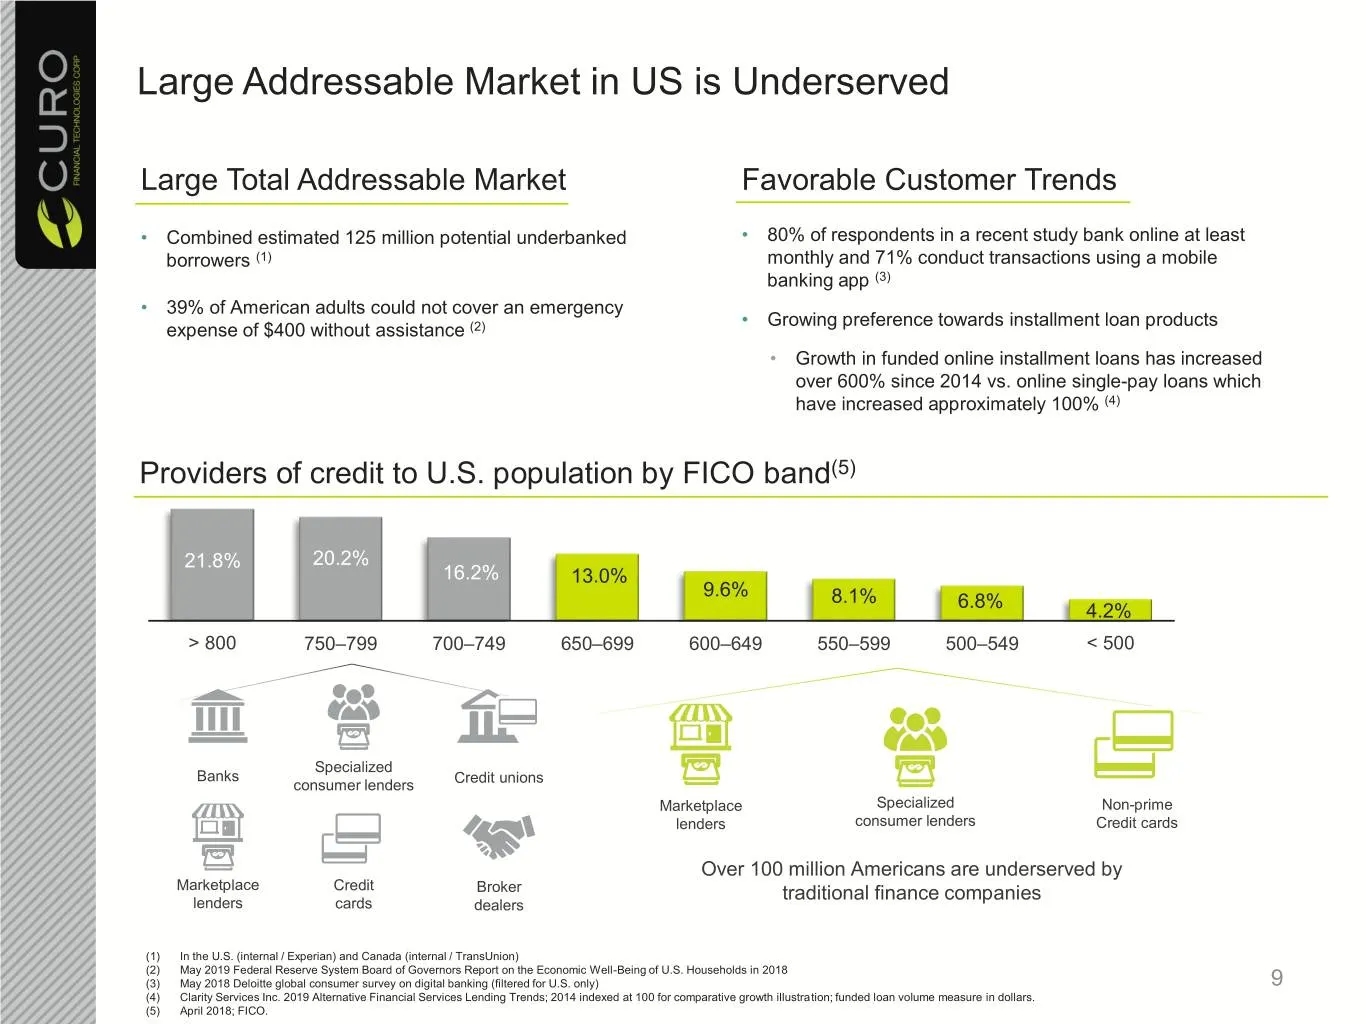
Large Addressable Market in US is Underserved Large Total Addressable Market Favorable Customer Trends • Combined estimated 125 million potential underbanked • 80% of respondents in a recent study bank online at least borrowers (1) monthly and 71% conduct transactions using a mobile banking app (3)
Slide 10: Canadian Market Remains Very Attractive
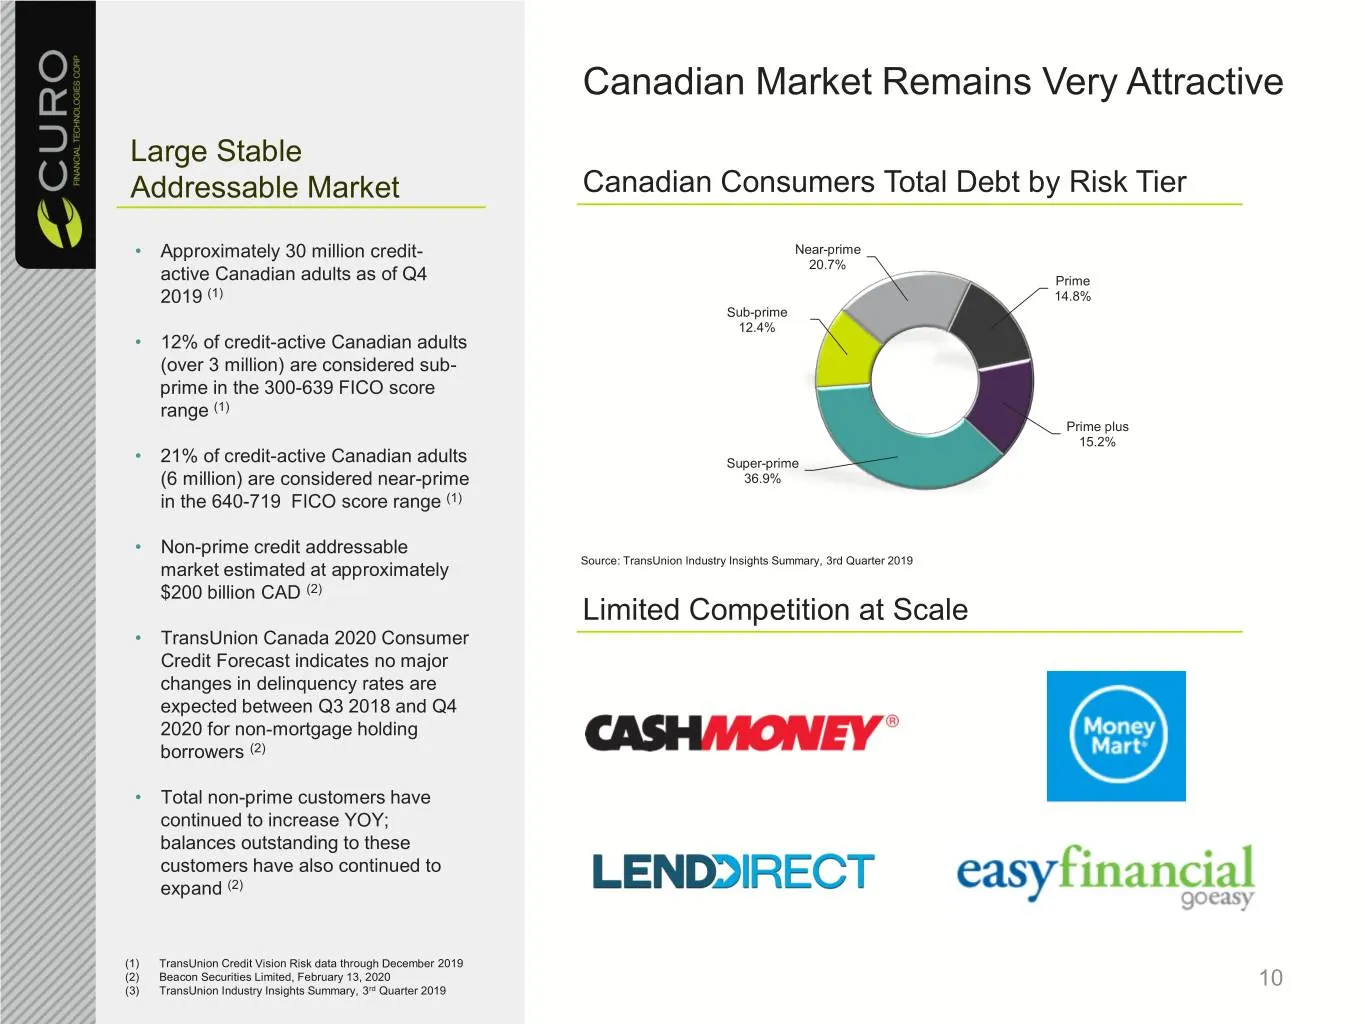
Canadian Market Remains Very Attractive Large Stable Addressable Market Canadian Consumers Total Debt by Risk Tier • Approximately 30 million credit- Near-prime 20.7% active Canadian adults as of Q4 Prime 2019 (1) 14.8% Sub-prime 12.4% • 12% of credit-active Canadian adults (over 3 million) are cons
Slide 11: U.S. Market Trends Continue to Favor CURO
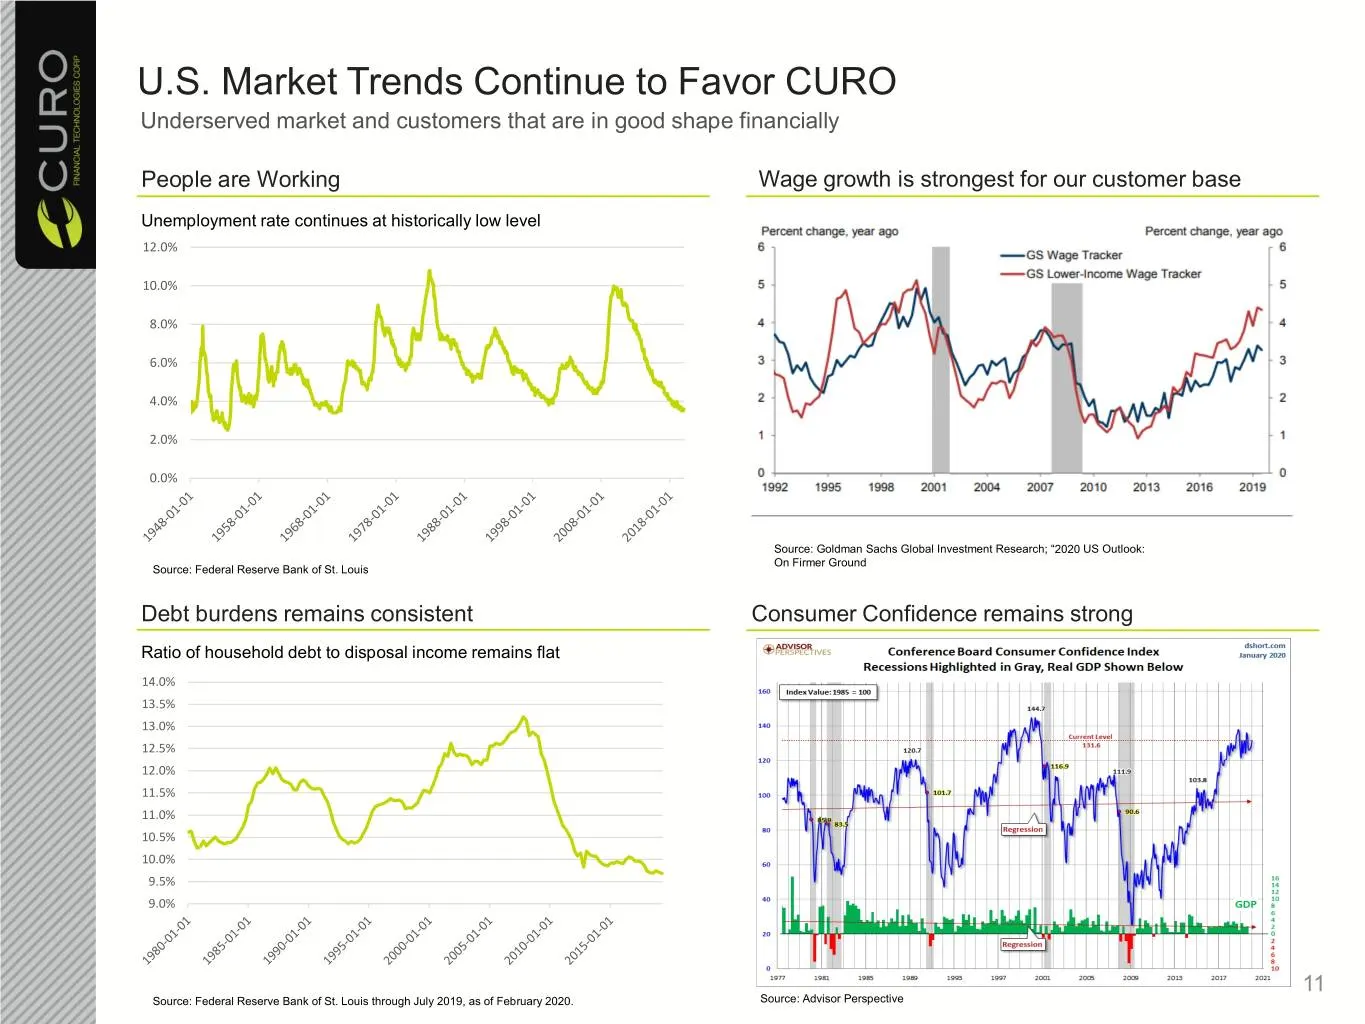
U.S. Market Trends Continue to Favor CURO Underserved market and customers that are in good shape financially People are Working Wage growth is strongest for our customer base Unemployment rate continues at historically low level 12.0% 10.0% 8.0% 6.0% 4.0% 2.0% 0.0% Source: Goldman Sachs Global Inve
Slide 12: U.S. Credit Outlook is Positive for CURO
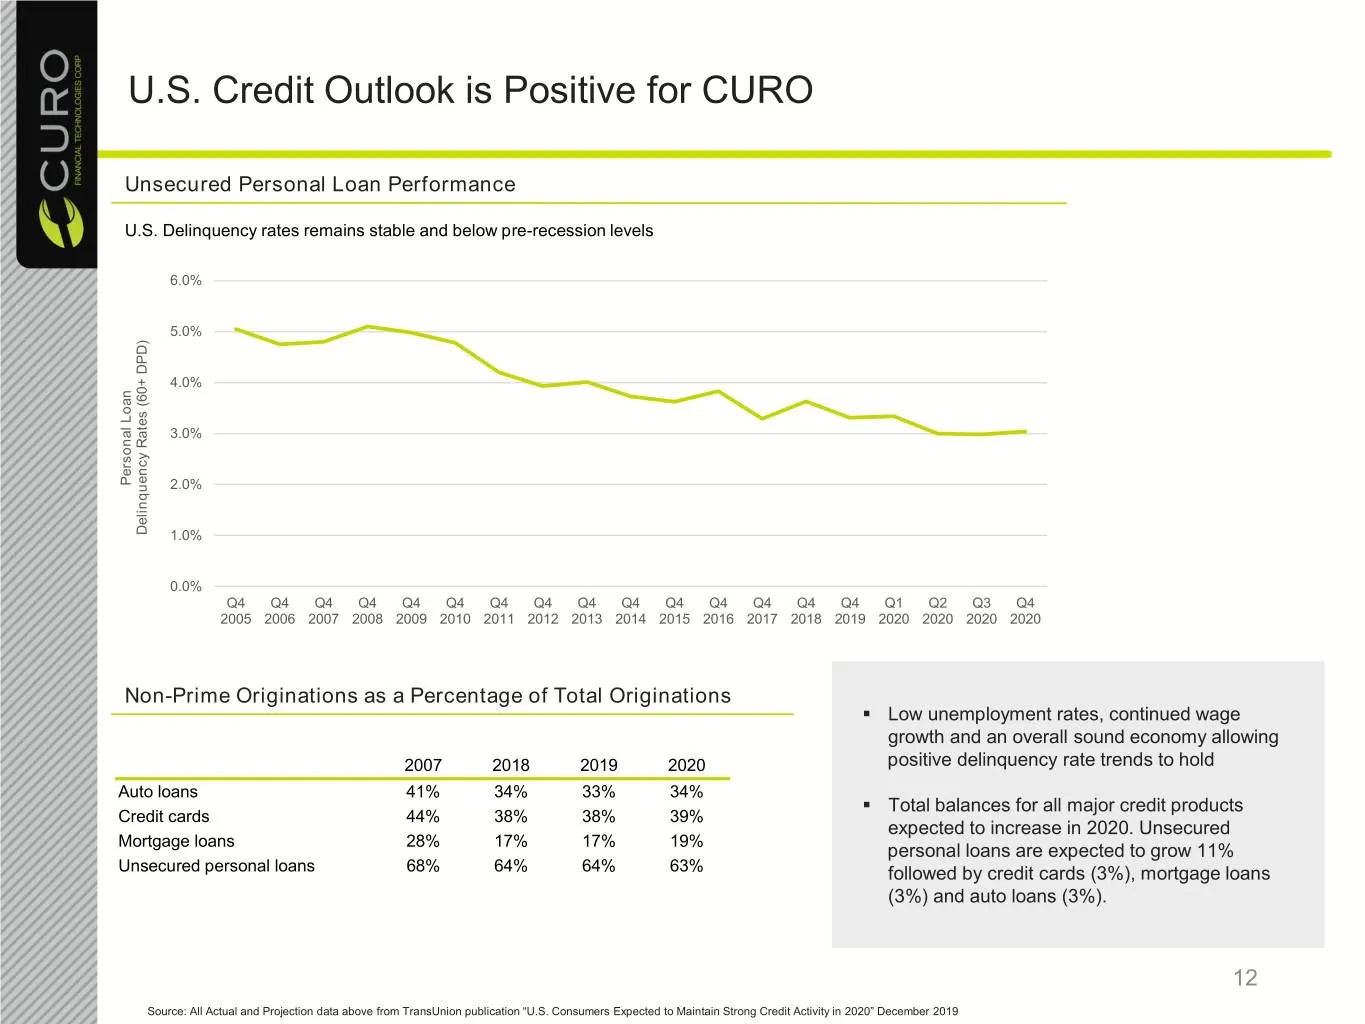
U.S. Credit Outlook is Positive for CURO Unsecured Personal Loan Performance U.S. Delinquency rates remains stable and below pre-recession levels 6.0% 5.0% 4.0% 3.0% Personal Loan Loan Personal 2.0% Delinquency Rates (60+ DPD) (60+ Rates Delinquency 1.0% 0.0% Q4 Q4 Q4 Q4 Q4 Q4 Q4 Q4 Q4 Q4 Q4 Q4 Q4 Q
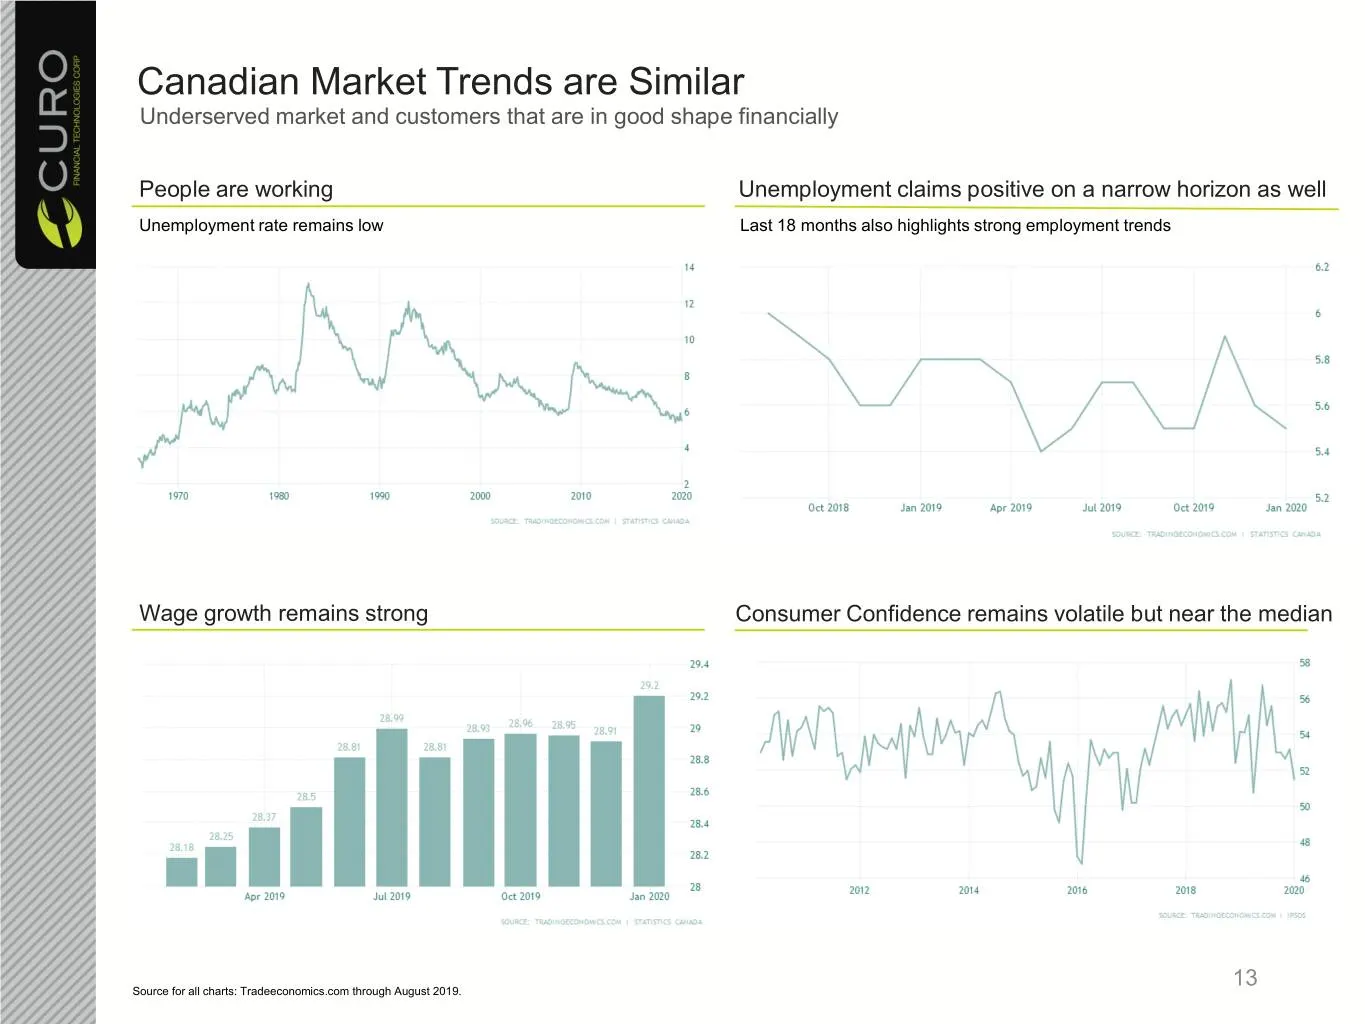
Slide 13: Canadian Market Trends are Similar
Canadian Market Trends are Similar Underserved market and customers that are in good shape financially People are working Unemployment claims positive on a narrow horizon as well Unemployment rate remains low Last 18 months also highlights strong employment trends Wage growth remains strong Consumer
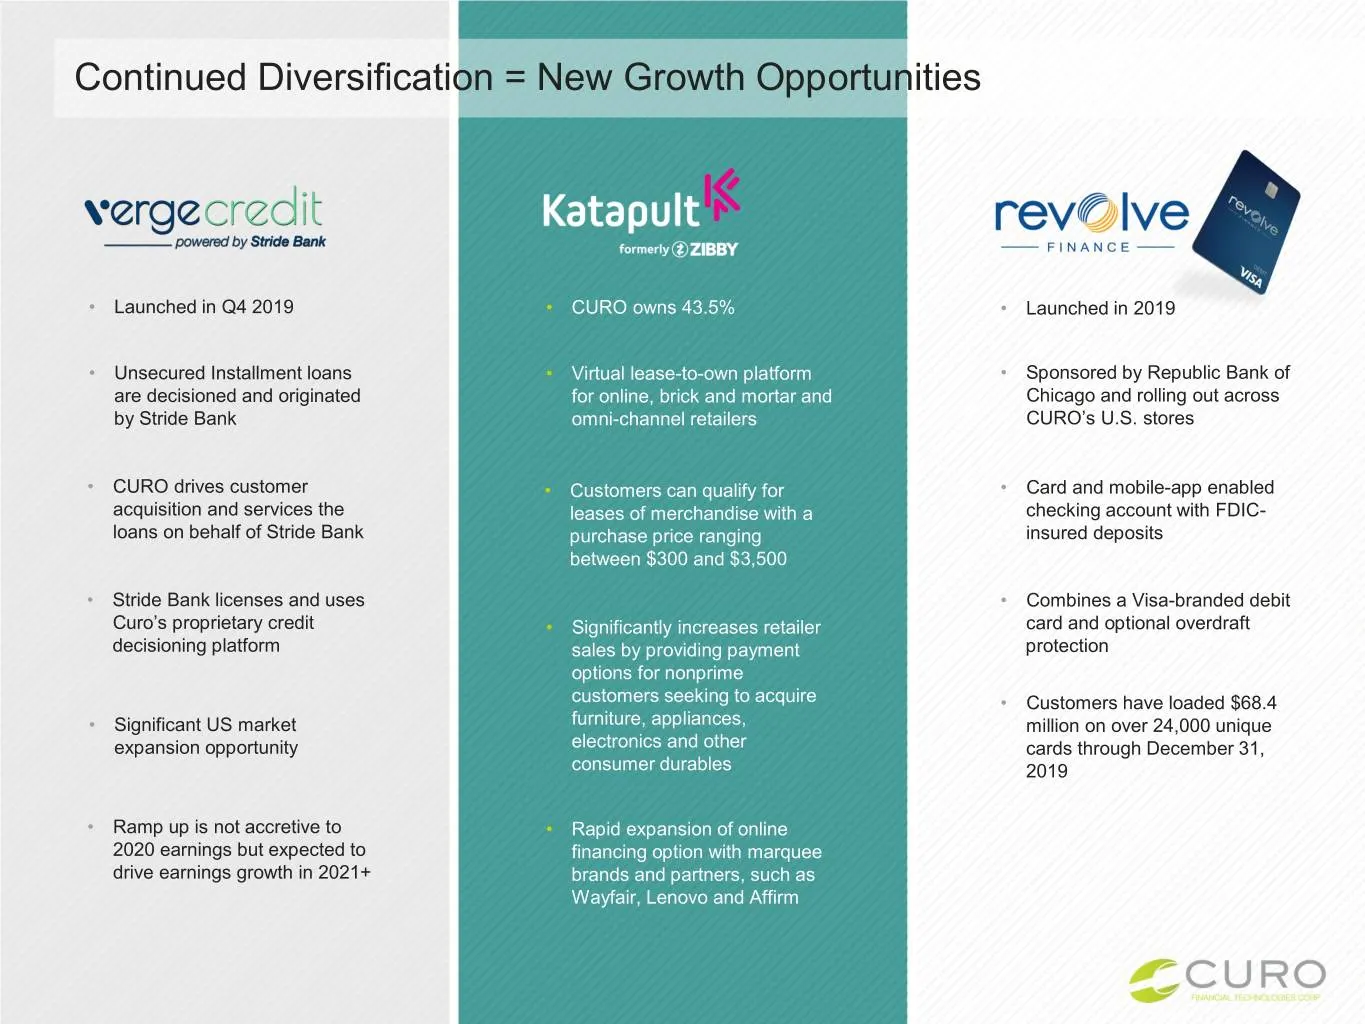
Slide 14: Continued Diversification = New Growth Opportunities
Continued Diversification = New Growth Opportunities • Launched in Q4 2019 • CURO owns 43.5% • Launched in 2019 • Unsecured Installment loans • Virtual lease-to-own platform • Sponsored by Republic Bank of are decisioned and originated for online, brick and mortar and Chicago and rolling out across
Slide 15: Financial Summary
Financial Summary 15
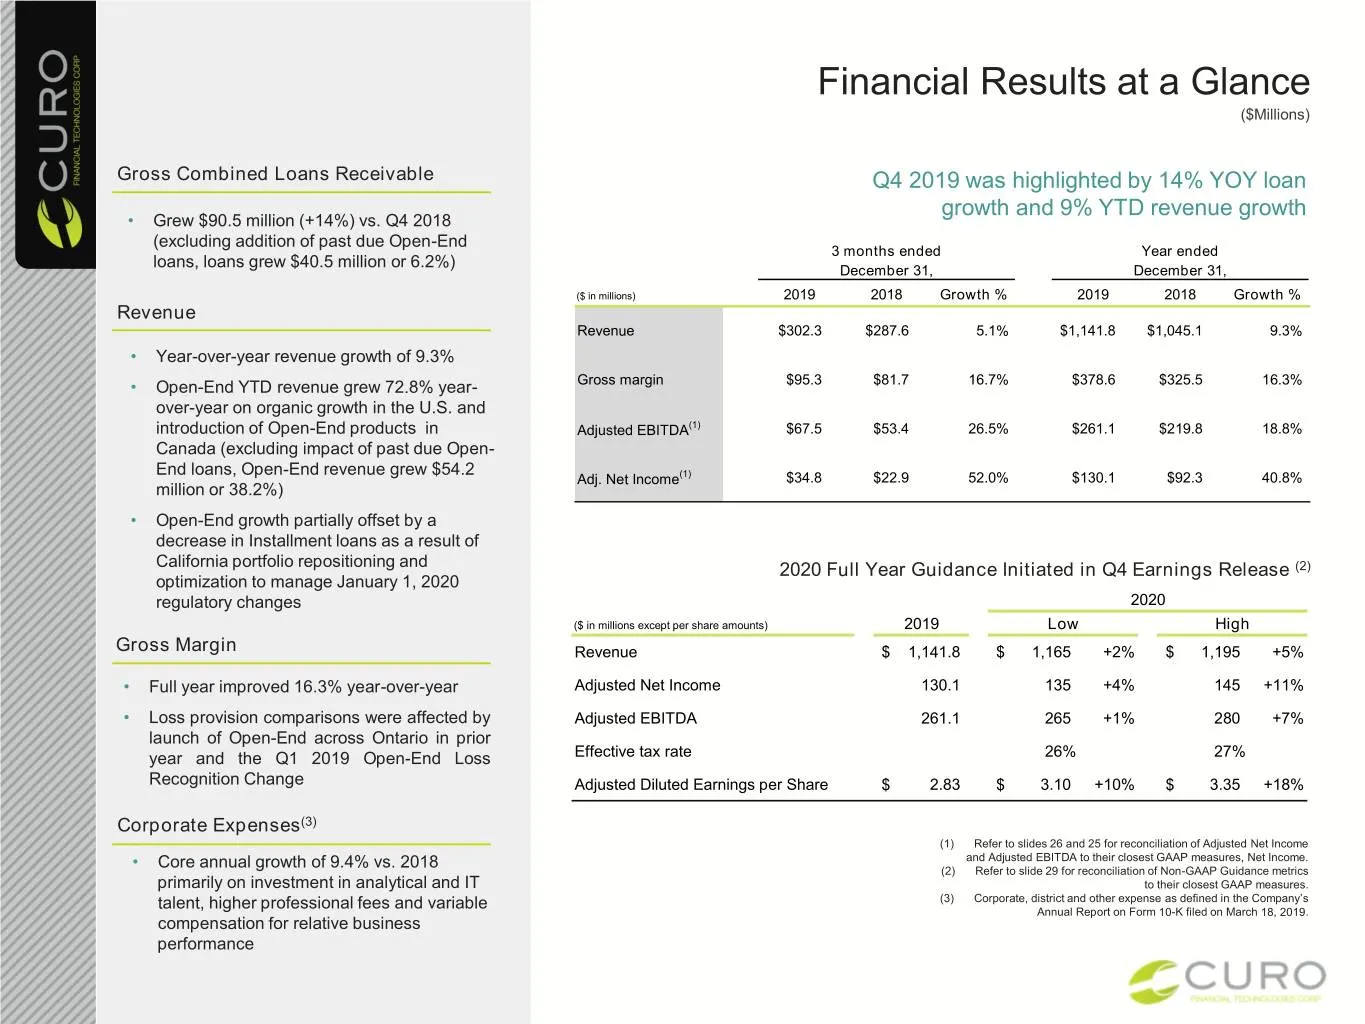
Slide 16: Financial Results at a Glance
Financial Results at a Glance ($Millions) Gross Combined Loans Receivable Q4 2019 was highlighted by 14% YOY loan growth and 9% YTD revenue growth • Grew $90.5 million (+14%) vs. Q4 2018 (excluding addition of past due Open-End 3 months ended Year ended loans, loans grew $40.5 million or 6.2%) Decem
Slide 17: Strong Loan Growth with Managed Mix Shift
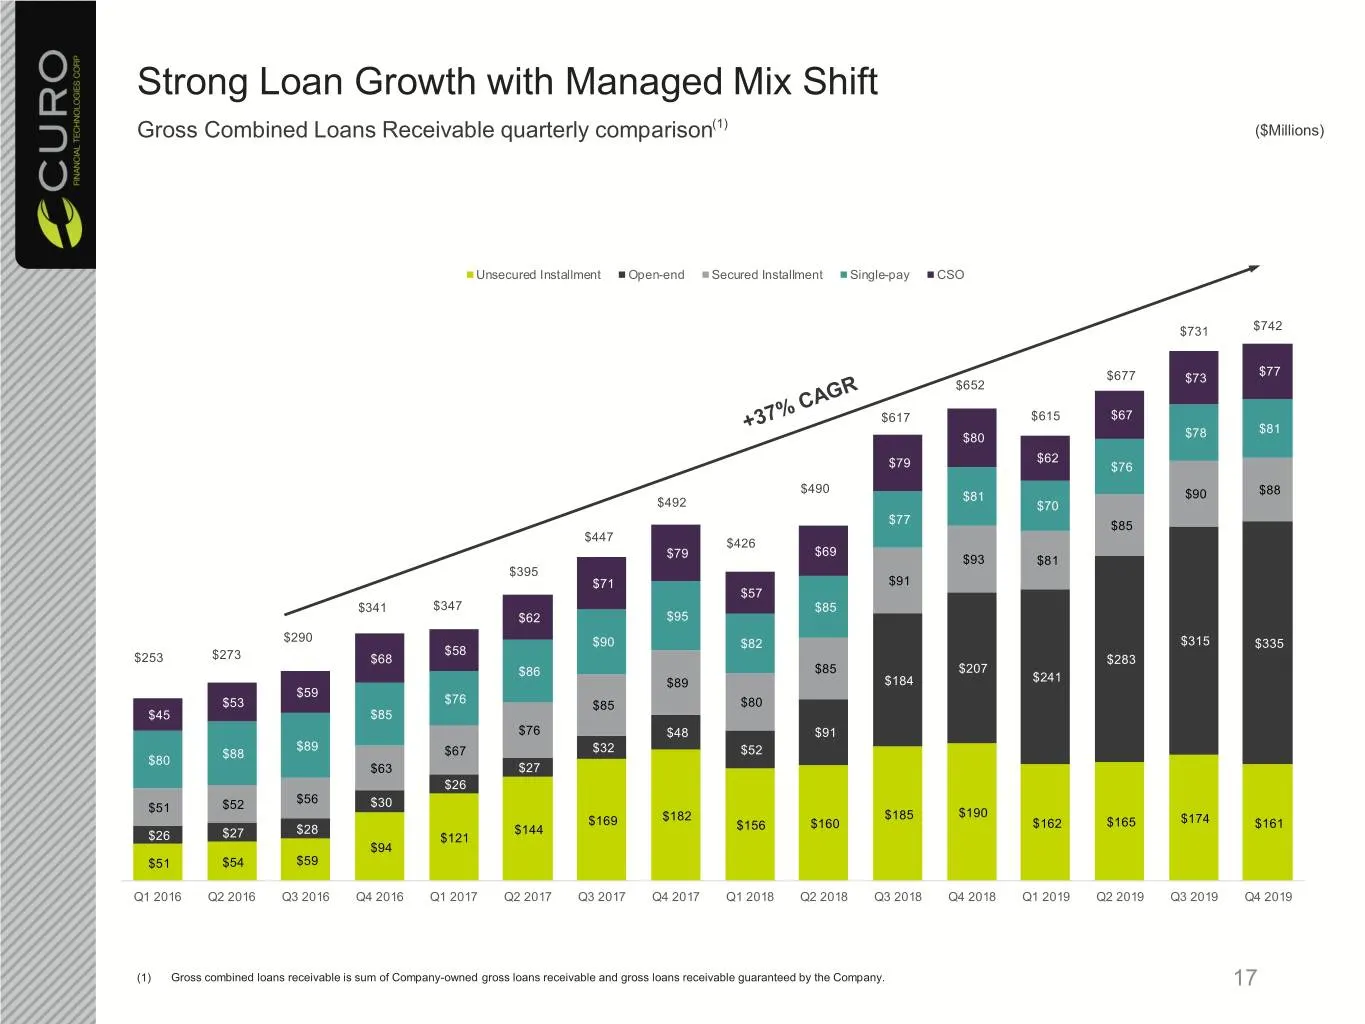
Strong Loan Growth with Managed Mix Shift Gross Combined Loans Receivable quarterly comparison(1) ($Millions) Unsecured Installment Open-end Secured Installment Single-pay CSO $731 $742 $77 $677 $73 $652 $617 $615 $67 $81 $80 $78 $62 $79 $76 $490 $88 $81 $90 $492 $70 $77 $85 $447 $426 $79 $69 $93 $8
Slide 18: U.S. Results – Solid Growth with Stable Margins
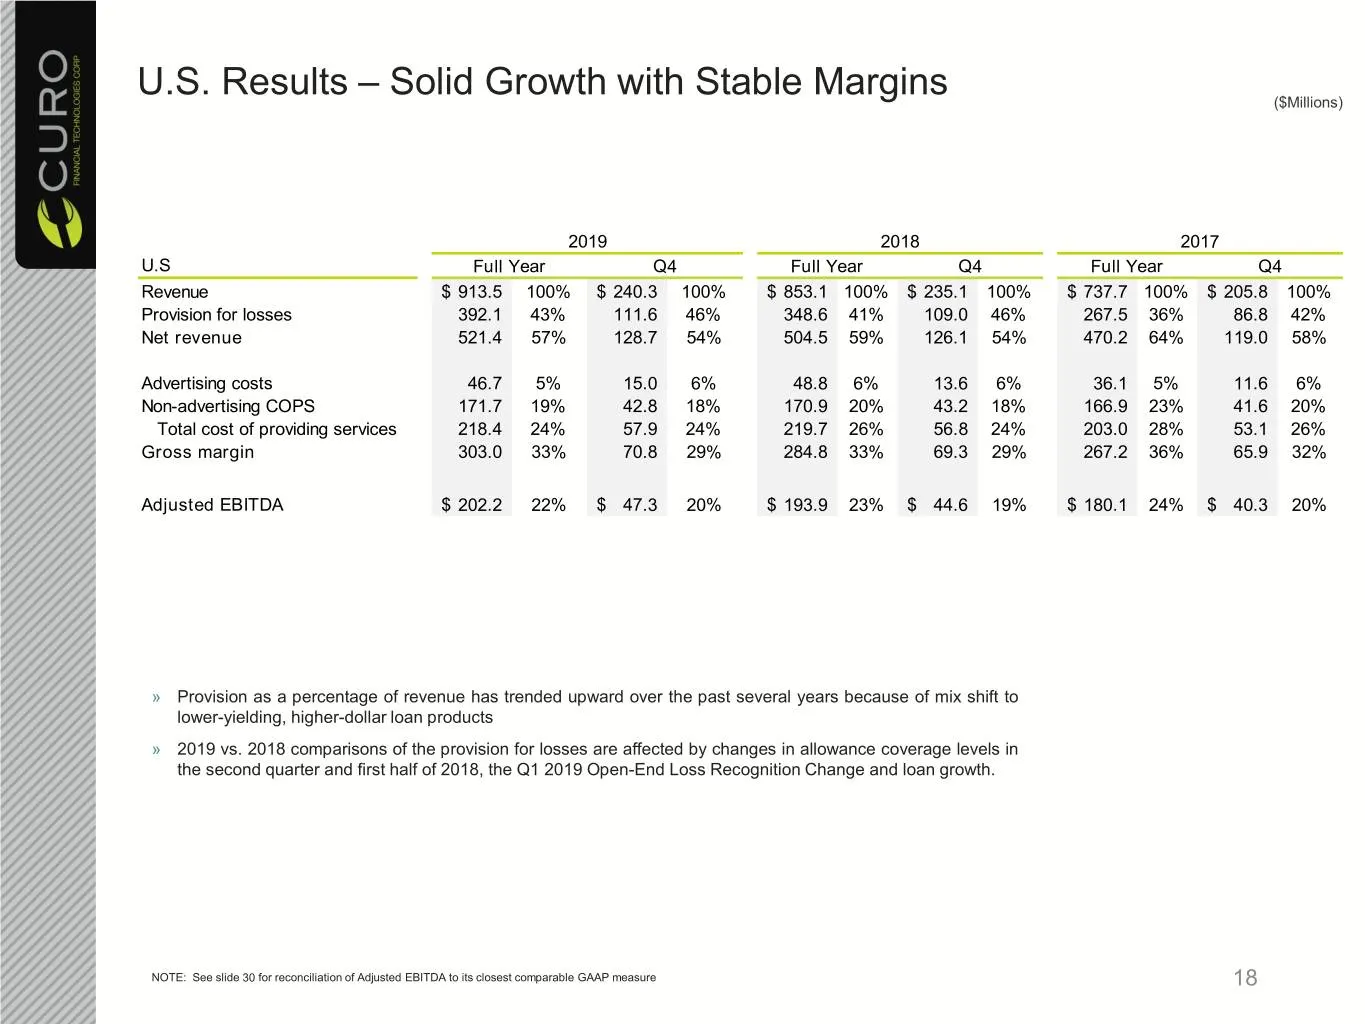
U.S. Results – Solid Growth with Stable Margins ($Millions) 2019 2018 2017 U.S Full Year Q4 Full Year Q4 Full Year Q4 Revenue $ 913.5 100% $ 240.3 100% $ 853.1 100% $ 235.1 100% $ 737.7 100% $ 205.8 100% Provision for losses 392.1 43% 111.6 46% 348.6 41% 109.0 46% 267.5 36% 86.8 42% Net revenue 521.
Slide 19: Canada – Valuable Transition to Multi-Pay Loans
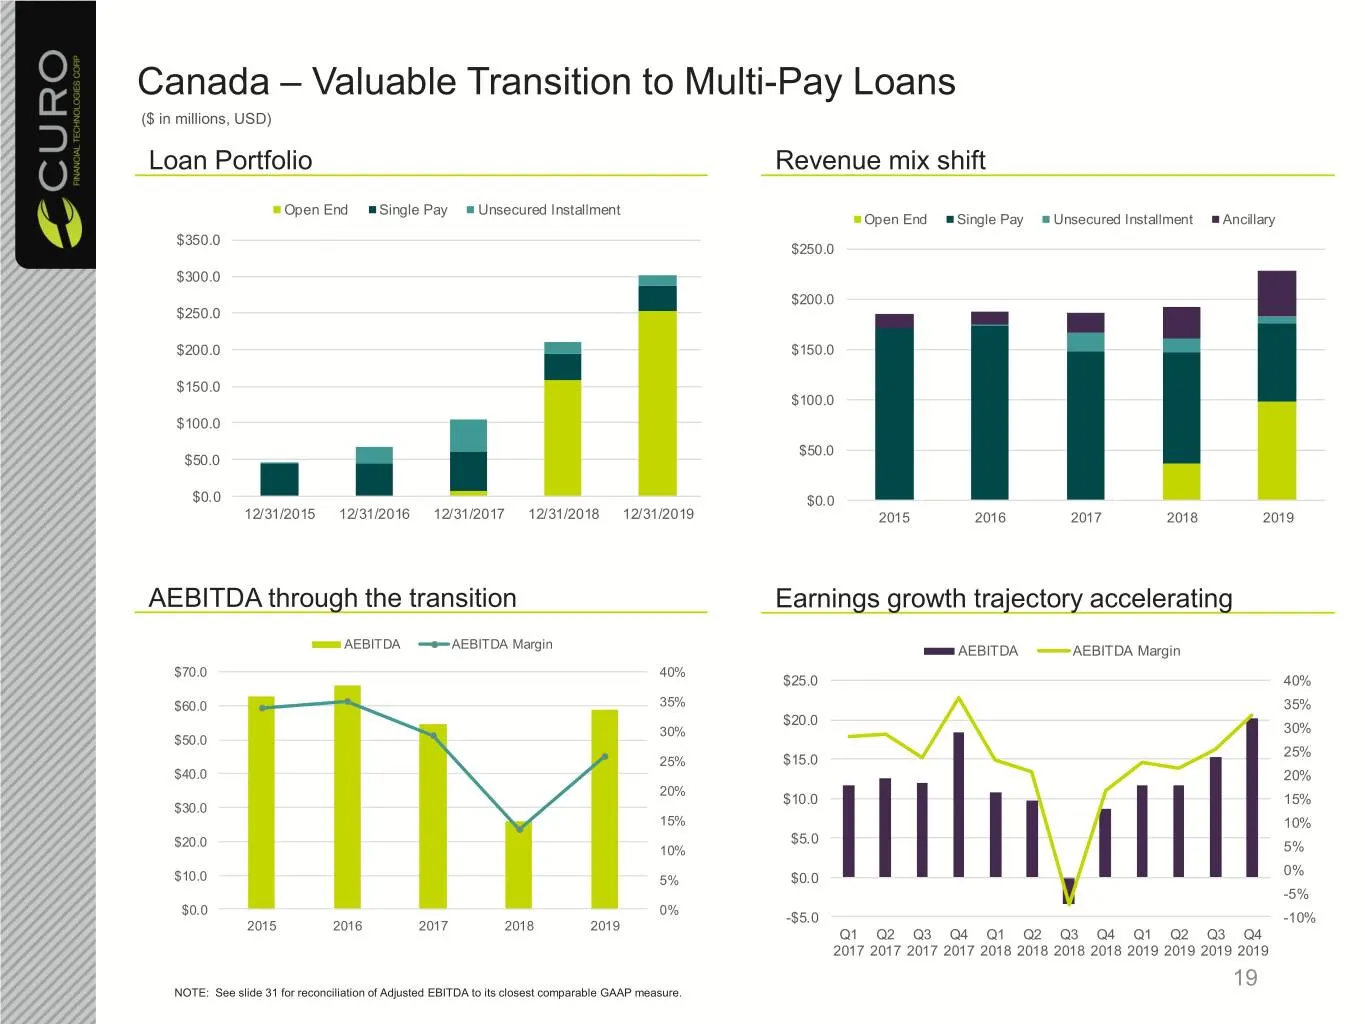
Canada – Valuable Transition to Multi-Pay Loans ($ in millions, USD) Loan Portfolio Revenue mix shift Open End Single Pay Unsecured Installment Open End Single Pay Unsecured Installment Ancillary $350.0 $250.0 $300.0 $200.0 $250.0 $200.0 $150.0 $150.0 $100.0 $100.0 $50.0 $50.0 $0.0 $0.0 12/31/2015 1
Slide 20: Improved Quarterly Net Charge-Off Rates
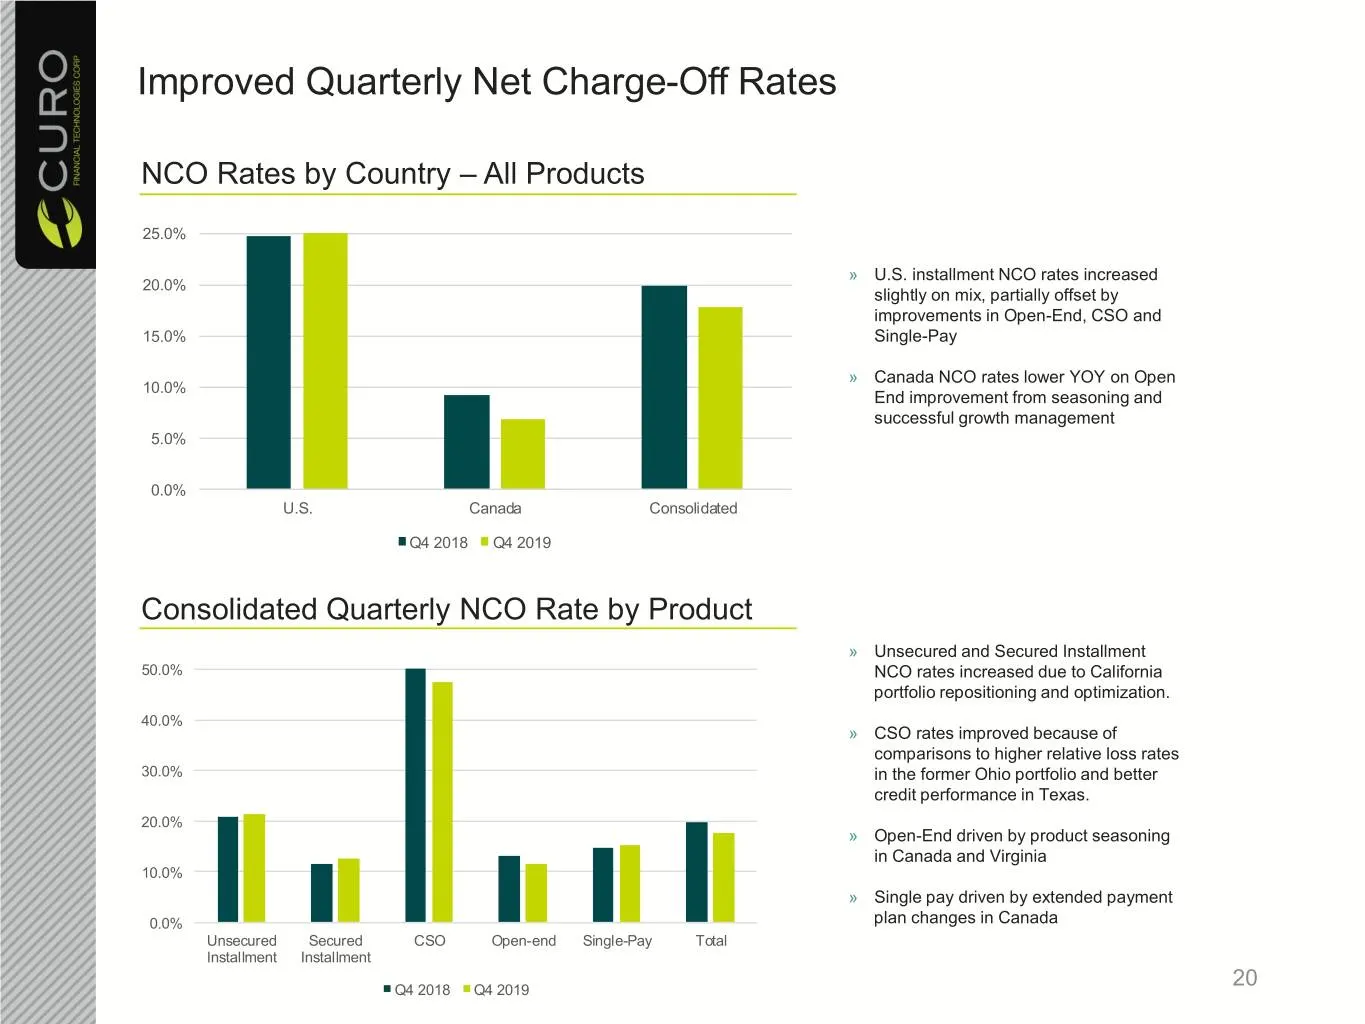
Improved Quarterly Net Charge-Off Rates NCO Rates by Country – All Products 25.0% » U.S. installment NCO rates increased 20.0% slightly on mix, partially offset by improvements in Open-End, CSO and 15.0% Single-Pay » Canada NCO rates lower YOY on Open 10.0% End improvement from seasoning and success
Slide 21: Cash Flow Illustration
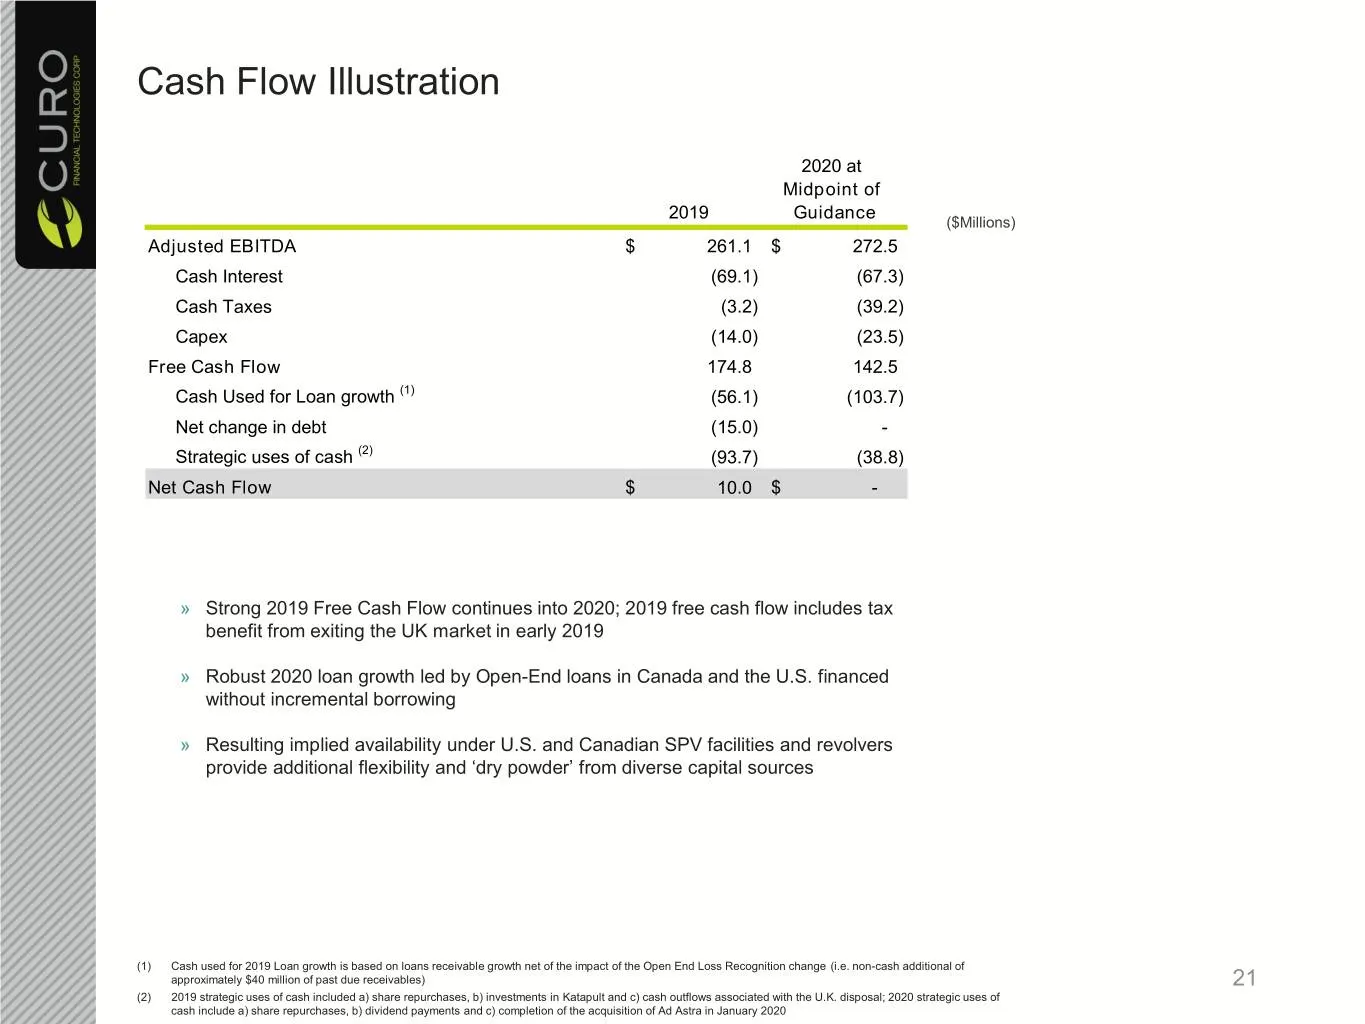
Cash Flow Illustration 2020 at Midpoint of 2019 Guidance ($Millions) Adjusted EBITDA $ 261.1 $ 272.5 Cash Interest (69.1) (67.3) Cash Taxes (3.2) (39.2) Capex (14.0) (23.5) Free Cash Flow 174.8 142.5 Cash Used for Loan growth (1) (56.1) (103.7) Net change in debt (15.0) - Strategic uses of cash (2)
Slide 22: Consolidated Summary Balance Sheet
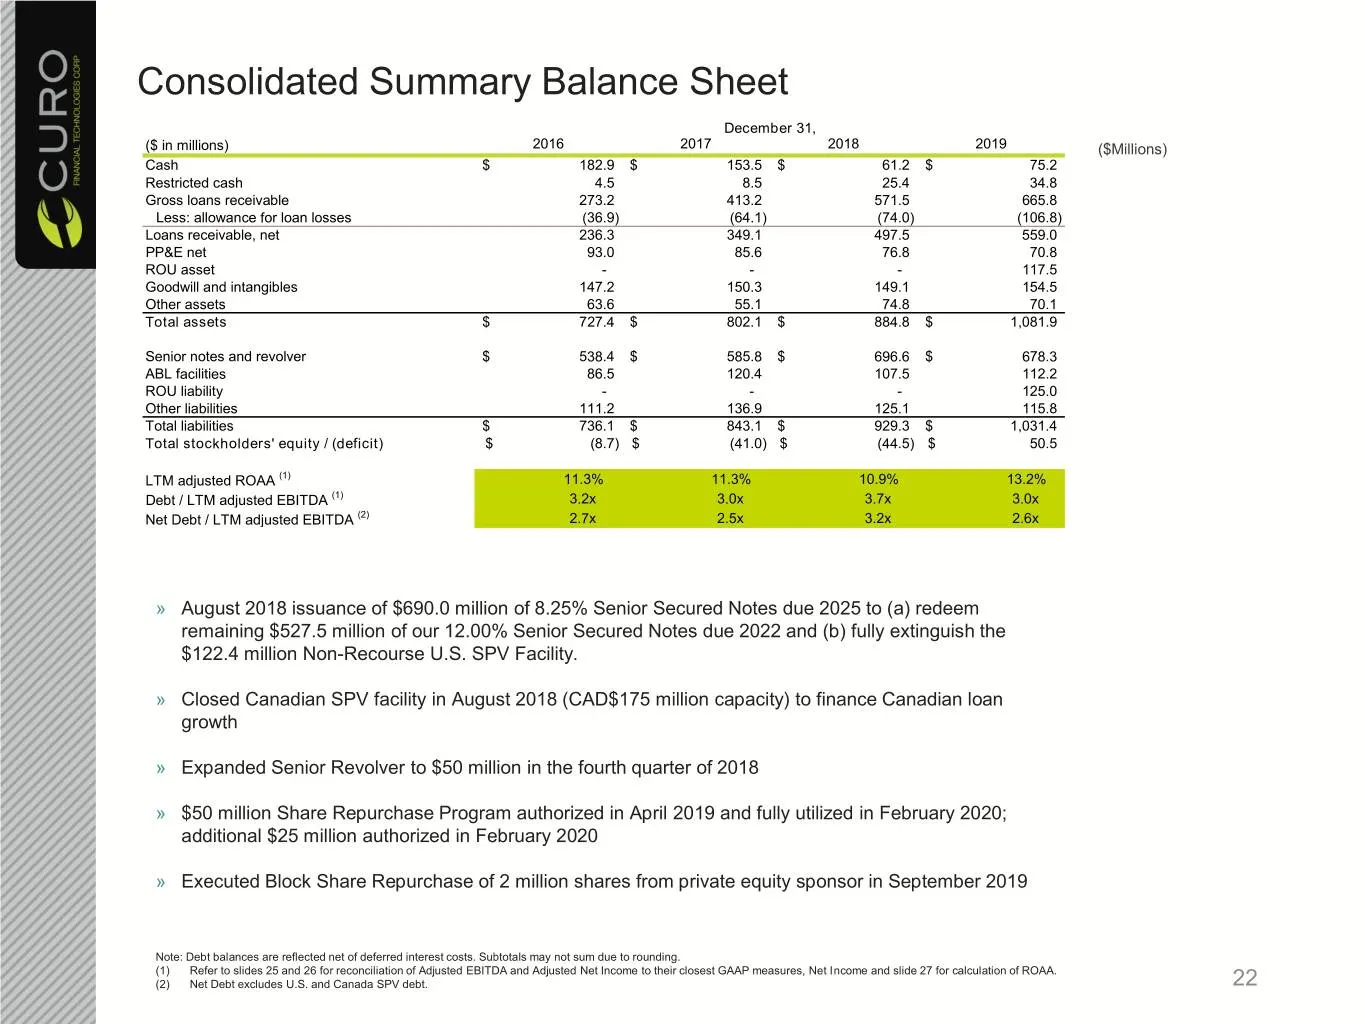
Consolidated Summary Balance Sheet December 31, ($ in millions) 2016 2017 2018 2019 ($Millions) Cash $ 182.9 $ 153.5 $ 61.2 $ 75.2 Restricted cash 4.5 8.5 25.4 34.8 Gross loans receivable 273.2 413.2 571.5 665.8 Less: allowance for loan losses (36.9) (64.1) (74.0) (106.8) Loans receivable, net 236.3
Slide 23: Key Investment Highlights
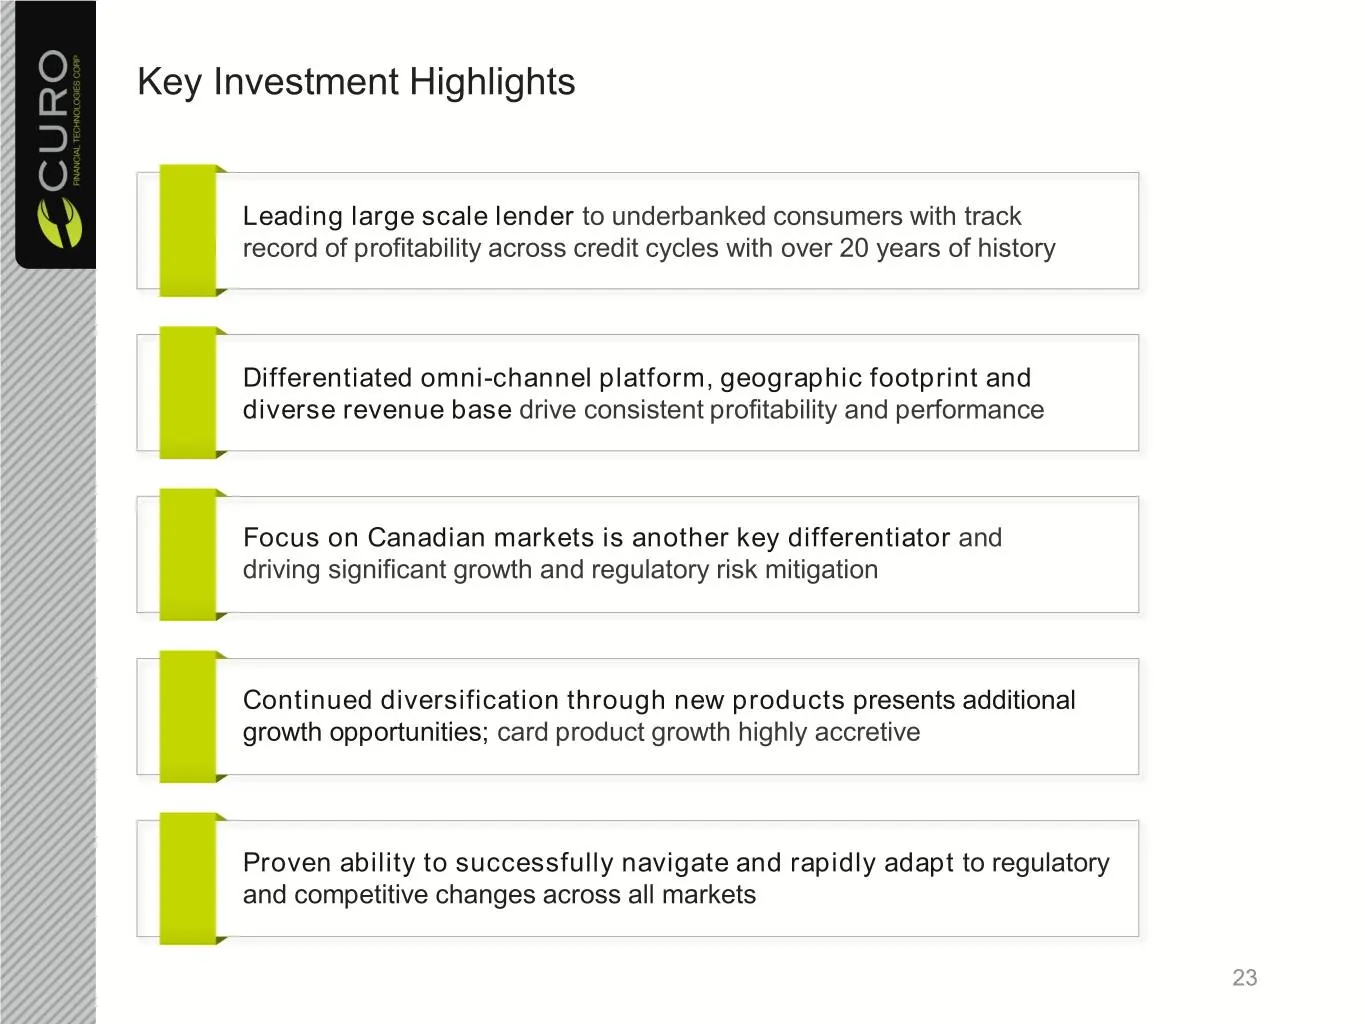
Key Investment Highlights Leading large scale lender to underbanked consumers with track record of profitability across credit cycles with over 20 years of history Differentiated omni-channel platform, geographic footprint and diverse revenue base drive consistent profitability and performance Focus
Slide 24: Appendix
Appendix 24
Slide 25: Historical Consolidated Adjusted EBITDA Reconciliation
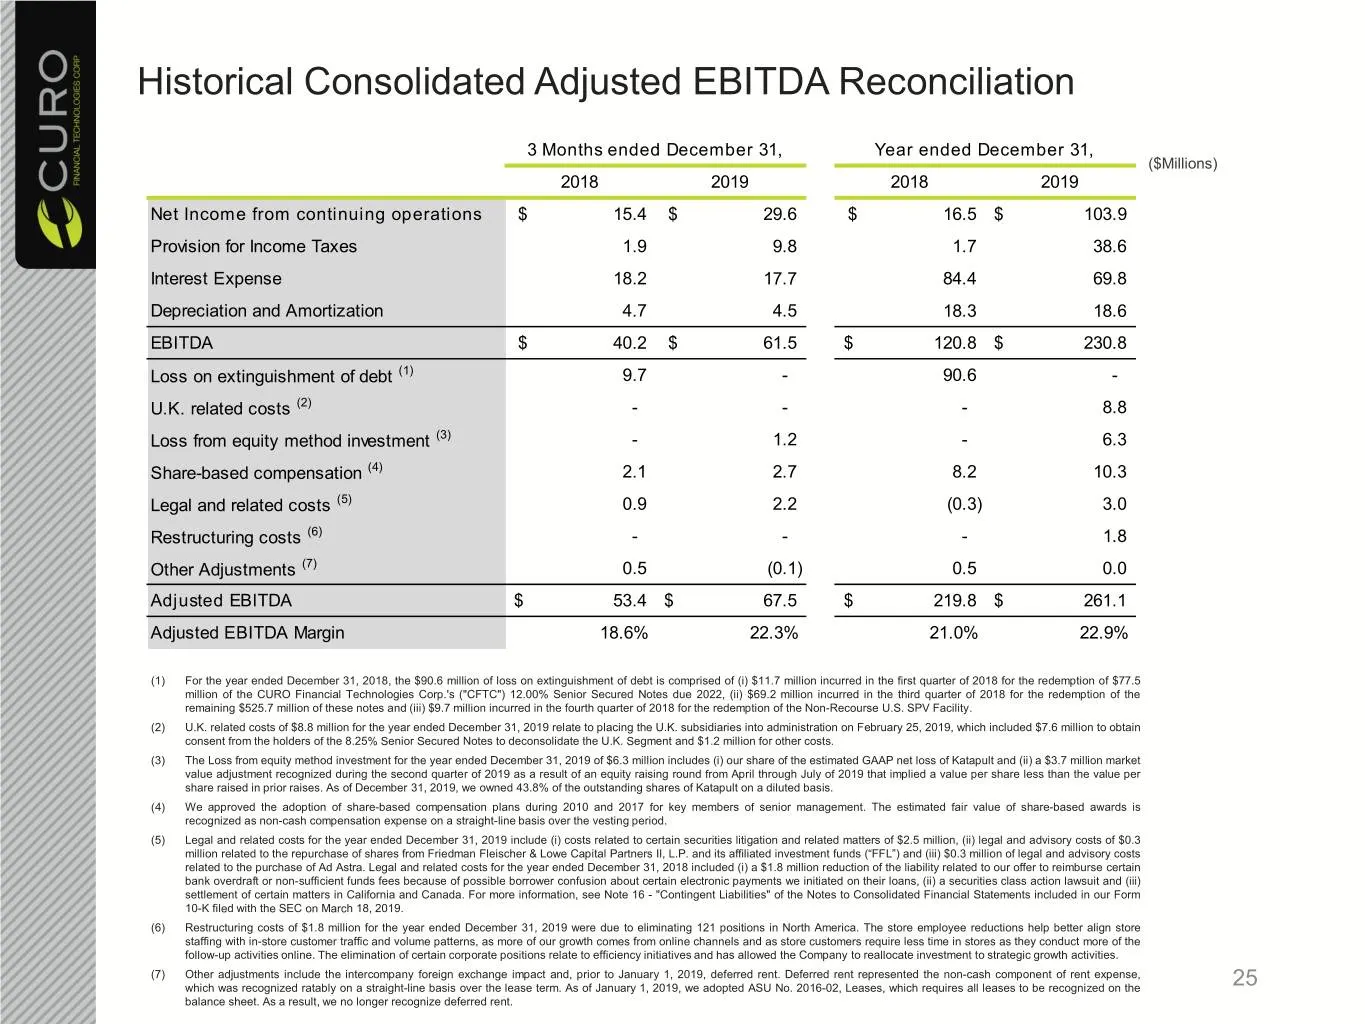
Historical Consolidated Adjusted EBITDA Reconciliation 3 Months ended December 31, Year ended December 31, ($Millions) 2018 2019 2018 2019 Net Income from continuing operations $ 15.4 $ 29.6 $ 16.5 $ 103.9 Provision for Income Taxes 1.9 9.8 1.7 38.6 Interest Expense 18.2 17.7 84.4 69.8 Depreciation
Slide 26: Historical Consolidated Adjusted Net Income Reconciliation
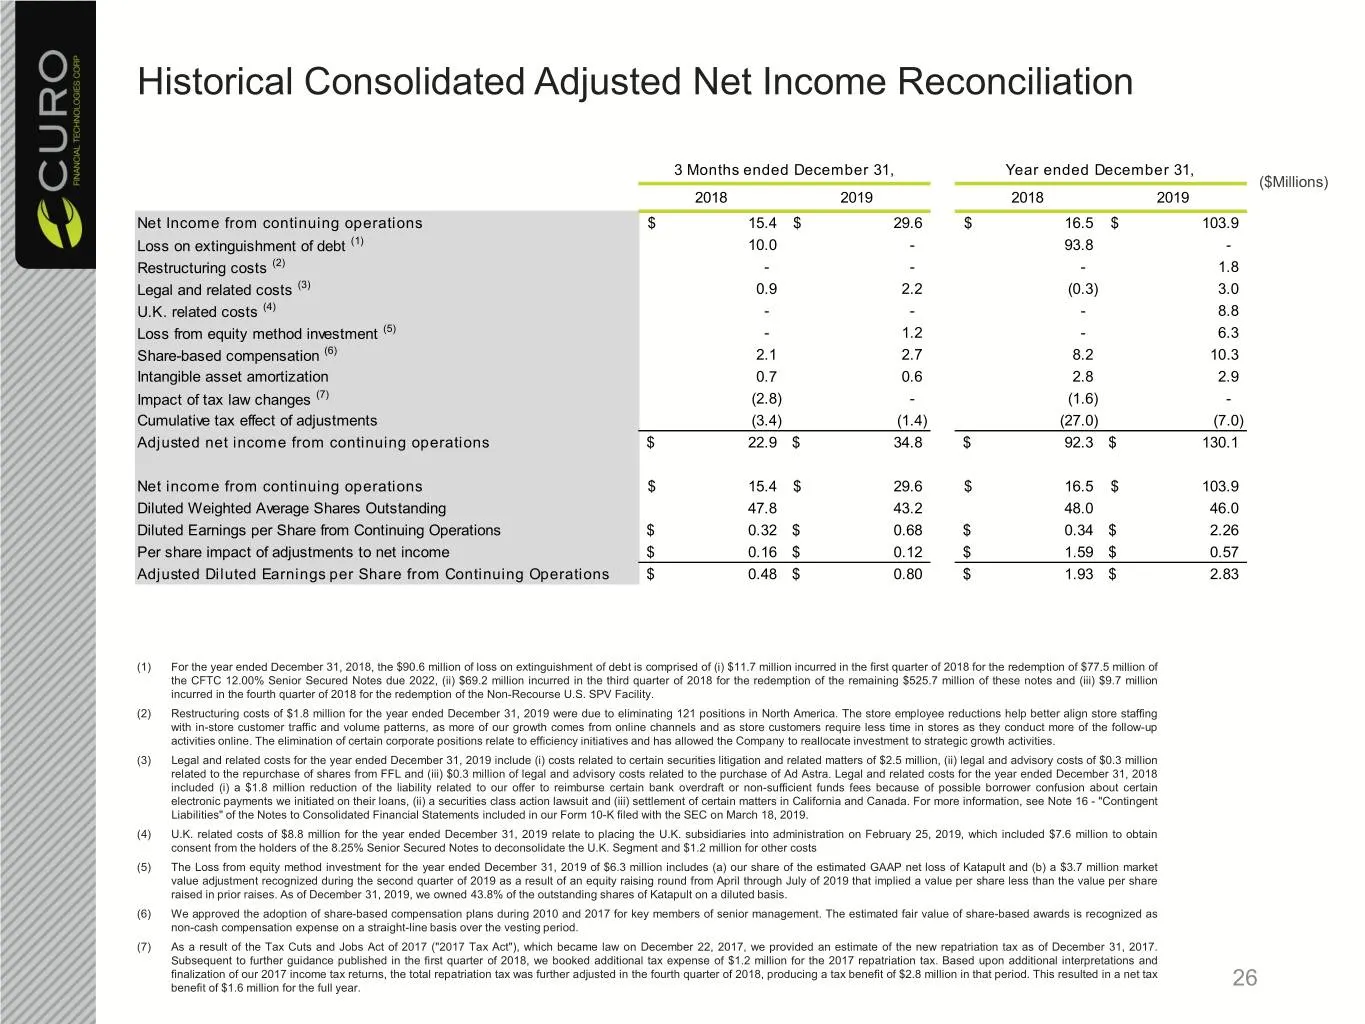
Historical Consolidated Adjusted Net Income Reconciliation 3 Months ended December 31, Year ended December 31, ($Millions) 2018 2019 2018 2019 Net Income from continuing operations $ 15.4 $ 29.6 $ 16.5 $ 103.9 Loss on extinguishment of debt (1) 10.0 - 93.8 - Restructuring costs (2) - - - 1.8 Legal a
Slide 27: Historical Gross Combined Loan Receivables and Adjusted ROAA Reconciliations
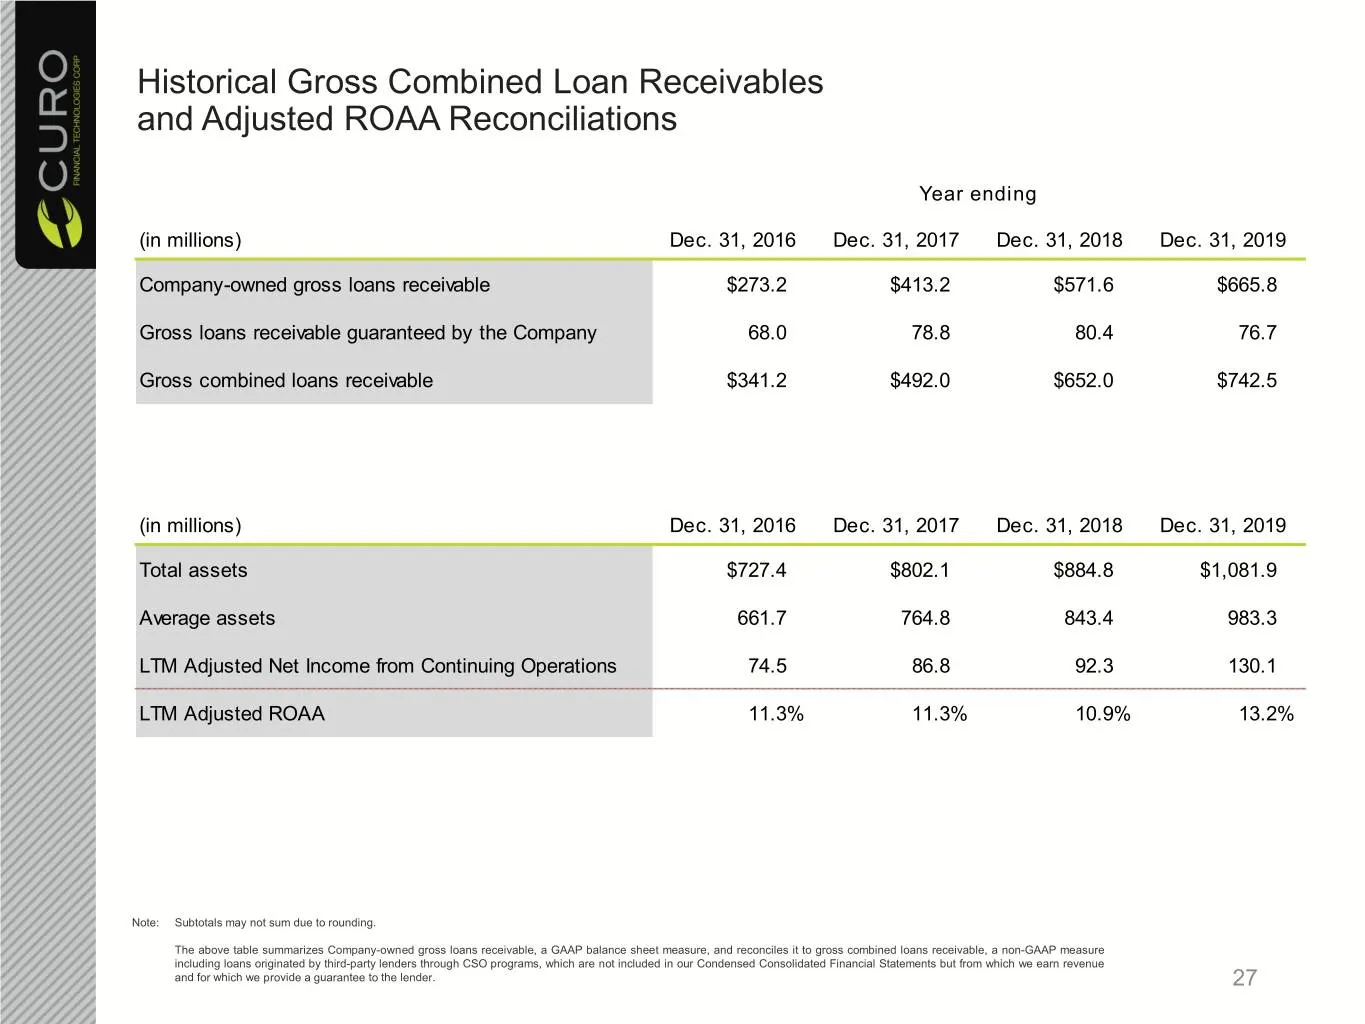
Historical Gross Combined Loan Receivables and Adjusted ROAA Reconciliations Year ending (in millions) Dec. 31, 2016 Dec. 31, 2017 Dec. 31, 2018 Dec. 31, 2019 Company-owned gross loans receivable $273.2 $413.2 $571.6 $665.8 Gross loans receivable guaranteed by the Company 68.0 78.8 80.4 76.7 Gross c
Slide 28: Adjusted Pre-tax Income and Adjusted Tax Expense Reconciliations
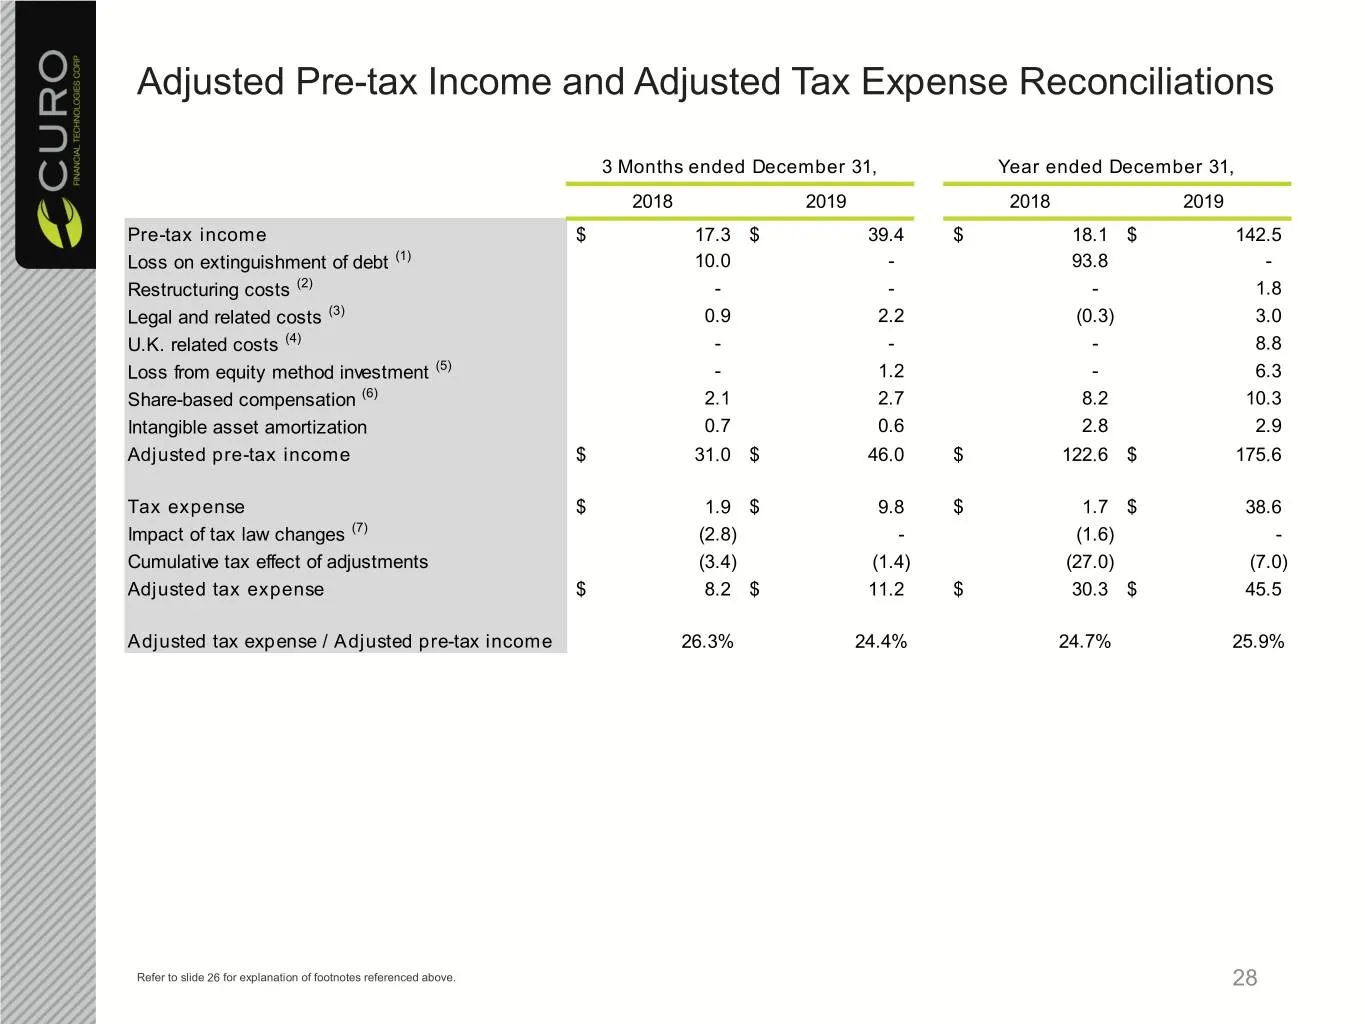
Adjusted Pre-tax Income and Adjusted Tax Expense Reconciliations 3 Months ended December 31, Year ended December 31, 2018 2019 2018 2019 Pre-tax income $ 17.3 $ 39.4 $ 18.1 $ 142.5 Loss on extinguishment of debt (1) 10.0 - 93.8 - Restructuring costs (2) - - - 1.8 Legal and related costs (3) 0.9 2.2
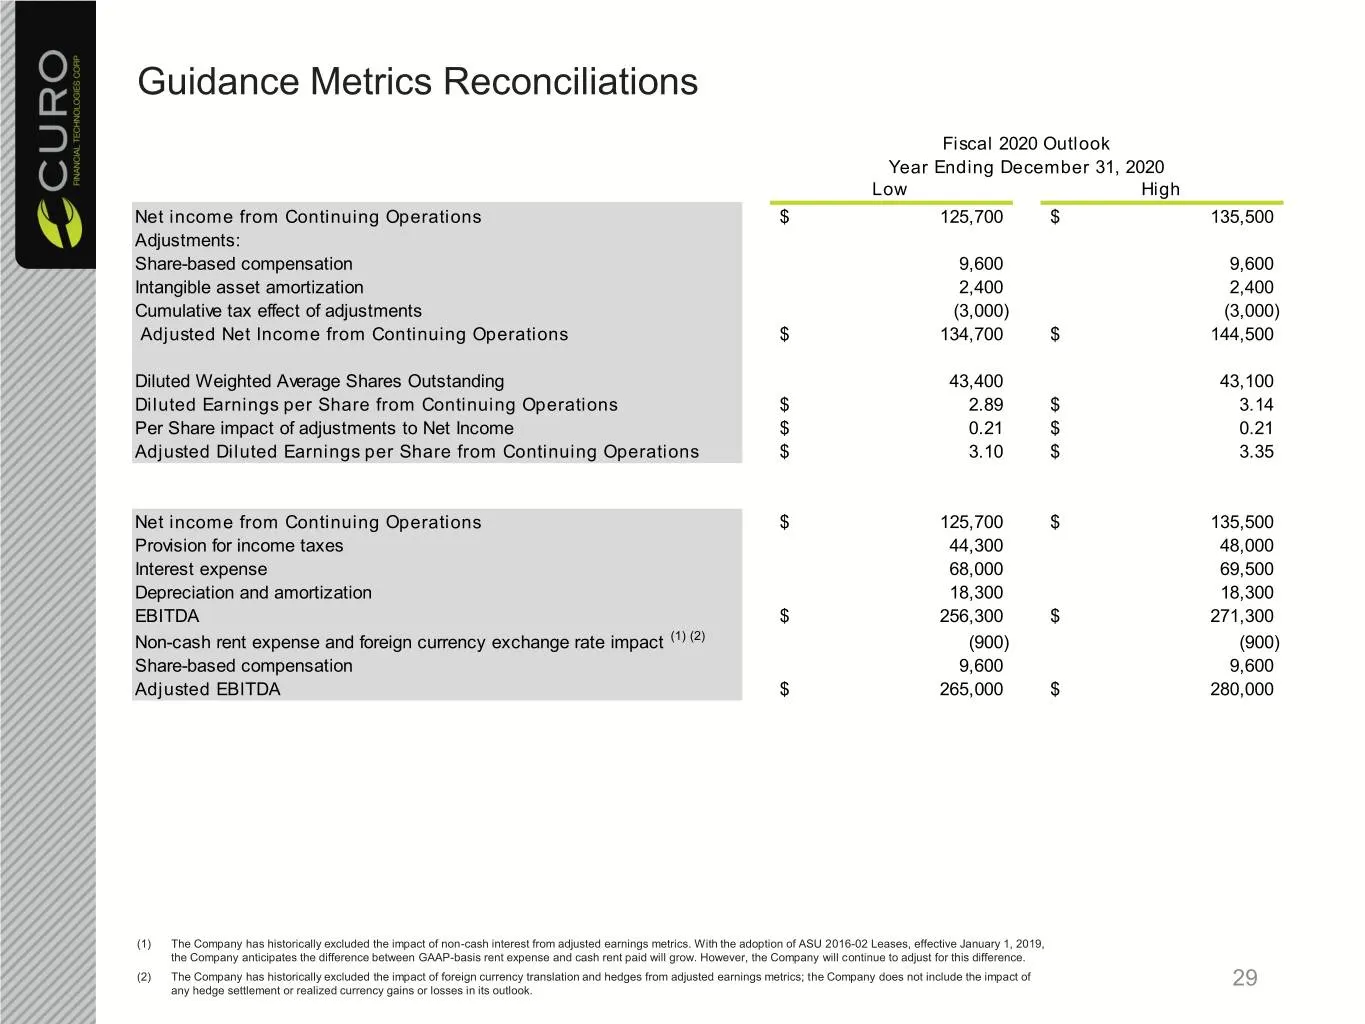
Slide 29: Guidance Metrics Reconciliations
Guidance Metrics Reconciliations Fiscal 2020 Outlook Year Ending December 31, 2020 Low High Net income from Continuing Operations $ 125,700 $ 135,500 Adjustments: Share-based compensation 9,600 9,600 Intangible asset amortization 2,400 2,400 Cumulative tax effect of adjustments (3,000) (3,000) Adjus
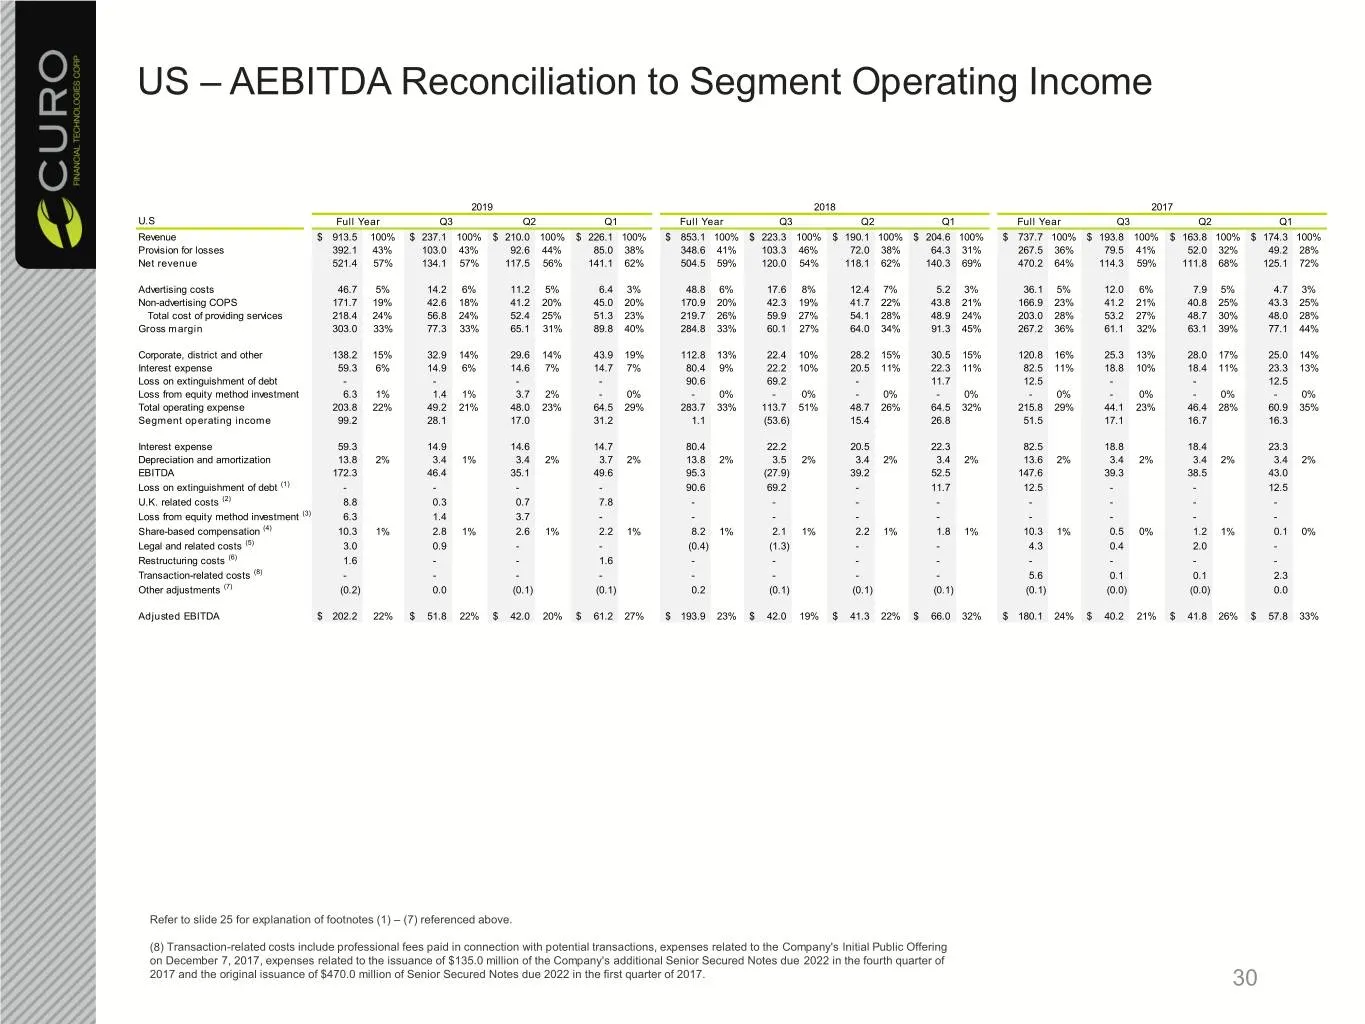
Slide 30: US – AEBITDA Reconciliation to Segment Operating Income
US – AEBITDA Reconciliation to Segment Operating Income 2019 2018 2017 U.S Full Year Q3 Q2 Q1 Full Year Q3 Q2 Q1 Full Year Q3 Q2 Q1 Revenue $ 913.5 100% $ 237.1 100% $ 210.0 100% $ 226.1 100% $ 853.1 100% $ 223.3 100% $ 190.1 100% $ 204.6 100% $ 737.7 100% $ 193.8 100% $ 163.8 100% $ 174.3 100% Prov
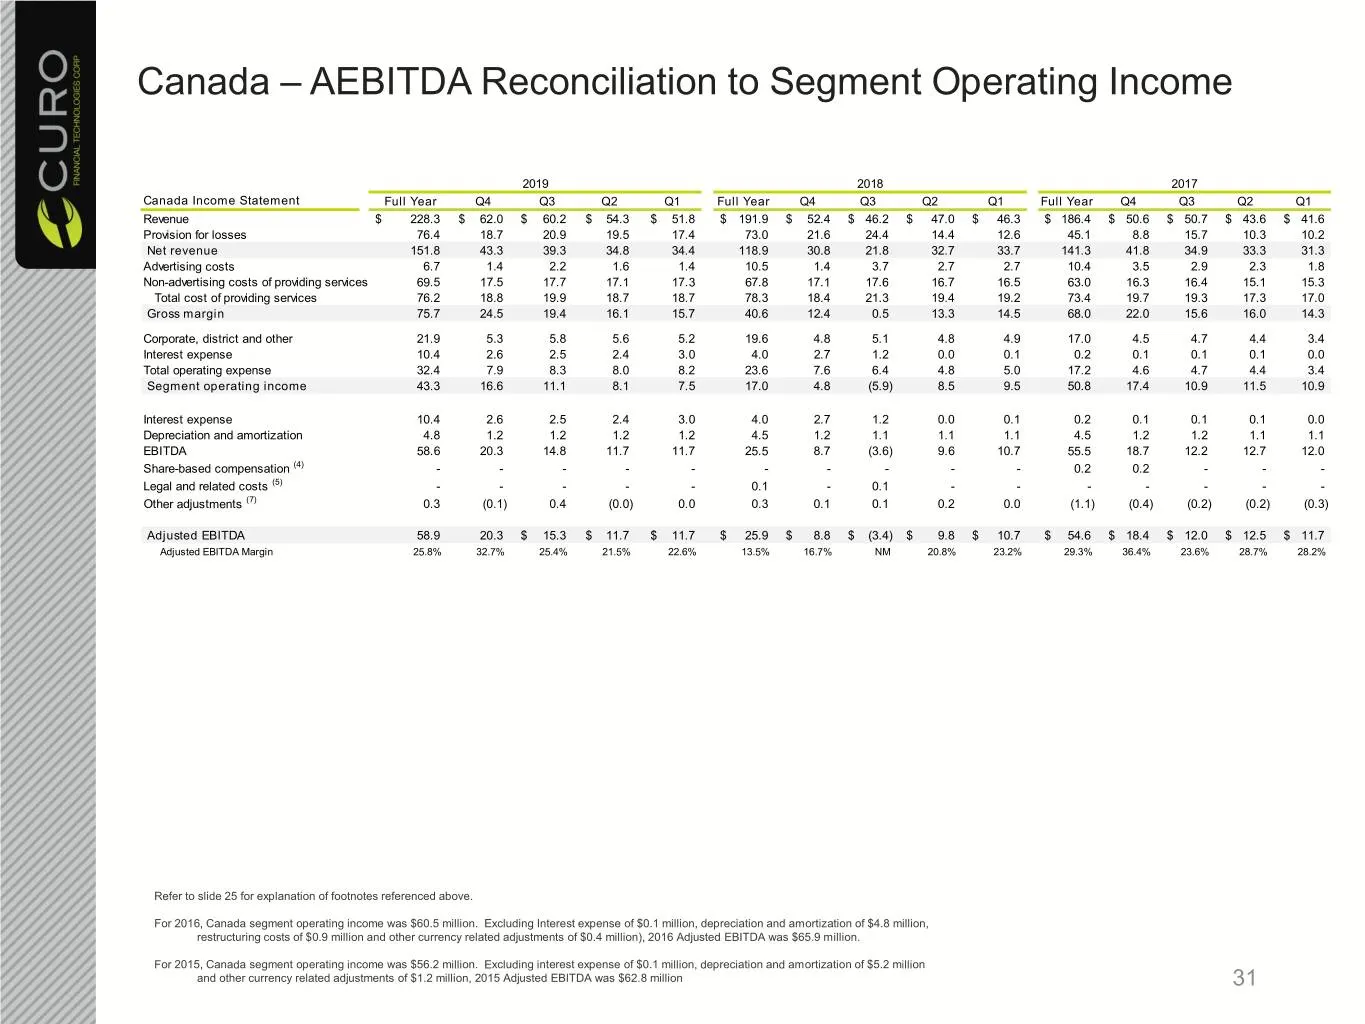
Slide 31: Canada – AEBITDA Reconciliation to Segment Operating Income
Canada – AEBITDA Reconciliation to Segment Operating Income 2019 2018 2017 Canada Income Statement Full Year Q4 Q3 Q2 Q1 Full Year Q4 Q3 Q2 Q1 Full Year Q4 Q3 Q2 Q1 Revenue $ 228.3 $ 62.0 $ 60.2 $ 54.3 $ 51.8 $ 191.9 $ 52.4 $ 46.2 $ 47.0 $ 46.3 $ 186.4 $ 50.6 $ 50.7 $ 43.6 $ 41.6 Provision for losse
Source: SEC EDGAR · 8-K filed Feb 26, 2020
More decks from Curo Group Holdings Corp
 Q4 2023 Earnings Presentation21 slides · Feb 12, 2024
 Investor Presentation (November 2023)15 slides · Nov 13, 2023
 Q3 2023 Earnings Presentation20 slides · Nov 2, 2023
 Debt Investor Presentation (October 2023)21 slides · Oct 23, 2023
 Investor Presentation (September 2023)15 slides · Sep 25, 2023
 Q2 2023 Earnings Presentation21 slides · Aug 3, 2023