First Niagara Financial Group Inc
First Niagara Financial — KBW Boston Bank Conference 2012
38 slides from First Niagara Financial's conference presentation, Feb 29, 2012
Slide 1: The Differentiated Choice -- Position and Performance
The Differentiated Choice -- Position and Performance John R. Koelmel Chief Executive OfficerGregory W. NorwoodChief Financial Officer KBW Boston Bank ConferenceFebruary 29, 2012
Slide 2: Safe Harbor Statement
This presentation contains forward-looking information for First Niagara Financial Group, Inc. Such information constitutes forward-looking statements (within the meaning of the Private Securities Litigation Reform Act of 1995) which involve significant risks and uncertainties. Actual results may di
Slide 3: Why Invest in First Niagara?
Why Invest in First Niagara? Why Invest in First Niagara? 3
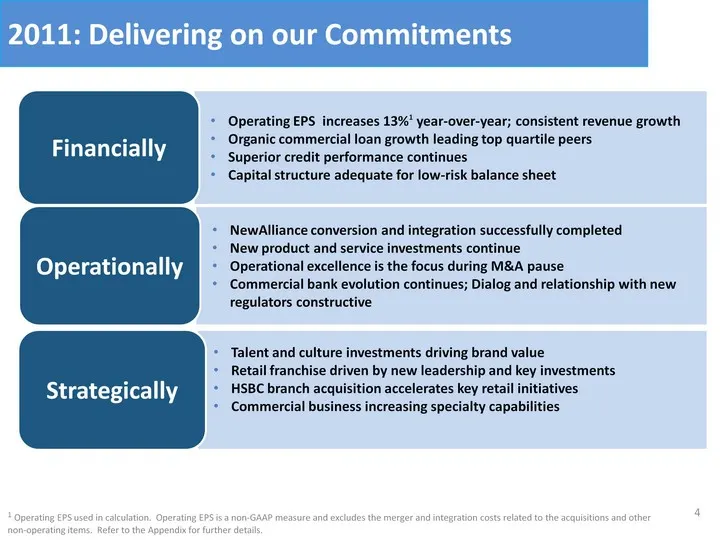
Slide 4: 2011: Delivering on our Commitments
Operating EPS increases 13%1 year-over-year; consistent revenue growthOrganic commercial loan growth leading top quartile peersSuperior credit performance continuesCapital structure adequate for low-risk balance sheet Financially NewAlliance conversion and integration successfully completedNew produ
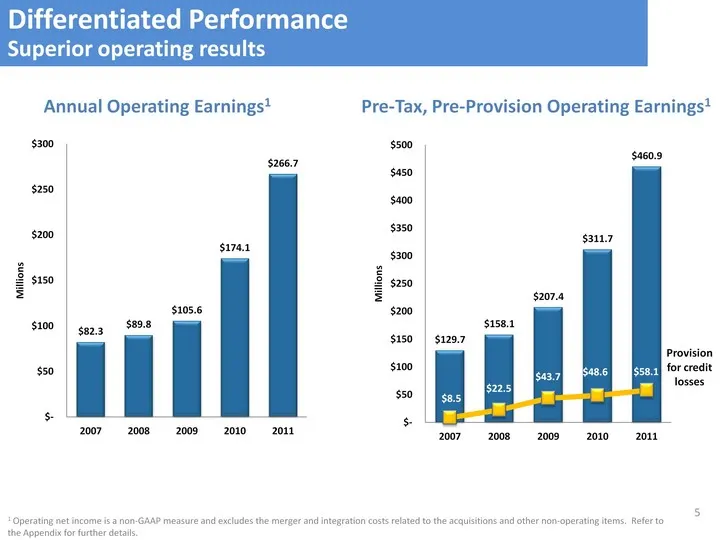
Slide 5: Differentiated Performance: Superior operating results
Annual Operating Earnings1 Annual Operating Earnings1 Pre-Tax, Pre-Provision Operating Earnings1 1 Operating net income is a non-GAAP measure and excludes the merger and integration costs related to the acquisitions and other non-operating items. Refer to the Appendix for further details. the Append
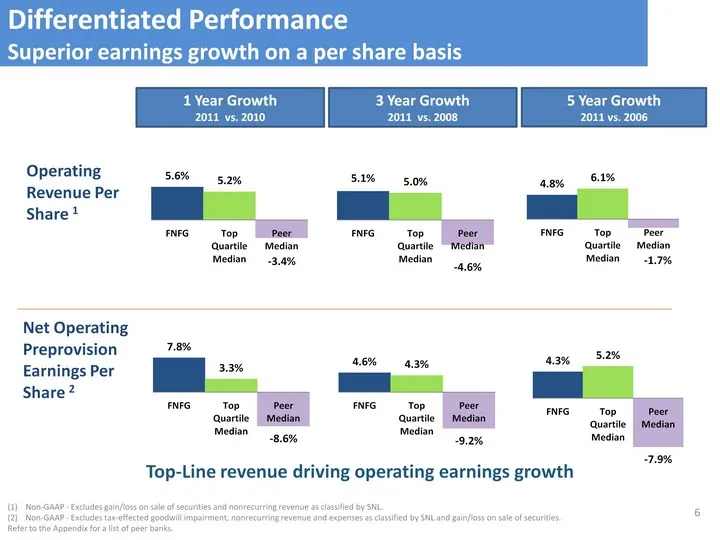
Slide 6: Superior earnings growth on a per share basis
Operating Revenue Per Share 1 Net Operating Preprovision Earnings Per Share 2 1 Year Growth2011 vs. 2010 5 Year Growth2011 vs. 2006 Non-GAAP - Excludes gain/loss on sale of securities and nonrecurring revenue as classified by SNL.Non-GAAP - Excludes tax-effected goodwill impairment, nonrecurring rev
Slide 7: 7
7
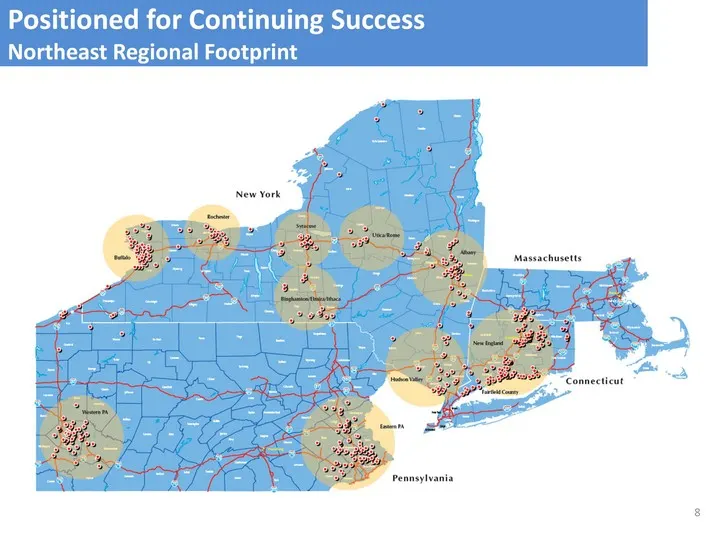
Slide 8: Northeast Regional Footprint
Positioned for Continuing Success Northeast Regional Footprint 8
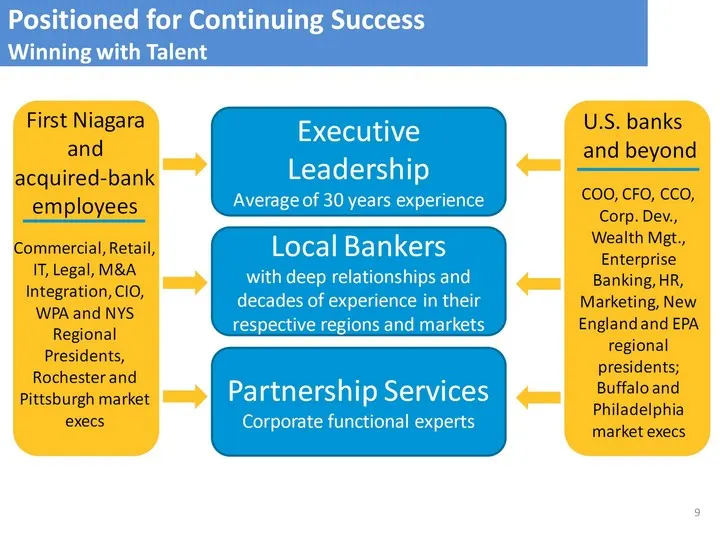
Slide 9: Winning with Talent
Positioned for Continuing Success Winning with Talent U.S. banks and beyond 9
Slide 10: Performance
Performance |
Slide 11: 11
11
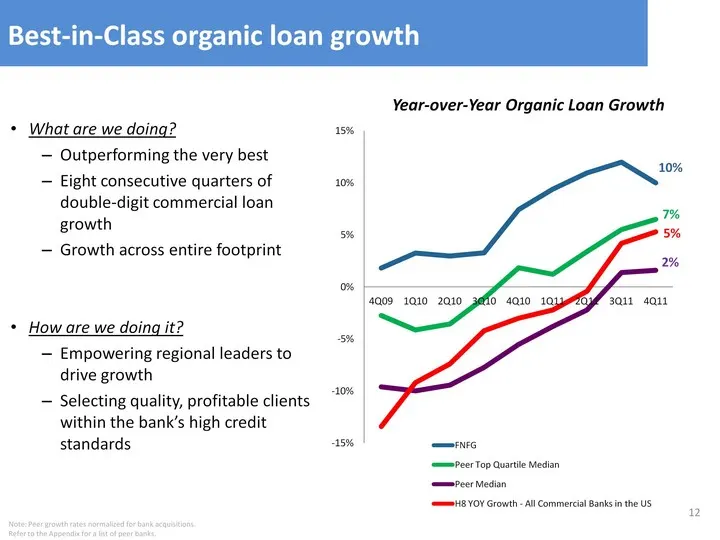
Slide 12: Best-in-Class organic loan growth
What are we doing?Outperforming the very bestEight consecutive quarters of double-digit commercial loan growthGrowth across entire footprintHow are we doing it?Empowering regional leaders to drive growthSelecting quality, profitable clients within the bank's high credit standards Year-over-Year Orga
Slide 13: Recognized for Best-in-Class Service
Recognized for Best-in-Class Service Eight #1 ratings in 2011 Greenwich Associates survey "I can trust this bank.""It delivers on what it promises.""It treats me with respect.""If a problem arises, I can count on a fair resolution.""I would recommend this bank to colleagues, friends and family in th
Slide 14: Superior Credit Quality is A Key Differentiator
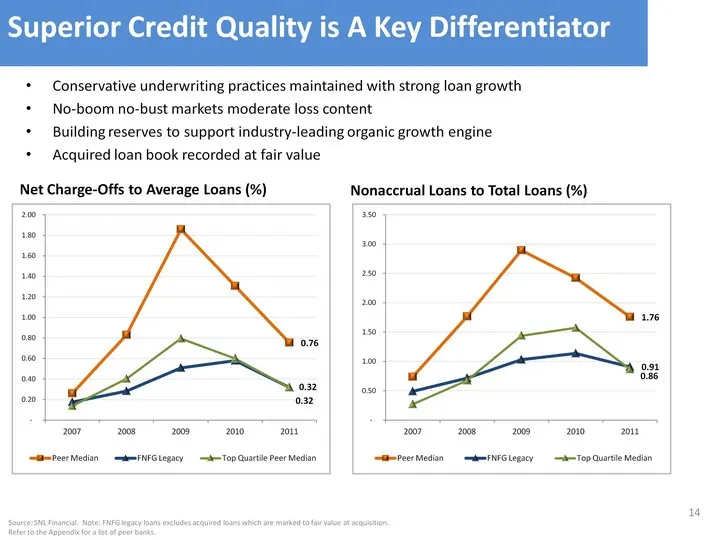
Conservative underwriting practices maintained with strong loan growthNo-boom no-bust markets moderate loss content Building reserves to support industry-leading organic growth engineAcquired loan book recorded at fair value Net Charge-Offs to Average Loans (%) Nonaccrual Loans to Total Loans (%) So
Slide 15: Commercial Services Opportunity
Capitalize on commercial business scaleDrive organic growth with proven, local talentInfrastructure investments continueFootprint provides ample opportunity for growthPursue growth through specialized banking capabilitiesInvest further in Healthcare capabilitiesLeverage ABL opportunity further over
Slide 16: 16
16
Slide 17: Strong deposit fundamentals
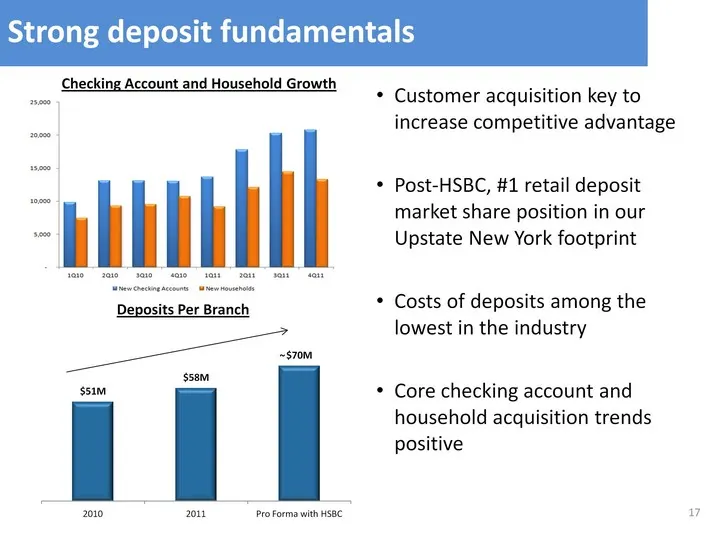
Strong deposit fundamentals Deposits Per Branch (CHART) Customer acquisition key to increase competitive advantagePost-HSBC, #1 retail deposit market share position in our Upstate New York footprintCosts of deposits among the lowest in the industryCore checking account and household acquisition tren
Slide 18: Access to Growth Markets
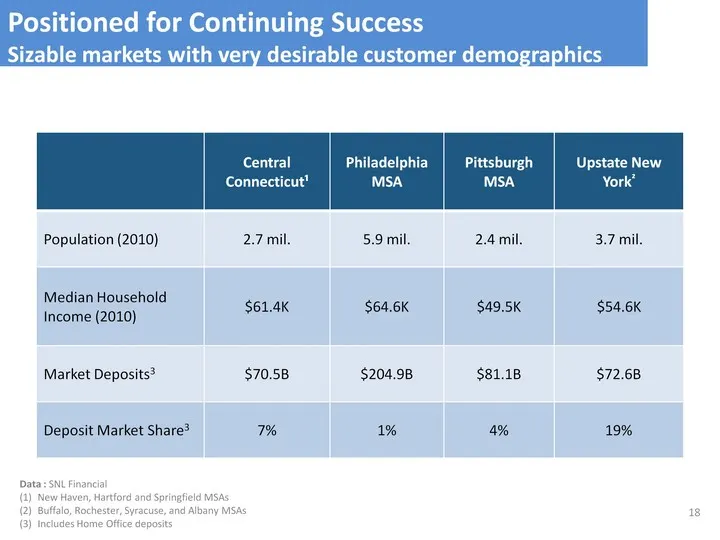
Access to Growth Markets Well Positioned to Take Market Share Well Positioned to Take Market Share Well Positioned to Take Market Share Well Positioned to Take Market Share Well Positioned to Take Market Share Well Positioned to Take Market Share Well Positioned to Take Market Share Well Positioned
Slide 19: Retail Deposit Services Opportunity
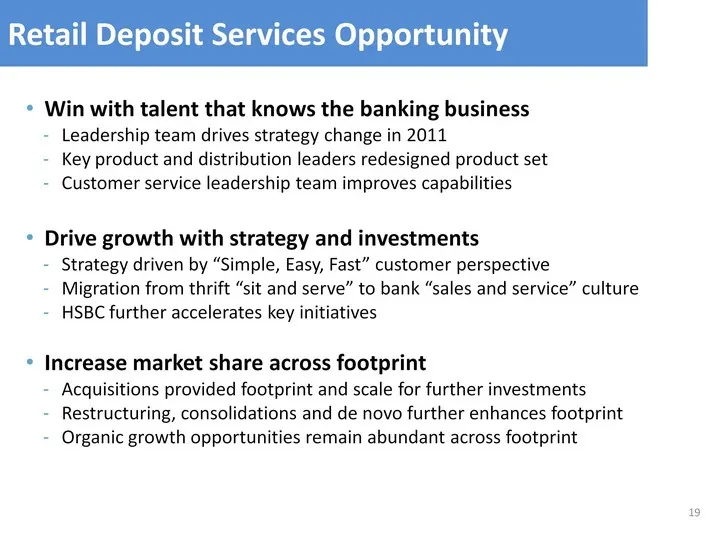
Win with talent that knows the banking businessLeadership team drives strategy change in 2011Key product and distribution leaders redesigned product setCustomer service leadership team improves capabilitiesDrive growth with strategy and investmentsStrategy driven by "Simple, Easy, Fast" customer per
Slide 20: 20
20
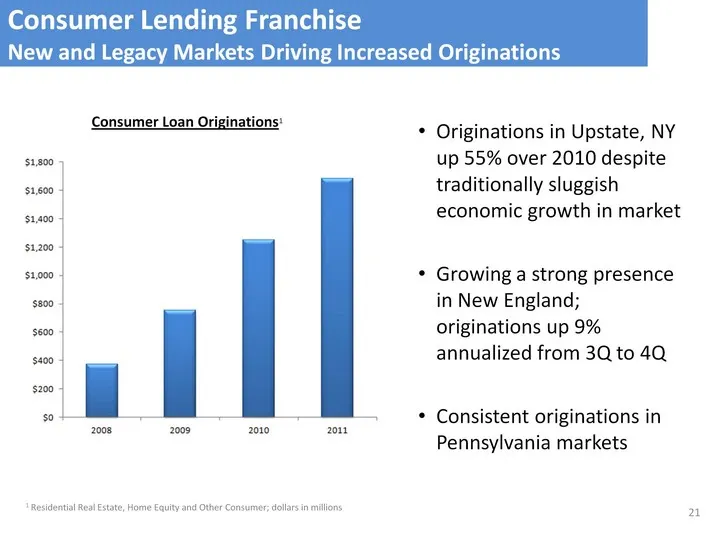
Slide 21: Consumer Lending Franchise: Increased Originations
Consumer Loan Originations1 1 Residential Real Estate, Home Equity and Other Consumer; dollars in millions Consumer Lending Franchise New and Legacy Markets Driving Increased Originations Originations in Upstate, NY up 55% over 2010 despite traditionally sluggish economic growth in marketGrowing a s
Slide 22: Recognized for Excellence in Small Business Service
Recognized for Excellence in Small Business Service Six #1 Small Business National Awards - Overall Satisfaction Treasury Management ServicesRelationship Manager PerformanceBranch SatisfactionTreasury Management Product CapabilitiesTreasury Management Operations AccuracyAnd#1 Regional winner in Over
Slide 23: Consumer Finance Opportunity
Win with talent that knows the businessTop leader in place throughout 2011 driving strategy evolutionRecruited key product and distribution leadersAverage tenure of new leadership team is 30 yearsImproved Service and Delivery capabilitiesImproving mortgage sales and servicingNew credit card processi
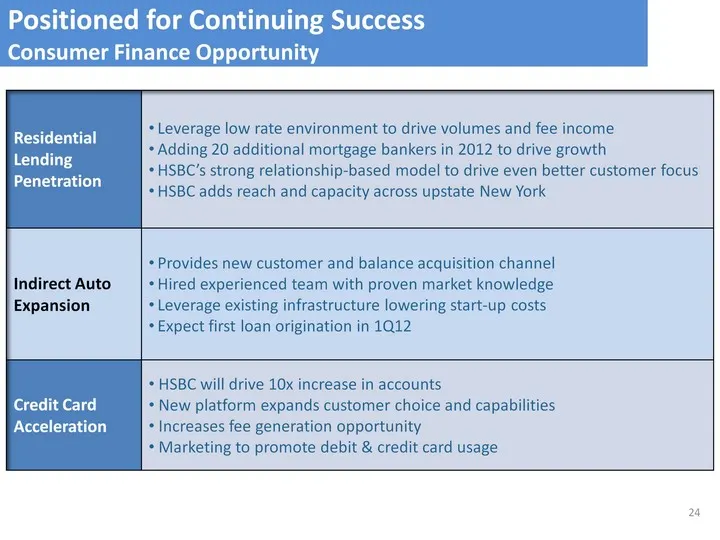
Slide 24: Consumer Finance Opportunity
Positioned for Continuing Success Consumer Finance Opportunity Residential Lending Penetration Leverage low rate environment to drive volumes and fee income Adding 20 additional mortgage bankers in 2012 to drive growth HSBC's strong relationship-based model to drive even better customer focus HSBC a
Slide 25: M&A
M&A
Slide 26: HSBC Branch Acquisition Update
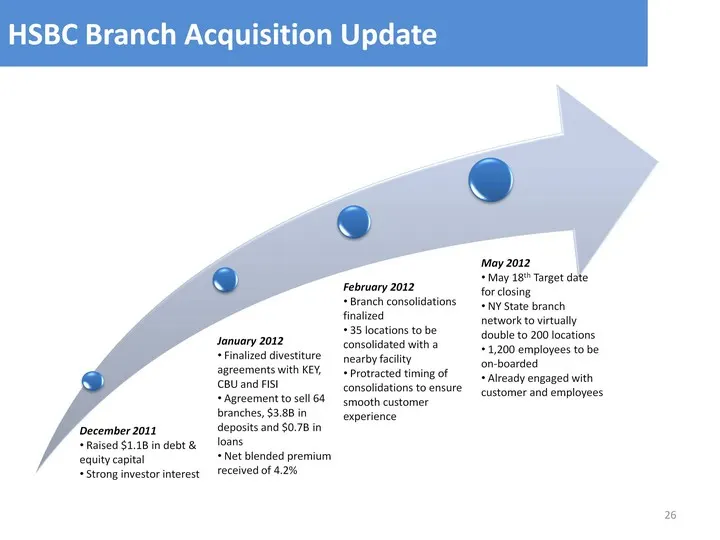
26 HSBC Branch Acquisition Update HSBC Branch Acquisition Update December 2011 Raised $1.1B in debt & equity capital Strong investor interest January 2012 Finalized divestiture agreements with KEY, CBU and FISI Agreement to sell 64 branches, $3.8B in deposits and $0.7B in loans Net blended premium r
Slide 27: M&A Pause
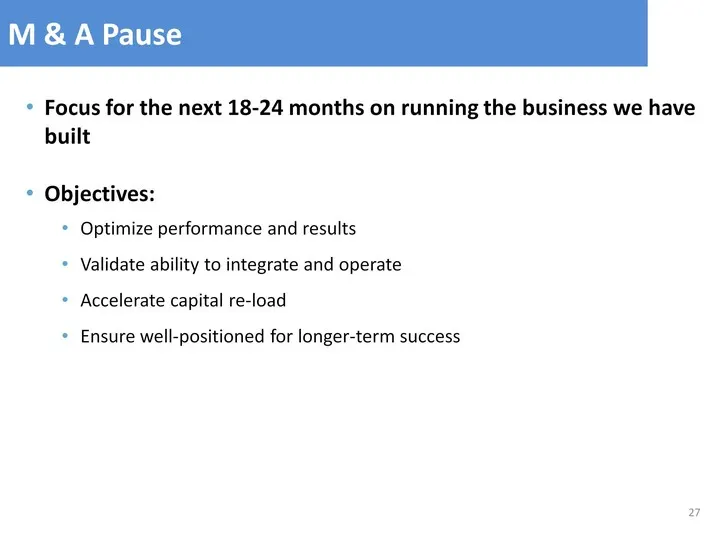
Focus for the next 18-24 months on running the business we have builtObjectives:Optimize performance and resultsValidate ability to integrate and operateAccelerate capital re-loadEnsure well-positioned for longer-term success M & A Pause 27
Slide 28: 28
28
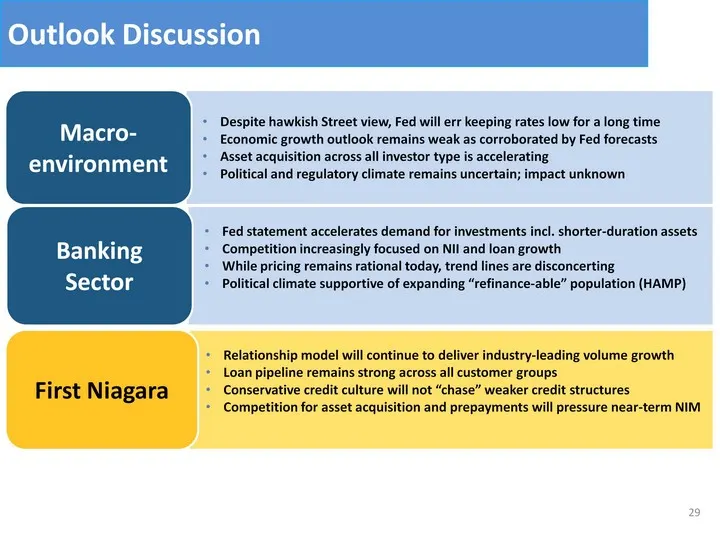
Slide 29: First Niagara Outlook Discussion
Despite hawkish Street view, Fed will err keeping rates low for a long timeEconomic growth outlook remains weak as corroborated by Fed forecastsAsset acquisition across all investor type is acceleratingPolitical and regulatory climate remains uncertain; impact unknown Macro- environment Fed statemen
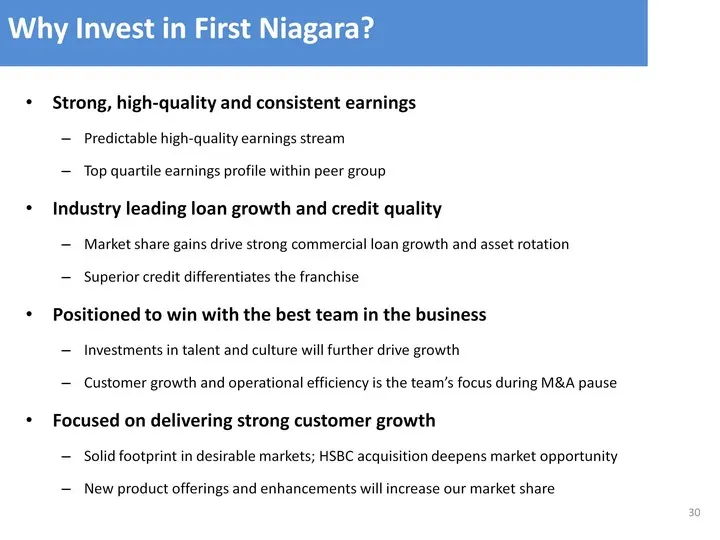
Slide 30: Why Invest in First Niagara?
Why Invest in First Niagara? 30 Strong, high-quality and consistent earningsPredictable high-quality earnings streamTop quartile earnings profile within peer groupIndustry leading loan growth and credit qualityMarket share gains drive strong commercial loan growth and asset rotationSuperior credit d
Slide 31: The Differentiated Choice -- Position and Performance
The Differentiated Choice -- Position and Performance John R. Koelmel Chief Executive OfficerGregory W. NorwoodChief Financial Officer KBW Boston Bank ConferenceFebruary 29, 2012
Slide 32: 32
32
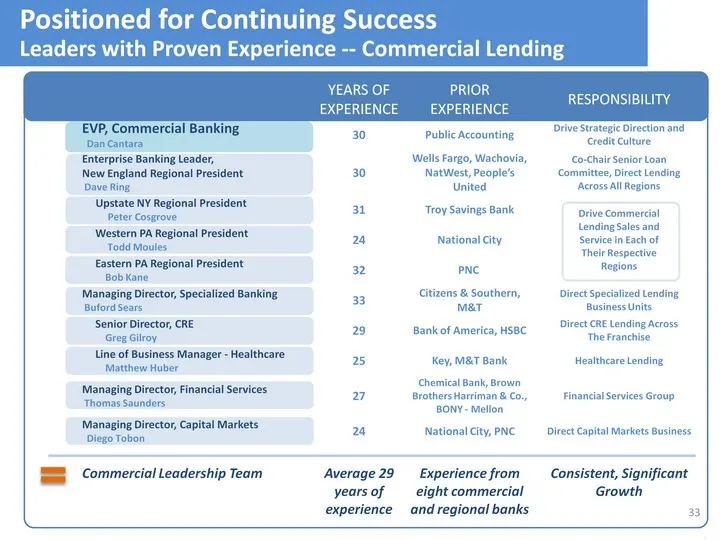
Slide 33: Leaders with Proven Experience - Commercial Lending
33 Positioned for Continuing Success Leaders with Proven Experience -- Commercial Lending Years of Experience Prior Experience Responsibility EVP, Commercial Banking Dan Cantara 30 Public Accounting Drive Strategic Direction and Credit Culture Enterprise Banking Leader, New England Regional Presiden
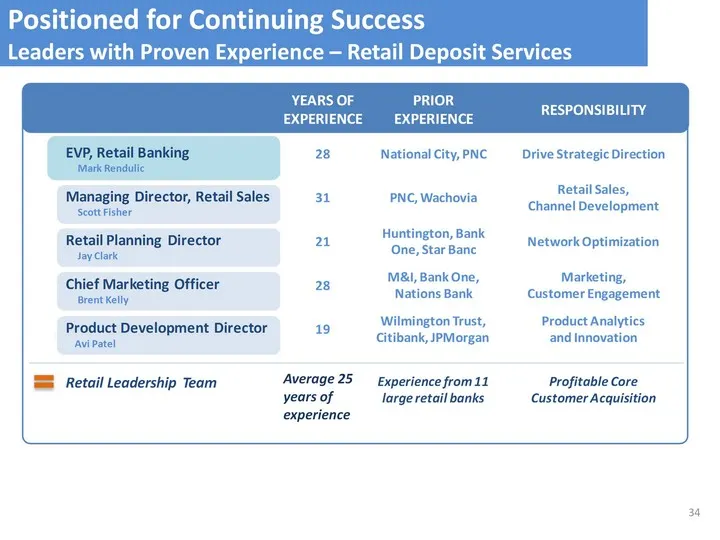
Slide 34: Leaders with Proven Experience - Retail Deposit Services
Positioned for Continuing Success Leaders with Proven Experience - Retail Deposit Services 34 Average 25 years of experience
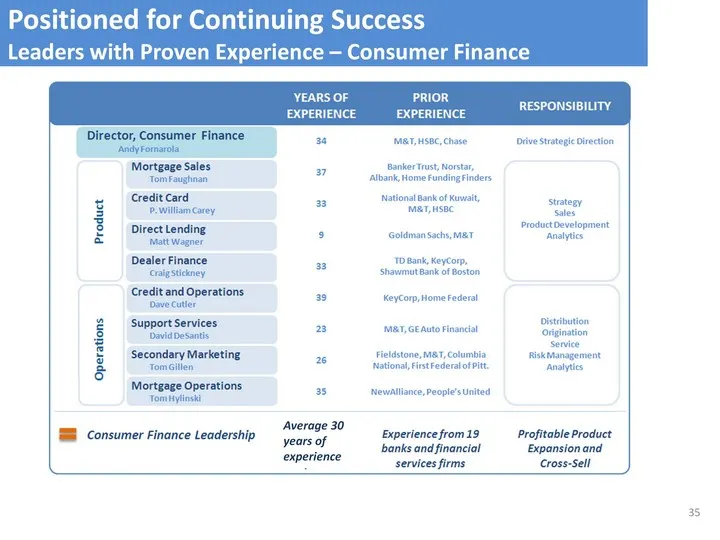
Slide 35: Leaders with Proven Experience - Consumer Finance
Positioned for Continuing Success Leaders with Proven Experience - Consumer Finance 35 Average 30 years of experience
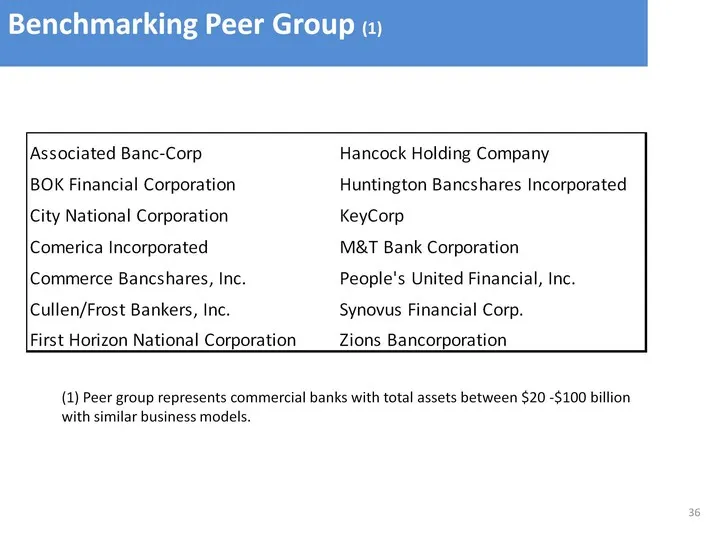
Slide 36: Benchmarking Peer Group
36 Benchmarking Peer Group (1) (1) Peer group represents commercial banks with total assets between $20 -$100 billion with similar business models.
Slide 37: Non-GAAP Measures
Non-GAAP Measures - This presentation contains financial information determined by methods other than in accordance with accounting principles generally accepted in the United States of America (GAAP). The Company believes that these non-GAAP financial measures provide a meaningful comparison of the
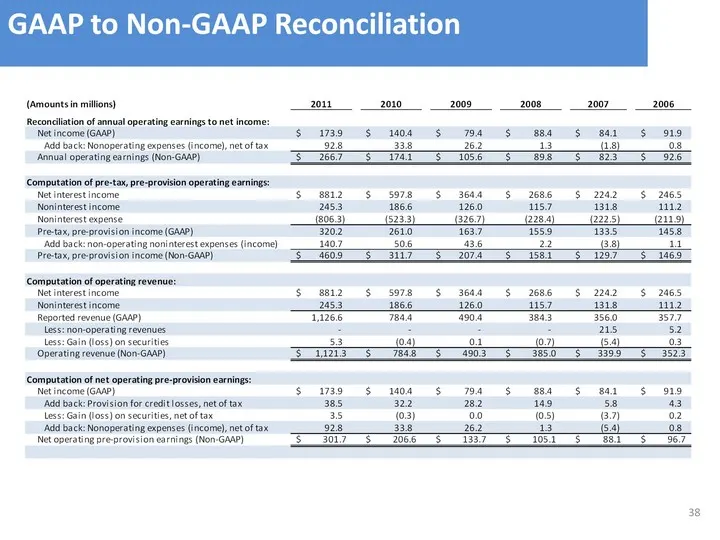
Slide 38: GAAP to Non-GAAP Reconciliation
38 GAAP to Non-GAAP Reconciliation
Source: SEC EDGAR · 8-K filed Feb 29, 2012
More decks from First Niagara Financial Group Inc
 Q4 2015 Earnings Presentation27 slides · Jan 21, 2016
 Merger or Acquisition (October 2015)18 slides · Oct 30, 2015
 Q3 2015 Earnings Presentation20 slides · Oct 23, 2015
 Q2 2015 Earnings Presentation20 slides · Jul 24, 2015
 Presentation (June 2015)11 slides · Jun 16, 2015
 Q1 2015 Earnings Presentation20 slides · Apr 24, 2015