Boardwalk Pipeline Partners LP
Boardwalk Pipeline Partners LP — 2015 Wells Fargo Energy Symposium
32 slides from Boardwalk Pipeline Partners LP's conference presentation, Dec 7, 2015
Slide 1: Boardwalk Presentation for 2015 Wells Fargo Energy Symposium
October 11, 2013 Boardwalk Annual Customer Meeting Nashville Customer Meeting Boardwalk’s Response to the Changing Market Kathy Kirk, Senior Vice President Marketing & Origination Presentation for 2015 Wells Fargo Energy Symposium December 2015 1 Boardwalk Louisiana Midstream: Sulphur Hub S utheast
Slide 2: Important Information
2 Important Information Forward-looking statements disclosure Statements made at this conference or in the materials distributed in conjunction with this conference that contain "forward-looking statements" include, but are not limited to, statements using the words “believe”, “expect”, “plan”, “int
Slide 3: Boardwalk Company Overview
October 11, 2013 Boardwalk Annual Customer Meeting Nashville Customer Meeting Boardwalk’s Response to the Changing Market Kathy Kirk, Senior Vice President Marketing & Origination Boardwalk Company Overview Southeast Market Expansion: Jasper, Forrest & Moss Point Compressor Station
Slide 4: Large and Diverse Platform of Infrastructure Assets
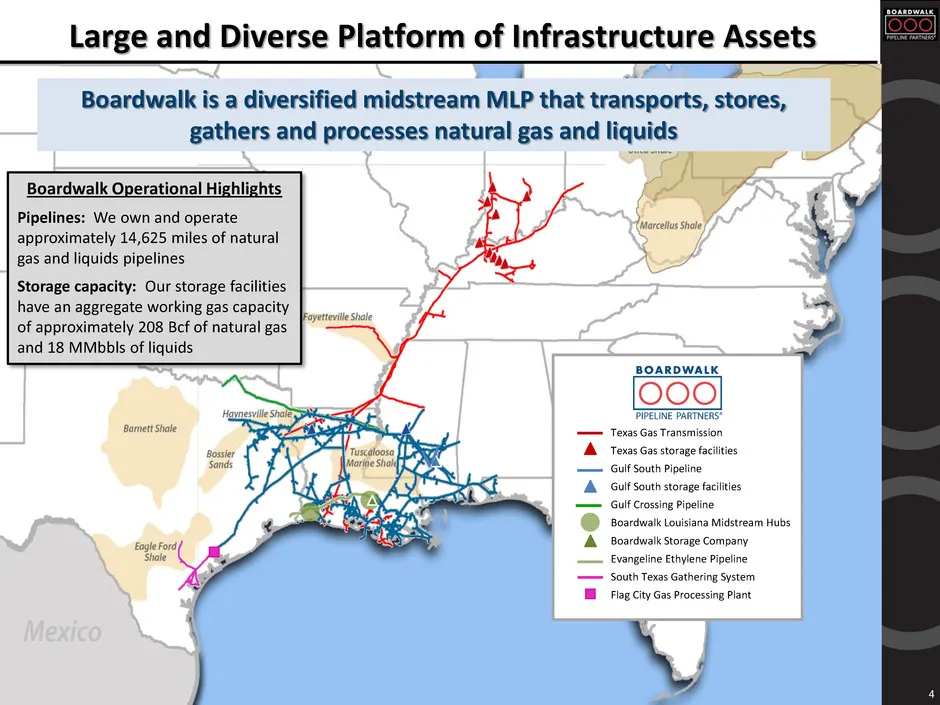
4 Large and Diverse Platform of Infrastructure Assets Texas Gas Transmission Texas Gas storage facilities Gulf South Pipeline Gulf South storage facilities Gulf Crossing Pipeline Boardwalk Louisiana Midstream Hubs Boardwalk Storage Company Evangeline Ethylene Pipeline South Texas Gathering System Fl
Slide 5: Organizational Structure
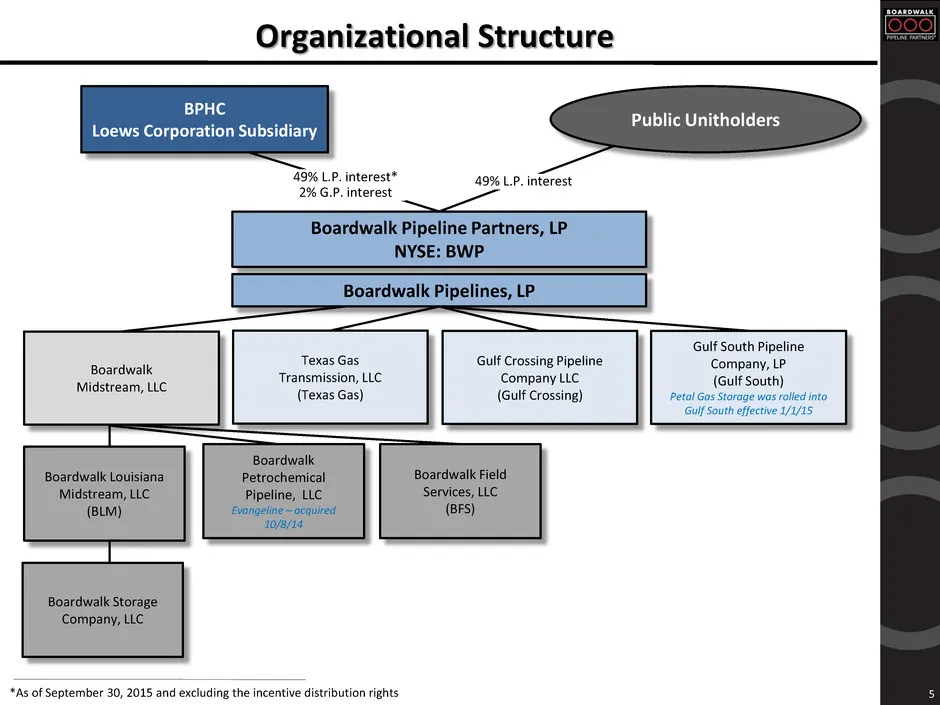
Organizational Structure 5 49% L.P. interest* 2% G.P. interest 49% L.P. interest BPHC Loews Corporation Subsidiary Boardwalk Pipeline Partners, LP NYSE: BWP Public Unitholders Boardwalk Pipelines, LP *As of September 30, 2015 and excluding the incentive distribution rights Boardwalk Midstream, LLC T
Slide 6: Introduction to Boardwalk's General Partner
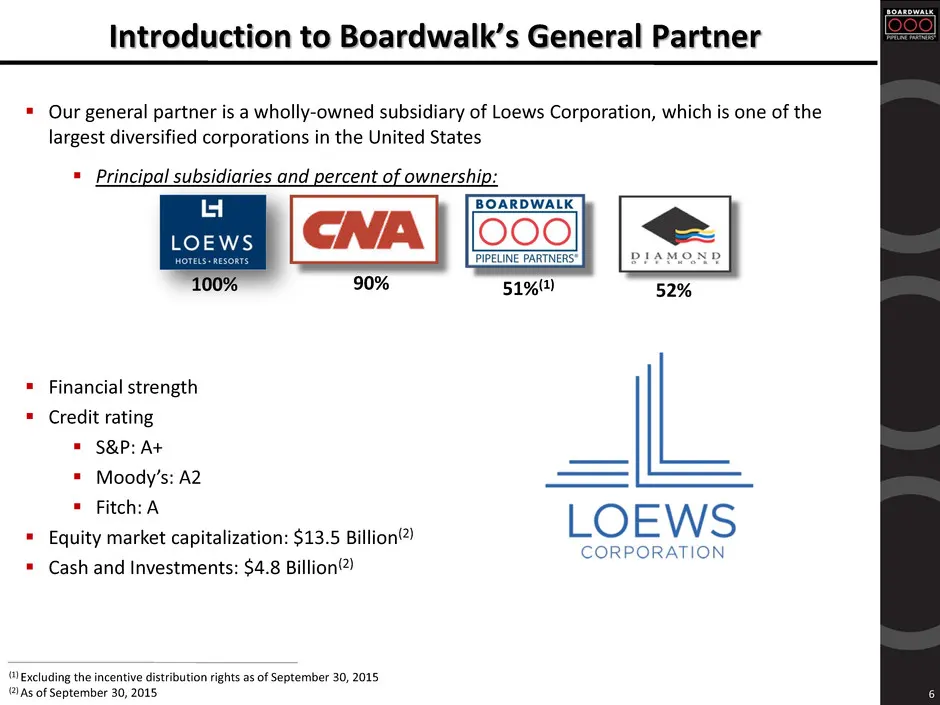
Introduction to Boardwalk’s General Partner 6 Our general partner is a wholly-owned subsidiary of Loews Corporation, which is one of the largest diversified corporations in the United States Principal subsidiaries and percent of ownership: Financial strength Credit rating S&P: A+ Moody’s
Slide 7: Boardwalk Strategy
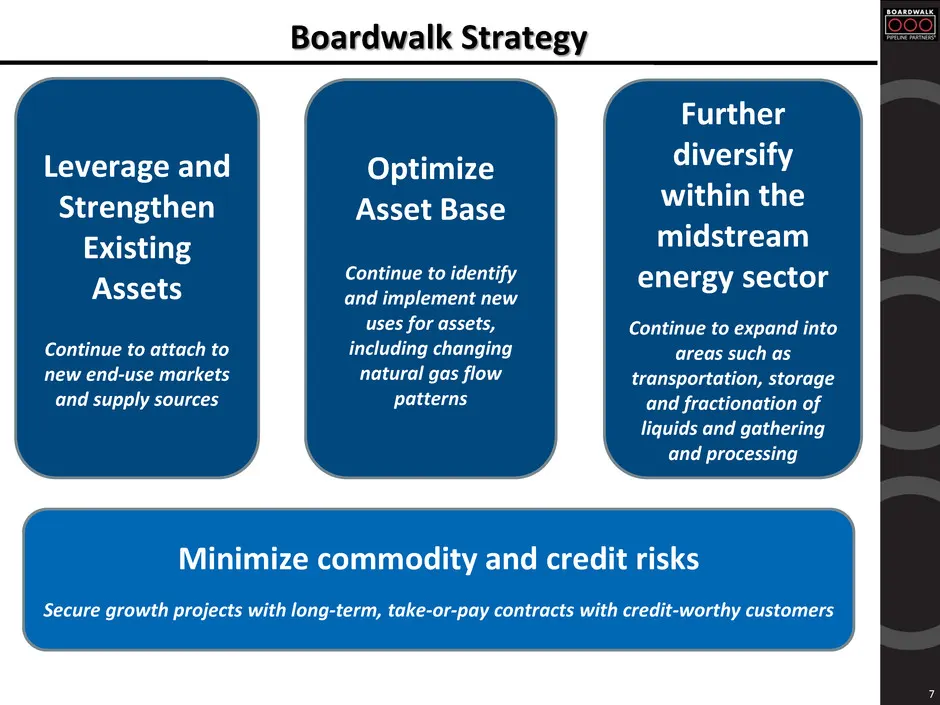
Boardwalk Strategy 7 Leverage and Strengthen Existing Assets Continue to attach to new end-use markets and supply sources Further diversify within the midstream energy sector Continue to expand into areas such as transportation, storage and fractionation of liquids and gathering and processing Optim
Slide 8: Strategy Execution and Recent Events
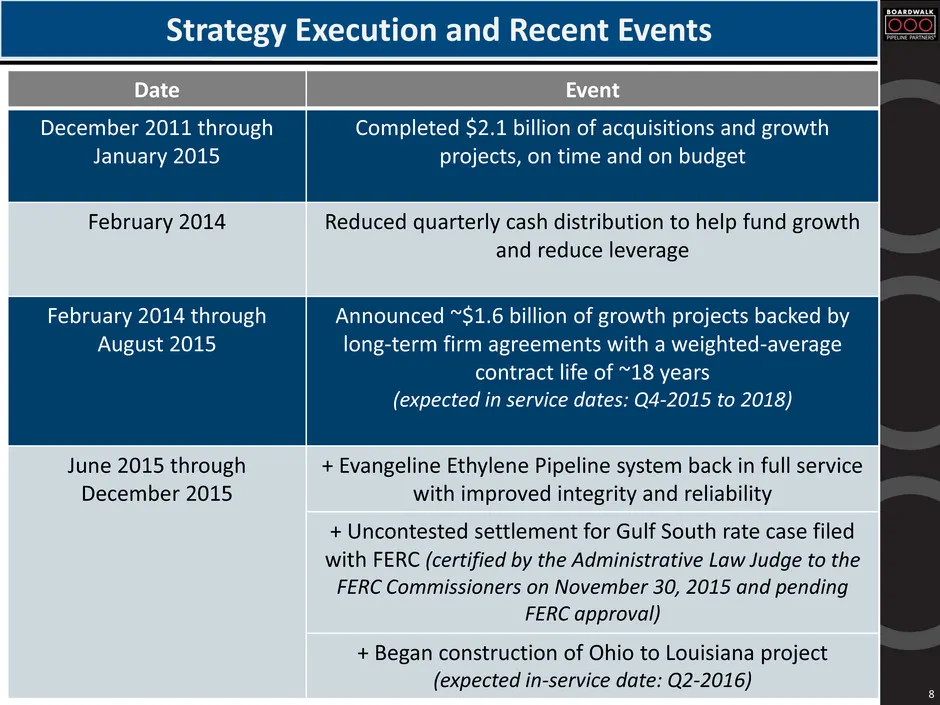
8 Strategy Execution and Recent Events Date Event December 2011 through January 2015 Completed $2.1 billion of acquisitions and growth projects, on time and on budget February 2014 Reduced quarterly cash distribution to help fund growth and reduce leverage February 2014 through August 2015 Announced
Slide 9: Growth Project/Acquisition Scope Strategy Timing Capex
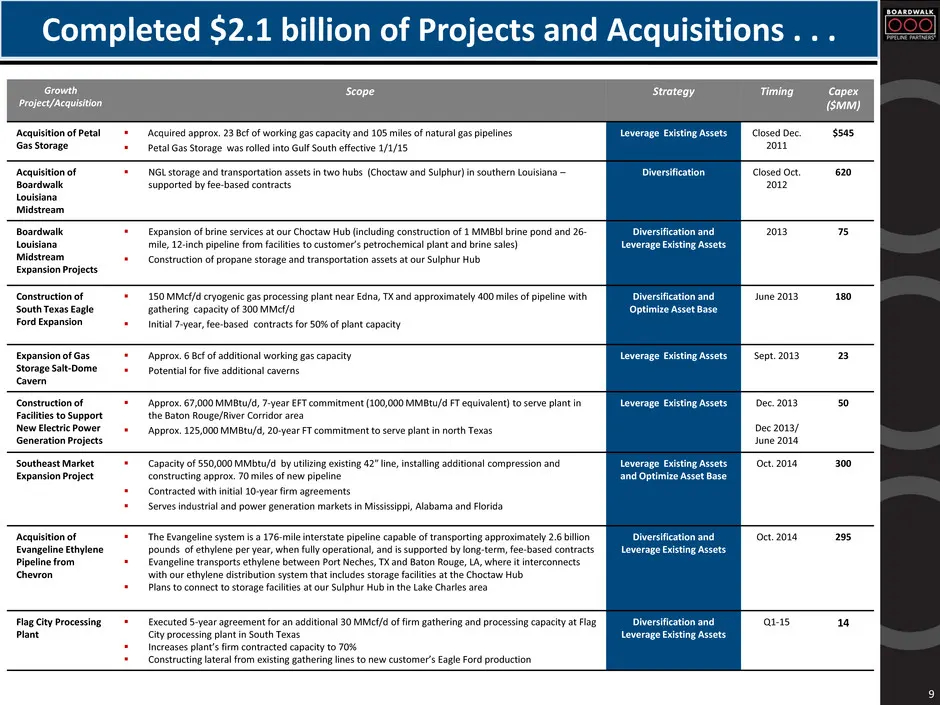
9 Growth Project/Acquisition Scope Strategy Timing Capex ($MM) Acquisition of Petal Gas Storage Acquired approx. 23 Bcf of working gas capacity and 105 miles of natural gas pipelines Petal Gas Storage was rolled into Gulf South effective 1/1/15 Leverage Existing Assets Closed Dec. 2011 $545 Acqu
Slide 10: Growth projects: Ohio to Louisiana, Northern Supply Access and others
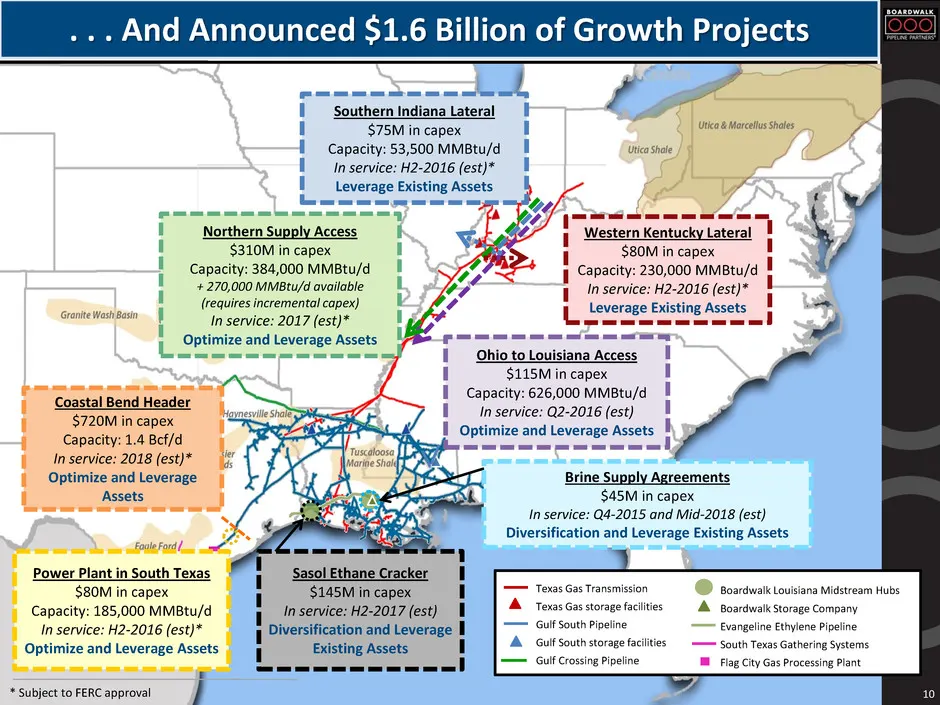
10 Ohio to Louisiana Access $115M in capex Capacity: 626,000 MMBtu/d In service: Q2-2016 (est) Optimize and Leverage Assets Northern Supply Access $310M in capex Capacity: 384,000 MMBtu/d + 270,000 MMBtu/d available (requires incremental capex) In service: 2017 (est)* Optimize and Leverage Assets Sa
Slide 11: Gulf South Rate Case Settlement Highlights
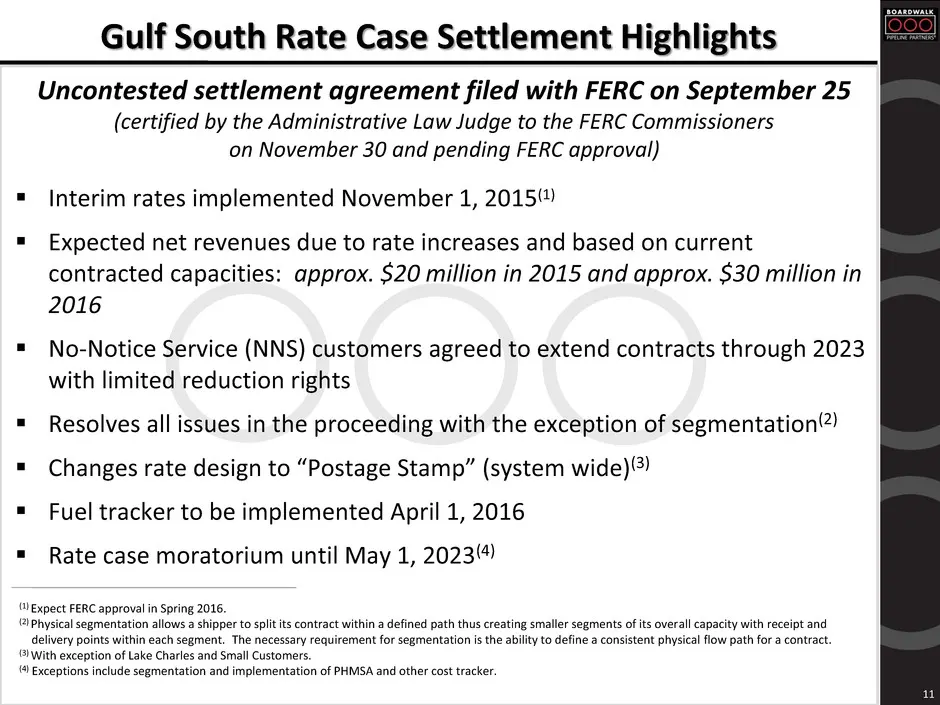
11 Gulf South Rate Case Settlement Highlights Financial Profile Uncontested settlement agreement filed with FERC on September 25 (certified by the Administrative Law Judge to the FERC Commissioners on November 30 and pending FERC approval) Interim rates implemented November 1, 2015(1) Expected n
Slide 12: Financial Overview
October 11, 2013 Boardwalk Annual Customer Meeting Nashville Customer Meeting Boardwalk’s Response to the Changing Market Kathy Kirk, Senior Vice President Marketing & Origination Financial Overview 12 Southeast Market Expansion: Jasper, Forrest & Moss Point Compressor Station
Slide 13: Financial Highlights
13 Financial Highlights Financial Profile Substantially a long-term, fixed-fee revenue base Significant portion of revenues backed by firm contracts with primarily investment-grade customers Financing strategy: – Utilize internally-generated cash flow, in excess of distributions, to help fund
Slide 14: Boardwalk Revenue Profile Backed by Firm, Long-term Contracts
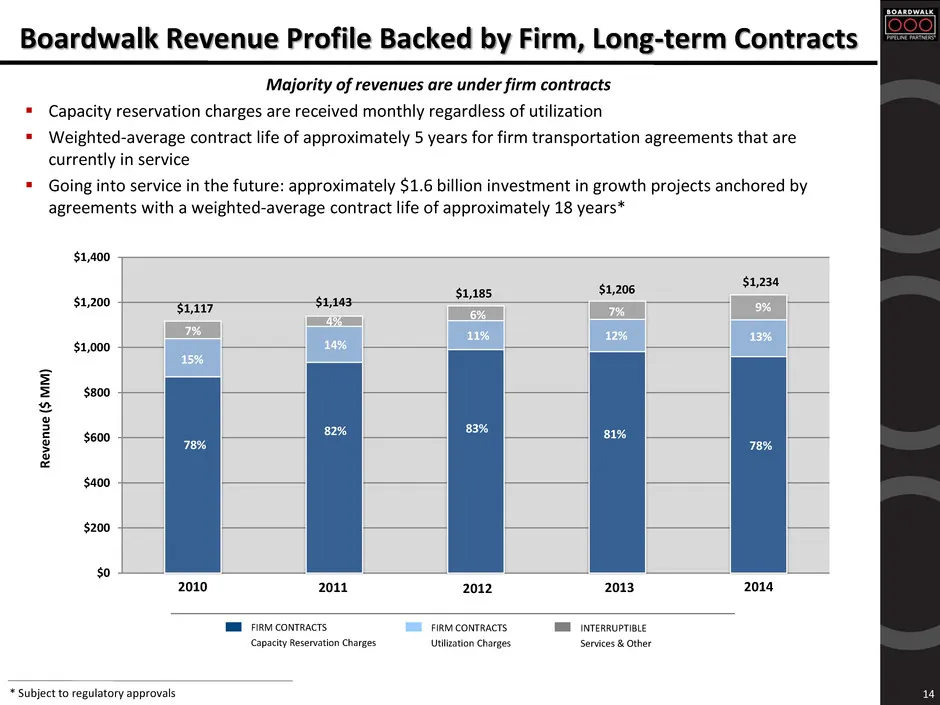
Boardwalk Revenue Profile Backed by Firm, Long-term Contracts 14 Majority of revenues are under firm contracts Capacity reservation charges are received monthly regardless of utilization Weighted-average contract life of approximately 5 years for firm transportation agreements that are currently
Slide 15: Revenue Estimates: Capacity Reservation and Min. Bill Charges
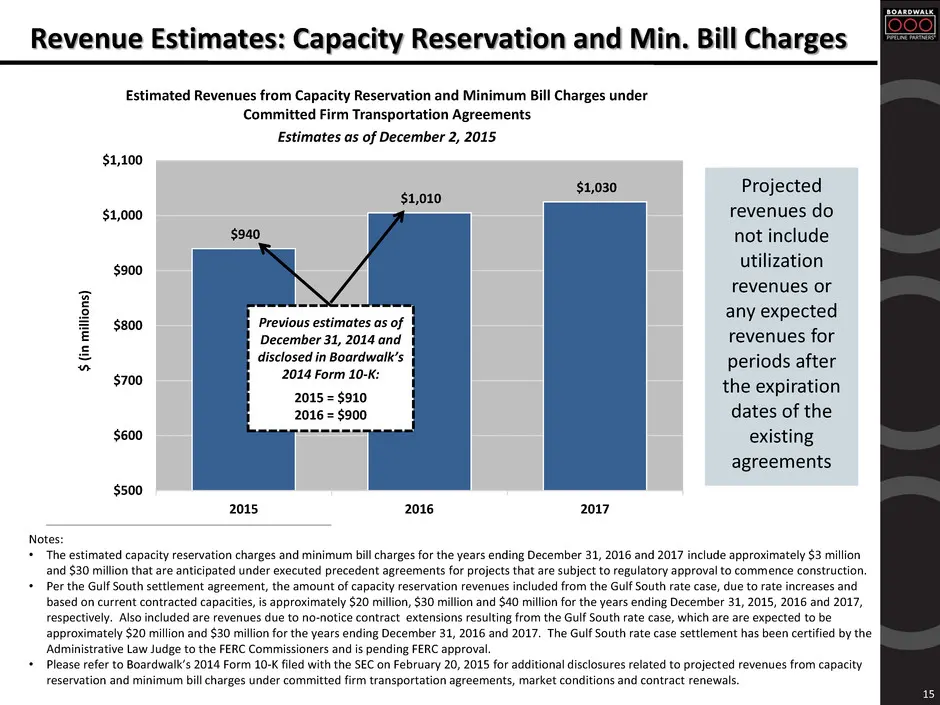
Revenue Estimates: Capacity Reservation and Min. Bill Charges 15 Estimated Revenues from Capacity Reservation and Minimum Bill Charges under Committed Firm Transportation Agreements Estimates as of December 2, 2015 Projected revenues do not include utilization revenues or any expected revenues for p
Slide 16: Capitalization
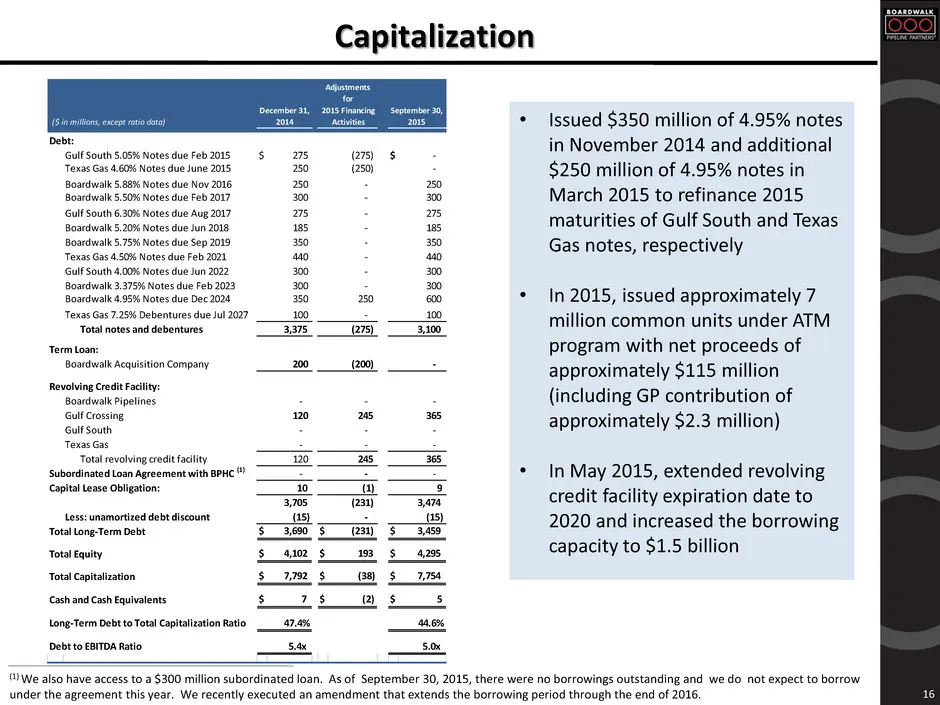
Capitalization 16 (1) We also have access to a $300 million subordinated loan. As of September 30, 2015, there were no borrowings outstanding and we do not expect to borrow under the agreement this year. We recently executed an amendment that extends the borrowing period through the end of 2016. • I
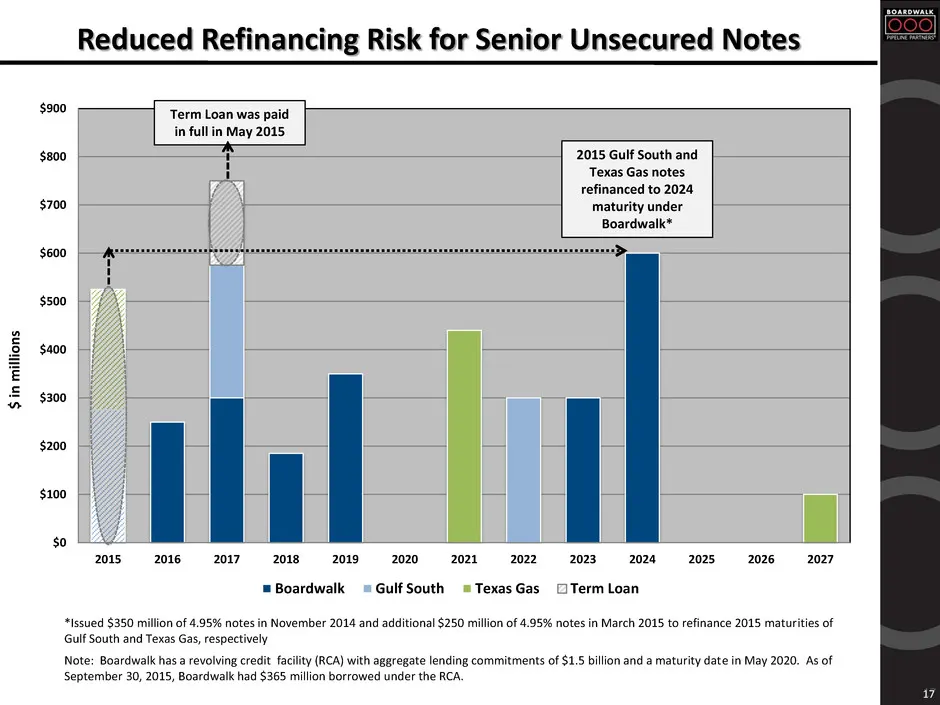
Slide 17: Reduced Refinancing Risk for Senior Unsecured Notes
$0 $100 $200 $300 $400 $500 $600 $700 $800 $900 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 2025 2026 2027 Boardwalk Gulf South Texas Gas Term Loan Reduced Refinancing Risk for Senior Unsecured Notes 17 $ in m ill io n s 2015 Gulf South and Texas Gas notes refinanced to 2024 maturity under Boa
Slide 18: Market Fundamentals and Boardwalk Growth Projects
October 11, 2013 Boardwalk Annual Customer Meeting Nashville Customer Meeting Boardwalk’s Response to the Changing Market Kathy Kirk, Senior Vice President Marketing & Origination Market Fundamentals and Boardwalk Growth Projects Southeast Market Expansion: Jasper, Forrest & Moss Point Compressor St
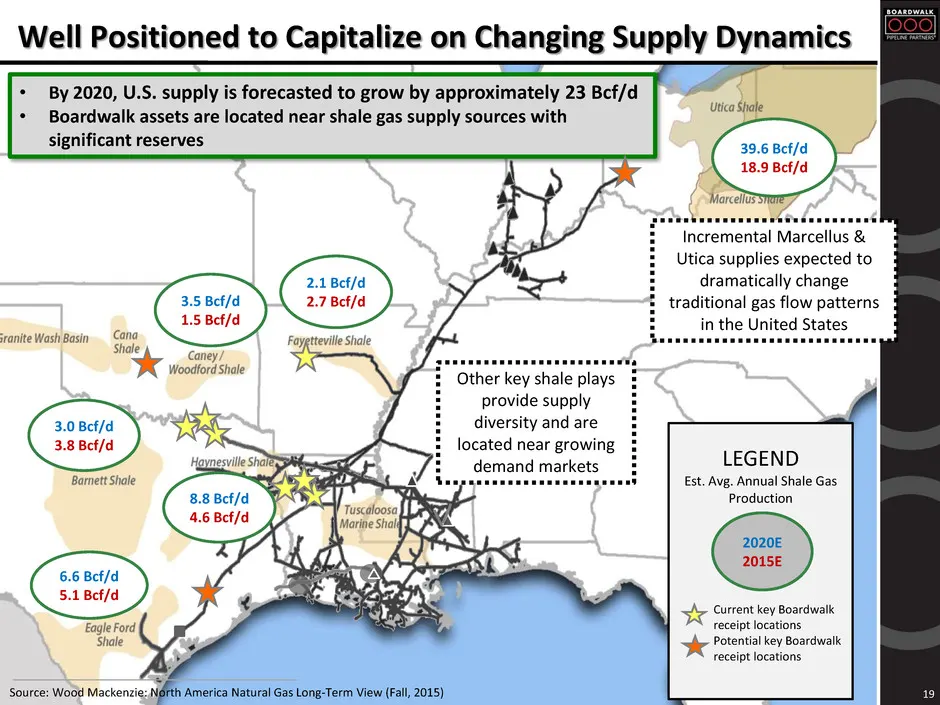
Slide 19: Well Positioned to Capitalize on Changing Supply Dynamics
19 Well Positioned to Capitalize on Changing Supply Dynamics Source: Wood Mackenzie: North America Natural Gas Long-Term View (Fall, 2015) Incremental Marcellus & Utica supplies expected to dramatically change traditional gas flow patterns in the United States • By 2020, U.S. supply is forecasted to
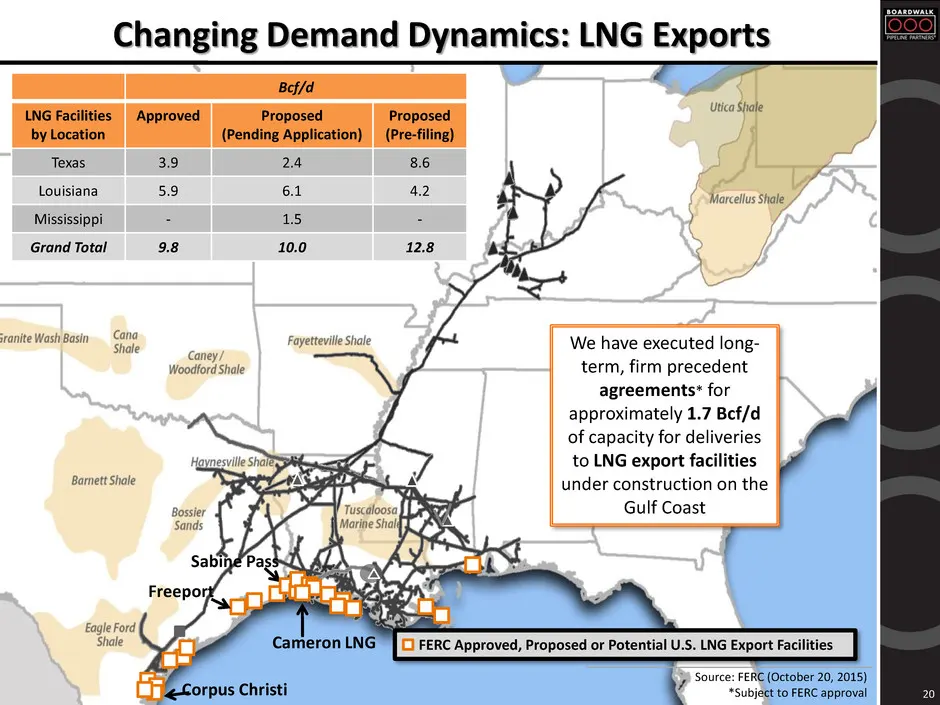
Slide 20: Changing Demand Dynamics: LNG Exports
20 Changing Demand Dynamics: LNG Exports Freeport Sabine Pass Cameron LNG FERC Approved, Proposed or Potential U.S. LNG Export Facilities Source: FERC (October 20, 2015) *Subject to FERC approval Corpus Christi We have executed long- term, firm precedent agreements* for approximately 1.7 Bcf/d of ca
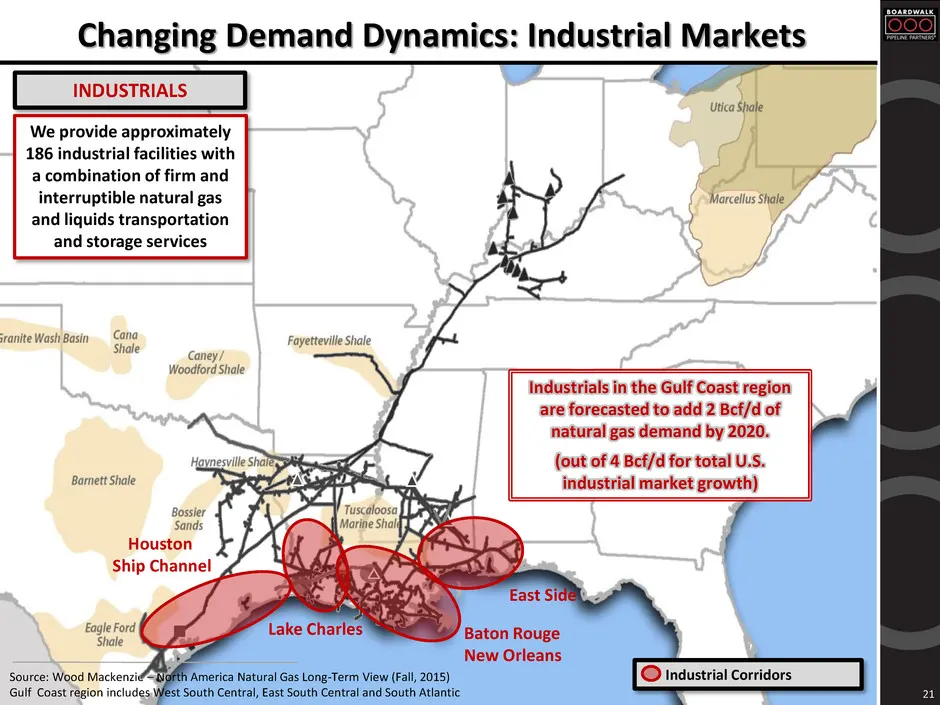
Slide 21: Changing Demand Dynamics: Industrial Markets
21 Changing Demand Dynamics: Industrial Markets We provide approximately 186 industrial facilities with a combination of firm and interruptible natural gas and liquids transportation and storage services INDUSTRIALS Houston Ship Channel Source: Wood Mackenzie – North America Natural Gas Long-Term Vi
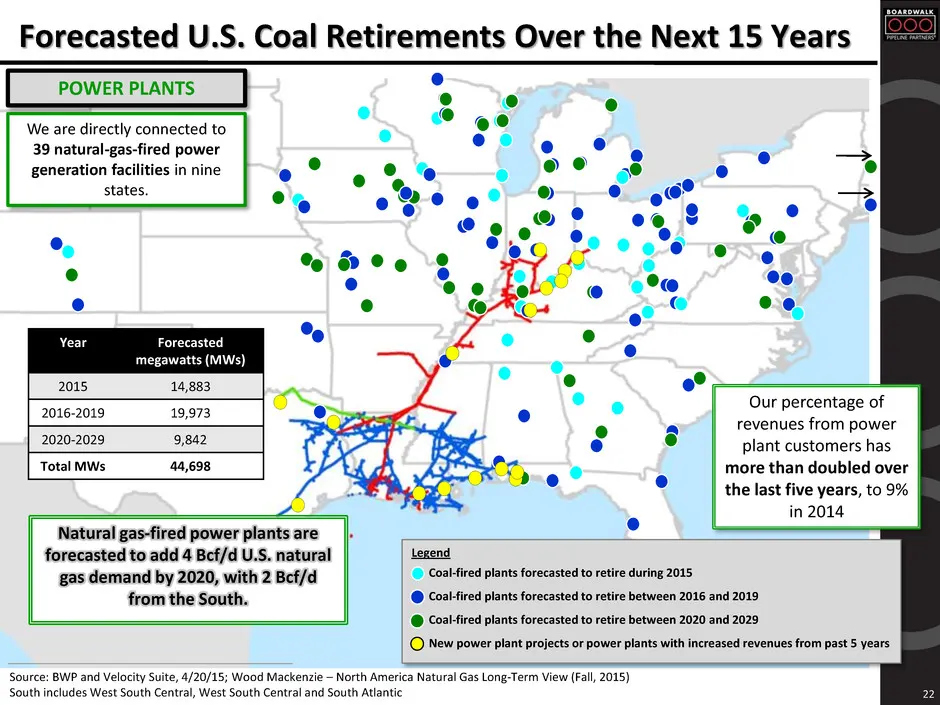
Slide 22: Forecasted U.S. Coal Retirements Over the Next Years
Forecasted U.S. Coal Retirements Over the Next 15 Years 22 Source: BWP and Velocity Suite, 4/20/15; Wood Mackenzie – North America Natural Gas Long-Term View (Fall, 2015) South includes West South Central, West South Central and South Atlantic Year Forecasted megawatts (MWs) 2015 14,883 2016-2019 19
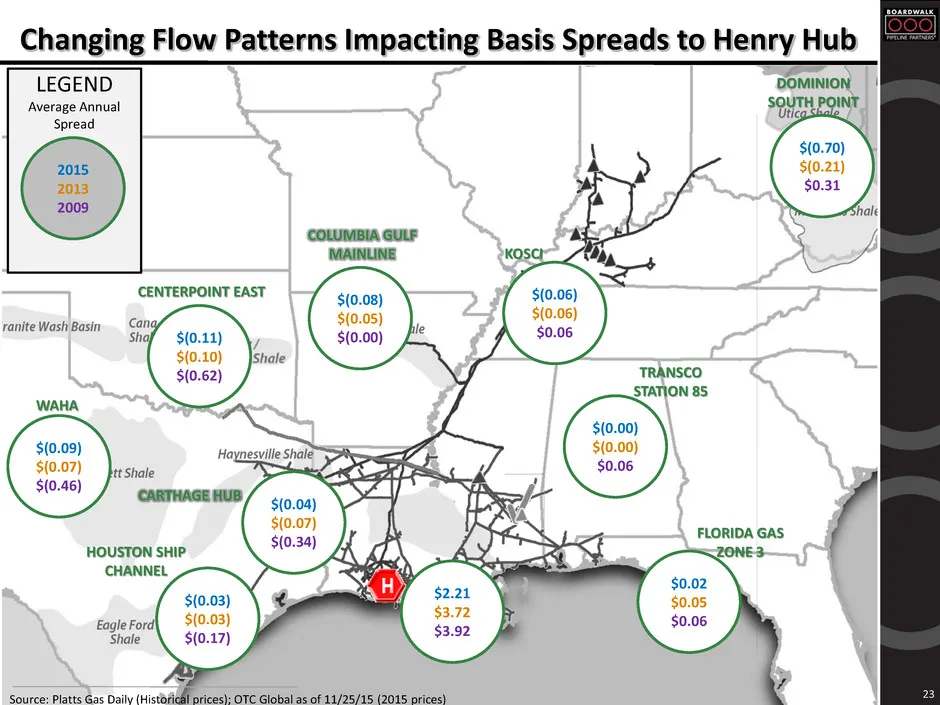
Slide 23: Changing Flow Patterns Impacting Basis Spreads to Henry Hub
Changing Flow Patterns Impacting Basis Spreads to Henry Hub 23 23 Source: Platts Gas Daily (Historical prices); OTC Global as of 11/25/15 (2015 prices) LEGEND Average Annual Spread CENTERPOINT EAST HOUSTON SHIP CHANNEL CARTHAGE HUB KOSCI TRANSCO STATION 85 FLORIDA GAS ZONE 3 $(0.09) $(0.07) $(0.46)
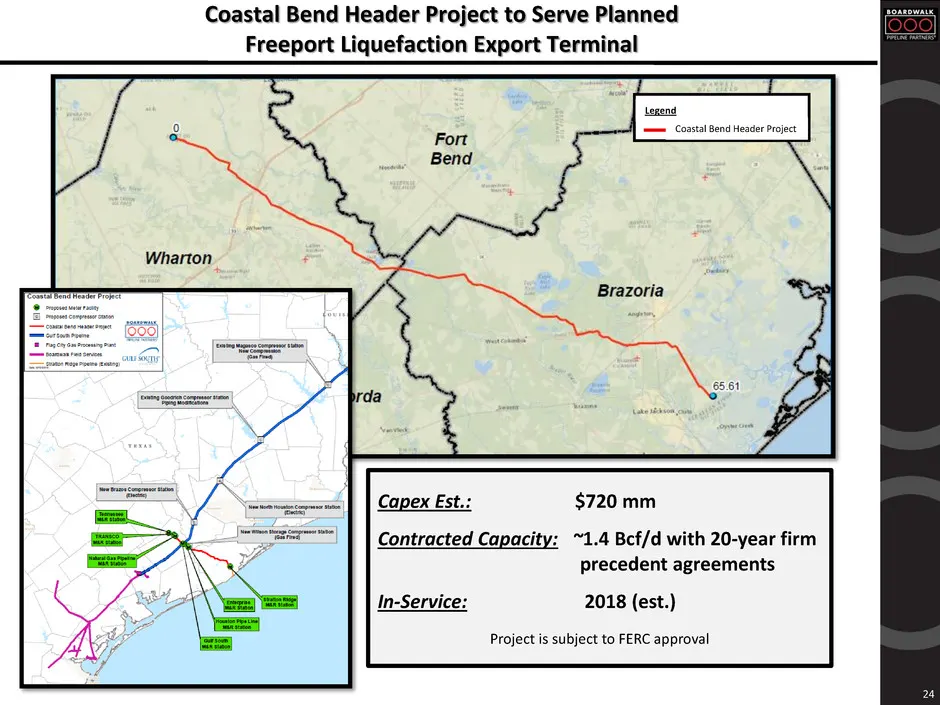
Slide 24: Coastal Bend Header Project to Serve Freeport Liquefaction Terminal
Coastal Bend Header Project to Serve Planned Freeport Liquefaction Export Terminal 24 Capex Est.: $720 mm Contracted Capacity: ~1.4 Bcf/d with 20-year firm precedent agreements In-Service: 2018 (est.) Project is subject to FERC approval Coastal Bend Header Project Legend
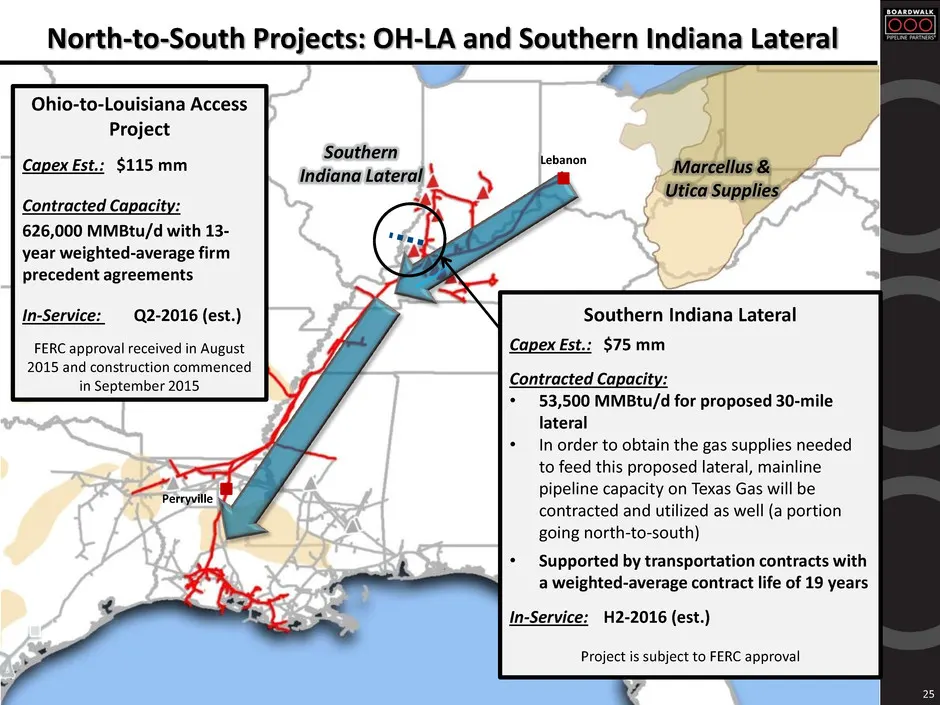
Slide 25: North-to-South Projects: OH-LA and Southern Indiana Lateral
North-to-South Projects: OH-LA and Southern Indiana Lateral 25 Lebanon Perryville Marcellus & Utica Supplies Ohio-to-Louisiana Access Project Capex Est.: $115 mm Contracted Capacity: 626,000 MMBtu/d with 13- year weighted-average firm precedent agreements In-Service: Q2-2016 (est.) FERC approval rec
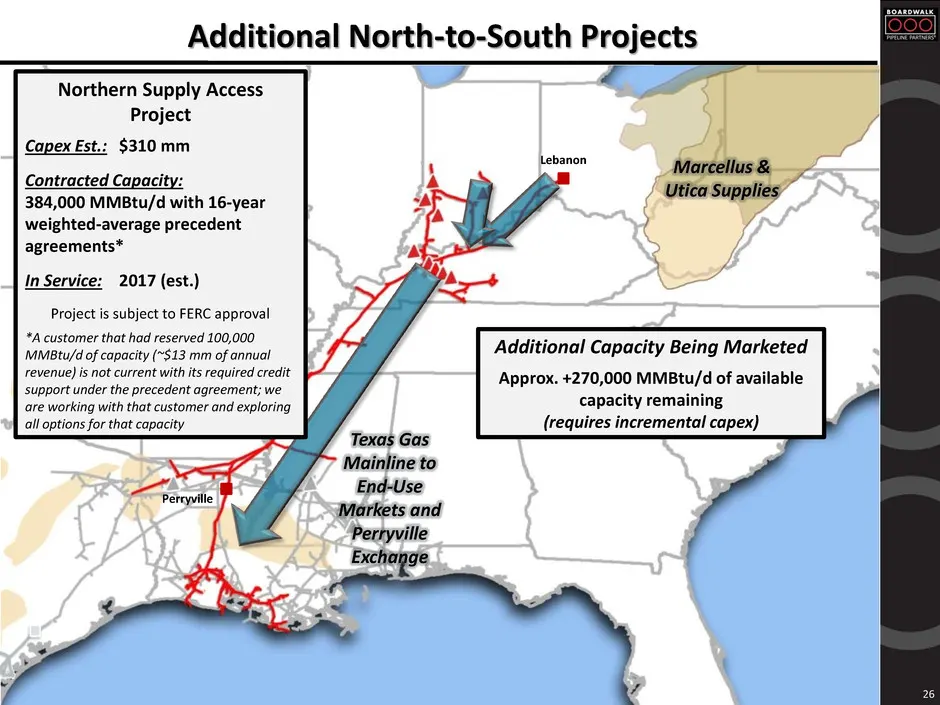
Slide 26: Additional North-to-South Projects
Additional North-to-South Projects Marcellus & Utica Supplies Texas Gas Mainline to End-Use Markets and Perryville Exchange 26 Lebanon Perryville Northern Supply Access Project Capex Est.: $310 mm Contracted Capacity: 384,000 MMBtu/d with 16-year weighted-average precedent agreements* In Service: 20
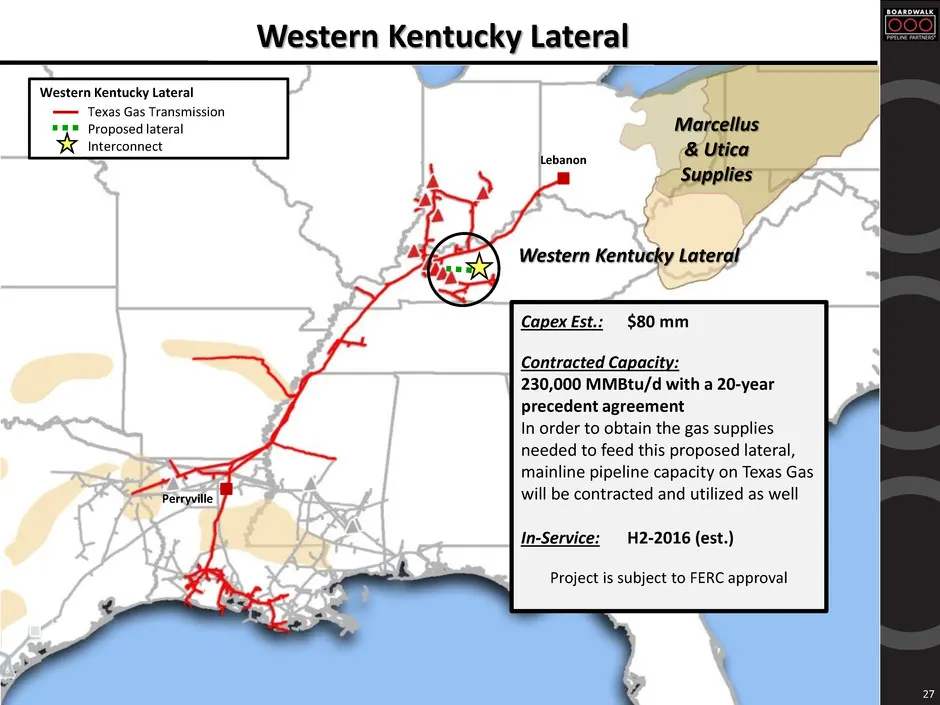
Slide 27: Western Kentucky Lateral
Western Kentucky Lateral 27 Lebanon Perryville Capex Est.: $80 mm Contracted Capacity: 230,000 MMBtu/d with a 20-year precedent agreement In order to obtain the gas supplies needed to feed this proposed lateral, mainline pipeline capacity on Texas Gas will be contracted and utilized as well In-Servi
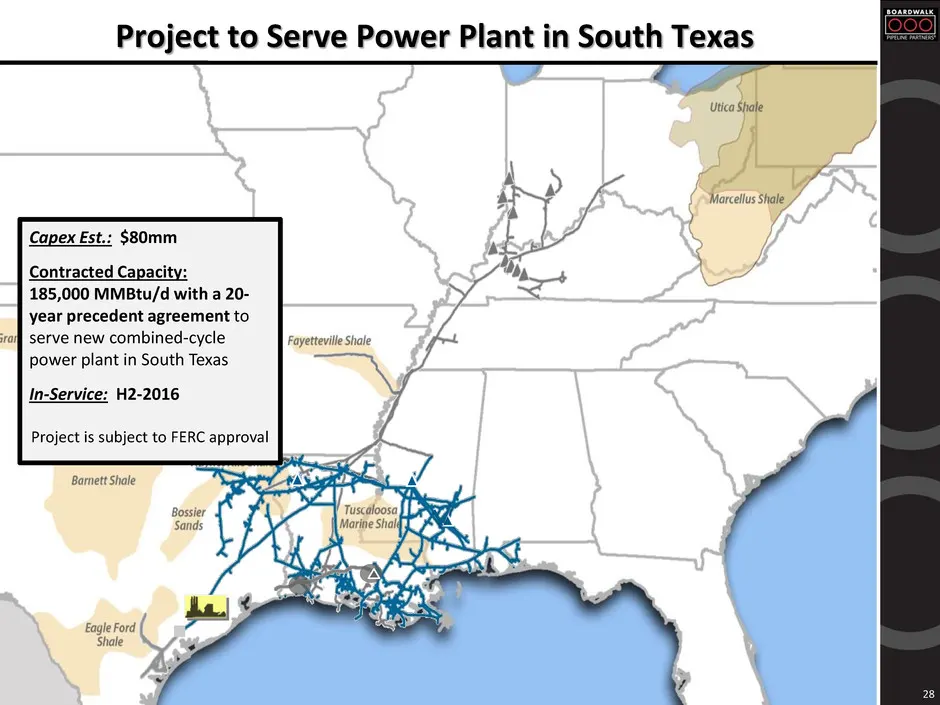
Slide 28: Project to Serve Power Plant in South Texas
28 Project to Serve Power Plant in South Texas Capex Est.: $80mm Contracted Capacity: 185,000 MMBtu/d with a 20- year precedent agreement to serve new combined-cycle power plant in South Texas In-Service: H2-2016 Project is subject to FERC approval
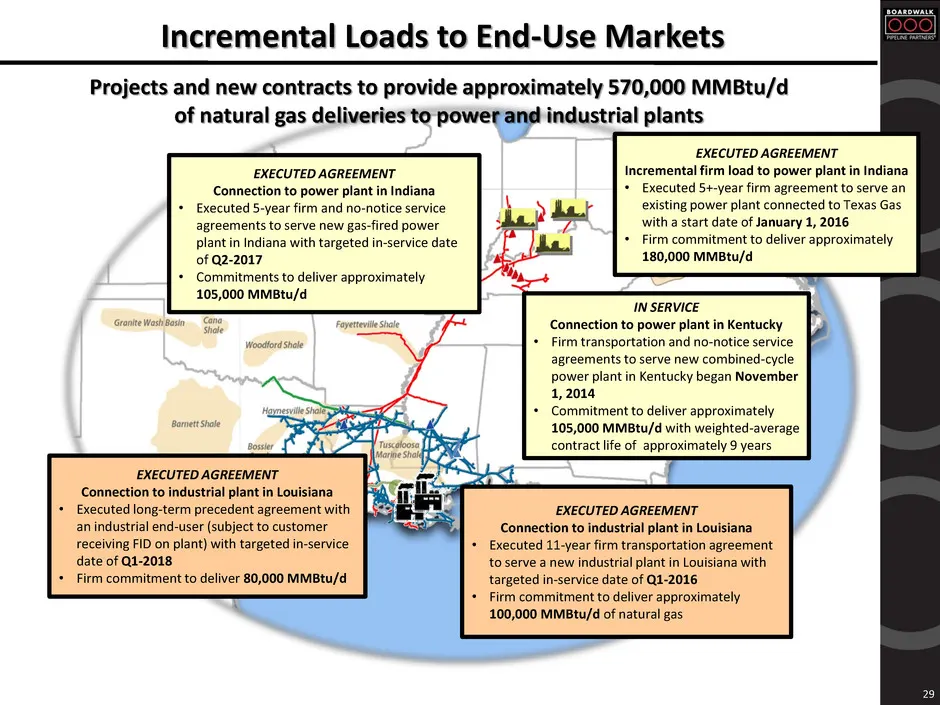
Slide 29: Incremental Loads to End-Use Markets
29 Incremental Loads to End-Use Markets IN SERVICE Connection to power plant in Kentucky • Firm transportation and no-notice service agreements to serve new combined-cycle power plant in Kentucky began November 1, 2014 • Commitment to deliver approximately 105,000 MMBtu/d with weighted-average contr
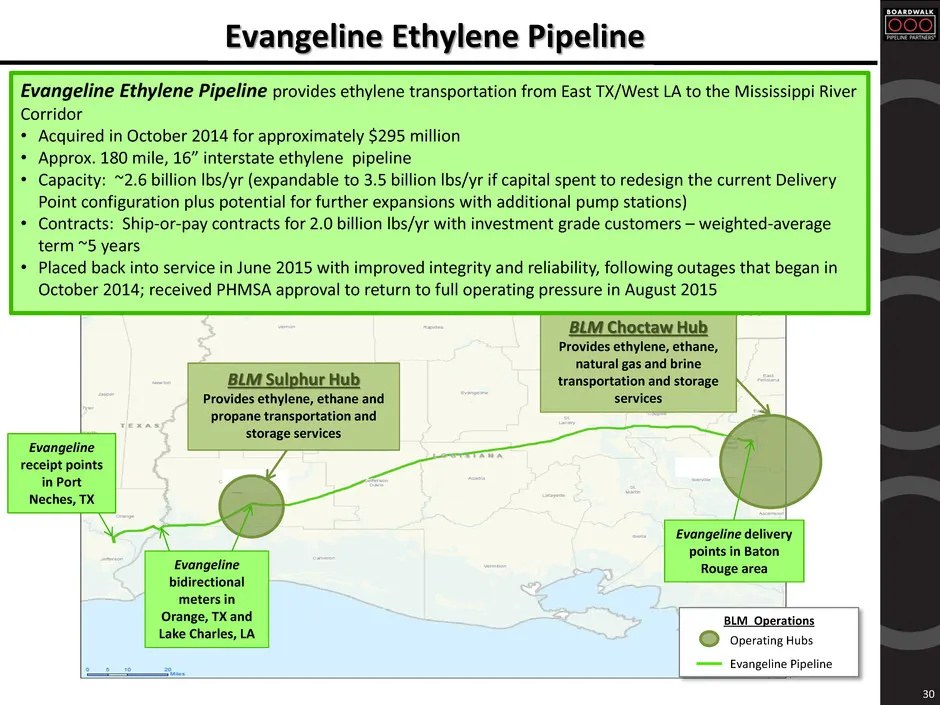
Slide 30: Evangeline Ethylene Pipeline
Evangeline Ethylene Pipeline 30 Evangeline receipt points in Port Neches, TX Evangeline delivery points in Baton Rouge area BLM Operations Operating Hubs Evangeline Pipeline Evangeline bidirectional meters in Orange, TX and Lake Charles, LA BLM Sulphur Hub Provides ethylene, ethane and propane trans
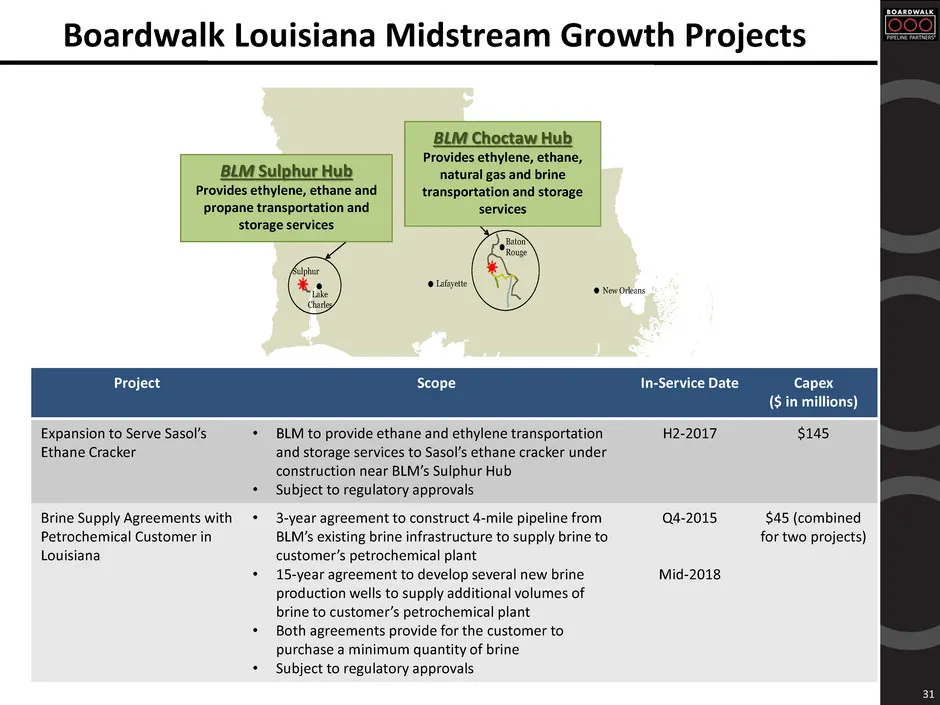
Slide 31: Boardwalk Louisiana Midstream Growth Projects
Boardwalk Louisiana Midstream Growth Projects 31 Lake Charles Lafayette New Orleans Sulphur Choctaw Area Facilities Sulphur Area Facilities Ethylene Pipeline Propylene Pipeline Natural Gas Pipeline Brine Pipeline E/P Pipeline PL Midstream Hubs Baton Rouge Sulphur Area Facilities Choctaw Area Facilit
Slide 32: October 11, 2013 Boardwalk Annual Customer Meeting Nashville Customer Meeting Boardwalk’s Response to the
October 11, 2013 Boardwalk Annual Customer Meeting Nashville Customer Meeting Boardwalk’s Response to the Changing Market Kathy Kirk, Senior Vice President Marketing & Origination Presentation for 2015 Wells Fargo Energy Symposium December 2015 32 Southeast Market Expansion: Jasper, Forrest & Moss P
Source: SEC EDGAR · 8-K filed Dec 7, 2015
More decks from Boardwalk Pipeline Partners LP
 Wells Fargo presentation (May 2017)28 slides · May 16, 2017
 2014 Citi 1x1 MLP/Midstream Infrastructure Conference36 slides · Aug 19, 2014
 NAPTP 2014 MLP Annual Investor Conference33 slides · May 20, 2014
 Corporate Update (October 2011)9 slides · Oct 17, 2011
 Investor Presentation (May 2009)27 slides · May 26, 2009