Sagent Pharmaceuticals — J.P. Morgan Healthcare Conference 2016
25 slides from Sagent Pharmaceuticals's conference presentation, Jan 11, 2016
Slide 1: Sagent Pharmaceuticals J.P. Morgan Healthcare Conference
Sagent Pharmaceuticals J.P. Morgan Healthcare Conference January 13, 2016 Exhibit 99.1
Slide 2: Forward-looking statements
The following information contains, or may be deemed to contain, “forward-looking statements” (as defined in and made pursuant to the safe harbor provisions of the U.S. Private Securities Litigation Reform Act of 1995). Most forward-looking statements contain words that identify them as forward-look
Slide 3: Today's Presenters
Allan Oberman CEO Sagent Pharmaceuticals Jonathon Singer Executive Vice President, CFO Sagent Pharmaceuticals Today’s Presenters
Slide 4: A Decade in the Making
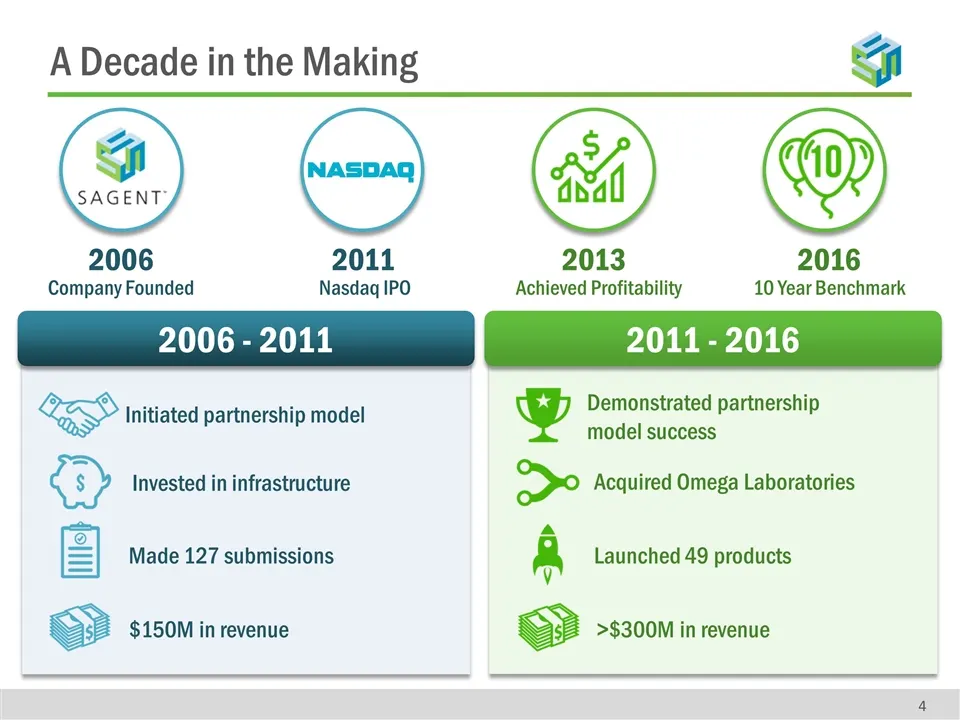
2006 - 2011 2011 - 2016 Initiated partnership model 2006 Company Founded 2011 Nasdaq IPO 2013 Achieved Profitability 2016 10 Year Benchmark A Decade in the Making Made 127 submissions $150M in revenue Invested in infrastructure Demonstrated partnership model success >$300M in revenue Acquired Omega
Slide 5: Favorable Market Dynamics
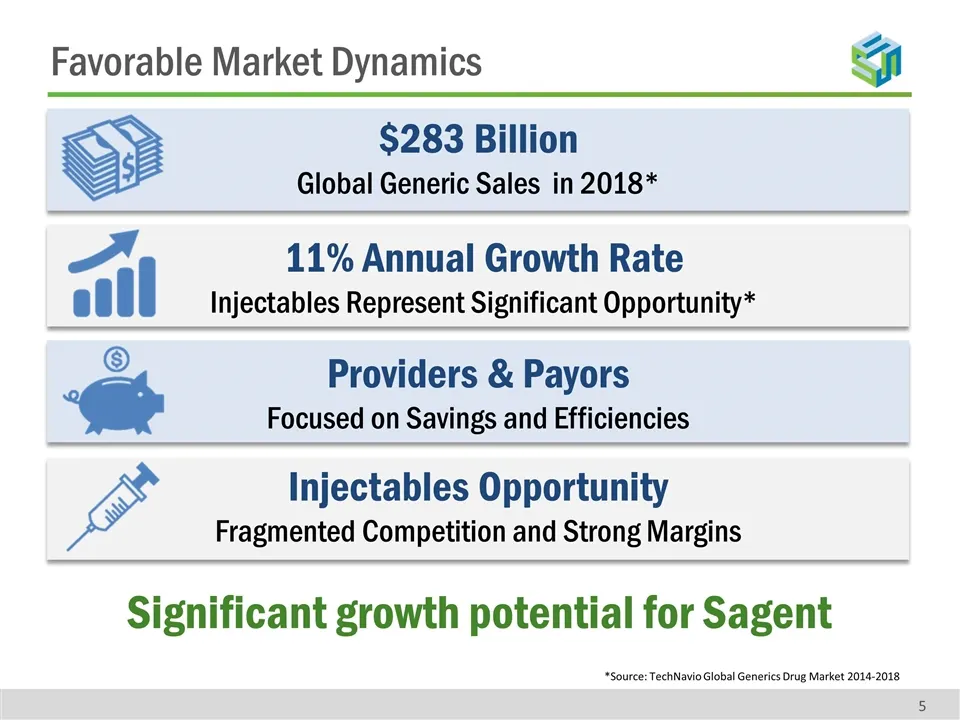
Favorable Market Dynamics 5 $283 Billion Global Generic Sales in 2018* 11% Annual Growth Rate Injectables Represent Significant Opportunity* Providers & Payors Focused on Savings and Efficiencies Injectables Opportunity Fragmented Competition and Strong Margins Significant growth potential for Sagen
Slide 6: Foundation for Success
Foundation for Success Robust Pipeline Differentiated Partnership Model Internal Manufacturing Capabilities Hospital-Centric Focus Growing Markets Strong Commercial Presence
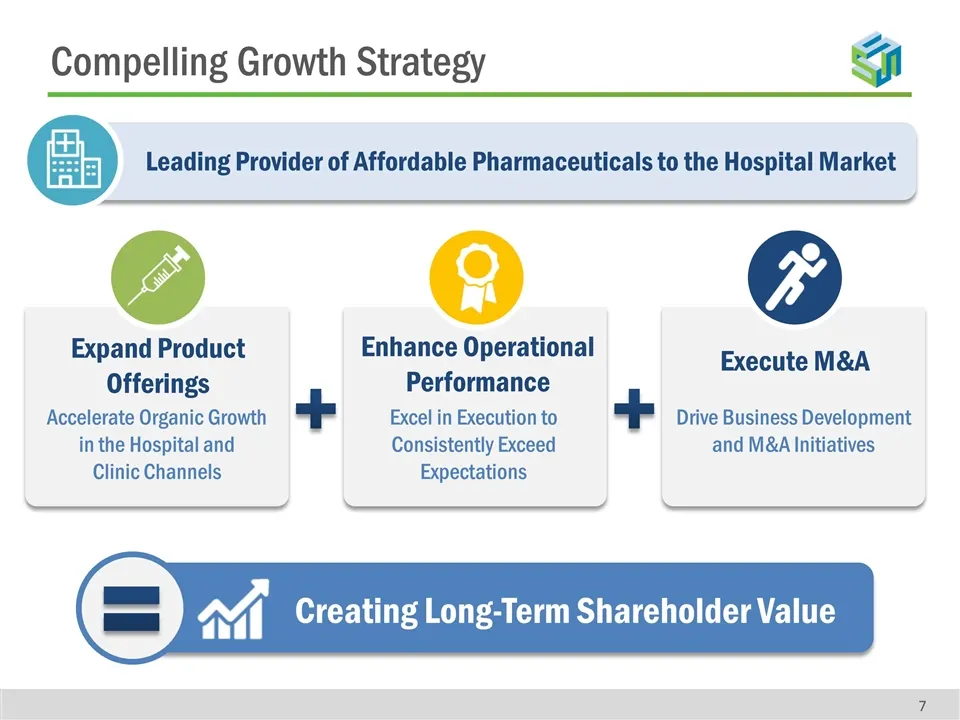
Slide 7: Leading Provider of Affordable Pharmaceuticals to the Hospital Market
Leading Provider of Affordable Pharmaceuticals to the Hospital Market Compelling Growth Strategy Accelerate Organic Growth in the Hospital and Clinic Channels Expand Product Offerings Excel in Execution to Consistently Exceed Expectations Enhance Operational Performance Execute M&A Creating Long-Ter
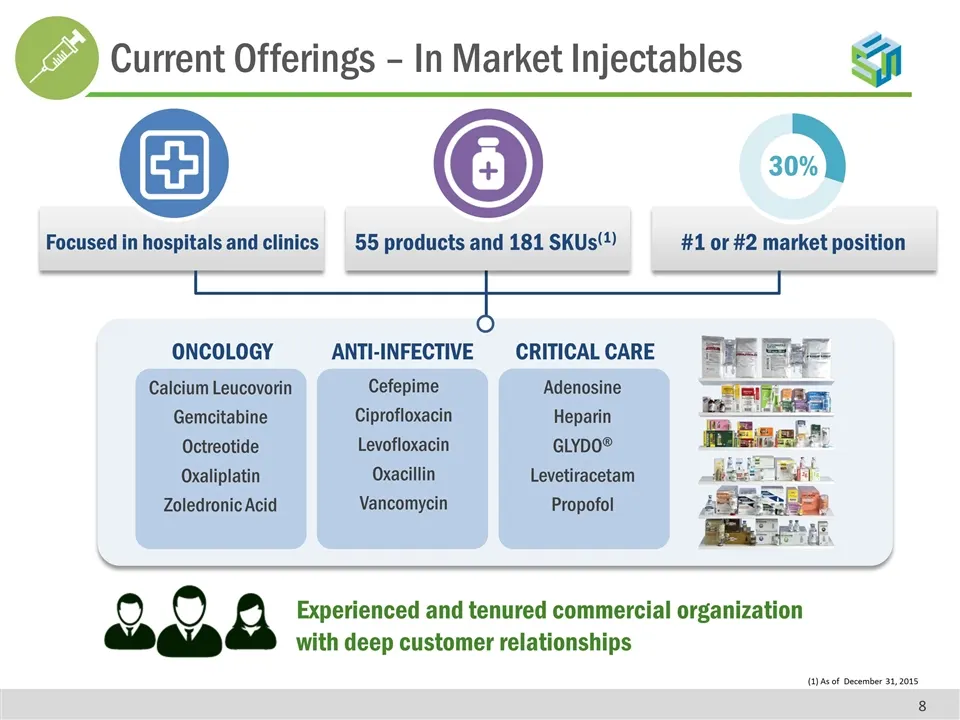
Slide 8: Current Offerings – In Market Injectables
(1) As of December 31, 2015 30% #1 or #2 market position 55 products and 181 SKUs(1) Focused in hospitals and clinics Calcium Leucovorin Gemcitabine Octreotide Oxaliplatin Zoledronic Acid Cefepime Ciprofloxacin Levofloxacin Oxacillin Vancomycin Adenosine Heparin GLYDO® Levetiracetam Propofol ONCOLOG
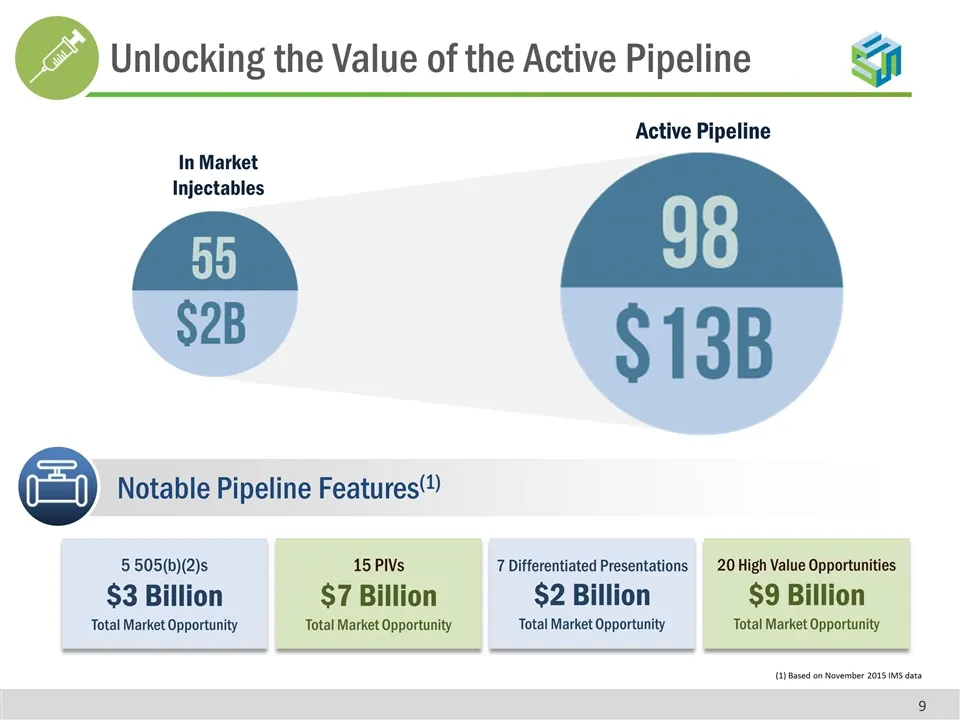
Slide 9: Unlocking the Value of the Active Pipeline
5 505(b)(2)s $3 Billion Total Market Opportunity 15 PIVs $7 Billion Total Market Opportunity 7 Differentiated Presentations $2 Billion Total Market Opportunity (1) Based on November 2015 IMS data Notable Pipeline Features(1) In Market Injectables Active Pipeline 20 High Value Opportunities $9 Billio
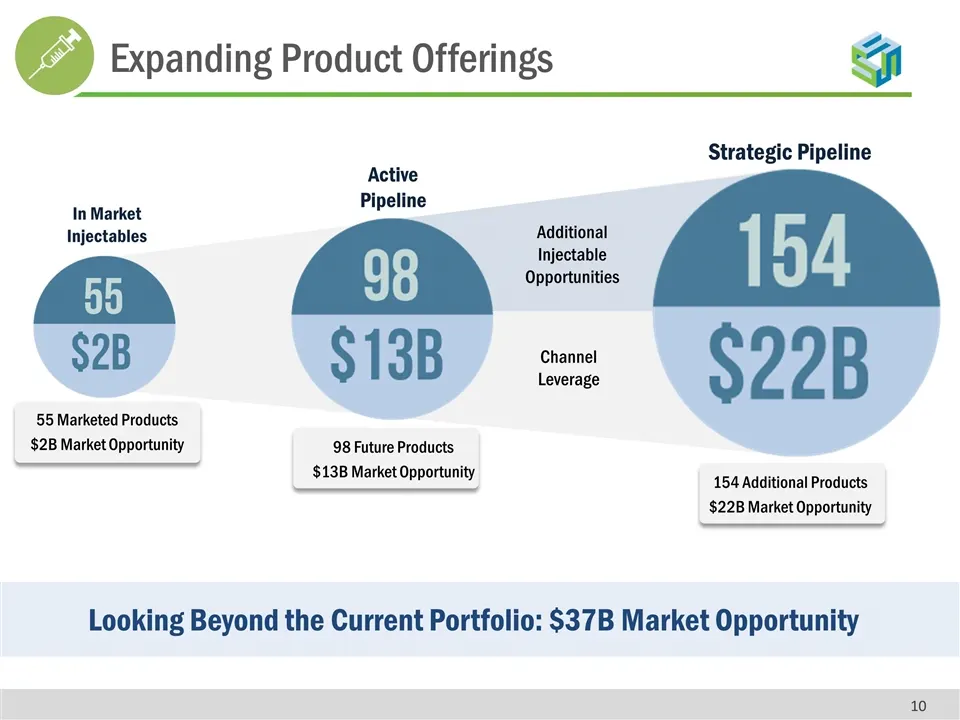
Slide 10: Expanding Product Offerings
55 Marketed Products $2B Market Opportunity Looking Beyond the Current Portfolio: $37B Market Opportunity In Market Injectables Active Pipeline Strategic Pipeline Additional Injectable Opportunities Channel Leverage 98 Future Products $13B Market Opportunity 154 Additional Products $22B Market Oppor
Slide 11: Enhancing Operational Performance
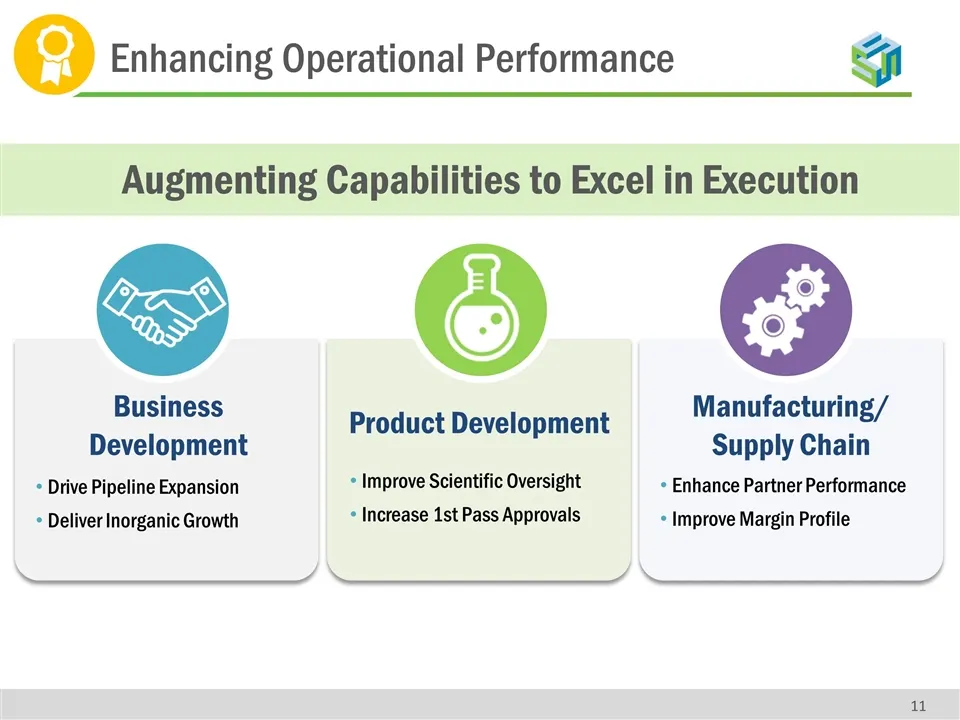
Enhancing Operational Performance Augmenting Capabilities to Excel in Execution Product Development Improve Scientific Oversight Increase 1st Pass Approvals Manufacturing/ Supply Chain Enhance Partner Performance Improve Margin Profile Business Development Drive Pipeline Expansion Deliver Inorganic
Slide 12: Unique and Differentiated Partner Model
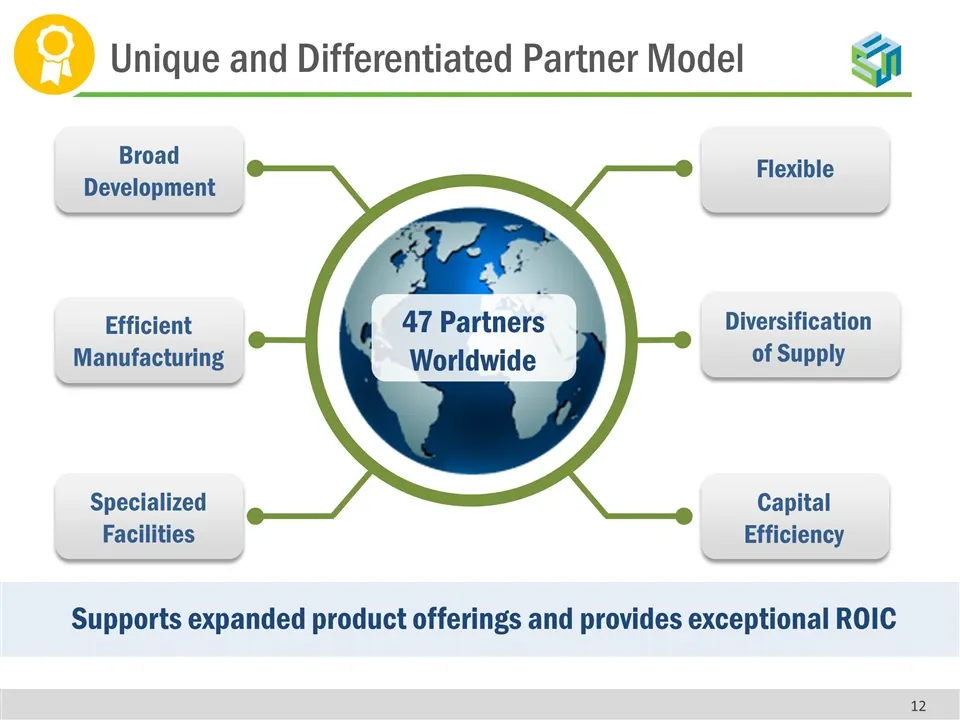
Flexible Capital Efficiency Broad Development Specialized Facilities Supports expanded product offerings and provides exceptional ROIC Diversification of Supply Efficient Manufacturing 47 Partners Worldwide Unique and Differentiated Partner Model
Slide 13: Internal Manufacturing Capabilities
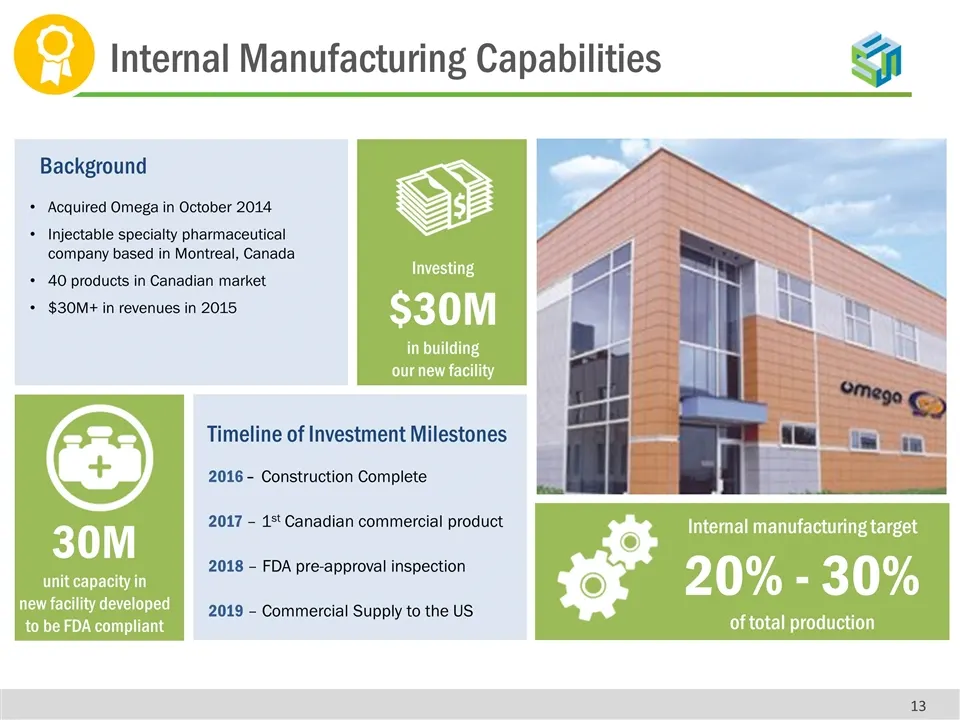
Acquired Omega in October 2014 Injectable specialty pharmaceutical company based in Montreal, Canada 40 products in Canadian market $30M+ in revenues in 2015 Background Investing $30M in building our new facility 2016 – Construction Complete 2017 – 1st Canadian commercial product 2018 – FDA pre-appr
Slide 14: Executing Growth Opportunities
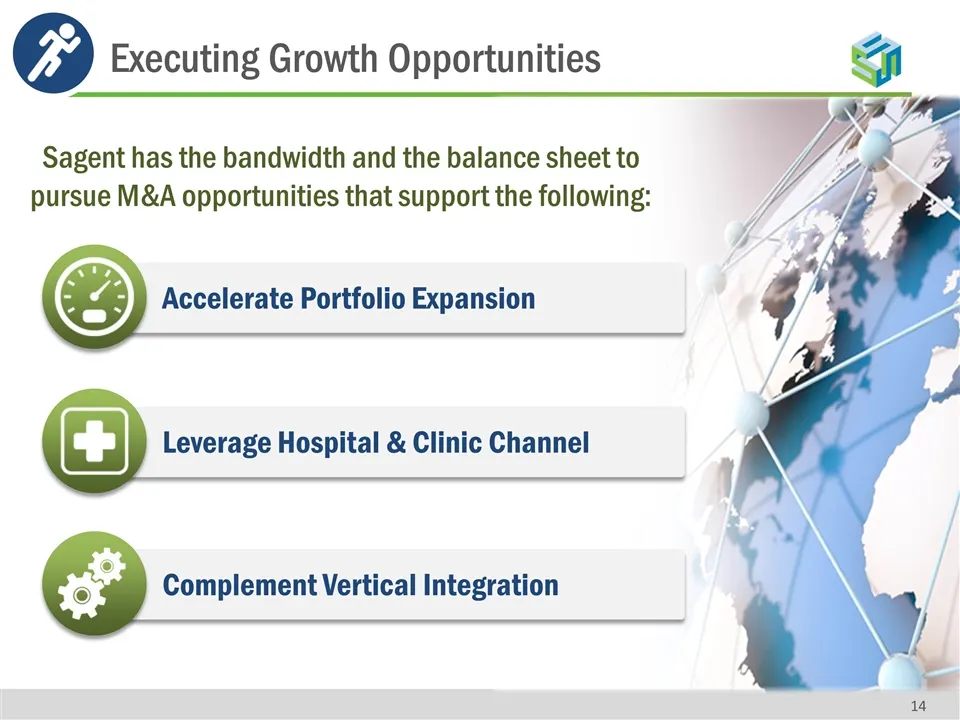
Sagent has the bandwidth and the balance sheet to pursue M&A opportunities that support the following: Leverage Hospital & Clinic Channel Accelerate Portfolio Expansion Complement Vertical Integration Executing Growth Opportunities
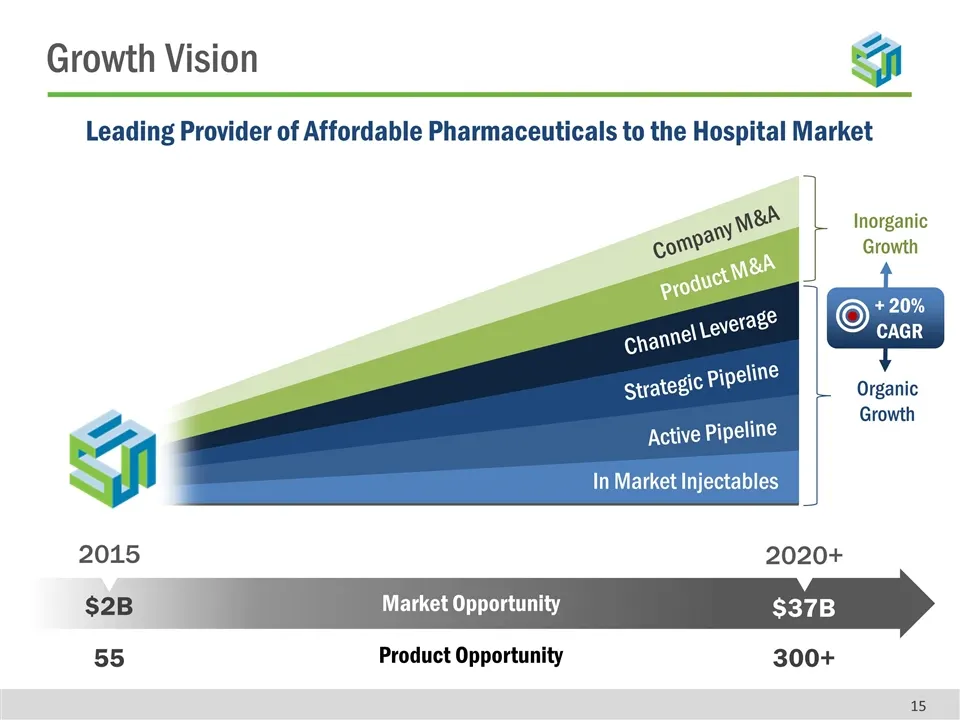
Slide 15: Growth Vision
Strategic Pipeline Active Pipeline In Market Injectables Product M&A Channel Leverage Company M&A $2B $37B 2015 2020+ Leading Provider of Affordable Pharmaceuticals to the Hospital Market Market Opportunity Inorganic Growth Organic Growth 55 300+ Product Opportunity + 20% CAGR Growth Vision
Slide 16: Performance Outlook
Performance Outlook
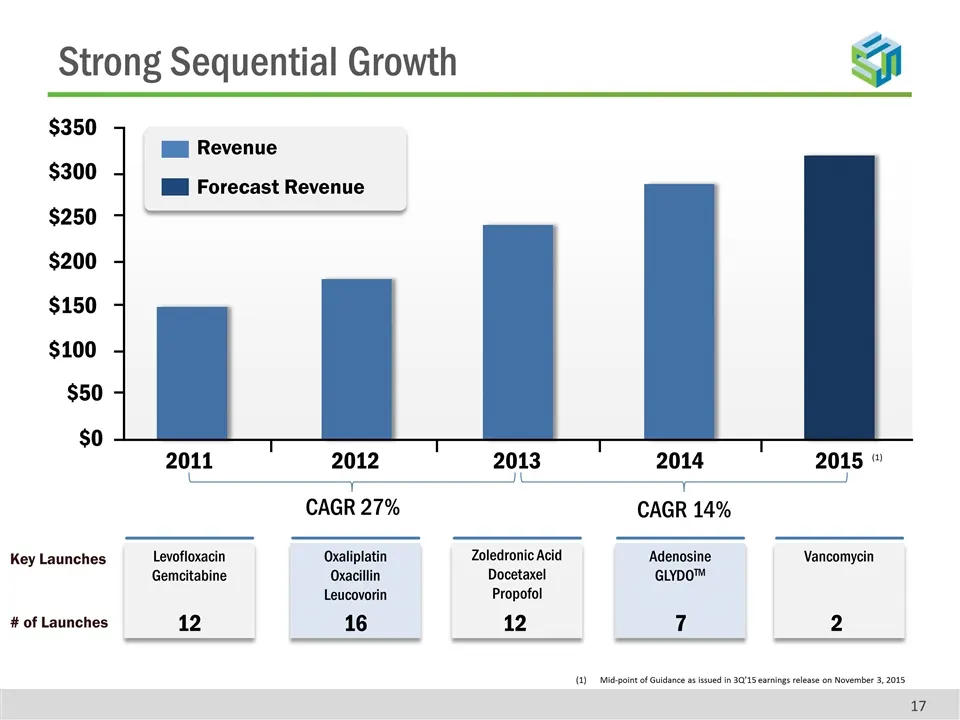
Slide 17: Strong Sequential Growth
Strong Sequential Growth Mid-point of Guidance as issued in 3Q’15 earnings release on November 3, 2015 (1) Revenue Forecast Revenue Levofloxacin Gemcitabine Key Launches # of Launches $350 $300 $250 $200 $150 $100 $50 $0 2011 2012 2013 2014 2015 Oxaliplatin Oxacillin Leucovorin Zoledronic Acid Docet
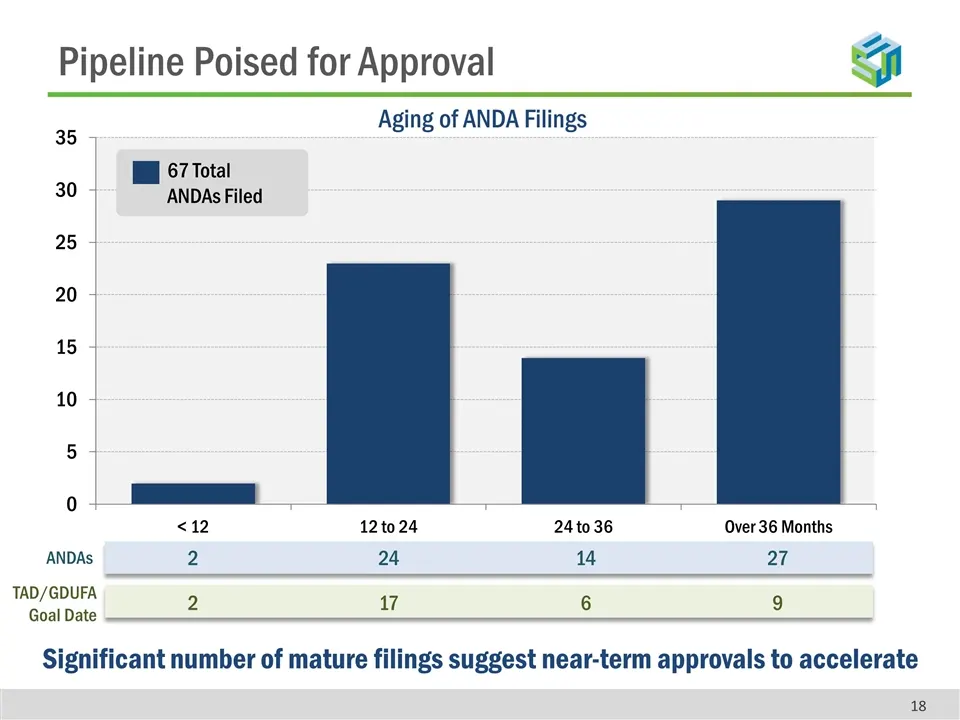
Slide 18: Pipeline Poised for Approval
Pipeline Poised for Approval 67 Total ANDAs Filed Aging of ANDA Filings Significant number of mature filings suggest near-term approvals to accelerate ANDAs 2 24 14 27 TAD/GDUFA Goal Date 2 17 6 9
Slide 19: SCP Strategic Alternatives
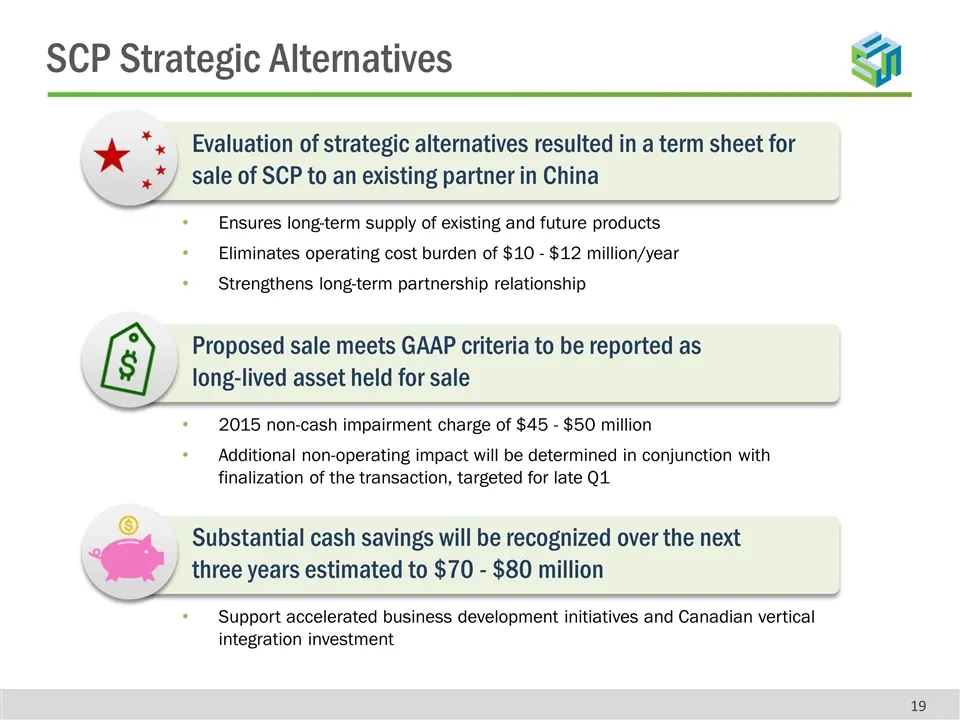
Evaluation of strategic alternatives resulted in a term sheet for sale of SCP to an existing partner in China Ensures long-term supply of existing and future products Eliminates operating cost burden of $10 - $12 million/year Strengthens long-term partnership relationship Proposed sale meets GAAP cr
Slide 20: Key Variables for 2016
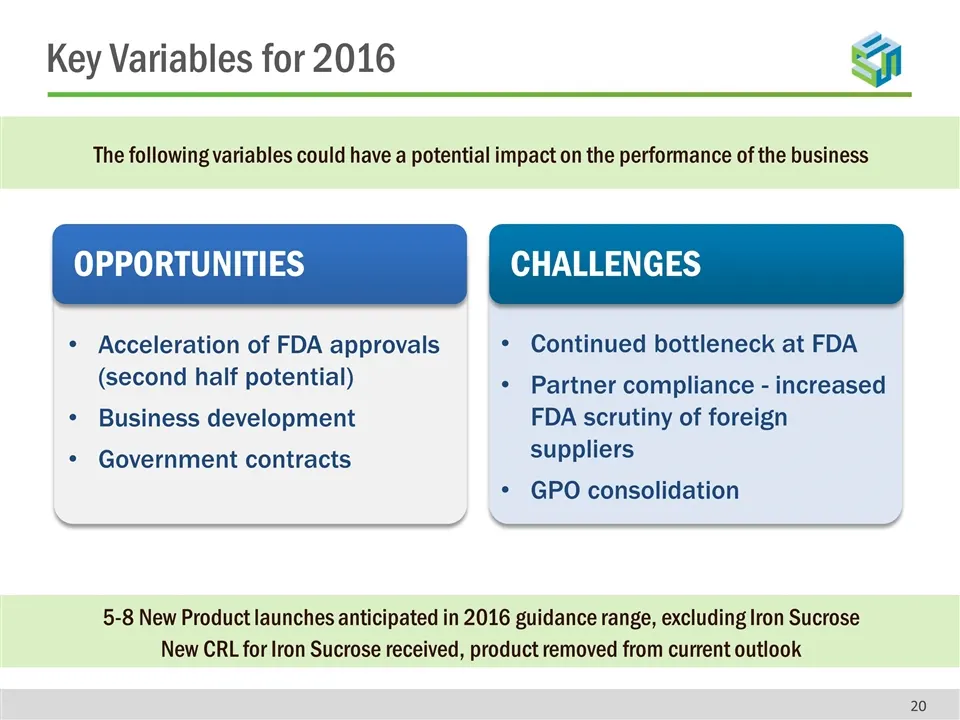
The following variables could have a potential impact on the performance of the business ? OPPORTUNITIES CHALLENGES Acceleration of FDA approvals (second half potential) Business development Government contracts Continued bottleneck at FDA Partner compliance - increased FDA scrutiny of foreign suppl
Slide 21: 2016 Financial Guidance
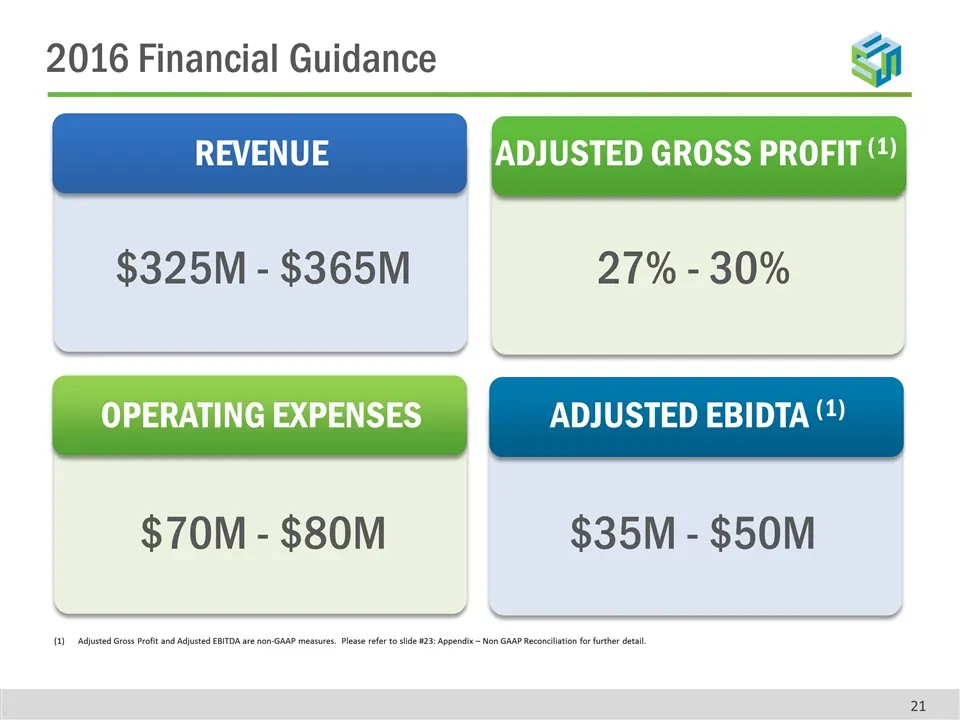
Adjusted Gross Profit and Adjusted EBITDA are non-GAAP measures. Please refer to slide #23: Appendix – Non GAAP Reconciliation for further detail. REVENUE ADJUSTED GROSS PROFIT (1) OPERATING EXPENSES ADJUSTED EBIDTA (1) $325M - $365M $70M - $80M $35M - $50M 27% - 30% 2016 Financial Guidance
Slide 22: Appendix
Appendix
Slide 23: Non-GAAP Financial Measures
Non-GAAP Financial Measures Sagent reports its financial results in accordance with accounting principles generally accepted in the United States (“GAAP”). This presentation, as well as earnings discussions, include a discussion of Adjusted Gross Profit, EBITDA and Adjusted EBITDA, which are non-GAA
Slide 24: Appendix – Non-GAAP Reconciliation
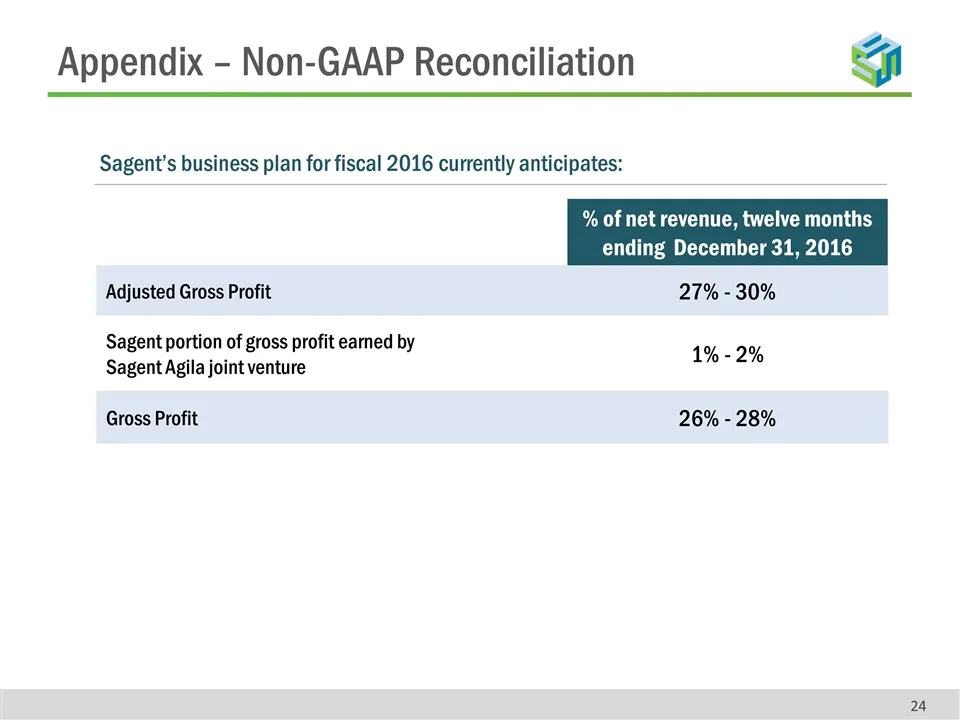
Appendix – Non-GAAP Reconciliation % of net revenue, twelve months ending December 31, 2016 Adjusted Gross Profit 27% - 30% Sagent portion of gross profit earned by Sagent Agila joint venture 1% - 2% Gross Profit 26% - 28% Sagent’s business plan for fiscal 2016 currently anticipates:
Slide 25: Appendix – Non-GAAP Reconciliation
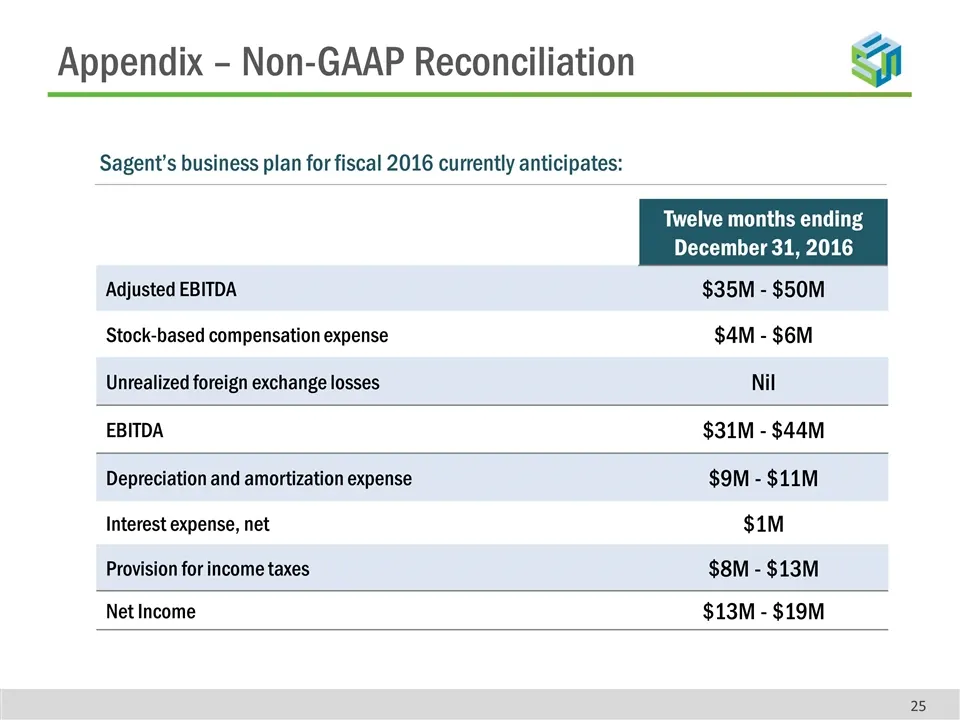
Appendix – Non-GAAP Reconciliation Twelve months ending December 31, 2016 Adjusted EBITDA $35M - $50M Stock-based compensation expense $4M - $6M Unrealized foreign exchange losses Nil EBITDA $31M - $44M Depreciation and amortization expense $9M - $11M Interest expense, net $1M Provision for income t
Source: SEC EDGAR · 8-K filed Jan 11, 2016